Will AI agents take SaaS profits, or help software incumbents keep them?
"Saaspocalypse" is the fear that AI agents will do the work people now do inside subscription software. If that happens, buyers could cut seats, switch products or keep more of the savings for themselves. The theme joins four histories: hosted business software, cheap cloud computing, machine learning, and the long effort to put AI to work in real company workflows. The alarm is real, but the evidence is early. Empor's software cohort was still growing in June 2026, while Stanford's survey found that few organizations had deployed agents in any business function. The answer so far is that agents can threaten particular interfaces and tasks. Incumbents can keep their profits where they control trusted records, permissions and the point where work is carried out. To do that, they must show they can charge for AI without giving away the value it creates.
A sales database in a rented room
In March 1999, four people sat in a rented one-bedroom apartment on San Francisco's Telegraph Hill and set out to sell business software that nobody would have to install. Marc Benioff had spent years as an executive at Oracle, the company that more than any other defined how big business bought software. His co-founders were Parker Harris, Frank Dominguez and Dave Moellenhoff. They incorporated Salesforce on 8 March 1999 to deliver customer-relationship management (the software a sales team uses to track customers, deals and calls) through a web browser.1
Benioff came from inside the system he wanted to replace. To see why that mattered, picture how a large company bought software in the 1990s. It paid a large upfront fee for a licence, bought or reused servers, installed the application, and hired staff or consultants to configure, patch and upgrade it. A typical project ran for months. Once it was in, the customer owned a working machine that grew harder to change every year. The vendor collected most of its money at the start, plus maintenance fees, and then had to sell the next big upgrade.
Salesforce proposed renting instead. The customer would pay a subscription, the vendor would run the software on its own computers, and every customer would share the same constantly updated system. The analogy is renting a serviced flat instead of building a house: someone else fixes the roof, and you pay monthly. The analogy fails in one important way. A flat is passive, but business software holds a company's records, decides who may see what, and shapes how people work. Moving out means moving all of that too.
The company called its campaign the "End of Software". Salesforce began offering its on-demand application in February 2000.2 The slogan was showmanship: Salesforce was still selling software. What it really announced was that a new layer of the industry had arrived and that the old one should be afraid. That pattern recurs throughout this story. Each new way of delivering software makes the layer beneath it fear being cut out, and each time the fear is only partly right.
The bargain, written down
The most reliable account of how the model worked is the 10-K annual report that Salesforce ($CRM) filed with the US Securities and Exchange Commission in 2006, not the company's later retrospectives. The filing set out the model plainly. Customers paid subscription fees based mostly on the number of users and the price per user. Contracts typically ran for 12 to 24 months. More than 90% of revenue came from subscriptions and support, not one-off licences or consulting.2 For investors, this was the attraction. Revenue recurred, could be forecast, and grew as customers added users.
The filing also showed the next step. In September 2005 Salesforce introduced AppExchange, an online directory where customers and other developers could publish applications that ran on top of Salesforce.2 A hosted sales database was becoming a platform. Outside developers built on it, customers stored more of their business in it, and leaving became harder each year. The company's own history lists the 2004 New York Stock Exchange listing and the AppExchange ecosystem as milestones.1 Those are the company's own words, written in hindsight, so they show how Salesforce sees itself and are not independent proof of why it won.
The weakness built into the strength
Hidden in the same filing is the sentence that matters most today. Salesforce warned investors that customers might not renew, might renew at lower prices, or might buy fewer subscriptions.2 In 2006 this was a standard risk factor about recessions, competitors and dissatisfied customers. It had nothing to do with artificial intelligence. It does show that seat risk came with the subscription model from the start.
The arithmetic is simple. A seat-based contract charges for the number of people who use the software. If ten sales representatives each pay for a seat, the vendor earns ten fees. If an assistant lets six people do the work of ten, the buyer may want six seats. The same assistant could instead make each seat so much more useful that the buyer pays more per head, or adds seats because each salesperson now handles more customers. Which outcome happens is the question this theme exists to answer.
That question came later. In 1999 Benioff's harder problem was physical: hosted software needed somewhere cheap, reliable and flexible to run. The next chapter is about how the industry built that place.
 Subscribe on LinkedIn
The cloud makes the rental model scale
On 14 March 2006 Amazon, then known mainly as an online retailer, launched a product with an unexciting name: Simple Storage Service, or S3. It let any developer store data on Amazon's computers over the internet and pay only for what they used.4 Later that year Amazon Web Services followed with EC2, which let customers rent computing power the same way.3 Amazon had built enormous internal infrastructure to run its own shop. It now offered that capacity to anyone with a credit card.
Two stories were moving side by side here, and it helps to keep them apart. The first was the software vendors' story: Salesforce and its imitators moved applications off customers' servers and onto their own. The second was the infrastructure story: Amazon, and later others, turned raw computing capacity into a service you could switch on and off. The first changed how companies bought applications. The second changed what it cost to start a software company.
A good analogy for cloud computing is the electricity grid. A factory once had to build its own generator. With a grid, it draws power when it needs it and pays by the unit. Cloud computing did the same for servers: a startup no longer had to build a small power plant before writing its first line of code. The analogy fails where the economics matter. Cloud capacity is supplied by a small number of very large companies, it can be scarce at times, and, as later chapters show, demand from AI can make it expensive and political in ways household electricity rarely is.
Hosted software had already failed once
The cloud did not invent hosted software. In the late 1990s a wave of "application service providers" (ASPs) promised to run business applications for customers over networks. Many failed. In August 2001 Computerworld surveyed the wreckage after the dot-com crash. Weak business plans, overspending, poor infrastructure economics and a glut of competitors had pushed many providers into closure or consolidation.5
This is the most useful counter-evidence from the period, and it narrows the story without overturning it. The ASP crash did not show that customers disliked hosted software. It showed that useful software can be delivered by companies whose own economics do not work. Many ASPs hosted someone else's application, one customer at a time, on hardware they had bought at boom prices. They carried the costs of an outsourcer without the scale of a utility.
The model that survived differed on three points. Salesforce ran one shared system for all customers, so each new customer added little cost. The 2006 filing stresses that multi-tenant design.2 Utility-style cloud infrastructure later made capacity cheaper to rent than to own. Subscription pricing turned a fragile hosting business into recurring revenue that compounded. The lesson still applies to AI infrastructure: demand forecasts do not prove that a supplier will earn a return. Utilization, power, financing and overbuilding decided the ASP era, and they still matter.
The platform race widens
Amazon did not stay alone for long. In 2008 Microsoft announced Azure, and Google launched App Engine, turning cloud computing into a contest between the largest technology companies in the world.6 Small software vendors could now launch globally without building a data center. Customers got the update model described earlier. The subscription became the default way to sell business software.
Amazon ($AMZN) belongs in this story as a diversified retailer whose AWS segment rents computing capacity. Its company-wide figures say little about software economics. Empor's scorecard puts Amazon's 2025 revenue at $717 billion, of which $129 billion, or 18%, is attributed to the theme. Most of the company is shops, logistics and advertising. When later chapters cite Amazon's growth or margins, the AWS business is only one part of what those numbers measure.
The cloud settled where software ran and how it was paid for. It did not make computers understand a sentence, read a contract or act for a user. That capability came from a much older line of research, which had spent decades failing to reach the market.
The long road from machine intelligence to useful software
In 1950 the British mathematician Alan Turing published a paper that opened with a question: can machines think? Turing reframed it as a game. Could a machine, conversing in text, imitate a person well enough that an interrogator could not tell the difference?7 He was not describing a product. He was proposing a test, and it later became the field's founding challenge.
Six years later John McCarthy, a young mathematician at Dartmouth College, organized a summer research project with Marvin Minsky, Nathaniel Rochester and Claude Shannon. Their proposal coined the term "artificial intelligence". It rested on a bold claim: that every aspect of learning or intelligence could in principle be described so precisely that a machine could simulate it.8 One summer was expected to make significant progress. The field spent the next seven decades learning how hard that sentence was.
Rules first
"AI" covers several competing approaches, not one invention. Early researchers tried to write intelligence down as explicit rules. In 1965 a Stanford team led by Edward Feigenbaum, Joshua Lederberg and Carl Djerassi built DENDRAL, a system that applied chemists' rules to work out the structure of molecules from experimental data.9 It worked within its narrow field, and it inspired the "expert systems" of the 1980s: programs that encoded the judgment of specialists as thousands of if-then rules.
Expert systems drew corporate budgets and a hardware industry built around them. Specialized "Lisp machines" were sold to run AI programs efficiently. In 1987 that market collapsed.9 General-purpose computers had caught up, the rule-based systems proved brittle and costly to maintain, and expectations had run ahead of what the systems could reliably do. The years that followed became known as an "AI winter".
This is the strongest historical warning against reading a striking demonstration as a market. The expert-system boom had real successes, paying customers and specialist hardware suppliers, and it still deflated. The same ingredients appear in the current cycle: impressive demos, a hardware boom and corporate pilots. Whether the outcome differs depends on reliability, cost and repeat use, the same things that decided the outcome in the 1980s.
Learning from examples
The other approach let machines learn patterns from examples instead of being told rules. Neural networks, loosely inspired by the brain's connections, existed for decades but needed more data and computing power than anyone could supply. That changed in 2012. Alex Krizhevsky, Ilya Sutskever and Geoffrey Hinton at the University of Toronto trained a deep neural network on a large image dataset using graphics processing units (GPUs), chips originally built for video games. Their system, later called AlexNet, cut image-recognition errors sharply.10
The result tied AI's future to two things the cloud era had made abundant: data and parallel computing. It also tied AI to chipmakers whose hardware could perform millions of simple calculations at once. That dependency now runs through the whole value chain.
The Transformer
In June 2017 Ashish Vaswani and seven colleagues, mostly at Google, published a paper titled "Attention Is All You Need". It proposed a neural-network design called the Transformer, which handled sequences such as sentences more effectively and, crucially, could be trained in parallel across many chips.11 That made it practical to train language models on enormous amounts of text.
A loose analogy: the Transformer reads a passage the way a careful reader weighs which words bear on which others. In the sentence "the contract the lawyer reviewed was void", it learns to link "void" to "contract" and not to "lawyer". The analogy stops at understanding. The model calculates statistical relationships; it does not know what a contract is, and fluent output is no guarantee of a true or sound answer. That gap between fluency and reliability matters again when businesses start trusting these systems with work.
By the early 2020s the ingredients existed: internet-scale text, GPU clusters rentable from the cloud, and an architecture that improved as it grew. What was missing was a way for ordinary people to use any of it.
The chatbot escapes the lab—and enters the office
On 30 November 2022 OpenAI, a San Francisco research lab, released ChatGPT as a free "research preview".12 The interface was a text box. You typed a question in ordinary language and got a fluent answer: an essay, a summary, a piece of code. It was easy enough to try in a minute and surprising enough that people shared it. It was also unreliable enough that its errors became part of its fame. It could invent facts with complete confidence.
The change was in distribution as much as technology. For decades, using software meant learning its menus and features. ChatGPT reversed that: the user stated the goal and the software worked out the route. The analogy is a universal front desk for software, a single place where you ask for what you need. It falls short of a universal employee. Early models made plausible mistakes, gave different answers to slightly different prompts, and still needed a person to check the work.
The incumbent's first move
The most important early response came from the company that already owned the office. On 16 March 2023 Microsoft ($MSFT) announced Microsoft 365 Copilot, connecting large language models to Word, Excel, PowerPoint, Outlook and Teams, and to the business data inside a customer's Microsoft environment.13 Satya Nadella, Microsoft's chief executive, framed it as a new way of working with the tools employees already used.
Copilot was the first large test of the incumbent strategy. Microsoft did not ask customers to adopt a new application. It placed AI inside software they already paid for, and charged extra for it. If that worked, AI would become an added layer of revenue on top of existing seats, the opposite of a Saaspocalypse. Microsoft also sat on both sides of the theme: its Azure cloud sold the computing power behind AI, and its applications sold the AI to end users.
Its numbers show both sides. Empor's scorecard records fiscal 2026 revenue of $332 billion, growth of 17.8% and an operating margin of 46.8%, the widest of the large cloud providers in the table. Its capital expenditure has risen to 34.9% of revenue, from 13.3% three years earlier. Microsoft is spending heavily to stay in the race. Those figures are company-wide and do not separate Copilot from everything else.
Coding as the proving ground
Software development was where AI first showed it could do bounded, checkable work. A randomized study across Microsoft, Accenture and an unnamed Fortune 100 company covered 4,867 developers, some given an AI coding assistant and some not. Those with the assistant completed about 26% more tasks. The estimate came with substantial uncertainty, and less-experienced developers gained more than veterans.14
That is strong evidence for its setting: a randomized trial in real companies, not a vendor survey. It is also narrow. Completed tasks are not the same as fewer engineers, lower software budgets or higher margins for the company selling the assistant. A developer who finishes more tasks may simply produce more software. If anything, that would increase demand for the tools around it.
Copilots and agents
The next step was the agent, and the distinction matters for everything that follows. A copilot suggests: it drafts the email and you send it. An agent acts: it uses tools across several steps, perhaps reading a customer record, drafting a renewal quote, checking a discount policy and filing the result. The analogy is the difference between a colleague who advises you and a colleague you have authorized to finish the job. It breaks down where software has needs that a trusted colleague does not: explicit permissions, audit trails, the ability to undo a mistake, and a human who answers for the outcome.
How far had companies gone? Stanford's Institute for Human-Centered AI reports that 88% of organizations in the survey it draws on used AI in 2025, up from 55% in 2023 and 78% in 2024. Seventy per cent used generative AI in at least one business function. Agent deployment, however, remained in single digits across nearly all functions.15 So experimentation was widespread and autonomous production work was rare.
Investors did not wait for that gap to close. In early 2026 they began asking a sharper question: would agents simply sit inside existing software, or would they go around it?
The week investors started pricing a software apocalypse
At the end of January 2026, Anthropic, the San Francisco model developer behind the Claude models, released plugins for Cowork, its workplace agent. They were designed for role-specific tasks across an enterprise.16 A chat window answers questions. Cowork was pitched as something that could do a job: legal review, sales preparation, marketing work, data analysis. Each of those jobs already had specialist software built around it, usually sold by the seat.
The market reacted within days. On 3 February, Reuters reported that shares in data, analytics and software companies fell sharply as investors worried that Anthropic's tools could automate the work those companies' products supported. Thomson Reuters, the legal and professional-information group, fell nearly 18% in a day, and RELX ($REL.L) and Wolters Kluwer ($WKL.AS) also dropped sharply.17 By 5 February, Reuters calculated that software and services shares had lost about $1 trillion of market value since 28 January, and noted that short interest in the sector had risen.18 Commentators named the episode the "Saaspocalypse".
What the market assumed
The market's reasoning was a short chain: if an agent could do the work, buyers might need fewer seats, putting subscription revenue at risk. Legal-information groups were hit hardest because their customers, lawyers and researchers, do exactly the reading and drafting that language models perform best.
It is worth being clear about what the selloff measured. It recorded a change in expectations about future cash flows. It did not record a single cancelled contract. Reuters Breakingviews argued at the time that the logic was "buggy": the trade treated very different businesses as equally exposed and assumed displacement on a timetable the evidence did not support.19 That is commentary, not proof, but it is the right test. A selloff shows what investors fear. Only renewals show what customers do.
The damage has lasted longer than a week. Empor's market data put Thomson Reuters' market value at $43 billion on 8 October 2026, down from $58 billion at the end of 2025. Wolters Kluwer has fallen from $25 billion to $19 billion over the same months. Across the 53 companies in Empor's business-software layer, the one-year share-price return is negative, at -3.7%. Meanwhile, Thomson Reuters' revenue growth in its most recent quarters, about 9.5%, was faster than its 3.0% for 2025. At least so far, the share price and the business are moving in different directions.
Two chains of cause and effect
The Saaspocalypse argument comes down to two competing chains.
The bear chain runs like this. Agents become reliable across multi-step tasks. A buyer's agent works across several products, so the buyer consolidates licences. Fewer people log in, so fewer seats are renewed. Meanwhile the vendor must pay model providers and cloud companies to run its own AI features, so its costs rise just as its pricing power weakens. The productivity gain goes to the buyer and to whoever supplies the model.
The incumbent chain runs the other way. An agent is useless without something to act on. It needs the customer record, the approval rules, the audit history, the connections to other systems, and the permission to change any of them. Those sit inside existing software. If agents must pass through the incumbent's records and controls, the incumbent can charge for the new work: per action, per outcome, or as an add-on to the seat. More automated work could then mean more software revenue.
Both chains are coherent. The question is which one the evidence supports, and for which kinds of software.
The fuel bill
One term matters more than any other in deciding between them: inference. Training builds a model once. Inference is the computing required every time the model answers a question or takes an action. A rough analogy is fuel burned on each trip. The analogy is imperfect because the cost per trip varies widely with the model chosen, the length of the task and how cleverly the software is engineered, and it has been falling as hardware and models improve.
Inference is why "more usage" does not automatically mean "more profit". A traditional software seat costs the vendor almost nothing extra once it is sold. An agent that works all day burns compute every minute, and someone pays for it. If the vendor charges more than the fuel bill, AI widens margins. If competition forces it to bundle agents for free, AI narrows them.
The aggregate spending picture does not support a collapse in demand either. In February 2026 Gartner forecast worldwide software spending of $1.434 trillion for 2026, up from $1.250 trillion in 2025.20 That category is far broader than subscription software, and it is a forecast, not a record of realized sales, so it cannot prove that SaaS vendors are safe. It does weaken the idea that businesses are already cutting software budgets wholesale.
To see where the money and the bargaining power might end up, it helps to stop arguing about AI in general and follow one task through the whole chain.
The value chain: from a chip to a completed task
Imagine a company asks an agent to prepare a customer's renewal. The scenario is hypothetical, but every step happens today. A chip in a data center processes the request. A cloud provider runs the model on that chip. The model calls the company's sales software, reads the customer's history, checks the pricing rules and drafts a quote. An employee reviews it and sends it. At the end of the quarter, the company's finance team decides whether the time saved was worth what it paid each supplier along the way.
That single task touches five layers. Walking them in order shows who supplies whom, what moves between them, and where the cash ends up.
Chips and buildings
The task starts with accelerators, the specialized chips that run AI models. NVIDIA ($NVDA) designs the dominant GPUs and AMD ($AMD) supplies competing accelerators and processors. Empor records growth in their data-center segments of 68.0% for NVIDIA and 32.0% for AMD in their latest fiscal years. Those numbers show where AI money lands first, though neither company is a software vendor and neither segment says anything about SaaS seats.
The chips sit in buildings that need land, power, cooling and network connections. Equinix ($EQIX) and Digital Realty ($DLR) lease that space and connect customers to one another. Their economics resemble real estate: large upfront construction, long leases, and returns that depend on keeping buildings full. Empor shows Equinix's revenue growth accelerating to 16.4% in the June 2026 quarter from 5.9% for 2025, which suggests rising demand for capacity.
Clouds
Next come the clouds, which rent the chips by the hour. Amazon's AWS, Microsoft Azure, Google Cloud from Alphabet ($GOOGL) and Oracle Cloud from Oracle ($ORCL) are the largest in the West. Younger specialists such as CoreWeave ($CRWV), Nebius Group and the European provider OVHcloud offer alternative capacity, often built specifically around GPUs. In China, 阿里巴巴 Alibaba Cloud, 腾讯 Tencent ($0700.HK) Cloud and 百度 Baidu ($9888.HK) AI Cloud serve a largely separate ecosystem with their own models.
Empor's data show both demand and its price. Combined revenue growth for the cloud layer reached 21.0% in the June 2026 quarter, against 14.5% a year earlier, and the combined operating margin was 26.5%. Capital spending by the listed cloud companies roughly doubled in a year, to $133 billion in the quarter to March 2026. Capex/revenue for the layer now runs at more than twice its usual level.
Those averages hide a split. Microsoft and Alphabet fund the build-out from enormous existing profits. Oracle's capital spending reached 82.6% of revenue in its 2026 fiscal year, and its free-cash-flow margin swung to -35.2%. CoreWeave more than doubled its revenue in 2025 to $5.1 billion, but its capital spending was about twice its revenue and it lost money. Growth is visible. A durable return on all that concrete and silicon is not yet visible; the ASP lesson still applies. Utilization, customer concentration, power and financing decide that, and the bills arrive before the answer.
Models
The third layer turns computing power into usable intelligence. OpenAI and Anthropic build frontier models. Databricks sells a data and AI platform. Meta Platforms ($META) releases its Llama models openly. IBM ($IBM) sells watsonx and hybrid-cloud tools to enterprises. In China, Z.AI ($2513.HK) and MiniMax, both now listed in Hong Kong, compete with domestic alternatives. Elastic, best known for search and observability tools, sits on the boundary: its search technology helps agents find information, and its search interface could also be bypassed by them.
A model is like an engine. Owning the best engine does not guarantee the best car, the best dealerships or the most profit. Engines can be swapped, and a better rival engine appears every few months. Model companies therefore face a hard question: does value collect in the model, or does it pass through to whoever owns the customer?
The listed evidence here is thin and misleading if read as an industry. Only three of the eight model and platform companies in the theme have comparable figures in Empor's scorecard. The biggest, OpenAI, Anthropic and Databricks, are private, and their financial disclosures cannot be set beside audited public accounts. The layer's combined operating margin in the June quarter was -51.9%. On this evidence, no layer-wide leader can be named, and fast revenue growth among model providers has not yet shown that model-making is profitable.
Applications and records
The fourth layer is where the Saaspocalypse argument is fought: business applications and systems of record. A system of record is the authoritative file for a business function, such as the customer ledger, the payroll database or the general ledger. "Filing cabinet" is a good first analogy, but it misses the important part. A system of record is live: it enforces who may see and change what, keeps an audit trail of every change, and drives the steps of the workflow. An agent preparing a renewal must read from it and write back to it.
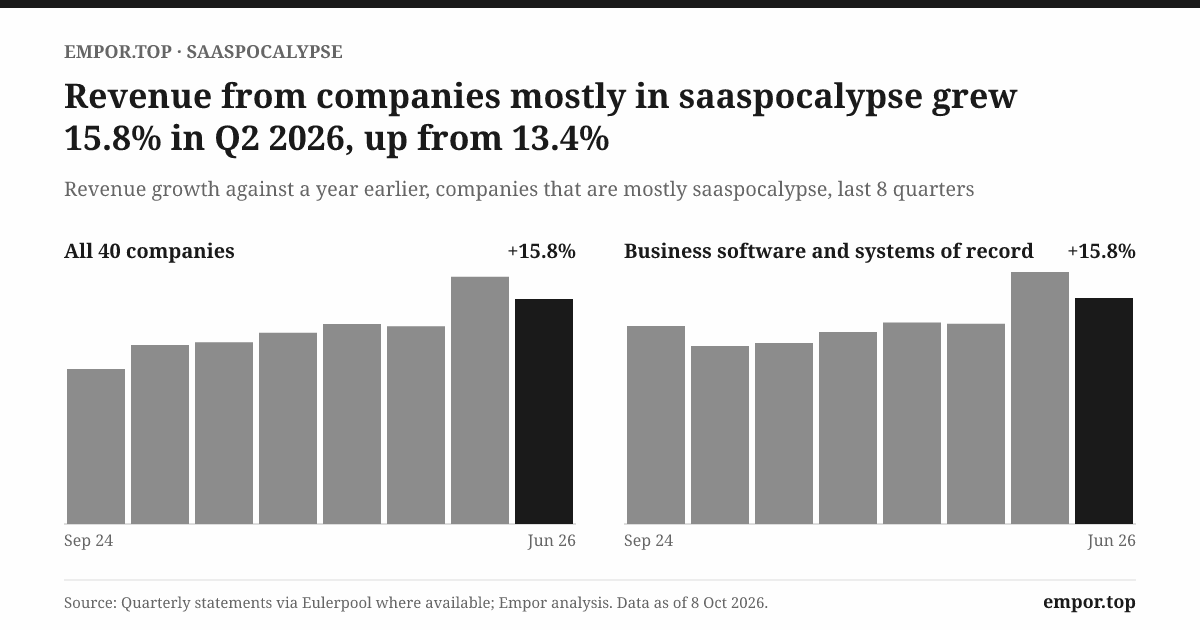
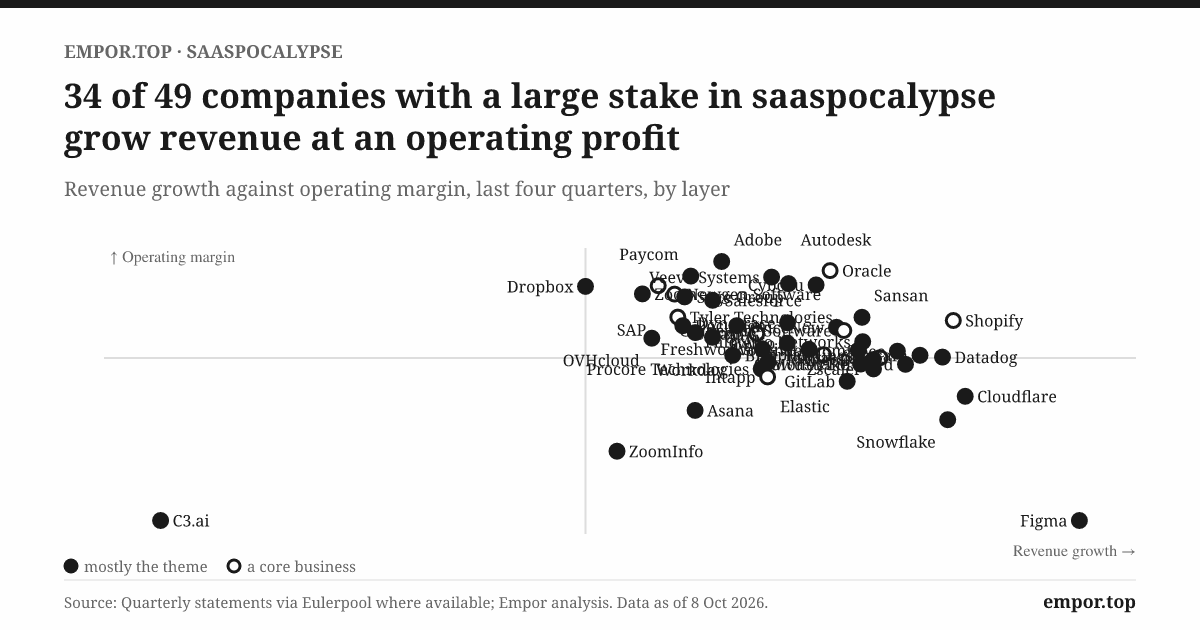
Empor's business-software layer, 53 listed companies from Salesforce to Japan's freee, grew its combined revenue 15.9% in the June 2026 quarter, up from 13.5% a year earlier. Fifty-two of the 53 grew. The combined operating margin was 16.9%, down 0.4 points from a year earlier. On this evidence, the businesses have not collapsed. The slight margin decline is consistent with heavier AI spending, though it does not prove it.
The buyer
The final layer is the buyer, the company paying for the renewal agent. It pays several suppliers: software seats or usage fees to the application vendor, token charges to a model company directly or through the vendor, and cloud bills. If the agent saves time, the buyer captures that value unless a supplier can charge for it. This is the layer with no company rows in Empor's tables, and it decides everything.
How the layers move together
If the AI boom passed through the chain in a simple way, cloud spending today would show up as changing software margins a few quarters later. It would be positive if cheaper capacity helped vendors, and negative if it armed their rivals. Empor tested this by setting each software company's operating margin against cloud capital spending at delays of up to four quarters.
The data do not show a consistent link at the expected delay for the software layer as a whole. Readings were scattered both ways. Snowflake and Palantir's margins tended to rise after capex climbed. Salesforce, ServiceNow, Cloudflare, Okta and Zscaler showed the opposite pattern. Most companies sat in between. There was no consistent link to the growth of AI-native challengers either, and only a loose, inverse one for model-company margins. These are a few years of numbers moving together. Interest rates, hiring cycles, accounting changes and post-pandemic normalization were moving at the same time. They are evidence, not proof of cause, and on this evidence, heavy infrastructure spending has not yet told us which software companies win.
Gartner's forecasts show the scale of the build-out. Gartner expects worldwide AI spending of about $2.6 trillion in 2026, of which roughly $1.43 trillion is infrastructure, $453 billion AI software and just $33 billion AI models.21 Separately, it forecasts $653 billion of data-center systems spending in 2026, up 31.7%.20 These are broad vendor-spending definitions, not SaaS revenue. They do show where most of the money is going today: into hardware and buildings, well upstream of the applications people use.
So the chain gives no simple answer. The answer is inside the software companies, where it depends on what kind of work each product does.
The contest inside the software companies
Consider three jobs. A sales team updates customer records after calls. A finance team closes the books at month-end. A designer builds a campaign for a product launch. All three use subscription software, but the software's hold on each job is very different.
The sales update is repetitive, digital and low-risk. A mistake costs a follow-up email, so an agent could plausibly do much of it. The month-end close touches regulated records. A mistake can mean a misstated account, auditors want a trail, and someone must sign off. The campaign is creative and judged by taste, and AI image generators already compete with parts of it directly. Asking whether AI threatens "software" lumps these together. The useful question is which part of each product an agent can replace, and who controls what the agent must touch.
The customer and the workflow
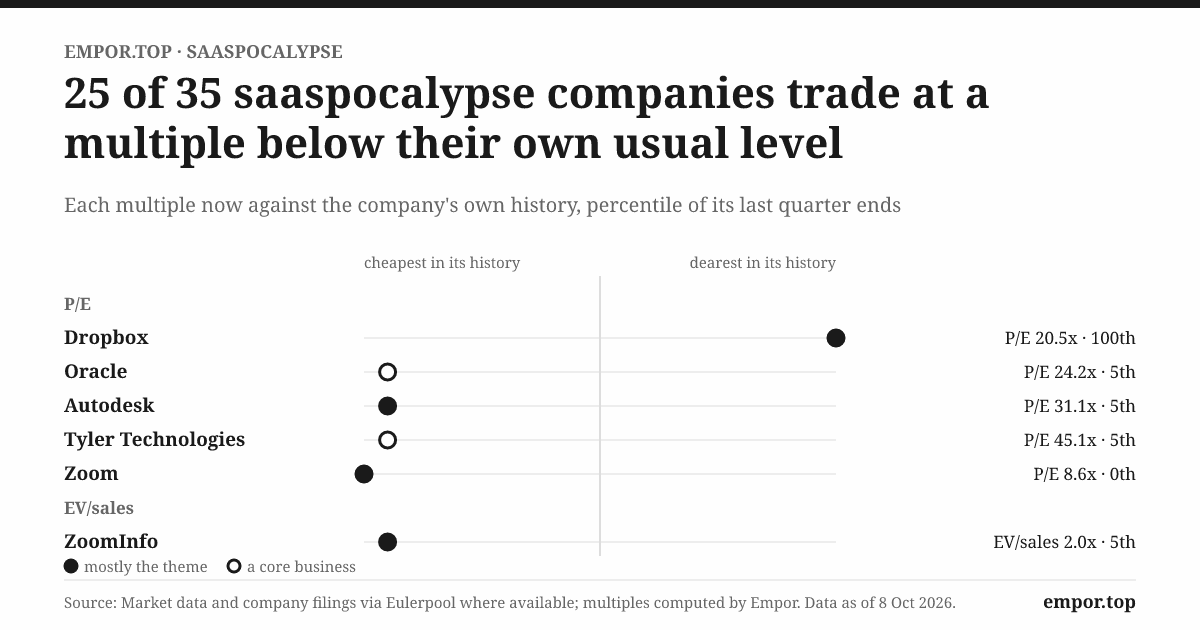
Salesforce is the central test. Its sales and service software holds customer records for a very large installed base, and its Agentforce product is a direct bet on the incumbent chain. Empor's numbers-to-watch table, drawing on company results, records Agentforce annual recurring revenue of about $800 million at the end of January 2026 and more than $1.5 billion by August. That is fast growth, but these are company-defined figures. Salesforce's overall revenue grew 9.6% in its 2026 fiscal year and 10.8% in the June quarter, and the two numbers together do not yet show whether Agentforce adds to the core business or replaces part of it. A free-cash-flow margin of 34.7% gives Salesforce room to absorb the cost of the change. The market values the company at 4.9 times sales, down from 8.7 a year ago.
HubSpot ($HUBS) sells similar customer and marketing software to smaller companies. Its revenue still grew 19.2% in 2025, yet its market value has fallen by about two-thirds in a year, to $11.5 billion. The market is treating mid-market customer software as easier to replace than Salesforce's large-enterprise systems, though the operating results do not yet show that.
ServiceNow ($NOW) runs IT, HR and customer-service workflows for large enterprises. It is arguably the purest test of whether an incumbent can sell agents that act inside its own processes. Empor records that its AI annual contract value passed $1 billion in July 2026. Growth was 24.0% in the June 2026 quarter, faster than in 2025. Its operating margin in that quarter fell to 4.1% from double digits, which shows how expensive the transition is, even if one quarter proves little.
SAP ($SAP) and Workday ($WDAY) hold the heaviest records of all: finance, supply chains, payroll and HR. These are the systems where errors have legal consequences and replacement projects take years. Workday reported 1.7 billion "AI actions" in its 2026 fiscal year. That shows usage, but an action is not a payment, and the company does not disclose how many convert to revenue. SAP grew 9.4% in the June quarter, accelerating through 2026. Neither company's disclosures separate AI revenue.
Professional content
Thomson Reuters, RELX and Wolters Kluwer combine proprietary content (case law, scientific papers, tax rules) with the software professionals use to work with it. Their position is double-edged. A general-purpose model trained on public text can now answer many questions that once required their databases. A model grounded in their authoritative, licensed content is also more trustworthy than one that guesses. Their recent results lean toward resilience. Thomson Reuters has accelerated, while RELX and Wolters Kluwer have kept their operating margins at 25–32% on slow, steady growth. Wolters Kluwer's revenue slipped 0.6% in its latest half-year, the clearest crack among the three, but one half-year is too little to show whether AI caused it.
Creative and developer tools
Adobe ($ADBE) sells creative and marketing software and has built its own generative tools, Firefly, under chief executive Shantanu Narayen. Adobe is the starkest gap between business and market. Empor's figures show revenue growing about 13% in its latest quarter, a 41.4% free-cash-flow margin and returns on capital above 40%. The market values Adobe at 3.7 times sales and 13.6 times earnings, multiples more typical of a business in decline. Either the market sees a cliff coming or it is wrong; the current numbers do not settle which. Figma ($FIG), the collaborative design tool, grew 40.9% in 2025 and reports 136% net revenue retention, meaning existing customers spent 36% more than a year earlier. Even so, its market value has fallen about 84% in a year, to $10.7 billion.
Atlassian ($TEAM) and GitLab sit in software development, where coding agents are most advanced. Atlassian's growth accelerated to 27.6% in its June quarter. GitLab still grew 21.7% but is slowing. The randomized evidence on developer productivity argues for more software being written, not less, but it cannot tell whether developers will need the same number of project-tracking and code-management seats.
Finance at the small end
Intuit ($INTU), Sage ($SGE.L), Xero ($XRO.AX), BILL, and Japan's Money Forward (マネーフォワード) and freee serve accounting, tax and payments, often for small businesses. Bookkeeping is a classic automatable task, but the ledger is a regulated record and the small-business owner often wants the software to do the task, not to employ fewer bookkeepers in-house. Revenue across this group is still growing well. Xero's 44% included an acquisition, and freee's 27.6% was organic. None discloses AI revenue, so their exposure cannot be measured from their filings.
Plumbing that agents may need
A separate group could gain from more agent activity whether or not seats shrink. Okta ($OKTA) manages identity, deciding who and increasingly which software agent may log into what. CrowdStrike ($CRWD), Palo Alto Networks ($PANW) and Zscaler ($ZS) secure the networks and devices agents run on. Snowflake ($SNOW), MongoDB ($MDB) and Elastic store and search the data agents read. Datadog ($DDOG) and Dynatrace ($DT) watch systems for failures. Cloudflare ($NET) carries web traffic, including traffic from bots and agents.
Their results are among the strongest in the theme. Datadog, Cloudflare and Snowflake each grew about 35% in the June quarter, faster than a year earlier, and MongoDB 30%. Okta and Datadog's market values roughly doubled in the year to June. The connection to agents is plausible: more automated software means more identities, more data queries and more systems to monitor. It is still a plausible link and not a measured one. None of these companies reports how much of its growth comes from agents as opposed to ordinary cloud migration, and several still report GAAP losses because of heavy stock-based pay.
The most exposed interfaces
At the other end are products whose value is largely a human-operated interface around a task an assistant can reach directly. Dropbox's revenue shrank 1.1% in 2025. ZoomInfo, which sells sales-prospecting data, grew 2.9%, and its customers spent 11% less than a year earlier (net revenue retention of 89%). Its market value fell about 71% in the year to June. Asana, a work-management tool, keeps only 97% of revenue from existing customers. Zoom ($ZM) grew 4.4% and DocuSign ($DOCU) 8.2%. Both are highly profitable, and both sell to customers who can increasingly get meeting summaries and document handling elsewhere.
Most of these slowdowns began before ChatGPT. Dropbox, ZoomInfo and Zoom were slowing in 2023 as pandemic-era demand faded and buyers consolidated tools. AI may be accelerating a decline that was already under way, and the figures cannot cleanly separate the two. The pattern still fits the bear chain best where the product's value lies in the interface and not in a record anyone else depends on.
The wider field
The remaining incumbents fall along the same line between replaceable interfaces and embedded records. Shopify ($SHOP) runs merchants' online shops and payments, and grew 33.7% in the June quarter. Much of its revenue is commerce, not software seats. Twilio ($TWLO) sells the communications pipes that agents can use to send messages or answer calls, and its growth accelerated to 22.1%. Box ($BOX) manages enterprise content and permissions that agents need to read safely. UiPath, which built an earlier generation of rule-based automation, is repositioning itself to orchestrate AI agents. That leaves it both threatened by agents and potentially needed to coordinate them.
Vertical systems run on records that are hard to move. Veeva ($VEEV) serves pharmaceutical companies under regulators' eyes. Guidewire ($GWRE) runs insurers' policies and claims. Tyler Technologies ($TYL) serves local governments with long procurement cycles. Procore ($PCOR) runs construction projects. Autodesk ($ADSK) supplies design software for architects and engineers. Samsara ($IOT) gathers data from trucks and equipment. Workiva ($WK) handles regulated financial reporting. Intapp serves law and accounting firms. Payroll providers ADP ($ADP) and Paycom ($PAYC) process money that must arrive correctly every pay period. Appian ($APPN) and Newgen Software ($NEWGEN) sell process automation that competes with custom-built agents and may also coordinate them. Japan's Sansan (business-contact data), Cybozu (サイボウズ), whose kintone tool lets non-programmers build business apps, monday.com and Freshworks ($FRSH) sit closer to the replaceable end of the line. Palantir ($PLTR) is a category of its own.
Palantir, which connects operational data to decisions for governments and large companies, has the fastest growth in the software layer: 56.2% in 2025 and 92.9% in the June 2026 quarter, with a 46.9% free-cash-flow margin. It is the strongest single piece of evidence that AI can create new software demand and not only redistribute it. It is also priced for that: 72 times sales. A business can perform well while its shares still disappoint, if the price already assumes more than the business delivers.
The challengers
If agents were already taking software profits, AI-native challengers should be showing it. They are not, yet, in the listed record. Empor's two public challengers tell a mixed story. C3.ai's revenue fell 35.7% in its 2026 fiscal year. SoundHound AI ($SOUN), which sells voice agents for restaurants and call centers, doubled its revenue in 2025 to $168 million but burned cash at a rate of 61% of revenue. Combined, the listed challenger layer grew 0.9% in the June quarter with deeply negative margins.
The most important challengers are private. Glean sells enterprise search that sits across many applications. Canva sells design tools and reported $3.5 billion of revenue in Empor's coverage. Replit lets people build applications by describing them. They do not publish audited accounts, so their economics cannot be compared with listed companies. The listed record therefore weakens the claim that challengers have already captured the software profit pool, but it cannot rule out future displacement, because the most promising challengers report the least.
Who leads, specifically
Leadership in this contest has to be stated narrowly. On disclosed AI monetization inside an existing customer base, Microsoft and Salesforce report the largest company-defined numbers, with ServiceNow close behind. These measures are defined differently, so the lead between them is contested. On growth combined with cash generation, Palantir leads the listed software layer by a wide margin, with Snowflake, Datadog and Cloudflare leading among data and infrastructure tools. On cash generation, Adobe, Veeva and Intuit lead. Nobody leads on proof that AI revenue is profitable after inference costs, because no one discloses it.
Vendors can build the agent. They cannot make customers pay for it.
The buyer holds the purse strings
Picture the meeting where this is decided: a chief financial officer's annual software review. On the table are the existing subscriptions, the AI pilots that business units ran last year, the bill for model usage, and several overlapping tools that do roughly the same thing. The team can keep everything, add AI on top, fund AI by cutting old licences, or decide the pilots did not pay. That meeting turns a productivity gain into a decision about who keeps the money.
G2, a software-review marketplace, surveyed more than 1,000 software buyers for its 2026 report. Half said AI had increased their software budgets. At the same time, 47% said they had reallocated more than 10% of existing software budgets to generative AI. Nearly half reported a CFO vetoing a software purchase that had already been approved.22 Both chains are visible here at once: AI is bringing new money into software and taking money from existing tools. These are survey answers, not audited spending or cancelled contracts, and the same company can do both.
What buyers must solve first
The buyer also faces practical obstacles that vendors' demos rarely show. Does the company have the rights to let a model read this data? Can security teams see what the agent did? Does the agent connect to the twelve other systems the task touches? Who answers for it when it sends the wrong price to a customer? Can the action be undone?
Permissions are the clearest example. An agent must be handed keys to particular rooms in the company: this customer database, not that one, read but not delete, for this task but not forever. The analogy breaks down at the details. Software permissions must also define scope, expiry, revocation and legal responsibility, and getting any of them wrong exposes the company. These requirements slow substitution. They also create new software demand, which is why identity and security vendors appear in this theme as potential winners.
The optimistic chain
In the expansion story, agents make more work affordable, letting incumbents sell AI on top of the records and controls customers already use.
Official labor projections lean this way for the software sector itself. The US Bureau of Labor Statistics projects employment at software publishers growing 19.3% and in computing infrastructure 20.3% between 2024 and 2034, with software developers up 15.8%.23 These are projections for one country, not observed outcomes. They do not suggest an industry in retreat.
The pessimistic chain
In the substitution story, agents reduce the number of people needed to operate software. The same BLS projections expect customer-service representative jobs to fall 5.5% and procurement-clerk jobs 8.7%.23 Those are exactly the roles that consume seats in service and procurement software.
Weighing the two
The evidence so far does not favor either extreme. Stanford's figures show that broad AI use and autonomous workflow replacement are different things: almost every organization uses AI, and very few let agents do production work.15 Spending estimates do not settle it either. Menlo Ventures estimates US enterprise spending on generative AI at $37 billion in 2025, up from $11.5 billion in 2024 and $1.7 billion in 2023, with $19 billion going to applications.24 That is fast growth into the application layer, which could be read as incumbents' opportunity or challengers' revenue. It is a venture investor's survey-based estimate and should not be set beside Gartner's far broader worldwide figures as if they measured the same thing.
Where value could go next
The surplus could settle in four places, and the answer can change over time.
While compute is scarce, value flows to the clouds and chipmakers. That is visible today in their growth and capital spending. Scarcity rarely lasts. If capacity outgrows demand, or efficiency gains cut inference costs, bargaining power shifts away from infrastructure owners toward whoever sells to the end customer. Overbuilding is a real risk for the most indebted builders.
If model companies control the screen people work in, value flows to them. That is the outcome the February selloff priced in.
If agents must run through trusted records and controls, value stays with application vendors, provided they can charge for agent work at margins that survive the fuel bill.
If competition among all of the above is fierce enough, value flows back to the buyer, who keeps the savings and pays suppliers less. That is the outcome investors in every layer should fear most, and it is the one the record cannot yet rule out.
Telling which of these is happening means watching signals that move before revenue does.
Four signals that can settle the argument
Return to the renewal meeting. What would the company need to see to decide whether the agent is a new product worth paying for, a cheaper replacement for software it already owns, or just another pilot? The same evidence matters to the investor. Four signals can settle it.
Production agent deployment
The first measures the share of organizations running agents in live work, not in pilots. It moves early because a company deploys before it renegotiates contracts. It distinguishes demos and copilots from the autonomous work that could actually replace seats. The best current source is Stanford HAI's annual AI Index, which found deployment in single digits across nearly all business functions.15 It is annual and depends on survey definitions. Repeated increases across independent surveys, together with reports of tasks completed without a human redoing them, would strengthen the substitution case. Deployment stuck at single digits for several more survey rounds would weaken it.
Paid AI alongside core retention
The second compares two numbers that companies report every quarter. One is paid AI: Microsoft's Copilot seats, which Empor's numbers-to-watch table records at 30 million paid seats in July 2026, alongside the Salesforce and ServiceNow figures discussed above. The other is the health of the core business: seat counts, net revenue retention, and growth of the subscription business without AI. This is the most direct test of whether AI adds to the incumbent's revenue or cannibalizes it. If paid AI keeps rising while core retention and growth hold, the incumbent chain wins. If AI revenue climbs while core retention slips, as it already has at ZoomInfo and Asana for reasons that may predate AI, the vendor is replacing its own revenue with new revenue. Every company defines these figures differently, so watch each company's trend over time and do not compare them with each other.
Budget substitution
The third tracks where AI money comes from. The G2 survey discussed above found substantial reallocation to generative AI.22 The survey is annual. The firmer evidence arrives quarterly in company disclosures of cancellations, downgrades and seat reductions. This signal settles whether AI budgets are additional or taken from existing tools. Reallocation followed by visible seat losses at the vendors being cut would support replacement. Rising total budgets with stable renewals would support expansion.
Margins after the fuel bill
The fourth is the gross and operating margin of software companies as their AI usage grows, the clearest record of whether inference costs are being recovered. Empor's latest reading shows the software layer's combined margin edging down as growth accelerated. Margins are reported quarterly, but they reflect many costs besides AI. Rising margins alongside growing paid usage would show that vendors are charging more than the fuel bill. Falling gross margins, deeper discounting or bundling AI for free would show that the savings are going to buyers and model suppliers.
The next reading
The next reporting round arrives quickly. Between late October and early December 2026, Microsoft, Alphabet and Amazon report cloud capital spending and growth. ServiceNow, Workday, Salesforce, Snowflake and Adobe report their core businesses alongside their AI products. Company dates can move. No single quarter decides anything: renewal cycles of one to three years mean most contracts signed before agents became credible have not yet come up for renegotiation.
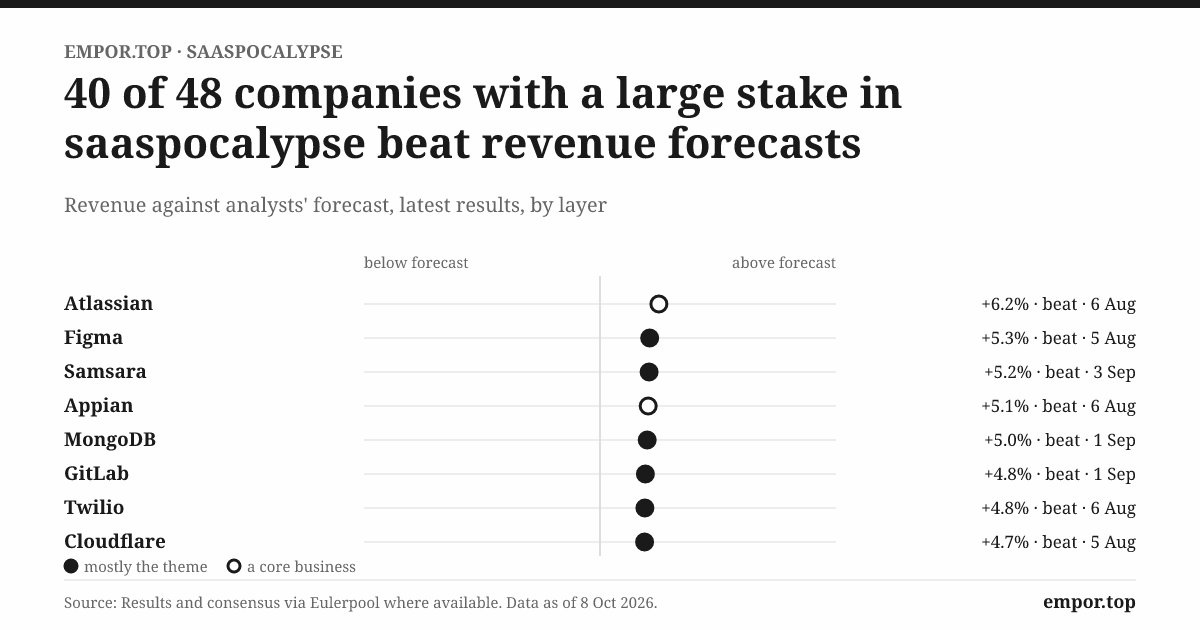
An AI action is not a seat, an annual recurring revenue figure is not profit, and beating analysts' forecasts says nothing about agents. Forty-seven of the 53 business-software companies beat revenue forecasts in their latest results, by a median of 1.7%. That shows forecasts were cautious, not that agents are helping. The signals above matter because they get closer to the actual transfer of money.
Epilogue: the seat is not the whole software business
Picture the same employee a few years from now. They still work with the same customer record, the same finance system and the same case queue. But they ask an agent to do the work instead of clicking through screens, and the agent reports back when it is done. The software is still there. The question is whether anyone still pays for it the same way.
The evidence supports the conditional answer set out above, though nobody has yet proved that incumbents can charge for the new work at margins that survive inference costs.
The history in this story keeps repeating one pattern: each new layer changes where power and profit sit without wiping out everything beneath it.
The seat is exposed; the records, controls and integrations beneath it remain essential.
The current figures still show growth, not collapse. They cannot rule out future pressure, because buyers decide at renewal and most renewals still lie ahead. The February selloff recorded fear. The operating results record a business that has not yet been tested.
Whether the agent becomes the software vendor's enemy or its next product depends on the CFO's renewal decision. The buyer will decide, one renewal at a time, who keeps the surplus.
Glossary
- SaaS (software as a service): Software delivered over the internet and usually sold by subscription, run on the vendor's computers rather than the customer's.
- Cloud computing: Computing, storage and networking capacity rented over the internet and paid for by use.
- Application service provider: An early hosted-software model in which a provider ran applications for customers; many failed after the dot-com crash.
- System of record: The authoritative business data and workflow history for a function such as finance, HR or customer accounts, including who may see and change it.
- Seat-based pricing: A charge based on the number of people using the software.
- Agent: Software that uses an AI model and other tools to carry out a task across several steps, with some authority to act.
- Copilot: An AI assistant that helps a person work inside an existing product but leaves the final action to them.
- Foundation model: A large AI model trained on broad data that can be prompted or adapted for many tasks.
- Transformer: A neural-network design that weighs relationships among the parts of a sequence such as a sentence; it underlies most modern language models.
- Inference: The computing needed to run a trained model each time it answers or acts, and a recurring cost for whoever provides the service.
- Net revenue retention: Revenue from an existing group of customers after expansions, reductions and cancellations, compared with a year earlier.
- Annual recurring revenue / annual contract value: Company-defined measures of the yearly value of subscription contracts; definitions vary between companies.
- Permissions: Rules governing which data and actions a user, or an agent, may access.
- Value capture: The share of the value a product creates that the vendor keeps as revenue and profit.
References
-
Salesforce.com Form 10-K for fiscal 2006 — US Securities and Exchange Commission, 2006 ↩↩↩↩↩
-
Committee report on cloud computing — US House of Representatives, via GovInfo ↩
-
Computing Machinery and Intelligence — A. M. Turing, Mind, 1950 ↩
-
Artificial Intelligence Coined at Dartmouth — Dartmouth College ↩
-
ImageNet Classification with Deep Convolutional Neural Networks — Krizhevsky, Sutskever and Hinton, NeurIPS, 2012 ↩
-
Attention Is All You Need — Vaswani et al., arXiv, June 2017 ↩
-
Introducing Microsoft 365 Copilot: your copilot for work — Microsoft, March 2023 ↩
-
The Effects of Generative AI on High-Skilled Work: Evidence from Three Field Experiments with Software Developers — Microsoft Research ↩
-
Cowork and plugins for teams across the enterprise — Anthropic, January 2026 ↩
-
Anthropic's new AI tools deepen selloff in data analytics and software stocks, investors say — Reuters via Investing.com, February 2026 ↩
-
US software stocks stabilize after bruising selloff on AI disruption fears — Reuters via Investing.com, 5 February 2026 ↩
-
AI apocalypse trade has a buggy logic — Reuters Breakingviews, 4 February 2026 ↩
-
Gartner Forecasts Worldwide IT Spending to Grow 10.8% in 2026 — Gartner, February 2026 ↩↩
-
Gartner Forecasts Worldwide AI Spending to Grow 47% in 2026 — Gartner, May 2026 ↩
-
Artificial intelligence, information technology, and employment, 2024–34 — US Bureau of Labor Statistics, July 2026 ↩↩
-
2025: The State of Generative AI in the Enterprise — Menlo Ventures, 2025 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube