Salesforce: Can the CRM Giant Turn "Digital Labor" Into Its Next Growth Engine?
I. Introduction & Episode Roadmap
On June 22, 2026, Salesforce stock closed lower for its fourteenth consecutive trading session — a persistent erosion in value that marked the longest losing streak in the company's history as a public firm. By the time the slide ended, shares hit $146.32, down roughly 42% for the year and nearly 60% from their peak in December 2024.
The streak was notable less for its depth than for its underlying driver. Fundamentals appeared stable: revenue continued to grow, operating margins remained near record levels, and cash generation was expanding. Investors were not dumping the stock because current financial performance was falling apart; rather, a growing group of market participants believed that the traditional software model Salesforce pioneered — renting customer databases on a per-seat basis — faced disruption from generative artificial intelligence. Wall Street dubbed this fear the "SaaSpocalypse." The underlying hypothesis held that if AI tools can generate custom software on demand, enterprise clients might question the need to license standard customer relationship management platforms.
That narrative shifted on August 26, 2026, when Salesforce reported second-quarter results for fiscal 2027. Revenue rose 11% year over year to $11.3 billion. Annual recurring revenue for Agentforce surpassed $1.5 billion, representing a year-over-year increase of more than 240%, while the broader AI and data portfolio approached $3.9 billion in annual recurring revenue, up over 210%. Management subsequently raised its full-year financial outlook.[^1] The following day, Salesforce shares jumped 22.6% — the stock's second-highest single-day gain on record, trailing only its August 2020 surge.1 The rally extended across enterprise software equities, temporarily halting the SaaSpocalypse narrative.
These contrasting valuations, occurring just sixty-five days apart, reflect a fundamental disconnect. The divergence between management's growth narrative and the verifiable metrics in the company's financial statements forms the central inquiry of this analysis.
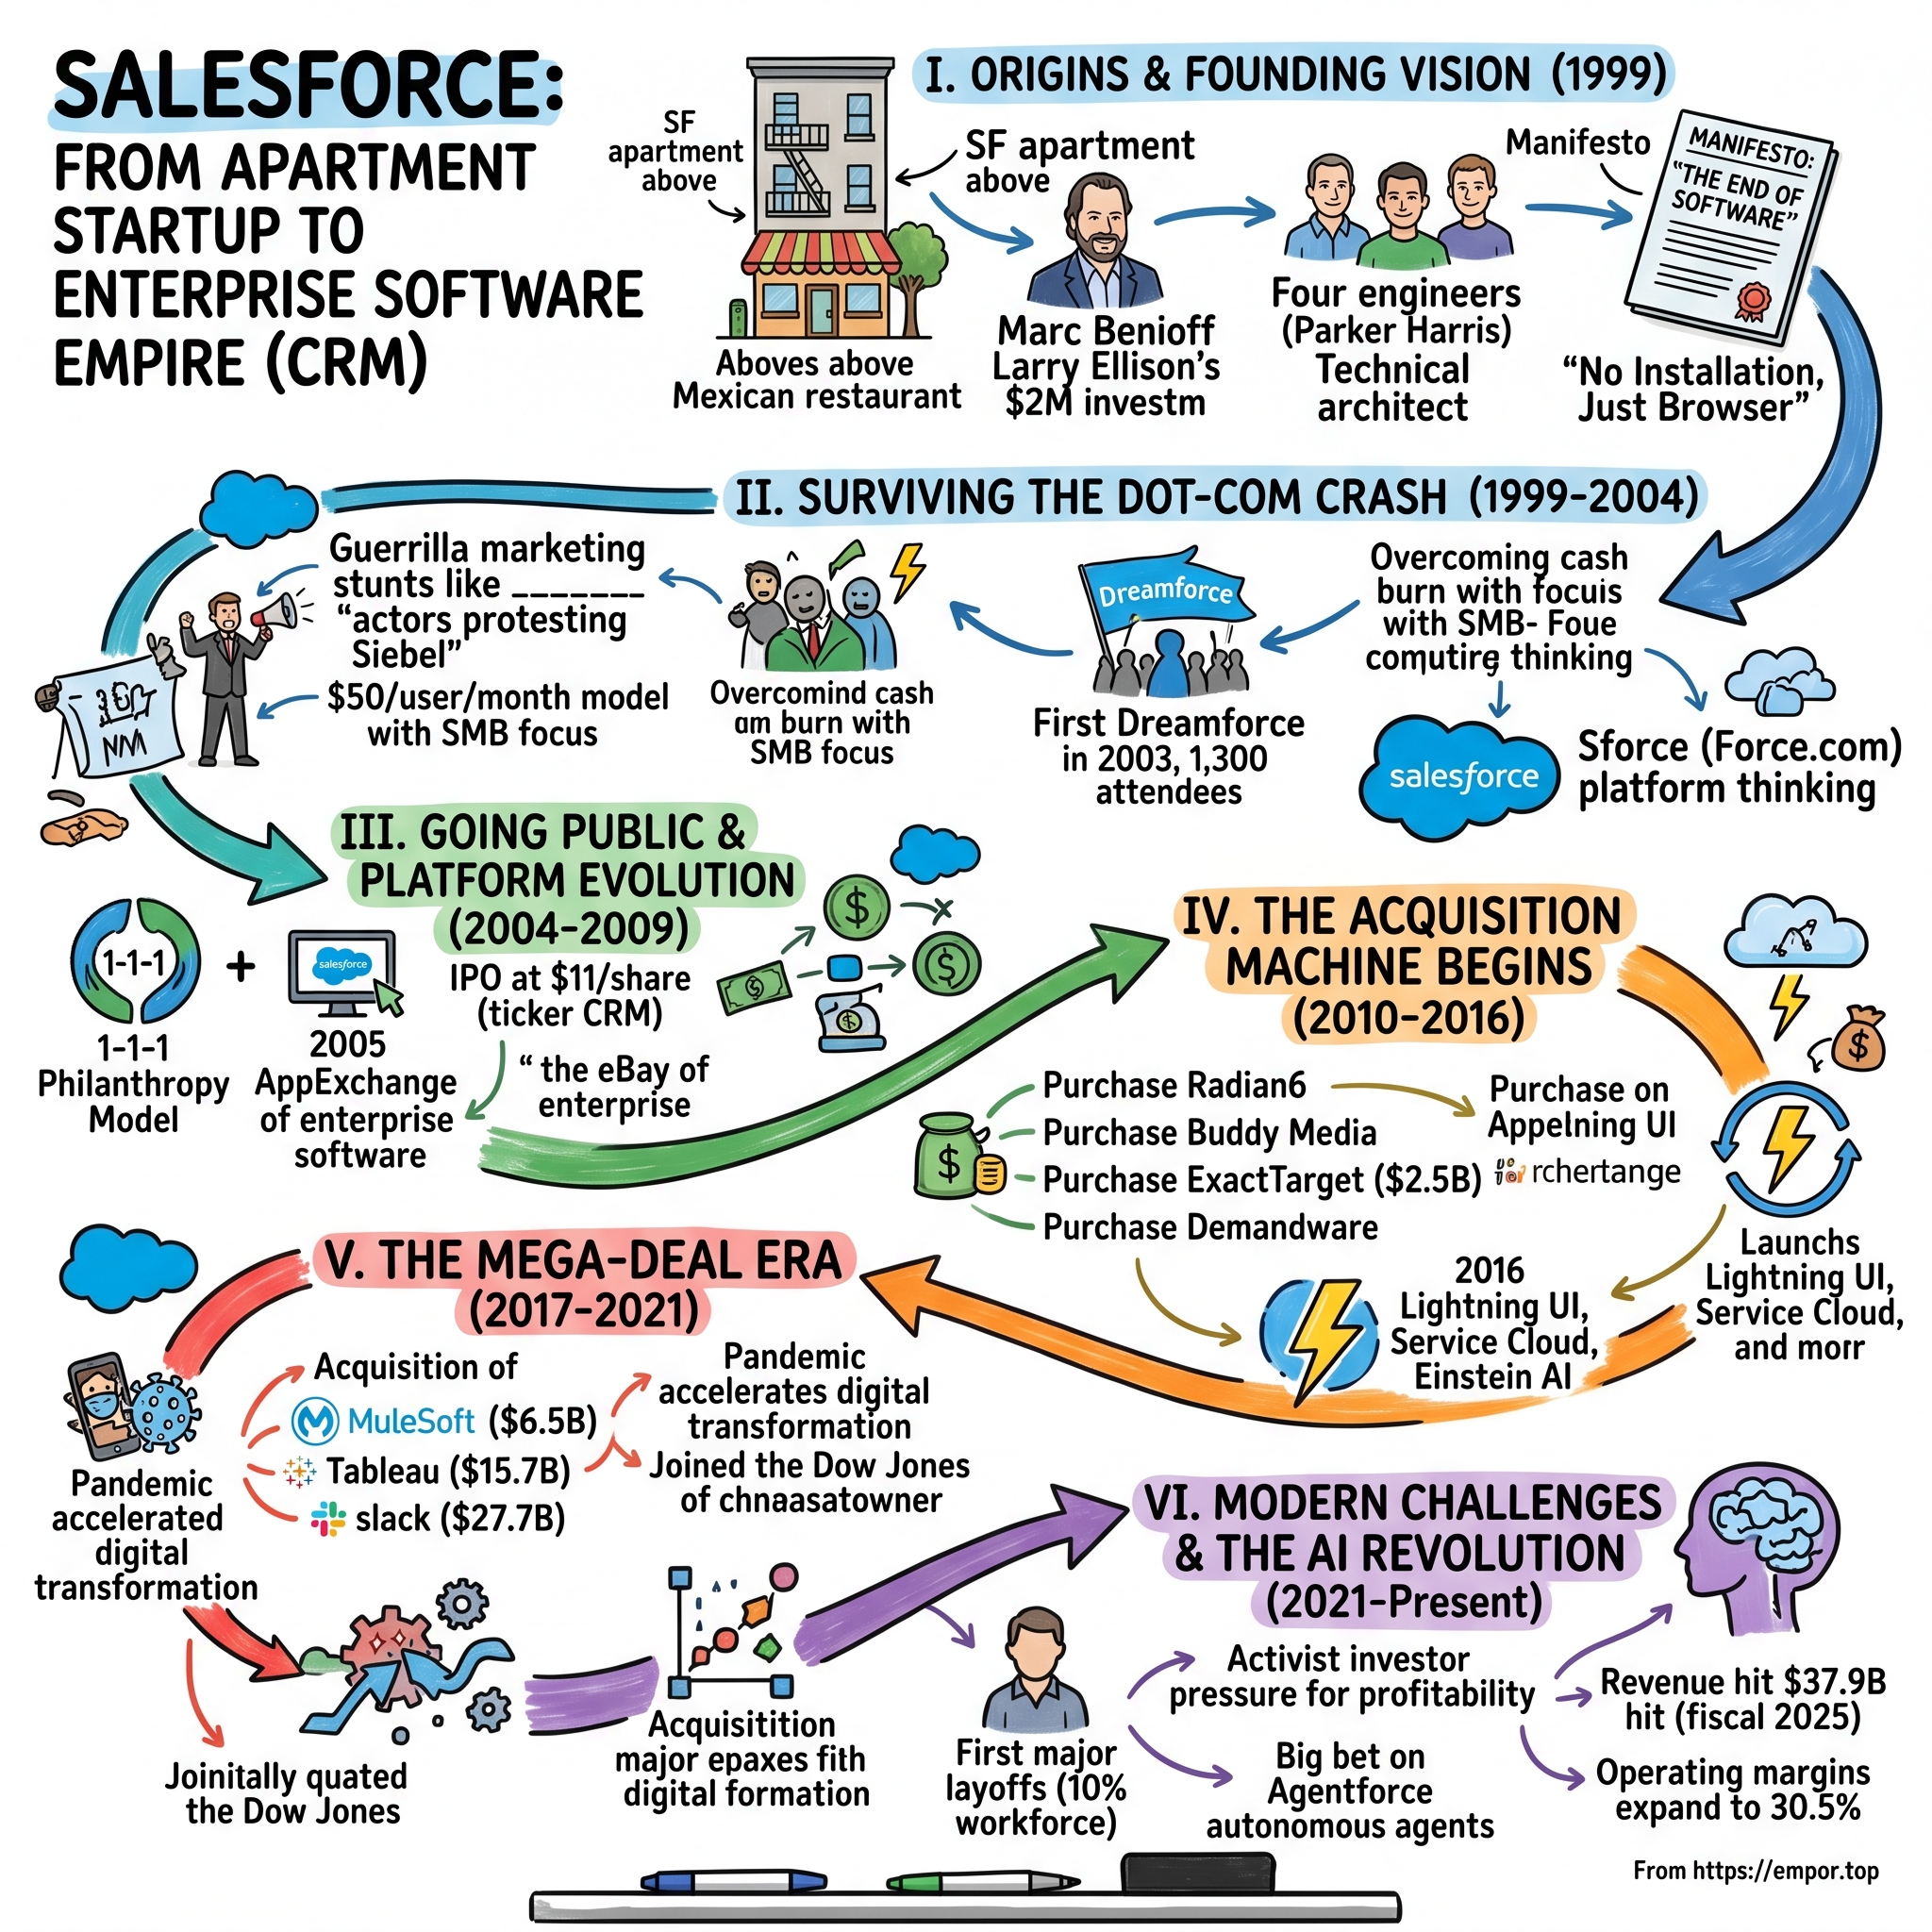
Founded in March 1999 in a rented San Francisco apartment, Salesforce launched on the premise that traditional, locally installed enterprise software was obsolete.[^3] Twenty-seven years later, the company closed fiscal 2026 with $41.5 billion in revenue, $14.4 billion in free cash flow, and a non-GAAP operating margin of 34.1%.[^4] IDC has ranked Salesforce as the leading customer relationship management vendor for thirteen consecutive years.[^5] The company holds a dominant position in the category it established.
Salesforce is now pursuing a major strategic shift: persuading enterprise clients to move beyond seat-based licensing models. Management has framed this transition around "digital labor" — deploying AI agents to execute tasks under consumption-based pricing rather than per-user fees. If successful, this model allows Salesforce to transcend the limits of mature seat-based subscription models, where expansion is constrained by customer headcount growth and incremental price increases. If unsuccessful, Salesforce risks settling into the profile of a mature, slowing enterprise software provider dependent on narrative valuation.
This analysis traces Salesforce's evolution and evaluates the core conditions required for its next growth phase. It begins with a brief overview of the company's origins and category creation before examining the major acquisition period from 2018 to 2021 — including MuleSoft, Tableau, and the $27.7 billion acquisition of Slack — testing market claims of overpayment against financial outcomes. The narrative then analyzes the activist investor pressure from 2022 to 2024 to assess whether management instituted structural changes or superficial adjustments. Finally, it evaluates Agentforce, weighing initial metrics against emerging counter-evidence. Throughout, the analysis examines a central question: what specific financial evidence is necessary to validate the bullish case, and whether those metrics have appeared in the financial reports.
That investigation begins with the initial decision to challenge established enterprise software incumbents.
 Subscribe on LinkedIn
II. Origins: Founding a Category (1999–2004)
Marc Benioff spent thirteen years at Oracle, joining at age twenty-three and becoming the company's youngest vice president by twenty-six. In his thirties, he had mastered Larry Ellison's playbook: aggressive sales execution, theatrical marketing, and public combat with competitors. He also gained a direct view of the friction in traditional enterprise software purchasing. Enterprise buyers signed multimillion-dollar licenses, spent eighteen months paying consultants to deploy the software, and often found the final product ill-suited to their operations.
During a 1999 sabbatical in Hawaii, Benioff revisited an idea circulating in Silicon Valley: hosting software centrally and delivering it over a web browser. The model eliminated dedicated servers, lengthy installation cycles, and multi-year implementation projects, replacing them with a subscription fee paid monthly like a public utility.
In March 1999, Benioff co-founded the company with engineers Parker Harris, Dave Moellenhoff, and Frank Dominguez in a rented apartment at 1449 Montgomery Street on San Francisco's Telegraph Hill.[^3] The founders dubbed the apartment "the Laboratory," dividing operations by floor, with engineers on one level and sales and recruitment on the other. By June, space constraints forced a move, and Benioff leased corporate offices at Rincon Center.[^3]
What distinguished Salesforce from competitors pursuing web-based software was less its underlying technology than its aggressive positioning. Benioff framed the company's mission around "the end of software" — not merely the end of bad or expensive software, but software itself as a product category. The company adopted a logo featuring the word "SOFTWARE" inside a red circle with a slash through it. The campaign directly targeted Oracle, SAP, and Siebel Systems, the dominant CRM provider at the time, led by fellow Oracle alumnus Tom Siebel. Salesforce staged mock protests outside Siebel's annual user conference, using hired actors carrying anti-software placards. The campaign secured media coverage and established a clear market framing: legacy on-premises vendors versus a modern cloud alternative.
Behind the marketing theater lay a structural shift in software economics that took the industry a decade to internalize. Under a software-as-a-service model, the vendor absorbs ongoing infrastructure and hosting costs. In exchange, the vendor can push simultaneous updates across all customers, monitor product utilization in real time, and collect recurring subscription revenue rather than relying on upfront perpetual license fees. While cash flow dynamics were less favorable in year one, long-term customer lifetime value proved substantially higher by year six. In 1999, few incumbent providers modeled software economics this way, delaying their response to the subscription threat.
When the dot-com crash occurred, Salesforce's focus on business clients rather than consumer internet startups helped it survive while many peers collapsed. The company reduced headcount and curbed expenditure as technology spending plummeted. Because clients paid recurring fees for software tied to daily sales operations, revenue grew from roughly $5 million in its first full operational years to over $100 million by 2003. That same year, Salesforce hosted its inaugural Dreamforce user conference in San Francisco, drawing 1,300 attendees — a modest gathering that eventually expanded into one of the business world's largest annual events.2
The company's initial public offering encountered regulatory friction when a profile of Benioff in The New York Times appeared during the SEC-mandated quiet period, forcing management to delay the listing from May to June 2004.3 The incident highlighted an early tension between Benioff's promotional approach and public market compliance requirements.
On June 23, 2004, Salesforce.com listed on the New York Stock Exchange under the ticker CRM, raising $110 million through the sale of 10 million shares at $11 apiece. The stock traded above $15 for most of its opening session and closed at $17.20, representing a first-day gain of more than 55%.34 Selecting "CRM" as its ticker symbol signaled management's ambition to define and lead the customer relationship management category.
Establishing a category, however, does not guarantee long-term defensibility. A web-based sales tracking tool could be replicated by competitors. Salesforce's subsequent strategic decisions focused on converting its early category leadership into an enduring moat.
III. Building the Platform Business (2004–2016)
Following its 2004 initial public offering, Salesforce faced a strategic choice common to expanding software vendors: continue building features to defend an application against imitators, or transform the core application into a foundation that enabled third parties to build on top of it. Salesforce chose the platform approach early. Between 2005 and 2008, the company launched AppExchange—a marketplace where third-party developers could publish applications running on Salesforce's infrastructure—and Force.com, the underlying platform that allowed enterprise clients to build custom software applications directly on Salesforce's data layer.
The strategic mechanism underlying this platform expansion is often loosely described as a network effect, but its precise driver was deep ecosystem switching costs. A pure network effect increases a product's value to all users as new participants join, as seen in communications networks. AppExchange created a different dynamic: software developers built tools where enterprise buyers were concentrated, clients remained on the platform to retain those application integrations, and systems integrators established dedicated consulting practices around the ecosystem. In the process, Salesforce cultivated a broad labor market of certified administrators who embedded the platform into standard enterprise operations. This network created professional career paths tied directly to Salesforce proficiency, cementing high organizational switching costs. These switching costs do not prevent competitors from capturing new clients, but they make replacing an incumbent system operationally complex and financially disruptive—a barrier central to evaluating whether AI agents will undermine Salesforce's enterprise footprint.
In 2009, Salesforce became the first cloud software provider to reach $1 billion in annual revenue. Alongside its commercial growth, management institutionalized the 1-1-1 model, dedicating 1% of equity, 1% of product, and 1% of employee time to philanthropic initiatives. While corporate social responsibility programs resist precise return-on-investment measurement, the policy served as an effective commercial and operational asset. In enterprise software sales and engineering recruitment, where financial terms are often competitive across vendors, the corporate reputation helped differentiate Salesforce in customer procurement and talent acquisition.
With its platform established, Salesforce initiated an aggressive acquisition strategy designed to expand its product scope. In 2012, the company acquired social media marketing platform Buddy Media for $745 million. In 2013, Salesforce paid $2.5 billion for email marketing provider ExactTarget, which formed the foundation of Marketing Cloud and marked the company's largest acquisition to that date.5 In 2016, it acquired e-commerce platform Demandware for $2.8 billion to establish Commerce Cloud.5
This acquisition playbook followed a consistent pattern: Salesforce identified an adjacent enterprise software category with a recognized market leader, acquired the asset rather than developing a competing product internally, integrated the offering into its broader product suite, and routed it through its established enterprise sales force. This distribution mechanism allowed acquired products to reach major enterprise accounts faster than independent vendors could manage on their own. Because Salesforce's enterprise sales organization functioned as a shared distribution infrastructure, attaching new products to the existing sales force generated unit economic efficiencies unavailable to standalone businesses.
However, this structural advantage also introduced strategic risk. Because management assumed its sales organization could accelerate an acquired company's revenue trajectory, valuation discipline weakened. High enterprise distribution capacity was frequently cited to justify premium acquisition multiples that standalone buyers could rarely support. Over time, this dynamic diminished the financial hurdles historically used to constrain corporate M&A.
That mindset set the stage for a four-year period during which Salesforce allocated roughly $50 billion to test the upper limits of its acquisition strategy.
IV. The Mega-Deal Era: Did Salesforce Overpay? (2018–2021)
In March 2018, Salesforce agreed to acquire MuleSoft for approximately $6.5 billion.5 MuleSoft developed integration software, serving as the connective middleware that enables disparate enterprise systems to exchange data. Large enterprise clients often run Salesforce for sales tracking, SAP for financial accounting, legacy mainframes for core operations, and dozens of specialized applications accumulated through corporate acquisitions. MuleSoft created the translation layer across these disparate platforms.
Strategically, the acquisition carried a defensive rationale. A customer relationship management platform's utility depends directly on the volume and variety of enterprise data it can ingest. If a competing vendor controls the data integration layer, that rival can restrict data flows into Salesforce. By acquiring MuleSoft, Salesforce secured direct control over data ingestion into its own ecosystem. Wall Street analysts initially characterized the price tag as steep—roughly twelve times forward revenue—while acknowledging the strategic logic. Subsequent financial performance has supported both assessments.
Fifteen months later, in June 2019, Salesforce announced an agreement to acquire Tableau for $15.7 billion in an all-stock transaction, closing that August.5 Tableau specialized in data visualization software, enabling business analysts to convert raw spreadsheet data into interactive executive dashboards. While Tableau led its product category, the transaction price represented a substantial premium relative to analytics peers.
Management's strategic rationale aimed to combine Salesforce's underlying customer data with Tableau's analytics interface, shifting the value proposition from passive record-keeping to actionable business intelligence. However, the transaction presented structural challenges. Salesforce already maintained internal analytics offerings, while Microsoft was aggressively distributing its competing Power BI tool as a low-cost addition to enterprise Office subscriptions. Acquiring a standalone leader while Microsoft commoditized the visualization layer assumed enterprise clients would continue paying premium pricing for dedicated tools. That assumption yielded mixed results; Tableau was subsequently cited by sell-side analysts as a drag on Salesforce's organic growth rate rather than an accelerator.6
On December 1, 2020, Salesforce announced its largest acquisition to date, agreeing to purchase enterprise collaboration platform Slack for an enterprise value of approximately $27.7 billion in cash and stock.[^11] The transaction, which closed on July 21, 2021, stood among the largest acquisitions in enterprise software history.7
Equity markets responded with immediate skepticism. Salesforce shares dropped nearly 10% following the announcement, with industry analysts noting that the transaction erased significant market capitalization in the days after disclosure.8 The primary objection centered on financial valuation relative to competitive pressure. While popular among users, Slack generated modest revenue compared to its acquisition price and faced intense competition from Microsoft Teams, which Microsoft bundled at no additional charge within its widely deployed enterprise software suites. Purchasing Slack at a high revenue multiple under direct competition from Microsoft required execution assumptions that investors struggled to model.
During the conference call following the announcement, Morgan Stanley analyst Keith Weiss questioned Benioff on the transaction price. Benioff defended the valuation by pointing to Salesforce's historical acquisition record with ExactTarget and Tableau, characterizing the purchase as a decision driven by timing and strategic conviction. Bret Taylor, then Salesforce's President and Chief Operating Officer, designated Slack as the overarching "system of engagement" for digital operations, emphasizing that the application would remain open to third-party integrations rather than functioning exclusively as a front-end interface for Salesforce.9
That positioning evolved rapidly after the deal closed. In June 2021, Benioff altered the narrative, declaring, "We're going to rebuild all of our technology, once again, to become Slack-first."10 The commitment implied a complete re-architecting of Salesforce's product suite around a messaging interface.
However, full execution of a Slack-centric architecture did not materialize. Throughout 2022 and 2023, as macroeconomic headwinds and activist investor pressure forced management to focus on operational margins, Slack was integrated as a standard component of the software platform rather than serving as the central application interface. In October 2025 at Dreamforce, management redefined Slack's role a third time: Benioff announced that "Slack has become agentic OS," introducing Agentforce 360 and positioning Slack as the conversational hub for human and AI agent collaboration across Salesforce's product line.[^16]
These evolving public narratives—transitioning from a standalone collaborative workspace, to an integrated platform component, and ultimately to an artificial intelligence operating system—reflected shifting strategic priorities for a $27.7 billion asset over a five-year span.
Financial performance metrics offer a counter-perspective to critics of the acquisition era. Salesforce has recorded no goodwill impairments on Slack, MuleSoft, or Tableau, and revenue from the acquired assets has grown. The combined integration and analytics product segment generated approximately $6.2 billion in revenue in fiscal 2026, with management noting on earnings calls that MuleSoft and Tableau feature in a vast majority of the company's largest enterprise transactions.[^4]11 Furthermore, during the second-quarter fiscal 2027 earnings call, management cited expanded Slack usage alongside Agentforce adoption as a contributing factor to the company's 11% year-over-year revenue increase.12
The absence of accounting impairments, however, provides incomplete proof of acquisition efficiency. Because Salesforce does not report standalone financial statements or distinct reporting unit carrying values for Slack, Tableau, or MuleSoft, an accounting write-down would occur only if the fair value of an aggregated business segment fell below its carrying value. At an enterprise expanding overall revenues and operating margins, aggregated segment reporting rarely triggers impairment thresholds for individual acquisitions. Consequently, the lack of write-downs reflects aggregated financial reporting conventions rather than definitive proof of acquisition pricing discipline. Additionally, technology sector goodwill write-downs historically occur when top-line growth decelerates rather than in the immediate years following deal completion.
Evaluating Salesforce's acquisition record requires separating operational scaling from valuation discipline. Broad assertions that major acquisitions systematically destroyed corporate value are contradicted by ongoing revenue growth, active customer deployment, and product integration. Conversely, evidence indicates Salesforce paid substantial premiums relative to standalone asset valuations, acquiring Slack prior to establishing a durable product integration roadmap. Validating the critical view would require sustained revenue deceleration in integration and analytics followed by goodwill write-downs. Retiring the critique would require Slack to demonstrate scalable, profitable execution of AI agent workloads under disclosed financial reporting metrics—an outcome management has outlined but not yet substantiated with granular data.
The symbolic height of this expansion phase occurred in August 2020, when Salesforce replaced Exxon Mobil in the Dow Jones Industrial Average—a shift widely interpreted as a marker of cloud software supplanting traditional energy in the industrial economy.[^19] Subsequent stock performance, however, diverged from that narrative: over the four years following the index substitution, Exxon Mobil's total returns significantly surpassed those of Salesforce.13 Benchmark inclusion reflected past historical expansion rather than guaranteed future equity outperformance.
By late 2021, the market's tolerance for acquisition-led expansion without clear margin discipline had reached its limit. Salesforce's growth-at-any-cost era concluded not through internal realignment, but under direct pressure from activist hedge funds.
V. The Reckoning: Activists, Layoffs, and Forced Discipline (2022–2024)
The setup: growth decelerating, margins going nowhere
Every activist campaign begins with financial metrics, and Salesforce's data in 2022 revealed growing operational inefficiency.
While revenue growth had historically exceeded 25%, it was decelerating. Meanwhile, non-GAAP operating margins remained stuck in the high teens—roughly half the level earned by mature enterprise software peers of comparable scale. Headcount had expanded rapidly during the pandemic on the assumption that the digital acceleration of 2020 and 2021 would persist indefinitely.
This combination produced negative operating leverage: Salesforce was adding operating expenses faster than revenue was expanding, just as top-line growth was slowing. In October 2022, Starboard Value acquired a stake in the company and publicly criticized its subpar combination of growth and profitability.
A co-CEO walks out the door
On November 30, 2022, Salesforce announced that Bret Taylor would step down as Vice Chair and Co-Chief Executive Officer effective January 31, 2023, leaving Marc Benioff as sole Chair and Chief Executive Officer.[^21]
Taylor possessed strong entrepreneurial credentials, having co-created Google Maps, sold FriendFeed to Facebook, served as Facebook's Chief Technology Officer, and founded Quip, which Salesforce acquired in 2016. His promotion to Co-CEO in November 2021 was widely viewed as a definitive executive succession plan. Fourteen months later, he resigned.
Management attributed Taylor's departure to a desire to return to entrepreneurial ventures. Reporting at the time cited operational friction, including his concurrent role as chairman of Twitter's board during Elon Musk's acquisition and disagreements over corporate strategy.
From a corporate governance perspective, the sudden departure of a designated successor after little more than a year created renewed uncertainty around succession planning at a firm led by a founder-CEO who was then in his late fifties with no other identified heir.
Five activists at the table
In January 2023, Elliott Management accumulated a multibillion-dollar position.14 Elliott joined Starboard Value, Third Point, ValueAct Capital, and Inclusive Capital, creating an unprecedented cluster of five activist hedge funds simultaneously targeting a megacap software vendor. Reports indicated Elliott focused heavily on expense discipline and succession governance.
Management acted rapidly. On January 4, 2023, before Elliott's stake became public, Salesforce announced it would eliminate approximately 10% of its workforce—more than 7,000 positions—and reduce its office space.15 In an internal memorandum, Benioff took personal responsibility for overhiring during the pandemic revenue surge.
While management publicly acknowledged the mistake, the rapid headcount expansion represented a significant capital allocation error, with the operational cost of the correction borne by departing employees.
On January 30, 2023, Salesforce appointed three independent directors, including ValueAct Chief Executive Officer Mason Morfit, offering board representation to secure activist alignment.16
The settlement that wasn't a settlement
On March 27, 2023, Salesforce and Elliott issued a joint statement announcing that Elliott would not proceed with board director nominations. Elliott Managing Partner Jesse Cohn stated he had "become deeply impressed by their strong ongoing commitment to profitable growth, responsible capital return and an ambitious shareholder value creation plan."17
The joint statement was notable for what it omitted: Elliott secured neither a board seat nor a formal standstill agreement.17
Activists of Elliott's scale typically require binding governance concessions. In this instance, management's newly introduced "New Day" operational framework, coupled with strong fiscal 2023 financial results, satisfied the fund's immediate objectives without a proxy contest. During the fiscal 2023 fourth-quarter earnings call, management emphasized this strategic pivot by pairing workforce reductions with explicit operating margin expansion commitments.18
The payoff, and it was real
The operational execution that followed demonstrated rapid margin expansion.
Non-GAAP operating margin rose from roughly 18.7% to over 30% within two years. Salesforce closed fiscal 2024 with revenue of $34.9 billion, up 11%, and a non-GAAP operating margin of 30.5%, fulfilling management's public target.[^27]
On February 28, 2024, Salesforce declared the first quarterly dividend in its history, at $0.40 per share, and expanded its share repurchase authorization by $10 billion.[^27] For a company historically built on aggressive reinvestment, initiating a cash dividend signaled a structural shift toward mature capital allocation.
By fiscal 2026, non-GAAP operating margin reached 34.1% while annual free cash flow reached $14.4 billion.[^4] Management raised the quarterly dividend on schedule, reaching $0.44 per share for fiscal 2027.[^4] By the second quarter of fiscal 2026, the company logged ten consecutive quarters of operating margin expansion.[^28]
Expanding operating margins by approximately 1,500 basis points on a $40 billion revenue base generated billions of dollars in incremental annual operating profit, establishing a clear record of meeting financial guidance.
The falsification test: is it fixed, or is it a cycle?
Whether this margin discipline reflects permanent structural reform or temporary compliance remains a central question for investors.
While most activist funds exited after capturing initial gains, Starboard Value re-engaged. In the second quarter of 2025, Starboard increased its Salesforce position by nearly 50%, expanding its holdings from approximately 850,000 shares to roughly 1.3 million. Managing Member Jeffrey Smith noted that Salesforce retained additional room to improve efficiency and profitability, even as the stock fell close to 30% from January 2025.19
An activist fund expanding its stake two years after an initial restructuring suggests that market participants view cost discipline as a response to external oversight rather than an internalized operating philosophy. When pressure is applied, margins expand; when oversight recedes, spending concerns re-emerge.
Evaluating the thesis that Salesforce has established permanent structural discipline requires weighing verified margin expansion and capital returns against recurring governance challenges. The evidence confirms management can maintain margin discipline under active scrutiny. However, validating whether that discipline persists independently depends on future capital allocation decisions—specifically whether management avoids margin stagnation or large, high-multiple acquisitions in the absence of active campaign pressure.
Both conditions face immediate evaluation, as Salesforce initiated new strategic actions in 2025.
VI. What Actually Drives the Business Today: Segments & Market Position
Reading the revenue lines, and a naming change worth noticing
In fiscal 2026, Salesforce reported $41.5 billion in total revenue. Service Cloud led the segment breakdown at approximately $9.8 billion, followed closely by Sales Cloud at $9.0 billion and Platform and Other at $8.9 billion. Integration and Analytics contributed around $6.2 billion, Marketing and Commerce generated $5.4 billion, and Professional Services accounted for the remaining $2.1 billion.[^4]11
In its fiscal 2026 Form 10-K, Salesforce introduced a notable reporting change by presenting these core product lines under updated names: Agentforce Sales, Agentforce Service, and Agentforce 360 Platform / Slack / Other.11
The underlying operations remained unchanged; only the nomenclature shifted. Legacy seat-based revenue now sits inside line items bearing the Agentforce label.
While corporations routinely update product naming—and Salesforce has re-architected its product architecture around artificial intelligence—the revised presentation alters how outside investors evaluate top-line performance. Because existing subscription revenue is aggregated under Agentforce-branded headings, primary financial statements offer limited visibility for isolating new AI revenue from pre-existing software seats. Consequently, evaluating the momentum of the AI transition requires relying on management's non-GAAP annual recurring revenue disclosures.
What the mix actually says
Combined, Service Cloud and Sales Cloud generate roughly $19 billion, representing nearly 45% of total revenue. As Salesforce's foundational offerings—case management on the service side and opportunity tracking on the sales side—these mature business units generate steady growth in the high single digits to low teens.
By contrast, corporate earnings presentations consistently highlight the smaller, faster-growing segments: Platform and Data 360 alongside Integration and Analytics. Focusing investor attention on high-growth areas reflects standard corporate communications, but it also highlights the maturity of the core CRM suite that still accounts for the vast majority of overall sales.
Geographically, the Americas account for approximately 65% of revenue, while Europe contributes 24% and Asia-Pacific represents 10%.11 This geographic concentration limits exposure to volatile emerging markets, but leaves Salesforce subject to European data-governance regulations and foreign currency fluctuations, which have impacted reported top-line growth by a percentage point or more in recent periods.
Market share: number one, and slightly smaller
IDC has ranked Salesforce as the leading CRM vendor for thirteen consecutive years. In its April 2026 tracker covering calendar year 2025, Salesforce held a 20.0% share of the global CRM applications market.[^5]
That figure represents a slight decrease from the 20.7% market share recorded in the prior year's tracker for calendar 2024.[^30]
While minor market share movements can reflect currency swings or adjustments in measurement methodology, the general direction remains clear. A market leader holding one-fifth of a category—still larger than its next several competitors combined—gradually yielding share to faster-growing rivals fits the standard profile of a mature enterprise franchise.
The switching-cost question, honestly stated
The bullish investment case rests heavily on customer switching costs, though public financial statements offer limited quantitative metrics to measure them. Salesforce does not publish gross or net revenue retention figures, nor does it disclose customer churn rates. Instead, investors must evaluate management statements, such as commentary on the second-quarter fiscal 2027 earnings call citing low customer attrition and rising net-new average order value as evidence of business stability.12
The qualitative argument for high switching costs remains strong. Large enterprise deployments involve custom code, deep integration across internal systems, extensive administrator training, and mission-critical executive reporting workflows. Replacing such an embedded software layer requires multi-year implementations, carries significant operational risk, and offers uncertain returns.
Nevertheless, without standardized retention disclosures, switching costs remain an inferred structural advantage rather than a quantified financial metric. Resolving whether these entrenched switching costs can withstand generative AI tools became the central test facing the company.
That test began in October 2024, when Salesforce launched its strategic response.
VII. The AI Pivot: Agentforce and the Data Cloud Bet (2024–2026)
What "digital labor" actually means
Stripped of marketing rhetoric, the underlying commercial premise is straightforward. For a quarter-century, Salesforce built its business by selling software licenses per seat: an enterprise with 5,000 sales representatives purchased 5,000 subscriptions, making revenue a direct function of client headcount and per-user pricing.
Agentforce proposes a structural shift: deploying software that executes tasks rather than merely recording them. Instead of a human customer support representative reviewing client history in a database and writing a response, an artificial intelligence agent reads the records, drafts the reply, queries the order management system, issues a refund, and resolves the support ticket. Under this model, clients pay based on units of work performed rather than user headcount.
Management frames this shift as a commercial transition comparable to the original migration from on-premises software to cloud subscriptions. While that characterization aligns with corporate positioning, it carries an inherent operational friction: if autonomous agents absorb customer support workloads, enterprise clients require fewer human support staff, directly reducing the required number of software seats. Consequently, Salesforce is deploying a product whose primary value proposition risks shrinking its legacy revenue base. For the strategy to succeed, consumption revenue from digital labor must expand faster than legacy seat subscriptions decline—an empirical outcome that financial disclosures have yet to validate.
Effective agentic execution requires broad data access beyond standard customer relationship records, encompassing order histories, billing platforms, and enterprise data warehouses. An agent restricted to a single database operates like a basic chatbot; an agent integrated across disparate systems can execute complex workflows. For this reason, the foundational transaction supporting Salesforce's agentic strategy was not an artificial intelligence startup, but an enterprise data integration provider.
Informatica: a real, verifiable data point on price discipline
In April 2024, Salesforce entered discussions to acquire enterprise data-management provider Informatica for an estimated $11 billion before abandoning negotiations.
Thirteen months later, in May 2025, Salesforce resumed negotiations following a decline in Informatica's stock price, agreeing to acquire the firm for approximately $8 billion, or $25 per share in cash.20 The transaction closed on November 18, 2025.[^32]
This sequence provides a clear counter-example to arguments that Salesforce lacks acquisition discipline. Management identified a strategic asset, rejected an initial price evaluation, paused negotiations for over a year, and ultimately acquired the same business at a discount of roughly 27%. That execution demonstrates genuine price discipline, balancing earlier criticisms of overpayment during the Slack acquisition.
However, the transaction structure altered Salesforce's debt profile. In June 2025, Salesforce executed a 364-day credit facility for up to $4.0 billion alongside a three-year agreement for up to $2.0 billion to fund the purchase and refinance Informatica's existing debt. The company drew the full $6.0 billion at closing, which remained outstanding at the end of fiscal 2026 on January 31, 2026.11 In March 2026, management consolidated those obligations into a single $6.0 billion, five-year senior unsecured term loan.21
As a result, net debt increased from approximately $2.5 billion at the end of fiscal 2025 to roughly $9.8 billion at the end of fiscal 2026, alongside $9.6 billion in cash and marketable securities.11
While that debt load remains manageable relative to $14.4 billion in annual free cash flow, it represents a shift in capital structure for a business that historically maintained a low-debt balance sheet and funded major acquisitions primarily with equity. Utilizing debt for corporate M&A introduces a different financial dynamic that has yet to be tested through a severe macroeconomic contraction. Extending debt maturities into a five-year term loan reflects standard liability management, but it establishes a new template for financing future large-scale transactions.
The ARR trajectory, and why it is genuinely extraordinary
Following Agentforce's launch in October 2024, the product recorded rapid initial customer adoption.
Within ninety days of release, the platform secured approximately 3,000 paying accounts, reaching $100 million in annual recurring revenue within two quarters. By the second quarter of fiscal 2026, ending July 2025, annual recurring revenue across Data Cloud and artificial intelligence products surpassed $1.2 billion—a 120% year-over-year increase—supported by more than 12,500 total Agentforce agreements, including over 6,000 paid contracts.[^28]
By the conclusion of fiscal 2026, annual recurring revenue for the combined Agentforce and Data 360 portfolio exceeded $2.9 billion, representing a year-over-year increase of more than 200%, with standalone Agentforce revenue reaching $800 million, up 169%.[^4] By the first quarter of fiscal 2027, reported in May 2026, Agentforce annualized revenue crossed $1.0 billion.
In the second quarter of fiscal 2027, reported on August 26, 2026, Agentforce annual recurring revenue exceeded $1.5 billion—up over 240% year over year—while the combined AI and Data 360 portfolio reached approximately $3.9 billion, up over 210%. Cumulative completed tasks, measured by Salesforce as "Agentic Work Units," reached 7.0 billion, with 3.2 billion executed during the second quarter alone, representing 97% sequential volume growth.[^1] During the earnings release, Benioff highlighted that portfolio ARR was approaching the $4 billion threshold.[^1]
Expanding a product line from inception to a $3.9 billion annual run rate in under two years represents an unusually rapid expansion pace for an enterprise software suite, particularly within an organization generating over $46 billion in annual revenue.
However, evaluating the sustainability of this expansion requires examining how these non-GAAP metrics are defined and tracked.
The disconfirming evidence, placed exactly where it belongs
Annual recurring revenue is a non-GAAP figure defined internally by Salesforce. It reflects an annualization of current contract rates or in-period usage. For consumption-priced products, this metric can incorporate active pilot usage that customers have not yet committed to renew under long-term contracts. Consequently, while ARR serves as a leading indicator of customer activity, it carries a wider variance than audited balance-sheet metrics.
By contrast, current remaining performance obligation (cRPO) offers a more standardized measure of committed revenue. Disclosed under GAAP principles, cRPO measures contracted revenue expected to be recognized over the subsequent twelve months, providing an audited view of committed customer backlogs.
A comparison of these metrics reveals a notable divergence. In the second quarter of fiscal 2027, while Agentforce ARR grew more than 240%, total cRPO expanded by 14% year over year to $33.5 billion.[^1] Full-year management guidance projects cRPO growth of approximately 14% as well.[^1] While a 14% expansion rate reflects steady enterprise demand, it indicates that rapid ARR growth in new product lines has not yet accelerated total corporate backlog growth.
Two operational factors account for part of this gap. First, Agentforce revenue remains a modest fraction of Salesforce's total revenue base, meaning rapid percentage growth has a muted effect on aggregate backlog metrics. Second, consumption-based billing models frequently operate outside fixed minimum commitments, allowing recognized usage revenue to accumulate without appearing in formal cRPO figures.
A second interpretation focuses on total corporate growth dynamics. On July 21, 2026, Morgan Stanley analyst Adam Wood downgraded Salesforce from Overweight to Equal Weight and lowered his price target by approximately 35%, citing weak cRPO growth as evidence that Agentforce adoption was not yet re-accelerating overall revenue.622 Wood noted that Agentforce, operating at a run rate of roughly $3.4 billion at the time, accounted for approximately 7% of expected $46 billion full-year revenue—a scale insufficient to offset deceleration in legacy business units such as Commerce Cloud and Tableau.22 Wood maintained a favorable view of product adoption itself, framing his downgrade around timing, aggregate scale, and valuation.
Other sell-side analysts highlighted moderating enterprise bookings throughout 2026, referencing chief information officer surveys indicating that enterprise buyers remained cautious regarding full-scale AI deployments.
Broader industry research aligns with this cautious perspective. Gartner projected that over 40% of enterprise agentic AI initiatives would be discontinued by the end of 2027 due to rising costs, unproven operational returns, and governance challenges, characterizing many initial implementations as exploratory pilots.23 While applicable to the broader software sector rather than Salesforce specifically, these industry figures highlight the historical challenge of converting initial enterprise trial deployments into permanent production contracts.
During the second-quarter fiscal 2027 earnings conference call, equity analysts questioned management on these structural dynamics. Goldman Sachs analyst Elizabeth Porter inquired why aggregate cRPO grew 14% alongside a 240% increase in Agentforce ARR, asking whether pilot-to-production conversion timelines were lengthening. Bank of America analyst Gabriela Borges questioned whether evolving commercial packages would generate stable unit economics as pricing models mature, while Guggenheim analyst John DiFucci asked whether low customer attrition and order value growth represented durable operational trends.12
Management responses emphasized strategic momentum while providing limited granular metrics. Chief Revenue Officer Miguel Milano acknowledged commercial flexibility, noting that enterprise agreements ranged from outcome-based structures to fixed enterprise licenses based on client preference.12 That flexibility underscores that commercial terms for agentic software remain unstandardized, complicating direct comparisons between consumption-based ARR and traditional seat subscription ARR.
When asked about competition between open-source models and frontier artificial intelligence architectures, Benioff stated that enterprise buyers prioritize integrated business outcomes over underlying model selection, dismissing concerns over model choice as secondary to application functionality.12 While defensible from a workflow integration standpoint, the response relied on qualitative customer feedback rather than standardized disclosure metrics.
The June selloff and the August reversal — and what neither proved
Equity markets responded to these mixed operational signals with sharp valuation swings throughout mid-2026.
During the fourteen-session decline ending June 22, 2026, Salesforce shares dropped to $146.32 as market participants priced in risks that generative AI development tools might enable enterprise clients to build custom CRM applications internally. On June 15, 2026, during the decline, Salesforce announced an agreement to acquire AI customer-service platform Fin (formerly Intercom) for approximately $3.6 billion in cash, expanding its customer support agent capabilities across 30,000 client accounts, with closing scheduled for the fourth quarter of fiscal 2027.[^36] The announcement failed to halt the share sell-off, as investors interpreted additional M&A as evidence of competitive pressure.
Following the second-quarter earnings release on August 26, 2026, Salesforce shares rose 22.6% in the next trading session, marking the second-largest single-day gain in company history.1 Management raised full-year fiscal 2027 revenue guidance to between $46.1 billion and $46.4 billion, up from the $45.8 billion to $46.2 billion range issued in February.[^1][^4] Alongside financial results, Salesforce announced an expanded partnership with Anthropic to integrate model capabilities under the Claudeforce brand.12
A detailed review of second-quarter earnings reveals that reported non-GAAP net income included non-operating financial factors.
Salesforce reported non-GAAP earnings per share of $5.90, compared to consensus expectations of approximately $3.27. However, approximately $2.53 per share of that total resulted from unrealized net gains on strategic investments, primarily a $2.6 billion mark-to-market upward valuation of Salesforce's investment in Anthropic.24 Excluding investment gains, non-GAAP operating earnings per share reached approximately $3.37, while non-GAAP operating margin stood at 34.1%, compared to 34.3% in the prior-year period.[^1][^28]
Thus, the quarterly results that drove the equity rally combined steady top-line execution, a $300 million adjustment to full-year guidance on a $46 billion revenue base, 14% cRPO expansion, rapid non-GAAP AI ARR growth, flat operating margins year over year, and a substantial mark-to-market gain on a private technology investment.
These investment accounting adjustments comply with GAAP reporting standards and were disclosed in full. However, the magnitude of the single-day equity rally reflected a sharp repricing from depressed June valuation levels rather than a complete resolution of long-term commercial questions surrounding agentic software monetization.
The operational reality sits between the market's two extremes. The June sell-off assumed enterprise software disintermediation before structural adoption occurred, while the August surge priced in full monetization before conversion metrics materialized. The verified data demonstrates rapid initial enterprise adoption of Agentforce alongside unstandardized unit economics that have not yet expanded total contracted backlogs.
The calibrated conclusion
The core investment thesis under evaluation holds that Agentforce can convert Salesforce's enterprise footprint into a durable, high-margin, consumption-priced growth engine.
Supporting evidence includes rapid initial product deployment, ARR expansion across consecutive fiscal periods, adoption within major enterprise accounts, data integration assets acquired through disciplined M&A, and strategic model partnerships.
Counter-evidence centers on specific financial and market indicators: a 14% cRPO expansion rate alongside a 240% reported ARR growth rate, sell-side downgrades targeting that divergence, unstandardized contract structures, industry projections of high pilot cancellation rates, and product reporting renamings that aggregate legacy seat subscriptions with new AI revenue lines.
These combined factors narrow the investment conclusion: Salesforce has established initial enterprise demand for AI agent capabilities, but financial statements have not yet verified that this demand converts into committed, long-term contractual revenue capable of accelerating overall corporate growth.
Validating the bullish case requires observable operational metrics: specifically, total cRPO growth accelerating above mid-teens percentages over subsequent quarters, followed by re-accelerating GAAP subscription revenue. Conversely, the thesis would be challenged if reported ARR continues to expand rapidly while cRPO growth remains constrained at or below 14%, indicating that pilot usage is not converting into permanent contracted commitments.
Capital allocation decisions provide additional context for evaluating management's outlook. Salesforce increased its cumulative share repurchase authorization by $20 billion to $50 billion in September 2025, reconfirming the $50 billion program alongside fiscal 2026 annual results in February 2026.[^28][^4] During fiscal 2026, the company returned $14.3 billion to shareholders—comprising $12.6 billion in share buybacks and $1.6 billion in dividends—utilizing nearly all of its $14.4 billion in annual free cash flow.[^4]
This capital return strategy supports two distinct interpretations. Repurchasing shares during market downturns aligns with standard corporate management of undervalued equity. Alternatively, allocating cash flow heavily toward buybacks can serve to support equity valuations while long-term commercial models remain under evaluation. The key indicator for investors will be whether share repurchases continue at scale during periods of equity recovery or remain concentrated during share price drawdowns.
This ongoing strategic transition ultimately turns on corporate governance, execution track records, and executive leadership.
VIII. Current Management: Incentives, Ownership, and Credibility
The founder who cannot outvote his shareholders
A single governance detail explains the dynamics of Salesforce's corporate trajectory over the past four years far more clearly than any strategic roadmap.
Marc Benioff has served as Chairman and Chief Executive Officer since founding the company in 1999. The 2026 proxy statement shows his beneficial ownership in the range of roughly 23 to 32 million shares, depending on the counting convention — representing approximately 3% of shares outstanding.25
Salesforce maintains a single class of common stock under a one-share, one-vote structure. Unlike peers such as Meta, Alphabet, or Snap, the company has no dual-class super-voting shares to shield management from shareholder votes.
Consequently, institutional investors hold decisive voting leverage. Institutional filings indicate that Vanguard holds approximately 10%, BlackRock holds roughly 9%, and State Street holds about 6% — giving each index provider a larger voting bloc than the founder.25
This voting structure proved pivotal during the 2023 activist campaign. When Elliott Management acquired its stake in January 2023, Benioff lacked the equity voting control to override activist demands. Any proxy contest would have been decided by index funds and proxy advisory firms, which typically support operational restructuring when margins lag peers. Management's rational response was to rapidly implement margin expansion commitments and settle before a shareholder vote occurred.
This capital structure shifts the primary governance risk away from traditional founder entrenchment. Instead, it creates a distinct profile: a founder-CEO with an outsized public profile, a modest economic stake, no structural voting immunity, and no designated successor.
Robin Washington and the consolidated seat
In March 2025, Salesforce appointed Robin Washington as President and Chief Operating and Financial Officer, consolidating operational and financial leadership under a single executive.
The appointment followed the retirement of Chief Financial Officer Amy Weaver, who managed the company's margin restructuring, and Chief Operating Officer Brian Millham, who stepped down in May 2025. Washington assumed both portfolios.
Washington brings extensive executive experience, having previously served as Executive Vice President and Chief Financial Officer of Gilead Sciences — a company reliant on high-margin cash flows from a focused product portfolio facing questions over long-term durability. She also served on Salesforce's board as Lead Independent Director beginning in 2022.
This background carries dual governance implications. On one hand, Washington possesses deep institutional knowledge and board-level credibility established during the activist negotiations. On the other hand, transitioning a Lead Independent Director into an executive management position eliminates the board's primary independent oversight role, absorbing that scrutiny into executive leadership.
Her public commentary on earnings calls has emphasized operational targets over broad positioning. During the second-quarter fiscal 2027 earnings call, Washington anchored forward expectations on quantitative metrics, highlighting that net-new annual order value growth was "the strongest it's been in four years," keeping the company "on track for second-half organic revenue reacceleration."[^1] This commitment establishes a clear, measurable benchmark for management execution over subsequent quarters.
The record, weighed
Salesforce's post-2023 capital allocation shows measurable discipline relative to its prior expansion period. In fiscal 2026, free cash flow reached $14.4 billion against $14.3 billion in total shareholder returns, aligning capital return programs with organic cash generation.[^4] This contrasts with the 2018–2021 period, when management allocated roughly $50 billion of enterprise value to three major acquisitions funded largely with stock.
However, two major capital allocation decisions remain unproven: the $6.0 billion term loan used to acquire Informatica and the $50 billion share repurchase authorization expanded in 2025. Evaluating long-term capital discipline requires monitoring execution on these programs over full market cycles.
Management has demonstrated consistent execution on public guidance. The company achieved the operating margin targets set during the activist campaign, initiated and increased its cash dividend on schedule, and raised full-year fiscal 2027 revenue guidance during a period of market uncertainty. Alongside fiscal 2026 results, management introduced a long-term target of $63 billion in revenue by fiscal 2030 — a trajectory implying roughly 11% compound annual growth without requiring top-line acceleration.[^4] Setting a long-range target that reflects steady growth rather than aggressive expansion provides a realistic baseline for financial planning.
Conversely, public narrative consistency exhibits notable gaps across three main areas.
First, management reframed Slack's strategic role three times in five years — transitioning from a standalone collaboration tool, to a core platform interface, to an artificial intelligence operating system — without providing explicit reconciliations for earlier strategic pivots.
Second, management has not provided audited metric disclosures to clarify the gap between reported Agentforce ARR expansion and aggregate cRPO growth. Disclosing contracted Agentforce backlog, contract renewal rates, or the proportion of AI ARR tied to binding minimum commitments would offer objective evidence of customer adoption.
Third, the sudden departure of the former Co-CEO remains unexplained, leaving ongoing ambiguity around executive succession planning.
Evaluating management's record yields a clear distinction between verified financial metrics and strategic narrative. On audited parameters — operating margins, free cash flow generation, dividend payments, and consensus financial guidance — management has fulfilled its stated commitments for three consecutive fiscal years. On strategic assertions — product integration roadmaps, AI contract conversion dynamics, and governance succession — public statements continue to outpace formal reporting disclosures. Investors evaluating the business must weight empirical financial results against unverified commercial narratives as the company navigates its next operational phase.
That distinction becomes essential when assessing Salesforce's competitive position, where market dynamics and strategic claims intersect.
IX. Competitive Landscape & Industry Structure
The five forces, applied properly
An examination of industry dynamics begins with buyer power, the force that has shifted most significantly.
At the enterprise level—among the global financial institutions, insurers, telecommunications providers, and manufacturers that form Salesforce's core customer base—buyer power remains low. Contracts span multiple years, implementations are deeply embedded, and switching costs require substantial engineering time and operational risk. In this segment, the enterprise switching-cost moat remains durable.
Conversely, buyer power is high and expanding in the small and mid-sized business segment. Competitors like HubSpot built scale by offering free entry-level tools before monetizing tier upgrades, accumulating hundreds of thousands of customers while expanding annual revenue at roughly 28%. For smaller organizations, the complexity and cost of Salesforce's core suite often exceed operational requirements.
Supplier power represents an increasingly vital factor in enterprise software. Frontier artificial intelligence model providers—including Anthropic, OpenAI, and major cloud hyperscalers—supply the underlying foundational architectures powering Agentforce. Salesforce has partially hedged this exposure by taking an equity stake in Anthropic and expanding its partnership through Claudeforce.1224 Nevertheless, the arrangement creates a structural dependency: Salesforce does not own the primary frontier models driving its autonomous agents, leaving input costs and technical roadmaps subject to third-party providers.
The threat of new entrants at scale remains low. Developing basic customer relationship software is straightforward; constructing an enterprise platform that secures regulated financial data, satisfies strict procurement standards, integrates with legacy IT systems, and maintains a global ecosystem of certified consultants presents a formidable barrier to entry.
Competitive rivalry is intense but rarely price-destructive among enterprise accounts, where purchasing decisions hinge on technical capability, integration breadth, and vendor incumbency rather than aggressive discounting.
The primary competitive challenge facing Salesforce stems from the threat of substitution.
Substitution: the only force that can break the moat
Historically, substitution posed minimal risk to enterprise CRM platforms, as organizations required a central system of record to manage customer data.
Generative artificial intelligence, however, introduces two potential substitution vectors.
The first vector—a custom, AI-generated application model that contributed to the June 2026 stock selloff—posits that enterprise clients might use automated coding tools to build bespoke software rather than license standard platforms. This scenario appears overstated. The primary hurdle in enterprise software is rarely code generation; rather, it lies in designing complex data structures, ensuring regulatory compliance, managing system integrations, executing data migrations, and preserving decades of custom business rules. Synthesizing software code without this underlying infrastructure yields an unintegrated application.
The second, more significant substitution risk involves workflow disintermediation, driven primarily by Microsoft.
The Microsoft mechanism, stated precisely
Microsoft Dynamics 365 holds a distant second position in global CRM market share, trailing Salesforce by a wide margin. Consequently, direct application replacement does not represent the primary competitive threat.
Instead, the structural risk stems from Microsoft Copilot operating across daily productivity suites.
In routine operations, sales and service representatives interact with Salesforce to log client notes, update deal stages, and review account histories. If enterprise workers execute these tasks directly within Microsoft Outlook or Teams via Copilot summaries and automated inputs, user engagement shifts away from the Salesforce interface. While underlying database subscriptions may initially persist, bypassing the primary software interface risks eroding daily user habits, perceived platform utility, and long-term pricing power—reducing Salesforce to a back-end repository.
This disintermediation mechanism presents a genuine long-term challenge. It does not require Microsoft to displace Salesforce's core database in procurement decisions, but merely to capture the front-end workflow surface within productivity applications that enterprises already license.
This threat clarifies why management reframed Slack as an artificial intelligence operating system in October 2025.[^16] Positioned as a conversational hub, Slack allows Salesforce to retain ownership of the primary user interface. However, this strategy places Slack in direct competition with Microsoft Teams, which benefits from pre-installed distribution and zero-incremental-cost bundling within enterprise productivity suites—the competitive pressure Slack encountered prior to its acquisition.
The fast followers, sized honestly
Adjacent cloud providers, including ServiceNow, HubSpot, and monday.com, have expanded annual revenues at rates exceeding 20%—roughly double Salesforce's top-line growth rate.
These growth comparisons, however, reflect standard market maturity dynamics. Because smaller software vendors operate from significantly smaller revenue bases, their percentage expansion rates naturally outpace larger incumbents. A market leader holding a 20% share and growing at 11% while smaller peers expand at higher rates reflects a maturing product category rather than systemic displacement.
A substantive competitive shift would require competitors to capture core market share within Salesforce's established enterprise accounts. Current evidence does not support that trend; management has reported specific competitive displacements of ServiceNow at major enterprise accounts, including Sunrun and Cornerstone.[^39] Disclosed win-loss records indicate that widespread disintermediation has not materialized.
The competitive assessment yields a clear conclusion: while workflow disintermediation represents a credible structural risk, it remains an unproven hypothesis in current financial and operational data. Market share statistics, customer retention commentary, and enterprise win rates show no immediate signs of displacement. If disintermediation begins to occur, its initial effects will appear in decelerating seat-count growth and compressed renewal pricing across Sales Cloud and Service Cloud well before impacting aggregate market share statistics.
X. Playbook: Business & Investing Lessons
Inventing a category is a distribution strategy, not a technology strategy
The "end of software" campaign is often remembered as aggressive marketing theater, but its strategic insight was fundamentally about distribution and market positioning.
Salesforce did not win because browser-delivered software was technically superior in 1999—it was frequently slower and less feature-rich than on-premises alternatives. Instead, it succeeded because framing the industry as old versus new forced enterprise buyers to align with a strategic narrative. A chief information officer evaluating Siebel Systems against Salesforce was no longer comparing technical feature lists; they were selecting an operational philosophy.
Category creation succeeds when an incumbent's historical strengths—an installed hardware base, complex on-premises deployments, and high implementation fees—are reframed as customer liabilities. Salesforce established that reframing a decade before subscription economics became the industry consensus.
Platform economics are real, and they are not the same as acquisition economics
Two growth drivers in Salesforce's history appear superficially similar but rest on fundamentally different economic models.
AppExchange and Force.com generated enterprise value by encouraging external developers and partners to invest their own capital and labor on top of Salesforce's core infrastructure. Salesforce incurred the fixed cost of building the platform, while economic value compounded through an expanding ecosystem.
By contrast, large corporate acquisitions attempt to create value by purchasing established software platforms outright and capturing revenue synergies through shared distribution. Platform expansion generates low-cost, high-margin ecosystem effects, whereas acquisition-led expansion requires paying substantial upfront control premiums and executing complex product integrations.
Both mechanisms operate within Salesforce today. For investors evaluating acquisitive software firms, isolating which model drives incremental growth is essential, as corporate leadership frequently cites distribution synergies to justify acquisition multiples that mirror platform network effects.
What activists actually change
Salesforce's confrontation with activist investors from 2022 to 2024 offers a clear case study in enterprise software governance.
The activist campaigns did not alter the company's core product strategy. The strategic roadmap pursued after 2023—expanding data platforms, deploying artificial intelligence agents, and acquiring adjacent software assets—aligned with long-term priorities management was already navigating.
What changed was operational execution and cost discipline. Workforce planning became structured, operating margin expansion targets were linked to explicit quarterly deadlines, and management initiated formal capital return programs through dividends and repurchases.
The broader takeaway, highlighted by Starboard Value's renewed stake in 2025, is that externally imposed discipline can remain temporary unless embedded into corporate governance. Cost control driven by activist oversight often persists only as long as active shareholder scrutiny remains present.
ARR is doing a lot of work, and it should be scrutinized
The most broadly applicable lesson from Salesforce's recent trajectory concerns financial metric interpretation.
Traditional seat-based subscription annual recurring revenue (ARR) serves as a reliable indicator of forward top-line performance because software licenses renew under predictable terms with quantifiable attrition rates. Consumption-based ARR introduces greater variability, as short-term usage can reflect exploratory pilot projects, seasonal volume spikes, or promotional credits. Annualizing quarterly consumption data can produce impressive top-line run rates before long-term commercial commitments are established.
This disclosure dynamic extends beyond Salesforce across the enterprise software sector. As vendors highlight artificial intelligence product adoption, non-GAAP metrics like AI ARR are increasingly reported ahead of standardized accounting disclosures, leaving public markets to calibrate how to weight these metrics against audited results.
Evaluating these claims requires comparing non-GAAP ARR disclosures directly against GAAP contracted backlog metrics, such as current remaining performance obligation (cRPO). When a company reports triple-digit growth in non-GAAP recurring revenue while contracted backlogs expand at modest mid-teens rates over consecutive quarters, the divergence indicates that initial customer usage has not yet converted into binding long-term contracts.
That fundamental metric comparison forms the core analytical framework for evaluating Salesforce's valuation outlook.
XI. Bull vs. Bear Case
The bull case, and the evidence under each claim
Scale in a category it still leads. Thirteen consecutive years at number one, roughly one-fifth of worldwide CRM applications spending, and more share than the next several competitors combined.[^5] That position was built over two decades and cannot be replicated with capital alone. The supporting evidence is the incumbency itself — the certified administrator labor market, the AppExchange ecosystem, and the fact that replacement projects at large enterprises are career-threatening.
Real AI monetization, growing faster than anything the company has launched. Agentforce ARR above $1.5 billion up 240%, the combined AI and data portfolio near $3.9 billion up over 210%, and agentic work units nearly doubling sequentially.[^1] Whatever the metric's limitations, customers are paying and usage is compounding. That is more than most enterprise vendors can demonstrate about their AI products.
Margin discipline that has held for three years. Non-GAAP operating margin above 34%, ten consecutive quarters of expansion through mid-2025, free cash flow of $14.4 billion, a dividend initiated and raised on schedule.[^4][^28][^27] This is the part of the story with the least ambiguity.
Acquisition criticism that has not converted into write-downs. MuleSoft and Tableau revenue has scaled into a $6.2 billion line, and Informatica was bought at roughly 27% below the price Salesforce refused a year earlier.[^4]20 The overpaying thesis is narrower today than it was in 2021.
The bear case, and the mechanism under each claim
The ARR-to-cRPO gap. This is the single most important unresolved question in the story. Contracted backlog growing 14% while the flagship AI product grows 240% is a divergence that has to resolve one way or the other.[^1]6 If Agentforce revenue were durable and contracted at scale, it would already be pushing cRPO higher.
Substitution at the workflow layer. Copilot embedded in Outlook and Teams does not need to beat Salesforce on features. It needs only to become the place where the work happens, leaving Salesforce as the system of record priced like one. Salesforce's counter — Slack as the agentic operating system — puts it in direct competition with a bundled incumbent.[^16]
Untested leverage. A $6 billion drawn term loan and net debt up roughly fourfold in a single year is modest against $14.4 billion of free cash flow, but it is a new posture for this balance sheet and has not been through a downturn.1121 The $50 billion repurchase authorization was expanded and deployed against a falling share price, which is defensible and also unfalsifiable as a signal until the next several quarters of cash flow statements are available.[^28][^4]
Structural deceleration. Growth has moved from above 25% to roughly 10–11%.[^4][^1] The fiscal 2030 target of $63 billion implies that management itself expects roughly low-double-digit growth to continue rather than accelerate.[^4] That is the honest framing: even the company's own long-range plan does not describe a reacceleration story. Anyone underwriting Agentforce as a growth inflection should reconcile that with the target management published.
Governance and succession. A co-CEO departure never explained, no disclosed succession plan, a founder with roughly 3% ownership and no voting protection, and the former Lead Independent Director now serving as President and CFO.[^21]25 None of these is a crisis. Together they describe a company where continuity depends on one person and the plan for his absence is not public.
Through the 7 Powers lens
Switching costs are the strongest power Salesforce holds, and the evidence is behavioral rather than disclosed — long contracts, deep customization, an entrenched administrator profession, and management's consistent commentary on low attrition.12 It is real. It is also the exact power that the Copilot mechanism is designed to route around rather than attack.
Scale economies are genuine in a specific form: one enterprise sales organization carrying an expanding product portfolio, and one R&D base amortized across a $41.5 billion revenue line.[^4] This is why acquisitions can work here that would not work elsewhere.
Network economies via AppExchange are frequently claimed and the weakest link in the chain. Salesforce has not published meaningful ecosystem usage or economic disclosure in years. Treat it as a legacy contributor to switching costs rather than an independent, currently-verifiable power.
Branding is real in the specific enterprise sense — the risk-reduction premium a buyer pays for the obvious choice. It shows up as pricing power at renewal, not as consumer affinity.
Cornered resource is the weakest claim of all, and it now runs backwards. The scarce resource in the AI era is frontier model capability, and Salesforce buys that rather than owning it.
Counter-positioning — the power that built the company, when on-premise vendors could not respond to subscription pricing without destroying their own economics — has fully reversed. Salesforce is now the incumbent whose per-seat model is the thing a counter-positioned entrant would attack.
Process power is arguably present in the acquire-and-attach machine, which the company has run more times, and more successfully, than almost any peer.
The composite picture is a company with strong, largely defensive powers, whose founding power has inverted, and whose newest bet depends on an input it does not control.
XII. Risk Radar
AI substitution risk. The primary strategic vulnerability stems from workflow disintermediation rather than a feature gap—a dynamic that drove the sharp equity selloff in June 2026. If enterprise users complete routine tasks within third-party productivity suites, the impact would surface first as slowing seat-count growth and softer renewal pricing in Sales Cloud and Service Cloud well before becoming visible in aggregate market share figures.
Execution risk on AI monetization. Transitioning to consumption-based pricing introduces greater operational uncertainty than predictable per-seat licensing. Management acknowledged during earnings commentary that enterprise clients are requesting varied payment models and that monetization strategies remain under refinement.12 In a consumption-driven model, forecasting errors tend to manifest as guidance volatility—the exact risk priced into sell-side analyst downgrades during 2026.6
Leverage and cost of capital. The Informatica transaction introduced debt financing to Salesforce's balance sheet for the first time at scale, refinanced in March 2026 into a $6 billion, five-year term loan.21 While current free cash flow easily covers these debt obligations, the financing structure establishes a precedent for future M&A. Credit-rating evaluations surrounding subsequent debt-financed acquisitions will serve as a key metric for monitoring capital discipline.
Data privacy and security. Salesforce manages customer records for a substantial portion of global enterprises. The deployment of autonomous AI agents expands operational exposure, as these software tools act directly upon sensitive corporate databases. A security breach or regulatory violation involving autonomous agents would directly impair institutional trust—the foundational asset supporting Salesforce's switching-cost advantage. Consequently, the transition to agentic workflows has heightened data governance risks across the platform.
Regulatory exposure. With Europe generating roughly 24% of total revenue, stringent data-residency requirements and emerging artificial intelligence governance frameworks represent an ongoing compliance burden.11 These regulatory mandates impose operational constraints on how autonomous agents process and transfer customer data across international borders.
Concentration in the Anthropic relationship. Headline earnings for the second quarter of fiscal 2027 were significantly elevated by an unrealized mark-to-market gain on a private AI investment, while the expanding Claudeforce initiative deepens both commercial and financial reliance on a single frontier model provider.2412 Because investment valuations fluctuate in both directions, any future downward mark would depress reported net income just as the gain expanded it.
XIII. Epilogue & What to Watch
Twenty-seven years after four founders began writing code in a San Francisco apartment, Salesforce is pursuing a structural reinvention that few category-defining software companies successfully navigate. The company executed its first pivot as an insurgent with minimal legacy revenue to protect. Today, it attempts a similar transition as an incumbent defending $41.5 billion in annual sales, operating in an equity market that has demonstrated a willingness to reprice its shares by 40% in either direction based on shifting strategic narratives.
Whether Salesforce can navigate this shift remains an open empirical question. Both the bullish and bearish theses rely on verifiable data points, while the decisive financial indicators have yet to materialize in full reporting disclosures.
Three core metrics will define the trajectory of this strategy and should be evaluated in order.
First, whether Agentforce and Data 360 ARR converts into current remaining performance obligation. Current remaining performance obligation represents the key metric for validating customer adoption. cRPO grew 14% year over year in the second quarter of fiscal 2027 and is guided to expand by approximately 14% for the full year.[^1] If AI annual recurring revenue reflects durable, contracted demand, cRPO growth must accelerate meaningfully above mid-teens rates over subsequent quarters. If cRPO growth remains flat, elevated ARR figures primarily describe exploratory pilot usage rather than committed enterprise backlogs.
Second, whether non-GAAP operating margin holds above 30% as AI infrastructure spending scales. Processing billions of agentic work units incurs variable compute expenses that test traditional software gross margins. In the second quarter of fiscal 2027, non-GAAP operating margin stood at 34.1%, slightly below the 34.3% recorded in the prior-year period.[^1][^28] Maintaining operating margins above 30% throughout an intensive AI infrastructure investment cycle would confirm that digital labor carries software-like economics. Margin compression, conversely, would indicate that Salesforce is supporting top-line expansion by absorbing higher infrastructure costs.
Third, the growth rate of the core subscription business. Sales Cloud and Service Cloud provide the primary revenue foundation, making their performance the clearest indicator of whether AI offerings generate net-new sales or merely offset seat-based subscription deceleration. If AI consumption revenue expands while core subscription growth moderates by a corresponding amount, the company is substituting predictable seat licenses with higher-cost usage models.
The near-term corporate calendar presents several explicit tests. Financial reports for the third and fourth quarters of fiscal 2027 will deliver subsequent cRPO disclosures to test customer contract conversion. The acquisition of Fin is scheduled to close in the fourth quarter of fiscal 2027, adding another software asset alongside Contentful as Salesforce continues absorbing Informatica.[^36] President and CFO Robin Washington's commitment to second-half organic revenue reacceleration creates a clear execution deadline.[^1] Meanwhile, Starboard Value's expanded equity position ensures that activist scrutiny remains active rather than historical.19
The analytical inquiry facing investors is not whether Salesforce maintains a mature enterprise franchise. The company possesses an established market footprint, a management team that has met financial guidance for three consecutive fiscal years, and a rapid initial product expansion in Agentforce.
The question is narrower: whether Salesforce is successfully transforming its business model for a third time—moving from on-premises software to cloud subscriptions, and now to autonomous digital labor—or whether it remains a mature incumbent promoting an AI narrative while daily workflow engagement shifts toward competing productivity platforms.
Current financial evidence does not confirm either outcome. It points to a single core relationship: the gap between reported non-GAAP annual recurring revenue and audited contracted backlog represents a critical metric in enterprise software, and its resolution over upcoming quarters will establish Salesforce's long-term growth trajectory.
References
-
Salesforce rockets 22% for second-best day ever, leading software rally — CNBC, 2026-08-27 ↩↩
-
Salesforce at 20: A timeline of the tech company's two decades in San Francisco — San Francisco Chronicle, 2019 ↩
-
Salesforce.com's IPO: Welcome to the Big League — CRM Buyer, 2004 ↩↩
-
Salesforce.com IPO Raises $110 Million — destinationCRM, 2004 ↩
-
Salesforce pays up for growth for Tableau, MuleSoft and others — CNBC, 2019-06-10 ↩↩↩↩
-
Salesforce's AI pivot hasn't gained enough traction to save its stock price, Morgan Stanley says — CNBC, 2026-07-21 ↩↩↩↩
-
What the $27.7B Salesforce, Slack deal means for the enterprise — CIO Dive, 2020-12-01 ↩
-
Salesforce To Buy Slack — A Case Study In Value Destruction? (Part 1) — Forbes, 2020-12-09 ↩
-
Salesforce.com (CRM) Q3 2021 Earnings Call Transcript — The Motley Fool, 2020-12-02 ↩
-
Salesforce CEO: We're going to rebuild all of our technology to become Slack-first — Yahoo Finance, 2021 ↩
-
Salesforce, Inc. Form 10-K, fiscal year ended 2026-01-31 — SEC EDGAR, filed 2026-03-02 ↩↩↩↩↩↩↩↩
-
Salesforce (CRM) Q2 2027 Earnings Call Transcript — The Motley Fool, 2026-08-26 ↩↩↩↩↩↩↩↩↩↩
-
Exxon trouncing Salesforce since software stock replaced oil giant in the Dow four years ago — CNBC, 2024-05-30 ↩
-
Activist investor Elliott Management takes stake in Salesforce — Euronews/Reuters, 2023-01-23 ↩
-
Salesforce is cutting 10% of its workforce, more than 7,000 employees — CNBC, 2023-01-04 ↩
-
Board changes could signal Salesforce's willingness to appease activist investors — TechCrunch, 2023-01-30 ↩
-
Salesforce and Elliott Issue Joint Statement — Salesforce Investor Relations, 2023-03-27 ↩↩
-
Salesforce (CRM) Q4 2023 Earnings Call Transcript — The Motley Fool, 2023-03-01 ↩
-
Activist Starboard buys more Salesforce stock after first demanding change in 2022 — Yahoo Finance, 2025 ↩↩
-
Salesforce acquires Informatica for $8 billion — TechCrunch, 2025-05-27 ↩↩
-
Salesforce, Inc. Form 8-K — Five-Year Credit Agreement dated March 11, 2026 — SEC EDGAR ↩↩↩
-
Morgan Stanley downgrades Salesforce to Equal Weight, cuts price target on July 21, 2026 — Martech Notes, 2026-07-21 ↩↩
-
Gartner Predicts Over 40% of Agentic AI Projects Will Be Canceled by End of 2027 — Gartner, 2025-06-25 ↩
-
Salesforce Q2 FY 2027: Can Agentforce Drive Revenue Reacceleration? — Futurum Group, 2026 ↩↩↩
-
Salesforce, Inc. Form DEF 14A (2026 Proxy Statement) — SEC EDGAR, filed 2026-04-16 ↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube