NVIDIA: The GPU Company That Became the AI Factory
I. The Chips Sold Out—and the Guarantee Behind Them
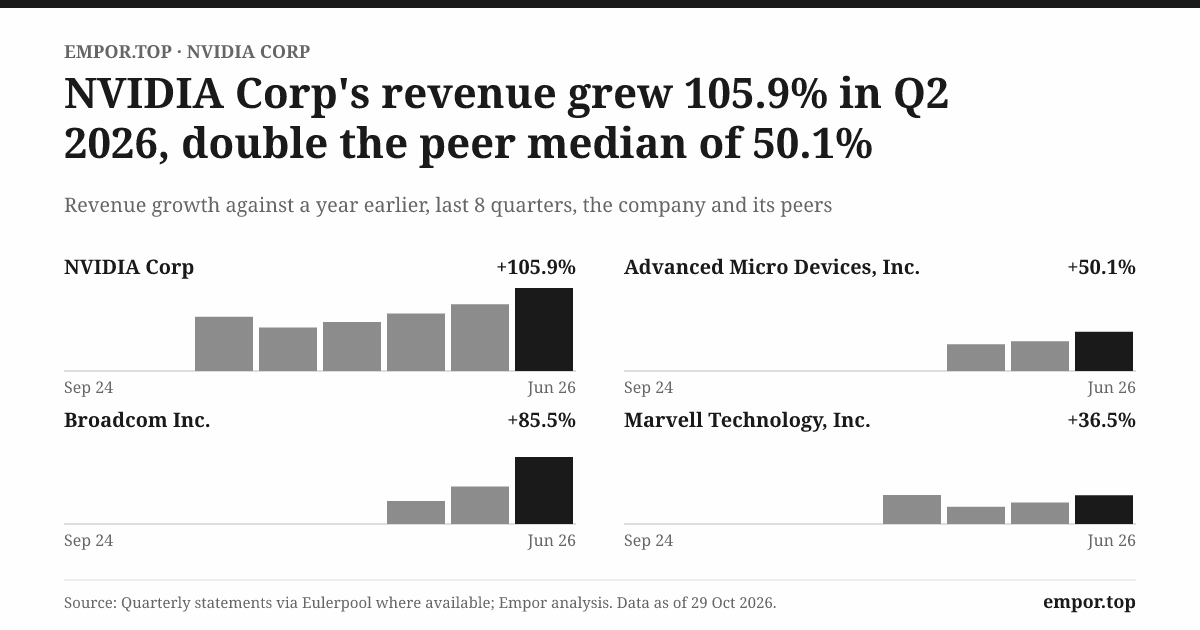
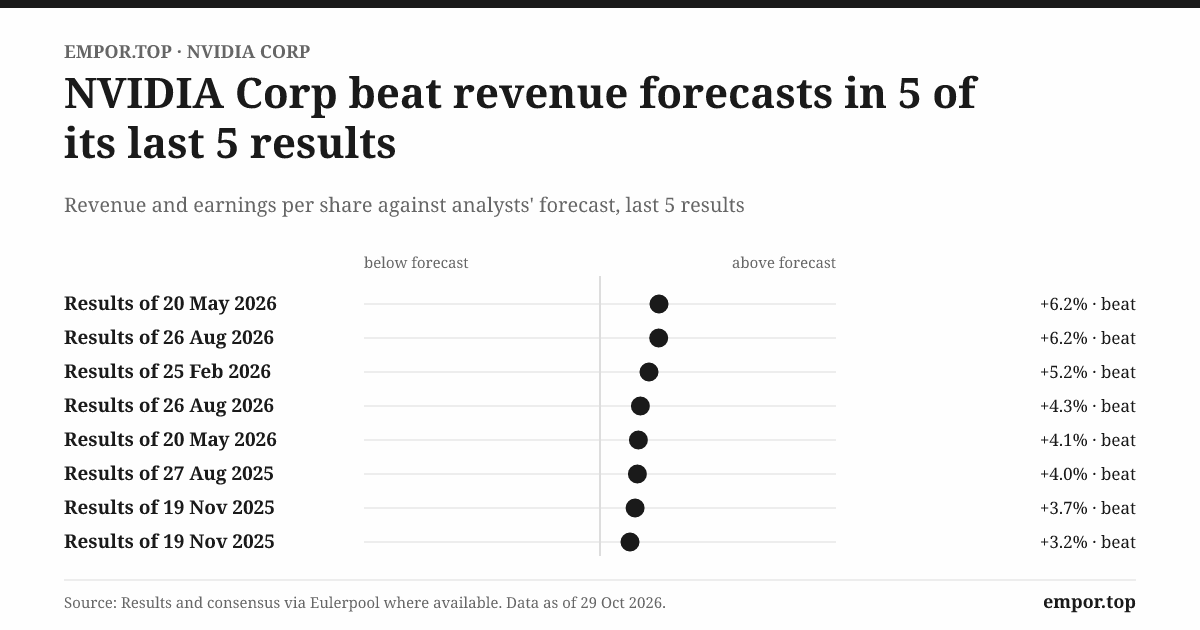
On August 26, 2026, Colette Kress, NVIDIA's chief financial officer, opened the second-quarter call the way most NVIDIA calls had opened for three years: with a record. Revenue for the quarter ended July 26 was $96.2 billion, more than double the same quarter a year earlier, and growth had accelerated for the fourth quarter in a row.12
Of that, $89.0 billion came from one segment, Data Center, which meant that roughly 92 cents of every dollar NVIDIA booked came from selling the machinery of artificial intelligence to the companies building it.1 A business that most people still associate with video-game graphics cards now books in a single quarter almost twenty times what it booked in the whole of fiscal 2016.3
The more revealing number had arrived nine days earlier, and it was not revenue at all. On August 17, NVIDIA said it would guarantee up to $105 billion of obligations tied to a giant data center campus in Pike County, Ohio, being developed by SoftBank's SB Energy and leased for 20 years to OpenAI.4 NVIDIA would also invest $1.5 billion in SB Energy and serve as the site's exclusive chip supplier.4
The guarantee did not cover the whole project, and it did not hand anyone a check. It covered defined portions of lease and power payments, plus a commitment to protect the site's minimum value, so that if OpenAI defaulted, NVIDIA would cover the gap between that guaranteed floor and whatever the owner could recover by re-leasing or selling the campus.4 Exposure is set to phase in as facilities come online, starting in NVIDIA's fiscal 2029.1
Put those two events side by side and the scale mismatch jumps out. A chip company that sells on purchase orders, usually recognizing revenue when a box is delivered, had agreed to stand behind the real estate, the electricity and the lease structure of one of its largest customers.5 On the call, Kress anticipated the obvious objection before an analyst could voice it. "We know some will call this circular financing," Kress said. "We see it differently."2 The argument was that frontier AI labs have exploding demand but lack "the decades-long infrastructure contracts and investment-grade financing capacity" to secure capacity on their own, and that NVIDIA's compute is "fungible and durable" enough to be redeployed if a customer stumbles.2 That is management's case. Whether it holds is the question running through this story.
Because the guarantee forces a set of harder questions about everything that came before it. Did CUDA, the software layer NVIDIA has nurtured for twenty years, make the company difficult to replace, or merely difficult to leave for now? Can a handful of enormous buyers keep spending at this pace, when NVIDIA itself says two direct customers made up more than a third of last fiscal year's revenue?5
Does supporting customers' financing accelerate real demand, or quietly shift risk from the buyer's balance sheet onto the seller's? And can Jensen Huang, who has run the company since the day it was founded, turn a historic lead into durable economics rather than a spectacular cycle?
The clock matters here. The latest reported quarter is the second quarter of fiscal 2027. Management guided the third quarter to $108 billion of revenue, plus or minus 2%, and assumed no China data center compute revenue at all, citing "ongoing geopolitical uncertainty."2 It also did something it had never done before: guided a full year ahead, projecting roughly 70% revenue growth in fiscal 2028 and calling that a supply-constrained figure.2 The next test arrives on November 17, when NVIDIA reports its third quarter.2
To understand why a graphics-chip company is now underwriting power contracts in Ohio, it helps to go back to a moment when NVIDIA could not underwrite its own payroll. Three decades ago, this company was a small team of engineers with about a month of cash, a broken chip and one customer deciding whether to let it live.
 Subscribe on LinkedIn
II. The Bet That Nearly Ended at Sega
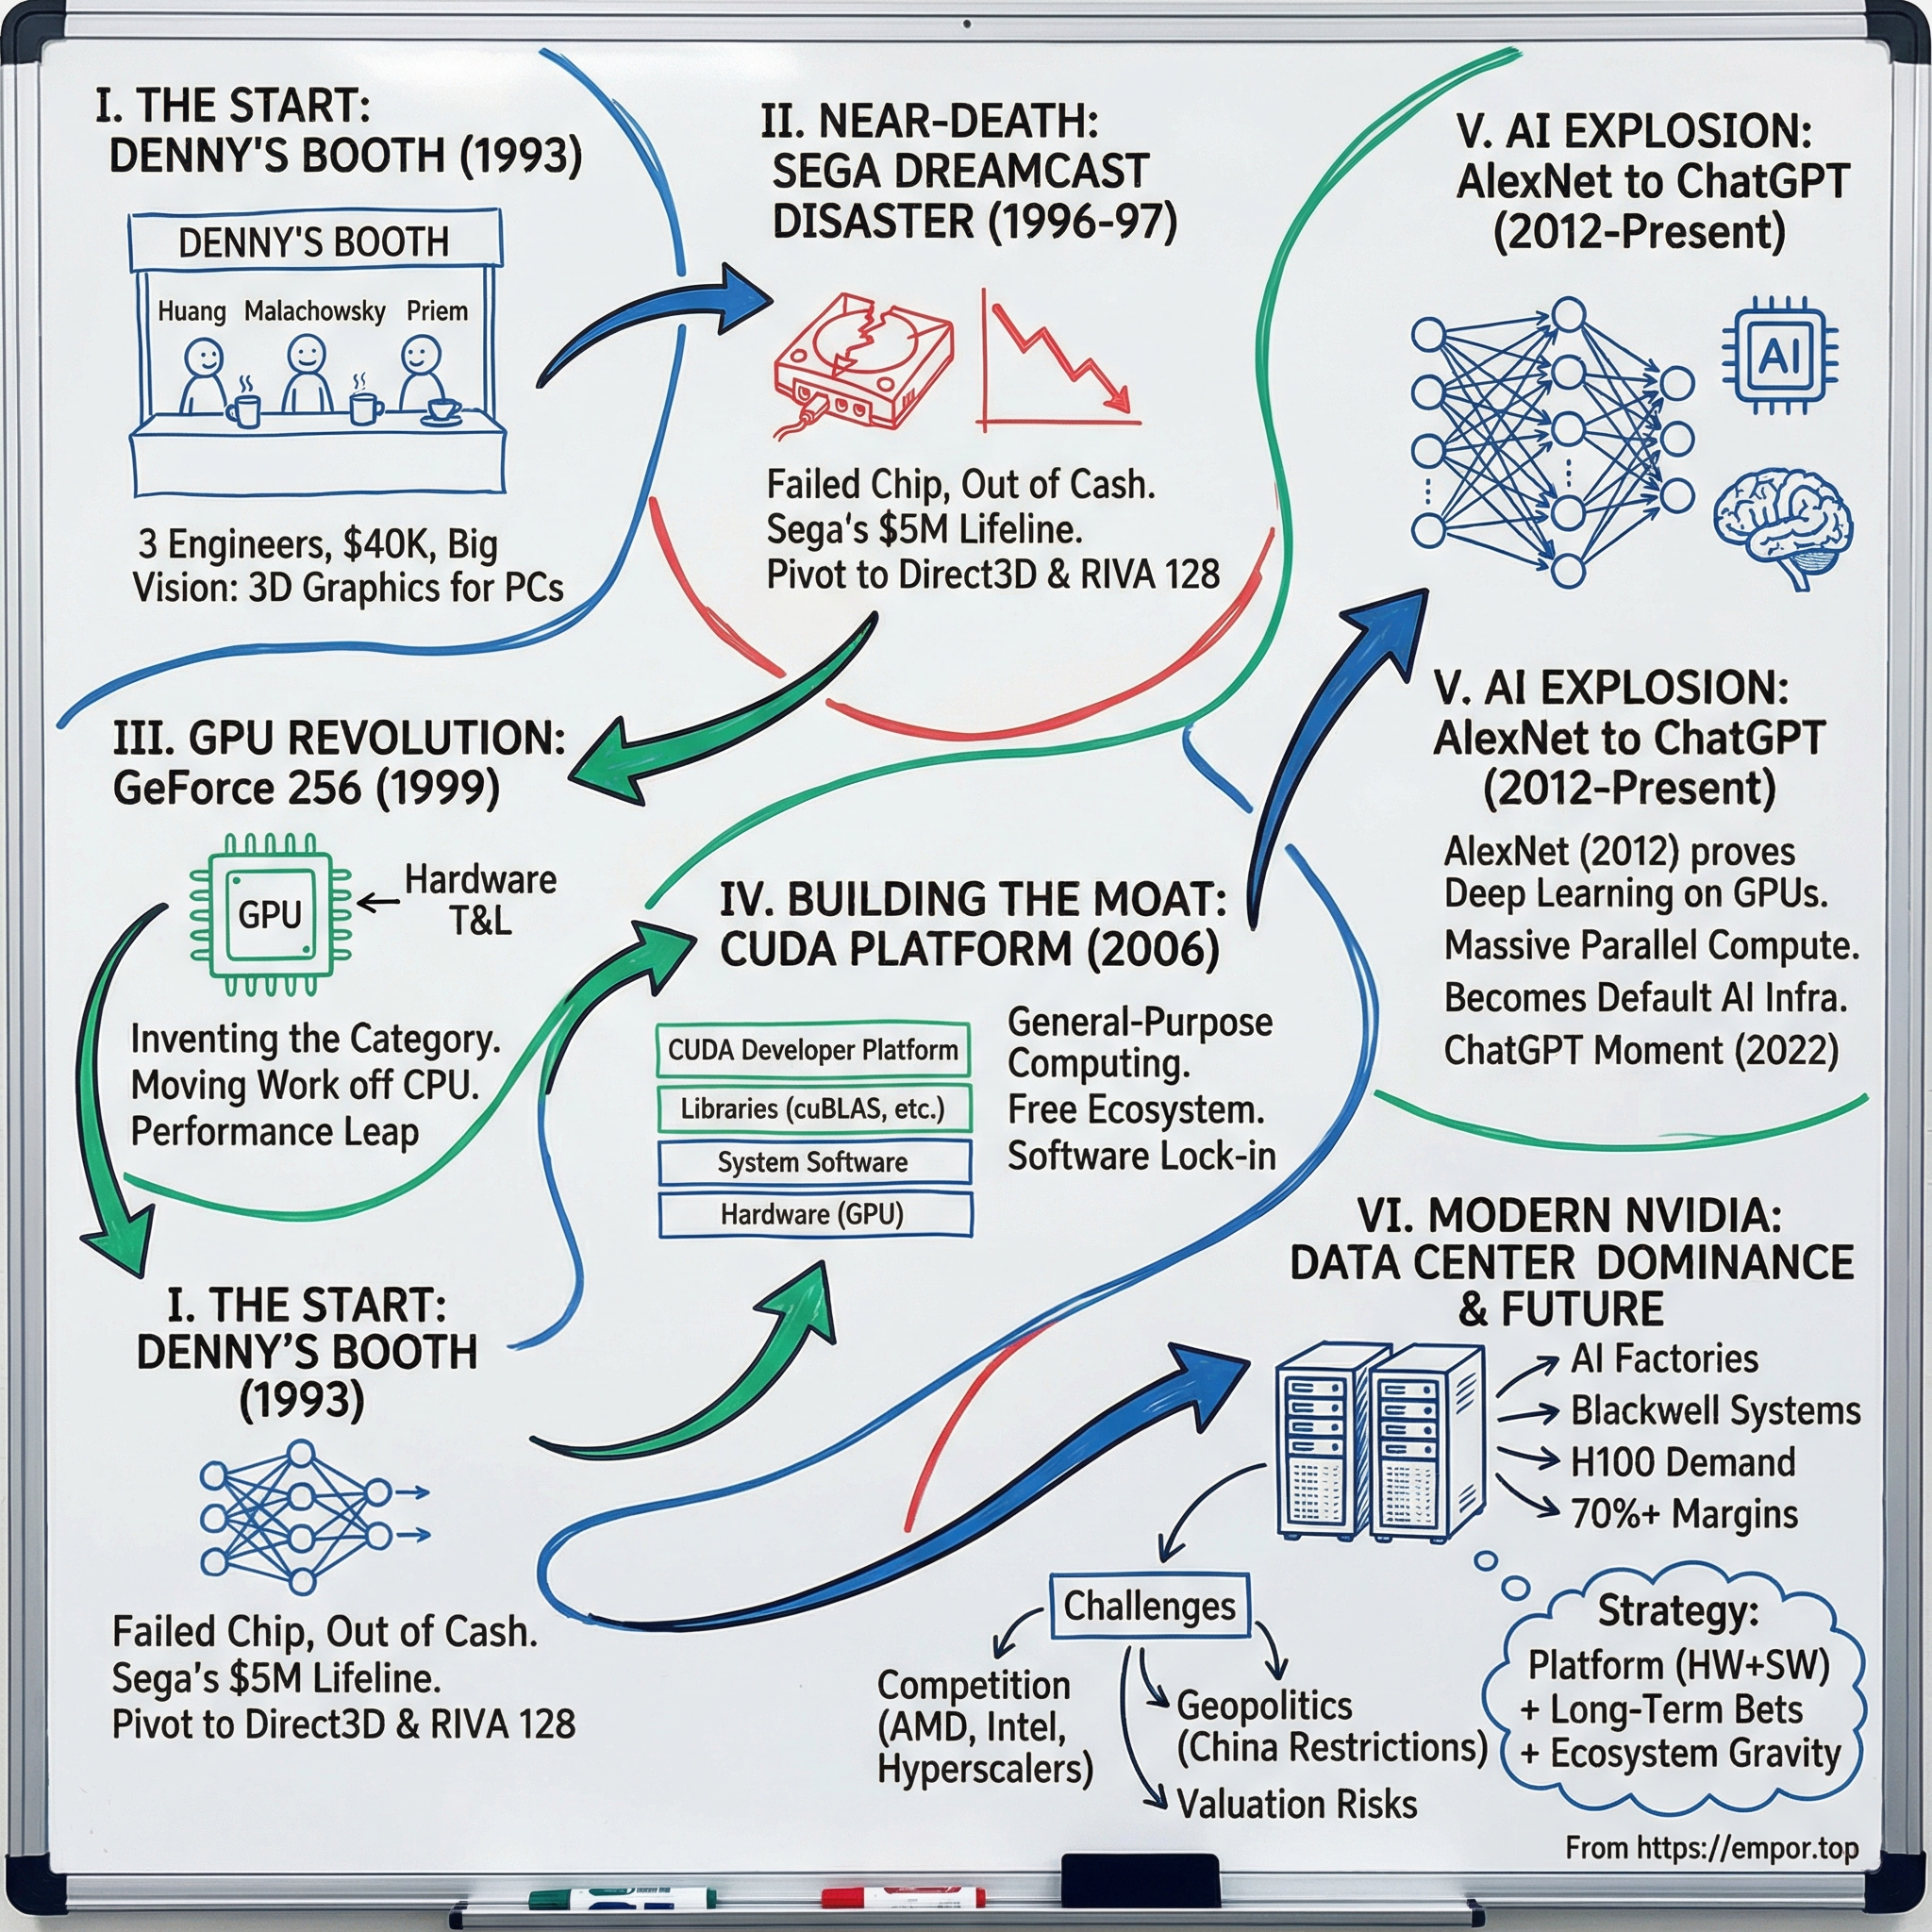
The founding scene is small enough to fit in a diner booth, which is exactly where it happened. In 1993, three engineers, Jensen Huang, Chris Malachowsky and Curtis Priem, met at a Denny's in San Jose to talk about building a chip that could render realistic 3D graphics on a personal computer.6 Huang liked the place for practical reasons: "It had all the coffee you could drink and no one could chase you out."6 The setting had a private resonance too.
Huang's family had immigrated to the United States from Taiwan, and the future CEO's first job, at fifteen, had been at a Denny's in Portland, washing dishes, busing tables and waiting on customers.6 Huang went on to earn an electrical engineering degree from Oregon State and a master's from Stanford, and to work at LSI Logic and AMD before co-founding NVIDIA in April 1993.78 The company's founding vision was modest by today's standards: bring 3D graphics to gaming and multimedia.7
The first product did not go well. NVIDIA's debut chip, the NV1, shipped in 1995 and rendered curved surfaces rather than the triangles that would become the industry's standard building block.9 It was sold at retail as the Diamond Edge 3D, and it failed.10 Yet NVIDIA had landed a prize anyway: Sega, then one of the giants of the console world, enlisted the startup to develop graphics technology for its next-generation machine.1011
Then the ground moved. In 1995, Microsoft released DirectX alongside Windows 95, and the rest of the PC industry lined up behind it.10 Huang later described the realization bluntly: NVIDIA had picked "the wrong architecture completely."10 The CEO faced a choice with no good option. Finishing the Sega contract meant spending roughly two years building on a technical approach the market had already rejected. Walking away meant running out of money.10
What Huang did next is the first great character moment in the NVIDIA story. Huang went to Sega's chief, Shoichiro Irimajiri, admitted the technology was wrong, and asked Sega to release NVIDIA from the contract while still paying in full.10 By Huang's own account, Sega got "absolutely nothing out of it."10 Irimajiri took a couple of days, then agreed, and Sega put about $5 million into NVIDIA, structured as an equity investment rather than a contract payment.911
Huang has said it was effectively all the money NVIDIA had, and that it bought the company roughly six more months.910 The company had perhaps 30 days of cash before that money arrived, and the period brought failed chips and layoffs that Huang has since described as among the most painful stretches of building NVIDIA.912 Asked in 2026 whether, knowing what lay ahead, Huang would start the company again, the answer was no.12
The reset was ruthless. NVIDIA abandoned its proprietary approach and built a chip for the standard the industry had chosen. The RIVA 128 shipped in 1997 and sold a million units in its first four months.9 Two years later NVIDIA went public.912 In July 2026, Huang flew to Tokyo, stood in the old Sega arcade in Akihabara next to Irimajiri, and said that "if not for what Sega did for Nvidia, Nvidia would not be here today."911
It is tempting to turn this into an origin myth in which every later bet was destined to pay off. The record does not support that reading. What the Sega episode established was narrower and more useful: NVIDIA's founders were willing to admit a strategic error quickly, cut deeply, and rebuild around where the market was actually going rather than where they wished it would go.
That instinct saved the company. It did not prove that the original strategy was sound, since it plainly was not, and it did not guarantee that later platform bets would be commercially successful. Several took a decade or more to pay. Survival bought NVIDIA the right to make its next decision. The next decision was about what a graphics chip could become.
III. The GPU Became a General-Purpose Computer
In 1999, NVIDIA launched the GeForce 256 and gave it a name that was part engineering and part marketing: the graphics processing unit, or GPU.7 The company has described that moment ever since as the invention of the GPU, and it set the stage for everything that followed.7
The real significance was less the chip's specifications than the category it named. A GPU was not an accessory that painted pixels; it was a processor in its own right, sitting alongside the CPU, designed to do enormous amounts of simple arithmetic at once.
That design choice deserves a plain-English explanation, because the entire modern company rests on it. A CPU is like a small team of brilliant generalists: it runs a sequence of instructions very quickly, juggling a few dozen threads. A GPU is more like a stadium full of people each doing one simple sum at the same moment.
NVIDIA's own programming guide puts it in engineering terms: CPUs are built to run a serial sequence of operations fast, while GPUs run thousands of threads in parallel, giving up single-thread speed for far greater total throughput, and they spend more of their transistors on calculation and fewer on caching and control.13 Shading millions of pixels in a video game is exactly that kind of problem. So, it turned out, are physics simulations, financial models and, eventually, neural networks.
The GeForce era also gave NVIDIA something it had lacked in the Sega years: credibility with the biggest customers in computing. Microsoft chose GeForce technology to power its first Xbox console, a striking turnaround for a company that had nearly died building the wrong console chip a few years earlier.10 The lesson NVIDIA seems to have drawn was that standards win, and that the way to escape commodity status inside a standard is to keep adding capability on top of it.
The problem was that in the early 2000s, getting a GPU to do anything other than graphics was an ordeal. A researcher who wanted to simulate protein folding had to disguise the math as a graphics problem and push it through graphics programming interfaces. In 2006, NVIDIA removed that disguise.
It introduced CUDA, short for Compute Unified Device Architecture, which let developers write computational workloads in familiar high-level languages like C and C++ and use the GPU's throughput without going through graphics APIs.137 NVIDIA describes it as opening parallel processing to science and research.7
CUDA was a strange bet for a company whose customers were gamers. Every GPU NVIDIA shipped carried the extra capability, which cost silicon, engineering time and money, for a market that barely existed. What CUDA created, slowly, was an installed base: libraries, tools, university courses and lines of code written by people who learned parallel computing on NVIDIA hardware. That accumulation is what investors now call a moat. In 2006, it looked more like a hobby.
Then came the proof point. In 2012, three researchers at the University of Toronto, Alex Krizhevsky, Ilya Sutskever and Geoffrey Hinton, entered a deep convolutional neural network in the ImageNet competition, a contest to classify more than a million images into a thousand categories. Their network, later known as AlexNet, achieved a top-five error rate of 15.3%, against 26.2% for the second-best entry.14 That is not an incremental improvement.
It is the kind of gap that ends arguments. And the hardware was ordinary: the network trained over five to six days on two NVIDIA GTX 580 gaming cards with 3 gigabytes of memory each.14 The paper even noted that the memory limit of a single GTX 580 constrained how large the network could be.14 NVIDIA's own timeline now says it "powered the AlexNet neural network breakthrough, sparking the era of modern AI."7
Here the story needs a careful separation, because technical milestones and commercial proof are different things. AlexNet showed that GPUs could do something remarkable. It did not show that NVIDIA would earn money from it. In fiscal 2016, four years after AlexNet and a decade after CUDA, NVIDIA's total revenue was about $5 billion and its net income about $614 million.35
The company was still, overwhelmingly, a graphics business. The return on CUDA did not arrive with the launch announcement, or with the research breakthrough. It arrived when hyperscale data centers started buying accelerators by the rack, more than a decade after the bet was made.
That gap is the right lens for the moat question. CUDA's installed base is meaningful evidence of switching costs: code written for CUDA, and engineers trained on it, make NVIDIA the easiest platform to buy. But switching costs are not a prison. Large customers with enough money and motivation can rewrite software, adopt alternative frameworks, or design their own chips for workloads they control.
Even NVIDIA's own programming guide notes that libraries and domain-specific languages such as Triton can provide GPU acceleration without writing CUDA code directly, which is convenient for developers and also a hint at how a software layer can, over time, abstract the hardware beneath it.13 Whether CUDA keeps NVIDIA the default, or becomes an expensive dependency customers work to reduce, is a question for later in this story. First, NVIDIA had to survive a lesson about what happens when demand is not what it appears.
IV. When the GPU Boom Became a Bust
On January 28, 2019, a Monday, NVIDIA did something companies hate to do: it cut its revenue forecast for a quarter that had already ended. The fourth-quarter outlook of $2.7 billion was slashed to $2.2 billion, a reduction of almost a fifth.15 Huang's statement did not dress it up. "Q4 was an extraordinary, unusually turbulent, and disappointing quarter," Huang said.15
The explanation was a lesson in how an apparently strong product position can turn into abrupt financial volatility. During 2017 and 2018, cryptocurrency miners had been buying gaming GPUs, because the same parallel arithmetic that rendered games could also crunch the calculations that mined digital coins. That demand looked like gaming demand on the way through the sales channel. Retailers and card makers stocked up.
Then crypto prices collapsed, the miners vanished, and the channel was left holding a pile of mid-range cards that real gamers did not need to buy at full price. NVIDIA's release cited excess mid-range channel inventory left over from the crypto boom, weaker demand in China, and customers who seemed to be waiting for lower prices on its new high-end Turing cards.15 Even the data center business slipped: several deals NVIDIA expected to close in the final month of the quarter did not, as customers turned cautious.15
When the final numbers arrived, fourth-quarter revenue was $2.21 billion, down 24% from a year earlier and down 31% from the previous quarter.16 Gross margin fell more than seven percentage points year over year, and inventory on NVIDIA's own balance sheet roughly doubled.16
Huang summarized the cause in a phrase that would become shorthand for the episode: "post-crypto excess channel inventory and recent deteriorating end-market conditions."16 The legal tail has been long. A securities class action over how NVIDIA described crypto-driven demand in that period was certified in March 2026 and remanded for further proceedings; NVIDIA has accrued no liability, saying a loss is not probable and cannot be estimated.1
The second reminder came three years later. In the second quarter of fiscal 2023, NVIDIA had told investors to expect about $8.1 billion of revenue. It delivered $6.7 billion.17 Gaming revenue fell 33% from a year earlier, as a sudden slowdown in consumer demand met, once again, a channel stuffed with inventory.17
NVIDIA implemented programs with channel partners to adjust pricing and to reposition high-end desktop GPUs ahead of its next architecture launch, which is a polite way of saying it helped partners clear old stock at lower prices.17 The same presentation noted that Data Center revenue grew 61% that quarter, and that revenue from hyperscale customers nearly doubled.17 The engine that would power the next era was already running while the old one sputtered.
What should an investor take from these two episodes? They are real counterexamples to the story of smooth, inevitable growth, but they are not verdicts on today's data-center business. Both tested what was then a graphics-dominated company, selling through distributors and retailers to consumers. The revenue base today is overwhelmingly Data Center, sold to a small group of very large buyers.
The mechanism is what matters, and the mechanism generalizes uncomfortably well: when a buyer orders ahead of its own end demand, the seller's revenue can look like structural growth right up until the moment the buyer stops ordering. In 2018 the buyers were crypto miners and retailers. In 2026 they are clouds and AI labs placing orders ahead of capacity that has not yet been built or filled.
What would make this cycle different? There are real candidates. End users are more diverse than a single speculative use case; inference, the work of running trained models for paying customers, produces repeat demand rather than one-time purchases; and the largest buyers have balance sheets far stronger than any 2018 card retailer.
Management also says NVIDIA compute is "fully utilized across every cloud we serve."2 What would make it the same is simpler: a larger and richer set of buyers, still placing orders ahead of proven returns. The answer depends on who those buyers are and how they got there.
V. CUDA Met Its First Large-Scale Customer
After AlexNet, the researchers who had stitched together gaming cards in university labs went to work for the companies with the deepest pockets in the world. Google, Microsoft, Amazon, Meta and, later, OpenAI and a crowd of AI labs needed to train neural networks far larger than anything that fit on two GTX 580s.
NVIDIA's job was to turn a research win into a product those buyers could deploy by the thousand. That meant data-center GPUs, then entire servers, then networking to tie servers together, then software to manage it all. A decade later, the result is a company that looks almost nothing like the one that cut its forecast in January 2019.
The scale is easiest to grasp through comparison. In fiscal 2026, which ended in January, Data Center revenue was $193.7 billion, about 90% of NVIDIA's total.5 Gaming, the business that built the company, brought in $16.0 billion. Professional Visualization brought in $3.2 billion, and Automotive $2.3 billion.5 Gaming is still a large business by any normal standard.
Inside NVIDIA it has become a rounding error on the main event. Total revenue that year reached $215.9 billion, up 65%, after growth of 114% the year before.5 Ten years earlier, total revenue had been about $5 billion.3 This is not a stable ten-year compounding pattern; it is a step change in scale and mix, layered on a historically cyclical base.
The business model underneath is more traditional than the numbers suggest. NVIDIA sells GPUs, systems, networking and related products, and it generally recognizes revenue when control transfers to the customer, usually on delivery.5 Most sales are made on purchase orders, and customers can cancel, change or delay those orders with little notice or penalty.5
NVIDIA does not disclose a recurring-revenue share or a standard contract term. The clearest window into contracted future revenue is small: at July 26, 2026, only $3.2 billion of remaining performance obligations came from contracts longer than one year.1 Set that against a company booking almost $100 billion per quarter, and the conclusion is plain. The backlog that matters is mostly intent, not contract.
Management prefers to describe that intent through its customers' spending plans. On the August call, Kress said the cloud industry's backlog had passed $2 trillion, and that capital spending by the five largest hyperscalers was expected to reach nearly $800 billion in 2026 and $1.3 trillion in 2027.2 Kress also cited global venture funding in AI of more than $400 billion in the first half of 2026, roughly 70% of which, by management's estimate, is spent on compute.2
These are the rivers NVIDIA drinks from, and they explain why management is confident. They also show the dependency in reverse. Hyperscaler capital budgets are set by boards that can cut them, and venture funding is the most cyclical money in finance. A company whose demand is a function of other people's capital spending has a demand curve that bends when the cost of that capital rises or when investors lose patience with returns.
NVIDIA's own reinvestment is modest beside those figures, which is part of the attraction of its model. Capital expenditures were $6.1 billion in fiscal 2026, under 3% of revenue, up from $3.4 billion, and the company said they would rise again in fiscal 2027.5
The heavy assets in this boom, the buildings, the power plants and the grid connections, sit on customers' balance sheets. That is why NVIDIA's returns on capital look so extraordinary, and why the August decision to stand behind some of those assets was such a departure.
Then there is the question of who is buying. In fiscal 2026, two direct customers accounted for 22% and 14% of revenue, together more than a third of the company. A year earlier the top three had each been around 11% or 12%.5 In the first half of fiscal 2027, three direct customers represented 16%, 15% and 13%, together 44%.1
NVIDIA does not name them. It also says certain indirect customers, those buying through cloud providers and system makers, individually account for 10% or more, and that one unnamed AI research and deployment company contributed a meaningful amount through cloud purchases.5
That distinction between direct buyers and end demand is where the analysis gets interesting. A cloud company that buys NVIDIA systems is not, in most cases, the final user of the compute. It rents that compute to others: AI labs, startups, enterprises, governments. Their willingness to pay for AI services is what ultimately funds the cloud's orders.
On the latest call, management divided the Data Center business into two halves: hyperscalers, at $49 billion of quarterly revenue, and a group it calls ACIE, covering neoclouds, industrial and enterprise buyers, at $40 billion, which grew 138% year over year.2 Huang argued that the ACIE half is "invisible to everybody" and growing about 100% a year, because those customers "don't buy custom chips" and need a full factory platform built for them.2
That framing is partly persuasive and partly untestable from outside. It is persuasive because neoclouds, sovereign projects and enterprises are genuinely different buyers from Google or Amazon, and their growth does diversify NVIDIA's revenue in one sense. It is untestable because many neoclouds rent their capacity to the same handful of AI labs that the hyperscalers also serve, so a diversified list of direct buyers can still sit on top of a concentrated set of ultimate users.
Kress said that AI labs for which NVIDIA expects to "leverage our balance sheet" will contribute roughly a quarter of the business next year.2 NVIDIA does not disclose end-user concentration, which means investors cannot fully see how much of the record shipments depend on a few labs' fundraising.
The conclusion is clear on one side and open on the other. AI is now the economic center of NVIDIA, not an option attached to gaming, and current demand is real enough to produce record shipments every quarter. But the company that once depended on retail gamers now depends on the capital budgets of a small club of buyers and their customers. To serve that club at scale, NVIDIA needed more than faster chips. It needed to own the wires between them.
VI. Mellanox: The Deal That Made the System Bigger Than the Chip
On March 11, 2019, six weeks after the guidance cut that embarrassed it in front of Wall Street, NVIDIA announced the largest acquisition in its history. It agreed to buy Mellanox Technologies, an Israeli company founded and run by Eyal Waldman, for a transaction value of about $7 billion.18
The timing looked odd. A company that had just admitted its gaming channel was clogged was spending a large share of its balance sheet on a networking business most gamers had never heard of. The deal closed on April 27, 2020, as the pandemic emptied offices and filled data centers.18
The logic was a bet on how AI computing would be built. Training a large neural network is not a job for one GPU, or even for one server. It is a job for thousands of GPUs working as if they were one enormous machine, constantly swapping partial results. The analogy is a kitchen. A faster chef helps, but if a thousand chefs are cooking one banquet and passing ingredients through a single narrow doorway, the doorway sets the pace.
Mellanox made the doorways: high-speed InfiniBand and Ethernet interconnects that let accelerators talk to each other with very little delay. Huang framed the deal in exactly those terms at closing: "The expanding use of AI and data science is reshaping computing and data center architectures."18 Waldman called it "a powerful, complementary combination of cultures, technology and ambitions."18
Six years later, the product logic is visible in NVIDIA's revenue. Networking had another record quarter in the second quarter of fiscal 2027, growing 18% sequentially, and Kress said Spectrum-X Ethernet had grown 2.6 times year over year.2 More important, networking changed what NVIDIA sells.
Management now describes its revenue opportunity per gigawatt of data-center capacity rising from about $18 billion in the Hopper generation, to $25 billion with Blackwell, to $40 billion with Vera Rubin, a figure that spans CPU, GPU, NVLink, InfiniBand or Ethernet networking and newly added Groq inference accelerators.2 Whatever one makes of those per-gigawatt estimates, which are management's own, they describe a company that has moved from selling components to selling coordinated infrastructure, and Mellanox is a large part of why.
Was it a bargain? The tempting answer is yes, given how central networking has become. The honest answer is that the public record cannot settle it. NVIDIA does not disclose acquisition-level returns for Mellanox, and calling $7 billion cheap would require a like-for-like valuation comparison with similar deals at the time, not hindsight about an AI boom nobody priced in 2019.
What can be said is that the acquisition was strategically adjacent to the system NVIDIA sells today, and that the combination has a clear product logic that shows up in revenue.
The deal NVIDIA did not complete is just as instructive, and it was far bolder. NVIDIA agreed to buy Arm, the British designer of the CPU architecture inside almost every smartphone, from SoftBank for about $40 billion.19 If Mellanox gave NVIDIA the wires, Arm would have given it the blueprint for the general-purpose processor sitting next to every GPU. Regulators on several continents balked. On December 2, 2021, the U.S. Federal Trade Commission voted to sue to block the deal, alleging harm in three markets where NVIDIA competed using Arm-based products: driver-assistance processors for cars, networking chips called DPU SmartNICs for data-center servers, and Arm-based CPUs for cloud providers.19 The FTC also argued NVIDIA could gain access to competitively sensitive information from Arm licensees, some of them NVIDIA rivals.19 In February 2022 NVIDIA abandoned the deal, and the FTC called it the first abandonment of a litigated vertical merger in many years.19
The Arm episode shows regulatory limits on how far NVIDIA can buy its way into adjacent bottlenecks. It was not a $40 billion capital loss, since the deal never closed, and NVIDIA went on to design its own Arm-based CPUs anyway. The company says its Grace CPU, introduced in 2021, had passed $5 billion of revenue over a trailing twelve months, and management expects CPU revenue to more than double in fiscal 2028.2 Sometimes the blocked acquisition becomes the in-house product.
Capital deployment today is on an entirely different scale. NVIDIA bought back $40.4 billion of its own shares in fiscal 2026 and approved another $80 billion authorization in May 2026, leaving $99.3 billion available at the end of July.15 In the second quarter alone it returned a record $26 billion to shareholders.2
At the same time, Kress disclosed that NVIDIA had invested "nearly $50 billion in the frontier AI labs," describing it as a small fraction of expected free cash flow.2 An analyst on the call added up the commitments and guarantees described in NVIDIA's CFO commentary and arrived at roughly $500 billion over several years, a figure management did not dispute directly, instead emphasizing that supply commitments are "essential" to building the products it needs.2
That is the new capital-allocation question. Mellanox was a single, bounded purchase of a technology NVIDIA needed. Today's strategic investments, customer guarantees and supply commitments deepen NVIDIA's exposure to the customer spending cycle. Whether that is the natural next move of a platform company or a concentration of risk depends heavily on the judgment of one man.
VII. Jensen Huang's Long Bet—and the Scorecard It Has to Pass
Thirty-three years after the Denny's booth, Jensen Huang is still in charge, having served as president, chief executive and a board member since NVIDIA's founding, a three-decade founder tenure that is rare among companies of NVIDIA's size.8 Huang is 63, and the CEO's public persona—the keynotes that run for hours, the habit of treating each product generation as a historic event—has become part of the company's brand.8
Behind the showmanship sits a remarkably consistent strategy. Over three decades, NVIDIA has kept doing four things: making the GPU more programmable, investing in software that makes the hardware easier to use, building bigger systems around the chip, and pushing toward data-center scale.
That consistency is real, and it has been rewarded. But consistency of vision is not the same as reliability of forecasts, and an investor deciding how much weight to put on Huang's next explanation should look at how Huang has behaved when things went wrong.
The 2019 warning is the cleanest test. When the crypto overhang hit, NVIDIA updated guidance before its scheduled earnings date and called the quarter "disappointing."15 That is a reasonable standard for candor. It was also an admission that management had misjudged the channel badly enough to miss its own forecast by about a fifth within weeks.15
The second test came from Washington. In fiscal 2026, NVIDIA took a $4.5 billion charge related to its H20 chip, a product designed specifically to comply with U.S. export controls on China, after the government changed the licensing requirements and demand for the product diminished.5 The H20 was itself a response to earlier rules; the earlier H800 had been designed to comply with controls issued in 2022.20
Each redesign was a rational answer to a policy change, and each one showed how quickly a government decision can strand inventory built for a specific market. Today, management assumes no China data center compute revenue in its outlook at all, and less than 1% of second-quarter Data Center revenue came from licensed Hopper sales to China-based customers.2 That is a prudent assumption, and also a recognition that one of the world's largest markets for AI chips is, for now, outside NVIDIA's forecast.
The third test is the newest: forecasting a full year in advance. On the August call, Morgan Stanley's Joe Moore asked why NVIDIA, which had never guided a year out, was suddenly doing so. Huang's answer was that "our supply allows us to confidently deliver 70%," and that customers, shareholders and suppliers should all see "the same view" because "everybody's putting a lot of resources at play."2
That is either a sign of unusual visibility or an unusually public commitment, and probably both. If it is met, the credibility gain will be large. If it is missed, the miss will be measured against a number Huang chose to publish.
Governance and incentives offer a mixed but mostly reassuring picture. As of March 2026, Huang beneficially owned 3.58% of NVIDIA, a stake that ties the CEO's personal wealth tightly to long-term shareholder outcomes.8
Huang's reported compensation for fiscal 2026 was $36.3 million, down from $49.9 million the year before even as profit rose, and 96% of the CEO's target pay was tied to performance.8 Those totals include the grant-date value of stock awards, not cash actually received. Kress, CFO through the entire AI build-out, remains in the role.8 Nine of ten directors are independent.8
Shareholders approved executive pay at the June 2026 annual meeting, but not unanimously: 1.07 billion votes were cast against, with 79 million abstentions.21 Opposition to some directors was higher, including 2.23 billion votes against long-serving director Stephen Neal.21
Those are not rebellions, but they are signals that a meaningful bloc of institutional holders has reservations about board tenure and refreshment at a company whose market value now runs into the trillions. The proxy discloses no related-person transactions requiring approval in fiscal 2026, beyond noting that Huang's adult son and daughter work at NVIDIA, neither as executives nor reporting directly to Huang.8
Huang's tone on capital deployment matters too, because it has become more expansive. Asked how NVIDIA balances investing in AI labs that are also designing rival chips, Huang called those investments a "once-in-a-generation opportunity" and said "the only regret that I have is that I didn't invest more and sooner."2
That is the language of conviction. It is also the language a skeptical shareholder would want a board to test, since equity stakes in customers both lift reported earnings when the ecosystem rises and tie NVIDIA's returns more tightly to the same few companies.
The verdict on Huang is that credibility is strong but testable, and the test has changed. In 2019 the question was whether NVIDIA's leadership understood its own sales channel. Today the question is whether the customers NVIDIA is financing can use their capacity profitably enough to keep ordering. On the call, Huang said compute is "very profitable today" and offered a second-hand data point about large data centers: "I heard the other day that return on investment capital is now less than a year."2
Those are claims about other companies' economics, offered without data. The next explanation Huang owes investors must include not only bookings and supply, but evidence about utilization and customer returns. Some of that evidence is already visible, though not in a keynote. It is on NVIDIA's balance sheet.
VIII. A Platform Company With a Supplier's Balance Sheet
Here is a puzzle worth sitting with. In fiscal 2026, NVIDIA reported net income of $120.1 billion. Its operating cash flow was $102.7 billion.5 Both numbers are enormous. But they are not the same number, and the gap of roughly $17 billion is more than three times NVIDIA's entire revenue in fiscal 2016.3 Where did the money go?
The first clue is ordinary working capital. When a company sells on credit, profit appears when the sale is booked but cash arrives only when the customer pays. When it builds inventory ahead of a product launch, cash goes out before any sale exists. In fiscal 2026, rising receivables absorbed about $15.4 billion of cash and inventory another $11.3 billion.5
The second clue runs the other way. NVIDIA's profit included an $8.9 billion non-cash gain on equity securities, the paper appreciation of stakes it holds in other companies.5 That gain lifted reported earnings without putting a dollar into the bank account. Partly offsetting both were non-cash charges like $6.4 billion of stock compensation.5
Over three years, the pattern is consistent. Net income rose from $29.8 billion in fiscal 2024 to $120.1 billion in fiscal 2026, while operating cash flow rose from $28.1 billion to $102.7 billion.5 Cash conversion is strong in absolute terms, which is the most important fact.
But it is slipping at the margin, and the first half of fiscal 2027 made the gap much wider. NVIDIA earned $118.0 billion of net income in those six months and generated $74.4 billion of operating cash flow.1 About $23.7 billion of the profit came from gains on equity securities, while receivables, inventory and prepaid assets absorbed cash.1
Those investment gains deserve their own sentence, because they change what NVIDIA's earnings mean. In fiscal 2026, other income totaled about $11.1 billion against pretax income of about $150 billion. In the first half of fiscal 2027 it was $24.1 billion against $141.4 billion of pretax income, so roughly one dollar in six of pretax profit came from outside operations, mostly from the marked-up value of stakes in other companies.51
At July 26, NVIDIA held $42.8 billion of marketable equity securities.1 Many of those holdings are in the same AI ecosystem that buys NVIDIA's chips. When that ecosystem is rising, the gains flatter earnings. When it falls, the same marks will reverse.
The second puzzle is receivables. Net receivables rose from $38.5 billion at the end of fiscal 2026 to $63.1 billion by July 26, 2026, an increase of almost two-thirds in six months.1 Five direct customers accounted for 22%, 14%, 13%, 11% and 10% of that balance, which means roughly 70% of everything owed to NVIDIA is owed by five companies.1 Days sales outstanding, a measure of how long NVIDIA waits to be paid, reached 60.2
The explanation is a deliberate change in terms. NVIDIA's standard practice is payment shortly after delivery. But it now permits terms of 90 days up to a year for investment-grade customers on large data-center builds shipped over multiple quarters.12 In plain language, NVIDIA is extending credit to its biggest buyers, and the receivables line is the measure of that credit. The customers in question are investment-grade, which matters.
But NVIDIA does not disclose receivables aging, overdue history, or the identities of the customers behind those balances. Its allowance for doubtful accounts in fiscal 2026 stayed at $4 million, with no additions or deductions, a figure that is essentially zero against tens of billions of receivables.5 That reflects a history of being paid. It cannot reflect a stress that has not yet happened.
Two smaller items complete the accounting picture. At July 26, NVIDIA carried $5.0 billion of unrecognized tax benefits, including $503 million of interest and penalties, and the IRS was examining its fiscal 2023 and 2024 returns.1 That is a judgment area worth watching but small against the company's cash. And the auditor's opinions on NVIDIA's fiscal 2026 statements and internal controls were unqualified, with no material weakness reported.5 The numbers are clean. The question is what they will look like when the cycle turns.
Inventory tells the other half of the working-capital story. It rose to $32 billion as NVIDIA prepared for the Vera Rubin launch.2 Behind that sits a much larger commitment. NVIDIA's supply commitments reached $279 billion by July 26, up from $119 billion a quarter earlier, reflecting the capacity it has reserved at foundries, memory makers and other suppliers to meet its forecast.1
Kress described those commitments as "essential" and front-loaded in the first three years.2 They are also, in effect, the mirror image of customer orders. NVIDIA has locked in more of its supply than its customers have locked in their demand.
None of this describes a weak balance sheet. At July 26, NVIDIA held $56.6 billion of cash, cash equivalents and marketable debt securities, invested in U.S. government and agency paper.1 Borrowings rose to $33.4 billion from $8.5 billion at fiscal year-end, reflecting new note issuance, and a $25 billion commercial-paper program had nothing outstanding.1
In June 2026, S&P Global Ratings upgraded NVIDIA to AA from AA-, citing AI-driven growth, strong margins, low capital intensity and free cash flow.22 That is about as strong as independent credit judgments get for a technology company. But S&P also named the risks, and they are the same ones this story keeps circling: reliance on a single foundry partner, the possibility of an AI-demand slowdown, and customers' growing dependence on capital markets to fund their purchases.22
The so-what is that NVIDIA is a platform company with a supplier's balance sheet. Its profits are extraordinary, its cash generation is very large, and its credit is top-tier. But as it grows, more of its balance sheet is made of promises from customers: money they owe, capacity they have reserved, and stakes whose value depends on their success. And in August, NVIDIA added a much larger kind of promise.
IX. The AI Factory Starts to Need a Landlord
Picture the site. Pike County is a rural stretch of southern Ohio, and the campus NVIDIA calls PORTS-Pike includes federal land.42 SB Energy, owned by SoftBank, is developing a data-center campus there with total planned capacity of up to 8 gigawatts, a power draw comparable to several large power stations running flat out.4 OpenAI will lease it for 20 years.
NVIDIA will be the exclusive chip supplier.4 The first 800 megawatts are expected online in 2028, and Huang said the initial 4.25 gigawatts of capacity alone could add up to $200 billion to NVIDIA's revenue.4 The project involves the Departments of Commerce and Energy, and is expected to require about 35,000 construction jobs through 2032.4
What NVIDIA agreed to do is precise, and the precision matters. It guarantees defined portions of OpenAI's lease and power obligations, along with a commitment to protect the site's minimum value. The cap is $105 billion for the initial 4.25 gigawatts.41 NVIDIA's exposure is designed to increase as facilities enter service and decline as OpenAI makes its payments, with the first exposure expected from fiscal 2029.1
If OpenAI defaulted, NVIDIA would pay the difference between the guaranteed minimum and what the owner could recover by re-leasing or selling the site.4 It is not a current cash payment. It is not a guarantee of every project cost. And the financing is not finalized: equity is meant to come first, possibly including proceeds from an SB Energy IPO and direct SoftBank investment, with project-finance loans and possibly bonds to follow.4
Before Ohio, NVIDIA's land, power and shell guarantees for AI-cloud partners had a maximum gross exposure of $3.5 billion.1 The Ohio arrangement multiplied that ceiling about thirty-fold in a single announcement, taking total maximum gross guarantee exposure to about $108.5 billion.1
The commercial rationale is real, and Huang described it vividly on the August call. "You can no longer procure technology per se and stand up this infrastructure," Huang said. Customers must secure land, power and shell, "which oftentimes is a couple, two, three years out."2 Huang compared it to NVIDIA's earlier decision to work directly with memory suppliers, which once looked odd for a chip company.2
The bottleneck has moved from silicon to electricity and real estate, and NVIDIA is following it. Kress added the essential economic point from management's side: the lease commitment secures a long-lived site, while the NVIDIA compute inside "can be upgraded repeatedly," potentially supporting multiple upgrade cycles over 20 years.2 OpenAI's existing and planned commitments, Kress said, represent approximately 12 gigawatts of NVIDIA compute.2
The scale of that single relationship is the part that deserves an investor's attention. NVIDIA has projected up to $600 billion of revenue from OpenAI by 2030, from 16 gigawatts of computing power that includes a 3.75-gigawatt expansion of the Ohio site.4 Against fiscal 2026 revenue of about $216 billion, that is a customer relationship sized like a second company.5
It also explains the guarantee. When one customer could be worth that much, removing the obstacle between that customer and its next data center looks less like charity and more like sales. The same arithmetic, read the other way, shows how much of NVIDIA's forecast now rests on one privately held lab's ability to keep raising money and keep filling capacity.
The Ohio deal is one of several new structures. For neoclouds, NVIDIA has introduced a revenue-sharing model in which it provides a take-or-pay commitment on a portion of a facility's capacity, a minimum revenue guarantee that gives lenders confidence, in exchange for a share of revenue above that floor. "We're not making loans," Kress said; "we get paid twice."2
For another frontier AI lab, NVIDIA will provide what it called "selective credit enhancement" for nearly 2 gigawatts of compute.2 And it has partnered with six large infrastructure investors, Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR, on financing platforms intended to raise more than $500 billion of third-party capital.2
Now lay out the risk chain, because each link is plausible on its own. A build could be delayed by power interconnection, permitting or construction. AI monetization could disappoint, leaving OpenAI with more capacity than paying demand. OpenAI could fail to raise the capital its plans require, since its growth, as Kress herself put it, is outrunning what its balance sheet and credit profile can support.2
Or the site could prove hard to re-lease at the guaranteed value if the market for gigawatt-scale AI campuses softened. Any of those could turn a demand-enabling agreement into a contingent liability that NVIDIA has to fund. Management's defense is that its compute is "fungible and durable and can be redeployed to support other customers."2 That argument is strongest for the chips and weakest for the building: a GPU can be moved to another cloud; a power contract in rural Ohio cannot.
Ohio also sits beside the other exposures this story has already met. Receivables concentrated in five customers, $279 billion of supply commitments, and tens of billions of equity stakes in AI companies are separate line items with separate accounting.1 But they rest on the same foundation: continued, funded demand for AI compute. In a good year they reinforce each other. In a bad year they would correlate.
The proof points are straightforward to name and will take years to observe: sites reaching service on schedule, OpenAI's lease payments, utilization of the capacity, the actual guarantee exposure NVIDIA reports each quarter, and the customer's ability to fund operations.
Until then, the guarantee is best understood as conditional and bounded, but large enough that customer credit and project execution have become part of NVIDIA's investment case. Which raises the largest question of all: is the lead that makes customers want NVIDIA in that building durable enough to justify the risk?
X. Why This Company Wins—and Why It Might Not
Picture the buyer: the head of infrastructure at a large cloud company or an AI lab, about to commit several billion dollars to the next cluster. On one side of the table sits NVIDIA, offering an integrated stack: GPUs, its own CPUs, NVLink to tie chips together inside a rack, InfiniBand or Ethernet to tie racks together, and twenty years of CUDA software that the buyer's engineers already know. On the other side sit the alternatives.
AMD sells merchant GPUs that compete directly. The buyer's own company, or a cloud partner, may have designed a custom accelerator for the workloads it controls. And then there is the quietest alternative of all: buying fewer chips, because the models got more efficient. Every purchase decision NVIDIA wins or loses happens in a room like that one. The question is why that buyer keeps choosing NVIDIA, and what would make them stop.
Start with the market evidence, carefully. When the European Commission reviewed NVIDIA's acquisition of the AI-workload software company Run:ai, it examined the market for discrete data-center GPUs and found that NVIDIA held an estimated 70% to 80% share by volume in the first half of 2024, while noting uncertainty in those volume estimates.23
That is an enormous installed lead. It is also a lead in a specific market definition, discrete data-center GPUs, which excludes custom chips that hyperscalers design for themselves. NVIDIA's dominance of GPUs is well established. Its share of total AI compute spending, including in-house silicon, is not something the Commission measured or NVIDIA discloses.
The cleanest way to test the moat is to walk through the forces acting on the business and the sources of power NVIDIA can claim, one at a time, and to put the counterevidence right next to each claim.
Why the buyer keeps saying yes
Begin with switching costs, the strongest affirmative argument. CUDA's installed base, its libraries, tools and the habits of the engineers who use them, reduces the friction of choosing NVIDIA and raises the cost of leaving. Management's version is that NVIDIA is "the only platform that runs every frontier model," closed or open, and that "nearly all open models run on NVIDIA."2 The disconfirming evidence is in the same call.
An analyst noted that OpenAI and Anthropic, two of the labs NVIDIA has invested in, are both designing their own custom chips, and that OpenAI had just made public claims about one of them.2 Huang's response was that custom accelerators are "inference-specific chips for one cloud or one service," while NVIDIA is a platform that runs anywhere.2
Both things can be true. The very largest customers are the ones with the scale and motive to reduce their dependence, and they are also NVIDIA's biggest buyers. Switching costs are real, but they bind smaller customers more tightly than the giants.
Next comes what Hamilton Helmer calls scale economies, and here NVIDIA's position is formidable. The company spent $18.5 billion on research and development in fiscal 2026 and employed about 42,000 people, roughly 31,000 of them in R&D.5 Few competitors can fund a new architecture every year across GPUs, CPUs, networking and software at once, and NVIDIA's scale lets it move from Blackwell to Vera Rubin while rivals are still matching the previous generation.
Management claims Vera Rubin delivers 35 times lower token cost than its predecessor.2 That is a management benchmark, not an independent one, but the cadence itself is the point. R&D is growing more slowly than revenue, which signals operating leverage rather than underinvestment, though it also means the absolute spending gap with rivals is widening.
Then there is what Helmer calls counter-positioning and process power, best seen in systems integration. The Mellanox acquisition and NVLink let NVIDIA sell what it calls a full AI factory, so the unit of competition has shifted from a chip to a rack and from a rack to a data center. Huang said rack-scale systems required NVIDIA to "reinvent the entire supply chain, reinvent systems, reinvent the technology."2
A rival that sells excellent chips must also persuade customers to assemble the rest of the system, which many non-hyperscale buyers, the neoclouds, sovereigns and enterprises NVIDIA calls ACIE, would rather not do. That is a genuine advantage in exactly the segment NVIDIA says is growing fastest.
Network effects are weaker than they look. Developers who learn CUDA make NVIDIA more valuable to the next developer, but this is closer to an ecosystem habit than a true network effect, since a model trained on NVIDIA can often be served on other hardware.
Brand, in Helmer's sense, matters mostly as trust: buyers believe NVIDIA systems will work at scale. Cornered resource is the power NVIDIA conspicuously lacks. It owns no fabs, and its most important supplier, TSMC, also makes chips for its competitors. S&P named reliance on that foundry partner as a key risk.22
Why the buyer might stop
Now turn the analysis around and look at the forces pushing back. Buyer power is the most important. Customer concentration is high, and five customers hold about 70% of receivables.51 Those are not price-takers.
They are among the most sophisticated purchasers of technology on earth, and every one of them has an internal chip effort or a partnership to build one. The bargaining power is currently masked by scarcity, because when supply is constrained the seller sets terms. But extended payment terms of up to a year are already a concession of sorts, and if supply catches up with demand, buyer power will reassert itself through price.
Supplier power is the second force. Memory makers have shown it this year. On the August call, Kress said memory pricing conditions were "extreme," had exceeded NVIDIA's own expectations and were heading higher, and reset the gross margin outlook: about 74% in the third quarter, a bottom of 71% to 72% in the fourth, then 72% to 73% in fiscal 2028 as price increases take effect.2
That is still an extraordinary margin for a hardware company. It is also a three-to-four-point decline from the second quarter's 75%, driven by a supplier NVIDIA cannot replace, and management's projected recovery is a forecast, not an outcome.2 Foundry and advanced-packaging capacity, concentrated at TSMC, is the other supplier constraint. Management expects supply to remain a bottleneck at least through the end of fiscal 2028.2
Substitutes form the third force, and the most subtle substitute is efficiency. In January 2025, the Chinese lab 深度求索 DeepSeek showed it could match leading models while using far fewer chips, and NVIDIA's shares fell 17% in a day.20 One DeepSeek paper showed it trained on about 2,000 NVIDIA H800s.20 NVIDIA's response was that DeepSeek's progress proved more chips would be needed, because "inference requires significant numbers of Nvidia GPUs and high-performance networking."20
By the latest reported quarter, the record mostly supports NVIDIA's reading: Data Center revenue has kept accelerating. But DeepSeek's lesson was never that demand would vanish. It was that the compute required for a given result can fall abruptly, which means price per unit of intelligence can fall too. If customers can get good-enough results with fewer or cheaper chips, order growth can slow even while AI usage grows.
Regulation is a force that Porter's framework tends to underweight, and for NVIDIA it is concrete. Export rules have already cost the company a $4.5 billion charge and removed China data center compute from its outlook.52 Antitrust is the other edge: regulators blocked the Arm deal and the European Commission examined NVIDIA's market position closely in the Run:ai review.1923
A company with a share above 70% of a market that governments consider strategic should expect scrutiny of its bundling, its pricing and its investments in customers. None of that has yet changed NVIDIA's economics. It does narrow the room for the kind of vertical expansion that built the company.
Rivalry and new entrants complete the picture. AMD is the closest merchant GPU competitor, and Google, Amazon and others design chips for workloads they control. It is important not to equate any one rival's product launch with commercial share; a benchmark claim is not a purchase order. But it is equally important not to equate NVIDIA's current share with permanence.
AWS, for example, announced in August that it would deploy an additional 2 million NVIDIA GPUs through the second quarter of fiscal 2029, even as it continues building its own chips.2 Customers are multi-sourcing at the same time as they are buying more NVIDIA than ever. That is the signature of a supplier that is preferred but not exclusive.
The strongest disconfirming evidence in NVIDIA's own record is cyclical, not competitive. Past downturns showed that inventory, channel behavior and price pressure can overwhelm momentum quickly.1517
Those episodes involved a different business and different customers. But the mechanism, buyers ordering ahead of their own demand, is the same mechanism that would hurt NVIDIA now, and the current buyers are ordering ahead of capacity that has not yet been built, financed or filled.
Weighing it all, the history narrows the moat claim rather than rejecting it. NVIDIA's advantage in ecosystem scale, systems integration and software familiarity is credible today and supported by market-share evidence, product cadence and customer behavior. The evidence does not show that customers are locked in, that the largest buyers lack alternatives, or that current gross margins will persist. The moat is strongest for mid-sized buyers who want a complete factory and weakest for the handful of giants who generate most of the revenue.
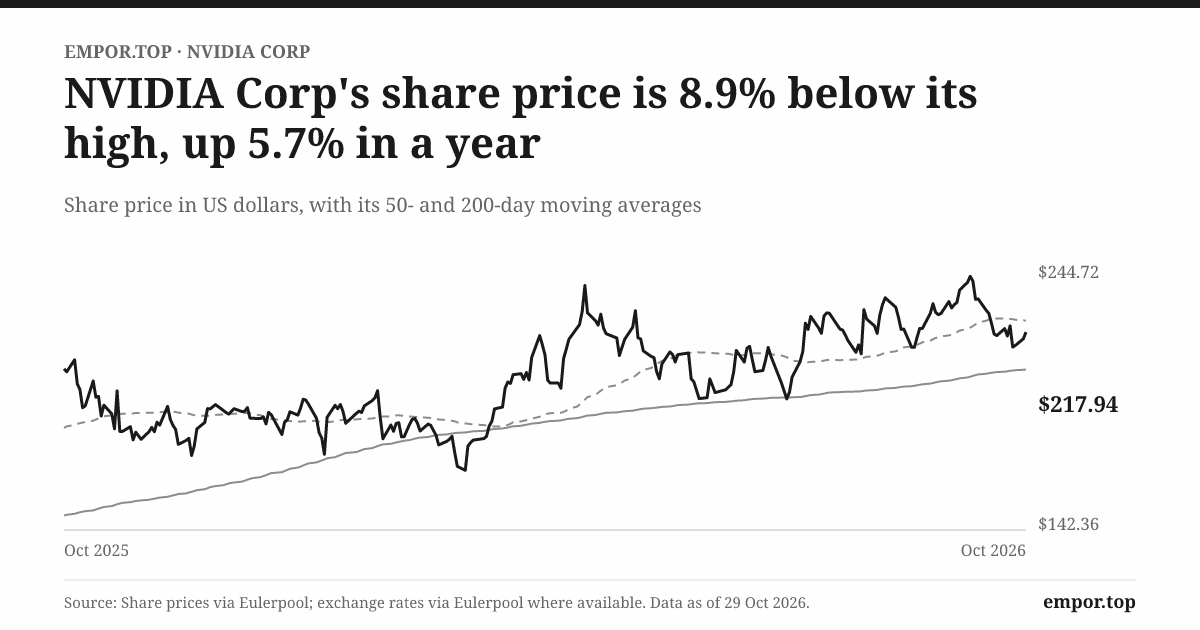
The market, for its part, is pricing a durable version of the claim. In July 2026, NVIDIA's market value stood at about $4.7 trillion.11 Against fiscal 2026 net income of $120.1 billion, a figure itself lifted by investment gains, that is a valuation of roughly 40 times trailing profit.5 A multiple like that does not assume a cycle. It assumes that today's earnings are a floor for years of further growth, which is exactly what management's 70% outlook for fiscal 2028 describes.
Three measures will test that assumption better than any keynote. The first is customer concentration by end user, not just by direct buyer; the latest reading has three direct customers at 44% of revenue, and the direction has been rising.1
The second is receivables collection and aging; receivables stood at $63.1 billion with days sales outstanding of 60, both rising, and NVIDIA does not yet disclose aging.12 The third is Data Center gross margin through the Vera Rubin transition; the company reported 75% in the second quarter and guided to a decline before a projected recovery.2
That leaves the investor split in sharp relief. NVIDIA may remain the preferred platform for as long as returns on AI infrastructure stay high, in which case its scale, cadence and systems advantage should keep compounding.
If customer economics disappoint, or alternatives become good enough for the biggest buyers, order growth and pricing could reset much faster than the installed-base story suggests, because purchase orders can be cancelled and guarantees cannot. The path that brought NVIDIA here offers a few lessons about which of those futures is more likely.
XI. Playbook: Business & Investing Lessons
Lay four moments on a single timeline: the Sega rescue,910 CUDA's launch,13 the Mellanox deal,18 and the Ohio guarantee.4 Each step made sense at the time. Together, they describe a company that grew by removing whichever bottleneck stood between its chips and its customers, and that keeps finding the next bottleneck further from silicon.
The first lesson is that a platform bet is earned one developer and one workload at a time. CUDA's payoff took more than a decade, from its launch to the research breakthrough and the later data-center market.13143 The gap between launch and payoff is the part most retellings skip.
The value lay in the installed base that made NVIDIA the default when the market arrived. Founders who expect a platform to pay back in one product cycle are not building a platform. Investors should treat a technical first as a down payment, not a return: CUDA is the proof that a platform compounds, and also the proof of how long the compounding can take.
The second lesson is that survival is a strategy only until the next decision. Huang survived Sega by admitting the architecture was wrong and rebuilding around the industry standard.10 NVIDIA survived 2019 by naming the inventory problem and waiting out the channel.15
Neither response would solve the risks NVIDIA faces now, which are about customers' financing rather than its own product mistakes. The quality that saved NVIDIA, a willingness to change course fast, is only valuable if it is applied before the problem shows up in the numbers. A company that reinvented itself under pressure has to prove it can also say no under prosperity.
The third lesson is to own the bottleneck customers cannot route around, and to know which bottlenecks you do not own. Mellanox helped turn NVIDIA from a chip vendor into a systems vendor, and networking now grows faster than almost anything else in the company.218
But the bottlenecks NVIDIA does not own have just reminded it of their power: the company says memory prices are compressing its margins and foundry capacity caps its growth.2 For NVIDIA, the line is this: the company that owns the rack still rents the factory.
The fourth lesson is the newest: growth can make a supplier responsible for more than supply. The Ohio guarantee may unlock gigawatts of deployment that would otherwise stall for lack of credit.
It also makes OpenAI's lease payments and SB Energy's construction timetable part of NVIDIA's story, alongside $279 billion of supply commitments and receivables concentrated in five buyers.1 Vendor-financing booms tend to begin with a good reason. A guarantee is a sale made in advance, and it is only as good as the customer who has to keep paying for it.
The discipline test for the next phase is not whether NVIDIA can ship faster. It already ships at scale. It is whether the customers can earn enough on what they buy to keep buying.
XII. Epilogue
Tonight, NVIDIA stands at the top of the most consequential buildout in modern computing. Vera Rubin began production shipments in August, and management expects it to account for about a fifth of Data Center revenue in the current quarter and to be the fastest product ramp in the company's history.2
NVIDIA is making multi-quarter deliveries to customers on extended payment terms. The Ohio campus is still a construction plan with unfinished financing.4 And on November 17, NVIDIA will report its third quarter against guidance of $108 billion.2
The forward story will be decided by a sequence of moments, each with an outcome that would mean something specific. The first is the November report itself. Meeting or beating guidance would extend the run of records, but the more informative lines will be in the details: whether Data Center growth broadens beyond the largest buyers, whether customer concentration rises again, and whether NVIDIA says anything more concrete about the end users behind its neocloud and hyperscale sales. A broader customer base would strengthen the case that this cycle is different from 2019. A narrower one would sharpen the dependence on a few labs' capital raising.
The second moment is whether the margin trough management forecast arrives and is followed by a recovery.2
If those increases stick and margins recover on schedule, it will be strong evidence of pricing power, because NVIDIA will have passed a supplier's cost shock through to its own customers. If margins keep sliding, it will suggest that buyer power, memory costs or competition are taking a share of the profit pool.
The third is collections. The extended terms granted this year mature over the next several quarters. Receivables that turn into cash on schedule would settle much of the concern about the gap between profit and cash. Receivables that keep climbing faster than revenue, or any disclosure of aging that shows balances stretching, would be the clearest early warning NVIDIA could give.
The fourth is Ohio. Over the next two years, investors will watch the campus's financing close, construction proceed, and the first capacity come online in 2028.4 Then comes the part that cannot be observed yet: OpenAI's lease payments, the utilization of the capacity, and the actual guarantee exposure NVIDIA reports as each facility enters service.
A smoothly running campus would make the guarantee look like an efficient way to sell systems. A delayed or underused one would make it look like credit risk in a chip company's clothing.
Behind all four sits the year-ahead growth forecast.2 Hitting it would vindicate Huang's decision to publish it; missing it would test his credibility.
The near-term demand case is strong. The central questions, about customer returns, end-user concentration and guarantee performance, remain open because they take longer to observe than a quarter. Which brings the story back to where it began, with the Ohio announcement and a question that has followed every gold rush. Is NVIDIA still selling the picks and shovels, or is it becoming part of the machinery that funds the mine?
XIII. Outro
Go back to the Denny's booth in San Jose, the one with the plaque that now says it launched a trillion-dollar company.6 The story that followed ran from a failed first chip to a GPU that found a second life beyond gaming.
The distance from that booth to the Ohio campus is the whole story: from rendering images to building the infrastructure on which artificial intelligence runs, and now to standing behind the bills for the buildings that house it.
NVIDIA spent thirty years proving that its chips could do almost anything. The next few years will test something no chip can prove on its own. The company that taught GPUs to think now has to prove its customers can afford to keep them thinking.
References
-
NVIDIA Form 10-Q for Q2 FY2027 — SEC, 2026-08-27 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
NVIDIA Q2 FY2027 Earnings Call Transcript — FactSet, 2026-08-26 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Nvidia to Provide Up to $105 Billion Guarantee for OpenAI's Ohio Data Center — Reuters, 2026-08-17 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
NVIDIA Form 10-K for FY2026 — SEC, 2026-02-25 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
NVIDIA Founder and CEO Jensen Huang Returns to Denny's Where NVIDIA Launched a Trillion-Dollar Vision — NVIDIA Blog, 2023-09-26 ↩↩↩↩
-
Jensen Huang Thanks Sega for the $5m That Saved Nvidia from Bankruptcy in 1995 — The Next Web, 2026-07-15 ↩↩↩↩↩↩↩↩
-
How the Kindness of Sega Saved Nvidia from Going Under — Time Extension, 2024-04-30 ↩↩↩↩↩↩↩↩↩↩↩
-
Nvidia's Jensen Huang Reunites with Sega Exec Who Saved the Company with $5M Investment — Video Games Chronicle, 2026-07-15 ↩↩↩↩
-
Jensen Huang Says He Wouldn't Start Nvidia Again If He Knew the Pain Ahead — Business Insider via Yahoo Finance, 2026-05-19 ↩↩↩
-
CUDA Programming Guide: Introduction — NVIDIA Documentation ↩↩↩↩↩
-
ImageNet Classification with Deep Convolutional Neural Networks — Krizhevsky, Sutskever and Hinton, NIPS 2012 ↩↩↩↩
-
NVIDIA Updates Financial Guidance for Fourth Quarter of Fiscal Year 2019 — NVIDIA Newsroom, 2019-01-28 ↩↩↩↩↩↩↩↩
-
NVIDIA Announces Financial Results for Fourth Quarter and Fiscal 2019 — SEC, 2019-02-14 ↩↩↩
-
NVIDIA Completes Acquisition of Mellanox, Creating Major Force Driving Next-Gen Data Centers — NVIDIA Newsroom, 2020-04-27 ↩↩↩↩↩↩
-
Statement Regarding Termination of NVIDIA Corp.'s Attempted Acquisition of Arm Ltd. — FTC, 2022-02-14 ↩↩↩↩↩
-
Nvidia Says DeepSeek Advances Prove Need for More of Its Chips — Reuters, 2025-01-27 ↩↩↩↩
-
NVIDIA 2026 Annual Meeting Results, Form 8-K — SEC, 2026-06-30 ↩↩
-
Nvidia Corp. Upgraded to 'AA' — S&P Global Ratings, 2026-06-11 ↩↩↩
-
European Commission Decision on NVIDIA's Acquisition of Run:ai, Case M.11766 — European Commission ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube