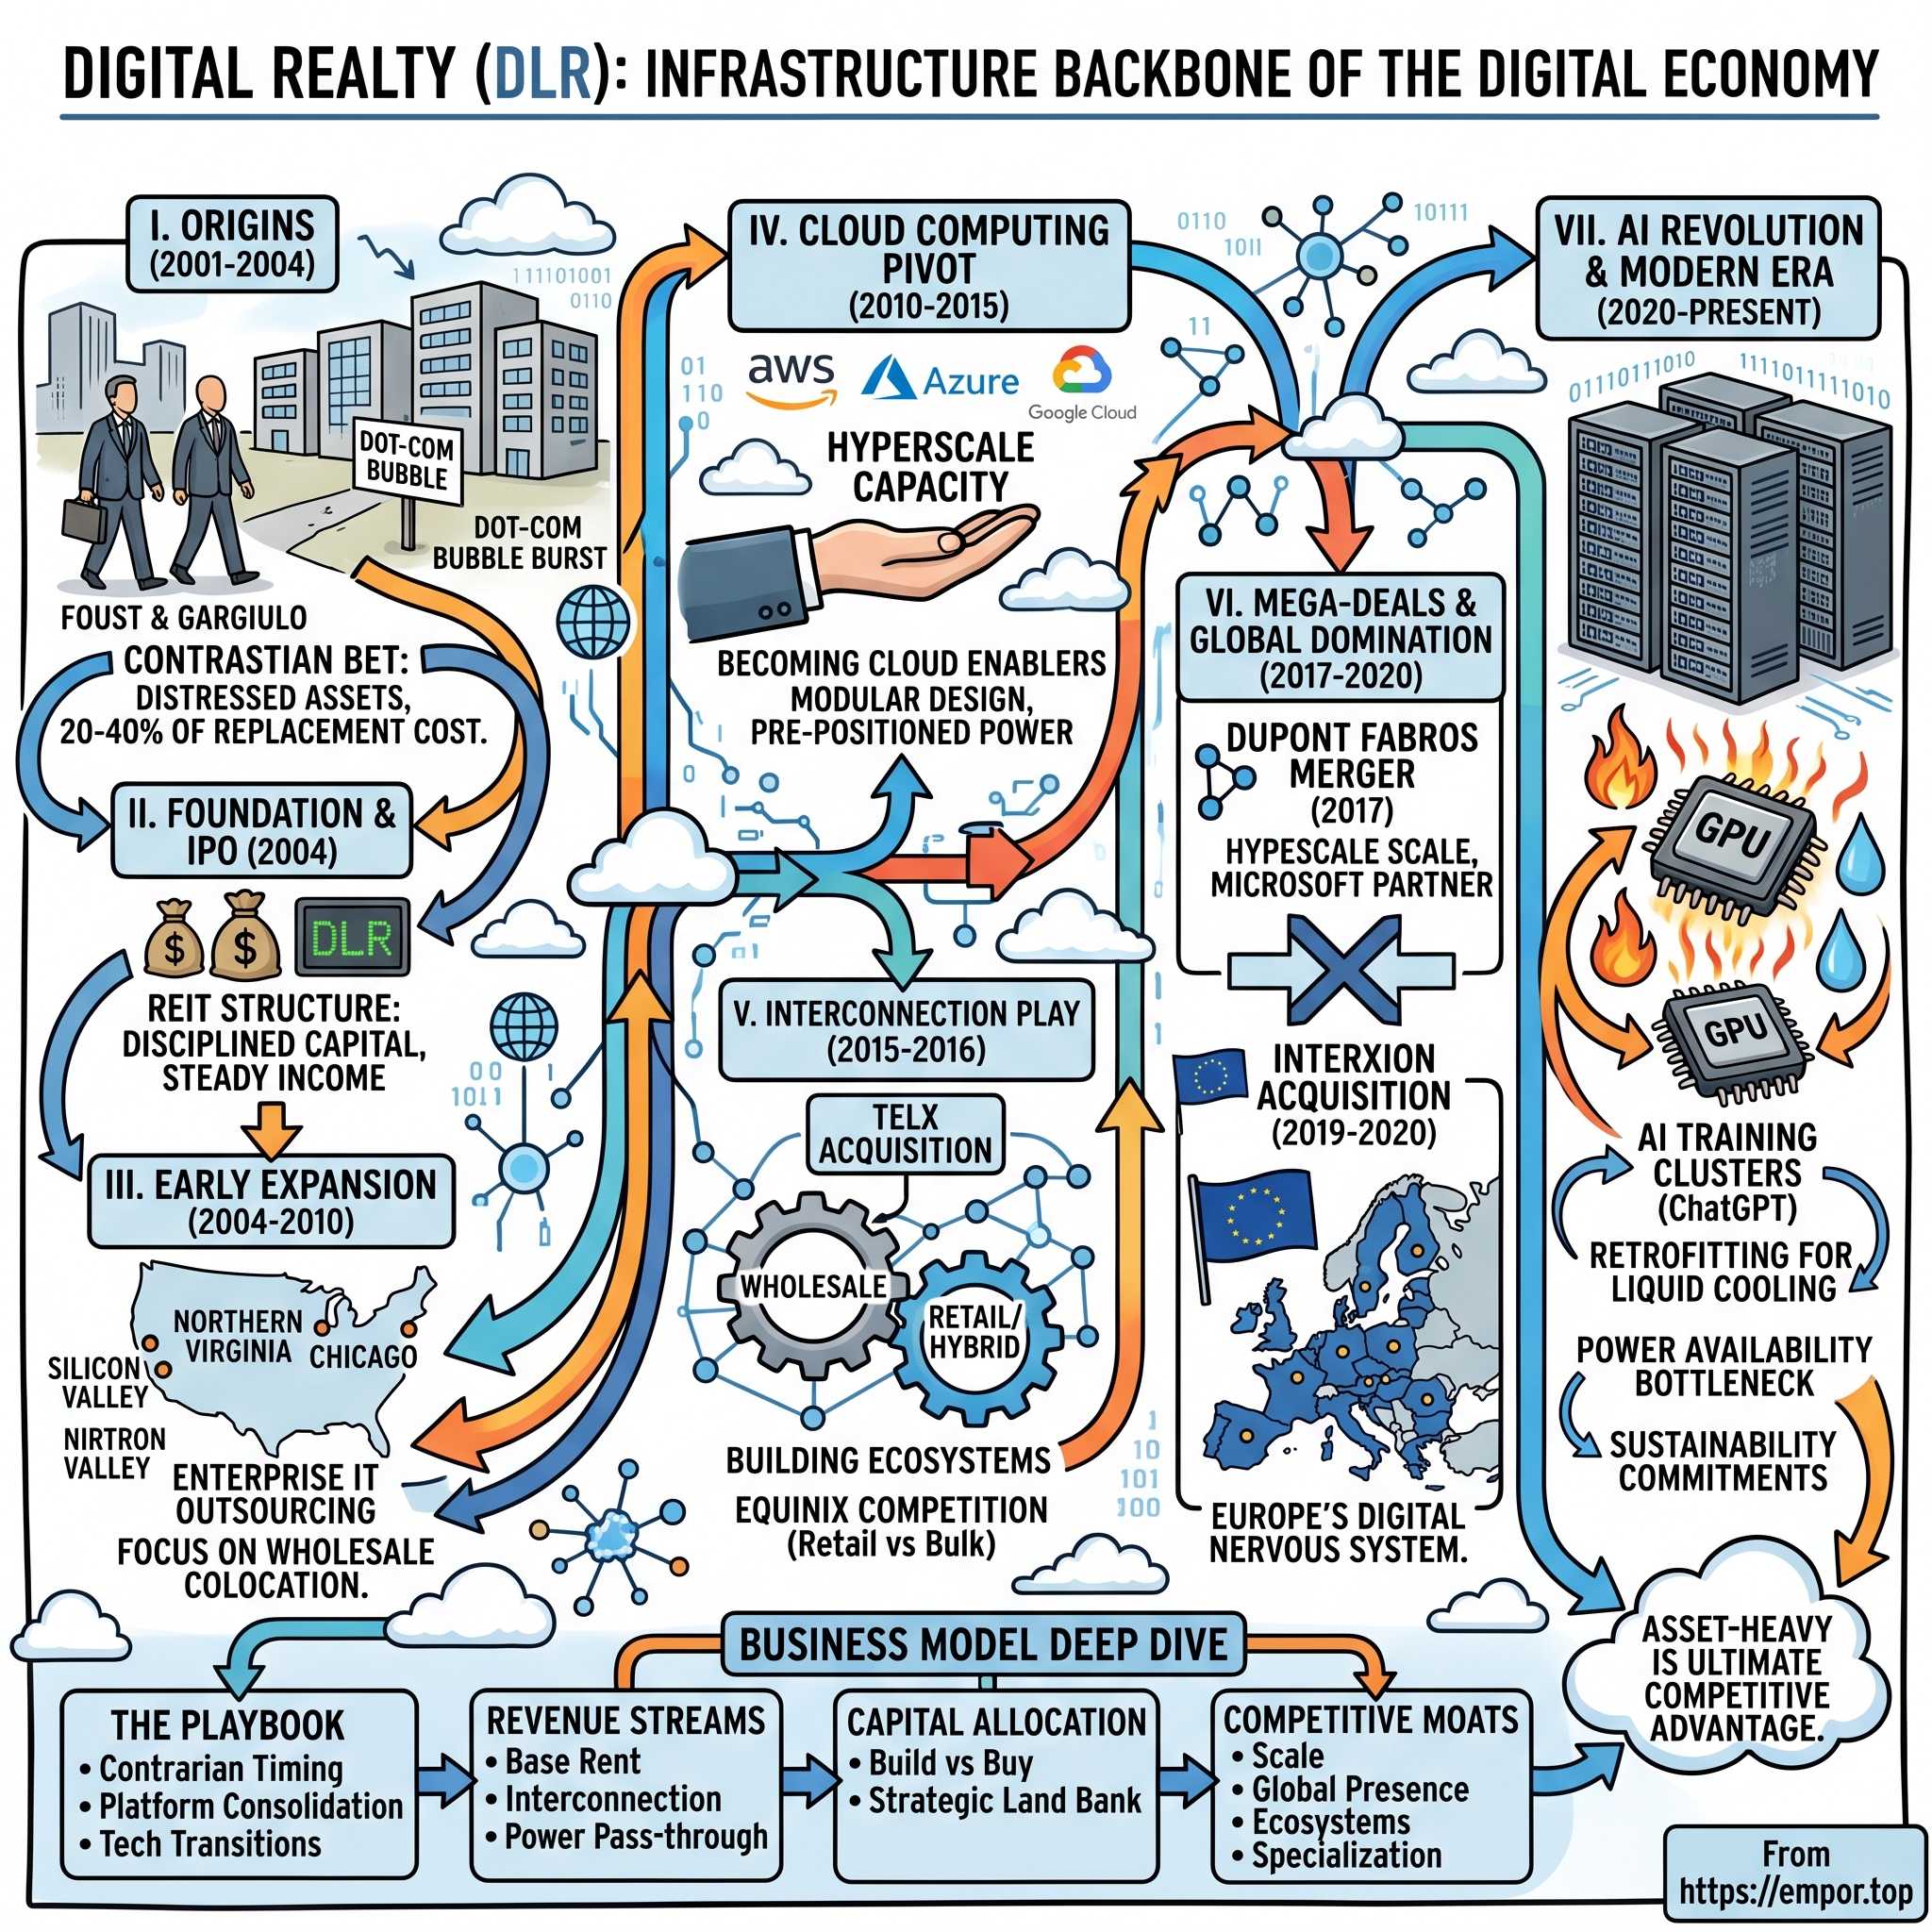
Digital Realty: The Infrastructure Backbone of the Digital Economy
I. Introduction & Episode Framework (10-15 min)
Beneath fields in Loudoun County, Virginia, dense bundles of fiber optic cable carry a substantial portion of global internet traffic. Above ground stand windowless concrete structures, ringed by electrical transformers and backup diesel generators, humming continuously as critical computing infrastructure. Tourists rarely visit these facilities, and historically, few traditional real estate investors focused on them either. Yet the question of who owns these facilities — and who holds the utility contracts that supply their electricity — has become central to the technology sector.
Digital Realty Trust owns a significant share of this infrastructure. The company operates a portfolio spanning more than 300 data centers across 50-plus metropolitan areas in over 25 countries, reporting its scale in the two primary capacity metrics of the industry: square feet of raised floor and megawatts of critical IT load.[^1] As of mid-2026, it carried a market capitalization of approximately $60 billion on trailing twelve-month revenue exceeding $5.6 billion, making it one of the largest real estate investment trusts globally and, by megawatt capacity, one of the largest data center landlords.[^12]
The central question of this story begins in 2001, when private equity firm GI Partners began acquiring unfinished and distressed data centers out of bankruptcy proceedings following the dot-com crash — facilities purchased at steep discounts to their original construction costs. Twenty-five years later, those assets and their descendants form much of the physical substrate supporting cloud computing and artificial intelligence workloads. How that expansion occurred, and how much of the value created accrued to public shareholders rather than tenants, equipment contractors, and power utilities, remains the key issue.
That dynamic highlights a fundamental challenge in Digital Realty's business model. Data center development requires intensive capital investment, while its largest hyperscale tenants — including Amazon, Microsoft, Alphabet, Meta, and Oracle — possess vast financial resources and engineering capabilities. These customers routinely buy land and construct proprietary facilities alongside their leased capacity. When key tenants have the option to build their own infrastructure, traditional assumptions about competitive moats and pricing power require careful evaluation.
Between 2018 and 2022, Digital Realty faced headwind conditions: wholesale leases renewed at flat-to-negative cash spreads, return on invested capital drifted toward the mid-single digits, and short sellers publicly targeted the data center REIT sector as a value trap.6 Subsequently, the rapid growth of generative artificial intelligence collided with severe power grid constraints in primary data center markets, reversing lease pricing trends. Whether that shift represents a structural repricing of power-backed real estate or a temporary cyclical supply squeeze is a central question for long-term investors.
This analysis follows six main sections. First, the company's distressed origins, examining GI Partners' bankruptcy roll-up strategy and the 2004 initial public offering. Second, a decade of wholesale expansion under founding CEO Michael Foust and the strategic divergence between Digital Realty and interconnection-focused Equinix. Third, an aggressive acquisition phase — including Telx, DuPont Fabros, Interxion, and Teraco — and its impact on per-share growth. Fourth, the 2022 stress period marked by rising interest rates, short-seller critiques, and executive leadership changes. Fifth, the AI-driven market environment under CEO Andy Power, defined by power availability constraints and off-balance-sheet joint venture financing. Finally, an evaluation of segment economics, management execution, and core performance metrics.
The story begins in bankruptcy court, where a private equity buyer recognized real estate value in infrastructure left behind after the technology crash.
 Subscribe on LinkedIn
II. The GI Partners Distressed Origin & IPO (2001–2004) (30-40 min)
In the autumn of 2001, the distressed assets of the internet boom were auctioned in courtrooms across the United States. Exodus Communications, once a premier web-hosting company with a market value reaching tens of billions of dollars, filed for Chapter 11 bankruptcy in September of that year. Global Crossing, which had constructed transoceanic fiber networks on borrowed capital, followed in January 2002 alongside AboveNet's parent company. The physical infrastructure left behind — facilities equipped with reinforced floors, diesel generators, chiller plants, and utility service agreements for tens of megawatts — sat largely empty, with some assets having never been energized.
The prevailing market consensus was clear and initially accurate: an oversupply existed across the sector. Bandwidth prices had collapsed, hosting demand had contracted sharply, and the timeline for infrastructure absorption remained uncertain.
Rick Magnuson formulated a different thesis. Through GI Partners, the private equity firm he founded in 2001 with anchor backing from a major public pension fund, Magnuson focused on physics and entitlements rather than immediate demand recovery. In this framework, a data center functions less like standard commercial real estate and more like an electrical substation with a roof, cooling infrastructure, and proximity to fiber routes. The building shell represents a minor fraction of capital costs; the primary value lies in power capacity, cooling systems, redundancy equipment, and municipal entitlements. While internet business models failed, the underlying power and physical infrastructure retained long-term utility.
Magnuson recruited an operational team led by Michael Foust, who would serve as the founding chief executive of Digital Realty Trust. Between 2001 and 2004, the firm acquired a portfolio of data center properties through bankruptcy auctions and distressed private sales. Management later noted these assets were purchased at substantial discounts to replacement cost, securing property in the low hundreds of dollars per square foot compared to replacement economics that were several times higher.[^1] The strategic logic was straightforward: acquiring critical infrastructure well below replacement cost allowed the firm to offer competitive rental rates against new developments while maintaining target investment returns.
By 2004, as technology spending recovered and real estate investment trust investors sought income, GI Partners transitioned the portfolio to public markets. Digital Realty Trust completed its initial public offering on the New York Stock Exchange on November 3, 2004, pricing at $12.00 per share and raising approximately $300 million based on an initial portfolio of slightly more than 20 properties encompassing roughly 5.6 million square feet.1 As the first major pure-play data center REIT, its market positioning was modest compared to modern narratives, framed primarily as industrial real estate anchored by technology tenants and backed by a steady dividend yield.
The REIT structure fundamentally shapes Digital Realty's operating model. To maintain exemption from corporate-level income tax, a real estate investment trust must distribute at least 90 percent of its taxable income to shareholders. While advantageous for income-focused investors, this mandate creates structural constraints for a capital-intensive business requiring continuous development spending. Unlike standard corporations that fund capital expenditure through retained earnings, a REIT must continuously access external capital markets — issuing equity, tapping debt, disposing of assets, or entering joint ventures — to fund expansion. Consequently, performance remains closely tied to prevailing capital market conditions: access to low-cost capital drives rapid expansion, whereas tight capital markets constrain growth.
A closer examination of the original portfolio qualifies the initial narrative. While GI Partners assembled valuable physical assets, the portfolio consisted largely of single-tenant powered shell space under long-term, fixed-rate leases to enterprise users. Initial investment returns were driven primarily by two external factors: purchasing assets at deep discounts to replacement costs and capitalizing on cap-rate compression as public markets re-rated technology real estate during the mid-2000s. These represented asset-pricing gains rather than operational outperformance or sustainable pricing power.
This distinction became clear in the 2010s as initial 10- and 15-year leases approached expiration. Renewal negotiations revealed that single-tenant powered shells with limited network connectivity functioned as commoditized real estate, leaving tenants free to build proprietary facilities, move to nearby competing developments, or negotiate lower lease rates. While initial value stemmed from discounted acquisition pricing in the early 2000s, long-term asset value would ultimately depend on interconnection density and power availability. Over the subsequent two decades, Digital Realty allocated tens of billions of dollars toward building network density ahead of the eventual shift in power market dynamics.
This structural transition set the stage for the decade in which Digital Realty pursued large-scale expansion.
III. Building the REIT Engine & Early Wholesale Scale (2004–2014) (35-45 min)
A visitor to Digital Realty's properties in 2009 would have observed an operation resembling a standardized industrial process. The company bought land near utility substations in key markets like Ashburn, Virginia, Santa Clara, California, and the western suburbs of Chicago. It secured power commitments from local utilities, poured concrete slabs, erected steel frameworks, and installed switchgear, diesel generators, and industrial chillers. Finally, it leased the resulting electrical capacity in blocks of one, two, or five megawatts to enterprise tenants, collected rent, and repeated the process across new sites.
Michael Foust executed that strategy throughout his decade as chief executive, from the 2004 initial public offering until his departure in 2014. Foust operated on the principle that supply, rather than demand, was the primary constraint on growth—believing that if the company could deliver finished megawatts faster and more cost-effectively than competitors, tenants would follow. Under his leadership, the company expanded its core North American hubs, entered London and Dublin to address European enterprise demand, and grew its property portfolio several-fold from its IPO base.[^1] In that era, the economics were straightforward: constructing facilities at stabilized returns above the cost of capital allowed development spreads to compound.
The underlying wholesale product requires clear definition. A wholesale data center lease grants a tenant physical space alongside guaranteed electrical capacity—contracting, for instance, for three megawatts of critical IT load within a dedicated suite. Digital Realty provided the building shell, power infrastructure, cooling systems, and electrical redundancy, while the tenant installed its own servers, networking gear, and internal architecture. Structurally, these agreements operated as triple-net leases in economic substance, requiring tenants to pay operating expenses, real estate taxes, and electricity costs. Rather than arbitraging utility rates, Digital Realty passed power costs through to tenants, generating revenue by selling secure access to power and engineered electrical reliability.
The growth of public cloud computing altered the trajectory of this business model. Following its launch in 2006, Amazon Web Services evolved from a developer service into core enterprise infrastructure, while Microsoft prioritized Azure and Google expanded its global cloud regions. These cloud providers required computing capacity across multiple geographies faster than they could construct proprietary facilities or staff them. Leasing wholesale space allowed hyperscalers to expand rapidly without carrying long-term development assets on their balance sheets, making Digital Realty a key landlord for the early cloud expansion.
However, a strategic divergence emerged between Digital Realty and competitors like Equinix.
While both companies operated windowless data center facilities, their underlying business models differed fundamentally. Equinix focused on carrier-neutral interconnection, housing hundreds of telecommunications networks within single facilities. The core product was not physical square footage, but physical cross-connect cables linking one tenant's equipment to another's. These cross-connects generated recurring monthly fees with minimal maintenance expense, while creating high tenant switching costs. A customer with hundreds of cross-connects inside a facility faced substantial operational risk and renegotiation friction if it attempted to relocate.
These structural differences produced distinct financial profiles. Equinix's interconnection-focused retail colocation model yielded gross margins in the mid-60% range alongside network effects, where each added network increased the facility's utility to existing tenants. In contrast, Digital Realty's wholesale model operated with gross margins near the low 50s, required greater capital expenditure per dollar of revenue, and generated lower tenant switching costs. A tenant leasing three megawatts of general-purpose compute capacity faced high relocation costs, but remained capable of moving if rental terms became unfavorable.
Foust maintained that wholesale scale offered its own structural advantages: acquiring land early, building at lower unit costs, and delivering capacity faster allowed volume to offset narrower margins. That thesis proved effective while land and electrical power remained broadly available.
The model faced a structural test between 2011 and 2014 as hyperscale cloud providers grew into Digital Realty's largest customer segment. If wholesale scale conferred genuine pricing power, lease renewal rates should have expanded alongside rising cloud demand. Instead, cash re-leasing spreads on expiring multi-megawatt leases turned negative in several legacy facilities, with tenants renewing at rates below their initial contracts.[^12]
This margin pressure illustrated the dynamics of customer concentration. When a small group of hyperscale tenants accounts for a major share of leasing volume, those buyers hold significant bargaining leverage. Cloud providers conducted competitive bidding processes across multiple landlords, aware that empty data center capacity generated no revenue while carrying fixed overhead. This monopsony power limited Digital Realty's pricing power in wholesale leasing, leaving growth dependent on total market volume rather than rental rate expansion.
Recognizing these structural limitations, management initiated a strategic pivot to build an interconnection business comparable to Equinix's model—a campaign that began under new executive leadership and a major acquisition.
IV. The Cloud Transition & Strategic Pivot: Telx to DuPont Fabros (2014–2018) (45-55 min)
Bill Stein assumed the chief executive role in late 2014, transitioning from his position as chief financial officer. As a finance executive rather than a real estate developer, Stein inherited an explicit mandate: resolve the margin compression and low switching costs inherent to the pure-play wholesale model, where expanding capacity in megawatts was no longer yielding commensurate profit growth.
The strategic imperative stemmed from a clear performance gap between Digital Realty and interconnection-focused peers like Equinix. Equinix generated higher returns per dollar of invested capital by selling high-margin network connectivity rather than raw physical space. Recognizing that organic development alone could not bridge this gap quickly, Digital Realty turned to inorganic acquisitions.
In October 2015, Digital Realty completed the acquisition of Telx, a U.S. colocation and interconnection provider, for approximately $1.886 billion.2 The transaction added roughly 20 carrier-neutral facilities across key metropolitan markets—including New York, Chicago, Dallas, Atlanta, and the San Francisco Bay Area—alongside meet-me rooms housing dense physical network convergences. Valued at a mid-teens multiple of adjusted EBITDA, the deal was priced competitively against Equinix's historical trading valuation of 16 to 18 times EBITDA.
While the strategic rationale was sound, operational integration proceeded slowly. Merging an interconnection provider into a wholesale real estate platform presented both cultural and sales alignment challenges. Wholesale leasing teams were incentivized on signed megawatts and delivered square feet, whereas interconnection economics relied on thousands of smaller, recurring monthly contracts and telecommunications sales motions. Consequently, while interconnection revenue expanded steadily post-acquisition, it initially lagged the compounding rates needed to rapidly justify the premium purchase multiple. Digital Realty had acquired physical interconnection assets, but constructing the operational capabilities to fully capitalize on them required several years.
A subsequent expansion opportunity emerged from regulatory intervention. When Equinix acquired European operator TelecityGroup, antitrust regulators mandated asset divestitures in overlapping metropolitan markets. In July 2016, Digital Realty acquired eight European data centers from Equinix for approximately $874 million—securing a strategic portfolio at a price difficult to achieve in an open market process.2 The acquisition provided immediate operational density across key European hubs where Digital Realty previously maintained a limited presence.
Shortly thereafter, management pursued the defining transaction of Stein's tenure.
On June 9, 2017, Digital Realty announced the acquisition of DuPont Fabros Technology in an all-stock transaction valued at approximately $7.8 billion including assumed debt.3 DuPont Fabros operated as a premier hyperscale landlord, owning 12 large-scale facilities concentrated in Northern Virginia, suburban Chicago, and Santa Clara. The portfolio encompassed roughly 3.5 million square feet and approximately 300 megawatts of critical IT load, leased primarily to major global technology companies.
The strategic rationale centered on footprint and customer relationships. DuPont Fabros controlled prime facilities and land in Ashburn, Virginia, backed by utility power commitments that required years to secure. The transaction also reshaped Digital Realty's customer base, positioning Microsoft and Meta at the top of its revenue concentration list.3 Acquiring the second-largest landlord in Loudoun County secured critical capacity in a market where power-anchored land was becoming increasingly scarce.
However, the transaction's valuation and financing structure introduced long-term financial trade-offs. Struck near a cyclical high for hyperscale valuations, the acquisition priced DuPont Fabros at a high-teens multiple of forward funds from operations and was funded entirely with Digital Realty common equity.3 For a real estate investment trust, evaluating an acquisition depends not merely on aggregate portfolio scale, but on whether the transaction expands per-share cash flow.
Financial results over subsequent years highlighted this dynamic. Between 2016 and 2020, Digital Realty's total revenue nearly doubled from roughly $2.1 billion to approximately $3.9 billion as acquired properties consolidated into financial reports.[^1] Yet over the same five-year period, core funds from operations per share remained largely flat, fluctuating within a narrow range in the low-to-mid six-dollar tier.[^12] While top-line scale expanded significantly, per-share earnings growth lagged due to the substantial equity issued to fund the acquisitions.
This outcome illustrated a key structural risk in REIT roll-up strategies. Digital Realty issued equity valued on its higher-margin, blended platform—which included its expanding interconnection business—to acquire bulk wholesale assets carrying lower operating margins and softer renewal pricing dynamics. Consequently, while the transaction increased physical capacity, it shifted portfolio mix toward lower-return wholesale leases, diluting overall earnings quality over time.
Management defended the acquisition as essential for hyperscale market leadership, arguing that a dominant Northern Virginia footprint was necessary to capture cloud tenant growth. However, on investor calls through 2018, analysts frequently questioned why cash re-leasing spreads in Northern Virginia remained flat to negative and why renewal rates on expiring hyperscale contracts experienced pressure.[^12] Management attributed these trends to lease vintage comparisons and specific contractual escalators, yet persistent flat per-share earnings underscored the structural pricing constraints in wholesale leasing.
Ultimately, the 2015-to-2017 acquisition phase yielded a mixed financial record. The Telx acquisition and European divestitures added essential interconnection capabilities and geographic density that would have taken years to build organically. Meanwhile, the DuPont Fabros transaction secured critical land, power capacity, and top-tier tenant relationships, albeit at a full valuation that expanded aggregate scale without expanding per-share profitability.
Yet management's consolidation strategy was far from complete. Behind the scenes, negotiations were already underway for what would become the largest transaction in data center industry history.
V. European Hegemony: The Interxion Mega-Deal & Global Consolidation (2019–2022) (45-55 min)
To understand what Digital Realty acquired in Europe, consider Interxion's campus near the Deutsche Commercial Internet Exchange in Frankfurt. By American hyperscale standards, the physical footprint is modest. However, the facility serves as a primary hub where a substantial portion of continental European internet traffic changes hands. Hundreds of network operators, financial institutions, content providers, and enterprise carriers connect within its walls. While a competitor can construct an adjacent building, replicating a quarter century of accumulated network density is far more difficult.
That network density drove the transaction. On October 29, 2019, Digital Realty announced an all-stock combination with Interxion valued at approximately $8.4 billion—at the time, the largest transaction in data center history.[^6] The acquisition closed in March 2020, during the initial onset of the global pandemic. The deal added more than 50 carrier-neutral facilities across roughly 13 European metropolitan areas, anchored in the key regional hubs of Frankfurt, London, Amsterdam, and Paris. The combined European operation was branded "Interxion, a Digital Realty company," with Interxion's chief executive, David Ruberg, appointed to lead the region.[^6]
The transaction carried a high valuation—a low-twenties multiple of forward EBITDA—under the strategic rationale that urban interconnection density cannot easily be replicated through standard development.[^6] Compared to the DuPont Fabros acquisition, the asset quality argument was stronger. Interxion operated a higher-margin business model characterized by smaller tenant footprints, a broader customer base, recurring cross-connect revenue, and lower churn. While the 2015 Telx acquisition established Digital Realty's domestic interconnection footprint, Interxion scaled that strategy globally.
In January 2022, Digital Realty extended this strategy to sub-Saharan Africa by acquiring a majority stake in Teraco, South Africa's leading carrier-neutral colocation provider, in a deal valuing the company at approximately $3.5 billion.[^11] Teraco held a position in Johannesburg and Cape Town comparable to Interxion's hub in Frankfurt, serving as the primary landing point for subsea fiber cables and inter-network traffic. Digital Realty subsequently increased its ownership to 77% by 2026.[^1] Although sub-Saharan Africa represents a small portion of consolidated revenue, the investment secured key interconnection hubs in an emerging region prior to widespread hyperscale expansion.
Alongside these physical acquisitions, management introduced a software integration initiative. PlatformDIGITAL served as the framework for Digital Realty's global architecture, offering enterprise clients standardized specifications, service levels, and commercial terms across its global footprint.4 The company subsequently launched ServiceFabric, a software-defined networking layer designed to allow customers to programmatically configure connections between customer environments, data center facilities, and major cloud platforms without manual provisioning.4
Strategically, automating cross-connects via software offers a path to scale high-margin interconnection services. In practice, as of 2026, these tools function primarily as features supporting core real estate leasing and cross-connect retention rather than standalone software revenue lines. Digital Realty does not report platform revenue separately in its financial disclosures.[^12] Consequently, these offerings reflect customer retention tools and strategic alignment rather than a transition into high-margin software services.
However, the assumption that Interxion would serve as a self-sustaining European growth engine faced immediate operational constraints. The primary barriers to expansion arose not from tenant competition, but from municipal power grids and regulatory planning authorities.
Prior to the acquisition's close, municipal authorities in Amsterdam had enacted a temporary moratorium on new data center construction due to power and land constraints. Shortly thereafter, local regulators in Frankfurt tightened energy allocations for new developments, while grid operators in Ireland restricted new power connections in the Dublin metro area. Furthermore, wholesale energy prices surged in 2022 following disruptions to European natural gas supplies, while regional data sovereignty regulations increased compliance costs and architectural complexity.5 As a result, expanding capacity across the core European markets—Frankfurt, London, Amsterdam, and Paris—proved slower, more costly, and subject to tighter regulatory oversight than initial acquisition models anticipated.
Evaluating the Interxion acquisition reveals a nuanced outcome. The thesis that existing urban interconnection density provides a defensible, high-margin revenue stream has proven accurate, as those core facilities continue to generate strong operating margins. However, the expectation of rapid capacity growth was constrained by power availability and municipal permitting rather than tenant demand. Going forward, key performance indicators for the region include revenue growth within the European interconnection and enterprise colocation segments, alongside the rate at which newly developed capacity is energized relative to announced development pipelines.
Ironically, the power grid constraints that limited European capacity expansion in 2021 would soon emerge as a critical source of pricing power across global data center markets. Before that shift occurred, however, macroeconomic headwinds and market skepticism would create severe pressure on the company's valuation.
VI. The Chanos Short Thesis, ROIC Crisis, & Balance Sheet Pivot (2022–2023) (40-50 min)
For a business whose model depends on borrowing money to build assets that yield a spread above interest costs, 2022 presented a severe operating environment. Central banks raised policy rates from near zero to above 5% within a single year. Consequently, real estate investment trusts across the sector faced roughly doubled capital costs while existing long-term contracts constrained immediate rent escalations. Digital Realty's stock, which traded near $175 per share in late 2021, fell to approximately $85 by the autumn of 2022—a decline of more than 50% in under twelve months.
In mid-2022, short seller Jim Chanos launched a fund specifically targeting legacy data center REITs.6 Taking the thesis seriously requires examining the financial logic beneath the market narrative.
Chanos presented three interlocking claims regarding the sector's structural risks.
First, he argued that major cloud platforms functioned as both primary tenants and formidable competitors. Possessing superior balance sheets and lower costs of capital, these cloud providers held strong incentives to construct proprietary facilities rather than pay third-party landlord margins. Over time, third-party wholesale capacity faced the risk of being commoditized down to utility-like returns.6
Second, he highlighted a sustained contraction in return on invested capital. According to his analysis, Digital Realty's return on invested capital drifted from between 9% and 10% in the 2008–2012 window down to the low-to-mid 5% range by 2021. With capital costs rising sharply in 2022, the company faced the prospect of deploying capital at returns near or below its cost of capital.6 For a REIT reliant on development spreads, a negative spread directly undermines long-term value creation.
Third, Chanos challenged industry accounting conventions regarding depreciation and capital intensity. Real estate investors traditionally emphasize funds from operations, which adds real estate depreciation back to net income on the premise that physical property retains value over time. While applicable to traditional commercial real estate, Chanos contended that data centers contain substantial mechanical and electrical equipment with genuine 15-to-20-year operational lifespans. Furthermore, rapid advances in server hardware can render existing rack power densities and cooling architectures obsolete.6 Under this framework, reported FFO systematically overstated distributable cash flow because ongoing maintenance capital expenditures represented a permanent cash drag.
These structural headwinds and market pressure prompted board action. In December 2022, the board appointed Andy Power as chief executive officer, succeeding Bill Stein.2 Power had served as chief financial officer since 2015 and as president since 2021, having structured much of the firm's capital allocation and acquisition strategy. Concurrently, long-tenured finance executive Matt Mercier was named chief financial officer.2
Power's background in real estate investment banking shaped the company's balance sheet pivot. On earnings calls in late 2022 and early 2023, management outlined specific capital targets: reducing leverage toward a net debt to EBITDA ratio in the mid-five-times range, curbing dilutive common equity issuance, and funding development through asset sales and joint ventures with institutional partners.[^12] On those calls, Power acknowledged past operational challenges directly, noting that wholesale development spreads had compressed and that historical expansion had relied heavily on share issuance.[^12]
An evaluation of historical performance shows that key elements of the short thesis were grounded in disclosed metrics. Wholesale cash re-leasing spreads remained flat to negative between 2018 and 2022, confirming customer bargaining power in that segment.[^12] Returns on invested capital compressed toward funding costs in 2022, and maintenance capital requirements exerted a larger drag on net cash flow than headline FFO figures implied.
However, two external factors altered the competitive landscape.
The first factor was power grid availability. The self-build argument assumed that access to capital was the primary constraint on data center supply. By 2022, grid capacity emerged as the binding bottleneck. In Northern Virginia, the main utility serving Loudoun County publicly announced that electrical transmission constraints would delay new service connections in the eastern part of the county, in some cases for years.5 Similar utility queues formed across major hubs in Dublin, London, Frankfurt, and Santa Clara. Under multi-year connection delays, capital and land ownership alone could not bring new capacity online. Strategic value shifted toward incumbents holding energized facilities, active substation commitments, and queued power rights.
The second factor was a sharp acceleration in computing demand. The public release of ChatGPT in late 2022 drove rapid expansion in artificial intelligence workloads. Training and serving large language models required significantly higher power density per rack and specialized cooling architecture. Within eighteen months, primary market vacancy rates dropped to record lows, and available capacity was pre-leased years ahead of delivery.
This supply-demand dynamic reversed market pricing trends. The negative cash re-leasing spreads that had characterized wholesale renewals inverted, enabling data center landlords to allocate scarce capacity at higher rental rates.
Ultimately, while Chanos's assessment accurately captured wholesale leasing dynamics and capital intensity over the preceding decade, it did not forecast the simultaneous emergence of grid power constraints and AI-driven computing demand. This outcome demonstrates that the short thesis was conditional on a supply-demand balance that fundamentally shifted. For long-term investors, the core analytical question is whether current pricing strength represents a permanent structural repricing of power-backed real estate or a temporary supply bottleneck.
VII. The AI Revolution, Power Constraints, & Private Capital JVs (2023–Present) (50-60 min)
Inside a modern artificial intelligence data center, the defining engineering feature is not the server rack, but the cooling infrastructure. Overhead insulated piping carries liquid coolant directly to cold plates mounted on high-power processors. Standard air cooling proves inadequate at high thermal densities, as liquid cooling is required to dissipate heat from dense computing clusters.
That technical transition shapes the underlying economics of data center operations. Traditional enterprise server cabinets consumed five to fifteen kilowatts of electricity and were cooled via chilled air systems. In contrast, modern AI accelerator racks consume forty to one hundred kilowatts or more—the electrical equivalent of dozens of single-family homes concentrated within a single cabinet footprint. Supporting these workloads requires reinforced structural flooring, re-engineered electrical distribution, and substantially higher aggregate power capacity per facility.
This shift presents dual financial implications for data center landlords. High-density capacity commands premium rental rates and favors operators with secured utility power and specialized engineering capabilities. However, legacy facilities built for lower rack densities cannot be easily retrofitted, requiring substantial capital investment that may not yield targeted returns. Consequently, while AI demand has increased the value of power-backed new developments, it has created valuation uncertainty for older properties. Management has maintained that traditional cloud and enterprise workloads continue to utilize legacy capacity.7 Evaluating the long-term absorption and capital requirements of these older assets remains a central task for investors.
Power availability quickly became the primary operational constraint across the industry. In industry discussions through 2024, Chief Executive Andy Power emphasized that grid capacity and utility interconnection queues had replaced construction capital as the primary bottleneck to growth, giving operators with pre-secured power commitments a significant competitive advantage.7 In response, Digital Realty shifted its development pipeline reporting from square footage under construction to contracted megawatt capacity.
However, scaling gigawatt-scale infrastructure requires tens of billions of dollars in capital. For a real estate investment trust obligated to distribute at least 90 percent of taxable income, committed to deleveraging, and cautious of equity dilution, funding this expansion entirely on balance sheet was unfeasible. To address this constraint, management pivoted to private capital joint ventures.
On December 7, 2023, Digital Realty and Blackstone announced a joint venture to develop four hyperscale campuses across Northern Virginia, Frankfurt, and Paris, representing an expected investment of approximately $7 billion.[^4] Under the agreement, Blackstone provided 80 percent of the equity capital, while Digital Realty retained a 20 percent interest and acted as managing member, earning development and management fees.[^4] The planned developments were designed to deliver several hundred megawatts of IT capacity.[^4]
This joint venture structure altered the company's financial model. Rather than funding 100 percent of development capital and absorbing total balance sheet leverage, Digital Realty funded 20 percent of equity requirements while generating recurring fee income on the partner's 80 percent contribution. This approach allowed the company to expand asset management fee revenue alongside property ownership, operating partially as an infrastructure investment platform.
Digital Realty subsequently expanded this private capital strategy with partners including GI Partners, Realty Income, and TPG, while acquiring a digital infrastructure investment platform from Columbia Capital to institutionalize its asset management operations.2 By 2026, co-investment joint ventures had become a core element of the company's growth strategy.
In June 2026, Digital Realty executed a key transaction within this framework, agreeing to acquire Blackstone's interests in three stabilized, fully leased Northern Virginia facilities developed through the joint venture for approximately $3.5 billion.8 This capital recycling approach allowed Digital Realty to earn development fees during construction, de-risk leasing, and subsequently acquire stabilized cash flows.
However, repurchasing stabilized assets involves trade-offs. By acquiring facilities post-stabilization, Digital Realty pays market valuations, allowing the majority of initial development spreads to accrue to the joint venture partner that bore the initial construction risk. Whether the combination of management fee income and a 20 percent equity stake generates higher returns than full project ownership depends on contract terms that remain undisclosed.8 While the structure mitigates balance sheet leverage and per-share dilution, its long-term impact on per-share value creation will depend on subsequent financial execution.
Concurrently, Digital Realty pursued large-scale land acquisitions in secondary power markets. In 2026, the company assembled approximately 1,440 acres at Astra Enterprise Park near Kansas City, securing a location capable of supporting up to two gigawatts of ultimate power capacity.2 Expanding into power-rich secondary markets offers a solution to utility bottlenecks in primary hubs. This strategy assumes that AI training workloads possess sufficient latency tolerance to operate at a distance from major internet exchanges—a trend supported by initial deployment patterns, but one that remains subject to long-term operational validation.
These market dynamics improved core operating metrics. Cash re-leasing spreads inverted from their 2018–2022 trend, expanding into the high single digits on a cash basis across both wholesale and colocation segments.[^12] Concurrently, the backlog of signed-but-uncommenced leases reached record levels,[^12] leading management to state that capacity delivery, rather than tenant demand, represents the primary operational constraint.[^12]
While an expanding backlog reflects strong customer demand, it also highlights execution risk. Converting signed leases into recognized revenue depends on delivering energized capacity according to utility interconnection timelines.
VIII. Business Model, Segment Economics, & Strategic Powers (Deep Dive) (40-50 min)
Strip away geography and acquisition history, and Digital Realty is essentially two businesses operating under a single brand, sharing facilities while obeying distinct economic rules.
The first is the 0-to-1 megawatt colocation and interconnection business. Customers in this segment include enterprise firms, network operators, financial institutions, content providers, and technology companies deploying artificial intelligence inference workloads near end users. Deployments are relatively small, ranging from a few server cabinets to several hundred kilowatts. Revenue per megawatt is substantially higher than in wholesale, as tenants pay for connectivity and managed services rather than raw space and power. Operating margins run well above the corporate average, supported by significant switching costs: a tenant with dozens of cross-connects to carriers and cloud providers inside a specific facility faces operational risk and substantial network re-architecture costs to move elsewhere. As a result, this segment has generated consistently positive renewal pricing.[^12]
The second is the wholesale business, encompassing leases of 1 megawatt and above. Customers are primarily major cloud and AI platforms signing multi-year agreements across large capacity blocks. Operating margins are structurally lower, as wholesale capacity functions closer to a commodity and electricity costs are passed through to tenants. Capital intensity per dollar of revenue is significantly higher, and buyers hold strong long-term negotiating leverage — a dynamic currently tempered by power constraints, but historically evident in flat or negative renewal spreads.
Housing both models under one umbrella creates a persistent strategic tension. The wholesale segment drives leasing volume, hyperscale relationships, and headline revenue expansion. The colocation segment generates durable, higher-margin cash flow. For more than a decade, management has sought to expand interconnection faster than wholesale capacity. In practice, however, wholesale expansion often outpaced colocation growth because large hyperscale transactions absorbed the majority of deployed capital.
A third business line is emerging that does not report as a separate operating segment. Digital Realty's private capital management platform earns development and asset management fees from institutional partners, generating high-return income with minimal balance-sheet capital requirements.[^4] Concurrently, the company has expanded ServiceFabric — adding support for AI agent protocols in 2026 — to convert physical cross-connects into programmable software connections.4 Neither line is broken out separately in financial statements today. However, if asset management fees expand, valuation metrics may increasingly reflect fee-earning investment platforms rather than traditional real estate cap rates.
Applying formal strategic frameworks helps clarify these dynamics. Under Hamilton Helmer’s 7 Powers model, Digital Realty's most defensible asset today is a cornered resource — not its physical real estate, but its portfolio of utility interconnection agreements, substation commitments, and grid queue positions across power-constrained metropolitan markets. These agreements represent contractual access to electricity in regions where new entrants face multi-year utility delays.5 Yet this advantage is cyclical rather than permanent; its duration depends on grid expansion timelines and regulatory approvals rather than proprietary technology.
Network effects exist, but remain localized within specific carrier-neutral facilities — primarily the Interxion, Telx, and Teraco hubs where hundreds of network operators physically interconnect. In these locations, each added tenant increases the facility's value to existing participants. While this creates a strong moat at the building level, it does not extend to suburban wholesale campuses, leaving Digital Realty's overall financial profile below that of pure-play interconnection peers like Equinix.
Scale economies provide a moderate to strong advantage, particularly in procurement. Global purchasing scale for transformers, switchgear, generators, and liquid cooling systems allows the company to secure favorable pricing and, more critically, priority delivery slots during supply chain bottlenecks. When lead times for high-voltage electrical equipment extend to several years, volume buyer status becomes a key operational differentiator.
Switching costs follow the segment divide: high within interconnection facilities, but lower in wholesale developments. Counter-positioning is largely absent, as well-funded private competitors actively replicate Digital Realty's build-and-scale strategy. Brand and process power remain moderate; while two decades of operational uptime establish credibility with enterprise clients, high reliability is a standard requirement in critical infrastructure rather than a unique differentiator.
Porter’s Five Forces analysis highlights additional competitive pressures. Buyer power is split, remaining elevated among hyperscale cloud tenants while lower among enterprise colocation users. Supplier power is high and increasing, driven by electric utilities controlling power access and an electrical equipment oligopoly — including vendors like Schneider Electric, Eaton, and Vertiv — dictating component lead times. The threat of new entrants is concentrated among well-capitalized private equity platforms, such as QTS under Blackstone, Vantage under DigitalBridge, and CyrusOne under KKR, which compete directly for land, power, and tenants without REIT dividend distribution mandates. The threat of substitution remains low near term, but moderate long term as hyperscalers weigh self-build options. Consequently, competitive rivalry remains intense across both wholesale real estate and interconnection markets.
This structural diagnostic indicates that Digital Realty's current competitive strength relies heavily on power availability constraints, layered over a smaller, highly durable interconnection franchise. While the interconnection business provides defensible returns, it represents a minority of total revenue. The larger wholesale business remains subject to supply dynamics that, while favorable during current power shortages, remain cyclical over longer horizons.
Navigating these opposing forces focuses attention on how management allocates capital.
IX. Management Credibility & Capital Allocation Audit (25-35 min)
Andy Power's career trajectory at Digital Realty presents an informative case study: he was present for, and helped execute, the very strategy he was later tasked with correcting. Joining as chief financial officer in 2015, Power structured and financed the acquisitions of DuPont Fabros and Interxion, as well as the substantial equity issuance programs that funded them. He assumed the presidency in 2021 and became chief executive in December 2022, taking charge of a company whose per-share earnings had stagnated for six years while balance-sheet leverage and rising capital costs became primary investor concerns.2
That history presents a dual perspective. On one hand, the strategic shift adopted after 2022 implicitly critiqued executive decisions in which he participated. On the other hand, the post-2022 course correction does not represent a complete leadership reset. The current executive team is largely the same group that oversaw the prior expansion, now operating under altered market dynamics and revised strategic priorities.
Matt Mercier, appointed chief financial officer in 2023 following a long internal tenure, has led the company's balance-sheet deleveraging and financial disclosure initiatives. Under his direction, reporting on re-leasing spreads, lease backlogs, and joint venture structures has expanded significantly.[^12] While detailed disclosures are straightforward to maintain during periods of operational tailwinds, their sustainability will be tested if market conditions soften.
A key driver of this historical pattern was executive compensation design. For much of the company's history, incentive structures prioritized growth in total funds from operations and relative total shareholder return against REIT indices.[^14] Targeting aggregate FFO growth incentivized portfolio expansion through asset acquisitions without penalizing dilution from equity financing. Under this metric, management could double total FFO by expanding the share count, even if per-share earnings remained flat. Consequently, executive incentives and long-term per-share shareholder value diverged during a period in which Digital Realty executed its two largest stock-funded acquisitions.
Following the 2022 strategic reset, the compensation framework was restructured to emphasize core FFO per share, return on invested capital, balance-sheet leverage targets, and sustainability metrics.[^14] This realignment directly addresses past structural incentives. However, evaluating its long-term effectiveness requires ongoing monitoring of capital allocation discipline—specifically whether management avoids large, stock-funded acquisitions justified primarily by aggregate platform scale.
A comprehensive assessment of Digital Realty's capital allocation track record reveals distinct performance phases:
First, initial distressed asset acquisitions between 2001 and 2004 generated substantial value by securing critical physical infrastructure at deep discounts to replacement costs, though this strategy was initiated prior to the public REIT offering. Subsequent value-accretive transactions included the 2016 acquisition of divested European data centers from Equinix, which secured strategically valuable assets at attractive entry multiples.2 More recently, the transition toward private capital joint ventures starting in 2023 represents a significant structural pivot, mitigating balance-sheet leverage while preserving development participation. Nevertheless, the full-cycle returns of this model remain unproven, as financial terms for the 2026 acquisition of Blackstone's joint venture stakes were not fully disclosed to allow independent verification.8
Second, acquisitions of colocation platforms Telx and Teraco yielded mixed financial results. While both expanded Digital Realty's high-margin interconnection capabilities in key strategic markets, each required prolonged integration periods before generating operational returns consistent with their initial transaction multiples.
Third, the large-scale acquisitions of DuPont Fabros and Interxion represented high-cost transactions. Combined, these deals represented approximately $16 billion in enterprise value and were funded primarily through equity, significantly diluting the share count and contributing to a six-year plateau in per-share earnings.3[^6] While these transactions secured crucial power capacity in Northern Virginia and network density across Europe—assets essential to the platform's current competitive positioning—they demonstrated that strategic necessity came at a premium price, financed with equity during periods when management maintained the stock was undervalued.
Ultimately, management's capital allocation track record presents a nuanced picture. Regarding communication, executive leadership directly acknowledged historical return-on-invested-capital compression during 2023 investor presentations rather than attributing margin weakness entirely to external factors.[^12] Furthermore, operational execution against post-2022 goals—including leverage reduction, disciplined equity issuance, and expanded joint venture partnerships—has aligned with stated targets. However, the multi-year stagnation in per-share financial metrics prior to 2023 demonstrates that recent performance gains have been heavily supported by broader market tailwinds rather than a prolonged history of per-share capital discipline.
Which sets up the only question that ultimately matters: from here, what would have to be true?
X. The Investment-Story Spine: Why Win / Why Not & Risk Radar (30-40 min)
The bull case for Digital Realty from 2026 forward rests on four load-bearing claims, each deserving to be stated in its strongest form and then stress-tested.
First: scale plus power queue priority. The company holds energized capacity, land, and utility commitments across primary global markets that no new entrant can replicate on a relevant timeline, and demand for those megawatts currently exceeds supply.5 The evidence supporting this is concrete — positive re-leasing spreads across both segments and a record leasing backlog.[^12] The vulnerability is duration. This advantage exists because power grids are constrained. Grids are being expanded, in some markets aggressively, and hyperscalers are pursuing dedicated power generation, including nuclear and gas-fired capacity, outside the conventional utility queue. The claim survives, but as a multi-year advantage rather than a permanent moat.
Second: the interconnection franchise. The zero-to-one megawatt business with dense cross-connect ecosystems carries high margins, genuine switching costs, and durable pricing power.[^12] This claim holds up best of the four, identifying the part of the business most deserving of a premium valuation. Its limitation is size: it remains the smaller share of revenue, and a decade of acquisitions has not altered the fact that the wholesale segment dominates the consolidated financial profile.
Third: the private capital model. Fee income on partner capital generates returns that no owned asset can match, breaking the historical link between physical expansion and per-share dilution.[^4] This represents the most critical open question in the story. While strategically sound and executed at scale, the model has not yet been demonstrated through a full development-to-stabilization-to-monetization cycle with disclosed returns. The verdict is plausible but incomplete, making it the single most important metric to monitor.
Fourth: the AI density wave. High-density, liquid-cooled capacity commands premium pricing that legacy specifications cannot match. While true today, this dynamic carries implications for the broader portfolio: if new developments earn premium rates due to advanced specifications, older capacity is effectively downgraded, making retrofit costs a tangible claim on future cash flow.
Against these sit the bear arguments, which remain deferred rather than defeated.
Hyperscaler vertical integration represents a persistent structural threat. The largest tenants continue to construct proprietary facilities for core workloads, leasing third-party capacity primarily for speed, geographic reach, and flexibility. If construction bottlenecks and power constraints ease, the historical pattern of flat-to-negative wholesale renewal pricing becomes the base case rather than an anomaly — reflecting market behavior when supply is adequate.6
Persistent low organic returns on invested capital remain unaddressed. The improvement since 2022 has been driven substantially by market pricing rather than a fundamental shift in the capital intensity of data center development. Skeptics point to the gap between reported funds from operations and true free cash flow after accounting for maintenance and re-specification capital — an analytical critique that was overwhelmed by surging demand rather than directly rebutted.
Execution risk on power delivery is the most immediate operational challenge. A signed lease backlog only generates value once energized. If utility substation commissioning slips — a frequent occurrence in constrained markets — contracted revenue is delayed while deployed capital earns no immediate return.
Balance-sheet and refinancing risks persist. The company carries substantial debt across multiple currencies, and refinancing obligations originally issued during the near-zero-rate era at higher prevailing rates increases interest expense, pressuring per-share performance even when operations perform well.[^1]
On the broader risk radar, four factors warrant close investor attention. Grid interconnection delays represent the primary operational bottleneck. Customer concentration poses commercial risk — a small group of hyperscale tenants accounts for a major share of revenue, maintaining significant bargaining power.[^1] Technical obsolescence of air-cooled legacy capacity creates asset-quality uncertainty that is difficult to quantify from public disclosures alone. Finally, political and regulatory scrutiny surrounding energy and water consumption is escalating across key regions — as seen in earlier moratoria in Amsterdam and Dublin, and increasingly contested local politics in Northern Virginia driven by rising residential utility rates. A business reliant on municipal and utility approvals carries external stakeholder risks that do not appear on financial balance sheets.
An activist investor would highlight three additional structural concerns. First, portfolio complexity: dozens of joint ventures, varied accounting consolidation methods, and an expanding off-balance-sheet footprint make consolidated statements increasingly difficult to evaluate. Second, disclosure transparency: the company does not break out segment-level returns on invested capital in a format that allows investors to independently verify whether wholesale developments clear their cost of capital. Third, asset quality: a clear accounting of which assets can support high-density workloads, alongside estimated retrofit costs, would resolve a central analytical uncertainty.
These factors do not render the investment thesis negative. Rather, they make it conditional — an appropriate framing for a capital-intensive platform operating under favorable market tailwinds after a challenging decade.
XI. Playbook: Lessons for Builders, REIT Operators, & Tech Investors (25-35 min)
A central theme connects Digital Realty's quarter-century arc: in 2001, the most valuable asset inside a bankrupt data center was its power service agreement—an entitlement the market largely ignored. By 2026, a secured power commitment remains the critical asset, but it is now aggressively priced. Over twenty-five years, the underlying physical scarcity never changed; only the market's recognition of its value evolved.
Physical infrastructure is technology in disguise. Every software abstraction eventually terminates in physical hardware requiring electricity and thermal management. Investors focused on the application layer periodically rediscover that the primary bottleneck sits several levels down—in transformers, transmission lines, and cooling capacity. The owners of those bottleneck assets do not need to pick which software applications win.
Measure capital allocation per share. The central lesson from Digital Realty's mid-decade expansion is that aggregate revenue nearly doubled while per-share earnings remained flat. The acquisitions were strategically sound, but equity dilution offset top-line growth. When management justifies transactions based on scale, market position, or strategic necessity, the critical evaluation remains: at what purchase price, using what financing currency, and with what impact on per-share cash flow over subsequent years?
Watch what the incentive plan measures. A compensation framework tied to aggregate funds from operations growth predictably rewarded portfolio expansion over per-share discipline. Executive compensation metrics offer one of the most reliable indicators of corporate behavior, making the proxy statement a critical counterpart to strategic presentations.
When public capital is expensive, private capital becomes a strategic tool. Joint venture structures enabled Digital Realty to participate in large-scale developments when issuing public equity would have been dilutive. However, trading the majority of development upside for management fees, lower risk, and balance-sheet protection involves tangible trade-offs. The ultimate value of this model depends on full-cycle investment returns rather than structural design.
Operating distinct business models requires distinct execution playbooks. Wholesale data center leasing is a scale-and-power business evaluated on development yields and cost management. In contrast, interconnection relies on network density, ecosystem cross-connects, and low tenant churn. Operating both models under unified sales incentives and corporate culture explains why integrating acquisitions like Telx required several years.
Evaluate short-seller theses on quantitative evidence. Although external market events ultimately muted the impact of the Chanos short thesis, its core financial arguments—that return on invested capital had compressed toward capital costs and that reported FFO masked maintenance capital intensity—highlighted genuine structural pressures. That analysis accelerated strategic shifts that management might otherwise have deferred.
Land banked with power commitments functions as a strategic option. Securing large parcels years ahead of development, backed by utility power commitments, requires modest upfront capital while creating substantial optionality during periods of power scarcity. The Kansas City land assembly reflects a land-banking approach Digital Realty has pursued since its early expansion in Ashburn.2 However, land banking carries geographical risk: long-term options only yield returns if tenant demand materializes in those specific locations, making secondary-market expansion a test of customer migration patterns.
XII. Epilogue & What to Watch (10-15 min)
Twenty-five years after the post-dot-com bankruptcy auctions, Digital Realty occupies a position its founders could hardly have anticipated: not merely a landlord for internet firms, but a critical counterparty to the electrical grid on behalf of global computing. The business has undergone two distinct repricings over that quarter century — first upward as technology real estate gained institutional acceptance, then downward as rising interest rates and compressing returns converged in 2022. Today, the platform is undergoing a third repricing, driven by an unprecedented surge in demand for artificial intelligence infrastructure.
For investors seeking to distinguish structural competitive advantages from cyclical tailwinds, three key metrics warrant close observation:
Cash re-leasing spreads, reported separately for the 0-to-1 megawatt and 1-megawatt-plus segments. This metric serves as a direct test of pricing power. The 1-megawatt-plus segment reveals whether Digital Realty or its hyperscale tenants hold the negotiating advantage in any given period. Having remained flat to negative for years, these spreads turned positive amid current power constraints; a deceleration or flattening would signal an easing of power scarcity. Concurrently, the 0-to-1 megawatt segment indicates whether the company's acquired interconnection footprint maintains its historical pricing defensibility.
Core FFO per share growth. Rather than relying on top-line revenue or aggregate funds from operations, core FFO per share provides the definitive measure of capital allocation discipline. This metric remained flat through six years of major acquisitions. If the private capital joint venture strategy functions as intended, its success will manifest here — driving per-share earnings growth without requiring dilutive equity issuance.
Development pipeline conversion: megawatts energized versus megawatts contracted. A record signed lease backlog demonstrates customer demand, but value creation occurs only when capacity begins generating revenue. The gap between signing a lease and collecting rent exposes grid connection delays, equipment lead times, and operational execution risks. Key indicators to track include the speed at which contracted capacity is energized and whether management maintains delivery schedules across consecutive quarters.
This trajectory highlights a notable shift in technology real estate. For two decades, capital markets favored asset-light software business models while discounting capital-intensive physical infrastructure. Digital Realty acquired land, constructed power shells, installed switchgear, and secured utility commitments. As artificial intelligence workloads expanded, physical infrastructure — electrical power, liquid cooling, and substation proximity — emerged as the primary bottleneck to technology expansion, repositioning capital-intensive real estate as a critical constraint on digital growth.
Whether grid availability constraints persist long enough to justify recent development capital remains an open question. The long-term outcome depends on how quickly electric utilities expand transmission capacity, how aggressively hyperscale tenants pursue alternative power solutions, and whether management can maintain per-share capital discipline during a favorable demand cycle. Digital Realty has secured favorable market conditions; its long-term financial performance will depend on its execution against them.
References
-
U.S. SEC EDGAR Database — Digital Realty Trust, Inc. (DLR) Filings ↩
-
Digital Realty to buy DuPont Fabros in $7.8 billion deal — Reuters, 2017-06-09 ↩↩↩↩
-
PlatformDIGITAL® & ServiceFabric® Enterprise Architecture — Digital Realty Technical Overview ↩↩↩
-
Data Center Capital of the World Faces Electric Power Crunch — Bloomberg, 2022-07-28 ↩↩↩↩
-
Short Seller Jim Chanos Launches Fund Targeting Legacy Data Center REITs — S&P Global Market Intelligence, 2022-07-06 ↩↩↩↩↩↩
-
Digital Realty CEO Andy Power Talks AI, Power Bottlenecks & Strategy — REIT.com (Nareit), 2024-03-15 ↩↩
-
Digital Realty Buys Out Blackstone Stake in $3.5B Northern Virginia Data Center Transaction — Data Center Knowledge, 2026-06-10 ↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube