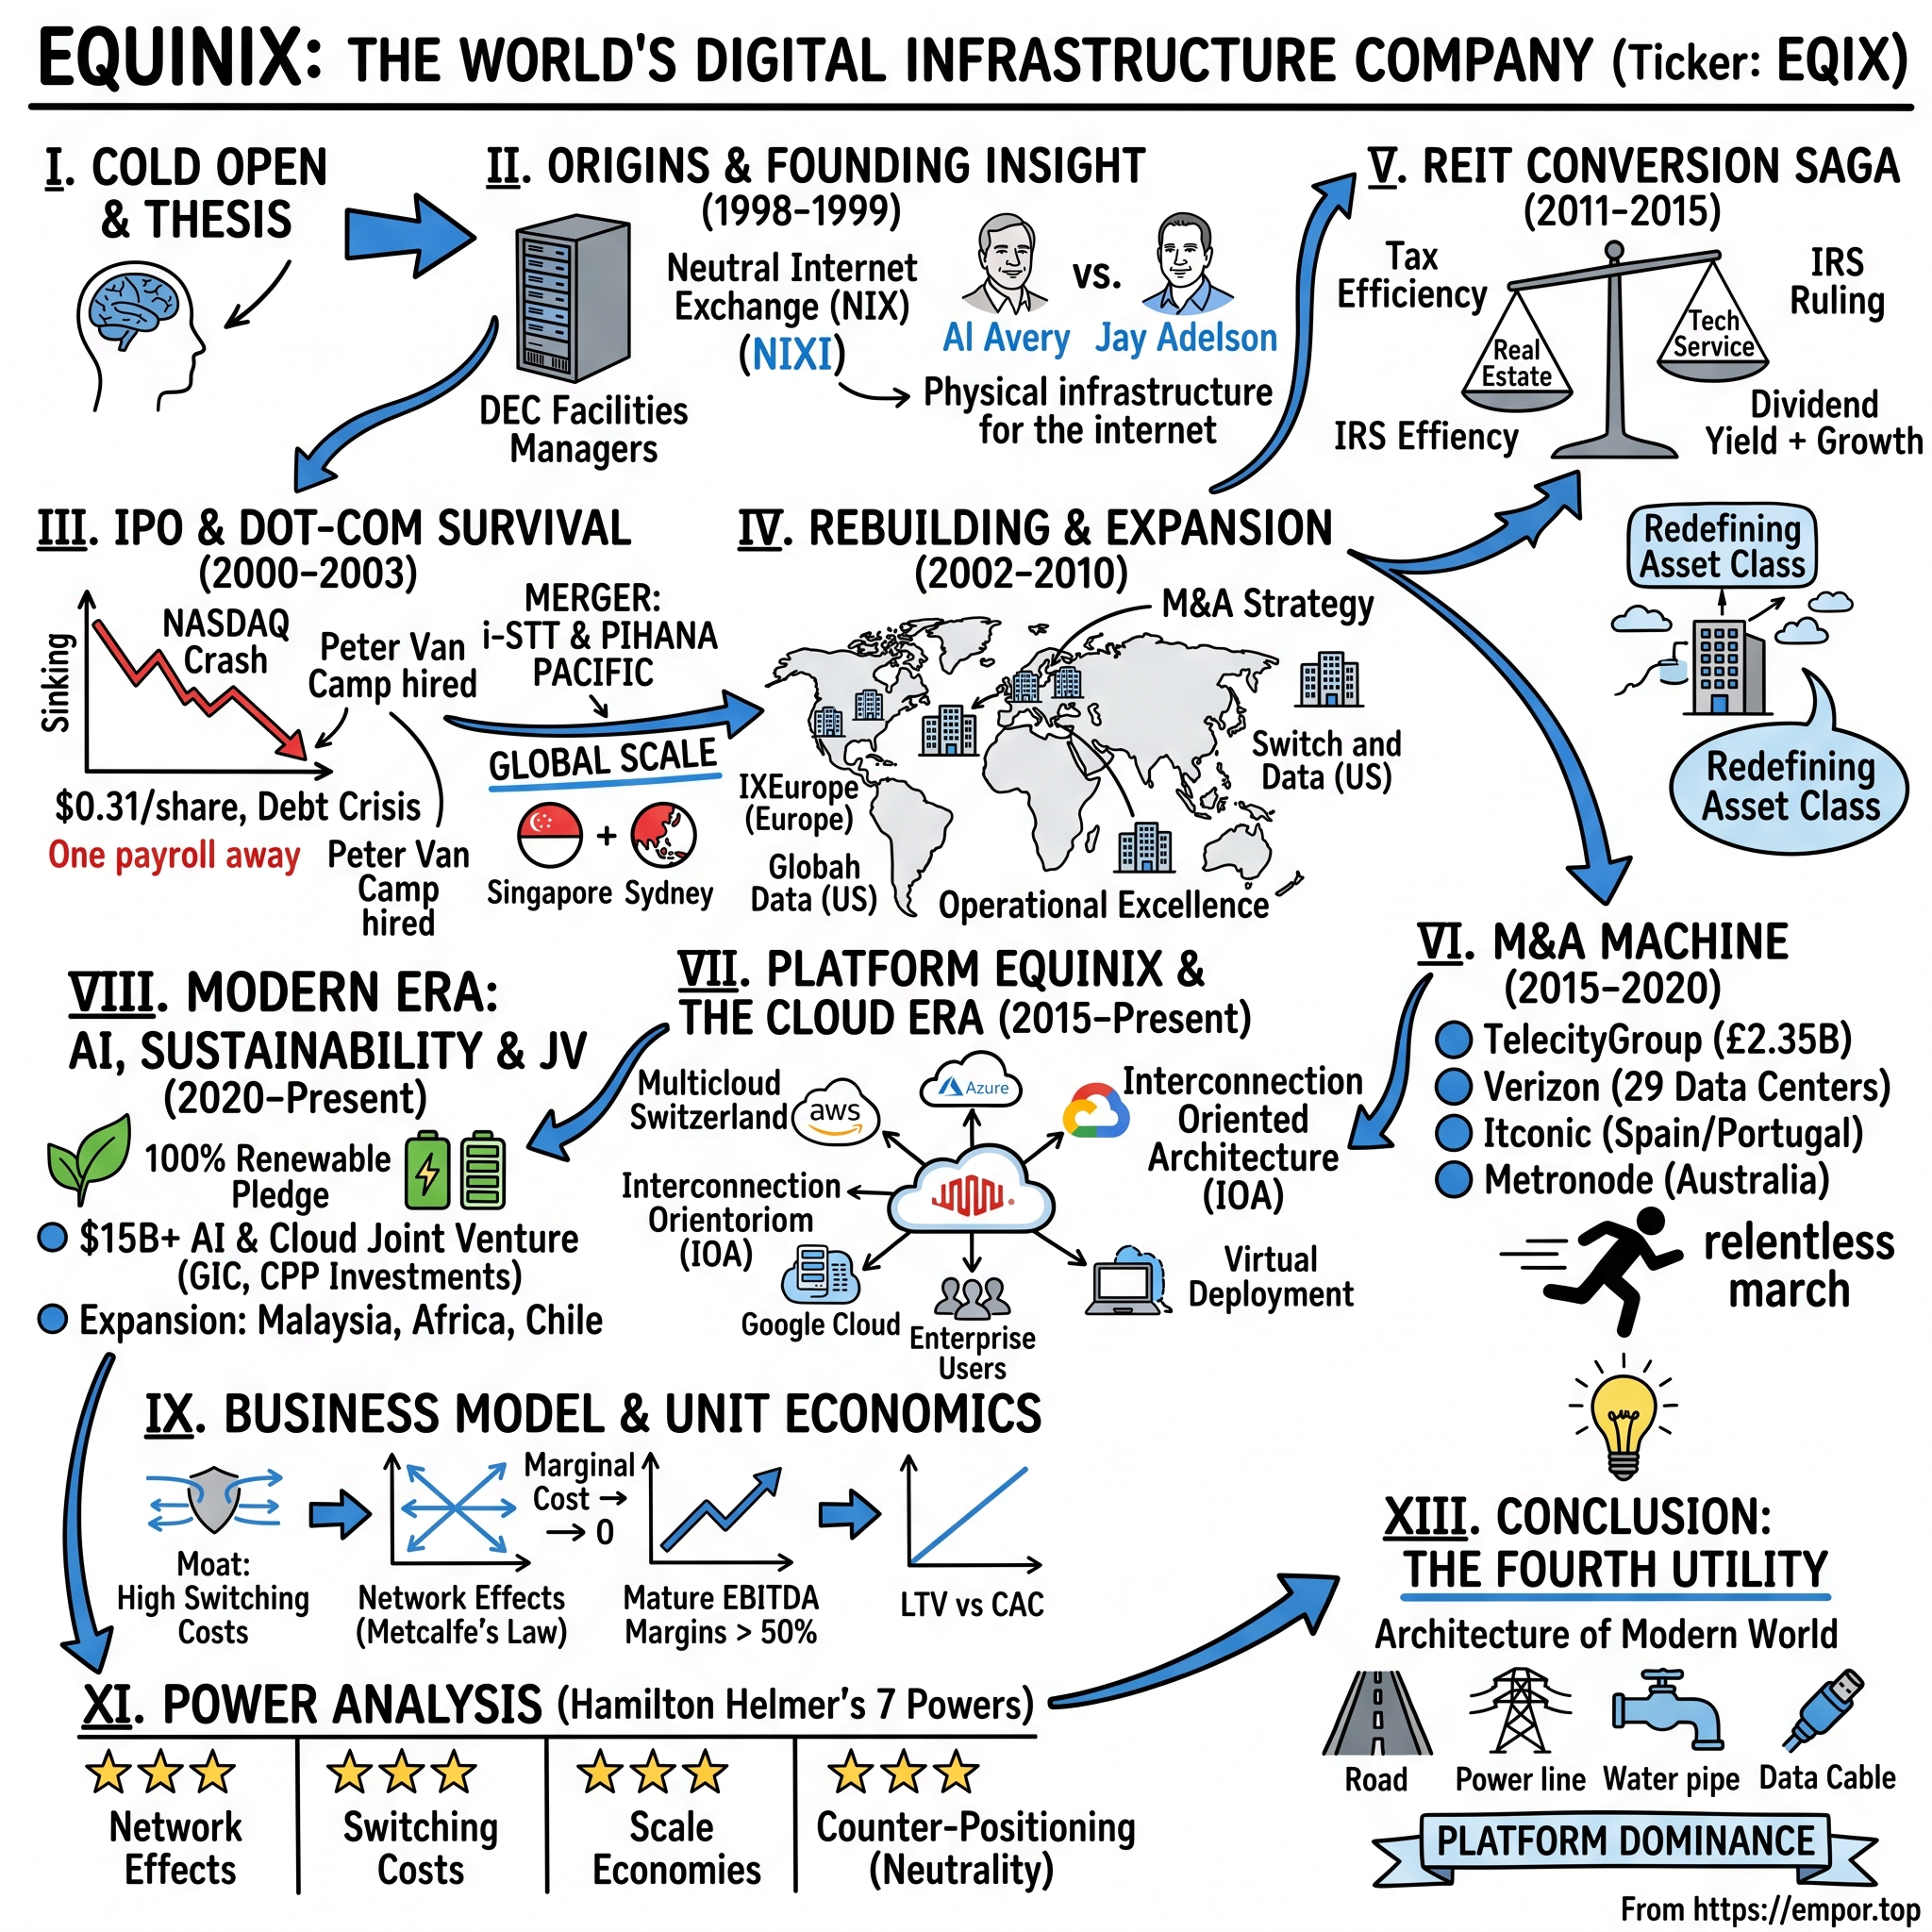
Equinix: The World's Digital Infrastructure Moat
I. Cold Open & Thesis: The Chokepoint of Global Internet Traffic
Drive west out of Washington, D.C., along the Dulles Greenway, past office parks and townhouse developments, and the landscape changes in a way that is easy to miss. The buildings get longer and lower, built without windows. Most carry no signage beyond a small placard at a guard booth displaying a three-letter code and a number. Behind them sit rows of container-sized diesel generators and banks of chillers that hum at a steady low frequency. Overhead, high-voltage transmission lines converge from three directions.
This is Loudoun County, Virginia, where an estimated third to half of global internet traffic passes through a few square miles. The county markets itself as "Data Center Alley." It did not set out to become one. It became a digital nexus after 1998, when two facilities managers who had kept equipment running for a struggling computer company decided that the internet's central bottleneck was not bandwidth or speed, but trust.
The company they founded was Equinix. On the surface, Equinix operates as a real estate business: it manages more than 270 data centers — styled as International Business Exchanges, or IBXs — across 35 countries and 77 metropolitan areas, reporting revenues of $8.75 billion for fiscal 2024 with adjusted funds from operations of roughly $3.35 billion.1[^2] Structured as a real estate investment trust, it owns or leases buildings and rents space inside them by the cabinet and by the kilowatt.
That real estate framing, however, obscures the core economics of the model. A wholesale data center operator — leasing twenty megawatts to a single hyperscale client on a fifteen-year triple-net contract — builds structural shells and sells bulk power. Its customer base is concentrated, capital-rich, and willing to relocate when pricing dictates. Equinix operates differently. Inside an Equinix IBX, thousands of separate entities — telecom carriers, cloud platforms, content delivery networks, financial institutions, and enterprise IT departments — place equipment in the same facility and link directly to one another through physical fiber cables running across the building. Equinix calls these cross-connects. At the end of 2024 there were more than 481,000 of them live across the platform.[^2]
That interconnection volume forms the company's operational moat. A cross-connect is a physical cable, but it also functions as a contract, a latency boundary, and a core component of a customer's production network topology. A large enterprise inside an Equinix facility might maintain forty cross-connects linking to cloud providers, telecom carriers, market data feeds, payment rails, and software vendors. Relocating requires more than moving server racks; it demands renegotiating and rebuilding dozens of separate counterparty connections in a new facility where those counterparties may not operate. Consequently, quarterly customer churn at Equinix has run in a narrow band of roughly 2.0% to 2.5% per quarter for years — a fraction of what most infrastructure businesses experience.[^2]
Under this structure, Equinix functions less like a conventional landlord and more like a digital exchange floor. In exchange models, platform value scales with participant density, reinforcing customer retention.
The strategic question for Equinix in 2026 stems from a shift in infrastructure demand. The buildout of artificial intelligence compute requires large-scale installations with heavy power capacity, inexpensive land, and high-capacity fiber, rather than dense multi-party interconnections. Training a frontier AI model depends less on proximity to dozens of network counterparties than on raw power efficiency. In response, Equinix developed xScale — a parallel, partially off-balance-sheet joint venture structure designed to capture wholesale AI workloads while seeking to preserve its core retail interconnection business as its primary profit engine.
Evaluating whether this dual approach can sustain Equinix's historical margins requires examining how the internet's early fragmentation created the demand for a neutral infrastructure intermediary.
 Subscribe on LinkedIn
II. Origins & The Carrier-Neutrality Insight (1998–1999)
In the mid-1990s, understanding why the internet suffered from severe throughput bottlenecks did not require inspecting consumer modems; it meant examining four physical buildings.
When the National Science Foundation decommissioned the NSFNET backbone in 1995 and transitioned internet infrastructure to commercial operators, it established a handoff architecture built around Network Access Points (NAPs) operated by incumbent telecommunications carriers in San Francisco, Chicago, New Jersey, and Washington, D.C. Every commercial network seeking to exchange traffic with competitors converged at these few chokepoints. The underlying design assumption—that a small set of regional exchange points could scale alongside exponential user growth—failed within eighteen months.
As traffic volume surged, the NAPs congested, making peak-hour packet loss routine. Beyond raw capacity constraints, the structural flaw was aligned with corporate incentives: incumbent carriers operated the NAPs while competing directly against the third-party networks attempting to connect through them. If a network experienced degraded performance inside a facility run by a competitor that preferred selling paid transit over providing free peering, the affected network had no mechanism to prove anti-competitive intent or seek independent redress. Asymmetric routing and selective latency created widespread friction across commercial networks.
Al Avery and Jay Adelson observed these dynamics from Digital Equipment Corporation (DEC), which operated the Palo Alto Internet Exchange (PAIX)—a West Coast facility that had evolved into a neutral meeting ground. Working as facilities managers responsible for power distribution, cooling, cable management, and physical security, Avery and Adelson recognized the operational value of neutral infrastructure. At PAIX, competing networks exchanged traffic without a single carrier controlling access terms, generating customer demand that outpaced DEC's willingness to commit capital.
In 1998, Avery and Adelson founded Equinix on a commercial model designed to eliminate operator conflict of interest. Rather than selling bandwidth or network transit, Equinix operated strictly as a neutral facility provider, offering physical space, power, cooling, security, and equal rights to cross-connect to any tenant in the building. The founders derived the company name from its core mandate: Equal, Quality, Universe, Internet, Network, InterXchange.
Early strategic capital came from technology companies seeking to bypass carrier-controlled bottlenecks, including Microsoft and Cisco Systems. Michelangelo Volpi, then heading corporate development at Cisco, joined the Equinix board alongside Scott Kriens, then chief executive of Juniper Networks.2 These strategic investors supplied both capital and equipment relationships, as their hardware and software clients represented prime candidates to populate Equinix facilities.
Equinix constructed its first facility, DC1, in Ashburn, Virginia. The location offered crucial logistical advantages: alignment along primary fiber routes out of Washington, D.C., proximity to the congested MAE-East exchange, available land, and power utility support. By establishing a neutral footprint early, Equinix created a self-reinforcing network effect: each additional carrier landing in Ashburn increased the site's value to subsequent networks, establishing the location as a central routing hub for North American internet traffic.
The falsification test: was neutrality actually protected?
Retrospective analysis often frames carrier neutrality as an obviously superior business strategy. However, market conditions in 1999 indicate that neutrality was a high-risk commercial posture whose long-term value depended heavily on external market dynamics.
In 1999, carrier neutrality appeared economically disadvantageous compared to bundled service models. Dominant competitors, including Exodus Communications, AboveNet, and Globix, expanded rapidly by bundling high-margin bandwidth transit with physical hosting space. Refusing to sell bandwidth meant forfeiting the primary revenue stream in data center hosting at the time, leading industry peers to view Equinix's unbundled model as inefficient under prevailing market assumptions.
The structural shift in favor of Equinix resulted from the telecom market downturn of 1998 to 2001. Widespread overinvestment in long-haul fiber drove bandwidth prices toward marginal cost, eroding the high-margin transit revenues that sustained bundled data center providers. Exodus Communications filed for bankruptcy in September 2001. Conversely, Equinix's unbundled model insulated it from falling bandwidth prices, leaving it in control of multi-tenant facilities where network participants had already established dense physical interconnections—an asset class resilient against fiber supply gluts.
This distinction highlights how macro capital cycles shaped Equinix's initial moat. By prioritizing multi-party interconnection over transit resale, Avery and Adelson built an infrastructure footprint that appreciated with participant density rather than commoditizing. However, surviving the broader telecom collapse required navigating severe liquidity pressures over the subsequent four years.
III. The IPO, Dot-Com Crash & The "One Payroll" Survival Story (2000–2003)
The timing was precarious.
Equinix went public on August 11, 2000, raising roughly $270 million at $12 a share.[^4] The Nasdaq had peaked five months earlier, in March, though in August 2000 broader market consensus held that equities had experienced a routine correction and were consolidating. Equinix priced its offering into what management viewed as a temporary pause; it was instead the second leg of a sharp, sustained collapse in tech valuations.
Steering the offering was Chief Executive Peter Van Camp, who had previously managed international operations at UUNET, then one of the internet's largest backbone providers. Van Camp’s background gave him direct insight into both the telecommunications carriers Equinix needed as anchor tenants and the financial strain developing across the sector.
That sector soon imploded. Equinix’s customer base was heavily concentrated in the segments most vulnerable to the downturn: telecom carriers, web hosting providers, and dot-com startups. Over the next two years, major counterparties filed for bankruptcy. Exodus Communications failed in late 2001. Global Crossing, which had laid 100,000 route miles of fiber funded by $12 billion in debt, filed for bankruptcy in January 2002—at the time the fourth-largest filing in U.S. history. WorldCom, the parent company of Van Camp’s former employer, filed in July 2002 following an $11 billion accounting fraud, marking the largest U.S. corporate bankruptcy to date. Each of these companies was an active tenant, a prospective client, or both.
Equinix’s stock price fell more than 98% from its offering price. However, equity decline alone understated the operational risk, because data center economics are defined by high fixed costs. Physical facilities, generators, and cooling systems require continuous capital outlay and power minimums regardless of cabinet occupancy. When utilization drops, revenue declines linearly while operational overhead remains fixed, turning operating leverage into a severe financial strain during a downturn.
By late 2002, Equinix reportedly held less than a month of operational cash to cover payroll, bringing the company close to liquidation.
The deal that saved it, and what it cost
To survive, Equinix executed a three-way restructuring in late 2002. It merged with Asia-Pacific data center operator Pihana Pacific and secured a $30 million cash investment from i-STT, a subsidiary of Singapore Technologies Telemedia (STT), the Singaporean state-linked telecommunications holding company. While $30 million would barely fund a single modern facility expansion today, it provided essential liquidity at the time. In exchange, STT acquired a controlling equity position in the combined entity.
To satisfy exchange listing requirements and manage the share count after severe stock price depreciation, Equinix executed a 1-for-32 reverse stock split in December 2002.
The high reverse-split ratio, combined with equity dilution from the STT investment and Pihana merger, wiped out most of the value held by initial public offering investors. While the corporate entity survived, the financial position of early public shareholders was largely erased.
This restructuring highlights a key distinction between competitive advantages and equity value: a business moat and common stock are distinct entities. Strong switching costs can make an underlying asset worth preserving without insulating existing common shareholders from recapitalization. For investors evaluating Equinix's switching costs, this history demonstrates that while structural retention dynamics made the physical infrastructure worth saving, they did not protect equity holders from severe dilution.
The survival of the physical platform underscored the underlying validity of the interconnection thesis. Throughout the telecom collapse, Equinix’s primary facilities in Ashburn, Santa Clara, Chicago, and newly acquired sites in Asia maintained client tenancy. Even as customers entered bankruptcy, trustees and asset buyers kept cross-connects active to avoid disrupting critical production network paths. Physical interconnection density proved durable even under conditions of widespread counterparty insolvency.
STT’s controlling interest persisted for years, influencing Equinix’s expansion strategy across the Asia-Pacific region. More immediately, the 2002 restructuring provided Equinix with cash reserves, an expanded footprint in Asia, and executive leadership tested by an industry-wide downturn as it began rebuilding its balance sheet.
IV. Building the Interconnection Ecosystem & European Footprint (2004–2010)
By 2007, the telecom crisis was five years in the past, revenue growth had resumed, and the board sought leadership to drive geographic expansion rather than turnaround operations. The board appointed Steve Smith as chief executive.
Smith joined from EarthLink following a long career at Hewlett-Packard, where he ran a multibillion-dollar IT services organization. His background in operations and sales reflected a deliberate choice by a board that viewed core technical design as proven and distribution as the primary challenge. Smith served as chief executive from 2007 to 2018, a period during which Equinix's revenue expanded roughly twentyfold as the company grew from a domestic colocation operator into a global platform.
The underlying model Smith inherited was operating effectively across core domestic markets through a multi-party network effect.
How the flywheel actually turns
The mechanics of this network effect rely on cumulative tenant density. A telecommunications carrier installs a point of presence inside an International Business Exchange (IBX) to sell connectivity to existing tenants. That installation adds another network route to the facility.
When an enterprise—such as a mid-sized asset manager—evaluates where to house its IT infrastructure, it requires redundant connections from multiple carriers because relying on a single network provider creates single-point-of-failure risk. Inside an IBX, adding second and third carrier links requires ordering cross-connects: physical fiber jumpers installed within days for a recurring monthly fee. Establishing equivalent redundancy outside a carrier-dense facility requires local-loop civil construction, securing right-of-way permissions, and lead times often spanning months. The enterprise chooses the IBX because the facility already contains its target counterparties.
Each added enterprise increases the facility's commercial value to subsequent carriers, which in turn attracts more enterprise tenants.
This compounding process accelerated with the rise of enterprise cloud adoption. Cloud providers, including Amazon Web Services, Microsoft Azure, and Google Cloud, required physical locations to terminate direct, private connections for corporate clients seeking to bypass the public internet. They established these private on-ramps inside the facilities where enterprise IT footprints were already concentrated. Once an on-ramp was active, any enterprise requiring low-latency cloud access gained a strong incentive to deploy in that same facility. The loop closed: network density attracted enterprise infrastructure, enterprise density attracted cloud access points, and cloud presence attracted additional enterprises.
The economics of interconnection differ fundamentally from traditional colocation. A cross-connect consists of a dedicated fiber strand and minimal installation labor. Once provisioned, it yields recurring revenue at gross margins above 90% with minimal ongoing capital requirements. By contrast, expanding colocation revenue—selling cabinets and power capacity—requires continuous capital expenditure to construct shell space and install power distribution units. Consequently, incremental interconnection revenue generates free cash flow at rates conventional colocation cannot match.
Buying the map: IXEurope and Switch & Data
The strategic limitation of this flywheel was its local scope. Interconnection density in Ashburn did not solve latency or routing requirements for clients operating in European financial centers. Furthermore, the key facilities where European networks historically exchanged traffic were finite and already established by regional operators.
Equinix addressed this geographical constraint through targeted acquisitions. In 2007, it acquired IXEurope for approximately $482 million, adding 14 facilities across major European network hubs in London, Frankfurt, Paris, and Zurich. The London assets—which formed the core of the LD4 and LD5 campus in Slough—became central to European financial market cross-asset trading infrastructure, while the Frankfurt sites expanded Equinix's presence alongside DE-CIX, the continent's largest internet exchange point.
In 2010, Equinix acquired Switch & Data Facilities Company for roughly $689 million. The transaction added 23 North American metropolitan markets, absorbed its main domestic retail colocation competitor, and secured critical carrier-hotel positions across key U.S. cities.
Judging the deals on the record
Evaluating these transactions on operational and financial results reveals distinct strategic outcomes.
With hindsight, the IXEurope acquisition proved to be a pivotal capital allocation move. Equinix purchased primary European interconnection hubs before broader real estate markets recognized multi-tenant neutral data centers as a distinct asset class with network-effect pricing power. As a result, Equinix paid valuations anchored to European industrial real estate rather than the recurring cash-flow multiples those facilities later commanded. Within a decade, comparable European interconnect assets traded at multiples that made the $482 million purchase price appear highly favorable to Equinix.
The Switch & Data acquisition represented a consolidation transaction executed at full market value. To secure regulatory approval, Equinix agreed to a Department of Justice consent decree requiring the divestiture of overlapping facilities in several metropolitan markets before closing. While the strategic rationale—eliminating a major domestic competitor and acquiring dense exchange positions—was sound, the transaction reflected market-rate pricing for established assets rather than an undervalued entry point.
Both acquisitions shared a structural financial constraint: they required substantial capital outlays at a time when Equinix operated as a standard C-corporation, paying full U.S. corporate income tax rates on the cash flow supporting its expansion. Resolving that tax drag required a multi-year effort to convert the company into a real estate investment trust.
V. The REIT Conversion Masterstroke & Capital Structure Innovation (2011–2015)
Every capital-intensive business eventually encounters the same operational constraint: expanding capacity requires more capital than internal operations generate. For software companies, this marginal cost is minimal; for Equinix, expanding meant constructing physical data centers.
Keith Taylor, who became chief financial officer in 2005, evaluated the financial implications of this model. Equinix generated strong operational cash flow, but paid corporate income tax at the U.S. statutory rate of 35% in the early 2010s before allocating remaining funds to capital expenditures. Meanwhile, the company's core assets—long-lived facilities generating contractual recurring rent—resembled real estate properties. Real estate investment trusts (REITs) paid no entity-level corporate income tax, provided they distributed at least 90% of taxable income to shareholders.
The structural difference was substantial. Over a decade, entity-level taxation routed billions of dollars into corporate taxes that REIT-structured peers re-invested directly into property development.
Taylor publicly introduced the concept of converting to a REIT on Equinix's fourth-quarter 2011 earnings call, and the board formally approved pursuing the transition in 2012. However, the company faced a fundamental regulatory challenge: the Internal Revenue Service (IRS) had not formally determined whether data centers qualified as real property under federal tax law.
Four years of arguing about what a building is
The regulatory distinction carried multi-billion-dollar implications. Under federal tax regulations, a REIT's income must consist primarily of "rents from real property," which includes land, buildings, and structural components. It remained unresolved whether essential data center equipment—such as two-megawatt uninterruptible power supply systems, industrial chillers, raised flooring, and backup diesel generators—qualified as structural components of a building or non-qualifying equipment.
The most complex question involved cross-connects. Equinix's highest-margin revenue stream came from recurring monthly fees for fiber jumpers linking tenant cages inside its facilities. If the IRS classified cross-connect fees as non-qualifying service income rather than real property rent, that revenue could jeopardize REIT qualification entirely.
In 2013, the IRS suspended processing data center REIT conversion applications while it established a formal position on whether data centers fit within statutory frameworks originally drafted for office buildings and shopping centers. Consequently, Equinix's planned conversion remained unresolved for nearly two years after management had publicly committed to the transition.
The regulatory uncertainty resolved in May 2015, when Equinix announced it had received a favorable private letter ruling from the IRS confirming that its data center assets and interconnection revenues qualified for REIT status.[^5] Equinix made the election retroactive to January 1, 2015. To purge accumulated earnings and profits from its C-corporation years—a tax requirement of conversion—Equinix distributed a special dividend of $1 billion to $1.1 billion in cash and stock.
What the structure actually changed
The conversion altered Equinix's financial trajectory in three compounding ways.
First, eliminating entity-level corporate tax on qualifying income increased cash available for capital deployment without changing underlying facility operations. The existing platform of buildings, clients, and cross-connects yielded more expansion capital per dollar of revenue.
Second, REIT status shifted the company's shareholder base. Equinix moved from being categorized primarily as a mid-cap technology stock held by growth investors into major REIT indexes, making it eligible for real estate institutional funds seeking yield and duration. Increased demand from income-focused institutional investors supported multiple expansion alongside technology-sector growth rates.
Third, an expanded equity base and real estate asset classification supported an investment-grade credit rating, lowering borrowing costs. In an industry where competitive positioning depends on building facilities at the lowest cost of capital, lower debt costs provided a durable financing advantage.
While market observers often characterized the timing as strategic foresight, external market conditions also played a significant role. Equinix's cost of capital declined in 2015 just as enterprise cloud adoption accelerated and European infrastructure assets came up for sale. Management had initiated the conversion in 2011 based on structural tax efficiency rather than predicting cloud market cycles. The conversion represented a sound financial restructuring whose ultimate impact was magnified by the macro environment into which it landed.
Equinix then moved to deploy its lower cost of capital toward expanding its global infrastructure platform.
VI. Global Domination via Mega-M&A (2015–2020)
In late 2015, a corporate contest for UK-based TelecityGroup reshaped the competitive landscape for European interconnection.
TelecityGroup was the United Kingdom's largest carrier-neutral data center operator, holding established positions across key European routing hubs in London, Amsterdam, Dublin, Frankfurt, Milan, Paris, Stockholm, and Warsaw. In May 2015, Telecity agreed to merge with Interxion, an Amsterdam-based operator that represented Equinix's closest European analogue. A combined Telecity-Interxion entity would have created a formidable European competitor possessing physical incumbency in critical facilities across the continent.
Equinix intervened by submitting a superior cash-and-stock offer. Telecity's board recommended the proposal, terminating the Interxion merger agreement. The acquisition, valued at approximately $3.8 billion, completed in January 2016.[^6]
Securing regulatory clearance from the European Commission required structural concessions. Due to high operational overlaps in London, Amsterdam, Frankfurt, and Rotterdam, regulatory authorities mandated asset divestitures. Equinix sold eight facilities to Digital Realty Trust, its primary global competitor. While this transaction strengthened a direct rival in four metropolitan markets, it allowed Equinix to secure an integrated continental interconnection footprint. The divested assets consisted of standalone facilities, whereas Equinix retained the broader multi-market interconnection network.
Buying Verizon's regrets
Sixteen months later, Equinix executed a major portfolio acquisition in North America. In May 2017, it completed the purchase of 29 data centers across 15 metropolitan areas from Verizon Communications for $3.6 billion in cash.[^7]
The rationale reflected the carrier-neutrality model established in the late 1990s. Verizon had assembled the portfolio primarily through its acquisition of Terremark, operating under the assumption that a telecommunications carrier could successfully bundle colocation with network transit. That approach suffered from an inherent conflict of interest: enterprise clients seeking colocation hesitated to anchor their network topology with a provider whose primary objective was selling its own transit. Verizon ultimately concluded that the physical assets held higher commercial value under a neutral operator.
The central asset of the transaction was the Network Access Point (NAP) of the Americas in Miami—a heavily fortified facility designed to withstand Category 5 hurricanes that serves as the primary routing point for internet traffic between North America and Latin America. Because international traffic flows concentrate at established hubs, the Miami NAP represented a location bound by network density that competitors could not replicate.
The operational outcome of the Verizon portfolio acquisition was more varied than the Miami acquisition suggested. Alongside high-density exchange positions, Equinix absorbed a collection of legacy enterprise colocation facilities built to carrier standards rather than International Business Exchange standards. These sites featured lower interconnection density and required substantial capital deployment to upgrade power infrastructure, cooling systems, and cabling infrastructure. The transaction delivered a primary regional interconnection hub, an expanded enterprise customer base, and a multi-year facility modernization requirement.
During this period, Equinix expanded its global footprint through additional targeted transactions. It acquired Bit-isle in Japan for approximately $280 million in 2015, consolidating facility footprints in Tokyo and Osaka. In 2022, Equinix acquired MainOne for roughly $320 million, entering West African markets across Nigeria, Ghana, and Côte d'Ivoire. That same year, it acquired Entel's data center businesses in Chile and Peru for about $705 million. Each transaction followed a consistent formula: acquiring established regional interconnection hubs prior to market maturation.
The one that did not work
A key counter-example in Equinix's capital allocation record was its acquisition of Packet, which provided an informative case study in the limits of expanding beyond physical infrastructure.
In January 2020, Equinix announced the acquisition of Packet, a bare-metal-as-a-service provider, for approximately $335 million.[^8] The product thesis aimed to bridge colocation and public cloud computing. Equinix already controlled the physical buildings, power capacity, and cross-connect fabric. By integrating automated, API-driven bare-metal server provisioning—offering dedicated hardware without hypervisor virtualization—Equinix sought to allow customers to deploy compute capacity within minutes inside the same facilities hosting their cloud on-ramps, branded as Equinix Metal.
Commercial adoption diverged from initial projections. Equinix Metal competed directly against established public cloud providers—including Amazon Web Services, Microsoft Azure, and Google Cloud—which possessed extensive developer ecosystems, broader service suites, and the financial capacity to operate compute infrastructure on narrow margins to drive platform adoption. As a real estate and physical interconnection provider, Equinix attempted to market a software-defined compute service against specialized software platforms. Following muted enterprise adoption, management repositioned the offering away from general compute toward specialized edge workloads, eventually initiating a phase-out of the standalone Metal product.
The outcome of the Packet acquisition offers a broader framework for assessing Equinix's adjacent-market expansions. Equinix's structural advantages derive from physical incumbency in specific, difficult-to-replicate facilities. Software offerings do not share those physical replication barriers. Moving higher up the technology stack required competing on software execution rather than physical network density. For investors evaluating management's digital services strategy, Packet demonstrates the execution challenges of deploying capital into software-adjacent products operating outside the core physical platform.
This distinction between self-reinforcing physical assets and software-defined services provides the analytical framework for evaluating Equinix's subsequent platform strategy.
VII. Platform Equinix, Fabric & The Cloud Era Ecosystem
Consider a problem that appears simple on the surface but exposes a core structural limitation of physical data centers. A bank in Frankfurt requires a private connection to Microsoft Azure in Amsterdam. Both the bank and Azure operate inside Equinix facilities, but they occupy separate buildings in different countries. Because a standard cross-connect is a physical fiber cable running across a single facility, it cannot bridge that geographic distance.
For most of Equinix's history, resolving this issue required purchasing a private circuit from a telecommunications carrier—a process involving contract negotiations, provisioning cycles spanning weeks, and fixed-capacity fees paid regardless of utilization. The traditional interconnection model was physically efficient within a building, yet geographically constrained.
Equinix Fabric—launched in 2014 as Cloud Exchange before being rebranded and expanded starting in 2020—eliminated that geographical boundary. By constructing a private network backbone across its metropolitan markets and layering software on top, Equinix enabled clients with a single physical Fabric port to provision virtual connections to cloud providers or corporate partners in any Equinix market. Customers could establish, alter, or terminate bandwidth dynamically through a web portal or API within minutes.
Conceptually, a physical cross-connect functions like a dedicated private road between two neighboring facilities. Fabric operates more like a switchboard: a single physical line connects into the exchange, enabling access to any participant on the network. This architecture converts physical interconnection into a software-defined service while preserving the value of the underlying real estate.
Strategically, Fabric represents an adjacent software offering that reinforces, rather than bypasses, Equinix's physical infrastructure assets. Fabric relies on existing tenant density across more than 70 metropolitan areas; a software-only network provider lacks the physical counterparty density to replicate those connections. By contrast, Equinix Metal attempted to market bare-metal compute where physical site incumbency offered little differentiation against established cloud providers like Amazon Web Services. This alignment explains why Fabric developed into a core platform feature while Metal was phased out.
Where the money actually comes from
The company's revenue breakdown highlights the structural drivers of its business model. Colocation—comprising cabinet space, power distribution, and environmental cooling—generated roughly 72% to 73% of recurring revenue, while physical and virtual interconnection accounted for approximately 18% to 19%, with managed infrastructure and auxiliary services making up the balance.[^2]
Evaluating the revenue mix strictly by size obscures a fundamental difference in margin profiles. Colocation generates gross margins between 60% and 65% while requiring continuous capital expenditures for building shells, power infrastructure, and cooling systems. By contrast, interconnection generates gross margins exceeding 90% with minimal ongoing capital requirements. A cross-connect deployed in an established facility requires only a patch-panel termination and a physical fiber strand.
Consequently, while interconnection accounts for roughly one-fifth of overall revenue, it generates a disproportionate share of incremental cash flow. This operational leverage dictates margin trajectory: expanding interconnection faster than colocation drives margin expansion without proportional capital outlays, whereas faster colocation growth increases capital intensity and exposes revenue to broader real estate pricing pressures.
Geographically, the Americas contributed roughly 44% to 45% of revenue, Europe, the Middle East, and Africa (EMEA) accounted for approximately 32% to 33%, and the Asia-Pacific region generated about 22% to 23%.[^2] The substantial contribution from EMEA reflects the long-term impact of acquiring IXEurope and Telecity Group, establishing a multi-continental footprint that gains regulatory relevance as data sovereignty laws compel enterprises to process and exchange data within specific national jurisdictions.
The on-ramp position, and the honest caveat
Equinix frequently highlights its concentration of public cloud on-ramps—the dedicated physical exchange points where enterprise services like AWS Direct Connect, Microsoft Azure ExpressRoute, Google Cloud Partner Interconnect, and Oracle FastConnect terminate. Management has stated that the platform hosts more cloud on-ramps than its closest competitors combined, estimating its global market share at roughly 40%.1
While this position represents a substantial operational advantage, several structural caveats apply. On-ramp metrics are calculated internally using company-defined criteria and comparison sets rather than independently audited industry standards. Furthermore, deployment decisions rest entirely with cloud providers rather than Equinix. Cloud platforms locate on-ramps in Equinix facilities to access existing enterprise customer density—a self-reinforcing network effect, but one dependent on customer retention rather than exclusive long-term contracts.
Broader operational metrics provide clearer evidence of customer switching costs. The company reported more than 481,000 active cross-connects at the end of 2024.[^2] Its client base exceeded 10,000 organizations worldwide, including thousands of network operators, cloud platforms, and IT service providers that form the core connectivity ecosystem, making the platform worth joining.1 Recurring revenue accounted for more than 90% of total revenue, while quarterly customer churn remained stable in its historical low-single-digit range.[^2]
Customer churn carries significant analytical weight because it reflects switching costs through observed customer behavior rather than theoretical design. Across more than a decade—encompassing the 2008 financial crisis, the shift toward public cloud computing, and global economic disruptions—tenants maintained their deployments at consistent rates. This sustained retention demonstrates the practical durability of the platform's interconnection moat.
This stability makes the accounting and governance challenges that emerged in 2024 particularly notable, as scrutiny focused not on the underlying physical moat, but on the financial metrics used to describe it.
VIII. Modern Management, The Hindenburg Short Attack & Legal Clearance (2024–2026)
On March 20, 2024, Hindenburg Research published a report titled "Equinix: How Almost $3 Billion In Boosted Maintenance Capex Drives The Real Estate Empire."3 Equinix shares fell sharply following the release, with Bloomberg covering the market reaction the same day.4 Within days, Equinix disclosed that it had received a subpoena from the U.S. Attorney's office and an inquiry from the Securities and Exchange Commission.
Understanding the allegation requires examining the specific financial metric it targeted.
AFFO, and why it is contestable
Real estate investment trusts do not report earnings like standard operating companies. Under GAAP, net income for an entity holding long-lived, depreciating real estate can be misleading because depreciation represents a heavy non-cash charge that rarely reflects the actual cash required to maintain physical properties. Consequently, the industry relies on funds from operations (FFO) and adjusted funds from operations (AFFO)—metrics that add back depreciation and subtract the capital expenditures necessary to maintain existing facilities.
The structural vulnerability lies in that maintenance subtraction. Capital expenditures are divided into two categories: recurring maintenance capex, which reduces AFFO, and expansion or growth capex, which does not. Categorizing expenditures requires managerial discretion. For example, if Equinix replaces a fifteen-year-old industrial chiller with a higher-capacity, more efficient model that supports greater equipment density, determining whether that expenditure constitutes property maintenance or growth capacity involves accounting judgment rather than a rigid legal definition.
Hindenburg's core allegation asserted that Equinix systematically classified maintenance spending as growth capital expenditures, artificially inflating reported AFFO by an estimated $3 billion over roughly a decade. The report emphasized that because executive compensation was linked to AFFO per share, management held a direct financial incentive to favor growth classification. Secondary claims alleged that Equinix oversold available power capacity relative to physical facility limits.
Rather than alleging empty facilities or fictitious tenant demand, the short thesis targeted the primary cash-flow metric used by investors to value the company, focusing specifically on an area governed by management discretion.
What the investigations concluded
Equinix responded through established corporate governance procedures. The board's Audit Committee retained independent legal counsel and accounting advisors to conduct an internal review, announcing on May 8, 2024, that the investigation was complete. The committee concluded that Equinix's financial statements were accurate in all material respects and required no accounting restatements.[^11]
The SEC investigation extended over twenty months. In November 2025, Equinix disclosed that the regulatory agency had closed its inquiry without recommending enforcement action.5
Separately, in August 2025, Equinix agreed to resolve the related shareholder class-action lawsuit through a $41.5 million settlement.6
Weighing it, without taking either side's word
Evaluating the aftermath requires distinguishing between legal clearance and capital-allocation scrutiny.
The official record establishes two clear facts: Equinix issued no financial restatements, and regulatory authorities declined to bring charges following a twenty-month investigation backed by subpoena power. Closing a lengthy accounting investigation without enforcement action indicates that regulatory authorities found no evidence of legal fraud or securities violations.
Conversely, regulatory clearance does not mean Hindenburg's analytical critique regarding capex classification was entirely unfounded. A finding that financial disclosures satisfy legal materiality standards differs from confirming that maintenance spending was categorized under the most conservative accounting convention available. The Audit Committee's determination of material accuracy met legal compliance thresholds rather than establishing an absolute standard for capex categorization. Similarly, the $41.5 million class-action settlement reflected standard litigation risk management rather than an admission of wrongdoing.
The primary operational outcome of the episode was an increase in financial reporting transparency. Subsequent regulatory filings included more explicit definitions distinguishing recurring maintenance capital expenditures from expansion spending, while financial analysts began subjecting capex classification boundaries to greater scrutiny on earnings calls.
For long-term financial analysis, tracking recurring capex as a percentage of revenue over multi-year periods provides an empirical check on capital efficiency. If maintenance expenditures were historically understated, the ongoing capital requirements of aging data center facilities will eventually manifest in higher recurring capex ratios over time.
The people running it now
The short attack unfolded during a planned executive transition.
Charles Meyers served as chief executive from 2018 until early 2024, overseeing revenue growth from approximately $5 billion to over $8 billion while initiating the platform's positioning for artificial intelligence infrastructure demand. In March 2024, immediately preceding the Hindenburg report, Equinix announced that Adaire Fox-Martin would succeed Meyers as President and CEO, with Meyers transitioning to Executive Chair.[^14]
Fox-Martin brought an enterprise software and cloud commercial background rather than traditional real estate or facility management experience. Prior to joining Equinix, she led Google Cloud's global go-to-market organization and served on SAP's executive board overseeing customer success and international sales. Her appointment reflected a strategic emphasis on managing enterprise relationships and navigating competitive dynamics with major cloud providers—entities that serve simultaneously as key ecosystem partners and potential infrastructure rivals.
Meanwhile, Keith Taylor has served as chief financial officer for nearly two decades, maintaining financial leadership across the 2002 restructuring, the REIT conversion, major global acquisitions, and the 2024 short attack. This long tenure provides institutional continuity and consistency in capital reporting, though it also means the CFO who structured the capital classification framework was responsible for defending it during the audit review.
Equinix's management track record reflects operational execution balanced against governance considerations. While the executive team has consistently met multi-year financial targets and focused on defending its core interconnection network, the 2024 accounting challenge highlighted how executive compensation incentives tied to AFFO metrics created potential alignment issues, leading to disclosure enhancements driven primarily by external market scrutiny.
This governance structure forms the operational framework as Equinix undertakes its largest capital deployment cycle to date.
IX. The AI Era Bottleneck & The Hidden Engine: xScale Joint Ventures
The contrast between two tenant profiles illustrates the strategic shift required by artificial intelligence workloads.
The ideal International Business Exchange tenant—such as a European insurer occupying forty cabinets in Frankfurt—draws roughly 200 kilowatts while purchasing thirty cross-connects linking to cloud providers, telecom carriers, market data feeds, and financial counterparties. That customer profile yields high interconnection revenue per kilowatt and exceptionally low churn.
By contrast, an artificial intelligence laboratory training a frontier model requires 150 megawatts—equivalent to the power consumption of 750 such insurers—on a single contiguous campus. High-density server racks drawing 80 to 130 kilowatts each exceed the thermal dissipation limits of traditional air-cooled facilities built in the 2010s, requiring direct-to-chip liquid cooling systems. Furthermore, AI training clusters require minimal interconnection, communicating primarily over internal fabrics and a small number of high-capacity external network pipes.
This divergence creates a fundamental strategic tension: bulk AI capacity generates substantial top-line revenue but yields lower margins per megawatt, minimal interconnection pull, and capital intensity that would strain Equinix's balance sheet. Conversely, the traditional retail colocation model generates high margins and strong retention through interconnection density. Capturing market growth requires serving wholesale AI demand without diluting the returns of the core retail platform.
The structure
Equinix's response to this divergence is xScale—a series of off-balance-sheet joint ventures designed to construct and operate large-scale hyperscale facilities funded primarily by institutional capital.
Under this framework, Equinix typically retains a 20% minority equity stake while contributing land, development expertise, and operational management. Institutional partners—including Singapore's sovereign wealth fund GIC, the Canada Pension Plan Investment Board (CPP Investments), and PGIM Real Estate—provide the remaining 80% of equity capital. In addition to its proportional equity share, Equinix earns recurring asset management, development, and operating fees.
The scale of this strategy expanded significantly in October 2024, when Equinix announced a joint venture with GIC and CPP Investments targeting over $15 billion of investment to expand xScale in the United States — the largest capital commitment in the company's history, structured so that the great majority of the capital sits outside its consolidated balance sheet.[^15]
The case for, and the case against
Proponents of the model argue that xScale allows Equinix to participate in hyperscale AI growth without taking on balance-sheet leverage that could imperil its investment-grade credit rating. By separating retail and wholesale capital structures, the company preserves the high-margin profile of its core IBX platform. Furthermore, management posits an adjacency flywheel: locating xScale campuses near existing IBX facilities provides hyperscale tenants with direct access to retail interconnection density, preserving retail demand.
However, a skeptical analysis highlights three structural counterarguments.
First, off-balance-sheet financing does not eliminate risk. Equinix commits management attention, operational execution, and brand reputation to these projects. Joint ventures with sovereign wealth funds and pension managers introduce governance constraints, explicit hurdle rates, and potential exit timelines that reduce operational flexibility relative to wholly owned assets. Moreover, complex joint-venture structures make financial disclosures harder for public markets to evaluate, often compressing valuation multiples.
Second, wholesale colocation carries structurally lower margin profiles. While management fees enhance return-on-equity metrics, absolute cash-flow generation is smaller than in fully owned assets. If hyperscale deployments account for an increasing share of overall market growth, Equinix risks diluting its consolidated operating margins over time. Maintaining mix discipline between lower-margin wholesale fees and high-margin retail rents presents an ongoing operational challenge as hyperscale demand scales.
Third, the assumed synergy between xScale and retail IBX facilities remains unverified. The assertion that hyperscale deployments drive incremental interconnection revenue into neighboring retail hubs serves as the primary strategic rationale for the dual-track strategy. However, Equinix does not disclose specific interconnection metrics or cross-connect revenue derived from xScale-adjacent capacity, leaving the commercial cross-pull unconfirmed by empirical reporting.
The constraint that binds everything
Underlying both the retail and wholesale models is a fundamental physical constraint that financial engineering cannot resolve: grid capacity.
Equinix's highest-density interconnection hubs sit in metropolitan markets facing severe electrical grid bottlenecks. In Loudoun County, Virginia, transmission constraints forced utility provider Dominion Energy to stage new service connections over multi-year timelines. In Dublin, Ireland, state grid operators implemented a moratorium on new data center connections starting in 2021 that remains largely in effect. Frankfurt has encountered combined grid constraints and municipal zoning restrictions, while Singapore instituted a data center moratorium in 2019, later releasing capacity only under strict environmental and efficiency standards.
These regional grid limitations directly constrain capacity expansion in Equinix's most profitable markets. Where interconnection density and pricing power are highest, utility constraints restrict the pace at which new capacity can be energized, limiting the immediate monetization of demand.
Equinix has mitigated these constraints through long-term power purchase agreements, on-site generation projects—including fuel cell deployments with Bloom Energy—and direct investments in substation and transmission infrastructure. While these initiatives provide incremental power, they do not resolve regional transmission deficits.
Consequently, assessing Equinix's growth trajectory depends less on total demand figures than on contracted power capacity by metropolitan area and the specific timelines required to energize new facilities.
X. Strategic Positioning: Hamilton Helmer's 7 Powers & Porter's 5 Forces
flowchart TD
    subgraph Equinix Ecosystem Moat
        A["Carrier-Neutral IBX Hubs"] --> B["Network & Cloud On-Ramp Density"]
        B --> C["481,000+ Cross-Connects"]
        C --> D["High Switching Costs & Low Churn"]
        D --> E["Pricing Power & Premium Returns on Capital"]
        E --> A
    end
Evaluating Equinix's strategic position requires testing how its structural advantages hold up against operational friction and market shifts, identifying the specific boundaries where each power operates or breaks down.
Helmer's 7 Powers, tested
Network economies represent Equinix's primary power and possess the strongest empirical support. Each additional network operator, cloud provider, or enterprise tenant inside an International Business Exchange (IBX) facility increases the site's value to all other participants, with Equinix capturing that economic surplus through recurring cross-connect fees. The durability of this effect is demonstrated by interconnection volumes that have compounded across successive technology cycles.
The structural limitation of this power is geographic: network effects operate at the metropolitan level rather than globally. Market dominance in Loudoun County does not guarantee advantage in a region where a competitor established initial density. Consequently, Equinix has historically acquired local incumbency in new geographies—such as IXEurope in Europe, TelecityGroup in the UK, Bit-isle in Japan, Entel in South America, and MainOne in West Africa—rather than building it organically. Network economies compound where Equinix holds established density, but cannot be easily transferred across markets.
Switching costs function as a second core power, evidenced by customer retention metrics across economic cycles. Maintaining quarterly customer churn in a narrow band of roughly 2.0% to 2.5% across two decades—through the 2008 financial crisis and the enterprise transition to public cloud infrastructure—demonstrates substantial operational friction in moving existing deployments.
The boundary of this power lies in customer composition. Switching costs are highest for clients with multi-party interconnection topologies and lowest for tenants purchasing basic cabinet space and power capacity. Legacy assets, such as portions of the portfolio acquired from Verizon, skewed toward standard colocation. Consequently, aggregate churn figures obscure an internal variance: clients with dense cross-connect networks remain virtually locked in, whereas pure colocation tenants retain conventional bargaining leverage at contract renewal.
Counter-positioning provided a decisive advantage during Equinix's initial expansion but is now largely spent. Incumbent telecommunications carriers could not build carrier-neutral facilities without undermining their own high-margin transit revenues, leading operators such as AT&T, BT, and Verizon to exit the data center hosting market. That structural transition concluded with Verizon's 2017 asset sale to Equinix. Today, the primary strategic threat stems not from legacy carriers unable to adopt neutrality, but from hyperscale platforms that own both ends of the transmission path and operate outside neutral exchange models.
Cornered resource exists in specific, non-replicable positions—such as the Network Access Point of the Americas in Miami, established carrier hotels, and early Ashburn footprints—where historical aggregation created irreplaceable connectivity hubs. However, Equinix does not hold exclusive control over all key routing assets, sharing market presence in major centers like New York's 60 Hudson Street or London's Telehouse. In the current market, electrical power allocations and municipal zoning approvals in tier-one metropolitan areas function as cornered-resource barriers that protect established incumbents collectively rather than Equinix uniquely.
Scale economies act as a supporting condition rather than a primary moat. While Equinix achieves operational efficiencies in procurement, capital costs, and global administrative overhead, physical real estate capacity can be replicated by competitors backed by abundant institutional capital. Scale supports execution efficiency but does not independently prevent client defection.
Process power and branding play minor roles in competitive differentiation. High operational uptime and facility maintenance represent baseline requirements in enterprise colocation, while corporate clients select data center locations based on counterparty density rather than brand identity.
Porter's Five Forces, weighted
Supplier power: high, and rising. The balance of power has shifted toward utility providers and equipment manufacturers over the past five years. Electric utilities in power-constrained markets—such as Dominion Energy in Virginia and EirGrid in Ireland—allocate electrical capacity on multi-year schedules beyond customer control. Concurrently, global supply chain lead times for high-voltage equipment, including transformers, switchgear, and backup generators, limit the pace of facility commissioning across the industry.
Buyer power: bifurcated. Enterprise customers operating complex cross-connect topologies hold minimal leverage, as the operational risk and capital expense of relocating infrastructure outweigh recurring rental costs. Conversely, hyperscale clients negotiating hundred-megawatt AI deployments exercise significant bargaining power, backed by self-build capabilities, alternative site options, and complete visibility into underlying data center cost structures. As wholesale deployments represent a larger share of growth, weighted-average buyer leverage increases.
Threat of substitutes: low near-term, non-trivial long-term. Physical infrastructure remains necessary due to optical routing constraints and regulatory data sovereignty mandates that prevent sensitive production traffic from operating entirely over public networks. However, peripheral substitution pressures exist through direct hyperscaler-to-hyperscaler private links, software-defined wide area networks over commodity internet, and emerging edge architectures.
Competitive rivalry: moderate in retail, intense in wholesale. Digital Realty represents Equinix's primary global peer, competing directly in European interconnection following its 2020 acquisition of Interxion. Additional regional competition comes from American Tower's CoreSite, Iron Mountain, NTT, and private wholesale operators including Vantage, QTS, and STACK. Rivalry is intense in wholesale colocation, where capacity is commoditized and capital is abundant, but remains subdued in retail interconnection, where established tenant density governs market position. Consequently, Equinix's competitive position is strongest in retail interconnection, where demand growth is slower, and weaker in wholesale capacity, where market demand is expanding fastest.
Threat of new entry: low in interconnection, high in wholesale. Capital alone cannot replicate a mature interconnection ecosystem, as initial tenants require an existing counterparty base to justify deployment. Conversely, barriers to entry in wholesale colocation are low for institutional investors capable of funding greenfield data center developments, leading to significant capital deployment in bulk power capacity.
XI. Playbook: Lessons for Founders & Capital Allocators
Neutrality is a business model, not a virtue. The original 1998 insight was not that carrier favoritism was unfair, but that in a market where participants cannot structurally trust one another, an independent venue can charge rent on that mutual distrust. The corollary is an operational discipline that most companies struggle to maintain: neutrality holds only if an operator refuses adjacent revenue streams. Refusing to sell bandwidth appeared to leave margin on the table for years, yet it was the precise reason competing carriers willingly entered an independent facility. When Equinix later attempted to operate as a direct compute participant through Equinix Metal, the offering struggled. Independence carries an ongoing cost, and sustaining it is the core product.
Cost of capital is a primary weapon in capital-intensive industries. In an industry where competitive advantage hinges on funding physical expansion at the lowest cost, financial structure is not merely a corporate finance function—it is core strategy. The 2015 REIT conversion altered no physical operations, yet it expanded Equinix's competitive positioning more than any single acquisition. A complete analysis, however, acknowledges the execution risks: the transition spanned four years, required an unprecedented IRS private letter ruling, and spent nearly two years in regulatory suspension. Capital advantages of this scale are accessible only to management teams willing to commit publicly to a restructuring with an uncertain regulatory outcome.
Partner capital belongs in the capital-intensive layer. The xScale joint venture framework—combining minority equity stakes, majority institutional funding, and recurring management fee streams—allows Equinix to participate in wholesale artificial intelligence infrastructure growth without overleveraging its balance sheet. The generalizable strategic principle is to deploy third-party capital for commoditized, capital-intensive infrastructure while retaining full ownership of scarce, high-margin interconnection assets. The strategic caveat remains its unproven commercial linkage: Equinix's core thesis that wholesale capacity drives incremental retail interconnection has not been confirmed through detailed segment disclosures, and off-balance-sheet joint ventures historically introduce financial opacity.
When a short attack targets a metric, the metric itself is the vulnerability. The 2024 Hindenburg Research report did not allege fictitious tenant demand; it targeted a discretionary accounting boundary managed by executives whose compensation depended on the outcome. The central governance lesson extends beyond crisis management—where Equinix mounted a thorough internal review and ultimately secured regulatory clearance. Rather, compensating executive leadership on a non-GAAP metric defined through internal discretion creates an inherent governance vulnerability. The remedy requires explicitly defining capital expenditure boundaries and disclosing them before external short sellers force the issue.
Acquire established incumbency rather than attempting to replicate it. Equinix's most successful acquisitions—such as IXEurope, Switch & Data, and TelecityGroup—secured established market positions where multi-party network ecosystems had already matured. Conversely, internal efforts to build adjacent software capabilities organically faced significant execution hurdles. Where network density governs market dynamics, capital buys time, and time remains the rarest input.
XII. Bear vs. Bull Case: Investor Stress Test
Why this wins from here
The mix argument. If interconnection revenue continues to grow faster than colocation, Equinix generates more cash per dollar of capital deployed, expanding operating margins without requiring structural business changes. This dynamic represents the highest-margin growth trajectory available to the company.
The analytical test this claim must clear: it is a rate-of-change argument rather than a static volume metric, and it carries structural limits. Equinix Fabric provisions software-defined virtual connections that clients can turn up or down dynamically—creating a revenue stream that is highly elastic in both directions, unlike a physical cross-connect cable that remains deployed until physically disconnected. If virtual connections displace physical cross-connects faster than overall interconnection demand expands, the mix thesis weakens even as absolute connection counts rise. Tracking cross-connect volume and interconnection revenue side by side reveals whether pricing power is holding or being eroded by competition.
The hybrid architecture argument. The early industry consensus that enterprise workloads would migrate entirely to public clouds and render colocation obsolete was disproved by observed corporate deployment patterns. Enterprises adopted hybrid and multi-cloud architectures to address cost constraints, latency requirements, regulatory compliance, and vendor lock-in risks—a topology that requires neutral exchange points to terminate connections. Private enterprise artificial intelligence deployments—where organizations run inference models on proprietary data within controlled environments—follow a similar architectural logic. Sustained low customer churn throughout the cloud expansion period provides empirical evidence for this retention dynamic.
The analytical limit: enterprise private AI deployments currently represent forward-looking projections rather than documented revenue streams. Equinix does not break out revenue attributable directly to AI deployments, and enterprise-scale inference may land inside public hyperscaler environments instead. Analysts view this capability as structural optionality with an unproven conversion rate, drawing parallels to the Packet acquisition when assessing how effectively the company monetizes adjacent market shifts.
The xScale argument. As detailed in the joint-venture strategy, xScale offers asset-light participation in hyperscale infrastructure growth. While structurally sound for balance-sheet management, the underlying premise—that wholesale capacity drives incremental retail interconnection revenue—remains unconfirmed by segment reporting.
What breaks it
Power availability. Electrical capacity represents the primary operational risk facing the company. Unlike financial or market risks that unfold across degrees, grid constraints operate as binary barriers by metropolitan area. If Equinix cannot energize additional capacity in core hubs such as Ashburn, Frankfurt, Dublin, Tokyo, or Singapore, market demand in those locations becomes unaddressable. Because these key markets contain the company's highest interconnection density, constrained growth forces expansion into secondary markets with lower counterparty density and conventional colocation dynamics—effectively shifting the business toward lower-margin operations. Monitoring contracted-and-energized megawatt capacity by metropolitan area provides the empirical test for growth potential.
Capital expenditure escalation on legacy assets. Data center facilities built between 2000 and 2010 were designed for power densities of 3 to 5 kilowatts per cabinet. Supporting modern workloads drawing 40 to 100 kilowatts per cabinet requires retrofitting power distribution systems, implementing liquid cooling infrastructure, and undertaking structural upgrades. This capital outlay remains mandatory regardless of whether accounting rules categorize the spending as growth capital or maintenance capex. Following the 2024 short seller report, capital classification has drawn heightened market scrutiny. If maintenance requirements increase materially as facilities age, growth in adjusted funds from operations (AFFO) will compress even if revenue remains stable.
Cost of capital. Operating as a REIT that distributes the majority of its taxable income obligates Equinix to fund ongoing expansion through external debt and equity markets. This structure exposes the business to interest rate sensitivity on two fronts: debt refinancing costs and the discount rates applied to long-duration real estate cash flows. While an investment-grade credit rating and laddered debt maturities mitigate immediate refinancing pressure, a sustained high-rate environment increases development borrowing costs while compressing asset valuation multiples.
Hyperscaler disintermediation. Major public cloud providers are expanding proprietary global fiber networks, subsea cables, and direct inter-region connections. As a larger share of global data traffic moves directly between cloud facilities over private backbones, the necessity of routing through neutral third-party exchange venues diminishes. While enterprise network termination requirements preserve baseline demand in the near term, the long-term migration of high-volume traffic flows around neutral hubs represents a gradual structural threat to interconnection growth.
Governance and capital allocation scrutiny. Skeptical institutional analysis centers on four operational questions: whether off-balance-sheet joint ventures obscure total leverage and capital returns; whether executive compensation metrics tied to AFFO were fundamentally restructured or merely disclosed with greater detail after 2024; whether legacy enterprise assets acquired from Verizon and other operators earn their standalone cost of capital or rely on cross-subsidization from core interconnection hubs; and whether multi-year revenue and expansion targets established at the 2023 investor day are being achieved transparently or revised over time.[^16] Evaluating management performance against successive investor day commitments provides a clear benchmark for corporate execution.
The three things that actually matter
Evaluating Equinix's long-term trajectory requires focusing on three primary operational metrics rather than headline financial disclosures.
First: cross-connect volume and interconnection revenue, evaluated together. This combined metric measures the durability of the company's network moat. Connection growth alone can mask unit price declines, while revenue growth alone can reflect temporary price increases offsetting volume stagnation. Tracking both figures side by side indicates whether the core interconnection flywheel is expanding or facing competitive compression. If cross-connect volume growth decelerates while colocation capacity expands, the business model transitions toward standard commercial real estate.
Second: contracted and energized power capacity by metropolitan market. Grid availability represents the physical constraint governing growth. Customer commitments cannot be monetized without energized capacity, and power allocations in primary interconnection hubs carry significantly higher commercial value than equivalent capacity in secondary markets. Power energization timelines establish the true boundary for revenue expansion.
Third: recurring maintenance capital expenditure as a percentage of revenue over multi-year periods. This ratio provides an empirical check on asset quality and maintenance classification. As older facilities require retrofits for high-density cooling and power distribution, the true cost of maintaining long-lived infrastructure manifests in multi-year capital expenditure trends regardless of single-year accounting categorizations. Sustained multi-year trends reveal the underlying capital intensity of the physical platform.
Nearly three decades after its founders established carrier-neutral colocation around a core thesis of counterparty trust, Equinix maintains an established position within its core physical exchange hubs. The long-term investment thesis depends on whether future internet traffic flows continue to aggregate inside neutral multi-tenant facilities or increasingly bypass them over dedicated private networks.
XIII. Source Leads & Earnings Call Roadmap for Writers
For analysts and writers evaluating Equinix, primary-source documents provide essential clarity on the company's financial and operational trajectory.
Start with the 2024 Form 10-K, filed February 12, 2025.1 Item 1 details the platform footprint, customer counts, and cross-connect metrics management emphasizes. Item 7 provides segment revenue breakdowns alongside materially expanded disclosures on capital expenditure categorization—offering a direct baseline to evaluate how financial reporting evolved following short-seller scrutiny. Additionally, the risk factor disclosures regarding electrical power availability and regional grid constraints offer a more unvarnished perspective than typical earnings call commentary.
The first-quarter 2024 earnings call, held May 8, 2024, stands out as a critical operational marker, as it coincided with the conclusion of the Audit Committee's internal investigation.[^11] Examining both the prepared remarks and the Q&A session highlights the distinction between management's formal assertions and the specific accounting questions raised by analysts.
The fourth-quarter and full-year 2024 call, February 2025, marked the first full-year report under CEO Adaire Fox-Martin, establishing her strategic vision for artificial intelligence infrastructure and the xScale joint venture model.[^2] Comparing her positioning of wholesale capacity and interconnection against Charles Meyers's earlier framing from 2022 and 2023 provides an empirical test of whether Equinix is maintaining its historical retail-first focus.
The 2023 Analyst and Investor Day established the multi-year financial framework against which current operational performance can be measured.[^16] Comparing long-term targets established at that event against actual disclosures offers a direct benchmark of management's execution credibility.
The Hindenburg report itself merits direct review.3 While short-seller reports function as adversarial documents, the core argument regarding capital expenditure classification raises substantive analytical questions regarding accounting boundaries, independent of regulatory findings.
Three recurring friction points in quarterly earnings calls provide ongoing indicators of operational performance: the consistency of management's definitions separating maintenance from growth capex; power energization timelines in Ashburn and constrained European metropolitan markets; and the comparative return on capital achieved through off-balance-sheet xScale joint ventures versus fully owned IBX developments—a metric management discusses qualitatively but has not fully unbundled in financial disclosures.
References
-
Equinix, Inc. Form 10-K Annual Report for FY2024 — SEC EDGAR, 2025-02-12 ↩↩↩↩
-
Equinix Initial Public Offering Prospectus (Form S-1/A) — SEC EDGAR, 2000-08-10 ↩
-
Equinix: How Almost $3 Billion In Boosted Maintenance Capex Drives The Real Estate Empire — Hindenburg Research, 2024-03-20 ↩↩
-
Short Seller Hindenburg Takes Aim at Data Center REIT Equinix — Bloomberg, 2024-03-20 ↩
-
Equinix Says SEC Ended Investigation Into Accounting Practices — Reuters, 2025-11-06 ↩
-
Equinix Agrees to $41.5 Million Settlement Over Executive Bonus Expense Allegations — Hall Benefits Law, 2025-08-15 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube