As trading fees hit zero, who actually gets paid to manage your money?
Wealth platforms turn household savings into investment accounts, advised portfolios or private-bank relationships. They include the apps and advisers that customers see, as well as the custodians, clearing firms, software and cash systems that maintain records and move money. The industry grew from four once-separate businesses: discount brokerage, low-cost funds, regulated custody and human financial advice. Mobile technology, bank deposits and data later connected them.
The subject matters because trading commissions have fallen to zero in much of the world, while large firms have bought adjacent layers of the system. Revenue now rarely comes directly from a trade. It comes from holding the account, earning interest on idle cash, maintaining tax and compliance records, distributing products and delivering advice more efficiently. Zero commissions did not eliminate the toll; they shifted more of it away from the trade ticket.
The rulebook, the broker and the expensive phone call
Washington, 1940
The story begins with a legal distinction rather than a product. By 1940, America had endured a market crash, a depression and a decade of disclosures about the treatment of ordinary savers by investment trusts and securities salesmen. Congress that year passed the Investment Advisers Act. It defined a person paid to advise others about securities and subjected that person to federal registration, disclosure and conduct rules.1
The law separated two similar-sounding jobs with different payment models. A broker executes a customer's instruction to buy or sell and was traditionally paid for each transaction. An investment adviser is paid to provide advice, usually through a fee, and owes the client duties associated with that relationship. Many firms have long performed both roles, leaving the distinction relevant to pricing, disclosure and liability. The Advisers Act did not create financial advice; it gave the activity a legal identity that could support a scalable business.
A third function sits beneath the adviser and is less visible to the public: custody. If an adviser designs a family's finances, the custodian combines elements of a land registry, bank vault and back office. It holds securities, records ownership, collects dividends, processes corporate actions and produces tax statements. The analogy has limits. Unlike a land registry, a custodian may move cash, extend credit and increasingly provide the software advisers use. That wider role becomes important later in the story.
The price of a phone call
For most of the twentieth century, buying a stock meant calling a broker and paying a commission set under an exchange's fixed schedule. The price was not closely tied to the work involved in the trade or the size of the customer. Execution was an expensive retail service, and full-service brokers bundled research, advice and a personal relationship into that fee.
That arrangement ended on May 1, 1975—“May Day” in industry shorthand—when fixed commissions were abolished and brokers began competing on price. SEC Commissioner A. A. Sommer Jr. spoke weeks later about what the change could mean for investors and the industry's structure.2 It quickly separated the act of making a trade from paying for a relationship. Institutions negotiated lower commissions almost immediately. Retail investors took longer to benefit, creating an opening for a particular kind of entrepreneur.
Chuck Schwab's wager
Charles “Chuck” Schwab founded his San Francisco firm in 1971 and shifted it toward discount brokerage in 1974, shortly before May Day, according to the company's biography of him.3 His premise ran against the industry's conventional model: cheaper trading could bring more people into investing, allowing a low-cost firm with a trusted brand to serve them profitably. He removed the stock-picking salesperson from the offer and sold execution and access.
The Charles Schwab Corporation $SCHW later became more than a discount broker, adding a bank, retail advice business and a large custody platform for American independent advisers. In the 1970s, however, it was an insurgent offering the established product at a lower price.
Jack Bogle's different wager
At the same time in Pennsylvania, John “Jack” Bogle was building a firm around a different low-cost proposition. Vanguard began operations on May 1, 1975, the day fixed commissions ended, with an unusual structure: the company is owned by its funds, which are owned by their investors, leaving no outside shareholders to pay.4 Schwab sought to reduce the cost of trading; Bogle sought to reduce the cost of owning investments.
The dates can be confusing. Vanguard was incorporated in 1974, began operations in 1975 and launched its first index fund in 1976. Each marks a different beginning. The next chapter starts with the last.
A question left open
May Day clearly reduced the stated price of a trade. But deregulation also left room for revenue not shown on a commission schedule: bid-ask spreads, sales loads on funds, the interest a firm retains on uninvested customer cash and, later, payments from market makers for order routing. Whether investors' total costs fell—and by how much—depends on including all of them.
The sibling story on financial brokers covers the economics of execution. Its relevance here is straightforward: as commissions collapsed, firms holding customer money needed other sources of revenue. Custody and advice were obvious candidates, though regulation limited their margins. They became durable businesses when account records, tax history, portfolio tools and customer trust accumulated in one place, making a move more consequential than changing a trading app. That bundle took decades to form. Its first component was a fund that initially attracted little demand.
 Subscribe on LinkedIn
Bogle's folly meets the personal computer
August 31, 1976
Bogle's First Index Investment Trust opened on August 31, 1976, raising about $11 million against underwriters' hopes of as much as $150 million.5 Critics called it “Bogle's Folly.” A fund designed to match the market rather than beat it looked, to many investors, like an admission of defeat.
An index fund is built to track a market rather than select individual winners—more like a supermarket basket than a chef's tasting menu. The analogy has limits: funds follow different rules, trade when an index changes and can produce different tax consequences. Two funds tracking “the market” can therefore deliver noticeably different results.
The launch showed that a cheap, sound proposition did not create demand by itself. Indexing took years of distribution, disappointing active-manager performance and a gradual change in advisers' views before it became a default option. Its eventual adoption changed the economics around it.
Why a cheap product changed the platforms
A low-cost, diversified portfolio available off the shelf made investment selection less central to the customer relationship. The harder tasks were opening an account, maintaining contributions, staying invested during downturns, handling taxes and planning for retirement. As fund fees fell, more of the economics shifted to customer acquisition, account administration, cash balances, distribution and advice.
A dentist and a modem
The other part of the shift came through personal computing. In 1982, physicist and inventor William Porter and Bernard Newcomb founded TradePlus, which became ETRADE. Their aim was to let individuals trade from a personal computer. ETRADE's company history dates an early online trade placed through its technology to July 11, 1983.6 An SEC staff report in 1997 described retail broker-dealers' use of proprietary software and dial-up order entry during the 1980s, with the internet accelerating that change.7
The full-service brokerage model was beginning to separate into its components. Customers who could see a quote and place an order without a phone call no longer needed a broker for execution alone. E*TRADE went public in August 1996 as web investing reached a wider audience.6 Regulators also adapted: from 1995, SEC guidance permitted electronic delivery of prospectuses, statements and other required documents, reducing a paper constraint on online accounts.8
Joining the product to the account
In January 1993, State Street's asset-management arm launched the SPDR S&P 500 ETF Trust, SPY, the first US-listed exchange-traded fund.9 An ETF is a fund whose shares trade on an exchange during the day like a stock. For wealth platforms, its importance was where it sat: a diversified portfolio could now be held in an ordinary brokerage account and bought through a ticker symbol. Bogle's product and Porter's access model had converged.
State Street $STT enters here as SPY's parent. Its current role in the wealth-platform chain rests primarily on its large custody and servicing business, rather than on the ETF.
Index funds, ETFs and employer retirement plans gave advisers—and later robo-advisers—a common set of building blocks. That simplified the investment product while increasing the importance of selecting and monitoring funds, and administering the accounts that held them. In India, comparable mutual-fund recordkeeping later became the business of specialist registrars, Computer Age Management Services $CAMS.NS and KFin Technologies $KFINTECH, which return later in the story.
Did the screen replace the adviser?
The popular prediction in the 1990s was that the web would make advisers obsolete. It made execution easier and information cheaper, but it did not answer the questions many households faced: how much to save, how to draw down a pension, which accounts to use for tax, how to handle insurance and an estate, or how to avoid selling in a panic. Demand for those answers remained; it needed a model suited to the new system.
Two decades later, Morgan Stanley bought E*TRADE, bringing a self-directed channel into an adviser-led firm as the two customer journeys converged. Before that, the industry had to develop the infrastructure that allowed advisers to operate without a wirehouse behind them.
The invisible market built for advisers
An adviser at the door
Consider an adviser leaving a large brokerage firm to start an independent practice. Clients may trust the adviser more than the firm’s letterhead. Yet the new business still needs securities custody, trade settlement, dividend and corporate-action processing, tax reporting, compliance systems and banking for client cash. A small practice cannot build that infrastructure itself. The client sees the adviser; the adviser relies on a custodian.
This is the third thread: independent advice. A registered investment adviser, or RIA, is a firm registered with the SEC or a state to provide advice for a fee. The model lets advisers own the client relationship while using shared infrastructure.
Clearing and custody, in plain words
When a trade occurs, clearing confirms what each side owes and ensures that securities and cash change hands. Custody then maintains the ownership record and handles what follows: income, stock splits, mergers and statements. It is a little like a port that also keeps title records for every container passing through it. The comparison breaks down because financial assets are not physical. They can be lent to short sellers, pledged as loan collateral and moved electronically within seconds. Those activities create revenue opportunities as well as risk.
Three rails
In the United States, three large firms became important infrastructure providers for independent advisers. Schwab built an institutional business alongside its retail brokerage. Fidelity, a private company, built one on its fund, workplace-retirement and clearing operations. Its institutional arm offers custody, clearing and brokerage to registered investment advisers, broker-dealers and family offices, and says it supports more than 3,300 firms.10 Pershing, part of BNY Mellon $BK, emerged from institutional clearing and serves both broker-dealers and advisers. BNY reports group-wide figures spanning custody, asset servicing and markets well beyond Pershing, so its consolidated results do not describe the economics of an adviser platform alone.
All three had substantial operating businesses before independent advice expanded. That mattered because custody favours scale: technology, compliance and operations carry high fixed costs, while each additional account costs relatively little to support.
Scale, and what scale means
SEC statistics illustrate the size of the wider advised-asset base. In 2025, 22,932 registered advisers reported about $177 trillion in regulatory assets under management, increases of 4.2% in adviser numbers and 21% in assets from a year earlier.11 The figure needs qualification. Regulatory assets under management, or RAUM, is reported on Form ADV. It includes large institutional and fund-management mandates, and some assets may be counted more than once. It is neither a measure of retail wealth nor the revenue base of a single platform.
The same caution applies to the asset measures common in industry disclosures. Assets under custody describe what a firm holds; assets under administration describe what it records; assets under management describe what it has authority to invest. They overlap, but are not interchangeable, and revenue per dollar can vary sharply across them.
The control panels on top
Custody provided the vault, but not the tools for an adviser’s working day. A small practice still needed portfolio accounting, performance reports, financial plans, model portfolios, rebalancing and compliance records without building its own technology department. Software providers filled that gap.
Envestnet became a portfolio-and-data link among advisers, asset managers and custodians. SS&C Technologies $SSNC acquired Advent and Black Diamond, products used by many RIAs for portfolio management and reporting. Orion Advisor Solutions developed a competing independent suite. Morningstar $MORN, through Morningstar Wealth, provides model portfolios and adviser tools alongside its larger data business. Addepar offers consolidated reporting to family offices and advisers serving wealthy clients. SEI Investments $SEIC supplies adviser processing and technology alongside other businesses. Broadridge $BR provides investor communications and back-office technology, while FactSet $FDS supplies data to many of these firms, making it an enabler rather than a platform. For the diversified companies, filings generally do not isolate wealth-platform revenue. SEI discloses an advisor segment, and Morningstar reports Morningstar Wealth separately; most others do not.
Private equity provided one indication of the value of such embedded systems. In November 2024, Bain Capital completed its acquisition of Envestnet for about $4.5 billion. The company said its platforms served roughly $6.5 trillion in assets.12 That “platform assets” measure covers assets touched by Envestnet’s software and data. It cannot be compared directly with a custodian’s holdings or an asset manager’s AUM, since the same assets can appear on several platforms. The deal nonetheless reflected switching costs: replacing a system that supports an adviser’s reporting, billing and models is a disruptive operational project.
The same idea in other countries
Other countries developed comparable systems shaped by local pension and tax rules. In the UK, Transact, owned by IntegraFin, and AJ Bell became administration platforms for advisers and investors holding pensions and tax-advantaged accounts. In Australia, superannuation and adviser rules supported HUB24, Netwealth, Praemium and AMP's North platform, while Iress and Bravura supplied much of the software. In India, CAMS and KFin maintain mutual-fund registers for fund houses. Each is local infrastructure rather than a replica of the American model.
How strong is the lock?
Custody can appear close to a monopoly because assets tend to remain where they are held. The record is more qualified. Changing custodians is difficult: every account requires new paperwork, clients need a reason to sign, tax lots must transfer accurately, and errors can damage an adviser’s reputation. But assets do move. Service failures, better technology, a merger that requires a platform change, or an adviser network changing its default custodian can all prompt transfers. The advantage is friction, not permanence.
Custody and workflow software allowed advisers with sufficient clients to operate independently. They did not address the larger problem that many households lacked enough money to attract an adviser. After 2008, a group of engineers set out to automate that.
The robot promise, and the limits of a cheap algorithm
After the crash
The 2008 financial crisis exposed the cost of opaque and conflicted financial products. In the same period, founders in New York and Silicon Valley saw an opening to make diversified investing more automatic and less expensive. Jon Stein and Eli Broverman started Betterment in 2008.13 Wealthfront, founded by Andy Rachleff and Dan Carroll, emerged from the same post-crisis period and eventually became a public company.14
A robo-adviser uses rules and software to select an investment mix from a questionnaire, keep it on target and, in some cases, harvest tax losses by selling losing investments to offset gains. Automatic rebalancing resembles an autopilot: it keeps a portfolio on its chosen course through market turbulence. But an autopilot does not choose the destination. It cannot judge whether a family can tolerate a 30% fall, whether a divorce changes its tax position or whether a business sale requires a different plan. It can act only on the information it receives.
The promise and the arithmetic
The original promise was disciplined portfolio management for people below a traditional adviser’s minimum, at a fraction of the fee. The service proposition held. The economics proved harder. An automated portfolio built from index funds is easy to replicate, while a fee of a few tenths of a percent requires very large balances to cover marketing, engineering and compliance.
Wealthfront’s figures illustrate the constraint. In its fiscal year to January 2026, it reported $364 million in revenue, up 18.2%, on $48.7 billion of managed assets. About a quarter of revenue—roughly $92 million—came from investment-advisory fees; most of the rest came from interest on customer cash. Advisory revenue per funded account was about $54 for the year. The company recorded a net loss, while June-quarter revenue was unchanged from a year earlier.15 One flat quarter does not settle the model’s prospects, but the mix shows how heavily its economics depended on deposits rather than portfolio-management fees.
The robots grow up
Surviving robo-advisers broadened their offers. Betterment now describes its business as automated investing, cash and savings accounts, retirement accounts, employer 401(k) services and a custody-inclusive platform for independent advisers.13 Each addition can increase customer balances or create another source of payment. The expansion suggests that a standalone robo-adviser was not a complete business model.
The strongest competition came from product manufacturers. Vanguard added Digital Advisor, a low-cost automated service, and Personal Advisor, which combines software with human planners. That turned Bogle’s low-cost-fund model into an advice offering and narrowed the independent robos’ price advantage. Under chief executive Salim Ramji, Vanguard then moved into custody for advisers, a development that returns later in the story.16
What survived
The early-2010s prediction that robots would replace advisers did not materialise. A narrower claim did: automation made portfolio management cheaper and extended parts of advice to more customers. Rebalancing, tax-loss harvesting and model portfolios are now common in adviser platforms, bank apps and brokerages. Whether a consumer robo-adviser can become a large, profitable standalone business remains unproven; the only listed pure play recorded a loss as quarterly revenue remained flat.
Empor’s data cannot yet show whether growth in consumer-investing apps feeds robo-adviser revenue. The history is too short to support a causal claim.
One founder drew a different lesson from the robo years. Jason Wenk founded Altruist to build a modern custodian and workflow platform for advisers, using automation to reduce back-office costs rather than replace the adviser.16 On the consumer side, meanwhile, a smartphone app was about to make “free” the stated price of a trade.
The day "free trading" became everybody's price
October 2019
On October 1, 2019, Charles Schwab announced that it would cut commissions on online US stock, ETF and options trades from $4.95 to zero, effective October 7, linking the announcement to its founder's new book.17 Other large discount brokers matched within days. The price Chuck Schwab had spent 45 years pushing down had effectively disappeared.
Schwab was not alone in setting the new price. On September 26, Interactive Brokers launched IBKR Lite, a commission-free US stock and ETF service for retail customers.18 A younger firm, however, had already made zero commissions seem normal.
Robinhood's front door
Vladimir Tenev and Baiju Bhatt, physics students who met at Stanford before building trading software, founded Robinhood Markets $HOOD in 2013.19 They were neither the first discount brokers nor the first to offer free trades. Their app was designed as a consumer product, with rapid sign-up, fractional shares, no account minimums and no commissions. For many younger investors, it became a first brokerage account.
The obvious question was who paid when customers did not. Robinhood's 2021 IPO prospectus said that most revenue was transaction-based, chiefly payment for order flow, supplemented by net interest on margin loans and customer cash, and fees for a subscription tier.19
Payment for order flow occurs when a market maker—an institution that stands ready to buy and sell securities—pays a broker to execute its customers' orders. Retail orders can be valuable because they are small and generally less informed about short-term price movements. The arrangement resembles a supermarket accepting supplier payments for shelf space, but the comparison has an important limit: brokers must seek best execution, and routing can affect the price a customer receives.
When "free" was tested
That limit was tested in December 2020. The SEC found that Robinhood had made misleading statements and omissions about its payment-for-order-flow revenue and had failed to meet its best-execution duty. For part of the period examined, the regulator found, customers received worse prices than they would have at other brokers, costing them more than the commissions they had saved. Robinhood agreed to pay $65 million to settle without admitting or denying the findings.20
The case is strong evidence that zero commissions did not necessarily mean zero cost. It does not show that every commission-free broker provided inferior execution: the SEC's findings concerned one firm and one period. But it showed why customers must examine the revenue source and its associated conflicts when an explicit price disappears.
The SEC had also raised the standard for broker-dealer recommendations. In June 2019, it adopted Regulation Best Interest and Form CRS, requiring plain-language disclosure of relationships and conflicts.21 FINRA, the broker-dealer self-regulator, now describes commission-free trading as a standard feature of the retail market.22
The incumbents answer
Older firms responded with more than price cuts. Schwab went to zero, then added scale by completing its acquisition of TD Ameritrade on October 6, 2020. The deal added millions of retail accounts and a large independent-adviser custody business.23 Interactive Brokers $IBKR, founded by Thomas Peterffy, a Hungarian-born programmer and early trading-automation pioneer, retained its focus on low-cost global brokerage while also providing account infrastructure and adviser custody. Its retail brokerage chiefly belongs in the sibling broker story; its account, custody and adviser operations belong here.
Morgan Stanley $MS made the clearest strategic move. In February 2020, it agreed to buy ETRADE for about $13 billion, saying the combination would unite its adviser-led wealth business with ETRADE's self-directed accounts, digital banking and employer stock-plan administration.24 The deal reflected a practical assumption: a self-directed investor could later become an advised client.
What comes after free?
Other firms offered distinct front doors. eToro built social trading, allowing customers to copy other investors. Webull focused on active-trading tools. Public.com positioned itself against payment for order flow. M1 Finance offered customer-designed “pies” that the platform rebalanced, while Acorns invested spare change from card purchases. Whether these services become wealth managers depends on customers bringing in and retaining meaningful balances—an outcome most disclosures do not yet establish.
The COVID-era trading boom in 2020 and 2021 showed both the appeal and the limits of such front doors. Millions of accounts opened in months, but many were small and traded frequently. Activity later declined as markets cooled.
Did zero destroy the profit?
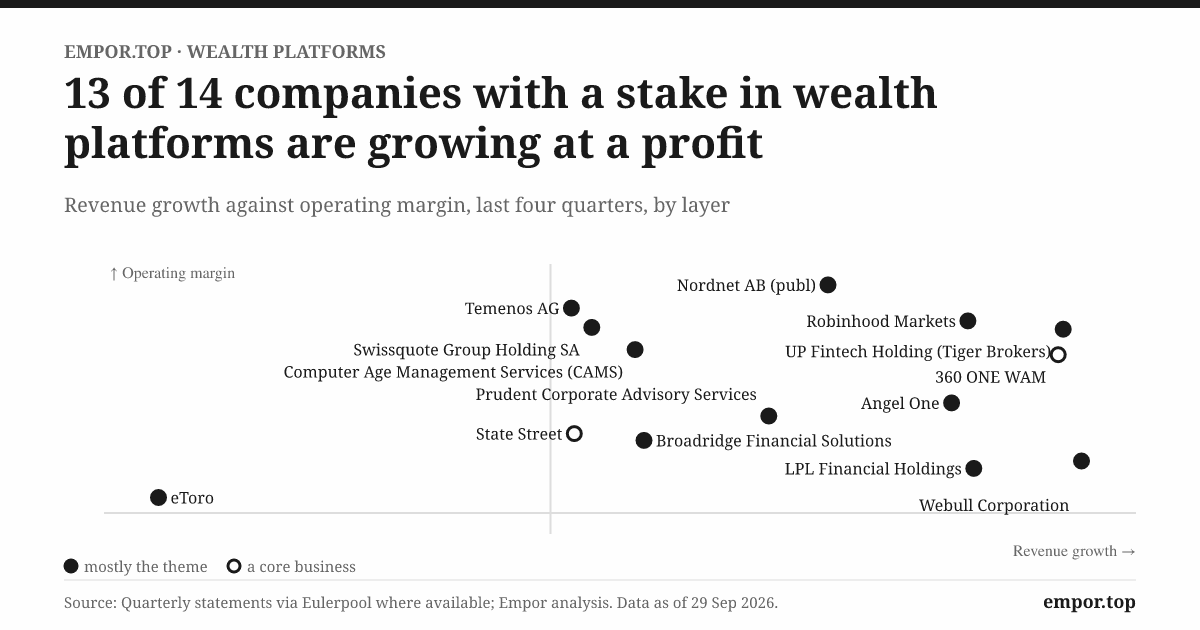
Zero commissions eliminated a visible revenue line, not industry profit. In Empor's data, Robinhood reported 2025 revenue of $4.5 billion, up 51.6%, and a 42.1% net margin. Interactive Brokers reported an 86% operating margin, reflecting automation as well as substantial interest income from customer balances and margin lending.15 Revenue shifted toward cash balances, credit, securities lending, market data, order routing, subscriptions and advice. The balance varies by firm.
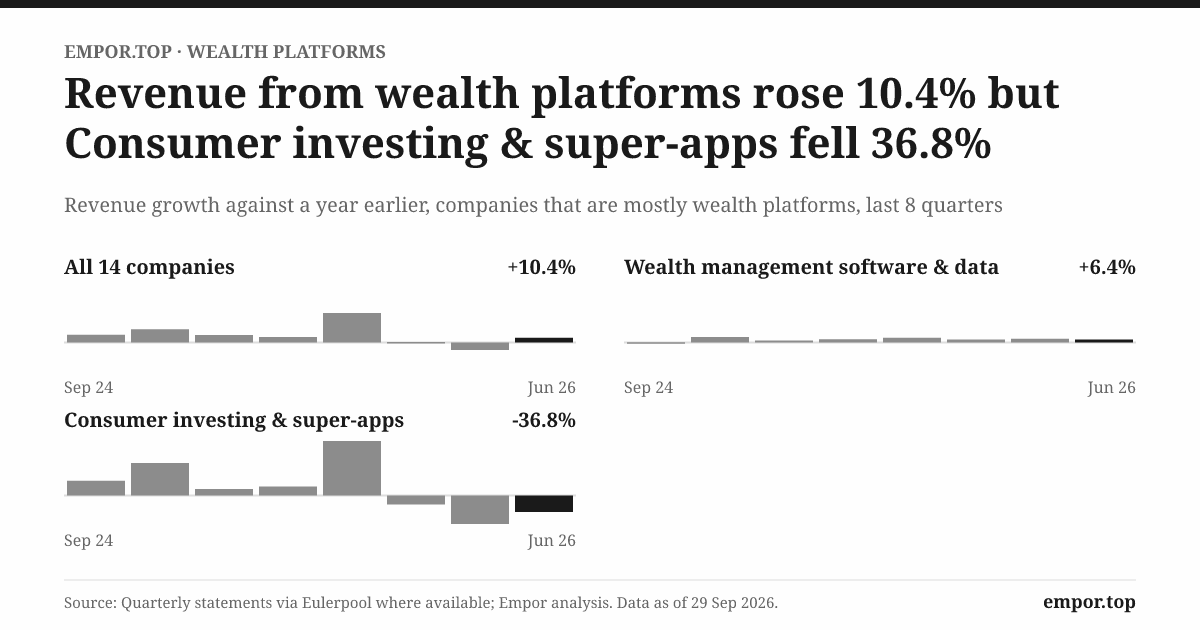
The consumer layer's headline figures require particular caution. Combined revenue for consumer-investing companies in Empor's data grew 120.9% in the June 2026 quarter, while their combined operating margin fell 20.7 percentage points. Accounting changes at a few firms—particularly a Korean broker whose reported revenue increased several-fold—materially affected those figures, alongside trading activity and interest rates. They do not show that every app is accumulating durable wealth.15 If a free trade is only an invitation, the next question is what customers are being invited into.
The account becomes a bank, an adviser and a factory for fees
One account, many years
A new investor may open an account to buy a single stock. Years later, that account may receive a salary, hold a Treasury fund or retirement savings, sit beside a mortgage, run a managed portfolio, refer its owner to an adviser and offer private-market funds. Each service creates a potential revenue source, often without a visible charge to the customer. The trade was the invitation; the primary account a household uses is the prize.
Following the money through the chain
The chain starts with the household. Income, pension contributions and investment returns create money to invest. An app, direct bank, adviser, employer plan or private bank wins the first account, gaining the relationship and an opportunity to market additional services.
Behind the brand, a custodian and clearing provider holds assets, settles trades and maintains tax records. Sometimes it is the same firm: Schwab and Fidelity operate retail brands while providing custody to other businesses. Sometimes it is an unseen supplier. Pershing, Apex Fintech Solutions and DriveWealth sell clearing and custody to other brands, and many consumer apps use their infrastructure.
Idle cash often enters a cash sweep, which automatically moves it into a bank deposit or money-market fund. It resembles an automatic car park for cash, though the analogy has limits: the platform, customer and partner bank may share the return, with the platform setting the split. If a platform pays little on swept cash while earning a market rate, the difference becomes profit. If customers move into higher-yielding products—a process known as cash sorting—that profit narrows.
Software then turns account records into plans, performance reports and model portfolios. Asset managers, lenders, insurers and private-fund sponsors may pay for distribution or earn fees on products sold through the platform.
The resulting revenue can include asset-based advice and management fees, administration charges, software subscriptions, interest spread on cash, portfolio lending, securities lending, distribution fees and, where permitted, payment for order flow. Bargaining power is greatest when a firm controls both the account record and the customer relationship. The asset manager whose fund occupies a platform shelf has less leverage.
Different firms, different combinations
The combinations vary. Schwab combines custody, retail brokerage and banking. Its 2025 revenue was $27.7 billion, with a 41.4% operating margin. Revenue grew 25% in the June 2026 quarter as client assets and interest income rose together.15 The company discloses client assets and fee-based advisory assets, but not a separate profit figure for independent-adviser custody. Its contribution to group margin therefore cannot be measured.
In Britain, AJ Bell runs a platform for advisers and direct investors. It reported an operating margin above 40% and about £122 billion of platform assets in June 2026. In Australia, HUB24 reported A$152 billion of platform funds under administration for its 2026 financial year, compared with Netwealth's A$136 billion.15 HUB24 was modestly ahead on assets, while Netwealth led on margin, leaving leadership among Australian adviser platforms open to interpretation.
In Sweden, Avanza Bank $AZA.ST and Nordnet $SAVE.ST combine investing with savings accounts, pensions and lending. Both reported operating margins in the mid-fifties. Swissquote combines similar services in Switzerland with foreign exchange, crypto and mortgages.15 These are digital banks centred on investing, and their earnings depend at least as much on interest rates as on stock markets.
At the upper end, Morgan Stanley, UBS $UBSG.SW through its global wealth business, and Bank of America's $BAC Merrill use self-directed, workplace and affluent relationships to offer advice and private banking. Wells Fargo $WFC also operates a large wealth business. All four are diversified banks, so group revenue and profit also include lending, trading and investment banking and cannot be treated as pure wealth-platform economics. SoFi $SOFI and Nubank's NuInvest approach the market from the other direction: investing helps banking super-apps acquire and retain customers. Neither discloses standalone investing economics.
Rates are the weather
Interest rates affect every firm in this section because each holds customer cash. Higher short-term rates can raise earnings on swept balances and margin loans. But customers may shift cash into money-market funds when rates rise, while competition may force platforms to share more yield. Rates are the weather: consequential, but not a business model by themselves.
Empor tested whether platform margins tracked the US federal funds rate and found no consistent industry-wide relationship. Schwab's operating margin moved against the rate after a lag of several quarters. One plausible, unproven explanation is that, as rates rose in 2022 and 2023, customers moved cash from low-yield sweeps faster than Schwab's earnings on those balances increased; the effect appeared later. Swissquote's net margin moved with rates, as expected. Most firms showed no clear pattern.15 A few years of data are evidence rather than proof: cash balances, deposit pricing, trading activity and business mix differ too widely for a single rule.
Markets require similar caution. Rising share prices increase reported asset balances even without new customer contributions. The S&P 500 was about 19% higher in the September 2026 quarter than a year earlier.15 That rise alone would have lifted reported client assets at many firms. Organic net new assets—external inflows less outflows, excluding market gains—better indicate customer choice.
Does custody always win?
The common argument is that custody benefits because consumer-facing brands come and go while the underlying vault remains. The data offer some support: Empor's custody-and-clearing companies grew revenue 15.4% in the June 2026 quarter, with a combined operating margin of 34.7%, up 5.4 percentage points from a year earlier.15 But the advantage has limits. Large apps can bring clearing in-house, adviser networks can change default custodians, and a custodian owned by a fund manufacturer may concern advisers who value independence. The advantage is friction, not permanence. In the United States, that friction is now being tested from two directions at once.
Two migrations decide the American contest
February 26, 2025
On February 26, 2025, Robinhood closed its purchase of TradePMR, a custody and portfolio-management platform for registered investment advisers founded by Robb Baldwin. Robinhood's filings describe the acquisition and its later launch of Robinhood Adviser Network, which refers customers to RIAs using TradePMR's platform.25 The self-directed-trading app had bought a route to human advice.
Two migrations are under way. Customers are moving, or being encouraged to move, from managing their own money to paying for advice. Advisers are moving—or declining to move—between custodians and networks. The firms that retain both the customer relationship and the account infrastructure may control the most valuable accounts.
Robinhood's graduation bet
Robinhood agreed to pay about $300 million for TradePMR, which had around $40 billion of assets under administration when the deal was announced.26 Robinhood reported 28.6 million funded customers in August 2026.15 If even a small share of those customers accumulate enough assets and complexity to seek advice, Robinhood could retain the referral and custody relationship rather than lose it to Schwab or Fidelity.
The evidence of execution remains limited. Robinhood's 10-Q confirms the acquisition and referral network, but also identifies regulatory and liability risks in referral arrangements, including under the SEC's Marketing Rule. TradePMR accounts also continue to rely on third-party clearing.25 Robinhood has not reported conversion rates, assets transferred or revenue from the network. For now, the acquisition is a strategic option rather than a demonstrated source of growth.
LPL's retention test
A different deal tests the adviser migration. LPL Financial $LPLA is the largest US independent adviser network. It provides compliance, technology, products, custody access and business support to advisers who retain more independence than wirehouse employees. On August 1, 2025, it closed its purchase of Commonwealth Financial Network, led by Wayne Bloom; the migration of Commonwealth advisers to LPL's platform was still ahead. LPL, under chief executive Rich Steinmeier, targeted retention of 90% of Commonwealth's assets.27
That target is an objective, not a result. An adviser network acquires human relationships as well as accounts, and advisers who chose a smaller firm's culture may leave when asked to adopt a larger firm's systems. Retention will test whether switching costs protect LPL or instead give advisers a reason to consider rivals while paperwork must be completed anyway.
LPL reported 2025 revenue of $17.0 billion, up 37.2%, and $13.5 billion of organic net new assets in August 2026 alone. Its 5.1% net margin reflects its model: much of revenue is paid through to advisers.15 Ameriprise Financial $AMP, which combines an adviser network with asset management and insurance, reported a much higher return on equity. Raymond James $RJF, which has both employee and independent advisers, competes for advisers made available by mergers. All three grew revenue in their latest quarters. The data do not isolate organic growth, however: recruited and acquired assets, as well as market gains, are mixed together. At LPL especially, revenue also moves with asset values because fees are tied to client assets.15 Private networks including Cetera and the RIA aggregator Focus Financial Partners compete for the same practices without publishing comparable figures.
The challengers in custody
For decades, Schwab, Fidelity and Pershing dominated US custody for independent advisers. Challengers include Altruist, Betterment's adviser platform, Interactive Brokers, TradePMR under Robinhood and State Street, which has signalled interest in the market. No public source provides custody market share across these firms, so the scale of any shift cannot yet be measured. What is visible is where strategic buyers have committed capital.
Vanguard buys a custodian
On August 26, 2026, Vanguard announced a definitive agreement to acquire Altruist. It said Altruist would continue as a standalone business and expected the deal to close later in 2026, subject to approvals.16 Vanguard did not disclose a price. Axios reported a value of about $4.6 billion; that figure came from independent reporting rather than the deal terms.28
The transaction joins Vanguard's low-cost fund business with Jason Wenk's adviser-custody platform, 50 years after Vanguard began. Advisers influence trillions of dollars in allocation decisions, and ownership of their operating platform places Vanguard closer to those decisions.
The question is whether a fund manufacturer can own adviser infrastructure without prompting concern that it will favour its own products. Independent advisers have valued custodians that do not sell them investment products. The conflict is not new—Schwab and Fidelity also manage funds—but Altruist had positioned itself as independent. Vanguard's standalone-operating promise will be tested by adviser and asset retention after closing, and by whether rival funds receive equal treatment on the platform. Neither outcome can yet be known.
What the margins say, and don't
Empor's figures show the custody layer with a combined operating margin of 34.7%, compared with 21.1% for adviser networks, while trading at a lower earnings multiple than consumer apps.15 That supports the view that infrastructure has been the stronger profit pool. It does not show that a newcomer can capture it. Schwab's margin reflects decades of accumulated accounts and cash balances. A challenger must first win accounts, often at lower prices, before it can establish whether its economics resemble those of an incumbent. The American contest remains undecided; elsewhere, the rules differ altogether.
India, Europe and China show that the tollbooth has a passport
Bengaluru, 2010
On August 15, 2010, India's Independence Day, the brothers Nithin and Nikhil Kamath started Zerodha in Bengaluru. The name combines "zero" with "rodha," the Sanskrit word for barrier.29 Zerodha was bootstrapped, charged flat low fees at a time when Indian brokers charged a percentage of each trade, and built its own trading platforms. It became one of India's largest brokers without outside capital.
The American story is not a template for the rest of the world. In every country the tollbooth takes a local form, shaped by who is allowed to hold money, which accounts carry tax benefits, and whether a foreign app is permitted to serve local customers.
India: from app to household
In 2016, four former Flipkart employees, Lalit Keshre, Harsh Jain, Ishan Bansal and Neeraj Singh, started Groww to make mutual-fund investing simple on a phone. They later expanded into stocks, derivatives and other products, and in 2023 acquired Indiabulls Mutual Fund and renamed it Groww Mutual Fund, adding product manufacturing to distribution.30 Groww, whose parent Billionbrains Garage Ventures $GROWW is now listed, reported revenue equivalent to $484 million for the year to March 2026 with a 57.7% operating margin, and trades at about 46 times earnings.15
India's securities regulator, SEBI, sets the rules for broker registration, leverage and client-money handling. Its materials describe discount brokers as a distinct category of low-cost, execution-focused firms, and this model has spread quickly among Indian investors.31 Angel One $ANGELONE, a traditional broker that moved to digital, Upstox, PhonePe's Share.Market, and INDmoney, which offers access to US stocks, compete for the same young investors. Prudent Corporate Advisory Services $PRUDENT distributes mutual funds through independent partners. Motilal Oswal $MOTILALOFS runs a wealth division within a diversified group. 360 ONE WAM $360ONE and Nuvama $NUVAMA serve rich families. Only some of these disclose clean segment economics for wealth.
The contest is often reported through active-client counts on the National Stock Exchange. Those counts show who is winning at sign-up. They don't show who is winning at wealth. An active client might hold very little, trade options frequently for a few months, or be active only because of one trade. The count says nothing about retained assets, profitability per customer or loyalty. Indian app economics also differ from American ones: SEBI's rules and India's revenue mix, heavy in derivatives trading and fund distribution, make comparisons with US payment-for-order-flow models misleading.
CAMS and KFin sit beneath all of this, keeping the unit-holder registers for India's fund houses. They are closer to a registry office than a fund manager and are paid largely on the assets they administer. CAMS's revenue growth moved closely with stock-market levels in Empor's tests.15 Their economics look more like infrastructure than those of the apps above them.
Britain and Australia: platforms built on pensions
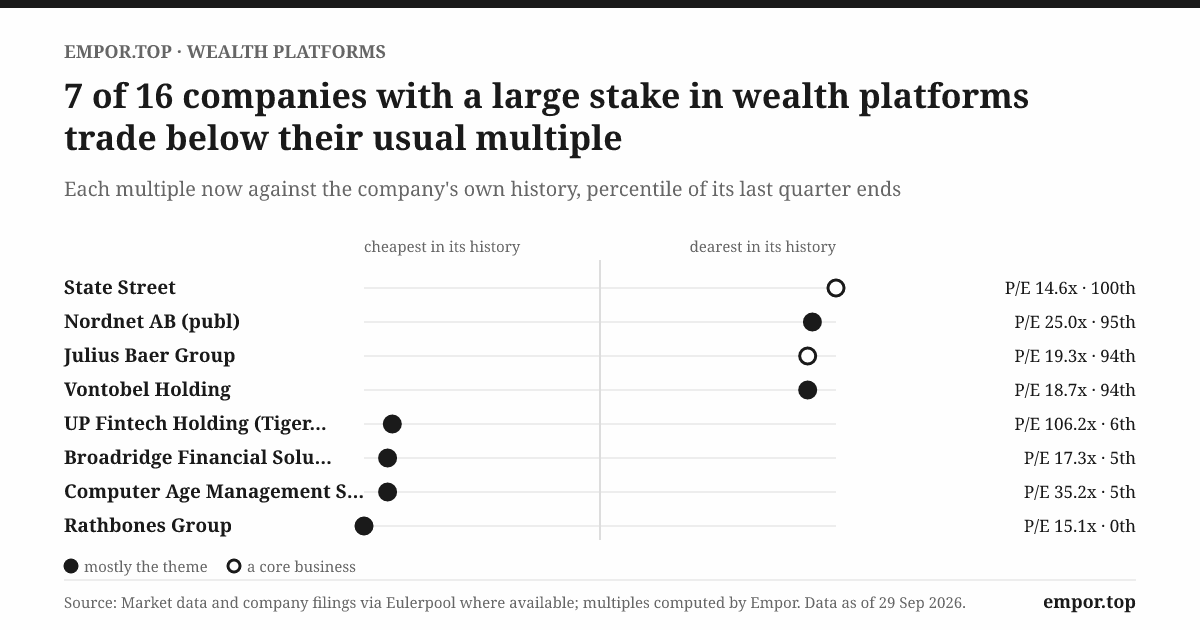
Transact and AJ Bell in Britain, and HUB24, Netwealth, Praemium and AMP North in Australia, show that adviser administration platforms can become regional toll roads when pension and tax rules route savings through them. Their valuations reflect that: HUB24 and Netwealth trade at around 44 and 70 times earnings respectively, far above the large US custodians, and a share-price fall over the past year shows how quickly those expectations can change.15 A good business at the wrong price can still disappoint shareholders.
Continental Europe: banks built around advisers and apps
Italy produced a distinctive model: networks of financial advisers attached to a bank. FinecoBank $FBK.MI combines a direct brokerage with adviser-led wealth management. Banca Mediolanum $BMED.MI, Banca Generali $BGN.MI and Azimut $AZM.MI distribute funds through large adviser networks. Swiss private banks such as Julius Baer $BAER.SW, EFG and Vontobel serve wealthy clients, and Britain's St. James's Place built a tied-adviser network for the mass affluent. In the Nordics, Avanza and Nordnet built the dominant direct platforms around tax-advantaged savings accounts. The reported revenue of many of these firms includes insurance and investment-contract accounting that inflates growth rates in some quarters. Net new assets and fee income are better guides than headline revenue.
China: permission outweighs product
China shows most clearly that a good app isn't enough. East Money $300059.SZ is a large domestic gateway combining financial data, a fund distribution platform and a brokerage, and it earns very high margins. Lufax, once a fast-growing wealth-and-lending platform, has shrunk sharply and is no model for growth. Noah Holdings serves wealthy Chinese families.
Futu, with its Moomoo brand, and Tiger Brokers built cross-border platforms that let mainland Chinese investors, among others, trade in Hong Kong and the United States. Futu reported 2025 revenue up 67.8% with an operating margin above 60%.15 In May 2026 Futu disclosed that it had received an investigation notice and a proposed administrative penalty from the China Securities Regulatory Commission over alleged unlicensed operations in mainland China.32 The CSRC then publicly described proposed action involving entities linked to Tiger Brokers, Futu and Longbridge over alleged illegal cross-border securities, fund-sales and futures activity.33 This is more than a routine regulatory footnote. It can redraw the customer base a platform is allowed to serve, whatever its product quality.
The episode disproves the idea that a good user experience creates a borderless wealth platform. A licence, capital controls and local permission can matter more. The high margins in Empor's data for firms across countries also can't be compared directly, because bank interest income, client-money accounting and local tax rules differ. Wherever the platform operates, the same question remains: which numbers would show that the story is true before revenue does?
What the numbers must prove before the story earns its ending
Back to the first trade
Return to the investor whose free first trade opened the previous chapters. The industry has shown that it can open an account cheaply. It has not yet shown, at scale and in public disclosures, that it can retain and deepen that relationship without shifting costs into poorer execution, lower cash yields or a forced platform migration. Four signals may provide the answer before the income statement does.
Four numbers to watch
Organic net new assets as a share of opening assets. This measures money customers actively add, less withdrawals, excluding market gains. It tends to precede revenue because fees follow assets. It addresses the central question: are platforms winning customer money or merely benefiting from rising markets? Individual firms report the measure monthly or quarterly. LPL reported $13.5 billion in August 2026, while AJ Bell reported £3.0 billion of net inflows for the quarter to June 2026.15 There is no comparable global measure, making this the most important missing number. Sustained positive flows at leading platforms would support the thesis; two consecutive periods of materially negative organic flows at major platforms would weaken it.
Assets per funded account. This indicates whether new accounts become lasting wealth relationships. A household's balance generally rises before it generates material advice or management fees. The measure distinguishes platforms gathering wealth from those gathering sign-ups. Few firms disclose it consistently. Wealthfront's roughly $48.7 billion across about 2 million funded accounts is a partial example, not a global benchmark.15 Rising balances alongside stable retention would suggest that customers are building their financial lives on a platform. Accounts growing faster than assets while marketing spending rises would suggest the opposite.
Adviser retention through conversions. This tests whether switching costs protect an acquirer. Advisers decide whether to stay before client fees move. The immediate test is LPL's 90% asset-retention target for Commonwealth, whose conversion was planned for the fourth quarter of 2026; LPL reports progress in quarterly results.27 Retention at or above target would indicate that consolidation created value. A shortfall would show that moving advisers to a new platform can send assets to rivals. Altruist's retention after Vanguard's acquisition closes will be the next test.
Customer cash and net interest sensitivity. This shows how much profit depends on interest rates. Cash balances and deposit pricing can change within a quarter, while asset-based fees adjust more slowly. Empor's latest macro reading puts the US effective federal funds rate at about 4% in the September 2026 quarter, roughly 15% below a year earlier.15 Firms report cash balances and net interest income quarterly. Falling rates are not automatically negative: lower interest income can be manageable if cash balances hold and asset-based fees grow. But if net interest income declines faster than rates for two quarters without an offset, profits may have been more cyclical than they appeared.
How the layers move together
The data show less consistency than the story's logic might imply. Empor's tests found some evidence that adviser-network revenue rose with stock markets in the same quarter, most clearly at LPL, where fees are tied to asset values. They found a similar relationship at Indian registrars such as CAMS and at some private banks, including Stifel and Vontobel.15 They did not find a universal relationship between interest rates and platform margins.
Several custody platforms, including AJ Bell, HUB24 and Netwealth, showed revenue growth moving against market levels. That may reflect slower growth from elevated bases rather than a direct effect of rising markets. There is also too little history to test whether consumer-app growth feeds custody or robo-adviser revenue. These patterns cover only a few years, during which markets, rates and trading activity often moved together. They do not establish causation.
The market has already expressed a view. The theme's shares returned 83.2% over three years but fell 8.9% over the past year. Consumer apps trade at about 39 times combined earnings, compared with 17 times for custody rails and less than 15 times for adviser networks.15 The industry thesis can prove correct while shares disappoint if investors paid too much for the wrong layer.
Two ways it could go
In the more favourable outcome, a first app account becomes a regular savings relationship. Cash, retirement and tax tools make it the household's main account, and some customers later seek advice. Advisers choose newer custody and workflow systems, while AI allows each adviser to serve more clients at lower cost. Recurring revenue grows faster than trading revenue, and lower rates shift earnings from cash spreads towards asset-based fees without reducing total profit.
In the less favourable outcome, accounts remain small and speculative. Rates fall and customers move their cash. Commissions cannot return. Advisers resist forced conversions and take clients elsewhere. AI turns planning and reporting software into a commodity rather than a moat. Customer acquisition proves rented rather than owned.
AI could support either outcome. It may increase adviser capacity and reduce service costs, or reduce differentiation in the reporting and planning software platforms sell. Evidence of higher adviser capacity, stable pricing and clean compliance records—not product launches—will determine which effect prevails.
Who gets paid
Schwab began with cheap execution and became a custodian. Bogle built around low-cost products, and Vanguard is now buying a newer custody challenger. Robinhood used free trades to acquire a route to adviser custody. LPL pursued scale and must now retain the advisers it acquired. Betterment and Wealthfront promoted automated portfolios and expanded into cash accounts. Each is a different answer to a household's changing financial needs.
The firms most likely to earn durable returns are those that control a trusted, funded account that is difficult to move, while providing useful advice or infrastructure around it. But the industry’s history makes a narrower point: owning the front door does not necessarily mean owning the house.
Glossary
- Assets under administration (AUA): Assets for which a firm keeps records or provides administrative services; it does not necessarily make investment decisions.
- Assets under custody (AUC): Assets a custodian holds and services. It measures operational scale, not investment authority.
- Assets under management (AUM): Assets over which a manager has authority to make investment decisions.
- Cash sweep: The automatic movement of uninvested account cash into a bank deposit or money-market fund.
- Clearing: The post-trade process of confirming, settling and recording a transaction.
- Custodian: A regulated firm that holds client assets and maintains the official account record.
- Fee-based advisory assets: Client assets that generate recurring advice or management fees rather than transaction commissions.
- Funded account: An opened account containing money or securities. Definitions vary by company.
- Independent adviser network: A business that provides advisers with compliance, technology, custody access and products while allowing them more independence than employees of a large brokerage.
- Model portfolio: A centrally designed investment mix used across multiple client accounts.
- Payment for order flow: Compensation a broker may receive for routing retail orders to a market maker.
- RIA: Registered investment adviser, a regulated US advisory firm.
- Regulatory assets under management (RAUM): The figure US advisers report on Form ADV; it is not interchangeable with company AUM.
- Robo-adviser: An automated service that uses software and rules to recommend and manage investments.
- Securities lending: Lending securities held in client accounts to borrowers, producing revenue that may be shared with clients.
References
-
The Laws That Govern the Securities Industry — U.S. Securities and Exchange Commission ↩
-
Remarks of Commissioner A. A. Sommer Jr. on the end of fixed commissions — U.S. Securities and Exchange Commission, May 1975 ↩
-
Report on the Technology Revolution in the Securities Industry — U.S. Securities and Exchange Commission, 1997 ↩
-
Use of Electronic Media — U.S. Securities and Exchange Commission, April 2000 ↩
-
State Street SPDR S&P 500 ETF Trust (SPY) — State Street Global Advisors ↩
-
Investment Adviser Statistics — U.S. Securities and Exchange Commission ↩
-
Bain Capital completes acquisition of Envestnet — Envestnet via SEC EDGAR, November 2024 ↩
-
Wealth Platforms theme data: pulse, scorecard, trends and links tables — Empor, 29 September 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Vanguard announces agreement to acquire Altruist — Vanguard, 26 August 2026 ↩↩↩
-
Schwab removes the final pricing barrier to investing online by eliminating U.S. stock, ETF and options commissions — Charles Schwab, October 2019 ↩
-
Interactive Brokers Group 2019 Annual Report — Interactive Brokers ↩
-
Robinhood Markets, Inc. IPO prospectus — U.S. Securities and Exchange Commission, 2021 ↩↩
-
SEC charges Robinhood Financial with misleading customers about revenue sources and failing to satisfy duty of best execution — U.S. Securities and Exchange Commission, December 2020 ↩
-
SEC adopts rules and interpretations to enhance protections and preserve choice for retail investors — U.S. Securities and Exchange Commission, June 2019 ↩
-
Charles Schwab completes acquisition of TD Ameritrade — Charles Schwab, October 2020 ↩
-
Morgan Stanley to acquire E*TRADE — Morgan Stanley, February 2020 ↩
-
Robinhood Markets, Inc. Form 10-Q for the quarter ended 30 June 2026 — U.S. Securities and Exchange Commission ↩↩
-
LPL Financial closes its acquisition of Commonwealth Financial Network — LPL Financial, August 2025 ↩↩
-
SEBI material on stock brokers — Securities and Exchange Board of India, April 2018 ↩
-
Futu receives investigation notice and administrative penalty — Futu Holdings, May 2026 ↩
-
Notice on proposed administrative action concerning cross-border securities activity — China Securities Regulatory Commission, May 2026 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube