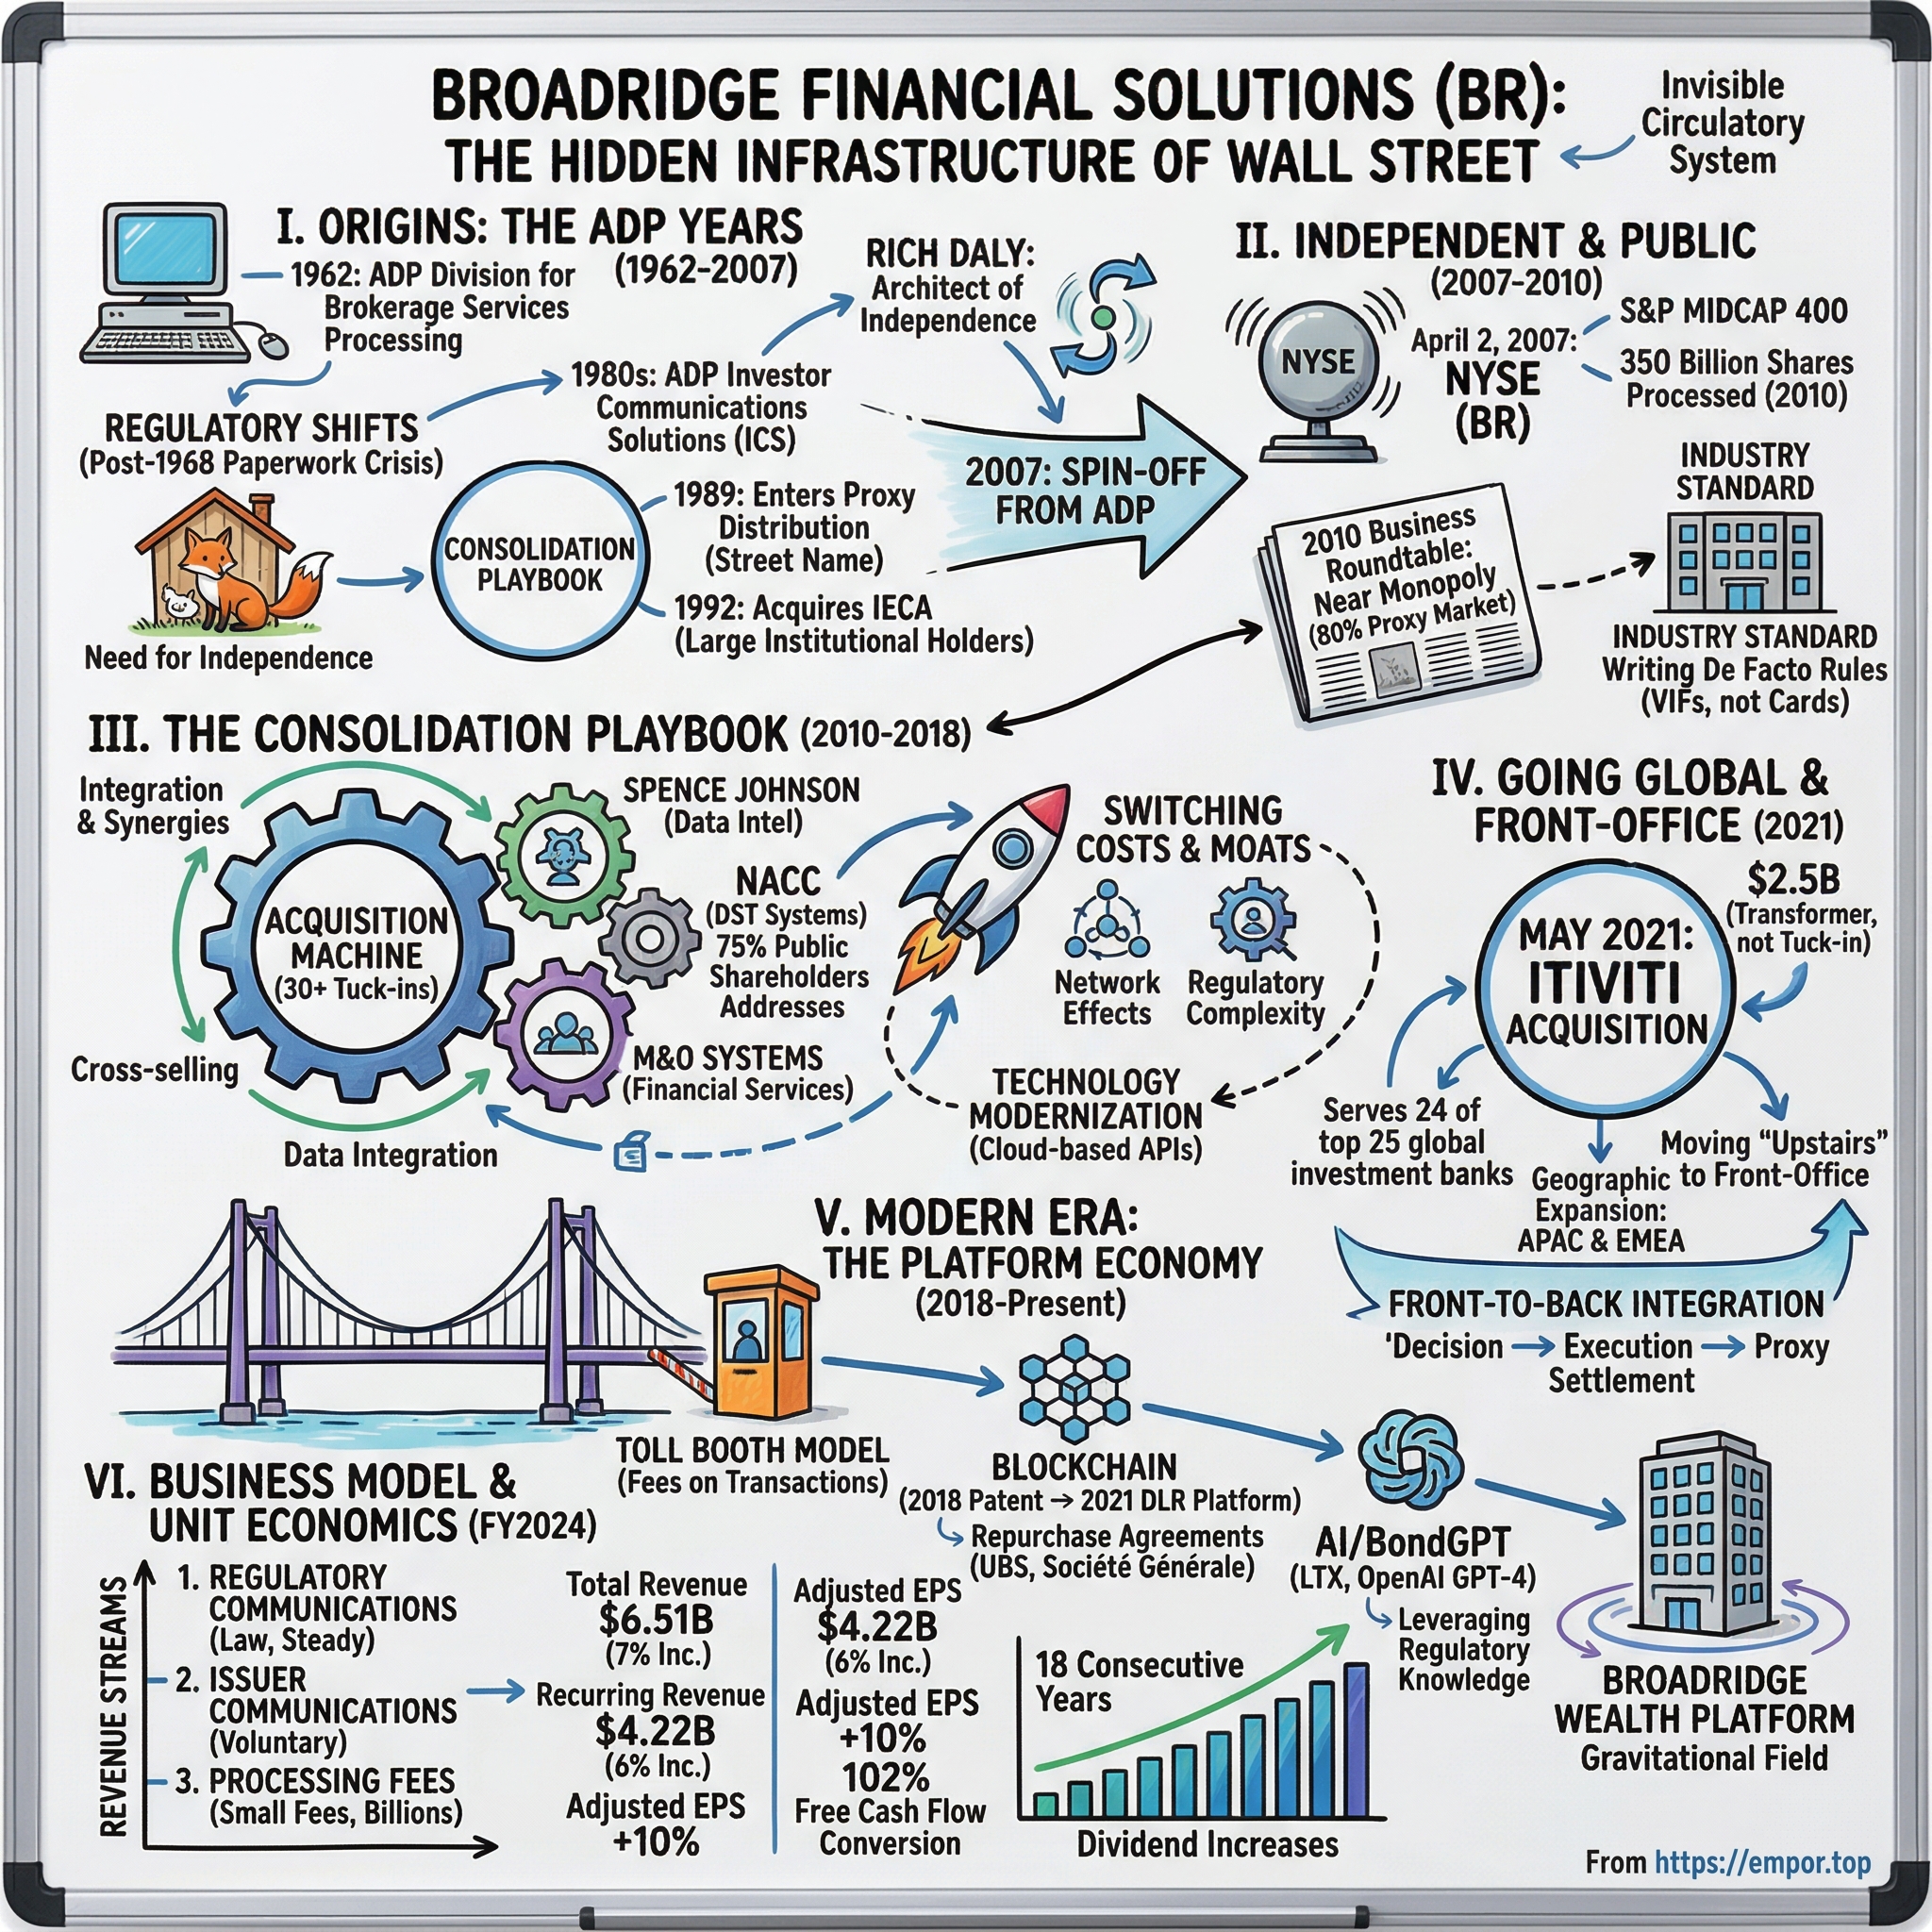
Broadridge Financial Solutions: The Hidden Infrastructure of Wall Street
I. Introduction & Episode Setup
Every spring, between March and June, a predictable ritual unfolds inside American households. Envelopes arrive — thick, printed on cheap stock — bearing annual reports and proxy ballots for companies whose shares sit in brokerage accounts. Most investors discard them. A minority open the mailers, log into a website, and cast votes for corporate directors they have never met. Almost nobody notices the fine print at the bottom of the card or the domain name where the vote is registered.
That website is ProxyVote.com. The envelopes were printed, packaged, and mailed by Broadridge Financial Solutions, a company headquartered in Lake Success, New York. In fiscal year 2026, Broadridge managed voting for more than one billion equity proxy positions, processed over eight billion investor communications across print and digital channels, and handled an average of more than $18 trillion in daily securities trades.1 As of June 30, 2026, the firm employed roughly 16,000 people across 28 countries and generated $7.477 billion in revenue for the fiscal year — up 9% from $6.889 billion in fiscal 2025 and $6.507 billion in fiscal 2024.12
Its name is Broadridge Financial Solutions, and until 2007 it did not exist as an independent company. It was formerly the Brokerage Services division of payroll processor Automatic Data Processing, until ADP's board decided it no longer wanted to fund the unit alongside its core businesses.3
The central puzzle is how a back-office unit inside a payroll provider transformed into a regulated chokepoint through which the governance of American public companies physically flows. The answer is not superior software, but a specific artifact of 1970s securities regulations, compounded over five decades by scale economics that competitors chose not to replicate.
Broadridge exhibits the traits of a classic monopoly: mandated demand, near-zero customer churn, high switching costs, and a fixed-cost base spread across essentially every retail brokerage account in North America. In fiscal 2026, client losses reduced recurring revenue by only about two percentage points, implying roughly 98% revenue retention.4 Management describes the business as "delivering today while building the digital, agentic, and tokenized business of tomorrow."4
However, a monopoly operating under a regulator-set fee schedule functions less like an unconstrained monopoly and more like a public utility. Utilities face a specific vulnerability: regulators can change the rules. On July 16, 2026, the SEC proposed Regulation E-Delivery, which would allow financial firms to make electronic delivery the default for regulatory communications rather than requiring investors to opt in.5 Broadridge's annual report acknowledges that if adopted as proposed, "the volume of physically delivered communications we process would decrease," and management anticipates "a modest decrease in our recurring revenue growth" as clients implement it.1
The central question for investors is not whether Broadridge operates a durable business, but whether its regulatory tollbooth is being repriced, whether the front-office platform management acquired for $2.5 billion in 2021 has delivered sufficient returns, and whether a company holding $216 million in blockchain utility tokens on its balance sheet remains the same entity that printed those physical envelopes.1 The analysis begins where that envelope originated.
 Subscribe on LinkedIn
II. Origins & The Regulatory Big Bang (1962–2006)
In 1962, the Brokerage Services division of Automatic Data Processing opened for business with a single client, processing an average of 300 trades per night.3 That is the entire origin story — no garage, no founder myth, no visionary sketching on a napkin. ADP was in the business of doing arithmetic for other companies at scale, and Wall Street back offices in the early 1960s were drowning in arithmetic.
They were also, quite literally, drowning in paper. Through the late 1960s, the New York Stock Exchange periodically closed early because brokerage firms could not physically reconcile the stock certificates piling up in their vaults. The industry's solution was to stop moving the paper. Certificates were immobilized in a central depository, and ownership became a book entry. Most street-name shares are registered in the name "Cede & Co.," the nominee used by The Depository Trust and Clearing Corporation, which holds shares on behalf of its participant broker-dealers and banks — who in turn hold them for their customers, the actual beneficial owners.1
This operational framework forms the structural foundation of the Broadridge business. When an investor buys a share of a company through a brokerage, the issuer's shareholder register does not list the investor's name; it lists DTC's nominee. The broker knows who owns the share, but the issuer does not. Under federal proxy rules, DTC executes an "omnibus proxy" transferring its voting rights to its participant nominees, and those nominees — the brokers and banks — must then deliver proxy materials to beneficial owners and request voting instructions.1 Some investors consent to having their names shared with issuers; those are non-objecting beneficial owners, or NOBOs. Objecting beneficial owners, or OBOs, can only be contacted through the intermediary.1
Inside that regulatory structure lay a massive operational burden. Federal rules create a legal obligation that falls directly on the broker, not on the issuer. The broker must reach every one of its customers on a strict deadline, without error, for every shareholder meeting of every company those customers own. Furthermore, the broker is contractually forbidden from simply handing its client list over to issuers. For a brokerage firm, proxy processing represents pure overhead, significant compliance risk, and a distraction from core trading and wealth management services.
So brokerages outsourced the work. Not just a fraction of the market, but virtually all of it. By the SEC's own account in a 2002 rule filing, ADP had since 1993 distributed "close to 100 percent of all proxies sent to beneficial owners holding shares in street name."6 Industry consolidation occurred due to scale economics: the fixed cost of building an infrastructure that integrates with every broker's back office, matches client positions against every corporate meeting calendar, and handles six-week seasonal proxy surges is immense. Meanwhile, the marginal cost of processing an additional broker's volume through an established network is negligible. A single dominant platform was the logical market outcome.
The executive who industrialized that position was Richard J. Daly. Daly founded a proxy services business, sold it to ADP, and joined the firm in 1989 as senior vice president of the Brokerage Services Group; by June 1996, he was leading the division.7 Daly recognized that this market is not won through novel software features. It is won by maintaining flawless execution during peak proxy season and consolidating regional processors to spread fixed operational costs across the broadest possible client base.
Falsification: did regulation hand ADP a free monopoly?
A simplified narrative suggests SEC mandates handed ADP a friction-free, high-margin toll road. The historical record reveals a more complex reality.
Because proxy reimbursement fees are pass-through expenses paid by issuers, they are not set by open-market negotiation. Instead, fee caps are established by stock exchanges and approved by the SEC, giving corporate issuers a direct channel to lobby for rate reductions. Issuers successfully lowered these fees on multiple occasions. In March 1997, the SEC approved a New York Stock Exchange proposal reducing the reimbursement rate for mailing each set of materials from 55 cents to 50 cents, cutting interim report fees by 25%—from 20 cents down to 15 cents—and introducing a new 10-cent preference management fee for each instance where physical mailing was eliminated.8 In March 2002, the SEC approved a further restructuring, concluding that the Proxy Voting Review Committee's recommended fee reductions for large issuers "were reasonable and should help to alleviate the burden and cost that large issuers currently bear."6 The pattern repeated: the NYSE convened a Proxy Fee Advisory Committee in September 2010, and the SEC approved a rebuilt fee schedule in October 2013.9
The structural mechanism is more significant than the specific monetary amounts. Each regulatory fee revision accomplished two outcomes simultaneously: it compressed unit pricing for traditional mail while establishing new fee categories that compensated the processor for eliminating physical paper—with the preference management fee introduced in 1997 standing as the clearest early example.8 The regulator was not seeking to break the processing provider, but rather to lower issuer costs by incentivizing operational automation.
The evidence demonstrates that regulation did not grant unchecked pricing power. Instead, it guaranteed mandated volume under a regulated price cap—a demanding operating model where margin growth depends entirely on driving unit costs down faster than regulatory price caps decline. That operational discipline prepared Broadridge for the shift to digital delivery, making the 2026 e-delivery proposal a continuation of a long-standing regulatory dynamic rather than an unprecedented shock. The long-term test remains clear: evaluate each regulatory fee restructuring against Broadridge's unit cost reduction trajectory.
By 2006, the division possessed a 44-year operating history, counted seven of the top ten U.S. broker-dealers on its securities processing systems, and maintained an average client relationship of ten or more years among its top 50 clients—which generated 74% of its revenue.3 It was a high-performing infrastructure business operating within a payroll processor. ADP's board subsequently decided to spin it off as an independent company.
III. The 2007 Spin-Off & The Digital Transition (2007–2010)
On March 30, 2007, ADP distributed one share of Broadridge Financial Solutions for every four shares of ADP common stock held on the March 23 record date, launching Broadridge as an independent NYSE-listed company.10 Richard Daly, then 53, became chief executive, while Arthur Weinbach, ADP's chairman, assumed the role of executive chairman.3 ADP's information statement articulated standard spin-off rationale: as a standalone enterprise, Broadridge could "pursue its growth strategies and prioritize investment spending as it sees fit, without having to compete for capital or senior management resources" against ADP's core payroll operations.10
The timing appeared precarious.
Nine months prior to the spin-off, the SEC was finalizing a rule with profound operational implications for high-volume mailers. Adopted in January 2007, the Notice and Access rule permitted companies to host proxy materials online and send shareholders a brief notice card rather than a full printed package.11 To public investors assessing a newly listed company whose primary expense was physical postage, the threat seemed straightforward: paper distribution was shrinking, and Broadridge was primarily a distributor of paper.
That initial interpretation proved incomplete. Financial disclosures from the period clarify what transpired during the transition.
Investor Communication Solutions (ICS) revenue declined 3% from $1.575 billion in fiscal 2008 to $1.531 billion in fiscal 2009 as paper suppression took hold.12 Revenue subsequently recovered to $1.670 billion in fiscal 2010, though this rebound was driven largely by event-driven mutual fund proxy campaigns rather than core equity growth.12 Underlying volume remained soft, with annual equity proxy position growth contracting by 1% in fiscal 2010.12
Profits held steady despite the revenue swing. Segment pre-tax earnings were $255.3 million in fiscal 2008, $248.9 million in fiscal 2009, and $272.8 million in fiscal 2010, maintaining a pre-tax margin of roughly 16% in each period. Broadridge noted in its fiscal 2010 annual report that the segment's "Margin was unchanged from 16.3%."12
Falsification: the digital transition was survivable, not accretive
A common narrative suggests Notice and Access benefited Broadridge because postage represents a zero-margin pass-through expense, meaning its reduction automatically expands profit margins. While postage is indeed pass-through revenue, company disclosures do not show margin expansion during those transition years. Segment margins remained flat throughout the rollout. The margin benefit from eliminating low-margin physical delivery was offset by lower per-position fee realization and the capital required to construct digital distribution channels.
Consequently, the financial record supports a narrower conclusion. The pessimistic view—that digital adoption would collapse Broadridge's revenue and margin structure—did not materialize. Conversely, the optimistic view—that digital delivery served as a catalyst for margin expansion—is unsupported by fiscal 2007 through 2010 results and offers limited precedent for subsequent regulatory changes, such as the SEC's 2026 e-delivery proposal. The period demonstrates operational resilience: mandated transaction volumes preserved the revenue foundation while the underlying delivery mechanism shifted.
The primary strategic setback of that era stemmed from a separate operation. Broadridge inherited Ridge Clearing & Outsourcing Solutions from ADP—a capital-intensive, credit-exposed clearing business that diverged from its fee-for-service core. On June 25, 2010, Broadridge transferred substantially all of Ridge's clearing client contracts to Penson Financial Services for $35.2 million, comprising a $20.6 million five-year subordinated note and 2,455,627 shares of Penson Worldwide common stock—a 9.5% stake valued at $5.95 per share.12 Penson later filed for bankruptcy, rendering the equity and debt consideration worthless. Broadridge exited an ill-fitting business line while accepting payment in the vulnerable securities of an unprofitable counterparty, illustrating a rare misstep in capital allocation.
Concurrently, Broadridge developed a centralized consent, preference, and distribution engine. This platform enabled brokerages to offer digital delivery to clients without constructing proprietary infrastructure, allowing Broadridge to collect processing fees regardless of whether communications were delivered physically or digitally. By July 2010, when the SEC issued its Concept Release on the U.S. Proxy System, the Commission noted that a single intermediary processed nearly all beneficial-owner distributions—treating that concentration as a structural component of the financial system.13
This infrastructure established the foundation for Broadridge's ongoing financial model, raising the question of how much of its revenue stream remains genuinely recurring.
IV. Segment Breakdown & Core Economic Engine
A visit to a Broadridge production facility during the second week of April reveals an operation that looks less like a software vendor and more like a high-volume logistics engine with a compliance department attached — high-speed printers, inserters, and a delivery schedule governed by SEC deadlines rather than software sprint cycles. The Global Technology and Operations side presents a stark contrast: a securities-processing utility running books and records for broker-dealers across more than 100 markets. In fiscal 2026, it provided fixed income trade processing to 22 of the 26 primary dealers in U.S. government securities and served the 15 largest U.S. wealth providers.1
Broadridge reports its business across these two segments, though the revenue split is lopsided. Investor Communication Solutions generated $5,560.8 million of fiscal 2026 revenue, representing roughly three-quarters of the total; Global Technology and Operations generated $1,916.0 million, or about 26%.21
However, segment labels obscure the primary driver of the company's economics: the underlying revenue mix. Broadridge categorizes its top line into three distinct streams, each exhibiting different operational behavior.
Recurring revenue — $4,878.0 million in fiscal 2026, up 8% — represents per-position, per-communication, and per-trade processing fees collected under multi-year contracts.2 This stream functions as the firm's core annuity.
Distribution revenue — $2,250.6 million, up 9% — reflects postage and physical production expenses largely passed through to clients.2 This high-volume, low-margin revenue depresses Broadridge's reported operating margin relative to its underlying economic strength. In fiscal 2026, distribution revenue rose 9% primarily due to postal rate increases of approximately $123 million rather than new business wins.1 When top-line revenue expands due to postal hikes, the increase reflects pass-through accounting rather than operational growth.
Event-driven revenue — $348.1 million, up 9% — is the volatile component of the business, driven by mutual fund proxies triggered by manager or fee changes, equity proxy contests, tender offers, and corporate actions.2 Management explicitly notes that the timing and financial impact of these events "are difficult to forecast." This volatility is pronounced: mutual fund proxy revenue surged 75% in fiscal 2025 before flattening in fiscal 2026.1
The moat, and where it actually lives
Broadridge's client retention metrics display notable stability, driven by clear operational mechanisms. In fiscal 2026, client losses subtracted about two percentage points from recurring revenue growth, compared to five percentage points added by new closed sales and four percentage points from internal growth in Investor Communication Solutions.4 The resulting revenue retention rate of roughly 98% reflects the structural role of financial infrastructure.
This high retention is sustained by switching costs. Replacing a broker-dealer's book-of-record platform or proxy distribution pipeline represents an operational and regulatory risk rather than a routine procurement choice. A failed migration risks missed votes, settlement errors, and regulatory enforcement from FINRA. Consequently, clients view the service fee as operational insurance relative to the risk of disruption.
Falsification: is 90%-recurring the same as recession-proof?
The assertion that a high recurring revenue mix renders Broadridge immune to broader market conditions is challenged by its financial disclosures. A notable test occurred between fiscal 2022 and fiscal 2024. Free cash flow conversion, which management targets above 100%, reached 48% in fiscal 2022 and 90% in fiscal 2023, before recovering to 102% in fiscal 2024, 104% in fiscal 2025, and 110% in fiscal 2026.4 Two consecutive years below target highlight the working-capital and investment volatility underlying the recurring revenue base.
Position growth represents a second structural vulnerability. Because Broadridge bills on a per-position basis, recurring revenue is tied to the number of brokerage accounts holding each security — a metric driven by retail market participation. Over ten years, equity position growth averaged 13% annually and mutual fund/ETF position growth averaged 7%.4 In fiscal 2026, equity positions grew 16% and fund/ETF positions expanded 6%.4 While these trends provide a substantial tailwind, they remain cyclical; a sustained contraction in retail investing would directly depress recurring revenue.
The business maintains strong client retention and a durable recurring foundation, but it is not immune to market cycles. Broadridge is protected against client churn while remaining exposed to shifts in investor behavior.
Before expanding beyond its core proxy processing infrastructure, the company engaged in a decade-long series of roughly thirty acquisitions.
V. The M&A Roll-Up Playbook (2010–2020)
The central strategic realization inside Broadridge in the decade following its spin-off was straightforward: the company possessed a distribution channel that was nearly impossible to replicate, yet it was being used to sell only a single core service.
Every major broker-dealer, mutual fund complex, and wealth platform in North America already maintained a Broadridge contract, data feed, and relationship manager. The marginal cost of selling an existing client a second product was dramatically lower than the cost of a competitor selling a first one. The resulting playbook was clear: acquire small, adjacent software and data providers offering strong products but limited distribution, integrate them into the established client network, and leverage high cross-sell attach rates.
Acquisitions proceeded steadily, primarily as small bolt-on deals. In 2016, Broadridge acquired the North American Customer Communications business of DST Systems, consolidating production scale in customer statements and trade confirmations. During the same period, it added institutional data analytics by acquiring Spence Johnson, later expanding fund document dissemination and private-debt portfolio management through FundsLibrary and ClearStructure. While individual transactions were modest, their cumulative impact transformed a proxy processor into a broader communications platform and a securities processor into an enterprise technology vendor.
The capital allocation framework funding this expansion became a central pillar of management's narrative: convert more than 100% of adjusted earnings into free cash flow, maintain a growing dividend, acquire adjacent software providers, and allocate remaining capital to share repurchases. The company's dividend history offers clear empirical evidence of this commitment. In August 2026, the board raised the annual dividend for the twentieth consecutive year, approving a 12% increase to $4.36 per share. The per-share payout climbed from $2.56 in fiscal 2022 to $2.90, $3.20, $3.52, and $3.90 in fiscal 2026, reflecting annual increases between 10% and 13%.24 Twenty consecutive annual increases over twenty years as an independent public entity reflect a deliberate policy rather than a coincidental trend.
Falsification: did the roll-up actually generate organic growth?
The optimistic narrative asserts that bolt-on acquisitions feed the core engine, which then converts them into sustained organic growth. The test of this premise lies in Global Technology and Operations (GTO), the segment that absorbed most of these acquisitions.
The fiscal 2026 financial bridge illustrates this dynamic. GTO recurring revenue grew 8% as reported and 7% in constant currency, but organic expansion accounted for only four percentage points of that growth, while two percentage points stemmed from acquiring Kyndryl's Securities Industry Services business and CQG.1 Examining specific product lines highlights the distinction further. Capital markets recurring revenue expanded 6% as reported and 5% in constant currency, with four percentage points generated organically and one point contributed by CQG; within that line, digital asset revenues tied to Canton Coins generated $16.5 million, providing a full percentage point of growth.1 Meanwhile, wealth and investment management revenue grew 11% as reported and 10% in constant currency, split evenly between five percentage points of organic growth and five points from the Securities Industry Services transaction.1
Adjusted for acquisitions and digital asset contributions, GTO's organic revenue engine grew at a mid-single-digit pace in fiscal 2026. While mid-single-digit organic growth in mission-critical financial infrastructure represents a stable operating performance, it differs materially from the assertion that bolt-on acquisitions inherently accelerate core expansion.
Two additional structural observations emerge from this acquisition strategy. First, the balance sheet reflects the cumulative financial weight of past transactions: goodwill reached $3.788 billion as of June 30, 2026, while goodwill, net intangibles, and deferred client conversion and start-up costs collectively represented approximately 65% of total assets.1 Broadridge's regulatory filings highlight the associated risk, noting that "it is possible we may incur impairment charges in the future, particularly in the event of a prolonged economic recession or loss of a key client."1 Second, the company's compensation committee introduced organic recurring revenue growth as a performance metric for fiscal 2026 performance-share grants, describing the modification as "responsive to feedback provided by some investors."14 This adjustment indicates that institutional investors were closely monitoring the gap between reported and organic growth.
While the bolt-on acquisition strategy delivered incremental scale, management subsequently pursued a significantly larger transaction.
VI. The Itiviti Mega-Deal: Going Global & Front-Office
In March 2021, near the peak of the fintech valuation cycle, Nordic Capital was shopping Itiviti — a Stockholm-headquartered trading technology firm built through a decade of European consolidation. Itiviti specialized in order and execution management and, crucially, the FIX connectivity layer that enables asset managers and brokers to communicate electronically. On March 29, 2021, Broadridge agreed to acquire Itiviti for €2.143 billion, or roughly $2.5 billion, in an all-cash transaction funded through a $2.55 billion term credit agreement.15 By a wide margin, it marked the largest acquisition in Broadridge's history.
Understanding the strategic motivation requires clarifying key industry terms. Broadridge's historic strength lay in the back office — the post-trade infrastructure of clearing, settlement, books and records, and regulatory reporting. Itiviti operated in the front office, managing how trade orders are initiated and routed. FIX, or the Financial Information eXchange protocol, serves as the messaging standard connecting both domains — effectively the universal communication protocol of institutional trading. By acquiring front-office connectivity, Broadridge sought to offer brokerages a single integrated stack from order entry to settlement, rather than competing solely for the back-office portion of workflows controlled by third-party systems.
The strategic rationale aligned with Broadridge's international expansion goals. At the time of the agreement, Itiviti counted 24 of the top 25 global investment banks as clients and served more than 2,000 brokers across 50 countries.15 For a firm that earned roughly 15% of its revenue outside the United States, the acquisition represented the single largest step toward international expansion in its history.1
The primary risk resided in the transaction's valuation. Itiviti generated approximately €210 million in recurring revenue in 2020.15 A purchase price of €2.143 billion represented roughly ten times recurring revenue — a valuation multiple typically associated with high-growth software-as-a-service companies, whereas Itiviti's top-line expansion was more modest. While management did not disclose an EBITDA multiple, it outlined specific target contributions: 2.5 to 3.0 percentage points to recurring revenue compound annual growth and approximately 2 percentage points to adjusted earnings-per-share growth over the fiscal 2020 to 2023 performance period, alongside accretion to adjusted EPS in the first full year after closing.15
Falsification: did front-to-back deliver the growth step-change?
Evaluating this transaction serves as a critical test of management execution, representing the company's largest capital commitment with five years of operating history now available to assess performance.
On its immediate financial commitments — near-term earnings accretion and baseline revenue contributions — the acquisition performed largely as projected. On the broader strategic thesis, however, results fell short of initial market expectations. In 2021, investors underwrote the premise that integrating front- and back-office operations would elevate Global Technology and Operations into the higher growth tier of specialized trading-technology peers. Five years later, GTO's organic recurring revenue expanded by four percentage points in fiscal 2026, while total segment revenue of $1,916.0 million continues to represent just over a quarter of Broadridge's total top line.1
The structural distinction between these markets explains the outcome. Back-office compliance infrastructure derives stickiness from operational and regulatory risk: replacing established systems threatens business continuity. Front-office trading technology, by contrast, depends on continuous software differentiation — a standard that competitors challenge with every product cycle. Order and execution management systems face pressure from specialized software vendors, internal technology builds at major investment banks, and shorter product lifecycles. Broadridge acquired global distribution and established trading applications, but it did not secure a second regulatory tollbooth, and client retention dynamics differ accordingly.
A notable counter-signal appeared in fiscal 2026 performance. GTO's pre-tax margin expanded from 11.3% in fiscal 2025 to 15.5% in fiscal 2026, driven by a 48% increase in segment pre-tax earnings to $297.8 million.21 This margin expansion reflects operating leverage on fixed infrastructure alongside the normalization of integration expenses following an intensive amortization cycle; GTO recorded $160.9 million in acquired-intangible amortization in fiscal 2026, compared to $42.7 million in Investor Communication Solutions — a direct legacy of the Itiviti purchase.1 Management expanded its front-office suite further in fiscal 2026 by acquiring CQG, a futures and options execution management platform, completing the deal on May 1, 2026, though financial terms were not disclosed.16
The evidence yields a nuanced verdict. The premise that Itiviti would transform GTO into a double-digit organic grower is unsupported by five years of financial results. However, the secondary thesis — that the acquisition provided international scale, product breadth, and operating margin upside — receives ongoing support. The primary indicator for tracking this thesis remains GTO's pre-tax margin: continued expansion beyond 15.5% would demonstrate structural efficiency gains, whereas a plateau would suggest fiscal 2026 gains were driven primarily by cyclical volume.
That execution responsibility falls directly on the leadership team charged with managing the platform and validating the investment.
VII. Current Management, Incentives, & Governance
Tim Gokey is not a company lifer. That distinction explains much of how Broadridge has operated since he assumed leadership.
Gokey spent eighteen years at McKinsey & Company, becoming a partner and leading the firm's North American financial institutions marketing and sales practice and, earlier, its North American CRM practice.14 He then ran the retail tax business at H&R Block from 2004 to 2009 and served as its chief corporate development officer from 2010 to 2012—a consumer-facing, seasonal, deeply operational role with significant parallels to proxy season.14 He joined Broadridge, rose to president and chief operating officer, and succeeded Richard Daly as chief executive officer in 2019. He also serves on the board of directors of C.H. Robinson.14
Daly remained as executive chairman and served on the board until retiring after the 2025 annual meeting under the company's director retirement policy, concluding an executive tenure that began when ADP acquired his proxy business in 1989.147 Eileen Murray, former co-CEO of Bridgewater Associates and former chair of FINRA's board of governors, succeeded Daly as board chair.14 Christopher Perry serves as president, overseeing global sales and client relationships.
What the incentive plan actually rewards
This is where the public narrative and regulatory filings diverge, with direct implications for corporate governance.
Gokey's fiscal 2025 total compensation was $17.2 million ($17,188,658), comprising roughly $1.08 million in salary, $6.46 million in stock awards, $6.95 million in option awards, $1.55 million in non-equity incentive pay, $1.10 million in pension and deferred compensation value, and about $42,000 in other compensation.14 Approximately 93% of his target total direct compensation was performance-based.14 As of July 31, 2025, his beneficial ownership stood at 701,213 shares, though 558,149 of those were vested or near-vesting stock options—leaving outright ownership of roughly 143,000 shares against an executive guideline requiring six times his base salary.14
The compensation structure reveals management's core incentives. Broadridge splits long-term executive equity roughly evenly between stock options and performance-based restricted stock units (PRSUs). For the PRSUs granted in fiscal 2025, the payout depended on a single metric: average Compensation Adjusted Earnings Per Share across fiscal 2025 through 2027, with payouts ranging from zero to 150% of target.14 The criteria omitted recurring revenue, organic growth, and return on capital, focusing entirely on earnings per share.
An EPS-only incentive structure rewards share buybacks, accretive leverage, and debt-funded acquisitions—financial levers management can execute independently of core operational expansion. Following shareholder feedback, the compensation committee added organic recurring revenue growth as a second performance metric starting with fiscal 2026 grants.14 Governance sentiment had already shown friction: at the 2024 annual meeting, say-on-pay support stood at 89.2% of votes cast—a passing mark, but noticeably below the mid-90% range typical for large-cap enterprises.14
A structural shift in award timing also affects year-over-year compensation comparisons. When Broadridge extended its PRSU performance period from two years to three years in fiscal 2024, the mechanical timing shift resulted in zero PRSUs being earned in fiscal 2025.14 While the extension aligned incentives over a longer horizon, it created a temporary drop in long-term payouts for that specific fiscal year.
Falsification: has management's regulatory playbook travelled?
Broadridge's domestic acquisition playbook encountered immediate friction upon entering Canada's concentrated banking market.
Broadridge completed its acquisition of Kyndryl Canada's Securities Industry Services (SIS) business on November 1, 2024. Twenty-five days later, on November 26, 2024, Canada's Competition Bureau announced it had obtained court orders to advance an investigation into Broadridge Software Limited and its affiliates under both the merger and the restrictive trade practices provisions of the Competition Act.17 The Bureau stated it was seeking information to determine whether Broadridge "has or is engaged in anti-competitive practices related to book of record platforms in Canada," including practices that may prevent competitors from supplying complementary software to broker-dealers, and separately whether the SIS acquisition was likely to substantially lessen competition.17 The regulator noted there was "no conclusion of wrongdoing at this time" and invited market participants to provide information.17 The investigation escalated in 2025, with the Bureau obtaining section 11 orders against six of Canada's largest banks in connection with the matter.18
Two parameters define the scope of this legal exposure. First, the Bureau noted it had one year from transaction completion to challenge the merger17—and no merger challenge was publicly announced during that window. Second, Broadridge's fiscal 2026 annual report states that there are "no material pending legal proceedings, other than ordinary routine litigation incidental to the business."1
The empirical evidence leads to a clear conclusion: claims of seamless international regulatory navigation are refuted by a formal antitrust investigation involving court-ordered document production from six major banks. However, the narrower interpretation—that the investigation represents an ongoing regulatory overhang rather than an immediate financial liability—is supported by the absence of a merger challenge within the statutory window and by the company's formal legal disclosures. Resolution will depend on a final Bureau finding or consent agreement, while a enforcement remedy targeting Canadian book-of-record practices would invalidate the benign interpretation.
Regulatory scrutiny abroad represents one dimension of strategic risk. The other is how the business manages technological transition across its core market.
VIII. Sizing the "Dark Horses": Blockchain, AI, & SEC Rule Shifts
In June 2026, Broadridge's Distributed Ledger Repo (DLR) platform processed approximately $7.5 trillion of tokenized transactions in a single month, averaging roughly $357 billion in daily repo trades.14 That marks a steep expansion from its mid-2021 launch volume of about $31 billion per week and its August 2025 average of $280 billion daily.19 The expansion in volume serves as a primary proof point in management's technology presentation.
However, trading volume does not translate directly into top-line revenue. Digital asset revenues related to Canton Coins contributed $16.5 million to fiscal 2026 capital markets recurring revenue.1 Broadridge does not separately disclose DLR platform revenue, but total capital markets recurring revenue stood at $1,184.2 million — accounting for roughly 16% of total company revenue.1
This disconnect illustrates the gap between operational adoption and commercial monetization. Repurchase agreements involve overnight swaps of cash and collateral; because identical collateral turns over continuously, notional volumes are vast while per-transaction fees remain tiny. Shifting that workflow onto a distributed ledger — allowing cash and collateral to settle atomically against a shared record rather than through overnight reconciliation — provides real operational efficiency for broker-dealers. However, it does not automatically allow the vendor to capture higher fees on a transaction that was already low-cost.
Management has framed these economics cautiously in public discussions. Asked on the fourth-quarter fiscal 2026 earnings call how tokenized securities are priced, CEO Tim Gokey clarified that the firm applies existing rate schedules — natively issued tokenized securities follow registered-holder rates, while custodial and synthetic models follow beneficial-owner rates — and described the opportunity around managing operational complexity rather than increasing unit prices: tokenization "introduces complexity for clients and there's no one better positioned than we are to help them solve it."20 This position suggests DLR functions primarily as defensive insurance against disintermediation rather than an immediate growth catalyst, pending separate disclosure of platform revenue.
The Canton Coin question
A second technological development involves an accounting structure unusual for a regulated infrastructure provider.
Since the fourth quarter of fiscal 2024, Broadridge has earned Canton Coins — the utility token used to pay traffic fees on the Canton Network's Global Synchronizer — in exchange for providing validator and super-validator services on that network.1 The company records these tokens at fair value on the date of receipt as revenue within the Global Technology and Operations segment.1 Following the adoption of Accounting Standards Update (ASU) 2023-08 in the first quarter of fiscal 2026, Broadridge remeasures its token holdings to fair value each reporting period, recognizing value changes in non-operating income.1
As of June 30, 2026, Broadridge held 1.5 billion Canton Coins with a cost basis of $13.3 million and a fair value of $216.1 million.1 Of that total, 1.3 billion coins valued at $189.9 million were restricted from transfer after the company elected, under a March 2026 Canton Network framework, to lock 70% of its lifetime and future earned tokens to maintain super-validator status; these restrictions decrease over time and are scheduled to expire in mid-2029.1 In the second quarter of fiscal 2026, Broadridge contributed 342 million coins — valued at $53.1 million at the time of the transaction — in exchange for 17.3 million non-transferable pre-funded warrants in Canton Strategic Holdings, Inc., an entity formerly known as Tharimmune that adopted a digital-asset treasury strategy following the placement.1 Broadridge exercised 6.1 million of those warrants into common stock in the fourth quarter.1 Consequently, total digital assets on the balance sheet reached $265 million at fiscal year-end, consisting of $216 million in tokens and $49 million in Canton Strategic Holdings stock and warrants.4
Remeasuring these assets produced a fiscal 2026 gain on digital assets of $227.0 million, equal to $1.94 per diluted share.2 Management excluded this gain from adjusted financial results, though it flowed through GAAP earnings — causing GAAP diluted earnings per share to jump 35% to $9.60, while adjusted earnings per share rose 12% to match that exact $9.60 figure.2 The identical headline EPS figures reflect offsetting accounting adjustments rather than a structural convergence between GAAP and adjusted core operating performance.
Evaluating this digital asset exposure requires weighing strategic logic against balance-sheet risk. Validating client network transactions and earning utility tokens requires minimal cash outlay and positions Broadridge within emerging ledger ecosystems. At the same time, the firm carries an illiquid, largely locked-up asset at sixteen times its cost basis, holds equity in a digital-asset treasury vehicle created from a restructured shell company, and recognizes token receipts as segment revenue. In its regulatory filings, Broadridge acknowledges that the value of digital assets remains "highly speculative" and that determining fair value "can be particularly challenging."1 That disclosure underscores how token mechanics have introduced new valuation variables to a traditionally predictable balance sheet.
AI and the rules
Broadridge's remaining operational initiatives involve artificial intelligence and regulatory shifts. LTX, the firm's corporate bond trading venue, launched BondGPT in June 2023 as a generative-AI interface for fixed-income queries21 and added Goldman Sachs, J.P. Morgan, TD Securities, Morgan Stanley, and Bank of America as participating dealers in June 2026.22 Securing participation from five major dealers validates the technology, though LTX remains a minor player in an electronic credit market dominated by established venues such as MarketAxess, Tradeweb, and Bloomberg. Consequently, LTX represents product optionality rather than a core revenue driver.
Regarding internal automation, management projected approximately $25 million in AI-driven productivity savings for fiscal 2027, stating during its earnings call that it plans to reinvest most of those savings into product development and client onboarding as it seeks to build an "agentic operating system" for clients.20 Company presentations report that clients achieve up to 30% operational cost reductions on day one of managed services engagements.23 However, $25 million in savings against an operating expense base of roughly $6.2 billion represents a minor financial efficiency rather than a structural margin expansion. The strategic question remains whether internal AI deployment will erode the value of Broadridge's business-process outsourcing services or expand its addressable market.
The interaction between regulatory mandates and business volume also shows signs of shifting. The SEC's Tailored Shareholder Reports rule, adopted in October 2022, required investment funds to deliver concise, visual shareholder reports, prompting Broadridge to build an end-to-end service for composing, filing, and distributing compliant documents with embedded XBRL.241 While that mandate generated incremental processing revenue, proposed regulatory updates like Regulation E-Delivery present potential headwinds for physical distribution volumes.
IX. Competitive Dynamics & Industry Plumbing
Consider the structural flow of corporate voting. When a public issuer or investment fund needs to communicate with shareholders, most owners do not appear directly on the corporate register because brokerages hold shares in street name. The legal duty to reach those investors falls on more than a thousand broker-dealers and custodian banks, nearly all of which outsource the entire workflow. Communications converge onto a single processing engine, fan back out across millions of retail and institutional accounts, and send collected votes back through the same channel. Broadridge operates at the narrow neck of this distribution funnel, collecting fees under rate schedules governed by stock exchange rules and SEC oversight.
Evaluating potential challengers clarifies where Broadridge's market position remains entrenched and where it faces genuine competition.
In investor communications, the primary direct challenger in U.S. beneficial proxy processing is Mediant, which was acquired by Motive Partners and Clearlake Capital and integrated into BetaNXT.25 BetaNXT competes for broker contracts and issues annual proxy guidance for corporate issuers. However, it confronts the same structural hurdle that enabled Broadridge's dominance: a competitor must construct nationwide seasonal infrastructure and establish connectivity across hundreds of broker back offices, all while operating under fixed regulatory fee caps. For venture-backed entrants, competing at scale under capped unit pricing represents a formidable operational hurdle.
Computershare operates in the adjacent market for registered shareholder servicing and transfer agency, where corporate share registers serve as the authoritative record. While Computershare competes with Broadridge for issuer contracts and collaborates on cross-market distributions, neither it nor peer transfer agent EQ—formerly Equiniti—has displaced Broadridge's control over North American beneficial proxy processing.
In technology and operations, the competitive landscape is far broader and significantly more contested. Processing giants FIS and Fiserv maintain extensive capital markets and banking relationships. SS&C Technologies dominates fund administration and alternative asset servicing through aggressive industry consolidation. Meanwhile, BNY's Pershing competes directly in wealth clearing and custody with the added advantage of a bank balance sheet. In enterprise technology, Broadridge operates as one vendor among several rather than an exclusive tollbooth—a dynamic acknowledged in its annual filing, which categorizes the market as highly competitive and cites client in-house technology teams as primary rivals.1
Falsification: is the proxy position really unassailable internationally?
Examining Proxymity provides a direct test of this market dynamic, as operational developments since 2020 have sharpened competition outside North America.
Proxymity is a digital proxy voting and shareholder communications platform spun out of Citi and backed by a global custody consortium comprising BNP Paribas, BNY, Citi, Clearstream, Computershare, J.P. Morgan, and State Street—a group that committed $26 million in additional growth capital in February 2025.26 The primary strategic implication is not the capital injection, which remains modest relative to Broadridge's scale, but the governance structure. When major custodian clients own a competing platform, they possess both the technical insights to guide product design and a clear incentive to sustain an alternative vendor.
Operational execution has expanded Proxymity's reach. In 2024, the platform launched Vote Connect Global with Citi Securities Services, introducing a North American product and investor portal that enables institutional clients to cast votes directly at global shareholder meetings, including within the United States.27 This expansion refutes the premise that Proxymity is strictly a European platform restricted by regional governance directives.
The evidence requires a calibrated verdict. The broad claim that Broadridge's proxy infrastructure faces no institutional or international competition is unsupported. However, the narrower assertion remains intact: Broadridge's core North American retail beneficial distribution engine—governed by high-volume print and digital compliance mandates—remains structurally protected, because Proxymity has gained traction primarily within institutional custody channels that operate under different workflows and economic models. The key indicator for monitoring this threat is whether a tier-one U.S. retail brokerage shifts its beneficial proxy distribution to an alternative platform. Until such a transition occurs, competitive pressure affects Broadridge's international expansion targets rather than its domestic core.
This distinction—between an unassailable domestic bottleneck and a contestable international technology market—defines the scope of Broadridge's economic moat.
X. Microeconomics & Seven Powers Analysis
Evaluating Broadridge through Hamilton Helmer's Seven Powers reveals that its business does not possess a uniform, seven-sided moat. Instead, the firm relies on two strong structural powers, two moderate operational capabilities, and three dynamics that offer limited competitive differentiation.
Scale economies — very high, and asymmetric by segment. The proxy and communications infrastructure operates on fixed-cost leverage: processing more than one billion equity proxy positions and eight billion investor communications requires seasonal peak capacity that a smaller rival would have to construct and leave idle for most of the year.1 This unit-cost advantage creates a formidable entry barrier. Crucially, this power resides almost entirely within Investor Communication Solutions; Global Technology and Operations possesses operational scale, but not market dominance.
Switching costs — very high, and structurally enforced. The two percentage points of annual recurring revenue lost to client attrition demonstrates this retention in practice.4 What makes these switching costs unusual is their origin: rather than stemming purely from software lock-in, they are driven by regulatory and reputational risk. A brokerage firm that botches a platform migration does not merely lose system features; it faces statutory non-compliance and regulatory penalties.
Cornered resource — high, but conditionally held. Broadridge does not own the underlying proxy mandate. Federal regulations impose the delivery obligation on brokerage nominees, while the reimbursement fee schedule is established by the New York Stock Exchange and approved by the SEC.9 This structural setup creates a central asymmetry: the regulator that mandates client demand also sets the price ceiling, retaining the authority to adjust both. A cornered resource derived from regulatory rules provides less pricing power than an asset owned outright.
Process power — high, and operationalized over decades. Executing zero-defect distributions across a thousand counterparties during a compressed six-week proxy season requires complex institutional coordination. This operational capability is reflected in the 91% digital adoption rate for proxy communications, which represents millions of investor consent preferences managed without breaking legal chain-of-custody standards.23
Network effects — moderate, and primarily standardization-driven. While issuers, brokerages, and investors benefit from converging on a standardized voting interface, this dynamic reflects operational efficiency rather than a compounding network effect. Adding another retail shareholder to ProxyVote does not increase the platform's intrinsic value to existing users.
Counter-positioning — low. As the established incumbent, Broadridge cannot counter-position against rivals; it can only defend against counter-positioning strategies, such as those attempted by digital-native or custodian-backed entrants.
Brand — low to moderate. The company's brand reflects institutional credibility among back-office executives rather than consumer mindshare, serving as a baseline requirement rather than a source of pricing leverage.
Applying Michael Porter's Five Forces highlights a critical dimension underemphasized by Hamilton Helmer's framework: buyer power, which is moderate-to-high and expanding. Broadridge's regulatory filings explicitly cite reliance on a relatively small number of major financial institutions and the necessity of retaining their business under favorable pricing terms.4 Tier-one banks exercise significant negotiating leverage, as evidenced in Canada, where six major institutions were compelled to provide documentation to competition authorities investigating book-of-record software practices.18 Conversely, supplier power remains low because paper, postage, and cloud infrastructure are commodities—though the $123 million postal rate increase in fiscal 2026 underscores that commodity inputs can still drive substantial cost fluctuations.1 Meanwhile, the threat of new entrants in beneficial proxy processing is low due to capital and regulatory barriers, whereas competitive rivalry remains intense across capital markets software.
The essential synthesis is that Broadridge's economic moat is not uniform. Roughly three-quarters of its top line sits behind a scale-protected, regulatory tollbooth that deters direct entry but operates under third-party price caps. The remaining quarter competes in a standard enterprise software market where Broadridge is an established player rather than an exclusive utility. Any investment analysis that applies monopoly chokepoint economics to the entire enterprise misjudges the one-quarter of the business facing conventional competitive forces.
XI. Financial Analysis, Valuation, & Capital Allocation
Broadridge delivered solid operational performance in fiscal 2026.
Recurring revenue increased 8% in constant currency, split among three percentage points from net new business, three points from internal position expansion, and two points from bolt-on acquisitions.1 Adjusted earnings per share climbed 12% to $9.60.2 Free cash flow reached $1.233 billion, up 17% and representing a five-year high conversion rate of 110% of adjusted net earnings.4 Closed sales—a key leading indicator of future recurring revenue—totaled $305.1 million for the year, anchored by a quarterly record of $158 million in the fourth quarter, while the recurring revenue backlog expanded to $470 million, or roughly 10% of recurring revenue.24
Capital returns reached a company record, distributing over $1 billion to shareholders through $603.7 million in share repurchases and $443.5 million in dividends, supported by a new $1.5 billion buyback authorization.24 Balance sheet debt remained manageable, with total principal debt standing at $3.275 billion—backed by $1.301 billion in GAAP operating income and no maturities until fiscal 2030—while net interest expense declined 19% to $99.9 million due to lower average borrowings and reduced interest rates.1
However, specific operating metrics warrant closer scrutiny.
Adjusted operating margin was flat at 20.5%.2 Chief Financial Officer Ashima Ghei attributed roughly 40 basis points of margin drag to reduced float income following interest rate cuts and to growth in pass-through distribution revenue, which dilutes margin percentages without diminishing absolute dollar income.23 While both factors represent structural margin mechanics, flat operating performance occurred during the final year of a multi-year plan that targeted continuous margin expansion.
The three-year scorecard. At its December 2023 Investor Day, management established financial targets for fiscal 2024 through 2026: annual organic recurring revenue growth of 5% to 8%, constant-currency recurring revenue growth of 7% to 9%, adjusted operating margin expansion of at least 50 basis points per year, and adjusted EPS growth of 8% to 12%.28 In its fourth-quarter fiscal 2026 presentation, under the heading "Broadridge delivered on its 3-year growth objectives," the company reported actual compound annual growth rates of 6% for organic recurring revenue, 7% for constant-currency recurring revenue, 32 basis points per year of margin expansion, and 11% for adjusted EPS.4
Evaluating performance against those targets shows that Broadridge met three of its four multi-year objectives. Organic recurring revenue landed in the middle of guidance, constant-currency recurring revenue hit the lower bound, and adjusted EPS growth finished near the top. Margin expansion, however, reached only about two-thirds of the targeted rate, even as it was presented under a headline asserting full objective delivery. During the earnings call, management addressed fiscal 2026's flat margin but did not provide specific commentary on the multi-year margin shortfall.
The e-delivery overhang. The SEC's proposed Regulation E-Delivery, introduced on July 16, 2026, would permit regulated entities to make electronic delivery the default for prospectuses, proxy statements, shareholder reports, and trade confirmations without affirmative investor consent—shifting from a guidance-based opt-in system to an opt-out regime.529 Company disclosures acknowledge the long-term trade-offs of this shift. Management anticipates no material impact on fiscal 2027 financial results, but noted that "as our clients implement the proposed rule changes, we anticipate a modest decrease in our recurring revenue growth" across a two-to-three-year implementation window, partially offset by reduced pass-through distribution expenses "which should increase our margins."1 During the earnings call, CEO Tim Gokey noted that the firm's InFocus platform supports dual composition for both digital and physical channels, maintaining that "even in a world where there's electronic default, there is still going to be print."20
This operational transition presents a dual economic effect: shifting away from physical paper expands margin percentages by shedding low-margin distribution revenue, but compresses absolute dollar revenue and per-position processing fees during the migration. As the fourth major restructuring of regulatory delivery rules in thirty years, the proposal follows a historical pattern: Broadridge has adapted to past regulatory shifts, though structural adjustments typically require multiple fiscal periods and temporarily weigh on top-line growth.
Valuation context. As of late August 2026, Broadridge shares traded near $183 with a market capitalization of approximately $21 billion, within a 52-week trading range of $134 to $257.30 Evaluated against fiscal 2026 adjusted earnings of $9.60 and fiscal 2027 projected adjusted EPS growth of 8% to 12%, the stock commands a mid-to-high-teens forward earnings multiple—a noticeable compression from the mid-twenties valuation multiple sustained throughout much of the prior decade.2 This valuation compression indicates that equity markets are questioning Broadridge's long-term terminal growth rate rather than its immediate operational execution, weighing the regulatory impact of default electronic delivery against the durability of its core financial infrastructure.
For fiscal 2027, management's guidance targets 6% to 8% recurring revenue growth in constant currency, 8% to 12% adjusted EPS growth, an adjusted operating margin of approximately 21%, free cash flow conversion above 100%, and closed sales between $290 million and $330 million.2 Event-driven revenue is projected to normalize to between $250 million and $300 million, following an elevated $348 million in fiscal 2026.20 Management is scheduled to present its next multi-year strategic and financial framework at its Investor Day on December 8, 2026.4
XII. Activist & Skeptical Investor Stress Test
An activist investor building a position in Broadridge and drafting a campaign letter would likely focus on several core vulnerabilities across management's reporting disclosures, balance sheet exposures, and operational execution.
1. Changing the reporting scoreboard. Beginning in the fourth quarter of fiscal 2026, Broadridge introduced a new metric — "equity revenue position growth" — which excludes small and fractional equity positions that generate no revenue. The company stated that prior-year comparative information for this metric was unavailable.4 The resulting gap is meaningful: while total equity position growth reached 16% in both fiscal 2025 and fiscal 2026, equity revenue position growth was lower at 12% in each year.4
That four-percentage-point gap highlights the operational impact of direct indexing and fractional-share trading. Retail brokerages increasingly divide shares into fractions and assemble portfolios containing hundreds of micro-positions — accounts that Broadridge must process but often cannot bill. While introducing a refined metric represents good disclosure practice, doing so without historical restatements during a quarter focused on headline position expansion invites scrutiny. The updated metric offers greater clarity on core revenue drivers, yet it leaves investors without a long-term historical benchmark for the specific volume driving revenue growth.
2. Unframed digital asset risks on the balance sheet. For a firm whose valuation relies on earnings predictability, holding $265 million in digital assets introduces uncharacteristic volatility, particularly given that 70% of its lifetime token earnings are voluntarily locked through mid-2029 alongside warrants in a digital-asset treasury vehicle created from a restructured shell company.14 Management properly excluded the $227 million mark-to-market gain from adjusted earnings, and the initial cash outlay was negligible.2 However, locking tokens accepts illiquidity to maintain validator status, the asset is carried at sixteen times its cost basis, and token receipts are recorded directly as segment revenue.1 A sharp decline in Canton Coin during fiscal 2027 would simultaneously depress reported revenue, non-operating income, and balance sheet asset values.
3. Flawed long-term executive incentive design. Prior to fiscal 2026, executive long-term incentive compensation relied exclusively on earnings-per-share metrics, rewarding debt-funded acquisitions and share buybacks over organic expansion. Management addressed this imbalance by adding organic recurring revenue growth to performance share criteria starting with fiscal 2026 grants, though the adjustment occurred only after explicit investor pushback.14
4. Framing a margin shortfall as target delivery. In its three-year performance recap, management highlighted full objective delivery despite achieving only 32 basis points of annual adjusted operating margin expansion against its stated goal of at least 50 basis points per year.4
5. Client concentration paired with regulatory scrutiny. Company disclosures acknowledge reliance on a concentrated group of major financial institutions and the necessity of maintaining their business on "favorable pricing terms."4 While client concentration in a mandated utility model is manageable in isolation, it carries heightened operational risk when paired with regulatory action, such as the Canadian Competition Bureau obtaining court orders against six major bank clients in its ongoing software investigation.18
6. Heavy reliance on intangible balance-sheet assets. Goodwill stands at $3.788 billion out of $8.945 billion in total assets, while net intangibles and deferred client conversion costs push total intangible assets to roughly 65% of the balance sheet.1 The write-down of Penson securities following the 2010 clearing exit serves as a historical reminder that acquired assets do not always compound as projected.12
And the bull rebuttal
The bullish counterarguments rest on established structural strengths and operating metrics.
High client retention reflects genuine structural lock-in. Client attrition of roughly two percentage points of recurring revenue per year, across a client base encompassing virtually every major North American broker-dealer, provides concrete evidence of high switching costs.4
Regulatory shifts have historically expanded processing revenues. Implementation of the Tailored Shareholder Reports rule created a new recurring compliance service line.24 Similarly, Regulation E-Delivery promises to reduce low-margin pass-through distribution expenses while accelerating a digital transition where Broadridge already maintains a 91% proxy digital adoption rate.123 Regulatory precedent, such as the 1997 preference management fee, demonstrates that fee structures historically compensate processors for driving paper suppression.8
Global Technology and Operations displays margin inflection. An expansion in segment pre-tax margin from 11.3% to 15.5% in fiscal 2026, alongside a 48% increase in segment earnings, offers initial evidence that past front-office acquisitions are generating operating leverage.21
Capital return discipline remains strong. Free cash flow conversion reached 110% of adjusted net earnings in fiscal 2026, supported by record share repurchases of $604 million and a twentieth consecutive annual dividend increase.42
This stress test yields a balanced perspective rather than a definitive verdict. Ultimately, Broadridge's valuation trajectory will depend on whether its regulatory fee engine adapts smoothly to digital default delivery and whether its expanded technology suite can sustain organic growth.
XIII. Playbook: Lessons for Builders & Investors
Lesson 1: The most durable monopolies build on tasks competitors avoid. Broadridge's dominant market position emerged because processing proxy communications was an operational headache—a high-risk, heavily regulated obligation that brokerages preferred to outsource. Competitors did not construct parallel infrastructure because few wanted the burden. The underlying principle holds: long-term moats form where regulatory mandates overlap with distasteful operational tasks. The strongest opportunities often hide on a compliance officer's risk register rather than a product feature roadmap.
Lesson 2: A regulated moat comes with a price ceiling. The same regulatory frameworks that guarantee processing demand also establish fee caps, giving corporate issuers a direct channel to lobby for rate reductions—a dynamic that played out in 1997, 2002, 2013, and again in 2026.8695 The only sustainable defense is to reduce unit operating costs faster than regulatory price caps decline. Businesses that mistake a regulatory mandate for pricing power face repricing risk, whereas those that leverage mandated volume while cutting unit costs preserve their profit spread.
Lesson 3: Workflow digitization is survivable, but not automatically margin-accretive. Conventional wisdom holds that eliminating low-margin, pass-through postage mechanically expands operating margins. However, Broadridge's experience during the 2007–2010 Notice and Access transition showed flat segment margins throughout the rollout.12 While shedding pass-through physical costs improves the overall revenue mix, those gains are offset by lower per-position fee realization and the capital required to construct digital infrastructure. Investors evaluating the 2026 e-delivery proposal as an automatic margin catalyst risk misjudging the net financial effect.
Lesson 4: Institutional customer retention stems from risk management, not feature velocity. While consumer fintechs spend heavily to acquire users who churn over modest rate differences, financial infrastructure providers retain clients for decades because switching costs are measured in regulatory risk rather than software licensing fees. In enterprise markets, the critical sales determinant is not feature differentiation but the operational consequence of a failed migration. Where operational failure carries statutory penalties, client churn approaches zero—as demonstrated by Broadridge's top 50 clients, who accounted for 74% of revenue at the 2007 spin-off while averaging over a decade of tenure.3
Lesson 5: Track changes in disclosure definitions. The most informative disclosure in Broadridge's fiscal 2026 financial reporting was not a headline revenue figure, but a structural definition: the introduction of equity revenue position growth, alongside the disclosure that prior-year comparative data was unavailable.4 Modifications to core reporting definitions often reveal the operational variables management is beginning to navigate.
XIV. Looking Forward & Epilogue
Broadridge enters fiscal 2027 in an unusual position for an infrastructure vendor: operationally strong, yet facing notable strategic uncertainty.
The underlying operating metrics remain robust. The firm recently reported its highest free cash flow conversion rate, largest capital return, record fourth-quarter closed sales, and twentieth consecutive annual dividend increase as an independent public entity.42 Management has expanded its franchise into futures and options execution, launched a multi-asset tokenization platform named DLx with a target market entry by the end of fiscal 2027, and placed more than $800 billion in assets under management onto an AI-powered custom policy voting engine.162023
The primary strategic uncertainty stems from external regulatory determinations. The SEC will decide, following a comment period scheduled to close in September 2026, how broadly to establish electronic delivery as the default standard — a ruling that directly impacts Broadridge's largest revenue stream.5 Concurrently, Canada's Competition Bureau will determine whether Broadridge's book-of-record software practices warrant regulatory remedies.17 Neither outcome rests within management's direct control.
For investors assessing the business over the medium term, three operational metrics contain the core signal.
First, equity revenue position growth. Distinct from total position growth, this refined metric — introduced in the fourth quarter of fiscal 2026 — tracks revenue-generating positions.4 It provides the clearer indicator of whether expanding retail participation continues to drive the billable base, or whether fractional trading and direct indexing are diluting account monetization relative to headline account expansion.
Second, closed sales and the recurring revenue backlog. Closed sales measure the annual recurring revenue from contracts signed during the period, net of a 5% allowance, with major implementations taking twelve to twenty-four months to generate revenue.1 The metric reflects recent operational variability: closed sales reached $342 million in fiscal 2024, declined 16% to $288 million in fiscal 2025, and recovered partially to $305 million in fiscal 2026 — remaining below the fiscal 2024 peak against fiscal 2027 guidance of $290 million to $330 million.312 The recurring revenue backlog of $470 million provides forward revenue visibility, with execution judged by whether closed sales surpass previous record levels.4
Third, GTO segment pre-tax margin. Reaching 15.5% in fiscal 2026, up from 11.3% in fiscal 2025, segment margin serves as the benchmark for whether the $2.5 billion acquisition of Itiviti and subsequent front-office investments are translating international expansion into operating leverage.21 Sustained margin expansion would validate the front-to-back integration strategy, whereas a plateau would suggest fiscal 2026 gains reflected cyclical volume rather than structural efficiency.
Other initiatives — including tokenized repo transaction volumes, digital token holdings, internal AI productivity targets, and bond trading venues — represent optionality that warrants modest weight until reflected in core segment metrics.
The central question concerns the firm's fundamental model. While Broadridge is frequently described as the financial system's central nervous system, its revenue model is governed by fee schedules set by the Securities and Exchange Commission. The historical record indicates a more precise characterization: Broadridge operates as a regulated utility that matured within a corporate parent, offering infrastructure-level volume reliability bounded by a regulatory price ceiling. That structural framework has enabled two decades of consistent compounding, even as the enterprise operates within boundaries established by external regulatory oversight.
References
-
Broadridge Financial Solutions, Inc. Form 10-K for the fiscal year ended June 30, 2026 — SEC EDGAR, 2026-08-04 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Broadridge Reports Fourth Quarter and Fiscal Year 2026 Results — Broadridge Investor Relations, 2026-08-04 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Broadridge Financial Solutions Information Statement (Form 10-12B/A Exhibit 99.1) — SEC EDGAR, 2007-03-16 ↩↩↩↩↩
-
Broadridge Fourth Quarter and Full-Year Fiscal 2026 Earnings Conference Call Presentation (Form 8-K, Exhibit 99.2) — SEC EDGAR, 2026-08-04 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Proposed Rule: Electronic Delivery of Information Under the Federal Securities Laws (Release No. 33-11430) — U.S. Securities and Exchange Commission, 2026-07-16 ↩↩↩↩
-
Notice of Filing of Proposed Rule Change by the New York Stock Exchange Amending Its Rules Regarding the Transmission of Proxy and Other Shareholder Communication Material (Release No. 34-45263) — U.S. Securities and Exchange Commission, 2002-01-11 ↩↩↩
-
Richard J. Daly, Chief Executive Officer, Broadridge Financial Solutions, Inc. — Biography, U.S. Securities and Exchange Commission Proxy Process Roundtable ↩↩
-
Notice of Filing of Proposed Rule Change by the New York Stock Exchange, Inc., Relating to the Reimbursement of Member Organizations for Costs Incurred in the Transmission of Proxy and Other Shareholder Communication Material (SR-NYSE-98-05) — U.S. Securities and Exchange Commission ↩↩↩↩
-
Order Granting Approval to Proposed Rule Change Amending NYSE Rules 451 and 465 and Related Provisions of Section 402.10 of the NYSE Listed Company Manual — Federal Register, 2013-10-24 ↩↩↩
-
ADP Completes Spin-Off of Broadridge Financial Solutions (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2007-04-02 ↩↩
-
Final Rule: Internet Availability of Proxy Materials (Release No. 34-55146) — U.S. Securities and Exchange Commission, 2007-01-29 ↩
-
Broadridge Financial Solutions, Inc. Form 10-K for the fiscal year ended June 30, 2010 — SEC EDGAR, 2010-08-10 ↩↩↩↩↩↩↩
-
Concept Release on the U.S. Proxy System (Release No. 34-62495) — U.S. Securities and Exchange Commission, 2010-07-14 ↩
-
Broadridge Financial Solutions, Inc. 2025 Proxy Statement (Form DEF 14A) — SEC EDGAR, 2025-10-02 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Broadridge Extends Capital Markets Franchise with Acquisition of Itiviti — Broadridge Press Release, 2021-03-29 ↩↩↩↩
-
Broadridge Completes Acquisition of CQG, Unlocking Globally Connected, Multi-Asset Trading Solutions — Broadridge Press Release, 2026-05-01 ↩↩
-
Competition Bureau Advances an Investigation into Broadridge's Business Practices — Competition Bureau Canada, 2024-11-26 ↩↩↩↩↩
-
Competition Bureau Investigation of Broadridge to Proceed After Court Orders — Lexpert ↩↩↩
-
$280 Billion in Average Daily Processed Trade Volumes on Broadridge Distributed Ledger Repo Platform — Broadridge Press Release, 2025 ↩
-
Broadridge (BR) Q4 2026 Earnings Call Transcript — The Motley Fool, 2026-08-04 ↩↩↩↩↩
-
LTX by Broadridge Launches BondGPT Powered by OpenAI GPT-4 — Broadridge Press Release, 2023-06 ↩
-
Goldman Sachs, J.P. Morgan, TD Securities, Morgan Stanley, and Bank of America Join LTX in Bid to Unlock Greater Liquidity in Corporate Bonds — Broadridge Press Release, 2026-06 ↩
-
Broadridge Q4 FY2026 Slides: 8% Recurring Growth, Tokenization Push — Investing.com, 2026-08-04 ↩↩↩↩↩
-
SEC Adopts Rule Requiring Tailored Shareholder Reports for Mutual Funds and ETFs — U.S. Securities and Exchange Commission, 2022-10-26 ↩↩
-
Untangling Motive and Clearlake's Acquisition of Mediant Communications — BetaNXT ↩
-
Proxymity Secures $26 Million Commitment in Additional Growth Funding From Existing Investors — Proxymity, 2025-02 ↩
-
Proxymity Launches Vote Connect Global with Citi Securities Services — Citi, 2024 ↩
-
Broadridge Highlights Path for Sustainable Long-term Growth at Investor Day 2023 — Broadridge Investor Relations, 2023-12-07 ↩
-
SEC Proposes Rule Changes to Make E-Delivery the Default Option — Ropes & Gray LLP, 2026-07 ↩
-
Broadridge Financial Solutions (BR) Stock Price & Overview — StockAnalysis.com ↩
-
Broadridge Reports Fourth Quarter and Fiscal 2024 Results — Broadridge Investor Relations, 2024-08-06 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube