Zillow Group: From Zestimate to the Whole Housing Journey
I. The Home Estimate That Crashed the Site
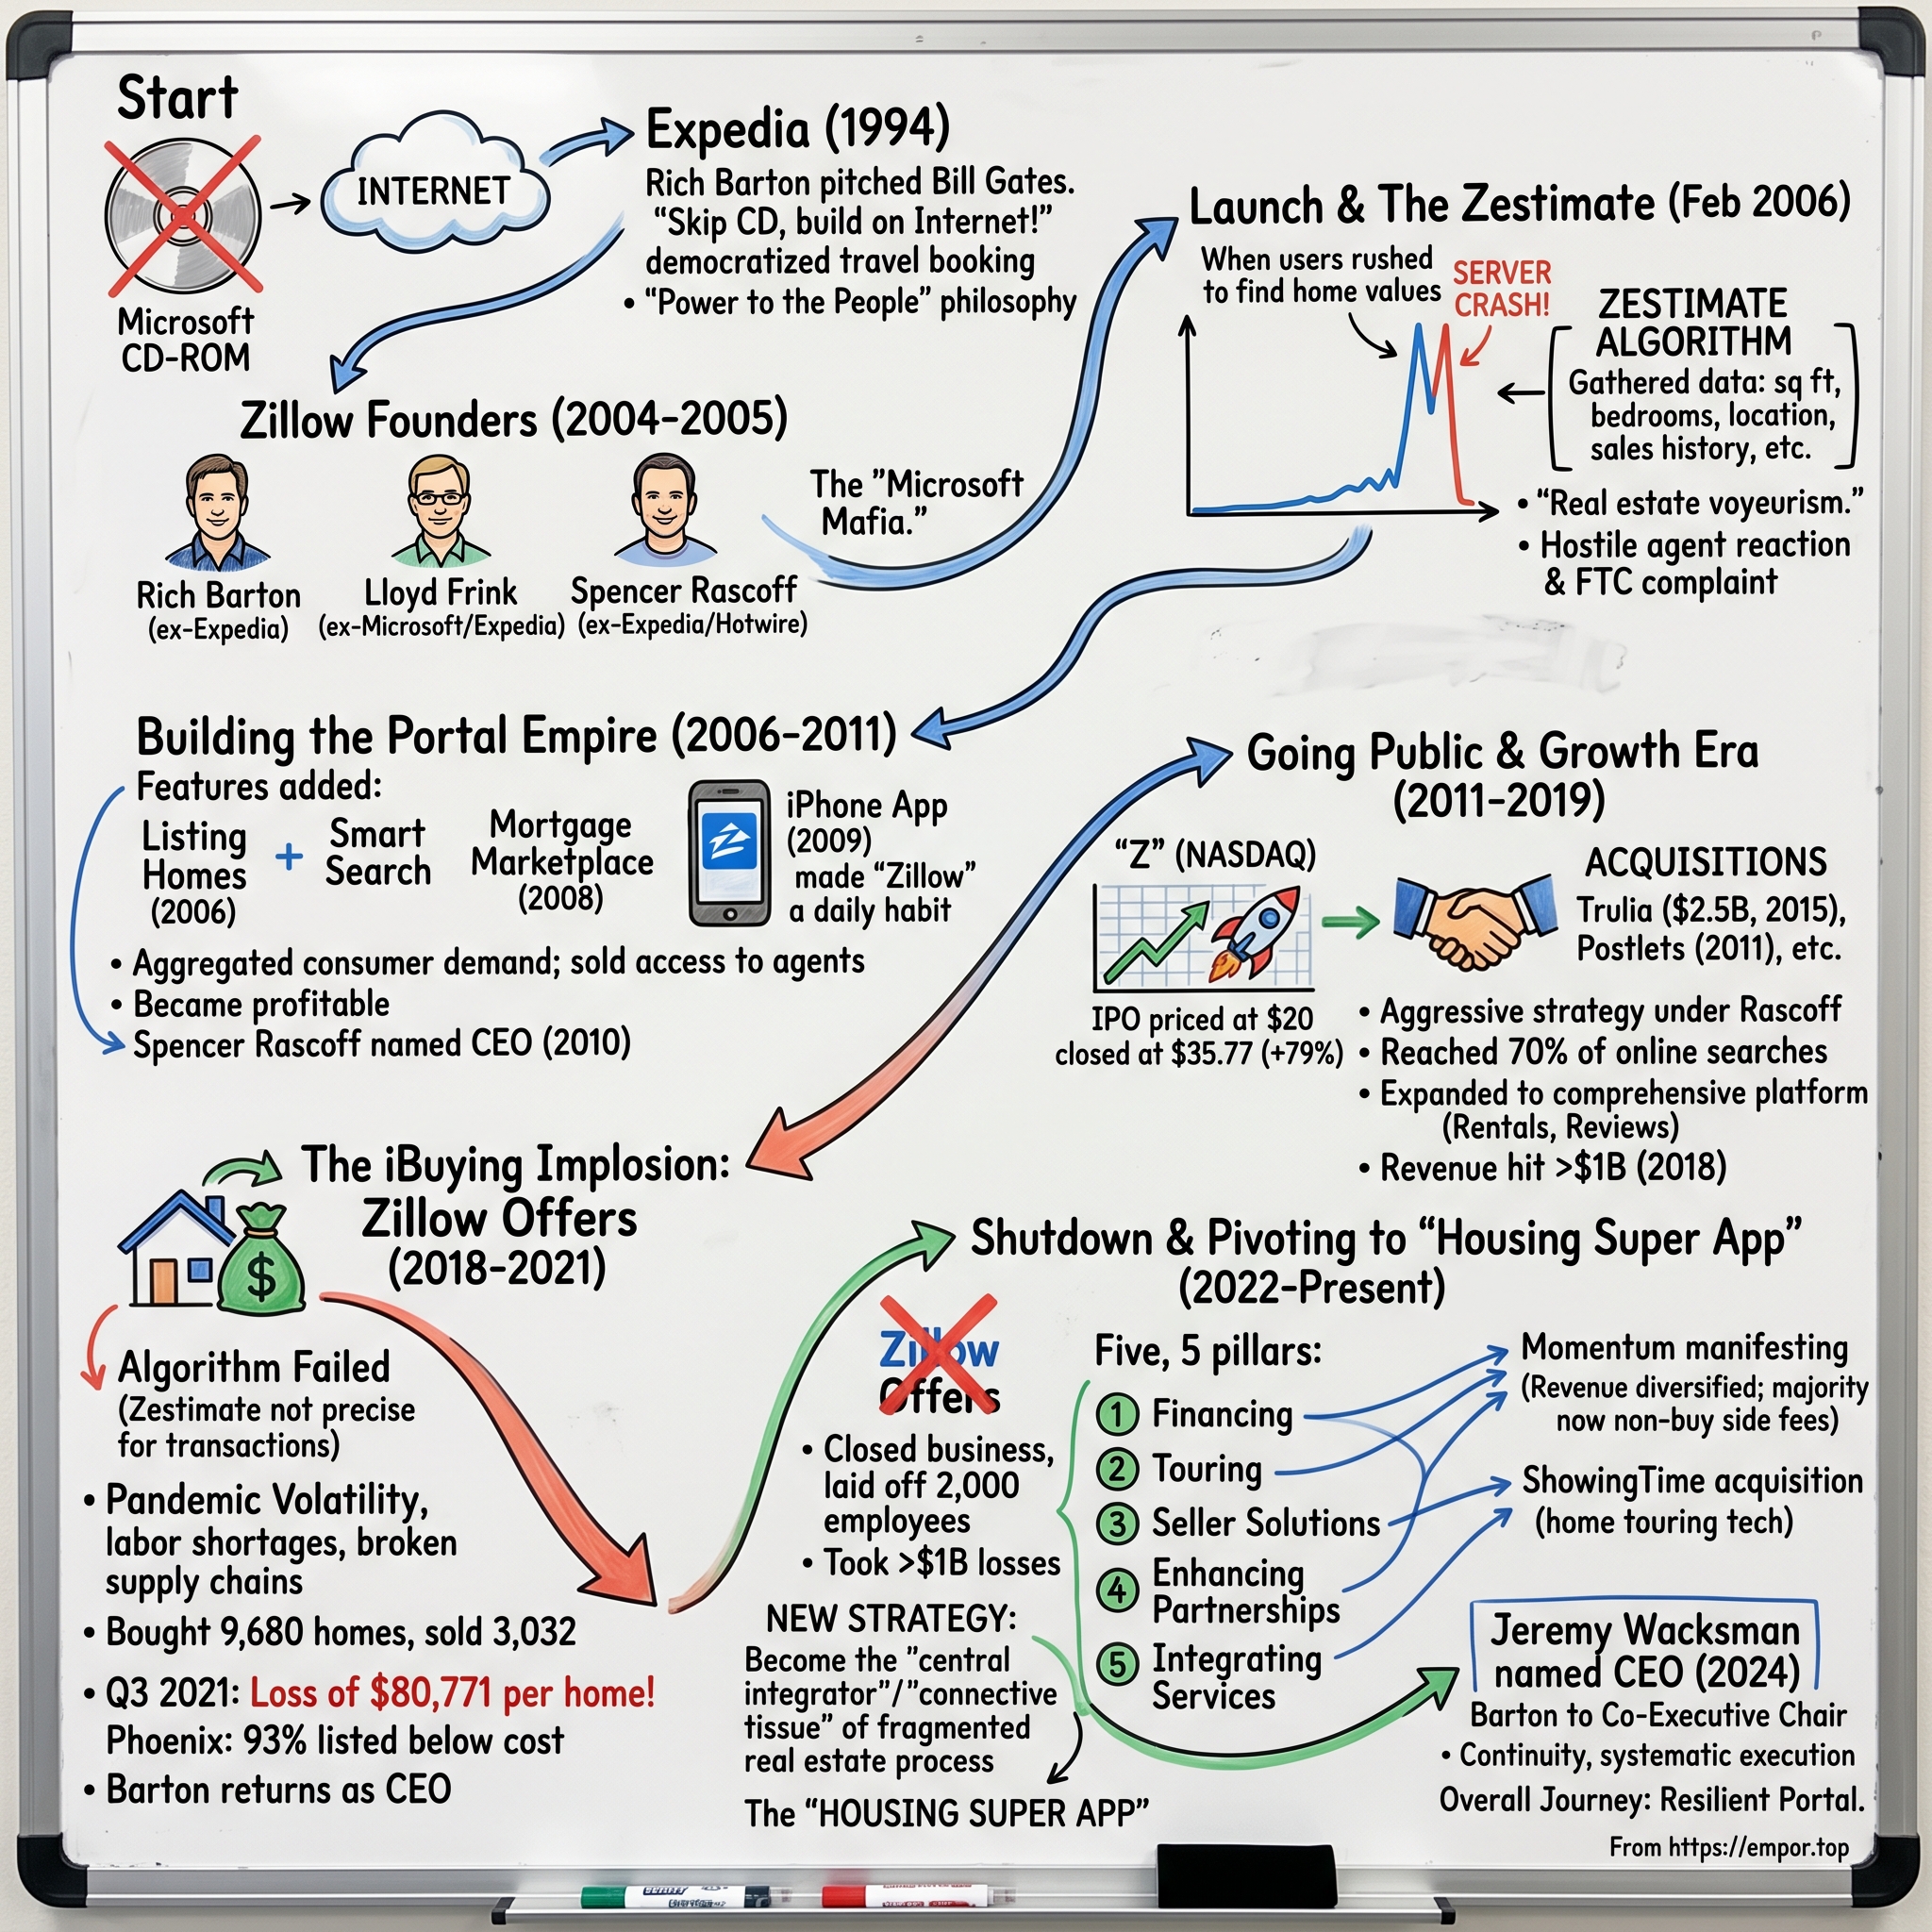
At midnight on Wednesday, February 8, 2006, a small Seattle company switched on a website that did something no American consumer had been able to do before: type in almost any address in the country and get back a number for what the house was worth. The site carried free value estimates and data on more than 60 million homes.1 By seven in the morning it had served more than 300,000 page views, and for much of the day visitors saw an apology instead of a price: the beta site, the message said, was down "due to overwhelming demand."1 By two in the afternoon the company's blog called the site stable, although access was still sporadic.1
The number people were crowding in to see was called a Zestimate, and it was a provocation as much as a product. Until then, the value of a house was something you learned from a real estate agent, a county assessor, an appraiser hired by a bank, or a neighbour who had sold last spring. The data existed in public records and in the listing databases that brokers shared among themselves, but it was scattered, local and hard for an ordinary person to read. Zillow's bet was that if you gathered it, ran it through a model and gave it away, people would come back again and again, not only when they were buying or selling, but whenever they were curious. Homes are the largest asset most families own. Curiosity about them turns out to be close to bottomless.
That first day sets up everything that follows. Zillow did not start as a brokerage, a lender or a landlord. It started as a promise to the consumer: we will show you what was hidden. The audience that promise built is now enormous. In the second quarter of 2026, Zillow's apps and sites averaged 239 million unique users a month.2 Almost twenty years after the servers buckled, Zillow is still, by a wide margin, the place Americans go to look at houses.
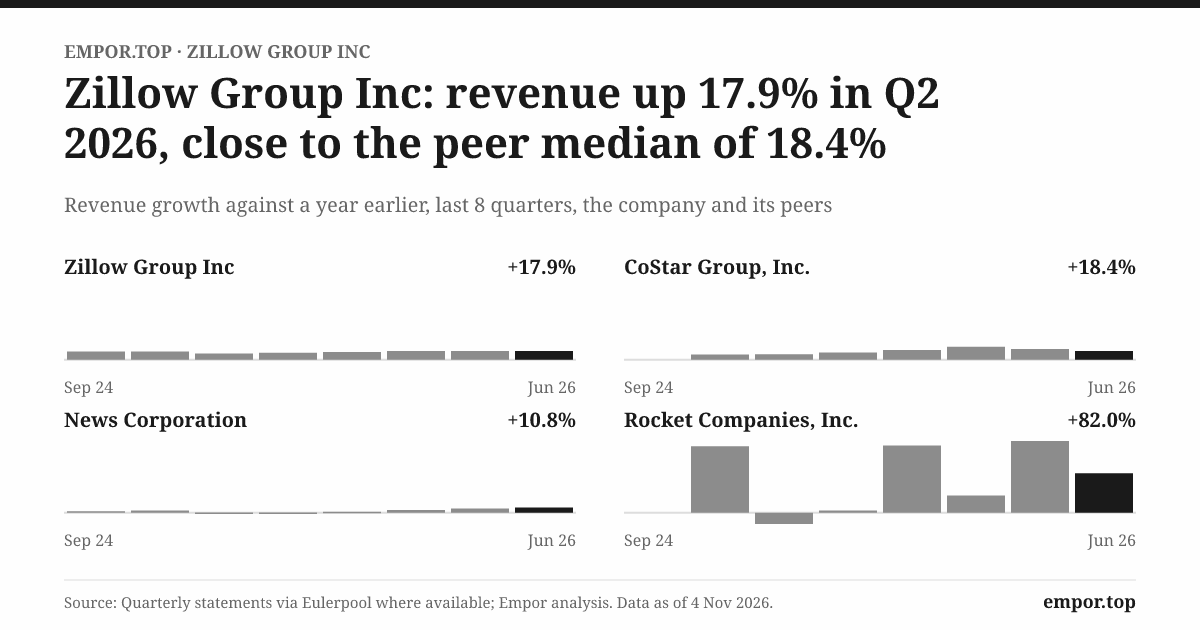
Yet the most interesting number in that same quarter is a mismatch. Revenue rose 18% from a year earlier, to $772 million, while those monthly users fell 2%.2 Zillow made noticeably more money from a slightly smaller crowd. That is either the sign of a business learning to earn more from each person who walks through its front door, or the sign of a business leaning harder on a fixed pool of agents, landlords and borrowers to pay for an audience that has stopped growing. Which of those it is turns out to be the question this whole story keeps circling.
Management has a clear answer. Zillow no longer describes itself as a listings portal. Chief executive Jeremy Wacksman calls it "the operating system for modern real estate," and the company says it is building toward a future in which renters, buyers, sellers and the professionals who serve them complete the whole journey, from search to keys, through an integrated Zillow experience.2 The company's investor materials now present buying, selling, renting and financing as one connected platform.3
The record gives reasons for both hope and caution. Revenue still depends heavily on how many homes change hands and how much agents, landlords and lenders are willing to spend to reach the people searching. Zillow does not own most of the listings it shows; brokers and multiple listing services supply them. It does not employ most of the agents its leads go to. And the one time it tried to become a principal in the housing market, buying and selling homes on its own balance sheet, the experiment ended in a multibillion-dollar retreat that still shapes how investors read every new ambition.
Three questions therefore run through the story. First, does Zillow's audience become a durable advantage in the transaction itself, or does it remain an advertising asset rented out to the industry? Second, can growth finally produce owner earnings, real profit left for shareholders after the cost of stock handed to employees and the money reinvested in the product? Third, can a company that wants to sit at the centre of every move keep its partners, its competitors' cooperation and its regulators on side while it does so?
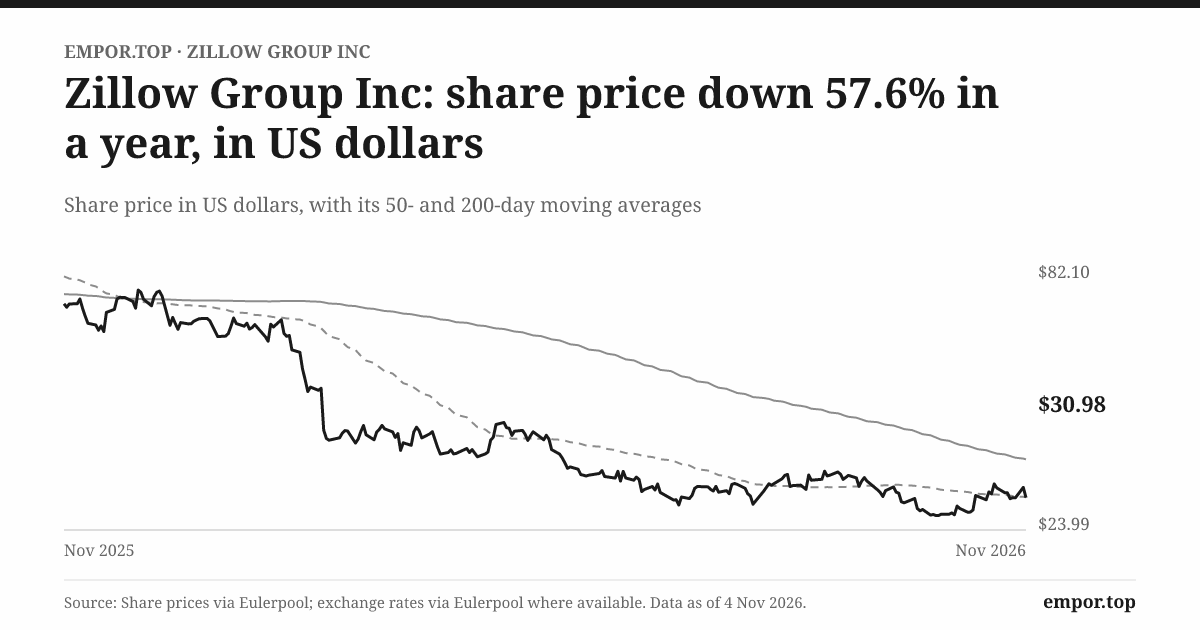
The present scale is real, and it should not be mistaken for profitability. Zillow's 2025 revenue was about $2.6 billion, but the company still posted a small operating loss for the year, and the net profit it did report was a sliver of revenue.4 The market has noticed the gap between audience and earnings. On November 4, 2026, the day Zillow is due to report its third quarter after the close,5 the Class C shares traded near $31, almost 60% below their high of the past year.6
To understand how a free number on a screen became a $2.6 billion business that still struggles to show a GAAP profit, the story has to go back to the two men who had already done this once, in a different industry, with airline tickets.
 Subscribe on LinkedIn
II. The Portal Built on a Consumer Promise
Rich Barton liked to tell investors that he had built his career on one idea: take an industry where professionals hoard information, put that information in front of consumers, and watch the industry reorganise around them. He had done it first inside Microsoft, where he founded the travel-booking unit that became Expedia and led it as chief executive after it was spun out.7 Travel agents had once been the only people who could see fares and seat availability. Expedia put the screen in front of the traveller. Barton later co-founded Glassdoor, which did the same thing for salaries and workplace reviews.7 His partner Lloyd Frink, a Microsoft veteran who had worked alongside him at Expedia, brought the engineering and product instincts that turned the idea into software.7
Real estate in the early 2000s looked like travel before Expedia, only more so. The listings that showed which homes were for sale lived in hundreds of local multiple listing services, cooperative databases owned and governed by brokers. Sale prices sat in county records that differed from one jurisdiction to the next. Agents controlled the flow of both, and they were paid, in most transactions, a commission measured as a percentage of the sale price. A buyer who wanted to know whether a house was fairly priced had to ask the person who would be paid more if the price were higher.
The Zestimate attacked that asymmetry directly. It was imprecise, and Zillow was candid that it was an estimate rather than an appraisal, but it gave every homeowner and every would-be buyer a starting number that did not come from someone with a commission at stake. It also had a quieter genius. Most people buy or sell a home only a handful of times in their lives, which is a terrible frequency for building a consumer brand. People check the value of their own home, and their neighbour's, far more often. The Zestimate turned an infrequent transaction into a habit.
From that wedge, Zillow added the pieces that made the habit sticky. It layered for-sale listings onto the map, so the curious could become shoppers without leaving. It moved early and aggressively into mobile apps, which mattered enormously in a category where people browse on the sofa and then drive past a house on a Saturday. It added rental listings, which brought in a younger, more frequent customer who moves every year or two rather than every decade. By the time of its 2018 annual report, the company's sites and apps were drawing well over a hundred million monthly unique users, and it employed more than 4,300 full-time staff.8
The business model that grew around this audience was not a toll on transactions. It was advertising, and it was aimed at the professionals who wanted to reach those consumers. The most important product, Premier Agent, let agents pay to appear alongside listings and to receive the contact details of shoppers who asked to see a home. Landlords and property managers paid to promote rentals. Lenders paid to reach borrowers. Revenue rose from about $325 million in 2014 to roughly $1.3 billion by 2018, as Zillow sold more of its audience's attention to the industry that served it.98 In 2016, 2017 and 2018, revenue grew at between roughly a quarter and a third a year.8
The company that grew around this model was run, for most of the 2010s, by Spencer Rascoff, a co-founder who had come up through the finance side and became chief executive while Barton moved to the chairman's seat.8 Rascoff's Zillow was a sales machine as much as a technology company: it built large teams to sign up agents market by market and priced leads by ZIP code, so that the most valuable neighbourhoods carried the highest price. It was the era in which the audience was converted into a reliable advertising business, and also the era in which the habit of large stock-based pay, standard for Seattle technology companies competing with Amazon and Microsoft for engineers, became embedded in the cost structure.
That success contains the central tension of the company, and it is worth stating plainly before the story moves on. Zillow's audience is valuable because agents, brokers, landlords and lenders want to reach it. But the content that brings the audience in, above all the for-sale listings, largely belongs to those same agents and brokers, flowing to Zillow through feeds from listing services and brokerages. Real estate is local, regulated and full of licensed intermediaries, and transactions happen rarely for any one household. A consumer portal in that world is powerful, but it is also a guest at someone else's party. It can sell the guests' attention back to the hosts. It cannot easily throw the party itself.
The founders understood this. Their public stance for years was that the agent would remain at the centre of the transaction for a long time, because buying a house is emotional, complicated and expensive enough that people want a human guide. Zillow's job was to be where the journey started. For a decade that was enough. By 2025, revenue had reached about $2.6 billion, roughly eight times its 2014 level.49
But "where the journey starts" is not where the money in a housing transaction ends up. Commissions, mortgage fees, title and escrow, moving costs: the large fees sit further down the funnel. Every few years Zillow has tried to move further down that funnel, and each attempt has tested whether the portal's partners would keep cooperating. The first big move, though, was not down the funnel at all. It was sideways, against the one rival that looked capable of becoming Zillow's equal.
III. The Trulia Deal: Buying Scale in the Portal Wars
By the summer of 2014, the online real estate market had sorted itself into a three-way race. Zillow had the brand and the Zestimate. Trulia, a San Francisco company with a strong design culture and a loyal following among younger buyers, had built a portal of comparable reach. Realtor.com had the closest ties to the industry's own organisations and data. All three were selling essentially the same thing to essentially the same customers: agent advertising, priced against the audience each could deliver.
In that kind of market, two portals spending heavily against each other to win the same agents is an expensive way to stand still. Every dollar of marketing one side spends to steal an agent, the other has to match to keep her. Consolidation offers an obvious escape, and on July 28, 2014, Zillow took it. It announced an agreement to acquire Trulia in an all-stock transaction, with each Trulia share converted into 0.444 of a Zillow Class A share.10 At announcement, the deal implied a value of about $3.5 billion, a 25% premium to Trulia's closing price on the last trading day before the news.10
Paying in stock was a deliberate choice. Zillow was a growth company with no meaningful profits and a richly valued share; its own equity was the cheapest currency it had. Using it meant Trulia's shareholders would share in whatever the combined company became, which helped persuade them to accept, and it meant Zillow did not have to borrow billions against an advertising business that was still losing money. The cost was dilution: Zillow's existing owners were handing a large slice of the company to Trulia's. A reorganisation also created the holding company structure that exists today, Zillow Group, with separate classes of stock.
The valuation deserves care, because two numbers tend to get blurred into one. The $3.5 billion figure was the implied value of the stock offered on the day the deal was announced. By the time the transaction closed in February 2015, Zillow's own share price had moved, and the purchase consideration recorded in the company's 2015 annual report came to about $2.0 billion.9 Neither number is "the price paid" in some absolute sense. The first describes what the market thought the offer was worth in July 2014; the second is the accounting value of the shares that actually changed hands. A listener who hears that Zillow "paid $3.5 billion for Trulia" is hearing the headline, not the ledger.
The deal also had to clear Washington. The Federal Trade Commission investigated whether combining the two largest portals would let Zillow raise prices to agents. In February 2015 it closed its review without action. The commissioners who explained the decision said the evidence did not suggest that a hypothetical monopolist of real estate portals could profitably impose a price increase on agent advertising, because agents had many other ways to find clients and spent much of their marketing money elsewhere.11 That finding is worth holding on to. The regulator decided that portals were not a market of their own, which was good for the merger but awkward for anyone who later wanted to argue that Zillow's portal position was an impregnable moat. If agents can easily take their advertising elsewhere, the portal's power over them is limited.
What did the acquisition actually deliver? The answer is more modest than the headlines suggested and more durable than the sceptics feared. Zillow Group kept both brands running, so it captured Trulia's audience without forcing users to switch habits.9 It removed its strongest direct rival from the bidding war for agents. And it gave the combined company enough reach that, for the next decade, the national portal market looked like Zillow first and everyone else a considerable distance behind. Zillow does not disclose a return on the Trulia investment, nor a set of comparable transactions that would settle whether a 25% premium was rich or cheap. The fairer test is what happened to the combined platform. Revenue roughly doubled in 2015 as Trulia's sales were folded in, and kept growing at more than 20% a year for several years after.98 Operating losses persisted throughout that period, though, which means the scale bought in 2014 did not by itself translate into profit.8
The Trulia deal established a pattern. When Zillow saw a strategic gap, it was willing to buy rather than build, and to pay a premium for it. Seven years later it applied the same logic to a very different kind of asset. In February 2021 Zillow agreed to buy ShowingTime, the dominant software that agents and brokers use to schedule home tours, for $500 million in cash.12 ShowingTime was not an audience business at all. It was plumbing: the system that coordinates who gets into which house at what time, used by hundreds of thousands of agents across the country.12
The strategic logic was clear. A shopper who finds a house on Zillow wants, above all, to see it, and the moment of booking a tour is the moment an anonymous browser turns into a client with a name, a timeline and an agent. Owning the scheduling layer put Zillow inside that moment. Whether it has paid off is harder to say. Zillow points to ShowingTime as part of a suite of professional tools, alongside the customer-relationship software Follow Up Boss and the transaction-management product dotloop, that it says are widely used across agents' daily workflows.3 It does not disclose ShowingTime's revenue, its profitability, or any measure showing that agents who use it are more likely to stay with Zillow or to buy more leads. Usage is a sign of a useful product. It is not yet proof that $500 million bought a revenue or retention advantage, and until Zillow publishes evidence of that kind, the honest verdict on ShowingTime is "plausible but unproven."
Trulia and ShowingTime were bets that extended the platform without changing its fundamental nature. Zillow was still an intermediary between consumers and the professionals who served them. In 2018, though, the company decided to stop standing beside the transaction and step into the middle of it.
IV. Zillow Offers: When the Portal Took the Other Side of the Deal
On the Tuesday afternoon of November 2, 2021, Zillow released its third-quarter results with a headline that would have been unthinkable a year earlier: the company planned to wind down Zillow Offers, the home-buying business it had spent three years building into the centrepiece of its future.13 The same announcement said Zillow expected to cut about a quarter of its workforce.13 A few weeks earlier, the company had stopped signing new contracts to buy homes, saying it had more houses in the pipeline than its renovation crews and local operations could handle.13 Now it was conceding that the entire model was too unpredictable to continue.
To see how a portal got there, rewind to 2018. That spring, Zillow began buying homes directly from sellers in Phoenix and Las Vegas, with the plan of making light repairs and reselling them quickly.8 The idea, known in the industry as iBuying, had been pioneered by start-ups such as Opendoor. Its appeal to sellers was obvious: no showings, no open houses, no months of uncertainty, just a cash offer and a closing date of your choosing. Its appeal to Zillow was even larger. A portal earns a few hundred or a few thousand dollars in advertising per transaction. A company that buys and resells the house touches the whole sale price and can attach a mortgage, title insurance and escrow to it.
There was also a seductive argument that Zillow was uniquely qualified. It had the Zestimate, built on more home-value data than almost anyone. It had the largest audience of people thinking about selling. If anyone could price homes accurately enough to buy them at scale, surely it was the company that had been estimating home values for twelve years. When Barton returned as chief executive in 2019,7 he put the home-buying business at the centre of the company's plans.
The business grew quickly. In 2019 Zillow's reported revenue more than doubled, largely because the sale price of every house Offers resold counted as revenue.8 By 2021, total reported revenue including home sales exceeded $8 billion.14 That headline figure is worth translating. A portal that earned roughly $2 billion a year from advertising and fees had become, on paper, a company several times larger, because it was now booking the full price of houses that passed through its hands. Revenue scale of that kind looks impressive and carries almost none of the margin of the advertising business. It brings something else instead: risk on every single house.
Think of the iBuying model as a chain of four bets. First, the price you pay for a house has to be close enough to its true market value that you can resell it at a profit after costs. Second, the repairs have to be done quickly and cheaply, which means armies of contractors in dozens of cities. Third, the house has to sell before market conditions shift, because every week it sits on the balance sheet costs money in interest, taxes and upkeep. Fourth, you have to do all this at enough volume that the overhead of the operation is spread across many homes. An advertising marketplace makes none of these bets. Zillow Offers made all four at once, with billions of dollars of houses.
In 2021, several of those bets went wrong at the same time. The pandemic housing boom had pushed prices up fast, and Zillow's pricing algorithms, trying to win more homes, bid aggressively. Labour shortages slowed renovations, so houses sat longer. And then price growth in some markets slowed sharply just as Zillow's inventory peaked. The company found itself holding thousands of homes, many worth less than it had paid. In the third quarter it recorded a large write-down on its inventory, and over the full year 2021 the write-downs totalled $407.9 million.14 Even after those reductions, inventory stood at roughly $3.9 billion at the end of 2021.14
The cash flows tell the story in their starkest form. In 2021 Zillow's operating cash flow was negative by about $3.2 billion, because buying houses counts as an operating cost for a company whose business is selling them.14 In 2022, as the inventory was sold off, operating cash flow swung to about positive $4.5 billion.4 Neither figure says anything about the health of the underlying portal. Together they show the size of the balance-sheet exposure Zillow had taken on, and then had to unwind.
Management's own explanation was unusually blunt. In announcing the wind-down, Zillow said that the unpredictability of forecasting home prices far exceeded what it had anticipated, and that continuing to scale Offers would bring too much volatility to earnings and the balance sheet, along with lower returns on equity than the company wanted.13 Its annual report for 2021 went further, describing pricing unpredictability, capacity constraints and operational challenges as the reasons the business did not fit Zillow's goals, and said the company expected the wind-down to be substantially completed by the third quarter of 2022.14 That is a rare thing in corporate life: a management team conceding not merely that execution slipped, but that the core assumption was wrong.
That assumption deserves its own verdict, because it bears directly on how much weight to put on Zillow's "data moat" today. The Zestimate is good at what it was designed for: giving a reasonable sense of value across millions of homes, where errors in individual cases wash out. Buying a specific house requires something different. It requires predicting the price at which that particular house will sell, several months out, in a local market that can turn within weeks, against sellers who know things about their homes that no dataset captures. Sellers who accepted Zillow's offers were, on average, the ones for whom Zillow had overpaid; the ones it had lowballed went elsewhere. That is adverse selection, and it is the reason a better estimate is not the same as a better trade. Zillow's data advantage was real, but the Offers record shows that it did not extend to forecasting short-term local price movements well enough to run a balance-sheet business at scale.
It would be wrong to turn that into a sweeping indictment. Offers was a serious capital-allocation failure and a costly one, in money, in staff and in credibility. But it was also discontinued decisively once its economics were clear, rather than nursed along for years. Zillow sold down the inventory, retired the debt it had used to finance the homes, and returned to being a business that does not own houses. Borrowings fell from about $2.5 billion at the end of 2020 to around $540 million by the end of 2025.4 The more useful question for an investor in 2026 is not whether Offers was a mistake, which management itself conceded, but whether the lesson stuck. Zillow's current strategy is again about moving closer to the transaction. The test is whether it can do that while keeping the capital, inventory and price risk off its own books.
V. From Search to Transaction: The “Housing Super App” Bet
In August 2024, Rich Barton handed the chief executive's job to Jeremy Wacksman, and stayed on as executive co-chairman alongside Lloyd Frink.7 Wacksman was not a newcomer brought in to fix things. He had joined Zillow in 2009, and over fifteen years had run marketing, then operations, then served as president, building much of the agent-facing business that pays the bills.7 If Barton was the visionary who had twice reimagined whole industries, Wacksman was the operator who knew where every dollar of Premier Agent revenue came from. His appointment signalled continuity of strategy and a shift of emphasis: less moonshot, more execution.
The strategy he inherited had been reframed after Offers. Barton had begun describing Zillow's goal as a "housing super app," a single place where a consumer could search, tour, connect with an agent, get a mortgage, make an offer and close, and where renters could find, apply for and pay for an apartment.14 The phrase borrowed from Asian consumer platforms that bundle messaging, payments and shopping into one app. Its promise was that Zillow could earn more from each move not by owning the house, but by being present at more steps of the journey and charging, directly or indirectly, at each.
The revenue engine that supports this ambition has three parts, and the size of each matters. In the second quarter of 2026, the For Sale segment, which covers agent advertising and leads, new-construction marketing, agent software and mortgages, brought in $549 million.2 Rentals, which includes listing packages for landlords and property managers plus fees charged per lease or application, brought in $209 million.2 A small Other line, mostly display advertising, contributed $14 million.2 In plain terms, roughly seventy cents of every dollar still came from the business of helping people buy and sell homes, and most of that from residential agent products.
The growth rates tell a different story about where the momentum lies. For Sale grew 14% from a year earlier. Within it, the core residential business grew just 7%, to $465 million, while mortgage revenue jumped 75% to $84 million, driven by a 95% rise in purchase-loan volume to $2.2 billion.2 Rentals grew 31%, led by a 42% surge in multifamily revenue, the business of advertising large apartment buildings.2 So the fastest-growing pieces of Zillow are the two that are furthest from the classic agent-advertising model: lending, where Zillow Home Loans earns origination fees and gains on selling loans, and apartment advertising.15
The quiet engine inside that residential line is a change in how Zillow charges agents, and it matters more than any single product. For most of its history, Premier Agent was sold like classic advertising: an agent paid in advance for a share of the leads in a ZIP code, whether or not those leads ever bought a house. Over the past several years Zillow has shifted much of this business to a performance model, known as Flex, in which partner agents pay little or nothing up front and instead pay Zillow a fee when a transaction they were connected to actually closes.4 The shift sounds technical. Its consequences are large. Zillow's income now rises and falls with closed deals rather than with ad budgets, which ties it more tightly to the transaction it wants to own. It also means Zillow carries more of the risk that a lead never converts, waits months to be paid, and has to track sales through to completion, which is part of why receivables, billed in arrears after closings, have grown faster than revenue.4
Flex is also the clearest evidence for the integration thesis that Zillow actually has, because it gives the company a direct financial reason to help each connected buyer reach the finish line, by booking the tour, pairing the buyer with a responsive agent and offering a mortgage. It is the opposite of the Offers model in one crucial respect: Zillow earns a share of the economic value of the sale without ever owning the house. The trade-off is dependence on a smaller group of high-performing partner agents who accept Zillow's terms, and on Zillow's ability to keep the share of commission it collects acceptable to them as the industry's commission structures come under legal and regulatory pressure. Zillow does not publish how many agents are on Flex, what share of residential revenue it represents, or how its take rate has moved, which makes it hard for outsiders to tell how much of the residential growth reflects more transactions and how much reflects a larger cut of each one.
Both deserve a closer look, because both carry the "super app" thesis. The mortgage business is the purest test of cross-selling. A buyer who finds a home on Zillow and works with a Zillow-connected agent can be steered toward a pre-approval from Zillow Home Loans. If that happens more often, Zillow earns on the same customer twice. The 95% jump in purchase-loan volume, at a time when Zillow estimated that the industry's purchase-origination volume was roughly flat, suggests the attach rate is rising.2 But the base is small: mortgage revenue of $84 million a quarter is about a tenth of total revenue, and lending brings its own exposures, including interest-rate risk on loans before they are sold and the warehouse funding Zillow borrows to originate them.15 Those borrowings are a reminder that each step closer to the transaction brings a little more balance sheet.
The rentals business is the clearest evidence that Zillow can grow independently of home sales. Rents and moves keep happening when mortgage rates make buying unaffordable, and landlords of big apartment buildings pay to fill vacancies. Here, though, Zillow's growth was given a boost that turned out to carry legal strings: the Redfin partnership.
Underneath the products, Zillow has made heavy and sustained investment. Research and development spending was about $553 million in 2025, roughly 21% of revenue, down from 28% two years earlier as revenue grew faster than the engineering budget.4 Zillow's investor materials describe a connected chain of products: search and Zestimate at the top, ShowingTime for tours, Follow Up Boss as the agents' client-management system, dotloop for paperwork, Zillow Home Loans for financing, and rental tools for applications and payments.3 The company also says that about 80% of its traffic arrives directly, by people typing in Zillow or opening the app, rather than through search engines.3 In March 2026, it held an AI investor summit to argue that its data and audience would let it build AI-driven tools that guide consumers and agents through the transaction.16
Here the narrative needs a clear line between reach and commercial proof. Zillow publishes a great deal about product presence and very little about the economics that would show the super app working. It does not disclose what share of revenue is recurring, how many Premier Agent partners renew each year, what fraction of buyers who connect with an agent through Zillow go on to use Zillow Home Loans, or how much revenue Zillow earns per completed transaction across all its products.15 Its filings describe the revenue model in detail, but the conversion rates that would prove integration are not among the published figures. Without them, an investor has to infer success from segment growth, which can also be driven by price increases, a changing mix of products, or a recovering market.
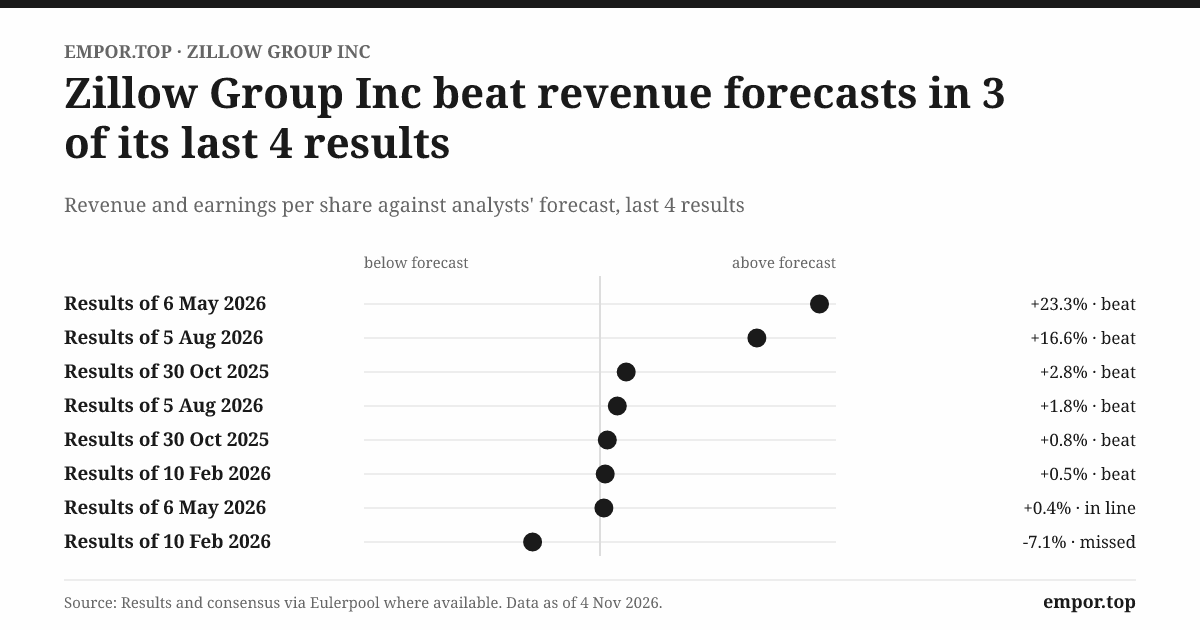
The language management uses over time is worth tracking too. On its fourth-quarter 2025 results, in its February 2026 strategy presentation and at the March AI summit, Zillow repeated a consistent story of an integrated transaction and set multi-year financial ambitions.316 By the second quarter, the company was calling itself the operating system for modern real estate.2 Consistency of message is a point in management's favour. But the measurable milestones it emphasises are mostly adjusted figures, revenue growth ahead of the housing market and adjusted EBITDA, rather than operating metrics that would prove the integration thesis directly. In the second quarter of 2026, Zillow also changed how it calculated adjusted EBITDA, excluding the legal costs of its fight with the FTC, and restated the first quarter accordingly, which lifted that quarter's adjusted EBITDA from $182 million to $198 million.2 There may be good reasons to strip out a one-off lawsuit. The effect, though, is that the measure management highlights most got better while the costs were real and still being paid.
So the verdict on the super app has to be framed as follows. The platform is clearly broader than it was: mortgages and rentals are growing quickly and now make up more than a third of revenue. But For Sale still supplied about 71% of second-quarter revenue, and the business is still exposed to the volume of home sales.2 The super app is a credible ambition with encouraging early signals. It is not yet evidence that Zillow has escaped the housing cycle. Whether it can depends less on Zillow's own products than on whether the agents, brokers and competitors around it keep playing by its rules, and in 2025 several of them stopped.
VI. The Portal’s Moat Meets Its Partners
In the spring of 2025, Zillow drew a line on its own website. Under rules it called Listing Access Standards, homes that a brokerage marketed publicly to some buyers, but kept off the shared multiple listing service for more than a day, would no longer be displayed on Zillow.17 The target was a practice that had been spreading through the industry: so-called private or "office exclusive" listings, in which a brokerage shows a home first to its own agents and clients, sometimes for weeks, before releasing it to the open market. Zillow said the rule protected consumers and transparency, because a buyer searching Zillow should be able to see every home that was genuinely for sale.17
Compass, the brokerage that had become the loudest champion of private listings, saw something else. In June 2025 it sued Zillow, alleging that the policy was an anticompetitive attempt by a dominant portal to dictate how brokerages and their sellers could market homes, and to punish firms that built alternatives to Zillow's audience.17 Zillow denied the allegations and defended the standards as a pro-consumer rule that it was entitled to set for its own site.17 The case is a dispute over marketplace rules, and as of this writing the claims on both sides remain allegations rather than findings.
The fight matters far beyond the courtroom, because it exposes the precise shape of Zillow's power. A portal with the largest audience can tell brokers: if you want your listings in front of our users, play by our rules. That is real leverage. But it is leverage borrowed from the brokers themselves, whose listings are the reason consumers come. If enough large brokerages decided that the value of keeping some homes off Zillow outweighed the exposure, the portal's inventory would thin and its users would notice. Zillow's position is strongest when brokers feel they cannot afford to be absent, and weakest when a big brokerage decides it can build its own audience.
So how strong is that audience, really? Zillow's case starts with scale. The company cites Comscore data showing it was the only large player in the category to consistently expand its reach with the real estate audience over the previous seven quarters.2 Its February 2026 investor presentation said it had more than twice the daily active app users of its next competitor.3 Those are company-supplied figures, built on third-party panel measurements, and they measure attention, not market share of transactions. Still, the direction is unambiguous: in a category where national competitors have spent heavily, Zillow remains the default.
The competitors are serious. Realtor.com has deep ties to the industry's own organisations. Redfin, now owned by the mortgage giant Rocket, runs both a portal and its own brokerage.18 And CoStar, the commercial real estate data company, has spent heavily to build Homes.com into a national rival, pitching agents on a different model for handling buyer inquiries. CoStar has also sued Zillow, accusing it of copying copyrighted listing photographs, a claim Zillow disputes.4 None of these rivals has displaced Zillow from the top spot by audience. The more important question is whether any of them needs to.
That is where the moat claim has to be tested by substitution and multi-sourcing rather than by traffic rankings. Consumers routinely search on more than one portal, and the cost of opening a second app is zero. Agents buy leads and advertising from several sources at once; the FTC concluded as far back as 2015 that portals were only one of many channels agents could use to find clients, which is why it let Zillow buy Trulia.11 Landlords list on multiple rental sites. Traffic leadership therefore does not, on its own, prove pricing power or customer loyalty. Zillow does not publish retention rates for its paying agents or landlords, nor the price it realises per lead over time, which are the figures that would show whether its customers are captive or merely convenient.15
There is also a newer substitution risk. Zillow's founding insight was that consumers would come straight to the destination with the best home data. If AI assistants begin answering "what's this house worth?" or "show me three-bedroom homes near good schools" inside a chat window, the consumer's front door could move. Zillow's response, set out at its March 2026 AI summit, is that it will be the data and transaction layer those assistants rely on, and that its own AI tools will make agents and buyers more productive.16 That is a plausible strategy, not an automatic moat. The Zestimate earned trust as a guide; the Offers years showed the limits of what home data alone could forecast. The question for AI is the same as for every earlier product: can Zillow turn better discovery into completed transactions and partner value, rather than just more page views?
The most instructive test of portal power came in rentals. In February 2025, Redfin agreed to make Zillow the exclusive syndicator of its multifamily rental listings, and to step back from competing for that business, in exchange for an initial payment of $100 million from Zillow.192 For Zillow, the arrangement promised to add a large block of apartment listings to its fastest-growing segment. In September 2025, the Federal Trade Commission sued both companies, alleging that the deal was effectively a payment by Zillow to a competitor to exit the rental advertising market, which the agency said would harm landlords and renters through higher prices and less choice.19 Several state attorneys general brought related claims.4
The companies fought the case, and Zillow's legal bills became visible in its results: litigation costs tied to the FTC matter came to $26 million in the first half of 2026 alone.2 Then, in August 2026, the parties settled. Under the stipulated final order, Zillow keeps a rental partnership with Redfin, but Redfin is required to re-enter the multifamily rental listings business as an independent competitor.2018 The settlement avoided a trial loss and a forced unwind of the whole relationship. It also limits what investors can claim about the original deal. Whatever benefit Zillow's Rentals segment drew from Redfin's exit, the order means that the rival will be back, and Zillow's rental growth will have to hold up against it.
What does this cluster of disputes say about the moat? It narrows the claim rather than rejecting it. Zillow's brand, direct audience and agent software give it a genuine distribution advantage: brokers and landlords want to be where buyers and renters are, and today that is Zillow. But that advantage is contested at the source of its content, where brokerages can withhold listings; at the point of purchase, where agents and landlords can spread their budgets across several platforms; and in the eyes of regulators, who have shown they will intervene when Zillow tries to buy its way past a competitor. The second-quarter numbers show that Zillow can raise monetisation for a time even as attention plateaus.2 The open question is how long revenue per user can keep rising before the agents and landlords paying the bill push back or go elsewhere, and whether the profit from that monetisation is actually reaching shareholders.
VII. Growth Is Not Yet Owner Earnings
Zillow closed its books on 2025 with a milestone it had been chasing for a long time. After net losses in every year from 2014 through 2024, it reported a full-year net profit: $23 million.4 Operating cash flow was $368 million. On the same income statement, though, share-based compensation, the value of stock and options granted to employees, came to $390 million.4 In other words, the expense of paying people in shares was larger than the company's entire operating cash flow and seventeen times its net profit. That single comparison is the doorway into the hardest question about Zillow: is this a business that produces earnings for its owners, or a business that produces revenue?
Start with the long view. Revenue compounded at about 15% a year over the decade to 2025, a fine record for any company, and one interrupted only by the Offers distortion and the 2022–23 housing slump.4 Profit tells a different story. Zillow reported net losses in almost every year from 2014 through 2024, adding up to roughly $2 billion of cumulative net losses from 2014 to 2025.49 Over the same twelve years, cash from operations added up to about $2.6 billion. A business that loses $2 billion on paper while generating $2.6 billion in operating cash is either being unusually conservative in its accounting or adding back very large non-cash costs. For Zillow, it is the second.
The 2025 bridge makes the mechanics concrete. Begin with $23 million of net income. Add back $390 million of share-based compensation and $264 million of depreciation and amortisation, both of which reduce reported profit without consuming cash in the year.4 Then subtract $337 million that working capital absorbed, as receivables rose and other balances moved.4 What remains is roughly the $368 million of operating cash. Each step is legitimate accounting. But only one of the large add-backs is economically free. Depreciation reflects money already spent on servers, offices and software. Stock compensation is a real cost paid in a different currency: every share given to an employee is a slice of the company that no longer belongs to existing owners.
The next layer is reinvestment. Zillow describes itself as a technology platform, and platforms are supposed to be capital-light. In 2025, though, it spent $267 million on property, equipment and intangible assets, much of it capitalised software development, about a tenth of revenue and up from about 8% the year before.4 Subtract that from operating cash and free cash flow comes to about $101 million.4 Subtract stock compensation as well, treating it as the cash cost it would be if Zillow paid its engineers in dollars, and the figure turns deeply negative. Zillow's own adjusted free cash flow is higher than the simple version, because it also adds back borrowings used to fund mortgage loans and the one-off $100 million Redfin payment.4 Investors can choose which definition they prefer. None of them makes the dilution disappear.
Zillow's answer to dilution has been to buy shares back, and lots of them. In 2025 it repurchased 9.5 million shares for $670 million and received another 3.1 million through the settlement of hedges tied to its convertible notes.4 In the second quarter of 2026 it bought back another 5.6 million shares for $200 million.2 The effect on the share count is visible: diluted weighted shares in that quarter were about 228 million, down from about 252 million a year earlier, nearly a tenth fewer.2 That is a genuine return of value to continuing shareholders. It also means that a large part of the cash Zillow generates is being spent to offset the shares it issues to staff. A company that pays its people with stock and then spends cash buying that stock back is, in the end, paying them in cash, only in a roundabout way that keeps the cost out of free cash flow.
The balance sheet shows the bill arriving. Cash and short-term investments were about $1.86 billion at the end of 2024 and $1.3 billion at the end of 2025.4 By June 30, 2026, cash and investments had fallen to $682 million.2 Part of that drop reflects the repurchases and the settlement of the last convertible notes in May 2025, which left Zillow free of convertible debt.4 In January 2026 it also arranged a $500 million revolving credit facility, maturing in 2031, which was undrawn when it filed its annual report.4 Liquidity is not a near-term concern; Zillow reports compliance with its covenants and has modest corporate debt. But the cushion that once let Zillow fund years of losses without worry is much thinner than it was.
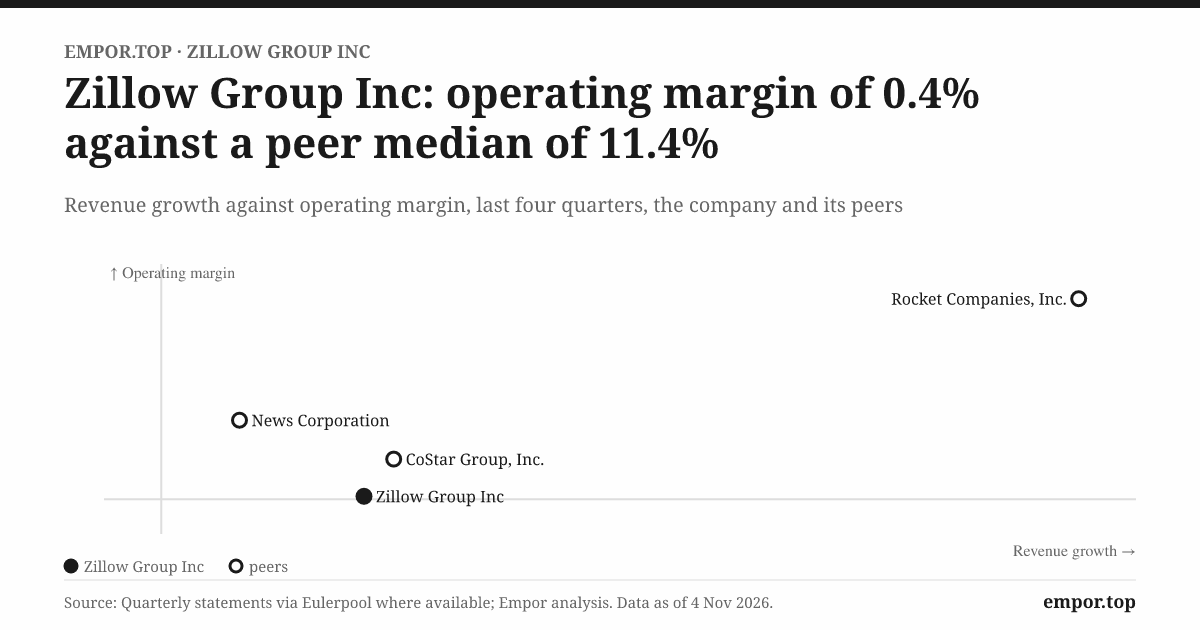
That thinner cushion matters for profits too, because interest income has quietly been holding up the bottom line. In 2025, other income, mostly interest on Zillow's cash pile, was $77 million.4 Pretax profit for the whole year was $25 million.4 Put those side by side and the operating business, before interest income, was still losing money: the year's operating loss was about $32 million, an operating margin of about minus 1%.4 As cash shrinks and rates fall, that interest income shrinks with it. Other income had already fallen from $151 million in 2023 and $127 million in 2024.4 So the first profitable year was, in part, a gift from the treasury.
Look at the quarters and the picture improves only unevenly. The first quarter of 2026 produced an operating profit of $36 million, a margin of about 5%, the best result in years.15 The second quarter slipped back to a $10 million operating loss, weighed down by $36 million of restructuring costs from job cuts and $10 million of FTC litigation costs.2 Management's preferred measure, adjusted EBITDA, which removes stock compensation, depreciation, restructuring and now FTC legal costs, was $176 million in that quarter, a margin of 23%.2 The gap between a 23% adjusted margin and a negative GAAP margin is not a rounding difference. It is the whole debate.
There is one more small signal worth a sentence. Receivables rose from $104 million to $149 million during 2025, and debtor days climbed from about 17 to 25.4 Zillow attributes the increase mainly to revenue billed in arrears, such as fees collected after a transaction closes, and says invoices are generally due within 30 days; no customer accounted for even a tenth of receivables.4 The company does not publish an ageing schedule, so investors cannot see how much is overdue. It is not a red flag, but it is the kind of metric that should stay flat as the business matures, and it went the other way.
Finally, the stock price. On November 4, 2026, Zillow's Class C shares traded around $31, valuing the company at about $7.5 billion, or 2.7 times trailing revenue.6 The price-to-earnings ratio, at roughly 136 times, looks extreme, but that is mostly because earnings are tiny. Small changes in profit swing the multiple wildly, so it is a poor guide either to cheapness or to expense. A fairer reading is that the market is paying a modest multiple of sales for a company with large revenue, a famous brand and little demonstrated GAAP profit, and is waiting to see whether margins can turn durably positive before it pays for more. Three numbers will settle it: GAAP operating margin; free cash flow after capital purchases and after accounting for dilution; and revenue growth by segment set against traffic. The lessons of how Zillow got here are worth drawing out before weighing which way those numbers are likely to move.
VIII. Playbook: Business & Investing Lessons
Put two moments side by side. In the autumn of 2021, crews in Phoenix and the other cities where Offers operated were finishing repairs on thousands of houses that Zillow could no longer sell at a profit, while headquarters prepared to lay off a quarter of the company. Five years later, Zillow's strategy deck shows a clean chain of software: search, tours, agent tools, mortgages, rentals, all stitched together, with no houses on the balance sheet.3 The distance between those two pictures is the education Zillow paid for. Several of its lessons apply well beyond real estate.
The first lesson comes straight out of the Offers wind-down: Zillow's data advantage did not make it good at trading homes. The $407.9 million of write-downs in 2021 marked that lesson.14 Founders with a data business who are tempted to become principals in the market they measure should remember that their counterparties get a vote, and they vote with their feet.
The second lesson is about workflow acquisitions: buy the workflow only if you can show who pays for the time saved. ShowingTime, which Zillow bought for $500 million,12 sits at an important point in the buyer's journey, and agents use it widely. Zillow has not published evidence showing who captures the value of the time it saves. Software that becomes essential to an industry is valuable. Software that becomes essential and free is a cost centre with good press.
The third lesson comes from the listing fights: a consumer audience is an asset only while consumers believe it serves them. Zillow's audience started with a promise to show people what had been hidden from them. Its Listing Access Standards continue that promise, in Zillow's telling,17 while Compass's lawsuit argues that the rules let a dominant portal control its suppliers.17 Whichever side prevails in court, the consumer's belief that Zillow shows them the whole market is the foundation of everything else. If buyers come to suspect that the best homes are being sold elsewhere, or that the portal's rules serve the portal rather than them, the habit the Zestimate created can unwind. Brands built on trust are durable until the moment they are not.
The fourth lesson is to read the share count alongside the income statement: in 2025, stock compensation exceeded operating cash flow.4
Taken together, Zillow's capital-allocation record runs in both directions. Trulia strengthened the platform, and ShowingTime gave Zillow a place in the touring workflow. Offers was a costly failure that the company had the discipline to close.13 What the record lacks is acquisition-level disclosure that would let an outsider judge returns, so verdicts on individual deals must rest on the health of the combined business. The broader lesson for founders is that distribution creates options, and each option that moves you closer to the transaction changes the capital you need, the execution you must master and the trust you must keep. That trade-off is exactly what the bull and bear cases are arguing about.
IX. Analysis & Bull vs. Bear Case
Picture the second quarter of 2026 from two seats. In the first, an optimist sees a business whose revenue grew even as its audience shrank, with mortgages and rentals growing fastest, and whose management said it was outperforming a housing market that grew just 6%.2 In the second, a sceptic sees a company still struggling to turn growth into GAAP profit, amid job cuts and legal costs, with most of its revenue dependent on home sales.2 Both are looking at the same numbers. The job here is to decide which reading the evidence supports more strongly, and where it is still genuinely undecided.
The case for Zillow, and what it rests on
The bull case is that Zillow has the rare combination of a mass consumer brand and deep integration with the professionals who serve that consumer. Its direct traffic, its homes database, its agent software and its growing lending and rental businesses could let it earn more from each move than any rival.3 The fastest-growing lines are the ones furthest from the cyclical agent-advertising core, which suggests the mix is shifting toward businesses that grow whatever the housing market does. If Zillow can keep revenue growing in the mid-to-high teens while holding costs roughly flat, operating leverage would turn small GAAP profits into large ones quickly, because so much of the cost base is fixed engineering and marketing.
The bear case is that most of Zillow's revenue still comes from For Sale, a business tied to the number of homes sold and the willingness of agents to spend; that housing and mortgage activity are cyclical and currently weak; that traffic has stopped growing; and that heavy stock compensation and capital spending make real owner earnings hard to establish. Add to this the legal and partner conflicts of 2025 and 2026, and the return of Redfin as an independent rental competitor, and the sceptic sees a company whose growth is expensive, contested and still dependent on the housing cycle.
The economics of the industry help adjudicate between them. Consider the forces that shape Zillow's profits. Buyer power, meaning the power of the agents and landlords who pay Zillow, is fragmented: no customer accounted for even a tenth of revenue in 2023 through 2025.4 But fragmentation does not mean weakness, because each agent can split budgets across portals, and the FTC's view that agents have many alternatives still stands.11 Supplier power is unusually high, because the key raw material, listings, belongs to brokers and MLSs, as the Compass dispute shows. The threat of substitutes is rising: AI assistants, Google's search results and brokerages building their own audiences could all intercept consumers before they reach Zillow. Rivalry is intense, with CoStar spending heavily on Homes.com, Rocket pairing Redfin with a mortgage machine, and Realtor.com holding its industry ties. The threat of new entrants at national scale is low, because building a comparable audience is enormously expensive. This is a structure that rewards the leader with reach, but caps its pricing.
Hamilton Helmer's framework for durable advantage sharpens the picture. Zillow's clearest power is branding, reinforced by the scale that spreads fixed engineering costs across a large audience. It has a network effect, but one weakened by the fact that MLS feeds make listings available to every portal. Switching costs are modest for consumers and may be rising for agents who run their business on Follow Up Boss and ShowingTime, though Zillow does not publish retention data to prove it. It has no cornered resource, since it does not own the listings, and the process power that might come from integrated transactions remains, so far, an ambition. So the moat is real but narrower than the "super app" framing implies: brand plus scale, supported by growing workflow switching costs, in an industry where suppliers and regulators set limits.
What would change the verdict
Management credibility has to be judged by behaviour over time, and the record is mixed. In Zillow's favour, the company shut Offers decisively once it understood the economics, and delivered second-quarter 2026 revenue above the top of its own outlook range.2 Against it, the Offers reversal remains a credibility cost, and the recent change to adjusted EBITDA, excluding FTC legal costs and restating the prior quarter upward, flatters the measure management emphasises.2 Investors need several consecutive years of positive GAAP operating profit, not just strong adjusted margins, before the recovery can be called proven.
Leadership pay is equity-heavy, which aligns executives with the share price but also feeds the dilution problem. Wacksman's reported total compensation was about $7.1 million in 2025, after $15.7 million in 2024, the year he became chief executive, when Barton's was about $7.5 million.7 Chief financial officer Jeremy Hofmann has held the role since 2023.7
Control is where an activist would focus first, and also where an activist would struggle most. The Class C shares that trade as Z are generally non-voting.7 Barton and Frink hold Class B shares with ten votes each, which gives them control of the company despite owning a minority of its economics.7 The largest holders of the voting Class A shares include Caledonia, with about 27% of that class, and Vanguard, with about 18%.7 Buybacks of Class A and C shares raise the founders' relative voting power over time; when the board authorised another $1.25 billion of repurchases in 2026, it included a condition limiting purchases that would push any single holder above 45% of the voting power.21 At the 2026 annual meeting, votes against directors ran at roughly 5% to 7% of votes cast for and against, and there was no say-on-pay vote; the next vote on how often to hold one is scheduled for 2027.721 Those figures do not show a revolt. They show a structure in which outside shareholders have little ability to stage one. A sceptical long-short investor would ask three things: why the company keeps spending cash on buybacks while GAAP operating profit is still negative; why stock compensation remains so large relative to cash flow; and why the measure management highlights keeps excluding costs that shareholders actually pay.
Weighing all of it, the bull case has a credible distribution and product-integration story, most convincing in rentals and mortgages, where growth has outpaced the market. The bear case is that growth remains cyclical and expensive, while weak GAAP profitability, partner conflict and the return of rental competition constrain how much of Zillow's audience value shareholders can capture. The balance would shift toward the bull case with durable GAAP operating margins, improving cash generation after dilution, and rental growth that persists once Redfin rebuilds its standalone business. It would shift the other way if traffic declines deepened, if revenue growth slowed to the pace of the housing market, or if a large brokerage succeeded in withholding meaningful listing supply.
X. Epilogue
Tonight, November 4, 2026, Zillow will report its third-quarter results after the market closes, and its management will take questions on a call at 5 p.m. Eastern.5 It will do so with an integrated-platform strategy laid out in detail, a fresh repurchase authorisation, a cash pile much smaller than it was eighteen months ago, a settled FTC case whose terms now have to be lived with, and a brokerage rival still in court over the rules of its marketplace.22017 Whatever the quarter shows, the questions that will decide the next few years are already clear.
The first moment to watch is Redfin's return to rentals. The August 2026 order requires Redfin to rebuild an independent multifamily rental listings business.20 If Zillow's rental revenue keeps growing at close to the 31% pace of the second quarter while that happens, it will be strong evidence that the growth comes from Zillow's own products and audience, rather than from a competitor's absence. If rental growth slows sharply as Redfin re-enters, investors will have learned how much of the gain was borrowed.
The second is the gap between revenue and traffic. Zillow's revenue has been growing far faster than its audience, which is a sign either of better products or of higher prices squeezed from the same customers. The company publishes enough to see the gap but not enough to explain it: it does not separate price increases from product mix or volume. Each future quarter in which revenue outpaces users will raise the question of how long that can continue, and whether agents and landlords are paying more because they are getting more, or because they feel they have no choice.
The third is the profit line that matters. GAAP operating margin has swung from loss to profit and back again.4152 Share-based compensation, capital purchases and free cash flow need to be read together, alongside the share count, to judge whether owners are actually being enriched. A year of positive GAAP operating profit, sustained through a housing slowdown, would do more for the investment case than any new product launch.
The fourth is the buyback. A $1.25 billion authorisation is large for a company with $682 million of cash and investments at mid-year.212 How much of it is used, how it is funded, and how far it lifts the founders' share of the vote will show what kind of capital allocator Zillow intends to be in its next chapter.
And the last is management's own voice. Future earnings calls will reveal whether Wacksman's team explains misses with measurable causes, sets milestones it can be held to and changes course when assumptions fail, as it eventually did with Offers, or whether the language of the super app keeps getting ahead of the numbers. Zillow has shown it can admit a mistake. The open question is whether it can prove a success.
XI. Outro
Go back to that February morning in 2006, the beta site groaning under 300,000 page views before breakfast, and the apology on the screen.1 The thing everyone wanted was a single number: what is my home worth? Nobody visiting that day was trying to hire an agent or apply for a mortgage. They were curious, and Zillow had found a way to make curiosity about the most important asset in most people's lives into a daily habit.
Twenty years later, Zillow is attempting something much harder than showing people the home. It wants to walk them all the way to the keys: the tour, the agent, the loan, the lease, the closing.42 That ambition puts it in a strange position for a company founded to challenge the industry's gatekeepers. To succeed, Zillow must become a kind of intermediary itself, and convince consumers, agents, brokers and regulators that this intermediary is different. The Zestimate made the home easier to see. Whether Zillow can make it easier to own, without becoming the very toll booth it once set out to remove, is the story that is still being written.
References
-
Zillow Group Reports Second-Quarter 2026 Financial Results — Zillow Group, 2026-08-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Zillow Investor Strategy Presentation — Zillow Group, 2026-02-10 ↩↩↩↩↩↩↩↩
-
Form 10-K for the year ended December 31, 2025 — U.S. Securities and Exchange Commission, 2026-02-11 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Zillow Group to Announce Third-Quarter 2026 Results Nov. 4 — Zillow Group, 2026-10-06 ↩↩
-
2026 Proxy Statement — U.S. Securities and Exchange Commission, 2026-04-15 ↩↩↩↩↩↩↩↩↩↩↩↩
-
2015 Form 10-K — U.S. Securities and Exchange Commission, 2016 ↩↩↩↩↩↩
-
Zillow and Trulia merger announcement, Form 425 — U.S. Securities and Exchange Commission, 2014-07-28 ↩↩
-
Statement on Zillow's proposed acquisition of Trulia — Federal Trade Commission, 2015-02-19 ↩↩↩
-
Zillow Group to Acquire ShowingTime, the Industry Leader in Home Touring Technology — Zillow Group, 2021-02-10 ↩↩↩
-
Zillow Group Reports Third-Quarter 2021 Financial Results & Shares Plan to Wind Down Zillow Offers Operations — Zillow Group, 2021-11-02 ↩↩↩↩↩
-
2021 Form 10-K — U.S. Securities and Exchange Commission, 2022 ↩↩↩↩↩↩↩
-
Form 10-Q for the quarter ended June 30, 2026 — U.S. Securities and Exchange Commission, 2026 ↩↩↩↩↩↩
-
Compass sues Zillow over listing policy — Associated Press, 2025-06-23 ↩↩↩↩↩↩↩
-
Zillow and Redfin settle FTC rental partnership case — Associated Press, 2026-08-24 ↩↩
-
Complaint against Zillow Group and Redfin — Federal Trade Commission, 2025-09-30 ↩↩
-
Stipulated final order in the Zillow–Redfin rental case — Federal Trade Commission, 2026-08-24 ↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube