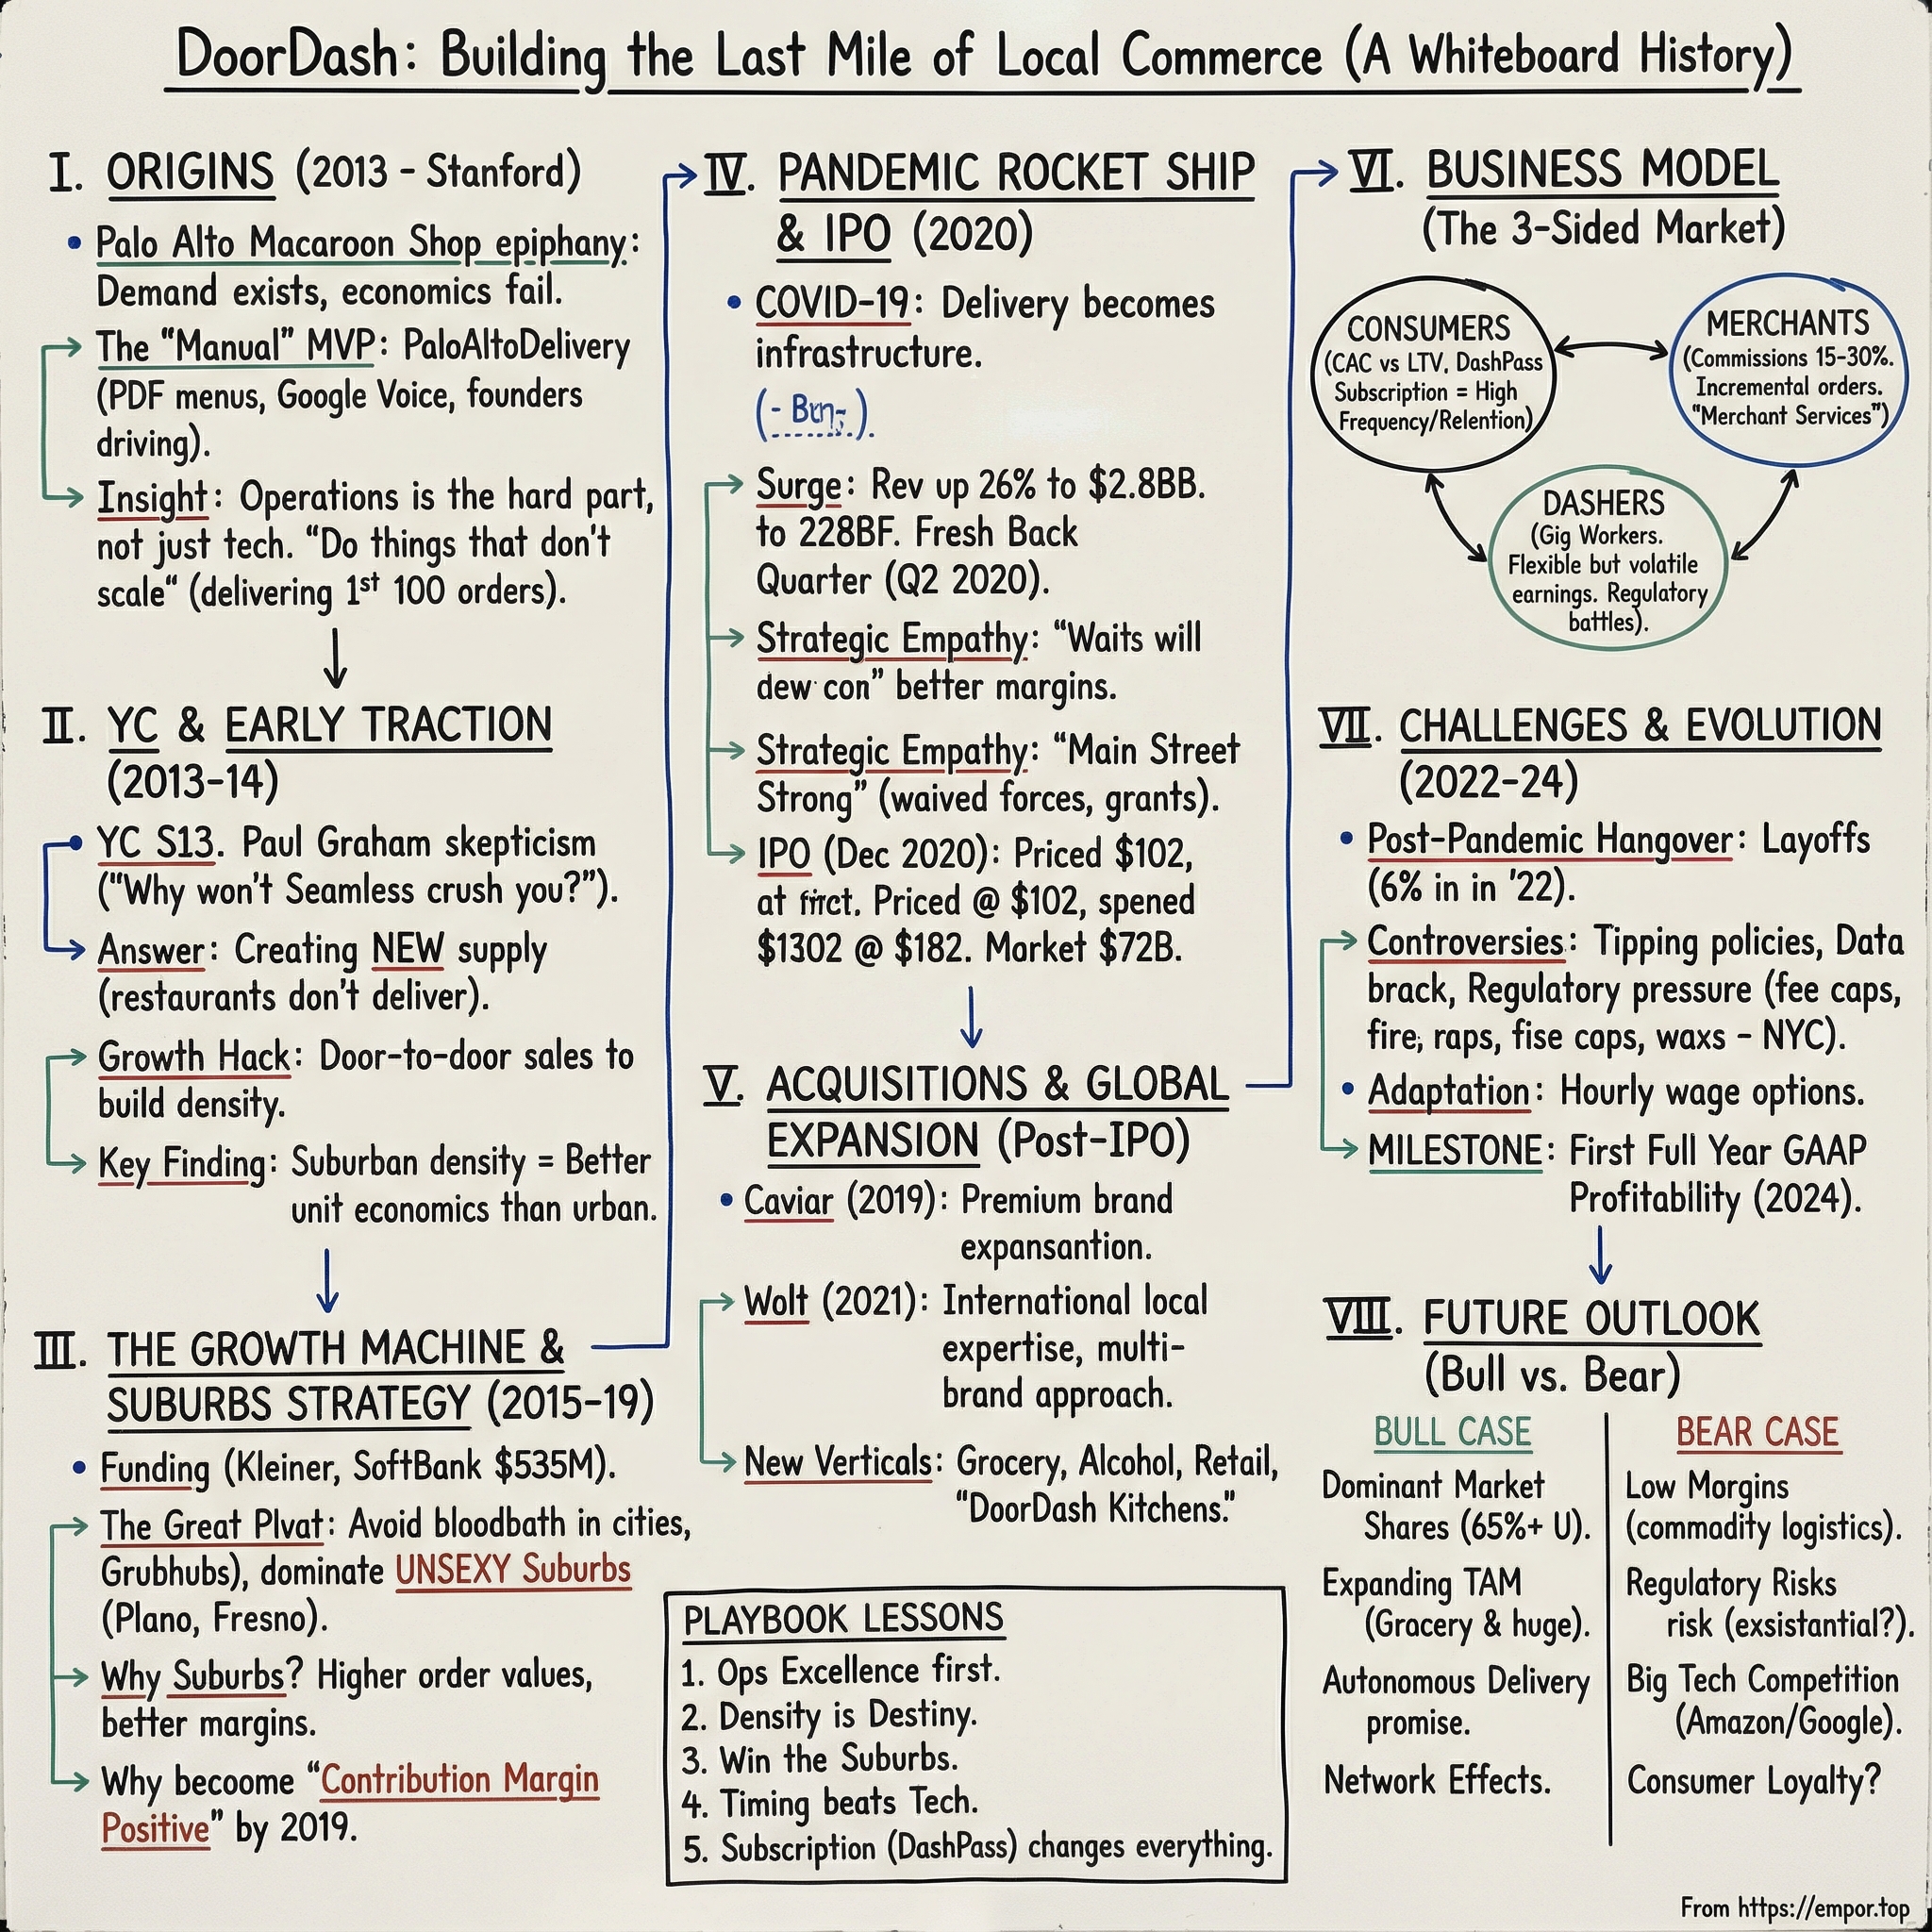
DoorDash: Building the Last Mile of Local Commerce
I. Introduction & Cold Open
On the morning of December 9, 2020, a company founded seven years earlier in a Palo Alto apartment opened for trading on the New York Stock Exchange — before moving its listing across the street to the Nasdaq in September 2023.1 Investment bankers had priced the initial public offering at $102 a share, above an offering range they had raised twice. The stock opened at $182 and closed its first session at $189.51, an 86% pop that assigned roughly $60 billion in market value to a business that had never earned a dollar of profit.23
The underlying paradox was stark. During the nine months ended September 30, 2020 — when pandemic lockdowns turned food delivery into essential civic infrastructure — DoorDash lost $149 million.4 Investors paid software-style valuation multiples for a low-margin courier service, betting on demand sparked by a public health crisis. The bear case seemed obvious: an errand business propped up by temporary pandemic conditions.
Five and a half years later, the debate has resolved unexpectedly. In fiscal 2025, DoorDash processed 3.17 billion orders worth $102.0 billion in Marketplace Gross Order Value, generating $13.7 billion in revenue and $935 million in GAAP net income.1 Merchants on the platform earned nearly $75 billion, while Dashers earned over $20 billion.5 Entering 2026, the company served more than 56 million monthly active users, including over 35 million paying subscribers across DashPass, Wolt+, and Deliveroo Plus.1
DoorDash joined the S&P 500 in March 2025, roughly a year after achieving sustained GAAP profitability.6 As of the close on September 4, 2026, the equity was valued at about $92 billion — barely above its day-one market capitalization, illustrating how much of the company's growth trajectory investors had already priced in during 2020.7
What this story is actually about
The primary question is no longer whether food delivery functions at scale in the United States. The sharper strategic questions center on execution and durability: How did four Stanford students using a Google Voice number and PDF menus beat a better-capitalized incumbent, out-execute Uber in American suburbs, and assemble the nation's largest last-mile logistics network? And how defensible is that position when a competitor sues over its founding tactics, when municipal ordinances alter local cost structures, and when its founders recently relocated DoorDash's legal incorporation using control stock representing under 6% of total equity?
The roadmap spans several chapters. It begins in a macaroon shop, moves through the tight venture capital environment of 2016, examines the suburban expansion that displaced Grubhub, and details the dual-class governance structure established at the IPO. It then analyzes unit economics — examining disclosed per-order metrics rather than theoretical models — and evaluates three expanding business lines within the platform: advertising, grocery and retail fulfillment, and white-label logistics. Next, it reviews the regulatory landscape from California's Proposition 22 to minimum pay rules in New York and Seattle, followed by an evaluation of management's track record against its public commitments. It concludes with the technologies that could alter delivery unit costs, including autonomous delivery trials operating in Phoenix.
Throughout, every structural claim is tested against disconfirming evidence in DoorDash's public record and financial disclosures. A competitive moat must be demonstrated by operational performance, not executive commentary.
 Subscribe on LinkedIn
II. Palo Alto Macaroon & Dorm Logistics: The Founding Story
The standard DoorDash origin story centers on a small macaroon shop in downtown Palo Alto in the autumn of 2012. Four Stanford students — Tony Xu, Andy Fang, Stanley Tang, and Evan Moore — were interviewing local merchants for a class project about business technology needs. The shop owner, they recount, pulled out a binder of delivery requests she had turned down because she could not justify paying a dedicated driver to wait for orders.8
That binder served as the founding artifact, reframing the core business problem. Where the students had assumed small businesses needed better software, the binder demonstrated a need for flexible, on-demand labor that removed delivery from restaurant payrolls. Delivery was not a software feature to bolt onto a restaurant; it was an operational capability most small merchants could not justify building independently.
Tony Xu was uniquely positioned to grasp that operational strain. His father had immigrated to pursue a doctorate in aeronautical engineering at the University of Illinois Urbana-Champaign, while his mother, a former physician in China, found her medical credentials unrecognized in the United States. Arriving with $250, she worked three jobs over twelve years — including serving at a local Chinese restaurant where her son worked as a dishwasher.4 She eventually saved enough to return to school and open a medical clinic.
Xu later built the company's public narrative around that experience, presenting DoorDash as an engine for independent business owners. Beyond marketing value, that background highlights a specific strategic orientation: solving the merchant's logistical constraints before designing the consumer interface.
The initial application was deliberately primitive. On January 12, 2013, the founders launched a basic website featuring handwritten menu listings from Palo Alto restaurants alongside a Google Voice number. Within hours, a customer placed the first order — prawn pad thai and spring rolls from a local Thai restaurant — which one of the founders delivered personally.4
The system operated without merchant partnerships, payment integrations, or dispatch algorithms. Instead, the founders managed incoming calls between classes using a shared spreadsheet and tracked delivery vehicles via Apple's Find My Friends application.
While corporate lore frames this period as an exercise in scrappy endurance, its primary value was analytical. The manual deliveries yielded operational datasets that purely software-based competitors lacked.
By driving the routes themselves, the founders observed key operational variables: the actual driver wait time inside a restaurant at 6:40 p.m. on a Friday, parking delays at suburban strip malls versus urban blocks, and how different cuisines held up over a twenty-minute transport. These variables formed the foundational parameters for DoorDash's future dispatch algorithms.
The falsification
Company narrative often implies that these early manual operations produced an uncopyable operational blueprint. The corporate record suggests a more modest reality. Incorporated in 2013 as Palo Alto Delivery Inc., the entity was not renamed DoorDash, Inc. until 2015.4 In those early years, routing relied on human dispatchers, and engineering constraints made scaling turbulent. The company's durable advantages were not established during this phase; rather, they were identified then and engineered later through substantial capital investment.
For investors, the core lesson is narrower than the popular myth: hands-on early operations enabled precise problem definition rather than an immediate competitive moat. Competitors could have gathered similar operational insights through short-term manual testing, though few prioritized doing so.
That gap between identifying the logistical problem and funding a scalable solution set the stage for the company's subsequent expansion.
III. Y Combinator, Early Traction, & Suburbia as a Strategic Moat
In the summer of 2013, the team joined Y Combinator, accepted the standard accelerator investment, and entered a market dominated by an established incumbent. Grubhub and Seamless — which merged that same year — operated a high-margin software marketplace: they collected orders online and routed them to restaurants that already employed delivery drivers. Their network concentrated on pizza and Chinese takeout in dense cities, requiring no fleet management, courier logistics, vehicle overhead, or delivery liabilities.
DoorDash's core structural insight was that this capital-light model constrained market size. The vast majority of American restaurants did not offer delivery — not from lack of consumer demand, but because maintaining dedicated drivers on payroll was economically impractical for individual locations. A pure order-routing marketplace could only serve the narrow subset of merchants that had already built delivery operations. By assuming the operational burden — recruiting couriers, managing algorithmic dispatch, and absorbing driver idle time — DoorDash expanded the addressable merchant pool from existing delivery establishments to virtually every restaurant in a market.
Business strategist Hamilton Helmer categorizes this dynamic as counter-positioning: adopting a business model an incumbent cannot replicate without harming its own core economics. Grubhub could not deploy a delivery fleet without transforming a clean software profit-and-loss statement into a lower-margin operational business, a shift its public equity investors were unlikely to support.
The suburban bet
The second key strategic decision was geographic, and it proved decisive in securing market leadership. While competitors such as Postmates, Uber, Caviar, and Grubhub focused on dense urban centers like Manhattan and San Francisco — where high population density appeared ideal for local network effects — DoorDash targeted suburban markets, beginning in Palo Alto and San Jose before expanding to suburban Phoenix and Dallas. The company's IPO prospectus later highlighted the results of this strategy: by September 2020, DoorDash held a 50% category share among U.S. local food delivery logistics platforms overall and a 58% share in suburban markets, placing it roughly 24 percentage points ahead of its closest competitor.4
The strategic value of suburban expansion extended beyond lower competitive intensity. A family dinner order generates significantly higher gross order value than a single urban office lunch, increasing the revenue captured per delivery trip. Suburban deliveries also benefit from faster drop-offs at driveways and parking lots, avoiding the delays of navigating high-rise elevators and security desks in urban residential buildings. This operational efficiency allowed couriers to complete more deliveries per hour. Furthermore, in car-dependent suburban environments, couriers provided their own vehicles, shifting fleet capital expenditures off DoorDash's balance sheet.
While urban density offers more potential orders per square mile, suburban geography yields higher order values and greater completed volume per courier-hour. For a business where time represents the primary marginal cost, suburban unit economics proved superior.
Capital arrived in progressive stages: a seed round in 2013 with participation from Khosla Ventures, a Sequoia Capital–led Series A in May 2014, and a Kleiner Perkins–led Series B in March 2015 that valued the company at approximately $595 million.910 Sequoia's Alfred Lin and Kleiner Perkins's John Doerr joined the board during this period and remained directors a decade later.11
The winter that nearly ended it
This expansion trajectory encountered a severe test in late 2015 when DoorDash sought a $1 billion valuation but failed to secure it. Sentiment across the on-demand sector was deteriorating as several early venture-funded delivery startups shut down, while public technology valuations contracted sharply in early 2016 during investment negotiations.
In March 2016, DoorDash announced a $127 million Series C round at a valuation of approximately $700 million — a modest increase over its prior round but a substantial discount from management's target, occurring in a market environment where flat valuations signaled distress.10 Xu later acknowledged, in a retrospective series published by Sequoia, that the company's survival was in doubt during this period.8
The broader analytical lesson is that DoorDash's core strategy was not obvious to venture investors in real time, even after three years of operating data. From the outside, prioritizing suburbs appeared to be an admission that the company could not compete in major urban centers. That historical pattern is instructive when assessing contemporary debates over DoorDash's expansion into grocery fulfillment, autonomous delivery, and international markets: the operational metrics that determine strategic success often become clear only long after capital has been deployed.
Ultimately, resolving this valuation freeze required neither a strategic pivot nor a contraction in operations, but rather a massive influx of growth capital.
IV. The Growth Machine: Overtaking Grubhub & Suburban Market Dominance
In March 2018, SoftBank's Vision Fund led a $535 million Series D investment in DoorDash.12 For a company that had struggled to raise a fifth of that amount two years earlier, the capital infusion fundamentally altered its operating capacity. DoorDash gained the liquidity required to execute the central mandate of local marketplace competition: acquiring courier and customer density across hundreds of postal codes simultaneously.
The mechanics of local food delivery turn on courier idle time. A Dasher who completes only two deliveries an hour earns less while imposing a higher fixed cost on the platform per transaction. Increasing that throughput to three deliveries an hour raises driver earnings while reducing unit costs, as the fixed overhead of waiting, driving empty, and navigating pickups is spread across more revenue-generating trips. Neighborhood-level order density is the primary variable that converts low-utilization routes into efficient ones. High order density per square mile also enables algorithmic batching—combining multiple restaurant pickups into a single courier route—further improving economics.
This dynamic makes hyper-local scale, rather than broad national presence, the decisive asset in food delivery logistics. Because density must be won postal code by postal code, deploying growth capital to capture suburban market share functioned as a calculated strategic lever rather than pure spending. It also exploited structural constraints among competitors: Uber Eats was simultaneously funding an international expansion across dozens of countries, while Grubhub was defending a high-margin order-routing model that public shareholders expected to generate consistent cash flow. Neither competitor was structured to concentrate capital exclusively on American suburban density.
The crossover
By March 2019, DoorDash overtook Grubhub to become the largest U.S. food delivery platform by consumer spending.[^13] That market share gap continued to widen over the following years. Third-party card-panel data from Earnest Analytics placed DoorDash at 60.7% of U.S. food delivery sales at the end of 2024, compared with 26.1% for Uber Eats and 6.3% for Grubhub—giving DoorDash a lead of more than 34 percentage points over its primary competitor.13
Two operational decisions reinforced this position. First, DoorDash aggressively onboarded national enterprise chains. Landing major restaurant brands expanded selection while converting brand partners into low-cost acquisition channels; when a national chain promoted delivery within its own mobile app and DoorDash fulfilled the order, the platform gained scale and consumer familiarity without incurring direct marketing expense. Second, the company launched its DashPass subscription service in 2018, establishing a recurring customer base whose long-term retention economics became central to the platform.
Myth versus record
Corporate narrative, however, has sometimes attributed this scaling success to technological acquisitions that the historical record does not support. In September 2017, DoorDash acquired Rickshaw, a small Y Combinator–backed delivery-logistics startup, in an undisclosed transaction where three team members joined and Xu characterized the deal as an acquihire.14 Although subsequent accounts occasionally framed the deal as the acquisition that rebuilt DoorDash's dispatch engine, the transaction was primarily a talent acquisition. The core routing and batching capabilities were engineered internally over several years and funded by venture capital.
Between 2017 and 2019, DoorDash secured dominance in the American market through structural insight, an early geographic focus on suburban expansion, and aggressive capital deployment that outpaced competitors' willingness to absorb losses. The first two factors reflect strategy; the third reflects market conditions. For investors evaluating the long-term durability of that market position, the central question is which of those drivers continues to sustain platform performance as early capital subsidies recede.
V. Pandemic Hyper-Scale, The Dec 2020 IPO & Governance Engineering
In March 2020, consumer demand shifted in ways no forecasting model had contemplated. Dining rooms closed overnight, transforming food delivery from a periodic convenience into the primary distribution channel for a large share of American restaurant supply.
DoorDash entered the pandemic with a 2019 Marketplace Gross Order Value of $8.0 billion—a figure the company noted represented under 3% of the $302.6 billion Americans spent on off-premise restaurant food that year—before order volume roughly tripled in 2020.4 Annual revenue expanded accordingly, climbing from $885 million to $2.886 billion.1
That extraordinary surge enabled the company's December 2020 initial public offering, even as it provoked intense market debate over whether investors were capitalizing a demand curve artificially inflated by a public health emergency. Underwriters proceeded with the offering, raising net proceeds of roughly $3.3 billion through the sale of 33 million shares.23
Yet the most consequential structure established during the listing was constitutional rather than financial.
The constitution written into the offering
DoorDash debuted with a three-tier equity structure: Class A carrying one vote per share, Class B holding twenty votes per share, and Class C carrying no voting rights. All Class B shares were allocated to Xu, Fang, and Tang, who collectively controlled approximately 69% of voting power upon completion of the offering—a concentration the prospectus noted would reach 79% if their outstanding equity awards were included.4 That authority was further concentrated through a voting agreement and irrevocable proxy granting Xu sole discretion to direct the vote of Fang's and Tang's Class B shares on all shareholder matters.4 Xu held this voting dominance despite owning an economic stake of around 5% at the time of the IPO.9
Proponents of super-voting structures argue that multi-class governance insulates founders from short-term market pressures, enabling decade-long strategic investments such as funding unproven international expansions or experimental logistics technology. That defense is logically coherent, yet it remains untested against a fundamental governance risk: the absence of an external mechanism to override a founder when strategic assumptions prove incorrect.
The corporate record provides a clear test of this vulnerability. Throughout 2020 and 2021, DoorDash expanded its headcount rapidly on the assumption that pandemic-driven demand curves represented a permanent structural baseline. On November 30, 2022, the company eliminated 1,250 corporate jobs—representing roughly 6% of its workforce—with Xu publicly acknowledging that management had over-hired and failed to discipline operating expense growth.15
While Xu's candid memo avoided macroeconomic excuses, the episode illustrates both the utility and limits of concentrated governance. Absolute founder control did not prevent a classic operational miscalculation—extrapolating a temporary demand spike into permanent baseline growth.
Nor does the workforce reduction clarify whether founder control exacerbated the initial over-hiring or accelerated the remedy. A plausible reading suggests that centralized authority enabled a faster, more decisive cost correction than a traditional board might have managed, even as the lack of governance checks permitted the unhedged hiring expansion in the first place. That trade-off underscores the inherent tension in dual-class corporate control.
That governance dynamic shifted from theoretical debate to concrete operational impact in 2026, when the co-founders exercised their voting power to execute a structural change without an obvious operating rationale—a decision examined later in this story.
VI. M&A Capital Allocation: Caviar, Wolt & International Multiples
DoorDash's record of capital allocation through mergers and acquisitions is frequently portrayed as a sequence of well-timed strategic moves. A closer examination of the corporate record presents a more complex and mixed performance.
Caviar (2019). In August 2019, DoorDash agreed to acquire Caviar from Square for $410 million in cash and preferred stock, completing the transaction on October 31.1617 The strategic rationale was straightforward: while DoorDash held a commanding position in suburban markets and casual dining, Caviar provided established relationships with upscale urban restaurants that had resisted mass-market delivery platforms.
Following the acquisition, Caviar's operations were integrated into DoorDash's platform, leaving the standalone brand as a front-end storefront for high-end merchants. Because DoorDash has never disclosed Caviar's revenue, order volume, or profit contribution separately, the financial return on the $410 million investment remains unverified in public filings. This reporting gap leaves an opaque track record, requiring investors to evaluate management's capital allocation without dedicated segment metrics.
Wolt (2021–2022). In November 2021, DoorDash announced an all-stock acquisition of Helsinki-based Wolt Enterprises Oy, valued at approximately $8.1 billion, to expand its operational footprint across Europe and Asia.18 By the time the transaction closed on June 1, 2022, a broader market downturn had halved DoorDash's equity valuation, reducing the reported transaction value at completion to roughly $3.5 billion.1920
While market commentators highlighted the transaction as a strategic use of equity as currency—enabling DoorDash to acquire a premier asset while absorbing a 56% decline in share price without spending cash—the underlying mechanics warrant a more critical assessment. First, an all-stock deal with a fixed exchange ratio automatically transfers equity market fluctuations to the transaction value; the reduced purchase price reflected market-wide valuation compression rather than deliberate risk management. Second, the valuation in shares understated the total commitment, as the newly acquired international operations required years of subsequent financial support.
Disclosed financial results challenge the narrative that Wolt provided an immediately profitable global expansion engine. International revenue reached $854 million in 2023 and $1.319 billion in 2024—reflecting top-line growth, but occurring while the segment remained a persistent drag on consolidated profitability as DoorDash funded merchant selection, subscriber adoption, and courier supply against entrenched regional incumbents.1
Management did not position the international segment as a net contributor to profits until well into 2025. The definitive outcome is that Wolt provided DoorDash with an operational platform and regional management expertise that would have been costly to build organically, though it required nearly three years of continuous investment before reaching self-sustainability.
SevenRooms and Deliveroo (2025). In 2025, DoorDash shifted its capital allocation strategy toward substantial cash deployments. On May 6, 2025, the company announced a $1.2 billion acquisition of SevenRooms, a guest-management and reservation platform, closing the transaction on June 13 for $1,152 million in cash and deferred consideration.211
That same week, DoorDash agreed to acquire UK-listed food delivery platform Deliveroo for 180 pence per share in cash. The transaction closed on October 2, 2025, for a total consideration of $3,724 million, adding $1,950 million in goodwill and $1,498 million in identified intangible assets to the balance sheet.221 Three weeks after announcing both transactions, DoorDash priced an upsized convertible note offering, issuing $2.75 billion of 0% Convertible Senior Notes due 2030.231
This sequence marked a structural pivot from the equity-funded, cash-preserving structure of the Wolt deal to debt- and cash-funded acquisitions. This shift occurred while DoorDash maintained a $5.0 billion share buyback authorization, under which it repurchased zero shares during fiscal 2025.1 Management prioritized international scale and software capabilities over direct capital returns to shareholders.
Initial financial results offer an early baseline: Deliveroo contributed slightly more than the roughly $45 million of Adjusted EBITDA management had guided for the fourth quarter of 2025, with management projecting approximately $200 million in Adjusted EBITDA for full-year 2026.5 Relative to the $3.7 billion purchase price, a $200 million annual EBITDA contribution represents a mid-single-digit yield prior to the costs of integrating a third software architecture. The long-term return on capital depends on whether Deliveroo's operating contribution expands significantly beyond that $200 million baseline as platform integration progresses.
VII. The Core Business: 3-Sided Unit Economics, 7 Powers & Merchant Squeezes
The business model functions as a time-based arbitrage connecting three distinct parties. Consumers pay the menu price, a delivery fee, a service fee tied to basket size, and a tip. Merchants receive the food price minus a commission—typically ranging from the mid-teens to roughly 30% depending on the selected service tier—purchasing demand generation and fulfillment capabilities they cannot easily maintain independently. Dashers receive base pay that varies with estimated time, distance, and job desirability, along with 100% of customer tips, which DoorDash passes through in full.1 DoorDash retains merchant commissions and consumer fees while funding courier compensation, payment processing, insurance, refunds, credits, and customer support.
What an order actually earns
Financial disclosures illustrate the precise economics of each transaction. In 2025, across 3.17 billion orders generating $102.0 billion in Marketplace Gross Order Value (GOV), the average order totaled about $32. DoorDash recognized $13.7 billion of revenue on that GOV—a net revenue margin of 13.4%, or roughly $4.32 per order. Contribution Profit, the company's measure of order earnings after direct generation and fulfillment costs, reached $4.84 billion, or 4.7% of GOV—approximately $1.53 per order. Adjusted EBITDA of $2.779 billion equated to about $0.88 per order, while GAAP net income of $935 million translated to roughly $0.29 per order.1
These figures define the underlying nature of the enterprise. A company netting less than thirty cents of GAAP profit per delivery does not operate as a software firm in the traditional sense; it functions as a logistics operator whose profitability depends on executing billions of transactions at marginal cost efficiencies.
This narrow per-order yield represents both the primary bear case—leaving minimal tolerance for transaction-level errors—and the bull case, given the consistent trajectory of margin expansion. Contribution profit rose from 3.7% of GOV in 2023 to 4.3% in 2024 and 4.7% in 2025, while Adjusted EBITDA expanded from 1.8% to 2.4% and 2.7% over the same span.1 A margin increase of roughly one hundred basis points of GOV over two years on a volume base that grew 53% reflects genuine operating leverage rather than product mix shifts.
Which powers are actually working
Analyzing the drivers of this leverage through Hamilton Helmer's 7 Powers framework highlights distinct areas of operational strength.
Scale economies remain the most powerful and tangible advantage, as fixed engineering, brand, and corporate expenses are spread across a growing order volume, reinforced by local delivery density and improved payment-processing terms. Network effects operate on a strictly local scale; as Chief Executive Officer Tony Xu observed during the second-quarter 2026 earnings call, there are "no global network effects in these kinds of businesses," making platform scale essential market by market.24 Order density in U.S. suburban markets provides little operational advantage in international cities such as Milan. Counter-positioning against Grubhub's asset-light marketplace was historically decisive, but that structural advantage has fully run its course now that Uber Eats operates an identical logistics framework. Consequently, switching costs established through subscription services represent the platform's primary active competitive defense.
Management frequently highlights the subscription flywheel as its key retention engine. On the second-quarter 2026 earnings call, Chief Financial Officer Ravi Inukonda detailed the underlying economic sequence: frequent consumers transition into DashPass, where members order more often and exhibit higher retention. That increased retention elevates gross profit per monthly active user, generating reinvestment capital for merchant selection and service quality, which fuels further subscription growth. Inukonda referenced a published January 2021 customer cohort as representative of the broader portfolio, disclosing that DoorDash added more U.S. paid DashPass members in the twelve months through the second quarter of 2026 than in the preceding twenty-four months combined.2425 DashPass members also accounted for roughly 75% of total grocery and retail orders.25
The pricing-power test
The strength of DoorDash's competitive moat faces a direct pricing-power test in courtroom challenges and municipal council chambers.
During 2020 and 2021, dozens of U.S. municipalities capped the commission rates delivery platforms could charge restaurants, with New York City and San Francisco eventually making their 15% delivery fee caps permanent. DoorDash's take rate in those markets compressed immediately, prompting the company to introduce explicit regulatory surcharges on consumer orders. These municipal interventions initially challenged the notion of merchant pricing power, demonstrating that local governments could restrict platform commission structures.
Subsequent legal developments, however, reshaped those regulatory limits. DoorDash, Grubhub, Uber Eats, and Relay filed suit, ultimately settling with New York City in April 2025 after the City Council agreed to raise the fee ceiling. While the revised framework preserves the 15% cap on core delivery, 5% for marketing, and 3% for payment processing, it allows an additional 20% for optional "enhanced services" such as expanded delivery radii and promotional placement—raising the potential total commission rate to roughly 43% from a prior effective ceiling near 23%.2627 A federal judge formally entered the settlement as a court stipulation in late April 2025.27
This progression illustrates that municipal ordinances can temporarily restrict posted rates, but DoorDash retains pricing flexibility rather than absolute pricing power. The company has demonstrated the capacity to restore unit economics through litigation, tiered opt-in pricing, and consumer surcharges, though each regulatory resolution requires legal expenditures, administrative effort, and potential conversion friction.
Concurrently, the voluntary nature of these merchant relationships faces legal scrutiny. In February 2025, Uber filed a lawsuit against DoorDash in California state court, alleging that DoorDash coerced restaurants into exclusive or near-exclusive delivery arrangements by threatening higher commission rates or reduced marketplace visibility.28 DoorDash characterized the lawsuit as an attempt to litigate rather than innovate and filed a motion to dismiss. In 2026, a California Superior Court judge rejected five of DoorDash's six objections, allowing the case to proceed to discovery.29 While the allegations remain unproven, the discovery process will provide empirical evidence on whether merchant retention reflects genuine platform switching costs or restrictive contractual leverage.
VIII. Hidden Growth Engines: Advertising, DashMart & White-Label Logistics
Consider a consumer packaged goods brand manager deciding where to allocate trade spend. She can purchase a standard display ad with unverified viewing, or she can buy a sponsored placement inside an application where a customer has already opened a shopping cart and will complete a purchase within ninety seconds — giving the platform the ability to measure incremental unit conversion down to the stock-keeping unit.
That high-intent placement forms the foundation of DoorDash's advertising business, representing the company's highest-margin product. Serving an ad impression alongside an existing order incurs virtually no incremental fulfillment cost — eliminating courier pay, food preparation costs, and refund risk — allowing revenue to flow directly to the bottom line.
DoorDash reported that its combined DoorDash and Wolt Ads business surpassed an annualized run rate of $1 billion during 2024, marking the fastest product to reach that threshold in company history.30 Expanding that infrastructure through 2025 and 2026, the platform introduced Smart Campaigns for smaller merchants and expanded its Symbiosis partner network, which nearly doubled its participating partners between June and December 2025.5 During the second-quarter 2026 earnings call, Chief Financial Officer Ravi Inukonda cited advertising as one of only two primary drivers behind the company's earnings beat.24
However, a fundamental disclosure limitation remains. DoorDash does not report advertising revenue as a separate reporting segment in its financial statements. Its annual report cites advertising only as one of several factors causing revenue growth to outpace gross order value.1 Consequently, the common market assumption that advertising generates the majority of DoorDash's operating income cannot be verified through public filings. While plausible based on unit economics, the claim remains unconfirmed.
This reporting opacity introduces strategic ambiguity. If high ad margins account for the bulk of platform profits, the core delivery business operates closer to breakeven than headline figures suggest — shifting the bullish monetization narrative into a potential structural vulnerability. Management could resolve the debate by disclosing standalone ad metrics, but has elected to maintain consolidated reporting.
The grocery and retail land grab
The second expansion driver encompasses all non-restaurant categories: grocery, convenience, alcohol, pharmacy, and increasingly apparel and auto parts.31 The strategic thesis relies on asset efficiency: DoorDash leverages its existing courier network to amortize fixed logistics costs across broader merchant verticals without funding a secondary delivery fleet.
Consumer adoption has expanded accordingly. Over 30% of U.S. monthly active users and nearly 29% of global users placed a grocery or retail order in December 2025, with management stating that the company attained category volume leadership in the fourth quarter of 2025.524 Basket sizes have similarly expanded as users integrate non-restaurant errands into the platform.
Yet the financial timeline presents a more demanding reality. After six years of category development, management announced in early 2026 that new verticals were expected to achieve gross profit positivity only in the second half of 2026 — a commitment reaffirmed in August.524 Gross profit measures revenue above direct fulfillment costs, excluding operating expenses and capital returns. A vertical scaling since 2020 that requires six years to cover direct delivery expenses is not an immediate high-margin catalyst; it represents a prolonged, capital-subsidized expansion strategy.
A related economic uncertainty surrounds merchant commission structures. On the second-quarter 2026 call, an analyst asked whether grocers paying near-zero commission rates during trial periods could be repriced upward. CEO Tony Xu declined to address specific contractual terms, noting instead that DoorDash frequently accounts for "100% of the growth" a grocer generates.24 While asserting strong long-term bargaining leverage, management's response leaves current take-rate economics unquantified, indicating that grocery fulfillment subsidies continue to weigh on consolidated operating margins.
DashMart and the return of the warehouse
The third growth initiative departs entirely from pure software marketplace dynamics. DashMart operates as DoorDash's owned inventory business, managing dedicated warehouses that purchase, stock, and sell convenience and grocery items directly.
Management frames this vertical integration as a solution to structural grocery supply chain flaws. Traditional grocers often face inventory drift and out-of-stock inaccuracies, leading to high order-fulfillment error rates when third-party couriers pick items off retail shelves. Direct warehouse ownership resolves inventory data discrepancies. Xu noted that DashMart Fulfillment Services facilities — which also serve partner retailers — achieve roughly ten times lower error rates than traditional store picks while capturing off-hours demand by operating near continuously.24
Acknowledging the capital requirements, Xu stated on an earnings call, "this is complicated. I mean this is building physical infrastructure."24
Balance sheet disclosures substantiate that operational shift. Property and equipment expanded from $778 million at year-end 2024 to $1.067 billion at year-end 2025.1 Furthermore, annual free cash flow remained flat at $1.8 billion despite a $300 million increase in operating cash flow, as capital expenditures for physical facilities, equipment, and capitalized software absorbed the incremental cash generation.1
This capital allocation directly challenges the traditional view of DoorDash as an asset-light software marketplace. By reinvesting operating cash flow into physical real estate and inventory, DoorDash is building a heavy fulfillment footprint whose ultimate return on invested capital remains to be demonstrated.
The Commerce Platform
The fourth driver focuses on enterprise software and white-label infrastructure, offering DoorDash's fulfillment and merchant tools directly to businesses for use on their owned channels. This suite includes DoorDash Drive white-label delivery, online ordering systems, branded mobile applications, tableside ordering, and guest management via the SevenRooms acquisition.
During the second-quarter 2026 earnings call, Xu reported that the merchant solutions business served over 150,000 active businesses, growing 40% year over year, while SevenRooms venue signups increased more than 100% year over year in December 2025.245 Structurally, integrating marketplace demand generation, direct-channel delivery, guest reservations, and customer databases transforms DoorDash from a delivery vendor into a core restaurant operating system.
This deep software integration establishes genuine switching costs across the merchant base. However, this same commercial lock-in forms the crux of Uber's ongoing litigation, which alleges that DoorDash maintains exclusive merchant relationships through contractual pressure rather than product performance. Consequently, upcoming court discovery will evaluate whether merchant retention stems from genuine product integration or anti-competitive leverage.
Together, these four growth initiatives yield distinct strategic profiles: an advertising business that is highly profitable but unsegmented in financial reports; a retail vertical scaling toward gross profitability after six years of investment; a physical fulfillment network absorbing cash flow for warehouse expansion; and a merchant software platform building switching costs while facing antitrust scrutiny. Across all four, DoorDash is reinvesting core restaurant profits into adjacent market positions — a strategy whose ultimate success will be judged by contribution margin expansion rather than expansion metrics alone.
All four initiatives depend on an underlying labor model that regulatory authorities across multiple jurisdictions continue attempting to restructure.
IX. Regulatory Warfare: Prop 22, Minimum Pay Laws & Gig Worker Falsification
In the autumn of 2020, California voters weighed a ballot measure that attracted more funding than any initiative in state history. Assembly Bill 5 had established a legal test that threatened to reclassify most gig couriers as employees—introducing obligations for payroll taxes, workers' compensation, unemployment insurance, overtime, and strict scheduling.
For DoorDash, the financial stakes were existential rather than incremental. The company's unit cost advantage relies on paying couriers only while an active delivery is underway. Converting couriers to hourly employees would turn idle time between orders—the precise operational variable DoorDash's algorithms are built to minimize—into a fixed expense borne directly by the platform.
The food delivery sector responded with unprecedented capital. The "Yes on 22" campaign spent over $200 million, with DoorDash contributing roughly $52 million, and the measure passed with approximately 58% of the vote.32 Proposition 22 preserved couriers' independent contractor status while guaranteeing an earnings floor during engaged time alongside healthcare stipends for eligible drivers. In July 2024, the California Supreme Court unanimously upheld the law.33[^35]
The mechanics of "engaged time" are central to this model. An earnings floor calculated strictly while a courier is fulfilling an order leaves DoorDash's primary cost lever intact: management retains control over how many drivers log on and what fraction of their time produces billable work. Conversely, an hourly floor covering all time spent logged into the app would transfer idle-time financial risk back to the platform. Subsequent municipal pay battles have turned on which of these two structural designs governs local operations.
New York City
New York City enacted rules that moved past California's framework. Rather than limiting pay floors to active trip time, the city established a per-hour minimum wage for app-based delivery workers excluding tips, and steadily escalated the rate. By January 26, 2026, the framework expanded to include grocery delivery platforms at $21.44 per hour before tips—a floor scheduled to reach $22.13 on April 1, 2026. The mandate covers roughly 80,000 workers while adding requirements for prompt checkout tipping choices, weekly pay issuance, itemized statements, and guaranteed bathroom access.34[^37]
DoorDash, Uber, and Instacart sought preliminary injunctions against the expanded mandates, but federal courts denied their requests on January 23, 2026.34 New York City's Department of Consumer and Worker Protection claimed its enforcement regime generated $1.2 billion in additional courier earnings between 2023 and early 2026.34
DoorDash responded by raising consumer delivery fees across the city and shifting the app's tipping prompt from pre-checkout to post-delivery—a revision management characterized as adhering to regulatory recommendations.35 That procedural change carries material economic consequences. Shifting tip prompts to after delivery reduces consumer tipping frequency, lowering courier tip income even as the mandated base wage increases. Consequently, DoorDash mitigated its compliance expense by passing costs directly to consumers through higher fees and indirectly to couriers through reduced tip volume.
Seattle, and two studies that disagree
Seattle enacted a minimum pay ordinance for app-based workers in 2024, creating an informative natural experiment on municipal labor intervention.36
An initial study by Carnegie Mellon researchers Yuan An, Andrew Garin, and Brian Kovak analyzed driver-app data from August 2023 through July 2024, comparing Seattle couriers with drivers across the rest of Washington State. Their findings challenged arguments on both sides of the debate: while pay per task increased, average tips dropped substantially, active couriers completed fewer deliveries, and overall monthly earnings remained largely unchanged. The researchers noted that higher compensation per order was effectively offset by lower order volume per driver.37
Conversely, a city-commissioned study released in early 2026—evaluating roughly 92,000 workers and 15 million delivery offers across five major platforms—reported more positive outcomes, asserting that driver pay increased, total order volume expanded, and consumer demand remained stable across the ordinance's first eighteen months.38
These diverging conclusions stem from differences in observation windows, datasets, and measurement criteria. The initial fee increases caused an immediate volume contraction, but consumer demand stabilized over the subsequent eighteen months as buyers adapted to higher pricing. A synthesized reading indicates that Seattle's regulation redistributed earnings across the driver pool rather than expanding overall worker income, while leaving DoorDash's platform economics functioning under a higher fee structure.
The falsification, stated precisely
The bearish argument that local food delivery platforms cannot operate under strict labor regulation is countered by empirical evidence. DoorDash navigated California's legislative and ballot battles, New York's rising pay floors, and Seattle's ordinance while continuing to expand domestic order volume and gross order value.
A more measured constraint, however, remains evident. In heavily regulated municipalities, DoorDash forfeits direct control over unit labor expenses, leaving its local profit margins vulnerable to policy changes. To preserve margins, the company relies on consumer surcharges—a strategy that depends entirely on sustained price inelasticity among consumers. Furthermore, platform stability rests on independent-contractor engaged-time models that remain untested at the U.S. federal level.
Two regulatory overhangs require close monitoring. First, international markets have become financially material, generating $2.257 billion in revenue during 2025, or roughly 16% of total revenue.1 The European Union's Platform Work Directive mandates that member states transpose its rules into national law by late 2026, introducing a rebuttable presumption of employment for gig workers. This framework stands in direct contrast to California's Proposition 22, applying strict labor standards across regions where DoorDash invested $3.7 billion through its Deliveroo acquisition.
DoorDash gained a partial legal defense through that acquisition: in November 2023, the UK Supreme Court ruled that Deliveroo riders were not "workers" for collective bargaining purposes because they maintained a genuine right to appoint substitutes.39 While that precedent protects operations in the United Kingdom, it holds no legal force in European Union regulatory proceedings.
The second overhang centers on domestic legal and tax liabilities. In September 2025, DoorDash settled a worker misclassification action brought by the San Francisco District Attorney for $2 million without injunctive relief, avoiding mandatory operational adjustments.1 However, the company faces ongoing financial exposure from a California Employment Development Department audit regarding payroll tax liabilities. DoorDash has contested a negative tax assessment active since January 2023 and recorded an undisclosed liability within accrued expenses as of December 31, 2025.1 This accrual represents management's most direct balance sheet exposure to courier reclassification risks.
A final cost dynamic underscores the sensitivity of DoorDash's labor economics. In its outlook for the second quarter of 2026, management disclosed a Dasher fuel relief program carrying a gross expense exceeding $50 million for the quarter.31 A logistics network requiring tens of millions of dollars in quarterly subsidies to maintain courier supply during fuel price shifts demonstrates that contractor labor costs are less flexible than the independent business model suggests.
That operational reality shifts attention to executive leadership and whether management's track record justifies the governance authority granted by the company's dual-class share structure.
X. Management Credibility, Capital Allocation & Earnings Call Synthesis
On August 5, 2026, DoorDash reported a second quarter in which adjusted EBITDA rose 40% year over year to $914 million — comfortably above its guidance range of $770 million to $870 million — even as GAAP net income fell 30% to $200 million.2531
The divergence between expanding operating metrics and declining GAAP earnings provides a clear entry point for evaluating management's operational discipline and strategic communication.
What the calls actually reveal
Management consistency can be measured across earnings calls. On the fourth-quarter 2025 call in February 2026, Chief Financial Officer Ravi Inukonda informed analysts that his full-year 2026 EBITDA expectation remained unchanged since the prior call, that profit margins would expand slightly over 2025 excluding Deliveroo, that Deliveroo would contribute roughly $200 million in Adjusted EBITDA, and that capital commitments across three core programs — a unified global technology platform, autonomous delivery, and merchant services — remained constant.40 Six months later, during the August call, Inukonda reaffirmed those investment priorities, noting they were running "on budget and on plan according to what I had estimated a couple of quarters ago."24
That consistency provides investors with a verifiable track record across reporting periods.
A more revealing exchange occurred when analysts pressed Inukonda on why second-quarter Adjusted EBITDA exceeded the top end of guidance by more than $40 million. Inukonda explained that late-quarter outperformance in advertising and order subtotals left no time to redeploy capital into growth initiatives, leaving DoorDash "happy to drop it to the bottom line." He added that investors should expect second-half results to land inside the previously guided range.24
That explanation illuminates management's financial philosophy: DoorDash treats revenue upside as reinvestment capacity rather than structural profit. When quarterly results beat guidance, it indicates that unexpected revenue arrived too late in the period to spend. While this long-term reinvestment stance is logically consistent, it implies that quarterly EBITDA surprises reflect tactical spending timing rather than fundamental shifts in earning power.
The August 2026 call also illustrated the boundaries of executive disclosures. Chief Executive Officer Tony Xu declined to detail grocer take rates or specify a ceiling for autonomous delivery adoption, stating that operational execution would determine market penetration. However, when asked about traffic generated by artificial intelligence shopping agents, Xu offered a candid assessment, noting that "the volume is quite low."24 The broader pattern reveals leadership that is disciplined regarding operating metrics but protective of merchant-level economics.
Testing the profitability claim
Through 2023, a central bear thesis posited that DoorDash could not achieve true GAAP profitability and that positive operating metrics were offset by stock-based compensation. Disclosed financial results have disproved that absolute claim: full-year 2025 GAAP net income reached $935 million, following $123 million in 2024 after years of accumulated losses.1
However, a nuanced critique remains, supported by the company's financial reporting.
Stock-based compensation totaled $1.051 billion in 2025, exceeding GAAP net income for the year.1 As a percentage of revenue, stock compensation decreased from approximately 13% in 2022 to about 8% in 2025 as revenue growth outpaced the compensation pool.1 Yet that margin improvement stems primarily from top-line revenue expansion rather than absolute spending reductions, with management guiding 2026 stock-based compensation higher, to between $1.3 billion and $1.4 billion.5
Equity dilution reflects this ongoing issuance. Combined Class A and Class B shares outstanding increased from approximately 419.7 million at year-end 2024 to about 434.2 million at year-end 2025.1 Despite generating nearly $1 billion in net income and holding an active $5.0 billion share repurchase authorization since February 2025, DoorDash repurchased zero shares during fiscal 2025, leaving the full capacity unexecuted.1 This paused buyback activity represents a shift from previous years, as the company had repurchased shares annually across 2022, 2023, and 2024.
The evidence demonstrates that while DoorDash's GAAP profitability is established, operating profits have not yielded direct capital returns to public shareholders. Instead, cash flow has been directed into strategic acquisitions, facility infrastructure, and employee equity compensation, causing per-share financial gains to lag net income expansion.
Why GAAP earnings are falling while EBITDA rises
The earnings divergence observed in 2026 stems from accounting mechanics related to recent acquisitions. The additions of Deliveroo and SevenRooms brought $1.498 billion in identified intangible assets alongside additional goodwill onto the balance sheet, incurring ongoing amortization expense.1 Consequently, management projected full-year 2026 depreciation and amortization of $1.1 billion to $1.2 billion,5 up from $747 million in 2025.1 Combined with elevated stock-based compensation, GAAP net income absorbs substantial non-cash charges that Adjusted EBITDA excludes by definition.
While this pattern is standard for acquisition-led expansion, it alters the analytical utility of non-GAAP metrics. Adjusted EBITDA excludes a growing share of the real capital costs associated with DoorDash's chosen growth strategy. For an unadjusted assessment of cash generation, free cash flow provides a clearer signal; in the second quarter of 2026, free cash flow reached $742 million, more than doubling from the prior-year period.25
The capital allocation record, weighed
Evaluating DoorDash's major capital deployments against empirical data highlights varying returns across its portfolio. The initial focus on suburban delivery density represents an unambiguous operational success, validated by category market share data. The Wolt acquisition required roughly three years of financial support before stabilizing, eventually establishing an international revenue foundation. Conversely, Caviar's standalone return on investment remains unquantified due to a lack of segment disclosure, while the $3.7 billion Deliveroo transaction remains in an early integration phase despite tracking slightly ahead of initial fourth-quarter 2025 Adjusted EBITDA guidance. Additionally, management demonstrated cost discipline during the 2022 corporate restructuring.
The broader record reveals executive leadership that deploys capital assertively, communicates strategic rationale consistently, and prioritizes growth options over direct capital returns to shareholders. However, public disclosures have yet to confirm a completed acquisition yielding a verifiably high return on invested capital. Until dedicated segment metrics substantiate those acquisitions, management's capital allocation track record remains partially unproven, leaving room for debate as the company enters its next phase of technology and logistics expansion.
XI. Skeptical Investor Stress Test & Bull vs. Bear Thesis
On August 6, 2026, a controlling block of stockholders consisting of Tony Xu, Andy Fang, Stanley Tang, and a collection of family trusts and holding entities executed a written consent. Between them, they held 25,884 Class A common shares and 24,215,044 Class B shares — controlling approximately 54.2% of DoorDash's total voting power.41
The consent approved reincorporating DoorDash from Delaware to Nevada through a statutory conversion, bypassing both a traditional shareholder meeting and a vote by holders of the remaining 411 million Class A shares. Under federal securities rules, public shareholders receive an information statement detailing the decision, with the conversion taking effect no earlier than twenty days after mailing.4142
The board's stated rationale asserted that Nevada's statute-based legal framework offers greater predictability than Delaware's judicial precedents, which management characterized as an increasingly litigious environment generating costly nuisance suits.42 Legal scholars and governance experts sharply debate that premise.
What remains indisputable is the statutory shift in governance authority. Nevada law raises the threshold to remove a director from a simple majority to a two-thirds vote, grants directors broader liability protections, narrows shareholder inspection rights, and explicitly permits directors to consider non-shareholder interests when evaluating decisions.42 While share classes convert on a one-for-one basis leaving economic stakes unchanged,42 legal accountability shifts substantially.
This structural transition provides corporate activists with a compelling case that goes beyond standard dual-class critiques. While prior deployments of super-voting shares were defended as insulating long-term operating decisions from short-term market pressures, relocating legal incorporation offers no operational rationale. Executives holding roughly 6% of the company's economic equity used 54% voting control to insulate themselves from judicial oversight, executing a fundamental corporate change without the consent of the shareholders who own the vast majority of the business.
The dissent that the structure absorbs
Public shareholders registered clear dissatisfaction prior to the reincorporation. At the annual meeting on June 10, 2026, lead independent director Shona Brown drew 84,442,121 votes against her re-election out of roughly 830 million total votes cast across all share classes. Co-founder Stanley Tang received 50.1 million votes against, director Alfred Lin drew 51.7 million against, and newly appointed director Milan Kovac received 25.5 million against. By contrast, the advisory vote on executive compensation passed with 801.4 million votes in favor against 28.9 million opposed, while auditor ratification for KPMG passed near-unanimously.43
While headline approval totals appear comfortable, the voting arithmetic reveals substantial public opposition. The co-founders' 24.2 million Class B shares command roughly 484 million votes, implying that public investors cast only about 346 million Class A votes. Assuming the founding block voted in favor of management's slate, approximately a quarter of votes cast by public shareholders opposed the lead independent director — the precise board member charged with representing non-controlling interests. Because DoorDash does not break out voting results by share class, these figures represent an analytical estimate, yet the direction of investor sentiment remains clear.
Under DoorDash's multi-class architecture, however, public shareholder dissent lacks an operational mechanism to compel change. Public investors cannot remove a director, block a corporate reincorporation, or force capital returns; their only effective recourse is selling their shares.
A parallel balance sheet risk warrants equal scrutiny. Following its 2025 acquisitions, DoorDash carried $5.5 billion in goodwill and $2.3 billion in intangible assets, together accounting for roughly 40% of its $19.7 billion in total assets.1 In the fourth quarter of 2025, the company evaluated goodwill under a single reporting-unit framework and concluded that fair value comfortably exceeded carrying value, recording no impairment charges.1 While single-unit testing complies with accounting standards, it allows severe underperformance in regional segments — such as international operations — to be masked by domestic strength. This accounting discretion represents a key balance sheet variable alongside ongoing intangible asset amortization.
Porter's Five Forces, applied
Rivalry remains intense yet structurally stable at the national level, where DoorDash commands roughly two and a half times the market share of Uber Eats. Metropolitan data, however, reveals a more competitive reality. At year-end 2024, DoorDash held a 38.4% share of food delivery sales in the New York City area against Uber Eats' 38.2%, while the two platforms were effectively tied in Los Angeles, with Uber Eats holding a marginal lead.13 Because local delivery logistics depend on neighborhood density rather than national scale, national market share figures overstate DoorDash's competitive stance in the nation's two largest metropolitan areas. Assertions of an unassailable domestic moat must account for these urban realities.
Buyer power operates along dual tracks. Consumers face negligible switching costs and routinely maintain multiple delivery apps on a single device, leaving subscription memberships as the platform's primary retention mechanism — a reality reflected in management's detailed DashPass disclosures. Meanwhile, merchants have gained bargaining leverage through municipal fee caps, direct-ordering software investments, and white-label alternatives such as Uber Direct.
Supplier power among couriers remains limited individually but is expanding collectively through legislative mandates rather than traditional labor bargaining — establishing a slower yet more durable form of cost pressure.
Substitutes represent a persistent constraint on platform pricing. Home cooking, pickup orders, first-party merchant applications, and grocery delivery from Amazon and Instacart compete for consumer spending, while autonomous delivery vehicles threaten to reset last-mile cost structures in favor of hardware developers rather than network orchestrators.
New entrants face formidable national capital requirements but low local entry barriers. While replicating DoorDash's nationwide footprint is economically impractical, well-capitalized competitors can deploy capital to capture market share within individual metropolitan areas, as demonstrated by city-level market data.
The 7 Powers, updated
Evaluating DoorDash through the 7 Powers framework confirms that scale economies remain its strongest asset, as demonstrated by expanding contribution margins. Switching costs continue to compound through DashPass subscriptions and enterprise merchant software integration. Conversely, counter-positioning against traditional order marketplaces has fully run its course, while network effects remain strictly local by management's explicit acknowledgement.
The operational framework warrants the addition of process power — accumulated operational expertise that competitors cannot easily duplicate. Chief Executive Officer Tony Xu articulated this dynamic regarding autonomous logistics, arguing that scaling robot delivery requires solving merchant loading constraints, estimating kitchen preparation times, navigating gated communities, and orchestrating hybrid routes combining autonomous and human couriers — capabilities that can only be developed by an active network operator.24
While conceptually sound, that operational thesis remains unproven at scale. DoorDash unveiled its custom Dot delivery robot on September 30, 2025 — a three-foot-wide, four-and-a-half-foot-tall vehicle capable of speeds up to 20 miles per hour, engineered to navigate roads, bike lanes, and sidewalks following seven years of internal development.4445 Operating in pilot zones across the Phoenix area, management targeted Dot to fulfill a high single-digit percentage of orders in its primary test market by year-end 2026.25 Demonstrating its commitment to autonomous engineering, the board appointed Milan Kovac — former head of Tesla's Optimus humanoid robot program — as a director in January 2026.46
An analytical evaluation requires distinguishing between technical progress and commercial viability. Operating autonomous robots in a single test market represents a technological milestone rather than a commercialized logistics solution. DoorDash's public risk disclosures explicitly acknowledge that competitors may deploy autonomous or drone delivery networks more rapidly, and that internal development may demand more time and capital than projected.1 For investors, autonomous delivery represents long-term optionality subject to specific benchmarks: whether Dot achieves its target penetration in Phoenix and whether the model can be expanded to secondary markets on competitive unit economics.
The bear case
Regulatory margin setting. Across an expanding number of municipalities, unit labor expenses are determined by legislation rather than algorithmic supply, forcing DoorDash to recover costs through consumer surcharges. That mechanism relies on sustained price inelasticity, leaving margins vulnerable if fee increases trigger consumer pullback.
Merchant disintermediation. Major restaurant chains possess strong incentives to drive order volume through owned digital channels. While DoorDash counters by selling enterprise ordering software to those same chains, that dual role forms the central subject of discovery in ongoing antitrust litigation with Uber.
Consumer trade-down. On-demand delivery remains a premium convenience service. A broader macroeconomic downturn directly threatens order frequency, presenting a demand test that DoorDash has not navigated at its current operational scale.
International returns. Management deployed $3.7 billion in cash and debt to acquire Deliveroo against an expected 2026 Adjusted EBITDA contribution of roughly $200 million, while expanding across European markets facing stringent gig-worker reclassification rules.
The bull case
A real cost position in local logistics. Contribution profit expanded from 3.7% to 4.7% of order value over two years while total order volume grew by more than 50% — demonstrating tangible operational leverage across suburban fulfillment networks.
A high-margin attached business. Digital advertising monetizes existing consumer intent at minimal incremental fulfillment cost, generating high-margin revenue that supports consolidated operating income, even as standalone advertising figures remain unsegmented.
Compounding membership. DoorDash added more U.S. paid DashPass members in twelve months than in the preceding twenty-four, with subscribers accounting for roughly 75% of grocery and retail orders — providing clear empirical evidence of growing platform switching costs.
Optionality that is actually being built. Operational progress includes active autonomous robot deployments, a merchant software business growing 40% year over year, and an ongoing unified platform integration across 41 global markets targeted for completion in the first half of 2027.24
The analytical conclusion is not a simple verdict on the stock, but rather a synthesis of three distinct realities: DoorDash has converted local delivery density into a profitable domestic operating engine; it has acquired an international footprint whose long-term financial returns remain unvalidated; and it operates under a dual-class governance structure that leaves public shareholders with no formal recourse if future capital allocation decisions prove mistaken. All three conditions exist simultaneously.
XII. Playbook: Strategic & Operational Lessons
Every good business story leaves behind transferable lessons. The useful version of that exercise includes the conditions under which each lesson stops working.
1. Attack where the incumbent's model forbids it from following.
DoorDash's founding decision was not to build a better food app. It was to take on the operationally demanding, low-margin courier layer that Grubhub's public shareholders were unlikely to endorse. Counter-positioning works precisely because an incumbent's rational self-interest keeps it anchored to its existing business model.
The caveat is that counter-positioning has a shelf life. Uber Eats operates an identical logistics framework today, and Grubhub's decline did not make DoorDash's position permanent. What preserved market leadership was the neighborhood density advantage built afterward, not the original structural insight.
2. Choose your geography before you choose your tactics.
Suburban expansion was not a fallback from dense urban centers; it was a superior business model. Suburbs provided larger family order values, faster drop-offs at driveways, courier-provided vehicles, and lower initial competition from rivals convinced that density required high-rise city centers.
The caveat is that this strategy remained invisible to public markets for years, leading venture investors to mark down the company's valuation during fundraising. Geographic contrarianism succeeds only if a enterprise can fund operations through the period when its approach resembles weakness — a hurdle DoorDash barely cleared in 2016 before securing substantial growth capital after 2018.
3. Do things that don't scale to learn what to build, not to build a moat.
Hand-delivering orders taught the founders where operational friction actually occurs during transport. That empirical insight shaped the parameters of the eventual dispatch engine. However, scaling that routing system required years of internal engineering and hundreds of millions of dollars in venture capital.
The primary takeaway centers on problem definition rather than structural defensibility. Manual operations function as an analytical research method with an expiration date.
4. Currency choice in M&A is a risk allocation, not a masterstroke.
Structuring the Wolt acquisition as an all-stock transaction ensured that DoorDash's equity valuation compression transferred to the seller, reducing the delivered transaction value by more than half between signing and closing. That outcome was favorable for DoorDash, but it reflected market-wide valuation adjustments rather than engineered foresight; the same equity structure in a rising market transfers value in the opposite direction.
The instructive contrast emerged three years later when DoorDash selected cash consideration for Deliveroo, funding the transaction in part through its first major convertible debt issuance. A management team that characterizes equity deals as strategic downside protection and subsequently deploys cash at the next major transaction signals that currency choice is situational rather than structural.
5. Sell the subscription before you need it, and the software after.
DashPass converted transactional buyers into subscribers exhibiting higher ordering frequency and retention, creating compounding revenue gains visible in cohort disclosures. The merchant software suite — encompassing online ordering, delivery dispatch, reservations, and customer analytics — applies that same retention thesis to the supply side of the marketplace, establishing higher switching costs.
The caveat is that neither program is cost-free. Subscription benefits represent platform-funded discounts, while merchant software lock-in faces legal scrutiny via antitrust litigation alleging contractual leverage over product performance. Switching costs established through unit economics remain durable; lock-in enforced through commercial leverage invites regulatory and legal resistance.
6. Watch what a management team does with its first billion dollars of profit.
DoorDash's response upon achieving sustained profitability in 2025 was to allocate $4.2 billion to acquisitions, issue $2.75 billion in convertible debt, authorize a $5 billion share repurchase program, and execute zero buybacks.1 That deployment reflects a clear executive preference for strategic optionality over direct capital returns, executed under a governance framework where control shares cannot be overridden.
Investors must evaluate whether their capital allocation priorities align with that corporate strategy before acquiring equity, because the dual-class voting architecture ensures public shareholders have no formal mechanism to alter that trajectory afterward.
XIII. Epilogue & Forward Watchlist
Thirteen and a half years after four founders posted PDF menus online and answered a Google Voice number between classes, DoorDash processes more than three billion orders annually across over 40 countries, supported by a courier network that earned more than $20 billion in a single year, while generating sufficient cash to acquire a listed European competitor outright.
The central through-line of the company's trajectory is not a raw technological breakthrough, but an early operational insight: local commerce is fundamentally a physical logistics problem where the primary hurdle is managing the fifteen minutes between a merchant's kitchen and a consumer's front door. DoorDash spent a decade systematically reducing the unit cost of those fifteen minutes.
What remains unproven is whether that logistical competence can be successfully transferred to new domains. Its international expansion via Europe involved substantial capital commitments with early financial returns; its grocery and non-restaurant retail vertical required six years of investment before approaching gross profit positivity; and its autonomous delivery initiative relies on red robot trials in Phoenix that have yet to yield disclosed commercial revenue.
Three things worth tracking
Contribution profit as a percentage of Marketplace GOV. This metric serves as the single clearest indicator of platform efficiency. It combines density economics, advertising contributions, subscription mix, courier pay, and order refunds into one figure, excluding corporate overhead and accounting adjustments. Contribution profit expanded from 3.7% of gross order value in 2023 to 4.7% in 2025.1 If this figure stalls while order volume grows, the operating leverage story loses traction; if it continues expanding through Deliveroo's integration, it will validate the international expansion strategy.
Paid membership count and its share of orders. Combined subscribers across DashPass, Wolt+, and Deliveroo Plus exceeded 35 million, with members accounting for approximately 75% of grocery and retail orders.125 Paid membership functions as the primary proxy for customer switching costs. Subscriber growth that outpaces total user growth signals deepening consumer habits; conversely, growth that demands increasingly generous benefits suggests the company is funding loyalty rather than earning it.
Free cash flow relative to adjusted EBITDA. The divergence between free cash flow and Adjusted EBITDA reflects the full financial cost of management's growth strategy—encompassing acquisition amortization, stock-based compensation, warehouse capital expenditures, autonomous technology development, and the ongoing expense of maintaining three separate software architectures until the unified platform launches in the first half of 2027.24 Free cash flow remained flat at $1.8 billion in 2025 even as Adjusted EBITDA expanded by 46%.1 A narrowing of this gap would provide strong evidence that capital investments are yielding operating efficiency; a widening gap would indicate that DoorDash is funding expansion that has yet to generate proportional cash returns.
Notably, management has declined to provide a long-term target margin. CFO Ravi Inukonda has repeatedly informed analysts that DoorDash does not manage toward a specific take rate, net revenue margin, or incremental margin, targeting instead the expansion of total profit dollars.2440 While managing for total gross profit is a logical approach for a scaling marketplace, it leaves investors without a company-defined performance benchmark, increasing reliance on external operating metrics.
The final question
Every element of DoorDash's business model ultimately turns on a single variable: the cost of moving a small item a short distance across a local market. Over thirteen years, the company has lowered that cost through algorithmic routing, order batching, suburban neighborhood density, and a labor structure that compensates couriers only during active deliveries.
Autonomous technology alters that cost equation directly. If delivery robots and drones can be deployed across a physical network at scale, last-mile unit costs drop beyond what software dispatch alone can achieve—raising the question of which market participant captures the resulting savings. If value accrues to the logistics platform that manages merchant integrations, consumer relationships, and real-world delivery exceptions, DoorDash's operational capabilities solidify into a durable competitive advantage. If value instead accrues to third-party hardware or autonomy developers that offer delivery capacity broadly, the fulfillment network DoorDash spent more than a decade constructing risks becoming a commoditized buyer rather than a proprietary moat.
CEO Tony Xu has explicitly argued for the former perspective, contending that operational execution across complex networks rather than standalone technology will dictate the outcome.24 The Phoenix test market serves as the initial benchmark where that strategic premise faces empirical evaluation—providing a concrete timeline for testing whether autonomous logistics will reinforce or undermine DoorDash's market position.
References
-
DoorDash, Inc. Form 10-K for the fiscal year ended December 31, 2025 — U.S. Securities and Exchange Commission, 2026-02-18 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
DoorDash IPO: DASH starts trading on the NYSE — CNBC, 2020-12-09 ↩↩
-
DoorDash IPO: Shares Surge 80% At Start Of Trading, Boosting Valuation To $60 Billion — Forbes, 2020-12-09 ↩↩
-
DoorDash, Inc. Form 424(b)(4) Final IPO Prospectus — SEC, 2020-12-09 ↩↩↩↩↩↩↩↩
-
DoorDash Releases Fourth Quarter and Full Year 2025 Financial Results — SEC Form 8-K Exhibit 99.1, 2026-02-18 ↩↩↩↩↩↩↩↩
-
DoorDash, TKO Group Holdings, Williams-Sonoma and Expand Energy Set to Join S&P 500 — S&P Global, 2025-03-07 ↩
-
DoorDash (DASH) share price, market capitalization and 52-week range — Stock Analysis, 2026-09-04 ↩
-
DoorDash ft. Tony Xu — The "Wrong" Moves That Built a Giant, Crucible Moments — Sequoia Capital ↩↩
-
The VC and founder winners of DoorDash's IPO — TechCrunch, 2020-11-13 ↩↩
-
What It's Like To Raise $127 Million As Silicon Valley's Bubble Bursts — Forbes, 2016-03-22 ↩↩
-
DoorDash, Inc. Definitive Proxy Statement (DEF 14A) — SEC, 2025-04-29 ↩
-
DoorDash raises $535 million Series D led by SoftBank — TechCrunch, 2018-03-01 ↩
-
DoorDash leads US delivery share, but some cities still competitive — Earnest Analytics ↩↩
-
DoorDash Acquires Delivery, Logistics Startup Rickshaw — Food Logistics, 2017-09-14 ↩
-
DoorDash Cuts 1,250 Jobs to Rein in Costs — Bloomberg, 2022-11-30 ↩
-
Square sells food-delivery service Caviar to DoorDash for $410 million — CNBC, 2019-08-01 ↩
-
Square Completes Sale of Caviar to DoorDash — Block, Inc., 2019-10-31 ↩
-
DoorDash agrees to acquire European delivery app Wolt — Financial Times, 2021-11-09 ↩
-
DoorDash Sees Tepid Q2 for Wolt as It Completes $3.5 Billion Takeover — U.S. News/Reuters, 2022-06-01 ↩
-
DoorDash Completes Acquisition of Wolt — DoorDash Investor Relations, 2022-06-01 ↩
-
DoorDash announces $1.2 billion SevenRooms deal — CNBC, 2025-05-06 ↩
-
DoorDash Announces Agreement to Acquire Deliveroo — DoorDash Investor Relations, 2025-05-06 ↩
-
DoorDash Announces Pricing of Upsized $2.5 Billion Convertible Senior Notes Offering — DoorDash Investor Relations, 2025-05-27 ↩
-
DoorDash Second Quarter 2026 Earnings Call — DoorDash Investor Relations, 2026-08-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
DoorDash Releases Second Quarter 2026 Financial Results — SEC Form 8-K Exhibit 99.1, 2026-08-05 ↩↩↩↩↩↩
-
DoorDash, Grubhub, Uber Eats settle with New York City over fee caps — CNBC, 2025-06-04 ↩
-
New York to raise cap on restaurant delivery fees to settle suits with Grubhub, DoorDash — Crain's New York Business, 2025 ↩↩
-
Uber sues DoorDash, alleging anti-competitive tactics — TechCrunch, 2025-02-14 ↩
-
DoorDash loses its challenge to Uber lawsuit — Restaurant Business, 2026 ↩
-
DoorDash Ads Launches New Features That Deliver Measurable Growth for Brands and Restaurants — DoorDash ↩
-
DoorDash Releases First Quarter 2026 Financial Results — SEC Form 8-K Exhibit 99.1, 2026-05-06 ↩↩↩
-
California Proposition 22, App-Based Drivers as Contractors and Labor Policies Initiative (2020) — Ballotpedia ↩
-
Uber, Lyft, DoorDash workers remain contractors due to California Supreme Court ruling — CalMatters, 2024-07-25 ↩
-
Major Victory for NYC Delivery Workers: Landmark Protections Take Effect Today — City of New York, 2026-01-26 ↩↩↩
-
An Update On The DoorDash Experience in NYC — DoorDash, 2023-12-04 ↩
-
App-Based Worker Minimum Payment Ordinance — City of Seattle Office of Labor Standards ↩
-
Study Finds That Seattle's New Minimum Pay Requirement for Gig Workers Failed to Boost App-Based Delivery Drivers' Earnings — Carnegie Mellon University Heinz College, 2026-01 ↩
-
Seattle report says gig worker pay law is working, countering claims by DoorDash and Uber — GeekWire, 2026 ↩
-
Gig economy: UK Supreme Court adds to developing case law with Deliveroo collective bargaining ruling — International Bar Association, 2023-11 ↩
-
DoorDash Fourth Quarter 2025 Earnings Call — DoorDash Investor Relations, 2026-02-18 ↩↩
-
DoorDash, Inc. Form 8-K reporting stockholder written consent approving Nevada reincorporation — SEC, 2026-08-11 ↩↩
-
DoorDash, Inc. Preliminary Information Statement on Schedule 14C regarding reincorporation in Nevada — SEC, 2026 ↩↩↩↩
-
DoorDash, Inc. Form 8-K reporting 2026 Annual Meeting voting results — SEC, 2026-06-11 ↩
-
DoorDash Unveils Dot, the Delivery Robot Powered by its Autonomous Delivery Platform — DoorDash Investor Relations, 2025-09-30 ↩
-
DoorDash rolling out Dot delivery robot in Phoenix area — AZFamily, 2025-09-30 ↩
-
DoorDash, Inc. Form 8-K reporting appointment of Milan Kovac to the board of directors — SEC, 2026-01-16 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube