SharkNinja: The Infomercial That Took Over the Appliance Aisle
I. The Demonstration That Became a $6 Billion Business
Picture the oldest trick in late-night television. A hand tips a bowl of cereal, a scoop of flour and a scattering of pet hair onto a carpet. The camera holds on the mess just long enough for the viewer to wince. Then a vacuum rolls through it in one pass, the carpet comes up clean, and a voice asks why anyone would pay twice as much for a machine that does the same job. There is no brand heritage in that scene, no lifestyle photography, no celebrity. There is only a problem, a fix, and a price.
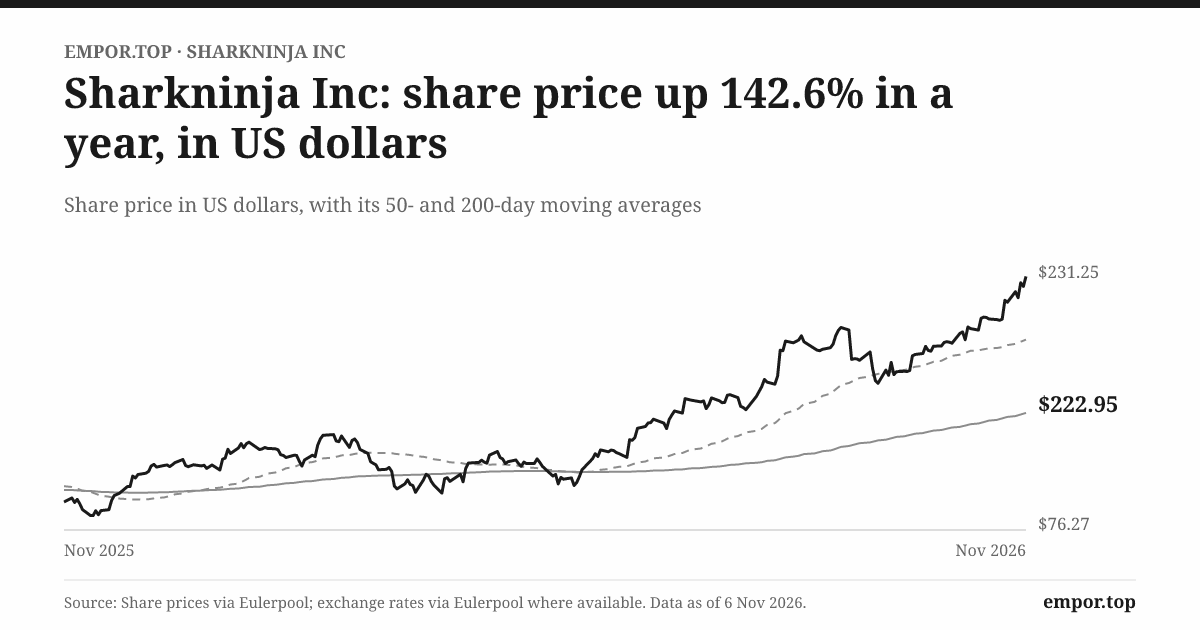
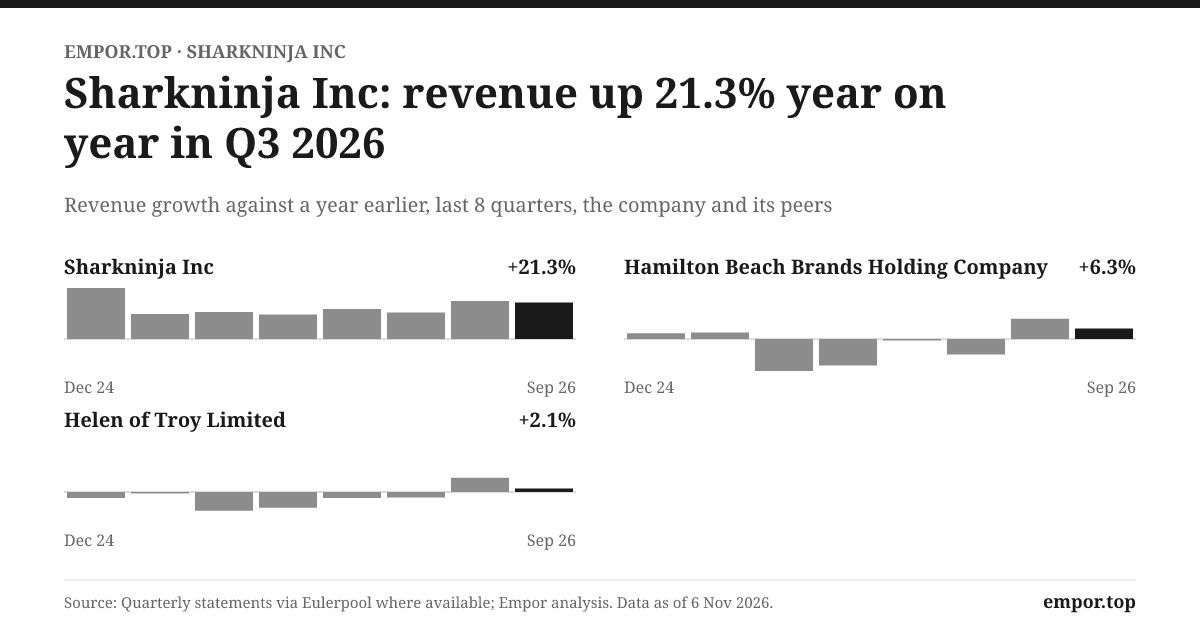
That scene is the seed of SharkNinja, and it is worth holding in mind, because nearly two decades later the same company sat in a very different room. On November 4, 2026, SharkNinja reported third-quarter sales of about $1.98 billion, up 21.2% from a year earlier, and said this was its 14th consecutive quarter of double-digit growth.1 Its share price closed that day at about $219, the highest level of the previous year and more than two and a half times the low of the same twelve months, valuing the company at roughly $31 billion.2 The company that once lived on cable infomercials now sells vacuums, blenders, air fryers, espresso machines, hair dryers, fans and LED face masks in dozens of countries, and in 2025 it sold about $6.4 billion of them.3
So the question at the centre of this story is not whether SharkNinja can sell a product. It plainly can. The question is whether the machine that produces those products is durable, or whether each hit simply has to replace the last one before the music stops. That matters because SharkNinja is a product-sales business, not a subscription business. Customers place individual orders that specify goods, quantity and price; the company says it has no significant long-term contracts that are satisfied over time.3 Every year it must convince retailers to give it shelf space and convince shoppers to pull a box off that shelf. Nothing renews automatically.
There is a second fact that sits awkwardly next to the first. In 2025, three customers each bought more than a tenth of everything SharkNinja sold, and together they accounted for 45.7% of sales.3 The largest, which the company identifies only as Customer A, alone took 23.8%.3 SharkNinja does not name them. A company that wins hearts on social media and in product reviews still depends, for almost half its revenue, on the purchasing decisions of three buying teams.
And there is a third fact, which arrived with that record quarter. Part of the surge in third-quarter profit came from refunds of tariffs SharkNinja had already paid, a windfall that will not recur in the same form.4 Sales grew strongly; profits grew even faster, and some of the difference was the refund.
Those three facts give the story its shape. The first thread is the product engine: whether it can keep launching into new categories and new countries faster than rivals copy it. The second is the retailer relationship: whether growth can broaden beyond a handful of very large accounts, and whether those accounts pay on time. The third is cash: whether the profits SharkNinja reports become money in the bank once tariff refunds fall away and the stockpile of receivables and inventory is collected and sold. The rest of this story follows those threads through a family appliance business, a Chinese owner, a spin-off on the New York Stock Exchange and a quarter that looked even better than it was. It begins, as SharkNinja's own legend does, with a vacuum that was cheaper than the one everyone admired.
 Subscribe on LinkedIn
II. The Price Gap Behind the First Shark
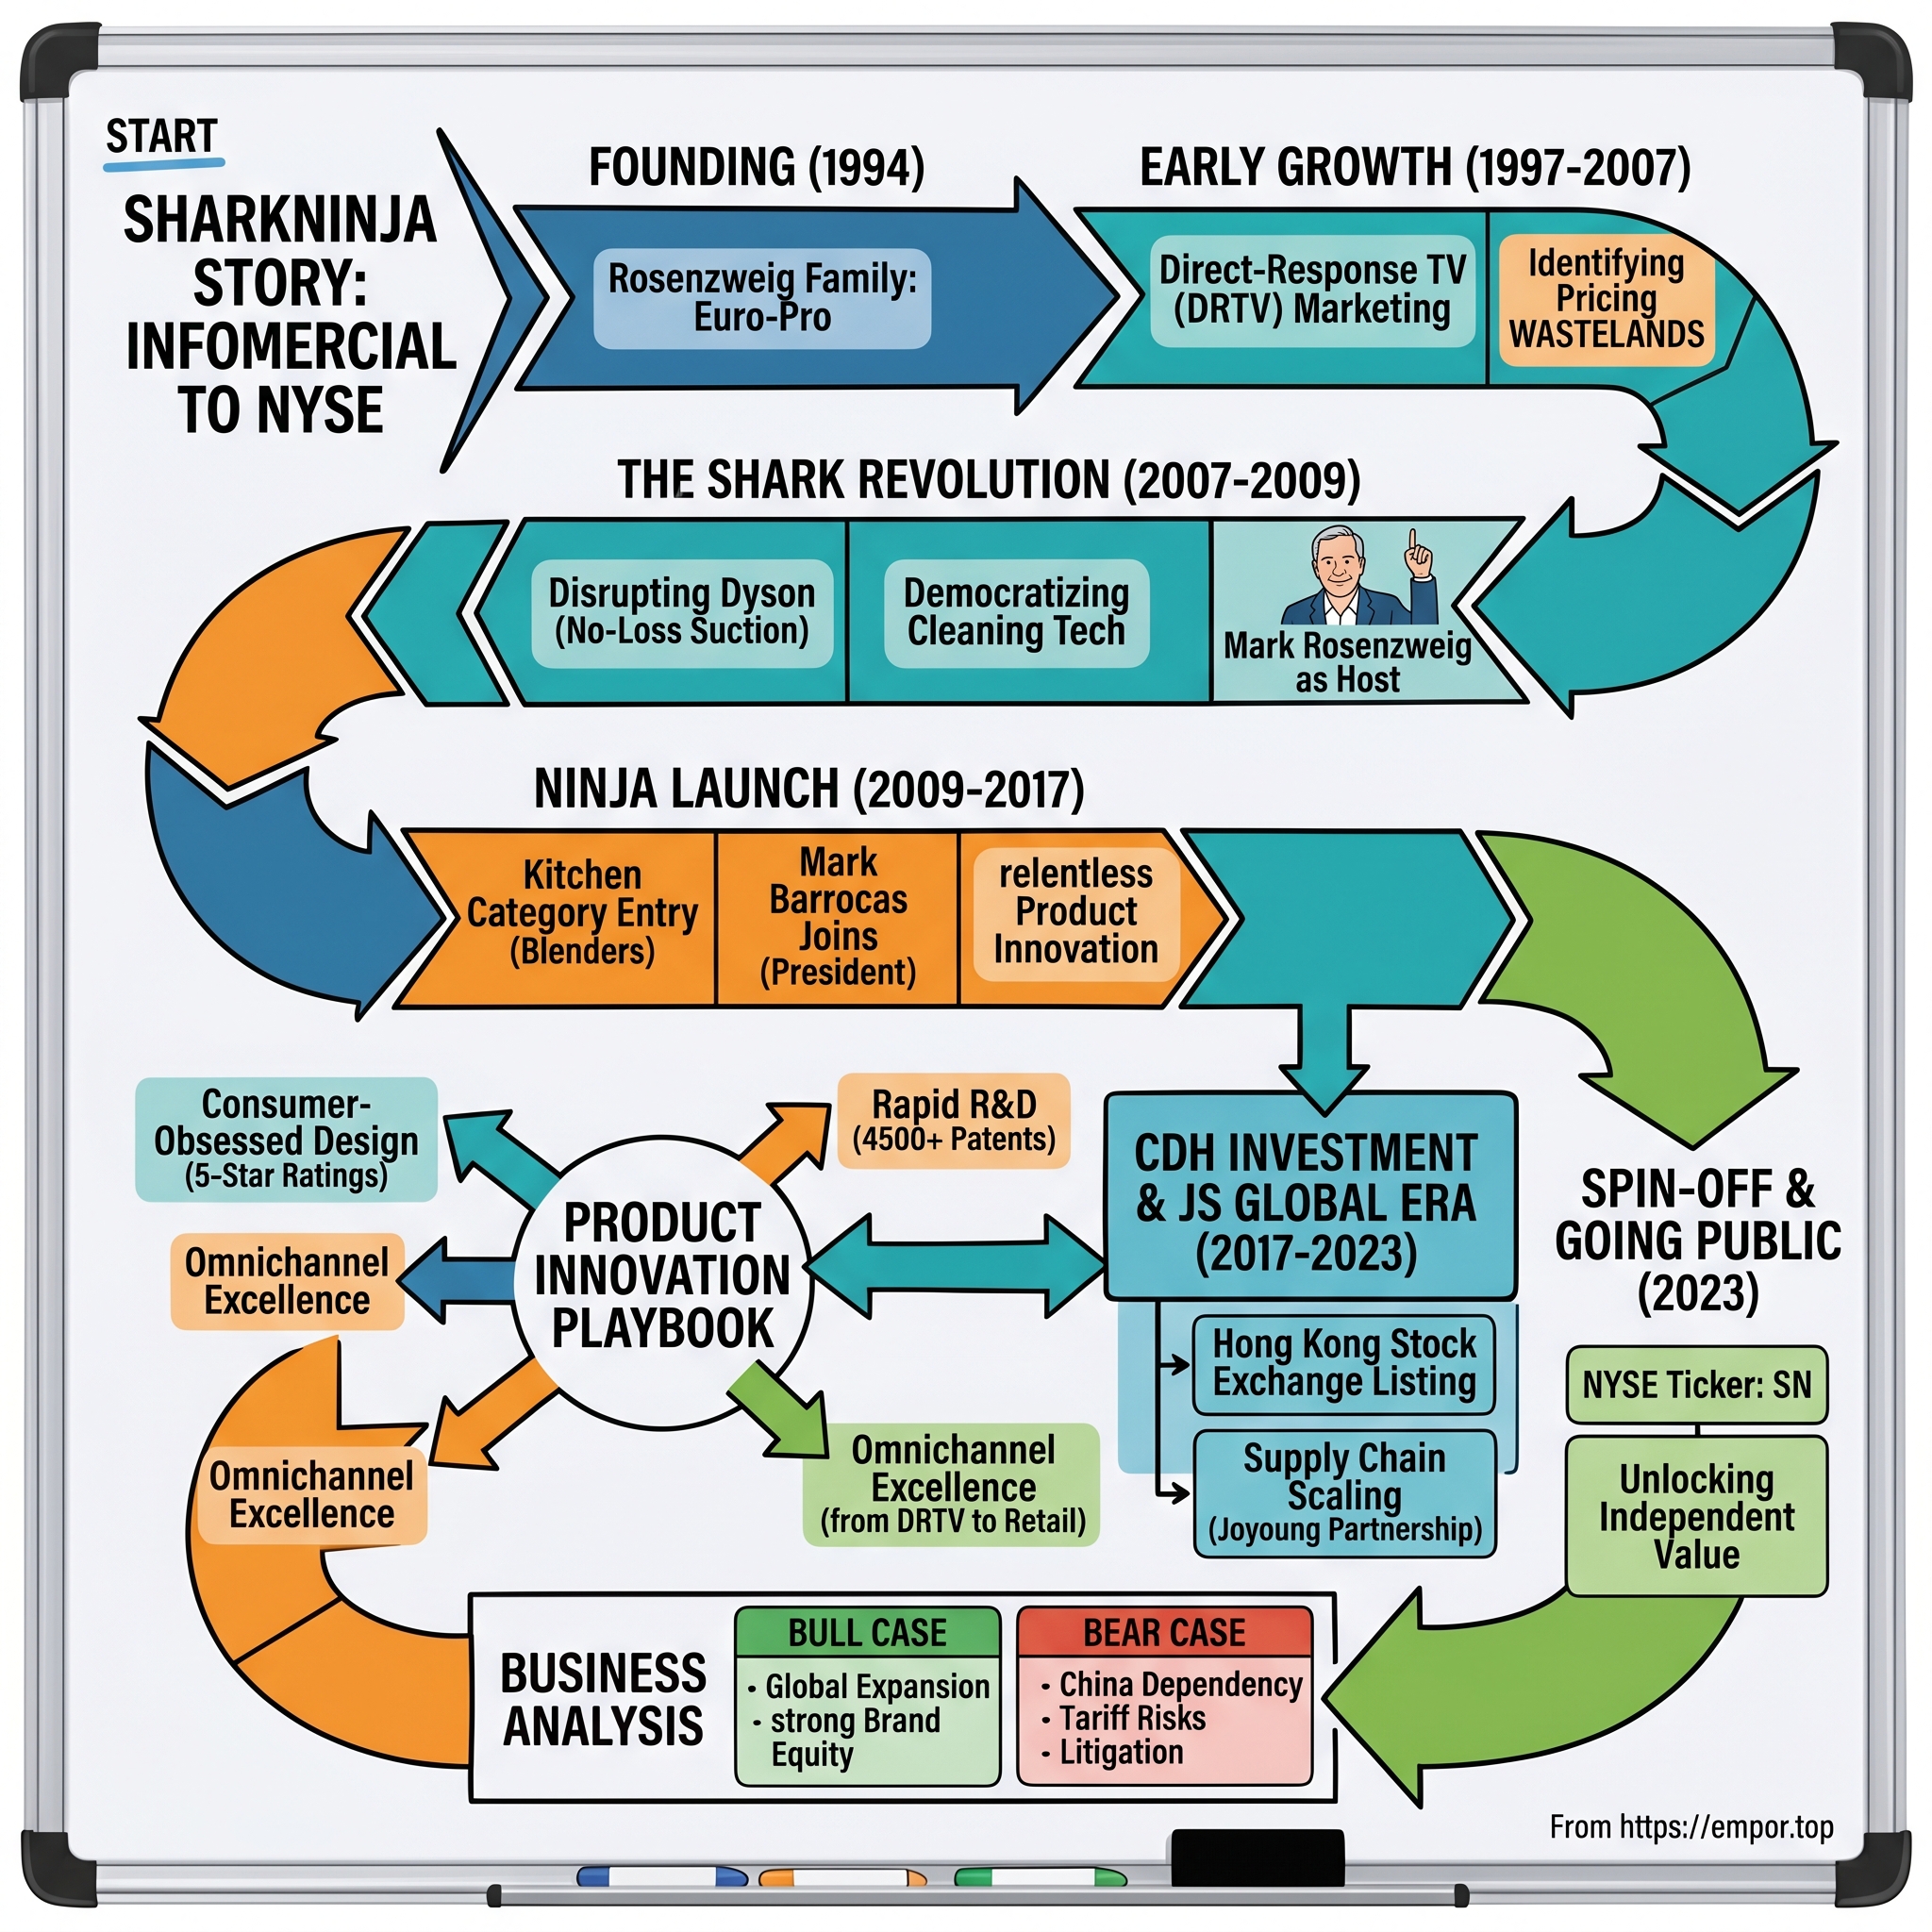
Before there was SharkNinja there was Euro-Pro, a Rosenzweig family business that sold sewing machines, irons and other small household appliances at modest prices.5 It was the kind of company that fills the lower shelves of a department store: competent, inexpensive and almost invisible. Brands like that live on thin margins and on the goodwill of retail buyers, and they rarely become household names.
Mark Rosenzweig decided to try something different. In 2000 he created the Shark brand for floor care.5 The bet was that the vacuum aisle had a hole in it. At the bottom sat cheap machines that clogged and lost power. At the top sat premium brands, most visibly Dyson, which had turned the cyclonic vacuum into a design object and charged accordingly. Between them lay a large population of shoppers who wanted something that worked well, did not want to pay premium prices, and had no way to tell from a box on a shelf which mid-priced machine was any good.
The infomercial solved that last problem. A shopper cannot feel suction through cardboard, but a camera can show a carpet being cleaned. Demonstration did more than sell product directly to viewers who called the number on the screen. It taught consumers what to look for, and it made a less expensive brand credible enough that the same shopper might pick it up at a retailer a week later. Television, in effect, did the job a store clerk used to do, and it did it for millions of people at once.
The defining push came in 2007, when Shark launched what it called No-Loss-of-Suction vacuum technology.5 The name was the pitch. Suction that fades as a bag or bin fills was the most familiar frustration in floor care, and it was also the claim Dyson had built its premium reputation on. Shark was now promising the same headline benefit at a lower price, and showing it on screen. The positioning was not subtle: here is the feature you have heard is worth paying for, and here it is for less.
It worked well enough that by mid-2015, when Euro-Pro renamed itself SharkNinja, the company described Shark as the top-selling vacuum cleaner in the United States and pointed to J.D. Power studies that rated Shark highest in customer satisfaction among upright vacuums in both 2014 and 2015.6 Those are the company's own claims in a corporate announcement, and they should be read that way, but they mark the moment a value brand stopped being a value brand in the consumer's mind and became simply a good brand.
The tempting version of this history is a straight line upward from that first infomercial. The record does not support it. The private years before the company's 2017 sale are poorly documented in public, and the figures that do survive for that period are uneven and hard to reconcile; the rename announcement in July 2015 claimed more than $1.6 billion of annual revenue across both brands, while the audited combined accounts that public investors can rely on begin much later, in the separation prospectus.67
Even inside the audited era, growth has not been smooth. Sales were essentially flat in 2022, and net profit fell by roughly 30% that year and by almost as much again in 2023.37 The long-run growth rate is impressive, but it is an average of good years and bad ones, and it includes periods in which product cycles and costs went against the company.
That matters for how to read the founding insight. Finding the price gap below Dyson was an effective positioning move. It was not a perpetual-motion machine. A price-value pitch invites imitation from below, and it can be squeezed from above if the premium brand cuts its own prices or if other mid-market rivals arrive with their own demonstrations. Shark's position would have to be defended, product cycle after product cycle, and the first proof that the formula could travel came not from another vacuum but from the kitchen.
III. The Ninja Bet: Repeat the Vacuum Playbook in the Kitchen
In 2008, Euro-Pro hired a president who did not come from appliances at all. Mark Barrocas had run Aramark Uniform Services and, before that, Broder Bros, a distributor of blank apparel.8 Those are businesses about logistics, account management and the grinding work of serving large customers, not about glamorous product launches. He arrived as president in 2008 and became a co-owner of the business, a position he held until its sale in 2017.8 He led the company for nearly two decades and became chief executive and a board member in 2023.8
The operator from outside the industry brought a useful kind of impatience. Within a year of his arrival, the company launched a second brand. In 2009 it introduced the Ninja Master Prep blender.5 The ambition was larger than one product. If demonstration could make a mid-priced vacuum credible against Dyson, perhaps it could make a mid-priced blender credible against the expensive machines that sat on the counters of serious cooks.
The kitchen is a very different room. A vacuum is bought grudgingly, when the old one breaks. A blender, a cooker or an air fryer is bought with appetite, often as a gift, and it competes for a few feet of counter space that consumers guard jealously. But the demonstration logic carried over almost perfectly. Ice crushed to snow on camera is as persuasive as flour vanishing from a carpet. Show the result, then sell the convenience: a smoothie in seconds, a dinner in one pot, crisp food without a deep fryer. Each Ninja product was, at heart, a short film with a happy ending.
From blenders, Ninja moved into cooking, then beverages, then food preparation more broadly. By the time of the 2015 rename, SharkNinja was claiming the leading market share in motorized kitchen appliances in the United States.6 The new corporate name itself told the story: a cleaning brand and a kitchen brand of roughly equal standing, joined under one roof. The same announcement described a company selling directly through infomercials and its own websites, through major retailers in the United States, the United Kingdom and Canada, and through distributors in 34 other countries, and it noted that SharkNinja had signed a lease for a new 150,000-square-foot headquarters in Needham, Massachusetts, and opened a design centre in London.6
The real test of a second brand is not whether it launches but whether it grows large enough to change the company's risk. Here the evidence is strong. By 2025, Ninja accounted for 52.6% of SharkNinja's sales and Shark for 47.4%.3 The kitchen brand born in 2009 had overtaken the vacuum brand that made the company famous. In the company's 2025 annual report, Ninja is described as the best-selling small kitchen appliance brand in the United States and as America's number one blending and processing brand for four consecutive years, citing Circana data.3 Food Preparation Appliances, the category built around those blenders and processors, grew 31.6% in 2025, one of the fastest rates in the portfolio.3
What does that prove? It proves that the playbook transferred once, from floor care to kitchen, and transferred at scale. A company that could only sell vacuums would be hostage to the replacement cycle of one product. A company split roughly evenly between two very different rooms of the house has two sources of demand that do not rise and fall together. That is a genuine reduction in risk, and it was earned by execution rather than by acquisition.
The way Ninja grows also reveals how fragile any single hit can be. In the second quarter of 2025, Food Preparation sales jumped 53% to about $405 million, which management attributed to the viral success of the Ninja SLUSHi frozen-drink maker and the CREAMi ice-cream machine; Barrocas said SLUSHi had earned 1.3 billion impressions globally that quarter.9 In the very same quarter, Cooking and Beverage sales fell about 4%, because air fryers and outdoor grills were lapping a strong prior year.9
Within one brand, in one quarter, a new craze was carrying the numbers while an older one cooled. Management's answer is to turn hits into franchises, adding a pro version or a new format before the first wave fades, and it used exactly that language on the call.9 That is a sensible discipline. It is also an admission that, in small appliances, every success comes with a sell-by date.
It does not prove that every launch works, or that the next category will follow the same arc. The company's own audited history includes the flat sales of 2022 and the profit declines that followed, years in which neither brand was enough to keep growth going in a hard consumer market.3 A brand extension is a bet until it becomes repeat sales, and the Ninja story is one very successful bet, not a law of nature. The fair verdict is that the kitchen push demonstrated transferable skill, and that skill would soon be backed by something SharkNinja had never had before: a wealthy strategic owner with a factory network in China.
IV. From Private-Equity Sale to the JS Global Platform
In 2017, SharkNinja changed hands. The buyer was led by 王旭宁 Wang Xuning, known in the company's filings as CJ Xuning Wang, the founder of 九阳 Joyoung, the Chinese kitchen-appliance maker.8 Wang is an engineer by training who, by his company's account, invented the first fully automatic household soymilk maker in 1994 and then built Joyoung around it, serving as its general manager and president until 2019 and its chairman until 2022.8 He partnered with the Chinese private-equity firm 鼎晖投资 CDH Investments to take control of SharkNinja and has chaired its board since that year.58 The proxy describes the deal simply: in 2017, he acquired SharkNinja. It does not disclose the price.
It was a logical match on paper. Joyoung understood Chinese manufacturing and the Chinese consumer; SharkNinja understood the American retailer and the American living room. Wang put the two under a new offshore holding company, JS Global Lifestyle, which listed in Hong Kong in 2019, and Barrocas became Global President of JS Global that same year while continuing to run SharkNinja.85 SharkNinja Global SPV, the entity at the heart of today's listed company, was incorporated in 2017 as a wholly owned subsidiary of JS Global.5
For investors reading those years, one boundary matters above all. JS Global's results were a blend of SharkNinja and Joyoung. Group revenue, group profit and group headcount from that era are not SharkNinja's, and anyone pulling numbers from JS Global's Hong Kong reports needs to remember that a large Chinese business sat alongside the American one. The financial history SharkNinja itself presents for the pre-listing period is a combined record of SharkNinja Global SPV and the issuer, prepared on a common-control basis, not JS Global's consolidated history.5
Inside the group, the relationship was more than ownership. JS Global's subsidiaries provided sourcing services for SharkNinja, helping to manage the factories that build its products. In 2023, SharkNinja's purchases of goods and services from related parties came to $1.04 billion, or about a quarter of its sales.5 That is a striking number. It meant SharkNinja's purchases from related parties equalled about one in every four dollars of its sales. For a minority shareholder, related-party flows of that size raise an obvious question: who sets the prices, and in whose favour?
The answer, over the following two years, was that the dependence largely went away. The sourcing-services agreement ended on July 31, 2025, and related-party purchases fell to about $232 million in 2024 and then to $95.5 million in 2025, roughly 1.5% of sales.3 SharkNinja had brought the sourcing work in-house, and the scale of money flowing to its former parent shrank by about nine-tenths in two years.
The relationship did not disappear, though, and it now runs partly in the other direction. Under a 20-year brand licence, JS Global's businesses pay SharkNinja a royalty of 3% on sales of licensed Shark and Ninja products, which brought in $16.8 million in 2025, up from $1.9 million in 2023.35 SharkNinja also earned $6.6 million of product-development fees from JS Global in 2025.3 At the end of September 2026, related-party receivables stood at $28.5 million and payables at $24.1 million, unsecured, interest-free and settled in cash in the ordinary course.4 These are small numbers against a $6 billion business. They are not evidence of material dependence, but they are a reminder that the former parent remains a counterparty with its own interests and that the controlling shareholder sits on both sides of the relationship.
The separation itself also moved real money. Before it was completed, SharkNinja made $485.4 million of distributions to JS Global and settled pre-separation intercompany financing.5 That cash went to the parent, not to the future public shareholders, and it was part of the price of independence rather than an ordinary dividend from earnings. It helps explain why SharkNinja's borrowings rose from about $511 million at the end of 2022 to about $871 million a year later.3
So what did the JS Global years give SharkNinja, and what did they cost? They gave it an owner who understood factories and a period in which sourcing could be coordinated across a larger group. They cost it a period in which a quarter of its spending flowed to related parties, and they left it with a debt load partly created to pay its former parent on the way out. The question that remained was how the company would be set free, and on what terms its new public shareholders would sit at the table.
V. The Spin-Off Left One Shareholder in the Driver's Seat
On July 31, 2023, SharkNinja's shares began trading on the New York Stock Exchange.7 There was no roadshow selling new shares to fund growth and no ringing of a bell to celebrate fresh capital. Instead, JS Global distributed SharkNinja shares to its own shareholders, one SharkNinja share for every 25 JS Global shares, and the American business simply walked out of its Hong Kong parent and into a New York listing.7
That mechanism matters more than it first appears. In a conventional initial public offering, a company sells new shares to outside investors, who pay cash, and a price is set by a book of orders. In a separation and distribution, the shares go to the existing owners of the parent, in proportion to what they already hold. Nobody new had to be persuaded to buy at a particular price, and the company raised no new equity. It also meant that whoever controlled JS Global would control SharkNinja in the same proportion on day one.
That person was Wang. At separation he and the entities he controlled held about 57% of SharkNinja.5 A Cayman Islands company headquartered outside Boston, run by an American management team, was majority owned by the Chinese founder of a soymilk-maker business. Few companies in the American appliance aisle had ever had a shape like that.
Over the following years Wang sold down. His entities sold 3.2 million shares in December 2023 and a further 9.1 million across three sales in 2024.5 By March 2026, the company's proxy reported his stake at 38.6%, with Fidelity's parent FMR the next-largest holder at 14.7%, and all directors and executive officers together at 40.8%.8 In early 2025, he still controlled about 48% of the voting power.5
The decline from majority to plurality changes the arithmetic of votes, but not the essential shape of control. SharkNinja's articles give Wang the right to appoint the chair of the board for as long as he and his affiliates own at least 30% of the shares.8 He is that chair. The board has a lead independent director, Peter Feld, a former chief executive of the chocolate maker Barry Callebaut and the market-research firm GfK, and the other directors apart from Wang and Barrocas are classed as independent.8 That is meaningful oversight. It is not the same as a widely held company where outside shareholders can, in principle, change the board.
There is a tidier way to see the trade-off. Concentrated ownership means a very large owner has a very large share of his personal wealth riding on the outcome, which aligns him with long-term value. It also means that outside investors cannot easily overrule him, that a takeover premium is unlikely to arrive without his blessing, and that each of his share sales adds supply to the market and raises the question of what he knows. Both things are true at once, and neither cancels the other.
One small number shows how a public company can look different from the inside. As of February 2026, SharkNinja reported just 13 holders of record.3 That is not the number of its shareholders; most shares are held in street name through brokers and custodians, so the true count of beneficial owners is far larger and not determinable from that figure. It is a reminder that the plumbing of ownership and the reality of ownership are different things.
The spin-off, then, gave SharkNinja a direct identity in the public market, its own audited accounts and its own currency for paying employees in stock. It did not disperse control. For investors, that is the governance frame within which every later decision sits, from executive pay to buybacks. But governance is the frame, not the picture. The picture is what SharkNinja actually sells, and by 2025 that had changed in ways the original infomercial could never have predicted.
VI. Four Categories, One Reportable Segment—and a New Growth Mix
Walk through SharkNinja's 2025 results and the product line reads like a tour of a house. In the hallway closet, the vacuums and mops that started it all. On the kitchen counter, an air fryer, a multi-cooker, an espresso machine that grinds its own beans. In the bathroom, a hair dryer and a styling tool. In the bedroom, a fan, an air purifier and, by 2025, an LED face mask. Each of those objects is a product launch, and together they tell you where the company believes its next decade of growth lives.
SharkNinja sorts all of this into four categories. In 2025, Cleaning Appliances brought in about $2.21 billion, Cooking and Beverage Appliances about $1.82 billion, Food Preparation Appliances about $1.55 billion, and Beauty and Home Environment about $826 million, adding up to roughly $6.4 billion of sales.3 Total sales grew 15.7%.3 The original category is still the largest, but it is no longer where the energy is. Cleaning grew 6.9% in 2025, while Food Preparation grew 31.6% and Beauty and Home Environment grew 45.3%.3
The shift is clearer still over two years. In 2023, Cleaning made up about 43% of sales; by 2025 it was about 35%. Over the same period Food Preparation rose from about 15% of sales to about 24%, and Beauty and Home Environment from 8% to about 13%.3 In other words, within two years, roughly eight percentage points of the company's revenue mix migrated away from vacuums towards blenders, frozen-drink makers, styling tools, fans and purifiers. That is not a company milking a single franchise. It is a company re-weighting itself in real time.
The third quarter of 2026 sharpened the pattern. Cooking and Beverage sales grew 36.6% to about $598 million, Beauty and Home Environment grew 45.8% to about $276 million, Food Preparation grew 18.3% to about $486 million, and Cleaning grew just 4.1% to about $617 million.10 At that pace, Cooking and Beverage was within touching distance of overtaking Cleaning as the largest category in a single quarter. Notice, too, what happened to Food Preparation: the category that grew 53% in the SLUSHi summer of 2025 was growing 18% fifteen months later, still healthy but visibly cooling as it lapped its own craze, while Cooking and Beverage, which had shrunk in that same 2025 quarter, became the fastest-growing large category.910
The leadership rotates. That rotation is the engine working as designed, and it is also the clearest evidence that no single category can be counted on to carry the company for long. The machines being commercialized now give a sense of why. Management pointed to products such as the Ninja Luxe Café espresso line, the Ninja Crispi portable air fryer, fans and air purifiers, and a beauty range that extends to face masks.110
There is a geographic story underneath the category story. In 2025, domestic sales grew 13.5% while international sales grew 20.8%.3 In the third quarter of 2026, U.S. sales rose 20.8% to about $1.22 billion, which management called the fastest American growth since the end of 2024, while international sales climbed 25.2% to about $663 million, and the United Kingdom, SharkNinja's most established overseas market, grew 13.3%.10 Barrocas told analysts that the company now operates in more than 30 countries with more than 180 partners, competes in 41 subcategories, and had TikTok Shop live in 14 countries ahead of the holidays.10 International expansion is not a footnote to the growth case; on recent evidence, it is one of its two engines.
Here is where an investor has to slow down. The obvious reading of those growth rates is that the newest categories are where SharkNinja makes its best money, and that Cleaning is a fading legacy business. The filings do not support that conclusion, because they do not say. SharkNinja reports a single reportable segment.3 It discloses sales by category, by brand and by region, but not profit by category. Nobody outside the company can tell whether an air fryer earns more or less margin than a cordless vacuum, whether a face mask is a profitable business or a loss-leading experiment, or whether the fastest-growing category is also the one consuming the most marketing money.
That gap matters because SharkNinja spends heavily to launch. Barrocas told analysts on the November 2026 call that the company spends more than $1.5 billion a year on media and promotions.10 Fast sales growth in a new category is partly a function of how much of that budget is pointed at it. A category growing 45% with heavy promotion might be less valuable than one growing 7% with almost none. Without category-level profit, the market is judging the engine by its speed, not its fuel efficiency.
There is also the question of what counts as a proven category. Cooking and Food Preparation have years of sales history and market-leading rankings behind them. Beauty is younger. Its sales are growing fast from a smaller base, and the company describes leading positions in parts of the category, but a single strong product cycle can flatter a young category's growth rate. The honest way to treat further category entries, from outdoor grills to whatever comes next, is as optionality: interesting, possibly valuable, not yet proven until repeat purchases and sustained sales show up in the numbers.
Management offers its own long-run evidence for the engine. On the third-quarter call, Barrocas claimed a 21% compound annual revenue growth rate over the previous 18 years.10 Measured against the audited era, that claim is broadly consistent: revenue compounded at about 18% a year from 2020 to 2025 and about 20% a year from 2022 to 2025.3 But a compound rate hides the path, and the path included a flat year. The fair conclusion is that the product engine has worked repeatedly across categories and geographies, more than once and at scale, which is rare in consumer hardware. It is not a guarantee that each new category will repeat the pattern. Why it has worked, and where it might break, is a question about competition.
VII. Why the SharkNinja Playbook Works—and Where It Breaks
The infomercial never really died. It moved to a phone screen. Today the demonstration is a thirty-second clip: a creator pours cereal on a rug, runs a Shark through it, then does the same with a Dyson and compares the results. Millions of strangers watch. The format is the same one that sold the first Shark vacuums, a visible mess, a visible fix, a visible price difference, but the audience is now global and the camera is held by someone the company does not employ.
That is the most important thing to understand about SharkNinja's edge. The company has industrialized the demonstration. SharkNinja says it takes an "always-on" approach to product development and tries to hit four consumer value points with every launch: speed, performance, quality and value, with the stated aim of winning over consumers "one review at a time."3 Behind the slogans are real resources. SharkNinja spent about $368 million on research and development in 2025, up from about $341 million the year before, though as a share of sales it eased from 6.2% to 5.8%.3 The company had about 4,100 employees by the end of 2025, many of them engineers and designers.3
The results show up in rankings. SharkNinja says Shark was the number one floorcare brand and the number one vacuum brand in the United States by dollar sales, and that Ninja was the best-selling small kitchen appliance brand, citing Circana data for the 52 weeks to January 3, 2026.3 Those are not small claims in categories where Dyson, Bissell, iRobot, Breville, Vitamix, NutriBullet and long-established kitchen brands all compete for the same shopper.
Now run the war game. Michael Porter's framework is a useful lens here, once. Rivalry is intense: in floor care, Dyson owns the premium end, Bissell and others fight in the middle, and robotic specialists like iRobot have their own following; in the kitchen, Breville and Vitamix anchor the high end while a long tail of brands, many of them sourcing from the same contract manufacturers in Asia, compete on price. The threat of substitution is real, because a consumer who wants clean floors or a quick dinner has many ways to get there. Supplier power is moderate: SharkNinja relies on outside factories, mostly in Asia, but runs a multi-sourcing strategy. And buyer power, on two levels, is high.
At the consumer level, switching costs are almost nil. Nobody is locked into a vacuum ecosystem. A shopper who owns a Ninja blender faces no penalty for buying a rival's air fryer. Brand loyalty helps, but it is earned purchase by purchase, and a single disappointing product generation can send consumers elsewhere.
At the retailer level, the bargaining power is concentrated. Those three large customers hold the keys to the most valuable shelf space in America and Britain.3 SharkNinja does not name them, and nobody should guess. But the arithmetic of the relationship is plain enough. Losing a large share of one big account's floor space, or being forced into deeper promotions to keep it, would hit SharkNinja's revenue far harder than it would hit the retailer's.
Against those forces, SharkNinja sets its consumer-facing brands and launch engine. Two brands that are each roughly a $3 billion business, rising research spending and leading category positions give it something most appliance makers lack: the ability to pull demand through the store rather than rely on the store to push it. A retailer that drops a best-selling brand annoys its own customers. That is real leverage, and it is the counterweight to buyer power.
Patents are part of the defence, but the company's own record shows their limits. In October 2022, an administrative law judge at the U.S. International Trade Commission issued an initial determination that SharkNinja's robotic vacuums infringed valid claims of multiple iRobot patents and recommended an order barring the import of infringing products.11 The Commission's final determination in 2023 went against SharkNinja on at least one patent. SharkNinja appealed, and in March 2024, after the relevant patent expired, the Federal Circuit stayed the appeal and the Commission's determination was vacated.12
There is no continuing injunction from that dispute. The lesson is not that SharkNinja is a serial infringer; it is that in crowded hardware categories the boundary between fast following and infringement can be contested, and that intellectual property is a shield with holes in it rather than a wall. SharkNinja says its 2025 annual report describes ordinary-course patent, false-advertising and product-safety matters and that management does not expect them to be material.3
So where does the playbook break? It breaks if a competitor learns to demonstrate as well as SharkNinja does, at a lower price, in a category where SharkNinja's brand is still young. It breaks if a large retailer decides to promote its own private label or a rival brand in a category where SharkNinja depends on that retailer for distribution. It breaks if a product generation disappoints, because the reviews that lift SharkNinja can also sink it. None of those failures is hypothetical in consumer hardware; all of them have happened to other brands.
The evidence supports a narrower and still impressive claim: SharkNinja has a brand-and-execution advantage, proven across two large brands, multiple categories and several countries. It does not have high switching costs or an unassailable moat. The thing to watch is whether category leadership and sales growth persist as rivals respond, and especially whether the company can keep pulling demand through the store without paying for it in price. And the place where that tension shows up first is not on the shelf at all. It is on the balance sheet, in the money retailers owe.
VIII. The Retailer's Order Is Not the Consumer's Cash
At the end of September 2026, a single unnamed retailer owed SharkNinja more than a quarter of everything the company was waiting to collect. Customer A accounted for 28.8% of SharkNinja's receivables on that date, up from 22.0% at the end of 2025.4 The same customer accounted for about 23% of sales in the first nine months of 2026, similar to its 2025 share.34 Its share of what SharkNinja was owed had grown faster than its share of what SharkNinja sold.
That gap is the clue at the heart of this section. A product company records revenue when it ships goods to a retailer, not when a consumer buys them off the shelf, and certainly not when the retailer pays. In between sit weeks or months of credit. If a growing share of sales goes to accounts that pay more slowly, profits will run ahead of cash. Nothing improper need be happening; it is simply the mechanics of selling through powerful retailers who negotiate their own payment terms.
Over the long run, SharkNinja turned profit into cash well. Across the six years from 2020 to 2025, it reported about $2.2 billion of net profit and generated about $2.1 billion of cash from operations, a conversion rate of roughly 95%.37 For a company that holds inventory for months and sells on credit to large retailers, that is a respectable record.
The recent record is very different. In 2025, SharkNinja earned about $701 million and generated about $634 million from operations, after receivables alone absorbed roughly $351 million.3 Then, in the first nine months of 2026, it earned about $590 million but generated only about $107 million from operations.4 Working capital swallowed roughly $747 million of cash. Receivables took about $461 million, inventory about $436 million, and prepaid assets about $283 million, partly offset by higher payables and accrued liabilities.4 Inventory at the end of September stood at about $1.43 billion, up 23.3% from a year earlier and up from about $1 billion at the end of 2025, when management had told investors that the stock built ahead of tariffs had sold through and inventory was in a healthy position.1013
Some of this is seasonal. SharkNinja builds stock and ships heavily into retailers ahead of the holiday quarter, then collects in the months after. A nine-month cash figure taken at the end of September will always look worse than a full-year one. Some of it is growth: a company growing sales at about a fifth a year needs more inventory and more receivables just to stand still. And some of the prepaid line likely reflects the timing of tariff-related payments and supplier deposits. But the scale of the gap, a little under one dollar of operating cash for every five and a half dollars of reported profit, is far wider than seasonality alone would normally explain for a company of this maturity.
A longer measure tells a similar story. Debtor days, the number of days of sales tied up in receivables, rose from about 89 in 2021 to about 102 in 2025.3 The cash conversion cycle, which adds inventory days and subtracts the days SharkNinja takes to pay its own suppliers, lengthened from about 114 days to about 138 days over the same period.3 Each additional day of that cycle, for a business of SharkNinja's size, ties up something like $18 million to $20 million of cash.
What would reassure an investor? An aging schedule would help, showing how much of the receivable book is current and how much is overdue. SharkNinja does not publish one in its annual or quarterly reports. It describes its loss-rate and specific-reserve methods for estimating bad debts, but not invoice ageing.34 Its allowance for credit losses actually fell to about $3.9 million at the end of 2025 from about $7.9 million a year earlier, after write-offs.3 On the surface, a lower allowance suggests confidence. But a receivable book that is both growing and concentrating in one account deserves more weight than a small reserve line.
It is important not to over-read this. SharkNinja does not name Customer A, and nothing in its filings suggests that the account is distressed or that it is paying late. Large retailers commonly negotiate long payment terms, and a shift in the mix of shipments towards them at quarter end would produce exactly this pattern. The company's 2025 annual report flags individually significant retailer receivables and the potential harm if a retailer's finances deteriorated, but it does not identify a major customer exit or bankruptcy.3
The verdict, then, is mixed in a specific way. The six-year record shows a business that historically converted profit into cash. The 2026 record shows that conversion weakening sharply as receivables, inventory and prepayments absorbed cash. Seasonality and growth explain part of it. How much is temporary will be settled by the full-year 2026 cash-flow statement, after the holiday collections, and by whether debtor days and inventory days come down from their current levels. Until then, the investor holds a company whose income statement is sprinting ahead of its cash-flow statement, in the very quarter when the income statement received an unusual boost.
IX. The Record Quarter Came With a Tariff Refund
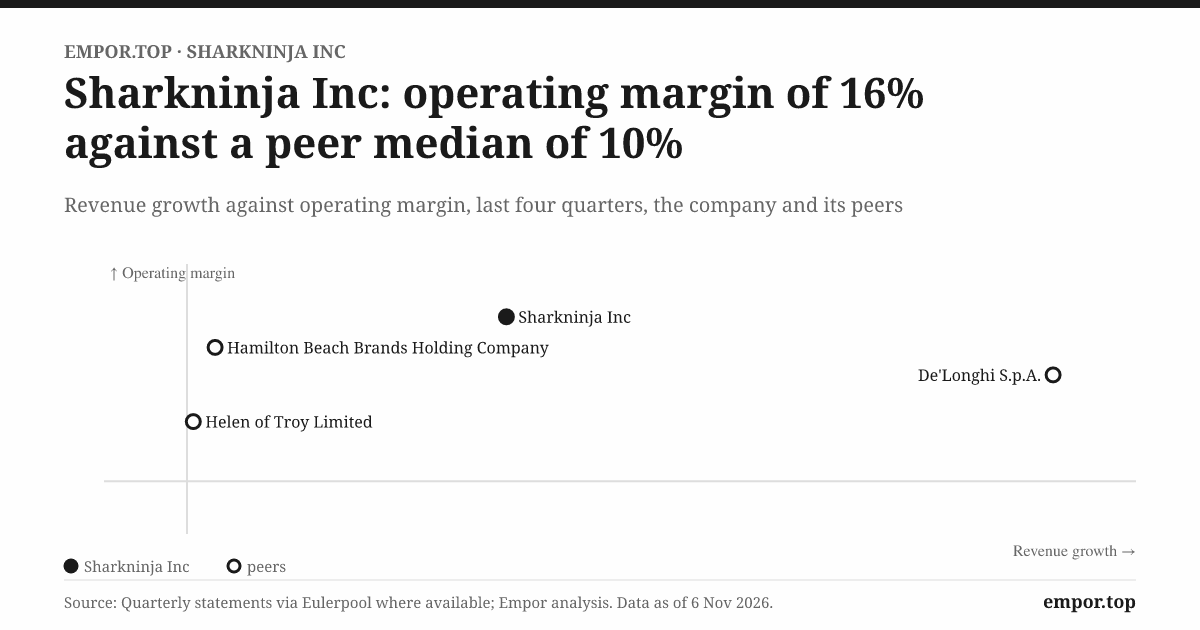
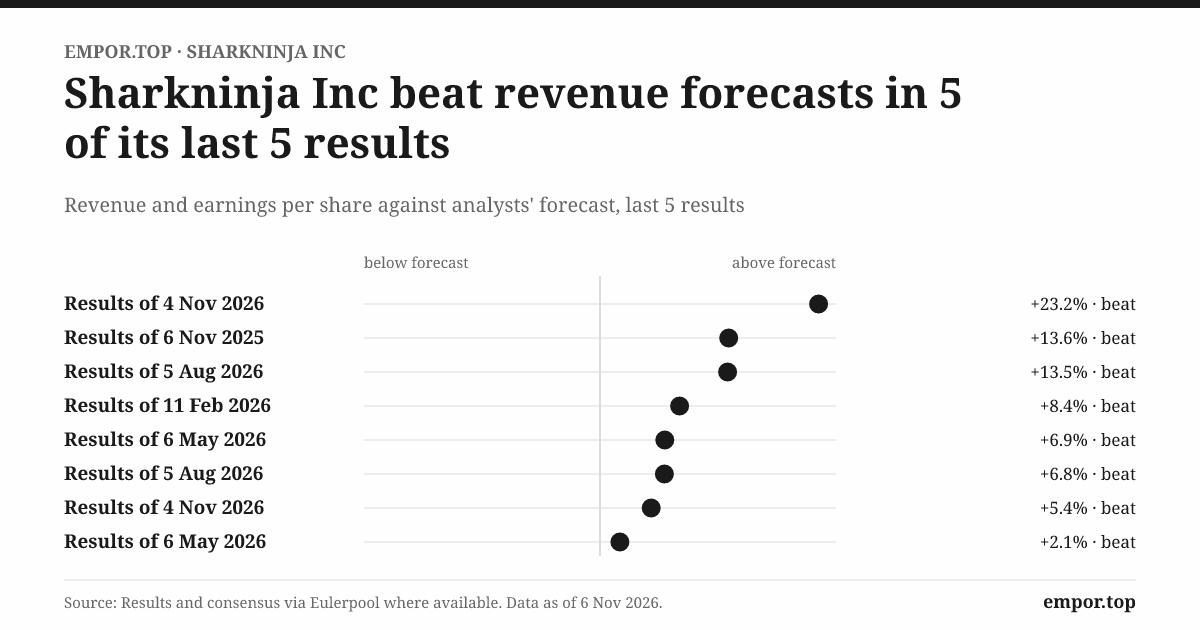
On November 4, 2026, SharkNinja's third-quarter numbers landed with the kind of headline that moves a stock. Sales up 21.2%. Net income up 79.3%. A reported operating margin of 22.4%, compared with about 16.6% a year earlier.14 Full-year guidance raised again. The share price closed that day at a 52-week high.
Inside the quarter was a second story. During the third quarter, SharkNinja recognized $243.8 million of accepted tariff refunds, of which $45.2 million was recorded as payable to its factory partners.4 These were refunds of duties paid under emergency-powers (IEEPA) tariffs that became recoverable, and on the call management explained their split. About $110 million related to duties paid in 2025; about $134 million related to duties paid in 2026.10 The 2025-related portion was excluded from adjusted results. The 2026-related portion was not, on the logic that it offsets tariff costs the company bore within the same year.10
That accounting choice matters for anyone reading the adjusted numbers. On a GAAP basis, gross margin rose about 910 basis points year over year to about 59.2%. On an adjusted basis, it rose about 560 basis points to about 55.9%.10 The gap between those two figures is roughly the prior-year refund. But the adjusted figure still contains the current-year refund, so even the "clean" gross margin was flattered relative to what a full year of tariff costs would have produced. Management said it reinvested part of the benefit in targeted areas during the quarter.10
The factory-partner payment is an unusual detail with a revealing logic. SharkNinja described the roughly $45 million due to its suppliers as recognition of their extraordinary partnership.10 Suppliers had absorbed some of the tariff burden through pricing, and the company chose to share part of the refund with them. That is a sensible way to preserve relationships with factories it depends on. It is also a reminder that tariff costs were never borne by SharkNinja alone, and that the economics of its supply chain are negotiated rather than fixed.
There was also a cash wrinkle. At the end of September, $186.1 million of tariff claims and interest remained receivable, and the company said it collected that amount in October.4 That is separate from the customer receivables in the previous section, and it means a significant cash inflow fell just after the quarter closed, which should help the fourth-quarter cash picture.
Strip away the refunds and the operating momentum is still real. Sales grew double digits across categories and regions. Adjusted earnings per share were $2.34, against $1.50 a year earlier, and adjusted EBITDA grew about 46%, to a margin of 23.3%.10 Management raised its 2026 sales-growth outlook to 18%–19% from 16%–17%, and adjusted earnings per share guidance to $6.65–$6.75 from $6.45–$6.55.10
The more interesting number is what that guidance implies for the fourth quarter. At the top of the range, fourth-quarter sales would grow about 17%, but adjusted gross margin would fall about 100 basis points year over year, and adjusted EBITDA would rise only about 9%.10 CFO Adam Quigley described the shift as simply the timing of certain tariff refund reinvestments.10 In plain English: some of the refund money that flattered the third quarter will be spent in the fourth, on promotions and investments that hold down margins. The third quarter was not the new normal; it was a quarter in which one-off income arrived before the associated spending.
This also tells you something about the underlying cost structure. SharkNinja's products are made by outside suppliers, and for most of its history much of that capacity sat in China. The tariff shock of 2025 forced a sprint. By August 2025, Barrocas said the company could produce about 90% of its American volume outside China, and by February 2026 nearly 100%, across a multi-country footprint in South-East Asia that he said had taken more than five years to build.913 That was a genuine operational achievement, and a necessary one: on the August 2025 call, management recalled planning at one point around a 145% tariff on Chinese goods.9
Watch how the assumed tariff rates moved over the following year, because they explain a good deal of the profit surprise. In August 2025, the company's outlook assumed 30% for China, 20% for Vietnam and 19% for the rest of South-East Asia.9 In February 2026, it assumed at least 20% for China and Vietnam and 19% for Indonesia, Thailand, Malaysia and Cambodia.13 By November 2026, the assumptions had fallen to 12.5% for China, Vietnam and Thailand and at least 10% for Indonesia, Malaysia and Cambodia.10
The moving-production strategy protected SharkNinja from the worst case. The falling rates, and the refunds, then handed it a better case than it had planned for. Diversified sourcing is valuable, but it does not remove the exposure. Tariffs, supplier pricing and currency moves in the Chinese yuan all feed into SharkNinja's cost of goods, and its 2025 annual report notes that supplier prices can move with the yuan under contractual terms even though purchases are made in dollars.3
The verdict is straightforward. Sales growth and adjusted results show genuine operating momentum. The exceptional refund materially amplified reported margin and earnings in a way that will not repeat. The lasting test is what margins look like in 2027, when prior-year refunds are absent from comparisons and the full cost of whatever tariff regime then applies is back in the numbers. That is a test of management as much as of the business, which raises the question of how far this management team has earned the benefit of the doubt.
X. Barrocas's Growth Record Meets the Owner's and the Board's Oversight
On the November 2026 call, Mark Barrocas sounded like a man who had been here before, which he had. He has run SharkNinja's operations since 2008, through the infomercial years, the Ninja launch, the sale to Wang, the Hong Kong era and the New York listing.8 Very few chief executives in consumer hardware have presided over a single company for that long, and fewer still have taken it from a regional appliance seller to a $7 billion global brand. His co-pilot on the call was a newer face. Adam Quigley, a SharkNinja finance veteran who had run planning and analysis since 2019, became interim chief financial officer in September 2025 and permanent CFO in November 2025, succeeding Patraic Reagan.8
Management's operating credibility rests on something more concrete than tone. It rests on the pattern of guidance. On the February 2026 call, Quigley guided to sales growth of 10% to 11% for the year and adjusted earnings per share of $5.90 to $6.00, explicitly assuming that the tariff rates then in force would persist.13 By November, the sales outlook had risen to 18%–19% and the earnings range to $6.65–$6.75.10 Starting conservative and raising repeatedly is a habit the market rewards, and it is the single best piece of evidence for management's credibility.
It is worth being precise about what the raise proves, though. Part of the gap between February's 10% and November's 18% is genuine demand, visible in American sales growth that accelerated to about 21% in the third quarter.10 Part of it is that the tariff environment management told investors to assume did not arrive: rates fell and duties came back as refunds. Guidance that is beaten because the cost assumptions turned out too pessimistic is still guidance beaten, but it says more about prudent planning than about forecasting skill.
The narrative itself was consistent across the two calls: growth from new categories and international markets, heavy investment in marketing and innovation, and tariffs as a cost to be managed through sourcing.1310 On the November call, the explanation for the fourth-quarter margin dip was specific, down to the timing of refund reinvestments, which is what a credible management team should offer when its own numbers contain a one-off.10
In February, Barrocas and Quigley also told investors that years of compounding had put SharkNinja in a net cash position at the end of 2025, and they presented the new buyback as the first time the company could prioritize capital allocation "in a more meaningful way" after two years of keeping inventory and working capital flexible.13 Nine months later, cash had fallen to about $488 million against about $709 million of debt, so the company was back in modest net debt, largely because working capital had absorbed the year's profits.410 That reversal is not alarming at this leverage. It does show how quickly the cash picture of a seasonal hardware company can change between one call and the next.
Capital allocation adds a second strand. In February 2026, the board authorized a $750 million share buyback. By the end of September, SharkNinja had repurchased about 1.30 million shares for about $169.7 million, an average of roughly $130 a share.4 With the stock at about $219 in early November, those purchases look well timed on paper. But the authorization is large, the shares are now far more expensive than when buying began, and the cash for it must come from a business whose operating cash flow was thin in the first nine months. A buyback is only as good as the price paid and the cash it displaces, and the long-term return on this one cannot yet be judged.
What SharkNinja has not done is buy growth. Barrocas has said the company did not acquire its revenue, and the 2025 annual report and the latest quarterly report describe no transformative acquisition.1434 The growth record is overwhelmingly organic, built product by product. That removes one common source of value destruction, overpaying for acquisitions, from the list of worries. It does not make every capital decision good. The separation was itself a capital-allocation choice whose terms were set while Wang controlled both sides.
The pay record deserves a careful reading rather than a headline. Barrocas's reported compensation was about $17.85 million in 2025, including a $13 million exceptional cash bonus.8 The board explained that bonus as recognition of strong performance under his leadership, and as a way to address the tax burden that he and another executive faced as a result of the separation from JS Global, which it said was not determinable at the time and was a significant cash burden.8
His 2024 compensation was about $33.5 million, swollen by a large listing-related equity award.8 In 2023, Wang personally funded a large cash bonus to Barrocas that SharkNinja recorded as an operating expense although the company paid no cash.3 None of these are recurring salary items, and comparing them year to year is misleading. But the pattern of large, exceptional payments, partly decided while a controlling shareholder held the purse strings, is the kind of thing outside shareholders notice.
And some did. At the June 2026 annual meeting, about 9.23 million shares voted against the advisory say-on-pay resolution, against about 115.5 million in favour.15 On its face that is about 7% opposition. But Wang's large stake sits inside the yes column if, as controlling holders typically do, he voted with the board. Measured against the votes of other shareholders, the opposition would be closer to one in eight. That is not a revolt. It is a signal.
The most important governance fact, though, is the auditor's. At the end of 2025, management reported a material weakness in internal control over financial reporting, involving the control environment, information-technology general controls and the execution of control activities.3 The auditor's opinion on the financial statements themselves was unqualified, and an earlier weakness had been remediated.3 A material weakness does not mean the numbers are wrong. It means the processes that should catch errors were not reliable enough, at a company whose receivables, inventory and tariff accounting have become more complex. For investors, remediation is the evidence to look for in the 2026 annual report.
Put these together and the picture is coherent. On revenue growth, guidance delivery and organic execution, Barrocas's record justifies operating confidence. On exceptional pay, shareholder dissent, concentrated control and the control weakness, the record tempers that confidence. Neither side cancels the other. And with the stock at a record high, the question is no longer whether management has done well. It is whether the price already assumes it will keep doing so.
XI. Analysis & Bear vs. Bull Case
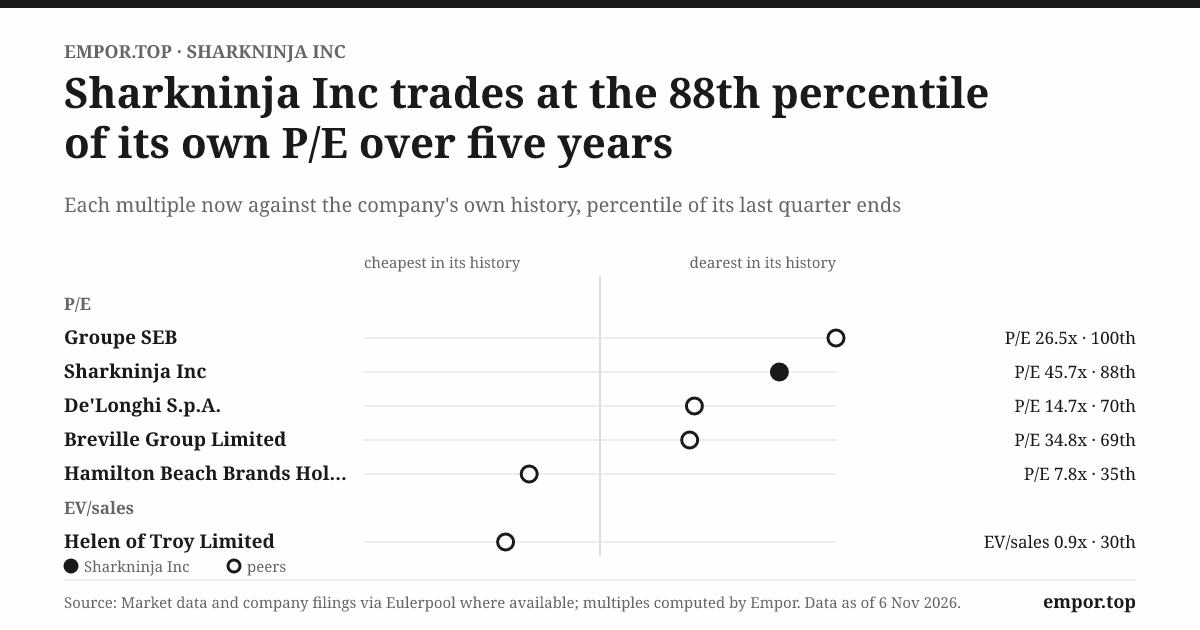
On November 4, 2026, SharkNinja's shares closed at about $219.25, the top of their 52-week range and roughly 2.6 times their low of about $84.57 over the same period. That valued the equity at about $31.2 billion and the enterprise, including debt and net of cash, at about $31.6 billion. The shares traded at about 45 times the company's 2025 earnings, against a five-year median multiple of about 32.5 times, and at about 25 times trailing EBITDA. The earnings yield, the inverse of the price-to-earnings ratio, was about 2.2%, and the free-cash-flow yield about 2.6%.23
Those figures are the lens through which bull and bear must be judged, and the headline multiple needs one adjustment. The 45 times is struck against 2025 earnings. On the last four quarters, which include the refund-boosted third quarter, a market-data service put the trailing multiple at about 36 times on November 5, and the forward multiple at about 30 times.2 At the midpoint of management's $6.70 adjusted earnings guidance for 2026, the stock traded at roughly 33 times this year's adjusted earnings, a figure that already includes the current-year tariff refunds.10
However it is measured, the market is paying well above SharkNinja's own five-year median. For context, the Italian small-appliance maker De'Longhi traded at about 20 times trailing earnings in early November.16 That comparison is rough, because De'Longhi's mix of coffee machines and heating products, its growth rate and its balance sheet differ, but it shows that the market is paying SharkNinja a substantial premium over a seasoned peer.
The bull case begins with breadth. SharkNinja is no longer a vacuum company; Ninja is the larger brand, the newer categories are substantial contributors, and international sales have been growing faster than domestic sales. The company has compounded revenue at about 18% a year over five years, largely organically, and has repeatedly raised guidance. Its return on invested capital was about 25% in 2025.3 Bulls argue that a company with that record, that breadth and that much headroom abroad deserves a premium multiple, and that the market is simply paying for a growth engine that has proven repeatable.
The bear case begins with the purchase order. Three retailers held almost half of 2025 sales, and one of them now holds more than a quarter of receivables. Working capital absorbed most of 2026's profits through September. Tariff refunds flattered reported margins, and management's own guidance implies lower adjusted gross margins in the fourth quarter. The products are discretionary, the categories are crowded, and switching costs are close to zero. Bears argue that 45 times earnings prices in sustained growth and stable margins in a business where neither is contractually secured.
Hamilton Helmer's seven powers offer a stricter test of the moat than the war game of competitive forces already run. Scale economies are present but modest: SharkNinja's size gives it advantages in media buying, retailer negotiations and supplier pricing, but contract manufacturing means rivals can access similar factories. Network economies are absent; one consumer's blender does not make another's more valuable. Counter-positioning was real at the founding, when a mid-priced demonstration-led brand attacked premium incumbents who could not cut price without damaging their own positioning, but it has faded as SharkNinja has itself become an incumbent.
Switching costs are negligible. Branding is the strongest candidate power: two brands that consumers recognize, trust enough to pay more than for unknown alternatives, and seek out by name. A cornered resource is hard to identify; patents help at the margin but, as the iRobot dispute showed, are contestable. Process power, the embedded organizational ability to launch products quickly and well, is the most interesting candidate, and SharkNinja's record of entering and leading multiple categories is consistent with it. But process power is hard to verify from outside and can erode as teams turn over.
The verdict on the moat, then, is that SharkNinja has meaningful branding and plausible process power, backed by evidence of category leadership across several product lines. It does not have the structural powers, network effects, switching costs or a cornered resource, that would lock in its returns. Its advantage is renewable rather than permanent: it must be earned again with each product generation.
The governance and capital test sits alongside. Wang's stake aligns him with value creation but limits outside influence. The buyback is the main visible return of capital, and SharkNinja does not pay a regular dividend. Debt was about $709 million at the end of September 2026, against cash of about $488 million and roughly $495 million of undrawn revolver capacity, with the term loan maturing in July 2028; leverage is modest, but the maturity is concentrated.4
Three measures matter most for tracking whether the bull or the bear case is winning. The first is customer concentration and debtor days: Customer A's share of sales was about 23% in the first nine months of 2026 and its share of receivables 28.8% in September, while debtor days stood at about 102 at the end of 2025, rising.34
The second is growth by category and geography: total sales grew 21.2% in the latest quarter, with international sales up 25.2% and Cleaning, the largest category, up only 4.1%.10 The third is cash conversion and operating margin after refunds: operating cash flow was about 18% of net income in the first nine months of 2026, far below the six-year average of 95%, and adjusted EBITDA margin was 23.3% in a refund-assisted quarter.410 The multiple leaves limited room for disappointment on any of the three.
XII. Playbook: Business & Investing Lessons
There is a moment in SharkNinja's story that captures its method more precisely than any annual report: the moment its vacuum made a mess vanish on television. The audience needed no history lesson; the demonstration did the work. Out of that moment came almost everything that followed, and out of the story that followed come four lessons that belong to this company.
The first is to show the problem before you sell the solution. SharkNinja made an invisible advantage visible, first on television and now through viral comparison clips, TikTok Shop live streams and five-star reviews. The principle has not changed in a quarter-century.
For founders, the lesson is that distribution is often a problem of legibility: the best product loses if its advantage is invisible. For investors, it is that a company whose edge is making value visible must keep spending to stay visible, which is why more than $1.5 billion a year goes on media and promotions. The demonstration is the moat's mortar, not its stone.
The second is that a second brand can be a second growth engine. Ninja grew into one, a rare outcome for a consumer company stretching into a new room of the house. SharkNinja gave it a separate identity and applied the same demonstration logic. The wider lesson is that transferable skill is worth more than a single franchise, but only when the second engine is built to stand on its own rather than borrowed from the first. Each new category still has to prove its own economics, and SharkNinja does not show investors those economics by category.
The third is that a launch is a beginning, not a moat. The real proof is in what follows: whether the category keeps selling in year three, whether the company holds price against copycats, whether the next generation wins as the first did. SharkNinja's setbacks are reminders that even a skilled launcher has bad cycles. The quotable form is simple: in consumer hardware, you are only as good as your next product.
The fourth is to scale the portfolio, but watch who holds the purchase order. SharkNinja has broadened across four categories, two brands and dozens of countries, which is exactly what reduces product risk. Yet its largest customer's share of receivables has climbed above its share of sales.34 Diversification of products is not diversification of customers. For founders, the lesson is that a big retail partner can be the fastest route to scale and the most dangerous single point of failure. For investors, it is that the most important number in a consumer-brand company is sometimes not on the product page but in the credit-risk note.
XIII. Epilogue
Tonight, SharkNinja stands at the edge of its most important season. The holiday quarter is when vacuums, air fryers and espresso machines become gifts, when retailers clear their shelves, and when the receivables and inventory piled up through the autumn are supposed to turn back into cash. The company enters it with sales-growth guidance raised to 18%–19% for the year, about $1.43 billion of inventory, a $750 million buyback authorization with most of it unspent, about $709 million of debt and roughly $495 million of undrawn revolver capacity.104
The next decisive moment arrives with the full-year 2026 results in early 2027. The first thing to read there is the cash-flow statement. If holiday collections bring operating cash flow back towards net income, and debtor days and inventory days fall from their elevated levels, the weak first nine months will look like seasonal timing amplified by growth. If cash remains well short of profit, the question shifts from timing to structure: whether SharkNinja's growth is becoming more expensive to finance as it leans more heavily on a few large retailers.
The second thing to read is the customer note. If Customer A's share of both sales and receivables stabilizes or falls while total growth stays strong, the growth is broadening. If its share keeps rising, SharkNinja is becoming more dependent on one buyer at precisely the moment when it is priced as if it were becoming more independent.
The third moment comes through 2027, quarter by quarter, as the tariff refunds drop out of the comparisons. Adjusted margins that hold near current levels without that help would confirm real operating leverage. Margins that slide back would show how much of 2026's earnings strength was a one-time gift. The same annual report will also say whether the material weakness has been remediated, which is the clearest evidence of whether the company's controls have caught up with its complexity.
And through all of it, the new categories will keep arriving. Each will be greeted with launch-week attention. Each should be treated as proven only when it produces sustained sales. The tension that remains is simple to state and hard to resolve: SharkNinja is priced for a growth engine, and its next set of results must show that the engine produces cash as reliably as it produces products.
XIV. Outro
Go back to the carpet. The bowl of cereal, the flour, the pet hair, and the vacuum rolling through it on a screen. The scene asked the viewer for one thing: to believe that what they were watching was true, and that the cheaper machine really worked. Millions of people believed it, and a family appliance business became a company that now reaches into nearly every room of the house.
That is SharkNinja's skill, and the measure by which it will be judged from here. The consumer can see the promise in a thirty-second clip. The investor has to see it in the numbers. The demonstration has always ended with a clean carpet. The question now is whether the books will end the same way.
References
-
SharkNinja (SN) Statistics and Valuation — Stock Analysis, 2026-11-05 ↩↩↩
-
2025 Form 10-K — SharkNinja, 2026-03-02 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q3 2026 Form 10-Q — SharkNinja, 2026-11-04 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Euro-Pro Cleans Up with New SharkNinja Identity, Blending Successful Billion Dollar Product Portfolios — SharkNinja, 2015-07-22 ↩↩↩↩
-
Proxy Statement for the 2026 Annual General Meeting — SharkNinja, 2026-04-27 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q2 2025 Earnings Call Transcript — SharkNinja, 2025-08-07 ↩↩↩↩↩↩↩
-
Q3 2026 Earnings Call Transcript — Stock Analysis, 2026-11-04 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
iRobot Announces Favorable Initial Determination in Patent Dispute — iRobot, 2022-10-11 ↩
-
SharkNinja Operating LLC v. International Trade Commission — U.S. Court of Appeals for the Federal Circuit, 2024-03-22 ↩
-
Q4 and FY2025 Earnings Call Transcript — SharkNinja, 2026-02-11 ↩↩↩↩↩↩
-
How SharkNinja Took Over the Home: CEO Mark Barrocas Interview — The Verge ↩
-
Annual General Meeting Results, Form 8-K — SharkNinja, 2026-06-18 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube