Regions Financial: The Bank That Bought Its Way Across the South—and Paid for It
I. Birmingham, Before the Merger
In November 2006, two banks that had grown up a few blocks apart in Birmingham, Alabama, became one. Regions Financial and AmSouth Bancorporation had spent decades competing for the same deposits, the same car dealers, the same churches' operating accounts and the same families' first mortgages. Now they were combining in an all-stock deal worth roughly $10 billion, and AmSouth alone brought about $58 billion of assets to the table.1 The logic looked almost too obvious to argue with. Two hometown rivals would stop spending money to beat each other, merge their branch maps across the South, and emerge as one of the largest banks in the country with its headquarters still in Alabama.
Two years later, the same institution was writing down the value of that ambition. In its 2008 accounts, Regions recorded a goodwill impairment of about $6 billion and reported a net loss of roughly $5.6 billion for the year.2 Goodwill is the accounting residue of a merger: the amount a buyer pays above the fair value of the assets it acquires, booked as an asset in the hope that the combined business will earn enough to justify it. When the deal closed, about $6.6 billion of goodwill had been assigned to AmSouth.1 In November 2008, the bank also accepted $3.5 billion of capital from the U.S. Treasury under the Troubled Asset Relief Program.3 The deal that was supposed to make Regions a regional fortress had, within twenty-four months, sent it to Washington.
That sequence is the cleanest place to begin, but it needs one caveat before it hardens into a morality tale. The 2008 impairment was taken against Regions' General Banking/Treasury reporting unit, the part of the company into which the merged franchise had been folded, not against a separate box labelled "AmSouth."2 The charge measured how far the market value of the whole combined banking operation had fallen below its book value in the depths of the crisis. It is a powerful verdict on the price paid for scale just before a credit collapse. It is not, by itself, an itemized bill for one acquisition.
To understand why Regions made that bet, it helps to rewind to what kind of bank it was trying to become. Regions' roots run back through three Alabama institutions, banks in Montgomery, Huntsville and Birmingham whose histories reach into the nineteenth and early twentieth centuries.4 For most of their lives they were the kind of lenders that financed cotton warehouses, county governments and Main Street hardware stores. Alabama law and federal rules kept banks penned inside state lines, and in many periods inside county lines. A bank grew by growing its town.
The modern company is something else entirely. Regions Financial Corporation is a bank holding company listed on the New York Stock Exchange under the ticker RF, and its operating business runs through Regions Bank and its subsidiaries.5 At the end of 2025 it had about $160 billion of assets and roughly $19 billion of shareholders' equity, earned about $2.2 billion of net profit, and employed nearly 20,000 people.5 In early November 2026 the stock market valued it at about $25.6 billion.6 That is big enough to matter to millions of households across the South, Midwest and Texas, and small enough that JPMorgan Chase, Bank of America and Wells Fargo each dwarf it.
So this story is really three questions braided together. The first is whether acquisition-led scale was worth the risk Regions took to get it, given what happened when the credit cycle turned. The second is whether a regional bank funded by ordinary checking and savings accounts can earn a respectable return across a full interest-rate cycle, rather than only when rates happen to be kind. The third is whether the current strategy, built around organic growth, fee businesses and a long-delayed modernization of the bank's deposit technology, is producing durable growth or simply a good stretch of the cycle.
The answers are not hidden in a slogan. They sit in deposit costs, charge-off rates, the fate of past deals, and the way the bank treated customers when fees became a source of profit. And they start with a much smaller decision, made more than half a century ago, when three Alabama banks decided they would be stronger together than apart.
 Subscribe on LinkedIn
II. The Local Bank Learns to Cross State Lines
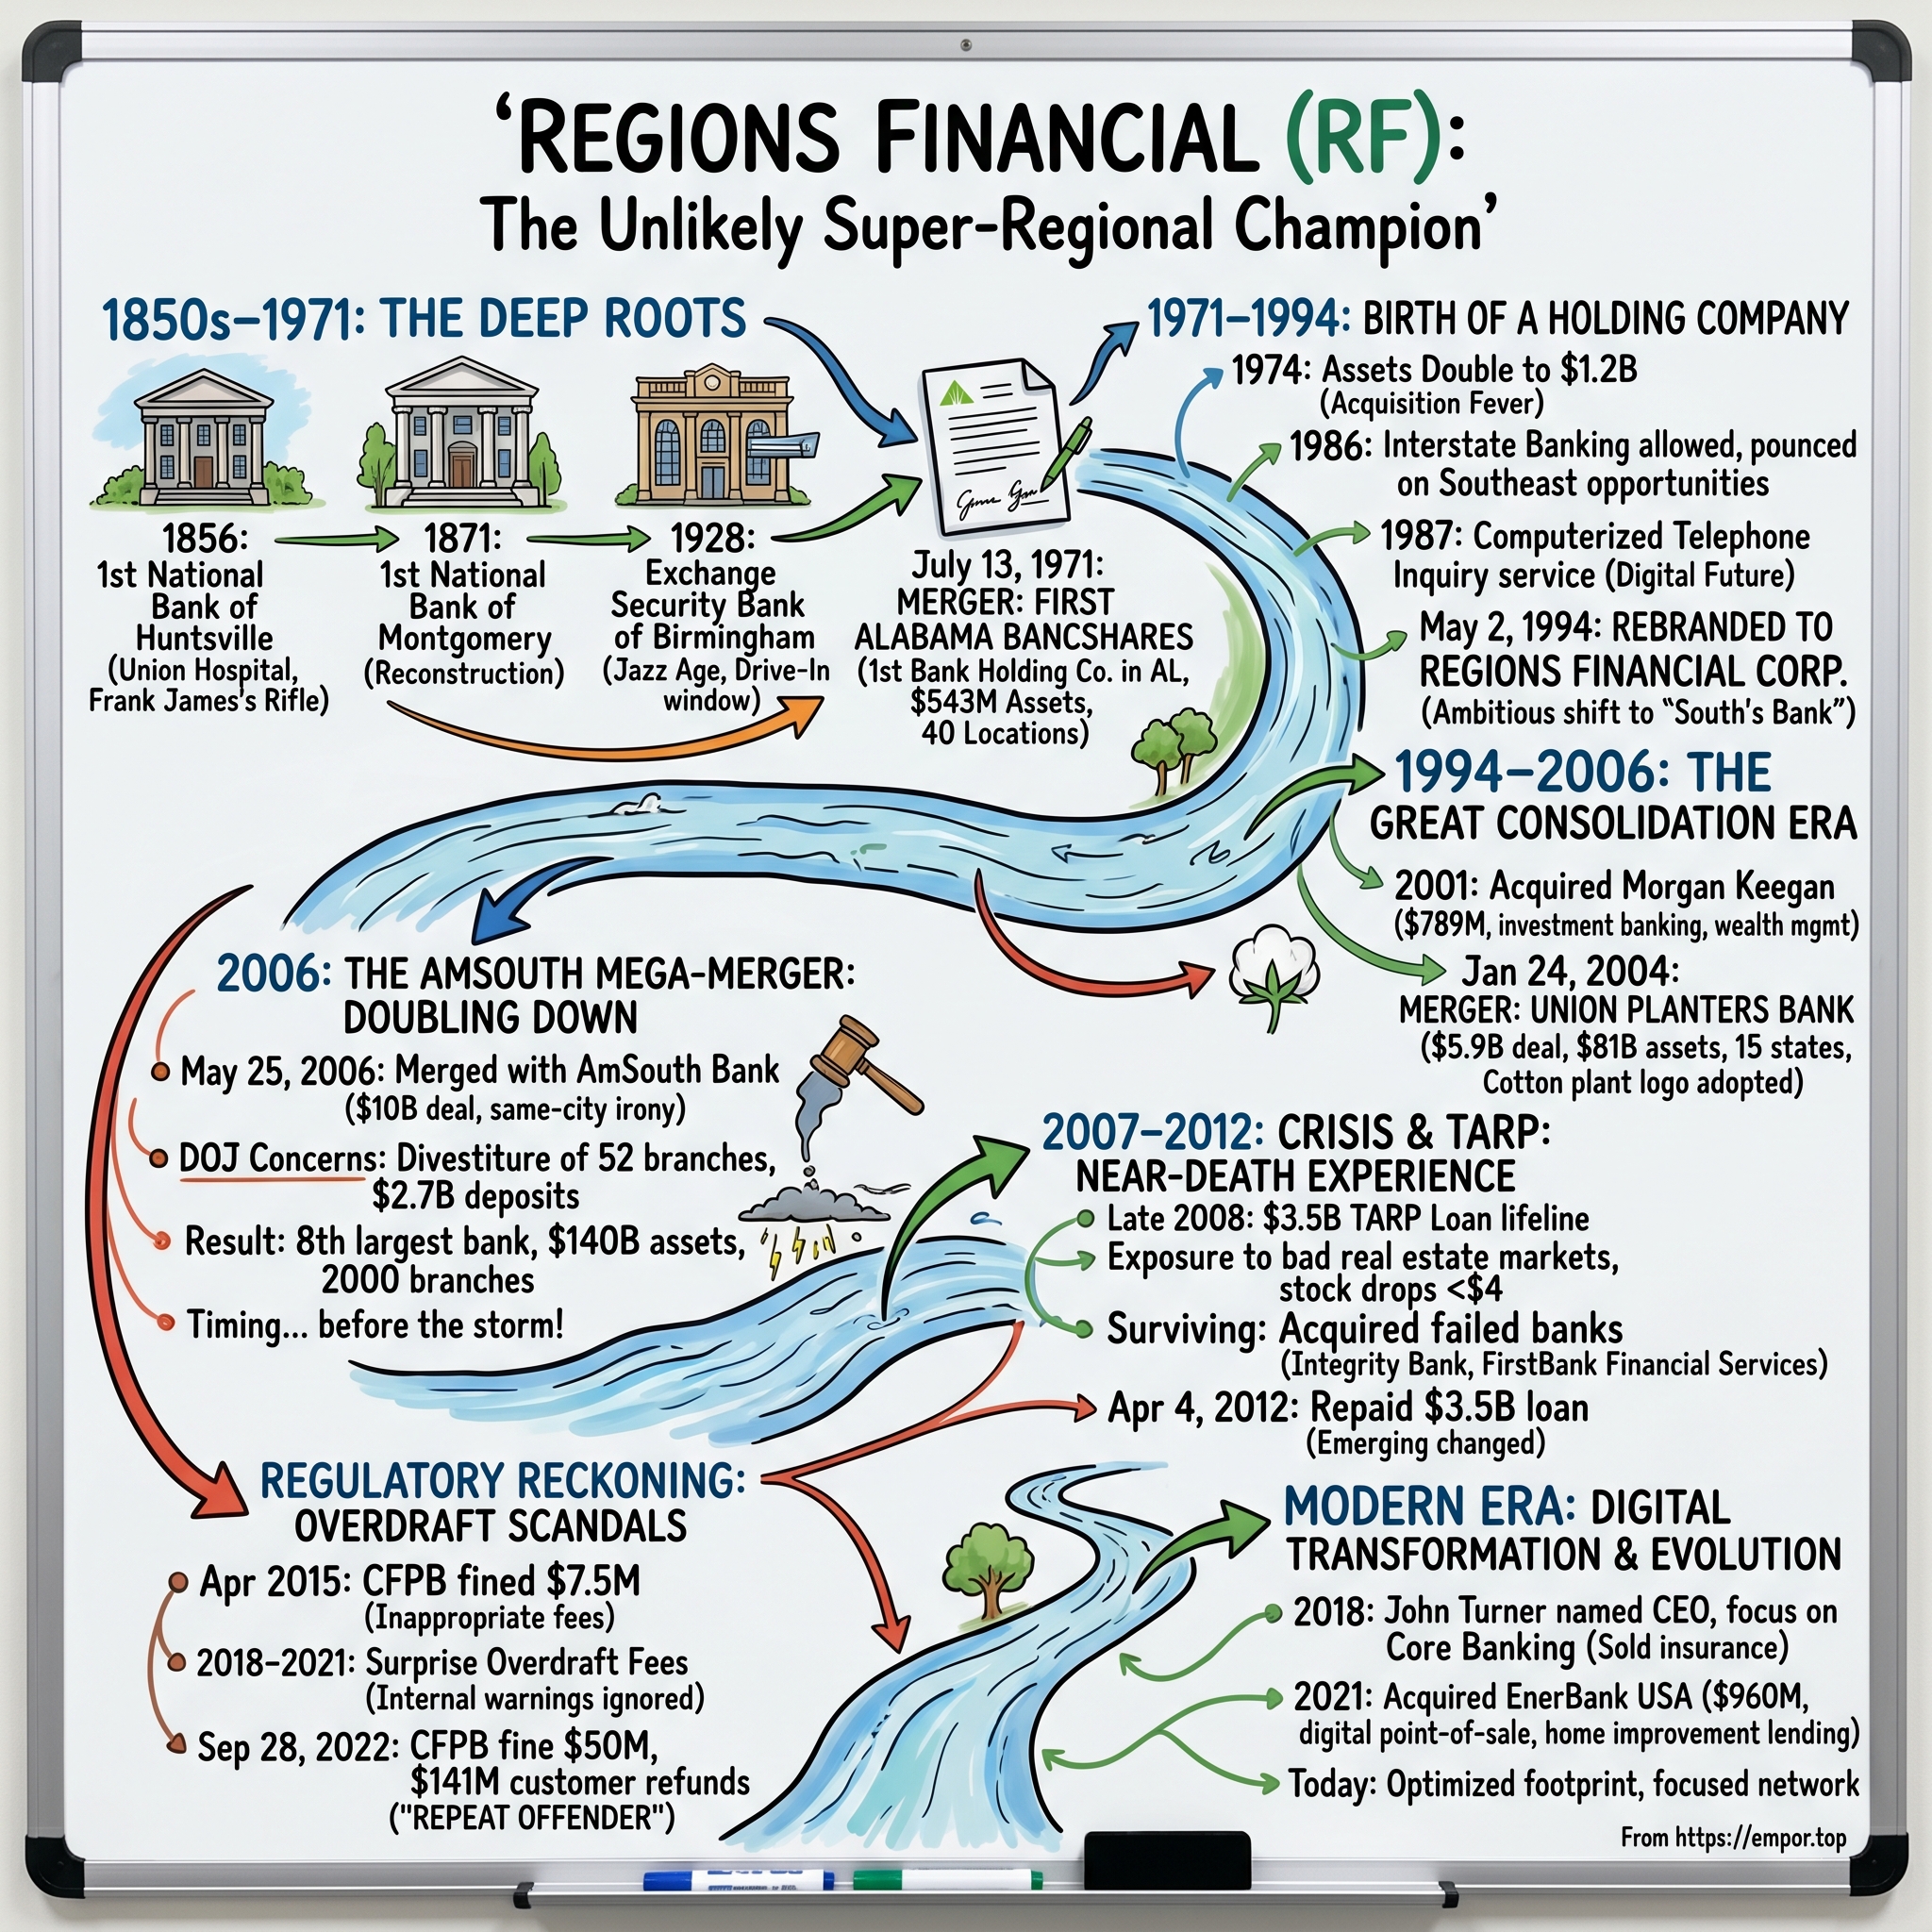
In July 1971, three Alabama banks combined under a single holding company called First Alabama Bancshares. The First National Bank of Montgomery, the First National Bank of Huntsville and Exchange Security Bank of Birmingham became the state's first multibank holding company, and the Federal Reserve's approval was close enough that it came on a split vote.4 Nothing about that day looked like the beginning of a Southern banking empire. It looked like three established local lenders finding a legal way to share capital, management and ambition inside a state whose banking rules still treated geography as destiny.
But the structure mattered more than the names. A holding company could own several banks, which meant it could buy more banks, which meant growth no longer had to come only from opening the next branch on the next corner. First Alabama spent the following two decades doing what many ambitious Southern banks did as the rules loosened: buying institutions in Alabama, then reaching into neighboring states such as Florida, Georgia and Tennessee once regional interstate compacts allowed it.4 By 1994 the old name no longer described the footprint, and the company rebranded itself as Regions Financial Corporation.4 The new name was a confession of intent. This was no longer an Alabama bank. It wanted to be the bank of a region.
The legal map was changing in its favor. The Riegle-Neal Interstate Banking and Branching Efficiency Act of 1994 dismantled much of the old prohibition on interstate banking, and by the late 1990s a bank holding company could buy across state lines subject to deposit-concentration limits and regulatory review.7 Those limits are worth pausing on, because they shaped every big Regions deal that followed. Federal regulators look at overlapping local markets, measure how concentrated deposits would become, and can force a buyer to sell branches where the combination would leave customers with too few choices.7 Interstate banking opened the highway; local antitrust rules decided where the toll booths sat.
Regions drove fast. The defining test of its model came in January 2004, when it agreed to combine with Union Planters, the Memphis-based bank that dominated much of Tennessee and the Mid-South. The presentation to investors described a stock-for-stock merger that would create an $81 billion-asset bank operating in 15 states and serving about 5.1 million customers.8 Management put numbers on the case. It forecast about $200 million of cost savings and promised that the deal would add at least 5% to cash earnings per share in 2005.8
Those were specific promises, and specificity is a virtue in deal-making because it gives shareholders something to check. The trouble is that the checking is hard. Once two banks merge, their expense lines, branch networks and loan books become one set of accounts, and later filings rarely isolate how much of the promised saving arrived, how much leaked away in retention bonuses and systems work, and how much was swamped by revenue changes that had nothing to do with the deal. Regions never published a clean scorecard showing realized Union Planters synergies against the $200 million target. Investors could see that the combined company grew larger and that it kept paying dividends. They could not see, in any precise way, whether the merger earned more than the stock Regions gave away to get it.
That distinction matters because merger premiums and exchange ratios tend to get confused with value creation. A stock-for-stock deal sets how many Regions shares each Union Planters shareholder receives. The premium tells you how much more than the target's prior market price the buyer agreed to pay. Neither tells you whether the combination will earn a return above its cost of capital over the next decade. The 2004 merger looked sensible at announcement because it combined two franchises with complementary geography and real cost overlap. Whether it created value depended on credit discipline and integration execution in the years after, and those years were about to become unusually hard to read.
There was also a leadership dimension. The Union Planters combination brought Jackson Moore, Union Planters' chief executive, into the top tier of the combined Regions, and it set a pattern in which leadership of the merged bank was shared and negotiated rather than simply imposed by the buyer.1 For a company that was assembling itself from merger partners, culture was not a soft topic. It decided whose credit standards, whose systems and whose branch managers would survive.
By 2005, then, Regions had learned a lesson that seemed to work: in the South, scale could be bought, and the price could be paid in stock rather than cash. It had a leading position in parts of Alabama, Tennessee and Mississippi, a growing presence in Florida, and a management team comfortable with large integrations. The obvious next question was whether it could go one step further. If combining with a Mid-South peer had built a larger regional bank, what would happen if Regions joined forces with the biggest rival in its own hometown?
III. The $10 Billion Bet on AmSouth
On May 25, 2006, Regions and AmSouth announced that they would merge in an all-stock transaction.1 From the outside, the story wrote itself. Birmingham would keep a top-tier banking headquarters. The combined company would have one of the densest branch networks in the Southeast, stretching from Tennessee and Alabama down through Florida and across to Louisiana and Texas. And the two banks' heavy overlap meant there would be plenty of duplicate branches, back offices and technology systems to cut.
Underneath, the deal was more of a merger of equals than the corporate structure suggested. Regions was the legal survivor, so the company's name and its stock listing carried forward. But AmSouth's chief executive, C. Dowd Ritter, became chief executive of the combined company, while Regions' leadership took the chairman's seat, and much of the organization drew on AmSouth's operating structure.1 AmSouth itself traced back to the First National Bank of Birmingham, so in a sense this was the city's two great banking lineages finally marrying.4
The headline price was about $10 billion.1 For AmSouth shareholders, that bought them a fixed number of Regions shares and a modest premium to the market. For Regions shareholders, the question was what they were getting in exchange for diluting their ownership. The merger proxy laid out the usual apparatus: comparisons of the offer with AmSouth's earnings, its book value and its tangible book value, and benchmarks against precedent bank deals of the era.1 Read today, that apparatus reveals the deal's central assumption. The banks were valued on earnings that had been flattered by a long housing boom, and the price was justified by projected savings and by the stability of those earnings. Paying well above tangible book value is perfectly rational when a deposit franchise is durable and the loans on the balance sheet are sound. It is dangerous when the loans are about to be marked down.
The goodwill figure is the clearest way to see this. Of the purchase price, about $6.6 billion was booked as goodwill, the excess over the fair value of AmSouth's identifiable net assets.1 That number is a forecast in accounting clothes. It says the buyer expects the combined franchise to earn enough, through deposits, relationships and cost savings, to justify paying that much more than the assets themselves were worth. In the fourth quarter of 2008, Regions concluded that the fair value of its General Banking/Treasury reporting unit had fallen so far that roughly $6 billion of goodwill had to be written off.2
It is worth being precise about what that write-down did and did not mean. The impairment was noncash. Regions did not send $6 billion out of the door when it recorded it; that money had been paid, in stock, when the deal closed. The write-down also did not reduce regulatory capital the way a credit loss does, because regulators already exclude goodwill from the core capital that absorbs losses.2 What it did do was formally concede that the expected value of the enlarged franchise had collapsed. The market had stopped believing the forecast, and the accountants had to agree. That is a failed valuation forecast, written down in public, rather than a cash loss equal to the charge.
The integration bill was real cash, however. Combining two large banks meant converting customers onto one set of systems, closing or selling overlapping branches, consolidating headquarters functions and paying severance. By the time it filed its 2008 accounts, Regions put the one-time, pretax cost of bringing the two companies together at about $822 million.2 Regulators added their own requirements. In approving the deal, the Federal Reserve required divestitures in local banking markets where the combination would have concentrated deposits too heavily, so Regions had to sell branches and their deposits to competitors as a condition of the merger.7 Every one of those steps consumed management attention at exactly the moment a housing market built on cheap credit was beginning to crack.
That timing is the hinge of the whole story. The deal closed on November 4, 2006.2 By then national home prices had already peaked, but the full damage was not yet visible. Regions and AmSouth were both heavy lenders to homebuilders, residential developers and homeowners borrowing against their houses. Florida, where AmSouth had a large presence and Regions had built one of its own, was among the frothiest housing markets in the country. Atlanta, another important market, was a homebuilding boomtown. The merger roughly doubled Regions' exposure to the exact categories of credit that would perform worst when property values fell.
Did management see it coming? Regions' 2006 and 2007 filings show that it knew it had concentrated exposure to residential construction and was watching it, while still describing credit quality as manageable. The 2008 annual report is blunter in hindsight: it describes residential homebuilder loans, condominium loans and home-equity lines in Florida as the center of the bank's losses, and it details aggressive efforts to sell problem loans and reduce homebuilder exposure.2 The pattern is a familiar one in banking. Concentration risk is visible in advance; its severity usually is not. The error was less a failure to know where the risk sat than a willingness to keep adding to it near the top of a cycle.
So was AmSouth a fair price for a stronger franchise? The fairest answer is that Regions bought something genuinely valuable at a price that assumed a world that did not last. The combined deposit base and branch network were real and remain central to the company today. The price, and the decision to double up on Southern real-estate credit just before a housing collapse, were not justified by what followed in the next several years. The impairment does not prove that the price alone caused the loss, because the whole banking industry's values collapsed together. It does show that Regions' estimate of the whole banking unit's value fell by roughly the amount of goodwill originally assigned to AmSouth.
Which leaves the harder question. A bad valuation forecast is embarrassing. A bad credit book can be fatal. Once property values began to fall in earnest, could the enlarged Regions survive the shock without permanent damage to its shareholders, or would it be forced into a retreat?
IV. The Crisis Makes the Acquisition Thesis Answer for Itself
By the autumn of 2008, the loans that had looked like ordinary community banking in 2006 were turning into a slow-motion avalanche. Developers who had borrowed to build subdivisions in Florida and Georgia could not sell the houses. Homeowners who had taken home-equity lines against rising values found their equity gone. And as unemployment climbed across the South, borrowers who had never missed a payment began to fall behind.
Regions' 2008 results told the story in two numbers that are easy to confuse: the goodwill impairment and the bank's net loss for the year, which included the impairment along with a sharp rise in loan-loss provisions.2 The headline loss, in other words, was mostly the accounting write-down. The real economic damage, the losses that ate capital and threatened depositors, came through the provisions: money set aside against loans that would not be repaid. Those losses kept coming in 2009 and 2010, long after the goodwill charge had been booked and forgotten by most of the market.
On November 14, 2008, Regions received preferred stock and warrants to buy common shares from the U.S. Treasury under TARP's Capital Purchase Program.3 The terms were standard for healthy-enough banks: the preferred shares paid a 5% annual dividend for the first five years, which at Regions' size meant about $175 million a year of payments to the government.3 The program also carried restrictions. While the government's money was outstanding, Regions could not raise its common dividend or buy back shares without Treasury's consent, and it was subject to limits on executive compensation.2
TARP was not the end of the capital story. In May 2009, the Federal Reserve's stress test of the largest banks concluded that Regions needed to add about $2.5 billion of extra capital to withstand an adverse scenario.9 Regions responded with a public offering of common stock, an issue of mandatory convertible preferred shares and an exchange offer for trust preferred securities.9 For existing shareholders, the effect was dilution at a terrible price. They had already given up a large slice of the company to AmSouth shareholders in 2006 at boom-era valuations. Now they gave up another slice to new investors at crisis-era valuations. That is the crisis's least visible cost and arguably its most lasting one: every future dollar of Regions' earnings would be shared among far more shares.
The management team that steered through this period was also the team that had built the merger. Dowd Ritter remained chief executive until 2010, when Grayson Hall, a career Regions banker, succeeded him; Hall would run the company for the next eight years.10 Hall's job was less glamorous than his predecessors': clean up the loan book, rebuild capital, find a path to repaying Treasury and decide which pieces of the company were worth keeping.
The most significant of those pieces was Morgan Keegan, the Memphis brokerage and investment bank that Regions had agreed to buy in 2000 for a reported $789 million.11 Morgan Keegan had given Regions a capital-markets and retail brokerage arm and a reason to call itself a diversified financial company. During the crisis it also gave it a headache, as mortgage-heavy bond funds tied to the brokerage collapsed and left a trail of investor claims. In January 2012, Regions agreed to sell Morgan Keegan to Raymond James for $930 million in cash, while keeping its own trust and wealth-management operations.11 Two other terms say as much as the price. Regions arranged to take a dividend of up to $250 million out of Morgan Keegan before closing, and it agreed to indemnify Raymond James, without a cap, for litigation tied to Morgan Keegan's conduct before the sale.11 Regions sold the business but kept its past.
The sale price was higher than the purchase price, and it is tempting to call that a gain. But a simple comparison of the two numbers misses most of the economics. Over a dozen years, Morgan Keegan generated earnings, required capital, consumed management attention and produced legal exposure that Regions kept after the sale. A fair accounting would include all of those, and Regions never published one. What the sale clearly did was narrow the company. Regions stepped back from investment banking and full-service brokerage and recommitted to being a bank that gathers deposits, makes loans and sells fee services to its own customers. That was a strategic choice, and it explains much of the company's shape today.
The sale also served an immediate purpose. In February 2012, Regions sold $900 million of new common stock and, together with the Morgan Keegan proceeds and cash on hand, used the money to repay Treasury.3 On April 4, 2012, Treasury announced that Regions had repaid the full $3.5 billion.3 The government had earned dividends throughout, and the bank was free of the restrictions that came with the money.
It was a real milestone. Many banks that took TARP never repaid it, and some failed. But repayment is not proof that the 2006 deal created value. It proves that the enlarged Regions survived, and that it survived by raising more equity, selling a major business and enduring several years of depressed returns. Even after repayment, the hangover lasted. As late as 2014 and 2015, Regions was earning only about 6% to 7% on its equity, well below what investors generally expect from a bank.12 The company did not reach double-digit returns on equity until 2018.5
The crisis left a final, quieter question. Banks that have been rescued by the public sometimes feel pressure to rebuild earnings by any means available, and one of the easiest available means is fees. As overdraft charges drew more scrutiny across the industry, how would a bank that had just leaned on taxpayers treat customers whose accounts dipped below zero?
V. The Overdraft Fees That Became a Trust Test
Picture a Regions customer in 2019 checking a mobile app before buying groceries. The balance on the screen says there is enough money. The card is swiped, the purchase is approved, and the customer walks out believing the transaction is settled. Days later, an overdraft fee appears anyway. The money that had been there when the purchase was authorized had been drawn down by other transactions before this one formally cleared, and the bank charged a fee on a purchase the customer had every reason to think was covered.
That pattern, which regulators call an "authorized-positive, settled-negative" overdraft, sat at the center of the Consumer Financial Protection Bureau's September 2022 consent order against Regions Bank. The bureau found that Regions charged these surprise fees from August 2018 through July 2021, and that customers paid at least $141 million in fees on transactions they had reason to believe they could afford.13 The most damaging part of the order was not the dollar figure. It was the bureau's finding that Regions knew customers did not understand the practice and kept charging the fees anyway.13
This was not the first time. In April 2015, the CFPB had already ordered Regions to pay a $7.5 million civil penalty and to refund about $49 million to customers.14 The earlier case centered on two failures. Regions had charged overdraft fees on ATM withdrawals and one-time debit-card purchases to customers who had linked savings accounts for overdraft protection but had never opted in to overdraft coverage for those transactions, which federal rules require. It had also charged overdraft and insufficient-funds fees on its Ready Advance deposit-advance product, despite telling customers it would not.14 Two separate products, the same failure: the bank's systems charged fees its own disclosures said it would not, or that customers had never agreed to pay.
The 2022 remedies were larger. Regions paid a $50 million civil penalty to the CFPB, and the order required at least $141 million in consumer redress.15 It is tempting to add those figures together and report a "$191 million fine," but that would mislead. The penalty was punishment paid to the government. The redress was customers' own money being returned to them. The first measures how seriously regulators viewed the conduct; the second measures how much revenue the practice had generated in the first place. The more sobering figure is the second.
A seven-year gap between two overdraft orders invites an uncomfortable reading. One enforcement action can be dismissed as a control failure in a complex system. A second, on a closely related fee practice, after the bank had publicly committed to remediation, starts to look like a business that had become structurally dependent on fees customers did not anticipate. In fairness, the conduct the bureau described had ended in mid-2021, more than a year before the order, so the 2022 settlement punished a practice the bank had already stopped.13 But stopping came after years of revenue, and under the shadow of the earlier order rather than ahead of it.
The consent-order process itself is now closed. The CFPB terminated the 2022 order in July 2025, after Regions had paid the penalty and completed the required redress.15 That termination matters: it means regulators were satisfied that the bank had fulfilled its obligations, and it removes a formal supervisory overhang. It does not end the story's legal tail. A shareholder derivative lawsuit, brought on behalf of the company against its directors and officers and tied to the 2022 order, survived part of a motion to dismiss, and in February 2026 a court stayed the case for 180 days while a special litigation committee of the board investigated the claims.5 The company has not disclosed the committee's conclusion, and the stay period has since lapsed.
A derivative suit is an odd beast for outsiders to read. Shareholders who bring one are not suing the company for money; they are suing management and directors on the company's behalf, arguing that oversight failures cost the company itself. Any recovery would flow to Regions, not away from it. But the case keeps a spotlight on governance: on what the board knew about overdraft practices, when it knew it, and whether directors pushed hard enough. Regions has said reasonably possible legal losses beyond what it has accrued were immaterial at the end of 2025.5 Then, in the third quarter of 2026, professional, legal and regulatory expenses rose to about $35 million, up roughly 17% from a year earlier, which the bank attributed mainly to higher legal settlement costs without naming the matter.16 The number is small against a bank earning more than $600 million a quarter. The lack of detail is the more notable part.
Why does a fee scandal belong in a story about a bank's economic engine? Because the engine runs on trust. A regional bank's cheapest and most valuable funding comes from customers who keep their paychecks and their emergency savings in a checking account that pays little or nothing, out of habit and confidence. Every surprise fee spends a little of that confidence. The overdraft orders show that Regions, at least in that period, was willing to spend more of it than its customers or regulators thought acceptable. The real test of whether the lesson stuck is not a terminated consent order. It is whether those customers, offered higher rates or better apps elsewhere, decide to stay.
That brings the story to the heart of what a bank like Regions actually sells.
VI. What a Regional Bank Sells: Deposits, Credit and Relationships
Start with a single customer. A dental practice in Nashville keeps its operating account at Regions, runs payroll through the bank's treasury-management system, and has a line of credit for new equipment. The practice owner's family has a mortgage and two checking accounts. On an ordinary Tuesday, the practice's deposits sit in Regions' accounts earning little or nothing, and Regions lends that money to a homebuilder in Birmingham, buys government-backed bonds, or funds a car loan in Orlando. The difference between what the bank earns on those loans and securities and what it pays to borrow the deposits is called net interest income. It is, by far, the largest source of Regions' revenue.
The economics of that spread are simple to describe and very hard to manage. When interest rates rise, the bank can charge more on new loans, and its existing variable-rate loans reprice upward. But depositors notice, too, and some move money to higher-yielding alternatives, forcing the bank to pay more to keep it. When rates fall, the process runs in reverse. A bank's profitability depends less on the level of rates than on how quickly its assets and liabilities reprice relative to each other, and on how many of its depositors will accept a low rate because they value the relationship.
On its third-quarter 2026 call, management described a deposit base in which roughly 30% of balances paid no interest at all.17 That is the crown jewel. A dollar in a noninterest-bearing checking account is free funding, and the larger that share, the wider the spread a bank can earn. The same call contained the counterpoint. Management acknowledged that some large commercial clients had moved interest-bearing balances off the balance sheet and into investment products, which reduced corporate deposits in the quarter.17 Even a relationship bank cannot stop a sophisticated corporate treasurer from chasing yield.
Regions organizes this machine into three businesses, and their weight is uneven. In 2025, the Consumer Bank generated about $4 billion of revenue and about $1.2 billion of pretax income, anchoring the deposit base with millions of household checking and savings accounts.18 Corporate Banking generated about $2.8 billion of revenue, of which about $955 million came from fees rather than lending spreads: treasury management, capital markets and commercial card services.18 Wealth Management is the smallest of the three, but in 2025 its revenue grew about 10% and client assets rose about 8%.18 The consumer franchise gathers the cheap money; the corporate franchise puts it to work and sells services around it; wealth adds fees that do not depend on the spread.
Fees matter more than they once did. In 2025 Regions earned about $2.5 billion of noninterest income.5 The biggest sources were service charges on deposit accounts at about $635 million, card and ATM fees at roughly $487 million, investment-management and trust fees around $362 million, and capital-markets income near $347 million.5 Morningstar DBRS puts noninterest income at about a third of total revenue and singles out mortgage servicing as a recurring stream.19 That mix diversifies the bank away from pure spread dependence, but it is not all equally reliable. Service charges and card fees track customer activity and are relatively steady, although the overdraft episode shows they are also exposed to regulation. Capital-markets income and mortgage origination swing with deal flow, rates and investor appetite. The fee mix is a cushion, not a guarantee.
Who does Regions compete against for that customer in Nashville? The honest answer is everybody. JPMorgan Chase, Bank of America and Wells Fargo bring national scale, enormous technology budgets and brand recognition. U.S. Bancorp, PNC and Truist are closer comparisons: super-regional banks with large footprints, broad product lines and overlapping Southern markets. Truist, itself born of the 2019 merger of two Southern banks, competes directly with Regions across much of the Southeast. Below Regions sit hundreds of community banks and credit unions that compete on local knowledge and personal service, and alongside it all sit digital banks and brokerage platforms that pay higher rates on idle cash. Regions is not a national competitor on equal terms with the giants, and it does not claim to be. Its case rests on being among the top deposit holders in its core markets, and on depth rather than breadth.
Where the moat leaks
Is there a moat? Run the five forces, and the picture is mixed. Depositors have real bargaining power, because moving money is cheap and digital alternatives pay more. Borrowers can shop, especially larger commercial clients with access to the bond market and private credit. Substitutes are everywhere, from money-market funds to fintech payment apps. New entrants face high regulatory barriers to becoming a full bank, but low barriers to competing for individual products. Rivalry among existing banks is intense and, in the South, getting more so as national banks open branches in growth markets. A bank's competitive advantage has to come from somewhere other than structure.
Regions' answer is granularity and relationships. More than 60% of its deposits come from consumers, the average deposit account held roughly $19,000 at the end of 2025, and no single depositor accounted for more than 1% of deposits as of mid-2026.519 That granularity matters, and the 2023 regional-bank failures showed why. Silicon Valley Bank collapsed in part because a concentrated base of large, uninsured, tech-industry depositors could move billions in hours. A bank whose deposits are spread across millions of small accounts is far harder to run on. Regions' estimated uninsured deposits were about $52 billion at year-end 2025, against available liquidity in the third quarter of 2026 of roughly $64 billion, about 170% of uninsured deposits.516 That is a materially safer funding position than the banks that failed.
Switching costs are real but uneven. A household with direct deposit, automatic bill payments, a mortgage and a credit card at one bank faces genuine friction in leaving. A business that runs payroll, receivables and payables through a bank's treasury-management platform faces even more. But those costs protect the relationship, not the price. The corporate clients who moved balances off the balance sheet did not leave Regions; they simply stopped letting it use their money cheaply. That is the moat's real shape: Regions can keep the customer more reliably than it can keep the spread.
Management points to a $16 billion pool of commercial client balances it manages in off-balance-sheet products, describing them as relationships it could potentially bring back onto the balance sheet.17 That is a possibility, not a forecast. Those clients chose off-balance-sheet products because they paid more, and pulling the money back would require Regions to pay more, too.
The Southeast footprint is the other part of the claimed advantage. Morningstar DBRS calls it attractive, and population and business growth across Florida, Texas, Tennessee and the Carolinas is real.19 But a growing market attracts competitors as well as customers, and the same agency notes that about 90% of Regions' deposits come from just eight states.19 Footprint is distribution: it puts branches near growing populations. It does not by itself prove share gains or durable pricing power, and the company does not publish customer retention rates that would let outsiders test whether its relationships are stickier than peers'.
The other half of the machine is credit, and it is where regional banks have historically lost the most money. Every loan Regions makes is a judgment that a borrower will repay, and the bank sets aside an allowance for the loans it expects will not. At the end of 2025, that allowance stood at about $1.7 billion, built from pooled loss forecasts, reserves on individual problem loans and qualitative adjustments for risks the models may miss.5 By September 2026 the allowance had fallen to about 1.6% of loans from roughly 1.8% a year earlier, as problem loans shrank.16 That release of reserves flatters current earnings, which is legitimate when credit genuinely improves. It also means part of today's profit comes from the bank deciding it needs a smaller cushion, and that cushion can be rebuilt just as quickly if the economy turns. When an analyst asks how much of an earnings beat came from lower provisions, this is the lever they are asking about.
The engine, then, is a cycle machine with a granular, relatively defensive fuel tank. If deposit costs continue to fall and older, low-yielding fixed-rate loans and securities keep rolling into higher-yielding replacements, earnings can keep improving. If customers demand higher deposit rates, or credit weakens in the commercial real estate and business loans the bank depends on, both spread income and loan quality can reverse. Regions has chosen a strategy for navigating that cycle that is very different from the one that defined its past. It no longer intends to buy its way forward. It intends to rebuild its plumbing.
VII. The Core-System Conversion Is the Next Big Bet
On October 16, 2026, the third-quarter earnings call reached the question analysts had been circling for months. John Turner, Regions' chairman and chief executive, and Anil Chadha, its chief financial officer since the spring, were asked about the bank's long-running project to replace its core deposit system. Management's answer was the most concrete it had given: a pilot was beginning, customers would be converted in waves through 2027, and the project was scheduled to be completed late in the second quarter or early in the third quarter of 2027.17
To appreciate why that matters, it helps to understand what a core deposit system is. Think of it as the bank's central ledger and nervous system combined. Every checking account opened, every debit-card swipe, every direct deposit and every overdraft calculation runs through it. Many American banks still run core systems whose architecture dates to the mainframe era, patched and extended over decades. They work, but they make it slow and expensive to launch new products, integrate with modern apps and analyze customer data in real time. Replacing one is like rebuilding a plane's engine in flight: the bank must keep every account running while moving millions of customers' records to new software.
The rewards can be substantial. A modern core can let a bank launch products in weeks rather than months, personalize offers, process payments in real time and reduce dependence on manual workarounds. The risks are equally real. Conversions at other banks have produced outages, frozen accounts, incorrect balances and angry customers, and a botched conversion can drive away exactly the deposit relationships the project is meant to protect.
The project also marks a strategic contrast with the bank's past. In the AmSouth era, Regions grew by buying franchises. Today, management says it is prioritizing organic growth and investment in technology over buying other banks.17 That is a defensible choice, given how the last big deal ended. It also means the bank's growth story now rests on execution rather than on the addition of someone else's balance sheet.
The third-quarter numbers give the starting point. Net interest margin, the spread the bank earns on its interest-bearing assets, was 3.68%, and the efficiency ratio, which measures how many cents of expense it takes to generate a dollar of revenue, was about 56%.16 Those are respectable figures for a regional bank, but they leave room for improvement, and the question is whether modernization will lower costs or simply add new ones. Here, management's own words in the Q&A were revealing. Asked whether the conversion would bring expenses down, Chadha indicated that technology investment would continue after it, including a new general-ledger platform.17 Equipment and software expense rose about 7% from a year earlier in the third quarter, driven by software-as-a-service charges.16 And headcount edged up from about 19,600 full-time equivalents at the end of 2024 to just under 20,000 at the end of 2025, while revenue grew only modestly.5 There is no evidence yet of operating leverage from technology. The bank is still in the spending phase.
There is a second dependency hidden inside the project. Like most banks of its size, Regions relies on outside technology providers for processing, online banking and other critical services, and it warns investors that failures or disruptions at those vendors could hurt its operations and its customers.5 The company does not quantify how concentrated that reliance is or name the provider behind its new deposit platform in its SEC filings. A conversion therefore puts two reputations on the line at once: the bank's own and that of the vendor whose code its customers will be living inside. Regions controls the timetable and the testing. It does not fully control the software.
Management also separated cybersecurity from the conversion, describing it as an ongoing defense cost and a basic customer-trust requirement rather than a one-time project.17 That framing is honest. Banks are among the most attacked institutions in the economy, and a breach can destroy confidence faster than any overdraft policy.
How should an outsider judge whether the modernization is working? Not by launch milestones, which are necessary but prove little. The measures that matter are customer behavior and costs: whether new-account growth accelerates, whether deposit costs stay disciplined, whether service reliability holds through each conversion wave, whether customers who are converted stay, and whether the efficiency ratio eventually improves. "Digital transformation" is a phrase every bank uses. Regions' version will be credible only if those numbers move.
The man running the rebuild
The person most accountable for that outcome is John Turner. He is often described as a Regions lifer, but his path was more interesting. Turner spent most of his career at Whitney, the New Orleans bank, where he rose to president of Whitney National Bank and Whitney Holding Corporation from 2008 to 2011.10 He joined Regions in 2011 as president of its South Region, ran the Corporate Bank from 2014, became president in 2017 and succeeded Grayson Hall as chief executive on July 2, 2018.10 Some data services list him as chief executive since 2011, but that conflates his arrival at the company with his promotion to the top job; he has led Regions for a little over eight years, not fifteen.
That record matters because it places Turner outside the AmSouth decision. He inherited a bank that had already survived its crisis, repaid TARP and sold Morgan Keegan, and his tenure has been defined by disciplined deposit-gathering, steady credit, and the absence of large bank acquisitions. It also means he presided over the 2022 overdraft order and the long delay of the core conversion, which have both become tests of his management.
His incentives are substantial. Turner's reported compensation was about $10 million in 2025, roughly level with the prior year, and the board says more than 60% of target executive compensation is tied to performance.20 He holds Regions stock worth about 465% of the requirement that he own shares equal to six times his base salary.20 Shareholders have broadly endorsed the arrangement: at the May 2026 annual meeting, about 609 million votes were cast in favor of executive compensation and roughly 40 million against, and all 13 director nominees were elected.21 The leadership bench has also turned over in an orderly way. David Turner, the long-serving CFO, who is no relation, retired at the end of March 2026 and was succeeded by Chadha.22 Dave Keenan, the chief administrative officer, will retire at the end of 2026, and Kate Danella, who has run the Consumer Bank, will move into his role.23 Planned succession is a strength. It also means the conversion will be delivered by a team that is partly new to its roles.
Management's credibility should be tested against results, not tone. Profit improved in 2025 and through the third quarter of 2026, but from fiscal 2022 to fiscal 2025, net profit fell at an average rate of about 1% a year.5 Some of that reflected a sharp rise in deposit costs after the Federal Reserve's rate increases, and some reflected securities repositioning losses that management chose to take to improve future returns. The recent rebound is genuine. Whether it is the start of a durable trend, or simply the favorable side of a rate cycle, is the question the conversion now has to help answer.
VIII. Playbook: Growth, Trust and the Price of Scale
Lay three documents side by side on a table in Birmingham. The first is the 2006 merger proxy, full of peer comparisons, synergy targets and confident arithmetic about what a combined Regions and AmSouth would earn. The second is the 2008 annual report, with its roughly $6 billion goodwill write-off and its candid accounting of what Florida condominiums and Atlanta subdivisions had done to the loan book. The third is the CFPB's 2022 consent order, a few dozen pages explaining how a bank charged fees on purchases its customers had every reason to think were paid for. Each document records a moment when a promise met its consequences. Together, they are the closest thing Regions has to an autobiography.
The first lesson comes from AmSouth, and it is about what scale is actually worth. The merger widened Regions' footprint and gave it a deposit base that still anchors the company. But its later impairment showed that scale could not protect the deal from peak-cycle credit risk. A bigger footprint is only worth what the acquired assets can earn through a full cycle. Bank acquisitions are usually priced on the earnings of the moment, but bank earnings of the moment are borrowed from the credit cycle. A buyer who pays for peak-cycle earnings with peak-cycle stock has bought a franchise and a bet at the same time, and only one of them shows up on the announcement slide.
The second lesson comes from TARP. The episode showed that public capital bought Regions time to fix itself, at a cost borne largely by shareholders who were diluted along the way. Capital is a bridge, not a business model. The bridge held because Regions had a deposit franchise worth crossing toward, and because it was willing to sell Morgan Keegan and issue stock at a painful price to get to the other side. Banks that survive crises usually do so by giving something up. Regions gave up a slice of its ownership and its ambition to be a diversified financial conglomerate.
The third lesson comes from the overdraft orders. A fee that customers cannot anticipate produces revenue for a while, and then it produces penalties, refunds, lawsuits and a reputation that follows the bank into every regulator's examination room. A fee that customers cannot predict is a liability before it becomes revenue. The orders brought refunds, a penalty, years under a consent order and a continuing derivative suit. Somewhere in that period, its competitors were using fee cuts as marketing.
The fourth lesson is still being written. The core conversion's success will depend on whether it deepens customer relationships and earns back its cost. If new accounts, deposit balances and fee relationships deepen after the conversion, the spending will have paid off. If the conversion simply replaces old costs with new ones, it will have kept Regions in the race without moving it forward.
An activist reading the record would press hardest on capital allocation. The company's history includes large acquisitions that built its footprint, and one of them was heavily impaired within two years. It includes a capital-markets business bought and sold over a dozen years without a clear public accounting of whether it earned its keep. Today, the capital story is different: dividends of about $1 billion paid in 2025, a payout of a little under half of net profit, and a new $3 billion share-repurchase program covering 2026 and 2027.5 In the third quarter of 2026 alone, Regions bought back about 3 million shares for roughly $95 million and declared about $255 million of common dividends.16 Returning capital is a defensible use of surplus when organic opportunities are limited. But a skeptic would want those payouts weighed against the bank's needs for technology investment, regulatory capital and a cushion for the next credit downturn, rather than celebrated as discipline on their own.
None of this means the bank is in trouble. The current balance sheet looks very different from the one Regions carried into 2008. Its common equity tier 1 ratio, the core measure of loss-absorbing capital, was estimated at about 10.8% at the end of September 2026.16 Credit indicators have been improving, liquidity is ample, and Morningstar DBRS upgraded the holding company's long-term rating to A (high) in August 2026, citing low-cost granular deposits, diversified fees, sound asset quality and strong capital.19 But stronger capital and better credit metrics describe today's starting position. They do not prove that the 2027 conversion will succeed, that today's returns will persist through a downturn, or that the lessons of 2006 and 2022 have been permanently absorbed. Those are the questions the bull and bear cases have to resolve.
IX. Analysis & Bear vs. Bull Case
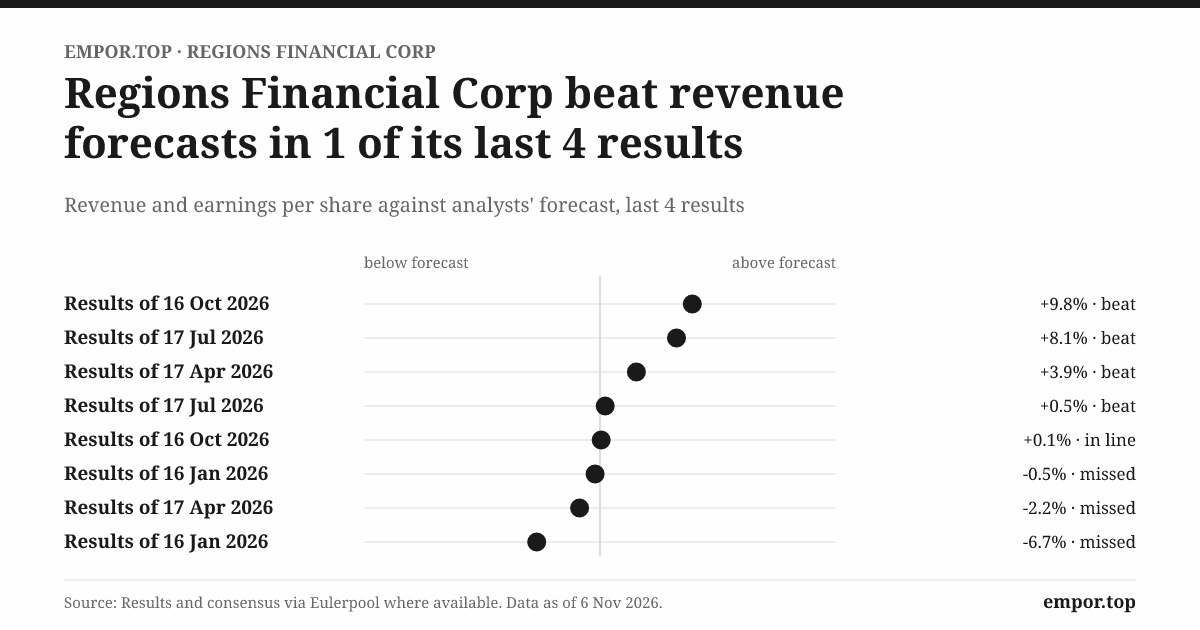
On October 16, 2026, Regions reported third-quarter earnings that looked, on their face, like the story's happy ending. Net income available to common shareholders was $611 million, or 71 cents a share, up about 11% from a year earlier.16 Margins had widened and credit metrics had improved, as described above.16 Analysts on the call did not dispute any of that. Instead, they asked how much of the improvement was structural, coming from older low-yielding assets maturing and being replaced at higher yields, and how much depended on interest rates and depositor behavior staying favorable.17 That is the right question, and it is the one the investment case has to answer.
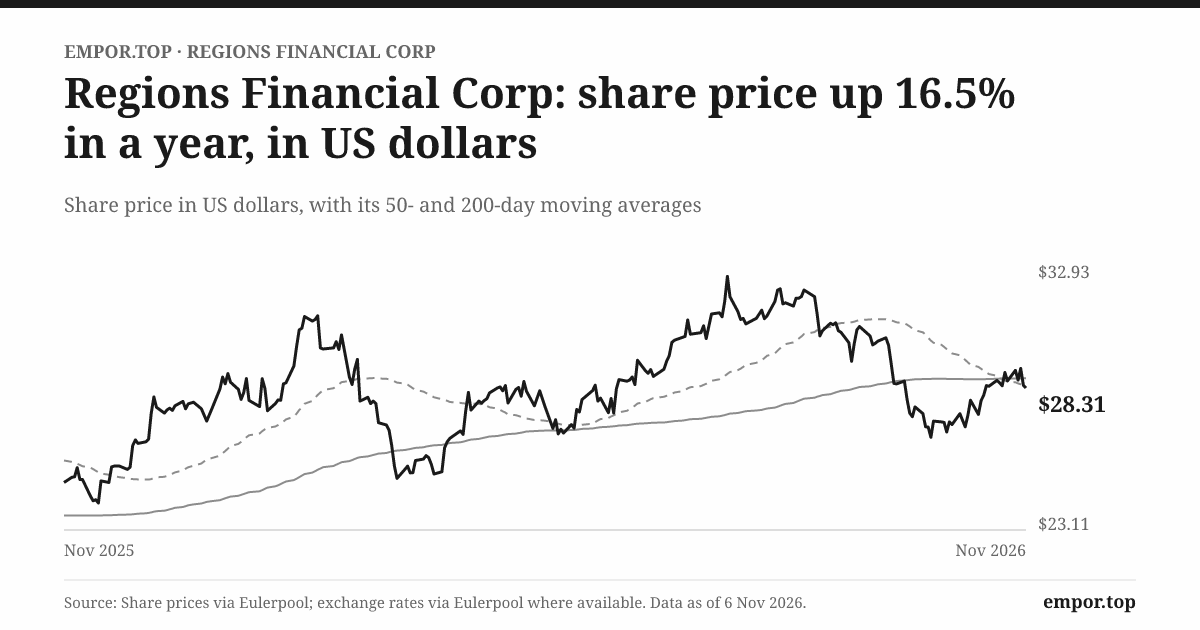
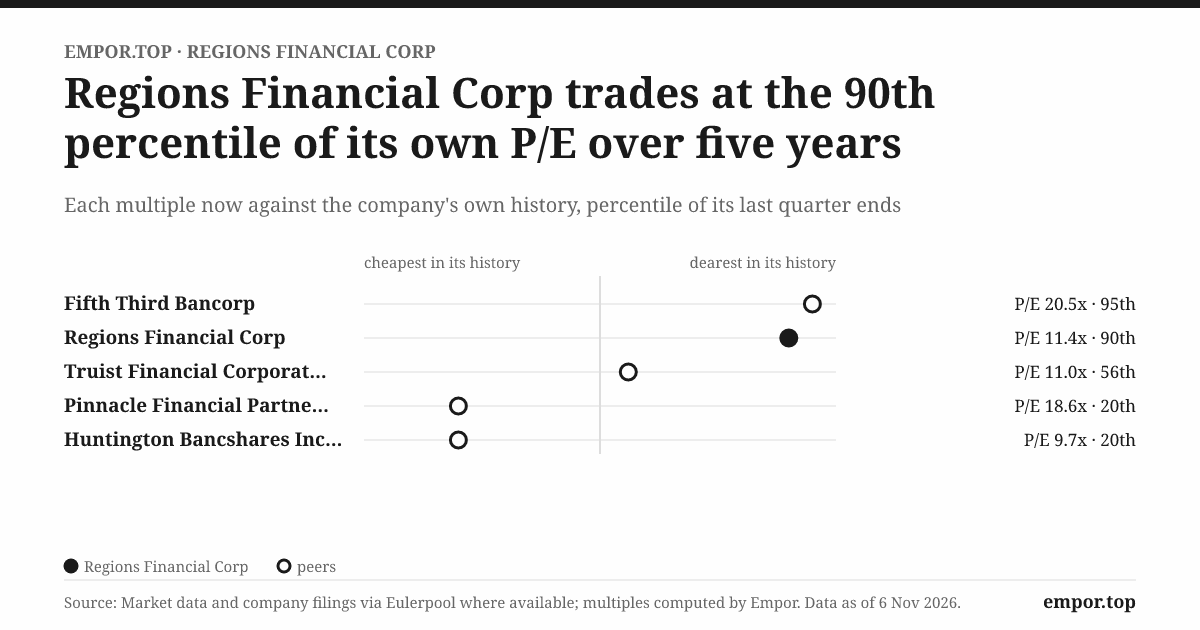
Start with what the market is paying. On November 4, 2026, Regions' shares traded at about $29, giving the company a market value of roughly $25.6 billion.6 That price represented about 11.5 times the last twelve months of earnings, compared with a five-year median of about 9.8 times, and about 1.4 times book value.5 The stock yielded about 3.8% in dividends. In plain terms, investors were paying more for each dollar of Regions' earnings than they had on average over the previous five years. That is not an extravagant valuation by the standards of the broader stock market, but it is above the bank's own recent history, which means the market is already pricing some of the recovery. At about the same time, U.S. Bancorp traded at roughly 11.6 times earnings, PNC at about 12.1 times and Truist at about 12.8 times.24 Regions is not an obvious outlier against its closest super-regional peers, though those comparisons use slightly different dates and methods. The market is not treating it as either a bargain or a premium franchise. It is treating it as a solid regional bank on the favorable side of a cycle.
The case for a steadier bank
The bull case begins with the strengths already described: Regions' granular deposit base, ample liquidity, fee businesses and improving credit metrics. Its allowance for credit losses covered about 275% of nonperforming loans, and criticized commercial real estate loans fell from about $3.7 billion to about $3.2 billion over the year to September 2026.16 It also generates enough capital organically to pay a meaningful dividend and buy back shares without needing acquisitions. If interest rates settle and deposit costs keep drifting lower while older fixed-rate assets reprice, earnings can keep improving for several years without any heroics.
Hamilton Helmer's seven powers offer a sharper way to test whether that franchise is a genuine competitive advantage. Scale economies exist in banking but mostly favor the national giants, whose technology budgets and brand reach Regions cannot match; within its core markets, density of branches and deposits gives it some local advantage, but not a dominant one. Network effects are weak; a bank's customers do not become more valuable to one another as the bank grows. Counter-positioning is absent, because Regions' model is the same one its peers run. Cornered resources are limited to the deposit relationships themselves, which are valuable but contestable. Process power, the advantage that comes from operating routines competitors cannot easily copy, is not visible in the record, and the core conversion is partly an admission that Regions' processes needed catching up. That leaves two powers that genuinely apply: switching costs, which protect relationships more than pricing, and local branding, whose trust can be dented.
The honest verdict from that exercise is that Regions has a real but modest moat, built from switching costs and local brand, sitting inside an industry where structural advantages are thin. The franchise is defensible. It is not impregnable, and it does not give the bank pricing power over its depositors when rates rise.
The case for a cyclical recovery
The bear case begins with the growth record. Over a decade, revenue grew about 5% a year and net profit about 7% a year, respectable rather than remarkable.512 A skeptic would also point out that Regions' assets grew only about 2% a year over the past decade, so most of its earnings improvement has come from wider spreads and better credit, not from a bigger business.
The second pillar of the bear case is concentration. Criticized commercial real estate is falling, but it remains above $3 billion, and a downturn in Texas office property or Florida housing could reverse the trend quickly.16 The bank's 2008 experience is not a forecast, but it is evidence of how fast concentrated regional real estate exposure can turn. The difference today is that Regions starts with stronger capital, better liquidity, and lessons learned. The similarity is that it still depends on the same regional economies.
The third pillar is deposit sensitivity. The 30% noninterest-bearing share is valuable, but depositors' willingness to accept low rates has eroded across the industry as money-market funds and digital banks have offered more. If rates rise again, Regions will face pressure to pay more. If rates fall sharply, its asset yields will compress. The bank's earnings are, in a real sense, a bet on a benign middle path.
The fourth pillar is execution and reputation. The core conversion carries a real risk of disruption, while the overdraft history and derivative case have exposed governance and customer-treatment vulnerabilities. And the third-quarter rise in legal settlement costs, though small, has not been explained in detail.
Weighing the two
The crisis remains evidence, not prophecy. It showed what happened when concentrated credit met a fresh integration and a collapsing market. Today's Regions starts from a materially stronger capital and liquidity position. That does not make the old risks irrelevant. It means they would bite a better-protected bank.
A skeptical long-term investor would ask one pointed question of management. If the bank continues to spend on its deposit conversion, a new general ledger and cybersecurity, and if those costs crowd out buybacks or slow the improvement in the efficiency ratio, what measurable customer or cost benefit should shareholders expect, and by when? Management has offered a conversion timetable, but not a public target for the efficiency gains or deposit growth that the project should deliver. That gap is not unusual for banks, but it leaves investors judging the investment largely on faith until the numbers arrive.
The fee story deserves the same conditional treatment. Management has highlighted strong quarters in treasury management and capital markets, and those businesses diversify the bank's earnings.17 But capital-markets income in particular depends on deal flow and market conditions, and a few strong quarters are not a trend. The test is whether fee growth persists through a period of market volatility, not whether it appears during a favorable one.
Two quieter signals round out the picture. The first is the credit view. Morningstar DBRS's August 2026 upgrade was a meaningful vote of confidence from an outside analyst whose job is to worry about the downside, yet the same report spelled out what could reverse it: a material decline in earnings or a severe deterioration in asset quality, and it flagged Regions' regional scale and concentration as lasting constraints.19 Rating agencies, in other words, see the same bear case equity investors do; they simply judge that the bank can absorb it today. The second is ownership. Regions has no controlling shareholder. Its largest holders are index-heavy asset managers, with Vanguard at roughly 14%, BlackRock at about 10% and State Street at about 7%, although those percentages rest on regulatory filings dated to the end of 2023 that none of the three had updated by the time the 2026 proxy was printed.20 The company counted about 32,000 holders of record in early 2026.5 That shareholder base tends to vote with management on routine matters, as the say-on-pay tally showed. It is less likely to supply the kind of concentrated, impatient pressure that forces a bank to explain exactly what its technology spending will return. That pressure, if it comes, will have to come from results.
Three measures will tell the story better than any narrative. The first is the share of deposits that pay no interest, which is the clearest gauge of whether the franchise's cheap funding is holding.17 The second is net charge-offs, which will show whether credit quality holds as the cycle turns.16 The third is the efficiency ratio, which will reveal whether the technology spending eventually produces operating leverage or simply becomes a permanent new cost.16 If all three hold or improve through 2027, the case for a steadier organic-growth bank strengthens considerably. If any of them reverses, the recovery will look more like a cycle than a transformation.
The verdict, then, is that Regions is a profitable, well-capitalized and currently improving regional bank whose valuation already reflects a good part of that improvement. The bull case rests on the deposit franchise, the footprint and credit discipline. The bear case rests on growth, concentration, deposit sensitivity and execution. Neither side is decisive yet, and the next eighteen months will supply much of the evidence.
X. Epilogue
Somewhere in Regions' operations centers in 2027, the first wave of customers will wake up to accounts running on a new deposit platform. If all goes well, they will notice nothing at all. Their balances will be right, their cards will work, their direct deposits will arrive and the app will look much as it did the night before. That is the strange thing about a successful core conversion: its best possible outcome is invisible. Only failure makes the news.
Management has said the conversion is scheduled for completion in mid-2027.17 Investors and customers will learn a great deal before then. Each wave is a test of reliability, and each quarterly report will show whether account growth, deposit balances and fee relationships are holding through the transition. A smooth conversion would remove one of the largest operational risks in the story; a troubled one would put the deposit franchise at risk.
The second watchpoint is cost. Chadha has already signaled that technology investment will continue after the conversion. That is a reasonable stance in an industry where technology never stops changing, but it means shareholders should not expect a sudden drop in expenses when the project finishes. The real question is whether, over the following years, the efficiency ratio improves as the new platform lets the bank do more with the same resources, or whether it drifts as new spending replaces old.
The third is credit. Texas and other commercial real estate markets remain the most likely sources of trouble, and criticized commercial real estate, though falling, is still a meaningful share of the loan book. Loan growth, if it accelerates, will bring its own risks, because the fastest-growing loans in any cycle are rarely the safest.
The fourth is earnings quality. When the full-year 2026 results arrive, investors will be able to separate how much of the improvement came from repricing of older assets, how much from fees, how much from lower credit provisions and how much from securities activity. Repricing gains are real but finite; once older assets roll off, that tailwind fades. Fee growth and stable credit are the more durable sources of improvement.
The fifth is the legal tail. The special litigation committee's work on the overdraft-related derivative case will eventually produce a recommendation, and the next annual report will show whether the rise in legal settlement costs was a one-off or the start of a pattern.516 Neither is likely to threaten the bank's capital. Both will say something about whether the board has fully closed the chapter that the CFPB formally closed in 2025, or merely survived it. And alongside all of it runs the capital question: with a $3 billion buyback authorization covering 2026 and 2027, management will have to choose, quarter by quarter, how much surplus capital to hand back and how much to keep for conversion costs and a possible downturn.5 The size of each quarter's repurchase will be a small, public tell about how confident the bank really feels.
All of these feed into the question that began this story. After decades of buying its way across the South, a crisis that tested its survival and a fee scandal that tested its customers' trust, has Regions built a more resilient bank, or has it simply learned to manage the same old risks with newer systems? The capital ratios suggest resilience. The deposit base suggests durability. The record suggests caution. The answer will come one quarter at a time.
XI. Outro
Go back to Birmingham, to the downtown streets where Regions and AmSouth once competed from rival towers. It was there, in 2006, that two hometown banks decided to become one regional giant. It was there, in 2008, that the enlarged bank accepted Treasury capital to survive the consequences. And it is there, today, that its leaders are promising a digital rebuild that will let the bank grow by earning customers rather than buying them.
Regions is a hometown bank that tried to become a regional colossus, discovered the price of scale in a crisis, and now has to prove that a deposit relationship can be its strongest form of growth. Buying a franchise took one signature in 2006. Earning a customer's next deposit takes every day after. The bank's test is whether it can turn decades of local relationships into durable returns without paying, once again, the price of its biggest bet.
References
-
2006 Regions–AmSouth Merger Registration Statement and Proxy (Form S-4) — Regions Financial Corporation, 2006 ↩↩↩↩↩↩↩↩
-
2008 Form 10-K — Regions Financial Corporation, 2009-02-24 ↩↩↩↩↩↩↩↩↩
-
Regions Repays $3.5 Billion in TARP Funds — U.S. Department of the Treasury, 2012-04-04 ↩↩↩↩↩
-
Regions Financial Corporation — Encyclopedia of Alabama ↩↩↩↩↩
-
2025 Form 10-K — Regions Financial Corporation, 2026-02-24 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Regions Financial Investor Relations — Regions Financial Corporation ↩↩
-
Order Approving the Merger of Regions Financial Corporation and AmSouth Bancorporation — Federal Reserve, 2006 ↩↩↩
-
Regions–Union Planters Merger Presentation — Regions Financial Corporation, 2004-01-23 ↩↩
-
Prospectus Supplement for Common Stock Offering — Regions Financial Corporation, 2009-05-20 ↩↩
-
Regions Financial Corporation Names John Turner CEO, Form 8-K — Regions Financial Corporation, 2018-04-25 ↩↩↩
-
Raymond James to Acquire Morgan Keegan — Raymond James Financial, 2012-01-11 ↩↩↩
-
Regions Bank Consent Order, File No. 2022-CFPB-0008 — Consumer Financial Protection Bureau, 2022-09-28 ↩↩↩
-
Regions Bank Enforcement Action (2015) — Consumer Financial Protection Bureau, 2015-04-28 ↩↩
-
Regions Bank (2022) Enforcement Action and Case Status — Consumer Financial Protection Bureau ↩↩
-
Regions Reports Earnings of $611 Million and EPS of $0.71 in 3Q 2026 — Regions Financial Corporation, 2026-10-16 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Regions Financial Q3 2026 Earnings Call Transcript — Stock Analysis, 2026-10-16 ↩↩↩↩↩↩↩↩↩↩↩
-
2025 Annual Report — Regions Financial Corporation, 2026 ↩↩↩
-
Morningstar DBRS Upgrades Regions Financial Corporation's Long-Term Issuer Rating to A (high) — Morningstar DBRS, 2026-08-27 ↩↩↩↩↩↩
-
2026 Proxy Statement — Regions Financial Corporation, 2026-03-23 ↩↩↩
-
2026 Annual Meeting Results, Form 8-K — Regions Financial Corporation, 2026-05-06 ↩
-
Regions Financial Announces David Turner to Retire, Anil Chadha to Serve as Chief Financial Officer — Regions Financial Corporation, 2026-01-12 ↩
-
Regions Financial Announces Upcoming Retirement of Dave Keenan and New Executive Leadership Appointments — Regions Financial Corporation, 2026-08-11 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube