Public Service Enterprise Group Incorporated: The Utility That Sold Its Power Plants
I. The Company That Chose Which Energy Business to Keep
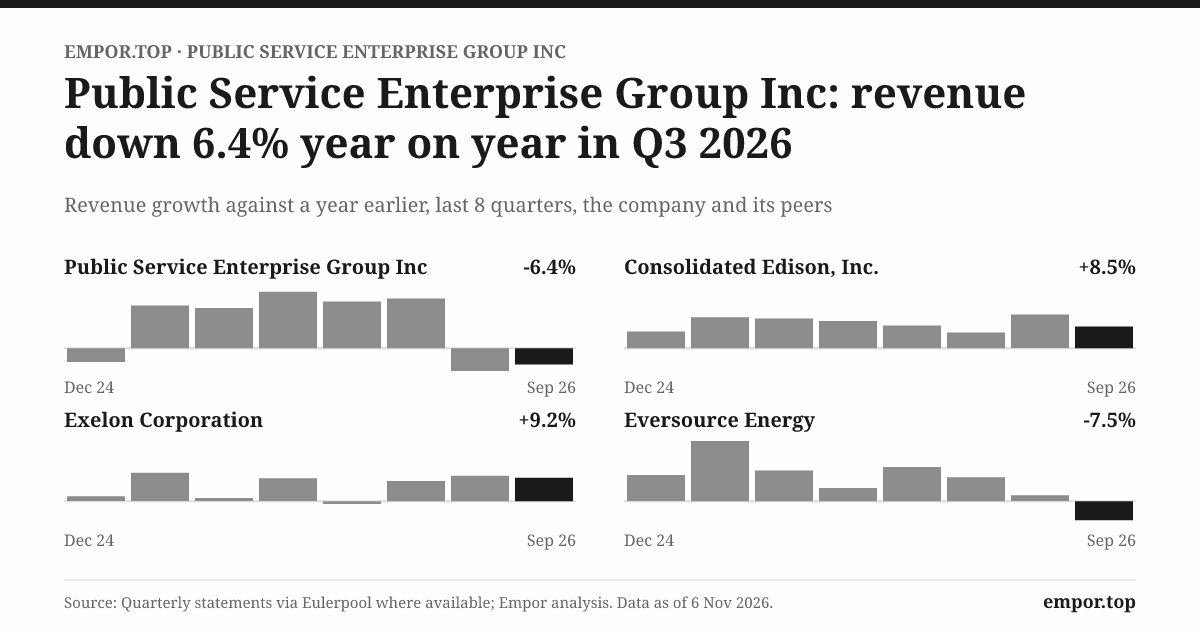
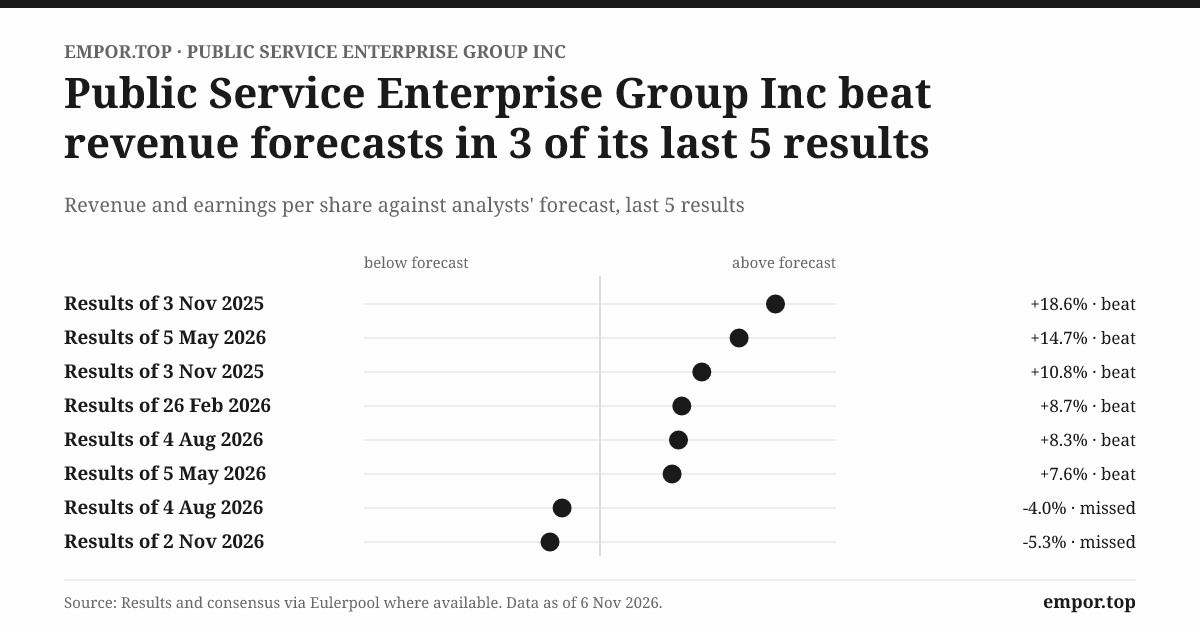
On the morning of November 2, 2026, Public Service Enterprise Group published its third-quarter results, and the release told two stories at once. One was steady. Non-GAAP operating earnings for the quarter came to $1.15 a share, a couple of cents better than a year earlier, and management reaffirmed its full-year range.1 The other story was a lurch. Net income under generally accepted accounting principles, the number the auditors sign, fell to $376 million from $622 million a year before, a drop of almost 40%.1 Two honest numbers, describing one company in one quarter, pointing in opposite directions.
The gap only makes sense once the company is split in two. PSEG reports a regulated utility, Public Service Electric and Gas, and a second bucket called Power & Other, which holds the nuclear plants, a contract to run Long Island's electric grid, and the parent company's leftover activities.2 For the first nine months of 2026 the utility earned $1.425 billion. Power & Other earned $26 million.2 For every hundred dollars of profit the group reported, roughly ninety-eight came from wires and pipes in New Jersey. In the third quarter alone, PSE&G earned $506 million while Power & Other lost $130 million.1
That is the opening puzzle of this story. PSEG is one of the oldest names in American energy, and for a quarter of a century it presented itself as something more than a utility: an energy company with a merchant generation arm that could earn market returns on top of a regulated base. The company's own logo still carries that ambition. The earnings no longer do. Today PSE&G delivers electricity to about 2.4 million customers and natural gas to about 1.9 million, across a territory that covers much of New Jersey's industrial and suburban corridor from Bergen County down through Trenton to the Camden area.3 The generation side has shrunk to a single, distinctive bet: 3,758 megawatts of nuclear capacity, roughly enough to light several million homes, concentrated in plants that run around the clock.4
So the first question an investor has to ask is what PSEG actually is now. Is it a regulated utility with a nuclear fleet attached, or a utility-and-nuclear hybrid with two engines of roughly comparable weight? The answer from the income statement is plain. The listed company's earnings center of gravity is the New Jersey utility. Nuclear matters, because it is carbon-free, hard to replace and capable of earning more when power prices rise, but in the current numbers it is not an equal profit engine. It is the swing factor.
The scale of the bet on the utility is the reason this distinction matters. Management's plan calls for $24 billion to $28 billion of capital investment between 2026 and 2030, more than nine-tenths of it in regulated businesses.1 To put that in proportion, the whole company generated revenue of about $12.2 billion in 2025 and carried about $24.4 billion of borrowings at the end of that year.4 The plan, in other words, asks PSEG to spend roughly two years of revenue on new poles, wires, substations, pipes and transmission lines over five years, and to persuade regulators to let it earn a return on every dollar.
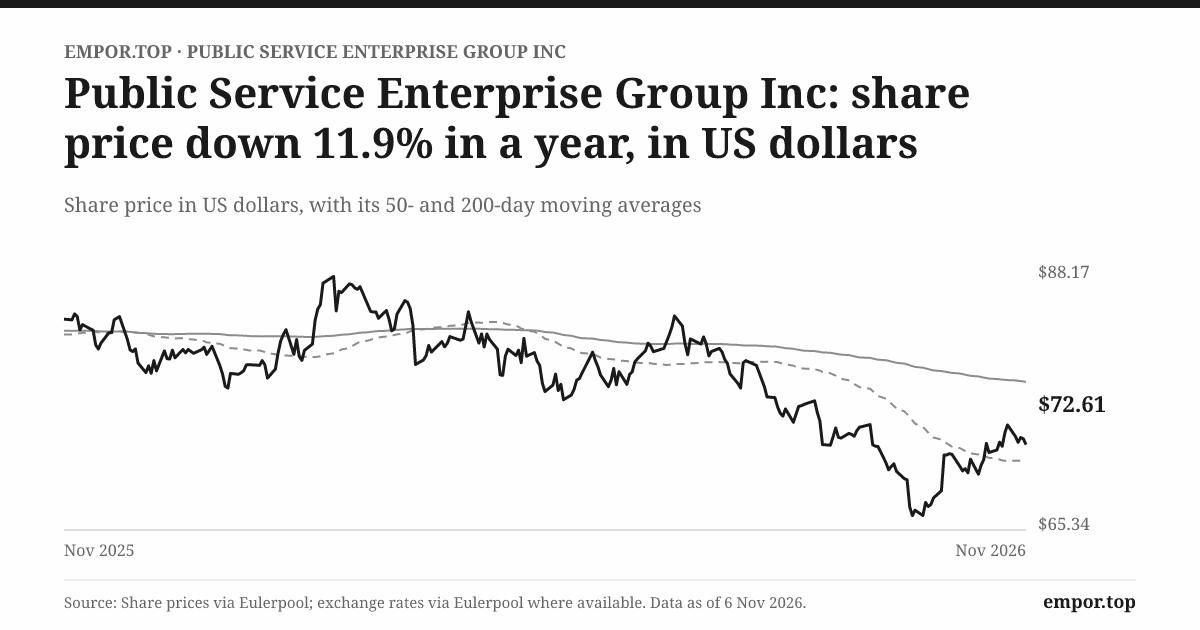
The market's verdict on that plan, as of November 5, 2026, was cautious rather than enthusiastic. The shares traded at $73.10, about 16% below their 52-week high of $86.95, giving the company a market value of about $36.6 billion and a dividend yield of about 3.6%.5 That is not the price of a stock the market thinks is broken. It is the price of a stock the market is waiting on.
What exactly is it waiting for? Four tests run through the rest of this story. The first is whether the regulated investment plan can sustain growth faster than PSEG managed over most of the past decade. The second is whether the company can recover those costs from customers without making service unaffordable in a state where electricity bills have become a political flashpoint. The third is whether PSEG can fund the capital program and keep raising its dividend without weakening its credit. And the fourth is whether the nuclear fleet, and the new wave of electricity demand from data centers and other large users, can improve the earnings mix rather than simply adding volatility.
Management's third-quarter presentation offered evidence on several of these at once. The company reported that its nuclear fleet ran at a 95.5% capacity factor in the quarter, meaning the plants produced almost all the electricity they physically could, and that more than 95% of expected 2026 nuclear output was already hedged.6 Yet on the call, when the subject turned to large-load customers such as data centers, management offered no new quantified pipeline or signed-deal contribution.7 The plants were working. The demand story was still a promise.
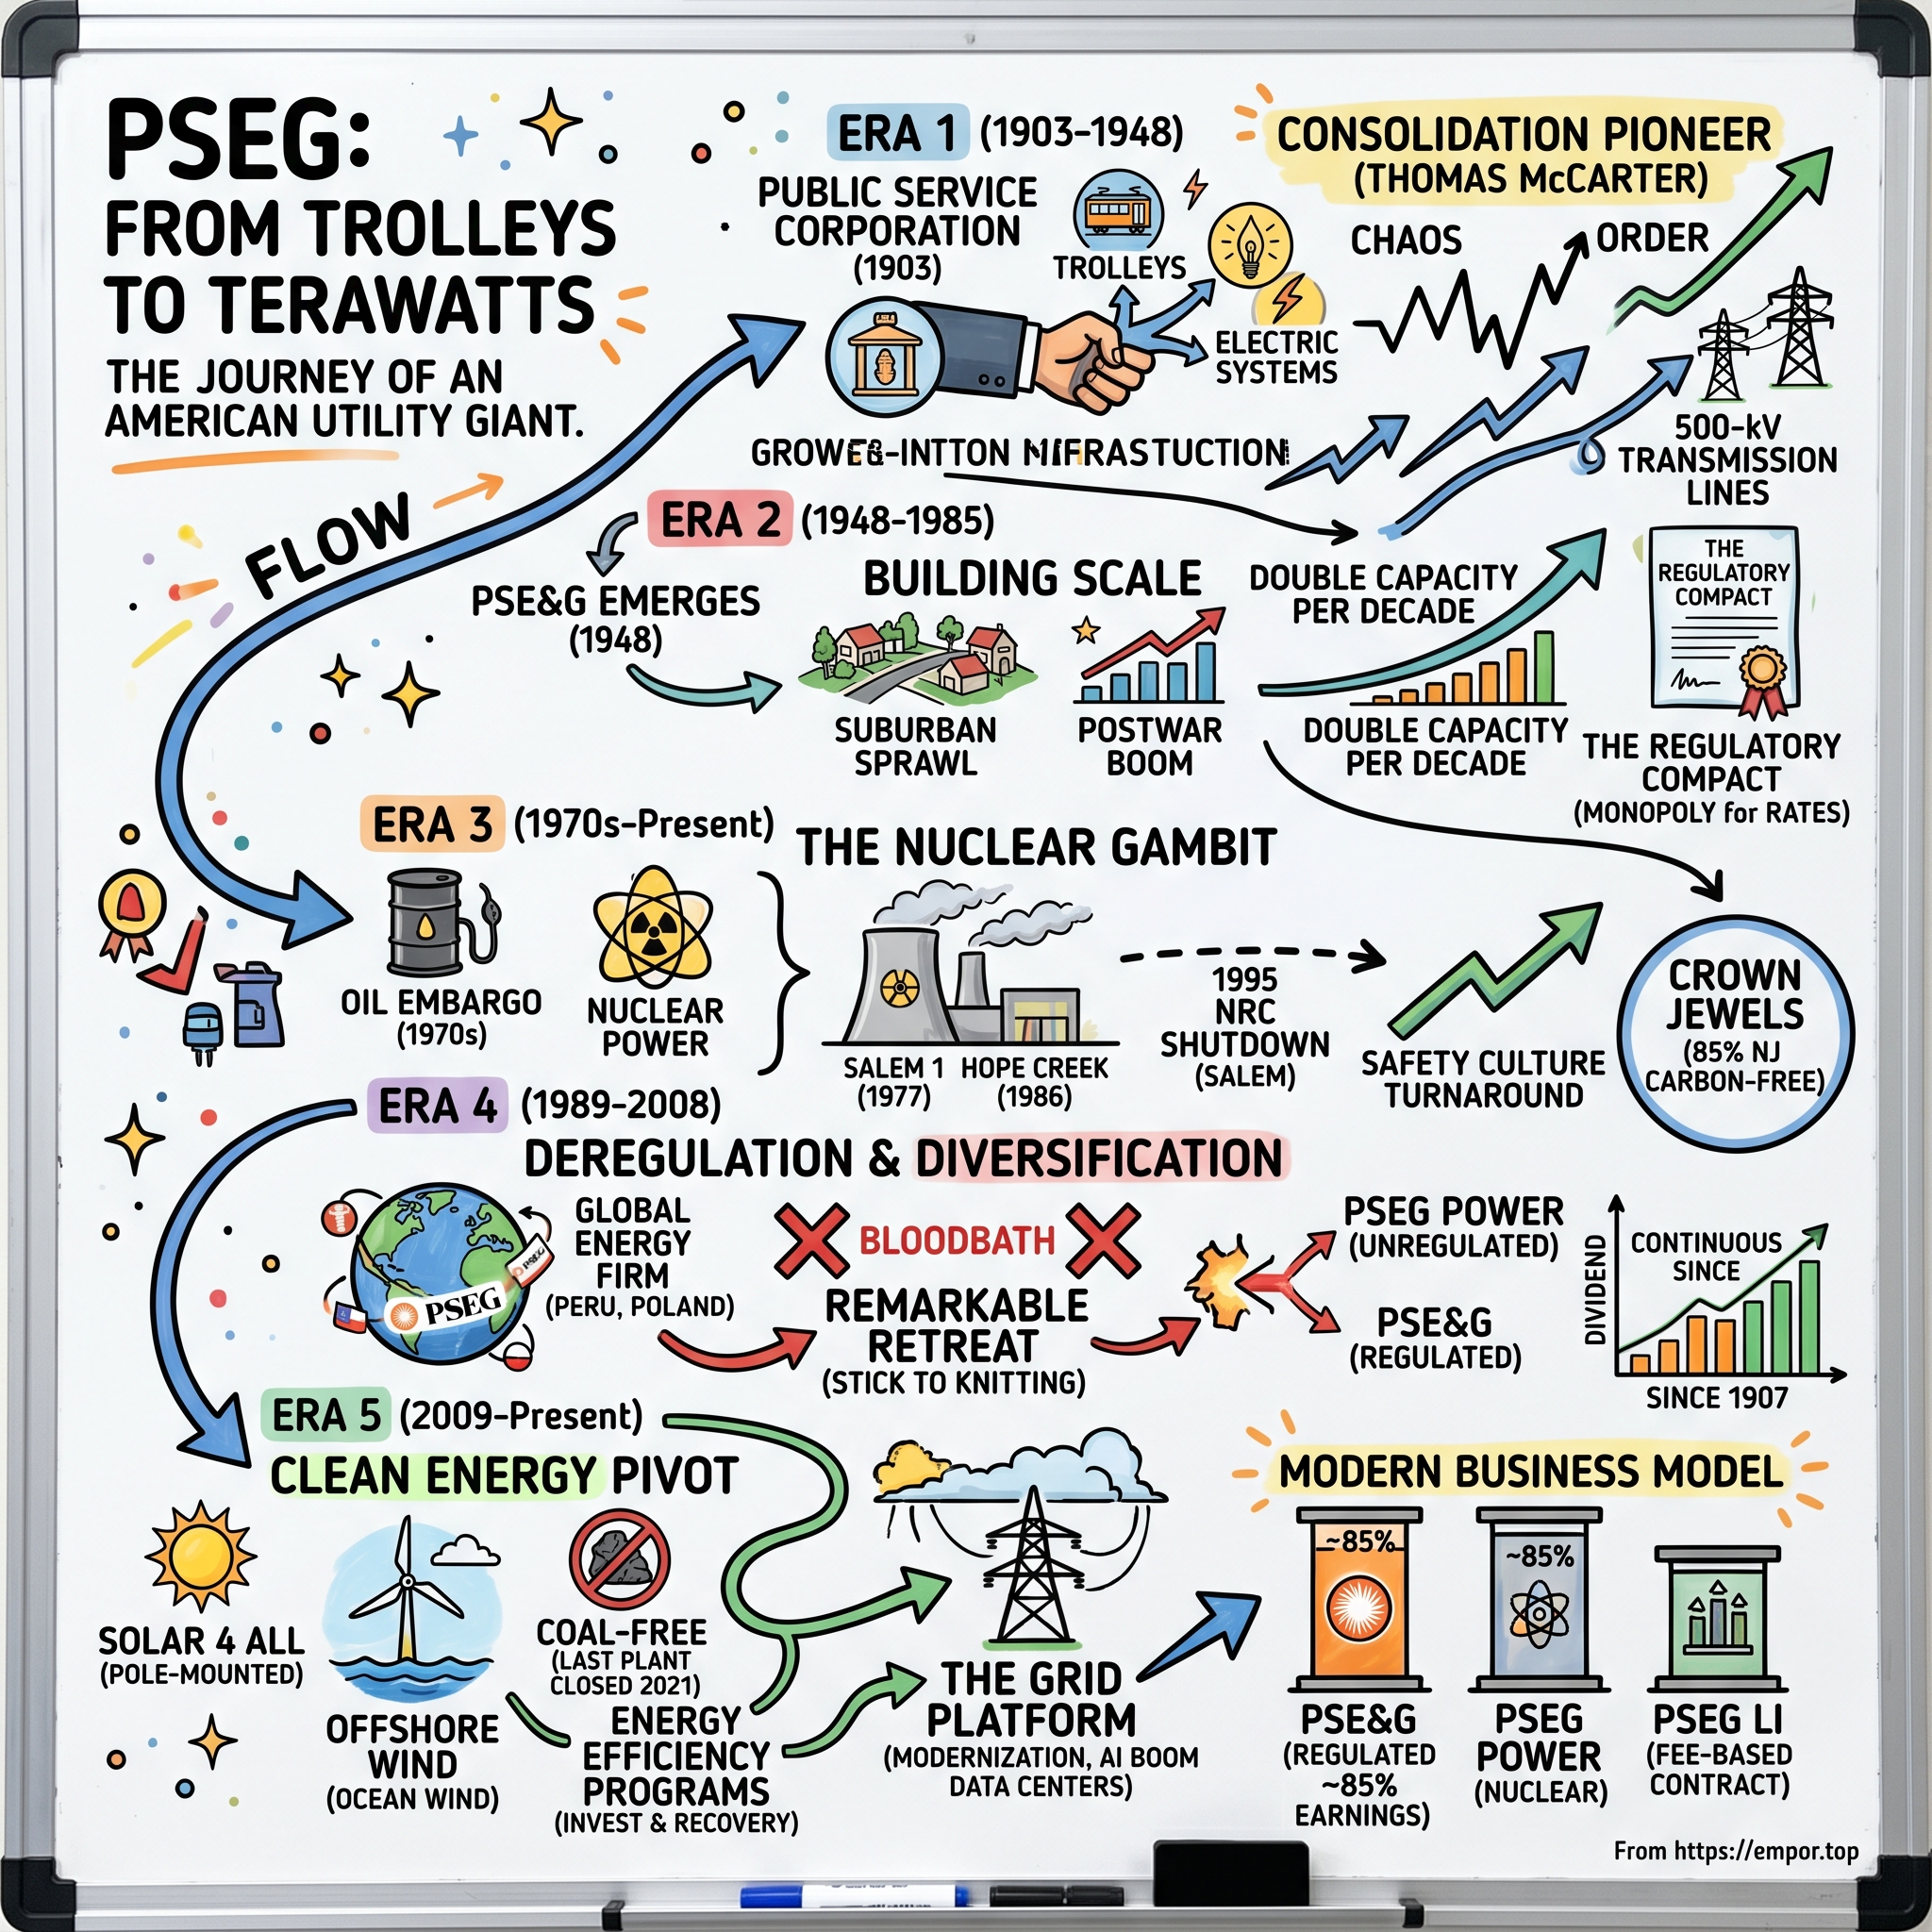
The difference between operating earnings and GAAP earnings is not an accounting curiosity here. It is the residue of a long history in which PSEG tried, repeatedly, to be bigger and broader than a New Jersey utility, and then narrowed its ambitions one decision at a time. The non-GAAP number strips out the market swings in the nuclear decommissioning trust and the mark-to-market moves on energy hedges; the GAAP number keeps them in.1 The volatility lives almost entirely in the part of the company that faces markets. The steadiness lives in the part that faces regulators. To understand why PSEG ended up with that arrangement, the story has to go back to a time when the company owned trolleys.
 Subscribe on LinkedIn
II. Four Hundred Companies, One New Jersey Utility
At the turn of the twentieth century, New Jersey's cities ran on a patchwork. Newark, Jersey City, Paterson, Camden and Trenton were filling with factories, and each town had its own gas works, its own small electric company and its own street railway, many of them undercapitalized, overlapping and in various stages of financial distress. In 1903 a lawyer and former state attorney general named Thomas N. McCarter took charge of a new corporation designed to clean up that mess: the Public Service Corporation of New Jersey, assembled from more than 400 gas, electric and transportation companies.8
McCarter was not an engineer. He was a political and legal operator who understood that the value of a network depended on whether it could be run as one thing. A trolley line needed electricity; a power plant needed customers along a coordinated grid; a gas company needed scale to build mains under streets that would otherwise be dug up by three competing outfits. Consolidation was a practical answer to fragmentation. One operator could plan capacity, raise capital in bulk and negotiate with municipalities as a single party, which is roughly what New Jersey needed as it industrialized.
The bargain had a second side, and it is the side that matters most for investors today. A company that consolidates hundreds of local monopolies becomes a very large monopoly, and very large monopolies attract regulators. The modern utility compact, under which a company gets an exclusive service territory and the chance to earn a reasonable return in exchange for accepting public oversight of its prices and service, grew up around businesses exactly like McCarter's. Public Service was profitable enough to begin paying a dividend on its common stock in 1907, and the company has paid one every year since.8 That record, now well over a century long, is one of the few corporate facts in American business that has survived two world wars, the Depression, nuclear construction cycles and the energy crises of the 1970s.
The early company was much wider than the one investors own today. Public Service ran trolleys and later buses across New Jersey, a business that eventually became Public Service Coordinated Transport.8 Federal pressure on sprawling utility holding companies in the 1930s and 1940s forced a reckoning with structures like McCarter's, and in 1948 the original holding company was dissolved, leaving Public Service Electric and Gas as the operating heart of the enterprise.8 The transit business limped on for decades as a regulated, increasingly money-losing service until it was sold to the newly created state agency New Jersey Transit in 1980.8 In 1985 the company reorganized again, creating Public Service Enterprise Group as a holding company above PSE&G, the structure that still exists.8
There is a pattern hiding in this compressed history. The company's boundaries have moved again and again, outward to absorb whatever infrastructure New Jersey needed, then inward when regulators, economics or the state decided a piece belonged elsewhere. Trolleys were once as central to the company as electricity. They are gone. The nuclear plants, the fossil fleet and an offshore wind stake would later follow the same arc of expansion and retreat, which is why this early history is more than a period piece.
The other thread running from 1903 to now is the question McCarter's consolidation posed without answering. How much of a public-service company's value comes from its physical network, the poles, pipes and rights of way that would be absurdly expensive to duplicate, and how much from the bargain with the public and regulators that decides what that network is allowed to earn? The network is a fact. The bargain is renegotiated in every rate case, every merger review and every election. PSEG's history can be read as a long experiment in how far a company can stretch beyond that bargain before it snaps back.
The first big stretch came not from buying more companies but from building something enormous on a marshy spit of land on the Delaware River.
III. The Nuclear Bet That Made a Utility More Than a Utility
Artificial Island is not really an island. It is a strip of land in Lower Alloways Creek Township in Salem County, built up over decades from dredged river sediment, on the New Jersey bank of the Delaware where the river widens toward the bay. It is flat, remote and quiet, which is part of why it became home to one of the largest concentrations of nuclear generation on the East Coast. Two reactors at the Salem station and a third at Hope Creek sit side by side there, their cooling towers and domes visible for miles across the marsh.
The decision to build them belongs to an era when American utilities believed electricity demand would keep doubling every decade or so, and when nuclear power looked like the cheapest way to meet it. Salem's first unit entered service in the late 1970s, its second in the early 1980s, and Hope Creek followed in the mid-1980s.8 Those plants took years to license and build, cost far more than early estimates and were designed to run for decades. The nuclear industry's construction record from that period is a cautionary tale of overruns and cancellations, and Artificial Island was not immune: Hope Creek was originally planned as a two-unit station and only one unit was built. This was a long-duration commitment of a kind few companies make. Once the concrete was poured, the economics would be shaped for the next half century by things nobody in the 1970s could forecast: deregulation, natural gas prices, carbon policy and the rise of data centers.
The ownership today tells a more specific story than the generic "nuclear utility" label suggests. PSEG owns all of Hope Creek, a 1,174-megawatt boiling-water reactor, and 57% of the 2,287-megawatt Salem station, with Constellation Energy owning the remaining 43%.4 PSEG also owns half of the Peach Bottom station in Pennsylvania, which Constellation operates.4 Add the shares together and PSEG's net nuclear capacity comes to 3,758 megawatts.4
That partnership with Constellation is a useful reality check. Constellation, spun out of Exelon in 2022, runs by far the largest nuclear fleet in the United States, and it is PSEG's partner at two of its three sites. PSEG is not a national nuclear champion. Its edge is narrower and more local: it operates the Salem and Hope Creek reactors, it has decades of operating history at one site, and it holds a position in New Jersey's power supply that would be very hard to recreate. No one is going to license and build three new large reactors on the Delaware any time soon. That scarcity is the asset's real moat, and it is a geographic and regulatory one, not one of national scale.
For most of the 2000s, owning those plants looked like a gift. Nuclear plants have high fixed costs and very low running costs, so when wholesale power prices were high, as they were when natural gas was expensive, every megawatt-hour the plants produced dropped a large margin to the bottom line. Then the shale revolution arrived. Cheap gas pushed down wholesale power prices across the PJM market, the regional grid that covers New Jersey and twelve other states plus Washington, D.C. A plant whose costs are mostly fixed does not get cheaper to run when the market price of its output falls. By the late 2010s, PSEG was warning that its New Jersey nuclear units could be forced into retirement without support.
The intervention came on April 18, 2019. New Jersey's Board of Public Utilities voted to award Zero Emission Certificates to Salem 1, Salem 2 and Hope Creek, a program funded by a charge on New Jersey electricity customers and worth roughly $300 million a year to the plants.9 The state's logic was that the nuclear units supplied more than 90% of New Jersey's carbon-free electricity, and that losing them would push the state backward on its climate goals and toward more fossil generation.9 PSEG's response welcomed the decision as a recognition of the plants' environmental value.9
Here is the uncomfortable question the ZEC award raises. What would those plants have earned without it? The honest answer is that PSEG itself had argued they might not have earned enough to keep running. That does not make the plants bad assets. It makes them policy-dependent ones. A nuclear unit's physical virtues, steady output, no carbon emissions, a long operating license, are real. Whether those virtues translate into shareholder returns depends on whether markets or governments pay for them. In 2019 the market did not, so the state did. Later, the federal nuclear production tax credit created under the Inflation Reduction Act gave existing plants a federal floor on revenue, which the company says it counts alongside hedging as a way to mitigate its exposure to wholesale prices.4
The plants' operating record is the strongest affirmative evidence.6 Capacity factor is simply the share of a plant's theoretical maximum output that it actually delivers; anything above 90% is the mark of a well-run nuclear fleet, because it means the units are rarely down for unplanned repairs. Hedging is a different kind of protection. It locks in a price for future output, which removes near-term guesswork but also caps the upside if market prices jump.
Neither number proves the plants earn attractive returns. Reliable output tells an investor the machines work. Hedge coverage tells an investor the price for next year is mostly settled. Neither says whether that price, minus fuel, staff, security, maintenance and the cost of eventually decommissioning a reactor, leaves a margin that justifies the capital tied up in the plants. On that, Power & Other's third-quarter loss is a sobering counterweight, even after accounting for the market-driven items that flowed through it.1
So the verdict on the nuclear bet is mixed but clear. The fleet is a strategically important, hard-to-replace source of carbon-free baseload power, and PSEG runs it well. Its economics are not self-proving. They depend on state support, plant performance, hedge prices and future market rules, all of which can move. And that leaves a complication for the next chapter of this story. If nuclear generation was valuable enough for New Jersey to subsidize, why did PSEG later decide to sell almost all of its other power plants? The first attempt to answer that question came in the form of a merger that would have made generation much bigger, not smaller.
IV. The Merger That New Jersey Would Not Approve
In December 2004, PSEG agreed to be acquired by Exelon, the Chicago-based owner of Commonwealth Edison and PECO and, at the time, the largest nuclear operator in the country.10 The price was roughly $16 billion in stock, and the combination would have created a company with about $79 billion of assets and about $27 billion of annual revenue.11 Exelon's chief executive, John Rowe, was building a national champion. PSEG's chairman, E. James Ferland, was selling a New Jersey institution to a Midwestern acquirer at a moment when scale looked like destiny in the power business.10
The strategic logic was easy to draw on a whiteboard. PSE&G brought millions of regulated customers in one of the densest service territories in the country. Exelon brought the biggest nuclear fleet in America and a large wholesale power business. Put the two together and you would have a regulated customer base attached to a giant generation operation, with Exelon's nuclear expertise running PSEG's plants and the combined fleet spread across the PJM market. The deal was a bet that bigger generation portfolios would earn more in the deregulated markets that had grown up around the turn of the century.
Then the deal met the regulators, and it met them on two very different fronts. Federal reviewers were mostly worried about market power: whether one company owning that much generation in the same regional market could push up wholesale prices. The U.S. Department of Justice ultimately allowed the transaction to proceed only with required divestitures of generating plants, announcing in June 2006 that the companies would have to sell assets to preserve competition in the regional power market.12 Federal energy regulators had cleared major steps the year before. On paper, by the summer of 2006 the hardest antitrust questions had answers.
New Jersey asked different questions. The Board of Public Utilities wanted the companies to prove that the merger would bring positive benefits to the state's customers, not merely avoid harm. It wanted to know what would happen to rates, whether the combined company would wield market power in New Jersey's own supply auctions, how reliability would be protected and what would happen to local jobs and headquarters functions. The review became one of the largest in the agency's history, drawing more than 30 interveners, about 2,600 discovery requests and testimony from 56 witnesses.11 Consumer advocates, competitors, unions and municipalities all had a stake.
For more than 19 months the application sat before the Board.10 Settlement talks went back and forth over how much in rate concessions the companies would offer and how much generation would have to be sold to mitigate market power in New Jersey. Exelon eventually warned that if a settlement was rejected, it would likely withdraw the application and terminate the merger agreement.10 On September 14, 2006, it did exactly that. Every other required regulatory approval was in hand. New Jersey's was not, and the companies said the gaps separating their settlement positions from those of the state were insurmountable, citing rate concessions and market-power mitigation among the main differences.10 Rowe said publicly that Exelon was very disappointed; Ferland said PSEG remained committed to its New Jersey customers.10
It is tempting to turn this into a morality play. One version casts the state as the hero, protecting ratepayers from a distant acquirer. Another casts it as the villain, scaring off a deal that would have created value. The record supports neither clean story. What the record establishes is the scrutiny and the deal's end. There is no counterfactual showing what New Jersey customers would have paid under a combined Exelon-PSEG, or what PSEG shareholders would have earned. Exelon itself later bought Constellation Energy Group in 2012 and then split its generation business back out as a new Constellation in 2022, which suggests that even the acquirer's vision of a regulated-plus-merchant giant did not survive intact.
What the failed merger did reveal is the governing constraint of PSEG's business. The company's shareholders own the equity, but the state of New Jersey effectively holds a veto over what that equity can become. A federal antitrust clearance was not enough. A board vote was not enough. The state's own regulator, applying a test about benefits to New Jersey, could stop a $16 billion transaction cold. That is not a flaw unique to PSEG; most American utility mergers face some version of it. But the Exelon episode showed how high the bar can be when a deal touches the state's largest utility and its largest generators at the same time.
The episode also shifted PSEG's strategy, slowly at first. In 2007 Ralph Izzo, a former physicist who had risen through the company's ranks, took over as chief executive, and he led PSEG for the next fifteen years.13 If PSEG could not become bigger by combining with someone else, it would have to make its existing New Jersey franchise work. Over time that meant spending more on the regulated utility, where returns depended on regulators rather than markets, and asking harder questions about the generation business that had once seemed like the company's growth engine. The questions took more than a decade to answer. When the answer finally came, it involved a for-sale sign on almost every power plant PSEG owned that did not have a reactor in it.
V. The Conglomerate Goes on a Diet
On August 12, 2021, PSEG announced that it had agreed to sell its entire fossil-fuel generating fleet to ArcLight Capital Partners, a Boston-based private-equity firm specializing in energy infrastructure. The portfolio comprised about 6,750 megawatts of gas-fired and other fossil plants spread across the Northeast and Mid-Atlantic, and the price was about $1.92 billion.13 Izzo framed the sale as the culmination of a strategic review of PSEG's non-nuclear generation and as a step toward becoming a primarily regulated, lower-carbon company.13 For a business that had spent two decades describing itself as an integrated energy company, it was a declaration of a different identity.
To see why the decision mattered, rewind to the deregulation era. In the late 1990s New Jersey restructured its electricity market, giving customers the right to buy power from competing suppliers and pushing utilities to separate the business of delivering electricity from the business of making it. PSEG responded by moving its power plants out of the regulated utility and into a separate subsidiary, PSEG Power, that would sell its output into the competitive wholesale market.8 The regulated utility kept the wires and pipes. Power kept the plants and the market risk.
The two halves live by entirely different rules, and the difference is worth dwelling on because it is the hinge of this whole story. A regulated distribution utility earns money roughly the way a landlord with a government-approved rent schedule does. It builds an asset, regulators decide whether the cost was prudent, and if so the asset enters the "rate base," the pool of investment on which the utility is allowed to earn a return set in a rate case. Revenue then rises to cover depreciation, operating costs and that allowed return. The utility's risk is mostly regulatory: will it be allowed to recover what it spent, and how fast?
A merchant generator lives more like a farmer selling crops at the market. It owns a plant with heavy fixed costs and sells whatever it produces at whatever the wholesale price happens to be, plus whatever the regional grid pays for promising to be available in the future, a payment known as capacity. When natural gas is expensive and power prices high, a well-located plant can print money. When gas is cheap, or when a capacity auction clears low, the same plant can lose it. Hedging smooths the ride for a year or two, but over a decade the generator's returns move with commodity prices and market rules that no single company controls.
For years PSEG argued that owning both kinds of business was an advantage: the utility's steadiness would support the balance sheet, and the generation arm would add higher returns. The shale-gas decade tested that argument hard. Cheap gas compressed power prices across PJM, and a fleet built or bought in a higher-price world earned less than its owners had once expected. That is the context in which the ArcLight sale has to be judged.
The headline number to keep in mind is not the sale price. It is the write-down. In connection with the sale PSEG recorded a pretax impairment of roughly $2.7 billion, reflecting the gap between what the fossil assets were carried at on the balance sheet and what a buyer was willing to pay.14 That charge is why 2021 looks the way it does in PSEG's financial history: an operating loss of about $856 million and a net loss of about $648 million, or $1.28 a share, in a year when the underlying utility kept doing what utilities do.14 Anyone measuring PSEG's growth from 2021 is measuring from a hole.
It is worth being precise about what the $2.7 billion represents. An impairment is not cash leaving the building in 2021. The cash went out years earlier, when the plants were built, bought or upgraded. The impairment is the accounting moment when the company admits those past investments were worth materially less than their book value. It is also not a full measure of lifetime returns, because the plants generated earnings and cash during the years PSEG owned them. But it is material evidence. A company with a clean record of disciplined capital allocation does not usually sell a major business for about $1.9 billion while recognizing a $2.7 billion loss on it. The fossil sale clarified PSEG's strategy and reduced its exposure to fossil generation. It also crystallized the cost of having owned those assets through a volatile merchant-power era.
Was it a bad price? There is no clean benchmark that answers that. No directly comparable portfolio sale with a published multiple exists to set beside the ArcLight deal, so it would be unsupported to declare that ArcLight got a bargain or that PSEG sold at a discount to peers. The supported test is the one the company's own books provide: the sale price was well below carrying value. The market, through ArcLight, put a lower value on those plants than PSEG's accounts had.
The strategic consequence was larger than the dollars. Once the sale closed in early 2022, PSEG's generation portfolio shrank to the nuclear fleet and a handful of smaller holdings.14 That narrower base strengthened the case that regulated growth, not merchant scale, would lead the next investment cycle. It also left the nuclear plants more exposed within the remaining company. When a fleet that once included gas, coal and nuclear becomes a fleet of three nuclear sites, every swing in nuclear economics shows up in Power & Other undiluted.
The offshore option that PSEG let go
A smaller episode around the same time revealed the same instinct from a different angle. PSEG had bought a 25% stake in Ocean Wind 1, a large offshore wind project planned off the southern New Jersey coast and led by the Danish developer Ørsted. Offshore wind was supposed to be the next great opportunity for East Coast utilities with clean-energy ambitions. In May 2023, PSEG completed the sale of its stake back to Ørsted, for proceeds that approximated its carrying value and that, the company said, allowed it to recover its cumulative outlays.15 Months later, Ørsted cancelled the project altogether as rising interest rates and supply-chain costs wrecked the economics of the first wave of U.S. offshore wind.
The exit limited PSEG's direct exposure, and getting money back on a project that subsequently collapsed was a better outcome than many of its peers achieved in offshore wind. But the episode is also a reminder that ambition and durable earnings are different things. Ocean Wind had been a headline in PSEG's clean-energy story. It never became a source of profit. The company's record of converting optional bets into recurring earnings, across fossil generation, offshore wind and the earlier international ventures of the deregulation era, is thin. That record should temper how investors treat whatever the next optional bet turns out to be.
By 2023, the man leading the newly focused company was Ralph LaRossa, who held the titles of chair, president and chief executive.16 LaRossa is a PSEG lifer who spent much of his career running the regulated utility before taking the top job, and his background fits the company the portfolio decisions created: a utility executive leading a utility.16 It is important to be fair about timing. The fossil sale and the Ocean Wind exit were chosen under Izzo's leadership. LaRossa inherited a narrower company; he did not design its narrowing. So the right test of his credibility is not whether he deserves credit for earlier portfolio choices. It is whether he delivers the investment plan, the earnings guidance and the funding commitments he has made himself. That plan is where the story turns next.
VI. The Rate Base Becomes the Growth Engine
Picture a rate case in Trenton. In a hearing room at the Board of Public Utilities, PSE&G's lawyers and engineers lay out what they have spent and what they want to spend: substations that need replacing, cast-iron gas mains from the early twentieth century that need digging up, transmission lines that need upgrading to carry more power, storm-hardening work after years of hurricanes and nor'easters. Across the room, the state's ratepayer advocate questions every assumption. The company wants a return on equity at one number; the advocate argues for a lower one. Commissioners weigh it all against the bills that will land in millions of mailboxes. The outcome of that process, repeated in different forms across distribution cases, infrastructure programs and federal transmission formulas, is PSEG's growth engine.
The company began 2026 with that engine running at higher revolutions than in most of its recent history. The $24 billion to $28 billion five-year capital plan, more than nine-tenths regulated, is designed to grow the regulated rate base by 6.0% to 7.5% a year from the end of 2025 to the end of 2030.1 That rate base was already about $36 billion at the end of 2025, up from about $34 billion a year earlier.4 In 2025 alone, PSE&G spent about $2.73 billion of capital, while Power & Other spent about $236 million excluding nuclear fuel; PSE&G also spent about $552 million on energy-efficiency programs that run through operating cash flow rather than capital.4 The proportions tell the strategic story. For every dollar PSEG puts into its remaining generation business, it puts more than ten into the regulated network.
There is a real physical need behind the plan, and it would be a mistake to treat it as mere empire-building. New Jersey's grid is old, dense and heavily loaded. Gas mains installed generations ago leak and need replacement. Electrification of heating and transport, and the arrival of power-hungry data centers in the PJM region, are changing where and how much electricity flows. Transmission lines that were adequate when the state's industrial load was falling may not be adequate as new load arrives. The investment plan is a response to these pressures, and regulators have approved large chunks of it in the past.
PSE&G earns distribution revenue through tariffs approved by the state Board and transmission revenue through an annual formula rate approved by the Federal Energy Regulatory Commission.4 The formula rate updates each year to reflect the actual cost of service, so transmission investment begins earning relatively quickly. Distribution is slower and more political, because it depends on base rate cases and special infrastructure programs that the state approves in batches.
One feature of PSE&G's design deserves particular attention, because it changes the risk profile of the business. More than 90% of the margin PSE&G earns on electric and gas distribution varies with the number of customers rather than the volume of energy they use.4 In plain terms, a mild winter or a cool summer, or customers installing rooftop solar and more efficient appliances, does relatively little to the utility's distribution earnings. That is a substantial cushion against weather and against the slow erosion of sales that has troubled utilities in other states. It does not remove regulatory risk or affordability risk. It moves the risk out of the weather forecast and into the hearing room.
In the third quarter of 2026, PSE&G remained the backbone of the group's results.1 But the quarter also showed the friction built into the model. Higher depreciation and interest costs on newly built assets arrived before the corresponding costs were fully reflected in rates, and those pressures, together with tax timing, offset part of the earnings gains that investment produced.2 This is called regulatory lag, and it is the hidden tax on a utility that is building fast. The company spends first, starts depreciating the asset and paying interest on the debt that financed it, and only later gets the higher revenue that covers those costs. The faster the build, the larger the lag can become, unless regulators allow quicker recovery.
The growth record needs a careful reading, because it can easily be made to say more than it does. Over ten years, PSEG's revenue grew only about 1.6% a year; over five years, about 4.8%; over the latest three, about 7.5%.4 Net profit grew about 2.3% a year over ten years and 2.1% over five, but about 27% a year over three.4 That last number looks spectacular until one remembers where it starts. 2022 profits were depressed in the aftermath of the fossil sale and other charges, so a three-year growth rate measured from that base is partly a recovery rather than an acceleration. The honest conclusion is that recent growth is above PSEG's long-run base rate, driven by regulated investment and an earnings base climbing out of a hole, but that the 6.0% to 7.5% rate-base target has to show up as realized regulated earnings growth, year after year, before anyone can call it a durable step-change.
Where affordability becomes the constraint
The friction that matters most is not accounting lag. It is the customer. In 2025, New Jersey electricity bills rose sharply as higher wholesale capacity costs from the PJM market flowed through to customers, and utility costs became a central issue in that year's governor's race.17 On January 20, 2026, her first day in office, Governor Mikie Sherrill declared a state of emergency on utility costs and directed the Board of Public Utilities to use bill credits to offset coming electricity supply increases and to consider pausing or modifying rate proceedings where the law allowed.17 The tension was obvious even before she took office: her plan to bring bills down sat beside a utility that wanted to spend tens of billions of dollars, much of it eventually recovered from the same customers.18
This is the place where the utility compact, explained once in its abstract form, becomes concrete. PSE&G's investment plan can only become earnings if the state agrees the spending is prudent and lets it into rates. The state can agree and still stretch the timing, trim the allowed return or demand offsetting concessions. None of that requires a hostile regulator. It only requires a regulator responding to voters who have just watched their bills rise. The supply portion of the bill, the cost of the electricity itself, is largely passed through and is not PSE&G's profit. But customers do not read their bills by line item, and political pressure does not distinguish between the parts a utility earns on and the parts it merely collects.
Cost allocation is the other quiet test. PSE&G bought and paid for about $1.65 billion of services and supply from affiliates in 2025, roughly $1.1 billion from PSEG Power and about $545 million in administrative billings from PSEG Services.4 Power's gas supply and nuclear ZEC sales to the utility were made at rates prescribed by the Board, and PSEG says technical services are generally billed at cost under federal and state affiliate rules.4 Those transactions disappear in PSEG's consolidated accounts, because the group is selling to itself. But they do not disappear for PSE&G's customers. If a dollar of shared corporate cost lands in the regulated utility rather than the unregulated side, customers pay for it. That is why the Board's affiliate and management audit of PSE&G matters as a governance test rather than a compliance footnote.19 At the end of 2025, the Board was still considering the audit's recommendations.4 The outcome will say something about whether the line between the regulated and unregulated businesses has been drawn the way regulators want.
PSE&G is not alone in New Jersey. Exelon's Atlantic City Electric serves the southern part of the state, and FirstEnergy's Jersey Central Power & Light serves much of the center and north. All three face the same Board, the same governor and the same customer anger about bills. What separates PSE&G is scale: it is by far the largest of the state's utilities by customer count, and its rate base dwarfs what smaller utilities can deploy. There is no clean same-date comparison of market share or valuation among them that settles who is best positioned, but the shared regulator means that a hard political turn against utility spending would hit PSE&G hardest in absolute dollars, simply because it has the most to spend.
Three operating measures will settle whether this engine is real. The first is annual rate-base growth against the 6.0% to 7.5% guidance; the 2025 reading of roughly 6% sits at the lower end of that range. The second is PSE&G's earnings growth once lagging costs enter rates, which shows whether investment becomes profit or merely becomes assets. The third is the customer outcome: reliability, affordability and the political temperature around both. The live wildcard is large-load demand. Data centers and other big users could justify more grid investment, and management has described the opportunity in general terms, but that pipeline remains unquantified.7 Until those customers sign, they are a reason to build, not a source of earnings.
Which brings the story back to the other half of PSEG, the one where the plants run beautifully and the earnings do not.
VII. One Nuclear Fleet, Two Very Different Earnings Stories
In the third quarter of 2026, the reactors on Artificial Island and the share of Peach Bottom that PSEG owns did almost everything asked of them. Their 95.5% capacity factor and hedge coverage remained high.6 Summer is when the PJM grid is most stressed and power is most valuable, and PSEG's units were there for nearly every hour of it. Yet the segment that owns those plants reported a GAAP net loss of $130 million for the quarter, against net income of $107 million a year earlier.1 On a non-GAAP basis, the same segment earned $68 million.1
How can a fleet run almost flawlessly and still report a loss? The first part of the answer is that Power & Other is not just nuclear. It holds the nuclear business, PSEG Long Island, which operates the electric grid of the Long Island Power Authority under an operations-services agreement, Energy Holdings, the Services company that provides shared corporate functions, and the parent company's own costs, including interest on holding-company debt.2 Intercompany transactions are eliminated when the whole group is consolidated.2 So the segment result is a blend of a generation business, a services contract and corporate overhead.
The second and larger part of the answer is accounting volatility tied to markets. PSEG must hold a nuclear decommissioning trust, a fund set aside to pay for dismantling the reactors when they are eventually retired. At the end of 2025 it held about $1.5 billion of equities and $1.4 billion of fixed-income securities.4 As explained earlier, market swings in the trust and energy hedges flow through GAAP earnings but are excluded from operating earnings. That is why the group's GAAP net income fell almost 40% in the quarter while operating earnings per share inched up.1 The GAAP decline is a poor stand-alone read on operating momentum. But the operating number is also management's construction, and investors should notice that the excluded items are not trivial and do not net to zero over every period.
It is equally important not to over-read the good numbers. Those metrics show availability and near-term price protection, not a superior cost position or permanently attractive margins.6 The non-GAAP $68 million in a strong operating quarter is a reminder of how modest the generation contribution has become relative to the utility.
That returns the story to the question first raised by the ZEC award. How much of the nuclear moat is the physical asset, and how much is policy support? The physical part is real: these are large, licensed, operating reactors at sites where new nuclear construction is effectively impossible in any useful time frame, and they produce carbon-free power that states and large buyers increasingly value. The policy part is also real, and it has done heavy lifting. As discussed, New Jersey's ZECs and the federal nuclear production tax credit have supported the plants' economics.94 Both could change. Neither is a law of physics.
There is a seductive version of this story in which data centers turn PSEG's nuclear plants into gold mines. Elsewhere in the country, technology companies have signed long-term contracts to buy nuclear output at premium prices, and analysts have speculated about similar deals in New Jersey. PSEG has discussed the large-load opportunity, but no quantified contract pipeline has been disclosed.7 Data centers are strategically relevant to the core grid business, because they require new connections and transmission, and they might one day matter to the nuclear plants. Today they are not an earnings segment, and treating them as one would be the same mistake investors made with offshore wind: confusing a headline with a cash flow.
The case for the nuclear fleet as a source of upside rests on realized energy and capacity prices, the hedges that lock those prices in, policy credits and the volatile accounting items that sit around them. When capacity prices in PJM rose sharply in recent auctions, that was good news for generators and bad news for customers, including PSE&G's customers. PSEG owns both sides of that trade. Higher capacity prices help the nuclear plants and inflame the affordability politics that constrain the utility. A company that sold its fossil plants partly to escape merchant-power volatility still carries a concentrated dose of it, and it now carries that volatility right next to its most politically exposed business.
The balance is unresolved and should be stated plainly. A reliable plant can still be a volatile earnings asset. PSEG's nuclear fleet is the first and is often the second. And whether the company can afford to keep building the utility while that volatility sits in the other half depends on a set of numbers that are less glamorous than reactors: the ones in the cash-flow statement.
VIII. The Dividend Is Not Paid by Free Cash Flow
There is a comforting way to read PSEG's cash-flow history, and it begins with a striking ratio. Over the twelve years from 2014 through 2025, the company reported about $17.5 billion of cumulative net profit and generated about $34.6 billion of operating cash flow, nearly twice its accounting earnings.4 For many businesses that kind of cash conversion is a sign of quality: profits that turn into cash, and then some.
For a utility, the reason is mostly mechanical, and understanding it removes most of the comfort. Utilities carry enormous fixed assets, and the depreciation charged against those assets reduces profit without consuming cash in the year it is recorded. In 2025 alone PSEG added back about $1.26 billion of depreciation and amortization, about $202 million of nuclear-fuel amortization, about $100 million of deferred taxes and investment tax credits and about $76 million of non-cash employee-benefit costs to reconcile net income to operating cash.4 The cash these add-backs help explain is real, but it is not spare cash. The depreciation exists because the assets wear out and must be replaced, and the replacement is precisely what the capital plan pays for.
So follow the cash out. Over the same twelve years, capital expenditure absorbed all of the operating cash flow and more, leaving cumulative free cash flow after capital spending of about negative $4.8 billion.4 On top of that, PSEG paid about $11.8 billion in dividends.4 Add the two together and the company needed something on the order of $16 to $17 billion from outside its operating cash flow over the period to fund what it spent and what it paid out. The balance sheet shows where most of it came from. Borrowings rose from about $9.1 billion at the end of 2014 to about $24.4 billion at the end of 2025.4 Debt to equity roughly doubled over the decade, from about 0.75 to about 1.44.4 Net property, plant and equipment rose from about $23.6 billion to about $42.2 billion over the same span, so the borrowing built real assets.4
That is the clearest description of PSEG's financing model: strong operating cash conversion, negative free cash flow after investment, a growing dividend and rising debt bridging the gap. It is not a scandal. It is how a growing regulated utility usually works, because the utility compact rewards investment by adding it to the rate base, and investment in excess of depreciation must be financed. But it does mean the dividend is not paid by free cash flow in any meaningful sense. It is paid out of operating cash flow while the capital program is financed in large part by debt. Ask the question the other way round and the answer is identical: if PSEG stopped borrowing, it would have to choose between the capital plan and the dividend.
The dividend itself has an unusual record of resilience. That century-long streak continued, and the annual cash payout rose steadily, from about $748 million in 2014 to about $1.3 billion in 2025.4 In 2025 dividends amounted to about 60% of net profit, and over the prior twelve years that ratio ranged from about 44% in a strong year to about 105% in 2022, when profit was depressed.4 A payout above 100% in a bad year is not a crisis for a utility with access to capital markets, but it is a reminder that the dividend's stability has been underwritten by the company's ability to borrow, not just by its earnings. History is a reason to expect continuity. It is not a guarantee.
What keeps the borrowing affordable is credit quality. As of the third-quarter 2026 filing, PSEG's senior notes were rated Baa2 by Moody's and BBB by S&P, both with stable outlooks, while PSE&G's senior secured debt was rated higher, at A1 and A.2 The gap between the parent and the utility tells its own story: lenders view the regulated subsidiary, with its secured claim on regulated assets, as meaningfully safer than the holding company that also owns nuclear plants and carries its own debt. PSEG reported about $2.8 billion of available liquidity at the end of 2025, against cash of only about $132 million.20 S&P's 2024 assessment described the business risk as excellent and the competitive position as strong, but classified cash flow and leverage as significant, an assessment consistent with a good franchise carrying a heavy financing load.21
The funding promise on trial
Management's central financial claim is that this investment plan can be funded without issuing new equity and without selling assets.1 PSEG has largely avoided issuing common equity to fund growth in recent years; the only share repurchases in late 2025, 850,000 shares at an average of about $80, were to settle employee compensation and share-purchase obligations rather than to return capital.4 A no-equity plan protects existing shareholders from dilution, and investors in utilities prize it for that reason.
But the promise has to be tested against arithmetic, not taken on faith. If the past twelve years are a guide, operating cash flow will not cover both capital spending and dividends; the plan simply spends more per year than the past decade did. That leaves three levers. Debt can keep rising, which puts pressure on the ratings that keep borrowing costs low. Operating cash flow can rise faster, which requires regulators to put new investment into rates quickly. Or the plan can bend: smaller, slower, or partly funded with equity after all. The most useful thing an investor can watch is the combination of annual free cash flow after capital expenditure and dividends, year-end debt and the rating outlook. If debt rises faster than the rate base and the outlook turns negative, the no-equity promise is under strain.
The skeptical investor's question writes itself. If regulated returns are as dependable as the bull case says, when do earnings and operating cash catch up with the growing asset base and the growing dividend? Return on equity was about 12.4% in 2025, respectable for a utility, while return on invested capital was closer to 6.4%, which is roughly what one expects from a business funded with a lot of relatively cheap debt.4 A utility can compound for decades on that formula, provided the cost of capital stays below the allowed return and regulators keep the gap open. The moment either of those conditions slips, the same leverage that amplifies returns starts amplifying the shortfall. Which is why the lessons of this story are less about clever strategy than about the hard limits on what a utility is allowed to be.
IX. Playbook: Business & Investing Lessons
Set two moments side by side. In August 2021, PSEG sold its fossil fleet to ArcLight at a loss.1314 Five years later, it planned $24 billion to $28 billion of investment over five years, almost all in regulated wires, pipes and transmission.1 One decision shrank the company. The next concentrated it. Between them sits most of what PSEG has to teach.
The first lesson is that a franchise can be durable without every asset in it being a good investment. PSEG's century-long dividend record reflects the durability of its New Jersey franchise. The fossil fleet did not, at least not as a source of shareholder value: the company owned it through the merchant-power era and then sold it for less than it was carried at. The wider lesson for founders and investors is that portfolio size and shareholder value are not the same thing, and a durable core can disguise a weak periphery for a long time. A century of dividends is a record of the franchise, not a certificate for every decision management made inside it.
The second lesson comes from Artificial Island. Policy can preserve an asset, but it does not erase its economics. The ZEC award and federal production tax credit helped support the fleet.94 Those interventions were rational public policy; the plants supply carbon-free power that would be very difficult to replace. But an asset whose survival required state support is an asset whose returns are, in part, a political decision. Investors who price PSEG's nuclear fleet as a pure physical moat are pricing the reactors and ignoring the legislature.
The third lesson is the utility compact itself, stated as bluntly as possible: build first, recover later. That sequence is the source of the business's great strength, a large, visible pipeline of investment opportunities with a regulated path to returns, and its main exposure: the gap in time and politics between spending the money and being allowed to earn on it. Governor Sherrill's emergency order on her first day in office did not change the law, but it changed the weather in which every future rate decision will be made.17 The compact is not a contract. It is a relationship, and relationships respond to public mood.
The competitive forces around PSEG are worth applying once, because they clarify where the real power sits. Individual customers have almost no bargaining power: there are millions of them, they are bound by tariffs and they cannot choose another set of wires to their homes. The power that buyers lack individually, they exercise collectively through regulators and elected officials, who have far more leverage over allowed returns than any customer has over a bill. Entry barriers are extraordinarily high, because a duplicate distribution network in northern New Jersey would be both absurdly expensive and illegal, and new nuclear generation faces technical and licensing hurdles that take a decade or more to clear. Substitution is the subtle threat: rooftop solar, batteries and efficiency can reduce how much grid electricity customers buy, though PSE&G's distribution margin is substantially decoupled from volume. Suppliers matter mainly in nuclear fuel, where PSEG relies on third parties for substantially all of its needs.4 The moat, then, is local infrastructure and regulation. It is not a demonstrated low-cost advantage, and the company's strongest claim is focus on a large, hard-to-replicate network rather than a record of consistently successful diversification.
The company's clean-energy credentials need to be kept in proportion. PSEG no longer owns coal or gas generation, and its remaining fleet is carbon-free. That describes the portfolio. It does not, by itself, establish superior returns or better customer outcomes. The fossil exit happened partly because the plants were not earning their keep, and the offshore wind exit happened because the economics were turning. Climate-friendly outcomes and shareholder-friendly outcomes can coincide, but they coincided here partly by subtraction.
Management incentives are the last lens. LaRossa's reported total compensation was about $13.87 million in 2025, of which about $9.0 million was stock awards and about $2.56 million incentive pay.16 It rose from about $11.78 million in 2023, through a period when reported net profit fell from about $2.6 billion to about $1.8 billion before recovering to about $2.1 billion.164 Shareholders approved the pay package with 93.8% support, and directors and executive officers together owned less than 1% of the shares.16 The largest holders, BlackRock at about 9.3% and State Street at about 6.1%, are index-scale institutions that reported holding their shares in the ordinary course rather than to influence control.16 There is no controlling owner and no activist on the register. That combination tells investors the incentive design is mainstream and broadly accepted. It does not prove guidance discipline, and the better test is simply whether the 2026 to 2030 rate-base and funding commitments are delivered.
Which points to the final lesson, and the one most specific to PSEG. The most relevant stress test for this company is not an activist campaign. It is a regulator and a customer asking the same question at the same time: are these investments earning approved returns while delivering better reliability, without an affordability backlash? A company that once tried to become a national power giant now succeeds or fails in Trenton.
X. Analysis & Bear vs. Bull Case
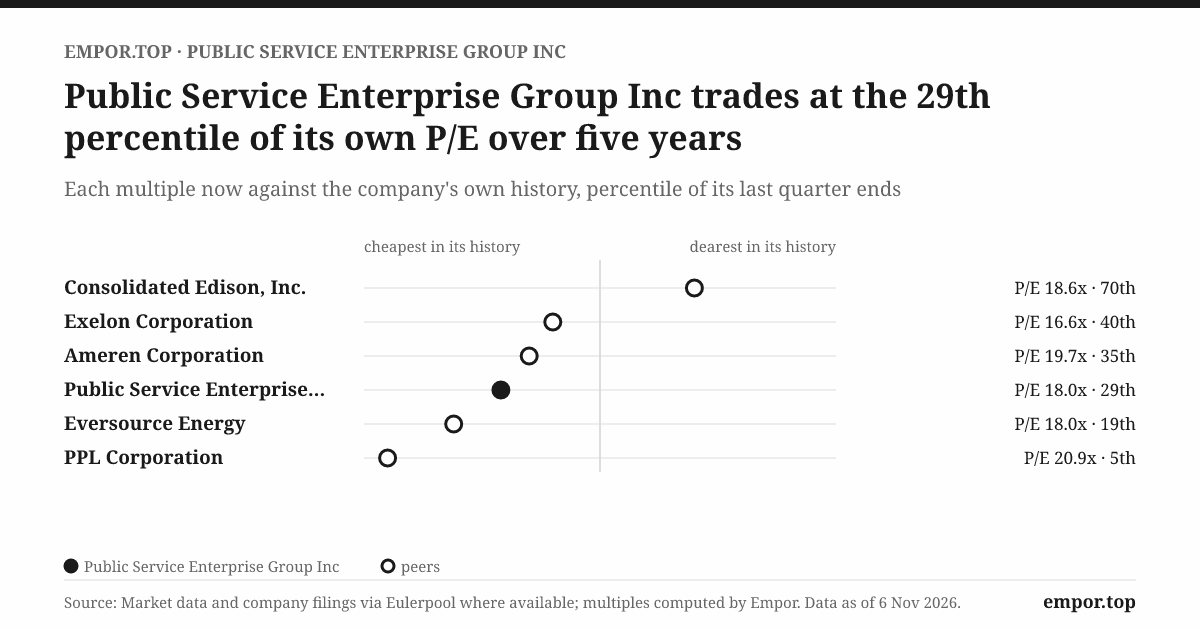
On November 5, 2026, PSEG's shares traded at about 18.2 times trailing earnings, below their own five-year median of about 20.0 times.5 The price was about 2.1 times book value and about 14.8 times enterprise value to EBITDA, with a dividend yield of about 3.6% and a free-cash-flow yield of about 5.4% on the trailing figures.5 Using the midpoint of management's 2026 operating-earnings guidance of $4.28 to $4.40 a share, the stock sat at roughly 17 times this year's expected operating earnings.1 The market, in other words, is paying somewhat less for PSEG's earnings than it has on average over the past five years, just as the company launches its largest investment program. The question is whether that discount reflects an opportunity the market is overlooking or risks it is pricing correctly. The evidence does not establish a discount against peers, because there is no clean same-date peer comparison to anchor it, and a lower multiple than the company's own history is not by itself proof of cheapness.
The bull case starts with the regulated growth mechanism described earlier: tariffs and a federal formula rate provide defined routes to cost recovery for prudent investment, while the nuclear fleet adds dependable, carbon-free capacity.4 In Helmer's language, the utility holds something close to a cornered resource, an exclusive territorial franchise backed by law and reinforced by scale economies in network density that no entrant could match. The nuclear plants add a second cornered resource of a different kind: licensed reactors on sites that cannot realistically be replicated. Switching costs are effectively absolute for the wires business, because a customer cannot move to another distribution network without moving house.
The bear case begins exactly where the bull case is strongest, with cost recovery. The company's own auditor, Deloitte, identified accounting for rate regulation as a critical audit matter, because judging whether deferred costs will eventually be recovered through future rates requires significant judgment.4 That is the accounting expression of the build-first, recover-later model: some of what sits on PSEG's balance sheet as an asset is a bet on future regulatory decisions. The Board's affiliate and management audit remains a cost-allocation test.19 At the federal level, the Roseland–Pleasant Valley transmission project has become a live test. PSE&G paid a $6.6 million civil penalty in 2024 to resolve a FERC enforcement investigation of the project, a January 2026 complaint challenged recovery of the project's costs, and FERC subsequently set the matter for a hearing process.422 The dollar amounts are bounded, but the principle at stake, whether a formula rate guarantees recovery or merely provides a path to it, goes to the heart of the bull thesis.
On earnings, the bull points to the third quarter's slightly higher operating earnings and the reaffirmed full-year range.1 The bear points to the same quarter's sharply lower GAAP net income, Power & Other's loss and a debt load already high relative to equity.14 Both are reading real numbers. The right way to reconcile them is to separate the market-driven GAAP noise, mostly decommissioning-trust and hedge marks, from underlying performance, while refusing to pretend the noise is irrelevant. It shows that one part of the company remains genuinely exposed to markets, and that exposure can surprise in either direction.
On funding, the bull notes that management says no new equity is planned to fund the capital program and that investment-grade ratings provide reliable access to debt markets.12 The bear notes that cumulative capital spending and dividends exceeded operating cash flow by a wide margin over the past twelve years, and that debt grew much faster than equity.4 A no-equity plan depends on cash generation, timely recovery and financing conditions all cooperating at once. Rising interest rates would raise the cost of every dollar borrowed while regulators decide whether to raise allowed returns to match, a timing gap that has hurt utilities before.
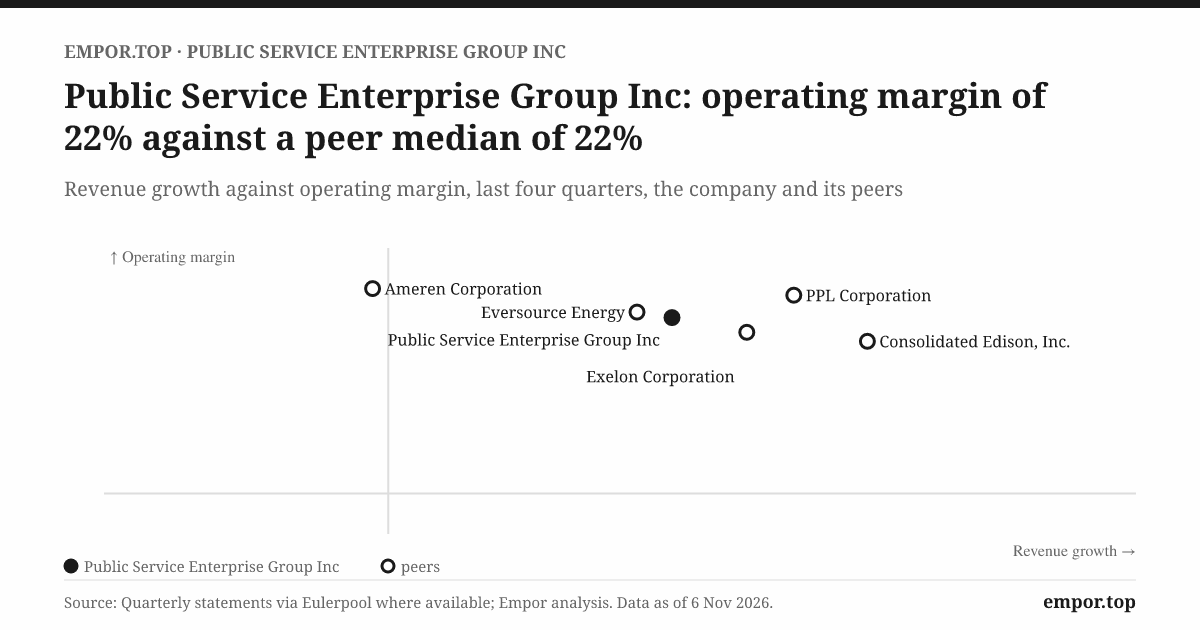
The competitive frame is clear: customers gain bargaining power collectively through the state, while PSEG lacks control over price. Helmer's framework points to the same constraint from another direction: PSEG has cornered resources and scale, but the power to set prices sits with the Board of Public Utilities and FERC. Brand power is weak, as it is for most utilities, and the recent bill increases have probably weakened it further. Process power exists in the nuclear operations, where consistently high capacity factors reflect accumulated know-how, but it shows up as reliability rather than as a price premium. Compared with Exelon's Atlantic City Electric and FirstEnergy's Jersey Central Power & Light, PSE&G has larger local scale and a larger investment program, but it faces the same regulator and therefore the same political ceiling. The moat is real; the toll on the bridge is set by someone else.
The three numbers to watch remain regulated rate-base growth, PSE&G earnings and leverage.4124 If the first two rise in step and the third stabilizes, the bull case is working. If the rate base grows while utility earnings lag and leverage keeps climbing, the plan is becoming a larger balance sheet rather than a better business.
Weighing it all, the bull case has a concrete growth mechanism and a durable franchise, which is more than many growth stories can claim. The bear case is not generic utility caution. Large capital needs, lagging cost recovery, debt dependence and unusually intense political oversight in New Jersey can each dilute the returns the plan is supposed to produce, and they can do it together. The decisive checkpoints are realized rate-base growth, PSE&G earnings and cost recovery, the debt and rating trend, and signed large-load agreements with clear cost-allocation terms. None of those will be settled in a single quarter.
XI. Epilogue
Tonight, PSEG stands at the beginning of the most ambitious investment cycle in its modern history and near the end of a year that has tested its relationship with its home state. The company has reaffirmed its 2026 operating-earnings range and outlined its five-year capital plan.1 The nuclear fleet is running well.6 The governor who campaigned on utility bills is in her first year in office.17 Each of those facts is a starting position, not a result.
The first moment that will matter is the full-year report early in 2027. It will show whether PSEG landed inside its guidance range, how much capital it actually deployed in 2026, and how fast the rate base grew. More important, it will show the gap between capital spent and capital reflected in rates. A widening gap means regulatory lag is eating the plan's returns; a narrowing one means the compact is working at the speed management needs.
The second set of moments will come from regulators. FERC's hearing process on Roseland–Pleasant Valley cost recovery will produce a decision at some point, and whatever it decides will be read as a signal about how secure formula-rate recovery really is.22 The Board's handling of its affiliate-audit recommendations will tell investors whether the line between PSEG's regulated and unregulated businesses satisfies the state.19 Neither outcome is likely to threaten the company's solvency. Both will shape how much confidence the market places in the word "recovery."
The third moment is whether a contract is signed. If data centers and other large users in PSE&G's territory sign agreements, the important detail will not be the size of the announcement. It will be who pays for the substations, lines and upgrades needed to connect them. If large customers bear their own incremental infrastructure costs, new load can grow the rate base without loading the burden onto households, which is the combination that makes the plan politically durable. If the costs are socialized, the same investment that grows PSEG's earnings will deepen the affordability fight.
The fourth moment is the nuclear segment's realized earnings. Investors should watch Power & Other's results alongside capacity factor, hedge coverage and the value of federal production tax credits, because the fleet's contribution depends on all of them moving together. A strong operating year with weak realized earnings would confirm that the plants are reliable but not especially profitable; a year in which higher contracted prices finally flow through would show the upside the bulls describe.
And the last test runs through every quarter: debt, free cash flow after capital spending and dividends, and the credit outlook. Management has promised to fund the plan without new equity or asset sales.1 If debt rises roughly in step with the rate base and ratings hold, the promise is credible. If leverage drifts higher while ratings outlooks turn, the plan will have to change shape, and the first thing to give is rarely the thing management announced most loudly.
The tension that remains is the one that has followed PSEG since McCarter. The company can build almost anything New Jersey needs. Whether it is allowed to earn a good return on what it builds is decided somewhere else.
XII. Outro
Somewhere in Newark or Paterson or Camden tonight, there is a utility pole that stands roughly where a pole stood in 1903, when Thomas McCarter stitched more than 400 companies into one.8 The wires on it are newer. The transformer is newer. The meter at the end of the line may be digital. But the job is the same one McCarter took on: keep the energy moving through a crowded state, and convince the public that the next piece of infrastructure is worth paying for.
PSEG spent much of the past half century trying to be more than that job. It built reactors, assembled a merchant fleet, tried to merge into a national giant and bought into offshore wind. It kept the reactors. It let the rest go. What remains is a company whose capital plan is more than nine-tenths regulated, rebuilding a century-old network for an electrifying future.1 Its success will be measured less by how much it announces than by what customers, regulators and cash flows allow it to earn. The utility that sold its power plants has bet everything on the oldest thing it owns.
References
-
PSEG Announces Third Quarter 2026 Results — Public Service Enterprise Group, 2026-11-02 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q3 2026 Form 10-Q — Public Service Enterprise Group, 2026-11-02 ↩↩↩↩↩↩↩↩
-
2025 Form 10-K — Public Service Enterprise Group, 2026-02-26 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Q3 2026 Earnings Presentation — Public Service Enterprise Group, 2026-11-02 ↩↩↩↩↩
-
Q3 2026 Earnings Call Transcript — Stock Analysis, 2026-11-02 ↩↩↩
-
Company Information and History — Public Service Enterprise Group ↩↩↩↩↩↩↩↩↩
-
PSEG Responds to BPU Decision to Award Zero Emission Certificates — Public Service Enterprise Group, 2019-04-18 ↩↩↩↩↩
-
Exelon and PSEG Announce Termination of Merger Agreement, Form 8-K Exhibit 99.1 — Exelon Corporation, 2006-09-14 ↩↩↩↩↩↩
-
2006 Annual Report — New Jersey Board of Public Utilities ↩↩
-
Justice Department Requires Divestitures in the Exelon–PSEG Merger — U.S. Department of Justice, 2006-06-22 ↩
-
PSEG Agrees to Sell Fossil Generating Portfolio to ArcLight — Public Service Enterprise Group, 2021-08-12 ↩↩↩↩
-
PSEG Completes Sale of Its 25% Equity Interest in Ocean Wind 1 — Public Service Enterprise Group, 2023-05-31 ↩
-
2026 Proxy Statement — Public Service Enterprise Group, 2026-03-12 ↩↩↩↩↩↩
-
Gov. Sherrill Orders Credits to Offset Electricity Hikes Coming in June — New Jersey Monitor, 2026-01-20 ↩↩↩↩
-
New Jersey's Next Governor Wants to Freeze Rates; Its Largest Power Company Wants to Spend — E&E News ↩
-
Public Service Electric and Gas Company Audit: Final Audit Report — New Jersey Board of Public Utilities, 2023 ↩↩↩
-
PSEG March 2026 Investor Update — Public Service Enterprise Group, 2026-03 ↩
-
North America Corporate Rating Component Scores — S&P Global Ratings, 2024-06-30 ↩
-
Summaries of July 2026 Commission Meeting — Federal Energy Regulatory Commission, 2026-07 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube