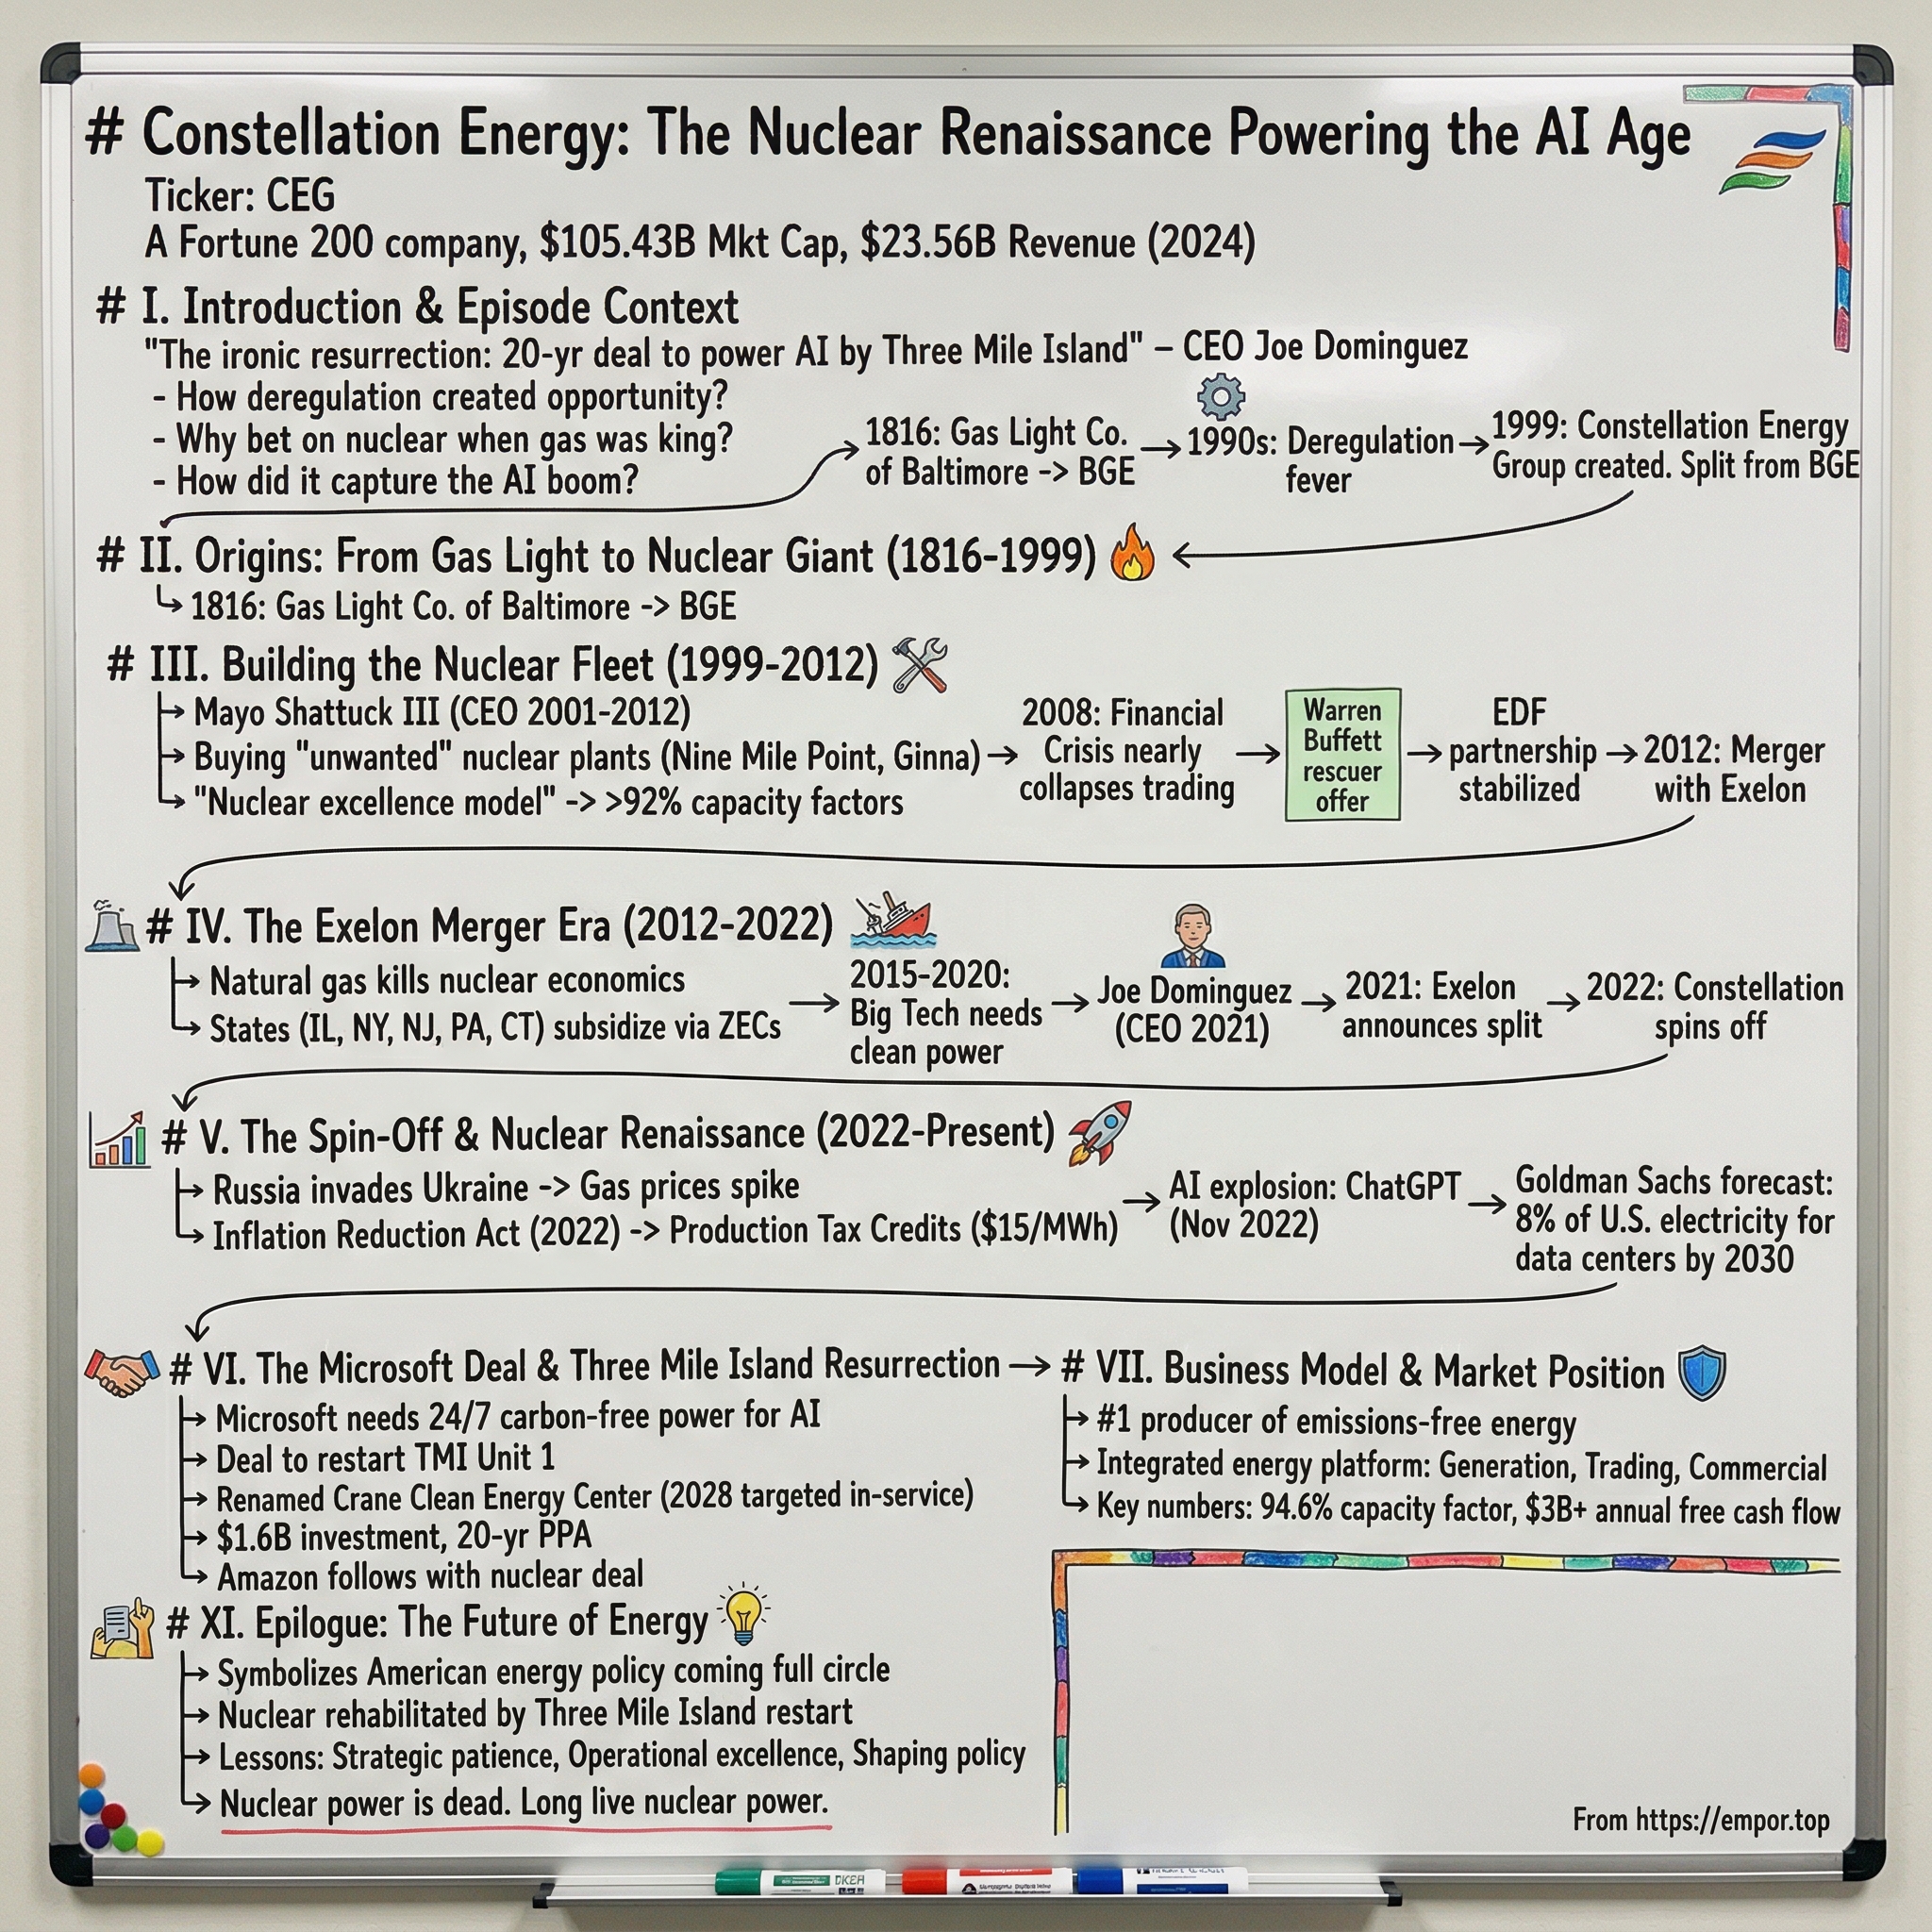
Constellation Energy: Betting the Grid on Nuclear
I. Introduction & Episode Roadmap
On a humid morning in Londonderry Township, Pennsylvania, a cooling tower that had been silent since 2019 sits inside a construction site that looks less like a demolition than a resurrection. Workers in hard hats move through turbine halls that were, until recently, on a decommissioning schedule — the industrial equivalent of a hospice plan. The site is Three Mile Island. Its Unit 1 reactor, the one that never melted down, is being brought back to life to sell electricity to Microsoft under a twenty-year contract.
That image — America's most infamous nuclear address rebuilt to feed artificial intelligence — is the shortest possible summary of what has happened to Constellation Energy Corporation over the last four years, and it is also the reason a careful investor should slow down rather than speed up.
Constellation trades on the NASDAQ Global Select Market under the ticker CEG, is headquartered in Baltimore, and describes itself as the largest producer of carbon-free electricity in the United States. As of early September 2026 the stock changed hands around $282, giving the company a market capitalization near $100 billion against a fifty-two-week range of $228.63 to $412.70 — a spread that tells you the market has not settled on what this business is worth.1 The all-time high was set in October 2025; the stock has spent the months since then giving back roughly a third of that peak while still sitting far above where it traded at its 2022 separation.
The central tension of this story is simple to state and hard to resolve. Merchant nuclear power — generating electricity from reactors and selling it into competitive wholesale markets, without a regulator guaranteeing your return — was for most of the past two decades one of the least loved asset classes in American finance. It was capital-hungry, politically fraught, and repeatedly uneconomic. Plants closed. Owners went to state legislatures for subsidies to keep the lights on. Then, almost overnight, the arrival of large-scale AI computing turned a fleet of always-on, zero-carbon, already-licensed reactors into something closer to beachfront property.
Two questions organize everything that follows.
First: how does a company that came within days of bankruptcy in September 2008 end up restarting Three Mile Island for the world's most valuable software company? The answer is not a single visionary decision. It is a chain of survival choices, subsidy fights, and a corporate structure that got separated at precisely the right moment.
Second, and more consequential for anyone owning the shares today: was the 2025 acquisition of Calpine Corporation disciplined consolidation, or an expensive bet placed near the top of a power-demand cycle? That deal closed in January 2026, added roughly $11.5 billion of goodwill to the balance sheet, and roughly tripled long-term debt.7 It is the largest capital allocation decision in the company's independent history, and it has not yet been tested by a downturn.
The roadmap: deregulation origins and why the merchant structure was chosen; the near-death experience of 2008 and the Buffett deal that wasn't; the decade inside Exelon, when Constellation was less a company than a division fighting to keep plants open; the 2022 spin-off and the extraordinary timing of the Inflation Reduction Act; the Microsoft deal and what it actually says about pricing power; Calpine and its regulatory aftermath; how the machine works today; whether management's credibility survives scrutiny; the competitive landscape; how much of the AI-power story is already in the price; and finally, what would have to happen for the bull or bear case to be proven right.
Start where the money started: with gas lamps in Baltimore.
 Subscribe on LinkedIn
II. Origins: From Gas Light to Deregulated Generator (1816-1999)
In 1816, Baltimore became the first American city to light its streets with manufactured gas. The enterprise that did it — the Gas Light Company of Baltimore — is the distant ancestor of what is today Constellation Energy, and it is worth exactly one paragraph of your attention, because the interesting history here is not the nineteenth century.
The through-line is Baltimore Gas and Electric, the regulated utility that grew out of those early gas and electric ventures and spent most of the twentieth century doing what regulated utilities do: build wires and power plants, serve a defined territory, and earn an allowed rate of return set by a state commission. It was a bond substitute with a hard hat. Predictable, unexciting, and — for a century — essentially unkillable.
Then the 1990s happened to the American electricity industry.
A wave of state-level restructuring split the vertically integrated utility into pieces. The theory was that generation — actually making electricity — was a competitive business, while transmission and distribution wires were a natural monopoly that should stay regulated. Maryland was among the states that went down this road. In 1999, BGE's corporate parent reorganized, separating the regulated wires utility from the generation and merchant energy businesses, and Constellation Energy Group emerged as the vehicle for the competitive side.
This is the single most important structural decision in the entire story, and it is worth being precise about what it meant.
A regulated utility earns money on the assets it builds. If costs rise, it files a rate case. If demand falls, it usually still recovers its fixed costs. The risk sits substantially with ratepayers. A merchant generator earns money on the spread between what it costs to produce a megawatt-hour and what the wholesale market will pay for it. When power prices are high, the merchant generator prints money. When natural gas gets cheap and drags power prices down with it, the merchant generator eats the loss with no rate case to run to.
Constellation chose to be the merchant. It chose commodity price risk over guaranteed returns. It built a trading and retail supply operation on top of the physical fleet — buying and selling power, hedging output forward, contracting directly with commercial and industrial customers rather than serving captive households at tariff rates.
That choice is why, even today, Constellation's economics look nothing like NextEra Energy's regulated Florida utility, and why comparing the two on a simple multiple of earnings tells you very little. It is also why the company's earnings swing with power prices, hedging decisions, and mark-to-market accounting in a way that a rate-regulated peer's simply does not. Investors who arrived at CEG in 2024 because of an AI narrative frequently underestimate how much of the reported number is a commodity book rather than an operating result.
The merchant model has one more property that matters enormously: it is asymmetric across the cycle. In the good years it looks like genius. In the bad years it can threaten the existence of the enterprise. Constellation spent the 2000s in the good years, buying reactors. Then it found out about the other half.
III. Building — and Nearly Losing — the Nuclear Fleet (1999-2012)
Picture the boardroom in Baltimore in mid-September 2008. Lehman Brothers has failed. Commercial paper markets — the short-term funding that large trading operations depend on the way a restaurant depends on its walk-in refrigerator — have effectively closed. Constellation's stock, which had been in the sixties earlier that year, is collapsing in real time. Rating agencies are circling. And the company's own traders are receiving collateral calls on positions that, under normal conditions, would have been routine.
Within roughly a week, a company that ran one of the largest nuclear fleets in the country was preparing for the possibility that it would not survive the month.
How it got there is a story of ambition that ran ahead of its balance sheet.
Through the 2000s, Constellation had been an aggressive consolidator of nuclear assets. It already had Calvert Cliffs on the Chesapeake Bay. It added Nine Mile Point in upstate New York and R.E. Ginna near Rochester. The logic was sound and, in hindsight, prescient: nuclear plants were being sold cheaply by utilities that wanted out of the business after restructuring, and a specialist operator running many reactors could spread engineering, refueling, and regulatory expertise across a bigger base than any single-plant owner could. Fleet scale in nuclear is real. It shows up in outage duration, in shared spare parts, in the ability to move experienced crews between sites.
But the company that owned those reactors was also running a large merchant energy trading business. And in a liquidity crisis, the trading book does not care how good your reactors are. It demands cash, immediately.
On September 18 and 19, 2008, Warren Buffett's MidAmerican Energy Holdings agreed to acquire Constellation for roughly $4.7 billion — $26.50 per share — accompanied by an immediate $1 billion cash injection that functioned as emergency liquidity. It was, in the truest sense, a rescue: a distressed price for a distressed asset, with the cash arriving first and the shareholder vote later.
Then the French arrived.
Électricité de France, already a Constellation partner on a nuclear joint venture, came back with a structure that let Constellation stay independent. Rather than buying the whole company, EDF proposed to buy roughly half the nuclear generation business — ultimately a 49.9% interest in five reactors for $4.5 billion, with an option to acquire up to $2 billion of additional non-nuclear assets, plus its own $1 billion immediate cash investment.8 On December 17, 2008, Constellation terminated the MidAmerican agreement and took the EDF path.8
Buffett did not leave empty-handed. The break-up package included $593 million in cash, 20 million shares — about 10% of the company — and a $1 billion note carrying a 14% interest rate.8 Read that number again. Fourteen percent. That is the price of survival for a company the market believed might not exist in ninety days. The stock fell about 12% on the announcement, closing at $25.29, as investors weighed independence against the certainty of Buffett's cash.8 The human cost was real too: the company announced more than 800 job cuts in December 2008 as it retrenched.
Why does an eighteen-year-old crisis belong in an analysis of a company whose current story is about AI data centers?
Because it is the strongest available piece of disconfirming evidence against the most seductive framing of the current investment case — that a licensed nuclear fleet is a bulletproof, annuity-like moat. Constellation's own history says otherwise. The reactors did not save the company in 2008; the reactors were what had to be half-sold to save the company. A nuclear fleet is a capital-intensive, cash-hungry, operationally unforgiving asset that sits inside a business with commodity and counterparty risk attached. The moat is real, but it is a moat around a castle that has previously needed a bailout.
The right conclusion is not that the moat is fake. It is that the moat is narrower than the current narrative implies: it protects against new supply, not against low prices, funding stress, or operational failure. Those are different risks, and history says they bind.
One more thread from this era matters later. Joe Dominguez — Constellation's chief executive today — was not running the company in 2008. He was Exelon Generation's general counsel through this period, and later oversaw the wind-down and decommissioning of the Zion Station plant in Illinois, which had closed in 1998. That is a modest data point, not a track record, but it is the earliest evidence available about how he handles the unglamorous end of the capital-allocation spectrum: shutting things down cleanly rather than defending them indefinitely.
Constellation survived 2008 as a smaller, half-French-owned, badly bruised company. It did not survive as an independent one for long.
IV. The Exelon Decade: Scale, Subsidy Fights, and the Case for Independence (2012-2022)
If the 2000s were about buying reactors and the 2008 crisis was about nearly losing them, the 2010s were about something harder to dramatize and more dangerous: slow economic erosion.
In 2012, Exelon Corporation acquired Constellation Energy Group. The combination created the largest competitive nuclear fleet in the United States — Exelon's Illinois and Pennsylvania reactors joined to Constellation's Mid-Atlantic and New York plants, plus the trading and retail platform. On paper it was the consolidation the industry had been pointing toward for a decade. In practice, it merged two businesses into one at almost precisely the moment the ground beneath them gave way.
The culprit was shale gas.
Here is the mechanism, in plain terms. In competitive wholesale power markets, the price everyone receives is generally set by the most expensive generator needed to meet demand in that hour — usually a natural gas plant. When gas is expensive, that marginal plant sets a high price and a nuclear reactor with near-zero fuel cost captures an enormous margin. When hydraulic fracturing floods the country with cheap gas, the marginal plant sets a low price, and the nuclear reactor — whose costs are almost entirely fixed, whose staffing is dictated by regulation, and which cannot simply throttle down profitably — collects less revenue against the same cost base.
Through the 2010s, that squeeze pushed multiple American nuclear plants below breakeven. Some closed. Others were scheduled to. Exelon's response was not primarily commercial. It was political.
The company fought, state by state, for Zero Emission Credit programs — mechanisms that paid nuclear plants for the carbon they didn't emit, on the argument that a zero-carbon megawatt-hour from a reactor deserved the same policy support a zero-carbon megawatt-hour from a wind farm already received. Illinois passed one. New York passed one. New Jersey passed one. In each case, the fight was contentious, litigated, and framed by opponents as a bailout.
This is worth pausing on because it establishes a pattern that recurs.
Constellation's predecessor did not simply operate inside a policy environment. It shaped one. The ZEC campaigns of the mid-2010s were, in effect, a demonstration that when the market would not pay for the attribute the company's assets uniquely provided — always-on, zero-carbon generation — the company would go and construct a market that did. A decade later, the same logic scaled to the federal level with the Inflation Reduction Act's nuclear production tax credit. That is a genuine, repeatable capability, and it is underweighted in most bull cases, which focus on hyperscaler contracts and ignore that the revenue floor beneath those contracts was legislated.
But it cuts both ways, and this is where the analysis has to be honest. A business whose economics have twice required a legislated support mechanism is a business with structural political exposure. Subsidies that were granted can be modified. The Illinois ZEC program, for instance, was always time-limited — a fact that shows up directly in the pricing of a later hyperscaler contract, as the next sections make clear. "Policy as strategy" is a competence when you win and an overhang when the legislature changes hands.
Meanwhile, inside Exelon, "Constellation" gradually became a brand rather than a strategy. It was the name on the retail supply contracts and the competitive generation business, sitting inside a holding company whose center of gravity was six regulated utilities serving customers from Chicago to Washington, D.C. Those two businesses want opposite things from a capital structure. A regulated utility wants a low cost of capital, a heavy capital expenditure program, and a boring risk profile. A merchant generator wants flexibility, tolerance for volatility, and a shareholder base that understands commodity cycles.
Holding them together meant the merchant business was permanently the junior partner in capital allocation debates, and the regulated business was permanently penalized by association with commodity earnings. By the end of the decade, both sides of the house had reason to want a divorce.
V. The 2022 Spin-Off and the Setup for the Nuclear Renaissance
February 1, 2022. Constellation Energy Corporation began trading as an independent company on the NASDAQ, spun off from Exelon with the competitive generation fleet, the retail and wholesale customer business, and Joe Dominguez — previously CEO of Exelon Generation — as chief executive.
The reception was polite rather than enthusiastic. Spin-offs of commodity businesses rarely arrive to fanfare, and in early 2022 the consensus view of merchant nuclear was still shaped by the previous decade: an asset class that periodically required rescue.
Six months later, Congress changed the arithmetic.
The Inflation Reduction Act, signed in August 2022, created a production tax credit for existing nuclear generation beginning in 2024, providing support up to roughly $15 per megawatt-hour and structured to phase out as market prices rise. Strip away the mechanics and what it did was install a revenue floor under exactly the asset base that had just been concentrated into a standalone public company.
It is difficult to overstate how favorable this sequencing was, and equally difficult to attribute it to management foresight. The spin-off was announced before the legislation passed. The correct reading is that Constellation had spent years arguing for precisely this policy — the ZEC campaigns were the state-level rehearsal — and then happened to become independent at the moment the federal version arrived. Skill created the conditions; timing delivered the payoff.
With a floor underneath the fleet, Dominguez's team set out a capital allocation framework in early 2023 that has been repeated with unusual consistency ever since: protect investment-grade credit metrics, grow the dividend by roughly 10% a year, invest only where returns clear a double-digit unlevered hurdle, and return whatever is left through buybacks. The company has, in fact, delivered the dividend piece — the board raised the annual per-share dividend 10% for 2025 and again signaled 10% growth for 2026, declaring a quarterly dividend of $0.4265 per share alongside its full-year 2025 results.13 The repurchase authorization was expanded to $5.0 billion, of which roughly $2.2 billion was deployed in the first four months of 2026 alone, with about $2.8 billion of remaining authority as of the second-quarter report.24
The first real test of the framework came quickly and quietly. In June 2023, Constellation agreed to buy NRG Energy's 44% interest in the South Texas Project nuclear plant for $1.75 billion, closing that November. It was a textbook bolt-on: an asset class the company already understood, in a market it wanted more exposure to, at a size that did not strain the balance sheet. The stock barely reacted.
That is exactly the point. South Texas is the benchmark against which the Calpine deal should be judged — not because bigger is worse, but because the type of discipline demonstrated by a $1.75 billion increase in a familiar asset is not the same as the discipline required for a transaction more than ten times that size in an asset class the company had far less of. Investors who cite South Texas as proof of capital allocation skill are citing evidence for a narrower claim than the one they are making.
By late 2023, Constellation had a clean balance sheet, a legislated revenue floor, a stated framework, and 22 gigawatts of nuclear capacity running at high availability. What it did not have was a reason for anyone outside the utility sector to care.
Then the AI industry discovered it needed electricity.
VI. The Microsoft Deal and the Crane Clean Energy Center
The announcement landed on September 20, 2024, and it did something that power sector news almost never does: it went viral.
Constellation and Microsoft signed a twenty-year power purchase agreement covering the full output of Three Mile Island Unit 1 — roughly 835 megawatts — a reactor that had been shut down in 2019 for economic reasons and placed on a decommissioning path.311 The plant would be renamed the Crane Clean Energy Center, after Chris Crane, the former Exelon chief executive who had died earlier that year.10
The symbolism did the marketing. Three Mile Island is, for most Americans, shorthand for nuclear failure — the March 1979 partial meltdown at Unit 2 that ended new nuclear construction in the United States for a generation. Unit 1 was the other reactor at the site, undamaged in that accident, and it ran safely for decades afterward. But the address is the address. Restarting it to power AI infrastructure was a headline that wrote itself.
Markets responded accordingly. Constellation shares jumped roughly 22% on announcement day.9 That is an extraordinary single-day move for a $50-billion-plus utility-adjacent company, and it was not really about 835 megawatts. It was the moment the market re-rated what a licensed nuclear plant was worth in a world of AI-driven electricity demand.
Now the economics, which are more interesting than the symbolism.
Constellation committed roughly $1.6 billion of capital to the restart, funded from operations, covering turbine and generator refurbishment, cooling system work, transformer replacement, and the regulatory process to reauthorize power operations.29 Contract pricing was not disclosed. Analyst estimates published around the announcement clustered in a wide band: Morgan Stanley's estimate of roughly $98 per megawatt-hour sat at the low end, with other estimates reaching $110 to $115, against wholesale power prices in the region closer to $50.29
That gap — call it roughly double the merchant price — is the number the entire AI-power thesis rests on. It is worth being precise about what it does and does not prove.
What it proves: a hyperscaler with a hard carbon-free commitment, a multi-year data center build plan, and effectively unlimited access to capital will pay a substantial premium for firm, always-on, zero-carbon electricity that can be contracted for two decades. Nothing else on the grid offers that combination. Wind and solar are cheaper per megawatt-hour but intermittent; batteries shift energy by hours, not seasons; new gas plants carry carbon that conflicts with corporate climate commitments and face multi-year turbine order backlogs.
What it does not prove: that this premium is uniform, durable, or available on every megawatt Constellation owns. The Crane price — whatever it actually is — reflects a specific plant, in a specific market, with a specific counterparty, at a specific moment. Later sections show a materially different structure for the company's next large deal.
The restart timeline has, unusually for a nuclear project, moved in the right direction. The original guidance pointed to 2028.3 By late 2025, Constellation had accelerated it, and the company now expects the plant online in 2027.2 The regulatory path has cleared step by step: the Department of Energy closed a $1 billion loan through its Energy Dominance Financing program in November 2025 to partially finance the restart, with the site already more than 80% staffed.21 The Nuclear Regulatory Commission published a draft environmental assessment and draft finding of no significant impact in June 2026, opening a public comment period that ran through early July.22 FERC granted a waiver permitting the transfer of capacity interconnection rights from retired Pennsylvania units to Crane, and the NRC approved a fuel license amendment.2
An investor should note both halves of this. The acceleration is genuine evidence of execution — nuclear projects overwhelmingly slip rather than pull forward, and this one has done the opposite through multiple checkpoints. But the plant has not generated a single commercial megawatt-hour yet. Restart is not the same as operation. The revenue starts when the reactor synchronizes to the grid, and that has not happened.
Finally, a structural detail that becomes critical in the competitive discussion. The Microsoft arrangement is a grid-connected virtual power purchase agreement. Constellation sells Crane's output into the PJM wholesale market like any other generator; Microsoft buys the associated clean energy attributes and the contracted economics. The electrons do not travel down a private wire into a Microsoft data center. That distinction sounds like a technicality. It became, within two months of the announcement, the most important regulatory question in the sector.
VII. The Calpine Acquisition: The Real Capital Allocation Test
For sixteen years, Energy Capital Partners had been the smartest money in American power. The private equity firm bought Calpine Corporation in 2017 for $5.6 billion of equity, taking private a company that had itself emerged from bankruptcy a decade earlier. Calpine's asset base was unfashionable at the time: a large fleet of natural gas combined-cycle plants concentrated in Texas and California, plus the Geysers geothermal complex in Northern California, the largest geothermal field in the world.
By January 2025, unfashionable had become indispensable. Data center demand was tightening reserve margins across ERCOT and PJM, and dispatchable generation — plants that can be turned up on command rather than when the wind blows — was suddenly the scarce commodity.
On January 10, 2025, Constellation announced it would acquire Calpine.46 The consideration was approximately $16.4 billion — 50 million newly issued Constellation shares plus about $4.5 billion in cash — with roughly $12.7 billion of Calpine net debt assumed on top, implying an enterprise value near $29 billion and a multiple of roughly 7.9 times projected 2026 EBITDA.4
It was the largest transaction in the company's history, and the seller had reportedly realized well over $25 billion in total value from a position that cost $5.6 billion. That asymmetry deserves to be named plainly rather than buried: the counterparty on the other side of this table was a specialist power investor with sixteen years of ownership experience, exiting at a moment of peak enthusiasm for exactly these assets. It does not prove Constellation overpaid. It does establish that the informational advantage sat with the seller.
The strategic logic was coherent, and it was not primarily about growth. It was about shape.
Before Calpine, Constellation was a nuclear-heavy generator concentrated in PJM and the Northeast, with roughly 32 gigawatts of capacity of which about 22 gigawatts was nuclear. That is a portfolio with a specific vulnerability: baseload nuclear runs flat out all the time and cannot follow load. It captures the average price, not the peak. Calpine brought more than 27 gigawatts of gas, geothermal, battery, and solar capacity concentrated in ERCOT and CAISO — assets that make money precisely in the hours when the grid is short and prices spike, and in geographies where Constellation had minimal presence.
Combined, the two companies reached roughly 55 gigawatts. Management framed the deal as adding about $2 per share of earnings and roughly $2 billion of incremental annual free cash flow. The intellectual case: nuclear provides the always-on floor and the carbon-free attribute hyperscalers want; gas provides the flexibility that makes a portfolio sellable as a firm product rather than a weather-dependent one. Selling "carbon-free power, delivered whenever you need it" requires both.
Regulators did not simply wave it through, and the resulting sequence is the most informative part of the entire episode.
FERC approved the transaction in July 2025 subject to divesting four PJM assets. Then, on December 5, 2025, the Department of Justice's Antitrust Division — acting alongside the Texas attorney general — filed a civil antitrust complaint and a proposed consent decree, the first time in roughly fifteen years the division had sought structural relief in a power generation merger. DOJ's concern was straightforward: combining Constellation's and Calpine's gas fleets in overlapping markets would reduce the competitive pressure that keeps bids honest. The remedy extended beyond FERC's list to include the 828-megawatt York 2 facility in Pennsylvania, the 605-megawatt Jack Fusco Energy Center near Houston, and a minority stake in the 385-megawatt Gregory Power Plant in Texas.
The transaction closed on January 7, 2026.5 Constellation separately sold the Brazos Valley Energy Center for $860 million, and in March 2026 agreed to sell five PJM facilities — Bethlehem, York 1, York 2, Hay Road, and Edge Moor, roughly 4.4 gigawatts of predominantly gas-fired capacity — to LS Power for $5 billion, satisfying the largest portion of the DOJ requirements and all of the FERC-mandated divestitures.23
That $5 billion price works out to roughly $1,142 per kilowatt of capacity, and it is the single most useful piece of evidence available on whether Constellation overpaid for Calpine.23 Consider what it implies: assets acquired as part of a portfolio bought at 7.9 times EBITDA were resold, within roughly two months of closing, at a price a sophisticated independent power buyer was willing to pay in a competitive process. On the second-quarter call, CFO Shane Smith pointed at exactly this data point, noting that "smart private equity buyers are willing to pay over $1,400 a kW for Texas assets."24 The divestiture arithmetic is a genuine mark-to-market validation, and it materially strengthens the case that the entry multiple was defensible.
Now the other side of the ledger, in the same passage rather than exiled to a risk list.
The purchase accounting left roughly $11.5 billion of goodwill on the balance sheet as of June 30, 2026, up from $420 million at the end of 2025.7 Long-term debt rose to approximately $19.1 billion from $7.25 billion over the same period.7 Shares outstanding increased to roughly 355 million from 312 million.7 Each of those is a straightforward mechanical consequence of a large cash-and-stock acquisition. Together they describe a materially different company from the one that existed eight months earlier — more levered, more acquisitive, and carrying a goodwill balance equal to a meaningful fraction of its market capitalization.
Goodwill is the accounting residue of paying more than the fair value of identifiable net assets. It sits on the balance sheet unamortized and is tested annually for impairment. It becomes a problem when the cash flows that justified the price fail to arrive — at which point the write-down is an admission, in public, that the deal did not work. Roughly $11.5 billion of goodwill on a company with a market value near $100 billion is not a crisis. It is a large, specific, testable claim about the future value of gas generation in Texas and California, and it has not been tested through a downcycle.
There was also a capital markets event worth reading carefully. In June 2026, funds affiliated with Energy Capital Partners, CPPIB, and the Teacher Retirement System of Texas — the former Calpine owners who had received Constellation stock as consideration — sold 11 million shares in a secondary offering raising roughly $3.1 billion in gross proceeds. Constellation itself received no proceeds; it concurrently repurchased 2 million of those shares from the underwriters for $558 million.25 This is frequently mischaracterized as Constellation raising equity at a discount. It was not. It was the seller monetizing the paper it had accepted, and the company using its buyback authorization to absorb part of the supply. That is a defensible use of capital — but it also means a portion of the "accretive repurchase" narrative in 2026 was, in substance, managing an overhang the deal itself created.
The honest verdict on Calpine as of today: the strategic rationale is sound, the entry multiple is supported by an independent resale mark, and the balance sheet impact is real and unretired. No write-off has occurred and none is presently indicated. But the deal is eight months old. The company's stated discipline has been demonstrated on small transactions and asserted on this one. The goodwill line is where the difference will eventually show up.
VIII. The Business Today: Segments, Fleet, and How the Machine Works
Strip away the narrative and Constellation is, mechanically, three businesses stacked on top of each other.
At the bottom sits the physical fleet: reactors, gas plants, geothermal wells, wind, solar, hydro, and batteries that convert fuel or weather into megawatt-hours. In the middle sits a wholesale trading and hedging operation that decides when and at what price that output is sold forward — months or years ahead of delivery — so the company is not simply exposed to whatever the spot market does on a given Tuesday. At the top sits a commercial and retail supply business that contracts directly with businesses, municipalities, and now hyperscalers, selling electricity as a product with terms attached rather than as an anonymous commodity.
Most investors focus entirely on the bottom layer, because reactors are photogenic. The middle layer is where quarterly earnings are actually made or lost.
The reporting structure reflects geography rather than technology. In its 2026 filings the company reports along regional lines — Mid-Atlantic, Midwest, New York, ERCOT, and Other Power Regions — with a separate Constellation Calpine segment carrying the acquired business through the integration period.7 Mid-Atlantic, home to the legacy nuclear fleet, remains the largest single contributor: it generated $6.49 billion of revenue in 2025 out of a company total of $25.53 billion.13
The financial trajectory across the independent era is worth laying out once, because it establishes the base against which every forward claim should be measured.
For 2024, Constellation reported revenue of $23.57 billion and GAAP net income of $11.89 per share — a figure inflated by mark-to-market gains on the hedging book — against adjusted operating earnings of $8.67 per share, which beat a guidance range the company had raised twice during the year.12 The gap between those two earnings numbers is not an accounting trick; it is what a merchant energy business looks like when derivative positions are marked at period end. Adjusted operating earnings is the number management guides to, is compensated on, and that analysts model. It is also, by construction, a number management defines.
For 2025, revenue rose to $25.53 billion, GAAP earnings came in at $7.40 per share, and adjusted operating earnings reached $9.39.13 The Mid-Atlantic increase that year — up roughly $965 million, or 17.5% — came from higher contracted retail energy prices, favorable realized hedges, and higher wholesale load revenue, offset by the absence of nuclear production tax credit revenue that had been recognized in the prior period.13 That last item is instructive: as market prices rise, the IRA credit phases down. The subsidy is a floor, not an escalator. Investors modeling both high power prices and full PTC support are double-counting.
The fleet itself: before Calpine, roughly 32,400 megawatts of owned capacity, of which nuclear was about 22 gigawatts, with wind, solar, and hydro making up most of the balance. Combined output post-Calpine approaches 300 million megawatt-hours annually — on the company's own description, around 10% of all carbon-free power produced in the United States, serving more than 16 million homes and businesses, with roughly 90% of output carbon-free.31 Constellation has committed to 100% carbon-free generation by 2040.31
Three operating metrics do most of the explanatory work.
The first is nuclear capacity factor — the share of theoretical maximum output the fleet actually produces. Constellation's runs in the low-to-mid 90s: 93.0% in the second quarter of 2026, against 94.8% a year earlier, with the fleet producing 44,160 gigawatt-hours in the quarter versus 45,170.2 In the third quarter of 2025 it hit 96.8%.28 These are excellent numbers by global standards, and the quarter-to-quarter variation is almost entirely refueling outage scheduling — reactors must be shut down every 18 to 24 months to replace fuel, and whether those days fall in one quarter or the next moves reported earnings without telling you anything about the business.
The critical analytical point about capacity factor is that it is already maxed out. A fleet at 93-95% has perhaps two or three points of theoretical upside, and each additional point costs more than the last. Whatever growth comes from here does not come from running the existing reactors harder.
The second is PJM capacity revenue — the money Constellation earns for promising to be available, separate from the energy it actually sells. In the most recent base residual auction, held for the 2028-29 delivery year with results released in July 2026, Constellation cleared 18,875 megawatts, up from 17,950 megawatts in the prior auction, worth roughly $2.2 billion for that delivery year.20 This revenue stream requires no additional capital and no additional fuel. It is close to pure margin, and it is set by an administrative auction process the company does not control.
The third is newly contracted long-term volume. In the second quarter of 2026 alone, Constellation signed 920 megawatts of long-term power purchase agreements with investment-grade counterparties, at terms running 15 to 20 years and an average duration of 18.5 years, with deliveries beginning between 2029 and 2032.2 Within that total, a 176-megawatt agreement with Walmart is structured to fund a 30-megawatt uprate at the Dresden plant in Illinois — squeezing more output from an existing reactor rather than building a new one.2 These stack on top of the Microsoft and Meta contracts.
Those three — capacity factor, cleared capacity revenue, and newly contracted long-term megawatts — are the operating spine. But for a company that has just tripled its debt and added $11.5 billion of goodwill, a fourth number belongs alongside them: leverage. The KPIs an investor should actually track are narrower than the ones the company presents, and the next section explains why management's own record makes that distinction necessary.
IX. Management & Capital Allocation: Testing Dominguez's Record
Joe Dominguez is a lawyer by training who spent more than two decades inside Exelon and its subsidiaries before becoming chief executive of the newly independent Constellation at the 2022 separation. He was general counsel through the financial crisis era, ran Exelon Generation before the spin, and has spent much of his public career in front of legislators and regulators rather than in front of turbines. That background shows in how he runs the company: the strategy has consistently been as much about constructing favorable policy and contract structures as about operating assets.
On August 4, 2026, the board elected Dominguez as its Chair, following the retirement of Robert Lawless from the board.26 Charles Harrington, who chairs the corporate governance committee, took on the lead independent director role with a $50,000 annual retainer, and Roger Crandall joined the board effective the following day.26
This is a governance watch item, and it should be flagged as one without overstating it. Combining the chair and chief executive roles concentrates agenda-setting authority in the person whose performance the board is meant to evaluate. The lead independent director structure is the standard mitigant, and it is present here. There is no current controversy attached. But the change arrived seven months after the largest acquisition in company history — precisely the period when independent board oversight of capital allocation matters most. That is a fact worth holding, not an accusation.
On incentives: Dominguez holds roughly 121,000 shares, worth approximately $41 million at current prices and representing about 0.04% of shares outstanding, against a stock ownership requirement of six times salary.14 The annual incentive plan weights operating net income at 70%, with the remainder allocated across customer satisfaction, nuclear fleet capacity factor, dispatch match, and renewable capture.14
That structure is genuinely informative. There is no metric rewarding transaction volume, no growth-in-assets target, no earnings-per-share hurdle that a debt-funded buyback could manufacture. A compensation design weighted overwhelmingly toward operating profit and plant performance is evidence against a simple empire-building reading of the Calpine acquisition. It is not conclusive — operating net income rises mechanically when you buy $2 billion of EBITDA — but the incentive is at least pointed at running assets well rather than accumulating them.
Now the harder test: does management's guidance behavior hold up?
The 2024 record was strong. Guidance was raised twice during the year and then exceeded.12 The 2025 record was mixed in an instructive way. The company trimmed the top end of its range during the year, narrowing full-year adjusted operating guidance to $9.05 to $9.45 per share — a midpoint slightly below where analysts sat — and management attributed the change substantially to operations and maintenance cost inflation.28 The full year eventually landed at $9.39, near the top of the narrowed range.13
The third quarter of 2025 was the clearest stress test. Constellation reported adjusted operating earnings of $3.04 per share against consensus of $3.09 — a miss of five cents, roughly 1.6% — on higher purchased power and fuel costs, even as revenue of $6.57 billion beat expectations and the nuclear fleet delivered that 96.8% capacity factor.28 The stock fell about 3% premarket.28
The analytically useful part is not the miss. It is the explanation. Management attributed the shortfall to controllable cost items — O&M inflation, purchased power and fuel — rather than to weather, macro conditions, or "market dynamics." Companies that blame the environment for misses tend to keep missing, because the environment is not something they manage. Companies that name a cost line have at least identified something they can act on. Across the 2022-2026 period, Constellation's explanations for variances have been specific and consistent across filings, releases, and calls. That is a modest but real credibility marker.
Guidance has since moved decisively higher. The 2026 outlook was raised twice, most recently to $11.50 to $12.50 per share alongside second-quarter results, when adjusted operating earnings came in at $2.55 per share against $1.91 a year earlier — driven, per the company, by the Calpine addition, higher PJM capacity prices, and commercial business performance.224 GAAP earnings for that quarter were $1.42 per share, down from $2.67, which is again the hedge book doing what hedge books do.2
At the March 31, 2026 business and earnings outlook session, management laid out a target of more than 20% base earnings-per-share growth from 2026 through 2029, with long-term rolling three-year growth of 10% or better, explicitly excluding potential upside from contracting the roughly 147 million megawatt-hours of annual available nuclear generation, additional gas contracting, and further capital deployment.30 That is an aggressive target set immediately after a transformational acquisition, and it is precisely the kind of forward promise that should be logged now and checked in 2028.
On shareholder oversight: at the April 28, 2026 annual meeting, shareholders elected eleven directors, approved executive compensation on an advisory basis, and ratified PricewaterhouseCoopers as auditor, while voting down a shareholder proposal seeking a report on the company's diversity, equity, and inclusion initiatives.27 A comfortable say-on-pay outcome at one annual meeting is a bounded finding about that meeting — it is not a durable assurance about future governance, and it should not be read as one.
The most valuable thing management said in 2026, though, was a limitation on its own story. Asked on the August 6 second-quarter call about new nuclear construction in New York, Dominguez said the company was "having some good conversations in New York about the future of nuclear," while making clear that nothing rose to the level of an imminent investment decision and that it would not yet appear in financial disclosures as capital.24 He described the approach as preparing sites — permitting, early site permits — so that multiple locations are ready once construction schedules, pricing, and customers can be pinned down.24
That is management voluntarily deflating the most speculative part of its own equity story, and it deserves to be weighted as a credibility positive. It also removes new-build from the near-term investment case entirely. Whatever happens to this stock over the next two to three years will be determined by restarts, re-contracting, capacity auctions, and Calpine integration — not by new reactors.
X. Competitive Landscape & Industry Structure
In November 2024, three FERC commissioners sat down to rule on what looked like a routine interconnection filing and produced the most consequential document in the AI-power sector to date.
The filing concerned Talen Energy's Susquehanna nuclear plant in Pennsylvania and an Amazon data center built adjacent to it. The structure was "behind the meter" co-location: rather than selling power into the grid and having Amazon buy it back, Talen would route output directly to the data center over a private connection, bypassing much of the transmission system — and much of the cost allocation that comes with it. The amended interconnection agreement would have expanded that arrangement.
FERC rejected it, two to one, on the grounds that the justification for the co-located arrangement was insufficient.15 The ruling did not ban co-location. It signaled that regulators intended to scrutinize whether these deals shift transmission costs onto other ratepayers and whether removing large generators from the market affects reliability and prices for everyone else.
The industry adapted rather than retreated. By June 2025, Talen had restructured: a 1,920-megawatt agreement with Amazon Web Services running through 2042, delivering 840 to 1,200 megawatts by 2029 and up to the full amount by 2032, restructured as a front-of-the-meter arrangement that did not require the FERC approval that had been denied.17 Utility Dive's reporting put the contract's estimated lifetime value near $18 billion, implying roughly $94 per megawatt-hour on average.17
That is a genuinely important data point, and it complicates a comfortable framing of Constellation's position. It is often argued that Constellation's grid-connected virtual PPA structure — used for both Microsoft and Meta — insulates it from co-location risk while competitors are exposed. The structural difference is real: Constellation's deals were designed from the start to sell into the market rather than around it. But Talen has already migrated to substantially the same structure, achieving a comparable price. Structure was a timing advantage, not a permanent one.
Map the rest of the field.
Vistra Corp operates roughly 44 gigawatts across a mixed fleet and has become Constellation's most direct competitor for hyperscaler nuclear contracts. On January 9, 2026, Vistra and Meta announced twenty-year agreements covering 2,609 megawatts — 2,176 megawatts from the operating Perry and Davis-Besse plants in Ohio, plus 433 megawatts from uprates at Perry, Davis-Besse, and Beaver Valley in Pennsylvania — with deliveries beginning in late 2026 and phasing in through 2034.18 Pricing was not disclosed.18 Notably, Vistra bought those plants in 2023 when they were, in the company's own framing, on a path to retirement.18 That is a reminder that the scarcity of licensed nuclear capacity was created by economics, not physics, and that competitors bought the same option Constellation held.
Talen Energy, with roughly 10.7 gigawatts including 2.2 gigawatts of nuclear, is smaller but strategically concentrated on the Susquehanna-Amazon relationship.
NextEra Energy is the largest by market value at well over $180 billion, but it is not a clean comparison. Its core is Florida Power & Light — a regulated utility with an allowed return — bolted to the largest renewables development platform in the country. Comparing NextEra's multiple to Constellation's is comparing a regulated annuity plus a development business to a merchant commodity operator. They respond to entirely different variables.
PSEG owns roughly 3.8 gigawatts of nuclear alongside a large regulated New Jersey utility — a hybrid with less merchant leverage in either direction.
Run the industry through Porter's five forces and the structure comes into focus.
Barriers to entry are as high as they get in any industry. Building a new nuclear plant in the United States requires NRC licensing that takes years, capital in the tens of billions, and construction timelines measured in decades — the two AWS units completed at Plant Vogtle in Georgia ran years late and billions over budget, and no comparable project has followed. No meaningful new nuclear supply arrives this decade.
Supplier power is low. Uranium fuel is a small share of a nuclear plant's total cost; the economics are dominated by fixed operating, staffing, and capital expenses. A doubling of uranium prices is an irritant, not a threat.
Buyer power is genuinely two-sided, and this is where most analysis goes wrong in one direction or the other. Hyperscalers are among the most sophisticated procurement organizations on earth, with in-house energy teams, alternatives including gas, geothermal, and small modular reactor investments, and the balance sheet to wait. But there are perhaps a dozen operating merchant nuclear plants in the country available to contract, and none can be replicated on any timeline relevant to a data center build plan. Both sides have leverage. Neither has a hammer.
Substitutes are real on cost and inadequate on the specific attribute being purchased. Solar plus four-hour storage is cheaper per megawatt-hour than a nuclear PPA in most of the country. It cannot deliver 800 megawatts continuously through a windless January week. What hyperscalers are buying is not energy; it is firmness with a carbon-free attribute, and the substitution set for that is narrow.
Rivalry is limited. A handful of merchant nuclear operators — Constellation, Vistra, Talen, PSEG — face many buyers. That is closer to an oligopoly than a competitive market.
Through Hamilton Helmer's 7 Powers, the strongest claim is cornered resource: an operating, licensed nuclear fleet that cannot be reproduced within the investment horizon. Secondary powers include scale economies in fleet maintenance, refueling engineering, and trading, and switching costs created by twenty-year contracts once signed.
But apply the historical falsification test to the cornered resource claim, and it narrows.
Constellation has owned a licensed nuclear fleet continuously since the early 2000s. Through the 2010s, that same fleet was worth so little that plants were closed, marked for decommissioning, and kept alive only by state legislation. Three Mile Island Unit 1 — the crown jewel of the current story — was shut down in 2019 because it could not earn its keep. A resource is only "cornered" if someone wants it. The scarcity did not change; the demand did.
The revised claim that survives: Constellation controls a physically scarce asset whose value is contingent on continued demand from a small set of buyers and on regulatory tolerance for the structures through which they contract. That is a strong position. It is not an annuity. The event that would falsify it is not a competitor building reactors — nobody can — but a slowdown in hyperscaler capital expenditure, a shift toward on-site gas generation, or a regulatory or state-level intervention in nuclear-to-datacenter power flows.
One further nuance belongs here rather than in a footnote. Constellation's June 2025 agreement with Meta covered 1,121 megawatts from the Clinton Clean Energy Center in Illinois over twenty years, beginning June 2027, plus a 30-megawatt uprate — and it was explicitly designed to replace the Illinois zero emission credit when that state program expires in 2027.16 Pricing was not disclosed.16 Structurally, this is a fundamentally different transaction from Crane. Crane was a restart requiring $1.6 billion of capital that would not have happened without a contract; Clinton was an operating plant losing a subsidy and needing a replacement revenue source. A seller replacing an expiring subsidy has materially less leverage than a seller being asked to resurrect a plant.
The conclusion an investor should draw: premium pricing on AI power contracts exists, but it is deal-specific rather than a uniform repricing of every megawatt-hour Constellation owns. Anyone extrapolating Crane-level economics across the full 147 million megawatt-hours of annual nuclear output is making an assumption the company's own contract history does not support.
XI. The AI Power Boom: How Much of the Story Is Already Priced In
The clearest window into what AI is doing to American electricity is not a technology conference. It is PJM's annual capacity auction — a procurement process where generators bid to be paid for promising to be available three years ahead, and the market clears at a single price.
For years these auctions were sleepy. Then the numbers moved.
The 2025-26 delivery year cleared at $269.92 per megawatt-day, a record at the time. The 2026-27 auction, with results released July 22, 2025, cleared at $329.17 per megawatt-day — a level that was itself the administrative price cap, with PJM securing 134,311 megawatts against 135,192 offered and peak load growing by roughly 5,500 megawatts driven primarily by data center expansion.19 Without a negotiated cap agreement in Pennsylvania, prices would have gone higher still.19
The next auction did not cool off. Results released July 15, 2026 for the 2028-29 delivery year again hit the cap, at $325 per megawatt-day — and PJM disclosed that absent the price collar, the auction would have cleared near $555 per megawatt-day regionally and $777 in the ComEd zone, while still leaving a roughly 6.8 gigawatt shortfall against the target reserve margin.20
Read that carefully, because it is the most important macro fact in this story. The auction is not clearing at the cap because the cap is low. It is clearing at the cap because the underlying supply-demand balance is severely tight and an administrative ceiling is suppressing the price signal. As one analyst quoted in the results coverage put it, the current system "doesn't work to bring online new capacity or stimulate demand response, the two things we need the most."20
For an existing generator, this is close to an ideal environment: scarcity rents without the competition that scarcity rents normally attract, because the barriers to adding supply are physical and regulatory rather than financial. The widely cited forecast that data centers could rise from roughly 3% of US electricity demand today to around 8% by 2030 is the demand-side version of the same story.
So the structural case is not in dispute. The question is what it is worth, and to whom.
Three cautions belong directly alongside the enthusiasm.
First, this tailwind is not proprietary. Every generator with capacity clearing in PJM captures the same auction price. Vistra, Talen, PSEG, and LS Power — which just bought 4.4 gigawatts of PJM gas capacity precisely because, in its CEO's words, "PJM is at the epicenter of the surge in electricity demand" — all benefit.23 A rising clearing price is a sector event, not a competitive advantage. What differentiates Constellation is the carbon-free attribute it can sell on top, not the capacity payment itself.
Second, the mechanical sources of growth are largely exhausted. Capacity factor is at practical maximum. Capacity prices are at an administrative cap, which means the next auction can match this one but cannot meaningfully exceed it without a rule change. The remaining levers are re-contracting existing output at premium prices, extracting uprates from existing reactors — the 30-megawatt increments at Dresden and Clinton are exactly this — and integrating Calpine. Each is real. None is unlimited.
Third, new-build is not available as a growth driver on any near-term view, on management's own account.24 The company is positioning sites and pursuing permits so that it can move when the economics and customers align, which is prudent. But an investor cannot underwrite reactors that have no schedule, no price, and no customer.
Which leaves the valuation question. At roughly $282 per share against 2026 adjusted operating guidance of $11.50 to $12.50, the stock trades near 23 times forward earnings — the reported forward multiple sits around 23.1 That is a substantial premium to the regulated utility sector, which typically trades in the mid-teens, and it embeds an expectation that the contracting engine keeps running and Calpine delivers. It is also well below where the multiple sat at the October 2025 peak, when the shares changed hands above $400. The market has already taken meaningful air out of the story once.
The useful framing is not whether the AI demand thesis is true — the auction data says it is — but whether the incremental news flow from here can exceed what a 23-times multiple already assumes.
XII. Playbook: Business & Investing Lessons
Four lessons come out of this history that generalize beyond one company.
Surviving the trough matters more than winning the peak. Constellation's entire current position rests on a simple counterfactual: it still owned reactors in 2024. That was not guaranteed. In 2008 it nearly lost the company and did sell half the nuclear business to a French state-backed buyer to stay independent. Through the 2010s, cheap gas made much of the fleet uneconomic and several plants were kept running only by legislated credits. The AI power boom did not create Constellation's advantage; it revalued an advantage that had been carried, expensively and unfashionably, through fifteen years when the market said it was worth little. Asset scarcity, when it finally pays, pays to whoever was still holding.
Policy as strategy, executed twice, is a capability — and an exposure. The state ZEC campaigns and the federal nuclear production tax credit were not lucky breaks. They were the outcome of a company systematically arguing that its assets provided a public good the market was not pricing, until legislatures agreed. Very few companies can do this. But the flip side is that a material portion of the revenue floor is a political artifact, and political artifacts have expiry dates. The Illinois credit's 2027 expiration is not an abstraction — it directly shaped the structure of the Meta contract for Clinton.
Capital allocation discipline is a spectrum, not a binary. The South Texas Project purchase was small, in a familiar asset class, at a size the balance sheet absorbed easily. Calpine was more than ten times larger, in a fuel type where Constellation had limited scale, funded with stock and debt, and generating $11.5 billion of goodwill. Both can be described as "disciplined," but the evidentiary bar is completely different. When a management team's reputation for discipline is built on small deals and then spent on a very large one, the reputation is a hypothesis rather than a track record. The LS Power resale mark is real evidence in Constellation's favor. It is not yet a verdict.
Scarce contracted capacity commands a premium, but the premium is not uniform. Crane required a restart decision that no rational operator would make without a contract, and the estimated pricing reflected that leverage. Clinton was an operating plant seeking replacement revenue for an expiring subsidy, with pricing undisclosed. Talen's restructured Amazon deal implies roughly $94 per megawatt-hour. The same underlying commodity — firm carbon-free electricity — clears at meaningfully different prices depending on who needs the deal more. Pricing power in this industry is situational, and any model that applies one contract's economics to an entire fleet is overstating the case.
Which brings the story to where it actually stands: a company with a genuinely scarce asset, a validated but untested large acquisition, and a share price that has already absorbed a great deal of good news.
XIII. Analysis & Bull vs. Bear Case
Bull Case
The demand shift is structural rather than cyclical, and the evidence is in market clearing prices rather than press releases. PJM capacity auctions have hit the administrative cap in consecutive cycles while leaving a reserve margin shortfall, which is what a genuine physical shortage looks like when a price ceiling is in place.1920 That environment lifts every megawatt Constellation owns, not just the contracted ones.
The contracting engine is producing. Microsoft, Meta, and Walmart agreements sit on top of 920 megawatts signed in a single quarter with investment-grade counterparties at an average tenor of 18.5 years.2 Long-duration contracts with creditworthy buyers convert a commodity business into something with visible, forecastable cash flows — the single most valuable transformation available to a merchant generator, and the reason the multiple has expanded at all.
Calpine addresses a real portfolio weakness rather than simply adding size. Baseload nuclear cannot follow load; gas can. Combining them lets Constellation sell a firm, shaped product across ERCOT and CAISO as well as PJM. The $1,142 per kilowatt realized on the LS Power divestiture provides an independent mark suggesting the entry price was not unreasonable.23
Capital returns have continued through the largest deal in company history, with a maintained investment-grade profile, 10% dividend growth, and $2.2 billion of repurchases in four months of 2026 against $2.8 billion remaining.24 A company that levers up for an acquisition and then stops buying back stock is signaling balance sheet stress; this one has not.
Management's incentive structure points at operations rather than deal-making, guidance misses have been explained with specific controllable causes, and management has publicly bounded its own most speculative narrative by saying new nuclear is not imminent.142428 Executives who talk down their own optionality are behaving unusually, and usefully.
Bear Case
The Calpine deal is the largest unresolved variable. Roughly $11.5 billion of goodwill and long-term debt up to $19.1 billion from $7.25 billion represent an unretired claim on future gas generation economics in Texas and California.7 Goodwill impairments do not happen in good times; they happen when power prices or demand growth disappoint, which is precisely when the equity would already be under pressure. The seller was a specialist power investor exiting after sixteen years at a moment of maximum enthusiasm.
Regulatory risk to the entire AI-power structure is live rather than theoretical. FERC's rejection of the Talen-Amazon interconnection agreement demonstrated that regulators will intervene in how nuclear output reaches data centers.15 Constellation's virtual PPA structure is genuinely less exposed than physical co-location — but Talen has already migrated to a front-of-meter structure at comparable economics, which means the structural advantage is narrower than it appeared in 2024.17 On the second-quarter call, analysts pressed management specifically on the timing of PJM co-location rule clarity, which is a reasonable proxy for how unsettled the ground remains.24
Pricing power is situational. The gap between a restart contract negotiated from strength and a subsidy-replacement contract negotiated from necessity is the clearest available evidence that Constellation cannot simply mark its entire fleet to Crane economics.
The identifiable growth levers are finite. Capacity factors are near maximum, capacity auction prices are at a cap, and new-build is explicitly not imminent.22024 What remains — re-contracting, uprates, Calpine integration — is real but bounded, and the 20%-plus base earnings growth target through 2029 assumes all of it executes.30
Customer concentration is rising as a structural matter. When incremental growth depends on twenty-year contracts with a handful of hyperscalers, those counterparties acquire influence over terms, and a change in their capital expenditure plans transmits directly into Constellation's contracting pipeline. Multi-decade contracts with investment-grade names are a genuine credit strength; they are also a concentration.
Finally, valuation. At roughly 23 times forward earnings the stock is priced well above regulated utility norms and requires the contracting story to keep compounding.1 The 52-week range from $228.63 to $412.70 is itself evidence of how violently sentiment on this name can reprice.1
An activist's questions
A skeptical investor would push on four things. Why combine the chair and chief executive roles seven months after the largest acquisition in company history, when independent oversight of integration matters most?26 What is the disclosed sensitivity of the Calpine goodwill balance to power price and demand assumptions, and at what point does the impairment test bind?7 Given that adjusted operating earnings — the metric guidance, compensation, and consensus all key off — is a management-defined measure that excludes large mark-to-market items, is enough disclosed for outsiders to independently reconcile it? And with roughly 0.04% of shares held by the chief executive, is the alignment as strong as the incentive plan's design implies?14
None of these are accusations. They are the questions that determine whether the story holds under pressure.
Where the evidence lands
The cornered-resource claim survives, but in a narrowed form: Constellation controls physically irreplaceable assets whose value depends on demand from a concentrated buyer set and on regulatory tolerance for how that power is contracted. The capital allocation claim is supported by the divestiture mark and by an incentive structure that does not reward deal-making, but it has not been tested through a downcycle and cannot be until one arrives. The management credibility claim is supported by specific, controllable explanations for misses, consistent framing across filings and calls, and a public willingness to deflate the new-build narrative — a genuinely uncommon behavior.
What would falsify each: a goodwill impairment or a covenant-driven pause in buybacks would break the capital allocation case. A materially lower-priced or structurally worse hyperscaler contract, or a failure to add contracted volume in coming quarters, would break the pricing power case. A slip in the Crane restart past 2027 would break the execution case. Each is observable, dated, and disclosed.
XIV. Epilogue: What the Next Chapter Looks Like
Two events over the next eighteen months will do more to settle this story than any amount of analysis.
The first is Crane. If the reactor synchronizes to the grid in 2027 as guided, Constellation will have done something no American operator has done at this scale — brought a retired, decommissioning-track nuclear unit back into commercial service on an accelerated timeline, through the NRC, with federal financing, under contract to a hyperscaler.22122 That would validate the restart playbook and, by extension, the idea that Constellation's fleet contains latent capacity nobody else can unlock. A slip would not be fatal, but it would recalibrate expectations for every subsequent claim about execution.
The second is Calpine's first full year of integrated results. The 2026 numbers include the acquired business for most of a year, but they are also the year of divestitures, purchase accounting adjustments, and integration costs. A clean 2027 is where the promised $2 billion of incremental free cash flow either shows up in cash flow statements or does not.
Beneath both sits the single most important capital allocation indicator: whether the goodwill balance carried from Calpine survives its first genuine stress test. Power price weakness, a pause in data center construction, or execution slippage in ERCOT would each pressure the assumptions underpinning it. Nothing in the current disclosures suggests impairment is imminent. That is a statement about today, not a forecast.
Three metrics deserve ongoing attention, and only three. First, newly contracted long-term megawatts and their tenor and counterparty quality — the quarterly signing rate is the cleanest real-time read on whether pricing power is holding and whether hyperscaler demand is still converting into signed obligations. Second, PJM cleared capacity volume and price, because that revenue arrives with no incremental capital and reveals the state of the underlying supply-demand balance three years forward. Third, leverage and the goodwill balance together — net debt trajectory against EBITDA, alongside any change in the goodwill line, which is where an unsuccessful Calpine would first become visible in the financial statements rather than in commentary.
New nuclear construction remains a genuine option rather than a plan. Management has been explicit that New York conversations, small modular reactor interest, and site preparation have not reached the point of appearing as committed capital.24 The right treatment is to watch for a status change — a signed customer, a disclosed budget, an announced schedule — rather than to assume it into any current view of the business.
And the largest open question is not about Constellation at all. It is whether regulatory tolerance for behind-the-meter co-location widens or narrows from here, because that determines the architecture of the next wave of hyperscaler power deals. If regulators become more permissive, data centers may increasingly contract directly with generators and bypass the wholesale market, changing who captures the premium. If they tighten further, grid-connected structures like Constellation's become the industry standard by default, and the company's early positioning turns out to have been more durable than it looks today.
A company that once sold half its reactors to survive now owns the most contested electrons in America. Whether that is a permanent repositioning or the top of a cycle is a question the next three years will answer, and the answer will be visible in signed contracts, cleared auctions, and one line on the balance sheet.
References
-
Constellation Energy (CEG) Stock Price & Overview — StockAnalysis ↩↩↩↩
-
Constellation Reports Second Quarter 2026 Results — Constellation Energy, 2026-08-06 ↩↩↩↩↩↩↩↩↩↩
-
Constellation plans 2028 restart of Three Mile Island unit 1, spurred by Microsoft PPA — Utility Dive, 2024-09-20 ↩↩
-
Constellation's $16.4B purchase of Calpine would create largest US power generator — Utility Dive, 2025-01-10 ↩↩
-
Constellation Completes Calpine Transaction — Constellation Energy, 2026-01-07 ↩
-
Form 8-K, Calpine acquisition agreement, 2025-01-10 — SEC EDGAR ↩
-
Form 10-Q for the quarter ended June 30, 2026 — SEC EDGAR ↩↩↩↩↩↩↩
-
Constellation Burns Out For Buffett — Forbes, 2008-12-17 ↩↩↩↩
-
Constellation Energy to restart Three Mile Island nuclear plant, sell power to Microsoft for AI — CNBC, 2024-09-20 ↩
-
Constellation to Launch Crane Clean Energy Center — Constellation Energy, 2024-09-20 ↩
-
Form 8-K, Microsoft PPA / Crane Clean Energy Center announcement, 2024-09-20 — SEC EDGAR ↩
-
Constellation Reports Fourth Quarter and Full Year 2024 Results — Constellation Energy Investor Relations ↩↩
-
Constellation Reports Fourth Quarter and Full Year 2025 Results — Constellation Energy, 2026-02-24 ↩↩↩↩↩
-
DEF 14A, Notice of Annual Meeting and Proxy Statement 2026, filed 2026-03-19 — SEC EDGAR ↩↩↩↩
-
FERC rejects interconnection pact for Talen-Amazon data center deal at nuclear plant — Utility Dive, 2024-11-01 ↩↩
-
Meta, Constellation ink 20-year nuclear power deal to support AI goals — Utility Dive, 2025-06-03 ↩↩
-
Talen to sell Amazon 1.9 GW from Susquehanna nuclear plant — Utility Dive, 2025-06-11 ↩↩↩
-
Vistra and Meta ink PPA for 2.6 GW of nuclear power in PJM region — Power Engineering, 2026-01-09 ↩↩↩
-
PJM capacity prices set another record with 22% jump — Utility Dive, 2025-07-22 ↩↩↩
-
PJM capacity prices hit price cap, reserve shortfall grows — Utility Dive, 2026-07-15 ↩↩↩↩↩
-
U.S. Government Backs Constellation's Plan to Launch Crane Clean Energy Center — Constellation Energy, 2025-11-18 ↩↩
-
Christopher M. Crane Clean Energy Center; Draft Environmental Assessment and Draft Finding of No Significant Impact — Federal Register, 2026-06-08 ↩↩
-
Constellation Announces Agreement to Sell PJM Generation Assets to LS Power as Part of FERC, U.S. DOJ Resolution of Calpine Transaction — Constellation Energy, 2026-03-18 ↩↩↩↩
-
Constellation Energy (CEG) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-08-06 ↩↩↩↩↩↩↩↩↩↩↩
-
Kirkland Advises Constellation on Secondary Public Offering of Common Stock and Concurrent Share Repurchase — Kirkland & Ellis, 2026-06 ↩
-
Form 8-K, board chairman transition and new director, 2026-08-04 — SEC EDGAR ↩↩↩
-
Form 8-K, 2026 Annual Meeting voting results, 2026-04-28 — SEC EDGAR ↩
-
Constellation Energy shares fall as Q3 earnings miss expectations — Investing.com, 2025-11-07 ↩↩↩↩↩
-
A fast-track PJM interconnection review could speed Three Mile Island restart: Constellation CFO — Utility Dive, 2024-09-20 ↩↩
-
2026 Business and Earnings Outlook, March 31, 2026 — Constellation Energy Investor Relations ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube