Old Dominion Freight Line, Inc.: The Network That Charges More
I. The Freight Is Coming Back. Is the Business?
On September 3, 2026, Old Dominion Freight Line put out a short update that looked like good news. Revenue per day in August was up 12.4% on a year earlier.1 Anyone who had followed this company through two hard years could be forgiven for reading that line and thinking the freight recession was over.
The next line told a different story. Tons of less-than-truckload freight moved per day fell 0.9%. Shipments per day fell 2.4%. The average shipment got about 1.7% heavier, which was the only reason tonnage didn't fall further.1 Old Dominion's trucks were carrying a little less freight than a year earlier, and its customers were paying a lot more for it. Excluding fuel surcharges, revenue per hundredweight, the price the company collects for each hundred pounds it moves, was up 4.8% for the quarter to date. Including fuel, it was up 11.3%.1
So what is the customer's higher bill buying? Part of the answer is diesel. When fuel gets expensive, LTL carriers pass the cost through as a surcharge that moves almost automatically with a weekly government fuel index. That raises revenue without saying anything about competitive strength.2 The rest of the answer is the question this story is built around. A customer who pays Old Dominion about 5% more per pound, with fuel stripped out, at a time when that customer is shipping less, is either paying for something real, or is being charged a premium that will be tested once freight is plentiful again and rivals want it back.
The stakes come from the last two years. In 2025 revenue fell 5.5% to about $5.5 billion. Net income fell almost 14%, to about $1.02 billion. The operating ratio, the share of every revenue dollar consumed by operating costs and the number LTL carriers live and die by, worsened from 73.4% to 75.2%.3 Then, in the second quarter of 2026, things turned. Revenue rose 10.4%, the operating ratio improved to 70.1%, and diluted earnings per share reached $1.68,4 which equalled the company's quarterly record from the third quarter of 2022.5 Tonnage per day in that quarter was still down 4.1%.4 The profit recovery arrived before the freight did.
That gap between revenue and tonnage leads to three questions, and the rest of this story tries to answer them. First, did Old Dominion build a lasting advantage from service and network density, or did it simply run the best version of a commodity business? Second, can that advantage hold through a long freight downturn, when customers have less to ship and every carrier has empty trailer space? Third, is management spending the cash this machine produces, on terminals, trucks, buybacks and pay, at the right pace and for the right reasons?
The company itself is simple to describe, which helps. Old Dominion Freight Line, Inc. is the listed operating company on NASDAQ, with no parent above it and one reportable segment.2 In 2025, about $5.45 billion of its $5.50 billion of revenue came from LTL services. The rest came from container drayage, truckload brokerage and supply-chain consulting, which together brought in about $50 million.2 So this is an LTL company. Those side services support the main business; they are not a second leg.
LTL, or less-than-truckload, is the part of trucking that moves loads too big for a parcel van and too small to fill a trailer: a pallet of motor parts, three crates of furniture hardware, a skid of packaged food. The carrier picks these shipments up from many customers, consolidates them in a terminal, hauls them overnight to another terminal, sorts them again and delivers them. Doing that well takes a great deal of fixed infrastructure. Doing it profitably takes enough freight running through that infrastructure every night to cover its cost.
That is why the August update is a puzzle and not a victory lap. If the best network in the industry can charge more, the open question is what happens to that ability when customers have less freight to send. To see why Old Dominion believes it can keep charging more, the story has to go back to one truck and one route in Virginia.
 Subscribe on LinkedIn
II. One Truck, One Route, and a Rulebook
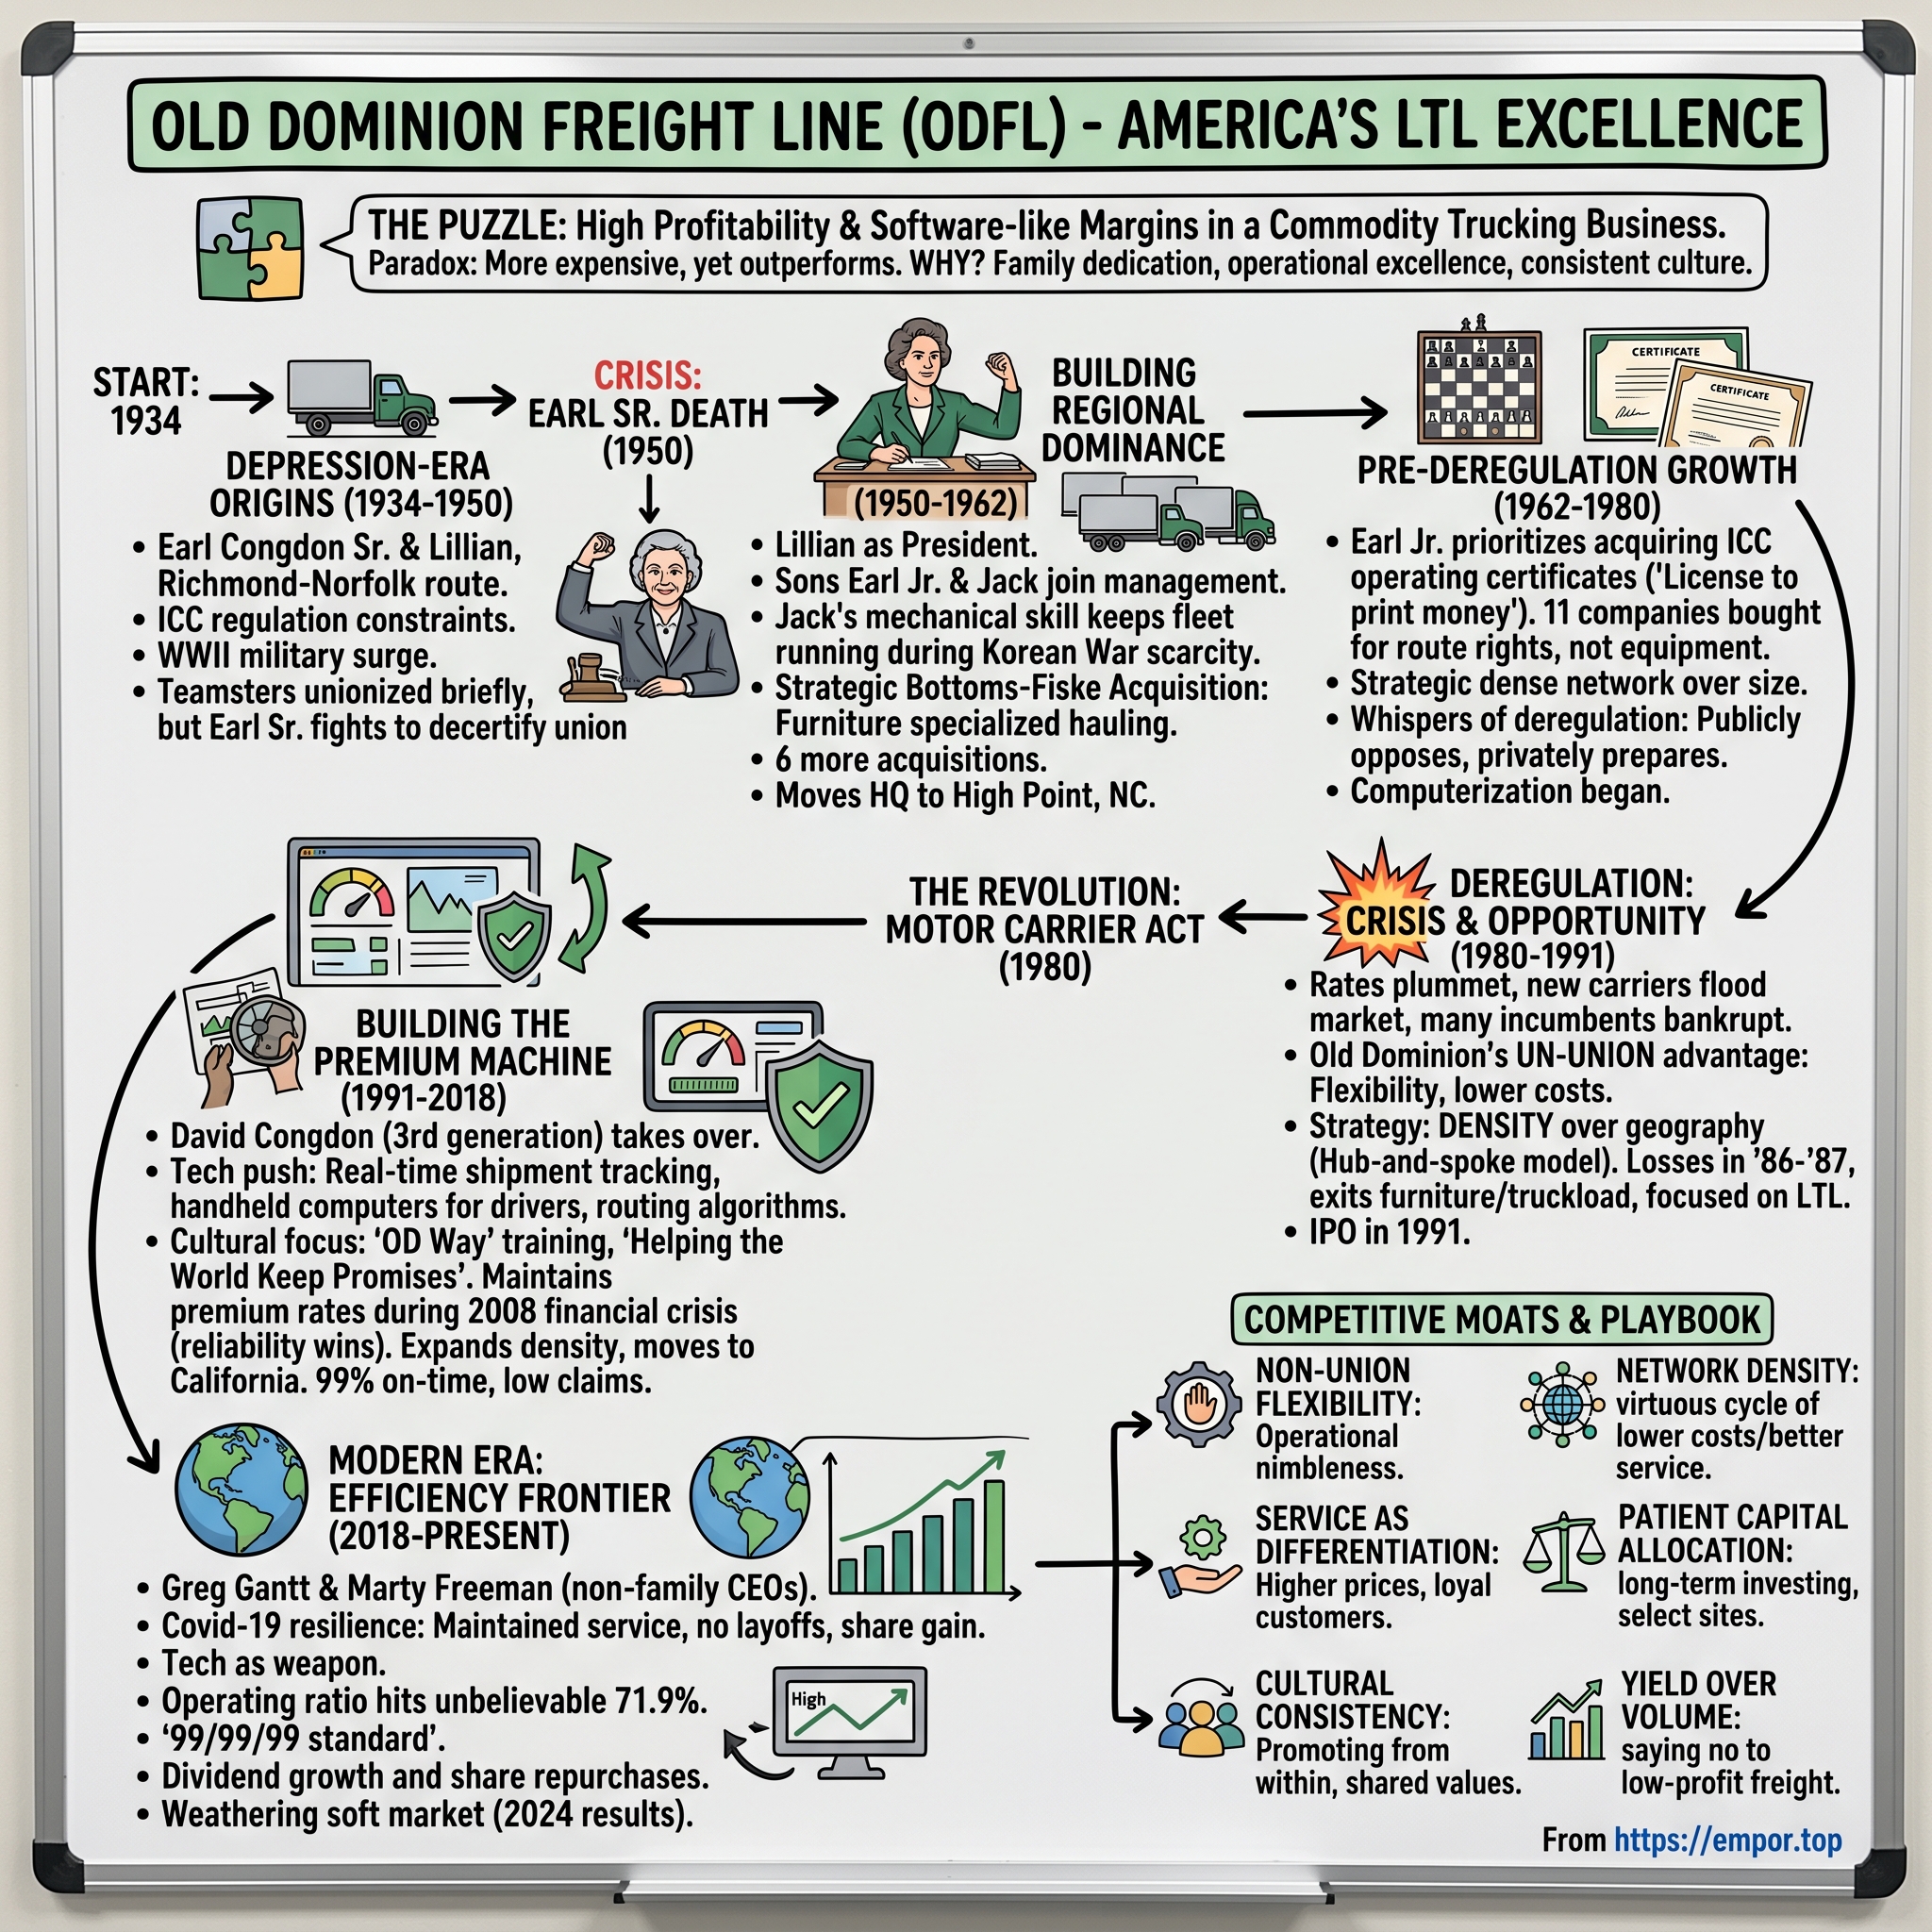
In 1934, in the middle of the Depression, Earl and Lillian Congdon started hauling freight in Virginia with one truck.6 The name they picked, Old Dominion, is the old nickname for the state, and in the early years the business stayed inside it. The company's own history places the original run between Richmond and Norfolk.6 An older published history puts it between Norfolk and Newport News,7 but either way it was a short haul along the Tidewater, run by a couple who knew every customer on the route.
Then Washington rewrote the rules. The Motor Carrier Act of 1935 brought interstate trucking under the Interstate Commerce Commission, which decided who could haul what, and where. Old Dominion received a certificate that let it keep serving its route and confined it to that route.6 For the next 45 years, this was how American trucking worked. Growth did not come from finding customers in a new city. It came from buying another carrier's operating rights, or from persuading the regulator to grant new ones.
World War II brought the first surge. Military traffic around Norfolk and the Hampton Roads bases filled the trucks, and by the 1940s the company had about 45 employees working out of three service centers. In 1948 it built its first new service center, in Norfolk.6 Peace was harder. Wartime volumes fell away, and a Teamsters-led strike followed. The Congdons shut the business for 11 weeks and reopened with non-union labor.7 Old Dominion has had no union since, and that early decision shows up again later in this story, in its cost structure, its flexibility and its risk disclosures.
Earl Congdon died in 1950. Lillian took the presidency and incorporated the company, and their sons Earl Jr. and Jack came into the business.6 In an industry run by gruff men with yard dust on their boots, a widow ran the company through the 1950s and remained chairman into the 1970s.6 What she put in place was a family business that grew by careful acquisition, adding certificates and terminals that joined up with the routes it already had, rather than by bold leaps.
The first big deal was in 1957, when Old Dominion bought Bottoms-Fiske Truck Line, which took its service into most of the major markets of North Carolina and southern Virginia.6 In 1962 the company merged with Bottoms-Fiske and moved its headquarters south to High Point, North Carolina, the center of the American furniture trade. Earl Jr. became president and Lillian became chairman.6 Through the 1960s and 1970s it added Barnes Truck Line, Nilson Motor Express, White Transport and then Star Transport, which brought it into the Northeast.67 The local route business had become a regional network.
The early record already shows the logic of the industry. Every certificate the Congdons bought was a right to serve a lane. A right to serve a lane is not the same as a profitable lane. A new lane only pays when enough freight flows over it, in both directions, to keep the trucks loaded and the dock crews busy. If the outbound trailer from High Point leaves full and comes back half empty, the round trip is barely worth running. What the Congdons learned was that density on the lanes mattered more than the number of points on the map.
By the end of the 1970s, Old Dominion was a solid southeastern carrier operating behind the protection of regulation. The ICC limited who it could compete with, and it also limited where it could go. Then Congress tore down that system, which meant the company could grow beyond its certificates, but had to find out whether it could do so without losing control of service and costs.
III. Deregulation Opens the Map—and the Losses
The Motor Carrier Act of 1980 made operating authority, which carriers had once bought and sold like taxi medallions, close to a formality. Old Dominion moved fast. Within a few years it was offering service to points in Florida, Tennessee, California, Dallas and Chicago without needing the regulator's approval for each one.76 For a company that had spent half a century working inside a list of approved routes, this was the moment the map opened up.
The opening had a price, and the price was paid in the yard. Deregulation let a carrier announce service to Dallas, but it did not hand it Dallas freight. To serve a new city, Old Dominion had to lease or build a terminal, put tractors and trailers in it, hire drivers and dock workers, and then win enough shipments to keep them busy. In the first half of the 1980s the company opened 27 service centers.7 Each one carried rent, wages and equipment costs from the first day. The freight to cover those costs came later, and sometimes much later.
Old Dominion also had a sharper sales pitch than most of its new competitors. Deregulation set off a price war, and the unionized national carriers, bound by national labor agreements, struggled to adjust. Old Dominion went after their customers and argued that its non-union workforce gave it more flexibility in scheduling and staffing.7 The company also brought in its first president from outside the family, John Ebeling, an industry veteran who pushed quality management and computerization.7 Ebeling had spent the years from 1978 to 1985 at ANR Freight Systems before joining Old Dominion,8 and his arrival marked a family company starting to bring in professional managers.
The company had also bought its way into a different business before deregulation hit. The 1979 acquisition of Deaton Trucking, a New Jersey carrier, took Old Dominion into full truckload and flatbed hauling.7 On paper, that diversified the company. In practice, truckload and LTL are different businesses that share trucks but not economics. A truckload carrier sells a whole trailer from A to B, and there is no terminal network to fill. An LTL carrier sells the use of its network, and its economics depend on how much freight flows through the terminals. Owning both did not solve the problem that was actually hurting Old Dominion: too much new LTL capacity and not enough freight for it.
The bill arrived in 1986 and 1987. Heavy investment plus fierce post-deregulation competition pushed the company into losses in both years.7 The family business had grown faster than its freight, and the costs of a wider network had arrived before the revenue to pay for them. The lesson would come back in every later chapter: a terminal opened ahead of the freight is a fixed cost, and fixed costs are cruel when volumes disappoint.
The recovery took time. By 1990 sales had reached $134.8 million, up 17% on 1989, with a net profit of $4.7 million, and the network had 47 service centers in 20 states, mostly in eight southeastern states.7 That is a thin margin, about 3.5 cents of profit on each dollar of revenue, but it was a profit.
Then came the decision that shaped the modern company. In 1991, Old Dominion stopped hauling furniture, the business tied to its High Point home, and sold Deaton's general-commodities truckload and flatbed division.7 It was a retreat, and a deliberate one. The company was choosing to be an LTL carrier, and only an LTL carrier, and to compete on the density of its own network rather than on how many services it offered.
Investors should note what that retreat says about management. Old Dominion's leaders had tried diversification and fast geographic expansion, and the losses told them to stop. Many companies never cut back after an expansion goes wrong; they keep spending to justify what they have already spent. This one narrowed its focus. The question it took into the 1990s was whether a newly public company could pay for the network it now wanted without chasing size for its own sake.
IV. The IPO, the Tuck-In Deals, and the Choice to Fill the Network
In late 1991, the narrowed Old Dominion went public at $12.50 a share and raised $15.6 million.7 By Wall Street standards it was a small deal, and the money went to repaying debt and funding geographic expansion.7 What mattered more than the cash was the discipline that came with being public. Every quarter after that, outside investors could see the operating ratio, the tonnage and the cost of each new terminal.
The 1990s growth model was not big, transformative mergers. Old Dominion bought pieces of other carriers, usually terminals, equipment and a foothold in a market, and folded them into its own operating system. In September 1995 it bought assets of Navajo, a Denver LTL carrier, including 82 tractors, 264 trailers and ten service centers, which opened markets in the Southwest. By the end of that year it operated 67 service centers in 35 states and Washington, D.C.7
The best-documented case came in 1998. In January Old Dominion bought selected assets of Fredrickson Motor Express, and in August it bought selected assets of Goggin Truck Line, two LTL carriers operating mainly in the Southeast.8 It did not take on these companies as going concerns with their management, culture and liabilities. It picked the parts it wanted. The assets acquired had an estimated fair value of about $18.2 million, and Old Dominion took on about $8.9 million of liabilities with them.8 It then liquidated about $7.4 million of the acquired assets.8 In other words, about four of every ten dollars of assets acquired were sold off or wound down soon after the deal, because they duplicated what Old Dominion already had.
The terminal count tells the same story. Fredrickson brought 26 terminals, 19 of which overlapped facilities Old Dominion already ran.7 Together the two 1998 deals added just nine service centers to the network.8 Old Dominion was buying the missing pieces of a map it had already drawn, and it threw out the rest. In January 1999 it added selected LTL assets of Skyline Transportation for $1.1 million.9 Early in 2001 it agreed to buy assets of Carter & Sons Freightway in Texas, with cash outlays and assumed equipment leases expected to total about $9.2 million.9
Did Old Dominion overpay? The filings do not settle it. The company reported that the pro forma effect of the acquisitions on revenue, operating income and earnings per share was not material,9 and it never disclosed the acquired businesses' earnings, so a clean purchase multiple cannot be calculated. What can be said is that these were small, asset-level deals with immediate disposals of what wasn't needed, not the sort of large bet that can sink a company.
The more revealing evidence is what came after. The acquisitions shortened the average haul and lifted regional revenue, which grew 22% in 1998 against 14% for inter-regional revenue.8 The operating ratio, though, barely moved, from 94.1% in 1998 to 94.4% in 2000, after dipping to 93.4% in 1999.89 At the turn of the century, Old Dominion was still keeping only about six cents of every revenue dollar as operating profit.
The way Old Dominion described itself in those years explains what it was trying to build. In its 1998 annual report it called itself an "inter-regional and multi-regional" carrier, and its pitch was speed. On key lanes of between 500 and 1,500 miles it published delivery standards of two to three days, which it said were faster than those of its main national competitors because its service-center network was more efficient. On regional lanes under 500 miles it offered one- or two-day delivery.8 About 71% of its revenue that year came from inter-regional freight.8 Old Dominion was positioning itself between the regional carriers, which were fast but local, and the national carriers, which were everywhere but slower. It wanted to be both fast and wide.
Then there were the people. The founding generation was passing. Lillian Congdon Crowder, who had run the company after her husband's death, died in the 1990s, and David Congdon, a younger member of the family, rose to president.6 He had been named chief operating officer in 1998,7 and he would later become executive chairman, the title he still holds.10 The family stayed in the building, but the company was being run more and more by professional operators who had grown up inside it.
What changed the margin was not another deal. It was a strategy to fill the network. In 2000 the company described its plan to win more share in markets it already served by offering "full state coverage" in 16 states east of the Mississippi, extended to 21 by mid-year. Where it lacked density, it used agents to reach remote points, intending to replace them with its own people and trucks as share built.9 It added a fuel surcharge in August 1999 and launched an expedited product, Speed Service, in early 2000.9 And it tracked what it called improvements in asset utilization, as depreciation, rents and operating taxes fell as a share of revenue.9
The early 2000s brought one more large tuck-in and a new home. The Carter & Sons purchase added 23 service centers in Texas and Oklahoma, and by 2002 sales had reached about $556.5 million.7 The company moved its headquarters to Thomasville, North Carolina, a move it links to a network upgrade and better technology.6 That technology was practical, not glamorous: handheld devices that recorded proof of delivery and gave real-time shipment status, dispatch and route-planning software, and a dock yard system that used radio tags to track trailers in and out of terminals.7 None of it would win a design award. All of it was aimed at the handoffs where an LTL carrier makes or loses money.
The next fifteen years were spent turning that idea into margin. By 2015 revenue had reached about $2.97 billion and the operating ratio had improved to 83.2%, from 85.5% in 2013.11 Old Dominion ran 225 service centers and had become the fourth-largest LTL carrier in the country by 2014 revenue.11 It said the growth had come "primarily" through organic market share gains, and that only 12 of the 71 service centers added since the end of 2005 had come in the previous five years.11 In other words, revenue was growing much faster than the terminal count. More freight was flowing through the same buildings.
That is a density story, not a deals story, and the record supports it. The question is how a carrier that once looked like a southeastern regional made its reliability visible enough, across a far bigger map, for customers to pay for it.
V. The Service Promise Becomes an Operating System
Follow one shipment. Late on a weekday afternoon, an Old Dominion driver backs up to a distributor's dock in suburban Atlanta and loads four pallets of plumbing fittings bound for a contractor supply house outside Indianapolis. The same truck has already collected a dozen other shipments on its route. By early evening it is back at the local service center, where dock workers scan each pallet, weigh it, and move it across the floor to an outbound trailer loaded by destination. Overnight that trailer goes to a breakbulk hub, where it is unloaded and sorted again. Another tractor takes it north. By the next morning or the one after, a local driver in Indiana is putting the fittings on a contractor's dock.
Each of those steps is a chance to get something wrong. A pallet loaded on the wrong trailer misses a day. A forklift spearing a crate becomes a damage claim. A trailer that leaves the hub two-thirds full means the company has paid for a whole truck and a whole driver to move two-thirds of a load. Old Dominion's whole business comes down to doing those handoffs thousands of times a night with fewer errors and fuller trailers than its competitors.
The company describes the mechanics plainly. Service centers handle local pickup and delivery. Each night they load outbound freight for other service centers, and the next day they deliver what arrived overnight. Linehaul dispatchers move freight between centers through integrated systems and load-planning software, and managers watch transit times, load factors and productivity measures daily.11 Tractors that run linehaul at night often do local pickup and delivery during the day, to get more hours out of each truck.11 On the second-quarter 2026 call, the company said it had made about 1,000 lane adjustments to speed up transit times, and that essentially all of its linehaul was run by its own drivers rather than outsourced.5
The economics follow from that design. The terminals, the trailers and the night shift are largely fixed. Each extra shipment that goes through an existing building and onto a trailer that would have left anyway costs very little to handle and adds almost its full price to profit. That is why density is the word every LTL executive repeats. More shipments per stop on a pickup route means more stops per hour. More pounds per trailer means a higher linehaul load factor. More pallets crossing the same dock means more productive labor. A new terminal works the other way round: it adds cost long before it adds density, which is exactly the trap Old Dominion fell into in the mid-1980s.
Old Dominion has built a very large version of that machine. At the end of 2025 it operated 260 service centers, owned 240 of them, and owned the facilities that accounted for about 96% of its total door capacity.2 It owned 10,184 tractors.2 It employed 20,591 full-time people, and none were represented by a union.2 Owning the real estate matters more than it sounds: in a downturn there is no landlord to pay, and in an upturn the company does not need anyone's permission to add doors.
The terminal count also hides how the network has grown. Over the ten years to 2025, Old Dominion opened a net 35 service centers, going from 225 to 260, while revenue nearly doubled.211 Most of the added capacity came from expanding, renovating and relocating existing buildings, not from planting new flags on the map.2 That is the 1980s lesson put into practice: grow the doors where the freight already is, and add a new city only when the lanes around it can feed it.
The company's argument to customers is reliability. In the first quarter of 2026 it reported 99% on-time service and a cargo claims ratio below 0.1%, which means that for every thousand dollars of revenue, less than a dollar was paid out for lost or damaged freight.12 In October 2026, the logistics research firm Mastio & Company again named Old Dominion the top national LTL carrier for quality, for the 17th year running, based on a survey of 1,647 logistics professionals in which the company ranked first in 24 categories.13 Marty Freeman, the CEO, made the point that matters most to investors when he said the award counted because "it is selected by shippers."13
That is real evidence. A 17-year streak in a survey of customers is not a slogan, and a claims ratio below one-tenth of a percent requires discipline every night in hundreds of buildings. But there is a gap between being preferred and being paid, and Old Dominion's disclosures don't close it. The company does not publish customer retention rates, the price premium it charges over peers on comparable lanes, or any measure of how costly it is for a shipper to leave. The premium has to be inferred from yield and margin data, and those are affected by mix, length of haul and fuel.
The customer base cuts both ways. No single customer accounted for more than 5% of revenue in any year from 2023 through 2025, and the company describes its customers as spread widely across industries and regions.2 That protects Old Dominion from any one account walking away. It also tells you that most customers are not locked in. A shipper can give Old Dominion its time-sensitive lanes and give a cheaper regional carrier everything else.
Third-party logistics brokers make that sort of splitting easier, and on the second-quarter 2026 call the CFO, Adam Satterfield, said brokers accounted for about a third of revenue. He added that the company prices every account to earn similar profitability, whoever brings the freight.5 That is a disciplined pricing policy, and it also means a third of the business arrives through an intermediary whose job is to shop for the best combination of price and service.
The labor arrangements need care. Old Dominion describes itself as a "single integrated, union-free organization."2 It cross-trains employees, uses flexible scheduling, and since 1988 has trained its own employees to become drivers. By the end of 2015, about 2,600 active drivers, roughly 27% of its driver workforce, had come through that program.11 A dock worker who becomes a driver already knows how freight is loaded, how the terminal runs and what the company expects, which is part of how service standards survive growth.
The absence of union work rules plausibly helps the company move people between the dock and the road as volumes shift. But many non-union carriers have not matched Old Dominion's results, so labor arrangements cannot explain the service record by themselves. The company also lists unionization among its risk factors, warning that restrictive work rules could hurt both its efficiency and its service.2
By 2022, all of this had carried Old Dominion to record revenue. The service system was real, it was measurable, and customers rated it the best in the industry. The cycle then tested how much of that record could be turned into pricing when demand fell away.
VI. Yellow's Exit, the Pandemic Boom, and the New CEO
On a Sunday at the end of July 2023, drivers and dock workers at Yellow Corporation, one of the best-known names in American LTL, arrived to find terminal gates locked. The company had laid off hundreds of non-union staff the Friday before. The Teamsters said Yellow was ceasing operations and filing for bankruptcy.14 About 30,000 jobs were at risk. Yellow owed about $1.5 billion, including $729 million to the federal government from a pandemic-era loan.14 Its daily shipments had already collapsed from about 49,000 in 2022 to an estimated 10,000 to 15,000 as customers fled.14
For Old Dominion, Yellow's collapse was the kind of moment its strategy had been built for. Freight that had moved through Yellow's terminals had to go somewhere, and the carriers that could take it without hurting their own service would keep the best of it. Between the second and third quarters of 2023, Old Dominion's daily shipments rose 5.7% and its operating ratio improved by 1.7 percentage points.15 It took that freight without visible strain because it had built ahead: the company said it typically ran with about 25% spare capacity and had grown its door count by about half through roughly $2 billion of real estate investment over the previous decade.15
The comparison with its peers is more revealing. Saia, the fast-growing rival that had been expanding its terminal network, grew daily shipments by 11.3% over the same stretch, roughly twice Old Dominion's rate, and absorbed more than 1,000 new employees while its operating ratio worsened.15 Old Dominion chose margin over volume, as it nearly always does. It took the freight it could handle well and left the rest for competitors.
The boom that came before Yellow's failure deserves its own look. When the pandemic pushed American spending from services to goods, warehouses filled, industrial supply chains strained, and LTL capacity became scarce across the industry. Old Dominion did not reinvent itself in those years. It used the terminal and service system it had spent decades building to serve that surge at higher prices. Revenue reached about $5.26 billion in 2021, with a 73.5% operating ratio.16 When capacity is short, shippers pay for the carrier that will actually pick up the freight, and that is exactly the moment a reputation for reliability earns the most.
The Yellow numbers need context, because the Yellow story is often told as the moment Old Dominion's advantage was confirmed. The company's own annual figures complicate that. In 2022, before Yellow failed, Old Dominion had a record year: revenue up about 19% to about $6.26 billion, net income of about $1.38 billion, and an operating ratio of 70.6%, down from 73.5% in 2021.16 Yet tonnage per day rose only half a percent that year.16
Like the rebound in 2026, the record year was driven almost entirely by price and fuel, not by more freight. Then, in 2023, the year Yellow's freight became available, revenue fell to about $5.9 billion. It fell again, to about $5.5 billion in 2025.2 By 2025 revenue was about 12% below the 2022 peak, and the operating ratio had worsened from 70.6% to 75.2%.163
The conclusion is not that Old Dominion handled Yellow badly. It took share in an orderly way and protected its service. The conclusion is that one competitor's failure, however large, could not offset a broad industrial freight recession. The pandemic boom had pushed the company to a peak of volume and pricing, and some of that turned out to be cyclical, not permanent.
In the middle of all this the company changed CEOs. On January 31, 2023, Old Dominion announced that Greg Gantt would retire as president and CEO at the end of June, and that Kevin M. Freeman, known throughout the company as Marty, would succeed him on July 1.10 Freeman had joined Old Dominion in February 1992. He had been senior vice president of sales from 2011 to 2018 and then executive vice president and chief operating officer.10 He was 63 when the succession was announced,10 with more than four decades in the trucking industry.17 Executive chairman David Congdon praised Gantt as "a steward of the Company's unique culture," and Gantt described the handover as part of a long-term plan to develop leaders from inside.10
This was a continuity appointment, not a turnaround hire. Freeman had sold the service promise to customers and then run the operation that delivered it. There was no new strategy, no new acquisitions program, and no change in the pricing philosophy. The tone of his early messages confirms it. Through 2025 Freeman kept describing a "prolonged period of macroeconomic softness" while insisting that the company's plan of "superior service at a fair price" would let it win market share.3
That consistency is a strength and also a risk. It means investors know what they are getting: a management team that will not chase cheap freight to fill trucks. It also means management's credibility rests on whether the strategy works through a downturn, not on whether it can describe a new one. The next test was whether this leadership could explain weak volumes plainly and adjust its capacity without damaging the service that justified its prices.
VII. The Freight Recession Tests the Price of Quality
Picture the second-quarter 2025 earnings call. Tonnage per day was down 9.3% on a year earlier. The operating ratio had worsened by 2.7 percentage points to 74.6%. Overhead had grown as a share of revenue.18 Analysts kept asking, in one form or another, whether Old Dominion would cut prices to win back freight. Adam Satterfield's answer was the company's creed in one sentence: "We don't feel the need to chase bad revenue."18
That sentence sums up how Old Dominion approached the recession, and 2025 shows what it cost. Shipments per day fell 7.5% across the year and tonnage per day fell 8.8%. Revenue per hundredweight rose 3.9%, and 4.8% excluding fuel surcharges.3 So the company held price; the decline in revenue came almost entirely from lower volume. With about 55% to 60% of its business tied to industrial customers,18 Old Dominion was exposed to a manufacturing economy that had been unsettled by tariff uncertainty, with customers delaying orders.18
Taking the 2025 operating ratio apart shows where the damage landed. Salaries, wages and benefits rose from 46.2% of revenue to 47.9%. Depreciation rose from 5.9% to 6.6%.2 Those two lines account for the whole 1.8-point deterioration and more; lower fuel and maintenance costs and slightly lower insurance claims recovered part of it.2 The story there is simple. The company kept its people, its terminals and its trucks, which it had bought for a bigger freight base, and spread those costs over fewer shipments. Depreciation rose in dollar terms too, by about $20 million, because the 2024 and 2025 capital programs were coming onto the books.2 That is what operating leverage looks like in reverse.
The fourth quarter of 2025 was the low point. Tonnage per day fell 10.7%, and the operating ratio for the quarter was 76.7%.3 Freeman told investors the company was "cautiously optimistic that we will see some recovery and demand within the industry," and argued that steady capital spending through the cycle had "differentiated us."19
The turn started early in 2026, though it did not look like one at first. In the first quarter revenue still fell 2.9%, tonnage per day was down 7.7%, shipments per day fell 7.9%, and the operating ratio worsened to 76.2% from 75.4%.12 Ex-fuel yield, though, rose 4.4%, and average full-time headcount was down about 7% on a year earlier, to about 20,300.12 The company was shrinking its labor force to match its freight while protecting its prices. Freeman said demand "improved as the quarter progressed," and credited the company's "long-term, disciplined approach to yield management."12
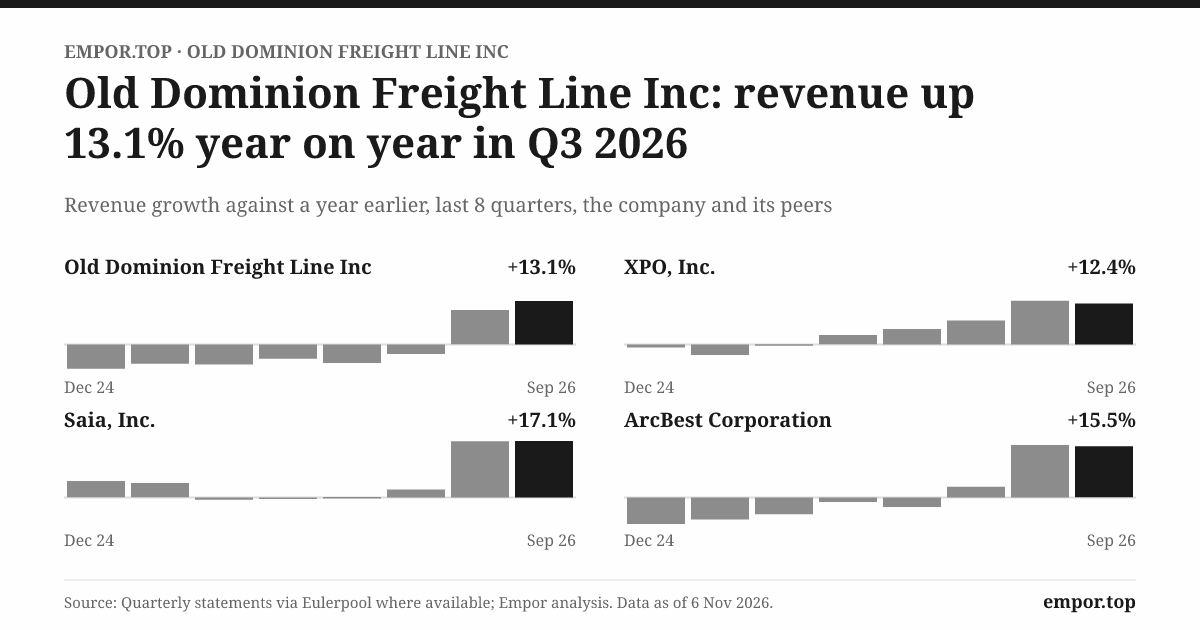
Then came the second quarter. Revenue rose 10.4% to about $1.55 billion. Operating income rose 30%. The operating ratio improved by 4.5 points to 70.1%.4 LTL revenue per hundredweight rose 15.2%, or 5.5% excluding fuel. Tonnage per day still fell 4.1%, and shipments per day were down 5.7%.4
That spread between the two price measures goes to the heart of the matter. Total revenue per hundredweight rose 15.2%, while the ex-fuel number rose 5.5%. Roughly two-thirds of the per-pound increase was fuel surcharge, money that tracks the price of diesel and largely flows straight back out as fuel expense. Satterfield's third-quarter outlook assumed diesel at about $4.95 a gallon.5 The 5.5% ex-fuel increase is the real evidence of pricing power, and it is meaningful: the company was raising its underlying rates while losing tonnage, which suggests customers were accepting increases instead of leaving. But it also means the headline 10% revenue growth was partly a fuel story.
The margin needs one more adjustment. In the second quarter, Old Dominion recorded $17.2 million of net gains on property and equipment disposals, which reduced its overhead line.4 That is about 1.1% of the quarter's revenue, which means the underlying operating ratio was closer to 71% than 70%. To its credit, management said so. Satterfield told analysts that, normalized for the gain, he expected the operating ratio to rise by 1.5 to 2 points sequentially in the third quarter, and he confirmed that guidance was on a GAAP basis because the company generally avoids non-GAAP measures.5 That is the kind of disclosure that earns a management team trust.
The question-and-answer session of that call says more than the prepared remarks. Freeman's prepared message was that demand had been improving since late 2025 and that Old Dominion had capacity to take more volume.5 Satterfield's answers were more measured. Through July, he said, revenue per day was up roughly 7.5% to 8% with tonnage down about 1%, and ex-fuel yield was tracking below the second quarter's pace because of freight mix. He expected third-quarter yield growth of 4% to 4.5%.5
Asked whether the macro picture supported a real recovery, he pointed to low inventories but described the ISM manufacturing index as in the low 50s without a breakout, and said the company was "not in the type of environment yet" that it saw in 2018 or 2021.5 When an analyst asked about competitors, Freeman said Old Dominion was "not having any capacity issues," while some rivals were struggling with end-of-month pickups, which was sending some freight to Old Dominion, temporarily.5
Put those answers together and the picture becomes clear. The prepared remarks spoke of improving demand. The answers spoke of mix, a still-modest manufacturing economy and some freight borrowed from struggling competitors. Both are true. Tonnage per day was improving sequentially, up 4% from the first quarter to the second, and Satterfield called the change from June into July "significantly better than our normal seasonality."5 But the year-over-year comparison stayed negative.
The August update fits that pattern. Revenue per day was up 12.4%, ex-fuel yield 4.8% for the quarter to date, and tons per day down 0.9%.1 That ex-fuel yield is slightly better than Satterfield's 4% to 4.5% guide, and the volume decline had almost disappeared. Freeman said "underlying demand trends" had remained "relatively consistent" through the quarter.1
The verdict is a narrower version of the bull case. The recovery has moved beyond pricing: volumes are improving month by month and the year-over-year decline is nearly gone. But as of the last disclosed month, the company was still moving less freight than a year earlier, and a large part of the revenue growth was fuel. Old Dominion has shown it can hold price in a recession. It has not yet shown that freight is coming back to it in volume. The figure that will settle it is simple: a sustained run of positive year-over-year tonnage, without a fall in ex-fuel yield. Until then, the recovery remains mostly a pricing story, and that raises the question of what management is doing with the money.
VIII. The Next Dollar: Terminals, Trucks, Pay, and Buybacks
Consider the capital decision Old Dominion faced at the start of 2026. Tonnage per day had just fallen almost 9% in a single year. The company's own CFO later said that service-center capacity was more than 35% in excess of current needs.5 Any ordinary business in that position would cut capital spending to the bone. Old Dominion planned to spend about $265 million,3 and in July it raised the plan to about $380 million.4
That decision needs to be judged against the cycle. In 2024, when the company still expected growth, it spent about $770 million on property and equipment. In 2025 it cut that to about $415 million.2 The company says it historically spends 10% to 15% of revenue on capital, and that some years will fall outside that range as it balances the size of its network with demand.2 In 2025, gross capital spending was about 7.5% of revenue. Spending on tractors and trailers alone fell from about $323 million in 2024 to about $174 million in 2025.2 The company stopped buying growth equipment and let its spare capacity absorb the slack.
The raised 2026 plan breaks down into about $180 million for real estate and service-center expansion, $155 million for tractors and trailers, and $45 million for technology and other assets.4 On the second-quarter call, Satterfield explained the $115 million increase: about $55 million of extra real estate spending reflected strategic property purchases, and about $60 million of equipment had been pulled forward from 2027. He said the company would lean toward replacing equipment rather than adding to the fleet.5 It also said it would keep headcount roughly flat through the second half of 2026, and could restart driver training in anticipation of growth in the spring of 2027.5
The thinking behind this is clear. Land near big metro areas is scarce and slow to permit, and a carrier that waits for the upturn to buy it will either pay more or wait longer. Buying in a weak market, when sellers are fewer and the network does not yet need the property, is a defensible way to allocate capital, and it fits the 2023 Yellow episode. The risk is the one the company's own risk factors name: projected freight growth may differ from what actually happens, and investments based on those projections can add excess capacity that hurts profitability.2 The 1980s are the reminder that this has happened to Old Dominion before.
The cash to pay for all this is plentiful. Operating cash flow was $1.37 billion in 2025 against net income of $1.02 billion. Most of the difference was about $365 million of depreciation, partly offset by lower accrued pay and payables.2 Depreciation is worth dwelling on: it is not an accounting curiosity here, but a reminder that the network needs constant replacement of trucks, trailers and buildings, even when the trailers are half full.
The quality of that cash is high. Customers pay on short terms, and receivables fell to about $472 million at the end of 2025 from about $502 million a year earlier, as revenue declined.2 The allowance for bad debts was less than $8 million, a sliver of the balance.2 Ernst & Young gave clean opinions on both the financial statements and internal controls, and the company describes its legal proceedings as ordinary-course matters that it does not expect to have a material effect.2 There is no hidden working-capital drain or accounting judgment that changes the picture. The profits are turning into cash.
Where did the rest of the cash go? Mostly back to shareholders. In 2025 Old Dominion bought back about $730 million of stock and paid about $236 million in dividends,3 almost $1 billion in total, or more than twice its capital spending. Shares outstanding fell from about 213 million at the end of 2024 to about 209 million at the end of 2025.2 Year-end cash fell to about $120 million.2 In the first half of 2026 it spent another $240 million on buybacks and $121 million on dividends, while operating cash flow was $646 million.4 At the end of 2025, about $1.54 billion remained on the 2023 buyback authorization.2
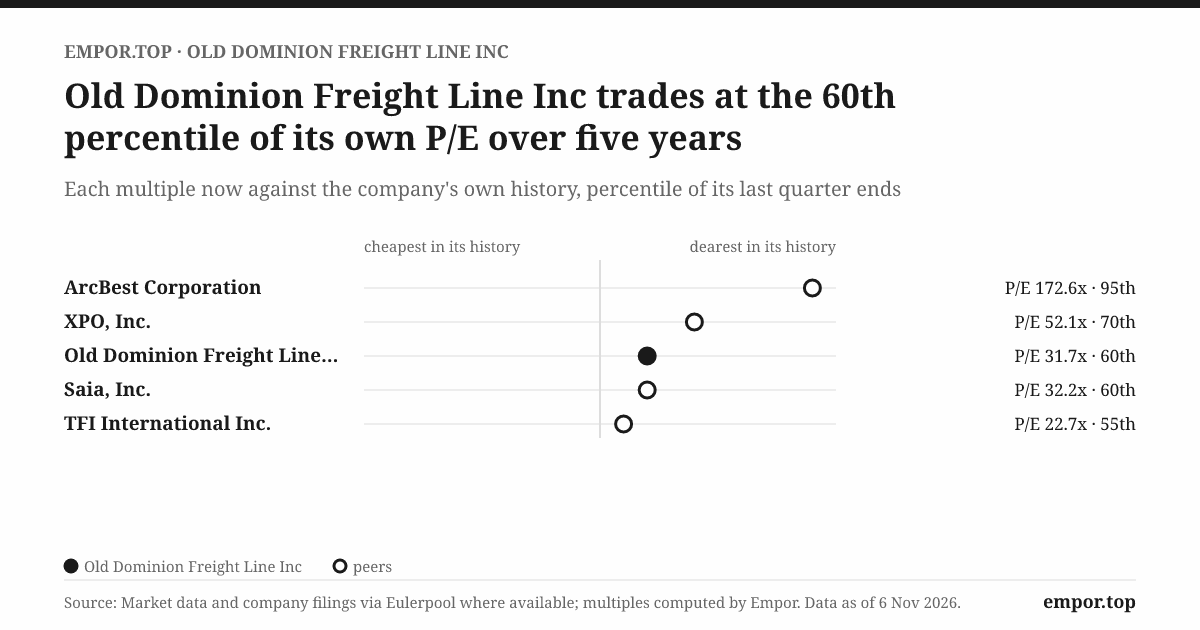
The test of the buybacks is the price paid. At the end of 2025, Old Dominion's shares traded at about 32 times trailing earnings, after about 32 times at the end of 2024.20 The company was buying back its own stock, repeatedly, at a multiple that assumes a lot of future growth. That is not necessarily wrong. A company confident in its long-run share gains might reasonably believe its stock is worth more than a cyclical trough suggests. But a skeptical investor would point out that buybacks at more than 30 times earnings only create value if earnings grow fast enough to justify the price, and that the cash spent on them was not spent on the network. To date, the company has not had to choose between the two; it has funded both.
Pay tells you what management is rewarded for. In 2025 Freeman's total compensation was about $11.6 million: about $1 million in salary, $2.4 million in stock awards and $8.2 million from the non-equity incentive plan.17 His total had been about $12.6 million in 2024 and $9.5 million in 2023.17 The incentive plan is unusual, and shareholders should understand how it works. It pays monthly, as a fixed percentage of pre-tax income, nothing below a threshold, and is capped at ten times base salary.17
So pay rises and falls with profit dollars, which is why the CEO's total fell when 2025 earnings fell. But the formula does not explicitly reward return on capital, market share, or per-share outcomes. A manager paid on pre-tax income has no direct incentive to overbuild the network, but also no direct penalty for spending capital that earns a poor return.
The owners keep watch. Vanguard holds about 11.1% of the stock and BlackRock about 6.7%. The Congdon family remains present: Executive Chairman David S. Congdon holds about 3.7% and his cousin John R. Congdon Jr., a director, about 4.2%. Directors and executive officers as a group hold about 8.2%.17 Eight of twelve director nominees are independent, and there is a lead independent director. John Kasarda held that role from May 2025 until the 2026 annual meeting, after which Andrew Davis took over.17
At the 2026 annual meeting, 96.8% of votes cast supported the say-on-pay resolution, while lead independent director John Kasarda received the largest withheld vote among the nominees.21 The company reports no related-party operating transactions, no fees paid to family entities and no loans or receivables between the company and its insiders.2 The governance question is about family influence on the board, not about cash leaking out through side deals, and the voting record shows outside shareholders largely content.
The balance sheet gives management a lot of room. At June 30, 2026, Old Dominion owed just $20 million of senior notes, all due within a year, and had drawn nothing on its credit facility.22 At the end of 2025, the $400 million revolver had about $362.5 million available after letters of credit, and operating lease liabilities were about $101 million. Those are a separate obligation from funded debt and should be kept apart from it.2 Old Dominion is, in practical terms, debt-free.
The forward test for this capital is the next upturn. The new terminals and the pulled-forward trucks will only have earned their place if tonnage grows into them, if terminal utilization rises, and if the operating ratio returns toward its best levels on volume rather than price alone. To judge whether that is likely, the analysis has to move from the yard to the market, and ask what kind of advantage Old Dominion actually has.
IX. Why Old Dominion Wins—and Where the Edge Can Break
A procurement manager at an industrial distributor in Ohio is reviewing next year's LTL contract. One bid is from a regional carrier and comes in several percent cheaper. The other is from Old Dominion. Last year, Old Dominion delivered almost every shipment on time and its claims were barely measurable. The regional carrier was fine most weeks, and had a bad month when a terminal got congested. The manager has to decide what reliability is worth: what it costs when a production line waits on a late pallet, when a customer gets a crushed crate, when someone spends an afternoon chasing a missing shipment. Old Dominion's whole business depends on how many managers decide that reliability is worth paying for, and how many keep deciding that when the cheaper carrier comes back with an even lower bid.
Start with the size of the field. The U.S. LTL market brought in about $51.8 billion in 2025, down 1.9%. FedEx Freight was the largest carrier, at about $8.8 billion. Old Dominion was second at about $5.4 billion, followed closely by Estes Express at about $5.0 billion and XPO at about $4.8 billion, then R+L Carriers, Saia and ABF.23 FedEx Freight was about 1.6 times Old Dominion's size. Those estimates come from an industry ranking, and the carriers' reporting periods and segment definitions differ, so they show the shape of the field, not exact market shares. On those numbers, Old Dominion had a bit over a tenth of the market.
The same ranking also contains the most uncomfortable number in this story. In 2025 the LTL market shrank by about 1.9%, and Old Dominion's LTL revenue fell by about 5.5%. Saia grew slightly, Estes held flat and XPO fell 1.4%.23 Old Dominion lost share in 2025, measured by revenue. Some of that was a choice: the company refused to cut price for volume, and mix and fuel affect revenue comparisons. But in mid-2025 Freeman had said its market share "remained relatively consistent."18 The full-year industry numbers are harder to square with that. The honest reading is that Old Dominion gave up some volume to defend its price, as its strategy intends, and that rivals with cheaper prices or new terminals picked it up.
The economics of the industry explain why that trade can still make sense. An LTL network is an expensive fixed web of terminals, tractors and night shifts. Freight density, and lanes where freight flows evenly in both directions, determine how hard those assets work. That makes downturns painful, because the costs stay while the freight leaves, and it makes density gains very valuable, because the next shipment through an existing building is almost pure profit.
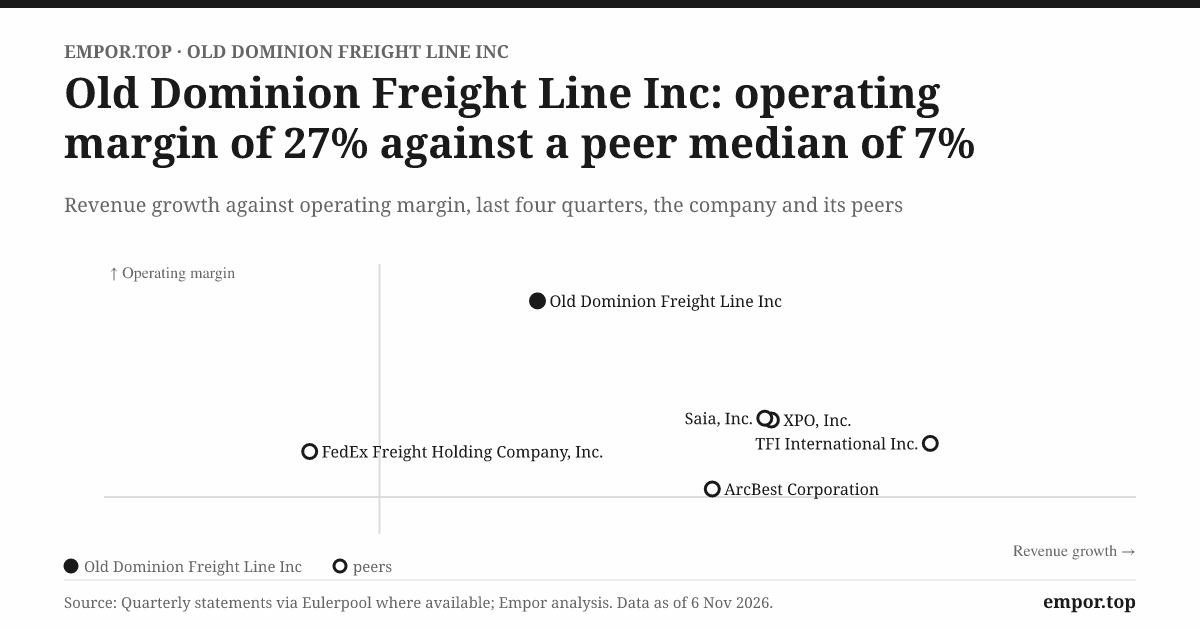
Satterfield told analysts that, excluding Old Dominion, the average operating ratio of the public LTL carriers in the first quarter of 2026 was about 94%.5 Old Dominion's first-quarter ratio was 76.2%.12 Put simply, in a weak quarter, Old Dominion kept about 24 cents of every revenue dollar as operating profit, while its average public peer kept about 6. Whatever else is debated, that gap is the clearest evidence of a cost and execution advantage in the industry.
Hamilton Helmer's 7 Powers framework helps sort out where that advantage comes from. Scale economies are the strongest candidate, but in the specific form of network density, not sheer size: FedEx Freight is bigger, so size alone cannot be the explanation; what matters is how much freight flows through each building. Process power, the hard-to-copy routines built up over decades, is the second: how the docks are loaded, how linehaul is planned, how cross-trained workers move between jobs, how claims are kept under 0.1%. These are not secrets, but competitors have found them hard to replicate.
Brand has real support in the 17-year Mastio streak, though it is brand in the business-to-business sense: a reputation that wins the first conversation, not a consumer loyalty that guarantees the order. Switching costs are where the evidence is thin. The company does not publish retention data, customers multi-source, and a third of revenue comes through brokers. Cornered resources, network effects and counter-positioning are hard to find. The owned real estate near major cities comes closest to a cornered resource, because good industrial land near cities is scarce, but rivals have shown they can still acquire terminals, as the auction of Yellow's properties showed.15
Porter's five forces point the same way. Buyer power is moderated because the customer base is broad and no customer exceeds 5% of revenue,2 but it is reinforced by multi-sourcing and brokers. Rivalry is intense: FedEx Freight, XPO, Estes, Saia, ABF, R+L and a range of regional carriers all compete lane by lane, and none has equal density on every origin-destination pair. Substitutes exist at the edges: shippers can consolidate freight into full truckloads, or use rail or parcel for some freight.
Satterfield said a shift of freight from truckload to LTL was in its "early innings."5 The threat of new entrants is low for national networks, because building one takes billions of dollars and years of density, but a local or regional carrier can still compete hard on the lanes it knows. Supplier power is mixed. There is no union to bargain with, but the company is exposed to wage markets for drivers, to truck manufacturers, and to insurance markets, where Satterfield said Old Dominion has absorbed double-digit premium inflation for years.5
The premium claim needs testing against the downturn itself. In 2025, ex-fuel yield rose almost 5% while tonnage fell almost 9%.3 That is pricing discipline, and it supports the idea that customers value the service. But revenue and net income still fell, and the operating ratio still worsened. Price discipline cushioned the shock; it did not eliminate the cycle. The 2022 peak, built on tonnage up just half a percent,16 makes the same point from the other side. Old Dominion's pricing power is real, but it works inside the freight cycle, not above it.
The risks that could break the case all run through volume and cost. A domestic industrial slowdown cuts shipments, and with more than half of the business tied to industrial customers, that is the main risk.18 Wages, insurance, equipment and real estate all inflate the cost base, and the company's whole model depends on yield rising faster than those costs. A September 2026 wage increase was planned.5 Fuel surcharges pass through most of the cost of diesel, but with a lag, which can squeeze margins when diesel spikes. And weak volumes reduce productivity at every step, from pickup stops per hour to linehaul load factors.
Technology deserves a sentence, not a thesis. Old Dominion invests in operating systems and plans about $45 million of IT and other spending in 2026,4 but there is no AI-driven revenue line and no disclosed technical moat. Asked about autonomous trucks, Satterfield was skeptical about the cost per mile and regulatory readiness, and said Old Dominion would not be on the "bleeding edge" of adoption.5 That is consistent with a company whose advantage is execution, not invention.
The verdict on the moat, then, is that it is real but narrower than its admirers sometimes claim. Old Dominion's density, its operating routines and its service record together make it the best-run large LTL network in the country, and the margin gap with its peers is the evidence. It is not a locked-in customer base. Customers can and do move freight elsewhere, and in 2025 some did. The edge can be tested with numbers. If tonnage turns positive and stays there, ex-fuel yield holds around its recent mid-single-digit growth, and the operating ratio returns toward the 70% level of 2022 on volume rather than price, the case for durable premium economics gets stronger. If shipments keep falling while the company starts discounting, or margins keep slipping, the case gets weaker.
X. Analysis & Bull vs. Bear Case
An investor puts three numbers side by side: a 70.6% operating ratio in 2022, 75.2% in 2025, and 70.1% in the second quarter of 2026.1634 Which one reflects what this business earns in a normal year? The answer decides almost everything about how the stock should be valued.
The ten-year record is strong. Revenue grew from about $2.97 billion in 2015 to about $5.50 billion in 2025, about 6.3% a year. Net income grew from about $305 million to about $1.02 billion, about 12.9% a year.113 That is roughly twice as fast as revenue, which is what density economics should do as more freight moves through the same network. The decade includes a pandemic, a boom and a recession, and the endpoints are not flattering to the company: 2025 was a weak year, not a peak. Even so, earnings more than tripled.
The bull case builds from there. Old Dominion's service, cost and balance-sheet advantages are already clear. Satterfield said that in past years of strong growth, Old Dominion's tonnage grew 8 to 10 percentage points faster than its competitors', and that those years produced 3 to 4 points of annual operating ratio improvement.5 If freight volumes return, the bull case says, the company will take a disproportionate share at its usual prices, and earnings will climb faster than revenue.
The bear case is just as clear: the freight cycle has exposed the limits of the service advantage, and yield cannot substitute for shipment growth indefinitely.
A skeptical long-short investor would push one question hardest: if customers can multi-source and freight is still weak, what measurable evidence shows that Old Dominion is holding price and share, not merely preserving its reputation? The company's honest answer would be that it is holding price, as ex-fuel yield shows, and that it gave up some share to do it. That is a deliberate trade, and one that has paid off in past cycles. But it means the bull case requires the upturn to arrive before customers grow comfortable with cheaper carriers.
The same investor would push on capital. Old Dominion returned about $1 billion to shareholders in 2025 at around 32 times earnings while raising its 2026 capital plan for a network with service-center capacity more than a third above current needs.520 Neither choice is reckless in isolation. Together they are a bet that freight will return and fill the network, and that the stock was worth buying at a peak-like multiple in a trough year.
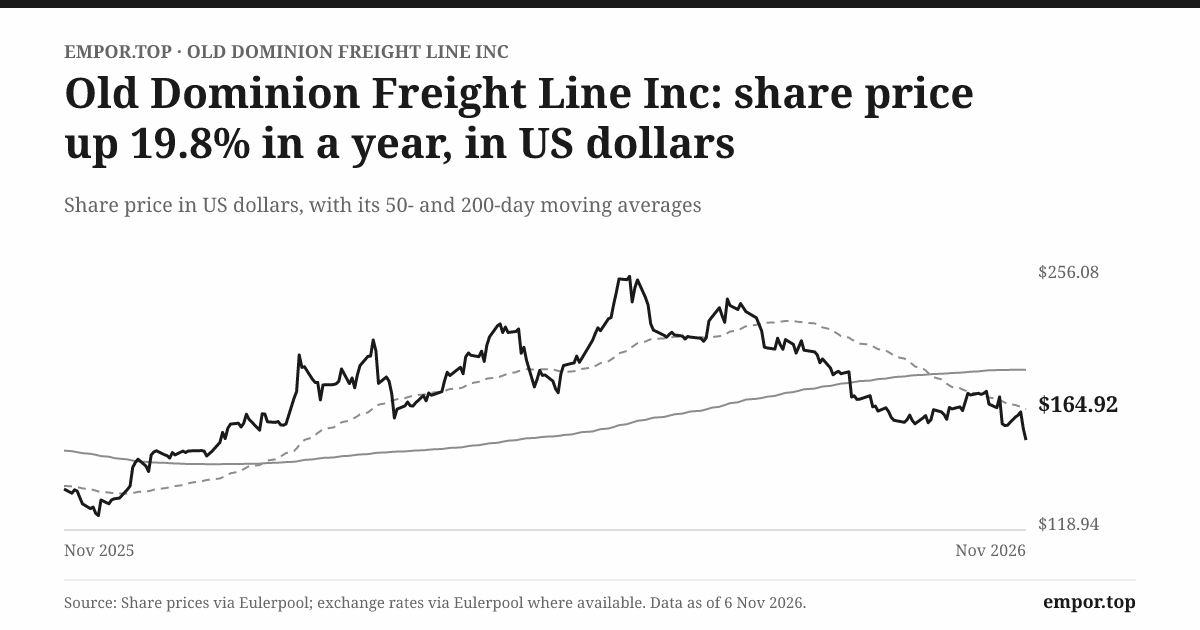
Then there is valuation. On October 26, 2026, Old Dominion's shares traded at about $183, giving it a market value of about $38 billion and an enterprise value about the same, because the company has almost no net debt.24 That is about 35 times trailing earnings, about 29 times forward earnings estimates, and about 21 times trailing EBITDA. The stock had risen about 34% over the previous 52 weeks.24
At year-ends since 2021, the trailing multiple has ranged from about 23 times, at the end of the 2022 record year, to about 40 times, at the end of 2021.20 Today's multiple sits toward the upper part of that range. Saia traded at about 32 times trailing earnings and about 15 times EBITDA,25 and XPO, with a different business mix, at about 54 times depressed trailing earnings but about 18 times EBITDA.26 On EBITDA, Old Dominion carries a premium to both.
What does the price assume? At 35 times trailing earnings that are still well below the 2022 peak, the market is valuing Old Dominion as though the recovery is already under way and the company will eventually earn its way back to, and beyond, its record. That is consistent with the company's history. It leaves little room for a recovery that stalls, or for tonnage that stays negative for another year.
Three numbers will decide which case is right. The first is LTL tonnage per day, which was down 0.9% year over year in August after three years of decline.1 The second is ex-fuel revenue per hundredweight, up 4.8% for the third quarter to date and running in the mid-single digits.1 The third is the operating ratio adjusted for property-sale gains, which was about 71% in the second quarter after the $17.2 million gain is set aside, against 70.6% at the 2022 peak.416 The answer for now is conditional. Quality is proven. Durable premium economics are plausible. The recovery, and the price the market is paying for it, still need to be earned.
XI. Playbook: What Old Dominion Teaches About Building a Network
Every few years, someone in Thomasville, North Carolina, has to decide whether to open a terminal in a city where Old Dominion does not yet have enough freight to fill it. That decision, repeated hundreds of times over 90 years, is the company's real history. Some of what it teaches is specific to trucking. Most of it applies to any business built on a network.
The first lesson is that a route is not a network until freight can use it twice. The 1980s expansion taught Old Dominion that trucks that leave full and return empty cost the same as trucks that leave full and return full. The company only became excellent when it stopped counting points on the map and started counting how much freight ran between them in both directions. For founders, the lesson is that coverage is a cost and density is a return; a network that promises everywhere and fills nowhere is just a fixed-cost problem.
The second lesson is to buy the missing node, then make it earn its place. Old Dominion's acquisitions were not trophies. Its Fredrickson and Goggin deals show the rule: it kept only the pieces that fit its operating system and discarded the rest. Most acquirers do the reverse: they buy a whole company and spend years justifying it. Old Dominion's rule was that an acquired terminal had to fit its own operating system, or it went.
The third lesson is that service is only a moat when customers will pay for it. Old Dominion's pricing data and customer losses in 2025 show both the value and the limit of its reputation. A reputation that customers praise and a reputation they pay for are different assets. Old Dominion has both, but not as much of the second as the first.
The fourth lesson is that a downturn shows whether discipline is real. It is easy to say a company won't chase bad revenue when freight is plentiful. Old Dominion said it in mid-2025 with tonnage down 9%,18 then held price and reported 99% on-time service in the first quarter of 2026.4 That is discipline under pressure, and it is rare in an industry where carriers have historically slashed rates to fill trailers.
The counterexample is the company's own past. Its 1980s expansion ended in losses. The 2026 capital plan is a similar bet, made with a much stronger balance sheet. Investing through the downturn is not automatically wise. It is wise when the freight comes back and fills what was built, which is why terminal utilization and return on capital, not revenue per shipment, are the measures that will settle it.
XII. Epilogue
Tonight, Old Dominion is two days from its next test. The company is scheduled to report third-quarter results and hold its conference call on October 28, 2026.27 Its last word on the quarter, the August update, showed revenue per day up double digits, ex-fuel yield up nearly 5%, and tonnage almost back to flat.1 The question for Wednesday is whether September tipped tonnage into growth, or whether August's near-flat reading was a pause in a long slide.
The call will also test whether management's story is holding together. In July Satterfield laid out a framework: third-quarter revenue growth of around 10%, ex-fuel yield up 4% to 4.5%, and an operating ratio about 1.5 to 2 points worse than the second quarter's 70.1% once the property gain is set aside.5 If the results land inside that framework, investors will have seen a management team that guides carefully and delivers. If yield comes in below the range, the explanation will matter: mix is a benign reason, discounting is not.
Two other things to listen for. The first is whether management changes the labor plan it outlined in July.5 If driver training restarts early, management is betting on volume. The second is the capital plan for 2027. A plan back in the 10% to 15% of revenue range would signal confidence that the new terminals will fill; a plan held below it would signal caution.
The questions that run through this story remain open. If freight volumes recover and Old Dominion keeps its pricing, the network will do what it did in the 2010s, and margins will expand as each additional shipment flows through terminals that are already paid for. If volumes stay weak and the ex-fuel yield gains fade, the premium narrows, and a stock priced at around 35 times trailing earnings will have to adjust. The question is not whether Old Dominion can execute; it has shown it can. The question is how much demand and how much pricing power the next cycle will give it to work with.
XIII. Outro
Go back to 1934, to Earl and Lillian Congdon and their one truck on a Virginia road. They made one promise to a small number of customers: the freight would get there. Everything that followed, the certificates and the terminals, the 1980s losses and the 1991 retreat, the tuck-in deals, the night shifts loading trailers in 260 buildings, was an attempt to make that promise at a larger and larger scale without breaking it.
Today the company counts more than 260 locations and more than 11,000 trucks,6 and its customers still rate it the most reliable national LTL carrier in the country. Its particular ambition was never to be the biggest. It was to turn reliability into density, and density into the right to charge more. Old Dominion built a national network one local promise at a time, and the freight cycle is still deciding what that promise is worth.
References
-
Old Dominion Freight Line Provides Update for Third Quarter 2026 (Form 8-K, Exhibit 99.1) — Old Dominion Freight Line, 2026-09-03 ↩↩↩↩↩↩↩↩
-
2025 Form 10-K — Old Dominion Freight Line, 2026-02-24 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Old Dominion Freight Line Reports Fourth Quarter 2025 Earnings Per Diluted Share of $1.09 — Old Dominion Freight Line, 2026-02-04 ↩↩↩↩↩↩↩↩↩↩
-
Old Dominion Freight Line Reports Second Quarter 2026 Earnings — Old Dominion Freight Line, 2026-07-29 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Q2 2026 Earnings Call Transcript — Old Dominion Freight Line (via Stock Analysis), 2026-07-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Old Dominion Freight Line, Inc. History — FundingUniverse (International Directory of Company Histories) ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Old Dominion Freight Line Announces CEO Succession Plan (Form 8-K, Exhibit 99.1) — Old Dominion Freight Line, 2023-01-31 ↩↩↩↩↩
-
Old Dominion Freight Line Reports First Quarter 2026 Earnings (Form 8-K, Exhibit 99.1) — Old Dominion Freight Line, 2026-04-29 ↩↩↩↩↩
-
LTL Shippers Select Old Dominion Freight Line as Top National LTL Carrier for Quality for 17 Consecutive Years — Business Wire via Webull, 2026-10-06 ↩↩
-
Trucking Company Yellow Shuts Down, Teamsters Say — Insurance Journal, 2023-08-01 ↩↩↩
-
Where Did Yellow’s Freight Go? — FreightWaves, 2023-10-30 ↩↩↩↩
-
Old Dominion Freight Line Reports Fourth Quarter 2022 Earnings Per Diluted Share of $2.92 — Old Dominion Freight Line, 2023-02-01 ↩↩↩↩↩↩↩
-
2026 Proxy Statement — Old Dominion Freight Line, 2026-04-20 ↩↩↩↩↩↩
-
Old Dominion Q2 Profit Slides as Market Weakness Persists — Transport Topics, 2025-07-30 ↩↩↩↩↩↩↩
-
Old Dominion Posts Lower Q4 Results While Investing in Growth — Transport Topics, 2026-02-04 ↩
-
ODFL Financial Ratios — Stock Analysis, accessed 2026-10-26 ↩↩↩
-
2026 Annual-Meeting Voting Results, Form 8-K — Old Dominion Freight Line, 2026-05-21 ↩
-
2025 Top 25 U.S. LTL Carriers — Logistics Management / Jindel Global, 2026 ↩↩
-
Old Dominion Freight Line to Webcast Third Quarter 2026 Earnings Conference Call — Old Dominion Freight Line ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube