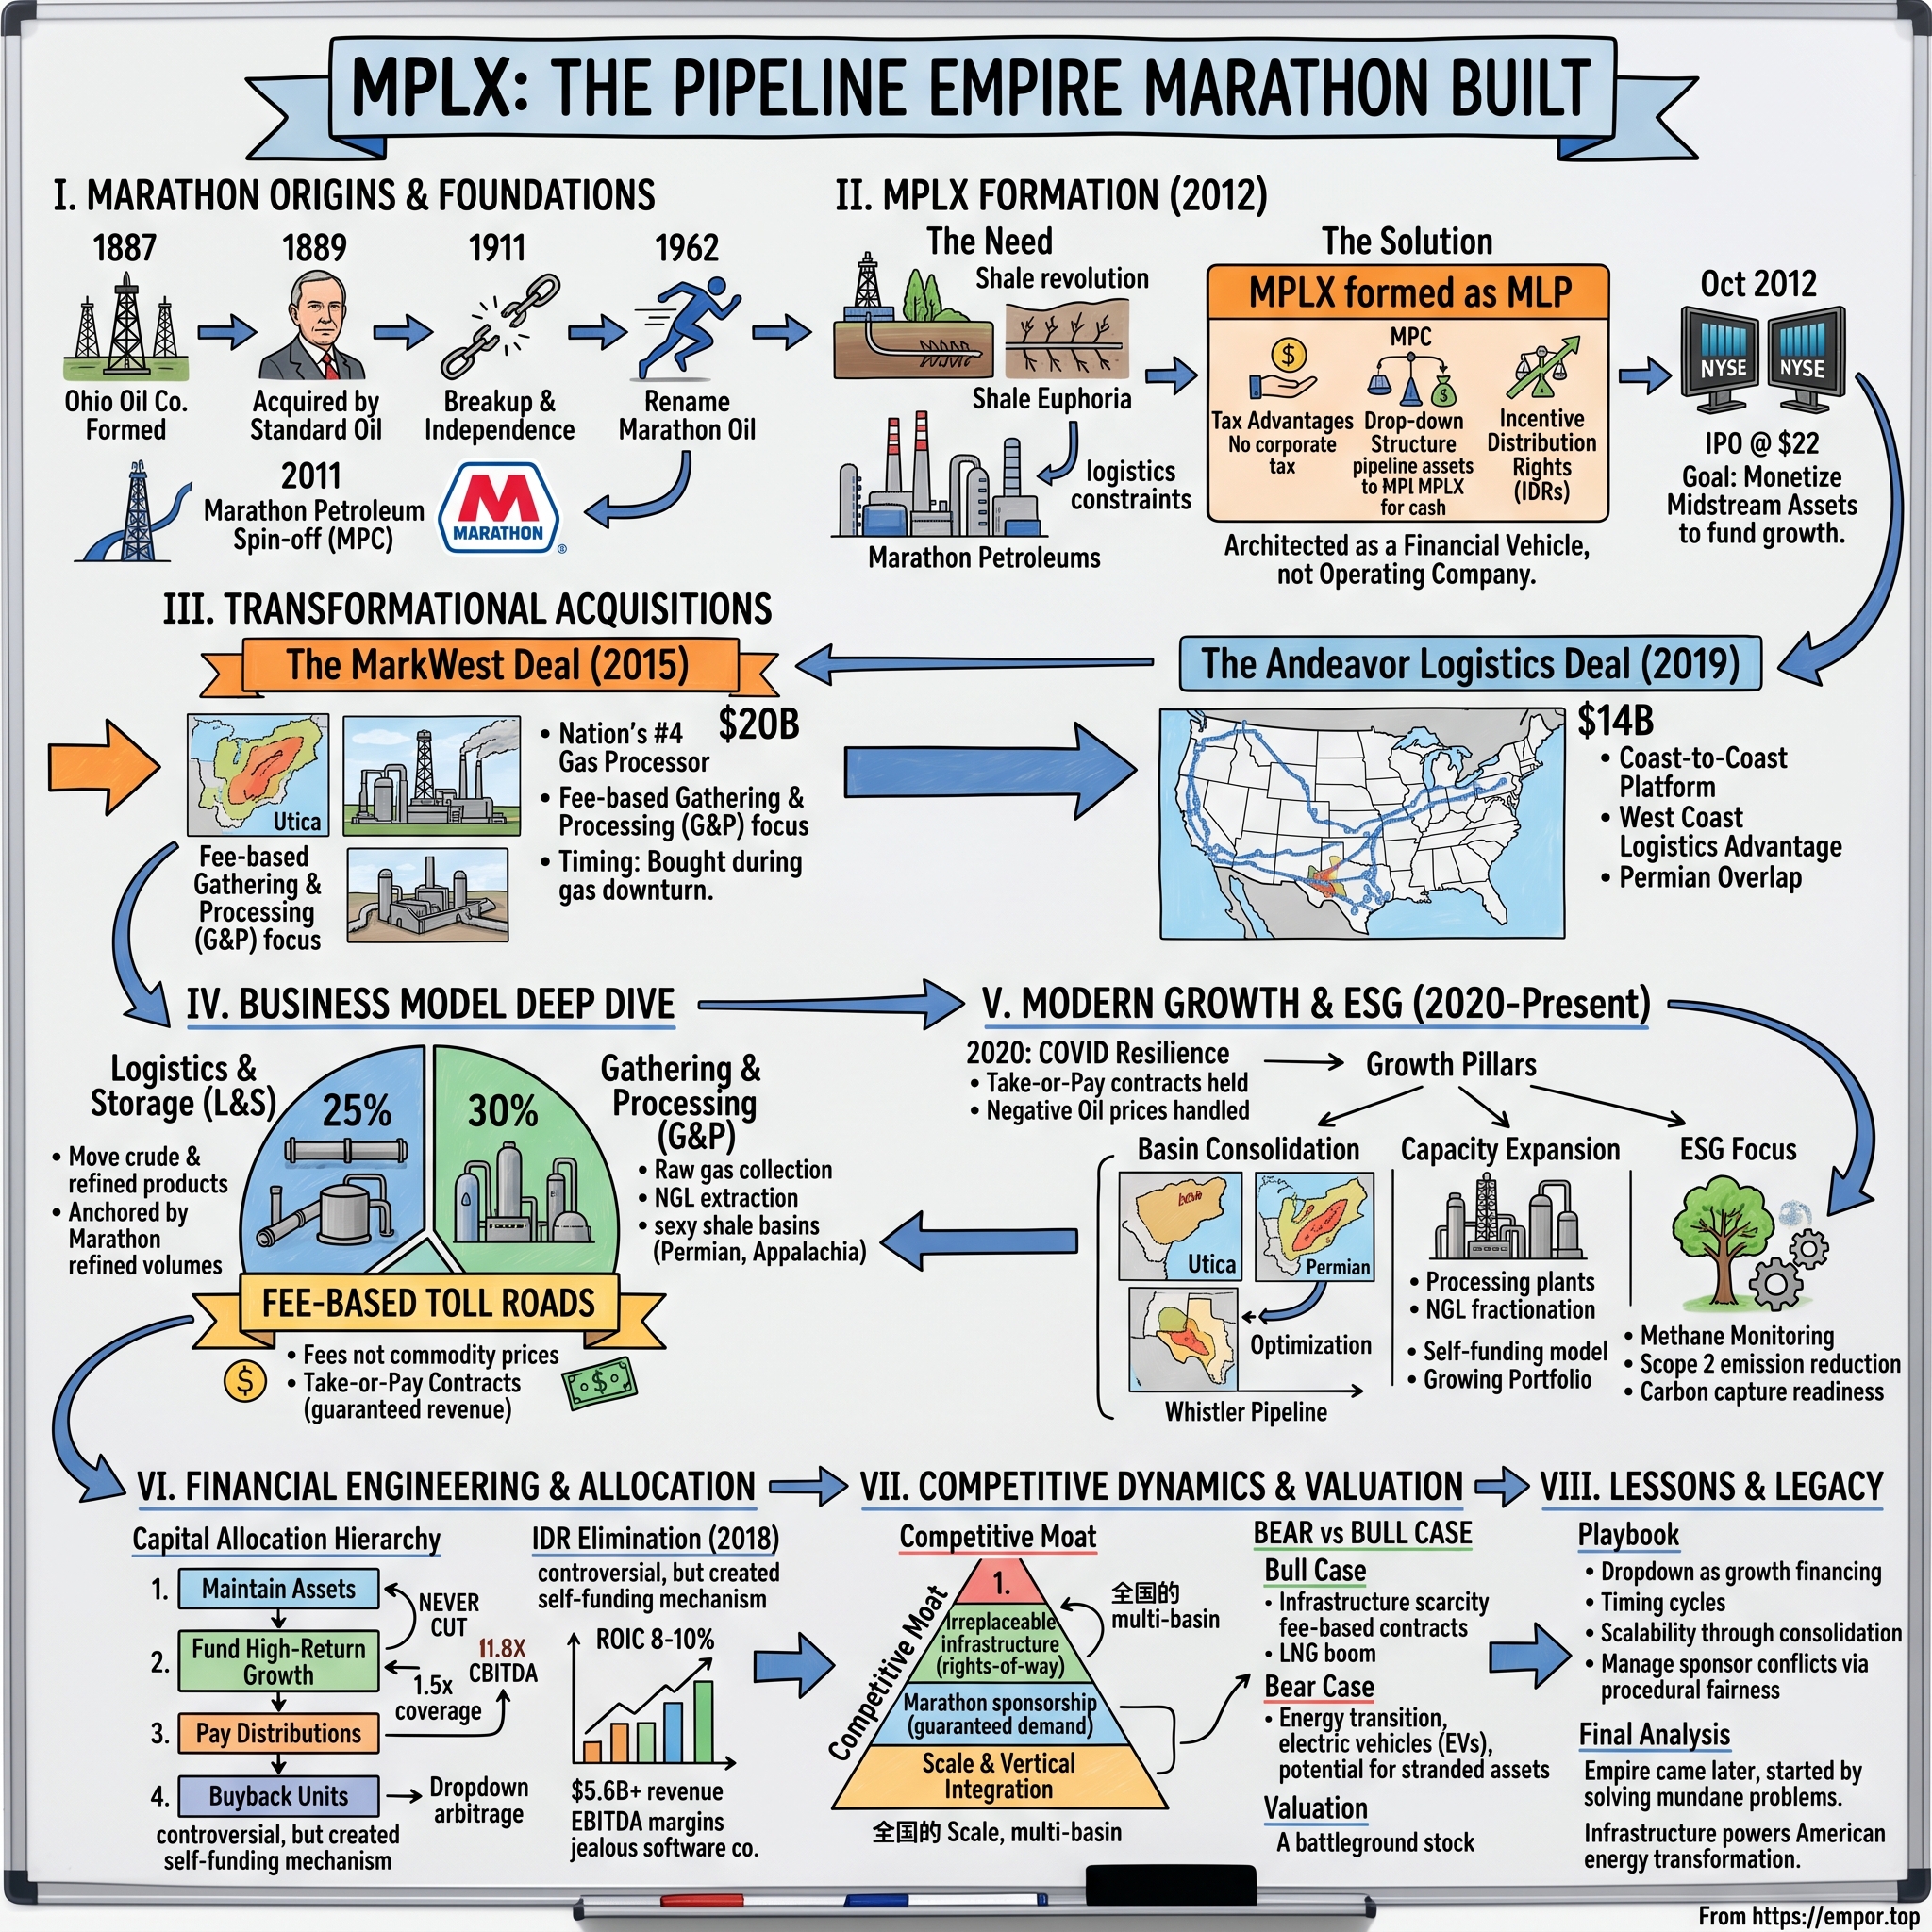
MPLX: The Pipeline Empire Marathon Built
I. Introduction & The Dropdown Machine
In late October 2012, a newly independent refiner from Findlay, Ohio, brought a small and slightly odd company to the New York Stock Exchange. Marathon Petroleum Corporation had been a public company for little more than a year. Now it was selling a minority slice of its own plumbing: a network of crude and refined-product pipelines across the Midwest, a butane storage cavern in Neal, West Virginia, and a few barge and tank assets that most refinery managers never thought about. The new entity was called MPLX LP. It listed on October 26, 2012, and raised a little under $400 million1.
Nobody in the room would have called it a growth story. The assets were old and depreciated, and they existed to serve Marathon's refineries. The legal form, a master limited partnership, was a tax structure, not a strategy. MLPs paid no federal income tax at the entity level as long as most of their income came from "qualifying" activities such as moving and storing hydrocarbons. They passed almost all of their cash to unitholders, who paid tax on it themselves. In a world of near-zero interest rates, investors would pay handsomely for that cash.
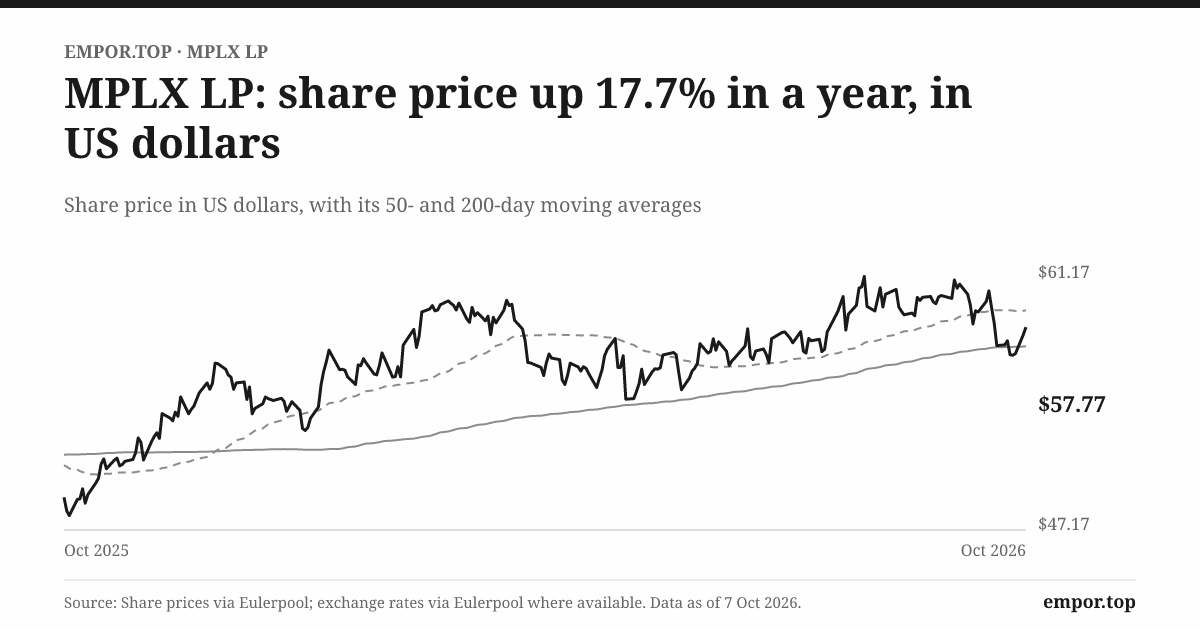
Fourteen years later, the small vehicle has become one of the largest energy infrastructure businesses in North America. On October 7, 2026, MPLX units closed at $57.77, giving the partnership a market value of about $58.8 billion and an enterprise value, including debt, of roughly $83.6 billion. It earned about $4.9 billion of net income in 2025 on $11.8 billion of revenue2. Over the twelve years from 2014 through 2025, it reported about $23.6 billion of cumulative net profit but generated about $42.9 billion of operating cash flow, and it paid out about $27.3 billion in distributions234.
That gap between profit and cash, roughly 182 cents of operating cash for every dollar of accounting profit, is the first clue to what MPLX actually is. The second clue is who owns it. Marathon Petroleum still owns about 64% of the common units and all of the general partner that controls the board2.
So the central question of this story is simple to state and hard to answer. Is MPLX an independent infrastructure compounder that happens to have a large shareholder? Or is it a captive financing conduit, built to move refinery-adjacent cash flows into a tax-efficient wrapper and then upstream to Marathon Petroleum, whose own buyback program depends on those distributions?
The honest answer, as this story will argue, is that it began as the second and became something closer to the first, without ever fully ceasing to be the second.
The MLP anomaly
To appreciate why MPLX is unusual, recall what happened to its peer group. In the early 2010s, MLPs were Wall Street's favorite income vehicle. Sponsors from Kinder Morgan to Williams to Enbridge housed their pipelines in partnerships. Many of those structures included incentive distribution rights, which handed the sponsor a rising share of every incremental dollar of cash paid out. By the end of the decade, most of the large ones had been rolled up, converted into corporations, or simplified out of existence, a process accelerated when the Federal Energy Regulatory Commission changed its policy on income tax allowances in pipeline rates in March 20185.
MPLX survived as a partnership. So did Enterprise Products Partners. Energy Transfer and Western Midstream persisted too, but the club of large, investment-grade MLPs that still look like their original design is small. MPLX's survival is not accidental. It reflects a choice by its parent, which has repeatedly decided the partnership is worth more as a separately traded, cash-distributing entity than folded back into the refiner.
Two engines
The business has two halves that behave very differently. The first is Crude Oil and Products Logistics, the pipes, terminals, tanks, barges and refinery-gate infrastructure that move feedstock into Marathon's refineries and finished fuel out of them. In 2025 it generated about $4.5 billion of segment adjusted EBITDA, nearly two-thirds of the total, and Marathon accounted for 88% of its revenue2.
The second is Natural Gas and NGL Services, a gathering, processing and fractionation network mostly inherited from the 2015 MarkWest acquisition and now extended into the Permian Basin. It generated about $2.5 billion of segment adjusted EBITDA, roughly a third of the total, and Marathon is almost irrelevant to it as a customer2.
One engine is a captive utility for a single refiner. The other is a third-party franchise competing for shale gas. How MPLX got both, and what the combination is worth, is the story. It begins, as so much in American oil does, with a fight against John D. Rockefeller.
 Subscribe on LinkedIn
II. Standard Oil Roots & The 2011 Separation
Findlay, Ohio, sat atop one of the great oil and gas fields of the 1880s. In 1887, a group of local producers formed The Ohio Oil Company to market their crude. Within two years, the company had been absorbed into Standard Oil, which controlled the pipelines and refineries that independent drillers needed to reach a market. It regained its independence only after the Supreme Court ordered Standard Oil broken up in 1911.
That origin is worth a sentence, not a chapter, because it contains the logic of everything that followed. Whoever owns the pipes decides who gets paid. Ohio Oil spent its early decades being squeezed by a pipeline monopoly. Its corporate descendant would spend the 2010s building one.
The company renamed itself Marathon Oil in 1962, was acquired by U.S. Steel in 1982, and re-emerged as an independent oil company in 2001. For most of that period, exploration and refining lived inside one corporation. The integrated model made sense when oil companies wanted control of the whole chain. By 2010 it was increasingly out of fashion. Investors wanted pure exposure to either drilling or refining, and conglomerate discounts were punished.
The 2011 split
In mid-2011, Marathon Oil separated its upstream exploration business from its downstream refining, marketing and transportation business. The downstream half became Marathon Petroleum Corporation, headquartered in Findlay, and began trading as a standalone company that summer1.
Gary Heminger, a long-time Marathon finance and downstream executive who had spent his career in Findlay, became MPC's chief executive. Heminger was not a geologist or a deal banker. He was an operator who understood refining margins, and he understood their central problem: they are brutally cyclical. A refinery can earn a fortune when the gap between crude prices and gasoline prices is wide and lose money when it narrows. Standalone refiners have historically traded at low multiples precisely because investors cannot trust the earnings.
The logistics assets attached to those refineries were a different animal. A pipeline that carries crude to a refinery gets paid by the barrel, whether the refinery's margin that month is good or bad. If you could separate those steady, fee-like cash flows from the volatile refining business and sell them to yield-hungry investors, the market would pay a much higher multiple for them.
The arbitrage
That is the original logic of MPLX, and it is worth stating plainly. A refiner like MPC traded at a single-digit multiple of earnings. A midstream MLP with contracted fees could trade at 10 to 12 times EBITDA or more, and pay no entity-level income tax. Assets that were worth one multiple inside MPC were worth a higher multiple inside a partnership. Selling them to the partnership, a little at a time, would unlock cash for the parent.
The shale boom made this logic more urgent. The Bakken, the Permian and Appalachia were producing crude and gas in places the pipeline map never anticipated. Crude moved by rail because pipes did not yet exist. Whoever built the takeaway capacity could earn a toll for decades. That required capital, and an MLP was the cheapest way to raise it in 2012.
The verdict on this period is clear. MPLX was not born out of a vision of independent midstream greatness. It was born because the parent needed a better-valued home for its steady assets and a cheaper source of capital. The question for the next chapter is whether the early years did anything more than move value from one pocket to another.
III. The IPO & The Dropdown Playbook (2012–2014)
The 2012 prospectus is a document about control. MPC's treasury team designed a partnership in which the public would supply capital and MPC would keep the steering wheel. The general partner, MPLX GP LLC, would be wholly owned by MPC. The general partner would appoint the entire board. Public unitholders would have no vote on directors. And the general partner would hold incentive distribution rights1.
The initial asset package was modest by design. MPLX received a 51% interest in Pipe Line Holdings, which owned crude and products pipelines and the Neal butane cavern, along with a stake in other storage and barge assets1. MPC kept the other 49%. That retained interest was not an oversight. It was inventory.
How the dropdown worked
The "dropdown" was the engine of nearly every sponsored MLP of that era, and it worked like this. The sponsor owns logistics assets. The MLP buys a slice of them, paying a negotiated multiple of their EBITDA. To fund the purchase, the MLP issues new units to the public and borrows. The sponsor receives cash, plus often new units. The MLP's distributable cash rises, so it raises its distribution. Its unit price rises, which lowers its cost of equity, which lets it buy the next slice.
As long as the MLP's cost of capital stays below the yield on the assets it buys, the machine can run indefinitely. It is a little like a family selling the rental apartment on the ground floor to a separately listed company it controls, using money borrowed from strangers, then collecting rent as the landlord's manager.
The incentive distribution rights were the turbocharger. They entitled the general partner to a growing share of distributions as per-unit payouts crossed set thresholds, ultimately up to 50% of incremental cash in the top tier1. In practice, the faster MPLX grew its distribution, the more of each new dollar went to MPC rather than to the limited partners who had supplied the capital.
What the numbers show
In 2014, MPLX was still small. It generated about $520 million of revenue and roughly $246 million of operating cash flow, and it paid distributions equal to about 85% of net income3. Its operating margin was about 47%, a figure typical of a pure pipeline toll business with almost no commodity exposure.
The economic meaning is less flattering than the margin suggests. Those were not new assets. They were old Marathon pipelines whose ownership had moved, at a negotiated price, from one Marathon-controlled entity to another. The public investor received a yield. MPC received cash, a growing IDR stream, and continued control. Value was undoubtedly created for MPC's shareholders through a lower cost of capital and the tax shelter. Whether any was created for the physical economy is doubtful.
The reception
Public investors were not naive. They were yield-starved. In 2012 and 2013, the ten-year Treasury yielded around 2%, and a growing partnership with a sponsor committed to feeding it assets looked like a bond with an equity kicker. MLPs as a class enjoyed enormous inflows. MPLX's units traded at a premium valuation precisely because its sponsor had a pipeline of assets to drop.
The verdict for these years is venue arbitrage. Good arbitrage, competently executed, but arbitrage. The weakness of the model was also obvious to anyone who looked. A dropdown vehicle can only grow as fast as its sponsor can feed it, and Marathon's logistics inventory was finite. By 2015, MPLX needed a way out of the captive shell. It found one in the gas fields of Pennsylvania, at the worst possible moment in the cycle.
IV. The $15.8 Billion Marcellus Pivot: MarkWest (2015)
By late 2015, the oil market had broken. West Texas Intermediate, above $100 a barrel in mid-2014, had fallen below $40. Shale drillers were laying down rigs. MLP unit prices had collapsed, and the self-reinforcing loop of cheap equity funding dropdowns had started running in reverse.
In the middle of this, MPLX was trying to close the largest deal in its history: the acquisition of MarkWest Energy Partners, the dominant natural gas gatherer and processor in the Marcellus and Utica shales of Pennsylvania, West Virginia and Ohio. MarkWest had been built over two decades by founder John Fox into the essential processing layer for Appalachian gas. When a producer drilled a well in the Marcellus, the raw gas needed to be gathered, stripped of its heavier liquids, and those liquids separated into ethane, propane and butane. In much of the basin, MarkWest did that work.
The deal was announced in July 2015 as an all-in transaction worth about $15.8 billion including debt[^8]. It was paid largely in MPLX units, plus cash contributed by MPC. As MPLX's unit price fell through the autumn, the value MarkWest unitholders would receive fell with it. Some objected loudly. John Paulson's Paulson & Co., a MarkWest unitholder, publicly opposed the deal in November 20156. MPC had already increased the cash it would contribute to the consideration. The deal closed on December 4, 2015[^8].
Why buy a gas processor?
The strategic logic was a response to the dropdown ceiling. MPC's logistics inventory could not sustain MPLX's growth forever, and every MLP built on a single refiner faced the same limit. MarkWest gave MPLX something no amount of dropdowns could: a large, third-party, fee-based business in the fastest-growing gas basin in the United States, with its own customers and its own organic growth projects.
It also changed MPLX's identity. Overnight, the partnership went from a Marathon logistics subsidiary to a diversified midstream company, and the gas business would eventually become about a third of its earnings.
The bill arrives
The financial statements of 2015 and 2016 show what the deal cost. Revenue nearly doubled in 2015 and then nearly tripled in 2016, reaching about $3.0 billion3. Borrowings jumped from about $0.6 billion at the end of 2014 to about $5.3 billion a year later. Total assets went from about $1.2 billion to about $15.7 billion. The small partnership had swallowed something more than ten times its size.
Profitability went the other way. Operating margin fell from about 47% in 2014 to about 23% in 20163. Return on capital employed collapsed from about 16% to under 5%, because MPLX now carried billions of dollars of purchase price on its balance sheet, including goodwill, that the acquired assets could not yet earn back. The debtor-days figure briefly spiked to about 152 at the end of 2015, an artifact of consolidating a year-end balance sheet against only a few weeks of MarkWest revenue rather than a sign of customers paying late.
The most revealing figure is the payout ratio. In 2016, MPLX paid distributions equal to about 373% of its net income3. In plain terms, it was paying out almost four dollars for every dollar it earned on paper. Some of that is the non-cash depreciation that always makes MLP earnings look thin. But it also signals a partnership straining to keep its distribution promise while its earnings caught up with its new capital base.
The preferred rescue
MPLX did not cut its distribution. Instead, in 2016 it issued about $1.0 billion of Series A convertible preferred units to private investors4. This was expensive capital, senior to the common units and convertible into them, but it shored up the balance sheet without the signal a distribution cut would have sent. It took until the end of 2025 for the last of those preferred units to convert and disappear2.
The verdict
Did MPLX overpay? On near-term numbers, almost certainly. It bought at the tail end of a shale processing boom with a currency that was falling in value, took on heavy debt, and spent several years earning low returns on the purchase.
Over the longer span, the answer narrows. The Appalachian gathering and processing system has become a durable earnings engine, and Natural Gas and NGL Services now generates about a third of segment adjusted EBITDA2. But the deal did not prove that MPLX could buy cheaply. It proved that a patient, well-capitalized sponsor could absorb a painful acquisition and wait for the basin to grow into it. That is a narrower and more conditional virtue, and it matters because MPLX is now making another large acquisition bet in the Permian.
The MarkWest deal made MPLX bigger and more independent. The next deal would make it much bigger, and much more tightly bound to its parent.
V. The Andeavor Megamerger & The Great MLP Extinction (2018–2020)
March 2018 was a bad month to own a pipeline partnership. The Federal Energy Regulatory Commission revised its policy so that MLP-owned interstate pipelines could no longer include an income tax allowance in their cost-of-service rates5. The logic was that partnerships do not pay entity-level tax, so customers should not be charged for it. MLP units fell sharply across the sector. Sponsors that had been planning to keep their partnerships separate started planning to fold them back in.
For MPLX, the FERC change landed in a year when it had already started dismantling its own structural problem. In early 2018, MPLX and MPC completed the final major dropdown and, in the same transaction, eliminated the general partner's incentive distribution rights in exchange for newly issued common units3. The 50% top-tier claim on incremental cash that had made MPC's general partner so valuable disappeared.
Why the IDRs had to go
The IDR problem is easiest to see as a hurdle. When the general partner takes half of every new dollar of distribution, an MLP buying an asset that yields 8% effectively needs it to yield nearly double that for limited partners to benefit. Mature MLPs with high distributions found that almost no acquisition cleared the bar. The structure that turbocharged early growth had become a tax on late growth. Eliminating it lowered MPLX's cost of equity and made larger, third-party deals economically sensible.
It also had a cost. The IDR exchange gave MPC additional units, increasing its ownership. And because the 2018 restructuring involved MPC exchanging rights and assets for units and cash, the partnership's book equity fell even as debt rose: borrowings reached about $13.4 billion at the end of 2018, and debt to equity rose to about 1.74x3.
Andeavor
In October 2018, Marathon Petroleum completed its acquisition of Andeavor, the former Tesoro, creating the largest refiner in the United States. Andeavor came with its own MLP, Andeavor Logistics LP, which owned West Coast and Rockies terminals, crude gathering in North Dakota, gas processing in the Rockies and the Anadarko, and logistics around Tesoro's refineries.
Two separately traded MLPs under one parent made no sense. On July 30, 2019, MPLX completed its merger with Andeavor Logistics, in a unit-for-unit exchange7. Borrowings rose to about $20.3 billion by year-end and total assets nearly doubled to about $40 billion3.
The verdict on the simplification is that it was unavoidable and broadly correct. One partnership with no IDRs and one cost of capital was more fundable than two with competing claims. But Andeavor Logistics did not come cleanly. It brought assets of uneven quality and a large goodwill balance, and the bill for that came quickly.
Elliott at the gate
In October 2019, Elliott Management, already an activist shareholder in MPC, published a plan recommending that Marathon Petroleum split into three companies: a refiner, a retail business built around Speedway, and a midstream company8. Elliott argued the conglomerate structure suppressed value and pushed for greater independence or a different structure for the midstream assets.
MPC's leadership responded with change, but not with the separation of MPLX. Gary Heminger retired as chief executive in 2020, and Michael Hennigan, who had been running MPLX, became MPC's CEO. The partnership itself remained a separately listed, MPC-controlled MLP. It is fair to say the activist pressure did not dislodge MPLX from MPC's orbit. It is equally fair to say the parent later found other ways to release value, and MPLX's structure became the vehicle for a stable distribution rather than a candidate for spin-off.
The 2020 stress test
Then the pandemic arrived. In April 2020, U.S. oil prices briefly turned negative. Refineries cut runs. Drilling plunged. For MPLX, this was the first real test of whether a fee-based midstream business is truly insulated from commodity cycles.
The accounting answer was brutal. MPLX reported a net loss of about $720 million for 2020, driven by roughly $3.4 billion of goodwill and asset impairments, much of it tied to gathering and processing assets whose expected volumes had fallen3. Operating margin fell to about 2.5%.
The cash answer was remarkable. Operating cash flow rose that year, to about $4.5 billion, and the partnership continued paying distributions3. The impairment was a confession that MPLX had paid too much for some of what it acquired, especially in the merger era. It was not a sign that cash had stopped flowing.
That distinction is the key to understanding the business, and it is the reason the next section looks closely at where the money actually comes from. The historical record narrows any claim of acquisition discipline: the impairments are evidence of overpayment in the 2015–2019 deal era. It supports a different claim, that contracted cash flows survived even the most severe demand shock in modern oil history.
VI. Anatomy of a Tollbooth: The Business Model Deep Dive
Picture a control room in Findlay with screens showing a map of the eastern half of the country. Lines in one color trace crude oil moving from Gulf Coast docks and Midwestern hubs into refineries in Ohio, Kentucky, Illinois, Michigan and Texas. Lines in another color trace finished gasoline and diesel moving out to terminals. In Appalachia, a third web shows gas moving from wellheads through gathering lines into processing plants, where liquids are stripped out and sent to fractionators.
None of the operators in that room work for MPLX. The partnership has no employees. Every operator, engineer and executive is employed by an MPC subsidiary and provided under service agreements2. That is the first fact about the business model, and it shapes everything else.
How a barrel pays
In Crude Oil and Products Logistics, MPLX earns money in a few ways. Interstate pipelines charge tariffs regulated by FERC, adjusted each year by an index tied to inflation. Many other pipelines, terminals and storage assets earn negotiated fees per barrel or fixed capacity payments. Much of the segment's revenue comes from Marathon under long-term transportation, storage and terminal agreements, many with minimum volume commitments2.
A minimum volume commitment is the most important contract in midstream. It works like a gym membership with a mandatory minimum. The customer commits to ship, say, 100,000 barrels a day. If it ships only 80,000, it still pays for 100,000, through what is called a deficiency payment. The customer bears the volume risk. MPLX gets paid either way.
Some of MPLX's Marathon arrangements are accounted for as leases, which is why the related-party revenue includes rental income and sales-type lease revenue alongside service fees2. Economically, Marathon is renting dedicated infrastructure inside and around its own refineries.
How a molecule of gas pays
In Natural Gas and NGL Services, the pricing units are different. MPLX charges producers a fee per unit of raw gas gathered and processed, and a fee per gallon for fractionating mixed liquids into purity products such as ethane, propane and butane. Many contracts include acreage dedications, meaning a producer commits all gas from a defined area to MPLX's system, and some include minimum volume commitments2.
Historically, part of the gas business took commodity risk through keep-whole and percent-of-proceeds contracts, where MPLX's payment depended on the value of the liquids it extracted. That exposure has shrunk. A legacy keep-whole arrangement with Marathon expired in March 2025, and the remaining commodity-linked contracts are a small minority of the segment2. MPLX reported no open commodity or interest-rate derivatives at the end of 20252.
Where the money comes from
In 2025, Crude Oil and Products Logistics generated about $6.6 billion of segment revenue and about $4.5 billion of segment adjusted EBITDA. Natural Gas and NGL Services generated about $6.4 billion of revenue but only about $2.5 billion of adjusted EBITDA2.
The revenue is roughly equal. The profit is not. The logistics business converts about 69 cents of every revenue dollar into EBITDA; the gas business converts about 38 cents. That is partly because the gas business passes through product costs and partly because processing plants are more operationally intensive than pipes. It means that, despite the diversification story, nearly two-thirds of MPLX's earning power still sits in the segment where Marathon accounts for 88% of revenue2.
Is it really insulated?
Management and most analysts describe MPLX as more than 85% fee-based or protected by minimum commitments, and the evidence largely supports the description. The test is history. In 2020, the worst year for U.S. energy demand in decades, operating cash flow rose. In 2023, when revenue dipped slightly, net income held steady34. Over a full decade, cash from operations grew every year from 2014 through 2024 and held flat in 20252.
The insulation is real, but it is not unconditional. It depends on two counterparties keeping their obligations. One is Marathon, whose refineries must keep running. The other is a group of Appalachian and Permian producers, whose drilling determines whether volumes exceed minimums or merely meet them. MPLX has transferred volume risk to its customers; it has not abolished it.
Working capital
The working capital tells the same story. Debtor days have sat near 50 for most of the past decade and were about 51 in 2025. Receivables from Marathon were about $624 million at year-end 2025, and third-party receivables about $735 million, with immaterial credit losses2. MPLX is paid quickly, by creditworthy counterparties, and its biggest receivable is owed by its own parent.
That last point is both reassuring and the beginning of a harder question. When your largest customer, your largest unitholder, your manager and your employer of record are the same company, who is negotiating on your behalf?
VII. The Two Masters: Governance & Related-Party Friction
Imagine a meeting of the MPLX GP board. On one side of the table are the officers who run the partnership. On the other side are the officers who run its largest customer. They are, to a striking degree, the same people.
Maryann Mannen is chief executive of both Marathon Petroleum and MPLX. She joined MPC in 2021 as chief financial officer after a long career in finance at TechnipFMC and its predecessors, became MPC's president, succeeded Michael Hennigan as CEO in 2024, and was elected chairman effective January 1, 2026, as Hennigan retired[^5]2. Her experience is in capital discipline and large engineering companies, not in pipelines specifically, and that background shows in MPLX's recent emphasis on returns and portfolio pruning.
C. Kristopher Hagedorn serves as MPLX's chief financial officer, in a leadership structure announced in October 2025[^5]. Executive compensation is set by MPC. MPLX pays MPC a fixed executive management fee, about $13.7 million in 2025, plus reimbursement for the people and services MPC provides2.
The money trail between parent and partnership
The related-party flows are large in both directions. In 2025, MPC provided about $6.0 billion of MPLX's revenue and other income, roughly 46% of the total2. Most of it was service revenue, with the rest from rental income, sales-type leases and other items. At the same time, MPLX paid MPC about $1.7 billion for purchases, services and rentals, nearly a quarter of its total costs and expenses2.
MPLX is also bound to about $4.1 billion of cash commitments under co-location agreements with MPC, with remaining terms of up to 43 years2. These are the arrangements under which MPLX's assets sit inside or beside Marathon's refineries. They tie the two companies together physically as well as financially.
What public unitholders do not get
Public unitholders own about 36% of the partnership2. They do not elect directors. They have no say-on-pay vote. They do not ratify the auditor. Directors and officers as a group own well under 1% of the units2. Executive pay is largely MPC equity and incentives tied to consolidated performance; Mannen's reported 2025 compensation was about $19.0 million, most of it in stock-based awards2.
The formal protection is the conflicts committee of the general partner's board, made up of directors who are not MPC officers, which reviews transactions in which MPC and MPLX interests diverge, such as asset transfers or contract terms. That is a meaningful process. It is not a vote.
Why the parent cannot pillage
The counterweight is economic. MPC owns about 647 million MPLX units2. At current distribution levels, that stake delivers more than $2.5 billion a year in cash to the parent. MPC has relied heavily on capital returns to its own shareholders, and MPLX distributions are a significant, steady source of the cash that funds them[^14].
This creates an unusual alignment. A controlling parent that wanted to extract value through transfer pricing would be robbing a partnership it owns two-thirds of, to benefit a refining business whose shareholders already own that same two-thirds indirectly. The arithmetic discourages it. The bigger risk for public unitholders is not theft; it is that MPC's priorities, such as refinery reliability, its credit rating or its own capital allocation, could shape MPLX decisions in ways unitholders cannot influence.
Testing the claim
The claim that alignment protects minority holders should be tested against the record. Against it: the IDRs that diverted a growing share of cash to MPC for six years, and the 2018 exchange that converted them into more units for the parent rather than simply retiring them. For it: since the IDRs disappeared, MPLX has grown its distribution, retired its preferred equity, repurchased units from the public, and maintained high coverage, all while MPC took the same per-unit payout as everyone else2.
The verdict is that the alignment claim survives, but in a narrower form. Parent control has not been used to strip the partnership since 2018. It was used, before 2018, to tilt the economics toward the sponsor. Unitholders are protected by MPC's self-interest, not by their own rights, and that protection is only as durable as MPC's dependence on the distribution.
That dependence was tested in a new way in 2025, when MPLX turned from caretaker to buyer again.
VIII. The Permian Reinvestment & Consolidation Era (2024–2026)
In June 2025, MPLX announced it would buy Northwind Midstream for about $2.4 billion in cash9. Northwind owned something unglamorous and increasingly valuable: a system in Lea County, New Mexico, that gathers sour natural gas, removes hydrogen sulfide and carbon dioxide through amine treating, and disposes of the acid gas by injecting it deep underground9.
The deal was one piece of a larger move. Over 2025, MPLX also bought the remaining 55% of the BANGL NGL pipeline it did not already own for about $703 million, and sold non-core Rockies gathering and processing assets for about $980 million in cash2. Total cash spent on acquisitions reached about $3.3 billion, alongside about $1.8 billion of capital expenditure2. After several years of harvesting, MPLX was investing at its fastest pace since the merger era.
Why sour gas?
Permian oil wells produce gas as a by-product, and as fields age, the gas-to-oil ratio tends to rise. In parts of the Delaware Basin, that gas is "sour," laced with hydrogen sulfide that is toxic and corrosive. Producers cannot sell sour gas until it is treated, and treating capacity with permits for acid gas injection is scarce. A producer drilling in Lea County needs someone to take that gas, or its oil wells cannot run at full rate.
That makes treating capacity more like a bottleneck than a commodity. Northwind's customers are drilling for oil; the gas is a problem they pay to solve.
Wellhead to water
MPLX's pitch is integration. Gas gathered and processed in the Permian produces NGLs. BANGL moves those NGLs toward the Gulf Coast. MPLX's interests in residue gas pipelines, including a 30% stake in the entity that owns the Whistler pipeline and an interest in the Matterhorn Express pipeline, move residue gas toward Gulf Coast demand centers and LNG export terminals2. Fractionation and export capacity sit at the end of the chain. The aim is to collect a fee at each step, from the wellhead to the water.
The logic is sound in principle. Whether it produces superior returns depends on whether MPLX can win third-party volumes in a basin where Enterprise Products, Energy Transfer, Targa and Kinder Morgan are already entrenched.
The auditor's flag
PricewaterhouseCoopers gave MPLX's 2025 financial statements an unqualified opinion, but it singled out one critical audit matter: the valuation of about $951 million of customer contract intangible assets recorded in the Northwind acquisition2. Those values were estimated using a multi-period excess earnings method, which depends on assumptions about future volumes, contract renewals and discount rates.
A critical audit matter is not a red flag of wrongdoing. It is the auditor saying that a large number rests on judgment. In plain terms, nearly 40% of what MPLX paid for Northwind was booked as the value of customer contracts. If Delaware drilling slows and volumes underperform, that is the asset most exposed to a future impairment. And MPLX has done this before: the 2020 impairment wrote down assets bought in earlier acquisitions.
The BANGL purchase carries its own contingency: an earnout of up to $275 million tied to performance targets through 20292. The remeasurement of MPLX's existing BANGL stake when it took full control produced a non-cash gain of about $484 million in 20252, which flattered reported net income that year.
Funding without new units
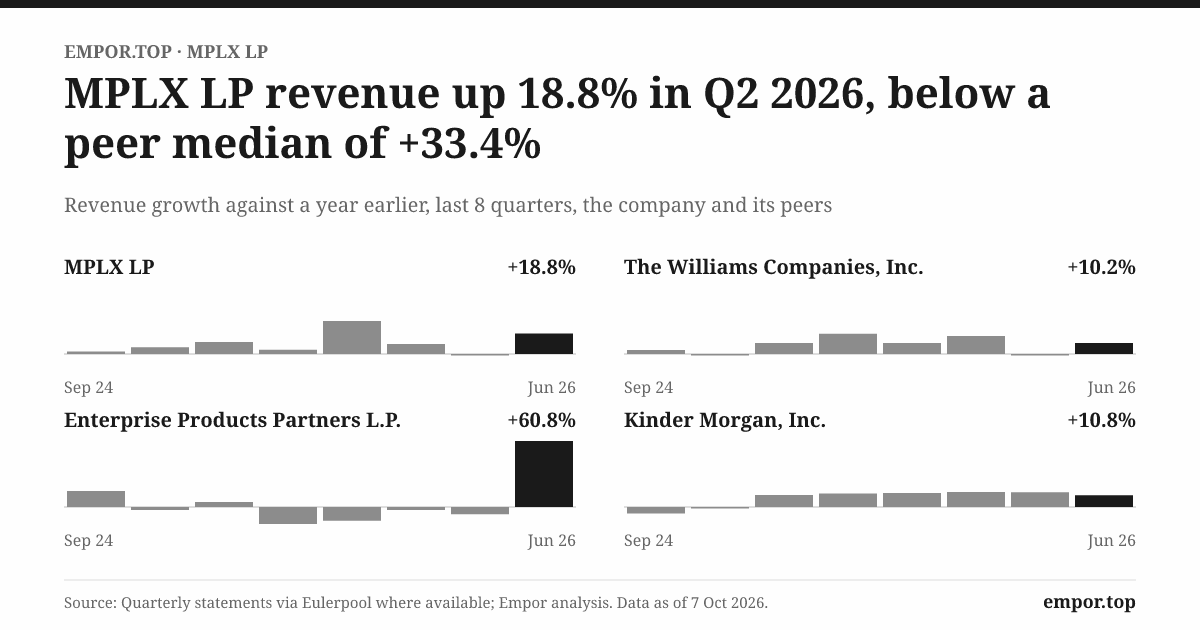
MPLX funded this burst of spending with debt and asset sales rather than new common units. Borrowings rose from about $21.4 billion at the end of 2024 to about $26.2 billion at the end of 20252. The Rockies sale produced a pre-tax gain of about $159 million2. By mid-2026, quarterly revenue was running nearly 19% above the prior year, reflecting the acquired businesses10.
The verdict
The Permian push is a calculated strategic bet, not a reckless one, but it is a bet. MPLX's history argues for caution in a specific way. Its two prior acquisition waves, MarkWest and the Andeavor era, both delivered strategic assets and both led to years of low returns and, eventually, a multi-billion-dollar write-down. The current deals are smaller relative to the partnership, are funded at moderate leverage, and target a bottleneck rather than a commodity service. That narrows the risk. It does not eliminate it. The evidence that would confirm the bet is straightforward: Natural Gas and NGL Services segment adjusted EBITDA rising meaningfully above its 2025 level of about $2.5 billion without impairments to the Northwind intangibles.
Which leads to the larger question: in the places where MPLX does compete, does it have an edge that rivals cannot erase?
IX. Strategic Position & The Moat Analysis
Imagine a gas producer in southwestern Pennsylvania deciding where to send its next decade of production. It can sign with the incumbent gatherer, whose pipes already run past its well pads and whose processing plants have spare capacity. Or it can try to build its own system, or persuade a competitor to build one.
Building a new interstate gas pipeline in the Northeast has become close to impossible. Projects have spent years in permitting and litigation, and several large ones were cancelled outright. Even intrastate gathering requires rights-of-way through hills, farms and towns. The cheapest, fastest path is almost always the incumbent's. That is the essence of MPLX's moat in Appalachia.
The 7 Powers
Cornered resource. MPLX's most defensible assets are things that cannot be easily recreated: permitted rights-of-way across Appalachia and through Midwest refinery corridors, processing complexes already connected to thousands of wells, storage caverns, and a 41% interest in LOOP, the deepwater oil port off Louisiana2. These were assembled over decades under looser permitting regimes. A new entrant would face a far harder process.
Switching costs. Producers typically dedicate acreage to a gatherer for long periods. Disconnecting from one system and connecting to another means new laterals, new compression, and often legal disputes. In the logistics segment, switching costs are physical: MPLX assets sit inside Marathon's refinery fence lines under multi-decade agreements2. Marathon could theoretically build alternatives, but it would be paying twice for infrastructure its own subsidiary already owns.
Scale economies. Pipeline economics reward size. Throughput capacity rises much faster than the cost of building a wider pipe, so a large pipe carrying more volume earns lower unit costs than a small one. Incumbents with existing large-diameter systems can price new volumes at marginal cost and still earn healthy returns.
What MPLX lacks is meaningful network effects or brand power. It is an infrastructure owner, not a platform.
Porter's five forces
Threat of new entrants: very low in Appalachia, moderate in the Permian. Permitting barriers protect the Northeast. The Permian is a different market, where new gathering and processing systems are built regularly and private-equity-backed operators like Northwind itself emerge and sell.
Supplier power: low. Steel pipe, compressors and construction labor are widely available, though inflation can raise project costs.
Buyer power: high in logistics, moderate in gas. Marathon supplies about 48% of total revenue and 88% of logistics revenue2. A buyer that concentrated would normally have enormous leverage. Here it is tempered by Marathon's ownership of the partnership. In gas, producers negotiate hard on new contracts but have limited alternatives once connected.
Threat of substitutes: low over the next decade. Pipelines remain far cheaper than rail or trucks for moving crude, products and gas. The long-term substitute is lower demand for refined fuels, which would affect the logistics segment over decades. In gas, demand from LNG exports and power generation, including for data centers, is rising, which supports volumes.
Rivalry: low in Appalachia, intense in the Permian. In the Delaware Basin, MPLX is a mid-sized player competing against larger, more integrated rivals.
Does the record support the moat?
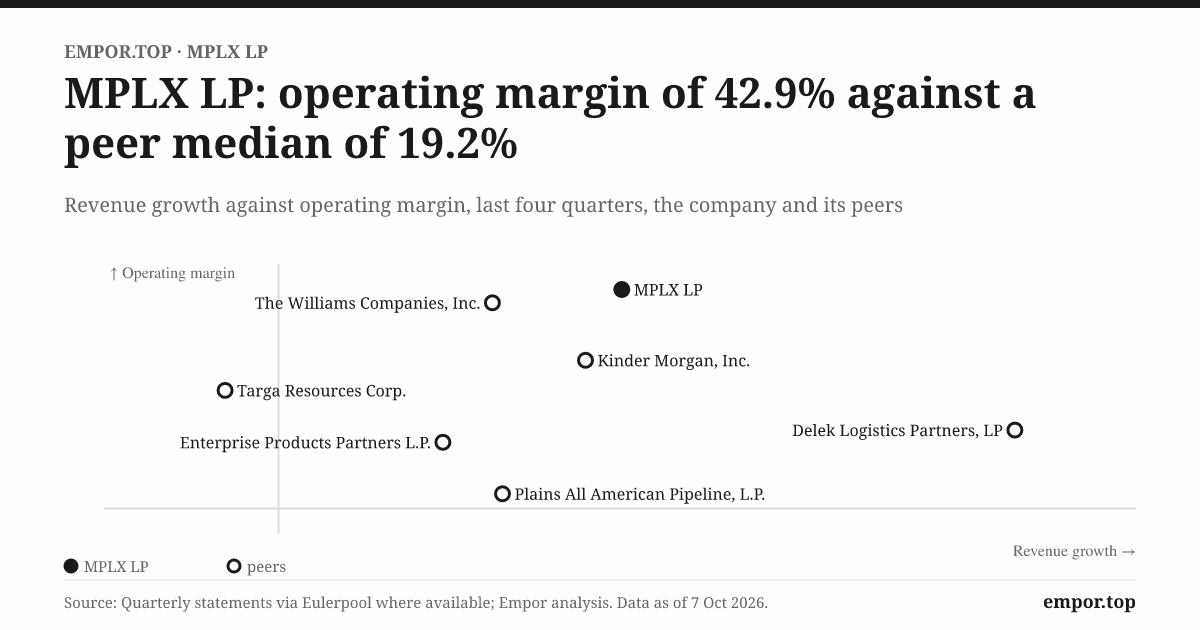
The strongest evidence for the moat is returns. MPLX's return on capital employed has held between about 12% and 15% every year from 2021 through 2025, and was about 14.5% in 20252. Its operating margin has sat in the 40s for most of that period. A business without pricing power or switching costs would struggle to sustain that through the inflation of 2022 and the rate increases that followed.
The strongest evidence against it is the same 2020 impairment. The moat protected cash flow, but it did not protect asset values bought at full prices. And the logistics moat has a shape worth stating clearly: it is very wide but only one customer deep. Its durability depends on Marathon's refineries running. If a refinery closes, the pipes that serve it lose most of their purpose.
The market prices MPLX at about 11.4 times EBITDA, a premium to Enterprise Products at about 9.5 times and Energy Transfer at about 8.6 times. That premium is the market's statement that it believes in the moat. The next section asks whether the balance sheet can carry the cost of keeping it.
X. Capital Allocation, Balance Sheet & Refinancing Stress Test
In February 2026, MPLX sold $1.0 billion of 5.30% senior notes due 2036 and $500 million of 6.10% notes due 205610. The proceeds refinanced $1.5 billion of 1.75% notes that came due in March 2026. It was a routine transaction. It was also a small lesson in what a decade of near-zero rates had done for MPLX, and what their end will cost.
Those 1.75% notes had been issued in an era when investors would lend to a BBB-rated pipeline company for less than 2% a year. Replacing them at well over 5% adds roughly $55 million to $65 million a year in interest expense. In a business generating more than $5 billion of distributable cash flow, that is manageable. It is also a reminder that a large share of MPLX's debt was locked in at rates that will not return.
The balance sheet
At the end of 2025, MPLX had about $26.0 billion of debt principal, almost all of it fixed-rate senior notes maturing between 2026 and 2058, and an undrawn $2.0 billion revolving credit facility2. Its covenant leverage, total debt divided by EBITDA as defined in the credit agreement, was about 3.7 times, against a ceiling of 5.0 times2.
Fitch affirmed MPLX at BBB with a stable outlook in April 2026, noting leverage around 3.7 times and distribution coverage of about 1.4 times11. Moody's and S&P rate it in the equivalent tier. The agencies also note the constraint: MPLX's rating is tied to MPC's credit profile, and heavy capital spending could keep free cash flow after distributions tight for several years11.
The coverage shield
The most important number for an MLP investor is distribution coverage: how much cash the partnership generates relative to what it pays out. In 2025, MPLX produced about $5.8 billion of distributable cash flow and paid about $4.0 billion in distributions, a coverage ratio of about 1.44 times2. That left nearly $1.8 billion of retained cash flow to fund growth and buybacks.
Coverage has declined, from about 1.65 times in 2023 and 1.59 times in 20242. The decline reflects distribution increases outpacing cash flow growth. It remains well above the 1.0 to 1.2 times that many MLPs ran at in the 2010s, but the trend is toward thinner cushions.
Over the long run, the payout ratio against accounting earnings tells a similar story of improving discipline. MPLX's median payout across twelve years was about 101% of net income, with that extreme 373% in 2016. In 2025 it was about 82%2.
Cleaning up the capital structure
The other quiet achievement of recent years is simplification. MPLX redeemed its $600 million of Series B preferred units in 20234. The Series A preferred units issued in 2016 converted into common units, with the last converting in 2025, leaving no preferred units outstanding2. MPLX repurchased about $326 million of common units in 2024 and about $400 million in 20252.
Does the claim of discipline hold?
The stress test is whether MPLX has ever had to raise equity or cut its distribution under pressure. The answer is mixed. It never cut its common distribution, even in 2016 or 2020. But in 2016 it issued expensive convertible preferred units to avoid doing so, and those preferred units diluted common unitholders when they converted over the following nine years. Discipline today is demonstrably stronger than it was a decade ago; the record shows it was not always so.
The verdict is that the balance sheet is strong and the refinancing headwind is manageable. The open question is whether coverage keeps sliding as distributions rise and capital spending stays elevated. That is the variable that determines whether MPLX can keep funding growth without returning to the capital markets for equity.
XI. Playbook: Business & Investing Lessons
Lesson 1: Own the tollbooth inside the fortress. The most durable part of MPLX is the least glamorous: the pipes, racks and tanks embedded inside Marathon's refinery fence lines, bound by agreements that run for decades and carry minimum commitments. A competitor would have to build parallel infrastructure inside a facility it does not own, for a customer that already owns the incumbent. For founders and investors, the lesson is that the best switching cost is physical. A contract can be renegotiated. A pipe already welded into someone else's plant is very hard to replace. A pipeline inside the customer's gate is not a supplier; it is part of the building.
Lesson 2: Kill the IDRs before they kill the company. For six years, MPLX's incentive distribution rights gave Marathon a rising claim on every new dollar of cash, rewarding growth at the sponsor level and taxing it at the unitholder level. The 2018 decision to eliminate them was the moment MPLX stopped being a feeder vehicle and started being a company that could make acquisitions on its own merits. Structures that reward a sponsor for growth tend to outlive the growth. Every sweetener a sponsor writes for itself eventually becomes a bill the public pays.
Lesson 3: Cash conversion beats accounting earnings. In 2020, MPLX reported a net loss of about $720 million. In the same year, its operating cash flow rose. Over twelve years, it turned about $23.6 billion of reported profit into about $42.9 billion of operating cash. Pipeline accounting is dominated by depreciation on steel that lasts for decades and impairments that reflect past purchase prices, not current cash. An investor who judged MPLX only on its income statement would have sold at precisely the wrong time. Depreciation is a memory of what you paid; cash is a measure of what you earn.
Lesson 4: When your parent's buyback depends on you, your distribution has a bodyguard. Related-party control is normally a governance warning. At MPLX, Marathon's two-thirds ownership and its reliance on more than $2.5 billion a year of distributions mean the parent has every reason to keep the partnership strong. But the lesson cuts both ways. That protection exists because of the parent's interests, not the minority holders' rights, and it would weaken if those interests changed. A controlling owner who needs your cash is a better partner than one who needs your assets.
Lesson 5: Basin monopolies are bought in pain and paid for over a decade. MarkWest was bought as oil prices collapsed, with a falling currency and a restive seller base. It brought years of thin returns, a 373% payout year, expensive preferred capital and, eventually, impairments. It also brought the Appalachian franchise that now supplies a third of the partnership's earnings. MPLX is attempting the same play in the Permian now. The basin you buy in a downturn will cost you twice: once at closing and once in patience.
XII. Analysis & Bear vs. Bull Case
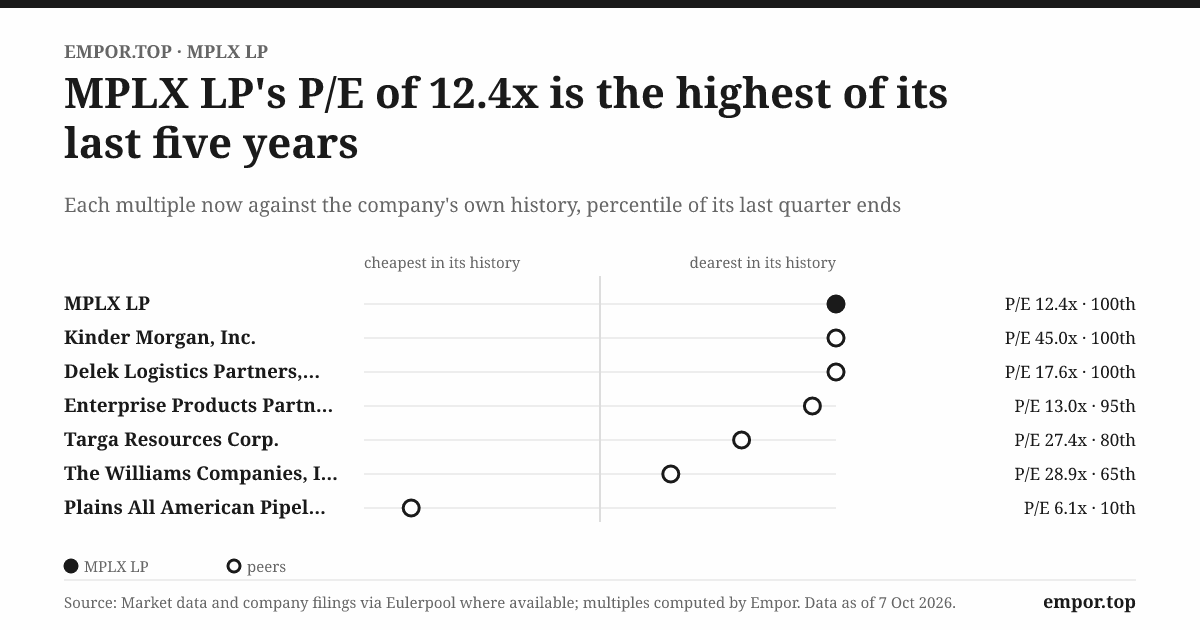
Imagine a portfolio manager with energy income capital to allocate. On the screen are three choices. Enterprise Products Partners trades at about 9.5 times EBITDA with a yield around 7.2%. Energy Transfer trades at about 8.6 times with a yield around 7.8%. MPLX trades at about 11.4 times EBITDA with a yield of about 7.5%. On a trailing basis, MPLX's price-to-earnings ratio is about 12.4, compared with a five-year median of about 10.3.
The question for the manager is not whether MPLX is a good business. It is whether it is good enough to justify paying more than for its rivals.
What the price assumes
At about 12.4 times trailing earnings and an earnings yield of about 8%, the market is not pricing heroic growth. It is pricing durability: that the distribution continues to rise steadily, that coverage stays healthy, that the Permian deals earn their cost of capital, and that Marathon remains a reliable anchor. The premium to peers reflects MPLX's lower leverage, its high coverage and its contracted logistics business. The premium to its own history reflects the market's growing confidence that the 2015–2020 mistakes are behind it.
The bull case
The bull case rests on four pillars. First, cash flow stability: more than 85% of earnings are fee-based or protected by minimum commitments, and the business demonstrated in 2020 that its cash flow can withstand a severe demand shock. Second, demand tailwinds in gas: Appalachian gas is increasingly sought for power generation, including for data centers, and Gulf Coast LNG export capacity is expanding, pulling Permian gas through pipelines in which MPLX holds stakes. Third, parent alignment: Marathon's large ownership and reliance on distributions make it a committed steward. Fourth, a clean structure: no IDRs, no preferred equity, moderate leverage and coverage above 1.4 times2.
The bear case
The bear case has four pillars too. First, governance: public unitholders have no vote on directors, pay or related-party arrangements. If Marathon's interests diverge from theirs, they have no recourse. Second, rising financing costs: refinancing low-coupon debt raises interest expense, and continued spending could push leverage toward the upper end of the comfortable range. Third, Permian execution: the $951 million of Northwind contract intangibles and the BANGL earnout create exposure if Delaware drilling slows, and MPLX's history with acquired assets includes a $3.4 billion impairment. Fourth, valuation: at a premium to both peers and its own history, the units offer less margin for error than they did when they traded at 10 times earnings.
The activist's stress test
A skeptical investor would push on three points. Why does a partnership with no employees pay its parent nearly a quarter of its operating costs, and how would anyone outside the conflicts committee know whether those charges are fair? Why is coverage declining while the partnership steps up acquisitions? And why should minority holders pay a premium multiple for a business whose most profitable segment depends on a single refiner? None of these questions point to misconduct. All of them point to risks that the premium valuation does not obviously discount.
Myth versus reality
Myth: MPLX is just a tax trick for Marathon. Reality: it started that way, but more than a third of its earnings now come from a third-party gas business that would be a significant midstream company in its own right.
Myth: Fee-based means risk-free. Reality: fees protect cash flow from price swings, but not asset values from overpayment, as 2020 proved.
Myth: The parent's control is a pure negative. Reality: it is a governance weakness and an economic protection at the same time.
Three KPIs to watch
- Distribution coverage ratio. It was about 1.44 times in 2025, down from about 1.65 times in 20232. A level that stays comfortably above about 1.35 times would indicate distributions are growing within the partnership's means; a continued decline would suggest they are not.
- Natural Gas and NGL Services segment adjusted EBITDA. About $2.5 billion in 20252. Whether it rises toward $2.8 billion or more as Northwind and BANGL contribute full years is the clearest test of the Permian thesis.
- Covenant leverage. About 3.7 times at the end of 2025, against a 5.0 times ceiling2. Staying below about 4.0 times would indicate the acquisition program is being financed responsibly.
The verdict: MPLX is among the more insulated businesses in midstream, and the evidence supports some premium to more commodity-exposed peers. But the premium is now pricing in successful Permian execution and continued parent alignment, and public holders have no lever to pull if either falters.
XIII. Epilogue
Tonight, MPLX units sit about 4% below their 52-week high, near the top of their trading history. The partnership has no preferred equity left, no IDRs, and quarterly net income around $1 billion10. Its parent remains its biggest customer, its controlling owner and the employer of every person who runs it.
The next chapters will be written in a few specific moments.
The Delaware Basin test. In the full-year 2026 results, Northwind and BANGL will contribute their first complete year inside MPLX. If gas segment earnings rise as expected and auditors find no reason to revisit the Northwind intangibles, the Permian push will look like the Appalachian strategy repeated with better timing. If volumes disappoint, the partnership will face a familiar sequence: a write-down, a defensive explanation, and questions about whether it learned from MarkWest.
The capital return balance. MPLX has raised its distribution steadily, and coverage has drifted down as a result. Management will have to choose between continuing large distribution increases and preserving cash for Permian expansion. Each new distribution announcement is a small signal about which priority Marathon and its leadership consider more important.
The structure question. Marathon has kept MPLX as a separate partnership through the FERC shock, an activist campaign and a pandemic. It could still decide to roll the partnership up, or convert it, if the tax or market calculus changes. For now, the evidence is that the parent values MPLX exactly as it is: a separately priced, separately financed, steadily distributing subsidiary.
The tension that remains is the one this story began with. MPLX has become a real infrastructure business with its own franchise. It has not become independent. Every key decision about its future will be made by people whose first duty is to another company.
XIV. Outro
Back in October 2012, MPLX was a small partnership with half of a pipeline system and a single butane cavern in West Virginia. To skeptics, it looked like a tax loophole with a ticker symbol, the kind of vehicle that appears in a boom and disappears in the bust.
Instead, it outlasted the boom, the bust, the FERC ruling, the activists, the pandemic and most of its peers. It paid out more than $27 billion along the way. And it did so not by escaping its parent but by becoming indispensable to it.
That is the paradox of MPLX: the midstream tax shelter that conquered the shale highway, and survived by turning itself into Marathon's durable tollbooth.
References
-
MPLX LP Form 424B4 IPO Prospectus — SEC EDGAR, 2012-10-29 ↩↩↩↩↩
-
MPLX LP Form 10-K for Fiscal Year Ended December 31, 2025 — SEC EDGAR, 2026-02-26 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
MPLX LP Form 10-K for Fiscal Year Ended December 31, 2024 — SEC EDGAR, 2025-02-27 ↩↩↩↩↩↩↩↩↩↩↩
-
MPLX LP Form 10-K for Fiscal Year Ended December 31, 2023 — SEC EDGAR, 2024-02-28 ↩↩↩↩
-
FERC Policy Statement on Tax Allowances in MLP Pipeline Rates — Federal Energy Regulatory Commission, 2018-03-15 ↩↩
-
Paulson & Co. Opposes MarkWest Sale to MPLX — The Wall Street Journal, 2015-11-11 ↩
-
MPLX LP and Andeavor Logistics LP Complete Merger — Business Wire, 2019-07-30 ↩
-
Elliott Management Urges Marathon Petroleum to Split into Three Companies — Business Wire, 2019-10-22 ↩
-
MPLX to Acquire Northwind Midstream for $2.4 Billion — Reuters, 2025-06-16 ↩↩
-
MPLX LP Form 10-Q for Quarterly Period Ended June 30, 2026 — SEC EDGAR, 2026-08-04 ↩↩↩
-
Fitch Affirms MPLX LP at 'BBB'; Outlook Stable — Fitch Ratings, 2026-04-16 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube