Lowe's Companies: The Eternal Number Two and the $10 Billion Pro Gamble
I. Introduction & Episode Roadmap
Drive down almost any suburban arterial road in America and the pattern repeats itself with eerie regularity. On one side of the highway sits an orange box. Across the median, or a mile further down, sits a blue one. Each spans the footprint of a couple of football fields. Each opens before most offices do, sells the same 80-pound bags of concrete and the same 16-foot pressure-treated boards, and stays open long after the contractors have gone home. To most shoppers they are interchangeable. To investors, they are anything but.
The blue box belongs to Lowe's Companies, a business that sold about $86 billion of hammers, refrigerators, lumber, paint and drywall in its fiscal year ended January 2026, from 1,759 big-box stores and, since late 2025, more than 540 wholesale branches across North America.1 By any normal standard, that is a giant. Yet Lowe's has spent roughly 35 years living in the shadow of The Home Depot, which rang up around $160 billion of sales in its 2024 fiscal year from a store fleet only modestly larger.2 Two companies, two nearly identical formats, and one of them turns each square foot of selling space into about a third more revenue than the other.
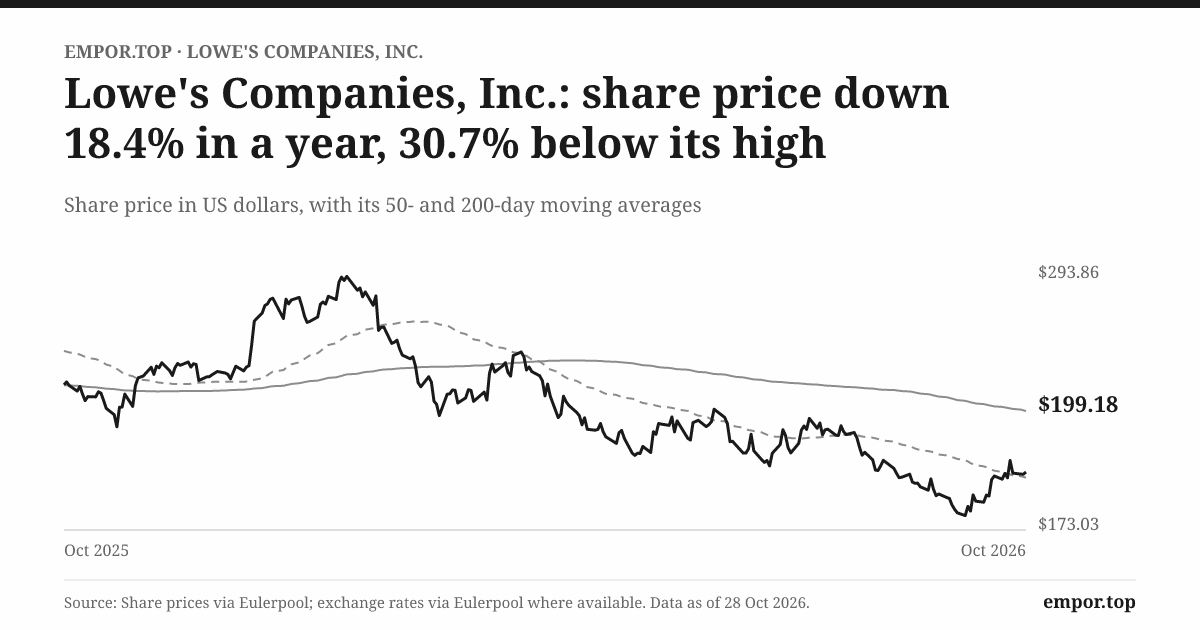
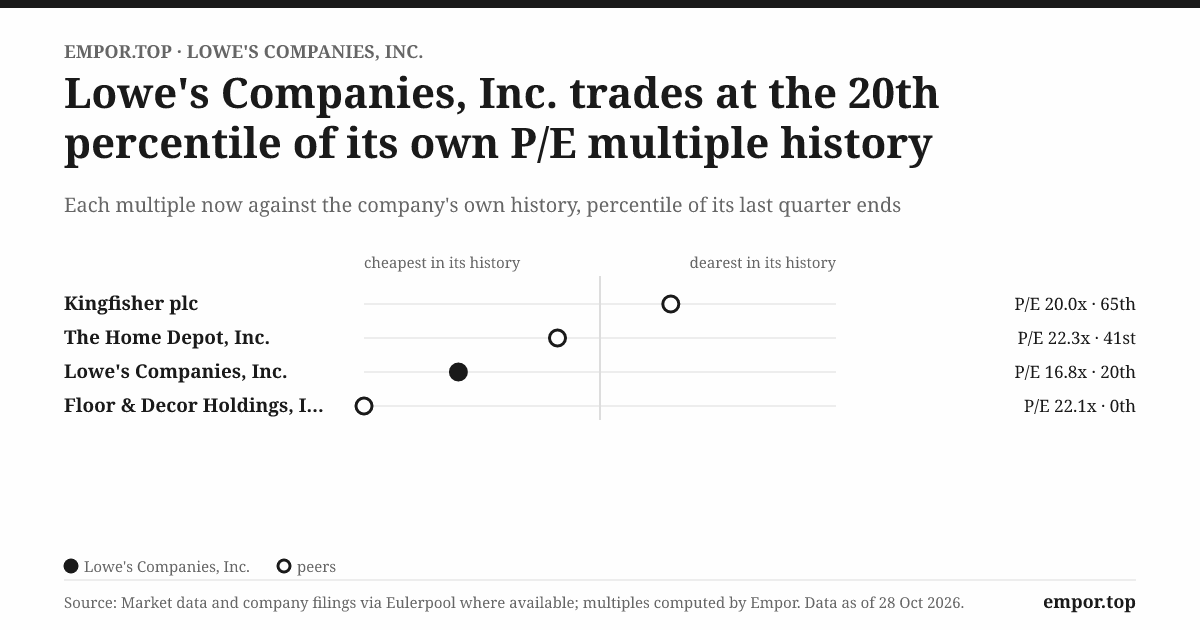
That gap is the spine of this story. It explains why Lowe's has traded at a discount to its rival for most of the last two decades, why it spent a generation buying back its own stock with borrowed money, and why, in 2025, it did something it had never done in a century of existence: it paid roughly $10 billion to become a wholesale building-materials distributor.1 Tonight the shares sit near $199, almost 31% below their 52-week high, valued at about 17 times trailing earnings against a five-year median of about 19.
The arc runs from a dusty country store in the foothills of the Blue Ridge Mountains, through a sourcing revolution that made Lowe's the leading home-centre chain in the American South, to a slow-motion defeat at the hands of two fired executives from Atlanta. It runs through a decade in which Lowe's handed back more cash to shareholders than its business generated, while a string of acquisitions in California, Australia, Canada and Mexico ended in write-downs. Then it turns on a single hiring decision in 2018, when Lowe's brought in a man who had spent twelve years running Home Depot's stores, and on the wholesale gamble that man made seven years later.
Four questions run underneath all of it. The first is whether Lowe's can bolt a wholesale distribution business onto a retail machine without eroding the margins and balance sheet that made the retail machine valuable. The second is whether the enormous buyback campaign of the last decade created real value per share or simply disguised a stagnant top line with leverage. The third is whether Lowe's can ever close the productivity gap with Home Depot, and with it the valuation gap. The fourth is quieter but may matter most in a downturn: what happens to a retailer that spent decades letting a bank carry its customers' credit risk, once it starts lending to builders directly?
The story moves in nine parts. It begins with the country hardware store that cut out the middleman, follows Lowe's as it lost its crown to the orange box, and then examines the buyback years and the foreign misadventures of the Robert Niblock era. It then turns to Marvin Ellison's arrival and the operational overhaul that followed, and to the $10 billion wholesale pivot into Foundation Building Materials and Artisan Design Group. From there it weighs the moat, draws the lessons, stress-tests the bull and bear cases, and ends with where Lowe's stands tonight. It starts, as so many American retail stories do, with a small-town merchant and a brother-in-law who saw something coming.
 Subscribe on LinkedIn
II. The Country Hardware Store That Cut Out the Middleman (1921–1978)
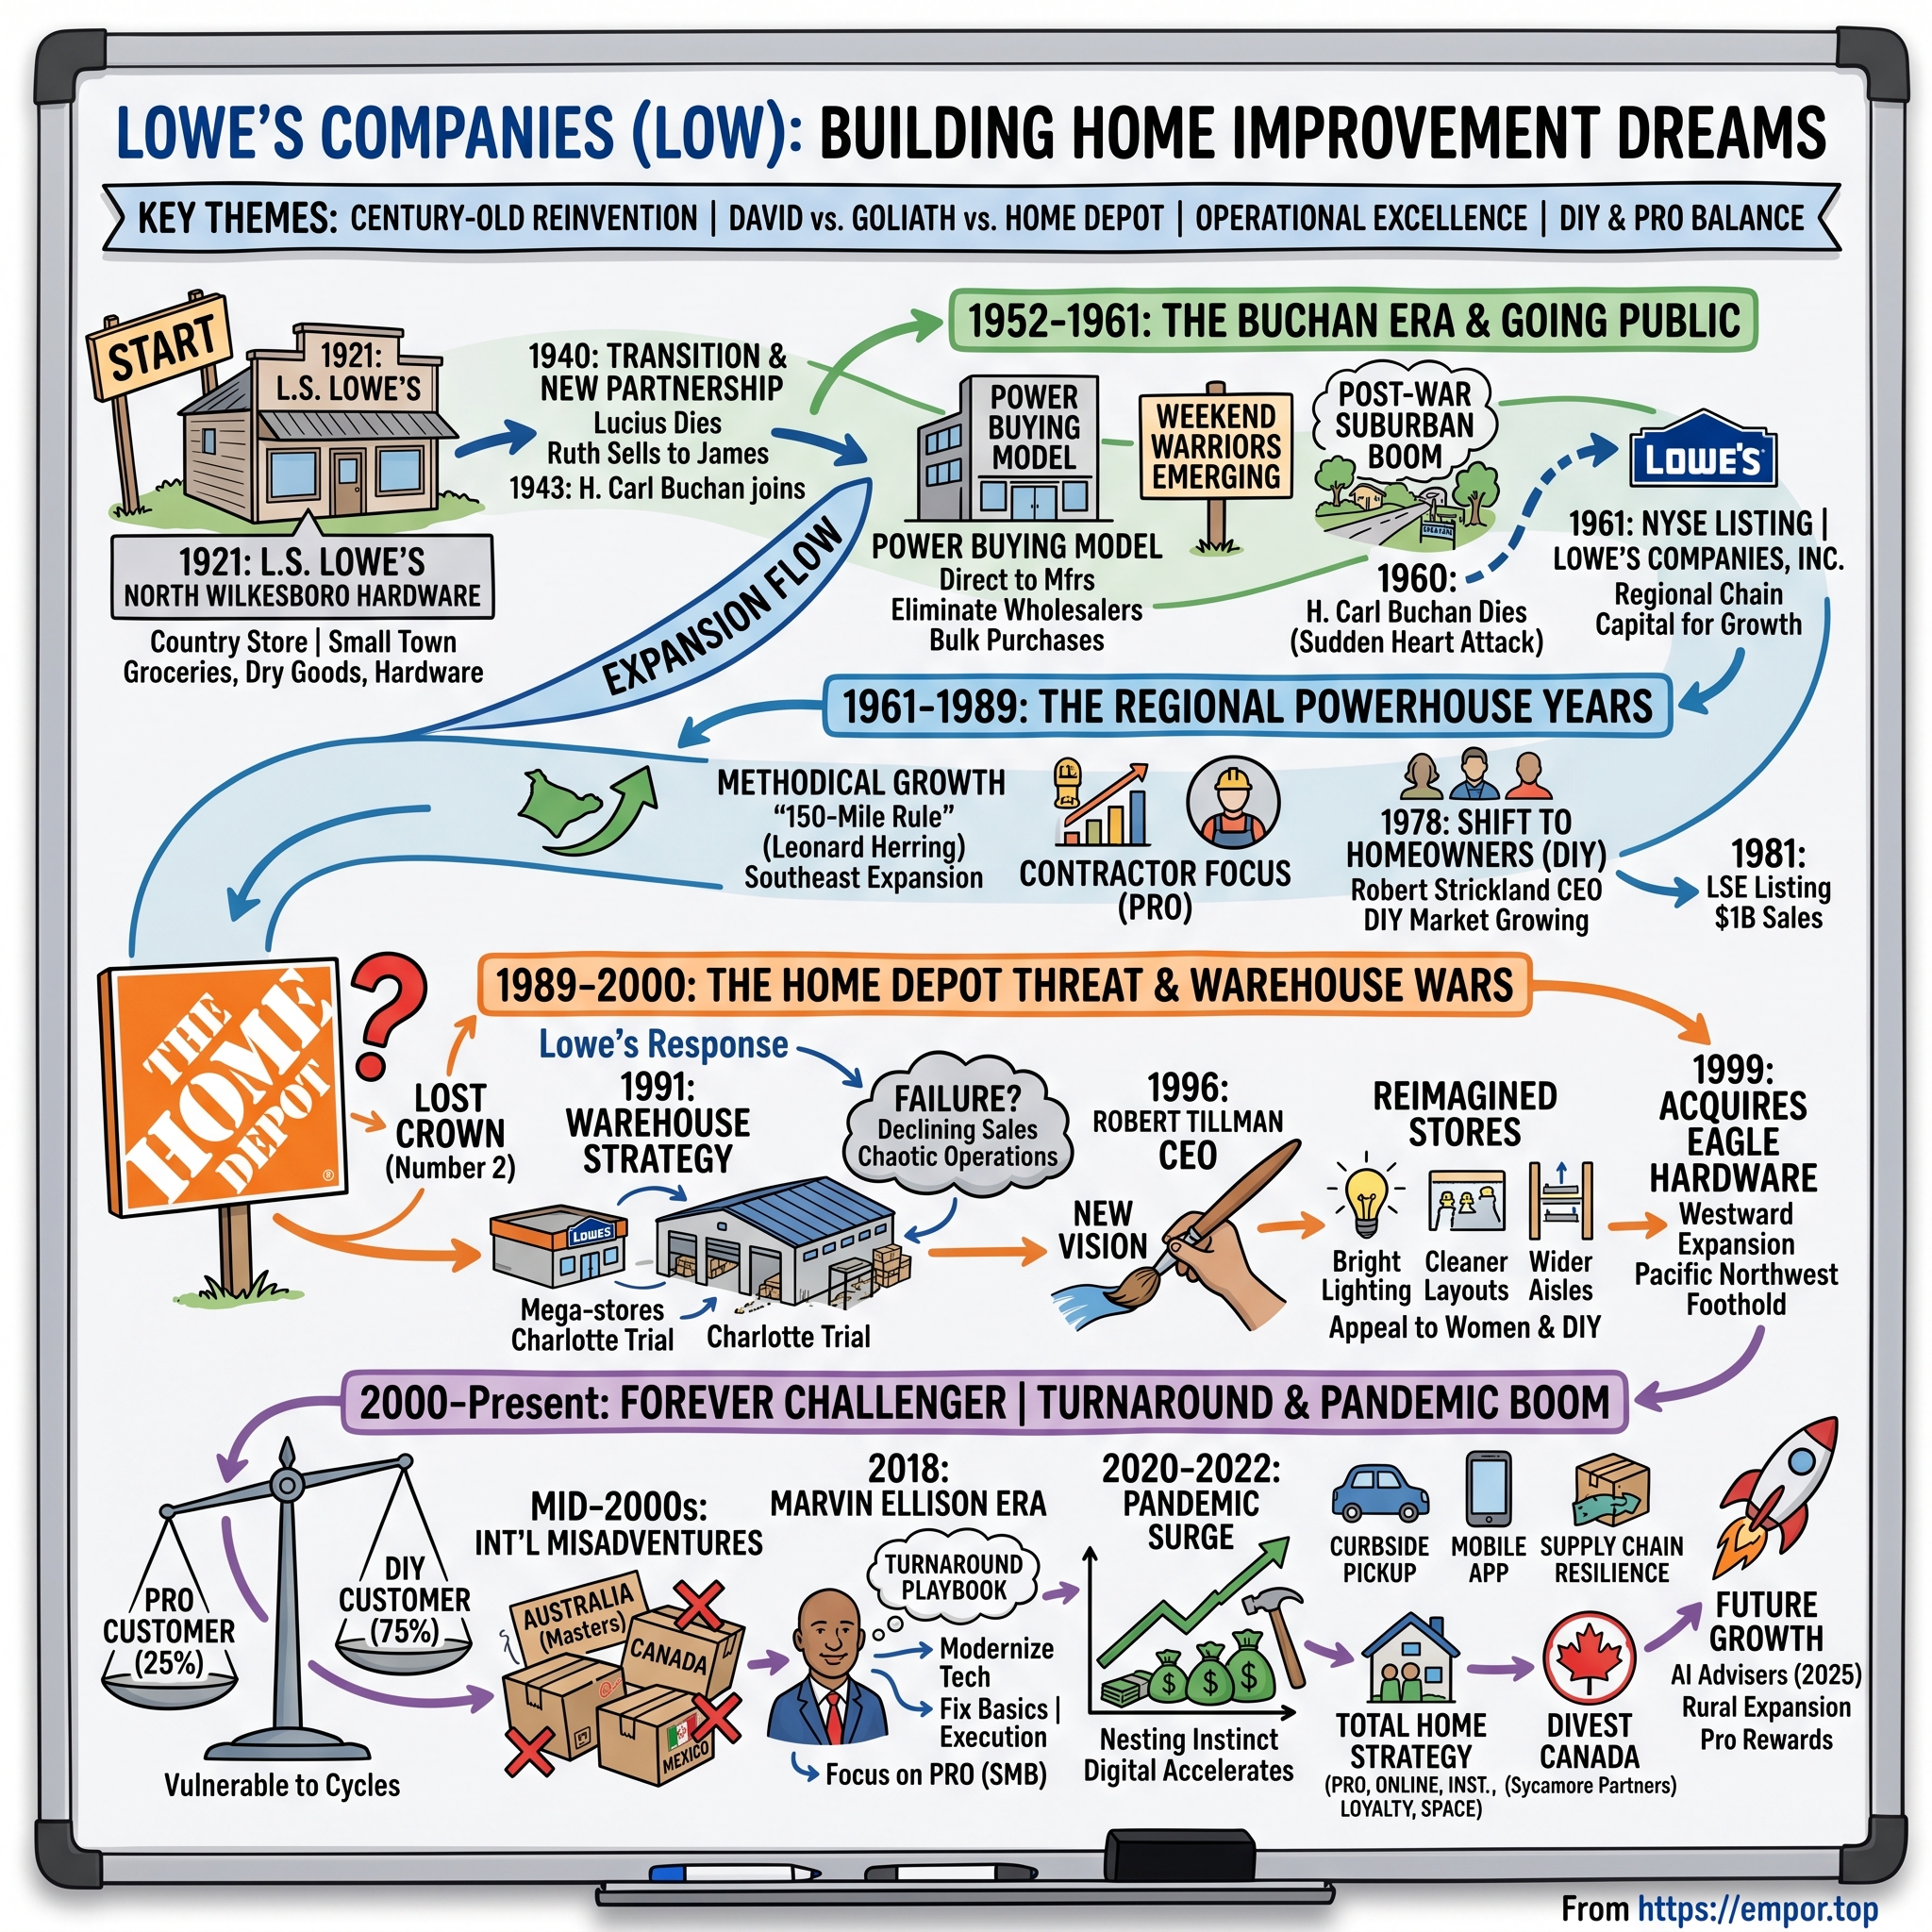
North Wilkesboro, North Carolina, sits where the Yadkin River bends out of the mountains, a railroad and tobacco town that in the early twentieth century served farmers from the surrounding hollows. In 1921 a merchant named Lucius Smith Lowe opened a hardware store there.3 It was the kind of mercantile shop that sold a little of everything a rural family might need, and like most such shops it bought its goods from wholesale jobbers who took a cut at every step between the factory and the shelf.
Lowe died in 1940, and the store passed through family hands.4 What turned it from a local shop into a company was the arrival of his son-in-law, H. Carl Buchan. During the war years Buchan took a half interest in the business, cleared out much of the general merchandise and reorganised the store as a warehouse for hardware and building supplies.3 He was betting on something that had not yet happened: that millions of returning servicemen would want houses, and that the people building those houses would need lumber, nails, pipe and wire in quantities no country store had ever stocked.
Buchan's insight was less about what to sell than about how to buy it. Instead of paying distributors' markups, Lowe's bought directly from manufacturers, which let it undercut rivals on price while keeping a healthy margin for itself.5 His early customers were mostly building contractors, the people who cared most about price per unit and least about store ambience.3 In 1952 Buchan took full control, acquiring his brother-in-law's half of the business in exchange, remarkably, for an automobile dealership and a cattle ranch.3 Sales that year were about $4.1 million. By 1959 they had reached $27 million, a more than sixfold increase in seven years.3
The numbers tell you why the model worked, but they also hint at its limit. Buying direct is an advantage only for as long as competitors do not do it too. Once a rival reaches similar scale and signs similar supplier contracts, the edge shrinks to a matter of execution. Buchan's real accomplishment was getting there first across a large stretch of the Carolinas and the Southeast, opening stores in Durham, Asheville and Charlotte by the mid-1950s and building a chain of 15 stores by 1960.4
The corporate form followed the growth. In 1955, with six stores operating, the business was incorporated as Lowe's North Wilkesboro Hardware, Inc.3 That detail matters less for the legal paperwork than for what it signalled: Buchan was no longer running a family shop but a chain, and chains need capital, managers and systems that a single merchant cannot supply alone. The company that went to public investors a few years later was built on that foundation.
He did not live to see what came next. Buchan died in 1960, and in 1961 the executives who succeeded him took the company public as Lowe's Companies, Inc.3 Two of those executives, Robert Strickland and Leonard Herring, would shape the company for the next three decades.5 Strickland was a Harvard Business School graduate who became chairman in 1978, and Herring served as president through the long transition that followed.5 They inherited a business with a clear formula: modest-sized stores, contractor customers, direct procurement and steady expansion through small and mid-sized towns where competition was thin. By the late 1970s, sales had grown from roughly $170 million at the start of the decade to more than $900 million.5
Those were good years to be a building-supply chain in the South. The region's population and housing stock were growing faster than the national average, and Lowe's grew with them, reaching about 50 stores by 1969.3 The model still leaned on contractors, which meant revenue moved closely with housing starts. In a boom that was a feature. In a bust it would become a weakness.
Then the housing market turned. In 1980, housing starts fell and Lowe's net income dropped by about a quarter.5 The lesson management drew was that a chain dependent on builders was hostage to the building cycle, so it set out to win a steadier customer: the homeowner. Lowe's redesigned its stores to work like supermarkets, putting seasonal and decorative goods at the front and basics at the back so shoppers would walk past more merchandise, and it lengthened hours and spent more on advertising.4 The first store in the new layout opened in Morganton, North Carolina.4
It worked, at least on its own terms. Sales topped $1 billion for the first time in 1982, and in 1983 do-it-yourself sales overtook sales to commercial customers for the first time, with total revenue of about $1.43 billion.3 In the space of a few years Lowe's had turned itself from a contractor's supplier into a homeowner's store.
That shift, sensible as it looked at the time, contained the seed of the problem that would define Lowe's for the next forty years. Buchan's original model was built around the professional customer and the economics of buying in bulk. The new Lowe's was built around a small-format store and a consumer who came in on Saturday mornings. The second model was more stable through the housing cycle, but it was also easier to attack, because it left the high-volume contractor, and the enormous store needed to serve him profitably, on the table. Somebody in Atlanta was about to pick it up.
III. Losing the Crown to the Orange Box (1978–1999)
In April 1978, two executives at a Los Angeles-based home improvement chain called Handy Dan were fired.6 Bernie Marcus had risen to chairman and president of Handy Dan; Arthur Blank worked alongside him.6 Marcus was 49, out of a job, and convinced that the industry was doing it wrong. With Blank, the merchandiser Pat Farrah and the investment banker Ken Langone, he opened the first two Home Depot stores in Atlanta in 1979.6
The concept was almost brutally simple: build a store so large, stock it so deep and price it so low that both the serious do-it-yourselfer and the professional contractor would drive past every other option to get there. Where Lowe's operated tidy stores of a few tens of thousands of square feet, Home Depot built superstores of around 105,000 square feet.5 Those boxes did several things at once. They carried enough inventory to fill a contractor's order on the spot. They spread fixed costs such as rent, staff and management over a far larger volume of sales. And they made Home Depot the cheapest place to buy almost anything in its markets, which brought in more traffic, which justified more stores.
Lowe's watched this happen and, for most of the 1980s, did not respond in kind. The reasons are understandable. Its small-format stores were profitable, its management team had just completed a hard-won pivot towards the consumer, and building giant warehouses would have meant writing off much of the fleet that had made the company successful. It is the classic incumbent's dilemma: the threat looked like a different business with worse aesthetics, and matching it meant cannibalising your own.
The verdict came in the late 1980s, when Home Depot's aggressive expansion of superstores carried it past Lowe's into the number one position in American home improvement.5 Lowe's has never regained it.
Lowe's began enlarging its stores in 1989, moving from roughly 20,000 square feet towards 60,000.3 By 1991 the company had committed fully, taking a $71.3 million restructuring charge to close, relocate or remodel about half its stores between 1991 and 1995.5 New stores grew from 45,000 square feet to 85,000 and then to 115,000.5 Measured by the size of the company at the time, it was a bet-the-franchise decision, and it was made under pressure rather than from strength.
The bet worked in the sense that it saved the company. Lowe's had about 309 stores in 1990, mainly across the South.3 Sales grew from about $3.1 billion in 1991 to $8.6 billion in 1996, and net earnings reached a record $292 million that year.5 In August 1995, Robert Tillman, who had been chief operating officer, succeeded Herring as president and chief executive.5 Under Tillman, Lowe's pushed beyond its southern base, committing $1.5 billion in 1998 to open 100 new stores in the western United States and, in 1999, buying the Washington-based chain Eagle Hardware for about $1 billion and converting its stores to the Lowe's banner.3
The pace of the late 1990s build-out is easy to miss in hindsight. Lowe's opened 37 new stores in 1996 alone, and between 1998 and 2001 it grew from 520 stores to 744 while the average store expanded from about 92,000 to 121,000 square feet.3 Total selling space rose from roughly 48 million to 81 million square feet in those four years.3 This was a company sprinting to occupy suburban sites before its rival could, yet in many western markets it arrived second, after Home Depot had already claimed those locations. Herring retired in August 1995, handing Tillman a company that had survived its near-death moment and was finally playing offence.5
By the end of the decade Lowe's was a genuinely national retailer. It operated 576 stores in 1999, with the average new box at more than 90,000 square feet, and sales reached $15.9 billion that year before climbing to $22.1 billion by 2001.3 Rather than copying Home Depot's raw-concrete warehouse feel outright, Lowe's leaned into brighter, more merchandised stores and a stronger appeal to homeowners decorating and furnishing their homes, which fit its consumer pivot of the 1980s.
Here the record cuts in two directions. The warehouse conversion was late, but it was executed at scale and kept Lowe's in the game as one half of a durable duopoly. That is no small thing: many regional hardware chains of the era did not survive the Home Depot onslaught at all. Yet the late start had a lasting cost. Home Depot had a decade's head start in the best real estate, in contractor relationships and in the purchasing scale that comes with being first to a national footprint. Lowe's ended the century with a store fleet that looked like Home Depot's, but with a customer base tilted towards the homeowner and away from the professional who buys every week. That tilt is what still shows up today in sales per square foot of about $440 at Lowe's against more than $580 at Home Depot.12
The question for the new millennium was what Lowe's would do with the cash its national fleet was about to throw off. The answer would say a great deal about its management.
IV. The $64 Billion Mirage: Share Cannibalism, OSH, and the Foreign Quagmires (2000–2018)
Picture the executive floor in Mooresville, North Carolina, in the mid-2010s. Robert Niblock, a Lowe's veteran of more than two decades who had run the company since the mid-2000s, was presiding over a business that looked healthy on the surface.7 Sales were growing by around 5% a year, earnings per share were climbing faster still, and the company was a reliable dividend payer. Yet on his desk sat a growing pile of problems: a money-losing joint venture in Australia, a Mexican store chain without scale, a recently acquired California hardware chain that was not working, and a Canadian acquisition that would eventually cost billions. Underneath it all was a technology platform that, by the end of his tenure, was badly outdated.
The engine that kept the earnings story intact was the buyback. In the twelve fiscal years from 2014 to 2025, Lowe's repurchased about $64.5 billion of its own stock and paid about $21 billion in dividends, a total of roughly $85.5 billion returned to shareholders.18 Over the same twelve years the business generated about $70 billion of free cash flow, which is operating cash after capital spending.1 The difference of roughly $16 billion, along with the cash later spent on acquisitions, came from borrowing. Total borrowings, including lease obligations brought onto the balance sheet by an accounting change in 2019, rose from about $11 billion at the start of 2015 to almost $45 billion by early 2026.1
The effect on the share count was dramatic. Shares outstanding fell from around 970 million to 561 million, a reduction of more than 40%.1 Because every remaining share now claimed a bigger slice of the profits, earnings per share grew much faster than profits themselves. Between the fiscal years ending January 2016 and January 2026, net profit grew about 10% a year, while EPS rose from $2.73 to $11.85, more than quadrupling.1
The side effect was equally dramatic. Shareholders' equity, the accounting difference between what a company owns and what it owes, went from about $10 billion to a deficit that bottomed near minus $15 billion before recovering to about minus $10 billion at the last fiscal year end.1 Negative equity sounds alarming, and in a weaker business it would be. In Lowe's case, it is the bookkeeping result of having bought back more stock than the company retained in earnings. What matters more is whether the cash flows supporting the debt are dependable, a question this story returns to when the bill for the wholesale deals arrives.
Was the buyback a good use of money? The fairest answer is that it was a reasonable use of money executed with uneven timing. Buying back stock at 15 to 20 times earnings is a decent return when a business is stable and borrowing costs sit near zero, as they did for most of the 2010s. The peak repurchase years, however, came in fiscal 2021 and 2022, when Lowe's spent about $13 billion and $14 billion respectively.18 Those were years when pandemic-inflated profits had driven the share price to record highs. A company that buys most aggressively when its own earnings are at a cyclical peak is not demonstrating the price discipline that defenders of buybacks like to claim.
The more serious criticism is that the buyback machine allowed the operating business to drift. Operating margins in the Niblock years sat in a band of roughly 8.5% to 9.6%, a long way below Home Depot's.12 And the capital that did go into growth had a poor record.
Start with Orchard Supply Hardware. Lowe's bought the California neighbourhood hardware chain in 2013, shortly after it had filed for bankruptcy protection, hoping to learn how to run a smaller, urban format.9 Five years later, in August 2018, Lowe's announced that all 99 stores in California, Oregon and Florida would close by February 2019, at an expected cost of $390 million to $475 million.10 Small-format hardware turned out to be a different business from big-box home improvement, and Lowe's had not cracked it.
Australia came next on the list of disappointments. In the late 2000s Lowe's entered a joint venture with Woolworths, Australia's dominant supermarket group, to challenge the home improvement leader Bunnings with a chain called Masters. Lowe's owned a third. In January 2016 it served notice that it wanted out, after a net investment of about $930 million, and warned of a non-cash impairment charge.11 Masters had faced a market leader with deep supplier relationships and local knowledge that a foreign partner could not easily replicate.
Mexico was smaller but taught the same lesson. Lowe's entered Mexico in 2010,4 but by November 2018 it said it intended to exit its chain of 13 stores, along with two non-core U.S. businesses.12 Thirteen stores could never generate the purchasing scale that makes big-box economics work.
Then there was Canada, the most expensive misadventure. In 2016 Lowe's bought RONA, the Quebec-based home improvement chain, in a deal reported at around $2.4 billion.13 It was meant to give Lowe's a dominant position north of the border. Instead it delivered years of integration problems and weak returns. In November 2022 Lowe's agreed to sell the entire Canadian retail business, by then about 450 corporate and affiliated dealer stores, to Sycamore Partners for $400 million in cash plus performance-based deferred payments, and warned of a pre-tax non-cash impairment of about $2 billion.13 The sale closed in February 2023.14
Put those four together and a clear pattern emerges. Each venture abroad or into a new format ran into the same wall: big-box home improvement depends on dense local supplier networks, regional distribution and purchasing scale that cannot be shipped across a border or shrunk into a neighbourhood store. Lowe's possessed those advantages in the United States and nowhere else. That history should shape how investors judge any new claim that Lowe's can win in an unfamiliar business, including the one it entered in 2025.
Meanwhile the core was falling behind. By the late 2010s, Lowe's was still running much of its business on an ageing technology stack, with poor inventory visibility across stores and a website that lagged its rival's. Home Depot, under its own leadership, had spent the decade building an integrated online and in-store network and courting professional contractors. Lowe's professional customers, the ones who buy every week and in bulk, were the most exposed to these gaps, and the company's sales stayed heavily weighted towards do-it-yourself homeowners.
By early 2018 the board had seen enough. Niblock announced his retirement, and the search for a successor began. The board's choice was a man who knew Home Depot's playbook from the inside.
V. Enter Marvin Ellison: The Home Depot Playbook in Mooresville (2018–2022)
On July 2, 2018, Marvin Ellison walked into Lowe's headquarters as president and chief executive.7 He arrived with an unusual résumé. He had spent 15 years in operations roles at Target, then more than 12 years at Home Depot, where from 2008 to 2014 he ran U.S. stores as executive vice president, overseeing about 2,000 stores, more than 275,000 employees and $65 billion of annual sales.7 He then left to run J.C. Penney, a department store in long decline, where he was chairman and chief executive when Lowe's called.7 He holds a marketing degree from the University of Memphis and an MBA from Emory, and he sat, then as now, on the board of FedEx.7
The J.C. Penney years are worth noting because they cut against the hero narrative. Ellison did not turn that business around, and nobody claimed he had. What Lowe's was buying was not a record of rescues but something more specific: a decade of knowing exactly how its largest rival ran its stores, managed its inventory and served its contractors. Lowe's did not need a strategy consultant to tell it what a better home improvement retailer looked like. It needed someone who had already operated one.
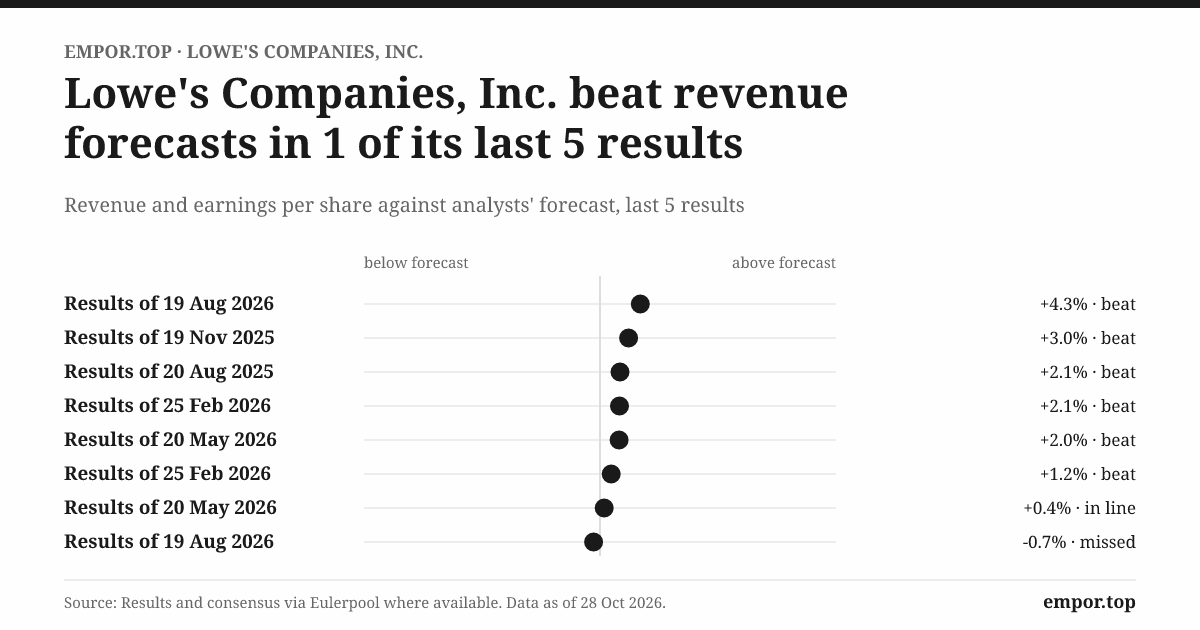
The quarter he walked into showed why the board had acted. In August 2018, Lowe's reported comparable sales growth of 5.2%, a hair below analysts' expectations in what was then a strong housing market, and cut its full-year earnings forecast by about 90 cents a share.9 Three months later the picture was worse: comparable sales rose just 1.5% against expectations of nearly 3%.12 Lowe's was underperforming in good conditions, which is a far more damning signal than underperforming in bad ones.
He moved fast. Within weeks of arriving, Lowe's announced the Orchard Supply closure.10 By November it had added the Mexican exit, two other non-core businesses and the closure of 51 underperforming stores in the U.S. and Canada to the list.12 On the same quarterly call, he pointed to persistent out-of-stocks as a reason sales had fallen short of expectations, an unusually blunt admission that the basics of retail were not being executed.12 Fiscal 2018 carried the cost of that clean-up: operating margin fell to about 5.6%, the lowest in the modern era.1
The strategy that followed had a deliberately unglamorous name: retail fundamentals. It meant replacing managers, rebuilding the supply chain and upgrading technology. Ellison brought in executives from Home Depot, Walmart and other large retailers. Lowe's began moving away from shipping products straight from vendors to stores and towards a network of regional distribution and bulk cross-dock centres, including dedicated facilities for big and bulky items such as appliances. It invested in handheld devices for store associates, digital tools for inventory, and a rebuilt Lowes.com. It also leaned harder into private and exclusive brands such as Kobalt and Craftsman, aiming to blunt Home Depot's advantage in power-tool brands.1
The overhaul also changed what Lowe's spent and whom it employed. Capital spending stayed modest, at roughly 2% of sales through the early 2020s before rising to about 2.6% in fiscal 2025, which says the transformation was mostly about doing existing things better rather than building new stores.1 The workforce shrank as productivity tools took hold: Lowe's had about 200,000 full-time associates in fiscal 2021 and about 167,000 by fiscal 2025, alongside roughly 109,000 part-timers.115 Management's label for this, perpetual productivity improvement, captures the idea well enough. Self-watering plant tables in garden centres, centralised communication tools for store staff and redesigned freight flows from truck to shelf are not the stuff of investor-day fireworks, but each one frees labour hours that can be cut or redeployed to serving customers.16
That plan later took the name Total Home, a framework that spread investment across the Pro customer, online sales, installation services, loyalty and space productivity.1 Management's claim was that a better-run Lowe's could serve the whole home, from a homeowner buying a light bulb to a contractor buying a pallet of drywall, and that this breadth would close the gap with its rival.
Then came a stress test nobody planned. In the spring of 2020, Covid-19 locked Americans inside their homes, and they responded by repainting bedrooms, building decks and turning spare rooms into offices. In the second quarter of that year, Lowe's comparable sales jumped 34% and Lowes.com sales rose 135%.17 Ellison credited the work done since 2018, saying the retail fundamentals strategy had "dramatically improved our technology and operational platforms".17 Annual sales leapt from about $72 billion in fiscal 2019 to nearly $90 billion in fiscal 2020 and peaked at about $97 billion in fiscal 2022.1
The second quarter of 2020 was the high-water mark of that surge. Net sales rose about 30% to $27.3 billion, and diluted earnings per share jumped 75% to $3.74.17 Lowe's had to manage crowded stores under health restrictions, sudden spikes in demand for categories such as paint and outdoor products, and a flood of online orders that its website had to fulfil through curbside and in-store pickup. That it did so without a collapse in service is a fair point in Ellison's favour, whatever one thinks about how much of the volume was luck.
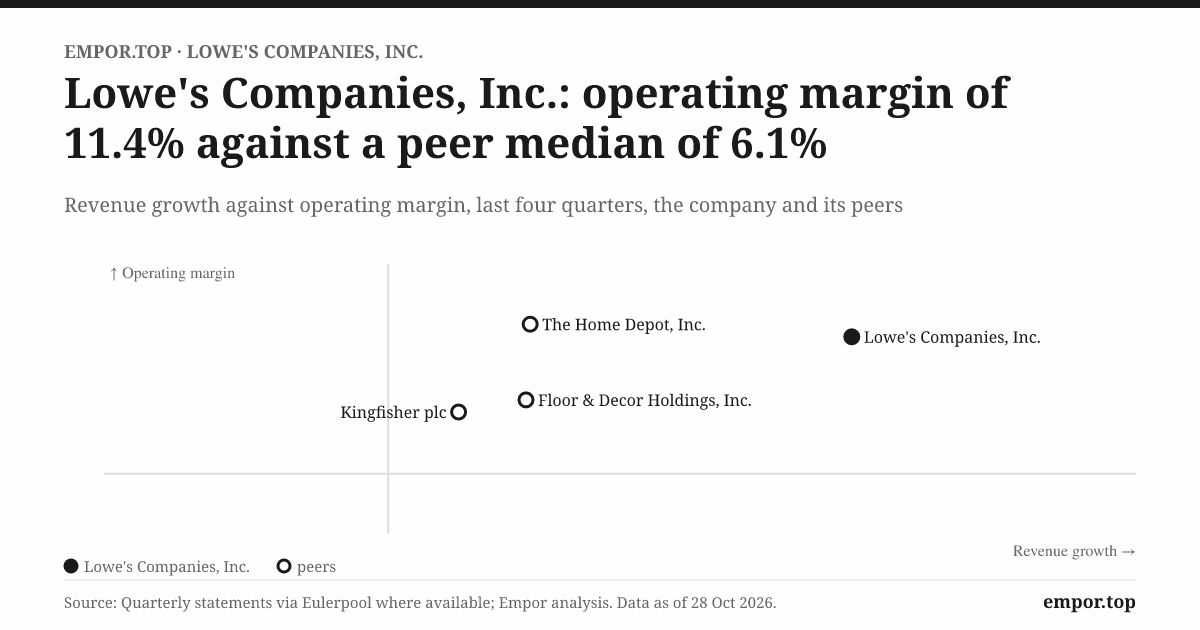
This is the moment where the consensus story and the record need to be separated. The popular version says Ellison transformed Lowe's and that the pandemic proved it. The record says something narrower. Operating margin did rise substantially, from 8.8% in fiscal 2019 to a peak of 13.4% in fiscal 2023, and has held around 12% since.1 That improvement survived the end of the pandemic boom, which is strong evidence that at least part of it reflects better operations rather than just higher volume. Sales are another matter. They fell back to about $86 billion in fiscal 2023 and $84 billion in fiscal 2024 as DIY demand normalised and Lowe's shed its Canadian business.1 Revenue over the five years to early 2026 actually shrank slightly, by about 0.8% a year.1
So the Ellison era delivered a better-run company, not a bigger one. Lowe's professional customer share remained stuck at roughly a quarter to 30% of sales, against about half at Home Depot.12 Margins improved; the mix did not. That distinction matters for everything that came next.
The incentive design reinforces the margin focus. Ellison's total reported pay was about $21.6 million in fiscal 2025, most of it in stock and option awards tied to return on invested capital and operating income rather than revenue alone.18 Shareholders approved the pay package by about 95% at the May 2026 annual meeting and rejected a shareholder proposal for an independent board chair by roughly four to one.19 Eleven of the twelve directors are independent, and Ellison combines the roles of chairman and chief executive.18 One small governance detail deserves a sentence: Lowe's bought about $237 million of shipping services from FedEx in fiscal 2025, where Ellison is a director. That is a fraction of a percent of cost of sales and the company describes the terms as arm's length.1 Brandon Sink, who succeeded David Denton as chief financial officer in 2022, has remained in place since, giving the finance team continuity through the acquisitions.18
By 2023, Ellison had fixed much of what was broken in the stores. What he had not fixed was the customer mix. And the organic route to professional customers had a ceiling that no amount of in-store improvement could break through.
VI. The $10 Billion Wholesale Pivot: Buying Foundation Building Materials & ADG (2023–Present)
In the summer of 2025, the numbers on the board in Mooresville told a clear story. Sales had fallen from about $97 billion at the peak in fiscal 2022 to about $84 billion in fiscal 2024.1 Existing home sales were stuck near multi-decade lows, as homeowners with cheap mortgages refused to move and trigger new spending on renovations. Comparable store sales had been negative for most of two years. And across the highway, Home Depot had already made its move: in June 2024 it closed the purchase of SRS Distribution, a specialty distributor to roofers, landscapers and pool contractors with more than 760 locations, for about $18.25 billion.20
On August 20, 2025, Lowe's answered. It agreed to buy Foundation Building Materials, a distributor of drywall, steel framing, ceilings and related products, for about $8.8 billion in cash.21 FBM had more than 370 branches across the United States and Canada, about 40,000 professional customers, roughly $6.5 billion of revenue and about $635 million of adjusted EBITDA, a measure of operating cash profit before depreciation and amortisation.21 Ellison said the deal would advance "our multi-year transformation of the Pro offering".21 The price worked out to about 14 times FBM's EBITDA, a full price for a distributor in a slow housing market rather than a bargain.
FBM was the second purchase that year. In April 2025 Lowe's had agreed to buy Artisan Design Group for about $1.3 billion in cash.22 ADG provides design, distribution and installation of flooring, cabinets and countertops for homebuilders and multifamily developers, with about $1.8 billion of revenue in 2024, 132 facilities and more than 3,200 installation staff across 18 states.22 Together the two deals cost Lowe's about $10.1 billion, adding to its wholesale footprint.1
The comparison with Home Depot's deal is instructive. Home Depot paid about twice as much for SRS, but it bought a distributor focused on roofing, landscaping and pools, categories where replacement demand runs steadily regardless of how many new houses are built.20 Lowe's bought businesses more tied to new construction: interior drywall and ceilings in FBM's case, and finishes for new homes and apartments in ADG's. Both companies reached the same conclusion, that the next leg of Pro growth lay outside the store, but they made different bets on which part of the building cycle to own. So far the market has rewarded the more defensive one.
The logic of the pivot rests on a physical limit of the big-box format. A store works well for what the industry calls the pick-up-truck Pro: the handyman, painter or plumber who needs supplies today and can load them himself. It does not work for a commercial drywall contractor who needs forty pallets delivered by crane to the fourth floor of a building site, on credit terms, at an agreed time. Those customers buy from distributors like FBM, which run fleets of flatbed trucks with boom cranes and extend trade credit. Lowe's could not reach them by improving its stores, because the store was the wrong tool. FBM gave it the right one.
The pivot also has a geographic and demographic logic. Lowe's has largely run out of places to open new stores in America; its square footage has barely moved in years.1 Management argues that the country needs millions of new homes over the next decade, and that owning the distribution chain to the builders who will build them positions Lowe's for the eventual recovery. On the August 2026 call, Sink framed the goal as taking advantage of 14 million homes over the next decade.16
That is the bull case in management's words. The record so far is more mixed, and the details of the balance sheet show what Lowe's has taken on.
The first change was in credit risk. For decades, Lowe's retail customers who wanted to pay over time used Lowe's-branded cards issued by Synchrony Bank, which funds the balances, collects payments and absorbs losses with no recourse to Lowe's.1 Lowe's earns a share of the programme's profit without carrying the loan book. That is why its receivables were only about $94 million at the start of 2025. Wholesale distribution works differently: contractors buy on account and pay 30 or more days later. With FBM and ADG on board, receivables jumped to about $1.09 billion by January 2026, more than eleven times the prior level.1 Lowe's now carries direct exposure to subcontractors who go bust, builders who pay late and the lien disputes that are routine in construction. The company says its allowance for credit losses is not yet material.1 That is the right starting point, but construction credit has never been tested on Lowe's books through a downturn.
The second change was in goodwill and intangibles. Lowe's booked about $8.3 billion of goodwill and acquired intangible assets from the deals.1 The largest piece, about $3.9 billion for FBM's customer relationships, was flagged by Deloitte, Lowe's auditor since 1962, as a critical audit matter because its valuation depends on assumptions about how long customers stay and how much they will earn.1 That is not a warning that the value is wrong. It is a reminder that if construction stays weak, these assets are where impairments would show up.
The third change was in debt. In September 2025 Lowe's raised $7 billion of new borrowing, $2 billion as a term loan and $5 billion in senior notes, to fund the acquisitions.1 Long-term debt reached about $39.9 billion at the end of fiscal 2025, and including about $4.8 billion of lease liabilities, total obligations were about $44.7 billion against roughly $1.4 billion of cash and short-term investments.1 Net interest expense was about $1.4 billion that year, around 16% of pre-tax income, and management expects about $1.6 billion in fiscal 2026.123 About $10.4 billion of debt matures across fiscal 2026 to 2028.1
The fourth change was in capital returns. Lowe's repurchased just $75 million of stock in fiscal 2025, down from about $4 billion the year before and $14 billion at the peak.1 For a company that had made buybacks central to its equity story, this was a fundamental shift: free cash after dividends is now going primarily towards paying down debt. S&P rates Lowe's BBB+ and Moody's Baa1, both investment grade with stable outlooks, but both flag the aggressive financial policy and the leverage target of 2.75 times adjusted debt to EBITDAR.2425 At the end of July 2026, Sink put adjusted leverage at 3.0 times and said the company expected to reach its 2.75 times target in mid-2027.16
The first half of fiscal 2026 showed how the new capital priorities work in practice. Lowe's repaid about $2.4 billion of debt in the six months to July, while repurchasing only a few hundred million dollars of stock, and it still raised its quarterly dividend to $1.25 a share.23 The second quarter alone generated about $3.1 billion of free cash flow, a reminder that the retail engine still throws off cash in volume even when sales are flat.16 The dividend is the one form of capital return management has protected throughout, and it consumes about 40% of net profit, near the top of its historical range.1 That leaves the balance sheet carrying the full weight of the acquisitions until leverage falls.
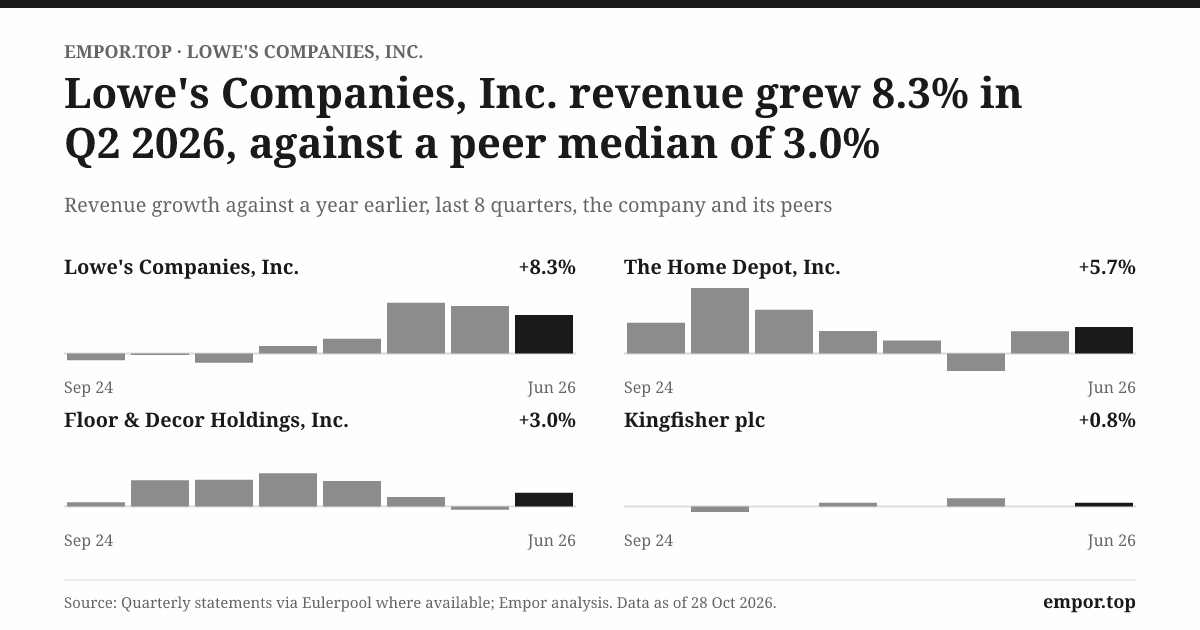
How have the acquisitions performed? Sales rose about 8% in the quarter ended July 2026, to roughly $26 billion, but comparable sales rose only 0.2%, which means almost all the growth came from the acquired businesses.23 Gross margin fell 80 basis points, partly because distribution earns lower margins than retail.16 Acquisition-related amortisation cost $96 million in the quarter.23 And on the August 2026 call, Sink acknowledged that the residential construction market was "bumping along at multiyear lows", noting that ADG is entirely exposed to residential building and FBM about 45%.16 Management cut full-year guidance to the bottom of its previous range: about $92 billion of sales, flat comparable sales and adjusted EPS of about $12.25.23
So the deal is less than a year old, it was bought at a full price, and it arrived into a housing slump. None of that means it will fail. Distribution assets bought in a downturn can look very cheap in a recovery, and Ellison has argued that the country must eventually build more homes. But the history of Lowe's ventures beyond its core, from Orchard Supply to RONA, suggests caution about assuming that owning a business is the same as running it well. The honest assessment is that the strategic logic is sound, the timing is unlucky, and the evidence that it is working does not yet exist.
To understand whether Lowe's can make this work, it is worth stepping back to ask what, exactly, protects the business it already has.
VII. Moat Analysis: 7 Powers & Porter’s 5 Forces
It is six in the morning in a suburb of Charlotte, and a plumber in a white van is deciding where to buy a water heater. There is an independent supply house twenty minutes away that knows him by name and gives him a contractor price. There is a Home Depot four minutes away. There is a Lowe's six minutes away. He needs the heater in the van within half an hour because a family has no hot water and he has three more jobs after this one. What he chooses, and why, is the whole moat question in miniature.
The first thing the scene reveals is that the big boxes do not compete primarily with each other. They compete with the fragmented world of local lumberyards, plumbing supply houses and independent hardware stores, and against that world they enjoy real advantages. They open earlier and close later, seven days a week. They carry tens of thousands of products under one roof. They buy at volumes that local suppliers cannot match. And they can serve the homeowner and the tradesman in the same building, which spreads the fixed cost of the store over two very different customer bases.
The second thing it reveals is that between the two boxes, the choice usually comes down to small things: which one is closer, which one has the item in stock, which one has a contractor desk that will load the van quickly. That is why the relationship between Lowe's and Home Depot has been, for most of their shared history, a rational duopoly. Prices are visible to everyone with a phone, neither side gains much from a price war, and both compete mainly on convenience, availability and service. Ellison described the industry on the August 2026 call as a "very rational and predictable" promotional environment, even as he noted that competitors had used tariff refunds to cut prices on grills, patio furniture and plants that July, which he called transitory.16 That episode is a useful reminder that rationality in a duopoly is a habit, not a law.
Hamilton Helmer's framework of seven powers offers a sharper way to sort out which advantages are durable. The strongest of Lowe's powers is scale economies. A retailer with 1,759 stores and nearly 200 million square feet of selling space can negotiate supplier terms, rebates and advertising support that no regional rival can match.1 The complexity of those arrangements is itself evidence of their size: Deloitte singles out the accounting for vendor funds, the rebates and allowances Lowe's earns across thousands of supplier agreements, as one of only two critical audit matters in the company's audit.1 Scale also explains why Amazon has never seriously threatened the core: shipping a 16-foot board or a pallet of concrete to a single home is ruinously expensive for an online seller, while Lowe's spreads the logistics across a store that a customer drives to.
But scale cuts both ways in a duopoly. Home Depot is larger, with about 2,300 stores and roughly twice the sales.62 Whatever scale advantage Lowe's has over the local lumberyard, Home Depot has over Lowe's. That is the deepest explanation for why the productivity gap has persisted for 35 years.
Process power, the second strength, is the advantage of a well-run operating system that competitors cannot easily copy. Ellison's era built real versions of this: a distribution network for big and bulky items, store-level productivity tools, and an appliance business that management says can deliver and install the broadest selection of major appliances next day in virtually every U.S. ZIP code.16 Appliances, Lowe's largest category, had posted seven straight quarters of positive comparable sales by mid-2026.16 Lowe's has also built a reputation for conversion technology: management says customers who use its online AI assistant, Mylow, buy at three times the rate of those who do not.16 These are management claims rather than audited figures, but the appliance record is consistent with a real operating edge in that category.
The recent numbers also show where process power has limits. In the quarter to July 2026, Lowe's gross margin was about 33%, down 80 basis points from a year earlier, partly because the acquired distribution businesses earn thinner margins than retail and partly because fuel and transport costs rose.16 Inventory climbed to about $17.7 billion, up roughly $1.4 billion, with about $500 million of that coming from FBM.16 A better operating system can manage these pressures; it cannot make wholesale distribution as profitable per dollar of sales as a big-box store.
Process power also shows up in cash. Lowe's operating cash flow over the last twelve fiscal years has been about 146% of its net profit, largely because depreciation is a non-cash charge and because the company holds about 110 days of inventory while paying suppliers in about 62.1 The negative or near-zero working capital this produces is part of why a company with negative equity can carry investment-grade ratings.
Switching costs, the third power, are weak for the do-it-yourself customer, who can cross the road without penalty, and only moderate for the professional. The MyLowe's Rewards loyalty programme has more than 30 million members, who management says shop more often and spend more per visit than non-members.16 For Pros, loyalty points, trade credit and job-site delivery create some stickiness. FBM's trade-credit relationships may add more, because a contractor with an open account and a branch that knows his job sites is less likely to switch over a small price difference. But FBM's customers were FBM's long before they were Lowe's, and nobody yet knows whether they will buy anything else from the blue box.
Branding is real but modest. Lowe's is a household name, and its exclusive and private brands, Kobalt, Craftsman and others, give it products a rival cannot sell. Yet Home Depot has its own exclusive lines and a stronger reputation among tradespeople, and DeWalt, which Lowe's calls the number one Pro-preferred brand, is sold at both.16 Network effects, where each new customer makes the service better for the others, barely apply to a hardware store. Cornered resources, assets competitors cannot get, are thin: prime suburban sites are valuable, but Home Depot has just as many, often across the street. Counter-positioning, the advantage of a business model incumbents cannot copy without harming themselves, protects both big boxes from lumberyards and pure online sellers, but not from each other.
Michael Porter's five forces round out the picture. The threat of new entrants is very low: replicating nearly 200 million square feet of retail space, the distribution centres behind it and the supplier relationships that stock it would take decades and enormous capital, and suburban zoning makes new big boxes ever harder to build. Supplier power is low, because Lowe's buys from thousands of manufacturers and can lean on private labels. Buyer power is moderate: individual shoppers have no leverage, but they have perfect price transparency, and in discretionary categories they can simply wait. The threat of substitutes is low, because a burst pipe or a broken water heater cannot be fixed with software. Over half of American homes are more than 40 years old, which creates repair demand that cannot be deferred forever.1 Competitive rivalry is the only force that runs hot, and it runs hot in one direction: towards Home Depot.
Put together, the analysis lands in a clear place. Lowe's has a strong moat against everyone except the one competitor that matters most. Its margins are defended by scale and process against the fragmented supply industry, and its core categories are protected from online disruption by the physics of heavy goods. But within the duopoly, it is the smaller player with the less valuable customer mix, and none of its powers is strong enough to close that gap on its own. That is why the FBM deal is best read not as an extension of the moat, but as an attempt to buy a piece of the professional market that the moat never reached.
The obvious next question is what Lowe's history teaches about whether such attempts succeed.
VIII. Playbook: Business & Investing Lessons
Every company's history teaches something, but Lowe's has the rare quality of having run the same experiments more than once, which makes its lessons unusually clear.
The first lesson comes from the buyback years. Picture the share count falling year after year, from nearly a billion to 561 million, while earnings per share quadrupled and the press releases celebrated record results. Meanwhile, the stores were running out of stock, the website lagged and the operating margin was stuck well below the rival's. The buybacks were not the cause of the drift, but they made it easier to ignore, because the number investors watched most closely kept rising. The lesson for any board is that per-share growth funded by debt should be judged against what the operating business is doing underneath. Financial engineering can disguise operational drift, but it cannot fix it. Lowe's needed a new chief executive and a complete operational overhaul before the margin moved.
The second lesson comes from the four foreign and format adventures. In Australia, Masters faced Bunnings, a market leader with deep supplier ties. In Canada, RONA bought for around $2.4 billion was sold for $400 million in cash.13 In Mexico, thirteen stores never reached scale.12 In California, Orchard Supply's neighbourhood format never fit.10 Each time, Lowe's assumed that what worked in American suburbs would work elsewhere, and each time the absence of local purchasing scale and distribution density proved fatal. A big box is only as big as the supply chain behind it, and supply chains do not travel. For investors, this is the most useful lens on the FBM and ADG deals: they are domestic and they come with their own management and supply chains intact, which is meaningfully different from the foreign ventures. But they are still a new business with different customers, and the burden of proof sits with Lowe's.
The third lesson is about the 2018 hire. Boards facing a turnaround often reach for a celebrated outsider or a visionary strategist. Lowe's did something more pragmatic: it hired the person who had run its biggest competitor's stores for six years and knew precisely where its own operations fell short. Within weeks, the distractions were gone. Within two years, the technology could handle a pandemic surge. Within five, operating margin had risen by more than four percentage points from the pre-Ellison level. When you are number two, the fastest route to better execution is to hire the person who taught number one how to execute. The limit of the lesson is equally instructive: operational know-how raised margins, but it did not change the customer mix. Some gaps cannot be closed by running the same format better.
The fourth lesson concerns the hidden risks of moving into a new customer segment. For decades, Lowe's had arranged its consumer credit so that Synchrony Bank carried the risk. When it bought FBM and ADG, it took on more than a billion dollars of trade receivables owed by contractors and builders.1 The change is easy to miss because it does not show up in headline sales or margins until something goes wrong. When a retailer starts selling to builders, it also starts lending to them. Any investor evaluating a company that changes its customer base should ask what risks the new customers bring that the old ones did not.
The fifth lesson is about negative equity. Lowe's balance sheet shows liabilities exceeding assets by about $10 billion, a figure that would terrify anyone reading it in isolation.1 Yet the company holds investment-grade ratings from both major agencies, pays a rising dividend and generates roughly $7 billion to $8 billion of free cash flow a year.124 The negative equity is the accounting residue of buying back more stock than the company retained in profit. Negative equity is a history lesson, not a death sentence, as long as the cash keeps arriving. The caveat is that this works only while cash flows are steady and borrowing is available. A business that pushes leverage to the limit in good times has less room to absorb a bad acquisition or a long downturn, which is exactly the position Lowe's now finds itself in.
IX. Bull vs. Bear Case & Skeptical Investor Stress Test
Imagine a conference room in midtown Manhattan this autumn, where a portfolio manager is presenting Lowe's to a skeptical investment committee. The stock has fallen from a high of about $287 to below $200. It trades at about 17 times trailing earnings, below its five-year median and Home Depot's multiple.12 Its enterprise value, which adds debt to the market value of the shares, is about $150 billion, or around 12 times EBITDA. The free cash flow yield, the cash the business generates relative to its market value, is about 6%. On the surface it looks like a high-quality business at a reasonable price. The committee wants to know why the market is so unenthusiastic.
The skeptic's first challenge is about where per-share growth will come from. For a decade, buybacks added several percentage points a year to EPS growth beyond what profits alone delivered. That engine is now switched off. With debt maturities and its leverage target still ahead, Lowe's will not be buying back meaningful amounts of stock for some time.116 Earnings per share now depend almost entirely on operating profit growth, and operating profit has been flat for three years, with EPS sliding from about $13.20 in fiscal 2023 to $11.85 in fiscal 2025.1 Management's own guidance for the third quarter of fiscal 2026 calls for adjusted EPS about 7% below the prior year.16
The second challenge is about the housing cycle. Lowe's has a larger share of DIY customers than its rival, and DIY discretionary spending has been weak. On the August call, Lowe's said its Pros were seeing homeowners who were more cautious, choosing smaller repair jobs over large remodels.16 The acquisitions add exposure to the weaker new-construction market. Lowe's chose to expand into the most cyclical corner of the market at the worst point in the cycle.
The third challenge is about the acquired assets. If housing construction stays weak through 2027, FBM customer relationships could be impaired and credit losses could rise.121 Neither would threaten Lowe's solvency, but both would test the claim that the deals were well priced.
The bear case, then, goes like this. Lowe's is the structurally weaker half of a duopoly, with persistent gaps in sales productivity and Pro mix that it has been unable to close organically.12 Its balance sheet remains heavily leveraged, with cash flow committed to deleveraging for now.123 Its most important strategic bet was made at a full price at the top of the private market for distribution assets, and the businesses it bought are exposed to the weakest part of the housing market. In this view, the discount to Home Depot is not an opportunity; it is the fair price of being number two with more leverage.
The bull case starts from the same facts and reads them differently. Housing activity is cyclical, and the current slump has lasted long enough that a recovery, whenever it comes, should lift both DIY and new construction. Ellison cited estimates from John Burns Real Estate Consulting of $20 billion to $50 billion of deferred home improvement projects waiting to be done.16 An ageing housing stock supports steady repair spending.1 Lowe's margins have held around 12% even through the downturn.1 If FBM can sell Lowe's tools, fasteners, paint and electrical supplies to its customers, the cross-selling could add revenue at high incremental margins. And if Lowe's narrows even part of the productivity gap with Home Depot, the multiple could converge towards its rival's.
Weighing the two, the evidence supports a narrower version of the bull case than its advocates often present. Lowe's has proven it can run its stores better; it has not proven it can change who buys from them. The Pro mix has stayed stubbornly around a quarter to 30% of sales despite eight years of effort, and the acquisitions buy Pro revenue rather than demonstrating that Lowe's can win it.1 Comparable sales grew for five straight quarters through mid-2026, but at a crawl: 0.2% in the latest quarter, with transactions down 2.1% and growth coming from higher average tickets.2316 The FBM deal could prove transformative, but the first year has coincided with deteriorating conditions in its end market, and the company does not yet disclose FBM's standalone sales growth or profitability. Until it does, investors are being asked to trust the strategy rather than verify it.
There is a fair counterpoint on management credibility. Ellison's team has generally been candid on calls: it cut guidance in August rather than hoping for a second-half rebound, it explained the cost of the FBM integration as a separate line, and it set a clear leverage target with a date attached.16 That pattern of discipline is a positive signal. But promises of capital discipline have been made at Lowe's before, and the company's record of acquisitions outside its core is poor. The FBM deal will be the defining test of whether this management team is different.
It is also worth asking who would push for change if the plan stalls. Lowe's has no controlling shareholder. Its three largest holders are index and asset-management giants, Vanguard with about 10%, BlackRock with about 7% and JPMorgan with about 7%, who together hold just under a quarter of the shares.18 Directors and executives as a group own less than 0.3%.18 That structure means management's accountability runs mainly through the board and the annual say-on-pay vote, which has been comfortable. An activist would find plenty to question here, from the price paid for FBM to the decision to combine the chairman and chief executive roles, but would also find a business with strong cash flows and a management team that has delivered on its operational promises. The more likely source of pressure is simply the share price: a stock still far below its high is a referendum on the acquisition strategy that management cannot ignore.
What does the current price assume? At about 17 times trailing earnings, the market is pricing Lowe's below its own five-year average and well below Home Depot, but not at the kind of multiple reserved for businesses in decline.12 The implied view is roughly that Lowe's will hold its margins, grow slowly with the housing market and gradually pay down its debt, without much credit for the FBM cross-selling story or a rapid re-rating towards its rival. In other words, the market is treating the wholesale pivot as a cost already paid rather than a source of upside already earned.
Three numbers will tell investors most about how this resolves. The first is comparable store sales, ideally measured against Home Depot's. Lowe's guided to roughly flat comparable sales for the full year.23 A sustained period in which Lowe's grows comparable sales faster than its rival would be the first real evidence that the productivity gap is narrowing. The second is adjusted leverage, which stood at 3.0 times in July 2026 against the target for mid-2027.16 Reaching that target on time would signal that the balance sheet can absorb the acquisitions and would open the door to resuming buybacks. Missing it would suggest the deals are absorbing more cash than planned. The third is the allowance for credit losses on commercial receivables, which the company currently describes as immaterial.1 Any meaningful rise would be the first sign that the risk Lowe's took on from FBM and ADG is becoming real.
None of these will be settled in one quarter. Together, they will show whether the $10 billion pivot was a turning point or another chapter in a long list of expensive experiments.
X. Epilogue & Reflections
Tonight, Lowe's is a very different company from the one Marvin Ellison inherited eight years ago. The foreign experiments are gone. The Orchard Supply stores are closed. The technology works. More than 99.9% of revenue comes from the United States.1 The stores are better run, the margins are higher, and the company has, for the first time in its history, a serious wholesale business serving professional builders. In that sense, the Ellison era has already succeeded at what it set out to do first: making Lowe's a disciplined operator.
The next chapter will be decided by a handful of moments. The first will come in November, when Lowe's reports its third-quarter results for fiscal 2026 and gives investors the next read on comparable sales, FBM's performance and the path of leverage.16 Management has already said it expects adjusted EPS to fall about 7% from the prior year's third quarter, so the real question will be what it says about the fourth quarter and fiscal 2027.16
The second moment will come in mid-2027, when management expects to reach its target of 2.75 times leverage.16 If it does, the board will face its first big capital allocation decision of the post-acquisition era: whether to restart large buybacks, pursue more acquisitions or keep paying down debt. That choice will reveal what the company has learned from the last decade.
The third moment is less predictable but more important: the housing turnover thaw. When mortgage rates fall far enough for homeowners to move again, both sides of Lowe's business stand to benefit, the stores from renovation spending and FBM and ADG from new construction. If the recovery comes in 2027, the timing of the acquisitions will look shrewd. If it does not come until 2029, Lowe's will have spent several years carrying debt and integration costs for businesses that are not yet paying their way.
Set against the four questions this story began with, the evidence leaves a mixed verdict: the wholesale strategy remains unproven, the buyback legacy limits flexibility, the productivity gap persists, and the new credit risk awaits a serious construction downturn.
Each outcome maps onto one of those questions. If FBM's sales grow faster than Lowe's store comparable sales once housing turns, and Lowe's begins to report meaningful cross-selling between the branches and the stores, the wholesale bet will have answered the first question in management's favour. If leverage reaches its target on schedule and buybacks resume without strain, the second question will look less worrying in hindsight, because the balance sheet will have proved it could absorb both a decade of repurchases and a $10 billion acquisition. If, instead, the company records an impairment on the FBM customer relationships or a jump in bad debts, the market will read it as confirmation that Lowe's once again paid too much to enter a business it did not understand. The difference between those futures is not visible in tonight's numbers. It will emerge quarter by quarter, in disclosures the company has only just begun to make.
There is something fitting about where Lowe's has arrived. Carl Buchan built the company by serving contractors and cutting out the middlemen who stood between them and the manufacturers. Robert Strickland and Leonard Herring rebuilt it around the homeowner when the contractor business proved too cyclical. Robert Tillman scaled it into a national chain and Robert Niblock financially engineered it. And now Marvin Ellison has spent $10 billion to bring Lowe's back to the contractor, this time as the middleman itself.
The record of a century suggests that being number two in American home improvement has been a very good business. Lowe's has compounded profits, paid dividends for decades and survived competitors that disappeared. What it has never done is catch the leader. The wholesale gamble is the most serious attempt yet to change that. Whether it works will depend less on strategy than on the oldest variable in the building trade: when America starts building again.
XI. Outro
In 1952, Carl Buchan traded an automobile dealership and a cattle ranch for full control of a hardware store in North Wilkesboro. He was betting that Americans would build more houses than anyone expected, and that the people building them would want to buy direct.
Seventy-four years later, behind a Lowe's store somewhere in the Sun Belt, a flatbed truck from Foundation Building Materials pulls out at dawn with a crane folded on its back and a load of drywall bound for a job site. The truck would have puzzled Buchan's customers, but the idea behind it would not. Lowe's spent sixty years learning that cutting out the middleman can make a regional champion. It spent the next forty learning that, against Home Depot, survival takes the fastest logistics, the tightest balance sheet and the nerve to change whom you sell to. Now it is betting the balance sheet on the hope that the builders will come back.
References
-
Lowe's Companies, Inc. Form 10-K for Fiscal Year Ended January 30, 2026 — SEC EDGAR, 2026-03-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
The Home Depot, Inc. Form 10-K for Fiscal Year Ended February 2, 2025 — SEC EDGAR, 2025-03-18 ↩↩↩↩↩↩↩↩
-
Lowe's Companies, Inc. Company History — Company-Histories.com ↩↩↩↩↩↩↩↩↩↩↩↩
-
Home Depot co-founder Bernard Marcus dies — Retail Dive, 2024-11-05 ↩↩↩↩
-
Lowe's Names Marvin Ellison President and Chief Executive Officer — Lowe's Companies, 2018-05-22 ↩↩↩↩↩
-
Lowe's SEC Company Facts XBRL Financial History — SEC EDGAR API ↩↩
-
Lowe's Earnings and Orchard Supply Store Closures — Fortune, 2018-08-22 ↩↩
-
Lowe's to Close All 99 Orchard Supply Hardware Stores — REBusinessOnline, 2018-08-23 ↩↩↩
-
Lowe's Plans to Exit Home Improvement Joint Venture in Australia — Lowe's Companies, 2016-01-18 ↩
-
Lowe's Announces Mexico Exit, Q3 Sales Miss — CFO.com, 2018-11-26 ↩↩↩↩↩
-
Lowe's Sells Canadian Division to US Private Equity Firm — Retail Insider, 2022-11-03 ↩↩↩
-
Lowe's Completes Sale of Canadian Retail Business to Sycamore Partners — Lowe's Companies, 2023-02-03 ↩
-
Lowe's Companies, Inc. Form 10-K for Fiscal Year Ended January 31, 2025 — SEC EDGAR, 2025-03-24 ↩
-
Lowe's (LOW) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-08-19 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Lowe's Reports Second Quarter 2020 Sales and Earnings Results, Form 8-K Exhibit 99.1 — SEC EDGAR, 2020-08-19 ↩↩↩
-
Lowe's Companies, Inc. Definitive Proxy Statement (DEF 14A) — SEC EDGAR, 2026-04-16 ↩↩↩↩↩
-
Lowe's Companies, Inc. Form 8-K Voting Results for 2026 Annual Meeting — SEC EDGAR, 2026-06-02 ↩
-
The Home Depot Completes Acquisition of SRS Distribution, Form 8-K Exhibit 99.1 — SEC EDGAR, 2024-06-18 ↩↩
-
Lowe's to Buy Foundation Building Materials for $8.8 Billion in Push to Expand Pro Business — Distribution Strategy, 2025-08-20 ↩↩↩↩
-
Lowe's to Acquire Artisan Design Group for $1.3bn — Financier Worldwide, 2025-04-17 ↩↩
-
Lowe's Reports Second Quarter 2026 Sales and Earnings Results — Lowe's Companies via Finviz, 2026-08-19 ↩↩↩↩↩↩↩↩
-
S&P Global Ratings Research Update: Lowe's Companies, Inc. Credit Profile — S&P Global Ratings, 2025-03-28 ↩↩
-
Moody's Ratings Credit Opinion: Lowe's Companies, Inc. Baa1 Senior Unsecured — Moody's Investors Service, 2025-04-10 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube