Alliant Energy: The Grid, the Load and the $15.9 Billion Bet
I. The Utility That Needs More Power
In the last week of October 2026, a utility holding company in Madison, Wisconsin, made two announcements a day apart, and together they told the whole story of where the American power business has arrived. On October 28, Alliant Energy said it had closed a loan package of up to $5.1 billion backed by the U.S. Department of Energy, thirty-year money aimed at new natural-gas plants, upgrades to existing gas units, a gigawatt of batteries and a large tank farm of liquefied natural gas.1 The Energy Secretary, Chris Wright, came along for the press release, saying the investments would drive down costs for families and businesses in Iowa and Wisconsin.1 The company put its own number on that promise: up to $1.2 billion of cumulative savings for customers over the life of the loans.1
The next day came the quarterly results, and the reason for all that borrowing. Alliant's two utilities, it said, now had 3.4 gigawatts of contracted demand from data centers, and the company expected its peak demand to rise by roughly 60% by 2031.2 It lifted its four-year capital plan by 19%, to $15.9 billion for 2027 through 2030, and it gave 2027 earnings guidance of $3.63 to $3.73 a share, which management framed as 8% growth over the midpoint of its original 2026 range.2
Put those numbers side by side and a puzzle appears. Alliant's entire stock market value on November 2, 2026, was about $18.4 billion. The company now plans to spend almost that much again on new assets in just four years. In 2025, its operations generated about $1.2 billion of cash, while its construction and acquisition spending ran to roughly $2.5 billion.3 The new plan calls for about $4.3 billion in 2027 alone, a single year of capital spending roughly equal to the company's entire 2025 revenue.4 A business that already invests more than it earns in cash has just decided to invest a great deal more.
That is not as reckless as it sounds, because Alliant is a regulated utility, and regulated utilities are paid, in effect, to build. Regulators in Iowa and Wisconsin allow the company to recover the prudent cost of the poles, wires, turbines and pipes it puts into service and to earn an authorized return on the money invested in them. More assets, approved and in service, mean more earnings. The more interesting question is not whether Alliant can grow its asset base. It plainly can. The question is whether that growth reaches the people who own the shares after everyone else has been paid.
Three questions run through this story. The first is whether the new large loads, overwhelmingly data centers, will actually show up, ramp up and pay rates that earn an acceptable return on the plants built to serve them. The second is whether growth in earnings will still look like growth per share once the company has paid interest on new debt and issued the new stock that the plan requires. The third is whether the regulators who set Alliant's prices will let the buildout proceed at a pace that households and small businesses in the Midwest can afford, since an essential service that becomes unaffordable tends to attract political attention long before it attracts more customers.
The company at the center of these questions is less famous than the technology giants whose servers it is preparing to power. Alliant Energy Corporation, listed on Nasdaq under the ticker LNT, owns two utilities: Interstate Power and Light, known as IPL, in Iowa, and Wisconsin Power and Light, or WPL, in southern and central Wisconsin.3 Together they serve more than one million electric customers and roughly 435,000 natural-gas customers.5 At the end of 2025 the whole enterprise employed 2,948 people, about a thousand of them at each utility.3 It is a mid-sized American utility by any measure, the kind of company that usually makes news only when a storm knocks out power or a rate case goes badly.
Data centers changed that. A single hyperscale campus can draw as much electricity as a mid-sized city, and it wants that electricity around the clock. For a utility whose sales grew slowly for most of the last decade, a contracted queue of several gigawatts is the most visible growth opportunity it has had in generations. It is also the most demanding. The power plants, batteries and transmission lines needed to serve that demand must be designed, approved, financed and built before the first server switches on, and the money to do it has to be raised in the present on the strength of revenues that arrive in the future.
The tension is between two true statements. Alliant provides something its customers cannot do without, through networks no competitor can easily duplicate, which is why its earnings have been unusually steady. And building more of that network is expensive enough that customers and shareholders could both end up carrying more cost than the growth is worth. Which statement dominates depends on construction, customer load, financing and regulatory recovery arriving together, on schedule, for years. To understand why the company is positioned to make this bet at all, and why investors should be careful about believing it is safe, the story has to go back to a merger of three Midwestern utilities and a decade-long detour that nearly turned Alliant into something else entirely.
 Subscribe on LinkedIn
II. Three Utility Lines Become One Company
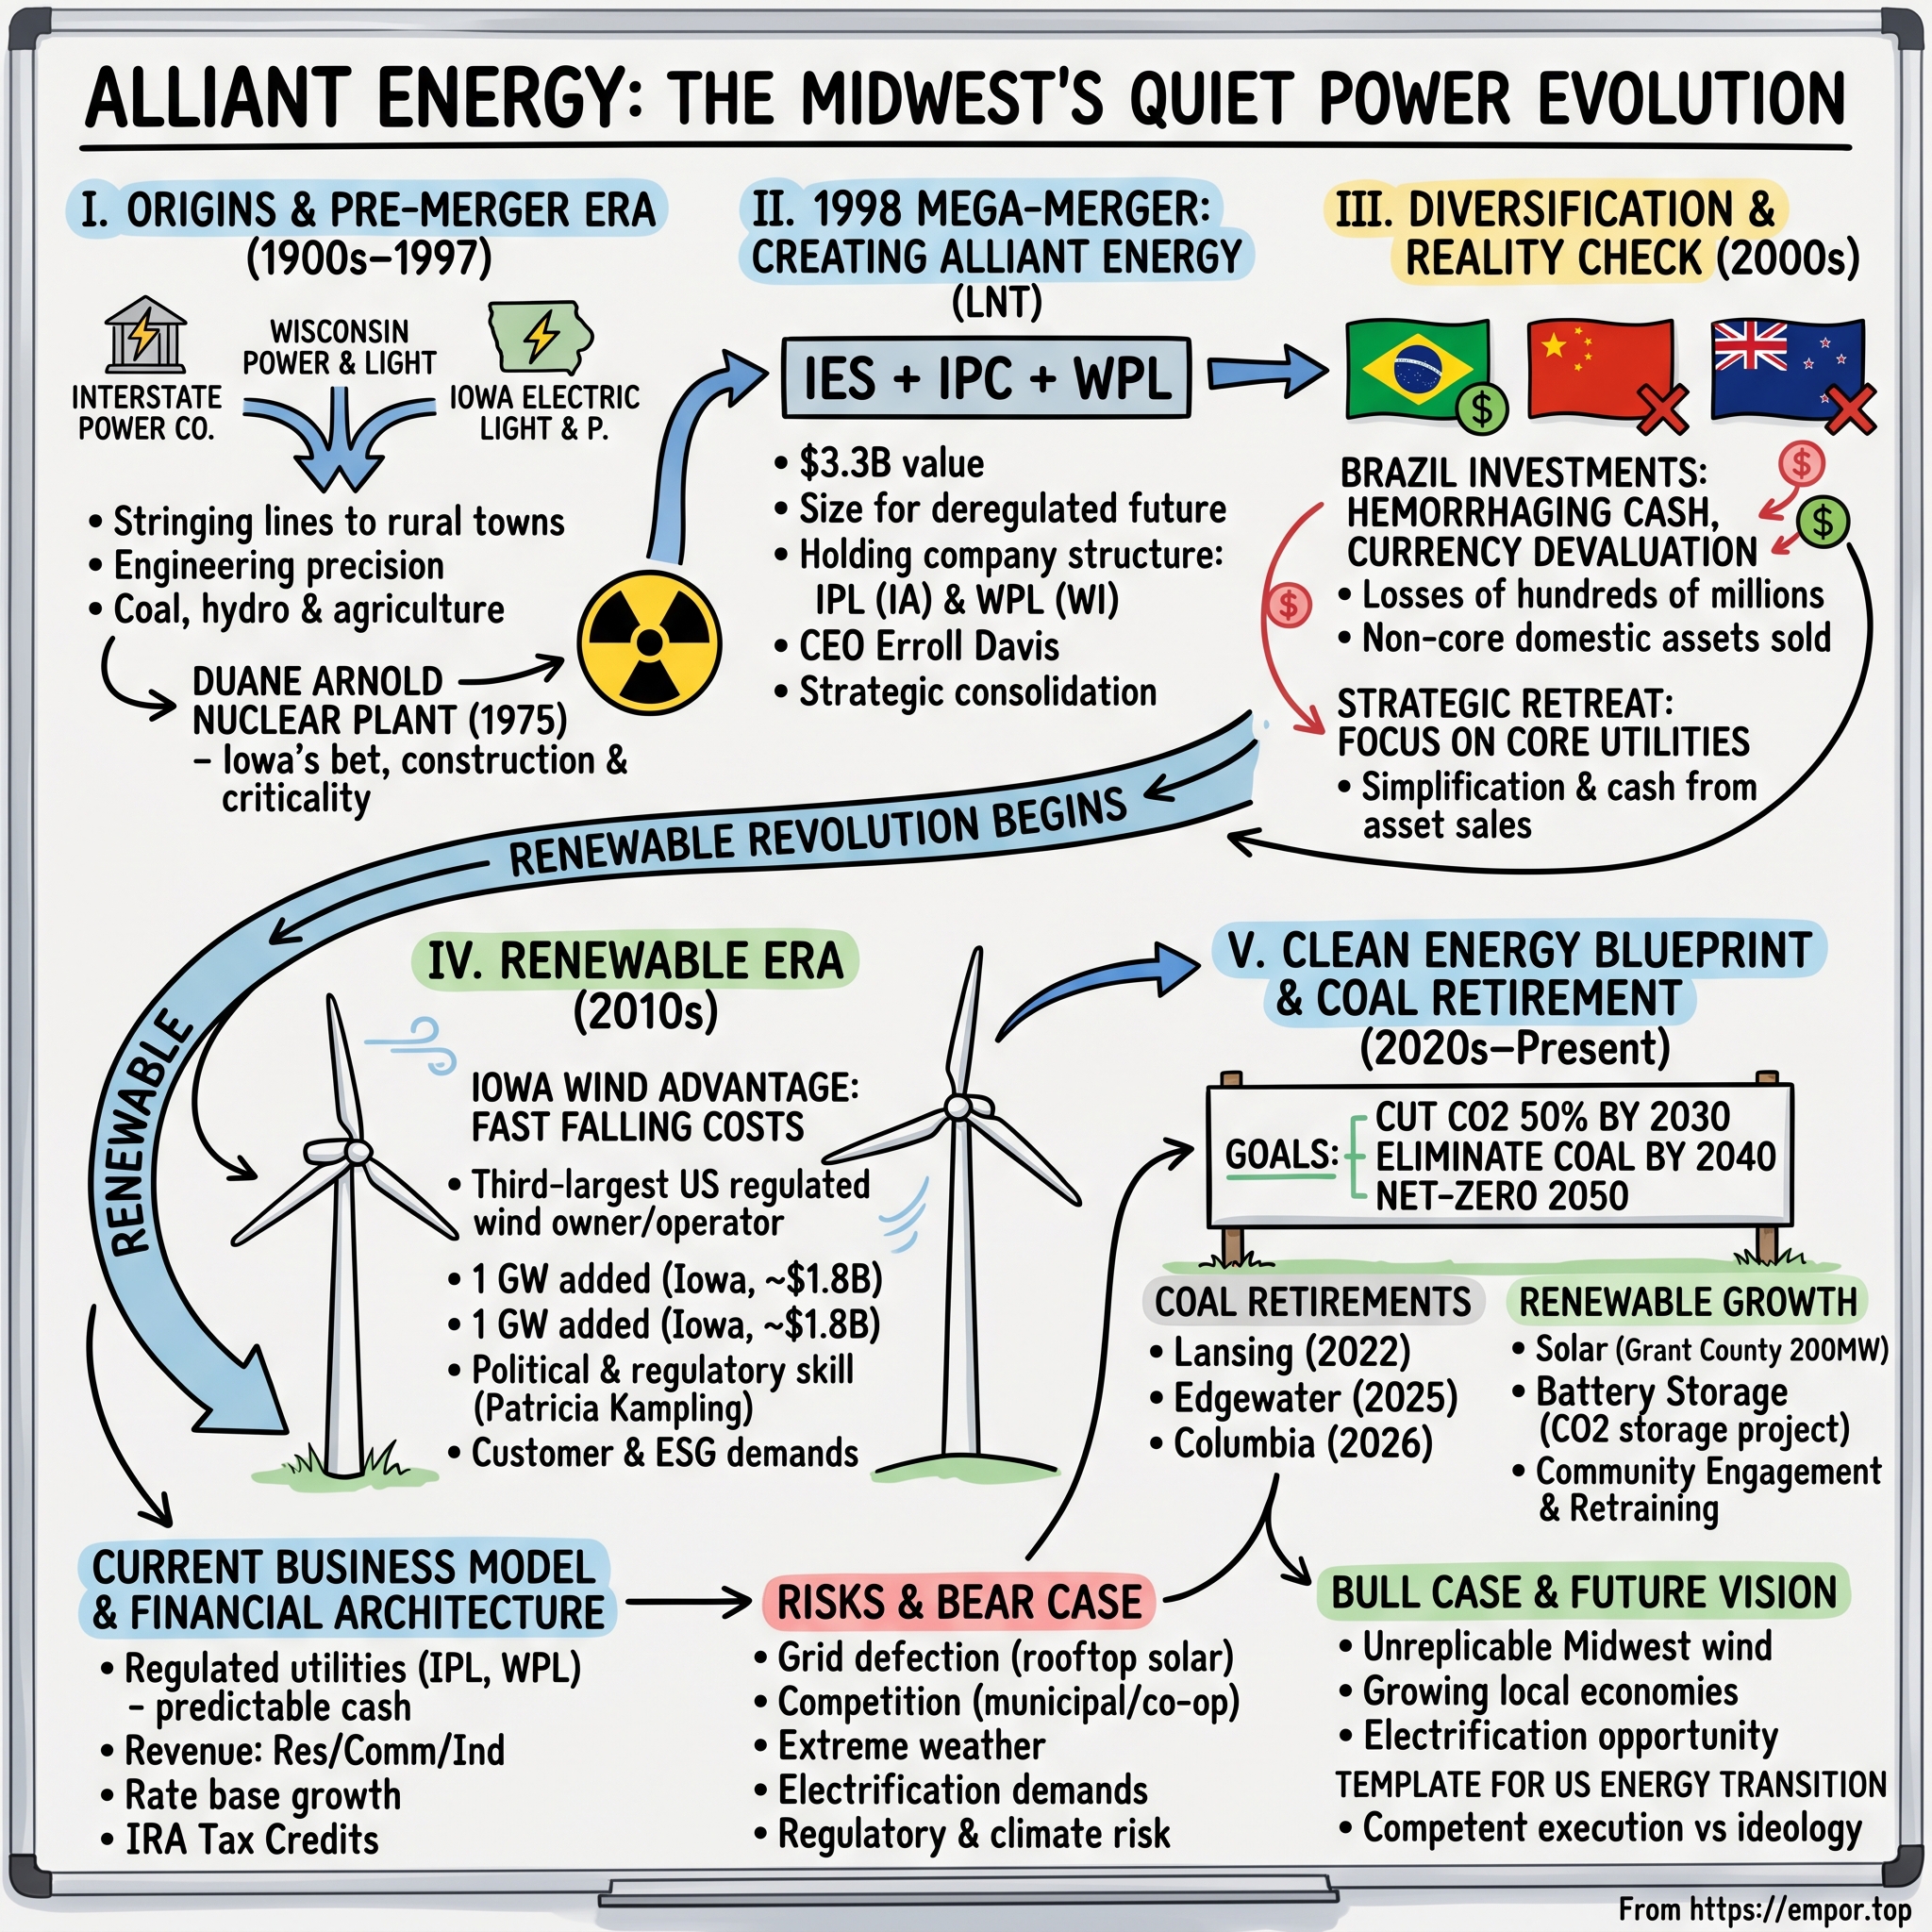
For most of the twentieth century, the companies that would become Alliant were the kind of businesses every small Midwestern city knew by sight: a utility office downtown, crews in bucket trucks, coal piles beside the river, a gas meter on the side of every farmhouse. They grew the way American utilities grew, by stringing lines to farms and towns, building power plants, and absorbing smaller neighbours. By the 1990s, three of them stood out in the territory where southern Wisconsin meets eastern Iowa. WPL Holdings owned Wisconsin Power and Light in Madison. IES Industries, based in Cedar Rapids, owned the old Iowa Electric Light and Power. Interstate Power Company served communities from its headquarters in Dubuque, along the Mississippi.
The 1990s were a nervous decade for companies like these. Policymakers in Washington and in many state capitals were talking about deregulating electricity, opening power generation to competition and letting customers shop for suppliers. Utilities that had spent a century as local monopolies wondered whether they would survive as small, single-state companies when competition arrived. Scale looked like protection. Mergers promised lower overhead, a larger balance sheet and more weight in the coming fight.
So the three companies combined. In April 1998, WPL Holdings, called Wisconsin Holdings in the merger terms, IES Industries and Interstate Power completed the merger that created Interstate Energy Corporation.6 The terms set the shape of the new company's ownership: Wisconsin Holdings shareholders kept their shares one for one, while each IES Industries share was exchanged for 1.14 shares of the combined company.6 A year later, in 1999, Interstate Energy took the name it still uses, Alliant Energy.6
It is tempting, with hindsight, to treat the merger as the first move in a grand consolidation strategy. The record does not support that. The exchange ratios describe how ownership was divided, not whether the combination was cheap or expensive against other utility deals of its era, and there is no evidence that it began a sustained acquisition programme. Alliant did not go on to buy its way across the Midwest. What the merger created was something narrower and, in retrospect, more durable: a two-state utility platform with distinct franchises, distinct assets and, crucially, distinct regulators.
That last point matters more than any other inheritance from 1998. Alliant does not have one regulator; it has two. The Iowa Utilities Commission sets IPL's rates, and the Public Service Commission of Wisconsin sets WPL's.3 Each state has its own approach to authorized returns, its own appetite for new investment and its own politics of affordability. When Alliant talks about its growth today, it is really talking about two regulatory negotiations that happen to roll up into one set of financial statements.
The corporate structure is simple, and it is worth keeping clear because it decides where the economics live. Alliant Energy Corporation is the listed parent. It owns IPL and WPL outright.3 There is no outside controlling shareholder above it and no sprawling group whose fortunes might be confused with the listed company's.3 The parent also holds some smaller interests, including an investment in the American Transmission Company and a handful of non-utility and venture holdings, but the utilities supply the overwhelming share of the business.3 When IPL wins a rate case or WPL completes a solar farm, that is the parent's earnings growing. When a utility's debt rating slips, the parent feels it.
What the merger could not settle was what kind of company Alliant wanted to be. In the late 1990s, the fashionable answer for an ambitious utility was not to stay a utility. Deregulation was supposed to reward the companies that moved fastest into competitive power generation, energy trading and fast-growing markets abroad. Alliant had a new name, a bigger balance sheet and management that believed the regulated utility business was too small a container for its ambitions. The next decade would test that belief, at considerable cost.
III. The Overseas Detour and the Retreat to the Midwest
Picture a utility executive from Madison in the late 1990s flying to São Paulo or to a provincial capital in China to inspect power assets his company now partly owned. It sounds improbable now, but at the time it was a respectable strategy. Developing economies needed electricity faster than their governments could build it, foreign capital was welcome, and American utilities had expertise in running power plants. Through its non-regulated subsidiaries, Alliant built a portfolio of international holdings, with investments in Brazil and China among the most significant.7
The theory was straightforward. The regulated utilities in Iowa and Wisconsin grew slowly and earned returns capped by regulators. Overseas generation and distribution assets, and non-regulated businesses at home, could grow faster and earn more. If the bet worked, Alliant would be a diversified energy company with a steady utility core and a high-growth international arm, the kind of story that might earn a richer valuation than a plain Midwestern utility.
It did not work out that way. Foreign power markets carried risks a Wisconsin regulator never posed: currency swings, contract renegotiations, political interference in tariffs, and partners whose interests diverged from Alliant's. Assets that looked attractive on paper turned out to be worth less than the company had invested. In 2005, Alliant recorded charges against the value of its Chinese assets that included $90 million before tax.8 That was not a rounding error for a company whose entire annual net profit a decade later was under $400 million.9
The exits followed. In 2006, Alliant reported $150 million of net proceeds from selling its investments in Brazil.7 The same period saw the company step back from other businesses that had once seemed central. It sold its interests in nuclear plants, letting WPL's share of the Kewaunee plant in Wisconsin and IPL's share of the Duane Arnold Energy Center in Iowa pass to owners who specialised in running nuclear units.7 The direction of travel was unmistakable: away from risks Alliant did not control, and back toward a business whose rules it understood.
The reasons the company gave at the time were about focus and financial strength. Selling non-core assets would reduce debt, simplify the company, and let management concentrate on the regulated utilities that produced the bulk of its earnings.7 Ratings agencies and investors had grown wary of utilities carrying large, volatile non-regulated exposures, and the early-2000s collapse of energy trading had shown how quickly those exposures could damage a balance sheet. Narrowing the business was a way of buying back credibility.
This episode deserves to be weighed honestly, because it is the most direct evidence in Alliant's own history about how the company allocates capital when it reaches beyond its core. It is meaningful contrary evidence against any claim that Alliant has always been a disciplined investor. Management of that era committed substantial capital to businesses where the company had no structural advantage, and it took charges and sold out when those businesses disappointed. Anyone tempted to describe Alliant's capital allocation as consistently careful has to account for that record.
It would be equally wrong, however, to draw too straight a line from the overseas detour to today's spending plan. Today's programme is different. The failure mode is not a foreign government rewriting a tariff. It is cost overruns, delays, demand that does not arrive and regulators who decide some costs should not be passed to customers. The old episode is a reason to test management's claims rather than accept them, not proof that the same outcome awaits.
What the retreat did produce was clarity. By the late 2000s, Alliant was again essentially two regulated utilities in Iowa and Wisconsin, with a parent company whose job was to finance them. The question became how a company like that grows at all, when the population of its territory is not exploding and the electricity use of its existing customers is roughly flat. The answer turned out to be blowing across the Iowa prairie.
IV. Wind Becomes a Utility Investment, Not a Side Bet
Drive west from Cedar Rapids in late autumn and the land opens into something close to an ocean of harvested corn, flat and wide under an enormous sky. The wind there rarely stops. For most of Iowa's history that wind was a nuisance for farmers and a curiosity for everyone else. By the late 2000s it had become one of the most valuable natural resources in the state, because the turbines that could turn it into electricity had become large enough, cheap enough and reliable enough to compete with conventional power plants, especially once federal tax credits were counted.
For Alliant, the timing was almost perfect. A company that had just retreated from far-flung ventures was looking for a way to grow that fit its regulated model. Wind offered it. Instead of buying assets in another country, IPL and WPL could build generation on land within or near their own territories, sell the output to their own customers and ask their own regulators to add the investment to rate base. Over time the company built a fleet of utility-owned wind farms in Iowa, Wisconsin and Minnesota, with names such as Whispering Willow, Cedar Ridge and Bent Tree.3 What had once been a side bet for independent developers became a core utility investment.
The distinction between a merchant bet and a regulated investment is the key to understanding everything Alliant has done since. A merchant wind developer builds a project, sells the power into the market or under contract, and lives or dies by the price of electricity. A regulated utility builds the same project under its regulator's oversight, with recovery through customer rates and an authorised return if the commission agrees. The utility is still exposed to execution risk, but it is largely insulated from the day-to-day price of power. It is the difference between opening a restaurant and being paid to run the cafeteria in a building whose tenants cannot leave.
Wind did something else for Alliant's accounts that a listener can see in a single unusual figure. Federal production tax credits, earned for every megawatt-hour a qualifying wind farm generates, reduce a company's tax bill. Alliant earned so many that its reported tax rate turned negative: in 2025, income tax was a benefit equal to roughly a fifth of pre-tax profit rather than a charge against it.9 That was a large reason net profit grew faster than revenue for a decade. The credits are real economic value, and much of it flows back to customers through rates, but they are also a policy creation, and their future depends on Washington as much as on Iowa's wind.
The scale of the buildout shows in the balance sheet. Alliant's property, plant and equipment, net of depreciation, rose from about $8.9 billion at the end of 2014 to about $20.3 billion at the end of 2025, more than doubling in eleven years.9 In 2025 alone, construction and acquisition spending was about $2.48 billion.3 For a utility, assets are the engine of earnings, and the engine got much larger.
Through the late 2010s and early 2020s, the investment shifted from wind towards solar and storage. In Wisconsin, where the wind resource is weaker than in Iowa, WPL built large solar farms, and both utilities began to add batteries that could store midday solar output for the evening peak. The fleet that had once been dominated by coal stations along the rivers became a mix of coal, gas, wind, solar and storage.
It is fair to ask whether all this created a lasting competitive advantage. The bull version says Alliant moved early, secured good sites, learned how to build renewables efficiently and established a regulatory track record that makes approvals easier. Some of that is plausible. Iowa's wind resource is genuinely excellent, and a utility that has built and run wind farms for years has learned things a newcomer has not. But the evidence available does not show that Alliant builds projects more cheaply than peers such as MidAmerican Energy, Xcel Energy or WEC Energy, runs them more reliably, or earns better returns on them. Many Midwestern utilities rode the same wind and the same tax credits at the same time.
The returns tell a sobering story. Alliant's return on equity hovered between roughly 10% and 11% for a decade, ending 2025 at about 11.0%, a level consistent with what regulators typically allow, not a sign of exceptional economics.9 Return on invested capital, which looks at the whole capital base rather than just shareholders' slice, drifted down from about 6.7% in 2014 to about 5.4% in 2025.9 Assets more than doubled, but each dollar of them earns a little less operating profit than it used to. That pattern is not unusual for a utility in a heavy building phase, because new assets often earn little until they enter service and are reflected in rates, but it is the opposite of the signature of a company with a widening moat.
The fairest conclusion is narrower than the company's own story. The wind era established renewables as a core regulated investment for Alliant and showed that management could execute a multi-year building programme and get it into rates. It did not prove a unique cost position. The test that matters for every new project is the same: does it enter service on time and on budget, and does it earn the return regulators authorised? And there was a complication hiding in the success. Wind and solar could add energy and assets, but they could not by themselves replace the coal plants that still kept the lights on during the coldest, stillest winter evenings.
V. Coal Retirements Meet the Reliability Test
On the shore of Lake Michigan at Sheboygan stands the Edgewater Generating Station, its stack visible for miles across the water. For decades it burned coal brought in by rail and ship. Inland, near Portage, the Columbia Energy Center has done the same, a pair of big coal units that Alliant operates and co-owns with two other Wisconsin utilities, Madison Gas and Electric and Wisconsin Public Service.10 These plants were supposed to be the closing chapter of Alliant's coal story. Instead, they became the clearest illustration of why the energy transition is harder than a slide deck makes it look.
The original plan was clean and ambitious. Columbia was to retire by the end of 2024.10 Then the date moved to 2026. Then, in December 2024, Alliant and its partners announced Columbia would stay open through 2029, to give them time to explore converting at least one unit to burn natural gas instead of coal.10 Edgewater's last coal unit followed a similar path: a planned conversion to gas slipped from 2022 to 2025 and then to 2028, subject to regulatory approval.10 Environmental groups criticised both decisions.10 The company framed them as choices about reliability, growing demand and affordability.10
Each delay has its own explanation, but together they form a pattern that matters for judging management's forecasts. Retirement dates are not promises carved in stone; they move when the grid's needs move. That is not necessarily bad management. It is what a responsible utility does when circumstances change. But it means that any date in Alliant's current resource plan, for a new plant or a closing one, should be read as a planning assumption that may shift, and history says the shifts have usually been later, not earlier.
To see why the coal plants hung on, it helps to understand the difference between energy and capacity. Energy is the total amount of electricity a power plant produces over a year. Capacity is the amount it can be counted on to produce at the moment the grid needs it most, typically on a frigid January evening or a scorching August afternoon. A wind farm might produce plenty of energy over the year but very little at the particular hour when demand peaks and the air is still. A solar farm produces nothing after sunset. A coal or gas plant, by contrast, can run whenever it has fuel.
Alliant does not get to decide for itself how much capacity is enough. Both IPL and WPL operate inside the Midcontinent Independent System Operator, known as MISO, the regional grid operator that runs the wholesale electricity market and the high-voltage network across fifteen states and the Canadian province of Manitoba. MISO requires each utility to hold enough accredited capacity to cover its peak demand plus a safety margin. And MISO has been changing how it accredits different resources, giving less credit to wind and solar for their contribution to reliability at critical hours and more weight to resources that can be dispatched on demand.3 Think of it as a landlord deciding that some tenants' rent cheques count for only part of their face value. A utility that thought it had enough capacity under the old rules might find itself short under the new ones.
Interconnection adds another constraint. A new power plant cannot simply plug into the grid; it must wait in MISO's queue for studies confirming the network can handle its output, and those queues have become long. A project that is approved, financed and ready to build can still be delayed by a transmission upgrade it has to wait for.
Those pressures explain the shape of Alliant's current plan, which is an all-of-the-above reliability strategy rather than a simple swap of coal for renewables. The company's six-year resource plan includes about 2.8 gigawatts of new natural-gas resources, about 1.3 gigawatts of storage and about 1.3 gigawatts of new renewables.2 The DOE loan package names the hardware explicitly: 1.6 gigawatts of new natural-gas generation, 240 megawatts of added capacity at existing gas plants, a gigawatt of energy storage and two billion cubic feet of liquefied natural gas storage, which lets the company hold fuel in reserve for the coldest days when pipeline gas is scarce and expensive.1
The money tells the same story more starkly. In the 2027–2030 capital plan, thermal generation and LNG account for about $6.8 billion, the largest single category, while renewables and energy storage together account for about $5.1 billion.4 For a company that spent a decade defining its growth through wind and solar, that is a striking reversal. The largest slice of the next four years of investment will go into machines that burn gas.
This mix carries its own risks. Gas turbines have become scarce as utilities across the country compete for the same equipment to serve the same data-center boom, which pushes up prices and stretches delivery times. Gas plants built today will run for decades, exposing customers to the price of natural gas and to whatever climate policy future governments adopt. Batteries are cheaper than they were but still young as grid-scale assets. Renewables face supply-chain and trade disputes; Alliant is among the companies fighting litigation over retroactive tariffs on imported solar cells and modules, a case on appeal whose outcome the company says it cannot predict.3
So the real exposure in this phase of the story is not ideological. It is execution and cost recovery across a mixed fleet, under rules that a regional grid operator can change. Alliant has to get new gas units, storage and renewables built and accredited before its constrained coal plants are no longer allowed, or no longer able, to carry the load. If the new resources are late, the company may have to buy capacity in the MISO market at whatever price prevails, or keep old plants running longer at rising cost. If they arrive on time and regulators approve their costs, they become rate base. That brings the story to the machinery that turns a power plant into a profit, and to the reason a utility can earn steady accounting returns while consuming cash year after year.
VI. What a Regulated Utility Gets Paid to Do
Follow a single kilowatt-hour on its journey to a kitchen in Cedar Rapids. It might start as wind spinning a turbine in northern Iowa, or as gas burned at a plant on the Mississippi, or as power bought from a neighbour through the MISO market. It travels across high-voltage transmission lines, steps down through a substation, flows along distribution wires on wooden poles and into the meter on the side of the house. At the end of the month, IPL sends a bill. Every step in that journey, from the turbine to the meter, is an asset someone paid for, and every asset IPL owns is something it expects to be paid for again, slowly, through rates.
That is the regulated-utility bargain: IPL and WPL serve everyone in their territories at prices regulators approve, with returns allowed on prudent investment.
Revenue in this model comes overwhelmingly from selling electricity and natural gas to retail and wholesale customers, with electric operations dominating and gas a much smaller business.3 Some costs pass straight through. Fuel and purchased power, and certain transmission charges, flow to customers through adjustment mechanisms, so a spike in gas prices raises bills without directly raising or lowering Alliant's profit.3 Base rates, which cover everything else including the return on investment, change only through rate cases, formal proceedings in which the utility asks for an increase and regulators, consumer advocates and large customers argue about how much is justified.
The capital cycle is easiest to grasp in four steps. The utility spends money building an asset. It seeks regulatory treatment, sometimes approval in advance, sometimes a prudence review afterwards. The asset enters service. Then, through the next rate case or a pre-agreed mechanism, its cost enters rates and the utility starts earning its authorised return. Between the first step and the last there can be years, and during that gap the money is spent but the return is not fully collected. Regulators partly bridge that gap with an accounting device called the allowance for funds used during construction, or AFUDC, which lets a utility record a return on money tied up in projects still being built. In 2025 AFUDC contributed about $89 million to Alliant's pre-tax income, and equity earnings from investments it does not consolidate contributed about $60 million more, against total pre-tax income of about $661 million.3 Roughly a fifth of reported pre-tax profit, in other words, came from items that are not cash from customers today. That is normal for a utility in a building phase, but it means headline earnings run ahead of the cash the business is generating.
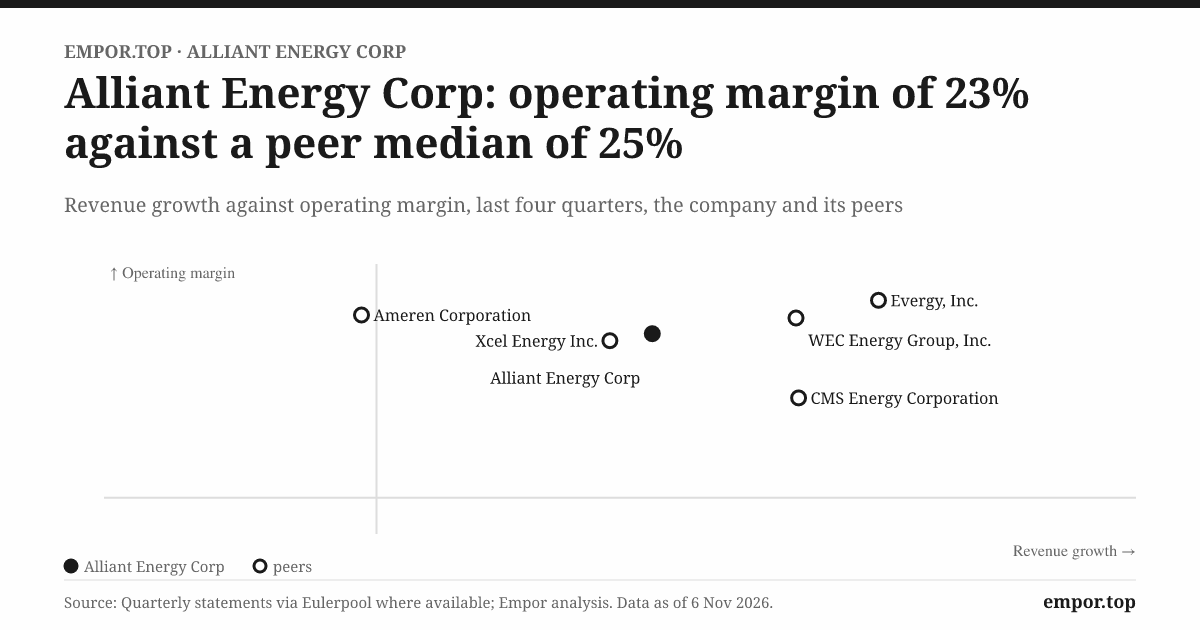
On the surface, the results look solid. Alliant's operating margin in 2025 was about 23.5%, and its return on equity about 11.0%.9 Those are healthy numbers for a regulated utility. But the cash flow statement tells the more important story. In 2025, operations generated about $1.2 billion of cash, while capital spending pushed free cash flow, the cash left after investment, to about negative $1.3 billion.9
That is not a one-year aberration. Over the twelve years from 2014 to 2025, Alliant's operating cash flow exceeded its reported net profit by about $1.7 billion, which on its own would be a sign of high-quality earnings.9 Depreciation, a non-cash expense, is large for a utility, so operating cash typically exceeds accounting profit. But over the same twelve years, after capital spending, cumulative free cash flow was about negative $9.0 billion, and the company paid about $4.4 billion of dividends on top.9 Add those together and the company needed more than $13 billion of outside money to fund its investment and its dividend over the period.
Most of it came from borrowing. Total debt climbed from about $3.9 billion at the end of 2014 to about $12.3 billion at the end of 2025, and the ratio of debt to equity rose from about 1.1 to about 1.7.9 The rest came from issuing new shares. Meanwhile, the dividend payout ratio typically sat between about 59% and 71% of profit.9 So the shape of Alliant's financial model is plain: it pays most of its earnings out as dividends, borrows heavily and periodically sells stock to fund an investment programme that exceeds the cash its operations produce. Shareholders receive a dividend funded, at the margin, by the capital markets. That works as long as the new investment earns more than it costs to finance.
A monitoring clue sits in the receivables. The number of days of revenue that customers owe Alliant at year-end jumped from about 24 in 2024 to about 40 in 2025.9 That can be a warning sign of customers struggling to pay. The company's own disclosures provide important context. IPL sells a large share of its customer receivables to a third party under a standing programme; at the end of 2025 it had sold $251 million of receivables and unbilled revenue, of which only $21 million was past due, against a $15 million allowance.3 By September 2026 the sold balance was $268 million with $24 million past due, and nine-month write-offs, net of recoveries, were about $10 million.11 The jump in debtor days is better explained by how these sale arrangements and their timing run through the balance sheet than by a collapse in customer credit. Still, the programme had no spare capacity at the end of September 2026, so the trend is worth watching as bills rise to pay for the buildout.11
A single quarter shows how the machine actually produces earnings. In the third quarter of 2026, Alliant's ongoing earnings per share rose to $1.52 from $1.12 a year earlier.4 The company traced the improvement first to higher revenue requirements from a growing rate base, worth about five cents a share at IPL and twelve cents at WPL, then to higher AFUDC, higher retail electricity sales and a hot summer that added about five cents.4 Against those gains stood higher operating and maintenance costs, higher depreciation and higher financing expense.4 That list is the regulated model in miniature. Growth comes from rate base and from customers using more power. The drag comes from the cost of the assets and the money borrowed to build them. Weather adds noise in both directions, which is why management reports its results with and without it.
The split between the two utilities in that quarter is also telling. More than twice as much rate-base growth showed up in Wisconsin as in Iowa, even though Iowa is where much of the new data-center load is arriving. The explanation is regulatory rather than operational: WPL has been granted base-rate increases, while IPL's base rates are frozen, so Iowa's investment shows up in earnings through other channels and on a different timetable. For an investor, the lesson is that Alliant's earnings are not a single stream but two, each shaped by a different commission's decisions.
And bills are where the model meets its limits. The regulators in Des Moines and Madison are not just accountants; they are political actors who must answer to households and businesses. IPL's retail electric base rates are subject to a freeze that originally ran through September 2029, accompanied by an earnings-sharing mechanism and a cap on distribution investment.3 In October 2026 that rate-stability plan was extended by a further year, so Iowa base rates are now set to stay flat through the end of 2030.412 In Wisconsin, WPL received base-rate increases for 2026 and 2027.3 A freeze helps customers and gives investors certainty, but it also means IPL must grow earnings without asking for higher base rates, relying instead on new large-load customers, specific riders and the earnings-sharing arrangement. The earnings-sharing mechanism cuts both ways: if IPL earns above a threshold, it has to give part of the excess back.
This is where the moat lives, and where it ends. Customers in Alliant's territories cannot choose another company to string wires to their homes; a second distribution network would be absurdly wasteful, which is exactly why regulators grant monopolies. That makes Alliant's position in its service area unusually durable. But the same regulators who protect the franchise also cap its returns and judge its spending. Wholesale electricity flows through MISO, so the company's generation competes in a regional market. Rooftop solar, efficiency and on-site generation by large customers can all chip away at sales. And no evidence available shows Alliant with a structurally lower cost of service or better customer retention than its peers. The franchise protects the wires. It does not guarantee that every new wire, turbine or battery will earn a good return, and that distinction becomes critical when a utility decides to build on the scale Alliant has just announced.
VII. The Data-Center Queue Turns Into a Capital Plan
In Cedar Rapids, Iowa, a city better known for oatmeal factories than for the internet, new buildings have been rising on the edges of town: long, windowless halls, ringed by security fences and substations, designed to hold rows of servers and the cooling systems that keep them from melting. By late 2026, a QTS data center there is expected to finish commissioning its first two buildings before year-end, and Google is taking transmission service from IPL on a ramp consistent with an accelerated schedule it had filed with the Iowa Utilities Commission.12 In Wisconsin, a Meta data center is already taking distribution service from WPL and is expected to begin taking transmission service in the first quarter of 2027.12
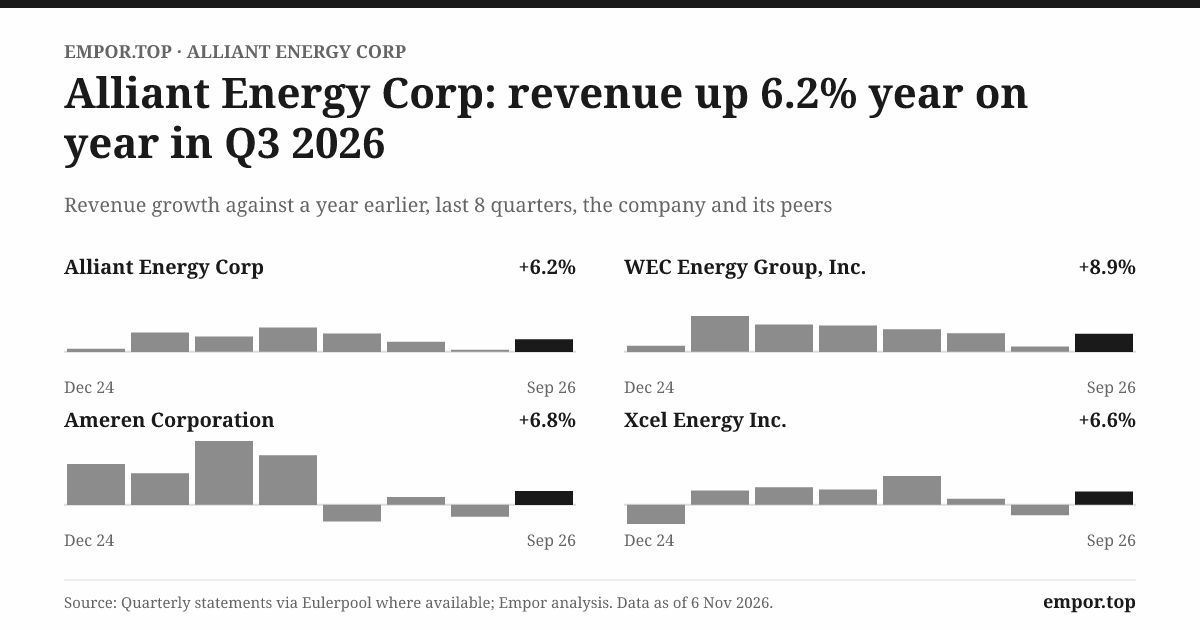
These are the customers behind the 3.4 gigawatts of contracted demand. To grasp the scale, consider that Alliant expects its peak demand to rise by about 60% by 2031, largely because of them.2 For a utility whose revenue grew only about 3% a year over the last decade, that is a step change.9 Data centers raise electricity sales directly, but they also require new generation and storage to supply them, new transmission to reach them, and new distribution and substation equipment to connect them. Each of those is an asset that can enter rate base.
The demand did not appear all at once. Back in April 2026, Alliant announced it had signed an electric service agreement for roughly 370 megawatts in Iowa, bringing total contracted data-center demand to about 3.4 gigawatts across five executed agreements.13 A small detail in that same release is more revealing than the headline. A data-center customer that had signed with WPL in Wisconsin in the third quarter of 2025 decided instead to locate at an IPL site in Iowa; the Wisconsin agreement was terminated and a new one renegotiated and executed with IPL.13 Alliant kept the customer because it owned utilities in both states. But the episode shows that a data-center developer is not a captive household. It shops among sites, states and utilities, and it can change its mind after signing.
That is the first reason to separate signed demand from realised economics. A contract for a gigawatt does not guarantee a gigawatt of use. Data centers are built in phases, and their actual load depends on how fast the owner fills the halls with servers. Contracts typically include minimum-payment provisions designed to protect other customers if the load does not arrive, but the company has not published the full terms, the duration of commitments or the customer-by-customer economics. What investors can see is a number of contracted gigawatts and management's word that the contracts protect existing ratepayers.
Management's plan for meeting this demand is now spelled out in the capital budget. Of the $15.9 billion slated for 2027 through 2030, about $6.8 billion goes to thermal generation and LNG, about $5.1 billion to renewables and energy storage, about $2.3 billion to electric distribution and transmission systems, about $0.6 billion to gas systems and about $1.1 billion to other items, including technology.4 Spending rises from about $2.9 billion in 2026 to about $4.3 billion in 2027 and stays elevated through 2029 before falling in 2030.4 Management says rate base, including construction work in progress, will grow at about 13% a year over the plan, up from about 12% in the previous plan.12
And there may be more. On the third-quarter call, management said the three sites behind the 3.4 gigawatts had room to grow, that seven more prospective sites sat in a broader pipeline of two to four gigawatts of data-center opportunities, and that it expected about one more gigawatt of large load to be contracted over the next six months.12 Each additional gigawatt, management estimated, could require roughly $2 billion to $3 billion of capital spending, mostly on capacity resources, with the next gigawatt ramping around 2029 and 2030.12 That is the bull case in a sentence: every signed gigawatt is a new tranche of rate base.
Who pays for the buildout
The harder question is how all of this gets financed. Alliant's plan relies on a combination of operating cash, the sale of roughly $2 billion of tax credits generated by its renewable projects, hybrid securities that rating agencies treat as part equity and part debt, DOE-backed loans and new common stock.12 Management told investors it plans about $2.7 billion of common equity over the period, of which about $1.1 billion is already secured through forward sale agreements, and that equity would fund about 40% of the incremental capital spending, at the low end of its previously stated 40% to 50% range.12
The tax-credit piece deserves a word of explanation, because it is one of the less obvious sources of money in the plan. Federal law now lets a company that earns clean-energy tax credits sell them for cash to other taxpayers who can use them. Alliant's renewable and storage projects generate more credits than it can absorb against its own tax bill, so selling them turns a policy benefit into roughly $2 billion of funding over the planning period.12 That is cheaper than issuing stock, but it ties part of the financing plan to the durability of federal energy policy, which has shifted more than once in recent years.
Not all of the new demand is digital. Management also pointed to Mesabi Metallics, an iron-processing company planning a plant in Lee County, Iowa, as a large industrial load outside the data-center pipeline.12 Such customers matter because they diversify the growth away from a handful of technology companies. But they are a modest counterweight; the scale of the plan is set by the data centers.
The share count is already moving. Between the end of 2025 and the end of September 2026, shares outstanding rose from about 257.1 million to about 259.4 million.11 Some of that came from the at-the-market programme, under which Alliant sells shares into the market gradually; about 930,000 shares were issued that way, around 230,000 more through the dividend reinvestment plan, and about 835,000 from the settlement of convertible debt.11 In 2026, the company amended the at-the-market programme to allow up to $1 billion of stock sales through 2029.11 Less than one percent dilution in nine months is modest. A $2.7 billion equity plan at today's share price would be something else: roughly 38 million new shares, or about 15% of the current count, spread across the plan.
Debt is rising too. At the end of September 2026, Alliant carried about $1.1 billion of short-term debt and about $11.5 billion of long-term debt.11 In 2025, S&P Global Ratings cut Alliant's issuer rating from A- to BBB+, a move the industry's credit summary attributed to leverage rising with capital spending.14 The utilities themselves remain rated A-, and the outlook is stable, but the downgrade marked the point where the balance sheet began to feel the weight of the plan.11
That is where the DOE package comes in, and it should be understood for what it is. It is not a grant and not a new profit centre. It is a source of cheaper debt. The guarantees allow up to $3.5 billion of borrowing for IPL and up to $1.6 billion for WPL, at interest rates lower than the utilities could get in the market; no amounts had been drawn as of the end of September.11 The projected $1.2 billion of customer savings over thirty years averages about $40 million a year, less than 1% of Alliant's annual revenue.1 Because a utility's cost of debt flows into customer rates, cheaper borrowing mostly benefits customers, not shareholders. It also comes with conditions: the money is available "subject to project advancement, qualification and financing terms," meaning the projects still need to be approved and built.1
The gap between rate base and earnings per share
Here is the most important arithmetic in the story. Management projects rate base growing about 13% a year, but earnings per share growing at least 8% a year from 2027 through 2030.12 Where do the missing five points go? Into the cost of financing the growth. New shares spread the earnings across more owners. New debt adds interest expense. Regulatory lag means some assets earn less than their full return for a while. And IPL's base-rate freeze means part of the new investment must earn its return through new customer contracts and special arrangements rather than general rate increases. The gap is not a sign that the plan is broken; it is the cost of building at this scale. But it is a reminder that the headline asset growth is not what shareholders receive.
On the call, analysts pressed on exactly these points: the timing of the additional gigawatt, the size of the potential capital upside, the share of equity in the financing and how long the higher growth rate could last.1215 Management's answers were more concrete on financing than on demand. It gave specific equity figures and a range for the capital required per gigawatt, but it could not yet name the next customers or guarantee when their load would arrive. Beyond the plan, management pointed to longer-term earnings growth of 6% to 8% or more.12 A Wisconsin large-load tariff, which will set the terms data centers pay in WPL's territory, awaits a regulatory decision expected in the first half of 2027.12 Individual customer rate applications are pending or planned for a second Google project in Cedar Rapids and for a QTS project in Clinton, Iowa, the latter in the first half of 2027.12
Three measures will decide this chapter. The first is the actual ramp of data-center load, the conversion of contracted gigawatts into energised, billed demand. The second is the return the company earns on its new rate base once projects enter service. The third is earnings per share after all the financing, debt and dilution are counted. On the first, the evidence is early but real: buildings are commissioning and customers are taking service. On the second and third, the evidence lies in the future. The plan is plausible, because it rests on contracted demand tied to the regulated core. It is not yet proof of profitable growth, and the person who must deliver it has been in the top job for less than three years.
VIII. Lisa Barton's First Full Buildout
Lisa Barton is an electrical engineer who became a lawyer, and then spent a career in the part of the power business most people never think about: the high-voltage lines that move electricity between power plants and cities. She earned a bachelor's degree in electrical engineering at Worcester Polytechnic Institute and a law degree from Suffolk University Law School.16 She started at Northeast Utilities, the New England company now called Eversource, worked as a consultant on power procurement and market strategy, and served as a lobbyist and senior counsel to gas and electric clients.16 In 2006 she joined American Electric Power, one of the largest utilities in the country, where she rose to run its transmission business as executive vice president and later became its chief operating officer.16
That background is unusually well matched to Alliant's current moment. A data-center buildout is, at bottom, a transmission and interconnection problem: getting huge amounts of power to specific sites, reliably, through a regional grid governed by MISO's rules. Barton spent years in exactly that world. She joined Alliant in February 2023 as president and chief operating officer, and took over as chief executive in January 2024.16 She is also chief executive of the two operating utilities, and she sits on the boards of the Electric Power Research Institute and the Edison Electric Institute, the industry's main trade group.16
Barton's tenure is still short relative to the investment cycle she is leading. The plan she unveiled in October 2026 runs through 2030, and the assets it funds will operate for decades. The decisions that will reveal whether she allocated capital well—the cost of the gas turbines, the timing of the batteries and the contract terms with data-center customers—will not be fully visible for years. Investors judging her now are judging intentions, early execution and the consistency of what she says.
Her pay rose sharply as the plan grew. Barton's total compensation was about $5.71 million in 2023, which included a $1.7 million signing bonus, about $6.97 million in 2024 and about $9.00 million in 2025.17 Over the same three years, Alliant's net income moved from about $703 million to $690 million and then to $810 million.17 The 2025 package was weighted toward stock awards of about $5.47 million and incentive compensation of about $1.84 million, which ties much of her pay to financial and share-price outcomes.17 Chief financial officer Robert Durian, who has held the job throughout the period, earned about $3.42 million in 2025.17
Stock-based pay links management to shareholders in principle. In practice, the measures matter: incentives that reward growth in earnings or rate base can encourage building more, while shareholders care about returns per share after financing. A board that wanted to align management tightly with owners would weight per-share results and returns on new capital heavily. That alignment is worth watching more than the headline pay number.
Ownership offers a further clue. As of March 2026, Alliant's directors and executive officers together held about 533,000 shares, less than 1% of the company, with no shares pledged.17 The largest holders named in the proxy were index and institutional managers: Vanguard with about 12.6%, BlackRock with about 9.1% and State Street with about 6.3%, each figure dated to their most recent filings and so a snapshot rather than a current reading.17 There is no controlling shareholder and no founding family. Management's personal wealth is tied to Alliant mostly through its pay packages, not through large personal stakes.
The shareholders, for their part, have not shown signs of revolt. At the May 2026 annual meeting, investors approved the say-on-pay resolution and re-elected the directors, with no material dissent recorded.18 A vote like that is a governance signal, but a weak one; index funds own a large share of the stock and tend to support management unless something is clearly wrong.
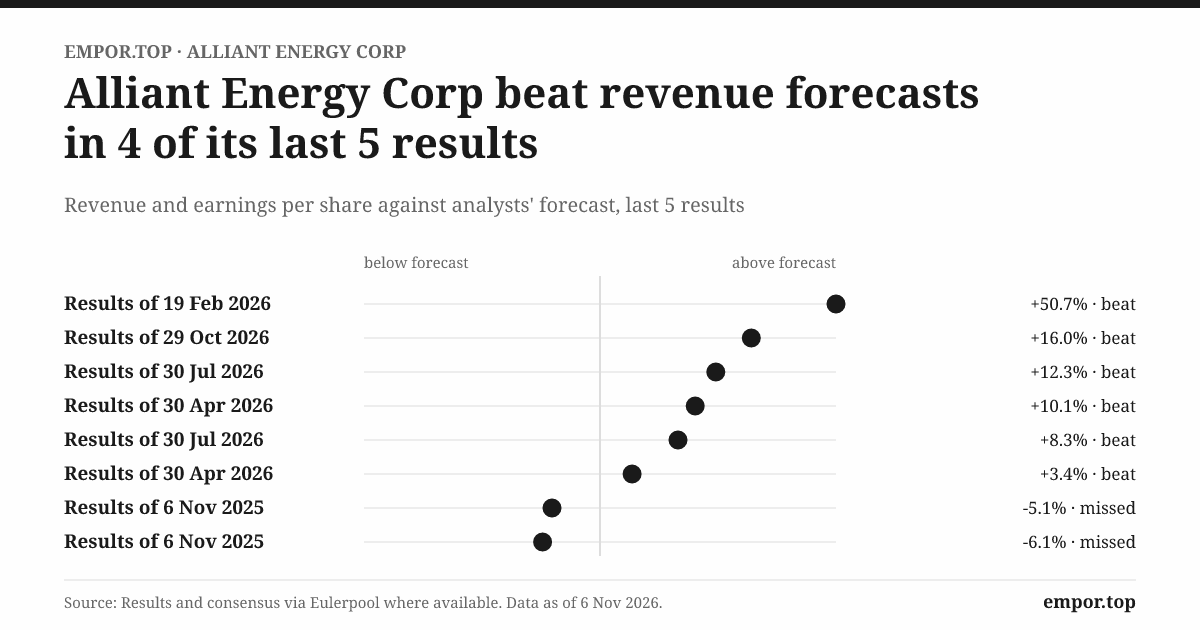
The better test of credibility is behaviour over time. Here the record so far is reasonably consistent. In its first-quarter 2026 release, Alliant reaffirmed 2026 guidance of $3.36 to $3.46 a share and noted a decade-long track record of compound annual earnings growth above 6%.13 That claim checks out: diluted earnings per share rose from about $1.71 in 2015 to about $3.13 in 2025, a compound rate of a little over 6% a year.9 In October, the company narrowed 2026 guidance to $3.41 to $3.46, the top half of the original range.4 Ongoing earnings per share for the first nine months of 2026 were up about 14%.4
Management was also candid about the quality of some of that growth. The third-quarter release noted that income-tax timing had helped results and that those variances would reverse by the end of the year, and it attributed part of the gain to higher equity earnings from corporate venture investments, which are not utility operating earnings.4 That disclosure is a point in management's favour; it would have been easy to let the strong quarter speak for itself.
The dividend shows how management is balancing the claims on its cash. Alliant targets paying out 60% to 70% of earnings and has said it expects to operate near the lower end of that range while investment is elevated.12 The 2027 dividend target of $2.25 a share is about 5% above the current annual rate, slower than the 8% earnings growth management is guiding to.4 That is a deliberate choice to keep a little more capital inside the company. It is also a modest one. Every dollar paid out as dividends is, at the margin, a dollar that must be replaced by issuing new shares or debt, and the company is still sending out roughly two-thirds of its profit.
The weaker part of the record is about dates. The coal retirements at Columbia and Edgewater slipped repeatedly, and the data-center customer that switched states shows how fluid even signed contracts can be.1013 Neither is a failure of honesty; both were disclosed. But they are reminders that utility plans move, and that the plan Barton is now selling, with its gigawatt-scale load and four years of record spending, contains many more dates that could move.
So the credibility question has a clear form. Do project schedules, load expectations and financing plans stay consistent from one quarter to the next as execution unfolds? Does the equity plan stay near $2.7 billion, or creep upward as costs rise? Does the 8% earnings growth target survive contact with turbine prices and regulators? Barton has given investors specific numbers to hold her to. The market, meanwhile, has already decided how much those numbers are worth.
IX. Analysis & Bear vs. Bull Case
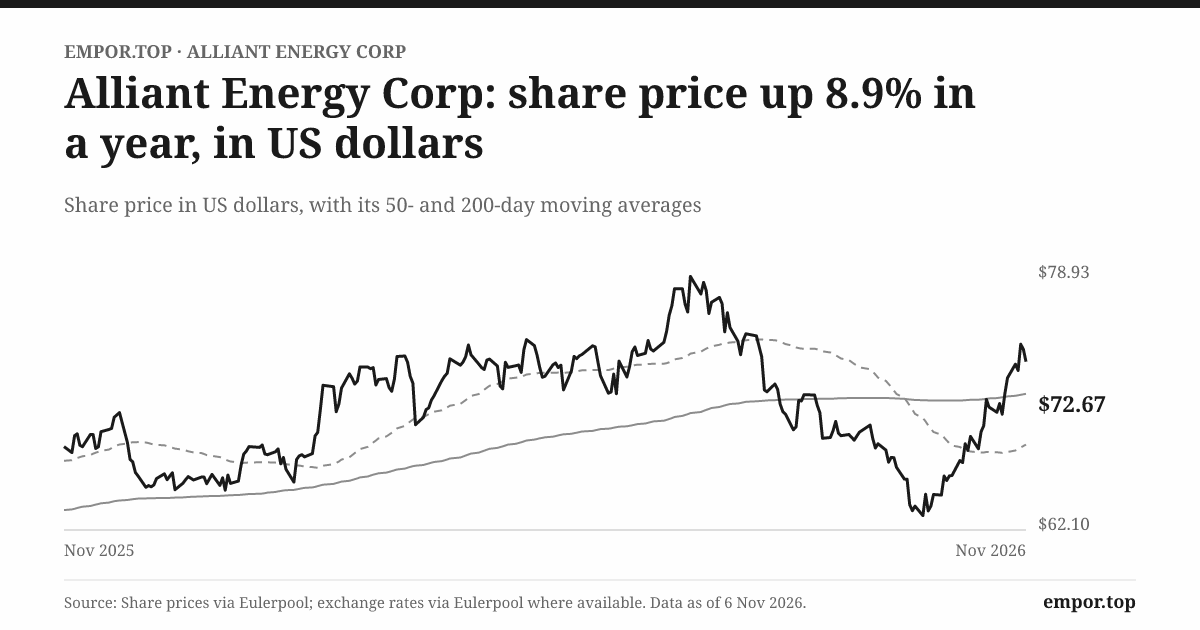
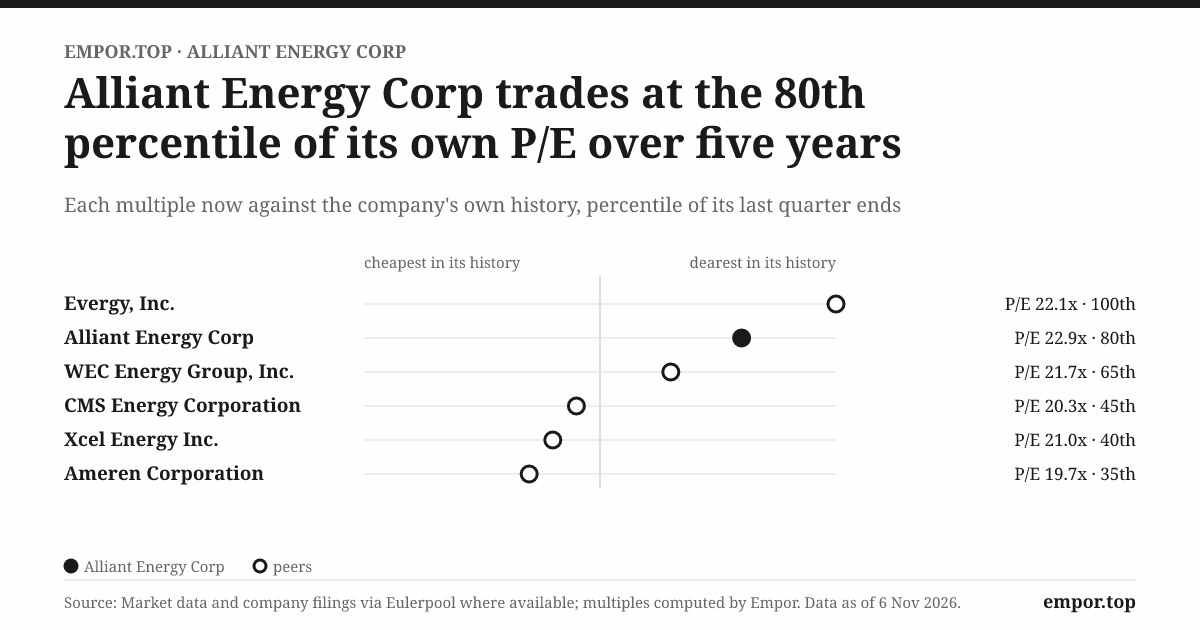
On November 2, 2026, Alliant shares closed at about $71.65, a little more than 8% below their 52-week high.5 At that price, investors were paying about 22.5 times the company's earnings over the previous twelve months, against a five-year median of about 20.9 times. The dividend yields about 3.0%, and the free-cash-flow yield is negative, at about minus 1.4%, because the company spends more on investment than its operations generate. On management's 2027 guidance midpoint of $3.68, the price works out to a little under 20 times next year's earnings.2
What does that price assume? Not a miracle. A multiple modestly above Alliant's own history suggests the market believes the data-center growth is real and that earnings will compound faster than they have in the past decade. It does not suggest the market is pricing in perfection. But it also leaves less room for error than the stock had when it was a slow-growing utility trading at a lower multiple. If growth disappoints, investors would lose both the earnings growth they expected and, potentially, the premium multiple.
The case on each side
The bull case is easy to state. Alliant owns essential-service franchises in two states, with a durable local network that customers cannot bypass. It has contracted data-center demand, some of it already taking service, that justifies a large regulated investment programme. The company projects rate base to grow about 13% a year, and management is guiding to at least 8% annual earnings growth through 2030.12 The DOE loans lower the cost of part of the financing. The dividend, which management targets at $2.25 a share in 2027, up from a current annual rate of $2.14, offers income while investors wait.4
The bear case is just as clear. The plan needs enormous amounts of outside capital. Cumulative free cash flow has been negative for a decade and will become more negative. Debt has more than tripled since 2014, the holding company has already been downgraded, and about $2.7 billion of new equity will dilute existing shareholders. Earnings depend on regulators approving costs promptly, and one of Alliant's two utilities is under a base-rate freeze through 2030. Gas turbines and construction labour are in short supply, which raises the risk of cost overruns. And the data-center customers are not captive: they can shift sites, slow their build-outs or fail to use the capacity they have contracted.
Five forces and seven powers
Michael Porter's five forces help explain why the utility business is both safe and limited. Rivalry among existing competitors is low in Alliant's retail service territories because the franchises are exclusive. The threat of new entrants is minimal for distribution, since no one builds a second network of poles and wires. But the bargaining power of buyers is more complicated than it looks. Households have little individual power, yet collectively they act through regulators, who set prices and can refuse costs. Data centers have real bargaining power before they sign, because they choose among states and utilities, as the customer that switched from WPL to IPL demonstrated.13 Supplier power is rising, because turbine manufacturers, battery makers and construction contractors are serving a national rush of utilities with the same needs. The threat of substitutes, including rooftop solar, on-site generation and efficiency, is modest for now but real at the margin, and a large data center that builds its own generation is a substitute in the most direct sense.
Hamilton Helmer's seven powers offer a sharper test of whether Alliant has a durable advantage. The closest fit is a cornered resource: the regulated franchise itself, a legal right to serve a territory that no competitor can obtain. But that power is granted and policed by the same regulators who cap its returns, so it protects the existence of profit more than its level. Scale economies exist in utility operations, but Alliant is mid-sized, not a giant, and nothing indicates it operates more cheaply than larger neighbours. Switching costs are high for households but low for a data-center developer choosing its first site. Network economies, counter-positioning and brand power do not meaningfully apply. Process power, a superior ability to build and operate assets, is the claim management would most like to make, and it is the one the evidence does least to prove: the record shows competent execution of wind farms and repeated delays in coal retirements, not a demonstrated cost or reliability edge over peers.
The verdict on the moat, then, is that it is real but narrow. It protects Alliant's right to serve its territory and to earn a regulated return. It does not protect the company from cost overruns, regulatory pushback, dilution, or the possibility that new assets earn less than the market assumes. The question that will decide shareholder returns is not whether Alliant's franchise survives, which it almost certainly will, but whether the new capital earns more than it costs.
A skeptical activist would push on one awkward feature of the plan. Alliant is simultaneously paying out more than half a billion dollars a year in dividends and planning to sell about $2.7 billion of new stock.912 In effect, it hands cash to shareholders with one hand and asks them for more with the other, paying underwriting costs and accepting dilution in between. Utility investors tolerate this because many own the shares for income, and cutting dividend growth can punish a stock. But an owner focused on per-share value could reasonably ask whether slower dividend growth and less equity issuance would leave more value per share in five years' time. The same activist would ask how much of the incentive plan rewards per-share returns rather than asset growth, and whether the company's large-load tariffs are strong enough to protect ordinary customers if a data center walks away. None of these questions shows the plan is wrong. They show where the plan is most exposed.
There is a contrast worth noting with Alliant's earlier strategy. The overseas push of the late 1990s failed partly because the company invested where it had no advantage and little control. The data-center plan sits on the opposite end of that spectrum: the customers are inside its territory, the assets fall under its regulators and the returns are set by rules it knows well. That narrows the risk, but it does not eliminate it, because the scale is far larger. A company whose overseas write-downs once ran to tens of millions of dollars is now committing billions a year.8
Three numbers will tell that story better than any narrative. The first is energised data-center load against the 3.4 gigawatts contracted; today a few buildings are taking service, and that number is rising. The second is the gap between rate-base growth and earnings-per-share growth, currently about 13% against at least 8%; if that gap widens, financing is eating the growth.12 The third is the share count, about 259.4 million at the end of September 2026 and climbing.11 An investor who watches those three can see most of what matters.
The near-term falsifiers follow directly. Contracted load that fails to ramp, especially if a large customer delays or cancels. New assets delayed or denied full recovery by regulators. Debt or share count growing faster than earnings per share. Any of those would mean the bear case is winning. A steady record of energised load, approved costs and per-share earnings growth near 8% would mean the opposite. The market has priced something in between, which is why the lessons of Alliant's own history are worth drawing out before looking ahead.
X. Playbook: Business & Investing Lessons
Between Alliant's overseas retreat and its October 2026 buildout lie a set of lessons that belong to Alliant more than to any other company.
The first lesson is that a franchise can protect the wires; it cannot guarantee a good return on every new wire. Alliant's regulators decide what each new asset earns, and Iowa's base-rate freeze runs through 2030. The broader lesson for investors in any regulated business is that a monopoly is a licence to earn an authorised return, not a promise of rising value. Value comes only when new investment earns more than the cost of the capital behind it, and customers are willing to pay.
The second lesson is that a megawatt under contract is a beginning, not an earnings result. Alliant's contracted demand is beginning to arrive, but the customer that moved from Wisconsin to Iowa is a reminder that commitments in a fast-moving industry can be rewritten. For founders and investors alike, the lesson is to separate bookings from revenue and revenue from returns. The gap between them is where the risk lives.
The third lesson is that cash spent building the future still has to be financed in the present. Alliant's cash-flow record shows how a business can produce more cash than its accounting profit suggests and still need substantial outside funding for investment and dividends. That is the arithmetic of any business that grows by building expensive, long-lived assets, from railways to semiconductor fabs. Investors who look only at earnings miss the debt and dilution that pay for them.
The fourth lesson is that a retreat can be a strategy, too. Alliant's costly exit from overseas and non-regulated businesses in the mid-2000s was an admission that a bold plan had failed. Yet that retreat produced the focused, two-state regulated utility that is now positioned for the data-center boom. Companies often treat strategic retreat as defeat. Alliant's history suggests that knowing which games to stop playing can matter as much as choosing which ones to start, provided the company learns from the exit rather than forgetting it.
XI. Epilogue
Tonight, Alliant stands at the point where plans become concrete, literally. In Cedar Rapids, QTS is finishing the commissioning of its first two buildings, and Google is ramping its load under the schedule it filed with Iowa regulators.12 In Wisconsin, Meta's data center is preparing to take transmission service in the first quarter of 2027.12 Those three sites are the first real test of whether contracted demand becomes billed demand on the timeline management has promised.
The next eighteen months are crowded with moments that will decide the story. The Public Service Commission of Wisconsin is expected to rule on WPL's large-load tariff in the first half of 2027, setting the price data centers will pay in that state and how much of the cost of serving them falls on other customers.12 The same commission is expected to decide in the first quarter of 2027 whether WPL may buy wind-development assets from an Alliant affiliate, a related-party transaction that regulators will scrutinise.3 In Iowa, individual customer rate applications for a second Google project and for QTS's Clinton campus will test how the Iowa Utilities Commission prices large loads under IPL's extended rate freeze.12 Management has said it expects to sign about one more gigawatt of large-load contracts within six months of its October call; if it does, the capital plan will likely grow again, and so will the financing need.12
Further out, the conversions and retirements at Edgewater and Columbia will show whether the reliability strategy works on schedule, and MISO's evolving rules on capacity accreditation could change the mix or timing of planned generation and storage. The DOE loans will begin to be drawn only as projects qualify, so each draw will be a small signal that a project has advanced.11 The solar-tariff litigation remains unresolved, and the company's guidance explicitly excludes the possible effects of pending lawsuits and disputes.2
What would each outcome mean? If the data-center load ramps on schedule, regulators approve large-load tariffs that protect other customers, and the new assets enter service near budget, Alliant could plausibly deliver its 8% growth with dilution held in check, and the premium multiple would look earned. If load ramps slowly, costs rise or regulators push back, the company would still own its franchise and pay its dividend, but per-share growth could fall short of the rate-base growth that dazzles in investor presentations. The most likely path, given the record, lies somewhere in between: some delays, some upside, and a steady negotiation with regulators over who pays.
The central questions remain open and testable. Each year's results will show whether the load arrived, whether the new rate base earned its return and whether earnings per share grew after the financing was counted. The plan is visible. Its payoff is not yet.
XII. Outro
Somewhere on the edge of an Iowa town this winter, a utility crew will be stringing high-voltage line toward a building full of servers that have not yet switched on. The crew works for a company that once tried to become a global energy player, retreated home, built wind farms across the prairie and now finds itself at the centre of one of the largest shifts in electricity demand in generations. The $5.1 billion of federal loans and the queue of contracted gigawatts are the visible signs of that shift.
Alliant is betting that the same regulated wires that made it dependable can become the platform for a new era of growth. Whether that makes the company more valuable will depend on who pays for the buildout, and on what the new assets earn once the servers are humming and the bills arrive.
References
-
Alliant Energy Projects up to $1.2 Billion in Customer Savings With $5.1 Billion Loan Package — Alliant Energy, 2026-10-28 ↩↩↩↩↩↩
-
Alliant Energy Announces Third Quarter 2026 Results and 2027 Guidance — Alliant Energy, 2026-10-29 ↩↩↩↩↩↩
-
Alliant Energy 2025 Form 10-K — SEC, 2026-02-20 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Third Quarter 2026 Earnings Release, Form 8-K Exhibit 99.1 — SEC, 2026-10-29 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Investor Relations Overview and At a Glance — Alliant Energy, accessed 2026-11-02 ↩↩
-
China Asset Valuation Charge, Form 10-Q Exhibit — SEC, 2006-08-03 ↩↩
-
Columbia County coal plant retirement delayed a second time, to 2029 — WPR, 2024-12-04 ↩↩↩↩↩↩↩
-
Alliant Energy Q3 2026 Form 10-Q — SEC, 2026-10-30 ↩↩↩↩↩↩↩↩↩↩
-
Alliant Energy Q3 Earnings Call Highlights — MarketBeat, 2026-10-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
First Quarter 2026 Earnings Release, Form 8-K Exhibit 99.1 — SEC, 2026-04-30 ↩↩↩↩↩
-
Q4 2025 Credit Ratings Summary — Edison Electric Institute, 2026 ↩
-
Alliant Energy Corporation (LNT) Q3 2026 Earnings Call Transcript — Seeking Alpha, 2026-10-30 ↩
-
2026 Notice of Annual Meeting and Proxy Statement — Alliant Energy, 2026-03-30 ↩↩↩↩↩↩
-
2026 Annual Meeting Voting Results, Form 8-K — SEC, 2026-05-20 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube