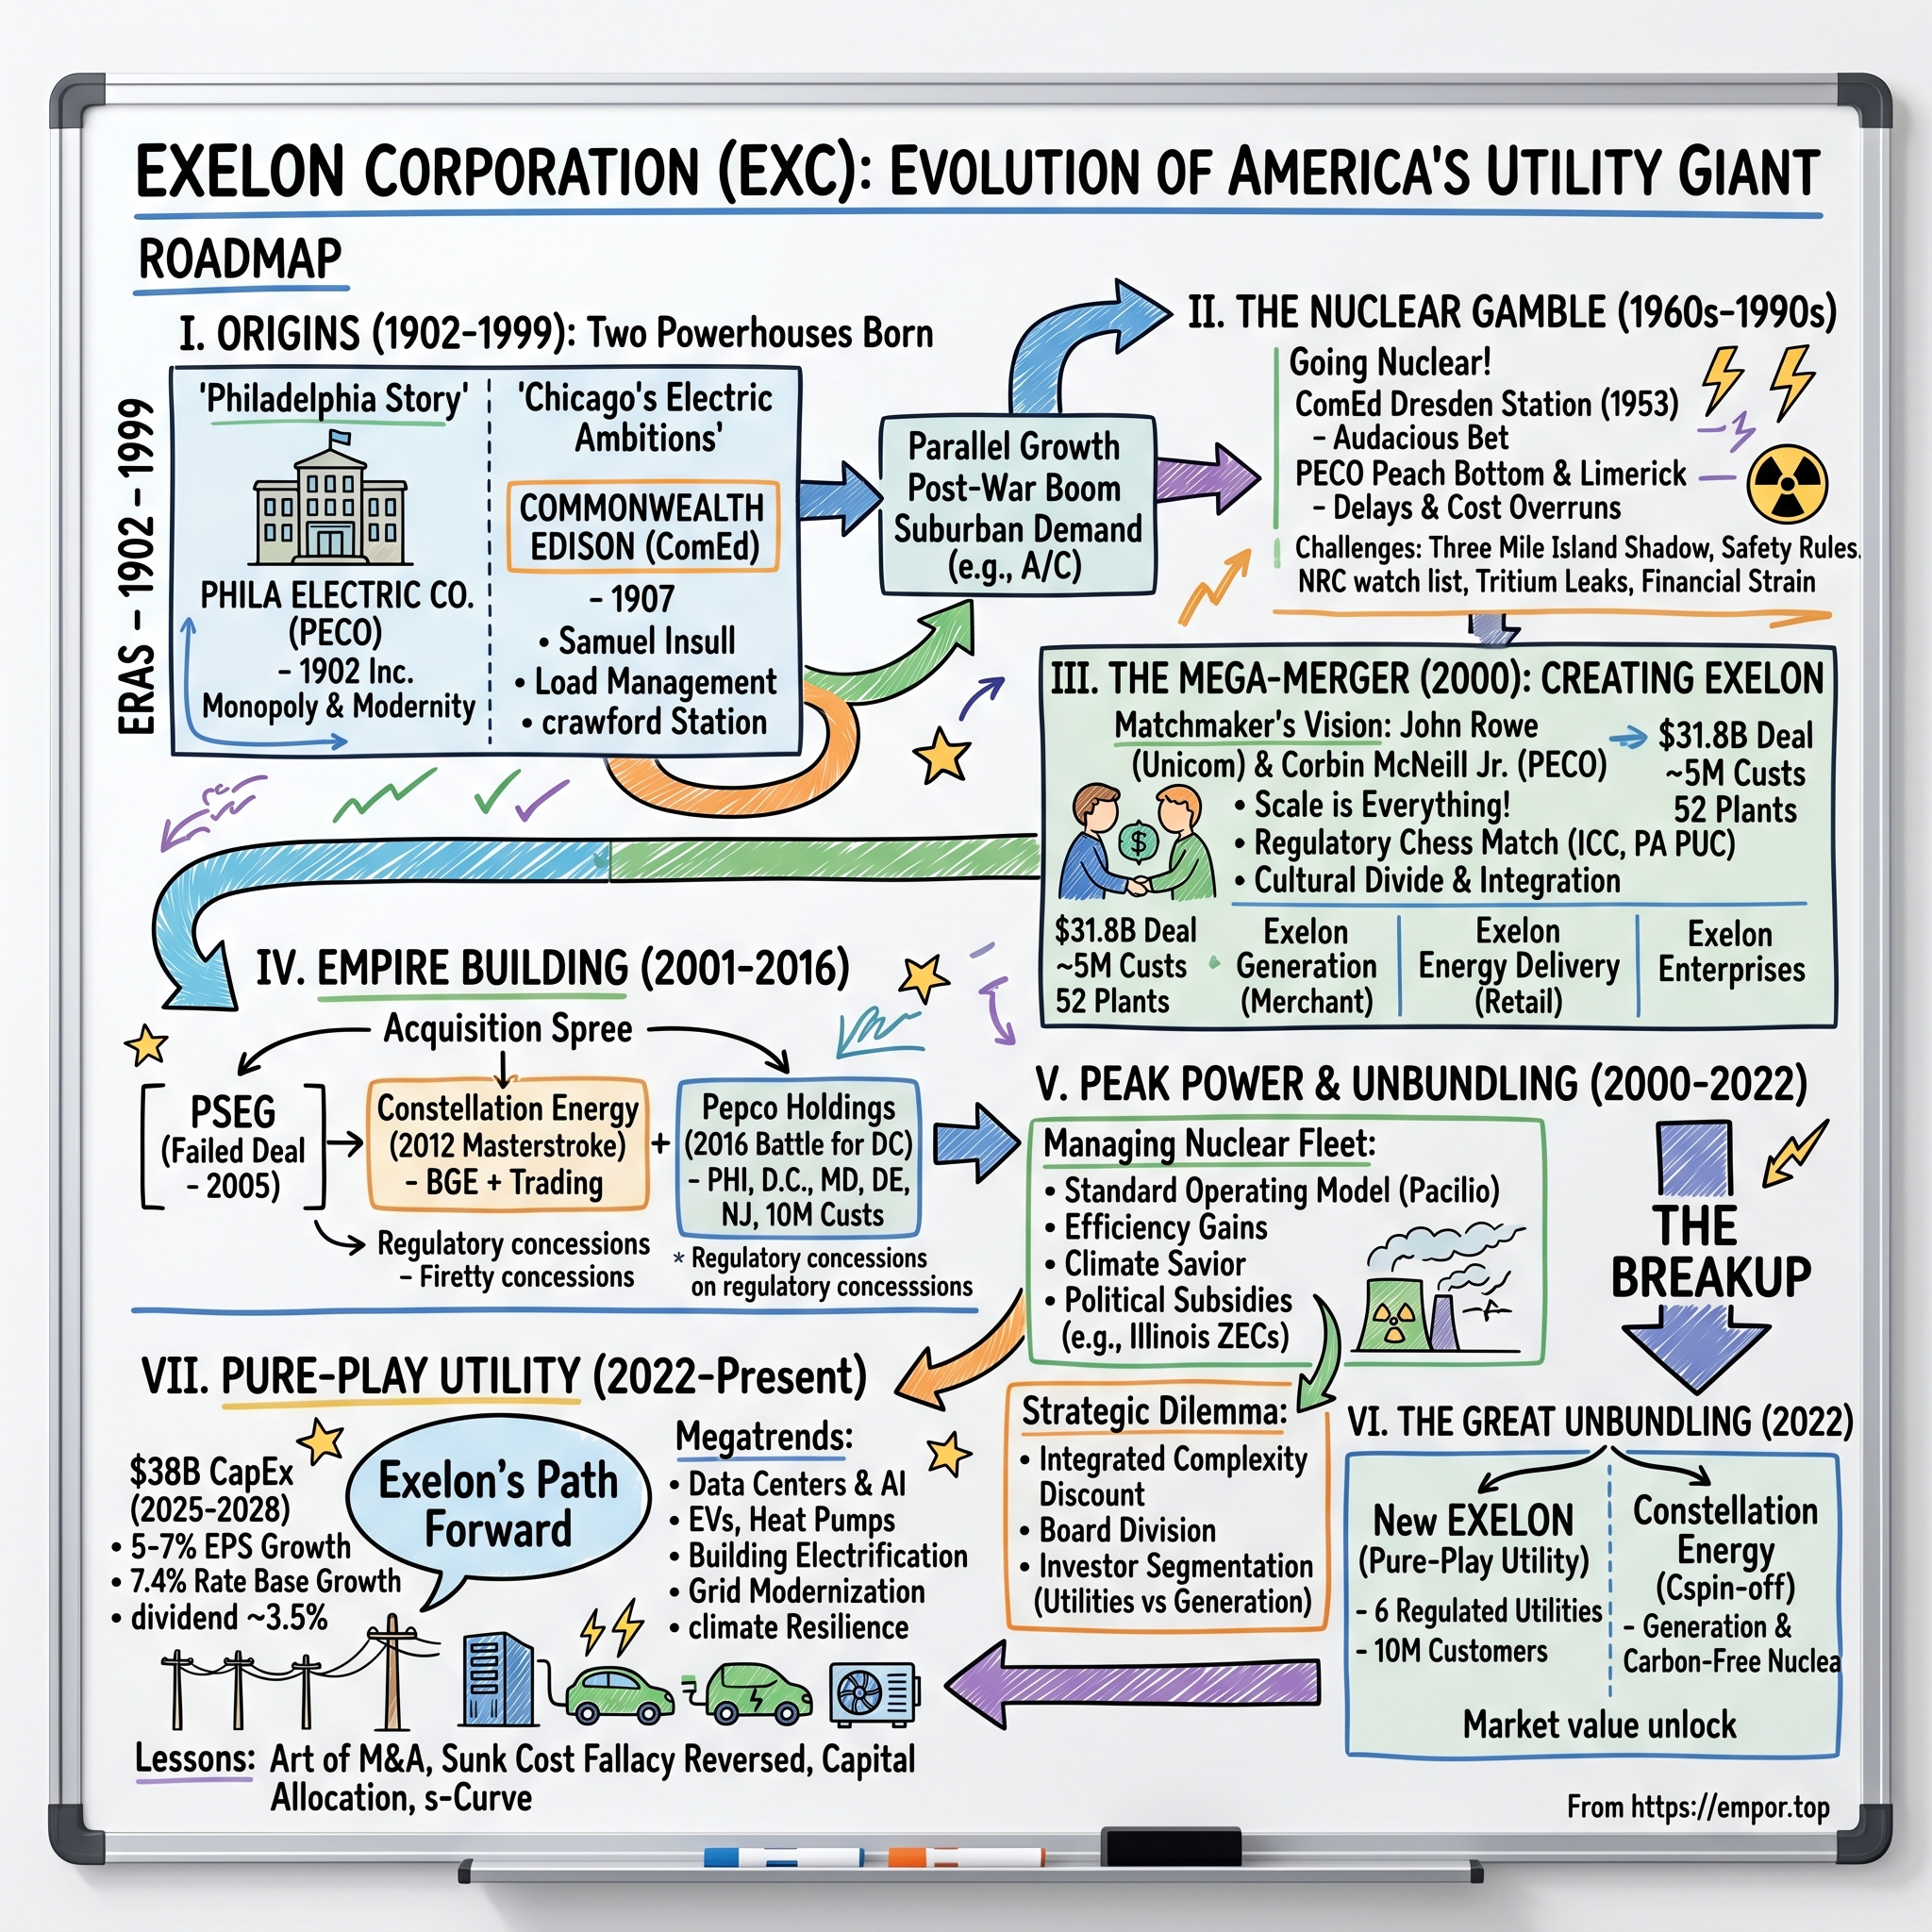
Exelon Corporation: The Evolution of America's Regulated Utility Powerhouse
I. Introduction & Episode Roadmap
On a February morning in 2022, two companies rang the opening bell on Wall Street for businesses that had been a single corporate entity just one day prior. One owned twenty-three nuclear reactors and a power trading desk. The other owned poles, wires, substations, gas mains, and roughly ten million customer relationships stretching from the South Side of Chicago to the Jersey Shore. The nuclear generator kept the name once held by a Baltimore utility — Constellation. The transmission and distribution company retained the name created in 2000 to describe the merger of two century-old monopolies — Exelon.1
What followed was one of the more instructive natural experiments in modern American utility investing. Market participants proceeded to value the two halves of the former balance sheet in radically different ways and for radically different reasons. The story of that divergence is the story of what Exelon Corporation is today.
How does a federation of nineteenth-century municipal lighting companies — gas lamps replaced by Brush arc lights on Chestnut Street, Samuel Insull's Chicago load-factor arithmetic — end up building the third-largest nuclear fleet on earth, ride a merchant power boom into a shale-gas bust, get caught in one of the most consequential political corruption scandals in Illinois history, amputate its generation arm, and re-emerge as the largest pure-play transmission and distribution utility in the United States? And then, having completed that restructuring, find itself sitting atop an interconnection queue filled with artificial-intelligence data centers demanding more power than the system has ever delivered?
The shape of the company today. Exelon trades on the NASDAQ Global Select Market under the ticker EXC. It owns no commercial generation assets. Every dollar of its earnings comes from regulated energy delivery — moving electrons and gas across six operating utilities serving approximately ten million customer accounts in Chicago, Philadelphia, Baltimore, Washington D.C., Wilmington, and southern New Jersey.[^2] These are not sleepy service territories; collectively, they represent some of the densest, oldest, and most politically active urban power grids in the country, rendering location both the business's core asset and its primary operational friction.
The financial baseline. For full-year 2025, Exelon reported adjusted non-GAAP operating earnings of $2.77 per share, up from $2.50 in 2024.[^2] The utility held over $55 billion in rate base—the regulatory value of capital assets on which it is permitted to earn a return—and was executing a multi-year capital program that expanded from an initial $35 billion to a $41.7 billion plan covering 2026 through 2029.[^3] In regulated utilities, capital deployment drives financial results: multiplying the approved rate base by the allowed return on equity, minus financing costs, determines virtually the entire income statement.
The central question. Can Exelon convert the PJM grid electrification surge — driven by data center demand, electric transport, and industrial reshoring — into durable 7% to 8% annual rate base growth, even as state regulators in Illinois and Maryland push back against customer bill increases? That tension forms the central investment thesis. It cannot be evaluated through a single quarter of results, nor resolved by management's strategic positioning alone.
The episode unfolds across ten sections: the origin monopolies, the atomic bet, the mega-merger and the merchant era, the Pepco acquisition, the Illinois bribery scandal, the corporate unbundling, the anatomy of the six-utility operating model, the 2023 regulatory decisions, the data center connection wave, and the analytical frameworks needed to evaluate the business model.
 Subscribe on LinkedIn
II. Origins & The Monopolies of the Industrial Age (1881–1999)
In 1881, the Brush Electric Light Company strung carbon arc lamps along Chestnut Street in Philadelphia. The lights hissed, sputtered, and emitted a glare so harsh that local merchants complained it distorted the appearance of their goods. Despite those initial complaints, electric illumination expanded rapidly. Within two decades, Philadelphia had become a fragmented market of competing generating plants, each operating under its own municipal franchise, voltage standard, distribution lines, and sales force. In 1902, that fragmentation was resolved through consolidation into a single regional entity: the Philadelphia Electric Company, later known as PECO.2
The economic rationale behind that consolidation remains central to Exelon's operating model in 2026. Electricity distribution is a high-fixed-cost business with minimal marginal costs. Building duplicate distribution lines along the same street doubles capital expenditure without expanding the customer base. Consequently, grid distribution naturally converges toward a single regional provider. Operating an essential monopoly service presents a fundamental regulatory choice between unchecked market power and state oversight.
Insull's bargain. Samuel Insull, Thomas Edison's former private secretary, established the framework for modern utility regulation. Arriving in Chicago in 1892 to lead the Chicago Edison Company—formed from the earlier Western Edison Light Company—Insull spent three decades consolidating regional providers. That process culminated in the 1907 merger of Chicago Edison's successor entities into Commonwealth Edison, the ComEd entity that serves northern Illinois today.3
Insull focused heavily on load-factor optimization. A generating plant operating at 20 percent utilization carries high fixed costs per kilowatt-hour, whereas operating at 60 percent dramatically lowers unit production costs. To equalize demand, Insull targeted customers with staggered peak usage hours—streetcars in the morning, factories at midday, and residences in the evening—using differential pricing to balance system load. By pairing larger turbines with a diverse demand profile, he achieved lower unit costs and reduced rates, attracting additional customers in a self-reinforcing growth cycle.
Insull then took the strategically novel step of advocating for state-level regulation. His rationale was commercial: if the state granted an exclusive franchise and capped the company's return on equity, competitors could not overbuild the territory, municipalities could not easily expropriate assets, and predictable cash flows would lower the company's cost of capital. Insull traded uncapped profit potential for structural certainty—the foundational trade utility investors make today.
The postwar expansion. After 1945, rapid suburbanization drove utility expansion across northern Illinois and the Philadelphia collar counties. Adoption of air conditioning, electric appliances, and single-family housing developments accelerated demand, turning capacity planning into a continuous expansion cycle. Although coal remained the primary fuel source, Philadelphia Electric initiated nuclear power feasibility studies by 1952, while the Chicago utility actively evaluated nuclear options as well.2
That nuclear pivot proved foundational. Exelon's two predecessor companies reached the end of the twentieth century not as conventional utilities that happened to combine, but as the two most nuclear-committed power producers in the United States. Over the next two decades, that technological commitment shaped the company's merger structure, merchant power exposure, and eventual corporate separation.
III. The Nuclear Buildout & ComEd's Financial Strain (1960s–1999)
A famous phrase has trailed the nuclear industry for decades: electricity "too cheap to meter." Commission Chairman Lewis Strauss used the phrase in 1954 to describe atomic energy broadly rather than commercial fission reactors specifically, but it became the industry's standard slogan—and no American utility embraced atomic power more aggressively than Commonwealth Edison.
ComEd constructed twelve commercial reactors across Illinois, spanning the Dresden, Quad Cities, Zion, LaSalle, Byron, and Braidwood stations. By the late 1980s, Illinois hosted more nuclear capacity than any other state, with ComEd's rate-paying customers essentially funding an industrial-scale technological rollout. Operationally, the reactors produced massive amounts of electricity; financially, however, the expansion severely strained the company.
The overbuild. By 1990, ComEd's generating capacity exceeded its peak demand by roughly a third—double the industry's standard 15% planning reserve margin. In practice, the utility had invested billions of dollars in heavy infrastructure that sat idle on most days of the year. Under standard utility regulation, surplus capital earns a rate of return only if state commissioners deem the investment prudently incurred. Increasingly, Illinois regulators challenged those capital expenditures.
Three Mile Island changed the arithmetic. The March 1979 partial meltdown at Pennsylvania's Three Mile Island facility released minimal radiation and caused no direct casualties, but it fundamentally altered the economics of nuclear plant construction. The Nuclear Regulatory Commission (NRC) imposed a wave of new engineering, redundancy, training, and documentation requirements, applying many retroactively to ongoing projects. Construction schedules that had been planned for years stretched into decades, dramatically escalating interest costs on borrowed capital.
Nowhere was this dynamic more punishing than at PECO's Limerick Generating Station in Montgomery County, Pennsylvania. Limerick faced sustained local opposition, capital constraints, and extensive redesigns; Units 1 and 2 finally entered commercial operation in the mid- and late 1980s at a multiple of their original budget.2 For PECO, completing Limerick represented a major balance-sheet risk.
ComEd faced a similar financial strain in 1986, when it needed roughly $7.1 billion to complete its remaining nuclear units—a burden that strained its credit rating and triggered repeated, contentious rate cases. Meanwhile, fleet operating performance deteriorated. Throughout the 1990s, roughly half of ComEd's reactors suffered chronic unplanned outages, prompting the NRC to place several units on its safety watch list. When reactors went offline, ComEd had to purchase replacement power on open wholesale markets while continuing to carry the debt service on idle plants, creating a severe double drag on earnings.
Then the rules changed. The Energy Policy Act of 1992 opened wholesale transmission access, and Illinois followed in 1997 with the Electric Service Customer Choice and Rate Relief Law. The state law mandated the separation of power generation from delivery and allowed retail customers to choose competitive electricity suppliers. The strategic implications were profound: nuclear assets constructed under a regulatory compact that assumed guaranteed cost recovery were suddenly exposed to fluctuating market prices. Industry participants referred to this gap between book value and competitive market value as "stranded costs"—a figure that for ComEd ran into the billions.
Enter John Rowe. In 1998, Unicom—ComEd's parent holding company—hired John W. Rowe as chief executive. A lawyer by background who had previously led New England Electric System and Central Maine Power, Rowe brought extensive experience in utility restructuring. His assessment was straightforward: ComEd could not survive market deregulation as a mid-sized regional operator burdened by an underperforming nuclear fleet. Strategic survival required either significant operational scale or an asset exit.
For investors, the lesson of this era was clear: regulatory protection is not absolute. The traditional utility compact is a political settlement, and political terms can be renegotiated after capital has already been deployed. Rowe's strategic solution was to build massive scale.
IV. The Mega-Merger & The Merchant Energy Era (2000–2012)
Rowe found a partner two states to the east. Under chief executive Corbin McNeill, PECO spent the 1990s achieving nuclear capacity factors that ranked among the highest in the nation. The strategic alignment was clear: ComEd possessed significant nuclear capacity burdened by operational issues, while PECO offered disciplined fleet management. Combining the two created a nuclear operating platform of unprecedented scale in the United States.
In October 2000, Unicom and PECO Energy completed a $31.8 billion merger to form Exelon Corporation. Rowe served initially as co-CEO alongside McNeill before assuming sole leadership. The transaction established a corporate structure that defined the enterprise for the next twenty-two years: regulated delivery utilities (ComEd and PECO) operating alongside an unregulated merchant generator, Exelon Generation. At launch, the combined company controlled approximately 20% of U.S. nuclear capacity and served more than five million retail accounts.
The underlying merchant thesis appeared compelling under early deregulation models: in competitive wholesale power markets, low-marginal-cost baseload generators capture significant profit margins when higher-cost gas plants set clearing prices. Because nuclear facilities carry high fixed capital costs but low marginal fuel costs, higher power prices generate wide operating spreads. Throughout the 2000s, Exelon Generation executed on this model by expanding plant capacity through uprates, maintaining high capacity factors, and hedging forward power sales to generate cash flow for dividends and share repurchases.
The Constellation bet, and what falsified it
In 2011, Rowe pursued a major strategic expansion by proposing to merge Exelon Generation with Baltimore-based Constellation Energy. Constellation brought the Calvert Cliffs nuclear station, a commercial fossil generation fleet, and an extensive retail and wholesale energy marketing organization. The $7.9 billion stock transaction closed in March 2012, expanding Exelon's generation platform to approximately 34 gigawatts while adding Baltimore Gas and Electric as a third regulated delivery utility.
The claim advanced by management held that combining merchant scale with Constellation's retail customer book would create a premier low-carbon power producer, using direct retail sales to hedge against wholesale market volatility.
The disconfirming evidence arrived almost immediately, driven by market geology. Rapid adoption of hydraulic fracturing unlocked vast natural gas reserves in the Marcellus Shale, directly within the PJM Interconnection footprint, driving down delivered gas prices. Because natural gas generators set the marginal clearing price in PJM, lower fuel costs pulled wholesale electricity prices down in tandem. Around-the-clock wholesale power prices in PJM, which had exceeded $60 per megawatt-hour prior to the shale boom, dropped below $25 per megawatt-hour during subsequent market troughs. While wholesale prices fell, Exelon's nuclear operating costs remained fixed, severely compressing generation margins.
The economic consequences persisted over the following decade. Free cash flow from merchant generation declined, placing pressure on Exelon's consolidated balance sheet and increasing borrowing costs across the enterprise—including for the regulated utilities that required capital to fund infrastructure investments. To prevent premature retirements of economically distressed nuclear plants, Exelon sought state-level support. These efforts resulted in zero-emission credit (ZEC) subsidies under Illinois's 2016 Future Energy Jobs Act and a parallel ZEC framework in New York. Ultimately, a merchant business founded on the premise of thriving in deregulated markets came to rely on legislative intervention to maintain operational viability.
The verdict. Over the 2012–2022 cycle, Exelon's merchant nuclear division failed to generate returns above its weighted average cost of capital, prompting management to evaluate strategic alternatives. For investors, the structural challenge centered on variance rather than total returns alone: combining a commodity-exposed merchant generator with regulated utilities introduced market volatility into a corporate structure prized for stability. Consequently, equity markets assigned Exelon a valuation discount relative to pure-play regulated peers, reflecting the unpredictability of merchant cash flows.
That persistent valuation discount ultimately set the stage for corporate separation. Before Exelon moved to unbundle its operations, however, it spent several years pursuing further regulated utility expansion.
V. Empire Building & Pepco Holdings: Creating America's Regulated T&D Giant (2014–2016)
Utility mergers in the United States are rarely won in corporate boardrooms. They are decided in state hearing rooms, where regulatory commissions with statutory mandates to protect ratepayers evaluate whether an out-of-state holding company's expansion serves local interests.
Exelon encountered that reality in New Jersey. In 2004, the company agreed to merge with Public Service Enterprise Group in a transaction valued at approximately $12 billion. Over the next eighteen months, the New Jersey Board of Public Utilities demanded substantial rate concessions and generation divestitures to mitigate market power concentration. By 2006, the required concessions rendered the transaction economically unviable, leading management to abandon the deal. The experience demonstrated that Exelon's generation portfolio was not merely a commodity risk, but also a regulatory obstacle that complicated acquisitions in states concerned about market power.
The Pepco solution. The April 2014 agreement to acquire Pepco Holdings Inc. for approximately $6.8 billion in cash, at $27.00 per share, followed a different strategic path. Pepco Holdings owned no significant generation assets. Instead, it comprised three pure-play delivery utilities: Potomac Electric Power Company, serving Washington, D.C., and its Maryland suburbs; Delmarva Power & Light, covering Delaware and Maryland's Eastern Shore; and Atlantic City Electric, operating in southern New Jersey. Crucially, these transmission and distribution networks were physically contiguous with Baltimore Gas and Electric.
The strategic logic addressed Exelon's core valuation challenge: if public markets were penalizing the enterprise for merchant power volatility, expanding the regulated asset base offered the most direct remedy. Pepco Holdings brought rate base assets that earned regulated returns independent of natural gas price fluctuations.
The battleground. Securing regulatory approval required consents from four distinct jurisdictions. Delaware and New Jersey approved the transaction with relatively minor conditions, while Maryland extracted meaningful rate concessions. Washington, D.C., however, posed a formidable hurdle. In August 2015, the D.C. Public Service Commission rejected the initial application. D.C. Mayor Muriel Bowser, who initially backed a negotiated settlement before facing public pushback, governed a city where Pepco was widely criticized for poor service reliability. Ratepayers and local officials questioned whether a Chicago-based holding company would address long-standing infrastructure deficiencies.
Exelon ultimately secured approval in March 2016 by committing to an extensive concession package. The final agreement included over $130 million in direct ratepayer credits, funding for microgrids and renewable energy initiatives, and legally binding reliability benchmarks. The commission approved the revised settlement despite ongoing opposition from the District's attorney general.
So what? The Pepco transaction illustrated the full economic cost of utility consolidation. Beyond the $6.8 billion headline purchase price, the effective cost included hundreds of millions of dollars in regulatory concessions, multi-year management overhead, and stringent operational mandates. Nevertheless, the deal established Exelon as the largest electric delivery utility in the United States by customer count, creating a contiguous service territory from Lake Michigan to the Atlantic coast that enabled operational efficiencies across storm response, procurement, and engineering standards.
The acquisition also underscored a defining characteristic of Exelon's corporate strategy: an ability to navigate complex state political processes to secure major regulatory outcomes. Within four years, federal prosecutors in Illinois would reveal the specific mechanisms behind part of that political influence.
VI. Governance Crisis: The ComEd Bribery Scandal & Deferred Prosecution Agreement (2011–2020)
On July 17, 2020, the U.S. Attorney's Office for the Northern District of Illinois filed a single count of bribery against Commonwealth Edison and announced a deferred prosecution agreement. ComEd admitted to the conduct and agreed to pay a $200 million criminal penalty—at the time among the largest ever imposed in an Illinois public-corruption matter.4
Understanding that resolution requires examining a legislative cycle nine years earlier that Exelon had previously presented as a major strategic victory.
The claim. Between 2011 and 2016, ComEd secured two Illinois legislative packages that reshaped its commercial foundation. The Energy Infrastructure Modernization Act of 2011, enacted over a gubernatorial veto, established a formula rate mechanism under which allowed revenues were determined by an annual mathematical formula rather than traditional case-by-case rate litigation, substantially mitigating regulatory lag on capital expenditures. The Future Energy Jobs Act of 2016 subsequently added zero-emission credit subsidies for Exelon's Clinton and Quad Cities nuclear facilities. Management cited these outcomes as proof of an institutional ability to secure constructive regulatory arrangements.
The disconfirming evidence. Federal prosecutors demonstrated that across that same 2011–2019 period, ComEd directed benefits to associates of Illinois House Speaker Michael Madigan, who controlled the state legislative calendar. These benefits included subcontractor payments to individuals performing minimal or no work, a paid internship pipeline for contacts from Madigan's Chicago ward, legal retentions, and a seat on ComEd's board of directors. ComEd admitted that the purpose of these actions was to influence the Speaker regarding key utility legislation.4
Executive consequences followed. In May 2023, a federal jury convicted four former executives and lobbyists—referred to in local press accounts as the "ComEd Four"—including Anne Pramaggiore, who had previously served as chief executive of ComEd and head of Exelon's utilities business. Pramaggiore had been a prominent industry executive who had actively promoted the grid modernization investments enabled by the 2011 legislation.
What it actually cost, and for how long. Beyond the $200 million fine, the primary financial impact centered on the loss of regulatory trust. Formula rates and multi-year capital plans rely on commission discretion and transparent utility disclosures. Following the 2020 deferred prosecution agreement, the Illinois Commerce Commission evaluated subsequent filings under heightened scrutiny. In 2021, state lawmakers passed the Climate and Equitable Jobs Act, which repealed formula ratemaking and instituted a multi-year rate plan framework requiring greater evidentiary justification.
The verdict. These events undermined the premise that Exelon's Illinois regulatory achievements reflected a repeatable, proprietary capability. With the illicit mechanisms exposed and eliminated, the company's regulatory thesis narrowed to its fundamental operating scale and grid management performance. The key test for the business model became whether ComEd could earn its allowed return on equity under the stricter post-2021 regulatory framework while securing rate treatment comparable to regional utility peers. Through 2025, that convergence remained partial at best.
The company's answer to the trust problem, when it came, was structural rather than rhetorical.
VII. The Great Unbundling: Spinning Off Constellation Energy (2021–2022)
By late 2020, the internal logic for separating the enterprise had become compelling. Exelon's regulated utilities commanded a premium earnings multiple relative to industry peers, whereas its merchant generation business traded at a far lower and less predictable valuation. Blended together under one roof, the market applied a persistent conglomerate discount to the consolidated entity. Activist investors—including Paul Singer's Elliott Management—had publicly campaigned for a breakup, reversing years of hesitancy by Exelon's board.
Three factors broke the stalemate. First, the merchant generation division had spent nearly a decade failing to earn its cost of capital, exhausting the argument that management should wait for wholesale power prices to recover. Second, the expansion of ESG-focused capital meant that holding fossil generation assets inside a utility holding company imposed a measurable valuation penalty, even though the nuclear fleet was overwhelmingly carbon-free. Third, a clean separation had become feasible without triggering a corporate tax liability, as the generation business could support an independent credit rating.
In February 2021, Exelon announced the tax-free spinoff of Exelon Generation into an independent public company. The transaction closed in February 2022, with Exelon shareholders receiving one share of Constellation Energy Corporation for every three Exelon shares held.1 Constellation assumed ownership of twenty-three reactors across fourteen sites—representing roughly twenty-one gigawatts of nuclear capacity—alongside fossil, hydroelectric, renewable, and retail energy marketing assets. Exelon retained the six delivery utilities.
On the first day of regular trading, Constellation closed at $53.01 per share and Exelon at $42.86.1 Both figures soon reflected historical baselines prior to a dramatic market shift.
The divergence, and what it teaches. What followed was not anticipated by either management team in 2021. Within two years, the compute requirements for training large artificial intelligence models converted continuous, twenty-four-seven carbon-free generation into a highly sought-after commodity. Technology companies began signing long-dated power purchase agreements at prices far exceeding historical merchant nuclear models—most notably Microsoft's agreement to fund the restart of Three Mile Island Unit 1. Constellation re-rated sharply upward, transitioning in market valuation from a utility-adjacent power producer to an infrastructure growth asset.
Exelon re-rated along a separate trajectory, trading as a pure-play regulated delivery utility valued for cash-flow predictability, dividend yield, and sensitivity to long-term interest rates.
Evaluating the separation requires separating hindsight from corporate strategy. The outcome does not demonstrate that management foresaw the AI-driven demand shock; that surge played no role in the 2021 spinoff rationale, and had the market shift been anticipated, shareholders might have preferred retaining greater generation exposure. Instead, the transaction illustrates a broader financial principle: combining assets with fundamentally different risk profiles depresses the valuation of both, whereas unbundling allows distinct investor bases to price each asset on its own fundamentals. The separation produced a simpler company to evaluate.
Structural simplicity, however, does not mean operational simplicity. Exelon today remains an enterprise defined by six distinct state regulatory relationships operating under a single ticker.
VIII. Anatomy of the Modern Pure-Play Utility: The 6 Subsidiaries & Segment Economics (2022–Present)
The core structure of Exelon is straightforward: it functions less as a single integrated business than as a holding company managing six separate regulatory relationships across six state-level jurisdictions. Consolidated earnings reflect the cumulative outcome of those six distinct negotiations.
The financial mechanics of regulated energy delivery are equally clear. A utility deploys capital into grid infrastructure—poles, wires, transformers, substations, gas mains, and meters. State commissions inspect those capital expenditures to determine whether they were prudently incurred, adding approved outlays to the utility's rate base. Regulators then establish an allowed return on equity and capital structure, designing customer rates to cover operating expenses, depreciation, taxes, and that authorized return. Expanding rate base drives earnings growth, provided regulators approve the capital deployment and permit the utility to realize its authorized returns.
Two factors can disrupt this model: a commission can disallow capital investments, or it can set an authorized return on equity so low that the spread above the utility's cost of capital compresses. Exelon has experienced both pressures since 2020.
The six operating negotiations
Commonwealth Edison — Illinois. ComEd remains the largest subsidiary, holding a rate base of approximately $22 billion—roughly 40 percent of Exelon's consolidated total—and serving four million electric customers across Chicago and northern Illinois. Regulated by the Illinois Commerce Commission under a multi-year rate plan framework, ComEd was assigned an allowed return on equity near 8.91% following the December 2023 order — meaningfully below the national average for vertically integrated and delivery utilities.[^7] ComEd functions as Exelon's primary growth engine, benefiting from a surge in northern Illinois data center interconnections, while simultaneously representing its greatest political risk.
PECO Energy — Pennsylvania. PECO holds roughly $14 billion in rate base—about a quarter of the enterprise total—serving approximately 1.7 million electric and 550,000 gas customers across Philadelphia and five surrounding counties. Regulated by the Pennsylvania Public Utility Commission with an allowed ROE around 9.65%, PECO has historically provided Exelon's most predictable regulatory outcomes. A key growth driver is its gas utility, where mandated replacement of legacy cast-iron and bare-steel mains provides a long, uncontroversial investment runway.
Baltimore Gas and Electric — Maryland. Representing approximately $11 billion in rate base—around a fifth of the consolidated total—BGE serves roughly 1.3 million electric and 700,000 gas customers in central Maryland under the Maryland Public Service Commission at an allowed ROE near 9.5%. BGE was the first of the group to operate under a multi-year rate plan, though Maryland regulators have grown notably more skeptical of that framework as customer bills have risen.
Potomac Electric Power Company — D.C. and Maryland. Pepco accounts for roughly $8 billion in rate base, or about 15 percent of the total, serving some 900,000 customers under two commissions simultaneously. Its capital program emphasizes urban grid resilience, including undergrounding overhead distribution lines, hardening feeders, and securing power delivery for a high concentration of federal facilities.
Delmarva Power & Light — Delaware and Maryland. Delmarva holds roughly $5 billion in rate base—around 8 percent of the total—serving about 540,000 electric and 140,000 gas customers across Delaware and Maryland's Eastern Shore.
Atlantic City Electric — southern New Jersey. Atlantic City Electric represents roughly $4 billion in rate base, or about 7 percent of the consolidated total, serving approximately 560,000 electric customers under the New Jersey Board of Public Utilities.
What the structure actually means for investors
Three analytical takeaways frame the segment economics.
First, geographic diversification is real but bounded. Spreading assets across six regulatory jurisdictions reduces single-state exposure compared to standalone regional utilities. However, ComEd and BGE collectively account for nearly 60 percent of Exelon's rate base, and both sit in states where affordability concerns have intensified political scrutiny. Portfolio risk remains concentrated in two core markets.
Second, the spread in allowed return on equity highlights shifting regulatory environments. The gap between PECO's 9.65% authorized return in Pennsylvania and ComEd's 8.91% in Illinois reflects diverging state regulatory climates for comparable delivery assets. Furthermore, when a subsidiary's earned return lags its authorized rate, it typically signals that operational costs are expanding faster than regulatory mechanisms permit recovery, creating structural earnings drag.
Third, operational execution cannot fully offset restrictive regulatory decisions. Exelon captures scale advantages in bulk transformer procurement, emergency storm response, and operational efficiency across its ten-million-customer footprint. Yet operational savings cannot override commission-established rate structures. In deregulated markets, operational efficiency translates directly into expanding profit margins; in regulated delivery, operational excellence primarily serves to strengthen the utility's position in subsequent rate cases.
That structural tension led directly to the state regulatory decisions that reset expectations in 2023.
IX. The 2023 Regulatory Shock: The ICC Rejection & Management's Pivot under Calvin Butler
On December 14, 2023, the Illinois Commerce Commission issued a ruling on ComEd's initial multi-year grid plan and rate request under the Climate and Equitable Jobs Act—the legislation that had replaced formula ratemaking. While market participants expected a routine rate adjustment, the commission voted to reject the grid plan outright and lowered ComEd's allowed return on equity to 8.91 percent, citing insufficient evidence of customer affordability, transparency, and equitable benefits for low-income households.[^7] Exelon's stock fell more than 10 percent in the following trading session, a sharp single-day decline for a regulated delivery utility valued primarily for earnings predictability.
The man who had to answer for it
Calvin Butler had assumed the role of Exelon chief executive at the end of 2022, succeeding Christopher Crane, who had led the company through its merchant power contraction and the Constellation spinoff before passing away in April 2024. Butler entered the chief executive seat with a professional background distinct from traditional utility leadership. Raised in Gary, Indiana, he worked in corporate law and government affairs at RR Donnelley and in state government before joining Exelon's Baltimore Gas and Electric subsidiary. He subsequently led BGE and then Exelon's consolidated utility platform, establishing an operational style centered on direct community and municipal engagement across Baltimore and Chicago.
That background proved relevant when the commission issued its December 2023 ruling. The ICC's rejection functioned less as a technical critique of ComEd's distribution engineering than as a challenge to institutional legitimacy—a regulatory body evaluating a four-year spending request from a utility that had recently admitted to a multi-year legislative bribery scheme.
The pivot
Exelon management adjusted its capital deployment strategy rather than contesting the ruling through extended litigation. The company paused non-essential distribution capital spending and reduced ComEd's capital plan by approximately $1.25 billion through 2026. In March 2024, ComEd submitted a revised grid plan developed with expanded stakeholder pre-engagement, securing commission approval for a scaled-back version late that year to re-establish a workable regulatory baseline.
In subsequent earnings calls, management framed the outcome around customer affordability, low-income support programs, and constructive regulatory alignment. When analysts questioned whether the 8.91 percent authorized return on equity represented a temporary penalty or a permanent baseline, management cited statutory rate-setting mechanics and potential adjustments in future rate cases without offering firm return guarantees. For institutional investors, this measured posture signaled a deliberate effort to rebuild regulatory trust rather than offer hasty financial assurances.
The verdict on the framework claim
The claim held that the multi-year rate plan structure under the Climate and Equitable Jobs Act de-risked ComEd's capital program by establishing long-term regulatory predictability in advance.
The evidence rejected that claim in its strongest form. Statutory planning frameworks do not provide political or regulatory guarantees. When rising customer bills trigger public pushback, multi-year frameworks can serve as instruments for capital cuts rather than protections for spending—a dynamic intensified in Illinois by ComEd's prior governance admissions.
The surviving, narrower claim is that multi-year rate plans mitigate regulatory lag—the delay between capital deployment and cash recovery—without eliminating regulatory risk. While economically valuable, this distinction shifts the primary analytical metric to ComEd's realized return on equity relative to its authorized rate. If ComEd consistently earns within 20 to 30 basis points of its authorized return, the multi-year framework functions effectively; if that gap widens, the framework operates as a mechanism for transferring value from equity holders to ratepayers.
That regulatory balance carries heightened significance given the substantial volume of capital seeking grid interconnections across ComEd's service territory.
X. The AI & Data Center Megawatt Rush: Transmission as the Growth Engine (2024–Present)
Driving west out of Chicago along Interstate 88, former farmland has increasingly transformed into massive concrete complexes—windowless data centers the size of shopping malls, ringed by transformer yards and industrial chillers, each drawing more electricity than a mid-sized city. Northern Illinois has joined Northern Virginia and Columbus, Ohio, as one of North America's three largest data center hubs, attracted by available land, dense fiber infrastructure, cooler weather, and historically ample grid capacity.
That grid surplus has vanished. By 2026, ComEd's large-load interconnection queue swelled to between 33 and 36 gigawatts of requested capacity—a figure exceeding the utility's entire historical system peak. For an enterprise that spent two decades operating under flat or declining electricity demand, this shift represents a fundamental structural transition rather than a routine forecast adjustment.
The discipline problem
An independent assessment of this demand surge diverges sharply from promotional industry framing.
The claim—frequently highlighted across the utility sector—is that an expanding interconnection queue directly converts into accelerated rate base growth.
The disconfirming evidence. Industry history shows that interconnection queues consist primarily of speculative proposals. Developers routinely submit applications across multiple utility territories to preserve optionality before securing capital or land, subsequently abandoning unviable projects. In the renewable energy queues processed by PJM and MISO over the prior fifteen years, cancellation rates routinely exceeded 50%. An interconnection queue represents a ledger of preliminary inquiries rather than a binding order backlog, making the raw 36-gigawatt figure an unrated demand metric.
Exelon's structural filter. To address speculative filings, Exelon required large-load applicants to execute agreements mandating upfront collateral and direct funding for dedicated substations, feeder lines, and transmission upgrades. This mechanism serves a dual purpose: it deters developers lacking committed financing while insulating existing ratepayers from stranded capital costs, preventing public and regulatory pushback over residential rate cross-subsidization.
The policy reduced speculative applications. Management narrowed its guidance to a "high-probability" pipeline of approximately 11 gigawatts—roughly one-third of the initial queue. While 11 gigawatts remains a substantial volume, the filtering process demonstrates that approximately two-thirds of the headline queue lacked execution certainty. Furthermore, this 11-gigawatt figure reflects internal management projections rather than fully contracted backlogs, requiring validation through completed grid energization.
Why transmission is the better business
This load growth drove a strategic reallocation within Exelon's capital expenditure program, shifting investment toward high-voltage transmission assets and away from localized distribution networks.
The regulatory distinction is significant. Local distribution infrastructure is governed by state utility commissions, which face direct political pressure regarding customer bill impacts. High-voltage transmission infrastructure is regulated by the Federal Energy Regulatory Commission (FERC) under formula rates featuring annual true-up mechanisms, authorized returns on equity typically ranging between 10.0% and 10.5%, and potential incentive adders for major grid upgrades. Consequently, federal oversight offers greater formulaic certainty than state-level ratemaking.
Exelon targeted compounded annual transmission rate base growth of approximately 16% through 2029, elevating consolidated rate base expansion to a 7% to 8% range, supported by its $41.7 billion capital plan covering 2026 through 2029.[^3]
Regional supply constraints further reinforced the need for infrastructure expansion. In the PJM capacity auction—which compensates generators for maintaining peak availability—clearing prices surged from $28.92 per megawatt-day for the 2024/2025 delivery year to $329.17 per megawatt-day for 2026/2027, an elevenfold increase.5 Because Exelon operates purely as a delivery utility, higher capacity clearing prices generate no direct generation revenue. Instead, they pass directly into end-user bills as supply charges—increasing ratepayer pressure while simultaneously demonstrating the regional grid strain required to justify major transmission additions.
The verdict. The transmission shift represents the most structurally supported component of Exelon's growth strategy, relying on federal formula ratemaking and clear physical capacity needs rather than discretionary state approvals. However, two operational constraints limit its overall impact. Transmission assets account for approximately 20% of Exelon's total rate base, meaning a 16% annual transmission growth rate provides only partial insulation against lower allowed returns across its larger distribution operations. Additionally, federal returns remain subject to regulatory oversight; state consumer advocates routinely challenge FERC incentive return structures, leaving higher-margin transmission earnings vulnerable to potential federal policy adjustments.
XI. Playbook: Business, Regulatory & Investing Lessons
Stripping away nearly a century and a half of history reveals four core lessons for utility investors.
1. The regulated utility is an equation, not a market position. Earnings approximate rate base multiplied by allowed return on equity, less the cost of the capital funding it. Everything a utility does — every storm response, every rate filing, every community initiative — is ultimately an input into two variables: how much capital the commission permits the utility to deploy, and what return it allows the company to earn. This is why utility analysis differs fundamentally from evaluating standard operating companies. There is no market share to win, no pricing power to exercise, and no product cycle to navigate. There is only the regulatory compact, renegotiated continuously.
It also explains the structural incentive known in utility economics as the Averch-Johnson effect: because earnings scale with capital deployment, utilities carry an inherent bias toward capital-intensive investments. A regulator's role is partly to restrain that bias. When a commission rejects a grid plan for insufficient affordability justification, it is performing precisely the oversight function that the regulatory model demands.
2. Volatility contaminates. Exelon's 2012–2022 merchant experiment demonstrated that pairing a commodity-exposed business with a regulated delivery utility does not average cash-flow risk; it imports market volatility. Rating agencies evaluate the consolidated balance sheet, and equity investors price the combined enterprise. A utility's primary competitive advantage is a low cost of capital, and any factor that increases the perceived variance of consolidated cash flows directly undermines that advantage. The corollary is a cautionary principle: any future move by Exelon into less-regulated adjacencies — such as generation, storage ownership, or unregulated grid services — warrants skepticism informed by the prior decade's merchant discount.
3. Political capital depreciates slowly but can be destroyed instantly. The Illinois record provides a stark case study. Legislative victories secured through illegal influence delivered short-term economic gains for roughly a decade, only to impose far longer-lasting structural penalties — a repealed formula rate framework, a below-average authorized return on equity, and a state commission predisposed to skepticism. That asymmetry underscores the central risk: a utility can spend decades building regulatory trust and forfeit it through a single corporate scandal.
4. In a high-cost-of-capital environment, jurisdiction is strategy. When interest rates hovered near zero, the gap between a 9.0% and a 10.2% allowed return on equity appeared negligible relative to borrowing costs. In a higher-rate environment, however, that spread drives most of the net equity return. This dynamic underpins Exelon's capital reallocation toward federally regulated transmission assets. The principle generalizes across the sector: in a tight-money environment, capital naturally flows toward jurisdictions and asset classes offering the widest spread between authorized returns and capital costs, alongside minimal political friction over cost recovery. Whether management executes that capital reallocation with discipline — rather than deploying capital wherever spending is authorized — remains the key metric to watch.
XII. Porter's 5 Forces, Helmer's 7 Powers & Skeptical Investor Stress Test
Frameworks built for competitive markets sit awkwardly on regulated monopolies, which is itself informative: the points where they break reveal where the primary enterprise risk resides.
Hamilton Helmer's 7 Powers
Cornered Resource — high, and genuinely so. Exelon holds exclusive, statutorily protected franchise rights to distribute electricity in Chicago, Philadelphia, Baltimore, and Washington, D.C., along with high-voltage rights-of-way through some of the most densely populated corridors in North America. The rights-of-way may represent the more valuable asset. Assembling land for a new transmission corridor through a major metropolitan area is virtually impossible. What Exelon owns cannot be replicated at any price.
Scale Economies — medium-high. Serving ten million customer accounts across six utilities provides procurement leverage in a supply-constrained equipment market, shared storm restoration crews that can be redeployed across state lines, and a consolidated back-office platform. The advantage is real but bounded, as regulators expect merger-related cost savings to be passed through to ratepayers in rate cases.
Process Power — medium. Rapid storm restoration, grid automation, and multi-jurisdictional regulatory management represent significant organizational capabilities developed over decades. However, these capabilities did not prevent the operational reliability issues in Washington, D.C., that nearly stalled the Pepco acquisition, nor did they avert the governance failures in Illinois.
Switching Costs — infinite, and therefore not a moat. Retail delivery customers cannot switch providers. While this appears to represent maximal market power, it actually creates a central vulnerability: because captive customers cannot leave, the utility's pricing is determined entirely through a political and regulatory process.
Branding, Network Economies, Counter-Positioning — not applicable. Customers do not choose their delivery utility, no new entrant is disrupting the network from below, and regulated monopolies do not counter-position against incumbents.
Porter's Five Forces
Threat of new entrants: effectively zero. Statutory franchises combined with extreme capital intensity prevent new market entry.
Bargaining power of suppliers: moderate and rising. Lead times for large power transformers have expanded past two years industry-wide, with specialized circuit breakers and conductors facing similar constraints. While Exelon's scale helps secure manufacturing slots, it does not expand total supply. Supply-chain bottlenecks have thus become a physical constraint on the pace of rate base growth, as a utility cannot earn a return on infrastructure it cannot procure.
Bargaining power of buyers and regulators: very high — the dominant force. State commissions determine authorized returns on equity, approve or reject capital spending plans, and hold statutory authority to limit utility earnings to protect customer affordability. Exelon has experienced these pressures directly in Illinois and Maryland. Concurrently, a second buyer class has emerged with substantial leverage: hyperscale data center operators sophisticated enough to negotiate interconnection terms aggressively and pit competing jurisdictions against one another for project siting.
Threat of substitutes: low to moderate. Distributed rooftop solar paired with battery storage erodes distribution volume at the margin. However, urban service territories characterized by multi-family housing and limited roof space face minimal exposure to grid disintermediation. Furthermore, AI-driven demand expansion points in the opposite direction: hyperscale computing facilities require continuous high-voltage capacity at scales that behind-the-meter resources cannot independently deliver.
Rivalry: none for customers, intense for capital. Exelon faces no delivery competition within its service territories. However, it competes directly with NextEra, Southern Company, Duke Energy, American Electric Power, and other major utilities for income-focused equity and investment-grade debt. That competition is measured in basis points of authorized returns and credit spreads.
The skeptical investor's stress test
A skeptical investor or short-seller examining Exelon would focus on three specific vulnerabilities, each requiring a direct assessment.
First, the affordability ceiling. Customer bills across Exelon's service territories face upward pressure from multiple sources simultaneously: distribution system upgrades, transmission expansion, and pass-through capacity charges driven by regional PJM auction price spikes. While each expenditure serves a specific operational purpose, their cumulative impact drives bill increases above general inflation. The political response is evident in recent decisions that rejected ComEd's grid plan and reduced authorized returns on equity below 9 percent. The downside case does not require an unexpected crisis; it requires only that state regulators in Illinois and Maryland maintain their current restrictive posture.
Second, the balance sheet. A $41.7 billion capital program funded by a company that must maintain investment-grade ratings is, structurally, a continuous financing exercise.[^3] Credit rating agency thresholds for funds-from-operations relative to total debt sit in the low teens, and Exelon targets a modest cushion above that level. If operating cash flow falls short — due to spending disallowances, earned returns lagging authorized levels, or delayed regulatory recovery — management faces limited options: issue equity and dilute earnings, reduce capital spending and slow growth, or absorb a credit downgrade and face higher borrowing costs. Utilities historically resort to equity issuance under these conditions, which explains why utility earnings-per-share growth consistently lags rate base expansion.
Third, the governance residue. While the ComEd bribery matter was resolved through a deferred prosecution agreement, questions remain regarding structural governance reforms. While board turnover, enhanced compliance controls, and the termination of illicit political influence practices can be documented on paper, the true test lies in long-term regulatory outcomes rather than compliance presentations.
Finally, Exelon's physical footprint carries ongoing climate and operational risk exposure: low-lying coastal service areas at Delmarva Power and Atlantic City Electric, aging underground infrastructure in Washington, D.C., and increasing storm frequency that elevates both emergency restoration costs and the reliability metrics tied to executive compensation. While storm restoration costs are generally recoverable through regulatory mechanisms, that recovery remains a lagging and contested process.
XIII. Analysis & Bull vs. Bear Case
Why this wins from here
The demand backdrop is the strongest in half a century, and it is not speculative in aggregate. While the timing and completion of individual data centers remain uncertain, the overall need across the PJM grid for expanded delivery capacity is clear. The elevenfold increase in PJM capacity auction clearing prices serves as a direct market signal of physical scarcity, and in a regulated utility model, scarcity converts into authorized capital spending.5 Exelon's service territory encompasses one of the three largest data center markets in North America, with interconnection inquiries far exceeding any previous volume in company history.
The transmission mix shift represents the most structurally sound element of the strategy. Unlike local distribution networks, high-voltage transmission operates under federal jurisdiction with formulaic cost recovery, annual true-ups, higher authorized returns on equity, and less direct exposure to state political pushback over customer bills. Exelon's projected compounded annual transmission rate base growth of roughly 16% through 2029 elevates overall consolidated rate base expansion into the 7% to 8% range.[^3]
The enterprise is now analytically straightforward. Following the Constellation spinoff, Exelon carries zero commodity price exposure and operates no merchant power generation, leaving a single core earnings mechanism driven entirely by regulated delivery. For income-focused investors, that operational transparency forms a central part of the investment case.
The dividend remains supported by a payout ratio of roughly 60% of operating earnings. That metric aligns with utility sector norms, allowing the company to fund the majority of its growth through retained cash flows and debt issuance rather than continuous equity dilution.
What breaks it
Regulatory friction presents the primary risk to the investment thesis. Regulators in Illinois rejected ComEd's initial multi-year grid plan while setting an authorized return on equity of 8.91%, and Maryland commissioners have grown increasingly critical of multi-year rate structures as customer bills have climbed. Because Commonwealth Edison and Baltimore Gas and Electric collectively represent nearly 60% of Exelon's rate base, these restrictive rulings reflect baseline operational conditions rather than distant tail risks. If these key subsidiaries consistently earn below their authorized returns, expanding rate base fails to generate proportional earnings growth for shareholders.
Macroeconomic interest rates create structural valuation headwinds. As a pure-play regulated utility, Exelon's equity valuation acts as a bond proxy, remaining sensitive to long-term interest rates through two distinct mechanisms: increased borrowing costs on a debt stack that requires continuous refinancing, and higher discount rates applied to predictable, slow-growing cash flows. Elevated interest rates can depress equity valuation multiples regardless of underlying operational performance.
Physical supply-chain and operational bottlenecks threaten capital execution timelines. Extended lead times for large transformers and specialized circuit breakers, constraints on skilled labor, and complex right-of-way permitting can delay infrastructure deployment. In a regulated framework where earnings depend on assets actively placed into service, any delay in executing the capital plan directly defers rate base growth.
The demand expansion narrative requires prudent analytical weighting. The investment thesis relies heavily on an interconnection pipeline that management filtered down from more than 33 gigawatts of raw requests to an 11-gigawatt high-probability target. Although this screening process eliminates speculative inquiries, the remaining 11 gigawatts reflect internal management projections rather than fully executed customer contracts. Until these projects are physically energized and added to the rate base, load growth from artificial intelligence functions as a growth option rather than a guaranteed earnings stream.
The calibrated conclusion
The historical evidence neither fully validates nor invalidates Exelon's central claim; instead, it narrows the scope of what investors can rely upon. The assertion that the enterprise possesses a durable regulatory moat was disproved in its strongest form by the Illinois bribery scandal, where legislative protection built on political influence collapsed under federal scrutiny. Conversely, the assertion that Exelon owns irreplaceable physical delivery assets across premier urban corridors remains entirely intact and forms the foundation of its business model. Finally, the expectation that artificial intelligence load growth will accelerate earnings growth is mechanically coherent, but remains to be proven through execution.
Ultimately, the strategic trajectory will not be determined by power demand alone. It will depend on whether state utility commissions permit the capital deployed to meet that demand to earn an adequate return while managing customer bill impacts.
XIV. Epilogue & Strategic Roadmap
Samuel Insull's bargain was elegant because it was symmetrical: the utility surrendered the right to charge whatever the market would bear, while the state surrendered the right to expropriate assets. Both sides gained predictability, enabling the vast capital required to electrify a continent to be raised at manageable costs.
A century and a half later, Exelon is testing whether that foundational compact still holds under conditions Insull never anticipated—a customer base with stagnant real incomes facing rising utility bills to fund clean-energy mandates and an industrial computing buildout. In states like Illinois and Maryland, legislatures have enacted decarbonization targets through laws such as the Climate and Equitable Jobs Act and the Climate Solutions Act, while simultaneously resisting the retail rate increases required to pay for them. Managing that friction represents the central operational task for management.
What to watch
Three key metrics provide the primary signals for the enterprise's financial trajectory.
1. Earned versus allowed return on equity across each operating utility, particularly ComEd and BGE. This comparison measures whether approved rate base expansion translates into net earnings for equity holders. A utility consistently earning within 20 to 30 basis points of its authorized return indicates a functional regulatory relationship. A widening gap signals unrecovered operating costs and a gradual transfer of value from shareholders to ratepayers.
2. Energized data center capacity rather than raw queue volume. The critical metric is not the total gigawatts in the interconnection queue, but the volume of load that moves through collateralized agreements into active grid connection. The conversion rate of the roughly 11-gigawatt high-probability pipeline into energized connections serves as the direct test of whether data center demand generates durable revenue growth.
3. Funds-from-operations to total debt. This credit metric governs whether the capital plan can be funded through investment-grade debt or requires dilutive equity issuances. Deterioration in this ratio is the primary mechanism by which expanding rate base fails to generate proportional per-share earnings growth.
Final reflection
The corporate trajectory spans from Insull's central stations through a fragmented nuclear buildout, a decade-long merchant generation detour that eroded capital, a political corruption scandal that impaired regulatory trust, and a corporate separation that left behind a simplified enterprise structure. Exelon operates as a pure-play delivery business—a platform for converting approved capital outlays into regulated returns, whose long-term financial performance depends on securing constructive regulatory terms.
The historical evidence supports a measured conclusion. Utility value is not created by attempting to bypass regulation; Exelon pursued that path at scale, where falling natural gas prices and reliance on state zero-emission credits exposed the volatility of merchant markets. Nor is value sustained by improperly influencing political processes; ComEd's bribery scandal resulted in a $200 million criminal penalty and persistent regulatory headwinds. Instead, durable utility value depends on deploying essential infrastructure capital under regulatory frameworks that balance utility returns with customer affordability. Exelon controls essential power delivery networks across six major urban corridors. Whether those regulatory frameworks remain stable will define the company's performance over the coming decade.
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube