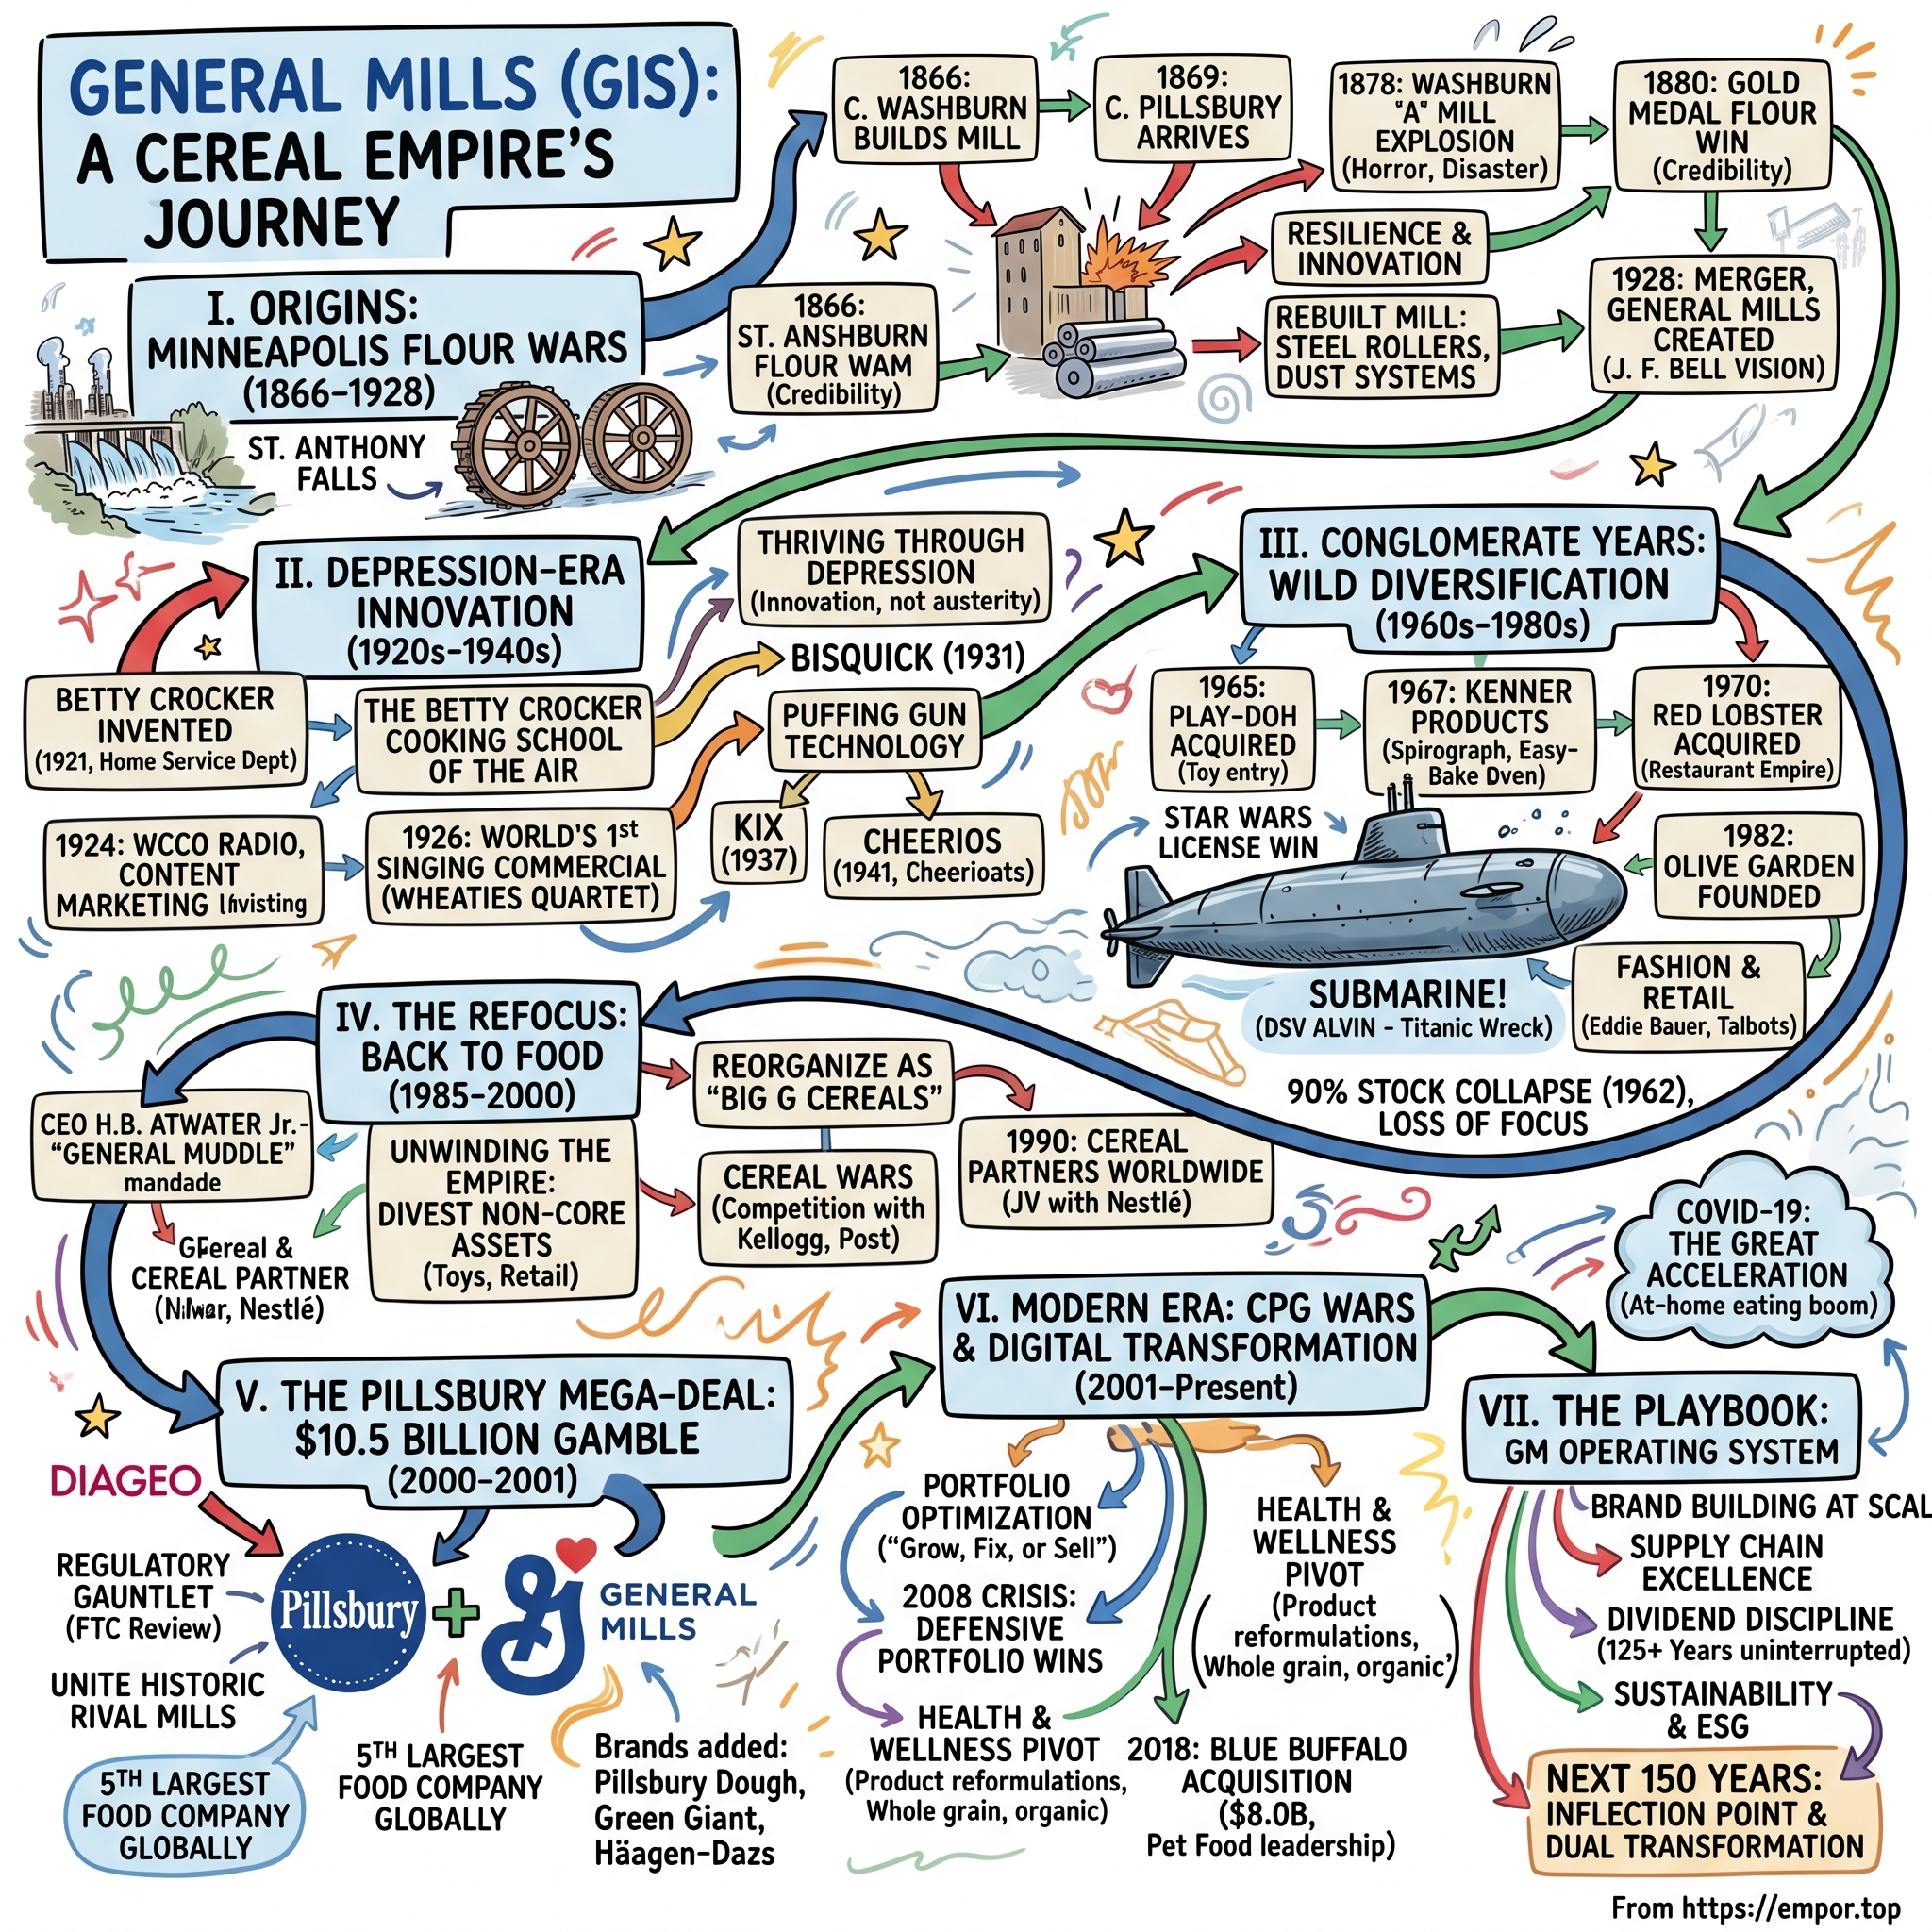
General Mills: The Cereal Empire, The Pillsbury Coup, and The $20 Billion Battle for the Pantry
I. Introduction & Cold Open
The Night the Mill Blew Up
On the evening of May 2, 1878, the night crew at the Washburn A Mill on the Minneapolis riverfront was grinding wheat as usual. The mill was only four years old and already the largest in the world, a limestone monument to the proposition that the prairie's grain harvest could be converted into capital at industrial scale. Then two dry millstones rubbed together, threw a spark, and ignited the fine flour dust suspended in the air. In seconds, the structure detonated. The blast was heard ten miles away in St. Paul. All fourteen workers inside were killed instantly. The ensuing fire leaped to the neighboring Diamond and Humboldt mills, killing four more.1
The Minneapolis Tribune reported that the city had "met with a calamity, the suddenness and horror of which it is difficult for the mind to comprehend." Between a third and a half of Minneapolis's total milling capacity was wiped out in a single night.1
What followed established an enduring operating pattern for the enterprise. Cadwallader Washburn, a Wisconsin businessman who had served as a Union general and state governor, did not pull back. He announced plans to rebuild almost immediately, and by 1880 a replacement A Mill was operational: safer, more automated, and substantially larger than the facility that had exploded.1 General Mills' corporate history credits Washburn with pioneering new dust-collection safety systems and adopting steel roller technology in the wake of the disaster.2 Catastrophe became an impetus to re-engineer the production engine.
From Riverbank to Pantry
Nearly 150 years later, the enterprise forged from that riverfront mill markets more than 100 brands across approximately 100 countries, alongside 50% stakes in two joint ventures reaching roughly 120 additional markets.3 Its brand roster forms a cross-section of modern packaged foods: Cheerios, Lucky Charms, Cinnamon Toast Crunch, Betty Crocker, Pillsbury, Totino's, Old El Paso, Nature Valley, Progresso, Annie's, international rights to Häagen-Dazs, and, following an entry into pet care in 2018, Blue Buffalo.3
Top-line scale, however, recently crested. In fiscal 2024 (ended May 2024), General Mills delivered $19.9 billion in net sales and $3.6 billion in adjusted operating profit, an adjusted operating margin of 18.1%.4 Two years later, the operational picture had deteriorated markedly. In fiscal 2026, net sales contracted to $18.4 billion, adjusted operating profit fell to $2.8 billion, and reported operating profit collapsed to $886 million following approximately $1.8 billion in pet-segment impairment charges and a $1.0 billion loss recognized on divesting its Brazilian operations.5 For fiscal 2027, management projected adjusted operating profit to contract by another 8% to 13%.5
The "$20 billion battle for the pantry" is not a retrospective victory lap. It frames an ongoing structural contest in which General Mills has been losing ground across multiple categories.
The Puzzle
The company's evolution followed an unconventional trajectory. A 19th-century commodity grain miller mastered the industrialization of consumer taste. It created Betty Crocker, a fictional domestic figure who became one of the most influential commercial personas in the United States. It pioneered broadcast radio jingles, diversified into consumer goods ranging from Play-Doh, Monopoly, and Star Wars action figures to the pressure hull of the Alvin deep-sea research submarine, launched the Olive Garden restaurant chain, acquired crosstown rival Pillsbury for $10.5 billion, and subsequently deployed $8 billion to purchase an upscale pet-food manufacturer.
For public market investors, the core question is whether that legacy model can still generate economic rent. General Mills achieved dominance through mass broadcast marketing and control over grocery shelf space. Can that formula generate premium returns when baseline unit volumes stagnate, private label and insurgent specialty brands capture market share, an expansive pet-care acquisition requires steep balance-sheet write-downs, and GLP-1 weight-loss medications compress daily caloric demand? The central issue is whether General Mills retains a defensible competitive moat, or whether the investment thesis has converged on an efficiency program funding a dividend yield.
Resolving that question requires returning to the Minneapolis riverbank where the machine was first built.
 Subscribe on LinkedIn
II. The Minneapolis Flour Wars & Birth of Big Food (1866–1928)
Geography as Destiny
St. Anthony Falls is the only major natural waterfall on the Mississippi River. In the 1860s, that hydraulic drop represented the most valuable commercial power source in the Upper Midwest, driving the waterwheels that turned industrial millstones. In 1866, Cadwallader Washburn established his first flour mill on the riverfront,6 and in 1877, John Crosby joined him to form the Washburn Crosby Company.7
Across the river stood a crosstown rival that would shape the company's trajectory for the next 125 years: Charles A. Pillsbury. The two enterprises contested every operational lever that governed a miller's margins, including water rights, rail tariffs, export distribution, and processing technology.7 That intense rivalry accelerated industrial expansion and established Minneapolis as the flour-milling capital of the United States.7
The technological hurdle was regional. Northern prairie farmers grew hard spring wheat, a grain high in gluten that made superior bread flour but resisted clean grinding on traditional millstones, which discolored the flour with pulverized bran. Millers who adopted modern middlings purifiers and chilled-iron roller technology unlocked that spring wheat, converting it into premium white flour. Washburn Crosby's rapid rebuild of the A Mill after the 1878 explosion established the firm at the technological forefront of the industry.2
The Birth of a Brand Name
In 1880, Washburn Crosby entered its flours into the Millers' International Exhibition in Cincinnati and took the gold, silver, and bronze awards. Capitalizing on the clean sweep, the partnership branded its top-tier flour "Gold Medal."7
The decision marked a critical inflection point in modern commercial food marketing. Flour had historically traded as an unbranded commodity sold by the wooden barrel. Introducing a distinct consumer trademark created an identifiable standard of quality and customer recognition. More than a century later, the company's core economic model continues to rely on that principle of turning commodity staples into branded equity.
James Ford Bell and the Commodity Trap
Following World War I, the American flour-milling sector ran into structural overcapacity. Peacetime demand normalized, grain prices dropped, and regional millers engaged in margin-eroding price wars over wholesale bakery contracts and rail freight allocations. In an undifferentiated commodity business, the lowest-cost operator dictates margins, while excess capacity depresses industry-wide returns.
James Ford Bell, son of longtime Washburn Crosby executive James S. Bell, recognized the limits of commodity scale. In 1928, Bell orchestrated the consolidation of Washburn Crosby with several regional milling operations to establish General Mills, instantly creating the largest flour-milling company in the world.72
Volume, however, was only the baseline defensive move. Bell's primary insight was that a commodity processor could escape cyclical margin compression only by shifting downstream into branded, packaged foods that consumers would request by name and grocery retailers would be compelled to stock.
That premise became General Mills' defining corporate strategy. Much of the company's subsequent history—from the launch of Wheaties to the acquisition of Blue Buffalo—represents an effort to solve Bell's central problem: how a bulk grain processor can generate sustainable economic rents above the cost of commodity agricultural inputs.
The company's initial answer emerged from a fictional domestic persona and an experimental radio broadcast.
III. Inventing Consumer Demand: Betty Crocker, Cheerios, & The Broadcast Revolution (1920s–1950s)
The Woman Who Never Existed
In 1921, Washburn Crosby ran a promotional puzzle contest for Gold Medal flour in The Saturday Evening Post. The prize was a pincushion. While the company anticipated a modest response, it received roughly 30,000 completed entries. Many arrived with letters asking practical baking questions: how to make a cake rise, why bread turned dense, and what to do with a stubborn pie crust.8
Samuel Gale, head of the advertising department, concluded that home bakers would find advice far more credible coming from a woman than from a male clerk. The company invented one. The surname honored William G. Crocker, a recently retired director; "Betty" was selected for its wholesome, cheerful ring. Florence Lindeberg, a secretary, won an internal contest to design the distinctive script signature penned at the bottom of every reply.8
In 1924, Betty Crocker expanded into radio with the Betty Crocker Cooking School of the Air on Minneapolis station WCCO.8 By 1945, Fortune ranked her the second most popular woman in America, behind only Eleanor Roosevelt.8
From a commercial perspective, Betty Crocker served as a scalable engine of consumer trust. She answered correspondence, published recipes, and converted a commodity bag of flour into an enduring consumer relationship. In modern brand marketing terms, she functioned as an artificial persona engineered to deliver an impression of personalized service across millions of households—an intangible asset no regional commodity miller could match.
Wheaties and the First Jingle
Wheaties debuted in 1924.7 Initial sales were sluggish. Then, on Christmas Eve 1926, a vocal quartet performed what General Mills identifies as the first commercial radio jingle.2 In 1933, the brand adopted "The Breakfast of Champions," a tagline conceived through its sponsorships of local baseball broadcasts.72
For investors, the central lesson of the early broadcast era was that General Mills did not merely manufacture food; it engineered consumer demand. Network radio, and later broadcast television, conferred substantial structural advantages on national advertisers: as sales volumes expanded, the marketing cost per package distributed steadily declined. That scale advantage in aggregating national attention persisted for decades. It also created the very distribution moat that digital fragmentation and internet-era marketing would eventually erode—a structural challenge explored in later sections.
Depression-Era Products
General Mills continued to introduce new packaged goods throughout the Great Depression, launching Bisquick in 1931 and Kix in 1937.67 During this era, the company also reinforced the shareholder payout record that remains a cornerstone of its corporate identity: counting its predecessor firms, General Mills has paid uninterrupted dividends since 1898, maintaining what management cites as a 127-year streak.95 That capital-allocation legacy carries distinct weight in the present day, as weakening operating cash flows in 2026 have shifted the dividend from a symbol of defensive resilience into a source of balance-sheet tension.
Cheerioats and Extrusion
In 1941, General Mills introduced Cheerioats, a puffed oat cereal marketed as a convenient, ready-to-eat alternative to traditional cooked oatmeal, fronted by a mascot named Cheeri O'Leary; the brand was subsequently renamed Cheerios.2
The economic logic rested on industrial transformation. A merchant miller sold bulk flour by the pound at thin commodity margins. A cereal manufacturer took raw grain, cooked it into dough, forced it through custom dies under heat and pressure—a mechanical process known as extrusion—and puffed it into lightweight, crisp shapes. Consumers paid for convenience, texture, and brand identity rather than the underlying agricultural inputs. Because a finished box of cereal consisted predominantly of expanded air and intangible brand equity, it captured premium gross margins compared to bulk milled grain. Cheerios quickly became the cornerstone of the company's "Big G" cereal portfolio, which remains at the core of its North America Retail segment today.
By the 1950s, the operating playbook was firmly established: low-cost agricultural inputs, proprietary extrusion processing, nationwide broadcast advertising, and established consumer trust. That combination generated substantial free cash flow—more than the core milling and cereal operations could readily absorb. Faced with mounting capital reserves, the next generation of management began directing funds toward businesses far removed from the kitchen pantry.
IV. Conglomerate Mania to Food Purity: Play-Doh, Red Lobster, & Spinoffs (1960s–1990s)
The Submarine Built by a Cereal Company
In June 1964, a research submersible named Alvin was commissioned for the Woods Hole Oceanographic Institution, embarking on an operational career that would carry scientists to the hydrothermal vents of the Galápagos Rift to document ecosystems thriving alongside superheated, mineral-laden water.10 The contract to build the deep-sea vessel had been secured by an unlikely bidder: General Mills, which submitted the winning proposal of $498,500, with design work spearheaded by company engineer Harold "Bud" Froelich.10
A commercial grain and cereal miller fabricating deep-sea research submarines stands as the ultimate artifact of the conglomerate era. Having accumulated precision engineering expertise through packaging machinery design and wartime defense production, General Mills operated on the prevailing assumption of 1960s management theory: that disciplined corporate leadership, technical talent, and abundant operating cash flows could be successfully deployed across virtually any industrial category.
Toys, Fashion, and Diversification
The push into consumer goods was even broader. General Mills acquired Rainbow Crafts, the creator of Play-Doh, in 1965, followed by toy manufacturer Kenner in 1967 and board-game maker Parker Brothers in 1968.7 Subsequent purchases brought specialty apparel retailers and fashion labels into the portfolio.7 For a period, the corporate parent of Cheerios and Wheaties also owned Monopoly, Nerf, and the license for Star Wars action figures.
The underlying corporate logic reflected the defensive posture of the era. Packaged-food volume growth had slowed, while strict federal antitrust enforcement made large-scale acquisitions within the grocery sector difficult to complete. Executives reasoned that a corporation with a strong balance sheet and proven marketing capabilities could apply those skills to any category capturing family disposable income. In practice, the operating requirements diverged sharply. The toy business was hit-driven and volatile, apparel followed unpredictable seasonal style cycles, and specialty retailing required real estate and store-level merchandising skills that a packaged-goods marketer did not possess.
Restaurants
The company's expansion into dining, by contrast, proved commercially durable. In 1970, General Mills acquired Red Lobster, a casual-dining seafood concept founded two years earlier by Bill Darden. Backed by corporate capital, the chain scaled rapidly; by 1976, Red Lobster operated 174 locations across 26 states, generating $174.1 million in sales.11 Applying that standardized operating model, General Mills developed and launched Olive Garden in 1982, expanding it into the largest full-service casual Italian dining chain in the United States.11
Unwinding
By the mid-1980s, the financial penalties of the conglomerate structure had become clear. Public market investors applied a persistent conglomerate discount to diversified holding companies, unwilling to value steady consumer staple cash flows alongside cyclical toy inventories and retail store leases. In 1985, General Mills executed a sweeping restructuring, divesting businesses that accounted for more than a quarter of its total sales. It combined Kenner and Parker Brothers into Kenner Parker Toys and spun off its apparel operations as Crystal Brands.7
The restaurant portfolio remained within the company for another decade before being separated. In 1995, General Mills spun off the division to shareholders as an independent public company named Darden Restaurants, honoring Red Lobster's founder.11 At the time of the separation, Darden operated more than 1,250 restaurants and held nearly 8.5% of the $47 billion U.S. casual-dining market.11 With the restaurant spinoff complete, General Mills returned to its core identity as a pure-play packaged-food manufacturer.
The Joint Venture Approach: Cereal Partners Worldwide
The same era produced a more durable international expansion strategy. Rather than contesting Kellogg for European shelf space from a greenfield standing, General Mills partnered with Nestlé in 1989 to establish Cereal Partners Worldwide (CPW).7 General Mills contributed its proprietary cereal formulations and brand identities, while Nestlé provided established distribution networks, local grocer relationships, and its globally recognized corporate trademark.3 General Mills holds a 50% equity stake in CPW, which distributes breakfast cereals across approximately 120 markets outside the United States and Canada, alongside an equivalent 50% interest in Häagen-Dazs Japan.3
While the joint venture offered an asset-light route into international distribution, its contribution has recently faced operational pressure. In fiscal 2026, General Mills recognized an $85 million pre-tax share of a goodwill impairment charge at CPW tied to market weakness in Australia, swinging the company’s net joint-venture earnings from a $58 million after-tax profit in the prior year to a $76 million after-tax loss.3 Although CPW generated approximately $1.7 billion in aggregate net sales on a 100% basis in fiscal 2026,3 the partnership functions primarily as a mature regional cash contributor rather than an engine of secular top-line growth.
The Takeaway
General Mills' capital-allocation record during the conglomerate era presents an instructive contrast. Diversification into toys and apparel diluted executive focus and misallocated capital into volatile sectors lacking sustainable competitive moats. Conversely, the dining venture built genuine economic value, scaling an enterprise large enough to be distributed cleanly to shareholders via spinoff. The broader lesson was that General Mills generated the most value when it recognized the limits of its core competencies and exited non-core holdings before they impaired consolidated returns.
That capital-allocation discipline was soon put to the test. At the start of the 21st century, management initiated a new wave of large-scale M&A—beginning with the single largest transaction in the company’s history: acquiring the crosstown rival that had contested the Minneapolis riverbank a century before.
V. The $10.5B Pillsbury Mega-Merger: Crosstown Conquest & The Modern CPG Machine (2000–2001)
The Scale Shock
By the late 1990s, the grocery industry was consolidating rapidly on both ends of the supply chain. Regional supermarket chains were merging into national operators, while Walmart's aggressive rollout of supercenters turned a single mass merchant into the primary retail gatekeeper for American consumer packaged goods (CPG). Food manufacturers responded with defensive horizontal consolidation, reasoning that only a supplier controlling an indispensable portfolio of anchor brands could negotiate on equal footing with a retailer commanding unprecedented shelf space.
Pillsbury, General Mills' historic Minneapolis milling adversary, had by then landed in foreign corporate hands. The brand belonged to London-based drinks conglomerate Diageo,12 a spirits-focused enterprise with little strategic rationale for retaining refrigerated dough and frozen pizza lines. For General Mills, Diageo's desire to streamline its portfolio created an unprecedented opportunity to acquire the crosstown rival it had battled for more than a century.
The Deal
On July 17, 2000, General Mills and Diageo announced an agreement for General Mills to acquire Pillsbury in a transaction valued at $10.5 billion.12 The transaction was structured to conserve cash by relying on equity and leverage: Diageo would receive 141 million newly issued General Mills shares, representing approximately 33% of the expanded company, while General Mills would assume $5.14 billion of Pillsbury debt.12 To protect Diageo against downside market risk, the terms incorporated a contingent cash collar: General Mills agreed to make a deferred payment of up to $642 million, tied to its share price on an agreed anniversary date.12
Chief executive Steve Sanger framed the combination as a revenue accelerator: "We are very excited about the addition of Pillsbury's businesses to our lineup, because we expect them to accelerate our top-line growth." Backing that forecast, management promised annual operating synergies scaling to $400 million by 2003 and lifted the company's long-term earnings-per-share growth targets.12
The Antitrust Fight
Federal antitrust regulators scrutinized the transaction for more than a year. Combining Betty Crocker and Pillsbury joined the two dominant players in domestic baking mixes, creating an unavoidable concentration of market power. To secure regulatory clearance, General Mills agreed to divest Pillsbury's dessert and specialty baking business—encompassing cake, frosting, brownie, and muffin mixes—along with the Hungry Jack and Martha White brands and several regional flour labels, including Robin Hood, to International Multifoods.13 International Multifoods also obtained an exclusive, royalty-free 20-year license to deploy core Pillsbury trademarks, including the Doughboy, across those divested categories.13
That split-trademark arrangement sparked regulatory friction that brought the transaction to the brink of collapse. On October 23, 2001, the Federal Trade Commission deadlocked 2–2 on whether to approve a consent decree or seek a preliminary injunction in federal court to block the merger; because neither motion secured a majority, the agency took no enforcement action.14 That procedural stalemate permitted the acquisition to proceed, closing on October 31, 2001.15 Interim movements in General Mills' equity value adjusted the final payout terms: Diageo received 134 million shares, alongside an adjusted contingent payment liability of up to $670 million payable 18 months post-closing based on the prevailing stock price.15 International Multifoods finalized its purchase of the carved-out baking assets, including a production plant in Toledo, Ohio, on November 13, 2001, for approximately $316 million.13
What General Mills Got
General Mills absorbed the crown jewels of the Pillsbury portfolio: refrigerated baked goods (crescent rolls, biscuits, and cookie dough), Totino's and Jeno's frozen pizza and snacks, Progresso canned soups, Old El Paso Mexican food lines, Green Giant canned and frozen vegetables, and international distribution rights for Häagen-Dazs ice cream. The combination doubled General Mills' operating scale, creating an enterprise with pro forma worldwide net sales exceeding $13.5 billion.15
The subsequent trajectory of Green Giant illustrates the long-term margin pressures embedded in some of these acquired volume engines. In 2015, General Mills divested the Green Giant and Le Sueur vegetable operations in North America to B&G Foods for approximately $765 million, offloading roughly $585 million in annual net sales while retaining overseas trademark rights in select markets.16 Packaged frozen vegetables had devolved into an undifferentiated, low-margin category dominated by aggressive private-label competition, rendering the asset a drag on consolidated operating returns.
How to Judge Pillsbury
In strategic terms, the Pillsbury transaction achieved its immediate commercial objectives. It extended General Mills' shelf presence far beyond center-store dry grocery into the high-traffic refrigerated dairy case, frozen food bunkers, and ethnic meal kits. That expansive footprint granted the company sufficient retail gravity to serve as "category captain" for major grocery chains—the lead supplier entrusted with analyzing register scanner data and architecting planogram layouts across entire supermarket aisles.
Over the long term, however, the merger's operating record proved decidedly mixed. Totino's, one of the central frozen assets acquired in the transaction, evolved into an acute operational headwind by fiscal 2026, when management acknowledged on the fourth-quarter earnings call that the brand had become a primary source of execution failures and market-share erosion.17 Furthermore, Diageo's 33% equity stake created a substantial overhang that weighed on General Mills' valuation multiples for years until the spirits group fully liquidated its position in the open market. The acquisition effectively engineered the modern General Mills operating machine, providing broad distribution scale and negotiating leverage. Yet scale alone could not insulate legacy center-store brands from secular volume stagnation or convert grocery shelf space into enduring top-line growth.
To understand how that expanded commercial machine operated at scale, one must look directly into the engine room.
VI. Anatomy of a $20B Food Giant: Segment Economics & Value Drivers Today
What Changed Between FY2024 and FY2026
Fiscal 2024 marked the financial high-water mark for the modern enterprise. In that year, General Mills generated $19.9 billion in net sales, even as organic sales slipped 1% and pound volumes contracted by 3 points, while producing $3.6 billion in adjusted operating profit, an 18.1% operating margin, and $2.5 billion in free cash flow.4 Post-pandemic price increases and aggressive cost cuts were temporarily masking underlying volume attrition.
That pricing cover evaporated over the ensuing twenty-four months. In fiscal 2025, net sales dropped to $19.5 billion, organic sales slipped another 2%, and adjusted operating profit contracted 7% to $3.4 billion.18 In fiscal 2026—a 53-week fiscal year ended May 31, 2026—net sales slid to $18.4 billion, organic sales fell 2% once again, adjusted operating profit tumbled 16% in constant currency to $2.8 billion, and adjusted operating margins compressed by 190 basis points to 15.3%.5 Adjusted diluted earnings per share dropped from $4.52 in fiscal 20244 to $3.55 in fiscal 2026,5 with management projecting a further decline to between $3.00 and $3.20 for fiscal 2027.5
In effect, General Mills surrendered three years of hard-won profit growth in just two years. Part of that contraction stemmed from intentional portfolio reshaping, including the divestitures of its North American yogurt business and Brazilian operations, alongside targeted price concessions. Yet a substantial portion reflected persistent baseline demand erosion. Dissecting where the company's operating profits now reside illustrates the scale of that challenge.
North America Retail: The Engine Is Smaller
North America Retail (NAR) encompasses U.S. cereal, grain and fruit snacks like Nature Valley, meals and baking solutions such as Old El Paso, Progresso, Betty Crocker, and Pillsbury refrigerated dough, alongside the Canadian retail business. It remains the company's undisputed operational anchor, generating $10.6 billion in net sales and $2.2 billion in segment operating profit in fiscal 2026.5
The underlying trajectory, however, reveals structural strain. As recently as fiscal 2024, the segment generated $12.5 billion in sales and $3.1 billion in operating profit.4 While part of that top-line reduction reflected the divestiture of the yogurt portfolio, organic net sales in fiscal 2026 contracted 3%, dragged down by 2 points of unfavorable price and product mix and a 1-point decline in unit volume.5 General Mills surrendered pricing power yet continued to bleed unit volume. In its annual report, management conceded it "did not achieve" its foremost objective of returning North America Retail to positive volume growth, even as household penetration expanded and 65% of its U.S. retail categories held or gained pound share.3
For equity investors, this development strikes at the heart of the core investment thesis. North America Retail is the flagship theater where branded pricing power is supposed to assert itself. When a consumer packaged goods titan must lower realized prices simply to stabilize market share by the pound, it signals that its legacy brands command a diminishing premium against private label and insurgent alternatives on grocery shelves.
North America Pet: A Premium Asset Under Pressure
The North America Pet segment, assembled around the Blue Buffalo acquisition and augmented by purchases of Tyson Foods' pet treats business and Whitebridge Pet Brands, delivered $2.6 billion in net sales and $499 million in segment operating profit in fiscal 2026.5 Although reported net sales climbed 6% thanks to the Whitebridge transaction, organic sales dropped 3%, and operating profit remained flat.5 Management noted that while Nielsen-measured retail takeaway improved by 1 percentage point, organic shipments lagged by 3 points, largely because retail channel partners reduced their inventory holdings.3
Pet margins remain structurally compelling at nearly 19% at the segment level—comfortably above the consolidated corporate average. The overarching vulnerability lies in stalling organic growth and the steep valuation multiple General Mills paid to acquire those cash flows, a capital-allocation dilemma detailed in Section VII.
North America Foodservice: Steady Business
North America Foodservice supplies bulk flour, frozen doughs, commercial baking mixes, and single-serve cereals to K-12 schools, dining establishments, commercial bakeries, convenience chains, and institutional distributors. The division generated $2.2 billion in net sales and $333 million in operating profit in fiscal 2026, with organic sales slipping 1%.5 A substantial portion of its commercial flour volume is indexed directly to wholesale wheat benchmarks, an arrangement the chief financial officer characterized as "dollar margin neutral" because contract pricing adjusts on a weekly cadence.19 While institutional foodservice will not fundamentally alter the broader investment thesis, it provides a steady, predictable cash generator. In the first quarter of fiscal 2027, the segment delivered a 4% increase in organic net sales and a 12% rise in operating profit.20
International: Improving from a Low Base
The International segment distributes core banners such as Old El Paso, Häagen-Dazs, and Nature Valley across Europe, Australia, Asia, and, until recently, Latin America. The division recorded $3.0 billion in net sales and $189 million in operating profit in fiscal 2026, rebounding 96% from a depressed fiscal 2025 baseline.5 The completed divestiture of its Brazilian operations in early September 2026 eliminated a persistent operational drag,21 helping lift segment operating profit by 14% in the first quarter of fiscal 2027.20 International represents the sole operating division showing unambiguous operational recovery, yet its operating margin remains roughly one-third that of North America Retail.
Holistic Margin Management
The operational engine keeping General Mills afloat carries a corporate moniker: Holistic Margin Management, or HMM. In regulatory filings, the company defines HMM as an enterprise-wide discipline combining productivity efficiencies, mix management, and net price realization to offset input cost inflation, defend margins, and fund brand reinvestment.3 On the factory floor and across logistics routes, it translates into an endless hunt for micro-efficiencies: shaving millimeters off packaging cartons, optimizing freight lanes, recalibrating ingredient blends without degrading taste profiles, and accelerating packaging lines.
The financial contributions are undeniable. HMM generated productivity savings equivalent to roughly 5% of cost of goods sold in fiscal 2026, augmented by more than $100 million from a dedicated supply-chain transformation initiative.3 Through fiscal 2030, leadership has targeted $3 billion in cumulative cost savings: approximately $2 billion via recurring HMM initiatives—averaging 4% of cost of goods sold annually—and $1 billion from structural supply chain and process redesigns.3 Management projected realizing at least $750 million of that aggregate target in fiscal 2027.5
Yet the strategic boundaries of cost optimization are etched plainly into the income statement. General Mills captured 4% to 5% annual HMM savings throughout the exact two-year window in which adjusted operating profit dropped from $3.6 billion to $2.8 billion. Productivity gains have become a treadmill requirement simply to maintain operating parity: they absorb commodity inflation, fund promotional discounting, and underwrite advertising campaigns, but they cannot manufacture top-line growth. For fiscal 2027, the company anticipated 4% to 5% input cost inflation,3 with the chief financial officer warning during the first-quarter earnings call that cost pressures would ramp from roughly 4% early in the year to near 6% by the fourth quarter, driven by higher-than-budgeted wheat prices.19 In competitive terms, HMM functions as an effective defensive shield, not a defensible economic moat.
The Walmart Relationship
Underpinning all four operating segments is a retail reality that rarely commands center stage in management presentations: acute customer concentration. In fiscal 2026, Walmart and its affiliates accounted for 22% of General Mills' consolidated net sales, including 31% of North America Retail revenue and 17% of Pet segment sales. Across both divisions, the five largest retail accounts generated 54% of North America Retail volume and 66% of North America Pet sales.3
Industry commentary frequently cites category captaincy—the advisory role wherein a dominant supplier helps a grocer curate shelf layouts and planograms—as proof of manufacturer leverage. In practice, category advisory services operate more like defensive overhead: an analytical concession a food giant must furnish simply to defend shelf space against a retail customer that holds the ultimate commercial upper hand. As mass merchants and warehouse clubs aggressively expand their private-label assortments and allocate prime display space to insurgent digital brands, General Mills' retail scanner analytics can slow shelf-space reallocation, but they cannot arrest it. Among the structural vulnerabilities confronting the enterprise, this degree of channel concentration represents one of the most consequential risks to long-term pricing power.
The operating machine that spans these four segments was assembled largely through aggressive corporate acquisitions, and that dealmaking track record warrants close scrutiny.
VII. The M&A Treadmill: Annie's, Blue Buffalo ($8B), Whitebridge ($1.45B), and The Yoplait Retreat ($2.1B)
A Portfolio in Constant Motion
When General Mills closed the sale of its Brazilian business in September 2026, management disclosed that the company had reshuffled roughly one-third of its net sales base through acquisitions and divestitures since fiscal 2018.21 Few packaged-food incumbents have overhauled their portfolios so extensively in less than a decade. Yet whether this continuous transaction churn created durable shareholder value remains an open question—one best evaluated asset by asset.
Annie's (2014)
In September 2014, General Mills agreed to acquire Annie's—the organic macaroni-and-cheese and snack maker recognized for its bunny mascot—for $46 per share, or approximately $820 million. The purchase price represented roughly four times trailing revenue, as Annie's had generated $204 million in net sales during its most recent fiscal year.22 Jeff Harmening, then serving as chief operating officer and announcing the transaction, noted that the organic and natural food segment had expanded at a 12% compound annual rate over the prior decade.22 Twelve years later, Annie's remains an active brand in the corporate portfolio listed in the company's annual report,3 with management evaluating its intangible assets annually. Because General Mills does not break out standalone financials for the brand, however, its ultimate return on invested capital cannot be independently verified.
Blue Buffalo (2018)
In February 2018, eight months after Jeff Harmening assumed the chief executive role, General Mills agreed to acquire Blue Buffalo Pet Products for $8.0 billion in cash.23 Founded as an upscale natural pet-food pioneer, Blue Buffalo had established strong brand loyalty across pet-specialty chains and e-commerce channels. It had generated roughly $1.3 billion in revenue and $319 million in adjusted EBITDA in 2017, meaning General Mills paid a rich multiple of approximately 25 times EBITDA.24
The transaction placed substantial leverage on the balance sheet. Funded through a combination of cash, debt, and approximately $1 billion in newly issued equity, the deal pushed net debt from roughly 3.0 times to 4.9 times EBITDA, prompting management to freeze the quarterly dividend—snapping a 13-year streak of annual increases—to direct operating cash flow toward debt paydown.24
The strategic rationale leaned heavily on the secular rise of "pet humanization"—the consumer tendency to treat companion animals as family members and pay premium prices for cleaner ingredient decks. General Mills wagered that its distribution muscle across conventional grocery aisles and mass merchants could scale Blue Buffalo far beyond its core specialty footprint. The distribution push delivered immediate revenue expansion, but sustaining underlying volume growth proved far more challenging.
Bolt-ons: Tyson Pet Treats and Whitebridge
Rather than pausing to digest its pet platform, General Mills pursued further category expansion. In May 2021, the company agreed to purchase Tyson Foods' pet treats business—comprising the Nudges, Top Chews, and True Chews lines—for $1.2 billion in cash. Factoring in an estimated $225 million tax benefit, the net effective purchase price settled near $975 million for an asset generating more than $240 million in annual sales.25
In November 2024, management doubled down again, announcing an agreement to acquire the North American premium cat feeding and pet treats business of Whitebridge Pet Brands, featuring Tiki Pets and Cloud Star, for $1.45 billion.[^26] The transaction closed on December 18, 2024, adding an operation with roughly $325 million in U.S. Nielsen-measured retail sales concentrated in pet-specialty and online channels.26 General Mills recorded approximately $1.09 billion of goodwill on the acquisition.3 Whitebridge represented the company's fifth pet-related transaction since 2018, following Blue Buffalo, the Tyson treats portfolio, Fera Pets, and European brand Edgard & Cooper.26
Selling Off Slower Businesses
As it assembled a pet portfolio, General Mills systematically pruned mature and structurally challenged food lines. In 2021, the company agreed to divest its 51% controlling interest in Yoplait's European business—which generated approximately $740 million in sales—to French dairy cooperative Sodiaal. In return, General Mills obtained full ownership of Yoplait Canada and secured a reduced royalty rate on the Yoplait and Liberté brands in North America.27 In 2022, it offloaded the Helper dinner kits and Suddenly Salad lines, which accounted for roughly $235 million in combined sales, to Eagle Family Foods for approximately $610 million.28
The defining retreat from center-store dairy came two years later. On September 12, 2024, General Mills agreed to divest its entire North American yogurt portfolio—encompassing Yoplait, Liberté, Go-Gurt, and Oui—to Lactalis in the United States and Sodiaal in Canada for $2.1 billion. The divested operations had generated roughly $1.5 billion in fiscal 2024 sales,29 implying a modest exit valuation of roughly 1.4 times revenue for a franchise that had once defined the domestic refrigerated dairy aisle. The U.S. transaction closed on June 30, 2025, carving out an asset that had generated approximately $1.2 billion in net sales during fiscal 2025.30
The retreat from international emerging markets was even more punishing. In 2012, General Mills had agreed to acquire Brazilian snack and seasonings manufacturer Yoki, a business with about 1.1 billion Brazilian reais in annual sales, as part of an ambitious strategy to double its Latin American business toward $1 billion.31 Financial press reports pegged the initial acquisition price at approximately $857 million. By March 2026, facing chronic currency volatility and operational friction, General Mills agreed to offload its Brazilian operations, including the Yoki and Kitano brands, to local food group 3corações for roughly 800 million reais, or approximately $153 million.32 Reflecting that stark value destruction, General Mills recognized a $1.0 billion net loss on the divestiture in fiscal 2026.5 The transaction formally closed in early September 2026.2120
Falsification Case #1: Yogurt
The claim: Established brand equity, refrigerated cold-chain distribution, and category captaincy at retail protect an incumbent packaged-food leader against insurgent disruption.
The record: Yoplait controlled roughly 25% of the U.S. yogurt market as recently as 2011, the year General Mills acquired a 51% controlling interest after licensing the brand domestically since 1977.33 Meanwhile, Hamdi Ulukaya had founded Chobani in 2005, purchasing an abandoned Kraft Foods processing facility in upstate New York for $700,000 and rolling out his first strained Greek yogurt to supermarket shelves in 2007.33 Over the ensuing decade, thicker, high-protein Greek yogurt surged from less than 1% to nearly half of all domestic yogurt consumption. General Mills' delayed response—launching a rushed Greek variant in 2010 that failed to gain consumer traction—proved costly. By 2017, Yoplait's sales were contracting at a 23% annual rate, and Chobani had eclipsed it as the top-selling yogurt brand in the United States.33 A General Mills innovation director later conceded the strategic misstep plainly: "It's no secret we were late."33
The verdict: The historical record falsifies the traditional CPG moat thesis whenever underlying consumer taste preferences undergo a fundamental structural shift. National cold-chain distribution and legacy promotional spending allowed Yoplait to defend retail shelf space for years, but they could not prevent shoppers from walking past it. Selling the business in 2024 at roughly 1.4 times revenue represented a tacit corporate concession that distribution access cannot rescue a misaligned product profile.
What would confirm or falsify the revised claim: The CPG distribution moat endures only as long as the underlying product formulation matches evolving consumer demand. The contemporary test for General Mills is whether its reformulation and functional extensions—such as Cheerios Protein, which management noted reached $100 million in sales17—can adapt quickly enough to prevent insurgent competitors from repeating the Chobani playbook across cereal and snacking aisles. Leadership has already acknowledged that small, agile specialty brands are capturing market share across North America Retail, notably in fruit snacks.1719
Falsification Case #2: Blue Buffalo
The claim: Acquiring Blue Buffalo would provide General Mills with a durable, high-margin growth engine insulated from center-store grocery stagnation and propelled by secular pet humanization.
The record: The segment's operating margins proved more resilient than its top-line trajectory. In fiscal 2024, Pet organic net sales declined 4%, even as segment operating profit rose 9%.4 Organic sales remained flat in fiscal 2025,18 and contracted 3% in fiscal 2026 despite modest gains in retail scanner takeaway.5 During the first-quarter fiscal 2027 earnings call, management revealed that dog food sales dropped by a high-single-digit percentage, driven down by weakness in the core Wilderness line, prompting leadership to acknowledge the need to "relook at the entire proposition" for that brand across formulation, packaging, and marketing strategy.19 In contrast, cat food expanded by double digits, lifted by the acquired Tiki brand.19
Balance-sheet accounting delivered the definitive verdict. At the close of fiscal 2026, General Mills recognized a $1.5 billion non-cash goodwill impairment charge on the North America Pet reporting unit, alongside a $250 million write-down on the acquired Nudges and True Chews brand intangibles.3 In its regulatory disclosures, the company noted that the impairment evaluation was triggered by a sustained decline in market capitalization and rising discount rates, while cautioning that the Blue Buffalo brand indefinite-lived intangible asset carried a heightened "risk of decreasing coverage."3
The verdict: The evidence materially narrows the original investment premise. Blue Buffalo remains a formidable premium brand with attractive operating margins near 19%, but it operates under the same structural laws as a mature consumer packaged goods line: susceptible to retailer de-stocking, economic trade-down, and emerging competition from refrigerated fresh pet food. It has not performed as an unencumbered secular compounder. Having paid 25 times EBITDA and subsequently written down roughly 19% of the initial $8.0 billion purchase price in goodwill, General Mills has generated a return on invested capital well below the hurdle rate required to justify that acquisition premium.
The KPI that settles it: Pet segment organic net sales growth. If organic growth re-accelerates into the mid-single digits while operating margins hold near 19%, the recalibrated thesis remains viable. A continuation of flat-to-contracting organic revenue, or an outright write-down of the Blue Buffalo brand trademark itself, would definitively falsify it.
The Overall M&A Record
Evaluating General Mills' portfolio reshuffling over the past quarter-century yields an unvarnished ledger. The 2001 Pillsbury mega-merger established category breadth and retail negotiating gravity. Annie's proved a culturally resonant but financially unquantified bolt-on. Blue Buffalo was acquired at an aggressive cyclical peak and has suffered steep goodwill impairments. The Tyson pet treats assets were written down within five years of acquisition. Whitebridge's Tiki cat line is generating double-digit gains, yet Yoki shed more than 80% of its acquired dollar value before being liquidated at an eight-figure salvage price. Yoplait, once a crown jewel of the dairy aisle, was offloaded at a distressed valuation multiple after missing an industry-defining consumer shift.
On the fourth-quarter fiscal 2026 earnings call, Harmening remarked that he took pride in the company's "disciplined" portfolio reshaping, while emphasizing that the hurdle rate for any future acquisitions is now "very, very high."17 The historical record provides far more justification for the latter caution than for the former assertion.
Because the executives who directed this capital-allocation cycle remain at the helm, the central question for shareholders turns on corporate governance and accountability.
VIII. Current Leadership, Execution, & The Earnings Call Stress Test
The Insider CEO
Chief Executive Jeff Harmening has spent his entire career at General Mills. After joining the company in 1994, he advanced through marketing roles across Betty Crocker, Yoplait, and Big G cereal, took the helm of Cereal Partners Worldwide as chief executive in 2012, returned to lead U.S. Retail in 2014, and rose to president and chief operating officer in 2016, chief executive in 2017, and board chairman in 2018.3 That deep institutional familiarity gives Harmening an intimate grasp of the company's manufacturing footprint, brand portfolio, and retail accounts. Yet that continuity also binds him directly to the strategic dilemmas now confronting the enterprise: he personally engineered the capital-allocation decisions of the past decade, directing the acquisitions of Blue Buffalo, the Tyson pet-treat lines, and Whitebridge, as well as the retreats from North American yogurt and Brazil.
Chief Financial Officer Kofi Bruce, who stepped into the role in 2020, brings a similarly internal resume. Bruce arrived at General Mills as treasurer in 2009 following finance roles at Ford Motor Company and Ecolab, subsequently serving as finance director for Yoplait and as corporate controller.3 In quarterly earnings calls, Bruce delivers a measured, granular defense of the balance sheet. Yet as the primary financial communicator, he has also borne the burden of walking back annual guidance across three consecutive fiscal years.
The most consequential leadership reorganization occurred in May 2026, when Dana McNabb, a 27-year company veteran whose tenure spanned leadership of U.S. Cereal, Europe and Australia, corporate strategy, and the combined North America Retail and Pet divisions, was appointed chief operating officer effective June 1, 2026, reviving an executive post that had sat vacant, alongside an election to the board of directors.34 In announcing the promotion, Harmening described McNabb as "a disciplined, strategic leader and results-driven operator" tasked to "restore profitable growth."34 McNabb now oversees all four operating segments.34 While market observers widely interpret the appointment as the establishment of a formal succession pipeline, management has made no explicit announcement regarding Harmening's tenure or the timing of an eventual transition.
Pay and Incentives
The executive compensation structure reflects conventional corporate performance benchmarks. According to the company's 2026 proxy statement, 80% of an executive's annual cash incentive is tied directly to corporate financial targets—evenly divided between organic net sales growth and adjusted operating profit growth—with the remaining 20% governed by individual performance metrics. In long-term equity incentives, half the award consists of performance share units evaluated across three-year organic sales growth and cumulative operating cash flow, adjusted by a relative total shareholder return modifier of up to plus or minus 25% and subject to a mandatory one-year post-vesting holding requirement.35 While the compensation architecture explicitly links payouts to cash generation and top-line expansion, the substantive governance question is whether realized executive pay has contracted in step with operational setbacks—an issue shareholders can evaluate at the upcoming virtual annual meeting on September 29, 2026.35
Falsification Case #3: Guidance
The claim: General Mills commands pricing power superior to packaged-food peers and can successfully rebuild unit volumes in the wake of post-pandemic inflation without relying on margin-dilutive promotions or price cuts.
The record: Tracking management's initial annual guidance against reported results provides an objective benchmark of forecasting reliability:
- In June 2023, management projected fiscal 2024 organic net sales growth of 3% to 4%. By December 2023, leadership lowered that forecast to flat to down 1%, citing "a slower-than-expected volume recovery" and a "faster normalization of competitive on-shelf availability."36 The fiscal year concluded with organic sales down 1% and volume down 3 points.4
- For fiscal 2025, the company guided organic net sales flat to up 1%.4 Actual organic sales contracted 2%.18
- For fiscal 2026, leadership initially forecast organic sales between down 1% and up 1%, with Harmening emphasizing that the company's "number one goal" was to "restore volume-driven organic sales growth."18 At the Consumer Analyst Group of New York (CAGNY) conference in February 2026, management revised organic sales guidance downward to a decline of 1.5% to 2% and reduced operating profit expectations to a contraction of 16% to 20%, pointing to "a slower pace and higher cost of volume recovery"—a revision that sent the stock down roughly 7%.37 The year ultimately closed with organic sales falling 2%, and the annual report acknowledged directly that the company did not meet its North America Retail volume recovery goal.53
The verdict: Across three consecutive fiscal years, General Mills missed its initial organic top-line guidance in the identical direction and for the identical structural reason. When consumer budgets tightened, the company's brands could not maintain premium pricing without surrendering unit volume, forcing management to fund promotional discounting simply to stabilize register takeaway. While executives have candidly acknowledged these execution shortfalls rather than blaming external anomalies, the repetitive pattern demonstrates that internal forecasting models have consistently overestimated consumer brand loyalty and pricing tolerance.
The KPI that settles it: North America Retail organic pound volume. Initial fiscal 2027 guidance forecasting organic net sales between down 1.5% and up 0.5% represents management's most subdued annual projection in years.5 Delivering results at or above the midpoint of that corridor without an intra-year downward revision would offer the first tangible evidence that forecasting discipline has re-anchored to market reality.
The Live Calls
Recent earnings calls highlight a leadership team promoting a new strategic narrative against persistent analyst skepticism.
On the Q4 fiscal 2026 call (July 1, 2026), Harmening outlined a sequential recovery strategy: while fiscal 2026 focused on resetting everyday retail price points, fiscal 2027 would target "a step change in the remarkability of our brands," anchored by product reformulations emphasizing protein, dietary fiber, bolder flavors, and fun.17 Wall Street analysts pressed leadership on execution specifics:
- Andrew Lazar of Barclays probed where North America Retail's lost market share had migrated. McNabb conceded that shelf share had been ceded not only to private label but also to agile insurgent specialty brands17—confirming that competitive pressure is squeezing the core portfolio from both budget and premium tiers simultaneously.
- Peter Grom of UBS questioned whether center-store category stagnation reflected temporary cyclical belt-tightening or secular decay. Harmening highlighted broad demographic headwinds and shifts toward protein and convenience, but acknowledged that underlying category trajectories remained difficult to forecast in an unsettled macroeconomic climate.17
- Tom Palmer of JPMorgan inquired about the operational timeline for the targeted $1 billion supply-chain and structural transformation savings. McNabb acknowledged that the initiative remained in its "early design phase,"17 leaving investors with limited visibility into near-term milestone delivery.
- Robert Dickerson of BTIG asked about the forward M&A pipeline. Harmening stated that capital allocation would prioritize stabilizing organic growth and reducing balance-sheet debt.17
On the Q1 fiscal 2027 call (September 23, 2026), management struck a more constructive tone, noting that newly launched products contributed 5% of net sales—up from 3% two years prior—and Harmening reported that legacy cereal banners Lucky Charms and Reese's Puffs were "back to growth."19 Consolidated organic sales stabilized at flat, while adjusted diluted earnings per share reached $0.75, down 13% in constant currency.20 Yet core operations remained under pressure: North America Retail organic net sales contracted 3% and segment operating profit dropped 15%, while North America Pet operating profit fell 12%.20 When Alexia Howard of Bernstein asked how long balance-sheet deleveraging would take to bring net debt back near 3.0 times EBITDA, Bruce acknowledged that the process would require "a couple of years."19 Underscoring that capital constraint, General Mills completed no share repurchases during the quarter, compared to $500 million in buybacks deployed in the prior-year period.20
Where Management Was Vague
Two critical strategic exposures continue to elicit imprecise responses from executive leadership.
The first is the operational turnaround timeline for the North America Pet division. On the fourth-quarter call, leadership cited an anticipated "low single digit headwind" from retailer inventory rebalancing in fiscal 2027,17 while the subsequent first-quarter call revealed that management must fundamentally rethink the Wilderness brand proposition across formulation, packaging, and marketing.19
The second ambiguity surrounds the long-term volume impact of GLP-1 appetite-suppressant medications. At CAGNY in February 2026, Harmening acknowledged that anti-obesity drugs "will have a lasting influence on the food market," steering consumer dietary habits toward smaller portion sizes and elevated intake of protein and fiber.38 Yet during the fourth-quarter call, management did not address the class of therapeutics directly,17 leaving investors without a quantified framework to assess how pharmaceutical appetite suppression might reshape center-store snacking and breakfast consumption.
Ultimately, executive credibility rests on whether the promised "remarkability" initiative translates into verifiable unit volume recovery over the coming quarters. That test leads directly to an examination of the structural competitive advantages General Mills truly commands.
IX. Strategic Powers & Five Forces Analysis
War-Game: The Cereal Aisle in 2026
Consider a grocery shopper standing in the cereal aisle in 2026. At eye level sits Honey Nut Cheerios. Directly beside it sits a supermarket private-label equivalent—toasted honey-nut oats in an almost identical yellow box, priced significantly lower. One shelf down sits an insurgent high-protein, low-sugar brand that originated online and earned national distribution at Target. Several aisles over, a consumer prescribed a GLP-1 appetite suppressant bypasses breakfast cereal entirely in favor of Greek yogurt and eggs.
That vignette encapsulates the structural battlefield General Mills confronts. Assessing the durability of the company's defensive perimeter requires evaluating its business through Hamilton Helmer's 7 Powers framework.
Hamilton Helmer's 7 Powers
Scale economies: real, but eroding. General Mills procures grain, packaging, and freight at national scale, operates high-throughput manufacturing plants, and amortizes marketing spending over vast distribution volumes, supporting its Holistic Margin Management initiatives. Yet manufacturing scale could not prevent North America Retail operating profit from contracting from $3.1 billion in fiscal 2024 to $2.2 billion in fiscal 2026.45 Meanwhile, the historic scale barrier of broadcast television advertising has steadily eroded as insurgent brands build awareness through social channels, targeted digital campaigns, and retail media networks.
Branding: bifurcated equity. Legacy trademarks including Cheerios, Lucky Charms, Pillsbury, and Old El Paso command enduring household recognition and emotional affinity. However, a 2-point contraction in price and product mix across North America Retail in fiscal 20265 demonstrates that the pricing power of branded equity reached its ceiling following cumulative post-pandemic price increases. Brand loyalty remains resilient where products offer distinct functional attributes—such as Cheerios Protein or Tiki Cat—but weakens rapidly in commoditized categories like commercial flour, basic baking mixes, and frozen pizza.
Cornered resource: none. Agricultural staples, sweeteners, edible oils, proteins, and packaging materials trade on transparent global commodity exchanges. While General Mills manages short-term volatility through systematic hedging—maintaining roughly 75% coverage on wheat for fiscal 202719—it possesses no proprietary ingredient sources, patented chemical compounds, or exclusive supply agreements that competitors cannot replicate.
Switching costs: negligible. Consumers face zero financial or operational switching costs when substituting a branded cereal or refrigerated dough roll with a private-label counterpart, and they can toggle back and forth between brands at every shopping trip.
Network effects: absent. The utility of consuming a box of Lucky Charms or Betty Crocker brownies does not increase as more consumers partake, denying packaged-food manufacturers the self-reinforcing adoption flywheels enjoyed by digital platforms.
Counter-positioning: incumbent disadvantage. Disruptors have repeatedly leveraged counter-positioning against General Mills: Chobani pioneered Greek yogurt, refrigerated fresh pet-food makers challenged shelf-stable kibble, and high-protein cereal startups bypassed center-store grocery aisles. In each instance, adopting the insurgent model early would have cannibalized General Mills' high-margin legacy manufacturing lines and packaging investments. Consequently, the company has historically responded by acquiring or replicating emerging formats after they gain critical mass. Blue Buffalo's entry into refrigerated fresh pet food in 202518 reflects this fast-follower playbook, with its Love Made Fresh offering scaling rapidly from a modest baseline.17
Process power: moderate and narrowing. Decades of proprietary engineering expertise in cereal extrusion, refrigerated dough preservation, and frozen snack assembly, combined with disciplined Holistic Margin Management routines, represent meaningful operational advantages. While these complex manufacturing capabilities cannot be replicated overnight, contract co-packers and private-label producers have steadily upgraded their processing technologies, narrowing the quality gap.
Summary: General Mills commands substantial scale and pockets of resilient brand equity, but it lacks switching costs, network effects, and cornered resources. Its foundational structural advantage remains low unit cost. However, operational results between fiscal 2024 and fiscal 2026 demonstrate that cost leadership defends operating margins only when brand equity can sustain a price premium.
Porter's Five Forces
Buyer power: acute. Customer concentration severely limits manufacturer leverage. Walmart alone accounted for 22% of consolidated net sales in fiscal 2026, while the top five retail accounts represented 54% of North America Retail and 66% of North America Pet volume.3 Retail gatekeepers control shelf planograms, slotting fees, end-cap merchandising, and promotional calendars—while competing directly with suppliers by expanding their proprietary store-brand portfolios.
Threat of substitutes: elevated and accelerating. The center-store pantry faces substitute pressure across multiple fronts: private-label cereal and baking staples, quick-service breakfast offerings, fresh perimeter groceries, ready-to-drink protein shakes, and pharmaceutical appetite suppression. The broader adoption of GLP-1 medications compounds substitution risk by steering consumer demand away from carbohydrate-dense snacks toward higher-protein alternatives.
Supplier power: low to moderate. Agricultural raw materials, energy, and packaging are standardized commodities traded on global markets. Nevertheless, periodic price shocks pass directly into production costs. Management's forecast of 4% to 5% input cost inflation in fiscal 2027, accelerating toward roughly 6% by the fourth quarter as wheat prices increase,319 underscores that input cycles retain substantial capacity to compress operating margins.
Threat of new entrants: moderate, but structurally expanding. Capital barriers to food manufacturing have lowered substantially. Contract manufacturers and co-packers allow venture-backed startups to commercialize formulas without building physical plants, while social channels, digital marketplaces, and retailer incubator programs provide capital-efficient customer acquisition. While maintaining national distribution across tens of thousands of grocery doors remains costly, insurgent brands can capture meaningful category share without ever achieving traditional conglomerate scale.
Rivalry: aggressive and structurally transformed. Industry rivalry underwent a dramatic shift following the corporate restructuring of Kellogg. After Kellogg separated into two entities in October 2023, Mars acquired snacking-focused Kellanova for approximately $36 billion, while Italian confectionery group Ferrero acquired WK Kellogg Co, the North American cereal operations, for $3.1 billion, with both transactions closing by the end of 2025.39 As a consequence, General Mills' primary cereal competitor is controlled by a private European confectioner, and its primary snacking rival belongs to a privately held American conglomerate. Because neither rival faces quarterly public-market earnings scrutiny, both can operate with longer investment horizons, potentially intensifying promotional discounting and marketing expenditure across the cereal and snack corridors.
Myth vs. Reality
Myth: Category captaincy grants General Mills control over grocery shelf space. Reality: Serving as category captain merely positions General Mills as an analytical advisor to retail merchants. Supermarket buyers retain sole authority over planograms and routinely allocate prime eye-level display space to their own private labels. The fact that Walmart accounts for 22% of consolidated revenue reflects structural retailer dependency, not supplier leverage.3
Myth: Holistic Margin Management functions as a competitive moat. Reality: Holistic Margin Management is an internal cost-control mechanism, not a competitive barrier. While HMM delivered productivity savings equivalent to roughly 5% of cost of goods sold in fiscal 2026, consolidated adjusted operating profit still fell 16%.53 Efficiency initiatives offset input inflation and fund promotional trade spending, but they cannot manufacture consumer demand.
Myth: The North America Pet segment serves as a secular growth engine. Reality: Organic net sales in Pet contracted in two of the past three fiscal years, culminating in $1.75 billion in non-cash impairment charges recognized in fiscal 2026.453 Segment gains remain concentrated in cat feeding led by the acquired Tiki brand, while the core Blue Buffalo dog food business continues to experience volume contraction.19
Myth: A century-long dividend record guarantees downside investment safety. Reality: While General Mills' uninterrupted dividend history is unbroken, balance-sheet leverage and contracting operating cash flows have narrowed payout coverage, transforming the dividend from a symbol of defensive resilience into an operational constraint.
These competitive pressures illustrate the structural friction General Mills faces across center-store aisles. The subsequent section examines the fundamental risks and industry shifts that could intensify that squeeze.
X. Material Risk Radar & The Skeptical-Investor Stress Test
1. GLP-1 Drugs
How it works: GLP-1 receptor agonists such as semaglutide and tirzepatide suppress appetite, prompting patients to disproportionately reduce their consumption of calorie-dense, sugary, and processed snack foods. Harmening has acknowledged that these therapies are "nudging some consumers toward smaller portions and more nutrient-dense protein and fiber-forward foods," with General Mills responding through extensions like Cheerios Protein, protein bars, reformulated granola lines, and smaller portion packs.38
How big it could be: A substantial portion of General Mills' North American portfolio relies on indulgent center-store staples: pre-sweetened cereals, Betty Crocker cake mixes and frostings, Pillsbury cinnamon rolls, fruit snacks, and Totino's pizza rolls. Management has not published a sensitivity analysis measuring the portfolio's exposure to GLP-1 adoption, leaving the ultimate revenue risk undisclosed. Yet pharmaceutical appetite suppression does not need to trigger an outright collapse in eating habits to disrupt financial projections. In categories where unit volumes are already stagnant or contracting, even a fractional, persistent volume headwind can turn mature cash-cow franchises into structural decliners. While higher-protein and fiber-rich offerings provide a strategic hedge, they remain a modest counterweight beside the company's vast legacy sweet-and-snack footprint.
2. Private Label and Insurgent Brands
How it works: Following cumulative post-pandemic price increases, budget-conscious households have systematically migrated toward supermarket private-label alternatives. Because modern store-brand quality increasingly rivals national brand benchmarks, many shoppers do not revert to branded staples once their routines adjust. On the fourth-quarter fiscal 2026 earnings call, leadership acknowledged that private label captured market share during the fiscal year, even as nimble insurgent brands took share on the premium end.17 During the first-quarter fiscal 2027 call, McNabb noted that financially stressed middle- and lower-income consumers continued to delay purchases until promotional discounts appeared on shelves.19
Why it matters: General Mills faces a structural squeeze from both ends of the retail shelf. At the low end, private-label lines capture price-sensitive shoppers unwilling to pay a branded premium. At the high end, agile specialty labels siphon away affluent consumers seeking specialized functional benefits, leaving legacy mass-market brands trapped in an increasingly commoditized middle.
3. Customer Concentration
How it works: With Walmart alone accounting for 22% of consolidated net sales and the top five retail accounts generating more than half of North America Retail revenue,3 any shift in a dominant merchant's inventory targets, shelf planograms, or private-label strategy flows directly onto General Mills' income statement. That vulnerability is already apparent: in fiscal 2026, Pet segment shipments lagged measured retail takeaway by two percentage points, an operational gap management attributed directly to major retail partners systematically tightening their inventory holdings.317 When a handful of retail gatekeepers command the bulk of distribution, inventory destocking moves from a logistical footnote to an acute drag on reported revenue.
4. Pet Food Trends and Fresh Food
How it works: Blue Buffalo built its brand equity as an exclusive, high-margin pet-specialty pioneer. Expanding distribution into mass merchants and grocery aisles delivered immediate volume, but diluted its premium perception. At the same time, younger pet owners are gravitating toward fresh, refrigerated, and gently cooked meal formats, while shifting demographically toward smaller dog breeds that consume less caloric volume by weight. Management acknowledged these changing ownership dynamics on the first-quarter fiscal 2027 earnings call when pressed on structural headwinds in dog food.19 The balance-sheet implications are acute: General Mills' annual report cautioned that the Blue Buffalo indefinite-lived brand intangible carried a heightened "risk of decreasing coverage" during its annual impairment assessment.3 With roughly $21 billion in goodwill and indefinite-lived intangible assets anchored to the balance sheet,3 additional non-cash impairment write-downs remain a substantial accounting vulnerability if premium volume continues to erode.
5. Balance Sheet and the Dividend
At the close of fiscal 2026, General Mills carried approximately $12.4 billion in long-term debt alongside $1.1 billion in debt maturing within twelve months, against just $454 million in cash and cash equivalents.5 Stockholders' equity contracted from $9.2 billion to $7.4 billion, primarily eroded by non-cash impairment charges.5 While the business generated $1.6 billion in free cash flow during the year, it disbursed $1.3 billion in common dividends and deployed $500 million toward share repurchases.3
The cash arithmetic is unyielding. Operating free cash flow comfortably covered the dividend alone, but fell short of funding both the dividend and share buybacks—a capital shortfall that explains why share repurchases ceased entirely in the first quarter of fiscal 2027.20 With a quarterly dividend of $0.61 per share translating to an annual distribution of $2.44, against management's fiscal 2027 adjusted earnings guidance of $3.00 to $3.20 per share,5 the forward payout ratio has surged to between 76% and 81%—a level far above historical norms. With the stock trading near $35, the resulting dividend yield hovers near 6.8%.9 In equity markets, a yield at that level rarely reflects defensive safety; it signals pronounced skepticism regarding forward earnings stability or dividend sustainability. The enterprise's unbroken 127-year dividend record5 exerts immense cultural and institutional pressure against an outright payout cut. Yet maintaining that distribution constrains capital allocation, inevitably prolonging the balance-sheet deleveraging process that leadership concedes will require "a couple of years."19
6. The Activist Stress Test
A skeptical activist investor scrutinizing General Mills would likely assemble a three-pronged critique.
First, split up or sell. The precedent established by Kellogg's 2023 corporate separation culminated in both successor entities being acquired—Kellanova by Mars and WK Kellogg Co by Ferrero—at meaningful valuation premiums.39 An activist could contend that General Mills should pursue a similar structural split, separating its mature, cash-generative center-store cereal and meals operations into a standalone, leverageable dividend vehicle while housing Pet and premium snacking within a faster-growing consumer entity. Alternatively, an activist could press to auction specific underperforming franchises to strategic buyers capable of extracting superior manufacturing synergies.
Management's likely response: Cereal, snacking, and baking divisions share integrated production plants, shared logistics lanes, unified sales teams, and collective bargaining leverage with major grocers. Unwinding those shared operations would create duplicative corporate overhead and diminish negotiating weight with retail gatekeepers. While that operational friction is real, it mirrors the exact synergy rationale management deployed for years to justify retaining European yogurt and Brazilian snacks before offloading both at steep valuation discounts.
Second, accountability. The chief executive who authorized the acquisition of Blue Buffalo at 25 times EBITDA remains board chairman and chief executive eight years later, presiding over $1.75 billion in pet-related impairments and three consecutive fiscal years of reduced top-line guidance. While reviving the chief operating officer role represents an initial governance step, an activist would demand a concrete succession roadmap, board refreshment, and executive compensation formulas tied directly to return on invested capital rather than near-term adjusted earnings metrics.
Third, capital allocation. Management deployed $1.2 billion toward share repurchases in fiscal 2025,5 retiring stock at peak post-pandemic valuations immediately before operating profits deteriorated and the share price slid toward multi-year lows. Repurchasing equity aggressively at cyclical highs only to halt buybacks when shares trade at an elevated dividend yield reflects a classic capital-allocation misstep that eroded rather than preserved shareholder value.
Where this leaves investors: In isolation, none of these operational headwinds threatens corporate solvency. The strategic concern is that every vector compounds in the same direction: compressing unit volume, eroding branded pricing power, intensifying retailer leverage, and narrowing balance-sheet flexibility. To be credible, any constructive investment thesis must articulate which catalyst can realistically reverse that collective drift.
XI. The Investment Thesis: Bull vs. Bear Case
The Bear Case
Persistent volume attrition. Organic unit volume in North America Retail has failed to expand for three consecutive years, despite targeted price concessions implemented in fiscal 2026, and segment organic net sales contracted again in the first quarter of fiscal 2027.320 If consumer demand weakness reflects structural pressures—compounded by the adoption of GLP-1 medications, the narrowing quality gap of private-label offerings, and shelf gains by nimble insurgent brands—productivity savings from Holistic Margin Management will merely decelerate the pace of decline rather than arrest it.
An unrewarded dealmaking ledger. General Mills' capital-allocation track record over the past decade has produced substantial balance-sheet write-downs without generating sustainable top-line momentum. Blue Buffalo was acquired at an aggressive peak multiple of 25 times EBITDA and subsequently incurred deep goodwill impairments; the acquired Tyson pet-treat lines were written down within five years; Yoki was liquidated at a steep salvage valuation; and Yoplait was offloaded at roughly 1.4 times revenue after surrendering its category leadership to Greek yogurt insurgents.2433229 The marquee growth bets funded over the past ten years have consistently failed to justify their acquisition premiums.
Intensifying competitive rivalry. Market structure across the center store has shifted unfavorably. Following the corporate separation and subsequent sales of Kellogg's legacy businesses, General Mills' primary cereal and snacking adversaries are now controlled by well-capitalized private conglomerates—Mars and Ferrero—unconstrained by quarterly public-market earnings scrutiny.39 At the same time, retail gatekeepers continue to prioritize their own high-margin store brands, while venture-backed specialty labels siphon away affluent shoppers, leaving General Mills' legacy mass-market portfolio squeezed from both pricing tiers.
Balance-sheet inflexibility. With leverage lingering well above management's 3.0-times EBITDA target, share repurchases halted, and the common dividend consuming the overwhelming majority of free cash flow,2019 General Mills faces a compressed margin for error. Elevated debt-service requirements and dividend commitments leave little discretionary capital to absorb unexpected commodity inflation or fund aggressive brand reinvestment.
Forecasting credibility deficits. Having revised its annual organic sales guidance downward across three consecutive fiscal years due to slower volume recovery and competitive shelf-space pressure,361837 executive leadership faces deep skepticism on Wall Street. Market participants are unlikely to price in management's fiscal 2027 turnaround targets until the company demonstrates verifiable top-line stabilization in reported results.
The Bull Case
Enduring cash conversion. Even amid severe operational headwinds and margin contraction, General Mills generated $1.6 billion in free cash flow during fiscal 2026 and projected an operating cash conversion rate of approximately 95% for fiscal 2027.35 For yield-oriented investors, few consumer staple incumbents deliver comparable aggregate cash payouts supported by a largely defensive, investment-grade operating base.
Emerging operational green shoots. While consolidated volume remains subdued, several portfolio indicators suggest stabilizing momentum. Consolidated organic net sales held flat in the first quarter of fiscal 2027, newly launched products expanded to account for 5% of net sales, legacy cereal stalwarts Lucky Charms and Reese's Puffs returned to growth, and Cheerios Protein crossed the $100 million mark. In premium pet care, Tiki Cat and Blue Buffalo's Love Made Fresh refrigerated offering each delivered approximately 80% growth in the fourth quarter of fiscal 2026, while the International and Foodservice divisions generated double-digit operating profit expansion.201917
A streamlined, higher-margin portfolio. Management's systematic pruning of structurally challenged assets—including the divestitures of North American and European yogurt, Brazilian operations, Helper dinner kits, and Green Giant vegetables—has removed chronic operational drags. The remaining core consists predominantly of market-leading cereal, snacks, Mexican meal solutions, refrigerated dough, premium pet food, and commercial foodservice, creating a more cohesive portfolio characterized by structurally higher gross margins.
A disciplined, proven cost engine. Holistic Margin Management represents General Mills' most consistent execution capability. A targeted $3 billion in cumulative cost savings through fiscal 2030—combining routine annual productivity gains with structural supply-chain optimization—provides substantial internal funding to absorb commodity inflation, underwrite promotional price points, and finance brand innovation without requiring external capital.3
Subdued market expectations. With the equity yielding near 6.8% and the share price down roughly 31% from its 52-week high,9 prevailing market valuations already reflect significant fundamental headwinds, multiple contraction, and skepticism over dividend durability. While an elevated yield does not guarantee intrinsic value, compressed multiples mean that even modest operational stability could catalyze a meaningful re-rating.
Weighing It
The historical evidence supports a calibrated, narrower version of the constructive thesis. General Mills is no longer the dependable high-single-digit total return compounder of past decades. That legacy model presumed baseline organic volume growth of 2%—a threshold the company has failed to achieve since the post-pandemic inflationary spike subsided. Instead, the operational record depicts a highly disciplined cost operator and potent cash generator whose legacy center-store brands have surrendered pricing power, and whose aggressive debt-funded acquisitions have yet to generate satisfactory returns on invested capital. Whether the equity functions as a classic value trap or an attractive mean-reversion opportunity hinges almost entirely on whether management's brand-remarkability initiative can restore unit volume growth without triggering another round of margin-dilutive promotional discounting.
The Three KPIs That Settle It
- North America Retail organic pound volume: The ultimate litmus test of whether brand equity can stimulate demand without relying on margin-eroding price cuts. Investors need to see quarterly volume trajectories inflect sustainably from contraction toward flat or positive territory.
- North America Pet organic net sales growth: The definitive benchmark for the Blue Buffalo investment thesis. While Whitebridge's Tiki Cat line provides double-digit momentum, the core dog food franchise—and the Wilderness line in particular—must stabilize and return to growth to validate the platform's acquisition premium.
- Free cash flow after dividend distributions: The vital metric governing balance-sheet flexibility. This surplus cash flow determines how quickly management can pare down debt toward its targeted 3.0-times leverage ratio and create capacity to reactivate share repurchases.
XII. Epilogue & Business Lessons
A Company That Keeps Rebuilding
The A Mill ruins are now part of the Mill City Museum on the Minneapolis riverfront.1 A few miles away, the enterprise that grew out of that limestone facility is executing another rebuild. In less than a decade, it has divested businesses that once defined its presence in grocery aisles, recognized substantial balance-sheet write-downs on its premier pet acquisition, and installed a veteran chief operating officer to oversee all four operating segments.
General Mills has rebuilt before. After the 1878 explosion, it rebuilt with advanced roller technology. In 1928, it consolidated regional millers to escape bulk commodity margins through branded packaged foods. Following the conglomerate experiments of the 1960s and 1970s, it dismantled its non-food holdings to refocus on pure-play food manufacturing. After acquiring Pillsbury in 2001, it scaled its distribution muscle across the supermarket. For public market investors, the core question is whether the current transformation will mirror those historic turnarounds—or settle into the trajectory of a mature cash generator funding an elevated dividend yield while unit volumes slowly erode.
Four Lessons
1. Branding is how a commodity business escapes the commodity trap, but it has to be renewed. James Ford Bell's decision to shift from bulk flour to consumer packaged goods insulated the company from cyclical agricultural margins. Yet brand equity is not a permanent annuity. As Yoplait's retreat before Chobani's Greek yogurt demonstrated, and as recent price concessions across North America Retail confirm, legacy brand recognition cannot sustain a premium price if product formulations fail to evolve alongside consumer tastes.
2. Beware diversification. Ventures into toys and fashion during the 1970s, the ill-fated expansion into Brazilian snacks, and the debt-funded purchase of Blue Buffalo at 25 times EBITDA each began as compelling growth stories. Yet acquisitions made at cyclical peaks or outside core operational capabilities generated margin dilution and subsequent balance-sheet impairments. Historically, General Mills created the most durable shareholder value when it recognized the limits of its core competencies and exited non-core holdings cleanly—as it did with Darden Restaurants—before they impaired consolidated returns.
3. Moats need maintenance. Dominant shelf space, national logistics networks, and category captaincy can slow market-share attrition, but they cannot force consumers to buy. Yoplait’s refrigerated distribution could not prevent shoppers from switching to Greek yogurt, just as center-store shelf presence cannot insulate legacy cereals and snacks from high-protein preferences, GLP-1 appetite suppression, and agile insurgent brands. In consumer packaged goods, retail distribution is an operating prerequisite, not an insurmountable barrier to entry.
4. Cost discipline matters, but it is not enough. Holistic Margin Management remains one of the most effective productivity engines in the packaged-food sector, systematically offsetting input cost inflation and generating cash to fund promotional spending. Yet recurring productivity savings could not prevent operating profit from contracting when baseline unit volumes stagnated. Cost efficiency creates essential operational flexibility, but productivity gains translate into sustainable enterprise value only when the brands they fund can command price and defend volume.
The company's future, like its origins on the Mississippi riverbank, will ultimately be decided by a straightforward commercial reality: whether consumers find enough value in its packaged foods to continue paying a premium over the raw commodities inside.
References
-
Washburn A Mill Explosion, 1878 — MNopedia, Minnesota Historical Society ↩↩↩↩
-
As America Turns 250, General Mills Reflects on 160 Years of Shared Traditions and Milestones — General Mills ↩↩↩↩↩↩
-
General Mills Form 10-K Annual Report for the Fiscal Year Ended May 31, 2026 — General Mills, 2026-07-01 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
General Mills Reports Fiscal 2024 Fourth-quarter and Full-year Results and Provides Fiscal 2025 Outlook (Exhibit 99, Form 8-K) — U.S. SEC, 2024-06-26 ↩↩↩↩↩↩↩↩↩
-
General Mills Reports Fiscal 2026 Fourth-quarter Adjusted Results in Line with Company Expectations (Exhibit 99, Form 8-K) — U.S. SEC, 2026-07-01 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
General Mills, Inc. — Encyclopedia.com (International Directory of Company Histories) ↩↩↩↩↩↩↩↩↩↩↩↩
-
General Mills Reaffirms Full-Year Guidance as International Profit Jumps 14%. Is the Turnaround Finally Working? — The Motley Fool, 2026-09-23 ↩↩↩
-
The First U.S. Human-Operated Submersible Changed the Course of Oceanography — IEEE Spectrum ↩↩
-
Darden Restaurants Inc. — Encyclopedia.com (International Directory of Company Histories) ↩↩↩↩
-
General Mills and Diageo Announce Agreement for General Mills to Acquire Pillsbury (Exhibit 99.1, Form 8-K) — U.S. SEC, 2000-07-17 ↩↩↩↩↩
-
International Multifoods Corporation Form 8-K on Acquisition of Pillsbury Dessert and Specialty Products Businesses — U.S. SEC, 2001-11 ↩↩↩
-
Federal Trade Commission Considers General Mills/Pillsbury Merger — U.S. Federal Trade Commission, 2001-10-23 ↩
-
General Mills Completes Acquisition of Pillsbury (Exhibit 99.1, Form 8-K) — U.S. SEC, 2001-11-02 ↩↩↩
-
General Mills To Sell Green Giant To B&G Foods — General Mills Investor Relations, 2015-09-03 ↩
-
General Mills (GIS) Q4 2026 Earnings Call Transcript — The Motley Fool, 2026-07-01 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
General Mills Reports Fiscal 2025 Fourth-quarter and Full-year Results and Provides Fiscal 2026 Outlook (Exhibit 99, Form 8-K) — U.S. SEC, 2025-06-25 ↩↩↩↩↩↩
-
General Mills (GIS) Q1 2027 Earnings Call Transcript — The Motley Fool, 2026-09-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
General Mills Reports Fiscal 2027 First-quarter Results and Reaffirms Full-year Outlook (Exhibit 99, Form 8-K) — U.S. SEC, 2026-09-23 ↩↩↩↩↩↩↩↩↩↩
-
General Mills Completes Sale of Business in Brazil to 3corações — General Mills Investor Relations, 2026-09 ↩↩↩
-
General Mills To Acquire Annie's — General Mills Investor Relations, 2014-09-08 ↩↩
-
General Mills Buys Blue Buffalo for $8 Billion in Push Beyond Human Food — The Wall Street Journal, 2018-02-23 ↩
-
General Mills' Major Acquisition and Dividend Freeze: What Dividend Investors Need to Know — Simply Safe Dividends ↩↩↩
-
General Mills to Acquire Tyson Foods' Pet Treats Business (Exhibit 99, Form 8-K) — U.S. SEC, 2021-05-14 ↩
-
General Mills Completes Acquisition of Whitebridge Pet Brands' North American Premium Cat Feeding and Pet Treating Business — General Mills Investor Relations, 2024-12-18 ↩↩
-
General Mills Announces Proposed Sale of European Yoplait Operations to Sodiaal — General Mills Investor Relations, 2021-03-23 ↩
-
General Mills to sell Helper, Suddenly Salad for $610M — Food Dive, 2022-05-25 ↩
-
General Mills Sells Yoplait and Liberté Yogurt Businesses to Lactalis and Sodiaal for $2.1B — Food Dive, 2024-09-12 ↩↩
-
General Mills Completes Sale of U.S. Yogurt Business to Lactalis — General Mills Investor Relations, 2025-06-30 ↩
-
General Mills to Acquire Yoki Alimentos (Exhibit, Form 8-K) — U.S. SEC, 2012-05-24 ↩
-
General Mills Brazil Sale: $1B Loss on Yoki Exit — The Rio Times, 2026 ↩↩
-
General Mills Loses the Yogurt Wars — Fortune, 2017-05-22 ↩↩↩↩
-
General Mills Names Dana McNabb Chief Operating Officer — General Mills Investor Relations, 2026-05-06 ↩↩↩
-
General Mills Notice of 2026 Annual Meeting of Shareholders and Proxy Statement (Schedule 14A) — U.S. SEC, 2026-08-10 ↩↩
-
General Mills Reports Fiscal 2024 Second-quarter Results and Updates Full-year Outlook (Exhibit 99, Form 8-K) — U.S. SEC, 2023-12-20 ↩↩
-
General Mills reduces forecast for fiscal 2026 — Food Business News, 2026-02-18 ↩↩
-
Food makers warn GLP-1s will have 'lasting influence' on sector — Food Dive, 2026-02 ↩↩
-
Kellogg split: How Kellanova and WK Kellogg ended up sold to Mars and Ferrero — Bakery and Snacks, 2026-02-27 ↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube