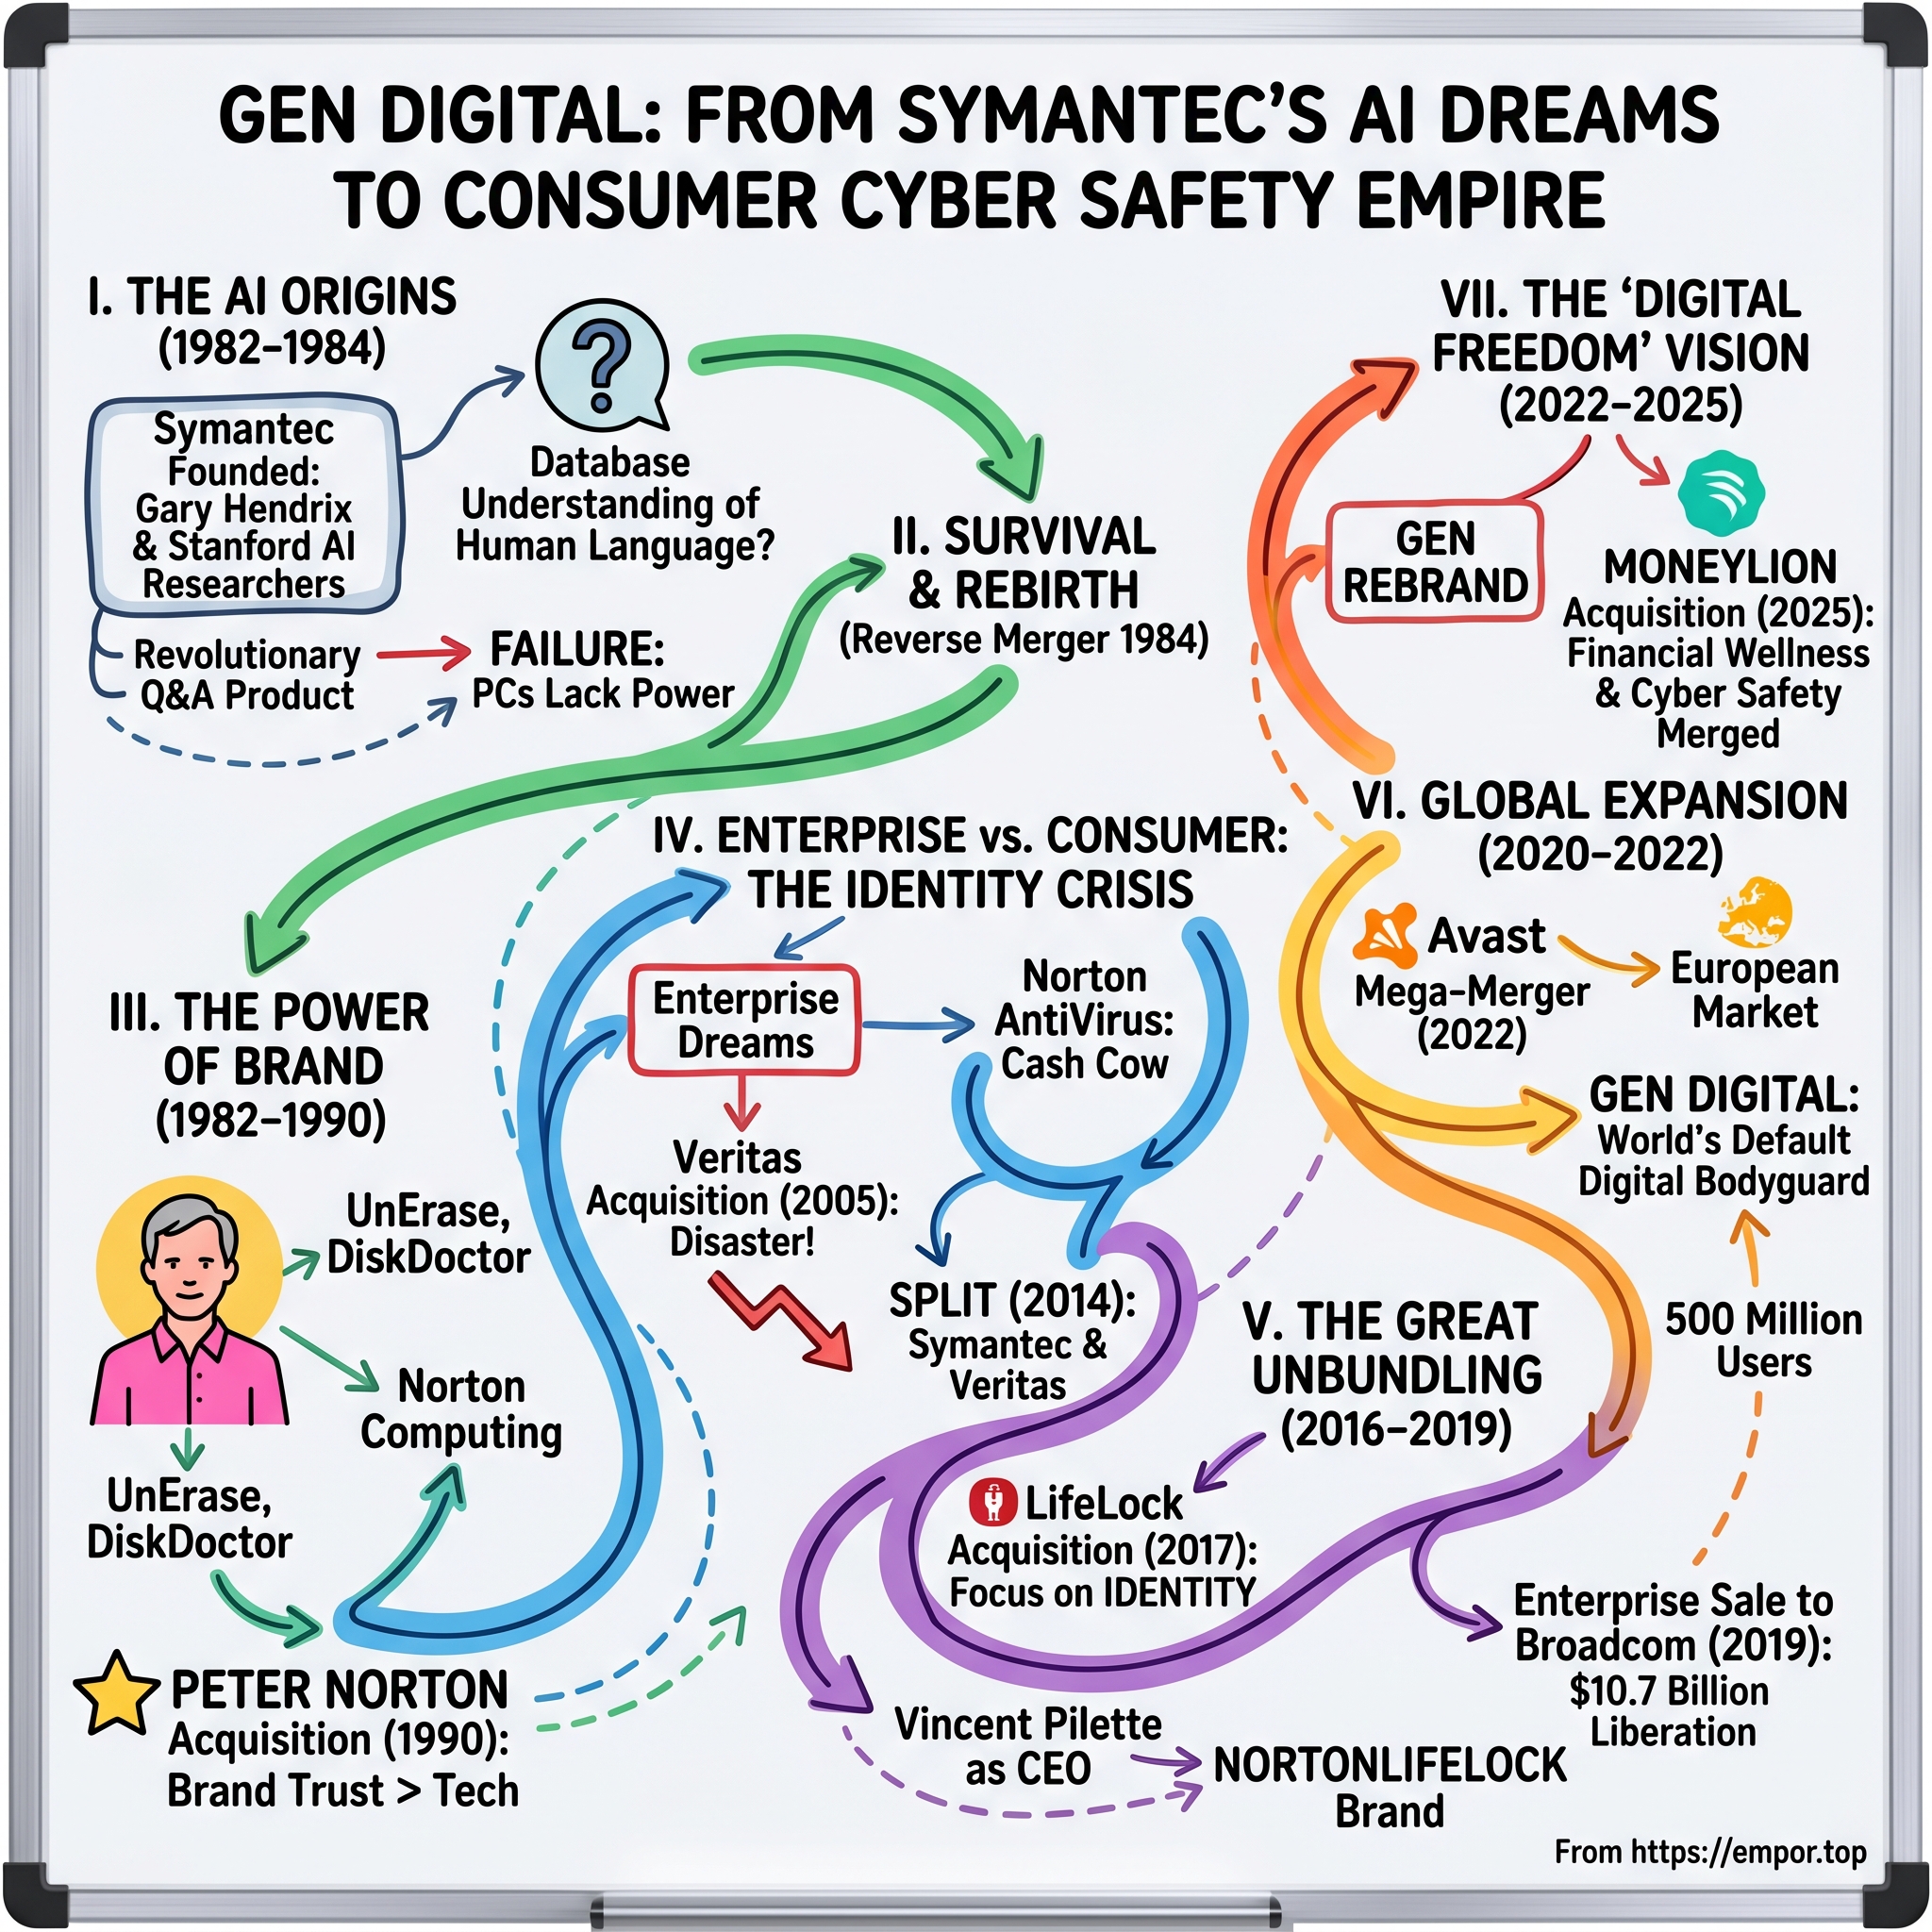
Gen Digital: From Symantec's AI Dreams to Consumer Cyber Safety Empire
I. Introduction & Episode Roadmap (10–15 min)
Picture two office buildings roughly 9,500 kilometers apart. One sits in the Sonoran Desert heat of Tempe, Arizona, far from the Silicon Valley campuses where the company spent its first four decades. The other stands in Prague, a short walk from the Vltava River, in a city where two Czech programmers once traded virus-removal code on floppy disks before the fall of the Iron Curtain.
Both sites serve as dual headquarters for Gen Digital. Most of the people whose digital lives the company protects never encounter that corporate umbrella. Instead, they know its consumer-facing brands: Norton, LifeLock, Avast, AVG, Avira, CCleaner, and MoneyLion.
The paradox at the center of this narrative sounds like a riddle. A business founded in 1982 as an artificial-intelligence research lab—aiming to teach computers to understand natural English—evolved into one of the most reliable cash generators in consumer software. It achieved that scale by monetizing products few consumers actively want to contemplate: protection against malware, online scammers, and identity thieves.
In the fiscal year ended April 3, 2026, Gen crossed $5.0 billion in revenue for the first time, up 27% on a reported basis, and delivered a non-GAAP operating margin of 50.9%.1 Free cash flow reached roughly $1.52 billion.1 The company operated with approximately 3,900 employees, generating well over $1 million in revenue per employee.2
That corporate identity reflects an evolving operating strategy. Symantec Corporation rebranded as NortonLifeLock Inc. in November 2019, and NortonLifeLock became Gen Digital Inc. in November 2022, trading on Nasdaq under the ticker GEN. Each name change marked a retreat from a historical anchor: first divesting its enterprise cybersecurity ambitions, and later shedding its identity as a single-brand American software house.
The company's customer scale is substantial, though segmented. Gen reports roughly 500 million total users worldwide, the vast majority using free software tiers.2 At the close of fiscal 2026, the company counted 79 million paid customers, up from 68 million twelve months earlier.1 By the first quarter of fiscal 2027, that figure reached 81 million.3
Crucially, those figures diverge from the operating metric that historically defined the business. Before acquiring MoneyLion, Gen reported approximately 40.4 million direct paying customers, direct average revenue per user of about $7.26 per month, and an annual retention rate of 78%.4 The expanded "paid customer" metric includes anyone logging at least one paid transaction over the trailing twelve months, absorbing marketplace and fintech users into the total.2 Understanding this definitional shift is critical to evaluating the underlying business.
This structural evolution poses a central strategic question: Is Gen Digital a durable consumer subscription franchise whose brand equity, user habits, and recurring billing relationships compound cash flows over time? Or is it a roll-up of maturing desktop antivirus assets reliant on auto-renewals, increasingly challenged as Microsoft, Apple, and Google integrate baseline security natively into operating systems?
The record suggests a middle ground. Core antivirus security continues to grow at low-single-digit rates, while top-line acceleration stems primarily from identity protection and consumer finance—offerings that carry narrower operating margins and different underwriting and regulatory exposures.
The analysis ahead examines that transformation in sequence: - The origins in an AI lab adjacent to Stanford University and Gordon Eubanks' turnaround; - Peter Norton's pioneering of consumer software branding, followed by Symantec's conglomerate era and the $13.5 billion merger with Veritas; - The whistleblower investigation, Starboard Value's activist campaign, and the enterprise sale to Broadcom; - Vincent Pilette's roll-up strategy across Avira and Avast, followed by the acquisition of MoneyLion; - An evaluation of the product engine, historical data controversies, unit economics, and capital allocation; and - The competitive landscape, management scorecard, and bull and bear investment theses.
Across four decades, Gen Digital's shareholder value was repeatedly created—and compromised—by portfolio transactions. Tracking those portfolio decisions reveals the durability of the underlying cash engine.
 Subscribe on LinkedIn
II. The Stanford AI Dream & The C&E Rescue (1982–1984) (20–25 min)
In 1982, "artificial intelligence" did not refer to generative chatbots composing poetry. It meant computer scientists attempting to coax a machine into answering plain-English questions—such as "Which salesmen in Ohio sold more than $50,000 last quarter?"—without forcing the user to master a formal query language. Gary Hendrix had spent years researching that exact problem at SRI International, the Menlo Park research institute spun out of Stanford University. That year, he founded Symantec alongside a group of Stanford researchers, funded by a grant from the National Science Foundation.6
The ambition was substantial, but the timing proved difficult. Hendrix's team set out to build a natural-language database product that interpreted user intent. Yet techniques of that caliber had been developed on minicomputers—refrigerator-sized machines owned by universities and corporate research facilities. The personal computer market was in its infancy; IBM had introduced the IBM PC only the prior year, equipped with memory that was minuscule by laboratory standards. Software engineered for larger computers did not easily translate to early microcomputers.
It was a classic failure mode for early software ventures: the technical premise was sound, but the product was built for hardware that consumers did not yet own. Symantec depleted its initial capital without completing a commercial product capable of generating cash flow. The company that would eventually report a 50% operating margin began life as an academic research project with no underlying revenue.
The rescue came from an operator with a distinctly commercial orientation. Gordon Eubanks had developed CBASIC, a widely adopted programming language during the CP/M operating system era. Alongside Dennis Coleman, he led C&E Software, which was designing an integrated file manager and word processor for the PC. In 1984, C&E and Symantec merged. The combined entity retained the Symantec name, Eubanks assumed the role of chief executive, and venture capitalist John Doerr backed the transaction and joined the board.6
Eubanks recognized what the research scientists had overlooked: Hendrix's natural-language engine did not need to run an enterprise database to be commercially viable. Instead, it could serve as an intuitive front end for a straightforward desktop PC application. The result was Q&A, launched in 1985, which paired a flat-file database with a natural-language query interface capable of understanding a vocabulary of roughly 600 words.6 For small-business owners, Q&A eliminated the need to memorize database command syntax, allowing them to search customer records by typing plain-English questions.
While Q&A earned critical acclaim, its commercial traction alone was insufficient to sustain the business. Symantec generated approximately $1.4 million in sales in 1985, and Q&A brought in only about $8 million across its first two years on the market.6 The company did not post its first profitable year until 1988, following six consecutive years of losses.6 Faced with the slow pace of organic product development, Eubanks instituted the strategic playbook that would govern the company for the next four decades: acquiring software assets rather than building them internally.
In 1987 alone, Symantec acquired Breakthrough Software, developer of the Time Line project manager; Living Videotext, maker of the ThinkTank outliner; and Think Technologies, which built programming compilers for the Macintosh.6 By 1988, sales had expanded to $19.6 million, and the company completed its initial public offering on June 23, 1989.6
This origin sequence established the corporate pattern. Symantec's first defining commercial transaction was a merger, and its subsequent growth was powered by programmatic dealmaking. From 1984 onward, the company developed an organizational core competency around buying external software products, integrating them, and distributing them through retail and commercial channels. That M&A engine eventually assembled the Norton franchise, drove the consolidation of Avira and Avast, and prompted the acquisition of MoneyLion—just as it had driven the $13.5 billion acquisition of Veritas. Strategic acquisition has remained the defining constant of the enterprise, and the core analytical question is identifying where that discipline created shareholder value and where it eroded it.
The next transaction provided the company with its enduring consumer identity—and it originated with a programmer who had accidentally deleted a file.
III. The Peter Norton Acquisition & Brand Moats (1982–1990) (30–35 min)
Every consumer software franchise has an origin story, and Norton's was built on a relatable human error. In the early 1980s, programmer Peter Norton accidentally deleted an important file on his IBM PC. Rather than retyping the lost work, he reverse-engineered how DOS managed disk storage.
He realized that deleting a file did not actually erase the underlying data from the drive; it merely flagged the storage clusters as available for overwriting. If no new data had taken their place, the original bits could be recovered. Norton wrote a program to automate that recovery, creating the foundation for the Norton Utilities suite and launching Peter Norton Computing in 1982.7
The library analogy explains its immediate appeal: discarding a book merely meant pulling its index card from the catalog while the volume remained on the shelf. Norton's UnErase tool simply rebuilt the card. For an early generation of personal computer users who risked losing a full day of work to a single errant keystroke, the utility felt indispensable—and consumers were eager to pay for that reassurance.
Norton's most durable breakthrough, however, was in marketing. System utility software was abstract, intimidating, and functionally opaque to lay users. Norton responded by placing his own portrait on the retail box: a smiling, bearded programmer with folded arms, posed in a shirt and tie, projecting calm competence. That photograph transformed an arcane diagnostic tool into an interpersonal relationship with a trusted expert. Decades before personal branding became standard software doctrine, Norton demonstrated that consumers buy peace of mind from an identifiable figure far more readily than they evaluate technical specifications.
This marked the debut of what eventually became Gen Digital's core economic asset: a consumer brand promising that someone competent is watching over the machine. The underlying mechanism is fundamental to the company's multi-decade history. A non-technical consumer cannot independently verify whether one security or utility engine outperforms another.
While independent testing laboratories publish comparative benchmarks, few retail buyers consult them. As a result, the purchasing decision is fundamentally an exercise in trust under conditions of information asymmetry. When buyers cannot directly measure software efficacy, a familiar brand serves as a proxy for product quality. That dynamic explains why the Norton moniker retained commercial value for more than four decades, even as the underlying codebase was rebuilt and replaced across multiple operating-system cycles.
By the late 1980s, system utilities had matured into a substantial retail software category. Brick-and-mortar storefronts such as Egghead Software and CompUSA represented the critical distribution channel, and Norton Utilities dominated those retail shelves. In August 1990, Symantec acquired Peter Norton Computing for approximately $70 million.7 Peter Norton received roughly one-third of Symantec's equity, valued at around $60 million at the time of closing, alongside a seat on the board.6 Overnight, the combined entity commanded approximately 34% of what was then an estimated $410 million utilities market.6
The financial impact was immediate and decisive. Symantec's top line grew from approximately $50 million in fiscal 1989 to $75 million in fiscal 1990, before surging past $116 million in fiscal 1991.6 By 1992, utilities accounted for roughly 65% of total corporate revenue.6 In less than a decade, the academic artificial-intelligence laboratory had effectively morphed into a commercial distribution vehicle for the Norton product line.
The most consequential strategic maneuver followed shortly after the merger. As computer viruses began propagating via shared floppy disks, Symantec attached the Norton name to an antivirus application. It proved to be an effective brand extension: the goodwill and trust Norton had established by recovering deleted documents transferred seamlessly to software designed to block hostile code. Over subsequent decades, the brand's positioning migrated smoothly from repairing physical drives to safeguarding the computer, and eventually to shielding personal identity.
Subjected to four decades of platform shifts, the thesis that brand equity creates an unassailable moat holds up only in qualified form. The Norton name has demonstrated remarkable survival across DOS, Windows, the open web, and mobile ecosystems—endurance that constitutes genuine commercial equity. Yet brand recognition has never insulated the company from platform commoditization, as operating system providers progressively integrated baseline utilities and security directly into the platform at no marginal cost.
The operating record reveals that while brand equity confers substantial renewal pricing power over existing subscribers, it does not ensure continuous expansion of the paying subscriber pool. The defensible portion of the brand moat resides in customer retention; its ability to drive organic, top-of-funnel acquisition against free native alternatives remains far more constrained.
The Norton acquisition endowed Symantec with an extraordinarily durable consumer cash-generation engine. How management chose to deploy those cash flows would define the next two decades of corporate history—channeling billions of dollars into enterprise acquisitions far removed from its core consumer audience.
IV. The Conglomerate Mirage: The Veritas Catastrophe & Strategic Schizophrenia (1990–2014) (35–40 min)
In the late 1990s and early 2000s, computer security became front-page news. Dial-up users found inboxes flooded with the ILOVEYOU worm, businesses scrambled to contain Melissa and Code Red, and a distinctive yellow Norton AntiVirus box became as customary a purchase alongside a new PC as a surge protector. For Symantec, this era represented an unprecedented commercial boom.
The distribution engine forged during those years established the commercial foundation that still supports Gen Digital decades later. Personal computer manufacturers pre-installed trial editions of Norton on new machines. Once the promotional trial lapsed, users received persistent warnings that system protection was expiring, prompting millions to convert to paying status. Shrink-wrapped retail boxes gradually gave way to digital annual subscriptions that automatically refreshed virus definitions. Symantec had effectively transformed a one-time software purchase into a recurring subscription that most consumers rarely thought to cancel—an OEM bundling, trial conversion, and auto-renewal mechanism that remains the architectural ancestor of every retention metric in Gen's modern financial reports.
Steady consumer subscription cash flow, however, frequently fuels expansive corporate ambition. John W. Thompson, a former IBM executive who became chief executive in 1999, envisioned transforming Symantec from a desktop utility vendor into a diversified enterprise software powerhouse. On December 16, 2004, Symantec announced an all-stock merger with Veritas Software, the market leader in enterprise data backup and storage management, valued at $13.5 billion.8 The combined entity was projected to generate roughly $5 billion in annual revenue, ranking as the world's fourth-largest independent software company.8
The strategic rationale posited that security and data availability represented complementary halves of enterprise infrastructure—a framework Symantec labeled "information integrity." Thompson emphasized that the transaction was "not a typical merger focused on reducing cost and redundant infrastructure" and that there would be "no overlap in strategic product lines or R&D."8 In practice, a transaction lacking operational overlap across product lines or development teams offered virtually no structural cost or engineering synergies. The transaction closed on July 2, 2005, with Symantec issuing approximately 483 million shares to Veritas shareholders.9
The strategic hypothesis offered an unusually clear, testable proposition: if corporate enterprise buyers truly sought to procure security and storage capabilities under a single vendor umbrella, a consolidated provider would steadily win market share from category specialists. In reality, the purchasing dynamics diverged sharply. Security and storage answered to fundamentally distinct corporate constituencies. Chief information security officers and enterprise storage architects managed separate budgets, operated on misaligned procurement cycles, and relied on different value-added reseller networks. Generating cross-portfolio sales across that institutional divide proved exceedingly difficult. Simultaneously, agile pure-play competitors eroded Symantec's security market share, while enterprise storage was being disrupted first by virtualization and subsequently by cloud architectures. Rather than creating an integrated colossus, the transaction left Symantec straddling two sluggish, diverging business lines.
The full cost of that strategic misstep became apparent a decade later. In October 2014, Symantec announced plans to separate into two independent, publicly traded companies. In August 2015, it struck an agreement to sell the Veritas business to The Carlyle Group for $8 billion.10 Amid deteriorating credit and software market conditions prior to closing, the agreed purchase price was renegotiated downward in January 2016 to $7.4 billion.11 Symantec ultimately received approximately $6.6 billion in net cash proceeds, after transaction costs and adjustments, alongside a minority equity interest in the privatized Veritas.11
Financial commentary often oversimplifies the transaction by asserting that Symantec directly lost the nominal difference between the $13.5 billion acquisition valuation and the $7.4 billion divestiture price. The economic reality was more nuanced, though no less damaging. Because Symantec executed the transaction entirely in equity, the financial burden took the form of massive shareholder dilution, with Veritas investors absorbing roughly 40% of the combined corporate equity.8 Furthermore, Veritas generated operating cash flows throughout its decade-long tenure within the corporate structure, an economic contribution that simple headline comparisons overlook.
Nonetheless, the fundamental capital-allocation verdict remains unsparing. Symantec printed nearly half a billion shares to acquire a sprawling enterprise asset, spent ten years attempting to realize non-existent synergies, and ultimately divested the business for little more than half its nominal entry price. For the stakeholders of the core consumer franchise—whose steady, high-margin cash flows subsidized the enterprise pivot—the era represented a decade of value destruction and strategic drift.
For contemporary investors evaluating Gen Digital, the historical episode provides a vital analytical framework. Management teams throughout the company's corporate history have repeatedly justified mega-acquisitions through strategic adjacency narratives, arguing that one software category naturally cross-sells alongside another. Veritas stands as the most cautionary case study in Symantec's corporate record that theoretical adjacency presented in boardrooms does not translate into unified customer purchasing behavior. That structural friction looms large when evaluating the subsequent acquisition of MoneyLion.
Yet following the Veritas divestiture, Symantec did not revert to a focused consumer software house. Instead, leadership embarked on yet another debt-financed enterprise acquisition, turning to private equity to source its next multi-billion-dollar transaction.
V. Whistleblowers, Starboard Activism, & The Broadcom Carve-Out (2015–2019) (40–45 min)
On the morning of May 11, 2018, Symantec shareholders woke up to a steep market collapse. The previous evening, the company disclosed that its board's audit committee had opened an internal investigation following concerns raised by a former employee, adding that it could not predict when its annual report would be filed. The stock fell about 33% in a single trading session, sliding from $29.18 to $19.52 and wiping out roughly $6 billion in market value.[^14] It was the kind of sudden governance crisis that frequently reshuffles executive leadership.
The origins of that collapse traced back two years to management's renewed pursuit of enterprise scale. In June 2016, Symantec agreed to acquire Blue Coat, a web-security company owned by Bain Capital, for $4.65 billion, appointing Blue Coat's chief executive, Greg Clark, as Symantec's new CEO.12 The strategic rationale posited that corporate security was migrating toward cloud environments, and Blue Coat's proxy and gateway architectures would position Symantec at the center of that transition. Clark was an aggressive dealmaker who had scaled Blue Coat through programmatic acquisitions, and he imported both his leadership team and his transactional playbook into Symantec.
Clark simultaneously executed a pivotal consumer expansion. In February 2017, Symantec closed its $2.3 billion acquisition of LifeLock, the identity-theft protection provider.13 Clark asserted that pairing Norton with LifeLock would establish a comprehensive cyber defense platform for consumers.13 In retrospect, this proved to be the most durable capital-allocation decision of his tenure. LifeLock shifted the consumer division's mission beyond device-level protection toward safeguarding individual identity, offering credit monitoring, notifications of Social Security number misuse, and remediation services for stolen credentials. That expanded perimeter laid the groundwork for the higher revenue per customer that continues to define Gen's financial model.
The enterprise integration, however, stumbled. Organic growth fell short of projections, and in May 2018 the board's audit committee initiated its probe into the presentation of specific non-GAAP financial measures and the timing of revenue recognition. In one examined transaction, Symantec had recognized $13 million in revenue during the fourth quarter of fiscal 2018; after internal review, the company determined that $12 million of that sum should have been deferred.14
When the probe concluded in September 2018, press reports indicated that investigators found no evidence of accounting fraud, recommending instead enhancements to internal controls and financial reporting processes.15 While the revised revenue figure was relatively small, the reputational impact was substantial. Investors faced months of uncertainty awaiting audited financial statements, creating severe friction for a cybersecurity vendor whose primary commercial currency was trust.
That institutional vulnerability invited activist intervention. In August 2018, Starboard Value disclosed an approximate 5.8% stake and launched a campaign for board representation.16 Starboard had established a track record of targeting lagging technology companies to enforce operational discipline, streamline spending, or force corporate divestitures. On September 16, 2018, Symantec settled the dispute by expanding its board to seat three Starboard nominees: Starboard managing member Peter Feld, technology executive Dale Fuller, and former Novellus Systems chief executive Richard "Rick" Hill.17
Those board appointments swiftly altered the company's trajectory. On May 9, 2019, Greg Clark stepped down as chief executive, and Hill stepped in as interim CEO. Concurrently, Symantec appointed Vincent Pilette, the chief financial officer of Logitech, as its new CFO.18 Pilette was a disciplined finance executive who had previously served as CFO at Electronics For Imaging following an extensive operational career. At Logitech, he had helped return a mature consumer hardware business to steady growth by controlling costs and sharpening portfolio focus. He stepped into Symantec as an analytical operator tasked with restoring credibility to a balance sheet that had just undergone months of scrutiny.
Events moved rapidly thereafter. Within three months, on August 8, 2019, Broadcom agreed to acquire Symantec's enterprise security business, including the historic Symantec brand name, for $10.7 billion in cash.19 Broadcom chief executive Hock Tan had constructed a sprawling semiconductor and software conglomerate by acquiring mature infrastructure software franchises and optimizing them for robust cash generation. Symantec's installed enterprise customer base aligned neatly with that operational model.
The transaction closed on November 4, 2019. Shedding its enterprise operations, the remaining consumer software business rebranded as NortonLifeLock Inc. and began trading under the ticker NLOK the following day.20 To return capital directly to shareholders, the board declared a special dividend of $12 per share.20 Pilette was named chief executive, and the company relocated its corporate headquarters from Mountain View to Tempe, Arizona.
How should this strategic chapter be evaluated? In terms of capital allocation, the Broadcom sale stood as an undeniable victory for the shareholders who held through the restructuring. After spending tens of billions across Veritas and Blue Coat to build an enterprise conglomerate, Symantec found a buyer willing to pay $10.7 billion in cash for the enterprise division alone—and management returned the bulk of those proceeds directly to investors rather than channeling them into another speculative acquisition. It represented the exact antithesis of the Veritas misstep.
A rigorous evaluation, however, requires recognizing the external forces that drove the outcome. The divestiture was not born of premeditated executive strategy; it was compelled by an escalating governance crisis. A whistleblower report ousted the chief executive, an activist investor forced a boardroom overhaul, and an incoming finance team seized an opportunistic bid from a specialized acquirer. Furthermore, the sale served as an implicit acknowledgment that Symantec's multi-decade quest to bridge enterprise and consumer security had failed. The company that emerged in Tempe was highly profitable and focused, but it was also, for the first time since the mid-1980s, substantially diminished in overall scale.
The strategic question confronting Pilette was whether a focused consumer business could generate durable top-line growth. His answer was to redeploy the consolidator playbook within the consumer security market itself.
VI. Vincent Pilette's Playbook: Avira & The $8.1B Avast Mega-Merger (2020–2022) (35–40 min)
Prague in 1988 was a gray, heavily monitored city in the closing months of four decades of communist rule. At the state-run Research Institute for Mathematical Machines, researcher Pavel Baudiš discovered a virus on a floppy disk and wrote a program to neutralize it. Baudiš and his colleague Eduard Kučera turned that utility into a software cooperative named Alwil, which later evolved into Avast.23 More than three decades later, that Czech programming partnership would supply half of Gen Digital's corporate identity, establishing Prague alongside Tempe as a co-equal corporate headquarters.
Before orchestrating that trans-Atlantic combination, however, Pilette initiated an aggressive operational streamlining in Arizona. His initial mandate was converting NortonLifeLock into a focused, highly cash-generative consumer subscription pure play. In July 2020, he appointed Natalie Derse as chief financial officer. Derse had spent nine years at eBay, most recently overseeing finance for its product, payments, risk, and trust divisions, following finance tenures at Stanley Black & Decker and General Electric.21
Derse provided the consumer-internet and subscription expertise necessary to optimize customer payments, churn management, and transaction risk. Pilette and Derse dismantled the enterprise overhead inherited from Symantec, guiding investors toward operating margins rarely seen in mainstream software.
The initial acquisition under this regime served as a calibrated proof of concept. In December 2020, NortonLifeLock agreed to acquire Avira, a German consumer cybersecurity specialist owned by private equity firm Investcorp, for approximately $360 million in cash, closing the transaction in January 2021.22 Avira brought an established freemium antivirus suite deployed across roughly 30 million active devices, concentrated primarily in Central Europe and emerging markets.22 Beyond expanding distribution across Germany, Austria, and Switzerland, Avira provided the Tempe executive suite with operational experience managing a "free-to-paid" conversion funnel—a commercial model fundamentally distinct from Norton's traditional reliance on PC manufacturer trial conversions and auto-renewing subscriptions.
In a freemium architecture, the free tier functions as a permanent, zero-marginal-cost customer acquisition engine. The vast majority of users never convert to paid tiers, but their operational footprint is minimal, while a predictable fraction eventually upgrades to premium utilities or identity monitoring. For the provider, the model replaces expensive digital marketing campaigns with organic software distribution.
Avast had constructed the largest freemium distribution network in consumer cybersecurity. Beginning in 2001, the company offered a fully functional free antivirus suite for home users, scaling the user base to 20 million by 2006.23 Avast subsequently absorbed its primary freemium competitor, AVG, and completed an initial public offering on the London Stock Exchange in May 2018, marking Europe's largest technology listing of that year.23
On August 10, 2021, NortonLifeLock and Avast announced a definitive merger agreement that valued Avast at up to $8.6 billion.24 The strategic rationale paired complementary assets: Norton possessed an intensely monetized, high-ARPU subscriber base situated predominantly in North America, while Avast commanded an expansive, top-of-funnel global user base with deep market penetration across Europe.
Management projected approximately $280 million in annual gross run-rate cost synergies, representing roughly 15% to 20% of combined operating expenses.25 The transaction closed on September 12, 2022, with NortonLifeLock delivering roughly $6.9 billion in cash—which included refinancing Avast's outstanding debt—alongside the issuance of approximately 94.2 million shares to Avast investors.27 Total consideration stood at approximately $8.7 billion, net of acquired cash.25
The transaction had to overcome a formidable regulatory hurdle before closing. In March 2022, the UK Competition and Markets Authority referred the deal to an in-depth Phase 2 investigation, citing concerns that consolidating two of the largest consumer security vendors would suppress competition.26 The CMA's unconditional clearance in September 2022 rested on a remarkable finding: the regulator concluded that Microsoft had upgraded its native Windows Defender security suite so substantially that it "now offers protection which is as good as many of the products offered by specialist suppliers."26
That regulatory determination represented an analytical double-edged sword. In the short run, it cleared the path for NortonLifeLock to consummate its landmark merger. Over a longer investment horizon, however, it constituted a formal finding by an antitrust authority that Microsoft's free, pre-installed operating system utility matched the efficacy of commercial standalone suites. The deal received clearance precisely because the market was deemed fully contestable by a zero-cost native substitute—posing an enduring challenge to the thesis that third-party antivirus vendors command pricing power based on superior protection.
Upon closing, NortonLifeLock rebranded as Gen Digital Inc., established dual corporate headquarters in Tempe and Prague, and transitioned its Nasdaq listing to the ticker GEN.27 Ondřej Vlček, Avast's chief executive, joined the combined enterprise as president. Vlček stepped down from the executive post in June 2024 while remaining on the board of directors and serving as a consultant on technology and innovation.28
How did the Avast integration perform against management's commitments? On operational discipline and cost reduction, execution proved formidable. By fiscal 2025—the final fiscal year before the MoneyLion acquisition altered the business mix—Gen delivered a non-GAAP operating margin of 58.4%.4 That expansion confirmed that the promised $280 million synergy program had been extracted from redundant corporate, administrative, and engineering overhead.
On top-line revenue acceleration, however, the thesis proved far more subdued. The core cross-selling rationale had promised that Avast's vast funnel of free international users could be systematically converted into premium Norton subscribers. Yet in fiscal 2025, combined company revenue grew only about 4%.4 Two years into the merger, the combined business operated less like a compounding consumer growth engine and more like a highly disciplined cash-extraction vehicle managing a mature desktop software base.
Confronted with low-single-digit organic growth across its core cybersecurity footprint, management sought its next expansion outside traditional antivirus entirely—pivoting directly into consumer fintech.
VII. The MoneyLion Acquisition & The "Financial Wellness" Frontier (2024–2025) (30–35 min)
Consider the scenario of a LifeLock subscriber receiving an alert at 11 p.m. warning that an unauthorized credit card application was attempted in their name. While the notification fulfills the product's core promise, it also marks the boundary of its utility. The customer is left navigating a web of subsequent anxieties: checking credit scores, placing bureau freezes, and verifying bank balances. For Gen's executive leadership, that consumer vulnerability suggested a commercial opportunity: What if the enterprise alerting the customer to a breach could also manage the broader financial architecture around it?
That strategic logic led directly to MoneyLion. On December 10, 2024, Gen announced an agreement to acquire the New York-based consumer finance platform for $82 per share in cash, representing approximately $1 billion in total equity consideration.29 Each MoneyLion shareholder also received a contingent value right, or CVR, entitling the holder to an additional $23 per share paid in Gen common stock. The payment would be triggered only if Gen's volume-weighted average share price reached at least $37.50 over 30 consecutive trading days within 24 months after the transaction closed.29 The acquisition closed on April 17, 2025.[^31]
The contingent value right functioned as an earn-out mechanism tied directly to post-closing equity performance. Under its terms, MoneyLion's former owners would capture an additional payout only if Gen's market valuation appreciated substantially. If the stock met the required benchmark, Gen would satisfy the obligation by issuing new shares—diluting existing shareholders, but only in an environment where substantial equity value had already been created. If the shares failed to clear that hurdle, the instrument would expire worthless.
At closing, Gen recorded the fair value of the CVRs at approximately $73 million.2 By September 2026, with roughly seven months remaining before the April 2027 deadline, Gen's shares were trading in the high $20s—well below the $37.50 hurdle—against a 52-week high of $31.65.32 At prevailing trading levels, the probability of the contingent payout being triggered appeared remote, reflecting current market pricing rather than an absolute forecast.
The acquired business comprised two primary divisions. For calendar 2024, MoneyLion reported revenue of approximately $546 million, an increase of 29%, with adjusted EBITDA of $92 million across a base of 20.4 million total customers.30 On the consumer side, its mobile application offered digital banking, short-term cash advances, credit-building products, and personal financial tracking tools. On the enterprise side, its Engine division operated an embedded financial marketplace, matching retail consumers with third-party loan, credit card, and insurance offers while collecting fees on completed referrals. In terms of scale, MoneyLion's top line represented approximately 14% of Gen's fiscal 2025 revenue, establishing the transaction as a material strategic realignment rather than a standard bolt-on acquisition.
Initial financial reporting reflected immediate top-line expansion. In fiscal 2026, Gen's Trust-Based Solutions segment—encompassing LifeLock, reputation management, and MoneyLion—generated approximately $1.66 billion in revenue, alongside $3.34 billion from the core Cyber Safety Platform.1 In the fourth quarter, Trust-Based Solutions expanded 23% on a pro forma basis, propelled by MoneyLion's standalone revenue growth exceeding 40%.5
Momentum carried into the subsequent fiscal year. By the first quarter of fiscal 2027, Engine had achieved an annualized revenue run rate of approximately $500 million, with total connected financial accounts expanding to roughly 110 million, up from 75 million at deal close.31 Concurrently, management reported that approximately one-third of Gen's paid customer base actively engaged with financial wellness features.5
A rigorous evaluation of those headline figures, however, reveals three substantial operational and structural caveats.
The first structural constraint involves profitability. On the fourth-quarter earnings call, management disclosed that the Cyber Safety segment operated at approximately a 61% operating margin, whereas Trust-Based Solutions generated roughly 30%.5 Consequently, each dollar of incremental growth generated by MoneyLion produces roughly half the operating profit of an equivalent dollar generated by Norton. This structural disparity explains why Gen's consolidated non-GAAP operating margin compressed from 58.4% in fiscal 2025 to 50.9% in fiscal 2026.41 While this compression stemmed from mix shift rather than operational deterioration, it altered the corporate profile: the consolidated enterprise could no longer be characterized as a pure 58% margin cash-extraction machine.
The second risk centers on macro cyclicality. Engine monetizes transaction volume when financial institutions are actively competing to originate loans. During a credit contraction, underwriting standards tighten, card issuers pare back customer acquisition budgets, and loan volumes shrink—dynamics capable of triggering sharp contractions in marketplace revenue. Core antivirus subscriptions, supported by automated annual renewals, exhibit no such sensitivity. By integrating MoneyLion, Gen introduced a pro-cyclical revenue stream into an equity story historically prized for its defensive resilience. Furthermore, MoneyLion's short-term liquidity and cash-advance products introduce direct consumer credit risk and compliance exposure to consumer lending regulations that standalone software publishers rarely encounter.
The third challenge involves cross-portfolio conversion. Symantec's corporate history, extending back to Veritas, illustrates that strategic adjacency is far easier to present in executive briefings than to realize in consumer behavior. A household that buys antivirus software and uses personal-finance tools may share the same demographic profile, yet that commonality does not guarantee that a security subscription naturally accelerates fintech adoption. To management's credit, early operational data shows concrete engagement, demonstrated by connected account growth and the proportion of paid subscribers interacting with financial tools.
The definitive economic validation, however, requires evidence on unit economics: whether existing Norton and LifeLock subscribers demonstrate higher retention rates or expanding annual contract values as a consequence of bundled financial offerings. On the first-quarter fiscal 2027 call, management projected more than $100 million in incremental annual revenue from embedded financial wellness and Engine expansion beginning in the second half of fiscal 2027, describing the MoneyLion integration as an application of Norton's recurring membership model rather than transactional monetization.531
A measured assessment suggests that the MoneyLion acquisition delivered accelerated top-line growth at the predictable expense of consolidated operating margins. The strategic hypothesis that Gen can assemble an integrated "cyber safety and financial wellness" membership remains untested over a full credit cycle rather than disproven. Concrete proof of success will require verifiable disclosures of elevated retention and expanding ARPU across bundled subscriber cohorts. Conversely, the thesis would be compromised if a macroeconomic tightening suppresses Engine's origination fees while Norton's standalone subscriber retention remains unaffected.
Supporting each of these disparate business lines sits a shared infrastructure of software engines, endpoint telemetry, and customer trust—a technical and commercial foundation that has, at key moments in the company's operating history, experienced severe institutional friction.
VIII. Product Engine, Threat Telemetry, & Operational Falsification (30–35 min)
That shared infrastructure is organized into two primary operating segments. The Cyber Safety Platform segment covers security suites such as Norton 360 and Avast One, antivirus for PCs, Macs, and mobile devices, virtual private networks, privacy tools, and device-cleanup utilities like CCleaner.2 The Trust-Based Solutions segment covers LifeLock identity monitoring, credit alerts, restoration services, identity theft insurance, ReputationDefender, and MoneyLion products.2
The underlying technology functions as a distributed sensor network on a global scale. Every one of Gen's hundreds of millions of installed endpoints acts as an active sensor. When a novel malicious file, phishing site, or scam pattern surfaces on a single machine, telemetry data is routed to central analysis pipelines, allowing updated behavioral signatures and heuristic protections to be deployed across the entire network. Scale confers a tangible technical advantage: a broader sensor footprint yields faster detection cycles.
The newest technical layer centers on artificial intelligence. Gen markets Genie, an AI scam detector that it has embedded in Norton, Avast and ChatGPT, as well as an "Agent Trust Hub" meant to protect consumers as AI agents start acting on their behalf.5 On the fourth-quarter call, Pilette was careful to say that "agentic revenue in fiscal year '27 will be modest but growing."5 That restraint highlights that Gen's AI features currently serve as defensive product positioning and retention mechanisms rather than an immediate driver of top-line expansion.
If the commercial model rests on endpoint telemetry and customer trust, the critical analytical task is testing how durable that trust proves under operational strain. Across its corporate history, Gen's constituent brands have encountered four distinct falsification tests—episodes where commercial growth targets collided with product integrity, user privacy, or regulatory boundaries.
The most severe breakdown involved Avast. In January 2020, an investigation by Motherboard and PCMag revealed that the world's most popular free antivirus was selling a record of what its users did online. The records included Google searches, map lookups, YouTube videos watched, LinkedIn pages visited, and visits to pornographic websites. The data flowed through an Avast subsidiary called Jumpshot, and its clients had included some of the best-known companies in the world.33 A product consumers had installed to protect their privacy was actively monetizing it.
Facing immediate public scrutiny, Avast shut the subsidiary down at the end of January 2020 and apologized.33 Regulatory enforcement followed. In February 2024, the US Federal Trade Commission announced an order requiring Avast to pay $16.5 million and banning it from selling or licensing browsing data from Avast-branded products for advertising purposes.34 The FTC alleged that Avast had collected browsing data from at least 2014 and that Jumpshot sold it to more than 100 third parties from 2014 to 2020, while Avast marketed its products as protecting consumers from online tracking.34
European regulators imposed parallel penalties. In the Czech Republic, the data protection authority fined Avast 351 million Czech crowns, about €13.9 million, for transferring pseudonymized browsing data from roughly 100 million users to Jumpshot in 2019. After Avast's appeals were rejected, the decision became enforceable in 2024.35
Jumpshot serves as a revealing falsification test for the thesis that consumer trust forms an unassailable moat. The breach was severe, yet NortonLifeLock proceeded with its multi-billion-dollar acquisition of Avast with full awareness of the scandal while regulatory proceedings remained unresolved. Furthermore, the monetary penalties were easily absorbed by annual cash flows. The more instructive finding lies in consumer behavior: Avast's user base survived, and the combined company continued to grow its paid customers. That resilience indicates that customer retention in desktop utilities is anchored far more by default habits, software friction, and consumer inertia than by actively evaluated brand trust.
The second test originated within Norton's core franchise. In 2021, Norton 360 began offering a feature called Norton Crypto, which let users mine the cryptocurrency Ether on their PCs while the machines were idle. Norton took a 15% cut of the proceeds, far higher than the typical 1% to 2% charged by mining pools.36 Security researcher Brian Krebs reported that users found the component hard to remove, and longtime customers objected that a security company was installing mining software on their computers.36
The feature was effectively made obsolete in September 2022, when Ethereum switched to a system that no longer relied on mining. While the direct revenue was negligible, the episode illustrated product governance under the pressure to expand average revenue per user: a software suite marketed for peace of mind bundled code that closely resembled the cryptojacking malware it was commissioned to block.
The third test involves LifeLock's history of regulatory enforcement. In March 2010, LifeLock agreed to pay $12 million, $11 million to the FTC and $1 million to 35 state attorneys general, to settle charges that its identity-theft prevention and data-security claims were deceptive.37 The FTC chairman at the time said LifeLock's protection "left enough holes that you could drive a truck through it."37 That enforcement followed an aggressive marketing campaign in which LifeLock's founder had advertised his own Social Security number on billboards as a demonstration of confidence.
Five years later, compliance failures recurred. In December 2015, LifeLock agreed to pay $100 million to settle FTC charges that it had violated the 2010 order, including failing to maintain a comprehensive information-security program and falsely advertising that it protected data with bank-level safeguards. It was the largest monetary award the FTC had ever obtained in an order-enforcement action.38 Although both settlements predated Symantec's 2017 buyout, they established a pattern of regulatory scrutiny that Gen inherited alongside the LifeLock brand.
Beyond regulatory actions, an intellectual property overhang has recently eased. In 2022, a federal jury awarded Columbia University about $185 million after finding that NortonLifeLock had willfully infringed two Columbia patents on malware-detection techniques.39 The district court later enhanced the award and added attorneys' fees. In March 2026, the Federal Circuit vacated the verdict, finding that the patents were directed to an abstract idea, reversed the portion of damages based on foreign sales, and vacated the enhanced damages and fees. It sent the eligibility question back for further proceedings.40 While the litigation is not completely closed, the ruling substantially mitigated the risk of a material cash judgment.
Taken together, these episodes illustrate a consistent operational reality. In consumer cybersecurity and identity monitoring, the product is fundamentally an institutional promise. Regulators have repeatedly penalized the company's brands when marketing narratives outpaced technical capabilities. Because Gen's identity offerings cater to consumer anxieties around digital vulnerability, fear-based marketing operates under strict regulatory boundaries. That permanent oversight acts as a defining constraint on the cash-generation engine examined next.
IX. Business Model, Financial Architecture, & Unit Economics (30–35 min)
The economic heart of consumer cybersecurity rests on a dynamic unusual in subscription software: the product delivers its primary value when it is invisible. Most subscribers never log into a dashboard, rarely interact with the interface, and renew automatically each year simply because an annual charge processes quietly in the background. Much like homeowners insurance, consumers pay for the absence of an adverse event. In a category where seamless protection requires minimal user intervention, customer inertia transforms into a formidable economic asset.
The baseline financials preceding the MoneyLion transaction capture this cash-generation machine in its purest form. In fiscal 2025, Gen generated $3.935 billion in revenue, up 4%, while delivering a GAAP operating margin of 41% and a non-GAAP operating margin of 58.4%.4 Non-GAAP diluted earnings per share expanded 14% to $2.22.4 That performance encapsulated the pre-MoneyLion financial formula: low-single-digit top-line expansion converted into double-digit per-share earnings growth through disciplined cost control, merger synergy extraction, debt retirement, and programmatic share repurchases, rather than accelerating organic end-market demand.
The consolidation of MoneyLion in fiscal 2026 dramatically altered that corporate profile. Reported revenue expanded 27% to $5.0 billion, while bookings rose 28% to $5.1 billion.1 Nearly all of that reported acceleration, however, reflected the inorganic addition of MoneyLion. On a pro forma basis—treating MoneyLion as if it had been consolidated across both periods—full-year revenue expanded approximately 9%.5 By the fourth quarter, the underlying divergence between segments was stark: the core Cyber Safety Platform grew only about 3%, while Trust-Based Solutions surged 23%.5 Non-GAAP earnings per share rose 15% to $2.56, while GAAP diluted earnings per share reached $1.57.1
Disentangling these two growth trajectories represents the central analytical challenge in evaluating Gen's financial architecture. The high-margin security core, which accounts for roughly two-thirds of total revenue, continues to expand at a mature, low-single-digit pace. Executive commentary emphasizing double-digit consolidated expansion is technically accurate, but that acceleration is propelled almost entirely by the newer, lower-margin Trust-Based Solutions portfolio. While management has transparently disclosed segment-level growth and margin differentials on earnings calls, market participants must resist conflating the growth profile of the fintech division with the profitability profile of the core security engine.
Initial results for fiscal 2027 reinforced this structural divergence. For the first quarter, revenue reached $1.336 billion, reflecting 11% non-GAAP year-over-year growth, with Cyber Safety contributing $846 million and Trust-Based Solutions delivering $490 million.3 On the subsequent conference call, management indicated that Cyber Safety grew approximately 4% while Trust-Based Solutions advanced 24% to 25%.31 The consolidated non-GAAP operating margin stood at 50.0%, and non-GAAP earnings per share rose 19% to $0.71.3
On the strength of that momentum, management raised full-year fiscal 2027 revenue guidance to between $5.375 billion and $5.475 billion, alongside non-GAAP earnings per share guidance of $2.87 to $2.97.3 Notably, the core security business demonstrated a modest uptick from roughly 3% growth to 4%. While an incremental one-percentage-point acceleration represents an encouraging operational signal, subsequent quarterly results will determine whether that improvement reflects sustainable cross-selling or merely temporary quarterly variance.
Evaluating subscriber health, however, has grown considerably more complex due to shifts in corporate disclosure. Prior to the MoneyLion transaction, Gen's operational scorecard anchored on three precise metrics: 40.4 million direct customers, a direct monthly average revenue per user of $7.26, and an annual direct customer retention rate of 78%.4 Direct ARPU had expanded only incrementally from $7.22 in the prior year, illustrating that while renewal pricing power existed, organic monetization gains were modest.4 Following the MoneyLion closing, management shifted its primary disclosure to an aggregated "paid customers" tally—reporting 79 million at the close of fiscal 2026 and 81 million in the first quarter of fiscal 2027—supplemented by qualitative disclosures that cohort-level ARPU ran 7% to 10% ahead of levels seen two years prior.135
Management also highlighted that LifeLock retention approached 90% during the first quarter of fiscal 2027.31 While these disclosures point to resilient engagement in premium tiers, the replacement of consistent, multi-year unit metrics with an expansive, transaction-inclusive customer definition and selective cohort commentary obscures the underlying trajectory of the core desktop subscription base. A rigorous analysis would benefit from the ongoing disclosure of the legacy direct-customer series alongside the broader platform figures.
The capital structure still bears the indelible imprint of debt-funded consolidation. Gen financed the Avast acquisition primarily with debt, pushing balance-sheet leverage well past management's long-term targets. In response, leadership committed to reducing net debt below 3.0 times adjusted EBITDA. On the fiscal 2026 year-end call, management reported achieving approximately 3.0 times net leverage, reaching its stated target a full year ahead of schedule.5
Deleveraging continued into fiscal 2027, with net leverage declining to 2.95 times by the close of the first quarter.31 The debt load, however, remains substantial: total outstanding debt stood at approximately $8.16 billion against $564 million in cash and cash equivalents.3 Across the three-year period culminating in fiscal 2026, management reported deploying roughly $6 billion in total capital, allocating approximately 40% toward debt reduction, 40% toward shareholder returns, and 20% toward strategic acquisitions.5
Credit rating agencies have acknowledged this rapid debt paydown. Fitch Ratings maintains a BB+ rating on Gen's senior unsecured debt, one notch below investment grade.42 While Fitch maintained a negative outlook in February 2025 on expectations that EBITDA leverage would remain above 3.5 times through 2026, it revised the outlook to stable in February 2026, citing faster-than-anticipated deleveraging.41 The debt maturity profile features term loans due in 2027 and 2029 alongside senior notes maturing between 2027 and 2033.2 With the initial maturities drawing near, prevailing interest rates make refinancing costs an important, though manageable, variable in capital planning.
Shareholder distributions have proceeded in parallel with debt service. During fiscal 2026, Gen repurchased $634 million of its common stock, distributed $312 million in cash dividends, and repaid roughly $3.6 billion in gross debt, inclusive of refinancing activity.1 The regular quarterly dividend stands at $0.125 per share.3 In the first quarter of fiscal 2027, the company deployed an additional $100 million toward share buybacks.31
The broader synthesis reveals a financial model that remains exceptionally generative, yet structurally more intricate than the standalone antivirus pure play of prior years. Recurring cash flows provide substantial support, but the balance sheet remains heavily leveraged for an enterprise whose core product engine expands at low single digits. Furthermore, the transition from a single-segment software business operating at 58% margins to a dual-segment platform running at roughly 50% margins invalidates simple historical valuation multiples. That structural shift sharpens the competitive question: Which rivals, native platforms, and specialized vendors are vying for those same consumer subscriptions?
X. Competitive Landscape, OS Encroachment, & Industry Structure (25–30 min)
Open a newly purchased Windows laptop, and the machine is already protected. Microsoft Defender runs quietly in the background, updates automatically, and incurs no incremental cost. On an iPhone, the question scarcely surfaces: Apple's operating system isolates each application within its own sandbox, and the vast majority of smartphone users never install standalone antivirus software. Every commercial sales pitch Gen mounts must overcome this baseline friction: persuading a consumer to pay for a layer of protection that the underlying platform already provides for free.
This competitive architecture divides into three distinct tiers.
At the apex sit the operating system and platform gatekeepers—Microsoft, Apple, and Alphabet's Google—which embed baseline security, encrypted browsing, and authentication directly into their ecosystems at zero marginal cost.
In the middle tier operate the dedicated consumer security suites. Gen commands the leading market share globally, followed in Western markets by McAfee, which an investor consortium led by Advent International and Permira acquired and took private in a transaction valued at over $14 billion that closed on March 1, 2022.43 Other established independent specialists in this tier include Bitdefender, ESET, Trend Micro, and Malwarebytes.2
The outer perimeter encompasses category specialists spanning identity protection, privacy, and personal finance: Aura in identity defense; Nord Security and Proton in virtual private networks and privacy tools; credit bureaus Equifax, Experian, and TransUnion; Intuit's Credit Karma; and consumer fintech platforms including Chime, SoFi, and NerdWallet.2 Gen's annual report formally identifies each of these entities as direct or indirect competitors, underscoring how broadly the competitive perimeter has expanded beyond traditional malware defense.2
The platform encroachment represents a secular challenge that has compounded over fifteen years. When Microsoft first introduced built-in security, industry observers widely dismissed it as rudimentary. The UK Competition and Markets Authority's 2022 determination during the Avast review—formally concluding that Microsoft Defender's native protection had reached parity with standalone specialist suites—signaled the structural maturation of that threat.26 Gen's regulatory filings are unvarnished regarding this dynamic, acknowledging that Apple, Google, and Microsoft embed security, privacy, and financial utilities "often at no additional cost," which "may reduce demand for our offerings," while noting that platform operators possess the technical leverage to restrict how smoothly third-party tools integrate with native operating systems.2
Gen's strategic response has been to continuously redefine the bundle. Because native operating systems offer baseline endpoint security without charge, Gen assembles a multi-layered suite that operating systems do not natively provide: dark web monitoring, identity restoration services, encrypted VPN tunnels, cross-platform scam detection, and, following the MoneyLion transaction, integrated consumer financial tools.
Management points to initial operational traction from this bundling strategy. By the conclusion of fiscal 2026, Norton 360 cross-selling penetration exceeded 26% of the installed base, premium higher-tier memberships crossed $500 million in annualized bookings, and mobile revenue expanded by nearly 50%.5
Yet bundling against platform gatekeepers is an asymmetric race. Every ancillary utility Gen layers into its subscription is a candidate for native operating system integration. Apple already bundles iCloud Private Relay, native password breach monitoring, and cryptographic passkeys directly into iOS and macOS. Gen's subscription bundle is an inherently moving target: to preserve pricing power, the company must continually introduce new capabilities faster than platform architects absorb them into default system settings.
At the top of the specialist tier, the relationship between Gen and McAfee resembles a disciplined duopoly. Both players rely on OEM distribution agreements with PC manufacturers, retail shelf presence, and aggressive second-year renewal step-ups. Neither participant has an economic incentive to initiate a price war; McAfee's private-equity owners prioritize cash generation to service debt, while Gen balances share repurchases and balance-sheet deleveraging. In this rivalry, Gen holds advantages in overall scale, an international freemium funnel inherited from Avast and Avira, and LifeLock's dominant brand equity in North American identity protection. However, a concentrated duopoly that relies heavily on auto-renewals naturally attracts heightened regulatory scrutiny.
That regulatory pressure has already materialized in binding commitments. Following a 2018 investigation into auto-renewal practices across the consumer antivirus sector, the UK Competition and Markets Authority secured formal legal undertakings from Norton in June 2021. The company agreed to grant auto-renewed UK subscribers the right to terminate contracts with pro-rata refunds, provide transparent disclosures whenever second-year renewal pricing exceeded introductory promotional rates, and proactively notify inactive customers who had not used the software for over twelve months with step-by-step cancellation instructions.45 As consumer-protection authorities in North America and the European Union scrutinize recurring negative-option subscription models, such mandates represent a persistent structural risk to the high-margin auto-renewal mechanics that underpin the company's cash generation.
Market observers also miscalculated the competitive fallout from regulatory interventions against foreign competitors. When the US Department of Commerce's Bureau of Industry and Security announced a comprehensive prohibition on Russia-based Kaspersky Lab on June 20, 2024—banning domestic software sales and barring signature and codebase updates after September 29, 2024—many investors assumed Gen would capture an immediate windfall of displaced American subscribers.[^46]
The commercial reality proved far less frictionless. Rather than abandoning its installed base, Kaspersky negotiated a wholesale transition with Pango Group. In September 2024, US subscribers discovered that their installed Kaspersky software was automatically updated and replaced with Pango's UltraAV security application.44 While a fraction of dissatisfied users migrated to Norton or Avast, the primary cohort of accounts transferred directly to an alternative provider. Gen has disclosed no material inflection in customer additions attributable to the ban, indicating that the event generated at most an incremental marketing tailwind rather than a structural reallocation of market share.
The competitive reality leaves Gen occupying a dual role: the clear market leader among third-party specialists, yet a structural underdog against native platform ecosystems. The durability of its business model hinges on remaining one bundle ahead of what operating systems provide as a free utility. Structuring that strategic position through standard industry frameworks reveals the precise pressure points across its business.
XI. Strategy & Business Frameworks (25–30 min)
Imagine a start-up founder in 2026 attempting to assemble a full-scale consumer cyber safety suite from scratch. The operational checklist is daunting: an around-the-clock threat telemetry laboratory, independent testing certifications, OEM bundling pacts with PC manufacturers, merchant payment routing, compliance frameworks for handling Social Security numbers and credit bureau feeds, and, above all, a customer acquisition budget capable of convincing anxious consumers to trust an unproven brand with their digital identities. The unit economics for a greenfield challenger rarely pencil out. That structural barrier forms the starting point for evaluating Gen Digital through classical strategy frameworks.
Porter's Five Forces offers the initial lens.
The threat of new entrants into a comprehensive, multi-product consumer safety platform is exceptionally low. Decades of brand equity cannot be bought overnight, identity monitoring demands complex data-sharing integration with credit bureaus alongside stringent regulatory compliance, and customer acquisition costs in retail and digital channels are prohibitive. The critical nuance, however, is that barriers to entry around discrete features are trivial. A standalone virtual private network, an encrypted password manager, or an AI-powered scam detector can be developed and brought to app stores within months. Consequently, the defensive moat protects the consolidated bundle rather than any individual utility.
The bargaining power of buyers is moderate to high, characterized by a fundamental asymmetry. Individual retail subscribers hold zero direct negotiating leverage over renewal prices, yet they enjoy an abundance of zero-cost alternatives, and technical switching costs between software applications are negligible. What prevents widespread customer defection is behavioral inertia, credit-card auto-renewals, and introductory discount structures—friction mechanisms that consumer-protection regulators across North America and Europe are aggressively challenging.
The bargaining power of suppliers is low to moderate across infrastructure, but bifurcated at key distribution nodes. Cloud computing capacity and server bandwidth are commoditized inputs. While credit bureaus control an oligopoly over credit-monitoring files, they also operate as direct competitors through their own identity protection suites, creating a fraught vendor-rival dynamic. The most influential suppliers are PC manufacturers: because OEM pre-installation agreements govern the top of the customer acquisition funnel, hardware makers hold substantial leverage in negotiating revenue-share percentages and pre-load bounties.
The threat of substitutes is exceptionally high and represents the primary secular force governing the entire industry. Native operating system security—exemplified by Microsoft Defender and Apple's sandboxed iOS architecture—serves as a permanent, zero-marginal-cost substitute. When an antitrust authority formally concludes that built-in platform utilities match the efficacy of commercial standalone suites, the commercial incentive for an ordinary consumer to pay for third-party antivirus is structurally undermined.
Competitive rivalry among established specialists remains moderate. Gen and McAfee operate as a disciplined duopoly in the premium tier, avoiding price-slashing wars that would erode industry cash flows and relying instead on marketing spending, feature bundling, and second-year renewal step-ups. Category specialists such as Bitdefender, ESET, and Trend Micro compete primarily on benchmark test scores and discounted pricing, leaving the premium market characterized by marketing competition rather than structural price disruption.
Hamilton Helmer's 7 Powers framework provides a more discerning test: Which structural mechanisms generate persistent economic rents that rivals cannot easily replicate?
Branding remains Gen's most powerful defensive asset. In an asymmetric information market where consumers cannot independently evaluate detection algorithms, recognizable monikers like Norton and LifeLock serve as proxies for security and competence. What makes this brand equity remarkable is its resilience: the brands retained commercial viability through the Jumpshot user-data controversy, the Norton Crypto misstep, and recurring FTC consent orders. Yet that brand power operates almost exclusively as an engine of customer retention and renewal pricing power over existing subscribers, rather than an organic acquisition magnet against free operating-system defaults.
Scale economies represent a second genuine power. The substantial fixed investments required for continuous threat telemetry research, product engineering, administrative compliance, and global brand campaigns are distributed across roughly 500 million total users. This massive operating base is the primary reason Gen's Cyber Safety Platform segment can sustain an operating margin of approximately 61%.5 A subscale challenger burdened with the same baseline research and development overhead cannot match that unit-cost efficiency.
Switching costs are moderate and largely synthetic. Unlike enterprise software environments, consumer cybersecurity entails no deep institutional data integration or mission-critical workflow lock-in. Instead, switching costs are forged from customer inertia, password manager credential vaults, historical identity restoration records, and automated recurring billing. Because these switching costs depend heavily on procedural friction and passive auto-renewals, they remain the company's most legally vulnerable power as regulators mandate simplified, one-click cancellation mechanisms and transparent renewal notifications.
Network effects are weak in the core security business. While larger endpoint telemetry footprints marginally enhance algorithmic detection speeds, the incremental benefit that any individual user derives from another user installing Norton or Avast is practically undetectable. The Engine division acquired through MoneyLion introduces a genuine two-sided marketplace dynamic—where an expanding pool of consumers attracts financial institutions, which in turn deepens the inventory of loan and credit offers. However, that network effect is still maturing and operates entirely within Gen's lower-margin consumer finance segment.
Counter-positioning, cornered resources, and process power are largely absent. Neither Norton nor LifeLock employs an unorthodox business model that incumbents are structurally paralyzed from adopting, nor does the company control proprietary algorithms or patents that competitors cannot circumvent. The closest approximation to process power lies in management's programmatic operational playbook—specifically its demonstrated ability to eliminate redundant overhead and extract hundreds of millions in cost synergies following the Avast transaction. Yet Symantec's historical misadventures with Veritas and Blue Coat demonstrate that operational synergy extraction has been highly dependent on specific leadership regimes rather than an indelible corporate trait.
The strategic synthesis clarifies Gen Digital's true economic posture. The enterprise commands two durable powers—brand equity and operating scale—paired with a synthetic switching-cost barrier that faces mounting regulatory headwinds. This structural foundation reliably protects the cash flows generated by its installed subscriber base, making it nearly impossible for an independent cybersecurity startup to challenge Gen head-on. Crucially, however, neither brand nor scale shields the business from the secular substitute that matters most: free, native security embedded directly by platform gatekeepers. Consequently, shareholder value creation depends almost entirely on capital allocation and strategic reinvestment—decisions entrusted to a tightly concentrated executive suite.
XII. Management Scorecard, Governance, & Capital Allocation (20–25 min)
Vincent Pilette has guided the enterprise through a profound structural reshaping. Arriving in May 2019 as chief financial officer amid an acute governance crisis, he was elevated to chief executive of a newly separated consumer business six months later. Over the ensuing years, he doubled the company's operating scale through Avast, steered it into consumer finance via MoneyLion, and in July 2025 assumed the role of board chair after Frank Dangeard stepped down for health reasons, while director Sue Barsamian was named lead independent director.47 This consolidation of the chair and chief executive roles concentrated substantial governance authority in a single executive whose operating record is now expansive enough to evaluate.
Evaluating that leadership tenure begins with operational execution. Over seven years, Pilette's management team executed several multi-billion-dollar portfolio transactions largely in alignment with its public commitments. The Broadcom divestiture returned substantial capital directly to shareholders, the Avast integration extracted the corporate overhead and cost synergies management had outlined, and the company achieved its balance-sheet deleveraging target—lowering net debt below 3.0 times adjusted EBITDA—a full year ahead of schedule.5
Forecasting discipline has followed a consistent cadence of conservative targets paired with measured outperformance. Gen raised its fiscal 2026 guidance over the course of the year and surpassed the revised targets, subsequently lifting full-year fiscal 2027 guidance following the first quarter.13 That pattern reflects systematic expectation management rather than speculative promotional targets.
Chief financial officer Natalie Derse, who has served in the post since July 2020, has served as a central operational anchor for that balance-sheet discipline, particularly across cash conversion and accelerated debt retirement.21 Executive communication on quarterly calls has maintained an analytical, measured tone: segment-level growth rates and margin differentials are consistently broken out, and management has explicitly tempered expectations regarding near-term monetization from emerging AI utilities.5
A closer examination of the executive compensation structure, however, reveals structural incentives that diverge from traditional capital-stewardship metrics. According to the fiscal 2026 proxy statement, the annual executive cash bonus was determined entirely by bookings growth, subject to meeting a baseline operating profit threshold, and ultimately paid out at 135% of target after the compensation committee applied adjustments reflecting the operational realities of MoneyLion following the acquisition.46 Concurrently, long-term performance stock units are divided equally between three-year relative total shareholder return against the Nasdaq Composite and average revenue growth.46 Notably absent from executive compensation criteria are direct hurdles tied to balance-sheet deleveraging, per-share free cash flow generation, or return on invested capital.
An analytical assessment of that framework highlights two governance tensions. First, weighting short-term incentives exclusively toward bookings growth inherently rewards debt-funded dealmaking that inflates top-line volume—precisely the mechanical contribution provided by MoneyLion. For an enterprise whose core desktop security franchise expands at low-single-digit rates, such an incentive design introduces an organizational bias toward acquiring external revenue. Second, while adjusting performance targets following a major acquisition is standard corporate practice, discretionary committee modifications inevitably cloud performance attribution. A discerning shareholder must weigh whether the 135% bonus payout reflected genuine organic outperformance or the accounting mechanics of consolidation—a distinction the proxy statement disclosures leave unresolved.
Capital allocation must also be evaluated against the company's broader historical arc rather than through the lens of recent quarters alone. The corporate lineage encompasses one of the most value-destructive mega-mergers in software history with Veritas, an aggressive debt-financed enterprise pivot with Blue Coat that precipitated an executive overhaul, and the acquisition of LifeLock—which, despite arriving with a $100 million regulatory settlement, established the high-ARPU identity monitoring foundation that anchors modern cash flows.38
Under Pilette, capital deployment has encompassed a highly advantageous divestiture to Broadcom, a disciplined European bolt-on with Avira, a landmark consolidation with Avast that excelled on cost reduction while delivering subdued top-line expansion, and an unproven pivot into consumer fintech through MoneyLion. Management has described its three-year capital deployment as balanced—allocating approximately 40% toward debt reduction, 40% toward shareholder returns, and 20% toward strategic acquisitions.5 Yet characterizing M&A as merely a 20% capital slice substantially understates its operational impact: absorbing MoneyLion structurally altered the enterprise's operating margin profile, cash-flow predictability, and regulatory exposure.
Consequently, the assertion that leadership represents a disciplined capital allocator holds true in a qualified sense. The executive team has demonstrated exceptional discipline in cost containment, operational restructuring, and hitting short-term financial targets. Its ability to create sustainable economic value through multi-billion-dollar strategic acquisitions, however, remains unproven. The decisive operational test is whether the integration of MoneyLion generates quantifiable expansions in subscriber retention and average revenue per user across the core cyber safety base through fiscal 2028—and whether executive leadership exercises the discipline to refrain from further large-scale fintech transactions before that synergy is empirically demonstrated.
With that operational and governance scorecard established, the competing investment arguments surrounding Gen Digital can be evaluated.
XIII. Bull vs. Bear Case & Critical Investor Radar (20–25 min)
Two investors examining Gen Digital's financial profile can reach sharply divergent conclusions. The first sees an enterprise generating more than $1.5 billion in annual free cash flow, expanding per-share earnings in the mid-teens, steadily retiring debt, and returning capital through programmatic share repurchases. The second sees a core cybersecurity business expanding at merely 3% to 4%, consolidated operating margins that have compressed by roughly eight percentage points, and executive leadership deploying capital into a cyclical consumer fintech sector where it has no prior operating track record. Both perspectives accurately capture distinct facets of the same corporate structure.
The bull case
The primary pillar of the bullish thesis rests on cash generation. Gen converts approximately 30% of reported revenue into free cash flow, delivering 15% non-GAAP earnings per share growth in fiscal 2026 alongside full-year guidance projecting 14% to 18% expansion for fiscal 2027.131 For long-term investors, compounding per-share earnings at that cadence while shrinking the outstanding share count offers a compelling equity profile—particularly given that demand for basic digital security and identity defense functions as a largely non-discretionary utility for millions of connected households.
The second argument views an intensifying threat landscape as an enduring secular tailwind. The proliferation of AI-assisted phishing campaigns, automated credential theft, and deepfake impersonation scams has made navigating the internet measurably more perilous for ordinary consumers. Offerings such as scam-detection tools and safeguards designed to monitor autonomous AI agents position Gen to monetize escalating consumer anxieties. While management's measured commentary indicates that direct revenue from agentic utilities will remain modest in the near term, the overall evolution of online threats expands the relevance of the consumer defense perimeter.
The third pillar is the modest re-acceleration within the core portfolio. Cyber Safety growth ticked up from approximately 3% to 4%, paid subscriber counts expanded across more than ten consecutive quarters, and higher-tier bundled memberships and mobile cross-selling continue to gain traction.531 If bundling security, identity protection, and personal financial tools successfully elevates customer retention—a hypothesis supported by LifeLock retention rates approaching 90%—customer lifetime value could expand meaningfully across the installed base.31
Finally, balance-sheet deleveraging restores capital-allocation flexibility. Having lowered net leverage below 3.0 times adjusted EBITDA and secured a stable credit rating outlook, management can channel a greater proportion of recurring free cash flow toward share buybacks and regular dividend distributions rather than debt retirement.3141
The bear case
The foundational bear argument centers on platform substitution. Operating system gatekeepers—Microsoft, Apple, and Google—continue to integrate baseline security, privacy defenses, and authentication utilities directly into their platforms at zero marginal cost. That threat is not merely theoretical: antitrust authorities have formally recognized that Microsoft Defender matches the efficacy of dedicated commercial suites.26 Meanwhile, younger, mobile-first cohorts increasingly navigate their digital lives without ever installing desktop antivirus software. In this context, low-single-digit expansion across Cyber Safety suggests a mature legacy market sustained by renewal pricing adjustments and bundling, rather than expanding underlying consumer demand.
The second risk involves regulatory pressure on recurring billing practices. Gen's customer retention relies significantly on passive credit-card renewals and customer inertia. In the UK, binding undertakings secured by the Competition and Markets Authority already mandate transparent cancellation rights, refund mechanisms, and proactive notifications for inactive accounts.45 Broader implementation of negative-option subscription rules in the United States or the European Union would directly test how much of the company's historical 78% direct customer retention rate reflects genuine product value versus procedural friction.4
The third concern is strategic drift and acquisition risk. The absorption of MoneyLion introduced a lower-margin, pro-cyclical fintech marketplace exposed to consumer credit cycles and stringent financial regulations. When combined with an executive incentive plan that rewards short-term bookings expansion, corporate history—most notably the Veritas conglomerate era—suggests an institutional tendency toward debt-funded adjacency deals. Skeptics argue that the likelihood of another dilutive acquisition remains higher than the market assumes, despite a historical record showing that software adjacencies frequently fail to generate durable operating synergies.
The fourth challenge stems from operational complexity and data-handling liabilities. Gen manages a fragmented architecture of acquired brands—including Norton, Avast, AVG, Avira, CCleaner, LifeLock, and MoneyLion—each operating on distinct legacy codebases and carrying historical regulatory entanglements. As the Jumpshot controversy demonstrated, a single privacy breach can trigger years of regulatory enforcement and reputational damage. An enterprise that now maintains connected financial account access across more than 100 million user links faces substantially amplified downside exposure from any technical failure or data-governance lapse.31
Weighing the evidence
The bullish argument is anchored in reported, quantifiable data: double-digit EPS expansion, robust free cash flow conversion, rapid balance-sheet deleveraging, and recurring quarterly guidance beats. The bearish thesis rests on structural, slow-moving dynamics: platform commoditization, mounting regulatory scrutiny of auto-renewals, and the corporate base rate of conglomerate acquisitions. Neither thesis has been conclusively disproven. The durability of the underlying cash engine is demonstrable; however, the assertion that Gen has transformed into a high-growth consumer platform remains unproven, given that top-line acceleration is concentrated within its lowest-margin segment. In essence, the empirical evidence points to a high-margin cash-compounding engine supported by a mature core, paired with an unproven fintech growth leg.
The three KPIs to watch
First, monitor Cyber Safety Platform bookings growth on a pro forma basis. This single metric distills subscriber volume trends, gross pricing realization, and organic monetization across Gen's highest-margin operations. Sustained expansion at or above recent mid-single-digit rates would validate the multi-tier bundling thesis; conversely, a deceleration toward flatline levels would indicate that native platform substitution is gradually eroding the core franchise.
Second, track underlying customer retention disclosures. The historical 78% annual direct retention rate serves as the baseline benchmark.4 Any sustained erosion—particularly in the wake of regulatory interventions targeting recurring negative-option subscriptions—would provide the earliest indication that behavioral switching costs and customer inertia are beginning to break down.
Third, watch net leverage discipline. Sustaining net debt below 3.0 times adjusted EBITDA without resorting to another debt-financed acquisition would confirm that balance-sheet stewardship and disciplined capital allocation have endured through the company's expansion into consumer finance.
XIV. Epilogue & Playbook Lessons (15–20 min)
Returning to the beginning clarifies the throughline. In 1982, a team of Stanford researchers funded by a government grant attempted to teach a computer to comprehend natural English—an ambition that foundered because microcomputer hardware was not yet equipped to support it. A commercial software operator rescued the enterprise by repurposing that natural-language interface for a straightforward PC database. A few years later, a programmer placed his portrait on a retail box of disk utilities and demonstrated that non-technical consumers buy reassurance from a trusted expert far more readily than they evaluate technical specifications. Four decades later, the corporate descendant of those three episodes protects hundreds of millions of users from digital threats that did not exist when any of those founders began.
Three structural lessons emerge from that forty-year operating record, each accompanied by an essential qualification.
The first is the unbundling paradox. Symantec's most value-accretive capital-allocation decision was selling its enterprise division rather than acquiring one. For fifteen years, successive management teams treated the high-margin consumer franchise as a financing vehicle for enterprise ambitions. Shareholder value was unlocked only when the enterprise was separated, leaving the consumer cash engine to stand on its own. The vital qualification is that this clarity was not conceived as a proactive internal strategy; it was compelled by an accounting investigation, board intervention by an activist investor, and an opportunistic buyout from Broadcom.
The second lesson is that in consumer utility software, brand equity routinely matters more than underlying code—up to a defined threshold. The Norton moniker has outlasted every operating-system transition, codebase rewrite, and security benchmark cycle across four decades. Because retail consumers cannot independently evaluate detection algorithms, the purchase is an exercise in buying peace of mind, an emotional benefit that attaches durably to familiar brand names. The operational limitation, however, is that brand recognition functions primarily as a retention and renewal-pricing moat over an installed subscriber base. It provides far less leverage as an organic acquisition engine against zero-marginal-cost security native to modern operating systems.
The third lesson governs the limits of programmatic consolidation. In a mature, low-growth software category, a disciplined consolidator that acquires direct competitors to eliminate redundant infrastructure can generate substantial economic value, as demonstrated by the operational integration of Avast. Yet Symantec's corporate history also demonstrates that the consolidator playbook falters when dealmaking ventures outside the core operational domain, as the $13.5 billion Veritas merger illustrated. The acquisition of MoneyLion occupies ambiguous ground between those precedents: while consumer finance targets the same household demographics, it sits far outside the underwriting, compliance, and product mechanics of digital security. Whether the transaction marks another disciplined value-creation step or a return to speculative adjacency will be determined by subscriber retention and unit economics over the next several fiscal years.
When Gary Hendrix launched Symantec in 1982, his natural-language software could not run effectively on the microcomputers of the era. More than forty years later, Gen markets conversational AI assistants designed to guide consumers through scam detection, identity monitoring, and personal finance. Navigating through multiple corporate rebrandings, boardroom crises, and high-profile regulatory settlements, the enterprise has converged on an operating model remarkably close to its founding premise: software that communicates with an everyday user in plain English, watching over their digital and financial lives.
References
-
Gen Crosses $5B in FY26 Revenue with Growth Accelerating to Double-Digits (Form 8-K Exhibit 99.1) — Gen Digital Inc. / SEC, 2026-05-07 ↩↩↩↩↩↩↩↩↩↩↩
-
Gen Digital Inc. Form 10-K for the fiscal year ended April 3, 2026 — US Securities and Exchange Commission, 2026-05-21 ↩↩↩↩↩↩↩↩↩↩↩
-
Gen Further Accelerates in Q1 FY27 and Raises Full Year Guidance (Form 8-K Exhibit 99.1) — Gen Digital Inc. / SEC, 2026-08-06 ↩↩↩↩↩↩↩↩
-
Gen Delivers Record Q4 and Full Year Fiscal 2025 Results — Gen Digital Inc., 2025-05-06 ↩↩↩↩↩↩↩↩↩↩
-
Gen Digital (GEN) Q4 2026 Earnings Call Transcript — The Motley Fool, 2026-05-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
History of Symantec Corporation — FundingUniverse ↩↩↩↩↩↩↩↩↩↩↩
-
Symantec and Veritas merge in deal valued at $13.5 billion — Computerworld, 2004-12-16 ↩↩↩↩
-
Symantec Completes Acquisition of Veritas — eWeek, 2005-07-02 ↩
-
Symantec to Sell Veritas to The Carlyle Group for $8 Billion — Reuters, 2015-08-11 ↩
-
Symantec and The Carlyle Group Amend Terms of Veritas Purchase Agreement — Symantec Corporation, 2016-01-19 ↩↩
-
Symantec to Acquire Blue Coat and Define the Future of Cybersecurity — Symantec Corporation, 2016-06-12 ↩
-
Symantec Completes LifeLock Acquisition, Creating a Comprehensive Digital Safety Platform — Symantec Corporation, 2017-02-09 ↩↩
-
Symantec Corporation Form 10-K for fiscal year 2018 — US Securities and Exchange Commission, 2018-10-26 ↩
-
Symantec Internal Probe Finds No Accounting Fraud, Recommends Some Changes — The Wall Street Journal, 2018-09-24 ↩
-
Activist Starboard Value Takes 5.8% Stake in Symantec, Seeks Board Seats — Reuters, 2018-08-16 ↩
-
Symantec Corporation Form 8-K: Agreement with Starboard Value — US Securities and Exchange Commission, 2018-09-17 ↩
-
Symantec CEO Quits Unexpectedly, Stock Sinks After Missing Estimates — SecurityWeek, 2019-05-09 ↩
-
Broadcom to Acquire Symantec's Enterprise Security Business for $10.7 Billion — Broadcom Inc., 2019-08-08 ↩
-
Symantec Completes Sale of Enterprise Security Assets to Broadcom — Symantec Corporation, 2019-11-04 ↩↩
-
NortonLifeLock Appoints Natalie Derse as New Chief Financial Officer — Business Wire, 2020-07-08 ↩↩
-
NortonLifeLock to Acquire Avira — NortonLifeLock Inc., 2020-12-07 ↩↩
-
How Prague's Avast went from Soviet-era security project to $4.5 billion IPO — VentureBeat, 2018-11-12 ↩↩↩
-
NortonLifeLock Agrees to Buy Avast for up to $8.6 Billion — Reuters, 2021-08-10 ↩
-
NortonLifeLock and Avast to Merge to Lead the Transformation of Consumer Cyber Safety — NortonLifeLock Inc., 2021-08-10 ↩↩
-
UK clears $8.1B merger between NortonLifeLock and Avast — TechCrunch, 2022-09-02 ↩↩↩↩
-
Gen Digital Inc. Form 10-Q for the quarter ended December 30, 2022 — US Securities and Exchange Commission, 2023-02 ↩↩
-
Gen Digital Inc. Form 8-K: Transition of Ondřej Vlček — US Securities and Exchange Commission, 2024-06 ↩
-
Gen Extends its Financial Wellness Offerings with the Acquisition of MoneyLion — Gen Digital Inc., 2024-12-10 ↩↩
-
MoneyLion Announces Fourth Quarter and Full Year 2024 Results — Business Wire, 2025-02-24 ↩
-
Gen Digital (GEN) Q1 2027 Earnings Call Transcript — The Motley Fool, 2026-08-13 ↩↩↩↩↩↩↩↩↩↩↩
-
A Look at Gen Digital Inc (GEN) After 6.4% Decline — GuruFocus, 2026-09-22 ↩
-
Leaked Documents Expose the Secretive Market for Your Web Browsing Data — Motherboard (Vice), 2020-01-27 ↩↩
-
FTC Order Will Ban Avast from Selling Browsing Data for Advertising Purposes and Require It to Pay $16.5 Million — Federal Trade Commission, 2024-02-22 ↩↩
-
Czech DPA imposed fine of 351 million CZK for GDPR infringement — Czech Office for Personal Data Protection, 2024 ↩
-
Norton 360 Now Comes With a Cryptominer — Krebs on Security, 2022-01 ↩↩
-
LifeLock Will Pay $12 Million to Settle Charges by the FTC and 35 States That Identity Theft Prevention and Data Security Claims Were False — Federal Trade Commission, 2010-03-09 ↩↩
-
LifeLock to Pay $100 Million to Consumers to Settle FTC Charges It Violated 2010 Order — Federal Trade Commission, 2015-12-17 ↩↩
-
Columbia University Awarded $185 Million for Patent Infringement by NortonLifeLock Inc. — Columbia News, 2022-05 ↩
-
Trustees of Columbia University v. Gen Digital Inc., Opinion No. 24-1243 — US Court of Appeals for the Federal Circuit, 2026-03-11 ↩
-
Gen Digital outlook revised to stable by Fitch, IDR affirmed at BB+ — Investing.com, 2026-02 ↩↩
-
Fitch Affirms Gen Digital Inc. at 'BB+'; Outlook Stable — Fitch Ratings, 2024-11-14 ↩
-
Investor Group Led by Advent International and Permira Completes Acquisition of McAfee — Business Wire, 2022-03-01 ↩
-
Some Kaspersky customers receive surprise forced update to new antivirus software — TechCrunch, 2024-09-23 ↩
-
Norton dodges UK courts after telling Brit watchdog it will be nicer to consumers — The Register, 2021-06-14 ↩↩
-
Gen Digital Inc. 2026 Proxy Statement (Form DEF 14A) — US Securities and Exchange Commission, 2026 ↩↩
-
Gen Announces Leadership Transition for its Board of Directors — Gen Digital Inc., 2025-07-22 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube