Grayscale Bitcoin Trust ETF (NYSE Arca: GBTC): The Trojan Horse That Broke Wall Street's Gates
I. Cold Open & Episode Roadmap
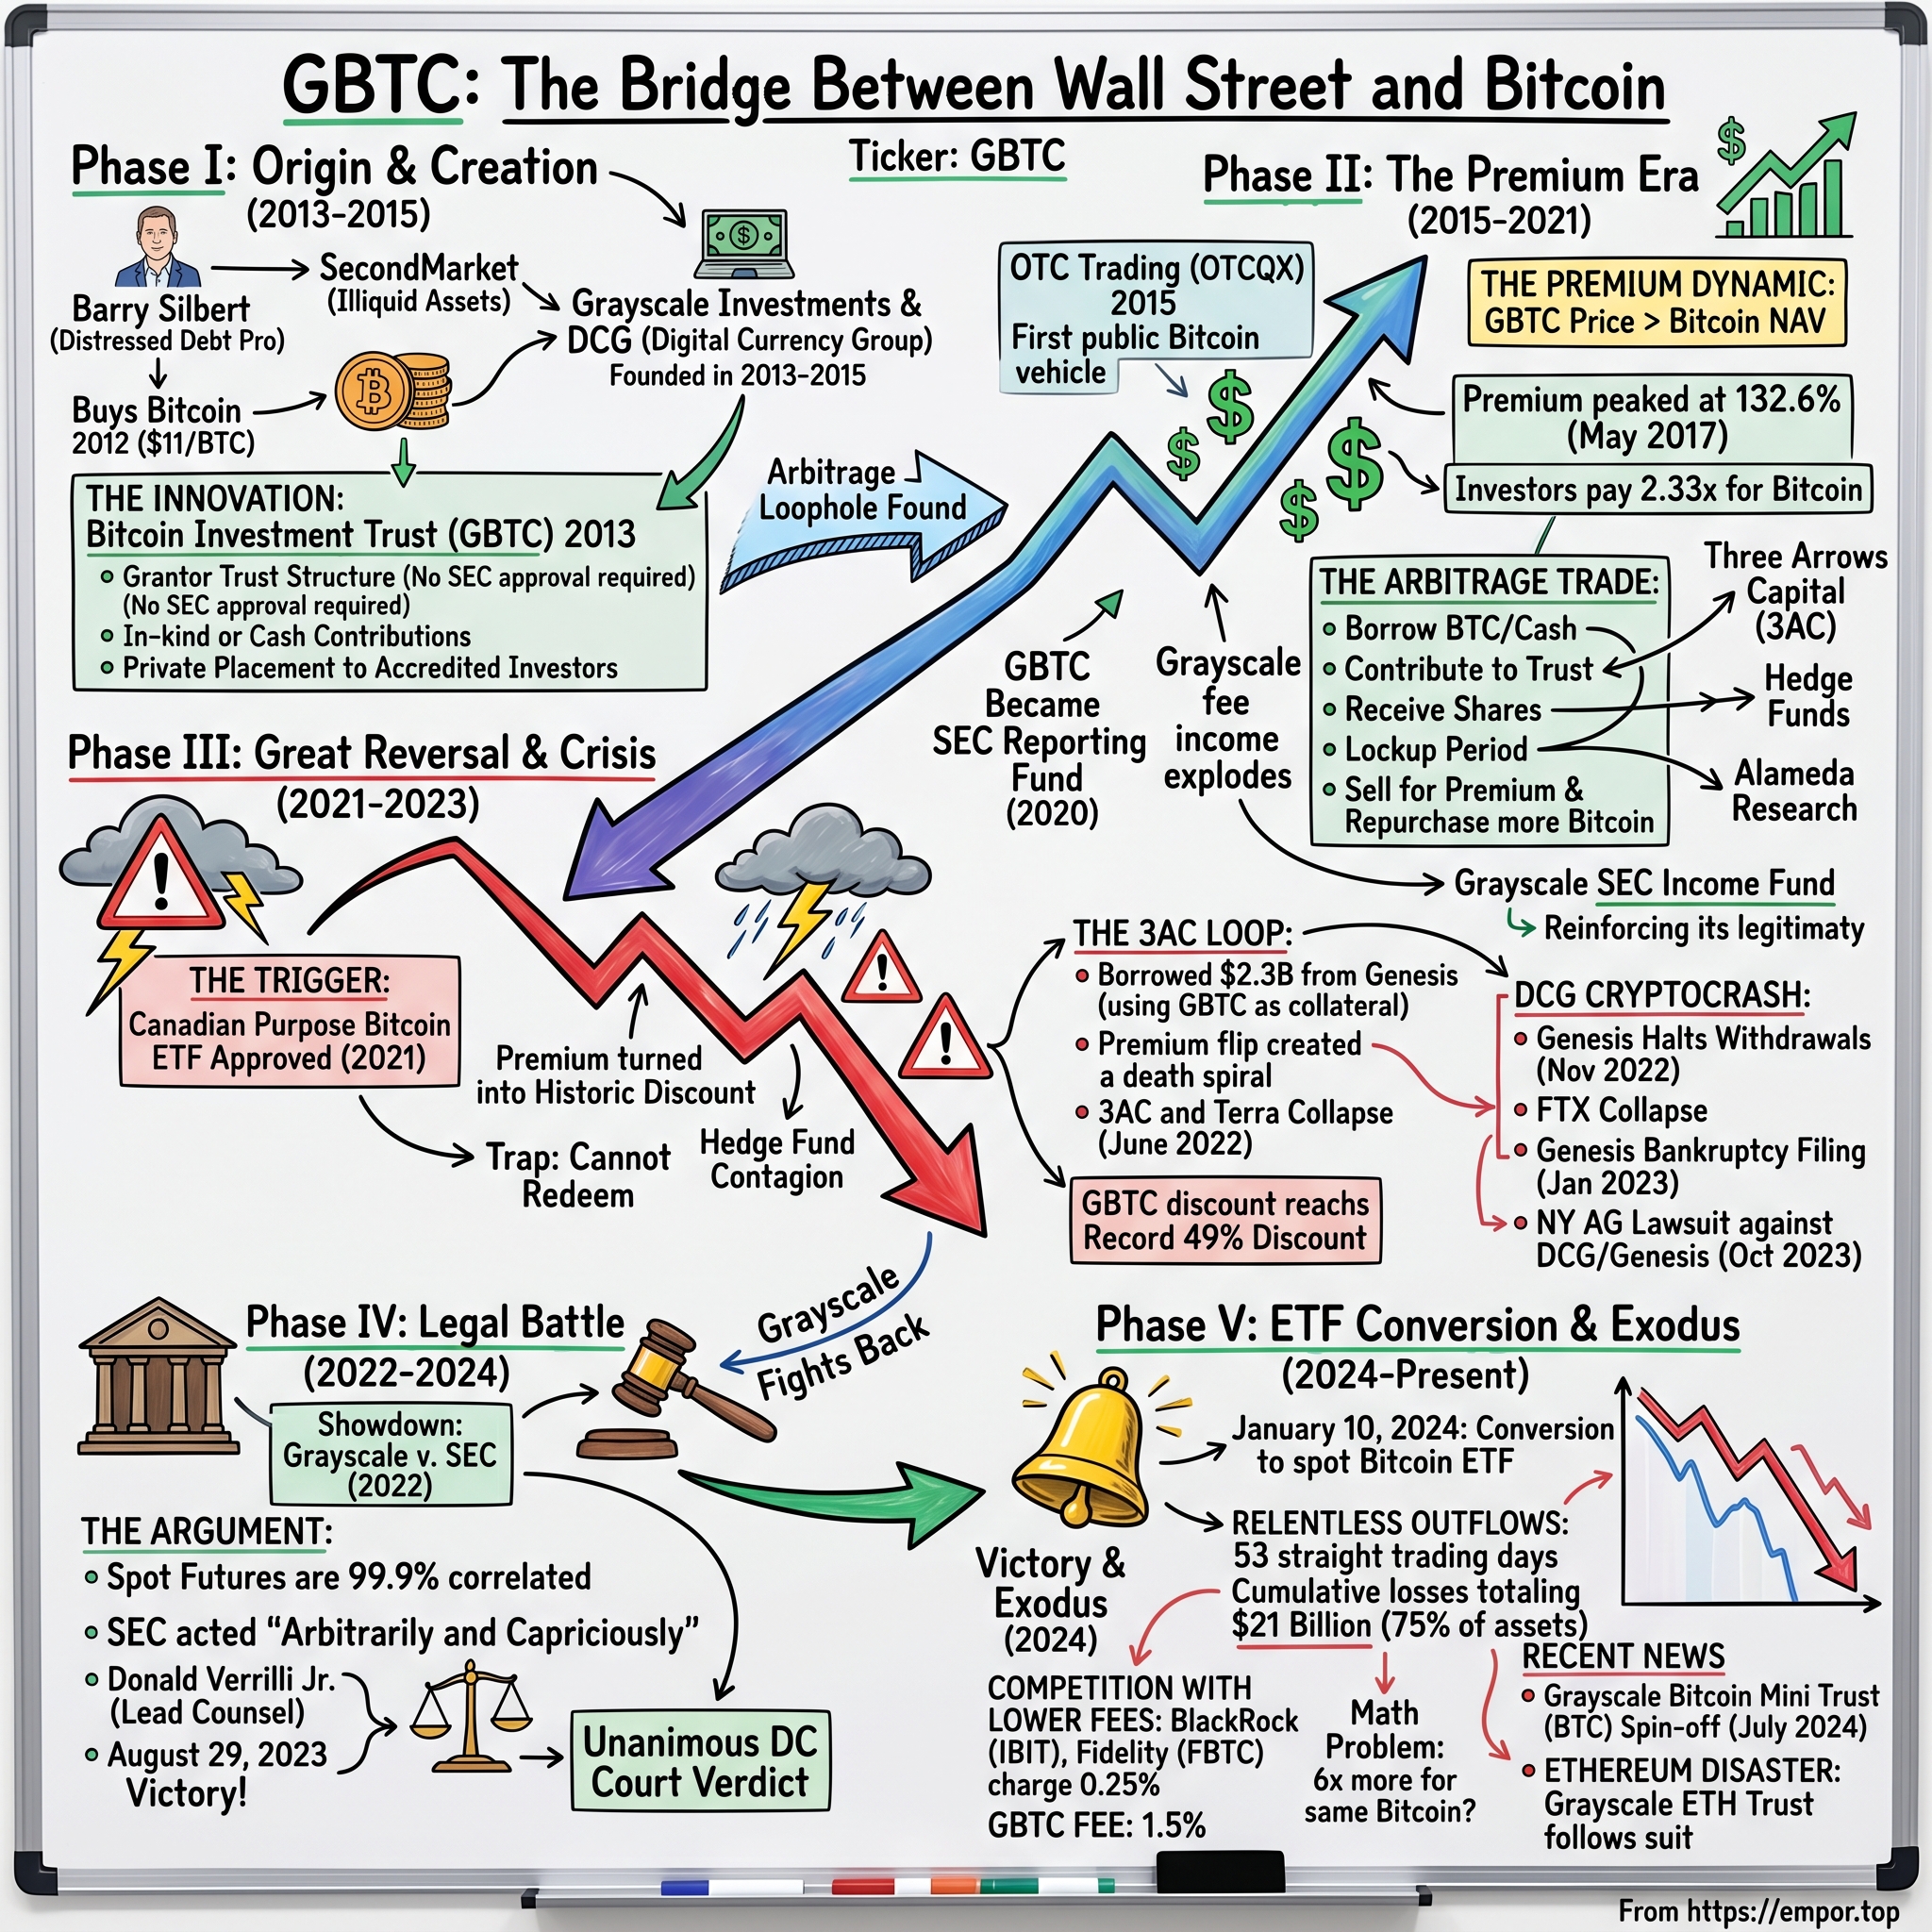
On the morning of January 11, 2024, a structural shift occurred across a $28 billion security. For nearly three years, shares of the Grayscale Bitcoin Trust had traded at an erratic discount to the digital assets in its custody. At the depths of the market downturn in December 2022, an investor could acquire a dollar's worth of bitcoin through GBTC for roughly fifty cents.1 Then, as the opening bell rang on NYSE Arca and GBTC commenced its first trading day as a spot bitcoin exchange-traded fund, that structural discount closed. For the first time since February 2021, the shares traded at essentially the value of the coins they held.2 Billions of dollars in trapped value were unlocked in a single session.
And then the capital walked out the door.
That dynamic forms the central paradox of the vehicle. For most of its history, GBTC stood among the most lucrative products in asset management: a passive wrapper around a single commodity, charging 2% annually, insulated from domestic competition for nearly a decade. It served as the primary conduit for wealth managers, family offices, hedge funds, and retirement accounts seeking bitcoin exposure before compliance departments permitted direct ownership of the underlying token. Yet the moment the trust secured the regulatory outcome its sponsor had spent years pursuing and litigating, its asset base began to erode. From a little over 619,000 bitcoin at the end of 2023,3 the trust shed roughly 447,000 bitcoin through redemptions over the ensuing two and a half years. That exodus drove cumulative net outflows of about $17.5 billion, the largest drain any fund in the category has ever suffered.4 By September 1, 2026, GBTC held approximately 130,481 bitcoin, valued at roughly $10.1 billion, leaving it as the third-largest spot bitcoin ETF in the country.4
The management fee, meanwhile, remained fixed. GBTC still charges 1.50% a year with no fee waiver, against 0.14% to 0.25% at its direct competitors.4
How should this vehicle be understood? One interpretation is a story of first-mover disadvantage: an incumbent that funded the legal campaign to open the market, only to watch lower-cost alternatives from rivals like BlackRock capture market share. Another is a calculated capital-harvesting strategy: a sponsor assessing a captive, tax-sensitive shareholder base and choosing fee preservation over an aggressive fee war it was ill-positioned to win. In practice, both explanations hold merit, and the tension between them defines the core investment question.
The analysis unfolds across seven parts. It begins with Barry Silbert, a restructuring banker turned secondary-market entrepreneur who recognized how regulatory friction traps asset value, and who structured a private trust to navigate institutional barriers. It tracks the flywheel era, when GBTC traded at a persistent premium to its net asset value and hedge funds treated the spread as an attractive arbitrage trade. It then examines the great inversion, when that premium collapsed into a deep discount that helped destabilize Three Arrows Capital and Grayscale affiliate Genesis. Next, it covers the landmark appellate victory in Grayscale Investments v. SEC, where a federal appeals court ruled unanimously in the company's favor. It details the subsequent ETF conversion, the capital flight, the choice to preserve the 1.50% fee, and the deployment of the Grayscale Bitcoin Mini Trust as a defensive hedge. From there, it evaluates the managerial transition under Chief Executive Peter Mintzberg, a postponed public offering, and ongoing litigation surrounding parent entity Digital Currency Group. Finally, it presents the valuation frameworks, stress tests the trust's operating economics, and outlines the institutional bull and bear cases.
A definitional distinction is essential at the outset: GBTC is not an operating company. It is a Delaware statutory trust that holds physical bitcoin and issues common shares against that inventory. The commercial enterprise collecting the sponsor fee is Grayscale Investments, a subsidiary of Digital Currency Group (DCG). For a fund shareholder, investment returns are dictated primarily by the trajectory of bitcoin alongside fee drag. For analysts evaluating why the expense ratio remains elevated, the answer lies in the corporate balance sheet and strategic incentives of Grayscale and DCG. This analysis tracks both dimensions, because the trajectory of the trust cannot be separated from the commercial requirements of its sponsor.
 Subscribe on LinkedIn
II. The Origin: Barry Silbert, SecondMarket, & The Reg D "Accredited Loophole" (1976–2015)
The restructuring banker who learned where value hides
Before building one of the digital asset industry's most prominent conglomerates, Barry Silbert worked as an investment banker at Houlihan Lokey on major corporate bankruptcies of the early 2000s, including Enron and WorldCom.5 The experience offered a foundational lesson in market structure: distressed assets often lose value not because they are inherently worthless, but because market participants lack an efficient mechanism to transact them. Illiquid claims, restricted stock, and odd-lot securities lingered in legal and administrative limbo because Wall Street's plumbing lacked channels to reach them.
Silbert, an Emory University finance graduate,5 applied that insight in the mid-2000s by founding Restricted Stock Partners, a brokerage designed to make secondary markets in illiquid assets.6 Rebranded as SecondMarket in 2008, the platform pioneered organized secondary trading in private venture-backed technology companies, facilitating transactions in pre-IPO shares of firms such as Facebook and Twitter for employees and early investors seeking liquidity.6 The through-line was central to his subsequent ventures: rather than creating a novel asset, Silbert focused on engineering institutional-grade wrappers that allowed restricted capital to access previously unreachable asset classes.
The 2012 epiphany
Silbert bought his first bitcoin in 2012, putting in about $175,000 when the price was around $11 per coin.7 At the time, bitcoin was virtually un-ownable for institutional investors. Trading took place primarily on fragile offshore exchanges, and custody required managing private cryptographic keys. Loss of a private key meant irreversible forfeiture of the assets, while key compromise resulted in theft—operational risks that barred registered investment advisers, pension funds, and institutional compliance desks from direct participation.
That operational friction mirrored the market bottlenecks SecondMarket was created to address. In 2013, Silbert's team launched the Bitcoin Investment Trust as a private placement for accredited investors.8 The design was deliberately conventional: a Delaware statutory trust held physical bitcoin in offline cold storage, while accredited investors acquired shares carrying standard CUSIP identifiers that could appear on brokerage statements alongside traditional equities and bonds. By relying on Regulation D, the private-placement safe harbor from registration under the Securities Act of 1933, Grayscale offered institutional and high-net-worth investors exposure to bitcoin without requiring prior SEC approval of the asset itself.
The vehicle operated much like a bonded warehouse: the underlying inventory was identical to tokens traded on retail exchanges, but packaging it within an institutional custody and administrative wrapper allowed regulated capital to participate—while permitting the sponsor to levy a toll for access.
May 2015: the OTC listing and the 2% toll
A critical turning point occurred in May 2015, when shares of the trust began trading on the OTCQX over-the-counter market under the ticker GBTC.4 The market mechanism hinged on SEC Rule 144, which permits the resale of restricted securities into the public market following a mandated holding period. Accredited investors created trust shares at net asset value by contributing either cash or bitcoin directly to the fund. Once the holding period expired, those restricted shares became freely tradable on the secondary market.
This mechanism transformed GBTC into the sole publicly quoted security in the United States backed by physical bitcoin. Retail brokerages and tax-advantaged retirement accounts could suddenly acquire bitcoin exposure through a standard ticker. In exchange, Grayscale levied an annual management fee of 2.0%, deducted daily from the trust's bitcoin holdings.3 By traditional asset management standards, a 200-basis-point fee on a static, single-asset portfolio was extraordinary—dwarfing broad-market index funds charging single-digit basis points. Yet in the absence of viable competing wrappers, Grayscale commanded near-monopoly pricing power for institutional-grade access.
Digital Currency Group: the conglomerate funded by a toll booth
In 2015 Silbert also formed Digital Currency Group, the holding company that would own Grayscale and a growing constellation of other businesses.5 After selling SecondMarket's non-crypto secondary business to Nasdaq around the same time, DCG assembled Genesis, a trading desk and crypto lender; CoinDesk, the industry's best-known news outlet; Foundry, a bitcoin mining pool and services business; and a large venture portfolio.5
DCG was frequently characterized as an aspiring "Berkshire Hathaway of crypto," yet the structural comparison reveals key differences. Berkshire Hathaway built its capital base on insurance float—low-cost policyholder reserves deployed into diversified, cash-generative operating businesses. DCG's financial engine, by contrast, relied on Grayscale's fee stream, while its lending unit, Genesis, grew increasingly entangled with GBTC itself. Rather than siloing operating liabilities from risk capital, DCG's structure allowed the same asset, GBTC shares, to show up as fee base, loan collateral, and trading inventory at once. That circularity would later prove systemic.
For investors, this foundation explains GBTC's competitive profile. The trust's initial dominance stemmed neither from proprietary technology nor from brand loyalty, but from a temporary regulatory monopoly: it offered an acceptable vehicle in an environment where regulators refused to permit a standard exchange-traded fund. While regulatory moats endure only as long as administrative resistance persists, that resistance held for years—allowing the trust to develop a lucrative market dynamic where its shares traded at a substantial premium to the underlying bitcoin.
III. The Machine: How the GBTC Arbitrage Flywheel Conquered Wall Street (2015–2020)
Paying two dollars for one dollar of bitcoin
In late August 2017, The Motley Fool published an analysis that captured an apparent market absurdity. Shares of the Bitcoin Investment Trust had closed at $832.99, while the underlying bitcoin backing each share was worth just $413.16. Investors were paying a premium of roughly 101.6% to hold bitcoin through a brokerage ticker rather than directly.9 During the peak of the 2017 cryptocurrency rally, that premium widened even further. In an efficient market, paying two dollars for one dollar of an identical, publicly traded asset appears indefensible.
The explanation lay in structural accessibility. Direct bitcoin ownership was feasible only for investors willing to navigate unregulated crypto exchanges and assume self-custody risks. It remained off-limits inside a Fidelity individual retirement account, a Charles Schwab brokerage account, or an employer-sponsored 401(k) window. For capital confined to traditional brokerage architecture, GBTC was the sole entry point—and investors willingly paid a steep premium to cross that threshold.
The premium also persisted because the supply of GBTC shares could not expand fast enough to satisfy surging demand. New shares could be issued only through private placements subject to a mandatory holding period, and the trust lacked an authorized redemption program. Capital entered through a sluggish one-way valve and could not leave. While a standard exchange-traded fund tethers its market price to net asset value through continuous creation and redemption—where authorized participants arbitrage mispricings by exchanging shares for underlying assets—GBTC operated with only half of that mechanism, and on a months-long delay.
The GBTC trade
Wall Street institutional desks quickly seized on the pricing anomaly. What became known across the industry simply as "the GBTC trade" operated through a repeatable five-step loop: a hedge fund borrowed bitcoin or cash, frequently from an institutional crypto lender; it delivered the bitcoin to Grayscale through a private placement, receiving newly minted GBTC shares at net asset value; it waited out the Rule 144 holding period; upon expiration of the lockup, it sold the unrestricted shares on the over-the-counter market to buyers paying a premium; and finally, it repaid the borrowed principal and pocketed the net spread.
So long as the premium endured throughout the lockup window, the trade generated an exceptionally high return on capital with seemingly negligible risk. The dynamic soon evolved into a self-reinforcing flywheel: a persistent premium attracted arbitrageurs; arbitrageurs deposited bitcoin to create new trust shares; new share creation expanded Grayscale's assets under management; surging assets generated widespread industry attention; that visibility fueled secondary retail demand; and sustained retail demand upheld the premium. Meanwhile, Grayscale quietly collected its 2% annual fee from an ever-expanding hoard of digital assets.
Yet the trade rested on a dangerous structural vulnerability. Every arbitrageur was, in practice, short a put option on the trust's premium: they harvested a steady spread as long as market conditions remained unchanged, but faced catastrophic downside if the premium collapsed during the months their capital was locked up.
January 2020: turning up the flywheel
The flywheel accelerated dramatically in early 2020 through a regulatory milestone that few mainstream market observers noted at the time. On January 21, 2020, Grayscale announced that its Form 10 registration statement had become effective, establishing the trust as an SEC reporting company registered under Section 12(g) of the Securities Exchange Act of 1934—the first digital-currency investment vehicle to achieve that status.10 SEC reporting obligations mandated audited financials, quarterly 10-Qs, and annual 10-K filings, providing traditional institutions with standardized regulatory disclosures. Crucially, reporting status also triggered an operational shift under federal securities law: shares acquired via private placement became eligible for a shorter Rule 144 holding period, compressing the mandatory lockup from twelve months to six.11
Halving the holding period effectively doubled the flywheel's velocity. Arbitrageurs could recycle their capital twice as fast each year, while their duration risk—the window in which an adverse shift in the premium could wipe out profits—narrowed from twelve months to six. The regulatory timing coincided fortuitously with the onset of the pandemic-era monetary expansion and crypto bull market. GBTC's asset base expanded rapidly throughout 2020, accumulating roughly 600,000 bitcoin by year-end, according to the trust's annual report.12 Regulatory disclosures from the same filing season revealed that Three Arrows Capital, the Singapore-based hedge fund founded by Su Zhu and Kyle Davies, held nearly 39 million GBTC shares by the end of 2020, establishing it as the trust's largest disclosed shareholder.13
Historical falsification point #1: the "permanent network effect" illusion
Throughout this era, the prevailing institutional thesis surrounding Grayscale posited that GBTC's early mover advantage had hardened into a permanent network effect. Proponents argued that the fund's superior liquidity, entrenched brand recognition, broad broker-dealer plumbing, and institutional familiarity created an insurmountable competitive moat. That hypothesis can be evaluated through the economic mechanism that eventually dismantled it: product substitution.
The empirical record decisively refutes the durable-moat thesis. GBTC's premium never reflected an authentic liquidity network effect; it was the product of artificial access scarcity combined with an absolute inability to redeem shares. The moment viable foreign and derivative substitutes emerged—most notably the launch of Canada's Purpose Bitcoin ETF in February 2021, alongside maturing European exchange-traded products and regulated futures contracts—the premium did not smoothly compress toward parity. Instead, GBTC slipped into a discount to net asset value for the first time in February 2021 and remained trapped there for nearly three years.2 A genuine liquidity moat would have absorbed the debut of a modest Canadian vehicle; what Grayscale possessed was simply a temporary monopoly on an access point, the economic rent of which evaporated as soon as alternative passages emerged.
The more defensible historical interpretation is narrower: GBTC possessed formidable early distribution across U.S. retail and retirement brokerage accounts, which explains why hundreds of thousands of bitcoin pooled within the vehicle. Yet that distribution was an artifact of regulatory friction rather than consumer loyalty or structural efficiency. The ultimate market test of that distribution advantage—a fully approved, low-cost U.S. spot ETF—remained three years away. In the interim, Grayscale's one-way valve transformed from a lucrative asset-gathering engine into an institutional liquidity trap.
IV. The Great Inversion: The Premium Evaporates & The Contagion Abyss (2021–2023)
February 2021: the flip
Consider the position of a hedge fund portfolio manager in early 2021, midway through a mandatory six-month GBTC lockup. The trade had been established when GBTC traded at a comfortable premium to its underlying bitcoin. The borrowing that funded the position was denominated in bitcoin. While waiting for the lockup to expire, the capital earned nothing; the trade's profitability rested entirely on the assumption that secondary market buyers would pay at least net asset value once the shares unlocked. Then, in late February 2021, trading screens flashed a condition unseen since the trust's public debut: GBTC traded at a discount to its net asset value.2
The arbitrage broke immediately. An institution that had created GBTC shares at net asset value now held securities worth less than the borrowed bitcoin required to mint them. Unlike a traditional open-end fund or ETF, GBTC offered no redemption mechanism: the shares could not be returned to Grayscale in exchange for the underlying physical coins. The only available exit was selling into the secondary market at whatever discount clearing prices dictated.
The reflexive spiral
That structural rigidity transformed the closed-end vehicle into a reflexive trap, where downward price pressure and forced selling fed directly on each other. As the discount widened, leveraged holders faced margin calls and liquidated shares, which drove prices lower and triggered subsequent rounds of margin calls. In a conventional open-end fund, secondary market selling prompts share redemptions that shrink the asset base, return pro rata assets to departing investors, and tether the market price back to NAV. GBTC could not shrink. The same fixed pool of shares simply circulated at ever-deeper discounts.
By October 2021, when Grayscale formally applied to convert GBTC into a spot bitcoin ETF, the discount had widened to roughly 20%.14 A year later, it sat near 36%.15 In December 2022, following the collapse of crypto exchange FTX, the discount reached an all-time low of roughly 47% to 49%.1 Each GBTC share represented a claim on bitcoin that public markets valued at barely half its face value.
The shadow leverage exposed
That valuation discount might have remained a painful but contained equity loss had GBTC shares been held exclusively by unleveraged market participants. Instead, trust shares had become ubiquitous collateral across the crypto lending ecosystem. When their market value collapsed, credit impairment moved rapidly through institutional balance sheets.
Three Arrows Capital sat at the center of the unwind. Its outsized GBTC position was heavily financed with debt, and its credit lines from Genesis were collateralized in part by 17.4 million GBTC shares.16 When the digital asset market turned down sharply in the spring of 2022 and Three Arrows Capital failed to meet a substantial margin call in June, Genesis moved to liquidate that collateral and filed a claim of roughly $1.2 billion against the hedge fund.16 Subsequent court records showed that Genesis had extended approximately $2.36 billion in loans to Three Arrows Capital that were undercollateralized.16 Three Arrows Capital entered liquidation that summer.13
The damage quickly reached the parent company. DCG stepped in to assume certain Genesis liabilities tied to Three Arrows Capital.17 The maneuver transferred a balance-sheet deficit from the lending subsidiary to the parent company, structured as a long-dated intercompany promissory note rather than an infusion of fresh equity capital. That arrangement deferred an immediate liquidity crisis, but it did not recapitalize the lending operation.
When FTX collapsed in November 2022, Genesis suspended all customer withdrawals. Among the affected creditors were retail participants in Gemini Earn, a yield program run by the Winklevoss twins' Gemini exchange, which had lent customer crypto assets to Genesis. In early January 2023, Cameron Winklevoss published an open letter on behalf of more than 340,000 Earn users, accusing Silbert of "bad faith stall tactics" over roughly $900 million in frozen funds, and subsequently demanded that DCG's board remove him as chief executive.18 Silbert and DCG disputed the allegations. On January 19–20, 2023, Genesis Global Holdco and two of its lending subsidiaries filed for Chapter 11 bankruptcy protection in New York.19
Historical falsification point #2: the conglomerate "synergy" thesis
DCG's central pitch for its corporate architecture was that controlling the full vertical stack of digital finance—asset management, lending, trade media, and mining—created operational resilience and proprietary distribution. The subsequent credit cycle subjected that thesis to an empirical test.
The market evidence decisively refuted the synergy narrative. The operating units were not counter-cyclical; they were correlated, sharing simultaneous directional exposure to digital asset prices and to GBTC specifically. Genesis lent against GBTC shares as collateral; the widening discount degraded that collateral; and the resulting credit losses flowed directly up to DCG. Throughout that period, DCG's sole robust cash-generating engine remained Grayscale's management fee on GBTC. That revenue stream, previously viewed as a core corporate asset, quickly drew market scrutiny. Critics contended that the sponsor had strong financial incentives to preserve its 2% fee and resist redemptions because the parent company relied on that cash flow. Grayscale maintained that federal regulatory constraints, rather than parent-level financial considerations, precluded an open-market redemption program. Yet the structural tension was evident, regardless of intent.
The narrower conclusion that survives: vertical integration provided DCG with formidable distribution and market intelligence during a credit expansion. However, it also created a contagion channel through which the market discount on a single investment trust could threaten the solvency of an entire corporate group. With the trust trading at a discount near 50%, legal challenges mounting, and its lending affiliate in bankruptcy court, Grayscale's remaining mechanism to eliminate the discount was the strategy it had pursued for years: converting GBTC into an exchange-traded fund. Because the SEC had repeatedly denied that application, Grayscale challenged the agency in federal court.
V. Suing the Sovereign: The Legal Masterstroke in Grayscale v. SEC (2022–2023)
Denial, and a lawsuit filed the same day
On June 29, 2022, the SEC denied NYSE Arca's proposed rule change to list GBTC as a spot bitcoin ETP.[^20] The legal standard hinged on Section 6(b)(5) of the Securities Exchange Act of 1934, which requires an exchange's rules to be "designed to prevent fraudulent and manipulative acts and practices." The Commission's longstanding position held that spot bitcoin markets were vulnerable to manipulation, and that the exchange had failed to demonstrate a sufficiently robust surveillance-sharing agreement with a regulated market of significant size.
Grayscale had spent months preparing for that rejection. The sponsor filed a petition for review in the U.S. Court of Appeals for the District of Columbia Circuit that same day.[^20] To lead the appellate team, Grayscale retained Donald B. Verrilli Jr., former Solicitor General of the United States, best known for defending the Affordable Care Act before the Supreme Court.[^20] Retaining Verrilli signaled a deliberate institutional strategy: rather than treating the denial as routine administrative pushback, Grayscale mounted a rigorous administrative-law challenge led by one of the country's prominent appellate advocates.
The argument: you cannot treat twins differently
Grayscale's case rested on a straightforward symmetry. By that time, the SEC had already approved ETPs that held bitcoin futures contracts traded on the Chicago Mercantile Exchange. Futures prices, Grayscale argued, derived directly from the underlying spot bitcoin market; if spot markets were vulnerable to manipulation, CME futures prices would inevitably reflect that same distortion. The CME surveillance arrangement that the SEC deemed adequate for futures funds should therefore provide equivalent protection for a spot fund, since both products drew their pricing from the identical underlying market. Grayscale contended that treating two economically linked vehicles differently without a coherent rationale was "arbitrary and capricious" under the Administrative Procedure Act, the federal statute requiring regulatory agencies to maintain consistent reasoning.
The economic logic mirrored a basic regulatory inconsistency: a food agency approving juice made from concentrate while banning fresh-squeezed juice over contamination concerns, without demonstrating why the concentrate was immune to the identical source risks. Under administrative law, disparate treatment of economically equivalent products without a rational justification fails the test of reasoned decision-making.
August 29, 2023: a unanimous panel
A three-judge panel comprising Chief Judge Sri Srinivasan, Judge Neomi Rao, and Senior Judge Harry Edwards ruled unanimously for Grayscale on August 29, 2023, with Judge Rao writing the opinion.[^20] The key line was blunt: "The denial of Grayscale's proposal was arbitrary and capricious because the Commission failed to explain its different treatment of similar products."[^20] The court vacated the SEC's order and remanded the matter to the Commission.
The scope of Grayscale's victory required precise interpretation. The court did not order the SEC to approve GBTC's conversion. It held that the agency had failed to provide a reasoned explanation for treating spot and futures filings differently. In theory, the Commission could have formulated an alternative, more rigorously reasoned justification for denial. In practice, the agency's primary legal defense had been dismantled, leaving approval as the path of least regulatory resistance. The SEC chose not to seek further review.
The stampede, and the irony
The market had anticipated that outcome. In June 2023, two months before the court's ruling, BlackRock filed for its iShares Bitcoin Trust, and peers including Fidelity, Invesco, and ARK Invest followed with their own applications. BlackRock's entry shifted institutional expectations: the world's largest asset manager, with an ETF approval record approaching perfection, had formally entered the queue. GBTC's discount to net asset value narrowed sharply through the second half of 2023 as investors priced in the rising probability of conversion.20
That convergence created the central strategic irony of the episode. Grayscale spent years and substantial capital on litigation to establish a binding legal principle, yet that principle was not proprietary. Once the D.C. Circuit established the precedent, it applied equally to every competing issuer. The lawsuit functioned as a classic public good financed by a single private firm: BlackRock and Fidelity did not need to litigate the issue themselves; they simply needed Grayscale to prevail.
For institutional allocators, this dynamic offered a clean demonstration of the distinction between winning a legal victory and capturing its commercial value. The appellate decision delivered immediate value to existing trust shareholders by creating the path to close the discount—a tangible gain for fundholders. Yet it offered no structural defense for Grayscale's ongoing fee revenue. On January 10, 2024, the SEC granted approval to the first wave of spot bitcoin ETFs, setting off an immediate fee war across Wall Street.
VI. The ETF Conversion & The Great Exodus: The 150 Bps Trap vs. The TradFi Behemoths (2024)
January 10–11, 2024: approval day
On January 10, 2024, the SEC approved rule changes permitting eleven spot bitcoin exchange-traded products to list and trade, issuing Release No. 34-99306.[^22] An accompanying statement from SEC Chair Gary Gensler struck a distinctly reluctant tone, emphasizing that the Commission's action had been forced by the D.C. Circuit's ruling and expressly disclaiming any regulatory endorsement of bitcoin, which he characterized as "a speculative, volatile asset."21 The following morning, GBTC commenced trading on NYSE Arca as an exchange-traded fund equipped with an active creation and redemption mechanism, and the structural discount to net asset value closed for the first time since February 2021.2
For existing trust shareholders, the transition delivered long-delayed vindication. Allocators who had acquired shares at discounts approaching 40% or more and held through conversion captured that full pricing spread alongside any underlying price appreciation in bitcoin. Activist investors and institutional desks that had spent two years demanding a redemption program finally secured an exit at net asset value.
The price list
The newly disclosed fee schedules signaled an immediate competitive divergence. BlackRock set the sponsor fee for its iShares Bitcoin Trust (IBIT) at 0.25%, accompanied by a temporary introductory waiver; Bitwise launched at 0.20% with a six-month waiver to zero on its first $1 billion in assets; and competing issuers largely clustered between 0.19% and 0.39%.22 Grayscale, by contrast, trimmed GBTC's annual sponsor fee from 2.00% to 1.50%, leaving it by a wide margin the most expensive vehicle in the category.22 20
In dollar terms, an investor holding $100,000 in GBTC pays roughly $1,500 annually in sponsor fees, compared to $200 to $250 for an equivalent allocation in a competing low-cost fund.4 Over a ten-year holding horizon, even before accounting for compounding effects, that differential extracts more than $12,000 from a $100,000 position. In an asset category where every fund holds the identical underlying commodity, that fee differential becomes the defining economic attribute of the product.
The great outflow bleed
The market's reaction was immediate and unrelenting. Capital drained rapidly from GBTC throughout its initial weeks of ETF trading. A portion of that selling was non-discretionary: the FTX bankruptcy estate liquidated the bulk of its GBTC holdings, valued at roughly $1 billion, shortly after conversion to raise cash distributions for creditors.23 Other distressed estates and arbitrageurs that had been trapped by the multi-year discount liquidated positions the moment an exit at net asset value became available. Yet a substantial share of the departures was purely rotational. For institutional allocators and retail investors in tax-advantaged accounts—or taxable accounts with minimal embedded gains—selling GBTC to reallocate into a 0.25% competitor yielded an immediate 125-basis-point annual fee reduction for the frictional cost of a pair of trades.
Within two months of conversion, GBTC's bitcoin holdings had fallen by approximately one-third.24 On May 29, 2024, BlackRock's IBIT formally surpassed GBTC to become the world's largest bitcoin fund.25 BlackRock accomplished in under five months what had taken Grayscale over a decade to build, illustrating the volume of institutional capital that had been awaiting low-cost access through an established global asset manager.
The outflow proved to be an enduring structural drain rather than an isolated post-conversion shock. Cumulatively, since conversion, GBTC has shed roughly 447,000 bitcoin through redemptions.4 Sustained price appreciation in bitcoin cushioned the fund's nominal dollar decline, which is why the trust still held approximately $10.1 billion in assets under management in September 2026.4
Historical falsification point #3: "liquidity justifies the fee"
During the conversion rollout, Grayscale's then-chief executive, Michael Sonnenshein, publicly defended the 1.50% fee by highlighting GBTC's market liquidity, operational track record, and institutional familiarity. The commercial argument held that investors would pay a premium to transact in the deepest, most established vehicle. That proposition can be tested through the market mechanism that ultimately challenged it: whether competing issuers could rapidly replicate that liquidity.
The empirical evidence decisively refuted the liquidity-justification thesis in its strong form. Within weeks of listing, IBIT and Fidelity's FBTC were trading massive daily volumes at tight spreads. In modern exchange-traded fund architecture, liquidity is not proprietary to the sponsor; an ETF's tradability derives from the depth of the underlying asset market and the presence of market makers willing to create and redeem shares. Because every competing fund held identical spot bitcoin, market makers manufactured institutional-grade liquidity across rival products almost immediately. Grayscale's day-one liquidity advantage was genuine, but it depreciated rapidly.
A narrower form of that advantage did endure: GBTC continues to report a median bid-ask spread of roughly 0.02%, ranking among the tightest in the category, and it retains active trading in listed options.4 Yet a two-basis-point transaction-spread advantage cannot economically justify a 125-basis-point annual fee gap for a buy-and-hold allocator. A modified, defensible claim is that GBTC's liquidity profile retained value primarily for high-velocity institutional traders—a specialized cohort that constituted a small and shrinking fraction of the asset base. The market's verdict on the broader claim was delivered in redemptions totaling roughly 447,000 bitcoin. That outcome framed the strategic puzzle confronting Grayscale's next era of leadership: if an elevated fee was not justified by secondary liquidity, what commercial purpose was it designed to serve?
VII. The New Guard: Peter Mintzberg, The Mini Trust (BTC), & Corporate Governance Clean-Up (2024–Present)
Clearing the decks
In late December 2023, only weeks before the Securities and Exchange Commission's statutory deadline on spot bitcoin applications, Barry Silbert resigned as chairman of Grayscale's board alongside Digital Currency Group president Mark Murphy.26 [^29] DCG chief financial officer Mark Shifke stepped in as chairman.[^29] Grayscale disclosed little about the move, but the timing pointed to a clear commercial objective: with Silbert personally named in the New York Attorney General's civil fraud lawsuit surrounding Gemini Earn, establishing distance between the sponsor's board and DCG's founder offered a cleaner profile for regulators and wirehouse gatekeepers.
Five months later, the executive suite turned over. Michael Sonnenshein, who had joined Grayscale in 2014 and served as chief executive since 2021, stepped down. On May 20, 2024, Grayscale appointed Peter Mintzberg as chief executive, effective that August.[^30] Mintzberg had served as global head of strategy for asset and wealth management at Goldman Sachs, following earlier senior strategy positions at BlackRock and OppenheimerFunds.[^30]
The transition signaled an institutional pivot. Sonnenshein had steered Grayscale during its regulatory monopoly and high-margin expansion. Mintzberg, by contrast, emerged from the traditional firms capturing Grayscale's market share—institutions where asset gathering depends on model portfolios, platform gatekeepers, and institutional due-diligence committees rather than first-mover novelty.
Yet the governance overhaul soon reversed course. On August 4, 2025, following Grayscale's confidential filing for an initial public offering, the firm announced that Silbert would return as board chairman, with Shifke remaining as a director alongside incoming independent board members from Bridgewater Associates, Apollo Global Management, Goldman Sachs, and Citadel.27 The founder's absence lasted roughly nineteen months. The episode revealed the boundaries of Grayscale's restructuring: while the firm installed seasoned traditional executives to lead fund operations, corporate control remained firmly anchored to DCG and Silbert.
The tax lock-in: why 1.50% survived
Why did Grayscale leave GBTC's expense ratio at 1.50% while rivals charged a fraction of that amount? The operational explanation rests primarily on capital gains taxation rather than secondary-market liquidity.
Consider an allocator holding GBTC in a taxable brokerage account with a purchase price near $10,000 per coin. With bitcoin trading in the $70,000 range, unrealized capital gains represent the vast majority of the position's market value. Liquidating GBTC to rotate into an alternative fund charging 0.25% immediately triggers federal long-term capital gains taxes of up to 20%, the 3.8% net investment income tax for higher earners, and applicable state levies. On a deeply appreciated holding, that tax liability can instantly consume 20% to 30% of total capital. Against that immediate reduction in principal, an annual fee savings of 1.25% would require well over a decade simply to break even on an undiscounted basis. For an investor with an older, low-basis position, holding GBTC remains mathematically rational despite the elevated management toll.
That friction created a captive shareholder base: investors whose economic interest favored remaining in a vehicle whose fee structure they opposed. Grayscale's strategy reflected an explicit revenue calculation: harvesting a 1.50% fee on this locked-in asset pool generated far more cash flow than matching a 0.25% industry standard on a marginally larger base. Against roughly $10.1 billion in GBTC assets, a 1.50% fee yields approximately $150 million in annual top-line sponsor revenue. By comparison, charging 0.25% on double that asset base would bring in only about $50 million. While Grayscale has not publicly framed its pricing in these terms, the decision is economically consistent with an asset-harvesting strategy.
That strategy, however, operates against a steady demographic and balance-sheet clock. Each year, some low-basis investors realize offsetting losses, transition into lower tax brackets, or transfer shares to heirs who benefit from a stepped-up tax basis that eliminates the embedded gain. The captive base is real, but it resembles a melting ice cube—and the 1.50% annual fee drag only accelerates the melt.
The Grayscale Bitcoin Mini Trust: the cannibalization hedge
On July 31, 2024, Grayscale introduced its countermeasure for fee-sensitive capital: the Grayscale Bitcoin Mini Trust, trading under the ticker BTC.28 Rather than launching an empty vehicle into a crowded market, Grayscale seeded the fund by carving out 10% of GBTC's physical bitcoin and distributing corresponding shares directly to existing GBTC holders.28 Grayscale structured the spinoff so that it was "not expected to be a taxable event for GBTC nor any beneficial owner of GBTC shares."28 The Mini Trust debuted with roughly $1.7 billion in assets under management and a sponsor fee of 0.15%, ranking at the time as the lowest in the spot bitcoin category.28
The corporate architecture formed a deliberate barbell strategy. GBTC served as the premium-fee cash cow for legacy capital locked in by embedded taxes, while the Mini Trust operated as a low-cost competitor designed to capture new inflows and defend against low-fee rivals. The structure allowed Grayscale to operate simultaneously as the high-margin incumbent and the low-cost challenger.
That defense carried an immediate internal cost. The 10% slice of GBTC assets transferred into the Mini Trust saw its annual fee yield drop from 1.50% to 0.15%—a 90% revenue contraction on that capital. Grayscale surrendered fee revenue to keep capital within its fund ecosystem that might otherwise have defected to low-cost alternatives like BlackRock's IBIT. While that concession was an economically rational alternative to outright redemptions, it illustrated how internal substitution could erode Grayscale's high-margin fee stream even when assets remained under its roof.
Judging the new guard by behavior
Evaluating the credibility of Grayscale's executive transition requires comparing strategic statements against operational actions. Management stated its ambition to reposition Grayscale as a diversified, institutional-grade asset manager. In execution, the firm accelerated new product rollouts, including first-in-market staking features,29 recruited senior leadership from major Wall Street institutions,27 and advanced preparations for a public equity offering. At the same time, it maintained the 1.50% fee on GBTC. That posture is internally coherent: an asset manager can build institutional-grade infrastructure across new product lines while deliberately maximizing cash extraction from a legacy vehicle. For GBTC holders, however, it signaled that corporate professionalization was not designed to yield fee relief. The firm treated GBTC's expense ratio as a calculated commercial choice rather than a temporary anomaly.
The deployment of the Mini Trust highlighted a parallel operational reality. During the conversion campaign, Grayscale contended that GBTC's secondary liquidity and market heritage would insulate its asset base from lower-priced rivals. The new regime did not rely on that thesis; instead, it launched an ultra-low-fee substitute. That structural maneuver amounted to an acknowledgment through corporate action that an established brand alone could not defend against low-cost competition.
Grayscale's corporate trajectory under Mintzberg has centered not on defending GBTC's historical economics, but on managing the trust's steady asset attrition while building alternative revenue streams across the wider platform. The durability of that balance sheet depends on how much cash flow GBTC continues to generate, and how rapidly that legacy asset base contracts.
VIII. The Business Model & Unit Economics: Anatomy of a Monopolistic Fee Machine Melting Under Sunlight
How the fee machine works
The daily mechanics of the trust illustrate how capital moves through the vehicle. The trust holds its underlying bitcoin with institutional custodians, primarily Coinbase Custody, alongside Anchorage Digital Bank as an additional custodian.4 Each day, the sponsor fee accrues at an annualized rate of 1.50% of the trust's net asset value.3 Periodically, the trust liquidates a fraction of its bitcoin holdings to remit that fee to Grayscale in cash. Because that toll is paid directly out of the underlying inventory, the quantity of bitcoin backing each GBTC share contracts steadily over time. An investor who holds GBTC for a decade will retain meaningfully fewer coins per share at the end of that period than at the beginning, even in the complete absence of secondary-market share redemptions.
For the sponsor, the operational model is exceptionally capital-light. Grayscale requires no portfolio managers, equity research desks, or credit analysts to run a single-commodity trust. While the firm pays custody, index licensing, exchange listing, administrative, and marketing costs, it bears none of the directional price risk of the digital assets in its custody. Under the trust's operating structure, the sponsor covers these ordinary operating expenses directly out of its management fee.3 Once an asset base reaches institutional scale, incremental administrative costs are minimal, allowing the vast majority of fee revenue to flow directly to operating profit.
What the numbers reveal
Grayscale's IPO registration statement, filed publicly on November 13, 2025, offered the clearest look yet at the whole firm's economics.30 31 For the nine months ended September 30, 2025, Grayscale reported revenue of $318.7 million, down 20% from about $398 million in the same period a year earlier, and net income of about $203 million, down about 9%.30 Average AUM over the period was $30.6 billion, down only 3.5%.30 The filing stated that the company derives "a substantial portion" of its revenue from GBTC and its Ethereum Trust (ETHE), without disclosing a precise split.31
Those disclosures highlighted an underlying structural shift. Revenue contracted far more rapidly than average assets under management. That divergence occurs when product mix deteriorates: high-margin capital departs vehicles charging 1.50%, while incoming assets flow into low-fee alternatives such as the Mini Trust products that yield only a fraction of that rate. Grayscale's effective fee realization is compressing. The melting ice cube dynamic is visible on the income statement, not merely on fund-flow trackers.
Even with that fee compression, the firm's profitability remained extraordinary. Generating roughly $203 million in net income on $318.7 million in revenue represents a profit margin exceeding 60%—a level achieved by few traditional asset managers. The strategic question for allocators and prospective public investors is not whether the business generates substantial cash flow today, but whether those earnings stem from an enduring distribution franchise or from the terminal runoff of monopoly pricing on a contracting asset base.
The run-rate lens
Evaluating the operating trajectory of GBTC reduces to three core variables: the quantity of bitcoin held, the market price of each coin, and the sponsor fee. Bitcoin held has fallen from roughly 619,000 coins at the end of 20233 to roughly 130,000 in September 2026.4 The headline fee adjusted only once, declining from 2.00% to 1.50%. Sustained appreciation in bitcoin's spot price cushioned the nominal dollar toll, preventing top-line fee revenue from collapsing in tandem with the coin count.
Myth versus reality
Myth: GBTC's outflows are over, so the franchise has stabilized. The reality reflects a structural slowdown rather than a stabilization. The acute phase of the exodus—driven by bankruptcy liquidations, arbitrage unwinds, and tax-neutral capital rotations—concentrated in early 2024. What followed is a persistent, structural bleed. While an ongoing attrition rate is less destabilizing than an acute liquidity shock, it remains a unidirectional drain with no internal mechanism to reverse it. The sole force that historically attracted large volumes of new bitcoin into GBTC was the premium-era arbitrage loop, an engine that cannot function in an exchange-traded fund tethered to net asset value.
Myth: Grayscale could win the assets back with a fee cut. The commercial reality of switching costs makes that outcome improbable. Allocators who departed in 2024 already absorbed the tax realization and administrative frictions of exiting; they have no economic incentive to repatriate capital merely to match fee levels they already receive from BlackRock or Fidelity. Lowering GBTC's expense ratio would primarily reprice the captive, tax-locked capital that currently remains in place. That dynamic explains why management has preserved the 1.50% fee. If a broad fee cut eventually occurs, it will likely indicate that the captive asset pool has decayed to the point where maximizing immediate cash flow is no longer commercially viable.
Myth: the Mini Trust proves Grayscale can compete on price. The product demonstrates a willingness to discount, but structural pricing parity does not guarantee asset gathering. Whether an ultra-low-cost fund can attract net new capital across major wealth platforms against financial institutions with superior distribution footprints remains an unresolved commercial test that fund-flow data, rather than headline expense ratios, will resolve.
That reliance on the spot price of bitcoin represents the central vulnerability in the operating model. Grayscale's fee revenue from GBTC functions as a leveraged bet that token appreciation will outpace unit attrition. When bitcoin's price rises faster than capital departs, nominal revenues remain resilient. If the underlying asset depreciates or trades sideways while redemptions persist, revenues contract along both dimensions simultaneously. For an underlying asset that has historically experienced drawdowns exceeding 50%, this structural exposure creates a volatile earnings profile—a dynamic institutional investors evaluating a public equity offering must underwrite. Before assessing that valuation, however, it is necessary to examine what structural defenses, if any, remain to protect Grayscale's franchise from its competitors.
IX. Strategic Frameworks: Porter's Five Forces & Hamilton Helmer's 7 Powers
A war-game setup
Consider an ETF strategist at BlackRock in early 2024 sketching the competitive landscape on a whiteboard: eleven funds, a single underlying commodity, identical institutional custodians, overlapping index methodologies, and identical trading hours on major exchanges. In that environment, the only viable commercial levers are price, brand trust, and distribution reach. From Grayscale's side of the table, the board looked vastly different: the same commodity, but burdened by a legacy 2% fee, a parent conglomerate entangled in bankruptcy litigation, and a shareholder base scarred by a three-year discount to net asset value. Two standard strategic frameworks formalize the competitive realities of that showdown.
Hamilton Helmer's 7 Powers
Cornered resource: expired. From 2015 until January 2024, GBTC's cornered resource was its status as the sole widely accessible U.S.-quoted vehicle holding physical bitcoin. The SEC's approval of competing spot products converted that exclusive access into an undifferentiated commodity overnight.[^22] There is no longer an underlying asset or custodial arrangement GBTC commands that rivals cannot duplicate.
Switching costs: bifurcated, and the sole surviving defense. For retirement accounts, corporate treasuries, and tax-exempt allocators, switching costs were negligible—and that capital departed rapidly. For taxable accounts with substantial embedded capital gains, switching costs remain high and very real. Yet this defense is inherently defensive: it shields an existing pool of assets from defecting, cannot attract new inflows, and steadily decays as shareholders rebalance or transfer assets to heirs.
Scale economies: commanded by traditional rivals. Asset managers such as BlackRock and Fidelity spread their compliance, marketing, and distribution expenses across trillions of dollars in aggregate assets. They can operate a spot bitcoin fund at 0.25% as one marginal product line among thousands. By contrast, Grayscale reported firm-wide assets under management of roughly $35 billion in September 2025.30 While substantial by crypto-native standards, that scale remains modest across the broader asset management industry.
Counter-positioning: exhausted. In 2013, Grayscale was uniquely counter-positioned against traditional asset managers: legacy firms could not touch digital assets without regulatory and reputational friction, whereas Grayscale embraced them. Once mainstream institutions entered the spot market, that structural asymmetry dissolved. Grayscale retains potential counter-positioning only along the digital asset frontier—in emerging tokens and novel structures traditional custodians still avoid.
Network effects: weak. Exchange-traded fund liquidity exhibits modest network characteristics: higher trading volume attracts market makers, narrowing bid-ask spreads and drawing incremental volume. Yet that liquidity dynamic was replicated almost immediately by lower-cost competitors. With its larger asset base, BlackRock's IBIT rapidly captured the stronger liquidity network effect.
Branding: mixed. Grayscale remains an established crypto-native brand with strong name recognition among digital asset enthusiasts. However, that brand carries the historical baggage of the 2% fee era, the multi-year discount, and the DCG-Genesis bankruptcy fallout. For a wealth-management gatekeeper building model portfolios, an institutional brand like BlackRock serves as a frictionless credential, whereas Grayscale often requires extended justification.
Process power: negligible for bitcoin. Holding digital assets with an institutional qualified custodian has become standardized operational plumbing. Grayscale demonstrated greater process innovation in adjacent digital products, notably in being first to enable staking in U.S.-listed Ethereum products in October 2025.29 While that capability illustrates operational flexibility for multi-asset expansion, it provides no structural moat for GBTC.
In Helmer's terminology, GBTC retains only a single functional power: tax-driven switching costs anchored to an eroding base of legacy capital. Every other traditional moat has either expired or is held more effectively by competing Wall Street titans.
Porter's Five Forces
Threat of new entrants: high. With the SEC's legal objections dismantled, the regulatory template for listing a spot commodity trust is thoroughly established. Any well-capitalized asset manager can launch an identical fund using the same custodians and benchmark providers. The primary barrier to entry is no longer regulatory clearance, but distribution reach.
Buyer power: high. Registered investment advisers and institutional model-portfolio managers evaluate basis points rigorously. Retail investors in tax-advantaged accounts can rotate between funds with minimal friction. Cumulative fund flows confirmed that dynamic: buyers who could leave did.4
Threat of substitutes: extreme. Every competing spot ETF holds the identical underlying token. Beyond rival funds, allocators can choose direct self-custody, brokerage-based spot trading, futures-linked exchange-traded products, or corporate bitcoin treasury vehicles. When underlying assets are identical, pricing and platform integration become the primary bases of competition.
Supplier power: moderate. Coinbase Custody serves a majority of spot bitcoin ETFs, concentrating operational custody risk within a single dominant provider. Grayscale has added Anchorage as an additional custodian, a sensible diversification.4 Liquidity providers also function as key suppliers: GBTC lists five, including Goldman Sachs.4
Competitive rivalry: intense. Aggressive fee compression rapidly drove headline expense ratios across the category toward 0.15% to 0.25%. Competition has shifted from basic product availability to institutional platform approvals, wirehouse model-portfolio placement, and advisor education, where the largest global asset managers hold entrenched advantages.
Both strategic frameworks converge on the same conclusion: GBTC operates as a legacy vehicle in a commoditized asset class, leaving Grayscale's commercial future dependent on products beyond its flagship trust. That reality elevates the question of corporate governance: who controls Grayscale, and whose financial needs the trust's ongoing fee stream ultimately serves.
X. The Activist & Skeptic Stress Test: Liquidation Estates, Lawsuits, & The DCG Overhang
The discount-era lawsuits
In December 2022, with the GBTC discount near its worst, Fir Tree Capital Management sued Grayscale in Delaware's Court of Chancery, seeking books and records to investigate what it saw as mismanagement and conflicts of interest, and pushing for fee cuts and redemptions.32 Fir Tree's thesis, in plain terms, was that the sponsor was collecting a monopoly fee while shareholders absorbed a discount the sponsor could help close.
In January 2023, rival issuer Osprey Funds sued in Connecticut state court, alleging Grayscale had marketed ETF conversion as a foregone conclusion to protect its market position.33 That case was ultimately settled in 2025.34
In March 2023, Alameda Research, then controlled by FTX's bankruptcy administrators, sued Grayscale, DCG, and executives including Sonnenshein and Silbert, arguing that Grayscale's refusal to allow redemptions and its "exorbitant" fees had suppressed about $9 billion of value across its bitcoin and Ethereum trusts, with more than $250 million of that belonging to FTX creditors.35
Each of these suits attacked the same weak joint: the sponsor's fee and redemption policies. Grayscale's defense was that SEC rules prevented it from offering redemptions until it could list as an ETF. The ETF conversion largely mooted the redemption argument. It did not moot the fee argument.
The DCG overhang
The larger legal overhang sits at the parent. On October 19, 2023, New York Attorney General Letitia James sued Gemini, Genesis and DCG, alleging more than $1 billion of fraud against Gemini Earn investors and naming Silbert personally.[^40] In May 2024, Genesis settled with the Attorney General in an agreement worth up to $2 billion for defrauded investors and agreed to stop operating in New York.36 The case against DCG and Silbert continued.
Then the bankrupt Genesis estate turned on its own former parent. In May 2025, Genesis filed suits in Delaware Chancery and in the Southern District of New York bankruptcy court seeking to recover more than $3 billion from DCG and Silbert, alleging that DCG used Genesis to support its own finances and withdrew more than $1.2 billion in the year before the bankruptcy.37 DCG has disputed the claims. In February 2026 a federal judge allowed a separate investor class action against DCG to proceed.38 None of these claims had been resolved as of the most recent public reporting reviewed for this article.
What a skeptical investor would ask
An activist or short-seller looking at GBTC's governance would focus on three questions.
First, loyalty. Grayscale acts as sponsor for GBTC shareholders, but its economic owner is DCG, which faces multi-billion-dollar claims. Every basis point of GBTC fee cut reduces cash available to DCG. The structure gives the sponsor a direct incentive to keep the fee high as long as outflows remain tolerable. That incentive exists regardless of anyone's intentions, and GBTC's fee has not changed since conversion.
Second, control. Grayscale's IPO filing proposed a dual-class structure in which DCG would hold Class B shares carrying ten votes each and no economic rights, preserving majority voting control after the listing.39 Public shareholders in the sponsor would have limited ability to influence GBTC pricing even if they wanted to.
Third, extraction. The IPO filing also described an Up-C structure, in which proceeds would buy LLC units from pre-IPO holders and include distributions and a tax receivable agreement benefiting DCG-controlled entities.31 39 Those are standard features in many sponsor IPOs, but in this context they route value from new public shareholders toward a parent facing large legal claims.
The fair counterweight: Grayscale has shipped products, cut fees on its new launches, hired seasoned institutional executives, and settled at least one discount-era lawsuit. But the core conflict, a high-fee legacy fund whose cash flows serve a parent under legal pressure, is intact. That tension frames the final question: what would have to happen for GBTC and its sponsor to do better or worse from here?
XI. Bull vs. Bear Case Analysis
The IPO that paused
The sponsor's effort to access the public equity markets highlights the firm's broader valuation dilemma. Grayscale submitted a confidential draft registration statement for an initial public offering in mid-2025, filed its Form S-1 publicly in November 2025, and sought a listing on the New York Stock Exchange under the ticker GRAY.39 Then market conditions deteriorated. On May 28, 2026, CoinDesk reported that Grayscale had paused IPO preparations and was unlikely to restart before the fourth quarter of 2026, amid weak post-listing performance by other crypto issuers and delays at Kraken's parent, ConsenSys, and Ledger.40 A Grayscale spokesperson declined to comment, citing the SEC-mandated quiet period.40 While the pause reflected a broader market judgment on the crypto-listing cohort rather than a company-specific setback, it deferred public-market price discovery that would have assigned an objective valuation to the franchise.
The bear case
The asset drain continues. Redemptions have already removed more than two-thirds of GBTC's peak bitcoin holdings. The remaining shareholder base is heavily concentrated in taxable accounts with low cost bases, but that protection steadily decays each year through estate planning, rebalancing, tax-loss harvesting, and investor attrition. Absent an aggressive fee reduction, the asset base will continue to erode—a pace that could accelerate if bitcoin appreciates to the point where the embedded tax penalty feels manageable relative to the cumulative drag of a 1.50% annual fee.
Revenue compression outruns asset scale. The sponsor's public filing documented the structural vulnerability of fee substitution: for the first nine months of 2025, Grayscale's revenue fell 20% while average assets under management slipped only 3.5%.30 If that divergence persists, Grayscale can gather net new assets and still see top-line revenue contract, because incoming capital arrives at low-double-digit basis points while departing capital once yielded 150 basis points.
Mini Trust cannibalization. Every dollar that rotates from GBTC into the Bitcoin Mini Trust surrenders 90% of its annual fee yield, dropping from 1.50% to 0.15%. To the extent the Mini Trust succeeds primarily by retaining Grayscale's existing clients rather than capturing market share from rival issuers, it accelerates the firm's top-line fee compression.
Parent-level contagion. Unresolved litigation against Digital Currency Group and Barry Silbert means the sponsor's controlling shareholder faces claims that exceed Grayscale's annual revenue. Adverse legal rulings could pressure DCG to extract additional cash dividends from Grayscale or pursue asset sales, while maintaining a reputational headwind across wirehouse and institutional wealth-management platforms.
Underlying token volatility. Grayscale's top-line sponsor revenue remains directly tethered to the spot price of bitcoin. A sustained cyclical downturn would compound ongoing redemptions, shrinking nominal revenue simultaneously through both coin outflows and balance-sheet asset deflation.
The bull case
A durable, high-margin tax shield. A substantial portion of GBTC's remaining capital carries deep unrealized gains, giving investors little economic incentive to liquidate. With bitcoin trading at elevated levels, a 1.50% fee on roughly $10 billion in assets continues to generate on the order of $150 million annually in high-margin cash flow. Even if that asset pool contracts at a steady pace, the cumulative cash extracted over the trust's remaining lifespan remains substantial.
A functional barbell defense. The Bitcoin Mini Trust provides Grayscale with a competitive low-cost wrapper capable of competing for fee-sensitive capital and keeping migrating allocators within the sponsor's fund ecosystem. If the Mini Trust captures its share of category inflows, Grayscale's aggregate digital asset franchise will prove far more resilient than GBTC's standalone redemption figures suggest.
A diversified long tail of crypto assets. Grayscale remains the most prolific digital-asset fund sponsor in the country, managing more than 40 products spanning over 45 individual tokens as of September 2025.31 The firm demonstrated operational agility by becoming the first sponsor to enable staking in U.S. spot Ethereum products,29 and its Grayscale Ethereum Staking Mini ETF drew $337 million in inflows by March 31, 2026, ranking as the top-performing U.S. Ethereum ETP in the first quarter.40 If institutional demand broadens beyond bitcoin and ether into alternative tokens, Grayscale's willingness to build and seed niche wrappers offers a structural counter-position against larger traditional managers that move more cautiously.
Institutionalization and governance professionalization. Assembling an executive team and independent board with senior credentials from Goldman Sachs, BlackRock, Bridgewater, Apollo, and Citadel represents a deliberate effort to make the firm legible to institutional gatekeepers and wealth-management platforms.[^30] 27 While administrative pedigree alone does not guarantee model-portfolio inclusion, it establishes the operational compliance profile required to compete for mainstream advisory capital.
Weighing the cases
The bull case for Grayscale as an operating asset manager is materially stronger than the case for GBTC as a standalone fund. For GBTC, the evidence supports a narrower conclusion: tax lock-in will moderate the pace of redemptions rather than reverse them, leaving the trust to function as a legacy vehicle to be harvested. For Grayscale the enterprise, the core strategic question is whether high-volume, low-margin products and alternative token wrappers can scale quickly enough to replace the high-fee legacy revenue before that base runs off. The financial results from the first nine months of 2025 showed that this transition had not yet achieved parity, as fee compression outpaced asset growth. The expansion of the firm's broader product pipeline, however, shows that an institutional pivot remains underway.
The three KPIs that matter most
- GBTC's bitcoin holdings over time. The physical coin count in the trust, rather than its dollar-denominated assets under management, provides the purest gauge of whether the captive shareholder base is stabilizing or continuing to erode.
- Grayscale's effective fee realization. Comparing total revenue against average assets under management reveals whether the firm's newer, lower-margin products are genuinely replacing the economics of the legacy trusts or merely replacing lost asset volume.
- Net organic inflows into the Grayscale Bitcoin Mini Trust. Sustained positive flows from outside the Grayscale ecosystem would demonstrate that the firm can win competitive mandates on price and distribution, whereas weak flows would suggest the Mini Trust functions primarily as a transitional holding pen for departing GBTC holders.
Whichever way those indicators resolve, the history of GBTC already offers market-structure lessons that outlast the vehicle itself.
XII. Playbook & Epilogue: Lessons from the Financial Trojan Horse
The lessons
Regulatory arbitrage is rented, not owned. GBTC's economics depended entirely on an administrative gap: no spot ETF, no redemption mechanism, and no viable alternative for conventional brokerage accounts. That regulatory friction yielded a decade of exceptional fee revenue. When regulators were forced to close the gap, those economics repriced almost overnight. Any enterprise whose margins depend on what regulators have yet to permit should be valued under the assumption that permission will eventually arrive.
First movers pave the road for their competitors. Grayscale financed the litigation that established the legal right to list spot bitcoin ETFs. Once established, however, that precedent became a public good available to every issuer. BlackRock, equipped with lower operating costs, vast distribution plumbing, and a cleaner institutional brand, promptly captured the premier share of the market. Opening an asset class and retaining commercial dominance within it are distinct capabilities.
Premiums create leverage, and leverage breeds contagion. GBTC's persistent premium attracted arbitrageurs who borrowed heavily to capture the spread, dispersing trust shares across the digital asset credit system as collateral. When the premium flipped into a structural discount, that leverage unwound through Three Arrows Capital, Genesis, and Digital Currency Group. A security trading detached from its underlying net asset value is never merely a benign pricing anomaly; it represents a latent transmission mechanism for systemic stress.
Taxes remain the ultimate switching cost. In an era of commoditized, single-asset passive funds, embedded capital gains liabilities can retain an allocator far more effectively than brand loyalty or perceived liquidity. Yet this defense is inherently decaying: it shields only pre-existing capital, attracts no net inflows, and erodes with every estate transfer, tax-loss harvest, and portfolio rebalancing.
Corporate ownership dictates fund pricing. The persistence of GBTC's 1.50% fee becomes legible only when examining who collects the cash flow. An investor evaluating any sponsored product must assess not only the headline expense ratio, but the corporate liabilities and balance-sheet requirements of the parent company that fee ultimately funds.
Epilogue
GBTC began as a bonded warehouse for an asset class institutional investors were forbidden to touch, and it closed its initial era as a high-toll bridge flanked by low-cost freeways. Along the way, it accomplished something that will outlast its declining market share. The trust proved the depth of demand for digital assets inside mainstream brokerage architecture, forced the spot ETF question into federal appellate court, and won. The cohort of spot bitcoin funds trading across Wall Street exists in its current form because Grayscale sued the Securities and Exchange Commission and prevailed.
Yet that landmark victory also dismantled its monopoly. The trust that spent three years fighting to trade at the value of its underlying coins finally did so, and every allocator with the freedom to leave promptly exited. What remains is a contracted legacy vehicle anchored by a tax-locked shareholder base, a sponsor striving to reposition itself as a diversified institutional asset manager, and a parent company whose ongoing legal entanglements continue to cast a shadow over fund governance. Barry Silbert's central 2013 insight was that the right wrapper could transform an unreachable asset into something any investor could own. He was proven right. Wall Street simply demonstrated that once everyone can build the wrapper, the packaging is no longer worth 2%, or even 1.50%.
References
-
Grayscale's GBTC discount to NAV hits all-time low of 47% — The Block, 2022-12 ↩↩
-
Grayscale's GBTC Discount Closes to Zero for First Time Since February 2021 — CoinDesk, 2024-01-11 ↩↩↩↩
-
Grayscale Bitcoin Trust ETF Form 10-K Annual Report for Fiscal Year Ended Dec 31, 2023 — SEC EDGAR, 2024-02-23 ↩↩↩↩↩
-
GBTC: Grayscale Bitcoin Trust Fee, Outflows & Review — Bitcoin ETF Directory, 2026-09 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Who Is Barry Silbert, The Former Crypto Billionaire That Cameron Winklevoss Is Accusing Of Accounting Fraud? — Forbes, 2023-01-10 ↩↩↩↩
-
From Toxic Assets to Digital Currency: Barry Silbert's Bold Bet — American Banker ↩↩
-
Grayscale Bitcoin Trust ETF (GBTC) Product Landing Page — Grayscale Investments ↩
-
Bitcoin Investment Trust's Premium Has Exploded — The Motley Fool, 2017-08-30 ↩
-
Grayscale Bitcoin Trust Becomes SEC Reporting Company — GlobeNewswire, 2020-01-21 ↩
-
Grayscale's Bitcoin Trust Is Now Open to More Investors as SEC Reporting Company — CoinDesk, 2020-01-21 ↩
-
Grayscale Bitcoin Trust Form 10-K for Fiscal Year 2020 — SEC EDGAR, 2021 ↩
-
How the fall of Three Arrows, or 3AC, dragged down crypto investors — CNBC, 2022-07-11 ↩↩
-
Grayscale Bitcoin Trust Hits 20% Discount as Firm Files for ETF Conversion — Decrypt, 2021-10 ↩
-
Shares in Grayscale's Bitcoin Trust Trade at 36% Discount to Fund's NAV — CoinDesk, 2022-10-04 ↩
-
Genesis Files $1.2B Claim Against Three Arrows Capital — CoinDesk, 2022-07-18 ↩↩↩
-
Genesis Confirms Exposure to Three Arrows Capital — CoinDesk, 2022-07-06 ↩
-
Why the Winklevoss brothers are in a $900 million crypto faceoff with Barry Silbert — CNBC, 2023-01-11 ↩
-
Genesis Global Holdco Files for Chapter 11 Bankruptcy — Reuters, 2023-01-20 ↩
-
'Grayscale Discount' Sinks to Lowest in 18 Months on Bets for GBTC Conversion to Bitcoin ETF — CoinDesk, 2024-01-09 ↩↩
-
Statement on the Approval of Spot Bitcoin Exchange-Traded Products — SEC Chair Gary Gensler, 2024-01-10 ↩
-
What will it cost you to buy a bitcoin ETF? Here are the cheapest and most expensive funds — CNBC, 2024-01-11 ↩↩
-
FTX Bankruptcy Estate Sells Over $1 Billion of Grayscale Bitcoin Trust Shares — Reuters, 2024-01-22 ↩
-
Grayscale's GBTC Bitcoin holdings have fallen 33% since its conversion — FXStreet, 2024-03-05 ↩
-
BlackRock Bitcoin ETF Surpasses Grayscale's GBTC in Total Assets — Bloomberg, 2024-05-29 ↩
-
Barry Silbert Steps Down as Chairman of Grayscale Investments — The Wall Street Journal, 2023-12-26 ↩
-
Barry Silbert returns to Grayscale as chairman as the firm prepares to go public — The Block, 2025-08-04 ↩↩↩
-
Grayscale Bitcoin Mini Trust (Ticker: BTC) Begins Trading on NYSE Arca as Grayscale Investments' Newest Bitcoin ETP — GlobeNewswire, 2024-07-31 ↩↩↩↩
-
Grayscale Adds Staking to Ethereum and Solana Investment Products in U.S. First — CoinDesk, 2025-10-06 ↩↩↩
-
Crypto Asset Manager Grayscale Files for IPO in the U.S. — CoinDesk, 2025-11-13 ↩↩↩↩↩
-
Grayscale Investments, Inc. Form S-1 Registration Statement — SEC EDGAR, 2025-11-13 ↩↩↩↩
-
Hedge Fund Fir Tree Sues Grayscale Over Bitcoin Trust Management — Bloomberg, 2022-12-06 ↩
-
Osprey Funds Sues Grayscale for Misleading Advertising on Crypto Trust — Bloomberg, 2023-01-30 ↩
-
Crypto Competitors Grayscale and Osprey Settle Two-Year Tussle Over Bitcoin ETFs — Decrypt, 2025 ↩
-
Alameda Sues Grayscale and DCG to Allow Redemptions, Reduce Fees — CoinDesk, 2023-03-06 ↩
-
Attorney General James Secures Settlement Worth $2 Billion from Crypto Firm Genesis Global Capital for Defrauded Victims — Office of the New York State Attorney General, 2024-05-20 ↩
-
Genesis Files Suits Against DCG to Recover Billions Worth of Allegedly Fraudulent Transfers — CoinDesk, 2025-05-20 ↩
-
Federal Judge Allows Silver Golub & Teitell Cryptocurrency Class Action Against DCG to Proceed — Silver Golub & Teitell LLP, 2026-02-25 ↩
-
Grayscale seeks NYSE debut in latest sign of crypto IPO momentum under Trump — The Block, 2025-11-13 ↩↩↩
-
Grayscale IPO delayed as crypto firms reassess public market plans — CoinDesk, 2026-05-28 ↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube