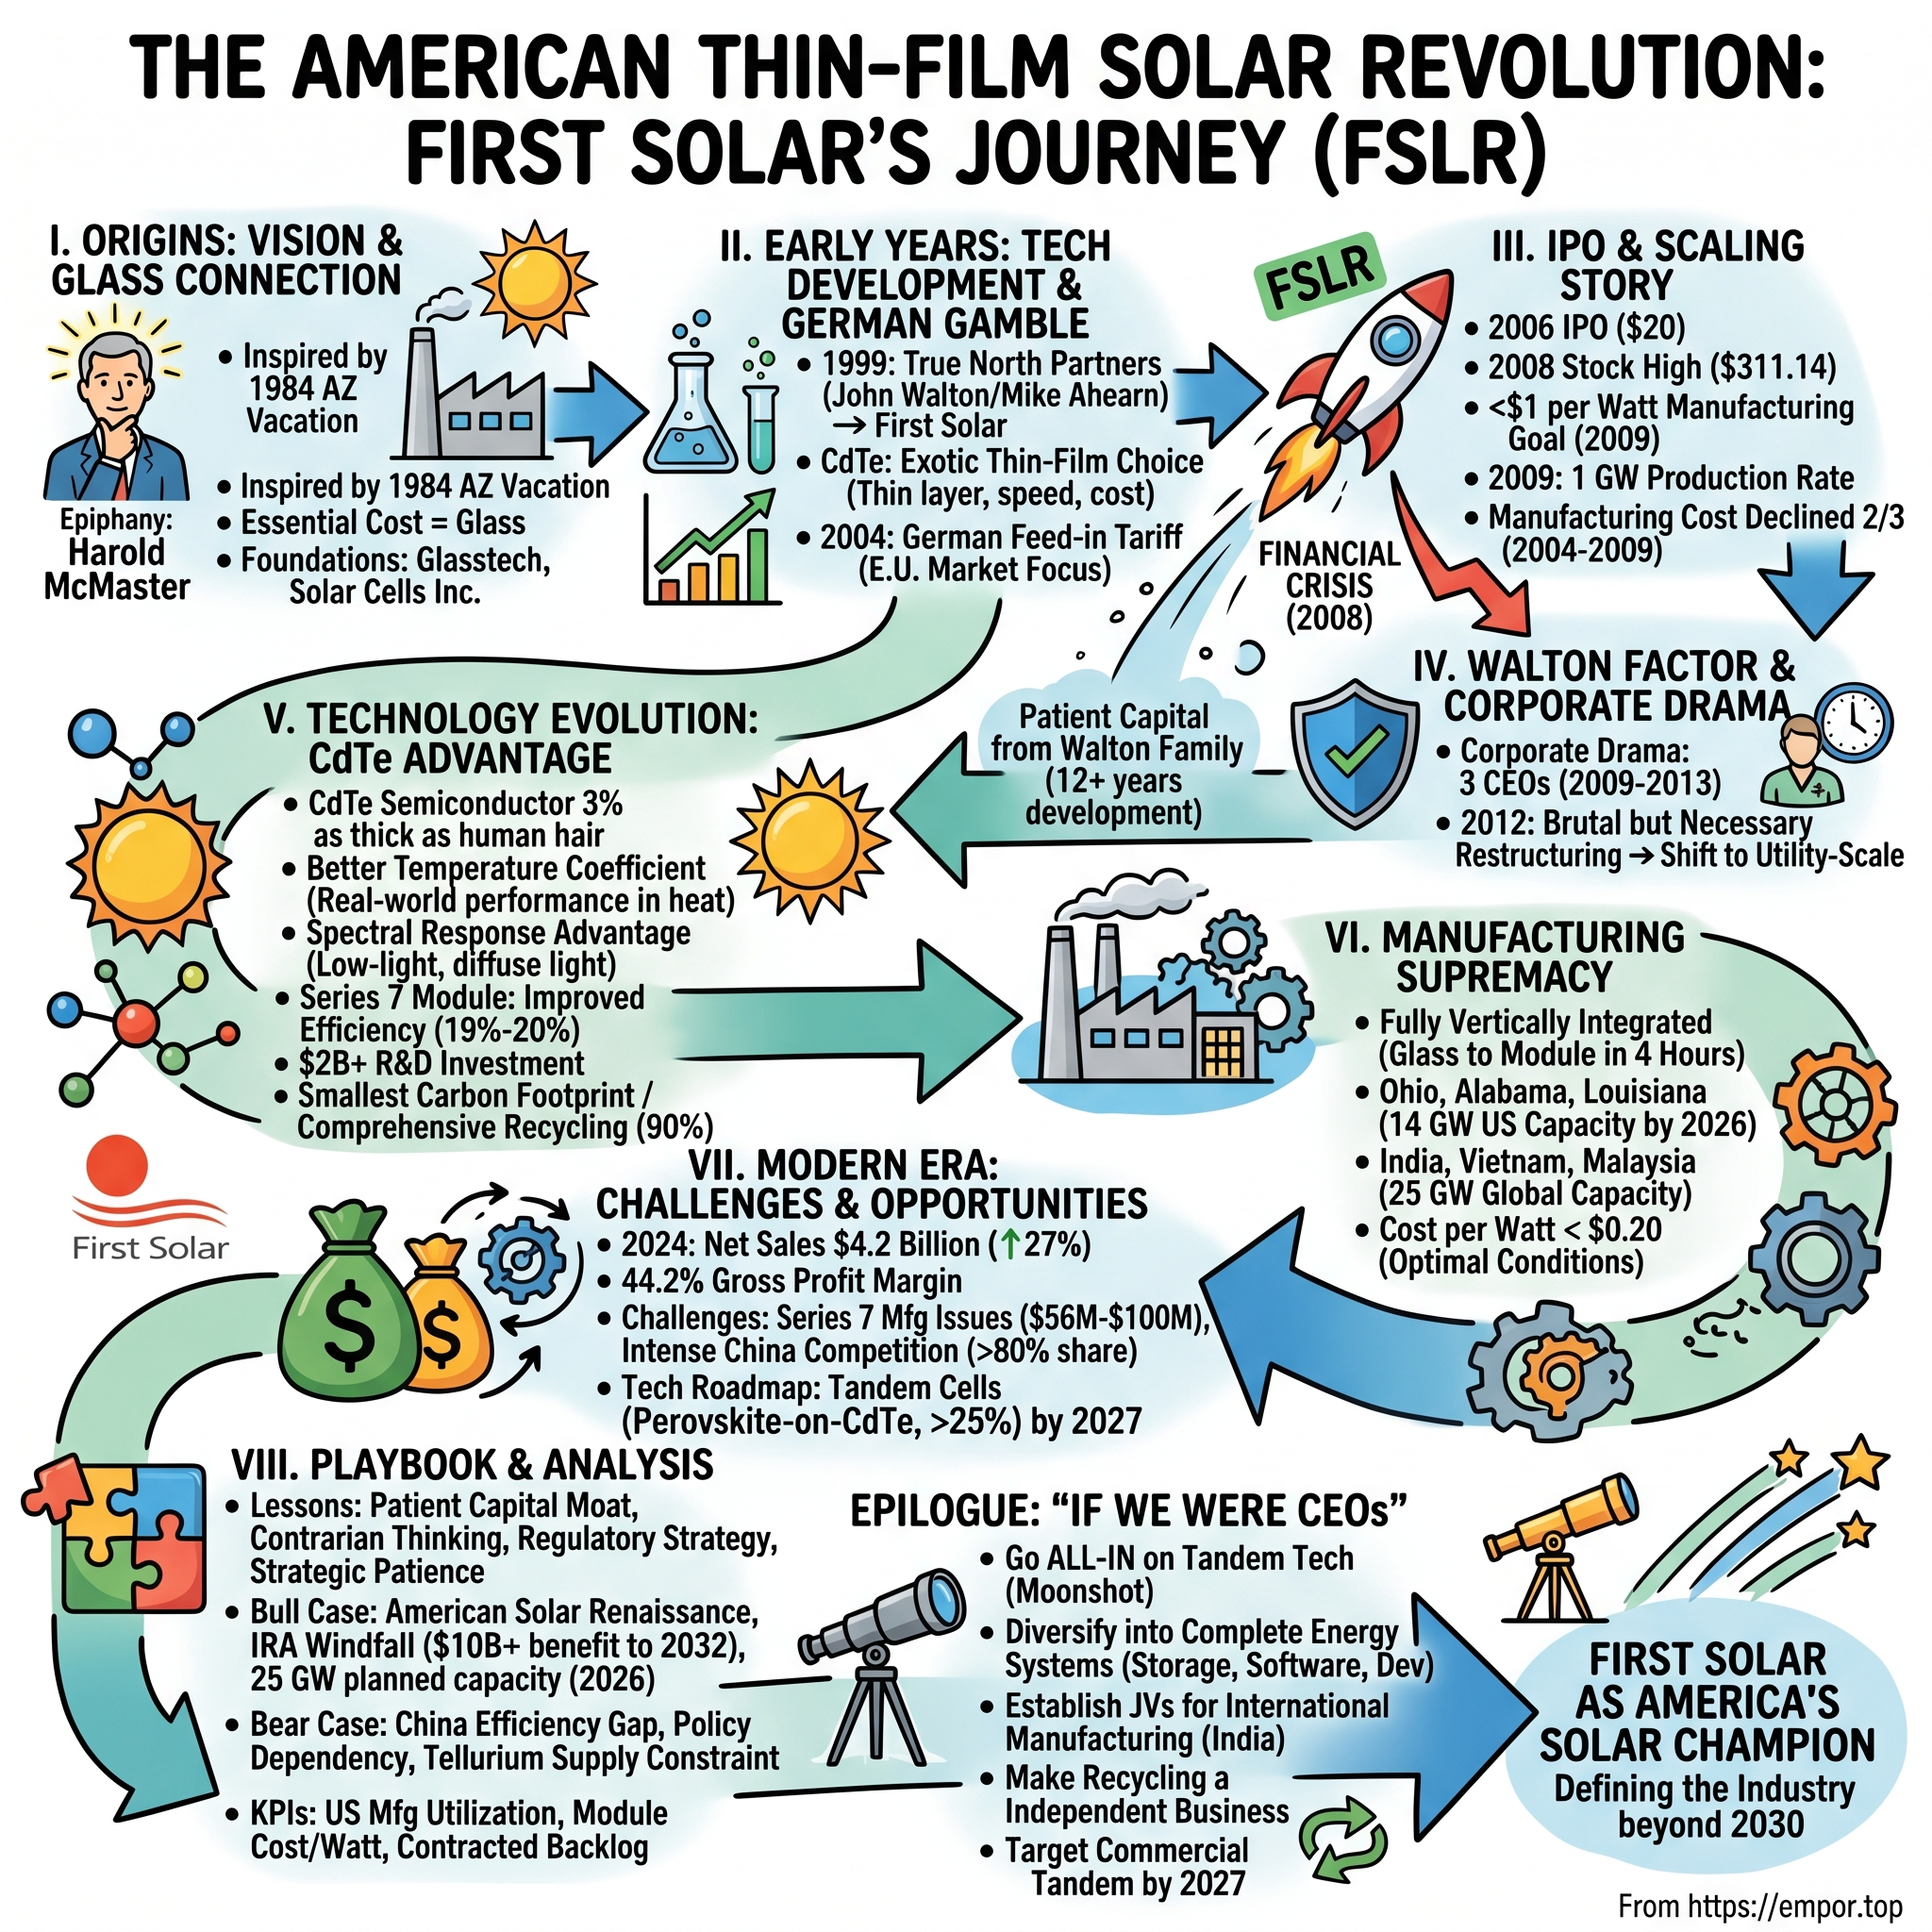
First Solar: The American Thin-Film Solar Revolution
I. Introduction & Episode Roadmap
In Perrysburg, Ohio, roughly twenty minutes south of downtown Toledo, a sheet of ordinary float glass enters one end of a manufacturing line and emerges about four hours later as a finished solar module. The process bypasses ingots, wafers, polysilicon, and foreign supply chains, using glass, a thin film of cadmium telluride a few micrometers thick, a lamination step, and a steel back rail.
Almost every other solar module globally is manufactured through a different process and predominantly outside North America. That distinct position—a single company operating a proprietary chemistry on one continent—defines First Solar's business model.
First Solar, Inc., traded on NASDAQ under the ticker FSLR, reported fiscal 2025 net sales of approximately $5.2 billion, gross profit of about $2.12 billion, net income of $1.53 billion, and diluted earnings per share of $14.21.1 It remains the only American company manufacturing utility-scale photovoltaic modules at gigawatt scale using a technology that Chinese competitors do not produce in volume. The company surpassed 100 gigawatts in cumulative module shipments during 2026, announcing the milestone alongside its second-quarter financial results.2 By mid-2026, its shares traded around $194, well below its 52-week high of $321, giving it a market capitalization near $21 billion.3
The divergence between operational milestones and a stock price down significantly from its peak highlights key market tensions.
Two figures underscore this dynamic. Guidance for 2026 targets gross profit of $2.4 billion to $2.6 billion on net sales of $4.9 billion to $5.2 billion—representing a gross margin near 50%, an unusually high figure for commodity hardware manufacturing.22 However, that same guidance incorporates Section 45X production tax credits estimated between $2.10 billion and $2.19 billion.2 Evaluated together, projected gross profits closely align with the value of these statutory tax credits.
This relationship forms a baseline context for evaluating the firm, explaining why a company achieving operational records trades roughly 40% below its recent high.
The central question. How did a Toledo glass inventor's venture—which spent its first decade producing commercial panels with limited demand and relied on backing from a Walmart heir—survive three major industry downturns to become a primary corporate beneficiary of U.S. clean-energy industrial policy? Furthermore, analysts must evaluate whether First Solar has built a durable manufacturing business or a structure primarily dependent on federal policy.
Why the market is uneasy. Over the twelve months ending September 2026, FSLR stock traded between roughly $183 and $321.3 Rather than reflecting operational volatility alone, this valuation swing underscores how the equity functions as a proxy for U.S. trade and energy policy—including Section 232 trade reviews, tariff schedules, and statutory tax credits. Investing in the stock requires evaluating potential legislative and regulatory shifts alongside operational execution.
The technology war in one sentence. Conventional crystalline silicon panels rely on purifying silicon into ingots at high temperatures, slicing them into thin wafers, processing those wafers into cells, and assembling the cells into modules—a multi-stage supply chain spanning several companies and countries. In contrast, First Solar deposits semiconductor material directly onto glass. That structural difference in manufacturing process shapes both its economic advantages and its operational vulnerabilities.
Roadmap. This analysis traces Harold McMaster's glass innovations and John Walton's patient capital funding; the German feed-in tariffs that drove commercial scale; the company's historical peak, subsequent 96% stock decline, and $393 million write-down following downstream acquisitions; Chief Executive Officer Mark Widmar's pivot away from legacy product lines; the financial impact of the Inflation Reduction Act; supply constraints around tellurium; and next-generation research in perovskites. Throughout, every claim regarding First Solar's competitive moat is evaluated against its historical execution and past strategic shifts.
First Solar's corporate history provides clear precedent, as the company has navigated multiple market cycles and strategic pivots that inform its present strategy.
 Subscribe on LinkedIn
II. Origins: Harold McMaster's Vision & The Glass Connection
Toledo called itself the Glass City for a reason. Libbey, Owens, Ford—the city's twentieth century was built on melting sand and rolling it flat. Into that environment came Harold McMaster, a physicist with a doctorate from Ohio State who spent his career engineering glass to perform beyond its traditional limits. He pioneered processes for tempered safety glass and founded successive companies—Permaglass, then Glasstech—around a core industrial insight: glass is best manufactured continuously on a moving line, not piece by piece.
McMaster was, by temperament, an engineer who viewed manufacturing challenges as the central problems to solve. That instinct became the foundation of First Solar's operational strategy.
In 1984 he founded Glasstech Solar, and in 1990, Solar Cells, Inc.4 The premise was straightforward: if glass could move continuously through a tempering line, it could move continuously through a semiconductor deposition line to emerge as a finished solar panel. While the rest of the photovoltaics industry borrowed from the semiconductor playbook—relying on silicon wafers, cleanrooms, batch processing, and cell yield—McMaster applied the float-glass industry's high-throughput model.
That distinction was radical in 1990. The photovoltaics industry was dominated by semiconductor and aerospace veterans who viewed a solar cell as a chip: expensive, delicate, and manufactured in small batches under exacting conditions. McMaster viewed a solar module as akin to an automotive windshield—a large, flat surface manufactured continuously at high temperatures with uniform properties. First Solar's core attributes—its four-hour manufacturing cycle, reliance on inline quality controls, and focus on overall throughput over record cell efficiency—originated from that single design choice.
Why cadmium telluride. Silicon faces an inherent physical constraint: it is an indirect bandgap semiconductor with a bandgap of roughly 1.1 electron-volts. As a result, silicon is an inefficient light absorber. Photons can pass through thin layers of silicon without capture, requiring silicon cells to be 150 to 200 micrometers thick to absorb sunlight effectively—a requirement that forces the industry to spend vast amounts of energy purifying and crystallizing silicon into ingots and wafers.
Cadmium telluride, by contrast, is a direct bandgap material with a bandgap near 1.45 electron-volts, sitting near the theoretical optimum for solar spectrum conversion. It absorbs light efficiently: a CdTe layer just one to two micrometers thick—about one-hundredth the width of a human hair—captures nearly all usable incoming sunlight. Where silicon requires a thick material wafer, cadmium telluride acts like a thin film coating, eliminating the need for polysilicon refineries and wafer factories.
McMaster's bet was to bypass the multi-stage silicon supply chain entirely and deposit semiconductor material directly onto moving glass.
The Walton anchor. By the late 1990s, Solar Cells, Inc. had validated the physical concept but struggled as a commercial business. In 1999, McMaster sold the enterprise to True North Partners, an investment vehicle formed in 1996 by John T. Walton—a Vietnam medic, Green Beret, crop-duster, and second son of Walmart founder Sam Walton—and Michael J. Ahearn, a Phoenix lawyer.4 They renamed the entity First Solar.
Walton provided capital, but more importantly, he provided time. His total equity commitment ultimately exceeded $150 million.4 While traditional venture capital funds operate on five- to seven-year horizons, Walton supported First Solar for more than a decade before commercial manufacturing proved viable—the company did not run a pilot line until 2002 and did not begin production at its first commercial factory until 2004.4 This extended horizon offered a structural cushion rarely available in venture finance. First Solar's early advantage stemmed as much from patient, concentrated capital as from its proprietary chemistry.
Ahearn brought complementary operational discipline. A lawyer by background with no prior experience in photovoltaics or heavy manufacturing, he managed a capital-intensive operation through years without meaningful revenue while maintaining Walton's backing. The structure—an inventor retiring from daily management, a financier-turned-operator, and a single patient backer—unfolded outside standard venture capital frameworks.
Testing the founding claim. The core thesis—that CdTe would prove inherently cheaper and faster to manufacture than silicon—remained unproven for roughly a decade. Early CdTe modules were unreliable and commercially uncompetitive. Field deployments suffered edge delamination and moisture intrusion, laboratory efficiency gains failed to translate to the factory floor, and early continuous-deposition attempts yielded low single-digit efficiency panels that degraded quickly. The technology became commercially viable only when First Solar developed vapor transport deposition—a high-temperature, near-atmospheric process that sublimates CdTe and coats moving hot glass inline, replacing batch vacuum chambers.
This process breakthrough carries analytical weight: CdTe's cost advantage was not an inherent property of the raw chemistry, but the result of sustained process engineering.
A note on the cadmium question. A key challenge facing the technology is its reliance on cadmium, a toxic heavy metal. Technically, cadmium telluride is a stable compound distinct from elemental cadmium; it is chemically bound, sandwiched between glass sheets, and encapsulated via lamination. Independent studies over two decades have consistently shown that CdTe emissions during routine operation and severe fire conditions are negligible. Nevertheless, commercial and regulatory concerns persisted around European end-of-life directives and customer procurement scrutiny. First Solar countered this risk by integrating module recycling directly into its business model, building recovery infrastructure alongside its manufacturing plants and funding end-of-life obligations. What began as a defensive compliance expense eventually matured into a competitive environmental differentiator.
Proving the physics and manufacturing process, however, solved only half the equation. First Solar still required scale and demand—which arrived from a legislative initiative 4,000 miles away in Germany.
III. The German Subsidy Boom & Early Scale (2000–2009)
Picture a Bavarian dairy farmer in 2005 doing arithmetic at his kitchen table. He could cover a barn roof and a field with solar panels, and the German government would guarantee to buy every kilowatt-hour he generated at a fixed, above-market price for twenty years. Local banks readily financed the buildout because it functioned less like an energy speculation and more like a sovereign-backed annuity topped with glass.
That farmer, multiplied across a country, became First Solar's first major market.
When Michael Ahearn took over as chief executive in 2000, his primary task was operational translation: converting a Toledo research line into a continuous, high-volume manufacturing operation. Germany's Renewable Energy Sources Act—the Erneuerbare-Energien-Gesetz, or EEG—provided the reliable market demand required to justify that capital commitment. The statute's 2004 amendments established generous, long-term, technology-specific feed-in tariffs, transforming solar modules from niche off-grid hardware into a financeable infrastructure asset class.
The consequence for First Solar was acute geographic concentration. By 2009, the overwhelming majority of the company's net sales came from European Union customers, with Germany dominant.5 An Ohio manufacturer had effectively become a primary supplier to German clean-energy fiscal policy. Management acknowledged this revenue vulnerability in regulatory filings, but diversifying away from the world's most lucrative solar market proved difficult while European deployment was accelerating.
Crucially, the EEG did not merely generate demand; it created bankable demand. Project finance requires predictable cash flows, and a 20-year fixed tariff backed by a sovereign credit offered exceptional visibility. Developers could secure high-leverage debt against projected power generation, allowing them to build utility- and commercial-scale projects far beyond what equity alone could fund. Consequently, module orders expanded to unprecedented volumes. This dynamic established a recurring template across global clean energy: targeted policy instruments make project cash flows bankable, low-cost capital floods the sector, and manufacturing capacity rapidly expands to meet—and eventually overshoot—demand.
The manufacturing engine. German deployment provided the volume necessary to achieve industrial scale, validating Harold McMaster's continuous-manufacturing thesis. First Solar expanded its flagship facility in Perrysburg, Ohio, and established a major manufacturing hub in Kulim, Malaysia, leveraging competitive industrial labor costs and proximity to Asian glass suppliers.
By the fourth quarter of 2009, First Solar reported a module manufacturing cost of $0.87 per watt, becoming the first producer in photovoltaics history to break the $1.00-per-watt threshold.5 The milestone marked a structural turning point for the industry, which had long viewed dollar-per-watt manufacturing as the benchmark where solar energy would transition from policy subsidy to economic competitiveness.
This cost reduction reflected First Solar's fundamental process advantage. In 2009, conventional crystalline silicon production required multiple energy-intensive steps across separate corporate entities—polysilicon refining, ingot growth, wafer slicing with significant kerf loss, cell fabrication, and module assembly—creating weeks of work-in-process inventory exposed to volatile raw material prices. In contrast, First Solar's integrated line transformed raw glass into a finished, packaged module in roughly four hours with minimal manual intervention. The result was a structurally lower cost base, significant fixed-cost operating leverage, and near-total insulation from silicon supply-chain bottlenecks.
By late 2009, First Solar achieved an annual production run rate exceeding one gigawatt, making it the largest photovoltaic module manufacturer in the world.4 For an enterprise whose early prototype panels had suffered field delamination a decade earlier, the expansion demonstrated the commercial viability of thin-film technology.
Yet early market dominance fostered two precarious assumptions: that First Solar's manufacturing cost lead was permanent, and that European policy support would endure indefinitely. Both assumptions were about to be tested—first by European fiscal retrenchment, and then by the rapid rise of Chinese state-supported silicon manufacturing.
IV. IPO, The $311 Peak, & The Catastrophic Solar Shakeout (2006–2012)
First Solar listed on NASDAQ on November 17, 2006, at $20.00 per share.6 Eighteen months later, in May 2008, the stock reached $311.14—a fifteen-fold surge that briefly made the Toledo thin-film manufacturer the most valuable solar company in the world.6 Sell-side models across the industry simultaneously extrapolated the company's declining manufacturing costs and Germany's expanding feed-in tariff schedule into the distant future.
Both projections broke at once. Market valuations had linked two trends assumed to be independent: First Solar's status as the industry's lowest-cost producer and an addressable market backed by twenty-year government commitments. But those dynamics were tightly coupled. High module margins encouraged rapid global capacity expansion, creating an oversupply that crashed module prices. That price collapse erased First Solar's cost advantage while simultaneously making legacy tariff rates fiscally unsustainable for European governments—a feedback loop between demand subsidies and rapid supply expansion that became a defining structural feature of the global solar market.
The policy cliff. When the European sovereign debt crisis hit, finance ministries in Berlin, Madrid, and Rome reassessed their feed-in tariff obligations. Spain retroactively cut subsidy rates, Germany accelerated tariff step-downs, and Italy restricted eligibility. Within roughly two years of the installation peak, the sovereign-backed cash flows underpinning European project finance evaporated, shrinking First Solar's primary customer base.
The silicon wave. Concurrently, the Chinese government designated photovoltaics as a strategic priority. State policy banks, provincial subsidies, and industrial grants funded massive capacity expansion across polysilicon, wafer, cell, and module production by companies including LONGi Green Energy, JinkoSolar, Trina Solar, and JA Solar. Polysilicon—which had spiked above $400 per kilogram during the 2008 supply shortage—collapsed toward $25 per kilogram.
That drop fundamentally altered competitive economics. First Solar's cost advantage rested on bypassing polysilicon entirely. As raw material prices plummeted, crystalline silicon module costs fell roughly 75% in two years, undercutting First Solar's $0.87-per-watt benchmark. First Solar's shares fell about 96% from their peak, bottoming near $11.83 in 2012.6 The world's most valuable solar enterprise briefly faced the threat of insolvency that claimed peers like Solyndra, Evergreen Solar, and Energy Conversion Devices.
The sudden downturn shaped an enduring operational conservatism. Within twenty-four months of its market peak, First Solar cut factory shifts, shuttered its German manufacturing facility in Frankfurt (Oder)—which had opened in 2007—and defended itself against skepticism regarding the viability of Western solar manufacturing. Executive leadership that navigated the crash retained a deep institutional memory of subsidy reductions and supply gluts, influencing the company's subsequent capital strategy.
The capital allocation failure. Rather than retrenching during the initial downturn, First Solar attempted to absorb the impact through vertical integration. To secure direct demand for its modules, the company acquired OptiSolar's project development pipeline in 2009 and NextLight Renewable Power in 2010, aiming to convert a merchant hardware vendor into an integrated project developer with guaranteed internal module sales.
The strategy faltered as market pricing continued to decline. In the fourth quarter of 2011, First Solar recorded a goodwill impairment charge of $393.4 million, writing remaining goodwill down to $65.4 million. Regulatory filings noted that substantially all goodwill from the OptiSolar and NextLight transactions had been allocated to the components business segment based on anticipated synergies, economies of scale, and vertical integration.7 When module prices collapsed, those projected synergies evaporated, revealing that the company had purchased project pipelines at peak market valuations.
The rooftop failure. A parallel effort to adapt cadmium telluride for commercial and residential rooftops ran into physical and economic limits. Lower module conversion efficiency required larger surface areas, additional mounting hardware, and increased installation labor per kilowatt. On space-constrained rooftops where labor and balance-of-system costs dominate, high-efficiency crystalline silicon modules provided superior economics. First Solar subsequently exited the rooftop market to focus exclusively on utility-scale, ground-mounted projects.
This outcome highlighted a fundamental economic trade-off: CdTe technology optimizes cost per watt when land and labor are abundant, but incurs penalties on a cost-per-square-meter basis when space is constrained. Utility-scale solar deployments align with the former, while rooftop applications require the latter.
The 2006–2012 cycle demonstrated how policy-driven demand and temporary raw-material shortages could mask long-term market realities. By expanding capacity rapidly and spending nearly $700 million on downstream project acquisitions at the peak of a subsidy boom, First Solar sought to defend a market position that rapid silicon cost deflation dismantled. What sustained the company through the downturn was less its initial strategic positioning than its robust balance sheet and patient shareholder backing.
V. The Walton Factor, Board Governance, & The Strategic Crossroads (2011–2016)
Most companies whose stock falls 96% do not get to choose their own future. Their shareholder registers decide for them through activist campaigns, lender terms, distressed asset sales, or frozen capital markets. First Solar avoided those pressures primarily because its dominant shareholder did not operate on a fixed exit timeline.
The Walton family interests, held through entities that succeeded True North Partners, controlled a stake that at its peak exceeded 30% of shares outstanding. Although John Walton died in an experimental aircraft crash in 2005, the family's capital orientation persisted. Through 2011 and 2012, First Solar faced no hostile takeover attempts, no forced liquidations of its manufacturing footprint, and no pressure to sell its Malaysian plants into a distressed market. The company maintained a low-debt balance sheet backed by a controlling holder with no near-term liquidity requirement.
This governance structure presented two distinct dynamics. On one hand, concentrated patient capital allowed First Solar to survive an industry crash that bankrupted better-funded competitors. On the other hand, it insulated the board from external accountability during a period when its core strategy had failed, delaying necessary strategic adjustments over the subsequent four years.
Between 2011 and 2013, the global solar manufacturing sector experienced a widespread shakeout. Solyndra—which had raised roughly $1.2 billion and secured a U.S. Department of Energy loan guarantee—filed for bankruptcy in September 2011. Evergreen Solar and SpectraWatt failed the same year, Q-Cells was sold out of insolvency, and Suntech defaulted on its debt. Even surviving Chinese manufacturers relied heavily on state-directed credit rather than operational profitability. Against this backdrop, First Solar's survival in 2012 reflected balance-sheet solvency rather than strategic foresight. Low debt, cash reserves accumulated during the subsidy boom, and a patient controlling shareholder sustained the enterprise.
Leadership churn. Rob Gillette, a Honeywell executive hired in 2009 to instill industrial discipline, was removed in October 2011 as the company's financial strategy unraveled. Michael Ahearn returned as interim chief executive until 2012, when the board appointed Jim Hughes, an energy executive from AES Solar. The turnover of three chief executives in five years reflected deep strategic uncertainty regarding the company's long-term orientation.
Hughes responded by shifting focus toward downstream system development. With module margins eroding and European demand contracting, First Solar expanded into turnkey utility-scale power plant development in the American Southwest, providing engineering, procurement, and construction (EPC) services with its modules embedded. This period produced major installations, including the 550-megawatt Topaz Solar Farm in San Luis Obispo County, California, and the 550-megawatt Desert Sunlight project in Riverside County, California—among the largest photovoltaic plants in the world at the time.
While turnkey systems revenue temporarily stabilized financial performance, the strategy masked an underlying operational vulnerability: whether First Solar's modules could compete independently on cost and efficiency. Furthermore, it created an organizational structure where the company's largest revenue driver was a low-margin, capital-intensive construction business competing against its own module customers.
Nevertheless, the Hughes era established a critical long-term asset: deep commercial relationships with U.S. utilities and independent power producers. Developing mega-projects required navigating interconnection queues, structuring power purchase agreements, and analyzing developer cost structures from the inside. When First Solar later exited construction services, it retained these utility relationships and institutional insights, offering a distinct commercial advantage over pure hardware manufacturers.
The TetraSun falsification. In 2013, management attempted to hedge against its proprietary technology by acquiring TetraSun, a silicon startup developing high-efficiency, copper-metallized cell architecture. The acquisition aimed to enter the high-efficiency and rooftop markets First Solar had previously abandoned, providing a crystalline silicon alternative alongside its core cadmium telluride line.
By 2016, the hedge had failed. TetraSun proved unable to achieve commercial production yields or target cost structures, prompting First Solar to discontinue the program. The company recorded impairment and restructuring charges while converting the Kulim lines that had been earmarked for TetraSun back to CdTe.8 The write-down marked First Solar's second major strategic failure driven by acquiring external technology or downstream demand.
However, TetraSun's intellectual property subsequently yielded unexpected utility. A decade later, First Solar asserted patents originating from the acquisition against TOPCon cell architecture, which had become the dominant crystalline silicon technology globally—a legal campaign detailed later in this analysis. While patent assertion against international producers remains a lengthy and uncertain process, the enforcement effort demonstrated how legacy intellectual property from failed acquisitions can retain strategic value.
By 2016, First Solar faced a fundamental crossroads. Its module dimensions were undersized relative to evolving industry standards, its manufacturing cost advantage had vanished, its downstream construction division was consuming capital, and crystalline silicon manufacturers were standardizing on larger module formats. Management was forced to reassess First Solar's core identity and long-term manufacturing strategy.
VI. The Widmar Era & The Masterstroke: Series 6 Pivot & EPC Exit (2016–2021)
Mark Widmar joined First Solar in 2011 as chief financial officer, arriving from GrafTech International following earlier finance roles at NCR. Rather than coming from a technology background, he brought a manufacturing accountant's focus on distinguishing between engineered cost reductions and structural cost ceilings. In July 2016, the board appointed him chief executive officer, while Michael Ahearn remained chairman.
Within four months, Widmar initiated what proved to be the most consequential strategic pivot in the company's history: writing off substantial capital investments to overhaul the core product line.
The dilemma. First Solar's Series 4 module was small—measuring about 0.72 square meters and producing roughly 100 watts. Meanwhile, crystalline silicon competitors were shipping modules two to three times larger. In utility-scale solar construction, module dimensions directly dictate balance-of-system costs. Every individual panel requires mounting hardware, wiring, racking clamps, and manual labor to install. Consequently, deploying small modules incurred significantly higher balance-of-system hardware and installation expenses per watt than larger alternatives, undercutting First Solar's overall system competitiveness even when module manufacturing costs were low.
The company's planned interim solution was Series 5: a framed assembly that grouped smaller panels into a larger structure. The project was already funded, and tooling had been ordered.
Widmar's call. In November 2016, First Solar announced it would cancel Series 5 entirely and accelerate development of Series 6—a large-format module of roughly 2.5 square meters designed to fit standard industry trackers used by crystalline silicon producers.9 Management guided to total restructuring and asset impairment charges between $500 million and $700 million. This included $475 million to $585 million in asset impairments covering Series 4 and Series 5 tooling, stored equipment, and canceled purchase orders, alongside up to $80 million in goodwill write-downs.10 Concurrently, the company reduced its global workforce by approximately 25%, eliminating about 1,600 positions.
Executing the shift carried substantial operational risk. Four months into his tenure, the chief executive scrapped the product roadmap, idled manufacturing lines during retooling, and accepted near-term declines in shipments and revenue to avoid launching an incrementally improved panel that remained structurally disadvantageous. Equity markets initially reacted with skepticism.
The strategic gamble ultimately restored First Solar's competitiveness on total installed system cost, leveraging a manufacturing process whose unit economics improved with larger panel surface areas. While later recognized as a key turning point, the pivot essentially corrected the board's prior commitment to an interim product architecture.
The transition also had distinct economic boundaries. Series 6 eliminated the balance-of-system cost penalty in racking, wiring, and installation labor per watt. However, it did not resolve the conversion efficiency gap relative to premium crystalline silicon. Because a larger module of lower efficiency covers more land area for equivalent power output, the relative economics on space-constrained sites remained unchanged. Thus, Series 6 restored First Solar to parity within its core market of utility-scale, ground-mounted projects on unconstrained land, rather than delivering a superior module across all applications.
Furthermore, the retooling required more time and capital than initial guidance indicated. Ramp-up bottlenecks weighed on operating results through 2018 and 2019 before production lines fully stabilized. This history highlights that major manufacturing retoolings in thin-film production carry multi-year execution risks that can delay projected cost benefits.
The downstream exit. The second major initiative of the Widmar era reversed First Solar's long-standing downstream integration strategy. Having previously accumulated project development assets to generate captive module demand—a strategy that resulted in a $393.4 million write-down in 2011—management initiated a complete exit from development and maintenance services. In 2020 and 2021, First Solar sold its North American operations and maintenance business to NovaSource Power Services, transferring roughly 270 employees and establishing NovaSource as the world's largest solar O&M provider,11 while separately divesting its U.S. utility-scale project development platform.12
The divestitures aligned with a clear operational rationale: project development and construction services were capital-intensive, cyclical, lower-margin businesses that created direct channel conflict with independent power producers and developers, who represented First Solar's primary customer base. Every megawatt developed internally created friction with third-party developers purchasing hardware.
By 2021, First Solar had transformed into a focused pure-play module manufacturer: exited from construction, rooftop applications, and project maintenance, operating with a single large-format product, a conservative balance sheet, and a proprietary thin-film chemistry.
Yet despite this operational focus, First Solar's panels still lagged crystalline silicon in baseline conversion efficiency, and its cost structure remained vulnerable in unprotected global markets. The catalyst that transformed its long-term financial trajectory emerged not from factory engineering, but from federal policy—a shift examined in the following section.
VII. Technology Deep Dive: CdTe Physics, Series 7, & Perovskite Tandem
Every solar datasheet highlights nameplate efficiency measured under standard test conditions: 1,000 watts per square meter of a specified spectrum at a cell temperature of 25 degrees Celsius. In practical utility deployments—such as a solar field in the Arizona desert in July—operating conditions differ sharply. Module temperatures frequently reach 60 to 65 degrees Celsius, ambient light spectra shift, and dust, humidity, and long-term degradation affect real-world output. First Solar's technical thesis centers entirely on this divergence between laboratory benchmarks and field conditions.
Temperature coefficient. All photovoltaic materials lose efficiency as temperatures rise, but thin-film and crystalline silicon degrade at different rates. Cadmium telluride modules experience a temperature coefficient of roughly -0.32% per degree Celsius above standard conditions, compared with -0.35% to -0.40% for typical crystalline silicon. While a difference of less than a tenth of a percent per degree appears modest, over a 35-degree Celsius rise on a summer afternoon, it compounds into a 1% to 3% output advantage during peak demand and power pricing hours. In hot, high-irradiance regions—including the U.S. Southwest, the Gulf, India, and the Middle East—the company estimates this thermal stability yields 2% to 4% more annual energy per installed watt than silicon alternatives.
Spectral response. Cadmium telluride's bandgap absorbs shorter, bluer wavelengths more effectively than silicon, allowing it to convert diffuse light—such as during hazy mornings or overcast conditions—proportionally better. Conversely, silicon performs better in the infrared spectrum. Although spectral response provides only a modest regional advantage, it reinforces CdTe's performance in warm, humid climates.
Degradation. First Solar warrants an annual degradation rate of approximately 0.3% for its current modules, compared with 0.5% or higher for standard crystalline silicon. Over a 30-year operational life, a 0.2-percentage-point annual difference expands cumulative generation by several percent—a meaningful shift in levelized cost of energy calculations that requires long-term, independent field validation.
Lifecycle. Bypassing polysilicon refining yields a short energy payback period—under one year by company accounting—and reduces water usage during manufacturing. First Solar also operates a closed-loop recycling program that recovers the vast majority of glass, laminate, and semiconductor material from retired modules. Beyond environmental positioning, this infrastructure addresses commercial and regulatory risks tied to handling cadmium, functioning as both an operational necessity and a compliance safeguard.
What the bifacial debate reveals. A central technical debate centers on bifaciality—the capacity of a module to generate electricity from light reflected onto its rear surface. Standard crystalline silicon modules are routinely bifacial, capturing a single-digit percentage energy boost on highly reflective ground. First Solar's CdTe modules, constructed on an opaque backing, cannot generate rear-side power. Management argues that bifacial gains are site-specific and frequently overstated in yield models relative to field performance, asserting that CdTe's thermal and spectral benefits offset the rear-side generation loss.
Ultimately, the debate demonstrates that CdTe's competitive advantages are geographically conditional. First Solar holds a distinct performance edge in hot, humid, land-abundant regions, but faces structural disadvantages in cold, space-constrained, or high-albedo environments. Consequently, CdTe offers targeted competitive strength in specific geographic segments rather than universal performance dominance.
Series 7 and CuRe. First Solar's Series 7 module extends the design logic of Series 6 through tailored U.S. optimizations, featuring a larger format exceeding 535 watts and integrated steel back rails instead of aluminum frames, engineered for single-axis trackers common in domestic utility projects. The latest process modification, branded CuRe, replaces copper with a more stable semiconductor dopant to increase open-circuit voltage and slow long-term degradation. On the second-quarter 2026 earnings call, management reported that CuRe was exceeding performance targets in high-volume production at Perrysburg and in multi-climate field trials, yielding efficiency gains of 10 to 15-plus watts per module, with implementation timing integrated into the redesign of the South Carolina facility's second phase.13
These chemistry modifications represent incremental process refinements designed to preserve parity with silicon improvements rather than a fundamental technological leap.
The efficiency problem, stated plainly. Commercial CdTe modules operate within a conversion efficiency range of approximately 19.5% to 20.5%, trailing mainstream crystalline silicon TOPCon modules at 22% to 23.5% and back-contact designs at even higher efficiencies. On space-constrained project sites, this efficiency gap increases balance-of-system costs by requiring additional land, racking, trenching, and cabling per megawatt. While CdTe's thermal and spectral gains mitigate part of this penalty, single-junction CdTe remains bound by the thermodynamic Shockley-Queisser limit in the mid-to-high 20% range. Research-cell efficiency benchmarks compiled by the National Renewable Energy Laboratory (NREL) illustrate the practical upper limits of single-junction CdTe chemistry.[^14]
The tandem lottery ticket. Overcoming single-junction thermodynamic limits requires tandem cell architectures. Placing a wide-bandgap perovskite layer on top of a CdTe base allows the top cell to capture high-energy blue photons while the bottom cell converts red and infrared wavelengths, raising theoretical conversion efficiency beyond 30%.
To acquire capabilities in this area, First Solar purchased Evolar AB—a Swedish perovskite technology firm founded in 2019 by former engineers from CIGS manufacturer Solibro—in May 2023 for approximately $38 million upfront, plus up to $42 million in milestone-based contingent payments.14 Approximately 30 Evolar researchers joined First Solar's technology teams in Santa Clara, California, and Perrysburg, Ohio.15
However, commercializing perovskite technology presents substantial technical hurdles. Although laboratory test cells demonstrate high conversion efficiencies, perovskite materials degrade rapidly when exposed to heat, moisture, and ultraviolet light, leaving long-term field stability unproven at commercial scale. On the second-quarter 2026 earnings call, management noted that its perovskite Series 6 pilot line remained on schedule for operational readiness in the first half of 2027, while smaller-format test lines continued working to improve baseline efficiency and reliability.13 Operational readiness for a pilot line in 2027 remains several steps removed from commercial volume manufacturing.
Given First Solar's prior write-down of its TetraSun silicon acquisition, market observers treat the Evolar transaction as a speculative technology option rather than a clear product roadmap. Key indicators of commercial progress will include multi-year accelerated life test results, outdoor field degradation data, and initial commercial supply agreements for tandem modules.
If core technology were First Solar's sole competitive driver, its market position would remain finely balanced. However, in August 2022, U.S. federal clean-energy policy fundamentally reshaped the financial economics of domestic solar manufacturing.
VIII. Geopolitics, The IRA Windfall, & Silicon Independence (2022–Present)
For twenty years, the central fact of the solar industry was China's manufacturing dominance. By the early 2020s, China accounted for the overwhelming majority of global polysilicon and nearly all wafer production, concentrating heavy refining capacity in the Xinjiang Uyghur Autonomous Region—a location chosen primarily for cheap, coal-fired electricity, the single largest cost input in polysilicon production.
Two major policy shifts disrupted that supply chain in the United States.
Trade enforcement. The Uyghur Forced Labor Prevention Act created a rebuttable presumption that goods with inputs from Xinjiang were produced with forced labor and thus barred from entry, shifting the burden onto importers to trace polysilicon back to its raw quartz.16 U.S. Customs detained large volumes of imported modules. Separately, anti-dumping and countervailing duty proceedings targeted Chinese-owned cell and module assembly routed through Southeast Asia, while Section 301 tariffs tightened further. The cumulative effect made importing crystalline silicon modules into the United States a legally and logistically complex risk for project developers.
First Solar includes no polysilicon in its bill of materials. Its supply chain—encompassing glass, tellurium, cadmium, laminate, steel, and aluminum—avoids the disputed region entirely. For U.S. utilities negotiating power purchase agreements with strict delay penalties, this decoupling provides supply chain visibility and schedule certainty rather than just environmental positioning.
However, trade enforcement has proven neither static nor fully predictable. Import detentions have fluctuated, duty rulings have faced appeals, regulatory exclusions have been granted and revoked, and new trade actions—including a Section 232 review of polysilicon that management highlighted during 2026—have introduced fresh policy variables.13 This policy landscape creates a dual effect for First Solar: trade barriers support domestic pricing, but regulatory uncertainty prompts utility customers to delay contract commitments, explaining the recent booking slowdown management reported. A business model anchored by trade policy inherently absorbs the regulatory volatility of that policy.
The subsidy. The Inflation Reduction Act's Section 45X Advanced Manufacturing Production Credit provides direct payments to domestic manufacturers for each clean-energy component produced and sold: roughly four cents per watt for a solar cell and seven cents per watt for a finished module. Department of the Treasury regulations finalized in October 2024 confirmed that a vertically integrated producer fabricating both components qualifies to stack both credits.[^18] Consequently, First Solar captures roughly eleven cents per watt—or about $33 per kilowatt—because it manufactures the complete module within an integrated facility.
To place that credit in context, international utility-scale modules have at times traded between eight and twelve cents per watt. An eleven-cent manufacturing credit is thus not a marginal incentive; in certain market conditions, the tax credit has approached or exceeded the total international selling price of competing modules.
This structure directly shapes the company's financial profile: Section 45X credits account for the vast majority of First Solar's gross profit. Excluding the tax credit, the underlying module manufacturing margin remains positive but represents only a fraction of reported profits. As a result, the company's gross margins—which approach 50%—reflect statutory tax policy as much as raw manufacturing efficiency.
Monetization. The IRA's transferability provisions allow manufacturers to monetize these tax credits immediately by selling them to third-party corporate taxpayers rather than waiting to offset future tax liabilities. First Solar has utilized this mechanism extensively, selling $857 million of its 2024 credits at roughly 95.5 cents on the dollar to generate about $819 million in gross cash proceeds.17 In June 2025, the company sold $311.9 million of 2025-vintage credits for $296.3 million,18 while contracting additional 2025 credit sales of up to $391.0 million under a separate agreement.19 For full-year 2026, management guidance projects total Section 45X credits between $2.10 billion and $2.19 billion.2
By converting tax attributes directly into liquid capital, First Solar has funded its expansion program without needing to issue equity or take on heavy debt.
The clock. However, these credits are statutory and subject to a defined sunset schedule. Under current law, qualifying solar components sold through 2029 receive the full credit, before stepping down to 75% in 2030, 50% in 2031, and 25% in 2032, before expiring entirely in 2033. Statutory adjustments remain an active factor; for instance, the 2025 reconciliation act (P.L. 119-21) altered Section 45X provisions by eliminating production credits for wind energy components after 2027.20 Consequently, First Solar's current gross margin profile reflects a legislative window rather than a permanent structural equilibrium.
The buildout. Monetized credit cash flow has directly funded physical manufacturing expansion. Beyond its historical hub in Perrysburg, First Solar expanded its domestic footprint to include a second Ohio complex in Lake Township, a facility in Lawrence County, Alabama, and a plant in Iberia Parish, Louisiana—announced in 2023 as a $1.1 billion investment.21 Additionally, a new finishing facility in South Carolina adds up to 3.5 gigawatts of capacity to complete modules from international semi-finished inventory, optimizing shipping costs, tariffs, domestic content requirements, and Section 45X eligibility. On the second-quarter 2026 earnings call, management reported total nameplate capacity at 17.7 gigawatts, with the South Carolina facility's first phase on track for production in the second half of 2026 and phase two scheduled for mid-2027.1322 Internationally, the company operates a 3.3-gigawatt factory near Chennai, India, where management indicated output is primarily sold into the domestic Indian market on a short-cycle, book-and-bill basis.13
This expansion creates a notable parallel to the company's 2009 surge: once again, policy incentives created high-margin economics, driving rapid expansion in manufacturing capacity. However, key structural differences exist this time. The current policy relies on domestic supply-side production credits rather than foreign demand subsidies, customer offtake is contracted several years in advance, and the statutory phase-down schedule is codified by law rather than subject to sudden finance ministry decree. While these factors offer greater predictability than past demand booms, First Solar's long-term returns remain tied to the eventual transition from policy support to standalone market economics.
IX. Management, Governance, & Capital Allocation Audit
Evaluating a management team relies less on peak-cycle commentary than on how leadership navigates market headwinds, making First Solar's 2026 corporate disclosures an instructive case study.
Widmar. A decade into his tenure as chief executive officer, Mark Widmar's record highlights several key strategic moves: canceling Series 5 in favor of Series 6, completely exiting downstream development and maintenance, executing a non-dilutive domestic manufacturing expansion, and acquiring perovskite technology to keep long-term technical options open. His public communications lean heavily into technical and granular operational disclosures. On the second-quarter 2026 earnings call, management disclosed that the company was carrying approximately $30 million per quarter in underutilization costs at its Malaysian and Vietnamese facilities while awaiting the outcome of a pending Section 232 polysilicon investigation before determining a long-term strategy for that capacity.13 Quantifying recurring idle-capacity expenses provides investors with a clear metric to evaluate operational drag.
When asked on the same call about the timeline for the Section 232 review, Widmar avoided offering firm projections, stating that the company wanted the measure implemented to achieve "the strategic intent and spirit of what it was set out to do," while acknowledging that utility customers were hesitating to sign long-term commitments amid trade policy ambiguity.13 The exchange illustrated the extent to which First Solar's commercial visibility remains tied to external regulatory decisions.
Bradley. Chief Financial Officer Alexander Bradley, who took the role in 2016 after leading project finance, has maintained a conservative balance sheet. First Solar funded its multi-gigawatt factory expansion through operating cash flows and Section 45X credit sales rather than taking on heavy debt or issuing new equity. Net cash stood at $2.4 billion at the end of 2025, then stepped down to $2.0 billion at the end of the first quarter of 2026 and $1.7 billion by mid-year as capital expenditures outpaced tax credit receipts, remaining within full-year net cash guidance of $1.7 billion to $2.3 billion.1222 Full-year 2026 capital expenditure guidance was set at $0.8 billion to $1.0 billion.22
Since 2016, management's capital allocation has adhered to strict boundaries. Across the Series 6 retooling, the downstream divestitures, and the domestic plant buildout, the company avoided dilutive equity offerings, kept leverage low, and refrained from re-entering residential or downstream construction markets. Furthermore, earnings disclosures consistently paired performance misses with operational explanations rather than broad macroeconomic generalizations.
Guidance discipline. Through the first half of 2026, First Solar reaffirmed its full-year guidance targeting shipment volumes of 17.0 to 18.2 gigawatts and net sales of $4.9 billion to $5.2 billion.222 Second-quarter net sales of $1.06 billion fell roughly 4% year over year, a drop management attributed directly to contract termination payments recognized in the prior-year period rather than softness in underlying demand.13 Meanwhile, second-quarter gross margin expanded approximately 12 percentage points year over year to 57.3%. Management disaggregated the margin expansion into specific drivers: an estimated $89 million net benefit from International Emergency Economic Powers Act (IEEPA) tariff adjustments, a higher proportion of modules qualifying for Section 45X tax credits, and lower overall logistics expenses, partially offset by higher domestic freight costs and increased import duties.213
Detailed margin disaggregation provides essential context for investors. Explicitly attributing a 57% gross margin to temporary tariff recoveries and tax credit mix clarifies that the headline figure does not represent an unadjusted operational run rate.
Contract architecture. A key feature of First Solar's commercial model is its long-term contract structure. Because the company books sales years in advance—extending through 2030 on its current backlog—it faces the risk that customers might cancel orders if global market prices drop. To mitigate this exposure, First Solar requires substantial non-refundable deposits and strict contractual termination penalties. This structure explains why fiscal 2025 results reflected recognized revenue from contract cancellations, which subsequently created a challenging year-over-year revenue comparison in the second quarter of 2026.13
This contract design carries dual implications. While termination penalties demonstrate commercial enforceability and protect cash flow when buyers default, cancellation fees represent non-recurring revenue. A rising frequency of cancellations signals broader demand headwinds rather than contractual strength. Ultimately, rigorous contract architecture shields realized prices against market declines, but it cannot prevent volume reductions—it merely converts canceled orders into structured financial settlements.
Backlog and contract quality. First Solar's contracted backlog totaled 47.9 gigawatts at the end of the first quarter of 2026 and 45.1 gigawatts at mid-year, valued at approximately $13.6 billion before technology adjusters, with deliveries scheduled through 2030 and roughly 41 gigawatts carrying domestic content provisions.22213 During the second quarter, domestic gross bookings totaled approximately 1.9 gigawatts at an average selling price near $0.36 per watt, inclusive of technology adjusters, whereas first-half bookings in India totaled approximately 1.1 gigawatts at roughly $0.20 per watt.13
This pricing data highlights two critical dynamics. First, the spread between domestic and Indian bookings—36 cents versus 20 cents per watt—reflects the financial value generated by U.S. trade protection and domestic-content policy incentives rather than intrinsic technological superiority. Second, total backlog contracted from 47.9 gigawatts to 45.1 gigawatts over the quarter. Management emphasized that it "continues to prioritize pricing, contract quality, appropriate risk allocation, and long-term value over short-term booking volume," pointing to nearly 2 gigawatts booked in July 2026, more than 2 additional gigawatts subject to contractual conditions, and another 2 gigawatts under active negotiation.13 While this disciplined approach preserves average selling prices, the net backlog contraction also indicates a slowing pace of new long-term customer commitments.
Looking ahead, institutional investors face three main strategic questions. First, the company maintains idled manufacturing capacity in Malaysia and Vietnam without a finalized operational timeline. Second, while domestic production is substantially committed through 2028, order visibility beyond that window remains limited. Finally, the primary driver of reported net profits—Section 45X tax credits—has a defined statutory phase-out schedule even as manufacturing expansion continues. Evaluating First Solar's long-term earnings potential ultimately depends on how effectively the business transitions to standalone market economics as policy subsidies step down.
X. Strategic Frameworks: Porter's 5 Forces & Hamilton Helmer's 7 Powers
Strip away the narrative and ask the structural question: why should this company earn excess returns, and for how long?
Counter-positioning — the strongest claim, and a conditional one. In Hamilton Helmer's 7 Powers framework, counter-positioning describes a business model an incumbent cannot copy without damaging its existing franchise. First Solar's version is clear: major crystalline silicon producers such as LONGi Green Energy, JinkoSolar, Trina Solar, or JA Solar cannot adopt cadmium telluride thin-film manufacturing without stranding tens of billions of dollars in polysilicon, ingot, wafer, and cell production assets. The economic incentive for incumbents to copy CdTe technology is practically non-existent.
However, counter-positioning protects a specific operational envelope. It does not prevent crystalline silicon from achieving lower baseline manufacturing costs per watt; it prevents silicon incumbents from entering CdTe manufacturing. That protection matters primarily in markets where buyers actively value CdTe's distinct attributes—such as domestic content tax credit eligibility, supply chain traceability, and high-temperature thermal performance. Thus, counter-positioning here is real, but it remains highly conditional on U.S. trade and industrial policies that restrict imported silicon modules. The moat's durability is therefore partly determined by legislative decisions in Washington rather than pure manufacturing economics in Toledo.
Process power. Decades of accumulated vapor transport deposition technology, doping chemistry, and yield engineering represent genuine tacit knowledge—intellectual capital that cannot be easily replicated by reading patents. The ongoing transition to CuRe dopant technology demonstrates that First Solar continues to advance along its internal learning curve. Process power represents the company's strongest self-generated capability, built primarily through sustained internal operational engineering rather than policy support.
Scale economies. Operating gigawatt-scale inline facilities that process raw float glass into finished modules in roughly four hours delivers low direct labor content per watt and substantial fixed-cost operating leverage. However, fixed-cost operating leverage functions in both directions. As demonstrated by the $30 million per quarter in idled-capacity charges across its Malaysian and Vietnamese plants, the same asset structure that expands operating margins during peak production creates negative operating leverage when manufacturing lines run below capacity.
Cornered resource — the weakest of the four. Proponents often cite proprietary CdTe deposition patents and long-term tellurium supply agreements as a cornered resource. While the patent portfolio is substantial, the tellurium position reflects supply management rather than control over a cornered resource. Tellurium is a secondary byproduct of copper refining, with global annual production limited to several hundred metric tons. First Solar contracts for tellurium supply rather than controlling the underlying mining assets. Securing a scarce raw material byproduct from third-party copper refiners—whose production decisions depend entirely on copper market dynamics—represents an operational supply constraint rather than an exclusive strategic moat.
Switching costs and brand — largely absent. Examining the powers First Solar lacks is equally instructive. Switching costs are virtually non-existent: solar modules adhere to standardized tracker dimensions, allowing utility developers who purchase First Solar panels today to switch to crystalline silicon for future projects without incurring significant capital conversion costs beyond minor tracking adjustments. Network effects are entirely absent, and consumer brand equity plays no role in utility-scale procurement, where purchasing decisions are made by corporate procurement teams and project finance committees. First Solar's primary commercial reputation functions as a bankability credential—project lenders accept CdTe modules without requiring additional technical risk premiums. While valuable, bankability can be replicated by any competitor with a verified operational track record and a balance sheet capable of supporting long-term performance warranties. Stripping away policy protections reveals a differentiated product operating within a commodity market structure.
Porter's Five Forces, evaluated. Threat of substitutes is the dominant and strongest force. Crystalline silicon TOPCon, heterojunction, and back-contact modules are produced globally at massive scale and lower baseline costs per watt. Unsubsidized silicon capacity built in Southeast Asia, India, or the Middle East stands ready to compete whenever trade barriers relax. Bargaining power of buyers is moderate and rising: utility developers and corporate hyperscalers are sophisticated, price-sensitive, and increasingly concentrated. Management highlighted roughly five gigawatts of recent bookings across three major utility projects, with about half attributed to Google and the remainder to two other large corporate accounts13—illustrating both demand validation and customer concentration in a single metric. Bargaining power of suppliers is bifurcated: key inputs like glass, steel, and aluminum are sourced competitively across mature commodity markets, whereas tellurium supply remains thin, inelastic, and tied to external copper mining volumes. Competitive rivalry presents a sharp geographic divergence: intense in international markets, where Chinese manufacturing overcapacity has depressed global module prices below sustainable return thresholds, but relatively controlled within the U.S. utility sector, where statutory trade barriers and domestic-content tax incentives restrict foreign competition.
Synthesis. Evaluated through structural frameworks, First Solar possesses one strong, self-generated advantage (process power), one strong but policy-dependent advantage (counter-positioning), one double-edged operational driver (scale economies), and one claimed asset that functions as an operational constraint (tellurium supply management). This combination forms a defensible competitive position, but not an unassailable one—particularly because the features most frequently described as structural moats remain heavily reliant on federal policy and statutory protection.
XI. Risk Radar & Historical Falsification Summary
Policy dependency. First Solar's dominant structural vulnerability remains policy dependency: the vast majority of its gross profit stems from Section 45X manufacturing tax credits, which face a statutory phase-down starting in 2030 before expiring in 2033. Revisions to domestic content rules, legislative changes, or restrictive Treasury interpretations could reduce these benefits earlier. The historical precedent lies in First Solar's own corporate record, where European feed-in tariff reductions erased a customer base that accounted for the overwhelming majority of net sales in roughly two years.5 Bull cases highlight that domestic production credits enjoy broader geographic and political support than foreign consumer subsidies, and that the credit step-down is codified well in advance. While that distinction is real, the company's 2011 crisis demonstrates that previous leadership misjudged policy stability under comparable market conditions.
Chinese overcapacity and the trade wall. Global crystalline silicon capacity far exceeds market demand, pushing international module prices down to levels where First Solar's non-U.S. operations produce thin economics. This divergence is evident in the company's booking data, which shows average selling prices near 20 cents per watt in India compared to 36 cents in the United States.13 First Solar's pricing premium relies directly on domestic trade protection remaining intact. Crucially, while trade barriers shelter domestic margins, management acknowledged that ongoing regulatory uncertainty surrounding trade enforcement has caused utility customers to delay long-term booking commitments.13
Tellurium supply constraints. Annual global tellurium production is measured in hundreds of metric tons, generated primarily as a byproduct of copper refining, making supply inelastic to solar demand. Expanding cadmium telluride manufacturing far beyond the mid-twenty-gigawatt range pushes directly against this raw material constraint. This supply ceiling caps First Solar's long-term share of the global photovoltaic market at a single-digit percentage, regardless of technical performance gains. To mitigate this bottleneck, the company relies on material thrifting—reducing tellurium content per watt—and recycling end-of-life modules.
Conversion efficiency limits. The two-to-three percentage point conversion efficiency gap between cadmium telluride and mainstream crystalline silicon TOPCon modules remains unclosed under single-junction technology, though the CuRe dopant provides incremental gains. If competing back-contact or silicon-tandem architectures achieve commercial module efficiencies above 25% at competitive costs before First Solar's perovskite tandem architecture becomes bankable, land-constrained utility projects will increasingly favor silicon panels despite domestic content incentives.
Litigation as a strategic wild card. Intellectual property acquired through the TetraSun transaction has become an active commercial tool. First Solar initiated patent infringement proceedings against JinkoSolar in February 2025 regarding TOPCon cell technology,23 and filed a U.S. International Trade Commission petition in February 2026 seeking to block imports of infringing TOPCon products.22 The U.S. Patent and Trademark Office upheld the patent's validity in January 2026, rejecting challenges from JinkoSolar, Canadian Solar, and Mundra Solar.24 However, in May 2026, China's National Intellectual Property Administration invalidated the corresponding Chinese patent in full, striking all seventeen claims for lack of novelty and inventive step.25
This litigation represents a potentially material asset in a fragmented global legal environment: an ITC exclusion order would severely restrict imported TOPCon modules in the U.S., but enforcement remains jurisdictional. Consequently, investors must treat this legal campaign as a contingent upside rather than a predictable earnings driver.
The falsification summary. Four core investment claims, evaluated against historical execution:
Claim: CdTe is structurally advantaged in solar manufacturing. The historical record refutes the broad version of this thesis. Cadmium telluride proved uncompetitive in commercial rooftop applications due to low power density per unit area, and it lost its manufacturing cost lead when polysilicon prices collapsed in 2011. The defensible thesis is far narrower: CdTe holds a performance advantage in ground-mounted, high-temperature, trade-protected markets where supply-chain traceability commands a premium. Non-U.S. gross margins, excluding tax credits, serve as the primary metric to test this claim.
Claim: Downstream integration widens the moat. First Solar refuted this claim through two explicit strategic reversals: first with a $393.4 million goodwill impairment in 2011,7 and later through the complete divestiture of its project development and operation-and-maintenance platforms.1112 The current pure-play manufacturing model reflects the lessons of those costly integrations, creating a clear strategic barrier against re-entering downstream construction.
Claim: M&A can hedge single-technology risk. Historical evidence contradicts this premise. The TetraSun acquisition failed to deliver commercial silicon production and was subsequently written off,8 even though its residual patents later yielded legal leverage. First Solar's acquisitions have repeatedly failed to achieve their primary strategic goals, occasionally generating secondary value through unforeseen channels. Although management signaled continued interest in technology acquisitions to accelerate its perovskite roadmap,13 past M&A execution suggests caution when evaluating future transactions.
Claim: Management allocates capital with discipline. The long-term record is nuanced. Canceling Series 5 to pivot to Series 6 and exiting downstream construction represented disciplined strategic decisions that prioritized long-term competitiveness over short-term revenue. Furthermore, monetizing manufacturing tax credits has funded multi-billion-dollar expansion without equity dilution. However, those successes must be weighed against two written-off acquisition programs and idled production capacity in Malaysia and Vietnam. Capital discipline describes the current executive team's operating record rather than the company's full history.
A note on accounting judgment. Two accounting practices require careful evaluation. First, First Solar records Section 45X tax credits as a reduction in cost of sales rather than as top-line revenue, generating elevated gross margin figures. Concurrently, the discount incurred when selling credits—the difference between face value and cash proceeds—is reported as a separate operating expense, with 2025 credit sales discounts totaling approximately $66.8 million.1 While compliant with accounting standards, this presentation prevents direct gross margin comparisons with industry peers unless adjusted. Second, the rapid expansion of domestic manufacturing capacity is backed by tax credits with a fixed statutory expiration. If post-2032 market economics fail to support standalone profitability, these newly built assets will face impairment testing. Given First Solar's history of recording substantial write-downs during past industry transitions, asset valuation remains a key financial sensitivity.
The KPIs that matter. Stripping away narrative leaves three metrics that define the company's trajectory. First, gross profit excluding Section 45X credits represents the true measure of standalone manufacturing profitability before statutory subsidies phase down. Second, contracted backlog volume alongside U.S. average selling prices must be evaluated together, as tracking gigawatts without pricing context obscures whether order volume is being maintained at the expense of margin. Third, U.S. fleet utilization and international underutilization charges provide the clearest operational indicator of whether global factory capacity matches end-market demand.
XII. Investment Analysis & Bull vs. Bear Case
The bull case. First Solar remains the sole manufacturer capable of supplying U.S. utility developers with domestically produced, polysilicon-free modules at gigawatt scale. That market position faces limited near-term competition: replicating a cadmium telluride production footprint requires proprietary thin-film technology unavailable to peers, while scaling domestic silicon manufacturing requires resolving upstream supply-chain constraints targeted by U.S. trade policy. The company's contracted backlog provides visibility through 2030 and is dominated by agreements carrying domestic-content provisions that First Solar is uniquely positioned to fulfill at volume.13 Furthermore, Section 45X credit monetization has financed physical expansion using internal cash flows rather than equity dilution, maintaining a net-cash balance sheet.1 Meanwhile, corporate demand has expanded as hyperscale data center operators contract directly for large blocks of module supply.13 Finally, the acquired perovskite program provides a low-cost technology option to potentially surpass single-junction conversion limits.14
The bear case. The vast majority of First Solar's gross profit relies on a statutory tax credit scheduled to step down and expire by 2033, even as the company continues building capacity against that timeline. Outside U.S. trade barriers, realized module pricing drops to roughly half domestic levels,13 underscoring how much of the company's current profitability reflects policy protection rather than baseline hardware economics. Total backlog contracted quarter over quarter while the company absorbed approximately $30 million per quarter in idle international capacity costs,13 leaving management's emphasis on pricing discipline unproven over shorter horizons. Single-junction conversion efficiency continues to trail mainstream crystalline silicon by two to three percentage points, while tandem alternatives remain unproven at commercial scale. Raw material constraints on tellurium cap long-term global market share, and corporate history demonstrates previous instances of expanding capacity at the peak of policy-driven demand booms.
The competitive comparison that matters. First Solar's relevant peer group consists not of domestic solar peers—which do not exist at comparable scale—but of global Chinese manufacturers on one side and domestic silicon module assemblers on the other. Against international majors such as LONGi, JinkoSolar, and Trina Solar, First Solar struggles to match baseline manufacturing costs per watt outside protected markets. Against domestic module assembly capacity built following the Inflation Reduction Act—which largely relies on imported silicon cells—First Solar competes on the depth of its integrated value chain. Assembly-only operations capture the seven-cent module credit but miss the four-cent cell credit, while struggling to meet strict domestic-content criteria. This second comparison highlights First Solar's most defensible current advantage, though that edge remains shaped by statutory tax credit design.
Reconciling them. These bull and bear arguments address two distinct time horizons. Through roughly 2029, the bull case rests on established conditions: Section 45X credits are codified in statute, manufacturing capacity is substantially contracted, backlog extends several years out, and trade protections remain active. The central strategic question concerns post-2029 performance—specifically, whether a cadmium telluride producer facing a two- to three-percentage-point efficiency deficit, inelastic tellurium supply limits, and the phase-out of production credits can generate attractive returns competing against international producers pricing modules at eight to twelve cents per watt.
Evaluating that transition requires tracking specific operational indicators ahead of statutory policy changes: whether gross profit per watt excluding tax credits expands as CuRe technology and Series 7 scale; whether new bookings maintain average selling prices as the tax credit step-down approaches and buyers negotiate post-2029 deliveries; whether perovskite pilot production yields verifiable outdoor field performance data; and whether idled manufacturing capacity in Malaysia and Vietnam is successfully redeployed. These empirical metrics will clarify First Solar's long-term trajectory well before the 2030 tax credit step-downs take effect.
Prevailing market commentary often frames First Solar as either a pure policy proxy or a compounder driven by proprietary technology. The empirical evidence supports a more nuanced conclusion: First Solar is a differentiated manufacturer leveraging a legitimate process advantage within a highly favorable, time-bound policy environment—managed by an executive team exercising current capital discipline, but navigating an enterprise with a documented history of capital misallocation during past demand peaks.
XIII. Epilogue & "If We Were CEOs"
Three strategic priorities would top the agenda for any executive leading First Solar, and all three point toward the same long-term horizon.
Solve tellurium structurally rather than contractually. Long-term offtake agreements fix volume and price, but they cannot guarantee raw material existence. Because tellurium is a secondary byproduct of copper refining, its extraction depends entirely on copper mining economics and whether refiners operate recovery circuits. Direct capital deployment—such as equity stakes, streaming agreements, or co-funding recovery infrastructure at major copper refineries—would convert a purchased raw material into a partially controlled asset. While critics might view this as repeating the vertical integration logic that led to past write-downs like OptiSolar, a key distinction exists: OptiSolar attempted to buy downstream customer demand, whereas tellurium investments would secure an essential, non-substitutable physical input.
Treat the perovskite program as a deadline, not a research project. The strategic value of tandem module technology depends entirely on when it reaches commercial scale relative to competing crystalline silicon roadmaps. If back-contact and silicon-tandem architectures achieve sustained module conversion efficiencies above 24% to 25% at scale before First Solar delivers a bankable tandem alternative, its technology option risks expiring without commercial value. Demonstrating pilot-line readiness in 2027 represents a necessary milestone, but the essential commitment requires establishing a firm commercial launch timeline backed by multi-year field-reliability data.
Turn the international fleet into a viable business or exit. Carrying approximately $30 million per quarter in underutilization costs—representing $120 million in annual drag—is a defensible short-term holding position while awaiting regulatory decisions, but an unsustainable long-term strategy. In India, where domestic content policies and tariff barriers mirror U.S. protections, redeploying idle international capacity offers a clear pathway to establish a second policy-sheltered market. The company is already selling essentially all Chennai output domestically.13 The strategic imperative is determining whether manufacturing facilities in Malaysia and Vietnam can be repositioned to serve protected domestic markets or must be closed rather than competing on price in unprotected commodity channels.
The final reading. First Solar occupies a distinct position in clean energy: an American manufacturer that survived by adhering to a proprietary technology through prolonged downturns, received critical support during key transitions from concentrated shareholder capital and federal legislation, and navigated a history marked by both strategic execution and capital misallocations.
The corporate narrative emphasizes process power and operational perseverance—an assessment supported by its manufacturing track record. However, the company's current financial outperformance relies heavily on statutory tax credits with defined expiration dates. Ultimately, the central investment question is not whether First Solar operates an efficient manufacturing model, but whether the underlying business—the float glass, the four-hour cycle, and the thin film of cadmium telluride—can generate attractive standalone returns when policy support phases down.
That question has an answer. It has not yet been written in the financial statements.
References
-
First Solar, Inc. Announces Fourth Quarter and Full Year 2025 Financial Results and 2026 Guidance (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2026-02-24 ↩↩↩↩
-
First Solar, Inc. Announces Second Quarter 2026 Financial Results (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2026-07-30 ↩↩↩↩↩↩↩
-
Reuters Company Profile & News — First Solar, Inc. (FSLR.OQ) ↩↩
-
First Solar, Inc. Form 10-K for the fiscal year ended December 31, 2010 — SEC EDGAR ↩↩↩
-
Bloomberg Company Directory — First Solar, Inc. (FSLR:US) ↩↩↩
-
First Solar, Inc. Form 10-K for the fiscal year ended December 31, 2011 — SEC EDGAR ↩↩
-
First Solar, Inc. Form 10-K for the fiscal year ended December 31, 2016 — SEC EDGAR ↩↩
-
First Solar cancels Series 5 module migration in favour of Series 6 — PV Tech, 2016-11-17 ↩
-
First Solar, Inc. Announces Acceleration of Series 6 Solar Module Production to 2018; Restructures Operations; Updates 2016 Guidance & Provides 2017 Guidance — Business Wire, 2016-11-16 ↩
-
First Solar Completes Sale of North American O&M Business to NovaSource — First Solar Investor Relations, 2021 ↩↩
-
First Solar Selling US Project Development Business — TaiyangNews, 2021 ↩↩
-
Earnings call transcript: First Solar tops Q2 2026 profit estimates — Investing.com, 2026-07-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
First Solar acquires Swedish perovskite specialist Evolar — pv magazine International, 2023-05-12 ↩↩
-
First Solar Strengthens Global Technology Position in PV with Acquisition of Evolar — Business Wire, 2023-05-11 ↩
-
Uyghur Forced Labor Prevention Act (UFLPA) — U.S. Customs and Border Protection ↩
-
First Solar Announces Sale of Section 45X Advanced Manufacturing Production Tax Credits (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2025 ↩
-
First Solar sells US$311.8 million in 45X manufacturing tax credits — PV Tech, 2025 ↩
-
First Solar, Inc. Form 10-Q for the quarterly period ended September 30, 2025 — SEC EDGAR ↩
-
The Section 45X Advanced Manufacturing Production Credit (IF12809) — Congressional Research Service ↩
-
First Solar to invest $1.1 billion in fifth US manufacturing facility — Reuters, 2023-08-10 ↩
-
First Solar, Inc. Announces First Quarter 2026 Financial Results (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2026-04-30 ↩↩↩↩↩↩↩
-
First Solar Initiates Legal Action Against JinkoSolar for Infringement of TOPCon Technology Patents — Business Wire, 2025-02-25 ↩
-
First Solar wins key round in TOPCon patent dispute — pv magazine USA, 2026-01-20 ↩
-
China invalidates First Solar TOPCon patent in major win for JinkoSolar — pv magazine International, 2026-05-22 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube