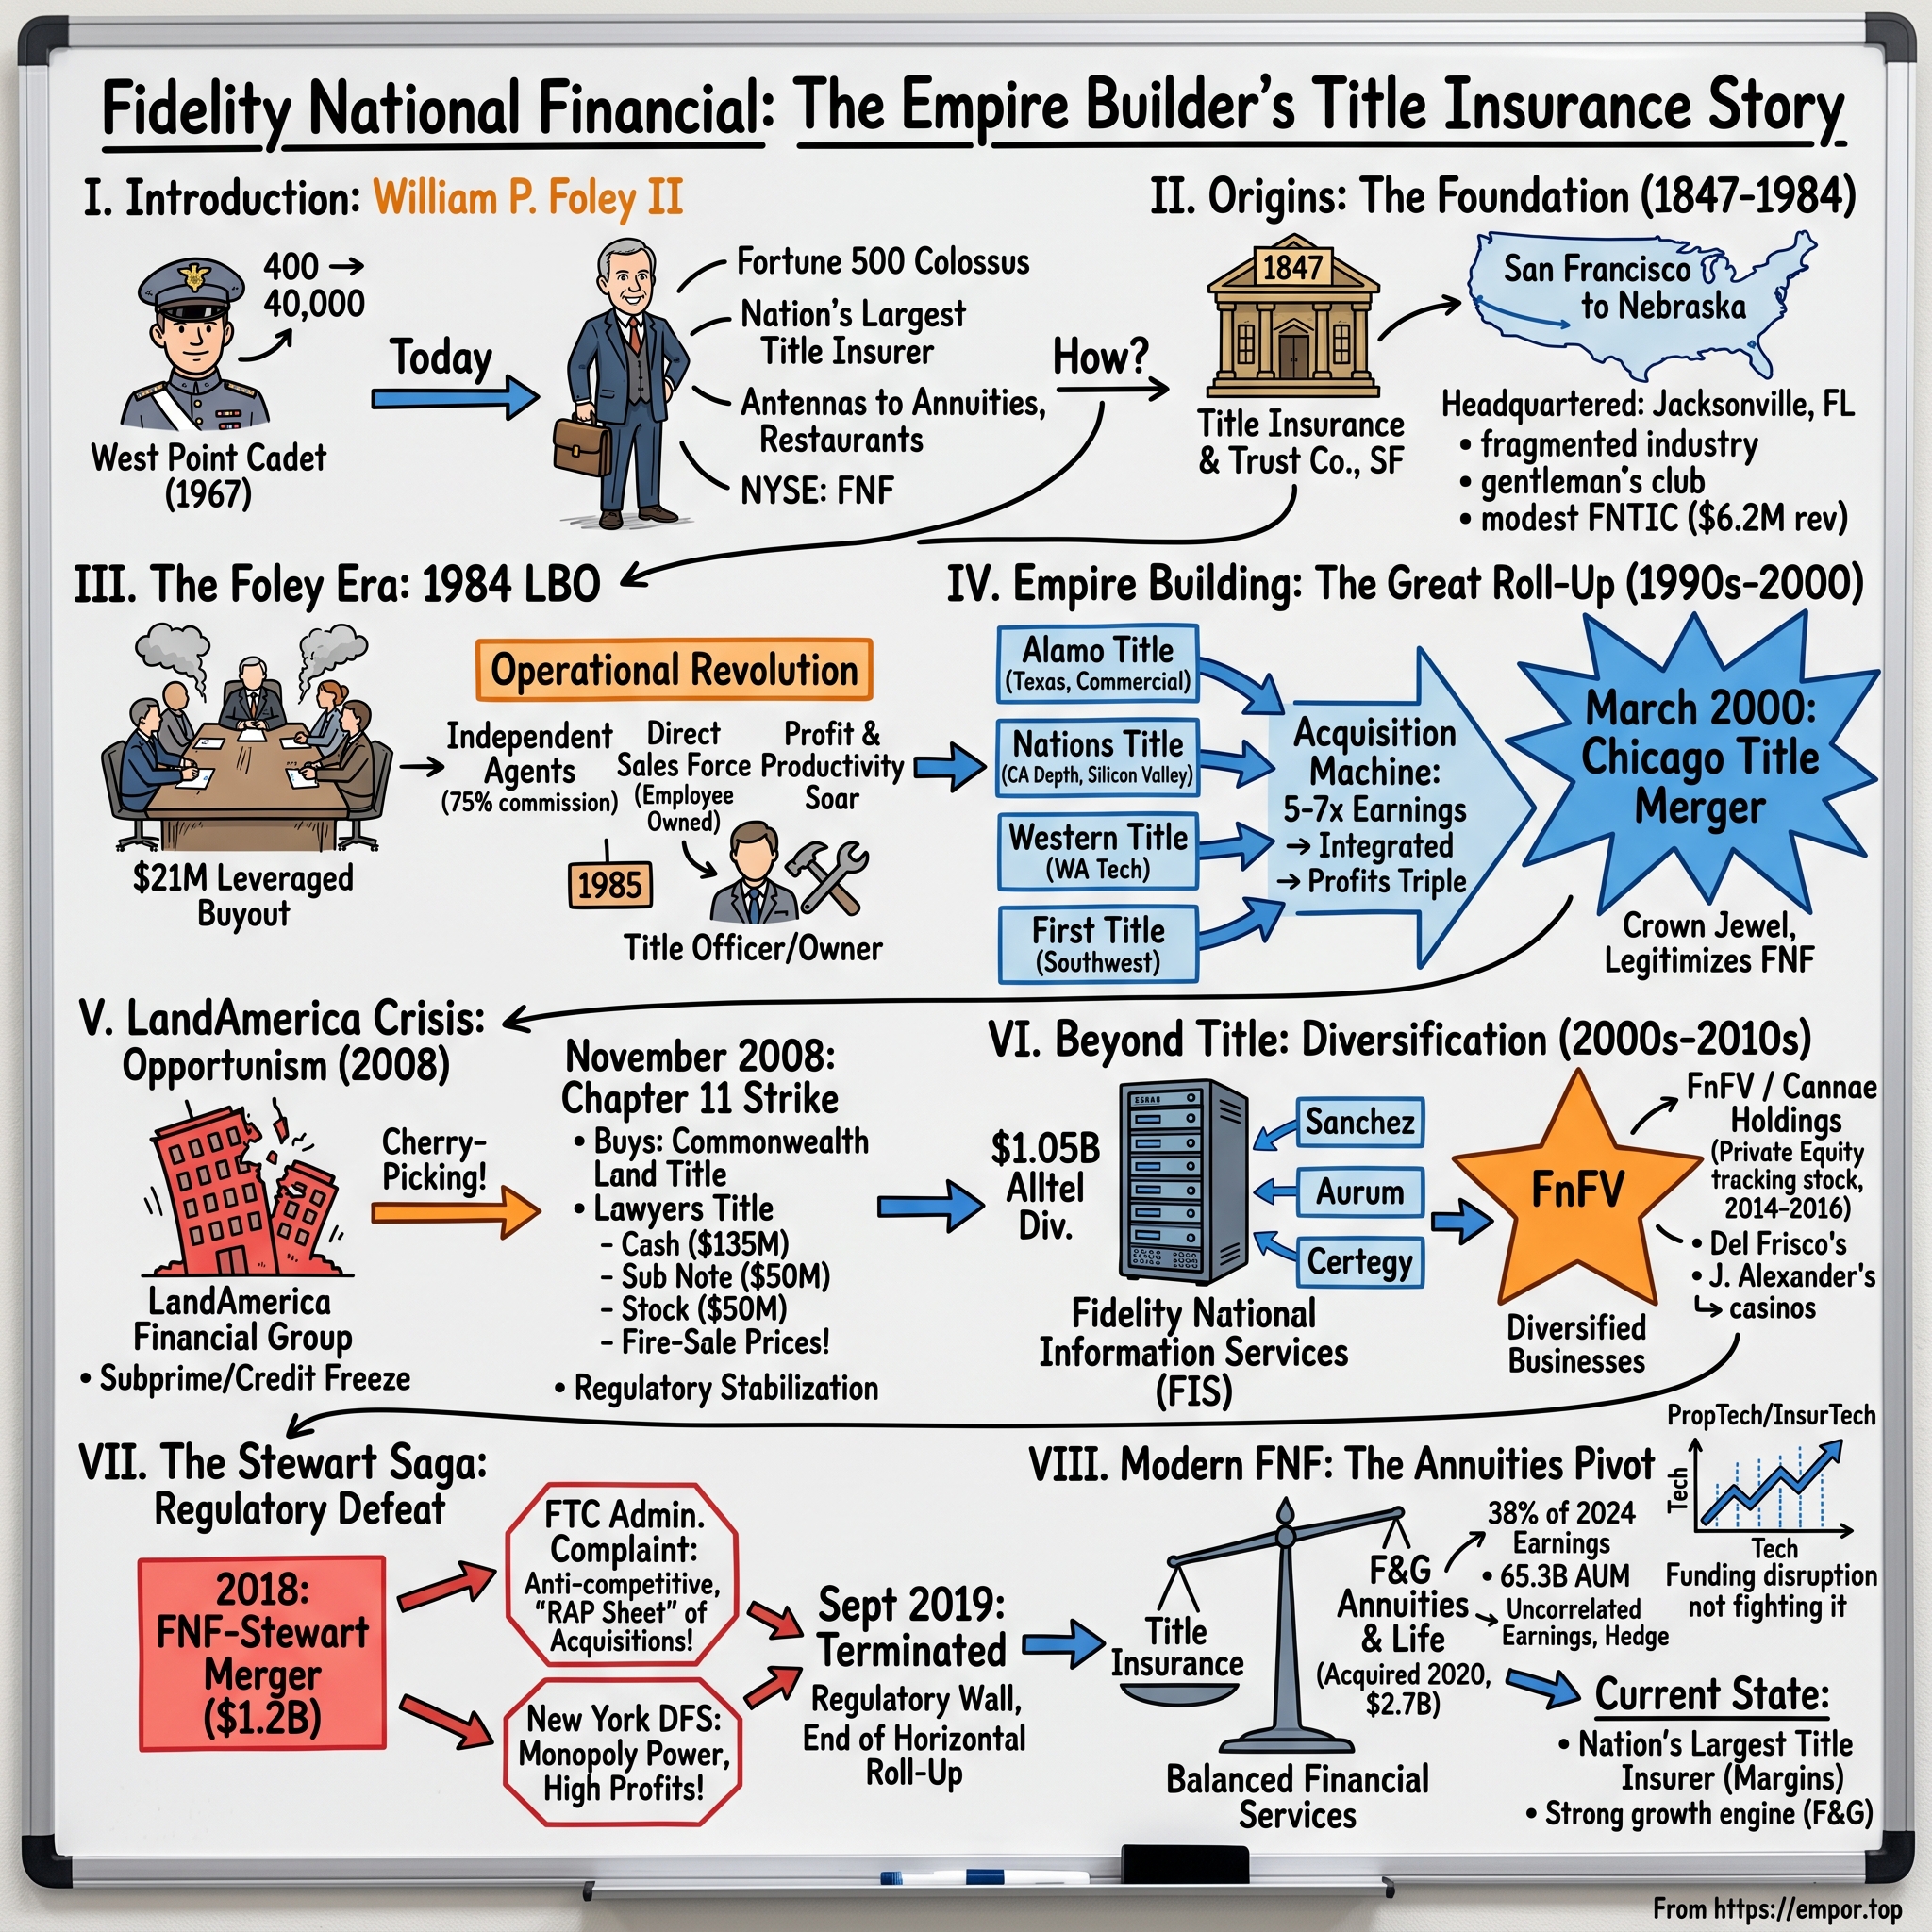
Fidelity National Financial: The Empire Builder's Title Insurance Story
I. Introduction & The Title Insurance Monopoly Puzzle
Somewhere in America this afternoon, a family is sitting at a conference table in a strip-mall office, signing roughly forty pieces of paper to buy a house. Most of those pages are mortgage documents. One of them is an insurance policy that the buyers did not shop for, do not understand, will almost certainly never claim against, and cannot realistically refuse. It costs them, on average, a few thousand dollars. Nobody in the room will explain, in any detail, what it does.
That policy is title insurance. And a meaningful share of the fee flows to a company headquartered in Jacksonville, Florida, that most Americans have never heard of.
Fidelity National Financial, Inc. (NYSE: FNF) sits at the center of the American real estate closing table. In the second quarter of 2026 alone, its title segment produced $2.5 billion of revenue on 273,000 closed orders, averaging $4,107 per file.1 Scaled across a full year, that represents a business that touched roughly a million property transactions and collected nearly $8.5 billion in title-related revenue in 2025.3 The American Land Title Association recorded $18.5 billion in total industry premium volume in 2025, up nearly 14% year over year — a reminder that title underwriting is a mid-sized industry operating as a mandatory toll on the largest asset class in the United States.2
The central strategic question is how this scale was assembled. In 1984, William P. Foley II, then a 39-year-old lawyer, led an investor group with a partner to acquire control of a money-losing Arizona title underwriter for roughly $21 million.4 Forty-two years later, that entity stands as the largest title insurance family in the United States, has spun off two separate multi-billion-dollar financial technology companies, holds roughly 72% of a publicly traded annuity business with $74.7 billion in assets under management, and has navigated an antitrust block, a housing depression, and a nationwide ransomware shutdown.1
How does a legally mandated, commoditized, price-regulated insurance product serve as the foundation for such expansion? And — for investors evaluating the company in 2026 — is the structure Foley built genuinely durable, or does it represent a cyclically levered bet on residential transaction volume wrapped in the narrative of a competitive moat?
The business model, briefly. Title insurance operates differently from traditional insurance lines. Auto or homeowner's policies protect against future contingent events based on actuarial probability. Title insurance looks backward. The insurer examines historical public records — deeds, liens, easements, divorce decrees, tax assessments, and mechanic's claims — to verify a clean chain of ownership before issuing a policy. The labor is front-loaded, and the premium is paid once at closing. Because title defects are identified and remediated before policy issuance, claims losses remain low: FNF's loss provisioning runs in the low single digits as a percentage of title premiums, compared to the 50% to 70% loss ratios typical of property and casualty lines.
This structural reality shapes operating performance. Low claims losses mean title insurance is less an underwriting business than a labor-intensive search, examination, and escrow operation. The primary cost drivers are operational: escrow officers, examiners, closers, and commission splits paid to independent agents. Consequently, operating margins are determined not by managing underwriting risk, but by flexing headcount in step with volatile real estate volumes — an operational challenge Foley targeted throughout his tenure.
Alongside title operations sits F&G Annuities & Life, Inc. (NYSE: FG), a fixed-annuity business FNF acquired in 2020 and subsequently distributed in part to shareholders while maintaining majority control. In 2025, F&G contributed 30% of FNF's adjusted net earnings.3 Management contends that F&G counterbalances real estate cyclicality. Skeptics counter that FNF substituted real estate volume exposure for credit and interest-rate spread risk, two drivers that may share underlying macroeconomic sensitivities during extended downturns.
The company's trajectory spans a 1984 leveraged buyout, a 2000 transaction that established industry leadership, a 2003 software acquisition that spawned a major fintech firm, a 2008 distressed asset purchase, a 2019 antitrust intervention that limited further title roll-ups, a 2020 entry into annuities, a 2023 ransomware disruption to nationwide closings, and a 2025 proxy contest at an affiliated holding company previously led by Foley. The narrative originates in a sector that had remained largely unchanged for more than a century.
 Subscribe on LinkedIn
II. Origins & Pre-Foley Era: The 137-Year Sleepy Industry (1847–1984)
To understand why title insurance exists in America and essentially nowhere else, start with a courthouse basement.
In most of continental Europe, and in Australia under the Torrens system, land ownership is settled by a government register. The state maintains a single authoritative record. If the register indicates that a party owns a parcel, that ownership is legally established, and if the register is inaccurate, the state compensates the property owner. Ownership is a fact certified by a sovereign.
America never built such a system. Instead, the United States established a recording system: deeds, mortgages, liens, and judgments are filed at county offices — more than three thousand of them, each with its own indexing conventions, staffing, retention practices, and historical record-keeping quirks. The county clerk does not certify ownership; the clerk merely certifies that a document was submitted on a given day. Determining who actually owns a parcel requires reconstructing the chain of title backward through those filings and verifying that no cloud on title was overlooked.
Think of it as the difference between a bank statement and a shoebox of receipts. Europe relies on the statement. America relies on the shoebox — three thousand shoeboxes, in fact — and title insurance is the industry that emerged to ensure the shoebox adds up.
The commercial solution arrived in the nineteenth century, when abstract and title companies in Philadelphia and California built private indexes of public records. By the turn of the twentieth century, the structure of the modern industry was established: private companies maintained proprietary "title plants" — geographically organized, parcel-indexed replicas of county records, far more searchable than public archives — and sold insurance policies backed by those examinations.
The industry Foley walked into. For most of the twentieth century, title insurance remained one of the least glamorous corners of American finance. It was intensely local. A title company in Maricopa County competed primarily with other local entities, relying on relationships with local real estate brokers, homebuilders, and attorneys. Underwriters — the entities carrying the ultimate policy risk — rarely interacted with property buyers. Instead, they contracted with independent title agents who conducted the search, managed the closing, held the escrow funds, and remitted only a minority share of the premium upstream. The agent typically retained the majority of the fee while transferring long-term claim liability to the underwriter.
That economic split defined the industry's strategic weakness. The party performing the local work captured most of the revenue, while the party carrying the balance-sheet risk received the smaller share. Furthermore, the underwriter exercised virtually no operational control over the quality of the search that dictated its future loss experience.
Into this fragmented market sat Fidelity National Title Insurance Company, a small underwriter that by the early 1980s was generating around $6.2 million in annual revenue while operating at a loss — a rounding error in an industry where it ranked roughly 48th.4
A falsification test before analyzing the strategy. A common narrative assumes that title insurance was always an inherently lucrative, high-margin fee business that Foley merely consolidated. The historical record demonstrates otherwise.
Pre-consolidation title underwriting was financially volatile and structurally risky. Underwriter loss experience depended on the diligence of thousands of independent agents whom the underwriter neither employed nor directly supervised. Defalcation — agents mismanaging or absconding with escrow funds — posed a persistent operational hazard, while unindexed municipal liens and outright forgery created claim tails that surfaced years after closing. Crucially, underwriters possessed little operating leverage during housing downturns because the core cost structure resided within independent agencies outside their control. Regional real estate slumps directly damaged underwriter balance sheets.
The pre-1984 baseline was not a stable, high-margin business. It was a fragmented, agent-dependent, credit-sensitive, and operationally unmanaged sector. Foley's subsequent expansion was not a matter of harvesting an existing competitive moat, but of constructing one by bringing the search, examination, and escrow operations directly in-house.
III. Enter Bill Foley: The 1984 LBO & The Direct Distribution Playbook
William P. Foley II was born in 1944 and did not arrive at title insurance through a traditional career path.21
He graduated from the United States Military Academy at West Point, a background that shaped his operational style: process-driven, comfortable with hierarchy, disciplined in execution, and attentive to quantitative measurement. According to his own later accounts, Foley also traded stocks from his dorm room while undergoing officer training.21
After commissioning into the U.S. Air Force, he worked in defense procurement, negotiating contract terms against major aerospace suppliers such as Boeing. The role provided practical training in analyzing complex cost structures and finding operational seams when negotiating with larger counterparties. Foley subsequently earned a law degree from the University of Washington and entered corporate legal practice in Phoenix.
By age 39, his profile combined military training, procurement negotiation, corporate law, and private investing—a background that encouraged him to view the industry's economics as an operational puzzle rather than an immutable convention.
The 1984 buyout. In 1984, Foley and Frank Willey—a fellow attorney who would serve as a long-term partner and board member—assembled an investor group to execute a leveraged buyout of a small, unprofitable title underwriter, incorporating Fidelity National Financial around a transaction valued at approximately $21 million.4 Foley assumed the roles of chairman and chief executive officer.
That $21 million purchase price represents less than FNF spent on share repurchases in a single quarter of 2026.1 The company began at a scale modern public markets would consider negligible.
The direct distribution decision. Foley's core operational thesis addressed the industry's economic imbalance: if independent agents retained most of the customer premium while underwriters absorbed long-term title risk, the underwriter should bring distribution and escrow functions in-house.
FNF allocated capital to build company-owned branch offices in high-growth counties, placing escrow officers, title examiners, and closers directly on FNF's payroll rather than relying exclusively on independent agent networks. This shift transformed the operating model through three compounding advantages:
First, loss control. Employing title examiners directly allowed FNF to standardize search protocols, implement internal audits, and maintain direct control over escrow funds, reducing underwriting risk from third-party agency errors.
Second, operating leverage in both directions. Direct branch networks convert fixed administrative overhead into flexible operating expenses. During housing downturns, management can consolidate branch offices and reduce staffing within a quarter. During market expansions, the company absorbs increased transaction volume without renegotiating commission splits. Contractual agency splits lack this flexibility because operational expenses reside outside the underwriter's control. This capability supports management's strategy of defending operating margins across housing cycles by aligning headcount with transaction volume.
Third, direct customer relationships. Under a direct model, lenders and real estate brokerages interact directly with FNF rather than independent agents. This direct connection proved essential as national mortgage originators expanded and sought standardized closing services across multiple states.
The direct model involves a structural trade-off: company-owned branches carry fixed facility overhead that agency networks avoid, making title margins more volatile during sharp volume shifts. FNF accepted higher operational beta in exchange for underwriting control and cost flexibility. Roughly four decades later, FNF maintains a balanced channel mix. In the second quarter of 2026, direct premiums totaled $767 million compared with $967 million in agency premiums—reflecting a hybrid model rather than a complete departure from independent agency networks.1
Employee ownership and the public listing. In 1985, FNF issued equity to employees, becoming what contemporaneous reports described as the first employee-owned title insurance underwriter in the United States.4 Beyond serving as equity capital for a leveraged entity, the program acted as a talent retention mechanism in a service industry where client relationships drive deal flow. Tying escrow officers and regional managers to equity aligned staff incentives with corporate performance.
FNF completed an initial public offering in 1987, securing a publicly traded currency that enabled Foley to pursue larger corporate acquisitions.
By the late 1980s, FNF remained a regional underwriter. However, it had established a scalable direct distribution model, a public equity currency, and an executive strategy focused on serial acquisitions as the primary engine for growth.
IV. The Great Roll-Up & The Spinoff Engine (1990s–2003)
The 1990s at FNF were defined by methodical, regional accumulation: Alamo Title, Nations Title, Western Title of Washington, and First Title Corp. Each transaction followed a consistent operational template: acquire a regional underwriter or agency network, fold its title plants into FNF’s centralized infrastructure, eliminate duplicated back-office functions, retain key revenue-producing escrow officers, and integrate the business.
While incremental on a deal-by-deal basis, this roll-up strategy constructed a critical long-term asset: a national footprint of title plants, providing a nationwide repository of land record data.
A title plant represents a key structural asset in title underwriting. It is a privately maintained, geographically indexed database of every recorded document affecting parcels in a given county, updated daily. Building a title plant from scratch in an established market is economically impractical, as it requires re-abstracting up to a century of public filings already compiled by incumbents. Consequently, plants are acquired rather than built. Every regional underwriter FNF acquired added to its plant network, creating a high barrier to entry against prospective national competitors.
March 2000: Chicago Title. In March 2000, FNF completed an acquisition that fundamentally altered its market position.
Chicago Title Insurance Company traced its lineage to 1847 and operated as an established industry leader, possessing commercial underwriting desks, blue-chip lender relationships, a deep national plant network, and strong brand recognition in institutional real estate. By contrast, FNF was a smaller regional underwriter focused on disciplined cost structure management.
FNF bought it, in a transaction completed in 2000 and valued at more than $1 billion.4 The number four player acquired the market leader and became number one.4
Initial market reaction was cautious. Investors questioned whether a smaller, more leveraged underwriter could successfully integrate a larger, culturally distinct organization where client relationships represented a primary asset. FNF executed the integration by rapidly consolidating duplicative information technology systems, corporate overhead, and back-office processing, operating on the premise that back-end infrastructure could be unified without disrupting front-end client services.
The Chicago Title integration demonstrated a core operational strength that defined FNF’s strategy over the subsequent two decades: integration speed. FNF systematically combined overlapping cost structures while preserving client-facing distribution networks and established brand identities. FNF continues to run Fidelity National Title, Chicago Title, Commonwealth Land Title, Alamo Title, and National Title of New York as separate customer-facing brands. The back-end infrastructure is unified under one corporate umbrella, while the front end operates across five distinct market brands. Maintaining separate brand identities protects localized commercial relationships and broker networks that drive deal flow.
This structure also leaves FNF with five separately licensed underwriting entities, which creates two distinct ways to evaluate its market share. In ALTA's 2025 tabulation, Fidelity National Title alone held 14.5% and Chicago Title held 13.1% as individual underwriters, with Commonwealth at 3.3%.2 Aggregate the family and FNF is comfortably the largest group in the industry; look at any single legal entity and it appears to sit behind First American Title's 23.1%.2 Both perspectives are accurate, and investors must distinguish between underwriter-level and group-level data.
2003: Mortgage technology and spin-offs. In 2003, FNF acquired ALLTEL's financial services software division for roughly $1.05 billion and combined it with its own mortgage technology assets to form Fidelity National Information Services (FIS).
The acquisition expanded FNF’s reach from title underwriting into core banking and mortgage servicing software. Management targeted the asset based on cash flow generation and potential operational overlaps between title settlement services and bank mortgage processing.
The technology expansion ultimately yielded corporate entities whose market valuations surpassed the core title insurer. FIS was separated from FNF and subsequently acquired Metavante as well as Worldpay in 2019, growing into a major global payments and banking technology firm. Meanwhile, FNF's mortgage servicing technology assets were spun off and eventually formed Black Knight — which Intercontinental Exchange acquired in a deal completed on September 5, 2023 at approximately $11.9 billion in final value.19
For investors, this track record presents a complex narrative. While the spin-offs generated substantial value for shareholders, they also showed that the most valuable things Foley ever built were not title insurance. The core title company served as an operational platform from which management launched adjacent corporate bets that, when successful, dwarfed the core title business. This structure explains both why FNF has historically traded with a conglomerate valuation discount and why management continually seeks adjacent growth opportunities.
The next test of this strategy arrived not through an expansion opportunity, but through an industry-wide crisis.
V. Crisis Opportunism: The 2008 LandAmerica Collapse
By the autumn of 2008, the American title industry faced the same collapse as the rest of housing finance, along with a distinct operational vulnerability: escrow cash management.
Title underwriters hold vast sums of client funds in transit. When a home buyer wires a down payment, the funds sit in escrow until the property transaction records several days later. Scaled across thousands of daily transactions, this creates a massive, short-duration cash pool. Industry standards require these funds to be held in instruments convertible to cash on demand, as failure to execute a wire prevents closings rather than simply incurring mark-to-market accounting adjustments.
LandAmerica Financial Group — then the nation's third-largest underwriter and parent of Lawyers Title and Commonwealth Land Title — held substantial exposure to auction rate securities. These instruments had been marketed as liquid cash equivalents with interest rates resetting at frequent auctions. When those auctions failed in early 2008, the securities did not default, but their liquidity evaporated. For a company dependent on same-day escrow liquidity, illiquidity was fatal.
LandAmerica filed for Chapter 11 bankruptcy protection in November 2008.
Foley's move. FNF completed the acquisition of LandAmerica's two principal title underwriters — Lawyers Title Insurance Corporation and Commonwealth Land Title Insurance Company — along with United Capital Title, on December 22, 2008.6 The consideration was approximately $235 million, structured across cash, a subordinated note, and FNF stock.6 LandAmerica's book value prior to the crisis had stood near $1.4 billion.4
Acquiring the third-largest industry underwriter out of bankruptcy at a fraction of its pre-crisis book value — at a time when prospective competitors lacked balance-sheet capacity — stands as a clear case of crisis opportunism. The transaction expanded FNF's market footprint beyond what organic growth could have achieved.
The disconfirming evidence. The common assumption is that scale in title insurance protects cash flows during housing downturns. FNF's 2008–2009 performance demonstrates otherwise. Title revenue fell sharply as transaction volumes dropped by more than half from their 2005–2006 peak. FNF managed the contraction through thousands of employee layoffs, branch office consolidations, and reduced capital returns. Scale did not insulate operating income. Instead, it ensured solvency and enabled the company to purchase distressed assets when competitors could not.
This historical record refutes the notion of cycle-proof earnings: title scale does not protect earnings in a housing crash; it protects solvency and creates option value on distressed assets. For investors evaluating FNF, the business model relies not on immunity from real estate cycles, but on surviving downturns to consolidate market share at the bottom.
The key metric for evaluating management's execution in future downturns is not top-line revenue, which declines predictably with volume, but the speed at which title operating margins stabilize after a volume shock, alongside the company's ability to act as a buyer at market troughs.
Having survived the crisis and expanded its market footprint, management shifted its focus toward corporate structuring and balance-sheet engineering.
VI. The Foley Web: Spinoffs, Tracking Stocks, & Cannae (2010s)
By 2016, an organizational chart of the corporate entities tied to Foley required tracing a complex web of shared governance and overlapping operations. The core remained FNF, the title underwriter. Alongside it sat FIS, the banking technology firm, which operated independently while sharing board members and corporate history. There was Black Knight, the mortgage technology company carved out of FNF's servicing assets. Finally, there was FNF Ventures (FNFV), a tracking stock created in 2014 to hold non-title investments accumulated across previous years.
The FNFV portfolio was eclectic, spanning restaurant chains like J. Alexander's and O'Charley's, auto parts manufacturer Remy International, a stake in Dun & Bradstreet, and timber holdings. This period marked a distinct shift from consolidating core financial services to managing an un-synergized corporate portfolio.
Tracking stocks are a confession. A corporation issues a tracking stock when management believes public markets are misvaluing a specific business segment but wishes to retain operational control. It attempts to capture the valuation benefit of a corporate spinoff without executing a true separation. Investors frequently discount tracking stocks because shareholders hold a claim on reported segment accounting rather than direct asset ownership, leaving them with limited recourse over corporate overhead allocations.
In 2017, FNF transitioned the structure into a full separation by spinning out FNFV as Cannae Holdings, Inc. (NYSE: CNNE) — a standalone entity managed externally by a Foley-affiliated firm that collected management fees.
The activist reckoning. The subsequent performance at Cannae offers a test of whether Foley's financial engineering consistently produces long-term shareholder value.
Cannae underperformed significantly over the following years. The external management arrangement — in which Cannae paid management fees to an entity controlled by its own chairman — drew scrutiny from corporate governance advocates, a criticism amplified by lagging investment returns. Cannae ultimately dismantled the structure. In February 2024, the company agreed to wind down its management services agreement with Trasimene. Effective July 2, 2024, the arrangement was amended to a fixed $7.6 million annual fee over three years alongside a $20 million termination fee — down from roughly $37 million paid in the twelve months ending June 2024. On May 12, 2025, the agreement was terminated outright, and Foley stepped down as chief executive, chief investment officer, and chairman, assuming the role of non-executive vice chairman.18
Governance changes did not fully satisfy activist investors. Carronade Capital launched a proxy contest at Cannae's December 12, 2025 annual meeting, nominating four directors to replace one-third of the board.16 Both Institutional Shareholder Services and Glass Lewis recommended that shareholders vote for the dissident slate.17 Support from both major proxy advisory firms reflected an independent critique of the holding company's historical capital allocation and corporate governance.
What this means for FNF, specifically. Although Cannae is an independent entity whose financial results do not flow through FNF's income statement, its trajectory illuminates the management philosophy overseeing FNF, where Foley serves as chairman. The historical record indicates a strong track record in acquiring and integrating operating businesses, contrasted with weaker results when strategy shifted toward broad portfolio assembly and external management arrangements.
Foley's core operational strength lies in integrating adjacent financial-services assets rather than general multi-sector investing. The value created through FIS and Black Knight stemmed from companies FNF directly operated and restructured, whereas the friction at Cannae arose from a holding company portfolio of non-core businesses. Investors evaluating FNF must distinguish between operational integration and portfolio management, viewing any potential shift toward external asset assembly as a departure from FNF's core strength.
By 2018, however, FNF's central strategic question was not further multi-sector diversification, but whether regulatory authorities would permit continued consolidation of the title insurance market it already dominated.
VII. The Antitrust Wall: The $1.2B Stewart Acquisition Defeat (2018–2019)
Every roll-up strategy eventually encounters regulatory limits. FNF met its boundary in a Washington conference room.
In March 2018, FNF agreed to acquire Stewart Information Services Corporation — the nation's fourth-largest title underwriter, a Houston-based institution with a century-plus history — for approximately $1.2 billion.7 The transaction followed the operational logic FNF had executed for three decades: acquire a subscale competitor, fold its title plants into FNF's network, eliminate duplicative corporate overhead, and retain key revenue-producing escrow officers.
However, market concentration presented a regulatory obstacle. FNF was already the largest title underwriter family in the United States, while Stewart ranked fourth. Because the four largest underwriting groups controlled the vast majority of national market share, combining the first and fourth players represented a structural consolidation of an established oligopoly rather than a routine bolt-on acquisition.
The complaint. In September 2019, the Federal Trade Commission issued an administrative complaint seeking to block the merger, with commissioners voting 3-to-1 to authorize legal action.7 The FTC focused its antitrust challenge not on residential title insurance, but on commercial transactions and local data infrastructure. Specifically, the agency charged that the transaction would substantially reduce competition in title insurance underwriting for large commercial transactions in 45 states and the District of Columbia, as well as title information services in 14 local markets.7
This distinction highlights where the industry's economic pricing power resides.
Residential title insurance, despite its high transaction volume, is a commoditized product subject to state premium rate regulation where individual consumers exercise minimal purchasing discretion. Large commercial transactions function differently. Insuring a billion-dollar office tower or a multi-state industrial portfolio requires an underwriter with a balance sheet capable of absorbing large policy risks, technical expertise to resolve complex ownership structures, and legal infrastructure to coordinate across multiple state jurisdictions. Only a small group of national underwriters can execute these transactions. The FTC complaint served as an official recognition of FNF's commercial franchise while simultaneously establishing that FNF would not be permitted to expand that franchise through major underwriter acquisitions.
The New York State Department of Financial Services separately opposed the transaction, creating an additional state-level obstacle.
The outcome. Facing prolonged regulatory proceedings, FNF terminated the merger agreement in September 2019 and paid Stewart a $50 million reverse termination fee.[^8]8
Why this was the most important strategic event of the decade for FNF. The financial penalty itself was secondary to the strategic impact: the regulatory intervention permanently closed FNF's primary engine of value creation since 1984 — acquiring major domestic title underwriters to expand market share. FNF retained the ability to execute smaller tuck-in acquisitions of local title agencies at 4x to 6x pre-tax profit, which management noted represented prevailing market valuations across geographic regions.5 However, large-scale consolidation within title underwriting was no longer viable.
This barrier altered FNF's capital allocation options. A business generating substantial free cash flow, blocked from reinvesting in its core acquisition playbook, faced three paths: return capital to shareholders, acquire non-title assets, or build new internal business lines. Given management's historical focus on serial acquisitions, expanding beyond title insurance became the primary direction.
This regulatory wall provides essential context for evaluating FNF's subsequent strategy after 2019. Corporate diversification was not solely a proactive vision, but also a direct consequence of reaching the regulatory limits of title market consolidation.
Within months, FNF identified its next major acquisition target outside the real estate sector.
VIII. The Modern Pivot: F&G Annuities & Living with 7% Mortgage Rates (2020–Present)
In June 2020, with global markets navigating pandemic lockdowns and the ten-year U.S. Treasury yielding well below 1%, FNF closed its acquisition of Fidelity & Guaranty Life for approximately $2.7 billion in cash and stock.
At first glance, the timing appeared counterintuitive. Purchasing a fixed-annuity underwriter at the trough of an interest-rate cycle meant acquiring a business whose core product promises a fixed yield at the precise moment investment yields hit historic lows.
How a fixed annuity business actually makes money. At its core, an annuity provider operates a spread business structurally analogous to a commercial bank. A retail saver deposits a lump sum in exchange for a contractual return—either a guaranteed multi-year rate or a return tied to an equity index with a cap and a principal-protecting floor. The insurer invests those funds primarily in investment-grade fixed-income portfolios, captures the yield, and retains the spread above credited rates. This float—the capital held between initial deposit and ultimate payout—typically remains on the balance sheet for years.
For an owner like FNF, the model offered three key strategic features. First, the liabilities are long-dated and protected by surrender charges that penalize early withdrawals, making the funding base unusually sticky. Second, sales volumes depend on retiree demand for guaranteed income—a driver aligned with broader demographics and prevailing interest rates rather than real estate transactions. Third, the business scales through national bank and broker distribution channels rather than a physical branch footprint.
The strategic rationale for FNF was straightforward: establish a second earnings driver whose performance metrics remain largely independent of mortgage rates and existing home sales.
The partial separation. On December 1, 2022, FNF executed a pro rata distribution of approximately 15% of F&G's equity to FNF shareholders, initiating regular-way trading on the New York Stock Exchange under the ticker FG while FNF retained roughly 85%.[^10] Three years later, on December 31, 2025, FNF completed a further special dividend of roughly 12% of F&G ownership—approximately 16 million shares valued around $500 million—reducing its stake to approximately 70%.3 By the second quarter of 2026, FNF's reported holding stood at approximately 72%.1
Management framed the partial spin-off as a mechanism to establish an independent public market valuation for an asset previously embedded within a title insurer's consolidated financial statements. The structure also created a separate equity currency, allowing F&G to raise capital independently without relying on direct funding from FNF. However, whether public markets have fully re-rated the combined entity remains debatable, as persistent holding-company discounts suggest investors continue to price in corporate complexity.
The scale F&G has reached. Assets under management before flow reinsurance reached $73.1 billion at year-end 2025, representing a 12% increase from $65.3 billion a year earlier on annual gross sales of $14.6 billion.3 By the second quarter of 2026, pre-reinsurance assets under management reached a record $74.7 billion—up 8% year over year—supported by quarterly gross sales of $2.7 billion and net sales of $1.5 billion.1 In full-year 2025, F&G generated $412 million in adjusted net earnings, accounting for 30% of FNF's consolidated adjusted total.3
A key structural feature of F&G's balance sheet is the gap between its $74.7 billion in gross assets under management and its $55.9 billion net asset base after reinsurance.1 That $18.8 billion difference reflects flow reinsurance, where F&G originates annuity policies and cedes a portion of the risk to third-party reinsurance partners and sidecar capital vehicles. Management points to this mechanism to demonstrate that F&G can expand sales without requiring ongoing capital injections from FNF, as sidecars generate fee income on ceded assets. While flow reinsurance provides operational capital efficiency, it also introduces reliance on third-party reinsurance capacity, which could contract during periods of credit market stress when balance-sheet support is most needed.
The housing test running in parallel. While F&G expanded its asset base, FNF's core title operations faced the sharpest real estate contraction since the 2008 financial crisis. As mortgage rates surged from roughly 3% to over 7%, refinance activity dissolved and existing home sales dropped to multi-decade lows.
The environment tested FNF's direct-distribution model. The title segment generated a 15.9% adjusted pre-tax margin for full-year 2025 on $8.5 billion in title revenue and $1.36 billion in adjusted pre-tax earnings, finishing the year with a 17.5% margin in the fourth quarter.3 Performance strengthened further in the second quarter of 2026, with title margins reaching 17.8% and adjusted pre-tax title earnings expanding 33% year over year to $448 million—a 230 basis point improvement over the prior-year period.1
Maintaining double-digit operating margins during a severe housing downturn demonstrates the cost structure's operational flexibility. However, the 2026 margin expansion resulted primarily from business mix rather than a broad recovery in transaction counts. Total fee per file rose 5% to $4,107, while commercial direct revenue reached $778 million in the first half of 2026—up 24% year over year—supported by 29 individual commercial transactions in the second quarter alone that each exceeded $1 million in premium across industrial, multifamily, and data center assets.15 Margin expansion driven by premium mix remains structurally more sensitive than volume-driven expansion, as commercial real estate carries its own cyclical risks and data center capital expenditure booms are inherently cyclical.
Management has acknowledged these near-term operational trade-offs. On the second-quarter 2026 earnings call, Chief Financial Officer Anthony Park cautioned analysts to expect modest margin compression in the second half of the year, explaining that accelerated recruiting and tuck-in agency acquisitions create upfront expenses before generating matching revenue: "The revenue doesn't come in at the same level in the beginning, but all the expense does."5 Chief Executive Officer Mike Nolan characterized the period as producing "our best recruiting performance these last two quarters as we've ever had."5
Front-loading operational investments to capture market share is a recognized expansion strategy. At the same time, executive guidance clarifies that peak quarterly margins should not be viewed as an uninterrupted baseline.
IX. Core Business Deep Dive: Economics, Title Plants, & Segment Financials
Strip away four decades of corporate history and financial engineering to examine the core mechanics: what determines whether Fidelity National Financial generates profit across changing real estate cycles?
The industry board. Four corporate families dominate title underwriting: FNF, First American Financial, Old Republic, and Stewart. In ALTA's 2025 data, First American Title held 23.1% as an individual underwriter, Fidelity National Title 14.5%, Old Republic Title 14.0%, Chicago Title 13.1%, and Stewart Title 10.9%, with the top ten underwriters controlling roughly 86% of an $18.5 billion premium market.2 Because FNF operates multiple licensed underwriting entities, its family-level market share sits well above any single-brand figure—a structure that also makes market concentration less visually apparent in single-entity regulatory tabulations.
The remaining market belongs to regional independents and agency-focused underwriters. These firms remain relevant competitors—Westcor, Title Resources, and WFG each hold meaningful market positions2—but they compete primarily through independent agents in targeted geographies rather than through integrated national direct networks.
Where the revenue actually comes from. The wide dispersion in fee per file represents a critical operational detail in title economics. A residential refinance file yields the lowest fee because the property's title was examined recently, the chain of ownership is short, and the administrative requirement is minimal. A residential purchase file yields materially higher revenue because the examination is comprehensive and escrow duties are heavier. A major commercial transaction can generate fees one to two orders of magnitude above a residential purchase, reflecting bespoke underwriting, multi-jurisdictional coordination, and significant balance-sheet liability.
For this reason, FNF's reported average of $4,107 per file in the second quarter of 2026 should not be interpreted as a uniform title insurance price.1 It represents a blended figure across distinct product categories that fluctuates based on volume mix as well as baseline pricing. When management reports a 5% increase in fee per file, investors must distinguish among home price appreciation, commercial deal mix, and regulatory rate adjustments—the last of which represents genuine pricing power, though title rates remain filed with and constrained by state insurance regulators.
The loss ratio, and why it is not a margin. FNF's title loss provisioning historically runs in the low single digits as a percentage of premium. While this low loss ratio might resemble extreme underwriting profitability, it reflects a different operational reality. The economics of title insurance require an underwriter to spend capital up front—on search, examination, and closing labor—to prevent title defects before policies are issued. The loss ratio remains low because the operational expense ratio is high. Operating expenses consume the overwhelming majority of title revenue, leaving pre-tax margins in strong quarters in the high teens.1
Practically, because claim losses remain small and predictable, the primary determinant of title profitability is operational expense management relative to transaction volume. The business lacks reserve release cycles to smooth earnings or catastrophic loss years to absorb. Title operating margin functions strictly as a metric of operational leverage.
Testing the moat with Helmer's framework. Evaluating FNF through Hamilton Helmer's 7 Powers framework highlights where structural advantages reside:
Scale economies—present, but more specialized than marketing claims suggest. The primary scale assets are FNF's national title plant network and its centralized technology platform. Management noted on the second-quarter 2026 earnings call that FNF's inHere digital closing platform touches roughly 80% of the residential sales transactions the company handles.5 Amortizing fixed technology investments across a million annual files creates a clear cost advantage over a regional competitor distributing similar expenses across fifty thousand orders. However, because title plants function as county-level databases, an established local independent holding a comprehensive county plant faces no meaningful cost disadvantage within its home market. The scale economy operates nationally, even as competition occurs locally.
Cornered resource—the strongest competitive pillar, as reinforced by federal regulators. Commercial title underwriting capacity at institutional scale remains a scarce asset. Large commercial borrowers and lenders require underwriters with balance sheets capable of absorbing nine-figure policy risks. Only a small group of national underwriters meets this standard, and federal regulators have established that this list cannot be further condensed through major mergers.7 FNF's premium economics reside primarily within this institutional capacity.
Switching costs—negligible for retail buyers, but significant for institutional partners. Individual homebuyers rarely select their underwriter and face no switching costs. Conversely, a national mortgage lender whose loan origination systems are directly integrated into a title provider's workflow—and that relies on that underwriter for uniform closings across forty states—faces operational friction when changing providers.
Counter-positioning—absent. FNF holds no structural model advantage that major incumbents cannot replicate. First American operates a comparable direct distribution network supported by similar technology. Competitors differentiate through operational execution rather than business model asymmetry.
Porter's forces, briefly. Entry barriers remain high due to title plant requirements, regulatory licensing, capital reserves, and distribution networks. Industry rivalry among the four major families is intense but disciplined, constrained by filed premium rates and shared competition for experienced escrow personnel. Buyer power is split: retail consumers possess minimal bargaining power, whereas institutional lenders and commercial sponsors exercise substantial leverage. Supplier power rests with key producers—escrow officers and agency principals who maintain local client relationships—explaining management's strategic focus on talent recruiting. Finally, the potential threat of substitutes represents the central long-term question for the industry.
The resulting picture is an advantaged business operating with a narrower moat than its market share implies: dominant within a structurally protected oligopoly, yet competing file by file on service quality and commercial relationships, with pricing bounded by state regulation and transaction volumes dictated by broader housing activity.
X. Current Management Audit & Capital Allocation Discipline
The executive team leading FNF today built their careers inside the organization rather than arriving as external turnarounds.
Mike Nolan became chief executive in 2022 after more than three decades inside the company, having risen through direct title operations. That operational background shows in his management approach: an emphasis on branch-level cost matching, recruiting escrow teams, and executing tuck-in agency acquisitions at defined valuation multiples. Having advanced through operations, his primary track record rests on maintaining the title segment's margin performance through the 2022–2026 real estate volume downturn.
William P. Foley II remains non-executive chairman. He is no longer involved in day-to-day operations and, since May 2025, has also stepped back from executive roles at Cannae.18 His continuing influence centers on strategy, acquisitions, and corporate structure — an architecture that represents both FNF's primary historical engine of value creation and its main governance question.
Anthony J. Park has served as chief financial officer for more than two decades, spanning the Chicago Title integration, the 2008 financial crisis, corporate spin-offs, and the F&G acquisition. Executive continuity in that seat across multiple structural transitions provides notable consistency in financial disclosure.
What the capital allocation record actually shows. In 2025, FNF returned approximately $800 million to shareholders — consisting of $546 million in dividends and $251 million in share repurchases — while ending the year with $659 million of cash at the holding company.3 In the first half of 2026, it returned roughly $417 million, comprising $278 million in dividends and $139 million in repurchases.5 At the end of the second quarter of 2026, notes payable stood at $4.38 billion against $7.45 billion in total common equity.1
Two main patterns emerge from these figures. First, management prioritizes the dividend over buybacks, returning roughly two dollars in dividends for every dollar spent on share repurchases. This strategy favors dividend predictability over opportunistic buybacks, contrasting with the company's historically opportunistic dealmaking. Second, FNF has not aggressively repurchased its own stock during the real estate downturn. Given management's stated confidence in the business, investors might question why FNF distributed approximately $500 million of F&G stock to shareholders in December 2025 rather than deploying comparable value into repurchasing its own equity.3 While management had valid reasons — such as building F&G's public float, managing tax efficiency, and preserving holding company liquidity — the capital allocation choice remains a key point of evaluation.
Testing credibility against the record. Evaluating management credibility requires comparing historical guidance against actual operational execution.
On title margins, management's public guidance remained consistent across multiple earnings calls: defend double-digit title margins through cyclical volume troughs. FNF delivered on this commitment, recording a 15.9% full-year title margin in 2025 and a 17.8% title margin in the second quarter of 2026.31 This operational performance reflects disciplined cost control during a severe real estate contraction.
Regarding F&G capital, management consistently asserted that the annuity business would self-fund through flow reinsurance without requiring capital injections from the parent company. The expanding gap between assets under management before and after reinsurance confirms that the mechanism is being used at scale.1 However, whether this reinsurance structure remains resilient under credit market stress remains untested.
By contrast, disclosure around F&G's underlying GAAP financial results is less straightforward. Full-year 2025 net earnings attributable to F&G common shareholders fell to $248 million from $622 million in 2024 — a decline of roughly 60%.9 Management and equity analysts focus primarily on F&G's adjusted net earnings, which presented a far steadier picture by contributing $412 million to FNF.3 The spread between GAAP and adjusted earnings stems from mark-to-market valuations and non-recurring items, which are standard adjustments in annuity accounting. However, investors should recognize that the narrative of F&G contributing 30% of earnings is a statement about a non-GAAP metric.3
Leadership transitions at F&G also present ongoing questions. Conor Murphy assumed the chief executive role following Chris Blunt's tenure. On the second-quarter 2026 earnings call, Murphy noted that F&G was evaluating strategic options for Peak Altitude, its owned-distribution platform, and expressed a preference for bringing in a 51% partner.5 Because acquiring owned distribution was a core element of F&G's original expansion thesis, reconsidering that structure warrants further explanation to shareholders.
In summary, management's execution record at FNF is asymmetric. On core title operations, operational commitments have been specific and consistently met. On corporate portfolio construction and segment disclosures, the track record is more complex and disclosures require closer scrutiny. This distinction provides essential context for evaluating the formal stress test of FNF's business model.
XI. The Historical Falsification Pass: Stress-Testing Thesis Claims
Every investment case rests on core thesis claims. For Fidelity National Financial, four central assertions dictate the bull case—and each must be evaluated against the strongest disconfirming evidence in the company's operating record.
Test 1: "The title moat protects margins and market share from disruption."
The mechanism that would break it: the government-sponsored enterprises deciding that lender's title insurance is unnecessary on select loans, or accepting an attorney's opinion letter in its place.
The evidence. In March 2024, the Federal Housing Finance Agency announced a Title Acceptance Pilot allowing lenders to sell select low loan-to-value refinance loans with clear existing title to Fannie Mae without requiring lender's title insurance or an attorney's opinion letter, with FHFA estimating borrower savings of $500 to $1,500 per transaction.13 The industry response was immediate: fourteen state attorneys general urged FHFA to terminate the pilot.15 An initial version of the waiver program was scrapped amid the pushback.14 Fannie Mae subsequently issued a request for proposal to identify suppliers for participation in the pilot,20 and by 2025 a second vendor had joined alongside the original participant.
The verdict. The claim survives, but only in a narrowed form. Adoption remains negligible—representing a low-single-digit percentage of transactions—constrained to a specific, low-risk refinance population and limited by secondary-market and private-label requirements that still demand title coverage. FNF's fee per file has risen, not fallen, through the entire period of the pilot's existence.13 So the disruption has not materialized.
However, the episode demonstrated that mandatory title coverage is a policy convention rather than an unalterable rule of nature. A federal regulator formally tested whether the requirement could be removed, and the industry defeated the initial attempt primarily through political mobilization rather than by proving product necessity. The competitive moat relies in part on regulatory capture, which remains durable until policy priorities shift.
What would falsify the narrowed claim: meaningful expansion of title-waiver eligibility beyond low-LTV refinances into purchase transactions, or a sustained decline in residential fee per file that is not explained by mix.
Test 2: "FNF's technology infrastructure creates an operational moat."
The mechanism that would break it: the infrastructure failing.
The evidence. On November 19, 2023, FNF disclosed in an SEC filing that an unauthorized third party had accessed certain of its systems and acquired credentials and data.10 Containing the breach within seven days required taking core systems offline, disrupting title, escrow, and closing operations nationwide for the better part of a week at a company that closes thousands of real estate transactions daily. The ALPHV/BlackCat ransomware group claimed responsibility on November 22.12 The subsequent investigation determined that data belonging to approximately 1.3 million customers had been taken.11 FNF carried cyber insurance with a $10 million retention.11
The verdict. The event refutes the strong version of the claim. A platform that can be taken offline for a week by a criminal group introduces concentrated operational risk rather than an unassailable moat. The infrastructure centralization that drives FNF's cost advantage—unifying back-end processing across five distinct market brands to serve a million annual files—is precisely what caused a single intrusion to become a nationwide disruption.
The narrowed claim that survives holds that FNF's technology produces genuine unit-cost advantages and customer-facing convenience, with inHere now engaged in roughly 80% of residential sales transactions and management extending it into post-closing property monitoring across 35 states.5 However, the centralized platform functions as an efficiency asset carrying tail risk rather than a defensive fortification.
What would falsify further: a second material incident, evidence of commercial mandates moving to competitors on security grounds, or security and compliance spending rising fast enough to visibly compress margin.
Test 3: "Foley's M&A and capital allocation always create value."
The evidence. Assertions of flawless capital allocation are refuted by specific historical transactions, including the $50 million paid to Stewart for a deal that never closed,8 Cannae's underperformance alongside the external-management arrangement that had to be dismantled at a cost of a $20 million termination fee,18 and the December 2025 proxy contest in which both major proxy advisers backed the activist against the incumbent board.1617
The verdict. The record supports a much more specific claim: Foley's organization creates substantial value when it acquires and operationally integrates businesses adjacent to its core, and has destroyed value when it assembles portfolios it does not operate. Chicago Title, LandAmerica, and the FIS lineage illustrate successful operational execution. Conversely, FNFV's restaurant and specialty holdings, along with the Cannae external-management structure, highlight the downside of holding-company portfolio assembly.
What would falsify the surviving version: FNF deploying meaningful capital into acquisitions outside title and annuities where it is a financial owner rather than an operator. The tuck-in agency deals at 4x–6x pre-tax profit that management describes5 represent the disciplined pattern. A large, unrelated platform purchase would be the warning sign.
Test 4: "F&G provides a financial cushion without adding risk."
The mechanism that would break it: traditional spread-business vulnerabilities—asset-liability mismatch, margin compression, or investment portfolio credit impairments.
The evidence. F&G's GAAP net earnings fell from $622 million in 2024 to $248 million in 2025, driven by mark-to-market and non-recurring items.9 That performance reflects a leveraged balance sheet responding to market shifts rather than a stabilizing earnings cushion.
The verdict. The claim is rejected in its stated form. FNF acquired a differently cyclical earnings stream rather than an acyclical cushion. Annuity spread businesses invest policyholder funds in credit—including structured credit and commercial real estate debt—causing reported earnings to move with credit spreads and interest rates.
The primary structural concern for investors is tail correlation across segments. A severe commercial real estate downturn could simultaneously impair F&G's investment portfolio, compress FNF's high-margin commercial title revenue, and reduce third-party appetite for the flow reinsurance sidecars that enable F&G to expand without parent capital injections. Those three exposures are marketed as diversified, but under market stress, they may prove correlated.
What would falsify or confirm: F&G's net investment spread trend, any ratings action, credit impairments in the investment portfolio, and—the cleanest signal of all—any capital contribution from FNF to F&G, which would directly contradict the self-funding narrative.
Four claims lead to four distinct outcomes: one narrowed, one refuted in its strong form, one replaced with a more specific operational framing, and one rejected outright. This pass does not dismantle the investment thesis, but it establishes the distinction between evaluating FNF on its operating mechanics versus relying on broad corporate narrative.
XII. Bull vs. Bear Case & Key KPIs to Watch
The bull case, stated at its strongest.
The foundation is the commercial franchise. Large commercial title underwriting is the segment with real pricing power, real scarcity, and — courtesy of the FTC — a legally frozen competitive structure.7 FNF's commercial direct revenue of $778 million in the first half of 2026, up 24%, with 29 individual million-dollar-plus premium transactions in a single quarter, is evidence that this business is performing at a high level across industrial, multifamily, and data center assets.5 This is the highest-quality earnings stream FNF has.
The second pillar is operating leverage on a housing recovery. Existing home sales have been at multi-decade lows. FNF has demonstrated it can earn a 17.8% title margin in that environment.1 If residential transaction volumes normalize toward historical levels, the incremental file flows across a cost base already sized for the trough. That is the mathematical shape of a coiled spring, and it is the clearest reason someone might own this stock.
The third is F&G's growth: $74.7 billion of AUM before reinsurance, compounding at high single to low double digits, with the flow reinsurance structure allowing growth without proportional parent capital.1
The fourth is a consistent, substantial capital return — roughly $800 million in 2025 across dividends and buybacks.3
The bear case, stated at its strongest.
First, the recovery may not arrive on schedule. "Mortgage rates must normalize and home sales must mean-revert" is the load-bearing assumption of the bull case, and it has been the load-bearing assumption since 2022. Every year it does not happen is a year of foregone earnings that no amount of cost discipline recovers. Worse, the lock-in effect — homeowners holding sub-4% mortgages who cannot afford to move — is a genuine structural impediment, not merely a cyclical one, and it decays slowly.
Second, the 2026 margin story is a mix story. Commercial and fee-per-file strength carried the improvement; residential volumes did not.15 Commercial real estate has its own cycle, and the data center construction wave currently feeding commercial title volumes is a capital expenditure boom with a finite life. Management has already guided to second-half margin compression on recruiting and acquisition costs.5
Third, the regulatory tail. The title waiver pilot was beaten back, not eliminated.1314 A product whose necessity a federal housing regulator has formally questioned carries permanent political risk, particularly in an environment focused on housing affordability and closing costs.
Fourth, F&G credit risk and structural correlation, as set out in Test 4.
Fifth — and least discussed — governance and complexity. FNF is a title insurer that consolidates a majority-owned public annuity company, has a chairman with an affiliated holding company that just lost a proxy advisory fight,1617 and reports a headline earnings contribution figure on a non-GAAP basis.3 Each element is individually explicable. Collectively they are the kind of thing that keeps a holding-company discount in place.
What an activist would attack. A skeptical investor pressing FNF would focus on three things. Why distribute F&G stock rather than repurchase FNF stock at trough valuations? Why does a business barred from transformative M&A since 2019 still carry $4.38 billion of notes payable rather than a materially different capital structure?1 And what is the actual argument for keeping 72% of a separately listed annuity company inside a title insurer's consolidated statements, rather than completing the separation and letting each business be valued by the investors who want it? Management has answers to all three. None of them are obviously conclusive.
The three KPIs that matter.
-
Title segment adjusted pre-tax margin. This is the single cleanest measure of whether the direct-distribution model works as advertised. It captures cost discipline, mix, and pricing in one number, and it is the metric management has publicly staked its credibility on defending through troughs.31
-
Total fee per file, read alongside residential purchase order counts. Fee per file measures value capture per transaction; order counts measure volume. Watching them together separates the mix-driven margin story from a genuine housing recovery — and reveals immediately whether any title-waiver or AOL substitution is actually biting.1
-
F&G net investment spread and AUM before flow reinsurance. Spread is the profitability of the annuity engine; AUM before reinsurance is its scale. Together they tell you whether F&G is growing profitably or simply growing — and spread compression would be the earliest visible sign that the diversification argument is failing.1
XIII. Epilogue: Title Insurance in an AI & Blockchain World
Around 2017, at the peak of enthusiasm for distributed ledgers, a frequent conference panel prediction held that blockchain technology would eliminate title insurance within a decade. Put land records on an immutable ledger, the argument went, and the entire industry would become an anachronism—a fee collected for solving a problem that technology had rendered obsolete.
Instead, the industry recorded $18.5 billion in total premium volume in 2025, up nearly 14% year over year.2
That prediction failed because it misunderstood what title insurance actually protects. A blockchain excels at establishing that a record has not been altered since it was entered. It cannot establish that the record was accurate when it was filed. Virtually every material title defect originates outside official recording systems: a forged signature on a decades-old deed, an unnotified heir in a probate sale, a mechanic's lien that attaches by operation of law prior to filing, an unaddressed marital interest from a divorce decree, or a fraudulent conveyance by an impersonator.
Placing those documents on a blockchain merely creates an immutable record of a fraud. Title insurance exists to compensate policyholders when physical-world transactions prove flawed. The core product is not record indexing; it is a financial backstop against defective documentation and human error.
Where technology is actually changing the business. The primary operational shift is occurring within title search and examination. Historically, examination required manual review of scanned records, interpreting legal descriptions, and determining whether a decades-old easement affected a current transaction. Today, machine learning models trained on proprietary plant databases can classify documents, match parcels, flag anomalies, and clear routine files automatically, lowering processing costs across uncomplicated transactions.
That automation provides tangible efficiency, helping explain how Fidelity National Financial maintained high-teens title margins during a period of depressed transaction volumes. However, the operational benefits have clear boundaries. Automated search lowers unit costs on straightforward files. Complex files—those involving title defects or multi-layered commercial ownership—still demand specialized human review and generate the majority of high-margin fee revenue. As a result, technology lowers unit costs on lower-margin files while leaving high-value commercial underwriting largely unchanged. It acts as margin support rather than a structural transformation of the underwriting model.
Competitive dynamics also constrain those gains. Competing underwriters are deploying comparable machine learning tools across similar plant data. Over time, industry-wide operational efficiencies in a price-regulated product tend to be competed into price or passed through to customers. First-mover scale provides a temporary operational advantage, but not necessarily a permanent competitive moat.
The final reflection. In 1984, William P. Foley II identified a legally mandated, structurally fragmented, and operationally inefficient industry where underwriters bore balance-sheet risk while third-party agents captured the majority of transaction fees. Over the subsequent decades, the company constructed a unified platform designed to capture those economics through direct distribution, rapid integration of acquired competitors, and opportunistic dealmaking during industry downturns.
That consolidation engine reached its regulatory limit in 2019 when antitrust authorities blocked further major title underwriter acquisitions. Since then, management has faced a strategic transition: identifying new growth opportunities after consolidating its primary market.
The resulting strategy relies on F&G annuities, localized agency acquisitions, share buybacks, dividends, and internal technology deployment. Whether this structure represents a sustainable second act or a necessary pivot away from a fully consolidated core business remains the central analytical question for investors. The operational record reveals an advantaged, disciplined core title business operating alongside an annuity diversification strategy that offers sound logic, but carries a shorter and more complex track record than the title roll-up that preceded it.
The title insurance market remains structurally protected by capital requirements, title plant assets, and regulatory barriers. The long-term investment outcome depends on how efficiently capital is deployed after the primary consolidation phase has closed.
References
-
FNF Reports Second Quarter 2026 Financial Results — Fidelity National Financial Form 8-K, SEC EDGAR, 2026-08-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
ALTA Reports 2025 Market Share and Title Insurance Premium Volume — American Land Title Association, 2026 ↩↩↩↩↩↩
-
FNF Reports Fourth Quarter and Full Year 2025 Financial Results — PR Newswire / Fidelity National Financial, 2026-02 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
History of Fidelity National Financial Inc. — FundingUniverse ↩↩↩↩↩↩↩
-
Earnings call transcript: Fidelity National Financial tops Q2 2026 estimates — Investing.com, 2026-08-06 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Fidelity National Financial, Inc. Form 8-K/A — LandAmerica title underwriter acquisition, SEC EDGAR, 2009 ↩↩
-
FTC Challenges Proposed $1.2 Billion Merger of Title Insurance Providers Fidelity National Financial, Inc. and Stewart Information Services Corporation — Federal Trade Commission, 2019-09 ↩↩↩↩↩
-
Fidelity National, Stewart Information Pull Plug on Merger After FTC Complaint — TheStreet, 2019-09 ↩↩
-
F&G Annuities & Life Reports Fourth Quarter and Full Year 2025 Results — F&G Annuities & Life Investor Relations, 2026-02 ↩↩
-
Fidelity National Financial, Inc. Form 8-K — Cybersecurity Incident, SEC EDGAR, 2023-11-19 ↩
-
Fidelity National Financial: Hackers stole data of 1.3 million people — BleepingComputer, 2023-12 ↩↩
-
Notorious ransomware gang takes credit for cyberattack on Fidelity National Financial — The Record, 2023-11 ↩
-
Director Sandra Thompson's Statement on Title Acceptance Pilot — Federal Housing Finance Agency, 2024-03 ↩↩
-
Fannie Mae scraps title waiver pilot program — HousingWire, 2024 ↩↩
-
14 Attorneys General Urge FHFA to Terminate Title Waiver Pilot — American Land Title Association, 2024-07-23 ↩
-
Cannae Holdings, Inc. Form DEFC14A — 2025 Annual Meeting Proxy Contest, SEC EDGAR, 2025 ↩↩↩
-
Advisory firms favor dissident in Cannae Holdings proxy fight — Jacksonville Daily Record, 2025-12-04 ↩↩↩
-
Cannae Holdings, Inc. Form 10-Q for the quarter ended June 30, 2025 — SEC EDGAR ↩↩↩
-
Intercontinental Exchange Completes Acquisition of Black Knight — ICE Investor Relations, 2023-09-05 ↩
-
Fannie Mae to Issue Request for Proposal to Identify Potential Suppliers for Participation in the Title Acceptance Pilot — Fannie Mae ↩
-
William P. Foley II 1944— Biography — Reference for Business ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube