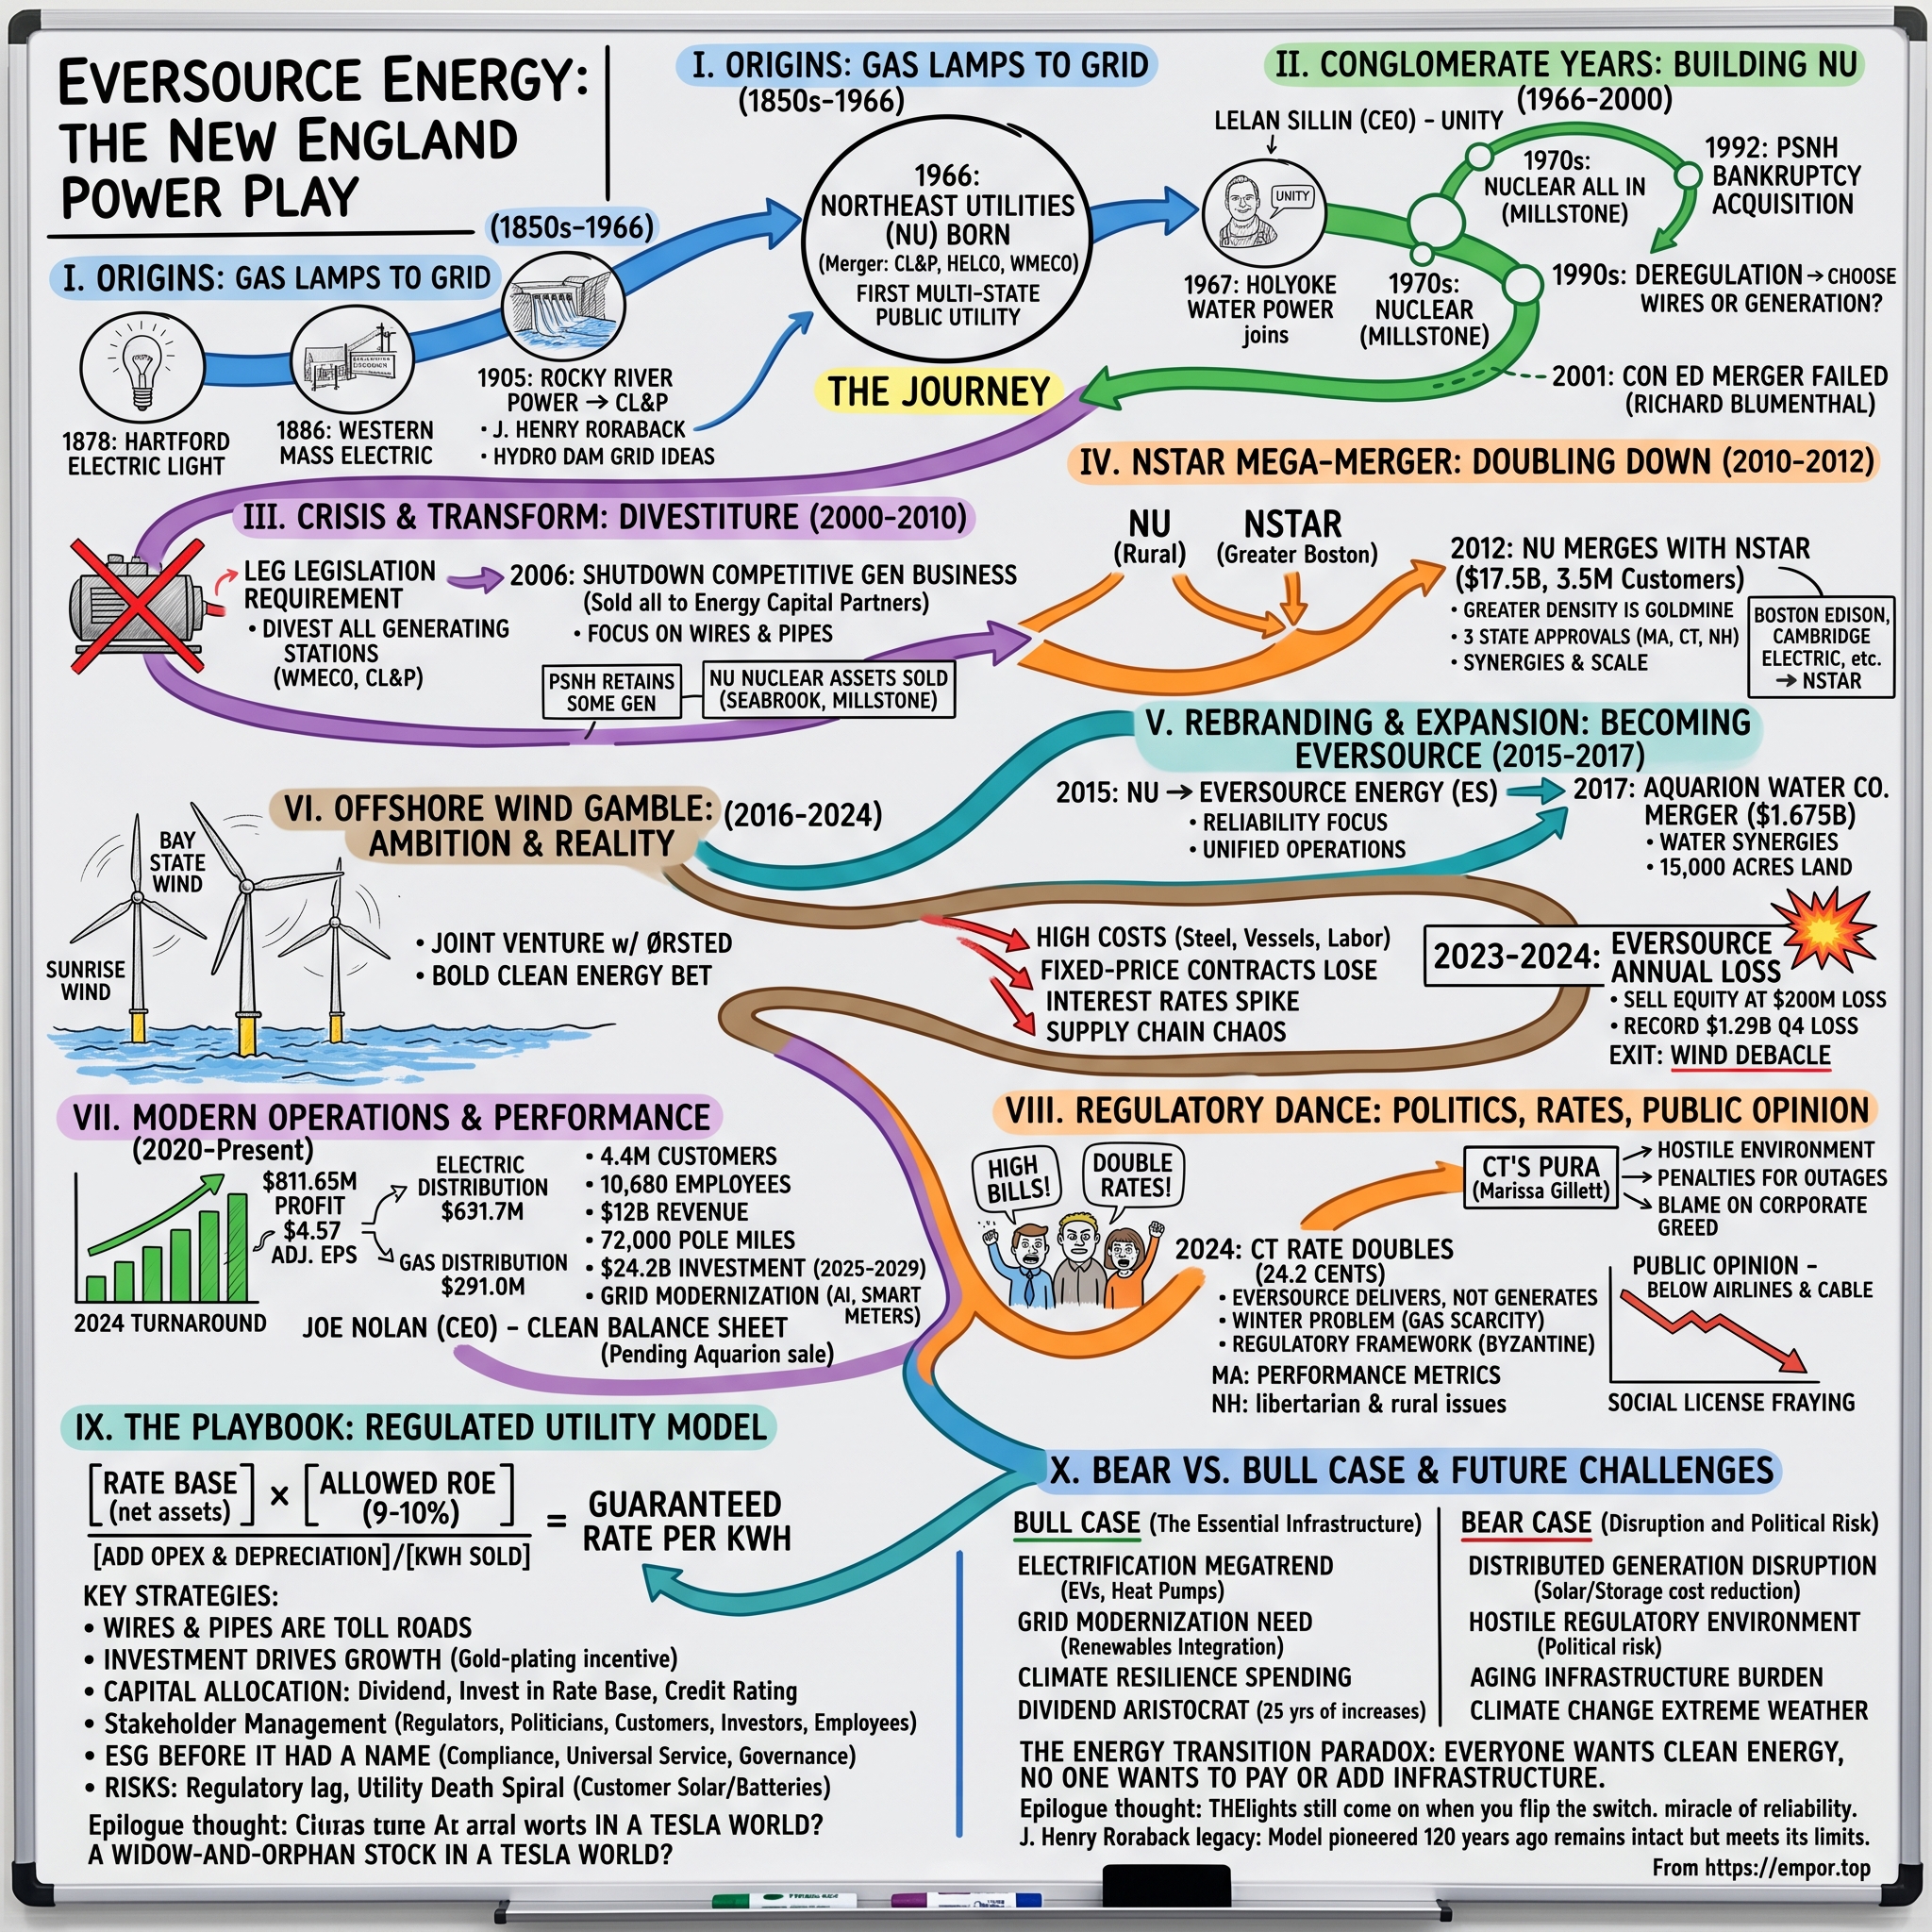
Eversource Energy: The New England Power Play
I. Introduction & Episode Roadmap
On a cold morning in late January 2024, Eversource Energy's management team faced Wall Street to explain how a utility whose core business model rests on earning a regulated, government-sanctioned return on electric lines and gas mains had just lost more than two billion dollars offshore.
The loss did not stem from a severe storm or an operational breakdown at a power plant. It came from an ocean—specifically, the stretch of the North Atlantic between Montauk and Martha's Vineyard, where Eversource had partnered to co-develop some of the first utility-scale offshore wind projects in the United States. The company disclosed pre-tax impairment charges of roughly $2.17 billion on its offshore wind investments, and for full-year 2023 it reported a net loss of $442 million—the sharpest financial downturn in the modern history of a corporate lineage lighting New England homes since the 1870s.1
That outcome highlights the central tension in Eversource's narrative. Structurally, the company operates a resilient distribution franchise: an exclusive right to deliver electricity and natural gas to roughly 4.4 million customers across Connecticut, Massachusetts, and New Hampshire. The utility generates approximately $12 billion in annual revenue and maintains a five-year capital expenditure plan that has expanded to $26.5 billion for 2026–2030.[^2] Competing providers will not construct a secondary grid in Hartford or Boston. Yet in roughly eight years, executive decisions in discretionary, non-regulated ventures destroyed more shareholder value than a decade of regulatory pushback could have inflicted.
The company's trajectory follows five distinct phases:
First, the long consolidation: a fragmented network of nineteenth-century gas-lamp and electric utilities merged town by town over a century into regional systems and multi-state holding companies, ultimately forming Northeast Utilities.
Second, the structural transformation: the NSTAR merger, announced in 2010 and closed in 2012, combined Boston's dense urban grid with Connecticut's energy infrastructure. The combined enterprise rebranded as Eversource Energy in 2015 and acquired Aquarion Water Company in 2017 as a diversification bet.
Third, the offshore detour: a joint venture with Denmark's Ørsted that ran into macroeconomic headwinds between 2021 and 2023, triggering heavy asset write-downs and a forced exit—a 2024 divestiture that shifted Eversource from an offshore growth story into a balance-sheet repair effort.
Fourth, the strategic pivot and its financial toll: the sale of Aquarion Water, completed on June 30, 2026, for $2.4 billion in cash—yielding roughly $1.7 billion in net proceeds applied toward debt reduction—which completed Eversource's transition back to what management frames as a "pure-play regulated pipes and wires utility."[^3]
Fifth, the forward outlook for investors: evaluating segment economics, navigating a complex three-state regulatory environment, and assessing whether a business that has twice reversed its corporate strategy can compound capital quietly over the coming decade. Recent regulatory actions show that even regulated revenue streams remain exposed. In March 2026, federal regulators lowered the base return on equity for New England transmission owners from 10.57% to 9.57% and ordered approximately $1.5 billion in regional customer refunds—a ruling that directly curtailed earnings in the single most profitable, formulaic part of Eversource's business.2
That is the central paradox: a utility protected from direct commercial competition, yet continually constrained by legislative mandates, regulatory proceedings, and political pressure—and one that, when attempting to expand beyond its core monopoly, voluntarily stepped outside its own protective moat.
 Subscribe on LinkedIn
II. Historical Foundations: Consolidation & Grid Formation (1850s–2000)
The origin of Eversource's network traces back to Hartford in 1878. The Hartford Electric Light Company began as a novelty business, selling illumination primarily to wealthy households and commercial properties at rates far higher than manufactured gas. Eight years later, Western Massachusetts Electric Company formed in Springfield. In 1905, Rocky River Power Company incorporated in Connecticut, renaming itself The Connecticut Light and Power Company in 1917—an entity that remains at the core of Eversource's Connecticut operations.3
In the late nineteenth century, power distribution was strictly local. Direct current technology could not transport electricity more than a mile or two from a generating plant. Consequently, every municipality seeking electric service required its own local plant, coal supply, distribution lines, and municipal franchise. This structure created hundreds of isolated, small-scale monopolies burdened by inefficient economics: high unit generation costs, lack of load diversity, and reliability dependent on a single local boiler.
The adoption of alternating current altered the physics of distribution, making long-distance power transmission viable and driving rapid consolidation. Larger generating stations produced electricity at significantly lower cost per kilowatt-hour, while interconnected grids allowed utilities to share reserve capacity. By serving both industrial mill districts and residential neighborhoods, consolidated systems flattened their load curves and maximized plant utilization. In utility distribution, corporate consolidation was the direct operational consequence of electrical engineering.
Aggressive consolidation throughout the 1920s eventually led to financial excess. Pyramided holding companies collapsed during the Great Depression, prompting Congress to pass the Public Utility Holding Company Act of 1935 (PUHCA). The legislation dismantled complex holding structures and strictly limited multi-state utility combinations for the next three decades.
That regulatory barrier made July 1, 1966, a pivotal milestone. On that date, Connecticut Light and Power, Western Massachusetts Electric, and Hartford Electric Light merged to form Northeast Utilities—the first multi-state public utility holding company approved under PUHCA following the law's passage.3 Northeast Utilities represented the first legally sanctioned effort to operate New England's power grid as a coordinated regional system rather than a patchwork of state utilities. Management bet that economies of scale across generation, transmission, and engineering would reduce customer costs while delivering stable shareholder returns.
That model functioned effectively for two decades before running into the central crisis of modern New England utility history: nuclear construction cost overruns. Public Service Company of New Hampshire (PSNH) had committed to building the Seabrook Station nuclear plant, a project plagued by severe budget expansion through the 1970s and early 1980s due to regulatory delays, design modifications, and intense public opposition. PSNH declared bankruptcy in 1988—marking one of the first major U.S. investor-owned utility insolvencies since the 1930s—and was acquired by Northeast Utilities in 1992.3
This episode established a structural pattern that recurred decades later. A regulated utility undertook a capital-intensive, technologically complex project expecting regulators to permit full cost recovery. When construction expenditures spiraled and regulatory approval faltered, shareholder equity was devastated. Decades later, offshore wind investments yielded a similar lesson: the regulatory compact protects prudent, approved, in-service investments, but it does not guarantee cost recovery for discretionary ambition.
The financial fallout from Seabrook also redefined New England's regulatory landscape. Although the plant was ultimately completed and remains one of the region's primary sources of carbon-free electricity, its construction losses solidified a political consensus that ratepayers should not absorb utility capital risks. That policy stance laid the groundwork for state restructuring legislation in the 1990s, performance-based ratemaking mechanisms in the 2020s, and a persistent regional regulatory framework focused on constraining utility returns.
The 1990s introduced a second major structural transformation. Restructuring legislation in Massachusetts, Connecticut, and New Hampshire mandated the unbundling of vertically integrated utilities, separating competitive power generation from regulated transmission and distribution. Northeast Utilities divested its fossil and nuclear power plants in subsequent years, transforming into a pure delivery company that earned returns by owning distribution infrastructure while passing wholesale energy costs directly through to consumers at cost.4
This structural shift defined the modern utility model. While company earnings became decoupled from wholesale electricity prices, political exposure to energy costs remained total. Because retail customers receive a single consolidated bill displaying the utility's logo, public dissatisfaction over high energy bills directly targets the delivery provider, even when pass-through commodity charges drive the increase.
By 2000, the corporate architecture was set: a multi-state delivery monopoly stripped of generation, earning regulated returns on capital rate base across three state jurisdictions and federal oversight. What it did not yet have was scale in the region's richest market. That was about to change.
III. The NSTAR Mega-Merger & Rebranding: Creating New England's Energy Behemoth (2010–2017)
Greater Boston represented New England’s premier utility market: dense customer distribution, steady load growth, a high concentration of commercial and institutional accounts, and—crucially for a rate-base business—lower service costs per customer due to geographic density. NSTAR, formed through earlier consolidations of Boston Edison, Commonwealth Energy, and their gas affiliates, held exclusive delivery rights across that territory.
In October 2010, Northeast Utilities and NSTAR announced a stock-for-stock merger of equals valued at roughly $17.5 billion including debt.3 The industrial logic appeared clean: combine Connecticut’s sprawling, storm-exposed, suburban and rural infrastructure with Boston’s dense urban grid, streamline administrative overhead, and create a unified transmission-planning entity across southern New England. The combined enterprise would control thousands of circuit miles of high-voltage transmission lines and tens of thousands of distribution pole miles.
The transaction highlighted the distinct dynamics of regulated utility acquisitions. In competitive sectors, acquirers negotiate primarily with target boards and shareholders. In utility markets, approval requires negotiating with public regulators. Massachusetts Attorney General Martha Coakley intervened aggressively, while Connecticut regulators raised similar concerns. Regulators did not block the merger, but conditioned approval on substantial structural concessions. To secure authorization in 2012, the companies agreed to rate freezes, direct customer credits, and commitments to long-term renewable power purchase agreements.3
These regulatory concessions reflected standard oversight, but they also clarified how value is distributed in utility mergers. In unregulated transactions, operational cost synergies typically accrue to shareholders. In regulated mergers, state authorities redirect a significant share of those savings to ratepayers as the price of regulatory consent. Consequently, an acquirer's primary benefit is not immediate expense reduction, but rather an expanded rate base for capital deployment and a larger strategic footprint. On that structural basis, the NSTAR merger succeeded: it established the combined company as the primary regional owner of southern New England's transmission backbone. Based strictly on near-term earnings accretion, however, initial returns were far more modest than original merger presentations implied—a distinction relevant to virtually every utility consolidation.
In February 2015, the consolidated enterprise replaced its legacy operating brands—CL&P, NSTAR, WMECO, and PSNH—unifying its operations under a single corporate name: Eversource Energy, trading on the NYSE as ES.3
Rebranding reflected operational necessity alongside corporate identity. Beneath the legacy logos operated four separate billing platforms, four storm-response protocols, four call centers, four sets of engineering standards, and distinct corporate cultures. Consolidating those functions delivered the merger's primary cost synergies over several years. Yet single-brand unification also created political concentration. Previously, local operating entities shielded the parent company from localized public pushback. Under a unified brand, customer dissatisfaction over Connecticut electric bills, Massachusetts storm-response delays, or New Hampshire regulatory filings focused on a single corporate target. Unifying the brand exchanged local political insulation for operational efficiency.
The NSTAR integration also demonstrated the structural limits of utility consolidation. Merging holding companies did not merge the underlying physical grids. Electric and gas assets remained separate operational units across three states, regulated by separate utility commissions with distinct rate-case calendars, authorized returns on equity, and performance metrics. Consolidation occurred primarily at the corporate layer: treasury operations, procurement, engineering standards, and information technology. Because overhead constitutes a relatively small share of total utility expenditures compared to capital investments and wholesale fuel costs, corporate synergies produced incremental efficiency gains rather than dramatic margin expansion. The primary strategic value lay in balance-sheet scale and capital optionality: a larger, more creditworthy holding company could finance major infrastructure projects, absorb regulatory setbacks in individual jurisdictions, and compete for regional transmission contracts beyond the scope of a single-state utility. However, that expanded balance-sheet capacity also provided the financial foundation for the company's subsequent entry into offshore wind development.
In June 2017, Eversource executed its first major discretionary expansion outside electric and gas distribution. The company agreed to acquire Aquarion Water Company for $1.675 billion including assumed debt, adding roughly 230,000 water connections across Connecticut, Massachusetts and New Hampshire.3
The strategic rationale matched Eversource's core competence: regulated water distribution offered a stable rate base, long-lived infrastructure assets, zero commodity price exposure, and a fragmented industry ripe for consolidation. Management framed the acquisition as a natural extension into adjacent rate-base utility operations. Although the purchase price represented a significant premium to Aquarion’s rate base and conventional earnings multiples, management justified the valuation by citing the scarcity of investor-owned water systems and opportunities for small-system acquisitions.
Although the 2026 sale of Aquarion later reframed the transaction, in 2017 Eversource appeared to have established a repeatable formula: acquire regulated utilities, invest capital into rate base, earn authorized returns, and compound earnings. Its next strategic move applied that same balance-sheet confidence to a venture operating outside the regulated utility model.
IV. The Offshore Wind Saga: Strategic Miscalculation & Unregulated Destruction (2016–2024)
By the mid-2010s, the strategic appeal of offshore wind appeared compelling to New England utilities. State governments across Massachusetts, Connecticut, and Rhode Island had enacted aggressive clean-energy procurement mandates. The federal government began issuing ocean leases in the North Atlantic, while European developers had established fifteen years of commercial operating history. Denmark’s Ørsted—the former state oil and gas company transformed into a global offshore wind developer—emerged as the primary technology and development partner in North America.
Eversource held a unique strategic position: it controlled the onshore transmission grid required to connect offshore projects and maintained established relationships with state regulators writing procurement rules.
In 2016, Eversource entered a 50/50 joint venture with Ørsted to co-develop a portfolio of North Atlantic offshore wind projects: Bay State Wind, South Fork Wind (130 MW), Revolution Wind (704 MW), and Sunrise Wind (924 MW).3 The strategic thesis centered on return enhancement. Regulated distribution utilities earned authorized returns on equity of roughly 9% to 10% under low operational risk. Unregulated offshore development offered higher projected returns, leveraging Eversource's balance sheet and regional transmission footprint.
However, the strategy overlooked a fundamental vulnerability: Eversource had no experience in complex marine construction, and its equity stake in the joint venture carried none of the regulatory protections that shielded its core utility business.
In a traditional regulated framework, capital expenditures undergo regulatory oversight. When a utility replaces a substation or distribution line, state commissions review the investments for prudence. Approved capital enters the utility's rate base, allowing the company to recover expenditures from ratepayers over decades alongside an authorized return on equity. State regulators act as structural shock absorbers, allowing utilities to pass through fuel costs and adjust for cost-of-capital changes over time.
In the offshore joint venture, no regulatory shock absorber existed. Project revenues were locked under long-term power purchase agreements executed between 2018 and 2020. Those contracts reflected the prevailing macroeconomic conditions of the era: cheap capital, low steel prices, and stable supply chains. Crucially, while revenue was contractually fixed, construction and financing costs remained unhedged.
When post-COVID inflation and supply chain bottlenecks emerged, the venture's economic structure collapsed. Specialized turbine installation vessels—constrained by global scarcity and Jones Act compliance requirements—faced extended operational delays. Equipment manufacturers raised prices for steel and turbines, while central bank rate hikes drove up borrowing costs throughout 2022 and 2023.
The sharp rise in interest rates proved particularly damaging. An offshore wind project functions financially like a long-duration fixed-income instrument, requiring heavy upfront capital commitments to generate fixed, long-term revenue streams over two decades. As the cost of capital rose three percentage points, the present value of future contracted revenues fell sharply while upfront construction costs surged. Because offtake prices were locked contractually, the joint venture could not pass higher costs on to buyers.
Developers across the Atlantic faced similar structural pressures, leading Ørsted to record substantial impairments and cancel several East Coast projects. However, while Ørsted was a dedicated offshore developer absorbing a cyclical downturn in its core industry, Eversource was a regulated electric utility exposing utility equity to severe merchant construction risks.
The financial reckoning arrived in the fourth quarter of 2023, when Eversource recorded pre-tax impairment charges of approximately $2.17 billion—roughly $1.95 billion after tax—resulting in a full-year net loss of $442 million.1 The write-downs exceeded the original purchase price of Aquarion Water Company and strained credit metrics on a balance sheet already committed to heavy utility capital programs.
Management executed a rapid exit. In February 2024, Eversource agreed to sell its 50% interests in South Fork Wind and Revolution Wind to Global Infrastructure Partners for roughly $1.1 billion in cash.5 In July 2024, it sold its 50% stake in Sunrise Wind back to Ørsted, and in September 2024, it completed the divestiture of its South Fork and Revolution holdings.6 Within nine months of the initial impairment disclosure, the company had fully unwound its offshore exposure.
While the swift exit prevented further capital erosion, it highlighted a major capital allocation misstep. A management team and board overseeing a utility with historical memory of the Seabrook nuclear cost overruns had assumed unhedged construction and financing risks in an unfamiliar industry under fixed-price revenue contracts.
The outcome stemmed from structural miscalculation rather than unpredictable macroeconomic shocks alone. Structuring fixed revenue against unhedged, long-duration construction costs created structural vulnerability; the subsequent inflation and interest rate spikes merely accelerated the scale and timing of the loss.
An alternative strategy aligned with core utility capabilities could have yielded a different outcome. Eversource's primary competitive advantage lay in transmission interconnection: securing cable routes, managing landfalls, upgrading substations, and integrating offshore power into its existing onshore grid. Building and owning rate-based onshore transmission assets to serve offshore generation—recovering costs through regulated tariffs—would have allowed Eversource to capture energy transition capital spending without incurring merchant construction or fixed-price revenue risks.
Instead, the company acquired a 50% direct equity interest in offshore generation, the segment where it lacked technical execution experience and regulatory protections. The choice reflected an emphasis on higher headline equity returns over strategic alignment with core monopoly capabilities.
The expansion also exposed governance limitations across multiple board cycles. The joint venture expanded over several years as cost pressures across the offshore sector became increasingly visible in industry disclosures. The multi-year interval between initial structural warning signs and the eventual exit demonstrated a sustained strategic commitment despite rising operational risks.
The operational assets created during the joint venture continue to function under new ownership. Revolution Wind reached 97% completion and was delivering over 300 MW toward its 704 MW capacity target by mid-2026, with the asset's long-term economics accruing to third-party investors.7 Eversource retained the financial impairment and a balance sheet requiring debt reduction, setting up the subsequent divestiture of its water utility assets.
V. Core Business & Segment Economics: Distribution, Transmission & Natural Gas
Strip away strategic diversifications and Eversource operates on a simple underlying economic engine: the company generates earnings by securing regulatory approval to deploy capital into rate base.
This is the literal mechanism of utility economics. Eversource invests in physical infrastructure—substations, transmission towers, distribution poles, gas mains, and meters. Approved investments, net of accumulated depreciation, form the utility's rate base. Regulators then set customer rates at levels designed to allow the company to recover operating expenses, cover depreciation, service debt, and earn an authorized return on equity (ROE) on the rate-base balance. Expanding the rate base faster than depreciation retires existing assets drives earnings growth. Conversely, failing to earn the authorized return—whether due to cost overruns or regulatory disallowances—creates a gap between allowed and realized ROE that dictates financial performance.
In this model, traditional pricing power and product innovation do not apply. Earnings growth depends on disciplined capital deployment and regulatory authorization, making segment allocation the critical strategic variable across distinct regulatory jurisdictions.
Electric Transmission — the crown jewel, and its 2026 crack
Electric transmission represents the high-voltage grid—the towers and lines carrying power across long distances before stepping down to local distribution networks. Historically accounting for 30% to 35% of Eversource's earnings, transmission has long served as the company's most attractive segment. It is regulated by the Federal Energy Regulatory Commission (FERC) rather than state utility commissions, which historically yielded higher authorized returns under a less politically charged process.8 Transmission tariffs rely on formulaic rates that update annually with actual expenditures, minimizing regulatory lag, while customer default risk remains negligible because system users consist of other utilities and the regional grid operator.
That stability was altered on March 19, 2026.
FERC issued an order lowering the base ROE for New England transmission owners from 10.57% to 9.57% and mandating customer refunds covering an initial complaint period from October 2011 through December 2012, alongside a retroactive period from October 2014 forward, including interest—totaling an estimated $1.5 billion across regional transmission owners, payable by May 2027.2 Eversource disclosed that the reduced base ROE would decrease future annual after-tax earnings by approximately $70 million based on its 2025 rate base, and recorded a $43.9 million after-tax refund charge in the first half of 2026.9 Management estimated its total potential refund obligation at roughly $880 million while pursuing legal remedies through a rehearing request, an extension of refund timing, and a motion for stay.7 Separately, on April 30, 2026, New England transmission owners petitioned FERC to raise the base ROE to 11.39% prospectively.10
The structural lesson extends beyond the immediate earnings impact. The core advantage of transmission—federal regulation insulated from state political oversight—introduced a different form of regulatory risk. A complaint initiated more than a decade earlier ultimately yielded a retroactive rate reduction with interest. Although the segment retains baseline advantages through above-average returns, formulaic adjustments, and demand growth driven by electrification and data center interconnections, the ruling demonstrated that federal rate structures remain subject to long-dated regulatory reassessment.
Electric Distribution — the workhorse and the political flashpoint
Electric distribution covers last-mile infrastructure: neighborhood distribution wires, pole-mounted transformers, and residential service connections. Generating roughly half of company earnings, the segment falls under the jurisdiction of three state regulatory bodies: Connecticut's Public Utilities Regulatory Authority (PURA), the Massachusetts Department of Public Utilities (DPU), and the New Hampshire Public Utilities Commission (PUC).
The investment thesis for distribution rests on grid modernization requirements. Upgrading infrastructure installed in the mid-twentieth century requires circuit hardening against severe weather, selective undergrounding, automated switching equipment to isolate outages, and capacity expansion to handle load growth from electric vehicles and heat pumps. In Connecticut, Eversource proposed approximately $1 billion for advanced metering infrastructure—smart meter deployments that expand rate base while improving operational visibility.7
However, distribution investments directly impact retail utility bills in a region with some of the nation's highest electricity rates. Because state commissioners are gubernatorial appointees accountable to public sentiment, rate requests face persistent regulatory scrutiny.
Natural Gas Distribution — a cash engine with a legislated expiry date
Natural gas distribution—operated through NSTAR Gas, Eversource Gas of Massachusetts, and Yankee Gas—contributes 15% to 20% of net earnings. The business experiences high seasonal demand during winter heating months and maintains ongoing capital deployment through mandated replacement programs for aging cast-iron and bare-steel mains, providing steady rate-base expansion.
The segment faces strategic headwind from state-level decarbonization mandates in Massachusetts and Connecticut. Legislative initiatives prioritizing building electrification and restricting expansion of natural gas connections create an operational paradox: utilities must continue investing heavily to maintain system safety on assets whose economic lifespans may be truncated by climate policy. While immediate customer defection remains limited due to high heating replacement costs and New England winter reliability demands, long-term asset depreciation and potential stranded-cost recovery remain key regulatory considerations.
Water — the round trip
The water utility segment, introduced via acquisition in 2017, was fully unwound in 2026. On January 27, 2025, Eversource reached an agreement to sell Aquarion Water Company, completing the divestiture on June 30, 2026, to the Aquarion Water Authority—a public entity established as a political subdivision of Connecticut—for $2.4 billion in cash, generating approximately $1.7 billion in adjusted net equity proceeds allocated to debt reduction.[^3] The transaction received PURA authorization on March 25, 2026, transferring water service across 59 municipalities primarily in western Connecticut to public management, while leading Eversource to record a second-quarter 2026 after-tax non-cash charge of approximately $115 million, or $0.31 per share.11
The divestiture marked the conclusion of Eversource's nine-year water utility investment, with net proceeds applied entirely to balance-sheet restoration following offshore wind losses.
How the three segments fit together
The structural dynamics of Eversource's remaining operating segments govern its overall risk and return profile.
Transmission historically yielded higher returns with lower state-level political friction, prompting management to direct a larger proportion of capital toward transmission rate-base growth relative to distribution. However, transmission expansion depends on regional competitive solicitations overseen by ISO New England, limiting independent capital deployment.
Conversely, distribution infrastructure offers extensive capital deployment opportunities across local grid networks, but operations remain subject to direct state political oversight. Gas distribution provides consistent infrastructure replacement opportunities, bounded by long-term policy uncertainties regarding terminal asset values.
Consequently, capital allocation is constrained not by a lack of investment opportunities, but by the necessity of deploying capital into jurisdictions offering sustainable returns without exceeding ratepayer tolerance.
The capital plan
Eversource's forward operational strategy relies on a large-scale regulated capital program. Following its fourth-quarter 2025 earnings announcement, the company outlined a $26.5 billion capital expenditure plan for 2026 through 2030—representing a $2.3 billion expansion over its prior five-year outlook—designed to expand its rate base from $30.6 billion in 2024 to $49.3 billion by 2030, reflecting an 8.3% compound annual growth rate.12 The projected funding structure comprises approximately 68% from operating cash flow, 27% from debt and alternative financing structures, 3% from storm securitization proceeds, and 2% from common equity issuances.12 Additionally, Eversource received preliminary selection for a $2.2 billion ISO New England transmission project, adding roughly $700 million to its long-term investment pipeline, with approximately half anticipated within the current five-year planning horizon.7
This capital execution plan forms the basis for long-term earnings growth, dependent on state and federal regulators allowing authorized returns across all operating jurisdictions.
VI. Management Credibility & Historical Falsification: Capital Allocation Under Fire
Joseph R. Nolan Jr. became President and CEO in May 2021, bringing a background that reflects the operational and regulatory history of the New England utility business. Over more than three decades with the organization—primarily on the NSTAR side—his career focused on customer operations, communications, and public affairs rather than engineering or finance.3 That background provides context for his executive style. Nolan is an operator and public-facing executive who built his career around storm response, municipal relations, and media communications—core competencies in a heavily regulated utility environment.
He inherited the offshore wind commitment rather than originating it, but moved quickly to end it. Less than a year elapsed between the initial impairment disclosure and the closing of the final divestiture, marking a decisive exit from the venture.
Executive Vice President and Chief Financial Officer John M. Moreira has since focused on balance-sheet repair: directing asset proceeds toward debt reduction, minimizing equity issuances, and prioritizing investment-grade credit metrics. The financing mix for the 2026–2030 capital plan—where asset proceeds and operating cash flow cover the bulk of obligations while common equity represents just 2%—reflects that strategy.12
Evaluating management credibility, however, requires testing corporate claims against operational and financial outcomes across three key assertions.
Claim 1: "Regulated monopoly status guarantees durable, recession-proof returns."
The clearest counterevidence emerged in 2023 when Connecticut's Public Utilities Regulatory Authority (PURA) drastically reduced Connecticut Light and Power's requested distribution rate increase from approximately $213 million to roughly $19 million. PURA also lowered the subsidiary's authorized return on equity from 9.25% to 9.0%, explicitly linking the reduction to management performance and storm-response deficiencies.13 The decision demonstrated that a delivery monopoly does not guarantee a fixed return when regulatory oversight turns hostile.
The regulatory environment has since seen sharp shifts. Eversource and Avangrid filed lawsuits against PURA and its chair, Marissa Gillett, alleging executive overreach. Gillett announced her resignation in September 2025, effective that October, and Connecticut lawmakers approved a substantially reconstituted PURA board in May 2026.1415 In August 2026, CL&P submitted its first general rate review since 2017, requesting a $451 million revenue increase with a proposed 10.25% ROE—a filing Nolan described on the second-quarter call as establishing "a sustainable path forward that balances affordability with investments needed."7 Separately, Connecticut approved $870 million of a $975 million storm-cost recovery request, enabling approximately $670 million in securitization proceeds.7
Verdict: the history does not reject the monopoly claim, but it narrows it sharply. The franchise is durable; the return on the franchise is not fixed, and has proven sensitive to the identity of individual regulators to a degree that should unsettle anyone modeling a steady authorized ROE. The reconstitution of PURA and the storm-cost approval represent genuine improvements in the operating environment, but they are shifts in political weather rather than structural guarantees—the same regulatory mechanism that turned against the utility in 2023 could turn again. The pending CL&P rate case serves as the immediate test. Watch the gap between allowed and realized ROE at the Connecticut and Massachusetts subsidiaries, and watch whether the $451 million request settles anywhere near the proposed 10.25%.
Claim 2: "Non-regulated ventures provide high-growth equity optionality."
This claim was decisively disproven by the offshore wind venture, which erased roughly $2.17 billion in pre-tax book value, triggered the utility's first full-year net loss in modern history, strained credit metrics, and forced asset sales under unfavorable market conditions. The promised growth optionality ultimately destroyed shareholder equity.
Verdict: rejected. Management has since committed to a pure-play regulated model, and the credible forward test is simple and observable: zero non-utility capital expenditure commitments in the 10-K. If that line stays at zero through the capital cycle, the lesson took. If an "adjacency" reappears, the record says discount it heavily.
Claim 3: "Prudent M&A enhances multi-utility scale and balance sheet strength."
The nine-year ownership of Aquarion Water provides a clear test of this assertion. Eversource acquired the water utility in 2017 at a premium multiple under a consolidation thesis, only to sell it in 2026 to raise liquidity following offshore wind losses. The divestiture required an after-tax non-cash charge, and net proceeds were redirected to debt reduction rather than rate-base expansion.[^3]11
A key nuance of the transaction was that the buyer was a state-created public entity—the Aquarion Water Authority. This delivered a willing, politically motivated counterparty at a $2.4 billion headline valuation, avoiding a distressed sale in a private market. However, because the exit represented a state entity repurchasing regional water infrastructure, it provides a unique political resolution rather than a repeatable source of balance-sheet liquidity.
Verdict: the claim is rejected in its general form. Eversource's record shows one large regulated merger that was strategically sound but heavily taxed by regulators, one diversification purchased at a premium and exited under duress at a loss, and one non-regulated venture that destroyed roughly two billion dollars. That is not a portfolio consistent with "prudent M&A enhances the balance sheet." What it is consistent with is a company that is good at operating utilities and has not demonstrated skill at buying and selling things. The forward KPI is holding-company debt as a share of total consolidated debt — management's stated intent is to keep it low, and that ratio is where balance-sheet discipline either shows up or does not.
A final note on narrative consistency, because it is the most reliable tell in this business. Across the 2025 and 2026 calls, management's language has been notably stable: pure-play, pipes and wires, balance sheet, 5–7% long-term growth with a stated expectation of reaching the upper half by 2028.7 There has been no rebranding of the strategy, no new adjacency floated, and the misses — the FERC ROE cut, the Aquarion charge — have been explained in specific numerical terms rather than deflected. That is a meaningfully better disclosure posture than the company displayed while the wind business was deteriorating. It is not yet a track record; it is two years of consistency following a period that demanded it.
VII. The Regulatory & Political Battlefield: PURA, Rate Shock, and Consumer Friction
Consider a Connecticut household opening an electric bill in the summer of 2023. The total balance was roughly double what it had been a year prior. The corporate logo at the top read Eversource, yet almost none of that sudden price increase stemmed from changes in Eversource's own delivery operations.
This dynamic represents a critical structural feature of utility regulation, driving nearly every political conflict in Eversource's service territory. Under post-1990s restructuring rules, Eversource procures "standard service" electricity—the default power supply for customers who do not select a competitive third-party provider—through periodic competitive solicitations. The utility passes these commodity costs directly to consumers with zero financial markup, earning no profit on the underlying energy. When global energy market disruptions caused natural gas prices to surge, New England's gas-fired wholesale power prices escalated in tandem. Standard service supply rates roughly doubled, reaching around 24 cents per kilowatt-hour in Connecticut in 2023.13
Retail customers rarely distinguish between energy supply and distribution delivery on a single consolidated statement. Consumers see an exclusive local utility, a doubled monthly bill, and a publicly traded corporation reporting earnings. Elected officials respond to vocal voter dissatisfaction, while state regulators—who exercise authority strictly over local delivery tariffs—face intense public pressure to utilize the only administrative lever within their control.
Through this mechanism, commodity price volatility that Eversource does not cause, cannot hedge, and does not profit from transforms directly into political and regulatory friction on the delivery returns the company does earn. This structural asymmetry explains why New England utilities frequently trade at persistent valuation discounts compared to peers in more benign regulatory environments.
The company's three main state regulatory jurisdictions present distinctly different operational environments:
Connecticut (PURA) has proven the most challenging. Under Marissa Gillett's chairmanship beginning in 2019, PURA instituted performance-based ratemaking, intensified scrutiny of capital projects, established an Office of Education, Outreach and Enforcement that drew national attention as a public-engagement model, and repeatedly capped allowed returns or ordered rate reductions.14 The relationship deteriorated into litigation and culminated in her resignation and a near-total reconstitution of the board.15 Eversource enters its pending rate case before a newly appointed slate of commissioners—a structural reset, yet one with inherently unpredictable dynamics. A new commission does not automatically signal a more permissive environment; the broader political pressures surrounding regional energy costs remain active, keeping customer affordability at the center of Connecticut utility politics.
Massachusetts (DPU) operates under a more conventional regulatory framework, but its decisions are shaped by the state's aggressive decarbonization mandates. The DPU's primary institutional tension involves balancing immediate ratepayer affordability against state-mandated capital investments required for building electrification, electric vehicle infrastructure, and grid reinforcement to handle new load. That tension remains difficult to resolve, forming the core of a strategic paradox that resurfaces in the final outlook.
New Hampshire (PUC) represents the smallest and most traditional regulatory body: a conservative, ratepayer-focused commission characterized by moderate allowed returns and stable administrative proceedings. Its principal role in Eversource's overarching investment profile is geographic and regulatory diversification—providing a third operating environment decoupled from political cycles in Hartford or Boston.
Understanding general rate cases is essential to evaluating utility asset value, as these proceedings formally establish revenue requirements. A rate case is a quasi-judicial process: the utility presents detailed testimony on operating expenses, capital rate base, and requested return on equity; state consumer advocates, state attorneys general, environmental groups, and industrial customers intervene; and commissioners ultimately issue binding multi-year rate determinations. CL&P's August 2026 application marked its first general rate review since 2017—a nine-year gap during which operating expenses, interest rates, and total system capital expanded significantly.7
That extended interval carries clear analytical significance. Utilities typically initiate general rate proceedings when existing rates fail to cover rising costs. A long delay suggests either that formulaic adjustment mechanisms and interim trackers provided adequate cash flow, or that management viewed the regulatory climate as too hostile to open its full accounting books. Given the adverse outcome of the 2023 proceeding, the latter explanation remains highly plausible. It underscores a key cost of regulatory friction: deferred rate filings widen the gap between a utility's allowed returns and the higher actual cost structure required to maintain its network.
Underpinning these multi-state regulatory dynamics is an unyielding physical constraint: New England is an energy island. Interstate natural gas pipeline capacity into the region remains tightly constrained, and efforts to expand pipeline infrastructure have repeatedly stalled over state-level environmental opposition, permitting hurdles, and cost-allocation disputes. During peak winter heat demands, natural gas is prioritized for residential heating, forcing power generators to rely on imported liquefied natural gas or oil-fired peaking units. Consequently, New England wholesale power prices experience extreme winter spikes, keeping retail electric rates among the highest in the nation.
For investors, this geographic constraint imposes a firm boundary: Eversource's long-term rate-base expansion is constrained not by a lack of infrastructure projects, but by the customer affordability ceiling across its service territory. Every dollar of new capital deployed into rate base adds to customer bills that are already elevated by underlying commodity costs outside the company's control. That ceiling represents a practical constraint on long-term rate-base compounding that standard capital spending projections do not fully capture.
VIII. Competitive Landscape, Industry Structure & Helmer's 7 Powers
Analyzing competition at Eversource reveals a structural paradox: in the conventional commercial sense, direct competition does not exist. No rival provider will construct a parallel distribution grid down a street in Manchester, New Hampshire. The franchise is exclusive, established by statute, and replicating the physical network would be both legally barred and economically unviable.
Consequently, industry analysis requires reframing the competitive framework. Competition does not occur over retail customers. Instead, it takes place on two fronts: capital allocation authorized by regulators—the right to deploy capital into rate base—and peer benchmarking, as utility commissions and state legislatures evaluate Eversource's operational performance and allowed returns against regional and national peers.
The regional peer group illustrates the shared constraints of northeastern delivery utilities. Avangrid, the Iberdrola-controlled owner of United Illuminating and Berkshire Gas, shares the Connecticut market with Eversource and joined it in challenging PURA decisions in court—a rare instance of regional peers aligning against a common regulator. National Grid USA, the American subsidiary of the UK-based energy group, represents the other major electric and gas delivery provider across Massachusetts and Rhode Island. Consolidated Edison operates the dense urban delivery system in New York, while Public Service Enterprise Group serves New Jersey. All of these entities face variations of the same northeastern operational headwinds: elevated retail energy rates, ambitious state climate mandates, and politically sensitive regulatory commissions.
A starker comparison emerges when evaluating Sunbelt utilities. Providers operating in the Southeast and Texas generally benefit from higher authorized distribution returns, faster population and load growth, lower regional power prices, and a less adversarial regulatory environment. Eversource's equity valuation discount relative to these peers is not a market inefficiency awaiting arbitrage; it represents a rational market adjustment for lower, more heavily contested returns in a slower-growing, higher-cost region.
Evaluating Eversource through Hamilton Helmer's 7 Powers framework clarifies where economic power resides—and where it breaks down:
Cornered Resource — high. The combination of exclusive franchise rights and physical grid infrastructure represents an exceptionally strong cornered resource. Rights-of-way, substations, distribution poles, and transmission interconnections cannot be duplicated at reasonable cost. This structural asset forms the foundation of the business and provides resilience against operational errors.
Switching Costs — high, with a structural nuance. Retail customers cannot switch delivery providers. In Connecticut and Massachusetts, consumers can select alternative competitive energy suppliers for the underlying commodity, but physical delivery and billing remain tied to Eversource's network. Full grid defection—combining rooftop solar with sufficient battery storage to navigate a New England winter—remains economically impractical for most customers because solar output reaches its annual low precisely when heating demand peaks. However, partial defection is already occurring: each added rooftop solar installation reduces the total kilowatt-hours across which fixed grid costs are allocated. This cost shift raises delivery rates for remaining customers, compounding the incentive for further solar adoption. While regulators attempt to address this through rate design, it exerts ongoing structural pressure on traditional volumetric revenue models.
Scale Economies — moderate. Consolidating IT, engineering, procurement, legal, and customer support infrastructure across 4.4 million customer connections produces genuine overhead efficiencies, while a multi-state footprint facilitates mutual aid during severe weather events. However, regulatory mechanisms limit long-term margin expansion from scale: demonstrated cost savings are typically passed along to ratepayers during subsequent rate cases. Consequently, operational scale enhances regulatory goodwill and financial resilience rather than driving sustained margin expansion.
Process Power — low. Severe storm recovery represents a complex logistical challenge requiring crew pre-positioning, mutual-aid coordination, damage assessment, and rapid restoration. If Eversource possessed proprietary process power in storm response, it would yield regulatory incentives and earned performance rewards. Instead, Connecticut regulators explicitly reduced the company's authorized returns in 2023 based on storm-response deficiencies.13 Operational execution has not translated into regulatory immunity.
Counter-Positioning and Branding — absent. Counter-positioning options do not exist against a statutory regulator, while customer brand equity for a delivery utility remains neutral at best.
The Negative Power — Regulatory Counter-Power. Helmer's framework assumes economic power accrues to the enterprise. In regulated utilities, an offsetting force dominates: state regulatory bodies possess statutory authority to set rates, disallow capital expenditures, and reduce authorized returns. Eversource's competitive moat provides strong protection against commercial rivals, yet offers minimal protection against regulatory intervention.
Porter's Five Forces analysis reinforces this structural dynamic: - Threat of New Entrants: Effectively zero due to statutory franchise protection. - Rivalry: Minimal, as service territories are geographically segmented. - Supplier Power: Moderate and rising. Global supply-chain shortages of large power transformers, switchgear, and high-voltage cabling have extended lead times across the industry. For a utility planning a $26.5 billion five-year capital program, equipment procurement delays directly defer rate-base additions and subsequent earnings growth. - Threat of Substitutes: Low to moderate, driven by distributed solar and battery storage. - Buyer Power: High, via state intervention. Individual retail customers lack bargaining power, but state attorneys general, consumer advocates, state legislatures, and utility commissions aggregate customer interests into formidable counter-power. In unregulated markets, atomized consumers exercise minimal pricing influence; in utility markets, state authorities act as their collective bargaining agent, exercising statutory authority to adjust corporate profitability.
This structural mechanism—buyer power exercised through state regulatory authorities—explains why an exclusive delivery monopoly trades at a persistent discount to its broader utility peers.
IX. Playbook: Business & Investing Lessons from a Regulated Monopoly
Every one of these episodes leaves behind a set of transferable lessons. Eversource's are unusually clean, because the company has run both the control experiment and the failed experiment within a single decade.
1. Learn the arithmetic of utility growth, because it is the whole model. A utility's earnings grow when rate base grows, and rate base grows when capital spending exceeds depreciation. Earnings growth is approximately the net increase in rate base, multiplied by the equity share of the capital structure, multiplied by the allowed return on equity. There is no other engine. This is why utility investors obsess over capital plans and authorized returns rather than revenue or market share—revenue is largely a pass-through of fuel costs, and market share is fixed by statute. It also explains why a company like Eversource can grow earnings in a region with essentially flat customer counts: the growth comes from investment per customer, not from more customers.
2. The corollary nobody puts on a slide: growth requires permission, and permission has a price. A capital plan is a proposal. Regulators can defer it, trim it, or approve the spending while setting a return that makes the spending unattractive. The distance between an announced $26.5 billion plan and realized earnings runs entirely through four regulatory bodies. Treat capital plans as the numerator of a fraction whose denominator is regulatory willingness.
3. Stick to the knitting—and understand precisely why. The offshore wind lesson is not "renewables are bad" or "diversification is bad." It is that a regulated utility's equity is priced for a specific risk profile: modest returns with an unusual degree of downside protection provided by the regulatory compact. When such a company takes merchant development risk, it hands its shareholders the full downside of a business with none of the compensating upside they would demand if they had chosen to own a developer. Shareholders who wanted offshore wind exposure could have bought Ørsted. They bought a delivery utility.
4. Distinguish structural moats from political weather. The franchise is structural—it survives recessions, elections, and management error. The allowed ROE is political weather. Confusing the two is the most common error in utility investing. Eversource's franchise never wavered through the worst three years in its modern history; its returns moved substantially with the identity of one commission chair.
5. Operating across multiple states is diversification, not hedging. A constructive Massachusetts outcome does not offset a punitive Connecticut one—they add. Multi-state exposure reduces the variance of the portfolio but multiplies the number of hearings, filings, political relationships, and storm-performance scorecards management must maintain. It is a genuine benefit, but it is a smaller one than it looks, and it comes with real overhead.
6. Utility stocks have two distinct personalities, and it pays to know which is driving. Most of the time they behave as bond proxies: a stream of slowly growing, regulated cash flows discounted at a rate that moves with long-term interest rates, so prices fall mechanically as rates rise regardless of operating performance. But in periods of balance-sheet stress or regulatory upheaval, they stop trading on rates and start trading on credit quality and regulatory outcomes. Eversource has spent the past three years firmly in the second regime—which is why the Aquarion proceeds, the debt paydown, and the credit metrics have mattered more to the stock than any macro view on rates.
6a. Beware the word "adjacency." Both of Eversource's value-destroying moves were sold internally and externally as adjacencies—water is pipes, offshore wind is electricity. The word does real rhetorical work: it makes a departure from the core business sound like an extension of it. The test that actually matters is not whether the new business resembles the old one superficially, but whether the source of the returns is the same. Eversource's returns come from a regulator granting recovery on approved investment. Water passed that test and still failed commercially because the entry price was too high. Offshore wind did not pass it at all. When a regulated utility describes a new venture as adjacent, the useful question is: who sets the price, and who bears the overrun?
7. Watch what happens to disclosure when the news is bad. The most useful management signal in this story is not the strategy but the specificity: the FERC charge quantified to $43.9 million, the refund exposure to $880 million, the Aquarion charge to $0.31 per share.7911 Companies that quantify their own bad news are easier to underwrite than companies that describe it qualitatively. That is not the same as being well managed, but it is a real and checkable attribute.
X. Skeptical Investor Stress Test, Material Risk Radar & Bull vs. Bear Case
If an activist investor were to build a position in Eversource today and draft a campaign presentation, the core arguments would be straightforward.
The opening critique would not focus on the offshore wind losses—that asset sale is complete. Instead, it would focus on board accountability. The argument centers on how a board that approved a multi-billion-dollar merchant construction venture, and separately paid a substantial premium for a water utility it later sold under duress, demonstrated a systemic capital allocation flaw rather than a sequence of isolated missteps. Proposed structural demands would likely include a formal board-level ban on non-utility capital expenditures, executive compensation tied directly to realized versus authorized returns on equity rather than adjusted earnings per share, and new directors with deep regulatory and construction experience.
A second line of critique targets holding-company capital structure. Although asset sale proceeds were directed to debt reduction, questions remain over whether leverage is falling quickly enough to restore balance-sheet flexibility, and whether litigating state regulators remains commercially sound. Challenging a state utility commission in court may be a valid legal strategy, but it carries long-term commercial risks given that the same agency oversees rate determinations for the next decade.
A third issue involves federal transmission refunds. An estimated $880 million in potential exposure, with a stay motion and rehearing request pending, creates a financial overhang that depends on judicial rulings rather than operational execution.7 An activist campaign would probe reserve accounting methodologies and analyze how an adverse final ruling would impact the long-term financing plan.
The final argument poses a fundamental question: over the past decade, did management's discretionary capital allocation create or destroy shareholder value compared to simply reinvesting in core rate base? The historical record indicates value destruction outside the core franchise. Reinvesting in regulated rate base yielded stable returns, while non-core expansions eroded balance-sheet strength.
Material risk radar
Regulatory risk remains the central uncertainty and operates as a two-sided variable. Connecticut's reconstituted utility commission could establish a more predictable ratemaking environment, or public affordability pressures could continue to limit authorized returns under the new board. The pending distribution rate case will serve as the immediate indicator. A secondary concern is regulatory contagion: if performance-based ratemaking mechanisms that constrain realized returns expand further into Massachusetts or New Hampshire, regional earnings expectations would require adjustment.
Cost of capital and refinancing risk is significant given the total debt burden and a capital plan that relies on debt and alternative structures for 27% of its funding.12 Because utilities refinance debt continuously, sustained elevated interest rates raise borrowing expenses faster than general rate cases can absorb them. If credit rating agencies exert pressure, management could be forced to choose between issuing equity or scaling back capital spending. Minimizing common equity issuances protects earnings per share in the short term, but provides less financial cushion if credit metrics weaken.
Storm and climate risk represents an ongoing operational hazard. Severe winter storms and hurricanes routinely trigger restoration expenditures running into hundreds of millions of dollars. Connecticut's approval of $870 million out of a $975 million storm recovery request highlights this balance: while most storm expenditures are ultimately recoverable from ratepayers, regulatory reviews are lengthy and disallowances remain a risk.7
Supply chain and execution risk presents operational bottlenecks. Extended global lead times for large power transformers, switchgear, and high-voltage cabling persist across the industry. Executing a $26.5 billion capital program requires securing long-lead equipment without triggering cost overruns or schedule delays.
Load growth dynamics present both opportunities and political risks. Data center interconnections, electric vehicle adoption, and building electrification represent structural demand growth for New England's grid. However, large interconnection requests frequently suffer from low completion rates, and if public authorities perceive that retail ratepayers are subsidizing infrastructure for commercial data centers, regulatory friction could escalate.
The bull case
The positive thesis holds that Eversource in 2026 presents a lower risk profile than in 2023, which equity valuations do not fully reflect. Non-regulated offshore wind exposure has been unwound, the water utility divestiture is complete, and net cash proceeds have been applied directly toward debt reduction. The remaining core enterprise functions as a pure-play delivery monopoly backed by a $26.5 billion five-year capital program targeting approximately 8.3% annual rate-base growth, a 5% to 7% long-term earnings per share growth objective guided toward the upper half of the range by 2028, and a dividend supported by a long history of annual increases.127 Additionally, the appointment of a reconstituted regulatory commission in Connecticut offers a structural reset, while regional grid electrification and data center interconnections generate new demand through Eversource's transmission network—further supported by a preliminarily awarded $2.2 billion regional transmission initiative.7 From this perspective, the equity trades at an attractive valuation discount driven by historical missteps that have already been fully written off.
The bear case
The cautious perspective argues that the valuation discount reflects persistent structural headwinds. New England retail electric rates remain elevated due to regional energy pipeline constraints, generating permanent public pressure on customer bills where regulatory disallowances on delivery returns serve as the primary political valve. Furthermore, the federal transmission ruling demonstrated that even federally regulated return structures remain vulnerable to retroactive downward adjustments with interest, removing a historically insulated earnings stream. With offshore wind and water assets fully divested, non-dilutive capital options are exhausted, meaning any future funding shortfalls must be addressed through debt, equity dilution, or reduced capital deployment. Ultimately, an 8.3% annual rate-base growth ambition faces practical constraints from a customer affordability ceiling across high-cost service territories.
Evaluating these opposing arguments reveals distinct analytical foundations. The positive case relies on testable operational execution and capital deployment metrics. Conversely, the negative case rests on structural regional political pressures that have persisted for years without a clear catalyst for relief. Neither thesis has reached a definitive conclusion.
A second-layer read
Several subtle factors below the primary narrative warrant careful analysis.
Regarding credit quality, the core rationale of the Aquarion divestiture was to defend investment-grade credit ratings after offshore wind impairments expanded leverage. The capital plan's minimal reliance on common equity issuance functions only if credit rating agencies accept the resulting balance-sheet metrics.12 Consequently, credit rating adjustments serve as a leading indicator of balance-sheet recovery before earnings improvements fully materialize.
In accounting judgment, two areas require ongoing tracking. First, financial reserves for potential federal transmission refunds depend on active legal proceedings, creating an estimate subject to future revision.9 Second, the depreciable lifespans of natural gas distribution infrastructure face long-term adjustments as state legislatures promote building electrification. In both instances, reported financial results rely on accounting estimates that remain subject to revision.
Regarding regulatory litigation, Eversource's legal challenge against Connecticut regulators created an unusual dynamic. Following the resignation of the commission chair and the appointment of a reconstituted board, the utility must now present its distribution rate review before new commissioners. Whether this aggressive litigation strategy improved or strained long-term regulatory relationships remains to be seen.
Finally, regarding asset flexibility, completing the offshore wind and water exits leaves the enterprise with no remaining non-core assets to monetize. While this reflects a pure-play operating structure, it eliminates discretionary asset sales as a capital mechanism if future liquidity demands arise.
The KPIs that matter
Evaluating Eversource's forward progress requires monitoring three primary key performance indicators.
First, realized versus authorized return on equity at local operating subsidiaries, especially Connecticut Light and Power. This comparison measures the effectiveness of the regulatory framework. Achieving returns near authorized levels confirms functional cost recovery; a persistent gap indicates that deployed capital earns sub-par returns, reducing the economic value of planned infrastructure investments.
Second, the final ruling on the pending Connecticut distribution rate review. The decision on CL&P's $451 million revenue increase request and proposed 10.25% return on equity provides the clearest test of whether the reconstituted regulatory commission establishes a more predictable operating environment.7
Third, capital plan execution measured by rate base placed in service. Tracking completed, regulatory-approved rate-base additions rather than announced capital spending reveals the real-world impact of supply chain lead times, regulatory disallowances, and financing constraints.
Quarterly earnings per share relative to consensus estimates are deliberately excluded from these primary metrics. For a regulated delivery utility, quarterly fluctuations largely reflect weather patterns, accounting timing, and share count adjustments rather than fundamental shifts in rate-base economics.
XI. Epilogue: The Energy Transition Paradox
A fundamental tension sits at the heart of New England energy policy, and Eversource operates directly inside it.
Massachusetts and Connecticut have codified some of the most aggressive decarbonization mandates in the United States, targeting sweeping emissions reductions between 2030 and 2050. These statutory mandates require transitioning heating and transportation from fossil fuels to the electric grid. Replacing oil and natural gas furnaces with heat pumps, and internal combustion vehicles with electric models, requires shifting massive energy loads onto power distribution networks. In many parts of Eversource's service territory, carrying that load will require roughly doubling substation, feeder, and transmission capacity.
Under existing legal frameworks, constructing that expanded infrastructure falls entirely to the franchised delivery utility. Because a regulated utility finances infrastructure by committing balance-sheet capital, it recovers those investments—alongside an authorized return on equity—strictly through retail customer rates.
This mechanism creates the core policy paradox: the same state governments that mandate extensive grid expansion contain regulatory commissions and legislatures obligated to protect consumers from rising utility bills. State authorities face competing, defensible pressures—recognizing that system modernization requires billions in capital deployment, while knowing low- and middle-income ratepayers cannot absorb sharp rate increases.
No internal corporate strategy can eliminate this friction. The tension resolves, if at all, through policy interventions: federal infrastructure subsidies, storm and capital securitization, alternative rate designs that redistribute costs across customer classes, and broader public consensus on the true expense of the energy transition. Eversource operates as a participant in that policy debate, not its author.
What management can control is far narrower: executing capital projects on schedule and on budget, maintaining storm restoration performance, presenting credible rate filings to state commissions, and keeping capital allocation strictly within regulated utility operations. Above all, management must rebuild regulatory and investor trust—credibility impaired when the company ventured into unregulated offshore wind development.
A modern delivery utility is neither a high-margin growth enterprise nor a technology venture; it is the custodian of a regulatory compact that grants exclusive monopoly rights and authorized returns in exchange for reliable service at defensible rates. Eversource spent years testing whether it could generate higher returns outside that traditional framework, an experiment that ultimately destroyed roughly $2 billion in shareholder value.
The central question for investors—to be answered through upcoming rate decisions, federal regulatory appeals, and execution of its $26.5 billion capital plan—is whether Eversource can execute its core regulated mandate with enough discipline to restore the long-term value of its franchise.
References
-
Eversource Energy Reports Full Year and Fourth Quarter 2023 Results — Business Wire / Eversource Energy, 2024-02-13 ↩↩
-
Eversource, Avangrid ask FERC to stay $1.5B refund decision — Utility Dive, 2026 ↩↩
-
Eversource Energy Form 10-K Annual Report for FY 2023 — U.S. Securities and Exchange Commission, 2024-02-27 ↩↩↩↩↩↩↩↩↩
-
Eversource Energy SEC Filings Browse & Search — U.S. Securities and Exchange Commission ↩
-
Eversource to sell offshore wind stake to Global Infrastructure Partners for $1.1 billion — Reuters, 2024-02-13 ↩
-
Eversource Completes Sale of Offshore Wind Assets to Global Infrastructure Partners — Eversource Energy, 2024-09-09 ↩
-
Eversource Energy (ES) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-08-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Electric Transmission Policy Overview — Federal Energy Regulatory Commission ↩
-
Eversource Energy Form 10-Q for the quarter ended June 30, 2026 — U.S. Securities and Exchange Commission, 2026 ↩↩↩
-
New England transmission owners ask FERC for increased ROE — Utility Dive, 2026 ↩
-
Eversource Energy Form 8-K — Aquarion sale completion — U.S. Securities and Exchange Commission, 2026-06-30 ↩↩↩
-
Eversource unveils $26.5B capital plan, boosting infrastructure spending — Hartford Business Journal, 2026 ↩↩↩↩↩↩
-
Connecticut Public Utilities Regulatory Authority (PURA) Decisions & Dockets — State of Connecticut ↩↩↩
-
Marissa Gillett to resign as PURA chair amid growing scrutiny — CT Mirror, 2025-09-19 ↩↩
-
Lawmakers give final OK to new PURA board — CT Mirror, 2026-05-06 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube