EQT Corporation: The Shale Giant's Vertical Gambit
I. Introduction & Episode Roadmap
There is a particular kind of anonymity that comes with being enormous and invisible at the same time. Roughly one out of every sixteen or seventeen molecules of natural gas burned in the United States on a given winter morning—heating a row house in Baltimore, spinning a turbine outside Richmond, feeding a chemical cracker on the Ohio River—began its journey a mile and a half beneath a pasture in Greene County, Pennsylvania, in rock laid down when the region was a shallow tropical sea. The company that pulled it out is headquartered in a glass tower in downtown Pittsburgh, employs a few thousand people, and carries a name most Americans have never spoken aloud.
EQT Corporation is the largest natural gas producer in the United States, operating in the Appalachian Basin at a scale of roughly six billion cubic feet per day of sales volume across Pennsylvania, West Virginia and Ohio.2 In a global context, that output is striking: a single company, operating in a single basin, produces gas at a rate that would place it among the larger producing nations on earth. It does so in an industry with no brand differentiation, no pricing power, no customer loyalty, and a product chemically identical to what every competitor sells.
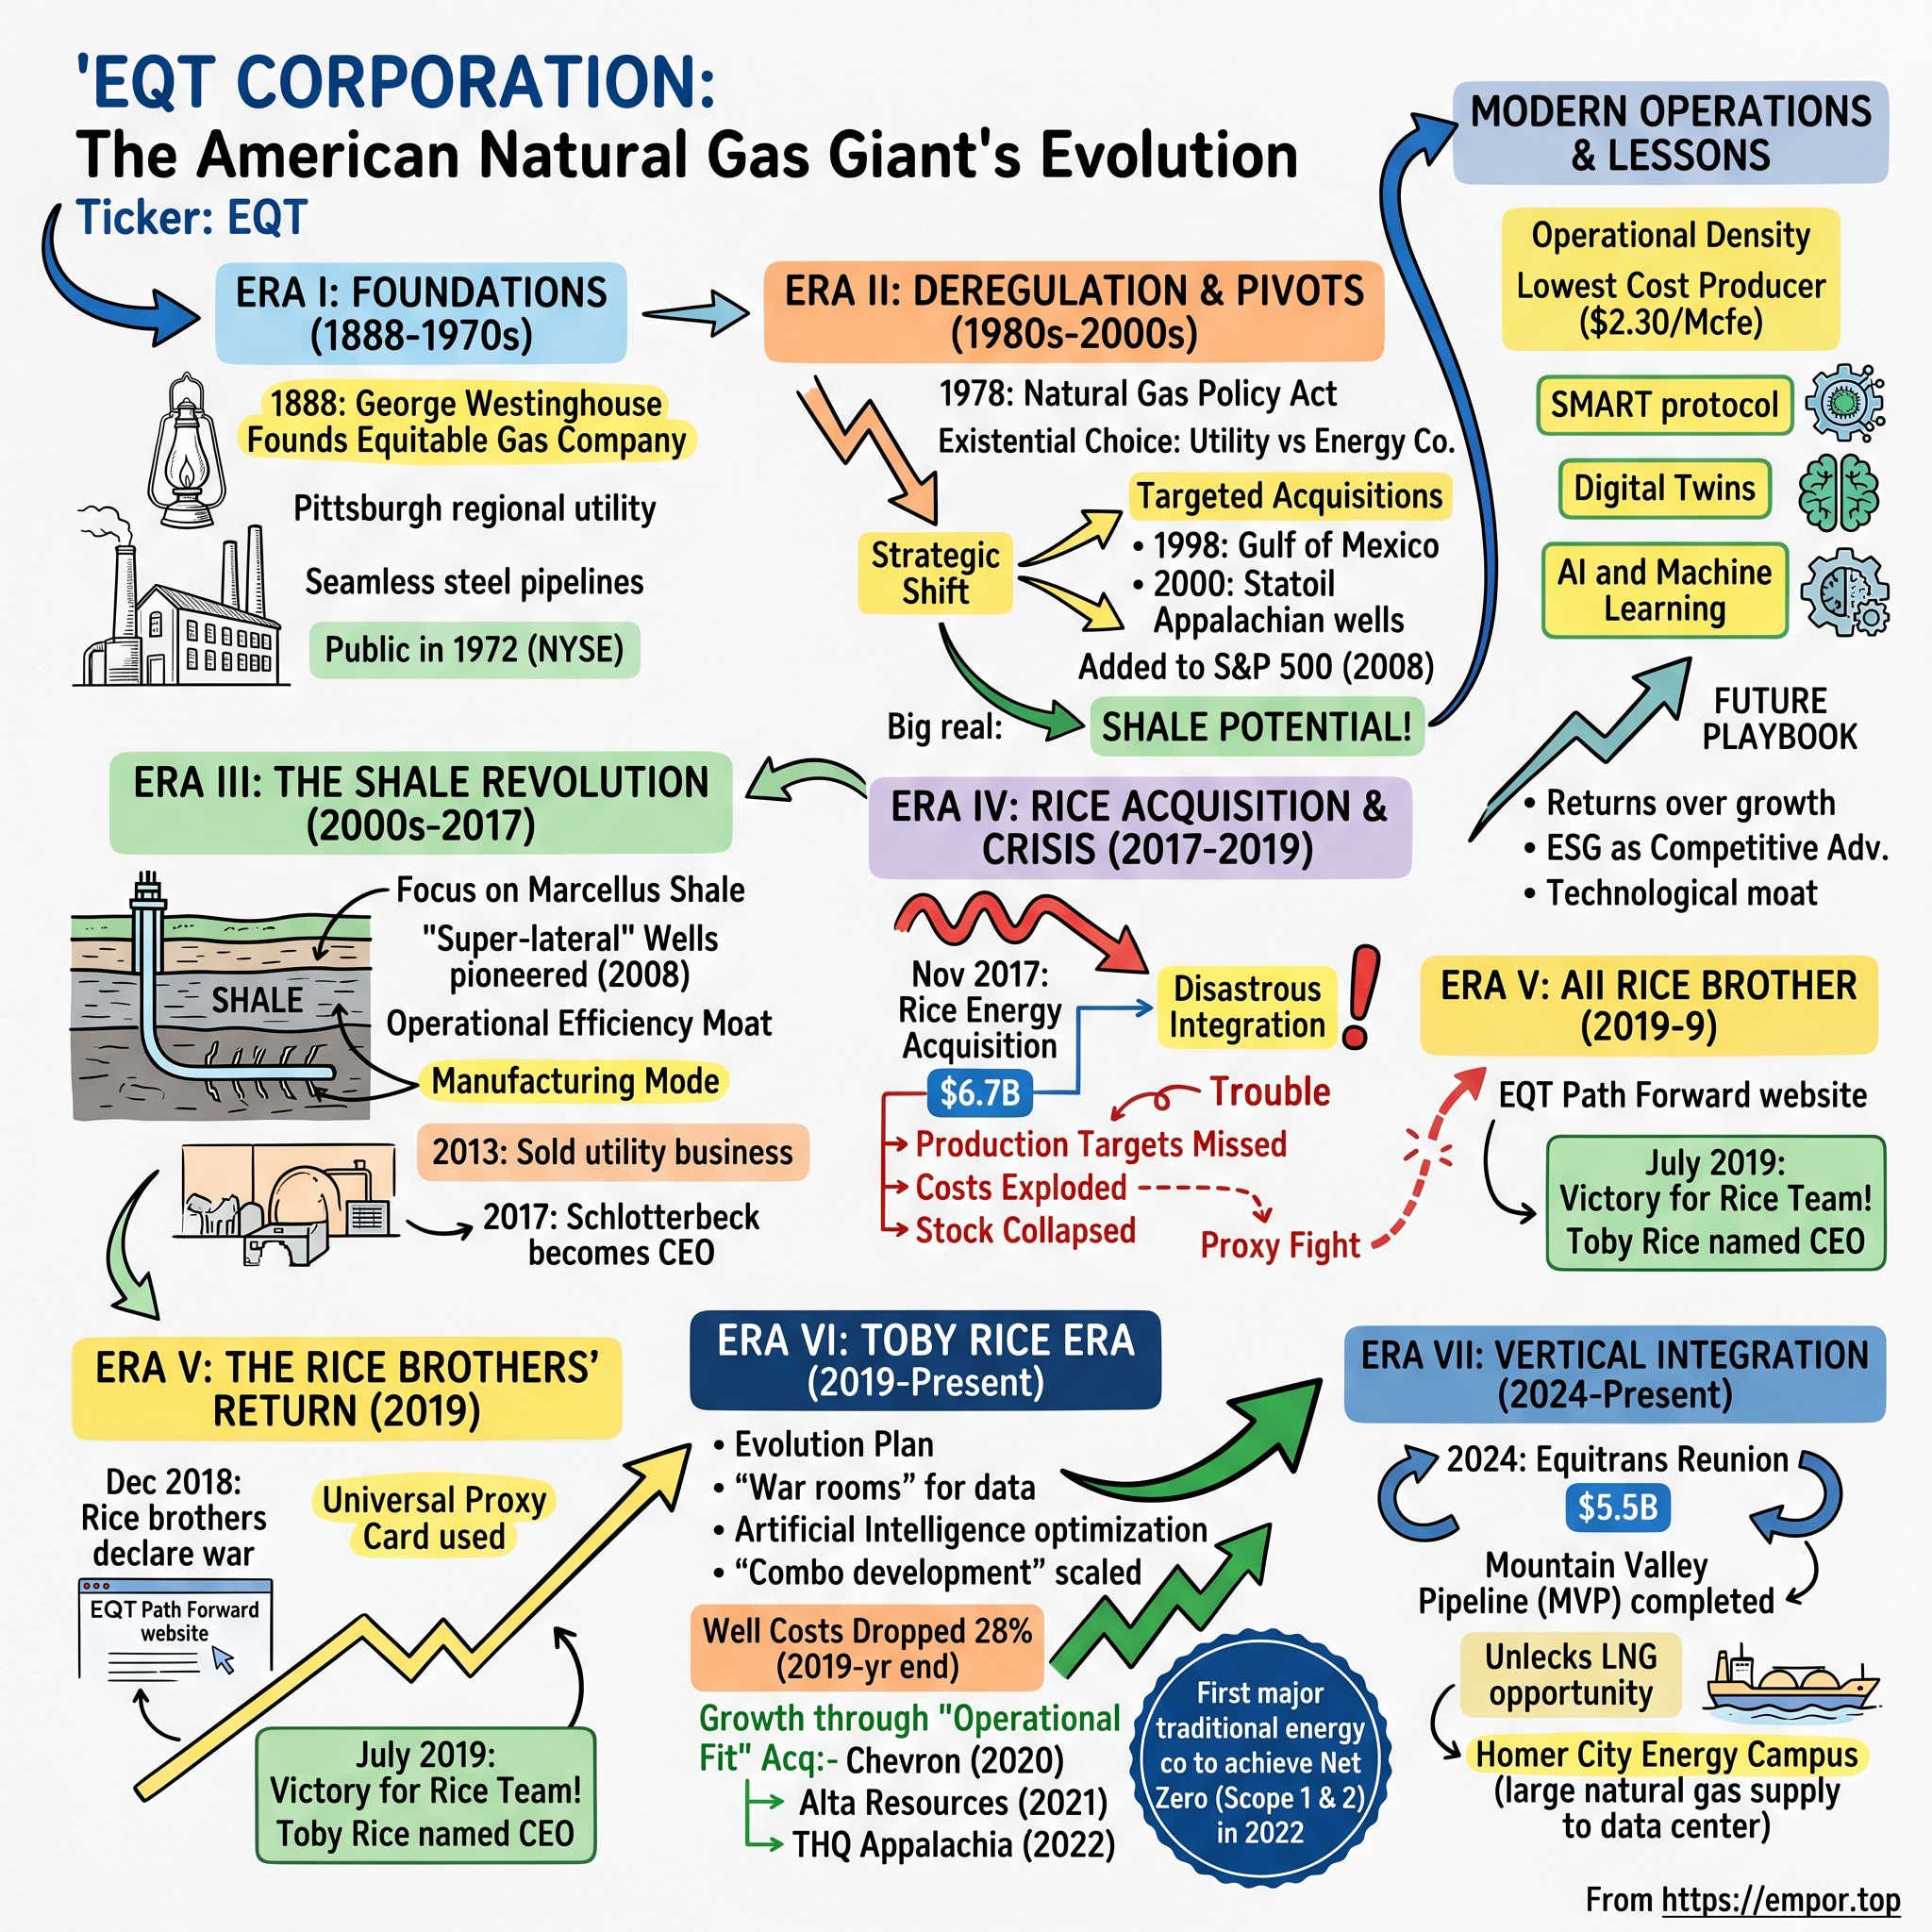
That paradox frames EQT's corporate trajectory. EQT is 138 years old. Founded by George Westinghouse—the alternating-current rival of Thomas Edison—as a Pittsburgh utility lighting streetlamps with gas from wells on his estate, the company spent a century as a regulated distribution utility. Then, in the span of fifteen years, it shed the utility, became America's largest gas producer through a $6.7 billion acquisition, watched that transaction strain its operational integration, spun off its pipeline business, lost control in a shareholder revolt led by the brothers whose company it had purchased, and ultimately re-acquired the pipeline business in an all-stock deal valued above $35 billion.[^4]
The spine of this story is a single question governing commodity markets: if a company cannot differentiate its product, where does durable advantage actually live? EQT's answer rests on two pillars. First, manufacturing discipline—treating shale development as a repeatable factory process rather than wildcatting, an operational framework introduced by the Rice leadership team following legacy execution gaps. Second, control of midstream infrastructure—because in a landlocked basin, takeaway capacity determines asset value, and pipeline tariffs define the margin between profitability and capital destruction.
Whether these factors create a structural moat or merely a temporary cost lead in a historically capital-intensive industry is a question to test against empirical evidence rather than management claims. Corporate declarations require evaluation against historical execution and disclosed financial results.
The roadmap for this analysis:
- Origins — from Westinghouse's streetlights to a regulated utility to a pure-play producer (1888–2013).
- The Marcellus boom and the M&A blunder — the Rice Energy acquisition and the integration failure that followed (2008–2018).
- The proxy war — how two founders in their thirties took an S&P 500 company from its own board (2018–2019).
- The Toby Rice playbook — operational rebuild and $8.8 billion of countercyclical acquisitions (2019–2023).
- The Equitrans reunion — re-bundling the pipes, taming the Mountain Valley Pipeline, and carrying $14 billion of debt (2024–present).
- The economics — basis differentials, cost curves, and what a "$2.00 breakeven" does and does not mean.
- Optionality — LNG tolling and the PJM data-center power boom, sized honestly.
- Competitive analysis — Helmer's 7 Powers and Porter's Five Forces, applied without flattery.
- Bull, bear, and the KPIs that would settle the argument.
The story begins in a city built on carbon.
 Subscribe on LinkedIn
II. Origins: George Westinghouse & The Utility Foundation (1888–2000s)
In the mid-1880s, Pittsburgh was the industrial furnace of North America—Carnegie's steel mills ran continuously, rivers were crowded with coal barges, and heavy smoke hung over the valley. On a hillside estate in the Homewood neighborhood, inventor George Westinghouse turned his attention to natural gas, which was seeping across western Pennsylvania and largely treated by locals as a fire hazard.
Westinghouse had already invented the railway air brake, enabling reliable train stopping and modern rail safety. While contending with Thomas Edison in the "War of the Currents" over alternating current, he drilled a gas well on his own property. Recognizing an engineering challenge, Westinghouse developed systems around the resource, patenting pressure regulators, distribution mains, and leak-resistant couplings.
Those inventions laid the foundation for Equitable Gas Company, chartered in Pittsburgh in 1888 to pipe natural gas into the city for street lighting and industrial use. That origin carries strategic weight: the company did not begin as an exploration firm hunting for reserves. It began as a distribution and infrastructure business designed to transport gas from the wellhead to urban demand. That infrastructure footprint—pipes, rights-of-way, easements, and service agreements—faded from corporate focus for a few decades in the early twenty-first century, only to re-emerge as a central asset.
For nearly a century, Equitable Gas operated as a regulated local distribution utility serving western Pennsylvania, West Virginia, and parts of Kentucky, alongside a modest production arm that supplied its own network. The economics of a regulated distribution utility resembled a toll booth: state regulators capped the allowed return on invested capital, generating predictable cash flows with minimal earnings volatility. Listed on the New York Stock Exchange in 1972 under the holding company Equitable Resources, it spent decades as a modest regional utility.
Regulatory restructuring reshaped the industry landscape. Beginning in the mid-1980s, Federal Energy Regulatory Commission Order 436 and Order 636 in 1992 required interstate pipelines to unbundle—separating commodity sales from pipeline transport and opening pipeline networks to third-party shippers. Before unbundling, pipelines acted as merchant intermediaries, buying gas at the wellhead and reselling it to local utilities. Afterward, pipelines operated strictly as open-access transporters, forcing producers to sell directly to buyers and manage logistics independently.
This regulatory shift divided an integrated supply chain into three distinct segments with contrasting risk profiles: exploration and production (commodity-exposed and capital-intensive), midstream transportation (fee-based and asset-heavy), and retail distribution (regulated and low-margin). For the next three decades, equity markets generally favored pure-play operators over integrated utilities.
Equitable Resources shifted its strategy toward production. During the 1990s and 2000s, the company acquired Appalachian well packages opportunistically, including assets from Statoil and Chevron. These acquisitions built a portfolio of thousands of shallow, low-rate conventional wells. Individually, these legacy wells produced low volumes; a conventional well often yielded in a full day what a modern horizontal well produces in minutes. However, they provided a critical structural asset: acreage held by production. Under standard energy leases, rights remain active as long as a well continues to produce commercial gas. Equitable’s legacy wells secured hundreds of thousands of mineral acres across Appalachia, maintaining title across generations.
By 2008, holding both a regulated utility and an aggressive shale-focused producer created capital allocation tensions. Conglomerates of this type often traded at valuations anchored by their slower-growing utility segments. Equitable Resources joined the S&P 500 in 2008, renamed itself EQT Corporation in 2009, and in 2013 sold its natural gas distribution business—the original Westinghouse utility franchise—to Peoples Natural Gas for roughly $720 million in cash and assets, completing its transformation into an independent producer and midstream operator.2
The sale marked the end of EQT's century as a local utility. What remained was its underlying midstream footprint: gathering lines, compressor stations, surface agreements, and long-standing rights-of-way across Appalachia. In a region where securing permits for new pipeline corridors would eventually become a multi-year regulatory hurdle, that legacy gathering network represented a major cost advantage.
EQT’s initial advantage was not created in a laboratory; it was built through legacy incumbency. That asset base gained immense strategic value when hydraulic fracturing and horizontal drilling made the underlying Marcellus Shale commercially viable.
III. The Marcellus Shale Revolution & The Flawed M&A Boom (2008–2018)
The underlying geology defines the mechanics of the entire shale era.
Conventional gas production is fundamentally a search operation. Natural gas migrates upward through porous rock until an impermeable dome traps it in a reservoir. Once an operator locates the trap and drills into the rock, subterranean pressure drives the gas to the surface. Finding the gas is the primary challenge; extraction is straightforward.
Shale inverts that paradigm. The Marcellus Shale is the source rock—the ancient organic mud in which hydrocarbons originally formed. Because the gas never migrated, it remains trapped inside dense rock with porosity so low that gas cannot flow naturally on any human timescale. Geologists knew of the Marcellus gas deposits as early as the nineteenth century, meaning discovery was never the obstacle. The challenge was physical extraction.
The commercial solution arrived in the 2000s through the combination of two technologies. The first was horizontal drilling: operators drill vertically roughly a mile and a half, then steer the drill bit horizontally through the shale layer for thousands of feet, keeping the wellbore inside the target formation. The second was multi-stage hydraulic fracturing: fluid, sand, and additives are injected at extreme pressure to fracture the rock, with sand propping the fractures open to allow gas to flow. The horizontal run, known as the lateral, became the primary economic metric of the shale boom. Because vertical drilling and surface infrastructure represent fixed upfront costs, longer laterals dilute those capital expenses over more producing rock. A 15,000-foot lateral yields far lower per-foot development costs than a 5,000-foot lateral. As a result, gas extraction shifted from speculative exploration to repeated industrial manufacturing, where low-cost operational efficiency determined profitability.
The Marcellus emerged as one of the most prolific gas plays globally. Between 2008 and 2016, Appalachian production expanded from a negligible fraction of national supply into North America's largest producing region, altering trade flows and shifting the United States from a projected liquefied natural gas importer to a major exporter. However, rapid supply growth triggered severe capital destruction across the sector. Unchecked drilling drove natural gas prices down, leaving producers with massive output but little free cash flow.
Under Chief Executive Officer David Porges, EQT aggressively pursued scale by expanding its leasehold across southwestern Pennsylvania and West Virginia, setting the stage for a major strategic move in 2017.
The Rice Energy Acquisition
Rice Energy stood out among Appalachian producers. Founded in 2007 by former BlackRock energy fund manager Daniel J. Rice III and managed alongside his sons—Daniel IV, Toby, and Derek—the company launched with family capital committed to an initial well site in Washington County, Pennsylvania. Approaching shale development from financial and engineering backgrounds, the team treated extraction primarily as a logistics and supply-chain optimization challenge. After going public in 2014, Rice Energy gained industry attention for executing some of the basin's longest laterals and fastest drilling times, while also developing a dedicated midstream infrastructure company.
In June 2017, EQT announced an agreement to acquire Rice Energy in a cash-and-stock transaction. The deal closed on November 13, 2017, valued at approximately $6.7 billion including assumed debt, with roughly $4.3 billion issued in EQT equity.7 The operational rationale was clear: Rice's core acreage in Washington and Greene counties directly abutted EQT's land positions. Merging the contiguous acreage enabled EQT to drill significantly longer laterals across unified lease blocks rather than stopping at property boundaries. EQT management projected billions of dollars in operational synergies and noted that the transaction elevated EQT past ExxonMobil as the largest natural gas producer in the United States.
However, capturing those theoretical synergies required integrating two starkly different operating models.
The Stumble
Within a year of closing, the acquisition encountered severe execution headwinds. EQT's post-merger well costs failed to converge toward Rice's lower cost structure. Drilling and completion expenditures exceeded budgets, production targets were reduced, and management frequently cited "operational complexity" on earnings calls to account for cost overruns.[^12] By the third quarter of 2018, EQT had missed targets for both capital costs and production volumes, creating a wide gap between promised deal synergies and realized financial performance.
Equity markets reacted sharply. EQT shares, which traded near $60 prior to the acquisition announcement, lost more than half their value over the following twelve months, eventually falling below $20. Steve Schlotterbeck, who had succeeded Porges as CEO and advocated for the transaction, resigned in March 2018 following disagreements with the board over executive compensation and corporate strategy.
The underlying failure was organizational rather than geological. While EQT had acquired high-quality inventory, it had not adopted Rice's operational model. Rice relied on small, cross-functional teams that shared real-time data across drilling, completions, land management, and water logistics, allowing rigs to move seamlessly from one wellhead to the next on multi-well pads. In contrast, EQT operated through traditional functional silos—drilling, completions, and land operating independently—with handoffs reliant on manual approvals and legacy scheduling tools. In a manufacturing-style commodity business, operational integration dictates returns, and EQT had absorbed the asset base without updating its workflow system.
The Spinoff
Facing pressure from activist investors—notably Jana Partners—who contended that EQT's integrated structure suppressed the equity market valuation of its pipeline assets, management pursued a corporate separation. In November 2018, EQT completed the spinoff of its midstream operations into a standalone public entity, Equitrans Midstream Corporation, trading on the New York Stock Exchange under the ticker ETRN.2
In theory, the transaction promised to unlock shareholder value. Midstream assets generate fee-based transportation revenue that public equity markets typically price at higher valuation multiples than volatile exploration and production earnings. By separating the two businesses, management aimed to capture a higher combined valuation for the standalone entities.
In practice, the terms and timing of the spinoff created structural financial friction for EQT. To support Equitrans's standalone credit profile and dividend capacity, EQT entered into long-term gathering and transportation agreements featuring rigid minimum volume commitments—contractual obligations to pay transportation fees regardless of actual gas throughput. This arrangement transformed what had been flexible internal cost transfers into fixed cash liabilities payable to an external counterparty during a period of depressed natural gas prices. Much of Equitrans's high-multiple cash flow represented margin shifted directly off EQT's income statement.
The 2018 separation ultimately failed to build net enterprise value, instead shifting cash flows between asset classes while saddling the upstream enterprise with fixed fee structures. EQT emerged from the spinoff as a captive shipper burdened by compressed operating margins, elevated financial leverage, operational friction, and a depressed share price.
These vulnerabilities left the corporation open to external intervention. The investors best positioned to evaluate EQT's operational shortcomings were the founders of Rice Energy, who had watched the post-merger execution from the inside.
IV. The Great Proxy War: Toby Rice & The Universal Proxy Revolution (2018–2019)
In early 2019, an unconventional activist presentation began circulating among EQT Corporation shareholders. Rather than relying on standard financial engineering—such as sum-of-the-parts valuation bridges, peer multiple comparisons, or calls for a strategic review—the deck detailed Gantt charts, rig-move schedules, software interface screenshots, and side-by-side well-pad photographs. The core argument was not simply that EQT was undervalued, but that legacy management was executing field operations inefficiently across the company's acquired asset base.
That technical focus on operational execution defined the Rice family's proxy campaign.
The Protagonists
Toby Z. Rice was 36 years old when the campaign launched. As Rice Energy's former president and chief operating officer, he had focused on field operations, pad logistics, and drilling schedules while his brother Derek managed geology and his brother Daniel IV served as chief executive officer.
The Rice leadership team combined operational experience with backgrounds in asset management. Central to their strategy was "e-Rice," a proprietary digital software suite designed to coordinate drilling, completions, water logistics, and equipment movement in real time. In shale development—where geological quality across core Marcellus acreage is relatively uniform—operational speed and equipment utilization directly dictate capital returns.
Following EQT's 2017 acquisition of Rice Energy, Toby Rice held approximately 3 percent of EQT shares and a seat on the board. After watching post-merger cost overruns accumulate, he left the company and launched a public campaign in December 2018 to replace EQT's executive management.
The Thesis
The dissident campaign centered on a quantified operational thesis: EQT was losing between $400 million and $500 million in annual free cash flow through operational friction and wasted cycle time.
To capture that lost cash flow, the Rice group presented a detailed operational plan: reduce well development costs by roughly $500 per lateral foot, extend average lateral lengths, implement continuous "combo development" across contiguous acreage, reorganize the workforce into cross-functional asset teams, and deploy the Rice software platform. The group backed its thesis with a 100-day execution roadmap that assigned specific management leads to each operational function.
EQT's incumbent management rejected the claims, arguing that the Rice team lacked experience managing an enterprise of EQT's size, that their software tools were overstated marketing points, and that EQT's internal restructuring was already yielding progress. After settlement discussions failed, the board mounted a full defense.
The Universal Proxy
The mechanics of the proxy fight broke new ground in corporate governance. In a traditional proxy contest, shareholders voted using separate cards for management or dissident slates, preventing investors from splitting their votes among candidates from both sides.
The EQT fight relied instead on a universal proxy card, which listed all management and dissident nominees on a single ballot, allowing shareholders to select individual directors across slates. Although the Securities and Exchange Commission did not mandate universal proxy cards for corporate elections until 2022, both sides agreed to use them, making the EQT election the highest-profile deployment of the mechanism in a U.S. board fight up to that point.
Proxy advisory firms split on the contest: Institutional Shareholder Services backed the Rice slate, while Glass Lewis initially recommended supporting the incumbent board.
At the annual meeting on July 10, 2019, shareholders voted decisively for the dissident nominees, leading to a complete reconstitution of the board, as confirmed in EQT's Form 8-K filing.3 Reuters reported that the brothers had gained control of an S&P 500 board less than two years after selling their company to it.4 Following the vote, the newly appointed board named Toby Rice president and chief executive officer.
Did They Deliver? The Falsification Test
Subsequent operational metrics provided a clear test of the activist group's claims.
Within eighteen months of the leadership change, EQT's reported drilling and completion costs per lateral foot declined from pre-campaign levels toward the low-$700 range and below. Average lateral lengths expanded, and the company began publishing granular cycle-time metrics—including feet drilled per day, completion stages per day, and idle days between pads—that legacy management had omitted.2 These operational improvements lowered the maintenance capital required to maintain production volumes, confirming the Rice group's diagnostic thesis.
However, field-level operational efficiency does not automatically guarantee long-term corporate outperformance. Eliminating wellhead waste is distinct from managing capital allocation, debt leverage, and major corporate acquisitions across volatile commodity cycles.
From a governance perspective, the campaign demonstrated that detailed operational disclosure can overcome incumbent defenses when dissidents possess verifiable asset-level data. Having secured control of the enterprise, Toby Rice assumed leadership of a company burdened by low natural gas prices, elevated debt levels, and rigid midstream transport commitments owed to the recently spun-off Equitrans.
V. The Toby Rice Playbook: Operational Transformation & Mega-Consolidation (2019–2023)
Upon taking leadership, chief executive officer Toby Rice immediately reorganized EQT's operational structure.
Under legacy management, a well's lifecycle passed sequentially through isolated departments. Land teams secured acreage, geologists selected targets, drilling crews completed vertical and horizontal runs, hydraulic fracturing teams completed the wells, and production teams managed long-term flow. Each handoff introduced operational delays. The new structure collapsed these divisions into integrated asset teams responsible for geographic regions end-to-end, operating on shared data platforms and unified master schedules. While administrative on the surface, eliminating idle time carried major financial weight in an industry where hydraulic fracturing crews cost well over $100,000 per day regardless of pumping activity.
The Factory Logic: Combo Development
The centerpiece of this operational redesign was combo development, which formed the manufacturing foundation of EQT's updated strategy.
The concept resembles a construction firm building an entire housing subdivision in a single continuous process rather than mobilizing equipment and crews for isolated, scattered sites. In shale operations, combo development coordinates equipment moves so drilling rigs walk sequentially from one wellbore to the next on a single pad before moving directly to an adjacent pad across contiguous acreage. Hydraulic fracturing crews follow in a continuous cadence, water arrives via permanent pipeline rather than truck convoys, and sand logistics are managed through central scheduling.
Executing this factory model required contiguous leaseholds. The Rice Energy acquisition in 2017, despite its early execution failures, provided the interlocking acreage blocks necessary for continuous operations. New leadership did not need additional land to launch the strategy; it needed to execute across the acreage EQT already owned.
EQT integrated real-time wellhead telemetry, automated scheduling, and cloud-based field reporting to replace manual workflows and reduce non-productive time. While management occasionally marketed EQT as a technology enterprise operating in natural gas, disclosed results showed measurable operational gains, including lower development costs per foot and shorter cycle times.2
Buying When Others Cannot
The second element of the strategy focused on countercyclical consolidation. Between 2020 and 2022, EQT announced three major transactions totaling roughly $8.8 billion, acquiring acreage adjacent to existing operations and applying its updated operational model.
Chevron's Appalachian assets, October 2020. EQT paid $735 million in cash for approximately 890,000 net acres of Marcellus and Utica rights—including about 125,000 core net acres overlapping EQT's operating footprint—along with associated production and gathering infrastructure.2 The transaction closed during the COVID-19 demand downturn, when natural gas traded near multi-decade lows and Chevron was rationalizing its portfolio toward Permian Basin oil. Acquiring core assets during a market bottom allowed EQT to expand its footprint at favorable valuations, though executing countercyclical deals required balance-sheet capacity when industry liquidity was constrained.
Alta Resources, July 2021. EQT acquired Alta's upstream and midstream assets in northeast Pennsylvania for approximately $2.925 billion, funded with $1.0 billion in cash and roughly 105 million EQT shares.2 The purchase expanded EQT's presence into dry-gas acreage with direct access to distinct pipeline networks serving New York and New England markets, providing geographic and pricing-basis diversification alongside volume expansion.
THQ Appalachia I (Tug Hill) and XcL Midstream, closed June 2023. Announced in September 2022, EQT acquired liquids-rich West Virginia acreage and an integrated gathering system for approximately $5.2 billion, comprising $2.6 billion in cash and roughly 55 million EQT shares.2
The Stress Test on Capital Allocation
The Tug Hill transaction highlighted the financial risks of transaction timing.
Management announced the Tug Hill acquisition in September 2022, near the peak of post-invasion European energy dislocations, when U.S. Henry Hub natural gas prices briefly approached $9 per MMBtu. EQT committed to a large, cash-heavy purchase in a highly favorable pricing environment.
By early 2023, U.S. natural gas prices collapsed to approximately $2 per MMBtu—a decline of roughly 75 percent driven by mild winter weather and expanding natural gas production from Permian oil wells. EQT closed the transaction into that market downturn, adding cash-funded debt as operating cash flow contracted. In response, EQT suspended its share repurchase program in 2023 and redirected free cash flow toward debt reduction.2
This period demonstrated three key aspects of EQT's capital allocation strategy.
First, the asset-level alignment of Rice-era transactions remained consistent: acquired acreage offered operational adjacency, integration into the factory model, and lower implied per-acre valuations than the 2017 Rice deal.
Second, acquisition timing varied significantly. While the Chevron purchase was executed countercyclically at low valuations, the Tug Hill deal was announced near peak commodity prices, reducing EQT's financial flexibility when market conditions reversed.
Third, low-cost operations alone do not fully insulate a producer from commodity price cycles. Maintaining a low cost structure dictates relative survival among producers during market downturns, but it does not guarantee continuous profitability or cash returns. EQT's decision in 2023 to pause share buybacks to pay down debt underscored that cost leadership functions primarily as a risk management tool rather than a complete buffer against price volatility.
Furthermore, operational efficiency could not resolve EQT's takeaway constraints. Even with reduced wellhead costs, EQT remained exposed to regional pipeline bottlenecks and fixed transport obligations owed to its former midstream subsidiary.
VI. The Equitrans Reunion: Re-bundling the Pipe & Mountain Valley Pipeline (2024–Present)
Understanding why EQT spent more than $35 billion in enterprise value undoing its 2018 spinoff requires examining the fate of a 303-mile pipeline crossing the Appalachian ridges of West Virginia and Virginia.
Conceived in 2014, the Mountain Valley Pipeline was designed to transport roughly two billion cubic feet per day of Appalachian natural gas southeast to the Transco pipeline system and growing power markets in Virginia and the Carolinas. The project launched with an initial budget of approximately $3.5 billion and a target in-service date of late 2018.
What followed was one of the most prolonged infrastructure litigation battles in modern U.S. history. Crossing the Jefferson National Forest along with hundreds of streams and wetlands, the pipeline faced repeated legal challenges from environmental groups in the U.S. Court of Appeals for the Fourth Circuit. Courts repeatedly vacated water-crossing authorizations, invalidated endangered species consultations, and rejected Forest Service permits, repeatedly halting construction. Pipe sat idle in laydown yards as project costs climbed past $6 billion and ultimately reached $7.5 billion to $7.8 billion—more than double the original estimate.
The project illustrated an industry-wide shift: building a major new interstate natural gas pipeline in the eastern United States had become extraordinarily difficult, regardless of capital backing. This dynamic inverted traditional energy sector economics. Historically considered low-risk, regulated infrastructure assets, interstate pipelines became high-risk development projects—and, because new buildout was effectively constrained, existing capacity became increasingly scarce and valuable.
Resolution required congressional intervention rather than judicial consensus. In June 2023, Congress included a provision in the Fiscal Responsibility Act that ratified all outstanding federal permits for the Mountain Valley Pipeline and stripped federal courts of jurisdiction over legal challenges—a rare legislative intervention for a single infrastructure project. Construction resumed, and the Federal Energy Regulatory Commission authorized the pipeline to enter service in June 2024, when natural gas began flowing.6
The Deal
On March 11, 2024—three months before the pipeline entered service—EQT announced a definitive agreement to acquire Equitrans Midstream in an all-stock transaction. Equitrans shareholders received 0.3504 EQT shares for each share of Equitrans, creating a combined entity with an enterprise value exceeding $35 billion.[^4] The Wall Street Journal characterized the transaction as one of the largest energy deals of the year and a reunion of two entities that had functioned as a single company until 2018.5 The transaction closed on July 22, 2024.[^5]
The strategic rationale rests on three core mechanisms.
Mechanism one: internalizing midstream tariffs. Prior to the merger, gathering and transmission fees paid to Equitrans represented external cash outflows. Following consolidation, these payments became internal transfers within the combined enterprise. While internal transfers do not generate net new revenue on their own, consolidation eliminates third-party contractual constraints, allowing EQT to coordinate production curtailments, gas routing, and capacity allocation. Furthermore, the minimum volume commitments that previously imposed fixed external cash liabilities were converted into internal accounting mechanisms.
Mechanism two: cost-structure compression. Following the transaction, management highlighted an unlevered free cash flow breakeven target approaching $2.00 per MMBtu on a NYMEX basis, indicating that at a $2.00 natural gas price, the combined company could fund maintenance capital while remaining cash-neutral prior to debt service.[^4] While consolidating fee streams mathematically lowers reported operating costs per unit, this breakeven threshold depends on underlying assumptions regarding baseline maintenance capital expenditure, regional basis differentials, and asset maintenance definitions.
Mechanism three: control of midstream takeaway. Controlling the Mountain Valley Pipeline and the supporting gathering footprint secures physical egress from EQT's core acreage to mid-Atlantic demand centers. In a basin where new interstate pipeline construction faces significant regulatory barriers, ownership of existing takeaway capacity provides a structural logistical advantage that competitors cannot easily replicate.
The Debt, and What Management Did About It
Upon closing, EQT assumed approximately $14 billion in total consolidated debt, combining its existing liabilities with Equitrans's project-financed balance sheet and Mountain Valley Pipeline cost overruns.[^5] Carrying substantial leverage into volatile commodity markets exposed the balance sheet to significant cash-flow risk.
To address this debt burden, management initiated a series of asset monetizations:
- In April 2024, prior to closing the merger, EQT agreed to sell non-operated natural gas assets in northeast Pennsylvania for approximately $1.25 billion in combined cash and equity consideration.8
- In December 2024, EQT formed a midstream joint venture with Blackstone Credit & Insurance, selling a non-controlling interest in a portfolio of regulated midstream assets—including its stake in the Mountain Valley Pipeline alongside transmission and storage infrastructure—for $3.5 billion in cash.[^6]
Combined with operational cash flow, these transactions allowed EQT to reduce debt significantly within eighteen months of closing, progressing toward its net debt target of approximately $5 billion.1 Regarding operational integration, management reported realizing more than half of its $425 million annual base synergy target on an annualized basis within the initial months following transaction close.[^5]
Weighing the Reversal
Evaluating this strategic shift requires examining the contradiction between EQT's recent actions and its historical decisions.
Between 2010 and 2018, industry analysts, activist investors, and EQT's board concluded that separating midstream gathering from upstream production would maximize market value, leading to the 2018 spinoff. Six years later, the same corporate entity paid substantial advisory fees to recombine the businesses in a multi-billion-dollar transaction.
Market participants offer two contrasting interpretations of this reversal. The first posits that underlying market dynamics fundamentally shifted. In 2018, the Mountain Valley Pipeline remained unbuilt, regional takeaway constraints appeared temporary, and interstate pipeline expansion seemed achievable. By 2024, pipeline development had become tightly constrained, making existing infrastructure an unrepeatable asset whose ownership aligned directly with EQT's operational needs.
The second interpretation views the sequence as a reflection of shifting market trends—unbundling assets when equity markets rewarded pure-play producers, and re-bundling them when markets favored integrated business models. Supporting this perspective is the baseline economic reality of landlocked basin development: a captive producer's transportation tariff represents midstream revenue regardless of corporate structure, a dynamic that remained unchanged between 2018 and 2024.
A balanced assessment lies between these viewpoints. The 2018 spinoff converted flexible internal cost structures into fixed external cash liabilities during a period of depressed natural gas prices. While the 2024 re-acquisition established operational coherence and was followed by disciplined deleveraging, the round-trip transactions imposed substantial financial costs on shareholders. For EQT's current asset base, vertical integration provides operational control, but long-term value creation depends on whether full-cycle cash flow justifies the acquisition price and total debt load—an outcome contingent on future natural gas prices and regional basis differentials.
Evaluating that outcome requires examining regional basis differentials—the critical pricing metric that determines realized revenue across Appalachian natural gas production.
VII. Core Business Economics: Marcellus Cost Curve, Basis Differentials & Capital Allocation
Consider a pricing anomaly in natural gas markets: during the summer of 2020, and on several shoulder-season days in subsequent years, spot natural gas at certain Appalachian trading hubs traded for just a few cents per million British thermal units (MMBtu). At the exact same time, natural gas at the Henry Hub benchmark in Louisiana traded for well over $1.50 per MMBtu.
That price spread is known as basis, and it represents the fundamental economic constraint for Appalachian producers.
Why Location Is Price
Unlike crude oil, natural gas cannot be economically transported by truck or stored cheaply at scale. It relies on fixed pipeline networks to move from the wellhead to end-use markets. When regional takeaway pipelines reach capacity, excess gas has no egress. Unconnected or excess gas rapidly loses market value, leaving producers with two choices: accept distressed local market prices or shut in production.
Appalachia presents an acute case of this constraint: it is the largest gas-producing region in North America, situated under states where regulatory and legal hurdles make constructing new pipelines exceptionally difficult, directly adjacent to major demand centers.9 Consequently, regional trading hubs such as Eastern Gas South (formerly Dominion South) have historically traded at a discount of 50 cents to more than a dollar per MMBtu relative to Henry Hub, with wider discounts during peak congestion periods.
This regional discount directly affects operating margins. If a producer's all-in development and operating cost is $2.00 per MMBtu and Henry Hub trades at $3.00, the implied margin appears to be $1.00. However, if regional basis discounts reduce the realized price by $1.00 relative to Henry Hub, the operating margin drops to zero. Basis is not a minor adjustment in Appalachian gas economics; it frequently determines net profitability. Geographical takeaway constraints can neutralize low wellhead development costs, explaining why firm transportation capacity—the contractual right to move specific volumes on specific pipelines—commands a substantial strategic premium.
This economic reality clarifies the logic behind EQT's vertical integration strategy. Ownership of gathering systems, transmission lines, and capacity on the Mountain Valley Pipeline does not alter the physical commodity. Instead, it ensures gas is deliverable to premium markets trading closer to national benchmarks, while internalizing fee streams previously captured by third-party midstream operators.
The Asset Base
EQT controls one of the largest natural gas positions in North America, holding more than one million net acres across Pennsylvania, West Virginia, and Ohio, with proved reserves in the high-20s trillion cubic feet equivalent range and daily sales volumes around six billion cubic feet.2 Through combo development, average lateral lengths expanded from roughly 10,000 feet in the mid-2010s to 15,000 to 20,000 feet on core contiguous acreage blocks, reducing per-unit capital intensity.
Following the Equitrans acquisition, EQT operates through two principal reporting segments: upstream production, which generates the vast majority of revenue and carries direct commodity price exposure; and midstream gathering and transmission, which provides steady, fee-based revenue insulated from spot gas price volatility. This midstream segment functions as a financial stabilizer, generating predictable cash flow to cover fixed debt service obligations during natural gas price downturns.
Capital Allocation, and the Discipline Question
Since the Equitrans merger, EQT has maintained a consistent capital allocation framework: fund maintenance capital, reduce net debt toward a target of approximately $5 billion, maintain the base dividend, and execute opportunistic share repurchases during commodity market weakness.1 Annual maintenance capital expenditure—the reinvestment required to offset steep initial decline rates from young shale wells—ranges near $2 billion.
A notable operational shift has been management's approach to production curtailments. Beginning in 2024, EQT repeatedly shut in natural gas production when regional spot prices dropped below economic thresholds, choosing to defer production rather than sell volumes into oversupplied markets.[^12] Chief Executive Officer Toby Rice described this tactic as managing underground gas reserves as inventory rather than producing at fixed rates regardless of price.
This practice marks a departure from historical industry behavior. During the early shale expansion, producers frequently prioritized volume growth despite depressed prices, contributing to market oversupply and capital destruction. Demonstrating a willingness to trim production to defend realized prices indicates an operational focus on free cash flow over volumetric growth. This strategy is also enabled by EQT's integrated structure: owning takeaway infrastructure allows the company to shut in wells without incurring third-party minimum volume commitment penalties on unused pipeline capacity.
Evaluating EQT's strategic trajectory reveals a mixed execution record. The operational efficiency targets outlined during the 2019 proxy contest were achieved and verified in disclosed cost metrics. Following the 2024 Equitrans transaction, debt reduction targets progressed primarily through rapid asset sales rather than relying on commodity price recovery. However, transaction timing has varied across market cycles. Additionally, EQT's strategic narrative has evolved across several distinct phases—from a pure-play low-cost producer, to an integrated midstream-upstream operator, to a supplier positioned for power demand and liquefied natural gas export growth—requiring ongoing evaluation of long-term capital efficiency against shifting corporate positioning.
This strategic evolution sets up the next key question: how much real market opportunity exists in LNG export capacity and data-center power demand?
VIII. Strategic Optionality: Global LNG Tolling & The AI/Data Center Power Boom
Proportionality is essential when evaluating energy sector growth stories. EQT's earnings remain overwhelmingly derived from selling natural gas into North American markets and collecting midstream fees. The two growth vectors examined in this section—international liquefied natural gas (LNG) exposure and direct gas-to-power supply for data centers—are structurally relevant and partially backed by agreements. However, both currently represent small components of the core business, offering strategic optionality rather than an immediate transformation of baseline cash flows.
Vector One: Selling Into the World
For most of modern energy history, U.S. natural gas operated as an isolated domestic market. Gas could not cross oceans without being supercooled to minus 260 degrees Fahrenheit into liquid form, and domestic export infrastructure was virtually nonexistent. Consequently, U.S. natural gas prices were determined strictly by domestic supply and weather conditions, allowing American gas to trade at $2 per MMBtu while European and Asian buyers paid substantial premiums.
The 2020s dismantled that isolation. U.S. LNG export capacity expanded from negligible levels in 2016 to become the largest in the world, with major project queues along the Gulf Coast expanding export capacity further through the end of the decade. For a domestic producer, this expansion shifts market dynamics: the marginal buyer of American gas is increasingly international, and global benchmarks—such as Title Transfer Facility (TTF) in Europe and Japan Korea Marker (JKM) in Asia—have historically traded at significant premiums to U.S. Henry Hub prices.
EQT's strategy centers on moving up the value chain from a wellhead seller to an active participant in the export supply chain. Rather than simply selling raw gas at the basin, the company has contracted for liquefaction capacity—known as tolling—and entered supply arrangements with Gulf Coast export facilities. The underlying mechanism is direct: when a producer pays a fixed fee to liquefy gas and sells the finished cargo at international index prices, it captures the spread between domestic and global benchmarks rather than forfeiting that margin to midstream intermediaries.
However, several operational and market constraints limit this thesis. First, because EQT's production sits in Pennsylvania while liquefaction terminals are located on the Gulf Coast, the strategy requires securing long-haul pipeline transportation, adding fixed costs that compress headline pricing spreads. Second, several counterparty export projects have encountered permitting delays, regulatory challenges, cost inflation, and shifting federal export policy; a tolling agreement tied to an unbuilt facility yields no economic return. Third, global arbitrage spreads remain cyclical: as international LNG liquefaction capacity expands worldwide, pricing spreads can narrow rapidly. Consequently, announced tolling agreements represent long-term strategic options with execution risk rather than immediate contracted earnings.
Vector Two: The Grid Next Door
The second growth vector stems primarily from geographical incumbency within a changing regional power market.
The PJM Interconnection operates the electrical grid spanning Pennsylvania, West Virginia, Ohio, Virginia, Maryland, and neighboring states. The region encompasses Northern Virginia's Loudoun County—the world's highest concentration of data centers—and has become a focal point for AI-driven electricity demand growth. After two decades of stagnant U.S. electricity demand, load forecasts across PJM shifted upward, capacity auction prices reached record highs, and regional supply conditions tightened faster than market participants anticipated.
This geographic positioning carries strategic weight for natural gas producers. Artificial intelligence training and data center workloads require continuous, 24-hour baseload power. While solar generation and battery storage expand rapidly, matching constant multi-hundred-megawatt industrial loads solely with intermittent renewables presents technical and economic hurdles. Furthermore, new nuclear generation requires long development timelines. In the eastern United States, combined-cycle natural gas turbines represent the primary dispatchable generation technology that can be permitted and constructed within a three-to-four-year timeframe.
EQT's production footprint and midstream gathering network sit directly within this high-demand grid region. While physical proximity does not constitute an exclusive moat—as peer Appalachian producers share similar geographic access—it provides a direct pathway to negotiate long-term supply contracts with power generators and data center developers at pricing structures decoupled from depressed local spot indices. Management has discussed this opportunity with increasing prominence on recent calls.[^12]
The Falsification Pass: What Happened Last Time EQT Bet on a Premium
Evaluating corporate optionality narratives requires reviewing historical precedents where producers attempted to capture commodity price premiums.
Beginning around 2021, EQT invested substantially in certifying its output as responsibly sourced gas—utilizing third-party auditing and continuous environmental monitoring to verify low methane intensity. Management's thesis asserted that European utilities and sustainability-focused industrial buyers would pay a structural premium for certified low-emission gas, allowing EQT to leverage its scale and measurement infrastructure into higher realized margins.
That expected pricing premium failed to materialize in an economically meaningful way. Market differentials for certified natural gas stabilized at a few cents per MMBtu—a negligible fraction of baseline commodity prices. Energy markets ultimately treated certification as a baseline license to operate and a requirement for customer access rather than a pricing mechanism.
This outcome underscores a broader principle in commodity markets: differentiation that the buyer does not pay for is a cost, not a moat. While the current LNG tolling and data-center power opportunities differ from certified gas by involving physical infrastructure constraints—such as firm pipeline takeaway and liquefaction access—the historical record across the industry shows that attempts by commodity producers to escape underlying market pricing through product differentiation face significant execution hurdles.
A defensible interpretation of EQT's optionality thesis acknowledges that the company holds meaningful call options on higher-priced demand channels. However, the ultimate value of these options depends on third-party project execution and persistent structural scarcity. Until EQT discloses binding, long-term contracts at pricing materially above regional spot benchmarks with volumes sufficient to impact consolidated financial results, these opportunities represent strategic narrative options rather than baseline earnings.
That framing sets up the harder question: strip away the optionality, and what is actually defensible about this business?
IX. Competitive Landscape: Helmer's 7 Powers, Porter's 5 Forces & Peer Benchmarking
Evaluating EQT's defensibility requires testing where its competitive position holds—and where it breaks down under industry pressure.
The Field
Expand Energy represents EQT's primary rival for scale leadership among U.S. natural gas producers, formed from the 2024 merger of Chesapeake Energy and Southwestern Energy. Expand's asset base spans the Haynesville Shale in Louisiana alongside northeast Pennsylvania acreage. That portfolio features a structural advantage that EQT lacks: Haynesville production sits within a few hundred miles of Gulf Coast LNG export terminals, connected by short, existing pipeline corridors. Consequently, Expand can supply export markets without navigating long-distance takeaway constraints out of Appalachia. EQT's counter argument rests on well economics: Marcellus wells are shallower and less expensive to drill than Haynesville's high-pressure, high-temperature reservoirs, and EQT controls its own midstream infrastructure. Both claims reflect operational realities, maintaining a tight competitive rivalry.
Antero Resources operates in the liquids-rich window of southwestern Appalachia, producing ethane, propane, and butane alongside natural gas. Because natural gas liquids pricing correlates with crude oil markets, these volumes lift average realized prices above dry-gas economics, providing commodity diversification that EQT only partially matches through its West Virginia assets. Antero also holds extensive firm transportation capacity, though it lacks EQT's post-Equitrans owned infrastructure footprint.
Range Resources drilled the discovery well that initiated the Marcellus development boom and holds some of the lowest-cost core acreage in the basin, backed by a long inventory runway and a conservative balance sheet. While Range's total production volume is roughly one-third of EQT's, its operational performance demonstrates that scale is distinct from per-unit returns.
Coterra Energy embodies corporate portfolio diversification, combining Permian Basin oil assets, Anadarko Basin holdings, and low-cost dry gas acreage in Susquehanna County, Pennsylvania. During periods of depressed natural gas prices, Coterra's oil revenue supports cash flow. EQT holds no equivalent structural hedge, operating as a direct play on natural gas within a single basin.
Helmer's 7 Powers
Scale Economies — real but bounded. Contiguous acreage combined with combo development generates measurable per-foot cost advantages, as dedicated hydraulic fracturing crews, permanent water pipelines, and continuous pad scheduling require spatial density. Integration with owned gathering networks deepens this efficiency. However, these scale advantages saturate: the operational cost gap between the largest producer and the third-largest is far narrower than the gap between mid-tier operators and small independents. Range Resources' per-unit economics on core rock illustrate that subscale producers can match large-scale cost structures on high-quality acreage.
Cornered Resource — the strongest of the powers, with clear structural limits. Two assets qualify. First, core Tier-1 Marcellus leaseholds are finite and largely consolidated under existing operators. Second, and more critically, the Mountain Valley Pipeline represents a functionally unrepeatable infrastructure asset: the project required a decade of legal challenges, more than double its original budget, and direct congressional action to complete.6 A competitor with unlimited capital could not construct an equivalent interstate pipeline on any practical timeline. However, this power carries clear limits: pipeline throughput capacity is finite and heavily contracted under long-term commitments, EQT sold a non-controlling interest in the pipeline system to Blackstone to reduce debt,[^6] and owning takeaway capacity protects EQT's realized prices rather than allowing it to extract monopoly rents from peer producers.
Process Power — moderate and eroding. The Rice operational model delivered a distinct competitive advantage in 2019, when much of the basin still relied on legacy scheduling practices. Seven years later, combo development, continuous pad drilling, centralized water logistics, and real-time digital scheduling have become standard operational practices across Appalachian producers. Operational techniques diffuse naturally across the regional labor market as engineering personnel move between firms. What persists is organizational coordination and local operating knowledge, which provides efficiency but lacks the formal defensibility of intellectual property.
Switching Costs — absent. Natural gas is a fungible commodity. Buyers do not pay a premium based on producer identity, as demonstrated by the failure of certified responsibly sourced gas to command structural price spreads.
Counter-Positioning — absent. EQT's manufacturing model involves operational choices that incumbent peer producers can adopt without undermining their core business models.
Branding and Network Economies — not applicable. Brand equity and network effects exert no commercial influence in wholesale natural gas markets.
Evaluating EQT across Hamilton Helmer's framework yields one strong power rooted in physical infrastructure scarcity, one moderate and eroding operational edge, one real but saturating scale advantage, and three powers that do not apply. That combination provides a stronger defensive posture than most commodity producers maintain, though it falls short of a structural moat.
Porter's Five Forces
Threat of new entrants: very low. Capital availability is not the primary barrier; rather, the two essential prerequisites for Appalachian production—core contiguous acreage and available pipeline takeaway capacity—are fully committed and effectively unbuildable. Ironically, the regulatory hurdles that complicate infrastructure development serve as an entry barrier protecting incumbent operators.
Bargaining power of buyers: high. Utilities, industrial consumers, and LNG exporters purchase natural gas based on transparent public benchmark indices. Individual producers possess zero pricing power over benchmark screens.
Bargaining power of suppliers: moderate and cyclical. Oilfield service providers, drilling rig contractors, and proppant suppliers gain pricing leverage during commodity upcycles and lose it during downturns. EQT's operational scale secures favorable contract terms and priority access to crews during tight market conditions.
Threat of substitutes: moderate, reflecting competing long-term and short-term trends. Over a multi-decade horizon, renewable power generation, energy storage, and potential nuclear expansion compete with natural gas for electricity generation. Over a shorter horizon, expanding LNG export capacity and growing power demand from data centers within the PJM grid reinforce natural gas demand.
Competitive rivalry: high. Appalachian producers compete directly for drilling equipment, field crews, water handling facilities, acreage swaps, and firm pipeline capacity. Competition focuses not on customer acquisition, but on securing physical takeaway logistics.
In summary, EQT operates within a well-defended position inside a structurally challenging industry. High entry barriers protect its production base, but fungible commodity pricing limits its ability to generate returns above broader market cycles.
X. Playbook: Strategic & Business Lessons
Lesson one: In a landlocked commodity, distribution is the business. EQT spent 2017 purchasing scale through the Rice Energy acquisition, only to discover that becoming the nation's largest natural gas producer provided little advantage if its output could not reach paying customers. The Appalachian basis differential illustrates a fundamental rule of commodity markets: economic value accrues to whoever controls the bottleneck, and in a constrained regional market, that bottleneck is takeaway infrastructure rather than wellhead production. Applied broadly, this defines the strategic rationale for vertical integration—expanding toward the scarce asset rather than the abundant one.
Lesson two: Operational expertise is a rare form of activist leverage. The 2019 Rice proxy campaign succeeded where financial activism often falters because the challengers presented granular engineering data detailing specific operational failures and practical solutions. The universal proxy card served as the governance mechanism, but domain expertise provided the persuasive force. For investors, the lesson is straightforward: skepticism is warranted when an activist campaign relies primarily on multiple expansion or financial engineering, whereas detailed plans focused on cycle times, lateral lengths, and per-foot development costs command serious attention.
Lesson three: Beware corporate restructurings driven by market trends. The cycle of spinning off midstream assets in 2018 and re-acquiring them in 2024 imposed substantial transaction fees, operational friction, and years of compressed margins on EQT as a captive shipper. The underlying error was not merely choosing wrong in 2018 versus 2024, but allowing prevailing market preferences for pure-play operators to override a grounded analysis of where the company's real value resided. Corporate structure should reflect the physical economics of the business rather than short-term market sentiment.
Lesson four: In cyclical commodities, capital discipline requires a willingness to defer sales. The first decade of the shale boom was defined by continuous volume growth that destroyed substantial capital across the industry. Curtailing production during price downturns—treating underground reserves as inventory rather than an obligation to pump—distinguishes operators managing for free cash flow from those prioritizing volume growth. Sustaining that operational flexibility is also significantly easier when a producer owns its midstream transportation, eliminating third-party minimum volume commitments during market troughs.
Lesson five: A cost advantage is a survival tool, not a guarantee of cycle immunity. EQT's experience in 2023—suspending share buybacks and reallocating free cash flow toward debt service following the peak-market Tug Hill acquisition—demonstrates that low operational breakevens do not insulate a producer from commodity downcycles. Low-cost operators navigate downturns by outlasting higher-cost competitors, not by escaping market volatility.
XI. Analysis & Investment Case: Bull vs. Bear Stress Test
Two analysts examining EQT can reach starkly different conclusions from the same underlying data. One sees an integrated infrastructure enterprise operating top-tier natural gas acreage in North America just as domestic demand reaches a structural inflection point. The other sees a single-commodity, single-basin producer carrying multi-billion-dollar merger debt into a market historically defined by oversupply. Both perspectives rely on verified facts.
The Bull Case
Cost position and the integrated breakeven. The combination of low-cost core acreage, continuous combo-development manufacturing, and owned midstream logistics yields an unlevered cash breakeven that management places near $2.00 per MMBtu.[^4] If sustained, this cost structure allows EQT to maintain operations during price downturns that force higher-cost competitors to shut in production—a position that enables low-cost operators to capture market share organically during market troughs.
Egress control in a constrained basin. Owning gathering networks, transmission lines, and capacity on the Mountain Valley Pipeline—the only major new southeast-bound pipeline constructed out of Appalachia in a decade—addresses the physical takeaway bottlenecks that have capped regional producer returns since 2014.6 This takeaway infrastructure represents EQT's least replicable asset.
Demand-side inflection. Expanding U.S. liquefied natural gas export capacity alongside rising power demand within the PJM grid offers structural demand tailwinds for domestic natural gas. If these demand channels materialize as projected, national benchmark gas prices could reset higher, widening margins for low-cost producers.
Demonstrated deleveraging. Management accelerated debt reduction through asset sales and a midstream joint venture executed shortly after the Equitrans transaction closed, rather than relying on a commodity price recovery.[^6]8 This rapid execution validates management's deleveraging commitments and mitigates acute balance-sheet risks.
The Bear Case, and the Activist's Questions
Commodity price vulnerability. Operational efficiency cannot insulate a natural gas producer from weather-driven demand slumps or broader supply growth. Moreover, associated natural gas produced alongside Permian Basin crude oil represents a structural supply threat: because oil producers drill primarily for crude, associated gas output remains largely price-insensitive and continues to expand, frequently capping domestic natural gas prices. A prolonged sub-$2.50 price environment compresses EQT's cash flows regardless of wellhead economics.
Leverage and acquisition costs. EQT assumed roughly $14 billion in debt upon closing the Equitrans merger.[^5] While subsequent debt reduction has been substantial, deleveraging required selling key assets—including a non-controlling stake in its core midstream portfolio to Blackstone.[^6] Consequently, the company funded its vertical integration in part by divesting a fraction of the newly acquired assets. Analysts and investors can fairly question whether the all-stock purchase price for Equitrans—executed after the Mountain Valley Pipeline had cleared major regulatory hurdles—transferred structural enterprise value from EQT shareholders to Equitrans equity holders.
Capital allocation friction. The Tug Hill transaction, announced near peak commodity prices in 2022 and closed into a sharp price collapse in 2023, contrasts with the narrative of strict countercyclical discipline. Similarly, pausing share repurchases in 2023 was a prudent operational decision, but it highlights that shareholder returns remain heavily dependent on commodity market cooperation.
Asymmetric regulatory and political exposure. While state regulatory environments in Pennsylvania and West Virginia have remained broadly supportive, the decade-long legal battle over the Mountain Valley Pipeline demonstrates the operational delays and cost overruns that environmental litigation can inflict. Future regulatory shifts regarding methane emissions, wastewater disposal, state permitting, or federal LNG export approvals pose downside risks. Furthermore, resolving the Mountain Valley Pipeline required extraordinary congressional intervention—a legislative outcome that cannot be assumed for future infrastructure projects.
Shifting corporate narrative. EQT's strategic positioning has evolved repeatedly—from a pure-play exploration and production firm, to an integrated upstream-midstream operator, to a supplier targeted at global LNG and data-center power demand. While each shift aligned with prevailing market conditions, investors must distinguish between long-term strategic execution and narrative positioning tailored to current equity market trends, weighting binding commercial contracts over management ambitions.
Single-basin concentration. Unlike diversified peers such as Coterra Energy or Expand Energy, EQT operates entirely within a single geographic region and commodity type. Operational disruptions, regional basis widening, localized regulatory changes, or regional service inflation impact the entire enterprise simultaneously.
The Calibrated Verdict
Weighing the evidence, the competitive moat claim holds in a targeted form. EQT maintains a verifiable low-cost operational base and a scarce takeaway infrastructure position, backed by management's track record of field execution since 2019. However, historical performance refutes the broader thesis that vertical integration and low cost structures render earnings immune to commodity cycles. As demonstrated by the 2023 buyback pause and the reliance on asset sales rather than organic cash flow to reduce debt after the 2024 merger, EQT remains a levered enterprise tied directly to natural gas prices. Strategic optionality claims around LNG tolling and data-center power demand remain unproven and should be evaluated cautiously until backed by long-term binding contracts.
Three KPIs That Would Settle the Argument
1. Realized price differential versus NYMEX Henry Hub. This metric serves as the definitive test of vertical integration. If controlling gathering networks and Mountain Valley Pipeline capacity delivers structural value, EQT's realized prices relative to national benchmarks must show durable improvement during regional bottleneck periods. If realized price discounts persist at pre-merger levels, the integration strategy fails to demonstrate clear commercial returns regardless of reported breakeven figures.
2. Total net debt trajectory toward the $5 billion target. The bear case centers heavily on financial leverage. Investors must evaluate not only the magnitude of debt reduction, but also its capital source: retiring debt through organic free cash flow confirms a self-sustaining enterprise, whereas debt reduction funded by asset sales or joint-venture transactions relies on finite capital tools.
3. Maintenance capital required to hold production flat. Maintenance capital intensity reveals underlying asset quality in shale manufacturing. Because unconventional wells experience steep initial production declines, the capital required to maintain baseline output dictates true free cash flow generation. Rising maintenance capital requirements at constant production volumes provide the earliest signal of inventory degradation, surfacing well before changes appear in reported proved reserves.
XII. Epilogue & Looking Forward
The contrast between EQT's origins and its current scale reflects a century-and-a-half shift in energy infrastructure. In 1888, George Westinghouse—having built his fortune developing railway air brakes—drilled a well behind his Pittsburgh home and piped natural gas to light city streetlamps. The enterprise he chartered spent the next century operating as a regulated local utility. By 2026, that same corporate lineage produces roughly 6 percent of the natural gas consumed in the United States, operates a pipeline network it spun off and subsequently re-acquired, and frames its future around global liquefied natural gas cargoes and data-center power demand.
At its core, EQT has spent the past seven years addressing structural and operational missteps from the preceding decade. The operational inefficiencies identified during the 2019 proxy contest were systematically resolved. The structural friction created by the 2018 midstream spinoff was reversed through the 2024 Equitrans acquisition. And the debt incurred to execute that re-bundling has been significantly reduced through disciplined asset sales. This sequence demonstrates a consistent record of field-level execution against clear operational problems.
What remains unresolved is whether correcting these execution gaps establishes a durably high-return enterprise or merely a resilient operator built to survive downturns. The coming decade will test a fundamental market question: does American natural gas evolve into a globally linked commodity with a structurally higher pricing floor—driven by Gulf Coast liquefaction capacity and regional data-center power demand—or does it remain a domestic commodity prone to periodic producer oversupply? EQT has positioned itself, through substantial capital commitment, as a primary beneficiary of the first scenario. Should the second scenario persist, the company's low cost structure may leave it as the most resilient incumbent, even if macro returns fall short of management's growth narrative.
The strategic thread originating with George Westinghouse remains central to the enterprise. Westinghouse achieved commercial success not merely by extracting natural gas, but by engineering the distribution systems required to transport it safely to paying customers. Nearly a century and a half later—and following an expensive detour through the belief that production and transportation were separate businesses—EQT has returned to that foundational premise: in landlocked commodity markets, controlling takeaway infrastructure dictates long-term asset value.
References
-
EQT Corporation Investor Relations Main Portal — EQT Corporation ↩↩
-
EQT Corporation 2023 Form 10-K Annual Report — U.S. Securities and Exchange Commission, 2024-02-14 ↩↩↩↩↩↩↩↩↩↩
-
Form 8-K: Results of 2019 Annual Shareholder Meeting (Universal Proxy Fight Vote) — U.S. Securities and Exchange Commission, 2019-07-10 ↩
-
Rice brothers win control of EQT board in proxy fight — Reuters, 2019-07-10 ↩
-
EQT to Buy Equitrans Midstream in All-Stock Deal Valued at Over $35 Billion — The Wall Street Journal, 2024-03-11 ↩
-
Mountain Valley Gas Pipeline Cleared to Start Up by US Regulator — Bloomberg, 2024-06-11 ↩↩↩
-
EQT Acquisition of Rice Energy SEC S-4 Prospectus / Joint Proxy Statement — U.S. Securities and Exchange Commission, 2017-09-29 ↩
-
EQT Corporation Form 8-K: Non-Operated Assets Sale in Northeast Pennsylvania — U.S. Securities and Exchange Commission, 2024-04-24 ↩↩
-
S&P Global Commodity Insights Natural Gas Analysis & Basin Coverage — S&P Global ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube