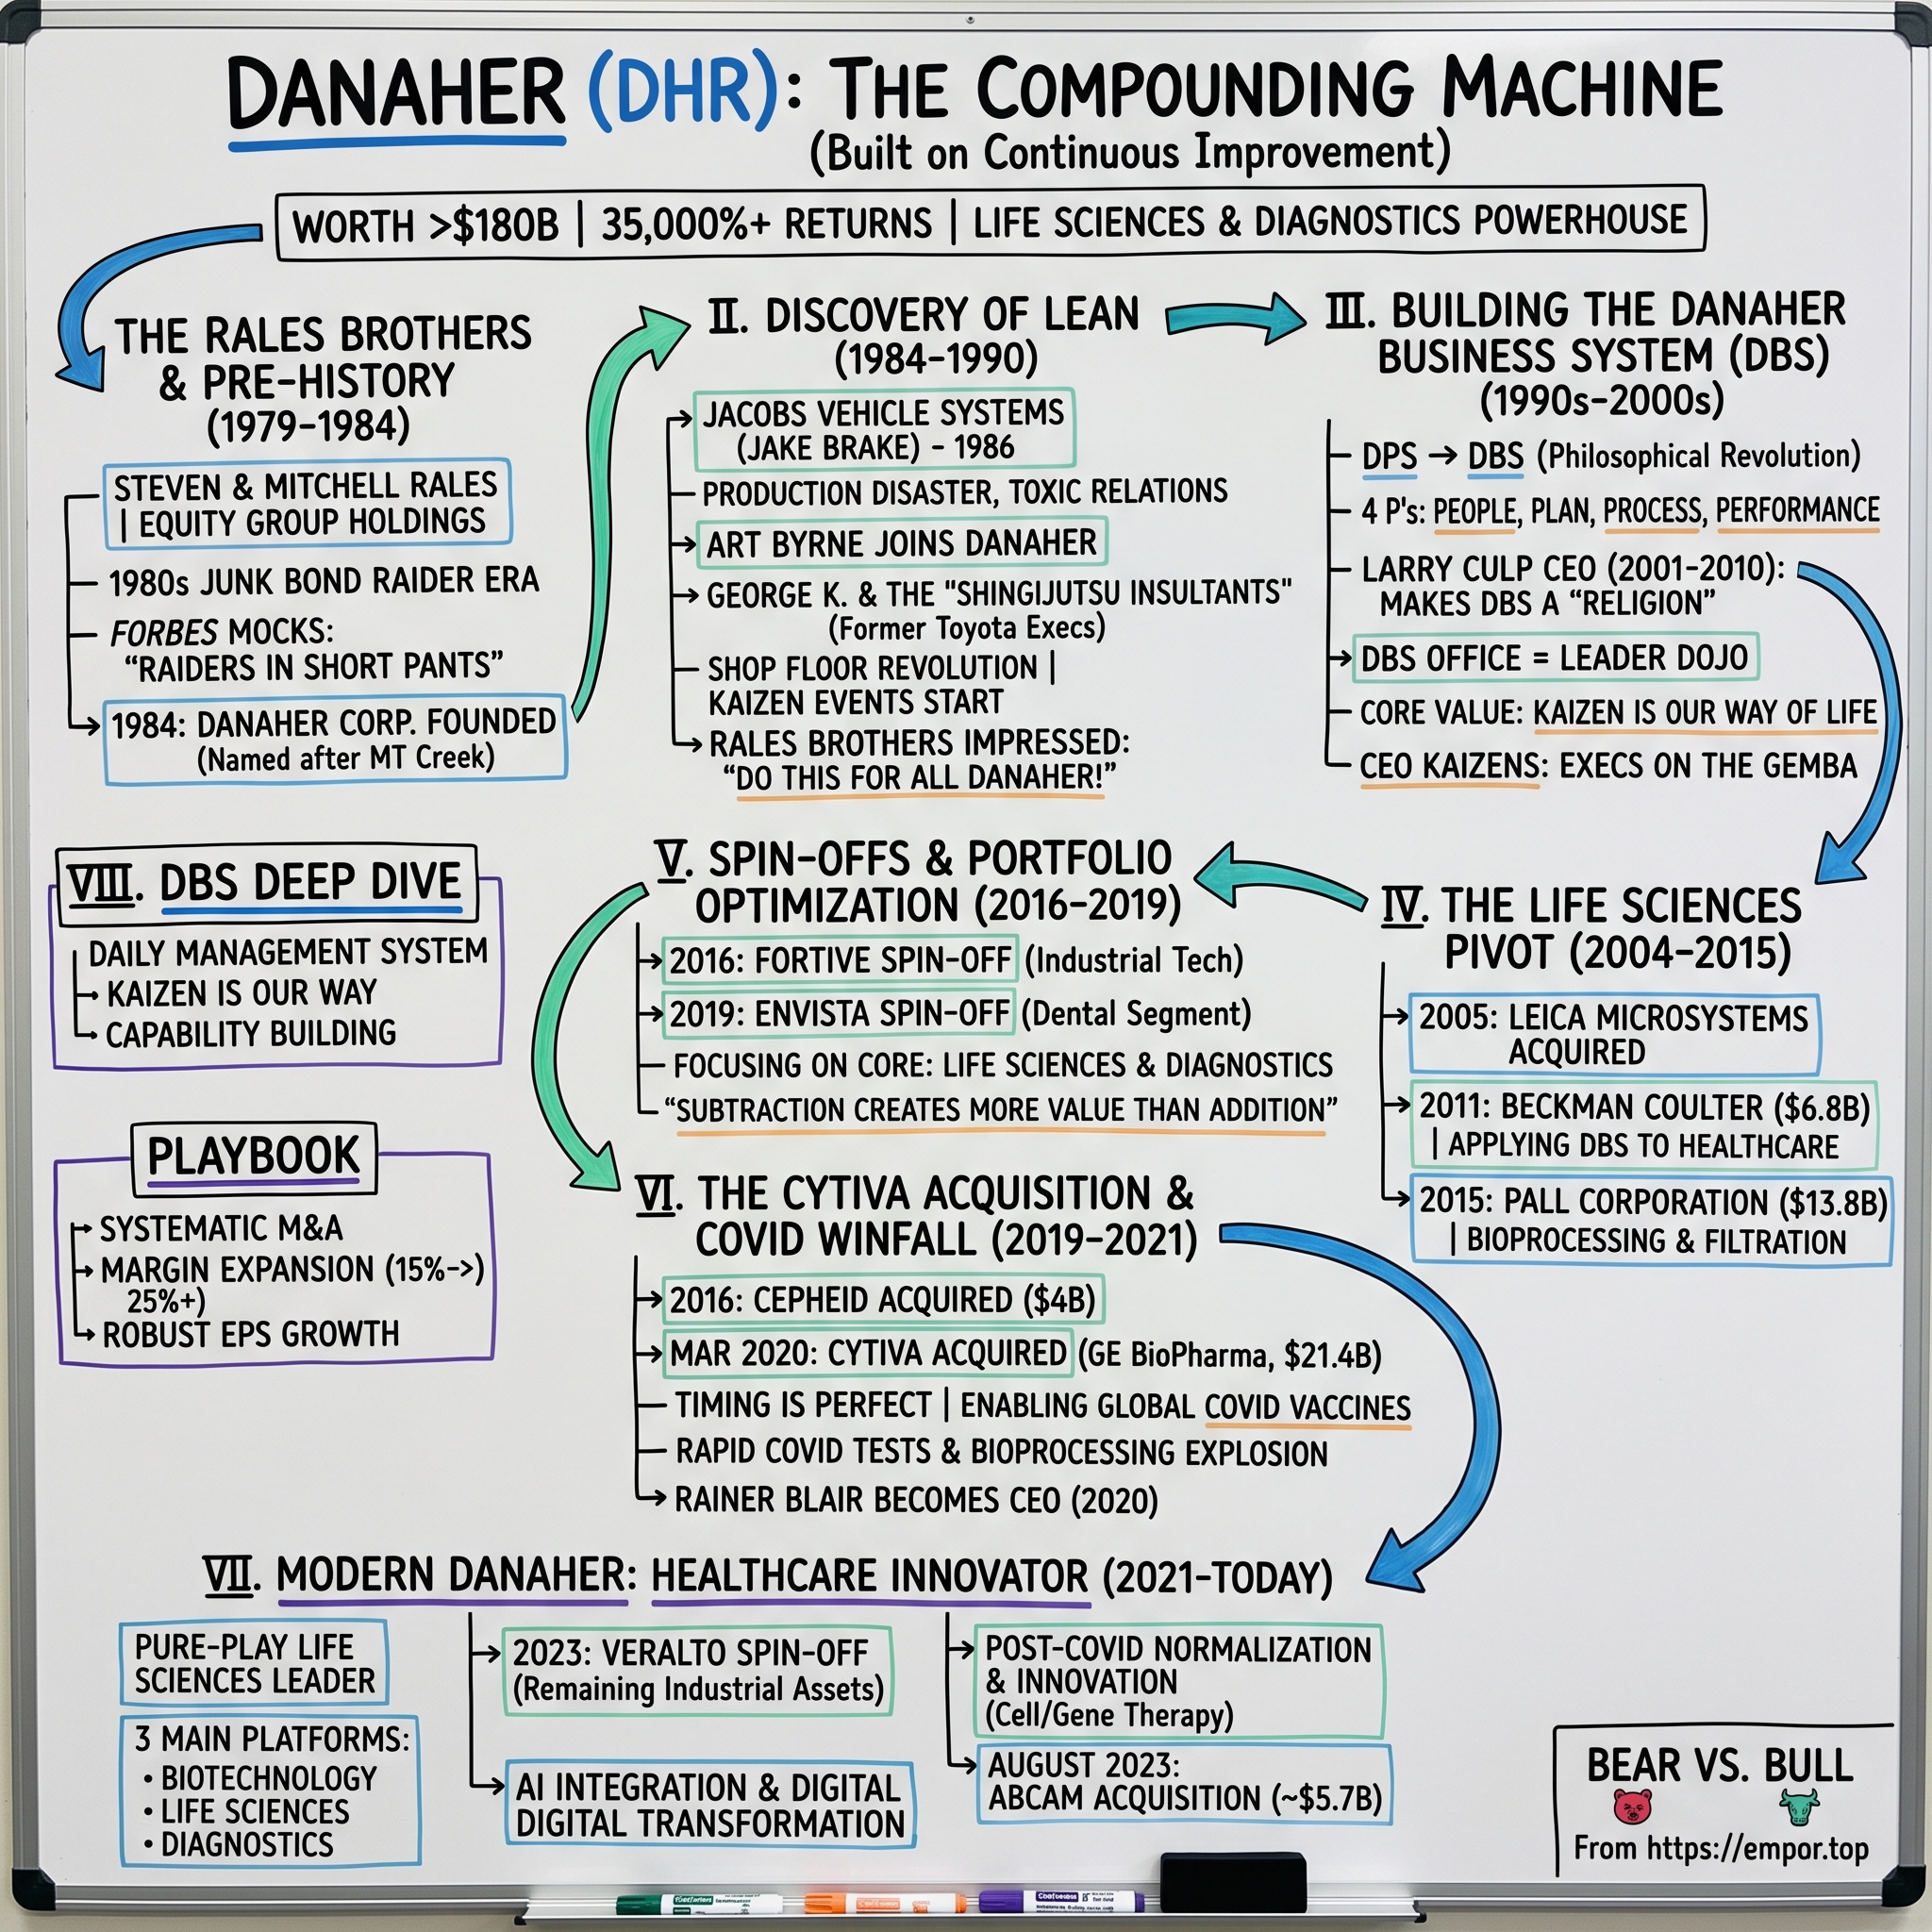
Danaher Corporation: The Compounding Machine Betting on the Bioprocessing Cycle
I. Introduction & Episode Thesis
Here is the number that defines Danaher in September 2026: roughly $145 billion of market value, spread across 703 million shares trading near $206 apiece.1 It is a very large number. It is also a smaller number than it was.
Over the twelve months ending this week, Danaher shares traded as high as $242.80 and as low as $160.93 — a peak-to-trough range of more than 50% of the low, in a company that sells reagents, antibodies, blood-gas analyzers and chromatography resin to hospitals and drugmakers.1 These are not cyclical products in the way steel or semiconductors are cyclical. Patients do not stop needing diagnostic tests. Biologic drugs do not stop being manufactured. And yet the equity has behaved as if it were levered to a commodity cycle, because for the past five years, it has been.
The cleanest way to see it is not in the share price but in the earnings. In 2021, Danaher generated $29.5 billion of revenue and adjusted earnings of $10.05 per share, up 59% in a single year.2 Five years later, management has guided full-year 2026 adjusted earnings to a range of $8.45 to $8.60.3 Some of that gap is structural rather than operational — the 2021 figure included the water-quality and product-identification businesses that departed in 2023 — but even measured on today's narrower portfolio, adjusted earnings per share have moved from $7.58 in 2023 to a guided midpoint near $8.52 in 2026: compounding in the low single digits, against a long-term financial model that promises double-digit-plus earnings growth.453
This is a company whose own investor deck, in the most recent version, prints a total-shareholder-return table showing Danaher returning 286% over ten years against 298% for the S&P 500.5 Management put a decade of underperformance in its own presentation. That is either unusual candour or unusual confidence that the ten-year window is the anomaly. This article is largely about which.
The paradox in one line. Two brothers whom Forbes dismissed in November 1985 as "Raiders in short pants" — and whose strategy the magazine called "cocky to the point of foolishness" — went on to build a management system that industrial companies still send executives to study.6 The Danaher Business System, or DBS, is treated by much of Wall Street as a genuine institutional edge, a repeatable machine for buying mediocre assets and making them good. And yet DBS did not stop a two-year bioprocessing bust that erased tens of billions of dollars of market value, did not prevent a sequence of guidance cuts in 2023 that damaged management's forecasting credibility, and did not prevent a fresh, smaller version of the same surprise in the second quarter of 2026.
That distinction — between what DBS has demonstrably done and what it has never demonstrably done — is the analytical spine of this story. It is also the most common place where the bull case on Danaher gets sloppy.
Where the company stands today. Danaher Corporation is headquartered at 2200 Pennsylvania Avenue in Washington, D.C., employs approximately 60,000 people, and reports in three segments: Biotechnology, Life Sciences and Diagnostics.7 In fiscal 2025 it generated $24.57 billion of revenue, up 3.0% reported and 2.0% on the core basis that strips out currency and acquisitions, with a GAAP operating margin of 19.1% and free cash flow of $5.3 billion.8 Roughly 80% of that revenue is recurring — consumables and service pulled through an installed base of instruments, the razor-and-blade model applied to laboratories.5
The portfolio arrived at this shape by subtraction as much as addition. Fortive left in 2016 with the test-and-measurement and industrial businesses.9 Envista, the dental platform, was separated starting in 2019.10 Veralto took the water-quality and product-identification businesses in 2023.11 What remains is close to a pure-play life sciences and diagnostics company — and on June 10, 2026, it added its largest acquisition since the COVID era, closing the $9.9 billion purchase of Masimo, the pulse-oximetry and patient-monitoring specialist.12
And on August 3, 2026, the board announced that Rainer Blair would retire and that Julie Sawyer Montgomery, the executive who has run Diagnostics, would become President and Chief Executive Officer effective October 1, 2026.13 Danaher is therefore three weeks away from a leadership change, one quarter into digesting a $9.9 billion acquisition, and one quarter removed from a bioprocessing revenue surprise that management insists was timing rather than demand.
The story of how it got here starts with a bankrupt real estate trust and a creek in Montana.
 Subscribe on LinkedIn
II. Origins: From Real-Estate Roll-Up to Industrial Conglomerate (1969–1990)
The origin story does not begin with a laboratory. It begins with a tax shield.
In 1979, Steven and Mitchell Rales — sons of a Washington-area businessman, in their late twenties and early thirties — formed an investment vehicle called Equity Group Holdings. What they eventually took control of was, in Forbes' description, "a bankrupt real estate investment trust with two years of tax-loss carryforwards that were to be used to shelter profits from newly acquired manufacturing businesses."6 In 1984 they renamed the shell after a creek in Montana where they had fished. Danaher Corporation was, at inception, less a company than a container.14
The financial press was unkind. That November 1985 Forbes piece mocked not only the strategy but the men: Steven was 34, Mitchell 29, and the magazine judged their real-estate mentality unsuited to running factories.6 The Raleses did what leveraged acquirers of the era did — they bought aggressively, some of it financed with junk debt, and they bought things nobody would call glamorous. The Easco acquisition brought them the hand-tool business that supplied Sears' Craftsman line, a franchise Forbes later valued at roughly $300 million of annual revenue.6 Socket wrenches. Not exactly the leading edge of American industry.
Why does any of this matter to someone evaluating a life-sciences company in 2026? Because the DNA set in those years never changed, and every subsequent chapter is a variation on it.
Three habits formed early and persist. First, growth by acquisition funded by internally generated cash and balance-sheet capacity, rather than by organic invention — Danaher has always been a buyer of positions, not a builder of them from scratch. Second, concentrated founder ownership: by 2000 the brothers together held roughly a third of the stock, and four decades on they still own a combined 10.7% and sit as Chairman of the Board and Chairman of the Executive Committee respectively.615 Third, a persistent taste for assets that are temporarily out of favour, structurally sound, and operationally sloppy. That pattern recurs with striking consistency — Beckman Coulter after a product recall and management turmoil, Pall after years of underperforming its own potential, and Masimo after an activist campaign removed its founder-CEO.
The genuine inflection, though, was not financial. It happened on a factory floor in Connecticut.
The Jake Brake moment. Danaher owned Jacobs Manufacturing, maker of the Jacobs engine brake — the "Jake Brake," the device responsible for the machine-gun clatter a heavy truck makes descending a hill. In 1987, executives at that division began importing something American manufacturing had mostly admired from a distance: the Toyota Production System. Art Byrne and George Koenigsaecker brought over the Japanese consultancy Shingijutsu, whose principals — Yoshiki Iwata and Chihiro Nakao — had been direct disciples of Taiichi Ohno, the architect of Toyota's system.16 They were, at the time, teaching at the University of Hartford.
What Shingijutsu taught was not a software package or a reorganisation. It was kaizen — a discipline of relentless, small, continuous improvement executed by cross-functional teams in intense week-long bursts, where the team does not merely diagnose a problem but physically rebuilds the production cell before the week ends.17 The unglamorous truth of lean manufacturing is that most of the value comes from removing things: inventory, floor space, handoffs, waiting time. It is closer to editing than to engineering.
Danaher became one of the earliest large North American adopters, and the practice spread from Jake Brake outward through the portfolio.14 What began as a manufacturing technique would, over the following two decades, be generalised into an operating philosophy that governs how Danaher hires, how it launches products, and — critically for investors — how it justifies the prices it pays for acquisitions.
In 1990, George Sherman arrived as chief executive, a Black & Decker power-tools veteran who set about converting a collection of purchased businesses into something resembling an operating company.6 The Raleses stepped back from day-to-day management into the ownership-and-capital-allocation roles they have occupied ever since — a division of labour that has now persisted for thirty-six years, and which is either the source of Danaher's long-horizon discipline or, to a sceptic, an entrenchment structure with no expiry date.
The roll-up had found a religion. The next twenty years were spent turning that religion into a valuation argument.
III. Building the Danaher Business System (1990s–2014)
The best contemporaneous evidence of what DBS actually did in its formative years is not a Danaher press release. It is a Forbes article from January 2000 titled "Shrink That Factory," written when the company was a $3 billion maker of hand tools and environmental controls — and when the magazine that had once mocked the Raleses had rather visibly changed its mind.6
Forbes described Danaher as "a cross between an American-style corporate raider and a Japanese operations fanatic," and called DBS what it plainly was at the time: "a knockoff of the Toyota Production System."6 The case study it offered was Fluke, the test-instrument maker Danaher had acquired. Under DBS, Sherman's team drove Fluke's selling, general and administrative costs down to 25% of revenues, cut factory floor space in half, and lifted the operating margin to 15% by 1999.6 Over the decade, Danaher's earnings per share compounded at 24% a year from 1994, and the stock rose roughly eighteenfold.6
That is the historical bedrock of the DBS-as-moat claim, and it deserves to be taken seriously. It is a documented, contemporaneous, third-party account of a specific acquired company whose cost structure was materially rebuilt. It is not a slide.
What DBS became. Over time the system expanded beyond the shop floor into a four-part framework the company describes as People, Plan, Process and Performance — a structure covering talent selection, strategic planning, execution and measurement. Danaher built an internal DBS Office that certifies practitioners and deploys them into newly acquired businesses, and it institutionalised "CEO Kaizen" events in which the most senior leaders spend a week working alongside factory associates on a specific operating problem.17 The company's language about this is deliberately cultural rather than procedural: "Kaizen is our way of life" is a stated core value, and Blair has described the appeal as "leaders dropping their rank at the door, getting their hands dirty."17
There is a reason to be careful here. Every large industrial company now claims an operating system. Thermo Fisher Scientific, Danaher's most direct and much larger competitor, attributes its own performance to the "PPI Business System" in exactly the same register.18 The existence of a named methodology proves nothing. What would prove something is a differential in outcomes against peers running comparable systems — and that test is applied in Section IX, where the evidence is genuinely mixed.
The Culp era. Larry Culp became chief executive in 2001 at the age of 38 and ran the company until 2014, a stretch during which Danaher's revenue and market value both grew several-fold and during which the acquisition machine ran hottest. Culp's contribution was less the invention of DBS than its industrialisation: converting a philosophy that worked when applied by a handful of true believers into a standardised process that could be deployed across dozens of businesses in parallel, and — crucially — into an underwriting discipline. If DBS could reliably add several hundred basis points to an acquired company's margin, then Danaher could rationally pay a price that a financial buyer could not.
That is the intellectual core of the whole enterprise, and it is worth stating plainly because it is where the risk sits. Danaher's willingness to pay high multiples is not a bug; it is the direct expression of a belief that the multiple compresses on its own through operational improvement. The strategy works if and only if the improvement is real, repeatable, and larger than the premium paid.
Culp also began the strategic redirection that defines Danaher today. Industrial products — tools, motion control, test and measurement — were cyclical, competitively crowded, and slowly commoditising. Healthcare and life-science tools offered something structurally better: instruments sold once that pull consumables forever, customers whose manufacturing processes are registered with regulators and therefore expensive to change, and demand driven by demographics rather than capital-expenditure cycles.
At least, that was the theory. The bioprocessing bust of 2023 would eventually demonstrate that life-science tools have a capital-expenditure cycle too — it is simply the customer's, not Danaher's. But that lesson was two decades away. First came the buying.
IV. The Life Sciences & Diagnostics Pivot (2004–2019)
Every acquisitive company has a deal that changes what it is. Danaher has had four. Two of them landed in this period.
The pivot began quietly. Radiometer, the Danish blood-gas analyser business, established the diagnostics beachhead in 2004. Leica Microsystems, acquired in 2005, established the life-sciences one, and gave Danaher a genuinely premium brand in optical instrumentation.7 These were sensible, mid-sized purchases in adjacent markets. They were not a strategy statement.
Beckman Coulter was a strategy statement. On February 7, 2011, Danaher announced it would acquire Beckman Coulter for $83.50 per share in cash, a total enterprise value of approximately $6.8 billion.19 The premium was substantial — roughly 45% over Beckman's closing price on December 9, 2010, the day market speculation about a sale began.19 Beckman generated about $3.7 billion of annual revenue, meaning Danaher paid roughly 1.8 times sales for a business whose diagnostic systems sat in hospital laboratories worldwide.19
For context on how large a bet this was: Danaher's entire 2010 revenue was $13.2 billion across 48,000 employees.19 The company was acquiring a business equal to more than a quarter of its own size, in a field it had entered only seven years earlier, at a 45% premium, for a target that had recently endured product-quality problems and management upheaval. Culp's public rationale was characteristically direct — Beckman was "an iconic company with a great brand, broad reach and technology leadership," and Danaher's contribution would be "the processes by which Danaher accelerates growth through new product innovation and driving sales, marketing and service, as well as its strength in continuously expanding margins."19
That is the DBS thesis stated as an acquisition rationale, and it is worth marking because it is testable. Fifteen years later, Beckman Coulter Diagnostics sits inside a Diagnostics segment that generated $9.94 billion of revenue at a 26.7% GAAP operating margin in 2025 — the highest-margin segment in the company.8 On the most recent earnings calls, Beckman Diagnostics has been described as growing mid-single digits globally with continued installed-base expansion, led by immunoassay reagents and the DxI 9000 analyser.20 Judged over fifteen years, the Beckman integration substantiates the claim that DBS can take a large, troubled, scaled asset and make it structurally more profitable. That is a real data point, and the strongest single piece of evidence in the DBS-as-moat argument.
Pall Corporation was the other one. On May 13, 2015, Danaher agreed to acquire Pall for $127.20 per share, an enterprise value of approximately $13.8 billion.21 Pall generated $2.8 billion of revenue in its fiscal year ended July 2014 — split between a $1.5 billion life-sciences segment and a $1.3 billion industrial one — meaning Danaher paid nearly five times sales.21 That is a rich price for a filtration company, and then-CEO Tom Joyce's justification revealed exactly what Danaher believed it was buying: "approximately 75% recurring revenues, mid-single digit organic growth and a solid margin profile."21
Filtration is worth pausing on, because it is genuinely central to everything that follows. When a biologic drug — a monoclonal antibody, say — is manufactured, it is grown inside living cells in a bioreactor, and the resulting broth is a soup containing the desired protein plus cell debris, host proteins, viruses and assorted contaminants. Getting the drug out of that soup involves a sequence of filtration and chromatography steps: coarse clarification, then capture on a chromatography resin that selectively binds the target molecule, then viral inactivation and filtration, then polishing, then sterile filtration into the final vial. Each of those steps consumes a physical consumable that is bought again for every batch, forever.
The reason this matters commercially is regulatory. When a drugmaker files for approval, the manufacturing process is described in the submission — including which resin, which membrane, which single-use bag. Changing a specified component after approval can require regulatory notification and, in some cases, comparability studies. In the industry's language, the supplier is "specced in." That is a genuine switching cost, and it is the mechanism behind essentially every durable claim Danaher makes about its bioprocessing business.
Pall gave Danaher the filtration half of that workflow. It was the platform on which the Cytiva bet would later be placed.
And then Danaher started selling. In July 2016 it completed the separation of Fortive, distributing the test-and-measurement, industrial-technology and retail-petroleum businesses to shareholders.9 In September 2019 it took the dental platform public as Envista.10 Both were profitable, well-run businesses. Both were sold anyway.
The stated logic was focus. The uncomfortable alternative reading — which an honest analysis has to hold alongside it — is that spinning out slower-growing, lower-multiple businesses mechanically improves the growth rate and margin of whatever remains, independent of any operating improvement. Both explanations are true simultaneously, and neither is a criticism. The separations were structured to be tax-free to shareholders under Sections 355(a) and 368(a)(1)(D) of the Internal Revenue Code, and outside tax counsel opined accordingly.7 Shareholders received the businesses rather than watching Danaher sell them and keep the cash — a meaningful distinction from the average conglomerate divestiture.
By the end of the decade, Danaher had assembled a focused life-sciences and diagnostics platform with a filtration backbone and a diagnostics engine. Then a virus arrived.
V. The Cytiva Acquisition, COVID Windfall, and the Bust That Followed (2019–2024)
In February 2019, General Electric was in the worst condition of its modern history and needed cash urgently. It had been preparing an initial public offering of its healthcare division. Instead, on February 25, 2019, it agreed to sell the biopharma business of GE Life Sciences to Danaher for approximately $21.4 billion — $21 billion of cash plus assumed pension liabilities, with a net purchase price of roughly $20 billion after anticipated tax benefits.22
The business generated about $3.2 billion of expected annual revenue, roughly 75% of it recurring, and it supplied the other half of the biologics manufacturing workflow that Pall did not: process chromatography hardware and consumables, cell-culture media, single-use technologies and development instrumentation.22 Danaher relaunched it in April 2020 under the name Cytiva. Regulators required a divestiture, and in October 2019 Danaher agreed to sell certain businesses to Sartorius — the German competitor that would spend the next several years as its closest peer.
The strategic logic was clean: Pall plus Cytiva meant Danaher could supply nearly the entire path from cell culture to final fill. The price was not clean. Roughly 6.7 times revenue for a tools business is a price that requires either sustained high-single-digit growth or substantial margin expansion, and preferably both.
Then the world's biologics manufacturing capacity was mobilised at once. Two Danaher businesses sat directly in the path. Cepheid — acquired in September 2016 for $53.00 per share, about $4 billion, when it generated $539 million of revenue and Danaher's entire Diagnostics segment was a $5 billion platform — made the GeneXpert system, a molecular diagnostic instrument that runs a self-contained cartridge and returns a PCR result in under an hour without a specialist laboratory.23 It was designed for tuberculosis testing in low-resource settings. It turned out to be almost perfectly suited to a respiratory pandemic. And Cytiva's chromatography resins and single-use bioreactor components were consumed by every vaccine and monoclonal-antibody manufacturing line on earth.
The financial result was extraordinary. Revenue rose 32% in 2021 to $29.5 billion, with core growth of 25%. Adjusted earnings per share rose 59% to $10.05. Free cash flow reached $7.1 billion. The operating margin hit 25.3%.2 Blair, who had become chief executive in 2020, called it "a tremendous year" and noted that Danaher had deployed $11 billion on acquisitions during it — including Aldevron, a Fargo, North Dakota manufacturer of plasmid DNA, mRNA and proteins founded in 1998, bought for approximately $9.6 billion in cash with roughly 600 employees.224
Hold that Aldevron number. It returns later, in a less flattering context.
The unwind. The problem with a demand shock is that customers respond to it by ordering more than they need. Through 2021 and 2022, large biopharmaceutical manufacturers — nervous about supply-chain fragility and long lead times — built substantial safety stocks of bioprocessing consumables. When lead times normalised and pandemic-driven volumes receded, those customers stopped ordering and drew down inventory instead. This is the classic bullwhip effect, and it hit a business Danaher had just paid $21.4 billion for.
The most instructive single day was April 25, 2023. Danaher reported a first quarter that beat expectations on both revenue and earnings — and the stock fell more than 6%, to around $239, because management cut the year.25 The details matter. Growth expectations for Danaher's largest bioprocessing customers, representing roughly 70% of bioprocessing sales, were reduced from 7–8% to about 6%. The remaining cohort — emerging biotechnology companies — went from an expected low-teens increase to an expected mid-teens decline, as the collapse of Silicon Valley Bank tightened funding and accelerated project cancellations. Full-year core revenue guidance moved from a mid-single-digit decline to a high-single-digit decline, and the adjusted operating margin outlook came down.25 Management said inventories would now normalise in the second half of the year rather than the first.
They did not normalise in the second half either. Full-year 2023 revenue fell 10.5% to $23.9 billion, with core revenue down 10.0%.4 The following year was not a recovery: 2024 revenue was flat at $23.9 billion with core revenue down another 1.5%, and adjusted earnings per share fell from $7.58 to $7.48.26 Two consecutive years of no growth, in a business bought on a growth thesis.
What the episode does and does not prove. It is important to be precise, because this is where most analysis goes wrong in one direction or the other.
It does not prove that Cytiva was a bad asset or that the moat failed. Through the entire downturn, Danaher did not lose the specced-in positions. The bioprocessing market remained a concentrated oligopoly of four credible suppliers — Danaher's Cytiva, Sartorius, Thermo Fisher and Merck KGaA — and customers did not switch vendors; they simply stopped buying for a while. The distinction between a share loss and a volume pause is the whole ballgame, and the evidence supports the latter. Bioprocessing generated more than $6 billion of revenue in 2025, with more than 80% of it tied to monoclonal antibodies, and Danaher states that Cytiva supported more than 90% of global monoclonal-antibody production volume that year.5 Customer retention was not the failure.
What it does prove is narrower and, for investors, more useful: Danaher's visibility into when its largest customers will actually order is poor. Management repeatedly told the market that destocking would end sooner than it did. The forecasting error was not a single miss but a sequence, and the sell side noticed. Two years of guidance revisions is a data point about a capability, not about a quarter.
Weighing it. The right conclusion is that the 2023–24 episode narrows the Danaher thesis rather than rejecting it. The claim that Danaher holds a defensible, high-switching-cost position in biologics manufacturing survives, supported by retention through a severe demand shock and by the concentrated structure of the supplier base. The separate claim — that DBS confers superior insight into end-market demand — is not supported. Those are different claims, and conflating them is the single most common error in the bull case.
The falsifiable test going forward is whether the recovery Danaher now describes is durable. That test is being run in real time, and Section VII shows the first ambiguous result. But before that: in the middle of the worst of it, Danaher decided to make itself smaller again.
VI. Portfolio Discipline: The Veralto Spin-off (2022–2023)
There is a specific kind of corporate courage in announcing a divestiture while your core business is falling apart. Danaher announced its intention to separate the Environmental & Applied Solutions segment in September 2022, and completed it on September 30, 2023 — the same year revenue declined 10.5%.114
The mechanics were straightforward and shareholder-friendly. Danaher stockholders of record on September 13, 2023 received one share of Veralto Corporation for every three Danaher shares held, and the new company began regular-way trading in early October.11 Veralto took thirteen operating companies with it — including Hach in water analytics, ChemTreat in water treatment, Trojan Technologies in ultraviolet disinfection, Videojet and Linx in industrial marking and coding, and Esko, Pantone and X-Rite in packaging and colour management.27 As partial consideration, Veralto made a $2.6 billion cash payment to Danaher on September 20, 2023.27
This was Danaher's third value-realising separation in under a decade. The pattern is now long enough to interrogate seriously, and the interrogation cuts two ways.
The generous reading is that Danaher has demonstrated an unusual willingness to shrink. Most conglomerates accumulate; very few systematically hand businesses back to shareholders. Each separation was structured to be tax-efficient, each created an independent company with its own currency and capital allocation freedom, and none involved a fire sale to a financial buyer at a discount. Blair's framing at the time was that the remaining company was "a more focused Life Sciences and Diagnostics Innovator with an enhanced long-term growth and earnings trajectory."4
The sceptical reading is that this is portfolio cosmetics with a tax-free wrapper. Every spin-off removed businesses growing more slowly and trading at lower multiples than the retained portfolio. Do that three times and the parent's reported growth rate and margin improve mechanically, without any operating improvement whatsoever. The remaining company then trades at a premium multiple partly justified by growth characteristics that were engineered through subtraction.
Both readings are correct, and it is intellectually dishonest to pick one. The honest formulation is this: the separations are demonstrably good governance and demonstrably good portfolio optics, and an investor should credit the first while declining to pay twice for the second.
There is one measurable consequence worth flagging. A narrower portfolio is a less diversified portfolio. In 2021, when bioprocessing was booming, Environmental & Applied Solutions was a steady $4.65 billion business growing modestly and providing ballast.2 By 2023 that ballast was gone — and the bioprocessing downturn hit a company with three segments instead of four, two of which shared exposure to the same biopharmaceutical customers. The 2023 revenue decline was therefore amplified by a decision made for entirely defensible reasons. Focus is a real benefit; it is not a free one.
What remained was a company whose economics now depend almost entirely on three questions: whether bioprocessing demand is durable, whether Life Sciences instruments can grow, and whether Diagnostics can be more than a steady compounder. Those are the questions the 2026 numbers answer, and the answers are not uniform.
VII. Modern Danaher: Segment Economics & the 2026 State of Play
Start with the segment that works, because it clarifies everything else.
Biotechnology — Cytiva and Pall's bioprocessing operations, plus a discovery-and-medical business — generated $7.29 billion of revenue in 2025 with core growth of 6.5%, the fastest in the company, at a GAAP operating margin of 25.6%.8 But the GAAP figure materially understates the economics. Strip out $902 million of acquisition-related intangible amortisation and $101 million of impairment charges, and adjusted segment operating profit was $2.87 billion — an adjusted margin near 39%.8 That is the real profit engine, and it is why the bioprocessing cycle dominates the equity story: roughly 30% of revenue produces roughly 41% of adjusted segment profit.
Diagnostics is the largest segment at $9.94 billion of 2025 revenue and the steadiest, at a 26.7% GAAP margin and about 28.6% on an adjusted basis.8 It houses Beckman Coulter Diagnostics, Cepheid, Radiometer, Leica Biosystems, HemoCue and Mammotome — and now Masimo. Core growth was 1.5% in 2025.8 That number requires context: Cepheid's respiratory testing revenue is a large, weather-dependent swing factor that Danaher now runs at roughly $1.6 billion a year, and China's volume-based procurement policies have imposed a sustained pricing headwind that management sized at $75–100 million for 2026.28
Life Sciences is where the story gets uncomfortable, and where the headline number is genuinely misleading. The segment reported $7.33 billion of 2025 revenue, core revenue down 1.5%, and a GAAP operating margin of 7.1% — against 25.6% and 26.7% in the other two.8 Read literally, that looks like a broken business.
It is not, and the accounting deserves to be unpacked carefully because it is the single most misread figure in Danaher's disclosures. That 7.1% is after $604 million of acquisition intangible amortisation and $446 million of other charges.8 On an adjusted basis, Life Sciences generated $1.57 billion of operating profit — a margin of about 21.4%.8 Not the company's best, meaningfully below its 2024 adjusted level of roughly 23.2%, but a normal profitable instruments-and-consumables business rather than a distressed one.
The charges themselves, however, are the real story — and they are not noise. In 2024, Danaher took a $222 million pretax impairment on an indefinite-lived trade name in its genomics consumables business, citing softness in the genomics market, discontinued drug development programmes and weaker demand at larger customers.7 In the second quarter of 2025, having decided to reorganise and integrate certain Life Sciences businesses, the company concluded that the same trade name was no longer indefinite-lived, and took a further $432 million pretax charge — $328 million after tax.7 Total: $654 million written off the same brand in two years.
Danaher does not name the business. What the filings do say is that the Life Sciences core sales decline was "led by the life science consumables business, primarily in North America, driven by lower demand for the plasmids and mRNA product lines at two large customers."7 Plasmids and mRNA is Aldevron's product line. On the second-quarter 2026 call, Blair referred to "Aldevron continuing to make progress aside from those two large customers that we've talked about previously."20 The filings stop short of the identification; the disclosed drivers point in one direction.
Whichever brand it is, the analytical point stands independently: Danaher deployed approximately $9.6 billion in 2021 on a genomics-consumables business at the peak of the mRNA boom, and has since written down brand value associated with that part of the portfolio twice, concluding along the way that the brand's economic life is finite rather than indefinite.247 Any assessment of Danaher's capital allocation that calls it disciplined without confronting this is incomplete. The company's goodwill has not been impaired — no goodwill impairment was recorded in 2023, 2024 or 2025 — but the trade-name writedown is a real, audited admission that a specific acquisition thesis did not develop as underwritten.7
The 2026 quarters: recovery, with an asterisk that arrived on schedule.
The first quarter of 2026 delivered $5.95 billion of revenue but only 0.5% core growth, because a light respiratory season cost roughly 250 basis points at Cepheid.29 Beneath that, the news was better than the headline: Biotechnology core revenue grew 7%, bioprocessing consumables grew high single digits, and — the number that moved the narrative — bioprocessing equipment orders grew more than 30% year over year, the first positive year-over-year equipment order comparison in nearly two years.28 Blair told analysts the company was "in the early stages of a multiyear investment cycle," seeing brownfield capacity projects now with larger greenfield investments expected to follow.28
Then came the second quarter, reported on July 21, 2026, and it is the most important data point in this entire article.
Revenue was $6.3 billion with 3% core growth — 4.5% excluding respiratory testing, a 150 basis point acceleration.320 Life Sciences, the problem child, grew 5.5% core, its strongest quarter in several years, with Pall's applied filtration business up about 10% on semiconductor and memory demand and Abcam delivering what Blair called "the best quarter here that we've had since the acquisition."20 Diagnostics grew 5% excluding respiratory.20 By almost every measure, the recovery thesis was working.
Except in bioprocessing, where it did not. Consumables grew only low single digits, because a small number of large chromatography resin shipments — typically $10–30 million each — moved out of the year entirely. Chief Financial Officer Matt Gugino quantified it: roughly a 500 basis point hit to bioprocessing growth in the quarter, on the order of $50–60 million, and "a little bit north of $100 million" shifting out of the second and third quarters into 2027, worth a couple of hundred basis points to full-year bioprocessing growth.20 Full-year core revenue guidance narrowed from 3–6% to 3–4%.3
The analyst pushback was the most revealing part of the call, and it was not deferential. Bank of America's Michael Ryskin went first and did not accept the framing: "Why is that revenue not coming back in 3Q and 4Q? You're not catching it back in 3Q, 4Q. Is this a multi-quarter rebase?"20 He followed up on the underlying issue directly — "is there anything that's changed with visibility in the business? We spent a couple of years worrying about destocking, and it seems like we've moved past that, but still, there's a lot of questions on visibility."20 Citi's Patrick Donnelly pressed the same nerve from another angle: "in terms of seeing multiple customers all push out within a few weeks of each other, seemingly all into 2027 — why would multiple customers all at essentially the same time do this push out?"20
Management's answers were consistent and specific. Blair attributed the delays to customer production-schedule changes and site-readiness challenges at "a few large commercial manufacturers where we're specced into those molecules," noted the deferrals spanned different molecules and geographies, and pointed to the order book as the countervailing evidence: consumables and equipment orders both grew mid-teens in the quarter.20 He also directly addressed the destocking comparison, arguing that the customer-inventory visibility processes built after 2023 are functioning and show market-wide inventory levels "quite a bit lower than they have been in prior years."20
How to weigh this. The bull interpretation is defensible: orders growing mid-teens across both product categories is difficult to reconcile with deteriorating demand, and a shipment that slips because a customer's plant is not ready is genuinely different from a shipment cancelled because a customer does not need the product. Gugino said explicitly that management thinks "it's highly unlikely that it does not return in 2027."20
The bear interpretation is also defensible, and it is not about this quarter. It is that in 2023 and again in 2026, Danaher's revenue was surprised to the downside by the ordering behaviour of a small number of very large biopharmaceutical customers, and that management did not see either surprise coming. The magnitudes are wildly different — 2023 was a multi-billion-dollar demand collapse, 2026 is a hundred-million-dollar timing shift — but the mechanism is identical, and it recurred after management had explicitly built processes to prevent it.
The calibrated conclusion: the recovery claim survives this quarter but remains unproven, and the concentration of bioprocessing revenue in a handful of large manufacturers is a permanent structural feature of the business rather than a passing condition. The specific event that would confirm the recovery is bioprocessing revenue — not orders — converting to mid-to-high single-digit growth in the fourth quarter of 2026 and holding there, with the deferred resin shipments actually recognised in 2027. The event that would falsify it is a second deferral, or order growth that fails to translate into revenue for another two quarters.
Masimo. Announced February 17, 2026 and closed June 10 — ahead of the second-half timeline the company originally guided to — the acquisition brought Masimo in at $180 per share, an enterprise value of approximately $9.9 billion, roughly 18 times estimated 2027 EBITDA or 15 times including full expected synergies.3012 Masimo generated about $1.5 billion of revenue in 2025, growing around 9%, so Danaher paid roughly 6.6 times sales.31
The targets are unusually specific and therefore unusually checkable: EBITDA above $530 million in 2027; more than $125 million of annual cost synergies (of which about $50 million in gross margin, $50 million in operating expense and $25 million in eliminated public-company costs) and more than $50 million of revenue synergies by the fifth full year; accretion of $0.15–0.20 per share in year one rising to roughly $0.70 by year five; and high-single-digit return on invested capital by year five.3028 That last figure deserves a moment's attention: a high-single-digit ROIC in year five is a modest return on $9.9 billion, and it tells you plainly that the value creation here is expected to come from compounding beyond year five, not from the deal economics as underwritten.
The strategic logic is the acute-care setting. Radiometer's blood-gas analysers and Masimo's pulse oximeters sit next to each other at the same hospital bedside and are sold to the same purchasing decision-makers, with Masimo stronger in the United States and Radiometer stronger in Europe — a geographic complementarity Blair described as producing "direct" call-point synergies.28
There is also a Danaher-typical wrinkle in the provenance. Masimo arrived having been through a bruising governance fight: activist investor Politan Capital won two board seats on September 19, 2024, defeating founder and chief executive Joe Kiani, whose nominees received roughly half as many votes as Politan's.32 A central plank of the activist case was Masimo's $1 billion acquisition of consumer-audio business Sound United in 2022, after which the stock fell 37%.32 Danaher, in other words, bought a technically excellent asset that had recently been mismanaged, at a moment when its governance had been forcibly reset — the same profile as Beckman Coulter in 2011. The pattern is consistent, which is itself informative.
Financing was conventional: cash plus debt, including a €3.0 billion euro-denominated note offering priced on April 22, 2026 across four tranches maturing 2028 through 2038, at coupons from 3.250% to 4.000%.33 Gugino guided to post-close leverage of about 2.5 times net debt to adjusted EBITDA, up from roughly 2.0 times at the end of 2025, and argued it would come down quickly.285
Competitive position, sized honestly. In life-science instruments, Danaher is not the leader. Thermo Fisher generated $44.56 billion of revenue in 2025 — nearly twice Danaher's entire company — with adjusted earnings per share up 5% to $22.87.18 Agilent, more narrowly focused, guided to $7.3–7.4 billion for fiscal 2026 in analytical instrumentation that overlaps directly with SCIEX and Leica Microsystems.34 In bioprocessing the picture is more favourable: Sartorius, the closest pure-play comparison, reported preliminary 2025 group revenue of approximately €3.5 billion, up 7.6% — roughly half the size of Danaher's Biotechnology segment and growing at a similar rate.35 That last comparison is the useful one. Danaher's bioprocessing recovery is tracking its closest peer rather than lagging it, which is modest evidence that the 2025–26 improvement reflects an industry cycle turning rather than share being lost or won.
VIII. Current Management: Incentives, Ownership, Capital Allocation Record
On August 3, 2026, Steven Rales — Chairman since 1984 — announced that the board had appointed Julie Sawyer Montgomery as President and Chief Executive Officer effective October 1, 2026, and that Rainer Blair would retire, staying on as a senior advisor through March 31, 2027.13 The timing is worth noting: six weeks after a quarter in which bioprocessing revenue disappointed, three months after closing the largest acquisition in six years, and with the incoming CEO having personally led that acquisition.
Assessing the outgoing regime. Blair became chief executive in 2020, meaning his entire six-year tenure ran through the COVID surge, the destocking collapse, two flat years and the current partial recovery. That is a brutal hand, and it complicates any simple verdict. But the record on guidance discipline is legible.
The 2023 sequence was a genuine credibility event: repeated downward revisions, an explicit prediction that destocking would resolve in the first half that proved wrong, then a further prediction of second-half resolution that also proved wrong.254 Against that, the 2025 and 2026 record is better. Full-year 2025 guidance issued in January 2025 called for approximately 3% core growth; the company delivered 2.0%.268 The initial 2026 guidance of 3–6% core growth was, by the second quarter, narrowed to 3–4%, with management repeatedly advising analysts to "anchor to the low end of that range for modelling purposes."20 That is a company that has learned to set beatable targets — which is itself a form of learning, if a modest one.
What is more revealing is what management does not claim. Asked on the first-quarter 2026 call about the shape of an academic-research recovery, Blair declined to forecast one: "It is difficult to say because what we're seeing in the academic funding area is related to government policies. We need to see a more constructive perspective on academic funding before we're ready to call an inflection point."20 He immediately sized the exposure — academia is less than 5% of revenue.20 That is a specific, bounded, non-promotional answer, and it is a marked contrast with 2023's repeated confident predictions about destocking timing.
The incoming CEO has a scorecard, and it is mixed in an instructive way. Sawyer Montgomery joined Danaher in 2017 at Beckman Coulter Diagnostics, leading commercial operations and R&D before becoming President in 2020, then Executive Vice President for the Diagnostics platform. The board's stated case is that Diagnostics grew from approximately $6.0 billion of revenue in 2017 to approximately $11.0 billion today, with operating profit roughly tripling.13 Mitchell Rales specifically credited her with leading the Masimo acquisition and the pending StatLab deal.13
Set that against her own platform's public targets. At Danaher's Diagnostics Investor and Analyst Day in September 2024, the Diagnostics platform presented a transformation from a roughly $6.3 billion business in 2018 with mid-single-digit core growth and an approximately 20.5% adjusted operating margin, to a roughly $9.6 billion business in 2023 with an approximately 27.5% adjusted operating margin — and set a long-term target of high-single-digit core revenue growth.36
The margin promise has been kept: Diagnostics ran at about 28.6% adjusted in 2025.8 The growth promise has not. Diagnostics core revenue grew 1.5% in 2025, declined 4% in the first quarter of 2026, and grew 2% in the second.82820 Respiratory seasonality and Chinese procurement reform explain a great deal of that gap, and excluding respiratory the segment grew 5% in the second quarter.20 But high-single-digit is not 5%, and the incoming chief executive presented that target two years ago under her own name.
This is not a disqualifying observation. It is the specific thing to hold management to. The most valuable question an investor can ask over the next two years is whether Danaher's stated long-term model — high-single-digit core revenue growth, 35–40% incremental operating profit fall-through, free cash flow exceeding net income, and double-digit-plus earnings growth — survives contact with a new chief executive, or gets quietly reset.5
Ownership, and the governance flag that comes with it. As of March 1, 2026, Steven Rales beneficially owned 42,240,297 shares, or 6.0% of the company, and Mitchell Rales owned 33,001,391 shares, or 4.7%.15 Together, roughly 10.7% — a genuinely large founder stake in a company of this size, held for four decades, and neither brother takes cash or equity compensation for board service.
But the pledging disclosure deserves more attention than it usually gets. Danaher's board adopted an anti-pledging policy in 2013 prohibiting directors and officers from pledging company stock — with an explicit exemption for shares already pledged at adoption. Those shares belong to the Rales brothers, were acquired in cash purchases between 1983 and 1988, and have been pledged "for decades, to secure lines of credit that reduce the need to sell shares for liquidity purposes."15
The scale is substantial. Of Steven Rales' holding, 31,000,000 shares held through limited liability companies plus 3,000,000 held by a charitable foundation are pledged. Of Mitchell Rales' holding, 26,171,000 shares plus 5,904,000 foundation shares are pledged.15 That is roughly 66 million shares — approximately 88% of the brothers' combined beneficial ownership and about 9.4% of shares outstanding — encumbered as collateral for personal borrowing. At the current share price that collateral is worth on the order of $13–14 billion.
The Audit Committee reviews these pledges quarterly as part of its risk oversight and has concluded they do not pose undue risk, and the pledged shares do not count toward stock-ownership requirements.15 The arrangement has survived multiple severe drawdowns, including 2023 and the 2025–26 decline, without incident — which is real evidence about collateralisation levels. But pledged founder shares are a standard governance flag for a reason: in a sufficiently sharp decline, forced selling by the two largest holders is a mechanical possibility that does not exist at companies without this structure. It is a low-probability, high-impact tail, and it is a permanent feature rather than a passing one.
Compensation, and where it sits relative to performance. Blair's total 2025 compensation was $23,795,280, up from $22,107,164 in 2024 and $20,903,282 in 2023.15 The CEO pay ratio was 343 to 1 against a median employee compensation of $69,440.15 Chief Financial Officer Matthew McGrew — who has since been succeeded by Matt Gugino — earned $7,967,519 in 2025, and Sawyer Montgomery $11,295,279.15
The uncomfortable pattern is straightforward: reported CEO compensation rose roughly 14% across three years during which adjusted earnings per share went from $7.58 to $7.80 and the share price declined materially. Danaher's defence is structural — half of Blair's 2025 annual equity award was delivered in stock options, which are worthless unless the price rises above the grant level, and the performance stock units were tied entirely to total shareholder return relative to the S&P 500, meaning realised value should track the underperformance.15 That is a legitimate distinction between reported and realised pay, and it matters. It does not fully dissolve the optics.
Notably, the Compensation Committee changed the programme for 2026: it increased the company-financial weighting in the annual cash bonus from 60% to 70%, moved adjusted EPS out of the annual bonus and replaced it with adjusted operating income, and rebalanced long-term awards to 60% performance stock units, 20% options and 20% time-vesting restricted units — explicitly to reduce "volatility in earned compensation caused by macroeconomic and geopolitical forces."15 Adding time-vesting stock is a retention response to a falling share price. That is a rational thing for a board to do and a fair thing for a shareholder to question.
Capital allocation, marked to market. Danaher repurchased no shares in 2023, then bought aggressively: approximately 23.5 million shares for about $6.0 billion in 2024, and 14.5 million shares for approximately $3.1 billion in 2025.7 A further 5 million shares were repurchased for approximately $900 million in the second quarter of 2026.20 The 2024 programme was executed at an average cost near $255 per share and the 2025 programme near $214 — against a current price around $206.71
That is roughly $9.1 billion deployed in 2024–25 at an average well above today's price. Buybacks are a long-duration decision and two years is not a verdict. But it is a fact, and it complicates the reflexive characterisation of Danaher as an opportunistic repurchaser. In 2025 the company returned approximately $4.0 billion to shareholders through buybacks and dividends while investing approximately $1.6 billion in research and development and approximately $1.2 billion in capital expenditure.15
The dividend, at $0.32 per share quarterly, is deliberately minor — a yield well under 1%.7 Danaher is not an income vehicle and has never presented itself as one; the capital allocation stack is unambiguously M&A first, buybacks second, dividend last. On that point management has been consistent, and consistency is worth something.
IX. The DBS Deep Dive: Testing the Moat Claim Against the Record
So: is the Danaher Business System a moat, or a very good corporate culture with excellent branding?
The question is not rhetorical, because the answer determines what an investor should pay. If DBS reliably converts acquired assets into structurally better businesses, then Danaher's balance sheet — $43.2 billion of goodwill and $17.8 billion of net intangibles against $83.5 billion of total assets — represents stored, compounding value.8 If it does not, that same balance sheet is a monument to overpayment. Roughly three-quarters of Danaher's assets are purchase accounting. There is no middle position.
The case for. The affirmative evidence is long-dated and specific rather than rhetorical, which is what makes it credible.
The Fluke case from the late 1990s is documented by a third party: SG&A cut to 25% of revenues, factory floor space halved, operating margin lifted to 15%.6 The Beckman Coulter integration turned a troubled $3.7 billion diagnostics business bought at a 45% premium into the anchor of Danaher's highest-margin segment over fifteen years.198 Pall's specification-driven filtration franchise was absorbed and became the foundation on which the Cytiva thesis was built.21 Danaher won a competitive auction for Abcam in 2023 — paying $24.00 per share against a rival bid at $22.50, an enterprise value of approximately $5.7 billion for a business generating roughly £362 million of revenue in 2022 — and by the second quarter of 2026 was reporting Abcam's strongest quarter since acquisition, with Blair citing both improved commercial execution and progress diversifying the customer base away from academic research toward biopharma and diagnostics.37720
That last point is a meaningful proof point precisely because it is recent, and because Abcam was widely assumed to be a problem. A high-priced acquisition made at a cyclical low, integrated during a downturn, now growing and margin-expanding, is exactly what the DBS thesis predicts. On the first-quarter 2026 call Blair described "DBS-driven commercial execution" gaining traction and "cost structure initiatives" driving margin expansion since acquisition.28 Those are the mechanisms the thesis names, applied to a specific asset, with an observable result.
The case against, placed directly alongside. Three pieces of evidence complicate the claim, and they should not be quarantined.
First: DBS did not prevent the two-year bioprocessing forecasting failure, and did not prevent its miniature recurrence in 2026. Danaher's own explanation for the 2026 slippage — customer production schedules and site readiness — is an explanation about information Danaher did not have. DBS is a system for improving processes Danaher controls. Customer capital-project timing is not one of them. This is a boundary condition on the moat, not a refutation of it, but it is a boundary that costs real money and it has now been demonstrated twice.
Second: the genomics-consumables trade-name impairments. A total of $654 million of pretax charges across 2024 and 2025 against a brand acquired in the portfolio's most expensive year, culminating in the conclusion that the brand no longer has an indefinite economic life.7 DBS is claimed as an acquisition capability, not merely an operations one. When the acquisition thesis itself requires a writedown, that claim is partially disconfirmed. It is worth noting the honest counterpoint: this is a non-cash charge against purchase accounting, no goodwill has been impaired anywhere in the portfolio, and the underlying business continues to operate.7 But an indefinite-lived asset being reclassified as finite-lived is an audited statement that expected future cash flows are lower than originally underwritten.
Third, and most usefully: the peer comparison. Thermo Fisher runs its own named operating system and grew revenue 4% in 2025 with adjusted EPS up 5%.18 Danaher grew revenue 3.0% with adjusted EPS up 4.5%.8 Sartorius, running no such famous system, grew 7.6%.35 Over ten years, Danaher's total shareholder return of 286% slightly trailed the S&P 500's 298%.5 If DBS were a decisive competitive advantage, one would expect it to show up in a differential against companies doing roughly the same thing — and over the past decade, it has not.
Extend the window and the picture inverts: over twenty-five years, Danaher returned 2,063% against 728% for the S&P 500 and 738% for the healthcare sector index.5 That is not a small gap; it is nearly three times the market over a quarter-century, and it is not the kind of result that arises from luck alone.
The calibrated conclusion. The record supports a narrower claim than the one usually made. DBS as an integration and margin-expansion capability is well-evidenced across four decades and multiple named assets, most recently Abcam. DBS as a source of demand foresight is not supported by any evidence and is contradicted by two episodes three years apart. And DBS as a source of ongoing outperformance versus sophisticated peers is currently unproven — supported over twenty-five years, absent over ten.
The most likely resolution is that DBS was a genuine and large advantage when Danaher's competitors were sleepy industrials, and is a smaller advantage now that its competitors are Thermo Fisher and Sartorius, who are neither sleepy nor industrial. Advantages erode as they are copied. That is not a scandal; it is the normal life cycle of an operating edge.
The falsifiable test: whether Masimo's disclosed synergy targets — more than $125 million of cost synergies and more than $50 million of revenue synergies by year five, with EBITDA above $530 million in 2027 — are actually delivered.30 Those are checkable in future filings, they were set by the incoming chief executive's own team, and they constitute the cleanest live experiment on DBS that Danaher has run in years.
X. Bear & Bull Cases
The bull case, stated at its strongest.
The structural argument starts with the bioprocessing oligopoly. Four suppliers — Cytiva, Sartorius, Thermo Fisher and Merck KGaA — supply the overwhelming majority of the world's biologics manufacturing consumables, and the barrier is regulatory rather than technical. Once a resin or a membrane is written into an approved drug's manufacturing filing, replacing it is a regulatory project, not a purchasing decision. That produces the rarest thing in industrial businesses: revenue that persists through a demand collapse without share loss, which is precisely what 2023–24 demonstrated. Cytiva supported more than 90% of global monoclonal-antibody production volume in 2025.5
Layered on that is the razor-blade structure across the whole company: approximately 80% recurring revenue, an installed base of instruments that generates consumable and service pull for a decade or more, and gross margins near 59%.58 Free cash flow has converted at well above net income — 124% year-to-date through the second quarter of 2026 — which is genuine evidence of earnings quality rather than an accounting artefact.20
The demographic and scientific tailwinds are real and slow-moving: an ageing global population, a durable shift in medicine from small molecules toward biologics, more than 20,000 biologics in development against roughly 600 FDA-approved today, and a growing molecular diagnostics market.5 Danaher's stated view is that artificial intelligence is a net accelerant — Blair argued on the first-quarter call that improving the roughly 10% success rate of the drug-development pipeline would increase pharmaceutical reinvestment, and separately noted early demand from customers building automated "autonomous science" laboratories, which requires instruments, automation and reagents Danaher sells.28 That is a plausible mechanism, though it remains a hypothesis rather than a demonstrated revenue line.
Finally: capacity. Net leverage near 2.5 times after Masimo, more than $5 billion of annual free cash flow, and a demonstrated willingness to both buy and separate businesses.285
The bear case, stated at its strongest.
Growth has not been there for five years. Setting aside the COVID distortion entirely, Danaher's core revenue growth was negative in 2023, negative in 2024, 2.0% in 2025 and guided to 3–4% in 2026.42683 The long-term model promises high single digits.5 Four consecutive years of a wide gap between promise and delivery is not a cycle; it is a track record.
Bioprocessing concentration is a permanent structural exposure, not a phase. A business where a handful of large customers can move a hundred million dollars of revenue between years by rescheduling plant readiness is a business with limited near-term forecastability, regardless of how good the order book looks.20
Life Sciences remains unresolved. The segment declined 1.5% in 2025, required $654 million of trade-name impairments across two years, and — despite a genuinely strong 5.5% second quarter driven substantially by semiconductor filtration demand at Pall rather than by life-science instruments — has not yet demonstrated sustained growth in its core instrument franchises against Thermo Fisher's scale and Agilent's overlap.8720
Valuation carries an assumption. At roughly $145 billion of market value against approximately $5.3 billion of free cash flow, the market is paying a multiple that implies growth reacceleration, not perpetuation of low-single-digit core growth.18 That is a bet on the bioprocessing recovery being durable — the very thing that just produced a downward guidance revision.
Masimo is unproven, and priced accordingly. Roughly 18 times forward EBITDA for a business expected to deliver high-single-digit ROIC in year five is not obviously a bargain, and every synergy figure is a management projection.30
Porter's five forces, applied concretely. Buyer power is the most underrated risk: bioprocessing revenue is concentrated in a small number of very large pharmaceutical manufacturers who can, and demonstrably do, unilaterally reschedule shipments. In Diagnostics, the Chinese government's volume-based procurement programme is buyer power exercised at national scale, and it has imposed a multi-year pricing headwind.28 Supplier power is modest, though management flagged petrochemical-derivative input costs as something they are watching after oil price volatility.28 Rivalry is intense but rational — a handful of scaled players competing on validated performance and workflow rather than price. Substitutes are the genuine long-term question: continuous-processing technologies and any manufacturing platform that shifts away from chromatography would change resin demand, though not on a five-year horizon. New entrants face the specification barrier, which is the strongest structural protection in the business.
Through Hamilton Helmer's 7 Powers, Danaher holds two clearly. Switching costs are the primary power, grounded in regulatory specification rather than customer inertia. Scale economies apply in service networks, global manufacturing footprint and R&D amortisation — $1.6 billion of annual R&D across an installed base most competitors cannot match.15 Cornered resource is arguable in specific franchises: Cepheid's GeneXpert installed base with its proprietary cartridge menu is genuinely difficult to replicate, and Masimo's sensor technology and clinical validation record has similar characteristics. Branding has real force in antibodies and reagents, where a validated catalogue number is a proxy for reproducibility — which is precisely why writing down a brand in that category is a meaningful signal. Process power is the DBS claim, and per Section IX it is real but smaller than advertised. Network economies and counter-positioning do not apply.
The three KPIs that actually matter. Investors tracking Danaher should watch three things and largely ignore the rest.
Bioprocessing revenue growth, not orders. Orders have been positive for several quarters; revenue has not followed. The convergence of the two is the whole recovery thesis, and management has committed to a mid-to-high single-digit fourth-quarter exit rate.20
Life Sciences adjusted operating margin. Not the GAAP figure, which is distorted by amortisation and impairment. The adjusted margin — roughly 21.4% in 2025 against 23.2% in 2024 — tells you whether the integration problems are resolving or persisting.8
Masimo synergy delivery against the disclosed targets. This is the live test of the acquisition machine, run by the incoming chief executive, with numbers she has already published.30
XI. Risk Radar
The risks worth naming are the ones with an identified transmission mechanism into Danaher's revenue. Generic macro anxiety is not one of them.
Demand-cycle risk in bioprocessing remains the dominant swing factor, and the mechanism is now well understood: biopharmaceutical customers' inventory management and capital-project timing determine when Danaher recognises revenue, largely independent of underlying drug demand. It has moved the stock materially twice in three years.2520 The mitigant is that consumables consumption ultimately tracks drugs actually manufactured, which is a physical process that does not pause indefinitely. The vulnerability is that the timing gap between those two things can be a year or more.
Integration and execution risk is concrete rather than hypothetical. Masimo is one quarter into Danaher ownership, and the StatLab acquisition — a roughly $250 million-revenue anatomical-pathology consumables business with more than 85% recurring revenue, announced in the second quarter of 2026 and expected to close by year-end — will follow.20 The genomics-consumables writedowns establish that Danaher's integration record is very good rather than perfect.7
Competitive risk in Life Sciences instruments is structural. Thermo Fisher's scale advantage in analytical instrumentation is not closing, and Agilent competes directly in mass spectrometry and chromatography.1834 Danaher's answer is product-led — the ZenoTOF 8600 and novus V55 mass spectrometers at SCIEX, flow cytometry at Beckman, and lab automation positioned for AI-driven drug discovery workflows.820 Whether new products translate into sustained share gain is not yet demonstrated.
Regulatory and reimbursement risk operates through two distinct channels. Product approvals gate revenue timing — Masimo received FDA 510(k) clearance for an AI-enabled opioid-induced respiratory depression detection solution shortly after closing, which is a positive but is also a reminder that patient-monitoring and diagnostic products cannot be sold until cleared.20 Separately, government pricing policy is an active headwind: China's volume-based procurement and reimbursement changes that began in late 2024 have pressured Diagnostics pricing, though management reported the impact moderating through 2026 as volumes improved.2820
Government research funding is a smaller, honestly-sized exposure. Academic and government customers represent less than 5% of Danaher's revenue, and management has declined to forecast a recovery, describing the market as stabilised but below normal.20 The transmission is direct — policy determines grant budgets, which determine instrument and reagent purchases — but the magnitude is contained.
Accounting judgment deserves explicit flagging. Danaher carries $43.2 billion of goodwill across five reporting units whose individual carrying values range from approximately $1.2 billion to $23.1 billion, tested annually using market multiples and discounted cash flows.78 The company elected to bypass the optional qualitative assessment and performed full quantitative tests, which is the more rigorous choice.7 No goodwill impairment has been recorded in the last three years. But the indefinite-lived trade name that was written down in 2025 is now carried at a level where, on the company's own disclosure, a further 10% decline in fair value would trigger only $8 million of additional impairment — meaning that particular asset has been written down close to its estimated worth.7 Ernst & Young serves as independent auditor.15
Leverage is elevated but not stressed. Long-term debt stood at $18.4 billion at the end of 2025 against $4.6 billion of cash, before the Masimo financing.8 With roughly 2.5 times net leverage post-close and more than $5 billion of annual free cash flow, refinancing risk is low — but the balance sheet capacity that made Danaher an opportunistic acquirer through the downturn is now partially consumed.28
XII. Epilogue: Lessons & What to Watch
The through-line from 1985 to 2026 is a company that has repeatedly been underestimated and has repeatedly earned the scepticism it received at the time. Forbes called the Rales brothers cocky to the point of foolishness, and then spent the following fifteen years writing about what they built.6 The bull case in 2021 treated a pandemic-driven demand shock as a structural re-rating, and the following two years corrected that.
The durable investing lesson is a distinction rather than a verdict. Danaher's demonstrated capability — buying scaled assets in regulated, consumable-driven markets and improving their cost structure and commercial execution over five to fifteen years — is genuine, documented across Fluke, Beckman Coulter, Pall and now apparently Abcam, and rare. Danaher's demonstrated inability — forecasting when a small number of very large customers will place orders — is equally genuine, has cost shareholders substantial value twice, and shows no sign of being solved by any operating system.
Treating those as the same capability is the most common analytical error in the bull case. A company can be excellent at operating businesses and mediocre at predicting demand for them, and Danaher is precisely that company.
The 2023–2026 period should be read as a stress test that the business model passed and the equity story failed. The specification-driven positions held. The customers did not switch. The cash flow never broke — free cash flow exceeded $5 billion in every year of the downturn.4268 What broke was the assumption that a high-quality recurring-revenue business is immune to the capital-expenditure cycles of the people who buy from it.
Three things determine the next chapter, and all three are observable.
The first is whether bioprocessing revenue growth converges with the order book. Management has committed publicly to a mid-to-high single-digit exit rate in the fourth quarter of 2026 and expects the deferred resin shipments to be recognised in 2027.20 Either that happens or the recovery thesis needs rewriting.
The second is whether Life Sciences becomes a growth business rather than a mix of a strong industrial filtration franchise and an underperforming instruments-and-consumables portfolio. The second quarter of 2026 was encouraging — but the growth came disproportionately from semiconductor filtration demand at Pall, which is a genuinely good business and not the one the segment's valuation depends on.20
The third is Julie Sawyer Montgomery. She inherits a company at an unusual moment: a newly closed $9.9 billion acquisition she personally led, a five-year growth drought, a compensation programme just restructured to retain executives through a share-price decline, and a long-term financial model her predecessors set that the company has not met since 2021. Her Diagnostics platform delivered its margin promise and missed its growth promise. Whether she reaffirms Danaher's high-single-digit growth ambition or resets it will be the most informative thing she does in her first year — and it will happen in public, on a conference call, with the same analysts who spent the July call refusing to accept the first explanation they were given.
XIII. Recent News
The eight months of 2026 have delivered more genuinely new information about Danaher than any comparable period since the Veralto separation.
Full-year 2025 results, reported January 28, 2026, closed a year of modest recovery: $24.57 billion of revenue with 2.0% core growth, adjusted earnings per share of $7.80 up 4.5%, and free cash flow of $5.3 billion.8 Management initiated 2026 guidance of 3–6% core revenue growth and $8.35–$8.50 of adjusted EPS.8
The Masimo agreement, announced February 17, 2026, was the largest capital deployment since Abcam and the first major acquisition since the downturn began.30 It closed on June 10, 2026, ahead of the originally guided second-half timeline, with Masimo becoming a wholly-owned standalone operating company within Diagnostics and its shares ceasing to trade on Nasdaq.12 Financing included a €3.0 billion euro-denominated note offering priced April 22.33
First-quarter results, reported April 21, 2026, showed 0.5% core growth against a light respiratory season, but adjusted EPS grew 9.5% to $2.06 on cost execution, and management raised the top end of full-year EPS guidance.29 The bioprocessing equipment order figure — more than 30% year-over-year growth, the first positive comparison in nearly two years — was the quarter's most consequential disclosure.28
Second-quarter results, reported July 21, 2026, delivered the year's central tension: accelerating growth across Life Sciences and Diagnostics alongside a bioprocessing revenue shortfall from deferred chromatography resin shipments.320 Full-year core revenue guidance narrowed to 3–4% while adjusted EPS guidance was raised to $8.45–$8.60, reflecting the earlier Masimo close and second-quarter execution.3 Danaher also announced the pending acquisition of StatLab, an anatomical-pathology consumables business, expected to close by the end of 2026, and repurchased approximately $900 million of stock.20
The chief executive transition, announced August 3, 2026, completed the year's reset: Julie Sawyer Montgomery becomes President and Chief Executive Officer on October 1, 2026, with Rainer Blair retiring and serving as senior advisor through March 31, 2027.13
Taken together, 2026 has clarified Danaher's operating baseline while leaving its central question open. The end markets outside bioprocessing are recovering faster than management expected entering the year. Bioprocessing orders are growing at a rate consistent with the recovery thesis. And bioprocessing revenue is not yet following. The third-quarter results, and the fourth-quarter exit rate management has committed to, will resolve considerably more than another quarter of earnings.
XIV. Links & Resources
The primary-source trail for Danaher is unusually good, because a company built on acquisitions leaves a public record of every price it paid.
For current operations, the 2025 Form 10-K is essential and repays close reading beyond the headline financials — the segment MD&A explains the Life Sciences decline in specific product terms, and Note 10 contains the trade-name impairment disclosures that the earnings releases summarise only in a footnote.7 The fourth-quarter 2025 earnings release carries the full segment table including the reconciliation from GAAP to adjusted segment operating profit, which is where the Life Sciences margin question is actually answered.8
The 2026 definitive proxy statement is the best single document on governance and incentives: the Rales pledging disclosure, the compensation tables, the 2026 programme redesign, and the pay-ratio arithmetic all sit there.15
Earnings call transcripts are where the live version of the story lives. The second-quarter 2026 call is the most valuable single transcript in the set — the analyst Q&A on the resin shipment deferrals, particularly the exchanges with Bank of America, RBC and Citi, is the clearest available window into how much confidence to place in management's timing explanations.20 The first-quarter 2026 call provides the contrasting optimistic framing from three months earlier, along with Blair's most detailed articulation of the AI thesis.28
On the transaction history, the original press releases give both the terms and the rationale as stated at the time, which is the fairest way to score them: Beckman Coulter in 2011, Pall in 2015, Cepheid in 2016, GE Biopharma in 2019, Aldevron in 2021, Abcam in 2023 and Masimo in 2026.19212322243730 The Veralto separation completion release and Veralto's own Form 10 registration statement document the third spin-off.1127
For the pre-life-sciences history, the January 2000 Forbes article "Shrink That Factory" is the most valuable contemporaneous account of what DBS actually did to an acquired company, and it contains the 1985 "Raiders in short pants" line in its original context.6 The Lean Enterprise Institute's account of the Jake Brake era documents the Shingijutsu introduction from the participants' perspective.16
For competitive benchmarking, Thermo Fisher's and Agilent's results releases and Sartorius' preliminary full-year figures provide the independent yardsticks against which any claim of Danaher outperformance should be measured.183435 And Danaher's own 2025 overview presentation is worth reading precisely because it includes the ten-year total-shareholder-return comparison that the bull case has to explain.5
References
-
Danaher Corporation (DHR) Stock Quote and Key Statistics — CNBC ↩↩↩↩
-
Danaher Reports Fourth Quarter and Full Year 2021 Results — Danaher Corporation, 2022-01-27 ↩↩↩↩
-
Danaher Reports Second Quarter 2026 Results — Danaher Corporation, 2026-07-21 ↩↩↩↩↩↩↩
-
Danaher Reports Fourth Quarter and Full Year 2023 Results — Danaher Corporation, 2024-01-30 ↩↩↩↩↩↩↩
-
Danaher Corporation 2025 Overview Investor Presentation — Danaher Corporation ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Danaher: Shrink That Factory — Forbes, 2000-01-10 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Danaher Corporation Annual Report on Form 10-K for the year ended December 31, 2025 — SEC.gov, 2026-02-24 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Danaher Reports Fourth Quarter and Full Year 2025 Results — PR Newswire, 2026-01-28 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Danaher Corporation Completes Separation of Fortive Corporation — Danaher Corporation, 2016-07-02 ↩↩
-
Envista Announces Pricing of Initial Public Offering — Danaher Corporation, 2019-09-17 ↩↩
-
Danaher Corporation Completes Separation of Veralto Corporation — Danaher Corporation, 2023-09-30 ↩↩↩↩
-
Danaher Completes Acquisition of Masimo Corporation — Danaher Corporation, 2026-06-10 ↩↩↩
-
Danaher Appoints Julie Sawyer Montgomery as President and Chief Executive Officer — Danaher Corporation, 2026-08-03 ↩↩↩↩↩
-
Danaher's Evolutionary Story — Danaher Corporation, 2023-10-08 ↩↩
-
Danaher Corporation 2026 Definitive Proxy Statement (DEF 14A) — SEC.gov, 2026-03-25 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Ask Art: What Was Danaher Like In the Early Days of Lean? — Lean Enterprise Institute ↩↩
-
Kaizen: Danaher's approach to global excellence — Danaher Corporation, 2024-02-01 ↩↩↩
-
Thermo Fisher Scientific Reports Fourth Quarter and Full Year 2025 Results (Form 8-K, Exhibit 99.1) — SEC.gov, 2026-01-29 ↩↩↩↩↩
-
Danaher to Acquire Beckman Coulter, Inc. for $83.50 per share or $6.8 Billion — Danaher Corporation, 2011-02-07 ↩↩↩↩↩↩↩
-
Danaher (DHR) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-07-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Danaher to Acquire Pall Corporation for $127.20 per share, or $13.8 Billion — Danaher Corporation, 2015-05-13 ↩↩↩↩↩
-
Danaher to Acquire the Biopharma Business of General Electric Life Sciences for $21.4 Billion — Danaher Corporation, 2019-02-25 ↩↩↩
-
Danaher To Acquire Cepheid For $53.00 Per Share Or Approximately $4 Billion — Danaher Corporation, 2016-09-06 ↩↩
-
Danaher To Acquire Aldevron — Danaher Corporation, 2021-06-17 ↩↩↩
-
Danaher's disappointing guidance weighs on the stock, forces reassessment — CNBC, 2023-04-25 ↩↩↩↩
-
Danaher Reports Fourth Quarter and Full Year 2024 Results — Danaher Corporation, 2025-01-29 ↩↩↩↩
-
Veralto Corporation Information Statement (Form 10 Registration Statement, Exhibit 99.1) — SEC.gov, 2023 ↩↩↩
-
Danaher (DHR) Q1 2026 Earnings Call Transcript — The Motley Fool, 2026-04-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Danaher Reports First Quarter 2026 Results — Danaher Corporation, 2026-04-21 ↩↩
-
Danaher To Acquire Masimo Corporation — Danaher Corporation, 2026-02-17 ↩↩↩↩↩↩↩
-
Danaher to acquire Masimo in $9.9 billion deal in diagnostics push — CNBC, 2026-02-17 ↩
-
Masimo CEO Joe Kiani ousted from board after proxy fight; Politan wins two seats — CNBC, 2024-09-19 ↩↩
-
Danaher Announces Pricing of Euro-Denominated Senior Notes Offering — Danaher Corporation, 2026-04-22 ↩↩
-
Agilent Reports Fourth-Quarter Fiscal Year 2025 Financial Results (Form 8-K, Exhibit 99.1) — SEC.gov, 2025-11-24 ↩↩↩
-
Sartorius achieves considerable profitable growth in 2025 and maintains positive outlook — Sartorius AG, 2026-02-03 ↩↩↩
-
Danaher Diagnostics Investor & Analyst Day Presentation — Danaher Corporation, 2024-09-05 ↩
-
Danaher to Acquire Abcam — Danaher Corporation, 2023-08-28 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube