Emerson Electric: The Automation Pioneer's $30 Billion Transformation
I. Introduction & Episode Roadmap
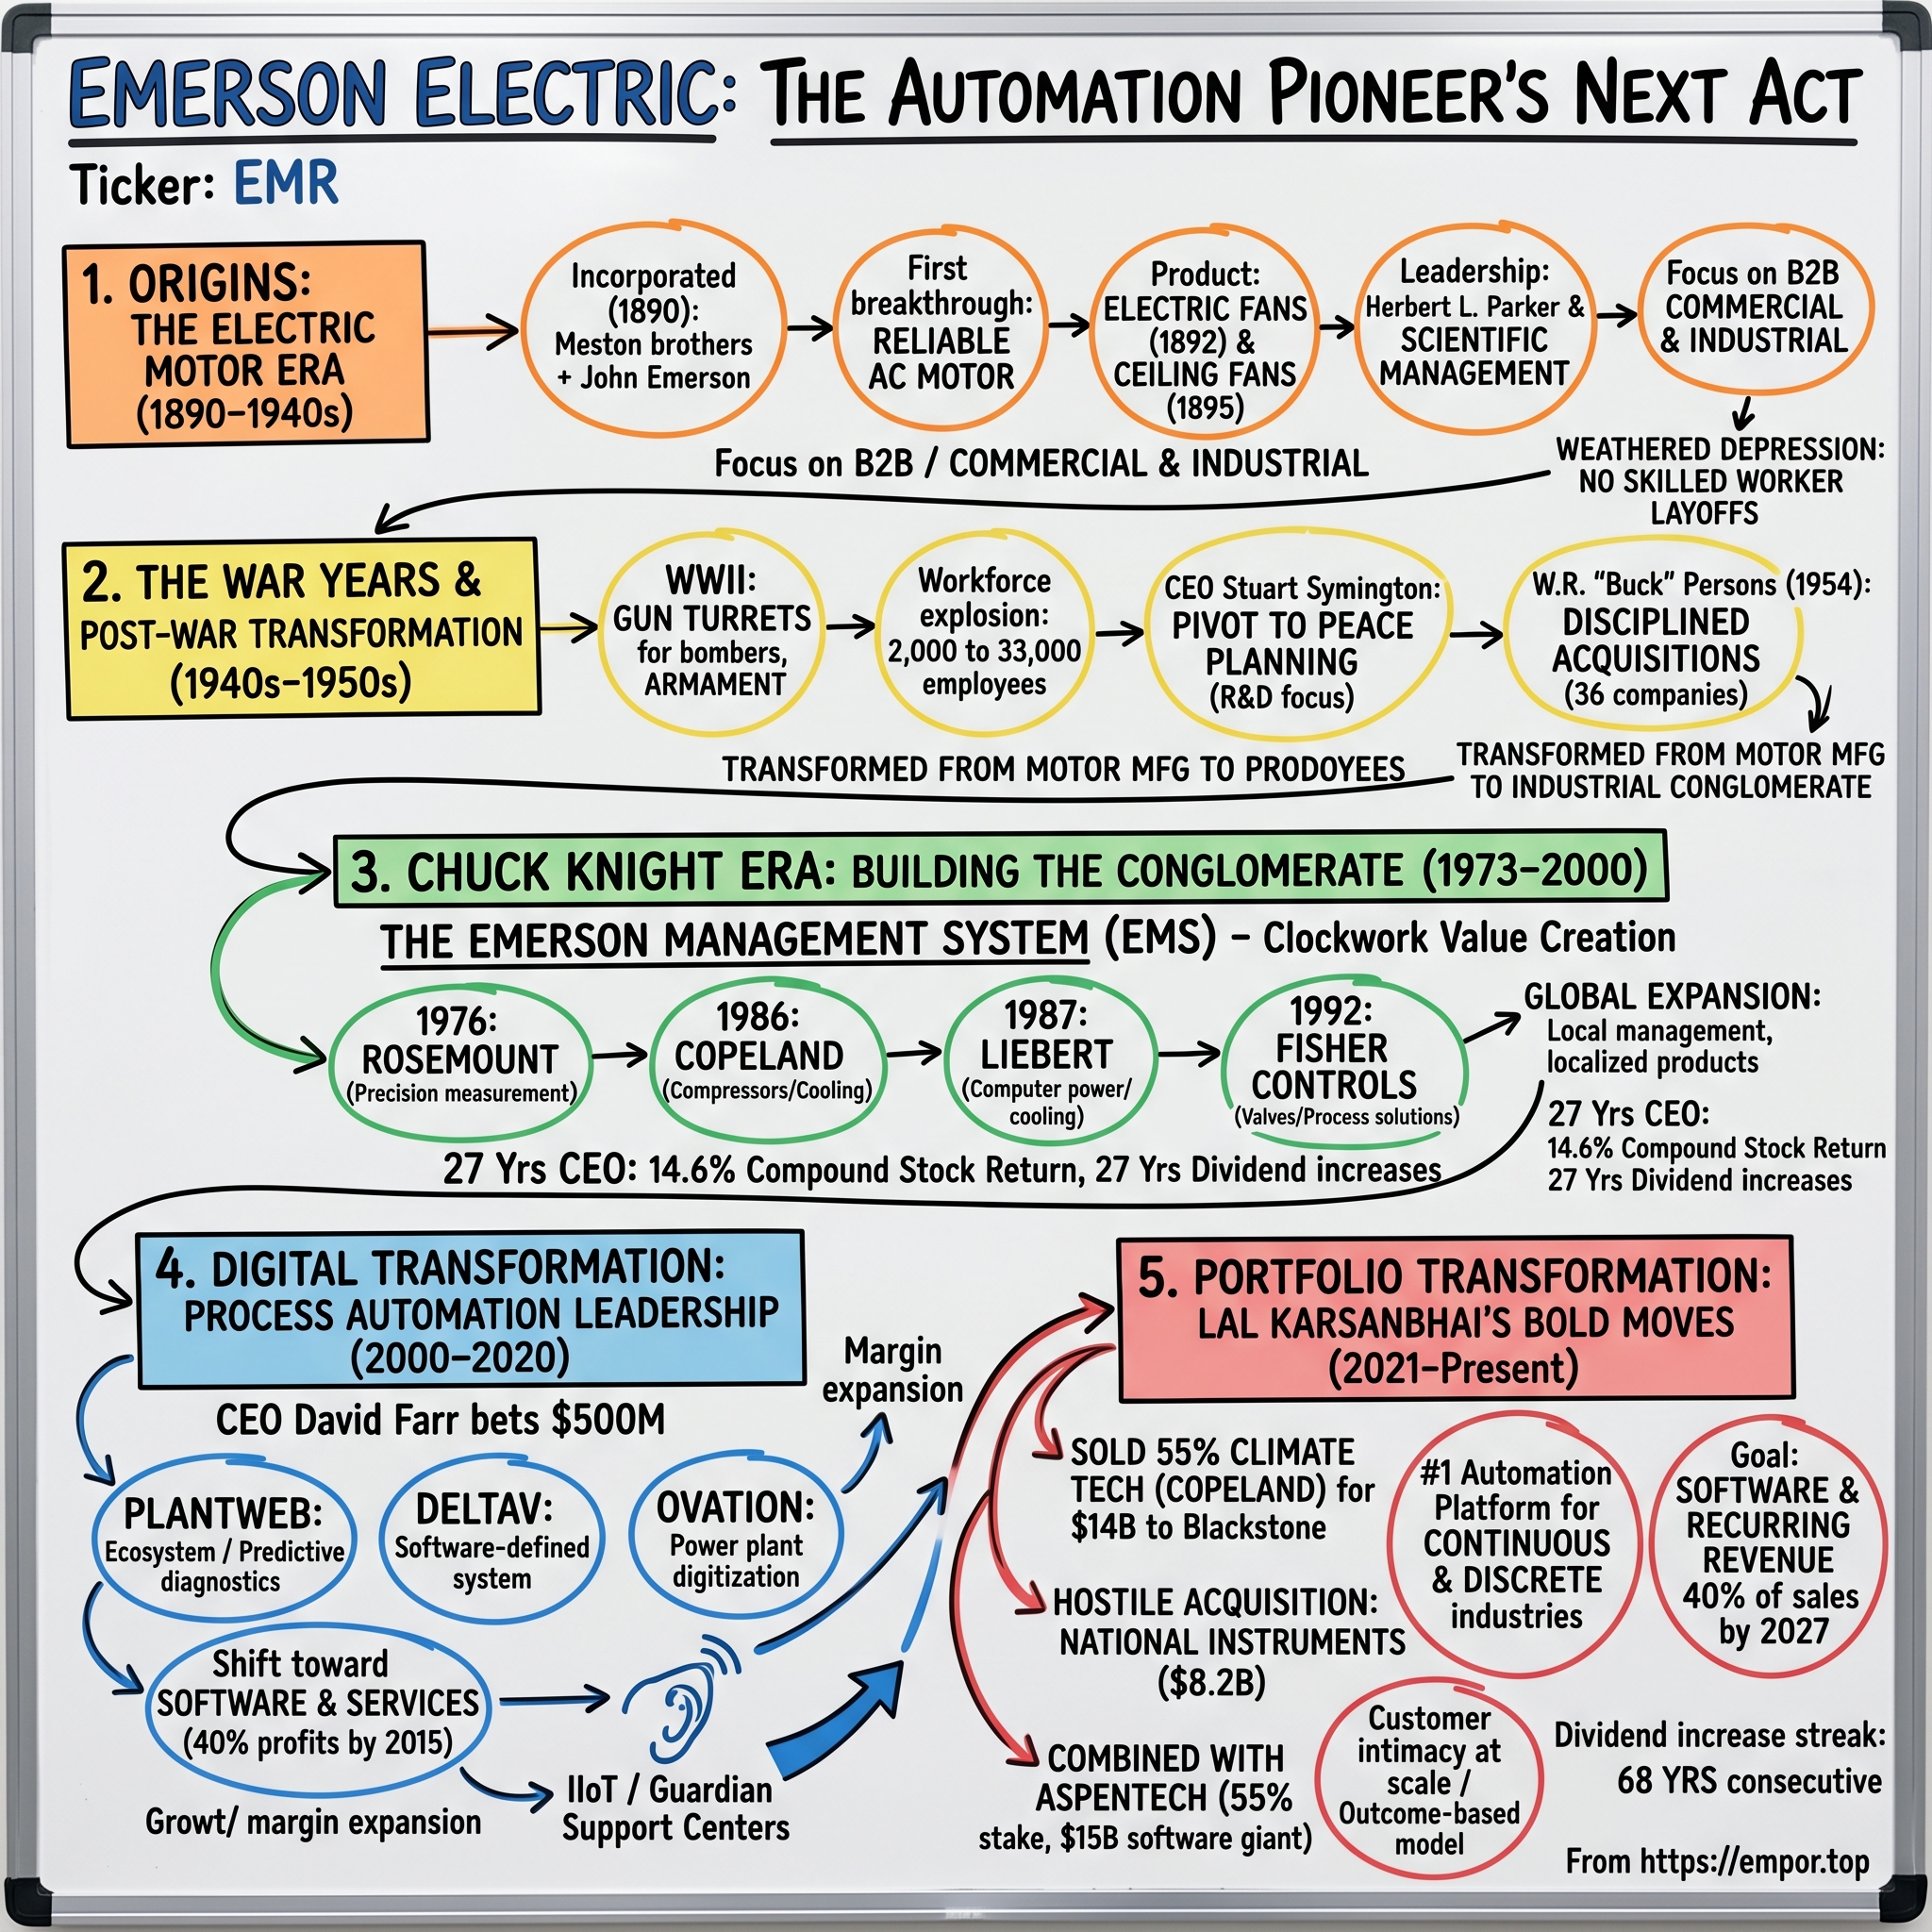
In the summer of 1890, John Wesley Emerson, a former Union cavalry officer and Missouri circuit judge, provided the financial backing for Scottish-born brothers Charles and Alexander Meston, who saw commercial potential in alternating-current electric motors. The company they chartered in St. Louis went on to manufacture the first electric desk fans sold in North America—a product that provided critical relief in the un-air-conditioned Mississippi Valley.
Fast-forward 136 years to 2026. The desk fans are gone, along with household motors, garbage disposals, wet-dry vacuums, pipe wrenches, and the climate compressor business that long anchored the enterprise's earnings. What remains is an industrial technology provider whose products are rarely visible to consumers, yet essential to basic infrastructure: control valves that regulate steam in nuclear power plants, transmitters monitoring pressure inside oil refineries, control systems preventing liquefied natural gas facilities from tripping offline, and simulation software used to design these complex facilities.
This operational focus underpins the modern financial story. Emerson Electric Co. (NYSE: EMR) closed fiscal 2025 with approximately $18.0 billion in net sales and adjusted segment EBITA margins in the high 27 percent range. In November 2025, management presented investors with targets of $21 billion in net sales and a 30 percent margin by fiscal 2028.1[^12] Reaching those targets required major portfolio restructuring: selling Climate Technologies—including the Copeland compressor franchise—to Blackstone in a transaction valuing the business at $14 billion,6 then redeploying the proceeds into large acquisitions of Aspen Technology and National Instruments.[^4][^5]4
The central analytical question is not whether the transformation occurred, but whether Emerson acquired a higher-quality enterprise or merely reshaped its business mix—swapping a hardware-heavy industrial conglomerate for a software and test package. Chief Executive Officer Lal Karsanbhai frames the strategic rationale around an architecture named "Boundless Automation," in which design software, test systems, control systems, and field instruments draw on a common data layer.[^12] Skeptics contend that Emerson paid peak-cycle valuation multiples for assets whose end markets subsequently decelerated, raising questions about whether the portfolio move resolves or shifts the legacy conglomerate discount.
Four themes frame this analysis. First, the transition from legacy industrial diversification toward a software-defined automation architecture, assessing whether the platform strategy generates genuine operational synergies. Second, the economic durability of customer switching costs in continuous process plants, which create annuity-like recurring revenue streams across Emerson's installed base. Third, the balance between capital allocation discipline and integration risk, as management applies its restructuring playbook to premium-priced acquisitions. Fourth, the strategic divide between continuous process control—where Emerson maintains established market leadership—and discrete factory automation, where the company remains an expanding competitor.
To evaluate why the strategic pivot in the 2020s was so dramatic, one must first examine what Emerson had become by the 2010s and why its traditional model operated successfully for decades without major intervention.
 Subscribe on LinkedIn
II. Origins & The Electric Motor Foundation (1890–1950s)
The company's origin was more contingent than heroic. The Meston brothers brought expertise in alternating-current machinery from Britain to St. Louis when the electrical industry had not yet resolved whether alternating or direct current would dominate. While John Wesley Emerson provided capital and his name, the technical bet belonged to the Mestons. Their early product line followed a simple sequence: manufacture electric motors, then build the equipment those motors could spin.
The desk fan established an operational pattern Emerson would maintain for over a century: identify applications where small, precisely specified motors could automate manual tasks, and own the design specification. Fractional-horsepower motors—the hidden drivers inside household appliances, power tools, and industrial machinery—became the company's economic foundation. Unseen by end users and engineered to tight tolerances, these components were purchased by original equipment manufacturers who prioritized operational reliability over brand names. This established Emerson as an invisible but non-substitutable component supplier.
World War II temporarily altered this commercial trajectory. Under Stuart Symington—an executive who later served as the first Secretary of the U.S. Air Force—Emerson converted to defense production, becoming the largest manufacturer of aircraft gun turrets and ranking among the top 60 U.S. corporations by wartime contract value. Symington also reshaped internal operations by desegregating the St. Louis plants and negotiating with an active labor union during an era when neither action was standard practice, establishing a pragmatic operational culture.
Postwar demobilization brought an immediate demand shock, leaving Emerson in the 1950s with manufacturing capacity built for a military buyer that had stopped ordering. Beginning in 1954, Chief Executive W.R. "Buck" Persons launched the company's first structured diversification strategy, completing 36 acquisitions over 19 years. By the early 1970s, this expansion created a manufacturer generating approximately $800 million in annual revenue across dozens of plants. Rather than accumulating unrelated assets, Persons acquired adjacent motor and component suppliers that shared core manufacturing processes.
For investors, this early history reflects institutional temperament rather than present earnings power, as those original business lines have been sold, spun off, or restructured. Emerson established three lasting principles during this era: embedding its components directly into customer equipment, treating acquisitions as a routine operational tool, and maintaining strict cost controls during demand downturns. These instincts formed the framework that subsequent leadership would build into a broader corporate management system.
III. The Conglomerate Era: Chuck Knight & David Farr (1973–2020)
Charles F. Knight was thirty-seven years old when he became chief executive in 1973. A consultant by training whose father’s firm had advised Emerson, Knight brought a conviction that defined the company for a generation: planning was not an annual ritual, but a continuous, adversarial process in which management had to defend every operating assumption.
The Emerson Management System
What became known as the Emerson Management System was, stripped of mystique, a rigorous operating cadence. Division presidents spent a substantial portion of each year preparing for planning conferences where Knight and his executive staff interrogated financial figures line by line—focusing not on abstract strategy, but on the specific cost reductions required to deliver targeted margins in a given quarter. The system relied on several non-negotiable principles: maintaining a best-cost producer position in every served market, identifying formal cost reductions to offset inflation before contemplating price increases, and refusing to fund growth claims without demonstrated operational efficiency.
These operating controls generated decades of consecutive annual earnings growth, establishing Emerson as a staple among quality-compounder portfolios. The company also established one of the longest dividend growth records in corporate history, a streak Emerson continues to extend and which management still cites as a key constraint on total balance-sheet leverage.1
Knight’s dealmaking strategy laid the groundwork for the modern enterprise. The 1976 acquisition of Rosemount expanded Emerson into process measurement—the transmitters monitoring pressure, temperature, flow, and fluid levels across industrial facilities. In 1986, Emerson acquired Copeland, securing the compressor business that anchored its Climate Technologies segment for thirty-six years. The 1987 purchase of Liebert added precision cooling and uninterruptible power systems for computer rooms. Finally, the 1992 acquisition of Fisher Controls brought control valves—the physical hardware executing process adjustments.
The combination of Rosemount and Fisher created a structural advantage in industrial automation. In a continuous process plant, operational control functions as a closed loop: sensors measure physical variables, controllers evaluate readings against target setpoints, and final control elements—typically valves—adjust flow to maintain equilibrium. By owning both the measurement devices and the final control valves, Emerson commanded both ends of the control loop, later integrating the central control software. This integrated hardware architecture established a durable process control franchise years before technology markets popularized the concept of an integrated platform.
David Farr and the digital layer
David Farr succeeded Knight as chief executive in 2000, inheriting an efficient manufacturing engine at a time when capital markets were discounting industrial conglomerates. Farr adopted a direct communication style with Wall Street and accelerated two strategic initiatives Knight had only begun: expanding global manufacturing footprints and building out software capabilities.
The foundation of this software strategy rested on Plantweb, a digital plant architecture, and DeltaV, a proprietary distributed control system. A distributed control system acts as a plant’s central nervous system—the software and hardware controllers that process thousands of sensor measurements per second, execute control logic, and display real-time operational interfaces to facility engineers. DeltaV’s core commercial innovation was delivering control systems as scalable, standard products rather than custom-engineered projects. This approach reduced installation timelines and made control automation accessible to smaller facilities. Plantweb added predictive diagnostics, enabling field instruments to report their own mechanical health so maintenance teams could address degrading components before failures caused unplanned outages.
Farr navigated the 2008 financial crisis by leaning on the Emerson Management System to limit decremental margins and protect the dividend. However, over the following decade, investors increasingly questioned the strategic rationale of combining disparate industrial and residential business lines. Pressure mounted in 2019 and 2020 when activist investor D.E. Shaw acquired a stake and publicly urged Emerson to split its industrial automation division from its commercial and residential solutions business while cutting corporate overhead. Emerson’s board responded by adding new directors and initiating a comprehensive cost review—effectively laying the groundwork for the portfolio separation that the next chief executive would execute.
Testing the "great capital allocator" claim
Despite Emerson’s reputation for capital discipline during the conglomerate era, its track record includes notable missteps in technology acquisitions.
In 2009, Emerson acquired Avocent for approximately $1.2 billion to expand its Network Power segment, combining data center thermal management from Liebert with Avocent’s IT management software and power distribution hardware. While data center demand expanded rapidly, the segment encountered severe headwinds: intense competition and pricing pressure from hyperscale cloud operators who designed custom infrastructure. Facing margin compression, Emerson recorded substantial impairment charges on the division. In 2016, the company sold a majority stake in Network Power to Platinum Equity at a valuation well below its cumulative investment. Under private equity governance, the business was rebranded as Vertiv, subsequently went public, and generated tens of billions of dollars in equity value—gains that accrued to outside investors rather than Emerson shareholders.
This episode highlighted an operational mismatch. An executive model optimized for low-cost manufacturing and incremental margin discipline proved ill-suited for technology assets requiring rapid product cycles, high software adoption rates, and sustained capital investment ahead of demand cycles. Emerson effectively acquired a software-adjacent technology asset but managed it with the cost-reduction playbook of a traditional hardware manufacturer.
That history remains relevant to Emerson’s contemporary strategy. When management proposed allocating more than $15 billion toward software and technology-adjacent acquisitions starting in 2021, investors faced a critical question: whether Emerson had transformed its operational capabilities or was repeating the integration risks of the Avocent era.
IV. The Great Portfolio Reshaping: Lal Karsanbhai's $30B Pivot (2021–Present)
Lal Karsanbhai does not fit the typical outsider-change-agent archetype. He joined Emerson in 1995, spent a quarter-century advancing through its ranks, directed European operations, and by 2018 served as president of Automation Solutions—the division destined to become the core of the modern company. Born in Kenya and educated in the United States, Karsanbhai developed a reputation among institutional investors for operational precision, often answering financial analysts with specific figures and target dates rather than broad strategic themes.
When he assumed the role of chief executive in February 2021, the mandate from a board responding to activist pressure was clear yet demanding: define Emerson’s primary corporate identity and divest non-core operations.
Selling the crown jewel
Climate Technologies was far from an underperforming division. The Copeland scroll compressor franchise held a leading global position in residential and commercial air conditioning and refrigeration, generating steady profits since Emerson acquired it in 1986. Divesting the unit tested portfolio discipline, as its strong cash generation had long shielded it from strategic scrutiny.
The rationale for divestment was structural. Climate Technologies' growth remained linked to residential construction and heating, ventilation, and air conditioning replacement cycles. While its margins were solid, they trailed those of the automation segment. More critically, the division competed for capital, executive bandwidth, and engineering talent against industrial automation, which offered higher returns and stickier customer relationships. Retaining both implied that corporate management could allocate capital across disparate end markets more effectively than public equity investors—a premise weakened by earlier missteps in Network Power.
In October 2022, Emerson agreed to sell a controlling 55 percent stake in Climate Technologies to Blackstone in a transaction valuing the business at $14 billion, closing the deal in May 2023.6[^14] In 2024, Emerson divested its remaining 45 percent interest to Blackstone for $3.5 billion in cash, fully converting the holding into deployable capital.1 Management simultaneously moved to divest the remaining commercial and residential assets, including the Ridge Tool business, while placing Safety & Productivity under strategic review.
The $14 billion valuation achieved in late 2022, amid tightening debt markets, represented a solid exit multiple for Climate Technologies. However, structuring the initial transaction with a retained minority interest meant Emerson temporarily shared downstream operational risks with private equity. Monetizing that remaining stake in 2024 resolved the exposure, converting a legacy manufacturing asset into strategic flexibility. The ultimate wisdom of this capital reallocation depends on the returns generated by the technology assets acquired in its place.
Building the software stack
The transaction with Aspen Technology relied on a complex structure that eventually sparked friction with minority shareholders. Rather than purchasing AspenTech outright in 2022, Emerson contributed two of its industrial software businesses—the OSI grid-management business and its subsurface geological simulation unit—alongside cash to secure a 55 percent controlling stake in an expanded, publicly traded AspenTech.[^5] Emerson subsequently increased its holding to approximately 57 percent.
This structure allowed Emerson to consolidate AspenTech’s financial results while conserving cash through asset contributions and preserving a public acquisition currency. However, it introduced persistent governance hurdles, creating conflicts of interest between the parent company and public minority shareholders whenever operational integration was proposed.
To eliminate this structural friction, Emerson moved to buy out the remaining minority stake. In November 2024, Emerson offered $240 per share for the equity it did not own.9 After resistance from AspenTech’s special board committee, the parties reached a final agreement in January 2025 at $265 per share in cash, valuing the minority buyout at approximately $7.2 billion.4 Emerson completed the transaction in March 2025, converting AspenTech into a wholly owned subsidiary.[^5] The $25-per-share price increase reflected a recurring pattern: Emerson has repeatedly raised purchase prices following initial board rejections, suggesting that initial offers serve as tactical negotiating positions rather than strict valuation caps.
AspenTech produces engineering software used to design, simulate, and optimize continuous process facilities such as chemical plants and oil refineries. Its core platforms, Aspen Plus and HYSYS, model complex process thermodynamics, enabling engineers to build and test facility designs digitally before physical construction. Complementary modules provide predictive asset maintenance, supply chain planning for feedstock and product distribution, and grid-management software through OSI. The business model generates high gross margins and predictable cash flows structured around annual contract value, reinforced by a user base of process engineers trained on Aspen software during their university education.
The claim that software insulates you from the cycle
Management argued that expanding recurring software revenue would cushion Emerson against broader industrial cycles. Financial performance through 2024 and 2025, however, challenged the notion that software provides complete insulation.
AspenTech’s annual contract value growth slowed during this period, weighed down by cautious spending among chemical producers in Europe and Asia—a deceleration management consistently attributed to customer capital constraints rather than market share loss.[^12]1 Industrial software purchases remain tied to broader facility operating budgets. When high energy costs force a European chemical producer to curtail output, management typically defers expanding software licenses. Recurring software revenue softens the immediate impact of industrial downturns, but it does not decouple the business from baseline sector expenditure.
Consequently, the thesis that software transforms Emerson’s business model holds true only in a qualified sense. Software subscriptions improve through-cycle operating margins and moderate the depth of earnings contractions, as recurring maintenance contracts continue even when new capital projects pause. However, software adoption does not make the enterprise immune to economic cycles. The definitive test for this strategic shift will be whether AspenTech can restore organic annual contract value growth to a high single-digit percentage rate during periods of depressed chemical sector capital expenditure.
This set the stage for Emerson’s next major transaction, where valuation risk—rather than strategic rationale—became the central focus for investors.
V. The M&A Capital Allocation Battlefield: National Instruments Deep Dive
In May 2022, National Instruments—an Austin, Texas-based testing software and hardware provider founded in 1976 by three University of Texas researchers and widely known for its flagship graphical programming environment, LabVIEW—announced it was reviewing strategic alternatives. Emerson had already initiated private takeover approaches.
Eight months of public pressure
Emerson's initial overtures were private. Throughout 2022, management submitted non-binding bids in the high $40s per share. When National Instruments' board declined to engage on those terms, Emerson broke with its historical dealmaking playbook by taking its bid public and hostile. In January 2023, Emerson disclosed an unsolicited proposal of $53 per share, valuing National Instruments at approximately $7.6 billion including net debt, while revealing it had quietly accumulated a small equity stake in the target. In response, National Instruments' board adopted a shareholder rights plan to limit further share purchases while conducting a formal sale process.
The auction strategy yielded immediate price competition. In April 2023, Emerson agreed to acquire National Instruments for $60.00 per share in cash, representing an equity value of approximately $8.2 billion.57 The transaction closed in October 2023.[^4]
The progression from the high $40s to $53 and ultimately to $60 per share marked a 25 percent price increase from Emerson's initial private valuation. Management justified the escalation by framing National Instruments as a strategically unique asset subject to genuine competitive bidding. Skeptics argued that Emerson's public escalation compromised its negotiating leverage, causing the final purchase price to reflect auction pressure rather than a disciplined assessment of intrinsic value.
Why NI at all
The strategic logic behind the acquisition centers on expanding beyond continuous process control. Emerson's traditional automation business serves continuous production facilities, regulating fluid flows and thermal conditions via transmitters and valves. Discrete manufacturing presents a distinct operational model, producing distinct units on assembly lines where automation requires robotics, motion control, programmable logic, and rigorous testing. Semiconductors, electric vehicle battery modules, and aerospace avionics require precise validation using automated test equipment and dedicated software.
National Instruments established a strong presence in semiconductor validation, aerospace and defense, and automotive testing. Software accounted for roughly 20 percent of its sales, anchored by LabVIEW, a graphical programming environment where engineers build test workflows visually rather than writing text-based code. LabVIEW's competitive moat mirrors that of AspenTech: broad adoption in university engineering curricula has created a global workforce whose accumulated intellectual property depends on the proprietary platform.
For Emerson, National Instruments provides the validation layer within its broader Boundless Automation architecture. In this combined stack, AspenTech models facility designs, National Instruments validates components during testing, and DeltaV control systems and Fisher valves manage continuous operations. Connecting operational data across all three phases enables Emerson to offer a unified lifecycle platform that standalone competitors struggle to replicate. Demonstrating a commitment to domain expertise, Emerson appointed Ritu Favre—a semiconductor industry veteran who had joined National Instruments prior to the takeover—to lead its newly formed Test & Measurement segment.
The stress test: did Emerson buy the top?
Emerson completed the acquisition at an enterprise-value-to-EBITDA multiple in the low twenties, transacting near the peak of a pandemic-driven demand cycle for semiconductor test and electronics validation. Shortly after the deal closed, a prolonged inventory destocking cycle hit discrete automation and semiconductor test markets. National Instruments' organic revenue contracted in the low-to-mid single digits, making the Test & Measurement business a persistent drag on Emerson's overall organic sales growth through fiscal 2024 and into fiscal 2025.1[^12]
Operational integration, however, progressed rapidly. Emerson targeted $165 million in total annual cost synergies and reported realizing over $100 million in the first year—ahead of its original timeline—by eliminating duplicate corporate overhead, consolidating manufacturing facilities, and enforcing strict expense controls through the Emerson Management System.[^12] This execution demonstrated the company's traditional strength in cost reduction, which remains the most predictable component of M&A value creation.
The outcome refines rather than invalidates Emerson's reputation for deal discipline. Management proved it can extract targeted cost reductions on schedule, but it also showed a willingness to raise purchase prices during contested auctions at cyclical peaks. Because cost synergies are finite and non-repeating, relying on expense reduction rather than organic growth yields lower-quality long-term returns. If Test & Measurement organic sales re-accelerate to a mid-single-digit percentage rate while maintaining margins, it will indicate Emerson acquired a durable growth platform despite the high purchase multiple. Conversely, lingering low-single-digit growth through the late 2020s would confirm that Emerson bought a cyclical business near its peak, potentially creating future goodwill impairment risks.
Having established the composition of Emerson's acquired portfolio, the central question turns to how these disparate assets perform as a unified industrial technology platform.
VI. Core Business Anatomy, Industry Structure & Economics
Consider a liquefied natural gas facility on the Gulf Coast. Natural gas arrives, is stripped of impurities, and is chilled to roughly minus 162 degrees Celsius, condensing into a liquid that occupies about one six-hundredth of its original volume. The multi-billion-dollar facility operates continuously for years. An unplanned shutdown costs the operator millions of dollars per day in lost output, and restarting operations takes days. Virtually every physical and digital control mechanism inside that facility falls into a product category Emerson sells.
Emerson today operates and reports through two primary business groups: Intelligent Devices and Software & Control.
Intelligent Devices — the physical layer
Intelligent Devices accounts for roughly two-thirds of total sales and encompasses the physical hardware directly interacting with industrial processes.
Final Control, built on the Fisher franchise, manufactures control valves, actuators, and regulators. A control valve is far more complex than a standard industrial valve; it is a precision-engineered assembly that must modulate the flow of corrosive, cryogenic, or superheated fluids under extreme pressure. It must position itself to within a fraction of a percent thousands of times daily, operating for years without leakage. In safety-instrumented systems, control valves serve as the final physical boundary against operational disaster, which is why valve selection is governed by strict engineering standards, third-party certifications, and plant-specific documentation built over years of operation.
Measurement & Analytical, built on the Rosemount brand, produces transmitters that track pressure, temperature, flow, and fluid levels, alongside analytical instruments that monitor chemical composition. Precision is paramount: in custody transfer applications, where ownership of a product transfers as it passes a meter, even a fraction-of-a-percent measurement error on a high-volume hydrocarbon stream represents significant financial value daily. High measurement accuracy is therefore a purchasing requirement that resists standard procurement cost-cutting.
Discrete Automation, which includes ASCO solenoid valves and AVENTICS pneumatic systems, serves factory automation by providing fluid power and control components that actuate machinery. This segment represents Emerson's most competitive and cyclical hardware exposure, competing directly against Siemens, Rockwell Automation, and numerous regional specialists.
Software & Control — the digital layer
Software & Control generates roughly one-third of total sales and represents the higher-margin segment of the enterprise.
Process Systems & Solutions houses DeltaV, the distributed control system for continuous processing, and Ovation, the specialized control system used in power generation and water utilities. Ovation's strategic importance has elevated due to expanding electricity generation and grid infrastructure driven by data center construction and broader electrification. Power-sector control spending has increased accordingly, and Ovation operates in a sector characterized by stringent reliability standards and lengthy qualification cycles.
Industrial Software comprises AspenTech, now fully owned following the completion of the minority buyout.
Test & Measurement consists of National Instruments, providing automated test equipment and validation software.
Industry structure
Continuous process automation operates as a global oligopoly dominated by six major providers: Emerson, Honeywell, ABB, Yokogawa Electric, Schneider Electric, and Siemens. Emerson maintains leading market positions in control valves and process measurement—market power accumulated through a massive installed base built over half a century rather than any individual product cycle. Market shares shift slowly because competition takes place at the plant level rather than the individual purchase order. Once a facility's control systems and field instruments are specified, the incumbent secures the recurring brownfield replacement stream by default. A competitor's primary entry point is typically limited to a new greenfield project, which may occur only once a decade.
Discrete automation presents a fundamentally different and less favorable industry structure. Siemens and Rockwell Automation control the programmable logic controller layer, which represents the point of maximum architectural leverage on a factory floor. Beyond that layer, the market is more fragmented, price-competitive, and subject to shorter capital cycles. Emerson remains a challenger in this domain. The acquisition of National Instruments represents an effort to enter discrete automation from an adjacent, defensible position—product testing and validation—rather than challenging established controller providers directly. While structurally coherent, this strategy remains unproven, as financial results through 2025 do not yet indicate that owning National Instruments has generated incremental market share gains in discrete automation.
This two-speed industry structure creates a meaningful variance in Emerson's earnings quality across its segments. The continuous process franchise provides pricing power, high operating margins, and structural durability. Conversely, discrete automation and test exposure offer growth optionality alongside heightened cyclicality and competitive risk. Evaluating Emerson requires recognizing that investors are paying a premium multiple for a high-quality process-automation franchise while absorbing discrete-automation risk across a portion of the portfolio.
Why the continuous process side is so difficult for competitors to displace deserves dedicated examination.
VII. Competitive Moats & Strategic Frameworks
A single document exists at every large process plant that explains more about Emerson's economics than any financial statement: the piping and instrumentation diagram, along with its accompanying instrument index. Tag by tag, it catalogues every device in the facility—listing manufacturer, model, calibration range, control loop, and safety classification. Produced by an engineering contractor years before startup and updated through commissioning, it serves as the operational reference for every maintenance planner and safety auditor throughout the plant's lifetime. Replacing an incumbent vendor requires rewriting portions of that document, re-validating the affected control loops, and, in regulated industries, re-qualifying the process with regulatory authorities.
Applying Helmer's 7 Powers
Switching costs serve as Emerson's cornerstone competitive advantage, driven by economics rather than customer inertia. Replacing a distributed control system in an operating facility generally requires a plant shutdown, with downtime in downstream oil and gas or chemical facilities costing millions of dollars per day. Because asset lifecycles in these plants typically span 15 to 25 years, a competitor offering a 15 percent discount on hardware provides savings of hundreds of thousands of dollars against a changeover cost measured in tens of millions, alongside operational risk on safety-critical infrastructure. This arithmetic favors the incumbent, allowing Emerson to adjust prices during soft demand cycles and enabling its aftermarket services to generate recurring revenue streams akin to software subscriptions.
The structural boundary of this advantage is that it protects the installed base rather than new project wins. On greenfield construction projects, facility owners incur no switching costs, allowing peers such as Honeywell, ABB, Yokogawa, and Siemens to compete aggressively on price and total project scope. Consequently, Emerson's market share shifts incrementally—one project at a time—meaning the moat secures cash-flow harvesting rather than automatic organic expansion.
Process power—the concept of the installed base functioning as a proprietary data asset—warrants rigorous scrutiny. Under management's thesis, tens of millions of deployed Emerson field devices generate operational data that feeds AspenTech simulation models, which produce recommendations executed through Emerson control systems, creating an integrated loop competitors cannot replicate. While the mechanism is logically coherent, empirical evidence of commercial differentiation remains limited. Emerson has not disclosed metrics demonstrating that AspenTech adoption rates on Emerson-controlled facilities exceed those on competitor platforms, and AspenTech historically served clients regardless of the underlying hardware vendor. As a result, process power remains a strategic hypothesis rather than an established competitive moat, requiring disclosure of software growth concentrated within Emerson's control-layer customer base for confirmation.
Counter-positioning represents the weakest moat claim. Divesting legacy hardware and acquiring software assets does not create a business model that incumbent competitors are structurally unable to copy—the core requirement of counter-positioning. Siemens has expanded aggressively into industrial software, Schneider Electric owns AVEVA, and Honeywell has pursued corporate separations to focus its operations. While Emerson moved earlier and more decisively than certain peers, labeling this shift counter-positioning overstates the competitive dynamic. The pivot achieved portfolio clarity, which public markets may reward with a higher valuation multiple, but competitors retain the capacity to replicate the strategy.
Porter's five forces, briefly
Threat of new entrants: Very low. Barriers to entry are regulatory and reputational rather than purely technological. Securing safety certifications, pharmaceutical validation approvals, nuclear qualifications, and hazardous-area clearances requires years of testing and substantial capital investment. Furthermore, plant managers rarely risk operational standing by specifying unproven vendors for safety-critical control loops.
Buyer power: Mixed across project types. On multi-billion-dollar greenfield liquefied natural gas or chemical projects, facility owners and engineering contractors run competitive procurement processes, extracting concessions on price and project scope for main automation contractor awards. Conversely, buyer power diminishes on brownfield equipment replacements and software renewals. This dynamic yields moderate pricing power overall, with the annual mix between greenfield and brownfield projects directly influencing realized operating margins.
Supplier power: Low to moderate. While Emerson's procurement scale provides leverage when sourcing commodity components, supply-chain disruptions between 2021 and 2023 demonstrated that semiconductor and electronic component shortages can bottleneck instrumentation and controller deliveries regardless of corporate scale.
Substitutes: Low. Physical flow control requires physical hardware, as valves cannot be virtualized. Furthermore, real-time safety functions require local execution rather than offsite cloud processing.
Rivalry: High and escalating. Competition is concentrated around large energy-transition and liquefied natural gas projects, where total automation scope is awarded as a unified package and major providers—including ABB, Honeywell, Siemens, and Yokogawa—compete for a limited pipeline of mega-projects.
For investors, the synthesis is that Emerson's competitive moat is structurally sound but narrower than corporate presentations suggest. The installed base protects a high-margin, predictable cash flow stream, but it does not automatically generate the 5 percent organic growth target pledged by management. Achieving that target depends on end-market expansion and cross-selling capabilities that have yet to appear in financial disclosures, elevating management's execution track record into the central variable for long-term underwriting.
VIII. Management Credibility, Governance & Capital Allocation Stress Test
In November 2025, Emerson management presented investors with explicit targets for fiscal 2028: reaching $21 billion in net sales—implying roughly 5 percent compound organic growth—achieving an adjusted segment EBITA margin of 30 percent, and returning $10 billion to shareholders.[^12] These concrete milestones provide a clear benchmark for evaluating the leadership team tasked with executing them.
Lal Karsanbhai has systematically executed the portfolio repositioning outlined at the start of his tenure. He promised to divest non-automation operations and followed through, selling Climate Technologies, divesting the tools businesses, and initiating a strategic review of remaining legacy units.61 He also committed to assembling a software-defined automation stack, achieving that goal through major capital deployments. While his operational execution score remains high, his capital allocation judgment faces scrutiny: Karsanbhai raised purchase prices significantly in contested auctions for both AspenTech and National Instruments, only to see both assets hit by cyclical demand slowdowns shortly after acquisition. Delivering a structural pivot and maintaining discipline on purchase prices require distinct skills.
Chief Financial Officer Mike Baughman operates under a focused mandate: driving margin expansion, maintaining free cash flow conversion above 100 percent, and reducing balance-sheet debt following the March 2025 buyout of AspenTech's minority shareholders.[^5] Deleveraging progress remains a transparent metric for investors tracking post-transaction capital discipline.
Ritu Favre, leading the newly formed Test & Measurement segment, oversees the National Instruments integration—the unit facing the most immediate pressure to justify its transaction valuation.
Incentives
Emerson's executive compensation framework ties performance payouts to underlying sales growth, adjusted EBITA margin, free cash flow, and return on invested capital (ROIC).1 Incorporating ROIC is critical for an enterprise that has deployed over $15 billion in capital acquisitions, as large transaction premiums naturally weigh on returns on capital. While rewarding capital efficiency aligns management with shareholder interests, the practical test rests on how the board's compensation committee handles goodwill and acquisition-related adjustments when calculating ROIC. Proxy statement disclosures on these discretionary adjustments warrant close investor scrutiny.
The activist question
The core question for investors is whether Emerson has replaced a legacy hardware conglomerate with a software and test conglomerate at peak-cycle entry valuations, and whether such a combination merits a pure-play technology valuation multiple.
Skeptics highlight a clear asymmetry in capital reallocation. Emerson sold Climate Technologies—a market-leading franchise with predictable economics—for $14 billion.6 It subsequently redeployed that capital by paying approximately $8.2 billion for National Instruments at a cyclical peak, after which organic sales contracted,5 and roughly $7.2 billion to buy out the AspenTech minority equity just as software contract growth slowed.4 Combined with the initial consideration for control of AspenTech, total outlay exceeded the proceeds from the Climate sale. Furthermore, the resulting portfolio comprises three distinct operations—process instrumentation and valves, process control software, and electronics test equipment—that serve overlapping but separate customer bases through different go-to-market channels.
Management counters this critique with its Boundless Automation framework: an integrated architecture connecting design software, test systems, and operational controls around a unified data layer to enable cross-selling across the product lifecycle.[^12] This strategy is architecturally coherent, and management has maintained narrative consistency by presenting the concept uniformly across multiple investor communications.
However, public disclosures have not yet validated this synergy thesis. Emerson has not published metrics detailing cross-sell revenue generated by the integrated stack, attach-rate data connecting AspenTech software expansion to Emerson control installations, or evidence that National Instruments secured test contracts it could not have won independently. The company has demonstrated a consistent capacity to capture expense synergies across acquired assets, but it has yet to prove that the portfolio generates revenue synergies. Given the earlier precedent set by Network Power, investors remain cautious about accepting integration benefits before they appear in top-line results.
Ultimately, the governance stress test indicates that Emerson's management has proven its ability to restructure operations and execute strategic sales, while revenue synergies and valuation discipline remain unproven. This balance sets the framework for the company's long-term outlook.
IX. Playbook: Business & Investing Lessons
1. Selling a good business is harder than selling a bad one, and more informative. Every management team divests underperformers; that is routine housekeeping. Divesting a profitable market leader because it generates lower long-term returns than alternative capital deployments signals genuine board discipline. The counterweight: strategic divestment is validated only by the performance of the acquired assets, a verdict that remains open. Reallocating capital without price discipline simply alters how value is destroyed.
2. Moats live in the control loop, not in the product catalog. The durable economics in industrial automation stem from being embedded in a safety-critical, documented, and regulated process where the cost of change far exceeds the price of the hardware. Equipment specified in a facility's permanent engineering documentation commands premium margins; items sold from a catalog compete on price. This provides a portable analytical test: assessing an industrial supplier requires verifying whether its products appear on regulatory-approved engineering drawings.
3. Cost synergies are reliable; revenue synergies are a hypothesis. Emerson delivered on integration cost targets ahead of schedule because eliminating duplicate corporate functions is an operational exercise that a disciplined management system executes effectively.[^12] Cross-selling requires changing how customers buy—a variable no acquirer controls. When underwriting an acquisition, investors can credit planned cost reductions while heavily discounting revenue synergies until they materialize in reported organic growth.
4. Paying a peak multiple and timing a cycle poorly are distinct errors, though both destroy value. The National Instruments transaction illustrates that a strategically sound acquisition can dilute returns if the entry multiple assumes peak-cycle demand. Investors evaluating large transactions must determine what earnings level a purchase price implies and whether that level represents cyclically normalized performance.
5. Beware the capability mismatch in adjacent acquisitions. The Avocent and Network Power episode provides the clearest lesson in Emerson's own history: an operating model optimized for cost reduction in slow-cycle hardware proved ill-suited for managing fast-cycle technology assets. The contemporary strategy makes a similar category of bet at five times the scale. The key mitigating distinction is that AspenTech and National Instruments sell to Emerson's existing customer base in slow-cycle industrial processes rather than to hyperscale data center buyers—a structural difference suggesting history may not simply repeat.
X. Analysis: Bull vs. Bear Case & Historical Falsification
Why Emerson wins from here
The bull case rests on three legs, and they are not equally strong.
The demand leg is the most concrete. Several large capital investment cycles run through Emerson's primary end markets simultaneously: liquefied natural gas export infrastructure additions, power generation and grid upgrades driven partly by data center electricity demand, reshoring of semiconductor and pharmaceutical manufacturing capacity in the United States and Europe, and broader life sciences expansion. These represent multi-year project commitments with long lead times, where automation architecture is specified early in engineering design. In particular, Ovation's established position across power generation and water utilities benefits directly from growing utility infrastructure spending—an instance where an acquisition completed decades ago provides exposure to an end market experiencing unexpected structural demand.
The margin leg is plausible and largely mechanical. Expanding adjusted segment EBITA margins from roughly 27.6 percent toward the 30 percent target by fiscal 2028 relies on software outgrowing hardware, sustained pricing power, and realizing remaining synergies from National Instruments.1[^12] Expanding margins by nearly two and a half percentage points over three years is achievable given Emerson's cost discipline, yet a significant portion depends on a favorable revenue mix shift. That mix shift, in turn, requires a recovery in software sales—the exact growth driver that recently decelerated.
The ownership leg is the most straightforward. Acquiring full control of AspenTech eliminates governance friction, removes minority interest leakage from consolidated cash flow, and allows Emerson to integrate product lines without seeking special committee approvals.[^5]
What could break it
Cyclical sensitivity presents the most immediate vulnerability. Emerson's top-line performance remains tied to industrial capital expenditure and plant maintenance budgets. Prolonged high real interest rates, sustained low capacity utilization among European chemical producers, or delays in the liquefied natural gas project pipeline could directly pull organic revenue growth below management's 5 percent annual target.
The balance sheet holds structural risk in goodwill and intangibles. After deploying over $15 billion across AspenTech and National Instruments, Emerson carries a substantial balance of intangible assets. While write-downs are non-cash accounting adjustments, an impairment would explicitly acknowledge that acquisition underwriting proved overly optimistic—a misstep Emerson previously experienced with Network Power. The catalyst for such an impairment would be a prolonged failure of software or Test & Measurement sales to recover. Consequently, the valuation assumptions and reporting-unit estimates supporting these carrying values represent critical accounting disclosures to monitor in annual reporting.13
Geopolitical exposure represents another understated factor. China remains a vital process automation market, where domestic competitors—supported by state policies encouraging industrial localization—are advancing from basic hardware components into complex control systems. Simultaneously, international trade restrictions on semiconductor equipment create headwinds for test and validation systems. While this dynamic threatens market share rather than corporate solvency, it cautions against projecting historical Asian expansion rates into the future.
Finally, execution risk stems from the sheer scope of the corporate transformation. Management has simultaneously altered the product portfolio, target customer segments, and operating model while integrating two major acquisitions and reducing debt. While each initiative is individually manageable, executing them concurrently during a period of sluggish demand increases the potential for operational slip-ups.
Historical falsification, weighed
Three core claims underpinning the bull thesis can be evaluated directly against Emerson's operational history.
Claim: Emerson is an excellent capital allocator. The clearest counterevidence remains the 2009 acquisition of Avocent and the subsequent divestment of Network Power. Emerson invested roughly $1.2 billion in a technology-adjacent asset, recorded significant impairments, and ultimately sold a majority stake at a depressed valuation in 2016—only to watch private equity owners create tens of billions of dollars in equity value under the Vertiv brand. That transaction involved a similar strategic rationale: purchasing software-adjacent assets to access faster-growing tech markets. Although the deal predates current leadership, it highlights recurring institutional challenges in technology underwriting. Verdict: the claim fails in its absolute form. It holds only in a modified sense: Emerson excels at operating acquired assets and extracting cost synergies, but exhibits an inconsistent record in deal underwriting. The key metric to watch is return on invested capital. A rebound into the mid-teens as acquired operations mature would support management's strategy, whereas an ROIC stalling in the high single digits would confirm that Emerson overpaid for top-line growth.
Claim: Emerson bids with discipline. Recent transaction history directly contradicts this assertion. In the takeover of National Instruments, Emerson's offer rose from initial private bids in the high $40s per share to a $53 public proposal, before closing at $60 per share in cash.57 Similarly, the buyout of AspenTech's minority equity expanded from an initial offer of $240 per share to a final price of $265 per share.94 Securing two major price increases within two years under the current chief executive indicates a clear pattern. Verdict: the claim is rejected in its strict form. A more realistic interpretation is that Emerson willingly pays full market valuations for assets deemed strategically essential, relying on aggressive post-merger cost cuts to validate purchase prices. Future dealmaking should be evaluated under that premise. The primary benchmarks going forward are whether total synergies from National Instruments exceed the $165 million target and whether organic sales growth in Test & Measurement rebounds above 5 percent.
Claim: Industrial software insulates the business from economic cycles. The slowdown in annual contract value growth during 2024 and 2025, driven by weakness in the chemical sector, disproves this claim in its strongest form.[^12] A more accurate framing is that software expands operating margins and dampens downside volatility, but does not decouple the enterprise from broader industrial capital expenditure. The key test will be whether AspenTech can restore annual contract value growth to the high single digits during periods when customer capital spending remains subdued.
A final assertion often cited by market commentators is that Emerson's long dividend record reflects balance sheet conservatism. Management maintains a decades-long dividend growth streak as a core priority,1 but a track record of dividend expansion reflects a capital allocation commitment rather than a debt-free balance sheet. Indeed, Emerson funded its recent transaction spree by expanding debt while preserving its payout. The strength of the balance sheet must be judged on leverage ratios and cash conversion rather than the dividend streak itself.
XI. Looking Forward & Key Forward KPIs
Management's medium-term commitments provide clear metrics for evaluating the transformation. By fiscal 2028, Emerson aims to generate $21 billion in net sales—requiring roughly 5 percent compound annual organic growth from its fiscal 2025 base of approximately $18.0 billion. The target also calls for expanding adjusted segment EBITA margins to 30 percent, up from roughly 27.6 percent in fiscal 2025, while returning $10 billion to shareholders through dividends and share repurchases, following approximately $2 billion in buybacks in fiscal 2025.1[^12]
Judged against Emerson's historical execution, these targets vary in credibility. The margin path is the most plausible, supported by the company's proven cost-reduction mechanisms and operational discipline. The top-line target presents a higher hurdle, as achieving 5 percent organic growth requires sustained expansion from discrete automation and test and measurement—segments that experienced recent organic contractions. Meanwhile, capital return commitments remain fully within management's control, though they could be reprioritized if executive leadership pursues further acquisitions, following the aggressive transaction cadence established since 2021.
Evaluating progress toward these fiscal 2028 targets depends on three key operational indicators:
First, Software & Control organic growth, specifically AspenTech's annual contract value. This metric serves as the primary test of the portfolio transformation. If software and control revenues compound at a high single-digit rate during periods of flat industrial capital expenditure, it will validate management's claim of acquiring a higher-growth asset. Conversely, if software expansion closely tracks client capital cycles, it would indicate that Emerson paid software-level valuation multiples for cyclical industrial assets, narrowing the investment thesis to the legacy process control franchise.
Second, adjusted segment EBITA margin trajectory. Reaching 30 percent from the high-27 percent range will signal whether product mix shifts and integration cost savings generate compounding gains. The composition of this margin expansion is critical: gains driven by software expansion and pricing power reflect durable structural progress, whereas margin improvements achieved through deferred capital investment or non-recurring cost reductions offer limited long-term sustainability.
Third, free cash flow conversion and the leverage trajectory. Converting over 100 percent of net earnings into free cash flow has long served as Emerson's operational benchmark. Following the March 2025 debt-funded buyout of AspenTech's minority shareholders, the pace of balance-sheet deleveraging provides a direct test of underlying cash generation.[^5]1 Free cash flow conversion also offers a more reliable gauge of earnings quality than adjusted metrics, as it is less susceptible to accounting adjustments.
These three key performance indicators are directly measurable against explicit commitments for fiscal 2028. By establishing target dates and numerical benchmarks, Emerson's leadership has defined the parameters of its own accountability, offering investors an objective framework to assess whether the $30 billion portfolio transformation ultimately generates long-term value.
XII. Primary Transcripts & Investor Evidence
Five primary corporate disclosures carry the central evidentiary weight for evaluating Emerson Electric's transformation.
The November 2025 investor conference serves as the anchor document for current corporate strategy. During the presentation, management established its fiscal 2028 financial targets, detailed the Boundless Automation framework as an operational architecture rather than a marketing slogan, and outlined the margin bridge toward the 30 percent objective.[^12] Comparing this disclosure against prior investor day presentations reveals narrative consistency, showing whether management maintained its core growth drivers or adjusted baseline expectations over time.
The fourth quarter fiscal 2025 earnings call and the accompanying annual report provide the empirical foundation for the restructured enterprise, detailing full-year net sales, segment operating margins, and the post-buyout cash flow and leverage profile for AspenTech.12
The March 2025 completion announcement for the remaining AspenTech shares documents the final transaction terms and tender offer mechanics.[^5] The release also provides management's explicit governance rationale for eliminating the public minority equity structure.
The fourth quarter fiscal 2024 call documents year-one integration progress for National Instruments, pairing reports of ahead-of-schedule cost synergy realization with commentary on demand softness across discrete automation and test markets. Prepared remarks emphasized expense reduction, while analyst questioning focused on organic revenue contraction.
The second quarter fiscal 2023 call, conducted weeks after the National Instruments transaction agreement, offers key evidence on executive valuation discipline. Analysts pressed management directly on the purchase price escalation—from initial private bids in the high $40s per share to the final $60.00 per share cash agreement—and questioned the timing relative to the test and measurement demand cycle. Evaluating management's commentary during that call against subsequent operational performance provides a direct benchmark for assessing corporate underwriting judgment.
References
-
Emerson Electric Co. FY2025 Form 10-K Annual Report — SEC EDGAR ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Emerson Agrees to Buy Rest of AspenTech for $7.2 Billion — Bloomberg, 2025-01-27 ↩↩↩↩
-
Emerson Electric to Buy National Instruments in $8.2 Billion Deal — Reuters, 2023-04-12 ↩↩↩
-
Emerson to Sell Climate Technologies Unit to Blackstone in $14 Billion Deal — Bloomberg, 2022-10-31 ↩↩↩↩
-
Emerson Electric Reaches Deal to Buy National Instruments — Wall Street Journal, 2023-04-12 ↩↩
-
SEC EDGAR — National Instruments Corp CIK 0000319201 Filings ↩
-
Emerson Proposes to Acquire Remaining Shares of AspenTech — Reuters, 2024-11-05 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube