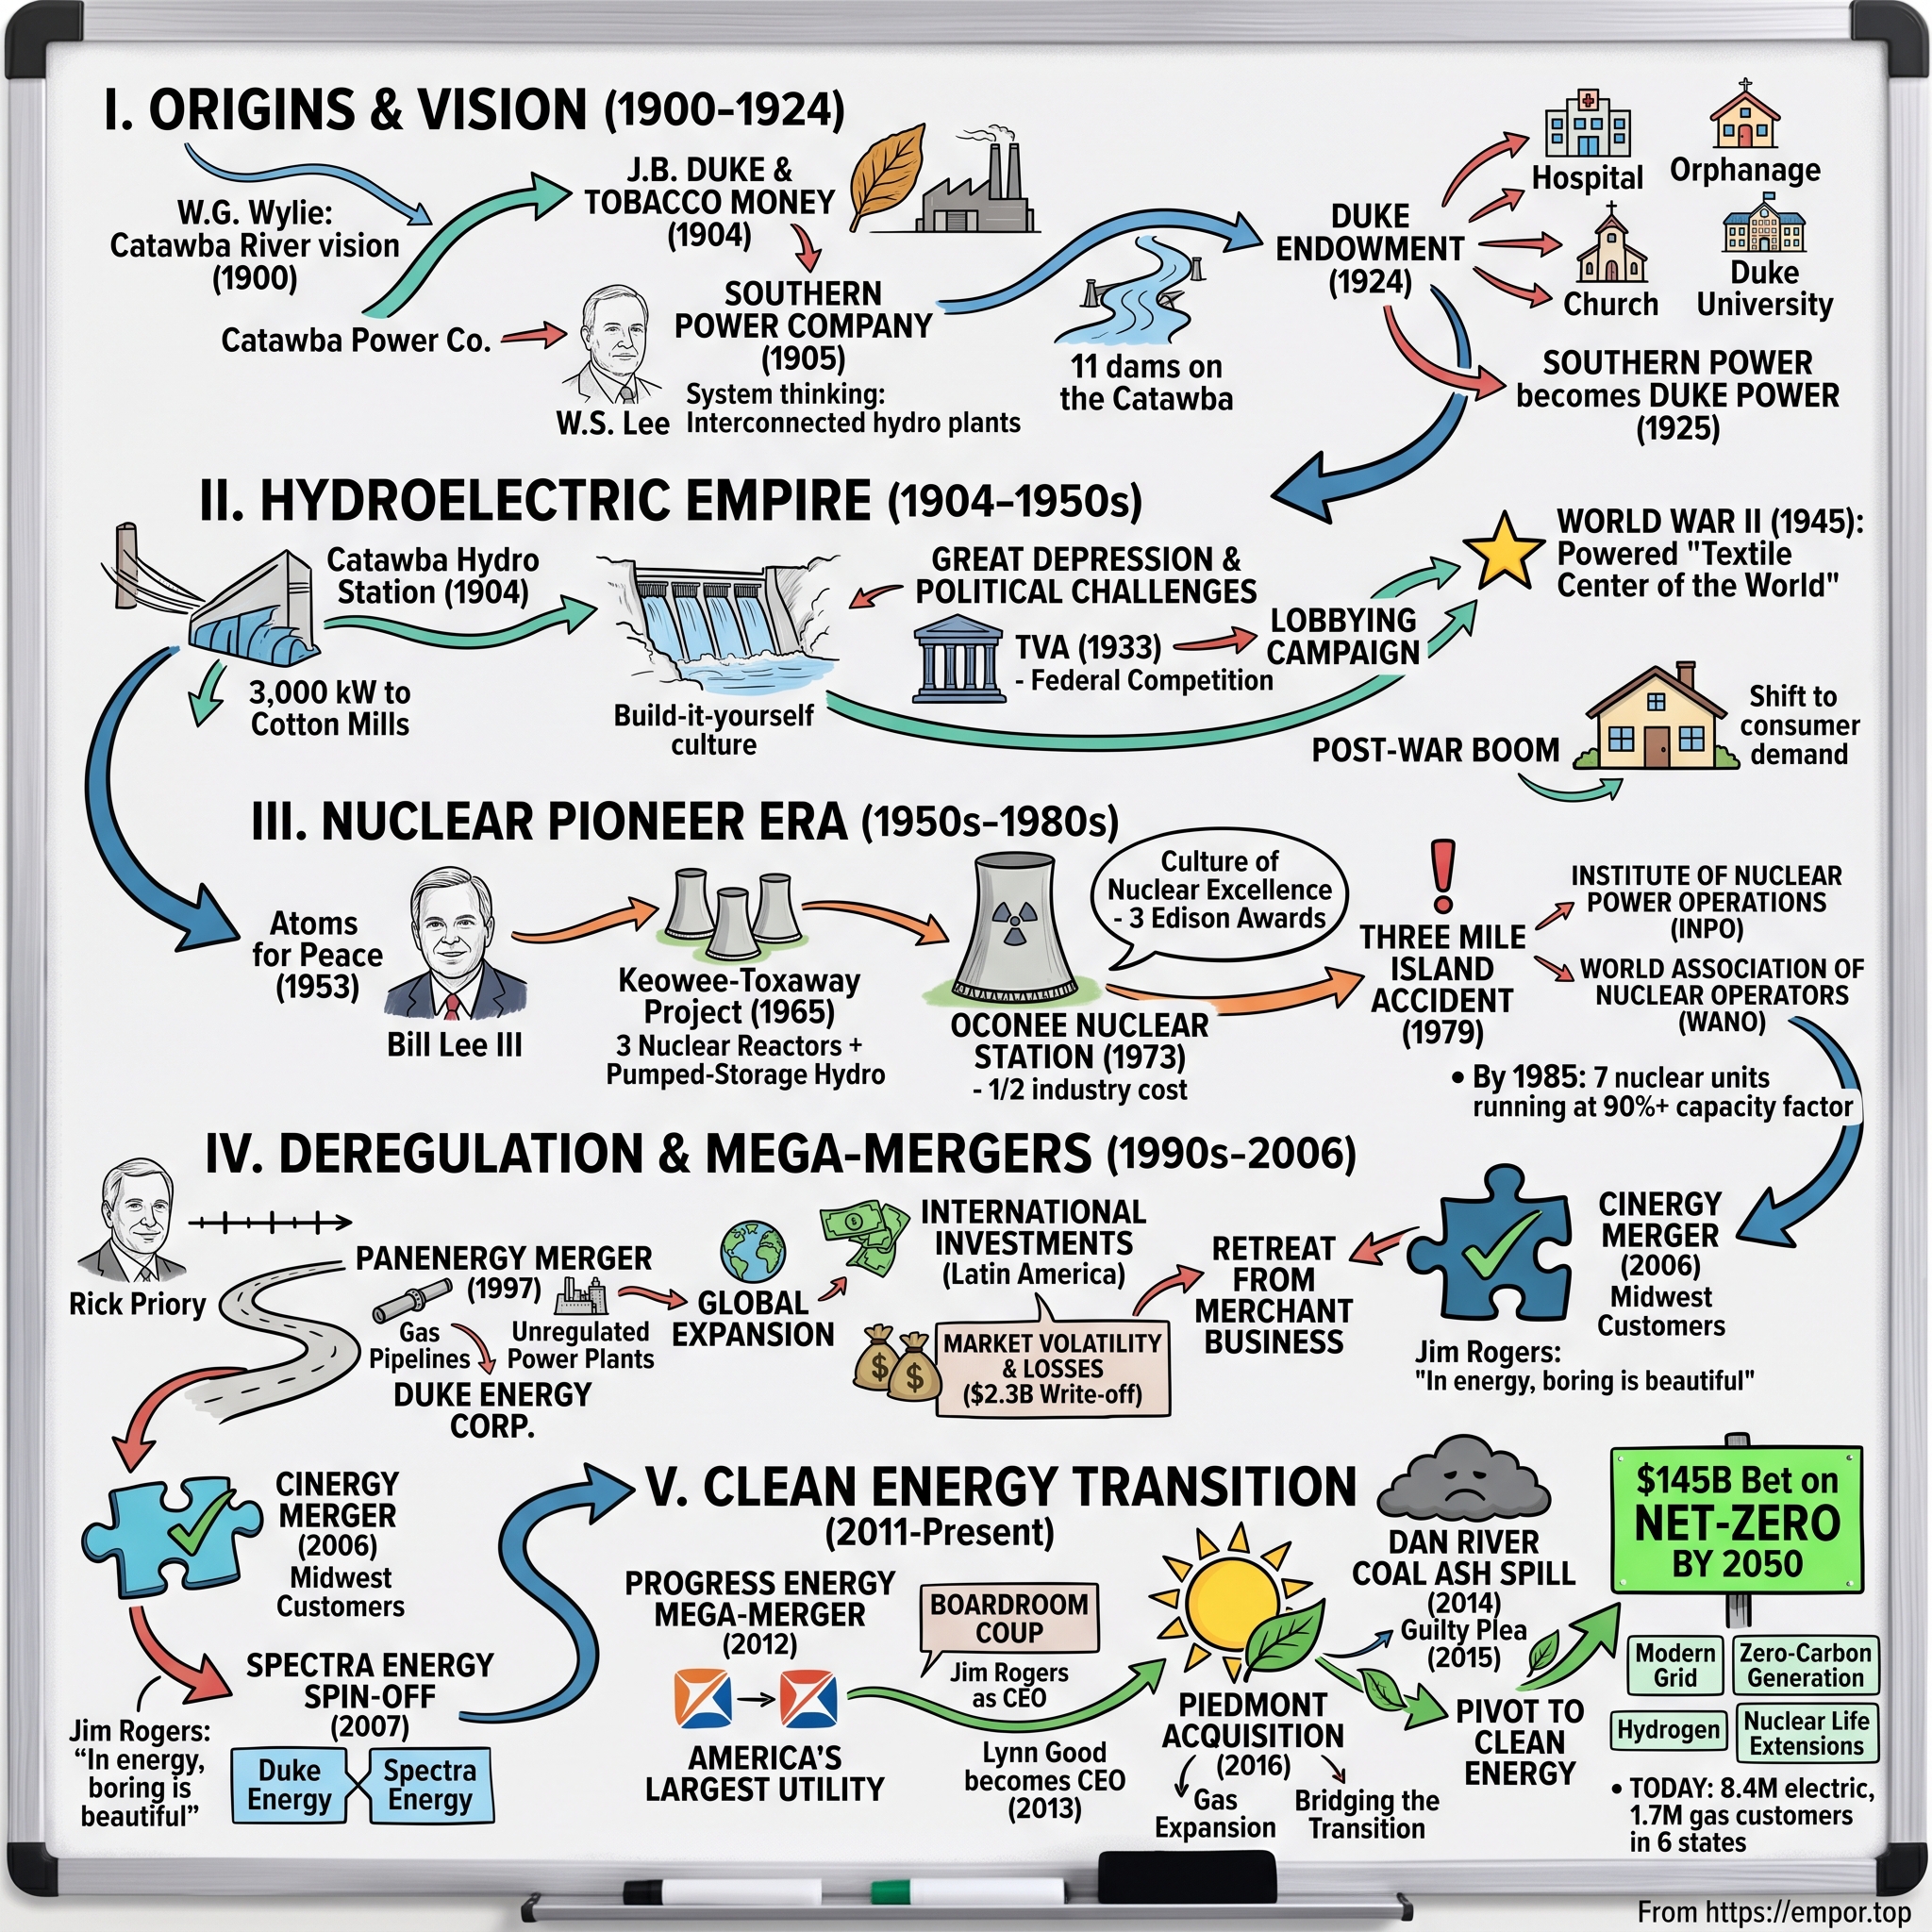
Duke Energy: From Tobacco Hydro to America's Regulated Energy Giant
I. Introduction & Episode Roadmap
There is a particular kind of American fortune that gets made twice. The first time, capital is accumulated in familiar industries — tobacco, railroads, or oil. The second time, that capital is quietly redeployed into essential infrastructure, so deeply embedded in the physical world that a century later its origins are largely forgotten.
Duke Energy represents that second kind of fortune. The capital that constructed the dams along the Catawba River originated in machine-rolled cigarettes. James Buchanan "Buck" Duke had already cornered the American tobacco market before turning his attention to regional water systems and their commercial potential. What he built with that capital has evolved, more than 120 years later, into one of the largest regulated electric utility holding companies in the United States. Today, the company delivers electricity to roughly 8.6 million customers across six states and natural gas to about 1.7 million customers, operating a generation fleet of approximately 55,000 megawatts and generating annual revenues of around $30 billion.12
That scale defines its modern footprint. The central question for Duke is not its physical size — utilities are capital-intensive by design — but how its corporate strategy has shifted over time. Duke has fundamentally altered its business model at least twice over the past three decades, with both pivots imposing substantial financial costs on shareholders.
The outline of this corporate trajectory is clear. For most of the twentieth century, Duke Power operated as a regional hydro and nuclear utility in the Carolinas, defined by strong engineering capabilities and close ties to its home-state political and regulatory establishments. In the 1990s, as energy deregulation swept the industry, Duke expanded beyond its core footprint, transforming into a merchant power trader, pipeline operator, Latin American asset owner, and global energy conglomerate. That diversification strategy ultimately faltered. During the 2000s and 2010s, the company unwound these holdings by spinning off pipeline assets, acquiring regulated regional utilities, and absorbing significant governance and environmental liabilities. By 2024, Duke had largely completed this retreat to re-emerge as a regulated pure-play utility, running a capital plan that management projected at roughly $83 billion over 2025–2029 and more than $145 billion over ten years.12
Now a third era has arrived: after two decades of stagnant domestic electricity demand, expanding data center buildouts and industrial reshoring have positioned Duke’s core service territories in the Carolinas and Midwest near the center of a major load-growth cycle.
The roadmap for this narrative follows the company's key structural shifts. First, the deployment of tobacco capital to build an interconnected hydroelectric system. Second, the nuclear expansion, during which Duke established operational practices later adopted across the utility sector. Third, the deregulation expansion and its subsequent, costly unwind. Fourth, the modern regulated model — marked by coal ash remediation, pipeline write-downs, and renewables impairments — alongside the current load-growth cycle driving management's expanded capital program.
Underlying every era is a fundamental industry discipline: a regulated utility’s story is a story about regulatory permission. Duke does not generate returns by expanding sales volume or setting market prices; it earns returns by securing regulatory approval to invest capital into rate-base infrastructure. Every strategic victory and operational failure in the company's history ultimately runs through that single mechanism.
 Subscribe on LinkedIn
II. The Tobacco Duke Origins & Founding Vision (1900–1924)
In 1900, the Catawba River ran out of the Blue Ridge Mountains through the Piedmont, flowing past Southern cotton mills powered by steam from rail-hauled coal. The region was industrializing, but at high cost because the Southeast lacked local coal deposits. Its primary energy resource was falling water.
Two figures recognized that potential early. Dr. Walker Gill Wylie, a South Carolina-born physician based in New York, sought to bring capital back to his home state. William States Lee was an engineer with a systems-focused approach. In 1900, they organized the Catawba Power Company and constructed a hydroelectric station at India Hook Shoals near Rock Hill, South Carolina, to supply electricity to the Victoria Cotton Mills.
The plant functioned, but the business model did not scale. A single dam tied to a single mill was a sound engineering project, but a limited commercial business. Scaling required a unified system: a chain of hydroelectric stations along the river basin tied together by transmission lines, ensuring that low water flow at one station could be offset by generation elsewhere. That level of development required capital far beyond what regional mill syndicates could provide.
The man with the money
That capital arrived through James Buchanan "Buck" Duke. By the mid-1900s, Duke had industrialized cigarette production using the Bonsack rolling machine and consolidated the industry into the American Tobacco Company. He brought a business strategy centered on scale, capital intensity, and vertical control.
The connection became part of company history: while treating Duke for a kidney ailment, Wylie pitched the hydroelectric potential of the Catawba River basin. Duke committed roughly $3 million, leading to the organization of the Southern Power Company in 1905 to construct the regional hydro grid Wylie and Lee had designed.
This initial commitment mattered far beyond the nominal sum. In 1905, $3 million in private, patient, single-owner capital functioned differently from capital raised through Northeastern utility syndicates, which demanded immediate debt service. Because Duke answered to himself, Southern Power could construct generation capacity ahead of demand, operating on the principle that providing low-cost electricity would induce textile mills to convert.
Manufacturing your own customers
Southern Power actively built its customer base rather than waiting for organic demand. Company representatives offered mill owners a combination of commercial sales and equipment financing: convert steam-driven line shafts to electric motor drives in exchange for long-term power supplies. In several instances, Duke interests took equity stakes in the mills or financed new facilities directly. This strategy built an anchored industrial customer base of textile mills operating at high load factors day and night — providing the predictable demand profile needed for a capital-intensive hydro system to recover its fixed costs.
This approach established an operational template that endured into 2026: a corporate preference for large industrial customers with predictable, continuous demand. When hyperscale data centers expanded a century later, the commercial dynamic reflected this early model — large individual customers with flat, round-the-clock loads negotiated directly, justifying capacity expansion ahead of demand. The core financial risk remained unchanged: who bears the cost if expected load fails to materialize?
Lee’s engineering design reinforced this commercial strategy. Rather than building isolated power plants, he constructed an interconnected river basin linked by regional transmission lines — an early, deliberate recognition that the grid itself, rather than individual generators, constituted the core asset. By the time these operating entities reorganized under the Duke Power Company name in 1924, the Carolinas possessed one of the most integrated regional power systems in the United States.
The foundational lesson of this era centers on capital structure rather than technical novelty: Duke’s primary early advantage was not proprietary hydroelectric technology, but access to concentrated capital that could afford to wait for long-term returns.
What that capital bought next was a fight.
III. Building the Hydro Empire & The Do-It-Yourself Era (1904–1950s)
Most utilities of that era built generation assets by contracting external engineering firms. Duke Power took a different path. From its early days, the company maintained an in-house engineering and construction organization — including surveyors, designers, and construction crews — to build its own dams, powerhouses, and eventually coal-fired steam stations.
While this self-build model resembled mere thrift, its strategic rationale ran deeper. A utility’s returns depend on the capital costs regulators allow it to recover from ratepayers. Building capacity below industry average costs allowed Duke to earn its permitted return on a leaner rate base while keeping consumer rates low. That cost discipline earned crucial political goodwill with state utility commissions. In-house construction effectively converted engineering capability into regulatory capital — establishing a durable cost-side advantage in an industry where legal monopolies faced little direct competition.
This engineer-driven culture, focused on self-execution and cost per kilowatt, became a defining throughline for Duke throughout the twentieth century. It also established the operational foundation that later supported the company's nuclear expansion.
The New Deal comes for the franchise
During the Great Depression of the 1930s, investor-owned utilities confronted unprecedented federal opposition.
The New Deal framework viewed electric power as a public necessity that private monopolies exploited for excess returns. Under this theory, utility infrastructure was best managed through public ownership. The federal government established the Tennessee Valley Authority as its flagship public power project, while the Public Works Administration funded municipal electric systems and rural cooperatives that expanded distribution lines into territories previously claimed by private utilities.
Duke countered this public power movement through constitutional litigation against federal energy projects, aggressive political lobbying, and local campaign tactics. Although public power advocates pushed for municipal and regional alternatives across the Carolinas, Duke successfully defended its service area. The Carolinas never established a federal power authority comparable to the TVA, leaving Duke’s private franchise territory substantially intact through the decade.
From an analytical standpoint, this conflict demonstrated the structural durability of Duke's regulatory franchise. Tested by a federal administration actively seeking to expand public power, the company’s state-granted service territory held firm. Duke's market moat rested not just on legal statute, but on an empirical record of defeating federal attempts to dismantle its monopoly territory.
The endowment as infrastructure
In December 1924, shortly before his death, James Buchanan Duke established The Duke Endowment with an initial gift of approximately $40 million, consisting primarily of Duke Power securities. The Endowment funded the expansion of Trinity College into Duke University while providing ongoing financial support to regional hospitals, rural churches, and child welfare institutions across North and South Carolina.
Beyond its philanthropic impact, the Endowment functioned as a mechanism for institutional stakeholder alignment. Because the founding indenture required the Endowment to retain significant holdings in Duke Power stock, the region’s prominent university, healthcare systems, and non-profit institutions became financially linked to the utility's ongoing dividend capacity and solvency. This structural alignment created a shared interest between the private power company and civic leadership across the Carolinas, reinforcing political support for Duke's regulatory franchise over subsequent decades.
The hydro system, however, faced a physical ceiling. Rivers only fall so far, and by mid-century the Carolinas were industrializing faster than the Catawba River basin could carry.
IV. The Nuclear Pioneer & INPO Leadership (1950s–1980s)
The post-war South shifted demographic and industrial patterns that utility planners had not fully anticipated: net migration reversed as manufacturing expanded. Textiles were followed by furniture, chemicals, tires, and eventually Charlotte's financial sector. Electricity demand in Duke's territory compounded at rates that rapidly surpassed the capacity of its hydroelectric system.
Duke initially addressed this growth with coal-fired steam stations constructed by its in-house workforce. In the mid-1950s, the company turned to nuclear power, joining the Carolinas-Virginia Nuclear Power Associates venture — an industry-funded experiment in small-reactor power when commercial nuclear electricity remained largely experimental. That early exposure mattered less for immediate generation capacity than for establishing technical and operational experience.
Keowee-Toxaway and the cost that nobody else achieved
In the mid-1960s, Duke committed to the Keowee-Toxaway project in upstate South Carolina, an integrated hydroelectric, pumped-storage, and nuclear complex centered on the Oconee Nuclear Station. Its three units were completed in the early 1970s.
Oconee gained industry attention primarily for its economics rather than its output. Duke constructed the plant at a capital cost per kilowatt significantly below the contemporary industry average, and Oconee later became one of the first U.S. nuclear stations to generate more than 100 million megawatt-hours.
While 1970s nuclear construction across the sector suffered widespread cost overruns — often attributed to shifting regulatory requirements following Three Mile Island — standard industry procurement structures created additional friction. Most utilities operated as single-project buyers, contracting separate architect-engineers and construction firms for one or two units without accumulating institutional experience. By contrast, Duke relied on its in-house workforce, standardized designs across sites, and repeated the construction process. Building Oconee's three units, followed by two units each at McGuire and Catawba, allowed the same organization to refine execution over successive projects.
This structural repetition defined Duke's primary operational advantage. Rather than relying on proprietary technology, the company developed an operational edge through repeated execution with a stable internal organization. For a regulated monopoly, this institutional memory functioned as a key operational asset — providing a benchmark for assessing subsequent capital programs, from natural gas expansion and grid hardening to potential small modular reactor deployments.
Bill Lee III and the industry's self-regulation
On March 28, 1979, a partial meltdown at Three Mile Island Unit 2 halted the expansion of the American nuclear power industry and prompted an institutional response across the sector.
William States Lee III, grandson of founding engineer William States Lee and chief executive of Duke Power, recognized that operational risk in the nuclear sector was inherently collective. Because a major accident at any utility threatened the regulatory licenses and public standing of all operators, individual operational excellence offered insufficient protection against systemic industry risk.
This recognition led to the establishment of the Institute of Nuclear Power Operations (INPO) in 1979. Headquartered in Atlanta, INPO was created to conduct peer evaluations of all U.S. nuclear plants and share performance evaluations with corporate executives, boards of directors, and insurers. The model relied on industry peer review, encouraging operators to share technical data and operational issues more candidly than was typical in formal regulatory filings.
Following the Chernobyl accident in 1986, Lee helped extend this framework internationally as a founding figure behind the World Association of Nuclear Operators (WANO), establishing peer evaluation across the global commercial fleet.
From a strategic perspective, this initiative served dual objectives. Establishing institutional standards helped mitigate tail-risk threats to Duke's asset base while reinforcing the company's operating credentials with regulatory authorities. Because Duke operated one of the largest nuclear fleets, protecting the sector's regulatory framework aligned directly with corporate self-interest.
The resulting nuclear fleet — comprising Oconee, McGuire, and Catawba, alongside Robinson, Brunswick, and Harris acquired in the 2012 Progress Energy merger — developed into a core financial asset for the company, providing amortized, zero-carbon, high-capacity-factor baseload generation.
Despite establishing a competitive operational fleet, Duke redirected its corporate strategy over the subsequent decade toward non-regulated business lines and geographic expansion.
V. The Merchant Energy Trap & The Spin-Off Correction (1990s–2006)
The prevailing ideology across the 1990s energy sector was straightforward: rate-regulated utilities were viewed as stagnant legacy operations, while trading desks and merchant generation offered superior growth and uncapped returns.
The Energy Policy Act of 1992 opened wholesale power markets, Federal Energy Regulatory Commission (FERC) orders in the mid-1990s mandated open transmission access, and natural gas had already undergone price deregulation. Driven by these regulatory shifts, a generation of utility executives concluded that traditional wire and pipe ownership offered uninspiring yields. They sought instead to mirror asset-light energy traders and merchant generators operating in competitive wholesale markets. Enron became the industry archetype, and capital markets rewarded companies that adopted its model.
Duke committed fully to this non-regulated expansion.
PanEnergy and the conglomerate build
The defining move occurred in 1997, when Duke Power merged with Houston-based PanEnergy Corp in a transaction valued at roughly $7.7 billion. The deal created Duke Energy Corporation and immediately established the company as a major operator of interstate natural gas pipelines, acquiring Texas Eastern, Algonquin, and Panhandle pipeline systems stretching from the Gulf Coast to New England.
The strategic rationale was internally coherent: by owning interstate natural gas pipelines, gas-fired merchant power plants, and the trading operations linking them, Duke aimed to capture profit spreads across the entire energy value chain rather than accepting a fixed, regulated return on a single infrastructure link. Building on this asset-backed trading strategy, Duke constructed merchant power plants in competitive regional markets, expanded a large-scale energy trading desk, and acquired power generation assets across Latin America.
For several years, the strategy appeared successful. However, the market conditions underpinning the model soon collapsed.
The crash
The California electricity crisis of 2000–2001 and Enron's bankruptcy in December 2001 exposed fundamental vulnerabilities in the merchant power business and contracted industry liquidity. Counterparties tightened collateral requirements, credit rating agencies issued downgrades, and an oversupply of merchant gas-fired plants built on optimistic spark-spread assumptions entered a market burdened by excess capacity and unfavorable gas prices. Trading operations previously valued as high-growth engines were revealed to be highly leveraged, mark-to-market-dependent structures with low earnings quality.
Duke experienced the fallout directly through major balance-sheet impairments on its merchant power plants and international assets, heightened earnings volatility, credit rating pressures, and intense scrutiny over its dividend payout — a critical concern for its income-seeking retail investor base.
Ultimately, Duke's merchant era represented a primary failure of capital allocation driven by strategy rather than execution. The company diverted capital generated by its low-risk monopoly franchise into commodity-exposed businesses where it possessed no structural competitive advantage, expanding near the peak of a market cycle. This historical misstep established a precedent against which subsequent management claims regarding capital discipline would be evaluated.
The retreat
Paul Anderson returned as chief executive officer in 2003 to initiate the unwinding of non-regulated assets, a process completed under his successor, Jim Rogers.
In 2006, Duke merged with Cincinnati-based Cinergy Corp in a stock transaction valued at approximately $9 billion. The transaction added regulated utility operations in Indiana, Ohio, and Kentucky to Duke's portfolio and brought Rogers — a former regulatory attorney skilled in public policy advocacy — to lead the combined company for the next seven years.
In January 2007, Duke completed the structural retreat by spinning off its natural gas transmission and midstream business to shareholders as Spectra Energy, divesting the PanEnergy assets that had served as the centerpiece of its 1997 expansion a decade earlier.
Taken together, these two transactions marked a decisive strategic pivot: Duke re-accumulated regulated customer bases while divesting competitive, commodity-exposed assets. Although strategically necessary, the retreat represented a costly multi-billion-dollar reversal. Shareholders absorbed the financial impact through asset write-downs, a decade of relative stock underperformance, and the opportunity cost of capital that could have otherwise been deployed into rate-base infrastructure.
Having determined that scale in regulated utility operations was its core strength, Duke sought additional regulated acquisitions. Its subsequent pursuit of Progress Energy in Raleigh would severely test its relationship with its primary state regulator.
VI. The Progress Energy Mega-Merger & Governance Fiasco (2011–2012)
On the morning of July 2, 2012, Bill Johnson arrived at work as chief executive officer of the newly expanded Duke Energy, the largest electric utility in the United States. By that evening, he was unemployed. The transition took only hours, executed through a board meeting that the North Carolina Utilities Commission would later describe as the culmination of a plan concealed from state regulators.
The maneuvers behind that decision began eighteen months earlier.
The deal
In January 2011, Duke announced an all-stock acquisition of its Raleigh-based neighbor, Progress Energy Inc., in a transaction valued at roughly $13.7 billion in equity alongside approximately $12.2 billion of assumed net debt8. Progress brought utility operations in the Carolinas and Florida, three nuclear plants—Robinson, Brunswick, and Harris—and a customer base that, combined with Duke's, exceeded seven million.
The operational logic was straightforward and drew little dissent. Combining two adjacent Carolinas utilities with overlapping service territories allowed the merged entity to dispatch generation jointly, share reserve capacity, and eliminate redundant infrastructure projects. Duke told regulators the transaction would yield substantial fuel and dispatch savings for ratepayers, committing to guaranteed cost reductions as a condition for regulatory approval.
Securing approval required eighteen months of regulatory review across two states. Yet the most contentious point in the negotiations was not financial; it was the question of executive leadership.
The twenty-minute coup
Under the negotiated agreement, Johnson—Progress's chief executive, a former attorney with a direct management style—was designated to lead the combined company as chief executive officer. Jim Rogers, Duke's chief executive, was to step into the role of executive chairman. North Carolina regulators endorsed the transaction with the explicit understanding that Johnson's leadership formed an integral part of the governance structure they were sanctioning.
The merger closed on July 2, 2012. Hours later, the newly constituted board convened, accepted Johnson's immediate resignation, and reinstated Rogers as chief executive.8
The North Carolina Utilities Commission reacted with fury rather than routine regulatory objection. The commission opened a formal investigation and summoned directors and executives to give sworn testimony—an extraordinary proceeding in which state regulators cross-examined board members over whether they had misled authorities to secure merger approval.
What it cost
To resolve the regulatory investigation later in 2012, Duke agreed to a series of concessions focused on institutional trust. The settlement mandated rate freezes and customer concessions that Duke valued at more than $100 million, alongside governance undertakings9, executive succession mandates, and a prohibition against recovering specific merger-related expenses from ratepayers. Lynn Good, Duke's chief financial officer, was named chief executive in July 2013—a leadership change directly driven by the commission's demand for fresh oversight.
This episode reveals a critical structural reality of regulated utility operations. In a public company operating in competitive markets, replacing a chief executive upon deal close represents a standard board personnel action. In a rate-regulated utility, however, state regulators act as key counterparties to the operational license. The financial returns a utility earns over subsequent years depend on the regulatory goodwill of commissioners who felt deceived. Duke spent years working to restore credibility in Raleigh—an effort tested almost immediately by an environmental crisis that consumed its remaining regulatory capital.
VII. Coal Ash Disaster, Regulatory Squeeze & Piedmont Gas Acquisition (2014–2018)
Coal ash is the long-term environmental byproduct of coal-fired generation. Decades of burning coal produce vast volumes of residue laced with heavy metals like arsenic, selenium, mercury, and chromium. Throughout the twentieth century, the standard industry disposal method was to mix the ash with water and store it in unlined earthen impoundments adjacent to cooling rivers. Duke maintained dozens of these impoundments across its regional footprint.
On Sunday, February 2, 2014, a corrugated metal stormwater pipe running beneath an ash basin at the retired Dan River Steam Station near Eden, North Carolina, collapsed. Approximately 39,000 tons of ash and 27 million gallons of contaminated basin water poured through the failed pipe into the Dan River, coating the riverbed gray for dozens of miles downstream into Virginia.
The breach went undetected by automated monitoring systems, discovered instead by a security guard during a routine patrol. Public notification followed only after delays that drew widespread public and regulatory criticism.
The criminal case
What transformed the Dan River spill from a costly environmental accident into a systemic corporate crisis was the scope of the federal response. Federal investigators broadened their inquiry beyond Eden to examine Duke's management of ash basins across North Carolina. In 2015, Duke Energy subsidiaries pleaded guilty to nine misdemeanor criminal violations of the Clean Water Act, agreeing to pay $102 million in fines, restitution and community service payments[^11], and accepting court-supervised probation with an independent monitor.[^11]
For a regulated monopoly whose business model relies on state permission to operate essential public infrastructure, a criminal conviction and federal probation in its home state represented a profound regulatory setback.
The cleanup bill
The federal criminal fines represented only a fraction of the total financial exposure. North Carolina's Coal Ash Management Act and subsequent environmental litigation forced a fundamental policy decision: whether to cap the ash basins in place or excavate the material entirely.
In early 2021, Duke reached a settlement with the North Carolina Department of Environmental Quality and environmental intervenors resolving the closure method for the remaining basins, committing to excavation of roughly 80 million tons of ash statewide.10 The accompanying rate-case settlement divided the cleanup costs: customers would bear a portion through rates over time, while shareholders would absorb roughly $1.1 billion of coal ash costs that Duke agreed not to seek to recover.10
That $1.1 billion write-off highlighted a structural limit within utility regulation. The core promise of rate-of-return regulation is that prudently incurred capital costs may be recovered from ratepayers. The coal ash settlement demonstrated that this regulatory framework has clear boundaries. When expenditures stem from management practices that regulators and courts find imprudent, cost recovery is denied and the financial burden falls directly on equity holders.
This episode narrowed the assumption that regulated utilities can automatically pass costs through to consumers. Cost recovery remains subject to retrospective regulatory scrutiny and political judgment, both of which depend heavily on regulatory trust — an asset Duke had already strained during its 2012 merger governance dispute.
Buying a gas utility mid-crisis
Against this backdrop of regulatory pressure, Duke closed the acquisition of Piedmont Natural Gas in October 2016 for $60 per share in cash, an equity value near $4.9 billion representing roughly a 40%-plus premium, plus assumption of about $1.8 billion of debt.2
Piedmont brought approximately one million natural gas distribution customers across North Carolina, South Carolina, and Tennessee. The transaction offered clear strategic alignment: as Duke retired legacy coal units and replaced them with natural gas generation, owning the local distribution franchise provided a second regulated rate base while securing direct integration with the gas infrastructure serving its power plants.
However, the cash-funded acquisition required substantial debt and equity issuance by a company already navigating an environmental crisis. Industry analysts noted that Duke was paying a high premium to expand its fossil fuel infrastructure at a time when long-term gas demand faced growing climate policy and decarbonization scrutiny.
While Piedmont's distribution operations performed reliably as a regulated gas utility, Duke's broader expansion into gas infrastructure included a second, far more ambitious project — one that would ultimately fail to survive legal and regulatory challenges.
VIII. The Unregulated Exit & Pipeline Write-Downs (2019–2023)
Utility executives in the 2010s confronted a familiar structural limit: rate-regulated operations offered steady, predictable growth bounded strictly by regulatory allowances. Seeking a secondary growth engine, Duke pursued two non-regulated ventures—an interstate natural gas pipeline and a commercial renewables developer. Both initiatives ultimately culminated in massive write-downs, forcing a fundamental reset of the company's corporate identity.
The Atlantic Coast Pipeline
The Atlantic Coast Pipeline was conceived as a 600-mile, 42-inch natural gas transmission line stretching from the Marcellus and Utica shale formations in West Virginia through Virginia and into eastern North Carolina. Led by Dominion Energy with Duke as a primary joint-venture partner, the project rested on a straightforward thesis: the Southeast was rapidly shifting generation from coal to natural gas, existing pipeline capacity was constrained, and new infrastructure would generate FERC-regulated returns backed by long-term contracts—many signed with the sponsors' own utility subsidiaries.
After securing its certificate from the Federal Energy Regulatory Commission, the project encountered the legal realities of modern linear infrastructure development. The challenge came not from regulators, but from persistent federal appellate litigation. Key authorizations—including U.S. Forest Service permits, endangered species consultations, and rights-of-way across the Appalachian Trail—were repeatedly challenged and vacated. Project cost estimates escalated from $5 billion to over $8 billion, while completion timelines slipped indefinitely.
In June 2020, the sponsors won a major legal victory when the U.S. Supreme Court upheld their Appalachian Trail crossing permit. Yet just weeks later, on July 5, 2020, Dominion and Duke canceled the pipeline entirely, citing compounding legal delays and cost uncertainties from remaining court challenges.
Duke recorded an after-tax charge of approximately $1.6 billion on the cancellation.52
The cancellation demonstrated that completing large multi-state infrastructure projects requires litigation durability as much as engineering capability—a distinction the project sponsors misjudged. The risk-reward dynamic proved severely asymmetrical for equity holders: a completed pipeline promised regulated returns in the low double digits, whereas cancellation resulted in a total loss of invested capital. This risk profile was already discernible before major capital deployment, as patterns of successful pipeline litigation across Appalachia had emerged by 2015.
The renewables fire sale
Duke's second non-regulated growth engine took longer to unwind and proved even more costly.
Over roughly a decade, Duke constructed a commercial renewables division operating outside its regulated utilities. The unit accumulated roughly 3,400 megawatts of utility-scale wind and solar capacity across the United States, selling power under long-term contracts and monetizing federal tax credits.
Management originally presented this business as a vehicle to capture growth in renewable energy beyond what state regulators permitted in traditional utility rate base. In practice, however, the unregulated model exposed Duke to volatile contract and merchant pricing, while requiring complex, expensive tax-equity financing. Because barriers to entry in commercial renewables depended on capital rather than operational capabilities, competition was intense. Furthermore, income-oriented shareholders valued these volatile, non-rate-based earnings at a lower valuation multiple than Duke's core regulated business. Duke was essentially deploying utility-grade capital to compete against independent power producers and infrastructure funds built specifically for higher-risk assets.
The exit proved financially painful. Across late 2022 and 2023, Duke recorded cumulative pretax impairment charges exceeding $3 billion to write the business down to fair value. In June 2023, Duke agreed to sell the utility-scale commercial renewables business to Brookfield Renewable at an enterprise value of roughly $2.8 billion, closing the transaction in October 2023 with net cash proceeds to Duke of approximately $1.1 billion after debt.34
Together, these two strategic bets resulted in more than $4.5 billion of combined pretax value destruction and left Duke with no surviving non-regulated growth platforms.
What "pure-play" actually means
By 2024, Duke rebranded itself as a pure-play regulated utility. This positioning reflected financial reality: earnings quality improved, the corporate narrative simplified, and capital previously earmarked for speculative ventures was redirected into regulated rate base, where it earned an allowed return.
Yet the "pure-play" designation was less a proactive strategy than a default position resulting from failed diversification attempts. While management's renewed focus on rate-base infrastructure brought genuine capital discipline, that discipline stemmed from strategic failure rather than corporate foresight. For investors, the crucial prospective question was not whether the simplified portfolio was superior—it clearly was—but whether management would maintain this discipline when future adjacencies appeared attractive.
In the near term, however, Duke did not need to search outside its service territory for growth. Increased demand came directly to its regulated footprint.
IX. Current Business Model, Segment Breakdown & Industry Structure
For nearly two decades, American electricity demand remained virtually flat. Efficiency gains from LED lighting, higher-efficiency industrial motors, and updated building codes offset population and appliance growth almost exactly. Utilities expanded earnings not by selling more megawatt-hours, but by replacing aging infrastructure and installing environmental controls.
Then large-scale digital and industrial demand arrived.
The two segments
Duke operates as two primary business segments under a single holding company balance sheet, with earnings heavily concentrated in its electric operations.
Electric Utilities and Infrastructure forms the core of the enterprise. This segment provides generation, transmission, and distribution to roughly 8.6 million retail electric customers across North Carolina, South Carolina, Florida, Indiana, Ohio, and Kentucky. Spanning a service territory of about 95,000 square miles, Duke operates an owned generation fleet of roughly 55,000 megawatts.2 The electric segment generates the overwhelming majority of consolidated earnings, contributing approximately 90 percent of the total.
The company's generation mix has shifted decisively over the past decade. Natural gas has become the primary energy source, followed by nuclear power, which remains the most valuable asset per megawatt due to its high capacity factors and lack of direct fuel-price or carbon exposure. Meanwhile, coal-fired generation has declined to a shrinking minority share, while solar and storage capacity expand from a small base.[^13] Across Duke's primary state jurisdictions, allowed returns on equity generally range from the mid-to-high 9 percent level to around 10 percent, set through state-by-state rate cases.2
Gas Utilities and Infrastructure combines the local distribution business acquired with Piedmont alongside natural gas operations in Ohio and Kentucky. Serving roughly 1.7 million customers, the segment accounts for approximately 10 percent of earnings. It operates as a steady, lower-volatility business driven primarily by new customer connections and mandated pipeline replacement programs.
How a utility actually makes money
This financial mechanism governs the utility business model, yet it remains widely misunderstood.
Duke does not earn a profit margin on the electricity it sells; fuel costs are passed directly through to customers without markup. Instead, Duke earns a regulated return on the capital invested in qualified infrastructure — known as the rate base. State regulatory commissions establish the allowed rate of return on the equity portion of that capital, approve which capital investments qualify as used and useful, and set customer rates designed to cover operating expenses while yielding that permitted return.
This structure creates three important financial dynamics:
First, growth stems from capital deployment rather than sales volume. A regulated utility expands earnings primarily by increasing its rate base. Consequently, multi-year capital expenditure plans — rather than traditional sales forecasts — serve as the primary indicator of future earnings potential in utility financial reporting.
Second, rate-of-return regulation creates a structural incentive to invest capital. Known in regulatory economics as the Averch-Johnson effect, this model encourages utilities to expand capital investment beyond what a competitive firm might select. The role of state regulators is to scrutinize these outlays. When evaluating Duke's planned $83 billion five-year capital program, the central analytical question is not whether the target is ambitious, but whether state commissions will deem each dollar prudent and allow it into the rate base.1
Third, the allowed return represents a regulatory ceiling rather than a guaranteed floor. Duke can earn below its authorized return on equity when operating costs rise faster than rate adjustments between formal proceedings — an exposure known across the industry as regulatory lag.
The load growth surge
Into this traditional regulatory framework arrived the largest demand shock in decades. Hyperscale data center campuses — the physical infrastructure supporting cloud computing and artificial intelligence workloads — consume power at a scale and continuity unlike residential or light commercial customers. A single large facility can require hundreds of megawatts of capacity, while a data center cluster can match the demand of a mid-sized city while operating at a far higher, continuous load factor.
Duke's operating territories sit near the center of this expansion. The Carolinas offer land, water access, competitive industrial utility rates, and a substantial baseline of zero-carbon nuclear generation favored by technology companies with clean-energy mandates. Simultaneously, Duke's Midwest utility footprints sit along major fiber corridors and industrial hubs, complemented by a wave of regional battery and electric vehicle manufacturing announcements.
Management has repeatedly revised its load-growth projections upward, citing this demand surge to justify extending nuclear operating licenses, constructing new combined-cycle natural gas facilities, and executing major transmission upgrades.1[^13]
This demand expansion introduces specific financial and regulatory uncertainties.
Announced data center capacity does not automatically translate into binding power contracts. Technology developers routinely submit interconnection requests across multiple utility territories for a single planned facility to preserve operational flexibility, inflating the aggregate request queue relative to actual realized demand. Consequently, the gap between megawatts queued in interconnection requests and megawatts fully energized and generating rate revenue represents a key analytical risk in Duke's outlook.
The structural risk for utility investors lies in the asymmetry of capital spending. If Duke constructs generation and transmission assets for anticipated demand that fails to materialize, those capital outlays remain embedded in the rate base. Covering the fixed costs of unutilized capacity would then fall on residential and small commercial ratepayers — a dynamic that historically invites political opposition and regulatory prudence disallowances.
As Duke's own history with coal ash and non-regulated expansions demonstrates, capital deployment that loses regulatory backing ultimately imposes its financial costs on shareholders.
X. Current Management, Capital Allocation & Operating Economics
Lynn Good stepped down as chief executive on March 31, 2025. Appointed in 2013 following a high-profile governance dispute and confronted months later by the Dan River ash spill, she spent nearly twelve years stabilizing state regulatory relationships and shrinking Duke back to its core utility franchise.
Her successor, announced in January 2025, was Harry Sideris — a three-decade company veteran who had previously directed the Florida utility, oversaw environmental and safety operations during the post-coal-ash restructuring, and served most recently as president and chief operating officer.11
The selection signaled a clear corporate priority. Rather than appointing a strategist or dealmaker, the board chose an operational specialist whose career was built in state regulatory proceedings, storm recovery, customer operations, and environmental compliance. For a utility whose prior non-regulated expansion produced multi-billion-dollar write-downs, and whose immediate mandate is executing a record capital program across six state jurisdictions, the appointment reflected a focus on execution and regulatory alignment.
Brian Savoy continues as chief financial officer, tasked with financing a capital plan whose scale makes balance sheet management the company's central constraint.1
The capital plan
For Duke, capital allocation functions as corporate strategy. Management has outlined a five-year capital plan of approximately $83 billion, alongside a ten-year projection exceeding $145 billion, organized across three main categories.1
The largest share is allocated to grid infrastructure — upgrading transmission lines, substations, storm hardening, distribution automation, and connecting new high-volume commercial customers. Grid investments carry relatively low regulatory risk because reliability improvements command broad political and customer support, particularly in hurricane-prone territories.
The second category covers zero-carbon generation and storage, incorporating utility-scale solar, battery storage, and nuclear investments such as reactor uprates and license extensions designed to maintain operations into the 2040s and 2050s. Extending the operating life of fully amortized nuclear plants provides cost-effective carbon-free capacity, though it carries execution risks associated with major component replacements at legacy facilities.
The third category focuses on natural gas generation, utilizing modern combined-cycle facilities to replace retiring coal capacity and provide dispatchable power when solar output declines at sunset.[^13] These assets face long-term policy risk: natural gas plants entering service in 2030 are intended to earn regulated returns into the 2060s, spanning decades of potentially shifting state carbon regulations.
The financial commitments
Management's financial targets follow the standard regulated utility framework: annual adjusted earnings per share growth between 5% and 7%, annual rate-base growth exceeding 7%, a dividend payout ratio of 60% to 70%, and credit metrics aligned with solid investment-grade ratings.1
Duke has paid a quarterly common stock dividend for more than 99 consecutive years, representing one of the longest payout records in corporate history.1 That history anchors an investor base focused on income stability, making dividend preservation a core executive constraint.
Executing this plan requires managing a clear financial trade-off. A utility distributing roughly two-thirds of its earnings in dividends cannot internally fund a capital program expanding its rate base at more than 7% annually. The resulting capital deficit must be funded through debt and equity issuances. Debt expansion is constrained by credit agency thresholds, including funds-from-operations-to-debt targets in the mid-teens percentage range. Meanwhile, issuing new equity risks diluting per-share earnings.
Consequently, the 5% to 7% earnings growth target depends entirely on execution financing. Achieving that target requires favorable rate-case outcomes, minimal regulatory lag, full recovery of storm restoration costs, and equity sales executed without eroding per-share value.
Ultimately, evaluating Duke's financial performance requires monitoring whether realized returns on equity consistently match allowed returns — demonstrating that capital outlays are successfully incorporated into the rate base.
This financial balance leads to the central question: how much of Duke's advantage is genuinely structural?
XI. Economic Moats & Competitive Framework (7 Powers & Porter's 5 Forces)
If a strategy consultant were handed Duke's business description without the company name, they would likely classify it as one of the strongest competitive positions in corporate America — before immediately noting that the enterprise possesses almost no pricing power. Both assessments are accurate, and the tension between them defines the core analytical puzzle of utility investing.
Through Hamilton Helmer's 7 Powers
Cornered Resource represents Duke's most formidable advantage, though the resource is legal rather than physical. State legislatures and regulatory utility commissions grant exclusive service territories, prohibiting competitors from constructing distribution lines to solicit Duke's customers. That state-sanctioned monopoly franchise survived the New Deal public power movement and, unlike a commercial patent, carries no expiration date.
However, a cornered resource generates economic rent only if an enterprise can price freely against it. Here, the advantage is strictly constrained: the same authority that grants territorial exclusivity caps the allowed financial return. Duke possesses a monopoly it is legally forbidden to exploit for market pricing. What the company actually owns is not pricing power, but a capital deployment right — the entitlement to earn a regulated return on whatever capital outlays state commissions permit it to enter into rate base.
Switching Costs are absolute but structurally unusual. A residential customer in Charlotte cannot switch electricity providers at any price; switching costs are functionally infinite because no alternative distributor exists within the service territory. This dynamic yields exceptionally predictable revenue streams, but generates no economic pricing premium. Because state commissions dictate customer rates, high switching costs accrue to cash flow stability rather than expanded profit margins.
Scale Economies represent Duke's most tangible operational advantage. Operating across six states allows the enterprise to borrow at tighter credit spreads than smaller single-state utilities while amortizing overhead — including nuclear engineering, IT systems, fuel procurement, and storm response teams — across roughly 8.6 million electric customers. Furthermore, Duke's balance sheet can absorb multi-billion-dollar storm restoration costs without triggering an existential liquidity crisis. In an industry where the core input is capital, a lower cost of capital constitutes a primary competitive edge — translating into lower customer rates and preserving crucial regulatory goodwill.
Process Power remains the most contested dimension of Duke's framework. The company's twentieth-century record — building the Oconee Nuclear Station at well below industry-average costs and pioneering safety practices through INPO — demonstrated deep institutional engineering capabilities. Whether that operational excellence persists in a form that guarantees superior execution today remains an empirical question. Duke's modern track record highlights clear contradictions: the same corporate culture that built a low-cost nuclear fleet also sponsored an interstate natural gas pipeline it could not permit and a commercial renewables business it ultimately wrote down and sold at a loss.
The remaining powers within Helmer's framework — network economies, counter-positioning, and branding — are largely absent. Customers do not select their electric utility based on brand preference.
Through Porter's Five Forces
Threat of new entrants: near zero. Immense capital intensity combined with legal territorial monopolies eliminates conventional commercial entrants. The primary threat of entry is political: municipalization, wherein a city seeks to condemn private distribution assets and form a public utility. While municipalization efforts are rare, protracted, and historically defeated, they represent a persistent tail risk that intensifies whenever customer rates escalate rapidly.
Bargaining power of buyers: high, but concentrated in regulatory bodies rather than individual retail customers. Real buyer power rests with state public utility commissions — including the North Carolina Utilities Commission, the Public Service Commission of South Carolina, the Florida Public Service Commission, the Indiana Utility Regulatory Commission, and commissions in Ohio and Kentucky — alongside FERC at the wholesale transmission level. These bodies establish authorized returns on equity, determine which capital outlays enter rate base, and issue binding prudence rulings after expenditures occur.
A second buyer class has acquired significant commercial leverage: hyperscale data center developers. A corporate customer seeking 500 megawatts of continuous capacity approaches the utility as a negotiator rather than a captive retail applicant. Equipped with internal energy procurement teams, these technology firms can readily re-site planned campuses in neighboring utility footprints across Virginia, Georgia, or Ohio. This shift represents a structural departure from traditional utility customer dynamics, making the design of large-load tariffs — specifically determining who funds initial infrastructure upgrades and who bears the stranded-asset risk if load fails to materialize — a critical financial variable for Duke.
Threat of substitutes: low, but gradually expanding. Distributed rooftop solar combined with battery storage erodes volumetric sales from affluent residential customer classes, sparking regulatory disputes over fixed-cost recovery akin to those seen in California and Arizona. A more significant long-term substitution threat comes from commercial self-generation, where large industrial or hyperscale customers construct behind-the-meter generation facilities to bypass the grid. While currently a marginal practice, on-site generation represents a plausible alternative for high-load customers.
Bargaining power of suppliers: moderate, with severe supply-chain bottlenecks. Because fuel outlays pass directly through to ratepayers via fuel-adjustment clauses, commodity price volatility impacts customer bills and political tolerance rather than utility profit margins directly. The critical supplier pressure resides in specialized electrical equipment and construction labor. Global demand for large power transformers, high-voltage circuit breakers, gas turbines, and specialized engineering labor has driven up procurement costs and extended lead times to multiple years. These supply constraints pose a direct risk to executing Duke's five-year capital plan on schedule and within budgeted cost allowances.
Rivalry: negligible in retail electricity markets, but intense in capital and expansion markets. While protected from direct retail competition, Duke competes aggressively against peer utility holding companies — including Southern Company, NextEra Energy, Dominion Energy, American Electric Power, and Sempra — for institutional equity capital, critical grid equipment, and large-scale industrial economic development projects. In competing for hyperscale data center projects, Duke's nuclear fleet provides a distinct zero-carbon baseload advantage, whereas its divestment of commercial renewables leaves it reliant on regulated solar outlays relative to developers like NextEra.
The structural synthesis is clear: Duke's economic moat is broad, legally entrenched, and bounded by regulated returns. It protects capital against downside loss far more effectively than it generates market-beating outperformance. Consequently, executive capital allocation and regulatory execution matter more for Duke than for companies operating in unconstrained markets — because a state-sanctioned franchise cannot insulate shareholders from the costs of flawed capital deployment.
XII. Historical Falsification Layer & Stress Test
A moat this legally secure invites a simplified investment thesis: Duke is a protected monopoly, utilities are safe, and investors can simply collect the dividend. However, the company's operational record over the past fifteen years repeatedly refutes that view. Testing the four central assumptions behind the bullish thesis against the strongest disconfirming evidence in Duke's history reveals where structural protections end.
Claim one: growth beyond the regulated franchise adds value. This assumption drove non-regulated merchant power and trading expansion in the late 1990s, and again motivated the buildout of commercial renewables in the 2010s — two distinct management teams, two decades apart, pursuing the same strategy. Both efforts ended in massive write-downs: billions of dollars written off merchant and international assets after 2001, followed by more than $3 billion in pretax impairments on commercial renewables before selling that division to Brookfield at a fraction of its invested capital.
This claim is not merely narrowed; it is rejected. Two independent attempts, under different leadership and in distinct market environments, yielded the same result. The underlying mechanism is structural: Duke's core advantages — exclusive territorial franchises, guaranteed cost recovery, and a low cost of capital derived from minimal business risk — do not translate into competitive markets against counterparties with purpose-built cost structures. Going forward, the primary indicator of strategic deviation remains straightforward: any material acquisition or capital commitment outside the regulated utility footprint.
Claim two: infrastructure adjacent to the utility is a safe extension. The Atlantic Coast Pipeline tested this thesis, resulting in a $1.6 billion after-tax write-down. Although the sponsors won a major U.S. Supreme Court ruling on Appalachian Trail crossings, Dominion and Duke canceled the project weeks later under the weight of escalating delays and litigation attrition. The narrowed claim that survives: infrastructure built inside the utility's state-regulated footprint — where the same commission approving the project also establishes rate recovery — carries far lower execution risk than multi-state linear infrastructure exposed to federal permitting and environmental litigation. That narrowed logic aligns with Duke's current capital plan, which focuses almost entirely on in-territory investments.
Claim three: large M&A delivers synergies smoothly. The 2012 Progress Energy merger delivered genuine joint-dispatch and fuel savings for customers, validating its core operational thesis. However, it also triggered a severe governance crisis that led to more than $100 million in ratepayer concessions, forced immediate leadership changes, and created years of regulatory strain in North Carolina. The narrowed claim: utility mergers can generate operational efficiencies, but the political capital required to secure and maintain regulatory trust is a material cost. In Duke's case, that goodwill was depleted immediately before major regulatory tests.
Claim four: legacy environmental liabilities are manageable and recoverable. The 2014 Dan River spill, nine federal misdemeanor guilty pleas, a $102 million criminal penalty, and roughly $1.1 billion in coal ash costs absorbed by shareholders rather than ratepayers directly reject the assumption that regulatory recovery is automatic. The surviving, narrower principle is that ordinary, prudently incurred outlays are recoverable, but expenses linked to conduct deemed imprudent by regulators or courts fall squarely on equity holders — a determination made years after the fact by regulatory bodies whose political posture can shift over time.
A single structural reality connects all four episodes: Duke's monopoly framework operates on the revenue side, offering negligible protection on the cost and capital side. The franchise guarantees a captive customer base, but it provides no guarantee that capital expended on their behalf will earn a permitted return.
Two forward tests
The forward-looking claims central to Duke's current narrative cannot yet be fully settled, requiring clear benchmarks to evaluate them as evidence emerges.
On rate base compounding: The primary test lies in final rate orders from public utility commissions in North Carolina, South Carolina, Florida, and Indiana. Analysts must monitor whether authorized returns on equity remain in the mid-to-high 9% range, whether multi-year rate plans and performance-based mechanisms retain regulatory support, and whether investments linked to large data center loads face prudence challenges. Settlement patterns that trim allowed returns or defer cost recovery would undermine rate-base compounding well before reflecting in reported earnings per share.
On financing: The key metric is the ratio of funds from operations to debt as capital expenditures peak. If elevated interest rates persist and credit metrics approach rating agency downgrade thresholds, management will be forced to issue additional equity. That dilution would compress per-share earnings growth regardless of underlying rate-base expansion. Consequently, the equity financing plan disclosed alongside quarterly earnings provides a more reliable indicator of long-term value creation than headline earnings-per-share guidance.
XIII. Analysis & Bull vs. Bear Case
Why Duke wins from here
The strongest version of the bull case rests not on an assertion of superior management, but on geography: Duke is favorably located at a moment when service territory location holds distinct value.
The core of the optimistic case centers on load growth. After two decades of flat demand, utilities across the Southeast and Midwest are receiving sustained requests for large, high-load-factor industrial and data center connections.1[^13] For a business that earns returns on deployed capital, demand expansion represents a vital catalyst: it converts capital outlays from a net cost imposed on existing customers into shared infrastructure supported by new volume. Rate-base growth funded by expanding customer demand is far more politically sustainable than outlays spread across a static customer base.
The second pillar is portfolio simplification. Following the sale of its commercial renewables business and the cancellation of its pipeline venture, virtually all of Duke's earnings derive from regulated utilities.34 Earnings quality has genuinely improved, leaving fewer non-regulated variables to generate unexpected financial volatility.
The third pillar is the nuclear fleet—11 units across six sites, largely amortized and operating at high capacity factors to produce round-the-clock, zero-carbon power. For hyperscale technology companies with 24/7 clean energy mandates, this fleet provides a differentiated source of supply, and extending these operating licenses represents Duke's most cost-effective source of firm clean capacity.[^13]
What breaks the case
The pessimistic case requires no extraordinary assumptions; it depends simply on customer electricity bills rising faster than ratepayers and state regulators will tolerate.
Affordability remains the binding constraint. A capital program of this scale, financed in an environment of elevated interest rates, flows directly into customer bills over time. Residential ratepayers across the Carolinas, Florida, and the Midwest exert political influence over state utility commissions, directly or through elected officials. The political economy of utility regulation ultimately centers on the rate increases a state will accept—a threshold that tightens during inflationary periods or when retail customers perceive that major infrastructure spending primarily benefits technology conglomerates rather than local communities.
Anticipated data center load may fail to materialize fully. Interconnection queues frequently overstate actual demand because developers file speculative requests across multiple utility territories. If Duke constructs infrastructure for gigawatts of anticipated load that materializes only in part, unutilized assets remain embedded in rate base, leaving residential ratepayers to absorb the fixed costs. The contractual terms of large-load tariffs—including minimum-take commitments, upfront capital contributions, and exit provisions—determine whether financial risk sits with corporate developers or retail customers, making these regulatory filings a critical focus for investors.
Severe weather imposes recurring, uninsurable operational costs. Coastal Florida and the Carolinas regularly incur hundreds of millions of dollars in hurricane restoration expenses. While these outlays are recoverable through state storm-cost mechanisms, cost recovery occurs with a lag, making each proceeding a potential source of regulatory friction.
Execution risks are concentrated and interdependent. Retiring coal capacity on schedule requires finishing new natural gas combined-cycle plants on time, completing nuclear license extensions and uprates on budget, and energizing transmission capacity as planned. These initiatives must proceed while peer utilities nationwide compete for identical turbines, transformers, and specialized construction crews. While Duke's historic self-build record demonstrates technical capability, the cancellation of the Atlantic Coast Pipeline underscores the persistent difficulty of managing complex permitting and litigation risks.
The structural skeptic's critique highlights historical capital allocation. Over a 15-year span, Duke's shareholders funded two failed non-regulated diversification campaigns, a governance dispute that damaged regulatory standing in North Carolina, and over a billion dollars in non-recoverable coal ash liabilities—all at an enterprise marketed as a low-risk investment. Critics argue this record warrants continued scrutiny of executive discretion rather than immediate credit for portfolio simplification, with particular attention to whether the equity issuances required to fund the capital plan will dilute rate-base expansion into modest per-share earnings growth.
The three KPIs that actually matter
For an enterprise of Duke's scale and complexity, evaluating long-term performance requires focusing on three fundamental financial and operational metrics.
Realized return on equity versus allowed return on equity, by jurisdiction. This master metric evaluates regulatory alignment and capital efficiency. A persistent gap between authorized and realized returns indicates that capital outlays are failing to convert fully into shareholder value due to cost overruns, regulatory lag, or disallowances.
Rate-base growth and the proportion tied to contracted large-load customers. While rate-base expansion drives overall earnings potential, the quality of that growth depends on its composition. Capital deployed under binding agreements with explicit financial commitments carries significantly lower risk than outlays based on uncommitted demand forecasts.
Funds from operations to debt. This key balance-sheet metric measures financing headroom. As a primary benchmark monitored by credit rating agencies, the ratio reveals whether capital outlays can be sustained without triggering credit downgrades or forcing excessive equity dilution.
XIV. Epilogue & "If We Were CEOs"
Every utility executive in America faces the same three-way trade-off, and the competing pressures do not resolve cleanly.
Maintaining reliability requires dispatchable natural gas, extended nuclear licenses, and generous reserve margins. Preserving bill affordability demands strict capital discipline and ensuring that new large-volume customers fund their own infrastructure. Fulfilling carbon commitments and state policy targets—including North Carolina's statutory carbon reduction framework—requires retiring coal plants rapidly while constructing clean generation that is intermittent and requires additional capital outlays in storage and backup capacity.[^13] Achieving any two of these goals is manageable; balancing all three requires constant negotiation before six state utility commissions, each operating under its own local political dynamics.
If an executive team were running Duke, two strategic priorities would dominate.
First, establish a bulletproof large-load tariff structure, treating it as the most consequential regulatory filing of the decade. A well-designed tariff requires hyperscale commercial customers to fund the infrastructure constructed specifically to serve them—through substantial upfront capital contributions, long-duration minimum-demand commitments, and exit clauses that place remaining financial obligations on departing developers rather than residential ratepayers. This is less a revenue calculation than a fundamental exercise in risk transfer. Executed properly, the structure enables Duke to expand generation and grid capacity aggressively while maintaining regulatory alignment. Executed poorly, the cancellation of a single major data center campus after Duke energizes a custom substation would force the company to litigate capital prudence under the same regulatory strain that followed the coal ash crisis.
Second, approach small modular reactor initiatives with the discipline that historical execution warrants. Duke possesses exceptional operational credentials in nuclear energy: decades of managing multi-unit facilities, an institutional legacy through INPO, and existing licensed sites with established grid connections, cooling water, and skilled workforces. These assets provide a strong foundation for participation. However, corporate history underscores key risks: a regulatory design certification does not guarantee a construction schedule, and a schedule does not dictate final capital costs. Duke's historically successful nuclear buildout at Oconee, McGuire, and Catawba relied on standardized designs and repeated internal execution rather than unproven technology. Furthermore, recent large-reactor builds across the Southeast incurred multi-billion-dollar cost overruns and multi-year delays. For Duke, a prudent strategy entails acting as an early operator rather than an early technology developer—ensuring that first-of-a-kind cost risks do not fall on captive ratepayers.
The broader historical parallel is striking. In 1905, James Buchanan Duke recognized that electricity could transform an agrarian region into an industrial base, and that profitability required constructing infrastructure ahead of demand for anchor industrial customers using patient capital. More than 120 years later, Duke Energy is following that same basic playbook—expanding generation and grid capacity ahead of demand for large-scale industrial customers, backed by capital markets willing to wait so long as the regulatory compact remains intact.
What has changed fundamentally is who absorbs the financial risk of failure. In the early twentieth century, Buck Duke risked his personal tobacco fortune on the Catawba River hydro grid. Today, that risk is shared between equity holders seeking a low-volatility income investment and captive retail customers with no alternative power provider. This model functions effectively when capital outlays are prudently managed and approved—yet, as the company's recent history demonstrates, it offers no self-correcting mechanism when capital deployment goes astray.
XV. Key Earnings Calls & Investor Primary Sources
For readers seeking the primary record beyond the corporate narrative, a handful of disclosures offer disproportionate insight into Duke's operational and financial reality.
The most recent annual report and Form 10-K remain foundational documents. The regulatory matters section, in particular, catalogues every open rate case, prudence challenge, environmental obligation, and litigation exposure in the granular detail omitted from press releases.72 Reading the disclosures on coal ash and asset retirement obligations alongside the rate-case narratives reveals the same underlying business risks expressed in accounting language.
The fourth-quarter and full-year earnings calls held each February serve as the forum where management resets the multi-year capital plan and rolls forward guidance ranges.1 A useful analytical discipline is comparing the load-growth forecasts across consecutive annual calls; the revision history of those projections provides far clearer evidence of actual demand trends than any single year's guidance.
Investor day and analyst conference presentations outline the jurisdiction-by-jurisdiction rate-case calendar, the resource planning pathways under state carbon reduction mandates, and the overarching financing structure — including the equity issuance assumptions that determine whether rate-base expansion actually translates into per-share earnings growth.1[^13]
The second-quarter 2020 earnings call remains the crucial reference point for the Atlantic Coast Pipeline cancellation and its associated write-down.56 Reading that transcript alongside management's prior commentary from 2015 through 2019 illustrates how corporate confidence was maintained right up to the project's abandonment.
The 2023 earnings calls surrounding the Brookfield transaction document the final accounting of the commercial renewables divestment and the subsequent redeployment of capital back into the regulated balance sheet.34
State public utility commission dockets — particularly within the North Carolina Utilities Commission's public filing system — contain the essential record omitted from investor decks.9 These files hold intervenor testimony, cross-examinations, public witness hearings, and formal commission orders that state directly how regulators evaluate the utility's capital deployment and cost-recovery requests. For an enterprise whose financial returns depend entirely on regulatory permission, commission dockets represent the most critical primary source available.
References
-
Duke Energy Investor Relations Portal — Duke Energy Corp ↩↩↩↩↩↩↩↩↩↩↩
-
Duke Energy Form 10-K for Fiscal Year Ended December 31, 2024 — US SEC EDGAR ↩↩↩↩↩↩↩
-
Duke Energy to Sell Commercial Renewables Business to Brookfield — Duke Energy Press Room, 2023-06-12 ↩↩↩
-
Duke Energy to Sell Commercial Renewables Business to Brookfield for $2.8 Billion Enterprise Value — Reuters, 2023-06-12 ↩↩↩
-
Dominion Energy and Duke Energy Announce Cancellation of Atlantic Coast Pipeline — Duke Energy Press Room, 2020-07-05 ↩↩
-
Dominion and Duke Energy Cancel Atlantic Coast Pipeline — The Wall Street Journal, 2020-07-05 ↩
-
Duke Energy SEC Filings & Form 10-K Reports — Duke Energy Investor Relations ↩
-
Duke Energy Board Ousts CEO Bill Johnson Right After Progress Merger Closes — Bloomberg, 2012-07-03 ↩↩
-
North Carolina Utilities Commission Official Portal & Docket Filings — NCUC ↩↩
-
Duke Energy Reaches Historic Settlement on Coal Ash Cleanup Costs in North Carolina — Duke Energy Press Room, 2021-01-25 ↩↩
-
Duke Energy Announces Executive Leadership Transition — Duke Energy Press Room, 2025-01-15 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube