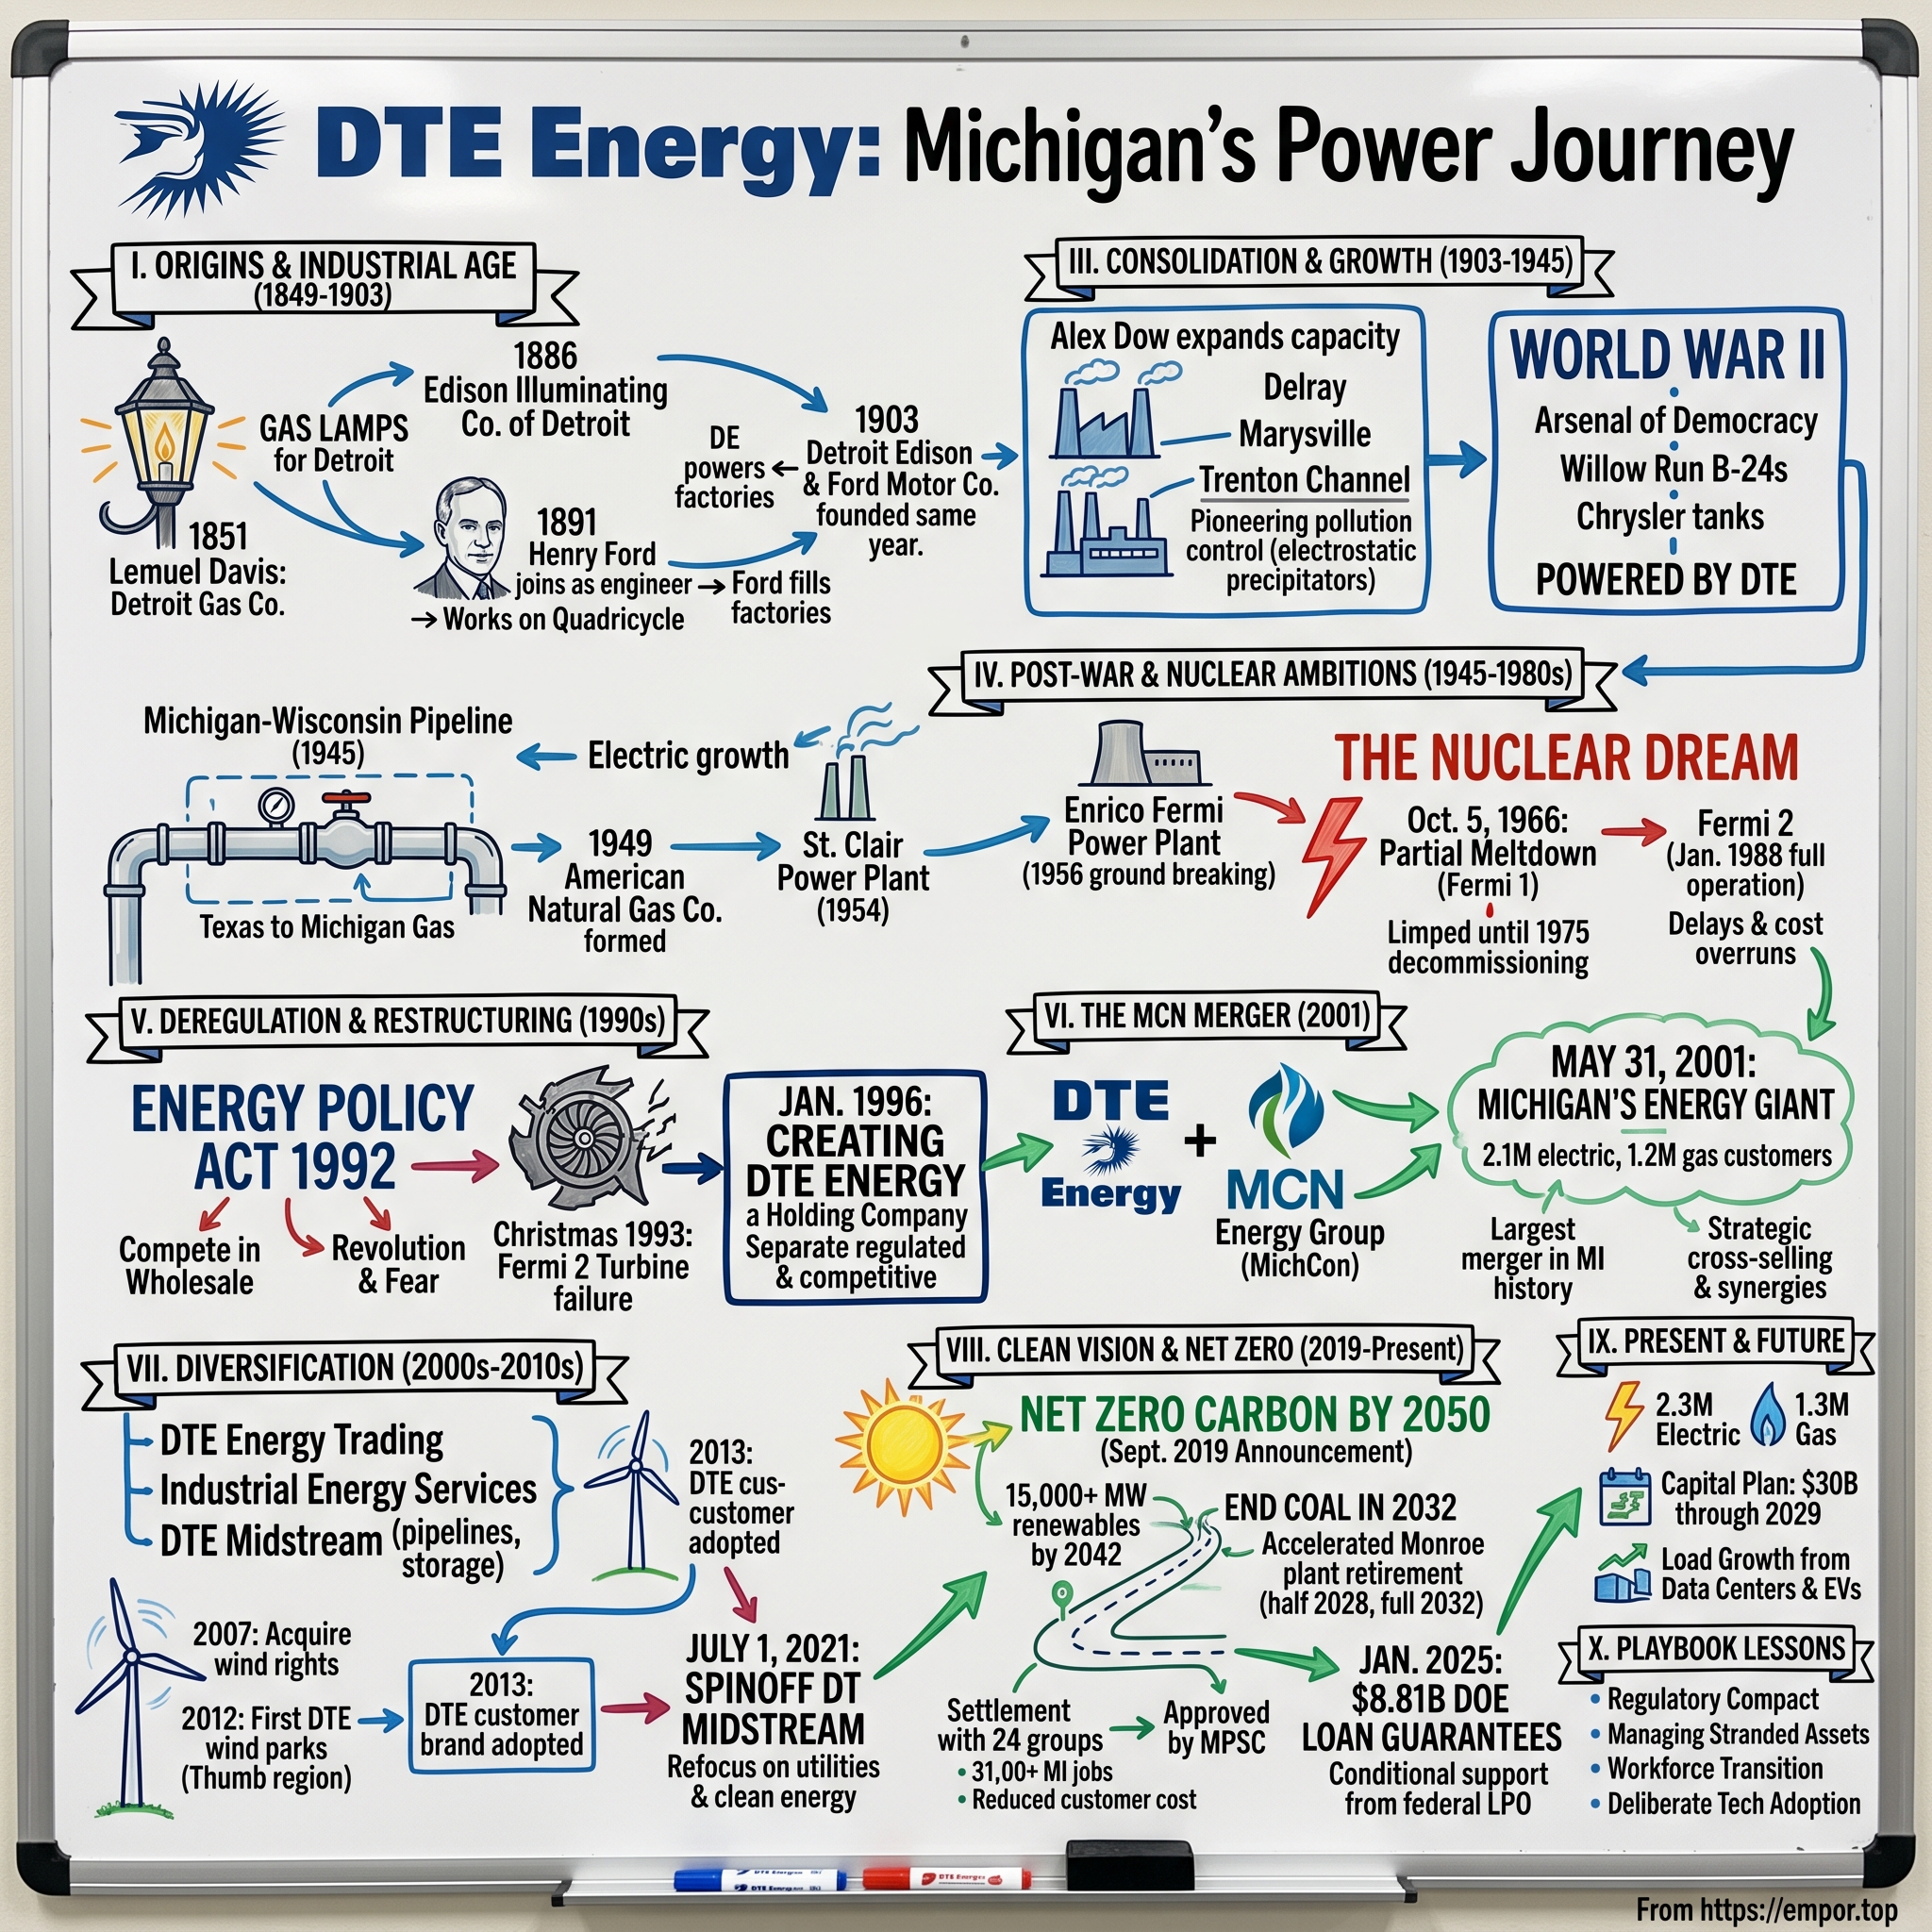
DTE Energy: Powering Michigan's Transformation from Industrial Age to Clean Energy Future
I. Introduction & Episode Setup
On a February night in 2023, freezing rain coated southeast Michigan in a glaze of ice roughly half an inch thick. Tree limbs — mature silver maples and oaks that shade Detroit's older suburbs — snapped under the weight, bringing down overhead distribution lines. By morning, more than 700,000 DTE Electric customers, roughly 30% of the company's customer base, had lost power, and some remained without electricity for nearly a week.1
That storm illustrates the core operational tension facing DTE Energy Company (NYSE: DTE). On paper, DTE operates one of the most protected utility franchises in corporate America: a legal monopoly providing electricity delivery to approximately 2.3 million customers across roughly 7,600 square miles of southeast Michigan, alongside natural gas service to about 1.3 million customers across the state.2 The company earns a regulator-approved return on invested capital, faces no direct startup competition, and maintains a captive customer base.
Yet that protected status comes with substantial political and regulatory exposure. Every dollar of approved return must be justified before the Michigan Public Service Commission in contested proceedings where the Michigan Attorney General intervenes on behalf of ratepayers, and where public memory of prolonged winter outages directly shapes regulatory scrutiny. A regulated utility does not compete for customers; it competes for regulatory authorization.
This structural dilemma has sharpened as DTE navigates an energy transition. The company's origins trace to gas street lighting in Detroit in 1851 and the coal-fired plants that powered the assembly lines of Ford, General Motors, and Chrysler.3 Today, DTE is retiring that fossil-fuel legacy — including the planned shutdown of its 3,066-megawatt Monroe plant, long one of the largest single carbon-emitting facilities in the U.S. power sector — while simultaneously contracting to supply gigawatt-scale electricity to artificial intelligence data centers.4 To fund grid modernization and cleaner generation, DTE is seeking ratepayer support for a five-year, $36.5 billion capital expenditure program — a 22% increase over its prior $30 billion plan — while ratepayers absorb consecutive rate increases and question system reliability.5
The following analysis traces how the company reached this point, beginning with Lemuel Davis's 19th-century gas company and Henry Ford's early career as a night engineer at Edison Illuminating. It examines the mid-century nuclear era and two defining incidents — the 1966 partial core meltdown at Enrico Fermi Unit 1, which prompted the phrase "we almost lost Detroit," and the Christmas Day turbine explosion at Fermi 2 in 1993. It details the 2001 acquisition of MCN Energy Group that combined Michigan's largest electric and gas utilities, the subsequent two-decade conglomerate structure, and the 2021 spin-off of DT Midstream that refocused the enterprise on regulated utilities.
Finally, the narrative turns to the strategic outlook under current leadership. Joi Harris became chief executive on September 8, 2025, after 34 years at the company, while her predecessor, Jerry Norcia, transitioned to executive chairman.6 Management's core thesis relies on Michigan's 2023 clean energy legislation, the company's CleanVision resource plan, and expanding demand from hyperscale data centers to drive long-term rate base growth. Evaluating that strategy requires testing each component against DTE's historical record of project execution and regulatory outcomes.
 Subscribe on LinkedIn
II. Origins: From Gas Lamps to Electric Dreams (1849–1903)
Detroit in 1849 was a town of roughly 21,000 residents along the Detroit River, closer in character to a frontier outpost than an industrial center. It was dark. Lighting the city was a speculative infrastructure venture: an entrepreneur had to construct a gasworks, lay pipe beneath unpaved streets, manufacture gas from coal, and persuade municipal authorities to grant a private enterprise perpetual rights to excavate public roads.
Lemuel Davis organized the City of Detroit Gas Company to execute that plan. In June 1851, 53 gas lamps burned along Detroit's streets for the first time.3 Fifty-three lamps did not constitute a modern utility system, but rather a demonstration project. Yet it established the structural template for subsequent expansion: sinking massive fixed capital into the ground upfront, securing a government franchise second, and collecting revenue slowly from a captive customer base third.
Three and a half decades later, that business pattern repeated with a new technology. The Edison Illuminating Company of Detroit was founded in 1886 to bring incandescent lighting to the city, licensed under Thomas Edison's patents.3 Electric light was then a luxury service competing directly against incumbent gas lamps, marking the first major substitution battle in the company's history.
A notable employee joined the firm in 1891. Henry Ford took a job as a night engineer at Edison Illuminating, and by early 1894 had been promoted to chief engineer.7 The position provided a steady salary, access to tools, and long night shifts monitoring gauges that offered time for mechanical experimentation. Ford built his Quadricycle in a shed behind his house with assistance from coworkers before resigning on August 15, 1899, to concentrate on building automobiles.8 In a notable historical parallel, the engineer who would later help drive DTE's largest source of industrial power demand first learned the energy business from inside the utility.
The modern corporate entity took shape in January 1903, when Detroit Edison purchased the securities of the predecessor companies and incorporated on January 17.3 Construction began that same year on the Delray 1 power plant. The timing reflected surging industrial demand: Ford Motor Company was also founded in 1903, beginning Detroit's transformation into the continent's densest concentration of heavy manufacturing.
What these early years established was not a technological advantage, but a legal and financial foundation. Generating and distributing electricity required capital at a scale that municipal governments preferred not to fund and competitors could not duplicate street by street. In exchange for exclusive territorial rights, the utility accepted an obligation to serve all customers within its service area at regulated prices. That arrangement — the regulatory compact — became DTE's foundational asset, though as subsequent history demonstrates, its terms remain subject to ongoing renegotiation.
III. Building Motor City & The Consolidation Era (1903–1945)
The load curve of a city inventing mass production evolved rapidly. In 1903, Detroit Edison sold power primarily for evening lighting. Within 15 years, it was supplying electricity to factories running assembly lines around the clock. This shift to industrial baseload demand fundamentally transformed the utility's unit economics, allowing expensive generating plants to run near full utilization rather than idling between dusk and dawn.
During this period, the company's expansion effectively mirrored Detroit's industrial boom. As Ford, General Motors, and Chrysler scaled production, Detroit Edison expanded its coal-fired generation through the 1920s, adding the Marysville and Trenton Channel plants alongside expansions at Delray. Each facility surpassed the last in capacity, capitalizing on the scale economies of thermal generation: larger boilers and turbines converted fuel to electricity more efficiently per dollar of invested capital. This established a core earnings driver that persists today: under rate-of-return regulation, a utility expands its net income primarily by growing the approved capital asset base on which it earns a return.
Meanwhile, Michigan's gas sector consolidated along a parallel trajectory. Detroit City Gas and several regional peers merged to form Michigan Consolidated Gas Company — MichCon — in 1937.3 Gas distribution differed structurally from electric service, featuring lower capital intensity per customer, a seasonal heating demand profile, and a business model rooted in underground cast-iron and steel mains. Decades later, replacing those aging mains would become a major driver of DTE's regulated capital investment.
World War II transformed the regional grid into critical national infrastructure. As Detroit's manufacturing plants retooled to produce tanks, aircraft engines, and ordnance for the wartime effort, power demand pushed system density to unprecedented levels. Operating under national priority mandates, the utility prioritized uninterrupted power delivery. That wartime strain reinforced a corporate culture centered on engineering conservatism and operational reliability — traits that guided management for decades, even as subsequent nuclear projects encountered severe complications.
In 1945, the completion of the Michigan-Wisconsin Pipeline connected southwestern natural gas supplies to Michigan, enabling MichCon to inject gas into depleted underground geological reservoirs converted into seasonal storage fields.3 Underground storage provided a significant structural advantage, allowing the gas utility to purchase fuel during lower-demand summer months and withdraw it during peak winter heating periods, mitigating both commodity price volatility and supply disruption risks.
By the end of World War II, both Detroit Edison and MichCon occupied dominant regional franchises anchored by extensive physical networks that presented formidable barriers to entry. As the postwar economy expanded, management faced the strategic choice of how to expand generating capacity to support future growth — a question utility engineers increasingly believed could be answered by nuclear power.
IV. Post-War Expansion, Fermi Meltdowns & Nuclear Disillusions (1945–1980s)
Initially, however, Detroit Edison expanded its conventional fleet. The 1950s marked a period of rapid growth for American electric utilities. Electricity demand grew at compounding rates, generating technology became increasingly cost-effective per kilowatt, and regulators regularly approved major capital additions. Detroit Edison opened the St. Clair Power Plant in 1954, then among the largest coal-fired stations in the world, and broke ground on River Rouge and later Monroe. The operating model appeared straightforward: construct larger facilities, expand sales volume, and earn a regulated return on the expanded asset base.
Yet the promise of nuclear power introduced a fundamentally different economic proposition. Beyond incremental efficiency gains, nuclear energy offered fuel so energy-dense that proponents believed marginal generation costs would fall near zero, shifting the economic equation almost entirely to upfront capital investment. Detroit Edison Chief Executive Walker Cisler became one of the industry's most prominent advocates, leading a consortium to build an ambitious sodium-cooled fast breeder reactor designed to produce more fissile material than it consumed. Built at Lagoona Beach on Lake Erie, the Enrico Fermi Atomic Power Plant Unit 1 represented the commercial nuclear industry's boldest technological venture.
On October 5, 1966, Fermi 1 suffered a partial meltdown. A loose zirconium liner plate inside the reactor vessel obstructed liquid sodium coolant flow through part of the core, melting two fuel subassemblies. Although no radiation was released to the public, the facility was permanently compromised as a commercial venture. Operations ceased in 1972 and the plant was placed into long-term decommissioning, with final license termination not yet completed.9 The incident gained national notoriety through John G. Fuller's 1975 book, We Almost Lost Detroit.
Beyond the dramatic narrative, the crucial outcome was financial. Fermi 1 never generated commercially meaningful electricity, resulting in substantial capital impairment. A technology promoted to investors and regulators as a structural cost advantage produced a total capital loss on the asset.
Despite that setback, Detroit Edison proceeded with nuclear development. In 1970, the company began constructing Fermi 2, a conventional 1,100-megawatt-class boiling water reactor on the same site. The plant did not enter commercial operation until 1988 — an 18-year construction timeline extended by post–Three Mile Island regulatory revisions, mid-construction design changes, and substantial accrued interest costs. These severe cost overruns dominated Detroit Edison's financial profile throughout the 1980s, triggering repeated regulatory disputes before the Michigan Public Service Commission over how much capital should be passed on to ratepayers.
Operational troubles continued after commissioning. On Christmas Day 1993, the main turbine-generator at Fermi 2 suffered a catastrophic failure when its rotor disintegrated, igniting the hydrogen coolant and taking the unit out of service for roughly a year.10 While the failure occurred on the plant's conventional side rather than within the nuclear reactor, the economic impact was comparable: a full year of replacement power costs and repair expenses on the company's single largest generating unit.
These developments highlight a central financial lesson: the historical record does not support the premise that nuclear capabilities provided a durable competitive advantage for Detroit Edison. Across four decades, the company's nuclear initiative yielded a complete capital write-off, an 18-year construction delay that strained the balance sheet, and a prolonged forced outage. While Fermi 2 currently operates as a reliable asset producing carbon-free baseload power under Michigan's clean energy framework — with an operating license extending into the 2040s — its history refutes the notion of nuclear power as a low-risk structural moat. Instead, it represents a single, highly concentrated asset where an unplanned outage removes a significant portion of generating capacity at once.
For Detroit Edison, the Fermi experience demonstrated the financial risk of concentrated technology bets within the regulated utility franchise. In response, management began looking outside traditional utility operations for future expansion — a strategy that found new impetus during the utility deregulation movement of the 1990s.
V. Reorganization, Regulatory Shocks & The $2.6B MCN Merger (1990s–2001)
The Energy Policy Act of 1992 opened wholesale electricity markets to competition and set off a decade of structural reorganization across the American utility sector. The prevailing logic across the industry was that if regulated wires businesses were destined to be slow-growth, return-capped annuities, utilities needed exposure to the unregulated businesses spawned by deregulation.
Detroit Edison responded by restructuring its corporate architecture. In January 1996, it formed a holding company, DTE Energy Company, with the regulated electric utility as a subsidiary.3 This holding company structure created a separate corporate layer capable of owning non-utility businesses, raising debt outside the utility's regulated capital structure, and transferring capital between operating segments — activities monitored closely by regulators seeking to prevent utility ratepayers from subsidizing non-regulated ventures.
The defining transaction of this era was DTE's acquisition of MCN Energy Group, the parent company of gas utility MichCon. Announced in 1999 and completed on May 31, 2001, DTE acquired MCN for $2.6 billion in cash and stock, representing an enterprise value of approximately $4.6 billion when including assumed debt.11 Upon completion, the combined enterprise served roughly 2.1 million electric customers and 1.2 million natural gas customers with a workforce of about 11,500 employees.11
The strategic rationale centered on gas-electric convergence — the industry thesis that operating both fuel types within a single territory would capture operational efficiencies, enable bundled customer services, and strengthen market positioning during deregulation. In Michigan, the geographic overlap of the two utility service territories across metropolitan Detroit offered tangible integration opportunities: field operations, meter reading, billing, customer call centers, and back-office functions could be consolidated across hundreds of thousands of shared accounts.
While DTE has historically framed the merger as a foundational success — creating the combined platform that generates the majority of its earnings today — the transaction proved both expensive and prolonged. The acquisition price represented a significant premium over MCN's pre-announcement share price. Securing required regulatory approvals also took time; the Federal Trade Commission initiated an antitrust review of the combination, delaying the deal's closing until roughly two years after its initial announcement.12 Integration expenses, including employee severance, software system consolidation, and corporate rebranding, hit the balance sheet immediately, whereas projected operational synergies materialized gradually over several years.
Ultimately, the MCN acquisition demonstrated DTE's ability to acquire and successfully operate an adjacent regulated network over the long term, though it also highlighted the financial limits of large-scale utility M&A. Paying a full upfront premium transferred much of the transaction's immediate value to MCN shareholders, leaving DTE to earn a regulated rate of return on an expanded asset base. Having absorbed the last major adjacent regulated utility in Michigan, DTE turned to unregulated markets to pursue further earnings growth.
VI. The Conglomerate Experiment & DT Midstream Spinoff (2000s–2021)
By the mid-2010s, DTE Energy presented investors with a dual corporate identity. One narrative highlighted a stable Michigan utility generating predictable rate base growth. The other presented a fast-growing non-utility platform: gas gathering and processing systems in the Marcellus and Utica shales of Appalachia and the Haynesville shale in Louisiana, interstate pipeline interests, an energy trading desk, on-site industrial energy projects at steel mills and refineries, reduced-emissions coal facilities, and landfill gas ventures.
The strategic thesis appeared compelling on paper. A regulated utility expands earnings primarily at the pace of its approved rate base—typically mid-single digits—because regulators strictly limit the volume of capital expenditure passed on to customer bills. Non-utility businesses faced no such regulatory ceiling. Management reasoned that constructing midstream gas infrastructure during the height of the American shale boom at attractive project returns would layer a faster-growing earnings stream on top of the utility core, accelerating consolidated growth.
DTE executed the operational plan. Through the 2010s, the company built a substantial midstream footprint, and non-utility operations grew to contribute a significant share of consolidated net income. The midstream assets were well-located, strategically integrated into key production basins, and cash-generative.
Yet equity markets did not reward the conglomerate structure. Investors value regulated electric and gas utilities at premium valuation multiples precisely for their low-risk profile—rate-regulated revenue, weather-normalized demand, protected franchise territories, and recession resilience. When a utility combines commodity-exposed midstream operations with its regulated core, public markets rarely average the two valuation multiples. Instead, equity investors tend to apply a conglomerate discount to the entire enterprise. Investors seeking a low-risk utility proxy sought pure-play options, while energy infrastructure investors preferred midstream entities without utility regulatory constraints. Consequently, DTE traded at a persistent valuation discount relative to pure-play regulated peers such as WEC Energy Group and in-state peer CMS Energy. Concurrently, Michigan regulators scrutinized parent-level debt raised partly to fund out-of-state pipeline projects, recognizing that such leverage sat above operating utilities whose captive ratepayers anchored the enterprise's credit quality.
Management addressed this valuation gap in October 2020 by announcing a plan to separate the midstream business. The transaction closed on July 1, 2021, when DT Midstream, Inc. (NYSE: DTM) was spun off tax-free to shareholders at a ratio of one DTM share for every two DTE shares held.[^13] The separation was structured through a Form 10 registration that gave DT Midstream its own capital structure and its own investor base.13
The market response validated the separation. Post-spin-off DTE emerged as an overwhelmingly regulated enterprise—with the vast majority of operating earnings generated by DTE Electric and DTE Gas—and its stock rerated upward toward pure-play peer multiples. Shareholders holding both equities captured the sum-of-the-parts valuation previously denied to the combined entity.
However, the spin-off also represented the reversal of a diversification strategy DTE had pursued for roughly fifteen years and backed with substantial capital. The equity value unlocked by the separation largely represented the recovery of value previously lost to the conglomerate discount. While the transaction demonstrated capital discipline, it also highlighted the market-enforced boundaries of utility diversification. That experience explains why current leadership maintains strict limits on DTE's remaining non-utility operations, treating them not as a primary driver of corporate expansion, but as a strictly bounded supplement to a utility-focused strategy.
VII. Modern Business Breakdown: Segments, Economics & Management
Beyond its historical evolution, DTE Energy in 2026 operates as a structured enterprise driven by three main business segments and a modest trading arm.
DTE Electric serves as the company's primary earnings engine. Generating, transmitting, and distributing power to roughly 2.3 million customers across southeast Michigan, the segment owns DTE's coal, natural gas, nuclear, and renewable fleet, while accounting for the vast majority of consolidated earnings and capital deployment. Of the company's five-year, $36.5 billion capital expenditure program, approximately $30 billion is allocated to DTE Electric.5 Within that allocation, capital designated for clean generation expanded from roughly $10 billion to $15 billion in the most recent plan update—representing the single largest line-item increase and underscoring management's growth priorities.5
The underlying economics govern the entire corporate strategy. A regulated utility does not earn a profit margin directly on the volumetric sale of electricity; rather, it earns an authorized return on the net book value of its regulator-approved capital investments—its rate base. The Michigan Public Service Commission has held DTE Electric's authorized return on equity at 9.9% across its last two rate cases, rejecting both management's requests for an increase to 10.5% and intervenor proposals for a reduction.1415 Consequently, earnings expansion depends entirely on executing approved capital projects, adding them to the rate base, and earning that authorized return. For utility shareholders, capital expenditure is not a cost center; it is the core source of earnings growth.
DTE Gas functions as the enterprise's steady foundation. Delivering natural gas to approximately 1.3 million customers statewide, its primary capital driver is a multi-decade project replacing legacy cast-iron and bare-steel mains with modern plastic and coated-steel piping. This infrastructure work represents a low-risk regulated asset: driven by safety mandates, free of technology risks, and consistently supported by regulators. In September 2026, the commission approved another phase of DTE Gas infrastructure spending while instructing the utility to enhance its customer assistance programs—illustrating the regulatory compact's balance of capital authorization and public service requirements.16
The segment nevertheless faces a long-term strategic question: in a state that has legislated a transition toward 100% clean electricity, what is the ultimate valuation of a distribution network dedicated primarily to residential heating? While decommissioning is not a near-term prospect, the segment's expansion relies on replacing existing pipe rather than expanding customer load, limiting its long-term growth ceiling relative to the electric franchise.
DTE Vantage provides targeted upside within the portfolio. This non-utility segment operates renewable natural gas projects capturing methane from agricultural dairy sites and landfills, provides industrial energy services such as on-site generation for steel production, and manages related carbon credits. During the second quarter of 2026, Vantage generated $45 million in net income, up $14 million year over year—a modest figure relative to the regulated core, but expanding.17 Management maintains strict boundaries on this unit, reflecting lessons learned from the prior midstream expansion to prevent non-regulated operations from diluting the company's utility valuation multiple.
Energy Trading completes the business portfolio, contributing $49 million to second-quarter 2026 net income, an increase of $17 million from the prior-year period.17 While these operations help hedge physical commodity exposures and capitalize on wholesale market dynamics, trading revenues remain inherently volatile and less predictable than regulated utility cash flows.
On a consolidated basis, DTE reported second-quarter 2026 net income attributable to the company of $282 million, or $1.35 per diluted share, up from $229 million, or $1.10 per share, in the second quarter of 2025. Operating earnings came in at $1.32 per share, falling short of consensus estimates.175 Underneath those top-line numbers, DTE Electric's segment earnings fell by $48 million year over year, while DTE Gas recorded a typical seasonal loss, meaning consolidated earnings growth was driven primarily by Vantage and energy trading.17 While a single quarter of non-regulated outperformance does not indicate a trend, it highlights how transient market conditions can temporarily mask weakness in the regulated core.
Leadership and governance. Chief Executive Officer Joi Harris assumed the leadership role on September 8, 2025, after a 34-year career at DTE. Appointed at age 55, Harris previously served as president and chief operating officer of DTE Gas before being named president and COO of the parent company in 2023.6 Her background centers on field operations, distribution, and service restoration rather than corporate finance. Given that grid reliability represents DTE's primary regulatory and political vulnerability, the board's selection prioritizes operational execution over financial dealmaking.
Upon her appointment, Harris's compensation package was set with a base salary of $1.2 million, an annual incentive target of 125% of salary, and a long-term incentive target of 500% of salary.6 With roughly six-sevenths of her target compensation tied to performance and the largest portion structured as long-term equity, the incentive framework aligns executive pay with multi-year total shareholder return rather than short-term earnings. The program incorporates operational grid reliability metrics alongside financial targets, though the effectiveness of these internal targets depends on how rigorously they reflect real customer outage experiences.
Former CEO Jerry Norcia transitioned to executive chairman on the same date, remaining a full-time employee and board member.618 While an active executive chairman can maintain continuity with regulators and major industrial clients during a long-term capital transition, dual leadership structures can also complicate executive authority and strategic shifts. Whether this arrangement provides strategic stability or governance friction remains an open question early in Harris's tenure.
Chief Financial Officer David Ruud faces the core capital challenge driving DTE's strategy: funding the $36.5 billion expenditure plan while preserving credit quality. Management has guided to annual equity issuances of $500 million to $600 million from 2026 through 2028, with comparable levels anticipated through 2030, while targeting a funds-from-operations-to-debt ratio of approximately 15%.5 Maintaining that balance sheet metric while issuing equity to fund capital spending represents the primary financial constraint under which DTE operates.
VIII. The Clean Energy Pivot, CleanVision IRP & The Data Center Surge (2022–Present)
Located on the western shore of Lake Erie, the Monroe Power Plant—with four units generating 3,066 megawatts of coal-fired capacity—long served as the operational backbone of DTE Electric. For nearly half a century, the plant provided baseload power to southeast Michigan's industrial core, while also ranking among the largest single-point sources of carbon dioxide emissions in the U.S. power sector.4 Determining how and when to retire the facility represents the most consequential capital allocation decision in the company's modern history.
DTE addressed this challenge through its CleanVision Integrated Resource Plan. Under Michigan regulatory requirements, utilities must submit long-range resource plans for approval; DTE resolved its filing through a settlement approved by the Michigan Public Service Commission in July 2023.19 The agreement accelerated the company's original retirement schedule, slating Monroe units 3 and 4 to shut down by late 2028 and units 1 and 2 by late 2032—three years ahead of DTE's prior timeline.4 Meanwhile, the company converted the two coal units at its 1,270-megawatt Belle River facility to natural gas-fired peaking service across 2025 and 2026, supported by $125 million in commission pre-approved conversion costs.20 DTE had previously retired the St. Clair plant in 2022, followed by Trenton Channel.
In utility accounting, early coal plant retirements involve specific financial mechanics. Retiring a coal asset before its full 40-year depreciated lifespan leaves undepreciated book value on the balance sheet as a stranded asset. Regulatory framework resolutions typically employ securitization, refinancing unrecovered asset balances through low-cost bonds repaid via dedicated customer surcharges to reduce carrying costs relative to rate-base treatment. By utilizing this mechanism, DTE can accelerate retirements without incurring direct earnings penalties, while replacing coal capacity with utility-owned solar, wind, and storage assets that enter the rate base to earn the authorized return on equity. For a rate-regulated utility, this structural shift turns early asset retirement into a driver of capital growth.
Statutory support for this transition followed four months after the resource plan settlement. On November 28, 2023, Michigan Governor Gretchen Whitmer signed a clean energy legislative package, including Public Acts 229 and 235, establishing a 50% renewable energy mandate by 2030 and a 100% clean energy standard by 2040, alongside expanded state siting authority for commercial-scale renewables.[^22] Codifying these mandates into statute provides legislative durability over administrative commission policy, converting a substantial portion of DTE's projected clean energy capital spending from discretionary investment into statutory compliance.
To meet these targets, DTE expanded the clean generation portion of its capital plan to approximately $15 billion, funding investments in utility-scale solar, wind, and battery storage.5 The utility also manages MIGreenPower, a voluntary green pricing program enabling major commercial and industrial customers—such as Detroit's automakers—to contract for renewable energy attributes. Because participant subscriptions directly fund project construction, the program allows DTE to add renewable capacity outside of traditional, contested rate cases.
Concurrently, regional load growth expectations shifted after two decades of stagnant electricity demand across southeast Michigan, where energy efficiency gains and industrial contraction had previously flattened sales volume.
The rapid expansion of artificial intelligence infrastructure fundamentally altered utility demand projections, as hyperscale data centers require power loads without recent precedent. In Washtenaw County's Saline Township, a major campus development backed by Related Digital, anchored by Oracle, and serving OpenAI emerged as a primary driver of new regional demand.
DTE Electric sought expedited approval for special customer contracts to supply an initial 1.4 gigawatts to the Saline Township site. On December 18, 2025, the Michigan Public Service Commission unanimously approved the contracts subject to specific conditions.21 The 19-year power supply agreement includes a 20-year extension option and mandates an 80% minimum billing demand—requiring the customer to pay for at least 80% of contracted capacity regardless of actual usage, compared to the 50% to 60% threshold in DTE's standard large-customer tariff.22 To protect retail ratepayers, the commission required DTE to absorb any unrecovered project costs, mandated acceptance within 30 days, and directed the company to file a generally applicable data center tariff supported by comprehensive cost-of-service studies in a separate contested proceeding.21
This commercial structure offers long-term revenue visibility, with two-decade take-or-pay terms from a creditworthy customer helping underwrite DTE's expanded capital plan. Management allocated roughly $5 billion of incremental DTE Electric capital to data center infrastructure agreements, including $2 billion tied to the initial site.5 A second contract for 1.0 gigawatt with Google remained pending commission approval as of second-quarter 2026 disclosures, alongside a development pipeline management described as several gigawatts, including approximately 2 gigawatts in advanced discussions.5
However, the regulatory approval underpinning the initial agreement faces legal challenges. Michigan Attorney General Dana Nessel has actively contested the commission's Saline Township decision. In February 2026, the Attorney General filed a motion to reopen the case, arguing DTE's formal acceptance language was insufficiently binding and could expose general ratepayers to cost shifts.23 In April 2026, she appealed the decision to the Michigan Court of Appeals, seeking to vacate the order and require a full contested hearing.24 Environmental intervenors joined the Attorney General in submitting supporting briefs in August 2026, and the appeal remains unresolved.25
Consequently, evaluation of DTE's data center expansion requires balancing contracted commercial terms against legal and regulatory risks. While the initial 1.4-gigawatt agreement features strong credit protections, its regulatory approval remains subject to judicial review, and the long-term tariff structure governing future data center load has yet to be finalized. An adverse court ruling or restrictive tariff determination could limit expected returns on the incremental capital integrated into DTE's long-term plan.
IX. Historical Falsification & Skeptical Investor Stress Test
Every utility investor deck presents a similar thesis: predictable rate base growth, constructive regulation, disciplined capital allocation, and improving system reliability. Evaluating DTE requires testing each of these core claims against the strongest disconfirming evidence in the company's own operating record — examining the specific actions of management, regulators, and customers.
Claim one: non-utility businesses accelerate shareholder returns. DTE's corporate history has already tested this premise. The 15-year midstream buildout and its 2021 unwinding functioned as a real-world experiment demonstrating that public markets penalize the combination of utility and non-utility assets. The lesson is not that DTE cannot operate non-utility businesses — DTE Vantage proves it can — but that equity markets do not reward utility holdings with unregulated assets at scale. The claim survives only in a narrowed form: non-utility operations can serve as a small optionality sleeve, while any material expansion of unregulated earnings would signal that management has overlooked past market feedback.
Claim two: nuclear energy provides a clean, low-cost baseload moat. This thesis is refuted in its strong form by DTE's four-decade nuclear record — defined by a failed breeder reactor, an 18-year construction period, and a major turbine failure. The surviving narrow version is that Fermi Unit 2 remains a valuable carbon-free generating asset whose primary operational characteristic is concentrated outage risk rather than a durable competitive advantage.
Claim three: the accelerated coal-to-clean transition is compatible with reliable service. This claim faces immediate pressure from recent operating performance. The February 2023 ice storm was part of a broader trend: a state-commissioned third-party audit released later that year found that DTE and Consumers Energy both exhibited worse-than-average interruption frequency and restoration performance relative to peer utilities.26 The Michigan Public Service Commission responded with escalating regulatory measures. In February 2025, the commission established a framework exposing each utility to penalties of up to $10 million for failing to meet reliability targets, including outage duration and circuit remediation.27 In June 2025, it issued formal orders directing specific reliability upgrades based on the audit.28 Meanwhile, service reliability remained a prominent political issue through Michigan's 2026 legislative campaigns.29
Two critical distinctions clarify this operational challenge. First, coal plant retirements do not directly cause customer outages; the overwhelming majority of interruptions stem from overhead distribution lines damaged by fallen trees rather than generation shortfalls. Second, for investors, public perception creates political reality regardless of grid engineering. Customers experiencing multi-day outages make little distinction between distribution failures and generation strategy; they focus on rising bills alongside service interruptions. That customer reaction forms the transmission mechanism through which reliability issues drive restrictive regulatory outcomes. Consequently, the claim is narrowed: the clean energy transition is technically compatible with grid reliability, but the pace of capital deployment remains constrained by outage performance. The key benchmark is sustained improvement in outage duration and frequency against commission targets.
Claim four: Michigan offers constructive, predictable cost recovery. The regulatory record is more supportive than critics claim, yet less generous than management's growth model assumes. In January 2025, the commission authorized DTE Electric an additional $217.4 million in annual revenue in Case U-21534 — well below the requested amount — while maintaining the authorized return on equity at 9.9%, rejecting both management's push for 10.5% and intervenor calls for a reduction.14 In February 2026, the commission approved approximately $242 million in the subsequent rate case while again holding authorized return at 9.9%.1530 Consumer advocates objected that these rate increases exceeded inflation while missing opportunities to enforce stricter accountability.31
This pattern indicates that DTE consistently secures a significant portion of its requested cost recovery, but rarely the full amount. Authorized returns have remained frozen while market capital costs have fluctuated, generating regulatory lag where capital spent today enters the rate base later. As a result, earned return on equity tends to lag the authorized rate. The claim thus narrows: Michigan's regulatory recovery is predictable in direction, but incomplete in magnitude. The critical metric to track is the spread between DTE Electric's earned and authorized returns across the capital cycle.
The activist stress test. A skeptical investor evaluating DTE's outlook would challenge three primary areas.
First, financing structure creates financial tightness. Funding a $36.5 billion capital program through $500 million to $600 million in annual equity issuances while targeting a funds-from-operations-to-debt ratio of approximately 15% leaves minimal financial cushion.5 A 15% ratio sits near the threshold where credit rating agencies evaluate potential downgrades for a Baa-rated utility holding company. If capital costs rise, rate cases underperform, or severe weather inflates unrecovered operating costs, management would likely issue additional equity at prevailing market prices, diluting the per-share earnings growth underpinning the investment case. The central risk is asymmetric: while the capital program drives top-line growth, its funding structure represents the largest threat to per-share returns.
Second, customer affordability presents a political constraint. Projected rate base growth of 7% to 8% translates directly into higher residential bills in a region with significant energy burdens. Consecutive rate increases, persistent reliability concerns, state legal challenges against major data center supply contracts, and active legislative debate over utility reform collectively create an environment where political rate caps could constrain growth before capital requirements do.
Third, corporate governance and customer concentration warrant scrutiny. The active executive chairman structure, executive incentive metrics based on internal targets, and heavy growth reliance on a small number of large commercial counterparties introduce operational risk. Hyperscale data center operators possess substantial negotiating leverage, the ability to select alternative jurisdictions, and options to build behind-the-meter generation, meaning projected data center demand cannot be treated as guaranteed utility revenue.
X. Competitive Strategy, Helmer's 7 Powers & Porter's 5 Forces
Applying competitive strategy frameworks to a regulated utility can appear paradoxical, given that direct market competition is largely prohibited by statute. Yet these analytical tools remain useful precisely because they pinpoint the actual sources of corporate value. For DTE Energy, that value stems almost entirely from a single mechanism: a state-granted monopoly. That single dependency leaves the enterprise in a more fragile strategic position than a broad list of competitive advantages would suggest.
Hamilton Helmer's 7 Powers.
Cornered resource serves as DTE's primary power and is nearly absolute within its physical footprint. DTE Electric holds an exclusive franchise to distribute electricity across roughly 7,600 square miles of southeast Michigan.2 No competitor can construct a parallel distribution network to serve those customers. While Michigan permits a limited electric choice program for a small, capped portion of commercial load, that mechanism is strictly bounded by statute and does not pose a structural threat to the core franchise. Unlike a commercial cornered resource—such as a unique mineral deposit or a proprietary patent—this moat was created by government franchise and remains subject to legislative and regulatory modification. It is fundamentally a political asset rather than a private property right, making regulatory management the core of the company's competitive moat rather than an adjacent risk factor.
Scale economies are substantial and represent an insurmountable barrier to potential entrants. The company's distribution feeders, substations, transmission lines, and generating fleet reflect capital accumulated over more than a century and expanded by billions of dollars annually.5 Crucially, however, scale in a regulated setting does not yield pricing power as it would in a competitive market, because regulators establish tariffs on a cost-of-service basis. Utility scale inflates the approved rate base rather than expanding profit margins per unit of output. Consequently, scale deters entry while remaining neutral with respect to customer pricing power.
Switching costs are effectively absolute for retail customers, who lack alternative delivery providers. Rather than an independent source of power, however, high switching costs are simply a downstream consequence of the franchise agreement; treating them separately would double-count the same legal protection.
Counter-positioning against external entrants is non-existent because no direct competitors exist. The nearest equivalent is internal: by negotiating the accelerated retirement of coal assets in the Integrated Resource Plan settlement, DTE positioned itself ahead of tightening state and federal environmental regulations. That move converted a prospective compliance liability into an approved capital investment program—a tactic of effective regulatory positioning rather than strategic counter-positioning in Helmer's framework.
Branding, network economies, and process power provide no meaningful competitive power. Utility brands rarely generate positive commercial value, as captive customers cannot select alternative providers and typically engage with the brand during service disruptions. Network economies are similarly absent, as adding a customer does not enhance service quality for existing users. While operational excellence might theoretically support a claim to process power, DTE's recent grid reliability record and subsequent commission oversight weigh against that conclusion.
In summary, DTE possesses a single primary power—a state-sanctioned monopoly maintained through a political compact—complemented by a massive capital barrier that deters entrants without generating above-market returns. This structure reflects the standard economic model of a regulated utility, explaining why public equity markets value the company on rate base growth and regulatory predictability rather than classic competitive differentiation.
Porter's 5 Forces.
Threat of new entrants: Virtually non-existent in the electric distribution business. Legal exclusivity combined with immense sunk capital creates an insurmountable entry barrier.
Bargaining power of buyers: Dynamics are bifurcated and shifting. Residential and small commercial customers possess no individual bargaining leverage, yet they exercise significant collective leverage through political and regulatory channels—specifically the public service commission, the attorney general, and state legislators, who have repeatedly trimmed rate requests and mandated reliability metrics. Conversely, large industrial and hyperscale data center developers command substantial commercial leverage. When selecting sites across competing states, data center operators can negotiate tariff terms, project timelines, and infrastructure cost allocations, or credibly threaten to deploy behind-the-meter generation. DTE secured favorable terms in its initial Saline Township contract—including an 80% minimum billing demand and a 19-year commitment—reflecting strong negotiating position in that isolated deal.22 However, as the utility transitions toward a general data center tariff litigated in contested commission proceedings, future counterparties will treat the Saline terms as a benchmark for negotiation.21 Buyer power across this growth segment is therefore likely to expand over time.
Bargaining power of suppliers: Moderate and subject to supply chain cycles. As DTE deploys $15 billion toward clean energy generation, it operates as a price-taker in global markets for solar panels, wind turbines, power transformers, switchgear, and utility-scale battery storage. Extended lead times for high-voltage equipment expose the company to cost inflation. While capital costs can eventually be passed to ratepayers, regulatory lag and prudence reviews ensure that initial cost overruns impact the utility's balance sheet first.
Threat of substitutes: Currently low, but structurally increasing over a long horizon. Behind-the-meter rooftop solar paired with battery storage represents the primary technological substitute. The core strategic risk is not complete grid disconnection, as customers still rely on the distribution network for backup power, but volumetric erosion—where high-usage customers reduce their grid purchases while relying on full delivery capacity. This dynamic can initiate a gradual utility load-loss cycle: fixed grid costs are spread across fewer sold kilowatt-hours, increasing volumetric rates and further enhancing the economic appeal of self-generation. The pace of this transition remains governed by Michigan's distributed generation tariffs and net-metering regulations.
Rivalry: Absent within the franchised service territory. The relevant competitive pressure is jurisdictional and capital-based. DTE competes with Consumers Energy within Michigan and with regional utilities in neighboring states for economic development projects and major industrial loads. More critically, the company competes globally for investor capital, as generalist utility investors evaluate DTE's rate base growth trajectory, balance sheet health, and regulatory environment against peer utilities nationwide. That capital market competition provides the primary external discipline on management decision-making.
Ultimately, both frameworks reach the same conclusion: DTE Energy's long-term financial returns are anchored by a political franchise and bounded by regulatory oversight, leaving operational execution as management's primary lever for value creation.
XI. Playbook: Lessons from a Regulated Utility Transformation
1. The regulator is the customer that matters. A utility's revenue is not negotiated with retail ratepayers; it is adjudicated in front of a public service commission. That makes regulatory credibility an unwritten yet vital balance-sheet asset. DTE's experience across recent rate proceedings illustrates this mechanism: the company secured meaningful revenue increases while regulators maintained a frozen authorized return on equity in an environment shaped by public scrutiny over outage performance.1415 The broader lesson is that a utility can convert capital expenditure into net income only at the pace its operational record earns regulatory approval. System reliability metrics are not cosmetic targets; they directly dictate rate-making outcomes.
2. Conglomerate structures destroy utility multiples even when the acquired businesses perform well. The spin-off of DT Midstream serves as a clear case study in corporate structure, demonstrating that sound underlying assets can still suffer valuation discounts under a conglomerate umbrella. The core dynamic rests on investor expectations: utility shareholders prioritize predictable returns, discounting volatile or commodity-exposed earnings streams more heavily than their standalone cash flows warrant. The strategic takeaway is that the highest-return capital allocation decision for a diversified utility is often divestiture rather than acquisition. Testing whether executive leadership has absorbed this principle requires monitoring whether non-utility operations gradually expand as a share of consolidated earnings.
3. When a new load class arrives, design tariffs before signing contracts. The nationwide data center expansion has required utilities to serve commercial counterparties offering substantial power demand, strong credit profiles, and long-term commitments, while introducing the risk of shifting infrastructure costs onto existing ratepayers. The structural mechanisms protecting the retail customer base are evident in the Saline Township agreements: high minimum billing demand thresholds that require developers to pay for reserved capacity regardless of usage, long contract tenors aligned with asset lifespans, customer-funded dedicated infrastructure, and explicit allocation of unrecovered project risk away from retail ratepayers.2122 Utilities that bypass these protections risk litigating them retroactively in contested proceedings against state attorneys general — a scenario reflected in DTE's ongoing legal dispute over whether expedited commission approval was procedurally appropriate.24
4. Early retirement of a depreciated asset is a financing challenge, not an environmental one. Unrecovered asset balances determine whether a utility resists decarbonization or accelerates it. When regulators establish clear recovery mechanisms — such as securitization bonds or regulatory assets — utility incentives realign, as replacing legacy generating units with new capital investments expands the approved rate base. DTE's decision to advance the retirement schedule for the Monroe power plant by three years in a regulatory settlement is best understood through this economic framework rather than as a statement of corporate values.4 For investors, evaluating early plant retirements requires verifying the underlying cost-recovery structure before assuming the transition is either financially dilutive or value-accretive.
5. Never underwrite a technology's promise against a promoter's projection. The early failure at Fermi 1 underscores a durable historical lesson: gigawatt-scale artificial intelligence demand forecasts, multi-gigawatt project pipelines, and statutory clean energy targets represent projections issued by parties with an interest in their adoption. Analytical discipline requires distinguishing contracted, approved, and fully funded capital commitments from aspirational corporate goals — and identifying where each figure in an investor presentation resides.
XII. Analysis: Bull vs. Bear Case & Key Investor KPIs
The bull case relies on a coherent sequence of structural drivers rather than a single catalyst.
First, state mandates establish a statutory investment floor. Michigan law requires 50% renewable energy by 2030 and 100% clean energy by 2040.[^22] Because statutory compliance spending is mandatory rather than discretionary, prudently incurred investments enter the rate base. That framework converts a significant portion of DTE's five-year, $36.5 billion capital program into compelled investment—the most favorable condition for a utility earning a regulated return on capital deployed.5
Second, new large-load demand provides volume growth after two decades of flat sales. DTE has secured an initial 1.4 gigawatts in contracted capacity at the Saline Township data center campus, has another 1.0 gigawatt contract with Google pending regulatory approval, and is negotiating several additional gigawatts in its development pipeline.521 Serving large commercial customers under high minimum-demand tariffs improves fixed network utilization. In theory, this spreads fixed grid costs across greater electricity volume, moderating bill pressure on residential customers while expanding rate base for shareholders.
Third, the 2021 spin-off of DT Midstream simplified the corporate architecture.[^13] By refocusing the enterprise on pure-play regulated utilities and strictly bounding non-utility operations, management eliminated the conglomerate discount that previously depressed equity valuation.
Fourth, executive leadership aligns with operational priorities. Chief Executive Officer Joi Harris brings a 34-year career in field operations to a company whose primary regulatory and political vulnerability is grid reliability, with the majority of her compensation tied to long-term performance metrics.6
If management executes across these four fronts, the model supports company guidance targeting 6% to 8% annual operating earnings growth through 2030, anchored by 2026 guidance of $7.59 to $7.73 per share—representing roughly 7% growth—alongside a steady dividend.5
The bear case does not question these structural drivers, but challenges the assumption of frictionless execution.
The primary objection centers on balance sheet tightness. Expanding the rate base by 7% to 8% annually requires capital spending that far exceeds internal cash generation. Management plans to bridge this funding gap through $500 million to $600 million in annual equity issuances alongside new debt, while targeting a funds-from-operations-to-debt ratio of approximately 15%.5 That target sits near the credit rating agency threshold where Baa-rated holding companies face potential rating downgrades.32 The primary risk is not insolvency, but per-share dilution: if adverse regulatory orders or storm-related costs depress the stock price, issuing equity to fund capital spending will dilute per-share earnings growth.
The second risk stems from regulatory and political resistance. The Michigan Public Service Commission held DTE Electric's authorized return on equity at 9.9% across two consecutive rate cases while trimming requested rate increases.1415 Meanwhile, the Michigan Attorney General is appealing the commission's approval of the Saline Township data center contract in the Court of Appeals,24 consumer advocates contend that approved rate increases outpace inflation,31 and utility accountability remains an active issue in state political campaigns.29 In a heavy capital expenditure cycle, regulatory lag and unrecovered costs are ongoing operational realities rather than distant risks.
The third challenge involves storm exposure and service reliability. Severe weather events trigger immediate restoration expenses that may not be fully recoverable, expose the utility to annual performance penalties of up to $10 million under the commission's reliability framework,27 and erode regulatory goodwill during rate proceedings.28 Although management has implemented an audit-driven grid enhancement program, sustained performance improvements remain unproven across a full multi-year cycle of severe weather.28
The fourth risk involves executing the generation fleet transition. Retiring 3,066 megawatts of dispatchable coal capacity at the Monroe plant by late 2032 in two stages, while replacing it with variable solar and wind generation alongside battery storage, presents complex regional grid engineering challenges.4 Because renewable resources exhibit different availability profiles than thermal units, grid stability relies heavily on battery storage deployment, wholesale power purchases, and natural gas peaking generation at Belle River.20 DTE must file its next integrated resource plan by December 2026, which will evaluate replacement options for the final two Monroe units under a 100% clean energy scenario and test whether technical modeling supports management's accelerated retirement schedule.20
Finally, commercial data center demand carries counterparty concentration risk. Hyperscale technology developers evaluate competing multi-state sites and retain options to deploy behind-the-meter generation. Contracting with a small group of large-load customers creates concentration exposure unusual for retail utilities, which is why the 80% minimum billing demand condition in the Saline Township agreement was critical to mitigating revenue risk.22
Weighing it. The bull and bear thesis arguments address different dimensions of DTE's outlook. The bull case focuses on the direction of rate base expansion, which state statutory mandates and data center load growth make highly predictable. The bear case focuses on the rate of conversion of asset growth into per-share earnings, where regulatory lag, equity dilution, and reliability penalties compress returns. Historical precedents support both perspectives: DTE has consistently expanded its capital asset base over time, while routinely securing lower rate adjustments and authorized returns than requested from regulators.
The KPIs that actually matter. Evaluating DTE's execution requires tracking three core metrics.
First, the spread between DTE Electric's earned return on equity and its authorized 9.9%. This metric synthesizes rate case authorizations, regulatory lag, operating cost discipline, and storm restoration expenses. A widening gap indicates that rate base growth is failing to convert efficiently into net income, regardless of total capital deployed.
Second, outage duration and frequency relative to commission reliability targets. System reliability serves as a primary driver of regulatory and political outcomes. Reliability metrics dictate financial penalties, shape public perception, and influence commission willingness to authorize future capital expenditures. Improving grid performance represents Chief Executive Officer Joi Harris's main operational mandate, making reliability trends the primary test of executive execution.
Third, funds from operations to debt relative to annual equity issuance. This ratio defines the financial balance sheet constraint for the capital program. If funds from operations fall below the 15% target, management must either increase equity issuance or defer capital spending—both of which slow per-share earnings growth. Investors should monitor this metric against the company's guided $500 million to $600 million annual equity issuance target.
Secondary metrics—such as quarterly non-regulated earnings variations or uncontracted data center announcements—remain secondary to these three operational and financial indicators.
XIII. Epilogue & Transcript Guide for the Article Writer
A photograph from March 1893 in the Henry Ford collection depicts the employees of the Edison Illuminating Company of Detroit standing outside their power plant.33 Among them is a 29-year-old night engineer who would, within a decade, help spawn the industrial demand that transformed that regional utility into a power giant. The line connecting that 1893 image to today's 1.4-gigawatt supply contract with an artificial intelligence data center in Washtenaw County is direct: in both instances, an emerging industry arrived in Michigan requiring vast electrical capacity, forcing the utility to construct generation and distribution infrastructure ahead of demand.
What has shifted is the allocation of commercial risk when building ahead of load. In 1903, Detroit Edison constructed the Delray plant on spec and waited for industrial demand to materialize. In 2026, DTE negotiates a 19-year minimum-demand contract first, seeks regulatory approval second, and defends that authorization in the Michigan Court of Appeals third.2124 The modern enterprise operates within a dense web of institutional obligations: a public service commission that sets its pricing, an attorney general who challenges its contracts, a state legislature that mandates a 100% clean energy standard by 2040, and 2.3 million retail customers with no alternative provider and little tolerance for service interruptions.
The central investment question for DTE Energy is focused and measurable. The core trajectory — that Michigan will transition toward cleaner generation, that artificial intelligence infrastructure requires significant electrical load, and that DTE retains a protected distribution monopoly — is established. The critical issue is whether a utility deploying a $36.5 billion capital program alongside a frozen 9.9% authorized return on equity, a tight balance sheet, and an active reliability mandate can convert its capital spending into per-share earnings growth at its guided pace. DTE's historical record offers a mixed precedent: the company has consistently constructed required infrastructure, but has routinely accepted lower revenue adjustments and authorized returns than requested from regulators.
For readers reviewing the primary source materials, key disclosures provide essential context on these operational and financial dynamics. The second-quarter 2026 earnings materials contain the clearest statement of the expanded capital plan, its allocation across segments, data center capital assignments, equity issuance plans, and credit metric targets, with analyst inquiry focusing on balance-sheet execution and financing timelines.517 The June 2025 announcement and accompanying Form 8-K set out the executive leadership transition and the compensation structure behind it.618 The commission's December 2025 order on the Saline Township contracts, read alongside the Attorney General's subsequent filings, presents the competing arguments regarding data center tariff terms and ratepayer protections.21232425 The 2023 integrated resource plan settlement and state clean energy statutes define the generation trajectory, which will be updated in the next resource plan due by the end of 2026.1920[^22] Finally, the sequence of rate decisions — including the January 2025 order in Case U-21534 and the February 2026 rate order — provides the clearest window into how authorized returns and cost recoveries compare against management's requested filings.141530
References
-
Michigan regulators seek penalties for repeat utility outages — Bridge Michigan ↩
-
DTE Energy Company 2024 Form 10-K Annual Report — U.S. Securities and Exchange Commission, 2025-02-13 ↩↩
-
DTE agrees to shut down coal-fired Monroe plant in 2032, three years ahead of schedule — Planet Detroit, 2023-07 ↩↩↩↩↩
-
DTE Q2 2026 slides: data center deals fuel growth despite earnings miss — Investing.com, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
DTE Energy Company Form 8-K (leadership transition and compensation) — U.S. Securities and Exchange Commission, 2025-06-18 ↩↩↩↩↩↩
-
Henry Ford When Employed by Edison Illuminating Company of Detroit, March 1893 — The Henry Ford ↩
-
Henry Ford leaves Edison to start automobile company, August 15, 1899 — HISTORY ↩
-
Enrico Fermi Atomic Power Plant Unit 1 Decommissioning Status — U.S. Nuclear Regulatory Commission ↩
-
NRC Event Notification and Inspection Reports — U.S. Nuclear Regulatory Commission ↩
-
A Michigan Mega-Merger: DTE to Buy MCN — Natural Gas Intelligence ↩↩
-
DTE Energy Company and MCN Energy Group Inc., Docket 0010067 — Federal Trade Commission ↩
-
DT Midstream Form 10 Registration Statement — SEC EDGAR, 2021-05-07 ↩
-
MPSC authorizes $217,380,000 in additional revenue for DTE Electric Co. — Michigan Public Service Commission, 2025-01-23 ↩↩↩↩↩
-
MPSC Approves $242.4 Million DTE Electric Rate Hike — Michigan Department of Attorney General, 2026-02-19 ↩↩↩↩↩
-
MPSC approves DTE Gas Co. investments in infrastructure, directs improvements in company's utility assistance — Michigan Public Service Commission, 2026-09-10 ↩
-
DTE Energy Co. Form 10-Q for the quarter ended June 30, 2026 — U.S. Securities and Exchange Commission ↩↩↩↩↩
-
DTE Energy Board of Directors elects Joi Harris as CEO; Jerry Norcia elected Executive Board Chairman — DTE Energy, 2025-06-23 ↩↩
-
Commission approves settlement agreement on DTE Electric Co.'s integrated resource plan — Michigan Public Service Commission, 2023-07-26 ↩↩
-
DTE Electric agrees to speed Michigan coal plant retirements, renewable and energy storage buildout — Utility Dive, 2023 ↩↩↩↩
-
MPSC approves DTE Electric energy contracts for data center with conditions to strengthen protections for other customers — Michigan Public Service Commission, 2025-12-18 ↩↩↩↩↩↩↩
-
DTE Energy's Saline data center contracts win quick state approval, despite uproar — Planet Detroit, 2025-12 ↩↩↩↩
-
AG Nessel Files Motion to Reopen 'Conditional Approval' of DTE Data Center Contracts — Michigan Department of Attorney General, 2026-02-05 ↩↩
-
AG Nessel Files Appeal of MPSC Approval of DTE's Saline Data Center Contracts — Michigan Department of Attorney General, 2026-04-17 ↩↩↩↩↩
-
AG Nessel Briefs Appeal Over MPSC Approval of DTE's Saline Data Center Contracts — Michigan Department of Attorney General, 2026-08-07 ↩↩
-
MPSC seeks comment on proposal to connect utility earnings with reducing duration and frequency of electric outages — Michigan Public Service Commission, 2023-08-30 ↩
-
Utilities could face $10M penalties for failing to improve reliability — The Detroit News, 2025-02-27 ↩↩
-
MPSC orders reliability improvements guided by major audit of Consumers Energy Co., DTE Electric Co. — Michigan Public Service Commission, 2025-06-12 ↩↩↩
-
DTE outage fuels calls for utility reform in Michigan Senate races — Planet Detroit, 2026-07 ↩↩
-
MPSC approves $242.2 million rate increase for DTE customers — Michigan Advance, 2026-02-19 ↩↩
-
MPSC Order on DTE Electric Rate Case Misses Opportunities to Hold Utility Accountable — Citizens Utility Board of Michigan ↩↩
-
DTE Energy Company Credit Rating Rationale & Report — Fitch Ratings ↩
-
Edison Illuminating Company Employees, Including Henry Ford, March 1893 — The Henry Ford ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube