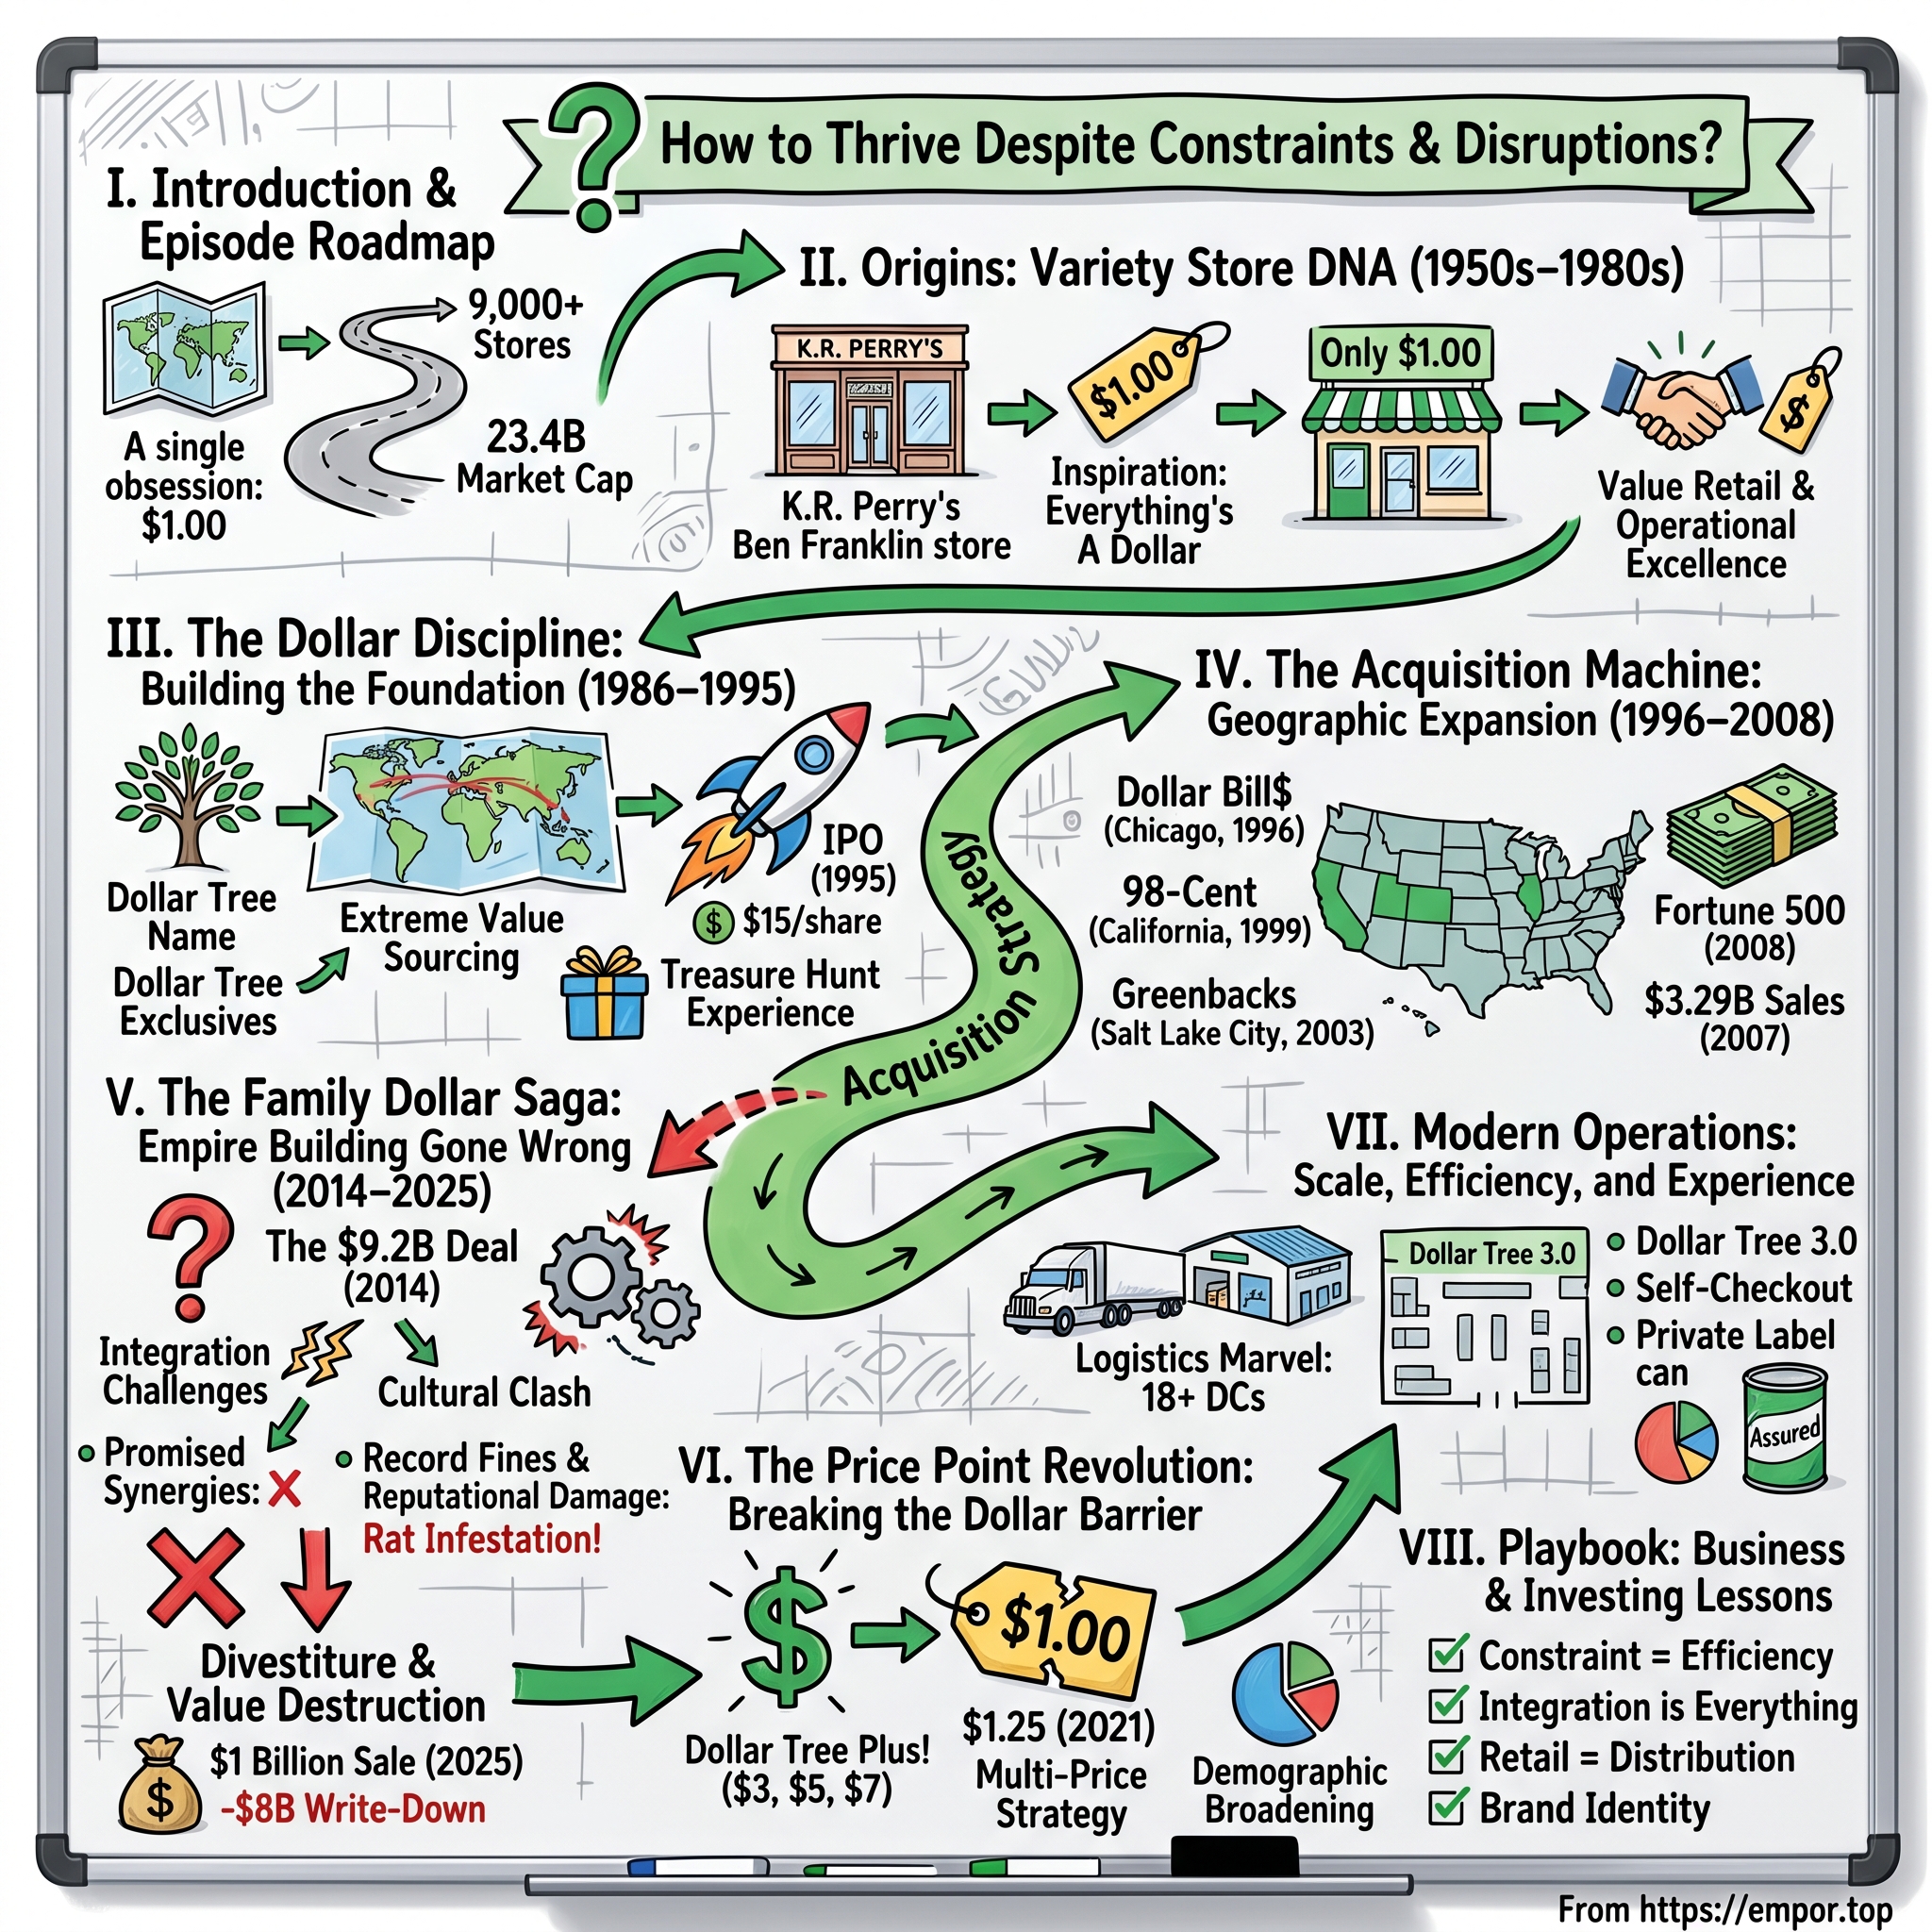
Dollar Tree: The Art of the Dollar
I. Introduction & Episode Roadmap
There is a distinct sound that defined American value retail for decades: the sound of a cash register not having to think. For thirty-six years, in every Dollar Tree store across the United States, the arithmetic was trivial. Four items in the basket meant four dollars. A child could budget for a birthday party, and a retiree on a fixed income could shop without a calculator. The price tag was not merely a price tag — it was the store's name, its core customer promise, and its entire operating system compressed into a single character.
That paradigm ended in the spring of 2022. Dollar Tree raised its base price point to $1.25, ending one of the longest-running fixed-price retail experiments in American history.1 It was not a routine marketing refresh; it was an admission that the strict pricing constraint that had long driven the company's growth had also, over time, capped its margins and limited its merchandise selection.
This is a case study in operational constraints — both productive and destructive. Dollar Tree spent three decades demonstrating how a self-imposed pricing limit can serve as a sharp competitive discipline. A single price point forces efficiency into every level of the organization: buyers cannot rely on easy markups, merchandisers must ruthlessly manage basket composition, and the supply chain has no buffer for inefficiency. On that discipline, the company built a network of roughly 8,500 stores generating over $18 billion in annual revenue.
Yet in a separate, far costlier venture, management attempted to apply that same operational playbook to an asset with fundamentally different economics. In 2014, Dollar Tree entered a bidding war for Family Dollar and acquired it for roughly $9.2 billion — buying a chain whose target customer, store format, margins, and merchandise mix bore little resemblance to its own.2[^3] A decade later, Dollar Tree agreed to sell the unit to investment firms Brigade Capital Management and Macellum Capital Management for a gross cash consideration of $1.0075 billion.34 The transaction closed on July 7, 2025.5
Between those two milestones lies a major case study in retail value destruction. The decade was marked by activist campaigns from Starboard Value and Mantle Ridge, billions of dollars in asset write-downs, a federal criminal plea following severe sanitation violations at a distribution center, and a board overhaul that ultimately installed the former chief executive of Dollar General as chairman and CEO of the company that had outbid him years earlier.[^7][^8]6[^10]
The central question facing the company in September 2026 is straightforward: stripped of Family Dollar, is Dollar Tree a structurally advantaged, high-return distribution machine with a defensible moat, or is it now a conventional small-box discount retailer competing directly for market share against Walmart, Dollar General, Five Below, Amazon, and cross-border e-commerce platforms like Pinduoduo's Temu?
Evaluating that question requires testing management's strategic claims against the company's disclosed operating performance rather than its marketing narratives. The analysis that follows examines that record.
 Subscribe on LinkedIn
II. Variety Store DNA: From K&K Toys to Only $1.00 (1953–1986)
In 1953, Norfolk, Virginia, was a Navy town defined by shipyards, military personnel, and families living on modest, predictable incomes. It was a natural fit for a variety store. K. R. Perry opened a Ben Franklin franchise there, joining thousands of small-town general merchandise outlets linked by a franchising system that provided store layouts, supply chain access, and brand recognition to independent operators responsible for local execution.
The Ben Franklin model served as a foundational training ground for a generation of American retail operators. It instilled a fundamental operating principle: retail profitability comes not from high markups on individual items, but from inventory velocity. A variety store depended on how rapidly it could convert inventory into cash. Perry's store, later rebranded K&K 5&10, operated as an early clinic in that arithmetic.
The next generation expanded on that foundation. In 1970, K. R. Perry, his son Doug Perry, and Macon Brock launched K&K Toys, capitalizing on the rapid growth of enclosed shopping malls across the United States. Toys fit the mall format well during that period, offering high retail margins, steady gift demand, and strong sales per square foot. The chain expanded to more than 130 stores along the East Coast.
Brock emerged as the operational anchor of the business. Colleagues described an executive focused on logistics and daily execution — monitoring truck deliveries, shelf stocking, and store operations. That ground-level focus proved critical when, by the mid-1980s, the mall toy model faced growing structural headwinds.
Mall toy retail was sharply seasonal, generating the vast majority of its annual profit during a few weeks in December while tying up working capital for the remaining eleven months. Meanwhile, competitive dynamics were shifting. Category specialists such as Toys "R" Us expanded rapidly, Kmart achieved national reach, and Walmart demonstrated that everyday low pricing combined with distribution scale could displace traditional variety stores.
Seeking a business with year-round cash generation — fast-turning inventory, cash transactions at the register with no receivables, and low sales friction — the founders examined alternative value formats. They took notice of "Everything's A Dollar," an early single-price concept that drew heavy customer traffic. In 1986, Doug Perry, Macon Brock, and Ray Compton opened a five-store trial called Only $1.00.
The divergent paths of the two companies illustrated a key retail lesson. While "Everything's A Dollar" expanded rapidly before eventually filing for bankruptcy in the 1990s, Only $1.00 laid the foundation for decades of growth. The single price point was not a defensible moat on its own; long-term success required structural efficiency in procurement, merchandise selection, and distribution. The founders' background in managing inventory velocity proved to be a far more valuable asset than the $1.00 price tag.
That origin also established a corporate culture focused heavily on store-level execution. Because the leadership team developed its skills as franchise operators rather than department store merchandisers or corporate strategists, management's default response to operational challenges was to inspect store operations directly. That practical orientation fostered strong ground-level discipline, but left the company with less institutional capability for high-level corporate strategy — such as evaluating business models or assessing major acquisitions. Decades later, that gap would lead to significant shareholder value destruction.
For investors, the origin story establishes a pattern that recurs throughout Dollar Tree's history: the company consistently excelled when optimizing its core cash-conversion engine, but struggled when confronting complex strategic repositioning.
III. The Dollar Discipline: Building the Fixed-Price Engine (1986–1995)
On April 27, 1989, a store opened at Jessamine Mall in Sumter, South Carolina under a new name: Dollar Tree. The name mattered more than it looked. "Only $1.00" described a rule. "Dollar Tree" described an experience — abundance, variety, something growing. It was the first sign that management understood it was selling a shopping trip, not a discount.
What happened over the following six years is the part of the story that deserves the most attention from anyone trying to value the company today, because it is where the actual operating machine was built.
The pure-play decision
In 1991, management sold the 130-store K&K Toys chain to KB Toys and redeployed the entire proceeds into dollar stores. This was a hard decision made easy only in hindsight. K&K was the profitable, known business. Dollar Tree was the new venture with a few dozen locations. Selling the mature asset to fund the younger one is the kind of capital allocation that sounds obvious in retrospect, but carries high risk in real time. The company formally became Dollar Tree Stores, Inc. in 1994.
That decision established an important pattern: for its first three decades, Dollar Tree's best capital allocation decisions were acts of subtraction.
How a dollar actually works
The single-price model is often described as a marketing gimmick. It was closer to a manufacturing constraint, and understanding its mechanics explains both the company's historical returns and its eventual crisis.
In a conventional retail operation, price is the output. The buyer sources a product, adds a markup, and the shelf tag reflects the result. At Dollar Tree, price was the input. The buyer started with $1.00, subtracted the target gross margin — historically in the mid-thirties as a percentage — subtracted freight, duty, and handling, and arrived at a landed cost the vendor either could hit or could not. There was no negotiation about the shelf price because the shelf price was fixed.
Flexibility had to exist elsewhere, primarily across three dimensions:
The first was pack size. If the cost of dish soap rose, the bottle got smaller — sixteen ounces became twelve, then nine. The customer still paid a dollar and the unit economics held, while the value proposition quietly eroded. Retail industry observers refer to this as shrinkflation. At Dollar Tree, it was not an occasional tactic; it was a core competency refined over decades of vendor negotiation.
The second was opportunistic sourcing. Closeouts, overruns, canceled orders, and discontinued packaging — the residue of third-party supply chain miscalculations — became Dollar Tree's inventory filler. This approach required a buying organization capable of committing to irregular lots quickly and a distribution network flexible enough to absorb non-standard inventory without operational disruption.
The third was direct importing. Long before the practice became widespread among regional retailers, Dollar Tree established direct relationships with manufacturers in East Asia, bypassing importer markups. That decision yielded a substantial cost advantage for three decades, though it eventually created a significant structural risk on the income statement.
Behind this mechanism sat a merchandising split that management described as roughly balanced between everyday consumables and discretionary, seasonal items — such as party supplies, greeting cards, glassware, and holiday decor. Consumables generated customer foot traffic, while discretionary goods drove profit margins, as a $1.00 party balloon carried far higher margins than a $1.00 can of soup.
The 1995 IPO
Dollar Tree went public on NASDAQ in 1995 at $15 per share, valuing the company at roughly $225 million.7 The offering was small, but capital was not the primary goal. The public listing provided equity currency and balance-sheet credibility, enabling the company to fund a multi-decade store rollout and finance owned distribution centers rather than relying solely on leased facilities.
The cost of the constraint, in one number
The impact of the fixed price point is best understood through unit inflation arithmetic. A product that cost sixty-five cents to land in 1990 and sold for a dollar generated thirty-five cents of gross profit. If the landed cost of an identical product rose over the next two decades due to global manufacturing inflation, the buyer had only two options: locate a lower-cost supplier or reduce the quantity inside the package. Raising the retail price was not an option. Over extended periods, repeatedly reducing package content alters the core value proposition: while the retail price remains a dollar, the customer receives less content per purchase. Because gross margin percentages remained stable, this gradual dilution of customer value went largely unaddressed on the financial statements.
Falsifying the moat claim
A long-standing thesis regarding Dollar Tree posits that the fixed $1.00 price point established an unassailable consumer brand and a durable price advantage.
The company's operating record challenges the strong version of that claim. Between 1986 and 2021, cumulative U.S. consumer price inflation reached approximately 90%, while Dollar Tree held its nominal price point constant. Maintaining that price required reducing package volumes over time. Maintaining a fixed nominal price point served as an unhedged exposure to long-term inflation.
This constraint directly impacted average ticket size. A store format where maximum item prices are capped lacks an organic mechanism to increase average basket value. Revenue growth depended almost entirely on increasing foot traffic or unit volume, both of which are harder to drive than price increases.
The evidence suggests that the fixed $1.00 price point served primarily as an effective customer acquisition mechanism and an operational discipline for procurement, rather than a structural economic moat. The primary durable assets proved to be procurement capability and distribution infrastructure. The key test of this model is whether traffic levels remain stable as price points rise above $2.00, a topic examined in Section VI.
Over the subsequent two decades, the company focused on expanding its distribution footprint, beginning with direct competitor acquisitions.
IV. The Acquisition Machine: Rolling Up the Contiguous U.S. (1996–2013)
In the mid-1990s, the American dollar-store landscape was fragmented among regional chains. Most had been founded around the same time by local entrepreneurs, each dominating a single metropolitan area, and each eventually hitting the same operational wall: the high capital cost of a modern distribution center. A hundred-store chain could not afford to build one, while a thousand-store chain could not survive without it.
That asymmetry formed Dollar Tree's core acquisition thesis for eighteen years, which it executed with steady consistency.
In 1996, Dollar Tree acquired Dollar Bill$, Inc., a 136-store chain around Chicago, securing a Midwest beachhead and an existing distribution footprint. In 1998, two transactions—98-Cent Clearance Centers in California and Only $One Stores in New York—established a coastal presence in two of the nation's most competitive real estate markets. The expansion continued in 2000 with the acquisition of Philadelphia-based Dollar Express and its 137 stores, followed in 2003 by Greenbacks, Inc., whose 168 stores out of Salt Lake City filled in the Mountain West. In 2006, Dollar Tree acquired the 138-store Deal$ banner from SUPERVALU INC.
The integration playbook was disciplined and repeatable: purchase a small-footprint, single-price variety chain, rebrand the storefronts, plug the locations into Dollar Tree's replenishment system, and align the merchandise with its single-dollar inventory. Integration took months rather than years because the acquired stores operated on business models nearly identical to Dollar Tree's own.
Supporting these acquisitions was a rapid expansion of the underlying logistics network. Dollar Tree broke ground on a combined store support center and distribution complex in Chesapeake, Virginia, expanding from a single distribution center in the early 1990s to seven by 2008. In 2004, the opening of a store in North Dakota completed the company's footprint across all 48 contiguous states.
This distribution density served as the financial engine of the business. Dollar stores sell low-priced items in high unit volumes, meaning freight costs represent a significant percentage of an item's retail price. Operating profitably required maximizing units per pallet and pallets per truck while minimizing stem miles—the distance from distribution centers to individual stores. Each new distribution center shortened regional delivery routes, reducing per-unit shipping costs to expand gross margins or fund higher product quality within the single-dollar price point. Scale in small-box retail was ultimately a function of route geometry.
The 2008 financial crisis provided a major stress test. As the U.S. economy contracted and middle-income households sought value, Dollar Tree delivered record performance. The company entered the Fortune 500 and emerged as the top-performing stock in the NASDAQ-100 for the year, proving the counter-cyclical resilience of its business model.
However, that success led to a critical strategic misjudgment. The strong financial performance convinced management, the board, and investors that Dollar Tree possessed a universal retail playbook—that the operational engine that had successfully absorbed regional competitors like Greenbacks could be applied with equal success to any retail format.
Falsifying the M&A competence claim
A closer examination of the transaction record challenges that assumption. Every successful acquisition between 1996 and 2006 shared identical core characteristics with Dollar Tree: the same price architecture, store footprint, customer mission, and supply chain design. These transactions were not strategic turnarounds; they were real estate and capacity purchases aimed at acquiring store leases and geographic coverage to deploy Dollar Tree's pre-existing operating system.
The sole multi-price transaction during this period—the acquisition of Deal$—highlighted the limits of that approach. Deal$ operated on a multi-price model and never matched Dollar Tree's core profitability. Management retained the banner primarily as an experimental laboratory rather than expanding it. Internally, however, leadership attributed the weak performance to limitations inherent in multi-price formats rather than recognizing the company's own lack of experience operating beyond its core single-price model.
The evidence indicates that Dollar Tree did not possess a broadly transferable acquisition capability, but rather a narrow, highly effective conversion playbook. Conflating the ability to convert identical store formats with the capacity to integrate fundamentally different retail models ultimately set the stage for the company's subsequent acquisition challenges, destroying billions of dollars in shareholder value.
V. The Family Dollar Saga: The $9.2 Billion Empire-Building Disaster (2014–2025)
In the summer of 2014, Family Dollar faced severe operational challenges. Same-store sales were deteriorating, its store network had suffered years of underinvestment, and activist investor Carl Icahn had acquired a major stake to push for a sale. The company was officially in play.
What followed was an aggressive bidding contest, and understanding why Dollar Tree prevailed is essential to understanding why winning the asset ultimately created a corporate crisis.
The bidding war
Dollar Tree moved first, agreeing in July 2014 to acquire Family Dollar in a cash-and-stock transaction.2 Dollar General subsequently intervened with a higher, hostile cash offer of $80.00 per share — representing a substantial premium over Dollar Tree's bid.
On price alone, Dollar General presented the superior bid. However, antitrust considerations blocked that path. Dollar General and Family Dollar overlapped significantly across rural footprints, consumable-heavy assortments, and core low-income demographics. By contrast, the Federal Trade Commission's eventual consent order for Dollar Tree required divesting only 330 Family Dollar stores — a minor fraction of an 8,000-store base.[^3] The divestiture scale required for a Dollar General combination was widely understood to be an order of magnitude larger.
Family Dollar's board accepted the lower offer because it carried far less regulatory risk. For Dollar Tree's management, securing the deal was viewed as a strategic victory rather than a costly overpayment. The acquisition closed on July 6, 2015, creating a combined enterprise of more than 13,000 stores generating roughly $19 billion in annual sales.[^3]
What was actually purchased
The purchase price totaled approximately $9.2 billion, representing roughly 11 times trailing EBITDA.[^3] While that valuation multiple might have suited a healthy retailer, it represented an aggressive price for a struggling asset.
More critical than the valuation multiple was the underlying operating model. Family Dollar operated with gross margins in the mid-twenties as a percentage of sales, compared to Dollar Tree's mid-thirties. That margin gap reflected structural differences rather than operational inefficiency. Family Dollar relied on selling national-brand consumables — such as laundry detergent, soda, diapers, and cereal — at everyday low prices to low-income urban and rural households acting as primary grocery shoppers. Dollar Tree focused on private-label and closeout merchandise, heavily weighted toward high-margin discretionary and seasonal items, catering to suburban, middle-income shoppers.
The two chains possessed distinct customer bases, supply chains, real estate strategies, vendor networks, and merchandising philosophies. They shared little beyond the word "dollar" in their names and a single parent company.
The synergy that never arrived
Management justified the acquisition on the grounds of scale — claiming combined purchasing power against Walmart and expanded distribution leverage. Neither benefit materialized as projected.
Purchasing synergies depend on shared procurement. Dollar Tree's merchandise buyers sourced generic goods against a rigid cost ceiling, whereas Family Dollar negotiated with national brand manufacturers like Procter & Gamble and Coca-Cola, where suppliers held pricing power. Dollar Tree's core discipline of enforcing strict package-size constraints was ineffective against major consumer packaged goods conglomerates such as Unilever.
Distribution synergies similarly required compatible logistics workflows. Dollar Tree shipped full pallets of stable merchandise to stores with predictable demand patterns. In contrast, Family Dollar demanded high-frequency replenishment of perishable and semi-perishable inventory — requiring cold-chain infrastructure to serve a store network plagued by volatile demand and difficult operating conditions.
By the late 2010s, structural headwinds manifested in financial impairments. Between 2018 and 2024, Dollar Tree recorded cumulative goodwill and asset impairment charges related to Family Dollar totaling billions of dollars — representing an explicit accounting recognition that cash flows could not support the original valuation.[^12] For investors, repeated goodwill write-downs served as clear evidence of sustained value destruction.
West Memphis
The operational strain eventually erupted into a regulatory crisis.
In early 2022, a U.S. Food and Drug Administration (FDA) inspection of Family Dollar's distribution center in West Memphis, Arkansas, uncovered a severe rodent infestation. The fallout was immediate: a voluntary recall covering numerous FDA-regulated products, the temporary closure of hundreds of stores across multiple states, and a federal criminal investigation. In 2024, Family Dollar Stores pleaded guilty and was ordered to pay over $41.6 million — marking the largest monetary criminal penalty in a U.S. food safety prosecution.[^7]
The violation highlighted systemic operational shortcomings. An infestation of that magnitude occurs when logistics facilities suffer sustained underinvestment and inadequate oversight, and when internal oversight mechanisms fail to escalate critical compliance breakdowns. The lean operational model that drove Dollar Tree's core store expansion proved dangerously unsuited to managing complex, regulated supply chain infrastructure without adequate capital support.
What the earnings calls revealed along the way
Throughout the Family Dollar integration, management established a consistent narrative pattern during earnings calls. For several years, executives attributed segment underperformance to timing issues — citing ongoing store renovation cycles, unannualized price investments, and pending store closures. Equity analysts repeatedly questioned whether the business simply required additional execution time or was fundamentally incapable of generating acceptable returns on capital, though management maintained that performance would improve.[^12]
This focus reflected an internal benchmark tied to operational milestones rather than capital opportunity costs. While individual annual renovation budgets appeared defensible in isolation, a decade of incremental expenditures ultimately resulted in an asset sold for roughly eleven cents on the dollar of its original purchase price.
The strategic lesson extends beyond this transaction: when a corporate segment relies on a multi-year turnaround narrative refreshed with annual milestones, the fundamental analytical question is not whether the latest plan is achievable, but why earlier iterations failed to deliver.
The exit
By 2024, the banner's position had become unsustainable. In March 2024, management announced plans to close approximately 1,000 underperforming Family Dollar stores. In June 2024, the company initiated a formal strategic review of the banner to evaluate potential divestiture options.
On March 26, 2025, Dollar Tree entered into a definitive agreement to sell Family Dollar to Brigade Capital Management and Macellum Capital Management for gross cash consideration of $1.0075 billion. The company projected net cash proceeds of approximately $800 million after taxes and transaction costs, alongside an anticipated tax benefit from the disposition.34 The transaction closed on July 7, 2025.5
Falsifying the capital allocation claim
The strategic thesis under evaluation — that acquiring Family Dollar established scale, a defensive competitive moat, and vendor leverage against Walmart — is refuted by the operating record. On procurement, the combined entity failed to achieve durable supplier cost advantages. On capital returns, an asset acquired for approximately $9.2 billion was sold a decade later for roughly one-ninth of its purchase price after absorbing billions of dollars in impairments and ongoing capital expenditures. Consolidated operating margins and return on invested capital were persistently depressed by the underperforming segment. Furthermore, the managerial attention required to remediate Family Dollar coincided with a pivotal decade during which Walmart expanded national grocery pickup, Amazon optimized same-day delivery, and cross-border e-commerce platforms established direct-to-consumer value channels.
The capital allocation thesis is falsified. Following the disposition, the key strategic test is whether management maintains discipline through organic store growth and share repurchases, or resumes transformative acquisitions as balance sheet capacity recovers. Any future large-scale M&A outside the core banner must be evaluated against this historical record.
This outcome raises a key governance question: what forces ultimately compelled the divestiture? The answer lies in activist shareholder pressure, exerted across two distinct campaigns spanning nearly seven years.
VI. The Activist Storm & Breaking the Dollar Barrier: $1.00 to $1.25 and Beyond (2018–2023)
Phase one: Starboard
Starboard Value founder Jeff Smith specializes in targeting companies where operational changes are delayed by corporate identity. In Dollar Tree, Starboard identified a retailer defending a single price point that decades of inflation had diluted, while carrying an underperforming acquisition it had failed to integrate.
In January 2019, Starboard disclosed a stake and publicly urged Dollar Tree to pursue two major strategic changes: sell Family Dollar and break the $1.00 price ceiling.[^8]
Management resisted both proposals. Executives argued that the single price point formed the core of the brand identity, asserting that customers valued pricing certainty above all else. Starboard countered that Dollar Tree was already raising prices implicitly through smaller package volumes, arguing that an explicit price change would allow the company to restore product quality and operating margins.
Management responded with a compromise: Dollar Tree Plus!, a limited pilot introducing higher price points into a small selection of stores. Designed as an exploratory test rather than a strategic shift, the initiative ran for years without resolving the core pricing dilemma. Starboard eventually exited its position, leaving Dollar Tree with a temporary proxy victory but an unresolved operational model.
The forcing function
Global supply chain disruptions in 2021 ultimately forced the pricing decision management had postponed.
Trans-Pacific ocean container shipping rates surged roughly tenfold from pre-pandemic levels, rising from a low-thousand-dollar range per container to over $20,000 at the peak. While rising freight costs compressed margins across the retail sector, the impact on Dollar Tree was acute. Because freight costs represented a fixed expense per container and revenue was capped by the $1.00 retail price multiplied by unit volume, elevated shipping costs threatened to eliminate gross margins on imported merchandise. Concurrently, domestic trucking costs and store-level wages rose significantly.
Package-size reductions could no longer offset cost increases of that magnitude. The fixed-price constraint that had driven the company's operating discipline for thirty-five years had become financially unsustainable.
Breaking the dollar
In November 2021, Dollar Tree announced it would move its base price point to $1.25 across the chain, with the rollout completed across stores in the first quarter of 2022.1
The financial impact was immediate. Because unit inventory costs remained unchanged at the moment of transition, the 25% price increase flowed directly to gross profit, expanding reported gross margins by hundreds of basis points over subsequent quarters.
Customer behavior also proved far less price-sensitive than leadership had long assumed. Foot traffic remained stable as shoppers continued to focus on relative value rather than the absolute dollar denomination. A customer comparing a $1.25 item at Dollar Tree to a $2.49 equivalent at a traditional grocery store still perceived a compelling discount.
The transition demonstrated that management had over-estimated customer attachment to the nominal $1.00 price point while underestimating the strength of the underlying value proposition. Removing the long-standing pricing cap expanded profitability and provided the merchandise flexibility required to restore product quality.
Phase two: Mantle Ridge
Following the base price increase, activist pressure shifted toward corporate governance. Mantle Ridge, an investment firm led by former Pershing Square partner Paul Hilal, focuses on governance-driven interventions centered on leadership selection and operational execution rather than asset divestitures.
In late 2021, Mantle Ridge disclosed a 5.7% stake in Dollar Tree valued at approximately $1.8 billion and pushed for a wholesale board refresh.6 In March 2022, Dollar Tree reached a settlement agreement that reconstituted a substantial portion of the board.6 As part of the agreement, former Dollar General chief executive Rick Dreiling was appointed Executive Chairman, with Hilal named Vice Chairman.
The appointment of Dreiling brought experienced operational leadership back to the business. Dreiling had previously led Dollar General through a period of substantial growth and operating margin expansion, focusing on core retail metrics such as inventory availability, store-level execution, and supply chain efficiency. In January 2023, Dreiling assumed the CEO role, taking direct operational control of the enterprise.
Dollar Tree 3.0
Under Dreiling's leadership, Dollar Tree expanded the initial Dollar Tree Plus! pilot into a multi-price framework, introducing price tiers ranging from $1.25 to $5.00 and higher in select product categories.
Management positioned the multi-price architecture not merely as a mechanism for price increases, but as a broader category expansion. Caps of $1.00 or $1.25 had previously excluded entire product lines — including frozen foods, brand-name household chemicals, larger toys, pet supplies, and basic apparel. Introducing higher price tiers allowed Dollar Tree to expand its addressable market and capture consumer demand that had previously shifted to competitors such as Walmart and Dollar General.
However, this strategy introduces operational complexities. The original single-price model derived efficiency from simplicity across store operations, inventory tracking, checkout processing, and customer expectations. A multi-price model requires price-tagging labor, expanded inventory management, and clear promotional communication to prevent customer friction at checkout.
For investors, managing the trade-off between category expansion and operational complexity represents a central strategic test for the company.
VII. Modern Operations & Core Economics: The Pure-Play Dollar Tree Engine (2024–2026)
A walk through a converted Dollar Tree store in 2026 reveals immediate physical changes from its 2019 predecessor. Frozen food cases line walls that were once filled with dry goods, larger-format merchandise occupies prominent endcaps, and color-coded tags on shelf edges denote a growing array of price points. The physical footprint remains largely unchanged—typically eight thousand to ten thousand square feet in a suburban strip center—but the assortment inside reflects a shifting operational center of gravity.
The standalone profile
Following the divestiture of Family Dollar, Dollar Tree operates as a standalone pure-play banner with more than 8,500 stores across the United States and Canada. The core business generates annual continuing-operations revenue in the high teens of billions of dollars, with reported gross margin in the low 30% range.8 Its merchandise mix remains roughly balanced between everyday consumables and discretionary items, with discretionary goods carrying substantially higher profit margins.
This balanced product mix serves as a key structural distinction between Dollar Tree and Dollar General, presenting both advantages and risks. A higher concentration of discretionary items expands profit margins and basket values during periods of economic expansion. However, it also increases vulnerability to downturns in consumer spending. A retail format with 50% discretionary exposure is less recession-resistant than its performance during the 2008 financial crisis might imply, as that earlier record was established when item prices were strictly $1.00 and low-cost consumer alternatives were fewer.
The unit economics, explained simply
The financial foundation of Dollar Tree's store expansion rests on favorable unit payback dynamics. Opening a new location requires a net capital expenditure of a few hundred thousand dollars, while store-level cash flows typically recover that initial investment within two to three years.8
Reinvesting capital at a two-to-three-year payback across hundreds of new store openings annually provides an organic growth engine that does not depend on debt-financed acquisitions or secondary business lines. This dynamic underscores the substantial opportunity cost of the Family Dollar transaction: the approximately $9.2 billion allocated to acquiring a low-return asset represented capital that could have alternatively funded more than a decade of high-return store expansion within the core banner.
Sales productivity for the format averages in the low-to-mid $200s per square foot. While modest compared to traditional department stores, this figure aligns with value retail benchmarks. It also highlights why securing low rental rates per square foot in secondary strip centers is not merely an operational convenience, but a fundamental prerequisite of the business model.
Why the format still works at all
Given that mass merchandisers like Walmart frequently offer lower per-unit prices and e-commerce platforms provide home delivery, Dollar Tree's store format relies on three distinct operational and behavioral factors to sustain customer traffic:
First, absolute price points often take precedence over unit economics for cash-constrained households. Customers managing strict weekly budgets focus primarily on total out-of-pocket expenditure at the register rather than per-ounce cost. A $1.25 item remains accessible even when a $6.99 bulk alternative offers superior unit value. This purchasing constraint allows small-box dollar stores to coexist alongside large-format hypermarkets.
Second, convenience and proximity minimize transaction friction. With relatively small store footprints, customers can complete purchases in under ten minutes. Located in neighborhood strip centers along daily driving routes, these stores capture quick fill-in shopping trips that large-format retailers are ill-equipped to serve efficiently.
Third, seasonal and closeout inventory creates a browsing atmosphere often described as a "treasure hunt." With approximately half the product selection continuously rotating based on seasonal demand and opportunistic vendor buys, routine shopping trips take on an element of merchandise discovery. This dynamic drives sales in higher-margin discretionary categories, aligning the format more closely with off-price retailers like TJX or Five Below than conventional grocery stores.
The shift toward a multi-price assortment introduces a strategic tension between these forces: higher price points risk eroding the absolute-price advantage that attracts budget-focused shoppers, even as they enhance merchandise breadth and treasure-hunt appeal.
The logistics layer
Supporting this store network is a logistics system comprising approximately two dozen distribution centers across the United States and Canada, featuring increased automation, palletized replenishment workflows, and a dedicated private fleet.8
However, implementing the multi-price strategy requires substantial supply chain investments. Expanding into frozen and refrigerated products necessitates cold-storage infrastructure within distribution centers, refrigerated transport capacity, and dedicated freezer display units in stores. Managing a temperature-controlled supply chain is structurally more complex and capital-intensive than distributing shelf-stable general merchandise. Consequently, investors must evaluate whether the higher capital intensity of multi-price operations will compress the historical return profile of new store rollouts.
What the segment comparison actually taught
The operational divergence between the two banners at the time of divestiture highlighted fundamental structural differences across key operating metrics:
- Real Estate Footprint: Dollar Tree operated predominantly in suburban shopping centers, whereas Family Dollar maintained approximately 7,500 locations concentrated in dense urban neighborhoods and rural areas.
- Margin Structure: Dollar Tree generated gross margins in the low 30% range, compared to the mid-20% range for Family Dollar.
- Merchandise Selection: Discretionary products represented nearly half of Dollar Tree's sales mix, versus roughly one-fifth for Family Dollar.
- Target Demographics: Dollar Tree served a broader middle- and lower-income suburban demographic, while Family Dollar focused primarily on lower-income households relying on the store for core grocery purchases.
- Capital Returns: Dollar Tree sustained a predictable two-to-three-year new store investment payback, while substantial portions of Family Dollar's asset base suffered recurring financial impairments.
These differences indicate that Family Dollar's underperformance stemmed less from an unviable retail concept—given Dollar General's profitable execution of a comparable model at scale—than from an operational mismatch. Dollar Tree attempted to apply a specialized single-price inventory engine to a complex multi-price grocery business without building the requisite supply chain and merchandising capabilities. Evaluating management's forward strategy requires recognizing that failure as an internal execution breakdown rather than an inevitable industry trend.
VIII. Management, Governance & Capital Allocation: The Post-Dreiling Era
In November 2024, Rick Dreiling stepped down for health reasons, bringing an abrupt end to a turnaround effort he had led for less than two years. The board named Mike Creedon as interim chief executive and made the appointment permanent in December 2024.9
Who is running the company
Creedon joined Dollar Tree as chief operating officer in October 2022, recruited from Advance Auto Parts, where he held senior field and operations leadership roles. His remit at Dollar Tree expanded over time to encompass supply chain and merchandising before his appointment to chief executive.9
This executive profile is notable for what it lacks. Creedon is neither a merchant nor a financier; he is a field-operations executive. Given that the two most severe operational breakdowns in the company's recent history involved store-level execution and distribution-center compliance, an operational background is directionally aligned with organizational needs. However, Creedon remains untested in the chief executive role, stepping into the position during the largest store format transition in the company's history and immediately following a major divestiture.
Paul Hilal remains on the board as vice chairman, providing an activist investor with a concentrated economic stake a direct voice in capital allocation. Compared to the 2015–2021 board that approved and defended the Family Dollar acquisition for years, this structure provides stronger governance oversight.
Incentives
Management relies on a compensation framework tied to return on invested capital, comparable store sales performance, and adjusted earnings per share from continuing operations.8 Removing Family Dollar's volume from the metric base sharpens executive incentives, as earning performance bonuses on consolidated sales growth is far more demanding without a low-margin sales base.
A key variable for investors is whether return on invested capital is calculated using metrics that accurately reflect the substantial capital deployed into store remodels and cold-chain supply chain infrastructure, or whether management relies on cumulative adjustments and exclusions. Retail leadership under transformation pressure often displays a tendency toward broadening definitions of adjusted earnings.
Where the cash goes
Following the divestiture, capital allocation focuses on three primary priorities: converting the legacy store base to multi-price layouts at an annual pace management describes in the low thousands of stores; investing in distribution automation and temperature-controlled supply chain capacity; and returning cash to shareholders through share repurchases funded by divestiture proceeds and continuing free cash flow.85
Credibility, weighed
On governance and strategy, current leadership accomplished what previous management resisted: exiting Family Dollar decisively rather than funding an extended remediation effort, reporting the unit as discontinued operations with clear disclosure, and committing to a multi-price rollout at scale rather than relying on perpetual pilots.
However, two significant caveats warrant equal weight. First, the company maintains a documented history of attributing guidance shortfalls to external headwinds — such as freight rates, weather, consumer softness, and tariffs — during periods when sector peers operating under identical conditions achieved superior performance. Equity analysts have repeatedly raised this discrepancy in earnings calls, highlighting that consistent execution matters more than quarterly explanations. Second, the ambitious timelines for the multi-price rollout remain subject to labor constraints and construction capacity, which historically delay large-scale retail conversions. Neither factor invalidates the strategic plan, but both emphasize that execution remains unproven.
As of September 2026, Dollar Tree presents a credible operational strategy, a streamlined portfolio, an operationally focused chief executive with a brief tenure, and an activist-influenced board. While this represents a stronger structural foundation than in 2019, long-term operational success has yet to be fully demonstrated.
IX. Strategic Playbook: Business, Investing, & Competitive Lessons
Stripping away company-specific details reveals four transferable lessons, each paid for with real shareholder capital.
Defensive M&A is not strategy. Dollar Tree acquired Family Dollar in large part to block Dollar General from acquiring it. That rationale was driven by a competitor's posture rather than the acquirer's operational capabilities. The warning sign was visible at signing: Dollar Tree's winning bid was lower than Dollar General's competing offer, prevailing primarily on regulatory feasibility. When the central justification for an acquisition is preventing a competitor from acquiring the asset, management implicitly concedes that the purchase carries defensive value rather than operational synergy—and defensive value rarely generates sustained cash flow. Investors should view competitor-blocking as a signal of strategic vulnerability rather than sophisticated dealmaking.
In value retail, logistics is the product. While consumers assume retailers compete on merchandise selection, extreme value items are largely commoditized and widely available. The durable competitive advantage resides in the unit cost of moving goods onto store shelves. Dollar Tree's regional distribution network, private delivery fleet, and palletized replenishment system represent its actual moat—unglamorous, capital-intensive, and difficult for subscale competitors to replicate. When evaluating a value retail business, operational analysis should focus on stem-mile distance, truck-cube utilization, and distribution center density rather than front-of-store merchandise variations.
Fixed constraints are operational tools, not corporate identity. The single-price architecture proved effective for three decades before turning destructive. The strategic error was not adopting the constraint, but elevating a tactical tool into a permanent corporate identity, which delayed necessary pricing adjustments for years after inflation had eroded underlying unit economics. When a retailer treats an operational parameter as an immutable core belief, that parameter often becomes the primary obstacle to necessary strategic adaptation.
Divestiture is active capital allocation. Selling an asset for roughly one-ninth of its purchase price reflects a severe strategic failure by the approving board. Yet mathematically, divestiture becomes the rational choice the moment an asset's forward return on incremental capital drops below available alternatives—and Dollar Tree maintained a core store rollout offering a two-to-three-year payback throughout the holding period. The critical evaluation metric is never historical acquisition cost, but the expected return on the next dollar deployed relative to alternative investments. Delaying that decision for a decade created far greater value destruction than the eventual accounting write-down.
These strategic lessons frame the fundamental question for the business: stripped of Family Dollar, how defensible are the company's remaining competitive moats?
X. Frameworks & Moat Analysis: 7 Powers, Porter's 5 Forces & Historical Falsification
Hamilton Helmer's 7 Powers, applied honestly
Scale Economies Shared — the strongest of the company's powers, and the one most likely to persist. A distribution network of roughly two dozen automated distribution centers serving a store base of this density produces a delivered-unit cost that no subscale competitor can match, while large direct import volumes command manufacturer attention that a regional chain cannot replicate. Assessment: real and durable, with the caveat that Walmart and Dollar General possess equal or superior versions of the same power.
Counter-Positioning — historically the company's most distinctive power, now largely surrendered by choice. A single-price format was something Walmart structurally could not copy without cannibalizing its own pricing architecture. Multi-price removes that incompatibility. A Dollar Tree carrying price points from $1.25 to $7.00 is simply a small-box value retailer—a category in which Dollar General has more stores, Walmart has superior buying power, and Five Below holds a sharper grip on teen discretionary shoppers. Assessment: this power is being deliberately traded away for broader category access. Whether that trade creates net value is the single most important open question in the investment case.
Process Power — genuine, underrated, and difficult to verify from the outside. Decades of institutional knowledge in pack-size engineering, closeout sourcing, and landed-cost negotiation represent know-how embedded in personnel and vendor relationships rather than software systems. The catch is that this capability was optimized for a $1.00 price ceiling that no longer exists, and its transferability to a multi-price, cold-chain-inclusive assortment remains unproven.
Cornered Resource — weak. The company holds a large portfolio of strip-center leases signed at historically low rates, providing a tangible cost advantage while those terms remain active. But leases eventually expire and renew at prevailing market rates, and secondary strip-center real estate is not scarce. This is a temporary timing benefit, not a cornered resource.
The remaining powers — switching costs, premium branding, and network economies — are effectively absent. A customer can defect to a Dollar General across the parking lot at zero cost, and frequently does.
Porter's Five Forces
Threat of new entrants: genuinely low, and for the right reason. The primary barrier is neither brand strength nor capital market access, but the impossibility of earning acceptable returns on a small store base before a distribution network exists. That structural chicken-and-egg problem has protected incumbents for decades.
Supplier power: low to moderate, but shifting unfavorably. In private-label and closeout merchandise, Dollar Tree dictates terms. In the national brand consumables brought in by multi-price assortments, leverage inverts. Furthermore, with a substantial share of inventory imported directly from overseas manufacturers, the effective "supplier" in a tariff environment is foreign trade policy, over which the company has no leverage.
Buyer power: negligible individually, severe in aggregate. Zero switching costs, high price transparency, and a customer base that shops multiple discount formats in the same week give consumers collective power over foot traffic.
Substitutes: high and intensifying. Walmart's grocery pickup, Dollar General's physical footprint, Five Below's discretionary selection, Amazon's low-priced offerings, and direct-to-consumer cross-border platforms like Temu, operated by Pinduoduo, all target overlapping portions of the customer's wallet. Temu poses a particularly direct threat because it attacks the highest-margin slice of Dollar Tree's assortment — cheap discretionary and seasonal goods — by tapping the same Chinese manufacturing base and bypassing physical stores entirely.
Rivalry: intense and structurally persistent, as mature retail formats compete for a budget-constrained consumer.
The consolidated falsification record
Four core claims from the company's operating narrative yield four clear verdicts.
The fixed-price moat claim is falsified. Holding a nominal price flat against roughly 90% cumulative inflation over three and a half decades degraded package volumes and unit economics until management was forced to institute a 25% base price increase. The forward test of the narrowed claim — that customer loyalty rests on value perception rather than a single price point — will be foot-traffic stability as items above $2.00 expand across the store base.
The M&A competence claim is falsified. The gap between the $9.2 billion purchase price and the $1.0075 billion sale price tells the story, while repeated write-downs and persistent operating margin compression confirm the execution breakdown. The forward test is behavioral: management's strict adherence to organic store rollouts in the post-2025 operating plan.
The direct import advantage claim is narrowed rather than falsified. Direct importing generated a genuine, sustained cost advantage for three decades. However, it also concentrated significant merchandise costs within a single region vulnerable to trade policy and shipping disruptions—shocks that materialized twice within five years. The forward test is gross margin resilience under active tariff regimes and the pace of verified supply-chain diversification.
The lean operations claim is narrowed. Decades of lean store operations generated strong capital returns, but inadequate oversight contributed to a federal criminal food-safety plea. The forward tests are inventory shrink as a percentage of sales and the continuous maintenance of regulatory compliance.
The absence of further disconfirming evidence across these records does not confirm the remaining claims. It simply indicates that the business model has yet to be fully tested at scale under its new multi-price format.
XI. Analysis & Bear vs. Bull Case: The "Why Win / Why Not" Investment Spine
Why Dollar Tree wins from here
The affirmative case rests on four mechanisms, presented with the evidence supporting each and the condition that would break it.
The portfolio is finally clean. For a decade, consolidated financials mixed a high-return, high-margin banner with a structurally lower-return one, obscuring the performance of both. Post-divestiture, what remains is a standalone business generating reported gross margins in the low 30% range and recovering new-store capital in roughly two to three years.8 The underlying mechanism is not a re-rating narrative, but the fact that capital is no longer absorbed by an asset earning below its cost. What would break this thesis: if the standalone enterprise carries corporate overhead designed for a chain twice its current size.
Multi-price expands ticket without requiring traffic. This represents the primary operational lever, as same-store sales growth in mature value retail is driven overwhelmingly by ticket size rather than foot traffic—which, in a saturated format, remains a zero-sum contest with Dollar General. The 2022 price increase provided proof of concept when customers absorbed a 25% base price increase with minimal traffic loss. What would break this thesis: evidence that consumer price elasticity behaves differently at $3.00 and $5.00 than it did at $1.25, an empirical question that the initial 2022 adjustment did not resolve.
The customer base skews higher than the sector assumes. Dollar Tree's suburban footprint attracts a more middle-income shopper than Dollar General's rural and urban customer base. This demographic dynamic provides countercyclical resilience: as household budgets tighten during economic downturns, Dollar Tree captures trade-down foot traffic from traditional grocery stores and mass merchandisers. What would break this thesis: discretionary items, which account for roughly half of the merchandise mix, are often the first purchases budget-stressed consumers reduce, causing trade-down gains and discretionary declines to partially offset each other. Furthermore, comparisons to performance during the 2008 financial crisis are limited, given that both the merchandise mix and the competitive landscape have evolved significantly.
Free cash flow has no competing claims. Net proceeds from the divestiture combined with ongoing free cash flow allow Dollar Tree to fund store remodels, logistics investments, and share repurchases without relying on additional debt. What would break this thesis: capital requirements for cold-chain expansion and distribution automation under the multi-price transition proving materially larger or longer than management guidance.
Why it may not
Tariffs represent the primary identifiable risk, directly compressing gross margins. Dollar Tree sources a large share of its merchandise through direct imports, historically concentrated in China, which the company explicitly cites as a principal risk factor.8 In a fixed-price or low-tier value format, passing through cost increases item by item is difficult. Management must either shift products into higher price tiers—risking customer pushback and eroding brand perception—absorb higher landed costs directly into margins, or reduce product pack sizes further. A broad import tariff would compress gross margins by hundreds of basis points unless offset. However, potential mitigations are slow to implement: shifting sourcing to alternative markets such as Vietnam, India, or Mexico requires quarters or years and rarely matches Chinese landed costs at equivalent quality.
Temu targets the high-margin discretionary segment. Cross-border platforms connecting Chinese manufacturers directly to American consumers compete using the same supplier network Dollar Tree relies on, but operate without physical stores, domestic distribution centers, or retail shelf constraints. The most vulnerable product categories—party supplies, craft items, seasonal decor, and low-cost toys—represent high-margin discretionary goods. Dollar Tree's primary defense is immediate availability: a customer purchasing event supplies for the weekend cannot wait for international shipping. That advantage holds for immediate, occasion-driven purchases, but weakens for planned spending.
Shrink and wage pressures erode store-level economics. Retail theft and rising state minimum wages place pressure on a store model designed with lean operating margins and small average transaction values. In a business operating with gross margins in the low 30% range, replacing one dollar lost to shrink requires roughly three dollars in incremental sales.
Execution friction presents the primary near-term risk. Converting thousands of stores annually to a multi-price format while training a high-turnover hourly workforce to maintain pricing accuracy across multiple price tiers creates potential operational drag. In effect, the company is trading the simplicity of a single-price model for expanded merchandising breadth—even though operational simplicity was historically a key competitive asset.
The activist stress test
A rigorous investment analysis of Dollar Tree centers on three core questions. First, corporate overhead: whether corporate support expenses built for a 16,000-store, two-banner operator have been appropriately scaled down to match a standalone 8,500-store business. Second, disclosure transparency regarding the multi-price rollout: store conversion numbers represent an operational input rather than a financial outcome; evaluating program success requires detailed reporting on same-store sales lift and margin trends in converted locations against control stores. Third, board governance: while the board of directors has been substantially reconstituted following activist intervention, ongoing performance depends on whether institutional capital allocation practices have permanently shifted.
The KPIs that actually matter
Three key operational metrics dictate the forward investment thesis:
Comparable store sales, decomposed into foot traffic and average ticket. This serves as the primary operational metric. The multi-price growth thesis relies on increasing average basket size while maintaining stable foot traffic. Persistent declines in foot traffic alongside ticket growth would indicate that the company is monetizing a shrinking customer base rather than expanding market share.
Gross margin percentage. This metric reflects the combined impact of tariffs, freight expenses, shrink, and merchandise mix, providing the clearest measure of whether procurement advantages remain intact under current trade conditions.
Return on invested capital on a continuing-operations basis. Dollar Tree's long-term compounding thesis depends on reinvesting capital into store rollouts and remodels at high return rates. For the post-divestiture strategy to succeed, ROIC for the standalone banner must increase materially above levels recorded during the Family Dollar holding period, demonstrating that the divestiture uncovered a high-return core business rather than simply eliminating an unprofitable segment.
XII. Epilogue & "If We Were CEOs"
There is a tidy narrative of Dollar Tree's trajectory: a successful retailer made one catastrophic acquisition, corrected course, and returned to its core strengths. That interpretation is overly generous. The $1.00 price point was already eroding operating performance before Family Dollar was acquired, and it ultimately required an activist campaign, a global pandemic, and a tenfold surge in freight costs to force a pricing adjustment. Over a single decade, management was slow to recognize structural shifts on the two largest strategic decisions facing the business.
What has changed as of late 2026 is the operating context rather than the definitive proof of execution. The balance sheet is unencumbered following the Family Dollar divestiture, the retail portfolio is streamlined, the board includes a major activist shareholder, and the multi-price format conversion is proceeding at scale. Chief Executive Mike Creedon leads an enterprise with tangible operational assets and few remaining excuses for underperformance.
From a strategic perspective, three operational priorities take precedence:
Accelerate sourcing diversification ahead of tariff shifts. Geographic concentration in merchandise sourcing remains a major identifiable threat to gross margins. Shifting procurement volumes to alternative manufacturing hubs in Vietnam, India, and Mexico is complex, time-consuming, and margin-dilutive during the transition—creating an incentive for management to defer investments to protect short-term quarterly earnings. Explicit disclosure of sourcing mix targets would provide investors with verifiable evidence that supply-chain risks are being actively managed rather than merely narrated.
Preserve the operational simplicity that multi-price risks eroding. The historical strength of the single-price model was cognitive ease for the customer and operational simplicity for store teams. Maintaining that advantage requires strict architectural discipline: confining higher price tiers to clearly defined zones—such as freezer aisles, dedicated endcaps, and specific departments—so the core store experience remains predictable. A store format that features multiple price points across every aisle risks confusing shoppers and sacrificing its core differentiation, turning the banner into a smaller, less efficient competitor to Dollar General.
Publish verified remodel economics before expanding rollout scale. Disclosing converted-store comparable sales lift and gross margin trends alongside a matched control cohort would settle the analytical debate over the multi-price transformation. Management possesses these operating metrics. Publishing them converts a strategic claim into an auditable benchmark—an essential step for a board and executive team seeking to rebuild credibility after writing down nearly $8 billion in capital during the Family Dollar era.
Four decades after its five-store trial in Virginia, Dollar Tree operates a retail format its founders would find unfamiliar in pricing structure but recognizable in operational focus. The banner name still references a single dollar, but the store economics no longer do. What remains is the foundation beneath the original price tag: a specialized distribution network, an established procurement organization, and the central question of whether those operational capabilities can deliver superior returns now that the pricing constraint that disciplined them both has been removed.
References
-
Dollar Tree Raises Prices to $1.25 — The Wall Street Journal, 2021-11-23 ↩↩
-
Dollar Tree to Buy Family Dollar for $8.5 Billion — Bloomberg, 2014-07-28 ↩↩
-
Dollar Tree to Sell Family Dollar to Brigade Capital and Macellum — Retail Dive, 2025-03-27 ↩↩
-
Dollar Tree Press Releases, including Completion of the Family Dollar Divestiture — Dollar Tree, Inc., 2025-07-07 ↩↩↩
-
Mantle Ridge Reaches Agreement with Dollar Tree Board — PR Newswire / Mantle Ridge LP, 2022-03-08 ↩↩↩
-
Dollar Tree SEC EDGAR Filings and Annual Reports — U.S. Securities and Exchange Commission ↩
-
Dollar Tree, Inc. Form 10-K Annual Report for Fiscal 2024 — U.S. Securities and Exchange Commission, 2025-03-26 ↩↩↩↩↩↩↩
-
Dollar Tree Announces CEO Leadership Transition to Mike Creedon — Reuters, 2024-12-04 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube