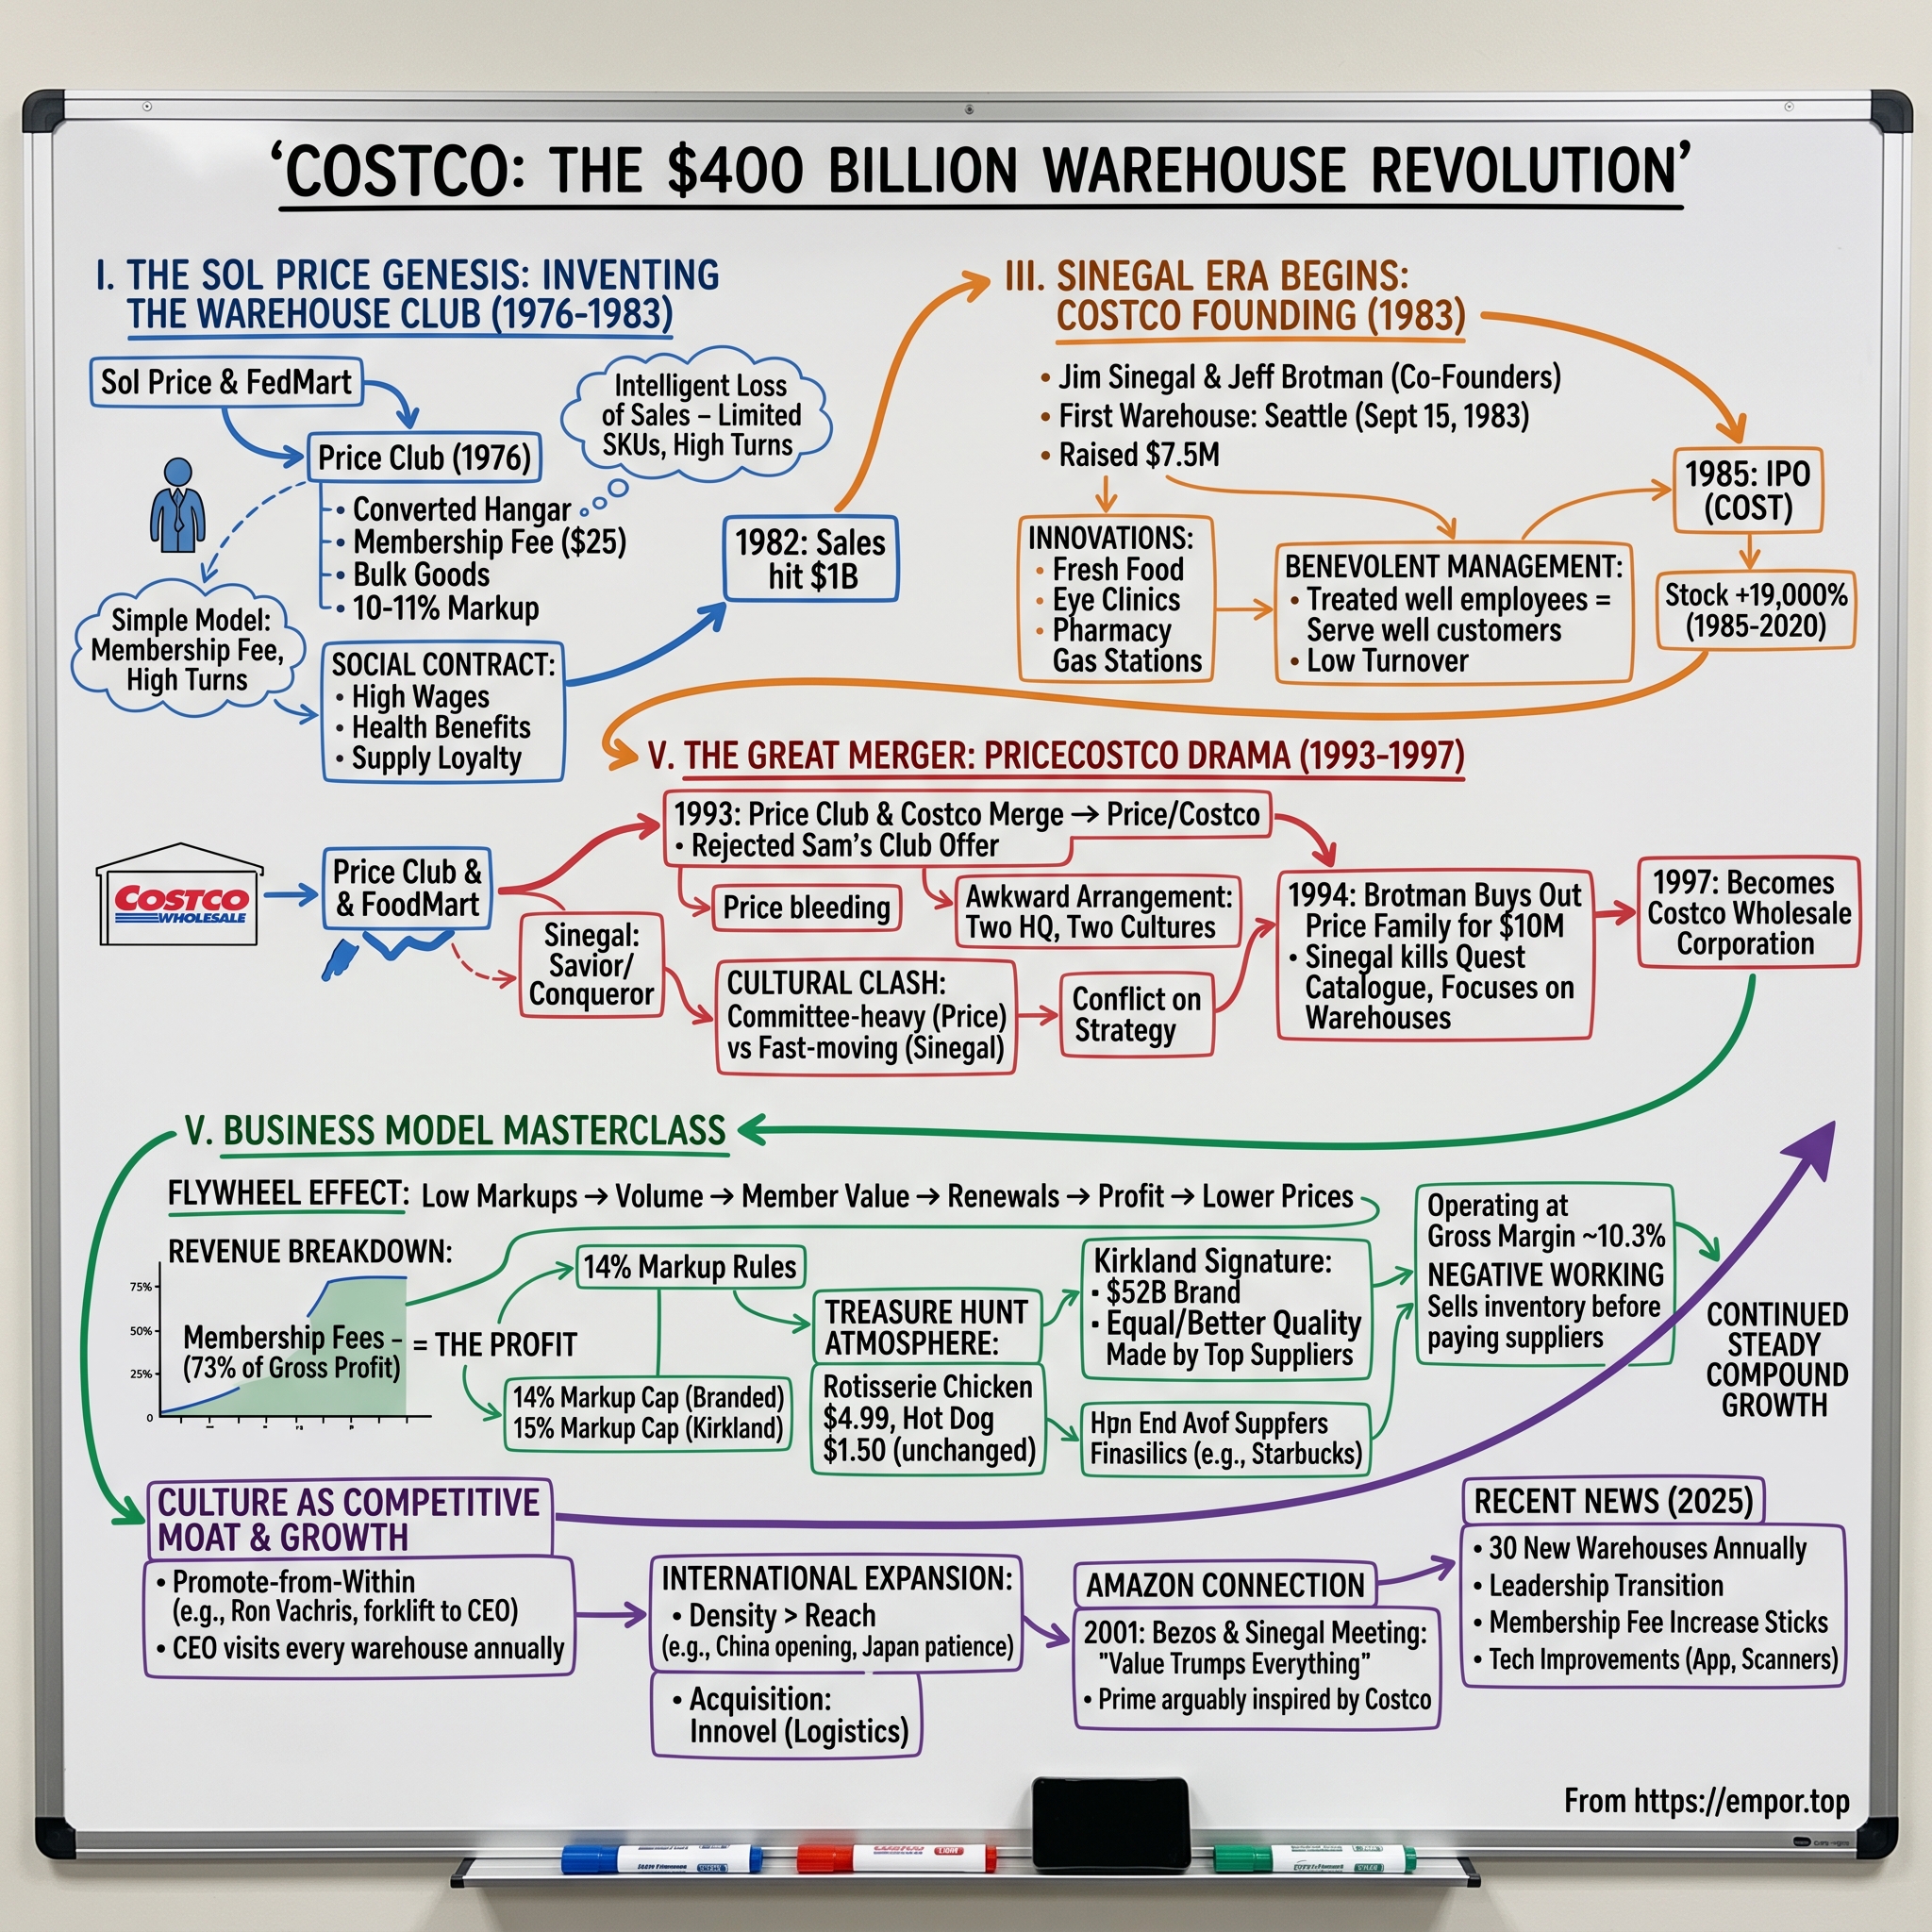
Costco Wholesale: Scale Economies Shared & The $250B Membership Machine
I. Introduction & Cold Open
Sometime around 2018, at a business luncheon in Issaquah, Washington, Costco's then-chief executive Craig Jelinek told a story about the hardest negotiation of his career. It was not with a supplier, a landlord, or a union. It was with an 80-year-old man over a hot dog.
Jelinek had gone to co-founder Jim Sinegal with what standard retail logic suggested was an obvious proposal: raise the price of the quarter-pound hot dog and soda combo, which had cost $1.50 since 1985 and by then was losing money on every unit. Sinegal's response, as Jelinek recounted it, was not a counterargument. It was a threat: "If you raise the effing hot dog, I will kill you. Figure it out."1
Jelinek figured it out. Costco built its own hot dog manufacturing plant in Los Angeles, then a second in Chicago, and kept the price at $1.50.1 Four decades after its introduction, through years of inflation, the combo still costs $1.50.
It would be easy to file this under corporate folklore. It is more useful to read it as a statement of accounting policy. The hot dog is a deliberate, permanent loss leader—a visible promise that Costco will not quietly claw margin back from members when it can. Everything else in the business model depends on members believing that promise.
The retail anomaly
Consider what Costco Wholesale Corporation (COST) actually represents as an economic entity. For the 52-week fiscal year ended 30 August 2026, the company reported net sales of $297.3 billion, up 10.2% on the prior year.2 It carries a market capitalisation of roughly $412 billion.3 It employs 341,000 people.4 And it operates under an internal policy—long stated by management and widely reported—that caps the markup on any branded item at 14% over cost and on any Kirkland Signature item at 15%, compared to typical supermarket markups of 20% to 25%.5 It runs no traditional advertising department and stocks fewer than 4,000 core items per warehouse.4
Here is the financial anatomy that results, using fiscal 2025 as the last fully audited year. Costco sold $269.9 billion of merchandise and generated about eleven cents of gross profit on each dollar. Selling, general, and administrative expenses consumed roughly nine of those eleven cents. What remained from merchandise sales—before counting a single dollar of membership fees—was under two cents on the dollar.67 Membership fee income of $5.32 billion then landed on top with virtually no incremental cost attached, producing total operating income of $10.38 billion on a 3.8% operating margin.67
That decomposition clarifies the core narrative, showing that membership fees accounted for slightly more than half of Costco's fiscal 2025 operating profit. A commonly repeated version of the Costco investment thesis puts that figure at 70% to 80%; on audited numbers, it was closer to 51%, because merchandise profitability has improved as the business scaled and higher-margin ancillary lines expanded. That distinction matters: it means the merchandise engine is no longer purely a break-even loss leader for subscriptions, making the framing that Costco is solely a subscription business directionally accurate but numerically outdated.
What this story covers
The narrative moves from Sol Price's San Diego, where the warehouse club format was created, through the opening of the first Seattle warehouse in 1983 and a 1994 merger that tested the company. It traces modern transition points—a credit card partner change, a $1 billion logistics acquisition, membership price increases, and a generational handover of both the CEO and CFO roles. Finally, it examines the valuation questions facing long-term investors in a company trading near 47 times trailing earnings with an operating margin capped by corporate policy.
Along the way, the framework that defined Costco among investors receives its own examination: Nick Sleep's concept of "scale economies shared," the idea that a company can turn cost savings into a compounding competitive weapon by refusing to keep them.8 The central question is not whether the theory is elegant, but whether it holds when the company is already the second-largest retailer globally, when its key growth driver is an online platform rather than a physical warehouse, and when the equity valuation assumes the flywheel never slows.
Start with the man who built the machine that Costco copied.
 Subscribe on LinkedIn
II. The Sol Price Genesis: The Roots of Warehouse Retailing (1954–1983)
In 1954, Sol Price, a San Diego lawyer who had never run a retail store, opened one at 2380 Main Street and introduced two practices local merchants considered absurd: charging customers a $2 lifetime membership before they could shop, and opening on Saturdays.9
The store was FedMart—so named because its initial target customers were federal, state, and municipal employees. The membership requirement was not a marketing gimmick; it was the load-bearing wall of the business model. By restricting entry to a defined, verified group, Price could argue he was operating a closed buying club rather than a public retailer—a distinction that carried significant consequences for fair-trade pricing regulations, credit risk, and shopper psychology. The member was not a customer to be squeezed for maximum margin, but a principal employing the store as a buying agent.
Price's operating philosophy fit on an index card: focus on the customer, offer quality merchandise at low prices, treat employees fairly, and the business takes care of itself. What elevated the card from a corporate slogan into an economic engine was strict operational discipline. Price rejected markup for its own sake, minimized overhead, and eliminated middle steps between manufacturer and shelf. He built bare-bones stores featuring concrete floors and unadorned steel racking, operating under the principle that every dollar spent on store decoration was a dollar taken from the customer.
The apprentice
In 1954, an 18-year-old named Jim Sinegal took a job at FedMart unloading mattresses. Over two decades, he rose through the organization, absorbing Price's operating economics as practical muscle memory: the precise cost of moving a pallet, why stockroom storage functions as a tax on the customer, and how a buyer negotiates when fully prepared to walk away.
That background explains the foundation of Costco's strategy. Sinegal did not invent the warehouse club; he was trained by the man who did, and he spent his career refining the format rather than reinventing it. As a result, Costco's corporate culture developed a distinctly monastic character, defined by inherited operational rules strictly defended against short-term temptations to expand margins.
Price Club and the accidental discovery
Price sold FedMart to a German retailer in 1975 and was pushed out of the company shortly after. At age 60, he launched a new venture. In July 1976, he opened the first Price Club inside a converted airplane hangar on Morena Boulevard in San Diego.10
The initial concept restricted membership strictly to business accounts—partly for sales tax administration, and partly because business buyers carried lower credit risk. Early sales were slow until Price noticed a crucial pattern in the transaction data: small-business owners purchasing office supplies and coffee were also buying products for their households, purchasing at unit volumes no traditional supermarket could match. When Price Club expanded access to select groups of individual members, sales volume expanded rapidly.
This shift revealed three self-reinforcing financial advantages that continue to underpin Costco's operations. First, upfront annual membership fees provided cash upfront before any goods were consumed, generating an immediate capital float. Second, rapid inventory turnover combined with standard payment terms created a negative working capital cycle: by the close of fiscal 2025, Costco held $19.8 billion in accounts payable against $18.1 billion in inventory, effectively allowing supplier credit to fund the merchandise sitting on warehouse floors.7 Third, the annual fee established a psychological commitment, transforming occasional shoppers into disciplined, repeat buyers.
Price had designed the underlying financial machine. What he had not yet done was scale it nationally, and by the early 1980s, his top executive was preparing to move north.
III. The Founding of Costco & Scaling the Flywheel (1983–1993)
On September 15, 1983, a warehouse opened at 4401 Fourth Avenue South in Seattle, in an industrial district better known for shipping containers than shopping.11 It was the first Costco.
The partnership behind it was unusual. Jim Sinegal brought thirty years of operational experience in buying, stocking, and selling at low cost. Jeff Brotman, a Seattle attorney from a local retailing family, brought capital, legal structuring, and connections.12 Sinegal ran store operations while Brotman built the corporate structure and served as chairman. The arrangement lasted for decades, avoiding the governance friction that would soon strain Price Club.
What Costco added to Sol Price's template was not a novel concept, but an intensification of its core operating rules.
SKU discipline as a strategic weapon. A conventional supercenter carries well over 100,000 distinct items. Costco carries fewer than 4,000 core items in a warehouse averaging roughly 147,000 square feet, supplemented by another 9,000 to 10,000 online.4 The underlying logic counters traditional retail assumptions about selection. Carrying one hundred competing products in a category leaves a retailer selling small volumes of each with minimal supplier leverage. Restricting the category to two items yields massive volume per item, unlocking lower purchase prices, faster inventory turns, reduced handling, fewer stockouts, and streamlined logistics. Costco's fiscal 2025 cost of goods relative to average inventory indicates that the company turned its inventory roughly 13 times that year, or once every four weeks.7 Strategic constraint, rather than broad selection, drives the efficiency.
Pallet-to-floor logistics. Goods arrive on pallets and move directly onto the selling floor. With no separate stockroom, unpacking, or re-merchandising, the building functions simultaneously as store and warehouse. This setup cuts the real estate and labor needed per dollar of throughput roughly in half compared to traditional retail formats.
The markup ceiling. Sinegal's policy—capping markups at 14% on branded goods and 15% on private-label items—mechanically passes cost savings to members without requiring managerial discretion.5 This caps structural margin expansion, preventing the quarter-by-quarter margin creep that can erode a discounter's value proposition. Sinegal bluntly characterized the temptation to raise markups as an addictive cycle that executive teams struggle to stop.5
Going public, and going fast
Costco completed its initial public offering at $10 per share on December 1, 1985, listing on NASDAQ.11 The operational expansion that followed was among the fastest in American retail history, with annual sales reaching approximately $3 billion within six years of opening its first warehouse.
A key structural element arrived in 1995 with the consolidation of several private-label lines into a single brand: Kirkland Signature. Private labels focused solely on low price often risk becoming commodity substitutes that consumers abandon during economic recoveries. Kirkland Signature was positioned to match or exceed national-brand quality at a meaningful discount. This strategy served a dual financial role: generating higher gross margins than branded alternatives while providing Costco's buyers bargaining leverage, as the threat of supplier replacement remained visible on the shelf.4
By the early 1990s, Costco had established a scalable operating model and a growing regional footprint. However, it faced mounting competition: the architect of the warehouse format was competing aggressively, and a far larger retail giant was expanding into the segment.
IV. The PriceCostco Merger & Founder Drama (1993–1997)
By 1993, the warehouse club industry faced a scale problem, and its name was Sam's Club. Walmart's club division had the balance sheet of the world's largest retailer behind it, expanding aggressively into markets that Price Club and Costco each considered their own. Two subscale operators competing head-to-head against Walmart was a losing proposition.
The solution was a merger of the teacher and the student. In 1993, Price Club and Costco combined to form PriceCostco.11 The transaction created the scale required to compete, reuniting Sinegal with the enterprise he had left a decade earlier.
It did not go well.
The friction ran along a fault line common to family businesses: the founder's son and the founder's protégé held incompatible visions for the future. Robert Price wanted to pursue real estate development and international joint ventures with a distinct capital allocation profile; Sinegal favored a single, unified, aggressively expanding warehouse operation. With the disagreement rooted in corporate identity rather than tactical execution, compromise proved impossible.
The resolution arrived quickly through a corporate split. In 1994, PriceCostco spun off its non-club real estate and select international joint venture interests into a separate entity, Price Enterprises, led by Robert Price. The remaining core—the warehouse business—continued under Sinegal, and in 1997 formally renamed itself Costco Wholesale Corporation.11
What the split actually decided
While this episode resembles personal drama, it effectively forced a decisive commitment to operational focus—a choice that benefited the surviving entity.
Simultaneously running warehouse clubs, property development, and minority-owned international ventures would have diluted management attention across three models with fundamentally different capital requirements, return profiles, and operating rhythms. Instead, Costco emerged as a single-format operator with one playbook, one brand, and one set of core metrics. Nearly every subsequent strategic decision—including buying out international joint venture partners decades later rather than managing around them—traces back to this commitment to total operational control.
The counterfactual warrants some skepticism as well. The spun-off assets retained value, and a patient conglomerate structure might have extracted returns that Costco surrendered. Yet the historical record over the next three decades demonstrates which model compounded capital: the focused warehouse operator grew into an enterprise generating hundreds of billions in annual sales, while the diversified vehicle remained modest by comparison. The evidence validated the focus strategy.
A second, quieter legacy also took shape. The merger and its dissolution taught Costco that scale acquired through consolidation is fragile, bringing mismatched cultures, external real estate decisions, and inherited management contracts. Over the following three decades, Costco expanded almost exclusively by building its own warehouses. Its only major acquisitions of the modern era were a logistics network and a minority stake in a business it already operated. For an enterprise of its size in a sector driven by consolidation, that restraint stands out, tracing directly back to the lessons of 1994.
This period left one critical issue unresolved. Sam's Club remained an active competitor, even if its growth rate lagged behind Costco's. The competitive challenge was postponed rather than eliminated, resurfacing in recent years with a well-capitalized, digitally advanced rival. The 1993 merger secured three decades of relative stability, not permanent immunity.
With ownership settled and the core model proven, Costco spent the next fifteen years pursuing a disciplined expansion strategy: opening more of the same warehouse format. High-stakes executive transitions would only return in the 2010s, when the founder prepared to step back.
V. Modern Inflection Points & Recent Trajectory (2012–2026)
Two handovers, twelve years apart
Jim Sinegal retired as chief executive on January 1, 2012, turning leadership over to Craig Jelinek, a company veteran who began his career as a warehouse manager. Investors scrutinized the succession, wondering whether Costco's operating discipline was tied strictly to Sinegal's personal leadership. Over the subsequent decade, the underlying model proved durable: pricing limits remained firm, the markup ceiling held, the hot dog price stayed fixed, and both sales and warehouse locations nearly doubled.
Costco announced a second leadership handover in October 2023, disclosing that Jelinek would step down and be succeeded by Ron Vachris, effective January 1, 2024.13 Vachris had joined Price Club in 1982 as a forklift driver, spending four decades advancing through warehouse operations, real estate, and merchandising before becoming president and chief operating officer. Promoting an insider from warehouse operations reflected a deliberate governance model, ensuring that executive decisions remained anchored in floor-level execution and member experience rather than short-term margin targets.
A more immediate shift for Wall Street occurred shortly thereafter. In March 2024, Richard Galanti retired as chief financial officer after 39 years. His discursive, uncommonly open monthly sales commentary had become legendary among financial analysts. His successor, Gary Millerchip, arrived from Kroger with a structured, metric-driven background. While Millerchip brought a more formal disclosure style, Costco's financial narrative remained consistent: management continued to frame gross margin performance around intentional price investment rather than the exercise of pricing power.
The credit card divorce (2016)
In 2016, Costco ended its long-standing exclusive credit card partnership with American Express and switched to Visa, with Citigroup issuing the co-branded card. The economic rationale was straightforward: Visa offered lower interchange fees, allowing Costco to pass the transaction savings to members in the form of enhanced cash-back rewards.
The initial rollout, however, suffered severe operational disruptions. Migrating more than 11 million cardholders simultaneously generated widespread service failures. Citigroup fielded over 1.5 million customer service calls as members reported missing cards, incorrect account numbers, unauthorized accounts, and hold times exceeding an hour.14 A subset of members canceled their accounts in response.
The episode illustrated both the strength and the boundaries of Costco's competitive moat. Despite substantial service friction, overall member retention remained high, demonstrating that member loyalty rested primarily on product pricing and warehouse utility rather than administrative polish. It also highlighted a distinct operational reality: Costco's logistical mastery on the warehouse floor did not automatically extend to managing large-scale consumer technology migrations.
Buying the last mile (2020)
On March 17, 2020, during the initial onset of domestic pandemic shutdowns, Costco acquired Innovel Solutions from Sears parent Transform Holdco for $1 billion in cash.15 Innovel operated 11 distribution and fulfillment centers, more than 100 final-mile cross-dock facilities, and over 15 million square feet of warehouse space, covering nearly 90% of the United States and Puerto Rico with approximately 1,500 retained employees.15
The acquisition served a focused strategic purpose. While Costco generates high sales volume in bulky categories like appliances, mattresses, and furniture, final-mile delivery in these categories historically suffered from high third-party freight margins, elevated product damage rates, and frequent customer complaints. Rebranding the network as Costco Logistics removed intermediary margin layers and brought high-friction deliveries under direct operational control. Importantly, Costco avoided expanding into general parcel delivery, where it possessed no cost advantage against established logistics carriers like Amazon.
Owning the joint ventures (2022)
On June 30, 2022, Costco paid $1.05 billion to acquire the remaining 45% minority stake in its Taiwan joint venture from its long-time local partner, securing full ownership. Management projected that the transaction would add roughly 1% to 1.5% to earnings per share.16
The deal reflected Costco's conservative approach to international capital allocation. Taiwan had long operated as one of the company's highest-volume international markets. Buying out a joint-venture partner in a mature market represented a low-risk deployment of capital: operational infrastructure was already established, local consumer demand was proven, and Costco was acquiring full ownership of a cash flow stream it already managed. Notably, this transaction stands as one of only two major acquisitions in Costco's modern history.
Repricing the membership (2024)
On September 1, 2024, Costco implemented its first membership fee increase in the United States and Canada since 2017. Annual dues for Gold Star members rose from $60 to $65, while Executive memberships increased from $120 to $130.17 Concurrently, the maximum annual 2% Executive reward cap rose to $1,250.4
The seven-year interval between fee adjustments underscored management's policy of treating membership dues as a long-term value commitment rather than a short-term pricing lever. Furthermore, because subscription revenue is recognized over time, the financial impact took multiple quarters to fully manifest. By the fourth quarter of fiscal 2025, annual membership fee income reached $1.72 billion—a 14% year-over-year increase—with less than half of that growth driven by the fee increase itself and the remainder generated by new member sign-ups and tier upgrades.18
In tandem with the fee adjustment, Costco began installing membership card scanners at warehouse entrances in August 2024, requiring members to scan physical or digital credentials prior to entry.19 While intended to curb unauthorized card sharing and encourage non-paying visitors to purchase memberships, the policy introduced procedural friction at warehouse doors—a notable trade-off for a retailer dependent on high-volume foot traffic.
Together, these five inflection points illustrate a corporate strategy defined by incremental, deliberate change designed to reinforce the core warehouse model rather than alter it.
VI. Current Management, Incentives & Governance
Costco's executive leadership model relies heavily on long-tenured internal promotions to preserve its operating culture. Chief Executive Ron Vachris began his career driving a forklift at Price Club in 1982, taking the top role forty-two years later as the company approached $300 billion in annual sales.13 His predecessor, Craig Jelinek, previously managed individual warehouses, while co-founder Jim Sinegal began his career unloading mattresses. This promote-from-within tradition functions less as corporate sentimentality than as an institutional mechanism for transmitting unwritten operational rules.
The principal exception within the senior executive team is Chief Financial Officer Gary Millerchip. Joining in March 2024 from Kroger, Millerchip brought external perspective on grocery supply chain finance, digital retail, and retail media—an area where Kroger had developed an established advertising business ahead of Costco.
How they get paid, and what it signals
Costco's executive compensation structure diverges notably from standard S&P 500 practices. Base salaries for top executives remain low relative to company scale, with the majority of compensation awarded in restricted stock units that vest over multiple years. Performance metrics focus on core operating fundamentals—sales growth, pre-tax operating income, and controllable costs—rather than earnings-per-share targets that can be altered through share repurchases.
This design reflects a specific risk profile rather than simple governance virtue. Restricted stock tied to time-based vesting rather than performance hurdles is less susceptible to short-term manipulation, though it offers fewer high-powered performance incentives. What it enforces is alignment with multi-year holding periods, matching a business model whose competitive advantage compounds over decades and whose individual quarterly results carry limited signal.
Capital allocation: the special dividend pattern, and its recent absence
Costco's capital allocation strategy prioritizes periodic special dividends over large, rigid regular dividend commitments. Instead of raising fixed dividend obligations that might prove difficult to maintain during downturns, the company distributes accumulated excess cash through sporadic payouts. Costco paid special dividends of $7 per share in 2012, $5 in 2015, $7 in 2017, and $10 in 2020, followed by a $15 per share declaration in December 2023—a $6.7 billion distribution paid out in January 2024.20
Share repurchases remain modest, serving primarily to offset equity compensation dilution rather than to shrink the outstanding share count. A $4 billion authorization approved in January 2023 retained $1.96 billion in remaining capacity at the close of fiscal 2025, with fourth-quarter repurchases totaling 285,000 shares at an average price of $983.13.4 For a business generating billions of dollars in annual free cash flow, buybacks of this scale represent a minimal capital drain, reflecting management's view that repurchasing shares at elevated valuation multiples can erode shareholder value.
Concurrently, the regular dividend has maintained a steady upward trajectory. In April 2026, the board raised the quarterly payout from $1.30 to $1.47 per share, translating to an annualized rate of $5.88.21
For long-term shareholders, the key structural question centers on the stretching timeline between special dividends. More than two and a half years have elapsed since the December 2023 declaration—the longest gap since the special dividend pattern began—even as balance sheet liquidity has expanded. Costco ended fiscal 2025 with approximately $15.3 billion in cash and short-term investments against $10.2 billion of total debt, maintaining a net cash position.7 While management is under no formal obligation to adhere to a fixed schedule, opportunistic cash return strategies require ongoing execution to remain credible, making capital deployment a central topic for investor scrutiny.
That liquid balance sheet, along with the operational engine funding it, forms the foundation for evaluating the company's long-term competitive trajectory.
VII. The Engine Room: Unit Economics & Segment Data
Walk into a Costco at 10 a.m. on a Tuesday and count what is visible: concrete floors, unadorned steel racking, stacked pallets, a small selection of large product displays, and almost nothing else. There is no signage budget, no visual merchandising team's fingerprints, and no decorative flourish. The building functions as a machine for moving volume, and its financial statements read exactly like the warehouse floor looks.
The arithmetic of a thin-margin giant
Fiscal 2025 provides the clearest full-year picture of this financial engine. Total revenue reached $275.2 billion, comprising $269.9 billion in merchandise sales and $5.32 billion in membership fees. Net income totaled $8.10 billion, or $18.21 per diluted share,6 while operating income reached $10.38 billion.7
Translated into cents on the dollar, the underlying business model becomes starkly legible. Costco retained roughly 11.1 cents of gross profit per dollar of merchandise sold and spent about 9.3 cents to run store operations—leaving under two cents of operating profit on merchandise sales alone. Membership fees contributed roughly two additional cents,67 bringing the total operating margin to about 3.8%.
Two distinct conclusions follow from these figures, pulling investment theses in opposite directions. The optimistic view holds that a retailer earning under two cents on merchandise is nearly impossible to undercut on price; a rival attempting to challenge it must operate below break-even on merchandise without a high-margin subscription fee stream to offset losses. The cautious view emphasizes that a 3.8% operating margin leaves minimal structural cushion. A 100-basis-point contraction in gross margin or a 100-basis-point overrun in selling, general, and administrative expenses would eliminate more than a quarter of operating income. The model's primary defensive strength and its core operational vulnerability are expressed by the exact same metric.
The cost efficiency supporting this model is reflected in the expense ratio. In the third quarter of fiscal 2026, selling, general, and administrative expenses were $6.19 billion on net sales of $69.15 billion—just under 9%.22 Conventional broadline retailers typically run overhead expenses in the high teens to low twenties as a percentage of sales. That cost differential serves as the primary engine of Costco's pricing advantage, originating from structural format design rather than below-market labor rates.
Where the sales come from
Geographically, fiscal 2025 net sales originated roughly 73% from the United States, 13% from Canada, and 14% from other international markets.4 However, segment margin disclosures reveal a more pronounced divergence: international operations outside the United States generated 27% of net sales while contributing 34% of operating income.4 International warehouses—particularly locations across Asia—generate higher structural margins than domestic units, driven by larger basket sizes, higher customer density, and lower relative real estate costs.
This profitability profile reframes the international expansion thesis. While bullish arguments often focus strictly on store count growth, the stronger operational driver is store mix. Each new warehouse opened in Asia operates at higher profitability than the average existing domestic location, allowing international expansion to expand overall margins rather than merely adding top-line revenue. The chief offsetting risks remain currency translation volatility and market-specific geopolitical exposures absent from the domestic base.
The physical store network expanded from 914 warehouses at the end of fiscal 2025—comprising 629 in the United States and Puerto Rico, 110 in Canada, and 175 across other international markets—to 939 locations by the end of fiscal 2026.42 Against fiscal 2026 net sales of $297.3 billion, average sales per warehouse comfortably exceeded $300 million in facilities averaging roughly 147,000 square feet.24 Sales density at this level substantially exceeds metrics achieved by conventional supermarkets or general-merchandise big-box retailers, enabling Costco to sustain competitive employee compensation alongside low product markups by distributing fixed operating overhead across extraordinary throughput volume.
The membership base, examined honestly
At the close of fiscal 2025, Costco reported 81.0 million paid members and 145.2 million total cardholders. Executive members numbered 38.7 million, accounting for approximately 73.6% of worldwide net sales.4 By the third quarter of fiscal 2026, paid memberships rose to 82.9 million and executive members grew to 41.2 million, expanding at a 9.6% year-over-year rate—more than double the growth pace of the overall membership base.2223
The executive tier serves as the company's primary commercial engine. A member paying $130 annually instead of $65 has, through purchasing behavior, determined that the 2% annual reward will more than offset the higher membership fee—a threshold requiring several thousand dollars in annual spending. Tier upgrades simultaneously expand high-margin fee revenue and segment for high-volume shoppers without requiring additional capital expenditure for new physical warehouses.
Renewal rates provide the clearest indicator of member retention, and recent figures reflect a subtle softening. In the United States and Canada, the renewal rate stood at 92.3% at the end of fiscal 2025 and 92.2% through fiscal 2026. Worldwide, the rate eased from 90.2% to 89.8%, and subsequently to 89.7%.42423 Management has consistently attributed this minor decline to channel mix, noting that an increasing proportion of new members join online—often through promotional campaigns—and renew at lower rates than members acquired at warehouse service desks.1823
While management's explanation remains consistent across quarterly reporting periods, the underlying trend signals a structural dynamic worth monitoring. If digital channels represent the marginal source of membership growth, and digital sign-ups exhibit lower long-term retention, the blended renewal rate faces continuous downward headwind that absolute membership growth temporarily conceals. Aggregate renewal figures remain exceptionally strong by retail standards, yet the data indicates that traditional warehouse-acquired members maintain superior loyalty compared to the faster-growing digital acquisition funnel.
VIII. Materiality Pass: Ancillary Businesses & Hidden Engines
Beyond the core physical warehouses, Costco operates a network of ancillary businesses that warrant rigorous financial sizing rather than uncritical enthusiasm.
Gasoline is the biggest, and it is not a side business. Costco operated 747 gas stations at the end of fiscal 2025, with fuel sales representing approximately 10% of total net sales.4 Fuel is sold at minimal gross markups compared to traditional convenience store chains, serving as the company's most reliable foot-traffic generator. A member queuing for fuel every ten days establishes a predictable visit cadence in close proximity to the warehouse entrance. On the third-quarter fiscal 2026 earnings call, management reported record gasoline volumes, explicitly connecting fuel operations to member loyalty by noting that fuel customers visit more frequently and spend materially more overall.23
The primary risk in fuel operations lies in margin volatility. Retail fuel margins expanded significantly during recent energy price dislocations, meaning margin normalisation represents an ongoing multi-year drag rather than a single-quarter adjustment. Electric vehicle adoption poses a gradual long-term shift; while Costco has begun installing charging stations, a charging bay does not replicate the volume economics or rapid dwell-time dynamics of a traditional fuel pump.
Costco Logistics is an enabler rather than a profit centre. The former Innovel network functions primarily to support large-item e-commerce fulfillment. Its operational impact does not appear as a reported standalone segment, but rather as a cost-efficiency driver enabling Costco to price installed major appliances below competing national retailers, while reducing product damage and customer complaint rates that historically eroded margins on furniture and appliance sales.
E-commerce is now material and growing far faster than the stores. Directly generated e-commerce accounted for approximately 7% of fiscal 2025 net sales, while broader digitally enabled sales—including Costco Travel—represented roughly 10%.4 Digital growth outpaced physical store expansion, with digitally enabled comparable sales increasing 20.9% for fiscal 2026 as a whole, compared to an 8.4% total company increase.2 Management attributed this expansion largely to enhanced personalization initiatives; during the second quarter of fiscal 2026, personalized product recommendation carousels generated over $470 million in e-commerce sales, while website traffic rose 32% and mobile application traffic surged 45%.25
This operational progress marks a notable evolution for a retailer historically slow to adopt digital capabilities. However, digital expansion introduces a structural tension with the core warehouse model. Warehouse profitability relies heavily on the physical "treasure hunt"—in-store browsing that drives high-margin, unplanned impulse purchases. A member purchasing a small selection of specific items through a mobile application presents a fundamentally different, and potentially lower, unit economic profile than a shopper traversing a 147,000-square-foot warehouse floor. Because digital sales remain capped at roughly a tenth of total business volume, Costco has avoided managing this channel conflict at scale, though it remains an impending structural challenge as online penetration grows.
Retail media is early and deliberately restrained. Industry estimates place Costco's advertising business at approximately $500 million in high-margin revenue—a modest footprint within a broader retail media market valued in the tens of billions of dollars.26 During the third quarter of fiscal 2026, the company announced a collaboration with Google Commerce Media and YouTube to streamline brand participation in its network, a move management characterized as a significant step.23 This strategic restraint is self-imposed and aligns with core corporate principles: management has consistently refused to clutter the member experience with advertising inventory to maximize short-term revenue. While this disciplined approach reinforces brand integrity, it also indicates that retail media is unlikely to generate the dramatic margin expansion projected by some market observers.
Costco Next is a cautionary tale, not an option. The curated marketplace—which allowed members to purchase directly from suppliers at a discount while Costco assumed no inventory risk—operated from 2017 until its abrupt shutdown in 2026, leaving only a website notice indicating storefronts were no longer available.27 The discontinuation arrived just a year after chief financial officer commentary highlighted rapid growth, noting on an earnings call that single-quarter sales had matched full-year results from the prior fiscal period.27
The termination of Costco Next serves as an instructive corrective against treating adjacent experimental initiatives as embedded free options. Rapid growth from a negligible baseline does not guarantee eventual scale, and Costco's management demonstrated a willingness to terminate programs that fail to align with core warehouse economics regardless of top-line expansion rates.
The services that never get discussed. Beneath headline operational units lies a cluster of in-warehouse ancillary services—including pharmacy, optical, hearing aids, tire installation, and the food court—alongside Costco Travel, which the company folds into its digitally enabled sales measure.4 Individually, these secondary services generate modest consolidated revenue. Collectively, however, they serve a critical operational function by multiplying household visit opportunities. Furthermore, large-ticket services allow members to quantify immediate subscription value; savings realized on a single pair of prescription eyeglasses or several vehicle refuelings can instantly offset annual membership dues.
Evaluating these ancillary offerings requires shifting focus from direct top-line revenue to their contribution toward membership renewal. Yet Costco provides no disclosure linking specific service utilization to renewal rates. This absence represents a notable analytical blind spot in corporate reporting: while filings detail overall purchasing categories and aggregate retention rates, they omit data illustrating how ancillary service adoption directly drives member retention.
IX. Hamilton Helmer's 7 Powers & Porter's 5 Forces
The powers, scored against evidence
Scale economies shared is the primary power, and it is real but not automatic. The mechanism, as Nick Sleep's Nomad Investment Partnership described it, is a self-reinforcing loop: scale lowers operating costs, savings are passed to the customer through lower prices, the customer buys more volume, and that added volume generates further scale.8 What makes Costco's version unusually durable is that the strict internal markup ceiling makes this pass-through structural rather than discretionary—no executive team has to choose to be generous each quarter.
The operational evidence of this engine appears in the extraordinary sales density and sub-9% expense ratio. The counter-evidence showing its limits lies in the operating margin, which has crept upward over the past decade rather than remaining flat. A business returning 100% of its scale savings directly to customers would not experience margin expansion. Costco returns most scale benefits rather than all of them, and that subtle gap is where a disciplined analyst should look for the first signs of strategic drift.
Counter-positioning is the strongest defensive power. A conventional retailer operating on 25% to 35% gross margins cannot match Costco's price points without crippling its own income statement. Attempting to match the warehouse club model requires abandoning high-margin categories, converting stores into bare-bones warehouses, discarding a vendor model dependent on promotional allowances, and cutting total SKU counts by 95%. Because protecting existing profit pools makes imitation irrational for incumbents, counter-positioning serves as a structural barrier.
Switching costs exist but remain modest and psychological. The annual membership fee creates a sunk-cost incentive, as members feel compelled to "earn back" their $65 or $130 annual dues by defaulting to Costco for household purchases. While grounded in behavioral economics, this dynamic lacks contractual lock-in, data switching friction, or technical integration. A member can simply choose not to renew, and roughly eight out of every hundred cardholders worldwide do exactly that each year.
Process power is substantial and underrated. Four decades of institutional refinement across cross-dock logistics, pallet-level floor movement, aggressive vendor negotiations, and inventory shrink control are difficult to replicate. The barrier arises not because individual operational techniques are proprietary, but because the entire low-cost ecosystem must be executed simultaneously. This systemic discipline produces the company's sub-9% operating expense ratio.
The powers Costco lacks are equally instructive. The business generates no meaningful network effects, as one member joining adds no direct utility for another. It holds no cornered resource, since Kirkland Signature is a well-regarded private label rather than an irreplaceable asset. Finally, brand power—in the traditional sense of extracting premium prices for identical goods—is the exact opposite of Costco's low-markup mandate.
Porter, war-gamed
Supplier power is low and asymmetric. Given Costco's tight ceiling of fewer than 4,000 core warehouse slots, gaining shelf placement represents a massive, concentrated revenue stream for any national consumer goods brand, while losing placement creates a visible hole in a supplier's quarterly results. Placing Kirkland Signature products adjacent to national brands reinforces that buyer leverage. The main constraint on this power is regulatory and reputational: a buyer wielding this level of leverage faces antitrust scrutiny, leading Costco to generally avoid pushing vendor negotiations into open confrontation.
Threat of new entrants is very low. The capital intensity, real estate footprint, and procurement scale required to match Costco's unit costs from a standing start are prohibitive. Furthermore, the warehouse model cannot be entered incrementally; a subscale warehouse club suffers from high overhead without achieving the purchasing scale needed to discount aggressively.
Rivalry is moderate and intensifying. Sam's Club raised its base membership fee from $50 to $60 and its Plus tier from $110 to $120 on May 1, 2026, narrowing the gap to Costco's $65 base and $130 Executive dues.28 Interpreted optimistically, a primary competitor validating higher membership pricing reduces the risk that Costco's fee adjustments alienate price-sensitive shoppers. Interpreted cautiously, it signals that Walmart's club division is actively investing in its own value proposition, operating as a better-capitalized competitor than the one Costco encountered in prior decades.
Buyer power is individually nil but collectively institutionalized. No individual member negotiates prices at the register. However, Costco effectively functions as a collective buying syndicate, negotiating on behalf of millions of households. This setup mirrors Sol Price's original member-agent concept, serving as an accurate description of where bargaining power resides.
Substitution represents the principal ongoing risk. E-commerce platforms like Amazon Prime, quick-commerce networks, hard discounters, and conventional grocers all target overlapping consumer spending. Costco's primary defense is not that alternatives are inferior, but that they address different consumer needs. None of these competing channels replicates Costco's specific combination of bulk pricing economics, curated product selection, and high-velocity physical discovery under a single roof.
X. Historical Falsification Layer: Testing Core Claims
A moat framework is only as good as the attempts made to break it. Here are the three claims most material to the investment case, each tested against the strongest disconfirming evidence in Costco's own record.
Test 1: Is the membership moat actually impregnable?
The disconfirming evidence. Two episodes matter. The first is the 2016 credit card partner migration, which subjected millions of members to two months of genuine service failure.14 The second is more structural: Costco was conspicuously late to e-commerce, ceding a decade to Amazon and relying on third-party arrangements before building its own capability. The third and most recent piece of evidence is the renewal rate itself, which drifted from 90.2% worldwide to 89.7% as the mix of digitally acquired members expanded.1823
The weighing. The card episode served as the strongest available stress test, and the moat passed it: members tolerated operational disruptions because the underlying price and utility proposition remained unaffected. The e-commerce lag cost Costco market share in a growing channel, but it did not erode its core member base, suggesting physical warehouses and online storefronts are less directly substitutable than initially feared. The renewal rate drift represents the active issue. While not a crisis—the absolute level remains extraordinary for a paid subscription—it reflects a genuine, management-acknowledged, mix-driven headwind rather than random noise.
The verdict. The claim survives in a narrowed form: member loyalty is exceptionally durable against service failures and competitive pricing, but it is not uniform across acquisition channels, with the fastest-growing channel proving to be the weakest. The key metric to watch is specific: whether the United States and Canada renewal rate holds above 92% as digitally acquired members become a larger share of the renewal pool.
Test 2: Is capital allocation flawless?
The disconfirming evidence. It is not. Costco Home—a standalone big-box concept dedicated to home furnishings, launched in 2002—failed to earn its cost of capital and was shut down. In April 2009, the company announced it would close its remaining locations in Kirkland, Washington, and Tempe, Arizona, by that July. Jim Sinegal called it "a valuable experiment" but concluded the single-category format did not fit long-term expansion plans.29 Costco Next met a similar fate seventeen years later.
The weighing. The pattern is consistent and diagnostic: Costco excels at replicating and refining its single core format, but struggles to build standalone concepts outside it. Set against those missteps, the two major acquisitions of the modern era—Innovel Solutions and the Taiwan joint venture buyout—were tightly targeted, directly adjacent to the core business, and executed smoothly. Crucially, the failures remained small, were identified quickly, and were closed without large write-offs. That record contrasts favorably with broader retail industry trends, where format diversification frequently destroys substantial capital before management intervenes.
The verdict. The claim narrows rather than breaks. Costco's capital allocation is disciplined within a tightly bounded definition of its core model, and management has demonstrated a willingness to shut down non-core projects promptly. However, the company should not be credited with broad strategic versatility, as the historical record does not support it. The primary metric to monitor is new warehouse productivity—specifically, whether newly opened locations reach mature sales levels on historical timelines, or whether marginal sites face diminishing returns as domestic footprint density rises.
Test 3: Does digital and adjacent optionality convert into commercial scale?
The disconfirming evidence. Costco Next grew for years, received praise on an earnings call, and was then abruptly discontinued.27 Meanwhile, retail media revenue remains a small fraction of what comparable retail peers have generated.26 On the record, the company's history of converting technical or digital capability into commercial scale outside the physical warehouse remains weak.
The weighing. The counter-evidence is more recent: digitally enabled comparable sales grew 20.9% in fiscal 2026, personalization initiatives generated measurable conversion gains, and the collaboration with Google indicates retail media is being actively built rather than merely discussed.22523 However, rapid growth rates from small initial baselines carry the exact risk highlighted by the Costco Next episode: early momentum does not ensure long-term scale. None of these adjacent lines is yet large enough to materially move a $10 billion operating income base.
The verdict. The claim remains intact but unproven. Costco's optionality is bounded by a strict structural constraint—any product or service must align with bulk, low-margin, member-value economics—and management enforces that constraint rigorously. A falsifying outcome would be retail media or e-commerce becoming a separately disclosed, high-margin profit driver. Conversely, a bear-case confirming outcome would be another sudden shutdown of an adjacent initiative previously highlighted positively on earnings calls.
XI. Current Risk Radar & Skeptical Investor Stress Test
The valuation problem, stated without euphemism
In early September 2026, Costco's shares trade at roughly $930, within a 52-week range of $844 to $1,097, giving the company a market capitalisation near $412 billion.3 Trailing twelve-month earnings per share—combining the fourth quarter of fiscal 2025 with the first three quarters of fiscal 2026—stand at approximately $19.88.622 That translates to a trailing earnings multiple in the mid-forties.
The stock has remained essentially flat over the past year despite a 10.2% increase in sales, demonstrating multiple compression in slow motion.
This dynamic illustrates the core mechanical challenge facing long-term investors. Costco's operating margin is structurally capped near 4% by its corporate pricing policy. Because expanding margins would require violating the low-markup commitment that drives high sales volume, there is no realistic path to software-like profit margins. Consequently, shareholder returns depend almost entirely on top-line revenue growth, modest operational efficiencies, and valuation multiple stability. If annual revenue growth slows from 10% toward the mid-single digits—as a maturing domestic store footprint and normalizing fuel prices suggest—a valuation re-rating from the mid-forties toward the low-thirties multiple would offset several years of earnings growth. That scenario does not require operational failure; it simply assumes the business normalizes.
This represents the primary risk to equity holders today, and it is a valuation risk rather than an operational one.
Wage inflation, which is a feature until it isn't
Costco pays well above conventional retail industry standards, treating elevated compensation as a competitive investment rather than a cost problem. Average hourly pay in the United States reached approximately $32.00 by the end of fiscal 2025, following a wage increase in March 2025 that raised starting rates to a minimum of $20.00 per hour and added $1.00 per hour to top-of-scale rates.4 A collective bargaining agreement covering roughly 5% of the workforce locked in an additional $1.00 hourly increase in March 2026, raising top-of-scale clerks to about $32.90 per hour, with another scheduled increase set for 2027.[^30]
The strategic rationale remains compelling: retention among United States and Canadian employees with more than one year of service reached approximately 94% in fiscal 2025, and low employee turnover generates direct cost savings across a labor-intensive store format.4 Yet the financial constraint is strict. With gross markups capped by policy, rising labor costs must be offset by labor productivity or they will directly compress merchandise margins. For an enterprise operating on a 3.8% operating margin, wage inflation is a material factor, explaining why management continues to invest heavily in front-end checkout and throughput technologies.
Tariffs, geopolitics and the international bet
Costco also operates within an evolving global trade environment. On the third-quarter fiscal 2026 earnings call, management confirmed that the company had submitted Section 301 tariff refund claims and anticipated processing over two to three months, while noting that final timing and recovery amounts depended on ongoing legal developments.23 Earlier in the year, executive leadership publicly committed to returning any recovered tariff funds directly to members through lower prices rather than retaining them as profit—a decision aligned with the company's core operating principles, though one that foregoes a potential near-term earnings boost.
The broader risk involves international exposure. Overseas warehouses represent Costco's highest-margin operations, yet they carry heightened exposure to foreign currency fluctuations and geopolitical risks. While new locations in China have generated strong initial customer demand, a business model that increasingly relies on Asian expansion introduces structural risk profiles absent from its historical domestic base.
Fuel normalisation and the traffic question
Gasoline sales have historically inflated top-line figures during periods of high and volatile energy prices. As fuel prices normalize, that reported sales boost unwinds, demonstrating why adjusted comparable sales metrics provide a clearer view of underlying customer demand. For fiscal 2026, Costco's total company comparable sales grew 8.4%, but moderated to 6.6% once fuel price volatility and currency fluctuations were excluded.2 That nearly two-percentage-point spread represents headline growth that long-term investors should not extrapolate into permanent operational gains.
The activist's questions
A skeptical investor evaluating executive performance would likely raise four specific analytical questions. First, why has management declared no special dividend in over two and a half years despite a growing net cash balance? Second, what are the precise incremental basket economics of a digitally acquired member compared to a warehouse-acquired member, given the lower renewal rates in digital channels? Third, what measurable return in converted memberships did the entrance-card scanner initiative produce when weighed against the door-level customer friction it introduced? And fourth, at what valuation multiple do share buybacks become value-destructive, suggesting the board should instead distribute excess capital directly to shareholders?
None of these issues indicates operational distress, but each highlights a meaningful gap in financial disclosure.
XII. Playbook: Lessons for Founders, Executives & Investors
Scale economies shared is a decision, not a discovery. Most businesses treat the operational savings that accompany scale as surplus to be captured—whether through margin expansion, executive compensation, or shareholder distributions. Costco treats cost savings as raw material for the next price reduction. That choice compounds because it alters the competitive equation asymmetrically: every dollar of savings passed on widens the cost gap a rival must close, and the competitor must attempt to close it from a higher cost base.8 The practical lesson is that this mechanism relies on mechanical execution; by embedding a strict ceiling into corporate markup rules, management removes pricing discretion from quarterly decision-making, allowing the policy to survive across multiple executive transitions.
Aligning three constituencies simultaneously. The member receives low prices, the worker receives compensation at the top of the retail sector, and the shareholder receives a cash flow stream backed by global renewal rates hovering near 90%. While traditional retail models often optimize for a single constituency while treating the others as competing expenses, Costco's framework assumes that lower employee turnover reduces store-level operating costs. Those cost savings fund lower product prices, which drive sales volume, which in turn generates the revenue needed to sustain elevated wages. However, because the financial loop depends on maintaining all three elements concurrently, the strategy cannot be partially adopted.
Constraint produces efficiency. The policy of maintaining fewer than 4,000 core warehouse items represents the single most consequential operating constraint in the company.4 Downstream efficiencies—including high inventory turnover, volume purchase leverage, worker productivity, and low inventory shrink—originate directly from this restricted assortment. While conventional retail strategy frequently equates broad item selection with commercial strength, Costco demonstrates the structural cost advantages of extreme SKU discipline.
Distinguishing the asset from the residual. Co-founder Jim Sinegal routinely resisted recommendations from retail analysts to raise markups from 14% to 16%—an adjustment that would have generated immediate profit growth with minimal visible near-term resistance. He rejected those suggestions on the grounds that member trust constituted the primary underlying asset, whereas short-term earnings were merely the operational output.5 The strategic takeaway is not to ignore capital market feedback, but rather to define explicitly which operating variable represents the enduring asset and which represents the residual, accepting lower near-term margins to protect customer trust.
Anchor customer trust in verifiable artifacts. The permanent $1.50 price point on the hot dog combo functions as an easily verifiable proof point of corporate value. Rather than relying on promotional statements, members can verify the pricing commitment directly at the food court. Kirkland Signature serves a similar function at scale, allowing shoppers to compare a private-label item against an adjacent national brand on the same pallet. For businesses built on customer trust, physical, easily audited price anchors offer stronger reinforcement than traditional advertising.
Succession as an institutional system. Costco has executed two chief executive transitions without altering its core operating strategy, promoting internal operators who developed their careers within warehouse operations. That continuity reflects a four-decade policy of internal promotion, ensuring candidates are evaluated on long-term execution rather than interview assessments. However, the structural trade-off is clear: while internal succession safeguards corporate culture, it limits external perspective. That insulation contributed to the company's decade-long delay in building digital capabilities and explains why the chief financial officer role eventually required an external hire.
Balancing operational discipline against strategic rigidity. The institutional discipline that enforces low markups has also generated notable strategic blind spots, including delayed e-commerce development, the failure of standalone formats like Costco Home, and the abrupt shutdown of Costco Next. Cultural rigidity reinforces the credibility of the core pricing promise while simultaneously slowing adaptation outside the warehouse format. An objective evaluation requires recognizing both outcomes as expressions of the same underlying operational mindset.
XIII. Bull vs. Bear Case & Forward Investment Thesis
The bull case
The bull case for Costco does not rest on corporate lore or organizational culture; it rests on four observable financial mechanics.
First, fee expansion operates with minimal capital intensity. Executive membership grew 9.6% year over year in the third quarter of fiscal 2026—more than twice the pace of total paid member growth—while executive members accounted for roughly three-quarters of worldwide sales.224 Tier upgrades double fee revenue per household without requiring additional warehouse capacity, inventory commitment, or significant marginal cost, making executive conversion the company's highest-margin growth driver.
Second, international expansion functions as a margin driver rather than merely a volume play. Overseas locations generated 27% of net sales while contributing 34% of operating income, meaning geographic expansion enriches overall operating margins as the global store footprint expands.4
Third, economic pressure favors the warehouse model. When consumer budgets tighten, bulk purchases and private-label products gain market share, reinforcing the membership value proposition. Costco achieved 6.6% adjusted comparable sales growth in fiscal 2026 during a period when much of the broader retail sector experienced flat performance.2
Fourth, digital channels are generating material scale. A 20.9% increase in digitally enabled comparable sales in fiscal 2026—supported by owned last-mile logistics infrastructure—directly addresses historical criticisms regarding the company's slow e-commerce adoption.2
The bear case
The bear case does not contend that the underlying business is flawed. Rather, it argues that current valuation already reflects operational excellence, leaving equity returns vulnerable if multiple headwinds converge.
Valuation presents the primary risk. A trailing earnings multiple in the mid-forties for a retailer with a structurally capped 3.8% operating margin leaves little cushion if top-line growth normalizes—a scenario that represents a standard baseline expectation rather than an operational failure.
Domestic saturation represents the second risk. With 629 warehouses operating across the United States at last count,4 each additional domestic site faces potentially diminishing returns relative to established locations. Management trimmed its fiscal 2026 net opening plan from 28 to 26 locations, deferring delayed openings into fiscal 2027 while maintaining a long-term goal of over 30 openings annually.23 While store opening delays often stem from routine real estate scheduling, the downward adjustment highlights the operational friction of sustaining rapid physical expansion.
Demographic shifts and channel substitution pose a third challenge. Smaller household sizes, urban living, and instant-delivery services run counter to a warehouse model built on vehicle access, paid membership, home storage space, and bulk purchasing. Costco's effort to accelerate digital sales mitigates this friction but introduces unresolved questions regarding basket economics and member retention.
The central tension of the bear case is clear: even with an intact competitive moat and strong operational execution, equity returns may disappoint if an elevated valuation multiple places excessive burden on top-line performance.
The three KPIs that matter
Three primary performance metrics carry the forward investment thesis.
Membership renewal rate, split between United States/Canada and worldwide. This metric serves as the primary benchmark of customer value retention. The critical test is not merely the aggregate level, but whether the domestic renewal rate can remain above 92% as lower-retaining, digitally acquired members represent a growing share of overall membership additions.
Executive member penetration and sales contribution. As the company's capital-light fee driver, the key indicator is whether Executive memberships continue expanding at approximately double the pace of total paid members while sustaining or increasing their nearly three-quarters share of worldwide sales.
Core comparable sales growth excluding gasoline and foreign exchange. Removing fuel price volatility and currency fluctuations isolates underlying merchandise volume growth. The spread between fiscal 2026 headline comparable sales growth of 8.4% and the adjusted figure of 6.6% represents top-line expansion driven by temporary external factors rather than core warehouse volume.2
XIV. Earnings Call Playbook & Primary Source Guide
Costco's disclosure rhythm is unusual and rewards a specific reading approach. The company reports monthly sales, which means most of the revenue news is already public before the quarterly call. The call, therefore, is almost entirely about margin composition, membership behaviour, and management's framing—which is where the analytical value sits.
Compare the two CFO eras deliberately. Richard Galanti's commentary across 39 years was discursive and unusually forthcoming, often volunteering detail no analyst had asked for. Gary Millerchip's is structured around drivers and metrics. When assessing narrative consistency, the right test is not style but substance: does the current explanation of gross margin, renewal rates, and price investment match what was said two and four quarters earlier? On the renewal rate specifically, the digital-mix explanation has been given consistently across fiscal 2025 and fiscal 2026, which is a mark in management's favour.1823
Three calls repay close reading. The December 2023 call, at which the $15 special dividend was declared, shows how the board frames a large one-time distribution against ongoing capital needs.20 The March 2024 call was the first under Ron Vachris and carried the CFO transition announcement, making it the cleanest available baseline for the current management regime's language. The September 2024 call covered the implementation of the fee increase and the initial member response, and is the reference point for judging how the deferred fee benefit has flowed through since.17
In the Q&A, listen for four pressure points. Analysts consistently probe the timing of the next fee increase and any special dividend; the sustainability of gasoline profitability; the trade-off between wage investment and merchandise margin; and, increasingly, the economics of digitally acquired members. Whether management answers those with specifics or with general reassurance is itself the signal—and on the tariff refund question in the third quarter of fiscal 2026, the answer was notably specific about mechanism and notably vague about amount, which is the appropriate posture for a genuinely uncertain item.23
Watch what management volunteers versus what it concedes. The most informative disclosures at Costco tend to arrive unprompted in prepared remarks—the renewal-rate mix explanation, the decision to trim the fiscal 2026 warehouse opening plan from 28 to 26, the commitment to pass tariff refunds back to members.23 Concessions extracted under analyst questioning are rarer, which is itself a data point about disclosure culture. When management does volunteer a negative before it is asked about, that is a credibility deposit worth crediting; when the same explanation is offered for four consecutive quarters without the underlying number improving, it stops being an explanation and becomes a trend.
Primary sources over commentary. The annual Form 10-K carries the disclosures that matter most and are least discussed: warehouse counts by country, employee headcount and retention, the international share of operating income, gasoline station counts, and the executive member share of sales.4 The quarterly 8-K earnings releases carry segment comparable sales in both reported and adjusted form, which is the only place the gasoline and currency distortion is stripped out consistently.22 The monthly sales releases are the highest-frequency read on the one operating metric that cannot be dressed up, and they arrive roughly three weeks before the quarterly call—meaning a careful reader already knows the revenue answer and can spend the call listening only for margin and membership colour.2
What is not yet in the record. Fiscal 2026's fourth-quarter and full-year results will complete the picture sketched by the monthly sales releases, and are scheduled to follow shortly after this writing. Three things in that release will matter more than the headline: the full-year membership fee income figure, which will show how much of the September 2024 price increase has now fully cycled through; the year-end renewal rates, which will test whether the digital-mix drift has stabilised; and the fiscal 2027 warehouse opening plan, which is the clearest available statement of how much domestic and international runway management believes it has left.
References
-
Costco co-founder told CEO 'I will kill you' following hot dog combo price hike suggestion — Fox Business ↩↩
-
Costco Wholesale Corporation Reports August Sales Results — GlobeNewswire / Costco Wholesale Corporation, 2026-09-02 ↩↩↩↩↩↩↩↩↩↩
-
Costco Wholesale Corporation (COST) Financials and Market Data — Stock Analysis ↩↩
-
Costco Wholesale Corporation Annual Report on Form 10-K for the fiscal year ended August 31, 2025 — SEC EDGAR, 2025-10-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
How Costco Makes Money, Despite $1.50 Hot Dog Combos — The Motley Fool, 2025-12-05 ↩↩↩↩
-
Costco Wholesale Corporation Reports Fourth Quarter and Fiscal Year 2025 Operating Results (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2025-09-25 ↩↩↩↩↩
-
Costco Wholesale Corporation Income Statement and Balance Sheet Data — Stock Analysis ↩↩↩↩↩↩↩
-
Investing Mastery with Nick Sleep: Nomad's Costco Investment — Quartr ↩↩↩
-
Sol Price: Retail Revolutionary — The FedMart Years, 1954 to 1975 — The Journal of San Diego History, San Diego History Center ↩
-
History of Costco: Company timeline & facts — TheStreet ↩↩↩↩
-
Costco's First Warehouse Store Was a Springboard to Global Growth — Seattle Business magazine ↩
-
Costco CEO Craig Jelinek to Step Down; Insider Ron Vachris Named Successor — The Wall Street Journal, 2023-10-18 ↩↩
-
Costco's transition to Visa cards riddled with problems — Houston Chronicle, 2016 ↩↩
-
Costco Acquires Innovel Solutions from Transformco for $1 Billion — PR Newswire, 2020-03-17 ↩↩
-
Costco Wholesale Corporation Acquires Minority Interest in Costco Taiwan — Costco Wholesale Corporation, 2022-06-30 ↩
-
Costco Raises Membership Fees for First Time Since 2017 — Reuters, 2024-07-10 ↩↩
-
Costco's Renewal Rate Slips to 89.8%: Temporary Dip or New Normal? — Nasdaq ↩↩↩↩
-
Costco membership scanners coming to clubs in sharing crackdown — Axios, 2024-08-07 ↩
-
Costco Declares $15-a-Share Special Dividend After Strong Quarter — Bloomberg, 2023-12-14 ↩↩
-
Costco Wholesale Corporation Form 8-K (Quarterly Cash Dividend Increase) — SEC EDGAR, 2026-04-15 ↩
-
Costco Wholesale Corporation Reports Third Quarter and Year-To-Date Operating Results for Fiscal 2026 (Form 8-K, Exhibit 99.1) — SEC EDGAR, 2026-05-28 ↩↩↩↩↩
-
Costco (COST) Q3 2026 Earnings Call Transcript — The Motley Fool, 2026-05-28 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Costco (COST) Q1 2026 Earnings Call Transcript — The Motley Fool, 2025-12-11 ↩
-
Costco (COST) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-03-05 ↩↩
-
Why retail media needs Costco more than Costco needs retail media — The Drum ↩↩
-
Costco Abruptly Ends Costco Next Online Marketplace Without Warning — BigGo Finance ↩↩↩
-
Walmart-owned Sam's Club raises its annual membership fee to $60 — CNBC, 2026-04-01 ↩
-
Costco Wholesale Corporation Announces Plans to Close Costco Home Stores — Costco Wholesale Corporation, 2009-04-02 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube