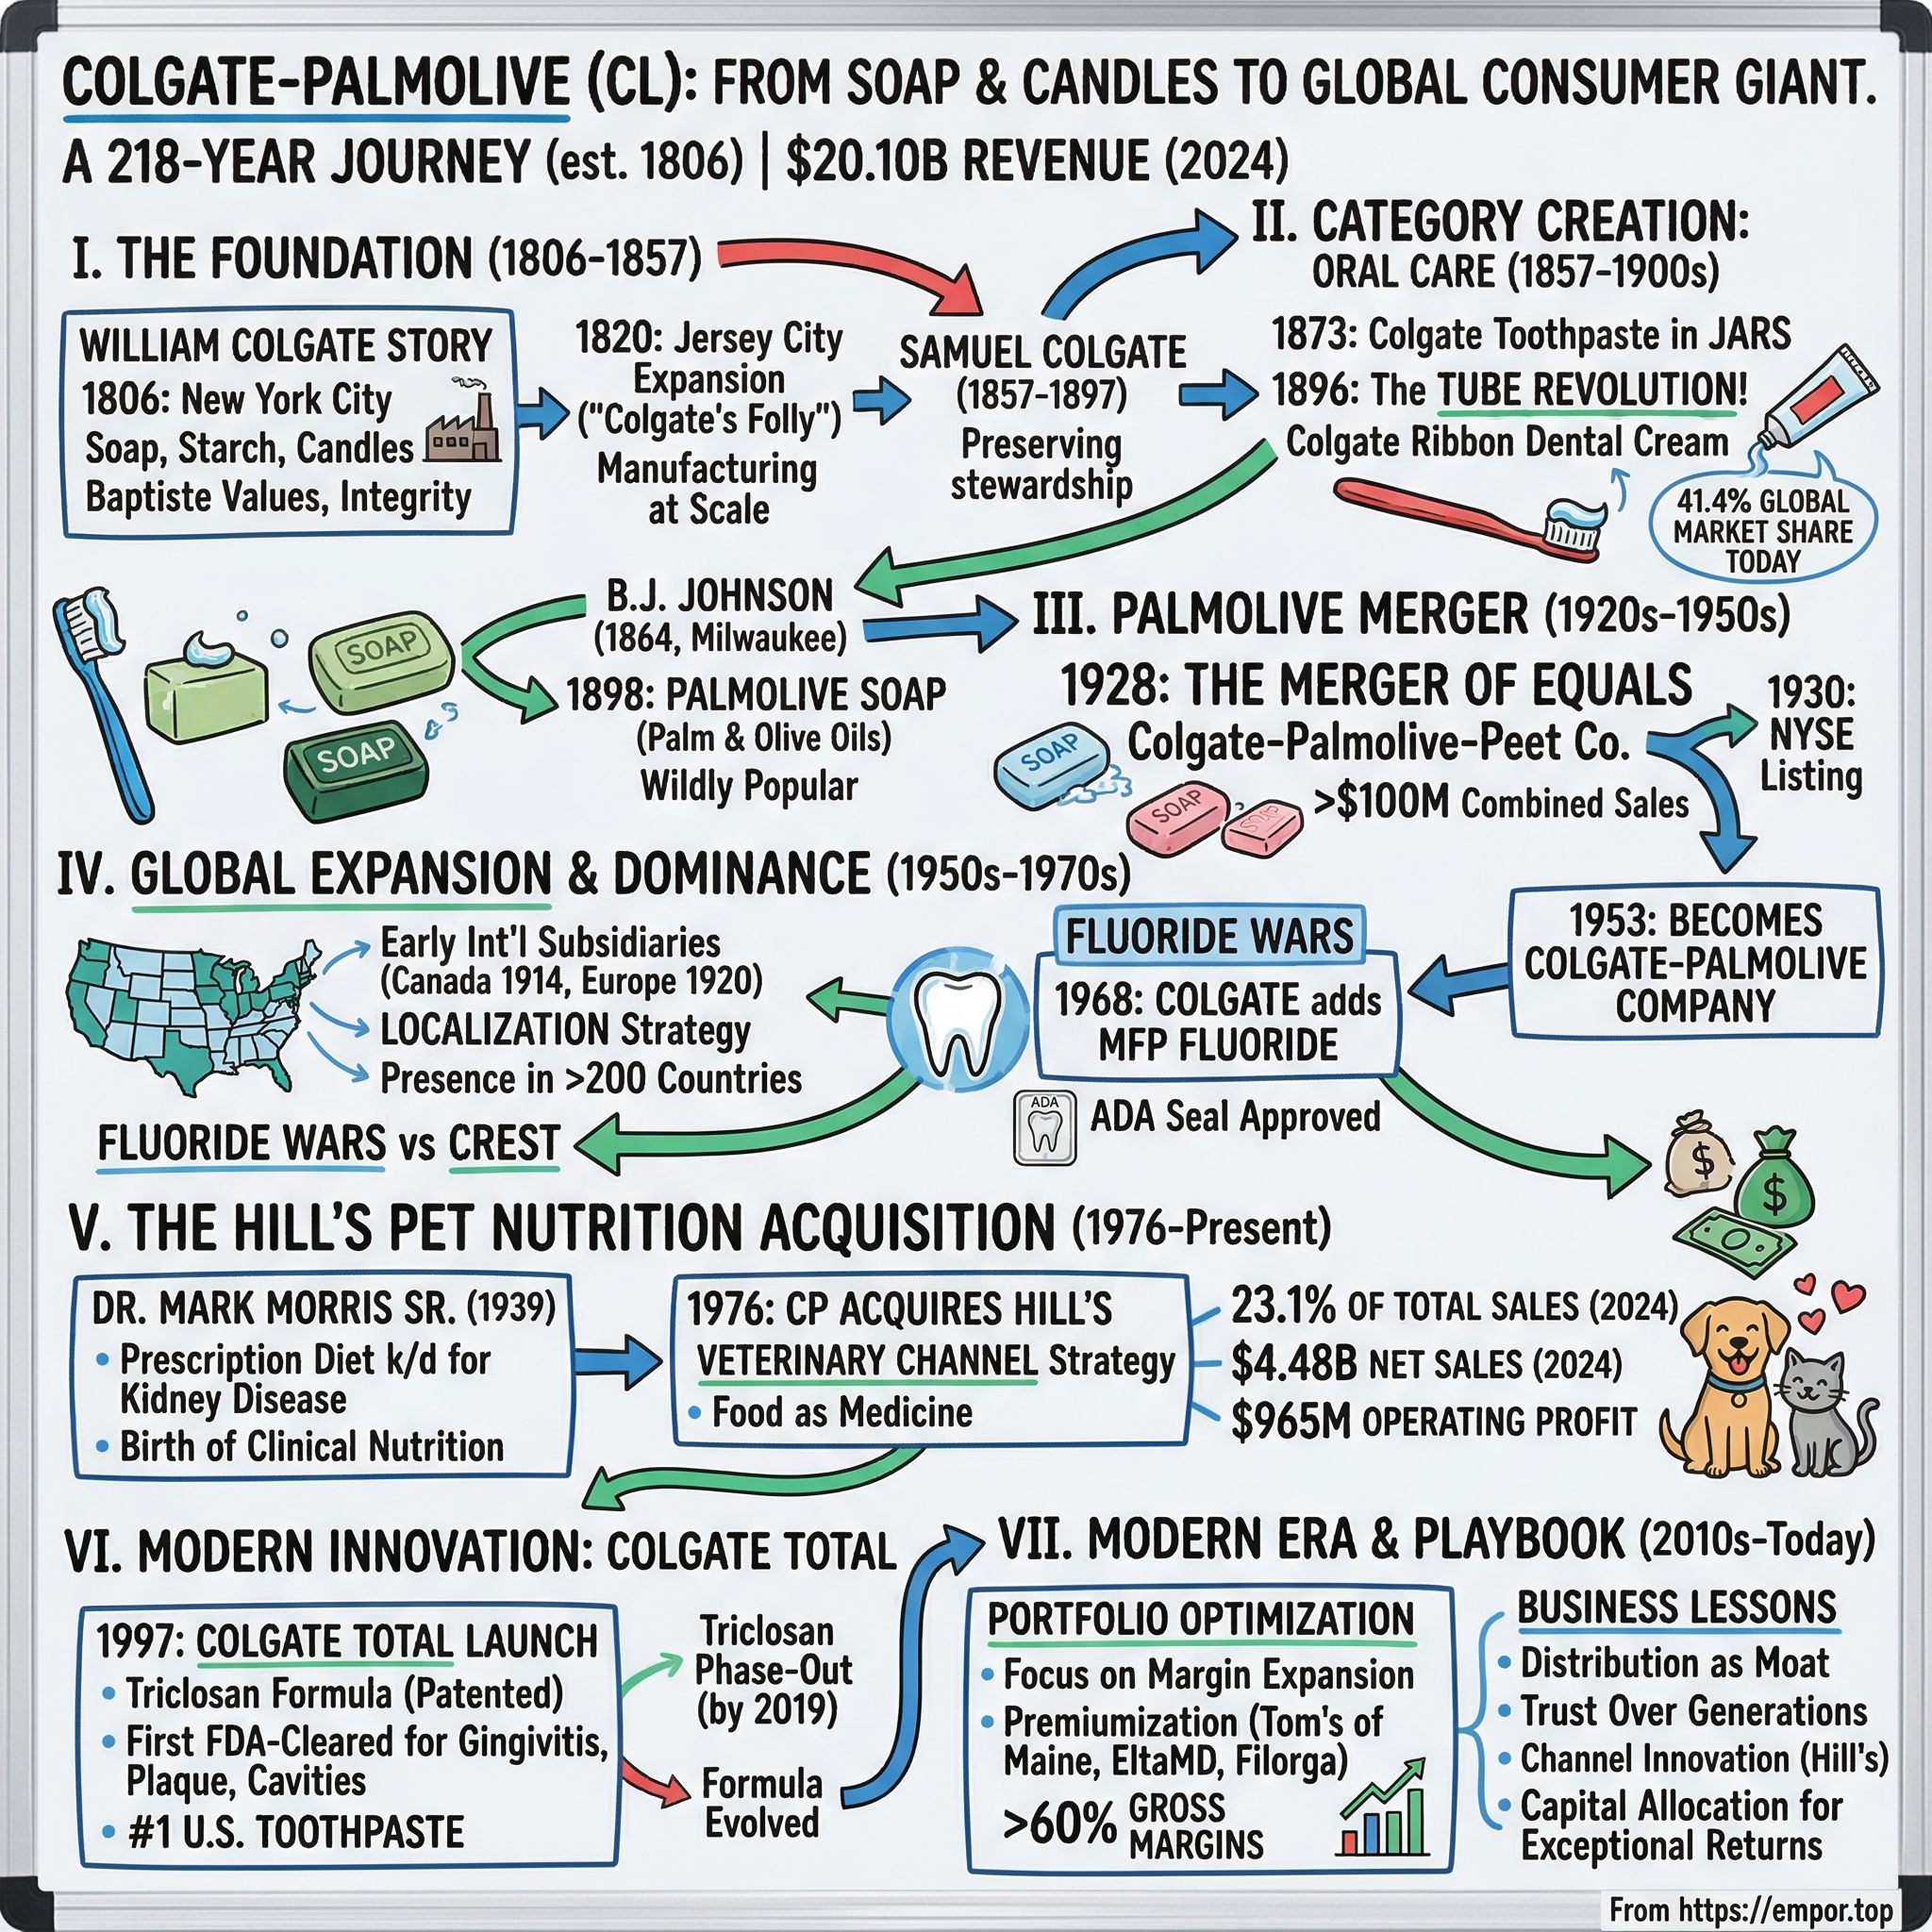
Colgate-Palmolive: The 218-Year-Old Habit Machine
I. Introduction & Episode Roadmap
There is a small ritual that happens roughly two billion times a day around the world, and almost nobody thinks about it. Someone reaches for a tube, squeezes, brushes for somewhere between forty seconds and two minutes, spits, rinses, and gets on with their life. The decision to buy that particular tube was made years ago, possibly by a parent, possibly by a dentist, and it has not been revisited since. That unexamined reflex is the entire business model of Colgate-Palmolive.
It is also, on the surface, one of the most durable business models ever constructed. The company sold $20.4 billion of net sales in fiscal 2025, at gross margins above 60% — the kind of margin normally associated with software, not with toothpaste and dish soap and dog kibble.1 It has paid a dividend without interruption since 1895 and raised it for 63 consecutive years, which places it in the small club of "Dividend Kings" that investors treat as a proxy for institutional permanence.2 The packaging innovation that made the whole thing possible — the collapsible metal tube that turned tooth powder from a shared jar into a personal, repeat-purchase product — dates to 1896 and is still, functionally, the format the company sells today.3
So here is the tension this story has to resolve. In that same fiscal 2025, GAAP earnings per share fell 25%, to $2.63 from $3.52.2 Operating margin on a reported basis collapsed from 21.2% to 16.2%, because the company took a $919 million pre-tax non-cash impairment — $794 million after tax — against its skin health business, the marquee "premiumization" bet it had spent nearly $1.7 billion to acquire six years earlier.12 Meanwhile in its home market, the United States, the category-tracking data for toothpaste showed Procter & Gamble's Crest edging ahead of Colgate for the first time in years. And Hill's Pet Nutrition — the profit surprise of the last fifty years, the acquisition nobody expected to become the company's highest-margin business — went into reverse on volume, with management describing the pet category on the third-quarter 2025 call as "quite sluggish."4
None of that is fatal. A company with 63 years of dividend increases has survived far worse: two world wars, the deconsolidation of an entire country's operations, the loss of a decade of Latin American currency value. But it does raise the question that matters for anyone holding this as a long-duration compounder: is Colgate still the same machine, running through an ordinary bad patch, or is something structural changing underneath the ritual?
Here is the route. We start in a Dutch Street soap and candle works in 1806 and move quickly — this history matters mostly because it explains the shape of the modern segment P&L, not because it is the investment case. Then the merger that created the company as it exists, the fluoride wars against Crest, and the century-long international head start that still shows up in the geographic profit split. From there we go deep: oral care and the competitive scoreboard as it actually reads in 2026; Hill's Pet Nutrition and the growth-durability question; the geography of profit, which is stranger than most investors assume; the premiumization M&A record, which now includes a genuine, quantified failure; and Noel Wallace's tenure, tested through the specific mechanism that reveals management quality — what was promised versus what happened.
The through-line: this is a business whose moat is habit and distribution, and habit is being tested at the shelf for the first time in a long time.
 Subscribe on LinkedIn
II. Origins: Soap, Candles, and the Invention of the Toothpaste Tube
In 1806, a 23-year-old English immigrant named William Colgate opened a starch, soap, and candle works on Dutch Street in lower Manhattan.3 The location matters more than the romance of it. Early nineteenth-century soapmaking was a tallow business — you rendered animal fat, you combined it with lye, you sold the result — and Manhattan in 1806 was a port with slaughterhouses, shipping, and a growing dense population. Colgate was not inventing a product. He was positioning himself at the intersection of a cheap input and a captive market.
The Colgate family was Baptist, seriously so, and that shaped the institution in ways that outlasted the founder. William Colgate tithed aggressively and his son Samuel Colgate carried both the business and the religious commitments forward; Colgate University in upstate New York carries the family name because of that philanthropy, not because of the toothpaste. For a modern investor, the interesting residue of this is cultural rather than financial: Colgate-Palmolive has, for most of its life, been an institution run by long-tenured insiders with a strong internal orthodoxy about how the business works. That is a strength when the orthodoxy is right, and a liability when the category shifts. We will come back to that when we get to Noel Wallace, a man who joined the company in 1987 and has never worked anywhere else.
The category-creation moment arrived two generations in. In 1873, Colgate began selling toothpaste in jars.3 This is not the innovation. A jar of dental cream is a shared household object — you dip into it, your siblings dip into it, it sits open in a humid bathroom. It is closer to a condiment than a personal-care product. The unit economics are bad: one jar serves a family, purchase frequency is low, and hygiene concerns cap adoption.
Twenty-three years later, in 1896, Colgate put the same product into a collapsible metal tube and called it Colgate Ribbon Dental Cream.3 Everything about the business changed. The tube made toothpaste portable, sanitary, and — critically — individual. Purchase frequency went up because consumption per household went up. Shelf presentation improved. The ribbon of paste extruding onto a brush became a visual signature that advertising could own. The company's own slogan at the time was disarmingly honest about where the value came from: "We couldn't improve the product, so we improved the tube."3
That sentence is the thesis of the entire company. Colgate has rarely won on formulation chemistry alone. It has won by turning a commodity into a branded habit and then making sure that habit is available everywhere. The tube was the first and cleanest example: a packaging change that converted a low-frequency household good into a high-frequency personal one, and in doing so created the repeat-purchase economics that fund a 60%-plus gross margin more than a century later.
The other half of the company was being built 900 miles west. B.J. Johnson's Milwaukee soap company developed a soap in 1898 made from palm and olive oils rather than tallow — hence Palmolive — and the product was successful enough that the company eventually renamed itself after it.3 By the turn of the century Palmolive was the best-selling soap in the world, sold on a proposition of gentleness and beauty rather than pure cleaning power. Note the pattern repeating: same commodity chemistry as every other soap, differentiated positioning, mass advertising, and a brand that consumers asked for by name.
The three-way combination came together in 1928, when the Palmolive-Peet Company — itself the product of an earlier merger with Kansas-based Peet Brothers — acquired Colgate, effective July 1 of that year.3 The combined entity brought together more than $100 million of pre-merger sales, an enormous figure for a consumer goods company in the 1920s. What the merger really assembled was a portfolio logic that persists: oral care and personal care and home care, sold to the same household, through the same retailers, on the same trucks.
Keep that structure in mind, because the modern company still looks like it. The segment reporting has changed names many times, but the underlying idea — one distribution system carrying multiple habitual-purchase categories into the same shopping basket — has not changed since 1928. What changed next was geography.
III. Building the Global Machine: Fluoride, Emerging Markets, and the Brand Shelf
Most American consumer goods companies went international after World War II, when the dollar was strong, Europe needed rebuilding, and the logistics of overseas operations had been solved by the war itself. Colgate went in 1914, to Canada, and then kept going — through Europe, Asia, Latin America, and Africa across the 1920s, well before the merger that gave the company its current name.3
Why so early? Partly because the products travelled well. Soap and toothpaste are non-perishable, small, high-margin relative to weight, and required no consumer education beyond "use this." Partly because the categories were unbuilt: in 1925, most of the world did not brush its teeth daily, which meant the opportunity was not to take share from a competitor but to create the habit from zero and be the brand attached to it. And partly, one suspects, because a company built on brand advertising discovered that the same advertising worked in translation.
The compounding effect of that head start is the single most underappreciated fact about Colgate-Palmolive today. When a company spends a century establishing the daily brushing habit in Brazil, Mexico, the Philippines, and India — building distribution into small independent retailers, kirana stores, and rural markets that Western competitors could not economically reach — it ends up owning a position that is not really about product superiority at all. It is about being the default. We will see this show up with unusual clarity in the geographic profit split, where Latin America generates a disproportionate share of the company's operating profit relative to its sales.
The mid-century chapter that mattered most, though, was scientific. In 1968, Colgate launched toothpaste with MFP Fluoride — sodium monofluorophosphate — the company's first genuine science-based differentiation.3 This was a defensive move as much as an offensive one. Procter & Gamble's Crest had launched with stannous fluoride in the 1950s and, crucially, had secured the American Dental Association's seal of acceptance, which gave it something Colgate's advertising could not manufacture: third-party clinical endorsement. Crest took the U.S. leadership position off Colgate on the back of that endorsement.
The lesson Colgate absorbed from losing the first fluoride round is the lesson it has applied ever since: in categories where consumers cannot evaluate the product themselves, the endorsement of a professional gatekeeper is worth more than any amount of advertising. Dentists for toothpaste. Later, as we will see, veterinarians for pet food. That is a specific, repeatable moat-construction technique, and it is arguably Colgate's most distinctive corporate skill. The rivalry it started — Colgate versus Crest, MFP versus stannous fluoride, dentist recommendations versus ADA seals — is still running in 2026, and Section IV is where we score it.
Around the science, the company kept doing what it had done since the 1890s: acquiring and extending brands that occupied a distinct position on a shelf. Ajax cleanser arrived in 1947. Palmolive dishwashing liquid in 1966 — the same brand equity built on hand-gentleness, now applied to the sink. Irish Spring deodorant soap in 1972.3 The corporate name was formalized as Colgate-Palmolive Company in 1953.3
What is worth extracting from that list is not the individual brands but the strategic pattern: Colgate built category breadth long before "four categories" became a slide in an investor deck. Each addition made the company's truck a little more valuable to the retailer, and each new retailer relationship made the next brand a little easier to launch. That is a flywheel, and it ran for roughly seventy years.
The thing to watch — and the reason the modern chapters of this story are tense rather than triumphant — is that the flywheel's power depends entirely on the retailer needing Colgate more than Colgate needs the retailer. For most of the twentieth century, with thousands of fragmented grocers, that was true. In a market where a handful of retailers control most of the volume and can manufacture credible store-brand alternatives themselves, it is much less obviously true. That shift is the pressure point running underneath everything that follows.
IV. The Oral Care Core: Industry Structure and the Crest Fight, Today
Walk into an American supermarket in 2026 and look at the oral care aisle. It is four to six feet of near-identical white boxes making near-identical claims — cavity protection, whitening, sensitivity, enamel, charcoal, "natural" — priced between roughly three and eight dollars. A shopper spends, generously, eleven seconds in front of it. This is the single most important eleven seconds in Colgate-Palmolive's business, because oral care is the largest and most iconic category inside the Oral, Personal and Home Care organization that accounts for more than three-quarters of company net sales.1
For most of the last three decades, those eleven seconds went Colgate's way almost automatically. The peak expression of that dominance was Colgate Total, launched in the United States in 1997 — a formulation built around triclosan that claimed twelve-hour antibacterial protection and, unusually for the category, carried FDA approval for gingivitis. It was the last time anyone in toothpaste created a genuinely new benefit platform rather than a new flavour of an existing one. It let Colgate charge a premium, it took share, and it gave dentists something specific to recommend.
What has replaced it as the innovation engine is the honest question, and the honest answer is: line extensions with better margins but less category-defining power. Whitening. Sensitivity. The naturals positioning acquired with Tom's of Maine. Higher-priced sub-brands in the same tubes. These are real, they support price/mix, and they are why gross margin has held above 60%. But none of them changed what the category is, and none of them created a new reason for a consumer to switch brands rather than switch varieties. When a company's innovation shifts from "why you should use our brand" to "which of our products you should buy," it is generally a sign that the category has matured and that competition is moving toward price and shelf space. That is precisely what the numbers now show.
The scoreboard, with actual numbers
Colgate's global toothpaste market share was 41.3% in fiscal 2025, down 0.4 points year over year.1 Take a moment with that number before the direction of travel. Forty-one percent of the global toothpaste market is an extraordinary structural position — roughly double what any single competitor holds worldwide, built across more than 200 countries and territories, and it has been remarkably stable for decades. On the global manual toothbrush category, Colgate holds a leading position as well.1 The moat is real. Nothing in what follows should be read as suggesting otherwise.
But the composition of that 0.4-point decline is what matters. Share was up in Europe, roughly flat in Asia Pacific, and down in North America, Latin America, and Africa/Eurasia.1 Three of the five regions losing ground, including the two that between them generate the largest slice of company operating profit, is not noise.
The sharpest data point is domestic. Colgate's U.S. toothpaste share sat at 33.5%, and category tracking data put Procter & Gamble's Crest at 34.7% — meaning that in Colgate's home market, the rival is now ahead.1 A necessary caveat, and the reader should hold it firmly: Colgate discloses its own share in its filings, and the head-to-head comparison against Crest comes from category tracking data rather than from any management statement. Colgate's executives do not stand on earnings calls and concede that Crest has passed them. The competitive framing throughout this section — Procter & Gamble in oral care and North America, Unilever in emerging-market personal care, Church & Dwight and Kimberly-Clark pushing value and price positioning — is analyst-sourced inference, not verified management admission. Management's own language on calls runs to "heightened competition" and "price and promotional gaps," phrasings that describe the pressure without naming who is applying it.5
That evasiveness is itself an analytical fact. A management team that will describe a symptom in detail but not name the cause is telling you something about how uncomfortable the diagnosis is.
Stress-testing the pricing-power claim
The bull case on Colgate has always rested on pricing power: habitual purchase, low absolute price point, strong brand, therefore the ability to push through cost inflation without losing volume. This is a moat claim, and moat claims do not break on margin — they break on substitution and lost shelf space. So that is where it has to be tested.
The disconfirming evidence is directionally real and, importantly, recent rather than historical. Private-label toothpaste has been gaining share in North America, and trade reporting through 2025 and 2026 described store brands taking facings from Speed Stick, from Tom's of Maine, and in some accounts from core Colgate itself. The honest caveat: this is secondary-sourced. It is not a figure the company breaks out in its 10-K, and an investor should treat it as directionally credible but unverified rather than as an established fact. What is verified in the company's own disclosures is the North America share decline and the regional pattern above, and on the second-quarter 2026 call management described U.S. shipments down 3% while consumption was up 1% — a retailer destocking dynamic rather than a consumer walking away.6
Weigh those against each other properly. A 1% consumption increase alongside a 3% shipment decline says the American consumer is still buying Colgate at roughly the same rate; the retailer is simply carrying less of it. That is a less alarming picture than outright demand collapse. But it is also exactly what the early phase of a shelf-space reallocation looks like: retailers do not announce that they are giving a facing to their own store brand, they just order less.
So the verdict on durable pricing power: narrowed, not rejected. Colgate still holds global category leadership by a wide margin, still earns gross margins above 60%, and still sees consumption growth in its home market. But two things that were not true five years ago are true now — the U.S. category leadership has flipped to Crest on tracking data, and private label is taking measurable share in a category long assumed immune to it. Those are the first hard data points against the pricing-power thesis in years, and they deserve to change the confidence level rather than the conclusion.
Myth versus reality
Three consensus beliefs about this business are worth checking against the record.
Myth: Colgate is the world's toothpaste company, and that position is unassailable. Reality: the global position is genuinely dominant and the number is enormous, but "unassailable" is doing work the evidence does not support. Share fell in three of five regions in fiscal 2025, including the home market, and the aggregate declined.1 A 41.3% share that drifts down 0.4 points a year is still a 41.3% share — and is also, compounded over a decade, a materially different business.
Myth: staples brands are insulated from private label because consumers trust what goes in their mouths. Reality: that argument held for a long time and is now being tested empirically for the first time in the modern era in North America. The mechanism working against Colgate is not consumer distrust of store brands — it is retailer shelf allocation, over which the consumer has no say and the brand has only promotional leverage.
Myth: high gross margin proves pricing power. Reality: gross margin proves the spread between price and cost of goods, which a company can protect for years by mix-shifting toward premium variants and trimming the value end while the underlying franchise loses units. The cleaner test is volume, and North America volume has been the weak line.6 This is the single most important analytical distinction in the whole story: margin is a lagging indicator of brand strength, volume is a leading one.
The two things worth tracking, in order: U.S. toothpaste share, and North America organic volume as distinct from price/mix. The second matters more than it sounds. Organic sales growth that comes entirely from price while volume declines is the signature of a company harvesting a brand rather than growing one. Four consecutive quarters of positive North America volume would substantially rehabilitate the pricing-power case; four more of price-only growth would substantially damage it.
Which brings us to the part of the portfolio that was supposed to be immune to all of this.
V. Hill's Pet Nutrition: The Veterinary-Channel Bet and Its Growth Test
In 1976, a company that sold soap and toothpaste bought a small Kansas maker of therapeutic pet food.3 On paper it made no sense. Hill's had no consumer brand to speak of, sold through veterinary clinics rather than grocery stores, and operated in a category — prescription dog food — that most people did not know existed. It was, by the standards of consumer goods M&A, a rounding error.
Fifty years later it is the most profitable thing Colgate-Palmolive owns.
The reason is the gatekeeper insight from Section III, applied with unusual rigour. Hill's did not build its position by out-advertising Purina. It built it by embedding itself in veterinary education, funding clinical nutrition research, and making Science Diet and Prescription Diet the products veterinarians learned on and recommended. When your dog has kidney disease and your vet hands you a bag, you do not price-shop that bag. You buy it, you keep buying it, and the price elasticity of your demand is roughly zero. That is a moat built through a professional intermediary rather than through consumer marketing — the same technique as the dentist recommendation in oral care, but executed in a category where the recommendation carries far more weight because the stakes are medical and the consumer is completely unqualified to evaluate the product.
The financial result in fiscal 2025: Hill's generated $4.6 billion of net sales, 22.6% of the company total, and $1.06 billion of segment operating profit, 21.2% of company operating profit.1 Sit with the implication of a segment that runs a structurally higher margin than any of Colgate's five geographic consumer segments. Pet food, a business with real manufacturing intensity and commodity protein inputs, out-earns toothpaste on a segment basis. The channel is doing that work.
Colgate has been putting capital behind it. In 2022 it agreed to buy three dry pet food manufacturing plants from Red Collar Pet Foods for approximately $700 million — a straightforward capacity purchase, because Hill's had been supply-constrained and was leaving demand unserved.7 In April 2025 it closed the acquisition of Prime100, an Australian fresh pet food business, for approximately AU$471 million (roughly $301 million), Hill's first move into both fresh pet food and the Australian market.8
Where the growth thesis meets the record
The standard bull framing on Hill's is that pet humanization is a durable multi-decade tailwind: households treat pets as family, spend accordingly, trade up to premium and therapeutic nutrition, and the trend only compounds. This is an optionality-and-growth claim, and the mechanism that would break it is not competitive share loss — it is category-level demand softening. And that is exactly what showed up.
In the third quarter of 2025, Hill's organic sales fell 1.3%, with organic volume down 4.2%.4 Management described the pet category on that call as "quite sluggish."4 Trade coverage through the period reinforced it.9 The specific weakness was in Science Diet dog, which management attributed to pet owners migrating toward smaller pets — a smaller dog eats less food, so the same number of pets generates less revenue — and to what it characterised as deteriorating pet ownership trends generally.4
Layered on top is a self-inflicted but deliberate drag: Colgate exited private-label pet food manufacturing, which management has quantified as roughly a two to two-point-three percentage point structural headwind to reported growth going forward.4 Strategically this is defensible — making store-brand kibble is precisely the low-margin, no-moat activity that Hill's exists to avoid — but it means that for several more quarters, headline reported growth and underlying volume will tell different stories, and headline growth will look worse than the business is while the comparison laps, then better than the business is once it does.
The most revealing disclosure is management's own guidance. Colgate has explicitly pointed Hill's back toward a 3–5% target growth rate.5 Read that carefully: guiding back toward a target is an admission that recent performance has been running below it. And the way the new Fresh line, built on the Prime100 platform, has been rolled out — deliberately measured rather than volume-aggressive — is a further tell. A management team that believed a category re-acceleration was imminent would be pushing capacity into it, not pacing it.
So the calibrated conclusion: the pet humanization thesis is narrowed, not rejected. Over twenty years it has been demonstrably real, and the structural margin advantage of the veterinary channel is intact — there is no evidence in the record of Hill's losing its clinical position to a competitor. What is not intact is the assumption of smooth multi-decade compounding. The category itself has softened on management's own characterization, the demographic mix is shifting toward pets that consume less, and the growth rate has fallen below the company's own stated target. This is a moat being tested by demand rather than by rivals — which is, in some ways, the harder problem, because a company can out-execute a competitor but cannot out-execute a shrinking category.
The capacity question nobody asks
There is a second-order issue worth a short aside. Colgate spent roughly $700 million on three dry pet food plants in 2022 to relieve a supply constraint that existed at the time.7 Fixed manufacturing capacity purchased at the top of a demand cycle becomes operating deleverage when volumes fall — the plants still cost what they cost whether they run at 95% or 70% utilization. Colgate has not disclosed Hill's capacity utilization, and it is not a metric the company breaks out, so this is a structural observation rather than a quantified problem. But it is the mechanism by which a volume decline in a manufacturing-intensive segment turns into a margin decline, and it is worth watching in the Hill's segment operating profit line rather than the sales line.
The KPI is unambiguous: Hill's organic volume growth, stripped of the private-label divestiture headwind, returning to and holding within that 3–5% band. Volume, not sales. Sales can be manufactured with price.
And this matters disproportionately, because Hill's has been quietly carrying the profit growth that the geographic segments were not delivering — which is where we go next.
VI. Geographic Economics: Why Latin America Is the Profit Engine and North America Is the Problem
Here is a fact that reliably surprises people who assume American consumer goods companies make their money in America.
In fiscal 2025, Colgate's Latin America segment generated $4.78 billion of net sales — 23.4% of company total — and $1.41 billion of operating profit, or 28.1% of the company's operating profit. North America generated $4.05 billion of net sales, 19.8% of the total, and just $784 million of operating profit, 15.6% of the company total.1 Europe contributed $2.96 billion of sales and $748 million of profit; Asia Pacific $2.81 billion and $760 million; Africa/Eurasia $1.17 billion and $255 million.1
Translate that into plain English. Latin America over-earns its revenue share by roughly five percentage points. North America under-earns its revenue share by roughly four. A dollar of Colgate revenue generated in Mexico or Brazil is worth substantially more to shareholders than a dollar generated in the United States. Europe and Asia Pacific, notably, both punch above their revenue weight too — it is specifically North America that is the structural laggard.
Why Latin America over-earns
Three mechanisms, and they compound. First, the distribution head start from Section III: Colgate has been building routes to small independent retailers across Latin America for roughly a century, and in markets where modern trade did not consolidate the way it did in the U.S., that direct-to-small-retailer network is genuinely hard to replicate. A new entrant cannot buy its way onto a hundred thousand corner-store shelves.
Second, household penetration. In several Latin American markets Colgate is not the leading toothpaste brand — it is effectively the generic word for toothpaste, in a category with near-universal household penetration. Brand-as-category-noun is the strongest form of the brand power that Hamilton Helmer's framework describes, because it removes the consumer's decision entirely.
Third, and most fragile: less private-label competition, historically, than in North America. Store brands require concentrated modern-trade retailers with the scale to commission their own manufacturing. Where retail remains fragmented, private label has less oxygen.
The tax on the profit engine
But the highest-margin geography has also, repeatedly, been the source of Colgate's largest write-offs, and this is where the geographic bull case has to be stress-tested against the company's own history rather than admired in isolation.
The canonical case is Venezuela. In 2015, Colgate deconsolidated its Venezuelan operations amid currency controls and hyperinflation, taking an after-tax charge of $1.058 billion — enough to swing the company to a quarterly loss.10 That was not a one-off shock arriving from nowhere; it was the terminal event in a decade of recurring remeasurement losses on Venezuelan and Argentine currency exposures through the 2010s. An entire country's business, built over generations, wrote down to zero.
So the correct framing of Latin America is not "high-margin engine." It is "high-margin engine that carries a recurring, occasionally catastrophic FX and sovereign-risk tax." Investors capitalizing that 28.1% profit share at a stable multiple are implicitly assuming the Venezuela event was idiosyncratic. The record says currency crises in Colgate's Latin American markets are periodic rather than exceptional. The margin premium is partly compensation for that risk, not pure evidence of a superior moat.
North America in 2026
Management has been unusually blunt about the domestic business, describing recent U.S. performance as "not satisfactory" — a phrase that stands out against the generally polished register of consumer-staples earnings calls.6 The mechanics, as covered in Section IV, are a destocking dynamic rather than a demand collapse. But North America is now the portfolio's weakest link and simultaneously its most exposed position: it absorbs the Crest share dynamic, the private-label encroachment, and the input-cost shock all at once.
That last item deserves to be made concrete, because "tariffs" is the kind of word that gets waved at rather than explained. In April 2025, Colgate cut its sales and profit outlook and disclosed an estimated $200 million of tariff-related cost.11 The mechanism is straightforward: Colgate manufactures in a global network and moves both finished goods and inputs — packaging, resins, specialty chemicals, and in Hill's case protein — across borders. A tariff is a tax applied at the moment those goods cross, and it lands in cost of goods sold. Then, on the first-quarter 2026 call, management cut its gross margin guidance after new tariffs were finalized on April 29, 2026, and characterized the vast majority of the impact as falling on North America.12
Put the pieces together and the North American situation reads as a genuine squeeze rather than a soft patch: the region losing category share, the retailer taking shelf space back, and the cost base rising from a policy source the company cannot negotiate with. Colgate's response so far has been what management calls surgical pricing — targeted adjustments rather than broad increases — which is the right tactical answer if you believe the pressure is temporary, and a slow bleed if you do not.
For investors, the geographic split creates an uncomfortable dependency. The profitable growth is offshore, in markets with real currency risk. The stable currency is domestic, in the market with the competitive problem. That is not a portfolio you can fix with cost cutting alone, and it explains a great deal about why management went shopping for higher-margin categories in the first place.
VII. The Premiumization Bet: M&A Record from Tom's of Maine to Filorga
The strategic logic was seductive and, for a while, widely admired. If the core categories are mature, low-growth, and increasingly exposed to private label, then use the balance sheet to buy into adjacent categories with higher growth rates, higher price points, and structurally better margins. Consumer staples companies have been running this play for two decades. Colgate ran it harder than most.
The first move was small and instructive. In March 2006, Colgate agreed to acquire 84% of Tom's of Maine — the natural oral care brand built by Tom and Kate Chappell — for approximately $100 million in cash, with the Chappell family retaining 16%.13 The deal closed on May 1, 2006.14 It gave Colgate a credible position in the naturals segment years before naturals became a mainstream consumer demand, and it was structured with unusual care to preserve the acquired brand's identity rather than absorb it. As premiumization deals go, it was cheap, strategically sound, and mostly worked.
Then the ambition scaled up, and the target moved from natural oral care to dermocosmetics — medical-adjacent skincare sold through dermatologists, aestheticians, pharmacies, and travel retail. In December 2017 Colgate agreed to acquire the PCA Skin and EltaMD businesses, closing in January 2018 for approximately $730 million combined.15 Then, in 2019, the largest acquisition in the company's modern history: Laboratoires Filorga, a French dermocosmetics company, for approximately €1.5 billion — about $1.69 billion.16
You can see why it appealed. Filorga sold anti-ageing skincare at prices multiples above anything in Colgate's core portfolio, through professional channels, with a strong position in China and in duty-free travel retail — at the time, one of the fastest-growing distribution channels in global beauty. It was the professional-gatekeeper playbook again, ported into a luxury-adjacent category. Dermatologists instead of dentists.
The record, which is now a genuine falsification
Capital-allocation claims break on the fate of prior deployments, and here the record is unambiguous enough that it does not require interpretation.
The first crack came in the fourth quarter of 2021, when Colgate wrote down Filorga's goodwill and trade name intangible, taking a non-cash after-tax charge of $518 million.1718 The stated cause was COVID-19: government restrictions and reduced consumer mobility had gutted consumption in exactly the duty-free, travel retail, and pharmacy channels the deal thesis depended on.17 At the time, this was defensible as a pandemic shock — an exogenous event that hit an otherwise sound asset, and one that would presumably reverse as travel normalized.
Travel normalized. The asset did not recover.
In the fourth quarter of 2025, Colgate took a further non-cash impairment against the skin health business of $919 million pre-tax — $244 million of trademark, $93 million of customer relationships, and $582 million of goodwill — or $794 million after tax.12 Management's stated reasons this time contained no exogenous excuse: lower than expected category growth rates and weaker than expected performance, particularly in China.15 That charge is what drove company operating margin from 21.2% to 16.2% and GAAP EPS down 25%.2
Do the arithmetic on the Filorga-related write-downs across the two events and roughly $1.49 billion has been impaired against a purchase price of about $1.69 billion, in six years.11716 Whatever else one says about it, that is a deal in which the great majority of the invested capital has been formally written off the balance sheet by the company's own accountants.
What the failure does and does not prove
It would be easy, and wrong, to conclude from this that Colgate is bad at M&A.
The EltaMD and PCA Skin businesses — acquired in the same strategic push, into the same broad category, roughly two years earlier — do not carry a comparable impairment in the record. EltaMD in particular built a genuine consumer following in medical-grade sun care in the United States. The distinction between the two outcomes is instructive: Filorga's thesis rested on two concentrated exposures, Chinese consumer demand and travel retail, both of which turned out to be far more cyclical and more correlated with each other than the deal model assumed. EltaMD sold into a domestic U.S. professional channel with no equivalent single-geography dependency.
So the calibrated verdict: the claim that premiumization M&A creates value is rejected for Filorga specifically — this is not a risk that might materialize, it is a loss that has been recognized twice — and left unproven but intact for EltaMD and PCA Skin, where the affirmative evidence is the absence of a write-down rather than any disclosed segment performance. That is a weaker form of evidence than it looks, and it should be held at the confidence it supports.
One further honesty note. No independent analyst benchmarking of these deals' EV/EBITDA multiples against comparable beauty and CPG transactions surfaced in the research for this piece. That absence should be stated rather than papered over with an assertion that Colgate overpaid at signing. The impairment history is the strongest available evidence on that question, and it is strong — but it is retrospective evidence of value destruction, not a clean demonstration that the price was wrong on the day.
The forward test is specific: does skin health stabilize post-impairment, or does it require a third write-down? And separately, how does Prime100 — a smaller, more recent, more geographically contained pet-food deal — perform against a management team that now has an expensive lesson in geographic concentration risk to draw on?
That question about learning leads directly to the man who has been signing these cheques.
VIII. The Noel Wallace Era: Strategy, Capital Allocation, and Management Credibility
Noel Wallace joined Colgate-Palmolive in 1987 and has never worked anywhere else.19 He started in the toothbrush business, moved through Mexico, ran North America, then ran Latin America — the profit engine — then took on global innovation and oversight of Hill's before becoming Chief Executive in April 2019 and Chairman in 2020.19 Nearly four decades inside one institution, with rotations through essentially every business that matters.
This is the classic Colgate profile, and it cuts both ways. An executive who has personally run Latin America knows exactly why that segment over-earns and exactly what a currency crisis does to it — that is genuine, hard-won institutional knowledge that no external hire could acquire. But a 39-year insider who has been steeped in one company's orthodoxy since the Reagan administration is also the person least likely to conclude that the orthodoxy needs replacing. When Wallace speaks publicly about reinventing a 220-year-old American icon, as he did on CNBC in April 2026, the reinvention on offer is continuity with better execution.19 Whether that is the right answer depends on whether the U.S. problem is cyclical or structural — and that is precisely the question the company has not yet answered.
Incentives, on paper and in practice
The compensation structure is, on paper, better designed than most. Colgate's proxy disclosure put Wallace's total compensation at approximately $16.5 million, of which roughly 75% is at-risk rather than fixed.20 The annual cash bonus is tied to organic sales growth. The long-term performance-based restricted stock units are weighted 50% to relative organic sales growth, 30% to relative net income growth, and 20% to free cash flow productivity, with a relative total shareholder return modifier.20
That is a genuinely growth-and-cash-disciplined structure. Note what is not in it: no revenue-scale metric that rewards acquisitions for their own sake, no EBITDA target that could be met by capitalizing costs, and free cash flow productivity as a discrete component — which is the metric most resistant to accounting manipulation. If you were designing a compensation plan to discourage empire-building at a mature staples company, it would look something like this.
The place where alignment gets thinner is ownership. For a 39-year employee and seven-year chief executive, Wallace's personal shareholding runs in the range of roughly 362,000 to 400,000 shares — on the order of 0.05% of shares outstanding.20 That is not a trivial sum in dollar terms, but it is a small stake relative to the equity that has passed through his hands over seven years of vesting, and it is consistent with a vest-and-sell pattern rather than with accumulating a compounding personal position. It is worth naming directly rather than assuming alignment from tenure alone. An executive who sells as it vests is optimizing the compensation plan; an executive who holds is betting alongside shareholders. The disclosure supports the former reading.
Guidance discipline, tested against the record
The most useful window into a management team is the gap between what they said would happen and what did.
The negative data point is the third quarter of 2025, when Colgate cut guidance in-quarter, lowering its organic sales range — partly attributable to the Hill's private-label exit, which was a known and disclosed factor, and partly to the softness in the pet category described in Section V.4 An in-quarter cut is a real credibility cost regardless of the explanation, because it means the guidance set roughly ninety days earlier was wrong.
The more interesting data point runs the other way. Colgate beat expectations in both the first and second quarters of 2026 and did not raise full-year guidance.126 On the second-quarter call, Wells Fargo's Chris Carey pressed management directly on why.6 The answer cited volatility in North American demand — a concrete, specific reason rooted in the destocking dynamic rather than a generic invocation of macro uncertainty.
Weigh those two behaviours together and the picture is of a management team that is conservative with the guidance range and willing to give a real reason when challenged, which is the better end of the staples-sector distribution. It is not, however, evidence of forecasting accuracy — declining to raise after two beats is prudent, but it is also what a team does when it does not trust its own visibility into the second half.
The restructuring treadmill
Here is the pattern that deserves the most scrutiny, because it is the kind of thing that hides in plain sight.
Colgate's 2022 Global Productivity Initiative concluded at the end of 2024. It was immediately followed by a new Strategic Growth and Productivity Program, approved in mid-2025, with roughly $300 million earmarked toward supply chain and efficiency work.21 In April 2026 that program was expanded again, with cumulative estimated charges now running $350 million to $550 million.12
One restructuring program rolling directly into the next, with no gap, is worth naming as a pattern rather than accepting as normal. There are two readings and an investor should hold both. The charitable one: this is continuous self-funded reinvestment, where each program's savings finance the next round of capability building, and the accounting charges are simply the honest recognition of costs that a less transparent company would bury. The sceptical one: a company that cannot hit its efficiency targets without repeated special charges is using restructuring accounting to keep adjusted earnings looking cleaner than reported earnings, indefinitely.
The evidence does not cleanly settle it. What tilts the sceptic's way is that reported operating margin fell to 16.2% in fiscal 2025 while the company was mid-program, and that the second program was expanded rather than completed on its original terms.112 What tilts the other way is the record cash generation — net cash provided by operations of $4.198 billion in fiscal 2025, which is not the profile of a company papering over an operating problem.2 The reasonable conclusion is that the restructuring cadence is a legitimate flag on management's efficiency-target-setting, not evidence of accounting manipulation.
Governance friction, weighed rather than over-indexed
Two data points, both real, neither dramatic. Say-on-pay approval dipped to roughly 86.7% at the 2024 annual meeting — the most notable compensation dissent in the company's recorded voting history, though still a comfortable pass rather than a rejection — before recovering into the low 90s at subsequent meetings.20 And in 2025, a shareholder proposal from the National Legal and Policy Center seeking to strip diversity criteria from director selection went all the way to a vote and was defeated by roughly 97% to 3%.22
That second item is worth a sentence of interpretation. Several large-cap peers quietly settled or negotiated similar proposals off their ballots in the same period. Colgate took it to a vote and won overwhelmingly. That is a governance-process data point in the company's favour — a board willing to let shareholders decide rather than manage the ballot — though it is not evidence of an activist campaign and should not be inflated into one.
On that subject: no Elliott, Trian, or comparable activist involvement in Colgate-Palmolive surfaced in the research for this piece. That is an absence of finding across the public record reviewed, not a confirmed clean bill of health, and it should be read as the former.
Where the record is straightforwardly strong
Shareholder returns are the least ambiguous part of the file. Colgate has paid dividends without interruption since 1895 and has increased them for 63 consecutive years.2 In March 2025 the board approved a new $5 billion share repurchase authorization alongside a 4% dividend increase, and in fiscal 2025 the company returned $2.9 billion to shareholders through dividends and buybacks.2 There is no evidence in the last two decades of dilutive equity issuance — a company generating over $4 billion of annual operating cash flow has had no need of it.2
That is the paradox of the Wallace era in one paragraph: capital returned to shareholders has been exemplary and consistent. Capital deployed into growth, in the single largest instance, has been written off. Both are true, and an investor has to hold them simultaneously.
Narrative consistency across the calls
One more test, because it is the cheapest reliable read on management credibility: does the story change depending on the quarter?
Tracking Colgate's language from the third quarter of 2025 through the second quarter of 2026, the answer is mostly no, which is a point in management's favour. The pet category was described as sluggish in late 2025 and the Hill's growth ambition was framed against a 3–5% target rather than quietly abandoned.45 North America was described as unsatisfactory rather than reframed as a temporary comparison issue.6 The tariff exposure was quantified in 2025 and then updated with a specific guidance change in 2026 rather than folded into a vague inflation narrative.1112 And the skin health impairment came with a plainly stated cause — weak category growth and weak performance in China — rather than a euphemism.15
That consistency matters more than it might appear. The classic warning sign in a decelerating consumer company is a management team that discovers a new explanatory framework every quarter: first it is weather, then it is retailer inventory, then it is a competitor's promotional intensity, then it is consumer sentiment. Colgate's explanations have stayed on the same three or four mechanisms across four consecutive calls, and the mechanisms are ones an outsider can independently check. That does not make the strategy right. It does mean the disclosure can be taken at close to face value, which is not a given in this sector.
Where the credibility gap remains is prescriptive rather than descriptive. Management has been clear and consistent about what is wrong. It has been considerably less specific about what structurally changes to fix North America beyond surgical pricing, productivity savings, and innovation — the same three levers every staples company reaches for. A specific plan when things go wrong is the highest bar for management assessment, and on the domestic business, that bar has not yet been cleared.
IX. Playbook: Business & Investing Lessons
Strip the 218 years down to transferable principles and five things stand out.
Distribution is the moat; innovation is just the key that opens the door. The collapsible tube, MFP fluoride, twelve-hour protection — each was a genuine innovation, and each bought Colgate perhaps a decade of differentiation before competitors matched it. What competitors could not match was a hundred years of building routes to market across two hundred countries, into retail formats ranging from Walmart to a single-shelf shop in rural Brazil. Innovation in consumer staples is temporary; physical and relational distribution compounds. When evaluating any consumer company, the question is not "is the product better" but "could a well-funded competitor reach the same customers." For Colgate's emerging-market positions, the honest answer is still mostly no. For its U.S. position, where the customer is reached through a handful of retailers who have their own store brands, the answer is increasingly yes.
The professional gatekeeper is an underrated moat-construction technique — and it fails in a specific way. Dentists for toothpaste, veterinarians for pet food, dermatologists for skincare: in every case Colgate inserted an expert intermediary between itself and a consumer who could not evaluate the product independently. This creates something stronger than brand preference, because the consumer has outsourced the decision entirely. But note the failure mode revealed by Hill's in 2025: a gatekeeper moat protects you from competitors, not from the category shrinking. When fewer households own dogs, or own smaller dogs, the veterinarian's recommendation is worth exactly as much as before and generates less revenue anyway. Moats built on capturing demand do nothing when demand itself contracts.
Boring, habitual, low-ticket categories generate extraordinary margins for a reason — and that same reason is now the vulnerability. A consumer buys toothpaste roughly monthly, spends a few dollars, and does not comparison-shop. Low absolute price means low price sensitivity; high frequency means the brand relationship is reinforced constantly; low involvement means switching requires an active decision the consumer has no reason to make. That is the engine of 60%-plus gross margins across a century. But low involvement cuts both ways. A consumer who never thinks about toothpaste is not loyal — they are inattentive. If the store brand sits at eye level and the Colgate is on the bottom shelf at twice the price, inattention works against the incumbent. Private label is not winning an argument. It is winning by default, one facing at a time.
Premiumization M&A is not automatically accretive just because the target has a premium price point. The Filorga lesson is specific and worth generalizing: the deal thesis was about category and margin, but the risk was about geography and channel. Chinese consumer demand and travel retail turned out to be a single correlated exposure wearing two hats, and when both went at once there was no diversification inside the asset at all. When a staples company buys into an adjacent premium category, the diligence question is not "is this category growing" — it is "what single macro variable does the entire cash flow depend on."
Complexity has a carrying cost, and restructuring programs are how it gets paid. Running four categories across more than two hundred countries and territories requires an organizational overhead that periodically has to be pruned. The tension worth watching is between financial-engineering-style restructuring — charges that flatter adjusted earnings while the underlying cost base creeps back — and genuine reinvestment that shows up as sustained margin improvement. The test is simple and takes years: does reported operating margin, not adjusted, trend up across a full program cycle? For Colgate, the fiscal 2025 answer was no, though the impairment distorts it. The fiscal 2026 and 2027 answers are the ones that will settle the question.
Those lessons set up the formal competitive analysis, where the pieces have to be assembled into a single view.
X. Porter's Five Forces, 7 Powers, and the Bull vs. Bear Case
Moat structure through the 7 Powers lens
Hamilton Helmer's framework asks which specific, durable advantage prevents a competitor from arbitraging away a company's returns. Colgate has two that are genuinely present and one that is contested.
Scale economies are real and mostly durable. A company doing $20.4 billion of sales spreads manufacturing, R&D, and — most importantly — advertising across a volume base no regional competitor can match.1 Advertising in particular has step-function economics: a national television campaign costs the same whether you have 5% share or 40%, so the leader's cost per share point is structurally lower. This power is strongest in emerging markets, where the fixed cost of building distribution is enormous and Colgate paid it a century ago.
Branding — Helmer's term for the durable premium a consumer pays because of habit and trust rather than measurable product difference — is the core Colgate power and the one now under visible pressure. It remains overwhelming in Latin America, where the brand is near-generic. It is intact but eroding at the margin in North America, where the evidence from Section IV is that share leadership has passed to Crest on tracking data and store brands are gaining. Branding power does not collapse; it decays, and the decay is measured in share points per year.
Switching costs are the contested one. Consumer staples have no contractual or technical switching cost — only habit. Habit is a real barrier, but it is the weakest form, and it can be broken by something as mundane as a shelf reset.
What Colgate does not have, and this matters: no network effects, no cornered resource (the formulations are not proprietary in any defensible way), no process power of the kind Toyota built, and no counter-positioning — the company is the incumbent, so counter-positioning works against it, not for it.
Porter's five forces
Buyer power is the dominant force and it is rising. Colgate's buyers are not consumers; they are Walmart, Amazon, and the mass and club channels. These are concentrated, sophisticated purchasers with full visibility into category economics and the ability to commission private-label alternatives from contract manufacturers. This single force explains most of the North America story: share erosion, shipment declines against positive consumption, and shelf-space reallocation are all expressions of buyer power being exercised.
Threat of substitutes in the traditional sense is low — nothing replaces toothpaste — but private label functions as a permanent, structurally advantaged substitute. The store brand does not need to be as good; it needs to be adequate and cheaper, sitting adjacent to the branded product, in a category the consumer does not think about.
Rivalry is intense but stable and largely rational among the branded players: Procter & Gamble in oral care and North America, Unilever in emerging-market personal care, Church & Dwight and Kimberly-Clark in value and price positioning. These are disciplined competitors who generally compete on innovation and advertising rather than price wars. The caveat from Section IV applies throughout — this competitive map is analyst-constructed, because management rarely names any of these companies directly on calls.5
Supplier power is moderate and cyclical, driven by commodity inputs — palm oil derivatives, resins, packaging, agricultural protein for Hill's — plus, in the current period, the tariff regime, which functions economically as a supplier price increase the company cannot negotiate.1112
Threat of new entrants into mainstream oral care is low; into premium and direct-to-consumer niches, meaningful but individually small.
The bull case
Global toothpaste share of 41.3% is a position of genuine structural dominance that no competitor is close to.1 The two highest-margin parts of the portfolio — Latin America and Hill's — are both businesses where the moat mechanism is understood and largely intact. Cash generation is exceptional and demonstrably converted to shareholder returns rather than empire-building, with $4.198 billion of operating cash flow and $2.9 billion returned in fiscal 2025.2 The compensation structure is tied to organic growth and free cash flow productivity rather than to scale, which is the correct design for a mature staples company.20 And the base business — stripping out the impairment — grew: organic sales rose 1.4% and base business EPS rose 3% in fiscal 2025.2 The underlying machine did not break; the acquisition did.
The bear case
North America is losing share simultaneously to a branded rival and to private label, and the company's response so far has been surgical pricing rather than a structural answer.16 Hill's is decelerating on management's own characterization, in a category management itself calls sluggish, with a self-inflicted two-point growth headwind still to lap.4 Roughly $1.49 billion has been written off against a $1.69 billion premiumization acquisition in six years, and the second write-down came with no exogenous excuse attached.117 Tariff and input-cost pressure is concentrated in the weakest region, compounding rather than offsetting the competitive problem.12 The most profitable geography carries a documented history of sovereign and currency losses, including a $1.058 billion after-tax deconsolidation charge.10 And restructuring-program-on-restructuring-program, now expanded to $350–550 million of cumulative estimated charges, is at minimum a flag on management's ability to set efficiency targets it can actually hit.1221
The activist's angle
What would a skeptical concentrated investor press on? Three things, most likely. First, portfolio complexity: a company running oral, personal, and home care across five geographies plus pet nutrition plus skin health has three quite different businesses stapled together, and the skin health piece has now destroyed capital twice — a separation argument writes itself. Second, disclosure: the company does not break out private-label share pressure, U.S. category dynamics in detail, or skin health segment economics in a way that lets outsiders assess the recovery, which forces investors to rely on tracking data and trade reporting. Third, accountability: two impairments on the same asset under the same chief executive, with a compensation structure whose long-term metrics — organic sales growth, net income growth, free cash flow productivity — do not obviously penalize a value-destroying acquisition.
Risk radar, with mechanisms
Tariffs: an unnegotiable cost-of-goods increase, roughly $200 million estimated in 2025, with a further gross-margin guidance cut in 2026, concentrated in the region least able to absorb it.1112 Latin America FX and sovereign risk: the mechanism is currency devaluation compressing dollar-translated profits, with deconsolidation as the tail outcome — the Venezuela precedent sits directly under roughly a quarter of segment operating profit.101 Category demand softness: in U.S. pet food, the mechanism is pet ownership and pet size, both outside company control.4 Private-label substitution in commoditized personal and home care: the mechanism is retailer shelf allocation, and the company's leverage is its willingness to fund promotion. Execution risk in the still-unfolding Strategic Growth and Productivity Program: the mechanism is that savings targets missed become either margin pressure or another charge.12
The KPIs that matter
Three, and only three, are worth tracking closely.
U.S. toothpaste market share. This is the single cleanest test of whether the brand power that underwrites the entire valuation is decaying or stabilizing. Stabilization would suggest the Crest crossover was a competitive blip; continued erosion would suggest the U.S. moat is structurally thinner than assumed.
Hill's organic volume growth, excluding the private-label exit. Volume specifically, because the private-label divestiture and pricing will both distort the reported sales line for several more quarters. Getting back into the stated 3–5% band on volume would confirm the category softness was cyclical.
North America organic volume, separate from price/mix. The distinction between growing and harvesting. Price-only growth with negative volume, sustained, is the profile of a brand being monetized on the way down.
XI. Epilogue & Reflections
Two hundred and eighteen years is a long time to sell soap.
The company that William Colgate started in 1806 has outlived the tallow trade, the candle business, the collapse of the shared toothpaste jar, two world wars, the Great Depression, the hyperinflation of half a dozen currencies, the loss of an entire national subsidiary, the rise of television advertising and its subsequent decline, the arrival of e-commerce, and the transformation of retail from thousands of independent grocers into a handful of buyers with more data about Colgate's shoppers than Colgate has. Any one of those could plausibly have ended it. None did.
What that survival record actually demonstrates is narrower than it first appears. It does not prove that habit-driven consumer brands are permanently durable — plenty of them are not, and the graveyard of once-dominant household names is well populated. What it demonstrates is that a business built on repeat purchase of a low-cost necessity, distributed everywhere, and continually reinvested in, can absorb an enormous amount of external shock without breaking. Durability of this kind is not immunity. It is a very large shock absorber.
And that is the honest tension to leave with. In a single fiscal year, Colgate-Palmolive's moat was stress-tested in two directions simultaneously, and the results came back mixed rather than reassuring. In its home market, the oral care franchise — the most iconic consumer position the company owns — lost the category-tracking lead to a rival it has been fighting since the 1950s, while store brands took shelf space underneath. And the flagship premiumization acquisition, the answer to the question of what a mature staples company does with its cash, was written down for a second time, this time with management citing its own weak performance rather than a pandemic.
Both of those happened at a company that simultaneously generated record operating cash flow, grew its base business, extended a 63-year dividend increase streak, and maintained a global category share no competitor approaches. That is not a contradiction; it is what a mature, high-quality, structurally challenged business looks like from the inside. The cash flow is real and the erosion is real, and they will coexist for years.
What resolves the ambiguity is not narrative but data, and the data arrives quarterly. Whether U.S. toothpaste share stabilizes or keeps sliding. Whether Hill's gets its volume back into the 3–5% band management has pointed to, or whether the pet category's softness turns out to be a demographic change rather than a cycle. And whether the Strategic Growth and Productivity Program is the last restructuring of this cycle — the one that finally right-sizes a two-century-old organization for a concentrated-retail world — or simply the next link in a chain that has no obvious end.
The habit machine still runs. The question that the next several years will answer is whether the habit belongs to Colgate, or merely to brushing.
XII. Recent News
Fiscal 2025 results, reported January 30, 2026. Net sales rose 1.4% to $20.382 billion, with organic sales also up 1.4%.2 Fourth-quarter net sales increased 5.8% to $5.230 billion on organic growth of 2.2%.2 GAAP earnings per share fell 25% to $2.63 on the skin health impairment, while base business EPS rose 3% to $3.69.2 Net cash provided by operations reached a record $4.198 billion and the company returned $2.9 billion to shareholders.2 Reported operating margin declined from 21.2% to 16.2%.1
The skin health write-down. The fourth quarter of 2025 carried a $919 million pre-tax non-cash impairment — $244 million against trademarks, $93 million against customer relationships, and $582 million against goodwill — equating to $794 million after tax, attributed by management to lower than expected category growth and weaker than expected performance, particularly in China.1223
Tariffs and margin guidance, April 2026. New tariffs finalized on April 29, 2026 prompted a gross margin guidance reduction on the first-quarter 2026 earnings call, with management characterizing the vast majority of the impact as landing in North America.12 This followed the roughly $200 million of estimated tariff cost disclosed during 2025 alongside a cut to sales and profit guidance.11
Restructuring program expanded, April 2026. The Strategic Growth and Productivity Program, approved in mid-2025 following the conclusion of the 2022 Global Productivity Initiative at the end of 2024, was expanded, taking cumulative estimated charges to a range of $350 million to $550 million.1221
Chief executive commentary, April 2026. Wallace appeared on CNBC to discuss reinventing the company, framing the current period around innovation and productivity rather than portfolio change.19
Second-quarter 2026 results, reported July 2026. Colgate exceeded consensus earnings expectations with sales in line, but did not raise full-year guidance despite having also beaten in the first quarter — management cited North American demand volatility when pressed by Wells Fargo's Chris Carey on the call.624 U.S. shipments were down 3% against consumption up 1%, and management described domestic performance as not satisfactory.6
Hill's Pet Nutrition. The Prime100 acquisition closed in April 2025 for approximately AU$471 million, and the resulting Fresh line has been rolled out on a measured basis.8 The exit from private-label pet food manufacturing continues to carry an estimated 2 to 2.3 percentage point drag on Hill's reported growth.4
XIII. Links & Resources
- Colgate-Palmolive Investor Relations
- FY2025 Form 10-K — SEC EDGAR
- Colgate-Palmolive Company Announces 4th Quarter and Full Year 2025 Results
- 2025 Proxy Statement (DEF 14A) — SEC EDGAR
- FY2021 Form 10-K — SEC EDGAR
- Our History — Colgate-Palmolive
- Q4/FY2025 Earnings Call Transcript — The Motley Fool
- Q3 2025 Earnings Call Transcript — The Motley Fool
- Q1 2026 Earnings Call Transcript — Investing.com
- Q2 2026 Earnings Call Transcript — Investing.com
References
-
Colgate-Palmolive Company Form 10-K, fiscal year ended December 31, 2025 — SEC EDGAR ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Colgate-Palmolive Company Announces 4th Quarter and Full Year 2025 Results — Colgate-Palmolive, 2026-01-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Colgate-Palmolive (CL) Q3 2025 Earnings Call Transcript — The Motley Fool, 2025-11-01 ↩↩↩↩↩↩↩↩↩↩
-
Colgate-Palmolive (CL) Q4 2025 Earnings Call Transcript — The Motley Fool, 2026-01-30 ↩↩↩↩↩↩
-
Earnings call transcript: Colgate-Palmolive tops Q2 2026 EPS view as sales meet forecasts — Investing.com, 2026 ↩↩↩↩↩↩↩↩↩
-
Colgate-Palmolive Company Invests in Growth of its Hill's Pet Nutrition Business with Agreement to Buy Three Manufacturing Plants from Red Collar Pet Foods — BusinessWire, 2022-08-01 ↩↩
-
Colgate-Palmolive Company Announces Agreement to Acquire Prime100 — BusinessWire, 2025-02-13 ↩↩
-
Hill's Pet Nutrition battles "sluggish" pet category — Pet Food Processing ↩
-
Colgate-Palmolive Swings to a Loss on Venezuela-Related Charges — Fox Business, 2015 ↩↩↩
-
Colgate Cuts Sales, Profit View as Tariffs Add $200 Million Cost — Bloomberg, 2025-04-25 ↩↩↩↩↩
-
Earnings call transcript: Colgate-Palmolive Q1 2026 beats forecasts, stock rises — Investing.com, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩
-
Colgate Purchasing Tom's of Maine; Enters Fast-Growing Natural Products Segment — Colgate-Palmolive, 2006 ↩
-
Colgate Completes Purchase of Tom's of Maine — Colgate-Palmolive, 2006 ↩
-
Colgate Announces Acquisition of PCA Skin and EltaMD Skin Care — Colgate-Palmolive, 2017 ↩
-
Colgate Announces Agreement to Acquire Laboratoires Filorga — Colgate-Palmolive, 2019 ↩↩
-
Colgate-Palmolive Records $518M Filorga Impairment, Launches Global Savings Initiative — Citeline, 2021 ↩↩↩↩
-
Colgate-Palmolive Company Form 10-K, fiscal year ended December 31, 2021 — SEC EDGAR ↩
-
Colgate-Palmolive CEO Noel Wallace on reinventing a 220-year-old American icon — CNBC, 2026-04-02 ↩↩↩↩
-
Colgate-Palmolive Company Proxy Statement (DEF 14A) — SEC EDGAR, 2025 ↩↩↩↩↩
-
Colgate-Palmolive earmarks $300M for supply chain, efficiencies — Supply Chain Dive ↩↩↩
-
National Legal and Policy Center shareholder proposal materials (PX14A6G) — SEC EDGAR, 2025 ↩
-
Colgate-Palmolive reports full-year 2025 sales growth as impairment weighs on GAAP earnings — Global Cosmetics News ↩
-
Colgate Announces 2nd Quarter 2026 Results — Colgate-Palmolive, 2026 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube