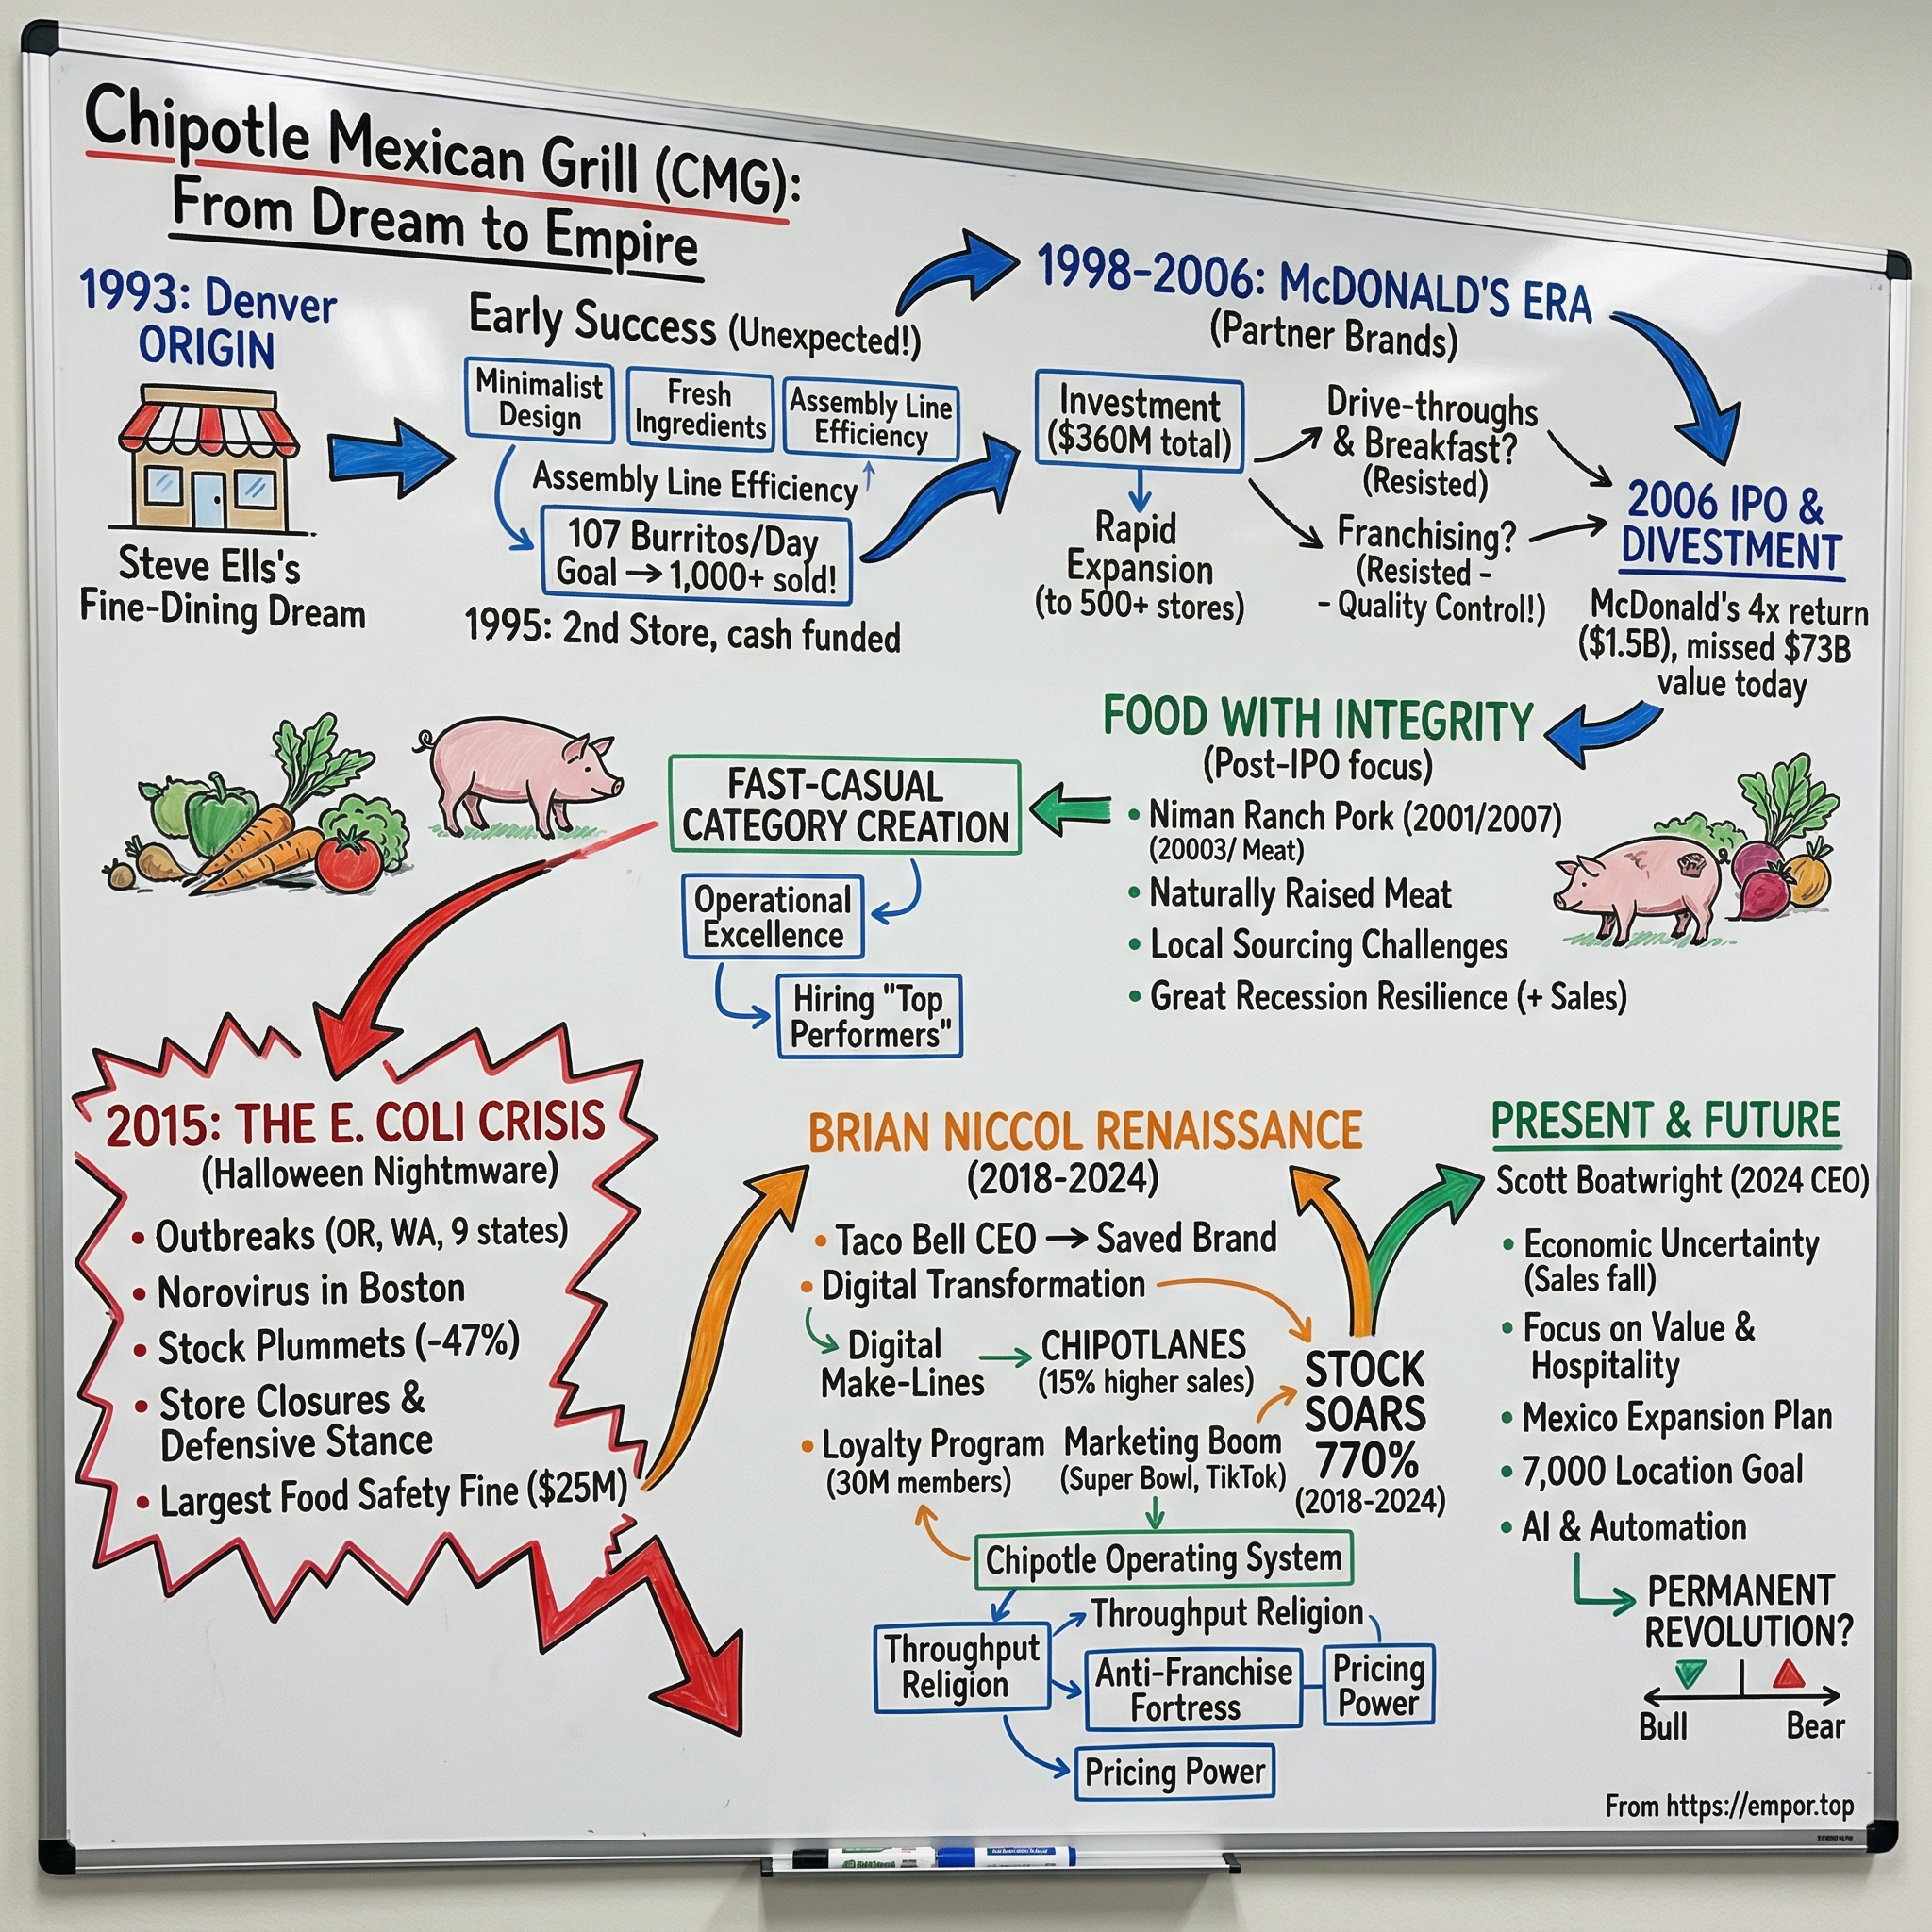
Chipotle Mexican Grill: The Burrito Machine That Forgot How to Grow
I. Introduction & Cold Open
On June 18, 2024, Chipotle Mexican Grill closed at an all-time high. The company had just executed a 50-for-1 stock split — one of the largest in the history of the New York Stock Exchange — timed, in the words of then-CFO Jack Hartung, to a moment when "our stock is experiencing an all-time high driven by record revenues, profits, and growth."1 The split's record date was that very day. Restaurant general managers and twenty-year crew members received one-time equity grants. It was a victory lap dressed as a capital-markets housekeeping item, and it was entirely earned: Chipotle had gone from near-death in 2016 to one of the most admired operating stories in American consumer business.
Fifty-six days later, on August 13, 2024, the architect of that comeback walked out. Brian Niccol — Chairman and CEO, the man who had arrived from Taco Bell in 2018 to a company still bleeding from a food-safety catastrophe — resigned to become Chairman and CEO of Starbucks.2 There was no succession runway, no eighteen-month handoff. The board named Chief Operating Officer Scott Boatwright interim CEO the same day.
Now hold that image next to a second one. In February 2026, Chipotle reported that full-year 2025 comparable restaurant sales had declined 1.7% — the company's first annual comp decline since 2016, the year of the E. coli wreckage. Transactions fell 2.9% for the year; only a 1.2% higher average check kept the number from being worse.3 Bill Ackman's Pershing Square, which had disclosed a 9.9% position in February 2025 on a thesis of a differentiated brand with "enormous growth opportunity and visionary leadership,"4 was gone — the entire remaining 21.5-million-share stake liquidated by year-end 2025 and confirmed to the market in early 2026.5 Chipotle shares, which had closed above $68 on a split-adjusted basis at that June 2024 peak, traded in the high-$30s in late August 2026, for a market capitalization near $49 billion. Roughly $30 billion of equity value had evaporated in two years without a single outbreak, recall, scandal, or accounting problem.
That is the puzzle this story is about. Nothing broke at Chipotle. No one got sick at scale. The balance sheet carries no debt worth discussing. Restaurants kept opening. What happened instead is more interesting and, for long-term investors, more consequential: a business whose entire equity story rested on a single compounding engine — build more units, grow sales at existing units, push more entrées through the line per hour — discovered that one of those three cylinders had stopped firing, and nobody could say with confidence when it would restart.
The roadmap ahead: the founding and the McDonald's years, told fast, because they are mostly prologue — though the argument the two companies had in the early 2000s turns out to be the argument Chipotle is still having with itself today. Then the 2015–2018 food-safety collapse, which was not one bad quarter but a multi-year systems failure that ended in the largest criminal food-safety fine in U.S. history. Then the Niccol renaissance, the era investors remember and are now implicitly asking whether they can get back. And then the real center of gravity: the 2024–2026 transition, slowdown, and attempted repair under Boatwright, where the live investment debate actually sits.
The throughline is simple to state and hard to answer. Chipotle is a single-format, company-operated restaurant compounding machine — no franchisees, no second brand, no meaningful international P&L, one menu architecture executed roughly 4,200 times a day. Every era of this story is a referendum on whether that machine's growth engine still works. Which brings us to the beginning, and to a young cook in Denver who never actually wanted to be in the fast-food business.
 Subscribe on LinkedIn
II. Origins: From Culinary Dream to McDonald's Bet (1993–2006)
Steve Ells had a plan, and the plan was not burritos. He had trained at the Culinary Institute of America in Hyde Park, New York, cooked in San Francisco, and wanted to open a proper fine-dining restaurant. What he needed was capital. What he had was an idea he'd absorbed watching the taquerias of San Francisco's Mission District, where an assembly line, a steam table, and a foil wrapper turned raw ingredients into a hot, cheap, enormous meal in about ninety seconds.
So in 1993 he borrowed $85,000 from his father and opened a burrito shop in a converted Dolly Madison ice cream store a few blocks from the University of Denver campus.6 The two of them ran the numbers and concluded the store needed to sell 107 burritos a day to break even. Within a month it was selling more than a thousand.7 The fine-dining restaurant never got built. Chipotle Restaurant No. 1 is still open.
It is worth pausing on what actually made that first store work, because the operating DNA has barely changed in thirty-three years. Ells's insight was not "fresh ingredients" — plenty of restaurants had those. It was that a narrow menu with a wide number of permutations could deliver the perceived variety of a full-service restaurant at the labor cost of fast food. The customer thinks they are ordering a customized meal. The kitchen is actually cooking a fixed set of roughly a dozen components in bulk, in-house, every morning, and then assembling them to order in front of the guest. Fixed prep, variable assembly. That is the trick.
The financial consequence of that trick is a P&L that looks different from a traditional quick-service restaurant. Because the food is prepared in each restaurant rather than shipped in from a central commissary, Chipotle runs a structurally high food cost — food, beverage and packaging consumed 29.7% of revenue in the second quarter of 20268 — and pays for it with a smaller building, a shorter menu, less equipment, and volume. High food cost, high volume, high throughput. It is the inverse of the McDonald's model, which is exactly why what happened next was so strange.
In 1998, McDonald's took a minority stake in Chipotle — a company with barely more than a dozen Denver locations — and over the following seven years invested roughly $360 million in total, taking majority and eventually near-total ownership while the chain expanded from about 14 restaurants to more than 500.9 For a period, the largest hamburger company on earth owned around 90% of the fastest-growing burrito company on earth, and had no idea what to do with it.
The friction was cultural and it was specific. McDonald's had spent half a century learning that the way you make money in restaurants is through drive-throughs, breakfast dayparts, franchisees, and supply-chain centralization. Ells resisted all of it. A drive-through, in his view, broke the theater of watching your food get made. Breakfast broke the ingredient discipline. Franchising broke control over execution. Every one of those refusals cost near-term profit dollars. Every one of them is now recognizable as the reason the format held together.
McDonald's exited through Chipotle's January 26, 2006 IPO at $22 a share — the stock opened at $44 — and completed its divestiture later that year, realizing roughly $1.5 billion on that $360 million.10 By the conventional standard of private-equity arithmetic, a four-bagger in seven years is a triumph. By the standard of what came next, it stands as one of the more expensive exits in corporate history. Chipotle's equity value would multiply many times over in the following two decades.
The reason this history matters in 2026 is not nostalgia. It is that the single-format discipline forged in that argument is the same discipline management is defending right now, under a new kind of pressure. When same-store sales stall, the obvious levers a restaurant CEO reaches for are the ones Ells refused: add a daypart, add a format, add a franchise partner to absorb local risk and fund local growth. Chipotle has taken none of those doors — a choice that preserved the coherence of the model and simultaneously removed every shock absorber. When traffic falls at a company that operates 100% of its own restaurants, there is no franchisee balance sheet to share the pain. It is all on the P&L, immediately.
That vulnerability had already been demonstrated once, catastrophically, less than a decade after the IPO.
III. Food with Integrity, the E. Coli Collapse, and the Long Rebuild (2006–2018)
In the years after the IPO, Chipotle built something rarer than a growth story: a moral position. "Food with Integrity" committed the company to naturally raised meat, responsibly sourced produce, and — critically — cooking in every restaurant rather than reheating from a plant. It was genuine differentiation. In a category where the competitive frontier was speed and price, Chipotle competed on the proposition that the food was actually better, and charged accordingly. Customers agreed. Between 2006 and 2015 the company compounded revenue relentlessly and became the reference point for an entire new category: fast casual.
But there was a bill attached to that position, and it came due in the autumn of 2015. Decentralized fresh preparation means that thousands of hourly employees, in thousands of kitchens, are performing food-safety-critical tasks — washing produce, holding proteins at temperature, staying home when sick — every single day, with no central kill step. A commissary model concentrates risk in a handful of facilities you can audit continuously. Chipotle's model distributed it across the entire fleet.
Between October and December 2015, that distributed risk converged. E. coli outbreaks linked to Chipotle restaurants spread across multiple states. A norovirus incident at a Boston location sickened 141 people, including members of the Boston College basketball team.11 The financial response was immediate and brutal. Fourth-quarter 2015 comparable restaurant sales fell 14.6%.12 For full-year 2016, comps declined 20.4% and revenue fell 13.3% to $3.9 billion.13 The company that had earned $476 million of net income in 2015 reported $22.9 million in 2016 — a 95% collapse in a single year, with the restaurant fleet still growing.
Here is where the standard version of this story usually turns triumphant, and where it deserves to be interrupted. The comfortable narrative is that 2015 was a tail event, that Chipotle rebuilt its food-safety systems into a competitive moat, and that the crisis is therefore a closed chapter. The company's own admissions say otherwise.
In April 2020, Chipotle entered a three-year deferred prosecution agreement with the U.S. Department of Justice, admitting to a charge of adulterating food and paying a $25 million criminal fine — at the time the largest ever imposed in a U.S. food-safety case.14 The DPA did not cover one incident. It covered a pattern spanning 2015 to 2018: the Boston norovirus outbreak, a 2016 norovirus outbreak in Simi Valley, California, a 2017 norovirus outbreak in Sterling, Virginia that sickened more than 135 people, and a 2018 Clostridium perfringens outbreak in Powell, Ohio that affected 647 people. In total, more than 1,100 people were sickened across the covered incidents. The admitted failures were mundane and repeated: food held outside safe temperature ranges, and sick employees who were not sent home despite written policy requiring it.
That record does real damage to any claim that food safety became a Chipotle moat. A moat implies a capability competitors cannot replicate. What the 2015–2018 sequence actually demonstrates is that decentralized fresh preparation carries a permanent, structural food-safety liability that must be continuously bought down with spending, training, testing, and management attention — and that Chipotle failed to buy it down for three consecutive years after the crisis that should have concentrated the mind completely. The honest framing is narrower: food-safety infrastructure at Chipotle is now a large, ongoing cost of doing business and a table-stakes competence, not a source of advantage. The company's own 2025 Form 10-K concedes the ceiling, stating that "even strong preventative controls and interventions from farm to restaurant cannot completely eliminate food safety risks."15 Investors should treat that sentence as the company's own upper bound on the claim.
Steve Ells stepped down as CEO in late 2017, moving to executive chairman, and Chipotle recruited Brian Niccol from Yum! Brands' Taco Bell division in February 2018.16 The exit was framed politely, but the substance was clear enough: the crisis had exposed two distinct gaps. One was systems — the operational plumbing to enforce safety and consistency across thousands of units. The other was leadership — a founder whose genius was culinary and conceptual, running a company whose binding constraint had become industrial-scale execution.
What genuinely changed operationally after 2015 is verifiable in outline: enhanced food-safety protocols, high-resolution DNA-based testing of produce, and the elevation of food safety to a named executive portfolio. What remained rhetoric is harder to separate, and the 2016–2018 outbreak record suggests the protocols took years to actually bind at the store level rather than the policy level.
The recovery, when it came, took roughly three years from trough to a fully restored traffic base — long, expensive, and requiring a criminal settlement to close out. That timeline is worth holding onto, because it establishes something important for the present moment: Chipotle has proven it can recover from a shock. A poisoning scare gives customers a specific reason to leave and, once resolved, no reason to stay away. What the company has never before had to prove is that it can recover from a drift — a slow, unglamorous erosion of value perception and habit with no single event to point at and no single fix to announce. That is precisely the problem of 2025. But before the drift, there was the greatest operating run in the company's history.
IV. The Niccol Turnaround: Digital, Discipline, and a Compounding Machine (2018–2024)
Brian Niccol arrived at Chipotle in March 2018 carrying a specific reputation: at Taco Bell he had run the marketing and product machine that made a value brand culturally relevant, and he thought in terms of systems and dayparts rather than recipes. He inherited a company where the food was still excellent, the brand was damaged but not dead, and the operations were, by his own later description, running with the parking brake on.
His diagnosis was that Chipotle's problem was not demand — it was capacity and access. The line was long, the line was slow, and there was exactly one way to buy a burrito: stand in it.
Three changes followed, and together they rebuilt the company. First, digital ordering was treated as a first-class channel rather than a nuisance. Second — and this is the piece that made the first one work — Chipotle installed a second make-line in the back of house, dedicated exclusively to digital orders. This is a genuinely elegant piece of operations design and worth explaining plainly: a single assembly line serving both walk-in guests and app orders forces the two demand streams to compete for the same seconds. Add a second line and the restaurant can serve two customer bases in parallel without either slowing the other, which means the same four walls can generate materially more revenue at high incremental margin, since the rent and the manager are already paid for.
Third, the Chipotlane: a drive-through lane with no menu board and no speaker, used solely to hand over orders placed on the app. This is the joke of the whole story, if you like your history ironic. Chipotle's founder had fought McDonald's for years over drive-throughs. Two decades later the company's best unit-economics innovation was a drive-through — just one that inverted the logic, using the lane for pickup rather than ordering, and thereby capturing the convenience without the menu-board bottleneck Ells had objected to.
The results compounded. Revenue grew from $5.59 billion in 2019 to $11.31 billion in 2024 — a doubling in five years.17 Net income over the same span went from $350 million to $1.53 billion, a more than fourfold increase, because the digital and throughput investments dropped through to margin rather than simply funding growth. Restaurant-level operating margins recovered into the high-20s percent range, and digital sales scaled to roughly a third of food and beverage revenue. This was the period that established the "beat and raise" reputation Chipotle's current management inherited and has since spent.
The Chipotlane deserves the sharpest analytical treatment here, because it remains the single clearest evidence-backed unit-economics advantage in the story. Roughly 80% of the company's new restaurants are now built with one, a mix management reaffirmed in its 2026 development guidance of 350 to 370 openings.18 The logic is not mysterious: a Chipotlane-equipped unit captures suburban pickup and commuter demand that a walk-in-only unit simply cannot reach, at modest incremental build cost on a site that was going to be built anyway. It is real, it is measurable, and it is the honest core of the bull case on new-unit economics.
It is also, importantly, a format advantage rather than a competitive one. Nothing prevents a peer from building the same lane. What Chipotle has is a several-year head start and a real-estate pipeline organized around it.
Then, at the top, the architect left. Niccol's departure to Starbucks was announced on August 13, 2024, effective within weeks — not on a planned succession timeline but mid-flight, at the company's high-water mark.19 For investors, this is the cleanest available lesson in the entire story about how to weight "management quality" as a thesis input. Pershing Square's own filing language six months later would name "visionary leadership" as a pillar of the investment case.20 Visionary leadership is a single-person asset with an unhedgeable departure risk, and it left.
And here the falsification test on management strength gets sharper, because the bench was thinner than the growth story implied. On July 9, 2024 — five weeks before Niccol's exit — Chipotle had already announced that CFO Jack Hartung, who had held the role for more than two decades and was as close to an institutional memory as the company possessed, would retire in 2025.21 Within a span of months, Chipotle lost both its CEO and its CFO. Both roles were filled with continuity in mind: Boatwright from the COO seat, and Adam Rymer, a fifteen-year internal veteran and Hartung protégé, as CFO.
Continuity hires are defensible. But the market treated the double transition as a manageable personnel event in the second half of 2024, and it was not repriced until operating results forced the issue through 2025. The claim "Chipotle has a deep management bench" was not tested by the 2024 announcements; it was tested by what the company did in the eighteen months after, with the two architects gone and the playbook running on autopilot.
V. 2024–2026: The Boatwright Era, the Slowdown, and Ackman's Round Trip
Scott Boatwright did not come up through culinary or marketing. He spent roughly two decades at Arby's, finishing as a senior vice president of operations responsible for more than 1,700 restaurants, before joining Chipotle in 2017 as chief restaurant officer in the immediate aftermath of the food-safety crisis.22 He is, by background and temperament, an operator: throughput, staffing models, training, retention. He was named interim CEO in August 2024 and made permanent in November of that year, and joined the board.23
That choice told you what the board believed the problem was. Hiring an operator rather than a brand-builder or a strategist was a bet that the Niccol playbook was correct and simply needed to be run harder. Rymer's appointment as CFO from within, effective at the start of 2025, doubled down on the same premise. Continuity by design — and simultaneously a wager that the prior decade's assumptions still held without the two people who had authored them.
The first crack had actually appeared before either of them took the chair, and it came from TikTok.
The portion problem
Beginning in the spring of 2024, videos circulated showing Chipotle employees serving what customers judged to be visibly smaller portions, sometimes filmed with the phone pointed at the make-line to encourage a heavier hand. The company's initial public posture was denial.24 Then, on the Q2 2024 earnings call in July, Niccol partly conceded the ground: there had been no directive to serve less, he said — "generous portion is a core brand equity" — while acknowledging that more than 10% of restaurants had portion-consistency problems requiring retraining.25
A shareholder class action followed in November 2024, alleging that Chipotle had understated customer dissatisfaction over portions in its risk disclosures. It has not gone away: Chipotle's second-quarter 2026 Form 10-Q still discloses the Stradford securities class action alleging false and misleading statements regarding portion sizes, together with consolidated derivative suits, and states that it is "not possible at this time to reasonably estimate" the outcome or potential liability.26 Anyone summarizing this episode as resolved is ahead of the filings.
The dollars at stake in that litigation are almost certainly immaterial to a company generating over $2 billion of operating income. The signal is not. A brand whose entire value proposition is "you get a lot of very good food for around ten dollars" had just spent a summer arguing with its own customers about the first half of that sentence — and had done so from a defensive crouch. Value perception, once dented, does not repair on the schedule of a press release.
2025: three cuts, in management's own words
The 2025 deterioration is best read through management's own progressive revisions, because the pattern is the analytical content.
By the third-quarter call on October 29, 2025, Chipotle had cut full-year comparable-sales guidance for the third consecutive quarter — moving from an expectation of roughly flat comps to a projected decline in the low single digits.27 Third-quarter comps came in at just 0.3% on revenue of $3.0 billion, with restaurant-level margin down about 100 basis points to 24.5%.
Boatwright's explanation on that call was consumer-driven and, notably, not competitive: research indicated that low- and middle-income guests were reducing frequency because of economic and inflationary pressure, not because they were defecting to rivals. Weakness was concentrated in households earning under $100,000 — roughly 40% of Chipotle's sales — and among 25-to-35-year-olds. He also made an admission that is more damaging than the macro framing, because it is squarely within management's control: digital order accuracy, he said, "has fallen off" after changes to restaurant incentive plans, and the bonus structure was being redesigned to weight accuracy over speed.27
That is a self-inflicted wound with a paper trail. The company changed how it paid its restaurant managers, the change degraded the thing customers notice most about a digital order — getting what they asked for — and it took a full year of transaction declines before the incentive was fixed. It is the strongest single piece of evidence for the bull reading that 2025 was an execution problem rather than a demand problem. It is also a direct mark against the proposition that operational excellence is an embedded Chipotle capability rather than something that requires constant, competent tending.
The full-year scorecard arrived on February 3, 2026: comparable sales down 1.7%, transactions down 2.9%, revenue of $11.93 billion — up 5.4%, but entirely on new units — and net income of $1.54 billion, essentially flat against 2024 on a larger base.28 Guidance for 2026 opened at approximately flat comparable sales.29 This is the crux of the deceleration, and it comes from management, not from analysts: a company whose long-term model requires mid-single-digit comps to hit its unit targets was publicly guiding to zero.
Ackman's round trip
Pershing Square's disclosure of a 9.9% stake in early February 2025 was, in the moment, read as validation. Ackman described a strong brand with a differentiated offering, an enormous growth opportunity, visionary leadership, and an undervalued stock, and signaled intent to engage with the board on composition, operations, and cost structure.30
Roughly twelve months later, the position was gone — the remaining 21,541,177 shares disposed of by December 31, 2025 and disclosed publicly in early 2026 — after fourth-quarter comps fell 2.5% on a 3.2% transaction decline.31 The stated exit logic was blunt: this had become a traffic problem, and traffic problems are structural until proven otherwise.32
It would be easy to score this as a celebrity investor's bad quarter. The more useful reading is about visibility. Pershing Square is a concentrated, research-intensive investor that spent months of diligence before taking a nearly 10% position in a business with no debt complexity, no segment opacity, and one product. And it still could not see twelve months forward. That tells you something durable about this particular business: because Chipotle sells a discretionary ten-dollar lunch to a broad consumer base with zero contractual commitment, its near-term earnings are genuinely low-visibility. There is no backlog, no subscription, no contract. Every quarter is re-underwritten by roughly a hundred million discrete purchase decisions.
2026: the stabilization attempt
Under the banner "Recipe for Growth," Boatwright's team spent 2026 running an unglamorous list: fix throughput, fix accuracy, fix value perception, add menu news.
The first quarter, reported April 29, 2026, delivered a return to positive transactions — comps up 0.5%, with transactions contributing about 60 basis points and check slightly negative, on revenue up 7.4% to $3.1 billion.33 Modest, but directionally the thing that mattered.
The second quarter, reported July 29, 2026, was better. Comparable sales rose 2.2%, composed of a 1.0% transaction gain and 1.2% higher average check. Revenue grew 9.3% to $3.35 billion. Digital sales reached $1.3 billion, or 38.3% of food and beverage revenue, up from 35.5% a year earlier. The company opened 100 new company-operated restaurants in the quarter, 80 with a Chipotlane, ending the period with 4,186 company-operated and 15 partner-operated restaurants. Full-year comparable-sales guidance was raised to low-single-digit growth.34
Three operational specifics sit underneath that improvement, and each deserves to be assessed on its own evidence rather than accepted as a package.
The high-efficiency equipment package — referred to on calls as HEEP — is a back-of-house hardware refresh: a dual-sided plancha that cooks chicken and steak faster and more consistently, a three-pan rice cooker allowing white and brown rice simultaneously with less waste, and a higher-capacity fryer for chips at peak.35 Management reported reaching 1,000 equipped restaurants with a target of 2,000 by the end of 2026, and stated that equipped locations produce two to three more entrées than the enterprise average during peak fifteen-minute windows.36 The measurement to watch is that it is a peak-window metric. Two to three extra entrées in the busiest quarter-hour is precisely where incremental capacity converts into sales, because that is the window in which customers actually balk and leave. It is a credible, quantified, physically grounded claim — and it is also self-reported, non-audited, and unaccompanied by a disclosed control group.
The "linebacker" — a dedicated crew member who restocks the line and expedites rather than assembling — exceeded 70% of restaurants for the first time in the second quarter, per Boatwright.36 This is a labor-cost decision as much as a throughput one: staffing an extra body during peak is money spent to protect speed.
The loyalty relaunch, "Rewards on Repeat," went live on April 13, 2026. Its design is notable for what it did not do. Where most loyalty overhauls in this period devalued points, Chipotle's relaunch was additive: points now stay alive with one qualifying purchase per year instead of expiring after 180 days of inactivity, monthly free-food "Freepotle" promotions returned, and a selectable birthday reward was added, against a base of more than 21 million active members.37 By the second quarter the company reported 23 million active members and daily enrollment up nearly 20% since the relaunch.36
That loyalty disclosure also contains the most interesting unresolved number in the whole quarter. Management noted that in-restaurant reward scanning reached only about 20%, versus roughly 90% attachment on digital orders.36 Roughly six in ten Chipotle transactions still happen in the restaurant, and on the large majority of those, the company does not know who the customer is. That is a genuine, addressable gap in the data asset that underpins any personalization or frequency strategy — and it means the "20 million member" figure is a weaker demand signal than it sounds, because it captures the digital-native customer far better than the walk-in one.
Two things should temper the whole 2026 recovery read. First, the comparison base. A +2.2% comp is being measured against a quarter in a year when comps declined 1.7% and transactions fell 2.9% — the two-year stack is still negative. Second, margins moved the wrong way even as sales improved: restaurant-level operating margin contracted 220 basis points year over year to 25.2%, and operating margin fell to 15.7% from 18.2%, with GAAP diluted EPS flat at $0.32.38 Chipotle grew revenue 9.3% and grew earnings per share by zero. Food, beverage and packaging costs rose 80 basis points as a share of revenue, other operating costs rose 90, labor rose 30.39 Some of that is the linebacker. Some is wage inflation and bonus accrual. All of it means the throughput initiatives are currently being funded out of margin, and the return on them has not yet shown up below the restaurant-margin line.
Then, in late July 2026, an industry-wide Cyclospora scare softened traffic again. Rymer quantified the drag at roughly 200 basis points and guided third-quarter comps to around 1% assuming it persists.36 Chipotle's own supply was not implicated, which is precisely the point worth drawing: a company built on fresh, distributed produce preparation carries category-level headline risk it cannot fully control, and a single unrelated pathogen story can erase a quarter of hard-won traffic recovery in weeks.
Which sets the single most important discipline for anyone following this story. Comparable sales dollars have been carried by pricing throughout this period; traffic has been the actual problem. The number to track is transaction growth, not comp growth. Whether the second quarter's +1.0% was durable execution repair or a one-quarter bounce against a soft base is, as of September 2026, genuinely unresolved.
To judge that, it helps to understand what kind of business is doing the recovering.
VI. The Core Business: Industry Structure, Competition, and Unit Economics
Strip away the brand and the story, and Chipotle is a startlingly simple industrial object. Its 2025 Form 10-K states the position plainly: the company manages U.S. operations across eleven regions and "aggregate[s] our operations to one reportable segment."15 There is no second brand to cross-subsidize the first, no franchise royalty stream, no consumer packaged goods line. At the end of 2025, 3,938 of Chipotle's restaurants were in the United States, against 104 company-operated and 14 partner-operated internationally — international was under 3% of the fleet and immaterial to the P&L.15 The company employed 130,301 people, of whom 127,116 worked in the U.S.
So when we discuss Chipotle's growth, we are discussing exactly three variables: how many American restaurants exist, how much each one sells, and what margin it holds. Everything else is commentary.
The category Chipotle invented, and who moved in
Chipotle did not just win fast casual; it defined the grammar. Line up at one end, choose a base, choose a protein, walk down the line adding components, pay at the other end. That grammar has since been adopted by essentially every serious entrant in the category, which is the central competitive fact of this decade.
Qdoba is the closest format twin — the same Mexican build-your-own architecture at a materially smaller footprint, and the least strategically interesting competitor precisely because it is the most similar and has never achieved comparable scale. Sweetgreen competes for the same higher-income urban lunch customer with a salad-first menu. Taco Bell, under Yum! Brands, has pushed upmarket through Cantina formats and relentless menu velocity, attacking Chipotle's value flank from below.
The most instructive comparison, though, is Cava — and it is instructive in a way that cuts against the easy version of the bull case, so it is worth getting the numbers exactly right.
Cava crossed $1 billion of revenue for the first time in fiscal 2025, reporting $1.17 billion, up 22.5%, driven principally by 130 net new restaurant openings. Its full-year same-restaurant sales grew 4.0%, of which 2.4 points came from menu price and product mix and 1.6 points from guest traffic.40 Set against Chipotle's -1.7% comp and -2.9% transactions, that is a genuine and meaningful gap: over the full year, a direct fast-casual peer grew traffic while Chipotle lost it. That is the strongest single piece of evidence that 2025 was Chipotle-specific rather than category-wide, and it deserves its weight.
But the same disclosure narrows the claim considerably. In Cava's fiscal fourth quarter, same-restaurant sales grew just 0.5% — and that was composed of 1.9 points of menu price and product mix offset by a 1.4% decline in guest traffic.40 Cava's restaurant-level margin also fell 100 basis points to 21.4% on delivery mix, tariff-driven food costs, and wage investment. By the end of 2025, in other words, the healthiest fast-casual growth story in America was also posting negative traffic and compressing margins.
That materially changes the conclusion. The claim "Chipotle's 2025 slowdown was purely self-inflicted, because the category was fine" survives for the full year but breaks down in the exit rate. The revised, defensible version is this: Chipotle underperformed its best peer by roughly 450 basis points of traffic across 2025, which is company-specific and is the correct measure of the execution gap — but by the fourth quarter the whole fast-casual category was seeing consumers pull back, meaning some portion of the problem was never Chipotle's to fix. The forward test is straightforward and observable: if Chipotle's transaction growth converges toward or above Cava's over the coming quarters, the execution-repair thesis is confirmed; if both track together at low or negative levels, the constraint is category demand and no amount of linebacker staffing solves it.
Unit economics: where the model still works
The single healthiest part of Chipotle's business remains new-unit development, and it is important to say so plainly given how much of this story is a critique. A new Chipotle restaurant requires an investment in the low-to-mid single-digit millions, and Chipotlane-equipped units — roughly 80% of the current build — generate higher average unit volumes than non-Chipotlane sites.34 Against restaurant-level margins in the mid-20s, that produces returns on invested capital that most restaurant developers would trade a great deal for.
The company is building 350 to 370 restaurants a year against a stated long-term goal of 7,000 restaurants in the U.S. and Canada.1534 From a base above 4,000, that path requires sustained development in the high-single-digit percentage range for the better part of a decade. Nothing observed in 2025 or 2026 suggests the development machine has broken — openings continued at pace straight through the comp decline, which is itself evidence that site-level returns remain attractive enough to justify the capital.
This is the real structural point about Chipotle's growth algorithm, and it is easy to miss: with roughly 8% annual unit growth, the company can deliver mid-to-high-single-digit revenue growth with zero comparable-sales contribution. That is exactly what 2025 demonstrated — revenue up 5.4% on comps down 1.7%. Unit growth is the engine that still fires. What comps do is determine whether that revenue growth converts into earnings growth, because comp dollars fall through to margin at very high incremental rates while new-unit revenue arrives carrying its own full cost structure. In 2025 and again in the first half of 2026, revenue grew and EPS did not. That is the arithmetic of a business running on one cylinder.
The cost side, and the limits of pricing
Chipotle's input basket is unusually exposed to things it cannot control. Beef and chicken costs, freight, and — newer to the story — tariffs. Management has flagged roughly 30 to 50 basis points of tariff-related cost-of-sales headwind, reflecting beef sourced partly from Australia and avocados from Colombia and Peru. On the third-quarter 2025 call, Rymer described inflation accelerating into the mid-single digits, driven primarily by tariffs and beef.27 By the second quarter of 2026 the picture had improved somewhat, with third-quarter inflation expected near 3% against pricing in the mid-2% range — a cost-price gap that is narrowing but has not closed.36
The strategically interesting decision is what management did not do. Facing mid-single-digit inflation in late 2025, Chipotle chose to roll off two points of price in early December rather than price through it.27 Read that against the portion controversy and the transaction declines and the logic is obvious: management concluded that its value perception was the binding constraint and that further price increases would deepen the traffic hole rather than fill the margin one.
That is a defensible call, and it is also an admission with real analytical content. Pricing power is the cleanest test of brand strength in restaurants. A brand with genuine pricing power passes through inflation and holds traffic. Chipotle, in 2025, concluded it could not — and its margins have absorbed the difference ever since, which is exactly what the 220-basis-point restaurant-margin contraction in the second quarter of 2026 represents. The company is currently buying traffic with margin. Whether that is a temporary investment or the new equilibrium is the open question, and the answer shows up in whether restaurant-level margin stabilizes in the mid-20s while transactions stay positive.
Why it wins, and why it might not
The affirmative case rests on three mechanisms with actual evidence behind them: the largest fresh-preparation supply chain in the category, which buys scale advantages in sourcing that a 400-unit competitor cannot match; the Chipotlane throughput and access advantage, backed by a multi-year build head start; and a digital and loyalty stack now handling nearly four dollars in ten.
The case against is one sentence long, and it is structural. Chipotle has no switching costs. A customer who chooses Cava or Qdoba or a Taco Bell Cantina on Tuesday pays no penalty, forfeits nothing, and can return on Wednesday with no friction. There is no contract, no installed base, no data lock-in, no ecosystem. The entire bull case therefore reduces to execution — speed, portion consistency, accuracy, value perception — and 2025 established, with an unusual degree of documentary clarity, that execution at Chipotle can erode within a few quarters when incentives are set wrong.
That places an extraordinary weight on the people setting those incentives.
VII. Management: Incentives, Capital Allocation, and Credibility Under Pressure
There is a particular kind of pressure that comes from being the person who took over from a legend, and Scott Boatwright has been operating under it since August 2024. The board's choice of an Arby's-trained operations executive over an outside brand-builder was not neutral; it encoded a specific view of what Chipotle needed. Adam Rymer's promotion from within — fifteen years at the company, trained directly by Hartung — encoded the same view a second time.41
The generous reading is stability: two executives who know the operating model intimately, taking over a proven playbook without the disruption of an outsider's re-founding. The skeptical reading is harder to dismiss. Continuity hires are, by construction, unlikely to challenge the assumptions that produced the plan they inherited — and 2025 produced three consecutive guidance cuts against those assumptions. If the forecasting framework was wrong, the people who built it are not the obvious candidates to find the error.
Guidance discipline as a credibility ledger
Track the 2025 sequence as a management-behavior record rather than a set of numbers. Chipotle entered the year with a growth outlook, revised down, revised down again, and revised down a third time by October, finishing with a full-year comp decline against an original expectation of growth. Boatwright's framing on the third-quarter call — that consumer trends had become genuinely difficult to predict — was candid, and the accompanying explanation was reasonably specific: pressure concentrated in sub-$100,000 households and in the 25-to-35 cohort, driven by unemployment, resumed student-loan repayment, and weak real wage growth.27
Give credit where it is earned. That is a more concrete answer than most consumer management teams give when they miss, and management did volunteer the self-inflicted portion — the incentive-driven decline in digital order accuracy — rather than hiding behind the macro. Volunteering an unforced error is a meaningful positive signal about disclosure culture.
But three cuts in four quarters is still three cuts. It means the forecasting apparatus that produced the initial 2025 outlook was substantially wrong about a business the incumbent team had run for years. The relevant test now is whether the 2026 guidance behaves differently. Management entered 2026 guiding to approximately flat comps — conservative on its face — and raised to low-single-digit growth after the second quarter.34 That raise came shortly before the Cyclospora-driven traffic softening in late July that Rymer sized at roughly 200 basis points.36 The company has therefore already raised into a quarter it then had to caveat. Whether 2026 closes without a cut is the single cleanest observable test of whether guidance discipline has actually been restored, and it will be answerable within two quarters.
Capital allocation: buybacks, no dividend, and what that means
Chipotle generates a great deal of cash and returns essentially all of the surplus through repurchases. In the second quarter of 2026 alone the company repurchased $630.7 million of stock at an average price of $32.55 per share, bringing first-half repurchases to $1.33 billion at an average of $34.35, with $1.68 billion of authorization remaining.39 Against a $49 billion market capitalization, buying back well over $1 billion in six months is a serious commitment of capital.
Two observations follow, and they point in different directions.
The favorable one: buying in the mid-$30s during a period when the stock traded between roughly $28 and $43 over the trailing year is, at minimum, not obviously value-destructive, and stands in contrast to the many companies that repurchase most aggressively at peaks. The company also carries no meaningful debt burden, held $667.1 million of cash and marketable investments at the end of the second quarter, and has an undrawn $500 million credit facility.39 There is no balance-sheet fragility here and no refinancing risk worth flagging.
The unfavorable one: Chipotle has never paid a dividend, and management continues to prefer reinvestment plus repurchases. That was straightforwardly correct when the company was compounding comps at mid-single digits and could redeploy every dollar at high returns. It is a harder position to defend when comps are flat to negative and the development pipeline consumes only a fraction of operating cash flow. The activist-style question — and it is a fair one — is whether a company with decelerating same-store growth and enormous free cash flow generation should be returning capital in a form that imposes external discipline, rather than concentrating the entire allocation decision in the hands of a leadership team that has not yet completed a full cycle of proving itself. Management's continued refusal is a genuine capital-allocation stance, and it deserves to be pressure-tested on calls rather than accepted as tradition.
Cultivate Next, Hyphen, and Autocado: optionality, correctly discounted
Since 2022, Chipotle has run Cultivate Next, a venture fund initially capitalized at $50 million and later doubled to $100 million, investing in restaurant technology.42 Two bets get the most attention.
Autocado is a cobot that cuts, cores, and peels avocados — roughly 26 seconds per avocado — before crew hand-mash them into guacamole. The Augmented Makeline, built by Hyphen, automates the assembly of bowls and salads on a lower line while crew build burritos, tacos, and quesadillas on top; the design logic is that nearly 65% of Chipotle's digital orders are bowls or salads, so automating that subset addresses both labor intensity and digital order accuracy.42 Both entered restaurant pilots in September 2024, in Huntington Beach and Corona del Mar, California respectively. Hyphen's pilot makeline has been reported to hit 350 meals per hour at 99% accuracy in testing, and Chipotle made a further investment in Hyphen alongside Cava late in 2025.43
Now apply the discipline that this kind of story requires. As of late 2025, roughly $25 million of the fund had been deployed into Hyphen, the augmented makeline remained in single-digit-location pilot and refinement — one San Jose unit was pulled back for modification — and neither system had been shown to move revenue or margin at fleet scale.43 A pilot at 350 meals per hour is a technical milestone. It is not commercialization.
Chipotle's own record on converting non-core initiatives into P&L impact argues strongly for discounting this heavily. The company launched ShopHouse Southeast Asian Kitchen and closed all fifteen locations in 2017; opened a burger concept, Tasty Made, and closed its only location in 2018; wound down its Pizzeria Locale fast-casual pizza chain, closing the last five locations in 2023; and launched Farmesa in 2023 and closed it in 2024.44 That is four separate format ventures, four wind-downs, across two management regimes. None of them was large enough to damage shareholders. All of them are evidence about the same organizational capability the automation program requires: taking a promising non-core idea from pilot to scale.
The calibrated conclusion is not that automation will fail — the operating logic is far sounder than a pizza chain, since it strengthens the core format rather than diversifying away from it, and that distinction matters. It is that the historical conversion rate from Chipotle pilot to Chipotle scale is poor, so this belongs in the investment case as unpriced future optionality with a wide distribution of outcomes, not as a driver of the next three years' margins. The event that would change that assessment is specific and observable: a disclosed multi-hundred-unit rollout commitment with quantified labor-hour or margin impact. Until then, it is a pilot.
Governance and the say-on-pay signal
Chipotle's proxy statement filed April 28, 2026 discloses meaningful board and management turnover across the transition period — Hartung's retirement as CFO, Curt Garner's expansion to President and Chief Strategy and Technology Officer, Jason Kidd joining as Chief Operating Officer, and the November 2025 election of Carnival Corporation CEO Josh Weinstein to the board.41 The compensation committee also retained Meridian Compensation Partners as a new independent consultant in 2025.
Two things are worth flagging honestly. First, the specific say-on-pay support percentage from the 2025 annual meeting is not disclosed in the sections of the 2026 proxy reviewed here, so no vote margin should be asserted. Second, the proxy does describe substantial off-season shareholder outreach specifically to discuss the 2025 annual meeting results including the say-on-pay vote, and it did retain a new compensation consultant in the same year. Companies that receive comfortable say-on-pay support typically do not organize outreach programs around explaining it. That is an inference, not a fact, and it should be verified against the 2025 annual meeting Form 8-K rather than assumed — but it is the kind of governance signal that tends to appear when shareholder patience is thinning alongside earnings misses.
Compensation and governance are one place where the company's relationship with its stakeholders gets tested. Labor is another, and there the record is more concrete.
VIII. Labor, Trust, and Regulatory Risk
In the summer of 2022, workers at the Chipotle in Augusta, Maine did something no Chipotle crew had done before: they filed a petition with the National Labor Relations Board to hold a union election. On the day the NLRB hearing on that petition was scheduled to begin, Chipotle closed the restaurant and terminated the staff.
The company's stated reason was staffing difficulty. The NLRB Region 1-Boston office pursued unfair labor practice charges alleging the closure and terminations were unlawful retaliation, and on March 24, 2023 the Regional Director approved a settlement: $240,000 in backpay and front pay to 24 employees, preferential hiring for any Chipotle opening in Maine, and the posting of a notice advising employees of their rights under the National Labor Relations Act at 40 stores across Chipotle's Northern New England sub-region.45[^46]
Accuracy matters on the characterization here, because it is often overstated. This was a settlement, not an adjudicated finding of illegality. Chipotle did not admit wrongdoing and denied that union avoidance motivated the closure, stating that it settled "not because we did anything wrong, but because the time, energy and cost to litigate would have far outweighed the settlement agreement."46
Even at that lower evidentiary bar, the episode belongs in any serious assessment of Chipotle's culture, because the facts are undisputed regardless of motive: the first store in company history to seek a union election was permanently closed on the day of its NLRB hearing, and the matter was resolved with a six-figure payment and a notice posting across 40 restaurants. A company that describes its people practices as a strength should expect that sequence to be weighed against the claim.
The economics behind that friction are not going away. Chipotle operates every one of its U.S. restaurants directly. That is the source of its execution consistency and the reason the brand held together through two crises — and it also means the company absorbs 100% of labor-cost risk, with no franchisee network across which to distribute wage inflation, scheduling regulation, or minimum-wage legislation. California's fast-food wage rules are the sharpest current example, and the pressure is structural rather than cyclical: labor consumed 25.0% of revenue in the second quarter of 2026, up 30 basis points year over year even as management pushed throughput initiatives designed in part to improve labor efficiency.39 A franchised peer facing the same wage law watches its franchisees' margins compress; Chipotle watches its own.
Food safety sits in the same category of permanent, structural cost. Since the deferred prosecution agreement, food safety has reported into a senior executive portfolio — Laurie Schalow serves as Chief Corporate Affairs and Food Safety Officer — and the company has invested in enhanced testing and supplier protocols. What is verifiably different is the organizational elevation and the testing regime. What has not changed, and cannot within this format, is the underlying exposure: fresh produce, distributed preparation, thousands of hourly employees making judgment calls about temperature and personal health every day. The late-July 2026 Cyclospora episode illustrated the residual risk perfectly — Chipotle's supply was not implicated, and traffic still took a roughly 200-basis-point hit.36
None of these are reasons the business cannot work. They are reasons the business is more capital- and management-intensive than its simple format suggests, and they explain part of why the company has been so reluctant to complicate the model further. Which makes the one area where it has complicated the model worth examining carefully.
IX. International and New Formats: Real Optionality, Correctly Sized
In July 2026, a Chipotle opened in Monterrey, Nuevo León — the first restaurant the company has ever operated in Mexico.36 There is an obvious joke available about a Denver-invented, San Francisco-inspired, thoroughly American interpretation of Mexican food arriving in Mexico three decades late, and management has been careful not to make it. The Monterrey opening came through a development agreement with Alsea, the Latin American restaurant operator, signed in April 2025, with Mexico City targeted for 2027.47
The wider international map has filled in quickly, and it is worth laying out precisely because the structure is more interesting than the scale. In the Middle East, Chipotle operates through Alshaya Group, the Kuwait-based franchise operator, which has built 17 restaurants across the Gulf since 2024 — seven in the UAE, seven in Kuwait, two in Qatar, and, on August 13, 2026, the first in Saudi Arabia at Sidra in Riyadh, with Bahrain and Jeddah flagged for 2027.48 In Asia, Chipotle announced its first entry in September 2025 through a joint venture with SPC Group, the Korean food conglomerate.49 Company-operated international restaurants — principally Canada and the United Kingdom — numbered 104 at the end of 2025, and management reported high-single-digit comparable sales growth in Europe in the second quarter of 2026.1536
Now the sizing, which is the entire analytical point. Against roughly 4,200 restaurants, the international footprint is a rounding error, and 2026 guidance contemplates only 10 to 15 international openings out of 350 to 370 total.34 There is no plausible arithmetic under which international moves Chipotle's consolidated P&L this decade.
So why does it belong in the story at all? Two reasons, both structural rather than immediate.
First, it is the pressure-release valve on the 7,000-unit North American target. A company that intends to saturate its home market within a decade must eventually answer the question of what comes after saturation, and the honest time to build international capability is while the domestic engine still funds it — not after growth has already stopped. Second, the chosen structure is genuinely capital-efficient: partner-operated restaurants with Alshaya, Alsea, and SPC place the buildout capital and local operating risk on partners with deep regional real-estate and regulatory expertise, while Chipotle contributes brand and system. Fifteen partner-operated restaurants worldwide at mid-2026 represent a small amount of Chipotle capital at risk relative to the option being purchased.38
The counterweight belongs in the same paragraph as the claim, not in a distant risks section. Chipotle's history of format and concept diversification is a string of wind-downs — ShopHouse, Tasty Made, Pizzeria Locale, Farmesa — and while international expansion of the core format is a categorically different exercise from launching a pizza chain, the relevant organizational muscle is partly the same: taking a Chipotle idea outside the American burrito store and making it work at scale. The company has not yet demonstrated that muscle. It is also relevant that the partner-operated structure that limits Chipotle's capital at risk equally limits its operational control, in a business where the company's own thesis holds that operational control is the moat.
The defensible conclusion is narrow: international is real, early, structurally sensible, and correctly designed to be cheap — and it is optionality, not a growth vector that moves earnings this decade. It should be assigned close to zero weight in any near-term valuation and monitored through one observable: whether partner-operated openings accelerate materially past the current 10-to-15-per-year pace, which would indicate the partners are seeing returns worth pressing.
Zoom out from the individual bets, and the shape of the whole thirty-three-year story starts to resolve into something more useful than a chronology.
X. Playbook: Durable Lessons
Format discipline is a moat — and a leash. Chipotle's refusal to add drive-throughs and breakfast under McDonald's ownership, and to franchise after 2015, kept one operating model coherent for three decades and produced the consistency that made the brand. It also removed every diversifier. When a single format's traffic softens, there is no second daypart to lean on, no franchise partner co-investing through the downturn, and no other brand carrying the quarter. The 2025 comp decline flowed straight to the consolidated line with nothing between it and shareholders. Discipline and concentration are the same decision viewed from opposite ends of the cycle.
Crisis recovery is possible, slow, and expensive — and it is a different problem from decline. The 2015 collapse took roughly three years, a leadership change, and a $25 million criminal fine to move past. But a poisoning scare has a discrete cause and a discrete resolution; customers leave for a reason and come back when the reason is gone. The 2025 slowdown had no such event. Nobody boycotted Chipotle. People simply came slightly less often, for a mix of reasons — value perception, order accuracy, wage pressure on their own budgets — that no press release can address. There is no evidence in Chipotle's history that it has previously solved that second kind of problem, because it has never previously had it.
Digital compounds only when in-restaurant execution holds. The Niccol-era build — app, second make-line, Chipotlane — was genuinely transformative, and by 2026 it was moving nearly 40% of food and beverage revenue. It did not prevent a transaction decline. A best-in-class ordering stack routes demand efficiently; it cannot fix an order that arrives wrong or a portion that disappoints. The most telling detail of the entire 2025 episode is that management traced an accuracy decline to its own incentive-plan redesign — the digital asset was working exactly as built, and the humans at the end of it had been paid to optimize for the wrong thing.
Leadership continuity risk is systematically underpriced in real time. In the six weeks between July 9 and August 13, 2024, Chipotle announced the retirement of a 20-plus-year CFO and the abrupt departure of the CEO who had authored its entire modern turnaround. Both facts were public, both were reported, and neither triggered a fundamental repricing. The market repriced eighteen months later, when results made the consequence legible. For investors, the operational lesson is not "sell on CEO departures." It is that when a thesis explicitly rests on management quality — as Pershing Square's did — the departure of that management is not a headline to absorb, it is a change to the thesis itself, and it should be underwritten as one on the day it happens.
Value perception is an operating metric, not a marketing one. The portion controversy of 2024 cost almost nothing in dollars and a great deal in narrative. It arrived through a channel — customer-shot video at the make-line — that no corporate communications function controls, and it was answered first with denial. In a business with no switching costs, the customer's felt sense of whether they got their money's worth is a real-time, unhedged input into next quarter's transactions.
Those lessons set up the structural question directly: given all of it, how strong is this franchise actually?
XI. Power Analysis: Porter's Five Forces & 7 Powers
War-game the industry from the outside, and Chipotle's position resolves into something more nuanced than either the 2023 consensus ("compounder") or the 2025 consensus ("broken") allowed.
Scale economies (7 Powers). Real, and the most durable advantage in the portfolio. At $11.93 billion of revenue and 4,000-plus restaurants, Chipotle buys avocados, beef, chicken, and rice at a scale no fast-casual competitor approaches, and spreads corporate G&A — $652 million in 2025 — across a base an order of magnitude larger than Cava's.17 The qualification is that scale economies in restaurant sourcing flatten out. A 1,000-unit competitor captures most of the available purchasing advantage; the marginal benefit of unit 4,001 over unit 1,001 is small. Cava is demonstrating exactly this as it scales. Real advantage, diminishing slope.
Process power. The strongest genuinely proprietary claim. The assembly-line-plus-Chipotlane-plus-second-make-line system is a compound operating design refined over thirty years and embedded in real estate, training, equipment, and labor models — the kind of thing that is easy to describe, hard to copy exactly, and impossible to copy quickly. The high-efficiency equipment package data point supports it: equipped restaurants producing two to three more entrées in peak fifteen-minute windows is a measured, physical performance gap over the company's own base fleet.36 The qualification is that process power decays without maintenance, and 2025 showed it decaying — the accuracy problem was a process-power failure inside the company's core competence.
Counter-positioning. Substantially weaker than the origin story implies. Chipotle's original counter-position was against traditional QSR: fresh preparation, higher price point, and a business model McDonald's structurally could not adopt without cannibalizing its own centralized supply chain. That position held for two decades. It does not protect against fast-casual peers, because Cava, Qdoba, Sweetgreen, and Taco Bell's Cantina format face no such structural constraint — they have simply built the same model. Counter-positioning against an incumbent is not counter-positioning against a fast follower.
Switching costs and network effects. Thin to nonexistent, and this is the load-bearing weakness of the entire investment case. Loyalty and app habit create preference, not lock-in. The 23-million-member rewards program is a marketing asset, not a moat, and the fact that in-restaurant scan rates run around 20% versus roughly 90% on digital means the program does not even fully observe the majority of transactions.36 There are no network effects of any kind: a burrito bought by one customer makes the product no better for the next. The 2025 transaction decline is precisely what an absence of switching costs looks like in practice — demand walked out with zero friction.
Porter, bear side. Threat of new entrants is high; the format has been fully replicated and capital for restaurant expansion is available. Supplier power is meaningful and asymmetric: beef and avocado costs are set in global markets, tariffs added 30 to 50 basis points of cost-of-sales pressure, and Chipotle's ingredient commitments narrow its substitution options relative to a QSR peer that can reformulate. Buyer power is total — the buyer is a consumer with no contract and unlimited alternatives. Rivalry is intensifying, not stabilizing. And because there are no franchisees, execution risk cannot be diversified across independent operators with their own capital at stake.
Porter, bull side. Chipotle holds the strongest cost position in fresh-prep fast casual, the largest and most refined throughput system, a development pipeline delivering roughly 350 restaurants a year at attractive site-level returns, and a loyalty base above 20 million that the 2026 relaunch is trying to convert from a discount mechanism into a frequency mechanism. Chipotle also retains something the frameworks capture badly: brand meaning. Three decades of association with fresh, generous, made-in-front-of-you food is not a moat in Helmer's sense, but it is a real asset that lowers the cost of every subsequent customer acquisition — provided the operations keep validating it.
The synthesis: Chipotle's powers are operational rather than structural. That is a meaningful distinction. Structural power — regulation, network effects, switching costs, patents — persists through management error. Operational power does not; it must be re-earned every quarter by execution. Chipotle earned it spectacularly from 2018 to 2023, gave some of it back in 2024 and 2025, and is currently attempting to re-earn it. An investor in this business is not buying a fortress. They are buying an execution machine, and underwriting the people running it.
XII. Bull vs. Bear, and What Would We Do
The bull case. The 2025 slowdown was self-inflicted and therefore fixable. The specific failures are documented and named: portion inconsistency that management admitted affected more than 10% of restaurants,25 a digital accuracy decline that management traced to its own incentive redesign,27 and a value perception the company chose to defend by rolling back price rather than pricing through inflation. None of those are secular. All of them have identified owners and observable remedies, and 2026 has shown the remedies working in sequence: transactions turned positive in the first quarter, comps reached +2.2% with +1.0% traffic in the second, the equipment package doubled its footprint toward 2,000 restaurants, and linebacker staffing crossed 70% of the fleet.333436 Cava's full-year 2025 traffic growth of 1.6% against Chipotle's -2.9% decline demonstrates that fast-casual demand itself did not collapse, which locates the problem inside Chipotle where it can be fixed.40 Meanwhile the development engine never stopped — 334 openings in 2025, 350 to 370 guided for 2026 — meaning the business can compound revenue at mid-to-high single digits while the comp problem is repaired.2834
The bear case. The format has no defensible moat against a field that has fully copied it, and the customer pays nothing to leave. Three guidance cuts in one year came from a management team one generation removed from the operators who built the playbook, and the same team has now raised 2026 guidance into a quarter it immediately had to caveat for a 200-basis-point traffic hit. Revenue grew 9.3% in the second quarter of 2026 and EPS grew zero, because restaurant-level margin fell 220 basis points and operating margin fell 250 — the throughput initiatives are currently consuming more margin than they are producing.38 Pricing power, the cleanest test of brand strength, was declined rather than exercised. Capital allocation rests entirely with an unproven leadership team, with no dividend and no external discipline, deploying over $1 billion of buyback in a single half-year. And the automation optionality that features prominently in the narrative sits against a company record of four consecutive format ventures wound down, roughly $25 million deployed into Hyphen, and pilots still measured in single-digit locations.4344 Add the exit of the most visible activist in American consumer investing after a twelve-month round trip, and the market's confidence problem is not irrational.
Weighing it. The strongest evidence for the bull reading is not the 2026 comp recovery — one quarter against an easy base proves little. It is the accuracy-incentive admission, because it is a documented, self-caused, remediable failure of exactly the kind that explains an execution gap rather than a demand collapse. The strongest evidence for the bear reading is not the stock decline. It is that Cava's fourth-quarter traffic also turned negative,40 which means part of the 2025 problem was category demand that no operational fix reaches, and that Chipotle's second-quarter margin compression shows the recovery is currently being bought rather than earned.
The honest verdict is that the history neither rejects nor confirms the turnaround thesis; it narrows it. Chipotle demonstrably retains its development engine and its throughput system. It demonstrably lost, and has not yet convincingly rebuilt, the operational consistency that those assets depend on. The claim that survives the record is the modest one: this is a well-capitalized, structurally simple, cash-generative business with a real format advantage, run by a competent operations team that has not yet completed a full cycle of setting a target and hitting it.
The activist stress test. A skeptical investor arriving today would ask four questions. Why does a company with decelerating comps and enormous free cash flow still refuse a dividend? Why did an incentive-plan change that degraded order accuracy take four quarters to identify and reverse? What is the disclosed, quantified return on the equipment package and linebacker staffing, given that restaurant-level margin has fallen 220 basis points while both scaled? And what specifically would cause management to slow the 350-restaurant-a-year development pace if comps do not recover — or is unit growth now doing the work of masking a comp problem? Management has answered the first three vaguely and the fourth not at all.
What to watch. This is a show-me situation, and the discipline should be narrow. Three KPIs carry nearly all the information:
Quarterly transaction growth — not comparable-sales dollars. Pricing has carried comps throughout this period; traffic is the actual disease. A second and third consecutive quarter of positive transactions would convert the 2026 inflection from a bounce into a trend.
Restaurant-level operating margin — the tell for whether throughput investment is being earned back or merely spent. Recovery toward the high-20s while transactions stay positive would validate the operating case; continued erosion with positive traffic would mean Chipotle is buying its customers back with margin.
Guidance behavior through the full year — whether 2026 closes without repeating the three-cut pattern of 2025. This is the credibility instrument, and it resolves without ambiguity by February 2027.
Everything else — international, automation, catering, Cultivate Next — is optionality that will not move the numbers on this timescale, and treating it as thesis-relevant today is how investors talk themselves past the parts that are.
XIII. Recent News
Q2 2026 results (July 29, 2026). Comparable sales rose 2.2% on a 1.0% transaction increase and 1.2% higher average check; revenue grew 9.3% to $3.35 billion; restaurant-level operating margin fell 220 basis points to 25.2% and operating margin to 15.7% from 18.2%; GAAP diluted EPS was flat at $0.32 on net income of $403.5 million. The company operated 4,186 company-owned and 15 partner-operated restaurants at quarter-end after opening 100 units, 80 with Chipotlanes.343839
Guidance revision. Full-year 2026 comparable-sales guidance was raised to low-single-digit growth from approximately flat, with 350 to 370 new restaurants planned and an effective tax rate of 24–26%.34 On the August 7 call, however, management flagged an industry-wide Cyclospora scare in late July that Rymer sized at roughly 200 basis points of traffic impact, guiding third-quarter comps to around 1% if it persists.36
Throughput rollout. The high-efficiency equipment package reached 1,000 restaurants with a target of 2,000 by year-end 2026; "linebacker" staffing exceeded 70% of restaurants for the first time.36
Automation. Autocado and the Hyphen Augmented Makeline remain in limited pilot rather than fleet rollout, with roughly $25 million of the $100 million Cultivate Next fund deployed into Hyphen as of late 2025.4243
Loyalty. "Rewards on Repeat," launched April 13, 2026, reached 23 million active members by the second quarter with daily enrollments up nearly 20% post-relaunch; in-restaurant reward scanning ran near 20% versus roughly 90% on digital orders.3637
International. The first Mexico restaurant opened in Monterrey in July 2026 through Alsea, with Mexico City targeted for 2027; the first Saudi Arabia restaurant opened in Riyadh on August 13, 2026, bringing the Alshaya-operated Gulf footprint to 17 restaurants, with Bahrain and Jeddah planned for 2027; European company-operated comparable sales grew high single digits in the second quarter.364748
Menu and catering. Chipotle Honey Chicken outperformed prior limited-time offers with an attachment rate above 25%; national catering piloting contributed 2–3% of sales at participating locations, with broader expansion planned for 2027.36
Capital returns. First-half 2026 repurchases totaled $1.33 billion at an average price of $34.35 per share, with $1.68 billion of authorization remaining; no dividend has been declared.39
Litigation. The Stradford securities class action over portion-size disclosures and consolidated shareholder derivative suits remain pending, with the company stating it cannot reasonably estimate outcomes.26
XIV. Links & Resources
- Chipotle Investor Relations
- SEC EDGAR — Chipotle filings (CIK 0001058090)
- Chipotle FY2025 Form 10-K
- Chipotle Q2 2026 Form 10-Q
- Chipotle DEF 14A Proxy Statement, filed April 28, 2026
- Chipotle Q2 2026 earnings press release
- Chipotle Q2 2026 earnings call transcript
- Chipotle Q3 2025 earnings call transcript
- DOJ deferred prosecution agreement coverage — Food Safety News
- NLRB Region 1-Boston settlement announcement
- CAVA Group FY2025 earnings release (peer benchmark)
References
-
Chipotle Mexican Grill Announces 50-for-1 Stock Split — Form 8-K Exhibit 99.1, SEC, 2024-03-19 ↩
-
Chipotle Announces CEO Departure — Chipotle Investor Relations, 2024-08-13 ↩
-
Chipotle Announces Fourth Quarter and Full Year 2025 Results — Chipotle Investor Relations, 2026-02-03 ↩
-
Activist investor picks up stake in Chipotle Mexican Grill — Nation's Restaurant News, 2025-02 ↩
-
Billionaire Bill Ackman Dumped His Fund's Stake in Chipotle — The Motley Fool, 2026-03-11 ↩
-
How Steve Ells built Chipotle Mexican Grill into a burrito empire — CNBC, 2017-11-29 ↩
-
Chipotle Reopens Doors to Restaurant No. 1 Following First Renovation in 24 Years — Chipotle Investor Relations ↩
-
Chipotle Mexican Grill Q2 2026 earnings press release — Form 8-K Exhibit 99.1, SEC, 2026-07-29 ↩
-
McDonald's Once Owned 90% of Chipotle: Why It Sold Its Stake Too Early — Benzinga, 2024-10 ↩
-
McDonald’s Once Owned 90% Of Chipotle: Why It Sold Stake Too Early — Yahoo Finance / Benzinga, 2024-10 ↩
-
Chipotle agrees to pay $25 million federal fine for role in some outbreaks — Food Safety News, 2020-04 ↩
-
Chipotle Mexican Grill, Inc. Announces Fourth Quarter and Full Year 2015 Results — Chipotle Investor Relations, 2016-02-02 ↩
-
Chipotle Mexican Grill Inc — Form 10-K for fiscal year 2016, SEC, 2017-02-07 ↩
-
Chipotle agrees to pay $25 million federal fine for role in some outbreaks — Food Safety News, 2020-04 ↩
-
Chipotle Mexican Grill Inc — Form 10-K for fiscal year 2025, SEC, 2026-02-04 ↩↩↩↩↩
-
Chipotle Names Brian Niccol Chief Executive Officer — Chipotle Investor Relations, 2018-02-13 ↩
-
Chipotle Mexican Grill Inc — annual Form 10-K financial statements, FY2016–FY2025, SEC EDGAR ↩↩
-
Chipotle Raises Full Year Comparable Sales Guidance on Strong Q2 Momentum — Chipotle Investor Relations, 2026-07-29 ↩
-
Chipotle Announces CEO Departure — Chipotle Investor Relations, 2024-08-13 ↩
-
Activist investor picks up stake in Chipotle Mexican Grill — Nation's Restaurant News, 2025-02 ↩
-
Chipotle Announces Retirement of CFO Jack Hartung in 2025 — Chipotle Investor Relations, 2024-07-09 ↩
-
Chipotle Names Restaurant Veteran Scott Boatwright Chief Restaurant Officer — Chipotle Investor Relations, 2017 ↩
-
Chipotle Mexican Grill names Scott Boatwright as permanent CEO — CNBC, 2024-11-11 ↩
-
Chipotle portions haven't shrunk, company says after TikTok criticism — The Washington Post, 2024-05-29 ↩
-
Chipotle denied viral outrage over portion sizes. Now shareholders are suing — Fortune, 2024-11-14 ↩↩
-
Chipotle Mexican Grill Inc — Form 10-Q for the quarter ended June 30, 2026, SEC, 2026-07-31 ↩↩
-
Chipotle (CMG) Q3 2025 Earnings Call Transcript — The Motley Fool, 2025-10-29 ↩↩↩↩↩↩
-
Chipotle Announces Fourth Quarter and Full Year 2025 Results — Chipotle Investor Relations, 2026-02-03 ↩↩
-
Chipotle stock sinks as restaurant chain reports falling traffic, weak guidance — CNBC, 2026-02-03 ↩
-
Activist investor picks up stake in Chipotle Mexican Grill — Nation's Restaurant News, 2025-02 ↩
-
Billionaire Investor Bill Ackman Exits Chipotle Completely, Buys Meta Stock Instead — 24/7 Wall St., 2026-02-13 ↩
-
Facing Losses, Ackman Exits Chipotle and Nike — Institutional Investor, 2026 ↩
-
Chipotle Announces First Quarter 2026 Results — Chipotle Investor Relations, 2026-04-29 ↩↩
-
Chipotle Raises Full Year Comparable Sales Guidance on Strong Q2 Momentum — Chipotle Investor Relations, 2026-07-29 ↩↩↩↩↩↩↩↩↩
-
CMG's Throughput Push Accelerates: Can the High-Efficiency Equipment Package Reshape Store Economics? — Nasdaq, 2026 ↩
-
Chipotle (CMG) Q2 2026 Earnings Call Transcript — The Motley Fool, 2026-08-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Chipotle Relaunches Rewards With "Rewards on Repeat," Delivering More Value Without Trade-Offs — Chipotle Newsroom, 2026-04-13 ↩↩
-
Chipotle Mexican Grill Q2 2026 earnings press release — Form 8-K Exhibit 99.1, SEC, 2026-07-29 ↩↩↩↩
-
Chipotle Mexican Grill Inc — Form 10-Q for the quarter ended June 30, 2026, SEC, 2026-07-31 ↩↩↩↩↩↩
-
CAVA Group Reports Fourth Quarter and Full Year Fiscal 2025 Results — SEC Form 8-K Exhibit, 2026-02-24 ↩↩↩↩
-
Chipotle Mexican Grill, Inc. — DEF 14A Proxy Statement, SEC, 2026-04-28 ↩↩
-
Chipotle Debuts Autocado and the Augmented Makeline by Hyphen in Restaurants — Chipotle Investor Relations, 2024-09-16 ↩↩↩
-
Hyphen automated makelines get investments from Cava, Chipotle — CNBC, 2025-12-30 ↩↩↩↩
-
Another Day, Another Failed 2nd Restaurant Chain for Chipotle — The Motley Fool, 2024-05-04 ↩↩
-
NLRB Region 1-Boston Obtains Settlement with Chipotle with $240,000 in Backpay and Front Pay, Preferential Hiring, and Notice Posting in 40 Stores — National Labor Relations Board, 2023-03 ↩
-
Chipotle agrees to settle lawsuit charging union busting in Maine — Restaurant Business, 2023-03 ↩
-
Chipotle Signs Development Agreement with Alsea to Open Restaurants in Mexico for the First Time — Chipotle Investor Relations, 2025-04-21 ↩↩
-
Chipotle Debuts in Saudi Arabia with First Restaurant in Riyadh — Chipotle Newsroom, 2026-08-13 ↩↩
-
Chipotle to Expand to Asia for the First Time Through a Joint Venture with SPC Group — Chipotle Investor Relations, 2025-09-10 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube