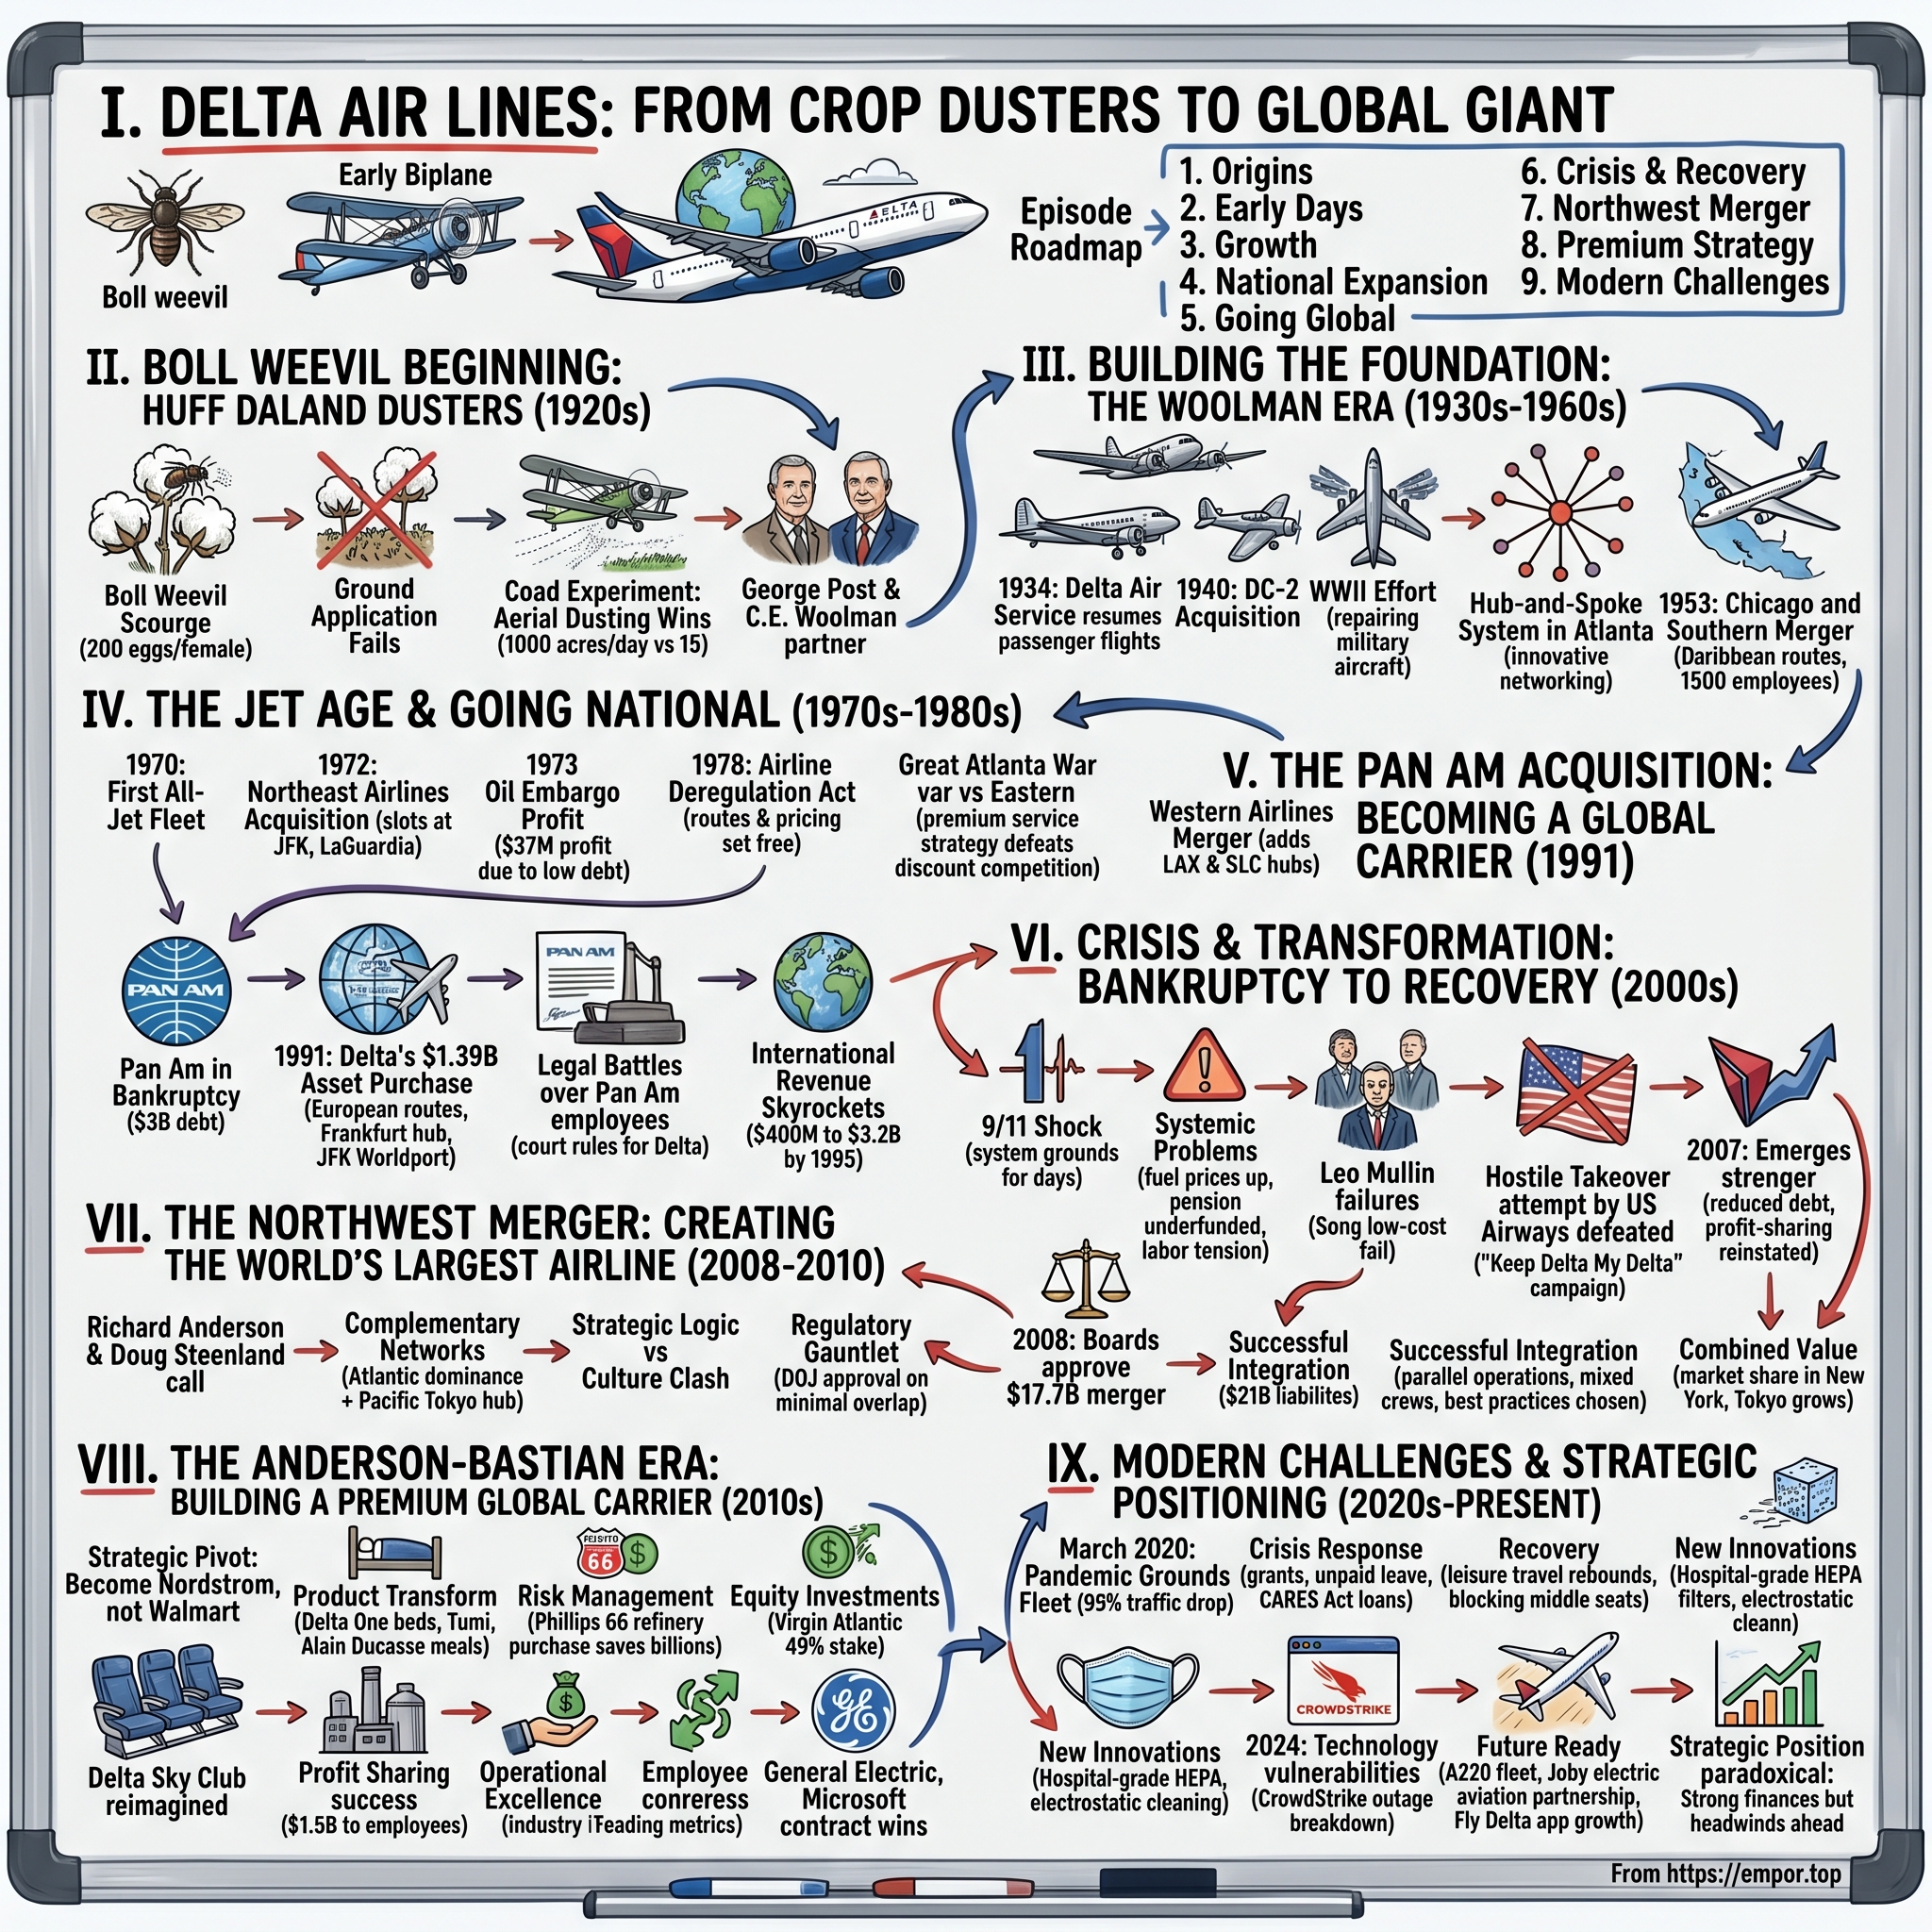
Delta Air Lines: From Crop Dusters to Global Aviation Powerhouse
I. Introduction & Episode Roadmap
In the spring of 1925, cotton fields across the Mississippi Delta faced severe devastation from the boll weevil—a beetle roughly a quarter-inch long that had crossed the Rio Grande decades earlier, threatening the region's economic foundation. On March 2, 1925, in Macon, Georgia, Huff Daland Dusters incorporated to combat the pest from the air, establishing what the company's museum identifies as the world's first aerial crop-dusting operation.1 Its chief entomologist, Louisiana State University extension agent Collett Everman Woolman, joined the enterprise that May while still on university leave.1
A century later, the corporate descendant of that agricultural startup reported $63.4 billion in annual operating revenue, transported over 200 million passengers, operated a fleet of 1,314 aircraft, and generated $8.2 billion in cash from a single credit card partnership.2 Delta Air Lines stands as the world's most profitable airline by most conventional measures, completing a long evolution from a regional crop duster to a global network carrier.
However, an origin story is not an investment case; the central question is what Delta actually represents today. Two competing narratives define the company, leading to starkly different analytical conclusions.
Under the first view, Delta is a capital-intensive, structurally cyclical transportation utility. It consumes billions of dollars in jet fuel at unhedged market prices, purchases aircraft from a duopoly with pricing power, relies on a heavily unionized pilot workforce whose contract expires at the end of 2026, and would generate modest returns on capital without its large, high-margin consumer finance business.
Under the second view, Delta is a premium consumer brand with a defensible network position. Over the past fifteen years, the company has worked to de-commoditize air travel, commanding a persistent price premium in hub markets where it maintains dominant airport gate control.
Financial results from the first half of 2026 highlight this tension. In the first quarter, Delta posted a GAAP pre-tax loss of $214 million when jet fuel prices spiked following geopolitical conflict in the Middle East.3 Just three months later, in the second quarter, the airline generated record adjusted revenue of $17.7 billion—a 14% increase delivered on just 1% capacity expansion, driving total unit revenue up 12.4%. This top-line expansion occurred even as Delta absorbed its highest quarterly fuel bill on record: $4.4 billion at $3.93 per gallon, representing a 75% year-over-year jump.4 Despite what Chief Financial Officer Erik Snell characterized as a nearly $4 billion annual increase in fuel expenses, management reaffirmed full-year adjusted earnings guidance of $6.50 to $7.50 per share, representing approximately 20% year-over-year earnings growth.4
These figures reflect either significant structural pricing power or the temporary benefit of industry-wide fare increases combined with a major competitor's demise. Spirit Airlines, which pioneered the domestic ultra-low-cost model, ceased operations on May 4, 2026, following its second bankruptcy in two years and roughly $100 million in sudden incremental fuel costs.5 On the second-quarter earnings call, Delta's chief commercial officer noted that ultra-low-cost industry capacity had dropped approximately 30%.6 Determining how much of Delta's 2026 financial strength stems from durable competitive advantage versus a windfall from a competitor's liquidation forms the central analytical objective.
The analytical roadmap begins with Delta's founding era and the development of the Atlanta connecting hub—a mid-century operations innovation that continues to generate cash today. The narrative then examines the crisis decades: the 1991 Pan American World Airways asset acquisition that expanded Delta's transatlantic footprint while straining its balance sheet, the 2005 Chapter 11 reorganization, and the 2006–2007 hostile takeover attempt defeated by Delta's creditors. Next comes the 2008 merger with Northwest Airlines, which established the template for modern airline consolidations, followed by the strategic shift toward premium travel led by Richard Anderson and Ed Bastian—including unconventional capital allocation moves such as purchasing an oil refinery and acquiring minority stakes in international carriers.
The second half disassembles Delta's revenue into its core drivers—premium cabin seats, the American Express co-branded credit card agreement, maintenance services, cargo, and refining operations—evaluating which segments generate returns above their cost of capital. It tests claims of durability against execution: comparing the July 2024 CrowdStrike operational breakdown against the company's reliability reputation, assessing carrying values for investments in Virgin Atlantic and Wheels Up against its capital deployment record, and examining pre-COVID share repurchases against balance sheet discipline commitments. Finally, applying competitive strategy frameworks, the analysis conducts an activist stress test and identifies the key metrics required to monitor the thesis.
The examination begins where Delta started: with an agricultural pest, a bank loan, and an executive who initially had no intention of running an airline.
 Subscribe on LinkedIn
II. Foundational Roots: Crop Dusters to the Atlanta Mega-Hub (1925–1990)
C.E. Woolman was not a pilot. He was an agricultural engineer with a degree from the University of Illinois who had spent years demonstrating farm equipment to Louisiana cotton growers, approaching aviation primarily as a practical tool to address an agricultural crisis. That perspective—treating aircraft as a means to a commercial end rather than an end in themselves—became a foundational cultural principle for the enterprise, distinguishing Delta from early aviation peers that prioritized flight operations over underlying business viability.
Huff Daland’s dusting fleet eventually expanded to eighteen aircraft operating from Florida to California and into Mexico, briefly creating one of the largest privately owned fleets in the United States.7 However, crop dusting remained inherently seasonal, geographically constrained, and tied to agricultural pest cycles. When the parent company sought to exit the business, Woolman assembled a syndicate of local investors—led by Monroe, Louisiana banker Travis Oliver—and purchased the assets. On December 3, 1928, they incorporated Delta Air Service, named after the Mississippi Delta region where operations began.1
The airline launched its first passenger service on June 17, 1929, operating a five-passenger Travel Air aircraft on a route from Dallas to Jackson, Mississippi, with intermediate stops in Shreveport and Monroe.1 Crucially, Delta began passenger operations without federal air mail subsidies. In the late 1920s, federal air mail contracts largely dictated commercial aviation economics, making passenger traffic a secondary revenue source. By flying passengers first and securing Air Mail Route 24 only in 1934, Delta developed an early operating model focused on making passenger revenues self-sustaining.7
In 1941, Delta relocated its corporate headquarters from Monroe to Atlanta.7 That geographic shift proved pivotal for long-term value creation. Atlanta sits within a two-hour flight of roughly three-quarters of the U.S. population, offers flat and expandable terrain, and lacks a competing regional airport to divide passenger traffic. While Delta initially selected Atlanta to serve its core Southeastern route network rather than to build a jet-age hub-and-spoke system, the location ultimately provided the structural foundation for the airline's dominant network model.
The invention of the bank. By the mid-1950s, Delta began systematically structuring its Atlanta flight schedules into synchronized operational waves, landing incoming flights within tight timeframes so passengers could cross-connect before aircraft departed in waves.7 This model functions like a central transit terminal where all arrivals dock simultaneously, enabling seamless transfers across routes. Mathematically, a hub connecting n spokes generates roughly n² potential city pairs; doubling destination count quadruples served markets. This structural network effect enables a centralized connecting hub to generate route density and unit revenues that point-to-point networks struggle to match.
The operational trade-off of bank scheduling is high fixed-asset intensity: gates, ground crews, and baggage infrastructure must be scaled to handle peak wave traffic, leaving capacity underutilized between pushes. Consequently, bank scheduling requires high volume and market concentration to generate adequate returns, turning major hubs into winner-take-most assets. By the early 1990s, Delta operated approximately ten daily connecting waves through its Atlanta hub.8
Growth by acquisition, with a pattern. Delta expanded its network footprint through targeted, geographically complementary acquisitions. On May 1, 1953, it merged with Chicago and Southern Air Lines, gaining its first international routes to Caracas and the Caribbean.8 On August 1, 1972, Delta acquired Northeast Airlines, establishing a presence in Boston and New York.8 Between 1986 and 1987, it acquired Western Air Lines for $680 million, adding hubs in Los Angeles and Salt Lake City to become the fourth-largest U.S. carrier.8 Rather than buying competing capacity in existing markets, Delta consistently acquired complementary route networks—a disciplined approach that later facilitated the successful integration of Northwest Airlines while highlighting the integration challenges of earlier industry asset buys.
Delta also acted as an early commercial adopter of jet aircraft, serving as the launch customer for the Douglas DC-8 in 1959 and transitioning to an all-jet fleet by 1970.7 Early adoption of new airframe technology delivered significant unit-cost advantages as fuel burn per seat dropped by roughly a third, though it also exposed the carrier to early-stage technical and capital risks that subsequently refined its fleet deployment strategy.
For long-term industry analysts, Delta's initial six decades highlight two enduring operational principles. First, its primary competitive asset—the Atlanta mega-hub—was forged through geography and sustained operational compounding, creating a network position that competitors find difficult to replicate. Second, the airline's growth strategy historically relied on geographic complementarity over market-share consolidation. Both principles faced severe pressure during the aggressive international expansion phase that followed.
III. The Crisis Era: The Pan Am Asset Grab, Bankruptcy & Hostile Takeover Defense (1991–2007)
In the summer of 1991, Pan American World Airways—the airline that pioneered transatlantic passenger service, introduced the Boeing 747, and served for four decades as the unofficial flag carrier of the United States—was in bankruptcy and liquidating its assets. Three bidders targeted Pan Am's transatlantic route authorities: a consortium of Trans World Airlines, United Airlines, and American Airlines, alongside Delta Air Lines operating independently. Delta won the assets with a bid package valued at roughly $1.39 billion, topping the consortium's $1.3 billion offer.9
In exchange, Delta acquired 45 aircraft, including 21 Airbus A310s, transatlantic routes to 19 European and Middle Eastern destinations, hub operations at Frankfurt and New York's John F. Kennedy International Airport, and the Pan Am Shuttle serving New York, Boston, and Washington, D.C.9 Delta assumed control of the shuttle service on September 1, 1991, and launched the transatlantic operation on November 1.10 Overnight, the regional Southeastern carrier transformed into a major transatlantic airline.
What the deal actually cost. The transaction also entangled Delta in an effort to reorganize a scaled-down Pan Am, advancing $100 million to support the launch. However, Pan Am continued to lose roughly $3 million per day, expected booking demand failed to materialize, and Delta cut off further cash advances. Pan Am ceased all operations on December 4, 1991.9 The pioneer of American international aviation shut down when its primary financial backer withdrew support.
The financial impact on Delta was immediate and severe. Driven by an economic recession, surging jet fuel prices, and new debt obligations, Delta reported a net loss of $506 million for fiscal year 1991. In response, management cut the workforce by 5%, froze wages, and slashed transatlantic fares by 45% in the summer of 1992 to fill newly acquired capacity.8 Losses resumed in early 1994, triggering the "Leadership 7.5" restructuring program that April. The initiative set a target to lower unit costs to 7.5 cents per available seat mile, remove $2 billion in operating expenses over three years, and reduce headcount by 20%.8 Although Delta returned to profitability by fiscal year 1995, service quality suffered: by 1997, the airline ranked last among ten major U.S. carriers in on-time performance.8
The Pan Am asset purchase established Delta's long-term transatlantic footprint and secured its strategic presence at JFK. However, the transaction demonstrated the risks of acquiring distressed international assets. Integrating the operations required nearly a decade, severely strained the balance sheet during an economic downturn, and imposed operational costs through wage freezes, workforce cuts, and degraded service reliability. The acquisition showed that buying distressed international route networks entails absorbing complex cost structures and execution risks long before expected revenue synergies materialize.
The 2000s: everything breaks at once. The early 2000s presented a compound crisis for legacy network carriers, characterized by the severe passenger demand shock following September 11, 2001, escalating crude oil prices, underfunded defined-benefit pension obligations, and expanding low-cost carriers eroding domestic short-haul margins. On September 14, 2005, under Chief Executive Officer Gerald Grinstein, Delta filed for Chapter 11 bankruptcy protection.7 Northwest Airlines filed for Chapter 11 on the same day, following prior bankruptcy filings by United Airlines and US Airways.
Chapter 11 bankruptcy served as a judicial mechanism to restructure liabilities across labor, pension, fleet, and debt holders. Delta utilized court protection to terminate legacy defined-benefit pension plans, reprice aircraft leases, renegotiate collective bargaining agreements, and reduce funded debt. Because every major U.S. legacy carrier underwent a similar court-supervised restructuring, historical balance sheet comparisons across that era reflect structural discharge rather than steady-state operating performance. In that context, Delta's current investment-grade credit rating—held by all three major rating agencies—marks a structural departure from its historic balance sheet volatility.2
The hostile bid. While Delta remained in court supervision, US Airways—led by Chief Executive Officer Doug Parker following its 2005 merger with America West Airlines—launched an unsolicited $8 billion cash-and-stock acquisition proposal on November 15, 2006. The bid offered $4 billion in cash plus 78.5 million US Airways shares directly to Delta's unsecured creditors' committee, projecting $1.65 billion in annual cost synergies.11 Parker later increased the offer. Because Delta was in Chapter 11, transaction approval rested with the creditors' committee rather than Delta's board of directors.
Delta management and employees campaigned against the takeover under the banner "Keep Delta My Delta," contending that a standalone reorganization offered higher recovery value than combining with an airline still completing its own operational integration. On January 31, 2007, the creditors' committee rejected the takeover proposal, citing concerns over valuation, integration execution risk, and regulatory scrutiny surrounding overlapping East Coast routes, prompting US Airways to withdraw its bid. Parker publicly stated that the committee was "ignoring its fiduciary obligation."12 Delta successfully emerged from Chapter 11 bankruptcy as an independent enterprise on April 30, 2007.7
Defeating the hostile bid allowed Delta to preserve its corporate culture and core hub network while controlling its emergence timing. Rather than undergoing a forced consolidation under US Airways' operating structure, Delta maintained operational independence, positioning management to initiate its own consolidation on terms it controlled 18 months later.
IV. The Northwest Merger: Blueprint for Modern Airline Consolidation (2008–2010)
Richard Anderson was an unconventional choice for an airline chief executive. A former Harris County, Texas, prosecutor who rose through Continental Airlines' legal department and later served as chief executive of Northwest Airlines, Anderson left aviation in 2004 to run a division of UnitedHealth Group. In 2007, Delta's post-bankruptcy board recruited him back to the industry to lead the carrier after it successfully fended off a hostile takeover.
In April 2008, Delta announced an all-stock combination with Northwest, offering 1.25 Delta shares for each Northwest share. The transaction created an industry leader generating over $35 billion in aggregate annual revenue, operating a mainline fleet of nearly 800 aircraft, and employing roughly 75,000 people across 390 destinations in 67 countries. Shareholders of both carriers overwhelmingly approved the deal that September, with about 99% of Delta votes and over 98% of Northwest votes cast in favor.13 The transaction closed on October 29, 2008—six weeks after Lehman Brothers collapsed, amid the worst financial market downturn in decades—creating the world's largest airline. Management targeted at least $2 billion in annual revenue and cost synergies against one-time integration expenses capped at $600 million, while committing from the outset to distribute equity in the combined carrier to U.S.-based employees.14
Why the map mattered more than the math. The strategic rationale rested on geographic complementarity. Delta held strong network positions across the Southeast and East Coast, alongside the transatlantic franchise acquired from Pan Am. Northwest brought dominance in the Upper Midwest through fortress hubs in Detroit and Minneapolis–Saint Paul, plus a premier asset in transpacific aviation: grandfathered landing rights at Tokyo Narita Airport dating to post-World War II agreements, providing an Asian gateway unmatched by other U.S. carriers. Because route overlap was minimal, the U.S. Department of Justice closed its antitrust investigation without requiring remedies or conditions.
That complementary structure contrasted sharply with the proposed US Airways–Delta combination, which would have created heavy route overlap along the East Coast, redundant hub capacity, and years of costly network rationalization. In commercial aviation, mergers tend to create value when combining adjacent, complementary route networks, but erode capital when consolidating redundant capacity.
Integration is a labor problem wearing an IT costume. The historic point of failure in airline integrations is pilot seniority. Because seniority governs pay rates, aircraft assignments, and work schedules, merging two seniority lists risks stripping years of accumulated standing from one group, often leading to protracted arbitration that can demoralize a workforce for a decade. The 2005 merger between America West and US Airways had served as an industry cautionary tale, as unresolved pilot seniority disputes forced the carrier to operate essentially as two separate airlines under a single brand for years.
Delta and Northwest addressed seniority integration early rather than deferring it, while granting employees an equity stake in the merged company—a structure Anderson characterized from day one as "a prime example of the Delta Difference."14 The Federal Aviation Administration granted a single operating certificate on December 31, 2009, and the reservation system integration was completed without the systemic operational breakdowns experienced in earlier industry mergers.15
While execution surpassed historical industry norms, the consolidation was not without friction. Delta closed inherited hubs in Cincinnati and Memphis, reducing local air service and impacting workforce headcount, while inheriting an aging fleet of Douglas DC-9 aircraft that required years of capital investment to retire. Nevertheless, relative to peer outcomes, the integration proceeded efficiently. By contrast, United Airlines and Continental Airlines merged in 2010 and spent years resolving IT and labor friction, while American Airlines and US Airways encountered similar integration delays following their 2013 combination.
The industry consequence. By the mid-2010s, industry consolidation reduced the major U.S. network carrier population from eight operators to four, with the surviving group controlling approximately four-fifths of domestic seat capacity. That structural shift altered competitive dynamics: while it did not eliminate price competition—as ultra-low-cost carriers expanded over the subsequent decade—it enabled network carriers to practice capacity discipline. The long-term durability of Delta's premium pricing strategy relies directly on this consolidated industry structure.
For investors, the Northwest deal demonstrated the strategic value of executing consolidation from a position of relative strength during a market downturn using equity as currency. The merger established the operating model that guided Delta's subsequent strategy: attempting to move away from pure price competition by allocating capital into premium products and service reliability that passengers would pay a premium to experience.
V. The Anderson-Bastian Playbook: The Premium Pivot & Unconventional Capital Deployment (2010–2019)
In the decade following the Northwest merger, Delta shifted from conventional operational management toward a fundamentally different commercial strategy.
Heading into the 2010s, industry orthodoxy held that air travel was a pure commodity where unit cost served as the sole durable competitive advantage. Southwest Airlines had validated that model in the United States, Ryanair and easyJet had demonstrated it in Europe, and Spirit Airlines was pursuing it in its most aggressive form—unbundling ancillary services, selling only a basic seat, and treating customer relationships as single transactions.
Richard Anderson and Chief Financial Officer Ed Bastian challenged that assumption. If air travel were entirely commoditized, Delta's revenue premium over industry peers would have decayed to zero. Because that premium persisted, management reasoned that a critical segment of passengers—particularly corporate accounts, but increasingly affluent leisure travelers—would pay higher fares for flights that departed on time, delivered baggage reliably, and offered enhanced cabin comfort.
Segmenting the cabin. The practical execution of this approach relied on product tiering. Transforming a traditional two-class layout into a multi-tiered ladder, Delta introduced Delta One lie-flat suites on long-haul and premium transcontinental routes, Delta Premium Select as a dedicated international premium-economy cabin, Delta Comfort+ as an extra-legroom product with a distinct fare class, and Main Cabin for core economy traffic. Each tier established an incremental price point, allowing the airline to capture additional revenue from existing passengers.
This structure applied retail merchandising principles to aircraft cabins. On the June 2026 earnings call, Bastian described the company's legacy approach from a decade earlier as "a blunt instrument" with limited pricing options, contrasting it with the strategy "to become true world class merchandisers and retailers."6
Reliability as a pricing weapon. The operational arm of the strategy targeted schedule execution. Because corporate travel managers award contracts primarily based on completion factor—the percentage of scheduled flights actually operated—Delta directed capital into maintenance, spare aircraft reserves, and crew scheduling to maximize completion rates, leveraging that operational stability during corporate contract negotiations.
Third-party metrics reflect the commercial impact of those investments. Business Travel News ranked Delta as the top airline among corporate travel customers for fifteen consecutive years, while Cirium named it North America's most on-time airline for the fifth consecutive year in 2025.2
However, annual regulatory disclosures highlight the ongoing cost of maintaining operational reliability. Delta's proxy statement reported a mainline domestic completion factor of 98.9% in 2025, compared with 99.1% in 2024, alongside mainline domestic on-time arrivals of 66.2%, down from 68.2% the prior year.16 While Delta maintained its leadership position relative to legacy peers across both metrics, performance declined year over year, demonstrating that operational excellence requires continuous operating expenditure rather than functioning as a permanent asset.
The refinery. In April 2012, Delta announced that its subsidiary Monroe Energy would acquire the Trainer, Pennsylvania refinery complex from Phillips 66 for $150 million, supported by $30 million in state financial assistance, while committing an additional $100 million to reconfigure the plant toward jet fuel production. Management projected annual fuel expense reductions of approximately $300 million and secured crude supply agreements with BP alongside product exchange arrangements with BP and Phillips 66 to cover roughly 80% of its domestic jet fuel requirements. Anderson characterized the transaction as "an innovative approach to managing our largest expense."17
Skeptics questioned the strategic rationale. Owning a refinery does not hedge crude oil prices, as Delta continued purchasing crude at prevailing market rates; instead, it hedges the crack spread—the margin between crude oil and refined jet fuel prices. In typical market conditions, that spread remains narrow, leaving the facility as a low-return industrial asset carrying substantial environmental compliance liabilities. Monroe incurred $312 million in Renewable Identification Number compliance expenses in 2025 against segment operating income of $157 million.2 For the full year 2025, refinery operations reduced Delta's average fuel cost by four cents per gallon.2
That financial dynamic shifted significantly in 2026 when refining margins expanded, an issue analyzed in subsequent operational coverage.
The equity stakes. The third element of the strategy involved acquiring minority equity stakes in foreign airlines rather than relying exclusively on commercial alliance agreements. Delta purchased a 49% stake in Virgin Atlantic in 2013, acquired 49% of Grupo Aeroméxico, bought an equity interest in China Eastern Airlines, and invested $1.9 billion in 2019 for approximately 20% of LATAM Airlines Group.
Management framed the equity strategy as an alignment mechanism, asserting that direct capital stakes encouraged international joint venture partners to coordinate schedules, pricing, and sales more effectively than contractual agreements alone, while defensively securing key alliance partners against rival bids.
Operating outcomes tested those assumptions. Following the demand shock from COVID-19, both LATAM and Grupo Aeroméxico entered Chapter 11 bankruptcy reorganization, substantially restructuring Delta's original equity investments. Delta subsequently participated in their court-supervised recapitalizations, holding by year-end 2025 an 11% stake in LATAM valued at $1.644 billion and a 19% stake in Aeroméxico valued at $377 million.2 The carrying value of Delta's 49% interest in Virgin Atlantic stood at zero as of December 31, 2025, alongside approximately $620 million in unrecognized equity method losses.2
That outcome indicates a long-standing strategic investment that, under formal accounting standards, generated no recoverable book value. While the underlying transatlantic joint venture produces revenue synergies separate from equity valuation, those commercial benefits stem from alliance coordination rather than the balance sheet value of the underlying shares.
Two conclusions emerge from this period. First, the premium strategy successfully re-established Delta's commercial positioning, supported by empirical operational metrics. Second, the associated capital allocation record proved far more mixed, with the primary impairment risks residing in international airline equity holdings rather than core fleet assets.
VI. Modern Economic Anatomy: Segments, Fortress Hubs & Unit Economics
A pivotal shift in Delta's revenue composition occurred in 2025. In 2024, the airline generated $24.5 billion from Main Cabin tickets and $20.6 billion from premium products. In 2025, Main Cabin ticket revenue declined 5% to $23.4 billion, while premium ticket sales rose 7% to $22.1 billion.2 On a total passenger revenue base of $51.8 billion, the gap between traditional economy and premium offerings narrowed to approximately $1.3 billion as the two revenue lines diverged.
This convergence provides tangible evidence for Delta's premium strategy, reflecting actual customer purchasing behavior rather than management projections. Delta has deliberately constrained main cabin capacity for several years—a trend Chief Commercial Officer Joe Esposito confirmed during the June 2026 earnings call, noting main cabin capacity was down 2% to 3% with no growth planned for 2027—while expanding premium seating at low single-digit rates.6
The four revenue engines. Delta's $63.4 billion in 2025 GAAP revenue divides into distinct business components operating under markedly different economic profiles.2
Passenger ticket revenue of $45.5 billion represents the core airline operation—capital-intensive, cyclical, and exposed to jet fuel price volatility. When combined with $4.2 billion from loyalty travel awards and $2.0 billion from travel-related services, total passenger revenue reached $51.8 billion. Cargo contributed $900 million. The remaining $10.7 billion in "other" revenue includes $5.1 billion in third-party refinery sales, $3.4 billion in loyalty program revenue, $937 million from ancillary services such as maintenance operations, and $1.3 billion from miscellaneous sources, including airport lounge access, travel products, and joint venture settlements.
Management groups these non-ticket streams under the umbrella of "diversified revenue," reporting that they accounted for 60% of total revenue in 2025 and 61% in the second quarter of 2026.14 However, this classification warrants analytical scrutiny. The metric is a corporate aggregation rather than an audited reporting segment, and it incorporates third-party refinery sales—a low-margin, high-volume commodity pass-through subject to severe spread volatility. While the expansion of non-ticket revenue is genuine, the headline percentage reflects management framing as much as structural diversification.
The physics: PRASM and CASM. Commercial airline economics center on two primary unit metrics measured per available seat mile—the industry's standard unit of capacity, representing one seat flown one mile.
Passenger revenue per available seat mile (PRASM) tracks unit revenue generation. Delta recorded a PRASM of 17.37 cents in 2025, compared to 17.65 cents in 2024.2 Cost per available seat mile excluding fuel (CASM-Ex) measures core operational expenditures prior to fuel costs. Delta's CASM-Ex stood at 13.86 cents in 2025, up 2.4% from 13.54 cents in 2024—a rate management described as aligned with its long-term target of low-single-digit cost growth.12
The spread between PRASM and CASM-Ex defines an airline's pre-fuel operating margin. Because of the industry's operating scale, small variations in unit metrics dramatically alter financial results: across Delta's roughly 298 billion available seat miles, a one-cent change in either PRASM or CASM-Ex represents approximately $3 billion in operating income.2
Fortress hubs and the local passenger. Delta's annual regulatory filings describe its domestic network as centered on core hubs in Atlanta, Detroit, Minneapolis–Saint Paul, and Salt Lake City. Management characterizes these interior hubs as possessing strong local passenger market share, high customer loyalty, competitive cost structures, and robust operating margins, complemented by coastal gateways in Boston, Los Angeles, New York–LaGuardia, New York–JFK, and Seattle.2
The Atlanta hub demonstrates the economic power of market concentration. In the summer of 2025, Delta operated 968 daily flights and 1.1 million weekly seats out of Hartsfield-Jackson Atlanta International Airport, serving 215 destinations—including 66 international routes—with 41,000 daily premium seats and 87% of departures on mainline aircraft, up from 79% in 2019.18 Overall, Delta accounted for more than 70% of the airport's total passenger volume.18
This degree of market dominance generates pricing power by capturing high-yielding local traffic rather than price-sensitive connecting passengers. While connecting traffic is price-competitive—a traveler from Boise to Tampa can choose among multiple hubs and carriers—local passengers originating in Atlanta often require specific nonstop schedules, giving the dominant carrier pricing leverage on key business routes.
By contrast, Delta's coastal hubs operate under different competitive dynamics. In New York, Los Angeles, Boston, and Seattle, Delta competes directly against major carriers including United, American, Alaska, and JetBlue. Rather than relying on hub dominance, Delta's coastal strategy depends on brand positioning and product differentiation to win corporate accounts at fare parity. This makes coastal revenues more vulnerable to shifts in premium travel demand compared to the protected cash flows of interior fortress hubs.
The peer comparison. In 2025, Delta generated $63.4 billion in revenue, $5.8 billion in operating income, a 9.2% GAAP operating margin, $5.0 billion in GAAP net income, and a 12.0% return on invested capital.1 By comparison, United Airlines generated a GAAP operating margin of approximately 8%, while American Airlines delivered record revenue of $54.6 billion but posted GAAP net income of $111 million—an 87% year-over-year decline—while carrying $36.5 billion in total debt compared to Delta's $14.1 billion.191
The financial divergence between Delta and American reflects long-term structural differences in balance sheet management, hub geography, premium seat mix, and loyalty program monetization that require years to alter. Conversely, the performance gap between Delta and United is significantly narrower, with United narrowing the margin differential in recent quarters. Consequently, evaluating Delta's competitive advantage against the legacy industry requires direct comparison with United rather than broader industry averages, which are distorted by weaker legacy and low-cost carriers.
VII. The "Hidden" High-Margin Engines: SkyMiles/Amex & Delta TechOps MRO
In September 2020, with global air travel down roughly two-thirds and Delta burning cash daily, the company turned to debt markets with an unusual collateral package: not aircraft, gates, or spare engines, but its frequent flyer program.
The debt offering was upsized from $6.5 billion to $9 billion—comprising $2.5 billion of 4.5% senior secured notes due 2025, $3.5 billion of 4.75% notes due 2028, and a $3.0 billion term loan, carrying a blended interest rate of approximately 4.75%.20 For an airline generating negligible revenue during a global pandemic, this pricing reflected strong investor demand. Crucially, the market was lending not against Delta's airline operations, but against the standalone cash generation of SkyMiles.
How the machine actually works. The mechanics of the program are straightforward. American Express issues co-branded Delta credit cards. To distribute SkyMiles to cardholders as spend rewards, American Express purchases miles directly from Delta in cash at a contractually negotiated rate. Delta collects the cash up front, defers the portion assigned to future award flights, and recognizes the remaining revenue immediately as brand licensing, marketing services, lounge access, and related performance obligations.
The underlying economics depend on redemptions. When a member eventually redeems miles, Delta fulfills the obligation with an aircraft seat. The marginal cost of supplying a seat that would otherwise fly empty is minimal—primarily limited to incremental fuel for one passenger and on-board refreshments. Because Delta dynamically manages redemption inventory, it retains direct control over award seat availability and mileage pricing.
Ultimately, Delta issues a private digital currency at a contractually established price and satisfies redemptions using self-controlled inventory. This high-margin cash flow structure explains why the loyalty program can secure financing on favorable terms even when core airline operations face severe stress.
The numbers and their trajectory. Remuneration from American Express reached $8.2 billion in 2025, an 11% year-over-year increase, supported by more than one million new card acquisitions for the fourth consecutive year.1 Delta's annual regulatory filings explicitly state management's expectation that annual remuneration will expand to $10 billion over the next several years.2 In the second quarter of 2026, remuneration reached $2.4 billion—a 16% increase marking the seventh consecutive quarter of double-digit expansion in cardholder spend—leading Chief Executive Officer Ed Bastian to guide full-year 2026 remuneration to approximately $9 billion, representing 10% annual growth.46
To put that in perspective, $8.2 billion exceeds the total 2025 revenue of most publicly traded airlines worldwide, generated without deploying additional aircraft capacity. At the end of 2025, Delta's deferred revenue balance for SkyMiles stood at $9.3 billion, while award travel accounted for 12% of revenue miles flown, with members redeeming approximately 35 million award tickets.2
Where the claim needs bounding. Three critical constraints qualify this high-margin revenue model.
First, the revenue stream represents a contractual arrangement rather than an independent asset. Program economics depend on a negotiated partnership with a single counterparty. While American Express is Delta's largest partner and Delta is American Express's primary airline partner—a relationship Bastian characterized during the June 2026 earnings call as mutually exclusive—this alignment also creates significant concentration risk.6 Any structural compression in co-brand credit card economics or regulatory intervention regarding credit card interchange fees would directly impact cash generation.
Second, loyalty revenue remains downstream of consumer credit trends. The sustained growth in cardholder spend reflects favorable employment conditions, healthy household balance sheets, and resilient discretionary spending among affluent consumers. In a broad consumer credit contraction, card acquisition rates and underlying spend would inevitably decelerate.
Third, Delta demonstrated that customer willingness to accept program changes has clear limits. In September 2023, management announced a sweeping overhaul of the SkyMiles program, tying Medallion status qualification exclusively to dollar spend and sharply restricting Sky Club lounge access for credit card holders. Following immediate pushback from high-value frequent flyers, Bastian conceded during a speech at the Rotary Club of Atlanta later that month that management had moved too fast and overreached, leading Delta to roll back several planned restrictions.[^21]
That episode provides valuable empirical evidence regarding the limits of Delta's loyalty moat. While switching costs remain real—most frequent flyers retained their accounts despite voicing frustration—Delta cannot unilaterally extract value from members without triggering customer pushback. The loyalty franchise provides durable, high-margin revenue through volume expansion and partner growth, but does not grant management unlimited pricing power to devalue benefits at will.
Delta TechOps. The second high-margin growth engine is smaller but expanding at a faster rate than the main airline.
Delta TechOps operates as the carrier's internal maintenance, repair, and overhaul (MRO) division. While most network carriers perform internal fleet maintenance, Delta monetizes its engineering capacity by selling MRO services to third-party airlines, engine manufacturers, and military clients, transforming a traditional cost center into a direct revenue driver.
The strategic rationale aligns with broader supply chain conditions. Commercial aviation faces a global shortage of engine shop capacity, driven by durability issues across newest-generation narrowbody engines. On the June 2026 earnings call, Bastian noted that modern engine technologies have exhibited significantly lower operational durability compared to legacy platforms.6 In this environment, internal MRO capacity provides Delta with a dual advantage: third-party service revenue and prioritized maintenance access for its own fleet.
Financial growth in the MRO segment has accelerated rapidly. The division generated $658 million in revenue in 2024 and $822 million in 2025.2 For 2026, Chief Operating Officer Dan Janki guided segment revenue to approximately $1.2 billion—a nearly 50% year-over-year increase—at low double-digit operating margins, while projecting a doubling of MRO revenue over the coming years supported by a record order backlog.6 In the second quarter of 2026, MRO revenue grew more than 30% year over year, driven primarily by service demand for legacy engine platforms.4
The division's expansion prompted a shift in financial reporting. Beginning with its 2026 financial guidance, Delta excluded TechOps from its core non-fuel unit cost metric (CASM-Ex) to ensure cost transparency for core airline operations.1 While this adjustment improves visibility into baseline airline costs, it also highlights how non-airline revenue streams can complicate unit cost comparisons across carriers over time.
Generating low double-digit margins on $1.2 billion in revenue produces approximately $130 million in operating income—a modest portion of Delta's $5.8 billion total operating profit. Consequently, TechOps functions primarily as an operational stabilizer and narrative driver rather than a dominant earnings contributor today. Converting its multi-year backlog into long-term profit will depend on executing third-party service contracts at scale while managing internal fleet requirements.
VIII. Current Management, Governance & Capital Allocation Track Record
Ed Bastian joined Delta in 1998 as vice president of finance and controller, subsequently serving as chief financial officer through the 2005 bankruptcy reorganization, the defense against US Airways, and the Northwest Airlines merger. He served as president during the operational integration before succeeding Richard Anderson as chief executive in May 2016. Bastian stands as the longest-tenured chief executive among major U.S. network carriers, a distinction highlighted by a Citigroup analyst during the airline's June 2026 earnings call.6
An accountant by training, Bastian articulates a brand-focused operational philosophy. His public commentary consistently emphasizes service quality, workforce alignment, and customer preference over pure network geometry or low-cost positioning. On the June 2026 call, he framed the company's strategy around service differentiation rather than price competition, stating, "it is not about trying to outsmart somebody on some network strategy or trying to undercut somebody on a lower point price point. This is about who serves best."6
While this strategic framing has remained consistent for a decade—reflecting a coherent commercial identity rather than shifting corporate messaging—it remains inherently qualitative. Assessing Delta's long-term durability requires evaluating these brand assertions against operational execution, governance structures, and financial metrics.
A management team that turned over quickly. For much of the preceding decade, Delta maintained exceptional executive stability around Bastian, President Glen Hauenstein—the architect of its revenue management and network strategy—and Chief Financial Officer Dan Janki, who assumed the finance role in July 2021. That stability gave way to significant leadership realignment.
Effective April 1, 2026, Delta executed a comprehensive C-suite realignment. Erik Snell, a two-decade company veteran who had served as chief customer experience officer since January 2025, was appointed chief financial officer, while Janki transitioned to chief operating officer. Peter Carter, formerly chief external affairs officer, assumed the presidency. Ranjan Goswami was named chief marketing and product officer, while John Laughter, chief of operations and president of Delta TechOps, retired after three decades, with Alain Bellemare assuming the chairmanship of TechOps.21 Concurrently, Joe Esposito took over as chief commercial officer.6
This sudden management turnover unfolded alongside rising jet fuel expenses. From a talent-development perspective, rotating financial executives into operations and customer-experience leaders into corporate finance builds multi-disciplinary leadership, reflecting Delta's tradition of internal promotion. Conversely, an alternative view suggests the carrier reorganized under pressure while navigating pilot labor contract discussions, operational resilience challenges, and non-fuel unit cost pressures. Future execution across non-fuel cost management will clarify the impact of these leadership shifts.
Compensation and governance. Delta structures executive pay with a heavy emphasis on equity, allocating 83% of the chief executive's target compensation and 76% of target compensation for other named executives to equity-based opportunities.16 Long-term incentive performance metrics focus on four key areas: cumulative free cash flow, relative cumulative pre-tax income against airline peers, relative total shareholder return, and a customer satisfaction metric.16
Evaluating relative pre-tax income against industry peers provides a rigorous benchmark for a cyclical industry by isolating operational execution from broader jet fuel price swings. Furthermore, Delta aligns executive pay with frontline employees by capping annual executive incentive payouts below target unless profit-sharing distributions are triggered for the workforce.16 In 2025, Bastian received $19.2 million in total compensation, representing a 29% decrease from 2024 that aligned with lower adjusted earnings.16 Shareholders endorsed this pay architecture, approving the say-on-pay proposal with 95% of votes cast at the 2025 annual meeting.16
The capital allocation record, tested. In recent years, Delta's capital allocation strategy has prioritized debt reduction. Adjusted net debt declined from $18.0 billion at year-end 2024 to $14.3 billion at the end of 2025, improving gross leverage to 2.4 times adjusted debt to EBITDAR against a long-term target of 1.0x, backed by $35 billion in unencumbered assets.1 Net debt dropped further to $13.6 billion by the second quarter of 2026, with management projecting gross leverage of approximately 2.0x by year-end while raising the quarterly dividend by 15%.4
Capital expenditure reached $4.3 billion in 2025 against $4.6 billion in free cash flow, while 2026 projections outline $5.5 billion in reinvestment alongside expected free cash flow of $3 billion to $4 billion.1 Fleet investments continued in January 2026, when Delta ordered 30 Boeing 787-10 widebody aircraft with options for 30 more, scheduled for delivery starting in 2031, accompanied by a long-term GE Aerospace service agreement for their GEnx engines.1
Delta's fleet strategy reflects a distinct approach to capital intensity. By maintaining older, fully depreciated airframes—such as Boeing 757s, 767s, and 717s—alongside new aircraft deliveries, a significant portion of its capacity carries minimal capital ownership costs. This flexibility allows management to trim capacity during demand downturns without incurring heavy fixed capital charges. However, older aircraft consume more fuel and demand higher maintenance outlays, creating cost pressure when jet fuel reaches $3.93 per gallon. On the June 2026 call, Bastian confirmed that incoming Boeing 737 MAX 10 deliveries expected in 2027 will allow the airline to accelerate the retirement of its 717 and 757 fleets.6
Nevertheless, claims of uninterrupted capital discipline warrant scrutiny when measured against pre-2020 capital deployment decisions, a subject examined in subsequent operational and balance sheet analysis.
IX. Historical Falsification Layer: Stress-Testing Core Investment Claims
Every investment thesis for Delta rests on three load-bearing claims: that its operational reliability provides a durable moat, that its international equity portfolio delivers network superiority, and that its post-bankruptcy capital allocation remains strictly conservative. Empirical evidence from major operational and strategic disruptions provides a direct test for each claim.
Claim 1: operational reliability is an unassailable moat.
On July 19, 2024, cybersecurity firm CrowdStrike released a faulty update to its Falcon sensor software, triggering system outages across Microsoft Windows machines globally. The outage disrupted hospitals, financial institutions, media networks, and global airlines simultaneously.
While all major carriers experienced disruptions, the operational divergence emerged during the recovery phase. United Airlines cancelled roughly 1,500 flights, whereas Delta cancelled approximately 7,000 flights over five days, affecting over one million passengers and generating estimated losses in excess of $500 million.22
The breakdown stemmed not from a direct cybersecurity breach, but from an internal software bottleneck. Delta's crew-tracking system—responsible for logging pilot and flight attendant locations, duty-hour limits, and legal flight assignments—failed to resynchronize after underlying IT infrastructure was restored. Although aircraft and flight crews were physically available, the system could not match personnel to scheduled flights.
In effect, crew-tracking software functions as an air traffic control system for personnel rather than aircraft. While invisible during routine operations, it becomes the primary bottleneck during major operational disruptions, determining how quickly a carrier can reconstruct its schedule. During the July 2024 event, Delta's platform was overwhelmed by the scale of the disruption.
The regulatory and legal consequences resolved with mixed results for the carrier. The Department of Transportation opened an inquiry shortly after the outage and closed it in November 2025 without issuing fines, stating that "Delta's passengers received prompt refunds, adequate baggage assistance, and appropriate assistance for passengers with disabilities."22 Conversely, Delta's $500 million lawsuit against CrowdStrike faced legal hurdles: on May 16, 2025, Judge Kelly Lee Ellerbe of Fulton County Superior Court dismissed counts alleging fraud, misrepresentation, product liability, and violations of the Georgia Fair Business Practices Act, allowing only gross negligence and computer trespass claims to move forward—with CrowdStrike's defense counsel arguing any residual liability was "contractually capped in the single-digit-millions."23 Meanwhile, passenger class-action lawsuits against both companies remained pending as of mid-2026.22
Verdict: Historical evidence does not disprove Delta's operational reliability thesis, but it narrows its scope. The airline maintains a clear advantage in routine physical execution—such as gate turnarounds, preventive maintenance, baggage handling, and crew scheduling depth—as reflected in industry performance rankings. However, that advantage does not extend to systemic IT resilience, where Delta underperformed peers using similar software architecture. The refined thesis holds that Delta excels during normal operations but exhibits vulnerability during catastrophic network disruptions. Former CFO and current COO Dan Janki acknowledged on the June 2026 earnings call that building "resiliency and capability around our crew resourcing" by integrating "more people process technology around that" remains an ongoing initiative.6 A second prolonged recovery breakdown would invalidate the reliability thesis, whereas demonstrating faster schedule restoration than competitors during a future network disruption would validate it.
Claim 2: international equity stakes create unique network superiority.
While the pandemic-era restructuring of Delta's LATAM and Aeroméxico equity stakes led to initial write-downs before Delta recapitalized both carriers, subsequent events exposed a separate structural vulnerability that equity ownership cannot mitigate.
On September 15, 2025, the Department of Transportation issued a final order terminating the antitrust immunity supporting the Delta–Aeroméxico joint venture, effective January 1, 2026. The regulatory decision was driven by actions outside Delta's control: the Mexican government had reduced slot allocations at Mexico City's Benito Juárez International Airport and relocated all-cargo services to a secondary facility, which federal regulators deemed a violation of the bilateral aviation agreement. Delta and Aeroméxico contested the ruling, estimating that revoking immunity would erase approximately $800 million in annual consumer benefits and jeopardize nearly 4,000 U.S. jobs.24 On August 20, 2026, the U.S. Court of Appeals for the Eleventh Circuit vacated the Department of Transportation's order, preserving the joint venture and its regulatory immunity.25
Although Delta prevailed legally, the conflict highlighted a key strategic limitation. A mature nine-year commercial alliance, reinforced by a major equity position, came close to unraveling due to an intergovernmental dispute over airport slot administration. The episode underscored that antitrust immunity—granted and overseen by regulatory authorities—serves as the primary driver of joint venture economics, whereas equity ownership offers minimal protection against regulatory intervention.
Furthermore, Delta's equity portfolio expanded beyond traditional commercial airline partners. Total carrying value for non-wholly owned investments reached $4.2 billion by year-end 2025, comprising a 15% stake in Hanjin KAL—the parent holding company of Korean Air—valued at $861 million, a 13% interest in WestJet acquired for $276 million in October 2025, and a 36% holding in private aviation operator Wheels Up.2 The investment in Wheels Up highlights capital allocation risks within non-core assets: its carrying value dropped 60% in twelve months, falling from $435 million to $173 million by December 31, 2025, for a business with limited synergy with Delta's mainline network.2
Verdict: The broad claim that international equity stakes ensure network superiority is unsupported by the historical record. Direct equity ownership has not insulated commercial partnerships from regulatory disruption, has resulted in equity write-downs and zeroed carrying values, and does not serve as the primary source of operational synergies. The refined claim holds that Delta's international joint ventures—including its transatlantic partnerships with Air France-KLM and Virgin Atlantic, its transpacific agreement with Korean Air, and its South American alliance with LATAM—provide genuine commercial and revenue benefits. Management reinforced this on the June 2026 earnings call, noting that joint venture partners form "the foundation of our profitability and our strategy in those regions."6 Consequently, analytical valuation should focus on joint venture cash flows while evaluating minority equity holdings as distinct, historically lower-return capital deployments.
Claim 3: post-bankruptcy capital allocation is strictly conservative.
Evaluating Delta's capital discipline over a full business cycle reveals significant shifts in financial policy.
On May 13, 2015, Delta authorized a $5 billion share buyback program, raised its dividend by 50%, and outlined a strategy to return over $6 billion to shareholders through 2017. Management committed to allocating at least half of free cash flow toward shareholder distributions while targeting $4 billion in adjusted net debt by year-end 2017, with then-Chairman Daniel Carp emphasizing an "even greater emphasis on returning our free cash flow to shareholders."26
While sustainable during periods of industry profitability, that payout policy was not inherently conservative given commercial aviation's severe negative operating leverage. During sudden demand shocks, airline revenues can contract rapidly while fixed capital charges, aircraft leases, maintenance commitments, and core labor expenses remain largely fixed.
When global passenger demand collapsed in 2020, Delta's annual revenue dropped 64% to $17.1 billion, resulting in a GAAP pre-tax loss of $15.6 billion. To preserve cash, the carrier reduced capacity by 61%, retired 227 aircraft, received $5.6 billion in federal CARES Act payroll support grants and loans, and executed over $25 billion in financing transactions. Delta closed 2020 with $16.7 billion in liquidity and $18.8 billion in adjusted net debt—more than four times the $4 billion target set three years prior.27
Verdict: The claim of strict capital conservatism does not hold for the pre-2020 period, though it is provisionally supported by post-pandemic debt reduction efforts. However, recent capital allocation decisions indicate a returning emphasis on equity distributions. Despite carrying gross leverage at approximately twice its 1.0x long-term target, Delta raised its quarterly dividend by 15% in mid-2026, with CFO Erik Snell affirming an ongoing commitment to "increasing shareholder returns" alongside debt paydown.4 Capital discipline during periods of elevated industry earnings is routine; the true test occurs when free cash flow contracts. Investors monitoring balance sheet strength should track the quarter-by-quarter ratio of capital returned to shareholders relative to debt reduction as leverage moves toward target levels.
X. Strategic Frameworks: Porter's 5 Forces & Hamilton Helmer's 7 Powers
Applying competitive strategy frameworks to Delta tests whether the company's financial results stem from structural, long-term competitive advantages or temporary industry dynamics.
Threat of new entrants: low and declining. Establishing a network carrier in the United States requires unassailable capital, scarce flight crews, tightly controlled airport gate slots, and multi-year regulatory approvals. Supply chain constraints have further heightened these entry barriers. On the June 2026 earnings call, Chief Executive Officer Ed Bastian noted that delivery delays from Airbus and Boeing—caused primarily by engine supply and durability issues—have eliminated the mechanism that historically allowed low-cost carriers to expand capacity faster than their unit costs grew.6 Consequently, the same supply chain disruptions inflating Delta's operating expenses also shelter the carrier from new low-cost competition.
Supplier power: high and structurally dominant. Delta relies on an aircraft duopoly, three primary jet engine manufacturers, and unhedged global fuel markets. Fuel price volatility caused significant margin compression in 2026. In June 2026, the International Air Transport Association nearly halved its full-year global airline net profit projection from $41 billion to $23 billion, citing an aggregate industry fuel bill surging nearly 40% to $350 billion. The association based its revised forecast on Brent crude averaging $95 per barrel and jet fuel reaching $152 per barrel—producing a historic $57 crack spread driven by geopolitical conflict in the Middle East.28
Labor costs present a secondary supplier challenge. Approximately 17,260 Delta pilots are represented by the Air Line Pilots Association under a collective bargaining agreement that becomes amendable on December 31, 2026, whereas the majority of Delta's remaining 100,000 employees remain non-union—a labor structure distinct from American Airlines and United Airlines.2 The prior contract, ratified on March 1, 2023, with 78% approval, provided cumulative pay increases of roughly 34% totaling over $7 billion in incremental expenses across four years.29 Contract negotiations grew adversarial in 2026 when the pilots' Master Executive Council exited an accelerated bargaining framework to enter formal Section 6 negotiations under the Railway Labor Act after management requested scheduling flexibility.30 Resolving this labor agreement represents the primary variable in Delta's cost structure, posing a direct challenge to management's target of maintaining low-single-digit non-fuel unit cost growth.
Buyer power: sharply divided by segment. Individual leisure travelers exhibit high price sensitivity, leverage digital search tools for price transparency, and face minimal switching costs. Conversely, corporate accounts contract based on schedule frequency, operational completion rates, and premium lounge networks, while business travelers accumulate personal frequent flyer status that reinforces corporate compliance. Delta's June 2026 reporting indicated that corporate revenues grew over 20% year over year, with higher ticket yields driving the gain rather than passenger volume expansion—demonstrating this pricing asymmetry.6
Substitutes: limited for long-haul travel. Direct substitutes for transatlantic and intercontinental passenger flights do not exist. However, virtual collaboration platforms provide a permanent alternative to routine domestic business travel. As a result, corporate travel volumes have recovered more slowly than business yields, compelling network carriers to rely on premium pricing rather than passenger volume growth.
Rivalry: intense, but modified by industry consolidation. The liquidation of Spirit Airlines in May 2026 removed a major source of low-fare pricing pressure from the domestic market. On the June 2026 earnings call, Delta management observed that ultra-low-cost industry capacity had fallen approximately 30%, adding that low-cost operators still needed to increase fares by another 5% to achieve break-even economics.6 While this capacity decline validates Delta's immediate pricing leverage, it also suggests that a portion of its 2026 revenue strength reflects a temporary consolidation windfall rather than an expanding competitive moat.
Evaluating Delta through Hamilton Helmer's strategic framework highlights four key sources of competitive power.
Network economies: strong within core hubs. The exponential connectivity benefits of bank scheduling compound effectively at interior hubs in Atlanta, Detroit, Minneapolis–Saint Paul, and Salt Lake City. However, these network effects do not extend to coastal markets, where Delta operates point-to-point networks that depend on product quality and brand perception rather than structural gate dominance.
Switching costs: high and defensible. High-tier Medallion members holding co-branded credit cards, lounge privileges, and substantial mileage balances face high friction when switching carriers. However, customer pushback following proposed program changes in late 2023 demonstrated the limits of this power: while switching costs lock frequent travelers into the loyalty program, they also prevent management from unilaterally paring back member benefits.
Scale economies: developing rather than established. Delta spreads fixed operational overhead across a large fleet and an expanding maintenance division. Nevertheless, its non-fuel unit costs remain among the highest in the industry due to top-tier wage structures and substantial airport capital investments. Chief Financial Officer Erik Snell framed this cost structure by asserting that generational airport infrastructure investments and competitive wage rates are already embedded in baseline expenses, allowing future capacity growth to generate operating leverage.6 This argument implies that scale economies represent a future efficiency target rather than an existing structural cost advantage.
Counter-positioning: diminishing over time. Counter-positioning occurs when an incumbent cannot copy a challenger's business model without damaging its core revenues. Ultra-low-cost carriers could not incorporate premium cabins or airport lounges without undermining their low-cost operating model. However, as ultra-low-cost capacity contracts, remaining network peers—most notably United Airlines—are actively adopting similar premium seating and loyalty strategies without structural impediments.
Process power: limited. Operational reliability has long been viewed as an embedded process advantage within Delta's culture. However, the operational breakdown following the July 2024 CrowdStrike outage, combined with modest declines in on-time arrival metrics, indicates that operational performance reflects sustained capital deployment rather than an uncopyable process capability.
Cornered resources and branding: concentrated assets. Delta holds valuable slot positions at congested airports such as LaGuardia and JFK, alongside historic international route authorities. Furthermore, its corporate brand equity is reinforced by fifteen consecutive top rankings in the Business Travel News corporate airline survey. While competitors hold similar assets, Delta maintains a higher concentration of premium slots and corporate brand preference within the U.S. market.
XI. Analysis & Bear vs. Bull Case (With Skeptical Investor Stress Test)
The bull case, stated as precisely as the evidence allows.
The first pillar is that Delta earns a large, contractual, high-margin cash stream that is uncorrelated with the cost of jet fuel. The American Express relationship is not merely additive; it fundamentally changes the shape of the business, converting a slice of Delta's earnings into something closer to a consumer payments annuity. Whether the $10 billion target arrives on schedule is the open question, but the growth trajectory has remained consistent through a pandemic, an inflation surge, and a fuel shock.
The second pillar is the internal mix shift within the airline itself. When premium ticket revenue grows while main cabin revenue shrinks, and the company deliberately trims main cabin seating rather than discounting to fill planes, the airline is choosing yield over volume—and succeeding. The second-quarter 2026 results offered a unique variation on this dynamic: main cabin unit revenue growth actually outpaced premium unit revenue growth because Delta had reduced main cabin capacity into a market where a major low-fare competitor had suddenly disappeared.6
The third pillar is the balance sheet. Investment-grade credit ratings from all three major rating agencies, a substantially reduced debt burden, and $35 billion in unencumbered assets give Delta a financial cushion no major U.S. carrier possessed heading into prior cycles: the structural capacity to navigate an industry downturn without emergency external financing.
The fourth pillar is upside optionality that remains underappreciated in standard valuation models. The maintenance repair and overhaul division is expanding rapidly off a modest base. Meanwhile, the Trainer refinery has finally delivered on its original strategic intent.
On the refinery, specifically. For fourteen years, the acquisition of the Trainer facility stood as a prime example of airline management straying beyond its core operational competence. In 2026, however, the crack spread expanded to record levels, temporarily transforming the asset into a lucrative hedge. Chief Financial Officer Erik Snell informed investors that the refinery represents "a strategic advantage" providing "a meaningful offset in a high crack environment," projecting that 2026 would be "one of its most profitable years."6 United Airlines Chief Executive Officer Scott Kirby publicly acknowledged the advantage, noting that the surging crack spread provides Delta with a "real benefit" that "will be unique to them."31
Two important caveats qualify that advantage. First, owning a refinery is not a traditional commodity hedge; Delta's overall fuel expense still rose 75% year over year in the second quarter of 2026, even after factoring in refinery gains. The facility mitigates the severity of a fuel price shock rather than eliminating it. Second, the operation carries inherent single-asset risk: a temporary operational outage cost Delta five cents per gallon in the second quarter, with an additional five to seven cents per gallon impact projected for the third quarter while the plant operated at roughly 75% capacity.46
The bear case.
The primary bear argument centers on cost inflation. Non-fuel unit costs climbed 6.8% in the second quarter of 2026—significantly exceeding management's low-single-digit target—as capacity growth lagged expectations and fixed expenses failed to spread across scheduled flights.4 While management attributes the spike to temporary timing issues and projects sequential cost improvement, that explanation faces immediate headwinds from upcoming labor negotiations. Delta's pilot contract becomes amendable at the end of 2026 amid increasingly formal Section 6 negotiations, in an industry environment where every wage increase granted sets a higher cost floor across the sector.
Second, capital intensity remains relentless. Delta projects $5.5 billion in capital reinvestment for 2026, holds a commitment for 30 Boeing 787-10 aircraft delivering starting in 2031, and maintains a substantial fleet of aging airframes that will eventually require replacement.1 Annual free cash flow guidance of $3 billion to $4 billion represents a solid cash generation profile, but it reflects what remains only after funding a capital expenditure program larger than the total market capitalization of most publicly traded global carriers.
Third, structural cyclicality has not been eliminated. Delta posted a GAAP pre-tax loss in the first quarter of 2026. Furthermore, historical experience demonstrates how quickly airline earnings visibility can degrade: management previously forecasted record financial results before withdrawing full-year guidance entirely three months later during a sudden macro disruption.
Fourth, recent pricing power may prove temporary. If the revenue strength of 2026 is largely the product of an industry-wide fuel surcharge response combined with the sudden liquidation of Spirit Airlines, a decline in crude oil prices or a resurgence in low-fare capacity could expose how much of Delta's premium pricing reflects genuine brand equity versus market conditions. Chief Executive Officer Ed Bastian argued on the second-quarter earnings call that top-line momentum "should remain sustainable even if fuel prices moderate."6 That assertion represents a management forecast rather than an established outcome, making it a critical benchmark for investors to monitor.
The activist stress test.
A skeptical long/short investor would begin with a sum-of-the-parts argument: carving out SkyMiles. The frequent flyer program independently supports investment-grade-level debt and comparable loyalty platforms command stand-alone valuations in the tens of billions of dollars. From an activist perspective, housing a high-margin consumer payments stream inside a capital-intensive airline compresses its market multiple.
Management counters that the loyalty flywheel cannot be separated from the operational network: members earn miles by flying, redeem them for seats, and value the currency because of network reach and lounge access. A spin-off would force a standalone SkyMiles to purchase seat inventory from Delta through arm's-length commercial agreements, creating friction that could erode value for both entities. Air Canada's historical separation and eventual repurchase of its Aeroplan loyalty program serves as an industry precedent for the risks of structural unbundling.
A more compelling activist critique focuses on portfolio complexity. Delta maintains ownership across an oil refinery, minority equity stakes in nine international airlines and aviation services firms, a private jet operator whose carrying value dropped 60% in a single year, a stake in an airport terminal developer, and a captive maintenance division that management recently excluded from its primary unit-cost metric.2 While each investment carried an initial strategic rationale, the aggregate holdings impose a significant disclosure burden on investors. Furthermore, a track record featuring a zeroed carrying value, a substantial write-down, and two partner bankruptcies raises legitimate questions about whether that capital would have generated higher risk-adjusted returns if directed strictly toward debt paydown.
A second activist critique targets financial disclosure practices. Delta highlights "diversified revenue streams" as a core metric while excluding TechOps from core CASM-Ex calculations. While neither practice violates accounting rules, both rely on management-defined definitions rather than audited reporting segments, making period-over-period tracking and cross-carrier comparisons more complex.
Finally, governance structures invite mild scrutiny. Although shareholders backed executive compensation with a 95% say-on-pay vote, the near-simultaneous April 2026 leadership shuffle involving the chief financial officer, president, and chief commercial officer during a period of non-fuel cost pressure warrants more explicit corporate disclosure regarding long-term succession planning and operational strategy.
What to actually track. Three primary metrics provide the clearest signal of Delta's long-term thesis execution.
American Express remuneration and its growth rate. As the primary driver of high-margin earnings, card remuneration is disclosed quarterly against an explicit $10 billion long-term target. Any sustained deceleration—especially if accompanied by a slowdown in new card acquisitions—would indicate that the loyalty program is maturing and compress Delta's valuation premium.
Premium ticket revenue versus main cabin ticket revenue. The relative trajectory of these two revenue lines provides empirical proof of whether de-commoditization is holding. If premium revenue growth decelerates while main cabin capacity continues to contract, Delta risks surrendering passenger volume without capturing offsetting pricing power.
Non-fuel unit cost growth against the low-single-digit framework. This metric reflects the combined financial impact of pilot contract negotiations, airport infrastructure investments, and operational software remediation. Sustained unit cost growth above low single digits would indicate that Delta is securing its revenue premium through a higher operating cost structure—creating a higher-cost airline rather than a defensible economic moat.
XII. Transcripts & Earnings Call Analysis: What Management vs. Analysts Are Saying
A distinct pattern emerges on Delta's quarterly earnings calls: executive management addresses unit cost inquiries with operational timelines, while answering top-line revenue questions with brand philosophy.
The clearest illustration occurred on the June 2026 call when Bernstein analyst David Vernon asked where Delta intended to deploy future capacity and whether returning Boeing 737 MAX 10 aircraft could erode market pricing. Chief Executive Officer Ed Bastian offered a concrete, industry-wide assessment, noting that aircraft availability had become a primary competitive bottleneck—driven by engine supply chain constraints rather than airframe availability—and confirming that Delta's domestic capacity expansion would focus on upgauging aircraft size and expanding long-haul routes into the Middle East and Asia rather than increasing flight frequencies.6
Conversely, when Citigroup analyst John Godyn asked why investors should view the carrier's margin expansion as a durable inflection rather than a temporary windfall, Bastian pivoted to thematic framing. Citing a decade of consistent strategy, management continuity, and frontline workforce execution, Bastian asserted that competitive advantage rests on service quality rather than network geometry, concluding that leadership saw no visible end to that trend.6 While effective for corporate positioning, such qualitative framing provides limited utility for financial modeling.
Exchanges regarding unit costs yield more actionable data. When Barclays analyst Brandon Oglenski questioned the timeline for returning to low-single-digit unit cost growth, Chief Financial Officer Erik Snell outlined a clear sequence: modest cost improvement in the September quarter, further progress in December, and a return to long-term cost targets once capacity growth normalizes, while quantifying expected operating leverage at two to three percentage points.6 Similarly, Morgan Stanley analyst Ravi Shanker obtained specific guidance regarding refinery outage impacts, while Goldman Sachs analyst Catherine O'Brien pressed management to clarify that the 20%-plus surge in corporate sales was driven primarily by higher ticket yields rather than passenger volume expansion.6
Consistency across time. A rigorous test of corporate credibility involves comparing management guidance across different phases of the industry cycle.
In January 2025, Delta projected what Bastian characterized as the strongest financial performance in company history. By April 9, 2025, management withdrew full-year guidance entirely, with Bastian citing unprecedented trade policy uncertainty, stating that demand growth had largely stalled, and acknowledging that the airline was preparing for a potential recession while flattening planned second-half capacity growth from an initial 3% to 4% target.32 The year closed with record revenue but lower profitability, as adjusted earnings per share fell to $5.82 from $6.16 in 2024, adjusted pre-tax income contracted, and adjusted operating margin declined from 10.6% to 10.0%.1
This sequence underscores that Delta over-promised at the start of 2025 and under-delivered on adjusted earnings, even after accounting for external headwinds such as trade friction and a federal government shutdown that management estimated reduced fourth-quarter revenue by approximately two percentage points.1 To management's credit, leadership withdrew unviable targets promptly, trimmed capacity swiftly, and provided detailed explanations for the shortfall. Conversely, the aggressive initial framing and the emphasis on "record revenue" in subsequent disclosures obscured the underlying contraction in unit profitability.
The 2026 trajectory presents a contrasting pattern. Management established full-year targets in January, reaffirmed them in April despite jet fuel price spikes that caused a first-quarter loss, and maintained them again in July. Reaffirming annual earnings targets through a multi-billion-dollar fuel expense increase represents a meaningful demonstration of operating leverage, assuming execution holds. The second half of 2026 serves as the decisive benchmark, with management guiding to a September-quarter operating margin of 11% to 13% and earnings of $2.00 to $2.50 per share, compared with $1.70 per share in the prior-year period.4
Finally, executive communications across 2025 and 2026 relied heavily on third-party recognitions from organizations including Cirium, The Points Guy, Business Travel News, Fortune, and Forbes. While these rankings substantiate Delta's premium brand positioning, an over-reliance on industry awards can obscure core operational metrics, particularly during quarters when financial performance diverges from corporate narrative.
XIII. Playbook: Business & Investing Lessons
1. In a commoditized industry, the escape route is product segmentation plus reliability—and it takes a decade.
Delta did not de-commoditize air travel by inventing new technology. It built a multi-tiered ladder of cabin products so customers could self-select into higher fare classes, then spent years executing operationally so those premium price points felt justified. The lesson applies across industries where conventional wisdom holds that customers care only about price. That premise is often true for marginal customers, but false for high-margin, profitable ones. However, the commercial payoff unfolds over a full business cycle rather than a few quarters—as demonstrated by premium ticket revenue surpassing main cabin sales more than a decade after the strategy began.
2. Attaching a high-margin annuity to a capital-intensive core alters the risk profile more than the return profile.
The value of the American Express relationship lies not merely in its profitability, but in cash flows that operate largely independent of jet fuel prices, weather disruptions, and aircraft utilization. In the first quarter of 2026, Delta posted an operating loss on a GAAP basis yet still received billions of dollars in contractual loyalty cash. That structural cash flow transforms a business that historically faced periodic bankruptcy into one that periodically absorbs a bad quarter. For investors, the key is identifying uncorrelated cash streams within cyclical enterprises—and evaluating counterparty risk and contract durability.
3. In mergers and acquisitions, network adjacency beats raw scale, and labor integration represents the primary deal risk.
The Northwest Airlines merger succeeded because the route networks were complementary and pilot seniority was addressed early by granting employees equity in the combined entity. Conversely, the proposed US Airways takeover faced structural hurdles for the opposite reasons—with Delta's creditors rejecting the bid due to heavy East Coast route overlap and regulatory risks. Underwriting a merger in a labor-intensive, network-based industry requires prioritizing route complementarity and workforce integration over optimistic synergy models.
4. Operational excellence is an ongoing operating expense, and technical debt is where it breaks.
Delta spent a decade investing in reliability, only to find its primary vulnerability in a crew-tracking platform overlooked outside operations. The broader lesson: an operational moat is only as deep as its least-modernized dependency, which often remains invisible until a system breakdown occurs. Investors should evaluate ongoing IT investments in mission-critical systems as required capital expenditure rather than discretionary spend, paying close attention when management characterizes infrastructure remediation as an ongoing initiative rather than a completed project.
5. Capital allocation targets set at the peak of a cycle are commitments made by a different company.
Delta's 2015 plan to return at least half of free cash flow to shareholders while reducing net debt to $4 billion was logical based on prevailing conditions, but it assumed passenger revenue could not experience a severe collapse. In businesses with high operating leverage, a liquidity buffer is a strategic asset that must be sized for catastrophic downside risks rather than average business conditions. While Delta has prioritized debt reduction post-2021, that policy has yet to be tested by a prolonged period of cash flow contraction, even as dividend payouts begin rising again.
6. Vertical integration into a commodity is a volatility trade, not a hedge—and can take over a decade to deliver.
The acquisition of the Trainer refinery stands as an instructive case of a widely criticized decision being validated by market conditions that were not originally underwritten. Delta did not hedge crude oil prices; it acquired a long position in refining margins, a distinct variable that expanded significantly during the 2026 fuel shock. That outcome reflects a combination of strategic positioning—given the relationship between jet fuel tightness and crack spreads—and market timing. Investors evaluating such non-core assets should base long-term valuations on mid-cycle refining margins rather than peak windfall conditions.
XIV. Links & Resources
For readers seeking to verify or extend this analysis, primary source materials are accessible across corporate filings, regulatory dockets, and industry databases.
Delta's Form 10-K for the fiscal year ended December 31, 2025, serves as the primary reference filing, detailing passenger revenue breakdowns by category, refinery segment financials including Renewable Identification Number compliance costs, equity investment carrying values, collective bargaining contract amendable dates, and capacity antitrust litigation disclosures.2 The airline's investor relations portal provides quarterly earnings releases and financial tables that separately outline the maintenance, repair, and overhaul business.33
Earnings call transcripts and investor presentation materials on the portal offer insight into real-time operational execution and executive commentary, with analyst exchanges highlighting areas where disclosure remains limited.6 Delta's annual proxy statements outline executive incentive targets and report operational metrics—such as completion factor rates and on-time arrival figures—that fall outside standard earnings reports.16 The carrier's complete regulatory history, including the 2008 Northwest merger filings and the 2020 SkyMiles debt offering disclosures, is publicly accessible via the SEC's EDGAR database.34
Beyond company disclosures, the International Air Transport Association's semi-annual outlooks establish macro industry benchmarks for fuel expenses, passenger traffic trends, and overall airline sector profitability.28 To assess whether Delta's financial outperformance reflects a structural economic moat or broader cyclical dynamics, the MIT Airline Data Project provides long-term comparative data tracking unit revenues, unit costs, and balance sheet leverage across major U.S. carriers.[^36]
For historical context, Thomas Petzinger Jr.'s Hard Landing provides a definitive account of U.S. airline deregulation and subsequent industry restructuring, offering essential background on the operational origins of modern network carriers. Additionally, the Delta Flight Museum maintains historical archives documenting the airline's agricultural founding, corporate evolution, and past network acquisitions, including the 1991 Pan American asset purchase.110
Finally, two ongoing legal matters warrant direct tracking: the CrowdStrike litigation in Fulton County Superior Court, where surviving claims for gross negligence and computer trespass will determine whether Delta recovers damages following its 2024 operational disruption, and the capacity antitrust multi-district litigation in the District of Columbia, which moved into class discovery following a September 2025 court ruling and which Delta continues to contest on the grounds that the allegations lack merit.232
References
-
Delta Air Lines, Inc. Form 10-K for the fiscal year ended December 31, 2025 — Delta Air Lines / SEC, 2026-02-10 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Delta Air Lines announces March quarter 2026 financial results — Delta News Hub, 2026 ↩
-
Delta Air Lines Announces June Quarter 2026 Results — Delta Air Lines, 2026-07-10 ↩↩↩↩↩↩↩↩↩↩
-
Spirit Airlines Shuts Down After 34 Years, Blames Higher Oil Prices — Insurance Journal, 2026-05-06 ↩
-
Delta Air Lines Events, Presentations & Earnings Transcripts (June quarter 2026 earnings call, July 10, 2026) — Delta Air Lines ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Delta's history: From dusting crops to connecting the world — Delta News Hub ↩↩↩↩↩↩↩
-
When Delta Took Over Pan Am's Transatlantic And Shuttle Routes — Simple Flying ↩↩↩
-
US Airways makes $8 billion bid for Delta — NBC News, 2006-11-15 ↩
-
US Airways withdraws hostile bid for Delta — NBC News, 2007-01-31 ↩
-
Delta, Northwest Stockholders Approve Merger to Create Premier Global Airline (Form 8-K, Exhibit 99.1) — Delta Air Lines / SEC, 2008-09-25 ↩
-
Delta and Northwest Merge, Creating Premier Global Airline — Delta Air Lines Investor Relations, 2008-10-29 ↩↩
-
Delta, Northwest can work as single carrier — MPR News, 2009-12-31 ↩
-
Delta Air Lines, Inc. 2026 Proxy Statement (Form DEF 14A) — Delta Air Lines / SEC, 2026 ↩↩↩↩↩↩↩
-
Delta Subsidiary to Acquire Trainer Refinery Complex — Delta Air Lines Investor Relations, 2012-04-30 ↩
-
Delta at ATL: Bigger and bolder at the world's largest airline hub in summer 2025 — Delta News Hub, 2025 ↩↩
-
American Airlines reports fourth-quarter and full-year 2025 financial results — American Airlines Newsroom, 2026-01-27 ↩
-
Delta Air Lines Announces Upsize of SkyMiles Financing to $9 Billion — Delta Air Lines Investor Relations, 2020-09-17 ↩
-
Delta names new CFO amid sweeping leadership changes — CFO Dive, 2026 ↩
-
DOT drops investigation of Delta for CrowdStrike outage — The Atlanta Journal-Constitution, 2026-06-16 ↩↩↩
-
Georgia judge dismantles most of Delta's $500M lawsuit against CrowdStrike — Transportation Today, 2025-05-28 ↩↩
-
DOT Ends Antitrust Immunity for Delta–Aeromexico JV — Airways Magazine, 2025 ↩
-
Aeromexico Announces Court Decision on Aeromexico-Delta ATI — Grupo Aeroméxico via GlobeNewswire, 2026-08-20 ↩
-
Delta Announces Plan to Return Additional $6 Billion to Shareholders Through 2017 — Delta Air Lines Investor Relations, 2015-05-13 ↩
-
Delta Air Lines Announces December Quarter and Full Year 2020 Financial Results — Delta Air Lines Investor Relations, 2021-01-14 ↩
-
Middle East Disruptions and High Fuel Prices Halve Airline Industry Profitability — International Air Transport Association, 2026-06-07 ↩↩
-
Delta Air Lines Pilots Ratify New Contract — Simple Flying, 2023-03 ↩
-
Delta Pilot Contract Talks Delay Could Hurt Flight Reliability — Aviation A2Z, 2026-08-13 ↩
-
Why This Airline Is Actually Earning $300 Million From Higher Fuel Costs — Simple Flying, 2026-04-20 ↩
-
Delta withdraws 2025 outlook, cites 'current uncertainty' — CFO Brew, 2025-04-09 ↩
-
Delta Air Lines Investor Relations Financials & SEC Filings — Delta Air Lines ↩
-
SEC EDGAR Database, Delta Air Lines Inc (CIK 0000027904) — U.S. Securities and Exchange Commission ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube