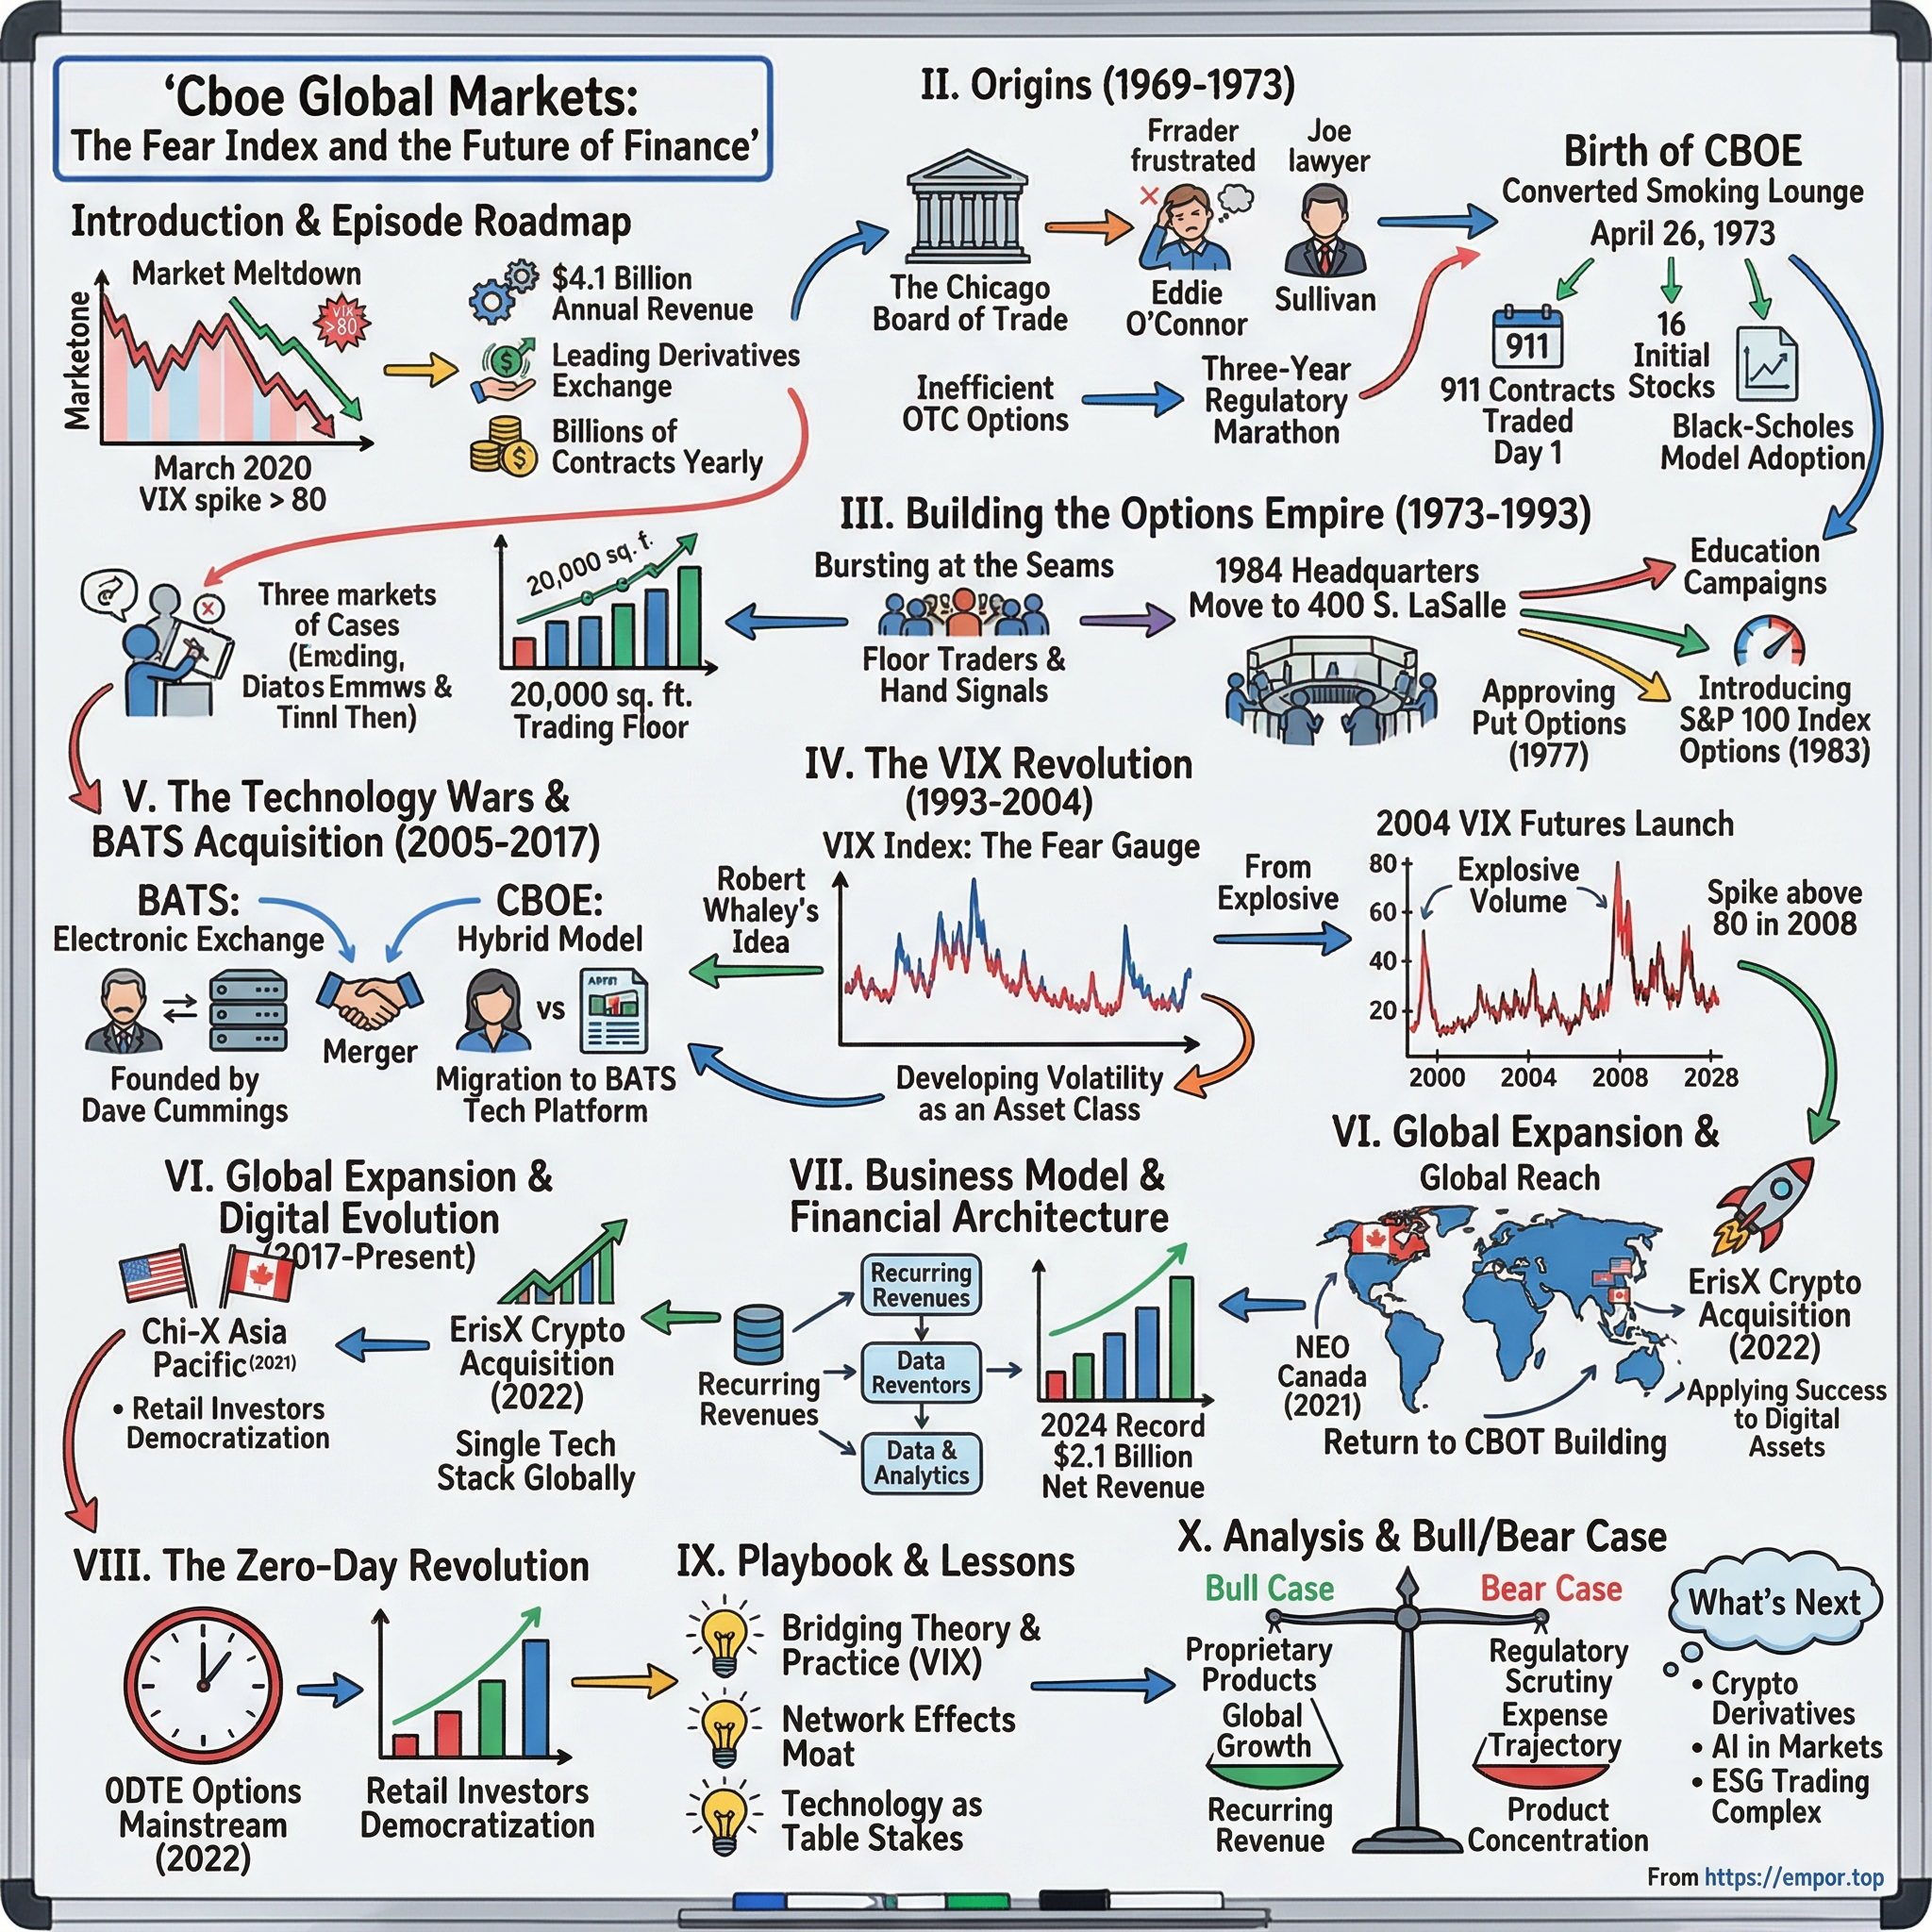
Cboe Global Markets: The Monopoly on Market Volatility
I. Introduction & Episode Roadmap
On the fourth floor of 433 West Van Buren Street in Chicago, several hundred floor traders and brokers still execute orders by open outcry. On any given Tuesday in 2026, a floor broker in a colored jacket walks an order for ten thousand S&P 500 index options into a pit, works it by voice against twenty market-making groups, and secures execution at a size that automated matching engines struggle to fill cleanly in a single block. Two floors of servers away, roughly 84% of the same product trades electronically in microseconds for retail accounts in Seoul and Sydney.1
That operational contrast — running a physical trading floor alongside high-speed electronic architecture — defines Cboe Global Markets. Valued at $32 billion by market capitalization in early September 2026, Cboe occupies a distinct position in public markets: a financial exchange whose core earnings depend primarily on the right to list options on an index it does not own.2
Understanding Cboe requires looking past its top-line revenue. In 2025, the company reported total revenue of $4.71 billion. However, $2.29 billion represented cost of revenues — consisting of Section 31 regulatory fees collected and remitted to authorities, liquidity rebates paid to market makers, and index licensing royalties. The key operating metric, revenue less cost of revenues, reached $2.43 billion, up 17% year-over-year. From that net revenue, Cboe generated $1.09 billion in net income and $10.42 in diluted earnings per share.3 Converting roughly forty-five cents of every net revenue dollar into net income places Cboe among the most margin-efficient exchange operators in global finance.
This operating model highlights the central structural dynamic of the business. In its 2025 Form 10-K, Cboe reported that approximately 68% of net revenue originated from its Options and Futures segments — with the vast majority derived from products built on exclusively licensed indices and Cboe's proprietary VIX methodology.4 The exchange's primary financial driver is an exclusive licensee. Its flagship contract, the SPX option, relies on an exclusive license from Standard & Poor's to list options on the S&P 500 — a contractual arrangement subject to periodic renegotiation and fixed expiration dates.
Episode architecture. The analysis traces five inflection points:
The Pit Era (1969–2003). A grain exchange seeking new trading volume creates the standardized stock option, resolves a five-year jurisdictional dispute with the SEC, and opens for trading in a converted smoking lounge.
The Volatility Engine (1989–2006). An academic index evolves into a tradable asset class, establishing Cboe's central piece of intellectual property in modern financial market structure.
The Tech Pivot (2016–2019). A legacy member-owned exchange acquires electronic competitor BATS, gaining a modern execution engine that proved more valuable than the acquired equity market share.
The 0DTE Revolution (2020–present). Same-day-expiry options expand from a niche product to approximately 60% of SPX trading volume, driving revenue expansion without a proportional increase in operating expenses.
Governance and Capital Realignment (2022–present). Following a digital asset write-off, executive leadership changes, board-led interim oversight, and the hiring of a chief executive officer from a competing exchange, Cboe announced a 20% workforce reduction by May 2026 while reporting record financial results.
A major head-count reduction alongside record financial performance underscores a broader realignment following a period of aggressive corporate expansion.
Myth versus reality, up front. Three common market assumptions about Cboe require clarification:
Myth: Cboe is a monopoly. Reality: Cboe holds an exclusive, time-limited license. Pure monopolies do not operate under contractual expiration dates negotiated with licensors whose bargaining leverage expands as trading volume grows. Cboe maintains contractual exclusivity reinforced by a deep, self-sustaining liquidity network.
Myth: The BATS acquisition transformed Cboe into a diversified multi-asset exchange group. Reality: By 2026, Cboe was actively divesting and winding down non-core international and digital assets. The lasting value of the BATS transaction stemmed from acquiring its execution technology rather than expanding into adjacent asset classes.
Myth: VIX is the primary revenue engine. Reality: VIX functions primarily as a flagship brand. In 2025, the Futures segment containing VIX futures generated $126.2 million in net revenue — roughly 5% of company net revenue — and experienced a minor contraction. Proprietary SPX index options serve as the core financial engine, while VIX serves as the category brand.
These three distinctions provide the analytical framework for the evidence that follows.
 Subscribe on LinkedIn
II. Origins: The Smoking Lounge Experiment & The Birth of Listed Derivatives (1969–1973)
In the late 1960s, the Chicago Board of Trade faced a structural limitation with agricultural commodities. Grain futures trading volume ebbed and flowed with harvests, weather patterns, and federal farm policy, causing CBOT's transaction fee revenue to fluctuate alongside it. Facing a plateau in its core market, the exchange sought new asset classes to list.5
It targeted the conventional over-the-counter put and call market—an archaic segment of Wall Street. Options had traded by telephone in the United States since the late eighteenth century, brokered by a small syndicate known as the Put and Call Brokers Association. Each contract was bespoke: counterparties negotiated the strike price, expiration date, and premium individually, with no standard terms and no secondary market. An investor who bought an option had to hold it until expiration while assuming counterparty credit risk.5
CBOT's core insight was that the primary barrier to liquidity was a lack of standardization. Transforming bilateral favors into standardized instruments created the foundation for an exchange-traded market.
Executing the plan required nearly five years of negotiation with regulatory authorities. CBOT formed an advisory committee of financial practitioners, academics, and institutional investors to navigate regulatory reviews with the Federal Reserve Board, the Commodity Exchange Authority, state securities commissioners, and the Securities and Exchange Commission. Regulators expressed concern over market integrity, given that options had faced potential legislative bans after the 1920s market crash before surviving through explicit hedging protections in the Securities Exchange Act of 1934.5
The resulting regulatory structure established Cboe's corporate independence. Once it became clear the SEC would act as the primary regulator, CBOT's leadership chose to spin off both the options exchange and its clearing organization as independent entities rather than operate under dual agency oversight. Existing CBOT members retained equity trading rights on the new venue while new memberships were sold—a structural division that later triggered decades of litigation, but established the Chicago Board Options Exchange as a separate corporate entity in 1972.5
Joseph Sullivan, Cboe's first president, directed the regulatory and commercial effort, persuading institutional investors, brokerage firms, and regulators that standardized options served a legitimate risk-management function rather than a speculative gambling operation.
Opening day. On April 26, 1973—timed to coincide with the Board of Trade's 125th anniversary—Cboe launched operations in a converted smoking lounge above the CBOT trading floor. The exchange initially listed call options on 16 underlying stocks, with put options prohibited. First-day trading volume totaled 911 contracts.5
Market conditions at launch were challenging. Equity prices were declining, overall trading volume was thin, and Wall Street brokerages were consolidating or shutting down. The SEC imposed strict operational constraints, limiting call options to no more than 20 underlying equities and requiring that each underlying stock be listed on either the New York Stock Exchange or the American Stock Exchange.5
Cboe's model relied on three core structural innovations that remain central to derivatives market structure in 2026. First, standardized contract specifications fixed the strike price and expiration date, leaving only the option premium subject to market discovery. Second, a central counterparty clearinghouse stood between every buyer and seller, eliminating bilateral credit risk. Third, standardization and central clearing enabled a continuous secondary market, allowing market participants to offset and close out positions prior to expiration.5
The clearing framework also reshaped industry structure. When the American Stock Exchange launched its competing options floor 20 months later, it initially proposed a separate clearing facility. Broker-dealers rejected managing fragmented clearing pipelines, prompting Amex to purchase a 50% equity stake in Cboe's clearing arm, which was reorganized as The Options Clearing Corporation (OCC). Subsequent options venues joined the clearing utility.5 By spinning off its clearinghouse, Cboe established the industry-wide infrastructure that rendered listed options fully fungible across competing exchanges—creating a market utility Cboe built but did not retain as an exclusive asset.
Trading volume expanded rapidly, prompting competing exchanges—including Amex, the Philadelphia Stock Exchange, the Midwest Stock Exchange, and the Pacific Exchange—to enter the market. In 1976, Cboe and Amex both listed options on MGIC Corporation, introducing the first multiply traded option contract and initiating long-term competition over market share.5
Industry growth triggered regulatory scrutiny. Following investor complaints and floor trading irregularities in multiply listed contracts, the SEC declared a moratorium on expanding options listings in October 1977. The regulatory review lasted more than a year, generating over 80 structural recommendations before the SEC lifted the moratorium in 1980.5
The episode demonstrated a central reality of exchange market structure: regulatory frameworks directly define the operational boundaries of the business model. This regulatory dynamic remained evident decades later, including Cboe's 2026 initiative to structure its event and prediction products as SEC-regulated securities rather than CFTC-regulated futures contracts.
III. Building the Options Empire & Demutualization (1974–2010)
Once the regulatory moratorium lifted in 1980, the central question for exchange operators became what other assets could underpin derivative contracts.
The answer was stock indices, and the enabling mechanical innovation was cash settlement. A standard equity option settles by delivering physical shares. An index option cannot — deliverable shares for hundreds of underlying companies would create administrative gridlock — so it settles in cash against a calculated benchmark value. Furthermore, most index contracts were designed with European-style exercise, permitting execution only at expiration. That structural combination transformed index options into essential institutional infrastructure: a pension fund hedging an equity portfolio avoids early assignment risk and physical stock deliveries, receiving a single cash adjustment instead.5
Cboe launched options on the S&P 100 (ticker OEX) in 1983 and on the S&P 500 (SPX) in 1985. The OEX trading pit became the central venue for institutional equity risk during the 1980s. Everything that followed — the VIX volatility index, zero-days-to-expiration (0DTE) contracts, and the broader volatility asset class — flowed directly from the decision to license benchmark equity indices from Standard & Poor's and list derivative contracts on them exclusively.
Crucially, Cboe did not own the underlying S&P 500 benchmark; it licensed the right to use it. In 2013, the exchange extended that commercial agreement, securing exclusive rights to list options on S&P Dow Jones indices — including SPX — through 2032, with non-exclusive rights running through 2033.6 That extension provided two decades of contractual certainty, negotiated when the franchise was valued at a fraction of its current capitalization.
That licensing contract remains the single most important intellectual property arrangement Cboe does not control, creating a strategic dependency that informs every subsequent phase of its corporate evolution.
Whose stock is it anyway? A foundational legal dispute from this era established a precedent that continues to shape market structure in 2026.
In late July 1983, the American Stock Exchange announced plans to list options on Golden Nugget, an actively traded casino operator listed on the New York Stock Exchange. Amex routinely sent courtesy notices to underlying companies ahead of new listings. Golden Nugget's chief executive officer responded by demanding that Amex cancel the listing. Amex declined, and Golden Nugget filed suit in Nevada federal court.5
Golden Nugget's legal strategy did not rely on securities law. Instead, the company alleged common-law misappropriation and trademark infringement, arguing that an exchange could not build a commercial product on an issuer's corporate identity without explicit consent. The litigation spanned four years. Amex prevailed at trial, and in September 1987 — weeks before the October market crash — a federal appeals court affirmed the decision.5
The ruling established a legal principle vital to derivatives exchanges: an option venue does not require corporate approval to list contracts referencing a publicly traded company, because derivative contracts are created, cleared, and guaranteed by the clearinghouse rather than the issuing entity. Underlying corporations hold no veto over derivative listings.
That principle carries direct implications for Cboe's modern product strategy, including its expansion into listing contracts based on individual corporate operating metrics without seeking issuer permission. The legal authority for those listings traces directly to the 1987 appellate decision.
The member problem. For the first four decades of its existence, Cboe operated not as a public corporation, but as a member-owned, non-profit exchange. Seat ownership conferred floor trading privileges, and governance prioritized member profitability over corporate margin expansion.
Industry tradition often suggests that member ownership provided patient capital for long-term product development, allowing a non-profit entity to spend years incubating index options. While member alignment supported early contract launches, governance by floor members ultimately impeded technological adaptation.
Because seat holders held veto power over exchange rules, floor traders resisted automated execution systems that threatened open-outcry market making. That structural delay created an opening for electronic competitors. The International Securities Exchange launched in 2000 as the first fully electronic U.S. options venue, capturing market share rapidly against the established floor-based incumbent. In 2003, ISE handled an average of roughly 972,000 contracts daily, representing 29.5% of total U.S. equity options volume. By the first half of 2004, ISE's share reached 32.5%, making it the world's largest equity options exchange by volume.7
Cboe responded on June 12, 2003, by launching a hybrid trading system that integrated electronic quote streaming with the traditional open-outcry pit — the result of a three-year technology development effort.8 While the hybrid model stabilized Cboe's market position, surrendering nearly a third of equity options volume to a four-year-old electronic startup highlighted the governance friction inherent in member ownership. Member control sustained early contract incubation, but protected legacy floor execution at the expense of market structure innovation.
Demutualization. Converting Cboe from a member-owned organization into a publicly traded corporation required resolving legacy ownership claims. In August 2006, two Chicago Board of Trade members filed a lawsuit contending that the 1972 spin-off agreement — which granted CBOT members trading rights on Cboe in perpetuity — entitled them to an equity stake in the restructured options venue. The legal challenge delayed Cboe's initial public offering for nearly four years.9
Cboe resolved the dispute through a financial settlement. Qualifying class members received $300 million in cash and 16,333,380 shares of Class B common stock. On June 18, 2010, CBOE Holdings completed its initial public offering, selling 13,455,000 shares at $29.00 per share and raising $301.2 million in net proceeds.9
Financially, the public offering functioned as a net capital wash, with the $301 million raised matching the cash paid to extinguish the 1972 membership claims. However, demutualization provided Cboe with corporate equity as acquisition currency, aligned governance around public shareholder returns, and eliminated floor member vetoes over strategic technology investments.
IV. The VIX Invention & The Financialization of Volatility (1989–2006)
Cboe's volatility franchise originated as an academic proposal. In 1989, Menachem Brenner and Dan Galai proposed a "Sigma Index" to measure market volatility directly, allowing investors to hedge market uncertainty rather than price direction. Galai already had ties to Cboe, having conducted the first empirical test of the Black-Scholes model in 1973 using the exchange's initial six months of trading data.5 Four years after Brenner and Galai's paper, Professor Robert Whaley designed the original VIX Index for Cboe. Published in the Journal of Derivatives in 1993, the index tracked expected 30-day volatility derived from implied prices of at-the-money S&P 100 options.10
For a decade, the VIX served primarily as a market sentiment indicator—a widely cited benchmark on financial television that could not be directly traded.
The 2003 rebuild. The impediment to trading the original index lay in its construction. Whaley's design averaged implied volatilities from a handful of options—a statistical metric that market participants could not easily replicate. To create a tradable derivative, an index must correspond to an explicit portfolio of underlying instruments, allowing market makers to hedge the positions they sell to customers.
In 2003, Cboe rebuilt the VIX in collaboration with Goldman Sachs. The updated methodology shifted the underlying benchmark from the S&P 100 to the S&P 500 and replaced the average of implied volatilities with a weighted aggregation of SPX put and call prices across a broad spectrum of strike prices.10 While the original VIX functioned like an opinion poll of select options, the revised formula established a precise portfolio recipe of out-of-the-money options that replicated 30-day variance. Because dealers could purchase the underlying option components to hedge their exposure, the index could support derivative contracts.
Cboe launched VIX futures on the Cboe Futures Exchange in March 2004 and introduced VIX options in 2006.10 Following the 2008 financial crisis—when traditional cross-asset correlations converged toward one and standard equity hedges broke down—institutional demand for direct volatility protection shifted from tactical hedging to a structural allocation.
Through this rebuild, Cboe established a new asset class based on a mathematical formula. Unlike the SPX option franchise, Cboe owns the VIX methodology outright. In its 2025 Form 10-K, Cboe listed its proprietary rights in the VIX methodology alongside its exclusive index licenses as foundational assets, noting that losing these rights would allow competitors to launch substantially similar volatility products.4 The index represents a rare category of financial intellectual property: a proprietary benchmark that generates recurring revenue without requiring royalty payments to an external licensor.
Where the claim breaks. Popular perception often frames the VIX as an all-weather gauge of equity market volatility. However, market structure developments reveal two critical limitations in that premise.
First, products tied to the index exhibited structural fragility. By early 2018, a retail and institutional trading complex had developed around short-volatility strategies via exchange-traded products. The largest vehicle was the VelocityShares Daily Inverse VIX Short-Term ETN (XIV), issued by Credit Suisse, which held approximately $1.9 billion in assets entering February 2018. On February 5, 2018, the VIX Index experienced its largest single-day percentage increase on record. XIV lost roughly 96% of its value in a single session, with its indicative value collapsing from $115.55 to $4.22.11 Because the intraday loss exceeded the 20% threshold specified in its prospectus, an acceleration event was triggered, forcing Credit Suisse to redeem the notes early.12
Although Cboe did not issue XIV and incurred no direct balance-sheet loss, the "Volmageddon" collapse highlighted how exchange-traded products built on the VIX could generate forced rebalancing loops, amplifying market movements in the underlying volatility index.
Second, the traditional benchmark measured a timeframe disconnected from changing trading habits. By 2022 and 2023, trading volume in S&P 500 options increasingly concentrated in contracts expiring on the day of execution. Because intraday price swings were not captured by a 30-day implied volatility calculation, a monthly benchmark failed to register short-dated market dynamics. On April 24, 2023, Cboe introduced the Cboe 1-Day Volatility Index (VIX1D), developed by its internal Cboe Labs unit, which aggregates weighted prices of afternoon-settled SPX options with zero to one day remaining until expiration.13
The launch of VIX1D addressed a measurement gap created by Cboe's own short-dated contract offerings. While the original VIX remains the benchmark for 30-day equity volatility, overall options trading has migrated toward shorter time horizons that the standard index does not capture. Financial disclosures reflect this structural shift: in 2025, net revenue in the Futures segment—where VIX futures trade—fell 5% year-over-year to $126.2 million even as index options volume reached record highs, while Futures operating margin compressed from 74.1% to 58.6%.3
This divergence between expanding SPX option volume and stagnating VIX futures revenue highlights the evolving dynamics driving Cboe's core business model.
V. The Technology Transformation: The $3.4B BATS Acquisition (2016–2019)
Dave Cummings founded Bats in 2005 out of frustration with legacy exchanges, which his Kansas City proprietary trading firm viewed as slow and expensive. The name — Better Alternative Trading System — signaled its intention to challenge incumbents. Within a decade, the company captured a significant share of U.S. equities trading and built a European venue, supported by an execution architecture designed entirely for speed.
By 2016, Cboe faced a stark operational divide. While its proprietary index option franchise generated high margins, its underlying trading technology remained constrained. Cboe Command, the legacy options platform, was costly to operate and difficult to modify. Meanwhile, all-electronic competitors operating with lower headcounts were lowering industry cost structures.
On September 26, 2016, Cboe agreed to acquire Bats Global Markets in a cash-and-stock transaction valued at approximately $32.50 per share, or about $3.2 billion at announcement, structured as roughly 31% cash and 69% Cboe stock.14 The transaction closed on March 1, 2017, at a final value of approximately $3.4 billion. Ed Tilly remained chairman and chief executive officer, while Bats CEO Chris Concannon became president and chief operating officer.15
Was it overpaying? On its face, Cboe appeared to pay a high valuation multiple for a cash-equities business characterized by thin transaction margins. However, the strategic rationale centered on technology infrastructure rather than equity market share.
Cboe was acquiring an execution engine. Over the subsequent years, Cboe decommissioned Cboe Command and migrated its options, futures, and European trading venues onto the Bats technology stack. That migration established the foundation for the company's modern operating leverage. In the second quarter of 2026, Cboe processed a 26% year-over-year increase in total options volume — including a 32% rise in index options — while adjusted operating expenses rose just 2% to $217 million.16 Adjusted operating EBITDA margin expanded by 6.4 percentage points to 72.2%.17
This performance demonstrated structural operating leverage nine years after the acquisition, allowing trading volume to expand significantly without driving up the fixed cost base. Modernizing the tech infrastructure was also a necessary prerequisite for subsequent market shifts; legacy options architecture built in the 1990s could not have processed the message volume generated by same-day-expiry trading.
Where the diversification claim breaks. Cboe originally presented the Bats transaction and subsequent international acquisitions as a strategy to build a diversified multi-asset exchange group. Financial segment disclosures over the following decade, alongside subsequent corporate divestitures, challenged that thesis.
In 2025, the North American Equities segment generated $1.67 billion in total revenue — representing 35% of the company's gross top line — but yielded $407.2 million in net revenue after liquidity payments, routing fees, and Section 31 regulatory remittances.3 Approximately three-quarters of gross revenue consisted of pass-through costs. Segment operating income reached $188.1 million, representing a 46.2% margin. By contrast, the Options segment generated $1.53 billion in net revenue and $1.11 billion in operating income, achieving a 72.7% margin.3 Options alone produced roughly three-quarters of Cboe's aggregate segment operating income.
The performance gap was also pronounced in the Europe and Asia Pacific segment. Net revenue in that unit grew 24% in 2025 — marking five consecutive quarters of top-line growth leadership — to $273.5 million, producing $53.9 million in operating income at a 19.7% margin.3 While achieving strong top-line expansion, operating at sub-20% margins diluted the group's overall profitability.
Corporate actions ultimately confirmed the economic reality. Between mid-2025 and mid-2026, Cboe wound down its Japanese equities business, completed the sale of Cboe Australia and Cboe Canada to TMX Group for $300 million, exited corporate listings in the U.S. and Europe, and began winding down its European derivatives exchange.18194 The company also recorded $17.7 million of cumulative impairment charges related to Cboe Canada in 2025, along with impairments tied to the Japanese wind-down.3
These exits disproved the broad multi-asset diversification thesis. Non-proprietary equity venues provided trading volume, market presence, and critical infrastructure, but failed to generate economic returns proportional to their operational complexity. Ultimately, the Bats acquisition succeeded as a technology and cost-structure transformation, even as its broader multi-asset diversification narrative unraveled. The equity venues served as the wrapper, while the matching engine was the true asset.
VI. The 0DTE Options Revolution & Market Microstructure (2020–Present)
What began as an incremental scheduling adjustment evolved into Cboe's primary growth engine.
For most of the SPX contract's life, expirations occurred monthly, then weekly. In 2016, Cboe added Monday and Wednesday expirations alongside Friday. In the spring of 2022, the exchange filled the remaining schedule gaps: Tuesday-expiring SPX Weeklys launched on April 18, 2022, followed by Thursday expirations on May 11, 2022—completing an expiration for every trading day of the week.20 By September 2022, Cboe added further expirations, noting that Tuesday and Thursday contracts had already generated more than 44 million traded contracts since launch.21
The structural consequence was not immediately obvious. With contracts expiring every trading day, every session offered an option with zero days to expiration. Zero-days-to-expiration (0DTE) was not a single product engineered by Cboe; it was the natural structural byproduct of completing the daily calendar.
Why participants trade 0DTE. Stripping away market jargon, an option's premium reflects two distinct components: intrinsic value if exercised immediately, and time value reflecting potential price movement before expiration. Eliminating the multi-day time horizon collapses the time premium. A same-day option is consequently inexpensive in dollar terms while remaining highly sensitive to underlying price movements.
That low dollar cost serves two distinct market segments. A retail trader can express a short-term view on the S&P 500 with limited capital, capping the maximum loss at entry. Simultaneously, an institutional desk hedging a specific macroeconomic announcement—such as a Consumer Price Index release or a Federal Reserve rate decision—can purchase protection strictly for the duration of the event rather than paying for a month of time value to cover a single afternoon.
Cboe management has consistently resisted characterizing 0DTE trading as speculative gambling, pointing to underlying order data. On the second-quarter 2026 earnings call, Rob Hocking, Global Head of Derivatives, stated that over 95% of 0DTE trades observed by Cboe are defined-risk strategies, with 50% to 55% structured as multi-leg spreads.16 In a defined-risk structure, the maximum potential loss is capped at entry. While this claim originates from an interested party, it relies on verifiable exchange order-type data rather than qualitative assertion, aligning more closely with structured risk management than unchecked speculation.
The scale. The adoption curve expanded rapidly across varying volatility regimes. In the second quarter of 2025, 0DTE contracts accounted for a record 57% of total SPX options volume. By the third quarter of 2025, average daily volume in SPX 0DTE contracts rose 62% year-over-year, representing over 61% of total SPX volume compared to 48% a year earlier.22 In the second quarter of 2026, SPX options reached a record average daily volume of 5.1 million contracts—with 3.1 million representing zero-day contracts—pushing total index options average daily volume to 6.2 million.16
To put that volume into perspective, when the International Securities Exchange captured nearly a third of equity options market share in 2003, its entire daily volume averaged under one million contracts. Cboe now processes more than six million index option contracts daily across a product suite where it faces no direct listed competitor.
Management's explanation of this liquidity moat warrants examination. On the first-quarter 2026 call, Hocking noted that SPX contract volume had expanded by more than 300% over five years for a product approaching its forty-third year. He disclosed that while roughly 84% of first-quarter 2026 SPX volume traded electronically and 16% via open outcry, approximately 58% of notional value was executed on the trading floor across eleven floor broker groups (the largest holding a 23% share), twenty market-making groups, and thirty-four connected retail broker platforms (the largest representing roughly 30%).1
While Cboe offered this detailed breakdown to demonstrate to analysts the operational difficulty a competitor would face in replicating the ecosystem if the S&P license ever lapsed, the underlying structural point is valid: a deeply fragmented liquidity network spread across dozens of floor and electronic intermediaries creates a self-sustaining network effect that is difficult for rival venues to displace.
Impact on market microstructure. Concentrated short-dated options trading creates verifiable secondary effects on market structure. Liquidity providers who sell same-day options must continuously adjust their hedges in the underlying market. Because a zero-day option's price sensitivity accelerates dramatically as expiration approaches, market makers must adjust their hedging positions rapidly throughout the session. Executing millions of these contracts daily concentrates dynamic hedging activity directly within the regular trading session, altering intraday equity market dynamics. Regulators, academics, and market participants continue to analyze whether this concentrated intraday rebalancing dampens or exacerbates price volatility, though empirical consensus remains unsettled.
A 2026 regulatory accelerant. In June 2026, U.S. regulators repealed the long-standing pattern day trader rule, removing trading frequency restrictions on smaller brokerage accounts. Cboe reported an immediate volume impact: SPX 0DTE average daily volume rose 11% month-over-month in June, with estimated retail participation expanding from 53% in April and May to 57% in June. Mini-SPX average daily volume grew 37% from May to June, while simple single-leg SPX order counts across the top nine retail brokerages rose over 40% alongside declining average order sizes.16
While Cboe framed this surge as expanding market engagement, the increase represents a regulatory tailwind independent of Cboe's operational execution. Arriving in the same year Cboe stock reached a 52-week high, this growth reflects external policy changes that carry inherent reversal risks. Regulatory frameworks that are repealed can be reinstated or modified, particularly if subsequent market volatility generates retail trading losses that attract legislative oversight.
Competitive counterattacks. Competitive pressure on Cboe's index options franchise has emerged from two main fronts.
First, CME Group expanded short-dated options on its equity index futures, including micro-sized contracts targeting retail accounts. However, a structural friction persists: futures options and index options operate in separate regulatory, clearing, and brokerage frameworks. A retail investor trading on consumer platforms accesses SPX and Mini-SPX options through a standard securities options account cleared through OCC. Trading CME futures options requires a dedicated futures account approval and clearing structure. Although not an insurmountable barrier, this account segmentation explains why decades of competing equity index futures have failed to displace SPX index options.
Second, newer competition has emerged from crypto-native perpetual futures and vertically integrated prediction venues, where a single entity operates the trading application, exchange, and clearing facility. Cboe management, including Executive Chairman Craig Donohue, has criticized the closed-silo model, arguing that it sacrifices capital efficiency because market participants cannot cross-margin risk across external venues, forcing market makers to commit redundant clearing capital.16 This capital-efficiency argument holds for institutional liquidity providers operating at scale. Whether retail traders prioritizing user interface over margin offset efficiency will find closed-silo venues attractive remains an unresolved question.
Regulatory oversight and capital efficiency. Short-dated options have drawn ongoing scrutiny from the SEC and FINRA, focused on potential systemic tail risk from concentrated intraday market-maker hedging and retail risk disclosure. To date, Cboe has not faced disclosed regulatory enforcement actions regarding 0DTE products. Furthermore, industry concerns over proposed OCC margin model adjustments in 2024 proved manageable: Cathy Clay noted on the second-quarter 2025 earnings call that industry consultation reduced the estimated capital impact on market participants from approximately 5% to 1%.23 While demonstrating current regulatory manageability, this outcome offers no guarantee against future rule changes.
Meanwhile, the unit economics of the options franchise remain robust. In the second quarter of 2026, Cboe's average revenue per contract for index options rose 3% year-over-year, while overall options revenue per contract increased 6% due to favorable product mix shift toward higher-margin index contracts.17 With index volume expanding 32%, average pricing up 3%, and adjusted operating expenses rising just 2%, Cboe demonstrated strong operational leverage.
This high-margin structure is supported by modest physical capital requirements. Cboe's 2026 capital expenditure guidance of $98 million to $108 million represents roughly 3.5% to 3.7% of its approximately $2.9 billion in annualized net revenue.17 Reinvesting roughly four cents of every net revenue dollar into physical and technology assets generates substantial free cash flow—providing Cboe with significant financial flexibility, while raising capital allocation challenges if corporate reinvestment strays into non-core acquisitions.
VII. Global M&A Expansion, Digital Misstep, & Leadership Reset (2020–Present)
In October 2021, amid widespread exchange industry enthusiasm for digital assets, Cboe announced an agreement to acquire ErisX. By the time the transaction closed in May 2022, cryptocurrency markets had contracted sharply. Regulatory filings later described an environment marked by deleveraging and bankruptcies, noting that efforts to syndicate minority ownership in the acquired business to outside investors had become increasingly difficult.24 Cboe proceeded with the acquisition regardless.
For four years, the exchange operator pursued capital deployment that prioritized corporate expansion over core strategic alignment.
The international expansion began with a plausible strategic premise: acquire local venues to channel Cboe's market data, routing infrastructure, and proprietary index products into new geographic markets. Cboe acquired Chi-X Asia Pacific in 2021—expanding its footprint into Japan and Australia—and completed the acquisition of Canada's NEO Exchange on June 1, 2022.24 Within four years, however, Cboe wound down its Japanese equities business and agreed to sell its Canadian and Australian venues.19 When analysts questioned whether exiting these exchange venues would impair international data revenue, management acknowledged that data sales were not dependent on local exchange ownership, explaining that demand for U.S. proprietary market data originated from international brokers seeking U.S. market access rather than local venue ownership in Sydney.22 That admission underscored the disconnect between venue acquisition costs and the actual drivers of data distribution.
ErisX. The digital asset expansion proved far more costly.
On October 20, 2021, near the peak of the digital asset market cycle, Cboe announced a definitive agreement to acquire ErisX—an operator of a U.S. digital asset spot market, a regulated futures exchange, and a clearinghouse. The transaction closed on May 2, 2022, with the business rebranded as Cboe Digital.2425 Cboe funded the transaction in part through a $190 million term loan draw and a $300 million issuance of 3.000% senior notes due in 2032.24 While total headline consideration was not disclosed as a single figure, regulatory filings revealed the asset allocation: $460.9 million assigned to goodwill, $95.0 million to intangible assets, and $8.4 million to working capital.24
The financial impairment followed almost immediately. Cboe recorded a $460.9 million goodwill impairment during 2022—effectively writing off the entire goodwill balance in the quarter the transaction closed—which drove a $491.4 million full-year operating loss in the newly created Digital segment.24 Annual cost of revenues exceeded top-line revenue, largely driven by liquidity payments intended to attract trading volume that failed to materialize at scale.
The transaction's compressed timeline highlights the speed of the capital destruction. Cboe signed the definitive agreement in October 2021, closed the deal in May 2022, and eliminated the entire goodwill value within the same reporting period. Rather than a business deteriorating over a prolonged period, the valuation was invalidated within weeks of closing by a market contraction already underway before the transaction finalized.
Management's public framing during the write-down reflected a sharp contrast with balance-sheet reality. Chief Executive Officer Ed Tilly characterized the remaining $220 million carrying value as an adjustment to market conditions while maintaining that the strategic commitment to digital assets remained intact. Chief Financial Officer Brian Schell echoed that positioning, while Chief Operating Officer Chris Isaacson described market volatility as a strategic tailwind for regulated execution venues.26 Executive leadership presented the impairment as a routine accounting adjustment rather than a fundamental strategic setback.
A final strategic resolution arrived twenty-three months later. On April 25, 2024, under interim Chief Executive Officer Fred Tomczyk, Cboe announced plans to wind down the Cboe Digital Spot Market in the third quarter of 2024, citing persistent regulatory ambiguity, while integrating its digital asset derivatives into its existing Global Derivatives and Clearing operations. Management projected annualized expense savings of $11 million to $15 million from the restructuring.27 Cboe subsequently folded the Digital segment into its Futures segment in the first quarter of 2025 and migrated digital futures contracts onto the Cboe Futures Exchange.3
The net economic result of the digital initiative comprised roughly $461 million in written-off goodwill, long-term debt raised to finance the acquisition, and $11 million to $15 million in annualized cost savings following the shutdown—a material capital loss for an exchange group generating approximately $1.1 billion in annual net income.
Governance. Executive governance underwent a sudden transition the following year. On September 19, 2023, Cboe announced the resignation of Chairman and Chief Executive Officer Edward T. Tilly after a board-led investigation conducted with independent counsel determined he had failed to disclose personal relationships with colleagues, violating company policies.2829 The board immediately appointed board member Fredric J. Tomczyk—the former Chief Executive Officer of TD Ameritrade who had served on Cboe's board since July 2019—as Chief Executive Officer.28 Following the investigation's findings, Tilly forfeited approximately $8.8 million in severance pay and roughly $892,000 in unvested benefits.29
While the governance breach highlighted oversight vulnerabilities, the board acted rapidly and enforced strict financial accountability, as the forfeiture of executive severance remains an uncommon outcome in corporate governance.
Tomczyk's tenure (September 2023 – May 2025) functioned as a period of operational stabilization. Tomczyk halted non-core acquisitions, closed the spot digital venue, and initiated a comprehensive portfolio review designed to rationalize the company's asset base. This strategic retrenchment streamlined operations prior to the next leadership transition.
On May 1, 2025, Cboe appointed Craig S. Donohue as Chief Executive Officer, effective May 7, 2025. Tomczyk stepped down from the executive role while remaining on the board of directors in an advisory capacity through June 2025.30
VIII. Current Management, Governance, & Capital Allocation Architecture
Craig Donohue represents a distinctive chief executive appointment for Cboe, possessing extensive executive experience across competing derivatives venues and clearing infrastructure.
Donohue spent roughly two decades at CME Group, serving eight years as chief executive officer from 2004 to 2012—a tenure during which CME acquired the Chicago Board of Trade and NYMEX to build the world's dominant listed futures franchise. He subsequently spent nearly a decade at the Options Clearing Corporation, serving as chairman of the board and as chief executive officer from 2016 to 2019.30 Few executives have led organizations across so many components of the U.S. derivatives market structure: a primary futures competitor, the central clearinghouse that clears Cboe's options trades, and now Cboe itself.
That background illuminates the company's strategic direction. The most consequential initiative during Donohue's first sixteen months was not a product launch, but an application to establish an internal clearing agency.
The behavioral record, in his own words, over five calls.
August 2025, his first full quarter. Asked directly about priorities and his predecessor's openness to major acquisitions, Donohue praised the existing strategy and team, asserting that performance was strong and that regarding acquisitions, "there's nothing that we need to do right now."23 The message emphasized continuity and reassurance.
October 2025. Cboe announced a strategic realignment: initiating sale processes for Cboe Australia and Cboe Canada, discontinuing U.S. and European corporate listings, and cutting costs across ETP listings, the European derivatives venue, and several risk-and-analytics units. Management projected the moves would lower net revenue by roughly 3% while reducing adjusted operating expenses by 8% to 10%.18 Asked about the shift, Donohue noted that the strategic review originated under Tomczyk and that his primary focus was accelerating it to completion.22
May 2026. The scope of the realignment expanded significantly. Chief Operating Officer Scott Johnston—who previously worked alongside Donohue at CME—announced that Cboe's workforce had doubled since early 2020 through acquisitions and expanded support functions. Johnston noted that strategy shifts created organizational mismatches, requiring cumulative actions to reduce headcount by approximately 20%.131 The workforce reduction eliminated roughly 332 positions from a base of 1,661 employees at year-end 2025, incurring $36 million to $46 million in pre-tax charges while targeting $40 million to $50 million in annualized savings.324 Total projected realignment savings increased to $100 million to $120 million annually, representing 12% to 14% of the 2025 adjusted expense base.33 The company also mandated a return to in-person work.
Nine months separated the initial assurance that no major changes were required from a 20% workforce reduction. One interpretation is that an incoming chief executive offered measured reassurance in month three while evaluating operations before implementing necessary cuts. A more critical view suggests investors should assign limited weight to early executive reassurances. Under either interpretation, management's performance must be evaluated against executed actions, which have remained specific and cost-quantified.
Executive churn.
The executive leadership team underwent almost complete turnover within eighteen months. Global President Dave Howson resigned effective August 1, 2025, and Head of Global Derivatives Cathy Clay resigned effective September 30, 2025, concluding her service on October 15.34 Rob Hocking assumed leadership of derivatives, while Chris Isaacson served as chief operating officer through 2025 before Scott Johnston joined in February 2026. Prashant Bhatia arrived to head enterprise strategy, veteran retail brokerage executive JJ Kinahan joined in October 2025 to lead retail expansion, and Heidi Fischer joined in June 2026 to manage equities and spot markets.2216
Turnover of this scale is neither inherently positive nor negative. Its ultimate impact depends on execution: if the new leadership team successfully secures clearing registration, executes the event-contract launch, and achieves cost-reduction targets, the turnover represents necessary organizational renewal. Conversely, if operational milestones slip while core derivatives earnings carry financial results, the leadership changes reflect structural disruption.
How management is paid — and what that reveals.
Cboe's annual incentive plan for named executive officers pays based on pre-established EBITDA and net revenue targets alongside individual performance, with payouts ranging from zero to 200%. Long-term equity incentives are split evenly between time-vesting restricted stock units and performance stock units tied to relative total shareholder return and three-year cumulative earnings per share, also capped at 200%.34 Although "rationalizing our business portfolio to optimize our return on invested capital" is highlighted as the first of four core strategic pillars,34 return on invested capital is omitted as a performance metric in both the short-term bonus structure and the long-term equity plan.
This omission is notable for an exchange group whose most significant recent financial misstep involved capital allocation. A compensation plan tied to EBITDA, revenue, EPS, and relative total shareholder return incentives top-line growth and equity performance, but does not directly penalize value-destroying acquisitions because goodwill write-offs are routinely excluded from non-GAAP performance metrics. If the board intends to prevent a recurrence of the ErisX impairment, incentive plan design provides the direct mechanism to enforce accountability, yet the framework remains unchanged.
For the 2023–2025 performance stock unit cycle, both metrics paid out at the maximum 200% of target, driven by relative total shareholder return at the 86th percentile and three-year cumulative adjusted diluted earnings per share of $27.08.34 Shareholders have consistently supported the structure. Advisory votes on executive compensation received 93.5% approval at the 2025 annual meeting, with say-on-pay support exceeding 84.4% in every year since the company's 2010 initial public offering.34 Donohue received a $6.0 million initial equity grant on May 7, 2025, divided equally between time-based RSUs vesting in 2028 and performance stock units tied to the same shareholder return and earnings per share metrics.34
Proxy disclosures reveal one additional adjustment. Former Chief Executive Officer Fredric Tomczyk received a time-based RSU grant on February 19, 2025, initially valued at $9.35 million, which was subsequently revised downward to approximately $6.92 million, reducing the award from 44,471 to 32,896 units.34 The adjustment occurred roughly ten weeks before his successor was named, aligning the award more closely with shareholder interests. However, because the compensation committee has not incorporated return-on-capital metrics following a $461 million digital asset write-off, the governance record presents a dual picture: a board willing to adjust individual executive grants, but hesitant to modify core performance metrics.
Capital allocation now.
Cboe's capital allocation strategy remains conservative following the prior decade's expansion. During the second quarter of 2026, the company repurchased $33 million of common stock and distributed $76 million in dividends at $0.72 per share—returning $108 million to shareholders against an adjusted cash balance of $2.3 billion and a debt-to-EBITDA leverage ratio of 0.7 times.1716 Chief Financial Officer Jill Griebenow stated that Cboe expects to repay a $650 million debt tranche maturing in the first quarter of 2027 using cash on hand.16
Griebenow also noted that the stock experienced its sharpest decline during the final weeks of June 2026, when quarter-end blackout periods restricted open-market repurchases outside pre-established 10b5-1 plans, adding that with greater flexibility the company "would have welcomed the opportunity to be more aggressive."16 While blackout restrictions explain the limited repurchases, the episode highlights that Cboe's buyback execution is not structured for rapid opportunistic intervention. A company maintaining $2.3 billion in cash that repurchases $33 million during a quarter management identified as presenting an attractive valuation is either exercising capital discipline ahead of debt maturities or operates under inflexible execution mechanics. The upcoming 2027 debt maturity supports the capital discipline thesis, while trading restrictions explain the mechanical constraints.
IX. Business Model & Financial Architecture
Understanding Cboe's financial architecture requires first separating gross top-line revenue from net operational revenue. In 2025, total revenue reached $4.71 billion, but $2.29 billion consisted of cost of revenues—comprising $1.71 billion in liquidity payments to market makers, $238.7 million in pass-through regulatory fees, $80.4 million in routing and clearing costs, and $256.3 million in royalty fees and other direct expenses.3 The remaining $2.43 billion in net revenue represents the core operating business.
Where the money actually is. In 2025, the Options segment generated $1.53 billion in net revenue—63% of the company's total—producing $1.11 billion in operating income at a 72.7% operating margin.3 By comparison, all other segments combined generated roughly $362 million in operating income on $898 million in net revenue.
North American Equities operates as a high-volume venue with thin net margins: generating $1.67 billion in gross revenue, but yielding $407.2 million in net revenue and $188.1 million in operating income.3 Europe and Asia Pacific delivered percentage growth—expanding 24% in 2025—though on a modest base of $273.5 million in net revenue and a 19.7% operating margin.3 The Futures segment, which houses VIX futures, saw net revenue decline 5% to $126.2 million, with operating margins compressing to 58.6% as costs from the former Digital segment were absorbed.3 Meanwhile, Global FX remained small but expanding, generating $91.1 million in net revenue at a 50.5% operating margin.3
The Data Vantage unit—encompassing market data, index licensing, connectivity, co-location, and analytics—generated $635.5 million in revenue in 2025, serving as management's primary diversification narrative.35 The unit provides recurring, subscription-based revenue, expanding in 2026 above management guidance with 19% growth in the first quarter and 15% in the second quarter.3317 Crucially, approximately 84% to 85% of this expansion originated from new units and subscriptions rather than fee increases, with roughly half of new sales generated outside the United States.1733
That composition carries strategic weight. Unit expansion indicates genuine organic demand, whereas price increases on a captive customer base signal rent extraction that risks regulatory pushback—a sensitive area given ongoing SEC scrutiny over market data pricing. Cboe's detailed breakdown provides valuable transparency in the exchange sector.
However, disclosures reveal that Data Vantage remains tightly tied to core trading activity. Strategic Enterprise Leader Prashant Bhatia noted that roughly two-thirds of Data Vantage's second-quarter 2026 growth stemmed from access-related revenue—specifically demand for options exchange connectivity purchased because index options volume surged 40%.16 Rather than an independent growth pillar, Data Vantage functions as a high-margin toll booth attached to the primary options venue.
The technology risk radar, briefly. Two operational topics present material long-term exposure, though neither represents an immediate crisis.
Regarding artificial intelligence, Cboe has adopted a measured operational stance. Former Chief Operating Officer Chris Isaacson described AI at the company as primarily an internal productivity multiplier across engineering, security, legal, and finance functions—underpinned by a data platform running on Snowflake and AWS, a center of excellence launched in mid-2024 with roughly 900 active associates, and agentic deployments across infrastructure and information security.22 Commercializing proprietary datasets into AI-derived products was framed as a future phase rather than an immediate revenue stream. This practical orientation positions AI as an expense-efficiency mechanism, partially explaining how Cboe processed a 26% increase in trading volume alongside a 2% expense rise. However, pursuing a 20% workforce reduction while citing AI-driven efficiency gains raises an ongoing question of whether cost reductions represent permanent structural improvements or temporary savings offset by restructuring charges.
On cybersecurity and operational resilience, Cboe faces asymmetric risk. The exchange's value proposition depends on providing uninterrupted execution when market volatility spikes. A multi-hour outage during a high-volatility session would cause reputational and franchise damage far exceeding the direct transaction fees lost. While no major operational outage has been disclosed, this represents a low-probability, high-severity tail risk that remains absent from financial statements until an event occurs.
The 7 Powers, honestly graded.
Cornered Resource. This represents Cboe's strongest yet most conditional advantage. Cboe holds exclusive licenses to list options on the S&P 500 and Russell 2000 while owning the proprietary VIX methodology outright, with approximately 68% of net revenue generated by the segments housing these products.4 While the VIX intellectual property is permanently owned, the flagship SPX franchise remains a licensed asset secured through 2032.
Network Effects. Liquidity creates a self-reinforcing competitive advantage. The deep liquidity pool in U.S. index options generates tight bid-ask spreads, which attracts order flow and further deepens available liquidity. Global Head of Derivatives Rob Hocking underscored this dynamic by disclosing that approximately $18 billion in premium trades daily in SPX options.22 However, this network effect remains bound to the underlying license; liquidity would follow the benchmark if exclusivity were ever lost, reinforcing the critical importance of the 2032 expiration date.
Scale Economies. Evident in financial results. Processing a 26% increase in options volume while holding adjusted operating expense growth to 2% in a single quarter demonstrates substantial operating leverage.17
Switching Costs. Often overstated in industry analysis. While institutional risk management systems and algorithmic trading strategies are configured around Cboe infrastructure, market participants maintain high connectivity across competing venues. Cboe's disclosures indicate that just three clearing members account for approximately 71% of market-maker transaction sides across its U.S. options exchanges, with all three actively clearing trades across competing options venues.4 Because major liquidity providers maintain multi-homed connectivity, switching costs would provide limited defense if index exclusivity were removed.
Concentration, stated plainly. Cboe's top ten customers accounted for approximately 57% of total revenue in 2025, with a single customer representing roughly 10%—generating $480.0 million, up from $403.1 million in 2024 and $389.4 million in 2023.4 None of these key counterparties operate under long-term volume commitments. While customer concentration is typical among financial exchanges, it highlights a structural risk: revenue depends heavily on a concentrated group of sophisticated, price-sensitive market makers whose absolute fee contributions continue to expand.
The supplier line item. Royalty fees and related costs within the Derivatives Markets segment rose 20% in 2025 to $201.8 million, up from $168.6 million in 2024, directly tracking trading volume expansion in licensed products.3 This line item reflects the direct cost Cboe incurs to operate its proprietary franchise. Because licensing royalties function as variable costs tied to trading activity, benchmark licensors directly participate in every record quarter—an economic reality that informs the strategic dynamics examined in the following section.
X. Strategic Position, Porter's 5 Forces, & Bull vs. Bear Case
Porter, applied.
Threat of new entrants: very low. Building a competing index options venue requires SEC exchange registration, OCC clearing integration, and a self-sustaining liquidity pool. The chicken-and-egg hurdle of attracting trading volume without existing liquidity makes de novo entry nearly impossible.
Buyer power: low in index options, high in cash equities. An institution hedging U.S. large-cap equity exposure has no direct listed substitute for SPX options. Conversely, an institution routing cash equity orders can choose across fifteen competing venues based on price. This asymmetry explains the structural margin gap between Cboe's high-margin Options segment and its thin-margin North American Equities segment.
Competitive rivalry: negligible in proprietary index options, brutal everywhere else. In late 2025, Global Head of Derivatives Rob Hocking noted that the U.S. multi-list options market comprised roughly twenty exchanges, with Cboe holding over a 24% market share.22 Twenty venues competing to trade identical, fungible contracts represents standard market commoditization.
Threat of substitutes: moderate and rising. Substitutes include CME Group's E-mini futures and options on futures, Nasdaq-100 index options, over-the-counter equity swaps, and crypto-native perpetual futures marketed to retail traders. On the second-quarter 2026 earnings call, management addressed perpetual futures directly, arguing that perpetuals complement options rather than substitute for them: perpetuals provide linear exposure with uncapped downside, whereas options offer convexity with defined risk, adding that decades of S&P 500 futures availability had not reduced SPX options demand.16 While technically sound, this argument assumes retail traders seeking leveraged exposure evaluate structural risk as rigorously as market infrastructure executives do. Furthermore, Hocking's observation that Cboe "may look to expand our continuous futures offering, where there's demand to do so" indicates internal strategic flexibility.16
Supplier power: high, specific, and dated. Licensing terms represent Cboe's most critical competitive exposure.
The 2032 problem. Cboe's exclusive right to list S&P 500 index options extends through 2032, followed by non-exclusive rights through 2033.6 Form 10-K disclosures explicitly state the operational risk: if S&P Dow Jones Indices declines to renew on an exclusive basis, Cboe would face multiple listings of its flagship contract, pressuring market share and margins; if the licensor declines to renew entirely, Cboe could lose the right to list SPX options altogether, singling out the S&P 500 license as an agreement whose loss or modified commercial terms would be materially adverse.4
S&P Dow Jones Indices collects variable licensing royalties—which reached $201.8 million in derivatives royalty expenses in 2025—that expand alongside trading volume. When a licensee's flagship contract expands volume by 30% annually while generating 72.7% segment operating margins, the licensor's negotiating leverage increases with each record quarter.
Executive disclosures reflect this commercial dynamic. In August 2025, when asked whether Cboe would restructure the contract to eliminate periodic renewal risk, Chief Executive Officer Craig Donohue emphasized long-term partnership alignment rather than contractual terms, noting S&P had been a partner for over forty years and expressing a desire for another forty.23 In April 2026, when an analyst asked about competing exchanges preparing for the 2032 license expiration, management responded by citing ecosystem depth: eleven floor broker groups, thirty-four retail platforms, twenty market-making groups, and balanced daily volume flow.1
Ecosystem depth provides a defense against volume migration, but does not eliminate repricing risk upon renewal. S&P Dow Jones Indices may seek a larger royalty share of an expanding franchise. Form 10-K filings explicitly list "change in the commercial terms" alongside contract loss as a primary material risk.4
How it compares. Comparing Cboe to its primary exchange peers highlights structural differences in asset ownership.
CME Group owns its dominant interest rate and equity index futures franchises alongside its clearinghouse, capturing vertical clearing economics that Cboe historically ceded to OCC—a structural gap Donohue seeks to narrow through Cboe Clear U.S.
Intercontinental Exchange built proprietary energy benchmarks and diversified into mortgage technology and fixed-income data, reducing earnings reliance on transaction volume. Nasdaq similarly expanded into financial technology, compliance software, and corporate services.
Cboe pursued international exchange acquisitions before divesting non-core operations to refocus on core derivatives. Consequently, Cboe remains the most volume-leveraged and single-product-concentrated operator among major peers—yielding higher operating margins and top-line growth, alongside structural exposure to market volume fluctuations and licensing renewals.
The activist stress test. A critical investment evaluation highlights four primary vulnerabilities:
First, capital allocation history: writing off $460.9 million in ErisX goodwill within weeks of closing in 2022,24 acquiring international exchange venues subsequently sold or wound down at impairment losses,19 and executing a 20% workforce reduction in 2026 justified by prior acquisition-driven headcount growth.31 This sequence reflects a multi-year capital deployment pattern across successive executive tenures and board oversight.
Second, executive incentive alignment: return on invested capital is listed as the company's primary strategic pillar, yet is omitted from executive compensation performance metrics.34
Third, disclosure asymmetry: detailed reporting on core index options volume contrasts with limited disclosure on legacy operations being exited, requiring investors to evaluate organic adjustments and regional carve-outs, such as Cboe Australia, to analyze underlying growth.17
Fourth, cyclicality versus secular growth: record 2025–2026 financial results coincided with heightened macroeconomic volatility—including trade tensions, federal government budget impasses, and March 2026 Middle East geopolitical conflicts that management noted drove demand for longer-dated hedges.1 Sustained lower market volatility would test the balance between structural option adoption and event-driven trading.
The bull case, stated fairly. Cboe operates the primary liquidity pool for U.S. equity index options at a time when U.S. equities represent nearly half of global market capitalization and over $20 trillion in assets are indexed or benchmarked to the S&P 500.16 Fixed operational infrastructure allows volume expansion to generate substantial operating leverage, demonstrated by 26% option volume growth alongside 2% expense expansion. International retail adoption is expanding, with South Korean broker connectivity growing from minimal representation in early 2024 to broad market coverage.16 Data Vantage revenue is expanding through new subscription units rather than price increases, the balance sheet maintains $2.3 billion in cash against a 0.7 times leverage ratio, and current management has demonstrated willingness to prune non-core assets to enhance margin efficiency.
The bear case, stated fairly. Net revenue remains heavily concentrated, with proprietary products driving approximately 68% of net top line, a single customer representing 10% of revenue, and three clearing firms handling 71% of market-maker clearing sides. Core licensing exclusivity for S&P 500 options expires in 2032 with a licensor holding substantial bargaining power. The 2026 volume surge in short-dated options benefited from the June 2026 repeal of the pattern day trader rule, representing a regulatory change subject to future policy modification. VIX futures net revenue contracted 5% in 2025 alongside compressing segment operating margins. Event and prediction market initiatives remain unapproved by regulators, with zero financial contribution included in 2026 management guidance.16 Capital deployment over the prior five years reflects significant write-downs and restructuring charges.
What the history actually supports. Empirical evidence confirms Cboe's structural advantage in index options, demonstrated by high operating margins, network liquidity effects, and sustained market share across U.S. options venues. However, because its flagship contract relies on a third-party license expiring in 2032, the franchise operates as a network-effects business on leased intellectual property. Management execution under current leadership shows verified cost discipline and asset rationalization, though capital allocation performance under new leadership remains untested following prior acquisition write-offs.
XI. Playbook: Business & Investing Lessons
1. Volume is vanity; net capture is sanity. Cboe's gross top line nearly doubles its net operational revenue because a substantial portion of cash-equities revenue consists of pass-through regulatory fees and market-maker liquidity rebates. An investor reading only gross revenue would conclude North American Equities was Cboe's second-largest business by a wide margin. An investor examining net revenue and segment margins would see a low-return utility attached to a high-margin options franchise. Only the latter reading anticipated the company's 2025–2026 asset divestitures. When a venue reports both gross and net figures, the gap between them reveals where the underlying economics reside.
2. Commercializing academic theory requires making it replicable, not just publishable. The VIX existed for a decade as an un-tradable sentiment indicator on financial news networks. Transforming it into a distinct asset class required the 2003 decision to reconstruct the benchmark as an explicit portfolio of out-of-the-money options rather than an abstract average of implied volatilities—because dealers can dynamically hedge a replicating portfolio, but cannot hedge a statistical index. For investors evaluating proprietary intellectual property claims, the test is not theoretical elegance, but whether counterparties can efficiently trade and hedge the underlying structure.
3. Buy the engine, not the market share. The public justification for acquiring Bats Global Markets in 2017 was multi-asset diversification into cash equities. The true economic return, realized nearly a decade later, came from its execution architecture, which enabled Cboe to absorb a surge in message traffic without expanding its fixed cost base—making high-frequency, same-day-expiry options economically viable. While Cboe eventually sold or wound down much of the acquired cash-equities footprint, it retained the matching engine. Mergers and acquisitions frequently deliver value through mechanisms distinct from initial press releases, reinforcing the need to evaluate which specific asset an acquirer is underwriting.
4. Pruning failed bets is necessary, but restructuring is not identical to capital discipline. Exiting the ErisX digital asset venture was structurally necessary. However, writing off $460.9 million in goodwill in the same year the transaction closed, spending twenty-three months winding down the venue, and requiring a chief executive replacement to finalize the exit reflects damage control rather than surgical capital allocation. Genuine discipline occurs during transaction underwriting rather than post-hoc impairment. Investors must distinguish between proactive strategic execution and forced cleanups of prior executive errors—while recognizing that current leadership's long-term capital allocation record remains unproven, as recent actions have focused on asset sales rather than new capital deployment.
4a. The exit outcome reveals what the acquirer truly purchased. Cboe acquired Bats for $3.4 billion, retaining the execution engine while eventually divesting much of the underlying trading footprint. It acquired ErisX for an undisclosed purchase price and recovered minimal capital. It later sold its Australian and Canadian venues for $300 million after four years of ownership. Across all three transactions, Cboe demonstrated competence in acquiring internal capabilities, but struggled when buying market positions. Technological capabilities compound within an established franchise, whereas market positions require an acquirer to excel in unfamiliar operating environments. That distinction provides a clear filter when evaluating corporate acquisition track records.
5. When regulatory frameworks define the moat, regulatory strategy becomes product strategy. Cboe's most consequential initiative in 2026 was structuring its proposed event contracts as SEC-regulated securities rather than CFTC-regulated futures, alongside filing for its own securities clearing agency registration to support them.16 That approach reflects an institutional playbook dating back to the exchange's regulatory battles in the 1970s: navigating formal regulatory channels to build structural barriers that preserve long-term market access and clearing efficiency.
XII. Epilogue & What to Watch
In June 2026, Cboe launched binary options on the Mini-S&P 500 under the Cboe Predicts banner, listed on Interactive Brokers with Schwab following.36 In July, the exchange filed with the SEC to list contracts based on company-specific performance metrics — beginning with 23 of the most actively traded U.S. equities — targeting a late-September or early-October launch pending approval.16 Management cited specific corporate metrics for the contracts, such as Nvidia data center revenue and Microsoft cloud revenue. In parallel, Cboe applied for temporary registration as a covered clearing agency, with full registration targeted within an 18-month window, and became subject to Subpart C of CFTC regulations effective June 16, 2026.16
This expansion represents a speculative initiative that requires realistic assessment. Cboe included zero prediction-market revenue in its 2026 guidance by its own statement.16 The SEC filing remains subject to regulatory approval, which the company explicitly declines to guarantee.16 Furthermore, the competitive landscape features vertically integrated retail platforms operating outside traditional securities regulatory frameworks. Cboe's past record of converting new-market entries into sustainable revenue — illustrated most recently by Cboe Digital — counsels caution before capitalizing this opportunity.
Where this event-contract initiative differs from prior digital asset ventures is the nature of distribution demand, which is driven by inbound broker interest rather than exchange promotion. Global Head of Derivatives Rob Hocking noted that while Cboe historically developed products and subsequently persuaded platforms to list them, with event contracts, the brokers are asking.16 While an inbound distribution pull provides a more favorable starting position, it does not constitute proof of commercial success.
A secondary initiative is unfolding in parallel. Cboe plans to extend U.S. cash equities trading to a 23-hour, five-day schedule in December 2026, pending industry readiness, with 24/7 execution as a longer-term goal, while voicing support for the SEC's proposed rescission of Rule 611 — the order protection rule that has shaped U.S. equity market structure for two decades.16 As the sole U.S. exchange group operating both registered lit exchanges and an alternative trading system, Cboe occupies an unusual seat in that debate. Whether extended trading hours generate incremental revenue or simply redistribute existing volume across a longer window remains uncertain; operationally, it functions as a low-cost call option on global trading migration, built on technology infrastructure Cboe already operates.
Underpinning these initiatives is the expansion of Cboe's clearing capabilities. To support this infrastructure build, capital expenditure guidance was raised to a range of $98 million to $108 million, up from $73 million to $83 million, partly to fund clearing infrastructure.16 Securing status as a registered securities clearing agency would allow Cboe to launch specialized instruments — such as event contracts, tokenized products, and derivatives settling outside conventional hours — without waiting on the Options Clearing Corporation, an industry utility Cboe co-founded but no longer controls. Chief Executive Officer Craig Donohue has been careful to frame this as complementary to OCC rather than competitive with it.16 Having previously chaired OCC's board and served as its chief executive officer for three years, Donohue possesses direct insight into the regulatory and operational boundaries between the utility and the exchange.
Three things to track. Not more.
First: SPX options ADV and the 0DTE share of it. This combination drives Cboe's core earnings engine, capturing product adoption, retail expansion, international broker onboarding, and broader market volatility in monthly volume disclosures. If average daily volume growth flattens while the zero-day market share plateaus, the secular growth story would shift back toward a purely cyclical volatility business.
Second: index options revenue per contract. Volume expansion without rate realization would indicate that Cboe is winning share in a commoditizing market. Volume growth paired with rate-per-contract growth — 3% year-over-year in Q2 2026 — is the observable, quarterly evidence that pricing power is intact.17 This metric is also the primary indicator to watch for potential margin compression if the S&P 500 licensing agreement is renegotiated on less favorable terms.
Third: Data Vantage organic net revenue growth and its new-unit share. Management guided organic growth to low double digits for 2026, excluding the Australian disposal.17 The critical element to monitor is revenue composition rather than headline growth: so long as roughly 85% of expansion stems from new subscription units rather than price increases, growth reflects organic market demand. If that balance flips toward pricing, expansion becomes a rent-extraction strategy carrying heightened regulatory risk.
In September 2026, Cboe Global Markets presents a striking corporate paradox: over eighteen months, the exchange group sold two international venues, wound down three non-core business units, replaced most of its senior leadership, cut a fifth of its workforce, and posted the best results in its fifty-three-year history. These facts are not in tension. They describe an organization refocusing operational resources on the primary franchise it operates better than anyone else — while operating with roughly six years remaining on the contractual licensing agreement that makes it possible.
References
-
Cboe Global Markets Q1 FY2026 earnings call transcript — Yahoo Finance, 2026-05-01 ↩↩↩↩↩
-
Cboe Global Markets Investor Relations — Cboe Global Markets, 2026-09-01 ↩
-
Cboe Global Markets, Inc. Form 10-K for fiscal year 2025 — US SEC, 2026-02-20 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Cboe Global Markets SEC Filings — Cboe Global Markets, 2026-02-20 ↩↩↩↩↩↩↩↩↩
-
Cboe Marks Golden Anniversary: 50 Years of Exchange-Traded Options — Financial History / Museum of American Finance, 2023-04-26 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
CBOE Holdings and S&P Dow Jones Indices Extend Licensing Agreement Through 2033 — PR Newswire, 2013-01-08 ↩↩
-
International Securities Exchange, Inc. Form S-1/A — US SEC, 2004 ↩
-
CBOE Holdings, Inc. Form 10-K for fiscal year 2015 — US SEC, 2016 ↩↩
-
Cboe VIX Index marks 25th anniversary as the world's barometer of equity volatility — World Federation of Exchanges Focus, 2018 ↩↩↩
-
Credit Suisse AG Form 6-K: Acceleration of VelocityShares Daily Inverse VIX Short-Term ETN — US SEC, 2018-02-06 ↩
-
Cboe Global Markets Launches 1-Day Volatility Index, Designed to Measure Volatility Over Current Trading Day — PR Newswire, 2023-04-24 ↩
-
CBOE Holdings Agrees to Acquire Bats Global Markets — PR Newswire, 2016-09-26 ↩
-
CBOE Completes $3.4B Bats Acquisition — ETF.com, 2017-03-01 ↩
-
Cboe Global Markets Q2 2026 earnings call transcript — Investing.com, 2026-07-31 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Cboe Global Markets Reports Results for Second Quarter 2026 — PR Newswire, 2026-07-31 ↩↩↩↩↩↩↩↩↩↩
-
Cboe Global Markets Reports Results for Third Quarter 2025 and Announces Strategic Realignment of Business Portfolio — PR Newswire, 2025-10-31 ↩↩
-
Cboe Announces Agreement to Sell Cboe Australia and Cboe Canada to TMX Group — Cboe Global Markets, 2026-04-22 ↩↩↩
-
Cboe to Add Tuesday and Thursday Expirations for SPX Weeklys Options — PR Newswire, 2022-04-13 ↩
-
Cboe to Further Expand S&P 500 Index Options Suite with New and Additional Daily Expirations — PR Newswire, 2022-09 ↩
-
Cboe Global Markets Q3 FY2025 earnings call transcript — Yahoo Finance, 2025-10-31 ↩↩↩↩↩↩↩
-
Cboe Global Markets Q2 2025 earnings call transcript — Investing.com, 2025-08-01 ↩↩↩
-
Cboe Global Markets, Inc. Form 10-K for fiscal year 2022 — US SEC, 2023-02-17 ↩↩↩↩↩↩↩
-
Cboe Global Markets Completes Acquisition of ErisX, Entering Digital Asset Market — PR Newswire, 2022-05-02 ↩
-
Cboe Writes Down Value of ErisX Acquisition — Markets Media, 2022 ↩
-
Cboe Global Markets Realigns Digital Asset Business, Leveraging Strength and Expertise in Derivatives and Clearing — PR Newswire, 2024-04-25 ↩
-
Cboe Global Markets Announces Leadership Transition — Cboe Global Markets, 2023-09-19 ↩↩
-
Edward Tilly joins Clear Street less than a year after resignation from Cboe — The TRADE, 2024 ↩↩
-
Cboe Global Markets Appoints Craig Donohue as New CEO — PR Newswire, 2025-05-01 ↩↩
-
Cboe layoffs: exchange cutting 20% of workforce in 2026 — Quartz, 2026-05-01 ↩
-
Cboe Global Markets Reports Results for First Quarter 2026 — PR Newswire, 2026-05-01 ↩↩↩
-
Cboe Global Markets, Inc. Form DEF 14A (2026 Proxy Statement) — US SEC, 2026-04-01 ↩↩↩↩↩↩↩↩
-
Cboe Global Markets Reports Results for Fourth Quarter 2025 and Full Year — PR Newswire, 2026-02-06 ↩
-
Cboe Introduces Cboe Predicts, Launching First Products in New Prediction Markets Suite — PR Newswire, 2026-06-23 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube