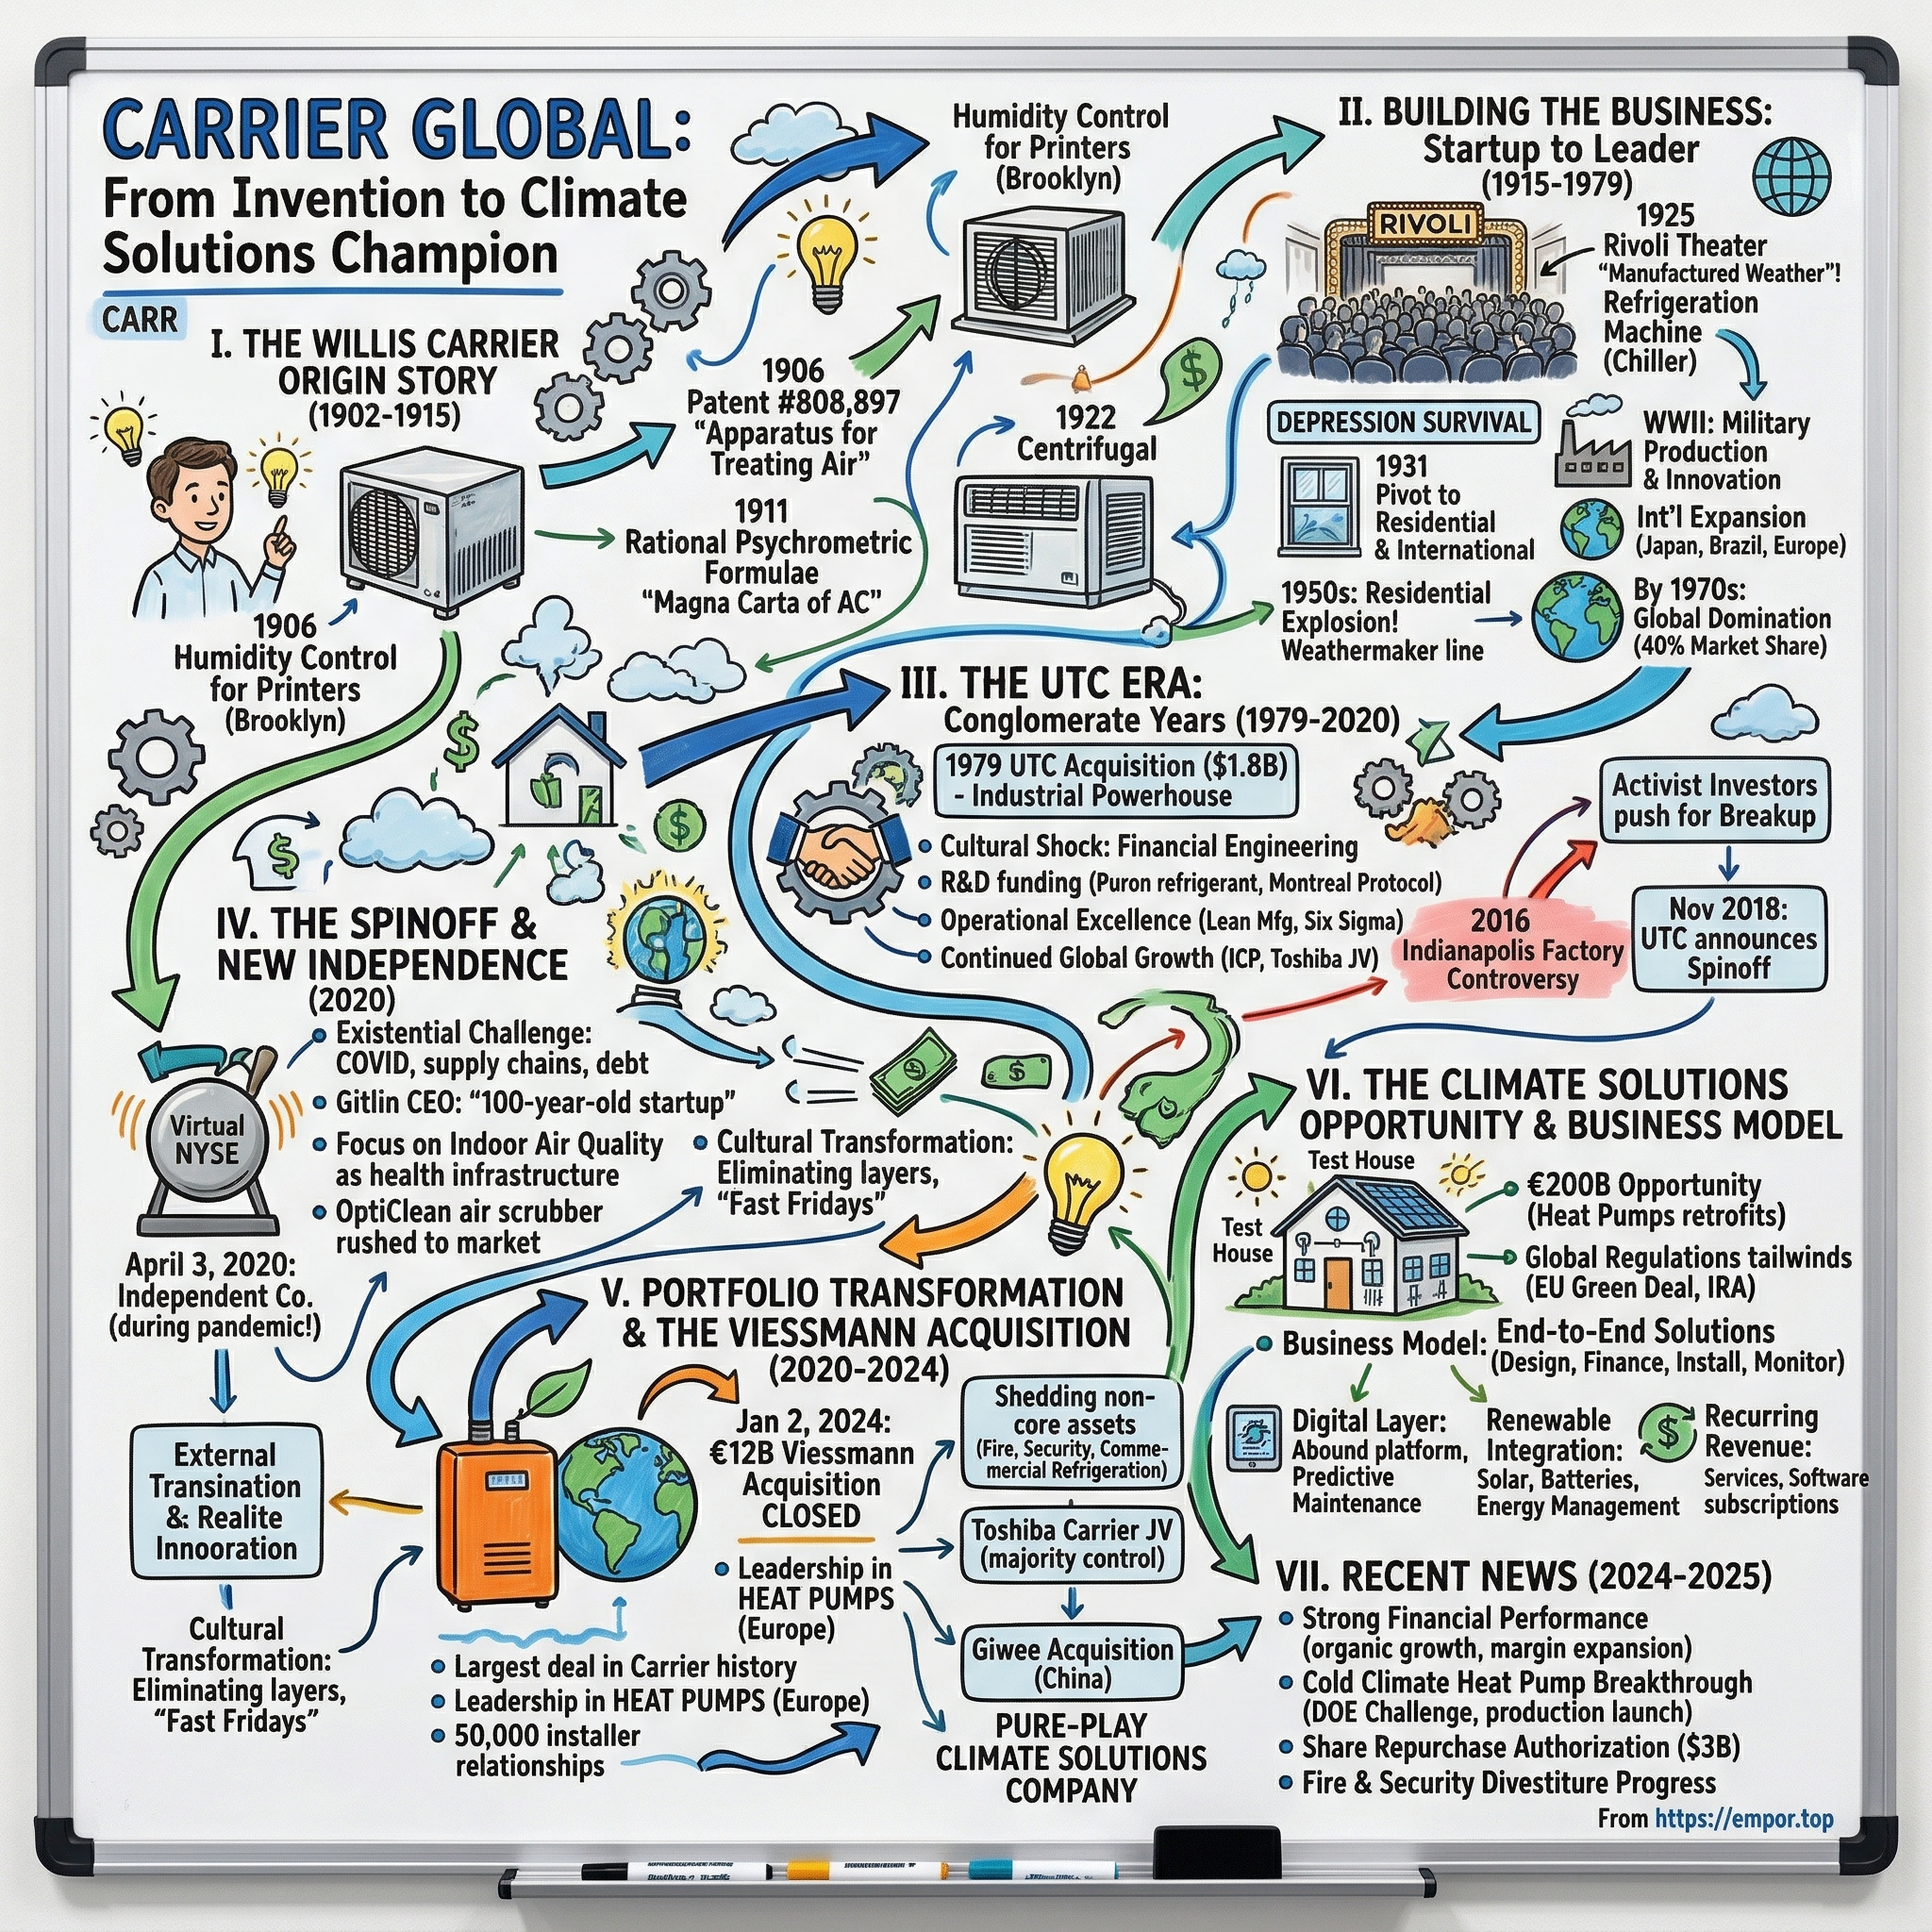
Carrier Global: From Willis Carrier's Invention to Climate Solutions Champion
I. Introduction & Episode Roadmap
Certain corporate narratives are best understood by examining their recent outcomes first. A company presents a focused portfolio, a record backlog, and executive projections of sixth consecutive years of double-digit growth in key segments—prompting an examination of the structural changes required to reach that position.
Carrier Global Corporation fits that pattern. On July 28, 2026, the company reported second-quarter sales of $6.35 billion, raised its full-year outlook to roughly $23 billion in revenue with adjusted earnings per share of about $2.90, and disclosed a total backlog exceeding $8 billion, up roughly 40% year over year.1 Overall quarterly orders rose about 40%, with commercial HVAC orders up about 65% and data center orders increasing fourfold.1 Chairman and CEO David Gitlin closed the earnings call by thanking "our 50,000 team members around the world."3
Yet, as of September 1, 2026, Carrier's shares traded near $57 with a market capitalization around $47 billion—below both their 50-day and 200-day moving averages, and well off a 52-week high near $77. That valuation sits beside two key industry benchmarks: Trane Technologies, the pure-play HVAC company Carrier seeks to match, carried an equity value near $97 billion, while Johnson Controls—the diversified building-systems provider whose model Carrier's strategy implicitly criticizes—was valued at roughly $84 billion.
The Question This Story Answers
The central question for investors is straightforward: how did the 124-year-old inventor of modern air conditioning spend four decades inside an aerospace conglomerate, execute an April 2020 spinoff laden with $11.0 billion in freshly issued debt, spend roughly €12 billion acquiring a German heating manufacturer near a cyclical peak, sell off nearly half its legacy portfolio to fund the deal, and still fall short of the pure-play valuation re-rating the strategy was designed to deliver?
Carrier management's core thesis since 2023 rests on portfolio simplification: trading legacy fire, security, and commercial refrigeration assets for higher-growth climate vectors—European residential heat pumps, commercial building chillers, and AI data center cooling. While transaction execution was swift and, based on disclosed transaction prices, well-timed, the operational outcomes present a more complex picture that requires careful analysis.
The Route
The analysis follows a clear sequence. First, the origin: a 25-year-old engineer solving a humidity problem in a Brooklyn print shop in 1902, establishing thermodynamic principles that continue to dictate industry profitability. Second, the United Technologies era from 1979 to 2020—a 40-year test of whether cross-selling integrated building systems creates real value, and what eventual asset sale prices revealed about the answer. Third, the spinoff into the initial wave of the COVID-19 pandemic, alongside the capital structure assigned to the newly independent company.
Fourth, the strategic portfolio transformation involving Toshiba Carrier, Viessmann, and the divestiture campaign—tested immediately by a sharp contraction in European heat pump demand within months of signing. Fifth, Carrier's current operating economics, focusing on the data center cooling business that now drives its equity story. The analysis concludes with a management and capital allocation audit, an earnings-call breakdown, durable business lessons, and a balanced evaluation of bull and bear cases with specific tracking indicators.
Prior to examining the historical context, one structural shift warrants attention. In 2024, Carrier reorganized its financial reporting around geographical regions rather than product categories: Climate Solutions Americas, Climate Solutions Europe, Climate Solutions Asia Pacific Middle East & Africa, and Climate Solutions Transportation.2 This structural change indicates management's view that regional factors—such as installer channels, building codes, subsidy regimes, and construction cycles—represent the primary operating constraints rather than underlying product technology. Whether that strategic positioning proves correct remains a key open question.
 Subscribe on LinkedIn
II. The Willis Carrier Origin Story & The Invention of Modern Air Conditioning (1902–1979)
The problem was ink. In the summer of 1902, the Sackett & Wilhelms Lithography and Printing Company in Brooklyn could not hold registration on multi-color jobs. Paper is hygroscopic — it drinks moisture out of humid air and swells, and it swells unevenly. Run a sheet through the press four times for four colors, and by the fourth pass the sheet is a different size than it was on the first. The reds do not land on the blues. In the humid New York summer, an entire category of commercial printing simply did not work.
The engineer sent to solve it was Willis Haviland Carrier, born November 26, 1876 on a dairy farm near Angola, New York, and a 1901 mechanical engineering graduate of Cornell.6 He had taken a job at the Buffalo Forge Company for ten dollars a week drafting heating plants — which is to say, he was hired to make air hotter, and the assignment that made him famous required doing the opposite.6 On July 17, 1902, he began the set of mechanical drawings that became the first modern air conditioning system.4
Why It Was Called "Treating Air"
The conceptual leap is worth slowing down on, because it is the reason "air conditioning" is not simply "cooling." Carrier's insight was that if you pass air over coils cold enough to drive it below its dew point, water condenses out of the air and onto the coils. You are not merely lowering temperature; you are removing moisture on purpose, and by choosing the coil temperature you choose the humidity. As Carrier's own account of the episode puts it, if he could control the humidity, he could control the temperature.8 Humidity became a dial. That is why the machine was called an apparatus for treating air rather than cooling it — and that is the name on U.S. Patent No. 808,897, issued January 2, 1906.5
Then came the part that mattered commercially. In 1911, Carrier presented "Rational Psychrometric Formulae" to the American Society of Mechanical Engineers, and it converted the field from craft to engineering.4 Before the paper, sizing an air conditioning system was closer to guesswork.
After it, a designer could calculate what a given machine would do to a given volume of air at a given condition — which meant a system could be specified, bid, warrantied, and sold on a promise. Every industry that later depended on controlled air — textiles, pharmaceuticals, semiconductors, and eventually server halls — inherits that framework. It is also the reason engineering credibility, not brand advertising, became the currency of commercial HVAC. That has not changed.
Seven Engineers and $2,500
The entrepreneurial break came in 1915. Buffalo Forge, retrenching, shut down its engineering department, and on June 26, 1915, Carrier and six colleagues — Irvine Lyle as treasurer and general manager, plus Edward Murphy, L. Logan Lewis, Ernest Lyle, A.E. Stacey Jr., and Edmund Heckel — incorporated Carrier Engineering Corporation on stock subscriptions totaling $2,500, opening offices in Buffalo, Chicago, Philadelphia, and Boston.7 The founding capital is almost comically small relative to the industry it started. What the seven actually contributed was the applied physics and the customer relationships; the capital came later, from customers who needed the problem solved.
The Centrifugal Chiller Rewrites the Addressable Market
The product that turned a consulting engineering firm into an industrial company arrived in 1922: the centrifugal chiller.4 The layman's version is that instead of using a piston to squeeze refrigerant — which limits you to relatively small capacities and, in that era, to toxic refrigerants like ammonia — Carrier used a spinning impeller, essentially a compressor built like a jet engine's fan stage, to move enormous volumes of refrigerant vapor.
That single change made large-scale comfort cooling economically and physically possible, and it opened venues that had been unreachable: Madison Square Garden installed Carrier centrifugal chillers in 1925, and by 1928 the Milam Building in San Antonio became the first skyscraper designed and built with comfort cooling.4 Movie theaters were the consumer wedge — air conditioning was, for a generation of Americans, something you bought a ticket to experience.6
The institutional consolidation followed the technology. On October 31, 1930, Carrier Corporation was incorporated in Delaware, merging Carrier Engineering with affiliated construction, refrigeration, and heating firms; headquarters moved from Newark to Syracuse in 1937, where the company stayed until 1990.7 Willis Carrier died in 1950, on the eve of the market that would define the company's second half-century.6 In 1955, Carrier acquired Affiliated Gas Equipment of Cleveland, adding the residential furnace brands that let it sell into the postwar suburb.7 Air conditioning then did something few products do: it changed where Americans could live. The Sunbelt migration and the mass-produced suburb are not separable from cheap residential cooling.
What the Founding Era Set in Stone
Two structural features of the modern investment case were set in this period and have never been undone. First, the money in this industry is made at installation and replacement, not at invention — the equipment is sold through contractors who are the actual decision-makers in most households. Second, the equipment is heavy, custom-fitted, and long-lived, which means whoever put the machine in the building has a claim on servicing it for decades. Willis Carrier built a company on the first insight. It took Carrier Global nearly a century — and a divorce from its parent — to systematically monetize the second.
III. Trapped in the Conglomerate: The United Technologies (UTC) Era (1979–2020)
By the late 1970s, Harry Gray had a habit. The chief executive who renamed United Aircraft as United Technologies Corporation in 1975 was building a conglomerate by acquisition, and the logic was macroeconomic rather than operational: pair the violently cyclical, politically exposed aerospace and defense businesses — Pratt & Whitney, Sikorsky — with steadier building-systems cash flows from Otis Elevator, and the consolidated earnings stream would be smoother than either half alone. Carrier, the largest air conditioning company in the world, was the obvious next piece.
The takeover was hostile and it was bitter, and it closed on July 6, 1979, making Carrier a wholly owned subsidiary of UTC.7 The consideration paid in 1979 is not restated in Carrier's modern filings and is not disclosed in the primary sources reviewed here. What is knowable, and more useful, is what happened over the following forty-one years.
The Cross-Selling Promise
The conglomerate thesis has an operating corollary that gets less attention than the financial one: if you own the elevator, the chiller, the fire panel, the security system, and the building controls, you can sell "the building" rather than the parts. UTC believed this explicitly.
When it acquired the British security group Chubb plc for about $1 billion in June 2003, the strategic rationale offered publicly was to use Chubb's customer base across Europe, the UK, Australia, and Asia to cross-sell products from Otis and Carrier.9 UTC's chief financial officer at the time described Chubb as "a $2.5-billion platform," adding that "if that was all we were going to do, we would never have started."9 It was not: UTC continued assembling a fire and security arm, eventually holding the Kidde, Edwards, Aritech, GST, Badger, and Gloria brands under one roof.25 Carrier itself bought International Comfort Products in 1999 for about $490 million in cash plus roughly $230 million of assumed debt, adding a Nashville-based residential and light commercial manufacturer with about $733 million of 1998 revenue.7
So: did the cross-selling work?
Historical Falsification: What the Exit Prices Revealed
This is the first place where the historical record delivers a verdict rather than an opinion, and it deserves to be stated next to the claim it tests. The claim was that integrated HVAC, fire, security, and building management create structural value together. The disconfirming evidence is the exit pricing — because a portfolio's parts are worth more separately than together only if the "together" was destroying value.
Between 2022 and 2024, Carrier sold Chubb's fire and security services business to APi Group for an enterprise value of $3.1 billion,14 Global Access Solutions to Honeywell for $4.95 billion,[^22] Industrial Fire to Sentinel Capital Partners for $1.425 billion,23 and the commercial and residential fire business — the Kidde and Edwards brands — to an affiliate of Lone Star Funds for $3 billion.25 That is roughly $12.5 billion of disclosed enterprise value for a collection of assets that, inside UTC and then inside Carrier, had spent two decades being described as strategically inseparable from air conditioning.
Buyers paid those prices to own the businesses without the HVAC attachment. Honeywell wanted access control for its own building automation stack; a private equity firm wanted a fire platform to run independently. No acquirer paid a premium for the adjacency to chillers. The most defensible reading of the evidence is that the cross-sell synergy was not merely unproven — it was affirmatively rejected by the market for these assets. The narrower version that survives is real but much smaller: shared channel and specification relationships in commercial buildings have modest value, which is exactly why Carrier kept its controls business while selling the security hardware.
The Capital Starvation Question
The second, more insidious cost of the conglomerate era was capital allocation. A business unit inside a conglomerate competes for investment against the parent's other priorities, and aerospace programs are capital-hungry and politically visible in a way that residential furnace tooling is not.
The clearest evidence for what Carrier had been denied is what happened once it could spend on itself: by the first quarter of 2026, management told investors that its global commercial HVAC sales were up 80% since the spin, backlog up 130%, share up 500 basis points, and margins up threefold — with the explicit explanation that at the spin the commercial business had margins around 5% and needed investment in product portfolio, capacity, field technicians, and specification engineers.3 A business that could triple its margins within six years of gaining control of its own capital budget was not a business that had been optimally funded before.
Indianapolis, 2016: Politics Versus Unit Cost
Then there was Indianapolis. In early 2016, Carrier announced it would move furnace production from Indianapolis to Mexico, and the plan became one of the defining set-pieces of that year's presidential campaign.11 The deal that followed preserved roughly 800 jobs in exchange for about $7 million in Indiana state tax breaks and grants over ten years, alongside a $16 million Carrier commitment to automate the plant.12 The automation clause is the tell.
Carrier laid off roughly 340 workers in July 2017 and about 215 more in January 2018, taking the plant from around 1,600 employees to roughly 1,100.12 The political intervention changed the location of the cost reduction, not its existence — the capital was spent domestically on machines instead of internationally on labor. For investors, the durable lesson is that manufacturing footprint economics in this industry are set by unit cost and freight, and public commitments that run against those economics tend to be honored in form and eroded in substance.
The end came on November 26, 2018, when UTC chief executive Greg Hayes announced the tax-free three-way separation into an aerospace company, Otis, and Carrier.10 Forty-one years after Harry Gray won his hostile fight, the conglomerate logic was formally abandoned by its own successor. What Carrier did not know yet was the shape of the balance sheet it would be carrying on the way out, or the world it would be walking into.
IV. The Spinoff & "100-Year-Old Startup" Independence (2020–2022)
Consider the timing. Carrier Global began regular-way trading on the New York Stock Exchange on April 3, 2020 — a week and a half after the S&P 500 bottomed in the fastest bear market in modern history, with American commercial construction sites shuttered, shopping malls closed, and nobody on earth able to forecast next quarter.13 A newly independent industrial company with no separate operating history, no established investor base, and no track record of its own was asked to introduce itself to the market during a global lockdown.
The Balance Sheet Carrier Was Handed
It was also handed a balance sheet designed to serve someone else's interests. In connection with the separation, Carrier issued an aggregate principal balance of $11.0 billion of debt and transferred approximately $10.9 billion of cash to UTC in February and March 2020.13 This is the single most important fact about Carrier's first years as a public company, and it is worth stating plainly rather than euphemistically: the parent monetized the spinoff by levering the child.
Carrier did not borrow $11 billion to invest in Carrier. It borrowed $11 billion and sent the proceeds to Farmington, Connecticut. Every capital allocation decision made between 2020 and 2024 — the divestiture sequencing, the deferral of buybacks, the choice to fund the Viessmann acquisition substantially in cash — traces back to that opening position.
The Lawyer Who Became an Operator
The man handed the problem was David Gitlin, and his background is more unusual than the résumé line suggests. Gitlin took a bachelor's degree from Cornell — the same university Willis Carrier attended — then a law degree from the University of Connecticut and an MBA from MIT's Sloan School.[^34] He joined UTC in 1997 as in-house counsel, then moved to the operating side at Hamilton Sundstrand, ran UTC Aerospace Systems as president, and served as president and chief operating officer of Collins Aerospace before taking the Carrier job; he was elected chairman in April 2021.[^34] A lawyer who became an aerospace operator is a specific kind of executive: comfortable with complex contractual structures and multi-party transactions, trained to think about downside cases, and — as the subsequent record shows — unusually willing to sell things.
His framing device was that Carrier was a "100-year-old startup," which is the sort of phrase that means nothing unless it produces different behavior. In Carrier's case it produced two concrete things. The first was a structured cost program, launched as "Carrier 600" and quickly escalated to "Carrier 700" as the targets were raised, aimed at taking structural cost out of a company that had spent four decades as a division rather than a business — reducing the sprawl of joint ventures, suppliers, and legal entities that a conglomerate subsidiary accumulates.
The second was the recruitment of an outside chief financial officer. Patrick Goris joined in 2020 from Rockwell Automation, where he had been chief financial officer after a career that included investor relations and segment finance roles; he now holds the title of executive vice president and chief financial and strategy officer.31 Notably, he was Carrier's second CFO in the company's first year of independence — a detail that would look like instability at a mature company and, at a newly spun business, mostly signals that Gitlin was willing to change his mind quickly about senior appointments.
What Carrier Actually Was in 2020
At the spin, Carrier was three businesses: HVAC, refrigeration, and fire and security. Roughly two-thirds of revenue came from HVAC, with refrigeration and fire and security splitting most of the remainder. The pandemic delivered a genuine, if temporary, tailwind: indoor air quality became a boardroom subject for the first time in decades, and demand for filtration, ventilation upgrades, and negative-pressure systems spiked. It also delivered something more durable — Americans stuck at home discovered how their houses actually performed, and the residential replacement cycle ran hot through 2021 and 2022. Revenue reached $20.6 billion in 2021 before the portfolio surgery began reshaping the reported base.
Myth vs. Reality: The Watsco Stake
One element of Carrier's North American position deserves correction, because it is widely misstated. Carrier's residential distribution in the United States runs substantially through joint ventures with Watsco, the largest HVAC distributor in North America — but Watsco holds the controlling interest in those Carrier Enterprise joint ventures and operates them, with Carrier retaining a minority position accounted for as an equity-method investment.13 Carrier does not own a third of Watsco Inc. The distinction matters for the moat argument: Carrier's distribution advantage is a contractual and relationship advantage inside vehicles it does not control, not an ownership lock on the channel. It is real, and it is thinner than the popular version.
The First Sale
The first genuine act of strategic will came on January 3, 2022, when Carrier completed the $3.1 billion sale of Chubb Fire & Security to APi Group, generating about $2.6 billion in net proceeds that management directed toward $750 million of debt paydown and roughly $1.6 billion of share repurchases in 2022, including a $500 million accelerated repurchase.14 Gitlin's stated rationale was that selling Chubb enhanced the growth, margin, and free cash flow profile of the company.14 It also established the pattern that would define the next three years: identify a business that does not compound, sell it to a buyer for whom it is core, and recycle the cash. What nobody knew in early 2022 was how large the next purchase would be.
V. The Great Portfolio Transformation: The Viessmann Bet & Divestiture Spree (2022–2024)
Every corporate transformation has a moment where management pivots from incremental adjustment to major strategic bets. For Carrier, that moment arrived over an 18-month span, carrying a substantial price tag.
Step One: Buying the VRF Franchise
The transformation began in Japan. On July 31, 2022, Carrier completed the acquisition of substantially all of Toshiba Corporation's stake in Toshiba Carrier Corporation for approximately $900 million—consolidating a joint venture the two companies had operated for years that generated roughly $2 billion in annual sales with 6,600 employees.15
The core strategic asset was variable refrigerant flow (VRF) technology. While conventional HVAC systems push air at a uniform temperature through central ductwork, VRF systems route refrigerant to individual indoor units, modulating supply so separate zones can heat or cool independently off a single outdoor machine.
VRF represents the dominant HVAC architecture across Asia and Europe and has steadily gained share in North American light commercial markets. Rather than continuing to license the capability through a joint venture, Carrier spent $900 million to acquire full ownership of the technology, compressor design engineering, and distribution channels.15 Four years later, that transaction stands out as the most clearly accretive deal of Carrier's restructuring: the Toshiba-branded VRF platform anchors Carrier's expansion in Asia, driving second-quarter 2026 revenue growth above 20% across India, Southeast Asia, and Australia.1
Step Two: The €12 Billion Bet on Viessmann
The next step was larger and far more consequential. On April 25, 2023, Carrier announced an agreement to acquire Viessmann Climate Solutions at an enterprise value of €12 billion (approximately $13 billion). The consideration was paid roughly 80% in cash and 20% in Carrier common stock issued to Viessmann Family Holdings, subject to long-term lock-up provisions and with Max Viessmann joining Carrier's board at closing.1617
Viessmann brought a century-old brand legacy and a leading position in European residential heating, with projected 2023 sales of about €4 billion and forecast EBITDA of roughly €0.7 billion. The target had compounded sales and EBITDA at 15% annually since 2020, supported by 11,000 employees, including over 1,300 dedicated service and support personnel.16 Carrier management framed the purchase price as approximately 13 times projected 2023 EBITDA after factoring in €200 million of expected run-rate cost synergies—driven primarily by procurement efficiencies and insourcing—with the majority expected by the third year.16 The transaction closed on January 2, 2024.18
Examining the underlying arithmetic clarifies the transaction's leverage. A €12 billion purchase price against €0.7 billion in standalone forecast EBITDA equates to a multiple of roughly 17 times prior to synergies. Reaching the advertised 13-times multiple required the full realization of the projected €200 million in cost savings. While such presentation is common in corporate M&A, it meant Carrier was underwriting a significant portion of the deal's return to its own operational execution, leaving little margin for error if market demand softened.
Historical Falsification: The European Heat Pump Crash
That market assumption was tested almost immediately.
Carrier's strategic thesis rested on the rapid electrification of European residential heating. Under European Union decarbonization targets and Germany's proposed building energy legislation, millions of legacy fossil-fuel boilers were expected to be replaced by electric heat pumps. Viessmann's premium brand equity and extensive installer network were positioned to capture that shift. Financially, replacing a boiler with a heat pump significantly increases the equipment content installed per household, turning a policy-driven replacement cycle into a revenue multiplier. However, demand had already peaked.
According to industry association data, European heat pump sales contracted in 2023, bringing an end to the surge in demand that followed the 2022 energy crisis.19 In Germany, severe political friction surrounding the heating legislation created widespread uncertainty regarding homeowner mandates and subsidies, suppressing market activity just as Carrier executed the purchase agreement.20 By 2024, total European heat pump sales had dropped by 23%.21
Carrier's subsequent disclosures illustrated the extent of the contraction. During the company's fourth-quarter 2025 earnings call, Gitlin detailed progressive downward revisions to the German market: Carrier had initially modeled total German heating equipment volume falling from roughly 715,000 units to 660,000, then reduced that target to 640,000, before the market ultimately settled around 600,000 units—well below historical baseline levels near 800,000.3 This represented a three-step downward adjustment within a single planning cycle for the acquired business's core market. Management maintained that the structural transition remained intact—with heat pumps expanding while boilers declined—arguing that the overall market was absorbing excess inventory built up during 2022 and 2023.3
Scoring the Bet
Evaluating the Viessmann acquisition requires separating macro timing from operational execution. The core electrification thesis did begin to reassert itself: European heat pump sales rebounded in 2025, reaching approximately 2.9 million units across 21 countries—a 13% year-over-year increase. Industry analysts attributed the recovery to lower electricity taxes, restored subsidies, and favorable energy pricing rather than technological breakthroughs.21 By the second quarter of 2026, Carrier's European residential sales grew in the high single digits, led by a 20% expansion in heat pumps that offset high-single-digit declines in traditional boilers. Gitlin cited renewed German government subsidies and an electricity-to-gas price ratio dropping below three as key catalysts.13 The underlying thesis proved directionally sound, even if initial timing proved flawed.
However, poor timing at a valuation of 17 times pre-synergy EBITDA carries real financial consequences, which remain evident in segment results. Climate Solutions Europe—the segment containing Viessmann—generated $5.04 billion in 2025 sales at an 8.8% operating margin, compared with 20.5% in Climate Solutions Americas.2 In the second quarter of 2026, despite top-line expansion, European operating margin contracted 70 basis points year over year to 7.2%.1
Gitlin publicly characterized these margins as disappointing and took operational action, replacing segment leadership by appointing Thomas Donato as president of Climate Solutions Europe in June 2026. Management targeted mid-teens operating margins over the next few years, with Gitlin acknowledging that the company should have pursued cost reductions more aggressively earlier in the integration.3 This executive shift marked a clear acknowledgment that underperformance extended beyond cyclical market weakness to internal operational execution.
The benchmark for assessing this acquisition going forward is straightforward: European segment operating margins must expand from roughly 7% toward the mid-teens as market volumes normalize. If margins plateau near 10% despite volume recovery, it will indicate that Carrier paid a substantial premium for an asset it has struggled to operate more efficiently than its previous owners.
Step Three: Selling Half the Company
Financing the Viessmann acquisition and reshaping the balance sheet required divestitures across the remainder of the portfolio, executed over a compressed timeframe. In December 2023, Carrier agreed to sell Global Access Solutions—encompassing access-control brands LenelS2, Onity, and Supra—to Honeywell for $4.95 billion, a transaction that closed on June 3, 2024.[^22]22 On March 5, 2024, the company signed an agreement to sell Industrial Fire (including Det-Tronics, Marioff, Autronica, and Fireye) to Sentinel Capital Partners for $1.425 billion, expecting net proceeds of over $1.1 billion dedicated to debt paydown.23
On October 2, 2024, Carrier completed the sale of its commercial refrigeration business to 海尔智家 Haier Smart Home for an enterprise value of $775 million, which included approximately $200 million in net pension liabilities, while retaining Carrier Transicold, Sensitech, and the Lynx digital platform.24[^26] Finally, on December 2, 2024, Lone Star Funds completed its $3 billion acquisition of Carrier's commercial and residential fire business, which was subsequently renamed Kidde Global Solutions.25
Executing four major multi-billion-dollar divestitures within a twelve-month window without price renegotiations or closing delays represents strong deal execution. Given that complex industrial carve-outs frequently encounter regulatory obstacles or delayed closings, this divestiture program stands as the clearest operational success of Carrier's leadership team, distinguishing transaction execution from M&A underwriting.
The Liability That Stayed Behind
However, one major legacy liability from the fire business remained with Carrier. Kidde-Fenwal, a manufacturer of aqueous film-forming foam, filed for Chapter 11 bankruptcy protection in May 2023 due to extensive litigation over per- and polyfluoroalkyl substances (PFAS) contamination. By September 30, 2024, the bankruptcy proceedings encompassed more than 8,000 lawsuits.26 In October 2024, Carrier proposed a comprehensive settlement framework totaling approximately $730 million. This proposal comprised roughly $615 million in cash payments over five years alongside approximately $115 million in net proceeds from selling Kidde-Fenwal's assets to Pacific Avenue Capital Partners, with roughly $540 million allocated to the bankruptcy estate and $190 million to water-contamination claimants.26 Objections from state attorneys general throughout 2025 extended the resolution process across multiple revised disclosure statements.
This pending litigation remains an active financial overhang. Because the liability is structured around a proposed settlement rather than a finalized court confirmation, cash outflow timing remains subject to change, and ultimate net costs depend on insurance recovery determinations.
VI. Pure-Play Climate Economics: Industry Structure, Moats, & Data Center Cooling
Walk into the basement of a forty-story office tower and you will find a machine the size of a bus. It was craned in before the walls were finished. It weighs more than the trucks that delivered it. It makes chilled water that gets pumped up through the building's risers to coils on every floor, and it will run for twenty-five years. Nobody replaces it casually. When it needs parts, they come from whoever built it. That machine — the applied chiller — is the economic heart of the company Carrier has spent six years becoming.
The Barbell
Today Carrier's revenue splits four ways by geography. In 2025, Climate Solutions Americas produced $10.47 billion at a 20.5% operating margin, Europe $5.04 billion at 8.8%, Asia Pacific/Middle East/Africa $3.34 billion at 13.4%, and Transportation $2.89 billion at 15.6%.2 Underneath that, the operating reality is a barbell. Roughly half the portfolio is short-cycle residential and light commercial equipment sold through distributors — high margin, high return, and violently exposed to interest rates and consumer confidence. The other half is long-cycle commercial HVAC and aftermarket service — lower unit margin at the point of sale, but backed by contracts, backlog, and an installed base.
The short-cycle half spent 2025 in a genuine downturn, and Carrier's disclosure of it was unusually specific. North American residential unit volumes for the industry ran around 7.5 million against what management estimates is a normal year near 9 million, after an industry that averaged 9.7 million units from 2020 to 2024 built roughly 3.5 million units of cumulative overage.3 In the fourth quarter of 2025, Carrier's residential sales fell close to 40% and the Americas segment margin dropped about ten points to just under 9% because factories were running at less than half the prior year's output.3 Management chose to keep those plants running at minimal levels rather than shut them down, carrying a couple hundred million dollars of extra inventory into 2026 — an operationally defensible call that cost reported margin to protect the ability to serve a recovery.3 By mid-2026 the call proved right: second-quarter residential sales rose 9%, field inventory finished the quarter down about 25% year over year, and management raised the full-year residential outlook to up high single digits.13
The Data Center Business
The long-cycle half is where the equity story now lives, and its name is data centers.
The physics deserve a plain-English explanation because it drives the whole opportunity. A traditional server rack dissipates a few kilowatts of heat, and you can remove that with cold air — blow enough of it through the room and the chips stay cool. Modern AI accelerator racks dissipate an order of magnitude more. Air simply cannot carry heat away fast enough at that density; the physics run out.
So the industry is migrating to liquid: chilled water plants outside, and increasingly coolant plumbed directly to cold plates sitting on the processors themselves. The device that manages the handoff between the facility's water loop and the servers' coolant loop is called a coolant distribution unit, or CDU — which, as Gitlin has pointed out to analysts, is functionally a small chiller, a machine Carrier has been building since 1922.3
Carrier's data center business went from roughly $1 billion of sales in 2025 to a raised 2026 outlook of about $2 billion, with roughly $500 million booked in the first half and $1.5 billion expected in the second, and an implied exit run-rate around $2.5 billion.13 The order momentum is more dramatic than the revenue: first-quarter 2026 global data center orders were up over 500%, second-quarter orders up fourfold, and by mid-2026 total company backlog exceeded $8 billion, of which commercial represents roughly two-thirds to 70% and data centers about 40% of that commercial backlog.13 Management stated that 2026 data center revenue was entirely covered by backlog.1
Two facts make this credible beyond the order numbers. First, capacity: Carrier repurposed an entire North American facility to air- and water-cooled chillers, expanded its Charlotte plant by 50%, announced a new facility in India, and by the second quarter of 2026 was finalizing a new U.S. site — Texas and Alabama the finalists — targeted to be running by the end of the first quarter of 2027, driving full-year capital expenditure to about $600 million.13 Companies do not spend that on capacity they have not sold.
Second, the share math Gitlin offered when asked about overbuild risk is the most useful thing management has said about this business: Carrier started from roughly 10% share in commercial HVAC in the U.S., so if data center capital spending slows, Carrier needs to hold something like 15–20% share to keep growing, while a competitor that started at 30% would need to reach 45%.3 That is a genuine structural asymmetry for a share gainer, and it is the correct way to think about cyclical risk in a business where everyone's backlog looks good simultaneously.
The Liquid Cooling Gap
Now the honest counterweight, which belongs here rather than in a distant risk section. Carrier's data center portfolio is heavily weighted to chillers — the mature, high-share-of-wallet part of the stack — while the fastest-growing frontier is liquid cooling, where the incumbents are different. Carrier introduced its first CDU in 2025, saw demand for a 1.3-megawatt unit in the second quarter of 2026, planned to launch a 2.5-to-2.6-megawatt unit that quarter and a 5-megawatt unit around year-end.13 That is a fast product cadence, but it is a 2025-vintage entry into a category where Vertiv and specialist players have been shipping longer.
Gitlin has been explicit that Carrier examined acquisitions in liquid cooling and chose organic development instead, describing the alternative deals as being "in the millions, not in the billions" range.3 That is a defensible capital allocation choice given the balance sheet — and it is also a decision to compete on engineering timelines rather than to buy an installed base. If liquid cooling becomes the specification-setting layer, that choice will be tested directly.
Seven Powers, Honestly Applied
Against Hamilton Helmer's seven powers framework, the portrait is uneven in an instructive way.
The strongest power is switching costs, and it is concentrated in applied commercial HVAC. Replacing a centrifugal chiller inside an occupied building is a construction project, not a purchase. That creates a service annuity, and Carrier has been systematically harvesting it: connected chillers grew from 17,000 three years ago to over 70,000, the Americas service attachment rate reached close to 60% after more than tripling in a year, global service coverage reached 110,000 chillers, and management estimates 70–80% of its high-complexity chillers sit under service contracts.3 Aftermarket grew double digits for five consecutive years through 2025, with modifications and upgrades — the highest-margin category — up 20%.3 This is the most verified moat in the company.
Cornered resource is the claim most often made about Viessmann, and it needs discipline. The asset is real: in European residential heating, the installer chooses, and Viessmann's direct-to-installer channel is a genuine constraint on competitors. Carrier is investing behind it, planning to double its number of qualified "SystemPro" installers — those certified to sell complete heat pump, battery, solar, and hot water systems — and reporting that those installers grew sales double digits in 2025.3 But a cornered resource should show up in pricing and margin, and Europe's 7–9% segment margins say it has not yet.12 The precise, non-promotional formulation is that Carrier owns a strong channel position whose economic value remains unproven under its ownership.
Scale economies apply to refrigerant transitions and compressor engineering — the mandated shift to low-global-warming-potential A2L refrigerants in North America requires redesigning entire product lines, which favors manufacturers who can amortize that across global volume. Process power shows up in the aftermarket playbook. Network economies are largely absent. And branding, in an industry where the contractor picks the equipment, is worth less than outsiders assume.
Five Forces and the Buyer-Power Shift
Porter's framework tells a similar story with different emphasis. Rivalry among Carrier, Trane Technologies, Johnson Controls, and ダイキン工業 Daikin Industries is intense and getting more so as all four chase the same hyperscaler budgets. Barriers to entry are high — refrigerant regulation, efficiency standards, safety certification, and contractor relationships take years to assemble. Substitutes are weak, because vapor compression is the physics and heat pumps are simply the electric version of the boiler. Supplier power is modest.
And buyer power is the force that has genuinely shifted: a homeowner replacing a dead air conditioner in August has almost no leverage, but a hyperscaler negotiating a multi-year, multi-site long-term agreement has a great deal of it. Carrier's own description of building "almost a rotable pool" of chillers to which customers have pre-allocated share is a description of a business where a handful of buyers set the terms.3 Concentration of that kind is a growth engine and a bargaining-power risk in the same sentence, and both belong in the model.
VII. Management & Capital Allocation Audit: Gitlin's Playbook & Disconfirming Evidence
On May 19, 2025, Carrier held an investor day and outlined its medium-term financial targets: 6% to 8% annual organic sales growth, over 50 basis points of yearly adjusted operating margin expansion, mid-teens adjusted earnings per share growth, near 100% free cash flow conversion, and roughly $15 billion of capital available for deployment over the medium term.30 Gitlin framed the transformed portfolio as "simplified, focused and balanced," positioning Carrier to accelerate organic growth while expanding margins.30
Seven months later, full-year results presented a different trajectory: 2025 organic sales fell about 1%, with revenue landing at $21.75 billion, adjusted operating margin at 15.1%, and adjusted earnings per share at $2.59.2 Free cash flow of $2.12 billion met expectations.2 Management had unveiled its medium-term growth framework at almost precisely the moment its short-cycle residential lines entered a downturn.
That sequence offers a key test of management credibility. While the framework was not inherently reckless—published before the sharp second-half residential contraction became fully visible—it emerged at a cyclical inflection point that management, despite monitoring channel inventories, failed to anticipate.
Subsequent explanations leaned heavily on macro conditions rather than execution issues. The notable exception was Europe, where Gitlin took personal responsibility for slow cost-cutting and replaced segment leadership instead of lowering targets again.3 Distinguishing between external market drag and internal operational shortcomings is a critical distinction for evaluating leadership.
Guidance Discipline After the Miss
Carrier's 2026 forecasting reflected greater conservatism following the 2025 miss. The company entered 2026 guiding to roughly $22 billion in revenue and $2.80 in adjusted earnings per share.2 After a strong first quarter—generating $5.3 billion in sales, $0.57 in adjusted earnings per share, and cash flow exceeding expectations—management refrained from raising full-year guidance, with Gitlin noting macro uncertainty ahead.3 Management waited until second-quarter results were finalized to raise its outlook to approximately $23 billion in revenue and $2.90 in adjusted earnings per share.1 This beat-hold-raise progression indicates a management team adjusting after overestimating near-term visibility.
Deleveraging, or Buybacks Funded by the Balance Sheet?
Capital allocation represents another area requiring close scrutiny.
When announcing the Industrial Fire sale in March 2024, Carrier stated it expected net leverage to drop to roughly 2 times EBITDA by year-end, enabling a resumption of share buybacks.23 Share repurchases resumed aggressively. In 2025, Carrier returned approximately $3.7 billion to shareholders—$2.9 billion in repurchases and $0.8 billion in dividends—retiring about 42 million shares and reducing the count from 878.3 million to 836.1 million.2 However, cash reserves dropped from $3.97 billion to $1.56 billion while total debt remained near $11.8 billion, driving net debt up from roughly $8.4 billion to $10.3 billion.2 Consequently, repurchases were funded partly by cash balance drawdowns during a year of declining earnings rather than pure organic free cash flow.
The strategic rationale hinged on the view that the residential slowdown represented a temporary destocking cycle rather than a structural decline, making buybacks at lower valuations value-accretive.
However, this strategy departs from explicit deleveraging goals. The 2026 financial plan allocates $1.5 billion to buybacks alongside a raised $600 million capital expenditure budget for data center expansion, tasking the balance sheet with funding both shareholder returns and organic capacity growth.12 With an equity valuation near $47 billion and net debt above $10 billion, allocation trade-offs emerge—particularly as management opted against liquid cooling acquisitions due to valuation concerns while continuing multi-billion-dollar buybacks.
Portfolio adjustments extended beyond the initial transformation milestone. In December 2025, Carrier agreed to sell Riello—an Italian thermal solutions business acquired as part of Viessmann—to Ariston Group for approximately $430 million in gross proceeds, earmarking proceeds primarily for share repurchases.27 In July 2026, Carrier announced the sale of its NORESCO energy-services unit to OPTERRA Energy Services, an LS Power subsidiary, for undisclosed terms.28 These transactions removed roughly $200 million in revenue from the 2026 outlook and created a $0.05 earnings-per-share headwind.1 While aligned with divesting non-core assets, these sales indicate that portfolio simplification required additional divestitures, including assets acquired in recent transactions.
Historical Falsification: The Software Optionality Claim
Carrier's digital software strategy spans several platforms: Abound building analytics, Automated Logic and WebCTRL building controls, Nlyte data center infrastructure management, QuantumLeap integrated data center software, and 75F—a Bloomington, Minnesota-based provider of wireless, cloud-native building automation acquired on July 23, 2026, for undisclosed terms.29 Gitlin informed analysts that 75F expands Carrier's addressable building-management market by roughly $20 billion, bringing 91 engineers and wireless auto-commissioning technology that eliminates individual manual setup for over a thousand sensors in a typical installation.3
While labor savings from automated commissioning represent a tangible operational benefit, broader recurring software revenue ambitions face industry-wide headwinds. Over the past decade, major HVAC equipment manufacturers have introduced software suites with subscription models, yet none has reported standalone software revenues of material scale relative to core hardware sales.
Structural barriers persist: commercial building owners remain reluctant to pay ongoing software subscriptions for physical mechanical assets, legacy building systems remain fragmented across incompatible protocols, and third-party service contractors frequently bypass proprietary software platforms. To date, Carrier has not disclosed separate recurring software revenue metrics for Abound or Automated Logic.
A clear contrast exists within Carrier's own segments. In cold-chain logistics, Carrier's Lynx digital platform expanded to roughly 220,000 paid subscriptions—over 110,000 on shipping containers, serving six of the world's top ten shipping lines—up from negligible levels four years prior, supported by an investment in NetVaso to expand shipboard connectivity.3 Commercial adoption succeeded because fleet operators gain measurable financial returns by eliminating manual container inspections and preventing cargo loss.
In stationary commercial buildings, these adoption drivers are less pronounced. Carrier has shown it can establish software subscriptions where operational metrics and buyer workflows align, but similar scale in commercial building software remains unproven. Consequently, digital software optionality warrants conservative valuation until Carrier reports explicit software revenue or demonstrates higher aftermarket attachment rates directly driven by its digital stack.
VIII. Earnings Call & Transcript Breakdown: Guidance, Analysts, and Market Friction
Earnings calls are where management's strategic narrative encounters sell-side skepticism. Over the past several quarters, Carrier's calls have followed a distinct pattern: executive updates highlighting order backlogs and portfolio transformations, followed by analyst questioning on why operating margins compress even as revenue expands.
That tone evolved alongside the restructuring. Across 2023 and 2024, management remained on the defensive, explaining debt taken on to fund the Viessmann acquisition, mapping out divestiture timelines, and defending European growth forecasts. Through 2025, the tone grew circumspect as residential demand in North America contracted sharply. By 2026, the discussions centered on a fundamental debate: whether top-line expansion driven by data center cooling generates high-quality earnings.
The Margin Interrogation
That debate intensified during the second-quarter 2026 call. Melius Research analyst Scott Davis noted the solid top-line performance while asking management to address "the margin decline issue" by separating product mix from price and cost dynamics.3 Chief Financial Officer Patrick Goris outlined several underlying mix factors: tariffs took effect in early April before offsetting price increases landed late in the month; within Europe, expanding sales of lower-margin battery and solar systems outpaced heat pumps; within transportation, container equipment volume carried lower margins than truck and trailer units; and in the Americas, lower-margin new construction outstripped replacement equipment.3 Together, these factors illustrated an ongoing operational pattern: Carrier's strongest top-line growth occurred in its lower-margin product categories.
Wolfe Research analyst Nigel Coe questioned the sequential margin outlook, asking why the Climate Solutions Americas segment operating margin was projected to drop from 24.4% in the second quarter to roughly 22% in the third. Goris attributed the decline to a sequential drop of $500 million to $600 million in high-margin residential and light commercial sales, offset by an increase in commercial equipment volume.3 Providing segment-level quarterly margin guidance offers investors greater transparency than typical industrial peer reporting.
Goldman Sachs analyst Joe Ritchie focused on capital deployment, asking about the revenue capacity of Carrier's expanding factory footprint and the proportion of the $8 billion backlog tied to data centers.3 In response, executive disclosures confirmed that data center cooling accounted for roughly 40% of the commercial backlog, while management outlined its market-share expansion thesis.
Analyst Jeffrey Sprague questioned whether second-quarter residential strength reflected genuine end-market demand or temporary channel restocking. Chairman and Chief Executive Officer David Gitlin clarified that the primary recovery would occur in the second half of the year, modeling projected 20% residential growth as ten percentage points from the end of prior-year inventory destocking, with the balance driven equally by mid-single-digit volume gains and mid-single-digit price realization.3 This detailed breakdown provided specific metrics for testing management's guidance against actual results.
During the fourth-quarter 2025 call, Barclays analyst Julian Mitchell pressed management on its market-share assumptions amid a double-digit industry downturn, while questioning residential pricing discipline. Gitlin detailed a conservative modeling scenario that assumed no recovery in mortgage rates, consumer sentiment, or housing turnover. Under those assumptions, second-half 2026 industry volumes would remain flat against 2025 levels—reflecting a two-year cumulative drop of 30%—with first-half industry units down 20% to 25%, and Carrier's residential sales down in the high single digits, supported by low-single-digit price gains.3 That exchange underscored management's willingness to outline underlying operating assumptions when challenged.
Analyst Christopher Snyder challenged the projected 20% second-half growth rate, pointing out that against prior-year contractions of 30% to 40%, two-year stacked growth remained flat.3 Gitlin defended the guidance by pointing to operational leading indicators: distributor field inventories were down about 25%, dealer call volumes tracked ahead of internal models, and equipment aging meant "there's only so long a customer can repair over replace."3 While these indicators supported management's outlook, internal dealer call data remains proprietary and unverifiable for external observers.
Double-Ordering, and the Question Management Asks Itself About China
Two additional operational dynamics warrant examination. First, regarding double-ordering—a late-cycle risk where customers place duplicate orders across multiple suppliers—Gitlin stated that Carrier was protected by multi-year agreements with hyperscalers and colocation providers. Under these contracts, buyers commit specific volume allocations, allowing Carrier to supply equipment into pooled inventories.3 Whether this structure eliminates duplicate demand or merely shifts inventory commitments remains an open question.
Second, management offered a candid assessment of its position in China, where residential and light commercial sales dropped 25% to 30%. Rather than offering a defensive outlook, Gitlin acknowledged that leadership was evaluating the capital required to improve performance against prolonged housing headwinds, noting "that's a question that we ask ourselves quite a bit."3 Public executive questioning of an underperforming unit often signals strategic reassessment, suggesting a potential restructuring or divestiture in line with Carrier's recent portfolio moves.
Consistency Across Calls
An audit of transcript narrative consistency presents a mixed record. The commercial HVAC and aftermarket strategy has remained consistent over the six years following the spinoff, supported by disclosed operational metrics—including order intake, backlog expansion, service attachment rates, and connected chillers—that tracked management's target trajectory. Conversely, residential forecasting proved inaccurate in 2025, requiring subsequent model recalibrations and detailed inventory disclosures.
Similarly, European growth projections proved overly optimistic for two years, culminating in segment leadership changes and executive acknowledgment of delayed cost restructuring. However, management has maintained the medium-term financial targets established at its May 2025 investor day—6% to 8% organic annual sales growth and mid-teens adjusted earnings per share growth—despite negative 1% organic sales growth in 2025 and raised 2026 guidance pointing to roughly 12% adjusted earnings per share growth off a depressed base. As of September 2026, leadership has neither adjusted these medium-term targets nor fully reconciled them with multi-year operating performance.
IX. Playbook: Business & Investing Lessons
The conglomerate discount is real, and exit prices provide its measurement. The ultimate test of whether a corporate parent adds value is what independent buyers will pay for its component assets. Carrier's fire, security, and commercial refrigeration businesses fetched roughly $12.5 billion across four transactions from buyers seeking those operations without HVAC integration. Four decades of "integrated building systems" narrative yielded no acquirer willing to pay a premium for combined capabilities. When management asserts that diverse divisions create shared value, the critical test is what a specialist would pay for each business individually.
Beware acquisitions where the structural thesis is sound but timing depends on public policy. The European electrification thesis remains valid—heat pumps replace fossil-fuel boilers while increasing equipment value per home. What Carrier underestimated was that policy-driven demand is politically vulnerable, and subsidy disputes can freeze market activity faster than underlying economics can revive it. Acquiring the market leader at roughly 17 times pre-synergy EBITDA near the peak of an energy-crisis demand surge turned a sound long-term thesis into a multi-year payback exercise. The broader lesson: when an acquisition's valuation reflects policy-backed growth expectations, investors must evaluate regulatory stability alongside technological merit.
Distribution networks and installers determine short-cycle HVAC outcomes, but channel control is often overstated. Carrier's North American channel position relies on joint ventures it does not control, while its European position depends on independent installer networks. Both represent real, defensible relationships, but neither provides complete lock-in. The test of channel strength is whether it delivers pricing power and margin expansion—making Europe's single-digit operating margins critical disconfirming evidence regarding the near-term value of the Viessmann distribution asset.
The aftermarket service annuity is a powerful industrial asset, but requires deliberate cultivation. Carrier manufactured commercial chillers for a century before systematically monetizing their ongoing maintenance. Expanding connected chillers from 17,000 to more than 70,000 and raising the Americas service attachment rate to roughly 60% required targeted investments in field technicians, replacement parts availability, and service-oriented product engineering. Installed-base economics are not automatic; they depend on an intentional operational program that generates cash flows far less cyclical than initial equipment sales.
Revenue growth expanding in lower-margin categories still creates value, but requires clear reporting. Carrier faces a distinct operating dynamic: raising revenue outlooks while operating margins contract, as its fastest-growing lines—data center cooling equipment, European solar and battery systems, and refrigerated containers—carry lower margins than the contracting residential replacement market. This trend reflects product mix arithmetic rather than operational underperformance. However, investors cannot interpret an expanding backlog as increased earnings power without analyzing underlying mix. Consequently, Chief Financial Officer Patrick Goris's target for total-company incremental margin conversion of 25% to 30%—varying by residential and commercial mix—remains the key metric determining the financial value of top-line expansion.3
X. Analysis & Bear vs. Bull Case
The bull case
The primary bull argument rests not on an immediate valuation re-rating, but on market-share expansion in commercial HVAC. Carrier entered independence in 2020 with roughly 10% of the U.S. commercial HVAC market and operating margins near 5%. By 2026, management reported commercial sales up 80% since the spinoff, backlog up 130%, 500 basis points of share gains, and margins roughly tripled.3 A company expanding share from a modest initial base in a growing market carries a distinct risk profile compared to an incumbent defending market leadership, as it can sustain growth through broader market deceleration by capturing competitor volume. That structural asymmetry represents the most grounded element of the optimistic case, supported by disclosed operational metrics rather than narrative assumptions.
Second, the aftermarket service business offers predictable long-term compounding. Management targeted a sixth consecutive year of double-digit aftermarket growth for 2026, with every commercial chiller deployed into a data center creating high-margin service revenue over its multi-decade operating lifecycle.13 The expanding equipment base—supported by a 50% expansion of the Charlotte facility, a repurposed North American plant, a new facility in India, and an additional U.S. manufacturing site—establishes a multi-year service stream that is not fully reflected in current reported earnings.3
Third, the short-cycle residential recovery provides significant operating leverage. Carrier's residential lines generate higher margins than its heavy commercial products, but plants operated at under half capacity during late 2025.3 Results through mid-2026 indicate that distributor channel destocking has largely concluded, with distributor field inventories down 25% to 30% year over year, second-quarter residential sales expanding 9%, and full-year guidance revised upward.13 Rebounding volume through previously underutilized, high-margin manufacturing plants converts directly into accelerated operating earnings.
Fourth, the simplified balance sheet supports balanced capital allocation. Annual free cash flow of approximately $2 billion allows Carrier to fund its planned $1.5 billion in share repurchases alongside $600 million in capital expenditures without incurring additional debt in a standard operating environment.12
The bear case
The bear case begins with a structural divergence: operating margins are contracting even as revenue expands. In the second quarter of 2026, Carrier's adjusted operating margin fell 190 basis points year over year despite organic sales growth and operational productivity gains, with every operating segment reporting lower margins.1 Furthermore, third-quarter guidance indicated a sequential step down in adjusted operating margin to roughly 16.5%.3 This margin pressure reflects structural product mix dynamics rather than temporary friction: top-line expansion is concentrated in commercial HVAC and transport refrigeration, which carry lower profit margins than residential equipment. If data center cooling represents a growing proportion of total revenue each year, blended operating margins face persistent downward pressure that overall volume expansion must overcome.
Second, European operations continue to drag on profitability. A $5 billion revenue segment operating at 7% to 9% margins two and a half years after the €12 billion Viessmann acquisition remains a primary concern for investors.12 Management replaced segment leadership in mid-2026 and targeted mid-teens operating margins over the coming years, though without specifying concrete operational milestones.3 Until European margins demonstrate sustained expansion, the financial returns on Carrier's largest transaction remain unproven.
Third, heavy exposure to data center demand introduces customer concentration risks. With commercial equipment representing roughly 70% of Carrier's total backlog and data centers accounting for about 40% of that commercial segment, a substantial portion of forward revenue relies on capital expenditures from a small cohort of hyperscale technology companies and colocation providers.1 These institutional buyers possess significant bargaining power and negotiate multi-year agreements that pre-allocate equipment allocations. If artificial intelligence infrastructure investments slow, order backlogs that currently offer multi-quarter visibility could quickly lead to manufacturing overcapacity, just as Carrier brings new plant capacity online. Management noted that its expanding facilities can be repurposed for general commercial applications, providing an operational hedge that has yet to be tested during an industry downturn.3
Fourth, Carrier remains a late entrant in direct-to-chip liquid cooling. Carrier introduced its first coolant distribution unit in 2025 and scheduled its 5-megawatt architecture for late 2026, while established specialists and market leaders like Vertiv held earlier mover advantages.13 Management explicitly chose internal product development over acquiring liquid cooling specialists due to high acquisition valuations.3 While Carrier maintains a strong position in traditional facility chillers, direct-to-chip cooling represents the technological frontier. Entering late to the layer that establishes system specifications risks relegating equipment suppliers to lower-margin commodity components within broader system architectures.
Fifth, legacy litigation risks persist. The proposed $730 million Kidde-Fenwal PFAS settlement framework remains subject to bankruptcy court approval and state legal objections, with structured cash payments extending over five years.26
Finally, the anticipated equity valuation re-rating remains unrealized. Carrier trades at a market capitalization of roughly $47 billion—approximately half that of pure-play peer Trane Technologies and below Johnson Controls—despite completing its portfolio restructuring, building an $8 billion backlog, and raising full-year outlooks. The market's valuation reflects ongoing skepticism regarding earnings quality, driven by margin compression, European integration challenges, product mix dilution, and cyclical residential volatility. Realizing a valuation convergence requires demonstrating sustained margin expansion alongside top-line growth.
The three indicators that settle the argument
1. Climate Solutions Europe segment operating margin. Operating margin in the European segment represents the primary benchmark for evaluating the Viessmann acquisition. The segment recorded an 8.8% operating margin in 2025 and 7.2% in the second quarter of 2026, compared to management's mid-teens target.12 Steady progression toward low double digits alongside recovering European heat pump demand would validate the strategic acquisition. Conversely, persistent margin stagnation near current levels during a volume recovery would indicate that Carrier paid a high valuation multiple for an asset it has struggled to optimize operationally.
2. Data center order conversion and manufacturing capacity utilization. Carrier provides detailed disclosures regarding total backlog, commercial HVAC composition, and data center allocation.1 The critical test is whether this backlog converts efficiently into reported revenue as the new U.S. manufacturing plant begins operations in early 2027, and whether order momentum continues beyond the initial artificial intelligence infrastructure expansion cycle.
3. Consolidated adjusted operating margin and incremental margin conversion. Reconciling product mix dilution requires demonstrating that Carrier can expand consolidated operating margins during periods of revenue growth. Management's medium-term targets specify over 50 basis points of annual margin expansion and 25% to 30% incremental margin conversion.330 Generating top-line growth with flat or contracting operating margins would indicate that the simplified climate portfolio delivers lower earnings quality than the broader industrial conglomerate it replaced.
XI. Epilogue & "If We Were CEOs"
If executive leadership were assumed tomorrow, three priorities would sit at the top of the agenda, and none involves another major acquisition.
The first is Europe, which requires treatment as an operational emergency rather than a market issue. Carrier management acknowledged the diagnosis—insufficient cost action and pricing discipline—and installed new leadership in mid-2026.3 What remains missing publicly is a dated, quantified restructuring plan specifying footprint reductions, the portion of the €200 million synergy target realized versus offset by inflation and volume deleverage, and targeted segment operating margins by specific dates. A company that provides quarterly segment margin guidance across other regions has remained notably vague regarding the segment with its widest credibility gap.
The second priority is scaling liquid cooling with greater urgency than the current organic trajectory implies, while acknowledging that Carrier entered the category late. The chiller franchise represents the core moat, while the coolant distribution unit serves as the entry point into next-generation architectures. Management's rationale for avoiding acquisitions was price discipline—a valid principle for a company that paid a high valuation for Viessmann. However, generating $2 billion in annual free cash flow while allocating roughly $1.5 billion to share repurchases creates a clear strategic choice: whether repurchasing equity at current levels delivers higher long-term returns than securing a defensible position in the fastest-growing segment of its own market.
The third priority is capital allocation transparency. Management should either reconfirm its May 2025 medium-term framework with a detailed explanation of how 6% to 8% organic sales growth and mid-teens earnings-per-share growth will be delivered, or formally update it. Maintaining an active multi-year framework that was contradicted by 2025 results without public reconciliation erodes the investor trust leadership earned through an otherwise disciplined divestiture program.
A distinct historical symmetry defines Carrier's position. In 1902, Willis Carrier solved a commercial challenge where hot, humid air ruined printing jobs by intentionally removing moisture from the air. One hundred twenty-four years later, the modern equivalent involves AI accelerator racks generating heat beyond air-cooling capacity, requiring heat transfer into liquid loops and external water systems. The underlying physics remain unchanged. What changed is that the enterprise built on those thermodynamic principles spent four decades as a division inside an aerospace conglomerate, six years restructuring as an independent public entity, and roughly $13 billion testing whether European residential heating would electrify on schedule.
The commercial HVAC and aftermarket expansion is working, supported by verified operating metrics. The European residential segment has yet to deliver expected returns. For now, public markets weigh European integration challenges more heavily than commercial HVAC share gains.
References
-
Carrier Reports Second Quarter 2026 Results — Carrier Global Corporation Investor Relations, 2026-07-28 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Carrier Reports 2025 Results and Announces 2026 Outlook — Carrier Global Corporation Investor Relations, 2026-02-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Carrier Global Corporation Events & Presentations (quarterly earnings conference calls and webcasts, including Q4 2025, Q1 2026 and Q2 2026) — Carrier Global Corporation Investor Relations ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
The History of Air Conditioning — Willis Carrier Timeline ↩↩↩↩
-
Patent for the Air Conditioner Issued to Willis H. Carrier — Library of Congress, This Month in Business History ↩
-
History of Carrier Corporation — FundingUniverse (International Directory of Company Histories) ↩↩↩↩↩
-
Who Invented Air Conditioning? The History of Willis Carrier — Carrier ↩
-
United Technologies buys Chubb and plans further acquisitions — The Globe and Mail, 2003-06-13 ↩↩
-
United Technologies to Split into Three Standalone Companies — The Wall Street Journal, 2018-11-26 ↩
-
Trump, Pence Announce Deal with Carrier to Keep Indianapolis Jobs — Reuters, 2016-12-01 ↩
-
New layoffs at Indiana Carrier factory year after Trump deal — Fox Business, 2018-01-11 ↩↩
-
Carrier Global Corporation SEC Filings (Forms 10-K, 10-Q and 8-K) — Carrier Global Corporation Investor Relations ↩↩↩
-
Carrier Completes $3.1B Sale of its Chubb Fire & Security Business to APi Group Corporation — Carrier Press Release, 2022-01-03 ↩↩↩
-
Carrier Completes Acquisition of Toshiba's Global Residential and Light Commercial HVAC Business — Carrier Press Release, 2022-07-31 ↩↩
-
Carrier Announces Portfolio Transformation to Create Global Leader in Intelligent Climate and Energy Solutions — Carrier Press Release, 2023-04-25 ↩↩↩
-
Carrier Nears $13 Billion Deal to Buy Germany's Viessmann — Reuters, 2023-04-24 ↩
-
Carrier Completes Acquisition of Viessmann Climate Solutions — Carrier Press Release, 2024-01-02 ↩
-
European Heat Pump Sales Fall in 2023, Industry Body Says — Reuters, 2024-02-27 ↩
-
Backlash Over German Heating Law Hits Heat Pump Market — Financial Times, 2023-09-15 ↩
-
Why heat pump sales are growing again — European Heat Pump Association, 2026-08-06 ↩↩
-
Form 8-K: Global Access Solutions Divestiture Closing to Honeywell — U.S. Securities and Exchange Commission, 2024-06-03 ↩
-
Carrier Announces Agreement to Sell Industrial Fire Business to Sentinel Capital Partners for $1.425 Billion — Carrier Global Corporation Investor Relations, 2024-03-05 ↩↩↩
-
Carrier Completes $775M Sale of its Commercial Refrigeration Business to Haier — Carrier Press Release, 2024-10-02 ↩
-
Lone Star Completes Acquisition of Carrier's Commercial and Residential Fire Business Forming Kidde Global Solutions — Lone Star Funds, 2024-12-02 ↩↩↩
-
Carrier proposes $730M PFAS settlement with Kidde-Fenwal — Manufacturing Dive, 2024-10-22 ↩↩↩
-
Carrier Announces Agreement to Sell Riello to Ariston Group — Carrier Global Corporation Investor Relations, 2025-12-16 ↩
-
Carrier Announces Agreement to Sell NORESCO to OPTERRA Energy Services — Carrier Global Corporation Investor Relations, 2026-07-27 ↩
-
Carrier Accelerates Intelligent Building Strategy with Acquisition of 75F — Carrier, 2026-07-23 ↩
-
Carrier Hosts 2025 Investor Day to Showcase Transformed Portfolio and Focused Strategy for Growth and Significant Value Creation — Carrier Global Corporation Investor Relations, 2025-05-19 ↩↩↩
-
Patrick Goris: EVP, Chief Financial & Strategy Officer — Carrier ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube