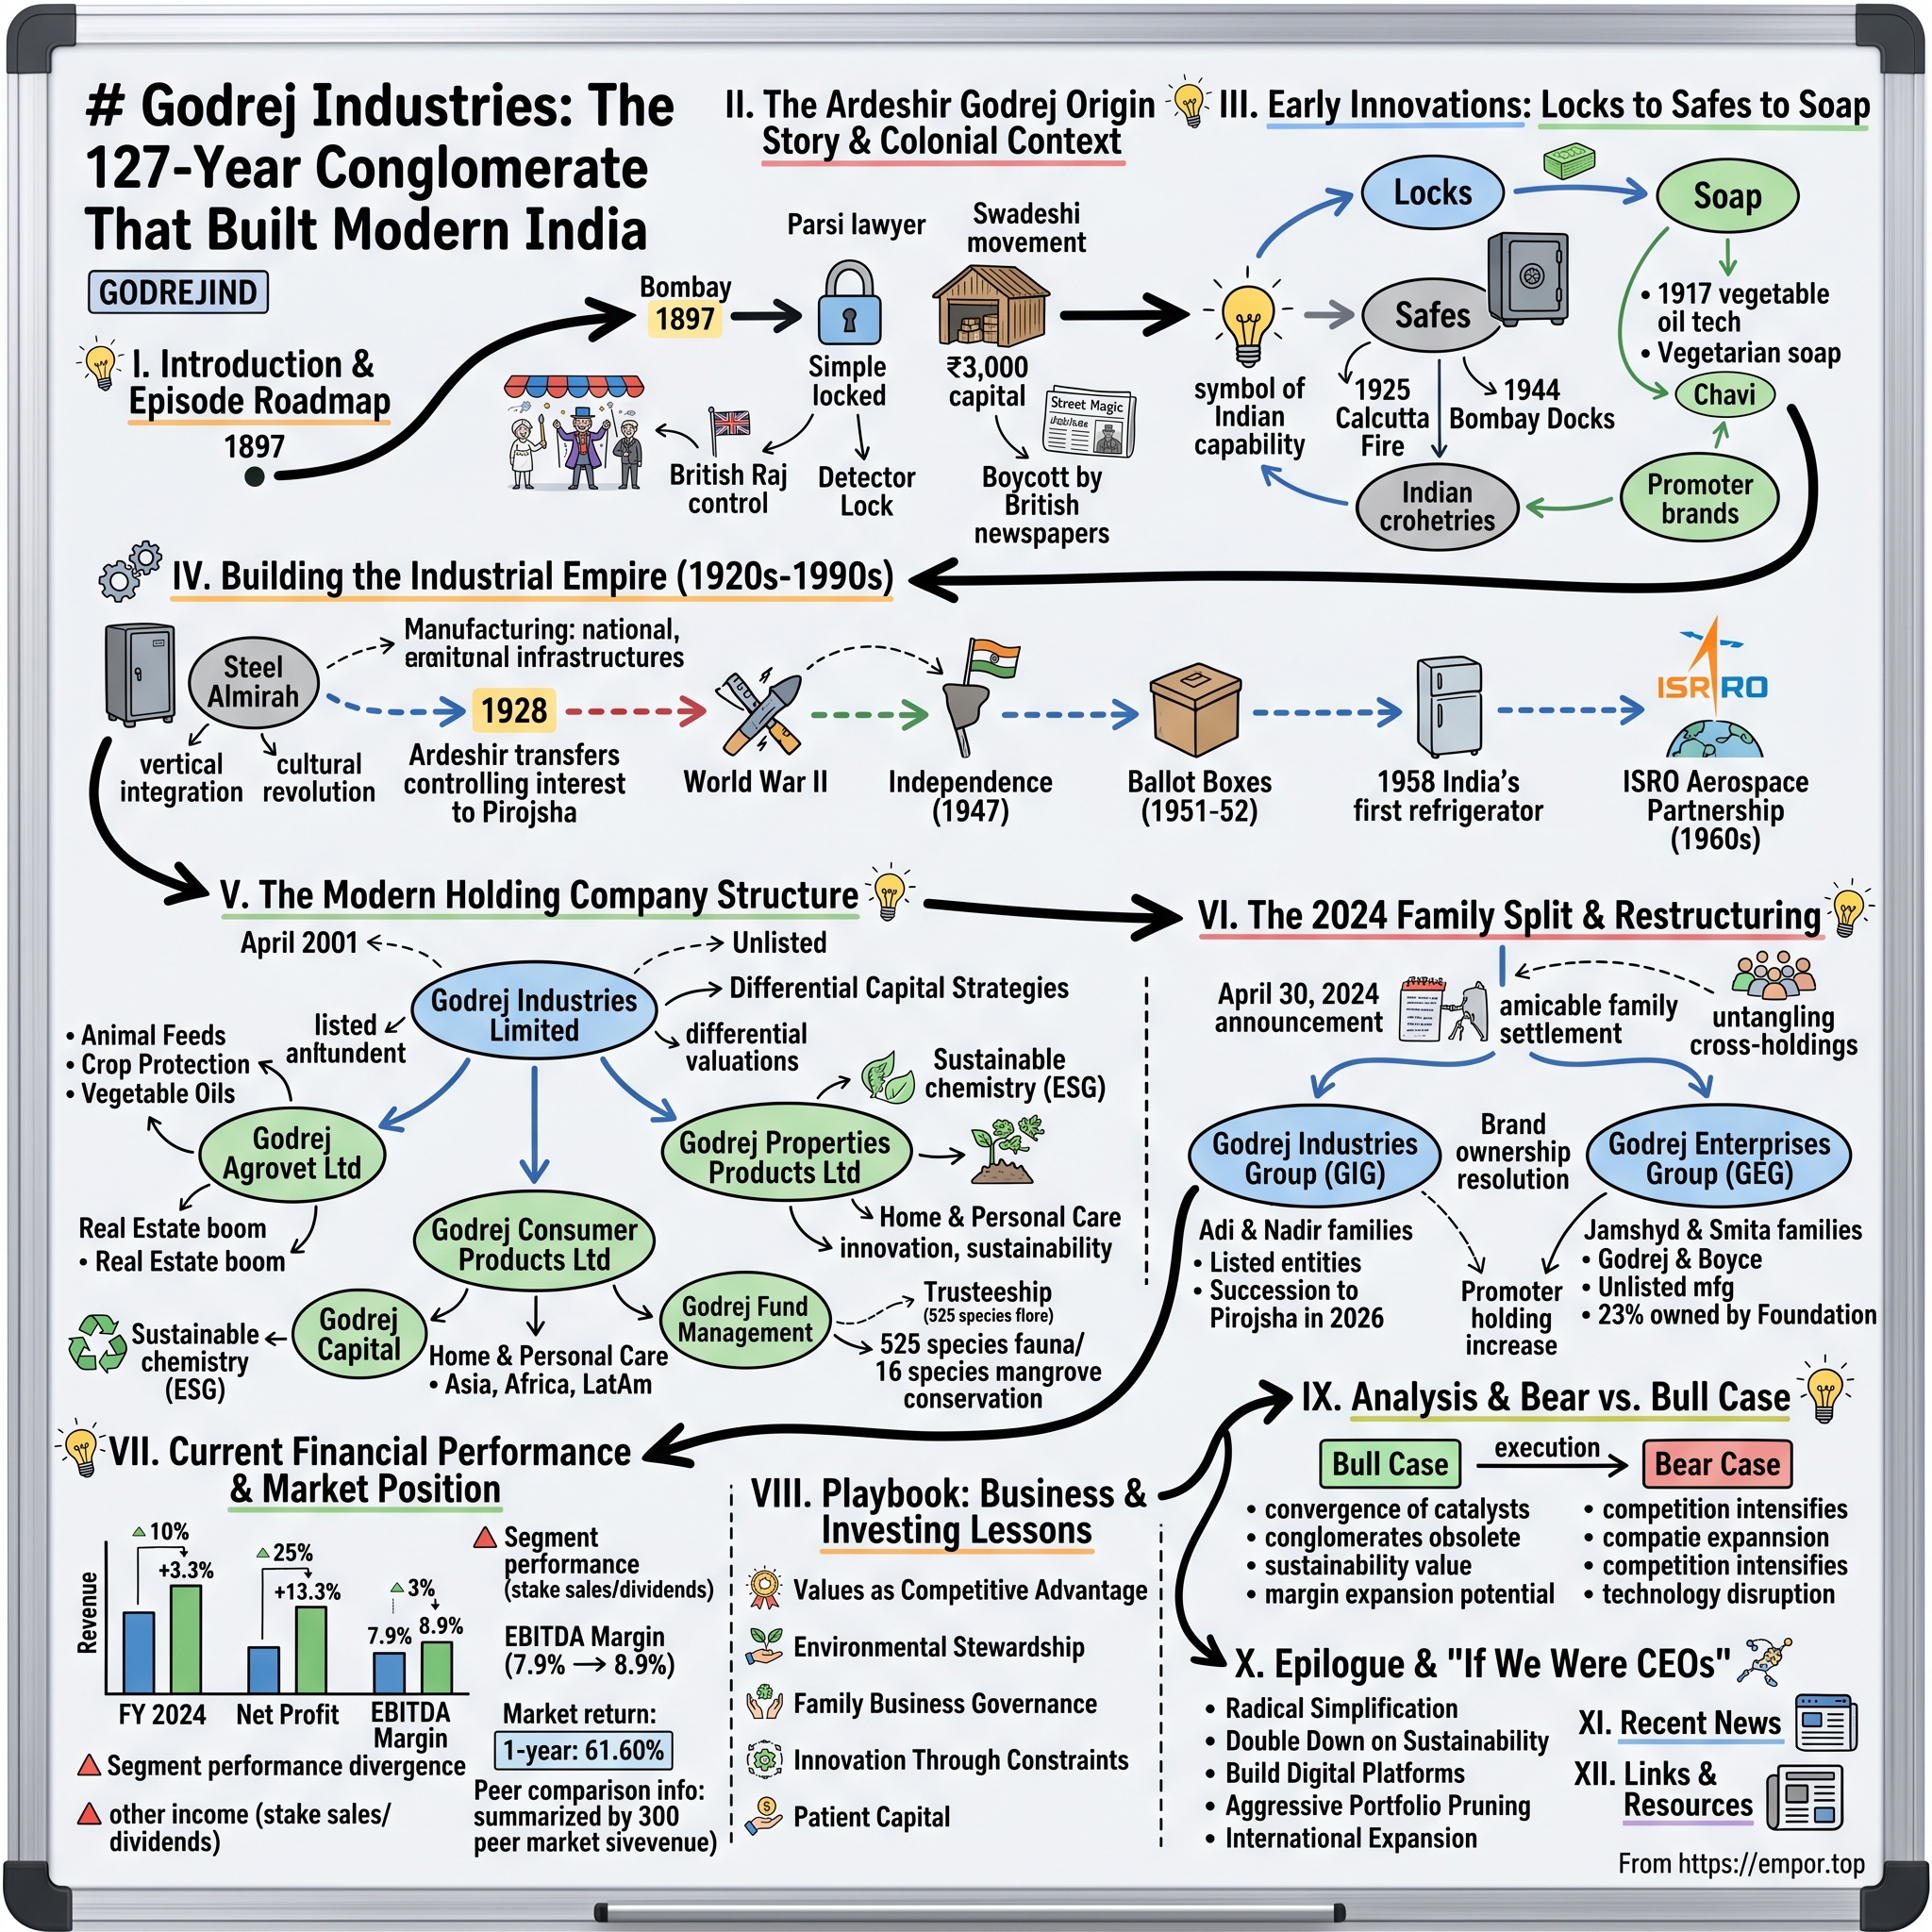
Godrej Industries: The 127-Year Dynasty, The SOTP Dilemma, and The New Empire
I. Introduction & Episode Roadmap
On the evening of April 30, 2024, the stock exchanges in Mumbai received a joint letter from four cousins: Adi Godrej, then 82, Nadir Godrej, 73, Jamshyd Godrej, 75, and Smita Godrej Crishna, 74.1 Together, they controlled one of India's oldest and most recognizable corporate dynasties. The filing announced that they had entered into a formal Family Settlement Agreement alongside separate brand and non-compete pacts.2 The Godrej Group, which had manufactured security locks since 1897 and India's first general election ballot boxes in 1951, was dividing into two independent corporate groups.
Indian family business partitions often unfold through acrimonious courtroom battles, contentious shareholder votes to unseat relatives, and strategic press leaks. This separation, by contrast, arrived as a detailed regulatory disclosure. It laid out trademark carve-outs, clear demarcations specifying which branch could deploy the Godrej brand name across distinct product categories, and a succession timetable planned more than two years in advance. Adi Godrej's son, Pirojsha Godrej, was slated to become chairperson of the listed corporate branch in August 2026.2 On August 14, 2026, he assumed that office.3
This analysis focuses on the corporate vehicle Pirojsha now leads: Godrej Industries Limited (NSE: GODREJIND). Structurally, it is an unusual entity, and that structural complexity forms the core investment debate.
On paper, Godrej Industries (GIL) functions as the flagship holding company for prominent consumer, real estate, and agricultural businesses. It owns approximately 23% of Godrej Consumer Products (GCPL), the maker of Goodknight household insecticides, Cinthol soap, and Godrej hair colour. It held roughly 45% of Godrej Properties (GPL)—which recorded the highest booking value of residential sales among listed Indian real estate developers in FY26—and roughly 65% of Godrej Agrovet (GAVL), India's leading producer of animal feed and palm oil processor.4 In addition, it controls approximately 91% of Godrej Capital, a young financial services business whose retail loan book expanded 64% during the prior fiscal year.5 Inside the standalone holding company sits a direct operating manufacturing asset: an oleochemicals business that generated ₹4,135 Cr of revenue in FY26.6
Public markets have persistently valued this portfolio at a steep discount to the market value of its underlying parts. In August 2025, credit rating agency CRISIL estimated the value of GIL's listed equity stakes alone at ₹65,611 Cr, compared to standalone net debt of ₹9,696 Cr.4 By May 2026, public markets valued the entire consolidated company—including the chemicals manufacturing operation and Godrej Capital—at approximately ₹37,884 Cr.7 In effect, public equity markets allowed investors to buy into the group's listed assets at a substantial haircut to their visible market prices. That valuation gap has remained both broad and enduring. The central dilemma for investors is whether this discount reflects an overlooked market mispricing or a rational appraisal of how the holding company allocates capital.
That dynamic frames the two competing perspectives on the stock:
- The bull reading: GIL provides a discounted, founder-led gateway to India's housing cycle, household staples demand, agricultural supply chain, and retail lending expansion, stewarded by a promoter family with a strong institutional reputation for governance.
- The bear reading: GIL functions as a capital sponge. The company has distributed no dividend to equity shareholders since 2019.7 Standalone debt has risen steadily as the parent firm routes funding into capital-intensive ventures, particularly Godrej Capital, leaving minority shareholders two steps removed from the operational cash flows of the underlying businesses.
This analysis traces capital allocation across each layer of the enterprise. It begins with the group's early industrial roots during the Swadeshi movement, drawing a clear line between what GIL retained and what the family settlement carved out. It then evaluates the 2001 corporate restructuring that established the modern holding company; Godrej Properties' growth alongside its 2022 capital allocation controversy; GCPL's international mergers-and-acquisitions drive and subsequent asset write-downs; the operating cycles shaping Godrej Agrovet; the competing capital demands of the oleochemicals business and Godrej Capital; the structural realities of the 2024 family split and the prime land assets at Vikhroli; and the mechanics behind the holding-company discount itself. Across each operational unit, the underlying question remains consistent: when Godrej Industries absorbs or deploys capital, where does that cash go, and do public minority shareholders ultimately realize the benefit?
 Subscribe on LinkedIn
II. The Roots: Swadeshi Locks to Post-Independence Nation-Building (1897–1990s)
A lawyer who would not lie
Ardeshir Godrej was born in Bombay in 1868 into a Parsi family. He trained as a lawyer before walking away from the profession on ethical grounds.8 According to company lore, the decisive break came in 1894 during a case in Zanzibar, where he resolved that the legal profession was not his calling.9 A series of false starts followed: he worked as an assistant in a chemist's shop and tried manufacturing surgical instruments, an effort that quickly failed.8 Then he turned to locks.
On May 7, 1897, production began in a small workshop at Lalbaug in Bombay. Colonial India then imported its locks.10 Ardeshir framed his venture around Swadeshi—the principle of Indian-made goods for Indian buyers. British-owned newspapers refused to publish his advertisements, objecting to the phrase "as good as imported variety." Only Indian-run publications such as Kesari, Tribune, and Bombay Samachar agreed to carry them.10 By 1902, Godrej had expanded from locks into safes, and by 1908, the company had patented a springless lock.10 His younger brother Pirojsha joined him in the early 1900s, providing the operational stewardship that turned an inventor's workshop into an enduring commercial institution.9
Soap without tallow
The product line most relevant to modern investors arrived in 1918. Most commercial soap at the time was manufactured from animal fat. Ardeshir launched Chavi, named after the Gujarati word for "key" in a direct reference to the lock business, which the company billed as the first soap in the world made without animal fat.8 Godrej's marketing made the political subtext explicit: "We score not only for Swadeshi, but also ahimsa."10 Vegetarian Indians who had avoided tallow soap were offered a domestic, animal-free alternative. Rabindranath Tagore endorsed it in the early 1920s, as did Annie Besant and C. Rajagopalachari. In the early 1930s, the company followed with Vatni, whose green-and-white wrapper carried a map of undivided India.8 Mahatma Gandhi once declined to endorse a competing venture, writing: "I hold my brother Godrej in such high regard that if your enterprise is likely to harm him in any way, I regret very much that I cannot give you my blessings."10
That soap business matters today for a fundamental operational reason: it is the direct ancestor of Godrej Industries. Converting vegetable oils into soap is applied chemistry, and splitting those oils into fatty acids, fatty alcohols, and glycerine remains the core of GIL's standalone chemicals business today. That 1918 innovation is the thread connecting the workshop in Lalbaug to the manufacturing plant at Valia in Gujarat.
Ballot boxes and refrigerators
After independence, Godrej became an integral part of India's civic and industrial infrastructure. When the Election Commission organised India's first general election in 1951, it commissioned Godrej to manufacture the ballot boxes.9 Accounts of the order differ in scale: Business Standard reported the order at 1.7 million boxes, while a history of the Vikhroli plant recorded nearly 12.83 lakh boxes—roughly 1.28 million—produced in four months, at rates of up to 15,000 a day.1011 The boxes were dispatched from the Vikhroli railway station to 23 states across the country. Godrej launched Cinthol soap in 1952, built India's first indigenous refrigerator in 1958,9 and decades later manufactured precision hardware for India's lunar and Mars space missions.9
What investors in GODREJIND do not own
This expansive industrial history can easily mislead an investor. The locks, safes, Storwel cupboards, refrigerators, aerospace engineering, and most of the land at Vikhroli belong to Godrej & Boyce. Under the 2024 settlement, Godrej & Boyce went to Jamshyd Godrej and Smita Godrej Crishna's Godrej Enterprises Group. It is unlisted.2
GIL descends directly from the soap line of the family tree. In the late 1990s, Godrej Soaps bought the brands for its toilet soaps, chemicals, and cosmetics from its parent, Godrej & Boyce.12 The ballot boxes, the consumer appliances, and the space hardware are part of the broader family story, but they sit entirely outside GIL's balance sheet. Conflating the two is an easy trap for investors new to the group. The next section covers how that soap business evolved into the modern holding company.
III. The Modern Architecture: Transforming Godrej Soaps into Godrej Industries (2001–2010s)
The 2001 split that created a holdco
At the turn of the millennium, Godrej Soaps Limited housed two fundamentally incompatible businesses under a single corporate roof. One was a branded consumer goods franchise—toilet soaps, hair dyes, and fairness creams distributed through neighborhood kirana stores across India. The other was a commodity chemicals operation, flanked by real estate holdings and passive investments. Public equity markets struggled with the combination: consumer franchises typically commanded premium brand valuation multiples, whereas cyclical commodity chemicals traded at steep discounts. Bound together, the company received the valuation benefit of neither.
The remedy was a corporate demerger. Shareholders approved a restructuring scheme transferring the consumer products division into an independent entity, Godrej Consumer Products Limited (GCPL). When the demerger took effect on April 1, 2001, the residual entity, Godrej Soaps, changed its name to Godrej Industries Ltd.12 GCPL retained the packaged consumer brands. Godrej Industries retained the chemical manufacturing assets, real estate interests, and a growing portfolio of equity holdings in group companies—including a substantial stake in GCPL itself, which stood at 23.74% by 2022.13
That transaction created the foundational structure Godrej Industries maintains today: an operating oleochemicals manufacturer wrapped inside a diversified holding company. Most of the market debate surrounding the company originates from that dual identity.
The incubation nursery
Two brothers steered this era, bringing contrasting professional backgrounds and temperaments. Adi Godrej, born in 1942, returned from MIT's Sloan School of Management in the 1960s to enter a family business operating under the License Raj—India's post-independence regime of strict industrial quotas and bureaucratic permits. He spent decades modernizing the group's operational management and professionalizing its ranks, later serving as president of the Confederation of Indian Industry in 2012–13 and chairing the Indian School of Business from 2011 to 2018.14 Nadir Godrej, nine years his junior, approached industry as a technical chemical engineer. After a year at IIT Bombay, he completed an undergraduate degree at MIT, earned a master's in chemical engineering from Stanford, and completed an MBA at Harvard. For decades, he served as managing director of Godrej Industries and chairman of Godrej Agrovet.15 A polyglot who speaks six languages and publishes poetry,15 Nadir supervised chemical production at GIL and feed milling at Agrovet, while Adi served as the group's dealmaker and public representative. When Adi stepped down as chairman of Godrej Industries in 2021 to become chairman emeritus, the chairmanship passed to Nadir.14
Under Adi Godrej's leadership, the group institutionalized a repeatable incubation model. Management deployed the parent balance sheet and the Godrej trade name to build greenfield ventures in real estate and agribusiness internally over several years, before taking them public to establish transparent equity valuations, with GIL retaining controlling equity stakes.
Godrej Properties was established in 1990.10 It completed an initial public offering in December 2009, pricing at ₹490 per share—the floor of its ₹490 to ₹530 issue band. When trading commenced on January 5, 2010, the developer closed its market debut with a valuation of roughly ₹3,750 Cr.16 The timing proved critical: the listing arrived barely a year after the 2008 global financial crisis had paralyzed Indian real estate financing, at a time when few private developers were able to raise equity capital.
Godrej Agrovet was founded in 1991 to modernize animal feed, agricultural inputs, and oil palm processing.10 In an early version of the group's "partner then list" playbook, Singapore's sovereign wealth fund, Temasek, acquired an approximate 20% stake in the company during the early 2010s. Agrovet opened its IPO on October 4, 2017, priced at ₹460, raised roughly ₹1,157 Cr, and listed on October 16.17 The transaction functioned primarily as an insider liquidity event: secondary share sales by existing holders accounted for about ₹865 Cr of the proceeds, compared to ₹292 Cr in fresh primary capital for the company.17 Temasek used the listing to monetize a portion of its private equity holding.
The architecture that resulted
By the late 2010s, Godrej Industries sat atop a multi-tiered corporate structure common among Indian family conglomerates. On a standalone basis, revenue and operating income derived predominantly from industrial fatty acids and fatty alcohols, supplemented by inter-corporate dividends and treasury yield. On a consolidated basis, however, the financial statements absorbed the operating volatility of a high-leverage property developer, a weather-sensitive agricultural processor, and eventually, a consumer lending franchise.
That architectural design produced a critical consequence for public markets: GIL's standalone debt service was not covered by operating cash flows from its chemical plants alone, but depended on dividend inflows from GCPL and Agrovet alongside continuous market refinancing. In a 2023 rating review, CRISIL made this reliance explicit, warning that GIL depended heavily on dividend receipts and debt refinancing to service its obligations, leaving standalone interest coverage weak.13 What anchored the parent company's high investment-grade credit rating was not its internal operating profitability, but the market value of the listed equity stakes it could pledge or sell in an emergency. In November 2022, CRISIL calculated the market value of those listed holdings at approximately ₹44,000 Cr, compared to standalone net debt of about ₹5,250 Cr.13
For equity investors, this holding-company framework meant that GIL's intrinsic value was overwhelmingly tied to the valuation of its listed subsidiaries—with Godrej Properties serving as the primary swing factor. That real estate engine became the focal point of the group's next major capital allocation test.
IV. The Core Value Engine: Godrej Properties & The Asset-Light Dilemma
From fringe builder to India's biggest seller of homes
In FY26, Godrej Properties sold 17,515 homes worth ₹34,171 Cr, a 16% increase over the previous year, while delivering 12.1 million square feet of completed space.18 That performance established it as the largest listed Indian real estate developer by booking value for the year. Prestige Estates ranked second at ₹30,024 Cr, Lodha followed at ₹20,530 Cr, and DLF placed fourth at ₹20,143 Cr.19 Godrej Properties had originally attained the industry's top spot in residential sales in FY21, under Pirojsha Godrej's executive leadership.3
That comparison requires careful qualification. DLF, the sector's most valuable developer by market capitalization, sells fewer total homes but controls massive, low-cost land reserves accumulated decades ago, allowing its super-luxury developments to generate exceptional profit margins. Lodha dominates the Mumbai Metropolitan Region through massive, high-margin integrated townships. GPL's lead in sales bookings demonstrates that it operates the most effective pan-India sales and distribution engine in the industry. That marketing reach, however, does not necessarily guarantee superior unit economics.
GPL's sales base is distributed across far more metropolitan markets than those of its peers. Its FY26 bookings were anchored by the Mumbai region at ₹10,313 Cr, Bengaluru at ₹8,802 Cr, and the National Capital Region at ₹7,410 Cr, with Pune and other cities contributing the balance. Both its South and Mumbai operating zones surpassed ₹11,000 Cr in annual bookings for the first time.18 While DLF remains heavily concentrated in the National Capital Region and Lodha in Mumbai, GPL can flexibly reallocate project launches across cities as regional housing demand fluctuates. The operational trade-off is friction: the company must simultaneously navigate municipal approvals, land acquisition, and contractor execution across four or five distinct regional markets.
The original formula: brand for land
GPL's early expansion was built on an elegant structural trade. Across urban India, private landowners held prime parcels but lacked a trusted corporate brand, access to institutional project finance, and the marketing machinery required to sell apartments off-plan before construction began. The Godrej Group possessed all three. Under a joint development agreement, the landowner contributed the parcel while GPL designed, branded, built, and marketed the project, dividing the top-line revenue or constructed area between the two parties. Because GPL did not need to purchase the land upfront, the business operated as a capital-light engine in its early years.
A hospitality analogy illustrates the trade-off. Under a joint development deal, GPL functions like a celebrity chef who opens a restaurant inside someone else's building in exchange for a share of revenue. Under an outright acquisition, the chef buys the building directly. The partnership model generates a high return on minimal upfront capital, but surrenders a substantial portion of project profits to the landlord. Outright land acquisition keeps the entire gross margin, but carries every downside risk—including holding costs and debt interest on land that can sit idle for years awaiting bureaucratic clearances. The asset-light arrangement worked smoothly as long as landowners had few reputable corporate suitors. Once rival national developers entered the bidding, landowners demanded more aggressive revenue splits, forcing GPL to consider buying property directly.
The company's competitive standing strengthened after two structural shocks transformed the broader real estate sector. The 2016 Real Estate (Regulation and Development) Act required builders to ring-fence customer advances in dedicated escrow accounts, curbing the widespread practice of diverting cash across projects. In 2018, the default of shadow-banking giant IL&FS cut off credit lines to leveraged regional builders. Homebuyers and lenders migrated decisively toward established, institutional corporate developers trusted to complete construction. GPL's run of nine consecutive years of booking growth, alongside 11 separate project launches in FY26 that each generated more than ₹1,000 Cr in sales, reflected that sector consolidation.18
Claim one: "GPL runs an asset-light model"
This proposition remains the most frequent marketing narrative surrounding Godrej Properties, but the company's financial filings directly contradict it.
As competition for prime urban land intensified, GPL shifted steadily from partnership joint ventures toward outright land purchases and heavier capital outlays. That transition is visible across its balance-sheet financing. In December 2024, GPL raised ₹6,000 Cr via a qualified institutional placement at ₹2,595 per share, earmarking the capital to acquire land and expand its project pipeline.20 The resulting equity dilution reduced Godrej Industries' ownership stake from 47.34% in August 2024 to 44.77% by June 2025.214 Even following that large equity injection, GPL's net debt expanded from ₹6,414 Cr at the end of FY26 to ₹7,637 Cr by June 2026, bringing its net debt-to-equity ratio to 0.39, while management signaled an internal ceiling to cap net debt below ₹10,000 Cr.22
Cash flows reflect the same capital-intensive reality. While GPL's FY26 operating cash flow of ₹7,830 Cr appeared healthy alongside ₹34,171 Cr in headline bookings, it grew by just 5% year on year.18 Management's stated operational objective for FY27 was simply to reach free-cash-flow breakeven.22 A genuinely capital-light developer would not regard operating cash breakeven as an operational milestone. Business development activity underlines the scale of this capital deployment: GPL added 18 new land parcels representing an estimated ₹42,100 Cr of booking potential in FY26—more than double its initial guidance—followed by an additional ₹9,500 Cr in the first quarter of FY27.1822
The verdict: GPL's operating history no longer supports an "asset-light" description. A more precise characterization is that GPL is brand-led. Its household name and perceived reliability allow it to pre-sell homes faster and secure institutional credit at lower borrowing rates than unbranded developers. However, the business now absorbs substantial capital, and it will remain capital-intensive as long as developer margins reward outright land ownership. The metric that reveals this tension is operating cash collection relative to gross sales bookings, an issue examined in Section XI.
Claim two: "Godrej governance is immune to bad deals"
On Thursday, February 3, 2022, after trading hours, GPL announced that its board had approved an investment of approximately ₹400 Cr in convertible warrants representing roughly a 10% equity stake in DB Realty. The board also authorized ₹300 Cr in equity from each party to form an equal joint platform targeting Mumbai slum redevelopment and Maharashtra Housing and Area Development Authority (MHADA) urban renewal projects, with GPL collecting a 10% development management fee.23 DB Realty's promoters had previously been high-profile defendants in India's 2G telecom judicial proceedings, while slum rehabilitation in Mumbai carries a well-documented history of protracted regulatory delays, legal disputes, and local political entanglements.
Equity markets reacted with swift disapproval. On Friday morning, GPL shares dropped as much as 10% to ₹1,502.35, eventually falling 16% across two trading sessions—a sell-off exacerbated by a soft third-quarter operating update showing pre-sales down 7% year on year.23 Foreign institutional brokerages strongly questioned the transaction, with one major desk arguing that the deal lacked strategic merit and criticizing its "convoluted" structure.23
GPL's board reconvened that same Friday evening and canceled the proposed transaction. Pirojsha Godrej told the Press Trust of India: "We've decided against going ahead post the feedback we received from various stakeholders including our minority investors," acknowledging investor anxiety "with the structure of the investment as well as with the slum redevelopment business in general."24 The company's subsequent regulatory filing maintained a narrow caveat, noting that it "may however continue to explore the possibility of evaluating projects with DB Realty on a case to case basis."24
How to read this. The episode presents a dual lesson for investors. The board rescinded the entire transaction within 24 hours of market pushback—an unusually rapid course correction in Indian corporate boardrooms, demonstrating real accountability to minority shareholders when dissent is voiced publicly and forcefully. However, the board had greenlit the transaction in the first place. The sequence demonstrated that in its aggressive pursuit of urban land, management's risk appetite could accommodate counterparty associations and opaque transaction structures that public institutional investors refused to tolerate. The governance claim is therefore nuanced rather than discarded: Godrej governance actively responds to external shareholder resistance, but it does not reliably prevent controversial capital allocation plans from gaining initial board approval. That distinction is vital for investors in Godrej Industries, because the holding company operates under substantially less public scrutiny than its consumer-facing real estate subsidiary.
The stock's volatility and the promoter's response
GPL shares have experienced pronounced cyclical swings. The company has highlighted to investors that since its January 2010 public listing, the equity has suffered drawdowns of more than 45% on five separate occasions, most recently during the 2025–26 correction.25 Amid that latest downturn, the Godrej promoter group acquired an additional 5% stake in GPL via secondary open-market purchases in FY26, increasing the promoter holding from 46.67% to 51.67% at an average price of approximately ₹1,775 per share, representing a total capital deployment of roughly ₹2,674 Cr.26 Public corporate disclosures available through early 2026 do not specify which individual promoter entity executed the equity purchases.25
This trading dynamic raises a critical capital allocation question for outside shareholders. Institutional investors subscribed to GPL's equity offering at ₹2,595 per share in December 2024; within roughly 15 months, the promoter group was repurchasing stock in the open market at a discount of nearly 32%. Stepping in to accumulate shares at lower valuations can be interpreted as promoter conviction and value discipline. Equally, it provides tangible evidence that the December 2024 institutional placement was priced near the peak of a real estate market cycle. Both interpretations are supported by the record.
GPL represents the operating arm of the Godrej corporate group most directly tethered to the Indian economic and credit cycle. Godrej Consumer Products is designed to serve as the stable, defensive counterweight—and its operational trajectory and international expansion are examined next.
V. The Consumer Flagship: Godrej Consumer Products (GCPL) & The M&A Hangover
The Indonesian bet
In April 2010, Adi Godrej described GCPL's acquisition of Indonesia's PT Megasari Makmur as "an important step in our global 3 by 3 strategy"—a blueprint targeting three emerging-market continents (Asia, Africa, and Latin America) across three core product categories (home care, personal wash, and hair care).27 Megasari manufactured HIT household insecticides, Stella air fresheners, and Mitu wet wipes, with market analysts valuing the transaction at ₹1,000 Cr to ₹1,200 Cr.27 It marked GCPL's fifth cross-border deal: during the same period, GCPL purchased Nigeria's Tura, having earlier acquired Keyline in the United Kingdom alongside Rapidol and Kinky in South Africa.27
The strategic rationale appeared straightforward. Emerging-market households shared similar everyday consumption needs with Indian consumers, and Godrej possessed decades of experience navigating fragmented, price-sensitive retail networks. Over the subsequent six years, GCPL expanded into dry hair extensions across sub-Saharan Africa through the Darling Group and, in April 2016, acquired US-based Strength of Nature—a maker of hair care products for women of African descent that generated $95 million in 2015 revenue at a 22% EBITDA margin, financed with dollar debt at roughly 2%.28 Adi Godrej declared that the acquisition would establish GCPL as "the leading company that makes hair care products for women of African descent," while GCPL's managing director guided that the transaction was "likely to be EPS accretive … in the first year."28
How that turned out
In the fourth quarter of FY24 (January–March 2024), GCPL absorbed an exceptional pre-tax accounting charge of approximately ₹2,389 Cr. That write-down included a ₹1,390.8 Cr impairment of brands and goodwill across its African operations—prominently including Strength of Nature—alongside a ₹927.2 Cr loss on the divestment of its East African subsidiaries and roughly ₹71 Cr in organizational restructuring costs.29 GCPL exited East Africa entirely and shifted its hair-fashion business in select markets to a capital-light royalty model, leaving management with a drastically curtailed expectation: guiding for Africa's profit after tax to recover from roughly breakeven to just ₹50 Cr over the medium term.29
The magnitude of that charge underscored a stark strategic miscalculation. Assets assembled over a decade to anchor an international growth platform were reduced to targeting annual net earnings of ₹50 Cr—a profit base comparable to a single mid-sized domestic Indian consumer brand. While severe currency devaluations in Nigeria and Argentina exacerbated reported earnings, the structural vulnerability ran deeper. The Godrej brand equity and distribution relationships that command retailer compliance and consumer loyalty across India carried little weight in Lagos or Buenos Aires. The decade-long cross-border M&A campaign tested whether the promoter group's consumer brand power could travel across borders, and the balance sheet bore the cost of the negative result. Outside India, pricing power proved durable only in select, localized franchises, predominantly in Indonesia.
The reset: Nisaba Godrej and Sudhir Sitapati
Nisaba Godrej, Adi Godrej's younger daughter, assumed the role of executive chairperson of GCPL in 2017.30 In May 2021, the company announced an executive succession: Sudhir Sitapati, executive director of Hindustan Unilever's foods and refreshment business and a Unilever veteran of more than two decades, would take charge as managing director and chief executive officer in October 2021.30 Public markets responded swiftly, driving GCPL shares up 15% on the day of the announcement. Brokerage Motilal Oswal upgraded the stock after maintaining a 'Neutral' rating for more than a decade, explicitly noting that institutional investors had long awaited "further rationality in capital allocation."30 The market's sharp reaction served as an immediate external verdict on the prior decade's acquisitive playbook.
Sitapati's operational roadmap centered on four strategic pillars: refocusing management attention on the core Indian franchise, driving penetration in lightly tapped domestic categories such as household insecticides and hair colour, pruning or restructuring value-destructive international operations, and anchoring performance metrics around volume growth.30
The Raymond deal
That commitment to disciplined capital allocation faced an immediate test in April 2023, when GCPL acquired Raymond's consumer care business for ₹2,825 Cr in cash, absorbing Park Avenue deodorants and KamaSutra condoms and deodorants.31 The purchase price translated to roughly 4.5 times FY23 revenue, or approximately 3.75 times net of an estimated ₹400 Cr tax shield arising from the slump-sale structure—even though the acquired business had generated merely ₹32.3 Cr of EBITDA in FY22 at an operating margin of roughly 6%.31 GCPL justified the multiple by pointing to structural headroom: Indian per-capita deodorant penetration remained a fraction of levels in Indonesia or Brazil, while GCPL's direct retail distribution footprint of 6.5 million outlets could dramatically scale Raymond's existing reach of 650,000 stores.31 Institutional analysts expressed caution regarding the valuation; Nuvama's Abneesh Roy highlighted intense competitive rivalry in personal grooming alongside the acquired portfolio's below-industry margins.31
The transaction underscored an enduring tension in GCPL's strategy. Unlike the speculative cross-border purchases of the previous decade, the Raymond acquisition stayed within domestic borders and aligned with a distribution-synergy thesis. Yet paying 4.5 times revenue for a subscale, single-digit-margin business required GCPL to execute an aggressive operational turnaround to earn back its cost of capital. Because subsequent segment disclosures do not isolate post-acquisition margins for the Park Avenue and KamaSutra brands, the ultimate return on that ₹2,825 Cr outlay remains unproven.
Where GCPL stands now
In evaluating GCPL's operating momentum, management consistently highlights "underlying volume growth"—a metric tracking organic physical unit sales stripped of price hikes, currency movements, and acquisitions. In consumer staples, volume expansion provides the cleanest gauge of household demand; revenue growth achieved purely through pricing adjustments often falters when price-sensitive shoppers migrate toward lower-cost alternatives. By anchoring guidance to physical volumes, leadership adopted a operational test that is difficult to manipulate through headline price inflation.
Operating metrics through early FY27 reflected steady domestic execution. On the Q4 FY26 earnings call, management reported 8% standalone underlying volume growth, standalone EBITDA margins of approximately 24.7%, and 20% top-line expansion across the Africa, US, and Middle East cluster driven by stepped-up media investments. In Indonesia, volume growth recovered to 4%, with management projecting further improvement in FY27.32 That operational momentum carried into the first quarter of FY27, with GCPL delivering 19% sales growth backed by 9% underlying volume growth, alongside an 11% increase in net profit.33
For Godrej Industries, however, its ownership stake in GCPL underwent an immediate structural adjustment. On September 24, 2026, GIL sold a 0.50% stake in GCPL—amounting to approximately 51.15 lakh shares at ₹880 each for ₹450.12 Cr—to members of the promoter family, trimming GIL's holding from 23.73% to 23.23% while leaving aggregate promoter group ownership unchanged.34 For GIL shareholders, this was a revealing transaction: the holding company converted a slice of its most liquid asset into cash by selling to the promoter family at the prevailing market price, precisely as its standalone funding commitments and debt obligations expanded (Section IX).
GCPL remains the most dependable dividend engine in Godrej Industries' portfolio. GIL's third listed operating pillar, by contrast, is far more cyclical and exposed to volatile commodity cycles.
VI. The Rural & Agritech Frontier: Godrej Agrovet & The Astec Reality Check
A conglomerate inside a conglomerate
Godrej Agrovet operates as a miniature conglomerate within the holding company, spanning cattle, poultry, and aqua feed, oil palm cultivation and processing, crop chemicals, dairy, and processed poultry. In FY26, consolidated revenue crossed ₹10,000 Cr for the first time, reaching ₹10,233 Cr, with profit after tax of ₹445 Cr.35 Its animal-feed operations moved roughly 4 lakh tonnes of product in the first quarter of FY27 alone, driven by a 15% increase in cattle-feed volumes.36 That scale reflects the competitive foundation highlighted in its 2017 prospectus, which positioned Agrovet as India's leading animal-feed producer and largest crude palm oil processor.17
Among these divisions, the palm oil operation enjoys the widest economic moat. Under India's national oil palm mission, state governments allocate exclusive geographic catchment zones to designated millers. Farmers within an assigned command area sell their fresh fruit bunches directly to Agrovet's processing facilities, creating an effective local procurement franchise protected from domestic poaching. The financial leverage inherent in that model emerged clearly in FY26, when segment profitability surged 68% on improved fruit arrivals and higher oil extraction yields.35 Yet even a protected domestic franchise cannot escape global commodity pricing: realization levels remain tethered to benchmark international crude palm oil rates set in Malaysia and Indonesia, exposing operating profits to swings entirely outside management's control.
The animal feed business operates under an entirely different economic logic. Producing compound feed is essentially a commodity formulation exercise: blending maize, soybean meal, and micro-nutrients according to nutritional recipes. Operating margins depend on the spread between raw grain procurement costs and the final price rural livestock farmers can bear. Favorable monsoon rainfall suppresses grain prices while lifting rural purchasing power, widening millers' margins; poor weather and crop shortfalls compress profitability from both directions. Agrovet counters these commodity pressures through bulk raw-material procurement, a rural distribution network covering thousands of dealers, and brand equity built on consistent nutritional formulation. While these advantages allow Agrovet to earn superior margins compared to fragmented regional mills, they offer little structural pricing defense when systemic grain inflation hits. In that sense, compound feed functions as the agricultural equivalent of Godrej Industries' standalone oleochemicals plant: a volume-driven conversion business tied directly to underlying commodity cycles.
The FY26 surprise: returns rose
A persistent criticism among institutional investors is that Agrovet operates as a structurally low-return enterprise that dilutes Godrej Industries' overall capital efficiency. The company's FY26 financial performance pushed back against that narrative. Return on net worth expanded from 14.6% to 18.7%, while return on capital employed climbed four percentage points to 20%.35 The year also marked a comprehensive leadership transition: Sunil Kataria assumed responsibilities as managing director and chief executive officer on September 1, 2025, while Burjis Godrej, Nadir Godrej's son, became executive chairperson on August 14, 2026—aligning with the group-wide leadership handover across the listed entities.35
The opening quarter of FY27, however, demonstrated how quickly volatile operating environments can erode headline returns. Consolidated EBITDA contracted 8% year on year as operating margins shrank 170 basis points to 9.1%. The crop-protection business bore the brunt of the downturn, with revenue falling 17% and segment operating profit declining 38% after erratic early monsoon rains delayed kharif crop sowing across key agrarian states.36 In response, an investor presentation titled "Recognizing the strengths & Reimagining the future" outlined plans for portfolio rationalization and an operational pivot away from a "commodity mindset."36 Introducing a comprehensive strategic reset immediately after delivering record annual earnings suggested that management itself recognized that FY26's operating margins might not represent a durable baseline.
Claim one: "Astec makes Agrovet a specialty chemicals business"
When Godrej Agrovet built its controlling stake in listed manufacturer Astec LifeSciences, the strategic thesis was clear: move up the agricultural value chain into research-driven contract development and manufacturing. By synthesizing proprietary active ingredients and advanced chemical intermediates for multinational agrochemical firms, Astec was meant to insulate Agrovet from low-margin animal feed with a steady stream of high-margin, sticky enterprise contracts.
The commercial outcome exposed the vulnerability of that thesis. In FY25, Astec recorded an EBITDA loss of ₹60.58 Cr and a net loss after tax of ₹134.71 Cr, battered by severe global inventory destocking and aggressive price competition from Chinese chemical manufacturers.37 Although operating performance stabilized at EBITDA breakeven of ₹0.54 Cr in FY26, the company still posted a net loss of ₹80.88 Cr on total revenues of ₹448 Cr, requiring a rights issue that saw Agrovet lift its controlling stake from 64.75% to 67.03% to inject capital.37 The 2024 family settlement even triggered an indirect change-of-control open offer for Astec's public minority equity, adding regulatory complexity to an asset already absorbing capital.2
The verdict: Astec's operating record refutes the claim that contract research insulated Agrovet from commodity downturns. Instead of providing defensive diversification, Astec introduced high-beta exposure to an agrochemical destocking cycle far more severe than the domestic poultry or dairy cycles. While operational losses have narrowed, Astec remains a drain on parent earnings. The real test is whether the subsidiary can sustain a full fiscal year of positive net earnings without turning to Agrovet's balance sheet for ongoing equity infusions.
Claim two: "Dairy is a high-margin consumer franchise"
In March 2025, Agrovet committed ₹930 Cr to acquire the remaining 48.06% equity in Creamline Dairy Products, which markets liquid milk and value-added dairy products across southern India under the Godrej Jersey brand, converting it into a wholly owned subsidiary.38 Management framed the buyout as a strategic accelerator that would expand its footprint in high-margin, value-added consumer categories such as curd, ghee, and flavored milk.38 Yet in FY26, the first full fiscal year following that transaction, Creamline's pre-tax profit before exceptional items halved from ₹27.85 Cr to ₹13.86 Cr, squeezed by sharp increases in farmgate milk procurement costs.35
Deploying ₹930 Cr of parent capital to consolidate full ownership of a regional entity generating less than ₹14 Cr in annual pre-tax earnings reflects aggressive valuation underwriting. Across southern India, private dairy processors operate in a fiercely contested market. They face state-backed cooperatives such as Nandini in Karnataka and Aavin in Tamil Nadu—which receive government procurement subsidies and can price milk below economic cost—alongside disciplined private competitors like Hatsun Agro. Operating margins in liquid pouch milk remain razor-thin, and building scale in value-added dairy requires heavy cold-chain logistics and consumer advertising. To date, the investment record does not support viewing Creamline as a high-margin consumer franchise. On disclosed numbers, the acquisition looks less like a high-return consumer asset and more like an overcapitalized regional processor struggling against structural margin limits.
What Agrovet means for GIL
Within the Godrej Industries holding structure, Agrovet functions as a mature, cash-generative operational anchor. Its foundational animal feed and oil palm milling businesses deliver reliable operational cash flow and upstream dividend payouts to the parent company. At the same time, Agrovet illustrates a capital allocation pattern evident across the wider conglomerate: while the established core businesses remain operationally sound, adjacent acquisitions—most notably Astec LifeSciences and Creamline Dairy—have absorbed substantial capital and executive oversight without delivering commensurate economic returns.
That dynamic mirrors the broader investment debate surrounding Godrej Industries. The parent company's value is not constrained by its core operating platforms, but by the capital channeled into subscale subsidiaries and capital-hungry ventures. That capital friction becomes even more pronounced when examining Godrej Industries' own standalone manufacturing balance sheet and its ambitious foray into retail lending.
VII. The Standalone Core & The Dark Horse: Oleochemicals vs. Godrej Capital
The factory inside the holding company
At Valia in Gujarat, GIL operates an integrated oleochemicals manufacturing complex.39 In simple terms, the plant fractions vegetable feedstocks—predominantly palm kernel oil—into basic chemical building blocks. Fatty acids are channeled into soaps, industrial rubber, and lubricants. Fatty alcohols serve as active foaming agents in shampoos and laundry detergents. Glycerine is refined for pharmaceutical formulations and cosmetics, while surfactants supply the core cleaning agents across household products. The fundamental chemistry is well established; operating profitability hinges on procurement timing, maintaining high plant capacity utilization, and steadily shifting production from basic commodity grades into higher-margin specialty derivatives.
The myth of the razor-thin margin, and the real cyclicality
Public commentary often dismisses this division as a low-margin commodity processor earning mid-single-digit operating margins. Disclosures from credit rating agency CRISIL, however, reveal an operating profile defined by sharp cyclical swings rather than structural poverty of margin:
- FY23: operating income reached ₹4,173 Cr with a 17% profit before interest and tax (PBIT) margin.21
- FY24: revenue fell to ₹2,697 Cr and the PBIT margin halved to 9%, as customers ran down inventories and geopolitical disruptions hit export demand.21
- FY25: top-line performance recovered to ₹3,503 Cr at a 10.6% PBIT margin.4
- FY26: revenue climbed 22% to ₹4,135 Cr, supported by 9% volume growth.6
- Q1 FY27: momentum accelerated, with revenue expanding 31% year on year to ₹1,161 Cr, PBIT surging 86% to ₹159 Cr, and export shipments rising 20%.33
Revenue contracted by more than a third in a single fiscal year before recovering, while operating margins halved and gradually rebuilt. This is not a structurally thin-margin business; it is a deeply cyclical one. Its primary competitors include domestic producer VVF in fatty alcohols and exports, alongside massive Southeast Asian refiners situated adjacent to equatorial palm plantations. In a global downturn, none of these producers possesses structural pricing power.
Despite that volatility, management is committing substantial capital to expand the complex. In July 2025, GIL announced a capital expenditure program exceeding ₹750 Cr designed to double fatty alcohol and erucic acid capacity, triple specialty chemical output, double refined glycerine production, and add 30,000 tonnes of primary surfactants, targeting a $1 billion global business before 2030.39 Chief executive Vishal Sharma—reappointed through March 2030—characterized the division as delivering "double-digit volumes and revenue growth year after year".639 The sharp contraction in FY24 stands as an immediate counterpoint to that claim, occurring just two years prior to the expansion announcement.
The verdict: The chemicals division generates healthy operating cash in upcycles and compressed returns during downturns. For GIL shareholders, the structural question is whether an asset-heavy, cyclical manufacturing facility belongs inside a holding company, where its operating swings add volatility to an entity primarily designed to steward long-term equity stakes. Because the ₹750 Cr capital outlay is funded directly from GIL's balance sheet, the factory competes directly with Godrej Capital for the parent company's retained capital.
The dark horse: Godrej Capital
Godrej Capital was constructed at rapid speed. Godrej Housing Finance began operations in November 2020, followed by the non-banking financial company (NBFC) arm, Godrej Finance, in March 2022.5 At its formal launch in April 2022, Pirojsha Godrej, serving as chairman, and managing director and CEO Manish Shah established an ambitious blueprint: an initial capital commitment of ₹1,500 Cr, an anticipated equity requirement of ₹5,000 Cr by 2026, and a targeted balance sheet of ₹30,000 Cr by 2026.40
Measured against its initial operational targets, the lending franchise expanded rapidly:
- Assets under management (AUM) reached ₹27,832 Cr by March 2026, up from ₹16,929 Cr a year earlier, a 64% increase, while annual loan disbursements grew 76% to ₹19,434 Cr.5
- Profit after tax rose to ₹232 Cr on total income of ₹2,478 Cr in FY26, from ₹152 Cr the year before.5
- Gross stage-three assets—loans overdue past 90 days—stood at just 0.29%.5
Retail lending economics, however, are governed by leverage. A non-bank lender borrows from commercial banks and debt investors to extend loans at higher interest spreads, relying on its equity capital as a loss-absorbing buffer. As of March 2026, Godrej Capital's consolidated gearing—total borrowings divided by net worth—climbed to 5.88 times, up from 4.73 times a year earlier, with credit rating agency CARE expecting it to rise to about 6–6.5 times.5 In practical terms, each rupee of Godrej equity supports close to six rupees of borrowed money. If credit losses spike even modestly across the portfolio, that thin equity buffer can be exhausted quickly—explaining why a fast-growing lender requires repeated equity infusions from its parent. For now, liquidity appears healthy, backed by ₹1,446 Cr of unencumbered liquidity and ₹8,684 Cr of undrawn bank lines at March 2026.5
The loan book is concentrated in two products: loans against property represented 52% of the NBFC's ₹18,062 Cr book, while business loans accounted for 27%. The housing finance book of ₹8,259 Cr is 76% home loans.5 For FY27, management targeted an AUM of ₹38,000 Cr, with roughly 70% from the NBFC side, while maintaining that the business needs to reach ₹1 lakh Cr of AUM before listing.41
The capital-need test
Management's guidance regarding Godrej Capital's capital requirements and public listing timetable has shifted repeatedly.
In January 2025, reports indicated that Godrej Capital planned an IPO "within 3 years", having already crossed the ₹10,000–15,000 Cr AUM threshold it had earlier named as the trigger for listing.42 In July 2025, Manish Shah told PTI: "Until such time as we list, the capital will come from the group. Most of it we have already received. We don't need a lot more capital over the next few years."43
Yet eleven months later, on June 2, 2026, the group stated that the IPO would come by 2031 and that ₹5,000–7,000 Cr had been set aside to support the lending business.44 In the same period, GIL moved Godrej Capital under a new intermediate company, Godrej Investment Limited, incorporated on January 5, 2026, into which GIL put ₹3,862 Cr of equity. The stated purpose was to "simplify borrowing and make it easier to bring in equity partnerships".45 In May 2026, GIL's board approved a further investment of up to ₹1,000 Cr in that vehicle.6
Part of this expansion reflects the natural mechanics of lending: accelerating loan disbursements consumes equity capital at a faster pace. The ₹3,862 Cr subscription is also close to GIL's existing investment in Godrej Capital, which was ₹3,454 Cr in June 2025,4 and Godrej Investment received the whole Godrej Capital stake.45 That alignment suggests much of the money went into reorganising the ownership chain rather than purely into new lending capital, although public disclosures do not break down how the cash moved. According to CARE, total group equity put into Godrej Capital was ₹3,737 Cr by March 2026, including ₹792 Cr in FY25 and ₹729 Cr in FY26.5
Nevertheless, the strategic pattern is unmistakable. Assurances that little more capital would be needed were followed within a year by an earmark roughly as large as everything invested before, while the targeted IPO horizon moved from about three years to about five. CARE also noted that the loan book is "relatively unseasoned" because most disbursements happened in the last two years, and that "asset quality performance across economic cycles is yet to be fully established".5 In FY26, return on assets was about 1%.5
The verdict: Godrej Capital is a real business with clean reported asset quality and credible growth. It is not yet proven. The loan book has not been through a credit cycle, returns are modest, and the parent's capital commitment keeps growing. It has turned GIL from a passive holder of stakes into the captive backstop for an expanding lender. CARE's ratings rest on the expectation of continued parent support, and GIL has said it intends to keep at least 51%.5 That support provides institutional comfort to creditors, but GIL's minority shareholders bear the underlying cost.
A second new business: wealth management
On June 2, 2026, the group introduced another financial services venture: Godrej Wealth, led by CEO Kunal Karnani, established to serve clients with ₹2 Cr or more of investable assets, including entrepreneurs, business families, and non-resident Indians. It targets ₹1 lakh Cr of assets under management and a network of 35 locations within five years.44 Pirojsha Godrej presented it as an institution for "long-term stewardship across generations", backed by "129 years" of Godrej trust.44 Asked about competition, Manish Shah said the company was focused on customer needs rather than on rivals.44
A new wealth business needs relatively little capital compared with lending. It does, however, enter a field crowded with bank-owned private-banking arms, independent wealth houses, and global banks, all hiring the same scarce relationship managers. Here the brand is the whole pitch. Whether trust built on soap and apartments carries over to managing someone's family fortune is a question only client inflows can answer. Until several years of disclosed net inflows are available to judge performance, the ₹1 lakh Cr target should be treated as an aspiration.
To understand why GIL is committing so much capital to finance and real estate, it helps to examine the 2024 family settlement that decided what each branch of the dynasty could and could not do.
VIII. The Great 2024 Family Settlement: Untangling 127 Years & The Vikhroli Land Reality
Why two families, one name
The Godrej empire had long been held in common by two family branches descended from the founding brothers. Adi and Nadir descend from Burjor Godrej, while Jamshyd and Smita descend from Naval Godrej. Over decades, their corporate cross-holdings multiplied: Godrej & Boyce held substantial equity across the listed operating companies, while individual family members owned shares on both sides of the corporate ledger. Operationally, the family had drifted into distinct spheres of influence. The Adi-Nadir branch steered the listed growth businesses—consumer packaged goods, real estate, agribusiness, and retail lending—while the Jamshyd-Smita branch oversaw industrial engineering, defence and aerospace manufacturing, and the family's historic Vikhroli land holdings.
The official regulatory announcement framed the division diplomatically, stating that the realignment was structured "to maintain harmony and to better align ownership in acknowledgement of the differing visions of the Godrej family members".2 At closing share prices on the day of the disclosure, the family's combined equity across the five listed group companies was valued at approximately ₹1.53 lakh Cr, against an aggregate market capitalization of ₹2.44 lakh Cr.2
Who got what
- Godrej Industries Group (GIG): Comprises GIL, GCPL, GPL, Godrej Agrovet, and Astec LifeSciences, along with unlisted holding entities including Innovia Multiventures, Godrej Seeds and Genetics, and Anamudi Real Estates. It is controlled by the Adi and Nadir families, with Nadir initially serving as chairperson and Pirojsha as executive vice-chairperson and designated successor.2
- Godrej Enterprises Group (GEG): Comprises Godrej & Boyce, Godrej Holdings, Godrej Infotech, and RKNE Enterprises, controlled by Jamshyd Godrej as chairperson and managing director alongside Smita Godrej Crishna's daughter, Nyrika Holkar, as executive director.2
Each branch agreed to step back completely from the management and governance of the other's operational entities. Residual minority cross-holdings were designated as passive public investments, subject to explicit restrictions preventing their sale to designated corporate competitors.2
The brand treaty
The trademark settlement divided the "Godrej" brand name along strict industry lines. GIG secured exclusive rights across consumer packaged goods, food, dairy, financial services, pharmaceuticals, agriculture, chemicals, oils and fats, and real estate development and related services. GEG received exclusive rights across aerospace, defence, furniture, consumer durables, locks, architectural security, information technology, and industrial engineering.2 Uncontested or nascent domains such as healthcare, hospitality, and education were designated as shared sectors that either branch can enter, provided each entity attaches a group-level descriptor—"Godrej Industries Group" or "Godrej Enterprises Group"—to distinguish itself in the marketplace.2 The pact imposed a six-year non-compete covenant from the effective date, after which either group may enter the other's product categories, but strictly without deploying the Godrej brand name.2
This trademark map contextualizes GIL's strategic roadmap. Financial services, wealth management, and real estate represent sectors where GIG holds outright, exclusive ownership of the brand. The holding company's aggressive balance-sheet deployment into retail lending and its June 2026 launch of wealth management represent deliberate campaigns to build scale within the specific commercial domains assigned to it under the settlement.
The leadership handover
The succession plan adhered precisely to the transition timetable established in the 2024 pact. Pirojsha Godrej was formally named chairperson-designate in April 2026.46 On August 13, 2026, GIL's board approved his appointment as a whole-time director with the title of executive chairperson, effective August 14, 2026, for a five-year term ending August 13, 2031.33 Nadir Godrej retired as chairman and managing director.3 Adi Godrej serves as chairman emeritus.3
Pirojsha, 45, completed a master's degree in international affairs at Columbia University before earning an MBA from Columbia Business School.3 He spent his executive career steering Godrej Properties into India's largest developer by booking value, subsequently founding both Godrej Capital and Godrej Ventures.3 He is, by background and temperament, a real estate and capital-markets operator. He now oversees a holding-company portfolio in which the developer he built represents the primary equity swing factor, while the lending franchise he founded is its largest consumer of capital. Whether he can allocate capital across that portfolio with detached neutrality—without favoring the high-growth ventures he personally originated—is the central governance test of his five-year term.
Myth vs. reality: the Vikhroli land bank
The most enduring misconception surrounding Godrej Industries and Godrej Properties concerns their relationship with Vikhroli.
The myth: Equity investors in GPL, and by extension holding-company shareholders in GIL, hold a direct economic claim on the Godrej family's vast 3,400-acre land bank in Vikhroli in north-east Mumbai—a parcel routinely cited as possessing more than ₹1 lakh Cr of long-term development value.147
The reality: The land is owned by Godrej & Boyce, and Godrej & Boyce belongs entirely to Jamshyd Godrej and Smita Godrej Crishna's unlisted Godrej Enterprises Group.247 The parcel was acquired in the early 1940s from the Bombay High Court receiver.21 Furthermore, the headline acreage significantly overstates buildable area. Adi Godrej clarified in 2011 that only about 1,000 acres are commercially developable; roughly 1,750 acres consist of ecologically sensitive mangrove forests legally protected from development, while another 300 acres have suffered informal encroachment.2
Following the 2024 partition, Godrej & Boyce and Godrej Properties confirmed that their commercial partnership would endure, structured with G&B as the owner-developer and GPL as the development manager operating under specific memorandums of understanding—a framework previously deployed on projects like Godrej Platinum and Godrej Vistas.47 Crucially, regulatory filings specify that "the proposed development will take place when Godrej & Boyce is desirous of developing the land."47 The brand agreement grants GIG the right to deploy the Godrej name when acting as development manager on G&B's Vikhroli acreage.2 Simultaneously, it grants GEG the exclusive right to use the Godrej brand for any real estate developed directly on its own land parcels.2 The commercial fee arrangements governing GPL's development-management mandates have not been publicly disclosed.
The verdict: The legal and corporate structure firmly refutes the assumption that GIL or GPL holds a proprietary option on Vikhroli. GPL merely holds the right to earn project management fees on individual parcels if, and only when, the unlisted landowner chooses to monetize them. Once the six-year non-compete expires, even that arrangement depends on GEG's ongoing commercial discretion and terms that can be renegotiated. Holding-company investors cannot rationally factor Vikhroli's underlying land value into GIL's net asset value.
With the dynastic boundaries and balance-sheet ownership clearly established, the final valuation dilemma turns to market pricing: calculating what the conglomerate's constituent pieces are worth, and deciphering why public markets enforce such a punitive holding-company discount against the whole.
IX. Capital Allocation, Leverage, & The Holding Company Dilemma
Adding up the parts
A sum-of-the-parts calculation illustrates how public markets price Godrej Industries, even if it cannot settle the broader debate over intrinsic value. The clearest independent appraisals emerge from the company's credit ratings:
- August 2024: listed equity stakes valued at ₹84,049 Cr, standalone net debt of ₹7,765 Cr, and cumulative investment in Godrej Capital of ₹2,681 Cr.21
- August 2025: listed equity stakes valued at ₹65,611 Cr, standalone net debt of ₹9,696 Cr, and cumulative investment in Godrej Capital of ₹3,454 Cr as of June 2025.4
The visible net asset value of the portfolio contracted by roughly 22% over that twelve-month period, driven primarily by a pullback in Godrej Properties' share price, even as standalone net debt climbed by nearly a quarter. Based on the August 2025 figures, listed holdings plus Godrej Capital at cost, minus net debt, yielded an indicative portfolio value of approximately ₹59,000 Cr—before assigning any value to the standalone oleochemicals manufacturing business. By May 2026, public markets valued the entire consolidated company at approximately ₹37,884 Cr.7 While market capitalizations fluctuate daily, the structural pattern remains unmistakable: public equity markets enforce a discount of at least a third against the visible value of the holding company's assets, and that haircut widens further once the cash-generative chemicals complex or an unlisted premium for Godrej Capital are factored into the equation.
Why the discount persists: the skeptic's case
1. Operating cash flows bypass public shareholders. Godrej Industries last distributed a dividend in August 2019, paying ₹1.15 per share.7 Dividend inflows from operating subsidiaries such as GCPL and Agrovet do not reach equity holders; they are absorbed by parent interest obligations, manufacturing capex at Valia, and equity injections into Godrej Capital. When a holding vehicle returns no cash to its owners, minority equity ownership reduces to a speculative bet on multiple expansion—the very outcome the market's holding-company discount prices in.
2. Standalone leverage continues to mount. In May 2026, GIL's board approved the issuance of up to ₹1,500 Cr in unsecured non-convertible debentures (NCDs).48 On September 11, 2026, a board committee authorized a private placement of up to ₹7,500 Cr in unsecured debentures.49 Those authorizations followed CRISIL's rating of ₹2,000 Cr in new debentures on top of ₹6,250 Cr in previously outstanding paper.4 CRISIL's figures indicated that standalone interest coverage contracted to approximately 1.37 times in FY25.4 The parent company's high investment-grade credit rating has historically rested on the market value of its underlying listed equity portfolio rather than internal operational earnings; CRISIL upgraded GIL in October 2024 citing net-debt cover in excess of eight times.21 That collateral buffer naturally erodes when subsidiary share prices soften while parent borrowings climb—both of which occurred across 2025.
3. Promoter creeping acquisition consolidates control over float. During FY26, the Godrej promoter group increased its equity stake in GIL from 69.64% to 74.64% through open-market purchases totaling approximately ₹2,000 Cr.26 Combined institutional shareholding stood at roughly 8%.7 That accumulation brought promoter ownership to the statutory ceiling of 75% for listed Indian companies, curtailing the public free float and leaving few external institutional voices positioned to advocate for governance reforms or capital distributions. Stepping in to accumulate shares signals insider conviction, but it also concentrates voting power, insulating management from external market pressure to institute a formal dividend policy.
4. Inter-corporate capital movements raise structural transparency questions. GIL's ₹3,862 Cr equity subscription to intermediate holding vehicle Godrej Investment was classified as a related-party transaction.45 Similarly, the September 2026 sale of GCPL shares to promoter family members functioned as an internal transfer among related parties at prevailing market prices.34 While individual transactions can be defended as commercially sound, the cumulative effect positions Godrej Industries as an internal merchant bank and treasury center for the broader group, leaving public minority shareholders exposed to capital reallocation decisions they cannot influence.
5. Consolidated financial statements remain opaque. The first quarter of FY27 highlighted the earnings distortion common to complex conglomerates: while consolidated revenue expanded 22%, net profit attributable to shareholders dropped 19% to ₹284 Cr, squeezed by escalating finance costs.5033 In the fourth quarter of FY26, other income accounted for approximately half of consolidated pre-tax profit, according to an independent market analysis.7 When headline earnings swing on treasury yields, non-operating income, and inter-corporate leverage rather than steady operational cash flow, public markets routinely apply a valuation penalty.
What an activist would ask for
An institutional activist evaluating Godrej Industries at an annual general meeting would focus on a concise list of structural questions. Why does a holding company whose underlying equity holdings exceed its market capitalization by tens of thousands of crores pay no dividend to its public shareholders, even as its operating subsidiaries upstream steady dividend streams to the parent? Why is an asset-heavy, cyclical oleochemicals manufacturing business—currently requiring a ₹750 Cr expansion—housed alongside a retail lending franchise with insatiable equity requirements? Why did management describe Godrej Capital's equity needs as largely met in July 2025, only to earmark an additional ₹5,000 Cr to ₹7,000 Cr eleven months later? And why is capital consistently shifted through internal related-party transactions rather than via arm's-length external equity partnerships that establish transparent market valuations?
None of these inquiries suggests regulatory impropriety, and management can offer strategic justifications for each step. However, Godrej Industries' public disclosures do not include an explicit capital allocation framework—such as a stated hurdle rate on new ventures, a dividend distribution formula, or a binding holding-company debt cap—against which public investors can measure execution. While Godrej Properties has publicly committed to maintaining net debt below ₹10,000 Cr,22 the parent holding company, which ultimately underwrites the group's financial architecture, operates without an equivalent leverage ceiling. With the promoter group controlling nearly 75% of the voting equity and institutional investors holding a negligible float, outside shareholders possess compelling arguments but minimal governance leverage to compel reform.
Management credibility, judged by behaviour
Management's stewardship displays distinct institutional strengths. The 2024 dynastic partition was concluded amicably without courtroom disputes or operational paralysis, adhering strictly to its announced timetable through the August 2026 executive succession. Compared to the acrimonious separations that have compromised other prominent Indian conglomerates, that orderly restructuring resolved a multi-generational ownership risk. Similarly, the board's immediate cancellation of the DB Realty transaction confirmed that leadership responds constructively to public shareholder pushback at Godrej Properties. Furthermore, Godrej Capital broadly delivered on its ambitious 2022 balance-sheet expansion targets.405
Alongside those achievements sits a documented history of capital misallocation. GCPL's decade-long international acquisition drive culminated in an exceptional pre-tax write-down of ₹2,389 Cr. Godrej Agrovet's buyouts of Astec LifeSciences and Creamline Dairy absorbed significant parent capital while delivering compressed operational returns. At Godrej Capital, forward guidance regarding equity requirements and public listing milestones altered materially within a single fiscal year. While management has demonstrated an ability to correct tactical missteps—occasionally within 24 hours—the broader corporate record reveals a recurring willingness to pursue balance-sheet-heavy expansions whenever liquidity is accessible and strategic narratives appear persuasive.
The next section evaluates these operational patterns against established strategic frameworks, separating durable competitive moats from temporary cyclical tailwinds.
X. Strategic Frameworks: 7 Powers & Porter's Five Forces
Hamilton Helmer's 7 Powers
Brand (strong domestically, limited internationally). The Godrej name represents the holding company's most valuable intangible asset. In India, brand equity allows Godrej Properties to pre-sell residential developments off-plan, enables Godrej Capital to secure institutional wholesale credit at favorable spreads, and persuades rural farmers to purchase animal feed at a premium to unbranded regional alternatives. Helmer defines brand power as the ability to command a price premium or higher volume for an objectively similar offering purely through seller identity, and on that standard, Godrej's domestic standing holds up. However, cross-border acquisitions demonstrated its geographic boundaries: as GCPL discovered across Africa and Latin America, brand equity built over decades in India failed to establish pricing power in unfamiliar retail environments. The 2024 family settlement introduced a further structural qualification: the brand is now split across two independent groups, with shared-space sectors open to both corporate branches deploying group descriptors.2
Scale economies (strong at GCPL, moderate at GPL, weak in chemicals). GCPL's retail distribution footprint across millions of outlets amortizes national advertising campaigns and trade promotions at unit costs smaller competitors cannot match. At Godrej Properties, a pan-India marketing engine provides operational scale in lead generation and raw-material procurement; however, real estate remains an inherently localized business where low land acquisition costs matter far more than national developer scale. In standalone oleochemicals, massive Southeast Asian refiners located alongside plantation belts hold decisive scale and raw-material cost advantages.
Counter-positioning (unproven at Godrej Capital). Godrej Capital's strategic thesis posits that combining digital underwriting with customer flow from the wider conglomerate—particularly Godrej Properties' homebuyer pipeline—creates an agile alternative to traditional commercial banks and legacy non-bank lenders. However, group-sourced assets represented approximately ₹3,000 Cr, or roughly one-sixth of AUM, in mid-2025, with management projecting that proportion to diminish over time.43 More critically, established non-bank incumbents such as Bajaj Finance, Tata Capital, and major housing finance companies face no structural barrier or business-model penalty preventing them from adopting identical digital underwriting methods. Without an asymmetric economic penalty preventing incumbents from responding, this reflects operational positioning rather than structural counter-positioning.
Cornered resource (weakened by the settlement). Historically, the Godrej family's 3,400-acre land parcel at Vikhroli was viewed as the group's single irreplaceable cornered asset. The 2024 partition resolved that status: the land sits wholly inside unlisted Godrej & Boyce, leaving GIL and Godrej Properties with a conditional, discretionary project-management arrangement rather than an economic title (Section VIII).
Switching costs (low across the portfolio). Customer lock-in is minimal across the operating portfolio. Consumers switch soap brands or household insecticides without financial friction; homebuyers evaluate real estate developers on a project-by-project basis; and industrial chemical buyers maintain multi-vendor sourcing to secure competitive pricing. Because switching barriers are low, competitive advantages across GIL's operating arms must be actively defended through continuous marketing, sales outlays, and operational execution.
Network effects and process power: There is no tangible evidence that any of the portfolio businesses benefit from two-sided network effects or proprietary, non-replicable operational process power.
Porter's Five Forces, business by business
Godrej Properties. Competitive rivalry among India's top-tier developers remains intense. Prestige Estates' booking value expanded to ₹30,024 Cr in FY26, substantially closing the gap with GPL's industry-leading total.19 Landowners exert substantial bargaining leverage in prime urban micro-markets, which prompted GPL's strategic pivot toward outright land purchases—a shift that eroded its historical capital-light profile. End-buyer leverage expands during periods of rising mortgage rates or localized inventory overhang. Conversely, barriers to entry remain elevated: stringent RERA compliance mandates and tight institutional project financing deter unorganized regional builders, consolidating market share among established corporate developers.
GCPL. Competitive rivalry is aggressive, led by multinational and domestic peers including Hindustan Unilever, Reckitt, and Dabur. In household insecticides, the most potent substitute emerges from the unorganized sector: illicit, low-cost incense sticks and counterfeit coils that erode branded volumes during inflationary downturns. While traditional retail distribution remains fragmented across millions of kirana stores, organized modern trade and rapid-delivery quick-commerce channels are consolidating buyer power in urban centers. On the supply side, volatility in palm oil feedstocks and crude-oil-linked packaging inputs imposes recurrent pressure on gross margins.
Standalone oleochemicals. Supplier power is exceptionally high, as primary raw materials—palm and palm kernel oils—are sourced from Southeast Asian suppliers subject to international benchmark pricing and export duties. Competitive rivalry from integrated Indonesian and Malaysian refiners is direct and persistent. Buyer power is similarly concentrated: industrial customers comprise large fast-moving consumer goods manufacturers—including GIL's own sister company, GCPL—whose procurement teams negotiate pricing aggressively. Within GIL's portfolio, oleochemicals confronts the least favorable industry structure, explaining why division margins fluctuate with global commodity cycles.
Godrej Capital. Competitive rivalry is intense across both core verticals: mortgages and loans against property, where well-capitalized public-sector banks, private lenders, and established housing finance companies compete on interest rates. Supplier power—represented by commercial banks and debt capital markets providing wholesale funding—is tempered by the perceived creditworthiness of the parent promoter group. Creditors lend at competitive spreads because they view Godrej Industries' balance sheet as a captive backstop, effectively embedding the holding company's solvency into the lender's operational funding model.
Putting it together
Evaluating the portfolio through these competitive frameworks reveals a structural paradox. The group's durable competitive advantages—anchored by brand equity and national distribution networks—are concentrated in its listed consumer and real estate arms, GCPL and Godrej Properties. Conversely, the weakest structural profiles belong to the assets Godrej Industries funds directly from its standalone balance sheet: a cyclical, price-taking oleochemicals manufacturing complex and an unseasoned retail lending franchise. That asymmetry sits at the heart of the holding company's valuation debate: the parent entity absorbs direct balance-sheet risk for its structurally vulnerable businesses, while remaining two steps removed from the operational cash flows generated by its strongest moats.
XI. The Investment Spine: Bull vs. Bear Case & What to Watch
The bull case: the discount narrows and compounding continues
GPL's bookings turn into cash. For FY27, Godrej Properties guided for more than ₹39,000 Cr in booking value, ₹24,000 Cr in customer collections, and approximately ₹9,000 Cr in operating cash flow, establishing free-cash-flow breakeven as its primary operational milestone.22 If the developer transitions from consuming parent balance-sheet capacity to generating surplus cash, the economic benefit to Godrej Industries compounds: GPL could institute meaningful dividend distributions back to the holding company, while removing the need for equity infusions or debt guarantees.
Godrej Capital proves its underwriting before listing. Management's long-term roadmap targets ₹1 lakh Cr in assets under management and a public listing by 2031, projecting that the lending business will represent approximately 10% of the wider group's market value by that date.44 If its reported asset quality—highlighted by gross stage-three assets of just 0.29%5—remains resilient as the loan book seasons through an economic cycle, the business could attract an external strategic equity partner, an outcome the intermediate Godrej Investment structure was explicitly designed to facilitate.45 Bringing in arm's-length institutional equity would establish an objective market benchmark for an asset currently valued only at book equity.
The chemicals manufacturing upcycle extends. The standalone chemicals business delivered 86% year-on-year PBIT growth in the first quarter of FY27, while its ₹750 Cr capital expenditure program aims to substantially scale higher-margin specialty derivative capacity, indicating that division operating earnings could hold well above their FY24 cyclical trough.3339
A simpler governance structure. With ownership and operational control consolidated under the Adi and Nadir family branch and Pirojsha Godrej installed as executive chairperson under a defined five-year mandate, corporate decision-making and capital allocation can proceed with greater agility than under the historical multi-branch consensus.
The bear case: a permanent holding-company tax and fragile operations
The discount lasts because the behaviour behind it lasts. Across Indian public markets, holding-company discounts seldom contract without a structural catalyst—such as an explicit dividend distribution policy, a share buyback, or the demerger of non-core operating assets. Management has announced no such measures. With promoter shareholding reaching the statutory 75% ceiling and institutional float curtailed to roughly 8%, external public shareholders lack the voting power required to compel governance reforms or cash distributions.726
Godrej Capital's first credit cycle. Non-bank lending against property and unsecured business loans to small and medium enterprises historically experience pronounced delinquency spikes during macroeconomic downturns. Godrej Capital's loan portfolio remains geographically concentrated in Maharashtra, Karnataka, and the National Capital Region, and has minimal operating seasoning across a full credit cycle.5 If credit losses escalate, the lending business would require immediate loss-absorbing equity capital—and Godrej Industries remains its captive, designated backstop.
Real estate reversal. GPL's strategic transition from joint-venture partnerships to outright land purchases imposes substantial carrying costs, land-acquisition debt, and operational cash commitments. Godrej Properties' equity has experienced peak-to-trough drawdowns exceeding 45% on five separate occasions since its 2010 market debut.25 Because GIL's investment-grade credit rating relies on the market value of its listed equity holdings rather than standalone operational cash flow, any sharp contraction in GPL's share price directly erodes the collateral buffer underpinning the parent company's borrowings.
Rising standalone leverage. GIL's standalone net debt reached ₹9,696 Cr by August 2025, and subsequent board authorizations paved the way for up to ₹7,500 Cr in fresh private debenture issuances.449 If oleochemical margins contract back toward FY24 troughs while standalone interest obligations rise, Godrej Industries could be forced to monetize additional equity stakes in its listed operating flagships to service its debts and capital commitments.
The risk radar, where it actually bites
- Interest rates and funding costs. Macroeconomic interest rates impact Godrej Industries across three parallel channels simultaneously: the coupon rates on its standalone debenture issuances, the net interest margins and borrowing spreads at Godrej Capital, and mortgage affordability for homebuyers at Godrej Properties. A sustained high-rate environment compresses margins across all three businesses at once—revealing a hidden balance-sheet correlation inside a portfolio that appears diversified on the surface.
- The monsoon and farm incomes. Agrarian weather volatility directly shapes portfolio performance. The delayed onset of the monsoon in the first quarter of FY27 curtailed Godrej Agrovet's crop-protection volumes and profitability.36 Weak farm incomes also dampen rural sales of GCPL's household insecticides and toilet soaps, while elevating default risks among small-business borrowers at Godrej Capital.
- Palm oil prices and trade policy. International price movements in crude palm oil and palm kernel feedstocks dictate raw-material economics across multiple group entities: feeding directly into margins at GIL's standalone oleochemicals plant, procurement pricing and farmer payout ratios at Godrej Agrovet, and input costs for GCPL's soap manufacturing. These margins remain vulnerable to export levies set by Indonesia and Malaysia, as well as import duty revisions enacted by the Indian government.
- Regulation of lenders. Godrej Capital operates under the regulatory supervision of the Reserve Bank of India and the National Housing Bank. Stricter capital-adequacy thresholds, elevated risk weights on retail lending, or tighter provisioning guidelines would accelerate the lender's equity consumption, requiring Godrej Industries to inject greater volumes of parent capital to sustain identical loan-book expansion.
- Execution at a time of change. The group is navigating multiple strategic initiatives concurrently: Pirojsha Godrej's assumption of the executive chairmanship, Sunil Kataria's executive leadership at Godrej Agrovet, an aggressive greenfield buildout in wealth management, and a major capital expansion in specialty chemicals. While each initiative is individually defensible, executing them simultaneously demands substantial capital and executive oversight.
The three KPIs that matter
-
GIL standalone net debt, together with cumulative equity invested in Godrej Investment and Godrej Capital. This metric provides the most transparent gauge of whether the parent holding company is taking on debt to underwrite retail lending expansion. It is tracked through periodic credit rating rationales and annual standalone disclosures.
-
Godrej Properties' operating cash flow as a share of booking value. This ratio reveals whether record-setting pre-sales booking numbers are converting into operational cash generation or being continuously consumed by outright land acquisition and project development outlays, benchmarked against FY26 disclosures and FY27 operating guidance.1822
-
GCPL's India underlying volume growth and consolidated EBITDA margin. Godrej Consumer Products serves as the primary dividend anchor and defensive stabilizer across the wider conglomerate. Domestic physical volume growth indicates whether the strategic operational reset initiated in 2021 remains intact, while consolidated EBITDA margins confirm whether international restructuring and brand divestments have permanently stemmed overseas earnings dilution.32
XII. Epilogue & "If We Were CEOs"
The August 2026 milestone
On August 14, 2026, Pirojsha Godrej assumed the role of executive chairperson of Godrej Industries and the wider group, adhering precisely to the transition timetable established by the family more than two years earlier.32 In an Indian corporate landscape where multi-generational successions frequently trigger public disputes, the leadership handover unfolded without institutional friction.
The mandate differs fundamentally from his previous executive responsibilities. Leading Godrej Properties required winning urban land, marketing residential units, and raising development equity. At Godrej Industries, the primary responsibility is allocating capital across disparate operating entities: deciding whether an incremental rupee belongs in a retail lender's equity base, a specialty chemicals expansion, a real estate land bank, or dividend distributions to holding-company shareholders. His opening weeks in office included authorizing up to ₹7,500 Cr in new debenture issuances and selling a slice of the GCPL stake to promoter family members.4934 While neither action establishes a definitive strategic departure, both align with the established pattern of a holding company deploying debt and asset reallocations to fund ongoing expansion rather than returning capital to public owners.
A playbook for the next chairperson's first thousand days
1. Separate the chemicals business. Demerge the standalone oleochemicals manufacturing complex or bring in an external strategic partner for a majority equity stake. The Valia plant has demonstrated strong operating profitability during cyclical upswings, and an independent corporate structure would establish a transparent market valuation. Removing an asset-heavy, cyclical manufacturing operation from Godrej Industries would transform the entity into a pure holding company, clarifying its financial profile and making its holding-company discount harder to justify.
2. Commit to passing dividends through. Institute a formal capital distribution policy dedicating a fixed proportion—such as 50%—of upstream dividend receipts from GCPL and Godrej Agrovet directly to public shareholders. A transparent payout formula represents the most direct mechanism to narrow the holding-company discount. It would break a dividend drought stretching back to 2019, signaling to the market that subsidiary cash flows belong in part to minority shareholders rather than serving solely to capitalize the group's next internal venture.
3. Bring in outside investors for Godrej Capital now. Management established the intermediate Godrej Investment structure specifically to facilitate equity partnerships and streamline borrowing.45 Securing an external institutional equity partner well before the targeted 2031 public listing, rather than relying on ongoing balance-sheet infusions from Godrej Industries, would establish an independent market benchmark for the lending franchise and impose market-tested capital discipline that captive parent funding rarely provides.
4. Settle the Vikhroli question with GEG. Replace the discretionary, project-by-project development-management arrangement with a formalized commercial framework detailing revenue-sharing parameters and an indicative development timeline alongside Godrej Enterprises Group. Even if net development margins prove modest, contractual clarity would eliminate valuation volatility, preventing public equity markets from alternating between speculative optimism over Vikhroli's underlying land value and apprehension that Godrej Properties could lose its development role once the non-compete covenant expires.
Adi Godrej's generation expanded the conglomerate by incubating operating companies and floating them on public exchanges. The 2024 family settlement and the August 2026 executive handover concluded that founding era. The Godrej Industries Group now steers prominent platforms across residential housing, consumer staples, agribusiness, and retail finance, alongside exclusive rights to deploy the Godrej brand across those domains. The defining question for the new executive chairperson is whether Godrej Industries will evolve into a vehicle that reliably transfers economic value to its public shareholders, or continue functioning as a capital sponge that absorbs it.
References
-
Godrej family split: Adi, brother to keep listed firms; cousin Jamshyd to get unlisted cos, land bank — The Tribune, 2024 ↩↩↩
-
Godrej family amicably splits 127-year-old conglomerate into two groups — Business Standard, 2024-05-01 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Pirojsha Godrej to take charge as Executive Chairperson of Godrej Industries from August 14 — Storyboard18, 2026-08 ↩↩↩↩↩↩↩
-
Godrej Industries Limited Rating Rationale — CRISIL Ratings, 2025-10-10 ↩↩↩↩↩↩↩↩↩
-
Godrej Finance Limited Press Release (Godrej Capital group ratings) — CareEdge Ratings, 2026-06-25 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Godrej Industries Strong Consolidated Revenue Growth of 19% in FY26 — InvestyWise, 2026-05 ↩↩↩↩
-
Godrej Industries Q4 FY26: Strong Profit Surge Masks Persistent Structural Concerns — MarketsMojo, 2026-05-15 ↩↩↩↩↩↩↩
-
Indian Firm Made the World's First Cruelty-Free Soap, Got Tagore to Model For It — The Better India ↩↩↩↩
-
Godrej's 126-year journey from building locks and safes to rockets launchers and satellites — Buildd ↩↩↩↩↩
-
Godrej Group division: Here's a look at 127-year-old history of the company — Business Standard, 2024-05-01 ↩↩↩↩↩↩↩↩
-
This Is Where the 12.83 Lakh Ballot Boxes for India's First Elections Were Made — The Better India ↩
-
Godrej Industries Limited Rating Rationale — CRISIL Ratings, 2023-01-03 ↩↩↩
-
Godrej Properties Reports ₹7,830 Crore Operating Cash Flow Alongside Record FY2026 Bookings — Free Press Journal, 2026-04-10 ↩↩↩↩↩↩
-
Godrej Properties leads listed realty firms as combined FY26 sales bookings rise 17% to INR 1.95 lakh crore — PropNewsTime, 2026-06 ↩↩
-
Godrej Properties shares: Rs 6,000 crore QIP concluded; BlackRock among 5 investors — Business Today, 2024-12-03 ↩
-
Godrej Industries Limited Rating Rationale (upgrade to AA+/Stable) — CRISIL Ratings, 2024-10-11 ↩↩↩↩↩
-
Godrej Properties Targets ₹9,000 Crore Cash Flow Amid ₹9,500 Crore Q1 Project Additions — Sahi, 2026-08 ↩↩↩↩↩↩
-
Godrej Properties slumps 10% as board approves investment in DB Realty — Business Standard, 2022-02-04 ↩↩↩
-
Real estate firm Godrej Properties calls off its deal with DB Realty — Business Standard / PTI, 2022-02-05 ↩↩
-
Godrej Properties promoters lift stake 5% in FY26 via buys — Multibagg, 2026-05-05 ↩↩↩
-
Godrej Properties Promoters Boost Stake By 5% To 51.67% With ₹2,674 Crore Open-Market Purchases — Free Press Journal, 2026-03-13 ↩↩↩
-
Godrej Consumer Products buys Indonesian Megasari — Business Standard, 2010-04-07 ↩↩↩
-
Godrej acquires US-based Strength of Nature — Forbes India, 2016-04-02 ↩↩
-
GCPL takes Rs 2,389 cr one-time hit over Africa market strategy tweak — Business Standard, 2024-05-07 ↩↩
-
Godrej Consumer soars 15% after appointing Sudhir Sitapati as MD and CEO — Business Standard, 2021-05-12 ↩↩↩↩
-
Here's why Godrej Consumer acquired Raymond's FMCG business — Business Today, 2023-04-28 ↩↩↩↩
-
Godrej Consumer Products Q4 FY26 Earnings Conference Call — InvestyWise, 2026-05 ↩↩
-
Godrej Industries: Q1 FY27 Unaudited Results Show 19% Revenue Growth, Names New Executive Chairperson — InvestyWise, 2026-08-13 ↩↩↩↩↩
-
Godrej Industries Sells 0.50% Stake In Godrej Consumer For ₹450.12 Crore — Sahi, 2026-09-24 ↩↩↩
-
Godrej Agrovet FY26 revenue crosses ₹10,000 crore, profit up 20% — ScanX, 2026 ↩↩↩↩↩
-
Godrej Agrovet Q1 FY27 slides: strategic reset amid mixed results — Investing.com, 2026-08 ↩↩↩↩
-
Astec Lifesciences Turns EBITDA Positive, Reduces Net Loss in FY26 — Whalesbook, 2026-07-08 ↩↩
-
Godrej Agrovet to acquire 48% stake in Creamline Dairy for Rs 930 cr — Business Standard, 2025-03-11 ↩↩
-
Godrej Industries' Chemicals to invest over Rs. 750 crore for capacity expansion — Indian Chemical News, 2025-07-03 ↩↩↩↩
-
Godrej Industries announces launch of Godrej Capital — PR Newswire, 2022-04-15 ↩↩
-
Godrej Capital Targets ₹38,000 Crore AUM In FY27, Eyes ₹1 Lakh Crore Scale Before IPO — Free Press Journal, 2026-06 ↩
-
Godrej Capital's Growth Accelerates, IPO on the Horizon — Angel One, 2025-01 ↩
-
Godrej Capital eyes 2-fold AUM rise by FY28, rules out capital infusion — Business Standard / PTI, 2025-07-06 ↩↩
-
Godrej Industries enters wealth management, targets ₹1 trillion AUM by 2031 — Business Standard, 2026-06-02 ↩↩↩↩↩
-
Godrej Industries sets up Godrej Investment; ₹3,862 cr — Multibagg, 2026 ↩↩↩↩↩
-
Godrej Industries appoints Pirojsha Godrej as Executive Chairperson — ScanX, 2026-08 ↩
-
Godrej & Boyce and Godrej Properties to continue alliance for land development in Vikhroli — Business Today, 2024-05-01 ↩↩↩↩
-
Godrej Industries Posts ₹1,241 Cr FY26 Profit, Approves ₹1,500 Cr Fundraise — Whalesbook, 2026-05-15 ↩
-
Godrej Industries: Approves ₹7,500 Crore Debenture Issue — InvestyWise, 2026-09-11 ↩↩↩
-
Godrej Industries Q1 FY27 Results: Revenue Rises 22%, PAT Falls 28% — Sahi, 2026-08-13 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube