Dalmia Bharat: Building India, One Cement Bag at a Time
I. Introduction & Episode Roadmap
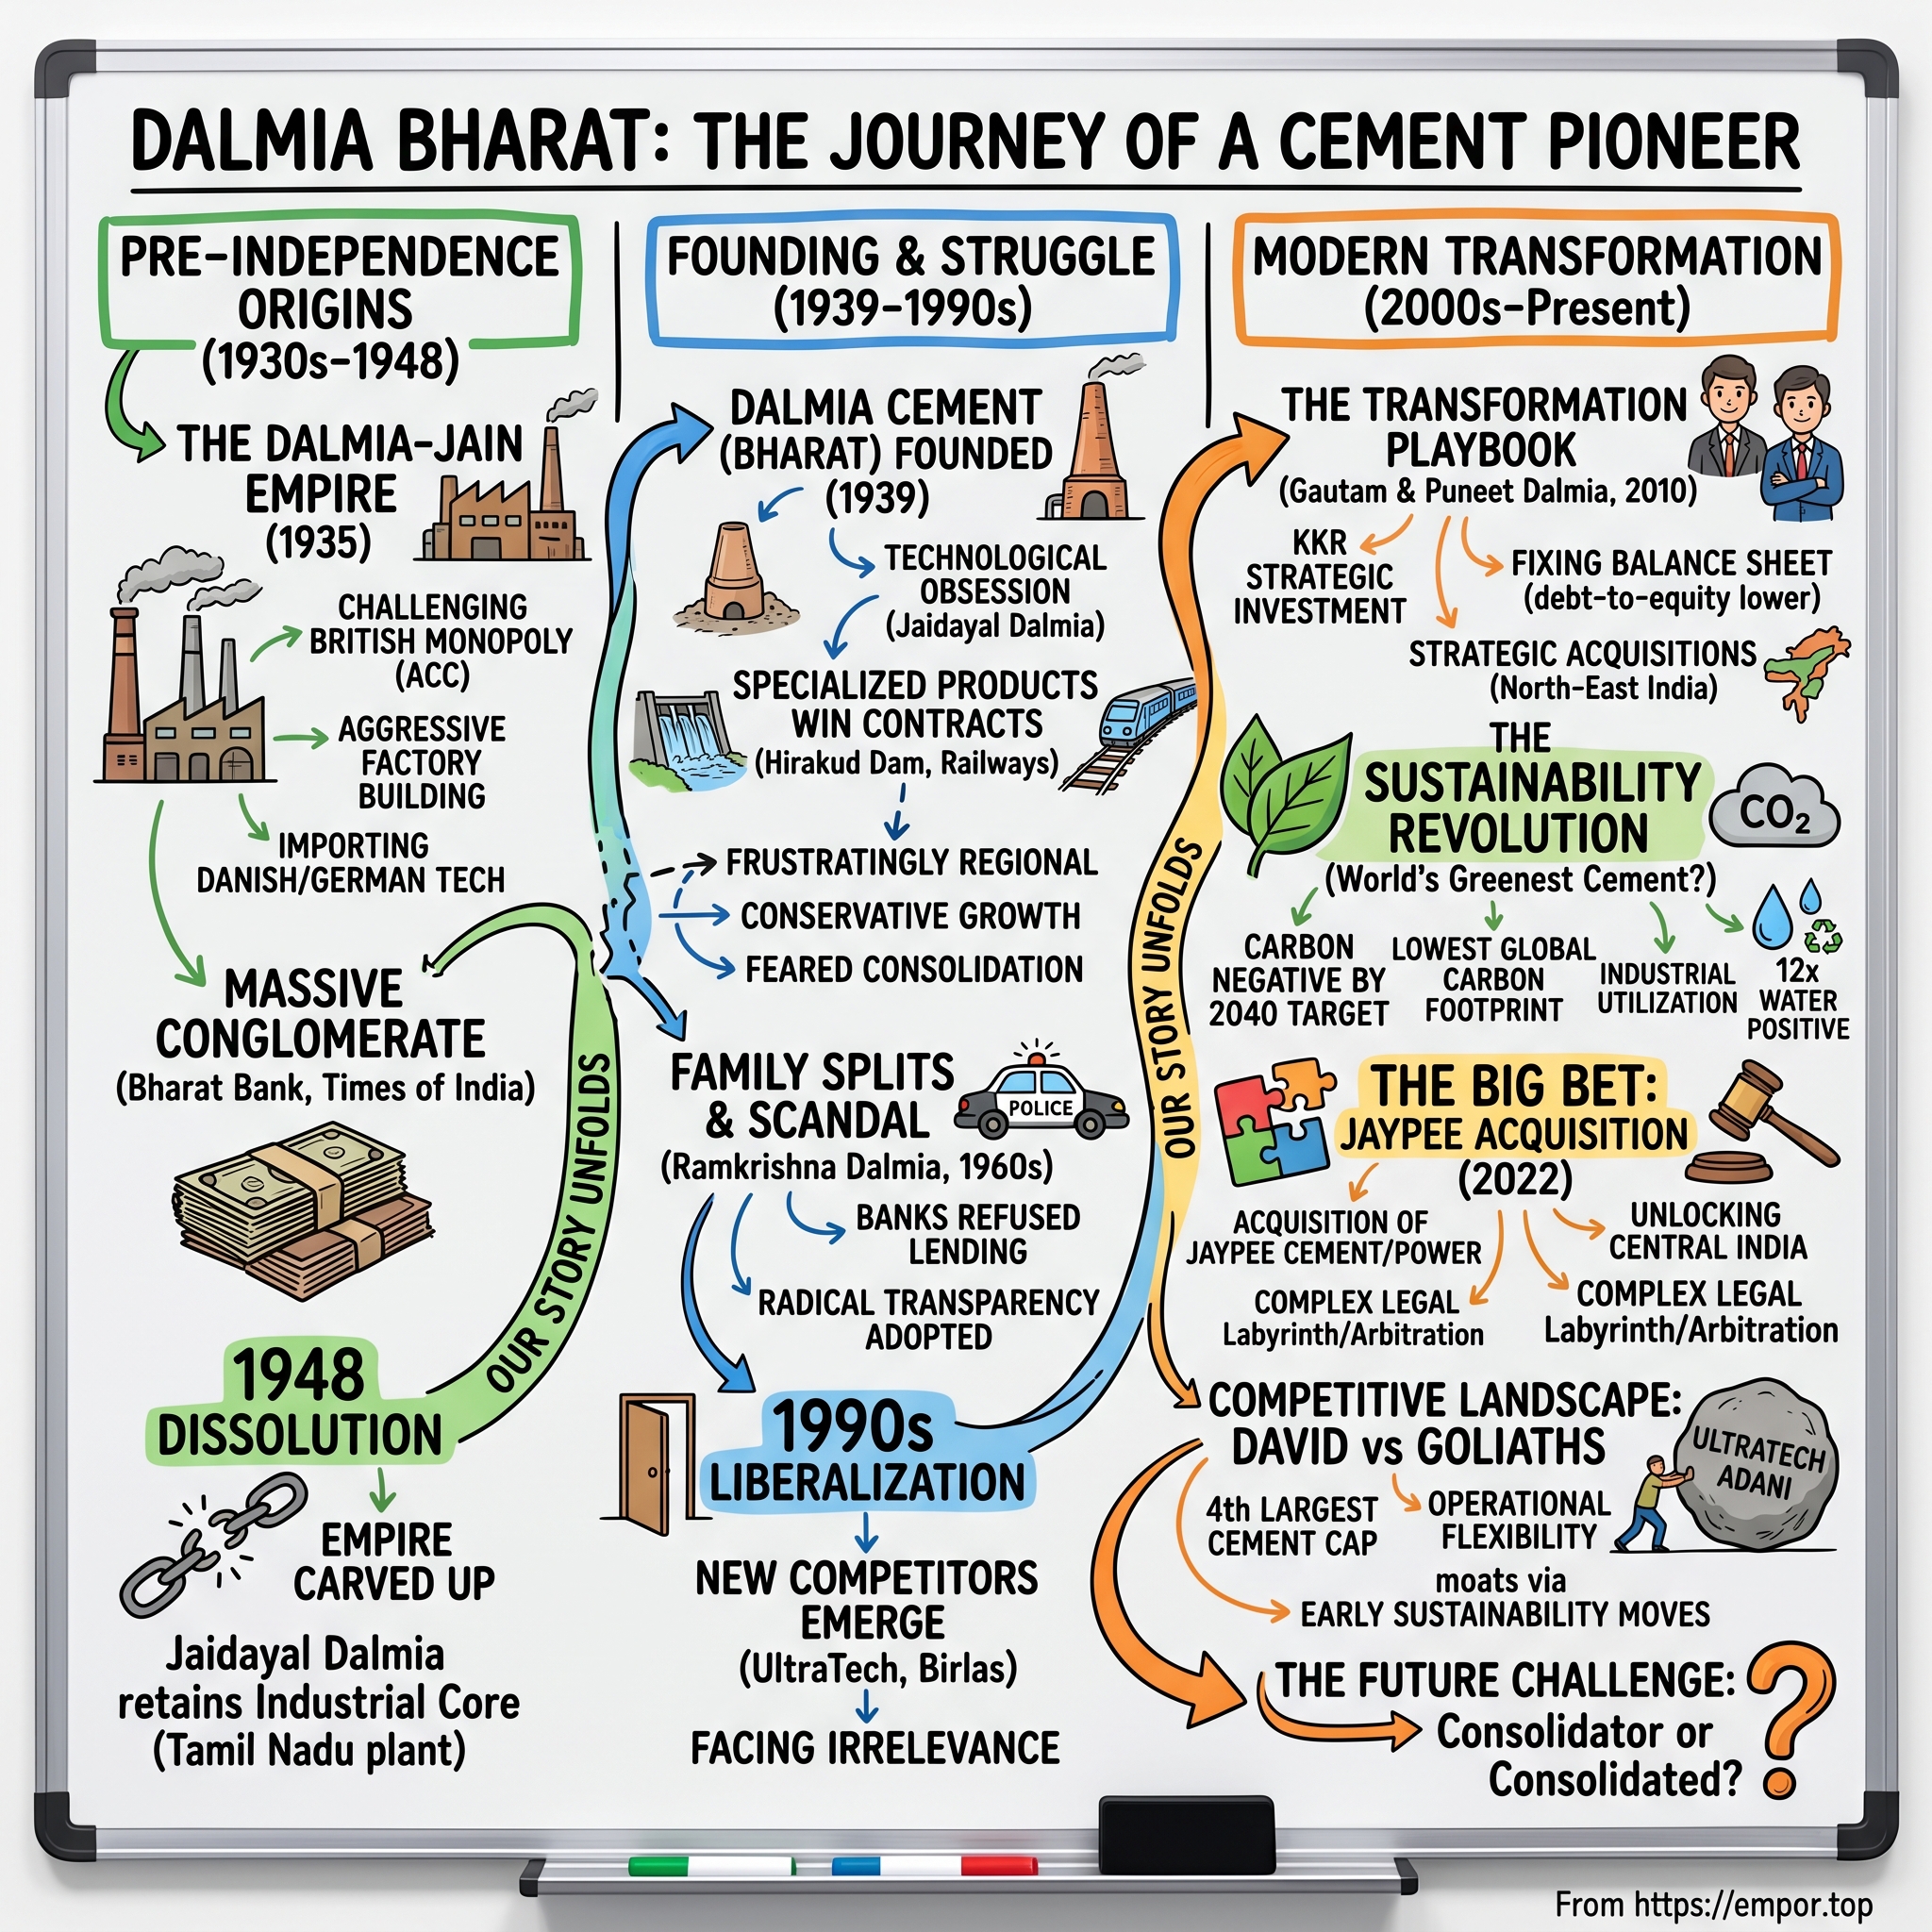
On 21 May 2026, executives from Dalmia Cement (Bharat) Limited signed a business transfer agreement with counterparties from Jaiprakash Associates and Adani Infra (India) Limited for a cement undertaking spread across Rewa in Madhya Pradesh and Churk, Chunar, and Sadwa in Uttar Pradesh. The transaction set an enterprise value of ₹2,850 crore for 5.2 million tonnes per annum (MnTPA) of cement capacity, 3.3 MnTPA of clinker, a 99 MW captive thermal power plant, and dedicated railway sidings.1
It was a favorable price. It was also a strategic retreat.
Three and a half years earlier, in December 2022, the same buyer had signed a binding framework agreement with the same seller for 9.4 MnTPA of cement capacity at an enterprise value of ₹5,666 crore.2 The transaction that finally closed in 2026 delivered little more than half the planned capacity for roughly half the original valuation. That outcome followed a four-year process involving arbitration, lender committees, insolvency proceedings, and the eventual entry of a rival bidder that acquired the parent company itself. For four years, Dalmia's shareholders watched a key growth vector sit frozen on the page.
That tension — operational efficiency colliding with the realities of a capital-intensive commodity industry where scale drives advantage — defines the narrative of Dalmia Bharat.
The company traces its roots to a 250-tonne-per-day kiln commissioned in 1939 in Tamil Nadu, at a location later named Dalmiapuram.3 It navigated India's partition, a family asset split that reassigned the Times of India, a government commission of inquiry, the imprisonment of its founder's brother, four decades of licensing-era restrictions, and subsequent family restructurings. Entering the 2010s as a regional producer with roughly 9 MnTPA of capacity anchored in Southern India and ranked around twentieth nationally, Dalmia exited the June 2026 quarter with 54.7 MnTPA of installed capacity across 19 plants, making it India's fourth-largest cement producer.4
The underlying industry dynamics are clear. Cement is not a unified national market; it functions as a network of regional markets bound by freight economics. Selling for roughly ₹5,000 per tonne at the factory gate, cement incurs significant transport costs beyond a few hundred kilometers. Competition turns on three factors: proximity of limestone reserves and grinding facilities to demand centers, energy and raw-material costs per tonne, and regional supply-demand balance that dictates pricing power. Dalmia has established a distinct position on cost structure, maintaining one of the lowest carbon intensities in the global cement industry by substituting industrial waste for clinker, alongside a defensible presence in East and North-East India. However, the scale gap remains unaddressed: at 54.7 MnTPA, Dalmia operates at roughly one-quarter of UltraTech's domestic capacity and nearly half that of the Adani Group's cement platform.56
The primary analytical question is not whether Dalmia is an efficient operator. Operational metrics indicate that it is. Rather, the question is whether superior unit economics within a smaller operational footprint can compound into sustainable shareholder returns, or whether those advantages are diluted when larger competitors add capacity and adjust regional pricing. Dalmia's return on capital employed, adjusted for goodwill from past restructurings, declined from 11.3% in FY21 to 6.5% in FY25 even as installed capacity expanded.7 This performance trend forms the core focus of the analysis.
The roadmap for this study follows eight key themes. First, the family lineage and the 1948 division of assets, establishing how historical restructurings shaped today's corporate structure. Second, the licensing era, characterized by technical adaptation alongside broader industrial constraints. Third, the 2010–2020 transformation, during which Puneet and Gautam Dalmia expanded the business through acquisitions with private equity backing from KKR. Fourth, the capital allocation track record evaluated against capital deployment outcomes. Fifth, the sustainability architecture, examining whether low-carbon operations create a durable advantage or simply represent an operating expense. Sixth, the complete Jaypee transaction history. Seventh, regional competitive dynamics. Eighth, financial performance and corporate governance considerations. The discussion concludes with an evaluation of the company's operational model, bull and bear investment cases, and key monitoring metrics.
The narrative begins where many Indian industrial histories originate: with an entrepreneur from Rajasthan, an essential commodity, and an established market structure to navigate.
 Subscribe on LinkedIn
II. The Dalmia-Jain Empire: Pre-Independence Origins & Split (1930s–1948)
In the early 1930s, on the flat alluvial plain of Bihar's Shahabad district, a company town rose around a sugar mill. It was named Dalmianagar. The facility — South Bihar Sugar Mills, commissioned in 1932–33 — became the largest in India. Around it grew a paper factory, a chemical works, a cement plant, worker housing, and dedicated railway sidings. It was an early demonstration of how a trading family from the Marwari heartland could build heavy industrial capacity to compete at scale.
The family was Agarwal, from a village in present-day Haryana, anchored by two brothers: Ramkrishna Dalmia and his younger brother Jaidayal.8 Having accumulated capital through commodity trading in Calcutta — including bullion and jute — the family expanded its business reach. In 1932, Ramkrishna's daughter married Shanti Prasad Jain, forming the Dalmia-Jain Group. By 1940, the combine operated sugar mills, cement plants, chemical factories, engineering works, and a paper mill.8
The group's entry into cement in 1936 challenged the established industry structure. At the time, the domestic market was dominated by Associated Cement Companies, formed in 1936 by merging ten existing producers into a combine that controlled pricing and distribution nationwide. Ramkrishna Dalmia entered the market directly, building factories across the country rather than accepting cartel terms.8 That competitive dynamic established a recurring industry theme: smaller producers continuously faced the challenge of competing against larger combines possessing superior plant networks, freight flexibility, and price-war endurance.
The industrial group Ramkrishna assembled in the 1940s grew rapidly in scope while remaining thinly capitalized. It spanned banking, insurance, aviation, coal, jute, railways, and publishing.9 In 1946, as British owners sold assets ahead of Indian independence, Dalmia acquired Bennett, Coleman & Company — publisher of the Times of India — for ₹2 crore.10 He held the business for roughly two years before transferring Bennett Coleman to his son-in-law Shanti Prasad Jain in 1948.10 The transfer highlighted the group's informal capital structure, where assets were frequently shifted across affiliated entities to meet financial obligations.
Internal friction led to a division of the business empire in 1948. The Dalmias and the Sahu Jains divided the empire, and the Dalmia brothers then divided their share between themselves.8 Ramkrishna assumed control of the media and financial assets, while Jaidayal took over the industrial assets: cement and sugar — specifically Dalmia Cement (Bharat) Limited, incorporated in 1939, and Orissa Cement Limited, which followed in 1949.8
At the time, price controls, licensing restrictions, and limited construction activity made cement appear the less attractive portfolio. Glamour and cash flow resided in publishing, banking, and insurance. Over subsequent decades, however, cement proved the more durable asset class, protected by physical moats: localized limestone reserves, integrated kilns, and freight economics that limited geographic penetration by distant competitors.
For investors, the 1948 division created long-term structural implications. Two distinct cement entities — DCBL in the south and OCL in the east — operated independently for seven decades. This division resulted in cross-holdings, minority stakes, related-party transactions, and a persistent holding-company discount. The 2018–19 corporate restructuring that consolidated these operations into a single listed entity effectively unraveled a governance structure established seventy years earlier.
Jaidayal inherited a cement platform, an initial allocation of production licenses, and an economy preparing for major infrastructure investment.
III. Jaidayal's Legacy & The License Raj Decades (1940s–2000s)
The first kiln at Dalmiapuram was small: a 250-tonne-per-day, semi-dry process unit commissioned in 1939.3 By comparison, the Chunar grinding unit that Dalmia started up in June 2026 has a capacity of 2.5 million tonnes a year, or roughly 6,800 tonnes per day.11 Jaidayal's initial plant represented less than 4% of the daily capacity of a single modern grinding facility.
Instead of scale, Jaidayal focused on capital discipline. Company history recounts his rigorous negotiations with European technology suppliers—primarily Danish engineering firms that dominated kiln manufacturing—to reduce the cost of imported equipment. By 1949, the Dalmiapuram plant had expanded to 500 tonnes per day using imported Danish machinery.3 This preference for acquiring top-tier technology at disciplined price points represents an early version of management's current cost-leadership strategy. While executive lore often embellishes such negotiations, verified records confirm both the Danish equipment sourcing and the resulting capacity expansion.
A more consequential legacy lay in technical specialization, anchored in Odisha. In 1950, the group established a plant at Rajgangpur under OCL Ltd to manufacture specialized cement for the construction of the Hirakud Dam.3 Large gravity dams generate intense heat as concrete cures, causing ordinary Portland cement to crack; producing low-heat and sulfate-resistant formulations in 1950 represented an advanced technical capability in India. Dalmia expanded its specialized product portfolio by developing broad-gauge concrete railway sleepers in 1973 and oil-well cement in 1984—a product engineered to set predictably under extreme heat and pressure thousands of meters underground.3
This technical focus established a recurring pattern: Dalmia frequently pioneered specialized products ahead of peers. However, converting early technical capability into durable pricing power proved difficult. For nearly four decades, pricing gains remained negligible due to a combination of regulatory policy and corporate governance challenges.
The external constraint was the Licence Raj. The cement sector operated under strict price controls, industrial licensing, and freight equalization—a government policy that subsidized transport costs so cement prices remained uniform across India. By neutralizing geographic cost advantages, freight equalization diminished the strategic value of locating plants near consumption centers. A producer near limestone deposits in Tamil Nadu realized the same price selling in nearby Chennai as a competitor shipping from Rajasthan. Consequently, producers had little incentive to optimize plant networks, and industry capacity expanded through administrative licensing rather than market demand.
Internal governance issues created further headwinds. In 1956, the Government of India appointed a Commission of Inquiry to investigate the Dalmia-Jain companies, chaired initially by Justice S.R. Tendolkar and later by Justice Vivian Bose.12 Delayed by prolonged litigation from the group, the Commission issued its final report in 1963.13 Justice Bose described the group's corporate structure as "so interlocked and complex because of black money and secret, undisclosed assets and undetermined income tax liabilities" that even dissolving the structure was not straightforward.12
A parallel criminal case culminated in 1962, when the Supreme Court ruled in R.K. Dalmia v. Delhi Administration regarding a conspiracy to divert funds from Bharat Insurance Company through an intermediate trading entity and conceal the transfers by falsifying corporate accounts.14 Ramkrishna Dalmia admitted to an investigating chartered accountant that he had misappropriated approximately ₹2.2 crore in securities from Bharat Insurance, losing the funds in speculative trading.14 He was subsequently convicted and imprisoned.
Although Jaidayal's branch assumed control of the cement business in 1948 and operated legally and operationally independent of Ramkrishna's entities, corporate reputation cast a long shadow. The Dalmia name carried a persistent governance discount throughout the late twentieth century, irrespective of plant performance. As Section IX explores, investors in 2026 must evaluate contemporary governance questions facing current management, distinct from historical founder actions.
For the remainder of the twentieth century, Dalmia's cement operations expanded slowly. Ownership fragmented further as Jaidayal's descendants divided family interests across separate corporate lineages—including Dalmia Brothers, Dalmia Bharat, and Renaissance—leaving a modest regional producer focused primarily on Southern India with single-digit million tonnes of capacity.8 Jaidayal's sons, Jai Hari and Yadu Hari Dalmia, managed the cement and sugar operations conservatively for decades.8 The company did not commission its first 27 MW captive power plant at Dalmiapuram until 2004.3
This was the platform inherited by the next generation: quality limestone reserves, proven technical capability, and a respected southern brand, but limited national scale. The leadership transition that would redefine the company's growth trajectory was already underway.
IV. The Modern Transformation Playbook: From #20 to #4 (2010–2020)
Puneet Dalmia began his career outside the family industrial business. In 1999, after completing a B.Tech at IIT Delhi and an MBA at IIM Bangalore, he co-founded JobsAhead.com, an online recruitment portal that captured roughly half the domestic market before Monster acquired it for about ₹40 crore.8 Although modest compared to the corporate balance sheet he would later manage, the experience gave him independent entrepreneurial credibility before entering the family business—providing standing to advocate for strategic change.
His cousin Gautam Dalmia brought operational continuity, holding undergraduate and master's degrees in electrical engineering from Columbia University alongside three decades inside manufacturing operations, where he later assumed responsibility for the group's environmental agenda.7 The resulting division of leadership established a clear structure: Puneet led strategy, capital allocation, and M&A as Managing Director and CEO, while Gautam served as Managing Director overseeing plant engineering and operational reliability. Their fathers' generation retained board representation through Chairman Yadu Hari Dalmia, who brought over forty-seven years of cement industry experience and a past presidency of the Cement Manufacturers Association.7
Upon taking charge, Puneet inherited a platform with roughly 1.2 MnTPA of capacity, expanding it organically between 2004 and 2010 through brownfield and greenfield projects.8 Two greenfield assets commissioned during that era—Ariyalur in Tamil Nadu in 2009 and Kadapa in Andhra Pradesh in 2010—remained core operational facilities, with Kadapa serving as the site of major subsequent expansion.3
Around 2010, management altered its strategic frame. Internal assessment indicated that Indian cement was entering a consolidation phase, where scale and proximity of grinding capacity to demand centers would determine survival. Recognizing that a sub-10 MnTPA regional producer faced eventual marginalization, management set a target to scale capacity from approximately 9 MnTPA to 30 MnTPA within a decade.
Three strategic moves drove the expansion.
The north-east foothold. In January 2012, Dalmia signed a shareholders' agreement to invest ₹250 crore for a 50% stake in Calcom Cement India Ltd, an Assam-based producer founded by the Bawri family, who initially retained operational management.15 North-East India represented a structurally attractive market where challenging terrain and high transport costs from outside regions enabled strong realisations for local grinding operations. Dalmia followed this investment by acquiring Adhunik Cements, consolidating a dedicated regional cluster.3
The consolidation of OCL. In 2015, Dalmia raised its equity holding in OCL India to 74.6%, bringing the eastern business fully under control.3 In November 2016, the boards of Dalmia Bharat, OCL India, Dalmia Cement (Bharat), and Odisha Cement approved a scheme of arrangement and amalgamation designed to unify the corporate structure into a single listed entity—creating India's fourth-largest cement producer with 25 MnT of capacity.16 Shareholders approved the restructuring in January 2018, and in April 2019 Odisha Cement was renamed Dalmia Bharat Limited, eliminating the cross-holding structure dating back to the 1948 family division.16
Opportunistic bolt-on acquisitions. Alongside major transactions, Dalmia executed a series of targeted asset purchases. In FY15, the company acquired Bokaro Jaypee Cement, a 2.1 MnTPA grinding unit in Jharkhand, buying a 74% stake from Jaiprakash Associates for around ₹690 crore.417 In FY19, it added Kalyanpur Cement (1.1 MnTPA in Bihar) and Murli Industries (2.9 MnTPA in Maharashtra), acquiring the latter through insolvency proceedings and bringing it into commercial production in FY22.37 The pattern was consistent: acquiring distressed or non-core grinding assets close to demand centers at low entry valuations and turning around their operations.
This acquisition playbook had two broader implications. First, Dalmia's capital cost advantage per tonne was significantly driven by buying troubled assets below replacement cost rather than relying solely on greenfield efficiency. Second, the successful integration of Bokaro Jaypee in 2014 established an operating relationship with Jaiprakash Associates—giving management confidence when negotiating a far larger agreement with the same counterparty in 2022.
The private equity catalyst. In 2010, KKR agreed to invest ₹750 crore (over $150 million at the time) in Dalmia Cement (Bharat), marking one of the larger private equity investments in Indian manufacturing.17 Beyond capital, KKR brought institutional governance, formal M&A discipline, and strict return benchmarks. Over a seven-year holding period, installed capacity expanded from 11 MnT to 25 MnT, and KKR realised approximately ₹2,752 crore in total—a 3.6-times return—completing its exit through a block deal in April 2017.18
The timing of KKR's departure is notable. While secondary accounts often cite 2018, public filings confirm the full exit occurred in April 2017.18 This distinction confirms that KKR exited before the OCL merger was finalized, before the sale of non-core refractories, and well before the 2022 Jaypee transaction.
By the end of the decade, the operational scale had transformed. Capacity grew at a compound annual rate of roughly 14% and revenue at about 17%, expanding Dalmia from a single-region producer into a multi-regional player operating fifteen plants across ten states serving twenty-three regional markets. The expansion unfolded across clear capacity milestones: 11.8 MnTPA in FY13, 24.0 MnTPA in FY15, 26.5 MnTPA in FY19, 30.8 MnTPA in FY21, 35.9 MnTPA in FY22, 38.6 MnTPA in FY23, 44.6 MnTPA in FY24, and 49.5 MnTPA in FY25.7
Management framed this achievement around capital discipline rather than raw scale, noting that the blended cost of adding capacity was under $75 per tonne—among the lowest in the global cement industry.8 Maintaining disciplined capital deployment enabled rapid volume growth, though sustaining return on capital faced increasing pressure as larger peers expanded nationwide.
V. Capital Allocation & Strategic Exits: Dissecting the Track Record
There is a particular kind of corporate discipline that reveals itself in what a company chooses to sell. In November 2022, Dalmia Bharat Refractories agreed to divest its Indian refractory business to RHI Magnesita, the Vienna-headquartered global leader in the category. The transaction was structured as a share swap: DBRL first transferred its domestic refractory operations into a subsidiary, Dalmia OCL. On 5 January 2023, RHI Magnesita acquired all outstanding shares of Dalmia OCL in exchange for 2.7 crore new shares of RHI Magnesita India issued at ₹632.5029 per share—amounting to total consideration of roughly ₹1,708 crore, or about €208 million.19 Dalmia OCL was not a peripheral asset; it comprised five manufacturing plants, over 300,000 tonnes of annual refractory capacity, and roughly 1,200 employees.19
Refractories—the heat-resistant linings inside cement kilns and steel furnaces—sit directly adjacent to cement manufacturing. That operational proximity makes the divestment strategically instructive. Promoters frequently retain adjacent businesses on the assumption of commercial synergies. Dalmia sold a mature business at a fair valuation to a specialized global operator and reallocated the proceeds into expanding cement capacity, demonstrating clear portfolio discipline.
Now for the broader evaluation.
Claim under examination: Dalmia's M&A is disciplined and its integration capability is strong.
The historical record contains notable counterevidence, starting with the company's own corporate history.
The Calcom transaction proved challenging to execute. The initial January 2012 agreement envisioned a 50% stake, with the founding Bawri family retaining operational management. The terms required restructuring when Dalmia sought controlling interest, leading to a November 2012 transaction that raised Dalmia's stake by an additional 26% and left the Bawri family with a 20% minority stake.15 Operational relations subsequently deteriorated. The Bawri group initiated legal proceedings alleging breach of the January and November 2012 shareholders' agreements, alongside claims of oppression and mismanagement. The dispute proceeded through the Company Law Board and the High Courts before referral to arbitration.20 Litigation remained active in 2016 while the partners publicly sparred as private equity investor KKR prepared its exit.21 Financing liabilities added further complexity: a dispute with GuarantCo over Calcom's debt repayment obligations was settled only in February 2020, eight years after the initial investment.22
An eight-year timeline from agreement to final legal resolution represents a prolonged integration period for an asset acquired to capture a high-margin regional market. The Calcom transaction demonstrated sound strategic rationale, but slow operational integration and extended litigation.
The return-on-capital problem. The most significant challenge to the thesis of disciplined capital deployment stems from financial performance. Dalmia's investor disclosures track an adjusted return on capital employed (ROCE)—which adjusts for goodwill created during past corporate restructurings—that declined from 11.3% in FY21 to 8.8% in FY22, 7.1% in FY23, 8.3% in FY24, and 6.5% in FY25.7 Measured against management's stated target framework of 14% to 15% ROCE, the business generated less than half its benchmark return in FY25 on its own preferred metric.7
Net earnings reflect the same trend. Profit after tax recorded ₹1,107 crore in FY21, ₹845 crore in FY22, ₹1,079 crore in FY23, ₹853 crore in FY24, and ₹699 crore in FY25. Over this five-year period, installed capacity expanded from 30.8 MnTPA to 49.5 MnTPA, resulting in lower net profitability despite a 60% expansion in production capacity.7 Annual revenue rose from ₹10,110 crore in FY21 to ₹13,980 crore in FY25, although FY25 top-line results fell below the ₹14,691 crore achieved in FY24.7 Management attributed the FY25 earnings decline primarily to lower regional cement realizations.7
Three distinct factors account for this divergence between asset growth and financial returns. First is execution timing: capacity built in advance of regional demand carries immediate depreciation and interest expenses while operating at sub-optimal utilization. Second is pricing dynamics: southern and eastern India, where Dalmia maintains its primary plant concentration, experienced sustained realization weakness. Third is industry-wide supply growth: during the Q4 FY26 earnings call, management projected that domestic producers will add between 160 million and 170 million tonnes of capacity across FY26–28.4 When industry supply additions outpace demand, regional pricing power contracts.
So what does the history do to the claim? The evidence does not invalidate management's M&A capability, but it narrows the scope of the thesis. The record confirms that Dalmia acquires capacity at attractive valuations and divests non-core assets effectively. However, it does not demonstrate that capacity deployment has consistently delivered strong returns on capital. Over the five years leading into FY25, returns remained subdued. A more accurate formulation of the thesis is that Dalmia operates as an efficient, low-cost builder of cement capacity whose financial returns remain dictated by regional pricing cycles rather than cost structure alone. Under this framework, equity returns depend heavily on regional market dynamics alongside operational execution.
In response, management established formal rules governing capital allocation. Dalmia described its policy as an industry-first initiative in India: directing up to 10% of operating cash flow to shareholder returns through dividends and buybacks, allocating up to 10% to an innovation and green energy fund, and committing the remainder to maintenance and growth capital expenditure. The policy caps net debt to EBITDA at 2.0x—permitting temporary exceptions only for major inorganic opportunities—while establishing a target ROCE of 14% to 15%.7
Formal frameworks set expectations; sustained performance determines their value. Balance-sheet discipline has remained intact, with net debt to EBITDA standing at 0.46x as of 31 March 2026.23 By contrast, ROCE targets remained unfulfilled through FY25. The key observable indicator for investors is whether adjusted ROCE recovers toward the mid-teens as expanded facilities in Belgaum, Pune, Kadapa, and Central India reach higher utilization, or whether returns remain bound within the 6% to 9% range observed since FY22. That return trajectory represents the primary determinant of long-term value creation.
Which brings us to the one part of the cost structure where Dalmia genuinely does something other producers do not.
VI. The Sustainability Engine: World's Greenest Cement or Cost Advantage?
To manufacture cement, producers heat limestone — calcium carbonate — to around 1,450°C in a rotary kiln. The extreme heat drives off carbon dioxide, leaving behind calcium oxide, which fuses into hard nodules called clinker. Clinker serves as the active ingredient; when ground with gypsum, it yields Portland cement. Roughly 60% of the process's carbon dioxide emissions stem not from fuel combustion but from the chemical reaction itself, as limestone releases carbon dioxide regardless of how clean the energy source is. Consequently, clinker production inherently generates carbon dioxide.
This chemical reality leaves industry operators with one primary immediate lever to reduce emissions: lowering the clinker factor, or the proportion of clinker used per tonne of finished cement.
That reduction is achieved through blending. Fly ash, the fine powder captured from coal-fired power station chimneys, and granulated blast-furnace slag, a glassy byproduct of steelmaking, both possess latent cementitious properties. When finely ground and combined with clinker, they participate in the hydration and hardening reaction. Portland Pozzolana Cement incorporates fly ash, Portland Slag Cement utilizes slag, and composite cements combine both additives. By substituting these industrial byproducts, producers can lower the clinker factor from approximately 0.95 in ordinary Portland cement down toward 0.55.
Dalmia has pursued clinker substitution more aggressively than most domestic peers. In its FY25 product mix, ordinary Portland cement represented only about 15% of sales volumes. Slag, pozzolana, and composite cements accounted for the remaining 85%, with Portland Slag Cement making up the largest individual share at roughly 42%.7 The company ranks among India's largest producers of slag cement and has established long-term supply agreements for both slag and fly ash.7
This focus on blended cement has driven a notable decline in carbon intensity. Net carbon dioxide emissions per tonne of cementitious material dropped steadily from 670 kilograms in FY14 to 546 kilograms in FY19, 492 kilograms in FY21, 463 kilograms in FY23, 459 kilograms in FY24, and 456 kilograms in FY25 — even as total installed capacity expanded from 11.8 MnTPA to 49.5 MnTPA over the same period.7 With global cement industry emissions averaging over 600 kilograms per tonne, Dalmia achieved the top global ranking from CDP for the lowest carbon footprint among cement producers.24 The company also stands as the first cement producer globally to join the RE100, EP100, and EV100 climate initiatives collectively, has pledged to become carbon negative by 2040, and reported achieving better than 20 times water positivity across its cement operations in FY25.7
Supporting this emissions profile is substantial capital investment in renewable energy rather than non-binding targets. By the June 2026 quarter, operational renewable energy capacity reached 449 megawatts — comprising 143 megawatts of captive solar, 88 megawatts of waste heat recovery, and 217 megawatts of group captive power — up from just 17 megawatts in FY20, bringing renewable sources to approximately 48% of the total power mix.11 Waste heat recovery plays a vital role by converting thermal exhaust from the kiln into electricity via boilers, capturing lost heat to supply low-cost power, though installation requires significant upfront capital.
Evaluating the thesis that sustainability leadership functions as a pricing-supportive competitive moat reveals clear limits to that claim.
Dalmia's operational data indicates that lower carbon intensity has not translated into superior pricing power. Consider the trajectory of net emissions as the company acquired external assets. Carbon intensity, after falling to 456 kilograms per tonne in FY25, rose to 463 kilograms in the first half of FY26 and reached 475 kilograms per tonne in the June 2026 quarter.711 The increase stemmed from the Central India plants acquired from Jaiprakash Associates, which operated with a higher clinker factor and a different product mix. This trend demonstrates that low carbon intensity is an attribute of a specific plant configuration rather than an inheritable corporate moat, diluting as scale expands through acquisitions.
Furthermore, realization data shows no premium linked to carbon metrics. Dalmia's average realization per tonne remains bound by regional market supply and demand. Net sales realization stood at ₹5,098 per tonne in the June 2026 quarter, a 6% sequential gain driven by broader regional price movements rather than environmental disclosures.11 In Indian retail cement markets, purchasing decisions by contractors, masons, and individual home builders depend on brand recognition, logistics availability, and price per bag, with little evidence indicating willingness to pay a premium for reduced clinker content.
Where Dalmia does capture higher realizations, the gains stem from conventional product branding rather than environmental positioning. Premium offerings — including the Dalmia DSP series and the Weather365 line — expanded to 25% of trade volumes in the June 2026 quarter, up from 22% a year earlier, while trade sales remained steady at 66% of overall volumes.11 These premium products are marketed and priced based on structural performance and technical durability rather than carbon footprint metrics.
Consequently, sustainability operates as a cost-reduction engine rather than a brand-driven pricing moat. Replacing clinker with slag or fly ash eliminates the costs of quarrying limestone, firing kilns, and consuming fossil fuels. These savings directly benefit operating margins. Dalmia reduced its total cost per tonne by ₹100 in FY26, recorded its lowest quarterly total cost per tonne in five years during the March 2026 quarter, and targeted an additional ₹150 to ₹200 per tonne in cost efficiencies by FY27 through logistics optimization, expanded renewable energy, clinker factor improvements, captive coal sourcing, and heat-rate gains.47 Maintaining a blended borrowing cost below 7% and an AA+ credit rating with a stable outlook from rating agencies further reinforces this cost structure.7
However, long-term technical promises warrant scrutiny regarding commercial viability. On 19 September 2019, Dalmia signed a memorandum of understanding with Carbon Clean Solutions to construct a 500,000-tonne-per-year carbon capture facility at a plant in Tamil Nadu — an unprecedented capacity commitment for a cement producer at the time.25 The announcement provided no capital budget or definitive timeline beyond a general two-to-three-year implementation goal.25 Through the June 2026 quarter, company investor disclosures report no operational commercial carbon capture facility at any plant.711 Seven years after the initial agreement, decarbonization progress continues to depend entirely on conventional levers — clinker substitution and waste heat recovery — while headline carbon-capture initiatives have yet to materialize in operational data. This gap underscores that achieving the company's 2040 carbon-negative goal relies on technologies that remain unproven at commercial scale.
Dalmia's cost efficiency remains real, but it does not substitute for structural scale or pricing power. To expand its market footprint and earnings base, the company has had to acquire additional physical capacity — leading directly to the complex, four-year transaction for the Jaypee assets.
VII. The Jaypee Acquisition Saga: From Litigation Gridlock to Revised Deal (2022–2026)
In December 2022, Dalmia's stock fell 5% the day after it announced what was intended as a transformative expansion.26
The announcement detailed a binding framework agreement to acquire the cement, clinker, and power assets of Jaiprakash Associates Limited and an affiliate: 9.4 million tonnes of cement capacity and 6.7 million tonnes of clinker at an enterprise value of ₹5,666 crore.2 The Competition Commission of India cleared the transaction in February 2023.27 On paper, the deal represented the single most important strategic expansion in Dalmia's modern history.
The rationale was geographic footprint. Dalmia's operational challenge was not plant efficiency, but regional concentration. As of the June 2026 quarter, installed capacity remained heavily weighted toward Eastern India, with roughly 21.6 million tonnes, and Southern India, with 17.0 million tonnes.11 Between those two regional hubs lay Central India—specifically Madhya Pradesh and Uttar Pradesh—a high-growth infrastructure market where Dalmia lacked grinding facilities within economic freight distance. Jaypee's assets occupied that target area, offering a path to convert Dalmia from a two-region specialist into a broader national producer.
However, the acquisition involved a financially distressed seller, and the transaction structure reflected those risks. The deal was divided into three tranches, a design indicating that the buyer recognized certain assets carried unresolved encumbrances.28 One tranche, covering the JP Super (later renamed Dalla Super) unit in Uttar Pradesh, carried an enterprise value of approximately ₹1,500 crore plus costs—and ultimately stalled the entire agreement.28
The gridlock. Three compounding factors froze the transaction.
First, legal disputes. Jaiprakash Associates was locked in arbitration with UltraTech Cement over the Dalla Super asset, stemming from a ₹1,000 crore claim linked to preference shares issued under 2017 contracts.28 UltraTech actively pursued the asset, indicating its intention to acquire Dalla Super once arbitration concluded.29 Consequently, Dalmia had contracted to buy a facility subject to a live legal claim from its primary competitor.
Second, creditor alignment. Lenders to Jaiprakash Associates, alongside the National Asset Reconstruction Company, struggled to finalize an agreement on how sale proceeds would be allocated. By March 2024—fifteen months after the initial signing—the transaction remained stalled by creditor negotiations and the ongoing UltraTech arbitration, leaving no clear path to closing.28
Third, corporate insolvency. Mounting debt defaults forced Jaiprakash Associates into the corporate insolvency resolution process under the Insolvency and Bankruptcy Code. Under insolvency proceedings, bilateral asset sales agreed prior to admission cannot proceed independently; the target assets become part of a debt resolution framework controlled by a committee of creditors and supervised by the National Company Law Tribunal. As a result, Dalmia's original 2022 framework agreement became legally unworkable.
The resolution by a third party. On 17 March 2026, the Allahabad bench of the National Company Law Tribunal approved Adani Enterprises' resolution plan for Jaiprakash Associates—a ₹14,535 crore offer encompassing cement facilities, power assets, real estate, and the Buddh International Circuit, with implementation across Adani Group entities scheduled within ninety days.30 Jaiprakash Associates was subsequently delisted from the BSE and NSE on 18 June 2026.31 In a parallel development, UltraTech resolved its ₹1,000 crore claim against Jaiprakash Associates through a redemption of preference shares routed via an escrow account to creditors, clearing the legal title on the underlying assets.32
The sequence that ultimately released the contested assets required Dalmia's largest competitor to settle its claim and its second-largest competitor to acquire the parent company.
The renegotiated outcome. Dalmia returned to negotiations not as a bilateral buyer from a distressed seller, but as an acquirer navigating a process overseen by Adani. On 21 May 2026, Dalmia Cement executed a revised business transfer agreement with Jaiprakash Associates and Adani Infra (India) Limited for the Rewa, Churk, Chunar, and Sadwa assets. The revised transaction secured 5.2 million tonnes per annum of cement capacity, 3.3 million tonnes of clinker, a 99-megawatt thermal power plant, and dedicated railway sidings at an enterprise value of ₹2,850 crore, expanding Dalmia's total operational capacity to 54.7 million tonnes per annum.1
Evaluating the outcome. On valuation metrics, the revised terms appeared advantageous: the acquisition closed at approximately ₹548 per tonne of cement capacity, substantially below greenfield replacement costs. Operational integration proceeded rapidly. Dalmia dispatched its first commercial shipment from Chunar within twenty-two days of deal completion; the 2.5 million-tonne Chunar grinding facility commenced commercial production on 20 June 2026, while trial runs at the 3.3 million-tonne Rewa clinker unit began in July 2026.11 During the subsequent earnings call, Managing Director Puneet Dalmia highlighted the strategic addition of 5.2 million tonnes of capacity in Central India, while executive management noted that Chunar achieved commercial operations within fifty days of closing.33
However, a comprehensive evaluation must account for the costs of delay. Four years of strategic execution yielded roughly 55% of the original target capacity. Contrast management's initial 2022 projections with the scrutiny faced on the first-quarter FY27 earnings call, where equity analysts focused questions on the pricing rationale, integration timelines, and long-term limestone access costs for the acquired units.33 Management offered measured forward guidance, projecting two quarters to reach EBITDA breakeven and seven to eight quarters before the Central India assets match Dalmia's corporate average EBITDA per tonne.33
The financial impact was immediate. The June 2026 quarter recorded ₹182 crore in exceptional acquisition-related expenses, driving reported profit after tax down 51% year-on-year to approximately ₹192 crore, despite a 9% increase in sales volumes.11 Net debt rose from ₹1,428 crore in March 2026 to ₹4,431 crore in June 2026, elevating the net debt-to-EBITDA ratio from 0.46x to 1.47x—remaining below management's 2.0x policy ceiling, but narrowing the balance-sheet buffer maintained earlier in the year.1123
The broader lesson illustrates a persistent feature of Indian corporate restructuring: distressed assets often trade at discounts because third parties hold underlying claims. Buying out of corporate distress offers valuation discounts, but surrenders control over execution timelines.
In the Indian cement sector, control over industry timelines increasingly rests with the market's two largest producers.
VIII. Competitive Dynamics & Strategic Moats: David Among Goliaths
In April 2026, UltraTech Cement commissioned three grinding units adding 8.7 million tonnes per annum (MnTPA) and crossed 200 million tonnes of installed domestic capacity—reaching 200.1 MnTPA in India and 205.5 MnTPA globally—making it the largest cement producer in the world outside China.5 Two years earlier, Ambuja Cements, the Adani Group's cement platform, crossed 100 MnTPA following the completion of the Orient Cement acquisition, expansion at Farakka, and debottlenecking, while setting out a path toward 118 MnTPA and ultimately 140 MnTPA.6 In February 2026, Shree Cement commissioned a 3.0 MnTPA production line at Jaitaran in Rajasthan, elevating its domestic capacity to 65.8 MnTPA.34
Dalmia, at 54.7 MnTPA, ranks fourth nationally. However, the operational reality is defined less by rank than by the capacity gaps between players. Dalmia operates at roughly 27% of UltraTech's size, about half the scale of the Adani platform, and approximately 83% of Shree Cement. Together, the top two producers command well over 300 MnTPA of capacity in a 600 MnTPA national market. Rather than a fragmented market with a long tail of equal competitors, Indian cement functions as a duopoly with a competitive fringe—and Dalmia represents the largest player within that fringe.
Applying Helmer's 7 Powers, three of the framework's seven sources of strategic advantage appear plausibly present, though none provides a decisive structural moat.
Scale economies exist, but primarily on a regional basis. Heavy freight costs and low unit value limit cement distribution, causing freight to erode margins beyond 300 to 400 kilometers from a grinding unit. Dalmia's cost structure reflects this spatial constraint: cement freight stood at ₹947 per tonne and clinker freight at ₹705 per tonne in the June 2026 quarter, against a net sales realization of ₹5,098 per tonne.11 Logistics represents the largest controllable cost component after power and fuel. Dalmia maintains operational density within its core Eastern and North-Eastern catchments, but lacks comparable scale elsewhere—underscoring the strategic urgency behind its Central India expansion.
Process power represents the company's most defensible operational capability. Operating high-substitution slag and fly-ash formulations requires precise materials engineering and strict quality control, as strength development curves for high-slag cements differ from ordinary Portland cement. Dalmia's lower clinker factor and net emission intensity of 456 kg of CO₂ per tonne in FY25 reflect this technical expertise; conversely, carbon intensity rose to 475 kg per tonne when newly acquired facilities joined the network, illustrating that this capability is plant-specific rather than automatically transferrable. However, process power in a commodity industry yields a cost advantage rather than pricing power—and in an oversupplied market, cost savings are often competed away through volume discounting rather than retained as profit margin.
Cornered resources represents the weakest of the three potential advantages despite initial appearances. Dalmia reports over 3.3 billion tonnes of limestone reserves and an average mine life exceeding twenty years across most facilities, alongside operating the sole clinker unit in Bihar.711 However, modern limestone leases in India are awarded through competitive auctions. Existing reserves provide operational continuity, but securing future deposits requires capital-intensive bidding rather than proprietary access. Reflecting these risks, equity analysts on the first-quarter FY27 earnings call pressed management specifically on future limestone reserve access costs.33
Notably absent from Dalmia's position are brand power capable of commanding structural price premiums, network economies, counter-positioning, and customer switching costs—as retail buyers face virtually no switching friction when purchasing cement.
Porter's five forces yields a similarly constrained competitive outlook. Supplier power is moderate overall but intensifying in fuel, where petroleum coke and coal prices are tied to global benchmarks. On the fourth-quarter FY26 earnings call, management warned that geopolitical friction in West Asia would add ₹125 to ₹150 per tonne to operating costs across the first two quarters of FY27 through elevated fuel, power, and packaging expenses.4 Power and fuel costs subsequently rose 10% sequentially to ₹1,045 per tonne in the June 2026 quarter.11 Buyer power remains low for individual home builders but significant for institutional buyers and infrastructure contractors negotiating bulk orders. The threat of substitutes remains minimal, as hydraulic cement lacks a commercial structural replacement at scale. High capital requirements, environmental clearances, and limestone lease acquisitions create substantial barriers to new entry—though these constraints have not prevented the Adani Group from scaling beyond 100 MnTPA in four years through targeted acquisitions.
That leaves competitive rivalry as the dominant and escalating force. Industry projections indicate 160 million to 170 million tonnes of new capacity will enter the market between FY26 and FY28, adding volume to a market operating below full utilization.4 When market leaders like UltraTech or Adani add grinding capacity in Eastern or Southern India, economic logic dictates maintaining high utilization through volume discounting. Dalmia faces strategic asymmetry in price wars, as its narrower regional footprint limits its ability to cross-subsidize discounting from other profitable markets.
Myth versus reality. Three prevailing market narratives surrounding Dalmia warrant examination against disclosed evidence.
Myth: Dalmia is the undisputed low-cost producer in Indian cement. Reality: Dalmia is an efficient producer, maintaining the lowest clinker factor and carbon intensity among major domestic peers. However, on total cost per tonne, it competes directly with Shree Cement, which has operated as the industry's cost benchmark for three decades and maintains a capacity footprint approximately 20% larger.34 Input optimization on specific cost lines does not automatically translate into an absolute cost floor across operations.
Myth: Green positioning will soon generate premium pricing through carbon taxes or green procurement mandates. Reality: Sustainable operations offer policy-related optionality rather than immediate pricing power. India has not established a carbon pricing framework or green procurement premium for cement that monetizes Dalmia's lower carbon footprint. Until such regulations emerge, environmental benefits remain confined to the energy and raw-material cost savings reflected in operating income. Investors must evaluate carbon efficiency as unpriced long-term optionality rather than a baseline cash-flow driver.
Myth: High promoter ownership guarantees aligned shareholder incentives. Reality: A 55.84% promoter stake aligns founding families with multi-year asset building, providing stability in a cyclical industry. However, concentrated equity control also means minority shareholders lack mechanisms to direct corporate strategy. Furthermore, this ownership structure exists alongside a live prosecution authorization naming all three promoter directors.3539 Alignment with long-term asset growth does not substitute for minority governance protections.
The strategic conclusion for investors is straightforward: Dalmia maintains a genuine cost position and defensible market share in Eastern and North-Eastern India, but lacks the national scale required to set industry pricing. Consequently, corporate earnings will remain heavily influenced by pricing and capacity decisions originated by larger competitors in Mumbai and Ahmedabad. This dynamic was demonstrated in FY25, when management attributed the annual net profit decline primarily to broader regional realization weakness rather than internal operational factors.7
This reality elevates the importance of capital allocation and governance choices under direct management control.
IX. Financial Anatomy, Management Quality & Governance Stress Test
In FY26, which company management characterized as its best operational year, revenue reached ₹14,804 crore—a 6% increase—while record EBITDA rose 28.1% to ₹3,083 crore. Net profit after tax expanded 65.5% to ₹1,157 crore, even as sales volumes grew a modest 2.2% to 30.0 million tonnes. With EBITDA per tonne reaching ₹1,027, the board recommended a final dividend of ₹5 per share.23 Net debt stood at ₹1,428 crore, yielding a net debt-to-EBITDA ratio of 0.46x that remained comfortably within management's 2.0x policy ceiling.423
Evaluated together, these results highlight a clear financial pattern: the earnings recovery was driven primarily by pricing and cost controls rather than volume expansion. While sales volumes grew by 2.2%, EBITDA expanded by 28.1%. Management delivered a ₹100 per tonne reduction in total operating costs across the year, achieving its lowest quarterly total cost per tonne in five years, while the chief financial officer targeted an ongoing annual cost reduction of ₹50 to ₹100 per tonne.4 This dynamic underscores the underlying operational reality: Dalmia remains a disciplined manufacturer whose profitability depends far more on regional cement realizations and raw-material costs than on top-line volume growth alone.
Performance in the June 2026 quarter reflected both operational strengths and external margin pressures. Revenue rose 7% year-on-year to ₹3,890 crore, supported by a 9% increase in sales volumes to 7.6 million tonnes—outpacing estimated industry volume growth of 7% to 8%. However, operating EBITDA fell approximately 9% year-on-year to ₹805 crore as input expenses escalated.11 On a sequential basis, raw material costs per tonne climbed 12%, power and fuel expenses rose 10%, and clinker freight costs increased 11%.11 Consequently, while EBITDA per tonne reached ₹1,055—a 3% sequential gain—operating margins compressed from 24.3% a year earlier to 20.7%.11 Executive guidance indicated an additional ₹70 to ₹80 per tonne of cost inflation expected in the September 2026 quarter.33
These quarterly metrics present a dual narrative for investors. On one hand, Dalmia continues to capture market share, backed by 9% volume growth against single-digit industry expansion and premium product lines reaching 25% of trade sales. On the other hand, earnings growth did not keep pace with volume gains—reflecting the margin compression that has characterized the company's performance over the preceding five years.
Management credibility and strategic execution. Assessing management on operational history rather than forward guidance yields a mixed track record.
On the positive side, executive communication has maintained consistent strategic focus across annual filings and investor presentations: pan-India expansion, cost leadership, balance-sheet leverage caps, and sustainability metrics. Balance-sheet discipline has remained intact, adhering to stated leverage ceilings. Management has also addressed operational shortfalls directly rather than attributing them to general market conditions; for example, lower 3% volume growth in the March 2026 quarter was explicitly linked to an unexpected equipment breakdown at an Eastern India facility.4 Furthermore, the executive suite has been deliberately professionalized with experienced leadership drawn from major competitors: K.C. Birla, Head of Growth and Expansion, previously served as Chief Financial Officer of UltraTech; Yatin Malhotra, CFO of Dalmia Cement (Bharat), previously held the CFO role at ACC; and the Group General Counsel was recruited from Ambuja and ACC.7 Corporate governance controls reflect structured oversight: independent directors chair the audit, nomination, and risk committees, with former Siam City Cement CEO Paul Heinz Hugentobler presiding over the audit and risk committees, EY serving as internal auditor, and Walker Chandiok & Co—a Grant Thornton member firm—acting as statutory auditor.7
Conversely, long-term capacity targets have undergone revision. During the fourth-quarter FY26 earnings call, management outlined a primary milestone of 75 million tonnes per annum by FY28.4 Three months later, investor presentations for the first quarter of FY27 adjusted the targeted capacity to 66.7 MnTPA by the third quarter of FY28, with management clarifying on the call that the 67 MnTPA figure represented a directional reference rather than a firm commitment.1133 The visible project execution pipeline—encompassing expansions at Belgaum, Pune, and Kadapa—does not fully bridge the gap to 75 MnTPA by FY28. This adjustment reflects the practical realities of project commissioning over multi-year horizons. Consequently, investors must evaluate long-term ambitions—such as reaching 110 to 130 MnTPA by 2031—with similar flexibility, recognizing that bridging the remaining gap requires substantial reliance on further inorganic acquisitions.
The governance stress test.
A primary ongoing governance consideration involves legal proceedings initiated by corporate regulators. On 28 January 2026, the Ministry of Corporate Affairs (MCA) issued an order approving criminal prosecution based on recommendations from the Serious Fraud Investigation Office (SFIO), following an investigation report dated 7 August 2025. According to disclosed details, the SFIO's primary allegations center on the unauthorized pledging of Dalmia Bharat group securities, which allegedly generated an unlawful gain of ₹40 crore for Managing Director Puneet Yadu Dalmia and a loss of ₹416 crore for IL&FS Securities Services Limited, alongside allegations regarding the approval of false financial statements. Two additional charges involve disputed share transactions and alleged unauthorized payments routed to promoter entities. The parties named in the approval include Puneet Dalmia, Gautam Dalmia, and Yadu Hari Dalmia, as well as Dalmia Bharat Limited and Dalmia Cement (Bharat) Limited, with prosecution directed under Sections 447 and 448 of the Companies Act and a proposed application before the National Company Law Tribunal seeking disgorgement and director liability. The report further alleges that three entities associated with Puneet Dalmia recorded approximately ₹45 crore in fictitious profits via fabricated contract notes issued by Allied Financial Services.35
The matter originated from actions initiated by Dalmia Bharat itself. In 2019, the company reported to law enforcement agencies that mutual fund units belonging to Dalmia Cement (Bharat) had been fraudulently transferred out of its dematerialized account and pledged by its depository participant, Allied Financial Services, with IL&FS Securities Services. The group pursued legal remedies through the courts, culminating in a March 2021 Supreme Court ruling that ordered the full restoration of the mutual fund units to the Dalmia Bharat group.36
The company's stance remains definitive. In a formal stock exchange filing dated 8 May 2026, Dalmia Bharat asserted that its subsidiary was the victim of third-party misappropriation by Allied Financial Services. The company cited the 2021 Supreme Court order releasing the assets and referenced a Delhi Police chargesheet alleging criminal conspiracy and fraud by Allied in connivance with IL&FS Securities Services. Management affirmed that the full recovery of funds is documented in its audited financial statements, characterizing media reports on the prosecution approval as unverified and published without prior clarification from the company.37
Evaluating these legal developments requires distinguishing regulatory authorization from judicial findings. The allegations remain at the prosecution-authorization stage; no court has established liability against the promoters, the company denies all charges in full, and the underlying context involves a documented third-party fraud in which Dalmia operated as the complaining party. Consequently, an SFIO prosecution recommendation cannot be equated with a judicial finding of wrongdoing.
However, the proceeding represents a material consideration for market participants. The government has authorized criminal prosecution against the chief executive and two promoter directors, referencing transactions that have remained unresolved for seven years and pertain to inter-entity financial transfers rather than core manufacturing operations. Furthermore, judicial resolution of complex financial prosecutions in India typically extends across multi-year horizons. Alongside these regulatory developments are minor compliance items: on 6 March 2024, the company paid penalties totaling ₹10.10 lakh for procedural delays in providing prior intimation for investor conferences, a matter that was subsequently rectified.38 While financially minor, such occurrences reflect on administrative disclosure hygiene.
A skeptical assessment centers on a core structural feature: Dalmia is a promoter-controlled group with a 55.84% equity stake and a history of inter-entity restructurings, where senior leadership faces authorized regulatory prosecution—contributing to an equity valuation discount relative to peers like UltraTech that extends beyond operating scale alone.39 Conversely, the counter-argument emphasizes that concentrated promoter ownership aligns long-term capital allocation with business growth, operational manufacturing performance remains solid, financial audits are conducted by reputable firms, and the initial loss originated from an external broker's fraud.
Both perspectives address real elements of the corporate profile. The practical implication for capital markets is that investors apply a higher governance risk discount to Dalmia Bharat than to fully professionally managed peers. That valuation discount is unlikely to narrow substantially until the legal proceedings reach final judicial resolution—reflecting not a verdict on liability, but the financial cost of prolonged regulatory uncertainty.
X. Strategic Roadmap: Path to 75 MTPA (FY27) and 110–130 MTPA (2031)
On 28 February 2025, Dalmia's board approved approximately ₹3,520 crore of capital expenditure across Karnataka and Maharashtra, encompassing a 3.6 MnTPA clinker unit and a 3.0 MnTPA grinding unit at its Belgaum plant, alongside a 3.0 MnTPA greenfield split grinding facility near Pune. The combined 6.0 MnTPA in new cement capacity raised total planned capacity to 55.5 MnTPA, inclusive of active projects in Assam and Bihar.40 Managing Director Puneet Dalmia characterized the investment as "a significant step in our Phase II expansion strategy, bringing us closer to strengthen our position as a pan-India player."40
The geographic alignment of these projects reveals a clear strategic intent. Belgaum sits in northern Karnataka, while the split grinding facility near Pune establishes a manufacturing footprint in western Maharashtra—marking Dalmia's first meaningful operating presence in western India. Combined with the Central India assets acquired from Jaiprakash Associates, the Belgaum-Pune corridor expands the company's regional coverage westward and northward beyond its historical southern and eastern strongholds.
The execution pipeline outlined during the June 2026 quarter details specific project timelines. The Belgaum project—comprising 3.0 MnTPA of cement and 3.6 MnTPA of clinker capacity—reached 78% completion, with commissioning targeted for the fourth quarter of FY27. Additions at Kadapa in Andhra Pradesh, adding 6.0 MnTPA of cement and 3.6 MnTPA of clinker, are scheduled for completion in the third quarter of FY28, while the Pune grinding unit is slated for the second quarter of FY28. Collectively, these additions are projected to expand stated installed capacity to 66.7 MnTPA by the third quarter of FY28.11 On the clinker side, commercial production at a 3.6 MnTPA line in Umrangso, Assam, commenced on 20 January 2026, elevating group clinker capacity to 27.1 MnTPA, with ongoing projects scheduled to expand total clinker capacity to roughly 34.3 MnTPA by the second quarter of FY28.7
The Umrangso expansion holds strategic significance beyond its absolute size. In North-East India, clinker availability—rather than grinding capacity—serves as the primary operational constraint, and transporting clinker into the region incurs high logistics expenses, with clinker freight averaging ₹705 per tonne in the June 2026 quarter.11 Establishing localized clinker production within the North-East directly replaces long-haul transport expenses with operating margin.
Financing requirements for this expansion pipeline remain structured within existing balance-sheet parameters. Capital expenditure for FY27, excluding acquisition outlays, was guided at approximately ₹2,200 crore in June 2026 investor disclosures, compared to earlier guidance of ₹3,200 crore to ₹3,400 crore indicated during the fourth-quarter FY26 earnings call.1133 Supported by FY26 operating EBITDA of ₹3,083 crore and an 88% cash-conversion rate, planned expenditure can be funded primarily through internal cash generation alongside modest debt drawdowns, while post-acquisition leverage of 1.47x net debt to EBITDA leaves operational headroom below management's 2.0x policy ceiling.71123
The principal analytical question centers on bridging the gap between current project commitments and long-term targets: advancing from 66.7 MnTPA to 75 MnTPA by FY28, and ultimately reaching 110 to 130 MnTPA by 2031. Disclosed organic projects extend capacity to roughly 67 MnTPA by the third quarter of FY28. Achieving 75 MnTPA within that timeframe will require undisclosed plant debottlenecking or additional asset purchases, while reaching 110 to 130 MnTPA by 2031 requires inorganic acquisition volume comparable to the company's entire cumulative expansion history. Management's revised framing during earnings calls—describing the 67 MnTPA capacity figure as a directional reference rather than a firm commitment—provides an observable signal regarding the timeline flexibility surrounding long-term targets.33
The three key performance indicators for investors. Moving forward, three core metrics will determine whether Dalmia's operational model delivers sustainable equity returns:
EBITDA per tonne. This metric serves as the clearest indicator of whether cost-management efficiencies can withstand input inflation and regional price competition. Having fluctuated between ₹1,000 and ₹1,060 per tonne in recent quarters, the critical test is whether operating profitability can remain above ₹1,000 per tonne amidst anticipated cost pressures in FY27, and whether management's target of ₹50 to ₹100 per tonne in ongoing annual cost reductions materializes in reported earnings.
Capacity utilization across new and acquired assets. Newly added grinding and clinker capacity carries fixed depreciation and capital expenses that dilute returns if underutilized. Investors must monitor whether the acquired Rewa and Chunar assets in Central India achieve corporate average EBITDA per tonne within the seven-to-eight quarter timeline targeted by management, and whether newly commissioned capacity at Belgaum, Pune, and Kadapa absorbs regional demand effectively.
Adjusted return on capital employed (ROCE). This metric provides the ultimate test of management's capital allocation thesis. Against a target policy framework of 14% to 15%, adjusted ROCE declined to 6.5% in FY25. If capacity expansion continues while ROCE remains bound in single digits across market cycles, volume growth will continue to dilute shareholder value regardless of how cost-effectively new capacity was acquired or constructed.
Secondary operational metrics—including carbon intensity, renewable energy share, and premium product mix—serve primarily as operational drivers of these three overarching financial indicators.
XI. Playbook: Business & Investing Lessons
The scale imperative in regional commodities is real, and it differs fundamentally from the scale imperative in network businesses. In cement, expanding capacity from 9 million to 55 million tonnes per annum did not create network effects or data moats; it established a network of regional positions, each of which must remain individually defensible. The scale that matters is operational density within an economic freight radius, not total tonnage on a national league table. This is why Dalmia's Central India acquisition was strategically more vital than its raw capacity implies—it was less about adding 5.2 million tonnes per annum than about establishing an entry into a market the company previously could not serve. The corollary is that pan-India competitors enjoy a structural advantage Dalmia lacks: the ability to fund regional price wars using profits generated in other markets.
Process efficiency and brand moats are distinct operational realities, and companies routinely conflate them. Dalmia's blended cement capability represents a genuine technical achievement that reduces unit costs and establishes an industry-leading carbon profile. However, it does not generate realization premiums per tonne. When a company's differentiation relies on input substitution in a standardized commodity, analysts must model it as a durable cost advantage rather than pricing power. Furthermore, observing how efficiency metrics behave under expansion provides a diagnostic test: carbon intensity rising from 456 to 475 kilograms per tonne following the Jaypee acquisition demonstrates that process efficiency resides within specific plant configurations rather than across the broader organization.
Distressed M&A trades a valuation discount for execution timelines outside the buyer's control. The Jaypee assets were acquired at roughly ₹548 per tonne of capacity—a fraction of greenfield replacement cost. However, the transaction required four years to complete, yielded 45% less capacity than originally contracted, incurred ₹182 crore in exceptional charges in the quarter of completion, and was ultimately unblocked by the strategic actions of two competitors rather than the buyer. Calcom taught a similar lesson a decade earlier through extended minority shareholder litigation. Before underwriting distressed acquisitions, investors must evaluate who holds competing claims, what regulatory or legal framework governs the asset, and what leverage the buyer retains if execution timelines stall.
Private equity can institutionalize a family-managed business, but the institutional discipline must endure beyond the sponsor's exit. KKR's seven-year tenure delivered a 3.6-times return while scaling capacity from 11 million to 25 million tonnes per annum and instilling governance processes the company previously lacked. The formal capital allocation framework, treasury guidelines, and executive recruitment from industry peers represent the enduring residue of that sponsorship. Yet the ultimate test of institutional transformation is not operational performance while private equity sits on the board, but how returns on capital behave after departure. Nine years after KKR exited, Dalmia's subdued return on capital employed indicates that corporate institutionalization has not fully insulated financial returns from broader industry cycles.
Operational excellence and shareholder value creation can diverge for prolonged periods in cyclical commodities. Dalmia has consistently refined its manufacturing operations for fifteen years—lowering unit costs, reducing carbon emissions, optimizing product mix, and maintaining a conservative balance sheet. Over the five years leading into FY25, profit after tax declined by more than a third. Both facts coexist. Investors who equate operational quality with investment performance in capital-intensive commodity sectors risk overlooking how macro pricing cycles and regional capacity additions dictate ultimate equity returns.
XII. Bear vs. Bull Case
Bear Case
Scale asymmetry is structural, not temporary. At 54.7 million tonnes per annum, Dalmia operates at roughly one-quarter of UltraTech's domestic footprint and about half the scale of the Adani Group platform. Both market leaders continue to expand, with UltraTech surpassing 200 million tonnes per annum and Ambuja Cements targeting 140 million tonnes by 2028.56 In absolute terms, the capacity gap widens even as Dalmia grows. Practically, this leaves Dalmia as a price taker across its markets, unable to cross-subsidize regional price wars or command equivalent leverage in bulk procurement for fuel and freight.
Regional concentration in the two weakest pricing markets. Eastern and Southern India together accounted for roughly 38.6 million tonnes of Dalmia's 54.7 million tonnes of total capacity in the June 2026 quarter.11 These two regions have experienced the industry's most persistent oversupply and price discounting. During the first-quarter FY27 earnings call, equity analysts pressed management on whether the pricing gap between Eastern India and other regions could be narrowed, signaling that market observers treat regional pricing weakness as a structural, ongoing concern.33
Execution and integration risk is concentrated in the next eight quarters. Major operational ramp-ups across Belgaum, Pune, Kadapa, and the newly acquired Central India facilities are concentrated between FY27 and FY28. Management's own guidance projects seven to eight quarters before the acquired plants match corporate average operating margins.33 Any execution delay directly pressures return on capital employed, which remains the company's weakest financial metric.
Governance overhang with no near-term resolution. Authorized criminal prosecution of the chief executive officer and two promoter directors, stemming from regulatory allegations that the company denies in full, introduces an unresolved overhang likely to persist across multi-year judicial horizons.3537 Regulatory uncertainty of this nature typically delays valuation re-ratings, even if ultimate legal rulings favor the company.
Input cost exposure that management cannot hedge away. Petroleum coke and coal prices remain tied to global benchmarks that management cannot hedge away. Executive guidance flagged ₹125 to ₹150 per tonne of cost inflation in the first half of FY27 across fuel, power, and packaging linked to West Asian geopolitical conflict, while power and fuel expenses rose 10% sequentially in the June 2026 quarter.411 While expanding renewable power capacity reduces electricity overhead, it does not lower kiln thermal fuel costs.
Bull Case
A cost position that is verifiable rather than asserted. Dalmia delivered a ₹100 per tonne operational cost reduction in FY26, achieving its lowest quarterly unit cost in five years, alongside blended borrowing costs below 7%, AA+ credit ratings, and ₹150 to ₹200 per tonne in targeted cost efficiencies through FY27.47 The lower clinker factor that drives the company's carbon metrics directly reduces raw-material expenses, functioning as an immediate bill-of-materials cost advantage rather than a symbolic sustainability metric.
A balance sheet with genuine optionality. Net debt to EBITDA stood at 0.46x in March 2026 and rose to 1.47x after absorbing the ₹2,850 crore Central India acquisition, remaining well within management's 2.0x policy ceiling.1123 In a consolidating market where secondary producers are frequently constrained by balance-sheet leverage, Dalmia maintains the financial capacity to pursue opportunistic acquisitions as distressed assets emerge.
Demonstrated share gain. Dalmia achieved 9% volume growth in the June 2026 quarter against estimated industry growth of 7% to 8%, while premium offerings expanded to 25% of trade sales volumes.11 Outpacing broader market demand demonstrates that the business continues to capture regional market share rather than simply defending existing positions.
Under-penetrated end demand. India's per-capita cement consumption remains well below the global average and far behind levels in China, supported by sustained public capital expenditure on highways, housing, and urban infrastructure. Dalmia's core manufacturing footprint across Eastern, North-Eastern, and Central India places its facilities in regional markets with long-term demand growth potential rather than mature saturation.
Aligned ownership. Promoter ownership stands at approximately 55.84%, providing strategic continuity, while management's capital allocation framework explicitly prioritizes return on capital employed over volume expansion for its own sake.739
Weighing it
Evaluating Dalmia through a structural industry lens indicates that the company possesses process power without pricing power. In a heavy-commodity market characterized by intense rivalry and low substitution risk, operational process efficiency creates a unit cost advantage that broader market pricing dynamics routinely transfer to end customers. The bull thesis does not rely on Dalmia out-earning national market leaders on an EBITDA-per-tonne basis; rather, it posits that superior cost discipline enables the business to operate profitably and expand at a scale where less efficient producers would struggle, while preserving balance-sheet optionality in ongoing industry consolidation.
Conversely, the bear thesis does not argue that Dalmia is inefficiently managed, but rather that operational excellence at one-quarter of the market leader's scale may be insufficient to earn the cost of capital across a full industry cycle. In a commodity sector where national scale dictates pricing power, cost leadership provides partial insulation rather than structural immunity. The multi-year decline in adjusted return on capital employed between FY22 and FY25 provides empirical evidence supporting that constraint.
Ultimately, both investment arguments converge on a single financial indicator: whether adjusted return on capital employed recovers into double-digit territory as newly added capacity reaches target utilization, or whether capital returns remain bound in single digits across regional pricing cycles.
XIII. Epilogue & What to Watch
Eighty-seven years after a 250-tonne-per-day kiln started up in Tamil Nadu, Jaidayal Dalmia's descendants lead India's fourth-largest cement producer. That corporate longevity is notable in an economy where many pre-independence industrial houses fragmented or dissolved. But continuity is not an investment thesis, and the next three years will determine whether the company's decade-and-a-half of expansion represents a durable foundation or an operational plateau.
The Central India expansion test. The Rewa and Chunar facilities represent Dalmia's first large-scale manufacturing presence outside its core eastern, southern, and north-eastern markets. While management executed a rapid initial dispatch within 22 days of deal completion, the critical operational test will unfold across FY27 and FY28, when these units must reach corporate average EBITDA per tonne against established regional competitors in Madhya Pradesh and Uttar Pradesh. If Dalmia successfully exports its cost-leadership model into Central India, its pan-India expansion thesis will gain empirical support. Conversely, if the acquired assets settle at structurally lower operating margins, it will indicate that the company's historical cost advantage was a function of specific regional dynamics rather than portable operational capability.
The consolidation endgame. India's two largest producers, UltraTech and Adani, have absorbed the majority of cement M&A activity over recent years. The Jaypee transaction illustrated the competitive asymmetry facing mid-tier players: the market leader acquired the parent company, leaving Dalmia to negotiate for a subset of manufacturing assets. The strategic question is whether Dalmia can sustain an independent position as the number-four producer—the premise underlying its target of 110 million to 130 million tonnes per annum by 2031—or whether ongoing industry consolidation will eventually force broader strategic shifts. A 55.84% promoter equity stake prevents unsolicited takeovers, keeping corporate destiny entirely in family hands, with public disclosures offering no indication of intent to yield independence.
The decarbonization frontier, judged on delivery rather than announcement. Achieving Dalmia's 2040 carbon-negative commitment depends on commercializing carbon capture, utilization, and storage, alongside significantly raising its thermal substitution rate—the proportion of kiln fuel replaced by municipal and industrial waste. Disclosures through the June 2026 quarter show no operational commercial capture unit stemming from the 2019 Carbon Clean partnership. Evaluating decarbonization progress requires tracking empirical operating metrics rather than corporate commitments: specifically, the reported thermal substitution rate and whether net carbon intensity per tonne resumes its downward trajectory after the dilution caused by the Central India assets.
The cost curve under input-price stress. A crucial operational test is unfolding across the upcoming fiscal quarters. Management has targeted ₹50 to ₹100 per tonne in ongoing annual cost reductions while separately guiding for ₹125 to ₹150 per tonne of cost inflation in the first half of FY27 from fuel, power, and packaging expenses.4 These two dynamics move in opposite directions, and their net impact will be visible in quarterly earnings. If internal efficiency measures absorb this input-cost shock and maintain operating EBITDA above ₹1,000 per tonne, it will provide empirical evidence that Dalmia's cost position is structural. If operating margins compress significantly, however, it will demonstrate that past cost leadership was driven largely by favorable global fuel cycles.
Cement remains a long-cycle business. The fundamental technology behind the Danish kiln Jaidayal Dalmia installed in 1949 remains the foundation of modern plant operations: heat limestone, produce clinker, grind, bag, and ship. Strategic success comes down to a single equation: owning the lowest-cost tonne of capacity closest to the end customer. Dalmia has spent decades mastering the first half of that equation. The next three years will test whether it can master the second.
References
-
Dalmia Bharat to Buy Jaypee Cement Assets for Rs 28.5 bn — Indian Cement Review, 2026-05-27 ↩↩
-
Dalmia Bharat signs binding agreement for acquisition of cement assets of Jaiprakash Associates — India Infoline, 2022-12 ↩↩
-
Dalmia Bharat Ltd (BOM:542216) Q4 2026 Earnings Call Highlights: Record EBITDA and Strategic Growth — GuruFocus / Investing.com, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩
-
UltraTech hits 200 MTPA capacity, tops global cement makers outside China — Business Today, 2026-04-17 ↩↩↩
-
Ambuja Cements Crosses 100 MTPA Capacity — Adani Group Newsroom ↩↩↩
-
Investor Presentation – Q2 FY26 — Dalmia Bharat Limited, 2025-11-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Banking, airlines, railways, coal, jute, newspapers: Ramkrishna Dalmia's business-building spree — Scroll.in ↩
-
How Samir Jain created the modern Indian newspaper industry — The Caravan ↩↩
-
Dalmia Bharat Q1 FY27 slides: volumes rise 9%, costs weigh on margins — Investing.com, 2026-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Commission of Inquiry into certain Dalmia-Jain companies — Rajya Sabha Debates, 1963-08-14 ↩
-
R. K. Dalmia vs Delhi Administration — Supreme Court of India, 1962-04-05 ↩↩
-
Partners spar in Dalmia arm ahead of KKR exit — M&A Critique ↩↩
-
Merges entities to create 4th largest cement play of 25 MnT capacity; simplifies group structure with one listed entity — Dalmia Bharat Group ↩↩
-
KKR to invest Rs 750 crores in Dalmia Cement to form the largest private cement company in India — Dalmia Bharat Group ↩
-
With Dalmia exit, KKR cements India success — Business Standard, 2017-04-21 ↩↩
-
RHI Magnesita completes acquisition of Indian refractory business of Dalmia Bharat Refractories Limited — RHI Magnesita, 2023-01 ↩↩
-
Binod Kr Bawri v. Calcom Cement Ltd. — National Company Law Tribunal (via CaseMine) ↩
-
Partners spar in Dalmia arm ahead of KKR exit — Business Standard, 2016-02-17 ↩
-
GuarantCo, Dalmia Cement settle dispute over Calcom repayment of dues — Business Standard, 2020-02-05 ↩
-
Dalmia Bharat: Robust financial performance in FY26, PAT jumps 65% — Dalmia Bharat Cement, 2026-04-28 ↩↩↩↩↩↩
-
Dalmia Cement (Bharat) Limited, globally ranked No. 1 by CDP for lowest carbon footprint — Dalmia Bharat Group ↩
-
Dalmia Cement (Bharat) Limited and Carbon Clean Solutions team up to build cement industry's largest carbon capture plant — Dalmia Bharat Group, 2019-09-19 ↩↩
-
Dalmia Bharat dips 5% a day after inking deal to buy Jaiprakash's biz units — Business Standard, 2022-12-13 ↩
-
CCI clears acquisition of Jaiprakash Associates' assets by Dalmia Cement — Business Standard, 2023-02-15 ↩
-
Dalmia's deal to buy Jaypee Cement assets lingers with arbitration — Business Standard, 2024-03-25 ↩↩↩↩
-
UltraTech keen to take over JP Super despite new deal — Construction World ↩
-
NCLT approves Adani Enterprises' resolution plan for Jaiprakash Associates — ScanX, 2026-03 ↩
-
Jaiprakash Associates receives final approval to delist from BSE and NSE starting June 18, 2026 under NCLT resolution plan — ScanX, 2026 ↩
-
UltraTech, JAL settle dispute; ₹1,000 cr redemption deal — Kotak Neo Market News, 2026 ↩
-
Earnings call transcript: Dalmia Bharat Q1 sales rise, shares slip — Investing.com, 2026-07 ↩↩↩↩↩↩↩↩↩↩
-
Shree Cement commissions RAS Unit-11 in Rajasthan, capacity rises to 65.8 MTPA — Indiablooms, 2026-02 ↩↩
-
Dalmia Group: MCA Asks SFIO To File Cases over ₹40 Crore Unlawful Gain to Promoter, ₹416 Crore Loss to IL&FS Securities — Moneylife, 2026 ↩↩↩
-
SC orders restoration of MF units to Dalmia Bharat group, stock zooms 11% — Business Standard, 2021-03-17 ↩
-
Dalmia Bharat clarification regarding alleged fraudulent transfers — InvestyWise, 2026-05-08 ↩↩
-
Dalmia Bharat confirms full compliance with SEBI norms in FY26 — ScanX, 2026 ↩
-
Dalmia Bharat to add 6 MnTPA cement capacity in Maharashtra and Karnataka — Dalmia Bharat Cement, 2025-02-28 ↩↩
-
JAL to sell stake in Bokaro cement unit to Dalmia for Rs 690 crore — Business Standard, 2014-03-24 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube