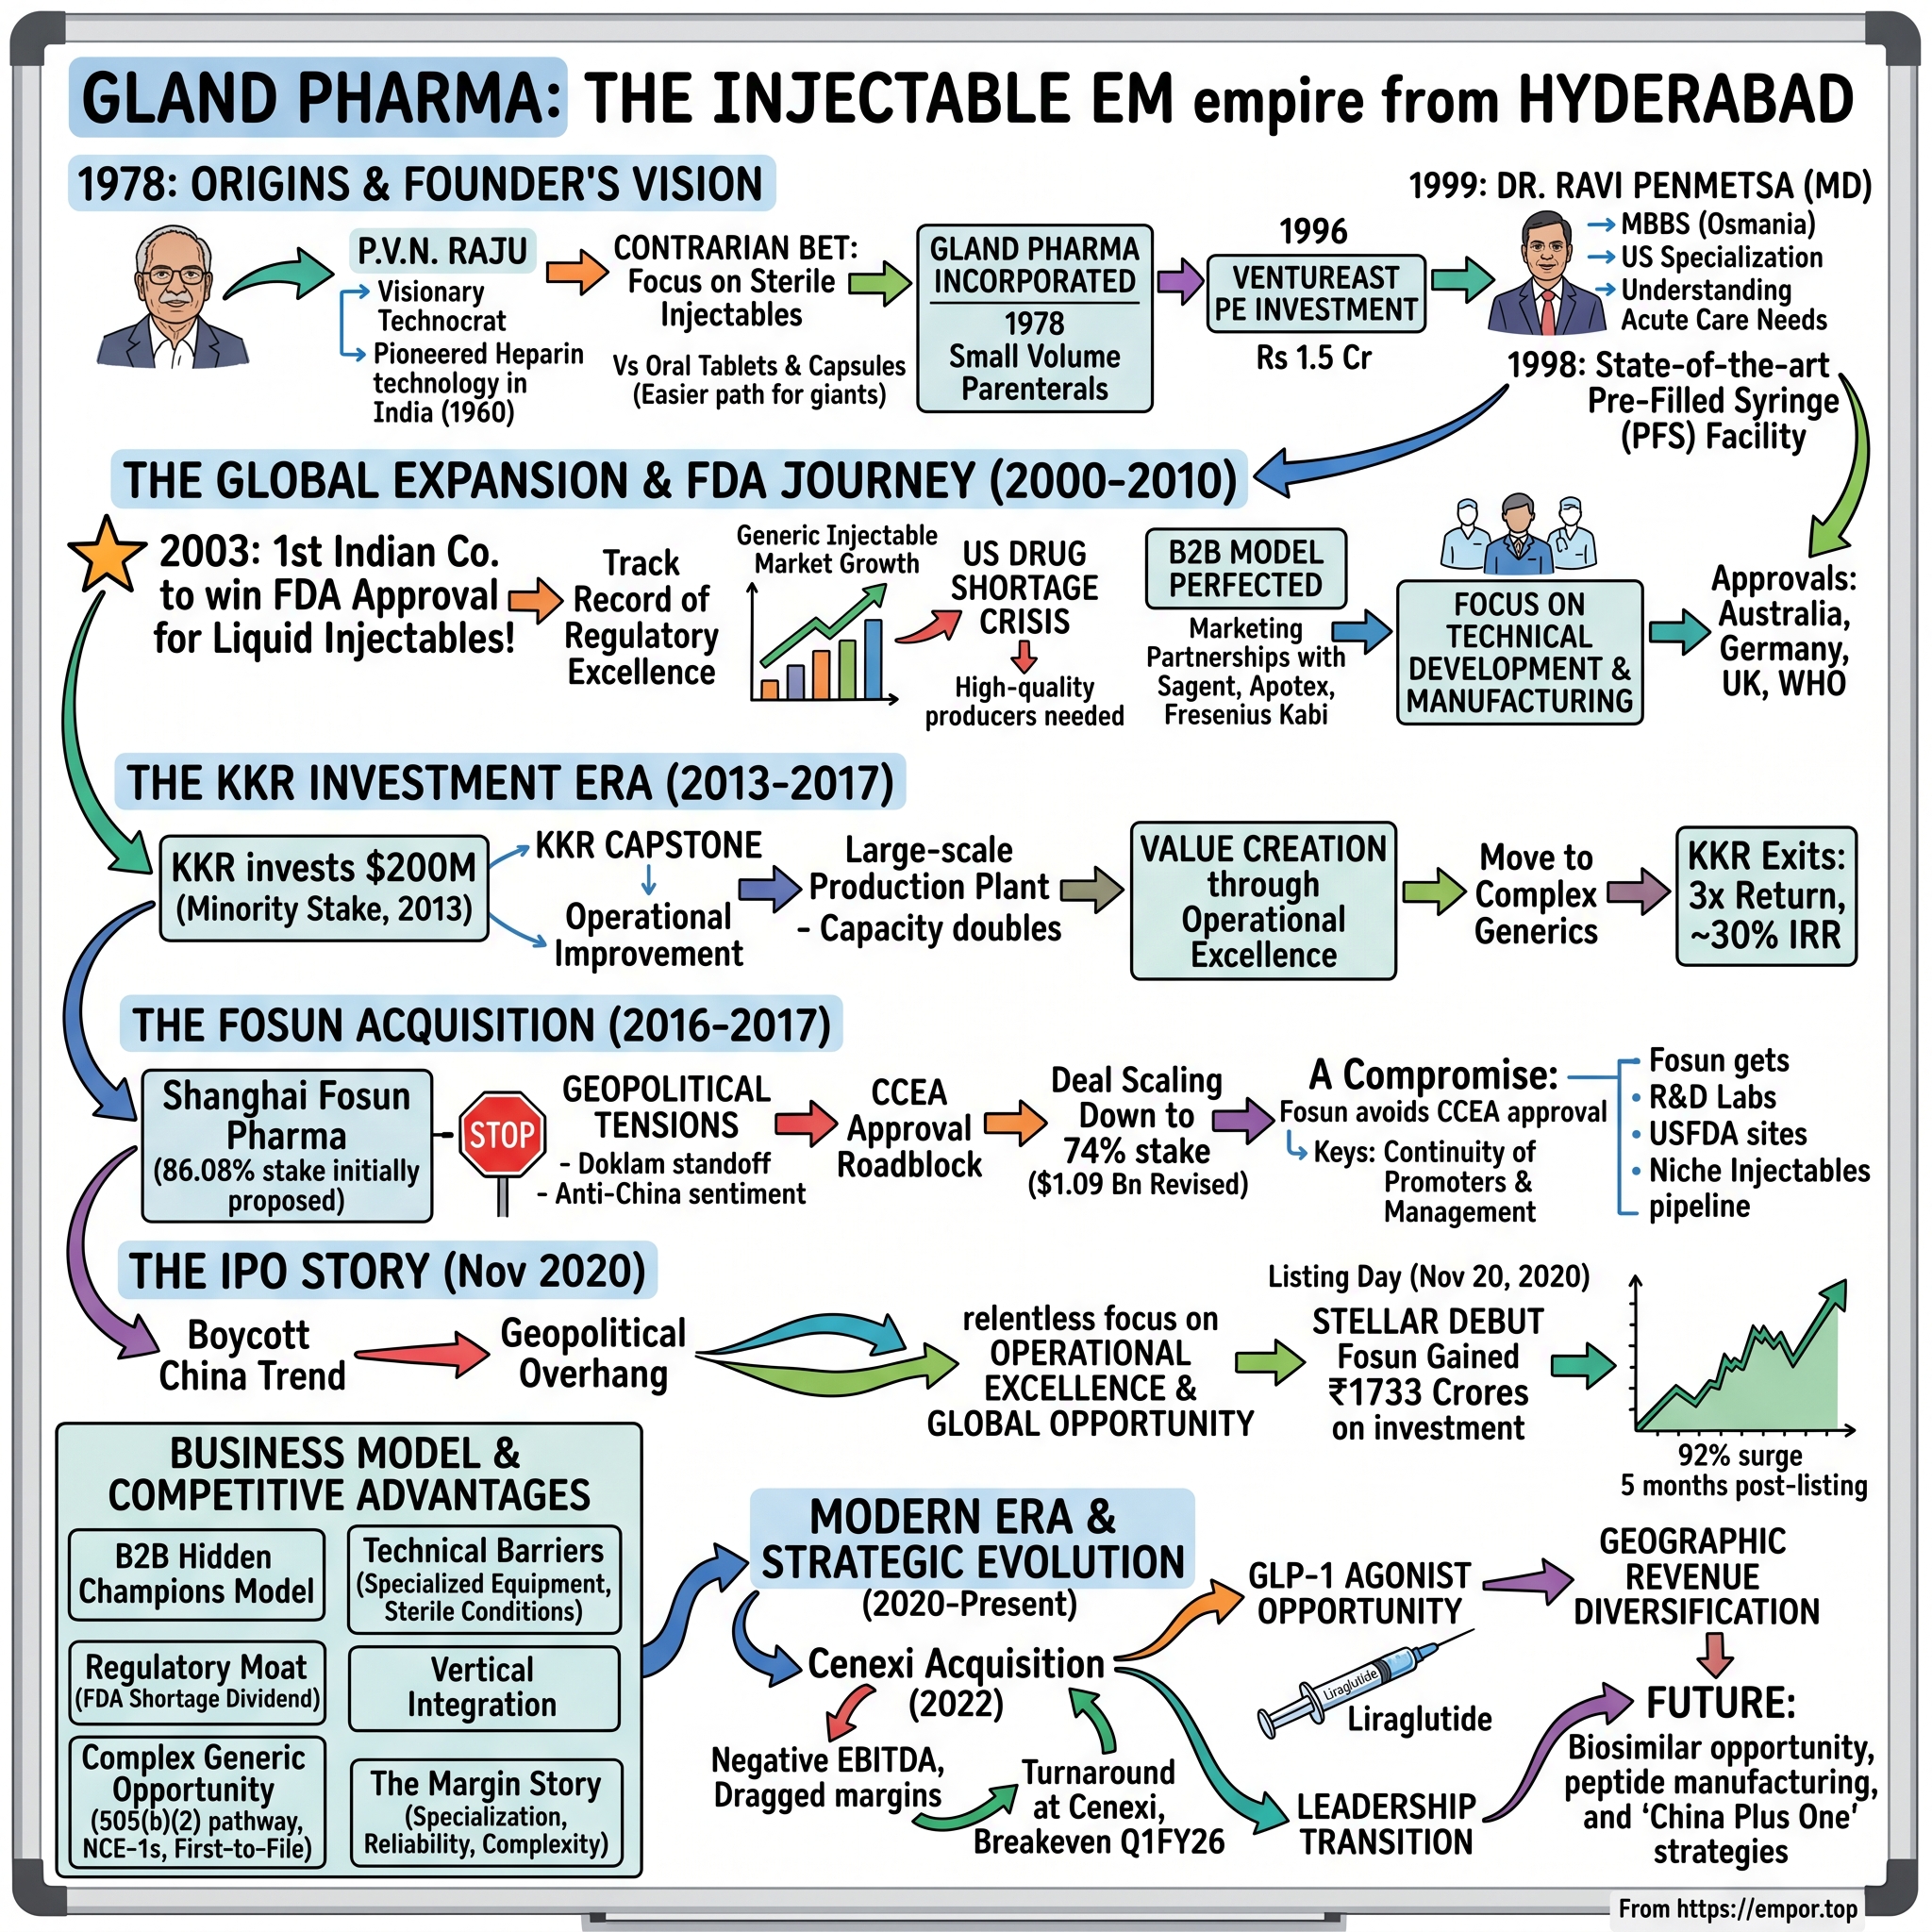
Gland Pharma: The Injectable Empire from Hyderabad
I. Introduction & Episode Roadmap
Start in an intensive care unit in Ohio, Ontario, or Lyon. A nurse draws heparin from a glass vial to keep a patient's blood from clotting, pushes an antibiotic through an IV line, and later hangs a bag of ready-to-use infusion. The label on the vial carries the name of a familiar distributor or generic drugmaker. What the label does not show is that the liquid inside may well have been formulated, filtered, and sealed into that vial on the outskirts of Hyderabad, at a Dundigal plant that most hospital pharmacists have never heard of.
That is the Gland Pharma story in a single image. The pharmaceutical industry typically chases profits through proprietary brand names, patent litigation, and commercial marketing. Gland took the opposite route. It built a business-to-business platform focused on sterile injectables, supplying the very drugmakers that might otherwise have been its competitors. The strategy was capital-intensive, unglamorous, and deliberately low-profile. For nearly four decades, it worked remarkably well.
Then, on November 20, 2020, the quiet contract manufacturer went public. Gland's shares listed at ₹1,701—a 13.4% premium to its ₹1,500 issue price—and closed the first day at ₹1,820, up 21%. That gave the company a market capitalisation of ₹29,848 crore and put it among India's ten most valuable drugmakers on its first day of trading.1 The IPO raised ₹6,479.55 crore through a ₹1,250 crore fresh issue alongside an offer for sale of roughly ₹5,230 crore, offloaded primarily by its Chinese parent. It was the largest IPO ever by an Indian pharmaceutical company.21 The timing was delicate: Indian and Chinese troops had fought a deadly border clash in the Galwan Valley only months earlier, yet the primary seller in India's record-setting pharma listing was a Shanghai-based conglomerate.
The Paradox at the Center
Two puzzles run through the story.
The first is ownership. Founded by a Telugu chemist's family in 1978, Gland passed through a private-equity cycle under KKR before becoming, in 2017, the flagship Indian asset of 复星医药 Fosun Pharma (Shanghai Fosun Pharmaceutical Group). Fosun Pharma is itself an arm of 复星国际 Fosun International, the conglomerate built by 郭广昌 Guo Guangchang. The takeover closed only after India's Cabinet Committee on Economic Affairs scrutinized the transaction during a tense border standoff. Nine years later, in September 2026, Fosun's stake fell below 50% for the first time.3
The second puzzle is fragility. A company with a spotless regulatory record, operating profit margins near 40%, and no debt still managed to lose roughly three-quarters of its market value between August 2021 and May 2023. The collapse was driven by a cluster of compounding shocks: intensified heparin competition from China, customer inventory destocking, the bankruptcy of a key US distribution partner, a contracted Russian vaccine deal that failed to materialize, and a French acquisition that lost money for two years before stabilizing.
The Road Ahead
This article moves through eight acts:
- Act I covers the founding bet on sterile injectables (1978–2003).
- Act II covers the B2B model that won over Western regulators and customers (2003–2013).
- Act III covers KKR's institutional bridge (2013–2017).
- Act IV covers Fosun's geopolitically fraught takeover.
- Act V covers the pandemic IPO boom and the crash that followed.
- Act VI examines the Cenexi acquisition in Europe.
- Act VII opens up the business: unit economics, moats, Hamilton Helmer's 7 Powers, and Porter's Five Forces.
- Act VIII covers the present: a leadership reshuffle, Fosun selling down, the GLP-1 and biologics options, and a skeptical stress test of the investment case.
The central question underneath it all: is Gland a durable compounding franchise, or simply a well-run factory whose margins are ultimately dictated by its customers? The company's history offers a more nuanced answer than either side of that debate usually concedes.
 Subscribe on LinkedIn
II. Origins & The Sterile Parenteral Choice (1978–2003)
Picture Hyderabad in the 1970s: a historic princely-state capital evolving into an industrial center, with an emerging pharmaceutical sector centered on state-owned plants and bulk chemical synthesis. P.V.N. Raju, a chemistry graduate who had trained abroad and established a modest chemical enterprise, incorporated Gland Pharma in 1978.4 From its earliest days, the company pointed to an accomplishment that helped define its identity: it pioneered heparin technology in India.5 Heparin is the anticoagulant relied upon across modern intensive care units, and it is purified from animal tissue.
Why Injectables, and Why It Mattered
That focus ran counter to prevailing industry trends. The Indian Patents Act of 1970 recognized process patents while eliminating product patents on pharmaceuticals. That legal framework allowed Indian chemists to reverse-engineer finished molecules with impunity, triggering a rush into oral tablets and capsules. Because solid oral formulations could be mass-produced inside standard clean rooms, hundreds of domestic drugmakers crowded into the category.
Sterile injectables demanded a far more rigorous craft. A swallowed tablet travels through the digestive tract, an environment already populated with microbes. An injectable bypasses the body's natural defenses entirely, entering directly into the bloodstream—often of an acutely vulnerable patient. Consequently, every vial must be completely sterile, free of visible particles, and devoid of fever-inducing bacterial fragments known as endotoxins. The operational gap resembles the difference between a commercial restaurant kitchen and a surgical operating theater: both clean their workstations, but only one must guarantee that nothing living survives the process. That manufacturing hurdle underpins the operational moats that defined Gland's later success.
Heparin proved an instructive starting point. Unlike conventional small-molecule medicines, it cannot be synthesized inside a standard chemical reactor. It is extracted and purified from animal tissue, historically porcine intestinal mucosa. That origin makes it half biological substance and half chemical compound, where consistent batch-to-batch quality is notoriously difficult to maintain. By learning to purify heparin to sterile injectable standards, Gland mastered two foundational disciplines of sterile manufacturing: managing an inherently variable biological raw material, and proving total aseptic purity in the finished dosage. Because fewer manufacturers can meet those standards, regulatory oversight is strict, and a single contamination failure can close an entire facility. This heparin franchise, spanning unfractionated heparin and its lower-molecular-weight derivative enoxaparin, remained an anchor decades later, generating roughly ₹1,200 crore of Gland's revenue in FY22.6 Later chapters examine how that heavy product concentration eventually turned against the company.
The Long March to the FDA
For its first two decades, Gland operated primarily as a domestic contract manufacturer of small-volume liquid injectables.5 It focused on foundational capabilities: mastering heparin chemistry, filling ampoules and vials, and supplying Indian institutional purchasers. Over time, Raju's son, Dr. Ravi Penmetsa, took on an expanded leadership role in scaling operations. In 2000, the company established an in-house research and development facility at Dundigal.4 That same year, it recruited Srinivas Sadu as an export manager—a hire who would later become instrumental in directing the firm.7
In 2003, the US Food and Drug Administration approved Gland's Dundigal manufacturing site.4 The inspection win opened access to the world's largest and most lucrative generic drug market, while illustrating a reality central to Gland's history: an approval is not the same as commercial success.
Company records show a multi-year gap between that initial 2003 inspection and Gland's subsequent US commercial launches. Gland launched heparin sodium injection in the United States and filed its first Abbreviated New Drug Application from a newer facility in the late 2000s, while commercial US shipments from its Pashamylaram site materialized later still.4 The initial constraint was commercial rather than technical. Gland lacked an American sales force, held no contracts with hospital group purchasing organizations, had no relationships with pharmaceutical wholesalers, and owned no brand recognized by hospital pharmacists.
Faced with that distribution barrier, the company adopted a business-to-business model that guided the next two decades. Rather than investing substantial capital to assemble a commercial front end in the United States, Gland focused on product development and sterile manufacturing, licensing its output to established generic marketers in exchange for a share of net profits. While several Indian peers spent the 2000s and 2010s acquiring Western distribution assets to build their own labels, Gland deliberately served as the supply engine behind those labels.
For investors, this formative era demonstrates an operational moat anchored in manufacturing complexity, alongside a structural vulnerability: Gland's revenue was ultimately bounded by its partners' commercial distribution capabilities. Act II examines how that B2B foundation transformed into an international business.
III. The B2B Engine & Cracking Developed Markets (2003–2013)
In the mid-2000s, the typical ambition of an Indian pharmaceutical executive centered on two assets: a commercial subsidiary in the United States and a sales office in New Jersey. Gland's leadership pursued a far less visible prize: a permanent place inside other drugmakers' regulatory filings.
Three Ways to Get Paid
Gland's business-to-business model rested on three commercial structures, which the company continued to outline in its investor materials decades later:4
- Own-filed ANDAs, out-licensed. Gland develops the generic formulation and files the Abbreviated New Drug Application in its own name. It then licenses commercial marketing rights to a distribution partner. Gland earns a baseline supply price per unit plus a share of the partner's profit on downstream sales.
- Partner-filed products. The marketing partner owns the regulatory dossier while Gland serves as the qualified, inspected manufacturing site. Gland earns a contracted supply price per unit, occasionally supplemented by milestone payments or royalties.
- Development and technology-transfer work. Gland provides custom formulation development, process scale-up, and aseptic filling for external drug innovators—a line of work that eventually grew into its contract development and manufacturing organization (CDMO) business.
Profit sharing proved to be the most consequential of the three mechanisms, amplifying both financial upside and operational risk. During an early 2025 earnings call, Gland's chief financial officer disclosed that profit sharing contributed 11.7% of quarterly revenue, with milestone income adding another 10.2%. In practical terms, more than a fifth of the top line depended directly on the realized profitability of its partners' commercial portfolios.8
The economic dynamic resembles a commercial retail lease where the landlord collects a percentage of tenant sales rather than a flat monthly rent. When retail foot traffic surges and goods sell at full price, the landlord prospers. But when intense discounting takes hold, the landlord's income drops immediately—even though the landlord has no control over the tenant's pricing strategy.
A hypothetical example illustrates the operational leverage at work. Suppose a marketing partner sells a vial of a generic injectable antibiotic in the United States for $10. Gland charges a base supply price of $2 to manufacture and package it, while the partner incurs $3 in distribution, regulatory, and administrative overhead. That leaves an operating profit pool of $5. If Gland's contract entitles it to a 50% profit share, Gland collects $2 in manufacturing revenue plus $2.50 in profit share, or $4.50 per vial.
Now suppose a rival drugmaker enters the market, driving the commercial price down to $6. Gland's baseline supply price remains $2, but the partner's distributable profit pool shrinks from $5 to just $1. Gland's 50% profit share falls from $2.50 to $0.50. Although the factory formulated, sterilized, and inspected the exact same vial under identical technical standards, Gland's realized revenue per unit drops by 44%, from $4.50 to $2.50. Because the plant's production costs did not decline, virtually all of that lost revenue is lost operating margin. This operating leverage explains why profit-sharing arrangements look exceptional during supply shortages, yet prove vulnerable when competitive supply expands.
Building the Physical Machine
To support this out-licensing model, the decade between 2003 and 2013 was defined by sustained capacity expansion. Gland commissioned its Pashamylaram manufacturing unit near Hyderabad and leased industrial land in the Visakhapatnam special economic zone, a site that eventually housed dedicated active pharmaceutical ingredient (API) and oncology formulation plants. It also constructed a dedicated penems facility to manufacture carbapenem antibiotics—an investment that required an isolated, segregated footprint to eliminate severe cross-contamination hazards.4 By 2025, that industrial network encompassed four finished-formulation facilities capable of producing approximately 1,200 million units annually, supported by three API plants generating roughly 11,000 kilograms per year.4
Manufacturing sterile injectables is not a uniform discipline; each delivery format requires distinct engineering and regulatory capabilities:
- Liquid vials and ampoules: the high-volume workhorses of acute hospital care, requiring high-throughput aseptic filling lines.
- Lyophilised vials: injectable powders freeze-dried under vacuum and reconstituted bedside by a nurse—a delicate process requiring precise thermal cycles to preserve molecular stability.
- Pre-filled syringes: drug-device combination products requiring microscopic dimensional tolerances to prevent plunger friction or silicone oil contamination.
- Oncology injectables: cytotoxic compounds that demand negative-pressure barrier isolators and specialized containment to protect both product sterility and plant operators.
Gland has highlighted that none of its manufacturing facilities have ever received a warning letter from the USFDA since their respective commissionings, while reporting that roughly 37% of its workforce operated within quality functions.4 In sterile manufacturing, quality personnel do not function as bureaucratic overhead; they represent the core capability that makes the output commercially viable in tightly regulated developed markets.
Pipeline Velocity
Regulatory filing velocity served as the commercial counterpart to physical factory capacity. By March 2026, Gland and its marketing partners had accumulated 388 ANDA filings with the USFDA, resulting in 337 approvals and 51 applications pending.5 Each approval functions as an incremental call option: while revenue from any individual off-patent molecule may be modest, aggregating hundreds of dossiers dampens the volatility of single-product price deflation while keeping high-fixed-cost fill lines running near capacity.
Yet assessing Gland's compliance record requires distinguishing corporate marketing claims from regulatory reality. While the company's clean record regarding formal warning letters holds true, its inspection history has not been entirely event-free, having received procedural Form 483 inspectional observations from the USFDA in both 2022 and 2024.910 As examined in Section VII, those observations were resolved without escalating into warning letters or import alerts, confirming that Gland maintained an institutional compliance discipline superior to the broader Indian generic peer group. It represented a genuine operational moat, but one that conferred resilience rather than permanent immunity.
By 2013, Gland had assembled advanced sterile manufacturing facilities, an expansive regulatory dossier portfolio, and durable partnerships with Western distributors. Operationally, however, it remained governed as a closely held family business. Transitioning from a regional contract manufacturer into an institutional global platform required external capital and corporate governance—a transition initiated when private equity stepped into the boardroom.
IV. The Private Equity Catalyst: KKR Takes the Reins (2013–2017)
In December 2013, KKR announced an investment of roughly $200 million for a minority stake in Gland Pharma, buying out the entire holding of earlier private-equity backer Evolvence India Life Sciences Fund.11 The stated rationale was straightforward. "Our partnership with KKR will help us in our next phase of growth as we look to materially expand our manufacturing capacities," P.V.N. Raju, the founder-chairman, said at the announcement, while Vice Chairman Ravi Penmetsa highlighted plans to leverage KKR's international network into new markets. Sanjay Nayar, then chief executive of KKR India, praised what he described as "a high-quality promoter family and management team."11 Alongside the secondary buyout, Gland's corporate timeline recorded approximately ₹1,000 million in fresh primary capital injected into the business.4
What the PE Playbook Actually Changed
The standard private-equity minority playbook is familiar: instituting independent board oversight, upgrading management information systems, enforcing capital discipline, and grooming the company for an eventual exit. Because Gland was privately held and the specific internal governance reforms under KKR were never publicly detailed, reconstructing internal return hurdles or operating targets would be guesswork. What is clear from the record is the commercial outcome: within two and a half years, Gland was institutionalized enough to anchor a high-stakes cross-border bidding contest.
Alongside institutional governance, the pivotal operational leadership arc centered on Srinivas Sadu. Having joined Gland in 2000 to lead exports, Sadu rose through the executive ranks—becoming vice president in 2003, a board director in 2005, and chief operating officer in 2011.7 Formally trained in industrial pharmacy at Long Island University in New York, he paired that technical grounding with an American MBA and executive finance certification from London.7 Sadu was not a member of the founding promoter family; he was a shop-floor operator whose career spanned manufacturing suites, export desks, and Western client management. In a contract manufacturing business where the true asset is a partner's confidence in plant compliance, that operating pedigree proved more valuable than promoter prominence.
Why the Timing Worked
KKR's entry aligned with a favorable structural cycle. In 2016, market reports surrounding the eventual sale process estimated that approximately $16 billion worth of US injectable drug patents would expire through 2019, inside an injectables market expanding at roughly 10% annually.12 Multinational generic drugmakers faced an acute shortage of sterile manufacturing capacity capable of passing rigorous regulatory audits. Throughout the early 2010s, several high-profile sterile injectable facilities across the United States and Europe suffered contamination incidents, warning letters, and production shutdowns. Sterile sites with unblemished USFDA track records were scarce, and Gland operated multiple qualified facilities.
By April 2016, an auction was underway, reportedly drawing bids from private-equity firm Advent International, US hospital-products supplier Baxter International, and Indian generic manufacturer Torrent Pharmaceuticals.12 The bidder roster illustrated Gland's strategic utility across the healthcare landscape: Advent saw a scalable platform buyout; Baxter saw an opportunity to bring a reliable outsourced supplier in-house; Torrent sought an immediate shortcut into complex injectables; and the ultimate winner, Shanghai-based Fosun Pharma, saw an operational bridge into Western regulated markets.
The transaction economics underscored the value created during the private-equity tenure. KKR had invested approximately $200 million for a minority holding in late 2013.11 Less than four years later, Fosun agreed to acquire up to 74% of Gland for as much as $1.09 billion, implying a total equity valuation of roughly $1.5 billion.13 While KKR's exact entry percentage and final realized proceeds were never publicly itemized, preventing a precise calculation of its internal rate of return, the directional payoff was unambiguous: Gland's valuation multiplied several times over between 2013 and 2017, propelled by an expanding US dossier pipeline, added cleanroom capacity, and a competitive auction among strategic acquirers.
For investors, the KKR era demonstrated that Gland possessed the rare assets for which strategic acquirers would pay a substantial premium: pre-cleared sterile capacity, regulatory compliance discipline, and an active filing pipeline. What the auction did not guarantee was how smoothly those assets would operate under new ownership. The incoming parent was an acquisitive Chinese conglomerate, and that change of control quickly entangled Gland in international geopolitics.
V. The Fosun Acquisition: Geopolitical Crossfire & The $1.1B Takeover (2016–2017)
In July 2016, Shanghai Fosun Pharmaceutical announced an agreement to acquire 86.08% of Gland Pharma for up to $1.26 billion.13 Fortune designated it India's largest inbound acquisition of the year. The founding family and KKR together held roughly 96% of the company and were preparing to offload nearly all of it.12
The Strategic Pitch
Fosun's stated rationale centered on internationalization and manufacturing capability. The transaction was designed to upgrade the parent company's sterile injectable manufacturing, leverage India's generic drug engineering talent, and "promote the internationalization of Chinese pharmaceutical companies."14 Industry analysts emphasized the commercial opportunity within China itself. Beijing's 集中带量采购 (volume-based procurement) programme was driving steep price reductions across public hospital formularies, penalizing high-cost domestic brands and favoring high-volume, cost-efficient generic producers. In theory, Gland's portfolio of sterile injectables could be registered in China and routed directly through Fosun's extensive domestic hospital network.
The Geopolitical Gauntlet
Then geopolitics intervened. In 2017, India's Cabinet Committee on Economic Affairs raised formal objections to the acquisition during a period of "heightened tensions between India and China over border dispute"13—a standoff centered that summer on the Doklam plateau. Under Indian foreign direct investment regulations, foreign acquisitions in existing pharmaceutical companies of up to 74% proceeded via the automatic route, whereas transactions above that threshold required explicit government clearance.15
On September 17, 2017, Fosun restructured the deal, scaling its planned stake down to 74% at a revised valuation not exceeding $1.09 billion.13 Fosun disclosed that the consideration included up to $25 million in contingent consideration tied to enoxaparin sales milestones. KKR secured a complete exit, while the stake acquired from the founding family was trimmed, allowing other existing shareholders to retain their positions.14 Because foreign ownership remained strictly within the 74% automatic threshold, the restructured deal bypassed the need for formal approval from the Foreign Investment Promotion Board or the CCEA, closing in early October 2017.1315
The maneuver served as a case study in regulatory arbitrage. The transaction was neither approved in its original form nor outright blocked; it was simply resized to fit statutory limits, leaving the industrial thesis intact at 74% equity ownership. Fosun gave up absolute control, the founding family retained residual upside, and KKR executed a clean exit in under four years.
Historical Falsification: Did the China Synergy Thesis Hold Up?
The most compelling pillar of the 2017 bull case posited that Fosun would serve as Gland's commercial gateway into mainland China. Gland's corporate timeline shows it submitted its initial filing to China's 国家药品监督管理局 (National Medical Products Administration) in 2019, securing a clinical waiver for the cardioprotective agent dexrazoxane.4 By 2023, management reported that its first Chinese regulatory approval had arrived, anticipating three or four additional clearances within nine months.6
Yet the company's subsequent disclosures revealed a far more modest commercial reality. In May 2024, Gland reported: "Progress is slower than expected. Nine products were filed, and three were approved. One product is commercialized with a limited contribution."16 By FY26, the strategic dialogue surrounding China had inverted: rather than funneling Hyderabad-manufactured injectables into Chinese hospitals, Gland was primarily focused on in-licensing a liposomal product from a Chinese partner to commercialize across Western regulated markets—the precise reverse of the original synergy thesis.17
The historical record firmly refutes the original premise. In the nine years following the takeover, Chinese ownership failed to generate meaningful Chinese top-line revenue. Fosun did provide patient balance-sheet backing, board stability, and a pathway to a domestic public listing, but that association came with enduring geopolitical friction. In April 2020, following border clashes in the Galwan Valley, India enacted Press Note 3, mandating prior government clearance for any foreign direct investment originating from countries sharing a land border with India.18 Consequently, every subsequent capital allocation decision involving a Chinese-controlled Indian firm carried heightened regulatory scrutiny. While market observers often cite a "Chinese promoter discount" weighing on Gland's valuation multiple—a headwind plausible in theory but difficult to isolate empirically—the ultimate test is whether that valuation gap narrows as Fosun progressively divests its holding, a dynamic explored in Act VIII.
Fosun held an exceptionally profitable asset. Its next move was to monetize a significant portion of it through India's public markets.
VI. The IPO & The Pandemic Super-Cycle (2020–2021)
November 2020 provided unusually fertile ground for a healthcare listing. Central banks had pinned interest rates near zero, retail brokerage accounts were multiplying across India, and pharmaceutical manufacturers were widely seen as pandemic-proof defensive assets. Gland opened its books to anchor investors on November 6 before the public offering began on November 9, priced within a band of ₹1,490 to ₹1,500 per share.2 The transaction allowed the company's backers to monetize: Fosun Pharma Industrial Pte, the Singapore-registered holding entity, divested roughly 19.4 million shares, alongside secondary sales by founder-linked entities including Gland Celsus Bio Chemicals and family trusts.2
Who Actually Bought
The subscription pattern revealed a stark divide in investor sentiment. Qualified institutional buyers oversubscribed their allocated tranche 6.4 times, whereas high-net-worth individuals took up only about half of their quota and retail individual investors subscribed for just 0.23 times their portion.1 In short, institutional fund managers embraced the offering while domestic retail participants largely stood aside. Business Standard noted that the listing "managed to sail through on the back of institutional investor support, even as retail and HNI investors shunned the issue."1 Meanwhile, the capital raised from the fresh-issue component was earmarked primarily to fund incremental working capital requirements.1
The Numbers That Justified the Euphoria
The operating metrics leading up to the public offering supported that institutional enthusiasm. Revenue expanded from ₹26,332 million in FY20 to ₹34,629 million in FY21, while EBITDA margins widened from 36% to 38%.19 For a contract manufacturing business, generating ₹38 of operating cash profit on every ₹100 of revenue represented an exceptional level of profitability.
The financial momentum crested in FY22. Driven by heightened pandemic hospital demand and aggressive precautionary stockpiling by overseas distributors, full-year revenue surged to ₹44,007 million and EBITDA reached ₹15,102 million—both all-time records.19 Although EBITDA margins compressed slightly to 34% from the prior year's 38%, the absolute earnings expansion masked any initial margin pressure.19
Public equity markets responded with euphoria. By August 2021, Gland's shares reached an intraday peak near ₹4,350—nearly three times its IPO price in less than nine months.20 At that apex, the company's market capitalisation more than doubled from the ₹29,848 crore recorded on its trading debut, briefly establishing Gland as one of India's most valuable pharmaceutical enterprises.1 Investors were no longer valuing Gland as a standard contract manufacturer; they were pricing it as a secular compounding platform.
That valuation also looked straight past the geopolitical backdrop. In April 2020, India had introduced Press Note 3, placing all foreign direct investment from neighboring land-border nations under mandatory government screening.18 Coming months after the deadly military skirmish in the Galwan Valley, Gland's ability to debut under a controlling Chinese parent while attracting overwhelming institutional demand suggested that global funds prioritized corporate fundamentals over diplomatic tensions. The investment narrative appeared bulletproof: a clean regulatory history, an unencumbered balance sheet, high-margin profit-sharing upside, and an expanding pipeline of generic injectables. For a brief window in 2021, geopolitical risk carried virtually no valuation discount.
The Warning Signs in Plain Sight
Yet the vulnerabilities that would unravel that premium were already embedded in the numbers. Much of the volume surge across FY21 and FY22 stemmed from temporary pandemic disruption, as hospital distributors stockpiled inventory against shipping delays—demand that would inevitably reverse once supply chains normalized. Furthermore, the core enoxaparin and heparin portfolio remained exposed to shifting raw material costs and rising competition from Chinese API suppliers. Crucially, Gland's profit-sharing contracts functioned as an operational amplifier: because the company absorbed downstream price cuts without an offsetting reduction in factory overhead, any deflation in US hospital pricing would flow directly through to operating margins.
Investors paying peak valuation multiples on 38% margins were treating cyclical tailwinds as permanent competitive advantages. When end-market pricing softened and customer destocking commenced, the operating leverage that had inflated Gland's margins worked in reverse with equal speed.
VII. The Post-Pandemic Hangover & The Operational Stress Test (2021–2023)
On the morning of May 19, 2023, Gland Pharma's shares plunged 20% in early trading, touching an all-time low of ₹1,070.80.20 The fourth-quarter financial results disclosed the previous evening were the weakest since the company's market debut. Revenue dropped 29% year on year, net profit sank 72%, and the operating EBITDA margin shrank to 21%.1920 As Business Standard observed, the stock had fallen 75.5% from its August 2021 peak of ₹4,350.20 In under two years, roughly ₹50,000 crore in shareholder value had vanished.
Myth vs. Reality: What Actually Broke
A prevailing market narrative attributed this collapse to an aggressive USFDA regulatory crackdown: severe Form 483 observations at Dundigal, halted manufacturing lines, and a shattered compliance moat. The regulatory record does not support that thesis. The agency's inspection of Dundigal in August 2022 was a pre-market audit under medical-device quality system regulations that resulted in a single observation, which the USFDA formally closed with an Establishment Inspection Report in January 2023.9 A subsequent unannounced Good Manufacturing Practice inspection at Dundigal in July 2024 yielded two procedural observations, which management confirmed involved neither repeat issues nor data integrity concerns.10 In August and September 2026, the company's Visakhapatnam oncology and API sites cleared a routine USFDA inspection with zero observations.21
Manufacturing compliance did not break Gland; compounding commercial exposures did. During the fourth-quarter FY23 earnings call, management outlined a convergence of simultaneous commercial pressures:6
- Heparin under competitive assault. Two Chinese manufacturers launched finished heparin directly in the United States, triggering severe price erosion. Combined revenue from unfractionated heparin and enoxaparin dropped from approximately ₹1,200 crore in FY22 to roughly ₹970 crore in FY23.
- The dissipation of pandemic-era demand. Domestic revenues tied to COVID-19 treatments contracted by roughly ₹380 crore, while sales of micafungin, an antifungal used in acute critical care, collapsed from about ₹440 crore to ₹65 crore.
- Customer vendor reallocation. A major marketing partner transferred 14 to 15 commercial products to alternate contract manufacturers.
- Counterparty insolvency. A key US distribution partner filed for Chapter 11 bankruptcy reorganization. Gland took a provision of ₹564.61 million against uncollected receivables—an impairment management characterized as unprecedented in the firm's operating history—for an account that had historically generated roughly ₹200 crore in annual business.166
- Channel destocking. Confronted with rising interest rates and higher inventory carrying costs, distribution partners aggressively trimmed buffer stocks from typical nine-to-twelve-month levels.
- Scheduled facility downtime. Gland temporarily idled its Pashamylaram penems manufacturing block to complete a planned capacity upgrade.20
Across the full fiscal year, total revenue fell 18% to ₹36,246 million while the EBITDA margin retreated from 34% to 28%.19 The company's investor disclosures acknowledged the structural headwind, citing "higher pricing pressure with increased competition."19
The central operational takeaway was unmistakable: nearly every disruption stemmed from customers, counterparties, and end-market pricing rather than manufacturing breakdown. Gland's cleanrooms and fill-finish suites functioned as designed. What failed was the underlying underwriting assumption that partner ordering volumes, distributor solvency, and downstream wholesale prices would remain stable. Addressing analysts on how the portfolio would stabilize, Sadu conceded that commercial prices for select large-volume generic molecules can plummet by "80% to 90%" following competitive market entry.6 It was an unvarnished summary of the pricing dynamics governing outsourced suppliers in the US generic landscape.
Historical Falsification: The Sputnik V Bet
The second dimension of the post-pandemic reset centered on capital allocation and strategic optionality. On March 16, 2021, Gland entered into an agreement with the Russian Direct Investment Fund to manufacture up to 252 million doses of the Sputnik V COVID-19 vaccine, with commercial deliveries scheduled to commence in the third quarter of 2021.22 Sadu indicated the company would deploy approximately ₹270 crore in capital expenditure, which included ₹90 crore to acquire an operational Hyderabad facility from Vitane Biologics in May 2021.23
Vaccine production, however, required capabilities fundamentally different from small-molecule sterile fill-finish. Biological manufacturing requires cultivating the active drug substance inside living cell cultures before formulating and aseptic filling into finished drug product. While Gland possessed deep expertise in high-throughput sterile packaging, it had never cultivated biological drug substances at commercial scale. Technology transfer faced persistent delays, and Russia's invasion of Ukraine in February 2022 created severe geopolitical and operational barriers to executing Russian-linked supply contracts. Consequently, Sputnik V never materialized as a meaningful disclosed revenue contributor in subsequent financial statements. By FY24, corporate presentations repositioned the Vitane site as Gland's foundation for a "foray into biologics CDMO business," with management characterizing biologics as "a long-term play" whose initial focus was "to obtain regulatory approvals for the facility."416
The verdict: the partnership failed to realize its initial commercial mandate. While the physical infrastructure survived as long-term optionality for biological contract manufacturing, assets acquired for an immediate pandemic windfall had to be repurposed for a multi-year pivot. The episode illustrated a broader lesson: technical fill-finish readiness does not guarantee commercialization, and when contracts hinge on state-backed sovereign entities, geopolitical volatility can dismantle an operational thesis regardless of factory compliance.
What the Stress Test Revealed
The 2021–2023 downturn demonstrated two concurrent realities. Operationally, Gland's manufacturing foundation remained sound, avoiding both warning letters and import restrictions. Economically, however, the business proved far more vulnerable to partner destocking, distributor solvency, and severe single-molecule price erosion than its peak valuation multiples had priced in. Facing compressed domestic returns and US pricing headwinds, management turned to its debt-free balance sheet to execute an acquisitive reset in Western Europe.
VIII. Capital Deployment & The European CDMO Pivot: The Cenexi Acquisition
November 29, 2022 presented an unusual study in corporate contradictions for Gland shareholders. During morning trading, Bloomberg reported that Fosun was exploring a sale of its 57.86% controlling stake, sending Gland's shares up as much as 8.7%. Gland formally stated it was "not aware" of any such plan.24 That evening, the company announced its first international acquisition.[^25] On the very day its parent company was reportedly testing buyer interest, Gland committed its cash reserves to a European purchase.
The Deal
Through its Singapore subsidiary, Gland signed a put-option agreement to acquire 100% of Cenexi Group for an equity value of up to €120 million, implying an enterprise value of €230 million.[^25] Founded in 2004, Cenexi operated four sterile and specialty manufacturing sites: Fontenay-sous-Bois, Osny, and Hérouville-Saint-Clair in France, alongside Braine-l'Alleud in Belgium. With 1,372 employees, it had generated €184.1 million in revenue in 2021.[^25] The acquisition brought specialized capabilities Gland lacked in Hyderabad: hormonal formulations, controlled substances, ophthalmic gels, needle-free injectors, and an established European customer base. Sadu presented the transaction as a move to "deepen access into the European markets" and to "solidify our identity as an injectable focused CDMO."[^25] The deal closed on April 27, 2023.6
The transaction structure carried practical operating consequences. In France, entering a put-option agreement is the standard legal mechanism for corporate acquisitions: French labour law requires buyers to formally consult target works councils before executing a binding purchase agreement. The buyer makes an irrevocable offer, granting the seller the right—though not the obligation—to accept once employee consultations conclude. While structurally routine, the framework signaled from the outset that Gland was entering a Western European labour regime where restructuring headcounts, altering shift patterns, or rationalizing plant footprints requires collective bargaining rather than unilateral management directives. That institutional friction proved critical once turnaround efforts began.
The commercial rationale was clear regardless of the purchase price. Gland's European footprint had been modest and contracting: revenue from the base European business was just ₹1,870 million in FY23, falling to ₹1,555 million in FY24.16 European health authorities and multinational drugmakers increasingly prioritized regional supply security, seeking sterile contract development and manufacturing partners with facilities spanning both low-cost Asian hubs and local Western markets. Cenexi gave Gland an immediate European manufacturing presence that would have taken more than five years to build from scratch. The strategic concept was sound; the challenge lay entirely in operational execution.
Did Gland Overpay?
On headline figures, the transaction multiple appeared unexceptional. Gland disclosed that Cenexi had earned approximately €23 million of EBITDA on €184 million of revenue in CY21, and about €26 million of EBITDA on €192 million in CY22.19 An enterprise value of €230 million implied an entry multiple of roughly 9 to 10 times trailing EBITDA and approximately 1.2 times annual revenue. During the 2020–2021 pandemic peak, leading Western sterile CDMO platforms routinely traded at far higher multiples.
The fundamental issue was not the headline multiple, but the underlying quality of the earnings. Once consolidated into Gland's accounts, the business deteriorated rapidly:
- Q3 FY24 (the initial full reporting year): Cenexi posted an operating EBITDA loss of ₹170 million. While management stated the business would have broken even operationally excluding one-off integration costs, it acknowledged that post-acquisition audits had "identified areas where Cenexi would need investments and significant improvements."25
- Q4 FY24: Operating results worsened sharply, with Cenexi recording an EBITDA loss of ₹720 million—a negative margin of 20%. Across its first eleven months of ownership in FY24, Cenexi lost ₹812 million at the EBITDA level.16 That drag pulled Gland's consolidated EBITDA margin down to 24%, even as the core Indian operations recovered to 34%.16
- FY25: Operating performance remained deep in the red. Cenexi recorded an EBITDA loss of €19 million on €164 million of revenue, representing a negative 12% margin.5 Operational disruption deepened when France's health regulator, ANSM, conducted an unannounced inspection at Fontenay-sous-Bois, causing weeks of lost production during audit and remediation, which was subsequently compounded when two pieces of manufacturing equipment broke down.84
That sequence answered the overpayment question more decisively than any multiple comparison could. An asset underwritten on roughly €23 million to €26 million of historic EBITDA had swung to a full-year operating cash loss of €19 million—a negative reversal exceeding €40 million relative to baseline deal projections. Furthermore, Gland had to inject capital into modernizing European equipment, deploying ₹1,607 million in Cenexi capital expenditures in FY24 alone.16 What had been framed as an attractively priced operating platform was, in reality, a capital-intensive turnaround whose remediation costs had not been reflected in the purchase price.
Management's Promises vs. Outcomes
Earnings call transcripts show how management's timeline adjusted under operational pressure. Following the French regulatory audit, Bank of America analyst Neha Manpuria asked on the Q3 FY25 call why a ten-day regulatory inspection was delaying operational breakeven by three full quarters. Sadu pointed to roughly three weeks of lost production across two successive audits, alongside ongoing corrective remediation. He moved the breakeven target to Q3 FY26.8
That recalibrated target was met. Cenexi reached EBITDA breakeven in Q1 FY26 with a 2% margin, after Fontenay received its ANSM GMP certificate and a new high-speed ampoule line began commercial operations.26 Operating margins registered at 3% in Q3 FY26 and 1% in Q4 FY26, though full-year results remained slightly negative at minus 2% on €182 million of revenue.5 Operational momentum continued into Q1 FY27, with Cenexi generating €2 million of EBITDA on €48 million of revenue, or roughly a 4% margin.17 Management targets double-digit margins by the end of FY27 and "mid-teen" EBITDA in the medium term.1727
The operational turnaround has progressed, but at a materially slower pace and from a deeper trough than early guidance suggested. Management's late-2023 framing of "adjusted operational breakeven" was contradicted by subsequent financial prints, even if the reset 2025 timeline held up. For institutional investors, the decisive operating benchmark remains Cenexi's EBITDA trajectory: can margins advance from low single digits into sustainable double digits, or will profitability plateau near 5%, leaving the mid-teens ambition unproven?
A strategic counterweight exists. Gland's chief financial officer noted that a landmark 55-SKU manufacturing contract finalized in 2026 would not have materialized "in a way" without Cenexi, arguing that the customer valued an end-to-end partner offering European manufacturing sites alongside Indian plants.17 If substantiated, Cenexi's enterprise value may rest as much on the commercial deals it enables across the broader franchise as on its standalone accounting returns. That thesis remains plausible, yet it cannot be fully verified until commercial volumes and revenues from that contract begin flowing in CY2029.17
IX. Inside the Machine: Core Business Economics, Moats, & Industry Structure
Step into a sterile filling hall and the defining element is the air. High-efficiency filtered air sweeps from ceiling to floor in a continuous laminar stream, and the cleanroom is maintained under positive pressure relative to the surrounding corridors so that airborne particles are forced out rather than pulled in. Operators gown up in meticulous stages. Glass vials emerge from depyrogenation tunnels heated to temperatures that destroy bacterial endotoxins, then advance beneath isolator barriers where automated lines fill and seal them. Every batch leaves an exhaustive audit trail, and every record is subject to regulatory inspection. This operational setting is where Gland's unit economics are forged.
The Revenue Architecture Today
Fiscal 2026 provides the cleanest full-year window into Gland's post-turnaround profile. Consolidated revenue rose 14.5% to ₹64,307 million, delivering a 26% adjusted EBITDA margin and adjusted profit after tax of ₹10,455 million.5 Beneath the consolidated totals, however, the group operated as two entirely distinct economic engines:
- The base business (India-centric Gland) generated ₹45,613 million in revenue—roughly 71% of the group total—at an adjusted EBITDA margin of 38%.5 This legacy operation generated virtually all of the company's operating profit.
- Cenexi contributed approximately €182 million (₹18,693 million), accounting for the remaining 29% of sales, while generating an EBITDA slightly below breakeven.5
Geographically, the United States remained the anchor, contributing ₹34,214 million, or just over half of group revenue. Europe, driven predominantly by Cenexi, contributed ₹14,035 million; the rest of the world brought in ₹11,117 million; Canada, Australia, and New Zealand added ₹2,269 million; and domestic Indian sales totaled just ₹2,672 million.5 An enterprise that began as a domestic supplier in Hyderabad derived only about 4% of its revenue from its home market.
Alongside geographic diversification, the commercial model underwent a deliberate structural pivot. Contract development and manufacturing services (CDMO) expanded 28% to account for 46% of consolidated revenue in FY26, while within the base Indian business, CDMO sales rose 33% to reach 23% of the top line.5 By the first quarter of fiscal 2027, CDMO work reached exactly 50% of consolidated sales.17 That transition fundamentally alters cash-flow mechanics: CDMO fees are earned per unit manufactured and per service rendered, decoupling Gland's income from the downstream pricing volatility of partners' generic portfolios. Returning to the commercial real estate analogy, Gland has steadily shifted from collecting a variable percentage of tenant sales to receiving predictable, fixed rent. The tradeoff is clear: insulation against severe wholesale price deflation comes at the expense of giving up the lucrative profit-sharing windfalls of a runaway generic launch.
Unit Economics: Why Two Businesses With Similar Gross Margins Earn Such Different Profits
A direct comparison inside Gland's financial reporting illustrates the operational mechanics of sterile manufacturing. In FY26, Gland's Indian base business posted a gross margin of 61%, whereas Cenexi recorded a gross margin of 76%.5 Judged by gross margin alone, Cenexi would appear to be the superior business. Yet the base business converted 38% of its revenue into adjusted EBITDA, while Cenexi generated an operating loss.5
The divergence lies in how the metric is constructed. Gland calculates gross profit simply as revenue minus the cost of materials consumed.5 For a European CDMO like Cenexi, clients frequently provide the expensive active pharmaceutical ingredients on consignment, keeping raw-material costs minimal on the income statement and driving gross margin artificially higher. The true operating expenses sit further down the ledger: Western European wages, continental energy tariffs, facility maintenance across aging plants, and substantial regulatory compliance teams whose payroll runs regardless of whether lines are active. In Hyderabad, the cost profile is inverted: raw materials account for a larger share of sales because Gland synthesizes or purchases its own bulk APIs, but Indian labor, utilities, and plant overhead remain structurally cheaper per unit.
Consequently, in sterile injectable manufacturing, capacity utilisation is the decisive operational variable. A high-speed aseptic filling line incurs nearly identical fixed overhead whether operating at 40% capacity or 85%. This operating leverage explains why the equipment breakdowns and regulatory remediation at Fontenay inflicted such severe financial damage in FY25. It also clarifies why executive commentary constantly highlights new ampoule capacity and volume absorption across European suites: once baseline fixed costs are absorbed, incremental production batches convert almost entirely into operating profit, whereas lost batches erase margin dollar for dollar.
The balance sheet mirrors this operational conservatism. Gland entered FY27 holding ₹35,466 million in total cash and ₹32,939 million in net cash, after generating ₹3,183 million in operating cash flow and deploying ₹1,132 million toward capital expenditures in the first quarter.17 The enterprise comfortably self-funds its capital program. The corresponding drawback is that an outsized cash reserve invested in low-yielding treasury instruments drags down return on equity. Gland's capital-allocation debate is therefore not about solvency, but about whether incremental capital can earn superior returns to those generated by recent expansion bets.
Competitive Landscape
Gland navigates three distinct competitive arenas:
- Global injectable majors: Multinational corporations such as Hikma Pharmaceuticals, Fresenius Kabi, Pfizer (via its Hospira business), and Sandoz. These incumbents operate direct hospital sales forces, maintain extensive commercial catalogs, and possess vast manufacturing networks. Several also partner with Gland as contract customers.
- Indian injectable challengers: The most direct domestic competitor is Eugia Pharma Specialties, Aurobindo Pharma's dedicated injectables subsidiary, which rivals Gland in batch scale and regulatory filing velocity. Peers such as Dr. Reddy's Laboratories, Sun Pharma, Cipla, and Caplin Point Laboratories also compete across selected dosage forms and emerging markets.
- Specialized sterile CDMOs: Independent fill-finish operators in Europe and North America compete for outsourced pharmaceutical development and commercial packaging contracts—the exact terrain occupied by Cenexi.
Where Gland maintains an edge: A structurally low unit-cost profile driven by large-scale batch runs and Indian engineering talent; an established filing pipeline that continuously delivers new regulatory dossiers; and, most crucially, a strict non-compete posture toward its partners. A global distributor can entrust an off-patent molecule to Gland without fearing that the manufacturer will launch an identical proprietary brand in the same hospital market.
Where Gland remains vulnerable: The company exercises minimal pricing power against consolidated American wholesalers and group purchasing consortia. It remains exposed whenever commercial partners re-internalize production or reallocate supply contracts—as demonstrated by the loss of 14 to 15 products in 2023. Furthermore, low-cost Chinese API producers can aggressively undercut Gland's legacy formulations, as seen during the post-pandemic heparin correction.
Hamilton Helmer's 7 Powers
Applying Hamilton Helmer's 7 Powers framework isolates which structural advantages Gland genuinely commands:
- Switching costs (strong, and the core moat): Transferring an approved sterile injectable to an alternate manufacturing facility requires filing prior approval supplements with the USFDA, conducting new stability studies, manufacturing commercial validation batches, and enduring months of regulatory and supply-chain risk. Once Gland is embedded as the designated site in a partner's regulatory dossier, commercial inertia is formidable. Falsification test: In 2023, a major partner transferred 14 to 15 commercial products to alternate suppliers regardless.6 Switching costs impose friction and delay, but they do not create an unbreakable lock-in. The more defensible conclusion is that site transfers are costly and protracted, ensuring customer defections unfold slowly and with ample advance notice.
- Process power (strong): Sustaining aseptic sterility assurance, optimizing complex lyophilisation thermal cycles, handling potent cytotoxic oncology compounds, and controlling particulate counts are capabilities accumulated through decades of shop-floor refinement. Gland's compliance history—underpinned by multiple regulatory audits concluded without warning letters or escalations—substantiates this operational discipline.1021
- Counter-positioning (strong, but narrowing): Multinational generic marketers routinely contract with Gland because Gland does not operate competing commercial brands. Frontline generic peers such as Dr. Reddy's or Sun Pharma struggle to secure identical outsourced business because their commercial arms compete directly with prospective clients. However, this advantage is gradually narrowing as Gland pursues proprietary complex formulations: with 15 co-development projects underway, including seven under the 505(b)(2) regulatory pathway, Gland is expanding its proprietary exposure, subtly blurring the boundary with its traditional customer base.5
- Scale economies (moderate to high): An installed finished-formulation capacity of approximately 1,200 million units annually allows Gland to dilute high fixed analytical, quality-assurance, and regulatory maintenance costs across enormous batch volumes.4 However, operational scale provided little shelter against acute price deflation when end-market competition intensified in 2023.
- Cornered resource (low to moderate): Hyderabad's dense concentration of sterile injectable engineering and microbiology expertise provides a deep regional talent pool, but those professionals can be recruited by well-capitalized domestic peers.
- Network effects (none): Adding an incremental distribution partner or generic dossier provides no direct structural benefit to existing partners.
- Branding (low, B2B only): Regulatory and compliance reliability establishes credibility among corporate procurement and quality assurance committees, but it yields minimal premium pricing power in public tenders or commercial auctions.
Porter's Five Forces
- Buyer power (very high): In the United States generic market, three dominant wholesale purchasing consortia control the vast majority of hospital and retail procurement. These buyers leverage their buying scale to extract aggressive price concessions from generic marketers, who inevitably transmit that pricing pressure back upstream to contract manufacturers. Gland's fourth-quarter FY23 margin contraction stands as the definitive case study.
- Threat of new entrants (low to moderate): Constructing an aseptic injectable facility capable of passing USFDA, EMA, and other developed-market regulatory audits requires hundreds of millions of dollars in capital expenditure and several years of validation. Sadu argued to analysts in 2023 that low-margin CDMO newcomers would find "survival in long-run... difficult."6 While plausible given the elevated compliance overhead, that assessment reflects management's perspective rather than an insurmountable barrier to well-funded competitors.
- Supplier power (moderate): Critical sterile packaging inputs—including specialized borosilicate glass vials, rubber elastomer stoppers, and pre-fillable syringe barrels—are controlled by a handful of global packaging conglomerates. Gland's backward integration into active pharmaceutical ingredient synthesis mitigates chemical supply risks, but its dependence on external packaging hardware remains intact.4
- Threat of substitutes (very low): Sterile parenterals occupy non-discretionary clinical niches. An intravenous antibiotic administered in an intensive care unit, an injectable anesthetic used during surgery, or an intravenous oncology infusion cannot be substituted with an oral tablet or capsule.
- Rivalry among existing competitors (high, particularly in commodity injectables): As soon as three or more generic manufacturers secure regulatory approval for an off-patent molecule, commercial auction dynamics frequently trigger severe price erosion. This intense competitive rivalry explains Gland's strategic push to redirect research capital toward complex drug-device combinations, depot formulations, and fee-for-service CDMO contracts.
The overarching takeaway from Gland's industrial architecture is a stark asymmetry: the company possesses formidable supply-side moats—disciplined aseptic processes, high customer switching friction, and an Indian cost advantage—yet sells into a structurally unforgiving demand environment dominated by monopsonistic buyers. Over the long run, Gland's operating margins will depend less on the technical perfection of its cleanrooms than on its ability to shift revenue toward complex formulations and fixed-service contracts where hospital buyers cannot easily play suppliers against one another.
X. Modern Era: Management, Governance, & Strategic Evolution
On the evening of May 15, 2026, Srinivas Sadu opened Gland Pharma's full-year earnings call as Executive Chairman. The company had just reported its best quarter ever: revenue up 22%, adjusted PAT nearly doubled, and a base-business adjusted EBITDA margin of 41%.5 Near the end of the Q&A, an analyst asked about something the press release had not mentioned: the new CEO search. Sadu answered that the company was "looking at candidates who have stronger CDMO background."27
The Leadership Carousel
The sequence is worth setting out, because it tests a narrative of stable leadership. Sadu became MD and CEO on April 25, 2019. He was elevated to Executive Chairman and CEO on June 10, 2024.28 In October 2024 the board hired an outsider, Shyamakant Giri, as CEO from January 2025. Giri had been at Amneal and Rivaara Labs, and had spent about 18 years at Abbott and AbbVie in India. Sadu moved to Executive Chairman only.29 In February 2026, just over a year into the role, Giri resigned "to pursue new opportunities," with effect from April 30, 2026.30 The company did not announce a successor at the time.30
The departure of a CEO with emerging-markets and commercial experience, followed by a search for someone with a CDMO background, suggests the board's view of what the job needs changed within about 18 months. That is not necessarily a bad sign; the business itself was changing quickly toward CDMO. But investors should note that the executive in charge today is the same long-serving operator who ran the company through the 2023 downturn and the Cenexi deal, and that the outside-CEO experiment did not last.
Sadu's Scorecard
Delivered: - He kept key partner relationships and the compliance record intact through the change from KKR to Fosun and through the IPO. Recent inspections, including a zero-observation outcome at Visakhapatnam in 2026, support the claim on quality.21 - He met the revised Cenexi breakeven target.26 - He oversaw the base-business margin recovery from 28% in FY23 to 38% adjusted in FY26.195 - He was candid at the low point, for example about price crashes of 80–90% on large molecules.6
Missed or open to criticism: - The Sputnik V capex did not produce the business it was bought for. - The early Cenexi guidance was too optimistic. - The China strategy under his leadership produced one commercial product with "limited contribution."16 - Growth guidance has shifted considerably. In May 2026 management guided to a four-year consolidated CAGR of 15%. Less than three months later, in August 2026, it raised that to 20%.2717 The upgrade came with a large new contract, so it may be justified. But a four-year target that moves five percentage points in one quarter is a reminder that long-range guidance here is aspirational.
Governance and alignment: Sadu is a professional manager, not a promoter. The company pays senior staff partly through employee stock options, and it removes ESOP costs when it calculates "adjusted" EBITDA.5 Investors should keep that adjustment in mind. Stock-based pay is a real cost, and headline "adjusted" margins look better because of it.
Fosun Sells Down
Fosun's stake has fallen in steps: about 74% before the IPO, about 58% after it, then 51.77% after a roughly 6% block sale for ₹1,754 crore in June 2024.313 On September 4, 2026, Fosun Pharma Industrial sold 75.05 lakh shares, a 4.55% stake, across 11 block tranches at an average ₹2,826.60 per share, raising ₹2,121.50 crore. Its holding fell to 47.22%.3 Domestic mutual funds took most of it. Kotak Mahindra Mutual Fund alone bought about 1.7% for ₹789.47 crore, with Axis and ICICI Prudential also buying large amounts.3 The stock closed about 1% higher, at ₹2,932.40.3
Fosun's own disclosures described a plan to sell about 6% in total, for roughly $294 million, which would leave it with about 45.76%. It said it would continue to consolidate Gland's results.32 Readers should follow the exchange filings for the final number, since the executed block reported so far is the 4.55% tranche. Fosun said the proceeds would go mainly to R&D, share buybacks and repaying interest-bearing debt. It launched a HK$1 billion H-share buyback funded mainly from the sale.32 The stated motive is the parent's own finances, not a loss of confidence in Gland. That fits Fosun's balance-sheet pressure going back to 2022.24
The policy background is also shifting. India's Press Note 2 of 2026 created an automatic route for minority investments of up to 10% from land-border countries, and reframed screening around control rather than any link to those countries.18 Fosun still controls Gland, so the change does not directly affect it. But it suggests Indian policy toward Chinese capital is less hostile than it was in 2020.
What the Analysts Are Probing
The Q1 FY27 call, held in August 2026, showed what the market is uncertain about. Much of the Q&A focused on the unnamed partner behind the 55-SKU agreement. Management described it only as a "specialty pharma global company" whose business is about 30–40% specialty and 60–70% generics. Analysts pushed on where production would happen and how fast revenue would ramp. The answer was that manufacturing would be mainly in India, with Cenexi handling European warehousing and logistics.17 Rest-of-world revenue was flat because of supply disruptions to Saudi Arabia. On the previous call, management had estimated the Middle East at about 2–3% of sales and said nothing had shipped to Saudi Arabia in the quarter.1727
Two patterns stand out. First, analysts accept the base business as sound and now spend their questions on timing: when contracts produce revenue, when Cenexi reaches double digits, when GLP-1 volumes start. Second, management's answers are more specific than they were in 2023. They include numbers, timelines and named molecules. But a lot of the promised value sits in FY2029–31, which is beyond most investors' forecasting horizon.
The Biologics and GLP-1 Horizon, Sized to Reality
Here the "certification is not commercialization" discipline matters most. The GLP-1 story (drugs such as liraglutide, semaglutide and tirzepatide) is real in the sense that Gland launched partnered liraglutide in the US and expanded pen and cartridge capacity to 140 million units a year.5 In Q1 FY27 it signed a collaboration covering semaglutide and tirzepatide for the US and EU. But management's own timeline expects major volumes only in FY2030–31.17 Management has also said that its growth guidance excludes GLP-1, and that anything from GLP-1 would be upside.27
Biologics is smaller still. The Dr. Reddy's biologics CDMO partnership brings in about ₹50–60 crore a year, which management called "normal business," with modest growth expected.17 That is less than 1% of revenue. The honest sizing is that GLP-1 and biologics are real options for 2029 and beyond. Today's earnings rest on sterile generic injectables and CDMO work. Given the Sputnik record, investors should wait for revenue before giving these options much value.
XI. Business & Investing Playbook: Durable Lessons
The May 2023 earnings call remains the defining case study of Gland's operating model. The company's market capitalisation had plunged by three-quarters from its pandemic peak, sell-side analysts were lining up with pointed questions, and Srinivas Sadu was walking through the financial damage: steep price erosion in heparin, a key commercial partner transferring more than a dozen products to rival suppliers, and an unprecedented bad-debt provision against a bankrupt American distributor.6 Crucially, Sadu was not describing an engineering breakdown inside Dundigal's cleanrooms. He was explaining what happens to an outsourced manufacturer when it exercises no control over the final mile to the customer. Most of the structural lessons of Gland's corporate history trace back to that vulnerability.
A company's history is most useful when it yields repeatable principles rather than a simple chronology. Five operational and strategic lessons stand out, along with the boundaries where each ceases to hold.
Lesson 1: The Hidden Moat of B2B Counter-Positioning
By deliberately avoiding a proprietary generic brand in the United States, Gland converted prospective rivals into core customers. That non-compete posture secured high-volume outsourced manufacturing contracts that vertically integrated Indian peers—who competed directly on Western pharmacy shelves—could rarely capture.
The boundary: Counter-positioning is only as durable as management's commercial discipline. As Gland expands into co-developed 505(b)(2) formulations and in-licensed specialty molecules, it must carefully segregate that proprietary pipeline from its partners' therapeutic franchises. The moment Western marketing partners perceive Gland as a direct commercial challenger, the counter-positioning moat dissolves.
Lesson 2: Specialization Beats Conglomeration in Operations
Focusing exclusively on sterile injectables channels organizational culture, engineering resources, and compliance capital into a single, unforgiving manufacturing discipline. While diversified generic drugmakers divide their operational and compliance bandwidth across oral solid tablets, topical creams, bulk chemical synthesis, and parenterals—frequently triggering USFDA warning letters or import alerts across multi-product sites—Gland maintains that none of its facilities has ever received a warning letter from the US regulator.4 While that assertion originates with the company, it aligns with a public inspection record that shows routine procedural Form 483 observations resolved without escalation.
The boundary: Operational specialization deepens therapeutic and single-molecule concentration risk. When Chinese competition commoditized heparin, Gland had no high-volume oral solids business to soften the blow.
Lesson 3: Technical Milestones Without Commercial Ownership Are Fragile
Throughout Gland's history, technical clearance has regularly been confused with commercial success. Every regulatory milestone—from the initial 2003 USFDA site clearance and early Chinese regulatory dossiers to the repurposing of biological capacity for Sputnik V—ultimately depended on a third party's commercial distribution, end-market pricing power, and counterparty solvency to generate sustained cash flow. The post-pandemic earnings contraction was triggered by customers and counterparties, not cleanroom failures. Institutional investors should therefore discount pure capability announcements until commercialization proves viable.
The latest iteration of this principle is the GLP-1 opportunity. Gland has installed pen and cartridge assembly lines and launched partnered liraglutide, but management has deliberately excluded GLP-1 volumes from near-term corporate guidance, deferring major commercial contributions to fiscal 2030 and 2031.517 That cautious framing reflects the historical record: technical capacity is installed, but downstream commercial volume remains an unverified option.
Lesson 4: Cross-Border M&A in Regulated Industries Is a Turnaround, Not a Purchase
On headline metrics, Cenexi appeared attractively valued at roughly 10 times trailing EBITDA. The true economic cost of the acquisition, however, encompassed two years of operating cash losses, protracted regulatory remediation following a French health authority audit, aging equipment failures, and sustained capital expenditure. Western European collective bargaining agreements, elevated utility tariffs, and legacy facility footprints demand an operational turnaround that headline transaction multiples routinely obscure. Emerging-market acquirers targeting Western manufacturing assets must underwrite the cost and timeline of industrial remediation, rather than the initial entry multiple.
Lesson 5: Geopolitical Hostage Risk Can Be Managed, But Not Removed
Gland navigated Chinese majority ownership through Doklam, the Galwan Valley clash, and the imposition of Press Note 3 without forfeiting US customer supply contracts or its Indian operating licenses. A restructured 74% transaction threshold, an autonomous Indian executive team, and a domestic public listing served as effective political shock absorbers.
The boundary: While geopolitical risk management preserved existing operations, it failed to deliver the strategic upside promised in 2017. Chinese hospital synergies never materialized, and the equity traded under an enduring ownership discount that will only be tested as Fosun divests its controlling stake. Structural buffers can protect an enterprise from regulatory expropriation; they cannot engineer cross-border commercial synergies.
The common thread running through Gland's history is an enduring asymmetry: exceptional execution inside the factory gates paired with limited strategic and commercial control outside them. The final section examines whether that dynamic is beginning to shift, or whether the company remains fundamentally tied to the fortunes of its partners.
XII. Bear vs. Bull: Valuation, Risks, & Skeptical Investor Stress Test
On August 11, 2026, Gland's stock surged 12% in a single trading session to ₹2,989.25, touching a four-year high following its first-quarter FY27 results. That rebound represented a roughly 90% advance from its 52-week low of ₹1,575 recorded on March 16, 2026.33 Just five months earlier, the market had been discounting the abrupt resignation of its chief executive and persistent softness across rest-of-world markets. By August, equity investors were once again pricing Gland as a 20% compounder.
The Dashboard: Three KPIs That Matter
- Base-business adjusted EBITDA margin. This metric tracks whether pricing discipline and product mix are holding across the Indian manufacturing core. Having compressed to 28% in FY23, base adjusted EBITDA margins recovered to 38% by FY26.195 If profitability sustains in the mid-to-high 30s, the post-pandemic reset looks like a cyclical trough. If it drifts back toward 30%, it signals that commoditisation has reasserted itself.
- Cenexi EBITDA margin. Operating margins at the European subsidiary must expand from roughly 4% toward management's promised double-digit target.17 This remains the clearest operational test of whether Gland's cross-border capital allocation is genuinely creating value.
- CDMO share of revenue. Contract development and manufacturing work reached 50% of consolidated sales in Q1 FY27.17 This metric measures how rapidly Gland is replacing volatile, price-exposed profit-share arrangements with predictable, contracted service fees.
The Activist's Stress Test
A skeptical long/short investor would focus on five structural vulnerabilities:
- The "cost-plus trap." Gland absorbs complete manufacturing and regulatory compliance risk, while marketing partners capture the lion's share of end-market pricing power. Profit-sharing and milestone receipts accounted for roughly 22% of revenue in a recent quarter.8 That substantial earnings stream remains tethered to wholesale prices that Gland cannot dictate.
- Subdued return on capital. Gland's own filings show return on capital employed and return on net worth hovering in the high single digits to low double digits between FY23 and FY25.4 In Q1 FY27, return on equity stood at 11%.17 That modest return profile is weighed down partly by Cenexi's extended turnaround and partly by ₹32,939 million in net cash sitting in conservative treasury yields.17 For a manufacturing core operating at 38% margins, mid-teen returns on equity are conspicuously low, placing the burden on management to deploy capital more productively.
- Aggressive capital expenditure. Management has outlined roughly ₹2,000 crore in capital expenditures across a five-year horizon.5 Given the mixed track record of prior large-scale capital deployments—most notably the unmonetized Sputnik V capacity and the protracted Cenexi turnaround—investors require project-level return transparency rather than headline capacity targets.
- Executive churn. The chief executive office changed hands twice within two years, clouding long-term operational continuity.2830
- Customer and geographic concentration. The United States accounts for just over half of consolidated revenue, leaving annual performance vulnerable to single-partner commercial realignments, as demonstrated by the sudden volume losses in 2023.56
The Bull Case
- Multi-year contracted visibility. A strategic 55-SKU manufacturing partnership with a global pharmaceutical company is projected to generate $90 million to $100 million in annual revenue once fully scaled, with commercial volumes commencing in CY2029 and technical transfer initiating in September 2026.17 This long-term contract provides structural visibility absent under the legacy profit-share framework.
- Mix shift toward complex formats. Regulatory filings for ready-to-use infusion bags have expanded to 21 dossiers and 18 approvals, addressing a US market estimated by management at $634 million. The pipeline is reinforced by complex injectables and 15 co-development formulations scheduled to begin commercialization in FY28.5
- Resolution of promoter overhang. With Fosun's equity ownership falling below 50% and domestic institutional funds absorbing block sales, the multi-year geopolitical discount may gradually unwind.3
- Operational leverage at Cenexi. High-speed ampoule additions at Fontenay are positioned to make the site Europe's largest dedicated ampoule facility, while Hérouville scales contract manufacturing for a vaccine and an ophthalmic gel. Against a high fixed-cost infrastructure, incremental batch volumes translate disproportionately into operating margin.5
- Scarcity value in GLP-1 fill-finish. Rapidly expanding demand for injectable weight-loss and peptide therapies provides a structural tailwind for pre-filled syringe and cartridge capacity, even if meaningful commercial revenues remain deferred until FY2030 and beyond under management's guidance.17
The Bear Case
- Resurgent price deflation. Renewed pricing pressure in US generic hospital tenders or aggressive market entry by low-cost Chinese bulk producers—mirroring the post-pandemic heparin shock—would immediately erode profit-share margins.
- Asymmetric regulatory risk. Although Gland maintains an exceptional compliance record, a single critical observation or warning letter across Dundigal or Pashamylaram would halt a significant portion of base-business cash flow. Recent clean audits reduce that likelihood, but they do nothing to diminish the financial impact should an escalation occur.
- Secondary supply overhang. Continued stake sales by Fosun could periodically flood the secondary market, creating technical resistance on share price performance regardless of operating results.
- Turnaround stagnation in Europe. Persistent French labor inflexibility and elevated continental operating costs could keep Cenexi's EBITDA margins stranded in the low single digits, leaving consolidated capital returns depressed and solidifying the 2022 acquisition as an enduring drag on group returns.
- Aggressive guidance assumptions. Management's decision to revise its four-year revenue compound annual growth rate target from 15% to 20% within a single quarter leaves little margin for operational error or regulatory delays on commercial agreements that do not ramp until 2029.
Peer Lens: Where Gland Sits
A peer comparison clarifies Gland's trading valuation without requiring arbitrary price targets. The company operates across three peer groups. Vertically integrated Indian generic producers—such as Aurobindo's Eugia subsidiary, Dr. Reddy's Laboratories, and Sun Pharma—own their Western commercial front ends, capturing a broader share of the value chain while absorbing direct marketing and pricing volatility. Pure-play Indian CDMOs and contract research organizations trade at elevated multiples based on predictable, contracted revenue streams. Meanwhile, global sterile CDMOs command valuation premiums anchored in scarce, pre-cleared aseptic filling capacity.
Gland exhibits characteristics of all three models. Its valuation re-rating through 2026 suggests equity markets have begun pricing it more like a dedicated CDMO, as contract services reached half of group sales.1733 Whether that multiple expansion endures depends on whether CDMO cash flows prove structurally more resilient than profit-share receipts—a resilience that has yet to be tested across a major industry downturn.
Risk Radar: What Is Actually Material
Evaluating risk through an operational lens filters out macro noise and isolates the variables that directly hit cash flow:
- Regional trade disruptions. Recent supply interruptions into Saudi Arabia illustrate how disruptions in localized markets can trim several percentage points off top-line growth.17
- Foreign exchange volatility. Because most contracts are denominated in US dollars and euros, currency fluctuations can create significant headline noise; foreign exchange swings moved from a ₹508 million gain to a ₹36 million loss across consecutive quarters, distorting reported net profits.17
- Component supply bottlenecks. Specialized borosilicate vials, elastomeric stoppers, and pre-fillable syringe barrels remain concentrated among a small cadre of global suppliers, where industry-wide shortages can abruptly idle automated filling lines.
- Concurrent execution friction. Capital allocation risk is elevated as management juggles a ₹2,000 crore domestic capex program, an ongoing executive search, and Cenexi's operational recovery simultaneously.527
Broader macro narratives—such as artificial intelligence disruption or shifts in discretionary consumer demand—remain largely irrelevant to sterile parenteral manufacturing and neither factors materially into the investment case.
Weighing It
Taken together, the evidence supports a more disciplined investment thesis than the peak multiples of 2021 implied. Gland does not operate an unassailable pricing franchise; the 2023 downturn proved that its realized margins are fundamentally bounded by downstream customer economics. Instead, it is an elite aseptic manufacturer steadily mitigating its exposure to generic price deflation by expanding its fee-for-service CDMO footprint and advancing complex delivery formats, even as it digests a capital-intensive European acquisition that has yet to earn its cost of capital.
The assertion that Gland possesses a durable operational moat holds within the sterile suites of its cleanrooms. Its commercial moat, by contrast, remains work in progress. Over the coming four to six quarters, Cenexi's margin trajectory and the resilience of Gland's CDMO mix will demonstrate whether the company has genuinely broken out of the cost-plus trap, or merely found a temporary respite from it.
XIII. Epilogue & Forward Horizon
Return to the intensive care unit and that glass vial of heparin. In 1978, the medicine traced back to a modest Hyderabad laboratory proving it could master sterile formulation. By 2026, it emerges from an industrial network spanning roughly 1,200 million units of Indian formulation capacity alongside four European manufacturing sites, supplying hospital markets across more than 60 countries.45 Over nearly five decades, the enterprise navigated virtually every modern corporate structure: a family-run enterprise, a private equity platform under KKR, a Chinese-controlled subsidiary, and a publicly listed manufacturer. With Fosun's recent selldown, Gland is transitioning once again, shifting toward a widely held Indian corporate structure anchored by domestic institutional investors alongside a foreign minority shareholder.
Where Gland Stands Today
The operational recovery is unmistakable. Base-business adjusted EBITDA margins have rebounded past their pandemic peak, Cenexi has progressed from double-digit operating losses to modest profitability, fee-for-service CDMO contracts now generate half of consolidated sales, and the balance sheet holds substantial net cash. Crucially, compliance discipline across the cleanrooms—the single standard Gland has always had to protect—has held firm through more than a decade of ownership transitions.
Each era left a distinct structural imprint. The founding Raju family established the sterile-first engineering culture and the heparin franchise. KKR institutionalized corporate governance and capital discipline, grooming the firm for a competitive cross-border auction. Fosun provided balance-sheet stability, facilitated a record-setting public debut, and introduced a geopolitical overhang that is only now beginning to clear as its ownership retreats below majority control. The public-market years contributed their own hard lessons: underwriting an outsourced supplier at peak-cycle margins is an expensive mistake, and executing an industrial turnaround in Western Europe takes far longer and costs far more than baseline acquisition models assume.
What remains unproven is how much economic pricing power Gland actually commands. Top-line expansion remains fundamentally tethered to partner commercialization, end-market pricing stability, and long-dated contracts that will not ramp into material volume until 2029. At the leadership level, corporate governance remains in transition, with management confirming that the board is actively searching for a chief executive candidate with dedicated CDMO experience.27
The Strategic Question
Can Srinivas Sadu and his eventual successor transform Gland into a premier global sterile injectables and biologics CDMO, or will it remain a high-specification fill-finish utility vulnerable to wholesale purchasing consortia, customer product reallocations, and geopolitical friction? The answer will not arrive through corporate guidance, but through verifiable operating data: Cenexi achieving its double-digit EBITDA margin target, the commercialization of the 55-SKU manufacturing partnership, and paying commercial volume filling newly installed GLP-1 pen and cartridge lines before the end of the decade.
Behind that operational question sits an equally important governance pivot. With Fosun's stake falling below 50%, a board long oriented around a single controlling shareholder must now answer to an increasingly influential base of domestic institutional funds.3 How the board handles the chief executive succession, and whether project-level capital allocation and return transparency improve as a result, will determine what kind of public company Gland becomes in its next chapter.
Closing Reflection
Gland Pharma demonstrates that the least glamorous discipline in modern healthcare—producing sterile injectables reliably, batch after batch, year after year—can support an exceptionally profitable business. Yet its history also delineates the boundaries of that model. Manufacturing excellence carried Gland through border crises, pandemic demand shocks, and an acute post-COVID earnings contraction. Whether that operational discipline can finally grant the company control over its own commercial destiny is the test that will define its next era.
References
-
Gland Pharma makes strong market debut on Friday, stock rises 21% — Business Standard, 2020-11-20 ↩↩↩↩↩↩
-
Gland Pharma launches Rs 6500 crore largest pharma IPO in India, offer opens Nov 9 — Medical Dialogues, 2020-11 ↩↩↩
-
Gland Pharma Stake Sale: Fosun Pharma Sells 4.55% For Rs 2,121 Crore, Holding Falls Below 50% — Free Press Journal, 2026-09-06 ↩↩↩↩↩↩↩
-
Investor Presentation Q4 & FY25 — Gland Pharma Limited, 2025-05-20 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Press Release: Gland Pharma Reports Record Revenues and Profitability, Q4 FY26 — Gland Pharma Limited, 2026-05-15 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Gland Pharma Limited (GLAND) Q4 FY23 Earnings Concall Transcript — AlphaStreet, 2023-05-18 ↩↩↩↩↩↩↩↩↩↩↩
-
Meet man who studied in US, UK, now leads Rs 32685 crore pharma company in India as CEO, MD: Srinivas Sadu — DNA India, 2024-02-16 ↩↩↩
-
Earnings Call Transcript Q3 FY25 — Gland Pharma Limited, 2025-02 ↩↩↩↩
-
Gland Pharma's Dundigal facility gets EIR from USFDA — Business Standard, 2023-01-04 ↩↩
-
USFDA conducts surprise inspection of Gland Pharma's Dundigal facility — Business Standard, 2024-07-25 ↩↩↩
-
KKR Snags Stake In Gland Pharma Limited For $200 Million — BioSpace, 2013-12-02 ↩↩↩
-
China's Fosun to buy India's Gland Pharma — Fortune, 2016-07-28 ↩↩↩
-
Fosun Pharma acquires 74% stake in Gland Pharma for $1.09 bn — Business Standard, 2017-10-04 ↩↩↩↩↩
-
Fosun Pharma To Partner with Gland Pharma Management Team With 74% Stake Purchase for over US$1 Billion — Fosun Pharma, 2017-09-18 ↩↩
-
Fosun Pharma Scales Back Purchase Of India's Gland Pharma — BioSpace, 2017-09-19 ↩↩
-
Press Release: Gland Pharma reports a strong Q4FY24 and FY24 financial performance — Gland Pharma Limited, 2024-05-22 ↩↩↩↩↩↩↩↩
-
Earnings call transcript: Gland Pharma posts strong Q1 growth (Q1 FY27) — Investing.com, 2026-08-10 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
India Opens the Door to Chinese Investment: A Complete Guide to Press Note 2, 2026 and the FEMA NDI Amendments — Legal 500, 2026-03-10 ↩↩↩
-
Financial Results Q4 FY23 & FY23 Investor Presentation — Gland Pharma Limited, 2023-05-18 ↩↩↩↩↩↩↩↩↩
-
Gland Pharma tanks 20%, hits record low on weak Q4 results — Business Standard, 2023-05-19 ↩↩↩↩↩
-
Gland Pharma's Visakhapatnam Facilities Clear USFDA Inspection With Zero Form 483 Observations — Medical Dialogues, 2026-09-03 ↩↩↩
-
Gland Pharma inks pact to supply 252 mn doses of Sputnik V Covid vaccine — Business Standard, 2021-03-16 ↩
-
Gland Pharma to invest ₹270 cr on facility to produce Sputnik V — News On Projects, 2021 ↩
-
Gland Pharma shares rise 7% as report says Fosun weighs sale of drugmaker — Business Today, 2022-11-29 ↩↩
-
Press Release: Gland Pharma's Q3FY24 Revenue stood at ₹15,452 Million — Gland Pharma Limited, 2024-02-14 ↩
-
Press Release: Gland Pharma reports revenue of ₹15,056 Mn for Q1FY26 — Gland Pharma Limited, 2025-08-05 ↩↩
-
Earnings Call Transcript Q4 FY26 — Gland Pharma Limited, 2026-05-20 ↩↩↩↩↩↩↩
-
Gland Pharma appoints Srinivas Sadu as Executive Chairman and CEO — Business Standard, 2024-06-08 ↩↩
-
Gland Pharma names Shyamakant Giri as new CEO — Medical Dialogues, 2024-10-19 ↩
-
Gland Pharma CEO Shyamakant Giri to Step Down in April 2026 — Medical Dialogues, 2026-02 ↩↩↩
-
Gland Pharma promoter Fosun divests 6% stake for Rs 1,754 cr via bulk deal — Business Standard, 2024-06-19 ↩
-
Fosun Pharma launches US$128M H-Share buyback following Gland Pharma stake sale — HealthCare Middle East & Africa, 2026-09-07 ↩↩
-
Gland Pharma rallies 12%, stock hits 4-year high post Q1 results — Business Standard, 2026-08-11 ↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube