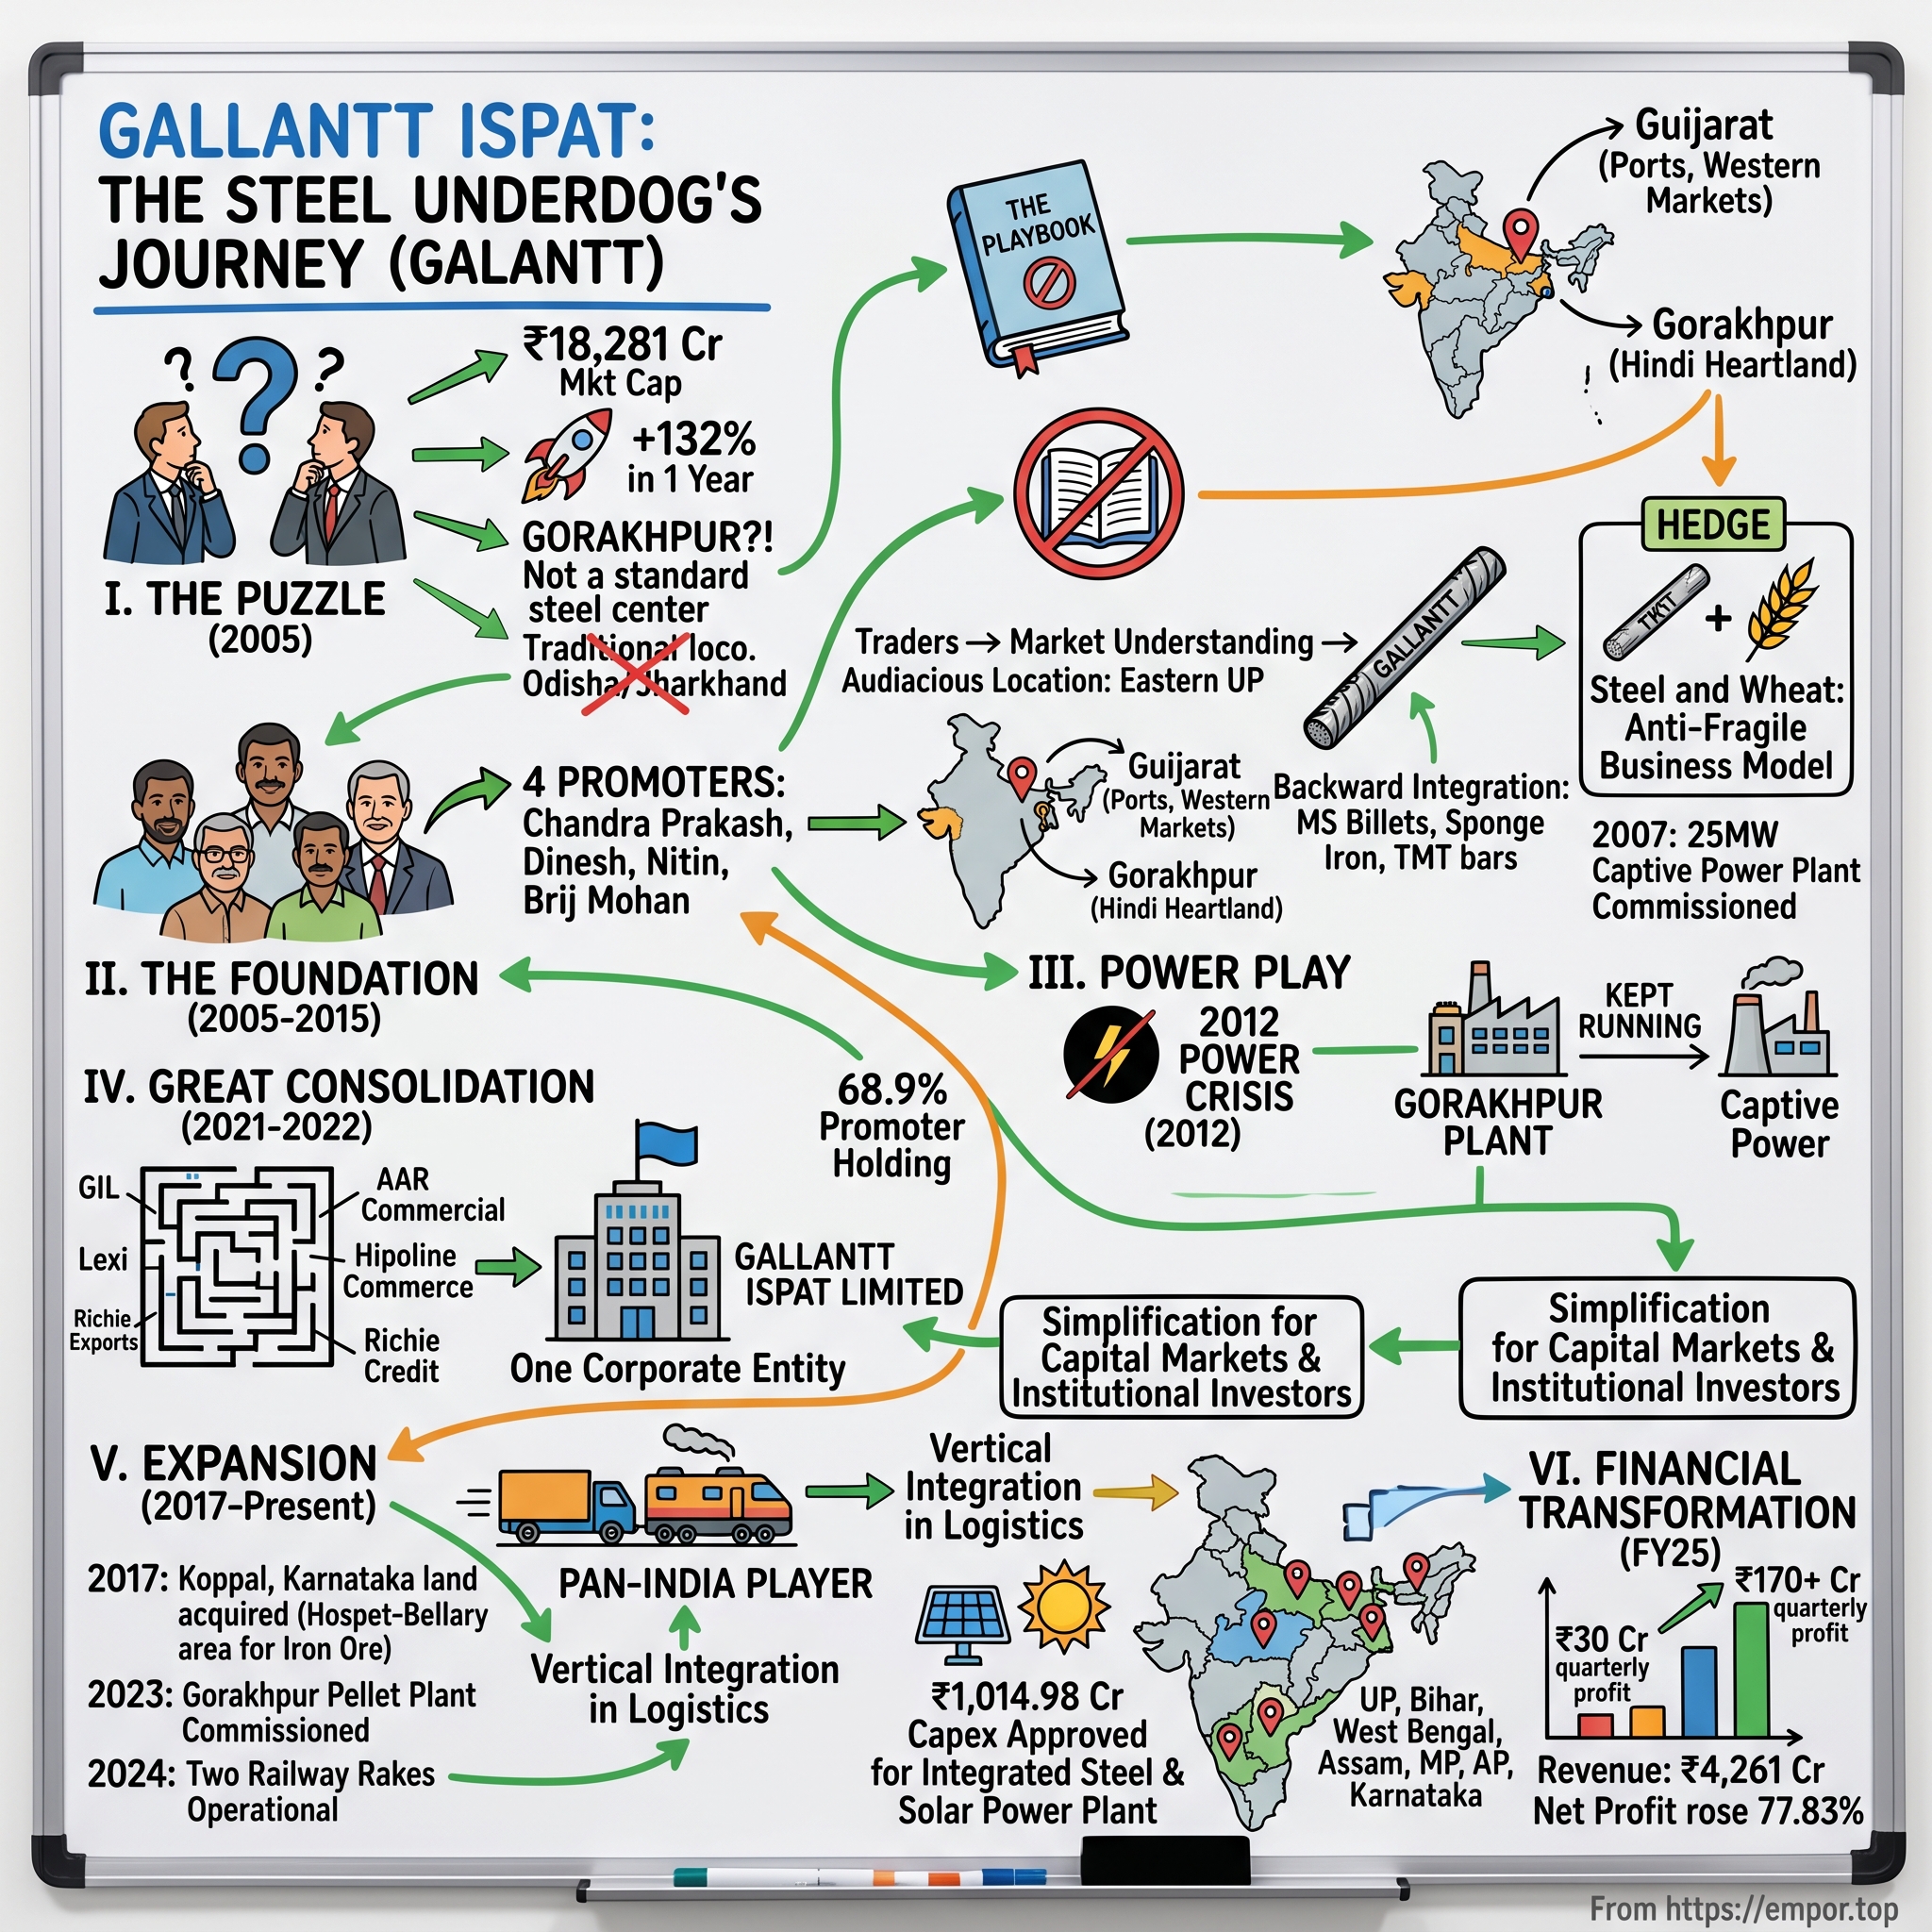
Gallantt Ispat: The Regional Steel Kingpin of the Hindi Heartland
I. Cold Open & The Regional Moat Puzzle
Two Days Before the Deadline
On December 29, 2005, three rotary kilns, a steel melt shop, and a rolling mill on a 122-acre site near the toll gate at Samakhyali, in Gujarat's Kutch district, commenced commercial production.1 The timing was decisive. Under the special fiscal incentive package then offered in post-earthquake Kutch, any manufacturing facility commissioned on or before December 31, 2005, could claim an uncapped refund of excise duty on its finished goods for five years.1 The promoters of newly incorporated Gallantt Metal Limited beat that cutoff with 48 hours to spare. Eight weeks later, they filed a prospectus to raise ₹37.12 crore from the public at par value, ₹10 per share.1
That opening moment captures the Gallantt playbook in miniature: the hustle of first-generation industrialists, a meticulous reading of state incentive schemes, modular plants assembled from small rotary kilns and induction furnaces rather than capital-intensive blast furnaces, and an intricate promoter web of related entities that would shape the next two decades.
From ₹1 Lakh to a ₹13,000-Crore Market Value
Two decades later, the consolidated listed entity, now named Gallantt Ispat Limited, reported FY26 revenue of ₹4,418.9 crore, EBITDA of ₹776 crore, and net profit of ₹484.3 crore.2 It operates two integrated facilities—one at Gorakhpur in eastern Uttar Pradesh and another in Kutch—with combined annual capacity of approximately 1 million tonnes of finished steel backed by 129 MW of captive power.3 In September 2025, India Ratings and Research (Ind-Ra), a Fitch Group company, upgraded the company's bank facilities to IND AA-/Stable.4 Management traces these operations back to 1984, when founder Chandra Prakash Agrawal reportedly started out with ₹1 lakh in capital.5
The public market rerating was extraordinary. Gallantt shares traded at ₹58.75 on June 30, 2023.6 By April 16, 2026, they touched an all-time peak of ₹928.50 following an 18% single-day advance.7 By September 2026, the stock had settled back to around ₹556, giving the company a market capitalization of roughly ₹13,430 crore at approximately 31 times trailing twelve-month earnings.8 While that remains one of the sharpest valuation re-ratings in Indian mid-cap steel, it stands well below the ₹17,836-crore market value recorded on the day of the September 2025 credit upgrade, and short of the "₹20,000 Cr+" claim still featured on the company's website.910
The Steel Industry Paradox
Steel manufacturing rarely confers durable economic moats. In India, primary steel is dominated by integrated giants such as Tata Steel, JSW Steel, and SAIL, which operate blast furnaces at multi-million-tonne scale and control captive iron ore reserves. Gallantt chose a different manufacturing route: converting iron ore into sponge iron in coal-fired rotary kilns, melting that sponge iron in electric induction furnaces, casting billets, and rolling them into thermo-mechanically treated (TMT) rebars for residential and regional construction.11 Historically, this secondary route has been vulnerable to widespread bankruptcies whenever commodity cycles turn down.
Yet Gallantt delivered high-teens EBITDA margins in recent years, operates free of term debt, and secured two credit rating upgrades within two years.24 The central question for this episode is straightforward to pose but difficult to resolve: how much of that margin profile reflects a genuine, defensible regional moat, and how much is the temporary byproduct of a favorable cycle, generous state tax subsidies, and early operational gains from a newly integrated pellet plant?
The Thesis, Stated Plainly
The bull thesis rests on geography. Gorakhpur is landlocked, far from seaports, and situated a long rail haul from the eastern mineral belt that supplies India's primary steelmakers. Ind-Ra highlighted the Gorakhpur complex as the only integrated steel plant in northern India, noting its "near-monopoly status in UP, offering pricing power."4 If that structural insulation holds, a regional producer anchored in one of the country's most populous and infrastructure-heavy states enjoys a freight-cost buffer that coastal and eastern mills cannot easily overcome.
The bear thesis centers on execution risks, cyclicality, and corporate governance. Gallantt remains a price-taker in an undifferentiated commodity and does not yet own an operational iron ore mine. A substantial portion of its recent profit growth has been supported by state fiscal incentives that will eventually expire. Meanwhile, the promoter group carries a documented history of related-party entanglements, including a 2017 inclusion on SEBI's list of suspected shell companies, an April 2023 nationwide search by the Income Tax Department, and, as of September 2026, a shareholder resolution seeking approval for up to ₹900 crore in transactions with a promoter-linked real estate entity.121314
This episode traces those dynamics step by step: the Gorakhpur origins, the modular build-out, the captive power and logistics backbone, the 2021–22 corporate consolidation, the backward-integration drive into pellets and mining, capital allocation into non-core ventures, the audited financial track record, a competitive war game against blast-furnace majors, a corporate governance stress test, and the balanced investment thesis. The story begins not in traditional steel centers like Jamshedpur or Kolkata, but in Gorakhpur with a family enterprise spanning flour and steel.
 Subscribe on LinkedIn
II. Origins: The Kolkata Trading Roots & The Gorakhpur Contrarian Bet (1984–2005)
Myth: Kolkata Traders Who Discovered the East
The standard industry retelling suggests that a group of Kolkata metal traders spotted an industrial vacuum in eastern Uttar Pradesh and made a bold greenfield bet on Gorakhpur. Corporate disclosures tell the opposite story.
In Gallantt Metal's 2006 prospectus, the company listed its registered office at "Centre Point," 21 Hemant Basu Sarani, in central Kolkata, under the Registrar of Companies, West Bengal.1 Kolkata served as the corporate and financial mailing address, but the manufacturing roots were already firmly planted in Gorakhpur. According to the prospectus, Chandra Prakash Agrawal had previously been associated with Govind Mills Limited, which operated an induction furnace and rolling mill in Gorakhpur with an annual capacity of 52,800 tonnes of mild steel ingots and round bars, alongside flour milling operations.1 By the time Gallantt Metal went public, Agrawal had accumulated approximately 18 years of commercial experience, including a decade in steelmaking.1
Reality: A Gorakhpur Operator Who Went West First
The contrarian move was not entering Gorakhpur, but temporarily expanding away from it. The promoters built their initial publicly listed facility 1,500 kilometres to the west in Kutch. The prospectus informed investors that the Gujarat plant would primarily sell into Gujarat, Rajasthan, and Maharashtra, avoiding direct competition with Govind Mills' northern home territory.1
Meanwhile, a separate entity, Gallantt Ispat Limited, had been incorporated in February 2005 "with a view to establish the steel unit in Gorakhpur" and had applied for industrial land from the Gorakhpur Industrial Development Authority (GIDA).1 The prospectus openly acknowledged the governance complications of this arrangement. Because Govind Mills, Gallantt Ispat, and a trading firm named Ganesh Laxmi Steel all operated within the same promoter network, the document warned that "this may lead to conflict of interest between group companies and affect the profitability of the Company."1 That disclosure foreshadowed nearly two decades of overlapping corporate entities that public market investors would spend years trying to parse.
The Three Founders
The 2006 prospectus detailed three distinct executive profiles.1
Chandra Prakash Agrawal, the chairman and managing director, oversaw general administration and corporate finance, serving as the central dealmaker and capital allocator. Two decades later, he remains at the helm past the age of 70, with shareholders reappointing him on the strength of his operating record.1516
Nitin Kandoi, then a 33-year-old commerce graduate who had spent a decade managing the steel division at Govind Mills, took charge of plant operations in Kutch. Gallantt's corporate leadership disclosures continue to list him as a co-founder and whole-time director.116
Dinesh R. Agarwal, then 38, brought a different background: 17 years in Surat's textile, yarn dyeing, and printing trade. His critical operational credential was directing Kadodara Power, which had commissioned a 2.43 MW gas-based captive power unit supplying five Surat textile processing houses.1 For an electric-arc and induction steelmaker whose unit margins would hinge on power self-sufficiency, bringing in a captive-generation specialist proved decisive. As of 2026, he oversees commercial operations and the Gujarat manufacturing unit.16
The Initial Capital Stack
The initial Kutch project required ₹190.82 crore in capital expenditure, funding a 99,000-tonne sponge iron unit comprising three 100-tonne-per-day kilns, a steel melt shop rated for 176,420 tonnes of billets, a 168,300-tonne rolling mill, and an 18 MW captive power plant.1 State Bank of India appraised the capital outlay, and a consortium of commercial lenders provided ₹114.5 crore in long-term debt.1 The promoters and affiliated investment entities—including P.B. Mercantiles and Gorakhpur Petro Oils—supplied the equity capital alongside proceeds from the initial public offering.1 Even the captive power equipment involved an inter-company transfer: a 25 MW turbine designed for coal was sourced from an affiliated entity, Sagar Energy & Steels, calibrated to yield 18 MW when fired by local Gujarat lignite.1
State fiscal subsidies formed an integral part of the project's financial architecture. Beyond the five-year excise duty refund, the prospectus outlined a commercial sales tax exemption covering up to 100% of eligible fixed capital investment over a ten-year operational span.1 That tax-optimized approach established a lasting operational playbook. From the post-earthquake incentives in Kutch in 2005 to the "super mega project" incentives granted to the expanded Gorakhpur facility in Uttar Pradesh, Gallantt has consistently aligned the timing and scale of its capital expenditures with regional industrial subsidy regimes.4
What the Origins Tell an Investor
The company's founding record supports the view of a hands-on, operator-led management team; the promoters had spent years running furnaces and shop floors rather than simply broking steel. Yet the archival record complicates the conventional myth of a visionary greenfield pioneer entering an untouched hinterland. The broader enterprise grew out of an established family milling and re-rolling business in Gorakhpur. Its first publicly listed facility was established where fiscal subsidies were most lucrative, not where an inland freight moat existed. Crucially, from its very first prospectus, the promoter group operated across multiple parallel entities that management itself acknowledged could create conflicting interests. The regional freight-moat dynamic only materialized once Gorakhpur was built into a fully integrated steelmaking complex—the transformation that defined the next phase of expansion.
III. The Secondary Steel Architecture: The Sponge-to-TMT Flywheel (2005–2015)
How Steel Gets Made: Two Routes
Stripping iron ore down to commercial steel begins with basic chemistry. Natural iron ore consists primarily of iron chemically bound to oxygen. Steelmaking requires removing that oxygen, calibrating the carbon content, and eliminating residual impurities.
The primary route executes this transformation inside a blast furnace. Iron ore, limestone flux, and metallurgical coke—derived from high-grade coking coal—are charged into the top of the furnace, producing liquid hot metal at the base. A basic oxygen furnace then refines that molten iron into crude steel. While extraordinarily cost-effective at multi-million-tonne scale, a blast-furnace complex requires massive upfront capital expenditure, typically running into thousands of crores of rupees before reaching minimum economic scale.
The secondary route adopted by Gallantt breaks this process into modular stages. First, iron ore pellets or lump ore enter a rotary kiln alongside thermal, non-coking coal. The coal reduces the ore in a solid state by stripping away oxygen, yielding porous direct reduced iron (DRI), commonly known as sponge iron. An electric induction furnace then melts this sponge iron alongside scrap metal; at Gorakhpur, Gallantt's furnace charge is approximately 80% sponge iron and 20% scrap.11 The resulting molten steel is cast into continuous billets, which are hot-rolled and water-quenched into thermo-mechanically treated (TMT) bars. Rapid surface cooling creates a hardened outer martensitic layer around a ductile ferrite-pearlite core, delivering the tensile strength and bendability demanded by structural building codes.
The defining operational advantage of this secondary architecture is modularity: producers can add kilns and induction furnaces incrementally as operating cash flow allows, avoiding the multi-billion-dollar commitments required by primary blast furnaces. The structural vulnerability is twofold. Induction-furnace rebar has historically faced quality discounts compared to blast-furnace steel in critical infrastructure, and the operating margin remains acutely exposed to market swings in non-coking coal, iron ore, and electricity prices.
Gorakhpur Comes Online
In December 2009, Gorakhpur-based Gallantt Ispat filed draft offer documents with SEBI for an initial public offering to raise approximately ₹40 crore.17 Company milestones date the commissioning of its initial 1.67-lakh-tonne integrated steel facility at Gorakhpur to 2009, followed in 2010 by the completion of an internal private railway siding.3 Operating under the Indian Railways station code MGIS, the dedicated siding allowed inbound rakes of iron ore and coal to unload directly inside the plant gates, avoiding the transit delays, double-handling losses, and road-freight costs of shuttling bulk minerals from public rail yards.14
Subsequent expansion unfolded incrementally. In 2014, the company prepaid the term debt used to construct the original Gorakhpur unit.15 In 2015, it acquired approximately 27.5 acres of land within Gorakhpur city limits.15 By 2017, annual steelmaking capacity at the site had roughly doubled to 3.3 lakh tonnes.3 By financing each phase predominantly through internal accruals rather than aggressive bank borrowing, Gallantt sidestepped the widespread balance-sheet distress that pushed heavily leveraged Indian steelmakers into insolvency proceedings following the 2008–2012 investment boom.
Branding a Commodity
While an intermediate steel billet is an undifferentiated commodity, a TMT bar destined for a two-story home in eastern Uttar Pradesh districts like Deoria or Basti enters a distinct retail channel. Purchasing decisions are guided less by institutional procurement managers than by individual homeowners relying on advice from local masons, building contractors, and regional dealers. Gallantt tailored its commercial distribution model around this retail dynamic.
Today, approximately 80% of total sales flow through a two-tier network of 34 distributors and more than 3,000 dealers, supported by direct marketing relationships with over 10,000 contractors, architects, and structural engineers managed from regional sales offices in Lucknow and Ahmedabad.143 Product offerings are split into two brand tiers: standard GALLANTT rebar for mainstream retail construction, and GALLANTT ADVANCE for higher-strength Fe 550D and Fe 600 grades featuring 360-degree ribbing designed for coastal environments and higher-specification structural engineering.14 To establish household name recognition, the company appointed actor Ajay Devgn as brand ambassador in 2021, and management noted during its July 2026 earnings call that actor Janhvi Kapoor had also joined the promotional roster.1518
How much structural pricing power this consumer branding genuinely secures remains an open question. Management has asserted that the brand commands "some premium over our peer group,"19 while annual reports cite a "realisation premium over unbranded peers."14 Neither disclosure quantifies this spread. Credit rating commentary from Ind-Ra offers a more circumspect assessment, pointing out that commodity TMT bars consistently accounted for 81% to 86% of net revenue between FY23 and the first quarter of FY26, a product concentration that "limits the company's ability to pass on an increase in raw material prices."4
In practice, brand recognition positions Gallantt above unbranded local re-rolling mills without insulating it from the broader commodity cycle. The first quarter of FY27 (ended June 2026) demonstrated these boundaries: when domestic rebar prices declined heading into the monsoon season, Gallantt's realised selling prices retreated in tandem.18
The Crash Years: A Mixed Survival Record
The standard narrative credits Gallantt's survival during the severe 2011–2016 domestic steel downcycle—when a flood of low-cost Chinese exports depressed global prices—to low financial leverage. Historical filings provide partial support for that view. Gallantt Metal's consolidated revenue contracted from ₹720 crore in FY15 to ₹616 crore in FY17, yet the company remained profitable throughout the downturn, keeping total borrowings largely below ₹100 crore.8 The pre-merger Gorakhpur operating entity, Gallantt Ispat, demonstrated similar balance-sheet resilience: revenue dipped to ₹425 crore in FY17 while net profit held at ₹56 crore.20
A cleaner test of operating resilience arrived in FY20, when softening domestic demand weighed on steel realisations ahead of the pandemic. Gallantt Metal's operating margin contracted to 3.7%, driving net profit down from ₹104 crore in FY19 to ₹22 crore.8 Pre-merger Gallantt Ispat saw net profit fall from ₹164 crore to ₹61 crore over the same fiscal period, while its debt burden rose to ₹322 crore by FY21.20
The survival claim therefore holds in a narrower sense. Conservative balance-sheet leverage shielded the group from insolvency during cyclical troughs, but it did not prevent operating profits from swinging sharply with raw material costs and finished steel prices. Dampening that volatility required deeper internal integration—beginning with captive power generation and dedicated logistics infrastructure.
IV. The Power & Logistics Engine: Captive Infrastructure as Margin Armor (2015–2020)
The Electricity Problem
An electric induction furnace is an energy-intensive machine. Melting down scrap and sponge iron into molten steel requires hundreds of kilowatt-hours per tonne, making electricity one of the largest components of conversion cost when purchased from the state grid at commercial industrial tariffs. In eastern Uttar Pradesh during the 2000s, persistent grid instability compounded this expense. For a steelmaker, a sudden power failure mid-heat is catastrophic: the furnace does not merely go dark; the entire charge of molten metal risks solidifying inside the crucible.
Gallantt addressed this operational vulnerability by building out captive generation, aiming to make as much of that electricity as possible essentially free.
Waste Heat: Free Electricity From Exhaust
A direct reduced iron kiln consumes non-coking coal to strip oxygen from iron ore, venting massive volumes of high-temperature exhaust gas. While traditional standalone sponge iron units released this thermal energy into the atmosphere, a waste heat recovery boiler (WHRB) routes the hot exhaust through steam turbines to generate electricity. Because the primary fuel has already been burned for iron reduction, the marginal fuel cost of the resulting power is zero—analogous to a car cabin heater drawing warmth from an engine that is running anyway.
Captive coal-fired units, including atmospheric fluidized-bed combustion boilers capable of burning low-grade coal and washery rejects, supply the balance of electricity required by the melt shops and rolling mills. Across its footprint, Gallantt operates 129 MW of captive power capacity, comprising 51 MW at Kutch and 78 MW at Gorakhpur.3 Ind-Ra confirmed that these captive facilities satisfy the entire electricity requirement across both manufacturing complexes.4
The critical operational metric is the proportion of power generated from waste heat. In FY25, WHRB generation supplied 31% of total power demand at Kutch and 41% at Gorakhpur, with Gorakhpur's waste-heat share rising to 52% in the first quarter of FY26 following the commissioning of expanded kiln capacity.4 Ind-Ra identified this expanding waste-heat contribution—rising across the consolidated company to 45% in 1QFY26 from 37% in FY25—as a primary structural catalyst for the improvement in EBITDA per tonne.4
This dynamic represents a genuine operating cost edge rooted in thermodynamics rather than commodity cycles: every incremental rotary kiln brought online yields its own stream of zero-fuel power, lowering the blended conversion cost of every billet cast.
Logistics: The Siding and the Tippler
An inland steelmaker hauling iron ore from Odisha, Madhya Pradesh, and Maharashtra alongside thermal coal from Coal India's mining belts lives and dies by rail economics. Commissioning an internal private rail siding in 2010 established the initial logistical foundation. Gallantt subsequently reinforced that corridor at Gorakhpur by installing a fully mechanized raw material handling system alongside a wagon tippler—an industrial cradle that clamps and rotates loaded railway wagons to empty bulk freight within sixty seconds.153 Ind-Ra cited Gorakhpur's internal sidings, 100% coal linkages for captive power generation, and minimal exposure to imported feedstock as structural competitive buffers, observing that the unit faces "lesser competition from imports, owing to Uttar Pradesh (UP) being a land-locked region."4
Falsification: Is Captive Power Full Insulation?
Management frequently frames captive infrastructure as comprehensive insulation from energy market volatility. A forensic review of the fuel supply chain indicates a more bounded reality.
The first constraint is fuel origin. While the captive power boilers at Gorakhpur secure 100% of their thermal coal under Coal India linkages, only about half of the reduction coal fed into the DRI kilns enjoys similar domestic linkage coverage. For the remaining kiln demand, 60% to 70% is sourced from domestic open-market thermal coal, with the balance met by high-grade South African imports procured through Japanese trading house Itochu.18 At Kutch, captive power boilers burn imported Indonesian coal discharged at Mundra or Kandla blended with regional Gujarat lignite, while the sponge-iron kilns run entirely on imported South African coal acquired from commercial traders.18 Ind-Ra emphasized that Kutch procures iron ore, coal, and scrap—which together account for 80% to 85% of the unit's total operating expenses—at open-market spot rates without captive mineral or fuel linkages.4
The financial impact of this exposure surfaced in the first quarter of FY27 (ended June 2026), when consolidated raw material costs climbed 9% year-on-year. Management attributed roughly half of that cost inflation to rising international coal benchmarks and higher ocean shipping rates caused by Middle East geopolitical tensions.18 Captive power shields Gallantt from state utility tariff increases and transmission outages; it cannot insulate the income statement from global coal cycles.
Captive infrastructure provides a decisive conversion-cost advantage over non-integrated secondary re-rollers that buy commercial grid electricity, but it remains distinct from a commodity price hedge. The only generation segment truly insulated from fuel volatility is the waste-heat boiler network, though a proposed 60 MW captive solar facility at Gorakhpur, slated for commissioning in the fourth quarter of FY27, is designed to expand that fuel-free base.18 Yet while the group was steadily assembling this industrial operating engine, its corporate web was attracting external scrutiny that no power plant could neutralize.
V. The Great Consolidation: The 2021–2022 Corporate Restructuring & NCLT Amalgamation
August 2017: The Shell-Company Letter
On August 7, 2017, the Securities and Exchange Board of India (SEBI) forwarded a list of 331 listed entities to stock exchanges, identifying them as suspected shell companies—conduits potentially used for tax evasion or balance-sheet round-tripping rather than commercial operations. Both Gallantt Ispat and Gallantt Metal were on that list. The exchanges immediately placed both counters under Stage VI of the Graded Surveillance Measure, the most restrictive monitoring tier, which capped price movements, required heavy upfront margins, and sharply restricted trading.12
For industrial operators running physical steel plants, being grouped with non-operating paper vehicles dealt a severe reputational blow. After the companies submitted documentation verifying their physical facilities, production records, and audited financials, the restrictions were revoked. On January 1, 2018, the companies formally notified the exchanges that they "no longer fall under the list of suspected shell companies."12 Both stocks touched their 20% upper circuit limits upon trading resumption that day.12
Although the regulatory cloud lifted, the episode exposed a deep structural vulnerability. Algorithmic screening by regulators and public market skepticism were driven in large part by the group's fragmented corporate architecture: an intricate web of cross-holdings, promoter-controlled investment vehicles, and parallel operating companies. Consolidating the enterprise into a single entity emerged as a commercial necessity.
The Twin-Structure Problem
By 2020, the operating business remained bifurcated across two separately listed corporate entities. Gallantt Metal held the Kutch manufacturing complex. Gallantt Ispat controlled the larger Gorakhpur facility, an 18 MW captive power installation, and a legacy agro-processing arm producing flour-based goods under the Gallantt brand.20 Orbiting these two operational anchors sat promoter investment and finance companies holding equity stakes in one or both listed firms. Gallantt Ispat, the larger and more profitable operating engine, carried total borrowings of ₹322 crore by March 2021.20
This parallel setup penalized public shareholders. Buying shares in either company meant owning an incomplete slice of the industrial platform, with corporate economics tied together through intercompany sales, shared branding, and interlocking ownership stakes.
The Scheme
To dismantle this bifurcated structure, management executed a two-step Scheme of Amalgamation and Slump Sale. First, Gallantt Ispat transferred its 18 MW captive power plant to Gallantt Metal as a going concern via a slump sale. Next, Gallantt Ispat—alongside four promoter-controlled investment and finance vehicles: AAR Commercial Company, Hipoline Commerce, Lexi Exports, and Richie Credit and Finance—merged into Gallantt Metal.21 The National Company Law Tribunal (NCLT) Kolkata bench sanctioned the arrangement in September 2021.21 A final order from the NCLT New Delhi bench on May 20, 2022, completed the legal amalgamation, with the unified surviving entity adopting the name Gallantt Ispat Limited.14
The transaction's share mechanics revealed how interconnected the legacy entities had been. The scheme cancelled 6,54,96,896 existing shares—principally the circular cross-holdings that the merging finance vehicles held in the listed counters—and issued 22,54,55,517 new shares. That left the unified company with a total of 24,12,80,945 shares outstanding.22 Promoter group ownership consolidated at 68.75% by March 2023 and has since crept up to 70.03% as of June 2026.8 Chandra Prakash Agrawal personally held 29.2% of the equity capital as of March 2024.22
The Skeptic's Question
Why absorb four Kolkata-registered finance and trading intermediaries into an operating steel manufacturer? Management presented the restructuring as a clean-up exercise: collapsing circular holdings, eliminating related-party transactions, and presenting lenders and public markets with a single, transparent balance sheet.
A more skeptical analyst, however, would probe the capital lineage. Folding closely held investment entities into a public flagship can absorb complex share-capital histories, historical valuations, and accumulated reserves into a broader listed capital base where they become harder to trace. That concern ceased to be theoretical in April 2023. Official sources cited by the Press Trust of India reported that nationwide Income Tax Department searches uncovered documentation regarding approximately ₹500 crore in allegedly fraudulent share capital, with premises covered during the operation including those linked to "hawala operatives, also known as entry operators."13 While Section X examines the subsequent developments and regulatory status of those inquiries, the timing was notable: the amalgamation presented to investors as a streamlining of corporate affairs became the exact nexus targeted by tax authorities.
What the Consolidation Delivered
From an operational reporting standpoint, the consolidation delivered immediate scale. Consolidated revenue tripled from ₹1,007 crore in pre-merger FY21 to ₹3,017 crore in FY22 as Gorakhpur's full operational output was folded into the listed accounts.8 Unifying the group's assets under a single balance sheet provided credit rating agencies with the scale and asset backing necessary to evaluate the business, culminating in India Ratings' upgrade to IND AA-.4
Institutional investors, however, have still not arrived. As of June 2026, foreign institutional investors held a negligible 0.02% of the equity, while domestic institutional holdings stood at just 0.08%, against a public float of about 30%.8 Instead, non-promoter equity remained heavily concentrated in corporate entities: "bodies corporate" held 19.89% at June 2025, and one of them, Nihon Impex, owned 9.79% at March 2024, up from 3.49% a year earlier.622
The reorganization achieved corporate simplification on paper. Whether it has become investable in the eyes of institutions is a separate question, and the market has not yet answered yes. With its corporate house at least formally in order, the company turned to its biggest cost exposure: the ore.
VI. Upstream Transformation: Pellets, Rakes, and the 1-MMTPA Scale-Up (2022–Present)
The Fines Problem
Indian iron ore comes out of the ground as lumps and fines, which are powdery particles. DRI kilns want lumps or pellets. Put fines straight into a rotary kiln and they choke it. For years, secondary steelmakers paid premium prices for lump ore or bought pellets from merchant pellet makers, which meant paying someone else's margin on every tonne.
A pellet plant solves this. Fines, often upgraded first in a beneficiation plant that separates iron-rich particles from waste, are rolled with binder into marble-sized balls and baked hard. The result is a uniform, strong kiln feed made from the cheapest form of ore.
The Pellet Plant and the DRI Kilns
Gallantt commissioned a 7.92 lakh tonne-per-year pellet plant at Gorakhpur in 2023, and the company calls it the completion of backward integration at that unit.14 It then added kilns. A 1.65 lakh tonne DRI kiln at Gorakhpur, costing ₹125 crore, was completed in FY25, together with a new 30-tonne induction furnace that management said raised production capability by about 10%.15 A further 500 tonne-per-day DRI kiln completed a 100-day first campaign during FY26.14
The volumes show integration taking hold. FY26 production was 819 kilotonnes of pellets, 915 kt of sponge iron, 883 kt of billets and 788 kt of TMT. External sales were only 49 kt of pellets, 125 kt of sponge iron and 81 kt of billets, against 766 kt of TMT.19 In other words, most of what the upstream plants make is now used inside the company, which is exactly what management says it is aiming for.19
The pellet plant needs 9 to 9.5 lakh tonnes of feed a year. Gallantt buys it from Odisha Mining Corporation, from several concentrate suppliers in Madhya Pradesh, and from Lloyds Metals in Maharashtra, which supplies 15% to 20% of the mix.18
Integration also brings a new kind of concentration risk. In the June 2026 quarter, a planned maintenance shutdown of the pellet plant forced Gallantt to buy more iron ore on the open market "at a higher cost than our normal captive route." Together with coal inflation, this contributed to a 20% year-on-year fall in EBITDA.18 A single integrated line gives better economics, but when it stops, the whole chain feels it.
The Railway Rakes
Rail wagons are a chronically scarce resource in India. In July 2023, Gallantt signed an agreement with East Coast Railway to buy and own two rakes (full trainsets of wagons) under the Railway Board's General Purpose Wagon Investment Scheme. Its reasoning was blunt: even paying a 15% premium on freight to get priority, "the availability of railway rakes is very difficult."23 The rakes cost about ₹55 crore. Under the scheme, the owner gets a 10% freight rebate for 15 years. Adding the 15% priority premium it would no longer pay, the company estimated total freight savings of about 25%.23 The second rake was delivered in February 2024.24
The 25% figure is management's own gross calculation, and the company has not published a before-and-after freight cost per tonne. The main benefit may be reliability rather than the rebate: a kiln that runs short of ore loses far more money than the freight bill.
The Scale-Up: Promised Timelines Versus Delivered Ones
In April 2025, the board approved ₹1,014.98 crore of expansion at Gorakhpur covering pellets, sponge iron, billets, rolling mill and a captive solar plant, and the FY25 annual report said the whole expansion was expected to be completed in the next financial year.1525 The shares hit a record high that day.25 The plan was to take Gorakhpur's billet capacity from 5.28 to 8 lakh tonnes, rolling from 5.28 to 8.05 lakh tonnes, and sponge iron from 5.45 to 5.6 lakh tonnes.11
A year later the plan had grown and the timeline had moved. By May 2026 the program had become a ₹3,000 crore capex plan: about ₹1,200 crore for steel capacity, ₹300 crore for solar and ₹1,500 crore for mine development.19 Commissioning of the steel expansion had moved to "H2 of this financial year," meaning the second half of FY27.19 Total capacity after the expansion was described as 1.3 million tonnes in May and 1.23 million tonnes in July.1918 About ₹775 crore had been spent by June 30, 2026.26
This is roughly a year's slip against the original annual report language, and the scope has more than doubled. Neither is unusual for Indian steel projects. For a company whose investors largely price the stock on delivery of the next leg, it is a data point on execution credibility to hold alongside the pellet plant's successful commissioning.
The Real Optionality: Captive Iron Ore
Earlier reports placed Gallantt's longer-dated optionality in a greenfield land parcel in Karnataka's iron ore belt. The company's current geographic disclosures list no Karnataka site. Its presence map shows only Kutch, Gorakhpur, two solar sites, sales offices, and mines in Rajasthan and Uttar Pradesh.3 Whatever that land's status, Gallantt no longer presents it as a live growth vector, and its value is not disclosed. The live optionality is mining.
On May 2, 2024, Gallantt won the Rajasthan government's e-auction for the Todupura composite licence block in Karauli district: 260.71 hectares with an estimated 85.42 million tonnes of ore.27 Its winning bid was a final price offer of 175.05%.27 In June 2025, Uttar Pradesh named it preferred bidder for two blocks in Sonbhadra, Bharhari Block B with 31.71 million tonnes and Near Sobna-Chakriya Block C with 18.88 million tonnes, intended to feed Gorakhpur.284
Two cautions keep this from being a simple bull point.
The first is price. In Indian mineral auctions, the "final price offer" is the share of the ore's published market value that the winner pays the state for every tonne mined, on top of royalty and other levies. A 175% bid means Gallantt has agreed to pay the state well over the market value of the ore as premium. Captive ore can still save money, mainly on logistics, grade control and merchant margins, but it will not be cheap ore.
The second is time. Management's target is to have all three mines operating in FY28. On the July 2026 call, the CEO himself called that timeline "very aggressive," with exploration still underway and environment and forest clearances pending.18 Ind-Ra's September 2025 rationale expected Todupura in FY28–FY29 and the Uttar Pradesh blocks in FY29–FY30, and said "the ability of the company to obtain the relevant approvals and operationalise the mine shall be closely monitored."4 The two sources also disagree on cost: Ind-Ra estimated about ₹750 crore for all three mines, while management now earmarks about ₹1,500 crore for mine development including beneficiation and a pellet plant in Rajasthan.418
Management says the mines will lift EBITDA by about ₹2,000 per tonne once running.19 Until a mine produces ore, that figure is a target, not an earnings stream. Winning an auction is not the same as producing ore, and Indian captive mining has a long record of blocks that took years longer than planned to reach production. Before looking at how the cash from all this has been deployed, a quick look at the smaller side businesses the group has run alongside steel.
VII. The Diversification Sizing: Wheat Flour, Lucknow Real Estate, & The Medicity Venture
Keeping It in Proportion
Gallantt's audited accounts report a single operating segment: iron and steel.14 None of the group's ancillary ventures is large enough to require standalone segment reporting under Indian accounting standards. Measured purely by top-line revenue, these peripheral activities appear negligible. Yet evaluated through the lens of capital allocation and corporate governance, they carry an outsized weight, introducing capital commitments and related-party exposures that belies their modest operational footprint.
The Flour Legacy
The promoter family's involvement in flour milling dates back to Govind Mills, which operated a flour milling facility alongside its Gorakhpur induction furnace.1 The pre-merger Gallantt Ispat entity formally housed a wheat products division that marketed packaged flour under the Gallantt brand.20 Eastern Uttar Pradesh is an agrarian heartland with substantial wheat cultivation, offering localized procurement and shared administrative infrastructure. Today, the group's website lists an "Agroing" consumer division alongside steel, cement, and real estate.10 The listed entity provides minimal operational disclosure regarding the scale of these agricultural assets, and the business has little direct bearing on the core equity thesis.
Shalimar Gallantt: The Real Estate Taste
Around 2020, the company completed a premium residential project in the Mahanagar neighborhood of Lucknow through a joint venture with regional developer Shalimar Corp.15 Summary financial filings note that this specific joint venture concluded in FY25.8 Viewed in isolation, the venture might have appeared to be a closed, legacy property experiment.
Subsequent corporate filings, however, indicate ongoing real estate ambitions. Gallantt's FY26 annual report disclosed that the company "has entered into a new venture of real estate and infra including construction of hotels and mall by partnering with renowned Shalimar Group," adding that "Gallantt Real Estate aims to expand its horizons" across "new high-end residential and commercial projects in Gorakhpur."14 Over the course of FY26, the carrying value of "Land at real estate business" on the balance sheet expanded tenfold, surging from ₹11.8 crore to ₹120.8 crore.14 Furthermore, company investor presentations began listing an overall land bank valued at approximately ₹300 crore as part of its operational assets.3
The Medicity and Lifespace Round Trips
Capital commitments to promoter-aligned property ventures accelerated over the next two years. In FY24, Gallantt acquired a 26% stake in Gallantt Medicity Developers, a special-purpose vehicle, for ₹7.8 crore, classifying it as an associate company.22 Corporate disclosures trace the initial development of the Gorakhpur Medicity project back to 2022.15 In June 2025, the same board meeting that announced the preferred-bidder selection for the Uttar Pradesh iron ore blocks also approved a ₹72.5-crore investment to acquire a 33% equity interest in Gallantt Lifespace Developers Private Limited (GLDPL), an unlisted real estate and construction company.28
Five months later, the board abruptly reversed course. On November 3, 2025, directors approved the divestment of the company's entire equity stakes in both Gallantt Medicity Developers and GLDPL, causing both entities to cease being associates.14 While the exit superficially suggested capital-allocation discipline, the corporate entanglement did not end there: rather than severing ties, the commercial and credit relationship with GLDPL continued to expand.
The Skeptic's Critique
Management's rationale for these investments centers on regional opportunity and asset utilization: surplus operating cash flow can generate commercial returns in familiar local markets, property assets are concentrated in the group's home territory, and formal equity holdings have been wound down.
The investor counterargument is that relinquishing minority equity stakes while continuing to extend advances, provide commercial credit, supply materials, and seek shareholder approvals for guarantees to the same promoter-linked entities does not eliminate governance risk. It merely removes the exposure from the equity line and shifts it into the working-capital and related-party footnotes.
While Section X details the full scale of these transactions, the structural takeaway is evident: Gallantt's non-core ventures generate negligible revenue, but they consume substantial capital flows. For institutional investors, this recurring reallocation of capital toward promoter-affiliated property ventures remains the primary justification for a lingering conglomerate discount—regardless of credit rating upgrades in the core steel business. Evaluating whether that discount is warranted requires examining the audited financial record, which follows.
VIII. The Balance Sheet, Financial Engine & Cash Conversion
Revenue: Flat-Lining at a Higher Plateau
Following the corporate amalgamation that lifted consolidated revenue to ₹3,017 crore in FY22, Gallantt's top line advanced in three incremental steps: ₹4,057 crore in FY23, ₹4,227 crore in FY24, ₹4,293 crore in FY25, and ₹4,419 crore in FY26.8 For four consecutive fiscal years, sales have remained lodged within the ₹4,000-crore to ₹4,500-crore band. During the fourth-quarter FY26 earnings call, management characterized the period as "a phase of consolidation with marginal volume growth," pointing to a modest 1.7% increase in sales volumes.19 Executive guidance projects that commissioning the current round of plant expansions will eventually propel annual revenue into the ₹5,300-crore to ₹5,400-crore range.19
During the July 2026 earnings call, an analyst pressed management on this plateau: with consolidated revenue growing just 2.9% in FY26 against a five-year compound annual growth rate near 34%, why should public markets expect double-digit expansion to resume? The chief executive officer termed the slowdown "marginal" and pointed once again to capacity additions scheduled for the second half of the fiscal year.18 While a plausible defense, it places the entire near-term growth narrative on commissioning timetables that have already slipped by roughly twelve months.
Profit: The Real Inflection
Profits, rather than top-line expansion, drove the market rerating. Consolidated net profit rose from ₹141 crore in FY23 to ₹225 crore in FY24, ₹401 crore in FY25, and ₹484 crore in FY26.8 Over that same span, operating margins roughly doubled from 9% to 16%.8 Company-reported EBITDA per tonne climbed from ₹8,308 in FY25 to ₹8,785 in FY26, holding firm at ₹8,787 in the first quarter of FY27.318
The composition of that unit profitability tells a more nuanced story. India Ratings disaggregates EBITDA per tonne into metrics with and without government fiscal subsidies. With incentives included, EBITDA per tonne expanded from ₹4,781 in FY23 to ₹7,550 in FY25 and ₹10,515 in the first quarter of FY26. Stripped of subsidies, the underlying progression registered at ₹4,540, ₹5,583, and ₹8,868 across the same periods.4 In FY25, Ind-Ra's figures indicate that state subsidies contributed approximately ₹181 crore to total operating profit, lifting EBITDA from an underlying ₹514 crore to a reported ₹694 crore.4 Looking further out, Ind-Ra projected a normalized medium-term baseline of ₹5,500 to ₹6,500 per tonne without subsidies—substantially below recent peak prints.4
Gallantt's own margin bridge from FY25 to FY26 attributed gains primarily to volume growth and an unspecified catch-all category labeled "others," which outweighed the drags of softer net realisations and higher raw material expenses.3 Management described this trend as "structural margin improvement per tonne, not cyclical steel price tailwinds."3 Yet because the company left "others" aggregated and unexplained, public filings offer investors no way to verify that assertion independently.
The Subsidy Is Real, and It Expires
The Gorakhpur manufacturing complex holds "super mega project" status under Uttar Pradesh's 2017 industrial investment policy. That designation entitles Gallantt to partial reimbursement of State Goods and Services Tax (SGST) over a ten-year window spanning FY23 through FY32, capped annually at 20% of eligible capital investment and cumulatively at 300% of fixed capital outlay.4 In April 2026, the company received ₹233.55 crore in SGST refunds covering taxes paid through June 2025; Gallantt shares surged to their all-time high within days of the disclosure.7 Meanwhile, the Kutch facility benefits from industrial incentive reimbursements under Gujarat's 2015 industrial policy through FY31.4 In addition, approximately ₹568 crore in historical claims under an earlier 2006 Uttar Pradesh incentive scheme remains unpaid and subject to litigation, notwithstanding an Allahabad High Court directive ordering the state government to expedite settlement.4
This contrast between reported profits and structural economics is pivotal. While management highlights structural margin gains, a meaningful fraction of recent profitability stems from state policy benefits that carry an explicit expiration date in FY32. These incentives represent genuine cash inflows, but they are intrinsically time-limited. Analysts and investors valuing the company on a multiple of headline earnings must treat this subsidy stream as a temporary fiscal tailwind rather than permanent operating earnings power.
ROE: The Disconfirming Record
Management reports that return on capital employed (ROCE) expanded from 13% to 23% over the past five years.19 Standardized database metrics present a more restrained picture, showing a current ROCE of 18.2%, a return on equity (ROE) of 15.6%, and a three-year average ROE of 13.7%.8 Even during its peak earnings year, the business has not demonstrated an ability to generate 20%-plus returns on equity across a complete commodity cycle. The recent margin expansion coincided with a firm domestic pricing environment, the commissioning of an internal pellet plant, and the initial cash windfall from state tax reimbursements.
Consequently, the thesis that post-merger Gallantt has transformed into a structurally high-return industrial business remains unproven. The audited data supports a more modest conclusion: capital returns have recovered from the lackluster low-teens of the pre-merger era, but they remain untested across an extended industry downturn. The true stress test will unfold over FY27 and FY28. If return on equity can hold in the high teens while finished rebar prices soften and subsidy contributions taper, the structural quality thesis will gain substantial credibility.
Cash Conversion and Leverage
On operating cash generation and balance-sheet deleveraging, the historical track record is unambiguous. According to Ind-Ra, cash flow from operations stood at ₹218 crore in FY22 before compressing to ₹74 crore in FY23 amid heavy working-capital absorption and capital outlays; it then expanded to ₹321 crore in FY24, reached ₹564 crore in FY25, and climbed to ₹602 crore in FY26.48 Free cash flow rebounded from negative ₹154 crore in FY23 to positive ₹312 crore in FY25.4 Net adjusted leverage—incorporating an outstanding corporate guarantee—dropped from 1.70 times EBITDA in FY23 to 0.29 times in FY25, while interest coverage improved to over 30 times.4
As of March 31, 2026, management reported holding approximately ₹800 crore in cash and liquid balances against ₹440 crore in total borrowings, yielding a net cash surplus of roughly ₹360 crore. The company carries no bank term debt, with its non-current liabilities consisting primarily of interest-free state industrial loans.194 Management highlighted that its cumulative capital expenditures over the preceding five years, totaling roughly ₹1,200 crore, were funded entirely through internal cash flows.19
Two caveats qualify this apparent balance-sheet strength. First, total gross borrowings stood at ₹548 crore at the close of FY26—a sizable liability for a company maintaining large liquid reserves, particularly as surplus funds have been directed into intercorporate deposits yielding 12% rather than extinguishing debt.819 Second, management's public messaging regarding future financing has been contradictory. During the May 2026 earnings call, the CEO stated that the company "will also consider debt and equity capital where appropriate." Minutes later in the same call, the Vice Chairman countered that for the ₹3,000-crore expansion program, "there is no equity program. It is all from internal generation," before framing "a balanced funding proposal with equity and external borrowing" as a key consideration for future medium-term outlays.19 By the July 2026 call, the executive stance had shifted once more, with management asserting that internal accruals would remain the primary financing engine and that directors "will only evaluate debt or equity where appropriate."18
The Credit Rating as Outside Verification
Successive credit rating upgrades from India Ratings—lifting Gallantt's long-term bank facilities to IND A+ in June 2024 and to IND AA-/Stable in September 2025—represent the most authoritative external validation of the operating platform.294 Ind-Ra justified the higher investment-grade standing by pointing to expanding unit EBITDA, a self-funded capital expenditure program, deepening backward integration, and steady subsidy inflows.4
That rating endorsement, however, was explicitly conditional. Ind-Ra warned that a negative rating action could be triggered if debt-funded capital expenditures drove adjusted net leverage above 1.5 times, cautioning further that "any unrelated diversion of funds could also lead to a negative rating action." The agency specifically underscored that it would monitor "any surplus liquidity extended as loan to related/unrelated corporates."4 While the credit rating reflects hard-won operational gains in the steel mills, it also established an explicit governance tripwire—a vulnerability examined in detail in Section X. Before confronting that stress test, the analysis turns to how Gallantt's regional secondary model holds up in direct competition with India's blast-furnace majors.
IX. Porter’s Five Forces & Hamilton Helmer’s 7 Powers Analysis
The War Game
Consider a major primary steelmaker attempting to capture market share in eastern Uttar Pradesh. It possesses superior metallurgy, an established national brand, and access to low-cost captive iron ore. What it lacks is a production base within trucking distance of Gorakhpur, Deoria, or Azamgarh. Its rebar must travel hundreds of kilometres by rail from eastern or southern India to a regional distribution yard, where rakes are unloaded, stored, and reloaded onto trucks for distribution to local retailers. Gallantt’s rebar, by contrast, rolls directly out of the factory gate and arrives at regional dealer yards within hours.
That dynamic encapsulates the regional competitive contest. Gallantt does not need the lowest production cost across India; it only needs the lowest delivered cost within its home territory. Management claims an addressable market share of approximately 25% across its core operating territories in Uttar Pradesh and Gujarat.193 That figure remains company-sourced and has not been verified by independent market audits.
Hamilton Helmer's 7 Powers
Scale economies: weak nationally, moderate regionally. At approximately 1 million tonnes of annual finished capacity, Gallantt is a minor operator alongside India's primary producers. Within its immediate catchment, however, fixed overheads for distribution, marketing, and logistics are amortized over a dense, localized dealer network. While this provides a tangible cost advantage, it remains modest and vulnerable to any competitor establishing capacity nearby.
Cornered resource: emerging, not yet proven. Gallantt's existing physical footprint comprises 112 acres at the Gorakhpur Industrial Development Authority complex and 116 acres at Kutch, supported by a dedicated railway siding with its own station code, two company-owned rakes, and domestic coal linkages.14 While assembling that logistical infrastructure took years, it is not irreproducible. Captive mines would transform this position into a genuine cornered resource once commercial extraction begins, though that advantage will be tempered by the steep 175.05% auction premium at Todupura.27 Until commercial ore is brought to the surface, that resource remains a financial option rather than an operating asset.
Process power: moderate. Operating an integrated pellet-DRI-induction chain with expanding waste-heat recovery and high plant utilisation requires specialized shop-floor discipline. The Gorakhpur complex operated at 93% capacity utilisation in the first quarter of FY27.18 At Kutch, however, rolling mill utilisation reached only about 66%—an imbalance management acknowledged as an operational challenge, showing that this operational efficiency is not uniformly distributed across the company.18
Branding: moderate and regional. The GALLANTT brand commands dealer loyalty and reportedly captures a realization premium over unbranded re-rolling mills. Yet the company has not demonstrated that this brand equity commands pricing parity against Tier-1 primary producers, nor does management disclose the actual monetary spread of that realization premium.14
Network effects: none. Steel manufacturing involves no network dynamics; each additional buyer creates no incremental utility for the rest of the customer base.
Switching costs: low. Building contractors and individual homebuilders can switch rebar brands with the arrival of the next truckload. Retailers are retained primarily through dealer margins, credit terms, and reliable delivery schedules—commercial incentives that well-capitalized competitors can readily match.
Counter-positioning: real but narrow. India's primary steelmakers optimize their operations for massive production runs, unit-train rail shipments, and regional warehouse depots. Serving thousands of retail dealers across tier-2 and tier-3 towns directly from a local plant does not fit their high-volume distribution model. The strategic threat is that primary producers could bypass that friction by acquiring regional secondary producers or establishing localized rolling facilities, rather than competing directly on Gallantt's secondary cost architecture.
The aggregate picture indicates that Gallantt’s competitive advantages are layered operational and logistical efficiencies rather than an impenetrable economic moat. In isolation, none of these advantages is insurmountable. Together, they explain why the company earns above-average margins within its geographic footprint. They do not, however, shield the business from a nationwide collapse in commodity prices.
Porter's Five Forces
Buyer power: high. Retail homebuilders remain acutely sensitive to price per bundle. At the same time, institutional accounts—which represent part of the company's network of more than 230 corporate and government clients—wield significant negotiating leverage.10 In the first quarter of FY27, Gallantt’s realized selling prices declined in lockstep with broader domestic benchmarks, demonstrating that local pricing follows the wider market rather than company directives.18
Supplier power: moderate-to-high. Feedstock procurement remains divided among state mining undertakings, merchant ore producers, Coal India linkages, and open-market coal importers. While the internal pellet plant eliminated dependence on merchant pellet converters, it did not diminish exposure to upstream iron ore suppliers. Ind-Ra highlighted this ongoing vulnerability to raw material price swings as a key constraint on the company's credit profile.4
Threat of substitutes: low. Reinforced concrete remains the foundational building standard for residential housing and civil infrastructure across India, leaving steel rebar with no viable commercial substitute in regional construction.
Threat of new entrants: moderate. Management estimates the replacement cost of Gallantt’s operating asset base at roughly ₹5,000 crore, compared with an actual cumulative capital outlay of ₹2,200 crore, presenting that differential as an entry barrier.3 Securing industrial land, railway clearances, environmental approvals, and fuel linkages requires substantial regulatory lead time. Nevertheless, Uttar Pradesh actively promotes industrial manufacturing, and its super-mega-project incentive framework remains open to competing capital investments.4
Rivalry: intense and rising. Macroeconomic pressures emerged clearly in the first quarter of FY27, when domestic mills faced headwinds as India temporarily became a net steel importer amid diverted global shipments, prompting industry representations for anti-dumping protections alongside existing safeguard duties.18 Locally, secondary induction-furnace operators and primary integrated mills pushing into retail TMT distribution compete aggressively for the same dealer shelf space.
The structural conclusion from these frameworks is that Gallantt’s regional freight buffer insulates conversion margins against distant mills during normal market conditions. It does not, however, insulate the selling price of rebar, which fluctuates with national and global steel supply. Because Gallantt’s edge is rooted in conversion and delivery costs rather than pricing power, that advantage endures only so long as fuel and mineral inputs remain securely hedged—placing capital allocation and corporate governance squarely at the centre of the investment case.
X. The Governance Stress Test: The 2023 IT Search, Related Parties, & Capital Allocation
April 26, 2023: The Convoy
On the morning of Wednesday, April 26, 2023, income-tax teams moved on Gallantt group premises in Gorakhpur: the Bank Road corporate office, the GIDA factory, and the promoter's residence.3031 Local media reported that more than 200 officers were deployed in Uttar Pradesh alone.31 According to official sources quoted by the Press Trust of India (PTI), roughly 60 premises were searched across Uttar Pradesh, Delhi, Gujarat, West Bengal, and Bihar, with investigators recovering approximately ₹6 crore in cash, ₹10 crore in jewellery, and documents relating to alleged fraudulent share capital of about ₹500 crore, while premises linked to entry operators were also searched.13 Regional outlets went further, reporting unverified claims regarding benami property and bureaucratic funds.31 Those assertions relied entirely on anonymous sourcing and remain allegations rather than substantiated findings.
On May 1, 2023, the company confirmed to stock exchanges that the Income Tax Department had conducted a search under Section 132 of the Income Tax Act across its plants, offices, and the residences of promoters and key executives, noting that authorities had "seized a few documents and records."32 Chairman Chandra Prakash Agrawal publicly denied any tax evasion or benami holdings, characterized the action as routine, and pointed out that the group had also undergone an income-tax search in 2014.5 Amid the regulatory overhang, the company's share price dropped to roughly ₹59 by late June 2023.6
What Actually Happened Next
The audited accounts provide the most authoritative postscript. Note 50 to the FY26 financial statements discloses that the tax department initiated assessments for seven assessment years following the search, completing them through assessment year 2024–25, and recorded that "at present, there is no demand outstanding towards income tax liability."14 The statutory auditor included an Emphasis of Matter paragraph drawing attention to the search disclosures, noting that tax proceedings and assessments through AY 2024–25 were concluded "without any addition in the taxable income," and leaving the audit opinion unmodified.14 In addition, Note 51 explicitly affirms that no proceedings under the Prohibition of Benami Property Transactions Act have been initiated or remain pending against the company.14
At the level of the listed corporate entity, the subsequent audit trail dispelled the most severe interpretations of the raid: no outstanding tax demand was levied, no audit qualifications were issued, no benami proceedings were initiated, bank credit lines remained intact, and credit rating agencies subsequently upgraded the company's facilities. That clean bill of health, however, leaves a narrower question that the public record cannot resolve: the ultimate regulatory disposition of the allegations regarding share capital and promoter-controlled entities outside the listed perimeter. Given the extensive web of unlisted entities that surrounds the operating business, that distinction remains material.
The Related-Party Ledger
This is where the governance stress test shifts from historical regulatory scrutiny to current balance-sheet reality. The FY26 annual report reveals that during the fiscal year, Gallantt extended ₹825.05 crore in revolving loans to Gallantt Lifespace Developers Private Limited (GLDPL)—the promoter-aligned property entity in which it had acquired a 33% stake and subsequently divested—and received the full principal back. Over the same period, Gallantt borrowed ₹46.5 crore from GLDPL, repaid the amount, and collected ₹16.22 crore in interest income. The annual report classifies GLDPL as a related party on the grounds that a relative of a director serves on GLDPL's board.14 In FY25, similar revolving loan disbursements to GLDPL had totalled ₹142.99 crore.14 The company also extended smaller short-term loans to other promoter-linked entities—including GL Steel and Power, Ganesh Laxmi Processors, and Gallantt Fincares—all of which were repaid within the financial year.14 Separately, as of March 31, 2026, Gallantt carried ₹293.65 crore in loans outstanding to other corporate bodies, an allocation that the Vice Chairman described during the May 2026 earnings call as surplus treasury deployment into "the intercorporate market at an interest rate of 12%."1419 In addition, Ind-Ra highlighted an outstanding ₹82.5-crore corporate guarantee backing a bank term loan for an affiliated group company with "no operational or strategic linkages" to Gallantt, noting an expectation that this credit backstop would be extinguished during FY27.4
Comparing these commitments brings the governance paradox into sharp focus. Over the course of a single year, Gallantt advanced revolving loans to a promoter-linked real estate developer equivalent to nearly one-fifth of the steelmaker's annual revenue. Simultaneously, the company maintained ₹440 crore in working-capital borrowings while informing public investors that it was actively deploying liquidity into 12% intercorporate deposits.19
The ₹900 Crore Resolution
The notice for the annual general meeting scheduled for September 30, 2026, includes a special resolution seeking shareholder approval for related-party transactions with GLDPL of up to ₹900 crore during FY27. That proposed umbrella limit comprises ₹200 crore in material purchases, ₹200 crore in finished goods sales, ₹200 crore in intercorporate deposits and loans, ₹50 crore in interest, ₹200 crore in financial guarantees, and ₹50 crore in guarantee commissions.14 For financial perspective, GLDPL reported FY26 turnover of ₹51.10 crore, profit after tax of ₹133.19 crore, and net worth of ₹402.67 crore; the requested transaction limit represents 1,761% of GLDPL's annual top line.14 The explanatory statement attached to the resolution states that the commercial framework enables Gallantt to "leverage GLDPL's expertise in mining and related services"—an unusual operational rationale for an entity characterized elsewhere in the same annual report as an unlisted construction and real estate firm. The disclosure adds that GLDPL "requires operational and financial support."14 Chairman Chandra Prakash Agrawal, whole-time director Prem Prakash Agrawal, and Chief Executive Officer Mayank Agrawal are formally identified as interested parties.14
Under listing regulations administered by SEBI, interested related parties are barred from voting on the resolution.14 Consequently, shareholder approval hinges entirely on the non-promoter public float of roughly 30%—a shareholder block dominated by corporate bodies, with institutional investors holding less than a tenth of a percent.8 That vote directly challenges the underwriting baseline of the company's credit rating. When granting its upgrade to IND AA-, Ind-Ra specifically assumed, "as confirmed by the management," that there would be zero cash-flow impact or capital expenditure directed toward real estate ventures across FY26 and FY27, citing any "unrelated diversion of funds" as an explicit trigger for a potential credit downgrade.4 The ₹900-crore resolution tests that management assurance to its limit.
An independent investor or governance analyst would press four fundamental questions. Why does a debt-free industrial steelmaker need to advance capital to, and guarantee the balance sheet of, a promoter-linked developer? At what interest rates, against what underlying collateral, and across what repayment tenors are these credit lines extended? Why was an equity stake acquired and then abruptly unwound within five months, and at what valuation was that divestment transacted? And why does the formal proxy statement cite mining expertise as the commercial justification for supporting a real estate entity? The public disclosures provide no answers.
Board, Auditor and CFO Turnover
Governance quality is equally reflected in leadership and oversight turnover. Between March 31 and mid-August 2026, the company underwent a concentrated series of executive, board, and audit departures:
- On March 31, 2026, Chief Financial Officer Sandip Kumar Agarwal, whole-time director Prashant Jalan, and independent director Udit Agarwal all stepped down, citing personal reasons and professional preoccupations. Concurrently, Dindayal Jalan joined the board as whole-time director and Vice Chairman.33
- On May 5, 2026, two independent directors, Smita Modi and Pankaj Khanna, resigned from the board, citing scheduling constraints and heavy professional workloads.2
- On July 21, 2026, statutory auditor Maroti & Associates submitted a resignation letter effective July 27, citing resource constraints alongside the "increased scale and complexity of the audit," while confirming there were no disputes with corporate management. Singhi & Co. was appointed to fill the casual vacancy.34
- Chief Financial Officer Pradyumna Kumar Satpathy, who presented the audited FY26 results during the inaugural earnings call in May, stepped down on August 15, 2026, following the appointment of long-time Chief Accounts Officer Amit Jalan as CFO on July 27.3419
Management presents these changes as steps toward institutional maturity. The company inaugurated quarterly earnings calls in May 2026 and reconstituted its board with prominent former civil servants and regulators, including a former Uttar Pradesh Chief Secretary, a retired Chief Commissioner of Income Tax, and an ex-regional director of the Reserve Bank of India.19 Both perspectives carry weight. Appointing distinguished public administrators to the board and transitioning from a regional audit firm to a larger accounting practice like Singhi & Co. represent textbook governance upgrades for a mid-cap manufacturer expanding toward national scale. Yet cycling through three chief financial officers in five months, absorbing the departures of four board directors, and navigating a mid-year statutory auditor resignation during the exact season when the board sought approval for a ₹900-crore related-party proxy resolution constitutes an executive churn that public markets cannot easily dismiss.
Verdict on Governance
The audited record tempers the governance debate in both directions. The 2023 income-tax search concluded without tax demands or audit qualifications for the listed operating company, dismantling the most punitive short thesis that framed the enterprise as an unviable paper vehicle. Conversely, the scale and velocity of capital flows involving GLDPL are substantial, expanding, and in direct friction with the conservative assumptions underpinning the company's investment-grade credit rating, undermining the narrative of a fully streamlined corporate structure. The critical signpost that will clarify this posture is the disclosure of actual related-party transactions across FY27: whether the proposed credit, sales, and guarantee limits with GLDPL are actively drawn down, or allowed to lapse as non-core property entanglements are phased out. That tension frames the concluding assessment of the company's investment merits.
XI. Bull vs. Bear Case: The Long-Term Investor Equation
The Bull Thesis, Tested
1. Integration keeps cutting costs. The operational evidence is concrete. Most upstream output is now consumed internally, the waste-heat recovery share of power generation continues to rise, and EBITDA per tonne excluding government subsidies roughly doubled between FY23 and the first quarter of FY26 under India Ratings' calculations.194 The subsequent operational layers—captive solar generation scheduled for FY27 and captive iron ore mines targeted for FY28—are structurally sound in direction. Management projects ₹30 crore to ₹40 crore in annual power savings once 78 MW of solar capacity is fully commissioned.19 What would confirm it: EBITDA per tonne excluding subsidies holding above Ind-Ra's projected medium-term normalized baseline of ₹5,500 to ₹6,500 through a cyclical downturn in rebar prices. What would falsify it: operating profit retreating toward the FY23–FY24 level of roughly ₹4,500 per tonne once broader commodity pricing softens.
2. The Uttar Pradesh and Gujarat demand runway. Management highlights national steel consumption expanding at 7% to 9% annually, noting that both Uttar Pradesh and Gujarat are deploying infrastructure capital at rates exceeding the national average.1819 Regional demand represents the least contentious pillar of the bull case. The structural vulnerability lies in regional supply: competing steelmakers observe the same end-market dynamics and can redirect long-product volumes into the territory.
3. Operating leverage from 1.23 million tonnes. If the Gorakhpur brownfield expansion is commissioned in the second half of FY27 and capacity utilisation reaches management's target of 90% to 92%, annual revenue guidance of ₹5,300 crore to ₹5,400 crore remains attainable. Furthermore, executive guidance outlines potential operating margins near 20% once captive iron ore mines are integrated into the blast-free secondary chain.19 The counter-evidence: project commissioning timetables have already slipped by approximately twelve months against initial annual-report milestones, while the rolling mill at Kutch operates at barely two-thirds of rated capacity.18
4. A net-cash balance sheet. Balance-sheet strength is corroborated by both credit rating disclosures and company reporting.419 The central question is who captures the economic surplus: public equity holders through productive capital expenditure and cash dividends, or promoter-linked entities through unsecured corporate credit. Direct shareholder distributions remain modest. The final dividend for FY26 was declared at ₹2 per share with a record date of September 23, 2026, and the majority of promoter-group shareholders waived their dividend entitlements. Historical payout ratios have hovered between 8% and 11% of annual net profit.35368
The Bear Thesis, Tested
1. A price-taker with no pricing power. The first quarter of FY27 substantiated this vulnerability. Finished rebar realisations softened ahead of the monsoon season, consolidated EBITDA declined 20% year-on-year, and executive leadership acknowledged that second-quarter performance was "definitely going to be muted."18 Ind-Ra's characterisation of Gorakhpur's "near-monopoly" describes its physical distribution presence across eastern Uttar Pradesh, not an ability to set prices independently of national benchmarks.4
2. Raw material exposure until the mines arrive. Input volatility remains an active earnings drag with an uncertain completion date. The Kutch manufacturing complex procures its iron ore, coal, and scrap at open-market spot rates, while the Gorakhpur complex continues to purchase all third-party mineral feed pending mine development.418 Securing captive iron ore reserves mitigates this vulnerability only after commercial production begins, and the net economic benefit must absorb the steep 175.05% auction premium pledged to the state.
3. Capital leaking out of the core. Reallocation of capital to non-core property assets represents the paramount live risk. It is manifested in ₹825 crore of revolving loans extended to GLDPL, an expanding real estate land inventory on the balance sheet, stated corporate ambitions to construct hotels and a shopping mall in Gorakhpur, and the pending ₹900-crore related-party proxy resolution.14 Unlike global commodity swings, this governance overhang is an internal decision that corporate leadership could resolve immediately—yet has chosen not to.
4. Earnings quality and valuation. Trading at approximately 31 times trailing twelve-month earnings in September 2026, the equity valuation reflects continued volume growth and margin resilience.8 That multiple is being applied to earnings augmented by temporary state tax subsidies that expire by FY32, and to unit margins that credit analysts do not expect to persist once subsidies phase out.4 The roughly 40% correction from the April 2026 peak illustrates the volatility of public market sentiment, punctuated by a 21.8% drop across five trading sessions in mid-May 2026.3778`
Risk Radar, Only Where Material
- Imports and trade policy. Surges in cheaper finished imports exert downward pressure on domestic long-product pricing, directly affecting secondary steel realisations unless countered by anti-dumping measures or higher tariff walls.18
- Geopolitics and freight. Reliance on seaborne thermal coal and imported feed at Kutch leaves operating conversion costs directly exposed to Middle East shipping disruptions and ocean freight inflation.18
- Regulation. Environmental and forest clearances for captive mines, timely disbursal of SGST reimbursements, and the resolution of the disputed ₹568-crore legacy incentive claim remain contingent on state administrative and judicial timelines beyond corporate control.4
- Execution. At ₹3,000 crore, the planned capital outlay exceeds Gallantt's existing gross block of ₹2,293 crore, and the multi-year program is being executed under a finance division that has seen three different chief financial officers within a single calendar year.21934
Weighing It
The operational record justifies a narrower claim than the unvarnished bull narrative: Gallantt Ispat is an efficient, backward-integrated, low-cost regional rebar manufacturer that has delivered structural improvements in conversion economics. The governance record, however, undercuts the broader thesis that the company has evolved into an institutional-grade compounding asset. What will govern long-term equity returns is whether free cash flow is consistently reinvested into steel operations and returned to public shareholders, or continuously channeled into promoter-affiliated property ventures. That distinction frames the investor playbook.
XII. Playbook: Lessons for Builders and Investors
1. Geographic Arbitrage Beats Global Scale, but Only on Cost
Gallantt demonstrates that an inland manufacturer in the right location can generate above-average operating margins in a heavy commodity business. The Gorakhpur facility does not undercut India's blast-furnace giants on raw production cost; it beats them on delivered cost into a landlocked market insulated by long-distance rail and road freight. The structural limitation, demonstrated in the first quarter of FY27, is that geographic insulation protects conversion and delivery costs, not finished product pricing. A regional secondary steelmaker remains a price-taker tethered to national commodity benchmarks. Operators adopting this model must stress-test their unit economics at the trough of the national pricing cycle rather than its peak.
2. Integration Has to Be Earned in Sequence
Gallantt's industrial expansion followed a disciplined progression: shop-floor re-rolling experience at Govind Mills, followed by billet melting and rolling at Kutch and Gorakhpur, captive power generation with waste-heat recovery, a dedicated private rail siding and wagon tippler, an internal pellet plant and company-owned rakes, and finally upstream captive iron ore mining. At each phase, operational cash flow from the preceding asset funded the next capital commitment, allowing the company to prepay its Gorakhpur term debt in 2014 rather than accumulating bank leverage.15 That discipline contrasts sharply with the debt-fueled capital expenditure boom of 2008–2015 that pushed dozens of leveraged Indian steelmakers into insolvency. Disciplined operational sequencing is what separates durable modular scale from balance-sheet distress.
3. A Promoter With Spare Cash in a Small City Needs Guardrails
When an industrial facility in a tier-2 city generates surplus cash faster than the core business can redeploy it into manufacturing, capital allocation often gravitates toward promoter-aligned local opportunities: regional land parcels, healthcare facilities, shopping centers, and commercial real estate. Gallantt's corporate history—from equity stakes in Medicity and Lifespace acquired and then swiftly unwound to ₹825 crore in revolving loans and a proposed ₹900-crore transaction umbrella with GLDPL—demonstrates why public shareholders require structural governance guardrails.222814 Effective investor protections include binding caps on related-party exposure, a transparent dividend distribution framework tied directly to operating free cash flow, and strict treasury mandates that prohibit deploying surplus liquidity into affiliated corporate entities.
4. Cleaning Up the Structure Is Necessary but Not Enough
The 2022 corporate amalgamation eliminated circular cross-holdings and consolidated operating assets onto a single balance sheet, paving the way for an investment-grade credit rating upgrade.224 Yet institutional equity ownership still rounds to zero.8 The strategic takeaway is that structural simplification is a prerequisite for attracting institutional capital, not a guarantee. Professional fund managers evaluate post-merger capital discipline alongside corporate structure. Presenting a simplified organizational chart while maintaining sizable related-party credit flows addresses only half of the governance equation.
5. Read the Rating Rationale Along With the Rating
Headline credit rating upgrades to IND AA- are often cited by management and retail investors as definitive proof of fundamental quality. The underlying rating rationale, however, provides far more actionable intelligence: it explicitly documents the agency's baseline assumption of zero cash allocation to real estate ventures, identifies sensitive downgrade triggers, and flags the continuous monitoring of intercorporate advances.4 Credit analysts specify the precise operational and financial conditions under which their rating thesis breaks down. For equity investors, those analytical caveats serve as an indispensable stress-testing checklist.
XIII. Epilogue & The 3 Critical KPIs to Watch
Where Gallantt Stands in September 2026
A week before its 22nd annual general meeting, scheduled for September 30, 2026, Gallantt Ispat resembles two distinct enterprises simultaneously.14 One is a disciplined regional industrial operator. It has integrated upstream from pellets to finished TMT rebar at Gorakhpur, runs its furnaces primarily on captive power, operates dedicated rakes and a private rail siding, has secured three prospective iron ore blocks, and maintains a net-cash balance sheet free of bank term debt. The other is a promoter-controlled group whose surplus cash has repeatedly flowed toward affiliated real estate developers, whose finance division and boardroom have experienced severe turnover within a six-month window, and whose equity register still features virtually no institutional ownership.
Management's blueprint for the next phase rests on an ambitious timeline: commissioning expanded steel capacity to reach 1.23 million tonnes in the second half of FY27, bringing 78 to 85 MW of captive solar generation online, operationalizing three captive mines by an FY28 target date that leadership itself characterizes as aggressive, and unveiling a broader medium-term growth plan in the second quarter of FY27.1819 The equity market's retrenchment since the April 2026 peak suggests that public investors now demand demonstrated operational delivery before underwriting the next valuation rerating.
The Three KPIs That Matter
1. EBITDA per tonne, excluding state subsidies. This metric provides the cleanest single gauge of whether upstream backward integration has structurally lowered conversion costs or whether cyclical commodity pricing and temporary state tax refunds have merely flattered reported earnings. Because company presentations and India Ratings calculate unit margins under differing definitions, investors must track a consistent series across commodity cycles. The most revealing tests will emerge during quarters when domestic rebar benchmarks soften.43
2. Captive raw material share. This tracks the proportion of iron ore, pellet, and electricity requirements supplied by the company's own assets: pellet plant capacity utilisation, the waste-heat recovery and solar share of total power generation, and, ultimately, commercial extraction volumes from its captive mining blocks. Bringing mines online by FY28 remains the critical operational hurdle; every quarter of developmental delay pushes the projected ₹2,000-per-tonne margin uplift further into the future.194
3. Related-party and non-core capital flows. This encompasses revolving loans, financial guarantees, and commercial advances extended to Gallantt Lifespace Developers and other promoter-affiliated entities, alongside balance-sheet real estate inventories and intercorporate treasury deposits, measured against manufacturing capital expenditures and direct shareholder dividends. India Ratings has explicitly warned that any "unrelated diversion of funds" could trigger a negative credit rating action.4 More than any plant expansion or mining clearance, how management navigates this balance-sheet boundary will determine whether public markets ever value Gallantt Ispat as an institutional-grade industrial pure-play.
References
-
Gallantt Metal Limited Prospectus (Public Issue of 37,120,000 Equity Shares) — Gallantt Metal Limited, 2006-02-23 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Gallantt Ispat Q4 FY26 Results & Earnings Call: Key Highlights — ScanX, 2026-05 ↩↩↩↩
-
Gallantt Ispat Q4 & FY26 Investor Presentation — Gallantt Ispat Limited, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
India Ratings Upgrades Gallantt Ispat's Bank Loan Facilities to 'IND AA-'/Stable (rating rationale filed with NSE) — India Ratings and Research / Gallantt Ispat Limited, 2025-09-09 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Gallantt Group director on Income Tax raid: 'Neither tax evasion nor benami property' — Aaj Tak, 2023-05-02 ↩↩
-
Iron & steel products stock zooms over 1100% in 25 months — Business Standard, 2025-07-30 ↩↩↩
-
Gallantt Ispat Shares Hit Record Highs on ₹233 Cr Subsidy Boost — Whalesbook, 2026-04 ↩↩↩
-
Gallantt Ispat Ltd consolidated financials, ratios and shareholding pattern — Screener.in ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Gallant Ispat shares rise 6% on credit rating upgrade — Business Today, 2025-09-10 ↩
-
Gallantt Ispat Gorakhpur steel plant — Global Energy Monitor ↩↩↩
-
Gallant Ispat, Gallant Metal surge 20% as trading in shares normalize — Business Standard, 2018-01-01 ↩↩↩↩
-
Income Tax Department Conducts Countrywide Raids Against Gallantt Group, Recovers Cash And Jewellery Worth Rs 16 Crore — Outlook Business (PTI), 2023-04-28 ↩↩↩
-
Gallantt Ispat Limited Annual Report 2025-26 (including Notice of 22nd AGM) — Gallantt Ispat Limited, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Gallantt Ispat Limited Annual Report 2024-25 — Gallantt Ispat Limited, 2025 ↩↩↩↩↩↩↩↩↩↩
-
Gallantt Ispat plans IPO to raise Rs 40cr; files DRHP with SEBI — Business Standard (PTI), 2009-12-25 ↩
-
Gallantt Ispat Q1 FY27 Earnings Conference Call Transcript — Gallantt Ispat Limited, 2026-07-28 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Gallantt Ispat Q4 & FY26 Earnings Conference Call Transcript — Gallantt Ispat Limited, 2026-05-06 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Gallantt Ispat Ltd (Merged) financial summary — Screener.in ↩↩↩↩↩
-
NCLT Sanctions Scheme of Amalgamation of Gallantt Ispat and Gallantt Metal — Business Standard, 2021-09-24 ↩↩
-
Gallantt Ispat Limited Annual Report 2023-24 — Gallantt Ispat Limited, 2024 ↩↩↩↩↩↩
-
Gallantt Ispat shares climb 10% on agreement to buy railway rakes — Business Today, 2023-07-10 ↩↩
-
Gallantt Ispat gets delivery of second railway rake — Business Standard (Capital Market), 2024-02-19 ↩
-
Gallantt Ispat hits record high on capex plan; stock zooms 47% in 1 month — Business Standard, 2025-04-15 ↩↩
-
Gallantt Ispat's Q1 FY27 Profit Slips as Pellet Shutdown Hits Margins, Capex Plan Stays on Track — TipRanks, 2026-07 ↩
-
Gallantt Ispat hits the roof after being declared as successful bidder for Karauli iron ore block — Business Standard (Capital Market), 2024-06-18 ↩↩↩
-
Steel stock jumps 7% after receiving orders for two iron ore blocks in Uttar Pradesh — Trade Brains, 2025-06-19 ↩↩↩
-
India Ratings Upgrades Gallantt Ispat Limited to 'IND A+' / Stable — India Ratings and Research, 2024-06-21 ↩
-
Countrywide Income Tax raids on Gallantt Ispat Limited of Gorakhpur — Dynamite News, 2023-04-26 ↩
-
Income tax raids continue for 3rd day on Gallantt Group — Dynamite News, 2023-04-28 ↩↩↩
-
Income Tax department raids Gallantt Ispat premises, seizes documents — Devdiscourse (PTI), 2023-05-01 ↩
-
Intimation under Regulation 30: Change in Management — Gallantt Ispat Limited (NSE filing), 2026-03-31 ↩
-
Gallantt Ispat appoints Amit Jalan as CFO and KMP effective July 27, changes auditor — ScanX, 2026-07 ↩↩↩
-
Gallantt Ispat FY26 PAT Rises 21%; ₹3,000 Crore Capex Underway — Whalesbook, 2026-09-20 ↩
-
Q4 Results: Gallantt Ispat Slips 4% Despite 6% Increase In PAT; Board Recommends ₹2 Dividend — HDFC Sky, 2026-05-06 ↩
-
Gallantt Ispat Ltd. Hits Intraday Low Amid Price Pressure on 18 May 2026 — MarketsMojo, 2026-05-18 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube