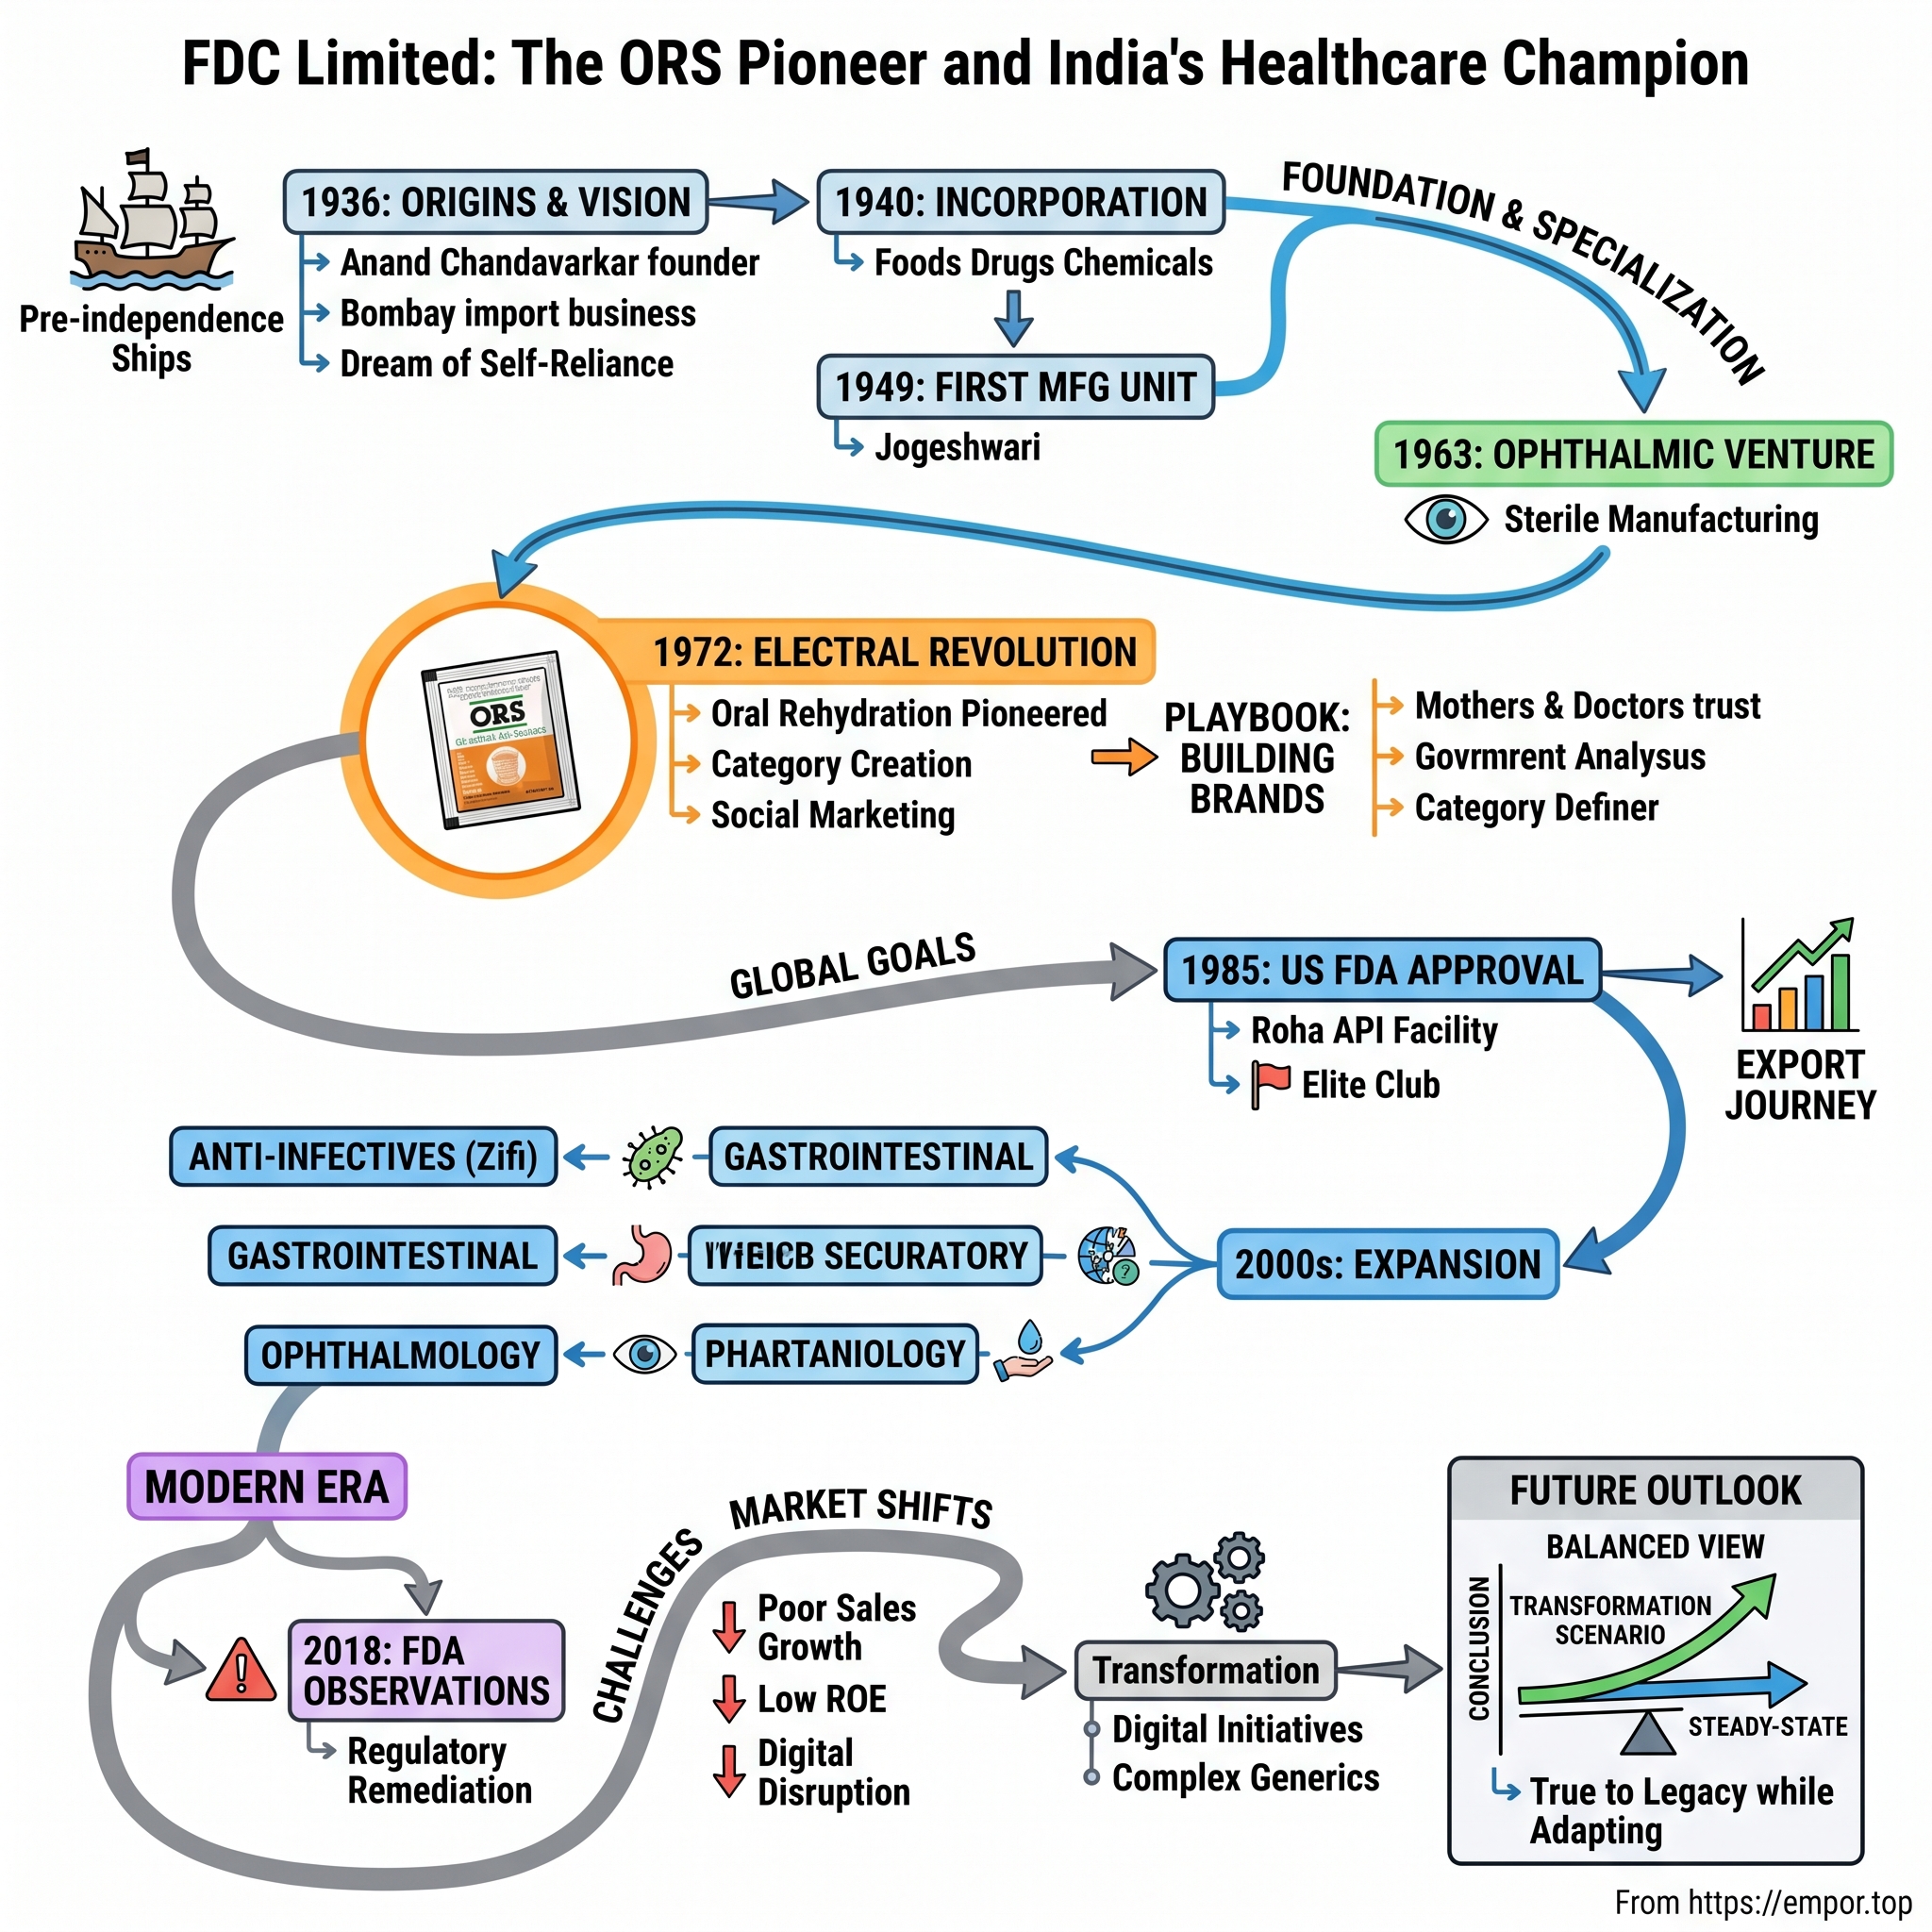
FDC Limited: The ORS Pioneer and India's Healthcare Champion
I. Introduction & Cold Open
Walk into almost any pharmacy in India — a glass-fronted counter in a Mumbai suburb, a single-room dispensary off a highway in Bihar, or a kiosk outside a district hospital in Tamil Nadu — and ask for "ORS." The pharmacist will rarely ask which brand is preferred. Instead, the customer is handed a thin orange-and-white sachet of Electral. The shopkeeper does not view this as a brand choice, nor does the prescribing physician, the mother caring for a dehydrated child, or the ward worker stirring a liter of water. In the Indian healthcare vocabulary, "ORS" and "Electral" have become virtually synonymous, much like "photocopy" and "Xerox."
That is a rare market position to hold, particularly given what Electral actually is: a public-domain mixture of glucose, sodium chloride, potassium chloride, and trisodium citrate. Standardized by the World Health Organization and intentionally left unpatented so developing nations could manufacture it freely, the formulation contains no proprietary molecule or trade secret. Any manufacturer with basic blending and sachet-filling equipment can produce it. Yet the company that introduced the WHO formulation to the Indian market in the 1970s continues to dominate the category more than five decades later.
That company is FDC Limited, originally founded as Fairdeal Corporation. It began in 1936 as a small Bombay trading agency importing infant foods, surgical instruments, and European formulations into a colonial market with virtually no domestic pharmaceutical manufacturing. Nine decades later, it is a debt-free, family-controlled pharmaceutical manufacturer generating approximately ₹2,171 crore in consolidated revenue across four manufacturing hubs. Its active pharmaceutical ingredient (API) plant cleared a U.S. Food and Drug Administration inspection in 1985, long before the broader Indian generics sector established a global presence. Today, two flagship brands — Electral and the oral antibiotic Zifi — account for roughly half of its domestic business.[^1]1
This history creates a central operational tension. On paper, FDC possesses a dominant consumer-healthcare franchise supported by pricing power, physician trust, broad national distribution, and a clean balance sheet. In practice, its return on equity has remained in the low teens for over a decade, revenue grew by just 3% in the most recent fiscal year, and its export segment has spent five years recovering from regulatory hurdles rather than expanding. Meanwhile, management's primary deployment of excess capital has been share buybacks, even though the founding promoter family already controls 69.66% of the equity.2[^11]
The key question is not whether FDC is a viable business; its solid gross margins confirm that it is. Rather, the question is why a company capable of creating such strong brand equity has struggled to compound value at a higher rate. Is this performance cap regulatory, structural, or strategic? Does the founding Chandavarkar family's conservative stewardship reflect the discipline that enabled a 1936 trading enterprise to navigate the License Raj, 1991 economic liberalization, price competition, and FDA oversight — or does it indicate a business currently managed for capital preservation rather than expansion?
The analysis unfolds in eight parts. First, the colonial origins and the nationalistic push that transformed an importer into a manufacturer. Second, the development phase from the 1960s through the 1980s, when FDC pioneered sterile ophthalmic manufacturing and built Electral into a market leader. Third, the export paradox: how an early 1985 FDA clearance demonstrated technical capability but failed to translate into global commercial scale. Fourth, an examination of the domestic core business that funds operations. Fifth, a review of capital allocation, cash reserves, and share buybacks. Sixth, a strategic assessment of competitive moats using standard business frameworks. Seventh, an evaluation of key operational and regulatory risks. Finally, a synthesis of the bull and bear cases detailing the critical metrics for investors to monitor.
The story begins in a rented office in Bombay, in a country that had not yet gained independence.
A note on how to read this company
A key analytical framework is essential when evaluating FDC: the company effectively operates two distinct businesses that require different analytical standards.
The first is a consumer healthcare franchise operating under a pharmaceutical structure. Flagship products Electral and Enerzal are purchased directly by consumers, selected primarily by brand reputation, used at home, and distributed through mass retail channels. The economics of this division depend on brand equity, retail placement, manufacturing unit costs, and government price controls.
The second is a conventional Indian branded-generics operation encompassing anti-infectives, ophthalmic solutions, and vitamins. These prescription products compete on sales-force reach and physician relationships against numerous similar alternatives, supplemented by a modest export business to regulated markets.
Much of the market misvaluation of FDC stems from applying high consumer-goods valuation multiples to a company whose overall growth rate is constrained by its standard generics portfolio and by price ceilings on its flagship rehydration products. Evaluating these two segments independently provides a clearer view of the company's financial performance.
 Subscribe on LinkedIn
II. Pre-Independence Origins & The Chandavarkar Vision (1936–1950s)
Bombay in 1936 was a city dominated by intermediaries. Its port shipped raw cotton out and imported manufactured goods, sustaining a merchant class that brokered transactions between European manufacturers and domestic consumers who lacked local alternatives. Healthcare was among the most vulnerable sectors; Indian hospitals and dispensaries relied entirely on imported formulations, surgical steel, and infant foods. When shipping schedules stalled, medical wards ran out of critical supplies.
Into that fragile supply ecosystem stepped Anand Chandavarkar, who established Fairdeal Corporation as a modest agency importing surgical instruments, infant foods, and basic formulations for the Bombay medical trade.[^1] In its initial years, the enterprise followed a conventional trading model: purchasing abroad, selling locally, maintaining margins, and managing credit. While thousands of such trading firms operated across colonial India, very few survived into the modern era.
Chandavarkar recognized early that relying solely on trading spreads created an inherent vulnerability. An importer's margin remained subject to upstream foreign suppliers and exchange-rate fluctuations. Moreover, Mahatma Gandhi's Swadeshi movement had elevated self-reliance from a political imperative to a compelling commercial rationale. If domestic consumers were boycotting foreign textiles, domestic healthcare could not remain dependent on imported drugs. For a trader managing customs clearances, this nationalist argument carried immediate operational weight: the supply chain was fundamentally fragile.
The transition from an import agency to a domestic manufacturer was formalized with the incorporation of FDC Limited on September 23, 1940.[^1] The timing proved critical. With the onset of World War II, shipping lanes to Europe faced severe disruption, and imports of German pharmaceuticals — previously a substantial portion of India's medical supply — effectively ceased. A domestic company with even basic formulation capabilities suddenly faced an undersupplied market. Strategic foresight and wartime logistics converged, accelerating FDC's entry into manufacturing.
FDC made its primary physical capital commitment in 1949, two years after independence, by establishing its flagship formulation facility at Jogeshwari in Bombay.[^1] Building a sterile pharmaceutical facility in post-independence India presented formidable hurdles: foreign exchange was strictly rationed, capital goods required import licenses, industrial capacity needed state approval, and pharmaceutical machinery was produced almost exclusively in hard-currency nations. Constructing the plant was as much an exercise in navigating bureaucratic hurdles as it was an engineering project.
This move also established FDC's enduring commercial strategy. Rather than competing directly against multinational pharmaceutical companies in patented, premium-priced therapeutics, FDC focused on high-volume, essential medications where multinational firms were absent or expensive: vitamins, anti-infectives, and basic treatments for common conditions. Operating with a domestic cost structure allowed the company to compete effectively on availability and price rather than international brand prestige.
Executing this strategy required building a vast commercial distribution network. FDC established direct relationships with tens of thousands of independent pharmacies and small-town clinicians across western India, relying on credit, trade terms, and personal trust. Developed systematically throughout the 1950s by FDC's field force, this unglamorous retail reach became the company's most durable asset. While unlisted on the balance sheet, this network provided the foundational infrastructure for FDC's subsequent product rollouts.
What the Jogeshwari decision actually bought
Beyond manufacturing capacity, the Jogeshwari facility secured a strategic regulatory asset: an industrial license in an economy where operating permissions were scarce. Under the industrial licensing regime governing India from the 1950s through the 1980s, manufacturing rights and production capacities were tightly controlled by state authorities. Incumbents with licensed facilities operated with significant protection from new entrants. For FDC, the License Raj functioned simultaneously as an operational bottleneck — requiring approvals for capital imports and capacity expansions — and a powerful competitive barrier.
This regulatory environment deeply influenced FDC's management philosophy. Operating under strict license allocations taught an entire generation of corporate leaders that growth was constrained primarily by capital availability, input supplies, and regulatory approvals rather than market demand. Consequently, management prioritized cash preservation, zero leverage, supply self-sufficiency, and cautious expansion. FDC's 2026 balance sheet — characterized by zero debt, substantial liquid reserves, captive API production, and multiple manufacturing facilities — reflects operational habits shaped during that era of state control, providing context for the company's persistent capital-allocation choices.
III. Category Creation: The Birth of Electral & Ophthalmic Leadership (1960s–1980s)
Sterile manufacturing presents some of the highest operational and regulatory hurdles in the pharmaceutical industry. While an imperfect tablet represents a commercial defect, a contaminated eye drop poses a direct clinical threat. In early-1960s India, establishing the required infrastructure—HEPA-filtered air, validated autoclaves, controlled environments, and rigorous microbiological testing—represented a major technical barrier. Consequently, when FDC entered sterile ophthalmic formulations in 1963 with its Pyrimon franchise, it established a technical capability well beyond standard low-cost formulation copying.[^1]
At the time, ophthalmic treatments across South and Southeast Asia were largely controlled by multinational importers, leaving products expensive, supply inconsistent, and access restricted to urban patients who could afford them. FDC addressed this gap by manufacturing sterile eye drops domestically for the mass market. Rather than competing in crowded oral solid markets, management targeted a category protected by technical manufacturing barriers, where operational capability mattered more than promotional expenditure. This technical orientation laid the foundation for the company's subsequent API development at Roha, its sterile facilities in Goa, and its contemporary ophthalmic export operations.
While ophthalmics demonstrated FDC's technical capability, its strategic trajectory was reshaped by a broader public health crisis.
The problem nobody could solve
During the 1960s and 1970s, diarrhoeal disease was a leading cause of pediatric mortality in India. The medical danger stemmed from rapid fluid and electrolyte depletion, leading to fatal hypovolemic shock. Standard clinical treatment relied on intravenous fluids, which required clinical facilities, sterile equipment, and trained healthcare personnel. In rural India, where medical access was distant or nonexistent, IV therapy was largely inaccessible to the broader population.
The clinical breakthrough emerged from physiological research on intestinal transport: sodium absorption in the small intestine is coupled with glucose transport. A precise balance of glucose and salts allows the intestinal lining to absorb fluids orally, even during severe inflammation. This enabled effective rehydration outside clinical settings using a simple oral solution.
In 1972, the World Health Organization standardized this formula as Oral Rehydration Salts (ORS). Published as a public-domain formulation without patent protections or licensing restrictions, the recipe was freely available for global manufacture.
Turning a formula into a brand
FDC commercialized the WHO formulation in India under the brand name Electral.[^1] From a chemical manufacturing standpoint, blending four commodity salts and packaging them in laminated sachets required basic technical execution rather than proprietary science. Competitor entry was technically straightforward, and numerous manufacturers eventually launched competing formulations.
FDC's commercial moat was built not through chemical differentiation, but through market creation across three distinct operational hurdles.
First, management had to shift clinical habits. Indian physicians had historically treated severe dehydration with intravenous fluids, viewing oral rehydration as an inadequate intervention for critical cases. FDC's sales force conducted extensive physician education across clinics, explaining the sodium-glucose co-transport mechanism, demonstrating proper solution preparation, and establishing clinical guidelines for oral therapy. By establishing oral rehydration as the standard of care, FDC positioned Electral as the category's benchmark brand.
Second, distribution required deep retail penetration. Because pediatric dehydration often occurred in rural areas with limited infrastructure, FDC leveraged the distribution network it had developed since the 1950s. The company expanded its reach to several hundred thousand retail chemists, medical practitioners, and rural clinics.[^1] Given the low unit price of an ORS sachet, building a standalone distribution network specifically for rehydration salts was economically unfeasible; Electral succeeded by utilizing FDC's pre-existing retail distribution pipeline.
Third, the company cultivated consumer trust at the point of care. Used primarily during acute childhood illnesses, ORS purchases relied heavily on physician recommendations and brand familiarity. This established long-term consumer habits and repeat purchasing without requiring heavy consumer advertising expenditure.
Through this strategy, FDC built durable, consumer-grade brand equity atop an unpatented formulation. Today, the Electral franchise continues to generate approximately one-quarter to one-third of FDC's domestic revenue.1
Backward integration, and a nod from the government
To protect its formulation supply chain under India's import-restricted economic regime, FDC initiated backward integration into active pharmaceutical ingredients (APIs). Between 1974 and 1985, the company established API manufacturing facilities at Roha in Maharashtra, having secured formal recognition for its in-house research and development from the Government of India in 1974.[^1] In an era of strict license allocations and import constraints, internal API production served primarily as a risk-mitigation strategy to ensure supply continuity rather than an immediate commercial export venture.
This operational phase highlights the specific nature of FDC's competitive advantage. The company's market position relied not on proprietary molecular patents, but on the confluence of early retail distribution, extensive practitioner education, and entrenched brand trust. While this combination created high barriers to entry within oral rehydration, it offered limited spillover benefits for expanding into unrelated therapeutic categories, such as chronic cardiovascular therapies.
This strategic boundary became increasingly relevant in later years as the company sought broader growth opportunities.
The economics of a two-rupee sachet
The unit economics of oral rehydration salts illustrate the structural dynamics of FDC's broader business model.
While an Electral sachet carries a retail price of only a few rupees, its raw materials—glucose, sodium chloride, potassium chloride, and trisodium citrate—are low-cost commodities. Consequently, the product yields high gross margins because direct material inputs represent a small fraction of the retail price.
However, because absolute revenue per sachet is low, sustaining profitability requires very high unit volumes. Distributing these volumes across India's fragmented retail market requires substantial operating expenditures below the gross margin line, including sales force compensation, distributor margins, logistics, and working capital to support trade credit.
This financial structure explains two defining features of FDC's financial profile. First, operating expenses associated with distribution absorb a significant portion of gross profits, leading to moderate net operating margins despite robust gross margins. Second, the substantial fixed distribution cost creates a formidable barrier to entry. Potential competitors must establish comparable distribution reach before achieving profitable scale, competing directly against an incumbent with established volume.
Conversely, this structure leaves the business vulnerable to price controls. When products are subject to National List of Essential Medicines (NLEM) price caps, fixed and inflation-linked operating expenses cannot be easily offset through price increases, leading to structural margin compression.
IV. Regulated Exports & The IPO Era (1985–2000s)
In 1985, an inspector from the U.S. Food and Drug Administration inspected an active pharmaceutical ingredient (API) plant in Roha, Maharashtra, and granted regulatory approval.
The context makes that milestone remarkable. In 1985, India was five years away from a balance-of-payments crisis and six years away from economic liberalization. International markets viewed the Indian pharmaceutical industry primarily as a sector that had abolished product patents on medicines in 1970 to reverse-engineer foreign formulations. The expectation that an Indian facility could satisfy U.S. current Good Manufacturing Practice (cGMP) standards was far from established. FDC's Roha site achieving US-FDA accreditation in 1985 put it among the earliest Indian pharmaceutical sites to clear that bar.[^1]
Over the following two decades, several Indian pharmaceutical peers leveraged similar early regulatory beachheads into global generic powerhouses—filing hundreds of Abbreviated New Drug Applications, litigating patents in U.S. federal courts, establishing direct overseas distribution, and expanding exports into the majority of their revenues.
FDC did not follow that path. Examining why offers essential insight into the company's underlying risk posture and commercial identity.
The 1996 listing and the manufacturing footprint
FDC completed its initial public offering in 1996, and the proceeds funded a multi-location manufacturing build-out: Goa for oral solids and sterile ophthalmics, Baddi in Himachal Pradesh for cephalosporins, plus facilities at Waluj and Sinnar.[^1] The Baddi site selection was particularly strategic: Himachal Pradesh offered substantial fiscal incentives that drew a large cluster of domestic pharmaceutical manufacturers, shaping formulation economics for two decades.
Cephalosporins represented the central strategic commitment of this era. As workhorse outpatient antibiotics in India, cephalosporins require dedicated, segregated production facilities to prevent cross-contamination with beta-lactam compounds—a strict regulatory and safety requirement that creates a genuine capital barrier to entry.
The commercial expression was Zifi, FDC's cefixime brand, which scaled through the 1990s and 2000s into the company's second mega-brand and a leader in oral cephalosporins.[^1] Zifi today contributes roughly a fifth to a quarter of domestic sales.1 Its competitive moat differs fundamentally from Electral's. While oral rehydration salts benefit from category equivalence, cefixime is a generic molecule produced by dozens of competitors, allowing prescribers to switch brands with minimal friction. Zifi's position relies instead on entrenched prescribing habits—physician familiarity reinforced by decades of continuous field-force presence. This represents a valuable commercial asset, though inherently softer than Electral's category dominance.
Myth vs reality: did the 1985 FDA clearance make FDC a global generics contender?
This early regulatory milestone is frequently cited as evidence of international potential, making it an important claim to evaluate.
The claim: early US-FDA accreditation positioned FDC to become a global generics powerhouse in the mould of the Indian companies that later dominated US generics.
The disconfirming record: Operating history refutes this expectation. Export formulations remained locked in a roughly 10–15% band of total revenue for decades.1 Four decades of consistent performance reflect a deliberate strategic choice rather than temporary execution hurdles. FDC avoided the capital-intensive, high-risk litigation model required for U.S. generic growth—such as Paragraph IV patent challenges, at-risk product launches, direct overseas distribution infrastructure, and substantial legal expenditures. Instead, management relied on localized distribution partners in less competitive markets, while steady domestic cash flows reduced the incentive to undertake aggressive international expansion.
The conclusion: Regulatory clearance demonstrates manufacturing capability to a specific standard, but it does not ensure commercial success in markets governed by complex legal, distribution, and sales barriers. Certification is not commercialization. The surviving reality is that FDC established durable, high-quality API and sterile manufacturing capabilities that provide cost efficiencies and support a modest export presence. Any investment thesis predicting rapid export growth must identify a fundamental shift in corporate risk appetite rather than relying solely on technical inspection compliance.
It is a thesis that would be tested, painfully, in the decade that followed.
A note on what the Roha plant really is
Evaluating FDC's export profile requires a precise understanding of the operational role played by its API manufacturing infrastructure.
Active pharmaceutical ingredients represent the biologically active compounds in medications—such as cefixime in Zifi or fluconazole in Zocon. API synthesis involves complex chemical processes, including multi-step organic synthesis, solvent recovery, crystallization, and purification to strict pharmacopeial standards. Formulations, by contrast, involve converting these active compounds into finished dosage forms—tablets, oral suspensions, or sterile drops—ensuring precise dosage delivery and shelf-life stability.
Historically, many Indian formulation manufacturers have sourced active ingredients externally, with a heavy reliance on imports from China over the past two decades. Global supply chain disruptions in 2020 exposed this vulnerability, highlighting the operational risks of external API dependence.
FDC's captive API capacity at Roha provides meaningful insulation against such supply shocks. Although external sales of APIs generate a modest ₹121 crore in revenue, the facility's strategic value as an internal supply buffer against input price volatility and raw material shortages exceeds its direct top-line contribution. Furthermore, vertical integration strengthens FDC's cost structure in key categories like cephalosporins compared to non-integrated formulators.
However, vertical integration also concentrates regulatory exposure. Because the Roha facility remains subject to U.S. FDA oversight, any adverse regulatory finding at the API level directly impacts both standalone chemical sales and the downstream formulation lines dependent on internal API supply.
V. Modern Era: Portfolio Breakdown & Strategic Realities (2010s–Present)
Behind nine decades of operational history lies a straightforward corporate structure: FDC functions primarily as a domestic Indian branded-formulations manufacturer, supported by a modest export arm and a captive active pharmaceutical ingredient (API) facility.
In fiscal 2026, consolidated revenue reached ₹2,171 crore, up from ₹2,108 crore in fiscal 2025—reflecting modest top-line growth of roughly 3%, compared to its five-year compound annual growth rate in the 8% to 9% range.1[^1] That deceleration highlights a key analytical tension: whether the recent slowdown represents a temporary operational patch or a structural ceiling on its legacy business.
Where the money actually comes from
Domestic formulations generate roughly 82% of total revenue, or about ₹1,781 crore.1 This segment remains the company's primary profit driver and shapes its operational priorities.
Export formulations contributed approximately ₹260 crore, or 12% of total revenue, expanding by 23.5% in fiscal 2026 following U.S. compliance remediation and product relaunches.1 While substantial on paper, that surge reflects a recovery from a depressed baseline following regulatory disruptions rather than an expansion into new markets. Exports have simply reverted toward their historical baseline of 10% to 15% of total sales.
API operations at the Roha facility generated about ₹121 crore, representing roughly 6% of revenue, supplying internal formulation requirements alongside merchant sales across North America, Europe, and Asia.1 The strategic value of this segment exceeds its top-line contribution, providing operational insulation against global supply chain disruptions and protecting FDC's cost structure in key therapeutic molecules.
Concentration, and what it costs
Two flagship brands—Electral and Zifi—account for between 45% and 55% of domestic sales.1 Complementing this core are Enerzal, an over-the-counter rehydration beverage representing FDC's effort to expand into non-regulated consumer healthcare; the Pyrimon ophthalmic line; Zocon (fluconazole); Vitcofol (vitamins and iron); and secondary brands such as Zipod, Zathrin, Cotaryl, and Mycoderm.
This concentration offers clear operational advantages while imposing structural limits. Relying on two key brands provides field-force leverage, allowing sales representatives to promote established names with existing prescriber trust. However, it also ties corporate expansion to two mature acute categories. Without a broad therapeutic base, the company lacks a portfolio cushion against volume fluctuations.
Crucially, FDC remains underrepresented in chronic therapies—such as cardiology, diabetology, and central nervous system disorders—which have driven growth across the domestic pharmaceutical industry over the past decade. Unlike chronic treatments that generate recurring, multi-year refills, acute medications treat single medical episodes. Consequently, FDC must continually regenerate its customer base each year, limiting its organic compounding potential.
The FSSAI crackdown: a regulator draws a wall around Electral
In the early 2020s, regulatory intervention reshaped the competitive landscape for FDC's leading product.
Because "ORS" is a generic scientific term rather than a registered trademark, commercial beverage manufacturers had increasingly adopted the abbreviation for commercial sugar-sweetened drinks that did not conform to WHO formulation standards—products whose high sugar content could exacerbate dehydration in pediatric patients.
To protect public health, the Food Safety and Standards Authority of India (FSSAI) instructed food and beverage companies to remove "ORS" branding from non-WHO-compliant products.34 Subsequent enforcement curtailed the commercial sale of beverage lookalikes across retail channels.
For FDC, this intervention effectively restricted the term "ORS" to standardized pharmaceutical formulations, establishing a regulatory perimeter around the category.
However, the commercial impact of this ruling requires careful interpretation. The FSSAI directive did not eliminate competition among pharmaceutical manufacturers producing WHO-compliant formulations, many of which compete directly on price. Rather, it resolved retail category confusion by stopping consumer volume leaks to non-medicinal beverages. While the policy benefited all legitimate ORS manufacturers, FDC captured the largest absolute gain due to its leading position, holding over 70% of the prescribed WHO-ORS segment.1 This intervention protected the broader medicinal rehydration market rather than FDC exclusively—and because regulatory policies remain subject to administrative revision, it constitutes a policy-derived advantage rather than a permanent proprietary moat.
The FDA decade: capability versus compliance
While domestic operations benefited from regulatory clarification, the export division faced extended compliance headwinds.
Between fiscal 2021 and fiscal 2024, regulatory inspections across FDC's Baddi, Waluj, and Roha facilities resulted in Form 483 observations, voluntary product recalls, and U.S. shipment delays, suppressing export revenues.1 These challenges illustrated an industry-wide reality: commercial success in regulated markets depends as much on documentation standards, data integrity, and quality governance as on basic chemical manufacturing capabilities.
That compliance setbacks occurred at a firm holding U.S. FDA clearances since 1985 indicates that evolving global regulatory expectations outpaced the company's historical quality-management systems. Addressing these deficiencies required multi-year remediation efforts and significant capital allocation.
By fiscal 2026, management confirmed that the Baddi and Waluj plants had cleared regulatory scrutiny, restoring direct shipments to the U.S. and driving a 23.5% export revenue recovery.1 While this resolution removes an immediate operational drag, maintaining compliance requires ongoing investment across multi-year inspection cycles, as FDC's operational history demonstrates.
Reading the management narrative
Evaluating FDC's strategic trajectory requires examining management disclosures over an extended period.
Across corporate filings, management's messaging has remained highly consistent: emphasizing core brand equity, quality compliance, balance-sheet conservatism, and gradual consumer-healthcare expansion.[^1]1 While consistent messaging can signal operational stability, it also reflects strategic inertia. Throughout a decade characterized by slowing top-line growth, export volatility, and range-bound returns on equity, corporate disclosures offered few explicit targets for expanding chronic-therapy revenues, growing the consumer division, or redeploying accumulated cash reserves.
Management provided clearer guidance regarding export remediation. Disclosed milestones—specifically clearing inspection hurdles at Baddi and Waluj—aligned with the operational turnaround and subsequent export recovery in fiscal 2026.1 This tracking between stated objectives and reported outcomes demonstrates operational execution, even as broader long-term strategic targets remain undefined.
VI. Capital Allocation, Buyback History & Governance Analysis
Every family business eventually faces the same fundamental question, one rarely asked outright in annual reports: what is this company ultimately set up to accomplish?
At FDC, the answer is written not in its vision statement but in its cash flow trends over the past decade.
The family at the centre
Executive leadership remains firmly with the founding family. Mohan A. Chandavarkar serves as Chairman and Managing Director, Nandan M. Chandavarkar as Joint Managing Director, Ashok A. Chandavarkar as Executive Director, and Ameya A. Chandavarkar as CEO of International Business and Executive Director.[^1] Promoter equity stands at 69.66%, held primarily through family vehicles including the Mohan Anand Chandavarkar Trust and the Ameya Family Discretionary Trust.2
This concentrated ownership dictates corporate behavior. Controlling nearly 70% of the equity insulates management from external pressure. Without an activist path, threat of a hostile takeover, or institutional leverage to compel a strategic review, accountability remains strictly internal.
This governance structure presents clear trade-offs. Operating with a multi-decade horizon releases management from short-term market anxiety, allowing the firm to weather factory disruptions, absorb multi-year regulatory remediation, and avoid overpriced acquisitions. Conversely, when controlling shareholders prioritize stability, operational inertia can easily become the baseline.
Cash in, cash parked, cash returned
FDC maintains a debt-free balance sheet with liquid reserves and investments historically ranging between ₹500 crore and over ₹800 crore.2 Relative to consolidated revenues of approximately ₹2,171 crore and low capital intensity, this reflects a significant cash position earning yields well below the returns generated by the core operating business.
How management deploys this capital reveals its strategic priorities. FDC has avoided large cross-border acquisitions, aggressive biopharmaceutical research, and major acquisitions of chronic-therapy portfolios—the primary avenue for addressing its organic growth ceiling.
Instead, management has consistently returned capital through tender-offer share buybacks: purchasing approximately 21.63 lakh shares in 2020; 29 lakh shares at ₹475 per share in 2022 for about ₹137.75 crore; and 31 lakh shares at ₹500 per share in 2023 for about ₹155 crore.[^6]5
Myth vs reality: is conservatism protecting shareholder value?
The claim, as management presents it: Maintaining a debt-free balance sheet and refusing to overpay for assets protects shareholder value while providing operational resilience.
The disconfirming record, from FDC's own numbers: Return on equity (ROE) has remained bound in the 11% to 13% range for over a decade.2 Research and development expenditures hover between 2.0% and 2.5% of sales—a modest allocation for a firm positioning innovation as a strategic driver.[^1] Meanwhile, domestic revenue expansion has averaged single digits, with consolidated top-line growth decelerating to 3% in fiscal 2026.1
Evaluating these factors requires balancing financial resilience against capital productivity.
First, the resilience argument is supported by operational history. FDC absorbed the 2021–2024 U.S. FDA compliance remediation, pandemic disruptions, and successive price revisions under the National List of Essential Medicines without taking on debt, diluting equity, or facing financial distress—an outcome that contrasts with leveraged peers in the Indian pharmaceutical sector.
Second, the value-creation thesis faces clear mathematical limits. A low-teens ROE on a zero-debt balance sheet indicates that while core formulation operations generate healthy returns, accumulated cash reserves dilute overall capital efficiency. Holding substantial capital in low-yielding liquid instruments reduces consolidated returns on equity. Share buybacks mitigate this drag by shrinking the share count and supporting earnings per share, but a buyback represents a capital distribution rather than a growth strategy. Retiring equity improves financial metrics without accelerating top-line expansion.
Third, repeated tender-offer buybacks under a 69.66% promoter shareholding function as a tax-efficient mechanism for distributing cash to all shareholders, including controlling family trusts. While commercially standard, this practice reflects capital return rather than operational reinvestment.
The calibrated conclusion: FDC's conservative balance sheet effectively mitigates operational risk, as demonstrated during regulatory and price shocks. However, historical return data shows it has not served as an engine for compounding value. Management has consistently favored predictable, moderate returns over the strategic risk necessary to accelerate growth.
What would falsify this analysis: Redeploying capital reserves into high-growth chronic-therapy or consumer-healthcare assets at reasonable valuations, accompanied by a sustained rise in ROE above historical levels. Without such deployment, current ownership dynamics suggest the established capital allocation model will persist.
A second-layer look
Additional governance and operational factors warrant attention:
Auditor and accounting signals. Financial disclosures show no history of restatements, going-concern qualifications, or auditor disputes. Given the company's substantial liquid portfolio, primary analytical focus centers on treasury investment valuations and income statement mark-to-market adjustments, which can distort reported quarterly profits relative to core operating performance.2
Related-party exposure. Promoter equity is held largely through family trusts detailed in ownership filings.2 Routine diligence requires monitoring related-party disclosures to ensure arm's-length commercial terms across corporate entities.
Key personnel. The concentration of executive leadership within the founding family highlights key-person reliance. No formal succession roadmap beyond the current executive leadership has been publicly outlined, even as international expansion is directed by a next-generation family executive.[^1]
Capital expenditure discipline. FDC has avoided speculative, high-cost capacity expansions for regulated markets that have caused capital destruction across peers. The absence of major asset write-downs or unutilized plant investments underscores management's disciplined approach to capital expenditure, counterbalancing growth criticisms.
VII. Competitive Moats: Helmer's 7 Powers & Porter's 5 Forces
Evaluating FDC's long-term durability requires addressing a central question: if a well-funded competitor decided to target the Indian oral rehydration market, what stops them?
A new entrant can easily manufacture the product—the formulation is in the public domain. They can price below FDC—the raw inputs are low-cost commodities. They can launch promotional campaigns. What they cannot easily replicate is the retail and clinical pipeline: getting several hundred thousand chemists to stock a second ORS brand alongside one that already turns over reliably, persuading a generation of physicians to change their prescribing habits, or convincing a parent during an acute medical episode to try an unfamiliar alternative. That operational barrier forms FDC's competitive moat.
Helmer's 7 Powers
Branding — very high. Electral's equity functions as a genericized trademark, established through prescription channels and reinforced by repeated use during acute medical care. Economically, this enables FDC to maintain market share without matching the lowest-priced sachet on the shelf. This represents the company's most valuable asset, built over decades of clinical trust that cannot be readily purchased by competitors. Zifi shares a similar advantage, though driven primarily by physician prescription inertia rather than direct consumer pull.
Scale economies and process power — high within the category. High-volume automated packaging, dedicated production lines, and captive API supply provide FDC with a low-unit-cost position in Indian ORS. Under price control regimes, where price ceilings apply uniformly across manufacturers, a low-cost producer preserves operating margins while higher-cost competitors face margin compression. However, this cost efficiency remains strictly category-specific and does not transfer to unrelated therapeutic areas like dermatology.
Cornered resource — moderate and policy-derived. The FSSAI directive restricting "ORS" labeling creates a protective regulatory perimeter around WHO-compliant formulations. While currently advantageous to FDC as the market leader, this perimeter is derived from administrative policy rather than proprietary intellectual property. Because FDC neither owns nor controls the regulatory framework, relying on it as a permanent structural barrier would be overly optimistic.
Switching costs — low to moderate. In acute anti-infectives, switching costs are minimal at the molecule level, as physicians can substitute cefixime brands without clinical friction. FDC's advantage stems from clinical habit rather than structural lock-in. The distinction is material: while true switching costs create high barriers to replacement, habit can erode over time under sustained commercial and promotional pressure.
Counter-positioning and network effects — absent. FDC operates without business-model asymmetries that competitors cannot replicate, and the business exhibits no network effects where additional users increase the product's value to others. Clearly identifying these absent dynamics prevents overestimating the breadth of the company's competitive advantage.
Process power in quality systems — contested. While regulatory manufacturing excellence might once have been considered a structural advantage, compliance challenges between fiscal 2021 and fiscal 2024 indicate that quality governance remains an operational requirement rather than a durable moat.
Porter's 5 Forces
Threat of substitutes — high and structural. Homemade sugar-and-salt solutions represent a zero-cost alternative, while commercial glucose powders and sports beverages occupy adjacent retail space. Although non-medicinal beverages lack clinical equivalence to WHO-ORS, price-sensitive consumers do not always distinguish between rehydration categories, making low-cost alternatives an ongoing threat.
Bargaining power of buyers — moderate to high. Institutional and government procurement tenders are awarded primarily on price, compressing margins on products already bound by regulatory price ceilings. At retail, pharmacy trade margins represent a point of friction, as chemists offered higher margins on competing sachets have an incentive to recommend alternatives.
Bargaining power of suppliers — low. Primary raw materials—including glucose, sodium chloride, potassium chloride, and basic chemical inputs—are widely available commodity materials. In addition, internal production at the Roha API facility covers a portion of FDC's active ingredient requirements, limiting supplier leverage.
Competitive rivalry — high. The Indian pharmaceutical market remains highly fragmented, with dozens of manufacturers producing competing cefixime formulations and generic oral rehydration salts. While competitive intensity does not threaten FDC's solvency, it places a ceiling on pricing power and organic growth.
Threat of new entrants — low to moderate. Establishing basic formulation capacity for oral rehydration salts requires modest capital. However, replicating FDC's national distribution footprint and long-standing prescriber trust presents a formidable barrier to new entrants. The primary obstacle is not manufacturing capacity, but commercial reach and established clinical reputation.
The comparison that matters
Comparing FDC with domestic branded-formulation peers—such as Mankind Pharma, JB Chemicals, and Alkem Laboratories—highlights key strategic differences. Peer companies have generally achieved higher revenue growth rates and superior returns on equity. That outperformance stems not from superior brand equity—few domestic healthcare brands equal Electral's market penetration—but from portfolio composition. Peers have aggressively built or acquired chronic-therapy portfolios that generate recurring, multi-year revenue, or executed acquisitions that opened new growth channels, thereby bypassing the volume constraints inherent in acute-care medications.
In summary, FDC's competitive moat is narrow and deep. It effectively protects existing operating profits within its core categories, but provides limited leverage for expanding into new therapeutic areas. For investors, distinguishing between defensive resilience and offensive compounding capability remains the central analytical consideration.
VIII. Material Risk Radar & Investor Stress Test
1. Price control is a permanent structural feature, not an event. Electral and Zifi fall within the National List of Essential Medicines, which means the National Pharmaceutical Pricing Authority sets ceiling prices for them.[^8] The pricing mechanism is straightforward and unforgiving: FDC cannot price its primary products based on brand equity. Annual price adjustments are indexed to wholesale price inflation, a general metric that does not reflect pharmaceutical cost dynamics. When packaging film, freight, and field-force compensation outpace general inflation, operating margins compress without a corresponding pricing lever to offset input costs. Consequently, regulatory price caps represent the primary reason why a market-dominant brand yields restrained financial returns.
2. The business is a bet on the weather. More than 60% of domestic revenue comes from acute therapies: diarrhoeal disease, seasonal infection, fever.1 Demand depends heavily on monsoon intensity, summer heat waves, and the seasonal incidence of waterborne illness. A mild season results in immediate volume stagnation without compensating annuity revenue, as FDC lacks a recurring chronic-patient base. This reliance on seasonal acute conditions explains FDC's uneven year-to-year revenue trajectory—a structural dynamic that operational efficiency alone cannot alter without portfolio diversification.
3. Regulatory compliance risk is live, not historical. Any renewed adverse inspection outcome at Roha, Baddi or Waluj would stall the export recovery.1 This risk is not theoretical; between fiscal 2021 and fiscal 2024, regulatory observations and delays suppressed international shipments, demonstrating that quality governance requires continuous operational focus.
4. The public-health paradox. FDC's largest commercial franchise relies fundamentally on the persistence of waterborne illness and inadequate sanitation infrastructure across India. Long-term improvements in municipal water supply, sanitation, and rotavirus vaccination coverage represent positive public health developments that structurally constrain oral rehydration volumes. While this transition unfolds over decades rather than quarters, it presents a permanent headwind for category expansion.
5. Governance and succession. A critical investor assessment highlights several structural factors: limited professionalization of senior executive leadership outside the founding family, minimal public clarity regarding succession beyond the current Chandavarkar generation, substantial cash reserves held in low-yielding instruments without a declared strategic deployment plan, and an absence of chronic-therapy acquisitions. At 69.66% promoter ownership there is no external mechanism to force any of this.2 The counter-argument—that family stewardship has delivered nine decades of operating history, a debt-free balance sheet, and zero governance scandals—is valid. However, business preservation and capital compounding represent distinct goals, and public market valuations reflect future growth expectations.
6. Trade and distribution concentration. FDC's retail chemist network represents both its principal competitive asset and a single-channel dependency. Structural shifts in Indian pharmacy retail—including the growth of organized retail chains and e-pharmacy platforms introducing private-label offerings and aggressive discounting—are altering channel bargaining power. Platforms promoting lower-cost, private-label rehydration options directly challenge FDC at its point of highest vulnerability: self-directed, non-prescription consumer purchases.
Taken together, these factors define an unusual risk profile. Catastrophic risk remains minimal due to FDC's zero-debt balance sheet, broad retail reach, and clean regulatory standing. Instead, the company operates under a series of structural growth ceilings.
The activist's version
To illustrate these structural constraints, it is instructive to consider the perspective an activist investor might present if corporate governance structures permitted external intervention.
First, an activist case would focus on capital deployment. Hundreds of crores in shareholder capital have remained parked for years in liquid instruments earning yields below the operating business's return on equity, lacking a specified strategic objective or deployment timeline. An activist would argue that holding excess liquidity reflects strategic indecision rather than operational prudence, urging management to either allocate the capital to accretive acquisitions or return it to shareholders.
Second, the critique would target portfolio strategy. Despite possessing one of India's most recognized healthcare brands, FDC has not acquired a meaningful chronic-therapy franchise during a decade when chronic categories drove domestic industry growth and the balance sheet possessed ample capacity to fund expansion. An activist would note that peer firms executing targeted acquisitions compounded value at higher rates, questioning the analytical basis for remaining focused exclusively on mature acute categories.
Third, an activist would challenge financial disclosure standards. Investors cannot independently track Electral unit volumes, Enerzal revenue contributions, or the breakdown between volume growth and price realization in the domestic market because corporate filings aggregate these metrics. Disclosing granular segment performance would provide clarity regarding the underlying trajectory of the consumer franchise.
Finally, the case would address governance accountability. With promoter shareholding near 70%, independent board members represent the sole formal oversight mechanism. An activist would examine what specific growth targets and capital-efficiency benchmarks the board has established for executive management.
Conversely, the defense of management's approach remains compelling: nine decades of continuous operation, zero corporate debt, no financial restatements, a half-century of brand dominance in oral rehydration, and cash reserves that have consistently insulated the business from external shocks. Both perspectives reflect genuine aspects of the business. Investors must ultimately evaluate whether historical conservatism ensures resilience for the next decade or primarily highlights the opportunity cost of unallocated capital.
IX. Investment Spine: Bull vs. Bear Case & Key KPIs
The bull case
The core argument for FDC rests on an irreplaceable asset operating with structural tailwinds. Rising summer temperatures and lengthening heatwaves expand the occasions when rehydration products are used, creating a broader demand pool among healthy adults alongside traditional pediatric needs. Public health awareness of oral rehydration continues to deepen, while enforcement by the Food Safety and Standards Authority of India against non-compliant lookalike beverages redirects consumer volume back toward standard formulations, where FDC maintains market leadership.
The second growth driver is Enerzal. Scaled as an over-the-counter electrolyte and energy brand, it generates revenue outside mandatory price controls at consumer-health gross margins while utilizing FDC's existing manufacturing base and retail distribution network. This represents high-leverage optionality because it addresses both regulatory price ceilings under the National List of Essential Medicines and seasonal acute volatility.
The third element is the international division recovery. With regulatory clearances restored at Baddi and Waluj, higher-margin ophthalmic and formulation exports can resume expansion, with 23.5% export revenue growth in fiscal 2026 serving as initial evidence.1
Finally, the balance sheet provides structural protection: zero debt, substantial liquid reserves, and predictable operating cash flow limit downside risk while offering capital capacity for strategic growth initiatives should management choose to deploy it.
The bear case
The bear case acknowledges these assets but questions whether they translate into shareholder value creation.
Return metrics highlight this drag. A return on equity remaining in the low teens for over a decade at a debt-free company with dominant brands reflects conservative capital allocation rather than core product strength.2 Accumulated cash reserves earn low treasury yields, while research and development expenditures hovering at 2.0% to 2.5% of revenue remain insufficient to generate a high-margin proprietary pipeline.[^1] Without substantial exposure to chronic therapeutic categories, revenue expansion remains constrained by seasonal acute illness cycles.
Regulatory price mechanisms impose further structural limits. Price caps under National List of Essential Medicines regulations constrain realization across flagship lines. A brand holding over 70% category share without pricing power sees much of its commercial surplus accrue to public health consumers rather than equity holders, providing a fundamental arithmetic reason for muted market valuations.
Market share dynamics reflect this ceiling. Domestic formulation growth in the mid-single digits compares unfavorably to an Indian Pharmaceutical Market expanding at 8% to 10% annually, indicating that FDC has gradually ceded relative market share.1 Sustained underperformance relative to broader industry growth characterizes a maturing enterprise.
The commercial outlook for Enerzal also warrants scrutiny. FDC has owned the brand for years. Translating a pharmaceutical detailing network into a mass consumer brand requires distinct capabilities—including consumer marketing, modern trade negotiations, and quick-commerce placement—that require substantial capital investment. Until segment-level reporting demonstrates sustained scale, Enerzal remains an unproven growth vector rather than a guaranteed catalyst.
Where the two cases actually meet
The central analytical synthesis is straightforward. FDC's competitive moat is durable, protecting a cash-generative profit pool. However, historical performance shows a consistent pattern: the company builds operational capabilities but exercises caution in commercializing them globally or redeploying capital aggressively. The early 1985 U.S. FDA clearance that yielded modest export scale, cash reserves held in treasury instruments rather than deployed into acquisitions, and an established brand in Enerzal that has yet to achieve mass consumer scale illustrate this recurring dynamic.
For investors, the key analytical question is whether this conservative posture represents a permanent characteristic of promoter family control or a strategy that current executive leadership may adjust over time. Disclosed corporate data does not resolve this question, defining the central uncertainty facing the company.
The three KPIs that actually matter
1. Domestic formulation volume growth separated from price adjustments, with Electral sachet volume as the primary indicator. Headline revenue growth combines price revisions allowed by regulatory authorities with underlying volume demand. Only volume metrics reveal true franchise momentum. If sachet volumes expand while overall domestic revenue remains subdued, price controls are the primary drag. If volume growth stalls, category share is eroding.
2. Revenue share from non-scheduled and consumer health formulations, tracked via Enerzal's expansion rate. This metric indicates whether FDC is diversifying beyond price-controlled categories. Reallocating revenue from price-regulated prescription drugs to free-priced consumer products improves operating margins and valuation multiples. Segment-level disclosures breaking out this performance would signal clear strategic intent.
3. Export revenue trends evaluated alongside U.S. FDA inspection outcomes at Roha, Baddi, and Waluj. International sales and regulatory compliance are directly linked. Quarterly export growth indicates whether international recovery is compounding or reflects a temporary base effect, while inspection classifications determine long-term market access. Adverse regulatory findings previously halted export growth between fiscal 2021 and fiscal 2024, emphasizing the need to evaluate sales data alongside compliance status.
What would actually change the story
Three specific operational shifts would require a revision of this thesis.
First, deploying liquid reserves toward accretive acquisitions in chronic-therapy or consumer-health categories at reasonable valuations would directly address criticisms regarding capital efficiency, demonstrating a shift in capital allocation strategy.
Second, establishing formal segment reporting for Enerzal and non-scheduled consumer lines would indicate management's commitment to scaling the consumer healthcare business.
Third, sustaining domestic volume growth at or above broader Indian Pharmaceutical Market rates over multiple years would confirm market share gains rather than seasonal fluctuations.
Conversely, renewed regulatory observations interrupting export shipments, combined with further share buybacks in lieu of business reinvestment, would confirm that historical capital preservation practices remain the governing corporate policy.
X. Epilogue & Playbook Lessons
Nine decades after a trading agency in colonial Bombay started importing infant foods, the product the company is best known for is a sachet of salt and sugar it does not own the intellectual property rights to.
Playbook Lesson 1: In commoditized products, the category is the moat — and you have to build it yourself. The WHO gave the ORS formula to the world precisely so that no one could own it. FDC's insight was that ownership of the molecule was never the point. What could be owned was the physician's default, the chemist's stocking habit, and the parent's reflex — none of which appear on a balance sheet and all of which took decades of fieldwork to create. Any business competing in a genuinely commoditized category should study this: the durable asset is the position the product occupies in the customer's mind at the moment of need, and it is built through education and presence rather than through patents.
Playbook Lesson 2: Balance sheet conservatism is insurance, and insurance has a premium. FDC's debt aversion is why it is nine decades old, why it survived the License Raj, liberalization, and the FDA remediation cycle without a distress moment, and why it never had to dilute shareholders at a bad price. That resilience is worth a great deal. But capital held as insurance is capital not compounding, and a decade of low-teens ROE is the premium being paid for that policy. The lesson is not that conservatism is wrong. It is that it is a choice with a measurable cost, and companies that present it purely as a virtue are showing only one side of the ledger.
Playbook Lesson 3: Regulation is not a single force, and its two faces can arrive at the same company simultaneously. FDC is a live case study in the difference between price regulation and classification regulation. The NPPA's ceiling on Electral takes value away from shareholders and gives it to patients. The FSSAI's restriction on the term "ORS" takes value away from beverage lookalikes and gives it to compliant manufacturers. Same company, same product, opposite directions. Investors in regulated industries should resist the instinct to treat "regulatory risk" as one undifferentiated threat and ask specifically which mechanism is operating and who benefits from it.
A final reflection. FDC is the most interesting kind of investment case: one that does not easily resolve itself. Here is a company with a brand most consumer businesses would trade a decade of earnings for, a manufacturing base with four decades of regulated-market history, no debt, and substantial cash reserves — alongside a decade of returns that a competent index fund could have matched. Everything required to compound value is present. What is absent is the decision to do it.
Whether that decision ever gets made is not a question of strategy, capability, or capital. All three are available. It is a question about a family that has controlled this business for nine decades and has never once been forced to choose growth over safety. The evidence suggests management will keep choosing safety. The evidence also suggests the family has been right about a great many things for a very long time.
References
-
FDC Limited Financial Results & Quarterly Disclosures — FDC Limited ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
FDC Ltd Financial Performance & Valuation Ratios — Screener.in ↩↩↩↩↩↩↩↩
-
FSSAI Direction on Barring Usage of Term 'ORS' on Non-WHO Standardized Drinks — Food Safety and Standards Authority of India ↩
-
FSSAI asks food companies not to use 'ORS' in brand names — Business Standard, 2022-07-12 ↩
-
FDC Board approves Rs 155 crore buyback at Rs 500 per share — Financial Express, 2023-08-10 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube