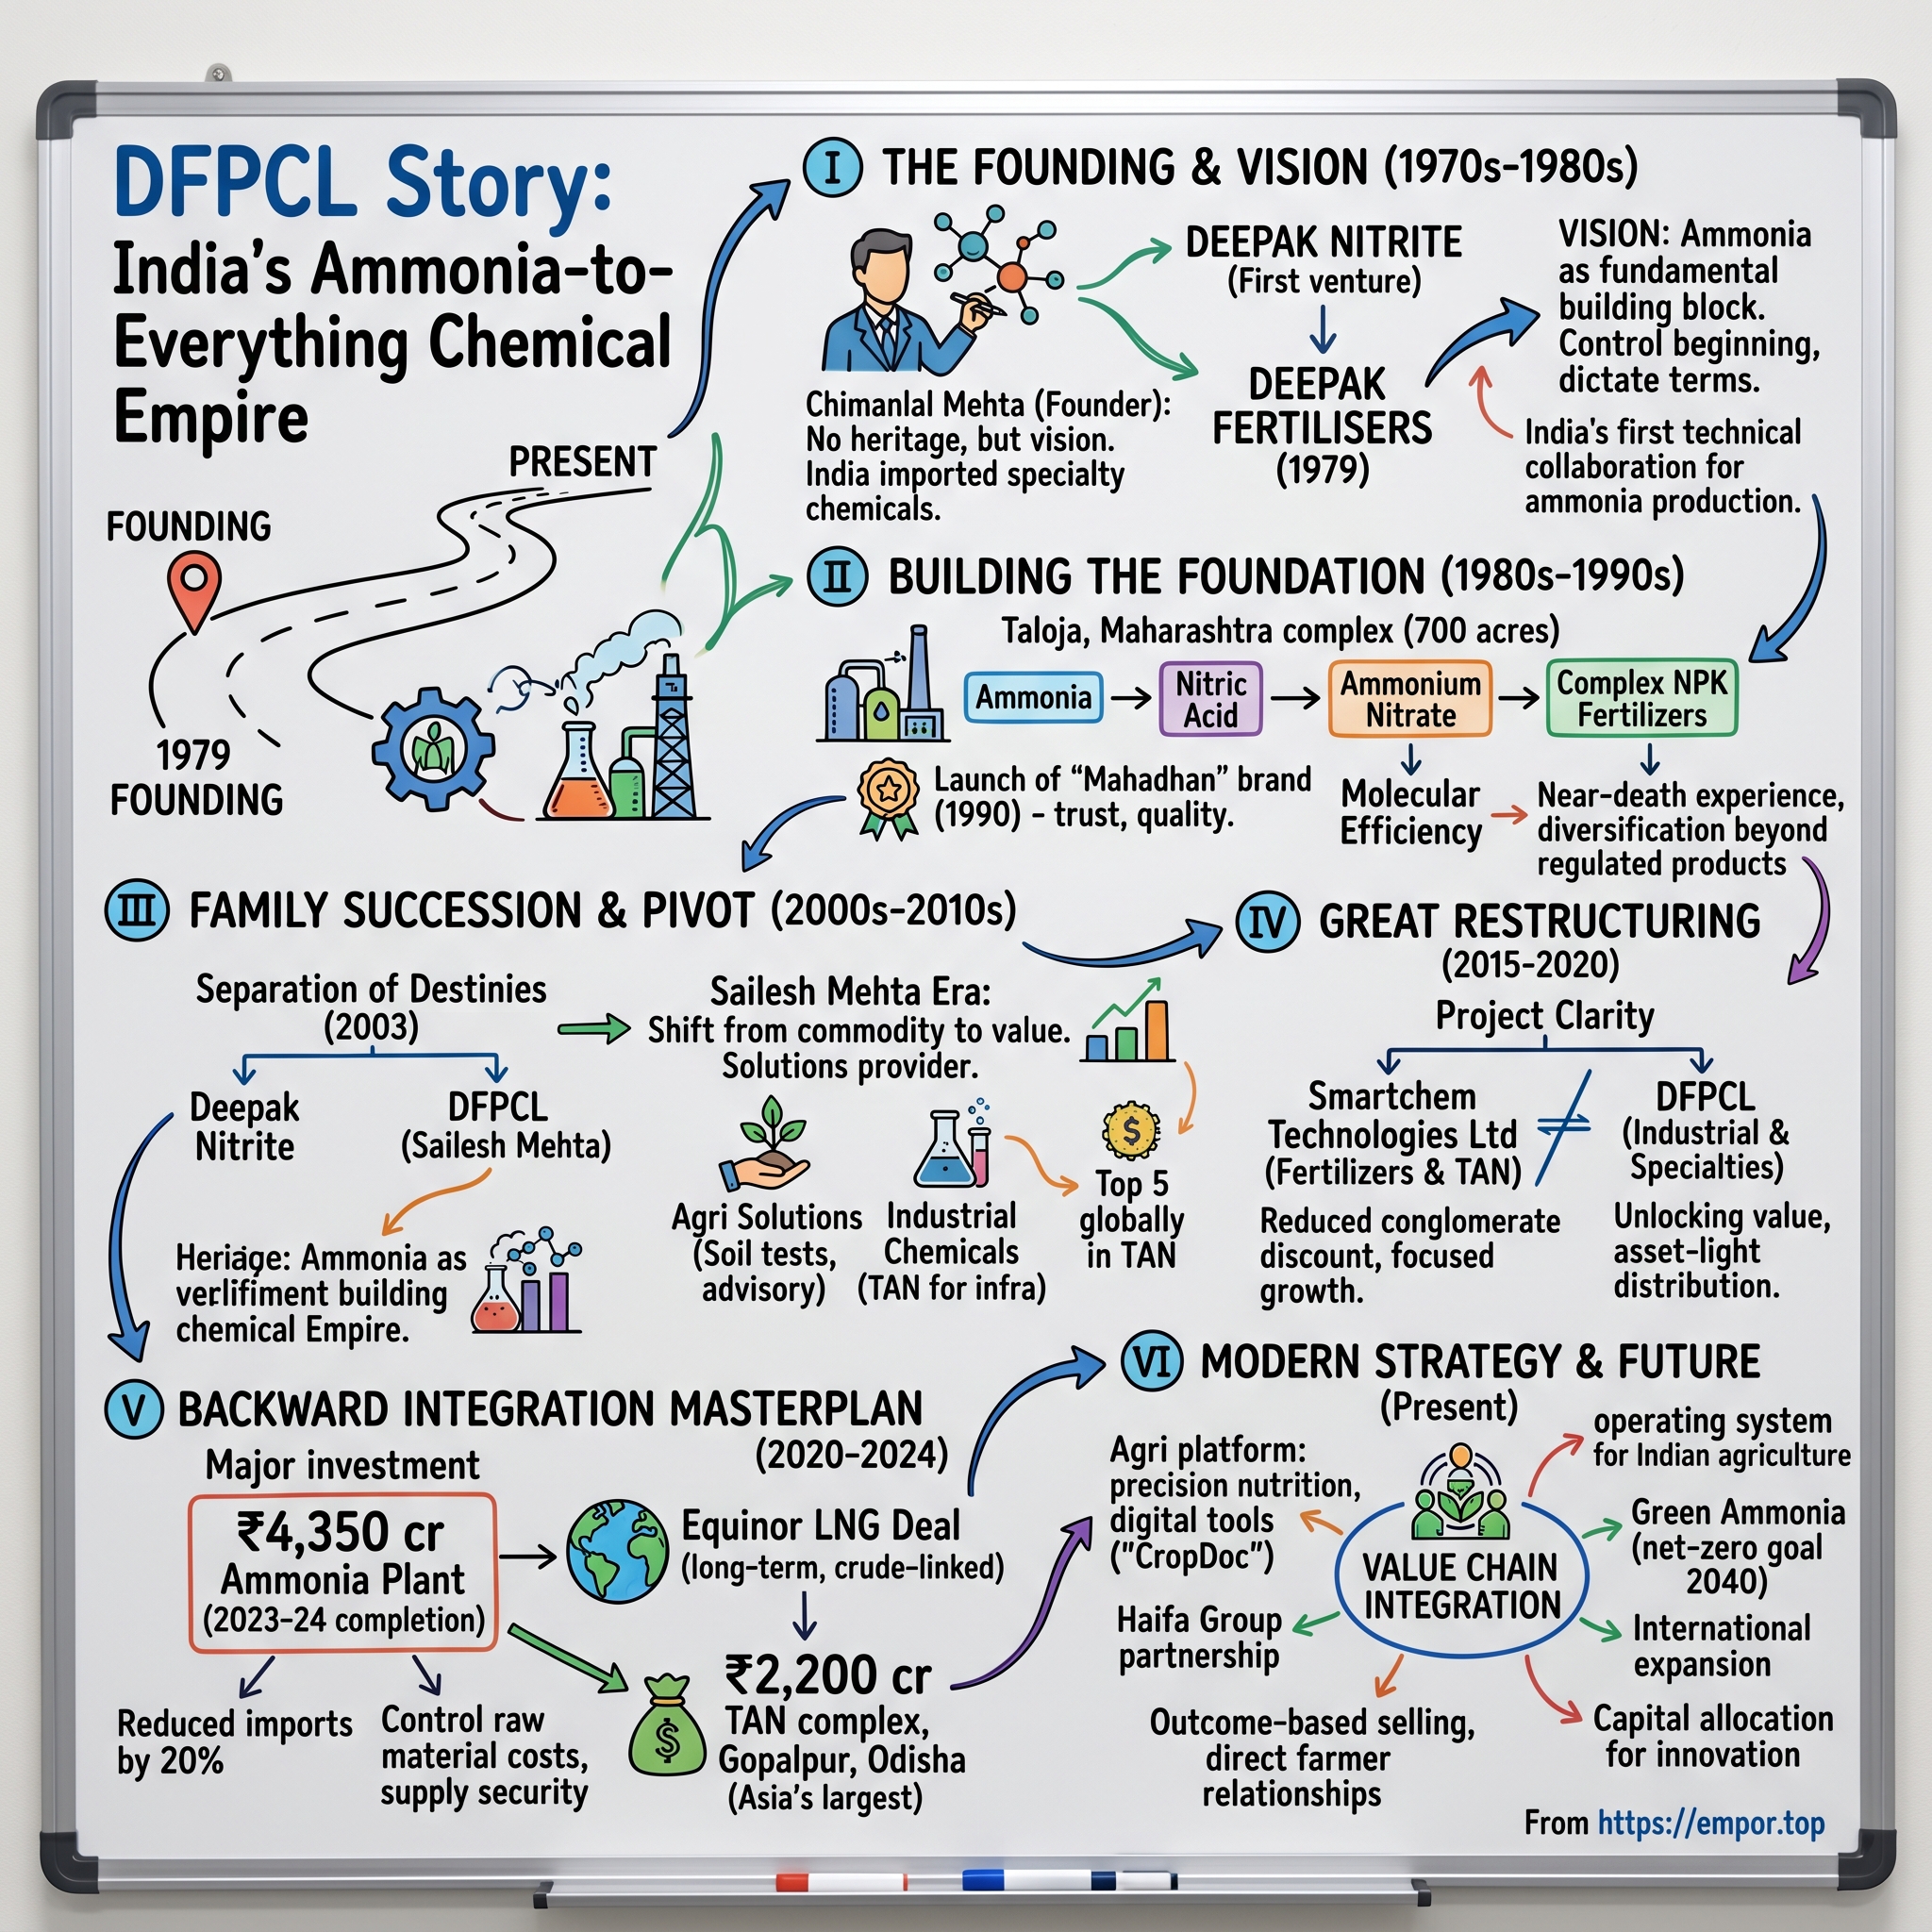
Deepak Fertilisers: India's Ammonia-to-Everything Chemical Empire
I. Introduction & Episode Roadmap
On July 31, 2026, during an earnings conference call hosted by IIFL Capital, Sailesh Mehta described the company's performance as historic. Deepak Fertilisers and Petrochemicals Corporation had reported an operating EBITDA of ₹845 crore for the three months ended June 2026—a 65% increase year-on-year—and a net profit of ₹490 crore, more than double the figure from the same period a year earlier.12 Management noted that this single quarter's profit equaled roughly 65% of the entire previous financial year's earnings.2
That statistic compresses the company's core dynamic into a single line—though not necessarily in the flattering light management intended.
One quarter equaled two-thirds of a full year's profit not because operational efficiency suddenly tripled, but because macro conditions aligned. In the June 2026 quarter, Middle East ammonia prices surged toward $600 a tonne amid US–Iran conflict, technical ammonium nitrate realisations spiked due to global supply tightness, and long-contracted shipments of Norwegian LNG began landing at Dahej under a formula price insulated from spot market volatility.12 Deepak Fertilisers, after spending roughly a decade and over ₹8,000 crore to build an integrated gas-to-ammonia-to-downstream manufacturing complex, found itself on the favorable side of a commodity spread it does not control.
This dynamic highlights the fundamental investment tension surrounding the company. Deepak Fertilisers—traded as DEEPAKFERT on the NSE, with a market capitalisation of about ₹19,668 crore (roughly $2.07 billion) at the end of June 20261—operates one of the most integrated industrial chemical complexes in Asia. It controls approximately 39% of India's technical ammonium nitrate market, 62% of concentrated nitric acid, and stands as the country's sole producer of low-density and medical-grade ammonium nitrate.1 These established market positions were built over four decades.
The core question for investors is narrower: can a company that committed ₹4,350 crore to an ammonia plant, ₹2,675 crore to a greenfield technical ammonium nitrate complex in Odisha, and ₹1,983 crore to a nitric acid facility in Gujarat convert that capital investment into durably higher, less cyclical returns—or has it merely exchanged one commodity exposure for another while adding significant fixed costs?
Recent financial performance illustrates this volatility. In FY26—the first full financial year with the new ammonia plant operational—consolidated revenue rose 12% to ₹11,506 crore, yet EBITDA fell 13% to ₹1,684 crore and profit after tax declined 22% to ₹739 crore.34 Just three months later, using the same asset base, the consolidated EBITDA margin jumped from 11.8% in the March 2026 quarter to 26.0% in the June 2026 quarter.1 The underlying operations did not transform in ninety days; market prices shifted.
Here is the analytical roadmap.
The analysis begins with the building-block thesis—the chemistry and economics of converting natural gas into ammonia, ammonia into nitric acid, and nitric acid into both NPK fertilisers sold under the Mahadhan brand and explosive-grade technical ammonium nitrate used in coal mining. The company's capital allocation strategy relies directly on identifying where value accumulates along this integrated production chain.
Next comes the capital allocation crucible—the period from 2013 to 2015 when Deepak Fertilisers launched a hostile takeover bid for Mangalore Chemicals & Fertilisers, lost a two-year bidding war to the Zuari Group, and simultaneously faced a cutoff of its domestic natural gas allocation by the Indian government.
The story then examines the sovereign policy trauma of May 2014, a defining event for the modern firm. That regulatory disruption prompted management to spend a decade and substantial capital pursuing feedstock self-sufficiency, shaping an operating philosophy that treats reliance on government policy as an existential risk rather than a protective moat.
A segment dissection follows, breaking down performance across mining chemicals, industrial chemicals, and crop nutrition to evaluate where underlying profits originate versus where they are accounted for.
Finally, the moat and cycle stress test applies analytical frameworks—including Hamilton Helmer's 7 Powers and Michael Porter's Five Forces—to examine which of the company's competitive advantages persist when challenged by cheap imported Russian ammonium nitrate, shifts in government subsidy policy, or a drop in global ammonia prices to $250 per tonne.
Before diving into the analysis, one common market assumption requires clarification. Industry commentary often asserts that Indian technical ammonium nitrate producers are protected by anti-dumping duties. In reality, India's definitive anti-dumping duties on ammonium nitrate from Russia, Indonesia, Georgia, and Iran—first imposed in September 2017—expired on September 11, 2022. The Ministry of Finance declined to accept the trade remedies authority's recommendation to extend the duties following a sunset review petitioned for by Deepak's own subsidiary.1213 That tariff protection ended four years ago, meaning any existing competitive moat depends on operational and structural factors rather than trade protection.
 Subscribe on LinkedIn
II. The Chimanlal Mehta Origins & The Building-Block Bet (1979–1990s)
Understanding why a chemical trader from a Gujarati Jain family decided in the late 1970s to build India's first merchant ammonia plant requires context on License Raj India. Industrial capacity was strictly rationed: entrepreneurs applied, waited, and found that the surest way to secure a manufacturing licence was to produce something the state desperately needed.
Chimanlal Khimchand Mehta—universally known as "C.K."—had already navigated this system. In March 1970, he founded Deepak Nitrite in Gujarat, commissioning sodium nitrite and nitrate plants at Nadesari near Vadodara.18 His background in chemical trading provided a practical education: traders often identify structural supply shortages before manufacturers do.
The critical shortage he identified was ammonia.
The basic chemistry underpins the company's entire strategy. Ammonia is nitrogen and hydrogen combined under immense heat and pressure through the Haber-Bosch process—the foundational industrial chemical reaction of the modern era. Manufacturers extract hydrogen from natural gas, draw nitrogen from the air, and react them to form the industry's primary nitrogen-bearing building block. Oxidising ammonia produces nitric acid. Reacting nitric acid back with additional ammonia yields ammonium nitrate—which, depending on crystallisation, serves as agricultural fertiliser or commercial explosives. Combining ammonia with phosphates and potash produces complex NPK fertilisers. Ammonia functions as the trunk of this industrial tree; all downstream chemicals are its branches.
In post-Green Revolution India, demand across every branch outstripped supply. Deepak Fertilisers and Petrochemicals Corporation (DFPCL) was incorporated in 1979 and became a public limited company in 1982.[^18] The company selected Taloja, in Maharashtra's Raigad district across the creek from Navi Mumbai, as its manufacturing hub. The location offered clear structural advantages: proximity to the western gas grid, nearby industrial customers across Maharashtra and Gujarat, access to the high-value regional horticulture belt, and closeness to Mumbai's deep-water port infrastructure. Commercial ammonia production began at Taloja in 1983.[^18]
The designation of "merchant" ammonia producer carried distinct operational risks and opportunities. Other Indian ammonia producers operated as captive units within integrated state-subsidised urea plants, consuming their own output using allocated low-cost domestic gas. Deepak planned to manufacture ammonia for open market sale or to process it into whichever downstream derivative commanded the highest margin. This represented a novel structural bet in the domestic market: construct the primary chemical trunk, then direct molecules toward whichever branch yielded the best seasonal return.
Throughout the 1980s, the company built out those downstream branches. Weak and concentrated nitric acid units came first, supplying local dye manufacturers, pharmaceutical intermediate producers, and explosives makers. In 1990, the company launched the "Mahadhan" fertiliser brand, marking its entry into the Indian farm market.[^18] In July 1992, Deepak executed a major forward-integration wave: dilute nitric acid, concentrated nitric acid, ammonium nitrate, and ANP fertiliser plants all commenced production, alongside a diversification into methanol.[^18] A 100 KTPA methanol unit still sits at Taloja today.1
Historical falsification: did early integration actually build a moat?
A common narrative surrounding this history suggests that C.K. Mehta's early integration created an unassailable low-cost position in western India. The historical record indicates a more complex reality.
The 1992 expansion wave was financed into an Indian interest rate environment that was brutal for leveraged industrials, landing just as the government began decontrolling complex fertiliser prices—a policy shift that pushed Indian farmers toward heavily subsidised urea and away from the NPK products Deepak had just built capacity for.6 Methanol, meanwhile, is one of the most violently cyclical commodities in the chemical universe, and a 100,000-tonne Indian plant had no cost position against a world-scale Gulf producer sitting on stranded natural gas. The company spent the second half of the 1990s discovering that integration protects against availability risk, but not against price risk.
Then, in 2005, the Taloja complex flooded completely.6 For an integrated single-site complex, severe flooding does not disable one plant in isolation; it brings down the entire connected chain.
This period yielded a second, subtler lesson. A merchant ammonia producer's great advantage lies in flexibility—pushing molecules toward whichever downstream product yields the highest margin. But flexibility only creates value if downstream processing capacity is balanced and switching costs remain low. Deepak's 1992 expansion built large, fixed, single-purpose facilities for methanol, nitric acid, and complex fertilisers all at once. That converted operational flexibility into four separate capital commitments, each tied to its own commodity cycle.
The initial twenty-five years demonstrate a clear lesson: vertical integration gave Deepak Fertilisers optionality about what to sell, alongside real cost advantages in logistics and shared utilities. It did not give the company control over product pricing. That distinction between managing feedstock availability risk and absorbing market price risk remains a central strategic thread throughout the company's subsequent growth.
III. Family Split & The Sailesh Mehta Transformation (2000s–2012)
Indian family business successions often descend into public courtroom battles. The Mehta family took a quieter route.
C.K. Mehta had two sons. The elder, Deepak C. Mehta—for whom both entities are named—took charge of Deepak Nitrite, the Gujarat-based specialty chemicals company. The younger, Sailesh C. Mehta, assumed leadership of Deepak Fertilisers.18 The division split assets cleanly by business lines rather than allocating fractional shares in a parent holding company, avoiding long-drawn board conflicts and creating two independently listed, managed companies. Sailesh joined the family business in 1985, became managing director of DFPCL in 2002, and assumed the chairman's role in 2012.6
Sailesh Mehta maintained a low-profile, pragmatic approach to leadership. Profiles describe him as a manager who handles setbacks methodically, while a consultant who worked closely with him observed that he possessed "a fighting spirit in his genes" and took "setbacks in his stride."6 His most-quoted statement on business management is understated: "There is no place for ego in business."6 That principle would soon be tested against his behavior in the next chapter, when he committed significant capital to a multi-year public takeover battle.
The strategic question Sailesh inherited in the early 2000s centered on the fundamental vulnerability of his father's structure: how to transition from a price-taking commodity supplier into a high-margin specialty producer.
His response—executed over two decades—focused on moving away from bulk price competition toward outcome-based customer applications across three primary vectors:
Technical ammonium nitrate (TAN). India's expanding coal sector relied heavily on surface open-cast mining, driving sustained demand for commercial blasting agents. Unlike agricultural fertilizers, industrial mining chemicals are sold to corporate buyers focused on explosive performance and site productivity rather than government-subsidized pricing. Deepak allocated capital to expand both high-density prill for emulsion explosives and low-density ammonium nitrate prill, which absorbs fuel oil to create ANFO. As a result, Deepak became—and remains—India's sole domestic manufacturer of low-density, high-density, and medical-grade ammonium nitrate.1 Producing specialized crystal formulations provides a narrow but distinct operational advantage over generic imports.
Industrial chemicals. Nitric acid serves as a non-substitutable chemical intermediate for nitroaromatics, polyurethane precursors, explosives, and active pharmaceutical ingredients. Deepak expanded its capacity for both weak and concentrated grades, eventually securing approximately 62% of India's concentrated nitric acid market.1 The company also entered the isopropyl alcohol market, a product line that would later experience sharp margin volatility driven by global supply shifts rather than end-market demand.
Crop nutrition. Instead of competing exclusively in standard bulk NPK blends, management shifted toward crop-specific, value-added formulations—developing the Smartek and Croptek product lines, followed by water-soluble fertilizers and bentonite sulfur.
In September 2016, Mehta engaged McKinsey & Company to formalize the transition from standard commodity manufacturing toward branded product offerings.6 This strategic review led to a corporate restructuring: effective May 1, 2017, under a National Company Law Tribunal order, Deepak demerged its fertilizer and TAN operations into a wholly owned subsidiary, Smartchem Technologies Limited, while retaining industrial chemicals and real estate assets within the parent entity.15 Management stated the reorganization aimed to enhance operational focus without issuing additional equity.15
That real estate portfolio included Ishanya—a roughly 400,000-square-foot lifestyle retail center in Pune, later renamed Creaticity. Building and operating a commercial shopping center represented a notable departure for an industrial chemical manufacturer. Retained under the parent company as a "Value Added Real Estate" asset,1 the project illustrates that capital allocation discipline was developed over time through experience rather than established at inception.
Ownership structure. Industry commentary sometimes assumes the promoter family holds a majority stake in DFPCL. In reality, promoter equity stood at 45.6% as of June 2026, with domestic and foreign institutional investors holding a combined 24.7%.1 While the family increased its holding through open-market stock purchases in early 2021,23 a 45.6% stake—though indicating significant insider alignment—remains short of absolute voting control.
By 2012, Sailesh Mehta had established a focused strategy, an expanding technical ammonium nitrate franchise, and a defined long-term roadmap. His next strategic move, however, would commit two years and substantial capital to acquiring an external rival.
IV. Capital Allocation Misfires: The Hostile Battle for MCF (2013–2015)
In July 2013, the Indian fertiliser sector witnessed an event rare in domestic corporate history: a hostile takeover attempt.
Deepak Fertilisers began quietly acquiring shares of Mangalore Chemicals & Fertilisers (MCF) on the open market. MCF presented a compelling target—a fertiliser manufacturer anchored by a deep-water port facility in Karnataka, situated within Vijay Mallya’s deteriorating UB Group empire just as Kingfisher Airlines collapsed and creditors began circling. The combination of a distressed promoter, a strategically situated southern asset, and a rival suitor—Saroj Poddar’s Zuari Group, part of the Adventz conglomerate—set the stage for a high-stakes corporate battle.
The strategic rationale was sound. Deepak’s manufacturing footprint was concentrated at Taloja on the west coast. Acquiring MCF offered direct distribution in southern India, valuable port infrastructure, and expanded volume in a market where raw material procurement terms depend heavily on purchasing scale. For proponents of industry consolidation, MCF represented the logical platform for expansion in Indian crop nutrition.
By April 2014, the market accumulation turned into a formal takeover bid. Having built a stake above 25%, Deepak launched an open offer to acquire an additional 26% of MCF, valuing that target tranche at approximately ₹190 crore.729 In response, the UB Group sought a white knight. Zuari Fertilisers—partnering with the incumbent MCF promoters as persons acting in concert—launched a counter-offer priced at ₹68.55 per share for a 26% stake, representing a total outlay of about ₹211 crore.7
An intense bidding war escalated throughout 2014. Both suitors received regulatory clearance from the Securities and Exchange Board of India in July 2014.7 By December 2014, Zuari raised the stakes, launching an open offer for a 25.9% stake at ₹91.92 per share—valuing the offer at roughly ₹282 crore.21 Deepak continued buying in the open market, accumulating a 29.05% stake in MCF by the end of December 2014.8
In early 2015, Sailesh Mehta elected to withdraw.
Over two trading days in April 2015, Deepak Fertilisers sold an 18.45% block in MCF for approximately ₹192 crore, reducing its stake to 10.60%.8 The company liquidated its remaining shares shortly thereafter. In total, Deepak sold its 31.25% equity position for ₹322.82 crore, generating a net profit of about ₹63 crore.6
Historical falsification: was this opportunistic capital deployment or a two-year distraction?
The optimistic interpretation portrays the outcome as a masterclass in capital discipline: management exited a bidding war before overpaying while securing a positive financial return. The ₹63 crore profit was genuine, refuting simplistic claims that the venture represented a write-off.
However, evaluating the transaction through the dual frameworks of opportunity cost and managerial bandwidth reveals significant strategic flaws.
First, consider the financial returns. Approximately ₹260 crore of equity capital remained locked in a non-controlling minority stake for nearly two years, generating a total gain of roughly 24%. On an annualized basis, this represented a low-double-digit return while exposing the company to concentrated equity risk and litigation uncertainty. For a business whose hurdle rates for internal projects and cost of capital sat noticeably higher, this allocation was less a value-creating maneuver than a costly tie-up of balance sheet capacity.
Second, and more critically, the campaign suffered from severe timing misalignments. The battle for MCF unfolded during the most severe operational crisis in Deepak’s history. In May 2014, midway through the bidding war, the Indian government abruptly halted domestic natural gas supply to the Taloja complex. By January 2015, market reports highlighted that Deepak was exhausting the financial flexibility required to sustain the takeover contest.19 Balance sheet resources and executive attention were absorbed by a contentious acquisition struggle precisely when the primary manufacturing complex faced a life-threatening supply outage.
Third, the aftermath demonstrates a clear strategic shift. Deepak Fertilisers has not attempted another hostile acquisition. Over the subsequent eleven years, the company’s only notable M&A transaction was the ₹121.45 crore acquisition of explosives manufacturer Chardham Chemicals, completed by subsidiary Deepak Mining Solutions on May 6, 2026.16 That deal represented a small, tightly aligned bolt-on designed to integrate raw explosives supply directly into the mining chemicals unit. This marked shift in corporate behavior offers compelling evidence that management learned from the MCF episode, pivoting decisively from external corporate raiding to disciplined, organic mega-projects.
The historical record yields a nuanced verdict. The outcome confirms Sailesh Mehta's willingness to abandon an escalating contest rather than overpay, but it disproves the notion that the MCF episode represented opportunistic capital allocation. The bid was a strategically defensible concept, poorly timed, executed against an aligned coalition of rivals, and eventually exited at modest gain. Crucially, management absorbed the lesson: the regulatory and feedstock shock at Taloja—from which the MCF battle briefly distracted leadership—became the catalyst that reshaped the company’s strategy for the next decade.
V. The 2014 Gas Stoppage Crisis & The 8-Year Structural Trauma (2014–2020)
Without warning, on May 13, 2014, the Ministry of Petroleum and Natural Gas—acting on a request from the Department of Fertilizers—ordered an immediate halt to domestic natural gas supplies to Deepak Fertilisers, cutting off approximately 0.5 million standard cubic metres per day.9 Deliveries ceased two days later, on May 15.9
An ammonia plant is not a light switch. It is a continuous-process unit operating at hundreds of atmospheres of pressure and several hundred degrees Celsius. Moreover, natural gas does not merely fuel the plant; it supplies the hydrogen atoms essential to the chemical reaction. Cutting the gas supply did not simply raise operating costs—it removed the primary raw material the plant was built to transform. Because the Taloja complex was fully integrated, shutting down ammonia production severed the trunk of the industrial tree, crippling downstream output of nitric acid, ammonium nitrate, and complex NP fertilisers.
From the government's perspective, the policy rationale was straightforward. Domestic natural gas from Indian fields was priced well below import parity and strictly rationed. The state prioritised urea manufacturers, who sold into a heavily controlled, politically sensitive price regime. Deepak Fertilisers, producing non-urea complex fertilisers and industrial chemicals, occupied a lower priority rank. When domestic gas supplies tightened, the state reassigned those molecules to urea producers.
Deepak Fertilisers responded by mounting a multi-year battle on two fronts simultaneously.
First, management challenged the order in the Delhi High Court, arguing that the decision was arbitrary, unfair, and discriminatory.9 In July 2015, the court ruled in Deepak's favour, directing that gas supply to the Maharashtra plant be resumed and holding that allocation policies must be applied "uniformly and without discrimination."10 Over the course of the dispute, the company secured four favourable High Court judgments.6
The second front involved receivables. Starting in June 2014, the Department of Fertilizers withheld subsidy payments owed to the company, arguing that Deepak had derived an undue benefit from cheap domestic gas. By March 31, 2016, withheld subsidies reached ₹795 crore.11 Deepak challenged the withholding in the Bombay High Court, and in June 2016, the Ministry of Chemicals and Fertilizers agreed to begin releasing arrears, paying out roughly ₹485 crore while holding back ₹310.52 crore in the interim.11
Meanwhile, the manufacturing complex had to keep operating. Operations at the ANP fertiliser facility were suspended from May 2014 until June 2015, forcing the company to reconfigure its operations to run on expensive imported spot LNG and imported merchant ammonia.6
Historical falsification: is regulatory standing a moat or a liability?
The crisis tests a common assumption among Indian fertiliser investors: that participating in the Nutrient Based Subsidy regime and maintaining long-standing regulatory relationships insulate producers from operating shocks. The 2014–2016 experience disproves that assumption directly through two mechanisms: sovereign priority over scarce inputs and sovereign control over corporate receivables.
Two analytical findings stand out. First, favorable court rulings did not restore operating economics. Deepak won repeatedly in court, yet spent years relying on expensive imported feedstock because judicial declarations of non-discrimination cannot manufacture non-existent domestic natural gas. Second, government subsidy receivables differ fundamentally from standard commercial assets; they represent claims against a counterparty that writes and enforces the rules. A government entity capable of withholding ₹795 crore for two years acts not merely as a customer, but as a regulator exercising sovereign authority. That risk persists: during the Q1 FY27 earnings call, twelve years after the initial disruption, management was still fielding analyst questions about inadequate subsidy alignment and the pace of government corrections.2
Consequently, Deepak Fertilisers' regulatory standing represents a net liability in crop nutrition and a neutral factor in industrial segments. Management drew the same conclusion, spending the eight years following 2014 focused on a single imperative: eliminating dependence on raw material allocations controlled by the state. That strategic shift culminated in the largest capital investment in the company's history.
VI. The $545M Mega-Bet: Backward Integration & Gas Security (2020–2024)
The strategic conclusion Sailesh Mehta drew from the 2014 natural gas crisis was clear, but financially demanding: if state policy controls domestic gas allocations and global markets set ammonia prices, the firm must own the conversion step directly and secure long-term private gas contracts.
The primary element of this strategy was a greenfield ammonia plant at Taloja, designed with a nameplate capacity of 1,500 tonnes per day—or roughly 510,000 tonnes annually—at a total capital cost of approximately ₹4,350 crore.27 When sanctioned, this project represented a capital commitment exceeding the company’s entire equity market valuation; in March 2020, DFPCL's market capitalization stood at ₹669 crore.1
The plant was commissioned on August 4, 2023, during the second quarter of FY24.17 With this asset operational, Deepak Fertilisers shifted from importing roughly 400,000 tonnes of merchant ammonia annually to internal production, combining its legacy 129,000-tonne unit with the new 500,000-tonne facility at Taloja.1
The second element required securing long-term feedstock. In February 2024, Norwegian state-owned energy major Equinor signed a 15-year LNG supply agreement with Deepak Fertilisers covering approximately 0.65 million tonnes—about 9 terawatt-hours—annually, with deliveries starting in 2026.5 Securing a 15-year supply arrangement from a European energy major provided dedicated gas intended primarily for captive ammonia production.5
Logistically, imported liquid natural gas requires regasification before pipeline transmission. In July 2025, group company Performance Chemiserve signed a five-and-a-half-year regasification agreement with Petronet LNG worth approximately ₹1,200 crore to process about 25.6 trillion British thermal units annually through the Dahej terminal, running from mid-2026 through 2031 to supply the Taloja complex.22
Equinor gas deliveries commenced in May 2026.2 Ammonia plant utilization averaged 94% in the June 2026 quarter following the resolution of feedstock constraints, while a debottlenecking project added roughly 10% to nameplate capacity.2 Management projected annual cost savings from the Equinor contract at approximately ₹300 crore—subject to crude oil and Henry Hub benchmark movements—with full integration expected by the fourth quarter of FY27.2
What the backward integration actually did to the risk profile
Evaluating the impact of backward integration requires distinguishing raw material availability risk from ongoing commodity margin exposure.
Prior to 2023, Deepak Fertilisers purchased merchant ammonia at prevailing global market prices. Downstream derivatives—including technical ammonium nitrate, nitric acid, and complex fertilizers—were priced relative to international ammonia benchmarks. Spikes in global ammonia prices drove input costs higher and compressed operating margins until cost increases could be passed through to end markets.
After 2023, the company manufactures ammonia using natural gas contracted under pricing formulas linked to crude oil and international gas benchmarks. This structure removes standalone input-availability risk for ammonia. In its place, the firm assumes spread risk: the variance between realisations on downstream chemical products and contracted natural gas feedstock costs. When global ammonia prices are high relative to natural gas, operating spreads widen significantly; when global ammonia prices decline relative to gas, spreads compress while the fixed overhead and depreciation of the ₹4,350 crore facility remain constant.
Consolidated financial performance across eight quarters illustrates this operating leverage.
In FY25, favorable commodity spreads drove revenue to ₹10,274 crore, operating EBITDA up roughly 50% to ₹1,925 crore, and net profit up 102% to ₹945 crore.20 In FY26, revenue increased 12% to ₹11,506 crore, yet EBITDA fell 13% to ₹1,684 crore and net profit dropped 22% to ₹739 crore as raw material inflation across segments—particularly crop nutrition—and delayed government subsidy adjustments compressed margins.34 The March 2026 quarter included approximately ₹70–75 crore in combined impacts from raw material cost escalation and a scheduled ammonia plant maintenance shutdown.3 By contrast, the June 2026 quarter (Q1 FY27) recorded a consolidated EBITDA margin of 26.0%.1
The same operational asset base and contract portfolio generated three distinct financial outcomes within eight quarters.
Backward integration successfully eliminated feedstock availability risk and sovereign gas allocation dependency—a central strategic objective following the 2014 disruption. However, it did not render the business immune to commodity cycles; rather, it altered cycle dynamics while increasing fixed operating leverage. During the Q1 FY27 earnings conference call, management acknowledged that earnings cycles persist, arguing that long-term LNG contracts, debottlenecked plant capacity, and an expanding specialty product portfolio should moderate the magnitude of future earnings fluctuations.2 While this represents a reasonable management target, it reflects ongoing cyclical management rather than permanent margin insulation.
The corporate restructuring — and what has not happened
Alongside physical capital investments, the company reorganized its corporate structure. In December 2022, DFPCL announced a composite scheme of arrangement to demerge its technical ammonium nitrate business from Smartchem Technologies into Deepak Mining Solutions Limited (DMSL), a wholly owned subsidiary, while amalgamating Mahadhan Farm Technologies into Smartchem.14 Management framed the reorganization as a move to provide focused leadership and unlock underlying business value.14 As a result, parent entity DFPCL operates as a holding corporate structure overseeing crop nutrition, mining chemicals, industrial chemicals, LNG trading, explosives operations, and residual real estate assets.1
However, the secondary market catalyst often anticipated by investors—a separate public listing of the mining chemicals business—remains pending. On the Q1 FY27 earnings call, management reaffirmed its commitment to list DMSL but noted that the execution structure (whether via an initial public offering or direct demerger) and timeline remain under evaluation.2 Nearly four years after the initial announcement, the listing remains an ongoing structural plan rather than an immediate market catalyst.
VII. Core Business Deep Dive: Industry Structure, Segments, & Economics
Walk the value chain and the whole company becomes legible.
Contracted Norwegian LNG lands at Dahej, is regasified, and moves to Taloja. There it becomes ammonia in the 500 KTPA plant. That ammonia splits two ways. One stream is oxidised into nitric acid — 885 KTPA of dilute and 231 KTPA of concentrated across the group — which either gets sold as industrial chemicals or gets reacted back with ammonia to make ammonium nitrate.1 The other stream goes into complex fertilisers. The ammonium nitrate stream, 587 KTPA of technical grade today, is the mining chemicals business.1 And with the Chardham acquisition, that chain now extends one step further, into the explosives themselves.
Three segments, three completely different businesses, three different sets of customers. In FY25, crop nutrition contributed 44% of group revenue, mining chemicals 28%, and industrial chemicals 16%.1 Note the mismatch between revenue and profit that runs through everything below: crop nutrition is the revenue giant and the earnings weakling.
1. Mining Chemicals / Technical Ammonium Nitrate
This is the crown jewel, and it earns that description honestly.
Deepak holds roughly 39% of the domestic TAN market and is India's only manufacturer of high-density, low-density and medical-grade ammonium nitrate.1 Capacity today is 587 KTPA — 544 at Taloja and 43 at a satellite unit at Srikakulam in Andhra Pradesh — with the 376 KTPA Gopalpur complex to come.1
The demand driver is India's open-cast coal and its infrastructure build. Every tonne of coal blasted out of a Coal India pit, every kilometre of highway cut through rock, consumes ammonium nitrate. This is about as direct a proxy for Indian industrial activity as exists in the listed chemical space.
The strategic move here — and it is the most genuinely differentiated thing this company is doing — is the shift from selling bags to selling outcomes. Management describes it as moving from "customers to consumers," and on the Q1 FY27 call framed the explosives acquisition as completing the value chain to enable a total-cost-of-ownership model: outcome-driven rather than input-driven, targeting mining productivity improvement, and explicitly positioned as not competing with the company's own explosives-manufacturer customers.2 In the June 2026 quarter, this B2C revenue reached ₹151 crore, up 42% year-on-year, at 17% of TAN revenue versus 16% a year earlier.1
That is meaningful progress and it is also, at 17%, still early. A one-percentage-point annual mix shift is not a transformation; it is a trajectory.
Now the honest part. Q1 FY27 TAN volumes were 130 KT, down 12% year-on-year and 21% sequentially, which management attributed to production and dispatch disruptions arising from changes to the PESO explosives regulator's online portal — a logistics disruption lasting a few days, not a demand or feedstock problem.12 Revenue nonetheless rose 36% year-on-year, because realisations improved sharply on the back of the US–Iran conflict.1 Read that carefully: the segment's best revenue quarter came with its volumes down 12%, on prices set by a war. Capacity utilisation in FY26 was 92%, which is genuinely excellent asset performance.1 But the earnings in this segment right now are a price story, not a volume story.
And the competitive structure is not as sheltered as it looks. Domestic peers include Rashtriya Chemicals & Fertilisers and Gujarat Narmada Valley Fertilisers. The far more important competitor is the import — and with the anti-dumping duty on Russian, Iranian and Georgian ammonium nitrate lapsed since September 2022,1213 the domestic price ceiling is set by landed import cost. Management itself attributes current strength partly to "lower import competition."2 Import competition that is currently low because of a geopolitical disruption is not a moat; it is weather.
Gopalpur. The greenfield 376 KTPA complex at the Tata Steel Industrial Park in Gopalpur, Odisha, is strategically excellent: it sits next to eastern India's coal belt, close to customers, at a port location favourable for exports. On completion, group ammonium nitrate capacity reaches roughly 1.0 million tonnes a year, which management says will make DFPCL the third-largest pure-play TAN producer globally.1
It has also taken a very long time and cost more than planned. Odisha's chief minister laid the foundation stone on December 9, 2021, for a project budgeted at ₹2,200 crore using Casale technology.2425 As of June 30, 2026, the project was 96% complete at a stated capex of ₹2,675 crore, with commissioning expected in Q2 FY27.1 That is roughly a 22% cost escalation and close to five years from groundbreaking to first product. In fairness, the period included a pandemic and severe global supply chain dislocation, and management has consistently maintained that the projects remain within approved costs as revised. But it is a material qualification on any narrative of flawless execution, and it is exactly the kind of history that should temper confidence in the ramp-up guidance of roughly 80% utilisation by Q4 FY27.1
2. Industrial Chemicals
The smallest segment by revenue and the one that best illustrates how exposed a chemical company is to things it cannot see coming.
Deepak is the largest nitric acid manufacturer in South East Asia, with roughly 62% of India's concentrated nitric acid market and 27% of dilute.1 Nitric acid has no substitute in nitroaromatics, explosives, or polyurethane chains — a genuine "threat of substitutes: low" position. The Dahej project in Gujarat adds 300 KTPA of weak nitric acid and 150 KTPA of concentrated, at a capex of ₹1,983 crore, taking group weak nitric acid capacity to roughly 1.2 MMTPA.1 The most important detail in that project is commercial rather than technical: 65% of the new concentrated nitric acid capacity has been tied up under a 20-year long-term contract.1 That is exactly the de-risking a capital-intensive commodity expansion needs, and it is more persuasive evidence of pricing power than any market-share statistic.
Isopropyl alcohol is a different story. It is frequently claimed that Deepak holds around 75% of the Indian IPA market. The company's own disclosure puts it at about 10% of the merchant IPA market, describing itself as one of the leading manufacturers and marketers.1 That is a very large difference, and the smaller number is the one to use.
And IPA is where the fragility shows. In Q1 FY27, IPA sales volumes were 4 KT — down 76% year-on-year and 71% sequentially — because the Government of India curtailed refinery-grade propylene quotas in response to the US–Iran conflict.1 Capacity utilisation on the 70 KTPA IPA plant fell to 29%, requiring a shutdown.1 The same geopolitical event that handed the mining chemicals segment a windfall took a downstream unit off-line by administrative order. This is the clearest possible illustration that the state's hand on Indian industrial feedstock did not disappear in 2014; it merely moved to a different molecule.
3. Crop Nutrition
The largest segment by revenue, at 44% of the group in FY25, and structurally the weakest by profitability.1
The assets are real: 800 KTPA of NPK, 300 KTPA of NP, 57 KTPA of bentonite sulphur, and the Mahadhan brand with genuine strength in Maharashtra, Karnataka and Gujarat.1 Deepak is India's only producer of prilled NP 24:24:0 and the only maker of crop-specific nutrient solutions combining NPK with micronutrients and its Nutrient Unlock Technology, and it describes itself as India's largest bentonite sulphur producer and market leader in specialty and water-soluble fertilisers.1
The specialty transition is measurable and it is working, slowly. Specialty and Croptek products reached 33% of crop nutrition revenue in FY26, up from 30%.3 In Q1 FY27 the specialty-plus-Croptek share stood at 43% of segment revenue — though notably down from 45% in the year-ago quarter.1
The economics remain hard. Q1 FY27 crop nutrition revenue was ₹1,367 crore, up 9% year-on-year but down 13% sequentially, with ANP and Smartek volumes of 128 KT flat year-on-year and down 27% sequentially on delayed and low rains plus a phosphoric acid shortage.1 Bulk manufacturing utilisation was 78% for ANP and just 63% for NPK.1 Croptek volumes actually declined 2% year-on-year. Bentonite sulphur volumes fell 44% year-on-year on elevated sulphur costs.1 And the segment sits at the mercy of three variables no management team controls: the monsoon, the imported price of phosphoric acid — which climbed from roughly $950 to $1,360 a tonne CFR between mid-2024 and mid-2026 — and the Department of Fertilizers' subsidy rate.1
The reported segment numbers make the point without commentary. In Q1 FY27 the chemicals segment delivered ₹805 crore of segment profit on ₹1,882 crore of revenue. Fertilisers delivered ₹44 crore on ₹1,367 crore.28
Sit with those two numbers for a moment, because they are the most important pair of figures in this entire story. Chemicals converted roughly forty-three paise of every rupee of revenue into segment profit. Fertilisers converted about three. And this was a quarter in which crop nutrition revenue grew year-on-year. The business is not failing; it is simply operating in a market where the selling price is set by a subsidy formula written in Delhi and the input cost is set by phosphate rock producers in Morocco and Saudi Arabia, with an Indian farmer's willingness to pay squeezed in between. No amount of brand equity survives that vice unimpaired.
That is the shape of Deepak Fertilisers: nearly half the revenue, a rounding error of the profit. The bull case for crop nutrition is a genuine specialty transition that lifts that segment margin over time. The bear case is that it remains a large, working-capital-hungry, weather-and-subsidy-dependent business attached to a good chemicals company. So far, the evidence supports the bear case on economics and the bull case on direction — and direction has been slow.
VIII. Strategic Frameworks: Porter's 5 Forces & Hamilton Helmer's 7 Powers
Strategic frameworks are useful only when applied adversarially. Testing Deepak Fertilisers against standard competitive models highlights where its operational advantages hold and where they remain exposed to external markets.
Hamilton Helmer's 7 Powers
Process Power — moderate, not high. The strongest asset here is the integrated Taloja complex: pipeline natural gas converted on site to ammonia, processed into nitric acid, and transformed into technical ammonium nitrate and NP fertilizers with shared utilities, thermal recovery, and zero intermediate transit. A non-integrated producer buying merchant ammonia must pay freight, handling, storage, and supplier margins at each stage. That cost advantage is structural and durable. What prevents this from qualifying as high process power is that the underlying chemical technology is widely licensable—the Casale process used at Gopalpur is accessible to any capitalized competitor—and as demonstrated by the 13% EBITDA decline in FY26, operational efficiency can still be overwhelmed by macro commodity pricing.425
Cornered Resource — moderate, and narrower than claimed. The 15-year Equinor LNG agreement provides a distinct supply arrangement unavailable to peers, made operationally viable through the Petronet regasification agreement.522 Specialized PESO operating licenses and sole-producer status for specific ammonium nitrate grades offer additional structural positioning.1 However, a long-term LNG supply agreement does not constitute a cornered resource under Helmer’s definition; it functions as a fixed-formula supply hedge. If global LNG prices decline significantly below the contracted formula, the agreement becomes a cost drag rather than a competitive advantage. Management’s projected ₹300 crore annual savings estimate remains explicitly dependent on crude oil and Henry Hub benchmark levels.2
Scale Economies — high in nitric acid, moderate in TAN. Controlling 62% of India's concentrated nitric acid market—expanding to Asia's largest producer post-Dahej—creates genuine scale in a product where transport economics limit long-distance imports.1 Nitric acid is hazardous, corrosive, and expensive to ship, offering clear geographic protection. Technical ammonium nitrate differs: standard ammonium nitrate can be transported efficiently by sea, and a 39% domestic market share provides limited pricing power when seaborne cargoes arrive duty-free.
Switching Costs — low to moderate, and unproven. Transitioning customers toward an outcome-based, total-cost-of-ownership model—where blast design, drilling patterns, and fragmentation metrics are tied directly to Deepak's technical services—could establish meaningful switching costs. At present, this represents a long-term corporate strategy; with B2C offerings accounting for 17% of TAN revenue, it does not yet define the segment's core economics.1
Branding — modest. The Mahadhan brand maintains strong recognition among regional farming communities, but domestic fertilizer brand premiums remain narrow, and the Nutrient Based Subsidy framework limits the margin premium any manufacturer can capture.
Network Economies and Counter-Positioning — absent. Neither framework applies to an integrated industrial chemical manufacturer, and omitting them avoids creating artificial strategic claims.
Porter's 5 Forces
Threat of new entrants — low, representing the company's strongest structural defense. Constructing a world-scale ammonia plant requires upwards of ₹4,000 crore and a four- to five-year development timeline. Producing explosives-grade chemicals requires stringent PESO regulatory approvals, while natural gas pipeline allocation remains strictly controlled. The Gopalpur project—requiring nearly five years from groundbreaking to commissioning alongside a 22% cost escalation—illustrates the substantial capital and execution barriers confronting potential competitors.124
Bargaining power of buyers — moderate to high, and rising. State-owned mining enterprises procure via structured public tenders and maintain options to multi-source or re-bid contracts. Agricultural buyers remain price-sensitive, with purchasing power constrained by government subsidy settings. Industrial customers for nitric acid in the pharmaceutical and polyurethane sectors operate as sophisticated corporate buyers. The 20-year Dahej CNA contract addresses this pressure by securing 65% of new capacity under long-term agreement, converting spot buyers into contracted counterparties.1
Bargaining power of suppliers — reduced for primary feedstock, high for secondary inputs. The Equinor supply agreement mitigates feedstock availability risks for ammonia. However, it provides no insulation against price movements in imported phosphoric acid, potash, rock phosphate, or refinery-grade propylene—all of which compressed operating margins over the past eighteen months.14
Threat of substitutes — low. Commercial blasting at scale has no viable economic alternative to ammonium nitrate, while nitric acid remains chemically non-substitutable across its primary industrial applications. This provides a durable structural baseline.
Rivalry — moderate domestically, high including imports. Among domestic producers such as RCF, GNFC, GSFC, and Coromandel, the market functions as a disciplined oligopoly. However, incorporating international supply—specifically Russian ammonium nitrate redirected from European markets post-2022 and entering duty-free following the expiration of anti-dumping duties—materially increases competitive intensity.1213
The framework verdict: Deepak Fertilisers maintains a defensible market position underpinned by capital intensity, regulatory licensing, geographic logistics, and chemical integration. However, it lacks systemic pricing power. Its primary competitive strengths protect operational volume and unit conversion costs rather than end-product realisations. As a result, consolidated profitability remains tied to global commodity spreads, defining the central investment dynamic of the business.
IX. Management Credibility, Capital Allocation & Skeptical Investor Stress Test
Evaluating management by comparing commitments against outcomes over long horizons reveals an operator with a mixed record on project timelines and a capital discipline shaped by hard-learned lessons.
What was promised and delivered. The ammonia plant, the central capital promise of the past decade, was commissioned in August 2023.17 Following gas procurement, the facility operated at 94% utilisation in the June 2026 quarter, augmented by debottlenecking that added roughly 10% to nameplate capacity.2 Similarly, the long-term Equinor contract signed in February 2024 for 2026 delivery commenced on schedule in May 2026.52 For a company stripped of its domestic natural gas allocation in 2014, establishing a private 15-year supply chain from a European energy major through an Indian regasification terminal to its Taloja complex represents a major operational milestone.
What slipped. Execution timelines tell a less consistent story. The greenfield project at Gopalpur, which broke ground in December 2021 with a ₹2,200 crore budget,24 progressed from 95% complete during the May 2026 earnings call3 to 96% complete by July 2026—advancing one percentage point over two months—with total estimated capital expenditure rising to ₹2,675 crore.1 Over the same period, completion at the Dahej nitric acid facility advanced from 86%3 to 93%.1 Management repeatedly targeted commissioning for both facilities in the second quarter of FY27, making operational delivery an immediate benchmark for market credibility.
Narrative consistency across calls. Management's framing of financial results varied markedly across earnings calls. On the May 2026 call, following a 13% full-year decline in EBITDA, leadership attributed performance to external headwinds: geopolitical raw material cost inflation, inadequate subsidy support, feedstock shortages, export restrictions, and a scheduled plant shutdown.34 Two months later, following a 65% year-on-year surge in quarterly EBITDA, management emphasized three structural strengths: the integrated supply chain, broader domestic growth alignment, and an expanding specialty product mix.2
While both explanations align with disclosed facts, the asymmetry is notable: disappointing periods are linked to external market conditions, whereas strong results are attributed to internal structural design. When questioned on the persistence of earnings volatility, management acknowledged that cyclical fluctuations remain inherent to the business, framing its strategy around moderating the severity of future swings rather than eliminating cycle exposure entirely.2
Where analysts pushed hardest. Analyst questioning on recent earnings calls focused on five core areas: commissioning schedules and ramp-up curves at Gopalpur and Dahej, the sustainability of elevated ammonia realisations, projected savings from the Equinor contract, the balance sheet deleveraging trajectory, and the listing structure for Deepak Mining Solutions Limited (DMSL).23
Management provided specific operational targets across most areas: annual contract savings estimated at approximately ₹300 crore subject to benchmark gas prices, peak net debt of ₹4,700 crore to ₹4,800 crore with deleveraging beginning in FY27, an 80% utilisation target for new capacity by the fourth quarter of FY27, and expectations that Middle East ammonia realisations near $600 per tonne would persist for several quarters.2 Conversely, guidance regarding the separate listing of DMSL remained general, reaffirming a commitment to list while leaving both execution structure and timing under evaluation.2
The activist's brief
A skeptical assessment of the company's financial position highlights several structural vulnerabilities.
First, reported leverage metrics reflect temporary peak earnings. Although net debt declined slightly from ₹4,824 crore in March 2026 to ₹4,719 crore in June 2026—reducing the reported net debt-to-EBITDA ratio from 2.86x to 1.40x1—this reduction stemmed primarily from annualized peak quarterly earnings rather than debt paydown. Total debt stood at ₹5,057 crore against cash reserves of ₹308 crore; measured against full-year FY26 EBITDA of ₹1,684 crore, leverage remains closer to 2.9x.
Second, major capital expenditures have yet to generate returns. Approximately ₹4,650 crore in capital projects remain under execution, supplementing the ₹4,350 crore already deployed for the primary ammonia plant.127 Capital expenditure reached ₹1,569 crore in FY26, with FY27 outlay projected at ₹800 crore to ₹1,000 crore before normalizing.3 Consolidated return on capital will depend on completing and fully utilizing the Gopalpur and Dahej complexes across standard pricing cycles.
Third, underlying earnings volatility persists. The company's strongest quarterly financial performance coincided with Middle East supply disruptions that inflated ammonia and technical ammonium nitrate realisations, even as raw material constraints reduced isopropyl alcohol plant utilization to 29%.1
Fourth, corporate complexity remains. The parent company continues to hold legacy non-industrial assets, including the Creaticity retail center in Pune.1
Fifth, corporate restructuring catalysts lack clear timelines. The proposed separation of the mining chemicals business under DMSL has remained in planning since December 2022 without a defined execution schedule.142
Sixth, government receivables present ongoing working capital exposure. Withheld subsidy arrears have affected cash flow since 2014 and continue to require ongoing management focus.112
Counterbalancing factors. Balanced against these operational risks are several structural factors: 45.6% promoter ownership supported by periodic open-market purchases,123 a demonstrated history of exiting unviable corporate acquisitions,8 successful legal enforcement that recovered hundreds of crores in withheld subsidy payments,1011 a 15-year natural gas supply contract reducing sovereign allocation risk,5 a 20-year off-take agreement securing 65% of new concentrated nitric acid capacity,1 and a ₹10 per share dividend declared for FY26 amid peak capital expenditure commitments.26
Market valuation. Equity markets have repriced the business significantly in advance of project completions. The company's market capitalisation expanded from ₹669 crore in March 2020 to ₹19,668 crore by June 2026—representing a 72% compound annual growth rate—while total shareholder count expanded from approximately 106,000 to 179,000.1 Over the same period, institutional equity holding rose from 23.5% to 24.7%.1 This valuation shift indicates that current stock prices reflect anticipated earnings from the Gopalpur and Dahej expansions, placing execution across upcoming quarters as the primary determinant of future performance.
X. Playbook: Business & Investing Lessons
1. Vertical integration converts variable cost into fixed cost—and that represents a strategic trade rather than an automatic upgrade. Before building its ammonia plant, an adverse ammonia market compressed operating margins for Deepak Fertilisers. Afterwards, a weak ammonia market compresses margins while the fixed overhead and depreciation of a ₹4,350 crore facility must still be absorbed. What vertical integration genuinely secures is raw material availability, control over product specifications, and the opportunity to capture wider operating spreads when market conditions align. What it does not guarantee is earnings stability. Investors evaluating backward integration must determine whether capital deployment eliminates an operational risk or converts it into a different risk carrying higher operating leverage. For Deepak, integration accomplished the latter—a trade-off rendered necessary because the risk it eliminated was sovereign dependence.
2. Never allow a sovereign entity to serve as both input supplier and customer paymaster. The 2014 natural gas stoppage remains a clear lesson in the hierarchy of state priorities. Deepak lacked contractual remedies, secured four favourable High Court rulings, yet still lost years of earnings because judicial declarations cannot produce scarce subsidised gas. The long-term response—a privately contracted 15-year supply chain anchored by a foreign energy major and independent regasification—addressed that feedstock vulnerability directly, though it required eight years and substantial capital to execute. However, the refinery-grade propylene quota curtailments of 2026 demonstrate that state intervention remains an ongoing factor across other chemical inputs.
3. Escaping price-taker status requires moving deeper into customer workflows—a process that moves slowly. Strategic plans often outline a clean transition from selling bulk commodities to delivering technical outcomes, such as shifting from standard ammonium nitrate bags to integrated mine blast services, or moving from commodity NPK fertilizers to specialized crop nutrition programs. In practice, outcome-based sales accounted for 17% of technical ammonium nitrate revenue after years of implementation, while specialty products represented between 33% and 43% of crop nutrition revenue depending on the quarterly reporting period.13 Portfolio mix transitions in capital-intensive industrial sectors typically advance by one or two percentage points annually, requiring investment models to reflect operational execution speeds rather than strategic targets.
4. Disciplined capital allocation includes knowing when to abandon an escalating contest. Two years into a hostile bid—with a competing coalition raising its counter-offer and the core Taloja manufacturing complex facing a raw material supply shutdown—Sailesh Mehta liquidated the company's stake at a modest profit and refrained from subsequent hostile acquisitions.86 While exiting avoided overpayment, launching the acquisition battle during an operational crisis absorbed executive focus and balance sheet flexibility when the core business was most vulnerable.
5. Verify market positions against primary regulatory and financial disclosures. Market commentary frequently attributes a 75% market share in domestic isopropyl alcohol to the company, whereas official disclosures report approximately 10% of the merchant market.1 Similarly, narrative assumptions often presume protection from anti-dumping tariffs, even though definitive duties on imported ammonium nitrate expired in September 2022.1213 Market assumptions surrounding mid-cap industrial firms frequently diverge from regulatory filings, where actual competitive positioning and tariff exposures are documented.
XI. Analysis & Bear vs. Bull Case
Why this company wins from here
The bull case rests on four legs, ordered by the strength of the supporting evidence.
The strongest leg is capacity coming online into a structurally tight market. Completing the Gopalpur expansion expands group technical ammonium nitrate capacity to roughly 1.0 million tonnes per year, while the Dahej project increases weak nitric acid capacity to about 1.2 million tonnes annually. This positions DFPCL as the third-largest pure-play technical ammonium nitrate producer globally and Asia's largest nitric acid manufacturer.1 These facilities are physically situated near primary demand centers, with construction between 93% and 96% complete. Furthermore, securing a 20-year off-take agreement for 65% of the new concentrated nitric acid capacity ensures that a majority of the Dahej expansion is contracted prior to operation.1 Provided Indian mining and infrastructure activity remains robust, this provides the clearest earnings visibility across the portfolio.
The second leg is feedstock cost predictability. Anchored by the 15-year Equinor LNG agreement—which phases into full ammonia feedstock coverage by the fourth quarter of FY27—management projects approximately ₹300 crore in annual supply savings.52 Coupled with 94% ammonia plant utilization and a 10% debottlenecking capacity gain, conversion economics at the Taloja complex are positioned at peak operating performance.2
The third leg is balance sheet deleveraging. Management has indicated that net debt is approaching its peak, expecting leverage to trend downward starting in FY27 as new manufacturing capacity generates incremental EBITDA.2 Capital expenditure is set to normalize following guidance of ₹800 crore to ₹1,000 crore for FY27.3 For a business generating ₹1,700 crore to ₹2,000 crore in EBITDA through a standard operating cycle against net debt of ₹4,700 crore, the balance sheet remains manageable—provided product spreads hold during the operational ramp-up.
The weakest leg is the specialty product re-rating. The proposition that an expanding specialty mix justifies a specialty chemical valuation multiple over a commodity multiple is theoretically sound. In practice, specialty products represent 43% of a crop nutrition segment that delivered ₹44 crore in segment profit on ₹1,367 crore of revenue in the most recent quarter, while outcome-based services account for 17% of technical ammonium nitrate revenue.1 The portfolio shift is genuine and directionally positive, but it is not yet substantial enough to alter the underlying business model.
What could break the case
Spread compression is the primary operational risk, and its impact is already documented. Middle East ammonia spot prices traded as low as $294 per tonne in late 2024 before rising to $545 per tonne by June 2026.1 Management anticipates elevated price levels for two to three quarters, suggesting a post-conflict equilibrium above historical baselines—while explicitly noting this remains a projection rather than a certainty.2 Should global ammonia realisations mean-revert toward $350 per tonne while contracted natural gas formulas remain fixed, operating spreads will compress against a larger fixed cost base than the company operated in FY24. The 13% EBITDA decline recorded in FY26 provides direct empirical evidence of this exposure.4
Import competition in the absence of tariff protection. With anti-dumping duties expired since September 2022, discounted Russian ammonium nitrate redirected from European destinations can enter India duty-free.1213 Current low import volumes reflect global geopolitical supply tightness rather than structural trade barriers. If global supply constraints ease, the price ceiling on domestic technical ammonium nitrate realisations will drop accordingly.
Execution delays during project ramp-up. The five-year construction timeline and 22% cost overrun at Gopalpur serve as the historical baseline when evaluating management's target of achieving 80% capacity utilization by the fourth quarter of FY27.124 A delayed ramp-up does not merely defer revenue; it forces depreciation and interest charges from ₹4,650 crore in deployed capital onto the income statement before volume contributions materialize, dampening return on capital employed.
Crop nutrition exposure to sovereign policy. Subsidy rate adjustments, disbursement delays, elevated phosphoric acid costs near $1,360 per tonne, sulphur inflation, and monsoon variability directly affect a segment generating 44% of group revenue while contributing a minor fraction of earnings.1 Management noted that 12 of 44 core agricultural districts faced below-normal rainfall, while an unfavorable price gap between diammonium phosphate and NPK formulations continues to weigh on farmer demand.1
Feedstock administrative risks outside natural gas. The administrative curtailment of refinery-grade propylene quotas—which reduced isopropyl alcohol plant utilization to 29%—demonstrates that government allocation decisions extend beyond natural gas inputs.1
The calibrated verdict
Evaluating the historical record against management's claims yields a clear verdict across three dimensions.
First, the historical record rejects the claim that backward integration rendered Deepak Fertilisers a structurally less cyclical business; financial performance in FY26 refutes that premise.
Second, the evidence narrows the claim that the firm has escaped commodity price-taker status. While management successfully eliminated raw material availability risk and established targeted positions in specialized ammonium nitrate grades and prilled NP formulations, the company remains a price-taker on product realisations across all primary business lines.
Third, the record leaves unproven the assertion that a specialty product shift will trigger a valuation re-rating. While mix disclosures confirm directional progress, the volume of high-margin specialty sales remains insufficient to insulate consolidated earnings during a broader commodity downturn.
The three KPIs that matter
Evaluating the company's forward performance depends on tracking three primary operational metrics:
1. The ammonia-to-gas operating spread. The differential between realized prices on ammonia-derived products and the contracted cost of natural gas feedstock. This single variable accounts for the variance between FY26 EBITDA of ₹1,684 crore and the accelerated Q1 FY27 earnings run rate. Middle East FOB ammonia benchmarks are disclosed quarterly, while natural gas costs track crude and international gas indices under the Equinor formula.
2. Capacity utilization at Gopalpur and Dahej. Management has targeted approximately 80% utilization by the fourth quarter of FY27.1 This metric provides the direct measure of whether ₹4,650 crore in growth capital converts into operational earnings on schedule.
3. B2C revenue share in mining chemicals. Outcome-based contracts represented 17% of segment revenue in Q1 FY27, up from 16% in the prior-year period.1 This figure reflects the extent to which technical mining services establish genuine customer switching costs, as it remains uninflated by underlying commodity price fluctuations.
XII. Epilogue & "If We Were CEOs"
There is a photograph worth imagining from December 2021: Odisha's chief minister at Gopalpur, turning earth for a ₹2,200 crore ammonium nitrate complex on the Bay of Bengal.24 Nearly five years later, that complex sits 96% complete, weeks from starting up, having cost ₹475 crore more than planned.1 Between those two moments, the company commissioned a world-scale ammonia plant, signed a 15-year supply contract with a Norwegian state energy major, acquired an explosives manufacturer, restructured into three operational business units, and delivered a financial year of declining profits followed immediately by the strongest quarterly result in its history.
That trajectory summarizes nearly five decades of compounding inside a capital-intensive, policy-exposed, commodity-priced sector: not a smooth growth line, but a sequence of large, irreversible commitments, only some of which have paid off.
The next growth avenues are already visible: higher-purity nitric acid for solar glass manufacturing, potential green ammonia partnerships combining India's renewable energy capacity with decarbonisation targets, and technical ammonium nitrate exports into Southeast Asia and Australia—a commercial direction signalled by the Chardham acquisition and existing Australian blasting operations.116 These options provide future strategic flexibility, but none generate meaningful current revenue.
If an independent executive team were evaluating strategic priorities for the business, three immediate actions would take precedence.
-
Resolve the DMSL corporate structure and set a firm execution deadline. The mining chemicals unit represents the highest-quality asset in the corporate portfolio, yet it has remained inside an announced-but-unexecuted corporate restructuring since December 2022, with the execution format still under evaluation.142 Whether the separation proceeds via an initial public offering or a direct demerger matters less than establishing a clear resolution. A prolonged restructuring plan provides no valuation benefit, and the ongoing ambiguity imposes a conglomerate discount on the parent company without delivering the strategic focus of a standalone entity.
-
Secure long-term offtake agreements for new capacity prior to commissioning. The most effective commercial decision in the recent capital expansion was securing 65% of the new concentrated nitric acid capacity under a 20-year agreement.1 That commercial structure should serve as the blueprint. The 376,000-tonne Gopalpur facility is entering a domestic market where landed price ceilings are set by duty-free imports; locking in multi-year take-or-pay contracts with explosives manufacturers and mining contractors would convert merchant commodity exposure into predictable cash flow, doing far more to improve the market valuation multiple than promotional messaging around specialty product mix.
-
Establish clear financial benchmarks and a definitive timeline for crop nutrition. Generating 44% of consolidated revenue while contributing minimal operating profit, the crop nutrition business must either transition into a high-margin specialty provider with pricing power independent of state subsidy regimes, or be recognized as a capital-intensive unit attached to a profitable industrial chemical producer. Deepening direct farmer relationships, expanding Croptek and water-soluble formulations, and reducing reliance on bulk Nutrient Based Subsidy products are sound initiatives. However, management should establish explicit margin targets and a firm deadline, given that the segment transition has been underway for a decade without producing a durable improvement in segment profitability.
What Deepak Fertilisers has constructed across four decades remains substantial. Expanding from a single merchant ammonia facility under License Raj regulation, the company weathered price decontrol, a site flood, a failed hostile takeover bid, and an abrupt sovereign feedstock cutoff—emerging with one of the most physically integrated industrial chemical value chains in Asia, secured by a 15-year private energy contract and strong domestic market positions in key chemical building blocks.
That asset foundation represents a durable industrial complex. Whether it translates into a durable earnings stream is a separate question—one that will be decided by operational execution across newly commissioned plants in Odisha and Gujarat, alongside future movements in global ammonia prices.
References
-
Earnings Presentation for the quarter ended 30th June 2026 — Deepak Fertilisers and Petrochemicals Corporation Ltd (NSE filing), 2026-07-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Earnings call transcript: Deepak Fertilisers posts record Q1 profit — Investing.com, 2026-07-31 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Deepak Fertilisers And Petrochemicals (DEEPAKFERT) Q4 25/26 earnings summary — Quartr, 2026-05-29 ↩↩↩↩↩↩↩↩↩↩↩
-
Deepak Fertilisers Latest Results: Revenue Up 12% YoY to ₹11,506 Crore in FY26 — ScanX, 2026 ↩↩↩↩↩↩
-
Equinor signs a 15-year LNG agreement with Deepak Fertilisers — Equinor, 2024-02-19 ↩↩↩↩↩↩
-
Deepak Fertilisers: On fertile ground — Forbes India ↩↩↩↩↩↩↩↩↩↩
-
Deepak Fertilisers bids for Mangalore Chemicals — Business Today, 2014-04-24 ↩↩↩
-
Deepak Fert sells 18.45% stake in MCFL for Rs 192 cr — Business Standard, 2015-04-17 ↩↩↩↩
-
Govt move to stop gas arbitrary, unfair: Deepak Fertilisers — Zee News, 2014 ↩↩↩
-
Deepak Fertilisers surges on favorable verdict from Delhi High Court — Business Standard, 2015-07-08 ↩↩
-
Deepak Fertilisers surges as government agreed to release subsidy — Business Standard, 2016-06-14 ↩↩↩↩
-
India: Termination of antidumping duty on imports of ammonium nitrate from Russia, Indonesia, Georgia and Iran — Global Trade Alert ↩↩↩↩↩
-
Govt won't extend anti-dumping duty on ammonium nitrate from 3 nations — Business Standard, 2022-09-01 ↩↩↩↩↩
-
Deepak Fertilisers announces demerger of its Mining Chemicals & Fertiliser Businesses — Indian Chemical News, 2022-12-16 ↩↩↩↩
-
Deepak Fertilisers completes demerger of its core business — Moneyworks4me, 2017-05-08 ↩↩
-
Deepak Fertilisers completes Rs 121.45 crore acquisition of Chardham Chemicals — Business Upturn, 2026-05 ↩↩
-
Deepak Fertilisers and Petrochemicals Taloja Chemical Plant — Global Energy Monitor ↩↩
-
Deepak Nitrite founder Chimanlal K Mehta passes away — Business Today, 2023-07-03 ↩↩
-
Deepak Fertilisers low on fuel to pursue MCF takeover battle — Business Standard, 2015-01-08 ↩
-
Deepak Fertilisers records over 21% YoY growth in Q4 PAT to Rs 278 crore — Business Standard, 2025-05-22 ↩
-
Mangalore Chemicals spurts after open offer from Zuari group — Business Standard, 2014-12-05 ↩
-
Petronet LNG inks ₹1,200 crore regasification deal with Deepak Fertilisers — Business Today, 2025-07-10 ↩↩
-
Deepak Fertilisers at 30-month high as promoter hikes stake via open market — Business Standard, 2021-03-17 ↩↩
-
CM Patnaik lays foundation for Technical Ammonium Nitrate Complex at Odisha's Gopalpur — Devdiscourse, 2021-12-09 ↩↩↩↩↩
-
Smartchem Technologies to invest Rs 2,200 crore in Gopalpur — Construction Week India ↩↩
-
Deepak Fertilisers announces Rs 10 per share dividend for FY26 — Business Upturn, 2026 ↩
-
Deepak Fertilisers gains on plan to set up new plant — Business Standard, 2017-09-25 ↩↩
-
DFPCL reports 22% YoY growth in consolidated revenue to Rs 3,256 Cr in Q1 FY27 — AgroSpectrum India, 2026-07 ↩
-
Deepak Fertilisers raises stake in MCFL, makes open offer — Business Standard, 2014-04-23 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube