CenturyPly: Building a Brand in India's Wood-and-Trust Business
I. Introduction & Episode Roadmap
Walk into a timber market in almost any Indian city — Kirti Nagar in Delhi, Kolkata's Canning Street, the lanes behind Mumbai's Reay Road — and you will find the same scene that has existed for fifty years. Stacks of plywood sheets leaning against each other, edges frayed. A shopkeeper who quotes you a price per sheet and a different, lower price if you pay cash. No warranty card. No batch number. No way, standing there in the dust, to know whether the glue holding those veneers together will survive a Chennai monsoon or a Delhi summer, or whether the wood inside is riddled with borer eggs that will hatch inside your kitchen cabinet three years from now.
The category nobody can inspect
This is not a small market. India consumes plywood and wood panels at industrial scale — a market variously sized between roughly ₹235 billion and ₹400 billion depending on whose definition of "wood panel" you accept — and roughly two-thirds to seventy percent of it still runs through exactly that scene: unbranded, uncertified, largely cash-settled, and completely unaccountable.1
Century Plyboards (India) Ltd is the company that decided the other third was worth owning. Listed on the NSE as CENTURYPLY and on the BSE as scrip 532548, it closed fiscal 2026 with consolidated revenue of ₹5,397 crore and a market capitalisation in the neighbourhood of ₹16,600 crore, trading at a trailing price-to-earnings multiple in the mid-fifties.2 It is, by ICRA's estimate, the dominant player in India's organised plywood segment with a 30–32% share, selling through more than 4,100 dealers and 19,000 retailers.3 It is also, increasingly, something else: a laminates manufacturer, a particle board manufacturer, and — the part that will decide the next five years — a challenger in medium-density fibreboard, or MDF.
What the numbers say before the story starts
That is the tension this story tracks. On one side is a genuinely durable position in plywood, built on brand, distribution depth, and — critically — two regulatory accidents that did more for Century's competitive position than any strategy meeting ever did. On the other side is an expensive, margin-diluting bet on MDF and particle board that has not yet proven it can earn plywood-like returns, financed by borrowings that grew from ₹327 crore at the end of FY23 to ₹1,765 crore at the end of FY26 — a 5.4x increase in three years while profits went sideways and then fell.2
The themes worth holding onto: brand as a solution to a trust deficit in a commodity category; regulation as an accidental moat; capital allocation inside a promoter-family structure that owns roughly 72% of the equity; and the question of whether "the next MDF leader" is a credible growth vector or a return-on-capital trap wearing a growth costume.
A note on posture before we start. Management at CenturyPly is articulate, accessible, and has run this company for four decades. That earns attention, not deference. Where the company says it will win, we will ask what evidence supports the claim and — more usefully — what in its own history would falsify it. As it happens, its own history has quite a lot to say.
 Subscribe on LinkedIn
II. Origins: A Timber Trader's Bet on Branding (1982–1986)
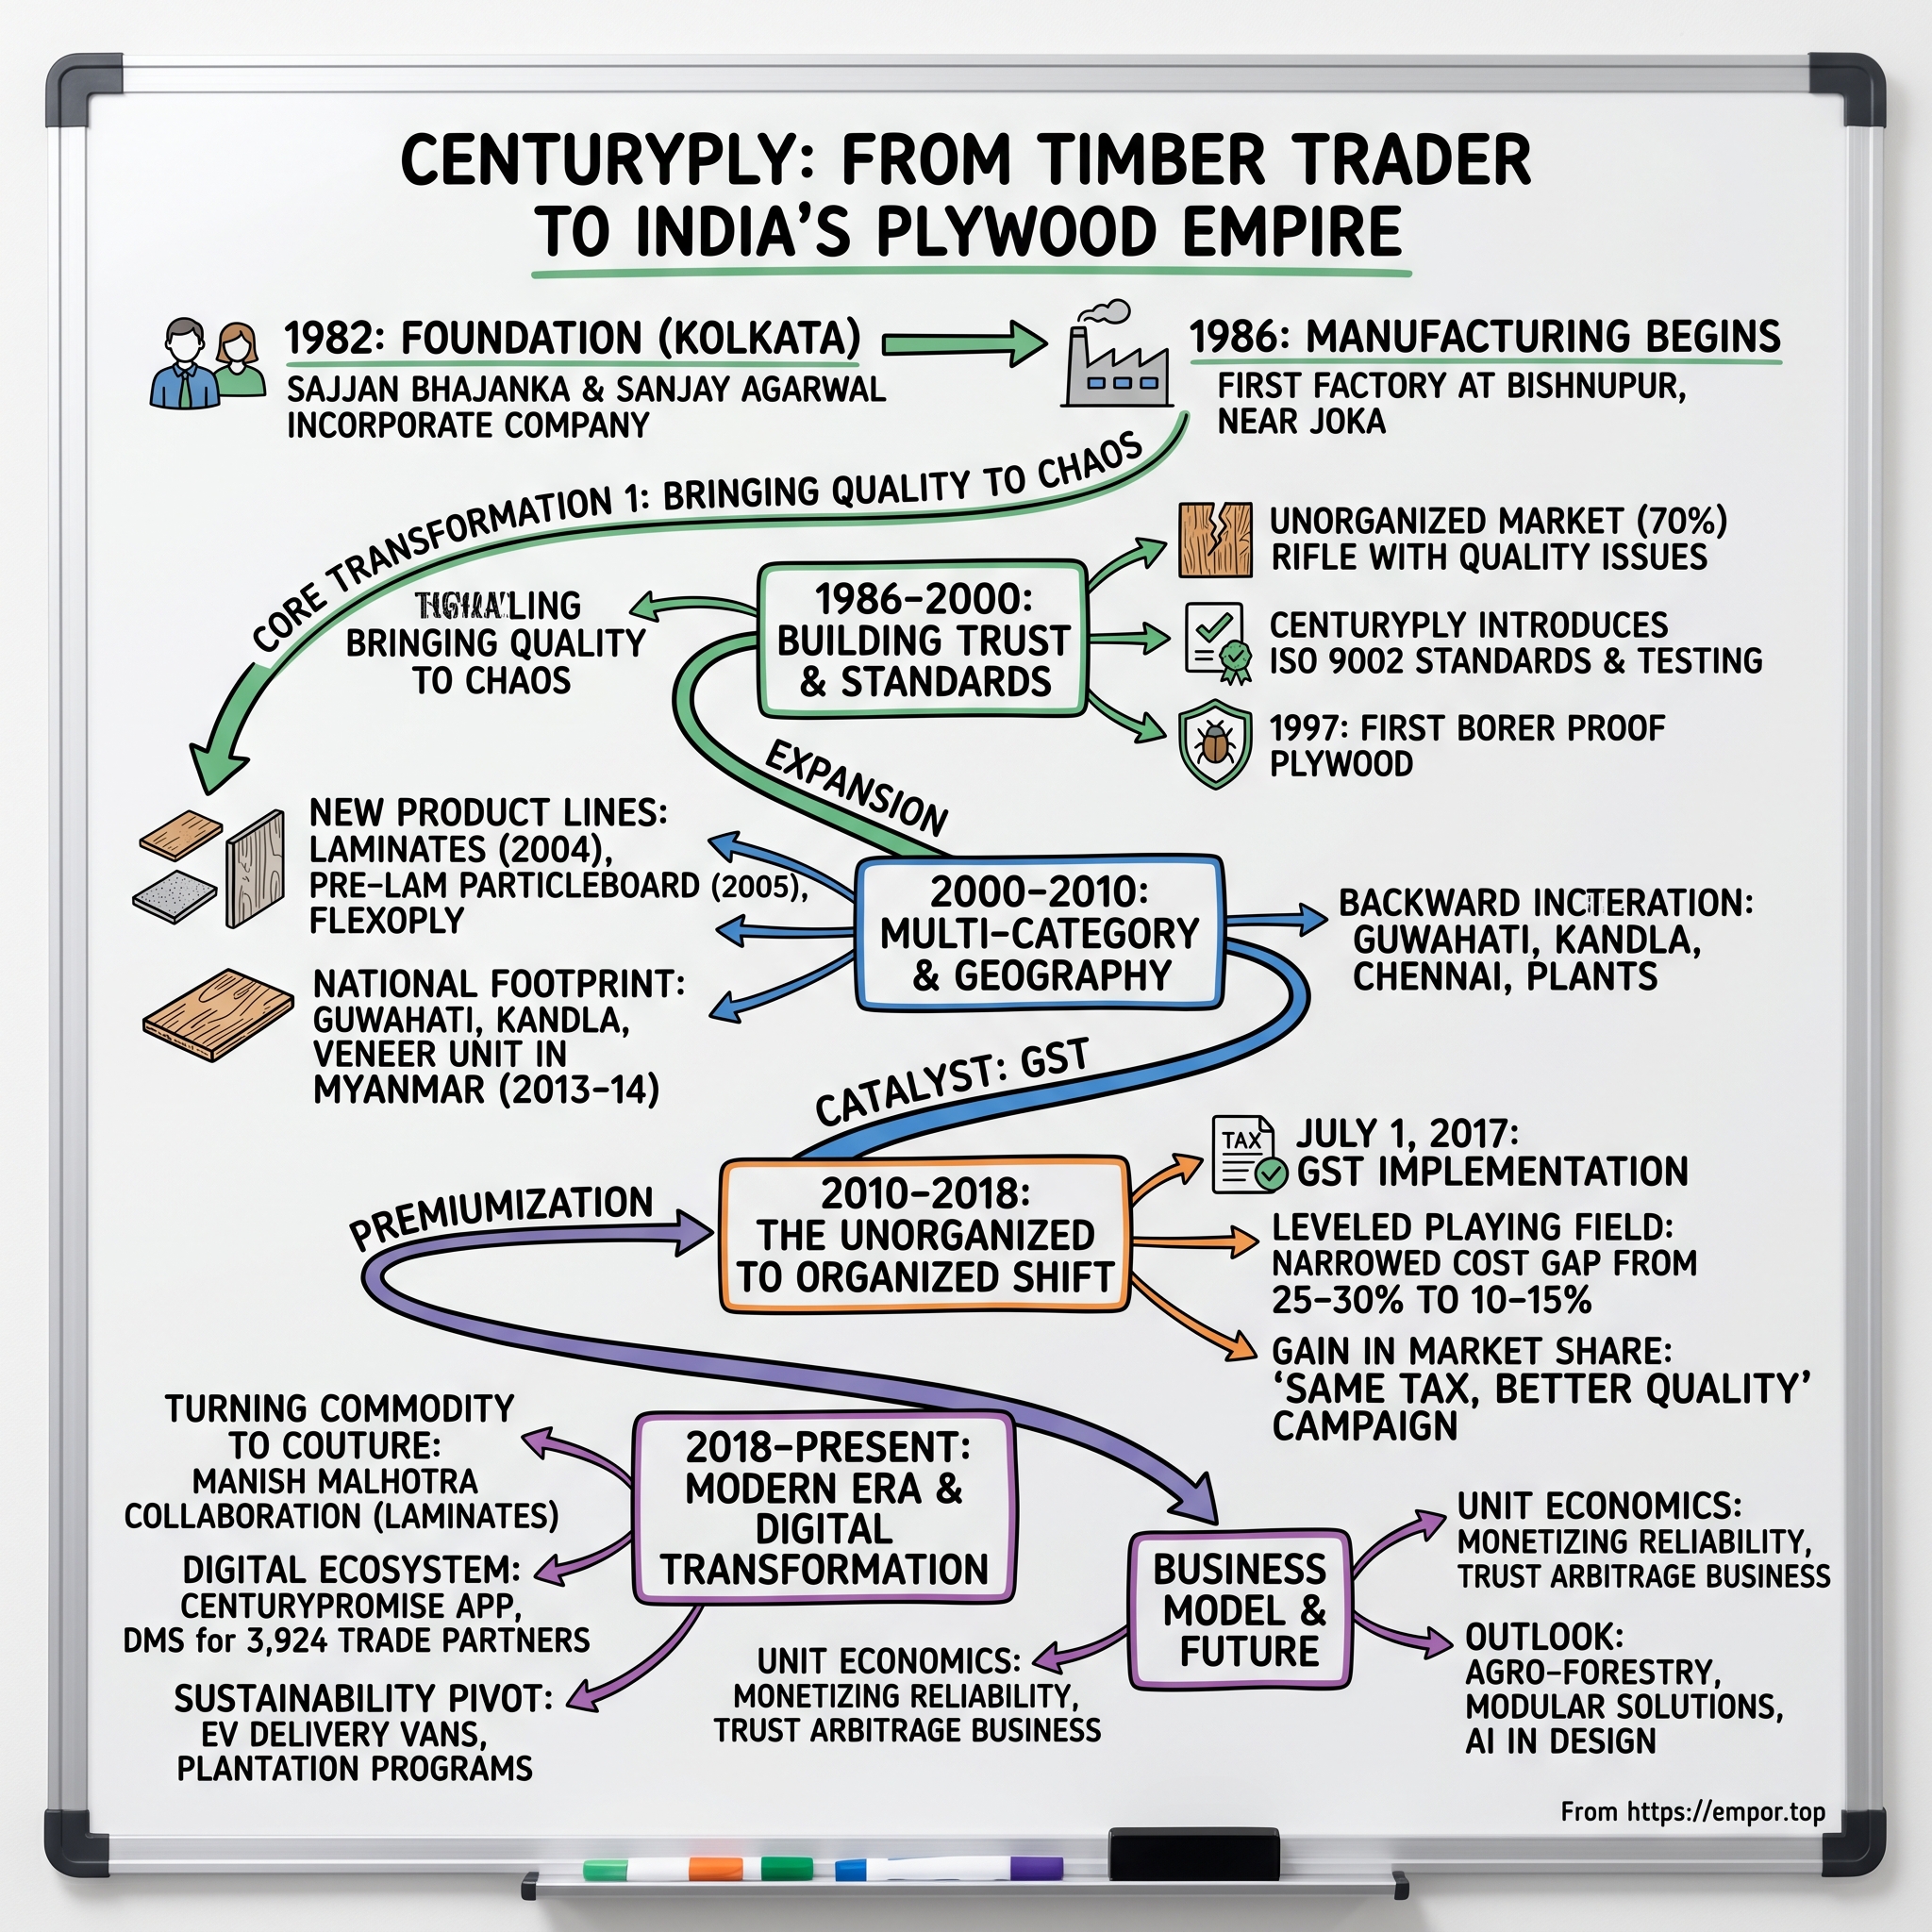
In January 1982, in a Kolkata still called Calcutta, a company was incorporated with the registration number L20101WB1982PLC034435.4 The men behind it were not manufacturers. Sajjan Bhajanka had started his working life in 1976 in the timber trade, and Hari Prasad Agarwal and his son Sanjay Agarwal came from the same Marwari trading milieu — merchants who bought and sold logs and had spent enough years watching the flow of wood through Eastern India to understand something the market itself did not.5
A market for lemons, in wood
What they understood was that plywood is a services problem disguised as a commodity. A sheet of plywood is a stack of thin wood veneers glued crosswise, and its entire value proposition — that it will not warp, delaminate, or get eaten — is invisible at the point of sale. You find out whether you bought good plywood roughly five years after the transaction, by which time the seller has moved on and you have no recourse. In economics this is a classic market for lemons: when buyers cannot distinguish quality, sellers have no incentive to provide it, and quality collapses toward the cheapest thing that looks acceptable on the shelf.
India in the early 1980s was exactly that market. Urban construction was accelerating, furniture demand was rising with a growing middle class, and every rupee of that demand flowed through a supply chain in which nobody could verify anything.
Why the founding story is not the investment story
The founders' bet was that this was not a permanent condition — that if someone could credibly signal quality and stay behind that signal for long enough, buyers would pay for it. The first factory went up at Kanchowki, Bishnupur, in the Joka area on Kolkata's southwestern edge, a site the company still operates today and which later became home to its resin manufacturing unit.6 The early years were the unglamorous ones: securing timber supply from a Northeast Indian forest economy that was still wide open, and building dealer relationships from nothing in a channel where every dealer already had five suppliers and no reason to prefer a sixth.
We should keep this section short, and not for lack of affection for founding stories. The honest reading of Century Plyboards is that the founding decisions mattered far less to where the company stands in 2026 than two things that happened to the industry from the outside — a Supreme Court judgment and a tax reform. The founders' contribution was to be positioned, credibly branded, and capitalised when those two gifts arrived. That is not nothing. Plenty of contemporaries were not. But it is a different claim from "brilliant strategy," and the difference matters when you are trying to work out whether the advantage is repeatable in a new category.
The first of those gifts arrived in December 1996. Before it did, the company spent a decade doing the thing that would let it take advantage: manufacturing a reason to be trusted.
III. Manufacturing Trust: Certification, Innovation, and an Accidental Moat (1986–2000)
Picture the sales call. It is 1993, a Century representative is sitting across from a plywood dealer in a Tier-2 city, and the dealer has heard this pitch before — everyone's plywood is waterproof, everyone's plywood is the best. What can you actually say that the man selling unbranded sheets three shops down cannot also say?
Century's answer was to import a vocabulary the Indian plywood trade did not yet have. The company positioned itself as the first Indian producer of veneer and plywood to obtain ISO 9002 certification, and in 1997 it introduced borer-proof plywood to the Indian market — a glue-line chemical treatment that kills the wood-boring insects that were, and are, the single most common cause of furniture failure in Indian homes.7 Century still builds its mid-market Sainik line on exactly this claim: termite and borer protection delivered through the glue line rather than as a surface coat.8
Reading the "firsts" correctly
Here is where a neutral read has to diverge from the corporate telling. Neither of those was a durable technical moat. ISO 9002 is a process certification available to anyone willing to document their processes and pay for the audit. A chemical borer treatment is chemistry that a competent competitor can replicate in a season. And they did: Greenply, Merino, Action Tesa and others closed the quality gap over the following decade, and by the 2010s "termite and borer proof" had become table stakes rather than a differentiator. Certification is not commercialisation, and a technical first is not a moat unless something stops the second mover.
What the firsts actually bought was time and a story. In a category where the scarce resource was not wood but credibility, being first to hold up a certificate — any certificate — let Century seed dealer trust ahead of everyone else and start compounding it. Distribution relationships in Indian building materials are sticky in a specific way: dealers extend credit, carry inventory, and take reputational risk with their own customers. Once a dealer has staked his name on your brand for a few years, switching costs are social as much as economic. The certification was the wedge; the dealer network was the actual asset being built.
That distinction is not academic, because it tells you what to expect when Century enters a new category. If the advantage were technical, it would travel — a better glue chemistry works in MDF as well as in plywood. If the advantage is a dealer network plus accumulated trust with carpenters, it travels only as far as those same people remain the buyers. Hold that thought until Section VII, where the buyer changes.
The moat that arrived by court order
Then the real moat arrived, and Century had nothing to do with it.
On 12 December 1996, the Supreme Court of India handed down its first sweeping interim order in T.N. Godavarman Thirumulpad v. Union of India, a case that had begun as a petition about a single forest patch and metastasised into judicial control of Indian forestry itself.9 The Court suspended tree felling across the country without central government permission and — the part that reshaped the plywood industry — ordered the immediate closure of all sawmills, veneer mills and plywood mills in Tirap and Changlang districts of Arunachal Pradesh and within 100 kilometres of that border in Assam, and barred any such mill from operating within eight kilometres of a demarcated forest boundary.10
Read that as an investor, not as a conservationist. In one order, the Court did three things simultaneously. It shut down a large slice of existing wood-processing capacity in the region that supplied Eastern India. It made new licences a matter of state forest department discretion under continuing judicial supervision — which in practice meant new licences became extraordinarily hard to obtain. And it therefore placed a hard ceiling on how many organised, licensed, scaled wood processors India could ever have.
For an incumbent that already held licences and already had plants, this was close to the ideal outcome: the supply of your product got tighter, and the supply of future competitors got capped at roughly whoever was already inside the door. Century's northeastern positioning meant it took real disruption in the short run, but the structural effect over the following two decades was protective. Regulatory scarcity is a genuine form of competitive advantage — Hamilton Helmer would file it near cornered resource — but it is worth being precise about its nature. It was granted, not earned. It protects the incumbent set as a whole, not Century specifically against Greenply. And it applies to plywood, where licences bind, far more than to MDF and laminates, where the binding constraint is capital rather than permission. Hold that distinction; it explains a great deal about Section VII.
The second regulatory gift would take another twenty years to arrive. In the meantime, Century had to build something worth protecting.
IV. Scaling the Platform: Multi-Category, Pan-India Manufacturing (2000–2010)
If the 1990s were about earning permission to be trusted, the 2000s were about earning the right to be everywhere.
Why plywood companies scale regionally, not nationally
There is a specific logic to how building-materials companies scale in India, and it is not the logic of a consumer packaged goods firm. Plywood is heavy, bulky, and low-value-per-kilogram. Freight is a meaningful share of delivered cost, which means a single mega-plant serving the whole country loses to a network of regional plants serving their own catchments. It also means proximity to raw material matters as much as proximity to customers — ICRA still cites Century's strategically located plants near raw material sources as a distinct credit strength, precisely because it lowers freight both ways.3
So Century built out. Over the 2000s the company assembled a manufacturing map that reads like a logistics diagram of Indian construction demand: Joka in West Bengal as the original base, Guwahati in Assam close to the northeastern timber flow, Kandla in Gujarat sitting on a port for imported logs, Chennai in Tamil Nadu for the South, Karnal in Haryana and Hoshiarpur in Punjab for the North.11 Each plant was a claim on a regional dealer network that could now be served in days rather than weeks.
It is worth pausing on what that map actually bought, because it is easy to read a list of factory towns as mere expansion. In a business where the customer's alternative is a local unbranded workshop with effectively zero freight cost, a national brand that ships from one plant is permanently uncompetitive outside its home region. The only way to be national in Indian plywood is to be a federation of regional manufacturers flying one flag. Century built that federation across a decade, and the discipline showed up later in a specific, measurable form: ICRA has repeatedly cited plant proximity to raw material sources as a structural cost advantage rather than a rounding item. A network like this is also slow and expensive to copy, which is exactly what makes it a better asset than any product patent the company has ever held.
Adjacency as distribution arbitrage
Alongside the geography came the category expansion. Flexoply arrived in 2002 — a bendable plywood aimed at curved furniture and interior work, a small product but a revealing one, because it targeted design applications rather than structural ones.7 Prelaminated particle board and high-pressure decorative laminates followed, and by the middle of the decade the company had begun edging toward the engineered-panel adjacencies that would later become MDF.
The category logic here deserves a beat of explanation, because "laminates" and "particle board" sound like the same thing to anyone outside the trade and are not. A high-pressure laminate is a decorative surface — layers of paper impregnated with resin and pressed into a hard sheet — that gets glued onto a substrate. Particle board is a substrate made by pressing wood chips and shavings with resin, cheaper and weaker than plywood. Plywood is the premium structural substrate. Put crudely: plywood and particle board compete to be the inside of your wardrobe, and laminate is the outside of it. Owning all three means Century sells to the same carpenter regardless of which price point he is building at, which is a genuinely different competitive position from selling only the premium option.
The strategic reasoning here is worth spelling out, because it is the load-bearing argument for everything Century has done since. If your real asset is a dealer network — thousands of shops that already stock your brand, already take your credit terms, and already have a relationship with the carpenters and contractors who actually specify materials — then the marginal cost of pushing a second product through that network is far lower than the cost a new entrant would pay to build the network from scratch. Every additional SKU that fits in the same shop, gets sold by the same salesman, and gets recommended by the same carpenter is incremental revenue on an already-paid-for distribution asset. This is distribution leverage, and it is the honest core of the CenturyPly investment case.
The same decade saw the beginning of a strategy that would take twenty years to be properly tested: international timber sourcing. As domestic forest access tightened under the post-Godavarman regime, Century began looking outward for the tropical hardwood face veneers — particularly gurjan — that Indian plywood buyers associate with quality. That decision looked prescient at the time and, as we will see, produced two complete cycles of entry, ban, and write-off. Section VI takes that apart.
Two audiences, one product
The final shift of this period was subtler and harder to date: the move from selling plywood as a builder's line item to selling it as a considered household purchase. Plywood is bought by the homeowner but chosen by the carpenter, which makes it one of those awkward categories where the payer and the decider are different people. Century's own FY25 disclosures still name this explicitly as a business dependency: sales are significantly influenced by the recommendations and referrals of professionals such as carpenters and architects.12 The company began building toward both audiences at once — advertising to households to create pull, and running dealer and carpenter engagement programmes to create push.
That two-sided demand machine was in place by around 2010. What it lacked was the one thing no amount of advertising could fix: a price gap of fifteen to twenty percent against competitors who simply did not pay tax.
V. The GST Inflection: When the Government Built the Moat (2010–2018)
Here is the number that explains sixty years of Indian plywood market structure. In June 2017, Equirus Securities initiated coverage on Century Plyboards and put the organised sector's price premium over the unorganised sector at roughly 15–20%, in a plywood market it sized at ₹15,000–16,000 crore of which unorganised players held about 70%.13
The arithmetic of the informal discount
Fifteen to twenty percent. That is the whole story. It was not that Indian consumers preferred bad plywood. It was that branded plywood cost meaningfully more, and the reason it cost more had less to do with wood and glue than with excise duty, VAT, and the fact that a compliant manufacturer paying full tax on a fully-documented supply chain competes against a workshop that pays neither. The unorganised sector's core competitive advantage was not craftsmanship. It was tax arbitrage.
Every brand-building rupee Century spent in the 1990s and 2000s was, in effect, spent trying to persuade customers to voluntarily overpay by a fifth. That it worked at all — that the organised sector held roughly a quarter to a third of the market on those terms — is the strongest single piece of evidence that the brand was real. But it also caps how far brand alone could ever go.
What GST actually changed
Then, on 1 July 2017, the Goods and Services Tax replaced India's layered indirect tax system with a single value chain in which every participant's input credits depend on their supplier having actually paid tax. This is the mechanism that matters, and it is worth explaining plainly rather than in tax-speak. Under GST, if you buy timber from someone who did not pay GST on it, you cannot claim credit for that tax when you sell the finished plywood — so you eat it. The system creates a documentary chain in which non-compliance is contagious: an unorganised manufacturer is a costlier supplier to anyone who is compliant, and the informal ecosystem starts to bleed at its edges.
Rate changes followed. The November 2017 GST Council rationalisation pulled a large tranche of wood-panel lines out of the 28% slab into 18%, including the laminate categories Century sells; Equirus had already flagged the laminates cut to 18% from 28% as a driver of the shift from unbranded to branded, on the simple logic that when the tax wedge shrinks, so does the price gap that keeps buyers loyal to the informal market.1413
The reform's tail was long and slow. Compliance costs rose gradually for small manufacturers. Some formalised. Some shrank. Some kept operating exactly as before, because enforcement in a market of thousands of tiny workshops was always going to be imperfect. The organised share moved, but it moved over years, not quarters. That pace is the honest answer to anyone modelling a step-function shift in Century's addressable market: the mechanism is real and the direction is clear, but the slope has been shallow enough that a decade after GST, the unorganised sector still holds around 70% of the plywood market by the company's own reckoning.15
There is a useful check available on that claim, and it is unflattering to the fastest version of the bull case. Equirus put the unorganised share of plywood at roughly 70% in 2017.13 Century's own FY25 report puts it at approximately 70%.15 Eight years, one enormous tax reform, and the headline structure of the market is roughly where it was. That does not mean nothing happened — the organised sector grew substantially in absolute terms as the whole market grew, and share statistics in a market this poorly measured carry wide error bars. But an investor should be sceptical of any model that assumes the informal sector melts away on a predictable schedule. It has not so far.
The company's response through this window was to make the branded proposition harder to ignore at the point of sale. Dealer network build-out, dealer and carpenter certification and loyalty programmes, and mass-media advertising aimed at the household rather than the trade were all pushed harder from the mid-2010s. The intent was to convert plywood from an invisible input specified by a contractor into a considered purchase the homeowner has an opinion about — because a homeowner with an opinion is a homeowner who will absorb a premium. Century's ability to take a 7% price increase in April 2026 and still grow volume is the closest thing to proof that this worked.
GST 2.0, and why it lands differently
Which brings us to the current echo, and it is genuinely current. At its 56th meeting in September 2025, the GST Council collapsed India's rate structure into three principal slabs and, effective 22 September 2025, moved plywood, MDF, particle board and related wood-panel categories that had still been sitting at 28% into the standard 18% slab, while trimming rates on certain input resins and adhesives from 12% to 5%.16 For a manufacturer, that is a two-sided benefit: the output price to the consumer falls without the manufacturer conceding realisation, and the input cost of the chemical side of the bill of materials falls too.
The analytical question is whether GST 2.0 does more than GST 1.0 did, and the honest answer is: probably somewhat, for a specific reason. GST 1.0 attacked the compliance advantage of the informal sector. GST 2.0 attacks the sticker price gap directly, and it does so in MDF and particle board — categories where the unorganised sector is weaker to begin with because the manufacturing is capital-intensive rather than labour-intensive. You cannot run an MDF line in a shed. So the second reform's benefit is skewed toward exactly the segments where Century has been building capacity, which is either fortunate timing or a fortunate coincidence, depending on how much foresight you are willing to grant.
What it does not do is change the fundamental competitive geometry within the organised sector, where Century's rivals get the identical benefit on the identical day. A tailwind that lifts every organised player equally improves the industry's economics; it does not improve Century's relative position. Watch the FY27 margin commentary for how much of the input-side benefit is retained versus passed through — that is where the pricing power question actually gets answered.
And the raw material side of the ledger, unfortunately, has been moving the other way for a decade.
VI. The Raw Material Problem: Timber Sourcing, and Where the Strategy Actually Failed (2000s–Present)
In 2014, the government of Myanmar banned the export of raw logs. Somewhere in Kolkata, a spreadsheet stopped making sense.
Century had built a unit in Myanmar for exactly this: procure timber from local sources, peel it into face veneer, and ship the veneer to Indian plywood plants. It was textbook backward integration, and while it worked it worked beautifully. Equirus, writing in 2017, credited the Myanmar and Laos sourcing structure with helping drive Century's cost of materials from 56% of sales down to 39% — a swing that, at Century's scale, is the difference between an ordinary panel maker and a very good one.13 The note went further, describing the arrangement as a strong competitive advantage precisely because smaller operators and the unorganised sector depended on companies like Century to source critical raw material.
The other edge of the 1996 sword
Here is what the Godavarman ruling did to the other side of Century's business. By locking down domestic forest access, it left the Indian plywood industry structurally short of the dense tropical hardwood it needs for face and core veneers. Farm and plantation timber — poplar, eucalyptus, and their cousins — covers the bulk of the industry's volume needs, but it does not substitute for gurjan on the face of a premium sheet. So the whole industry imports, and Century decided to import through its own subsidiaries rather than through traders.
Two ventures, two bans, two write-offs
That decision has now failed twice, and the record is in the company's own filings.
Myanmar first. After the 2014 export ban and the political disruption that followed the 2021 coup, the operation became unviable. Century disposed of its entire investment in wholly-owned foreign subsidiary Centuryply Myanmar Private Limited, with the subsidiary deconsolidated with effect from 28 February 2023, recognising a loss of ₹49.25 crore. The FY24 annual report states the reason without euphemism: due to political disturbances and an adverse business situation in Myanmar, the subsidiary had to close down its operations and the entire investment was disposed of.17
Laos second, and it is a near-perfect replay. Century had established a presence in Laos and was setting up an independent veneer unit there to secure face veneer supply, with the Laotian quota system explicitly cited as part of the attraction.13 The Laos government then banned the export of raw wood and veneer, undercutting the thesis almost as soon as it was funded.18 The unwinding took years. In FY24 the group signed an agreement to sell the assets of Century Ply (Singapore) Pte Ltd — the holding vehicle — and booked an impairment loss of ₹11.06 crore. In the June 2024 quarter the shares were transferred, and a further ₹13.33 crore was recognised as an exceptional loss attributable to the parent. Century Ply (Singapore) Pte. Ltd., Century Ply Laos Co. Ltd and Century Huesoulin Plywood Lao Co. Ltd all left the group with effect from 23 April 2024.19
Add it up: roughly ₹73 crore of realised losses and impairments across two international sourcing ventures, recognised across FY23, FY24 and FY25. Against a company that earned ₹384 crore in FY23, this is not existential. It is also not a rounding error, and more importantly it is not a one-off. It is the same strategy, executed twice, broken twice, by the same mechanism — a sovereign government deciding that exporting unprocessed forest products is a bad deal for its own economy.
Testing the Gabon replacement claim
The replacement is Gabon. Century Gabon SUARL, a wholly-owned subsidiary, began commercial production in February 2021 with capacity to peel roughly 200 cubic metres of timber a day, and ICRA now cites the Gabon unit as backward integration supporting veneer supply.[^20]3 The company's public framing of the Laos exit was a strategic pivot to Gabon rather than a distressed retreat.
The filings let us test that framing with unusual precision, and it does not survive intact. In FY25, Century's purchases of raw materials from Century Gabon SUARL totalled ₹14.58 crore, up from ₹10.94 crore the prior year.20 Gabon contributed ₹6.51 crore of profit and held ₹30.76 crore of net assets, about 1.3% of consolidated net assets.21 Against consolidated revenue of ₹4,528 crore, ₹14.58 crore of veneer is roughly three-tenths of one percent of the top line.
So the plain read is this. The claim that "international sourcing is a proven, repeatable Century capability" is rejected by the record, not merely unproven: two full entry-to-write-off cycles in a decade, driven by a risk — export bans — that the company does not control and has not demonstrated it can anticipate. The narrower claim that survives is that Century can operate a small overseas veneer unit and that Gabon is currently profitable at a scale too small to matter. Whether the larger claim gets rehabilitated depends on one observable thing: whether Gabon purchases scale into a genuinely material share of veneer input over the next two or three annual reports, or whether the company quietly opens a third geography. A company that has genuinely learned would also be diversifying across geographies rather than concentrating in one, since the failure mode is country-specific policy.
The risk is not historical. Myanmar imposed a fresh log export ban in 2024 amid its civil conflict, and Indian plywood and veneer buyers responded by pushing processing capacity into Myanmar itself and into the northeastern Indian states — with an estimated $40 million of timber a year now moving across the border outside official channels, a trade that carries its own compliance and reputational exposure for anyone buying at the end of that chain.22 Industry bodies have warned that log supply shortage is a live risk to the Indian plywood industry rather than a solved one.23
For an investor, the mechanism to watch is simple: timber and crude-linked chemical inputs are the two largest cost lines, both are volatile, and ICRA explicitly attributes Century's operating margin collapse from 16.1% in FY23 to 13.7% in FY24 to 10.9% in FY25 partly to exactly this volatility.3 Which is the natural bridge to the other half of that margin story — the one Century chose.
VII. The MDF Bet: Growth Engine or Margin Trap? (2018–Present)
If you want to understand why medium-density fibreboard exists, look at the back panel of any flat-pack wardrobe. MDF is engineered wood: hardwood and softwood residuals broken down into fibres, mixed with resin and wax, and pressed under heat into a dense, perfectly uniform board. Unlike plywood, which is layered veneers with grain and knots and personality, MDF has no grain at all. It machines cleanly, routs into decorative profiles, takes paint and laminate perfectly, and — crucially for factory furniture — is dimensionally identical from sheet to sheet.
Why MDF exists, and why India is behind
That last property is why MDF is the substrate of global ready-made furniture. Century's own annual report makes the bull case with an arresting comparison: globally around 70% of furniture is made using MDF, whereas in India the figure is roughly 30%, and industry estimates suggest MDF's share of the Indian wood panel market could rise from 5% toward 50% by 2030.24 India's furniture market is shifting from the carpenter who builds your wardrobe in your living room over three weeks to the factory that ships it flat-packed. MDF is what that factory buys.
That 50%-by-2030 figure deserves a harder look than it usually gets, because it is doing a lot of work in this sector's bull case and it is not an observation. It is an industry estimate, cited by a company in the document justifying its MDF capital expenditure — which is not disqualifying, but is a reason to check it rather than adopt it. Two things should give pause. First, it implies roughly a tenfold share shift inside five years in a market whose structure has demonstrated it changes slowly: the organised-versus-unorganised split in plywood barely moved across the eight years following the single largest tax reform in Indian history. Second, the two statistics in that sentence are not measuring the same thing. "70% of global furniture uses MDF" is a statement about how furniture is built; "MDF's share of the wood panel market" is a statement about panel volumes across all end uses, including construction and shuttering applications where MDF cannot substitute for plywood at all. Treating the first as evidence for the second is a category error that appears throughout this sector's promotional literature. The directionally correct version of the claim — that MDF gains share as Indian furniture manufacturing industrialises — is well supported. The specific number is not, and no investor should size a capex programme against it.
So the strategic logic is sound in direction if not in magnitude. The category is real, the shift is real, and a panel company that ignored MDF would be ceding its own future to substitution — note that the substitution threat here is partly internal, with MDF eating the lower end of plywood demand inside Century's own portfolio.
The execution is where it gets expensive. Century built an MDF plant at Hoshiarpur in Punjab with roughly 198,000 cubic metres of annual capacity at a project cost around $66 million, and then, through wholly-owned subsidiary Century Panels Limited, built a second and larger unit at Badvel in Cuddapah district, Andhra Pradesh. The Badvel facility added 313,500 CBM, doubling group MDF capacity to 627,000 CBM.25 By the June 2026 quarter the Andhra unit had been debottlenecked from 700 to 950 CBM per day.26
The four lines that contain the whole argument
Now the numbers that decide the argument. In the June 2026 quarter — Century's best quarter ever on revenue — the segments reported as follows: plywood grew 32.4% year on year at a 16.9% EBITDA margin, the highest the plywood business has ever recorded; laminates grew 14.7% at 10.2%; MDF grew 28.9% at 7.0%; and particle board grew 155.7% off a small base at 3.7%.27
Read that carefully, because it is the entire thesis in four lines. MDF is growing at almost exactly the rate plywood is growing. And it is doing so at less than half plywood's profitability. Every incremental rupee of MDF revenue is worth roughly forty paise of the operating profit that a rupee of plywood revenue generates. The company is buying growth, and the currency it is paying in is return on capital.
Management's position is that this is a ramp-up phenomenon rather than a structural one, and that MDF should head toward a 15%-plus EBITDA margin as soon as possible, with double-digit margins across core segments targeted by the fourth quarter of FY27.28 There is a real argument behind that. MDF is a fixed-cost business — you are running a continuous press line, and utilisation drives everything. A plant at 60% utilisation and a plant at 90% utilisation have wildly different unit economics from identical assets.
And there is evidence for it inside Century's own filings, which is the more interesting version of the argument. In FY25 the standalone MDF business — essentially Hoshiarpur, the mature plant — earned a 15.41% EBITDA margin, down from 21.70% the year before but still a respectable number, on volume of 241,388 CBM at 82% capacity utilisation.29 Meanwhile Century Panels Limited, the subsidiary housing the new Badvel MDF and laminate lines, lost ₹100.46 crore in FY25 — equal to 54% of the group's entire consolidated profit for that year, against a ₹4.95 crore loss the prior year.21
FY25: what a ramp-up actually costs
That single disclosure explains the most damaging year in Century's recent record. In FY25 the parent company earned ₹284.56 crore standalone.21 Consolidated net profit was ₹186 crore, down 43% from ₹325 crore in FY24 and down 52% from ₹384 crore in FY23.2 The gap between the two is overwhelmingly the new MDF subsidiary bleeding while it ramped. Individual quarters were worse than the annual figure suggests: Q1 FY25 consolidated PAT fell about 60% year on year, and Q2 FY25 fell 58.7% to ₹39.96 crore, with finance costs in that quarter up 180% year on year.3031 Consolidated finance cost for FY25 came in at ₹69.03 crore against ₹30.83 crore in FY24, an increase of 124%.32
So the picture for FY25 is not ambiguous. Revenue grew 16.5%. Profit fell 43%. The delta was ramp-up losses at a new plant plus interest on the debt that built it plus raw material inflation the company could not immediately pass on. Management guidance going into that year did not anticipate the magnitude — ICRA's January 2024 rationale had projected FY25 revenue growth of 16–18% with operating margins likely to sustain around 16%, and revenue came in almost exactly on that projection while margins landed at 10.9%.333 The revenue forecast was right; the margin forecast was wrong by more than five percentage points. That is a useful, specific record: the company's demand read has been good, and its cost and ramp read has been poor.
The recovery, sized honestly
The recovery since has been genuine. FY26 delivered consolidated revenue of ₹5,397 crore, up 19%, with PAT up 44% to ₹268 crore and operating margins recovering 190 basis points to 12.8%.343 The September 2025 quarter saw consolidated net profit rise 72.42% year on year.35 And the June 2026 quarter set records on both lines: revenue of ₹1,561 crore up 33.5%, consolidated PAT of ₹83.3 crore up 57.4%, operating EBITDA of ₹198 crore up 55%, with margins at 12.7% against 11.0% a year earlier.3627
But note what the recovery is and is not. FY26's ₹268 crore of profit is still 30% below FY23's ₹384 crore, on revenue that is 48% higher. The company has grown its way back toward a profit level it already achieved three years ago on a much smaller and much less leveraged asset base. That is a rebound from a self-inflicted trough, not proof that MDF economics have normalised. The plywood business, at a record 16.9% margin, is carrying the group.
Century is the challenger here, not the incumbent
The competitive reality check is the part that gets least airtime. In MDF, Century is a challenger, not the leader. Greenpanel Industries — spun out of Greenply in the 2019 demerger that split plywood from wood panels — commissioned a 231,000 CBM MDF line in Tirupati district, Andhra Pradesh, with commercial production effective 29 March 2025, taking its consolidated installed MDF capacity to 891,000 CBM per annum.3738 That is materially ahead of Century's 627,000 CBM group capacity, from a company for which MDF is not a diversification but the whole business.
This matters for the thesis in a specific way. Century's edge in plywood rests on brand and dealer distribution in a category where the enemy is an unbranded workshop. In MDF the enemy is a scaled specialist with more capacity, comparable access to the same trade channel, and no legacy plywood business whose margins it is trying to protect. ICRA names the problem directly: lumpy capacity additions in the organised MDF and particle board segments are producing demand-supply mismatch, and Century faces intense competition from organised players in exactly those categories.3 Note the asymmetry — organised competition in MDF and laminates, unorganised competition in plywood and particle board. Those are different games requiring different weapons, and Century's weapon was built for the second one.
So where does that leave the claim that MDF is Century's next growth engine? The revenue half is proven: MDF was 23% of company revenue in FY25 with volume up 59%, and it is growing at roughly plywood's rate off a bigger capacity base.24 The value half is not. The claim survives only in its narrow form — MDF is a material revenue contributor whose returns are currently dilutive to the group and whose normalisation is a management target rather than a demonstrated outcome. The confirm/disconfirm event is specific and dated: the FY27 quarters, and whether MDF segment EBITDA margin climbs from 7% toward the low-to-mid teens or stalls in single digits while capacity keeps arriving.
The other thing that arrived with the capacity was debt.
VIII. Capital Allocation and Management Credibility Under Stress (2022–Present)
There is a page in Century's FY25 annual report laying out how the company intends to generate ₹12,000 crore of revenue by 2031. Among the bullets, under the heading of financial discipline, are three phrases: Invest out of accruals. Prepay debt. Shrink working capital cycle.39
That page was published in a year in which consolidated borrowings had risen from ₹327 crore at the end of FY23 to ₹1,586 crore at the end of FY25, and would reach ₹1,765 crore by March 2026.2 Stating the aspiration and the record side by side is not a gotcha; it is the necessary context for evaluating any forward guidance this management team gives about capital discipline.
The operators
Start with the people, because in a promoter-controlled company they are the strategy. Sajjan Bhajanka has been Chairman and Managing Director since the mid-1980s and was awarded the Padma Shri in the 2025 civilian honours list for contributions to trade and industry — an award he received in January 2025 and characterised in typically plain terms as making any industrialist or social worker happy.40 He is a builder in the literal sense, having also constructed one of the Northeast's largest cement operations outside this company. Sanjay Agarwal, co-founder and now CEO and Managing Director, runs the operating business and signs the sustainability disclosures.41 The next generation is inside: Keshav Bhajanka sits on the board's Risk Management Committee and fronted the laminates brand push, and Nikita Bansal, Sanjay Agarwal's daughter, is an executive director.4212
The alignment case is straightforward and largely holds up. Promoters held approximately 71.8–72.3% of the equity as of recent disclosure, a stake that has been stable, and executive compensation reads as unremarkable for a company of this scale — the ratio of the Chairman's and CEO's remuneration to median employee pay was 85.71x each in FY25, with the CEO's remuneration down 21.6% year on year and the Chairman's up 52.5%.243 A CEO taking a pay cut in a year when consolidated profit fell 43% is a small but real data point in favour of alignment.
Governance: the clean opinion and the footnote
Governance texture, honestly reported. The FY25 statutory audit was conducted by S.R. Batliboi & Co. LLP, of the EY network, appointed at the September 2024 annual general meeting, and the auditors issued an unqualified opinion on both standalone and consolidated financial statements, signed at Kolkata on 29 May 2025.44 That is the clean headline.
The footnote is more interesting. Under the Companies Act's audit trail requirements, the auditors recorded that the group used multiple accounting software packages with edit-log functionality, except for the SAP application, where the audit trail was not enabled at the transactional and database level throughout the year for all relevant transactions; the company's own note states this could not be enabled for technical reasons.4546 The auditors added that they found no instance of the audit trail being tampered with where it was enabled. This is not a qualification and it is not fraud. It is, however, a genuine internal-controls gap in the primary ERP of a ₹5,000-crore company, disclosed for the year, and it is the sort of item a skeptical investor should note and then watch for in the following year's report rather than wave through.
Two other items belong here for completeness rather than alarm. Century sought informal guidance from SEBI on the Prohibition of Insider Trading Regulations — specifically on whether gifting shares among promoters constitutes a contra trade and on the identification of promoter-group members as designated persons — and SEBI published its interpretive response in May 2025.47 That is a company asking a regulator a question and getting an answer; it is the opposite of an enforcement action. Separately, the FY24 accounts disclose political donations of ₹5 crore to the Indian National Congress and ₹1 crore to the All India Trinamool Congress, within the statutory limit under Section 182(1) of the Companies Act.48 Legal, disclosed, and worth a sentence in any governance file.
The stress test
Now the capital allocation stress test, which is where the real argument lives.
The 5.4x increase in borrowings over three years funded a genuinely large physical build: the Badvel MDF and laminates complex, a particle board plant, a Tamil Nadu unit at Gummidipoondi that started operations in June 2025, and a plywood capacity expansion programme first flagged around September 2024 as a roughly 30% capacity increase.4950 Capacity across the portfolio moved substantially: plywood from 339,600 to 399,600 CBM, particle board from 72,000 to 312,000 CBM, MDF from 313,500 to 627,000 CBM.25
ICRA's June 2026 assessment is measured and worth taking seriously precisely because it is not promotional. The agency reaffirmed [ICRA]AA with a Stable outlook — not a positive outlook — and attributes the FY26 debt increase primarily to higher working capital utilisation in line with the increase in scale rather than to fresh project debt. It projects leverage improving from 2.6x total debt to operating profit at March 2026 to 2.2–2.3x by March 2027 and 1.6–1.7x by March 2028, with FY27 capex of only ₹400–420 crore and term loan repayments of ₹95.3 crore comfortably covered by operating cash flow. Liquidity is characterised as adequate, supported by ₹430 crore of undrawn working capital limits and ₹30.2 crore of cash and liquid investments at March 2026.3 The explicit downgrade trigger is a debt service coverage ratio falling below 2.25x on a sustained basis, against 2.8–2.9x projected for FY27 — a real but not enormous cushion.
Management's own framing on the August 2026 call was consistent with this: no large capex planned in the short term, maximum generated cash flow directed toward debt repayment, and a stated intention to hold long-term debt at roughly one times EBITDA.28 The rise in FY27 working capital debt was attributed to the mechanical consequence of 33% revenue growth against a roughly 60-day debtor cycle — which is a concrete, checkable explanation rather than a deflection, and reflects a business ICRA describes as working-capital-intensive at 23% intensity in FY26.3
Against that, the forward pipeline is not small. In May 2026 the board approved an Odisha project of over ₹870 crore across phases, adding 120,000 CBM of plywood in two tranches and 240,000 CBM of particle board, with plywood phase one targeted for Q1 FY30, phase two for Q1 FY31 and particle board for Q1 FY32 — funded through a combination of debt and equity, with the particle board scope potentially convertible to MDF.5152 A greenfield Uttar Pradesh plywood plant has slipped to Q1 FY29 pending land acquisition, and management acknowledged on the August 2026 call that no suitable land parcel had been selected in Odisha yet.28 To reach ₹12,000 crore of revenue by 2031 — a target first articulated publicly in September 2023 and roughly 2.2x FY26 revenue — management estimated on that call that roughly ₹2,500 crore of capex would be needed for the incremental ₹4,000 crore of revenue.5328
A calibrated verdict on management
Here is the calibrated read. On guidance discipline, this management team has a mixed and specific record: consistently good at forecasting demand and volume, consistently poor at forecasting the margin and interest cost of its own capacity ramps. The FY25 miss was not a rounding issue and was not adequately flagged in advance. On capital allocation, the domestic capacity building has produced the revenue it promised and has not produced the returns; the international sourcing deployments produced roughly ₹73 crore of write-offs. Nobody should describe this record as surgical or disciplined. Nor is it reckless: the leverage is covered, the assets are real and operating, the auditor is clean, the promoters have not pledged their control stake in the ways that turn leverage into a solvency event, and the FY26–FY27 recovery is being delivered rather than merely promised.
The ₹12,000 crore target should be treated as a stress-testable scorecard, not a plan. It requires the MDF margin thesis to work, continued organised-share gains, and roughly ₹2,500 crore of further capital deployed at returns Century has not yet demonstrated in its newer categories. What would falsify it early is straightforward: net debt to EBITDA rising rather than falling through FY27 and FY28 while MDF margins stay in single digits. That combination, if it appears, means the capex cycle is not self-funding and the equity story changes character entirely.
Before judging whether the target is plausible, though, we need to look at the field Century is playing on.
IX. Industry Structure & Competitive Position
Start with an honest admission about the numbers, because the industry's own data is a mess. India's plywood and wood panel market gets sized anywhere from roughly ₹235 billion to ₹400 billion depending on whether you count only plywood, plywood plus laminates, or the full engineered panel universe including MDF and particle board.1 Equirus sized the plywood market alone at ₹15,000–16,000 crore in 2017.13 Anyone quoting a single precise figure for "the Indian plywood market" is quoting a definition, not a measurement. What is not in dispute is the structure: the unorganised sector holds roughly 65–70% of plywood, and Century's own FY25 report puts it at approximately 70%.15
The measurement problem is itself an investment consideration. If nobody can size the informal sector accurately, then nobody — including management — can measure organised-share gains accurately either. Claims about formalisation progress are therefore inference rather than observation, and should be weighted accordingly. The observable proxies are better: organised players' volume growth versus overall category growth, and whether branded producers can raise price without losing volume. Those are checkable every quarter.
The field
The named field. Greenply Industries is the number-two branded plywood player, and since the 2019 demerger it is a focused plywood and veneer company rather than a diversified panel group. Greenpanel Industries, the other half of that demerger, is the MDF category leader at 891,000 CBM of installed capacity.38 Action Tesa pioneered HDHMR and competes hard in engineered panels and laminates. Merino Industries is a large privately-held laminates player with genuine export credibility. Rushil Décor plays in both laminates and MDF with an export tilt. Below them sit older names like Kitply, Archidply and Sarda Plywood, and beneath everything, the long tail of thousands of unbranded workshops.
Five forces, segment by segment
Run Porter's five forces across this and the picture is unusually asymmetric by segment.
Supplier power is elevated and rising, and it is the most under-appreciated force in the industry. Timber suppliers are not concentrated firms — they are sovereign governments issuing export bans, plus a domestic farm-forestry base that takes years to respond to price. Century has now been on the wrong end of that power twice. The chemical side is no better: resins and adhesives are crude-oil derivatives, and ICRA specifically flags anticipated FY27 pressure from higher crude-linked input prices amid West Asian instability.3
Buyer power is genuinely two-tiered. At the retail end it is negligible — a homeowner buying twelve sheets has no leverage, and the actual decision-maker is a carpenter who responds to brand familiarity and dealer relationship rather than price alone. At the institutional end — builders, furniture manufacturers, contract projects — buyer power is real and rising, particularly in MDF where the customer is often a factory buying truckloads against specification. As the furniture industry industrialises, the mix shifts toward the buyers with leverage. That is a slow structural headwind to pricing that the MDF growth story does not usually mention.
Threat of new entrants is where the segment asymmetry bites hardest. In plywood, licence scarcity under the post-Godavarman regime still constrains new organised capacity. In MDF, laminates and particle board, the barrier is capital, and capital is available — which is exactly why capacity has arrived lumpily enough for ICRA to describe a demand-supply mismatch.3 Century is diversifying from a category with high entry barriers into categories with lower ones. That is a defensible commercial choice and a real dilution of moat quality, and both statements are true at once.
Substitutes are live and, unusually, internal. MDF and HDHMR substitute for plywood at the lower end. Century sells both, which converts an external threat into an internal mix question — but the mix question has an unfavourable answer at current margins, since substitution moves revenue from a 16.9% margin product to a 7% margin product.
Rivalry is intensifying, and in a specific direction. GST 2.0 narrows the informal price advantage further, which pulls unorganised players either upmarket or out, and simultaneously hands every organised competitor the same benefit on the same day. The counterintuitive consequence is that formalisation, which is the bull case for the industry, is also the mechanism by which competition inside the organised segment gets harder. A market where Century competes against unbranded workshops is a market where its brand is worth a 15–20% premium. A market where Century competes against Greenply, Greenpanel, Action Tesa and Merino is a market where brand is worth considerably less, because everyone has one. The organised-share thesis and the pricing-power thesis sit in mild tension with each other, and very little published commentary on this sector acknowledges it.
Seven Powers: what Century has and what it does not
On Hamilton Helmer's 7 Powers, Century's strongest holdings are brand and scale economies, both aimed at counter-positioning against a tax-arbitraging informal sector — a brand that supports genuine premium pricing across a portfolio spanning the price spectrum, delivered through a distribution network ICRA counts at over 4,100 dealers and 19,000 retailers.3 Add the regulatory licence scarcity as a cornered-resource-adjacent effect, with the caveats already stated. What Century does not have is process power — nothing in its manufacturing is proprietary in a way competitors cannot replicate — or switching costs, since a dealer can stock a rival brand tomorrow and a carpenter can recommend one. That absence is precisely consistent with MDF margins failing to differentiate from a scaled specialist. Powers that come from brand and distribution transfer imperfectly into a category where the buyer is a factory procurement manager comparing board density and price per cubic metre.
The import picture, corrected
Two data points on imports deserve mention because both are commonly misunderstood. First, Nepal — not China — dominates India's plywood import volumes at roughly 86% of the total, a function of geography, tariff treatment and the sheer economics of moving low-value-density product overland.54 That flow has recently been disrupted by delays in Indian quality certification under India's Quality Control Orders, with Nepali plywood exports reported down 46.8% amid the certification backlog — a de facto non-tariff barrier that helps domestic organised producers while it lasts, though it is an administrative situation rather than settled policy.5556 Second, on MDF anti-dumping duties against Vietnam, Malaysia, Indonesia and Thailand: the status remains contested and unresolved. Nobody should model protection that has not been granted.
Which brings us to the two-sided argument.
X. Bull Case, Bear Case, and What Would Change the Story
The bull case
Why Century wins from here. The core of the bull case is not MDF and it is not the 2031 target. It is that the plywood business is quietly excellent and getting better. A 16.9% segment EBITDA margin in the June 2026 quarter — the highest the company has recorded — achieved alongside 32.4% revenue growth, after a 7% price increase taken in April 2026 that the market absorbed, is a specific and hard-to-fake demonstration of pricing power.2736 Companies without brand strength do not raise price 7% and grow volume simultaneously. Layer onto that a structural shift that still has enormous runway — roughly 70% of the plywood market remains unorganised a decade after GST — plus GST 2.0 compressing the informal price advantage in exactly the categories where Century has been adding capacity, plus a housing and renovation cycle that ICRA expects to support 13–15% consolidated revenue growth in FY27 to ₹6,100–6,200 crore.15163 If MDF margins normalise toward management's 15% target, consolidated profitability re-rates without needing a single additional rupee of revenue, because the revenue is already there at the wrong margin. And the promoter family's roughly 72% unpledged stake means the people making capital allocation decisions bear the consequences.
The bear case
Why the case breaks. The bear argument is not that Century is a bad company. It is that it may be a good company doing an expensive thing.
Start with the possibility that MDF is simply a lower-margin category, permanently, for a challenger. Century's own standalone Hoshiarpur MDF operation earned 15.4% in FY25, which supports the ramp-up thesis — but Hoshiarpur is a mature plant in the North with an established position, and Badvel is competing in the South against Greenpanel's Andhra capacity in a market ICRA describes as having a supply overhang. If the honest steady-state for challenger MDF is 10–12% rather than 15%, then the capacity build is diluting group return on capital rather than expanding it, and consolidated ROCE of 11.5% is the number that tells you so.2
Then the leverage arithmetic. Debt has grown faster than profit for three consecutive years. FY26 profit of ₹268 crore is still below FY23's ₹384 crore, while borrowings are 5.4x higher.2 ICRA's deleveraging path to 1.6–1.7x by March 2028 is a projection, not an observation, and it assumes both the revenue ramp and stable debt — while the board has already approved ₹870 crore of Odisha capex to be funded partly by debt.352 The company has published an intention to invest out of accruals and prepay debt in the same document in which its balance sheet did the opposite.39
Then execution risk, which is the least discussed and best evidenced. This management has a documented pattern of underestimating the cost and duration of its own ramps. The Uttar Pradesh greenfield has already slipped to FY29. The Odisha site had not been selected as of August 2026 despite board approval in May.28 And two international sourcing ventures were fully written off.
Then the timber and chemical input exposure, which is structural rather than cyclical: an Indian panel maker is short tropical hardwood by design and long crude-linked resin costs, with no hedge available for the first and limited hedging for the second. Century hedges its foreign exchange exposure as required, which mitigates the currency component of imported raw material cost but does nothing about the underlying commodity or the policy risk attached to it.3
And then the softest but most persistent bear point: the organised-versus-unorganised share statistic that anchors the long-term bull case has barely moved in eight years. If the informal sector is stickier than consensus assumes — because enforcement is imperfect, because cash still works, because a carpenter buying for a price-sensitive customer does not care about a warranty card — then the entire addressable-market expansion story runs at half the assumed speed, and a mid-fifties trailing multiple is being paid for a slower compounding machine than advertised.
Finally, valuation as a risk transmission mechanism rather than a valuation judgment. A trailing P/E in the mid-fifties embeds an expectation that FY26 and FY27 are the beginning of a normalisation, not a cyclical high.2 A repeat of FY25 — a year in which revenue grew and profit halved — would collide with that expectation. That is not a prediction; it is an observation that the multiple leaves little room for the specific failure mode the company demonstrated as recently as fifteen months before the current fiscal year began.
The activist's questions
The activist's questions. A skeptical investor sitting across from this board would ask four things. Why does a company with a genuinely superior plywood franchise keep deploying incremental capital into categories where it is the challenger rather than the leader, instead of returning it or deepening the moat it already owns? Why does the group structure include a long list of small investment subsidiaries — Adonis Vyaper, Apnapan Viniyog, Ara Suppliers, Arham Sales and several others each carrying ₹160–165 lakh of net assets and near-zero profit — that add consolidation complexity without visible operating purpose?21 Why was the SAP audit trail not enabled for a full financial year, and what is the remediation timetable? And why does the FY25 annual report state in one place that the company has over 4,161 dealers and 19,072 retailers, and in another that it has 19,072 dealers and 25,500-plus retailers, when the same figure cannot be both?5758 That last one is not a scandal, but distribution reach is a KPI investors use to judge the company's single most important asset, and a company that cannot label it consistently in one document has not treated it as a metric that matters.
The three numbers that decide it
The KPIs. Three, and only three, actually decide this story over the next several years.
First: MDF segment EBITDA margin. This is the whole argument in one number. It stood at 7.0% in the June 2026 quarter against plywood's 16.9%. Management targets 15%-plus. If it closes toward the low-to-mid teens through FY27, the MDF bet is validated and the group's return on capital re-rates. If it sits in single digits while capacity keeps arriving, the bet is a margin trap and every future capex announcement should be read as value-destructive until proven otherwise.
Second: net debt to EBITDA through the capex cycle. ICRA's path is 2.6x at March 2026 improving to 2.2–2.3x at March 2027 and 1.6–1.7x at March 2028. This is the cleanest single test of whether management's stated intention to fund growth from accruals is behaviour or aspiration. Deterioration against that path, particularly if accompanied by fresh project debt for Odisha, falsifies the capital-discipline claim directly.
Third: plywood segment EBITDA margin and realisation. The unglamorous one, and arguably the most important, because plywood is where the moat actually is. As long as plywood holds mid-teens margins with volume growth and successful price increases, the franchise is intact and funding the experiment. If plywood margins compress — whether from timber costs, from MDF cannibalising its own lower end, or from organised competitors pushing back — the thing paying for everything else has broken.
Risk radar
Risk radar, sized to materiality. Raw material and timber supply is first, because the mechanism is direct: sovereign export bans compressing gross margin, evidenced twice already and live now in Myanmar. Execution risk on the MDF transformation is second: capital already committed against segment returns that remain unproven. Leverage and refinancing risk is third, with the specific trigger being ICRA's 2.25x DSCR downgrade threshold against 2.8–2.9x projected. Housing and real-estate cycle sensitivity is fourth — a demand elasticity risk rather than a company-specific one, evidenced by FY25's slowdown and FY26's rebound. Everything else — cybersecurity, technology disruption, ESG compliance cost — is real but second-order for a company that presses wood into boards, with the partial exception of formaldehyde emission and air-quality regulation, which ICRA flags as a rising compliance cost that Century may not be able to fully pass through.3
XI. Future Outlook
The next five years turn on a question that is simpler to state than to answer: does a brand-and-distribution advantage built in plywood actually transfer into MDF?
The optimistic case rests on channel logic. A dealer who has sold CenturyPly plywood for fifteen years, who has credit terms and a relationship, is a lower-friction route to market for Century's MDF than a new entrant could ever build. The pessimistic case rests on customer logic. The fastest-growing MDF demand does not come through that dealer at all; it comes from furniture factories buying against specification, where the brand on the board matters less than density, moisture resistance, and price per cubic metre. Those are two different businesses, and Century's advantage is decisive in only one of them.
The bet, in concrete and steel
The capacity additions now in flight — the Tamil Nadu unit operating since June 2025, the Hoshiarpur greenfield plywood plant slated for the third quarter of FY27, the Chennai brownfield expansion, and the Odisha programme stretching to FY32 — are the physical form of a bet that the answer is yes.492652 The honest observation is that adding capacity into a category that ICRA already describes as having a demand-supply mismatch converts share gains from a possibility into a requirement. Century will not simply be riding category growth; it will need to take volume from Greenpanel and others while they are also adding lines. Watch the plywood greenfield ramp closely as an early read: ICRA explicitly flags post-implementation stabilisation risk on the 60,000 CBM unit commencing in FY27, and this is a category Century knows how to run.3 If the ramp is clean there, the execution concern narrows to unfamiliar categories. If it is not, the concern is general.
Optionality, sized correctly
Adjacent optionality deserves a sentence and not a paragraph. The Manish Malhotra designer laminate collaboration, launched in July 2023 across three ranges with a full advertising campaign, was a genuinely creative piece of category marketing — the first fashion-designer tie-up in Indian laminates.59 It also sits inside a laminates business that generated ₹652.94 crore of standalone revenue in FY25, essentially flat against ₹657.63 crore the prior year, with volumes down 6.4% amid a subdued interiors market.60 Interior solutions, restroom turnkey products and designer collaborations are real initiatives and small numbers. They are not a growth pillar and should not be modelled as one.
Which leaves the real question, unresolved and resolvable. Century Plyboards is a company with one demonstrably excellent business, one large and growing business whose returns are unproven, a balance sheet that has been stretched to build the second, and a management team with a good demand record and a poor cost-and-timing record. FY27 and FY28 will produce the evidence: either MDF margins converge toward plywood's and the leverage unwinds on ICRA's projected path, in which case a genuinely diversified panel platform emerges — or they do not, in which case the company is a very good plywood business that spent five years and 5x its debt buying revenue at half the margin.
The reader who tracks three numbers will know which one happened well before the narrative catches up.
XII. Recent News
Results
The June 2026 quarter, reported on 4 August 2026, was the strongest in the company's history on both revenue and profit: consolidated revenue of ₹1,561.38 crore, up 33.52%, and consolidated net profit of ₹83.3 crore, up 57.38%, with standalone profit after tax of ₹94.49 crore, up 39.32%.3627 Operating EBITDA of ₹198 crore was up 55% with margins at 12.7%.36 A 7% plywood price increase taken in April 2026 was absorbed by the market alongside volume growth; a roughly 15% MDF price increase taken in the same window was largely rolled back as wood prices moved, which is a useful live illustration of the difference in pricing power between the two categories.28 Century also launched what it described as India's first Total Cover Assurance Program for its Club Prime plywood, offering ten-year defect coverage — a warranty-led trust play that is a direct descendant of the 1997 borer-proof positioning.27
Policy
GST 2.0 took effect on 22 September 2025, moving plywood, MDF, particle board and laminates from 28% into the 18% standard slab and cutting select input resins and adhesives from 12% to 5%.16 The read-through to FY27 margins is the specific thing to watch in coming quarterly commentary: how much of the input-side benefit Century retains versus competes away.
Capacity and ratings
On the capacity side, the Tamil Nadu unit at Gummidipoondi began operations in June 2025.49 The board approved the Odisha plywood and particle board project of over ₹870 crore on 22 May 2026, though as of the August 2026 call a land parcel had not yet been finalised.5228 The Andhra Pradesh MDF facility was debottlenecked from 700 to 950 CBM per day, and the Hoshiarpur greenfield plywood plant is expected to commence operations in the third quarter of FY27.27 ICRA reaffirmed its [ICRA]AA (Stable) long-term rating and [ICRA]A1+ short-term rating on 30 June 2026, projecting FY27 revenue of ₹6,100–6,200 crore and operating margins of 12.5–13.5%.3
XIII. Links & Resources
Primary investor materials sit on the company's investor information portal, including the annual report archive and quarterly investor presentations.61 The FY25 annual report is the single most useful document for anyone doing original work on this company — the Schedule III consolidation schedule in Note 47 and the related-party disclosures are where the subsidiary-level economics that segment reporting obscures actually become visible.62 The FY24 annual report carries the Myanmar disposal note.17 ICRA's rating rationales provide the most useful independent third-party read on leverage, market share and capex, and are freely available.333 Exchange filings are accessible via the BSE company page for scrip 532548 and the NSE quote page.6364 For competitive benchmarking in MDF, Greenpanel's manufacturing facilities disclosures give the capacity comparison directly.38 Screener.in aggregates the consolidated financial history in a usable form.2 And for the regulatory history, the Supreme Court's December 1996 Godavarman order and the WWF-India account of the case's industrial consequences are both worth reading in full.910
References
-
India Plywood Market Size, Share, Trends, Forecast 2034 — IMARC Group ↩↩
-
Century Panels Limited: Ratings reaffirmed (consolidated view of Century Plyboards (India) Ltd) — ICRA, 2026-06-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Annual Report 2024-25 — Century Plyboards (India) Ltd, corporate identity number and corporate information ↩
-
Century Plyboards chief Sajjan Bhajanka, conferred with Padma Shri, thanks govt for appreciating his work — ANI, 2025-01-26 ↩
-
Annual Report 2024-25 — registered office and Bishnupur resin manufacturing unit, Century Plyboards (India) Ltd ↩
-
Annual Report 2024-25 — Sainik brand product description, Century Plyboards (India) Ltd ↩
-
T.N. Godavarman Thirumulkpad vs Union Of India & Ors, Supreme Court of India, 1996-12-12 ↩↩
-
The Godavarman Story: India's Forests and the Judiciary — WWF-India ↩↩
-
Annual Report 2024-25 — manufacturing facilities listing, Century Plyboards (India) Ltd ↩
-
Annual Report 2024-25 — Management Discussion and Analysis, SWOT: weaknesses, Century Plyboards (India) Ltd ↩↩
-
Equirus Securities Initiating Coverage Note on Century Plyboards — 2017-06-07 ↩↩↩↩↩↩
-
Revised GST rate on Plywood, veneered panels and similar laminated wood (GST Council, 2017-11-10) ↩
-
Annual Report 2024-25 — branding and market structure section, Century Plyboards (India) Ltd ↩↩↩↩
-
Classification Guide for Plywood: HSN Code & GST Rate (56th GST Council, effective 2025-09-22) — Tally Solutions ↩↩↩
-
Annual Report 2023-24 — Note 46, disposal of Centuryply Myanmar Private Limited — NSE archives, 2024-08-30 ↩↩
-
Century Ply develops alternate strategy for Laos ban crisis — Global Wood Markets Info ↩
-
Annual Report 2024-25 — Note 50 to the Consolidated Financial Statements (exceptional item, disposal of Century Ply (Singapore) Pte Ltd and Laos entities) ↩
-
Annual Report 2024-25 — Aggregated Related Party disclosure for the year ended 31 March 2025 ↩
-
Annual Report 2024-25 — Note 47, Additional Information pursuant to Schedule III of the Companies Act, 2013 ↩↩↩↩
-
High Demand in India Intensifies Timber Smuggling From Myanmar — The Diplomat, 2026-03 ↩
-
India's plywood industry at risk due to log supply shortage — Wood Based Panels International ↩
-
Annual Report 2024-25 — MDF business review, Century Plyboards (India) Ltd ↩↩
-
Annual Report 2024-25 — pre- and post-expansion installed capacity disclosures, Century Plyboards (India) Ltd ↩↩
-
Century Plyboards: Q1 FY27 Revenue Jumps 33.5% on Strong Execution — earnings conference call summary, InvestyWise, 2026-08 ↩↩
-
Century Plyboards Q1 FY27 investor presentation summary — InvestyWise, 2026-08 ↩↩↩↩↩↩
-
Century Plyboards (India) Ltd (BOM:532548) Q1 2027 Earnings Call Highlights — GuruFocus via Yahoo Finance, 2026-08 ↩↩↩↩↩↩↩
-
Annual Report 2024-25 — Management Discussion and Analysis, segment performance FY 2024-25 ↩
-
Century Plyboards slide as PAT slumps 60% YoY in Q1 FY25 — Business Standard, 2024-08-05 ↩
-
Century Plyboards slide as PAT slumps 59% YoY in Q2 FY25 — Business Standard, 2024-11-13 ↩
-
Annual Report 2024-25 — Note 30, Finance Cost, Consolidated Financial Statements ↩
-
Century Plyboards (India) Ltd: Ratings reaffirmed; rated amount enhanced — ICRA, 2024-01-12 ↩↩
-
Century Plyboards closes FY26 on a strong note, backed by capacity expansion and operational gains — EquityBulls ↩
-
Century Plyboards India: consolidated net profit rises 72.42% in the September 2025 quarter — Business Standard, 2025-11-13 ↩
-
Century Plyboards Reports Robust Growth in Q1 FY27; Consolidated Net Profit Rises 57.39% YoY — EquityBulls, 2026-08 ↩↩↩↩
-
Greenpanel Inds commissions new MDF plant at Andhra Pradesh — Business Standard, 2025-02-26 ↩
-
Annual Report 2024-25 — "How the Company intends to generate ₹12,000 Crore in revenues by 2031", Century Plyboards (India) Ltd ↩↩
-
Century Plyboards chief Sajjan Bhajanka conferred with Padma Shri — The Tribune, 2025-01-26 ↩
-
Annual Report 2024-25 — Business Responsibility and Sustainability Report, statement of Sri Sanjay Agarwal, CEO & Managing Director ↩
-
Annual Report 2024-25 — Risk Management Committee composition, Century Plyboards (India) Ltd ↩
-
Annual Report 2024-25 — ratio of remuneration of each Director to median employee remuneration, FY 2024-25 ↩
-
Annual Report 2024-25 — Independent Auditor's Report of S.R. Batliboi & Co. LLP, dated 2025-05-29 ↩
-
Annual Report 2024-25 — Auditor's report on audit trail (edit log) under Rule 11(g), SAP application ↩
-
Annual Report 2024-25 — Note 51 to the Consolidated Financial Statements, audit trail disclosure ↩
-
In the matter of Century Plyboards (India) Limited under SEBI (Prohibition of Insider Trading) Regulations, 2015 — SEBI Informal Guidance, May 2025 ↩
-
Annual Report 2023-24 — Note 45, political donations, Century Plyboards (India) Ltd ↩
-
Century Plyboards gains as new Tamil Nadu unit starts operations — Business Standard, 2025-06-27 ↩↩↩
-
India's Century Plyboards plans to expand plywood production capacity by 30% — Global Wood Markets Info, 2024-09 ↩
-
Century Plyboards to invest ₹870 crore in Odisha unit — ScanX ↩
-
Century Plyboards Expansion Into Odisha for Plywood and Particle Board Manufacturing — InvestyWise, 2026-05-22 ↩↩↩↩
-
Century Plyboards Ltd sets revenue target of Rs 12,000 crore by 2031 — Business Standard, 2023-09-27 ↩
-
India Plywood Imports 2024–2025: Price Surge, Volume Drop & Global Supplier Trends — GTAIC ↩
-
Nepal's plywood exports plunge 46.8 percent amid delay in Indian quality certification — Kathmandu Post, 2026-03-08 ↩
-
Plywood and Panel Imports in the Post Quality Control Orders (QCOs) Era — FIPPI ↩
-
Annual Report 2024-25 — distribution network, "over 4,161 dealers and 19,072 retailers" ↩
-
Annual Report 2024-25 — corporate snapshot, dealers and retailers figures ↩
-
Century Laminates ties up with Manish Malhotra to bring fashionable laminates — afaqs!, 2023-07-12 ↩
-
Annual Report 2024-25 — laminates business review, Century Plyboards (India) Ltd ↩
-
Annual Report 2024-25 (full document) — Century Plyboards (India) Ltd ↩
-
BSE company page, scrip 532548 — Century Plyboards (India) Ltd ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube