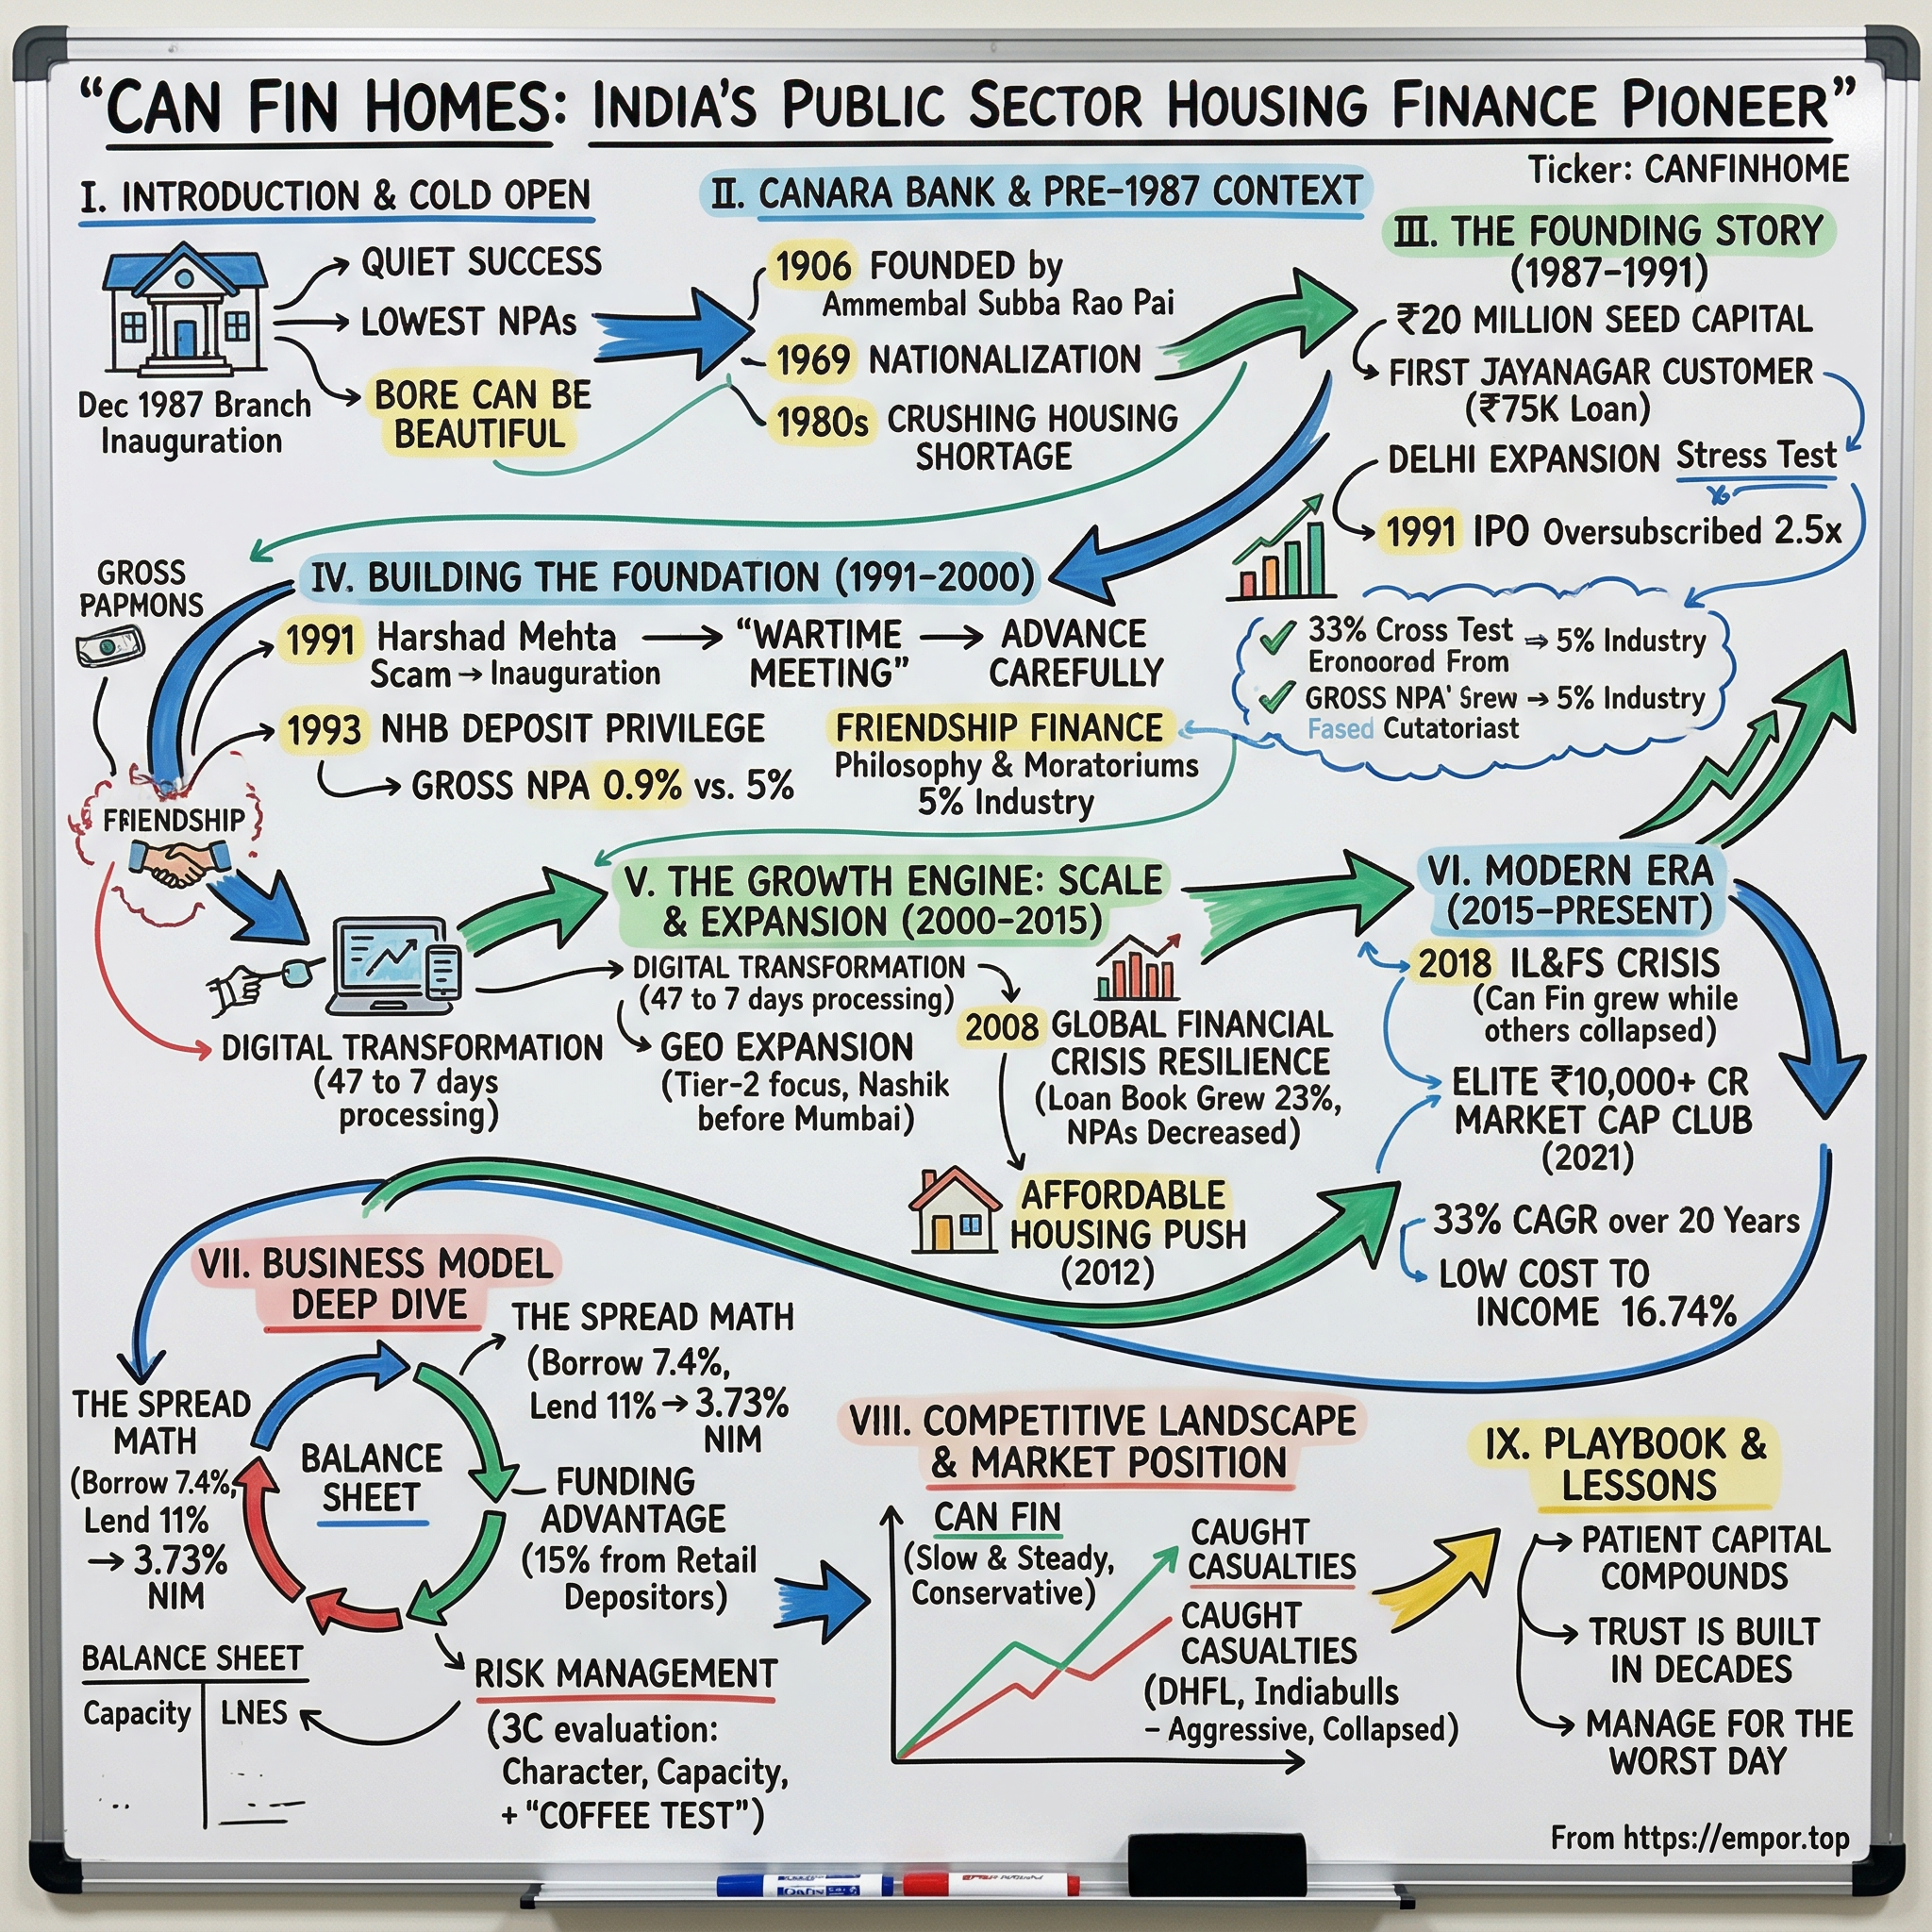
Can Fin Homes: The Salaried-Borrower Housing Financier Canara Bank Can't Quite Let Go Of
I. Cold Open
On the morning of July 8, 2026, five Can Fin Homes branches switched on a new computer system.
That is the whole event. No ribbon cutting, no press release fanfare, no analyst day. Five branches out of two hundred and fifty. Loan applications were keyed in, sanctions issued, disbursements pushed, NACH mandates registered — the ordinary plumbing of a mortgage lender, running for the first time on software the company had been building, testing and deferring for the better part of three years. Management later told analysts the pilot produced "no major issues affecting business."1
For most companies this would be an IT footnote. For Can Fin Homes it was arguably the most consequential operational event of the decade, because this is a company whose entire investment identity rests on the proposition that nothing dramatic ever happens to it. Thirty-nine years of uninterrupted profit. Thirty-nine years of uninterrupted dividends.2 Gross non-performing assets that have not breached one percent through a demonetisation, a shadow-banking collapse, a pandemic and a rate cycle. In a sector littered with the corpses of housing financiers that grew too fast — DHFL most spectacularly — Can Fin Homes has been the one that didn't.
On September 2, 2026, the market valued that record at roughly ₹10,565 crore, with the shares around ₹794 and a trailing price-to-earnings multiple of about 9.4 times.3 For a lender that earned ₹1,085.75 crore in FY26, grew profit 27%, and posted a return on equity above 23%, that is not the multiple of a franchise the market believes in.4 It is the multiple of a franchise the market suspects is about to be competed away.
There is a reason for the suspicion, and it is not the profit line. It is the book. In FY26 Can Fin Homes disbursed ₹10,531 crore, up 23% year on year and fractionally ahead of its own ₹10,500 crore guidance — a genuinely good number after a FY25 in which disbursements grew barely 5%.45 And yet the loan book grew only 10.4%, short of the 11–12% management had guided.6 Money went out the front door faster than ever. It also came back out the side door faster than ever, as existing borrowers refinanced away to banks and larger housing financiers offering cheaper rates. On the Q1 FY27 call in July 2026, management put a number on the squeeze: the rate gap between Can Fin Homes and larger lenders had widened from around 55 basis points to more than 100.1
That is the tension this story is about. Can Fin Homes has spent four decades building a machine optimised for a single job — lending small amounts to salaried Indians who pay it back — and has done that job better than almost anyone. The question for the next decade is whether being very good at that job still confers an advantage when a Bajaj-backed competitor with three times the book, a quarter of the bad loans and unlimited access to capital is chasing the same borrower.7
Sitting over all of it is the strangest fact in the file. Canara Bank, the public-sector bank that founded this company in 1987, still owns 29.99% — one basis point below the threshold that would trigger a mandatory open offer.8 It has tried to sell that stake, or part of it, in 2016, 2017, 2018, 2019 and 2020. It sold a slice once. It walked away the other times, each time citing price.91011 Today the credit rating agencies cite Canara Bank's "stated position that CFHL is a core and strategic investment" as a pillar of the company's AAA rating — while simultaneously listing a stake sale as a downgrade trigger.12
A company whose cheapest funding depends on a parent that has repeatedly tried to leave. That is where this story begins.
Here is the route: why a nationalised bank needed a mortgage subsidiary at all; how the model was built between 1987 and 2015; the three episodes since 2015 that actually moved the stock — the promoter-dilution saga, the funding crisis that separated the survivors from the dead, and the growth stall and technology rebuild of 2024 to 2026; then the economics, the competitive map, the capital allocation record, and finally an honest accounting of what could break the case.
 Subscribe on LinkedIn
II. Origins, Compressed: Why a Bank Needed a Subsidiary
Picture Indian banking in the mid-1980s. Nationalised since 1969, run to a social mandate, staffed by officers on transferable service, with lending priorities set as much in Delhi as in any credit committee. A branch manager in a district town had a queue of borrowers and a rulebook that told him what agriculture, small industry and exports deserved. What that rulebook did not tell him was how to underwrite a twenty-year loan against a half-built house, or how to price the risk that a schoolteacher in Hubli might lose her job in year nine.
Mortgages are a specialist craft. They require long-dated funding, legal capacity to enforce against property, valuation discipline, and — critically — the patience to make money on a spread of two or three percentage points across a decade. A nationalised bank's branch network was superb at gathering deposits and terrible at any of that. The mismatch was not ideological; it was operational. India had a housing shortage measured in tens of millions of units and a banking system structurally unsuited to financing it.
The policy answer was the dedicated housing finance company: a non-bank lender that did nothing but mortgages, funded itself in wholesale markets and through a specialised refinancing window, and could be regulated as its own species. The National Housing Bank was established in 1988 as the apex regulator and refinancier for exactly this population of lenders — an institution whose whole purpose was to lend cheaply, long, to companies that lent long to homebuyers. That refinance window remains, four decades later, a live line in Can Fin Homes' funding stack, and one it draws on at rates that no commercial lender would offer.
Can Fin Homes arrived a year ahead of its own regulator. It was incorporated in 1987 — the International Year of Shelter for the Homeless, a coincidence the company still puts in its corporate history — as the first housing finance company floated by any nationalised bank in India.2 The founder chairman was B. Ratnakar, a Canara Bank man. The founding shareholder register was a snapshot of who mattered in Indian housing finance at the time: Canara Bank itself, Can Bank Financial Services, HDFC — then the private-sector pioneer of the industry, later its consolidator — and the Unit Trust of India.2
Keep the founding in proportion. The heritage is not the story; the structure is. Two things were set in 1987 that still determine how this company earns money in 2026.
The first is the funding architecture. Can Fin Homes was born with a bank's name on the door and a bank's balance sheet standing behind the brand without ever being contractually obliged to support it. Nearly forty years later, ICRA's rating rationale spells out exactly what that is worth: "the shared brand name helps the company secure funds at competitive rates from other lenders."12 Not a guarantee. Not a capital commitment. A brand, board seats, and a credit committee somewhere in Bengaluru that thinks of Can Fin Homes as family.
The second is the governance structure, which is the mirror image of the first. Canara Bank's association is not passive. As of March 2025, the company's nine-member board included three Canara Bank nominee directors, and two members of the senior management team — including the Deputy Managing Director — were on deputation from the bank.12 The bank conducts quarterly monitoring visits. Can Fin Homes is not a subsidiary in any accounting sense; it is an associate, consolidated nowhere, controlled by nobody, and supervised by a shareholder holding just under 30%.
That is an unusual arrangement, and it has an unusual consequence: the company's cost of capital is partly a function of a relationship that neither party has ever formalised or fully exited. Everything that follows in this story — the funding advantage, the governance overhang, the periodic stock-price shocks whenever Canara Bank's intentions change — descends from a corporate structure designed in 1987 for reasons that had nothing to do with any of it.
The next twenty-eight years were spent building an actual lending business inside that structure.
III. Building the Model: 1987-2015
The first branch opened in Jayanagar, Bengaluru, on December 26, 1987 — a Saturday, in a residential neighbourhood of retired government servants and young families, roughly the demographic the company would spend the next four decades lending to.2 Within a year it had opened in Delhi, its first office outside the south.2 In 1989 the shares were listed, and the company began the run of uninterrupted profits and dividends it has been quietly compounding ever since.2
Then, for a very long time, almost nothing happened quickly.
The loan book crossed ₹100 crore in 1991.2 It took until 2012 — the company's twenty-fifth year — for annual disbursements to cross ₹1,000 crore and for the fiftieth branch to open.2 Read that again: a quarter of a century to fifty branches. During the same window, HDFC built the dominant mortgage franchise in the country and LIC Housing Finance built the largest book. Can Fin Homes built neither. It built a habit.
The habit was a deliberate narrowing. Rather than chase book size, the company aimed at a specific and rather unglamorous customer: the salaried or professional borrower of middle income, taking a small-ticket loan against a modest property, with an instalment-to-income ratio kept below 65%.12 The average housing loan today is around ₹26 lakh and the average non-housing loan around ₹14 lakh, with an effective tenure of seven to eight years against a contractual twelve to twenty.12[^13] These are not the loans that make league tables. They are the loans that get repaid.
Why does that borrower behave so well? The mechanics are simple and worth spelling out, because they are the entire engine. A salaried borrower has an income stream that a lender can verify from documents and monitor through a bank account. The instalment is deducted automatically. The house is usually the family's only significant asset and their actual residence, which means default is not a financial decision but a catastrophe. And because the ticket is small relative to household income, the borrower can absorb a bad year without breaking. Stack a few hundred thousand of those together and the default rate becomes a boringly stable number rather than a distribution with a fat tail.
The evidence bears this out with unusual precision. Management disclosed on the Q3 FY26 call that gross NPAs in its salaried book run at roughly 0.5–0.6%, while the self-employed book runs at 1.5–1.7%.[^13] Same company, same underwriting culture, same collections team — three times the loss rate purely from borrower type. Can Fin Homes' celebrated asset quality is, to a large extent, a mix decision that was made in the late 1980s and never revisited. That is worth keeping in mind for later, because management has now decided to revisit it.
Two regulatory permissions were secured along the way, and one of them has been widely misread. Can Fin Homes registered with the National Housing Bank and became one of the small number of housing finance companies licensed to accept deposits from the public — the company still describes itself as among "very few HFCs permitted by NHB for taking deposits."2 This is routinely cited, including by the company, as a funding-cost advantage. It is not, and the numbers are not close. As of March 2025, public deposits accounted for 1% of Can Fin Homes' total funding.12 At the end of FY26, deposit balances stood at ₹220 crore against a loan book of ₹42,209 crore.4 The license is real. The advantage is rounding error. This point recurs later, because it is the clearest example in the file of a moat that exists in the narrative and not in the balance sheet.
The permission that actually mattered was the credit rating. Can Fin Homes received its AAA rating in 2014 — the same year it opened its hundredth branch and crossed ₹100 crore of operating profit.2 From that point the company could borrow from banks, issue commercial paper and place non-convertible debentures at rates available only to the top tier of Indian credits. Everything about its spread economics flows from that rating, and the rating flows partly from the Canara Bank association.
The pace picked up in the 2010s. The core banking migration in 2013 and the loan book crossing ₹10,000 crore in the same year.2 Net profit past ₹100 crore in 2015. By 2017, the company's thirtieth year, the book was above ₹13,000 crore and the customer base past 100,000.2 The pan-India footprint that the company describes today — 250 branches across more than 100 cities in 21 states and union territories — was largely assembled in this period.2
One characterisation from the conventional retelling of this history does not survive contact with the disclosures, and it is worth correcting now rather than later. Can Fin Homes is frequently described as having built its book through its own branches rather than through the direct selling agents — commission-paid brokers — that drove volume at more aggressive lenders. That is not what the company reports. In the December 2025 quarter, DSA-sourced business accounted for 79% of origination, and management set a target of bringing that down to 60% by FY28 by scaling an in-house sales force.[^13] Nearly four-fifths of a supposedly branch-led lender's new business came from brokers. The underwriting discipline is real and the numbers prove it. The origination model is not the one the story implies. What Can Fin Homes actually built was a credit filter, not a distribution network — and a credit filter is a much narrower thing to own.
That distinction sat dormant for years. Then, starting around 2015, a series of shocks arrived that tested which parts of the model were structural and which were merely habit.
IV. Two Decades That Actually Moved the Stock: 2015-2026
A. The promoter who kept packing his bags
In December 2016, Canara Bank told the market it planned to dilute its stake in Can Fin Homes to 30%.13 In February 2017, the stock rose on the news that the promoter intended to sell.14 Consider how strange that is. In most listed companies, a founding shareholder heading for the exit is a negative signal. Here, the market read it as a liberation — a well-run mortgage lender potentially escaping public-sector ownership into the hands of a buyer who might run it harder.
The first tranche went through in March 2017. Canara Bank sold 13.45% of Can Fin Homes to Caladium Investment Pte Ltd, a Singapore vehicle affiliated with the sovereign fund GIC, for approximately ₹754 crore at ₹2,105 per share.9 For Canara Bank, which needed capital, this was a straightforward monetisation of a non-core asset. Read the transaction for what it was rather than what it was framed as: a bank selling a piece of a business it had built, at a price it liked, because it had a hole in its own balance sheet.
Then the pattern set in. In March 2018, Canara Bank called off the divestment of its remaining stake, saying the price quoted was below expectations.10 The stock fell hard. In September 2019, the bank was back, inviting bids for 3,99,30,365 shares — the entire 29.99%.11 In January 2020, it called the process off again.11 Canara Bank's own shares slipped on the news.
Four attempts, one completed sale, and a promoter stake that has sat at 29.99% ever since — reaffirmed as recently as the FY26 disclosures, with no encumbrance.8 The remainder of the register today is institutionally heavy: roughly 24.5% domestic institutions, 12–13% foreign institutions, and a notable non-institutional holder, Chhatisgarh Investments, at about 6.3%.15
What does the pattern actually tell an investor? Three things, and only one of them is comforting.
The uncomfortable reading is that Canara Bank has never resolved whether this asset is core or for sale, and its behaviour and its statements point in opposite directions. ICRA's July 2025 rationale records that Canara Bank "has a stated position that CFHL is a core and strategic investment for it."12 Four sale processes in five years is not the behaviour of an owner who believes that. The gap between the stated position and the revealed preference is the governance fact here, and no amount of rating-agency language closes it.
The second reading is that this is a live, quantified risk to the cost of funds. ICRA lists its downgrade triggers explicitly: deterioration in asset quality or gearing, "a change in the bank's support philosophy towards the company or a stake sale."12 In plain terms, the AAA rating is partly on loan from Canara Bank, and Canara Bank has spent a decade trying to hand back the keys. Should a sale complete to a buyer without a comparable credit profile, the rating premise changes — and since the rating is what makes the borrowing cheap, and the borrowing cost is what makes the spread, the chain runs directly to the P&L.
The comforting reading, such as it is, is that price discipline has been maintained. Canara Bank has walked away from bids twice rather than accept a low price. Whatever else that indicates, it does not indicate distress selling.
For minority shareholders the practical implication is unglamorous: there is a permanent, unhedgeable overhang of roughly 30% of the equity, controlled by an owner with a demonstrated willingness to start a sale process and a demonstrated willingness to abandon one, on a timetable no outside investor can see. That is not a reason to avoid the stock. It is a reason not to model the current structure as permanent.
B. 2018-19: the year the sector found out who was solvent
In September 2018, Infrastructure Leasing & Financial Services defaulted. The Indian credit market did what credit markets do when a AAA-rated institution turns out not to be one: it stopped lending to anything that looked similar. Mutual funds that had been rolling non-bank commercial paper simply stopped rolling it. Overnight, a whole class of lenders discovered that their business model had a hidden assumption — that short-term wholesale funding would always be available to finance long-term assets.
Housing finance companies were at the centre of it, and the most instructive casualty was the one that looked, superficially, most like Can Fin Homes. Dewan Housing Finance — DHFL — was also a small-ticket housing lender, also serving middle-income India, also with a long profitable history. It funded itself aggressively in wholesale markets, grew its book far faster, and drifted from retail mortgages into project lending. When the funding window shut, the asset-liability mismatch became a solvency question, and DHFL collapsed into what became one of India's largest financial frauds and eventually a resolution under the bankruptcy code.
Can Fin Homes came through with its rating intact and its book intact. The instinct is to attribute this to the deposit license and the bank parentage. Only half of that is right, and the half that is right is worth being precise about.
The deposit license contributed essentially nothing — deposits were then, as now, about 1% of funding.12 What actually protected the company was a combination of asset choice and access. On the asset side, a book of small salaried mortgages does not develop credit problems in a liquidity crisis; it simply keeps paying. On the funding side, the AAA rating and the Canara Bank name kept the bank lines and the National Housing Bank refinance window open at a moment when both were being rationed. The National Housing Bank does not lend against sentiment; it lends against eligible housing assets, and Can Fin Homes' entire book was eligible.
There is also a structural weakness the crisis exposed and that has never fully gone away. Can Fin Homes runs, and has always run, negative cumulative asset-liability mismatches in the under-one-year buckets, because home loans run twelve to twenty years and the borrowings that fund them do not.12 As of March 2025 the company held ₹2,302 crore of on-book liquidity and ₹3,770 crore of undrawn sanctions against ₹10,317 crore of debt maturing over the following six months.12 That is a manageable position with committed lines, and an uncomfortable one without them. Every housing financier lives with this. It is why the rating matters so much, and why "we survived 2018" is a statement about access to credit, not about being self-funded.
Gearing tells the same story from a different angle. ICRA flags high leverage as an explicit credit challenge: 6.9 times as of March 2025, down from 8.0 in FY23 and 10.5 back in March 2018, but still "higher than most peers."12 The deleveraging is real and the direction is right. The level is not a strength.
The honest verdict on the crisis period: it validated the asset side of the model conclusively, and it validated the funding side conditionally — conditional on a rating that rests partly on a shareholder relationship the shareholder keeps trying to end.
C. The alumni problem
In September 2022, Girish Kousgi resigned as MD and CEO of Can Fin Homes, citing personal reasons.16 He surfaced shortly afterwards as MD and CEO of PNB Housing Finance — a larger, listed, directly competing housing financier.17 He then left that role too, stepping down effective October 28, 2025, and in October 2025 was appointed MD and CEO of IIFL Home Finance.18[^20]
Kousgi is a useful character precisely because he is a mobile one. His career reads as a tour of Indian retail lending — ICICI Bank, HDFC, IDFC, Tata Capital — before Can Fin Homes, and two further housing financiers after.17 That trajectory tells you something uncomfortable about the "unique culture" claim that gets attached to Can Fin Homes: the skills that produce a clean mortgage book are portable, and the market prices them accordingly. If Can Fin Homes' advantage were genuinely cultural, an executive could not simply carry it down the road. That he moved twice more suggests the industry treats this expertise as a hireable commodity, not a proprietary system.
His successor is the counter-example. Suresh S. Iyer took over as MD and CEO in March 2023 — an internal, long-tenured executive rather than a lateral hire — and was reappointed for a further two years effective March 18, 2026.19 His compensation is a fact worth stating plainly rather than editorialising around: total remuneration of approximately ₹2.2 crore, entirely cash, with no ESOP component and effectively no personal shareholding in the company.20
This is not a scandal; it is a structure. Public-sector-linked compensation norms in India do not accommodate equity grants of the sort that align a chief executive's net worth with minority shareholders'. But the consequence is real and should be named. At Can Fin Homes, the alignment between management and shareholders rests entirely on process, board oversight and professional pride — not on ownership. When management chooses between defending spread and defending growth, or between a cautious technology rollout and an aggressive one, there is no personal balance-sheet consequence pulling in either direction. Investors who value skin in the game should price that; investors who believe equity compensation encourages short-termism may not mind. Either way, it is not a detail.
And there is one episode under this management team that tests the "nothing dramatic ever happens" premise directly.
On July 25, 2023 — four months into Iyer's tenure — Can Fin Homes disclosed to the exchanges that employees at its Ambala branch had committed a fraud estimated at ₹38.53 crore.21 The mechanism was mundane and therefore damning: employees misused cheque-signing authority to transfer funds to personal bank accounts, over a period of time, before detection on July 24, 2023.22 Three individuals were named, an FIR was lodged, and the company approached eleven banks to trace the funds.22 The shares fell around 8%.23 Can Fin Homes took the ₹38.53 crore as a one-time hit to profitability and stated that assets and asset quality were unaffected, and that verification indicated the incident was isolated to that branch.2123
Set the amount aside — against FY24 profit of ₹751 crore it was a bad quarter, not a solvency event.12 The signal is what matters. A company whose entire equity story is process discipline discovered that a single branch could move ₹38.53 crore out of the building over an extended period without a control catching it. ICRA's subsequent rationale records the remediation in detail: a centralised disbursement and reconciliation system, quarterly cluster-level risk management, and maker-checker document verification at head office before disbursement requests go to banks.12 The agency's judgement was that these "have strengthened its fraud control systems."12
That is the right way to weigh it. The failure was real, it was internal, and it happened recently. The remediation was specific, verifiable and endorsed by a third party, and there has been no repeat disclosed in the three years since. The claim "Can Fin Homes has excellent operational controls" does not survive intact; the narrower claim "Can Fin Homes had a serious control gap in cash movement, fixed it centrally, and has not had a comparable incident since" does. Notably, the remediation — centralisation, automation, removal of branch-level discretion — is the same direction of travel as the technology programme that follows. The fraud may well have been the argument that got the IT budget approved.
D. The stall, the rebuild, and the competitor that arrived in between
In FY25, Can Fin Homes disbursed ₹8,568 crore against ₹8,178 crore the prior year — growth of about 5%.5 Management had been pointing at high-teens growth. This was not a rounding difference; it was roughly a quarter of the intended pace.
The received explanation is that the growth stall was caused by the technology transformation. The evidence does not support that, and getting the causation right matters for judging what FY26's recovery actually proved.
Management's own account, given in May 2025, attributed the FY25 shortfall to two specific geographies: Karnataka and Telangana. In Karnataka, the company's home market, business was disrupted by delays in the registration of sale transaction documents — the state's shift to the digital e-Khata property record system, which stalled property registrations and therefore mortgage disbursements across the market.5 Telangana was separately weak, running roughly 33% below the prior year in the first quarter of FY26.6 These were external, regional and transient. The IT programme was underway, but the core loan systems had not yet been switched on anywhere.
That distinction matters because it changes what FY26 tells you. FY26 was not a company grinding through a technology migration and growing anyway. It was a company recovering from a state-level property-registration bottleneck while the technology migration kept being pushed to the right.
The recovery itself was genuine. Q3 FY26 disbursements hit ₹2,727 crore, up 45% year on year — flattered by the weak e-Khata-affected base, but a record in absolute terms.[^13] Q4 brought ₹3,245 crore, an all-time high, taking the full year to ₹10,531 crore.6 Net interest margin improved through the year to 4.14% in Q3 as borrowing costs fell faster than lending rates, with spreads widening from 2.55% in Q1 FY26 to 2.93% in Q3.[^13] Profit for FY26 reached ₹1,085.75 crore, up 27%; stripping one-time items, management put the underlying growth at 20%.46 Asset quality improved rather than deteriorated: gross NPAs of 0.85% at year end, provision coverage up from 49% to 56%, and a fifth consecutive quarter of falling absolute delinquencies.6
And yet the loan book grew 10.4%, below the 11–12% guided.6
This is the single most important number in the FY26 file, and it deserves to be understood mechanically rather than skimmed. A mortgage book is a bathtub. Disbursements are the tap; scheduled amortisation, prepayments and balance-transfer refinancing are the drain. Can Fin Homes opened the tap 23% wider in FY26 and the water level rose only 10%, because the drain widened too. Management had budgeted about ₹6,000 crore of rundown and got roughly ₹6,600 crore.6 By Q1 FY27 the quarterly rundown had reached ₹1,857 crore, against a historical norm management put at ₹1,350–1,400 crore.1[^13]
Where is the water going? To competitors. Balance-transfer-outs — customers refinancing their loan to another lender — ran at roughly ₹400–408 crore a quarter.1 Management's explanation on the Q3 FY26 call was partly technical: about 54% of the book was on annual interest-rate resets, meaning those borrowers waited up to a year for a rate cut that banks passed on immediately, and 80% of prepayments came from that cohort.[^13] The company responded by migrating customers to quarterly resets — the annual-reset share fell from 71% at the start of FY26 to below 15% by year end, with about 85% of customers on quarterly terms.6[^13] That is a real, competent operational fix to a real problem.
But the underlying cause is not a reset calendar. On the Q1 FY27 call, management was explicit that the rate differential against larger players had gone from about 55 basis points to over 100, and that customer retention had become "challenging."1 Their proposed remedies — trying to convert loan customers into deposit customers, offering solutions to reduce prepayments — read as tactical rather than structural. A hundred basis points on a ₹26 lakh loan is real money to a salaried borrower, and no reset mechanism makes that gap disappear.
Meanwhile, the technology programme kept slipping. As of the Q3 FY26 call in January 2026, the peripheral modules were live — HRMS, document management, Aadhaar data vault — with the deposit module due that month, but the two systems that actually matter, the Loan Origination System and Loan Management System, had been deferred to Q1 FY27.[^13] Management guided that the switchover would cause three to four days of downtime, one to two weeks of stabilisation, and a one-time business impact of ₹250–300 crore in the transition quarter.[^13] IBM was engaged as systems integrator, with PwC and KPMG on consulting and implementation, and incremental IT cost of ₹40 crore was flagged for FY27, pushing the cost-to-income ratio toward 19–19.5%.[^13]
Then Q1 FY27 arrived and the LOS/LMS had not gone live across the network. What went live on July 8, 2026 was a five-branch pilot; full rollout across all 250 branches was targeted for completion before the Q2 results.1 That is a second deferral of the most consequential piece of the programme.
To be fair to management: the pilot worked, they said so specifically and in operational detail, and Q1 FY27 was a strong quarter regardless — disbursements of ₹2,609 crore against a ₹2,500 crore target, up 29%; profit of ₹268 crore, up 20%; NIM of 3.81% against 3.75% guided; gross NPAs down to 0.87% from 0.98%.124 Cost-to-income rose to 19.52% from 18.33%, exactly as flagged.24
The calibrated conclusion: the claim that the FY25 stall was a transformation-related air pocket is wrong on causation but roughly right on consequence — FY25 was a geography problem, not a technology problem, and the company grew through it. The claim that execution risk on the technology programme is retired is clearly false. The system that touches every loan the company writes has slipped twice, has a guided ₹250–300 crore one-quarter revenue cost still ahead of it, and had touched five branches out of 250 as of the last disclosure. The Q2 FY27 result, due in October 2026, is the first real test.
And the timing is unfortunate, because while Can Fin Homes was rebuilding its plumbing, the competitive landscape changed shape.
On September 9, 2024, Bajaj Housing Finance opened the largest Indian IPO of that year: ₹6,560 crore at ₹66–70 a share.25 It was subscribed 63.6 times.25 It listed on September 16 at ₹150 against an issue price of ₹70 — a 114% first-day gain.26 A housing financier founded in 2008, granted its National Housing Bank registration in 2015 and originating mortgages only from FY18, arrived on the public market with a valuation and a capital base that let it price aggressively for as long as it wanted.
By FY26 the gap was structural rather than notional. Bajaj Housing Finance ended the year with assets under management of ₹1,40,706 crore, up 23%, and profit of ₹2,560 crore, up 18%.7 Gross NPAs were 27 basis points; net NPAs 11.7 Against Can Fin Homes' ₹42,209 crore book and 85 basis points of gross NPAs, that is roughly three and a third times the scale with roughly a third of the delinquency.47
This is the disconfirming evidence that the "best-in-class asset quality" claim has to survive, and it does not survive in its strongest form. Can Fin Homes has excellent asset quality relative to Aavas Financiers, which closed FY26 at ₹23,450 crore of AUM with 1.05% gross NPAs, and relative to Home First Finance at ₹15,878 crore and 1.8%.2728 It does not have the best asset quality among housing financiers of comparable or greater scale. A better-capitalised competitor is currently demonstrating that you can grow a mortgage book at 23% a year and keep credit costs lower than Can Fin Homes' — which undermines the implicit trade-off at the heart of the Can Fin story, that clean books require slow growth.
That is the state of play going into the economics.
V. The Business Model: How a Housing Financier Actually Makes Money
Strip away the branch network, the brand and the four decades, and Can Fin Homes is an arbitrage machine with a credit filter bolted to the front.
The arbitrage is this. In the June 2026 quarter, the company's borrowings cost 6.98% and its loan portfolio yielded 9.81%.24 The 2.83 percentage points in between is the spread — the raw material of everything. Layer on the fact that a chunk of the book is funded by shareholders' equity rather than debt, and the spread becomes a net interest margin of 3.81%.24 Multiply that margin by a ₹42,961 crore book, subtract operating costs and credit losses, tax the remainder, and you have ₹268 crore of quarterly profit.24 That is the whole business.
Which means there are exactly four levers, and it is worth understanding each one on its own terms, because they behave very differently.
Lever one: the cost of funds. As of the June 2026 quarter, bank borrowings made up 62% of the funding stack, National Housing Bank refinance 15%, non-convertible debentures 14%, and commercial paper 8%.24 Deposits — the license the company has advertised for four decades — were the remainder, around 1%.12 The mix has shifted meaningfully over eighteen months: bank borrowings rose from 53% while NCDs fell from 22%.24
That shift was a deliberate rate-cycle bet, and it worked. Roughly 80% of the bank borrowings are linked to the repo rate, which means when the Reserve Bank cuts, Can Fin Homes' funding cost falls almost immediately — management disclosed that about 65–70% of liabilities reprice within a month.[^13] Bonds, by contrast, are fixed until they mature. In a falling-rate environment, floating bank debt is exactly what you want, and the company moved toward it. Incremental bank borrowing was available at around 6.8–6.9%, and National Housing Bank refinance at a blended 6.3%.[^13]
Notice what that last number means. The refinance window prices roughly 60 basis points inside the company's best commercial alternative. That is the genuine, license-gated funding advantage — not deposits. It is available because Can Fin Homes' book is almost entirely eligible housing finance, which is precisely what the National Housing Bank exists to refinance. It is also capped: the company drew a ₹1,000 crore sanction in the March 2026 quarter, meaningful but not transformative against ₹36,915 crore of total borrowings.[^13]
The flip side of the floating-rate bet is that it reverses. In a rising-rate cycle, 65–70% of liabilities repricing within a month becomes an immediate margin squeeze, and the company's ability to pass it on depends on how quickly it can reset borrower rates without triggering the balance-transfer exodus already running at ₹400 crore a quarter. Management is currently enjoying the good half of that trade.
Lever two: the yield on assets, which is really a mix decision. Here is where the strategy is changing, and where the historical record cuts against the current plan.
The company's disclosed portfolio split depends on which definition you use — a genuine disclosure quirk worth flagging. Can Fin Homes' own FY26 results describe housing loans as 72% of the book and non-housing, including commercial real estate, as 28%.4 ICRA, using a narrower definition, put housing at 76% as of March 2025, or 86% including commercial real estate residential loans, with non-housing at 24%.12 The company's Q1 FY27 investor deck reported 71% housing and 29% non-housing.24 Brokerage coverage using a third convention reported roughly 84% housing and 16% non-housing.[^13] None of these are wrong; they are different perimeters around top-up loans, staff loans, loans against property and builder exposure. An investor tracking "non-housing mix" as a KPI needs to pick one definition and stay with it, because the company's own materials do not.
Whatever the perimeter, the direction is unambiguous: non-housing is going up, and so is the self-employed share. Management guided to lifting non-housing from 16% toward 20% and the salaried-to-self-employed mix from 68:32 toward 65:35 by FY28.[^13] In Q1 FY27, self-employed disbursements grew 44% against 21% for salaried, and non-housing grew 32% against 28% for housing.1 The mix shift is happening faster than the guidance implies.
The rationale is sound: those loans carry higher yields, and in a market where large lenders are undercutting Can Fin Homes by 100 basis points on prime salaried mortgages, moving toward segments where the competition is thinner is a rational response. But it must be stated alongside the company's own disclosure that self-employed gross NPAs run 1.5–1.7% versus 0.5–0.6% for salaried.[^13] Can Fin Homes' celebrated sub-1% gross NPA is an average over a mix that is being deliberately shifted toward the worse half. Management has committed to keeping gross NPAs below 1% through the transition.[^13] That is the promise to hold them to. Anyone who models the historical loss rate forward without adjusting for the mix shift is extrapolating an input that management has told you it is changing.
Lever three: operating costs. This is the cleanest genuine advantage in the business and the least discussed. Can Fin Homes ran a cost-to-income ratio of 18.53% in Q3 FY26, rising to 19.52% in Q1 FY27 as technology costs landed.[^13]24 ICRA measured operating expenses at 0.6% of average managed assets in FY25.12 For context, a diversified non-bank lender doing consumer or small-business credit typically runs cost-to-income in the 30s or 40s. Can Fin Homes operates 249 to 250 branches, mostly small, mostly staffed thinly.424
But recognise what produces that number, because it is not purely virtue. A cost base that lean is partly the arithmetic consequence of outsourcing origination to DSAs — brokers whose commission is an acquisition cost embedded in the loan rather than a salaried headcount. It is also the consequence of not building the digital sourcing, analytics and customer-relationship infrastructure that competitors have. The technology programme now underway is, in a sense, the company paying deferred maintenance. Management has guided cost-to-income to 19–19.5% for FY27 and a return to 18% within three years.[^13]1 That is the trajectory to watch: if the ratio stabilises above 19% after the transition costs roll off, the lean-cost advantage was partly an underinvestment that has now been corrected at permanent expense.
Lever four: credit costs, and this one is barely a lever at all. FY26 credit cost was approximately 10 basis points of assets; management guided 15 basis points for FY27 as a conservative estimate, and then in July 2026 revised that back down to 10.61 Total provisions carried at March 2026 were ₹499 crore, including a ₹59 crore management overlay and ₹40 crore against restructured accounts.4 Provision coverage on gross NPAs reached 56%.6
Ten basis points is an almost invisible number. It means the credit filter is working. It also means there is no upside left in this lever — credit costs cannot go meaningfully lower, so every future improvement in returns must come from spread, mix, scale or cost. And there is one item ICRA flagged that deserves attention: slippages from the restructured book, 1.3% of the portfolio as of March 2025, "continue to be relatively higher than the rest of the book."12 Small, contained, disclosed — but it is the one pocket where the loss rate does not behave.
Two remaining structural facts complete the picture. Capital adequacy stood at 25.1% as of March 2025, comfortably above requirement, which means the company can fund several years of book growth from retained earnings without returning to the equity market.12 And gearing at 6.9 times, which ICRA explicitly names as a credit challenge and expects to stay capped below 8.0.12 Those two facts point in opposite directions and are both true: well capitalised against regulatory minimums, more levered than peers on an equity-to-assets basis.
Put it together and the honest description of Can Fin Homes' economics is narrower than the marketing version. There is no deposit-funding moat. There is a modest, capped refinance advantage from the National Housing Bank, a meaningful rating-driven borrowing advantage that is partly borrowed from Canara Bank, a genuine and durable credit-selection capability, and a lean cost base that is partly a strength and partly an artefact of underinvestment now being remedied. That is a good business. Whether it is a defensible one depends on who else wants the customer.
VI. Competitive Landscape & Industry Structure
Ask management who they compete with and the answer is instructive for what it excludes. On the Q1 FY27 call in July 2026, the named competitors were LIC Housing Finance and Bajaj Housing Finance — not banks.1
That is a slightly odd answer for a lender whose core customer is a prime salaried borrower, since State Bank of India and HDFC Bank price mortgages more cheaply than any housing finance company can. But it is a revealing one. The banks are not competing for Can Fin Homes' new customer so much as harvesting its existing one: the balance-transfer flow that widened the drain in FY26. Management's own framing of the retention problem — that the rate differential against larger players moved from 55 to over 100 basis points — describes a refinancing threat, not an origination threat.1 The banks are not going to build branches in tier-three towns to chase a ₹26 lakh loan. They will happily take that loan off Can Fin Homes' books in year four when the borrower has a payment record and walks into a branch.
Run the industry through Porter's five forces and the picture sharpens.
Rivalry is the dominant force, and it is intensifying. A mortgage is the most commoditised product in retail finance. There is no brand loyalty worth measuring, no switching cost beyond paperwork and a modest fee, and the product is identical across providers apart from price and speed. The only two things a lender can compete on are rate and turnaround time — which is precisely why Can Fin Homes is spending ₹40 crore of FY27 operating cost on a loan origination system whose principal benefit is a shorter turnaround, with management projecting a 20% productivity improvement.[^13]
Supplier power is the cost of funds, and the supplier is the market. Can Fin Homes has no negotiating leverage over the repo rate, over what banks charge it, or over how much National Housing Bank refinance is available. It manages the exposure — floating versus fixed, tenure, timing — but it does not set the price. This is what makes the AAA rating so valuable and its dependence on the Canara Bank relationship so uncomfortable.
Buyer power at the individual level is negligible and at the aggregate level is total. No single borrower can negotiate. But the aggregate borrower base has demonstrated, at ₹400 crore a quarter, exactly how quickly it will leave for a better rate. Buyer power in mortgages does not manifest as negotiation; it manifests as prepayment.
Threat of substitutes is genuinely low. There is no alternative to mortgage debt for an Indian household buying a home. This is the one force working in the industry's favour, and it is why the sector grows with GDP and urbanisation regardless of who wins.
Threat of new entrants is where the last two years happened. For most of Can Fin Homes' life, entry barriers looked real: a National Housing Bank license, a credit rating, a distribution footprint, an underwriting track record. Bajaj Housing Finance demonstrated that a well-capitalised group could compress all of that into roughly a decade — registered in 2015, originating from FY18, and by FY26 running a book more than three times Can Fin Homes' with materially lower delinquency.725 The barrier was never the license. It was capital and patience, and a listed Bajaj entity has more of both.
Now apply Hamilton Helmer's 7 Powers, which asks the harder question: not "does the company have advantages" but "does it have anything a competitor cannot replicate at acceptable cost."
Scale economies: No. At ₹42,209 crore of assets, Can Fin Homes sits mid-pack — larger than Aavas Financiers and Home First Finance, materially smaller than LIC Housing Finance, PNB Housing Finance and now Bajaj Housing Finance.472728 Scale in lending buys cheaper funding and operating leverage, and Can Fin Homes has too little of it to matter.
Network economies: No. Mortgages have none.
Counter-positioning: No. There is nothing in Can Fin Homes' model a larger competitor is structurally unable to copy. The reverse is closer to true: Bajaj Housing Finance's tech-first origination is something Can Fin Homes is currently spending three years and ₹40 crore a year trying to imitate.
Switching costs: Weak, and demonstrably so. The balance-transfer numbers are the switching-cost measurement, and they say the cost is low enough that a 100 basis point gap moves customers.
Branding: Modest and mostly borrowed. The Canara name confers legitimacy in south Indian markets and helps with funding, which ICRA says explicitly.12 It does not command a price premium — Can Fin Homes is the one cutting rates to retain customers.
Cornered resource: Partially, and this is the strongest claim available. The National Housing Bank deposit and refinance eligibility, combined with an AAA rating supported by a 29.99% public-sector bank shareholder, gives Can Fin Homes access to funding that a comparable independent lender cannot obtain. But the resource is jointly owned. ICRA's rating sensitivities make the dependency explicit: a change in Canara Bank's support philosophy or a stake sale could adversely affect the rating.12 A cornered resource that a third party can withdraw is a lease, not a deed.
Process power: Yes, narrowly, and this is the real one. Four decades of underwriting a specific borrower type, with a documented sub-1% gross NPA record through multiple credit cycles, is institutional knowledge that cannot be bought off a shelf. It shows up in the numbers with a consistency that is hard to fake. But process power in lending has a well-known failure mode: it is only power while you stay inside the process. Can Fin Homes is now deliberately moving toward self-employed and non-housing borrowers, where its own disclosed loss rate is three times higher, precisely because the segment its process was built for is being priced away from it.[^13]
That is the war-game summary. Can Fin Homes holds one genuine power, narrowly defined, plus a funding advantage it does not fully own. It is being attacked at both ends: on price by banks and large housing financiers harvesting its seasoned book, and on growth by a better-capitalised entrant that has demonstrated it can grow faster with cleaner credit. The company's response — mix shift, in-house sales, technology, rate defence — is coherent and is being executed. It is not a moat-widening strategy. It is a margin-defence strategy, and it should be evaluated as one.
The natural question is what management has done with the cash the machine has produced while all this unfolded.
VII. Capital Allocation & the Canara Bank Relationship
Capital allocation at Can Fin Homes is, by the standards of Indian financials, almost anticlimactic. There is no acquisition history to assess. The company has grown its book from ₹100 crore in 1991 to ₹42,209 crore in 2026 entirely organically.24 It has not bought a competitor, launched an asset-management arm, entered insurance distribution, or diversified into unrelated lending.
State that carefully, though, because "no acquisitions" is not the same as "acquisition discipline." Discipline implies a test that was passed. Can Fin Homes has never seriously attempted an acquisition, so the discipline has never been tested. What can be said is narrower and still meaningful: there is no record of diworsification, no history of writing off failed ventures, and no pattern of strategy shifts that consumed capital and produced nothing. In a sector where the graveyard is full of housing financiers that drifted into project lending and developer finance, the absence of drift is itself informative. It is the same conservatism that shows up in the loan book.
The dividend record is the second pillar. Can Fin Homes has paid a dividend every year since listing in 1989.2 For FY26 the board declared ₹7 as an interim dividend, paid December 29, 2025, and ₹8 as a final dividend on a ₹2 face value share, with a record date of July 3, 2026 and payment on August 3, 2026 — ₹15 in total.192930 Against FY26 earnings, that is a payout ratio in the high teens.
Is that the right number? It is defensible on the arithmetic. A lender growing its book at 10–14% must retain enough capital to support the risk-weighted assets, and with capital adequacy at 25.1% and gearing at 6.9 times, Can Fin Homes has room but not unlimited room.12 Retaining roughly 80% of earnings funds growth without equity dilution — which matters, because issuing equity at 9 times earnings and roughly 1.5 times book would be value-destructive for existing holders. The conservative payout is consistent with the balance-sheet position and with a management team that has never shown appetite for financial engineering.
An activist would push on exactly one point here, and it is worth articulating the argument rather than dismissing it. A lender earning above 20% on equity, trading below 10 times earnings, with capital adequacy 10 percentage points above its regulatory floor, is a textbook buyback candidate. Retiring shares at this multiple would be immediately accretive to book value per share and to earnings per share, and would signal that the board thinks the stock is mispriced. Can Fin Homes has not done it. The likely reasons are structural rather than strategic — a buyback would mechanically raise Canara Bank's percentage stake above 29.99% and into open-offer territory unless the bank participated, and public-sector-linked governance is not built for opportunistic capital actions. But the constraint is worth naming: the promoter structure that supports the rating also forecloses the most obvious value-accretive capital action available to the company.
Which brings us back to the relationship itself, in its current form.
The board comprised nine directors as of March 2025, of whom three were Canara Bank nominees, and two senior executives including the Deputy Managing Director were on deputation from the bank.12 Canara Bank conducts quarterly risk-monitoring visits and provides guidance on risk and compliance.12 Funding lines from Canara Bank exist, extended on what ICRA describes as an arm's length basis, and the agency notes that "its dependence on the bank has, however, declined over the years."12
Read the whole arrangement without sentiment and it is genuinely double-edged. Three nominee directors on a nine-person board is substantial influence without control — enough to shape strategy, not enough to be accountable for it. Quarterly monitoring by an experienced bank risk function is a real second line of defence, and after the Ambala fraud, an arguably necessary one. But a board with a third of its seats held by nominees of a shareholder who has repeatedly tried to sell has an obvious question hanging over every long-horizon decision: whose time preference is being served?
The related-party dimension deserves a brief note. Canara Bank is simultaneously a shareholder, a board-representing party, a lender to the company, and a competitor in home loans. That combination would attract scrutiny in most jurisdictions. Can Fin Homes discloses these arrangements in its annual report related-party notes, and ICRA characterises the credit limits as arm's length.12 There is no indication in the public record of a transaction on non-commercial terms. But investors relying on the "strategic parentage" narrative should note that the same parent competes with the company for mortgage customers.
The unresolved question — will Canara Bank sell — has no answer available from public disclosure. As of the FY26 filings the stake remained 29.99% and unencumbered, with no active process disclosed.8 What can be said with confidence is bounded: across the sale processes publicly reported in 2016, 2017, 2018, 2019 and 2020, only one transaction completed, and each abandonment was attributed to price.9101113 Investors should treat the current structure as a position that could change without warning, in either direction, with material consequences for both the share register and the credit rating.
What the record teaches, though, extends well beyond one shareholder register.
VIII. Playbook: What This Company Teaches
Narrow focus compounds — and then it binds. Can Fin Homes chose one borrower type in the late 1980s and stayed with it for thirty-five years. The payoff was a loss rate so low it barely registers in the P&L, and a reputation that survived two sector-wide crises. The cost only became visible when growth needed to reaccelerate. A lender optimised for one segment cannot simply pivot: the moment Can Fin Homes moved toward self-employed and non-housing borrowers to defend yield, it moved into a book where its own disclosed loss rate is three times higher. Specialisation is a machine for producing consistency, not optionality. The bill comes due when the specialised market gets crowded.
Verify which advantage is doing the work. For four decades Can Fin Homes has cited its deposit-taking license as a differentiator, and analysts have repeated it. Deposits are 1% of funding.12 The actual funding advantage comes from the AAA rating, the repo-linked bank borrowing mix, and the National Housing Bank refinance window. This is the general lesson: when a company has several plausible sources of advantage, the balance sheet will tell you which one is real, and it is often not the one in the presentation.
A licence-and-parentage advantage is a lease. The most valuable thing Can Fin Homes owns is access to cheap money, and the most important input to that access is a rating that a rating agency has explicitly said depends on a shareholder's support philosophy.12 Advantages you rent from a third party should be discounted relative to advantages you own.
Execution risk exists in boring businesses too. A company with no acquisitions, no leverage adventures and no strategic drift still managed to lose a fiscal year of growth to a state government's property-registration digitisation, and has now twice deferred the core-system replacement that its future productivity depends on. Operational risk in lending is not only credit risk.
Controls are proven by failures, not by their absence. The Ambala fraud demonstrated that a company can have four decades of clean credit outcomes and still have a hole in its cash-movement controls.2122 The remediation was specific and third-party validated.12 The right posture toward operational-control claims is to ask what has actually been tested, not what has never gone wrong.
Parent-subsidiary ambiguity is its own risk class. Neither arm's length nor committed, neither controlled nor independent — this structure produces a rating benefit, a governance question, a permanent equity overhang, and a foreclosed buyback, all at once. It is distinct from operating risk and should be assessed separately.
IX. Risk Radar
Rate-cycle and refinancing risk. This is the first-order risk in the business and it cuts both ways. With about 80% of bank borrowings repo-linked and 65–70% of liabilities repricing within a month, Can Fin Homes' funding cost falls fast when the Reserve Bank cuts and rises fast when it hikes.[^13] The FY26 margin expansion — spread from 2.55% to 2.93% across three quarters — was substantially a gift from the rate cycle, not an operating achievement.[^13] In a tightening cycle the same structure compresses spread immediately, and the company's ability to reprice borrowers upward is constrained by the balance-transfer flow already running. Management guides to a steady-state spread of 2.75% and NIM of 3.75%, below where both currently sit — an implicit acknowledgement that the current margin is above normal.[^13]
Prepayment and balance-transfer risk. The FY26 lesson: disbursement growth of 23% produced book growth of 10.4% because rundown exceeded budget by ₹600 crore.6 By Q1 FY27 quarterly rundown was ₹1,857 crore against a ₹1,350–1,400 crore historical norm.1[^13] Falling rates help the funding cost and simultaneously accelerate the exodus, because a borrower two years into a loan can now refinance at a rate Can Fin Homes will not match. The migration to quarterly resets addresses the timing lag; it does not address the 100 basis point pricing gap management itself disclosed.1
Execution risk on the technology transformation. Live and unretired. LOS/LMS was deferred from FY26 to Q1 FY27, then rolled out to five pilot branches on July 8, 2026, with full deployment across 250 branches targeted before the Q2 FY27 results.[^13]1 Management has guided a one-time business impact of ₹250–300 crore in the transition quarter plus three to four days of downtime and one to two weeks of stabilisation, with ₹40 crore of incremental FY27 cost.[^13] For a company guiding to ₹13,000 crore of FY27 disbursements, a ₹250–300 crore transition hit is roughly two to three percent of the year — absorbable if it lands as guided, meaningfully damaging if the stabilisation period runs long across a national branch network.1
Competitive and pricing risk. Bajaj Housing Finance's FY26 scale and credit metrics establish that a competitor can grow at 23% with 27 basis points of gross NPAs.7 LIC Housing Finance and the large banks compete on rate for the same prime salaried customer. Can Fin Homes' stated response is to protect spread at 2.75–2.8% and avoid aggressive price cuts beyond that level.[^13] That is a disciplined answer and it has a predictable consequence: if the company will not match on price, it loses seasoned customers, which is exactly what the rundown data shows.
Asset-quality mix risk. The deliberate shift toward self-employed and non-housing lending raises portfolio yield and raises expected losses.[^13] Management has committed to holding gross NPAs below 1% through the transition.[^13] Add the restructured book, at 1.3% of the portfolio as of March 2025, where ICRA notes slippages run higher than the rest of the book.12
Governance and overhang risk. A 29.99% promoter stake held one basis point below the open-offer trigger, by an owner with four disclosed sale processes and one completed transaction on the record, whose exit is named by ICRA as a rating-downgrade trigger.12 No company-side control over timing.
Concentration and channel risk. Two related exposures that receive less attention than they deserve. Geographically, the FY25 experience showed how much a single state's administrative change can matter — Karnataka's e-Khata registration delays visibly dented a full year of national disbursement growth.5 Channel-wise, 79% DSA-sourced origination as of Q3 FY26 means most new business arrives through intermediaries whose loyalty is to commission.[^13] Management's plan to cut that to 60% by FY28 by scaling from 90 marketing executives toward 250 is the right direction, but it substitutes a fixed-cost sales force for a variable-cost broker channel — which improves control and worsens operating leverage if volumes disappoint.[^13]
Regulatory risk. Housing finance sits under National Housing Bank and Reserve Bank oversight, and changes to deposit-acceptance rules, risk weights, capital norms or the terms of subsidy schemes flow directly into the economics. Nothing material is currently pending in the public record; the exposure is structural rather than event-driven.
Cybersecurity and data risk. Elevated during the transition, by definition. ICRA notes that Can Fin Homes "has not faced any material lapses over the years" on data security and customer privacy — a bounded observation about the historical record, not a forward assurance, and one made against a company that did experience a significant internal fraud in 2023.12
X. Bull & Bear Case
The bull case, stated at its strongest
The core of it is that a lender earning above 20% on equity, with credit costs of ten basis points and capital adequacy of 25%, trading at roughly 9 times earnings, is mispriced — and that FY26 proved the growth algorithm still works.3412
The supporting evidence is real. FY26 delivered record disbursements of ₹10,531 crore, ahead of guidance, with each quarter setting a new peak; profit of ₹1,085.75 crore, up 27%; gross NPAs improving to 0.85% with provision coverage rising to 56%; and a fifth consecutive quarter of falling absolute delinquencies.46 Q1 FY27 continued it: 29% disbursement growth, 20% profit growth, NIM ahead of guidance, gross NPAs down to 0.87% from 0.98%, and a sixth consecutive quarter of improving NACH bounce ratios.124
Management's operational response to the FY26 rundown problem was fast and specific: migrating 85% of the book from annual to quarterly rate resets within twelve months to close the pricing lag, and scaling the in-house sales force from 30–35 people to 80–90 in FY26 with a target of 150 in FY27 and 250 within two years, alongside 15 new branches in FY26 and 28 planned for the first half of FY27.6[^13] Per-executive sourcing productivity rose from ₹101 crore in Q1 FY26 to over ₹250 crore in Q3.[^13] That is a management team that identified a problem, named it publicly, and moved.
The funding position is genuinely strong: AAA reaffirmed by both ICRA and CARE, ₹49,138 crore of rated borrowing programmes, National Housing Bank refinance at a blended 6.3%, ₹4,000 crore of undrawn bank sanctions, and a liquidity coverage ratio of 563.5% at March 2026.1231[^13]4
And the FY27 guidance is specific and testable: ₹13,000 crore of disbursements, 14% AUM growth, spread of 2.75%, NIM of 3.75%, ROA of 2.4%, ROE above 18%, credit cost of 10 basis points.61 Management has, for two consecutive years, either met or narrowly exceeded its disbursement guidance.
The bear case, stated at its strongest
The bear case is not that the numbers are bad. It is that the numbers are good for reasons that are ending.
The margin is cyclical and management has said so. Spread widened from 2.55% to 2.93% across FY26 because borrowing costs fell faster than lending rates in a cutting cycle.[^13] Management guides steady-state spread at 2.75% and NIM at 3.75% — below current levels.[^13] Roughly a third of the FY26 margin improvement is guided to reverse. Any bull case built on extrapolating current margins is extrapolating something the company itself has told you peaks.
Book growth is being competed away in real time. The FY26 result — 23% disbursement growth, 10.4% book growth, missing the company's own 11–12% AUM guide — is the bear case in a single line.6 The mechanism is a 100 basis point pricing disadvantage against larger lenders that management has disclosed and has no stated plan to close, because closing it would violate the spread guidance.1[^13] Can Fin Homes has chosen margin over volume. That is a legitimate choice; it is also a choice that caps growth.
The asset-quality claim is being narrowed by the company's own strategy. The sub-1% gross NPA record was produced by a book that was 71% salaried, where losses run 0.5–0.6%.12[^13] Management is deliberately moving toward 65:35 and toward more non-housing, where losses run 1.5–1.7%.[^13] Simultaneously, Bajaj Housing Finance demonstrated that at 3.3 times the scale, 27 basis points of gross NPAs is achievable.7 The claim "best-in-class asset quality" survives only against smaller specialist peers, not against the scale competitor.
Execution risk is unretired and has already slipped twice. As of the last public disclosure, the core loan systems were live in five branches out of 250, with a ₹250–300 crore transition hit still ahead.1[^13] A brokerage flagged in October 2025 that the transformation could disrupt disbursements and said it would wait for execution clarity before turning constructive — a caution that, in the event, proved conservative for FY26 but has not yet been tested against the actual go-live.32
The origination model is broker-dependent. 79% DSA sourcing is not the profile of a lender with a distribution moat.[^13] It is the profile of a lender that buys its volume in a competitive market, which means volume can be bid away by anyone willing to pay a higher commission.
Governance leaves alignment to process. A chief executive with approximately ₹2.2 crore of all-cash compensation, no ESOPs and effectively no shareholding, operating under a board with three nominees from a shareholder that has repeatedly attempted to exit.2012 No buyback is practically available because of the open-offer threshold. Minority shareholders are relying entirely on institutional process for alignment.
The control record has a real blemish. ₹38.53 crore misappropriated by branch employees over an extended period, detected in July 2023, in a company whose premise is process discipline.2122
Weighing it
The bull and bear cases are not symmetric, and it is worth saying which parts of each survive.
The asset-quality claim survives in narrowed form: Can Fin Homes' underwriting is genuinely good, demonstrably better than its closest specialist comparables, and worse than the best-capitalised scale player. The claim should be stated as "excellent credit selection within a chosen segment," not "best-in-class asset quality," and it carries a live caveat because the segment is being changed on purpose.
The funding-advantage claim survives in substantially narrowed form. The deposit license is not a moat. The National Housing Bank refinance advantage is real but capped. The rating-driven bank-borrowing advantage is real and material — and partly contingent on a shareholder relationship that ICRA names as a downgrade trigger.
The management-credibility claim survives largely intact on guidance discipline, which is the fairest test available. Can Fin Homes guided ₹10,500 crore of FY26 disbursements and delivered ₹10,531 crore.6 It guided a Q1 FY27 target of ₹2,500 crore and delivered ₹2,609 crore.1 It flagged the cost-to-income increase before it happened and it landed where flagged.[^13]24 Against that, FY25's shortfall was explained with specific, verifiable external causes rather than deflection, and the IT timeline has slipped twice with the slippage disclosed each time rather than discovered by analysts.5[^13]1 That is a mixed but broadly credible record — a management team that misses on things outside its control and tells you promptly, and hits on things inside its control.
The growth claim does not survive. The proposition that FY26 demonstrated a restored growth algorithm is contradicted by the company's own AUM guidance miss and by the pricing gap management disclosed. What FY26 demonstrated is that Can Fin Homes can originate at record volumes; what it did not demonstrate is that it can retain the resulting book against cheaper competition.
The single number that would falsify or confirm the revised case is the gap between disbursement growth and AUM growth. In FY26 it was 23% versus 10.4%. FY27 guidance implies ₹13,000 crore of disbursements against 14% AUM growth — a narrower but still wide gap.6 If that gap compresses, the competitive pressure is being managed. If it widens again, Can Fin Homes is running a treadmill.
XI. Looking Forward
Three things will determine what this company looks like in three years, and all three are observable.
Does the technology programme land? The five-branch pilot went live on July 8, 2026 and management targeted full deployment across 250 branches before the Q2 FY27 results.1 The Q2 FY27 print, due in October 2026, is the first quarter in which the guided ₹250–300 crore transition impact and the operational disruption could actually appear.[^13] Two things to watch: whether the disbursement run-rate holds through the switchover, and whether cost-to-income behaves as guided at 19–19.5% for FY27 before returning toward 18%.[^13]1 If the ratio settles permanently above 19%, the historical cost advantage was partly deferred investment rather than structural efficiency.
Does book growth follow disbursement growth? FY27 guidance is ₹13,000 crore of disbursements — potentially ₹13,200–13,400 crore — supporting 14% AUM growth, against expected rundown of about ₹7,000 crore and net additions of ₹6,000 crore.16 Those are precise, falsifiable numbers. The rundown line is the one that matters, because it is where the competitive pressure shows up before it shows up anywhere else.
Does Canara Bank move? Unknowable from public disclosure. What is knowable is the consequence structure: a sale to a buyer with a weaker credit profile puts the rating premise in question, a sale to a stronger buyer could remove the overhang and change the governance calculus entirely, and continued inaction preserves the status quo, including the foreclosed buyback.
The three KPIs worth tracking, and only three:
1. The gap between disbursement growth and AUM growth. This is the master metric for Can Fin Homes. It captures competitive intensity, pricing power and retention in one number, and it is the number that broke in FY26 despite everything else going right.
2. Cost-to-income ratio through and after the LOS/LMS go-live. The cleanest test of whether the technology spend produces the promised 20% productivity improvement or simply resets the cost base higher.
3. Gross NPAs in the self-employed and non-housing book as the mix shifts toward 65:35. Management has committed to holding total gross NPAs below 1% while deliberately increasing exposure to a segment with three times the loss rate. Either the underwriting travels or it does not, and this is where it will show first.
XII. Recent News
Q1 FY27 results, July 2026. Profit after tax of ₹268 crore, up 20%; net interest income of ₹427 crore, up 18%; profit before tax of ₹339 crore, up 22%; earnings per share of ₹20.12 against ₹16.81.24 Disbursements of ₹2,609 crore, up 29% and ahead of the ₹2,500 crore internal target.33 The loan book reached ₹42,961 crore, up 11%.24 NIM of 3.81% against 3.75% guided; spread of 2.83%; yield of 9.81% against borrowing cost of 6.98%; ROA of 2.39%.24 Gross NPAs of 0.87% and net NPAs of 0.42%, both improved year on year.24 Cost-to-income rose to 19.52% from 18.33%, reflecting technology spend.24 The shares fell about 3% on the print.1
Technology rollout. Five pilot branches went live on the new core loan platform on July 8, 2026, processing sanctions, disbursements, customer creation and NACH transactions without major disruption per management; full rollout across 250 branches targeted before the Q2 FY27 results, with Q2 disbursement guidance held at ₹3,000 crore.1
FY27 guidance reaffirmed. ₹13,000 crore of disbursements, 14% AUM growth, ROA of 2.4%, ROE above 18%, NIM above 3.8%, credit cost of 10 basis points.1
Competitive commentary. Management named LIC Housing Finance and Bajaj Housing Finance — not banks — as primary competitors, and disclosed that the rate differential against larger players had widened from roughly 55 basis points to over 100, making retention challenging; balance-transfer-outs edged up from ₹400 crore to ₹408 crore.1
FY26 full year and dividend. Profit of ₹1,085.75 crore, up 27%; disbursements of ₹10,531 crore; loan book of ₹42,209 crore; NIM of 4.19% and spread of 2.92%; ROE of 23.12%; debt-to-equity of 6.4; provisions of ₹499 crore including a ₹59 crore management overlay; liquidity coverage ratio of 563.5%; 249 branches across 21 states and union territories.434 Total FY26 dividend of ₹15 per ₹2 share — ₹7 interim paid December 29, 2025 and ₹8 final paid August 3, 2026.192930
Governance. The 39th AGM was held on July 29, 2026 by video conference.34 Suresh S. Iyer was reappointed MD and CEO for a further two years effective March 18, 2026.19 Canara Bank's holding remained 29.99% and unencumbered as of the FY26 disclosures, with no active divestment process reported.8
Ratings. CARE Ratings reaffirmed Can Fin Homes at CARE AAA (Stable) in November 2025.31 ICRA assigned [ICRA]AAA (Stable) to a ₹10,000 crore NCD programme and reaffirmed existing ratings in July 2025, taking total rated borrowing programmes to ₹49,138 crore.1235
XIII. Links & Resources
- Can Fin Homes investor relations, presentations and announcements — canfinhomes.com36
- Can Fin Homes company overview and corporate history — canfinhomes.com2
- Can Fin Homes Annual Report 2024-25 (PDF)37
- Can Fin Homes Annual Report 2023-24 (PDF)38
- Board of Directors — canfinhomes.com39
- Key Managerial Personnel — canfinhomes.com40
- ICRA rating rationale, July 16, 2025 (PDF)12
- Q1 FY27 earnings call transcript, July 20261
- Q4 FY26 earnings call summary6
- Q3 FY26 result update and concall highlights, ICICI Securities (PDF)[^13]
- Q3 FY25 result update, Nuvama Wealth Research (PDF)41
- National Housing Bank, list of housing finance companies by total assets (PDF)42
- Screener.in company financials — CANFINHOME43
- Trendlyne shareholding pattern — CANFINHOME15
References
-
Earnings call transcript: Can Fin Homes Q1 FY27 results — Investing.com, 2026-07-20 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
About Can Fin Homes — Company Overview and Milestones, canfinhomes.com ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Can Fin Homes Ltd Share Price Today Live NSE/BSE — Bajaj Finserv, 2026-09-02 ↩↩
-
Can Fin Homes Reports Quarterly and Annual Results — Construction World, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Can Fin Homes targets 20% disbursement growth in FY26 on rate relief — Business Standard, 2025-05-05 ↩↩↩↩↩
-
Can Fin Homes Q4 FY26 earnings call: record disbursements, stable spreads and benign credit costs — ScanX, 2026 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Bajaj Housing Finance FY26 results: net profit up 18% to ₹2,560 crore — ScanX, 2026 ↩↩↩↩↩↩↩↩
-
Canara Bank holds 29.99% stake in Can Fin Homes for FY26 — ScanX, 2026 ↩↩↩↩
-
Canara Bank sells 13.45% stake in Can Fin Homes — Business Standard, 2017-03-10 ↩↩↩
-
Canara Bank calls off divestment process in Can Fin Homes — Business Standard, 2018-03-31 ↩↩↩
-
Canara Bank calls off stake sale in Can Fin Homes again — Business Standard, 2020-01-14 ↩↩↩↩
-
Can Fin Homes Limited: [ICRA]AAA (Stable) assigned to Rs. 10,000-crore NCD programme; ratings reaffirmed — ICRA, 2025-07-16 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Canara Bank plans to dilute stake in Can Fin Homes to 30% — Business Standard, 2016-12-05 ↩↩
-
Can Fin Homes gains on promoter stake sale plan — Business Standard, 2017-02-15 ↩
-
Can Fin Homes MD & CEO Girish Kousgi resigns citing personal reasons — Business Standard, 2022-09-19 ↩
-
Girish Kousgi assumes charge as new MD & CEO of PNB Housing — India Infoline ↩↩
-
PNB Housing Finance CEO Girish Kousgi steps down; Jatul Anand to lead on interim basis — People Matters, 2025 ↩
-
Can Fin Homes Declares ₹7 Interim Dividend for FY26 and Reappoints Managing Director — Angel One, 2025-12 ↩↩↩↩
-
Suresh S. Iyer Biography: Managing Director & CEO of Can Fin Homes — StockLens ↩↩
-
Can Fin Homes says employees of Ambala branch committed Rs 38.5-cr fraud, FIR registered — Business Today, 2023-07-25 ↩↩↩↩
-
Can Fin Homes Employees in Ambala Branch Commit Rs38 Crore Fraud — Moneylife, 2023-07 ↩↩↩↩
-
Can Fin Homes shares plunge 8% on fraud at Ambala branch; NBFC sees 'one-time' hit on profit — Business Today, 2023-07-26 ↩↩
-
Can Fin Homes Q1 FY27 slides: 20% profit growth, margins expand — Investing.com, 2026-07 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Bajaj Housing Finance IPO — issue dates, price band, subscription — Chittorgarh, 2024-09 ↩↩↩
-
Bajaj Housing Finance more than doubles on debut — Business Standard, 2024-09-16 ↩
-
Aavas Financiers FY26: AUM grows 15% to Rs. 234.5 bn, PAT up 14% YoY — ScanX, 2026 ↩↩
-
Home First Finance FY26 profit jumps 41.4% to ₹540.4 Cr, AUM grows 24.9% — Whalesbook, 2026 ↩↩
-
Can Fin Homes fixes record date for ₹8 final dividend — ScanX, 2026 ↩↩
-
Can Fin Homes credits ₹8 final dividend per share on Aug 3 — ScanX, 2026-08 ↩↩
-
CARE Ratings reaffirms ratings of Can Fin Homes at 'CARE AAA; Stable' — Business Standard, 2025-11-19 ↩↩
-
Why Motilal Oswal retained 'Neutral' on Can Fin Homes despite Q2 FY26 beat — Business Standard, 2025-10-23 ↩
-
Can Fin Homes exceeds Q1 disbursement guidance at ₹2,609 crore, reaffirming 14% AUM growth goal — Sahi, 2026-07 ↩
-
Can Fin Homes schedules 39th AGM on July 29, 2026; reports record PAT of ₹1,085.75 crore in FY26 — ScanX, 2026 ↩↩
-
ICRA reaffirms top-tier credit ratings for Can Fin Homes' ₹49,138 crore borrowing programmes — TipRanks ↩
-
Can Fin Homes Investor Presentation and announcements — canfinhomes.com ↩
-
Can Fin Homes Annual Report 2024-25 (PDF) — canfinhomes.com ↩
-
Can Fin Homes Annual Report 2023-24 (PDF) — canfinhomes.com ↩
-
Can Fin Homes Q3 FY25 Result Update (PDF) — Nuvama Wealth Research ↩
-
List of Housing Finance Companies by Total Assets as on 31-03-2024 (PDF) — National Housing Bank ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube