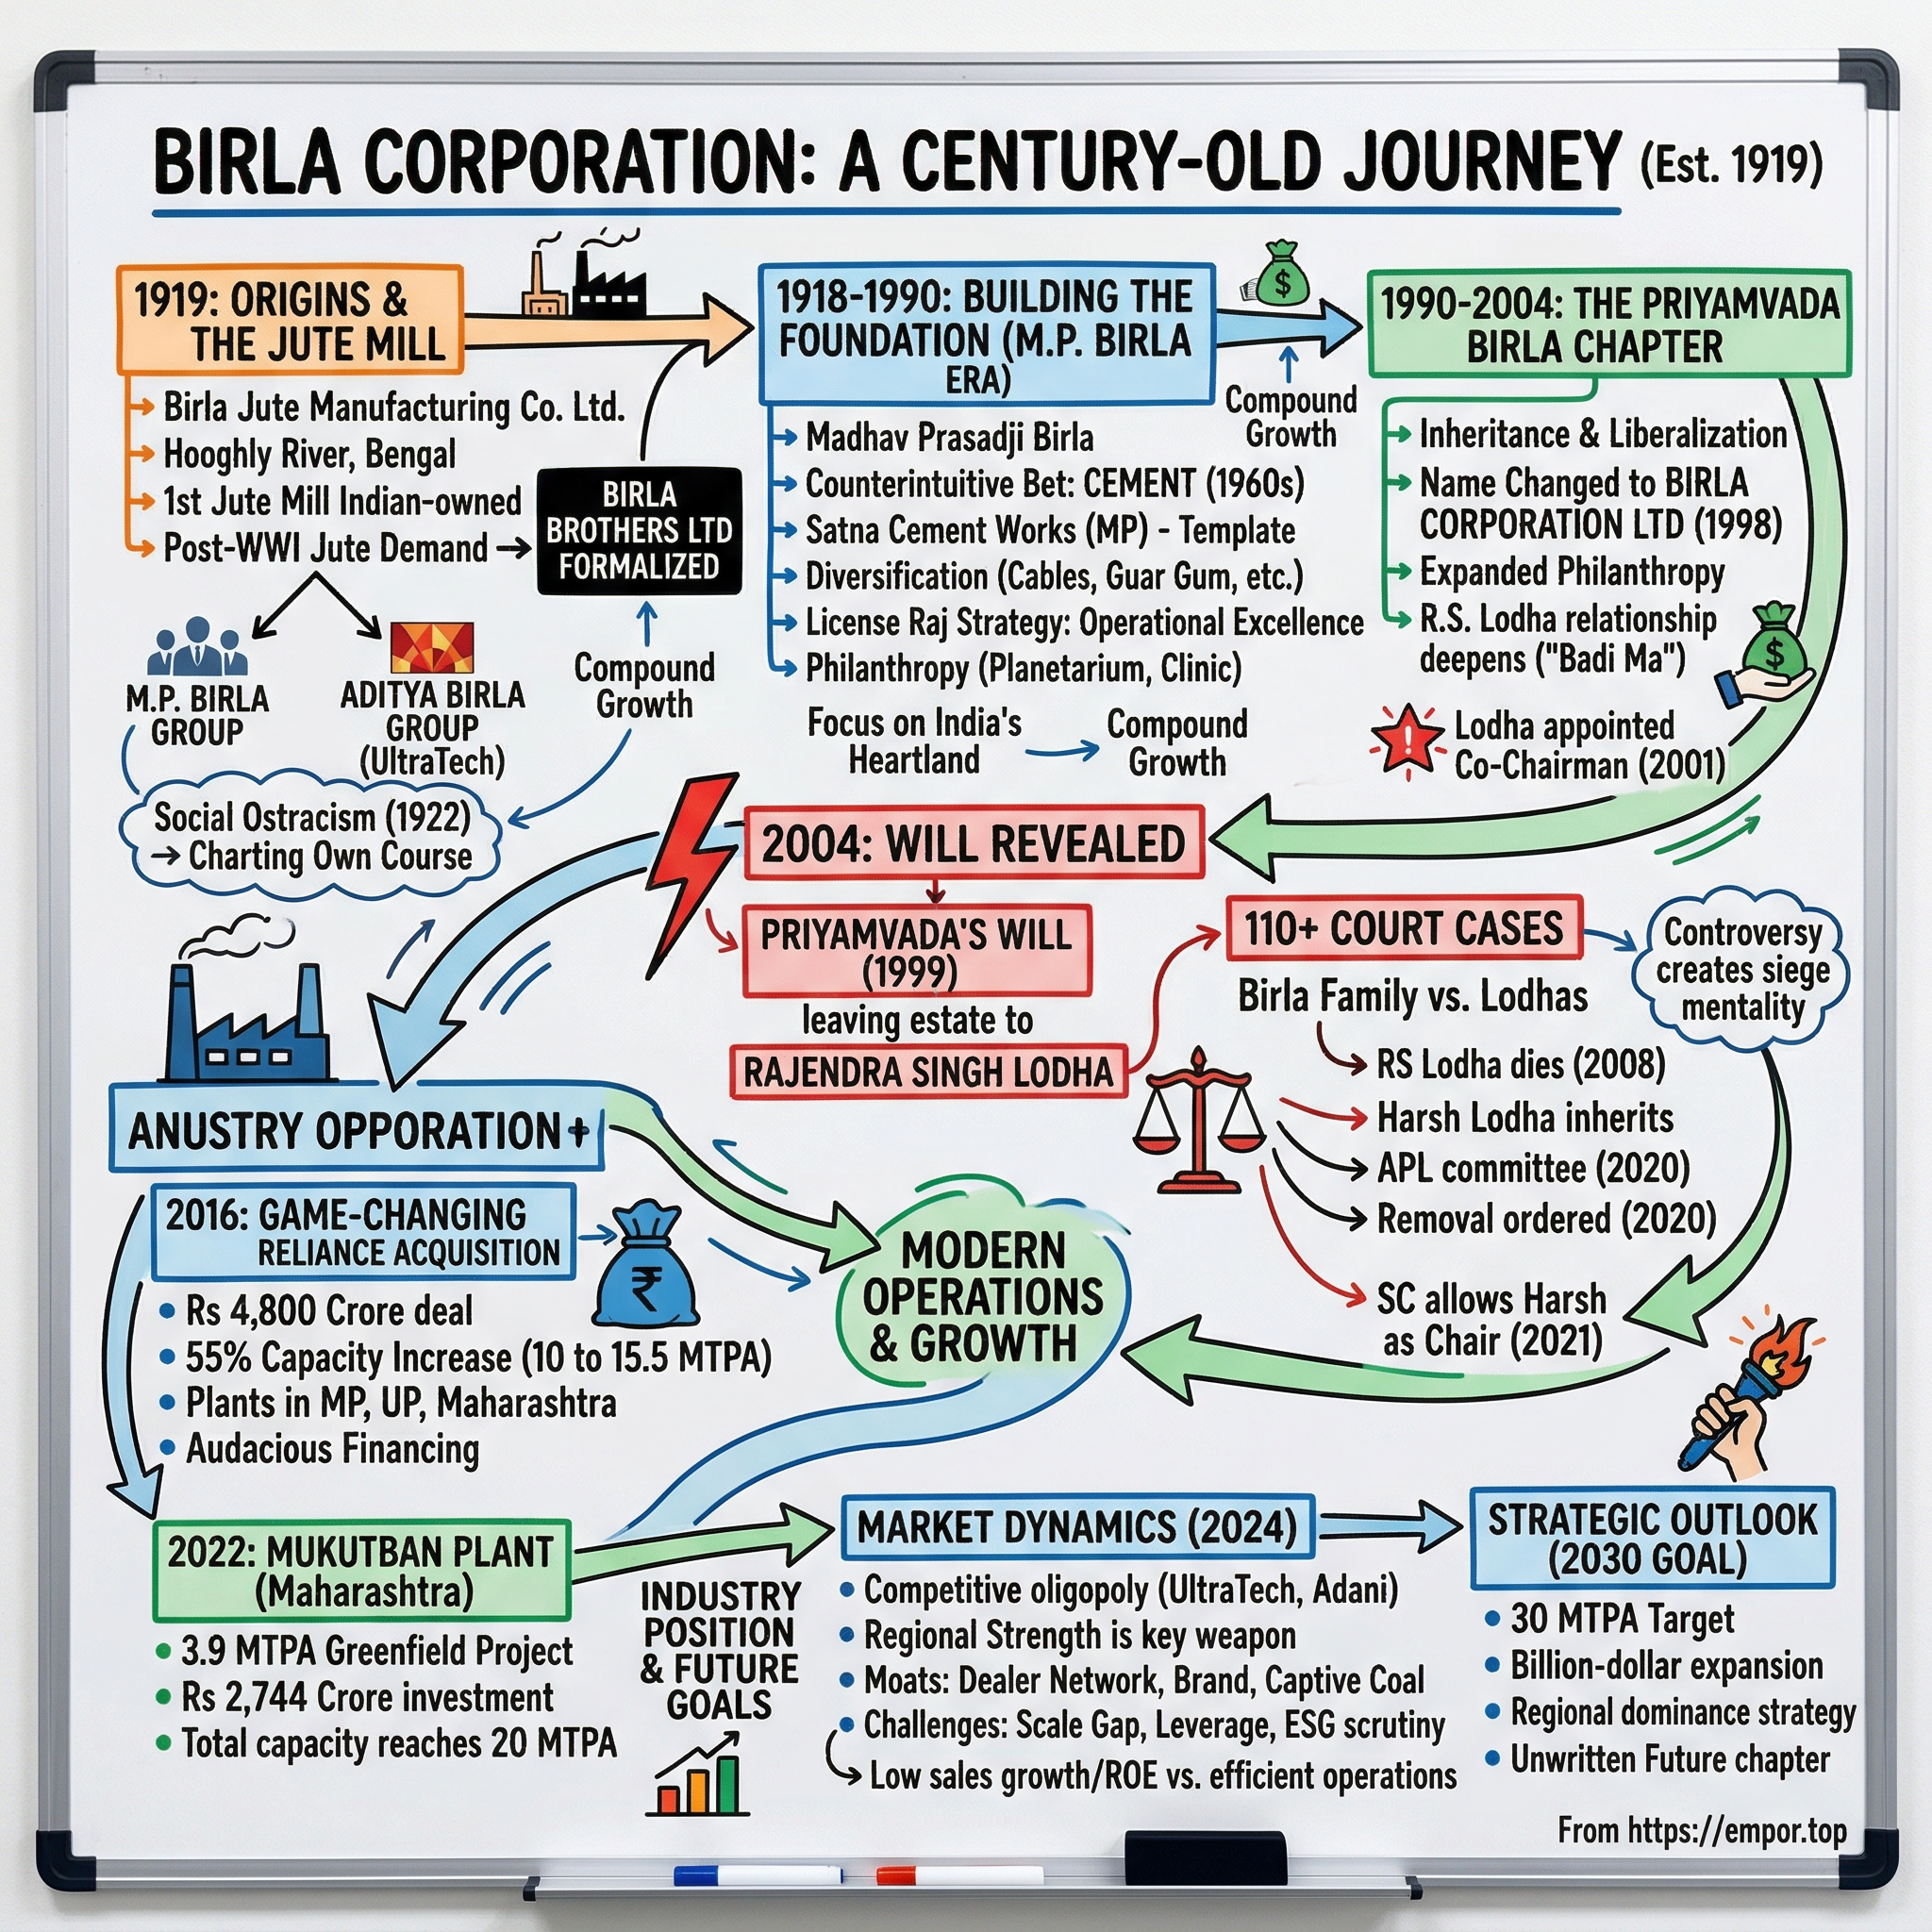
Birla Corporation: Cement, Family, and the Fight for Control
I. Introduction & Episode Roadmap
On the morning of August 1, 2026, in a company that has been filing annual reports since the year after the First World War ended, 888 shareholders gathered — physically or by proxy — for the 106th Annual General Meeting of Birla Corporation Limited.1 The agenda was unremarkable. Adopt the accounts. Approve a dividend of ₹12.50 per share. Fix the cost auditor's fee. Reappoint a director retiring by rotation.
Three of those four resolutions passed with about 98.8% support. The fourth — the reappointment of Harsh V. Lodha, the company's chairman — passed with 79.17%.1
That gap is the entire story. When the scrutinizer's report was filed with the exchanges two days later, it showed something that almost never happens at an Indian promoter-controlled company: the promoter and promoter group had voted against the chairman in 64.31% of their electronic votes, while backing him unanimously in the physical poll at the meeting itself. Public institutional shareholders — the mutual funds and foreign investors who are supposed to be the source of governance friction — supported him at 99.27%.1 This was not an activist campaign. It was a family arguing with itself, in public, through a voting register.
That is a strange thing to find at the top of a company that, by every operating measure, just had its best year. In the twelve months to March 31, 2026, Birla Corporation sold a record 18.72 million tonnes of cement at 95% capacity utilisation, generated consolidated revenue of ₹9,655.61 crore, and commissioned a third grinding line at Kundanganj in Uttar Pradesh that took group capacity to 21.4 million tonnes a year.23 The business is running hot. The boardroom is not settled.
Birla Corporation is three companies at once, and the tension between them is what makes it interesting. It is a century-old industrial survivor — founded in 1919 as Birla Jute Manufacturing Company, the first jute mill started by an Indian entrepreneur, and still running that mill today.4 It is a mid-sized cement producer in an industry consolidating around two enormous players. And it is a company whose ownership was contested in court for two decades and, on the evidence of that August vote, is not fully settled even now.
Three questions frame everything that follows.
First, the scale question. Birla Corporation has told the market it will grow from 21.4 million tonnes to 27.6 million tonnes of capacity by fiscal 2029.3 In the same window, UltraTech Cement — part of the Aditya Birla Group, a completely separate business house from the M.P. Birla Group that controls Birla Corporation — crossed 200.1 million tonnes of Indian capacity in April 2026 and has budgeted over ₹16,000 crore to push consolidated capacity past 240 million tonnes.5 The Adani platform of Ambuja Cements, ACC and Orient Cement stood at 109 million tonnes at the end of June 2026 and expects 119 by the close of this fiscal year.6 Birla Corporation's entire expansion programme adds roughly what UltraTech adds in a good eighteen months. Does a regional player of this size still have a defensible position, or is it slowly being squeezed?
Second, the returns question. Capacity has grown. Earnings power has not obviously followed. In fiscal 2021, on revenue of ₹6,785 crore, the company earned a net profit of ₹630.14 crore. In fiscal 2026, on revenue 42% higher and a gross fixed asset base roughly 28% larger, it earned ₹557.58 crore.3 Five years of expansion have not yet produced a higher absolute profit than the pre-expansion peak. That is the central analytical puzzle, and no amount of narrative about brand equity resolves it.
Third, the governance question. Does the promoter split visible in the AGM voting file represent a live risk to minority shareholders, or a procedural artefact of a long-running estate dispute that the courts have largely resolved?
A fourth thread runs underneath all three, and it is easy to miss because it is a matter of naming rather than economics. Birla Corporation is not part of the Aditya Birla Group. It has no financial, managerial, or ownership connection to UltraTech beyond a shared ancestor four generations back. The two companies are competitors in the same markets with the same surname on the letterhead, and one of them is roughly ten times the size of the other. Any analysis that lets the name do work the balance sheet cannot do will go wrong quickly.
The story runs chronologically: a compressed origin, a two-decade succession war, a pair of acquisitions that defined the modern balance sheet, a decade of building plants, and then the hard current questions about competition, capital allocation, and control. Along the way there is a useful running test — every time this company has spent money to get bigger, what did the money actually earn?
 Subscribe on LinkedIn
II. Origins, Condensed: From Jute to Cement (1919-1990)
The Hooghly River south-west of Calcutta was, in the second decade of the twentieth century, the most industrialised stretch of water in Asia — and almost none of it was Indian-owned. Jute mills lined both banks, spinning the coarse golden fibre grown in Bengal into the gunny bags that carried the world's grain, sugar, and cement. The mills were Scottish. The managing agencies were Scottish. The clubs were Scottish.
Ghanshyamdas Birla, a Marwari trader who had made money in the wartime jute and cotton markets, broke into that world by building rather than buying. Ground was broken at Birlapur in 1919 for Birla Jute Mills — the first jute mill started by an Indian entrepreneur, and the seed of what became not just this company but the wider Birla industrial group.34 A century later it is still owned by the same lineage of management, which the company presents as a point of pride and which, as Section VI shows, is also a small annual cost.
The pivot that actually built the modern company came a generation later. Madhav Prasad Birla — M.P. Birla, the name still on the cement brand — took what was a single-product jute manufacturer and turned it into a diversified industrial house.4 The critical decision was made in 1957, when the company diversified into cement with an integrated plant at Satna in Madhya Pradesh.3 It is worth pausing on how unglamorous that call would have looked at the time. Jute was the profitable, established, export-earning business. Cement in 1950s India was a controlled commodity, its prices and distribution administered by the state, its capacity rationed by licence.
But Satna sat on limestone. Central India's Vindhyan belt holds some of the best cement-grade limestone reserves in the country, and a company that established mining leases there in the 1950s and 1960s acquired something that could not be replicated later at any price. In 1967 a second integrated plant went up at Chanderia in Rajasthan; in 1974 a grinding unit at Durgapur in West Bengal; in 1998 another at Raebareli in Uttar Pradesh.3 Each was a permission granted in an era when permissions were the scarce resource.
It is worth spending a paragraph on how cement is actually made, because the whole competitive structure of this industry falls out of the physics. Limestone is quarried, crushed, mixed with clay and other additives, and fed into a rotating kiln heated to roughly 1,450°C. At that temperature the mixture fuses into hard grey nodules called clinker. Clinker is then ground with gypsum — and, in blended cement, with fly ash or slag — into the fine powder sold in bags. Two things follow. First, the kiln is the expensive, energy-hungry part: an "integrated plant" is one that has a kiln and a limestone mine, while a "grinding unit" is just the milling end and can be built for a fraction of the cost anywhere clinker can be shipped. That distinction runs through every capacity announcement in this story. Second, cement is heavy and cheap. A tonne sells for around ₹5,000 and costs real money to truck a few hundred kilometres, so every plant serves a circle drawn around it. Cement is not a national market; it is a mosaic of regional ones, and a company's geography is its strategy.
This also explains the industry's other defining trait: enormous fixed costs and no ability to store output economically. A kiln that is running at half load still incurs most of its depreciation and interest. That is why capacity utilisation is the number cement analysts watch first, and why the difference between a plant at 90% and a plant at 40% is not a difference of degree but of solvency. Birla Corporation would learn that lesson expensively in the 2020s.
That is the real inheritance. The Satna cluster is not valuable because a Birla built it. It is valuable because it is a low-cost integrated asset sitting on captive limestone in the middle of a country that has been pouring concrete for forty years, and because building an equivalent asset today would require a limestone block auction, an environmental clearance, and a decade.
The company that emerged from the licence era was therefore lopsided in a way its name concealed. It was called Birla Jute Manufacturing Company until 1998.4 By then jute was a minority of revenue and cement was the business. The rename to Birla Corporation Limited was an accounting of reality rather than a rebranding exercise.
For investors, the takeaway from the first seventy years is narrow but real: this company's durable competitive asset is a set of mineral concessions and plant locations acquired under a permit regime that no longer exists, in a business where geography determines cost and cost determines survival. Everything else in the origin story — the jute mill, the Birlapur legacy, the founder's role in Indian industrial nationalism — is heritage, not economics. What happened next had nothing to do with limestone and everything to do with a single sheet of paper signed in 1999.
III. The Will, the Widow, and the Fight for Control (1990-2016)
Priyamvada Devi Birla became chairman of the company in 1990, after her husband M.P. Birla's death. Under her chairmanship the group crossed ₹1,300 crore in turnover and the company took its modern name.4 She was, by the standards of the Indian corporate establishment, an unusual figure: a widow running an industrial house in her own right, without sons, in a business culture organised almost entirely around male primogeniture.
She died on July 3, 2004. What followed has occupied Indian courts ever since.
A will dated April 18, 1999 was produced.7 It left her estate — the shareholdings that carried control of Birla Corporation and several other M.P. Birla Group companies — not to the extended Birla family, but to Rajendra Singh Lodha, the family's chartered accountant and the company's co-chairman. Six members of the Birla family challenged it. The dispute became one of the longest-running succession fights in Indian corporate history, litigated through probate suits, contempt applications, appeals, and special leave petitions across more than two decades.
Consider what that document actually did, because the shock of it in 2004 was not merely about money. Indian business houses are dynastic institutions; the Birla name is arguably the most storied of them all. A will that routed an estate reported at around ₹5,000 crore — and with it the chairmanship of a listed industrial company — to the family's professional adviser rather than to any Birla was a repudiation of the entire logic by which such houses transmit control. The reaction was proportionate. What followed was not one lawsuit but a thicket of them: probate proceedings, contempt applications, disputes over the appointment and powers of estate administrators, and appeals stacked on appeals, running in parallel across trial courts, the Calcutta High Court, and the Supreme Court for more than two decades.
R.S. Lodha died in 2008, four years into the fight.7 His son, Harsh Vardhan Lodha — himself a chartered accountant, like his father — inherited both the claim and the war. And here is the detail that makes Birla Corporation genuinely unusual as a governance case study: for most of the following fifteen years, Harsh Lodha ran the company as chairman while the legal basis of his family's control was actively contested in court.
The mechanism that made this so precarious deserves explanation, because it is unfamiliar even to experienced investors. When a will is disputed, an Indian court can appoint an administrator pendente lite — literally an administrator "while the suit is pending" — to hold and manage the estate's assets until the dispute is decided. In a normal estate that means custody of property and bank accounts. In this estate it meant custody of controlling shareholdings in listed and unlisted companies, which carry voting rights, which in turn determine who sits on boards. The estate's caretaker, in other words, held the levers of corporate control over operating businesses employing thousands of people. Whether and how far those caretakers could use those levers became the central battleground.
The litigation reached its most dangerous point for him in September 2020, when a single judge of the Calcutta High Court passed an order that the estate's court-appointed administrators interpreted as meaning he had ceased to be a director of certain M.P. Birla Group companies. Forms were filed with the Ministry of Corporate Affairs on that basis. The company's own FY26 annual report describes those filings, in unusually pointed language for a statutory document, as having been made "on the basis of an illegal direction from one of the Administrators pendente lite" and states that there had been no cessation of his directorship.3
On December 14, 2023, a Division Bench of the Calcutta High Court — Chief Justice T.S. Sivagnanam and Justice Hiranmay Bhattacharyya — modified the earlier order and nullified those actions.7 The reasoning matters more than the outcome. The court held that an administrator of an estate steps into the shoes of the deceased and can exercise no greater power than she herself possessed; control over a company derives from actual shareholdings, not from personal influence.7 Harsh Lodha retained his directorships. The Birla-side defendants in the probate suit filed special leave petitions against that judgment, and on March 22, 2024 the Supreme Court declined to grant any interim relief.3 An earlier round had gone the same way: in 2021 the Supreme Court rejected the Birla family's petition against the dismissal of a contempt plea against Lodha.8
So the legal position as of today is reasonably clear in his favour, and it has been reached slowly, through appellate courts, over twenty-two years.
What has not been resolved is the underlying question of who, inside the promoter structure, actually agrees on that outcome. The Birla Corporation promoter block is not a family holding shares directly; it is a lattice of investment companies and group entities — 23 of them held 62.90% of the equity as of March 31, 2026.3 Those entities are themselves the subject matter of the estate dispute. A court can decide who has the right to vote a share. It cannot make everyone holding that right agree.
Which is precisely why the 2004 will belongs at the front of this story rather than in a footnote about corporate controversies. It is not settled history. It is the direct ancestor of what happened at the 106th AGM, where the promoter group's electronic votes and its physical votes pointed in opposite directions on a single resolution. Section VII returns to that vote with the numbers. The point to carry forward is that Birla Corporation's control structure has never had a clean, uncontested moment in the twenty-two years since Priyamvada Birla's death — and that the operating story of the last decade, the acquisitions and the plants and the capacity race, all happened underneath that unresolved question.
In 2015, with the litigation grinding on and the Indian cement industry entering its most acquisitive phase in history, Harsh Lodha's management team decided the company needed to get much bigger, very quickly.
IV. The Reliance Cement Deal: Scale at What Price? (2015-2016)
In the summer of 2015, LafargeHolcim had a problem that was, from Birla Corporation's side of the table, an opportunity. The merger of Lafarge and Holcim had created overlapping positions in India, and the Competition Commission required divestment. Assets in eastern India went on the block.
On August 17, 2015, Birla Corporation announced it had agreed to acquire Lafarge India's integrated cement unit at Sonadih in Chhattisgarh and its grinding unit at Jojobera in Jharkhand — 5.15 million tonnes of capacity, plus the Concreto and PSC brands and the management team — for an enterprise value of ₹5,000 crore.9 Harsh Lodha called the assets a fit with "our strategic vision and ambition of enhancing our competitiveness in our chosen markets."9 The market agreed enthusiastically; the stock moved sharply on the announcement. On paper, the deal solved the company's structural weakness in the east and took capacity from about 10 million tonnes to 15 million.
It never closed. The transaction ran into a problem that anyone who has done Indian mining M&A will recognise immediately: the limestone. Transferring mining leases attached to divested cement assets required approvals that, in the wake of India's 2015 mines legislation, proved impossible to obtain in the form the deal assumed. By February 2016, Lafarge India had told Birla Corporation it could not proceed. Birla Corporation's response was to say publicly that it had consulted its lawyers, did not accept Lafarge's contention, and would pursue the matter legally.10
Here is the part that deserves attention. Six months of work, a signed agreement, a public commitment to a strategic direction — and it evaporated on a due-diligence question about mineral rights that was knowable at the outset. The strategic logic had been sound; the execution risk had been badly priced.
What happened next was fast. On February 4, 2016 — two days after saying it would take Lafarge to court — Birla Corporation announced an agreement with Reliance Infrastructure to acquire the entire equity of Reliance Cement Company Private Limited for an enterprise value of ₹4,800 crore.[^11] The assets were an integrated plant at Maihar in Madhya Pradesh and grinding units at Kundanganj in Uttar Pradesh and Butibori in Maharashtra. The press release said the acquisition would take total capacity from 10 to 15.5 million tonnes and would be funded "through existing cash reserves and incremental debt."[^11] It closed on August 22, 2016.1112
Strategically, this was a better fit than the Lafarge assets had been. Maihar sits beside Satna. The company was buying capacity in the cluster it already dominated, with limestone reserves, a captive coal linkage, and — crucially — plants built in the 2010s rather than the 1960s. Birla Corporation's oldest units are fuel-hungry by modern standards; CARE Ratings has repeatedly noted that the efficient units housed inside RCCPL are what hold up consolidated margins against the drag of the ageing standalone plants.13 Ten years on, RCCPL is not a bolt-on. It is roughly half the group: in FY26 the subsidiary sold 9.45 million tonnes against the parent's 9.46 million.3
Now the price.
₹4,800 crore for 5.5 million tonnes of cement capacity worked out to roughly $140 per tonne.11 Five months after Birla Corporation closed that deal, Nirma bought the whole of Lafarge India — an 11-million-tonne platform with three integrated plants, two grinding stations, and an established brand — for about $1.4 billion, or roughly $127 per tonne.14 The aborted Birla-Lafarge transaction had implied about $151 per tonne.14
Read those three numbers together and a pattern emerges. In the single most competitive window for Indian cement assets in a decade, Birla Corporation paid more per tonne for a smaller, less complete asset than the buyer of the full Lafarge platform paid for a bigger one. It also paid it to a seller who was, by common consent, exiting a non-core business to reduce leverage — Reliance Infrastructure's stated purpose for the proceeds was debt reduction.15 A motivated seller and a buyer who had just publicly lost a deal is not a combination that produces disciplined pricing.
The balance-sheet consequence was immediate and visible in the ten-year record. Group borrowings, which had been running around ₹4,000 crore, sat at ₹4,254.94 crore at the end of FY2016-17 against a net worth of ₹3,304.99 crore — a debt-equity ratio on long-term loans of 1.26 times, the highest of the decade.3 It took nine years of deleveraging to bring that ratio to 0.51 by March 2026.3 That is the real cost of the RCCPL deal, and it is not captured in any per-tonne comparison: the company spent most of the following decade paying for it, which is precisely the decade in which its two largest competitors were compounding capacity.
The counter-argument deserves a fair hearing, because it is not weak. Nirma bought a national footprint with assets scattered across regions; Birla Corporation bought density in the one cluster where it already had scale, brand, and dealers, which is worth more per tonne to it than to a generic buyer. And greenfield replacement cost in India at the time was well above $100 per tonne, so $140 for operating plants with limestone was not absurd on an absolute basis. The strategic logic was defensible.
But the price has to be judged by what it produced. And the honest scoreboard, a decade later, is mixed rather than vindicating. The capacity was real and it works. The returns have been slower to arrive than the capital was. One blunt way to frame it: the whole company — 21.4 million tonnes, ten plants, the brand, the jute mill, everything — carried an equity market capitalisation of roughly ₹6,800 crore in mid-2026.16 The market today assigns the entire enterprise's equity a value of about 1.4 times what the company paid for 5.5 million tonnes of it in 2016.
That is the single most useful thing to hold on to about Birla Corporation's capital allocation history. The company has repeatedly been willing to pay for scale. It has not yet demonstrated that the scale it bought earns a return above what it cost. Which brings us to the plants it built itself — where the same question shows up with even sharper edges.
V. Building Out Capacity: Kundanganj, Mukutban, and the Cost of Growth (2016-2026)
Mukutban is in Yavatmal district, in the cotton belt of Vidarbha in eastern Maharashtra — a part of India better known for agrarian distress than for industrial investment. Ground was broken there in 2019.3 It was the largest single capital project in Birla Corporation's history: a 3.9-million-tonne integrated cement plant, with its own limestone mine, its own waste-heat recovery system, its own township, at a cost of ₹2,744 crore.17 For a company whose entire market capitalisation would later be around ₹6,800 crore, this was a genuine bet-the-decade project.
Then COVID arrived. Commercial production began in April 2022, later than planned.13 And the ramp-up that followed is the most instructive sequence in this company's recent history, because it is the closest thing to a controlled experiment on how long Birla Corporation takes to convert steel and concrete into earnings.
The numbers are unforgiving. In fiscal 2023, Mukutban ran at about 20% utilisation.13 The plant's waste-heat recovery system and its captive limestone mine were both late to operationalise, so the unit spent its first year producing at low volume with a cost structure designed for high volume. The consolidated effect was severe: group EBITDA per tonne collapsed to ₹491 in FY23, and consolidated net profit fell to ₹40.50 crore — down from ₹398.59 crore the prior year and ₹630.14 crore the year before that.133 A company that had been earning north of ₹600 crore made less than ₹50 crore. Total debt to operating profit blew out to 5.8 times.13 The plant reached EBITDA breakeven only around March 2023.
Then it worked. Utilisation roughly doubled to 48% in FY24; group EBITDA per tonne recovered to ₹815 and leverage fell to 2.7 times, prompting ICRA to revise its outlook back to Stable from Negative in May 2024.13 By the June 2026 quarter, Mukutban was moving 750,000 tonnes in three months — annualising to roughly three-quarters of nameplate, four years after commercial production started.18
Four years. That is the honest number for how long this management team needed to take a greenfield integrated plant from first production to healthy — though not full — utilisation, and it happened during a period of decent national cement demand. It is also worth noting why the plant is still not full. On the July 25, 2026 earnings call, CEO Sandip Ghose explained that Mukutban's lead distance — the average haul from plant to customer — was around 400 kilometres, well above the group average of 335, and that the company was deliberately reshaping its product mix toward closer markets rather than trucking cement all the way to Mumbai.18 Cement is a low-value, high-weight product; freight economics mean a plant's addressable market is essentially a circle drawn around it. Mukutban was built at the edge of its own circle.
Against that backdrop, the company's next capacity leg deserves scrutiny rather than applause.
The immediate step went smoothly. In March 2026, RCCPL commissioned a third grinding line at Kundanganj at a cost of about ₹300 crore, adding 1.4 million tonnes and taking consolidated capacity to 21.40 million.3 Grinding units are the easy end of cement capex — you are bolting a mill onto an existing site and shipping in clinker — and the speed reflected that.
The larger programme is a different order of difficulty. In May 2025, the boards of Birla Corporation and RCCPL approved investment of ₹4,335 crore to lift capacity from 20 to 27.6 million tonnes by fiscal 2029: roughly ₹2,300 crore to expand clinker capacity at Maihar, and about ₹2,035 crore for three new grinding units at Prayagraj, Gaya, and Aligarh.17 The FY26 annual report reaffirms the 27.6-million-tonne target for FY2028-29.3 A longer-dated 30-million-tonne ambition has circulated in market commentary; it does not appear as a stated target in the FY26 annual report, and should be treated as aspiration rather than guidance.
The financing plan is where management's credibility gets tested in real time. On the Q1 FY27 call, CFO Aditya Saraogi held to three numbers: capex of ₹900 crore for FY27, of which ₹120 crore had been spent in the June quarter; net debt of about ₹2,000 crore by year-end against ₹2,300 crore at the end of June; and an unchanged peak net debt guidance of ₹4,000 crore, with net debt to EBITDA not exceeding 2.5 times.18 Asked directly how much of the programme had been spent so far, the answer from Chief of Manufacturing and Projects Rajat Prusty was blunt: "almost nil," with order placement still ahead.18 When an analyst suggested FY28 capex might jump to ₹2,500 crore, Saraogi called it premature but confirmed a significant increase.18
Read plainly: the ₹4,335 crore programme has barely started. Nearly all of the execution risk, and nearly all of the debt, is in front of the company rather than behind it. The Mukutban precedent says that when this company builds an integrated line — and Maihar's clinker expansion is exactly that, not a grinding unit — the gap between commissioning and earning can run to years. Management's answer, consistent across the Q4 FY26 and Q1 FY27 calls, is that utilisation is already above 90% and there is no room to defer.1819 That is a legitimate argument. It is also the argument every cement company makes at the top of a capex cycle.
The cost lever is real, and it is doing work. Birla Corporation's power and fuel position is not green marketing. The company holds captive limestone across its plants, operates its own thermal generation, and has assembled 43.35 MW of waste heat recovery — capturing hot exhaust gas from the kiln and using it to make electricity, essentially running a small power station on waste — alongside 42.8 MW of solar and 18 MW of hybrid capacity as of March 2026.[^21] Green power rose to 31.00% of consumption in FY26 from 24.83%, and power and fuel cost fell to ₹993 per tonne of production from ₹1,035.3 Management has targeted 37-38% green power and expects waste heat recovery to reach about 50 MW, with another 17-18 MW arriving with the Maihar line.1819 The Bikram coal block, which the company now operates, is expected to supply around 120,000 tonnes this year rising to 350,000 next year — enough, on Prusty's account, to cover roughly a third of captive power plant coal requirement.183
This is the clearest evidence in the whole file that the operating team knows its business. Cost per tonne fell in a year when petcoke prices rose 35%.3 That is not luck.
And yet the single most important number went the wrong way. EBITDA per tonne is the metric that decides whether any of this matters, because it is where cost discipline and pricing power meet. For FY26 the cement division delivered ₹786 per tonne, up 15.08% year on year — with the March quarter reaching ₹971.32 Then in the June 2026 quarter it fell to ₹675, down 5.6% from a year earlier, as power and fuel costs rose and price increases taken in April and May had to be rolled back in June under competitive pressure.2021 Realisation actually rose about 2% year on year to ₹4,947 per tonne; the margin still shrank.21
What management is doing about it is worth describing precisely, because the answer reveals the strategy's limits. Since blended cement is already 87.72% of volume and premium products are already 61.33% of trade sales, the mix lever is close to exhausted — you cannot keep upgrading a bag that is already the premium bag.3 The remaining levers are cost and channel management: the internal programme the company calls Unnati, built around cost optimisation and dealer engagement, and a customer relationship platform used to track realisation and logistics by territory.3 These are competent, unremarkable initiatives of the kind every large cement company runs. They can defend a margin. They cannot manufacture a price increase that the market will not support. Ghose was explicit about this on the July call: if larger players decline to raise trade prices, the company will "have to figure out how we protect our margins in that segment, which could be a variety not necessarily by taking up prices."18
That is the whole test, compressed into one quarter. When costs rise, can Birla Corporation pass them on? In the June quarter, the answer was no — and Ghose's own explanation on the call was that the company had "maxed out" on trade and blended cement volumes, the very segments where competitors declined to raise prices.18 Being concentrated in the highest-margin channel is an advantage right up until that channel is where the price war isn't being fought and the price recovery isn't happening either.
VI. Segment Reality: Cement Carries the Company, Jute Is Heritage Overhead
The arithmetic of Birla Corporation is almost embarrassingly simple. Of ₹9,655.61 crore of revenue from operations in FY26, cement contributed ₹9,156.99 crore — 94.83%. Jute contributed ₹498.09 crore, or 5.16%. Everything else was ₹0.53 crore.3
The revenue share overstates jute's importance, because jute does not contribute profit. It consumes it. Birla Jute Mills posted negative EBITDA of ₹2.99 crore in FY26, an improvement from negative ₹6.13 crore the year before, and a segment-level loss of ₹7.00 crore.3 Two consecutive years of negative EBITDA, on the company's own accounting.
The cause is straightforward and outside management's control. India's raw jute output has been stuck around 75 lakh bales, and prices spiked sharply from November 2025 onward — by roughly 92% year on year in the March quarter, which pushed the division to a cash loss of about ₹12 crore in that single quarter against a ₹4 crore profit a year earlier.23 Daily production fell about 18%. To its credit, the mill cut conversion cost 8% and grew exports 23.95%, which is why the full-year loss narrowed rather than widened.3 Management's own outlook is candid: FY2026-27 "could be another challenging year" as raw jute prices continue to climb.3
One technical note on how the loss is reported, because the two figures in the annual report differ and both are correct. The negative EBITDA of ₹2.99 crore measures the mill's operating cash performance before depreciation and interest. The segment result of ₹7.00 crore is the loss after those charges are allocated.3 Neither is material to the group, but the gap is a reminder that a business running at a small operating loss is running at a larger economic loss once the capital tied up in it is charged for.
Why keep it? The company's answer, implicitly, is heritage — Birlapur is the mill that started everything, and it is described in the annual report as the oldest jute mill to have remained under the same management since inception.3 There is a workforce and a set of local obligations attached to a facility that has operated for over a century in West Bengal. The economics are immaterial in both directions: a ₹3 crore EBITDA loss against ₹1,571 crore of group EBITDA is a rounding error.3 There is no plausible path by which jute geotextiles or export diversification make this division matter to the investment case, and readers should treat any framing of jute as hidden optionality with scepticism. It is a small, persistent, values-driven cost.
The group numbers themselves deserve one caution: do not smooth them. FY26 consolidated revenue of ₹9,772.56 crore and net profit of ₹557.58 crore looked like a breakout year — profit up 89% — but the comparison base was depressed.23 The five-year profit sequence tells the truer story: ₹630.14 crore in FY21, ₹398.59 crore in FY22, ₹40.50 crore in FY23, ₹420.56 crore in FY24, ₹295.22 crore in FY25, ₹557.58 crore in FY26.3 That is not a growth curve. It is a cyclical business with an expansion programme layered on top, and the highest profit in the sequence is still the oldest one.
Which raises the obvious question of who is steering, on what mandate, and with whose consent.
VII. Current Management, Incentives, and the 2026 Governance Flashpoint
The operating team at Birla Corporation is, by Indian mid-cap standards, notably stable — and notably conventional.
Sandip Ghose became Managing Director and CEO effective January 1, 2023, succeeding Arvind Pathak, who had stepped down for personal reasons.22 Ghose is not a lifer; he is a chartered accountant who spent his formative years in consumer marketing at Unilever before moving into cement as a senior vice president at Lafarge India in 2007. He joined MP Birla Cement in 2015 to run sales, marketing and logistics, rose to chief operating officer, left in 2020, and came back two years later to run the company.23 That biography explains a great deal about the strategy on display: the relentless emphasis on the trade channel, on premium brands, on blended cement as a branded product rather than a commodity, is a fast-moving-consumer-goods mind applied to a bulk material.
The strategy is at least internally consistent, which is more than can be said for many mid-cap Indian industrials. Blended cement reached 87.72% of volume in FY26 from 82% the year before, premium products contributed 61.33% of trade channel sales, and the two flagship premium brands grew volumes 21.81% and 23.69%.3 Under pressure on the Q1 FY27 call, Ghose refused to soften the position: asked whether the company would shift toward the non-trade segment where prices were recovering, he pushed back explicitly, saying the company was "not going to change our strategy to reduce trade and increase non-trade."18 Whether that conviction is right is arguable. That it is consistent across calls is verifiable.
Aditya Saraogi serves as Group CFO and has been the company's finance voice across the recent cycle, handling the leverage questions on calls directly and without evasion — supplying net debt, capex, incentive accruals, and per-tonne cost figures on request rather than deflecting to investor relations.18 Harsh V. Lodha remains Chairman. The board also includes four independent directors: Anup Singh, a former ITC executive director; Chitkala Zutshi and Rajni Sekhri Sibal, both retired Indian Administrative Service officers; and the development economist Rajeev Malhotra.[^26]
Now the vote.
The reason the August 1, 2026 scrutinizer's report matters is not that a chairman got 79.17% instead of 98%. It is who voted against him. Public institutional shareholders — the constituency that normally supplies dissent at Indian companies, and that holds roughly 14.8% through foreign institutions and 6.1% through domestic mutual funds — supported the resolution at 99.27%.116 The opposition came from inside the 62.90% promoter block, where 64.31% of promoter e-votes went against the chairman's reappointment, even as the promoter representatives present physically at the meeting voted for him unanimously.13
There is no way to read that as anything other than a split inside the controlling structure. Some of the investment companies whose shareholdings are the subject matter of the Priyamvada Birla estate litigation are voting one way; others are voting the other way; and the resolution being fought over is the chairmanship of the man on the other side of that litigation.
What this evidence does establish: the control question at Birla Corporation is live in 2026, not historical. Twenty-two years of court proceedings have determined who may vote the shares. They have not produced a promoter group that agrees.
What it does not establish: operational mismanagement. This is an important distinction and it should not be blurred. The dissent is not about strategy, capital allocation, or disclosure. Institutional shareholders — who have every incentive to object to a chairman they consider a liability — backed him overwhelmingly. The operating team has run a conventional, well-telegraphed capacity playbook and has not, on the record of recent calls, missed guidance it set or reversed a stated strategy under pressure.
The right posture is monitoring, not verdict. The specific things worth watching are narrow and checkable: the vote share on the same resolution at the next AGM, any change in board composition or in the identity of promoter-group entities in the shareholding disclosure, any related-party transaction disclosure involving promoter investment companies, and any escalation in the pending special leave petitions before the Supreme Court.
The smaller items, sized honestly. In August 2026 the Joint Commissioner of CGST and Central Excise, Nagpur-I, issued RCCPL a demand-cum-show-cause notice for ₹10,30,06,338 plus equivalent penalty and interest, alleging wrongful availment of input tax credit across FY21 and FY23 based on a negative balance in the GST annual return. The company received intimation on August 11 and disclosed it the following day, stating that the notice lacks merit, that RCCPL had received a favourable order in a similar matter previously, and that there is no impact on its financial position.24 Against ₹1,571 crore of group EBITDA, this is bounded and small. It is worth one sentence, not a section. Separately, the FY26 annual report records no audit qualifications, adverse remarks, or disclaimers in the statutory auditors' report, and no qualifications or adverse remarks in the auditors' CARO reports for the subsidiaries.3 Promoter share encumbrance is not flagged as a rating consideration in CARE's June 2025 rationale, and pledged holdings are reported as insignificant in market data compilations — a clean signal, though a narrow one bounded to those records.1316
On management credibility, judged by behaviour rather than assertion. The useful test is whether stated targets survive contact with bad quarters. On this record they have. Across the May 2026 and July 2026 calls, the FY29 capacity target, the ₹900 crore FY27 capex figure, the ₹2,000 crore year-end net debt target, the ₹4,000 crore peak, and the 2.5 times leverage ceiling were all repeated unchanged — including in the quarter when margins compressed.1819 When analysts pushed for a full-year EBITDA per tonne number, the CFO declined rather than offering a figure he would have to walk back, calling it premature.18 When asked whether geopolitical uncertainty might delay the expansion, the answer was a flat no with a stated reason.18 That is a management team that says less than analysts want and does not change its story between quarters.
The less flattering read is that consistency is cheap when the capex programme has not started. Nearly all of the guidance being reaffirmed concerns spending that lies ahead. The credibility test that matters has not been administered yet: what management says in the quarter when the Maihar line is commissioning into a weak market and the debt is at its peak. Mukutban's FY23 is the closest historical analogue, and the company's disclosure through that period was factual rather than defensive — the annual report and rating rationales record the utilisation collapse and the margin damage plainly.133 That is a point in its favour, but it is one observation.
The capital allocation scorecard. Three data points define this management regime's record: a ₹5,000 crore acquisition agreement that collapsed on mineral-rights diligence; a ₹4,800 crore acquisition completed months later at a higher per-tonne price than the best comparable transaction of the same window; and a ₹2,744 crore greenfield plant that took four years to approach healthy utilisation.
The quantitative consequence is visible in the returns. On a standalone basis, the FY26 annual report shows return on capital employed of 7.33%, up sharply from 4.50% in FY25, and return on net worth of 8.94% consolidated against 5.01% the prior year.3 Independent compilations put ROCE around 8% in FY19, roughly 7% in FY25, and near 10% in FY26.16 The widely repeated claim that returns have simply halved over five years is too crude — FY26 was a genuine recovery year, and the FY23 trough was Mukutban-driven rather than structural. But the recovery has to be measured against the right benchmark, and the right benchmark is FY21: higher absolute profit on a materially smaller asset base. Gross block grew from ₹11,213.62 crore in FY21 to ₹14,332.61 crore in FY26 while net profit fell.3
The calibrated conclusion: the claim that Birla Corporation's expansion has created shareholder value is not yet rejected, but it is unproven and has been unproven for five years. FY26 is one data point of recovery against four of dilution. What would confirm it is a return on capital employed that holds in double digits through the next capex wave rather than only in the year between waves. What would falsify it is a repeat of the FY23 pattern when Maihar's clinker line commissions.
That is a company-specific question. But it is being asked inside an industry that has changed shape entirely underneath Birla Corporation's feet.
VIII. Industry Structure & Competitive Position
Picture the Indian cement industry in 2016, the year Birla Corporation bought Reliance Cement. UltraTech had about 66 million tonnes of domestic capacity. Ambuja and ACC together had roughly 60. Birla Corporation, post-deal, had 15.5. The gap was large but comprehensible — the leader was four times the mid-cap.
Now picture 2026. UltraTech and the Adani platform together control something on the order of 309 million tonnes, against about 126 million a decade earlier.25 UltraTech crossed 200.1 million tonnes of Indian capacity on April 17, 2026, becoming the largest cement company in the world outside China by capacity and sales volume, and has committed over ₹16,000 crore to reach beyond 240 million tonnes consolidated.5 It took the company 36 years to reach its first 100 million tonnes and under seven to add the second.5 Adani, which had no cement business at all before 2022, ended June 2026 at 109 million tonnes across Ambuja, ACC and Orient Cement, with six new units in trial production and a stated path to 119 million tonnes by the end of this fiscal year.6 In December 2025 the group approved merging ACC and Orient Cement into Ambuja under a single "One Cement" platform, targeting margin gains of up to ₹100 per tonne from consolidated manufacturing, logistics and marketing.26
Birla Corporation, at 21.4 million tonnes, is now roughly one-tenth of UltraTech and one-fifth of Adani. Its full FY29 target of 27.6 million tonnes is smaller than the capacity Adani added in the last two years alone. The scale gap is not closing. It is widening, and it is widening faster during the expansion than it was before it.
Does that matter? In cement, less than the raw numbers suggest — and more than regional players like to admit.
Cement's saving grace as an industry is that it is not really a national market. It is a set of overlapping regional markets defined by freight. A tonne of cement is worth roughly ₹5,000 and costs meaningful money to move a few hundred kilometres, which is why lead distance is a KPI and why Birla Corporation's average haul of 335 kilometres is a strategic variable rather than a logistics detail.18 A plant competes with the plants within its circle, not with total national capacity. On that basis Birla Corporation is not a minnow: ICRA has assessed its capacity market share in the central region at 11%, and the company's presence spans central, northern, eastern and western markets, which CARE cites as insulating performance from any single region's downturn.13
But three things have degraded that defence.
First, national players now have plants inside the regional circles. Adani's acquisitions and greenfields, and UltraTech's absorption of India Cements and Kesoram's cement business, mean the big two are not distant abstractions — they are local competitors in central and eastern India.25 Second, scale confers cost advantages that travel: fuel procurement, freight contracts, and now the ₹100-per-tonne synergy Adani expects from platform consolidation.26 Third, and most immediately, the industry is adding capacity faster than demand is absorbing it. Roughly 43 million tonnes came on stream during FY26 alone, leaving industry utilisation around 70%, and leading players have announced capital expenditure of about ₹120,000 crore through FY2027-28.3 Excess capacity in a commodity is a pricing problem by definition.
Running the five forces on this business produces an uncomfortable picture. Rivalry is intensifying and the evidence is direct rather than theoretical — price hikes taken across April and May 2026 were rolled back in June.21 Buyer power is high and rising: cement is sold through dealers to price-sensitive rural homebuilders and through tender to institutional buyers, and neither has switching costs. Supplier power is the one force Birla Corporation has genuinely neutralised, through captive limestone, its own coal block, and self-generation. Substitutes are effectively absent; nothing replaces concrete at scale in Indian construction in the next decade. New entrants are, unusually, a real threat — not from startups but from cash-rich conglomerates buying their way in, exactly as Adani did.
On the 7 Powers framework, the honest reading is that Birla Corporation holds one power and a fragment of a second. The genuine one is cornered resource: limestone leases at Satna, Maihar and Chanderia acquired decades ago, plus the Bikram coal block. That is a real, non-replicable asset. The fragment is branding. The company and its analysts assert MP Birla brand equity, and there is supporting evidence — premium products at 61.33% of trade sales, blended cement at 87.72% of volume, more than 10,000 dealers and 20,000 retailers across 13 states.34 But the harder proof point is missing. Brand power in cement should show up as a sustained price realisation premium against UltraTech and Dalmia in the same district, and neither the company's disclosures nor the calls provide that comparison. What the disclosures do show is realisation of ₹4,869 per tonne in FY26, essentially unchanged from the prior year, in a year the company itself describes as one in which it "was unable to raise prices in the face of intense competition for market share."3
That is a direct test of the brand claim, and the brand claim does not pass cleanly. It survives in a narrowed form: MP Birla appears to command dealer loyalty and mix advantage — customers buy the premium SKU — without commanding the ability to move price against the market. The falsification test is specific: if brand power is real, EBITDA per tonne should recover ahead of peers when regional prices firm, and the trade-channel price gap versus national brands in Uttar Pradesh and Madhya Pradesh should narrow. If instead the company continues to describe itself, as Ghose did in July, as unable to lead price because larger players won't move, then what looks like brand is really just channel mix.18
There is no scale power here, no network economies, no switching costs, and no counter-positioning — Birla Corporation is doing the same thing as everyone else, only smaller. Process power is the plausible candidate for the future: the cost work is real and compounding. But process power in a commodity gets competed away when the largest player has more of it.
Myth versus reality. Four consensus narratives attach to this company, and they are worth checking against the record.
Myth: Birla Corporation is a Birla company, part of the same group as UltraTech. Reality: it is not, and the confusion is more than pedantic. Birla Corporation belongs to the M.P. Birla Group, whose controlling shareholdings have been in litigation since 2004; UltraTech belongs to the Aditya Birla Group. They share a founding ancestor and nothing else — not management, not capital, not strategy. Any investor implicitly assuming Aditya Birla Group backstopping is mispricing the balance sheet.
Myth: FY26's 89% profit surge signals a step-change in earnings power. Reality: it is a recovery off a weak base, and the ten-year record makes that unambiguous — FY26's ₹557.58 crore remains below FY21's ₹630.14 crore.3 What genuinely improved was operational: utilisation from 91% to 95%, blended cement mix, and a fall in power and fuel cost per tonne. Those are durable improvements. The headline profit growth rate is not a trend.
Myth: the MP Birla brand gives the company pricing power in its core markets. Reality: it gives it mix, not price. The evidence for mix is strong; the evidence for price is absent, and FY26 realisation was flat at ₹4,869 per tonne while the company's own annual report attributes that to an inability to raise prices amid competition.3 A brand that lets you sell the premium SKU but not raise the price is a distribution asset, not a moat.
Myth: the promoter dissent at the 2026 AGM was an activist or institutional challenge to management. Reality: institutions supported the chairman at 99.27%; the opposition was internal to the promoter block.1 The correct reading is control friction, not a referendum on operating performance — and those are very different risks with very different resolutions.
Five-year revenue growth of roughly 7.3% a year with a three-year average return on equity of about 6.4% is what that structural position produces.16 Capacity has grown faster than earnings power. That is not a temporary phenomenon; it is the arithmetic of adding assets in a market where your competitors are adding them ten times faster and the price is set by the marginal seller. The bull and bear cases both start from that fact and diverge on whether the next five years break the pattern.
IX. Playbook: What This Company Teaches About Cyclical, Family-Controlled Industrials
Every long-lived company is a case study in something. Birla Corporation is a case study in five things that recur across Indian family-controlled industrials, and that transfer well beyond cement.
Patient capital has a specific, measurable duration — and it is longer than pitch decks assume. The Mukutban sequence gives an unusually clean measurement: first production in April 2022, EBITDA breakeven around March 2023, roughly half utilisation by FY24, and about three-quarters by mid-2026.1318 In a high-fixed-cost business, a plant running at 20% is not a plant earning less than expected; it is a plant destroying value while the depreciation and interest run. The general lesson is that in capital-intensive commodity manufacturing, the interval between commissioning and contribution is where investor patience is actually tested, and it is routinely underestimated by everyone including management. When evaluating any expansion announcement in this sector, the useful question is not "what does it cost" but "what does the balance sheet look like if this asset runs at a third of nameplate for two years."
M&A executed under time pressure produces worse prices than M&A executed on a plan. The Lafarge-then-Reliance sequence is not a story about a bad acquisition; RCCPL was a good asset that has become half the company. It is a story about sequencing. Having publicly committed to eastern expansion and then lost the asset, Birla Corporation transacted again within months, in the same hot market, at a higher per-tonne price than the buyer of the larger, more complete platform paid weeks later. The transferable lesson: when a company announces a deal to replace a failed deal, the second price is almost always worse, because the counterparty knows the buyer needs the transaction more than the transaction needs the buyer.
Family-control governance is not a static attribute; it is a latent state that can reactivate. Screening tools treat promoter holding as a number — 62.90%, high, therefore aligned. The Birla Corporation record shows why that is insufficient. A promoter block can be simultaneously large, unpledged, and internally at war, and the war can go dormant for years before resurfacing in a routine reappointment resolution twenty-two years after the triggering death. For minority shareholders, the practical implication is that in companies where the underlying ownership has been litigated, the AGM voting file is a more informative document than the shareholding pattern. It is also freely available and almost never read.
Legacy divisions survive for reasons that are not economic, and that is worth pricing rather than moralising about. A ₹3 crore annual EBITDA loss is not a reason to avoid a stock. But a management team that keeps a century-old mill running for identity reasons is telling you something about how it will weigh non-economic factors in future decisions — plant closures, headcount, regional political relationships. The pattern is common across Indian family conglomerates and is best treated as a disclosed preference rather than a scandal. The question to ask is only whether the same instinct might one day apply to something that costs ₹300 crore instead of ₹3 crore.
Read the ratio, but check the basis. A smaller, more technical lesson sits in Birla Corporation's own disclosures and generalises across Indian mid-caps with large subsidiaries. The company reports return on capital employed in its statutory ratio schedule on a standalone basis, while roughly half its cement volume and its most efficient plants sit inside a wholly owned subsidiary.3 A reader taking the standalone figure as the company's return on capital would be measuring the wrong entity. Whenever an operating business has been housed in a subsidiary — often for tax, incentive, or acquisition-structuring reasons — the headline ratios in the parent's filings describe a fragment. The remedy is unglamorous: rebuild the ratio from the consolidated statements, and treat any divergence between the two as a question to ask on the next call rather than a discrepancy to ignore.
The through-line connecting them is a single trait: this is a company that optimises for continuity. It keeps its mill, keeps its management, keeps its strategy across calls, keeps building in the same clusters. In a cyclical commodity industry, continuity is genuinely valuable — it is how you survive four decades of price cycles. It is also how you end up one-tenth the size of the leader.
X. Bear vs. Bull Case
The bull case, stated at its strongest.
Start with the demand backdrop, because everything else in the bull case sits on it. Indian cement demand grew around 9% in FY2025-26 to about 490 million tonnes, driven by housing and infrastructure, and the sector continues to receive substantial budgetary support.3 Against that, Birla Corporation ran at 95% capacity utilisation for the full year and 108% in the March quarter.2 A company selling everything it can make in a growing market has the one precondition that makes expansion rational: it is genuinely constrained. Saraogi made exactly this point when asked on the Q1 call whether geopolitical uncertainty might cause a deferral — the company operates above 90% utilisation and is "constrained for growth in the market that we are operating," so there is no question of deferral.18 That is a coherent answer, not an evasion.
The cost position is the most evidenced part of the bull case, and it deserves credit precisely because it is measurable rather than asserted: power and fuel cost per tonne fell in a year when petcoke rose 35%, green power moved up more than six percentage points, waste heat recovery is expanding, and the captive coal block is beginning to substitute for purchased fuel.318 This is a company that has repeatedly converted engineering work into per-tonne savings.
The regional entrenchment argument holds up better than the national scale argument suggests. Freight economics protect incumbents inside their circle, the central India position is a double-digit capacity share, and dealer density in rural Uttar Pradesh, Bihar, Madhya Pradesh, Maharashtra and Rajasthan is a distribution asset that takes years to build.1318
And the balance sheet is not stressed. Debt to equity stood at 0.51 at March 2026, improved from 0.56; interest cover was 5.92 times; net worth was ₹7,364.70 crore.3 CARE Ratings reaffirmed CARE AA with a Stable outlook and CARE A1+ on July 2, 2026 — a reaffirmation, not an upgrade, and it followed ICRA's earlier revision of its outlook to Stable from Negative in May 2024 once Mukutban's ramp restored coverage metrics.2713 A company entering a large capex cycle with an AA rating and net debt of ₹2,300 crore against ₹1,571 crore of annual EBITDA has room.183
The bear case, stated at its strongest.
The scale mismatch is structural and it is compounding. Even on full delivery of the FY29 plan, Birla Corporation will be a fraction of two competitors who are themselves still growing, and one of whom is explicitly buying growth. Nothing in the plan closes the gap; the plan barely holds the ratio.
The returns record is the hardest fact in the file, and it has already been laid out: five years of expansion, a larger asset base, and lower absolute profit than the pre-expansion year. FY26's recovery in return on capital is real but is one year, achieved in the gap between capex waves, and the next wave is entirely ahead.
The pricing power evidence is live and negative. The June 2026 quarter showed the mechanism in a single quarter: costs up, realisation nominally up, margin down, hikes reversed within sixty days.2118 Management's framing — that the company was a victim of its own success in maxing out the trade channel — is candid, but candour about a structural weakness does not remove the weakness.18
The governance overhang is current, not historical. A chairman reappointed with 79.17% support against majority promoter e-vote opposition is a signal that the control question inside a 62.90% block is unresolved, and the mechanism by which that could hurt minority shareholders is not abstract: contested control tends to produce board instability, delayed decisions, and — in the worst case — capital allocation shaped by intra-group considerations rather than returns.1
And jute is a persistent small drag with two consecutive years of negative EBITDA and management's own guidance that the coming year could be worse.3
Where it sits against the peer set. The most instructive comparison is not with UltraTech or Adani, whose scale makes the comparison uninformative, but with the other mid-sized regional players fighting the same battle: Nuvoco Vistas, the Nirma-owned entity built from the Lafarge India platform bought in 2016; Dalmia Bharat, which has been ramping the former Jaiprakash assets in central India; and Shree Cement, the long-standing low-cost operator. Each of these is a plausible acquirer, acquiree, or share-taker in Birla Corporation's markets, and Dalmia's central India ramp was the specific competitive threat analysts raised on the July call.18 The relevant observation is that the mid-tier is no longer a stable category. Over the past decade it has been steadily emptied by acquisition — India Cements and Kesoram's cement business into UltraTech; Sanghi, Penna and Orient into Adani.25 Birla Corporation, with a 62.90% promoter holding tied up in contested estate litigation, is structurally difficult to acquire. That protects it from being taken over. It does not protect it from being outgrown.
An activist's stress test. What would a skeptical investor actually push on here? Three things. First, the capital allocation authority: why is a company that has generated a sub-cost-of-capital return on its last ₹7,500 crore of deployment being trusted with another ₹4,335 crore, and what governance mechanism exists to stop the programme if the first phase disappoints? Second, disclosure: the company reports return on capital employed on a standalone basis in its ratio schedule, while the economics live in the consolidated entity where RCCPL sits; a consolidated ROCE disclosed on a consistent basis would make the expansion far easier to judge.3 Third, the promoter structure: 23 entities holding the promoter block, several of them the subject matter of estate litigation, is exactly the kind of complexity that invites questions about related-party flows and voting alignment — and the AGM split has now made those questions concrete rather than hypothetical.31
The calibrated conclusion. This is a "show me" situation, and the framing should be neither dismissive nor promotional. The cost-position claim is largely proven. The brand-power claim survives only in a narrowed form — mix advantage without price leadership. The management-execution claim is intact on operations and unproven on capital allocation. The balance-sheet-strength claim is currently valid but is about to be tested by a programme that has barely started spending.
Three things would confirm the bull case, and they are the only three worth tracking closely.
EBITDA per tonne, quarter by quarter. This is the master KPI. It aggregates pricing power, cost work, mix, and channel strategy into one number. The relevant question is not whether it recovers from ₹675 — seasonality alone should help — but whether it re-establishes a trend above the ₹786 full-year FY26 level while input costs stay elevated. If it does, the cost lever is beating the pricing weakness. If it does not, the company is a price taker with good engineering.
Capacity utilisation at the new assets, specifically Mukutban and the Maihar clinker line when it arrives. Mukutban is the honest benchmark for how this team ramps. Watching whether Maihar behaves better — faster to breakeven, faster to two-thirds utilisation — is the single cleanest read on whether execution has improved since 2022.
Return on capital employed through the capex cycle, not between cycles. A double-digit figure in FY26 proves the assets can earn when they are full and nothing new is being built. The claim under test is whether that holds while ₹4,335 crore goes into the ground.
XI. Material Risk Radar
The risks that matter here are the ones with a clear mechanism to earnings. Generic macro anxieties are not on this list.
Input cost inflation is the most immediate mechanism, and it is already operating. Cement's cost stack is dominated by fuel — petcoke and coal for the kiln, diesel for mining and freight — and power. The June 2026 quarter showed the transmission with unusual clarity: management attributed roughly ₹150 per tonne of combined bag and fuel impact in the quarter to geopolitical factors, and guided to a further ₹70-80 per tonne sequential increase in the September quarter.18 Because cement prices are set regionally by competitive dynamics rather than by cost, there is no automatic pass-through. Every rupee of unabsorbed cost lands in EBITDA per tonne.
**
Competitive pressure from consolidation is the slow-acting version of the same risk. Adani's platform consolidation is explicitly targeting cost synergies, and cost leaders in commodities eventually set the price floor.26 Birla Corporation's exposure is concentrated where it is strongest: Ghose noted on the July call that central India prices had been soft for roughly a year on competitive dynamics, and that the company's dependence on the region had increased with the Kundanganj line — a rare instance of management naming the downside of its own expansion.18 Analysts pressed specifically on Dalmia Bharat ramping up the former Jaiprakash assets in the same region.18
Execution risk in the capex programme is the largest company-specific risk, because the precedent is documented. The Maihar clinker expansion is an integrated project of the type that took four years to ramp last time, and the current programme is larger and faster-paced than the one that produced Mukutban. Management has reaffirmed the FY29 timeline on consecutive calls, and pre-project activities including environmental clearance were described as on plan as of July 2026.18 The risk is not that the plant does not get built; it is the gap between commissioning and contribution.
Leverage risk is a function of that execution risk rather than independent of it. Net debt is guided to peak around ₹4,000 crore from ₹2,300 crore, with the covenant-style constraint being net debt to EBITDA below 2.5 times.18 That ratio is safe if EBITDA holds. It is not safe if EBITDA per tonne stays near ₹675 while debt rises — which is precisely the combination the June quarter previewed. CARE's negative rating triggers are explicit and worth knowing: net debt to operating profit sustained above 3.50 times, announcement of a major debt programme that moderates the capital structure, or cash and equivalents falling below ₹300 crore.13 The rating is stable conditional on the capex staying phased and the earnings holding.
Governance and control risk is the one that peer cement companies do not carry in this form. The mechanism by which the AGM split could damage minority shareholders runs through board composition, strategic continuity, and the possibility that unresolved estate litigation produces disruptive changes in who controls the promoter entities. It is not currently affecting operations. It is a tail risk with an unusually long history of resurfacing.
Demand risk has a specific seasonal channel in this business. Roughly four-fifths of Birla Corporation's volume moves through the trade channel, and a large share of that is rural housing in Uttar Pradesh, Bihar, Madhya Pradesh and Rajasthan — construction financed out of farm incomes.18 That makes the monsoon a direct input to the demand curve rather than a background variable. The FY26 annual report flags the point explicitly, noting that Indian Meteorological Department forecasts pointed to 2026 monsoons potentially running significantly below the long-period average, which would raise food prices and squeeze the rural wallet.3 Ghose raised the same concern on the July call, noting that a delayed monsoon had kept volumes strong through the June quarter but that a poor harvest could carry into the December quarter.18 A company concentrated in the rural trade segment gets the margin benefit of that channel and the volatility of it in the same package.
One accounting judgment worth noting. FY26 exceptional items included an expected credit loss of ₹35.68 crore on West Bengal incentive receivables and a ₹28.05 crore impairment of mining rights in Himachal Pradesh and Maharashtra, against a ₹91.32 crore recognition of Maharashtra industrial promotion incentives relating to earlier years.2 State incentive receivables are a recurring judgment area for Indian cement companies — the company accrued ₹33 crore of incentives in the June quarter and expects ₹130-135 crore for the full year across Mukutban and Kundanganj — and their timing meaningfully affects reported realisation per tonne.18 Investors comparing realisation across quarters should be aware that incentive accruals move the number: Saraogi explicitly walked analysts through a roughly ₹50 per tonne sequential distortion from lower incentive booking in the June quarter.18
XII. Epilogue: A Century-Old Name Still Fighting Its Own Family
There is a particular kind of Indian company that outlasts everything — the licence raj, liberalisation, three or four demand cycles, a pandemic — without ever quite becoming a leader. Birla Corporation is that company. It has been operating continuously for 107 years. It survived the loss of the industry that gave it its name. It survived a twenty-two-year fight over who owns it. It is currently selling more cement than at any point in its history.
And it is one-tenth the size of the company that shares half its founder's name.
What Birla Corporation is today is legible enough: a mid-sized cement producer entrenched in the limestone belt of central India, running its plants near capacity, executing a real cost programme, and beginning a capacity expansion that will roughly double its debt before it produces a tonne of clinker. Wrapped around it is a jute mill that loses a few crore a year and is kept for reasons that have nothing to do with returns. Above it sits a chairman whose family's claim to the shares was litigated for two decades and who was just reappointed against the electronic votes of most of his own promoter group.
Two questions will decide how this decade reads in retrospect. The first is whether the August 2026 dissent settles quietly — a procedural artefact of estate administration that fades as the courts finish — or whether it is the first visible tremor of another round of the control fight that has shaped this company since 2004. Nothing in the public record answers that yet.
The second is more prosaic and probably more consequential for shareholders. The last leg of expansion — Reliance Cement, Mukutban, Kundanganj — grew the company by roughly half and left absolute profit below where it stood before the building started. The next leg is bigger. Management's case is that utilisation is maxed, the market is growing, and the cost machine is working. The historical record says this team takes longer than planned to convert capacity into earnings and has paid full prices for scale.
There is a version of this story where the answer is straightforwardly good. Indian cement demand grows through the back half of the decade, regional prices firm as the current wave of capacity gets absorbed, the Maihar clinker line commissions on time into a tight market, and a company already running at 95% utilisation with a working cost programme converts 6.2 million additional tonnes into the return on capital its last expansion never delivered. Nothing in the record makes that implausible.
There is another version where the capacity arrives into a soft market, the peak debt guidance of ₹4,000 crore turns out to be the optimistic case, EBITDA per tonne stays closer to ₹675 than ₹1,000, and the company spends another five years deleveraging while the two national players keep compounding. That version has already happened once, between 2016 and 2021.
Both can be true. The gap between them is the investment question: a company with genuine industrial durability — a century of surviving cycles, irreplaceable mineral assets, real engineering competence — and a financial durability that has weakened even as the enterprise has grown. Whether the next 6.2 million tonnes closes that gap or widens it is not knowable today. It is, however, measurable quarter by quarter, in a single number the company reports every three months.
XIII. Recent News
Q1 FY27 results and earnings call (July 25, 2026). Consolidated net profit fell 3.2% year on year to ₹115.73 crore on revenue from operations of ₹2,646.45 crore, up 7.8%. Cement volumes grew about 5% to 5.05 million tonnes at 98% utilisation, but EBITDA per tonne dropped 5.6% to ₹675 as power and fuel costs rose and April-May price increases were reversed in June.2021 On the call, management reaffirmed FY27 capex guidance of ₹900 crore, a year-end net debt target of about ₹2,000 crore against ₹2,300 crore at quarter-end, unchanged peak net debt guidance of ₹4,000 crore, and the FY29 capacity target — while declining to guide on full-year EBITDA per tonne, calling it premature.18
106th AGM and scrutinizer's report (August 1-3, 2026). Shareholders approved the FY26 accounts, a ₹12.50 per share dividend, and cost auditor remuneration with about 98.8% support each. Harsh V. Lodha's reappointment as director passed with 79.17% support after the promoter and promoter group voted against in 64.31% of e-votes while supporting unanimously in the physical poll; public institutions supported at 99.27%. The consolidated report by scrutinizer Anil Kumar Murarka was filed with BSE and NSE on August 3, 2026.1
GST show-cause notice to RCCPL (August 11-12, 2026). The subsidiary received a demand-cum-show-cause notice for ₹10.30 crore plus equivalent penalty and interest from CGST Nagpur-I, alleging wrongful input tax credit availment across FY21 and FY23. The company stated the notice lacks merit, cited a prior favourable order in a similar matter, and reported no impact on RCCPL's financial position.24
Credit rating reaffirmed (July 2, 2026). CARE Ratings reaffirmed long-term ratings at CARE AA with a Stable outlook and short-term ratings at CARE A1+ across bank facilities and non-convertible debentures.27
Kundanganj Line III commissioned (March 2026). RCCPL's third grinding line at Kundanganj, Uttar Pradesh, added 1.4 million tonnes at a cost of around ₹300 crore, taking consolidated capacity to 21.40 million tonnes.3
Full-year FY26 results (May 9-11, 2026). Record cement sales of 18.72 million tonnes, cement production crossing 19 million tonnes for the first time, consolidated total income of ₹9,772.56 crore, and net profit of ₹557.58 crore, up 89.2%. The March quarter delivered the highest-ever quarterly volumes and 108% utilisation.228
XIV. Links & Resources
Primary company materials. The FY2025-26 annual report is the single most useful document for this company: it contains the ten-year consolidated financial summary, the segment breakdown, the plant-by-plant power and green energy data, and — unusually — the company's own detailed account of the administrator litigation in the director reappointment disclosure.3 The investor relations pages carry the annual report archive, quarterly financial results, and the earnings call transcript library, which is where the operating story is told most candidly.[^32][^33][^34] The board of directors page carries current composition and biographies.[^26] Birla Corporation's AGM page hosts meeting notices and voting outcomes.[^35]
Earnings calls. The Q1 FY27 transcript filed with the exchanges on July 28, 2026 is the best recent window into competitive dynamics in central India, the Mukutban lead-distance constraint, and the financing plan for the FY29 expansion.18 The Q4 and full-year FY26 call from May 11, 2026 covers the premiumisation strategy, the green power roadmap, and the ₹4,300 crore net-of-GST framing of the capex programme.19
Credit research. CARE Ratings' June 2025 rationale sets out the strengths-and-weaknesses framework in plain language, including the important point that the older standalone plants are fuel-inefficient and that RCCPL's newer units carry consolidated margins; it also lists the explicit rating triggers.13 ICRA's May 2024 rationale is the best single source on the Mukutban ramp-up, with year-by-year utilisation and operating profit per tonne figures.29 CARE's 2024 rationale provides the prior-year comparison.30
Transaction history. The company's February 2016 press release on the Reliance Cement acquisition gives the deal terms, advisers, and management rationale in the company's own words.[^11] Contemporaneous coverage of the Lafarge agreement, its collapse, and Nirma's subsequent purchase of the full Lafarge India platform provides the comparative pricing that makes the RCCPL valuation assessable.9101415 CemNet's completion report and World Cement's coverage document the closing.1112
Litigation. The SCC Online summary of the Calcutta High Court's December 14, 2023 Division Bench judgment is the clearest available account of the Priyamvada Birla will case timeline and the reasoning that limited the administrators' powers.7 Coverage of the Supreme Court's 2021 refusal to entertain the Birla family's petition covers the prior round.8
Industry structure. CemNet's analysis of India's capacity race documents the decade-long consolidation and the combined position of the two largest groups.25 UltraTech's own release on crossing 200 million tonnes and Adani's Ambuja quarterly disclosures provide the current scale benchmarks, and CemNet's report on the One Cement merger explains the platform consolidation.5626 CRISIL's projection of capacity additions across fiscals 2026-28 frames the supply overhang.31
References
-
Birla Corporation AGM results show promoter dissent on Lodha reappointment — ScanX, 2026-08 ↩↩↩↩↩↩↩↩↩
-
Birla Corp FY26 Results: Record Cement Sales of 18.72 MT; Net Profit Surges 89% to ₹558 Crore — ScanX, 2026-05 ↩↩↩↩↩↩↩
-
Birla Corporation Limited Annual Report 2025-26 — NSE corporate filings, 2026-07-09 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
About Us — MP Birla Cement (Birla Corporation Limited) ↩↩↩↩↩↩
-
UltraTech surpasses 200 Million Tonnes Per Annum Capacity in India — UltraTech Cement, 2026-04-17 ↩↩↩↩
-
Ambuja Delivers Sustainable Q1 FY'27 Performance Driven by Value-Led Growth and Operational Excellence — Adani Group, 2026-07 ↩↩↩
-
Calcutta High Court modified order granting major relief to Lodhas in Priyamvada Birla Will Case — SCC Online Blog, 2023-12-14 ↩↩↩↩↩
-
SC rejects Birla SLP against HC dismissal of contempt plea against Lodha — Business Standard, 2021-07-12 ↩↩
-
Birla Corp in Rs.5000 cr deal with Lafarge for cement units — Moneylife, 2015-08-17 ↩↩↩
-
Birla Corporation to move court against Lafarge-Holcim — Business Standard, 2016-02 ↩↩
-
Birla completes acquisition of Reliance Cement — CemNet, 2016 ↩↩↩
-
Birla Corp completes acquisition of Reliance Cement — World Cement, 2016-08-25 ↩↩
-
CARE Ratings Press Release — Birla Corporation Limited, 2025-06-03 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Nirma cements $1.4-bn Lafarge India buyout — Business Standard, 2016-07-11 ↩↩↩
-
Non-Core Exit for Reliance, Opportunity for Birla — M&A Critique ↩↩
-
Birla Corporation Ltd — Screener.in consolidated financials and shareholding ↩↩↩↩↩
-
Birla Corp Q4 Profit Rises 33%, Eyes Expansion by 2029 — Construction World, 2025-05 ↩↩
-
Transcript of the investors/analyst conference call on Q1 FY27 results — Birla Corporation Limited, filed with BSE 2026-07-28 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Birla Corporation Limited Fiscal Year 2026 Earnings Conference Call Highlights — InvestyWise, 2026-05 ↩↩↩↩
-
Fuel cost, price pressure push down Birla Corp Q1 profit 3.2% to ₹115.73 cr — Business Standard, 2026-07-25 ↩↩
-
Birla Corp reports lower 1QFY27 profit — CemNet, 2026-07 ↩↩↩↩↩
-
New head for Birla Corporation coming in 2023 — Global Cement, 2022-11 ↩
-
Sandip Ghose rejoins MP Birla Group, will take charge as MD & CEO — HRKatha, 2022-11 ↩
-
Birla Corporation subsidiary RCCPL faces ₹10.30 crore GST show cause notice — ScanX, 2026-08-12 ↩↩
-
Adani Group to merge Ambuja, ACC and Orient Cement into single platform — CemNet, 2025-12 ↩↩↩↩
-
CARE reaffirms Birla Corporation's AA credit ratings with stable outlook — TipRanks, 2026-07-03 ↩↩
-
Birla Corporation Q4 FY26 results: Net profit rises 15% to ₹294.8 crore — Business Standard, 2026-05-09 ↩
-
Birla Corporation Limited: Rating reaffirmed; outlook revised to Stable from Negative — ICRA, 2024-05-17 ↩
-
CARE Ratings Press Release — Birla Corporation Limited (Revised), 2024-06 ↩
-
India's cement capacity addition to see 75% jump over fiscals 2026-28 — CRISIL Ratings, 2025-11 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube