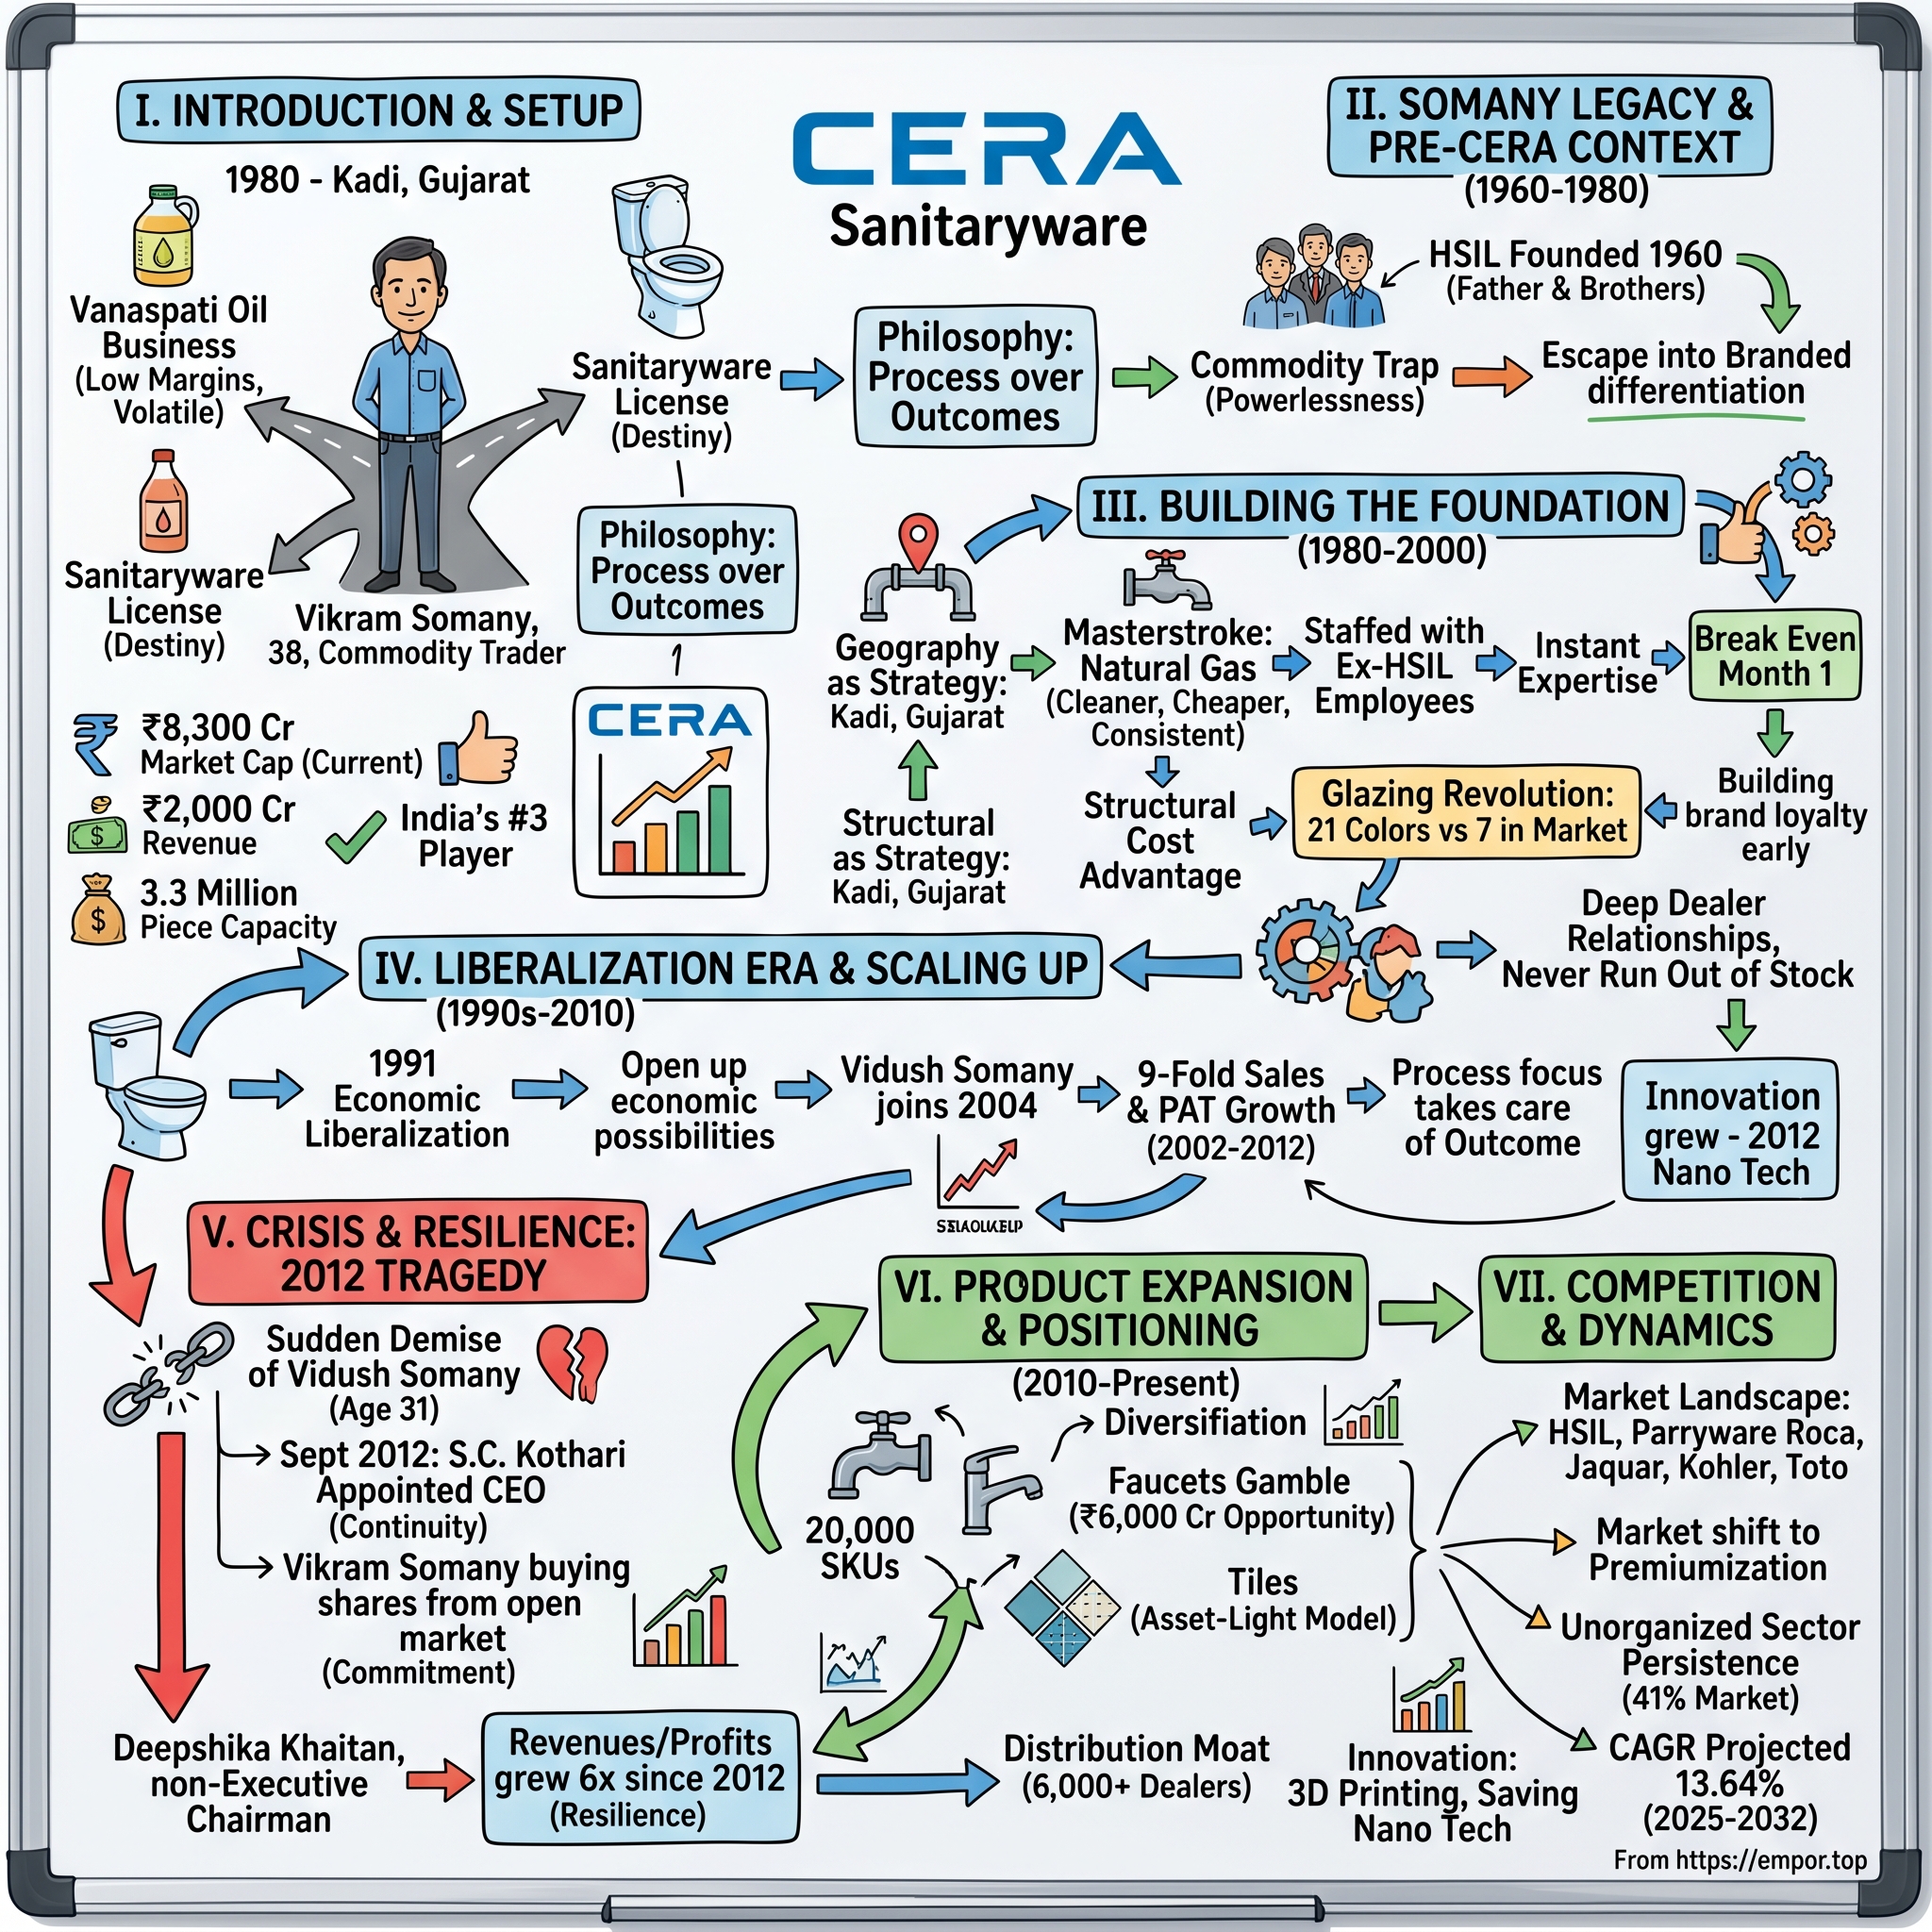
CERA Sanitaryware: Building India's Bathroom Brand — Twice
I. Introduction & Episode Setup
On a Friday morning in early August 2026, the management of CERA Sanitaryware dialled into an earnings call to report the best revenue quarter in the company's history. Sales for the June quarter came in at ₹486 crore, up 19.5% over the prior year — the kind of number a building-materials company in India dreams about after two years of grinding, uneven demand.1
By the close of trading, the stock was down 4.15%.1
That gap — between a top line that is finally working and a market that refuses to reward it — is the puzzle this story is built around. Because underneath the growth, the operating margin had collapsed to 10.1% from 13.1% a year earlier, gross margin had fallen from a historical 50%-plus to somewhere in the mid-forties, and profit after tax had gone backwards.1 For the full year ended March 2026, CERA had grown revenue to roughly ₹2,050 crore while net profit fell 17.1% to ₹204 crore.2 The company was selling more and earning less.
Set against that is a balance sheet most Indian mid-caps would envy. Borrowings of about ₹47 crore against a net worth of ₹1,472 crore.3 Cash and equivalents of ₹943 crore as of June 30, 2026 — very nearly half the company's annual revenue sitting idle.1 CRISIL reaffirmed the company at AA/Stable and A1+ in July 2025; CareEdge reaffirmed its own AA/Stable in August 2025.45 This is not a business in distress. It is a business whose economics have temporarily stopped working while its financial position remains close to pristine.
So the central question of this episode: how did the son of a sanitaryware family — who started his own career not in ceramics but in vanaspati oil and de-oiled cattle feed — build one of India's three or four largest organized bathroom brands, and why, forty-six years in, is that brand's profit shrinking while its revenue grows?
There is a second thread running underneath, and it is the one that matters most for anyone thinking about this company on a ten-year view. Twice, over a decade, CERA tried to own or co-own tile manufacturing capacity. Twice it exited. The first attempt ended in a divestment completed in March 2023 with an impairment recognised along the way; the second ended in March 2025 with the entire investment written off and a further settlement paid out to walk away.67 Management's story today is one of capital discipline — debt-free, dividend-generous, capex-cautious. The record of the last decade offers a more complicated read.
This episode will test three things. First, whether the core sanitaryware-and-faucetware franchise has a genuine, evidenced moat — dealer distribution, brand, a cost position in gas-fired kilns — or whether those are legacy talking points that recent input-cost inflation has quietly falsified. Second, what to make of a founder who is still Chairman and Managing Director in his fifth decade, fourteen years after the death of the son he had been grooming to succeed him. And third, whether premiumisation — new brands at the top and bottom of the price ladder — can outrun a real-estate cycle that has been unkind to every listed building-materials name in India for two straight years.
The place to start is 1980, in a small town in north Gujarat, with a man who had spent a decade learning exactly how much he hated selling a commodity.
 Subscribe on LinkedIn
II. Origins: From Commodity Trader to License-Raj Manufacturer
The Somany name was already in Indian bathrooms before Vikram Somany ever fired a kiln. His father, along with his brothers, had set up Hindustan Sanitaryware in 1960 — the country's first organized sanitaryware company, and for two decades the default answer to the question of who made India's toilets.8
Vikram Somany did not inherit that business. Family restructuring left him running something considerably less glamorous: vanaspati oil, the hydrogenated vegetable fat that sat in every Indian kitchen, and de-oiled cakes, the pressed residue sold on as cattle feed and fertiliser.8 It is hard to design a better education in the miseries of commodity economics. Two products with no brand, no switching cost, no pricing power, and margins set entirely by the spread between agricultural input costs and whatever the market would bear that week. In a good year you made money. In a bad year the same volume made you nothing. The business taught him, in the most expensive way available, that the only thing worth owning is something a customer will ask for by name.
So when he signed a memorandum of understanding in 1978 and received a license around 1980 to manufacture vitreous china sanitaryware, he was not entering a new industry so much as escaping an old one.8 The plant went up at Kadi, in Mehsana district, Gujarat — a location that looks arbitrary on a map and was anything but.
Three decisions from those first years still shape the company's cost structure and its self-image.
The first was human. Somany staffed the new plant with former Hindustan Sanitaryware people.8 Ceramic sanitaryware is a deceptively brutal manufacturing process to learn: you are pouring liquid clay slip into plaster moulds, drying it, glazing it, and firing it at over a thousand degrees, and the ware shrinks by roughly a tenth as it goes. Warping, cracking, glaze defects and dimensional drift are not exceptions — they are the daily condition of the business. The difference between a plant that yields 90% first-quality output and one that yields 70% is not equipment; it is people who have already made every mistake once. Hiring out of the incumbent bought him a decade of learning curve on day one.
The second was energy. Kadi sat near a gas field, and Somany built the kilns to run on natural gas at a time when Indian ceramic plants overwhelmingly burned coal or oil.8 Gas fires cleaner and more evenly, which lifts yield; it also, at 1980 Indian gas prices, cost less. This became the founding legend of CERA's cost position, and it is still invoked. It deserves to be tested against 2026 conditions, and Section IX does exactly that — because the weighted average gas cost the company paid in the June 2026 quarter was ₹48.43 per cubic metre, against ₹33.17 a year earlier.1 A structural cost advantage built on cheap gas is only an advantage while the gas is cheap.
The third was product. In a market where the incumbents offered seven colours, CERA launched with twenty-one.8 This sounds trivial. It was not. Under the license raj, sanitaryware was a seller's market — supply was rationed, and a manufacturer could sell whatever it made. Somany's insight was that in exactly such a market, the cheapest way to differentiate is variety, because a customer who wants an avocado-green washbasin will wait for it and pay for it. It was, in effect, a premiumisation strategy in an era before anyone in India used the word. The plant reportedly broke even in its first month.8
What is worth carrying forward from this section is not nostalgia but a philosophy: Somany has consistently described his approach as prioritising process over outcomes, and his stated ambition has never been market leadership for its own sake.8 That is an unusual posture for an Indian founder, and it produced an unusually conservative company. It is also, as we will see, a posture that sits awkwardly next to two failed tile ventures. In 2001 he exited the commodity business entirely to concentrate on sanitaryware — the clean break that set up the growth decade.8
That growth, though, did not really come from him.
III. Scaling Through Liberalization (1990s–2010)
The company took the name CERA Sanitaryware in 1998, and Vikram Somany consolidated control in 2002. But the story of the next decade belongs to someone else.
Vidush Somany — Vikram's only son — joined the business in 2004, in his early twenties, and what followed was the steepest sustained expansion in the company's history. Sales multiplied roughly ninefold between 2002 and 2012, with margins improving alongside; by the end of that run the business had gone from a mid-single-digit share of the organized sanitaryware market to something closer to twenty percent.8 Revenue for the year ended March 2012 stood at ₹319 crore with net profit of ₹32 crore — small numbers by today's standard, but the product of a decade of compounding at a rate few Indian building-materials companies have matched before or since.9
It is worth being precise about where that growth came from, because the mechanisms are still the ones the company relies on.
Quality as a marketing weapon. The company brought in foreign consultants and ceramic scientists to attack defect rates.8 In a category where the unorganized sector competes almost entirely on price, and where a cracked or crazed washbasin is a permanent, visible reminder of a bad purchase, yield improvement does two things at once: it lowers unit cost and it justifies a price premium. That is the rare investment that widens the margin from both ends.
Scale at a single site. Rather than scattering capacity, CERA concentrated at Kadi, which grew into what the company describes as the largest single-location sanitaryware plant in the country.8 Ceramic manufacturing rewards this. Kilns run continuously; the marginal cost of an additional line at an existing site is far below a greenfield equivalent, and the technical staff who understand your specific clay body and glaze chemistry are already on the payroll.
Deliberate positioning below the import line. CERA aimed at the mass and mid-premium segments rather than the luxury tier.8 This was, in hindsight, the most consequential strategic choice of the era. Liberalisation brought Kohler, TOTO and Duravit into India at the top of the market. By sitting one rung down, CERA competed against domestic peers and the unorganized sector — where its brand and distribution mattered — rather than against global design houses with century-old catalogues.
Sustained brand spend. Advertising and promotion ran above 4% of revenues during that period, against roughly 3% today.85 For a product a consumer buys perhaps twice in a lifetime, brand is largely built through the dealer and the plumber, not the end user — but television and print spend is what gives the dealer something to point at.
The most consequential capital decision of the era, though, was faucets. CERA had been selling taps and fittings under its own brand for years while outsourcing the actual manufacture — a low-risk way of testing whether the CERA name travelled from ceramic into brass.8 It did. So in 2010-11 the company committed to building its own faucetware plant, in Andhra Pradesh, as part of a capital expenditure programme of roughly ₹100 crore spread over three years.
The logic was straightforward and, unusually for a diversification, correct. Faucets and sanitaryware are sold to the same dealer, specified by the same architect, installed by the same plumber, and bought in the same shopping trip by the same consumer. Owning the manufacture rather than renting it meant controlling quality, capturing the manufacturing margin, and being able to design distinctive products rather than badge someone else's. Sixteen years later, faucetware is the fastest-growing part of CERA and, at 40% of revenue in the June 2026 quarter, close to overtaking the core.1
Hold that thought, because it is the control experiment. When CERA integrated vertically into an adjacent category that shared its customer, channel and brand, it worked. When it later tried the same trick in tiles, it did not — twice. The difference between those outcomes is the single most useful thing this company teaches about capital allocation, and we will come back to it.
By 2012, then: a founder in his sixties who had built a franchise, a son in his early thirties who had scaled it, a new faucet plant coming online, and a clear line of succession. And then, in the space of a few weeks, the succession was gone.
IV. The 2012 Succession Crisis
In August 2012, Vidush Somany died. He was thirty-one.10
A note on sourcing before going further, because it matters for how much weight to place on what follows. The account of Vidush Somany's death in August 2012 and its aftermath is corroborated by independent secondary sources — a contemporaneous stock update published in September 2012 and a later long-form retrospective — rather than by a primary news obituary that this analysis was able to locate.108 The broad facts are consistent across those accounts and are consistent with the company's subsequent filings and leadership changes. They should be read as well-supported rather than as unimpeachable primary record.
What makes this episode analytically valuable — as opposed to merely sad — is that it is a genuine discontinuity. Family business resilience is one of the most over-claimed qualities in Indian equity markets. Nearly every promoter-controlled company describes itself as having long-term orientation and institutional depth. Almost none of them are ever tested. CERA was tested, without warning, at the exact moment the person driving its growth was removed from it.
The response tells you something about how the company was actually built. S.C. Kothari, a long-serving executive who had already retired, returned as chief executive within weeks, and a chief operating officer was promoted from within.108 There was no external search, no marquee hire from a multinational, no consultant-led restructuring. The bench that existed was the bench that was used.
That is only possible if the bench was real, and one specific detail suggests it was. Somany had, by his own account, built an organisation in which he delegated heavily and in which some employees were paid more than he was.8 For an Indian promoter-run mid-cap, that is genuinely unusual — the more common pattern is a founder who is the single point of failure for every decision and the highest-paid person in the building by a wide margin. (It is also worth noting, and we will return to it in the next section, that this description does not hold today: Vikram Somany's own compensation is now a multiple of both his employees' median and his listed peers'.)
Now the falsification test the outline rightly flags. The claim that "revenues and profits grew roughly sixfold since 2012" is repeated in almost every retelling of this company. Does it survive checking?
It does, and precisely. Revenue for the year ended March 2012 was ₹319 crore and net profit ₹32 crore.9 For the year ended March 2026, revenue was approximately ₹2,050 crore and profit after tax ₹204 crore.23 That is 6.4 times on both lines over fourteen years — a compound annual growth rate of roughly 14% on revenue and the same on profit, through demonetisation in 2016, the GST transition in 2017, and the pandemic. The multiple is real. The CAGR it implies is good but not extraordinary, and it is important to say both things: a headline "6x" sounds transformative; 14% a year for fourteen years is the more honest and more useful framing.
There is a further wrinkle, and it is the one that matters for a forward-looking view. That 14% average conceals a decisive slowdown. Screener's decade view shows ten-year sales growth of 8%, five-year growth of 11%, and three-year growth of 4%.3 The compounding happened mostly in the first half of the period. The most recent three years — FY24, FY25, FY26, at ₹1,871 crore, ₹1,915 crore and ₹2,050 crore of revenue — represent near-stagnation followed by a modest recovery.3 An analyst put this to management bluntly on the February 2026 call: given a strong real-estate cycle since 2021, why had sales been "highly stagnant over the last 3 or 4 years"? The CFO's answer conceded the premise — "you are right that for the last 2 years, there had been stagnancy in the growth" — and pointed to a second-half revival that had, in fairness, begun to show up.11
So the 2012 succession claim survives the test in a narrow, useful form: the company demonstrably did not break when its heir apparent died, and it compounded well for the following decade. What it does not prove is that the company has resolved succession. It proves the opposite, and that is where the present begins.
V. Current Leadership, Ownership & Capital Allocation
Open CERA's May 2026 investor presentation to the leadership page and the first face is Vikram Somany: B.Sc., FCMI (U.K.), founder of the business in 1980, "over four decades of industry experience," and — the phrase the company chooses — "actively involved across strategic planning, operations and execution."12
Sit with that for a moment. Forty-six years after founding, and fourteen years after losing the son he had spent eight years training, the founder is still Chairman and Managing Director and still described by his own company as actively involved in execution. Formal succession beyond him has not been resolved in any public document.
That is not a scandal. It is, however, a structural fact that a long-term owner has to price, and it is not the sort of thing that resolves gradually. It resolves either through a planned handover that has not yet been announced, or through an unplanned event of the kind that already happened once in this company's history.
Deepshikha Khaitan. The most important governance development of recent years is the steady, verifiable promotion of Somany's daughter. She has been associated with CERA for over twelve years, moved into the Joint Managing Director role in 2020, and was reappointed as Vice Chairman and Joint Managing Director for a further five-year term effective April 1, 2025 — a reappointment approved by shareholders through a postal ballot.1213 Two things are worth flagging. First, this is an executive role, not a ceremonial one: the company's own description credits her with driving design innovation, product development and R&D, alongside channel expansion and brand initiatives.12 Older secondary sources that describe her as a "non-executive chairman" are simply out of date.8 Second, shareholders reappointed her again at the 28th Annual General Meeting on July 23, 2026, in a meeting where voting participation reached 83.34% and promoter and institutional holders were fully supportive.14
The rest of the bench is more institutional than it once was, and reads as a deliberate hiring-in of category experience. Anupam Gupta serves as Executive Director (Technical), with thirty-four years across cement, textiles, chemicals and ceramics, seventeen of them at the Aditya Birla Group. Vikas Kothari is Chief Financial Officer, a chartered accountant with prior stints at the Aditya Birla Group and Reliance Industries. Chief Business Officer Ramesh Baliga arrived from Jaquar and Watertec India — that is, from the company that dominates the category CERA is trying to grow into. Sandeep Abraham, President–Sales, came from Roca and Parryware Roca; Rahul Jain, President–Marketing, from Roca and AkzoNobel; the divisional heads of faucetware and sanitaryware manufacturing came from HSIL, Kohler and LG.12
Read plainly: this is a founder-run company that has hired its operating layer almost entirely from its competitors. That is a reasonable way to import capability. It is also a reminder that the "institutional depth" of 2012 — veterans who had grown up inside CERA — has been substantially replaced by lateral hires whose tenure is measured in years, not decades. On the August 2026 call, management acknowledged a leadership transition within the Senator and Polipluz verticals and said an internal successor had been identified, while cautioning that these are "long-term investments" requiring "several years" to establish a meaningful presence.1 Churn at the top of new initiatives is not fatal, but it is the kind of detail that belongs in the record.
Ownership. Promoters held 54.41% as of June 2026, foreign institutions 15.42%, domestic institutions 14.07%, and the public 16.08%.3 The promoter stake is held chiefly through Vikram Investment Company Pvt Ltd, and the shareholding pattern shows no promoter pledge — a genuinely clean structure by Indian mid-cap standards, though anyone underwriting this should verify pledge status directly from the most recent exchange filing rather than take it on trust.14 Somany's personal holding was estimated at roughly ₹15 billion — about ₹1,500 crore — of company stock.15 That is real alignment, and it is the strongest single argument against worrying too much about the pay issue we are about to discuss.
On the institutional side, one name stands out. Nalanda India Equity Fund held 9.6% as of March 31, 2026 — by some distance the largest non-promoter holder, ahead of Canara Robeco (3.0%), UTI (2.8%) and HSBC (2.6%).12 Nalanda is a concentrated, long-duration investor known for holding Indian mid-caps for a decade or more and for a stated preference for exactly this profile: high return on capital, low debt, founder-run, boring. Its presence is not a recommendation, but it is a data point about who has done the work and stayed.
Pay versus performance. Vikram Somany's total compensation for the year ended March 2025 was approximately ₹8.8 crore, of which roughly ₹7.8 crore was fixed salary — about 89% of the package — and the balance other components.15 Two comparisons frame it. Against the company's own employees, it was roughly nine times the median employee's pay. Against listed Indian building-industry peers, where median CEO compensation runs around ₹1.6 crore, it was on the order of 450% above the peer level.15
Name it plainly: that is a governance flag. A package that is nearly all fixed salary and several times the peer median is, structurally, weak pay-for-performance — the founder was paid the same whether FY26 profit rose or fell 17%, and it fell. The mitigating facts are equally real: he owns roughly ₹1,500 crore of stock, so the overwhelming majority of his economic exposure is to the share price rather than the salary, and no shareholder revolt has surfaced. The FY26 AGM resolutions passed with promoter and institutional support and 83.34% participation.14 The honest conclusion is that this is a second-order concern rather than a thesis-breaker — but it is a real one, and it sits in a category of founder-privilege items that tend to become first-order only when performance stays poor.
Capital allocation, read straight. This is where the analysis has to be careful, because the same set of facts supports two very different stories.
The bullish reading: near-zero debt, with gearing of 0.01–0.05x and interest cover above 35 times.45 Strong liquidity, growing to ₹943 crore by June 2026.1 A dividend of ₹75 per share for FY26, with the payout ratio climbing from roughly 33% of profit in FY24 to 34% in FY25 to 47% in FY26.23 Both major rating agencies reaffirmed at AA.45 Auditors Singhi & Co., appointed from the 24th AGM through the 29th, have issued no qualified opinion.14
The less flattering reading of the same facts: a company that has grown revenue at 4% a year over three years, is sitting on cash equal to nearly half its annual sales, has raised its dividend payout by fourteen points in a single year, and has deferred its one major growth investment. The proposed greenfield sanitaryware plant — originally budgeted at ₹130 crore — was put on hold owing to subdued market demand, with a revised estimated cost of about ₹150 crore whenever it does proceed and a gestation period of 18 to 24 months.52 FY26 capex was earmarked at around ₹23 crore and actually came in at ₹14.5 crore.162 FY27 is planned at ₹43–45 crore, of which ₹15 crore is an office-space acquisition and only ₹4–5 crore is the faucetware capacity expansion.21 The greenfield decision has been pushed to the end of FY27.1
A rising payout ratio alongside a deferred expansion is not a sign of confidence. It is management telling you, in the only language a balance sheet speaks, that it does not currently see enough demand to justify building. That may well be the right call — building sanitaryware capacity into a soft cycle is how companies destroy returns. But it should be described as what it is: caution, not aggression. The company is choosing to return capital because it cannot yet see where to deploy it.
Which raises the obvious question: what is the business that this capital is being cautiously withheld from?
VI. The Business Today: Segments and What Actually Drives Value
Strip away the brand architecture and CERA is four businesses of very unequal quality bolted onto one distribution network.
In the June 2026 quarter, sanitaryware contributed 47% of revenue and grew 14% year on year — roughly 10 points of that from volume and 2 from price. Faucetware contributed 40% and grew 25%, of which about 18 points were volume and 4 price. Tiles contributed 11% and grew 22%. Wellness — showers, spa products, the aspirational end — contributed 2% and declined 7%.1
Those four lines have very different stories, and the differences are the investment case.
Sanitaryware is the core, and it is mature. This is the original business, the Kadi plant, the vitreous china, the forty-six years of brand. It is still the largest segment and it still grows, but it grows roughly with the market. Capacity utilisation tells the more interesting story: 85% in the September 2025 quarter, 82% in December, and then 61% in the June 2026 quarter — the collapse driven not by demand but by the company running on a single kiln amid gas supply uncertainty, cutting production by 30–35%.16111 A business with a headline capacity constraint that suddenly has forty points of spare utilisation is not capacity-limited; it is input-limited. That is a different, and less comfortable, kind of problem.
Roughly 60% of sanitaryware is outsourced rather than made in-house, mostly from the Morbi ceramic cluster in Gujarat, with CERA reserving its own kilns for higher-value, complex, robotics-intensive products.25 This is an intelligent asset-light structure in normal times — you own the margin-rich SKUs and rent the commodity ones. It becomes a liability when the cluster itself is disrupted, which is exactly what happened through FY26. Management has responded by internalising higher-volume SKUs at a modest cost of ₹2–3 crore and has stated a long-term ambition of a 50-50 in-house-to-outsourced ratio.1 That is a sensible adjustment, and it is also an admission that the previous mix carried more supply risk than was understood.
Faucetware is the growth engine, and it is the strongest evidenced advantage in the portfolio. Growing at 24–25% in each of the last two reported quarters, running at 96–102% capacity utilisation, manufactured in-house since 2011, and now within striking distance of the core segment by revenue.2111 The company's technical claims here are specific and checkable rather than atmospheric: robotic surface grinding for uniform chromium plating, what it describes as India's first PVD multi-colour production facility, and CNC machining for precision.12 For a reader without a manufacturing background: a faucet is a brass casting that must be machined to tolerances tight enough to seal water at pressure and then plated with a finish that survives twenty years of hard water and abrasive cleaning. Doing that consistently at scale is genuinely hard, and it is why the category has a small number of large winners rather than a long tail.
The catch — and it is a large one — is that at 96% utilisation, the segment is out of room. The capacity expansion from 4.3 lakh to 5 lakh units per month costs only ₹4–5 crore and starts contributing in the fourth quarter of FY27.21 That is a 16% capacity increase arriving three quarters from now, against a segment growing at 25%. Simple arithmetic says faucetware growth must decelerate in the interim, whatever the demand picture looks like. Any bull case that extrapolates the current faucetware growth rate straight through FY27 is ignoring the company's own capacity disclosure.
Tiles is the problem child, and it gets its own section because its history is load-bearing for the capital-allocation question. Note for now only its volatility: +5.7% in the December 2025 quarter, −8.3% in the March 2026 quarter, +22% in the June 2026 quarter.1121 A segment swinging thirty points quarter to quarter at roughly a tenth of revenue is not yet a business; it is an inventory position.
Wellness is immaterial. Two percent of revenue, growing 31% in one quarter and shrinking 7% in the next.21 It deserves a sentence, not a thesis.
Across all four sits the brand ladder, which is the company's answer to margin pressure. Senator is the super-premium tier — a differentiated retail format with dedicated dealers, generating ₹10.5 crore of revenue in FY26 against a target of ₹40–45 crore in FY27, with flagship stores expanding from 35 to a planned 50 by the end of FY27.21 CERA Luxe sits beneath it. The core CERA brand occupies mass-premium. And Polipluz, launched at the bottom, targets rural and semi-urban buyers in a segment the company itself describes as dominated by unorganized players selling substandard product — ₹8.5 crore of FY26 revenue against a ₹30–35 crore FY27 target, distributed through 65 distributors and 750 dealers as of the December 2025 quarter.12211
Here is the honest read on premiumisation. The company reports its product mix each quarter: premium was 42% of sales in the September 2025 quarter and 44% in the December quarter, with mid-segment at 36% then 35%, and entry-level at 22% then 21%.1611 That is a real shift in the intended direction, but it is a two-point shift over one quarter, not a step change. And the two new brands at the extremes of the ladder generated ₹19 crore combined in FY26 — under 1% of revenue — against a combined FY27 target of ₹70–80 crore.2 Management has been candid that these need years, not quarters.1 Premiumisation at CERA is currently a strategy with early, directional evidence and a very small revenue base, not a proven margin lever. If it were working at scale, blended realisation and gross margin would show it, and in FY26 they showed the opposite.
Which brings us to the part of the portfolio where the company has already run this experiment twice — and lost both times.
VII. The Tiles Diversification: A Twice-Told Cautionary Tale
In November 2015, CERA's stock jumped on the news that it had acquired a controlling stake in a tile manufacturer.17 The logic was intuitive and, on a whiteboard, excellent. CERA sold bathroom products through 6,000-odd dealers. Those same dealers sold tiles. The consumer specifying a bathroom bought sanitaryware, taps and tiles in a single decision. Owning the tile made CERA a one-stop shop, deepened the dealer relationship, and captured a share of a wallet it was already influencing.
It is the same argument that had worked beautifully for faucets four years earlier. It did not work here.
Attempt one: Anjani Tiles. CERA acquired 51% of Anjani Tiles, an Andhra Pradesh vitrified tile manufacturer, for approximately ₹18.36 crore, moving directly into tile manufacturing.17 By August 2021 — under six years later — the company had signed a memorandum of understanding with Anjani Vishnu Holdings for the sale of its entire 51% stake in both equity and preference shares.18 Consideration of ₹28.69 crore was received in five tranches, and Anjani Tiles ceased to be a subsidiary on March 23, 2023.6
On the surface: ₹18.36 crore in, ₹28.69 crore out. A gain. But read it properly. That is roughly 56% cumulative on the nominal investment over seven and a half years — around 6% a year before considering that a ₹5.74 crore impairment was recognised along the way, and before considering the management attention consumed. Over the same window, CERA's core business was generating operating returns on capital employed of 34–45%.5 A venture that returned mid-single digits annually while the core compounded in the high thirties was not a modest success. It was a substantial destruction of opportunity cost, dressed up as a break-even exit.
Attempt two: Milo Tile LLP. Even as the Anjani experience was unfolding, CERA took a different route to the same destination. In 2018-19 it took a 26% stake in Milo Tile LLP for ₹8.06 crore, structured as an alternate tiles-supply arrangement rather than outright control.
This one ended worse, and the company's own disclosure is unusually explicit about why. During FY2022-23, Milo was unable to maintain product quality parameters, which forced CERA to discontinue procuring tiles from it and to raise claims for inferior-quality product supplied.7 The matter went to arbitration under the terms of the agreement. In mediation, both parties agreed to an amicable settlement in March 2025 under which CERA retired from the LLP without any claim on its capital or share of profits — and paid a further ₹160 lakh as full and final settlement.7 The entire ₹8.06 crore investment was written off as non-recoverable, with ₹6.56 crore of impairment already provided through FY2023-24 and the remaining ₹1.50 crore taken in the March 2025 quarter.7
Total damage on attempt two: ₹8.06 crore written off plus ₹1.6 crore paid out to exit. Roughly ₹9.7 crore of value gone, in a venture whose stated purpose was to secure a reliable supply of tiles and which instead produced tiles CERA could not sell.
Now weigh the two together, because this is the falsification test for the company's most-repeated current claim — that it allocates capital with discipline.
The scale is small. Combined, the two tile ventures involved something under ₹27 crore of gross investment against a company that now generates over ₹200 crore of annual profit. No reasonable observer would call this an existential misallocation. But scale is not the only axis. Frequency matters: this was not one mistake, it was the same mistake made twice, through two different structures — majority control and minority partnership — across a decade, with the second initiated while the first was still visibly underperforming. Consequence matters: both ended in exit, one at an economic loss and one at a return far below the company's own cost of doing anything else. And remediation matters: CERA has not exited tiles, it has changed its approach to them.
The current model is asset-light and outsourced — over 1,800 designs sourced from third-party manufacturers, sold under the CERA brand through the existing dealer network, with no manufacturing capital at risk. Tiles ran at roughly 9–11% of revenue through FY26.215 This is the humbler and more evidence-consistent version of the strategy, and it is defensible: if the strategic point of tiles was always to complete the bathroom offering for the dealer, then owning kilns was never necessary to achieve it.
But it has not been running long enough to be judged. The segment fell 8.3% in the March 2026 quarter and rose 22% in the June 2026 quarter — numbers too volatile and too recent to establish a trend.21
The calibrated conclusion: the history does not reject CERA's capital-discipline claim outright, but it narrows it considerably. The evidence supports a claim that management is willing to cut losses — both exits were executed, neither was escalated, and the Milo write-down was provided for progressively rather than dumped in one quarter. It does not support a claim that management is good at choosing where to deploy capital outside its core. Those are different virtues, and only the first is in evidence. The test that would confirm or falsify the revised claim is specific: does the asset-light tiles model produce two or three consecutive quarters of stable growth and non-dilutive margin contribution — or does the segment get quietly wound down a third time?
And any judgment on tiles has to account for who CERA is fighting there, and everywhere else.
VIII. Industry Structure & Competition — the Part That Actually Matters
Here is the uncomfortable framing for CERA shareholders: in the two categories where CERA competes hardest, the company that matters most is not listed, does not report quarterly, and is roughly four times its size.
Jaquar. The Jaquar Group generated revenue of ₹7,548 crore in FY25 and was targeting ₹8,703 crore in FY26, against a longer-term ambition of ₹12,000 crore within two years.19 It claims close to 60% of India's bath fittings market. It operates eight plants — seven in India and one in South Korea — with 3.3 lakh square metres of capacity, expanding to 5.3 lakh square metres via three new facilities in Bhiwadi and Gujarat, backed by ₹800–1,000 crore of investment over two years.19 Annual output runs to 52.9 million bath fittings and 4.8 million sanitaryware pieces.19
Set that against CERA's faucetware capacity of 4.3 lakh units per month — about 5.2 million units a year — expanding to 5 lakh units a month for ₹4–5 crore.2 Jaquar is spending in two years roughly forty times what CERA plans to spend in one, in the category CERA calls its growth engine.
Jaquar's founder Rajesh Mehra frames the difference in one line: "We are a manufacturing company. We are not an outsourcing company."19 That is a direct shot at CERA's model, where roughly 60% of sanitaryware is bought in. The market-share figures should be treated as soft — they come from company and trade-press sources, not audited disclosure, and CERA's own investor materials notably do not state a precise category ranking anywhere in the May 2026 presentation.12 But the revenue and capex numbers are hard enough, and they say something unambiguous: CERA's faucetware growth is real and impressive off a small base, and it is happening in a category where the leader has four times the revenue and is investing to press that lead.
Hindware. The old "Big Three" framing — CERA, HSIL, Parryware — needs correcting, and the correction cuts in an interesting direction. Hindware Home Innovation Limited, the demerged consumer-products arm of the original HSIL, reported FY25 consolidated sales of ₹2,523 crore, down 9.12% from ₹2,776 crore, and swung to a net loss of ₹68.29 crore from a ₹25.77 crore profit the prior year.2021 The March 2025 quarter alone produced a ₹30.95 crore loss.20 By the June 2026 quarter it had returned to a modest profit of ₹4.35 crore.21
Two nuances matter. Hindware's consolidated revenue exceeds CERA's, but it spans consumer appliances and plastic pipes as well as bathware — so it is not a like-for-like comparison, and the bathware-only business is materially smaller than the headline. And on profitability, there is no comparison at all: CERA earned ₹204 crore in FY26 while Hindware was recovering from a loss year.320 The right conclusion is not that CERA is now bigger than Hindware; it is that CERA is decisively more profitable than a competitor that was once its peer, and that Hindware's distraction has been CERA's opportunity.
Everyone else. Parryware, owned by Spain's Roca Group, competes across the mid-premium and premium bands. Kohler, TOTO and Duravit occupy the import and luxury end — the tier CERA deliberately avoided in the 2000s and is now, via Senator, trying to enter from below. RAK Ceramics competes on the ceramic side. And in a genuine two-way encroachment, the tile majors — Kajaria Ceramics and Somany Ceramics — have been pushing into bathware from the adjacent category at the same time CERA has been pushing into tiles from its side.
Market structure. India's bath fittings market was estimated at around USD 11.5 billion in 2025, growing at a compound rate near 7.7% toward 2030.22 The broader sanitary ware market is projected to compound in the high-single digits over a similar horizon.23 Organized players are commonly estimated at around 60% of the market, with the unorganized sector under 40% — a directional figure repeated across trade sources rather than an audited statistic, and it should be read as such.23 Gujarat, and Morbi in particular, dominates national ceramic manufacturing; the Morbi cluster established in the 1990s is among the largest ceramic clusters in the world.23
None of this is explosive growth. A category compounding at 7–8%, tied to residential real estate and renovation cycles, in which the organized share is slowly rising, is a respectable place to compound — but it means every point of company growth above the mid-single digits has to come from share gain or price, and both are contested.
The five forces, honestly applied.
Buyer power is moderate and split. The dealer network is fragmented — 6,540 dealers and over 24,400 retailers as of FY25 — which limits any single dealer's leverage.5 But the mix has been moving the wrong way. Retail fell to about 65% of sales in FY25 from 67% in FY24, with project and institutional sales rising.5 Project sales carry structurally higher discounts, and CARE explicitly flagged this shift as one driver of FY25 margin compression alongside higher dealer discounts offered to liquidate inventory.5 Roughly 35% of revenue comes from project sales tied to real-estate completion timelines.4 Selling more to developers and less to walk-in consumers is exactly the mix shift that erodes brand pricing power.
Supplier power is the acute issue and it is covered in the next section, but note the shape: natural gas from two suppliers (69% GAIL, 31% Sabarmati), brass at globally set prices, and 60% of sanitaryware volume bought from a single geographic cluster.12
Substitution and new entry is where the moat is most defensible. Building a national dealer network takes decades, and a consumer buying a toilet cares about a brand name in a way they do not for a length of pipe. But the unorganized sector still holds meaningful share on price, and Polipluz exists precisely because CERA has concluded it cannot ignore that end of the market.
Rivalry is the honest weak spot, and management said so on the record. Asked in February 2026 whether price increases would cost market share, management's answer was revealing: over time everyone takes the same increase, so share doesn't shift much on price.11 That is a description of a category with parity pricing dynamics — which is another way of saying nobody has enough brand power to price independently for long. An analyst on the same call added a dealer-sourced observation that CERA had been the last player to announce a price hike.11 Being last to raise prices in an inflationary input environment is not a sign of pricing power. It is what a company does when it is worried about volume.
Distribution as a moat deserves the most scrutiny, because it is the claim the company leans on hardest. The affirmative evidence is genuinely substantial: 13 company-owned Experience Centres averaging 7,000 square feet, 272 dealer-owned Style Galleries, 292 Style Hubs in tier-B and tier-C towns, and 1,613 retailer-owned Style Centres with over 1,400 more planned over three to four years.12 Add 13 customer-care offices and 453 dedicated service technicians, with complaints attended within 24 hours.12 Loyalty programmes covering over 28,000 enrolled retailers, generating ₹1,680 crore of tracked secondary sales.1112 Tier-3 cities account for 41% of sales — more than tier-1's 36%.11 That last figure is the most persuasive: a brand that sells more in small towns than in metros has done real distribution work that an import brand cannot replicate quickly.
What is missing is the harder evidence. The company does not disclose dealer retention rates, same-dealer sales growth, or share of dealer wallet. Its dealer management system rollout — which would generate exactly that data — was live with only about 200 dealers as of the September 2025 quarter, out of over 6,500.16 Management described the ambition well: dealer-wise inventory and retail coverage, "information that was earlier not available."16 The candour is welcome. The implication is that for four decades, this distribution moat has been asserted rather than measured.
Which is a fitting place to turn to the numbers that have actually been measured — and are going the wrong way.
IX. Current Strategy & the Margin Story
The tension defining FY25 and FY26 can be stated in one sentence: CERA sold more of everything and made less money doing it.
Revenue went from ₹1,871 crore in FY24 to ₹1,915 crore in FY25 to roughly ₹2,050 crore in FY26. EBITDA went from ₹295 crore to ₹293 crore to ₹269 crore. Operating margin compressed from 16% to 15% to 13%. Net profit rose from ₹239 crore to ₹246 crore and then fell to ₹204 crore — a 17.1% decline in a year of 7% revenue growth.312 Return on equity fell from 18% to 14%.12
Two inputs explain most of it, and both are worth understanding mechanically.
Brass. A faucet is mostly brass, and brass prices move with global copper and zinc. Management disclosed the trajectory precisely: roughly ₹640 per kilogram before the December 2025 quarter, rising about 12% during it to around ₹800; ₹665 per unit in December 2025, ₹880 by June 2026, ₹900 by July.111 That is a 35% increase in nine months in the primary raw material of the segment growing fastest. Management indicated further price increases would follow if brass moved past ₹950–1,000.1
Gas. This is the more consequential one, because it directly falsifies the founding-era cost story. The weighted average gas cost was ₹33.53 per cubic metre in the December 2024 quarter, ₹35.70 a year later, and ₹48.43 in the June 2026 quarter against ₹33.17 in the year-ago period — a 46% year-on-year increase.111 Gas ran at about 3.3% of revenue.1 Worse, the company's own sustainability disclosure shows gas consumption per tonne of finished product rising from 279.0 standard cubic metres in FY24 to 309.0 in FY25 to 314.7 in FY26 — the plant is using more gas per unit, not less, even as gas gets more expensive.12
The 1980 bet on gas-fired kilns near a gas field was a genuine cost advantage for four decades. In 2026 it reads as an input-price exposure. Any framing of gas kilns as a durable structural moat should be retired; what remains is a quality advantage in firing consistency, which is real but is not the same claim. And in the June 2026 quarter the exposure went further than price: gas supply uncertainty forced CERA to run a single kiln, cutting production 30–35% and costing roughly ₹3.7 crore, or 0.75 percentage points of margin.1
Discounts. The third driver is the one that says most about pricing power. Management attributed the roughly 300 basis point margin decline in the December 2025 quarter primarily to increased trade discounts — dealer discounts offered to move inventory in a soft retail market — with brass costs second.11 CARE's August 2025 rationale independently flagged the same mechanism: higher sales discounts to sustain momentum, impacting both profitability and the working capital cycle.5 When a branded company has to discount to hold volume, the brand is doing less work than the brand narrative implies.
The response. Management took price. Cumulatively, sanitaryware prices rose about 12% and faucetware about 16% over two quarters, executed in stages: roughly 4% and 11% in March 2026, then surcharges of 10% and 5% in April, then further increases of 8% and 5%.21 By August 2026 management described the increases as well absorbed and said gross margin should recover toward 51% by the December 2026 quarter if brass holds and gas stabilises.1
Alongside that, working capital has genuinely improved — inventory days from 80 to 68, receivable days from 38 to 30, and the net cycle from 75 days to 50.1 The full-year figure improved from 80 days to 64.12 This is real operational work and it deserves credit; it is the clearest evidence in the current numbers that the operating layer is executing.
Now the credibility test, which is where the earnings calls earn their keep.
In November 2025, on the September-quarter call, management guided operating margin to 14.5–15% for the full year.16 In February 2026, having just printed 10.2%, management told analysts the quarter was a one-off driven by phasing of publicity and CSR spend and the build-out costs of Senator and Polipluz, that margins would return to "at least 13%, 14%" in the fourth quarter "itself," and that "16%, 17% should be looking very likely in the second half of next financial year."11
Track what happened. The March 2026 quarter did recover, to a 15.2–16% EBITDA margin, vindicating the near-term half of that guidance.212 Then the June 2026 quarter came in at 10.1% — a second sub-11% quarter within three — and the full-year FY27 margin guidance issued alongside it was 13.5–14%, not the 16–17% floated in February.1 Management again attributed the shortfall to one-time items, quantified this time with more rigour: a ₹6.3 crore retrospective wage settlement, ₹3.7 crore from single-kiln operation, ₹4 crore from closing out old low-margin project contracts, and about 1.5 points from delayed retail pass-through of the May price increases — aggregating to roughly 4.35 percentage points, which would have put normalised margin near 14.5%.1
The fair assessment is mixed and should be stated as such. On the positive side, the explanations are specific, quantified line by line, and internally consistent — this is not vague blame-shifting, and the underlying cost drivers are independently verifiable in the gas and brass disclosures. On the negative side, this is now the second consecutive year in which a mid-teens margin guide has been walked down over the course of the year, and the "one-off" framing has been applied to three separate quarters with three different sets of one-offs. At some point a recurring series of non-recurring items becomes the operating reality of a business with concentrated input exposure and limited pricing power. Management's own quiet revision — from "16-17% in H2 FY27" in February to "13.5-14% for FY27" in August — is the most honest number in the file, and it is the one to anchor on.
Context, fairly given. This is not a CERA-specific stumble. The listed Indian building-materials complex — CERA, Kajaria, Somany Ceramics, Hindware — has been through a broad de-rating across FY25 and FY26 amid a real-estate and renovation demand slowdown, and Hindware's swing to a full-year loss is a sharper version of the same pressure.20 CERA remained solidly profitable throughout, at a 9.7% net margin in FY26, and continued to generate cash.12 Singling out this management for a sector-wide cycle would be unfair. Equally, crediting them for a recovery that is mostly cyclical would be unearned.
The open question the article set out to test — whether premiumisation is actually shifting realised prices — has a partial answer in the transcripts. Premium mix moved from 42% to 44% across two quarters, and price contributed 2 points of sanitaryware growth and 4 points of faucetware growth in the June 2026 quarter against volume contributions of 10 and 18 points respectively.16111 So: growth is overwhelmingly volume-led, price realisation is positive but modest, and the premium mix is drifting up slowly. Premiumisation is happening. It is not yet doing the heavy lifting that the margin recovery thesis requires.
X. Bull vs. Bear: The Investment Case, Tested
The bull case, stated at its strongest.
Start with the balance sheet, because it is the least arguable part. Roughly ₹943 crore of cash against ₹47 crore of borrowings gives this company something rare in Indian building materials: the ability to be wrong for several years without any financing consequence.13 Both rating agencies at AA with stable outlooks, interest cover above 35 times, and a promoter family holding 54% with no pledge.453
Then the faucetware franchise. A quarter of growth for two consecutive quarters, in-house manufacturing since 2011, running at effectively full capacity, and now 40% of revenue.21 Whatever else is uncertain, this segment is taking share in a growing category with real manufacturing capability behind it.
Then distribution, which no new entrant can replicate on any reasonable timeframe: over 6,500 dealers, 24,000-plus retailers, more than 2,100 branded retail touchpoints of various formats, and — most tellingly — a sales mix skewed toward tier-3 India.51211 Add a service organisation of 453 technicians with 24-hour response.12 This is the part of the business that took forty years and cannot be bought.
And finally the optionality: a premium brand ladder, a value brand for the unorganized-dominated bottom of the market, ₹85 crore of FY27 brand investment behind a new campaign, and enough cash to fund a ₹150 crore greenfield plant out of accruals whenever demand justifies it.15
The bear case, stated at its strongest.
Margin compression is not hypothetical, it is present tense, and it has now persisted through six of the last eight quarters in some form. Two of the last three quarters printed EBITDA margins near 10% — levels an analyst on the February 2026 call described, without contradiction from management, as a multi-decade low.11 The cost drivers behind it are structural rather than transient: gas up 46% year on year, brass up 35% in nine months, both set by markets CERA does not influence.1
Capex has been deferred, and the deferral is management's own verdict on near-term demand. A company with ₹943 crore of cash choosing to spend ₹43 crore — a third of it on office space — while raising its dividend payout from 34% to 47% is not signalling that it sees attractive places to invest.123
Tiles has failed twice as a diversification vector and the third form is unproven. Whatever the merits of the asset-light pivot, the record is two ventures, a decade, and two unwinds.67
Competitive intensity is rising from both directions. Jaquar at four times the revenue and forty times the capex in faucets.19 Kohler, TOTO and Duravit at the premium end that Senator is trying to enter. Kajaria and Somany Ceramics pressing in from tiles. The unorganized sector still holding meaningful share on price. And the company's own admission that price moves don't shift market share because everyone follows — the signature of a category with limited individual pricing power.11
Governance carries two flags: founder compensation roughly 450% above the peer median and overwhelmingly fixed rather than performance-linked, and an unresolved succession question fourteen years after the event that first exposed it.15
Applying Helmer's 7 Powers. Of the seven — scale economies, network economies, counter-positioning, switching costs, branding, cornered resource, process power — CERA can make a credible case for two and a partial case for a third.
Branding is the strongest. A consumer buying a toilet or a faucet twice in a lifetime, unable to assess ceramic body quality or plating durability, relies on a name. Four decades of advertising at 3–4% of revenue has built one. This is a genuine power. Its limit is visible in the discounting: a brand with full pricing power does not raise dealer discounts to hold volume.115
Scale economies apply in a specific and real way. The Kadi plant is the largest single-location sanitaryware facility in India, and ceramic manufacturing has meaningful fixed-cost absorption.8 Management explicitly attributed part of the December 2025 margin miss to weaker fixed-cost absorption on a lighter quarter.11 But scale in sanitaryware is a domestic-comparison advantage that Jaquar exceeds on the fittings side.
Process power is a partial case. The specific technical claims — robotic glazing, PVD multi-colour faucet plating described as an India-first, 3D printing for faucet design, CNC machining, the first Indian sanitaryware company to achieve ISO 9002 and ISO 14001 — are concrete and, if accurate, represent accumulated capability that takes years to build.12 What is missing is the KPI that would prove it: CERA does not disclose first-pass yield, defect rates, or warranty return rates. Process power asserted is not process power evidenced.
Switching costs are essentially absent at the consumer level — nobody is locked into a toilet brand — and weak at the dealer level, where multi-brand stocking is the norm. Network economies do not apply. Counter-positioning did apply in 1980, when colour variety and gas kilns were a stance the incumbent could not easily copy; it does not apply today. Cornered resource does not apply; there is no scarce input CERA controls.
Two-and-a-half powers out of seven is a respectable but not commanding position. It describes a good business with a genuine consumer franchise operating in a competitive, cyclical, input-exposed category — which is roughly what the 19.2% return on capital employed and 14.8% return on equity in FY26 actually say.3
The activist stress test. What would a skeptical investor challenge?
First, the cash. ₹943 crore earning treasury returns inside a business whose operating return on capital net of cash and investments ran at around 34% in FY25 is a material drag on blended returns.51 The company has responded partially, raising the payout ratio to 47%, but a hoard equal to half of annual revenue with capex deferred invites the question directly: buy back, pay out, or build. Choosing none of the three indefinitely is a choice.
Second, pay. A largely fixed package at several times the peer median, in a year when profit fell 17%, is the textbook target for a governance-focused holder.
Third, guidance discipline. A margin guide walked from 14.5–15%, to a promise of 16–17% by H2 FY27, to an actual FY27 guide of 13.5–14% — inside twelve months — is a pattern worth pressing management on, not a single miss.16111
Fourth, disclosure. For a company whose central claim is distribution, the absence of dealer retention, same-dealer growth, or share-of-wallet data is a conspicuous gap. The DMS rollout may close it. Until it does, the moat is a story.
The net read. CERA is a well-capitalised, founder-aligned, genuinely branded business with one clearly working growth engine and one clearly demonstrated failure mode. The moat claims — distribution, brand, cost position — are plausible and long-standing but thinly evidenced with hard operating KPIs in public materials. The gas-kiln cost advantage in particular has been substantially falsified by 2025-26 input conditions and should not be carried forward as a structural claim. Whether this business wins from here depends less on strategy than on execution against inputs it does not control, in a cycle it does not control, against a private competitor investing far more than it is.
XI. Current Risk Radar
Demand cyclicality. Roughly 35% of revenue comes from project sales tied to real-estate completion timelines, and CRISIL identifies this exposure as a principal rating constraint.4 The mechanism is direct and already visible: developer-channel sales carry higher discounts, so a mix shift toward projects compresses margin even when total volume holds.5 Retail's decline from 67% to 65% of sales in FY25 is a small number describing a real dynamic.5
Input-cost inflation. The single most material risk, and the one that has already crystallised. Gas at ₹48.43 per cubic metre against ₹33.17 a year earlier, brass from ₹665 to ₹900 per unit in seven months.1 CERA cannot hedge either meaningfully, and its recourse is price increases that, on its own management's account, the whole category takes together — meaning cost inflation is passed through with a lag rather than absorbed by advantage.11
Supply chain concentration. Two related exposures. Gas comes from two sources — 69% GAIL, 31% Sabarmati — and supply uncertainty was severe enough in the June 2026 quarter to force single-kiln operation.1 Separately, roughly 60% of sanitaryware is outsourced, heavily to the Morbi cluster, which experienced its own gas-driven disruption through FY26.21 The company's mitigation — internalising high-volume SKUs at ₹2–3 crore and targeting a 50-50 in-house ratio long-term — is directionally right and modest in scale relative to the exposure.1
Competitive intensity. Covered above; the specific forward risk is that Jaquar's ₹800–1,000 crore capacity expansion lands in the same window as CERA's ₹4–5 crore faucetware debottlenecking.192
Capital-allocation execution in tiles. A third misstep would move this from an idiosyncratic history to a pattern, and would materially damage the credibility of the discipline narrative.
Succession. Not a near-term operational risk. The bench is deep and largely externally recruited, and Deepshikha Khaitan's executive mandate is now formalised through 2030. But a founder actively involved in execution at 46 years of tenure, with no announced handover plan and a precedent of unplanned discontinuity in this exact company, is a structural overhang rather than a resolved question.
What is not a material risk here. Refinancing and cost of capital, given ₹47 crore of debt against ₹943 crore of cash. Regulatory overhang: no qualified auditor opinion has been reported from Singhi & Co., no promoter pledge appears in the shareholding pattern, and the FY26 AGM resolutions passed without dissent surfacing.14 These are bounded observations about specific recent records, not a general assurance that nothing exists.
One accounting note worth flagging for anyone building a model: from the June 2026 quarter, CERA reclassified turnover discounts, which reduced reported revenue by about 2.5% and mechanically improves the reported margin percentage without changing absolute EBITDA.1 Year-on-year comparisons across that boundary are not clean.
XII. Playbook: Lessons on Building and Allocating Capital
Strip away the specifics and CERA offers three transferable lessons — two of them the company would happily claim, and one it would rather not.
Lesson one: contrarian infrastructure bets compound, but only inside the circle of competence.
The two best capital decisions in CERA's history were both infrastructure bets that looked eccentric at the time. Gas-fired kilns near a gas field in 1980, when Indian ceramic plants burned coal, delivered four decades of cost and quality advantage.8 Building faucetware manufacturing in 2010-11 after years of outsourcing the category delivered the company's current growth engine.8
Note what those two had in common. Both were investments in the production of things CERA already sold, to customers it already had, through channels it already owned. The faucet decision in particular was sequenced beautifully: outsource first, prove the brand travels, then build. That is how a conservative company takes a risk — by removing the demand uncertainty before committing the capital.
The tile ventures inverted the sequence. CERA bought manufacturing capacity in 2015 and took a supply-partnership stake in 2018-19 before establishing that it could win in tiles, and in a category where the competitive set was entirely different — Kajaria and Somany and the vast Morbi cluster, not the bathroom brands CERA knew.17 The asset-light model it has settled on since is, in fact, the model it should have started with: sell tiles under the CERA brand through the CERA dealer network, and let someone else own the kilns.
Lesson two: institutional depth is only proven when it is used.
The 2012 succession crisis is a genuine data point on family-business resilience precisely because nothing about it was scripted. The response — a retired internal veteran recalled as CEO within weeks, a COO promoted from within, no external search — was possible only because Somany had spent years delegating and building a bench, including paying some employees more than himself.108
The uncomfortable corollary is that the same lesson creates the current concern. The bench that absorbed the 2012 shock was built over decades inside the company. Today's leadership layer is largely recruited from Jaquar, Roca, Kohler, HSIL and the Aditya Birla Group.12 Lateral hires bring capability faster but carry less institutional memory and are more mobile — as the acknowledged leadership transition in the Senator and Polipluz verticals illustrates.1 Whether the 2026 bench would absorb a 2012-style shock as well as the 2012 bench did is untested.
Lesson three: knowing when to exit is a real virtue, and it is not the same as knowing what to enter.
Read charitably — and the charitable reading has merit — the Anjani and Milo unwinds show a management willing to cut losses rather than escalate commitment. Both were exited. The Milo impairment was recognised progressively across FY24 and the March 2025 quarter rather than deferred.7 Anjani was sold in structured tranches over eighteen months rather than dumped.186 Neither required a rights issue, a write-down large enough to threaten the dividend, or a restatement. In an Indian mid-cap landscape where failed diversifications are often kept alive for years to avoid admitting error, that restraint is worth something.
Read less charitably: the same failed venture was entered twice in two structural forms across a decade, and the second entry began while the first was already visibly underperforming.
Both readings are true, and the resolution is the useful part. Exit discipline and entry discipline are separate capabilities. CERA has demonstrated the first. It has not demonstrated the second outside its core, and until the asset-light tiles model produces a few quarters of stable growth, "disciplined capital allocator" remains a claim narrowed to "disciplined loss-cutter" rather than one the record establishes in full.
XIII. What to Watch — Forward KPIs
Everything above condenses into a small number of things worth actually tracking. Three matter more than the rest.
1. Faucetware revenue growth, and the capacity that constrains it.
This is the single clearest live test of whether CERA has a genuine, evidenced advantage rather than a legacy franchise. Faucetware grew 24.3% in the March 2026 quarter and 25% in the June 2026 quarter, and reached 40% of revenue.21 Sustaining above roughly 20% year on year would confirm real share gain in a category where Jaquar is four times larger and investing heavily.
The complication to watch alongside it is capacity. Utilisation ran at 96–102% through recent quarters, and the expansion from 4.3 to 5 lakh units per month only begins contributing in the fourth quarter of FY27.1112 So the honest question is not just whether growth stays above 20%, but whether it does so without the company simply importing more outsourced product — which would grow revenue while diluting the manufacturing advantage that makes the segment interesting.
2. EBITDA margin trajectory against the company's own FY27 guide.
Management has guided to 13.5–14% for FY27, having printed 10.1% in the first quarter and having claimed a normalised 14.5% adjusting for one-offs.1 The mechanics of the recovery are specific and testable: gross margin recovering toward 51% by the December 2026 quarter if brass holds near ₹900 and gas stabilises; old low-margin project contracts rolling off; the May 2026 price increases reaching full retail pass-through.1
Watch the sequence, not the annual number. If the September 2026 quarter shows recovery toward the low teens and December approaches the guide, the one-off framing was accurate. If a third consecutive quarter comes in near 10% with a fresh set of non-recurring explanations, the correct conclusion is that this is the new structural margin of a business with concentrated input exposure and category-level pricing parity — and the mid-teens history becomes the anomaly rather than the norm.
3. The greenfield plant decision, due by the end of FY27.
This is the cleanest available read on management's own demand conviction, and it comes with a hard deadline. The ₹130 crore project was deferred; the revised cost is about ₹150 crore; the gestation period is 18–24 months; funding would come entirely from internal accruals; and the decision has been pushed to the end of FY27.51 Sanitaryware capacity utilisation — 85%, then 82%, then 61% under single-kiln constraint — is the input that should drive it.16111
Proceeding would signal that management sees demand it can fill and is willing to put the idle cash to work. Deferring again would confirm that the deferral is not a cyclical pause but the company's settled view of its own growth runway — which would make the rising dividend payout the more permanent policy and reframe CERA as a cash-returning compounder rather than a growth business.
A fourth item, lower in priority but worth monitoring: whether tiles under the asset-light model strings together consecutive quarters of stable growth after swinging from −8.3% to +22% in two quarters.21 That is the final test of whether the third attempt breaks the pattern.
XIV. Recent Developments & Close
The most recent chapter runs across four documents.
The August 2026 call on the June quarter is the current state of play: record revenue of ₹486 crore, up 19.5%; EBITDA margin at 10.1%; a quantified bridge of one-time items totalling about 4.35 percentage points; FY27 guidance of 18–20% revenue growth and 13.5–14% EBITDA margin maintained; a working capital cycle improved to 50 days; cash at ₹943 crore; and a stock that fell 4.15% on the day.1 Alongside it, a ₹43 crore capex plan, an ₹85 crore brand budget behind a new campaign fronted by Kriti Sanon, and Senator flagship stores expanding from 35 toward 50.1
The May 2026 call on the March quarter is the counterpoint: a genuine recovery quarter with revenue up 11.4%, EBITDA margin at 15.2%, faucetware up 24.3% and tiles down 8.3%, a ₹75 per share dividend, and the greenfield plant formally deferred at a revised ₹150 crore.2
The February 2026 call is the credibility document. It contains the sharpest analyst exchange in the recent record — an investor telling management directly that a 10% margin was a multi-decade low and asking what had changed in three months — and management's answer that the quarter was a one-off, that margins would return to 13–14% "in Q4 itself," and that 16–17% was "very likely" in the second half of FY27.11 The first prediction proved right. The second has already been superseded by the company's own guidance.
And the April 2025 reappointment of Deepshikha Khaitan as Vice Chairman and Joint Managing Director, ratified again at the July 2026 AGM, remains the clearest formal statement the company has made about leadership continuity.1314
Put them together and the picture is neither the one the bulls describe nor the one the bears do.
CERA is a business with a real consumer brand, a real distribution asset built over four decades, one segment that is genuinely working, and a balance sheet strong enough that none of the current difficulty threatens the enterprise. It is also a business whose founding cost advantage has been substantially eroded by input prices it does not control, whose pricing power looks weaker under stress than its brand narrative implies, whose management has now walked down a margin guide two years running, and whose two attempts to extend beyond its core both ended in exit.
The question the episode has been building toward is whether this company has learned enough from those two tile misadventures to keep its capital discipline intact through the next demand cycle. The evidence is genuinely mixed. The deferred greenfield plant and the ₹4–5 crore faucetware debottlenecking are exactly what a chastened, disciplined allocator would do. The ₹943 crore of idle cash and the jump in dividend payout to 47% are what a company does when it has run out of ideas. Both descriptions fit.
What is missing from the current management bench is a clear, evidenced answer to the harder question — not "why did CERA win," which four decades of history answer well, but "why does CERA win from here." The May 2026 investor presentation lists the structural tailwinds and the company-led growth drivers, and every item on both lists is plausible.12 None of them is accompanied by the operating metric that would prove it: no dealer retention rate, no same-dealer sales growth, no first-pass yield, no share-of-wallet data, no stated market-share position. For a company whose central claim is a distribution and brand moat, that absence is the most important thing the disclosures do not say.
The dealer management system is being built, covering about 200 dealers as of late 2025 and rolling out further.16 When it produces the numbers — dealer-wise inventory, retail coverage, information the CFO conceded was "earlier not available" — the moat will be either evidenced or falsified.16 Until then, an investor in CERA is underwriting a brand built over forty-six years, a faucet business that is unambiguously working, a founder who has been right more often than not, and a set of advantages that remain, on the public record, asserted rather than measured.
References
-
Earnings call transcript: Cera Sanitaryware Q1 2027, revenue rises 19.5% as margins slip — Investing.com, 2026-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Earnings call transcript: Cera Sanitaryware's Q4 2026 shows recovery — Investing.com, 2026-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Cera Sanitaryware Ltd — financials, ratios and shareholding, Screener.in ↩↩↩↩↩↩↩↩↩↩↩↩
-
CRISIL Ratings — Cera Sanitaryware Limited, rating action, 2025-07-04 ↩↩↩↩↩↩
-
CARE Ratings — Cera Sanitaryware Limited, press release, 2025-08-26 (PDF) ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Cera Sanitaryware completed divestment of its stake in Anjani Tiles — Business Standard, 2023-03-24 ↩↩↩↩
-
Cera Sanitaryware unaudited financial results and Milo Tile LLP divestment disclosure — InvestyWise ↩↩↩↩↩↩
-
Cera Sanitaryware — Strength in the depth of darkness (company history and 2012 succession retrospective), Lucky Marshmallow ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Cera Sanitaryware net profit rises 49.95% in the March 2013 quarter (contains FY2012 comparatives) — Business Standard, 2013-04-25 ↩↩
-
Stock Update: Cera Sanitaryware — Intelsense Capital Blog, 2012-09 ↩↩↩↩
-
Cera Sanitaryware Limited — Q3 FY 2025-26 Earnings Conference Call Transcript, 2026-02-05 (PDF) ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
CERA Sanitaryware — Investor Presentation, May 2026 (PDF) ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Cera Sanitaryware confirms leadership re-appointment through postal ballot — TipRanks, 2025 ↩↩
-
Cera Sanitaryware shareholders approve FY26 financials and dividend at 28th AGM — ScanX, 2026-07 ↩↩↩↩↩↩
-
Shareholders may not be so generous with Cera Sanitaryware Limited's (NSE:CERA) CEO compensation — Simply Wall St ↩↩↩↩
-
Cera Sanitaryware Limited — Q2 FY 2025-26 Earnings Conference Call Transcript, 2025-11 (PDF) ↩↩↩↩↩↩↩↩↩↩↩
-
Cera Sanitaryware jumps after acquisition of controlling stake in Anjani Tiles — Business Standard, 2015-11-23 ↩↩↩
-
Cera Sanitaryware divests 51% stake in subsidiary Anjani Tiles — Business Standard, 2021-08-17 ↩↩
-
Jaquar, the unlisted manufacturing giant — Business Today, 2026-09-02 ↩↩↩↩↩↩
-
Hindware Home Innovation reports consolidated net loss of Rs 30.95 crore in the March 2025 quarter — Business Standard, 2025-05-26 ↩↩↩↩
-
Hindware Home Innovation Ltd — consolidated financials, Screener.in ↩↩
-
India Bath Fittings Market — size, share and forecast to 2030, Mordor Intelligence ↩
-
India Sanitary Ware Market — size, share and forecast 2033, IMARC Group ↩↩↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube