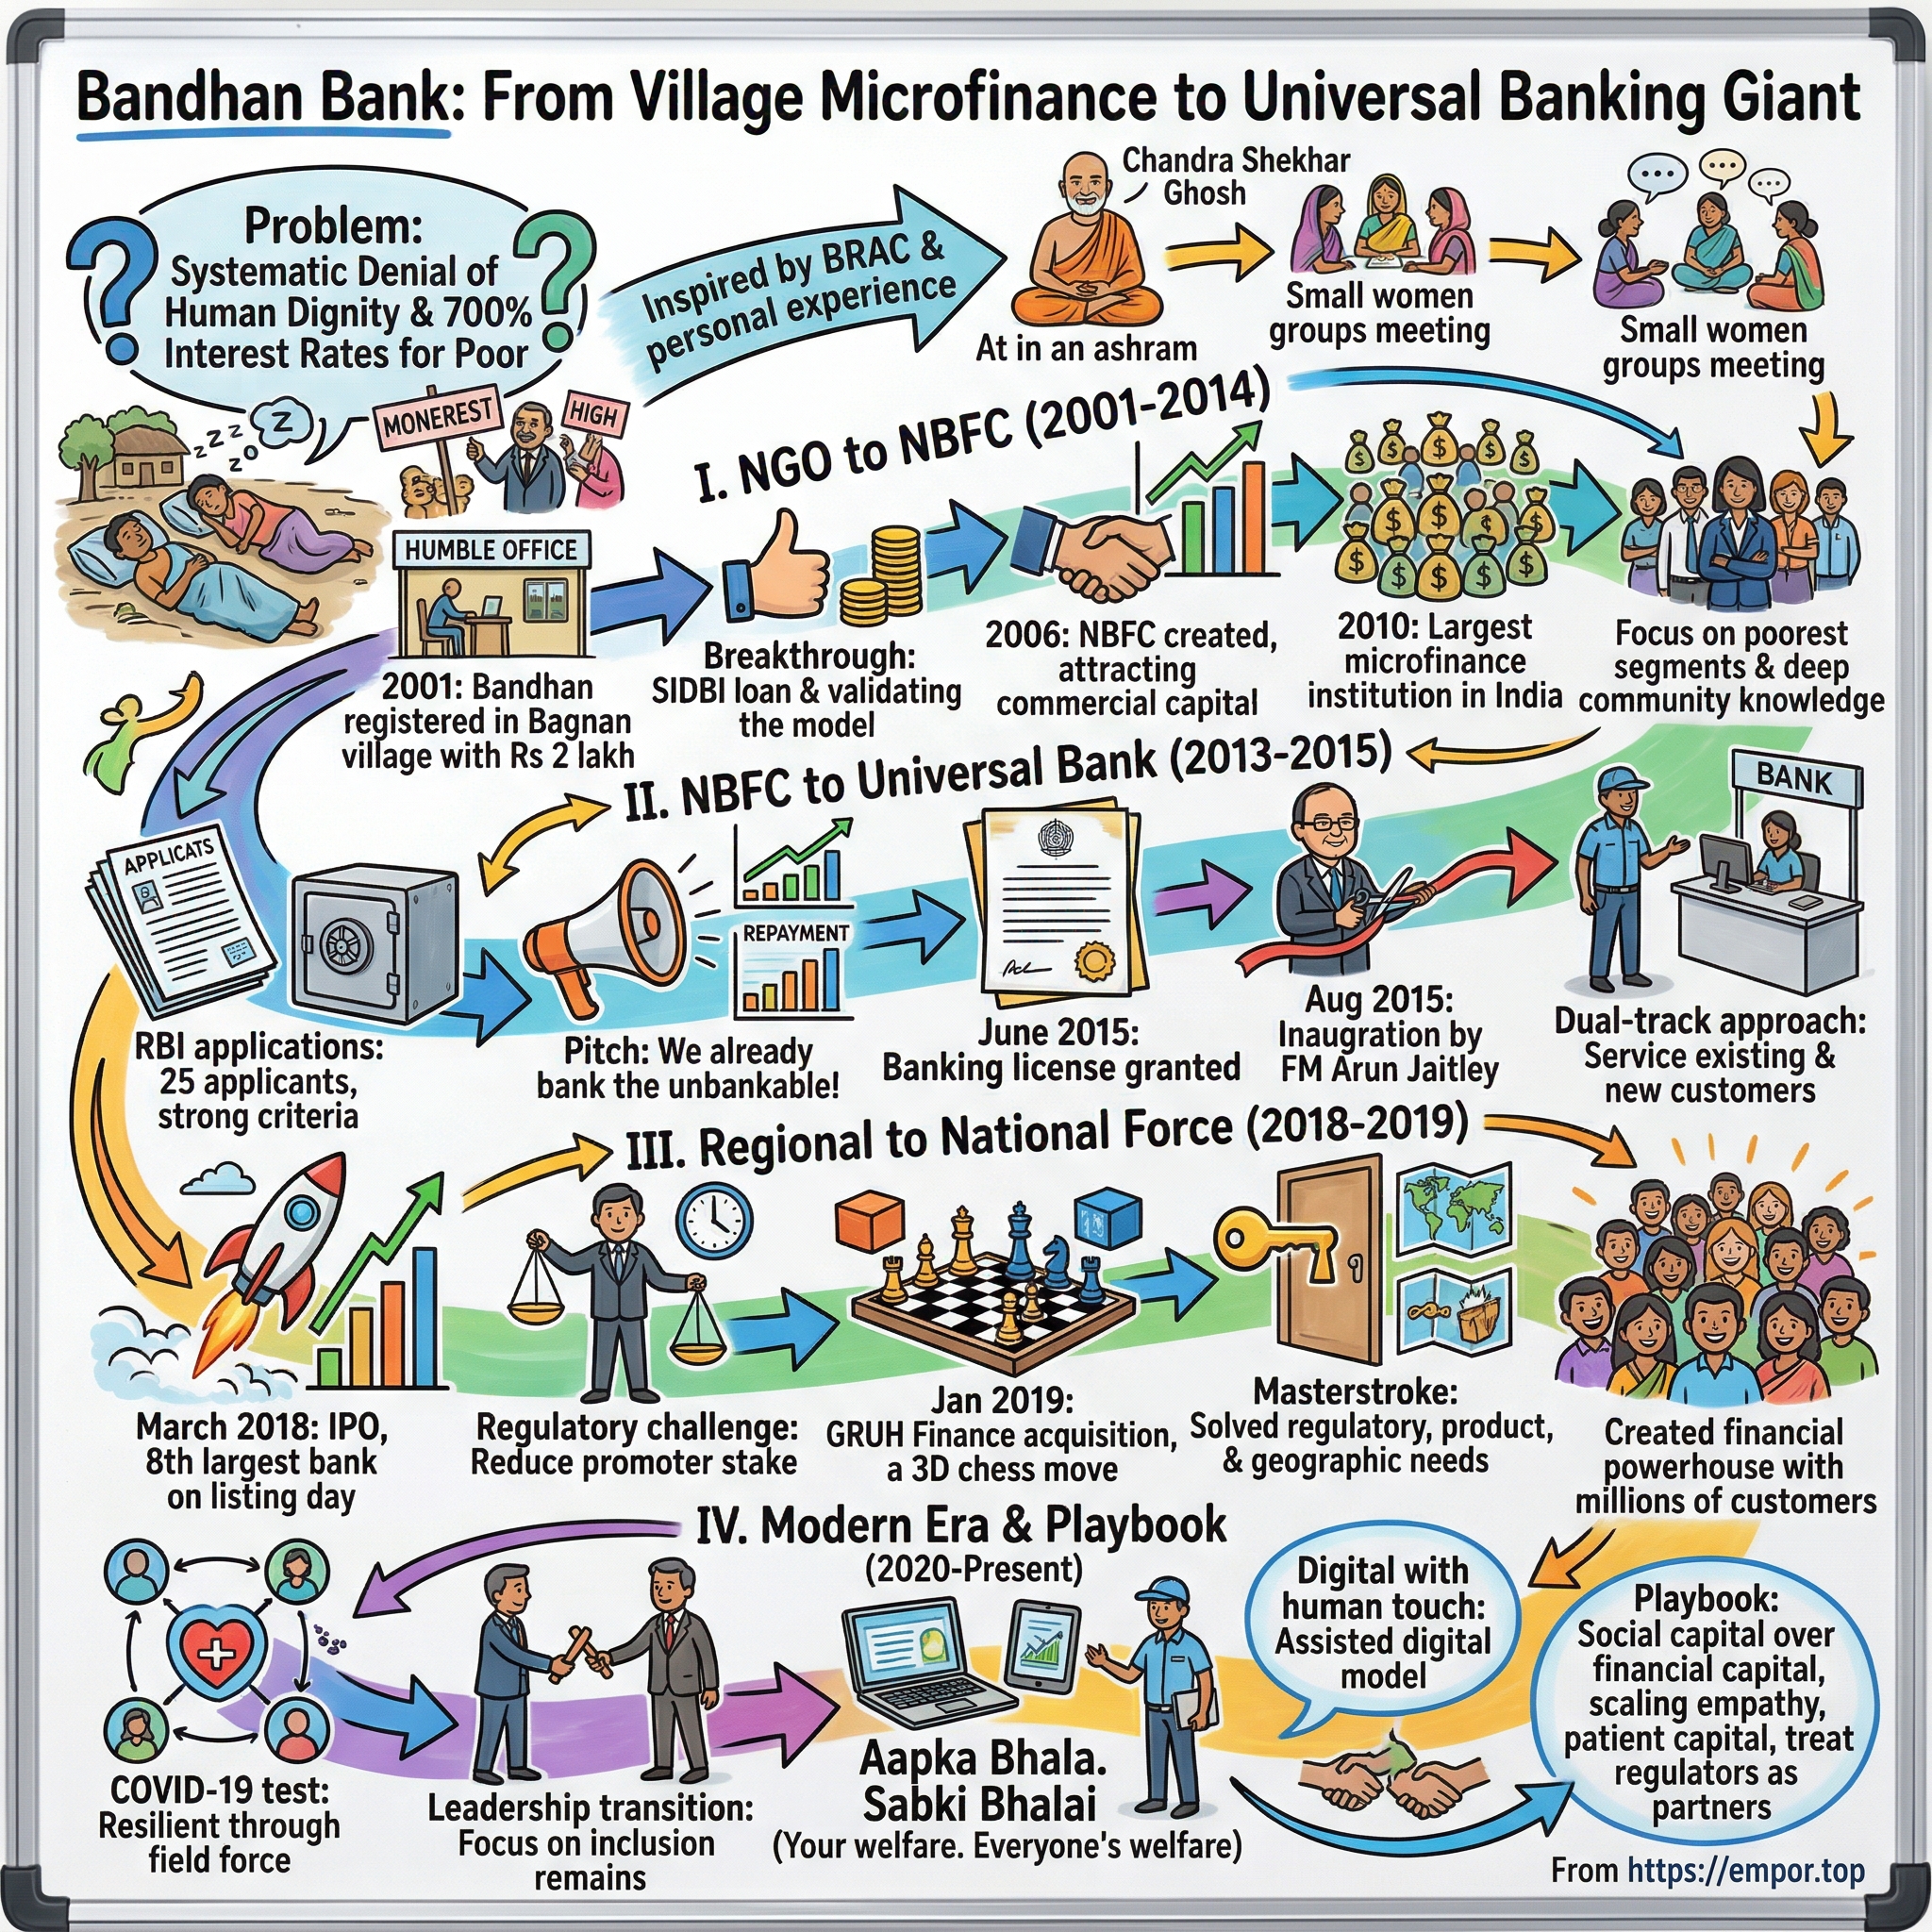
Bandhan Bank: From Village Microfinance to Universal Banking Giant
I. Introduction & Episode Setup
A photograph from August 23, 2015 captures a pivotal moment in Indian financial history. India's Finance Minister, Arun Jaitley, stood on a stage in Kolkata to inaugurate a new institution: a new universal bank — the first headquartered in eastern India since Independence.1 Standing beside him was a founder who, fourteen years earlier, had been a mid-level NGO employee scraping together two lakh rupees — roughly the price of a used motorcycle — from his brother-in-law and a private lender to start lending to village women in West Bengal.2
That origin story is well known and remarkable, but it offers limited utility for investors trying to evaluate the bank today.
By mid-2026, Bandhan operated as a major financial institution. As of June 30, 2026, the bank carried gross advances of about ₹1.56 lakh crore and deposits of ₹1.65 lakh crore, operating 6,388 banking outlets across 35 states and union territories, employing 74,744 people, and serving 31.8 million customers.3 Its loan book had diversified into roughly three equal segments: microfinance accounted for about 34%, housing and retail stood at 33%, and wholesale banking accounted for the remaining 33%.3 A decade earlier, microfinance comprised virtually the entire portfolio.
This transformation was not a smooth strategic transition. Instead, it was repeatedly driven by external pressures: regulatory actions that froze branch expansion and CEO remuneration, an acquisition executed under a compliance deadline at a valuation disputed by the market, political intervention in Assam that disrupted the core credit model, the COVID-19 pandemic, and a forensic audit into claims under a government credit guarantee scheme.
The financial results illustrate the impact of these challenges. In FY26 — the fiscal year ended March 31, 2026 — Bandhan reported a profit after tax of ₹1,224 crore on a balance sheet exceeding ₹2.1 lakh crore, yielding a return on assets of 0.6% and a return on equity of 4.8%.43 These metrics reflect an institution still managing legacy asset-quality pressures rather than a business with a durable competitive moat. Equity markets have priced in this performance: in late August 2026, the stock traded around ₹174, representing approximately 1.1 times book value, compared with its 2018 initial public offering price of ₹485.5
Understanding Bandhan's current position requires evaluating four key structural shifts, each testing a core premise of the bank's original growth thesis:
The grassroots engine. Joint liability groups, weekly doorstep collections, women borrowers, and historically near-perfect repayment underpinned the model. Proponents argued that social collateral functioned as a structural moat, a claim tested directly by events in Assam.
The regulatory inflection. In April 2014, the Reserve Bank of India granted in-principle universal banking licences to just two of twenty-five applicants — IDFC and Bandhan — selecting them over prominent conglomerates including Tata, Birla, Bajaj, Reliance, and Religare.6 While securing a deposit-taking franchise successfully lowered funding costs, the geographical concentration of those deposits created unexpected vulnerabilities.
M&A under duress. In 2019, Bandhan executed an all-stock acquisition of GRUH Finance, HDFC's affordable-housing subsidiary, at a valuation analysts estimated at roughly 13 times trailing book value.7 Management framed the deal as strategic diversification, though regulatory ownership deadlines heavily dictated its timing.
The credit crucible and the reset. A series of shocks — demonetisation, political pressure in Assam, the COVID-19 pandemic, a forensic audit by the National Credit Guarantee Trustee Company into ₹22,750 crore of microloans, and a bad-loan sale of ₹6,872 crore to asset reconstruction companies in December 2025 — severely stressed the balance sheet.89 Following these crises, the founder stepped down in July 2024 and was succeeded by a veteran State Bank of India executive tasked with instilling conventional banking discipline.1011
Whether this transition toward conventional operational discipline succeeds remains the central question. The story begins with the bank's origins.
 Subscribe on LinkedIn
II. The Founder's Journey & The Microfinance Philosophy
Ramchandrapur is a village in Tripura, wedged into Bangladesh on three sides. Chandra Shekhar Ghosh was born there in 1960, the eldest of six children in a 15-member household supported by his father's sweet shop — a business that, by Ghosh's description, could barely feed the family.2 As a schoolboy, Ghosh worked in the shop, weighing sweets, collecting coins, and observing how a small cash business turned inventory daily.
That background proved foundational: the executive who would later construct a financial institution around daily and weekly cash cycles learned the rhythm of petty commerce well before studying statistics.
In 1978, Ghosh entered Dhaka University to study statistics. Unable to afford housing, he relied on a religious mentor, Brojonand Saraswati, who provided lodging and meals at his ashram while Ghosh paid tuition by tutoring.2 After completing his master's degree in 1985, Ghosh joined the Bangladesh Rural Advancement Committee (BRAC), one of the world's largest non-governmental organizations and a pioneer of modern microfinance alongside Grameen Bank.2
During more than a decade at BRAC, Ghosh observed two parallel realities in rural Bangladesh: informal moneylenders charging annualized interest rates in the hundreds of percent, and impoverished borrowers repaying small, structured loans with high discipline when terms were manageable. His key insight was operational rather than sentimental: the binding constraint on rural credit was distribution cost, not default risk — and if an institution could drive down the cost of reaching borrowers, manageable loss rates would follow.
In 1997, Ghosh moved to Kolkata to join the Village Welfare Society, a non-profit focused on rights awareness.2 In Kolkata's urban markets, he identified a similar credit mismatch: vegetable sellers and small vendors routinely borrowed from informal financiers at steep daily rates, rolling over debt each morning despite maintaining cash discipline that traditional banks rarely captured.
In July 2001, at age 41, Ghosh resigned from his position. Securing ₹1.65 lakh from his brother-in-law and ₹35,000 from a private lender, he launched Bandhan-Konnagar as a non-profit in Konnagar, West Bengal, starting with ₹2 lakh in total capital and three employees.2 The name Bandhan translates to "bond."
Initial expansion proved difficult, as rural prospective borrowers initially viewed an unfamiliar lender with skepticism. Bandhan's model — issuing small loans to peer-guaranteeing groups of women with weekly doorstep collections — required building credibility village by village.
The falsification pass: is doorstep loyalty actually a moat?
For two decades, Bandhan's core investment thesis rested on a key premise: its doorstep relationship model cultivated borrower loyalty and repayment discipline that competitors could not easily replicate. Proponents argued that weekly contact, joint liability groups, social pressure, and local presence established an enduring trust franchise.
That thesis faced its clearest test in Assam.
Assam represented one of Bandhan's largest regional markets, where the bank held roughly 55% of the state's total microcredit portfolio.12 Ahead of the 2021 state elections, severe flooding in 2019 had already strained borrower finances and highlighted aggressive industry collection practices. In December 2020, the Assam legislative assembly enacted legislation regulating microfinance institutions and curbing door-to-door collections. Concurrently, the state government announced a relief program to settle debt on behalf of stressed borrowers, offering incentives of up to ₹25,000 per compliant borrower at a budgeted cost of up to ₹8,250 crore.1213
The fallout demonstrated the limits of microfinance loyalty models. Once borrowers anticipated government intervention, the joint liability mechanism inverted: rather than enforcing peer repayment, group members collectively deferred payments. Bandhan's overall collection efficiency, which historically exceeded 98%, dropped to about 92% by September 2020 and remained near 90% in October 2021, with defaults concentrated in West Bengal and Assam.1415 At the peak of the crisis, analysis indicated that approximately 68% of Bandhan's Assam microfinance book and 42% of its West Bengal book suffered from credit stress.12
These events do not imply the doorstep model lacked value; it sustained two decades of expansion and strong repayment discipline under normal conditions. Rather, they highlight a structural boundary: social collateral is a low-cost substitute for legal collateral that functions until a stronger external incentive overrides it. A state government promising loan relief provided that stronger incentive. Consequently, the relationship moat proved conditional, depending on political stability that the bank could neither control nor underwrite.
This vulnerability helps explain why an institution built on unsecured group microcredit subsequently sought diversification into housing finance and wholesale banking. Yet before Bandhan could execute that transformation, it first had to secure access to institutional funding.
III. Building Bandhan: The NGO to NBFC Transformation (2001–2014)
In 2001, pitching a commercial bank was straightforwardly unviable for a former non-profit worker with no collateral, no corporate credit history, and no institutional assets seeking funds to lend unsecured to village women in weekly micro-instalments.
For eighteen months, commercial institutions rejected the concept.
The breakthrough came in September 2002 from a development institution rather than a commercial lender: the Small Industries Development Bank of India sanctioned a loan of ₹20 lakh.16 Ghosh has consistently cited this approval as the most critical milestone in Bandhan's history — ranking it above its subsequent non-banking financial company (NBFC) licence, universal banking licence, and initial public offering.16 While ₹20 lakh was a modest sum, it provided the one asset Bandhan could not generate internally: an institutional counterparty willing to underwrite the credit model. That initial sanction allowed Bandhan to expand into Bagnan in West Bengal's Howrah district, turning a localized experiment into a scalable microfinance operation.
The operating playbook
Between 2002 and 2014, Bandhan constructed what was effectively a low-cost distribution engine built on three operational pillars.
Local, cost-efficient hiring. Rather than recruiting trainees from business schools, Bandhan hired local staff from the same districts as its borrowers. These employees spoke local dialects, understood community dynamics, and could be trained efficiently to execute a standardized routine: conduct weekly group meetings, collect cash payments, reconcile accounts, and escalate delinquencies. This approach kept field officer costs at a fraction of traditional banking overhead while leveraging deep local familiarity.
Minimal physical infrastructure. Instead of establishing full-service bank branches, Bandhan deployed Doorstep Service Centres — low-overhead operational hubs from which field officers operated. These centres avoided capital-intensive features like retail queue management systems or cash vaults. Rather than requiring borrowers to visit a branch, field officers conducted transactions directly in the field.
Weekly cash collections. Collecting payments weekly added operational touchpoints per rupee disbursed, but provided tight risk management visibility. Annual monitoring yielded 52 data points per borrower rather than 12 under monthly cycles, allowing field staff to detect delinquencies within days rather than months. Combined with joint liability group structures, this system sustained high repayment rates through standard economic cycles.
Bandhan adapted its corporate structure to keep pace with its expanding balance sheet. In 2006, it acquired an NBFC, consolidating its lending activities under Bandhan Financial Services Private Limited, and registered as an NBFC-MFI with the RBI after the regulatory framework was established following the 2010 microfinance crisis in Andhra Pradesh. By the time it submitted its application for a universal banking licence, Bandhan was the largest microlender in the country by a wide margin.6
Institutional equity followed this operational expansion. The International Finance Corporation and Singapore's GIC provided growth capital ahead of the banking conversion, offering long-term equity backing essential for a business model reliant on operating scale.
What the NBFC years actually proved, and what they didn't
By 2014, Bandhan's pre-banking operations had validated three core operational assumptions: high-touch rural lending yielded viable unit economics, the model could expand across eastern and north-eastern India without operational breakdowns, and credit losses remained low under normal macroeconomic conditions.
However, these years left a fourth critical assumption untested: the model's resilience against correlated systemic shocks that hit entire borrower communities simultaneously and disrupt collective repayment incentives. The 2010 Andhra Pradesh microfinance crisis had already demonstrated how state legislative intervention and mass defaults could threaten large microlenders. Bandhan's geographic focus in eastern India shielded it from that specific crisis, leaving its model untested against regional political or environmental disruptions.
Furthermore, the NBFC structure imposed a financial ceiling. As a non-banking lender, Bandhan depended on commercial bank loans for wholesale funding, borrowing at market rates and lending onward at a margin. Every incremental rupee of credit growth required additional wholesale debt. During rising interest rate cycles, funding costs escalated across the entire liability base. Overcoming this structural constraint required transitioning from wholesale borrowing to a deposit-taking retail bank franchise.
In 2013, the RBI opened the door.
IV. The Banking License Inflection: Breaking the Reserve Bank Mold (2013–2015)
The 2013 bank licensing round was, in the Indian financial establishment's telling, a contest among conglomerates. The Reserve Bank of India invited applications, and corporate India responded in force: Tata, Aditya Birla, Bajaj, Reliance, L&T, Religare, IDFC, IFCI, and a long tail of non-banking financial companies and public institutions filed. Two applicants later withdrew, leaving twenty-five applications on the table.6 RBI Governor Raghuram Rajan established a high-level advisory committee chaired by former governor Bimal Jalan to screen the submissions, and the committee submitted its recommendations on February 25, 2014.6
The process then paused as India approached a general election, requiring clearance from the Election Commission before the central bank could act. Regulatory permission arrived on April 1, 2014, and the RBI issued its formal announcement the following day.6
Only two applicants received approval: IDFC, an established infrastructure financier and the conventional institutional choice, and Bandhan Financial Services, a Kolkata-based microlender started fourteen years earlier with ₹2 lakh.6 Corporate suitors including Tata, Birla, and Reliance were passed over, triggering a prompt sell-off in the shares of listed applicants that missed out.
The rationale behind Bandhan's selection extended beyond narrative appeal. The RBI's stated objective for the licensing round was financial inclusion — extending credit and deposit services to unbanked populations. Bandhan was not merely proposing to reach the unbanked; it was already the country's largest microlender operating in eastern regions where formal banking penetration was thinnest. Measured against the regulator's explicit scoring criteria, granting Bandhan a license aligned directly with existing operational reach rather than a speculative mandate.
The in-principle approval established an eighteen-month window and a stringent set of conditions.6 Bandhan spent that period converting its microfinance infrastructure into a commercial banking engine.
Launch day and what it revealed
On August 23, 2015, Bandhan Bank formally inaugurated operations with 501 branches, 50 ATMs, and 2,022 Doorstep Service Centres converted from its microfinance offices across 24 states — backed by an initial capital base of ₹2,570 crore against the RBI's minimum requirement of ₹500 crore.1
Two operational choices stand out from launch day. First, opening 501 full-service branches on day one was unprecedented for a de novo Indian bank. While new banking entrants typically start with a few urban locations and expand gradually, Bandhan converted an established microfinance distribution network into a licensed branch footprint overnight, delivering the exact physical coverage the regulator sought. Second, capitalizing at more than five times the regulatory minimum sent a deliberate signal to regulators, prospective depositors, and equity markets that a former microlender possessed institutional balance-sheet strength.
The economics of the conversion
The structural transition from an NBFC-MFI to a commercial bank unlocked a fundamental shift in funding economics.
An NBFC-MFI relies on commercial bank loans for wholesale funding. A commercial bank takes deposits from the public — particularly low-cost current and savings account (CASA) balances. When a lender maintains high yields on its loan portfolio while cutting its funding costs roughly in half, its net interest margin expands substantially without requiring a change in core asset mix.
That mechanism reshaped Bandhan's financial profile. In its early years as a bank, Bandhan generated net interest margins well above traditional banking benchmarks, resembling a consumer finance company backed by a retail deposit franchise. Even by FY25, following extensive portfolio diversification, the bank reported a net interest margin of 7.1%.3 By comparison, most major Indian private banks operate with net interest margins between 3.5% and 4.5%.
While elevated margins support short-term profitability, they are also diagnostic of underlying risk. A net interest margin near 7% or higher reflects risk-premium pricing on unsecured loans rather than a traditional pricing moat. Between 2015 and 2018, public markets treated Bandhan's elevated margins as a durable competitive advantage, when they were more accurately compensation received in advance for prospective credit volatility.
The falsification pass: did banking status deliver cheap deposits everywhere?
The primary thesis supporting the banking conversion held that securing a universal banking license would give Bandhan nationwide access to low-cost retail deposits, permanently decoupling its funding from wholesale markets.
The historical record over the subsequent decade supports a much narrower conclusion. Deposit collection remained heavily concentrated in eastern India. As of June 30, 2026 — after eleven years of national branch expansion — the eastern region still accounted for 52% of the bank's total deposits, West Bengal alone generated 41%, and only 43.5% of retail deposits originated outside the east.3 In contrast, the asset side tells a different story: 62.1% of advances now sit outside the eastern region.3 Bandhan successfully geographic-diversified its lending book, but struggled to replicate that geographic diversification on the liability side.
This geographic imbalance imposes direct cost friction. Branches operated outside the eastern core incur standard administrative overhead while generating lower deposit volumes per location. In FY26, Bandhan's operating expenses stood at 4.0% of average assets, rising to 4.3% in the quarter ended June 30, 2026, alongside a cost-to-income ratio of 61.5%.3 These figures represent substantial operational drag for a bank facing margin compression: the eastern region continues to fund the institution, while national branch operations absorb the expense of attempting to build a secondary deposit base.
The bank's deposit mix reflects similar structural friction. Although the CASA ratio rose to 29.4% in June 2026 from 27.1% a year earlier, it remains below the 40%-plus threshold maintained by leading private-bank peers.3 Bandhan's liability base is granular and retail-oriented — with CASA and retail term deposits comprising 74% of total deposits — but it is not cheap.3 The overall cost of funds reached 6.4% in the June 2026 quarter.3
Verdict: The hypothesis that banking status would unlock nationwide low-cost funding is not invalidated, but its scope must be narrowed. Bandhan established a stable deposit franchise, but not a low-cost one, and that stability remains concentrated in its original home markets. The primary metric tracking this dynamic — the share of retail deposits sourced outside the eastern region — slipped from 45.2% to 43.5% over the past year.3
In the initial three years following launch, these structural friction points were masked by rapid asset growth, extraordinary net interest margins, and the valuation momentum of an upcoming initial public offering.
V. Public Listing & The Regulatory Squeeze (2018)
In March 2018, Bandhan Bank launched what was then the largest initial public offering ever by an Indian bank, raising ₹4,473 crore at a price of ₹375 per share in an issue open from March 15 to March 19.17 Investor demand was robust: overall subscription reached 14.6 times the available shares, driven by qualified institutional buyers who submitted bids for 38.7 times their allocation.18 When trading began on the BSE on March 27, the stock listed at ₹485 — a 29% premium — before closing its first day at ₹477.20.19
That initial closing price pushed Bandhan's market capitalization above ₹58,000 crore, making it India's eighth-largest bank by market value just thirty-one months after commencing operations — placing it ahead of legacy institutions with century-long histories and national branch networks. Public equity markets were not pricing a mature banking franchise; they were capitalizing an exceptionally high net interest margin and assuming its persistence.
The clock nobody was watching closely enough
Embedded in the universal banking license conditions was a requirement that would define Bandhan's trajectory over the next two years. The promoter entity, Bandhan Financial Holdings Limited, held an 82.3% stake in the bank. Under Reserve Bank of India rules, the promoter shareholding had to be reduced to 40% within three years of commencing operations — establishing a firm deadline of August 2018, just five months after the public listing.[^20]
Although the IPO diluted the promoter's position, it fell far short of the regulatory threshold. August 2018 passed without the promoter stake reaching 40%.
The central bank responded in September 2018 by imposing strict penalties. The RBI required Bandhan to obtain prior regulatory approval before opening any new banking outlet — effectively freezing branch expansion — and halted remuneration increments for managing director and chief executive Chandra Shekhar Ghosh at existing levels.[^20]
Each penalty targeted a distinct strategic dimension. The branch freeze directly stalled the bank's expansion engine, preventing it from opening locations to gather retail deposits in new geographic regions. The executive pay freeze served as a public regulatory signal of individual accountability; as a result, Ghosh's annual compensation remained capped at ₹2.10 crore for FY20 with no performance bonuses or pay increases.20
These regulatory restrictions persisted for nearly two years. The RBI permitted branch expansion to resume only in February 2020, seventeen months after imposing the freeze, while the restriction on executive remuneration was lifted in August 2020 — two full years after the deadline, and only after the promoter entity successfully lowered its stake to 40%.2120
The falsification pass: how good is this management at regulation?
An implicit thesis underpinning investor optimism between 2015 and 2018 was that Bandhan's leadership possessed superior regulatory foresight, having secured a universal banking license ahead of major corporate conglomerates.
The promoter dilution failure challenges that premise. The requirement was neither an ambiguous guideline nor a sudden policy change; it was a clear numerical mandate with a fixed deadline established in the original April 2014 licensing terms. Management had four years, including a public offering, to execute a compliant capital plan, yet failed to meet the deadline. The penalty was not merely a financial fine, but an operational embargo on branch expansion enforced precisely when public equity markets were pricing the stock for rapid growth.
Furthermore, the enforcement actions fundamentally altered Bandhan's strategic flexibility. Once the central bank imposed restrictions, potential M&A counterparties recognized that Bandhan urgently required a corporate transaction to dilute its promoter holding.
Four months after the RBI imposed penalties, Bandhan announced one of the most expensive acquisitions in modern Indian financial services.
VI. The GRUH Finance Acquisition: Strategic Diversification or Regulatory Fire Sale?
GRUH Finance was one of the most admired small institutions in Indian finance. A subsidiary of HDFC Limited, it lent for affordable housing in Gujarat, Maharashtra and the surrounding states, to self-employed borrowers with informal income documentation — the segment that mainstream mortgage lenders found too fiddly. It had decades of low credit losses, a conservative culture, and a return profile that made it a perennial "compounder" on Indian buy-side screens. It also traded at a valuation that reflected all of that.
On January 7, 2019, Bandhan Bank and GRUH announced an all-stock merger. GRUH shareholders would receive 568 Bandhan shares for every 1,000 GRUH shares held.722
The market's verdict arrived within twenty-four hours and was not subtle. Bandhan fell. GRUH fell harder — down 24% over three trading sessions.7 Analysts at the time calculated that HDFC had monetised its GRUH stake at roughly 13.3 times trailing book value, that the transaction would be around 12% dilutive to Bandhan's book value per share and roughly 5% dilutive to earnings per share.7 Housing finance peers were trading at a fraction of that multiple.
What Bandhan bought, and what it was actually buying
The strategic case, as presented, was coherent on its own terms. The merger would instantly give Bandhan a large, secured, long-duration mortgage book; a branch presence in western India, where it had almost none; a genuinely differentiated affordable-housing underwriting capability; and HDFC as an anchor shareholder.
But look at the second column of benefits. The deal took promoter holding from 82.3% down to about 61% in a single step, because issuing Bandhan shares to GRUH's holders mechanically diluted BFHL.23 And it brought HDFC onto the register with a 9.89% stake — a holding that HDFC itself acquired specifically in the context of the RBI's shareholding norms.24
So the transaction that solved a large part of Bandhan's regulatory problem was also the transaction that cost it the most. The sequencing is what indicts it. If you announce a 13-times-book acquisition four months after your regulator freezes your branch network for failing a shareholding test, and the acquisition happens to fix a third of that shareholding test, you have not made a capital allocation decision. You have paid a compliance premium and called it strategy.
It is also worth noting that even after GRUH, the promoter was still at 61% against a 40% requirement. The remaining gap was closed the old-fashioned way, in August 2020, when BFHL sold 33.74 crore shares — 20.95% of the bank — in a block deal at a floor price of ₹311 per share, raising roughly ₹10,500 crore and finally bringing the stake to 40%.23 The regulator lifted the CEO pay freeze days later.20
Which raises an uncomfortable counterfactual: a block trade was always available. It was executed eighteen months after the GRUH announcement, at a price below where Bandhan had been trading, and it worked. The premium paid for GRUH was, at least in part, the price of not having done that first.
The falsification pass: did the acquisition deliver?
The claim was that GRUH gave Bandhan an immediate, high-quality, profitable growth vector in affordable housing.
Seven years of evidence are now available, and they are mixed in a specific and instructive way.
On the asset quality side, the acquired business has done its job. The housing book has been the most stable part of Bandhan's balance sheet through every subsequent shock. As of June 2026, of the bank's ₹48.8 billion of gross NPAs, only ₹3.5 billion sat in housing — against ₹31.0 billion in the microfinance book.3 The mortgage portfolio behaved exactly as advertised.
On the growth side, it has not. Housing advances stood at ₹345.4 billion in June 2026, having grown just 5.7% year on year — and having shrunk 0.7% sequentially from March.3 The bank's own FY26 disclosure put housing growth at 8% for the year, against 46% for non-housing retail and 33% for wholesale banking.4 Housing disbursements in the June 2026 quarter were ₹15.0 billion, down from ₹24.6 billion in the March quarter.3 Seven years after acquiring one of India's best affordable-housing franchises, Bandhan's mortgage book is the slowest-growing major segment it owns.
And on the returns side, the dilution was permanent while the earnings were not. Bandhan issued equity at a 13-times-book valuation to acquire a business yielding roughly 9%, funded by a deposit base costing over 6%. The arithmetic of that spread, net of operating costs, does not produce the returns the bank had been earning on 20%-yield microloans — which is precisely why the market marked the stock down on announcement.
Verdict: the claim survives only in its defensive form. GRUH bought Bandhan durability, and durability turned out to be worth a great deal in 2021. It did not buy growth, and it did not buy returns. The event to watch is whether housing disbursements re-accelerate under the current management's secured-lending push; if the mortgage book continues to grow at single digits while retail and wholesale compound at 25%-plus, the acquisition will have been, in effect, a very expensive purchase of ballast.
Two years after the merger closed, ballast was the only thing keeping the bank upright.
VII. The Asset Quality Crucible: Microfinance Shocks, Pandemic, & The NCGTC Forensic Audit (2020–2024)
Weekly group microfinance contains a critical structural vulnerability: its reliance on physical assembly. The operational model requires borrowers to gather in person each week to make cash repayments. When physical gatherings cease, the monitoring and enforcement mechanism halts across all affected villages simultaneously. In March 2020, national pandemic restrictions halted those gatherings nationwide.
The sequence of shocks
Demonetisation in November 2016 had provided an early warning by removing 86% of India's currency from circulation overnight, temporarily disrupting cash-based collections. While Bandhan absorbed that shock without systemic default, it demonstrated that macro policy decisions could stall collection operations independent of borrower creditworthiness.
The compounding shocks of COVID-19 and political intervention in Assam subsequently overlapped. While pandemic disruptions impaired borrowers' capacity to pay, loan-relief promises in Assam weakened repayment incentives in a core market. Bandhan maintained heavy exposure to both risks.
Balance-sheet metrics reflected the impact. Gross non-performing assets (NPAs), which averaged roughly 1.5% prior to the pandemic, rose to 6.81% by March 31, 2021, and reached 10.8% in the quarter ended September 30, 2021.25 That quarter generated a net loss of ₹3,009 crore, driven by ₹4,630 crore in total provisions: ₹1,500 crore in accelerated NPA provisioning, ₹2,100 crore in additional standard asset provisions, and ₹1,030 crore set aside for restructured accounts.25 In one quarter, provisioning absorbed more capital than the bank had earned in most complete financial years.
Equity markets reacted sharply to the asset-quality deterioration. Following the release of results in January 2021, Bandhan's stock dropped 13% in a single trading session, with market analysis highlighting portfolio concentration risk — noting that a lender with heavy exposure to a single product across two primary states faced structural vulnerabilities distinct from a broadly diversified institution.26
The guarantee claims and the forensic audit
During the pandemic, the Indian government extended credit guarantee coverage to microcredit lenders through the Credit Guarantee Fund for Micro Units, administered by the National Credit Guarantee Trustee Company (NCGTC). Having disbursed substantial microloan volumes in FY21, Bandhan submitted claims under the scheme.
The government agency settled an initial claim of ₹916.61 crore. However, when Bandhan filed a secondary claim of ₹1,296.32 crore in the second quarter of FY24, the NCGTC withheld payment and appointed EY to conduct a forensic audit.27
The investigation examined a microfinance loan portfolio totaling approximately ₹22,750 crore. Managing Director Chandra Shekhar Ghosh stated publicly in February 2024 that the audit stemmed primarily from the size of the claim.28 Market observers viewed that explanation with skepticism, as industry inquiries focused on loan eligibility under guarantee guidelines and whether defaulting accounts had been refinanced to maintain performing status.27
The timing of public disclosures raised additional governance concerns. The audit commenced in December 2023 but became public in January 2024, prompting Bandhan to issue a clarification regarding the audit's scope.27 For an institution already under regulatory scrutiny, disclosing a forensic review reactively impaired investor confidence.
Following a ten-month review, the NCGTC issued its final assessment on October 10, 2024. The agency set the total approved claim at ₹1,231.29 crore as of March 31, 2024. Accounting for the ₹916.61 crore previously disbursed, the regulator authorized the release of the remaining ₹314.68 crore.29
The outcome yielded contrasting interpretations. While the approval of an additional ₹314.68 crore closed the inquiry without public adverse findings, the approved total fell significantly short of the bank's supplemental request. Against the ₹1,296.32 crore additional claim submitted, the agency authorized ₹314.68 crore, leaving a substantial gap between management's claims and final regulatory payouts.
The clean-up
Balance-sheet pressure persisted after the resolution of the audit. In the quarter ended June 30, 2025 — eight months after new leadership assumed office — net profit dropped 65% year-on-year to ₹372 crore as quarterly provisions doubled to ₹1,147 crore, gross NPAs rose to 4.96%, and the microfinance loan portfolio contracted by 15%.41
Rather than maintaining legacy non-performing loans on the balance sheet, executive leadership initiated portfolio sales to asset reconstruction companies. In December 2025, Bandhan completed the transfer of two stressed loan pools representing ₹6,872 crore in total outstanding principal.9 An unsecured NPA portfolio past due by more than 180 days, carrying ₹3,165 crore in principal, was sold to Asset Reconstruction Company (India) Limited (ARCIL) for ₹569.75 crore on a security receipt structure. Concurrently, a written-off unsecured portfolio of ₹3,707 crore was transferred to Phoenix ARC for ₹331.97 crore.9 Both pools comprised microfinance and small-enterprise loans.
The transaction pricing reflected realistic market values for distressed microcredit, yielding realization rates of approximately 18% on the non-performing pool and 9% on the written-off portfolio. Furthermore, Bandhan retained 46.75% of the security receipts in the ARCIL transaction and 62.16% in the Phoenix ARC deal, retaining residual credit exposure rather than realizing a complete cash exit.9 Management subsequently fully provided against the gross carrying value of those retained security receipts.3
The asset sale reduced reported non-performing assets. Gross NPAs declined from ₹70.2 billion at the end of the September 2025 quarter to ₹48.0 billion by December 31, 2025, with the portfolio sale accounting directly for ₹26.0 billion of the reduction.3
The falsification pass: was the underwriting ever as good as claimed?
The central thesis supporting Bandhan's microfinance expansion held that joint liability group structures combined with proprietary credit scoring insulated the lender from severe tail-risk losses.
Historical loss data does not support that premise. Across FY25 and FY26 alone, Bandhan recorded fresh NPA slippages of ₹53.7 billion and ₹54.8 billion, along with technical write-offs of ₹24.1 billion and ₹23.7 billion, prior to the ₹26.0 billion asset sale to reconstruction companies.3 Combined with the provisioning cycles of FY21 and FY22, total credit costs over a five-year period exceeded tens of thousands of crores. In FY26 alone, total provisions reached ₹4,131 crore, representing an annual credit cost of 3.0%.43
The underlying structural issue concerns the distribution of credit risk. Unsecured microfinance does not generate a steady, predictable default rate. Instead, extended periods of low default rates (1% to 2%) are periodically interrupted by sharp loss spikes when geographic or political disruptions induce correlated defaults across borrower groups. High net interest margins on unsecured portfolios function less like traditional interest spreads and more like insurance premiums collected against periodic systemic claims.
Verdict: The thesis of superior microcredit underwriting quality is unsupported by full-cycle asset performance. Under normal operating conditions, Bandhan's collection infrastructure delivers high recovery rates; however, during systemic regional disruptions, social collateral provides negligible downside protection. Consequently, lagging indicators such as gross NPA ratios offer limited predictive utility compared to state-level monthly collection efficiency metrics. For example, monthly collection efficiency in West Bengal registered at 98.4% in March 2026 before easing to 98.2% in June 2026 and subsequently stabilizing.3
By the time the NCGTC concluded its audit in October 2024, Bandhan's founding executive had departed the institution.
VIII. Leadership Transition & Current Management: The Partha Pratim Sengupta Era (2024–Present)
The announcement came in April 2024, and the market read it immediately as bad news: Bandhan's stock fell on the day, and by mid-April was at a four-year low.30 Chandra Shekhar Ghosh would step down as managing director and chief executive when his term expired on July 9, 2024, after twenty-three years running the institution he had founded.10 He described the departure as voluntary.10
The circumstances made that hard to read cleanly. The forensic audit was live and unresolved. The RBI had appointed an additional director to Bandhan's board — Arun Kumar Singh, a thirty-five-year Reserve Bank veteran — with effect from June 24, 2024, a term since extended to June 2027.3 A regulator-nominated director on a private bank board is not routine; it is a supervisory posture.
Ratan Kumar Kesh, the executive director and chief operating officer, took over as interim chief executive from July 10, 2024, for up to three months.31 The search for a permanent successor ran in parallel.
The man they chose
On October 10, 2024, the RBI approved Partha Pratim Sengupta as managing director and chief executive for three years, with a requirement that he take charge no later than November 10.11 The stock rose 9% on the news.11
Sengupta's résumé is a deliberate statement about what the board thought the bank needed. Nearly four decades in banking. Deputy Managing Director and, critically, Chief Credit Officer at State Bank of India — the single largest credit book in the country. Then Managing Director and Chief Executive of Indian Overseas Bank, a public sector lender he led out of the RBI's Prompt Corrective Action framework, which is the regulatory intensive care unit for banks with impaired capital and asset quality.113
That is not a growth executive. That is a workout specialist with a regulator's phone number.
The rebuild around him has been thorough and points in the same direction. Kesh reverted to executive director and chief operating officer.3 Rajinder Kumar Babbar joined as executive director and chief business officer after twenty-three years at HDFC Bank.3 Rajeev Mantri, formerly CFO of Citi India, is chief financial officer.3 The heads of human resources, branch banking, retail assets, collections, credit administration, information technology and treasury are drawn substantially from Axis Bank, IndusInd, Kotak and Ujjivan.3 The non-executive chairman is Debasish Panda, a 1987-batch IAS officer who chaired the Insurance Regulatory and Development Authority and sat on the boards of the RBI, SBI, Bank of Baroda and LIC.3
Bandhan has, in two years, replaced a founder-led microfinance culture with a professional commercial-banking bench. Whether that is an upgrade or simply a different set of blind spots is genuinely open — the new team has no institutional memory of what makes a joint liability group work, which is still a third of the loan book.
Ownership today
Bandhan Financial Holdings held 37.53% of the bank as of June 30, 2026, with the promoter group at 37.54% in total — comfortably inside the RBI's revised framework, which followed a working group recommendation to raise the long-term promoter ceiling to 26% after fifteen years.3233 BFHL has continued to sell down steadily.
One correction to the widely repeated version of the shareholder register: HDFC is no longer there. HDFC Ltd pared roughly 3% in April 2022, and HDFC Bank sold its entire remaining 4.31% during the December 2023 quarter, with its CFO describing the position as "part of our treasury action."3435 As of June 2026 the largest disclosed public holders were SBI Balanced Advantage Fund at 5.49%, Life Insurance Corporation at 3.69%, and Kotak Multicap at 3.38%, with Norway's Government Pension Fund Global at 1.84%.32 The anchor strategic shareholder that the GRUH deal delivered has been gone for over two years.
Management credibility: the guidance test
Here is where the analysis gets uncomfortable, and where earnings calls earn their keep.
On the Q4 FY26 call in April 2026, management laid out FY27 guidance: advances growth of 14–15%, and credit costs improving toward 1.6–1.7% by the end of the year.36 Sengupta's accompanying statement emphasised "disciplined execution and diversifying business model."4
One quarter later, on the July 21, 2026 call, the return on assets target for the fourth quarter of FY27 was cut from 1.6–1.8% to 1.0–1.4% — a reduction of roughly 40 basis points at the midpoint, attributed to about 30 basis points of margin pressure and 10 basis points of higher operating expenses.3738 The previously stated goal of reaching a 6.5% net interest margin by the fourth quarter was deferred; management's language shifted to holding the current 6.2% being "a great achievement."37
Sengupta's explanation was that funding costs had risen without any policy rate increase: "The impact of higher funding costs, despite no increase in the repo rate, is already visible."38 Deposit costs rose about 20 basis points sequentially as larger banks competed for the same retail money.38
Two observations. First, the explanation is externally verifiable and plausible — deposit competition in a tight liquidity environment is real and affects every mid-sized bank. Second, it does not fully excuse the miss, because the FY27 guidance had been set only three months earlier, in the same rate environment, by the same management. Guidance that requires revision within one quarter of being issued is, by definition, guidance that was not stress-tested.
To management's credit, three things were handled well on that call. Credit cost guidance was not cut — it was reaffirmed at 1.6–1.8%, which is the harder number to defend and the one that actually drives the recovery case.37 The segment-level growth split was disclosed rather than buried: 20%-plus for non-microfinance, 5–10% for the microfinance book, against actuals of 27% and roughly flat.37 And when analysts pressed on cost, the answers were specific rather than rhetorical. Technology spend had risen 65% year on year to 9.5% of operating expenses from 6%, driven by vendor price inflation and hardware costs, and Mantri said the bank was targeting roughly 10% as a steady state, with productivity benefits from new loan origination and CRM systems expected only around FY28.3738
The most concrete evidence of execution came in an answer to a question about operating leverage: Sengupta disclosed that secured assets sourced directly through branches had risen to over ₹900 crore a month from around ₹200 crore, as the bank reduces its dependence on third-party direct selling agents.38 That is a real, measurable structural improvement in unit economics, and it is the kind of detail that distinguishes a plan from a narrative.
When CLSA's Piran Engineer pushed on whether margins could expand at all with microfinance down to 30–35% of the book, management's answer was notably unpromotional: a 100 basis point microfinance yield increase taken in February 2026 would not be repeated until external risks receded.38 That is a bank declining to reach for yield. Given this bank's history, that is the single most reassuring thing in the transcript.
IX. Segment-Level Deep Dive & Core Business Economics
If you had described Bandhan's June 2026 balance sheet to an investor in 2018, they would not have recognised it.
The loan book divides almost evenly into three parts. Microfinance — the Emerging Entrepreneurs Business, comprising group loans plus small business and agri loans — stood at ₹526.4 billion, or 33.8% of gross advances. Housing and retail together were ₹506.4 billion, about 33%. Wholesale banking was ₹512.8 billion, about 33%.3 A year earlier, microfinance had been 39.5%. At the IPO, it was the overwhelming majority of the book.3
Secured lending crossed the halfway mark and reached 56.8% of advances in June 2026, up from 42.9% two years earlier.3 That is a genuine and rapid structural change.
The microfinance engine: still the margin, still the risk
The EEB book is not growing. Average EEB advances of ₹524.6 billion in the June 2026 quarter were down 3.4% year on year, and the period-end book shrank 2.3% sequentially.3 Active borrowers were 12.9 million, unchanged from a year earlier after dipping to 12.4 million in March.3
This is deliberate contraction, not lost share, and it is the correct response to what happened to the industry. India's microfinance sector went through its worst cycle since Andhra Pradesh over FY25 and FY26 — NBFC-MFI assets under management fell roughly 19% year on year by June 2025, and sector gross loan portfolio declined 14% by March 2025 — driven by borrower overleveraging, weakening joint liability group discipline, high field-officer attrition, and regional shocks.39 The industry's self-regulatory body imposed "Guardrails 2.0" from April 1, 2025: a maximum of three lenders per borrower, a ₹2 lakh household indebtedness ceiling, and no fresh disbursement to anyone more than sixty days overdue.39
The good news is that the cycle has turned. Sector portfolio at risk between 31 and 180 days fell to 2.0% by March 2026 from 6.3% a year earlier, and disbursements turned positive year on year in the December 2025 quarter after five quarters of contraction.40
Within Bandhan's own book, the leading indicators corroborate this. EEB collection efficiency was 98.9% in the June 2026 quarter, with Assam at 99.5% and West Bengal at 98.7%.3 The share of fully-paying customers rose to 97.3% from 96.3% in March.3 The EEB stress pool — SMA 1 plus SMA 2 plus NPA — fell 31% year on year to ₹39.8 billion.3 And the vintage curves, which track how each disbursement cohort performs by months on book, show the FY26 cohorts running dramatically below the FY25 cohorts at the same maturity.3
Two structural features are worth flagging as evidence on the over-indebtedness question. About 63% of Bandhan's microfinance borrowers have a loan only with Bandhan, and roughly another 24% have one other lender — so around 96% of the portfolio sits at two lenders or fewer.3 That is materially better than the industry's problem cohorts and reflects the bank's rural, single-lender geography.
The economics remain what they always were. Blended yield across the whole book was 12.0% in the June quarter, which implies the microfinance component is still doing the heavy lifting on the revenue line — housing and prime wholesale simply do not price anywhere near that.3 And the risk remains concentrated too: of ₹48.8 billion of gross NPAs in June 2026, ₹31.0 billion was EEB.3
Housing: the anchor that stopped growing
The mortgage book, at ₹345.4 billion, is 76.2% pure home loans, 22.9% loan against property, and a sliver of construction finance.3 Borrowers are 56.5% self-employed and 42.0% salaried — the affordable-housing mix GRUH was built for.3 Its NPA contribution is ₹3.5 billion on a ₹345 billion book, roughly 1%.3
It is doing exactly one job: it is not blowing up. As discussed, it is not growing either.
Retail and wholesale: where the growth actually is
Non-housing retail is the fastest-growing thing Bandhan owns, up 45% year on year to ₹161.0 billion.3 Within it, vehicle finance is the largest at 38% of the segment, followed by personal loans, gold loans, and term-deposit-backed overdrafts.3 It is small enough that the growth rate is not yet meaningful for the group.
Wholesale banking is a different matter entirely, and it is the least-discussed part of the Bandhan story. It grew 38.4% year on year to ₹512.8 billion and is now the single largest segment.3 Within it, the Financial Institutions Group and healthcare/education lending is ₹203.1 billion, corporate banking ₹220.5 billion.3 The disclosed credit quality is reasonable: 96% of the FIG and healthcare/education book is externally rated A- or better, and 76% of the corporate book is BBB+ or better — which also means roughly a quarter of the corporate book is BBB or below, or unrated.3
Here is the analytical point that deserves emphasis, because it does not appear in the bank's own framing. Bandhan has replaced one concentration with a different one. It went from a bank whose risk was correlated to rural politics in two states to a bank with a third of its book in wholesale credit — a business where it has essentially no operating history, competing against every bank in India, on price, for the same rated corporate borrowers. The margin on that book is thin, the competition is intense, and corporate credit has its own cycle. Diversification by segment is not the same as diversification of risk if the new segment is one where you have no edge.
The liability side
Deposits were ₹1,648.9 billion in June 2026, up 6.6% year on year but down 0.9% from March.3 The composition improved even as the total stalled: retail deposits grew 15.6% to ₹1,219.6 billion while bulk deposits and certificates of deposit fell 9.7% on an average basis — the bank is deliberately shedding expensive wholesale money.3 Current accounts grew 31.6% on an average basis, savings 0.5%.3
The savings account statistic is worth pausing on. Average savings balance per account was ₹41,600 for general banking customers and ₹1,400 for microfinance customers.3 Microfinance deposits contribute just 2.4% of total deposits.3 The old dream — that three crore micro-borrowers would become three crore depositors — has not materialised in any economically meaningful way. Bandhan's deposit franchise is a conventional retail bank sitting on top of the microfinance business, not an outgrowth of it.
The economics net out as follows: 12.0% yield, 6.4% cost of funds, 5.6% spread, 6.2% net interest margin, 4.3% operating costs against average assets, and 1.8% credit cost — leaving a 1.0% return on assets.3 The margin is still exceptional. The operating cost is heavy. And the credit cost, even at its improved level, still consumes most of what is left.
X. Strategic Frameworks: Porter's 5 Forces & Helmer's 7 Powers Analysis
Stripping away the narrative framing raises a basic competitive question: what, specifically, stops a rival from taking this bank's business?
Hamilton Helmer's 7 Powers
Branding — real, but geographically bounded. In rural West Bengal and the north-east, Bandhan commands genuine customer affinity. It operated as the lender that stepped in when traditional banks did not, giving resonance to its tagline, Aapka Bhala, Sabki Bhalai.4 The empirical evidence for this power sits on the liability side rather than the asset side: the bank holds 41% of its deposits in West Bengal alone, a sticky retail base that has endured three major crises and a founder transition.3 However, brand equity that fails to travel remains a regional asset, and Bandhan has struggled to export its deposit franchise across India for more than a decade.
Counter-Positioning — historically decisive, now spent. From 2001 to 2015, Bandhan deployed a model that incumbents could not structurally replicate. A state-owned bank could not deploy field officers to collect two hundred rupees weekly from village groups due to its cost structure and labor constraints. That dynamic represented classic counter-positioning: incumbents declined to imitate because doing so would undermine their existing operations. That structural barrier no longer exists. Small finance banks, non-banking financial company microfinance institutions, and several private banks now run identical group-lending routines in the same districts.
Scale Economies — moderate and partly self-cancelling. Bandhan's banking license grants it a funding cost advantage over non-bank microlenders. Yet the offsetting operational expense is substantial: a 61.5% cost-to-income ratio and operating expenses at 4.3% of average assets reflect the heavy drag of maintaining 4,400 dedicated banking units—out of 6,388 total outlets—to serve a contracting microfinance book.3 Scale in doorstep microcredit yields headcount and branch overhead rather than expanding operating leverage.
Switching Costs — asymmetric. Switching costs remain high for eastern retail depositors, who have banked with Bandhan for years and display little tendency to move. Conversely, switching costs are negligible for micro-borrowers, who incur no penalty when taking subsequent loans from competing lenders. Notably, the fact that 63% of microfinance borrowers rely solely on Bandhan is not proof of borrower loyalty; rather, it reflects rural geography where Bandhan is the sole available lender.3 In competitive districts, that single-lender share declines significantly.
Process Power, Network Economies, Cornered Resource — absent. Bandhan possesses no proprietary underwriting technology that competitors like CreditAccess Grameen or Ujjivan cannot replicate. Credit bureau data is shared industry-wide, and regulatory guardrails now apply uniformly across lenders.39 Network effects are similarly absent, as individual borrowers gain no advantage from other borrowers using Bandhan. Finally, the one cornered resource Bandhan historically held—a scarce universal banking license—was diluted when the central bank introduced on-tap licensing for small finance banks.
A rigorous evaluation under the 7 Powers framework indicates that Bandhan holds one durable power (a regional brand driving sticky eastern deposits), one eroding power (funding scale relative to non-bank peers), and no others.
Porter's Five Forces
Rivalry: high and intensifying. Bandhan faces intense competition across all major business lines: small finance banks in microcredit and small-ticket secured loans; non-bank microlenders in group loans; specialized housing finance firms in affordable mortgages; and mainstream commercial banks in wholesale lending. In wholesale banking, Bandhan lacks a distinct competitive edge, as a BBB-plus corporate borrower choosing between Bandhan and a major private bank has little reason to pay a premium rate.
Buyer power — borrowers: high. Microfinance borrowers face negligible switching costs and, in competitive areas, multiple alternative lenders. Sector-wide over-indebtedness directly reflects this buyer power. The primary counterweight is regulatory rather than competitive: Guardrails 2.0, which limits borrowers to a maximum of three lenders, functions as an industry-wide cap on buyer power.39
Supplier power — depositors: moderate and rising. A granular base of 31.8 million retail customers limits reliance on any single wholesale funder.3 However, the quarter ended June 30, 2026, highlighted clear boundaries to this advantage: deposit costs rose by about 20 basis points sequentially without a central bank rate hike, driven entirely by aggressive bidding for retail funds among larger peers.38 Depositors collectively hold pricing power over a mid-sized bank in a tight liquidity environment.
Substitutes: moderate. Digital lending applications, government direct benefit transfers, gold loans, and informal moneylenders all compete for small-borrower credit demand. While none has displaced group microfinance, each reduces borrower dependence on traditional group loans.
New entrants: moderate. Regulatory capital mandates and central bank supervision present meaningful entry barriers, while the microfinance downturn of FY25 and FY26 has dampened new entrant interest.39 Nonetheless, the availability of on-tap small finance bank licensing keeps the door for new competitors structurally open.
The composite structural assessment indicates that Bandhan operates in a challenging competitive environment. It controls one defensible asset—an eastern retail deposit franchise—while competing without structural advantages in the wholesale and non-housing retail segments driving its asset growth. This balance is not fatal, but it yields bank-average return profiles, matching how equity markets currently price the institution.
XI. Playbook: Key Business & Investing Lessons
1. A very high net interest margin in unsecured lending is often a liability disguised as an asset. Bandhan earned near-double-digit margins for years, which equity markets capitalized as a durable competitive moat—making it India's eighth-largest bank by market value on its first day of public trading. Those elevated spreads were not a structural moat; they functioned as insurance premiums collected in advance against periodic, correlated credit shocks. When that risk materialized during the pandemic cycle, a single quarter's provisions of ₹4,630 crore wiped out several years of retained earnings.25 When a lender operates with margins well above industry benchmarks, investors should assume credit risk is deferred rather than absent, shifting the analytical focus to identifying the shock that will trigger it.
2. Deferred regulatory compliance is ultimately paid for at a steep compliance premium. Bandhan had clear visibility from April 2014 regarding its promoter stake dilution mandate and deadline.6 Failing to meet that deadline triggered a seventeen-month regulatory freeze on branch expansion.[^20] Four months into that embargo, the bank announced an acquisition of GRUH Finance at roughly 13 times trailing book value, which mechanically resolved roughly one-third of the promoter dilution requirement.723 The subsequent block sale that fully met the regulator's target demonstrated that a less expensive capital solution was available from the beginning.23 Enforceable regulatory mandates carry firm deadlines; missing them transforms standard corporate restructuring into a distressed transaction that counterparties price to their advantage.
3. Converting a non-banking lender into a commercial bank reshapes the entire operating business, not just its funding costs. Securing a retail deposit franchise delivers a clear, structural reduction in liability costs. However, banking status introduces rigid operational obligations: reserve and liquidity requirements that immobilize balance-sheet assets, mandatory branch allocations, priority-sector targets, and intensive supervisory oversight that can restrict expansion, freeze compensation, or result in a regulator-appointed director joining a bank's board.3 Analysts evaluating non-bank financial companies undergoing bank conversions must account for regulatory drag alongside anticipated margin expansion.
4. Executive professionalization is primarily a balance-sheet recognition event rather than a soft cultural shift. The initial impact of new executive leadership was not a sudden strategic pivot, but immediate asset-quality recognition. Within a year of taking office, the incoming management team offloaded ₹6,872 crore in stressed microfinance loans to asset reconstruction firms at realizations between 9 and 18 paise on the rupee, absorbed ₹4,131 crore in FY26 provisions, and allowed full-year profit to decline to ₹1,224 crore.94 Founder-led institutions often exhibit structural reluctance to mark down legacy loan books. In contrast, incoming leadership possesses clear incentives to write down non-performing assets early, resetting the operational baseline. Consequently, severe trough earnings in initial transition years and subsequent recoveries both warrant analytical discounting.
XII. Bear vs. Bull Case Analysis
The bull case
The clean-up appears to be genuinely complete. Gross non-performing assets fell from 5.0% in June 2025 to 3.1% in June 2026, while net NPAs declined from 1.4% to 0.9%, the microfinance stress pool contracted 31% year-on-year, and quarterly credit costs dropped from 3.5% to 1.8%.3 Provision coverage including technical write-offs stands at 85.9%.3 Reported net profit for the June 2026 quarter rose 35% year-on-year to ₹502 crore, driven primarily by lower provisioning.42 With a capital adequacy ratio of 18.2% against a regulatory minimum of 11.5%, the bank maintains a substantial capital buffer to absorb potential losses and fund balance-sheet expansion without diluting equity.3 Quarterly net profit has now increased for four consecutive quarters from its trough.
The mix shift is measurable, not aspirational. Secured loans expanded to 56.8% of gross advances while microfinance contracted to 33.8%, representing a portfolio shift of roughly 15 percentage points over two years.3 Non-microfinance advances grew 27.4% year-on-year.3
Sector timing is turning favorable. The broader microfinance credit cycle shows clear signs of stabilization, with sector-wide portfolio at risk between 31 and 180 days falling to 2.0% from 6.3% a year earlier.40 Bandhan enters this recovery phase with a contracted, heavily provisioned balance sheet alongside a retrenched competitor set.
The deposit franchise remains intact. Retail deposits grew 15.6% year-on-year despite intense operational stress, a founder transition, and an extended forensic audit.3 This resilience offers the most direct empirical evidence of persistent brand equity in core regional markets.
Leadership aligns with the immediate operational mandate. A former State Bank of India chief credit officer who previously led a public-sector bank out of regulatory prompt corrective action brings the appropriate background for balance-sheet restructuring.11
The bear case, and the activist stress test
The core profit engine is shrinking, and lower-yielding segments cannot replicate its economics. Microfinance advances contracted 3.4% year-on-year on an average basis, yet continue to supply the dominant share of portfolio yield.3 The expansion vectors replacing microcredit—corporate banking rated BBB to AA and mortgages yielding single digits—cannot generate equivalent interest spreads. This dynamic highlights the bank's core structural tension: net interest income declined from ₹114.9 billion in FY25 to ₹108.3 billion in FY26, even as total assets expanded 10.6%.3 Asset growth is not generating proportional revenue.
Management's updated guidance places clear bounds on profitability. The portfolio mix shift cannot be framed as an immediate earnings driver when executive leadership reduced its fourth-quarter FY27 return-on-assets target from 1.6–1.8% to 1.0–1.4% just three months after setting it, deferred its 6.5% net interest margin target, and described maintaining the current 6.2% margin as an achievement.3738 An exit return on assets of 1.0% to 1.4% sits at or below historical cycle averages for mid-sized Indian private banks, establishing a modest operational ceiling set by management itself.
Operating overhead presents an unaddressed structural challenge. Operating expenses rose 19.4% year-on-year in the June 2026 quarter, far outstripping a 5.9% increase in net interest income.3 The cost-to-income ratio expanded from 52.1% to 61.5%, while pre-provision operating profit fell 18.6% year-on-year even as reported net profit surged 35%—a divergence reflecting lower provision requirements rather than core operational expansion.3 Maintaining 6,388 banking outlets and 74,744 employees alongside a contracting microfinance portfolio indicates structural overcapacity, while a 65% year-on-year increase in technology spending offers productivity benefits that management does not expect until FY28.37
Governance and disclosure histories continue to impose a valuation discount. A Reserve Bank of India nominee director remains on the board through June 2027.3 While the NCGTC forensic audit concluded without formal adverse findings, the regulator approved an incremental claim of just ₹315 crore against the ₹1,296 crore requested.29 Additionally, Bandhan retained 46.75% and 62.16% of the security receipts in its December 2025 distressed loan sales, retaining residual risk rather than achieving a complete balance-sheet exit.9 While no single factor is disqualifying, their cumulative weight explains why public equity markets continue to price the stock near book value.
Geographic concentration has altered its structure rather than disappeared. West Bengal still generates 41% of total deposits and roughly one-quarter of advances.3 Concurrently, the share of retail deposits sourced outside eastern India declined over the past year.3 Performance in the June 2026 quarter underscored ongoing political sensitivity, as early delinquencies ticked up in April around state elections in West Bengal, requiring executive management to clarify how subsequent slippages were contained.38 The structural vulnerabilities exposed in Assam remain unneutralized, even if aggregate balance-sheet exposure has decreased.
Key operational risks. Four primary risks warrant close tracking: deposit repricing in an increasingly competitive funding environment, which management cites as the principal constraint on net interest margins; execution risk in a wholesale banking portfolio constructed over three years by an executive team without a shared operating history; recurring political and regulatory intervention in core microcredit markets; and technology cost inflation, which management attributes to global supply constraints with no expected efficiency offset until FY28.3837
Reconciling the two
The bull and bear cases are not symmetric, and empirical evidence leans more decisively in one direction.
The asset-quality recovery is backed by consistent empirical evidence. Multiple independent metrics—including vintage performance curves, monthly collection efficiencies, stress-pool contraction, and customer repayment profiles—align in demonstrating balance-sheet stabilization. This dimension of the bull case rests on firm empirical ground.
By contrast, an earnings recovery remains unproven. Pre-provision operating profit is declining, net interest income contracted in FY26, and operating expenses continue to outpace top-line growth. The entirety of the June 2026 quarter's net profit expansion derived from reduced provisioning. Consequently, the bullish thesis depends on credit costs stabilizing between 1.6% and 1.8%, operational leverage emerging, and net interest margins holding at 6.2% despite documented funding cost pressures—assumptions that run counter to management's own updated guidance.
The most rigorous conclusion is that while Bandhan has successfully executed the initial phase of balance-sheet repair by recognizing and provisioning legacy non-performing assets, it has yet to demonstrate that the restructured franchise can generate durable risk-adjusted returns on its capital. That outcome will ultimately be determined by pre-provision operating profitability rather than declining gross non-performing asset ratios.
XIII. Epilogue & Forward-Looking KPIs
There is a temptation to close Bandhan's story on its origin narrative — the sweet shop, the Dhaka ashram, the ₹2 lakh in initial capital, and the West Bengal village. It remains a remarkable piece of Indian business history, and Bandhan's founding achievement is not diminished by its subsequent record as a listed company. Tens of millions of rural borrowers obtained formal credit who otherwise relied on informal moneylenders.
Yet the core investment question is narrower: can an institution built to do one thing exceptionally well be restructured, under regulatory mandates and new management, into a bank that executes three conventional businesses adequately? The empirical record to date indicates that while balance-sheet restructuring is underway, consistent financial returns have not yet followed.
Three key metrics provide the clearest test of this transition:
1. Operating profit growth, quarter over quarter and year over year. Investors should track operating profit before provisions rather than headline net income, which currently reflects the reversal of prior credit provisions — a non-recurring tailwind. Operating profit fell 18.6% year-on-year in the June 2026 quarter and dropped 20.6% across FY26.3 Until operating earnings inflect and sustain positive momentum, Bandhan's turnaround remains a balance-sheet repair narrative rather than a core earnings recovery.
2. Credit costs relative to management's FY27 guidance of 1.6% to 1.8%. This metric represents the single target management reaffirmed even while lowering its margin and return projections, making it a critical test of management credibility.37 Credit costs stood at 1.8% in the June 2026 quarter, down from 3.0% in FY26.3 Holding credit costs within this guided range across a full fiscal year — including seasonally weaker quarters — would validate leadership's risk controls; a breach would indicate that legacy credit pressures remain uncontained.
3. Retail deposit share sourced outside the eastern region. Liabilities remain regionally concentrated, with non-eastern retail deposits accounting for 43.5% of total retail deposits in June 2026, down from 45.2% a year earlier.3 This metric demonstrates whether Bandhan can build a truly national deposit franchise or remain a regional funder supporting national lending operations. Diversifying the deposit base would justify the overhead of national branch expansion, whereas persistent regional concentration leaves the bank absorbing national administrative costs on a localized funding base.
Secondary metrics — portfolio mix shifts, gross non-performing asset ratios, branch totals, and digital adoption statistics — remain downstream of these three fundamental performance indicators.
Bandhan's initial two decades proved that microfinance could deliver formal credit to India's rural poor at scale. Its decade as a licensed commercial bank has highlighted a sobering reality: a specialized microcredit model cannot survive contact with public capital markets, correlated systemic shocks, and central bank regulations without being fundamentally dismantled and rebuilt into something more conventional. The emerging institution resembles a mid-sized Indian private bank backed by a sticky regional deposit franchise and informed by a hard-earned lesson on the dangers of concentration risk. Whether this restructured franchise can consistently earn its cost of capital will become visible on the operating profit line long before it appears anywhere else.
References
-
Jaitley to inaugurate Bandhan Bank in Kolkata today — Business Standard, 2015-08-23 ↩↩
-
How a visionary built a private bank starting with a Rs 2 lakh microfinance company — The Weekend Leader ↩↩↩↩↩↩
-
Bandhan Bank Investor Presentation Q1 FY27 — Bandhan Bank, 2026-07-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Press Release: Bank's Q4 FY26 PAT up 68% YoY at Rs 534 crore — Bandhan Bank, 2026-04-28 ↩↩↩↩↩↩
-
RBI grants bank licence to IDFC, Bandhan — Business Standard, 2014-04-02 ↩↩↩↩↩↩↩↩
-
A Jinxed Acquisition? A Day after Bandhan-Gruh Merger, Shares Tumble — Entrepreneur India, 2019-01-08 ↩↩↩↩↩
-
Audit of Rs 22,750 crore microloans due to large claim amount: Bandhan CEO — Business Standard, 2024-02-13 ↩
-
Bandhan Bank sells over Rs 6,800 crore stressed assets to ARCIL, Phoenix — Business Standard, 2025-12-29 ↩↩↩↩↩↩
-
Chandra Shekhar Ghosh hangs up boots as Bandhan Bank MD and CEO — Business Standard, 2024-07-09 ↩↩↩
-
RBI approves Partha Pratim Sengupta as MD and CEO of Bandhan Bank — Business Standard, 2024-10-10 ↩↩↩↩↩
-
Why microborrowers in Assam are refusing to repay their loans this poll season — ThePrint, 2021 ↩↩↩
-
Assam govt inks pact with MFIs for stressed borrowers — Business Standard, 2021-06-21 ↩
-
Bandhan Bank's collection efficiency ratio at 92 per cent in September — Business Standard, 2020-10-07 ↩
-
Bandhan Bank collection efficiency improves to 90% — Business Standard, 2021-10-09 ↩
-
Chandra Shekhar Ghosh's Bandhan banks on building ties with the underprivileged — Forbes India, 2014 ↩↩
-
Bandhan Bank IPO: Biggest ever bank issue launched — Zee Business, 2018-03-15 ↩
-
Bandhan Bank IPO — subscription and issue details, Chittorgarh ↩
-
Bandhan Bank settles with over 27% premium — Business Standard, 2018-03-27 ↩
-
RBI lifts ban on Bandhan Bank CEO's remuneration following promoter's stake cut — Business Today, 2020-08-17 ↩↩↩
-
RBI lifts ban on Bandhan Bank network expansion — Business Standard, 2020-02-25 ↩
-
Bandhan Bank boards approve merger with Gruh Finance in all-stock deal — Business Standard, 2019-01-08 ↩
-
Bandhan Financial Holdings sells 20.95% stake in Bandhan Bank — Business Standard, 2020-08-03 ↩↩↩↩
-
RBI's promoter shareholding norm: HDFC buys 9.89% stake in Bandhan Bank — Business Standard, 2019-10-30 ↩
-
Bandhan Bank dips 7% on disappointing September quarter results — Business Standard, 2021-11-01 ↩↩↩
-
Portfolio concentration weighs on Bandhan Bank, stock down 13% post results — Business Standard, 2021-01-22 ↩
-
Unravelling the forensic audit controversy at Kolkata headquartered Bandhan Bank — Business Today, 2024-01-10 ↩↩↩
-
Bandhan Bank clarifies the NCGTC audit is only on CGFMU loan claims — Business Standard, 2024-01-09 ↩
-
Update on CGFMU and ECLGS Claim from NCGTC — Bandhan Bank, 2024-10-10 ↩↩
-
Bandhan Bank stock hits 4-year low; Ghosh's retirement plan weighs — Business Standard, 2024-04-19 ↩
-
Ratan Kumar Kesh announced as interim MD & CEO of Bandhan Bank — Storyboard18, 2024-07-06 ↩
-
Shareholding Pattern for the quarter ended June 30, 2026 — Bandhan Bank, 2026-07 ↩↩
-
RBI panel suggests hike in promoter stake cap to 26%, non-promoter to 15% — Business Standard, 2020-11-21 ↩
-
Housing finance major HDFC pares 3% stake in Bandhan Bank for Rs 1,521 cr — Business Standard, 2022-04-08 ↩
-
HDFC Bank offloads its entire 4.31 per cent stake in Bandhan Bank — Business Standard, 2024-01-16 ↩
-
Bandhan Bank Q4 FY26 earnings call summary — Investywise, 2026-04 ↩
-
Bandhan Bank Q1 FY27 Earnings Call: Cuts ROA Guidance by 40 bps, Non-EEB Portfolio Expands 27% YoY — Cofacto, 2026-07-21 ↩↩↩↩↩↩↩↩↩
-
Earnings call transcript: Bandhan Bank Q1 profit rises, but ROA view cut — Investing.com, 2026-07-21 ↩↩↩↩↩↩↩↩↩↩
-
NBFC-MFIs: Asset Quality and Earnings to Remain Under Pressure — CareEdge Ratings ↩↩↩↩↩
-
India's microfinance sector past stress peak, portfolio quality improves: MFIN — Business Today, 2026-02-28 ↩↩
-
Bandhan Bank Q1 FY26 results: Net profit down 65% on rising bad loans — Business Standard, 2025-07-18 ↩
-
Bandhan Bank's Q1 profit up 35% on lower provisions, asset quality improves — Business Standard, 2026-07-21 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube