CreditAccess Grameen: India's Microfinance Giant and the Quest for Financial Inclusion
I. Cold Open & Stage Setting
On the morning of August 8, 2018, order books opened for an unconventional public offering in Indian capital markets history. The issuing company had no factories, major brands, patents, or physical collateral against the loans that comprised virtually all of its assets. Its borrowers were rural women—most with no formal credit history—taking out loans smaller than the cost of a mid-range smartphone. Its underwriting model relied on a core premise: that five women who know each other well enough to vouch for one another provide better security than a traditional mortgage.
Investors bid anyway. The offer, priced between ₹418 and ₹422 per share, comprised roughly 2.68 crore shares—about 1.49 crore freshly issued and 1.19 crore sold by existing shareholders.1 CreditAccess Grameen raised approximately ₹1,130 crore, and its shares began trading later that month.2 Nineteen years after a Bengaluru schoolteacher started issuing micro-loans in a village on the city's outskirts, the enterprise she founded had become a publicly traded financial institution.
Eight years later, the scale of the operation has fundamentally shifted. As of June 2026, the company managed ₹30,319 crore in assets across 2,276 branches in 457 districts—spanning 16 states and one union territory—supported by 21,981 employees.3 It remains India's largest standalone non-bank microfinance institution, though management has quietly moved away from leading with that description as the business evolves.
The central paradox of the business lies in its earnings volatility. In the quarter ended June 2026, CreditAccess Grameen recorded a profit after tax of ₹493.4 crore, translating to a return on assets of 5.9% and a return on equity of 24.4%—profitability metrics typical of high-margin technology firms rather than unsecured lenders serving low-income rural households.34 Yet just one year prior, in the June 2025 quarter, net profit stood at ₹60.2 crore.3 For the full fiscal year ending March 2025, the company earned ₹531.4 crore, delivering a return on equity of 7.7%—barely higher than its cost of debt.5
This eightfold swing in quarterly earnings within four quarters is not a statistical anomaly. It illustrates a business model where earnings are exceptionally sensitive to asset quality, making credit volatility the central variable in evaluating CreditAccess Grameen.
The volatility stems from a structural mismatch between stable revenue and unpredictable credit costs. Interest income generated from a portfolio of small, high-yield loans remains steady quarter to quarter. However, credit costs—comprising provisions and write-offs for non-performing loans—can fluctuate by up to five percentage points of the portfolio in a single year. For a lender operating on a net interest margin of roughly ten percentage points, a five-percentage-point swing in credit losses marks the difference between high profitability and near-zero earnings.
A second misconception concerns the company's credit rating, which often features in bullish investment arguments. CreditAccess Grameen is not rated AA+. It carries an AA- rating with a stable outlook from CRISIL, ICRA, and India Ratings.3 While this represents the highest rating among dedicated non-banking financial company microfinance institutions (NBFC-MFIs) and provides a tangible funding cost advantage, the gap relative to broader financial peers is narrower than market commentary often implies.
The following sections examine how a non-profit initiative in Karnataka expanded into a ₹30,000 crore lender; how Dutch capital and commercial banking leadership restructured the firm after the sector's crisis in Andhra Pradesh; how its acquisition of a Chennai-based competitor required three years of integration; how the joint-liability lending model experienced two documented failures; how the 2024–25 credit cycle wiped out a year of earnings and forced a reset of financial guidance; and how, as of September 2026, the recovered business operates under a promoter seeking to sell its controlling stake—an open question that remains central to the company's equity valuation.
 Subscribe on LinkedIn
II. The Genesis Story: From NGO Mission to NBFC Architecture (1999–2009)
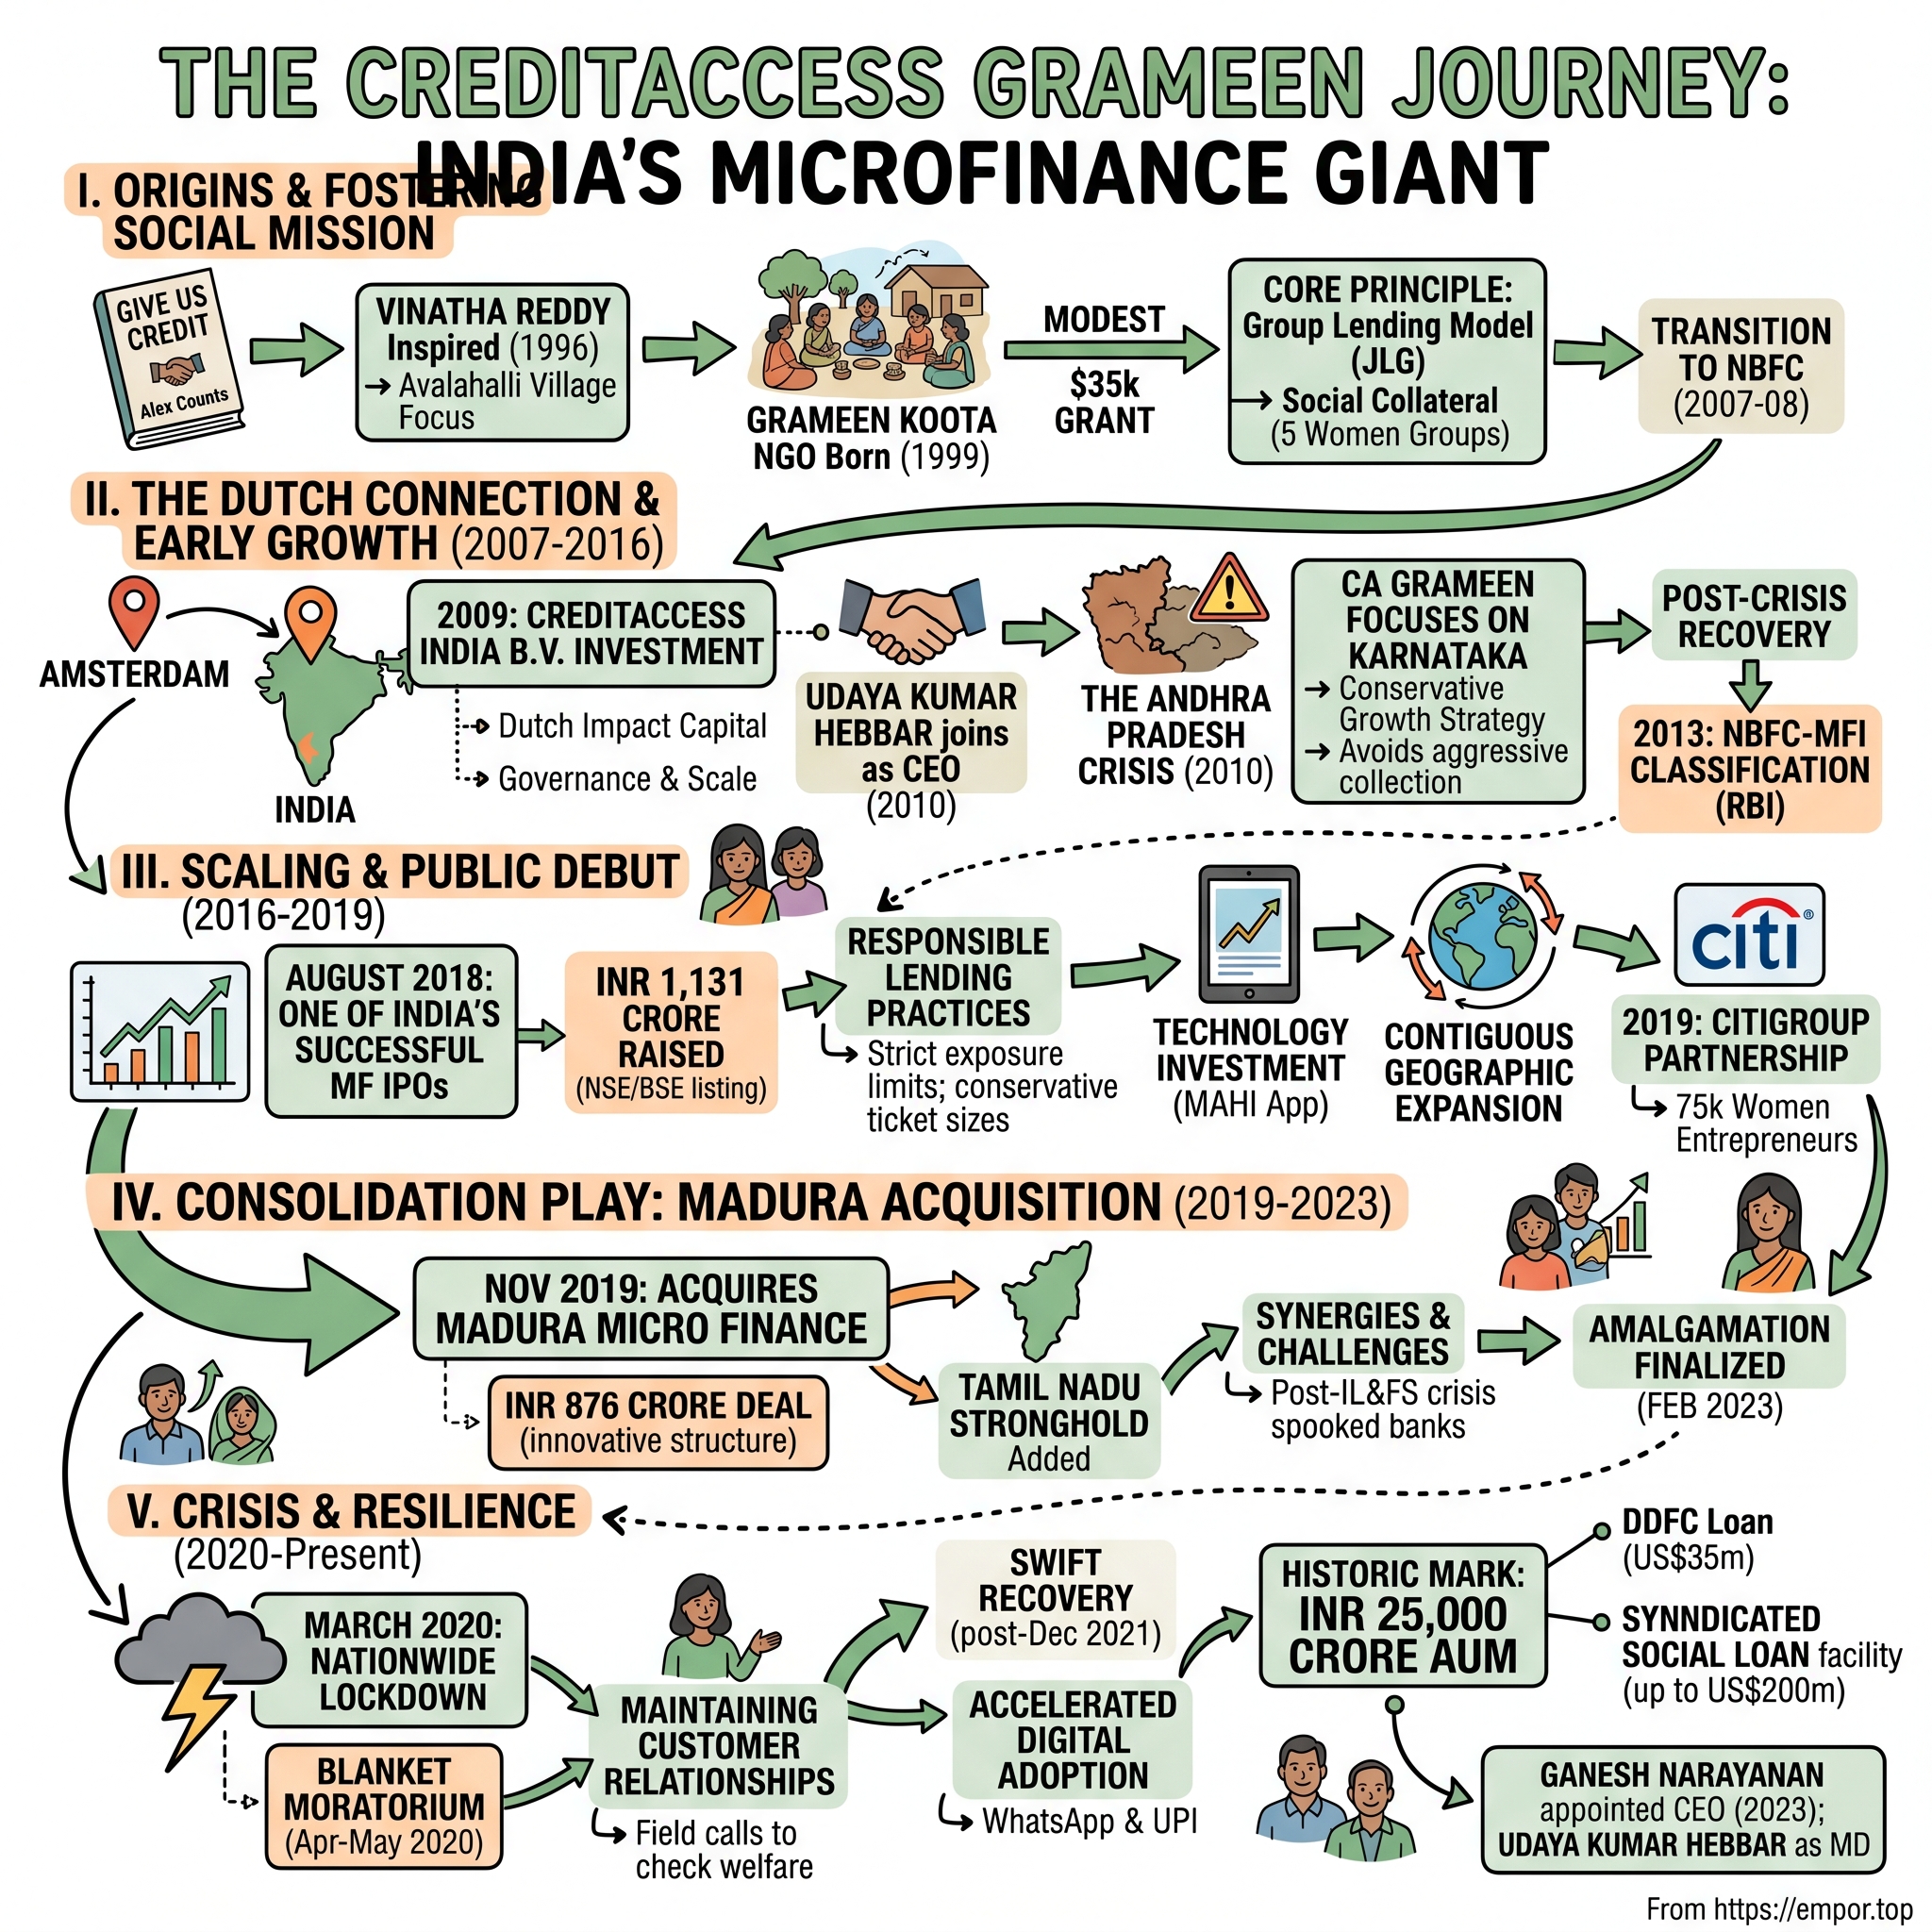
In the late 1990s, Vinatha M. Reddy was running a rural Montessori school called Gurukul in Avalahalli village near Bengaluru through a trust founded by her grandmother. After reading Give Us Credit by Alex Counts—a chronicle of Muhammad Yunus and the Grameen Bank in Bangladesh—she wrote to Counts for guidance.6 The inquiry led to an invitation from Yunus to attend his training program in Bangladesh. Upon her return, Reddy submitted a project proposal that qualified through her registered non-governmental organization (NGO) and secured a $35,000 grant from the Grameen Foundation.6
That initial grant provided the seed capital for an enterprise that would eventually expand into a multi-billion-dollar institution. Grameen Koota launched operations in 1999 as a micro-lending project under the T. Muniswamappa Trust in the same village as the school.6
Why social collateral works, and what it actually is. The mechanism Reddy imported formed the core of the business model. Where traditional lenders demand physical assets to secure a loan, microfinance institutions serving landless rural households rely on social capital. Under the joint-liability model, borrowers form small groups of five women who vouch for one another. These groups gather at weekly center meetings, known as kendras, held at fixed times and locations, where loan repayments are collected publicly.
Public collection is central to the mechanism. By making repayment a visible weekly event within the community, the model transforms an uncollateralized claim into a socially enforced obligation. Peer pressure replaces legal enforcement, while borrowers perform the monitoring themselves at minimal cost to the lender.
Frequency serves as a second, practical risk control. A weekly schedule on a one-year loan provides roughly 50 opportunities to detect household distress. A quarterly lender discovers default only after three months, long after funds are spent. Although frequent collections incur high operational expenses for field staff, they convert credit risk into an operational task managed through physical presence. This trade-off—accepting high operating costs in exchange for early warning indicators—became the fundamental economic bargain of microfinance, favoring operators that minimized collection costs per visit over those with sophisticated credit scoring.
The corporate re-plumbing. By the mid-2000s, growth was constrained by capital access rather than borrower demand. Because trusts cannot raise equity and commercial banks limited their exposure to non-profits, the organization transitioned from an NGO to a non-banking financial company (NBFC) in 2007. In 2008, it raised ₹9.2 crore from venture fund Aavishkaar and expanded into Maharashtra.2 The formal NBFC-MFI license—a regulatory classification established later—was granted on September 5, 2013.2 This structural evolution reflected a deliberate shift from non-profit operations to regulated finance to secure institutional leverage.
Falsification pass: does social collateral survive contact with politics?
The central premise of joint liability—that peer enforcement ensures high repayment rates through economic cycles—faced early testing in the company's home state.
In 2009, mass defaults emerged across four Karnataka towns, including Kolar and Ramanagaram. A local body known as the Anjuman Committee instructed Muslim borrowers to halt repayments, arguing that interest was impermissible and asserting that MFI operations—such as women attending meetings with unrelated men or traveling for training—were culturally inappropriate.7 Default rates in the impacted locations rapidly exceeded 50%.7
Subsequent research revealed that religious objections masked broader structural and behavioral issues. Approximately 20% of defaulters selectively serviced loans from certain lenders while defaulting on others, demonstrating strategic behavior alongside religious compliance.7 Underlying drivers included high household debt, a sharp downturn in the local silk industry, relaxed underwriting, and weakened field monitoring.7 The committee's edict provided social cover for defaults rooted in economic strain and moral hazard.
The calibrated conclusion.
The Karnataka experience demonstrated the limits of joint liability. Social collateral is not an absolute guarantee against credit loss; rather, it functions as a cost-effective monitoring system dependent on three conditions: manageable borrower leverage, strict field discipline, and the absence of external political or social authorization to default. If any of these conditions break down, the social networks that facilitate repayment can rapidly spread contagion and default.
The events in Kolar served as an early warning. A year later, a broader systemic crisis unfolded in Andhra Pradesh, threatening the viability of the entire Indian microfinance sector.
III. The CreditAccess Pivot & The Post-AP Crisis Crucible (2009–2016)
In October 2010, the government of Andhra Pradesh promulgated an ordinance restricting microfinance recovery in the state. The proximate trigger was a wave of reported borrower suicides and public fury over collection practices, unfolding just weeks after SKS Microfinance had completed a heavily oversubscribed initial public offering. The sequence—record listing, public backlash, and state intervention—unfolded in roughly ninety days.
The consequences extended far beyond Andhra Pradesh. Commercial banks, which supplied nearly all wholesale funding to microfinance lenders, halted lending to the entire category. An industry whose loan portfolio was sound outside one state discovered that its liability structure represented a single point of failure, driving several regional lenders out of business.
The Dutch entry. Into this wreckage stepped CreditAccess India B.V., an Amsterdam-headquartered entity specializing in micro- and small-enterprise financing. Its shareholder roster resembled a multilateral coalition rather than a private equity fund: Olympus ACF held 15.4%, the Asian Development Bank 8.8%, Asia Impact Invest 8.8%, and the Italian Bishops' Conference 8.1%, with individual investors, high-net-worth individuals, and family offices holding nearly 59% across approximately 247 shareholders.2
That shareholder structure shaped the company's trajectory. This was not a private equity fund bound by a typical seven-year exit timeline. Capital arrived in tranches over a decade: ₹53.2 crore in 2013 alongside Creation Investments and Incofin, a controlling stake acquired in 2014, and ₹120 crore in 2015 as the lender expanded into Madhya Pradesh and Chhattisgarh.2 While "patient capital" is a common phrase in impact investing, the deployment schedule reflected that exact approach.
The banker in the microfinance shop. In 2010, the board hired Udaya Kumar Hebbar as chief executive. Hebbar was not from the non-profit development sector; he had spent more than a decade each at Corporation Bank and ICICI Bank, joining from Barclays, where he had managed commercial banking and payment operations. He brought more than forty years of banking experience with a focus on operations, rural lending, and agricultural finance.8 He joined the board in August 2015 and became managing director and chief executive officer in 2016.8
What a career operations banker brought to a microfinance institution was not ideological vision, but operational discipline. The organizational framework that came to define the firm reflected traditional banking principles: field staff received full-time fixed salaries rather than commissions—ensuring that loan officers who disbursed credit were also responsible for collections—and branch offices followed standardized, low-cost formats replicated district by district across contiguous geographies. Crucially, the company began integrating credit bureau checks into its underwriting decisions in 2011.2 In 2011, evaluating a rural borrower's existing debt across other lenders before disbursement was not standard industry practice; it marked an early step in the sector's gradual effort to assess total household leverage.
Regulation as an industrial policy. The Reserve Bank of India's response to the Andhra Pradesh crisis established the formal NBFC-MFI regulatory category in 2011, introducing a "qualifying assets" mandate that required at least 85% of net assets to consist of microfinance loans.9 The framework imposed margin caps, interest rate ceilings, and household income limits. While these rules constrained operations, they also created an entry barrier for compliant institutions by defining legitimate microfinance parameters and effectively sidelining informal operators whose practices had sparked the crisis.
In practice, the qualifying-asset rule forced a clear operational identity. Institutions seeking an NBFC-MFI license had to maintain the vast majority of their balance sheet in small, uncollateralized household loans, preventing them from shifting into larger, secured lending when microfinance faced headwinds. The constraint established regulatory boundaries around the core business, ensuring that eventual portfolio diversification required formal regulatory approval rather than internal discretion.
Falsification pass: does a deep-pocketed promoter insulate the book?
A common argument among proponents is that institutional ownership and conservative underwriting shield the company from sector-wide shocks. The November 2016 demonetisation episode provided a direct test of this thesis, demonstrating that institutional backing offers capital resilience rather than immunity.
When the Indian government withdrew high-denomination banknotes from circulation in November 2016, liquidity dried up across the rural economy, directly disrupting weekly center-meeting collections. The impact on CreditAccess Grameen was evident in its balance sheet: the promoter injected ₹350 crore in fresh equity and ₹200 crore through compulsorily convertible debentures in 2017—a capital infusion the company described as a demonstration of confidence in the model following demonetisation.2
A lender does not raise more than ₹500 crore in equity-like capital in a single year because operations are running smoothly. Institutional backing did not prevent credit losses; it funded the balance sheet repair. The promoter's balance sheet acted as a capital buffer rather than an operational shield.
This distinction remains central to evaluating CreditAccess Grameen. The company's historic competitive advantage has not been immunity to industry crises, but rather its ability to absorb losses, maintain capital adequacy, and expand market share as weaker competitors contract. Conflating capital resilience with crisis immunity overlooks the underlying earnings volatility inherent in the model.
By 2017, with its balance sheet recapitalized and its branch network standardized, the promoter faced a new strategic constraint: owning a private entity operating a public-market business model without listed equity to fund further consolidation.
IV. Going Public & National Scaling (2016–2019)
In 2018, Grameen Financial Services renamed itself CreditAccess Grameen Limited, signaling its transition from a regional micro-lender to a broader commercial institution.2 While the original "Grameen Koota" brand originated as a local non-profit initiative in Karnataka, the new corporate identity reflected an entity structured for public markets, credit ratings, and national expansion.
Structurally, a microfinance institution operates as a leveraged spread lender, raising wholesale debt to disburse retail loans, with growth bounded by its equity capital. Every rupee of permanent capital enables multiple rupees of lending capacity. Going public achieved three key strategic objectives: it raised primary equity to support portfolio expansion, provided Amsterdam-based CreditAccess India B.V. a partial exit mechanism, and established a publicly traded equity currency for future acquisitions.
Following the oversubscribed initial public offering, the shares listed in August 2018. Management deployed the newly raised capital primarily through branch network expansion. In 2019, the company entered five states in a single phase: Jharkhand, Rajasthan, Gujarat, Uttar Pradesh, and Bihar.2 The operational strategy relied on contiguous expansion. Rather than entering isolated high-growth markets, the firm expanded district by district from existing clusters, allowing new branches to leverage established supervisory structures, local recruitment pipelines, and regional oversight.
This methodical geographic rollout underpinned the firm's cost structure. Microfinance profitability depends heavily on minimizing operating expenses per rupee lent while maintaining strict supervision over field staff handling cash in remote areas. Contiguous expansion supported both objectives, preserving operational control that fragmented expansion across non-adjacent territories could erode.
Geographic diversification accompanied this expansion. By reducing reliance on any single state, the company mitigated regional concentration risk. The value of this policy became evident in early 2025 when political intervention disrupted collections in Karnataka, the firm's founding state and historically its largest exposure; the resulting losses were substantial but manageable because the majority of the loan book was distributed across other states. Maintaining concentration limits slowed potential growth during favorable market conditions but preserved balance sheet stability during localized downturns.
The Citi transaction, correctly sized. In early 2019, Citi India provided a ₹200 crore facility—approximately $29.5 million—to CreditAccess Grameen, structured with risk participation from the Asian Development Bank to fund loans for 75,000 women entrepreneurs at an average loan size of roughly $390.10 Market commentary occasionally misreported this deal as a $75 million facility, confusing the number of targeted borrowers with the dollar value of the loan. Clarifying the actual figure is essential, as the misinterpretation exaggerated the scale of the company's international funding relationships while those channels were still developing.
The transaction illustrated the company's evolving liability strategy: international commercial banks would extend credit to an Indian micro-lender, provided a multilateral development finance institution shared the risk. Development institutions served as a credit bridge to attract commercial capital. Over time, foreign borrowings expanded to account for nearly a quarter of the company's total liability mix without requiring credit guarantees.3
The competitive board at listing. By 2018, the Indian microfinance sector comprised three distinct institutional models. Universal banks like Bandhan Bank had converted from micro-lenders and were diversifying into broader commercial banking. Small finance banks, including Ujjivan and Equitas, obtained retail deposit licenses, offering lower funding costs alongside higher compliance expenses and urban branch overhead. Meanwhile, dedicated NBFC-MFIs—such as Spandana Sphoorty, Satin Creditcare, Fusion Microfinance, and Muthoot Microfin—continued focusing exclusively on rural micro-loans.
CreditAccess Grameen chose to remain a specialized NBFC-MFI, competing on cost efficiency. This decision reflected a fundamental strategic trade-off. While small finance banks raised retail deposits at interest rates of 6% to 7%, they incurred regulatory reserve requirements and substantial branch operating costs. Conversely, dedicated NBFC-MFIs funded operations through wholesale borrowings at 9% to 10%, but maintained significantly leaner operating models in high-yield rural markets. Management bet that superior operating efficiency and a leading credit rating in the NBFC-MFI tier could offset the funding cost advantage enjoyed by deposit-taking banks.
That model produced strong average returns across economic cycles alongside elevated earnings volatility within them. This underlying structural dynamic set the stage for the company's next strategic move: a cash acquisition of a major competitor that introduced complex integration challenges.
V. The Madura Micro Finance Acquisition: Consolidation & Stress-Testing (2019–2023)
Madura Micro Finance had an unusual pedigree. It traced back to the former promoters of Bank of Madura, which had launched micro-lending operations in 1995 before merging into ICICI Bank in 2001.11 By September 2019, Madura was India's eleventh-largest NBFC-MFI, serving 11.1 lakh borrowers with a gross loan portfolio of ₹2,053 crore, a net worth of ₹368 crore, and 430 branches across 82 districts in six states—with Tamil Nadu accounting for roughly 70% of its portfolio.11 The lender was led by Tara Thiagarajan as chairman and managing director.
For CreditAccess Grameen, the primary strategic appeal was geographic. Tamil Nadu was a large, high-density microfinance market where CreditAccess Grameen held a limited presence. Building a comparable footprint of 256 branches and 8 lakh borrower relationships organically would have required years of capital deployment; an acquisition offered immediate scale.
The architecture. Announced on November 27, 2019, the transaction valued Madura's equity at ₹875 crore—representing 2.4 times its September 2019 book value and 9.2 times its annualized first-half FY20 earnings.11 The deal used a two-step structure: an initial cash purchase of a 76.2% controlling stake for ₹666.4 crore, followed by an equity swap for the remaining 23.8% under a scheme of amalgamation, resulting in approximately 1.85% equity dilution.1112 Crucially, the cash component was funded without incurring new debt; instead, CreditAccess Grameen raised capital by securitizing and assigning portions of its existing loan book—a capital-efficient funding strategy.11
Management framed the transaction around scale and strategic positioning. Managing Director Udaya Kumar Hebbar highlighted expected benefits including improved competitive positioning, larger scale, deeper regional presence, portfolio diversification, optimized leverage, and enhanced profitability. Board chairman Paolo Brichetti framed the transaction around the social mission of extending credit to underserved low-income households, while Thiagarajan described the merged entity as a stronger operating platform.13 Furthermore, management assured investors that the acquisition would be earnings-accretive from the onset of consolidation.11
Evaluating the valuation. At 2.4 times book value for a profitable NBFC-MFI with a dominant position in a key target market, the valuation multiple was aligned with prevailing 2019 standards for Indian financial institutions. However, the ultimate test of M&A success rests not on the entry valuation, but on post-merger execution—where subsequent events challenged management's projections of rapid, seamless consolidation.
Falsification pass: testing the integration timeline.
When announcing the transaction, the company published an indicative timeline target: closing the majority stake acquisition by March 2020 and completing the legal amalgamation before November 2020, within approximately twelve months of board approval.11
While the majority stake acquisition closed on schedule in 2020,2 the legal merger encountered major delays. The National Company Law Tribunal order amalgamating Madura into CreditAccess Grameen was issued only in 2023—roughly 27 months behind management's original schedule.2 Consequently, for nearly three years during the COVID-19 pandemic, CreditAccess Grameen operated Madura as a separate subsidiary with its own board, regulatory filings, and IT systems.
Two additional balance-sheet and operational factors complicate the narrative. First, as of March 2024, the balance sheet carried ₹375.7 crore in transaction-related goodwill, accounting for roughly 5.7% of total equity.14 While manageable, this premium over book value requires sustained earnings performance to avoid impairment risks. Second, because the acquisition closed immediately prior to nationwide COVID-19 debt moratoriums, management's ability to evaluate the underlying credit quality of the acquired portfolio was effectively paused during the initial post-closing period.
The calibrated conclusion.
Strategically, the acquisition achieved its primary goal: establishing CreditAccess Grameen as a major lender in Tamil Nadu, which remains one of four core states where the institution expands its individual-lending portfolio.15 However, the assertion that the transaction was seamlessly and immediately accretive is contradicted by the execution timeline. Legal integration required three years instead of the planned twelve months, taking place during a period when debt moratoriums obscured portfolio performance. Ultimately, the transaction delivered strategic market position but suffered from adverse timing and delayed execution—explaining why management subsequently refrained from further large-scale acquisitions.
More broadly, the acquisition illustrates that microfinance loan books cannot be integrated like standard commercial loan portfolios. Microfinance assets rely on ongoing relationships between field officers and borrower groups in specific villages. Retaining field personnel maintains portfolio performance; losing them risks collapsing the social collateral enforcing repayment. For this reason, the transaction agreements explicitly committed to retaining Madura's personnel and maintaining existing operational leadership, explaining why integration proceeded cautiously.11 The extended merger timeline reflected not merely regulatory delays, but a deliberate effort to avoid disturbing the field-level relationships sustaining repayment discipline.
This outcome raises a fundamental question: if inorganic growth introduces multi-year operational and integration complexity, how effectively does the company's core organic lending engine generate returns?
VI. Business Model Deep Dive: Serving the Underserved & The 7 Powers Framework
Picture a branch. It is not a standard bank branch, but a couple of rooms on the first floor above a shop in a small town—equipped with a safe, tablets, a few desks, a branch manager, and several field officers. Almost nothing happens inside. The actual work occurs at dawn when field officers ride motorcycles out to villages for center meetings, collect repayments in public, and return.
That is the core physical infrastructure. Understanding why it is difficult to replicate requires examining what alternative delivery models cost.
What the company actually sells now. Group lending—the classic joint-liability income-generation loan—remains the core, but the product mix has shifted rapidly. Retail finance expanded to 20.6% of assets under management by June 2026, up from 18.1% three months prior and 5.9% a year earlier.315 Within retail finance, the primary component is graduated unsecured individual business lending, which management reported at 91% of the retail portfolio.4 This individual product operates under two tiers: Unnati, featuring an average ticket size of around ₹1.7 lakh for borrowers with verifiable cash flows, and Unnati Lite, offering ₹75,000 to ₹1 lakh for customers advancing up the income ladder whose cash flows cannot yet be fully validated.15 The remaining retail portfolio includes mortgage-backed business loans, affordable housing finance, and a small two-wheeler loan book.
The pricing disclosure from the June 2026 investor call reveals more than the portfolio mix alone. Individual business loans are priced roughly 50 basis points above group loans due to the absence of peer guarantees. Loans against property carry an interest rate of around 20.5%—approximately one percentage point below standard microfinance rates—and excluding the housing book, which accounts for about 1% of assets, virtually the entire portfolio yields over 20%.4 Rather than diversifying into lower-yield, lower-risk assets, the institution is extending its high-yield rural franchise into products that carry lower operating and credit costs per rupee lent.
The arithmetic of a branch. While CreditAccess Grameen does not disclose branch-level financial statements, aggregate disclosures provide a clear operational picture. Across 2,276 branches and 21,981 employees as of June 2026, the typical branch operates with roughly ten staff members—a manager and a team of field officers.3 Serving a customer base that management estimates at approximately 44 lakh, each branch supports roughly 1,900 borrowers, translating to a few hundred clients per field officer.15 Rather than focusing on sales pitches, these officers cover fixed weekly collection routes where the marginal cost of adding a borrower is minimal. Consequently, geographic density drives branch economics: an underutilized branch incurs losses, a fully utilized branch generates high returns, and branch expansion fundamentally serves to maximize route density rather than expand real estate.
The funding advantage, measured honestly. The company's average cost of borrowing fell to 9.2% in the March 2026 quarter—a 60 basis point decline over the fiscal year—with marginal borrowing costs hovering around 8.9%.15 For comparison, Muthoot Microfin, a listed NBFC-MFI peer, reported a cost of funds of 10.43% in the December 2025 quarter.16 This represents a funding advantage of approximately 120 basis points against a major peer, rather than the 250 to 350 basis point gap frequently cited in optimistic market commentary.
Whether a 120 basis point differential constitutes a competitive moat remains open to debate. In a commodity lending business, such a funding gap is meaningful but not decisive, allowing the firm either to offer lower borrower rates at equal margins or to maintain wider spreads at market rates. The durability of this advantage stems from the company's credit rating, which reflects its scale, capital base, and history of navigating sector crises without debt restructuring—a combination difficult for emerging competitors to replicate quickly. Conversely, management has signaled that borrowing costs have reached their floor: during the May 2026 earnings call, Chief Executive Officer Ganesh Narayanan stated that funding costs had effectively bottomed out, offering limited room for further reductions and anticipating range-bound or slightly higher rates.15
This statement explicitly bounds the company's cost-of-funds tailwind. Investment models projecting continued funding-cost compression to drive margin expansion directly contradict management's guidance.
The operating cost advantage, which is the bigger one. The broader competitive advantage lies in operating efficiency. In FY24, at the peak of the preceding credit cycle, CreditAccess Grameen maintained an operating expense to loan portfolio ratio of 4.5%.14 By the June 2026 quarter, its cost-to-income ratio stood at 29.3%.3 Delivering this level of efficiency while physically conducting weekly visits across millions of households represents a formidable operational barrier, resulting directly from structural decisions instituted after 2010: salaried field personnel, low-cost standardized branches, contiguous geographic expansion, and centralized technology.
Technology infrastructure provides the underpinning for this operational scale. The company's systems process over 30 lakh transactions daily, comprising 10 to 15 lakh loan repayments, 20 to 25 lakh credit bureau checks, and 70,000 to 80,000 loan applications.15 Underwriting relies on a centralized business rules engine that management updates quarterly across state, district, and customer cohorts, enabling granular credit policy adjustments by region.4
Applying the seven powers, with a skeptic's pen. Evaluating the institution through the lens of strategic frameworks yields a nuanced assessment. Scale economies exist but remain modest: the funding advantage over scaled peers stands at approximately 120 basis points and is self-limiting by management's admission. Process power represents the company's strongest strategic attribute—salaried field execution, disciplined weekly center meetings, contiguous coverage, and a flexible credit rules engine have created an operating cost structure that peers have struggled to replicate over the past decade. Because process advantages reside in institutional culture and thousands of trained employees, they are difficult for competitors to copy quickly.
Counter-positioning against traditional commercial banks is effective, as standard banks cannot economically deploy field officers to collect ₹500 weekly village repayments without disrupting their higher-cost models. However, counter-positioning against small finance banks is less pronounced: deposit-taking institutions benefit from lower funding costs, and whether superior operating efficiency ultimately outweighs cheaper deposit funding across an entire credit cycle remains an open question. Finally, traditional brand equity, network effects, cornered resources, and switching costs are largely absent in microfinance; borrowers frequently take loans from multiple lenders, creating systemic vulnerability to over-indebtedness.
What this means. Ultimately, CreditAccess Grameen's durable advantage is operational rather than financial. It manifests in a low cost per rupee lent and the agility with which its field force can shift focus from loan growth to debt collection—a capability demonstrated when management prioritized collections over disbursement for eighteen months.15 What this operational edge does not provide, however, is immunity from sector-wide credit shocks; no cost advantage insulates an unsecured lender when its customer base becomes broadly over-leveraged.
That vulnerability soon manifested across the industry.
VII. Regulatory Overhaul, Pandemic Recovery, & The 2024–2025 Industry Stress Test (2020–Present)
The pandemic, briefly. COVID-19 arrived weeks after the Madura control acquisition closed, and the Reserve Bank's moratorium suspended the one thing the model depends on: the weekly centre meeting. The company front-loaded expected credit loss provisions and held capital adequacy well above requirement. It is worth noting management's own later comparison: on the May 2026 call, Narayanan observed that return ratios through the recent microfinance credit cycle were "meaningfully higher than what we delivered through the COVID crisis, despite higher credit costs."15 Whether that reflects a genuinely more resilient model or a differently-shaped shock is a fair question — but the comparison is at least self-consistent across the two events.
The 2022 deregulation. On March 14, 2022, the RBI issued a Master Direction that rewrote the rules, effective April 1 that year. It defined a microfinance loan as a collateral-free loan to a household with annual income up to ₹3,00,000; it required lenders to cap a household's total monthly loan repayment obligations — across microfinance and other collateralised borrowings — at 50% of monthly household income; and, critically, it replaced hard interest rate and margin caps with a requirement for board-approved pricing policies subject to supervisory review.17
This was framed at the time as liberation, and for two years it was. Freed to price for risk, the sector expanded margins. But the same Master Direction contained the seed of what went wrong. A 50% obligations-to-income cap is only as good as the income estimate and the completeness of the leverage data behind it. When every lender is separately assessing self-declared household income and querying bureaus with reporting lags, the aggregate leverage of a household can be materially higher than any single lender believes.
The crack-up. Through FY25 the microfinance sector went through its worst credit event since Andhra Pradesh. Sector gross loan portfolio fell roughly 14% to ₹3,81,200 crore by March 2025; gross NPAs surged to about 16% from 8.8% a year earlier; and loans overdue 30 to 180 days had already climbed to 6.4% by the December 2024 quarter from 2%.18 Assets under management growth for NBFC-MFIs collapsed to roughly 4% in FY25 from 28% in FY24.18
The proximate causes were a familiar cocktail: households borrowing from four, five, six lenders at once; heatwaves and localised flooding hitting rural cash flows; and in Karnataka — CreditAccess Grameen's home and largest state — an outright political intervention.
The Karnataka intervention. On February 12, 2025, the Karnataka government promulgated an ordinance against coercive microfinance recovery, subsequently enacted as the Karnataka Micro Loan and Small Loan (Prevention of Coercive Actions) Act, 2025, which received the Governor's assent on March 24, 2025.19 The legislation was aimed at unregulated lenders and did not apply to RBI-registered NBFCs, and management credited the industry body MFIN with engaging the state government and the RBI to keep the scope narrow.20 But the operational damage was immediate and had nothing to do with legal applicability. On the May 2025 call, Hebbar described stress becoming visible from the last week of January 2025 because of "operational ambiguities in anticipation of the ordinance, on-ground hostile environment, media & political sensitivities, and collections being limited to centre meetings," with disbursements falling to 57% of normal in February and 65% in March.20
That is the Kolar lesson at state scale, sixteen years later. When public authority signals that non-repayment carries no consequence, the social collateral evaporates within weeks.
What it cost. The March 2025 quarter produced profit after tax of ₹47.2 crore against total income of ₹1,407.7 crore — the number that made the crisis visible to equity investors.5 Full-year credit cost reached ₹1,929 crore, or 7.7% of the average on-book portfolio; total write-offs for FY25 were ₹1,124 crore, of which ₹479 crore represented accelerated write-offs of non-paying accounts past 180 days, adding ₹151 crore of credit cost the company chose to take early.20 Gross NPA ended March 2025 at 4.76% against 1.18% a year earlier, with expected credit loss provisions of ₹1,308.6 crore.514
Assets under management fell 2.9% year on year to ₹25,948 crore and the borrower base shrank 4.6% to 46.94 lakh — the first contraction in the company's listed history.5
The industry's self-imposed brake. MFIN's guardrails limited the number of microfinance lenders per borrower and capped total borrower indebtedness — including unsecured retail loans — at ₹2 lakh, with the third iteration effective April 1, 2025 tightening the lender cap to three.18 The mechanism is simple and, unusually for self-regulation, appears to have worked: because every member reports to the bureaus, the cap is enforced at the point of underwriting. CreditAccess Grameen's own disclosure tracks the effect precisely — the share of its assets lent to group borrowers with more than three lenders fell from 25.3% in August 2024 to 3.3% by March 2026, while the share of assets held by borrowers who bank only with CreditAccess Grameen rose from 26.6% to 46.1%.15
That second number is the one to watch. A unique borrower cannot be brought down by another lender's aggression. Nearly doubling that share is the single most substantive structural improvement in the book.
The recovery. By the December 2025 quarter, profit after tax had recovered to ₹252.1 crore, delivering a 3.5% return on assets, with monthly PAR 15+ accretion falling to 18 basis points in December 2025 from 47 basis points in September, and total portfolio at risk declining to 4.4%.21 The March 2026 quarter brought ₹340 crore of profit and a 4.4% return on assets, with disbursements up 44.1% sequentially.15 Full-year FY26 profit was ₹778 crore on a 2.7% return on assets and 10.7% return on equity.15
A necessary accounting flag. FY26 credit cost came in at 6.74% against guidance of 5.5–6.0% — and management disclosed the composition candidly: 6.10% from new portfolio at risk and 0.64% from raising expected credit loss provisioning rates.15 During the March 2026 quarter the company implemented a new forward-looking ECL model incorporating macroeconomic scenarios, overseen by a newly formed board-level ECL committee, and took an additional ₹39 crore of provisioning to reflect a higher weighting for a major external event — specifically the ongoing West Asia conflict.15 Stage 1 provisioning rose to 1.63%.15
Investors should hold two thoughts about this simultaneously. Building conservatism into a provisioning model before losses appear is defensible risk management. It also introduces significant management judgment into reported earnings, and the model change happened to land in the quarter that determined whether FY26 guidance was met. The company missed the lower end of its ROA and ROE guidance by a small margin as a direct result.15 A skeptical analyst would want to see the ECL committee's weightings behave symmetrically — released when conditions improve, not only added when they deteriorate.
A note on what expected credit loss actually means. Under the accounting standard Indian lenders follow, loans sit in one of three buckets. Stage 1 is performing, and the lender must nonetheless hold a provision for losses expected over the next twelve months. Stage 2 is loans whose credit risk has increased significantly, where the provision must cover expected losses over the loan's whole life. Stage 3 is impaired. The critical feature is that Stage 1 provisioning is forward-looking by construction — the lender is required to guess. Raising the Stage 1 rate from below one percent to 1.63% therefore reduces reported profit today on loans that are, at this moment, paying perfectly well.15 That is either prudence or smoothing depending on what happens next, and the honest position for an outside investor is that it cannot be distinguished in real time.
By the June 2026 quarter the recovery was clearly established: portfolio at risk down to 2.2%, gross NPA at 2.18%, X-bucket collection efficiency at 99.68%, credit cost of ₹212.5 crore for the quarter, and PAR 15 accretion running at about 15 basis points a month.34
The business came back. The question is what the two-year detour revealed about the people running it.
VIII. Current Leadership, Capital Allocation, & Governance Stress-Test
On the May 2025 call — the one where he had just reported the worst quarter of his tenure — Hebbar closed his prepared remarks by announcing that he would retire as managing director on June 25, 2025, and move to a non-executive nominee director role.20 It is a striking piece of timing: the architect of the modern company handing over at the trough.
Ganesh Narayanan was appointed managing director and chief executive for a five-year term effective August 5, 2025, following RBI approval, with Hebbar taking up the non-executive nominee directorship.22 Narayanan brought over 27 years in banking and financial services across ICICI Bank, Fullerton India Credit and YES Bank; he had joined CreditAccess Grameen in January 2020 as chief business officer, been promoted to chief executive in August 2023, and was the executive who built the retail finance division that is now the growth engine.22
Two observations follow. The succession was internal, long-telegraphed and staged over roughly two years, which is what good succession looks like. And the retail finance strategy is not a new chief executive's pivot — it is the continuation of the business line its author has been running since 2020. That reduces execution risk. It also means the strategy has no independent internal check.
Guidance discipline: the record, not the rhetoric.
This is where the analysis has to be uncomfortable, because the company's guidance record through the last cycle was poor in a specific and instructive way.
In May 2024, alongside a strong FY24 — profit after tax of ₹1,446 crore, up 75%, a 5.6% return on assets and 24.9% return on equity — the company published FY25 guidance of 23–24% portfolio growth, credit cost of 2.2–2.4%, return on assets of 5.4–5.5% and return on equity of 23.0–23.5%.14 The same presentation reiterated an FY25–FY28 medium-term frame of 20–25% growth and 22.0–23.5% return on equity.14
Within two quarters that entire structure collapsed. By late October 2024 management had cut portfolio growth guidance to 8–12%, return on equity to 12–14%, and raised credit cost expectations by 230–250 basis points; the stock fell 12% on November 29, 2024 as Goldman Sachs and Nomura downgraded, with Goldman describing the de-rating as structural rather than cyclical and saying it had been "negatively surprised by the accelerating decline in asset quality."23 Guidance was revised again in January 2025 to 7–8% growth — and the company missed even that, ending FY25 with the portfolio down 2.9%.205 Actual FY25 credit cost was 7.7% against original guidance of 2.2–2.4%.2014
Then FY26 guidance of 5.5–6.0% credit cost was also missed, at 6.74%.15
That is two consecutive years of missing credit cost guidance, with the first miss exceeding three times the original number. The generous reading is that no lender forecasts a sector-wide credit event plus a state ordinance. The less generous reading — and the more useful one — is that the May 2024 guidance was constructed on an assumption of a stable operating environment in a business that has now experienced four major disruptions in a decade, and that publishing a four-year medium-term return-on-equity target for a cyclical unsecured lender was an act of confidence the history did not support.
To management's credit, the disclosure quality during the collapse was high. The company broke out exactly how much of the credit cost came from new delinquency versus provisioning-rate changes, disclosed accelerated write-offs separately with their earnings impact, and published portfolio-at-risk data segmented by how many lenders a borrower had.2015 That is more granular than the sector norm, and it allowed outside analysts to track the deterioration in near real time. Transparency in the downturn is a genuine positive. It does not retroactively repair the forecasting.
The current guidance, held at the same confidence. For FY27, management has guided to 20–25% AUM growth, net interest margin of 12.8–13.2%, cost-to-income of 33–35%, credit cost of 3.0–4.0%, return on assets of 4.0–4.8% and return on equity of 16–20%.15 Asked in July 2026 whether the strong first quarter warranted an upgrade, Narayanan declined, saying the company would watch one more quarter before revising.4 Asked in May 2026 why the credit cost band was so wide, the chief financial officer attributed it to the new forward-looking ECL model and evolving global uncertainties.15
Wider bands and reluctance to raise guidance after one good quarter are both improvements on the FY25 approach. The test is whether they hold when growth accelerates.
Control-environment changes worth noting. Alongside the leadership transition, the company made two structural changes to its risk architecture during the crisis that are more informative than any statement of intent. It increased internal audit frequency from every 60 days to every 40 days, supported by real-time analytics, and deployed a dedicated quality-control team for targeted collections across geographies; it also constituted a board-level committee to set expected credit loss scenario weightings each quarter.15 Increasing audit frequency under stress is a costly, unglamorous decision that reduces short-term profitability, which is precisely why it carries information. The ECL committee cuts both ways, as discussed above: it institutionalises provisioning judgment at board level, and it also formalises a lever over reported earnings.
Capital allocation and the dividend question. The outline version of this company says it retains earnings to fund leverage. The record is more specific: the company declared a dividend of ₹10 per share announced on May 7, 2024 for FY24 — and has declared no dividend for FY25 or FY26.24 So it is not a company that has consistently refused to pay; it is a company that began paying at the top of the cycle and stopped when earnings collapsed. That is defensible for a leveraged lender rebuilding capital, but it should be described accurately: this is a cyclical, capital-retentive payout policy, not a philosophy.
The capital story management prefers is compounding, and it is a fair one. Net worth grew from ₹2,734 crore in FY20 to ₹8,347 crore by the June 2026 quarter, roughly 20% compound growth, of which management says 86% came from internal accruals.4 Debt to equity stood at a conservative 3.0 times at March 2026 with capital adequacy of 24.4%, and 24.9% by June.153
The overhang that dominates everything else. In August 2024, reports emerged that the Amsterdam promoter was exploring a sale of the company. A formal process began in October 2025 with Bank of America as banker; by early February 2026, Axis Bank had reportedly emerged as the sole formal bidder for the 66.28% promoter stake at approximately 2.6 times trailing book value, in a structure that would have made CreditAccess Grameen a bank subsidiary.25 Axis declined to comment at the time, saying it was not in a position to discuss M&A.25 Earlier reporting had valued the stake at roughly ₹14,000 crore.26
Then on February 23, 2026, Axis Bank told the exchanges it had "neither submitted nor plans to submit any bid for acquiring a stake in CreditAccess Grameen Ltd."[^27]
The process did not end there. On August 6, 2026, CreditAccess India B.V. sold 36,57,500 shares — 2.28% of the company — in an open-market block deal, reducing its holding from 66.21% to 63.93%, with the stated rationale of providing liquidity to its own long-term investors and broadening the free float.[^28]27
Here is the activist question an outside investor should be asking. A promoter that has run a formal sale process, failed to complete it, and then begun selling into the open market is a promoter with an intention. CreditAccess India B.V. is not a strategic parent; it is a vehicle holding capital for 247 shareholders, some of whom have been invested since 2009.2 Those shareholders need liquidity, and there are only two routes: a block sale to a strategic buyer, or progressive sell-downs into the market.
The bull framing is that a bank acquirer would transform the funding cost overnight, and that a wider free float improves index eligibility and institutional ownership. The bear framing is that a controlling shareholder that has publicly failed to find a buyer at a reported 2.6 times book creates a standing supply overhang and a marked-to-market ceiling on how the market will value the equity. Both are true simultaneously. What an investor should watch is not the rumour flow but the actual filings: further promoter sell-downs, or a definitive agreement.
Meanwhile, the operating business is being pointed at a much larger target than microfinance alone.
IX. Portfolio Optionality: Non-MFI Scaling & The Digital "Phygital" Engine
A sentence during the May 2026 earnings call reframed the company's direction: management stated that CreditAccess Grameen was "no longer in the business of financing only one woman per household," but was instead building the capability to serve as "the financial life cycle partner of the entire household."15
That shift represents an effort to redefine the institution from a microfinance lender offering auxiliary products into a broad rural household lender using microfinance as an entry vehicle. Named "Project Shakti," the strategy sets ambitious targets: reaching ₹50,000 crore in assets under management by calendar year 2028, addressing a potential market of 23.5 crore low-to-middle-income rural and semi-urban households by 2030, and maintaining an annual growth rate of at least 20% over a decade.415
The strategic logic is sound, functioning defensively as well as offensively. Unsecured group lending carries structural tail risk, as the FY25 credit cycle demonstrated: when a rural macroeconomic shock or political intervention occurs, the entire portfolio is exposed simultaneously through a single product line, customer demographic, and collection mechanism. Diversifying into secured mortgage-backed lending and larger individual loans spreads that risk across asset types. The strategy also addresses customer attrition. Historically, the institution lost its longest-tenured borrowers once their capital requirements exceeded microfinance limits. During the July 2026 earnings call, Chief Executive Officer Ganesh Narayanan highlighted this gap, estimating that while CreditAccess Grameen held roughly ₹30,000 crore in loans across its client base, those same households held approximately ₹40,000 crore in debt with competing lenders.15
What the evidence supports so far. Initial customer quality metrics indicate strong underlying credit profiles: Unnati individual loan borrowers average 7.7 years of tenure with the firm and carry a mean credit score of 732, while mortgage clients average 6.2 years of tenure with a mean score of 714.4 The Unnati portfolio is sourced entirely from existing internal clients, whereas the mortgage book relies on a mix of 55% internal and 45% external sourcing, with management projecting a 60:40 internal ratio over time.4 Crucially, management reported that throughout the recent credit cycle, portfolio at risk past 30 days for the Unnati loan book remained below 3%—a stark contrast to the sharp rise in group-lending delinquencies.4
This performance represents a practical stress test rather than a theoretical model. It suggests that transitioning vetted, long-tenured borrowers into larger individual loans yields superior repayment discipline. However, two qualifications apply: the retail portfolio remained relatively small during the stress period, and the figures reflect management disclosures rather than audited segmental reporting.
Beyond generating incremental revenue, retail lending alters customer retention dynamics. Under the traditional microfinance model, borrowers who successfully maintained credit for six or seven years inevitably outgrew microfinance borrowing limits, forcing the institution to lose its lowest-risk clients. By introducing graduation products, the lender retains these seasoned borrowers, stabilizing its core customer base even if initial margins on newer products remain modest.
Where skepticism is warranted. During the July 2026 call, management addressed concerns regarding return dilution, stating that all non-microfinance products were profitable except two-wheeler loans, while noting that mortgage lending would require a portfolio of roughly ₹1,000 crore to achieve full breakeven after head-office cost allocations.4 This acknowledgment highlights that secured offerings have not yet achieved operating scale. Furthermore, managing rural property loans requires title verification, property valuation, and asset recovery—disciplines distinct from routine weekly cash collections at center meetings.
Regulatory caps impose another structural boundary. Under Reserve Bank of India rules for NBFC-MFIs, qualifying microfinance assets were originally required to exceed 85% of net assets, a threshold lowered to 75% in March 2022 and further reduced by an RBI circular on June 6, 2025, to a minimum of 60% of total assets net of intangibles.917 While these regulatory changes expanded scope for product diversification, when asked during the May 2026 earnings call whether the MFI license would constrain a 20% annual growth target over ten years, Narayanan conceded the limitation and outlined potential mitigants—including securitization, portfolio assignments, co-lending arrangements, and potential corporate restructuring.15 That response underscores an unresolved strategic choice facing the firm as non-microfinance assets grow.
The digital layer. The company's customer application, Grameen Mahi, onboarded 8.4 lakh borrowers during FY26 and recorded 15.4 lakh active users by June 2026, representing roughly 34.5% of total clients.154 Concurrently, non-cash and digital collection channels expanded to 24.2% of total repayments in the June 2026 quarter, up from 16.3% a year earlier.4
However, the operational impact of these digital tools must be evaluated realistically. Despite digital adoption across more than a third of borrowers, over 99% of routine collections still occur during physical center meetings.15 Rather than replacing field operations, the digital application serves to lower cash-handling expenses, establish an additional communication channel, and generate leads for retail products. Similarly, management's assertion that artificial intelligence is currently integrated into credit underwriting, compliance tracking, and customer interactions remains unverified by external metrics and should only be validated as it impacts operational expense ratios or asset quality trends.15
The calibrated conclusion.
The expansion into retail finance offers the firm's most tangible growth optionality, progressing faster than typical diversification initiatives to represent 20.6% of total assets under management, with leadership targeting 24% to 25% by the end of FY27.315 Nevertheless, near-term profitability remains heavily dependent on the economics of group lending, while secured products remain unproven at scale. The key performance indicator determining the long-term success of this transition will not be portfolio share alone, but how individual and secured loans perform through a subsequent credit downturn when operating at substantially higher volumes.
That potential downturn will depend largely on broader sector dynamics—a structural environment that warrants direct examination.
X. Industry Dynamics, Porter's 5 Forces, & Competitive Benchmarking
Indian microfinance presents a distinct market structure: vast, socially sensitive, structurally fragile, and, as of 2026, significantly more concentrated than two years prior. Evaluating the sector through Michael Porter's five forces reveals a business landscape that fits neither the unassailable fortress envisioned by bulls nor the pure commodity trap alleged by bears.
Threat of new entrants: low, and declining further. Entry barriers in microfinance are organizational and regulatory rather than technological. A newcomer must secure an NBFC-MFI license, comply with qualifying asset mandates, construct a physical branch network dense enough to manage weekly center meetings, recruit and supervise thousands of cash-handling field officers in remote areas, and secure wholesale debt without an established operating history. The 2024–2025 credit crisis heightened these hurdles by illustrating the severe earnings impact on subscale lenders. Consequently, new capital has flowed primarily toward digital consumer lending platforms rather than physical rural branch networks.
Bargaining power of suppliers (wholesale lenders): moderate and highly cyclical. Wholesale debt providers have repeatedly shown a tendency to curtail funding across the entire microfinance category during downturns, irrespective of an individual institution's underwriting quality—a dynamic that triggered post-2010 regional failures and constrained liquidity across the sector during the 2024–2025 downturn. CreditAccess Grameen manages this constraint more effectively than its peers, supported by an AA- credit rating, foreign borrowings representing 24% of its liability mix, a ₹425 crore private non-convertible debenture issuance in the June 2026 quarter, cash and equivalents of ₹3,535.5 crore, undrawn credit lines of ₹2,993 crore, and an active funding pipeline of ₹9,440 crore.34 Nevertheless, maintaining over 10% of total assets in liquid cash equivalents imposes a drag on interest earnings, representing a practical acknowledgment that wholesale debt access remains vulnerable during severe market stress.
Bargaining power of buyers: negligible individually, decisive collectively. While an individual borrower possesses virtually no pricing leverage, collective borrower actions—or local political interventions—can halt loan repayments across an entire region. The 2009 Kolar defaults and the 2025 Karnataka legislative intervention reflect the same underlying vulnerability at different scales. This risk escapes standard credit-pricing models yet constitutes the single largest structural vulnerability in the joint-liability lending framework.
Threat of substitutes: moderate and rising. Traditional informal moneylenders remain the primary historical substitute, though at substantially higher interest costs. More significant competition stems from digital consumer lenders, commercial banks, and financial technology firms extending unsecured retail credit into rural households. This overlap is acknowledged by regulatory guardrails: the Microfinance Institutions Network's borrowing rules explicitly include unsecured retail credit within household indebtedness limits because borrowers were stacking multiple loan products.18 Additionally, government direct-benefit welfare transfers act as a dual force—enhancing baseline household cash flows while occasionally coinciding with political messaging that weakens loan collection discipline.
Industry rivalry: intense, but increasingly consolidated. Non-banking financial company microfinance institutions command the largest share of the sector's loan portfolio at approximately 40%, followed by commercial banks at 31%.18 Following the 2024–2025 stress test, the competitive field bifurcated. Muthoot Microfin managed a portfolio of roughly ₹13,079 crore with a 4.40% gross non-performing asset ratio and a 10.43% cost of funds as of December 2025—demonstrating recovery but operating with a higher funding cost structure.16 Meanwhile, competitors such as Fusion Microfinance and Spandana Sphoorty entered the downturn with thinner capital buffers, culminating in a consolidated net loss for Spandana in the June 2025 quarter. From the banking side, universal lenders like Bandhan Bank and specialized small finance banks compete with lower deposit costs, offset by higher urban branch overhead and expanding product lines that dilute their operational focus on rural micro-lending.
CreditAccess Grameen's internal market share assessment remains notably conservative, with management estimating its customer base at roughly 7% of microfinance borrowers nationally.15 Rather than indicating market dominance, this figure highlights the institution's position as the leading operator within a fragmented industry. Consequently, future expansion is constrained not by total market size, but by internal risk parameters and broad industry underwriting discipline.
Myth versus reality. Three persistent assumptions regarding CreditAccess Grameen are contradicted by regulatory and financial filings, each artificially inflating the institution's perceived competitive moat.
The first concern involves the credit rating. Although market commentary frequently cites an AA+ rating, official results presentations report an AA- rating with a stable outlook from CRISIL, ICRA, and India Ratings across fiscal years 2025, 2026, and the June 2026 quarter, with ICRA and India Ratings maintaining AA- status since fiscal year 2023 following upgrades from A+.52132 While maintaining the highest rating among dedicated NBFC-MFIs across consecutive downturns represents a notable operational achievement, the official score remains two notches below public assertions.
The second misjudgment concerns funding cost advantages. Optimistic market commentary often projects a 250 to 350 basis point borrowing cost advantage over competitors, which contrasts with disclosed metrics showing a 9.2% borrowing cost against a major listed peer at 10.43%.1516 The actual spread is approximately half the popularized estimate, and management has explicitly noted that this cost differential has ceased widening.15
The third misconception centers on profitability expectations. A 24% return on equity reflects peak cyclical performance rather than an average operating state. Disclosed historical averages from fiscal years 2017 through 2026—a decade encompassing three major sector shocks—show a through-cycle baseline of a 3.4% return on assets and a 13.9% return on equity.15 Valuing the institution based on peak returns projects financial performance that is inconsistent with its multi-year operational record.
The competitive verdict. Against dedicated NBFC-MFI peers, CreditAccess Grameen maintains advantages in borrowing costs and operating efficiency. These differentials widened during recent stress as scale and credit ratings became increasingly valuable when wholesale liquidity tightened. Conversely, comparisons against small finance banks and deposit-taking institutions remain inconclusive: banking platforms benefit from cheaper retail deposits and broader diversification, but incur higher branch operating overhead and strict regulatory compliance requirements that specialized NBFCs avoid. Claiming that an NBFC-MFI model inherently outperforms deposit-taking banks across an entire credit cycle is unsupported by empirical evidence—explaining why the controlling shareholder's initiative to explore a sale to a commercial bank represented a coherent strategic direction.
XI. Strategic Playbook & Investment Lessons
Stripping away the institutional details reveals core lessons for business leaders and financial analysts—each accompanied by a nuance grounded in CreditAccess Grameen's operational history.
One: Patient capital provides a competitive edge in cyclical lending, but it carries a deferred liquidity requirement. CreditAccess India B.V. supported the business through the 2010 Andhra Pradesh crisis, injected ₹550 crore of equity and quasi-equity following demonetisation, and allowed management to focus on long-term expansion without quarter-to-quarter earnings pressure.2 This patient backing created a clear structural advantage over competitors bound by fixed private equity fund lifecycles. Yet patient capital eventually seeks an exit: after twelve years of controlling ownership, the promoter launched a formal sale process, navigated a failed takeover bid, and initiated open-market share sales.25[^28] Long-term stability ultimately gave way to a persistent equity overhang.
Two: Owning the customer relationship preserves operational flexibility. Employing salaried field staff rather than commission-based agents and maintaining internal control over origination and collections established both the firm's low cost structure and its collection discipline. When delinquency surged in fiscal 2025, leadership redirected the entire field organization from loan disbursement to debt recovery. While commission-driven agents lack incentives to pursue past-due accounts, salaried officers evaluated on portfolio quality align field execution with risk management.
Three: Early regulatory compliance builds competitive barriers, but political intervention can dismantle them. The Reserve Bank of India's 2011 qualifying asset framework, the 2022 Master Direction, and self-regulatory rules from the Microfinance Institutions Network established operational standards that compliant lenders absorbed while non-compliant operators failed to adapt.91718 However, regulatory structures offer limited protection against political dynamics: as events in Karnataka demonstrated, state-level legislative actions can abruptly disrupt collection operations regardless of institutional compliance.19
Four: Operating efficiency provides a more durable advantage than funding costs. CreditAccess Grameen maintains a borrowing cost advantage of roughly 120 basis points over scaled peers—a margin that management acknowledges has plateaued.1615 In contrast, its operating expense advantage is larger, more resilient, and harder for competitors to copy, supported by twenty thousand trained employees and a decade of standardized processes. In high-yield, small-ticket rural lending, an enduring competitive moat stems not from cheaper wholesale capital, but from the operational capacity to conduct weekly physical collections efficiently across thousands of villages.
Five: Ownership structure functions as an active operating variable rather than a background detail. For equity investors, a controlling promoter seeking liquidity introduces strategic uncertainty. The ultimate resolution of this ownership structure will determine whether CreditAccess Grameen continues operating as an independent non-banking lender or transitions into a commercial bank subsidiary—two distinct corporate structures with different funding costs, risk tolerances, regulatory requirements, and growth trajectories.
Six: In unsecured lending, credit quality depends on ecosystem-wide discipline. A lender's internal underwriting standards cannot fully insulate its portfolio from broader systemic over-indebtedness. Because borrower creditworthiness depends on total household debt across all institutions, credit bureau infrastructure and industry leverage caps function not as administrative overhead, but as vital shared plumbing essential to preserving asset quality across the sector.
XII. The Investment Spine: Bear vs. Bull Case & Key Forward KPIs
The bull case, and what actually backs it.
The strongest argument for CreditAccess Grameen is that a proven operating platform has emerged from a severe credit downturn with a cleaner balance sheet, stronger capital reserves, and a significantly less leveraged borrower base. The evidence is structural rather than rhetorical: the share of assets lent to group borrowers with more than three lenders dropped from twenty-five percent to low single digits, the proportion of unique borrowers nearly doubled, and monthly new delinquency accretion slowed to roughly fifteen basis points.154 This reflects an institutional shift in borrower composition, enforced by industry-wide guardrails that constrain competitors as well.
The second pillar rests on market headroom. With an estimated seven percent national market share among microfinance borrowers, expansion is not limited by overall market size.15 The third pillar is retail finance, where graduating long-tenured, high-credit-score clients into individual and secured loans has so far yielded better credit performance than the core group book.4 The fourth is a track record of compounding capital: net worth roughly tripled between fiscal 2020 and 2026, driven overwhelmingly by internal accruals through two major industry crises.4
Framed through strategic analysis, the defensible competitive claims center on process power in field operations and a modest scale advantage in wholesale funding. Across industry forces, the lender benefits from high entry barriers and favorable competitive dynamics, but remains vulnerable to collective buyer behavior when political interventions disrupt collections.
The bear case, and where it bites hardest.
First, and most critically, this is a business where a severe downturn means two years of depressed earnings rather than a single poor quarter. Fiscal 2025 incurred a seven-point-seven percent credit cost against initial guidance of two-point-two to two-point-four percent alongside a sixty-three percent drop in net profit, while fiscal 2026 recorded a six-point-seven-four percent credit cost against five-point-five to six-point-zero percent guidance.201415 Industry guardrails reduce the likelihood of a repeat, but voluntary self-regulation does not eliminate structural credit risk.
Second, political and climate risks cannot be fully neutralized through geographic diversification. State-level intervention disrupted operations in the company's largest market within the past eighteen months, prompting management to explicitly cite the risk of potential state regulations similar to Karnataka's when issuing fiscal 2026 guidance.20 Management also noted during its July 2026 briefing that it was monitoring El Niño patterns, observing no immediate rural impact while deferring firm conclusions for several months.4
Third, the controlling shareholder overhang remains unresolved. A promoter that initiated a formal sale process, faced a public denial from the reported lead bidder, and subsequently began selling shares in the open market creates a persistent supply overhang and strategic uncertainty surrounding future ownership.25[^27][^28]
Fourth, accounting judgment plays an expanding role in reported profitability. The adoption of a forward-looking expected credit loss model, governed by a board committee that sets quarterly scenario weightings, introduces significant management discretion.15 The thirty-nine crore rupee geopolitical overlay may prove prudent or discretionary, but it requires investors to underwrite an opaque modeling framework.
Fifth, management's own forecasts project narrower profitability. Guidance for fiscal 2027 sets net interest margins at twelve-point-eight to thirteen-point-two percent, down from fourteen-point-four percent in the June 2026 quarter, as the lender passes credit cost reductions to borrowers under its board-approved pricing policy.1543 Valuations that project peak margins forward directly contradict management's operational target.
One risk that deserves separate naming: refinancing.
As a wholesale-funded lender, CreditAccess Grameen relies on commercial bank loans, non-convertible debentures, and foreign borrowings that mature independently of credit cycles. In prior industry downturns, the primary constraint across the sector was wholesale liquidity rather than isolated asset quality, as institutional lenders curtailed funding to microfinance broadly. In response, the company maintains a substantial, deliberately costly liquidity buffer alongside offshore debt channels.34 Investors should evaluate this liquidity as insurance carrying an explicit drag on asset returns during favorable years—and as the structural buffer that prevented debt restructurings across three separate market shocks. Reducing this liquidity buffer to boost short-term returns would signal a fundamental shift in risk tolerance.
The activist's question.
A skeptical institutional investor would focus on three specific vulnerabilities. First, whether an institution that missed its initial fiscal 2025 credit cost guidance threefold merits confidence in its multi-year asset targets for calendar 2028. Second, whether transaction goodwill and a three-year integration delay with Madura raise execution concerns regarding potential future acquisitions floated by leadership.152 Third, whether open-market share sales by a controlling promoter during a period of record operational earnings offer a valuation signal that outweighs management guidance decks.
Specific operational benchmarks will determine whether the investment thesis shifts. On the upside, maintaining credit costs within the guided three to four percent range over consecutive quarters, while expanding retail assets past twenty-five percent of the portfolio with low underlying delinquency, would confirm a structural transformation and validate management's targets.154 Conversely, an accelerating delinquency accretion rate alongside rapid disbursement growth would signal that the institution is pursuing volume late in the cycle—repeating the underwriting missteps that preceded the fiscal 2025 downturn.
The three KPIs that matter.
One: monthly new PAR 15+ accretion, in basis points. This metric offers the earliest warning of asset quality deterioration, long before non-performing loan ratios or provision charges reflect the stress. Accretion measured approximately forty-seven basis points in September 2025, eighteen basis points in December 2025, and roughly fifteen basis points through the initial months of fiscal 2027.214 An upward trend would mark the initial break in the recovery trajectory, with credit costs reflecting the impact two quarters later.
Two: the retail finance share of assets, paired with the retail book's own delinquency. While asset share reflects management targets, tracking it alongside segment delinquency measures execution quality. Retail loans reached twenty-point-six percent of total assets, targeting twenty-four to twenty-five percent by the close of fiscal 2027.315 Strategic diversification will be validated only if delinquency in this segment remains significantly below the core group portfolio as the retail book scales.
Three: the share of assets held by unique group-lending borrowers. Reaching forty-five-point-seven percent in June 2026, up from twenty-six-point-six percent in August 2024, this figure measures balance sheet insulation from over-leveraged clients borrowing across multiple institutions.415 It represents the company's primary structural safety indicator; any stagnation or reversal during periods of rapid loan growth would signal a return to competitive over-lending.
Where the analysis lands.
The historical record supports a disciplined version of the bullish thesis rather than an uncritical one. CreditAccess Grameen has demonstrated across demonetisation, the pandemic, and the fiscal 2025 downturn that it can absorb systemic shocks without compromising capital adequacy or wholesale funding access, while recovering faster than industry peers. Disclosed through-cycle averages from fiscal 2017 through 2026—a three-point-four percent return on assets and a thirteen-point-nine percent return on equity—reflect realistic long-term performance rather than peak annual metrics.15 However, operational discipline does not shield earnings from broader credit volatility; twice within a decade, severe credit events significantly depressed profitability. Investors are underwriting a premier field operator in a structurally volatile sector, at a time when cyclical conditions are improving but long-term ownership remains unsettled.
CreditAccess Grameen is embarking on an ambitious transition toward an integrated household lender, targeting fifty thousand crore rupees in assets while its controlling promoter seeks an exit. Throughout its evolution, operational execution has outpaced forecasting accuracy. Which of those two characteristics defines the coming three years remains the central question for investors.
References
-
Credit Access Grameen Limited IPO – Date, Price Band, Issue Size — HDFC Securities ↩
-
CreditAccess Grameen Limited Corporate Presentation — CreditAccess Grameen Limited, 2023-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
CreditAccess Grameen Limited – First Quarter FY26-27 Results — CreditAccess Grameen Limited, 2026-07-24 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
CreditAccess Grameen Limited Q1 FY27 Earnings Conference Call Transcript — CreditAccess Grameen Limited, 2026-07-24 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
CreditAccess Grameen Limited – Fourth Quarter & Full Year FY24-25 Results — CreditAccess Grameen Limited, 2025-05-16 ↩↩↩↩↩↩
-
A profile of Vinatha Reddy: Inspired by "Give us Credit" — Women's World Banking ↩↩↩
-
Udaya Kumar Hebbar – Director Profile — CreditAccess Grameen Limited ↩↩
-
Press Release on RBI's circular on "Review of Qualifying Assets Criteria" — Microfinance Institutions Network (MFIN), 2025-06-09 ↩↩↩
-
Inclusive Finance in India: Citi Partnering with CreditAccess Grameen to Finance 75,000 Women Entrepreneurs — Citi, 2019-09-05 ↩
-
CreditAccess Grameen and Madura Micro Finance – Transaction Overview — CreditAccess Grameen Limited, 2019-11 ↩↩↩↩↩↩↩↩
-
CreditAccess Grameen to acquire Madura Micro Finance for Rs 876 crore — Business Standard, 2019-11-27 ↩
-
CreditAccess Grameen to acquire Madura Micro Finance – company announcement, 2019-11-27 ↩
-
Q4 & FY24 Investor Presentation — CreditAccess Grameen Limited, 2024-05-07 ↩↩↩↩↩↩↩
-
CreditAccess Grameen Limited Q4 FY26 Earnings Conference Call Transcript — CreditAccess Grameen Limited, 2026-05-08 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Muthoot Microfin Ltd – Latest Quarterly Results Analysis — ICICI Direct ↩↩↩↩
-
Master Direction – Reserve Bank of India (Regulatory Framework for Microfinance Loans) Directions, 2022 — Reserve Bank of India, 2022-03-14 ↩↩↩
-
Microfinance Sector in India — Brickwork Ratings, 2025-05-28 ↩↩↩↩↩↩
-
The Karnataka Micro Loan and Small Loan (Prevention of Coercive Actions) Act, 2025 (Karnataka Act No. 15 of 2025) — PRS Legislative Research, 2025-03-25 ↩↩
-
CreditAccess Grameen Limited Q4 FY25 Earnings Conference Call Transcript — CreditAccess Grameen Limited, 2025-05-16 ↩↩↩↩↩↩↩↩↩
-
CreditAccess Grameen Limited – Third Quarter FY25-26 Results — CreditAccess Grameen Limited, 2026-01-20 ↩↩↩
-
Ganesh Narayanan Appointed MD & CEO of CA Grameen — Construction World, 2025-08-08 ↩↩
-
CreditAccess Grameen shares tumble 12% on Goldman Sachs, Nomura downgrades — Business Today, 2024-11-29 ↩
-
CreditAccess Grameen Ltd Dividend History, Yield & Record Date — INDmoney ↩
-
Axis Bank Emerges Sole Bidder for CreditAccess Grameen; May Create Wholly-Owned MFI Arm — Outlook Business, 2026-02-02 ↩↩↩↩
-
Axis Bank Evaluates Bid for Promoter Stake in CreditAccess Grameen — Angel One, 2026-01-27 ↩
-
CreditAccess Grameen: Promoter Sells 2.28% Stake via Block Deal — InvestyWise, 2026-08 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube