Weyerhaeuser: The Forest That Has to Pay
I. A Company Built to Outlast Its Own Timber
Somewhere in the pine country of the American South this autumn, a crew pressed a seedling into cut-over ground. If the stand grows the way foresters plan, nobody will harvest it until the late 2050s. The person who eventually signs the timber sale may not have been born yet. That is the clock Weyerhaeuser lives on.
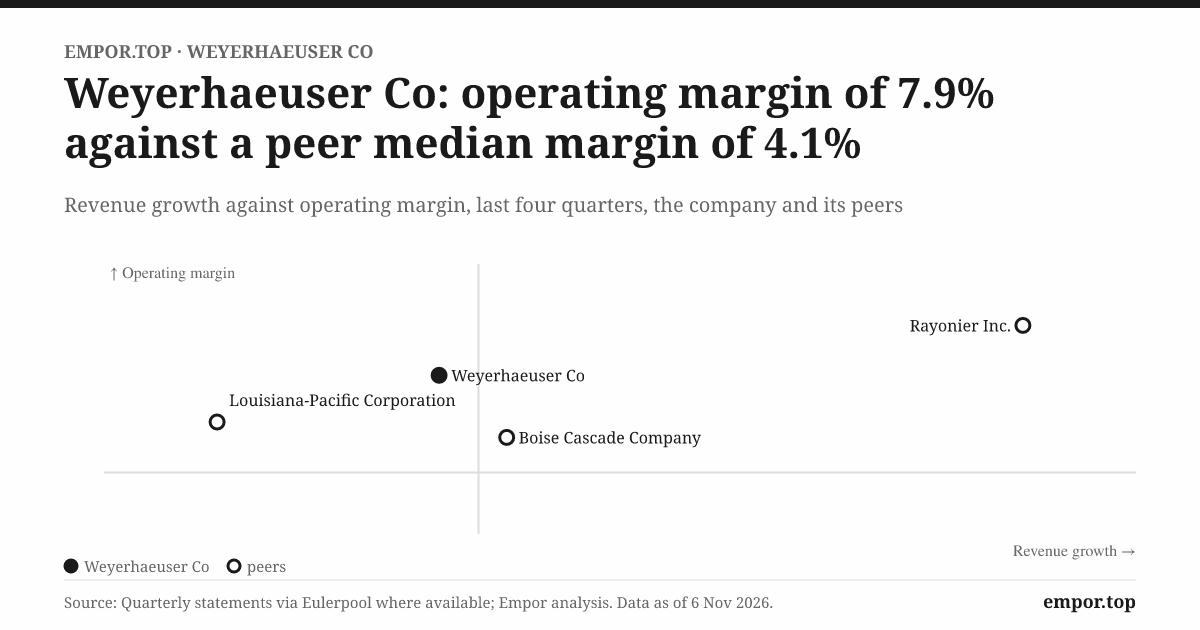
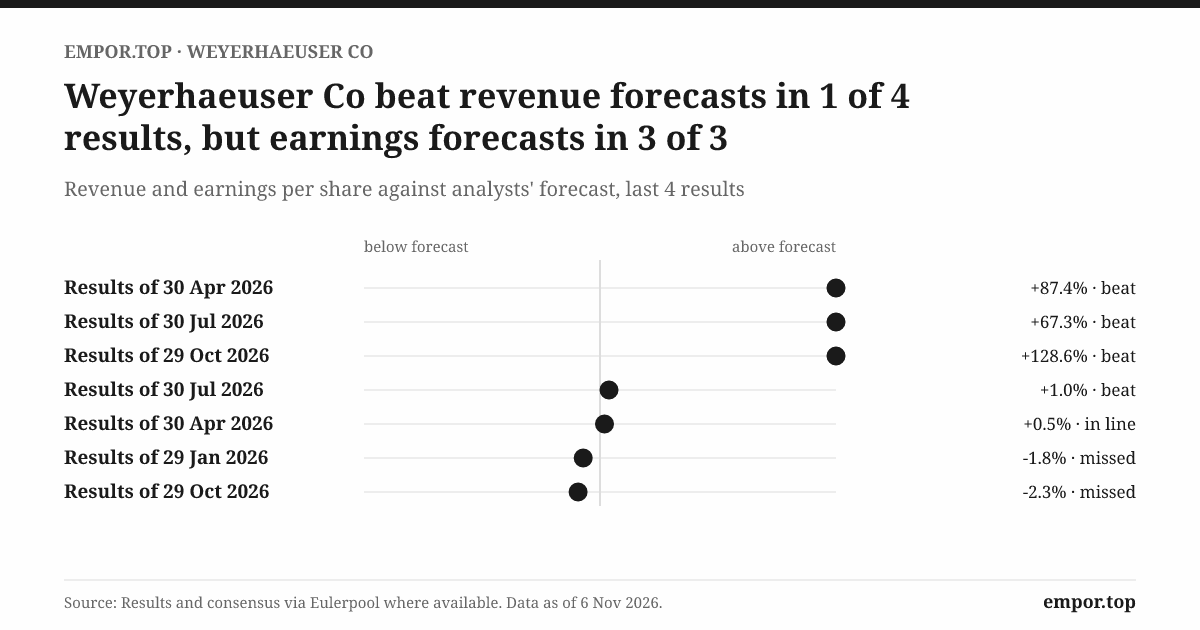
Wall Street runs on a different clock. On October 29, 2026, Weyerhaeuser reported its third quarter, the 91 days that ended in September.1 The company sold about $1.86 billion of logs, lumber, panels, engineered beams and land in those three months. After paying for everything it took to produce and sell them, it was left with roughly $100 million of operating income.2 That is about five cents of operating profit for every dollar of sales. It came from a company that controls one of the largest private forests on earth.
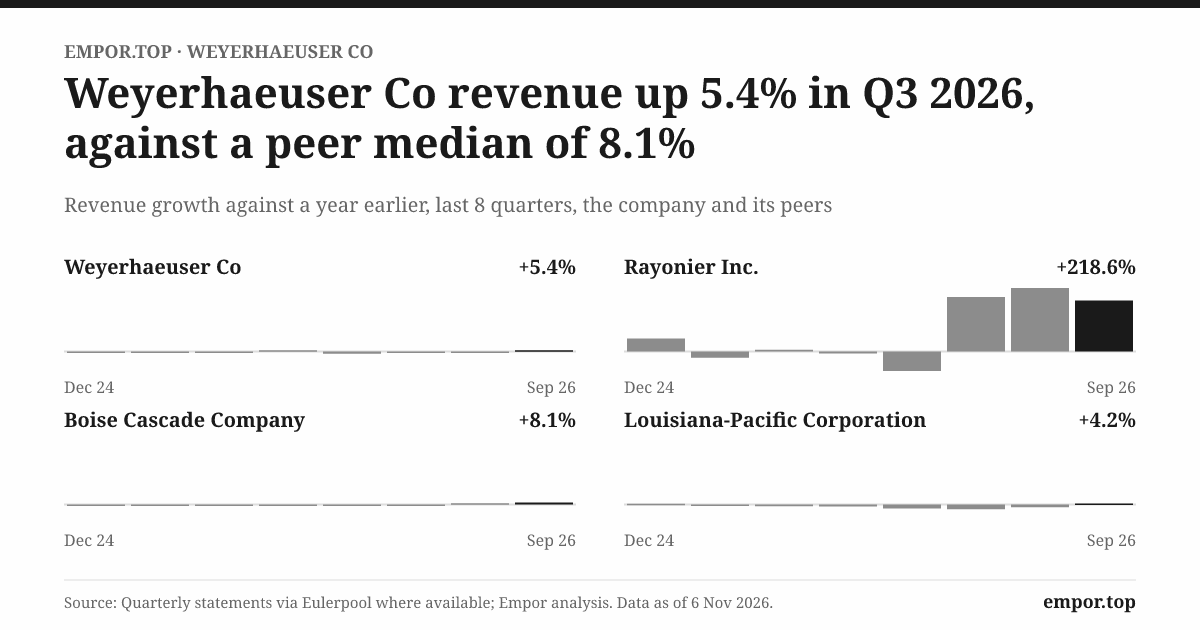
Underneath the headline the quarter got stranger. Sales were up about 8% on the same quarter a year earlier, mostly because lumber fetched better prices. Net earnings went the other way, falling about 24% to $61 million, or eight cents a share.23 Higher prices had arrived. Higher profits had not.
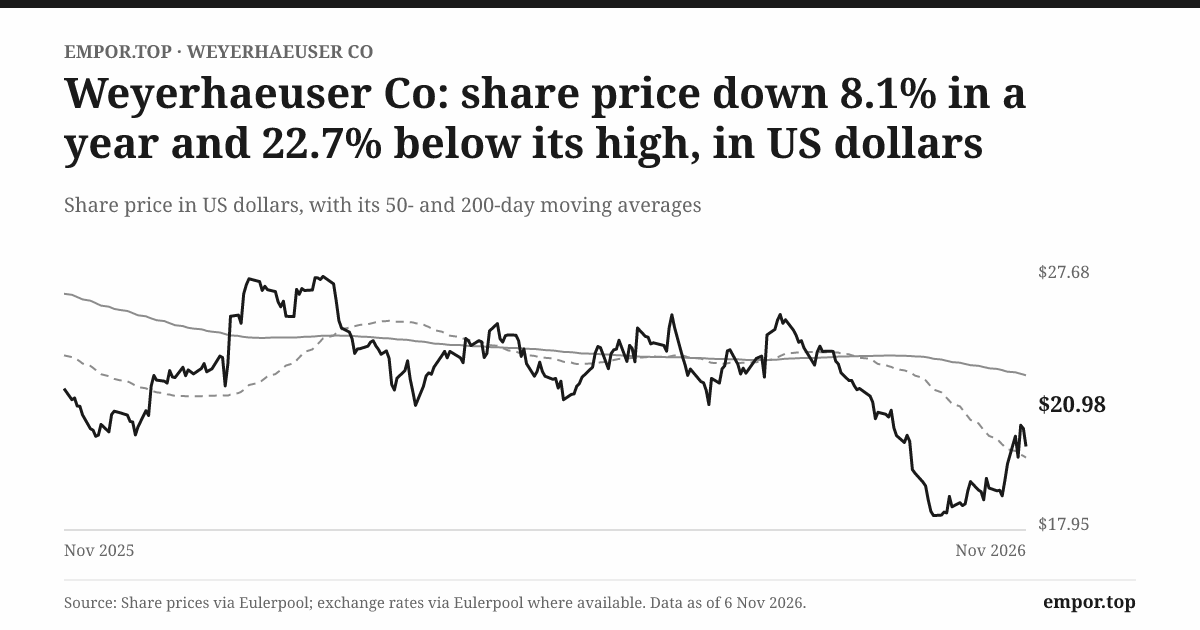
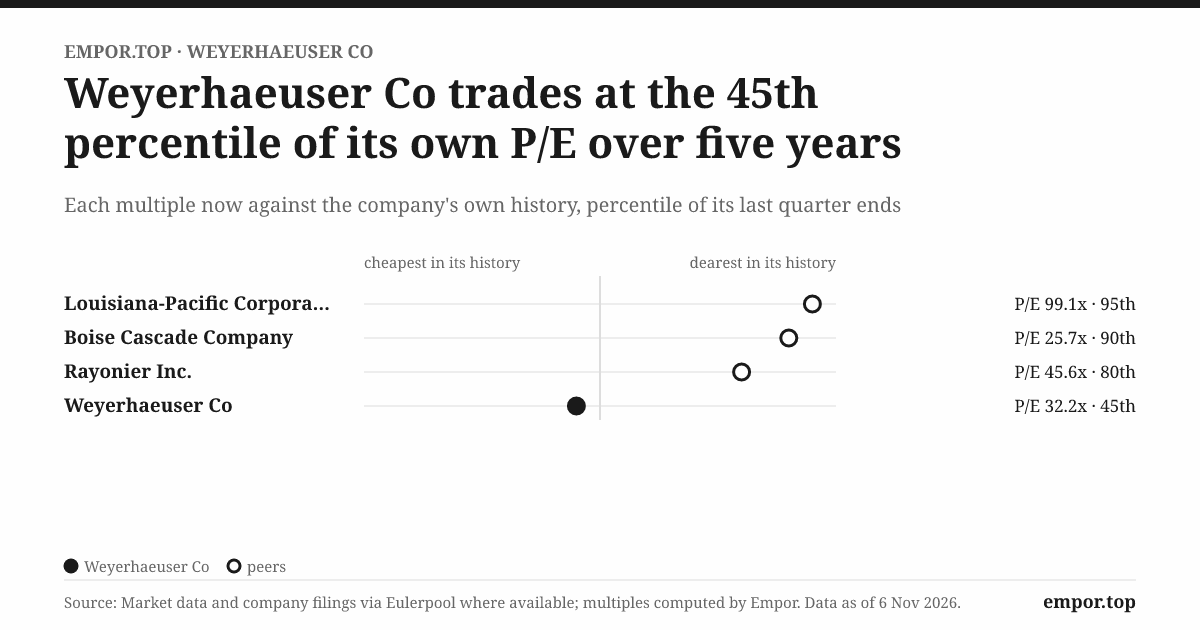
The stock market seems to be grading on a curve. On November 6, 2026, Weyerhaeuser shares closed near $21, about 23% below their 52-week high, for a market value of roughly $15 billion.2 At that price investors were paying about 32 times trailing earnings. That is almost exactly the company's own five-year median multiple of about 33.5 times, so the market is not treating this as a crisis. The dividend yields about 4%.4 Yet free cash flow over the last twelve months was negative, so the company has been paying its dividend out of something other than surplus cash.52
That gap between the forest's patience and the quarter's arithmetic is what this story is about. The trees will keep growing whatever the next earnings release says. What moves with the cycle is everything that turns trees into money: the price of a two-by-four, the number of houses American builders start, the cost of diesel for log trucks, and the timing of the occasional big land sale. Those are what decide whether the dividend is covered.
So the question is not whether Weyerhaeuser owns valuable land. It plainly does. The question is whether that land, and the mills attached to it, can earn adequate returns, fund new investment and keep paying shareholders through a long, grinding weak spell in housing.
Answering it means going back through three turning points. The first came in 2010, when Weyerhaeuser stopped being a sprawling forest-products conglomerate and became a real estate investment trust, a REIT. Was that a lasting strategic fit, or mainly a tax and balance-sheet reset? The second came in 2016, with the Plum Creek merger, the deal that made Weyerhaeuser the largest timber REIT in the country.
Did it buy a durable advantage at a sensible price? The third is happening now. Can the core businesses earn their way out of a downturn without leaning on asset sales and a stretched balance sheet?
It helps to be clear about what is being judged. Weyerhaeuser is a single, widely held NYSE company with no controlling parent and no private-equity owner. There is no hidden growth engine in some affiliate. Its timberland-holding subsidiaries sit inside the consolidated numbers.5 The company has three reporting segments. Timberlands grows and sells logs. Wood Products turns logs into lumber, oriented strand board and engineered wood. Strategic Land Solutions sells land and rents out the rights that sit on and under it.5 What investors see is what there is.
That simplicity is also the tension. The land renews slowly and reliably. The earnings do not. To see why, the story has to start where the land itself came from: a railroad, a German immigrant, and a deal so large that for a while nobody could match it.
 Subscribe on LinkedIn
II. The 900,000 Acres That Made the Company
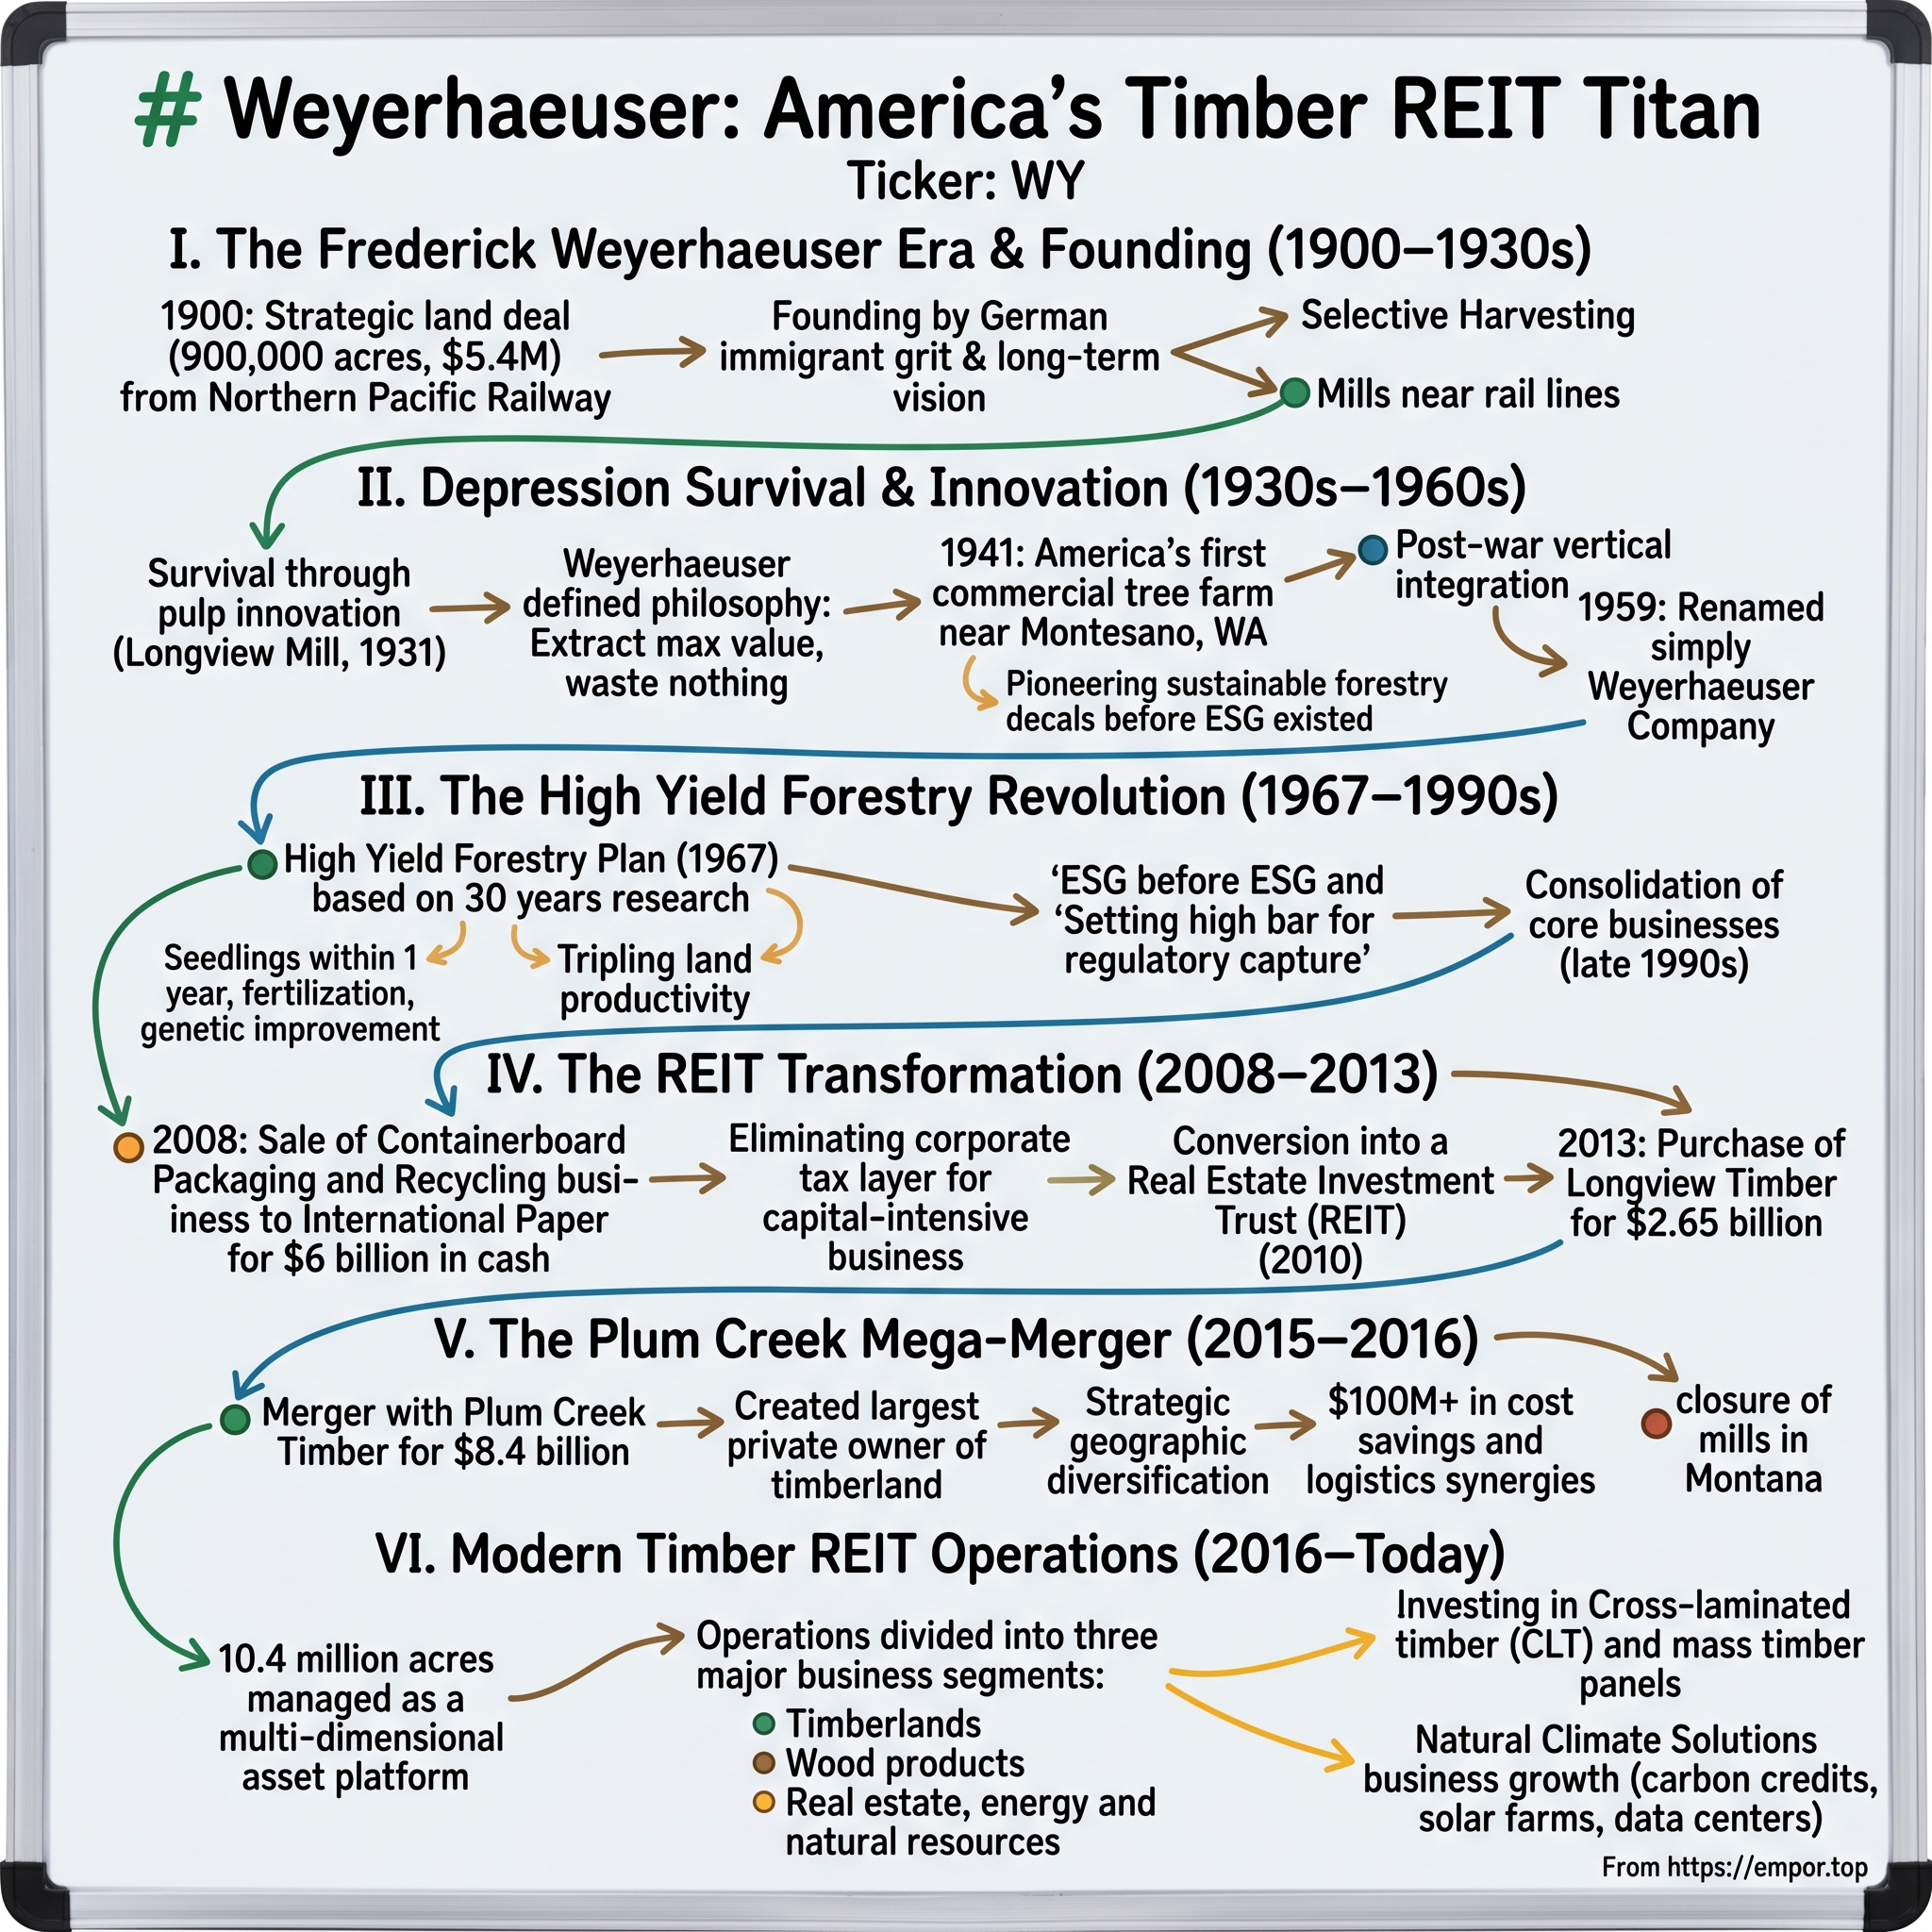
In January 1900, James J. Hill controlled more Pacific Northwest land than he had any use for. Hill was president of the Great Northern Railway and majority owner of the Northern Pacific, and through the railroad's federal land grants he held huge stretches of forest in Washington.6 A railroad earns money by hauling freight, and uncut timber hauls nothing. Hill needed someone who would cut it.
His buyer lived down the street in St. Paul. Frederick Weyerhaeuser had left Germany at eighteen, worked in Erie, Pennsylvania, and moved to Rock Island, Illinois, in 1856. After the Panic of 1857 he and a brother-in-law bought a sawmill, and over the next four decades he built a web of lumber partnerships across the Upper Midwest's white-pine country.6 By the 1890s those forests were running out. A lumberman who wanted to stay in business needed a new forest.
Hill sold Weyerhaeuser and his partners 900,000 acres of Washington timberland at $6 an acre, about $5.4 million in total.6 Accounts differ on how many partners joined him: the company's own filing counts fifteen, while a state history counts eleven.76 Either way, it was one of the largest private land transactions in American history up to then. It was also a deliberately long bet. The buyers were paying for trees that would take decades to cut through and, if replanted, decades more to grow back.
Today Weyerhaeuser owns or controls more than ten million acres of U.S. timberland, eleven times that founding purchase.5 It is tempting to read that continuity as a moat that has simply grown with time. The history argues for more caution. An acre's value has never come from the acre alone.
It comes from what grows on it, how close the nearest mill is, what the logs fetch, what it costs to cut and haul them, and what else the land could be used for. A huge forest a hundred miles from a buyer is a scenic view, not a business.
The founders seemed to understand that early. Weyerhaeuser's companies did not just sit on timber. They built mills. In 1929 the company opened what was then the world's largest mill at Longview, Washington, and Longview later carried it into pulp and paper.6 That move into pulp, which turned smaller logs and sawmill leftovers into salable fiber, helped keep the operation running through the Depression, when demand for lumber collapsed along with construction.
The bigger shift was intellectual. For most of the nineteenth century American logging moved on once a forest was cut, and the cut-over land was left behind. In 1941 Weyerhaeuser dedicated the nation's first certified tree farm, on the Clemons tract near Montesano, Washington, with Governor Arthur Langlie at the ceremony.6 The idea was simple and radical for its time: treat a forest as a crop. Replant it, protect it, and harvest it again.
Under George H. Weyerhaeuser, who became president in 1966, "high-yield forestry" became the company's guiding principle.6 In plain terms it meant engineering a forest's output: improved seedlings, planned spacing, thinning, fertilizing and carefully timed rotations, all aimed at growing more wood on each acre, faster. Critics pointed to its costs, including clearcutting, wetland drainage and chemical use.6 For the business, though, it turned forestry science into a production plan. A decision made in a nursery decades earlier would show up as harvest volume in some future year.
That is the real inheritance. Weyerhaeuser is not valuable because it once bought cheap land from a railroad baron. It is valuable to the extent that it has kept turning land into a managed, renewable flow of logs that someone will pay for.
The land, though, cannot answer the question that has run through the company's whole history: how much of a tree's final value should the landowner try to capture itself? Should it own the sawmill, the pulp mill, the box plant, the homebuilder? For most of the twentieth century Weyerhaeuser's answer was "most of it." The next era began when the answer changed.
III. The Forest Owner Becomes a Timber REIT
By 2008 Weyerhaeuser had become something its founders would have struggled to recognize. It made containerboard and corrugated boxes, recycled paper, ran pulp mills, built homes and sold lumber, all alongside its forests. Each business had its own customers, its own cycle and its own appetite for capital. Box plants follow e-commerce and the consumer economy. Homebuilding follows mortgage rates and land banks. Timber follows housing, export demand and patience. Put together, they made a conglomerate whose parts rarely all worked at once.
The first big piece left in 2008. Weyerhaeuser sold its containerboard, packaging and recycling business to International Paper for about $6 billion.6 It is easy to underrate what that removed. Packaging was a large manufacturing operation with industrial customers, steady volumes and economics quite different from either timberland or construction lumber. Selling it shrank the company and made it simpler. It also left it more exposed to housing just as American housing was collapsing.
Much of the sale money went to the balance sheet. The company later reported that $2.1 billion of the proceeds went to paying down debt.7 That was a sensible use of cash in the middle of a credit crisis, and it set up the next move. For tax purposes, Weyerhaeuser became a REIT effective January 1, 2010, and filed its 2010 return as one.7
Why would a forest company want to be treated like a landlord? Under U.S. tax law, a REIT that distributes most of its taxable income generally pays no corporate income tax on the income from its qualifying real estate, which for Weyerhaeuser means growing and selling standing timber. That income is generally taxed once, when shareholders receive dividends, rather than twice: first at the company and again at the investor level.
To make the switch, Weyerhaeuser first had to clear out profits it had accumulated as a regular corporation. It did so with a special dividend of $26.46 a share, declared in July 2010 and paid on September 1 of that year.87 It was an accounting purge as much as a payout: the price of admission to the new tax regime.
There was also a catch. A built-in-gains tax applied to real property sold in the first ten years after the conversion, so the land could not simply be flipped for a tax-free gain.7 And the REIT structure did not cover everything. The mills, which turn logs into lumber and panels, are not real estate. They sit in taxable REIT subsidiaries and pay corporate tax like any manufacturer.5 That split is why Weyerhaeuser's reported tax rate swings so wildly from quarter to quarter: it depends on whether profits land in the untaxed timber or the taxed mills.3
One point about REITs is often misunderstood. The law requires a REIT to distribute most of its taxable REIT income. It does not require a dividend that tracks GAAP earnings, it does not fix the dividend at any particular level, and it does not shelter shareholders from a commodity downturn. Weyerhaeuser's board still decides what to pay. Later in this story that distinction becomes the central question.
The new REIT soon showed what kind of company it wanted to be by buying more forest. On July 23, 2013, Weyerhaeuser completed its purchase of Longview Timber for about $2.65 billion in cash, including roughly $1.07 billion of Longview's debt that it took on.9 The deal added about 645,000 acres of Pacific Northwest timberland, expanding the company's holdings in the region by about a third.9
To pay for it, Weyerhaeuser sold new common shares and mandatory convertible preferred stock. The newly simplified company was asking shareholders for more capital to grow the land base, an early hint that acreage would be bought with equity as well as cash.
The next step was another sale, this time of the business that had nothing to do with trees. In July 2014 Weyerhaeuser's homebuilding subsidiary, Weyerhaeuser Real Estate Company, was combined with TRI Pointe Homes in a Reverse Morris Trust valued at about $2.8 billion.10 A Reverse Morris Trust lets a company hand a division to its shareholders and merge it with another firm without a large tax bill.
Weyerhaeuser shareholders could swap their shares for stock in the enlarged homebuilder, and the homebuilding operation left the listed company entirely. The divestiture also added a large one-time gain to 2014 net income through discontinued operations.11 That gain is why 2014 reported profits look so far above what the remaining business earned. A reader looking at Weyerhaeuser's long-term earnings should keep that in mind.
Taken together, the decade was a deliberate narrowing. Out went packaging, homebuilding and, around the same time, smaller operations such as hardwoods and shipping.6 What stayed was land and the mills best placed to use its logs. The REIT election did not cause that strategy, but it rewarded it. The more of the company's value sat in timber, the more of its income could escape corporate tax.
The verdict on the conversion therefore has two parts. As a tax and balance-sheet reset, it worked: debt came down, the shape of the company became coherent, and the income from growing trees escaped a layer of tax. As a strategic fit it was real but incomplete, because the company kept a large manufacturing business that never had a REIT's stability. And the REIT structure itself creates no cash. It only decides who pays tax on cash the forests and mills produce.
The narrowing also raised a question about scale. If the business was now mainly about owning and managing timberland, would a much larger timberland base be better? And what price, in cash and in new shares, was worth paying to assemble one? Two years after the TRI Pointe deal, Weyerhaeuser gave its answer in the biggest transaction in the history of the American timber industry.
IV. The Plum Creek Deal: Scale at What Price?
For years Weyerhaeuser and Plum Creek Timber had been the two giants of a fragmented business, and they looked like mirror images. Weyerhaeuser was the old Pacific Northwest dynasty with sawmills and a century of forestry research. Plum Creek, led by Rick Holley, had assembled millions of acres across the South, the Northwest and the Northeast, and had made a specialty of selling higher-value parcels to conservation buyers and developers.1213 Weyerhaeuser's chief executive, Doyle Simons, saw that putting the two together could create a land base no other owner could match.
The courtship took months. In May 2015 Weyerhaeuser made a proposal that implied 1.27 of its shares for each Plum Creek share. By early October the discussion had reached a 10% premium, which corresponded to 1.60 Weyerhaeuser shares per Plum Creek share.13 Under the May proposal, Simons would run the combined company and Holley would become non-executive chairman.13 On November 6, 2015, the two companies signed a merger agreement.13
When the deal was announced, the companies put its value at about $8.4 billion, including Plum Creek's debt, and said it would bring roughly 6.2 million acres of timberland into the combined company.12 It was paid entirely in stock. On February 19, 2016, when the merger closed, each Plum Creek share converted into 1.60 Weyerhaeuser shares, and Weyerhaeuser issued about 279 million new shares.14
By then Weyerhaeuser's own stock had fallen, so those shares were worth about $6.4 billion at $22.87 each. The company also took on about $2.1 billion of Plum Creek's long-term debt and an $837 million note payable to a timberland joint venture.14
There was a piece of financial engineering on top. Holders of Weyerhaeuser stock did not want to be diluted by 279 million new shares, so at announcement the company said it would buy back about $2.5 billion of its stock after closing.12 Simons had told Plum Creek's board that the buyback would fall somewhere between $2 billion and $3 billion.13 The economic effect was to turn an all-stock merger into something closer to a 70% stock, 30% cash acquisition: Plum Creek holders got shares, and Weyerhaeuser then used cash to retire a slice of its enlarged share count.
That buyback came from the same treasury that had to fund dividends, so the deal's cost was not limited to the shares issued.
What the land cost by the acre
Did Weyerhaeuser overpay? The simplest test is to divide price by acres. An $8.4 billion headline across 6.2 million acres works out to about $1,355 an acre. Morgan Stanley's fairness analysis for the deal gave reference points from comparable transactions: timberland in the U.S. South had traded at a mean of about $1,822 an acre and a median of about $1,771.13 The same analysis put the Pacific Northwest at a mean of about $3,011 and a median of about $3,340 an acre.13
At first glance that looks like a bargain: forest bought for roughly a quarter less than Southern pine was going for and far below Northwest prices. Here is the consensus version of the story. Weyerhaeuser bought scale at a discount.
The record is murkier, and the reason is in the land itself. Plum Creek's acreage was not all premium Southern pine. It included large holdings in the Northeast, the northern Rockies and other regions where timber grows more slowly, mills are farther apart and per-acre values have traditionally been lower. The headline price also bought more than trees.
It included manufacturing assets, a real estate development business, mineral and natural-resource rights, and a joint venture. Comparing a blended, multi-region total to a benchmark for one region's timber sales tells you the price was not obviously extravagant. It cannot tell you the price was cheap.
There is a fresher reference point. In October 2026 Weyerhaeuser agreed to sell about 81,000 acres of what it called noncore Arkansas timberland for $146 million, roughly $1,800 an acre.3 On the Q3 call, an analyst asked how that price compared with broader Southern timberland values. Chief Financial Officer David Wold described the acreage as lower-quality, fragmented ground far from the company's mills.3
If even land Weyerhaeuser regards as second-tier can fetch Southern-benchmark prices a decade later, the 2016 entry price looks less risky in hindsight. But that is a statement about land values. It is not proof that the merger created value for shareholders, because Weyerhaeuser also issued a great deal of stock, and its share count and returns have to carry that.
What scale was supposed to buy
What scale was supposed to deliver was a set of operating gains, not a lower price per acre. The combined company would get lower overhead per acre, shared forestry methods, and a larger, more flexible log supply that could be sent to whichever buyer, mill or export market paid best. Weyerhaeuser's management directed Morgan Stanley to assume about $100 million a year of run-rate synergies.13 Against a merger worth more than $8 billion, that was a modest figure. The deal was a bet on land and on long-term flexibility, not on cost cuts.
Making the combined footprint work had real costs. In 2016 the company moved its headquarters from Federal Way to Seattle.6 In the decade that followed it sold, closed or restructured parts of its manufacturing and land portfolio, and its workforce shrank from about 12,600 people in 2015 to about 9,410 counted in 2025.154 Some of that shrinkage came from divestitures, not just efficiency, so it cannot be read simply as a productivity gain. It does show a company that has repeatedly pruned itself to fit the land base it assembled.
The merger left a lasting human signature too. Rick Holley, the Plum Creek chief who agreed to be acquired, has chaired the combined board as an independent, non-executive chair.4 That continuity has value. It also means the board's leader helped design the deal whose returns investors are still trying to judge.
Today Weyerhaeuser remains the largest timber REIT in America by acres, with about 10.3 million U.S. acres.16 The size claim is settled. What remains open is whether size has changed the economics: lower costs per ton delivered, better prices for logs than smaller owners get, higher returns on the land. The company's returns over the decade since the deal, which this story turns to next, are the evidence. They show a business whose fortunes depend less on its acreage than on a set of sawmills sitting on top of it.
V. The Mills and the Timberland Have Different Cycles
Follow a single Douglas fir from a ridge in western Washington. For decades it does nothing but grow. Then a harvesting crew fells it, cuts it to length and loads it onto a truck. At that moment the tree becomes revenue, and the question is where it goes. It might be sold as a log to an outside sawmill, shipped to Japan, or sent to one of Weyerhaeuser's own mills. If it goes to Weyerhaeuser's mill, it is booked twice: once as a log sale inside Timberlands and again as lumber sold by Wood Products.
That journey maps the company's three segments. Timberlands grows and harvests trees and sells logs, both to outsiders and to its own mills. Wood Products saws and presses logs into lumber, oriented strand board, plywood and engineered wood such as I-joists and laminated beams, and distributes them to lumberyards and builders. Strategic Land Solutions sells parcels whose highest value is no longer as timber, and leases rights such as minerals, energy, recreation and, increasingly, carbon.5
The proportions matter. Wood Products is by far the biggest revenue block, accounting for most of Weyerhaeuser's sales to outside customers.5 It is also the business with the most moving parts: commodity prices that can double or halve within a year, mill operating rates, labor and energy costs, freight, and the number of houses American builders start. Timberlands' revenue moves with harvest volumes and log prices, which are cyclical too but usually swing less than lumber does. Strategic Land Solutions is the smallest and the lumpiest, because one large land sale can make or break a quarter.
The third quarter of 2026 showed how those cycles interact. Wood Products sales rose by about $157 million from a year earlier, led by structural lumber, where realized prices rose by about a quarter.21 Timberlands sales to outside customers slipped by about $8 million.2 So revenue grew. Yet operating income fell, because higher manufacturing and freight costs, smaller insurance recoveries, the absence of a gain from selling a mill the year before, and higher corporate overhead ate up the price gains.2 Higher lumber prices did not reach the bottom line.
The segment detail sharpens the picture. Wood Products' adjusted EBITDA fell by about $38 million from the second quarter to $91 million, and the company's oriented strand board operations, the panels sheathing most new American houses, lost money on an EBITDA basis.3 Timberlands earned about $133 million of adjusted EBITDA, up modestly from the prior quarter on a better South.3
Strategic Land Solutions contributed $86 million, down $43 million from the second quarter.3 Adjusted EBITDA across the company was $248 million, up 14% from a year earlier, a far better figure than the GAAP earnings line. The gap between the two is mostly depletion, interest and tax.3
On the call, Wold quantified one cost that was hurting: gross pressure from freight and energy had risen to about $20 million to $25 million a month, against roughly $10 million the company had first expected, and the company could pass only about half of it on to vendors and customers.3 Stockfish was equally plain about demand.
Mortgage rates were back above 7%, he said, and elevated rates "continue to weigh on consumers and housing activity."3 Those two remarks explain most of the quarter. A mill business with high fixed costs got higher prices but not enough of them, while fuel and freight rose faster than management had planned.
Exports add another moving part. Logs from the Pacific Northwest have long sailed to Japan and China, and that trade has been disrupted by tariffs. Stockfish said the company had been shipping about one vessel of logs a quarter to China since late 2025, expected three in the fourth quarter, and believed a 10% Chinese tariff on logs would be removed relatively soon.3 Export demand is a useful outlet when American mills are buying less. It is also a policy decision made in Beijing and Washington, not in Seattle, which adds to the uncertainty rather than reducing it.
The size of the swing
Zoom out and the cycle is brutal. In 2021, the pandemic housing boom sent lumber to record prices. Weyerhaeuser earned an operating margin of about 36% on roughly $10.2 billion of revenue, and revenue stayed near that level in 2022.5 By 2025 revenue had fallen to roughly $7 billion and operating margin to about 6.7%.5 In the third quarter of 2026 it was about 5.4%.2 The land base barely changed through that whole period. What changed was what wood was worth.
The 2025 annual report shows where the damage landed. Wood Products' net contribution to earnings fell by $402 million from 2024, a drop of 88%.5 That one line accounts for most of the fall in Weyerhaeuser's profits. The land kept producing logs. The mills stopped producing much profit.
It is worth asking why owning both the forest and the mill does not smooth the ride more. In theory the two hedge each other. When lumber is cheap, the mills should be able to buy logs cheaply, and when logs are dear, the landowner benefits. In practice, both log prices and lumber prices respond to the same thing, housing demand, so they tend to fall together.
Integration lowers the risk of being cut off from fiber, and it lets the company decide where each log goes. It does not stop both businesses from shrinking in the same bad year.
Why customers do not create a moat
Who buys from Weyerhaeuser? Lumber dealers, home centers, builders, industrial users, other sawmills and export buyers in Asia. No single customer accounted for 10% or more of sales in 2025.5 That spreads the risk of losing any one account. But it also says something less flattering. Lumber, panels and logs are sold at prices set by the market, and a buyer who does not like Weyerhaeuser's price can buy from a Canadian producer, a regional mill, an engineered-products rival such as Louisiana-Pacific, or an import.
The company bills on delivery, with payment usually due within a month, and the vast majority of its sales are single transactions rather than long-term contracts.5 There is little lock-in in that model.
The landowning side faces its own competition. American timberland is fragmented among public REITs, private family owners, institutional timberland investment managers, and federal and state governments. Weyerhaeuser's roughly 10.3 million U.S. acres compare with about 4.1 million for the combined Rayonier and PotlatchDeltic platform that the company itself cited in its May 2026 presentation.16 Rayonier, for its part, names Weyerhaeuser alongside private timberland managers and state forest lands as competitors.17 Being the largest single owner is not the same as having market power. In any given timber basin, a sawmill can usually buy logs from many landowners.
Management's case for its scale is specific. Weyerhaeuser describes a delivered-log model: rather than selling standing timber for a buyer to cut, it harvests and delivers the logs itself, which management says lets it control costs, flex volumes and route each log to its highest-value use.16 It also presents itself as a low-cost operator across forests and mills.18 On the Q3 call, Stockfish described cost leadership as part of the company's "DNA."3 These are claims to test, not facts to accept.
The test is in measures the company does publish in parts: the cost to deliver a log, the price each log fetches compared with regional benchmarks, the share of mill capacity actually used, and segment returns across a full cycle. Over the decade covered by its recent filings, the strongest counterevidence is the 2021-to-2025 collapse itself. Scale did not stop operating margins from falling from the mid-thirties to the mid-single digits.
Run that through the classic five competitive forces and the shape is clear. New competitors cannot easily create a ten-million-acre forest, so the barrier to entry for landowning is high. Buyers have many choices and face low switching costs. Substitutes exist at the edges, from steel framing to imported lumber. Suppliers matter mostly as fuel, freight and labor, and the Q3 freight shock showed how little pricing power the company has when those costs jump. Rivalry among producers is intense and cyclical. The forest is a scarce asset. The products it makes are not.
That leads to the strategy question Weyerhaeuser's management has chosen to answer with concrete and steel. If commodity lumber and panels offer little protection, can the company turn more of its own timber into higher-value products? And can it do so without adding so much fixed cost that the next downturn hurts even more?
VI. A $500 Million Bet on Engineered Wood
Picture a modern floor joist under construction in a suburban subdivision. Instead of one sawn plank, it is a manufactured beam made from long strands of wood, bonded with resin under heat and pressure into something straighter, stronger and more predictable than the tree it came from. That is the idea behind TimberStrand, Weyerhaeuser's laminated strand lumber. Builders like it for the same reason a carpenter prefers a ruler to a branch: it is consistent.
On November 18, 2024, Weyerhaeuser announced it would build a new TimberStrand plant in southeast Arkansas, near Monticello. The investment was about $500 million, and the plant was expected to add roughly 10 million cubic feet of annual capacity, about the size of the company's existing TimberStrand mill in Kenora, Ontario.19 Management said that at full output it should generate more than $100 million of adjusted EBITDA a year, with nearly 200 jobs, and aimed to start operations in 2027.19
The logic was neat. The plant would draw most of its logs from the 1.2 million acres Weyerhaeuser owns in Arkansas and would double the company's North American TimberStrand capacity.19 Stockfish called it a chance to grow the engineered-wood business and take TimberStrand into the U.S. South.19 Logs from the company's forest would become a product priced well above commodity lumber, inside a plant the company controls.
There is an obvious reason to like this move. It is a direct attempt to address the weakness the 2021-to-2025 margin collapse exposed. Engineered wood is less exposed to the day-to-day swings of commodity lumber prices. It also lets Weyerhaeuser capture more value from its own Southern pine, rather than selling logs to someone else's mill at market prices. If it works, the forest feeds a higher-margin product and the mill network becomes a little less commodity-like.
Set against the rest of the company, though, the size of the bet is clear. Weyerhaeuser spent $474 million on capital projects in 2025, of which $109 million went to the new plant.5 At the start of 2026 it expected to spend $400 million to $450 million on ordinary capital projects, plus about $300 million on Monticello.5 Over two years, the one plant would consume roughly as much capital as a full year of everything else the company does to maintain and improve its forests and mills.
Then the plan changed. On the Q3 call, Wold lowered the 2026 estimate for ordinary capital spending to about $375 million and cut expected Monticello spending for the year to about $250 million.3 He attributed the Monticello change to "normal variability in the timing of cash outlay."3 Start-up remained expected in mid-2027.3 Management also indicated that the total project cost would run moderately above the original $500 million estimate.3
That combination is worth reading closely. Spending less this year can mean discipline: when cash is tight, you trim what you can. It can also mean that spending has simply moved into 2027, while the total bill has gone up. Under questioning from analysts, Wold described the Monticello change as timing rather than a change in scope, and he declined to give 2027 capital guidance until the start of the new year.3
So far the record shows a project that is on schedule but costing somewhat more than planned, being built while the cash it consumes is scarcer than when it was approved.
Monticello is also excluded from the company's adjusted funds-available-for-distribution measure, which it uses to frame shareholder returns.3 That treatment is defensible for a one-off growth project. But shareholders should not lose sight of the fact that the cash is real. Every dollar spent in Arkansas is a dollar that cannot go to dividends, buybacks or debt.
How should investors judge a project like this? Not on announced capacity or management's EBITDA estimate. Those are design targets. The proof will come in a sequence of facts: the final cost at completion, the actual commissioning date, how quickly builders and distributors qualify the new product, actual orders compared with qualification, the share of capacity the plant runs at, its realized margins, and finally the extra free cash flow it produces after ramp-up costs.
Each step can slip. A new plant that starts up into a housing recession can run well below capacity for years, adding depreciation and fixed costs before it adds profit.
One small number frames the kind of company making this bet. Weyerhaeuser spent about $7 million a year on research and development in each of 2023, 2024 and 2025, about a tenth of a percent of sales.5 A decade earlier it spent more than three times as much.15 This is not a company building a large research pipeline.
It grows through capital projects: buying land, building mills and improving what it has. Monticello fits that pattern. The innovation in TimberStrand already exists. The open question is whether Weyerhaeuser can make more of it, in a new place, at a good margin.
There is a final caveat. The company has not published a long history of returns from comparable engineered-wood projects, so investors cannot easily compare this one against past results. The case rests on delivery and on post-launch economics. Mid-2027 will begin to supply the first evidence.
Monticello is the old-economy route to higher value: build a better product from the same logs. Weyerhaeuser has also been pitching a newer route, one that earns money from the forest without cutting it down.
VII. The New Forest Economy Has to Prove Its Scale
Stand at the edge of a Weyerhaeuser tree farm in Louisiana and the land looks like it has one job: growing pine. Management has spent the last few years arguing that it has several. The ground might hold a solar farm, a wind lease or a geothermal reservoir. Its pore space might store captured carbon dioxide. Its standing trees might generate carbon credits, and its wetlands might back mitigation credits that developers must buy when they disturb wetlands elsewhere. Weyerhaeuser calls this natural climate solutions, and it sits inside Strategic Land Solutions.5
Before judging the pitch, it helps to separate two very different kinds of money that run through the segment. The first is recurring. Leases for minerals, energy, recreation and other rights produce income year after year without giving up the land. The second is episodic. When the company sells acreage, whether to a conservation buyer, a developer or another timber owner, it books a one-time gain. Both count as land income. Only the first is a business with a run rate.
The episodic part has been large. In 2025, segment earnings included $266 million of gains from timberland sales.5 That is serious money in a year when consolidated net earnings were only about $324 million.5 It also shows why reported earnings can mislead. A large land sale can lift a quarter, and its absence the following year can make the business look worse than it is.
In the third quarter of 2026, the segment's adjusted EBITDA fell again, and management guided to another decline of about $45 million in the fourth.3 That is a segment whose earnings depend on the timing of transactions.
What about the climate business itself? Here Weyerhaeuser has started giving more detail. On the Q3 call, management said Climate Solutions had produced about $140 million of adjusted EBITDA in the first nine months of 2026, already more than in all of 2025.3 The company said it had sold about 340,000 forest carbon credits so far in the year, on pace for its highest annual volume since the program began.3
It reported that two solar sites were operating, five were under construction, groundbreaking had taken place on its first biocarbon facility in McComb, Mississippi, and an exploration agreement covered 145,000 acres for geothermal energy in Oregon and Washington.3
Those are real activities, and the growth is real. But the details the company provides still fall short of what an investor would need to treat this as a second earnings engine. Weyerhaeuser does not publicly break out the revenue, margins and invested capital of climate solutions, how much of its EBITDA comes from recurring leases versus one-time transactions, the realized price per carbon credit, or the acreage that is actually under contract.
Biocarbon, by management's own account, is still a couple of years from meaningful EBITDA.3 Until those measures are disclosed, the right label is optionality: valuable possibilities around a timber business, not a business in their own right.
Management's own targets make the scrutiny more important. In its 2026 proxy, Weyerhaeuser describes a goal of $1.5 billion of incremental adjusted EBITDA by 2030, measured against a 2024 baseline.4 Its total adjusted EBITDA in 2025 was about $1 billion.4 In other words, management is targeting earnings growth of a size larger than the whole company's recent earnings. The company identifies climate solutions, Monticello and productivity programs as the main levers. That is an ambitious bar, and it gives investors a clear test. Each year's reported progress, separated into recurring and one-off sources, will show whether the target is on track.
A careful observer should also note how the language has shifted. In earlier investor materials, management framed natural climate solutions mainly as a long-dated opportunity built on the land's attributes.18 By 2026 the framing had become more like a business line, with year-to-date EBITDA and volume figures announced on earnings calls.3 That change in tone is a good sign if it is backed by audited numbers. It is a warning sign if confident language runs ahead of disclosure.
The deeper point is about how earnings should be read. A company with land to sell can always produce income by selling some of it. That income is real, but it consumes the asset base that produces future income. So investors need to see Weyerhaeuser's earnings both including and excluding disposals. Excluding them, they need to see whether recurring land income is growing. And they need the capital deployed in each climate project, so they can judge the return.
For now, the honest conclusion is that land and natural-resource income can be material in particular periods, and climate solutions is growing, but the company has not provided a clean public breakdown sufficient to establish the recurring scale of that business. That matters most when it comes to the dividend, because asset sales and episodic gains have been part of how Weyerhaeuser has paid its shareholders through the downturn.
VIII. The Dividend Meets the Downcycle
Every quarter, on a schedule as regular as a planting season, Weyerhaeuser's board declares a dividend. In September 2026 it paid 21 cents a share, about $151 million in all for the quarter.83 Shareholders have come to treat that payment as the company's heartbeat. The question is what pays for it.
Start with the long record, because it is genuinely good. Over the twelve years from 2014 through 2025, Weyerhaeuser produced about $16.7 billion of cash from operations against about $11.5 billion of net profit.511 That gap is not an accounting trick. A large share of a timber company's costs are non-cash: depletion, which spreads the cost of the trees over the years they are harvested, plus depreciation on mills and roads.
Those charges reduce reported earnings but do not consume cash in the year they are booked. In 2025 alone, depletion, depreciation and amortization were about $509 million.5 So a forest company should generate more cash than its profits suggest, and Weyerhaeuser did.
What happened to that cash is the next clue. After capital spending, those twelve years produced about $11.6 billion of free cash flow. Dividends took about $10.6 billion of it, roughly 91 cents of every free dollar.5 Buybacks, debt repayments and acquisitions had to fit into what was left, or be funded by asset sales and borrowing. Over the full cycle, Weyerhaeuser has behaved like the income vehicle its REIT structure encourages: almost everything it could distribute, it did.
The trough is where that habit becomes a problem. In 2025, cash from operations fell to about $562 million, capital spending was $474 million, and free cash flow came to just $88 million.5 Dividends paid that year were about $606 million.5 The shortfall had to come from somewhere, and it did. The company's cash balance fell from about $464 million at the end of 2025 to $299 million by September 2026.52
Pension contributions made 2025 worse: cash paid into the pension plans rose to $219 million from $18 million the year before.5 The dividend payout, measured against net profit, reached about 187% in 2025.5 The shortfall continued over the latest twelve months.
Time, bought with a credit line
Weyerhaeuser is not in distress. At the end of 2025 it had no borrowings on its $1.75 billion revolving credit facility, which runs to June 2030, and no commercial paper outstanding.5 It repaid about $500 million of a maturing note in August 2025.5 Wold told analysts on the Q3 call that total debt stood at about $5.4 billion and that the company had no debt maturities until late 2027.3 As of September 30, 2026, it reported that it was in compliance with its debt covenants.2
The credit agencies, however, have started to notice the trend. Moody's rated Weyerhaeuser Baa2 with a stable outlook in late 2025, but its comparison table showed adjusted debt of about 5.1 times EBITDA for the twelve months to September 2025, interest cover of only about 2.2 times, and free cash flow equal to minus 12% of debt.20 For an investment-grade company those are stretched figures.
In March 2026 S&P affirmed its BBB rating but moved the outlook to negative.21 A negative outlook is not a downgrade, but it tells investors the agency sees a meaningful chance of one if metrics do not recover. Liquidity and a revolver buy time. They do not prove that the payout is sustainable.
The best way to understand the payout is to separate its parts. In late 2020 Weyerhaeuser adopted what it calls a "base plus variable supplemental" framework.22 The base dividend is meant to hold through the cycle. On top of it, the company aims to return 75% to 80% of its annual adjusted funds available for distribution, through supplemental dividends or buybacks.8
In good years the variable part is large. The company paid supplemental dividends of $1.45 a share in early 2022, 90 cents in early 2023 and 14 cents in early 2024. None has been declared since.8 The framework did exactly what it was designed to do: as cash flow shrank, the variable payout disappeared.
The base dividend's own history is the strongest test of how safe it is. Before the pandemic Weyerhaeuser paid 34 cents a quarter. After the March 2020 payment, it paid no regular dividend until December 2020, when the new base dividend restarted at 17 cents.8 Today's 21 cents is still well below that pre-2020 level.8 So the record shows a management team and board willing to cut the dividend sharply when the outlook darkens.
That history narrows any claim that the current base is untouchable. It also shows the framework's honesty: the base was reset to a level the company believed it could carry, and Wold reiterated that it is designed to withstand periods of weaker markets.3 The base dividend, at about $600 million a year, has now been tested by a trough in which free cash flow did not cover it.
Capital allocation through the downturn has another wrinkle. Weyerhaeuser kept buying back shares while cash flow fell: about $125 million in 2023, rising to $160 million in 2025.5 In May 2025 the board authorized a new $1 billion repurchase program, with $938 million left at year-end.5 Through September 2026, buybacks slowed sharply to about $30 million.2 Then on the Q3 call, Stockfish said the company viewed repurchases as "a particularly attractive opportunity right now" and expected to step them up in the fourth quarter, partly funded by the Arkansas land sale.3
Selling forest to buy back stock can make sense if the market undervalues the land. It also means the asset base shrinks to support the share count, and it competes directly with debt reduction at a time when a rating agency is watching leverage.
The man responsible, and what he was paid
The person who carries those decisions is Devin Stockfish, a chief executive whose path to the job was unusual for a timber company. He began his career as a mechanical engineer at Boeing, then went to Columbia Law School and practiced corporate law at K&L Gates before working in-house at Starbucks and the chemicals distributor Univar.4 He joined Weyerhaeuser as assistant general counsel in 2013 and became general counsel in July 2014.415
Then he made an unusual move for a lawyer. He went into the forests, running Western Timberlands and then all of Timberlands before becoming chief executive in January 2019.4 Stockfish therefore knows both the contracts and the woods. He has led the company through a pandemic boom and a long bust.
His pay has moved less than the company's results. Stockfish's reported total compensation was about $13 million in both 2023 and 2024 and about $14 million in 2025, while net income fell from $839 million in 2023 to $324 million in 2025.45 The proxy's "compensation actually paid," an SEC measure that marks equity awards to market rather than counting cash, tells a fuller story: about $15.2 million, $4.5 million and $10.3 million in those three years.4 Because most of his pay is in stock, the value he actually realizes does fall when the stock falls.
The structure is what matters most. For 2025, Stockfish's performance share units were tied entirely to Weyerhaeuser's three-year total shareholder return relative to a peer group, with payouts capped if absolute returns are negative.4 His annual bonus paid out at 98% of target, based 60% on financial measures and 40% on controllable business metrics.4
For 2026 the board added a second long-term measure, growth in adjusted EBITDA per share, with a 25% weighting, alongside relative TSR at 75%.4 That change pushes pay toward operating results, not just stock performance against peers. Shareholders approved the 2025 pay package with more than 94% support.4
Not everyone is convinced. In April 2026 the real-estate activist Land & Buildings published a report listing Weyerhaeuser among 21 large REITs whose shareholder returns had trailed the peers their own boards chose for pay benchmarking over one, three and five years. It urged shareholders at those companies to vote against say-on-pay and against compensation committee members.23
That is a pointed criticism, and it is backed by a straightforward screen. It should be read for what it is. It was a sector-wide pay campaign covering many REITs, not a Weyerhaeuser-specific activist push for board seats, asset sales or strategy change.
Who would have to act if shareholders lost patience? Weyerhaeuser has no controlling owner. Its four largest holders as of March 2026 were index and institutional managers: Vanguard with about 16%, BlackRock with about 8.5%, and First Eagle and Wellington with a little over 5% each.4 Ten of the eleven directors are independent, and the chair is not an executive.4 That structure makes a sudden takeover of the board unlikely. It also means accountability runs through proxy votes and engagement rather than through a dominant shareholder, which is exactly the channel Land & Buildings was trying to use.
In the end, management's credibility will be decided by actions rather than slogans. "Through-cycle returns" is easy to say in a trough. The next few decisions, about how much to buy back, how much land to sell, and whether to protect the rating or the payout first, will show what the phrase really means. And what the company does when a target slips will matter more than the targets themselves.
IX. Business & Investing Lessons
Go back to the seedling in the Southern pine. It will grow a little every year, whatever housing does. It is the most patient piece of capital in the American economy. Every year until harvest, though, its owner has to pay for roads, firefighting, taxes, foresters and the interest on the debt that bought the land. The seedling is patient. The bills are not. That contrast is the source of Weyerhaeuser's lessons.
The first lesson is that a forest is patient capital, but a mill is fixed-cost capital, and the two do not fail at the same speed. In the boom, Weyerhaeuser's mills looked like a money machine. Four years later, they did not. The trees did not change.
The mills' prices did, and their costs did not fall with them. For investors the point reaches well beyond timber. A business built on a durable asset can still be a cyclical business, if the money actually comes from processing that asset into a commodity. Judge the company by its weakest link in the value chain, not its strongest.
The second lesson is that scale is only a moat when it changes the economics. The Plum Creek merger made Weyerhaeuser the undisputed giant of American timber. A decade later, the evidence that scale has produced lower costs, better log prices or higher returns than smaller rivals remains mostly management's own argument. The delivered-log model, the integrated mill network and the size of the land base are plausible advantages.
A plausible advantage becomes a real one only when it shows up in a measure a competitor cannot match, such as cost per delivered ton, price per log or return on capital through a full cycle. Bigness by itself is a statistic, not a strategy.
The third lesson is that a tax structure can shape distributions, but it cannot manufacture cash. The 2025 payout gap made that arithmetic plain: the REIT label does not change it.
The fourth lesson is that an option is not a business until customers pay for it. Weyerhaeuser's climate projects and new Arkansas plant are real possibilities, some already earning money. Their value still depends on recurring revenue, disclosed margins and returns on capital.
The final lesson pulls the others together: the measure that matters for a company like this is conversion. Weyerhaeuser owns an irreplaceable asset. The investing question has never been whether it is irreplaceable. It is how much cash that asset turns into, after the mills, roads and new plants are paid for, across a whole housing cycle. On that measure the company's record is good over twelve years and poor over the last two. The next chapter will decide which of those records is the exception.
X. Analysis & Bear vs. Bull Case
Investors who buy Weyerhaeuser at about $21 a share are paying roughly 32 times trailing earnings, almost exactly the company's five-year median of about 33.5 times.2 The stock trades at about 17.7 times enterprise value to EBITDA and yields about 4% in dividends.2 Its return on invested capital over the past twelve months was about 3.9%, and its free cash flow yield was negative.2 The puzzle is simple: why would the market pay a historically normal price for a company earning historically weak returns?
The most likely answer is that investors are valuing Weyerhaeuser on what they expect it to earn in a normal year, not on what it earns now. That is a reasonable way to value a cyclical company, but it carries an assumption. It assumes there will be a normal year, and that it will arrive soon enough to matter.
Peer prices offer only rough context. Rayonier, a timberland REIT with a different land mix and no comparable mill network, traded at about 35 times trailing earnings on the same day, and Louisiana-Pacific, a building-products company concentrated in engineered siding and panels, at about 78 times.2425
Those earnings bases differ too much for the comparison to say more than this: the whole sector is priced for recovery, not for the current trough.
Where the moat is real, and where it is thin
The full competitive case starts with Hamilton Helmer's seven sources of lasting advantage. Weyerhaeuser has one clearly. That is a cornered resource: about 10.3 million acres of U.S. timberland, much of it close to mills and ports, that no rival could assemble today at any reasonable price or speed.16 It may have a second: scale economies in harvesting, logistics and overhead across an integrated system. But that advantage is real only if it shows up in costs, and the company has not demonstrated a persistent cost gap over smaller owners in its public numbers.
The other powers are weak or absent. Weyerhaeuser has no network effects. Switching costs are low, because a lumber yard can change suppliers with a phone call. Its brand carries some weight in engineered wood, where builders specify products by name, but little in commodity lumber or logs. Counter-positioning, where a rival cannot copy a model without damaging its own, does not apply. Process power, the hard-to-copy operating know-how that Toyota made famous, may exist in a century of forestry science, but it has not produced a lasting margin advantage either.
Porter's five forces give a matching picture. Barriers to entry are high for landowning and moderate for mills. Buyer power is meaningful because no customer is large, but every customer has alternatives and buys at market prices.5 Supplier power shows up in freight, fuel and labor, and the third quarter's cost surprise showed how little of that the company can pass on.3 Substitutes, such as steel framing, concrete and imported wood, cap prices at the margins. Rivalry is fierce across Canadian, Southern and European producers. A scarce asset feeding fragmented, cyclical markets is the honest description.
A few less visible risks belong in the same picture. Weyerhaeuser carries the environmental tail of a century of mills. A remediation case over the Port of Everett had been set for trial in May 2026, and the company has a long history of cost-allocation litigation over the Kalamazoo River, where it was found not responsible for the specific past costs at issue.5 Management describes its legal proceedings as ordinary-course and not expected to be material, and the auditor gave clean opinions on both the financial statements and internal controls for 2025.5
Weather is a more immediate operating risk. Fire, storms, drought and pests can destroy standing inventory or force salvage harvests, and the company's Q3 results already reflected smaller insurance recoveries than a year earlier.2 None of these is a reason to value the company differently today. Each is a reminder that a forest is an inventory kept outdoors.
The bull case and its tests
The first argument for owning Weyerhaeuser is the platform. Its land base is large, spread across the Pacific Northwest and the South, and supported by forestry and harvesting expertise built over a century. Smaller owners cannot reproduce that platform. The Arkansas sale at roughly $1,800 an acre for land the company calls lower-quality suggests the private market still values timberland generously.3 If the land is worth what such deals imply, the stock may be underpinned by asset value even in a weak cycle.
The bear case answers that land and logs are not price-setting assets. Owning the most acres does not let Weyerhaeuser set the price of a log in any particular basin, let alone the price of lumber. Scale did not stop operating margins from falling from about 36% to below 7% within four years. And asset value only helps shareholders if it is realized. Selling land at a good price can fund buybacks, but each sale shrinks the forest that will produce future earnings.
The second bull argument is recovery. American housing has been held back by mortgage rates that were back above 7% this autumn.3 If rates fall and housing starts recover, realizations could rise quickly, and Weyerhaeuser's mills have shown in 2021 how much profit that can produce. Monticello would add a higher-value product to that recovery. Management's goal of $1.5 billion of incremental adjusted EBITDA by 2030 rests heavily on that combination.4
The bear reply is timing. Weak demand can leave a new plant running well below capacity, while its depreciation and operating costs start immediately. The dividend, buybacks, debt reduction and capital spending all compete for a cash flow that did not cover the dividend in 2025. If recovery is delayed by a year or two, something has to give: the buyback, the balance sheet, or the dividend that was already reset once in 2020.
The third bull argument is the new forest economy. Climate solutions earned more in the first nine months of 2026 than in all of 2025, and carbon credit volumes are at record levels.3 Leases for solar, geothermal and carbon storage could turn land attributes into long-term income that does not depend on lumber.
The bear reply is disclosure. Without published revenue, margins, recurring versus one-time income and capital deployed, it is impossible to know whether climate solutions is a durable second engine or a growing stream of transactions. Valuing it like an established business would be premature.
On balance, the investment case is a cyclical recovery story, supported by valuable land and a targeted move into higher-value products. It is not a story of demonstrated near-term growth. The valuation, at the company's own median multiple, does not look obviously cheap against history. And with current returns and free cash flow so weak, there is little room to treat optionality as earnings already in hand.
Compared with Rayonier and the combined Rayonier–PotlatchDeltic group, Weyerhaeuser has more than twice the acreage, a larger delivered-log operation and much heavier exposure to wood products manufacturing.1617 That makes it both more powerful in a lumber upturn and more vulnerable in a downturn. Against building-products companies such as Louisiana-Pacific, the overlap is mainly in engineered wood and panels, and unadjusted earnings multiples say little, because those companies do not own the forests.
Stockfish's credibility should be judged on things that can be checked. Will Monticello start up on time and at a cost close to the revised estimate? Will capital returns match the cash actually generated? Will guidance match outcomes? Will his answers on calls stay direct when results disappoint? On the Q3 call he answered questions on freight costs, Monticello spending and buybacks with specific numbers, even when he declined to give the next quarter's repurchase figure.3 That is a good habit. It will matter more when the news gets worse.
Three measures will tell most of the story. The first is Wood Products earnings and price realizations, where adjusted EBITDA was $91 million in the third quarter and falling from the second.3 The second is Timberlands adjusted EBITDA, together with harvest volumes and log prices, which reached about $133 million in the quarter and edged up.3 The third is free cash flow after capital spending compared with the base dividend. That measure was $88 million against a dividend of about $606 million in 2025, and negative over the latest twelve months.52
Behind those numbers sit four deciding events: the Monticello start-up and the share of capacity it runs at, the timing of any housing and lumber recovery, the split between recurring and one-time land earnings, and the next credit-rating action. Each is scheduled or measurable. None has been settled.
XI. Epilogue
Tonight, Weyerhaeuser sits in the uncomfortable middle of its own story. The forests are growing. The mills are running, mostly below their potential, into the weakest housing market in years. The new plant in Arkansas is rising out of the ground. And the board is due to consider its next quarterly dividend on November 12, 2026.8
The next eighteen months will unfold in a rough order. First comes Monticello's completion and start-up, which management expects in mid-2027.3 Then the ramp-up: how fast the plant reaches full output, how much its products sell for and what it actually earns. Only after that will investors see whether engineered wood improves Wood Products' margins enough to change the segment's character. Management has promised more than $100 million of annual adjusted EBITDA at full output. That number has to be reported, not projected.
At the same time, Timberlands and Strategic Land Solutions have to show that they can produce repeatable cash without depending on large timberland sales. The Arkansas sale will close, if management's timetable holds, by year-end.3 It will flatter the fourth quarter and fund buybacks. The year after will reveal what the land businesses earn without it.
The quarter immediately ahead already carries guidance. Management expects Timberlands earnings to be comparable to the third quarter, Strategic Land Solutions adjusted EBITDA to fall by about $45 million, and Wood Products to be moderately lower before any change in lumber and panel prices.3 Wold also warned that any big move in fuel costs would show up in results.3 In other words, the company expects the year to end weaker than the third quarter, unless prices rescue it.
Investors will also be able to measure management against its own words. Capital spending for 2027 will be set out early in the new year.3 The total cost of Monticello will become known. The pace of buybacks will show whether Stockfish's "particularly attractive opportunity" was a plan or a phrase. If delays or shortfalls appear, the way management explains them will matter as much as the numbers.
And then the dividend. The real proof that Weyerhaeuser can pay shareholders through a cycle is coverage: free cash flow after necessary capital spending, compared with the base payout, while leverage holds steady or falls. If housing recovers, coverage will return quickly, and the 2025 shortfall will look like a passing storm. If housing stays weak through 2027, the company will face the choice it made once before, in 2020, between the payout and the balance sheet.
Some questions will remain open even then. Monticello's full-cycle returns cannot be known until the plant has lived through a cycle. The climate solutions business will not have a reliable recurring earnings figure until the company publishes one. Those uncertainties are real, and no amount of acreage resolves them.
XII. Outro
In 1900, Frederick Weyerhaeuser and his partners paid about $6 an acre for a forest they would never see fully harvested.6 They were buying time: decades of growth that only future owners could turn into money. A century and a quarter later, that patience still runs through the company. Its foresters plant for the 2050s. Its land base is the largest of any timber REIT in America.
But the forest is both inheritance and inventory. It grows slowly, and it still has to find a buyer. Every tree ends up as a log sold at a market price, a board priced by the housing market, or an acre priced by the next bidder. Weyerhaeuser's story has always been the effort to make something that lasts for generations pay its way every quarter.
An enduring asset does not make earnings or cash flow enduring. The forest will keep its promise to grow. Whether the company can keep its promise to pay is the question the next cycle will answer.
References
-
Weyerhaeuser Reports Third Quarter 2026 Results — Weyerhaeuser Company, 2026-10-29 ↩↩
-
Quarterly Report on Form 10-Q, quarter ended September 30, 2026 — Weyerhaeuser Company / SEC, 2026-10-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Weyerhaeuser (WY) Q3 2026 Earnings Call Transcript — The Motley Fool, 2026-10-30 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
2026 Annual Meeting and Proxy Statement — Weyerhaeuser Company / SEC, 2026-04-01 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
2025 Annual Report and Form 10-K — Weyerhaeuser Company / SEC, 2026-02-13 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
2010 Annual Report and Form 10-K — Weyerhaeuser Company / SEC, 2011 ↩↩↩↩↩
-
Form 8-K/A, Completion of Acquisition of Longview Timber LLC — Weyerhaeuser Company / SEC, 2013 ↩↩
-
TRI Pointe Homes Closes $2.8 Billion Merger with Weyerhaeuser Real Estate Company — TRI Pointe Homes / SEC, 2014-07-07 ↩
-
2014 Annual Report and Form 10-K — Weyerhaeuser Company / SEC, 2015-02-13 ↩↩
-
Weyerhaeuser and Plum Creek Merger Announcement — Weyerhaeuser Company, 2015-11-08 ↩↩↩
-
Plum Creek Merger Proxy Background and Fairness Analysis — Plum Creek Timber Company / SEC, 2016 ↩↩↩↩↩↩↩↩
-
2016 Merger Consideration and Acquired Assets — Weyerhaeuser Company / SEC, 2016-03-31 ↩↩
-
2015 Annual Report and Form 10-K — Weyerhaeuser Company / SEC, 2016-02-17 ↩↩↩
-
May 2026 Investor Presentation — Weyerhaeuser Company, 2026-05 ↩↩↩↩↩
-
Weyerhaeuser Investor Presentation — Weyerhaeuser Company / SEC, 2025-09 ↩↩
-
Weyerhaeuser set to build $500M plant in Southeast Arkansas — The Arkadelphian, 2024-11-19 ↩↩↩↩
-
Moody's Comparative Credit Metrics — Moody's Ratings, 2025-11-24 ↩
-
S&P BBB Affirmation and Negative Outlook Record — Cbonds, 2026-03-13 ↩
-
Weyerhaeuser Company Declares Dividend on Common Shares — Weyerhaeuser Company, 2022-05-12 ↩
-
2026 Executive Compensation Halftime Report — Land & Buildings, 2026-04 ↩
-
Louisiana-Pacific (LPX) Valuation Statistics — Stock Analysis, 2026-11-08 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube