Parker-Hannifin: The Parts Behind Everything That Moves
I. The $9 Billion Test
On August 13, 2026, Parker-Hannifin announced that it now owned Filtration Group Corporation.1 Nothing about the moment was cinematic. There was no product launch and no new factory to cut a ribbon in front of, just a press release saying a company most consumers have never heard of had bought another company most consumers have never heard of. The price was the part that mattered: $9.25 billion in cash, the largest cheque a 109-year-old Cleveland manufacturer had ever written.2 For that money Parker got a business that makes filters for air, fuel, oil, water and industrial processes, and sells about 85% of them as replacements for filters that have already worn out.3
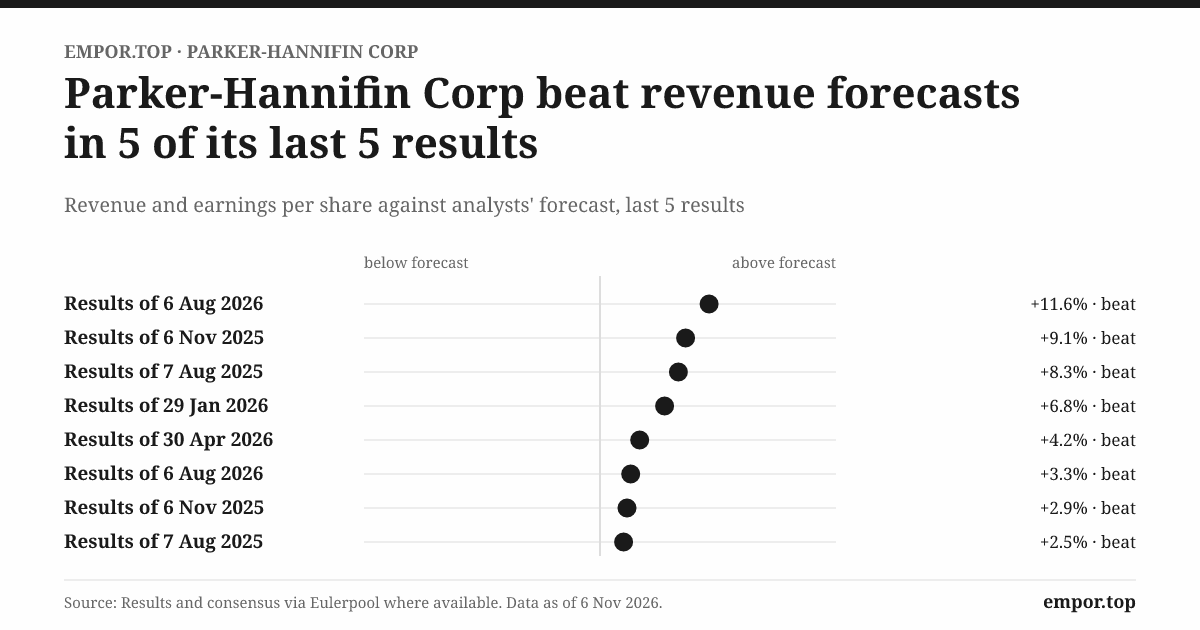
Less than three months later, on November 5, Parker reported the first quarter that included the new business, and on the surface it looked like a victory lap. Sales rose 18% to a record of about $6 billion. Orders were up across every reporting segment, the backlog of orders not yet shipped reached a record $13.7 billion, and management raised its forecasts for the full fiscal year.4 Jennifer Parmentier, the chairman and chief executive, told analysts it was the first quarter in more than three years in which Parker's existing businesses had grown sales by double digits without counting acquisitions.5
Look at the balance sheet from the same quarter, though, and the mood changes. At the end of June, before the deal closed, Parker owed about $8.5 billion.6 By the end of September it carried $12.7 billion of long-term debt plus $2.8 billion of commercial paper, the short-term IOUs big companies sell to money-market funds.7 Management expects interest costs for the year to roughly double, to about $690 million.5 Another acquisition, the commercial and defense aerospace business of CIRCOR, was still waiting to close, with a $2 billion delayed-draw loan lined up to pay for it.7
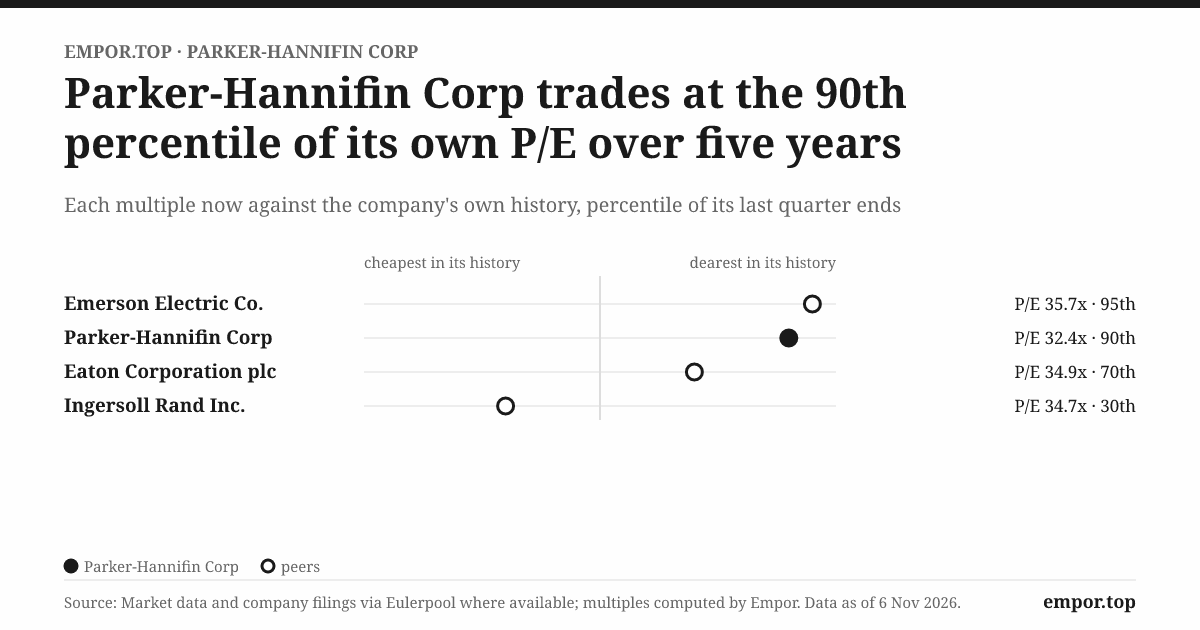
The market's verdict on all of this is priced into the shares. On November 5, Parker traded at about 31 times its trailing twelve months of earnings, against a five-year median of about 25 times.6 Investors are paying more for each dollar of Parker's profit than they usually have, at the very moment the company has taken on the biggest financial obligation in its history. That premium is a bet that the operating machine will absorb the new businesses, deliver promised savings and pay down the debt quickly, without an industrial slowdown getting in the way.
So this episode is about three questions. The first is how a company that makes thousands of unglamorous parts, many of them sold in fragmented markets where no one supplier dominates, earns operating margins above 20%. The second is whether Parker's century-old habit of buying specialized businesses still creates value now that the deals cost many billions of dollars instead of a few hundred million. The third is whether the margin gains of the last decade are durable or partly a gift of good timing, and would survive the next serious downturn in manufacturing.
Before going further, it helps to say plainly what Parker is, because the name gives no clue. Parker-Hannifin Corporation is an Ohio company listed on the New York Stock Exchange, and it does not sell a single hero product.6 It makes hoses and fittings that carry hydraulic fluid in excavators, seals that keep gases where they belong, valves, pumps, pneumatic cylinders, filters, fuel systems, flight-control actuators, braking components for aircraft, and the electronic controls that increasingly tie these things together. No single product accounted for more than 1% of its sales in fiscal 2026.6 Parker's value lies in the sheer number of engineered components it sells, the engineering that goes into fitting them to a customer's machine, and the distribution network that gets replacements to a mine site or an airline hangar fast. In fiscal 2026, which ended in June, that added up to about $21.5 billion of revenue and $4.6 billion of operating profit.6
The operating momentum is real. The open question is whether the earnings Parker bought, and the savings it has promised, arrive fast enough to justify the price and bring the debt back down. To see why management believes they will, and why a skeptic might hesitate, the story has to start with a failure, on a mountainside in Pennsylvania, more than a century ago.
 Subscribe on LinkedIn
II. The Brake Failure That Started a Century of Rebuilding
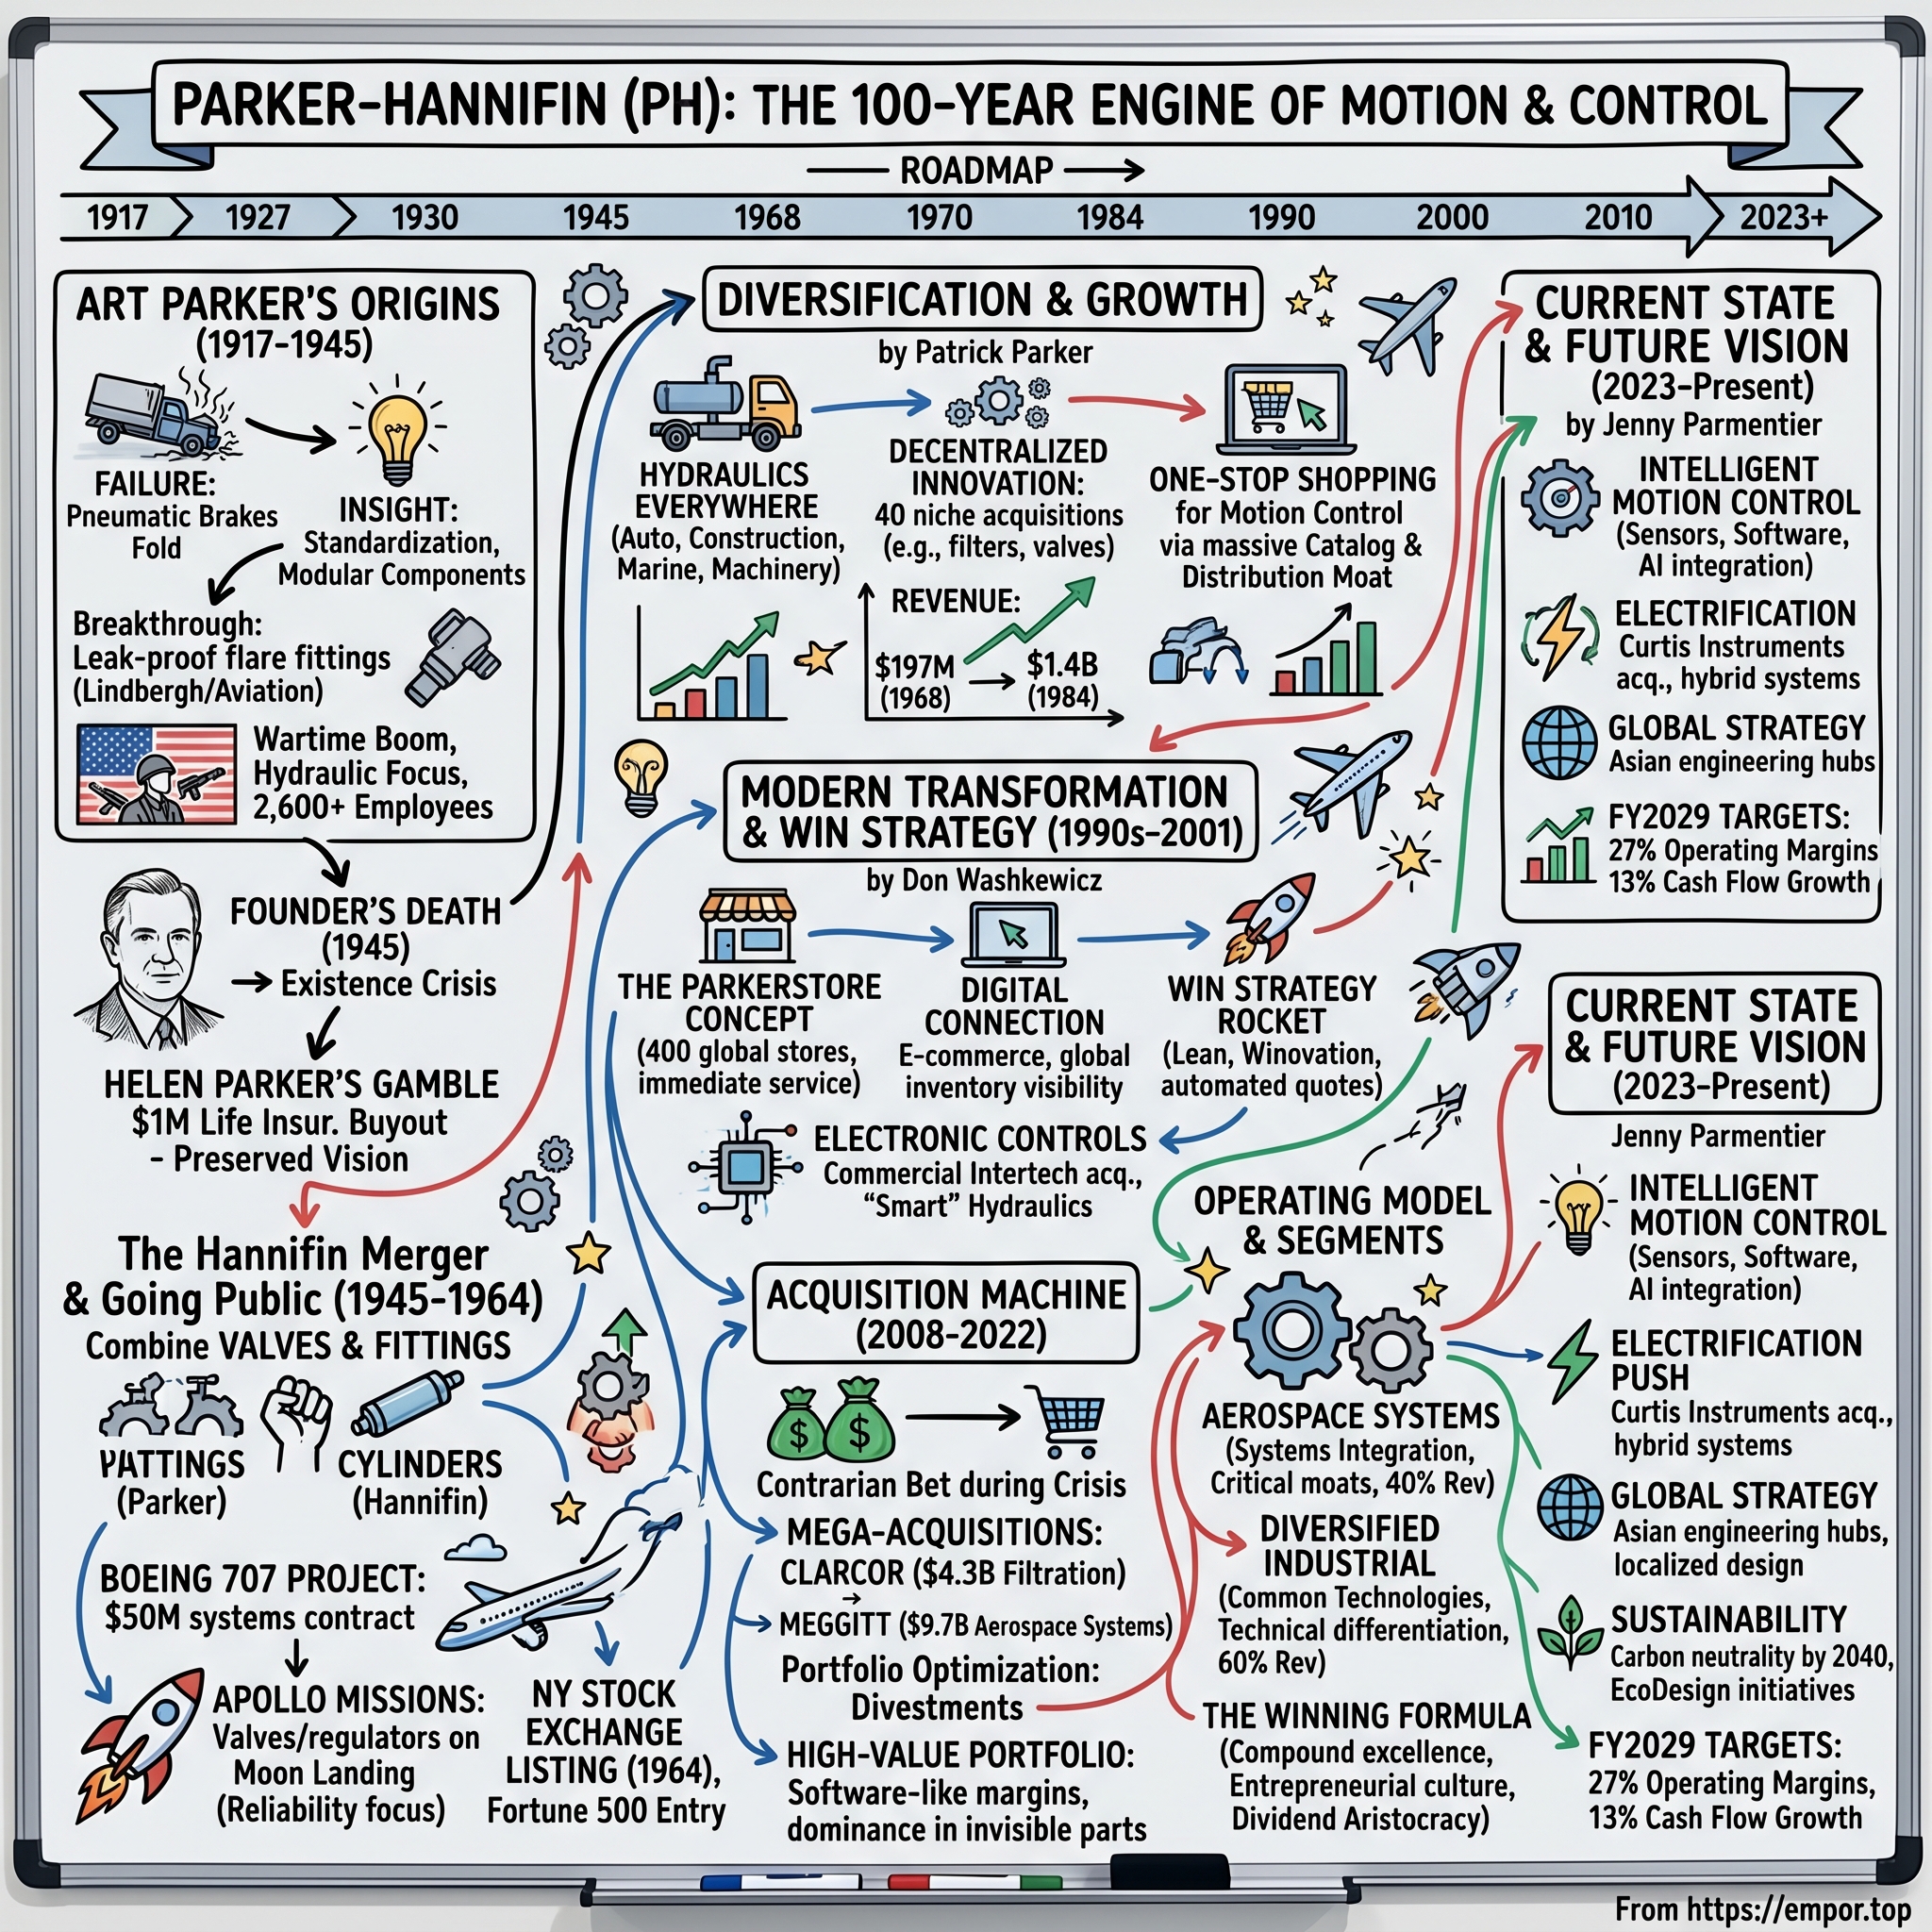
Arthur LaRue Parker was an electrical engineer, a Case Institute of Technology graduate who believed he had invented something better: a pneumatic braking system for trucks and buses, using compressed air rather than muscle to stop heavy vehicles.8 On March 13, 1917, he founded the Parker Appliance Company on Cleveland's near west side to sell it.8 For a young company whose product was literally about stopping safely, what happened next is almost too neat. On a promotional trip, the truck carrying the company's entire inventory went over a mountainside in Pennsylvania.8 With its stock destroyed, the business could not continue, and Parker closed it.
What he did next defined the company more than the brake ever did. Parker did not raise money from investors or go looking for a rescuer. He went to work as an engineer for the New York, Chicago and St. Louis Railroad, the Nickel Plate Road, and saved his wages.8 In 1924, seven years after the first start, he reopened the business.8 The brake was no longer the center of the story. What kept the reborn Parker Appliance alive was something less glamorous: fittings, the small connectors that join tubes and hoses in a fluid system so that nothing leaks.
Fittings turned out to be the right product at the right moment, because aviation was taking off. Aircraft designers wanted hydraulic and fuel systems that were compact, light and leak-free, and Parker's fittings did exactly that.8 In the late 1920s, Charles Lindbergh asked Parker to develop a leak-free fuel system for the Spirit of St. Louis, the plane he flew solo across the Atlantic.8 It is a wonderful piece of company lore, and it also tells an investor something useful. From the beginning, Parker's best business was not a finished machine but the critical small part inside someone else's machine, the part that had to work every time because failure was catastrophic.
Then came the war. In 1940 Parker Appliance employed 910 people; a year later it had about 2,600, as government aircraft orders flooded in and the company opened operations in Los Angeles to sit near the aircraft builders.8 For a small Cleveland firm, nearly tripling in a year was both a triumph and a trap, because it tied the company to a single, enormous, temporary customer.
The trap snapped shut after Arthur Parker died in 1945. Government business collapsed with the end of the war, and the company came close to bankruptcy.8 The decision that saved it belonged to his widow, Helen Parker. She refused to liquidate the firm, put her husband's $1 million life insurance policy into it, and hired new management to rebuild the industrial business.8 The rebuild worked through a mix that will sound familiar later in this story: new products, new markets, more efficient manufacturing and acquisitions of fluid-power businesses.8 By 1951 sales had reached about $12.2 million.8
The acquisition that gave the company its name came in 1957, when Parker bought Hannifin Corporation of Illinois, a maker of hydraulic and pneumatic cylinders, valves and hydraulic presses.8 The combination mattered because it moved Parker from connecting fluid systems to powering and controlling them. The merged Parker-Hannifin listed on the New York Stock Exchange on December 9, 1964, with 4,400 employees.8 Over the following three decades it bought more than 100 companies, worked on the space program, and moved into refrigeration and filtration; sales passed $2 billion in 1988.8
None of this history explains Parker's earnings today; a fitting sold to Lindbergh has nothing to do with a filter sold to a data center in 2026. What the early years do explain is a habit. Parker survived by changing what it sold and who it sold to, first from brakes to fittings, then from aircraft to industry after the war, then from components to systems through acquisitions. The founding myth is not a tale of inevitable success. It is the story of a company that kept rebuilding itself because the alternative was closing again. That adaptive streak is the thread that runs to the present, where the question is no longer survival but whether all those acquired pieces genuinely add up to something more than a very long catalogue.
III. Why Thousands of Parts Can Add Up to a System
Picture the engineering team at a company that builds mid-sized excavators. Their new machine needs to lift, swing and dig, so it needs hydraulic pumps and cylinders to provide the muscle, valves to direct the fluid, hoses and fittings that will survive years of vibration and pressure spikes, seals that will not weep oil in a Canadian winter, filters to keep the hydraulic fluid clean enough not to destroy the pump, and increasingly an electronic controller and electric motor in place of some of the diesel. The team can buy each of those from a different specialist. Or it can ask one supplier to engineer much of the package together, guarantee that the pieces work as a system, and then make sure that when a hose bursts on a job site three years later, a replacement is available at a distributor down the road.
That second option is Parker's pitch, and the company has built itself to make it. Whether the pitch amounts to a durable advantage, or simply puts Parker into many competitive markets at once, is the central question of this section.
Start with how the money comes in. Parker does not sell subscriptions. Most of its products ship against purchase orders, or against releases under blanket orders that customers and distributors place within master agreements, and most revenue is recognized when goods leave the dock; a smaller amount of custom or installation work is booked over time.6 The company does not disclose a typical contract length, minimum purchase commitments, or what share of its revenue recurs.6 That matters, because "recurring" is a word investors love to hear about industrial companies. At Parker, repeat purchasing is real, since filters clog, seals wear and hoses fail, but no contract obliges customers to keep buying from Parker, and new equipment sales depend on whether factories, builders, farmers and airlines are spending.
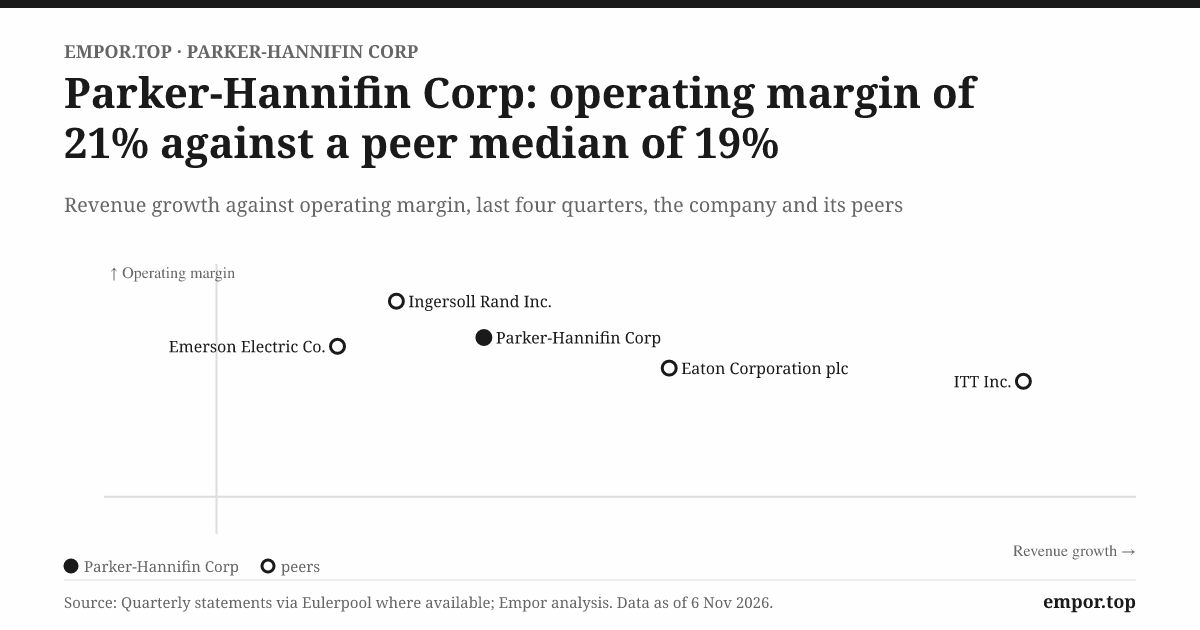
The business divides into two segments of very different size and character. Diversified Industrial is the bigger one, with about $14.4 billion of fiscal 2026 sales and $3.44 billion of segment operating income.6 It covers motion systems such as pumps, motors and cylinders; flow and process control; filtration; and engineered materials like seals and shielding. Aerospace Systems is smaller, at about $7.06 billion of sales and $1.83 billion of segment operating income, but it grew faster, with organic sales up 13.4% in fiscal 2026.6 It also earned more per dollar: a segment margin of about 26.0%, against 23.8% for the industrial side.6 Two-thirds of the revenue, then, comes from industry and one-third from aircraft, but aerospace punches above its weight in profit and in growth.
The aerospace business is where the replacement logic is strongest, and it is worth slowing down to explain it. When Parker designs a fuel pump or a hydraulic actuator into a new airliner, the part is certified as part of that aircraft. For the decades the aircraft flies, airlines and repair shops need spare parts and overhauls, and the certified design is very hard to swap out. In fiscal 2026, aftermarket revenue was about $3.46 billion of Aerospace Systems' $7.06 billion, nearly half.6 That is the closest thing Parker has to an annuity. It is not the same as saying all aerospace revenue is recurring: the other half depends on aircraft builders' production rates and defense budgets, and aftermarket demand itself falls when planes are parked, as the pandemic demonstrated across the industry.
Who does Parker compete against? The honest answer is: almost everybody, one product at a time. In industrial hydraulics and motion, the rivals include Bosch Rexroth and Danfoss; in pneumatics, Japan's SMC; in valves and process instruments, Emerson and Swagelok; in filtration, Donaldson; in hoses and power transmission, Gates.6 In aerospace the list includes Eaton, Honeywell Aerospace, Moog, RTX, Safran and Woodward.6 Parker itself says no single competitor overlaps every Diversified Industrial product group.6 That cuts both ways. It means Parker never fights one giant across its whole portfolio, and no single competitor's price war can hit everything at once. It also means there is no single market in which Parker is the obvious, dominant leader, and no company-wide market share figure that would prove the portfolio adds up to a moat.
So where might an advantage come from? Parker's own answer rests on two mechanisms. The first is engineering support: putting application engineers alongside customers early, so that Parker parts are designed into a machine before it goes into production. Once a component is designed in, tested and qualified, switching it means re-engineering and re-testing, which costs a customer time and risk even when a rival offers a lower price. The second is distribution. Parker sells through a large network of independent distributors and its own branded stores, so that a farmer or a mine operator can get a replacement hose quickly. In industries where an idle machine costs far more than any hose, speed of replacement is worth paying for.
Both mechanisms are plausible, and both have limits that the record exposes. Qualification creates switching costs mainly where certification or reliability requirements are steep, which is true on an aircraft and much less true for a pneumatic fitting in a packaging line. Distribution is an advantage only so long as the distributor's customers keep asking for Parker by name, and many distributors carry competing brands. The decisive data for testing the moat, such as customer retention rates, how often customers dual-source the same part, and how much price Parker realizes relative to costs, are not published. Parker does not disclose its top-customer, top-five or top-ten revenue shares; it describes a diverse customer base and says it is not exposed to a concentration of credit risk.6
That silence does not mean the advantage is fictional. It means the honest claim is narrower than "Parker has a moat." The defensible version is that Parker has product- and application-specific advantages, strongest in certified aerospace parts and in the replacement end of its industrial businesses, made stickier by the breadth of what one supplier can offer and the network that delivers it. The best indirect evidence for those advantages is the profit line: a company competing as a commodity supplier in fragmented markets does not usually earn segment margins in the mid-20s.
Which raises the obvious follow-up. Parker's margins were not always this high. Twelve years ago they were roughly half today's level, with the same products, many of the same competitors and the same distribution network. Something changed inside the company, and Parker has a name for it.
IV. The Win Strategy Turns the Factory into a Repeatable Playbook
In 2001, Donald Washkewicz, then chairman, chief executive and president, launched something he called the Win Strategy.8 At the time, it sounded like the kind of corporate program every industrial company announces and few remember. Parker was a sprawling collection of divisions, many of them built through acquisition, each with its own habits. Washkewicz's idea was that a decentralized company could still run on shared disciplines, and that the sum of many small improvements, in pricing, purchasing, factory flow and lead times, could be very large.
A quarter-century later, Parker still describes the Win Strategy as its operating system. When it completed the Filtration Group purchase, Parmentier said that, "using The Win Strategy," the acquisition was expected to compound earnings per share and create shareholder value.1 The phrase appears in nearly every presentation the company gives. The question for an investor is whether it is a genuine engine or a brand applied after the fact to results that the economic cycle delivered.
In practical terms, the system works like this. Parker keeps its operating divisions small and close to their customers, with general managers who are responsible for their own profit and loss. Over that decentralized structure it lays common practices. One is strategic pricing: rather than setting prices as cost plus a standard markup, divisions are pushed to price according to the value a part delivers, so a rare, critical component is not priced like a commodity. Another is lean manufacturing and continuous improvement, with "kaizen" events in which teams walk the factory floor and remove waste, a practice borrowed from Japanese manufacturing. A third is supply-chain management and productivity targets. And there is a heavy emphasis on safety, quality and on-time delivery, which management treats as leading indicators for everything else. When Parmentier described the first weeks of owning Filtration Group, the first thing she mentioned was that teams had already begun kaizen events focused on safety.5
By its fiscal 2023 investor presentation, Parker had refreshed the playbook and attached ambitious targets to it, framing the goal as top-quartile performance against its industrial peers on measures such as margins, earnings growth and cash flow.9 Language like that is easy to write and easy to test, so here is the test.
The headline result is striking. Parker's operating margin rose from about 11.5% in fiscal 2015 to 21.6% in fiscal 2026, a gain of about ten percentage points.6 To put that in human terms: for every $100 of goods it sold a decade ago, Parker kept about $11.50 as operating profit. Today it keeps more than $21. Over the ten years to fiscal 2026, revenue grew about 6.6% a year, while net profit grew about 16.3% a year.6 When profit grows two and a half times as fast as sales for a full decade, the company is either changing its mix, getting more efficient, buying higher-margin businesses, or all three.
At Parker it is all three, and separating them is the analytical task. Acquisitions such as CLARCOR and Meggitt brought aftermarket-rich, higher-margin businesses into the portfolio, so some of the margin gain was bought rather than built. Aerospace's growing share lifted the average because aerospace earns more. But the most telling evidence for the operating system comes from the years when demand did not help. In fiscal 2025, revenue was essentially flat, down about 0.4%, yet operating margin rose from about 19.6% to 20.5%.6 A company whose margins expand when sales do not is doing something internally; there was no volume tailwind to flatter that year.
Now the counter-record, because the Win Strategy has lived through bad years too. In fiscal 2016, revenue fell about 10.6%, and net profit fell about 20%.6 In fiscal 2020, with the pandemic hitting the last months of the year, revenue fell about 4.4% and net profit fell by a similar fifth.6 Here the evidence is interesting. Operating margin barely moved in either downturn, about 11.4% in fiscal 2016 against 11.5% the year before, and about 14.5% in fiscal 2020 against 14.8%.6 Parker defended its margin rate, but it did not defend its profits; lower sales still meant materially lower earnings. That is the honest shape of the claim. The operating system appears to make Parker more profitable per dollar and to stop margins collapsing in a downturn, but it does not repeal the cycle. Revenue still swings with manufacturing activity, and the earnings that hang off revenue swing with it.
There is another subtlety. Parker's best margin gains have come in a period with no deep industrial recession. Fiscal 2016 was a sharp, painful slowdown, but the margins of that era started from a much lower base. The current 21.6% margin has never been tested by a downturn of that depth. A skeptic is entitled to say the playbook's resilience at today's margin level is unproven, while acknowledging that its past behavior in downturns is encouraging.
Cash is the other test of whether earnings are real, and here the record is solid but not spotless. Over fiscal 2015 through 2026, Parker generated about $28.8 billion of cash from operations against about $21.7 billion of net profit, so cash ran at roughly 132% of reported earnings.6 Part of that gap is accounting: amortization of the intangible assets that come with acquisitions reduces reported profit but costs no cash, so a serial acquirer will naturally show cash flow above profit. In fiscal 2026 depreciation and amortization added back about $937 million.6 The less flattering detail is working capital. In fiscal 2026, rising inventory absorbed about $272 million of cash and receivables another $114 million, partly offset by $290 million from paying suppliers more slowly.6 Inventory has been creeping up for years: measured as days of cost of goods held, it has risen from about 49 days in fiscal 2015 to about 86 in fiscal 2026.6 Some of that reflects mix, because aerospace businesses carry more inventory, and some reflects the supply-chain disruptions of the early 2020s. Either way, it means more cash is tied up in warehouses than a decade ago, and that cash would be slow to free if orders fell. There is a quieter detail in the payables line too. Parker runs a supplier-finance program, in which banks pay Parker's suppliers early and Parker settles with the bank later; obligations under it rose to about $262 million at June 2026 from about $175 million a year earlier.6 Parker says its own payment terms do not change when a supplier uses the program, so this is not hidden debt, but it does mean part of the cash benefit from stretching payables depends on banks being willing to keep financing Parker's suppliers.
Parker also reinvests modestly in the conventional sense. Research and development expense was about $267 million in fiscal 2026, roughly 1.2% of sales, and capital spending was about 2.1% of sales.6 That is light compared with many technology-heavy manufacturers, which fits a model built on applications engineering and incremental product development rather than big laboratory bets. Management plans to lift capital spending to about 2.5% of sales in fiscal 2027.6
The verdict on the Win Strategy, then, is that the long-run evidence supports a real improvement in how Parker runs itself: margins expanded in flat years, held their rate in down years and converted to cash over the long run. What the record does not yet prove is that today's margin level survives a severe industrial recession, or that the playbook can be laid over ever-larger acquired businesses at the same speed. The single best metric for watching that is organic sales growth alongside segment margins through the next down-cycle. And because so much of Parker's shape now comes from businesses it bought, the next part of the story has to be about the deals.
V. The Acquisitions That Changed Parker's Shape
On August 2, 2021, Parker made the boldest offer in its history. It agreed to buy Meggitt, the British aerospace and defense engineering group, for about £6.3 billion.10 The price represented a premium of about 70.5% to Meggitt's share price before word of a bid emerged.10 Meggitt made brakes and wheels, sensors, fire-protection systems, seals and fuel-containment systems for aircraft, and it had struggled during the pandemic as airlines grounded fleets. Parker was paying nearly double what the market had recently thought Meggitt was worth, betting that the pandemic slump was temporary and that a combined business could cut costs and serve aircraft makers better.
The deal had to run a gauntlet. Because Meggitt was a British defense contractor, the UK government reviewed it on national-security grounds, and the Competition and Markets Authority examined the overlap between the two businesses.11 Clearance came with a condition rich in irony for a company founded to sell brakes: Parker had to divest its own aircraft wheels and brakes business, which it sold to Kaman for $440 million.12 Parker completed the Meggitt acquisition in September 2022.13 By then sterling had weakened sharply against the dollar, so the cash cost in dollars was lower than it looked at announcement, about $7.2 billion.13 Parker targeted about $300 million of cost savings from combining the businesses.10 The deal nearly doubled the size of Parker's aerospace business.12
Was 70.5% too much? A premium alone does not answer that. The real test is what the business earned afterwards. What can be seen is encouraging, though not conclusive. Parker's sales jumped about 20% in fiscal 2023 as Meggitt arrived, and aerospace has since become the faster-growing, higher-margin segment.6 Borrowings peaked at about $13 billion at the end of fiscal 2023 and fell to about $8.5 billion by June 2026, as cash flow was used to pay down the acquisition debt.6 Management later said it had returned leverage to its target in seven quarters after Meggitt.3 A post-pandemic recovery in air travel helped enormously, which means some of Meggitt's success was timing that Parker correctly bet on rather than synergy it created. Parker has not published a clean return-on-investment figure for Meggitt, so the verdict stays at "the bet appears to have paid off, helped by the cycle," not "proven."
Meggitt was the most dramatic chapter, but it was not the first deal to reshape Parker. In December 2016 Parker agreed to buy CLARCOR, a filtration company with about $1.4 billion of annual sales and roughly 80% of revenue from aftermarket replacements, for about $4.3 billion in cash including net debt.14 The premium there was about 17.8%, far gentler than Meggitt's.14 CLARCOR made Parker a far more serious filtration company, and it planted the logic that would later justify Filtration Group: a filter is a part designed to wear out, so a large installed base of equipment using your filters is a stream of repeat purchases.
Not every acquired piece stayed. In November 2024 Parker completed the sale of its North America Composites and Fuel Containment division, a business with about $350 million of annual sales that had come with Meggitt, to SK Capital Partners.15 Parmentier explained the sale as part of a strategy of asking whether Parker is the best owner of each business.15 Parker also sold smaller non-core filtration assets.6 A generous reading is that this is good portfolio pruning, the corporate equivalent of selling the furniture that came with a house you bought for the location. A skeptical reading is that large acquisitions always come with pieces the buyer did not really want, which means the headline price includes assets that will later be sold, perhaps at a lower return. Both readings can be true at once, and they argue for judging each deal by the cash it returns, not by the vision in its announcement.
The deals kept coming. In September 2025, Parker completed a roughly $1 billion purchase of Curtis Instruments, which makes motor speed controllers, instrumentation and power-conversion equipment, from Rehlko.16 Curtis, with expected 2025 sales of about $320 million, fits a specific bet: that mobile machinery such as forklifts, aerial work platforms and small construction equipment will increasingly go electric, and that the electronic controls will be as important as the hydraulics they replace.16 That is the clearest sign in the portfolio that Parker is buying exposure to a technological shift rather than simply buying more of what it already does.
Then came Filtration Group. Announced on November 11, 2025, it was Parker's largest deal ever: $9.25 billion on a cash-free, debt-free basis for a company forecast to generate about $2 billion of 2025 sales at an adjusted EBITDA margin of about 23.5%.2 Do the arithmetic and Parker paid about 4.6 times sales and about 19.6 times the business's estimated adjusted EBITDA, its earnings before interest, taxes, depreciation and amortization.2 Parker expects about $220 million of annual cost savings by the end of the third year.2 Add those savings to the EBITDA and the multiple falls to about 13.4 times.2 That is the number management emphasized, and it is the right number only if the savings show up.
Management's case for the business went beyond the multiple. Parmentier told analysts that Filtration Group had grown organically at a mid-single-digit compound rate from before the pandemic to the present, faster recently than Parker's own industrial business, and that the combined filtration operation would be weighted even more heavily toward replacement sales.3 The company committed to EBITDA margins above 30% for the acquired business once savings were in, and pointed to roughly $140 million of additional cash benefits, in present-value terms, mostly from tax attributes.3 Just as telling was what she said the deal was not. "We're not announcing a major shift in any strategy here," she said.3 That is reassuring if the strategy is working, and it is also a reminder that Parker's answer to almost every strategic question is another acquisition run through the same playbook.
On the announcement call, finance chief Todd Leombruno was careful to say that Parker had built no sales synergies into the deal's justification, only costs.3 He laid out the return target with unusual directness: Parker aimed to deliver a high-single-digit return on invested capital by year five.3 That is worth translating. A high-single-digit return on a $9.25 billion investment means roughly $700 million to $850 million of after-tax operating profit a year, five years out. That is roughly the cost of capital for a company like Parker, not dramatically above it. In plain English, management's own target is for Filtration Group to earn its keep by year five, not to be a bargain. An analyst on the call estimated the return at about 8% with synergies, and Leombruno said that was "pretty close."3
Is the price high or low against the market? There is no clean benchmark. Filtration businesses with heavy aftermarket mix have historically commanded high multiples, and Parker's own shares trade at about 22 times EBITDA, so Parker was paying a lower multiple for Filtration Group, after synergies, than the market pays for Parker itself.6 That is the financial logic of a high-multiple acquirer: buy earnings at a lower price than the market puts on your own, and the arithmetic flatters you, as long as the market keeps its valuation of you. It does not prove the deal is cheap. The underwriting test is Parker's return on invested capital after integration.
And there is one more pending deal in view. Parker agreed to buy CIRCOR's commercial and defense aerospace business for about $2.55 billion, and at the end of September it was still waiting to close, with a $2 billion delayed-draw term loan available but undrawn.7 Until it closes and proves itself, it is an integration and financing test, not a contribution. The record across these deals is a company that has paid up for strategic assets, used its cash flow to pay down debt afterwards, and sold the pieces that did not fit. Whether that record extends to deals of today's size depends heavily on the person now running the company.
VI. Jenny Parmentier Inherits the Playbook—and Raises the Stakes
Jennifer Parmentier became chief executive on January 1, 2023, three months after the Meggitt deal closed.17 She inherited a company in the middle of digesting its largest acquisition to date, carrying about $13 billion of debt, with an ambitious set of targets attached to its refreshed strategy.6 She was not an outsider brought in to shake things up. She came up through Parker's operating divisions and served as chief operating officer before taking the top job, so she was, in effect, a product of the Win Strategy put in charge of it.17 People who follow the company know her as "Jenny," and her public style is plain-spoken and operational. On calls she talks about safety, on-time delivery, kaizen and order rates more readily than about grand visions.
Her first three years produced results that would make any chief executive look good. Over the three fiscal years ending June 2026, net profit grew about 20.5% a year, even though revenue grew only about 4.1% a year.6 Net margin rose from about 10.9% in fiscal 2023 to about 17% in fiscal 2026.6 She paid down Meggitt debt, sold the composites business, bought Curtis, and then struck the Filtration Group deal.
How much of that is hers? Attribution is genuinely difficult. The margin expansion began long before her tenure, the aerospace recovery was an industry-wide tide, and Meggitt's arrival mechanically lifted earnings in her first full year. What can be said fairly is that she kept the machine running through a period of flat industrial demand, and that the margin gains in fiscal 2024 and 2025, when sales growth was weak, are the clearest evidence of execution rather than luck. The three-year period also includes some flattering accounting: fiscal 2025's tax rate was unusually low at about 14%, which boosted net profit that year.6
The partner who matters most in this story is Todd Leombruno, the chief financial officer.17 He is the person who has to make the Filtration Group arithmetic work, and his statements on that deal are the clearest promises against which to measure management. On the November 2025 announcement call, he said Parker remained committed to operating around a net debt to adjusted EBITDA level of about two times, and that the target was to return to that level within six quarters of closing, faster than the seven quarters it took after Meggitt.3 At closing, he expected leverage of about three times.3 By the first-quarter call in November 2026, he reported net debt at about 2.7 times adjusted EBITDA, with the new debt carrying average interest rates slightly over 4.5%.5 That is a commitment with a date on it, which is exactly what a skeptic should want. If leverage is near two times by early 2028, management will have done what it said. If it is not, the miss will be visible.
Pay is designed to tie these executives to results. Parmentier's reported total compensation was about $22.76 million in fiscal 2026, up from about $19.32 million the year before, with most of it in performance-based annual incentives and long-term equity awards tied to measures such as earnings growth, cash flow and returns.17 Shareholders approved the pay package at the October 2026 annual meeting with about 92% support, up from about 88% in 2025, and every director was elected.1819 That is a comfortable vote, not a rubber stamp; roughly one in twelve votes cast went against the package.
Two governance features deserve attention precisely because things are going well. First, Parmentier is both chief executive and chair of the board. Nine of the ten directors are classified as independent, and the board has a lead independent director, but the combined role means the person whose strategy the board is supposed to oversee also runs its meetings.17 Second, insider ownership is small. No director or executive officer beneficially owns more than 1% of the shares; the largest holders are index and institutional managers, with State Street at about 7.8%, Vanguard at about 7.5% and BlackRock at about 6.8%.17 There is no founding family or controlling shareholder to restrain the chief executive. When a company is executing a series of very large acquisitions, these features place more weight on the board's willingness to hold management to its deal targets. Parker's proxy reports no material related-party transactions, and its directors and officers are barred from pledging company shares as collateral.17
Capital allocation over the longer span tells a consistent story. From fiscal 2015 through 2026, Parker generated about $25.4 billion of free cash flow.6 About $6.6 billion, roughly a quarter, went to dividends.6 The cash pile did not grow; cash and short-term investments actually fell by about $1.7 billion over the period, to about $501 million at June 2026.6 So the rest went into acquisitions, debt repayment and share buybacks. The rhythm is visible in the balance sheet: debt rose to fund CLARCOR, rose again around fiscal 2019 and 2020 as further acquisitions were funded, surged with Meggitt, then fell steadily before Filtration Group.6 Parker borrows big for a deal, pays down hard, and then borrows again. It has not issued equity to fund recent deals.6
That pattern is coherent, and the record shows it has worked so far. It is also a pattern in which the company is rarely far from its next large financing. The September 2026 bond offerings that funded Filtration Group raised $2.4 billion of U.S. notes and €2.025 billion of euro notes.20 Credit agencies rated Parker A– at Fitch, A3 at Moody's and BBB+ at S&P, and in May 2026 S&P moved its outlook to positive, citing strong performance and forecast leverage of about 2.7 times in fiscal 2027, provided Filtration Group was integrated successfully.621 That favorable view predates the funding, so the agencies' post-close assessment is the next one to watch.
The first-quarter call offered a live look at how management handles scrutiny. When Jamie Cook of Truist asked about Filtration Group's performance and synergies, Parmentier said, "We feel very confident in the $220 million in synergies."5 When Scott Davis of Melius asked about the acquired business's on-time delivery and quality, she said, "We're not ready to disclose any specific numbers."5 Neither answer is evasive by the standards of a first quarter after closing; integration plans take time. But they show the gap an investor needs to close. Confidence is not a metric. On the announcement call, Parmentier declined to give a dollar phasing of the synergies, and the first-year contribution in the fiscal 2027 guidance is about $40 million of the $220 million.35 The rest has to arrive in years two and three.
The skeptical test of this management team is therefore specific. After years of stressing disciplined capital deployment, can Parmentier and Leombruno show measurable synergy delivery, cash conversion near the promised 100% of earnings, and leverage heading to two times, all while a further aerospace deal is waiting to close? The first quarter of results under that test has just arrived.
VII. The First Quarter After Filtration Group
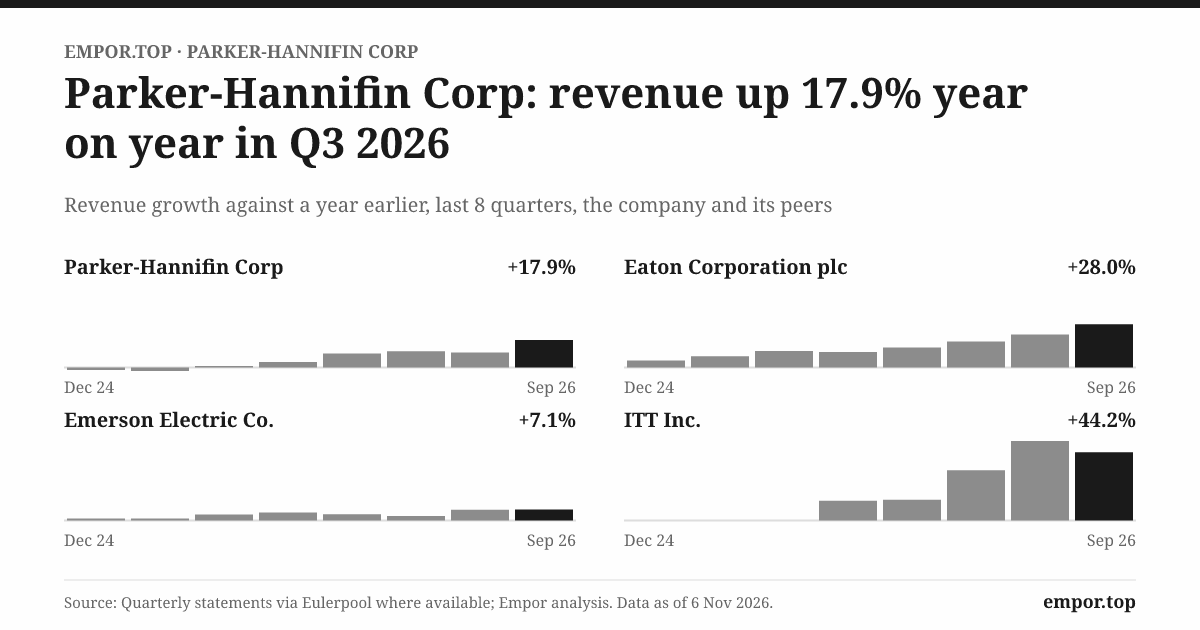
On November 5, 2026, Parker reported the quarter that ended September 30, and the first number on the page was the one management had been waiting to say: sales up 18% to about $5.99 billion, a record.4 That headline concealed three different stories, and the first job is to pull them apart.
The first story is organic growth, sales from businesses Parker owned a year earlier, excluding acquisitions and currency. It was 11.5%.4 That is the most important number in the release, because it cannot be bought. Acquisitions added about 7 percentage points, mostly Curtis for the whole quarter and Filtration Group for about seven weeks.4 Filtration Group contributed about $285 million of sales.5 Currency and other items subtracted about half a point, and inside that line was a small sign of the times: Parker returned about $27 million of tariff-related charges to customers and recovered about $6 million from the U.S. government in connection with tariffs imposed under the International Emergency Economic Powers Act.4 That detail matters because it shows that much of Parker's tariff exposure was passed through to customers in prices, and then passed back again.
The second story is breadth. Every reporting segment grew. Diversified Industrial North America grew organic sales about 9.4%, Diversified Industrial International about 11.6%, with Asia-Pacific up about 23%, and Aerospace Systems about 13.9%.4 Orders, measured on a rolling twelve-month basis, were up 13% for Parker overall, accelerating from 12% the quarter before; international industrial orders rose 14% and aerospace 14%.4 When Andrew Obin of Bank of America asked about the industrial recovery, Parmentier said there was "nothing that we see right now that would cause us to be concerned about the outlook."5 She described aerospace bookings as the second-highest quarter of bookings in Parker's history, with both original-equipment and aftermarket sales up about 14%.5
There is a fashionable theme an analyst was always going to raise: artificial intelligence and the data-center boom. Mig Dobre of Baird asked about it, and Parmentier's answer was refreshingly modest. Data centers were about 1.5% of Parker's sales at the end of the fiscal year, "not yet large enough for its own vertical."5 An investor looking for an AI story in Parker will not find a large one, and the company is not pretending otherwise. Its growth this quarter came from the old engines of industrial capital spending, aircraft production, and the replacement of worn-out parts.
The third story is profitability, and this is where the reader has to keep two numbers in mind at once. Parker reported a segment operating margin of 24.4% on a GAAP basis, the standard accounting rules, and 28.6% on an adjusted basis.4 The four-point gap is mostly the cost of acquisitions themselves: amortization of the intangible assets Parker paid for, such as customer relationships and technology, plus integration and deal expenses.4 Management prefers the adjusted number because amortization is a non-cash charge. That is a fair argument about cash flow, but a misleading one about value: the amortization is the accounting echo of the billions Parker paid, so ignoring it means judging the deal as if the purchase price had been free. The same gap shows up in earnings per share. GAAP diluted EPS was $6.92, up 10%; adjusted EPS was $8.90, up 23%.4 Net income on a GAAP basis rose about 9%, slower than sales, because higher interest and amortization ate part of the growth.4
The two numbers diverge most sharply in North America industrial. On an adjusted basis that segment's margin rose 0.6 points to 27.6%; on a GAAP basis it fell 1.8 points to 23.0%, because that is where most of the newly acquired businesses' amortization and integration costs land.4 Aerospace's GAAP margin rose to about 26.6%, the highest in the company, and international industrial's GAAP margin climbed to about 24.0%.4 The underlying business, in other words, is earning more per dollar, while the acquired businesses carry a heavy accounting cost. That is normal in the first year of a big acquisition, and it is also exactly why both figures need to stay visible.
Then there is the backlog, now a record $13.7 billion.4 Backlog is a comforting number, since it represents orders already placed. But it is not revenue yet, and customers can delay or cancel. Rising backlog in a recovery can partly reflect longer lead times as well as stronger demand. It is a good indicator of near-term demand. It is not proof of long-run pricing power.
Management raised its full-year forecast. Parker now expects fiscal 2027 sales to grow 16% to 19%, including organic growth of 7.5% to 10.5% and about 9 points from acquisitions.4 The midpoint of organic growth moved from 7% to 9%.5 Adjusted EPS guidance is $36.45 to $37.25, and GAAP EPS guidance is $29.65 to $30.45.4 The roughly $7 per share between those two ranges is, again, mostly acquisition amortization and costs. Free cash flow is expected at $3.5 billion to $4.0 billion, with capital spending rising to about $625 million.4 Leombruno said most of the $2.10 increase in adjusted EPS guidance came from higher segment operating income rather than below-the-line items.5 That is the right kind of raise: it comes from operations, not from tax rates or share count.
The forecast for the December quarter gives a sense of how management expects the year to unfold: sales of about $6.2 billion, up roughly 19.5%, organic growth of about 10%, an adjusted segment margin of about 27.6% and adjusted EPS of about $8.82.5 When David Raso of Evercore pressed on profitability, Leombruno said the guidance implied incremental margins in the "high 30s, low 40s."5 Incremental margin is the share of each extra dollar of sales that drops to operating profit. If Parker's average margin is in the high 20s and each new dollar of sales earns close to 40 cents, then growth by itself pushes the average up, which is the operating leverage that makes a volume recovery so valuable to an industrial company and a volume decline so painful. The same mechanism that flatters the guidance on the way up would work in reverse in a slowdown.
A careful reader should still note what is inside the guidance. Filtration Group is expected to contribute about $1.85 billion of sales for the roughly ten and a half months Parker will own it this fiscal year, and about $0.50 of adjusted EPS accretion.5 Interest expense will rise to about $690 million from about $340 million excluding the deal.5 So the raised forecast includes a large acquisition contribution measured on an adjusted basis that excludes the acquisition's largest accounting cost. None of that is hidden; it is disclosed. But it means the quarter proves organic demand is strong, while it cannot yet prove that Filtration Group has earned its price.
Cash flow in the quarter was mixed. Operating cash flow was about $752 million, slightly below the year-earlier $782 million, while Parker paid about $9.1 billion, net of cash acquired, for acquisitions.4 The quarter's free cash flow of about $640 million is the opening installment on a full-year target that management describes as about 100% of adjusted net income.5 The first fiscal quarter is often seasonally weaker for cash, so one quarter says little; the full year will say much more.
Three measures will tell the story from here. The first is organic sales growth by segment, now running at 11.5% for the company, because it separates the health of the existing business from acquired growth. The second is the pair of segment margins, GAAP and adjusted, now 24.4% and 28.6%, because the gap between them should narrow as integration costs fade and because the GAAP figure carries the true cost of the deals. The third is free cash flow set against net debt, now about 2.7 times EBITDA, because the whole acquisition case depends on cash paying down borrowing. Inventory days, at about 86 last fiscal year, is the warning light to keep in peripheral vision: if orders soften and inventory keeps climbing, cash conversion is the first thing to suffer.6
The quarter, in short, is evidence of genuinely strong demand, broad across geographies and especially strong in aerospace and Asia. It is too early to call Filtration Group a success, and the guidance leans on adjusted figures that exclude its largest cost. Which brings the story to the market's price, and what that price is assuming.
VIII. Analysis & Bull vs. Bear Case
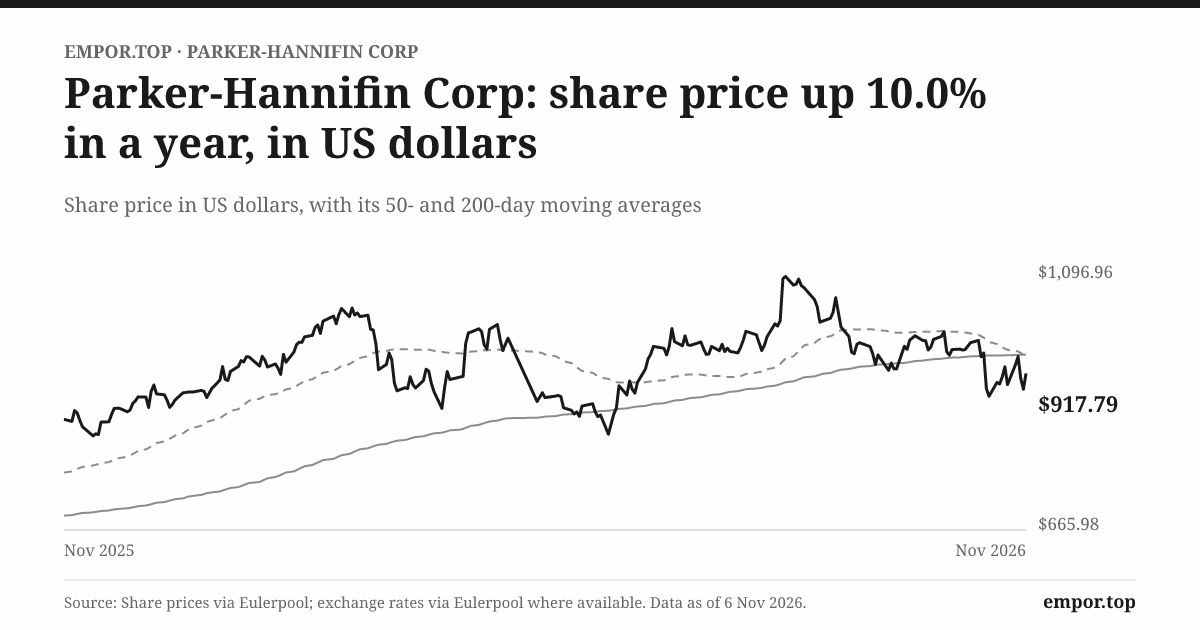
At about $892 a share on November 5, Parker's market value was about $116 billion, and its enterprise value, including net debt, about $133 billion.6 The shares were about 17% below their 52-week high of roughly $1,074.6 Even after that decline, the stock traded at about 31 times trailing earnings, against a five-year median of about 25 times, for an earnings yield of about 3.2%.6 Put plainly, an investor buying Parker today receives about $3.20 of last year's profit for every $100 invested and is betting that profit will grow fast enough to make up the difference.
The multiple looks less extreme on management's forward numbers. At the midpoint of adjusted EPS guidance, about $36.85, the price is about 24 times; on GAAP guidance, about $30.05, it is nearly 30 times.4 Which one is the right lens is the whole argument. Bulls use the adjusted number because amortization is non-cash. Bears use GAAP because the amortization reflects real money that Parker spent buying businesses, money that has to earn a return.
The bull case is a story of compounding. Parker sells critical components in hundreds of niches, has an operating system with a long record of raising margins in good years and holding them in bad ones, and has increasingly tilted its portfolio toward aftermarket revenue, in aerospace and now in filtration, where replacement demand is steadier than new-equipment demand. The organic growth of 11.5% in the latest quarter, the broad order growth and the record backlog all point to strong demand.4 Aerospace in particular is in a long upswing, and the aftermarket half of the business rises with every hour an installed fleet flies. If Parker delivers its Filtration Group savings, deleverages to two times on schedule, and keeps margins rising, earnings could compound at double digits for years, and today's premium multiple would look reasonable in hindsight.
The bear case starts with the same facts and reads them differently. Industrial demand is cyclical, and the current strength is a recovery after more than three years without double-digit organic growth, which means the comparison base was soft.5 Parker's customers can choose among many specialized suppliers, and the company publishes no customer retention, concentration or multi-sourcing data to prove they would not. The margin gains of the past decade have never been tested at today's level by a severe recession. Inventory has climbed steadily, so a downturn would tie up cash just as the company is trying to pay down a much larger debt load. And the latest acquisition cycle is the most expensive in Parker's history, with a management target that, by its own description, aims for a return roughly in line with the cost of capital by year five.3 At 31 times trailing earnings, the share price leaves little room for an integration stumble or an industrial slowdown.
It helps to run the competitive question through two classic frameworks. Michael Porter's five forces ask about rivals, buyers, suppliers, substitutes and new entrants. Rivalry at Parker is intense but local: each product line has a handful of serious competitors, from Danfoss in mobile hydraulics to Donaldson in filtration to Moog and Woodward in aerospace controls, and none of them competes across the whole portfolio.6 Buyer power is hard to judge, because Parker does not disclose its largest customers; aircraft makers and big equipment builders surely have leverage on new-equipment pricing, while the thousands of smaller customers buying replacements through distributors have much less. Supplier power shows up in raw materials, since Parker depends on steel, brass, copper, aluminum, nickel, rubber and plastics, and its margins can be squeezed when costs rise before prices catch up.6 The threat of substitutes is real in one important area: electrification can replace hydraulic systems in some mobile machinery, which is precisely why Parker bought Curtis. New entrants face high barriers in certified aerospace parts and much lower ones in commodity fittings.
Hamilton Helmer's 7 Powers framework asks which durable advantages let a company earn more than its cost of capital for a long time. Of the seven, two plausibly apply. The first is switching costs, strongest in aerospace, where a certified component is designed into an aircraft for decades, and meaningful in industrial equipment where a part has been engineered into a machine. The second is a form of scale economy in distribution: a vast network of distributors and stores that a smaller rival cannot easily replicate, and that grows more valuable as it carries more products. Parker might also claim process power, Helmer's term for an embedded operating culture that rivals cannot easily copy, which is how a strategist would describe the Win Strategy. But process power is notoriously hard to prove from outside, and the evidence here is the margin record, not any disclosed measure of cost advantage. The verdict on the moat is that it exists, but in a narrower form than "Parker dominates motion control." It is a collection of product- and application-specific advantages, strongest where certification and replacement needs are greatest, and much weaker where parts are standardized and customers can multi-source.
The valuation comparison with peers adds context but not proof. Eaton traded at about 34 times trailing earnings and Emerson at about 34 times, both higher than Parker, while Illinois Tool Works traded at about 25 times.222324 Eaton has become a favorite for its electrical and data-center exposure, Emerson for its automation software; Illinois Tool Works, the closest cousin to Parker in its decentralized, operating-system culture, trades at roughly Parker's own historical median. Different mixes make these comparisons descriptive rather than decisive. What they do suggest is that the market is pricing Parker more like a growth industrial than like the steady compounder it was valued as a few years ago.
Return on capital is the measure that matters most for a serial acquirer, and here the picture is in motion. Return on capital employed reached about 20% in fiscal 2026, up from about 15.6% in fiscal 2015.6 But return on invested capital over the twelve months to September, measured after tax against equity plus net debt, was about 11.3%, down from about 15.8% for fiscal 2026, because Filtration Group's purchase price landed in the capital base before most of its earnings arrived.6 That decline is the arithmetic of a big acquisition, and management's job over the next few years is to reverse it.
Several risks are material enough to keep in the same frame. An industrial slowdown or softer orders from equipment makers would hit volumes, with the decline magnified in earnings. Material costs and tariffs can pressure margins when price recovery lags, though the latest quarter suggests Parker has generally passed tariff costs through. Integration of Filtration Group, and of the pending CIRCOR aerospace business, raises execution risk at a time of higher leverage, with interest costs set to roughly double this year.5 Environmental liabilities are a smaller but genuine overhang: Parker has accrued about $82 million for environmental matters and estimates reasonably possible costs up to about $292 million.6 Earnings quality deserves one more look as well. Other income contributed about $330 million in fiscal 2026, around 7% of pretax profit, and about $218 million of that came from Parker's share of earnings in businesses it does not consolidate, along with smaller gains from pension accounting, currency and asset sales.6 Those are real earnings, but they are not the product of Parker's factories, and they can move independently of the core business.
On management credibility, the record cuts in Parker's favor without settling the question. The auditor issued unmodified opinions on the fiscal 2026 financial statements and internal controls, with no material weakness identified.6 Management has made specific, dated promises on leverage and synergies, and it hit its post-Meggitt leverage target. The open issues are structural: a chief executive who also chairs the board, minimal insider ownership, and a reliance on adjusted figures that exclude the largest cost of the strategy. None of these is unusual among American industrial companies. Each places more weight on reported results, not adjusted narratives, as the measure of whether the strategy works.
So what has to go right? Organic growth needs to stay positive through whatever slowdown comes next. Synergies need to show up in GAAP margins, not only adjusted ones. And free cash flow needs to bring leverage to two times on schedule. The premium multiple is the market saying it believes all three. The lessons from Parker's long history are about what happens when a company keeps that kind of promise, and when it does not.
IX. Playbook: Business & Investing Lessons
Go back to that truck on the Pennsylvania mountainside, the company's entire inventory scattered across the slope. Arthur Parker had built a business around a product, and when the product was gone, so was the business. What he built next was different: a business around a capability, designing small, reliable parts that made other people's machines work. Over the next century, the products changed again and again, from fittings for aircraft to hydraulic cylinders to filters and electronic motor controls. The capability stayed.
The first lesson is that a failed product can be the beginning of a company, if the founder learns what the customer actually needed. Parker's brake did not survive, but the knowledge of how to keep fluids and pressure under control in a moving vehicle did, and it carried the company into aviation and then into industrial motion control. For founders, the point is that the first product is usually a hypothesis. For investors, it is that durable industrial franchises tend to be built on problems customers will pay to solve repeatedly, not on a single clever invention.
The second lesson is that a thousand niches can make a portfolio, but only if the parts work for customers. Parker's breadth, a catalogue so wide that no product is more than 1% of sales, is genuinely protective. No single competitor, product failure or customer can sink it. But breadth alone is not a moat. It becomes one only where engineering, certification and distribution make it hard for a customer to walk away, which is why Parker's advantages are strongest in aerospace and in replacement parts and weakest where its products are standardized. The lesson for investors is to ask, product by product, why a customer would keep buying, and to distrust any argument that scale settles the matter.
The third lesson is that synergies are a promise until cash proves them. Parker's Meggitt deal looked expensive at a 70.5% premium, and it has so far worked out, helped by an aerospace recovery that Parker correctly bet on and partly by luck of timing. Filtration Group looks less expensive after synergies, at about 13.4 times EBITDA, but only if $220 million of annual savings arrive on schedule. Management's own goal is a high-single-digit return by year five. A price justified by promised savings is a bet on the future, and the scorecard is cash, not adjusted EPS.
The fourth lesson is that margin gains are powerful, but they do not repeal the cycle. Parker doubled its operating margin in a decade, and the Win Strategy deserves real credit for that. Yet in fiscal 2016 and fiscal 2020, profits fell by about a fifth even as margins held. Operating discipline can stop a downturn from becoming a disaster. It cannot stop a downturn. Investors who value Parker as if its margins make it immune to industrial cycles are confusing resilience with immunity.
The fifth lesson is that a capital-allocation record is a living document. Parker's history includes CLARCOR, Meggitt, Curtis and Filtration Group on one side of the ledger, and the forced sale of its own wheels-and-brakes business, the sale of Meggitt's composites unit and smaller divestitures on the other. Every buy has been followed by a period of paying down debt; every large deal has left something to prune. The pending CIRCOR aerospace deal is the next entry. A company that buys businesses for a living earns its reputation one integration at a time, and loses it the same way.
X. Epilogue
Tonight, Parker stands at a familiar point in its own rhythm: just past a giant acquisition, carrying the debt that came with it, with strong demand at its back and a promise to the market about how quickly it will pay down that debt. Filtration Group has been inside the company for less than three months. CIRCOR's aerospace business is still waiting to join it.
The next moments that will decide this chapter are already on the calendar. In early 2027, Parker will report its December and March quarters, the first full quarters with Filtration Group inside. Those reports will show whether organic growth holds near the 9% midpoint management now expects, and whether the GAAP segment margin starts to close the gap with the adjusted figure as integration costs fade.5 On May 13, 2027, Parker will hold an investor meeting in New York, where management is likely to set out new targets.5 That meeting will be the moment to compare what was promised in November 2025, a return to two times leverage within six quarters and $220 million of savings by year three, with what has been delivered.3
If the next year goes the way management describes, the evidence will be clear. Organic growth will stay positive, free cash flow will land between $3.5 billion and $4.0 billion, the synergy run-rate will move well beyond the first-year $40 million, and leverage will fall toward two times by early 2028.45 In that world, the premium multiple will look like an accurate reading of a company compounding through another transformation.
If it goes wrong, it will probably go wrong in a familiar way. An industrial slowdown would cut volumes. Inventory, already high, would absorb cash. Leverage would fall more slowly, and the CIRCOR deal, if it closes, would add more debt at the wrong time. Synergies might arrive, but later, while the adjusted figures keep looking better than the GAAP ones. In that world, the market would likely stop paying a premium for Parker's earnings.
Some things investors will still not be able to see. Parker does not disclose its customer concentration, a company-wide recurring-revenue share, or an ageing schedule for its receivables.6 Those gaps do not mean anything is wrong. They mean the moat and the quality of revenue have to be inferred from margins, cash and organic growth, rather than measured directly. The next twelve months will put each of those measures to work.
XI. Outro
In 1917, a young engineer watched his first company go over the side of a Pennsylvania mountain. A century later, Parker's parts are inside airliners crossing oceans, excavators digging foundations, factories running around the clock and the electric machines that are slowly replacing diesel ones. Most people who depend on them every day will never know the name on the part.
That anonymity is the point. Parker-Hannifin has spent a hundred years trying to make specialized engineering repeatable, to turn the skill of making one critical part work into a system for making thousands of them work, across customers who will never meet one another. Its biggest bets now ask a harder question than whether the parts work. They ask whether every new business Parker buys belongs inside that system, and whether the machinery can keep moving while the debt comes down.
References
-
Parker Completes Acquisition of Filtration Group Corporation — Parker-Hannifin, 2026-08-13 ↩↩
-
Parker to Acquire Filtration Group Corporation — Parker-Hannifin, 2025-11-11 ↩↩↩↩↩
-
Parker-Hannifin Filtration Group Acquisition Call Transcript — Stock Analysis, 2025-11-11 ↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Parker Delivers Record Fiscal 2027 First Quarter Results — Parker-Hannifin, 2026-11-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Parker-Hannifin FY2027 Q1 Earnings Call Transcript — Stock Analysis, 2026-11-05 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Parker-Hannifin Form 10-K for fiscal year ended June 30, 2026 — SEC, 2026-08-21 ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Parker-Hannifin Form 10-Q for quarter ended September 30, 2026 — SEC, 2026-11-05 ↩↩↩
-
Parker Hannifin Corp. — Encyclopedia of Cleveland History, Case Western Reserve University ↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩↩
-
Meggitt Acquisition Announcement — Parker-Hannifin, 2021-08-02 ↩↩↩
-
Parker-Hannifin/Meggitt Merger Review Report — UK Competition and Markets Authority, 2022 ↩
-
Parker Hannifin Completes $6.3 Billion Acquisition of Meggitt — Aviation Today, 2022-09-15 ↩↩
-
Parker-Hannifin Form 8-K, completion of Meggitt acquisition — SEC, 2022-09-28 ↩↩
-
Parker and CLARCOR Announce Definitive Agreement — Parker-Hannifin Form 8-K Exhibit 99.1, SEC, 2016-12-01 ↩↩
-
Parker Completes Divestiture of North America Composites & Fuel Containment Division — Parker-Hannifin, 2024-11-04 ↩↩
-
Parker Completes Curtis Instruments Acquisition — Parker-Hannifin, 2025-09-18 ↩↩
-
Parker-Hannifin 2026 Definitive Proxy Statement — SEC, 2026-09-18 ↩↩↩↩↩↩↩
-
Parker-Hannifin Form 8-K, 2026 Annual Meeting voting results — SEC, 2026-10-28 ↩
-
Parker-Hannifin 2025 Definitive Proxy Statement — SEC, 2025-09-18 ↩
-
S&P Upgrades Parker-Hannifin Outlook on Strong Performance — Investing.com, 2026-05-15 ↩
 LinkedIn
 WhatsApp
 Reddit
 Hacker News
 Email
 Kindle
 RSS Feed
 Spotify
 Apple Podcasts
 Amazon Music
 Audible
 YouTube